Kingfisher PLC · LSE:KGF
Kingfisher — Merger or Acquisition (July 2002)
60 slides from Kingfisher's merger presentation, July 2002
Slide 1: A Transformation Strategy
KING) SHER A Transformation Strategy
Slide 2: Francis Mackay, Chairman
Francis Mackay Chairman
Slide 3: Today's agenda
Today’s agenda • Transformation – rationale – update on process – management • Our strategy for Home Improvement – strengths and opportunities – reinvigoration plans • Questions
Slide 4: Our plan for the future
Our plan for the future • Two independent pan-European businesses
Slide 5: Our plan for the future
Our plan for the future • Two independent pan-European businesses • Clear, accountable management structures
Slide 6: Our plan for the future
Our plan for the future • Two independent pan-European businesses • Clear, accountable management structures • Local marketing but leveraging international scale
Slide 7: Our plan for the future
Our plan for the future • Two independent pan-European businesses • Clear, accountable management structures • Local marketing but leveraging international scale superior returns on invested capital
Slide 8: Transformation creates value
Transformation creates value • Clear management of Home Improvement to enhance performance • Separation provides transparency • Separation creates focus
Slide 9: Funding plan
Funding plan • £3.3 billion cost funded by £2 billion rights issue and new debt • 1-for-1 rights issue at 155p • 50% discount to 5 July price • 33% discount to TERP
Slide 10: Impact of buy-out
Impact of buy-out • Dilutive due to fall in world equity markets since our 15th May announcement – KGF down 20% – FTSE 100 down 12% – UK general retail sector down 12% – CAC 40 down 13%
Slide 11: Impact of buy-out
Impact of buy-out • Only modest integration benefits assumed Note: Based on 310p per share
Slide 12: Impact of buy-out
Impact of buy-out • Only modest integration benefits assumed • EPS dilutive in 2003/4 Note: Based on 310p per share
Slide 13: Impact of buy-out
Impact of buy-out • Only modest integration benefits assumed • EPS dilutive in 2003/4 • Modestly enhancing in 2004/5 Note: Based on 310p per share
Slide 14: Impact of buy-out
Impact of buy-out • Only modest integration benefits assumed • EPS dilutive in 2003/4 • Modestly enhancing in 2004/5 • Further EPS upside on delivery of full integration benefits Note: Based on 310p per share
Slide 15: Key Milestones
Key Milestones Offer • Nil paid dealing commences 11th July • Last date for acceptance 2nd August • EU anti trust clearance Mid August • Offer submitted to CMF/COB Mid August Management control passes • Offer period (5 weeks) End September • Acquisition complete End September
Slide 16: KESA separation should unlock potential value
KESA separation should unlock potential value • Leading European brands • Second most profitable electricals retailer in Europe • Strong cash generator • Proven, experienced management team • Separation following offer completion – management fully focused – transparency enables full valuation
Slide 17: Separation of Electrical & Furniture
Separation of Electrical & Furniture • By most appropriate option for long term shareholder value • Cash in excess of requirements to be returned to shareholders
Slide 18: A Transformation Strategy
KING) SHER A Transformation Strategy
Slide 19: Geoff Mulcahy, Chief Executive
Geoff Mulcahy Chief Executive
Slide 20: No 1 in European home improvement
No 1 in European home improvement • Market size €130 billion
Slide 21: No 1 in European home improvement
No 1 in European home improvement • Market size €130 billion • Forecast to grow strongly
Slide 22: No 1 in European home improvement
No 1 in European home improvement • Market size €130 billion • Forecast to grow strongly • Common products
Slide 23: No 1 in European home improvement
No 1 in European home improvement • Market size €130 billion • Forecast to grow strongly • Common products • Fragmented supplier base
Slide 24: No 1 in European home improvement
No 1 in European home improvement • Market size €130 billion • Forecast to grow strongly • Common products • Fragmented supplier base Winners will maximise advantages of scale
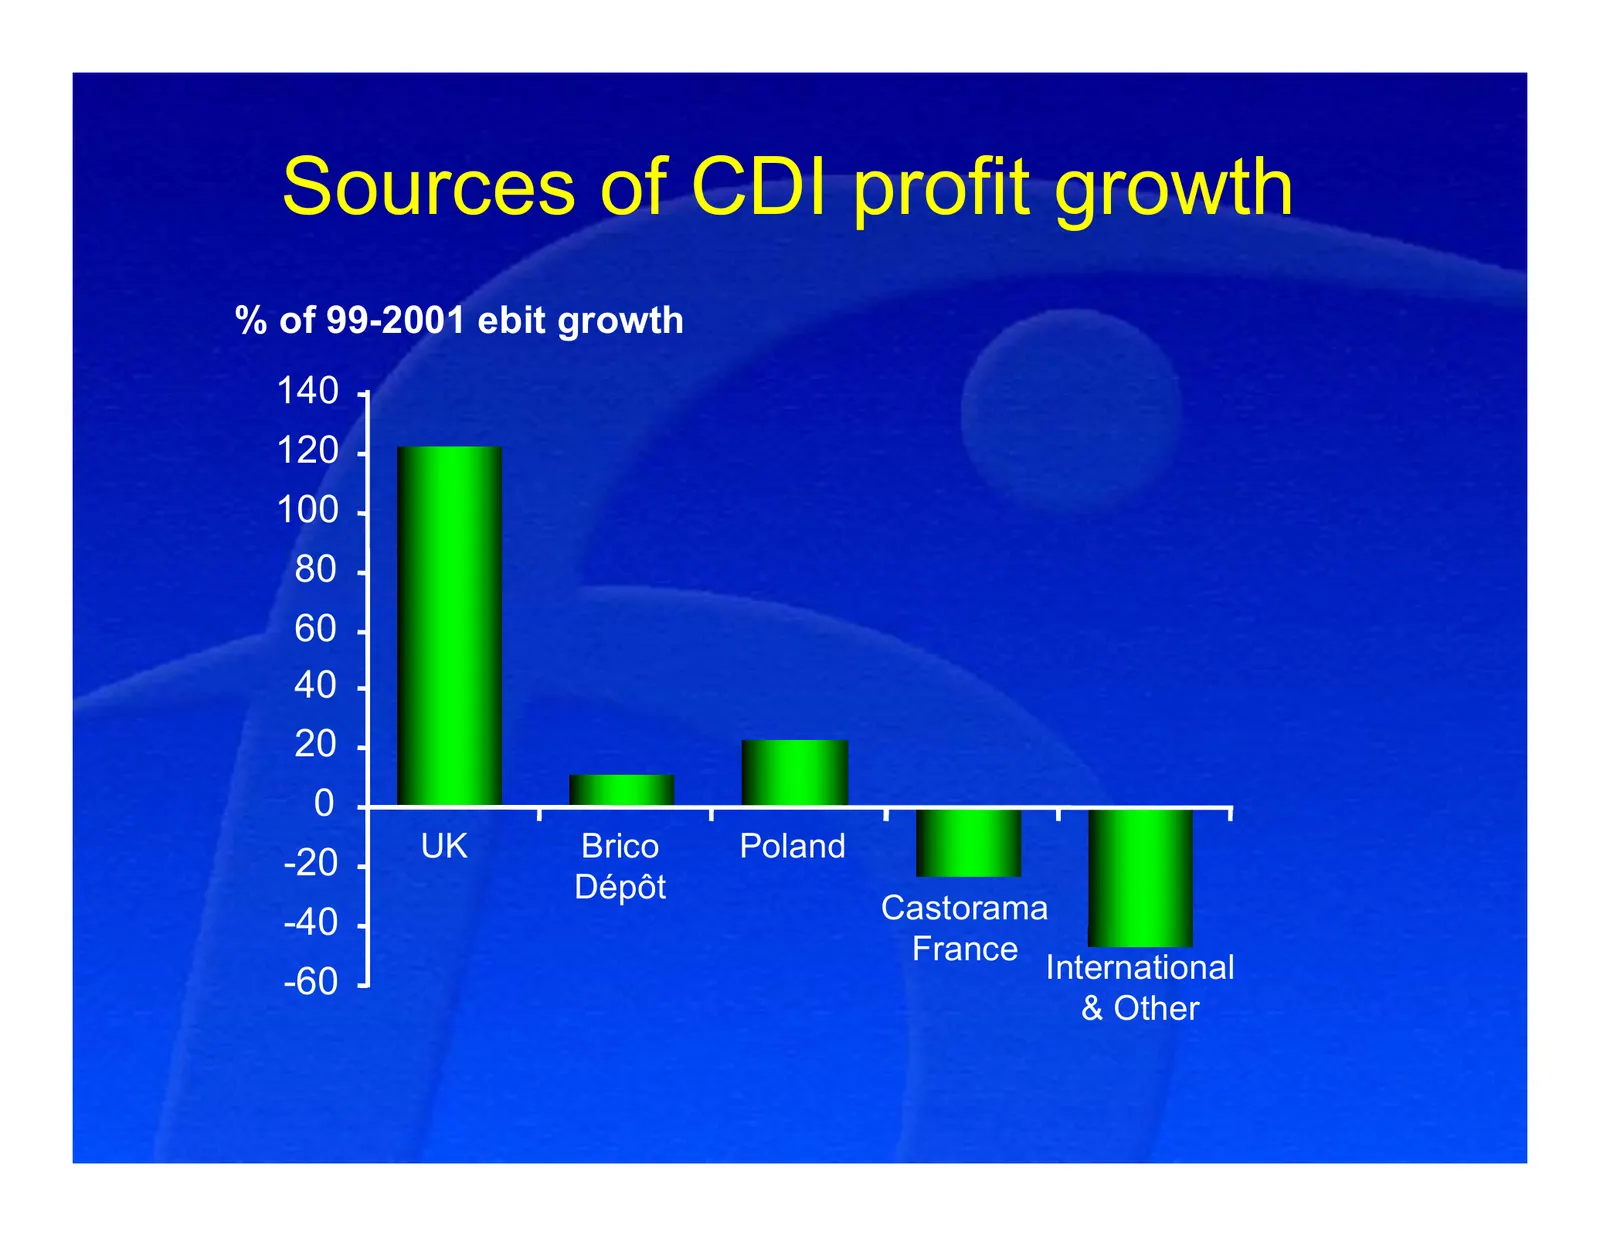
Slide 25: Sources of CDI profit growth
Sources of CDI profit growth % of 99-2001 ebit growth 140 120 100 80 60 40 20 0 UK Brico Poland -20 Dépôt -40 Castorama France -60 International & Other
Slide 26: Our three point agenda for growth
Our three point agenda for growth • Backing the biggest winners: – B&Q, Brico Dépôt, Castorama Poland and Screwfix
Slide 27: Our three point agenda for growth
Our three point agenda for growth • Backing the biggest winners: – B&Q, Brico Dépôt, Castorama Poland and Screwfix • Restoring Castorama France as a winner
Slide 28: Our three point agenda for growth
Our three point agenda for growth • Backing the biggest winners: – B&Q, Brico Dépôt, Castorama Poland and Screwfix • Restoring Castorama France as a winner • Focusing our international efforts
Slide 29: Building on B&Q, a world class business
Building on B&Q, a world class business • Leading operating practices: • Leadership • Cost Price Reduction Programme • Far East sourcing • Own brand range development • Profitable catalogue and internet business
Slide 30: Building on B&Q, a world class business
Building on B&Q, a world class business • Leading operating practices: • Leadership • Cost Price Reduction Programme • Far East sourcing • Own brand range development • Profitable catalogue and internet business • Category killing warehouse format
Slide 31: Building on B&Q, a world class business
Building on B&Q, a world class business • Leading operating practices: • Leadership • Cost Price Reduction Programme • Far East sourcing • Own brand range development • Profitable catalogue and internet business • Category killing warehouse format • Successful expansion in Asia
Slide 32: Growing strongly in France
Growing strongly in France • Limited but consistent product range
Slide 33: Growing strongly in France
Growing strongly in France • Limited but consistent product range • EDLP
Slide 34: Growing strongly in France
Growing strongly in France • Limited but consistent product range • EDLP • Targeted offer – trade professional – serious DIY enthusiast
Slide 35: Brico Dépôt
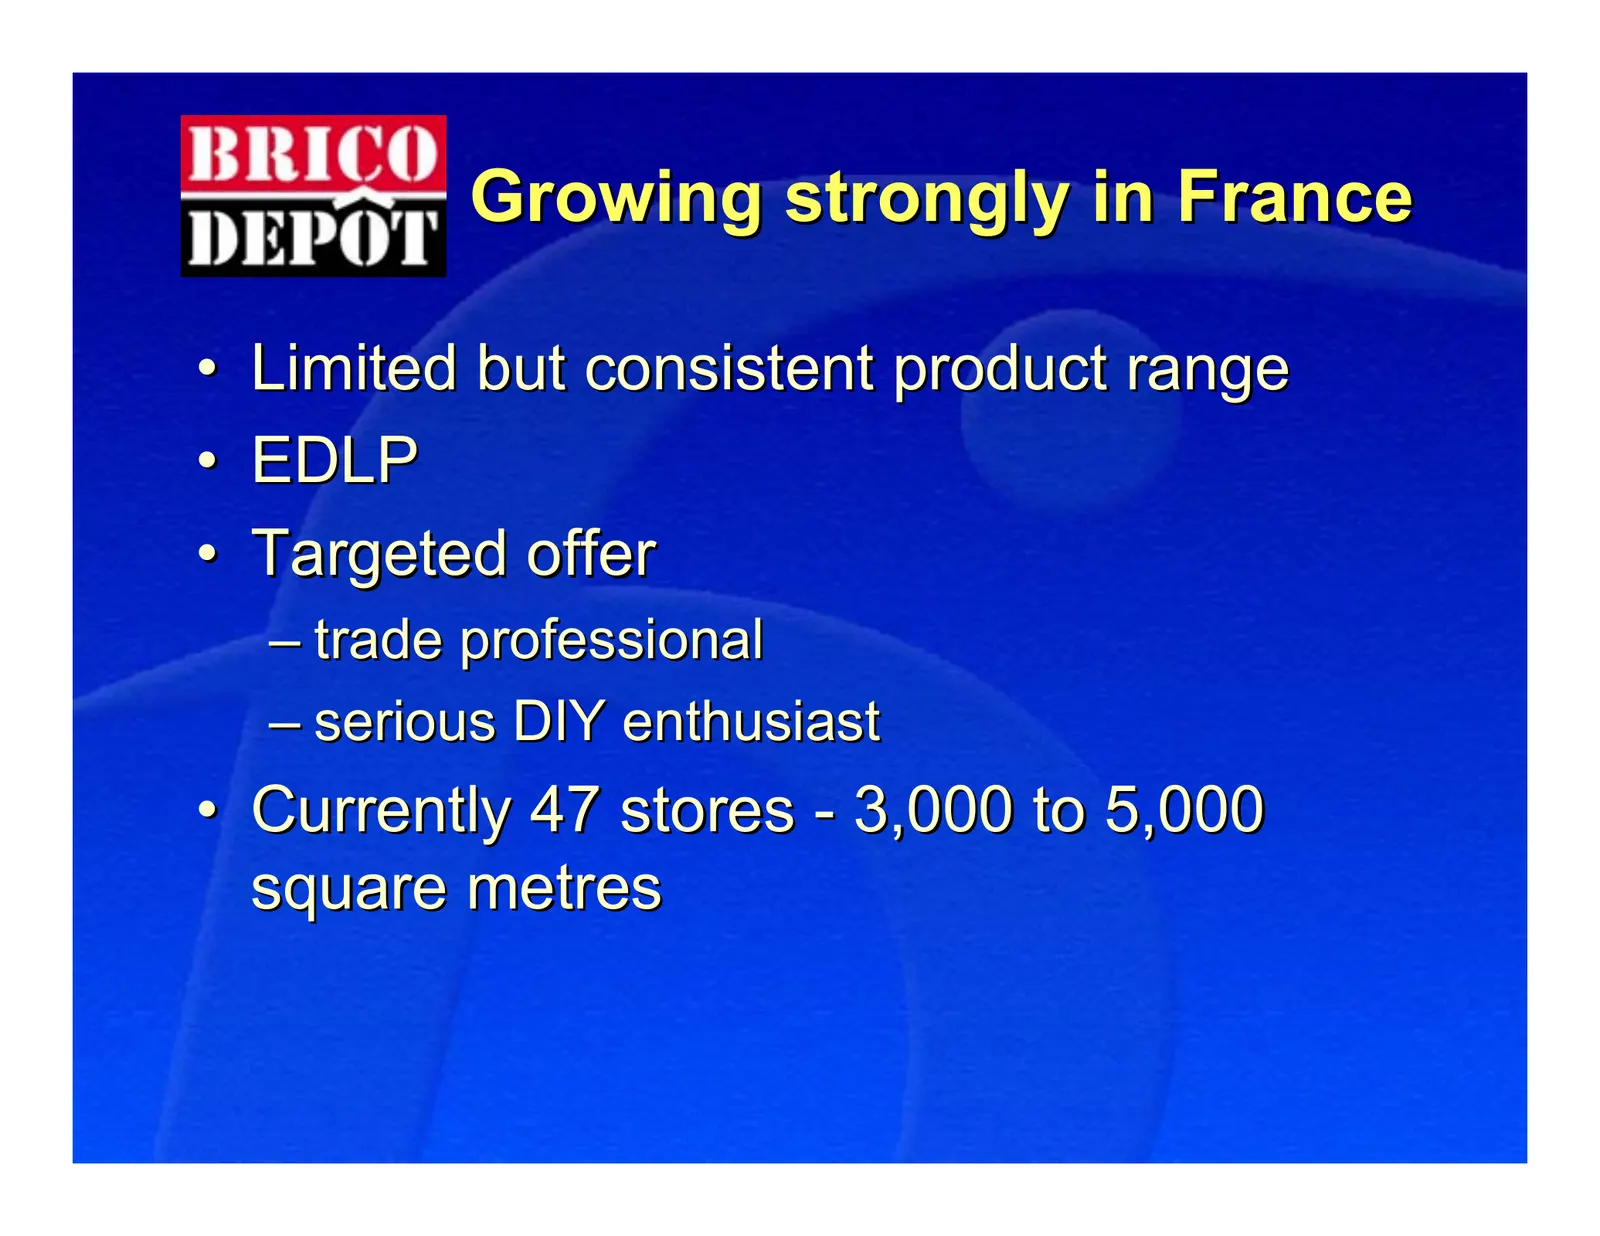
Brico Dépôt Store numbers 47 34 26 Sales €m CAGR: 34% 669 1999/00 2000/01 2001/02 516 2001/02 LFL % 371 9.2% 3.1% 0.5% 1999/00 2000/01 2001/02 Castorama Brico Dépôt French France Market
Slide 36: Growing strongly in France
Growing strongly in France • Limited but consistent product range • EDLP • Targeted offer – trade professional – serious DIY enthusiast • Currently 47 stores - 3,000 to 5,000 square metres
Slide 37: Growing strongly in France
Growing strongly in France • Limited but consistent product range • EDLP • Targeted offer – trade professional – serious DIY enthusiast • Currently 47 stores - 3,000 to 5,000 square metres • Target of 100 stores
Slide 38: Poland performance and market position is strong
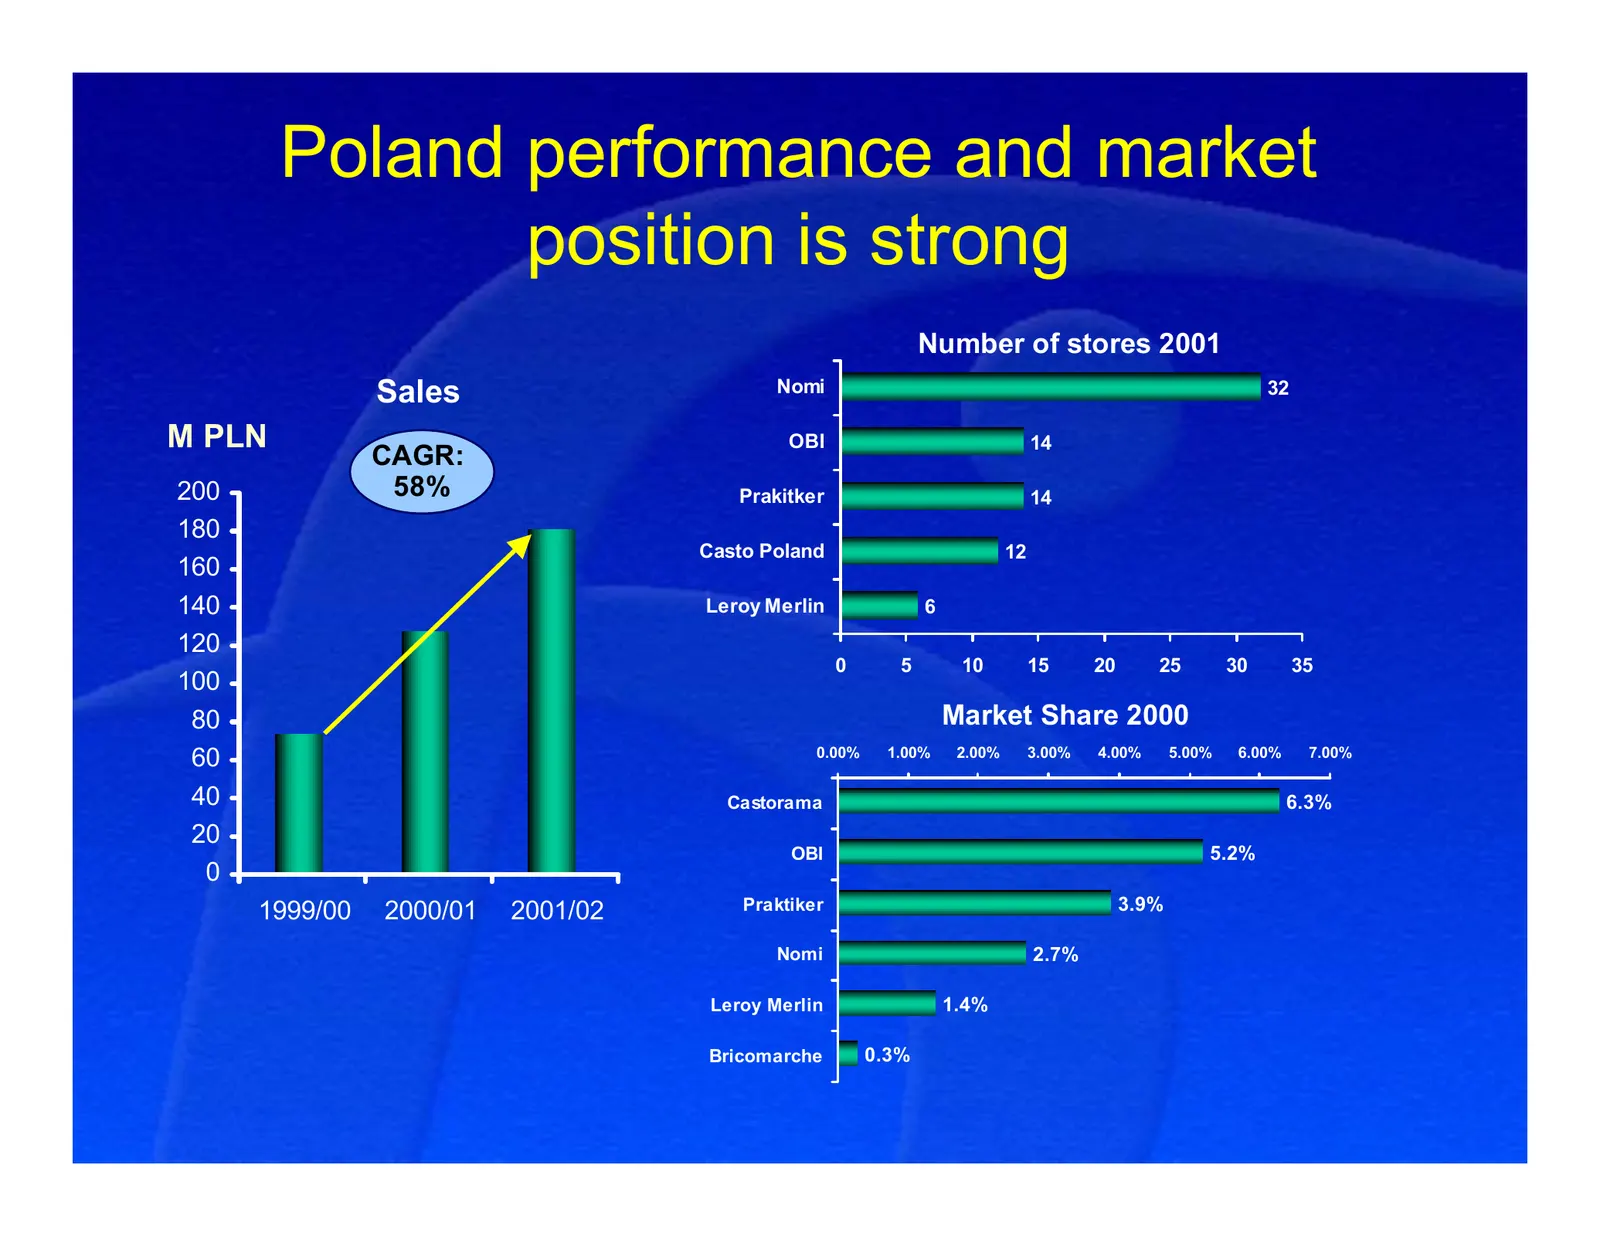
Poland performance and market position is strong Number of stores 2001 Sales Nomi 32 M PLN OBI 14 CAGR: 200 58% Prakitker 14 180 Casto Poland 12 160 140 Leroy Merlin 6 120 0 5 10 15 20 25 30 35 100 80 Market Share 2000 60 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 7.00% 40 Castorama 6.3% 20 OBI 5.2%
Slide 39: French market growth has been good
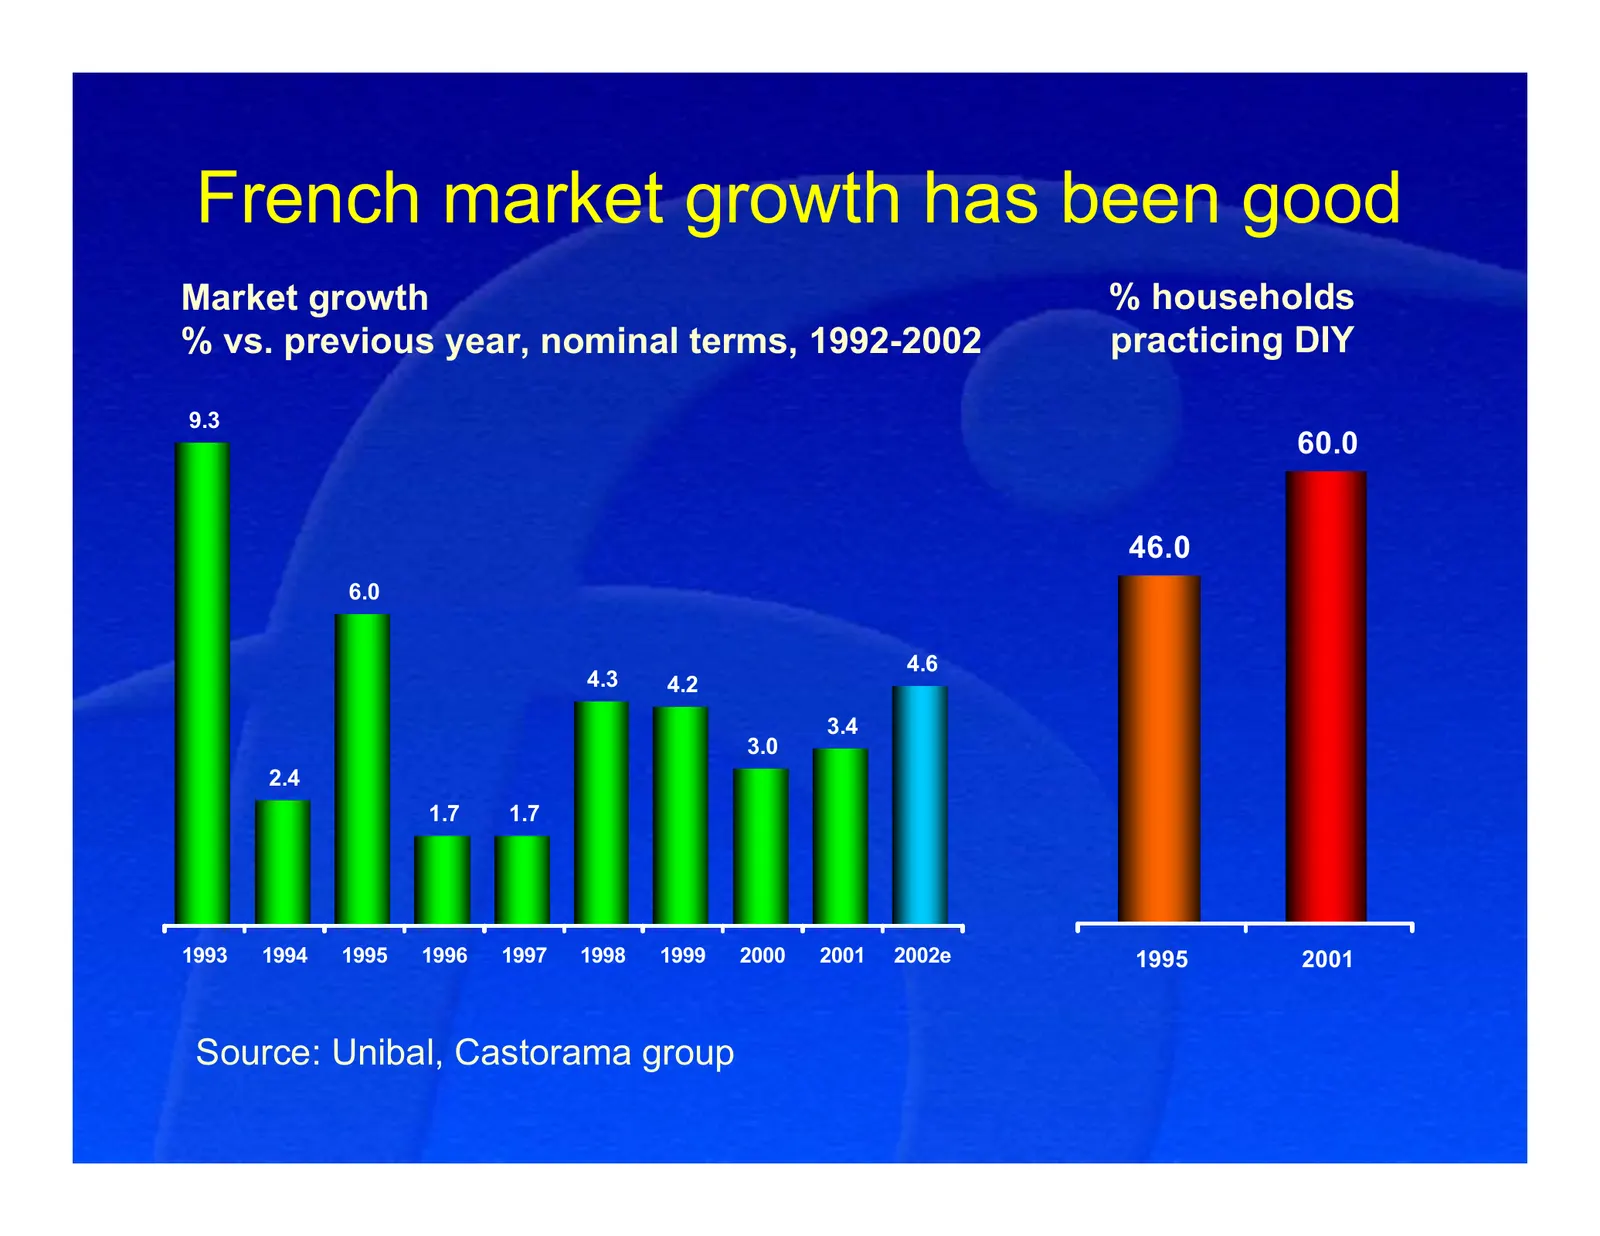
French market growth has been good Market growth % households % vs. previous year, nominal terms, 1992-2002 practicing DIY 9.3 60.0 46.0 6.0 4.6 4.3 4.2 3.4 3.0 2.4 1.7 1.7 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002e 1995 2001 Source: Unibal, Castorama group
Slide 40: In close to half of Castorama France stores, sales have declined
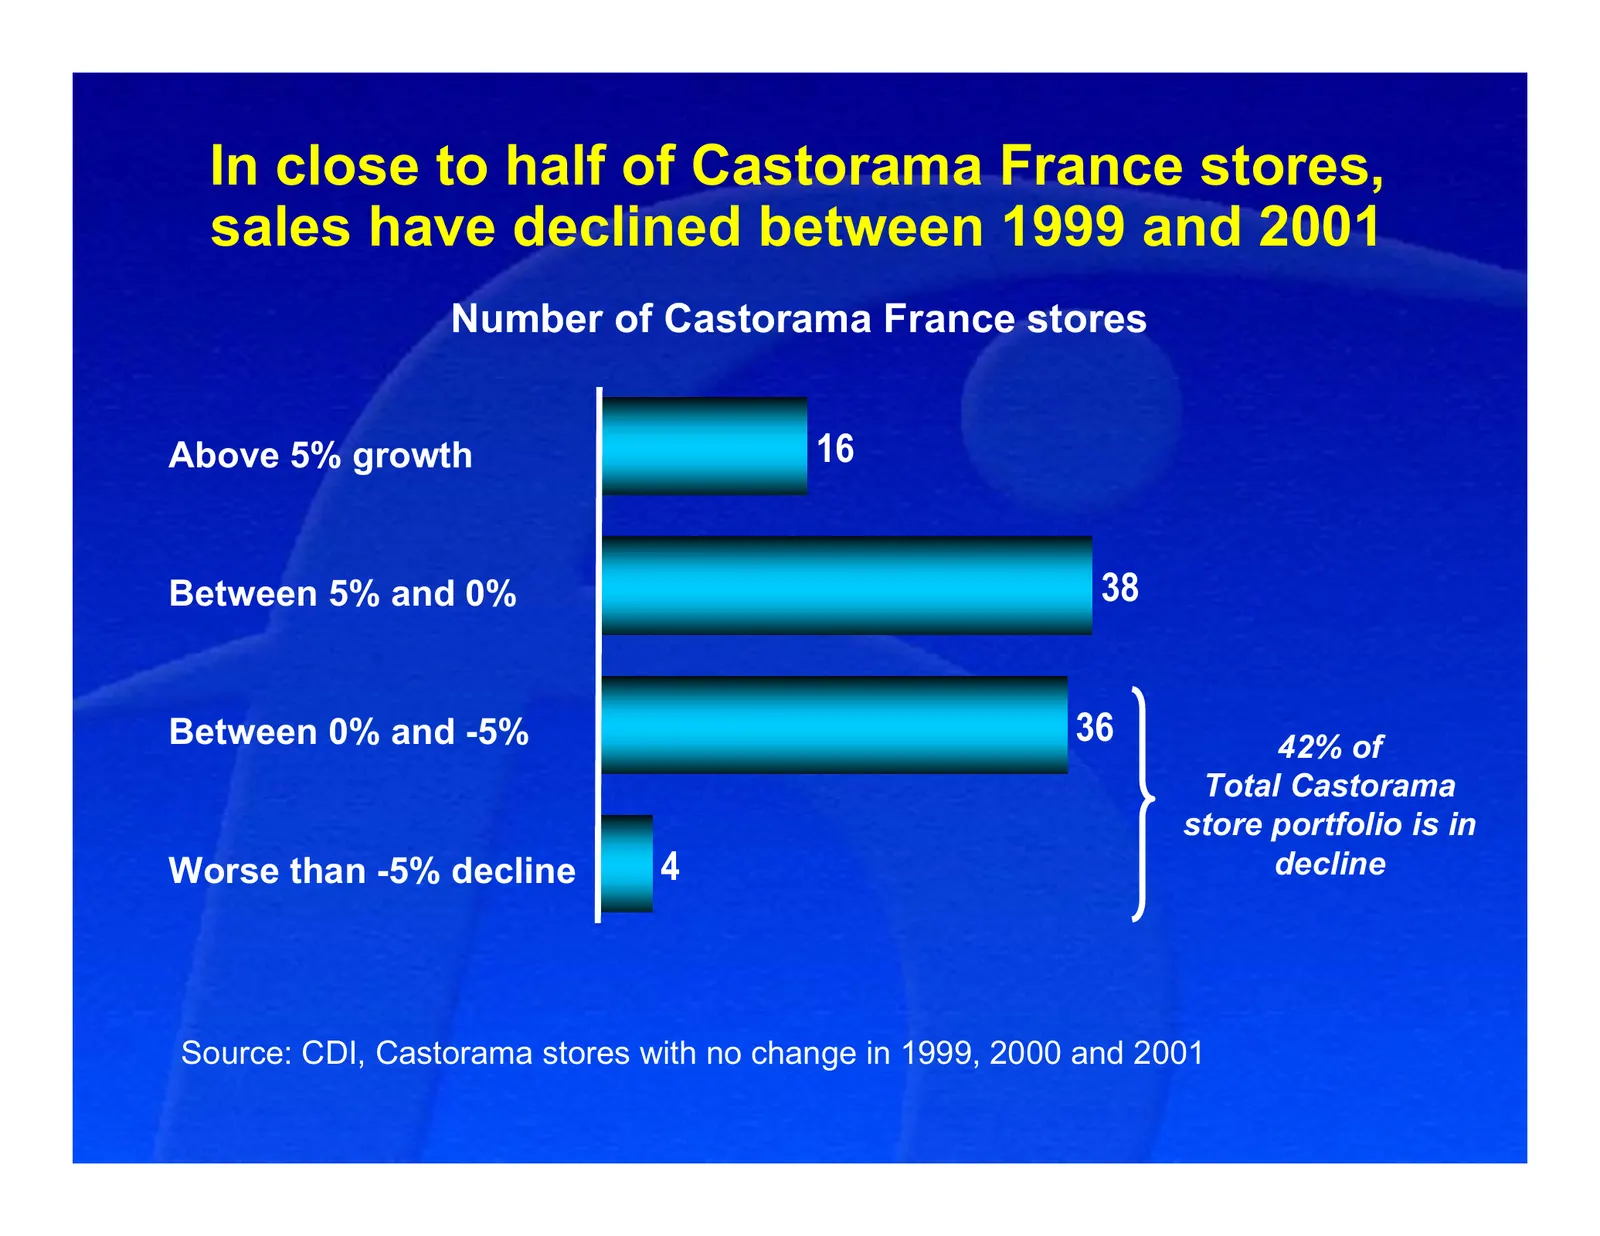
In close to half of Castorama France stores, sales have declined between 1999 and 2001 Number of Castorama France stores Above 5% growth 16 Between 5% and 0% 38 Between 0% and -5% 36 42% of Total Castorama store portfolio is in Worse than -5% decline 4 decline Source: CDI, Castorama stores with no c
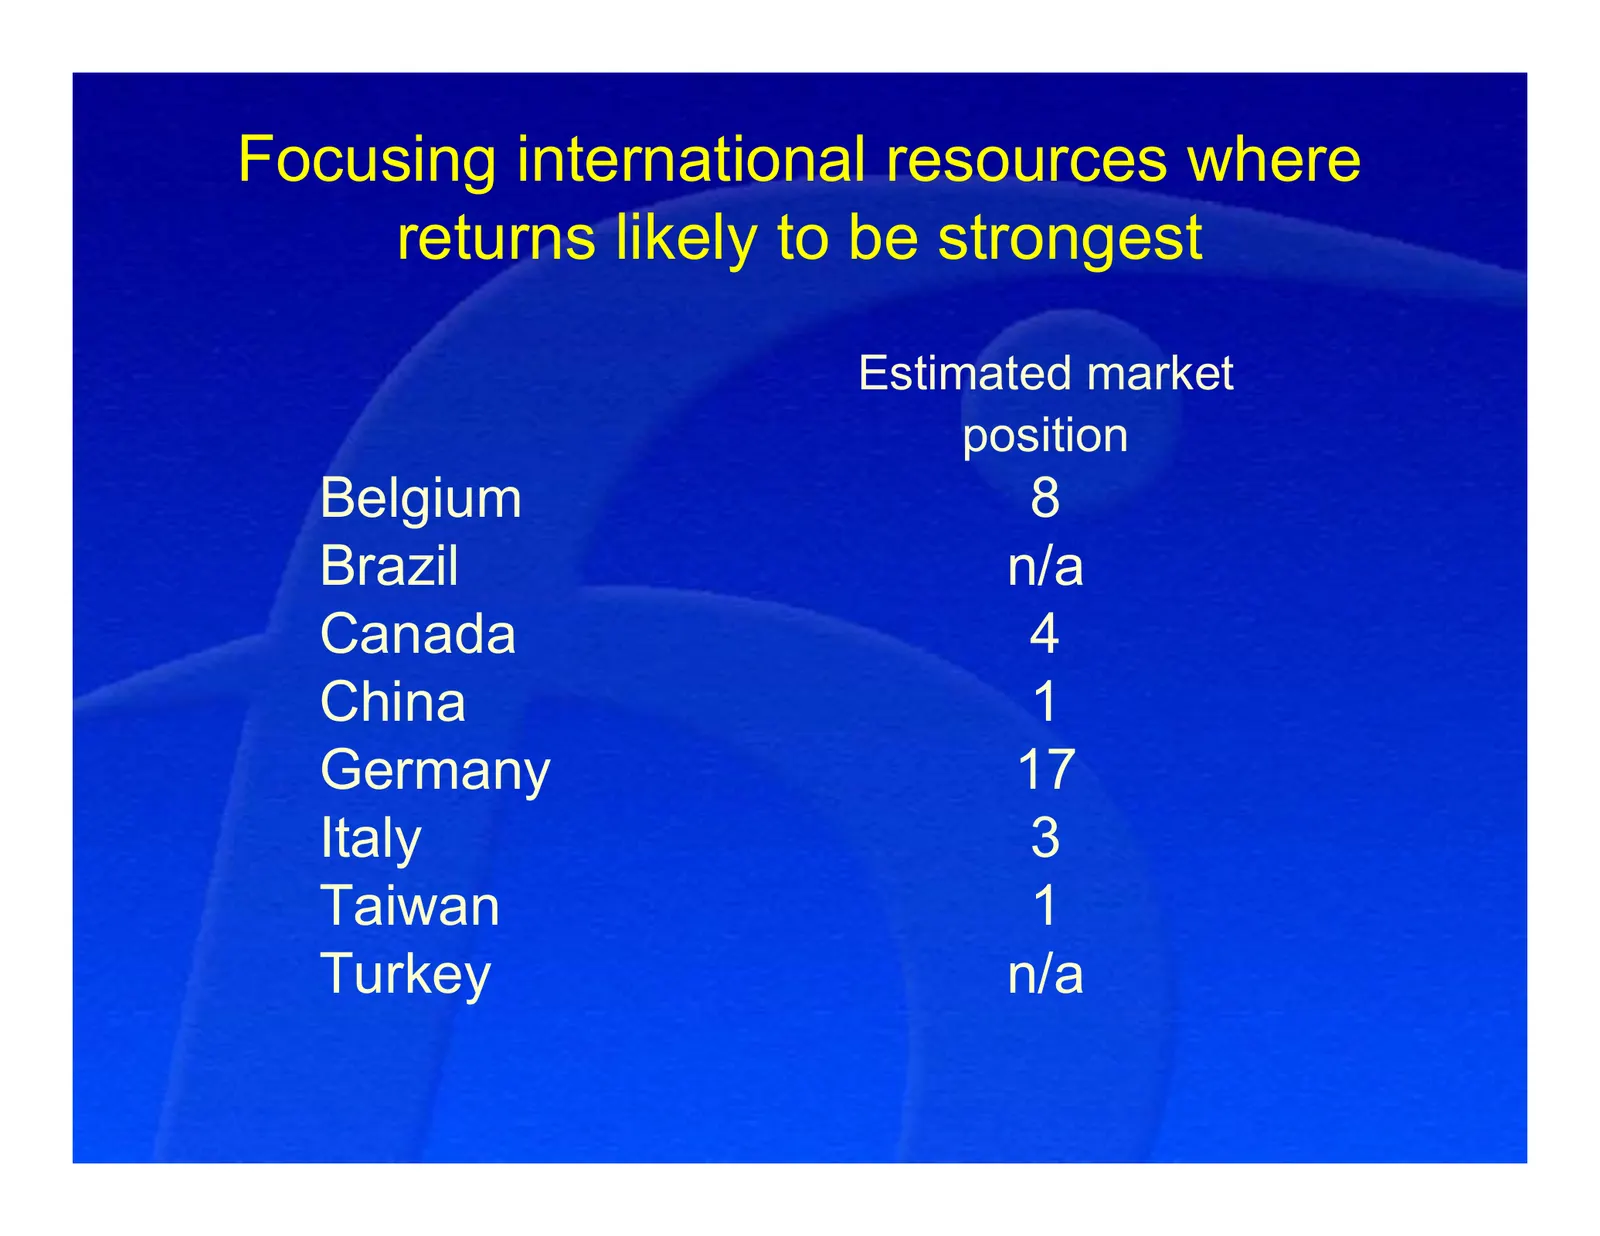
Slide 41: Focusing international resources where returns likely to be strongest
Focusing international resources where returns likely to be strongest Estimated market position Belgium 8 Brazil n/a Canada 4 China 1 Germany 17 Italy 3 Taiwan 1 Turkey n/a
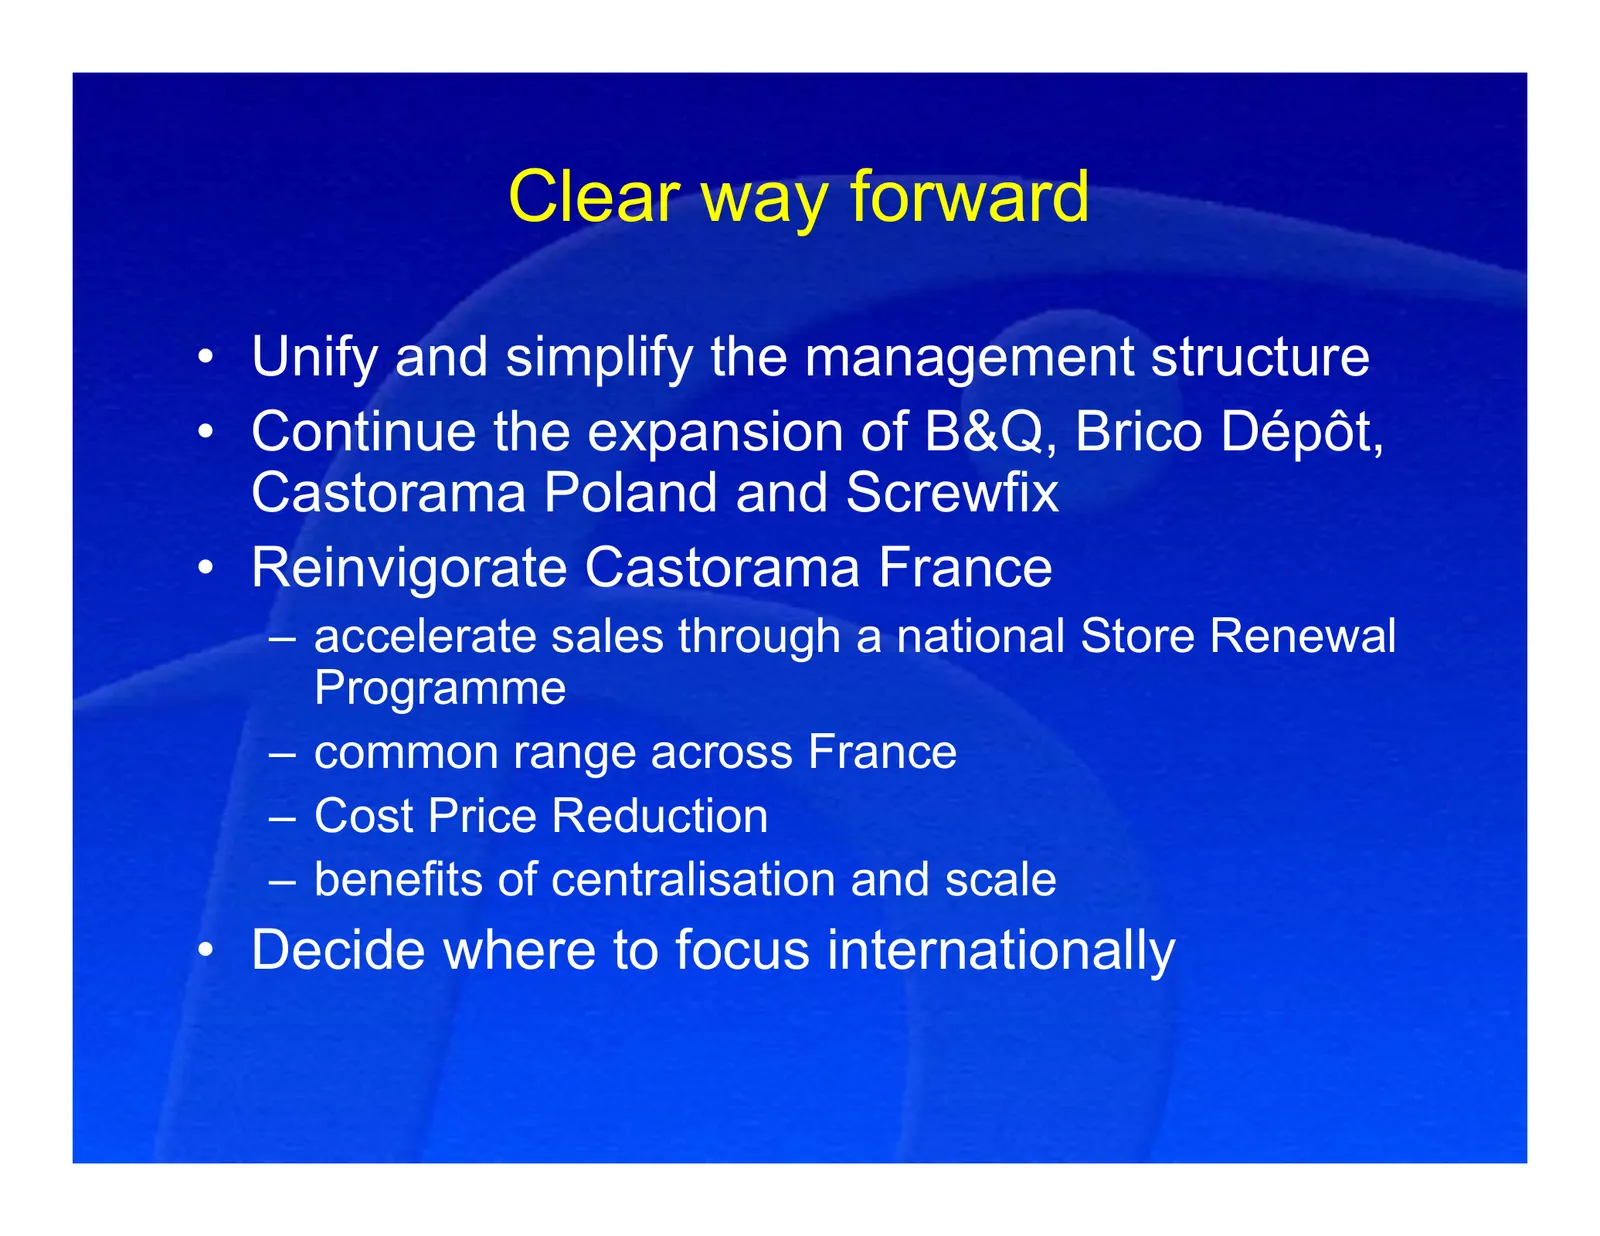
Slide 42: Clear way forward
Clear way forward • Unify and simplify the management structure • Continue the expansion of B&Q, Brico Dépôt, Castorama Poland and Screwfix • Reinvigorate Castorama France – accelerate sales through a national Store Renewal Programme – common range across France – Cost Price Reduction – benefits of
Slide 43: We would manage via the existing strong teams
We would manage via the existing strong teams • Harness strong operational teams • Castorama and Brico Dépôt head offices to stay in France • Some consolidation of the Kingfisher and CDI small head office teams, but no compulsory redundancies
Slide 44: We already have some good examples of teamwork
We already have some good examples of teamwork • B&Q capital cost savings learnt from Réno-Dépôt • Joint buying between B&Q and Brico Dépôt
Slide 45: Significant financial benefits will flow from our plans
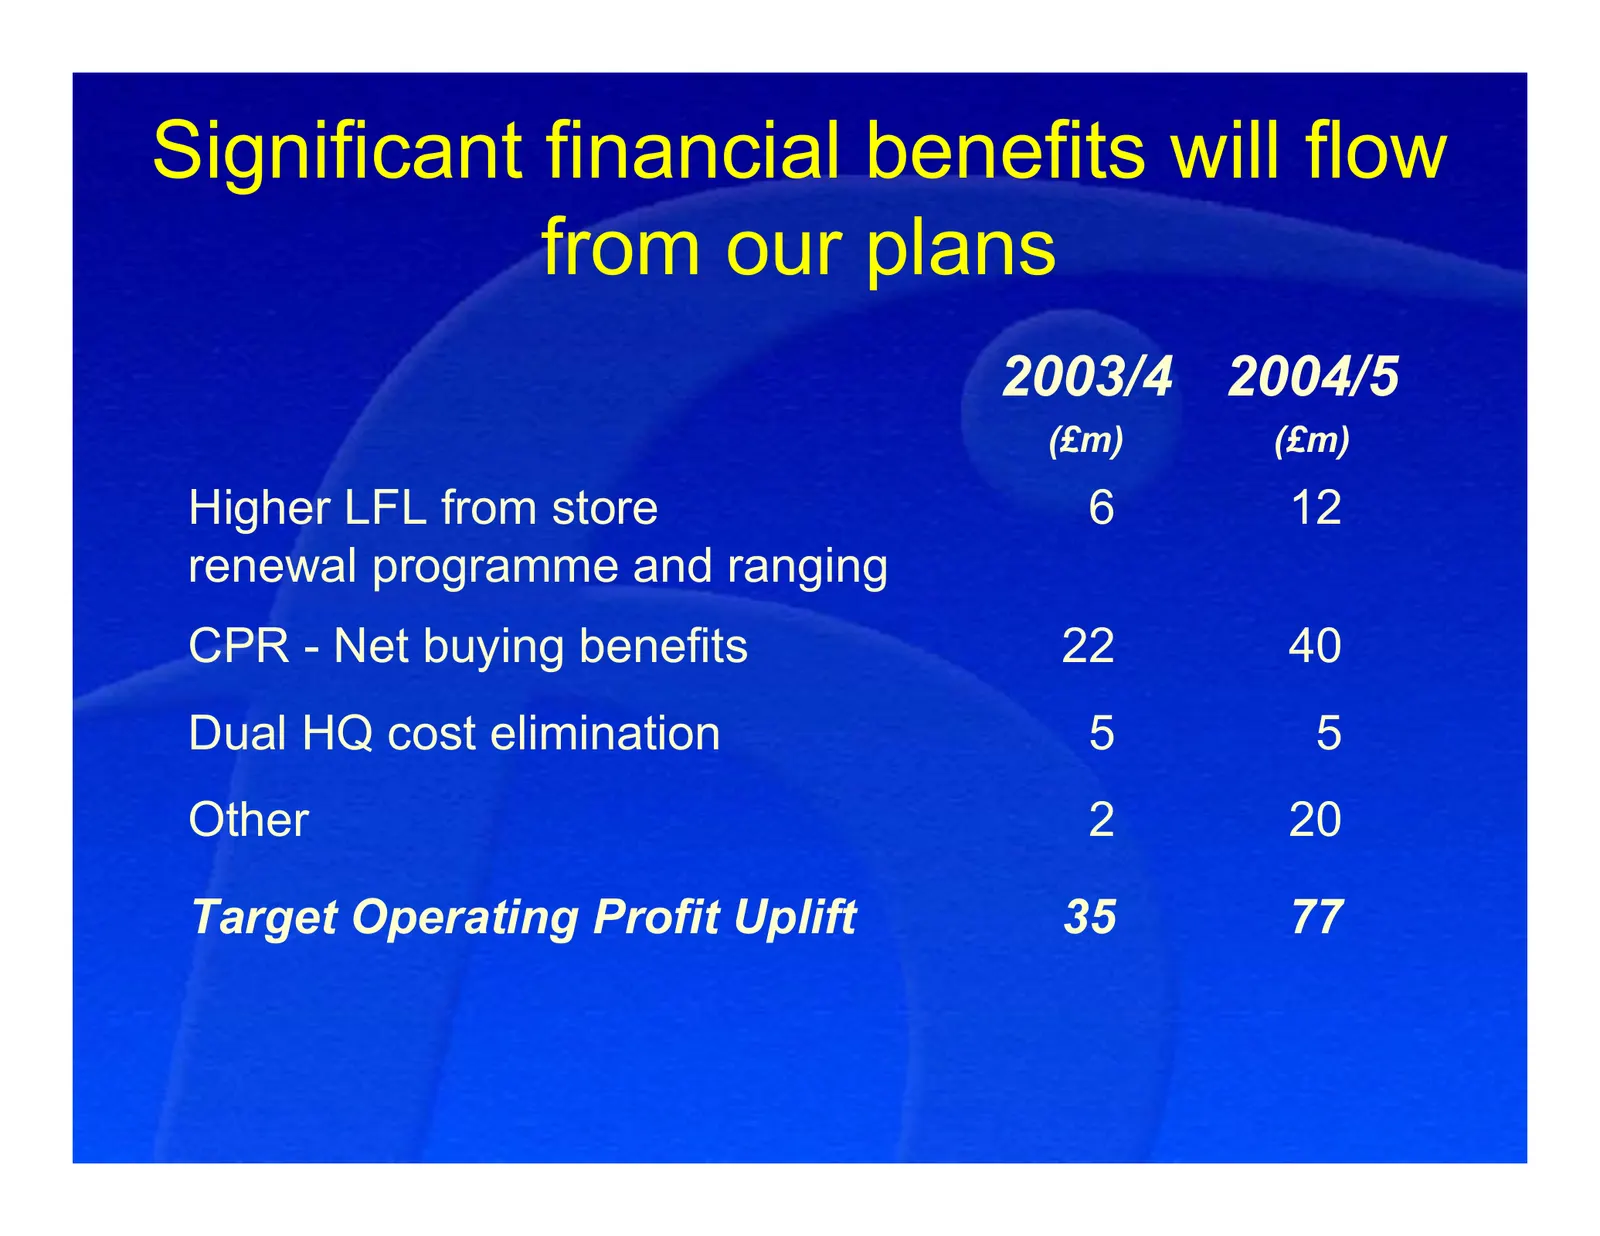
Significant financial benefits will flow from our plans 2003/4 2004/5 (£m) (£m) Higher LFL from store 6 12 renewal programme and ranging CPR - Net buying benefits 22 40 Dual HQ cost elimination 5 5 Other 2 20 Target Operating Profit Uplift 35 77
Slide 46: Store Renewal programme in France
Store Renewal programme in France • Castorama stores to receive catch-up renewal investment
Slide 47: Store Renewal programme in France
Store Renewal programme in France • Castorama stores to receive catch-up renewal investment • Best practices to be introduced – store layout (planograms) – overall SKU reduction – improved pricing strategy – range control
Slide 48: Store Renewal programme in France
Store Renewal programme in France • Castorama stores to receive catch-up renewal investment • Best practices to be introduced – store layout (planograms) – overall SKU reduction – improved pricing strategy – range control aiming for LFL above the market
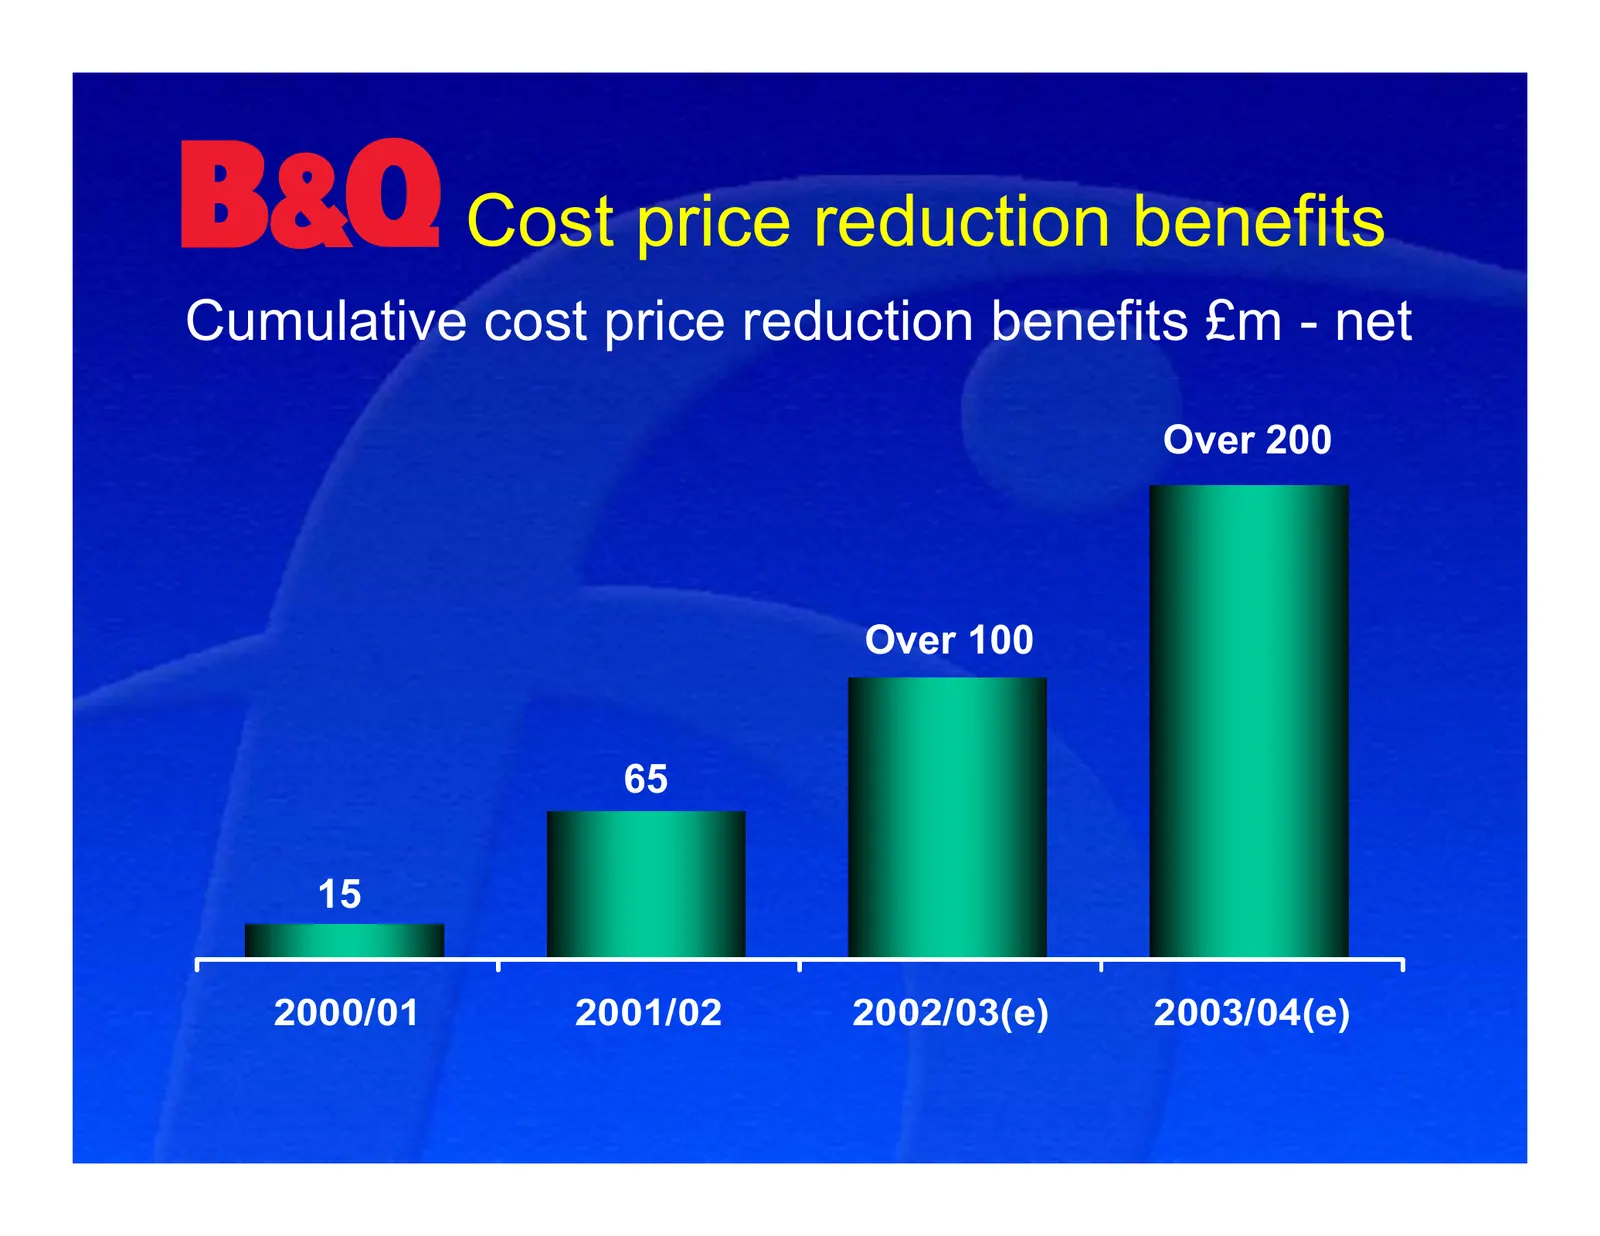
Slide 49: Cost price reduction benefits
Cost price reduction benefits Cumulative cost price reduction benefits £m - net Over 200 Over 100 65 15 2000/01 2001/02 2002/03(e) 2003/04(e)
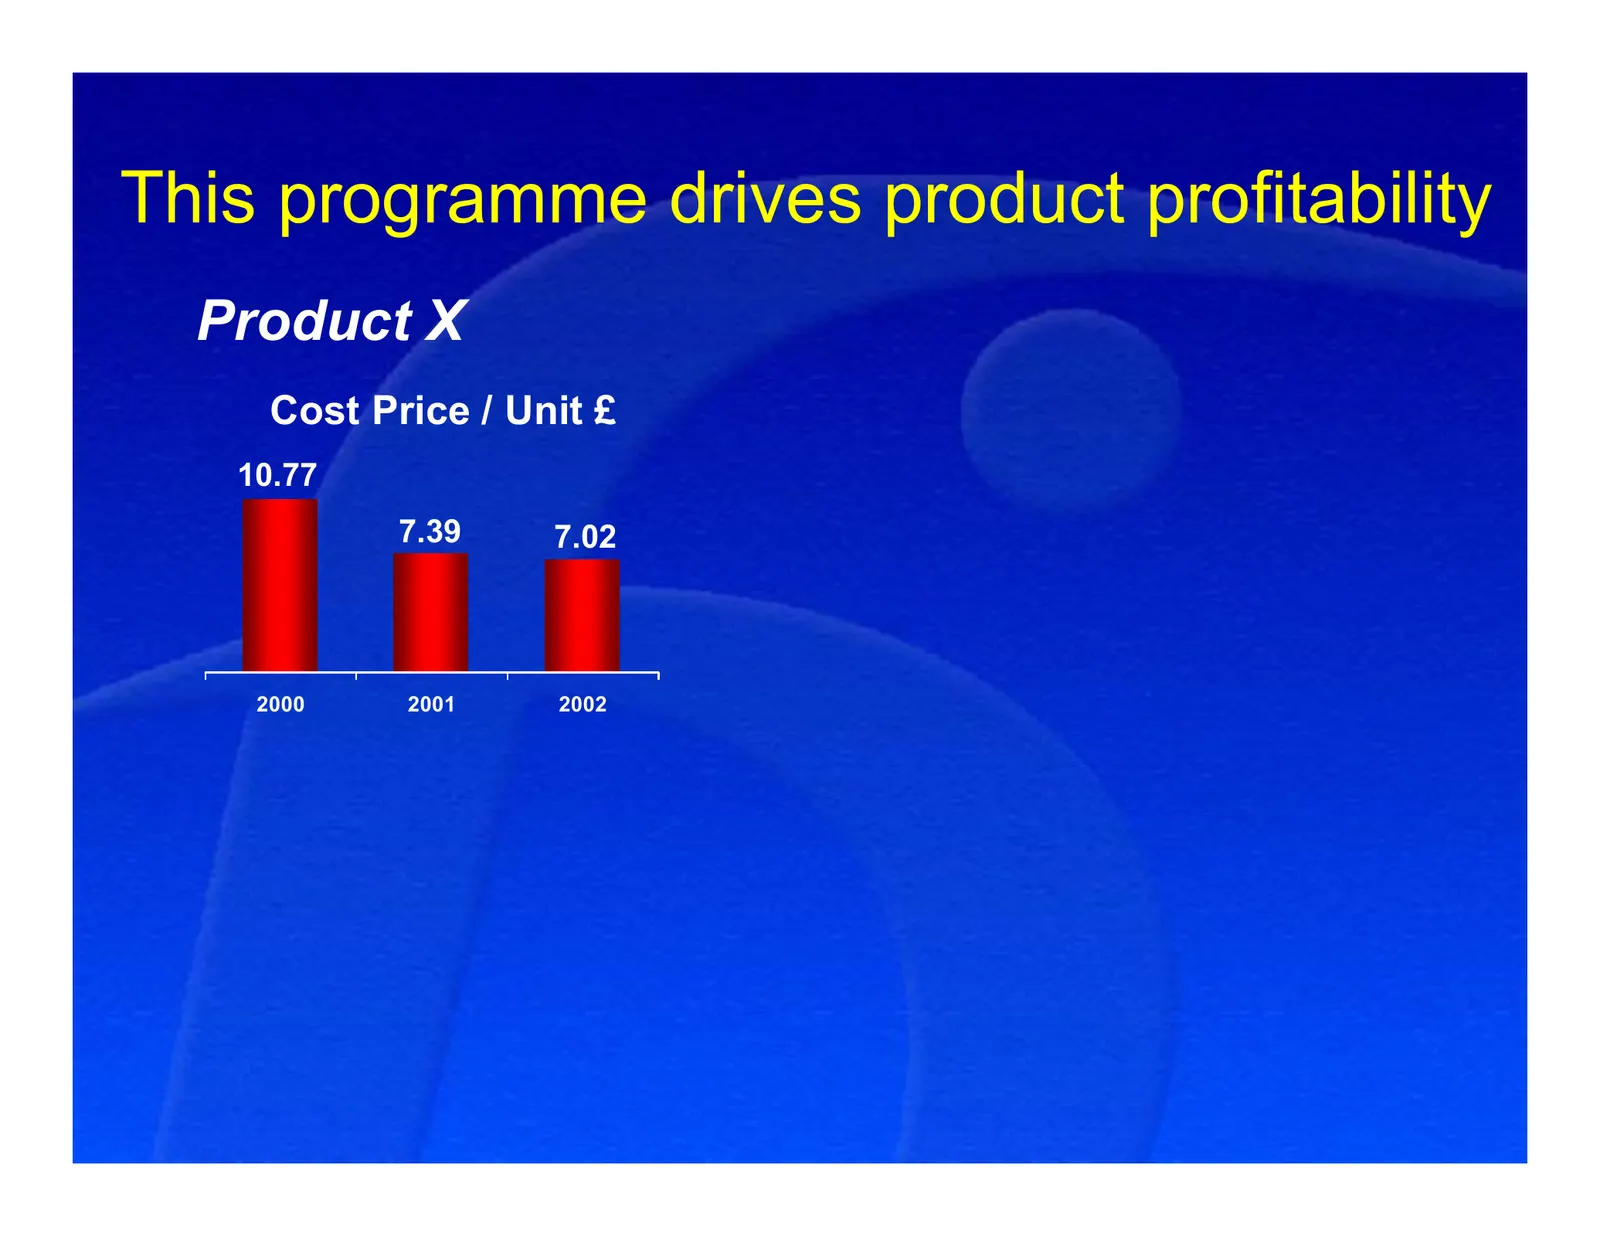
Slide 50: This programme drives product profitability
This programme drives product profitability Product X Cost Price / Unit £ 10.77 7.39 7.02 2000 2001 2002
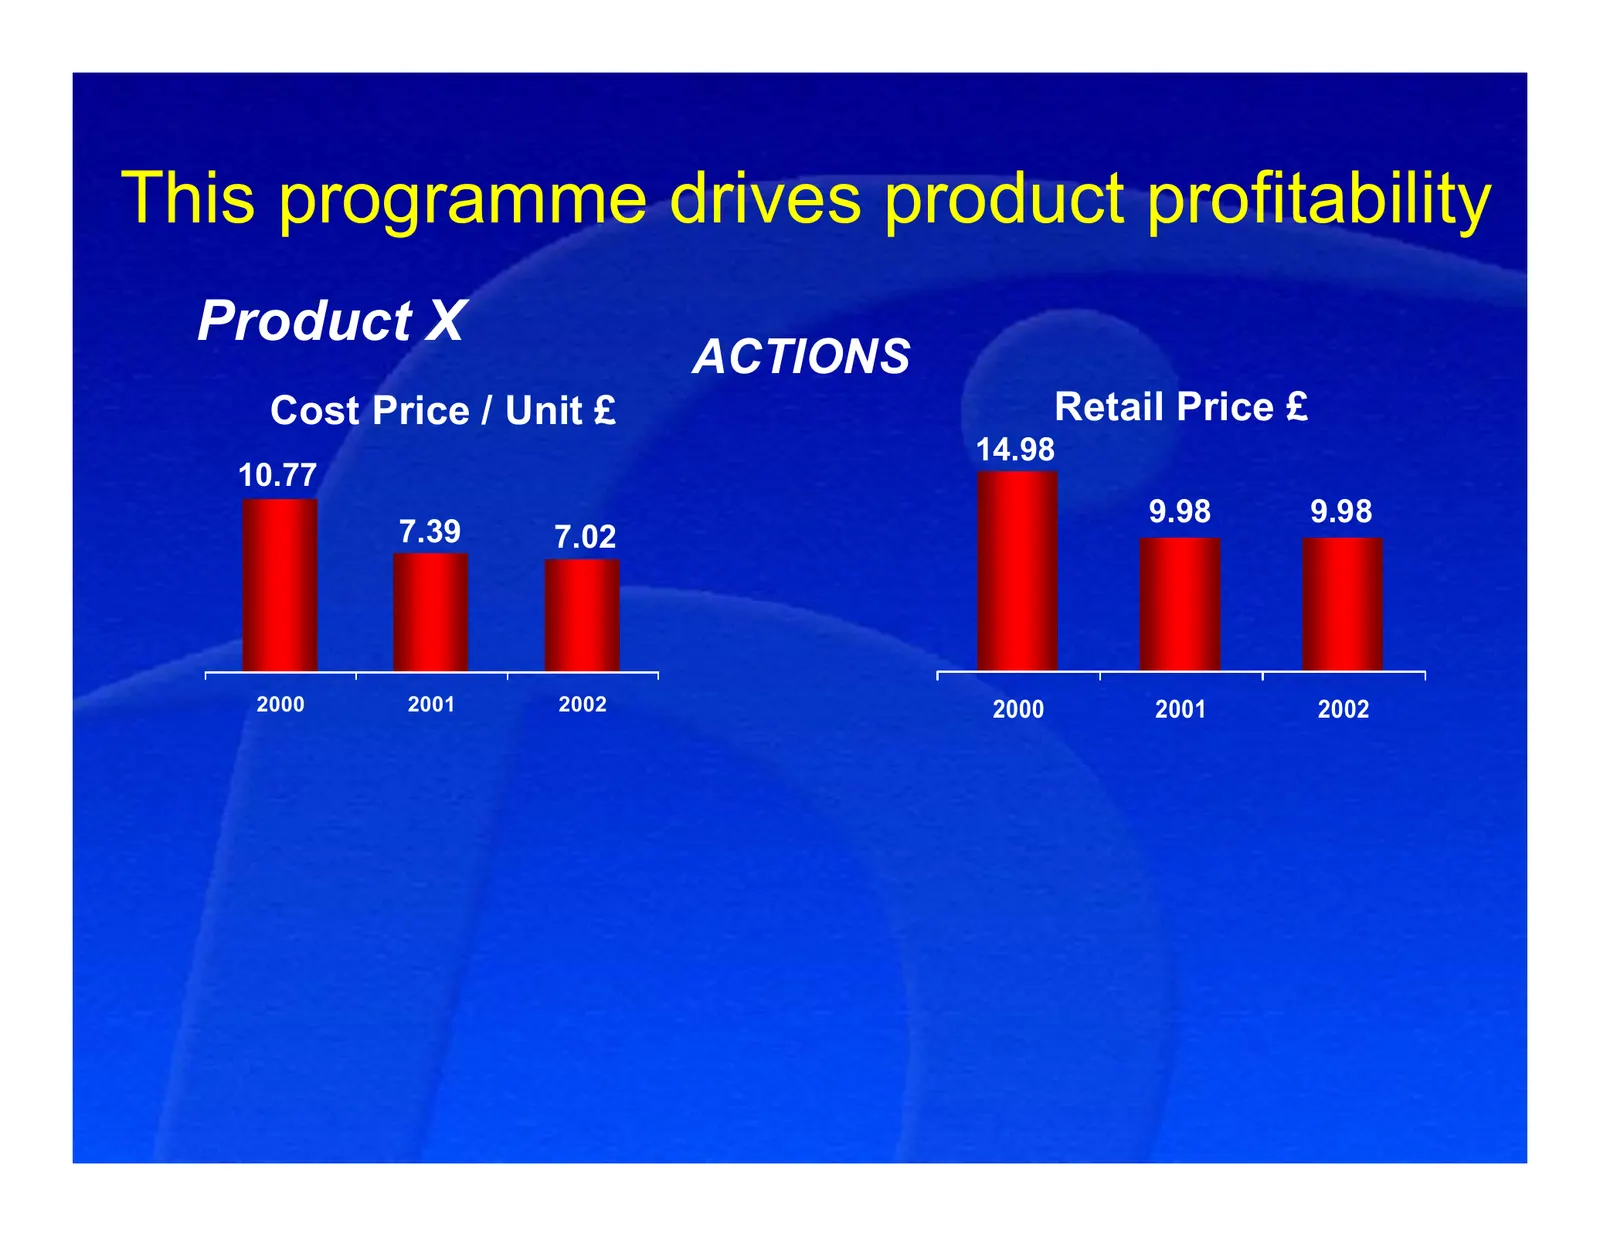
Slide 51: This programme drives product profitability
This programme drives product profitability Product X ACTIONS Cost Price / Unit £ Retail Price £ 14.98 10.77 9.98 9.98 7.39 7.02 2000 2001 2002 2000 2001 2002
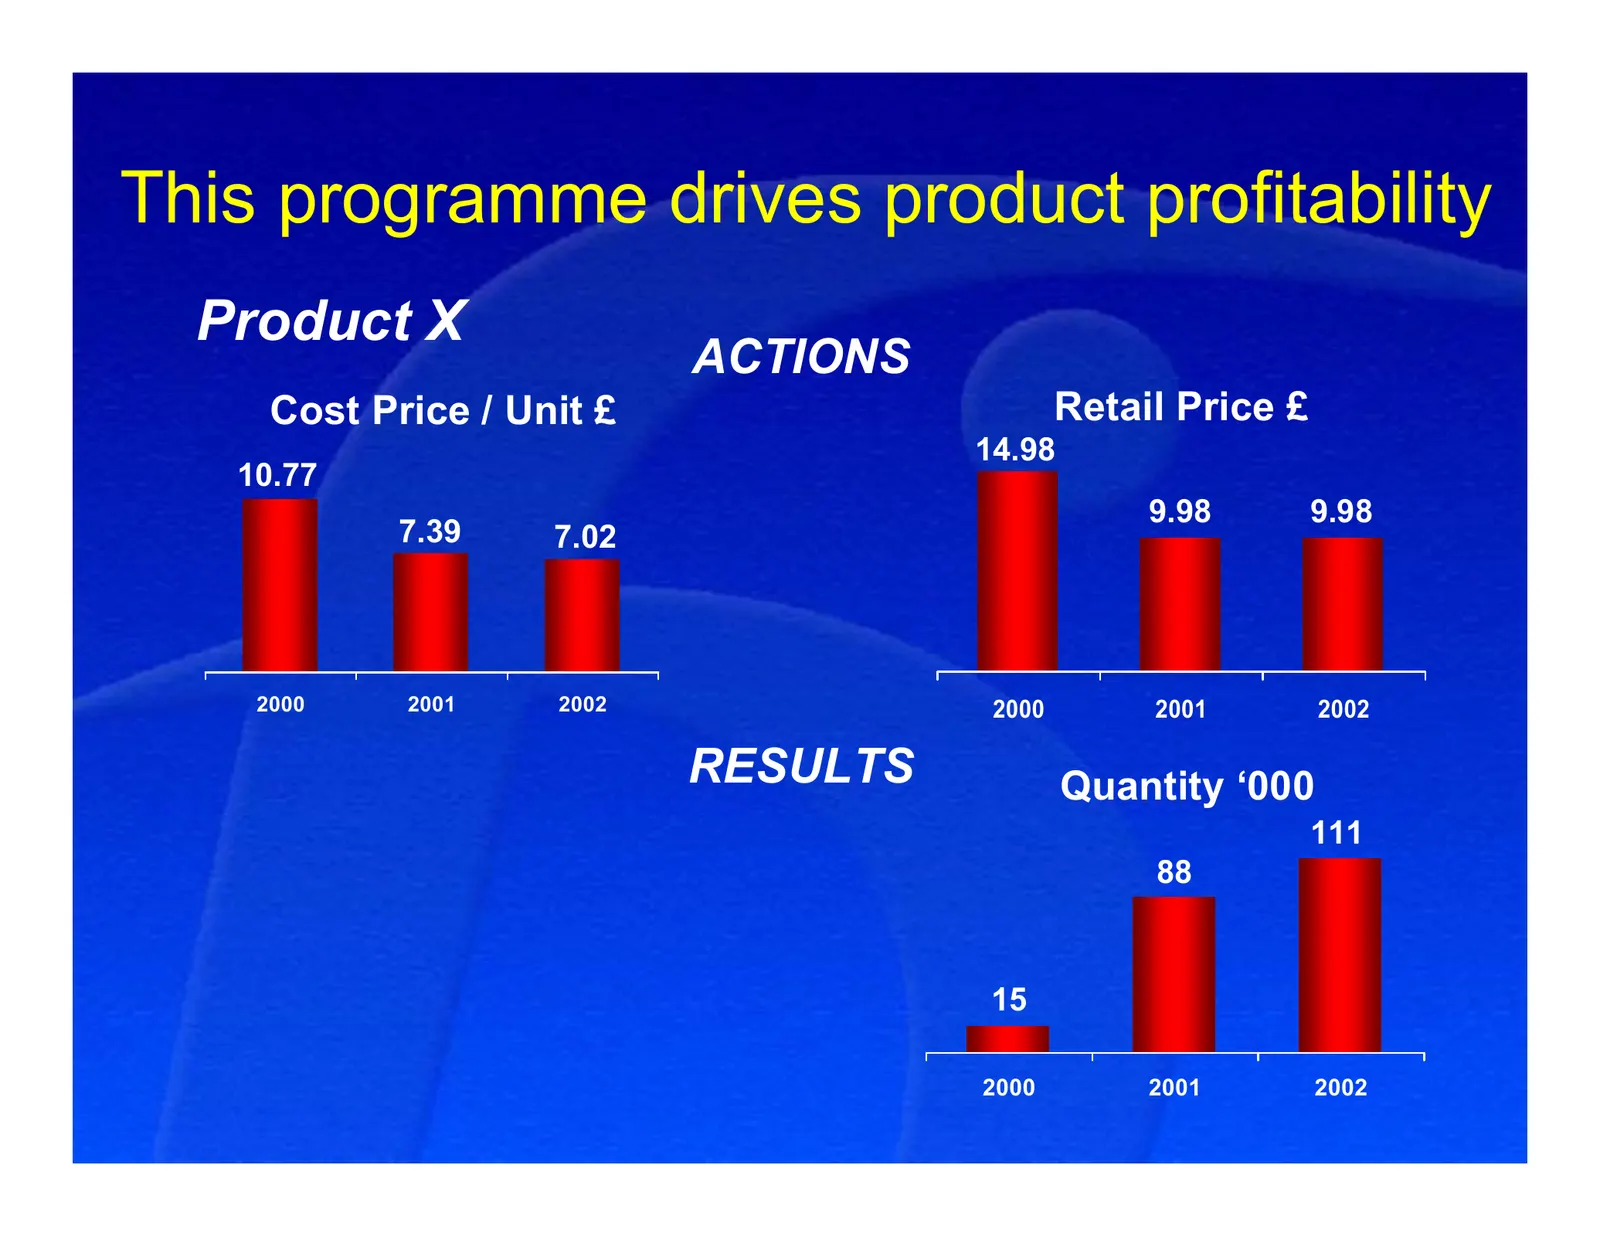
Slide 52: This programme drives product profitability
This programme drives product profitability Product X ACTIONS Cost Price / Unit £ Retail Price £ 14.98 10.77 9.98 9.98 7.39 7.02 2000 2001 2002 2000 2001 2002 RESULTS Quantity ‘000 111 88 15 2000 2001 2002
Slide 53: This programme drives product profitability
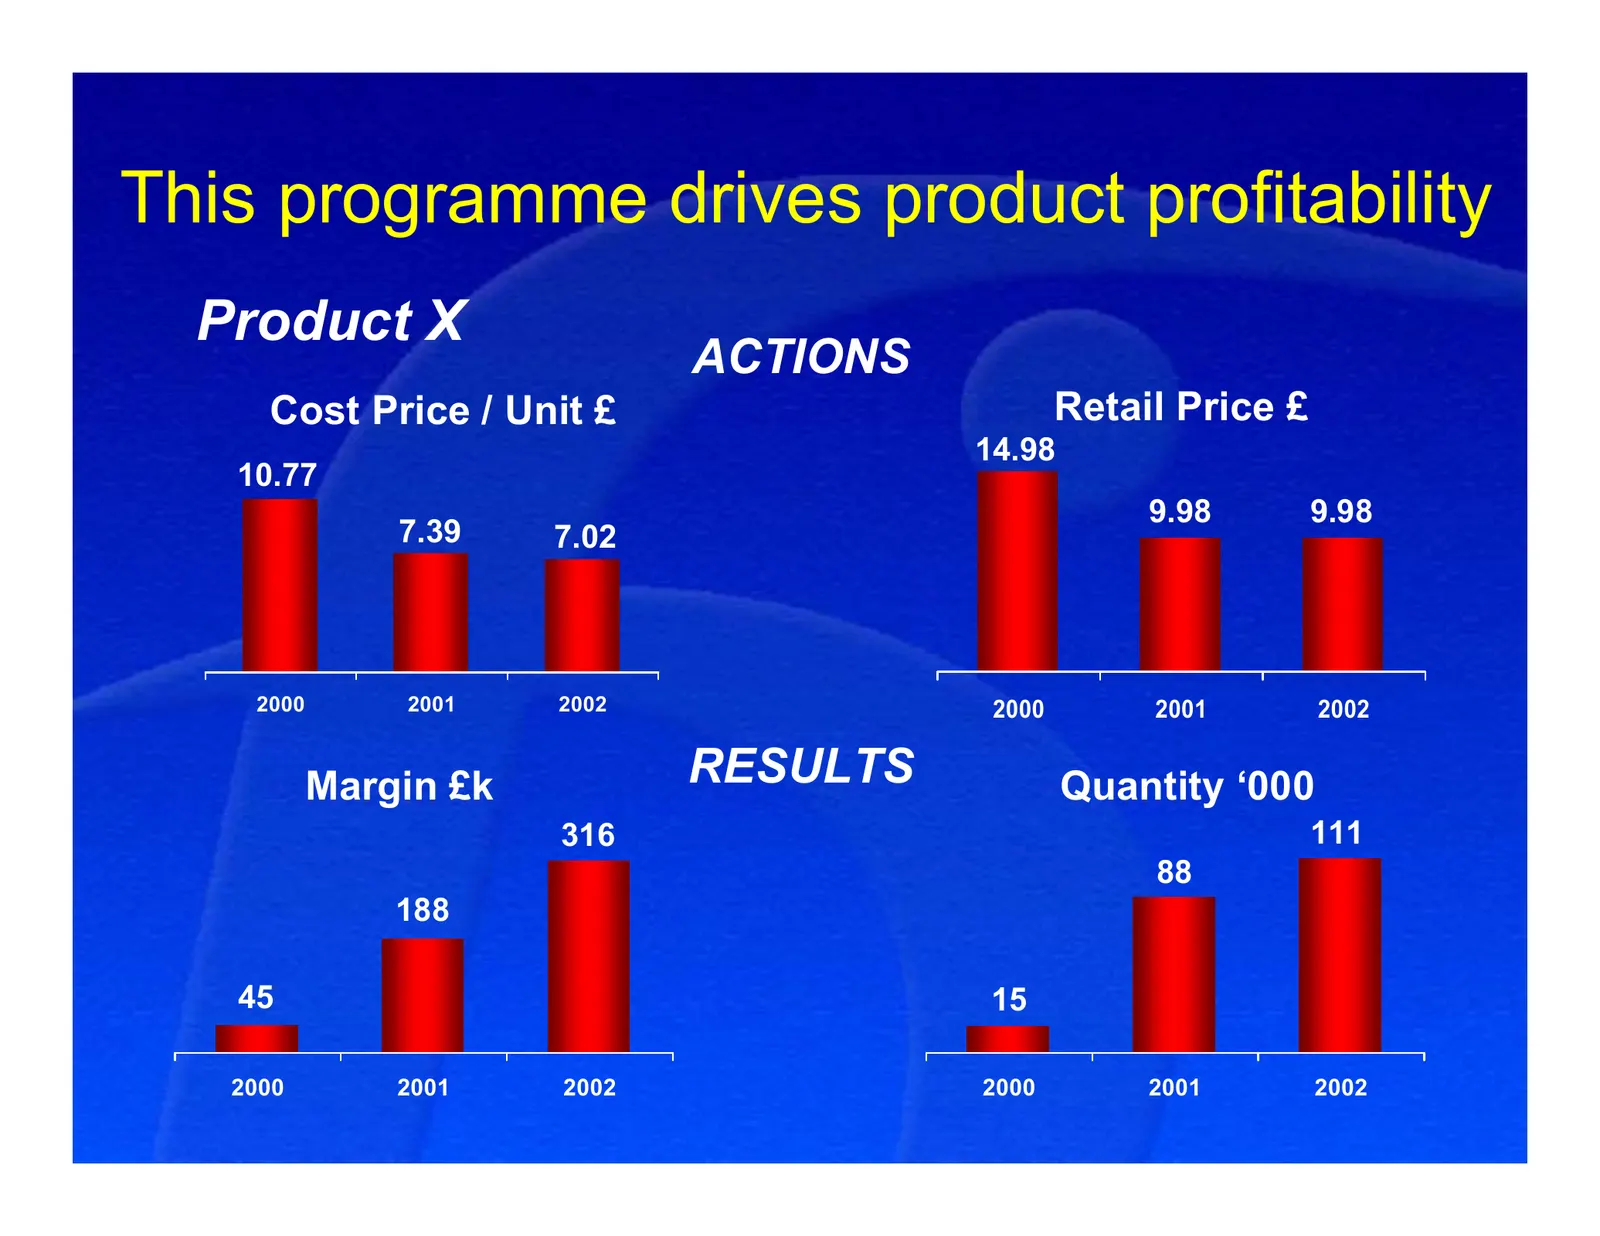
This programme drives product profitability Product X ACTIONS Cost Price / Unit £ Retail Price £ 14.98 10.77 9.98 9.98 7.39 7.02 2000 2001 2002 2000 2001 2002 Margin £k RESULTS Quantity ‘000 316 111 88 188 45 15 2000 2001 2002 2000 2001 2002
Slide 54: Initial programme plan
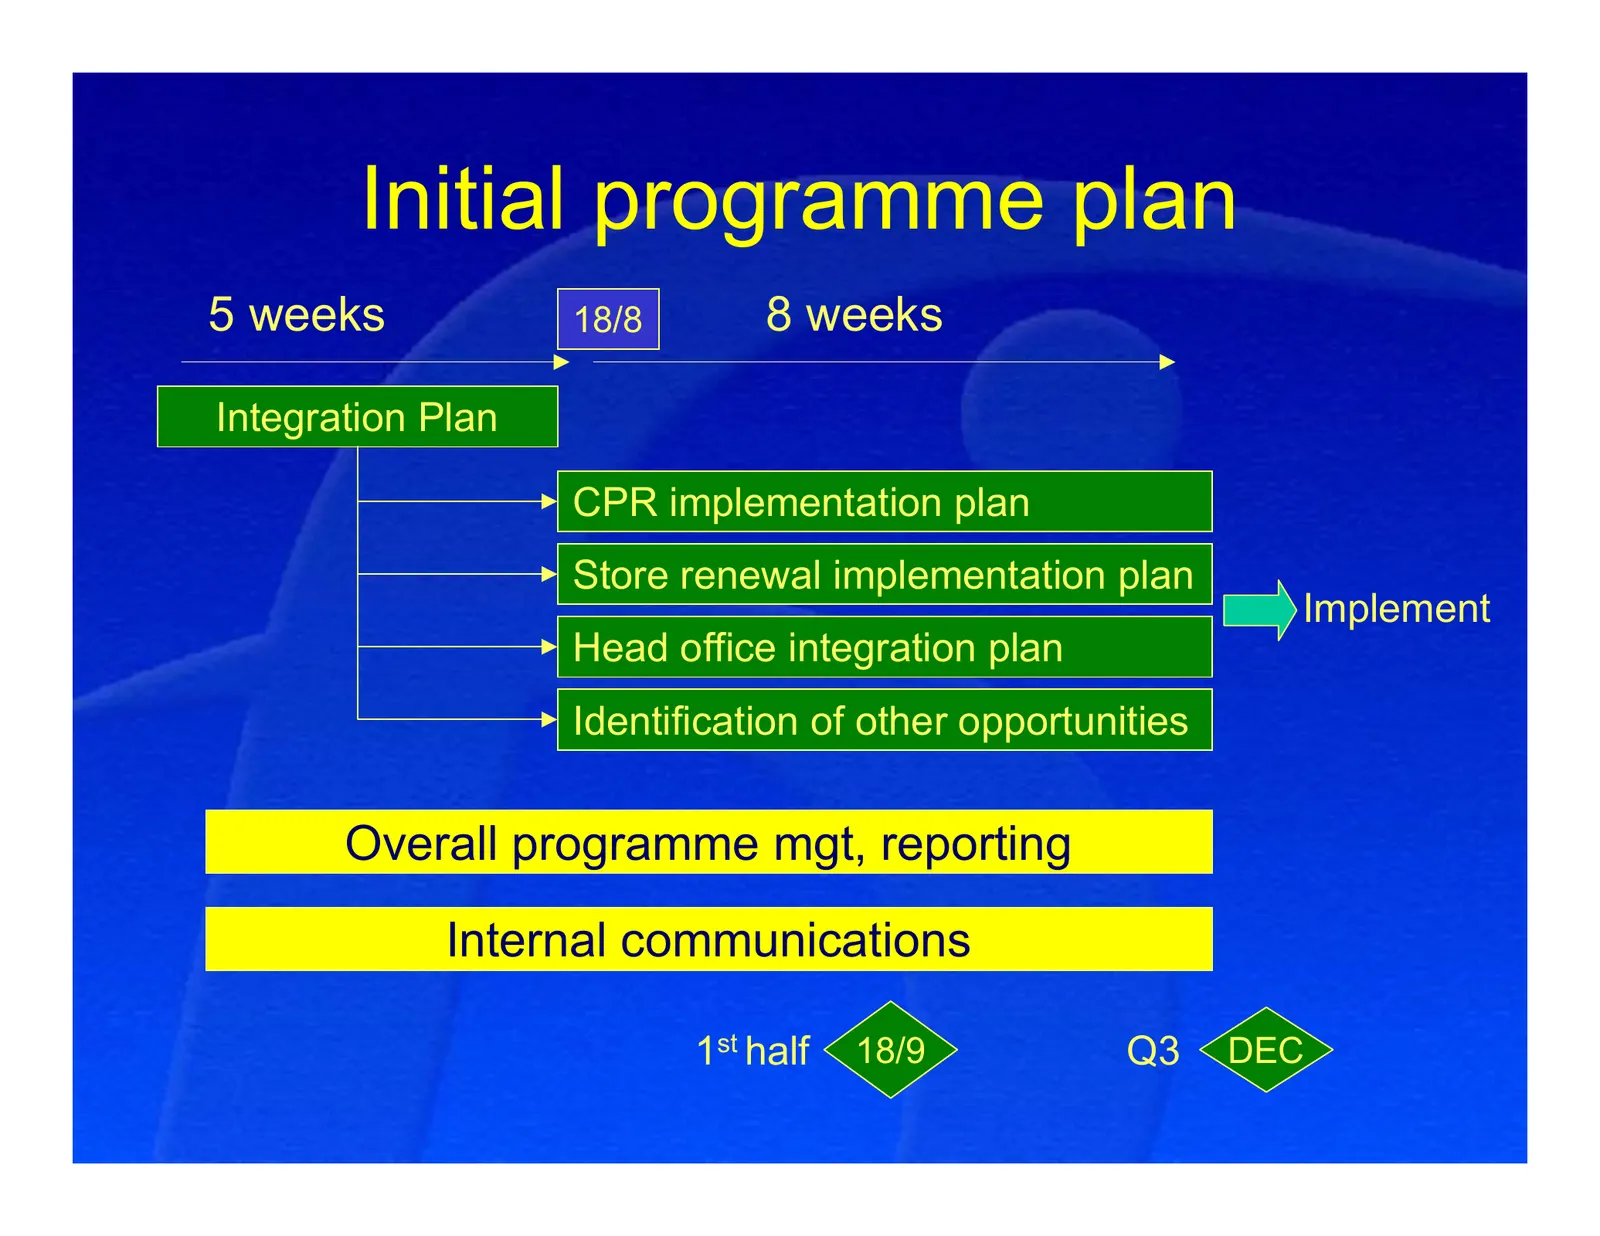
Initial programme plan 5 weeks 18/8 8 weeks Integration Plan CPR implementation plan Store renewal implementation plan Implement Head office integration plan Identification of other opportunities Overall programme mgt, reporting Internal communications 1st half 18/9 Q3 DEC
Slide 55: We believe the medium term offers enormous possibility
We believe the medium term offers enormous possibility • Common buying – 30% to 40% common European ranges • Common infrastructures
Slide 56: We believe our plan for Castorama in France will work
We believe our plan for Castorama in France will work • We have a talented and motivated French team in place • Successful DIY operating principles common to many countries
Slide 57: Our three point agenda for growth
Our three point agenda for growth • Backing the biggest winners: – B&Q, Brico Dépôt, Castorama Poland and Screwfix
Slide 58: Our three point agenda for growth
Our three point agenda for growth • Backing the biggest winners: – B&Q, Brico Dépôt, Castorama Poland and Screwfix • Restoring Castorama France as a winner
Slide 59: Our three point agenda for growth
Our three point agenda for growth • Backing the biggest winners: – B&Q, Brico Dépôt, Castorama Poland and Screwfix • Restoring Castorama France as a winner • Focusing our international efforts
Slide 60: A Transformation Strategy
KING) SHER A Transformation Strategy
Source: Internet Archive copy of kingfisher.co.uk
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
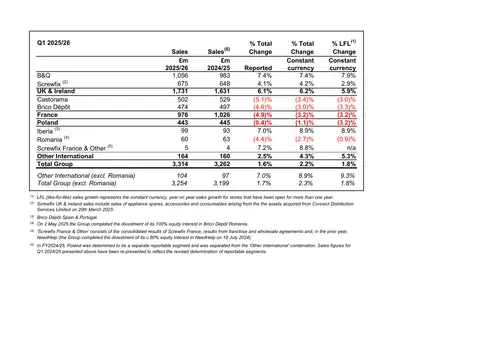 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025