Kraft Foods — Merger or Acquisition (March 2015)
35 slides from Kraft Foods's merger presentation, Mar 25, 2015
Slide 1: Filed by Kraft Foods Group, Inc. pursuant to Rule 425
Filed by: Kraft Foods Group, Inc. Pursuant to Rule 425 under the Securities Act of 1933 and deemed filed pursuant to Rule 14a-12 of the Securities Exchange Act of 1934 Subject Company: Kraft Foods Group, Inc. Commission File No.: 001-35491 The following presentation was given during the investor cal
Slide 2: Creating a Global Food & Beverage Leader
Investor25, March Creating Presentation a 2015 Global Food & Beverage Leader
Slide 3: Safe Harbor and Forward-Looking Statements
Safe Forward-Looking Except Exchange “future”, substance of could timing, successfully the operations transaction integrating or any Additional This respect 4”) Commission Heinz THE Investors http://www.sec.gov. will Participants Kraft proposed 2015. statement/prospectus the it merger with forward-l
Slide 4: List of Participants
List ofCahill John Chairman Alexandre Chairman, Co-founder Bernardo 2Chief Executive Participants Hees and Behring H.J. andChief Heinz the Officer, Managing Executive Company H.J. Heinz Partner, Officer, Company 3G Kraft Capital Foods Group
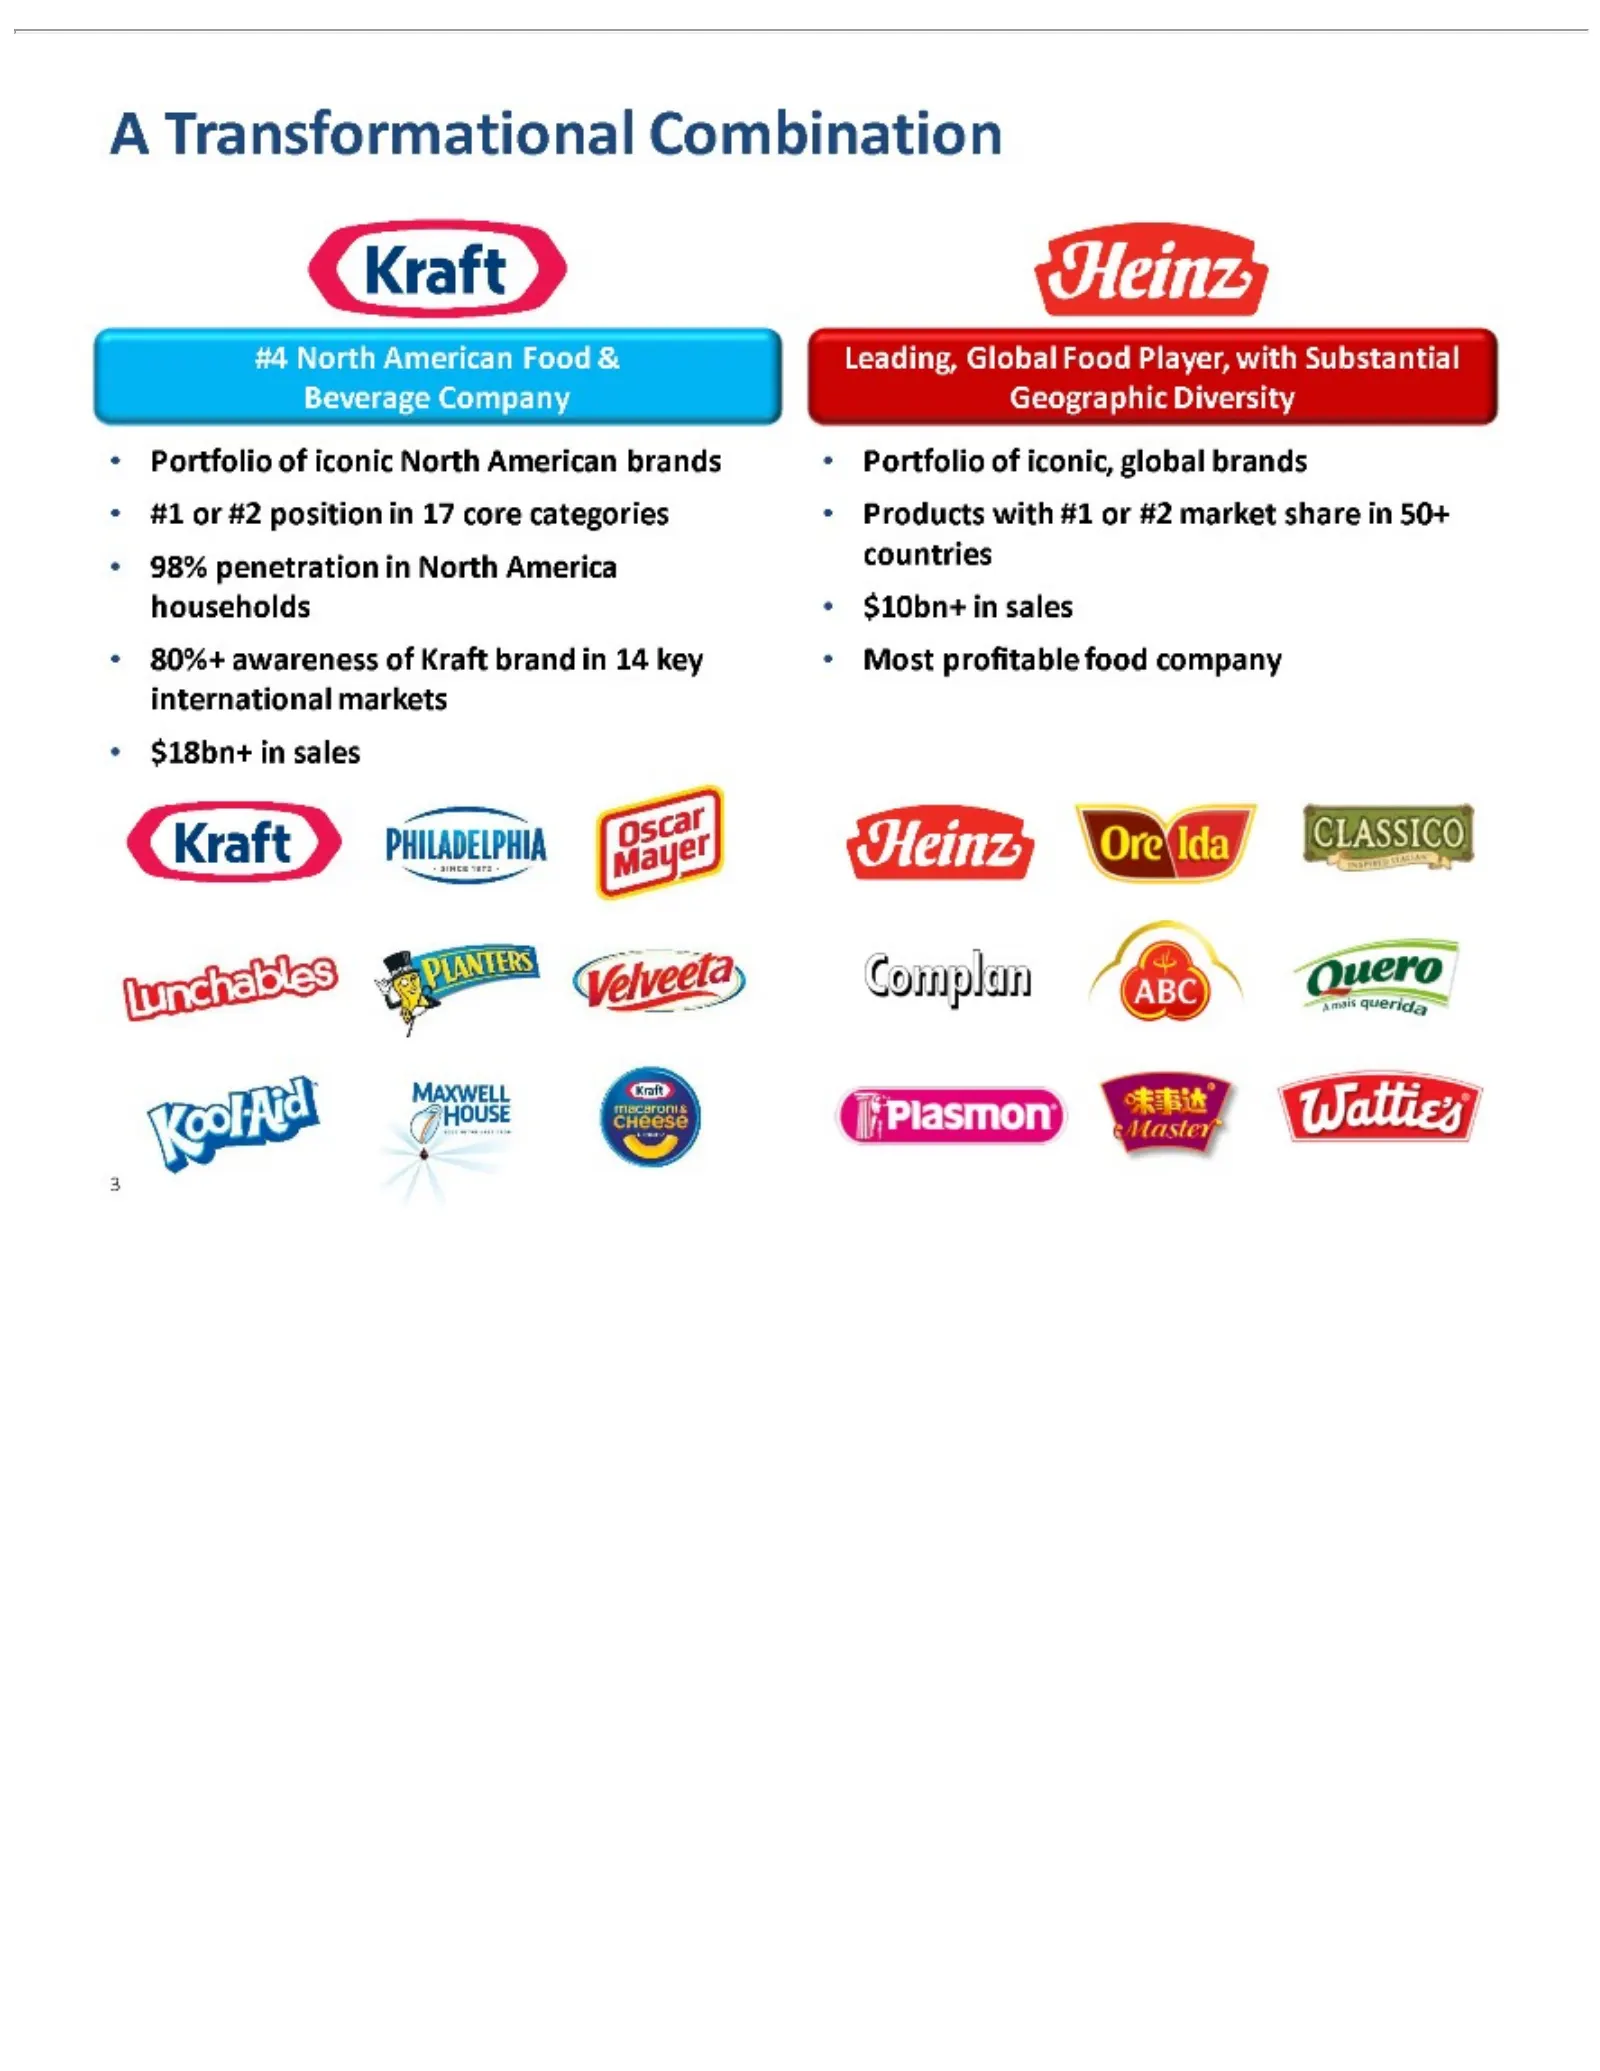
Slide 5: A Transformational Combination
A Transformational #4 #1 98% 80%+ $18bn+ Leading, Portfolio Products $10bn+ Most [Graphic North or penetration profitable #2 awareness in position Appears with Global American ofsales iconic iconic, #1food Food in of or in Here] North global North Food Combination 17 Kraft #2 company Player, core ma
Slide 6: Transaction Overview Agenda
Transaction Agenda Kraft Heinz 4A Transformational Overview Overview Highlights Combination
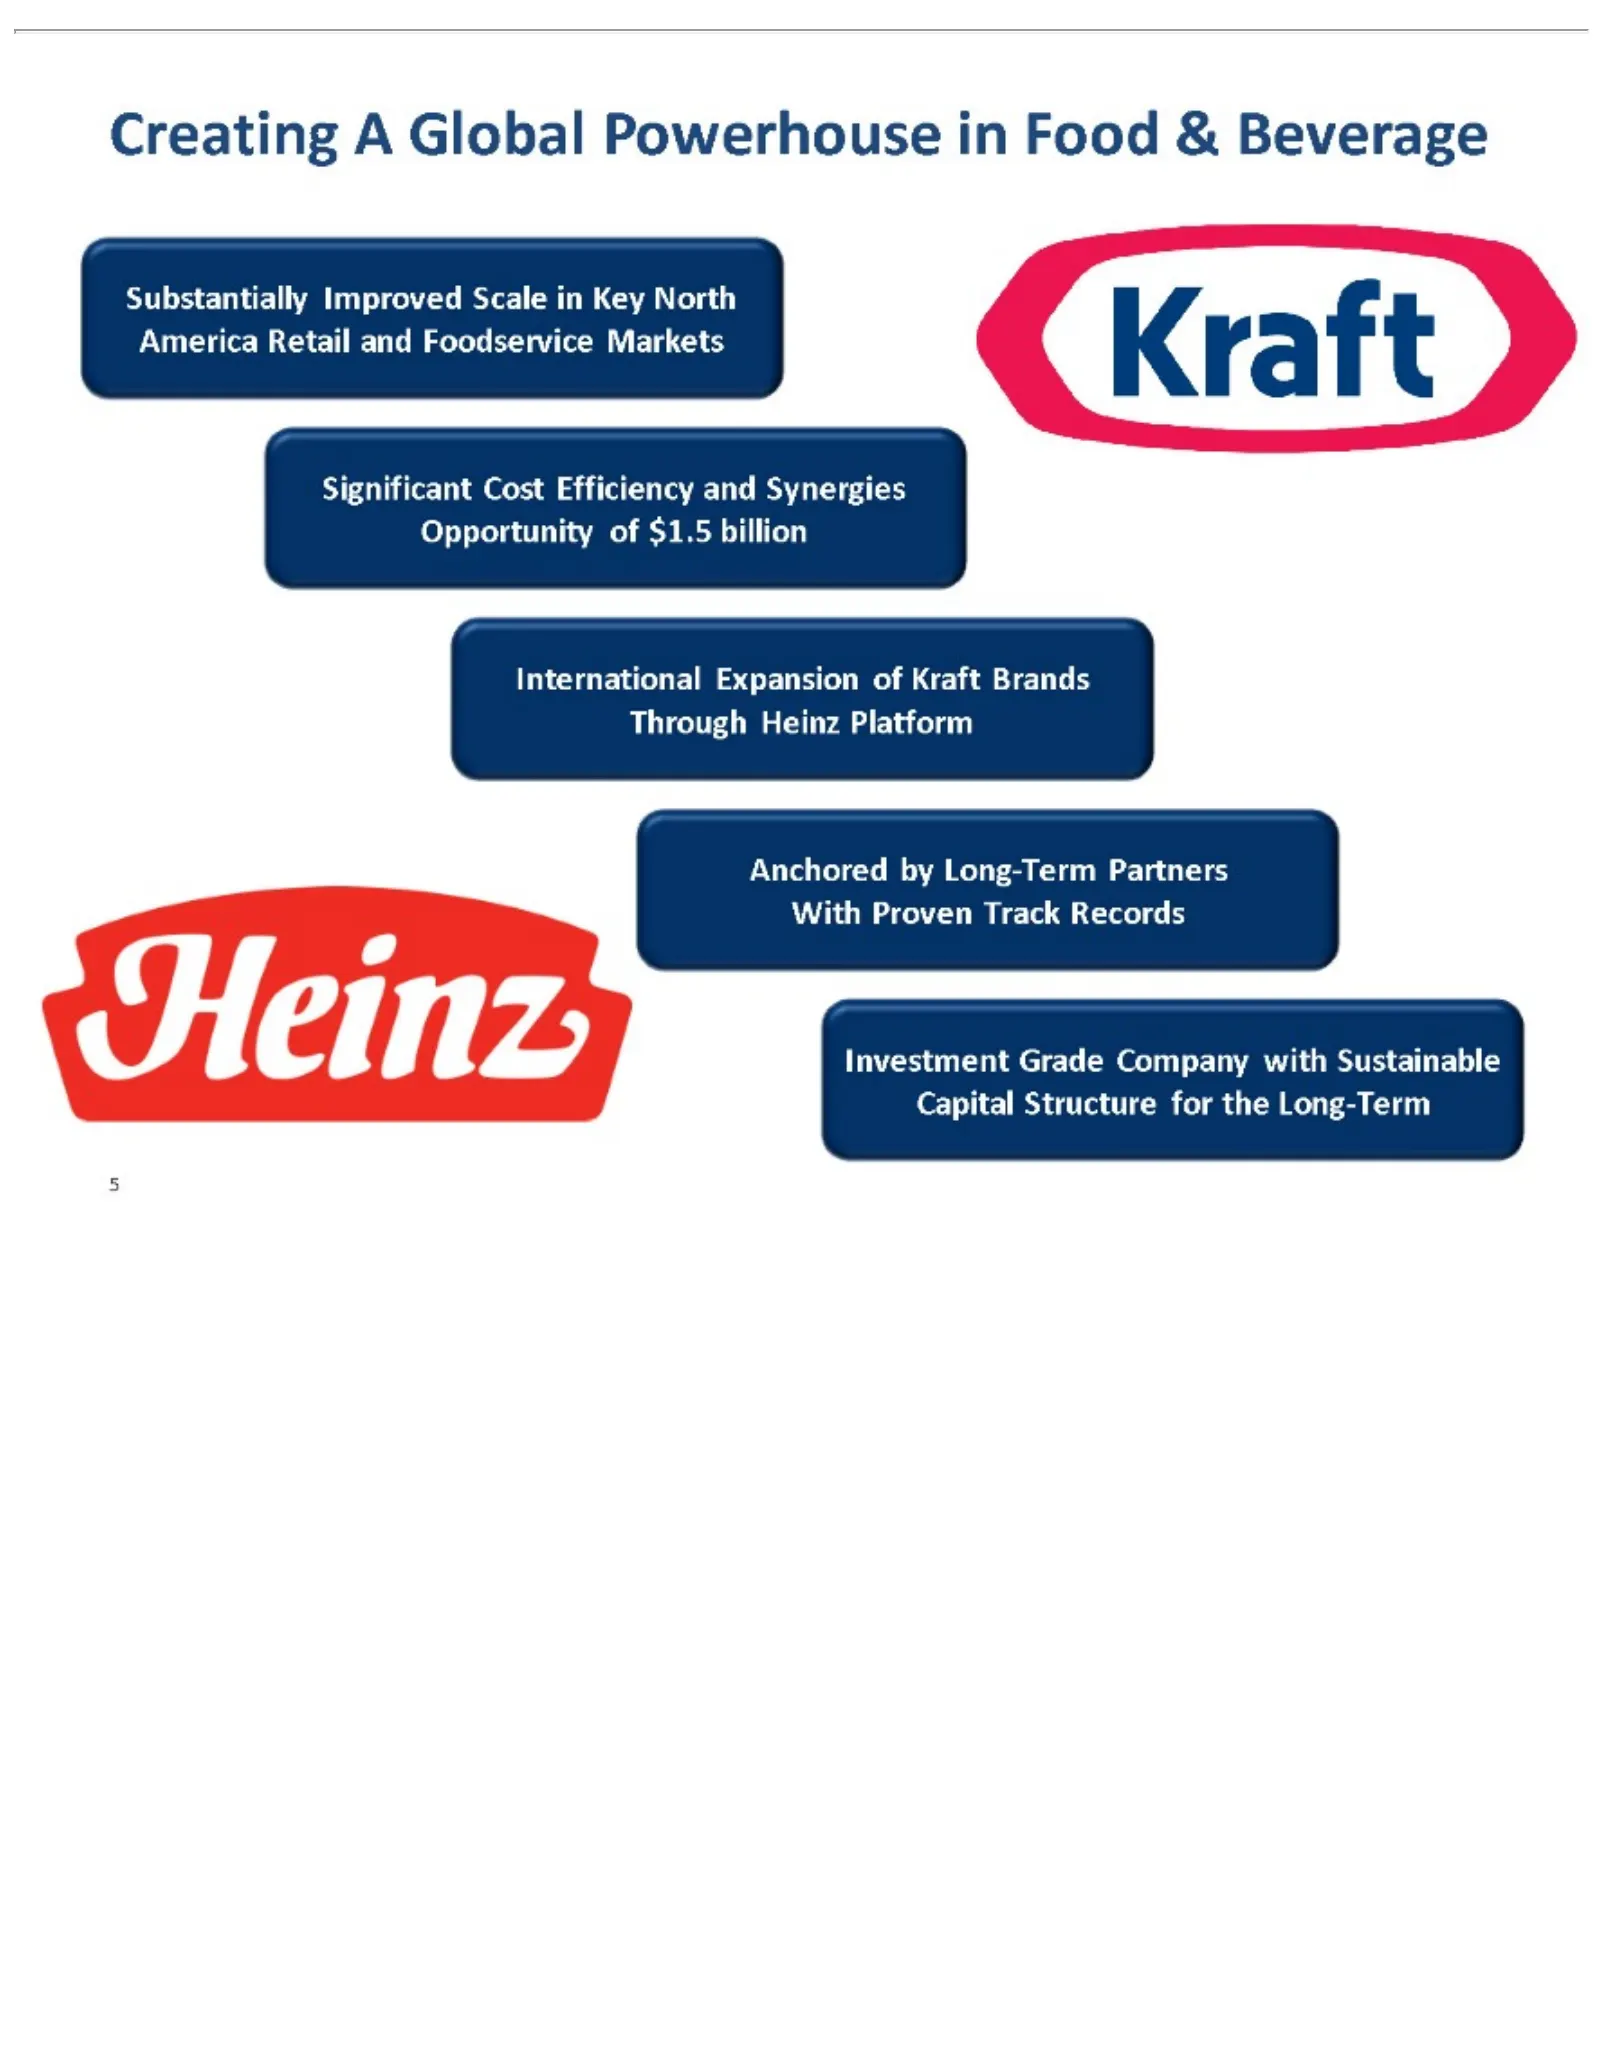
Slide 7: Creating a Global Food & Beverage Powerhouse
Creating Substantially America Significant Opportunity International Through [Graphic Anchored With Investment 5Capital Proven Structure A Retail Heinz Appears by Global Cost Grade of Track Expansion Long-Term Improved $1.5 and Platform Efficiency for Here] Company Powerhouse Records Foodservice bil
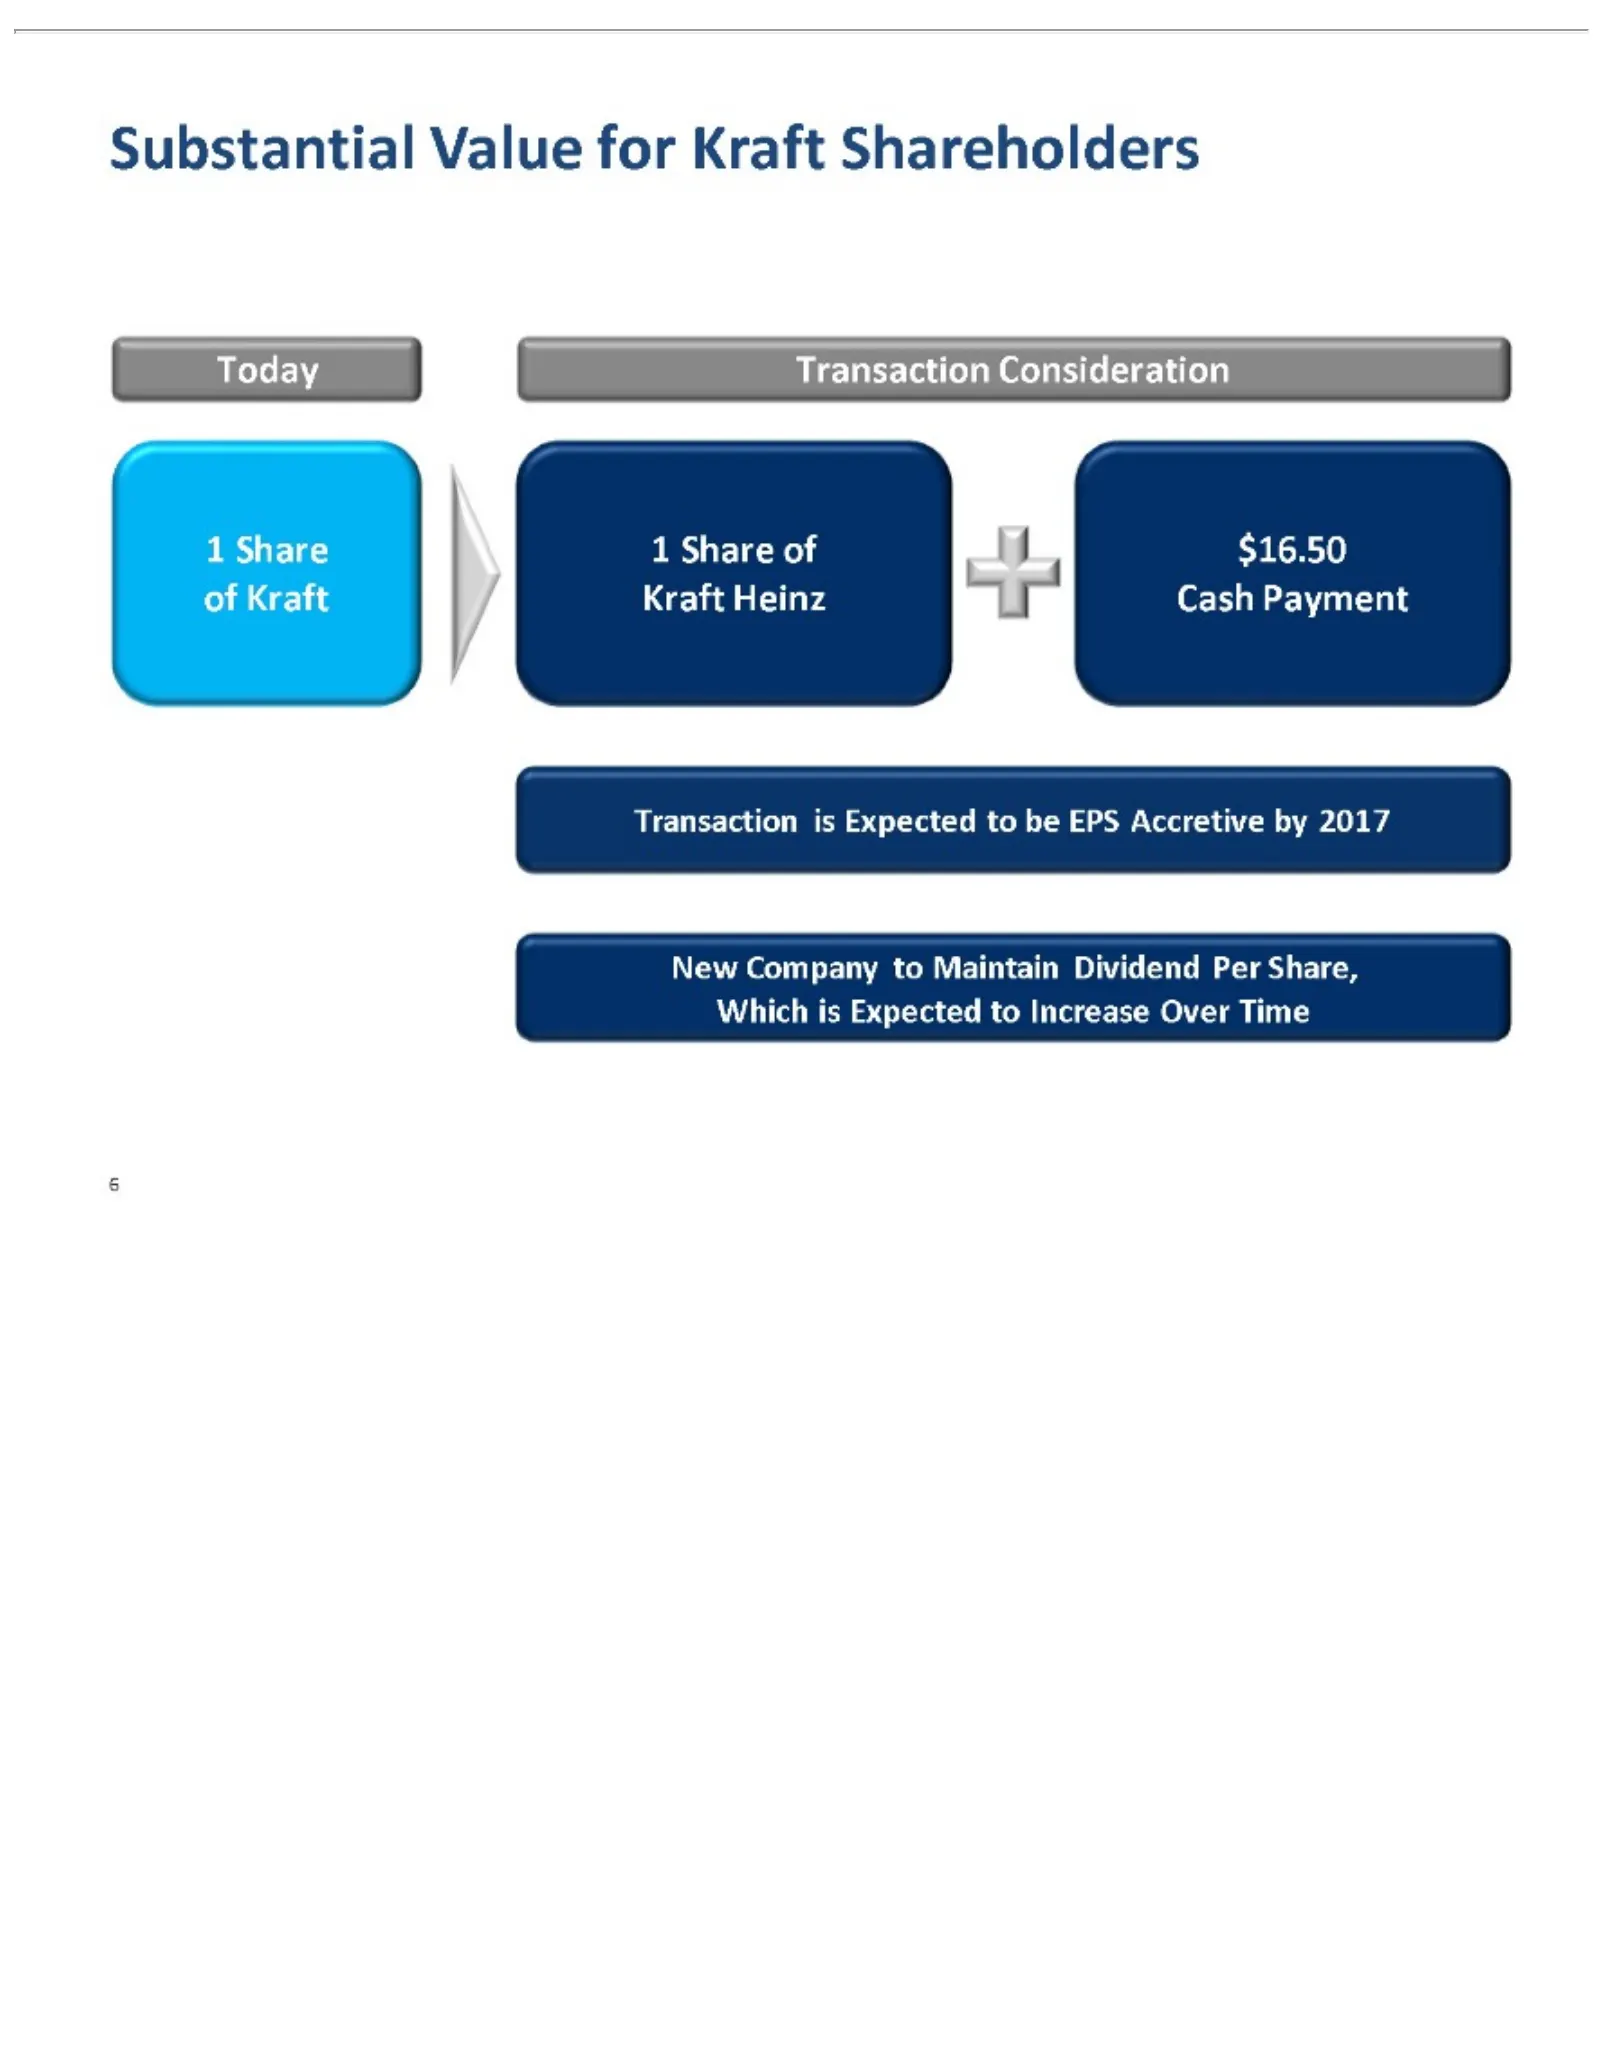
Slide 8: Substantial Value Creation for Kraft Shareholders
16Which Substantial Transaction Today of Kraft New Share CompanyValue Consideration isKraft 1toShare Expected for is Heinz ExpectedKraft ofto$16.50 Maintain toCash Shareholders Increase Payment be Dividend EPS OverAccretive Time Per Share, by 2017
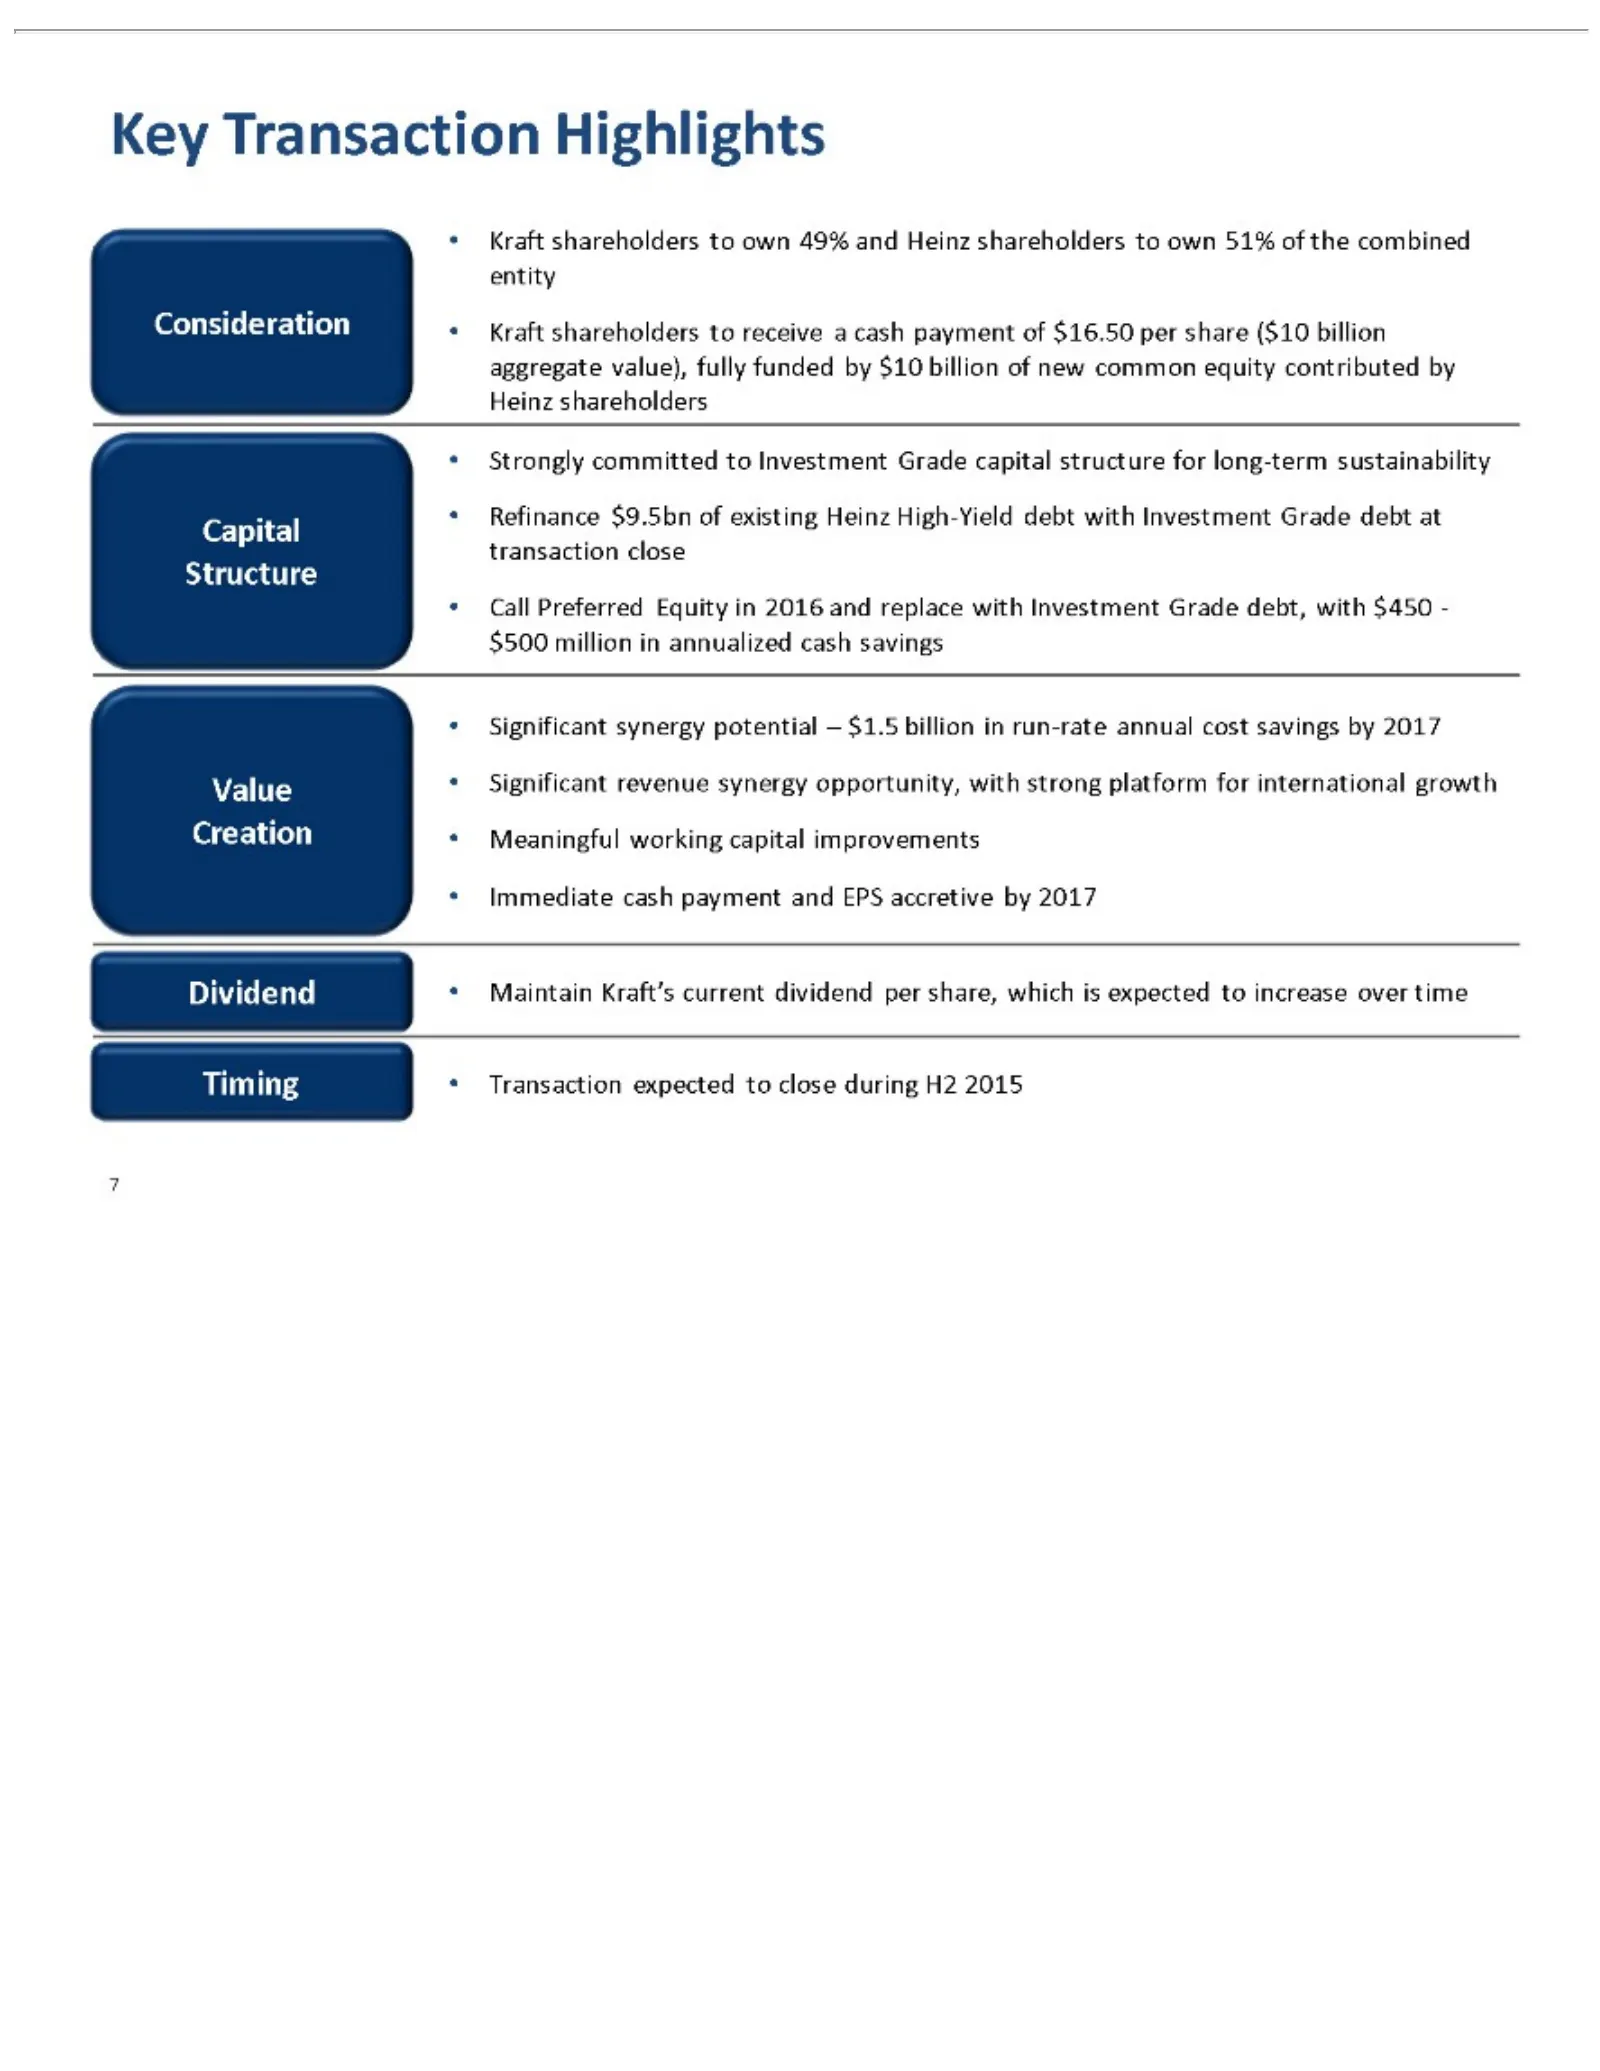
Slide 9: Key Transaction Highlights
Key Consideration entity aggregate Heinz Capital transaction Structure $500 Value •Creation Dividend 7Timing Kraft Strongly Call Significant Immediate Transaction million Preferred •shareholders shareholders Significant • •Refinance Transaction •value), Meaningful committed Maintain close cash syner
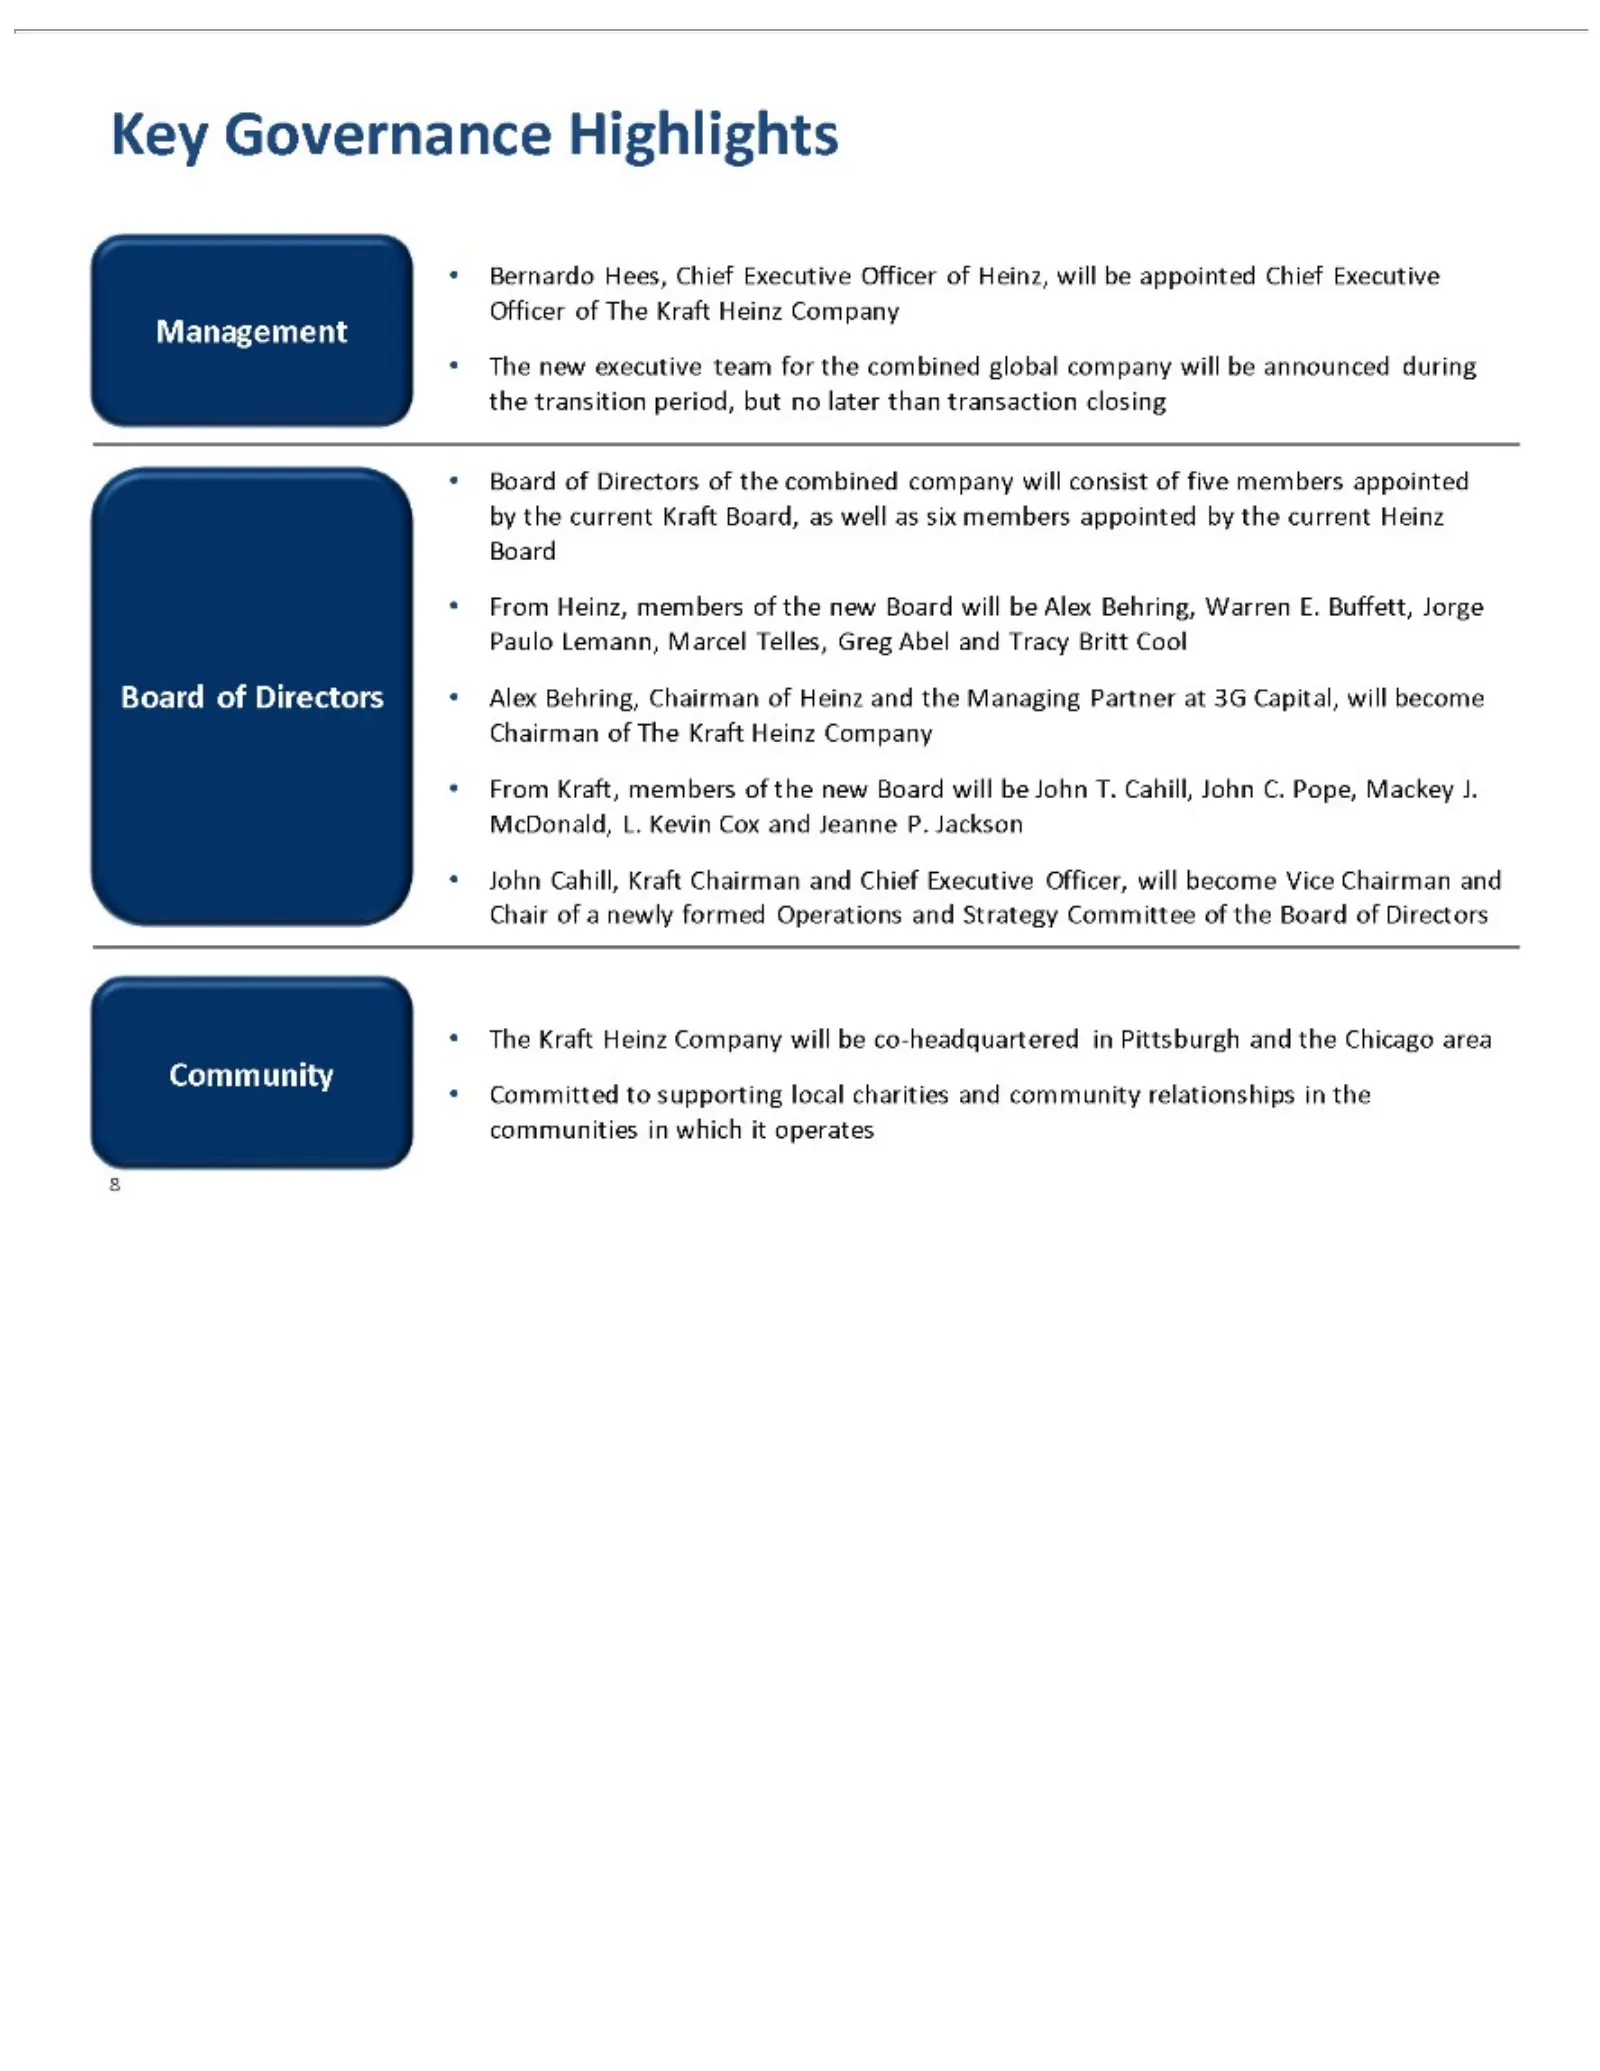
Slide 10: Key Governance and Management
Key Officer Management the by Paulo Board Chairman McDonald, •Chair Community 8communities The Bernardo Board From John the transition Governance new Kraft of Lemann, of current Cahill, Heinz, Kraft, of ofaDirectors The of newly executive Directors Hees, Heinz L.•The in period, members Committed Kra
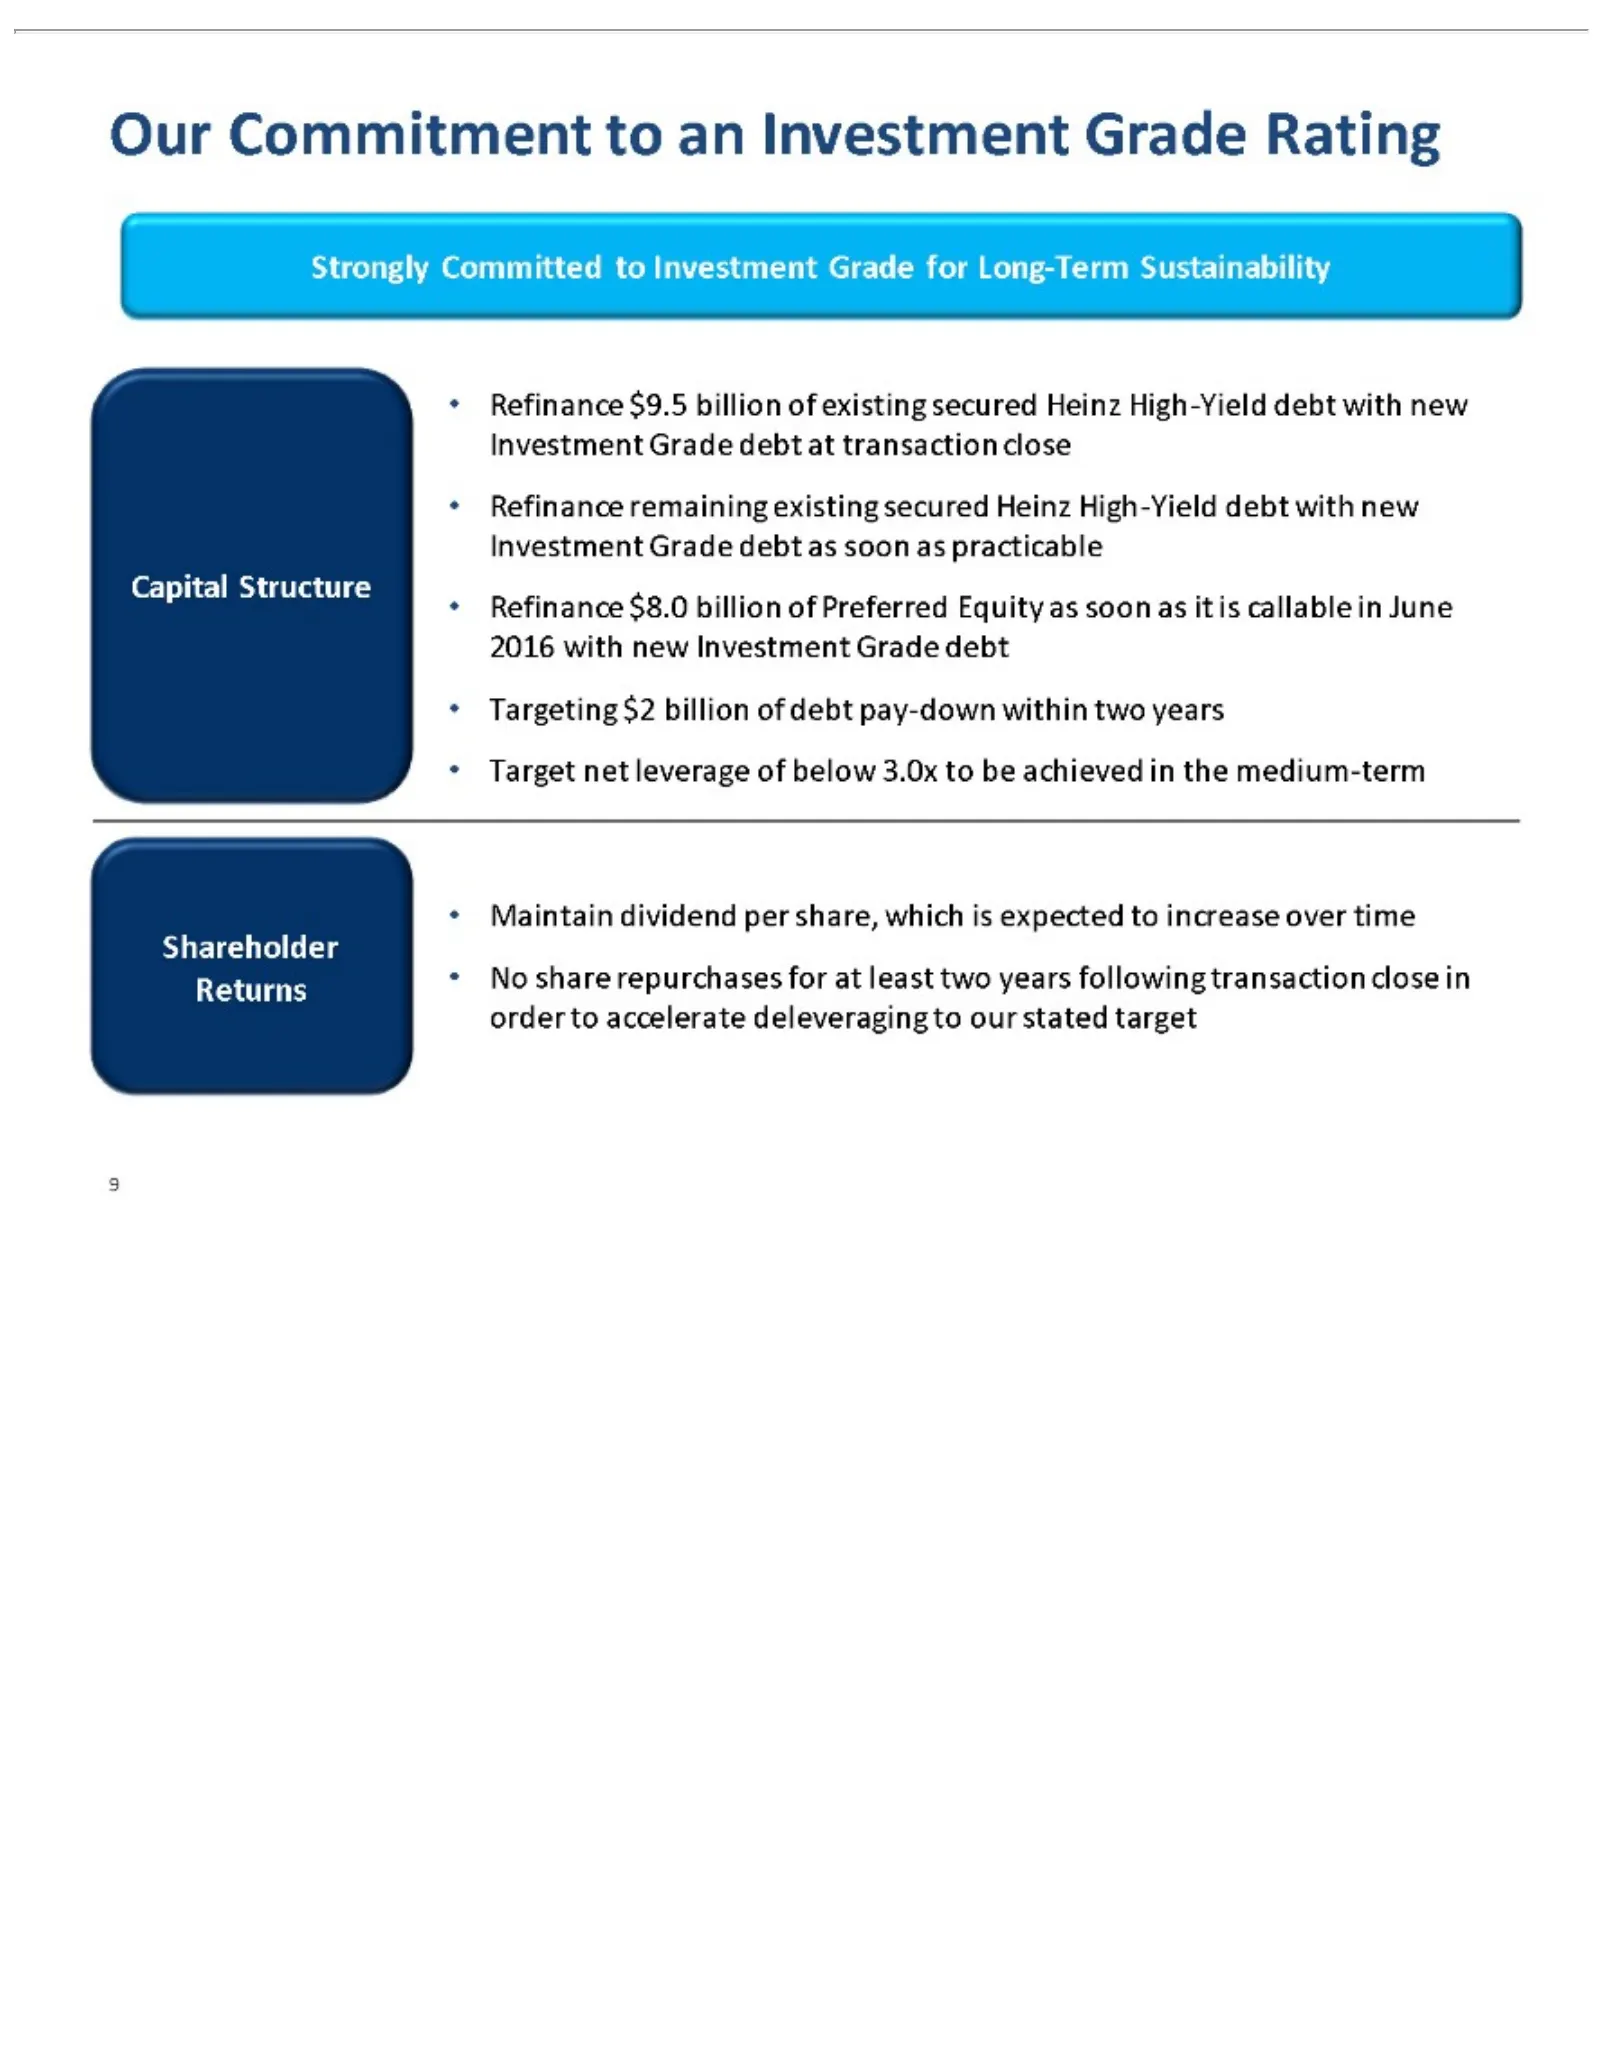
Slide 11: Strongly Committed to Investment Grade Capital Structure
Our Strongly Investment Capital •2016 Returns Shareholder 9order Targeting Target Refinance Maintain Commitment with toStructure net •accelerate Committed No new dividend $2 Grade leverage $9.5 remaining share billion Investment billion •to debt deleveraging Refinance repurchases per an to of ofexis
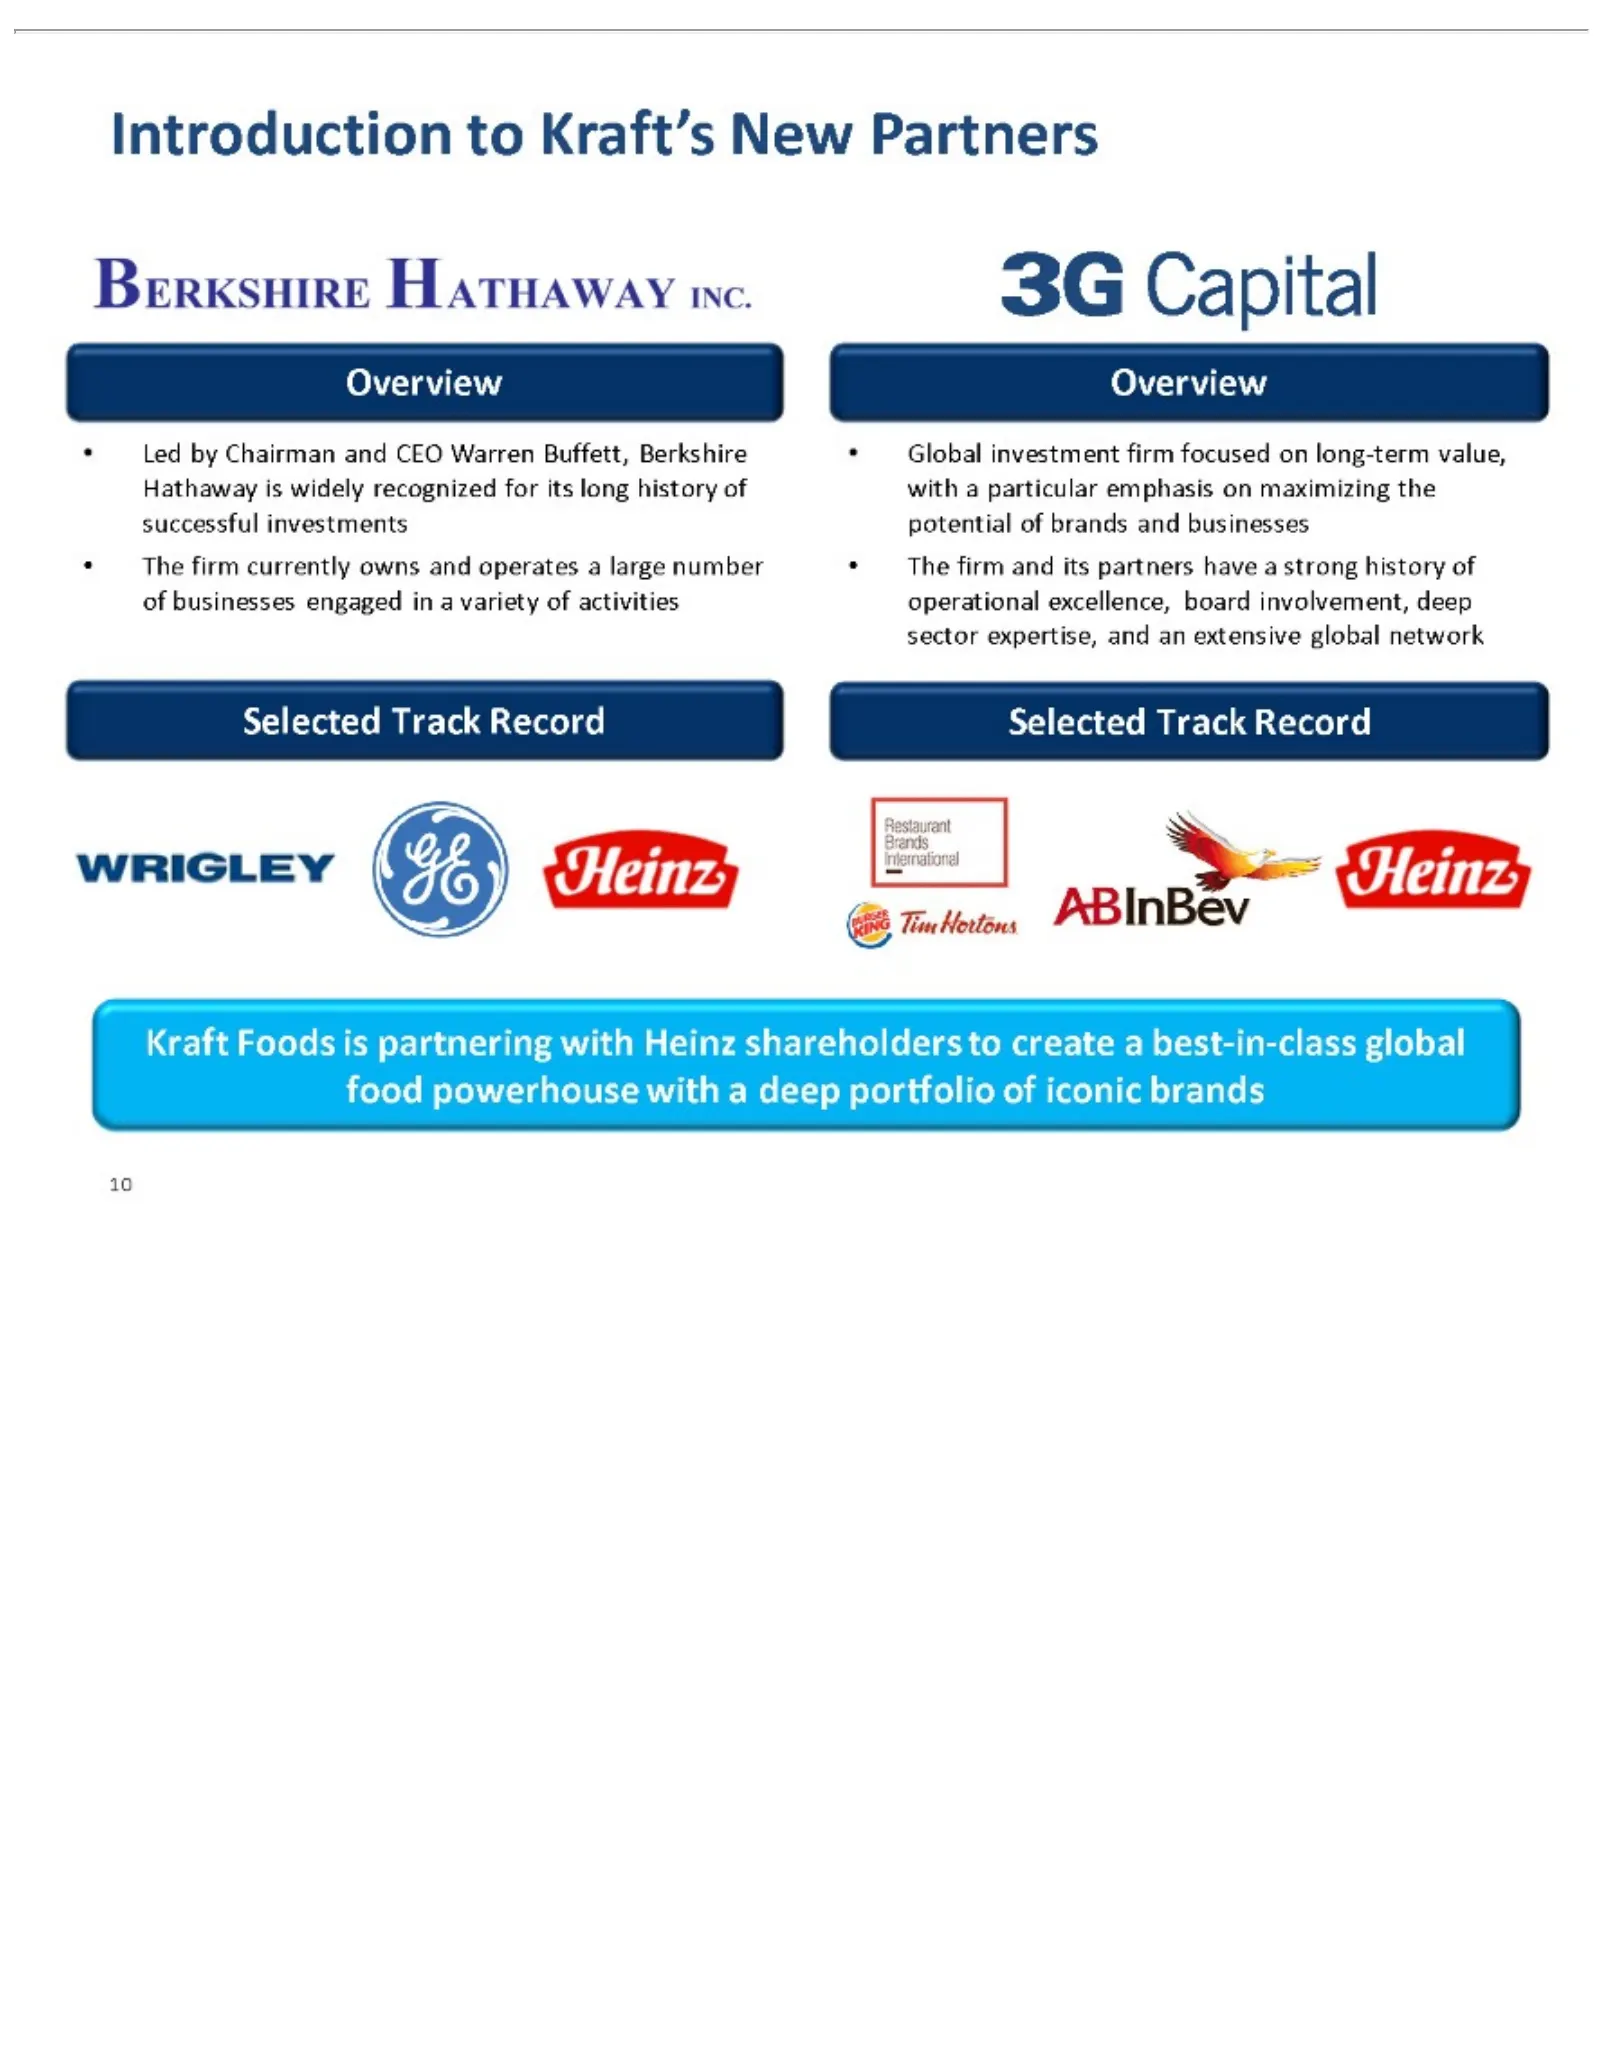
Slide 12: Introduction to Berkshire Hathaway and 3G Capital
Introduction Hathaway •successful of Global Overview involvement, Selected [Graphic Kraft 10The Led businesses Foods firm byinvestment Track Chairman Appears is currently investments is to widely deep engaged partnering Record Kraft’s Here] firm sector and recognized owns in New CEO focused aexperti
Slide 13: Kraft Overview Agenda
Transaction Agenda Kraft Heinz A 11Transformational Overview Overview Highlights Combination
Slide 14: Kraft North America Overview
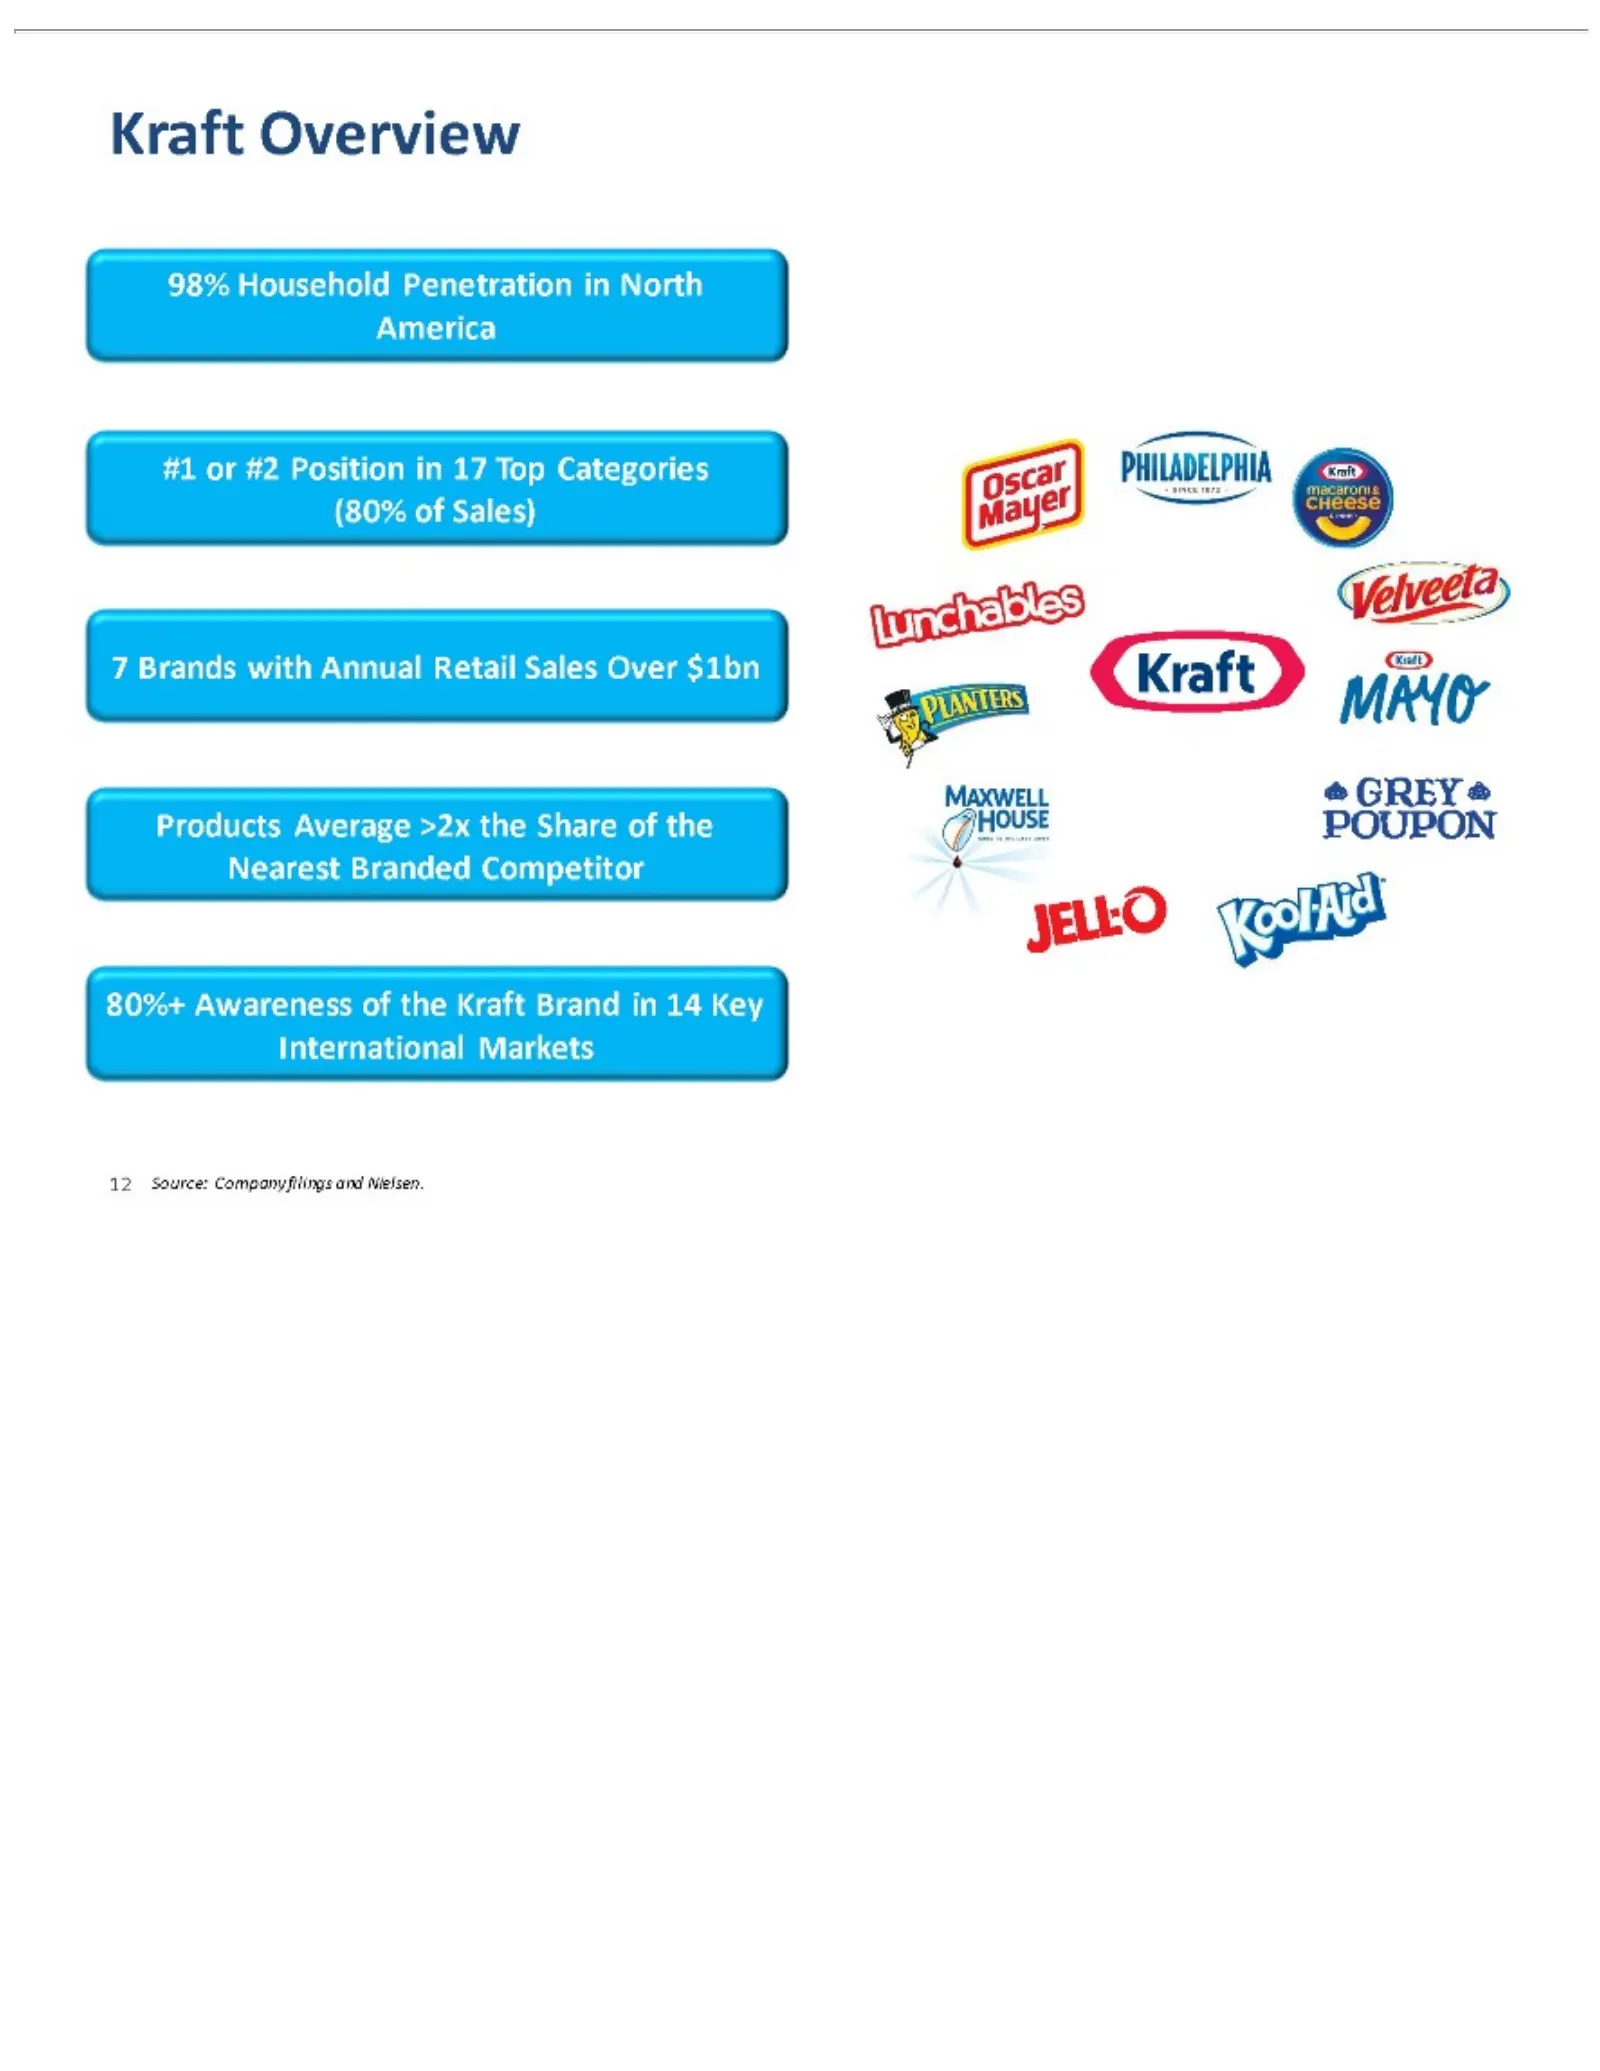
712 Kraft 98% #1 America (80% or Household #2 Overview of Products Nearest [Graphic 80%+ Brands Sales) Position International Source: Awareness Brandedwith Average AppearsPenetration in Company Markets17 Annual Top Competitor of >2x Here] the filings the Categories Kraftin Retail Share andNorth Bran
Slide 15: Unmatched Portfolio of Leading Brands
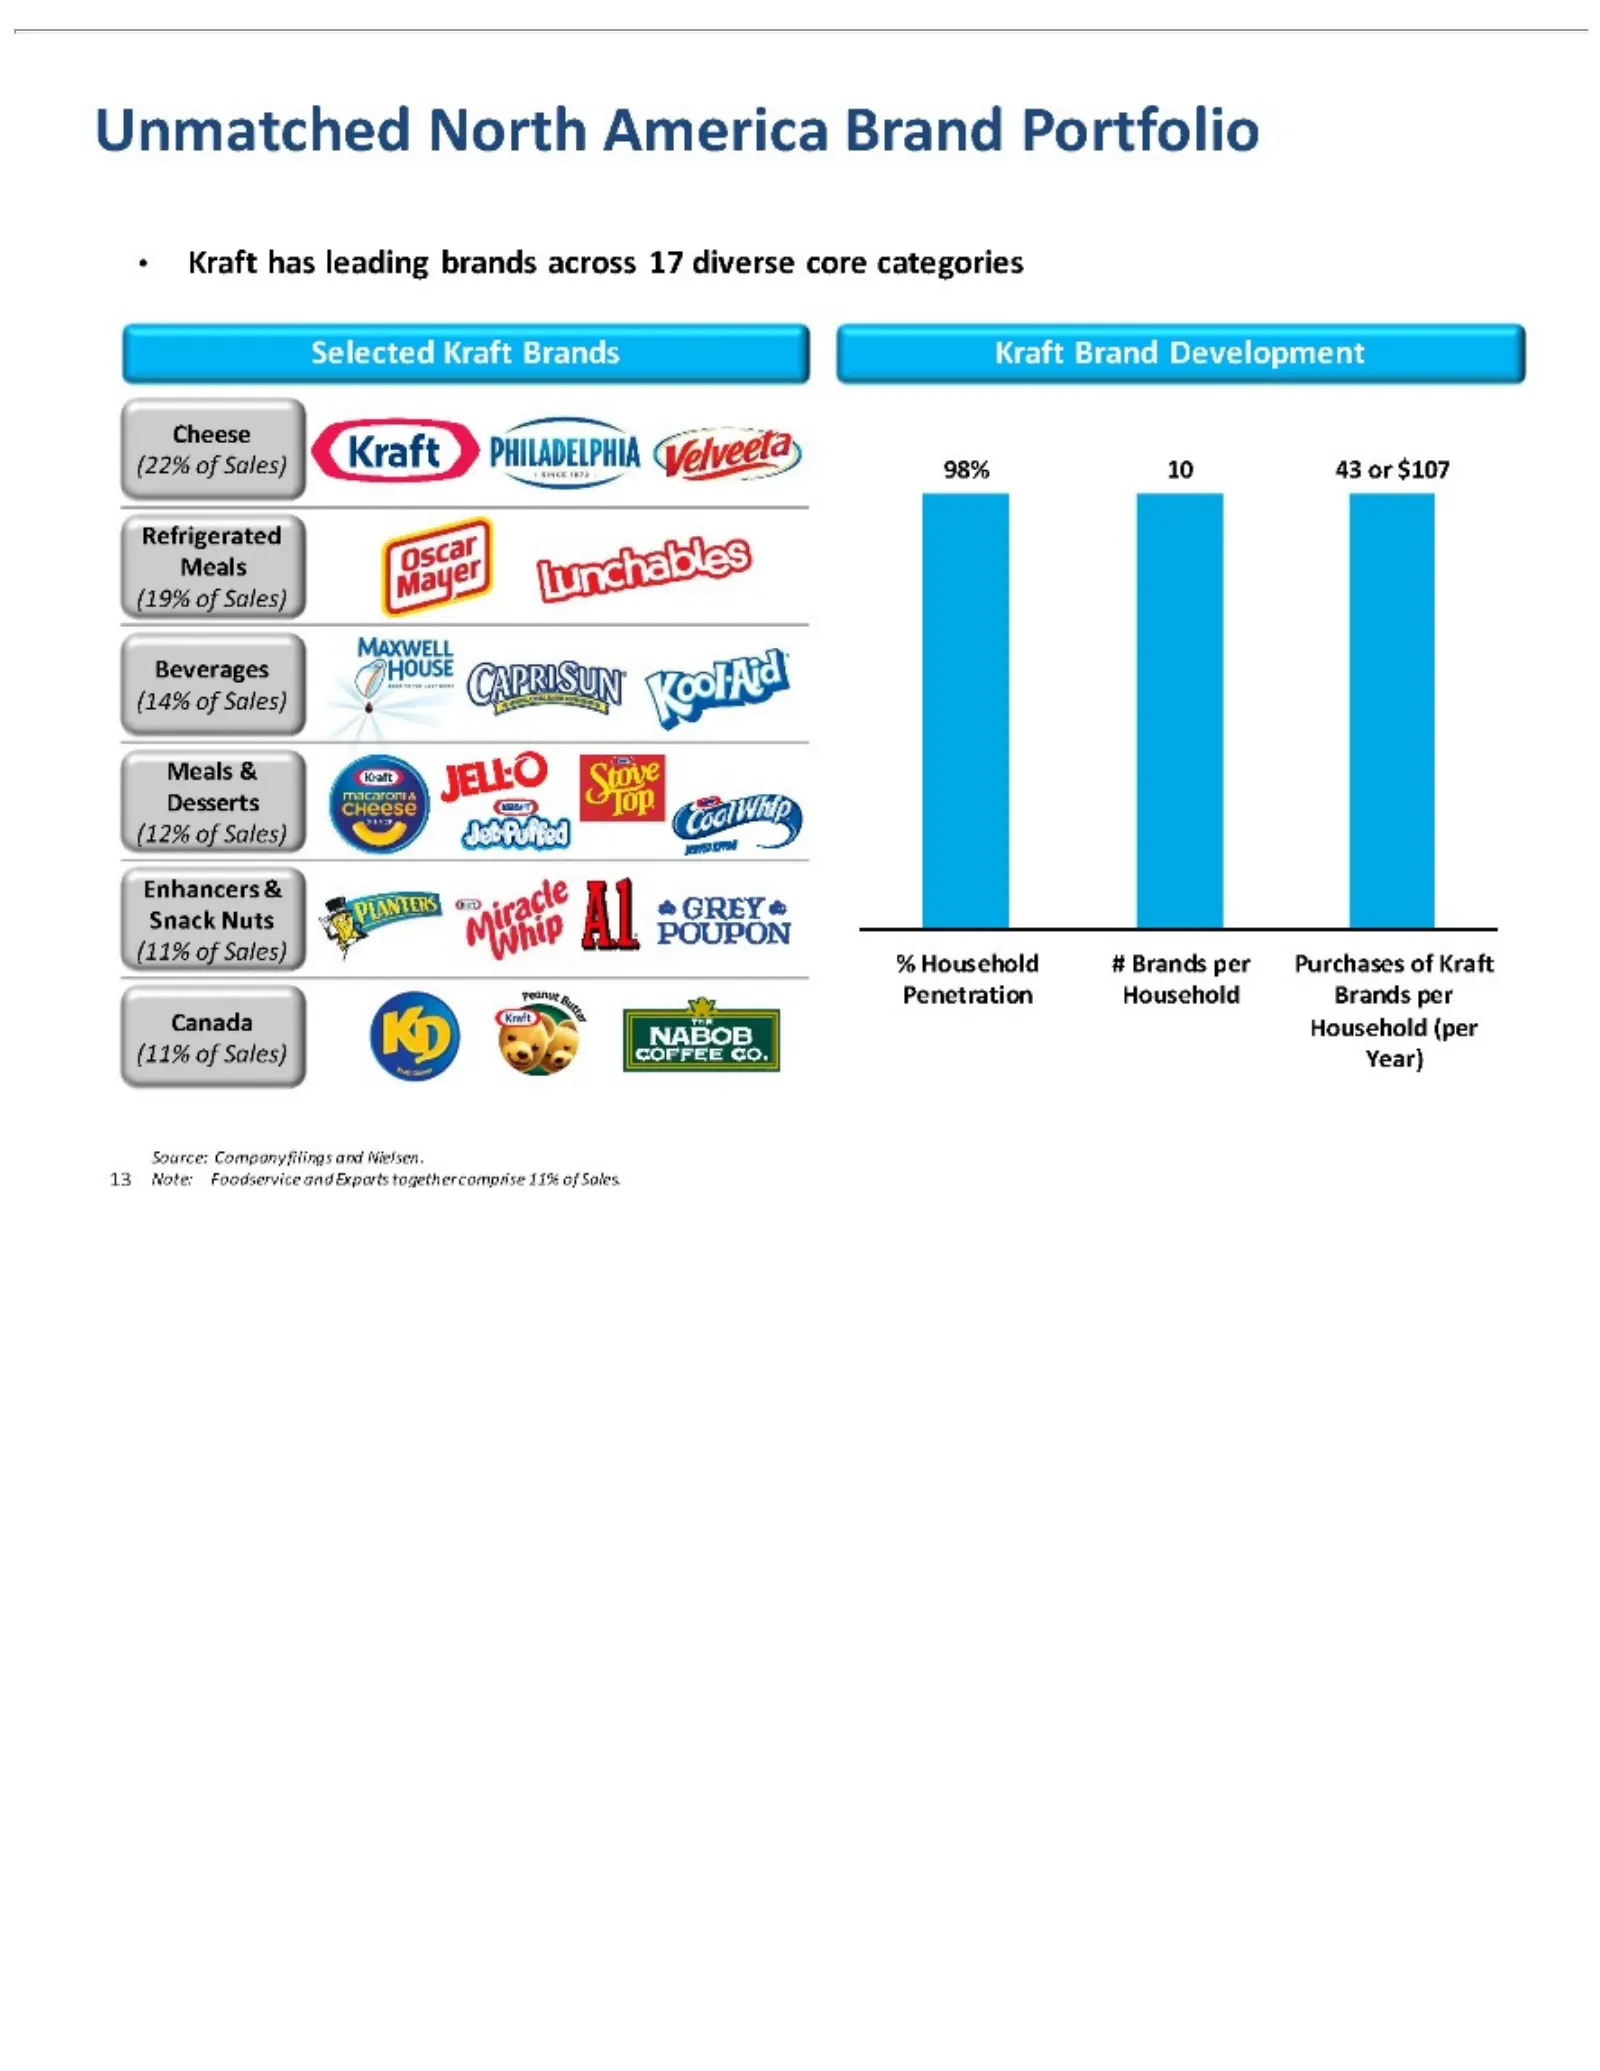
•Unmatched Selected (22% Cheese (19% Refrigerated (14% Beverages Meals (12% Desserts Enhancers Snack Penetration Canada (11% Source: 13Kraftof Nuts & has Household Company Sales)% Sales) Note: Kraft &leading Household North Foodservice Brands Year) 98% Household America filings brands (per 10Kraft B
Slide 16: Leading North American Food & Beverage Player
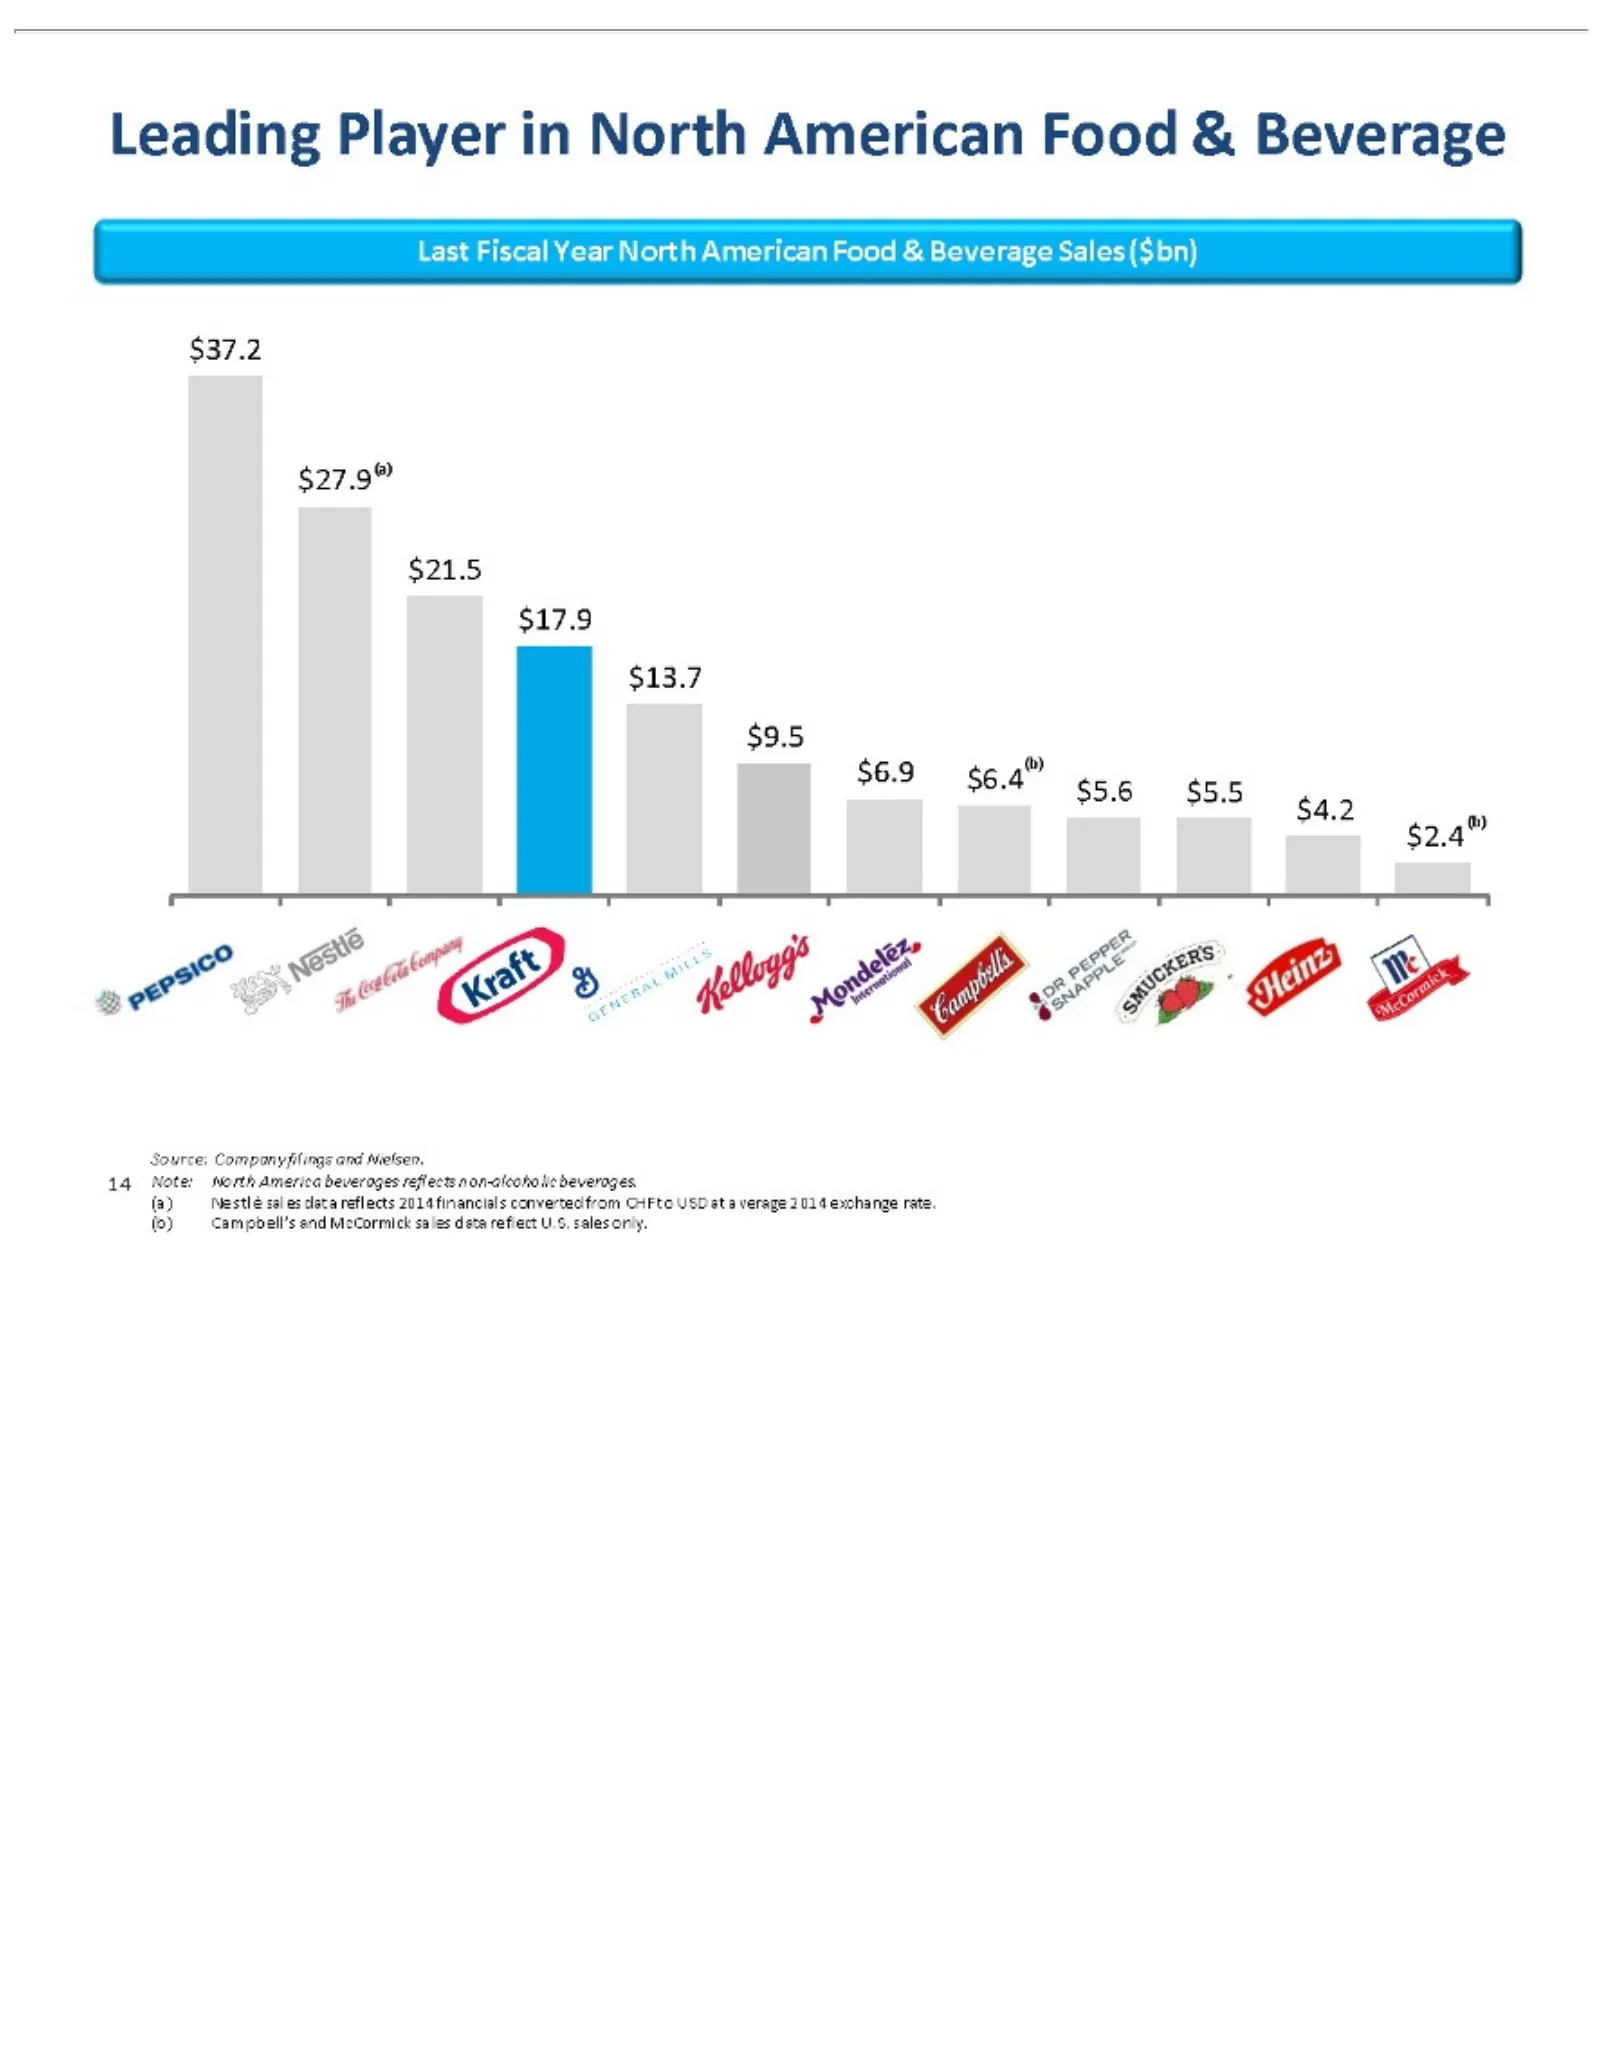
$37.2 Leading Last $27.9 $6.9 Fiscal $9.5 $13.7 $17.9 $21.5 $5.6 Source: $2.4 $4.2(b) 14 (a) Player YearNorth $6.4(b) $5.5 Company Note: inNorth NorthAmerican filingsAmerican America Food Food&& and Nielsen. beverages Beverage Beverage reflects Sales ($bn) beverages. non-alcoholic
Slide 17: Foodservice Sales vs Peers
Nestlé Campbell’s Transaction Agenda Kraft Heinz A 15Transformational Overview Overview sales and Highlights dataMcCormick reflects Combination 2014 sales financials data reflect converted U.S. sales from only. CHF to USD at average 2014 exchange rate.
Slide 18: Heinz Overview
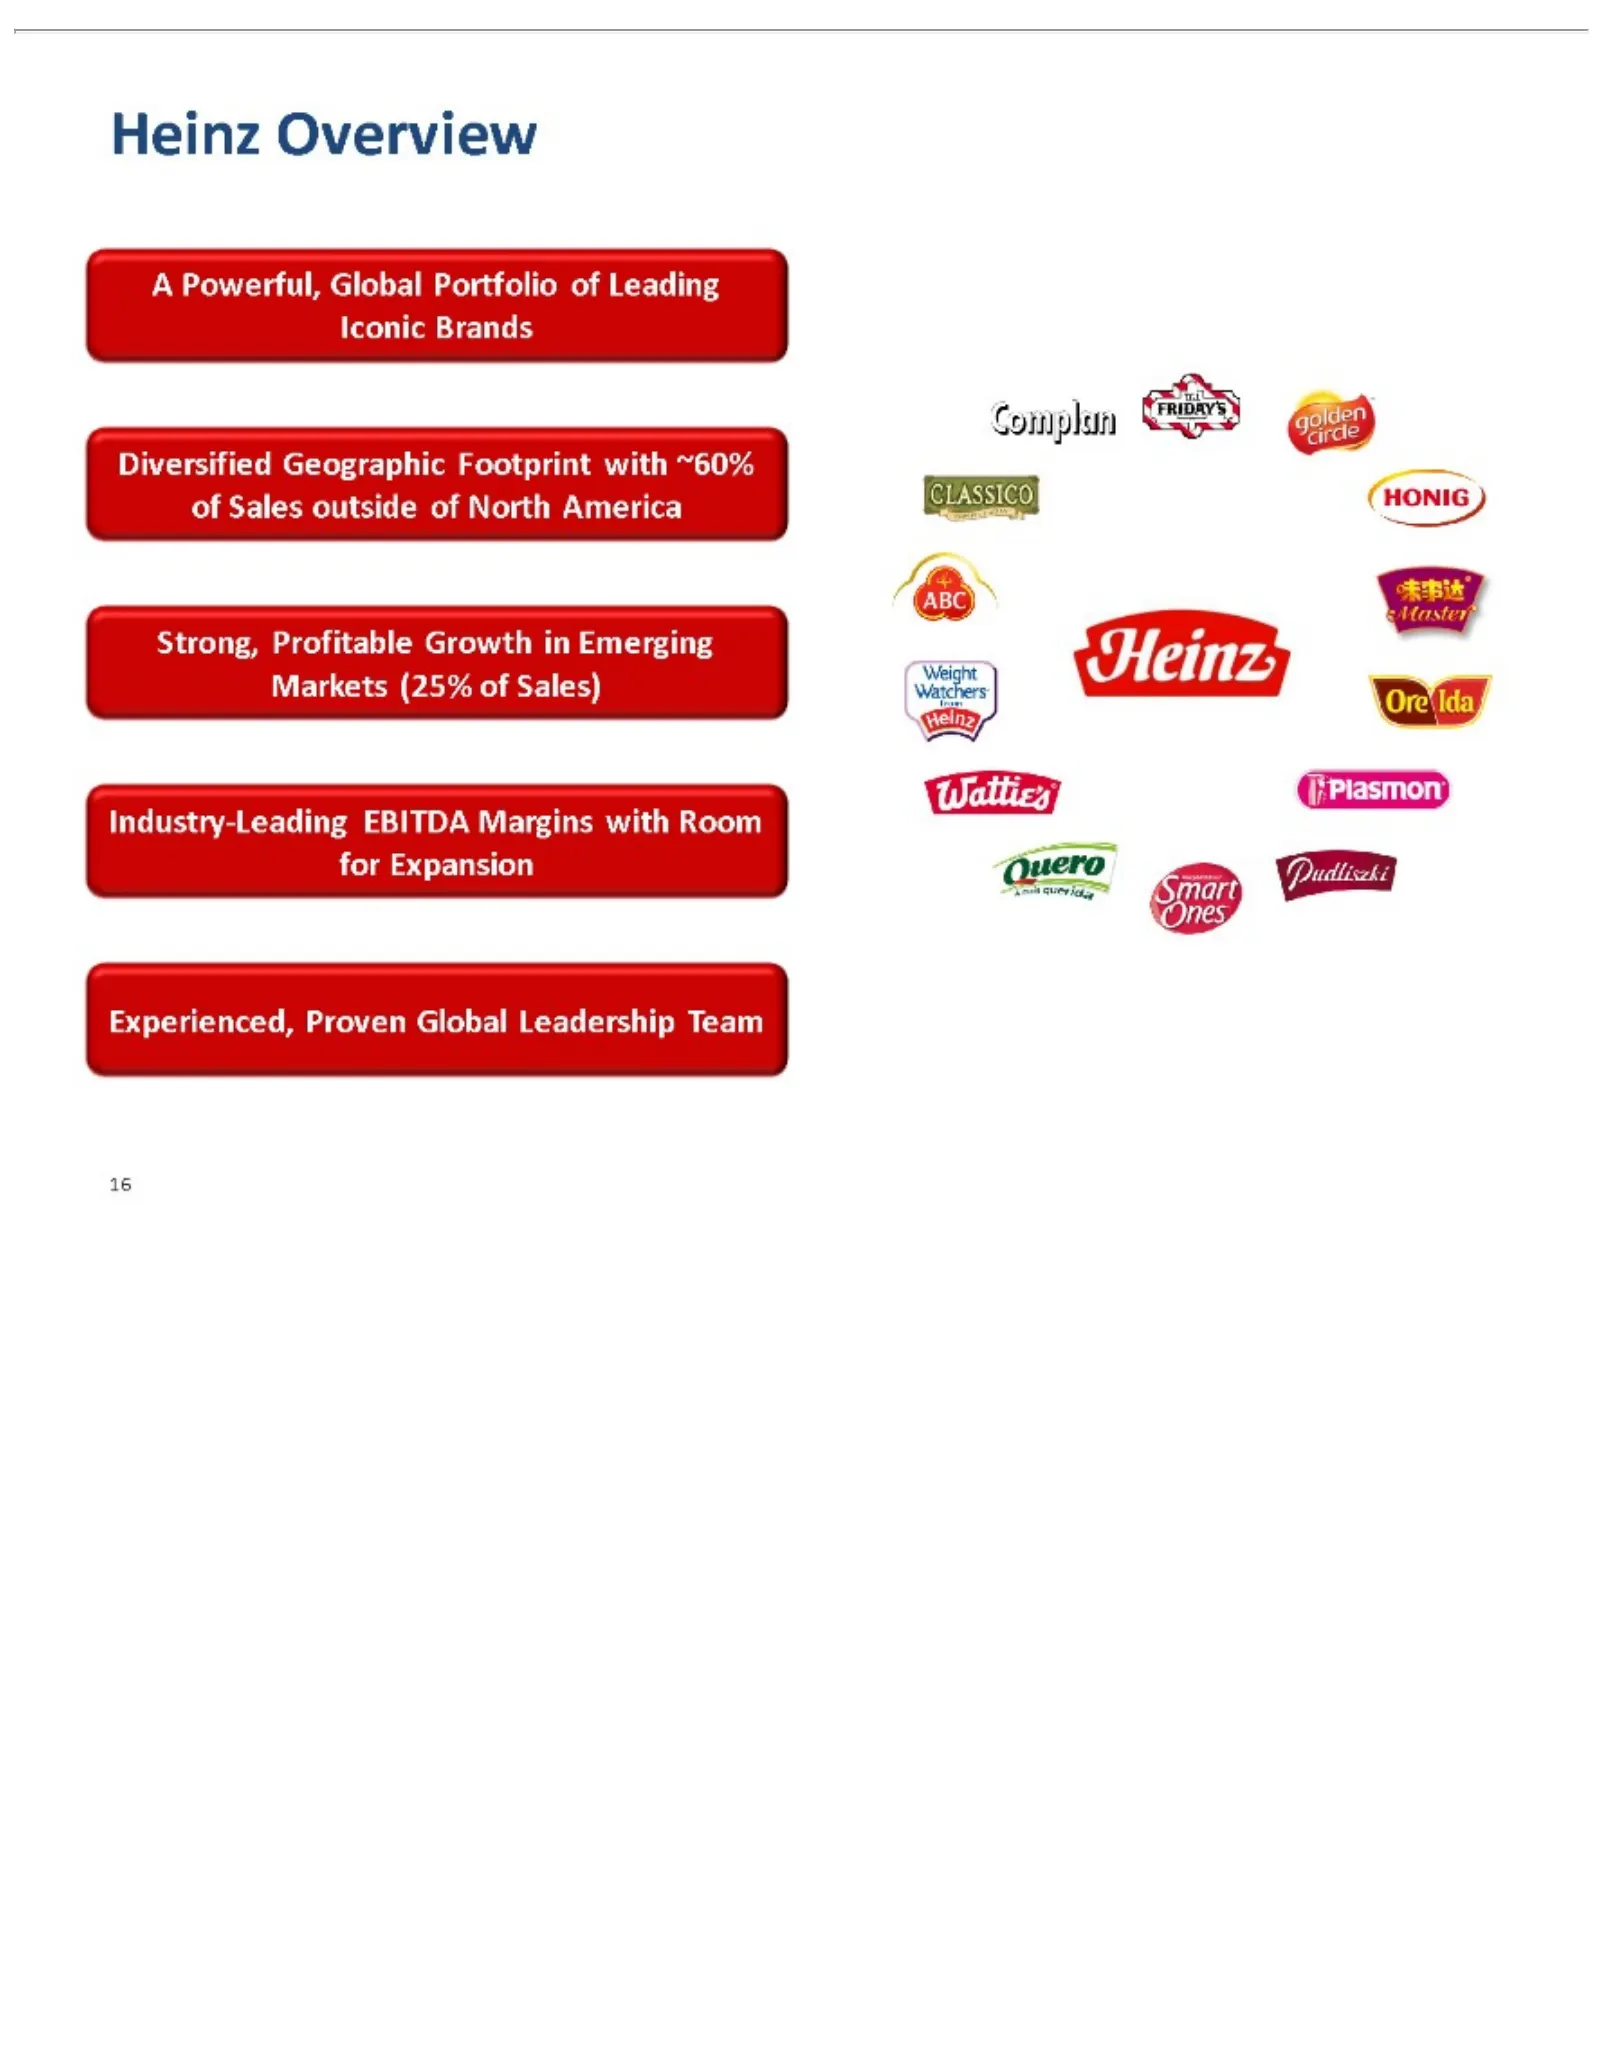
Heinz A Iconic Diversified of Strong, Markets Industry-Leading for [Graphic Experienced, 16 Powerful, Sales Expansion Overview Brands Profitable outside (25% Appears Geographic Global Proven ofofSales) EBITDA Here] Growth North Portfolio Global Footprint America inMargins Leadership Emerging of Lead
Slide 19: A Powerful, Diversified Portfolio of Leading Brands
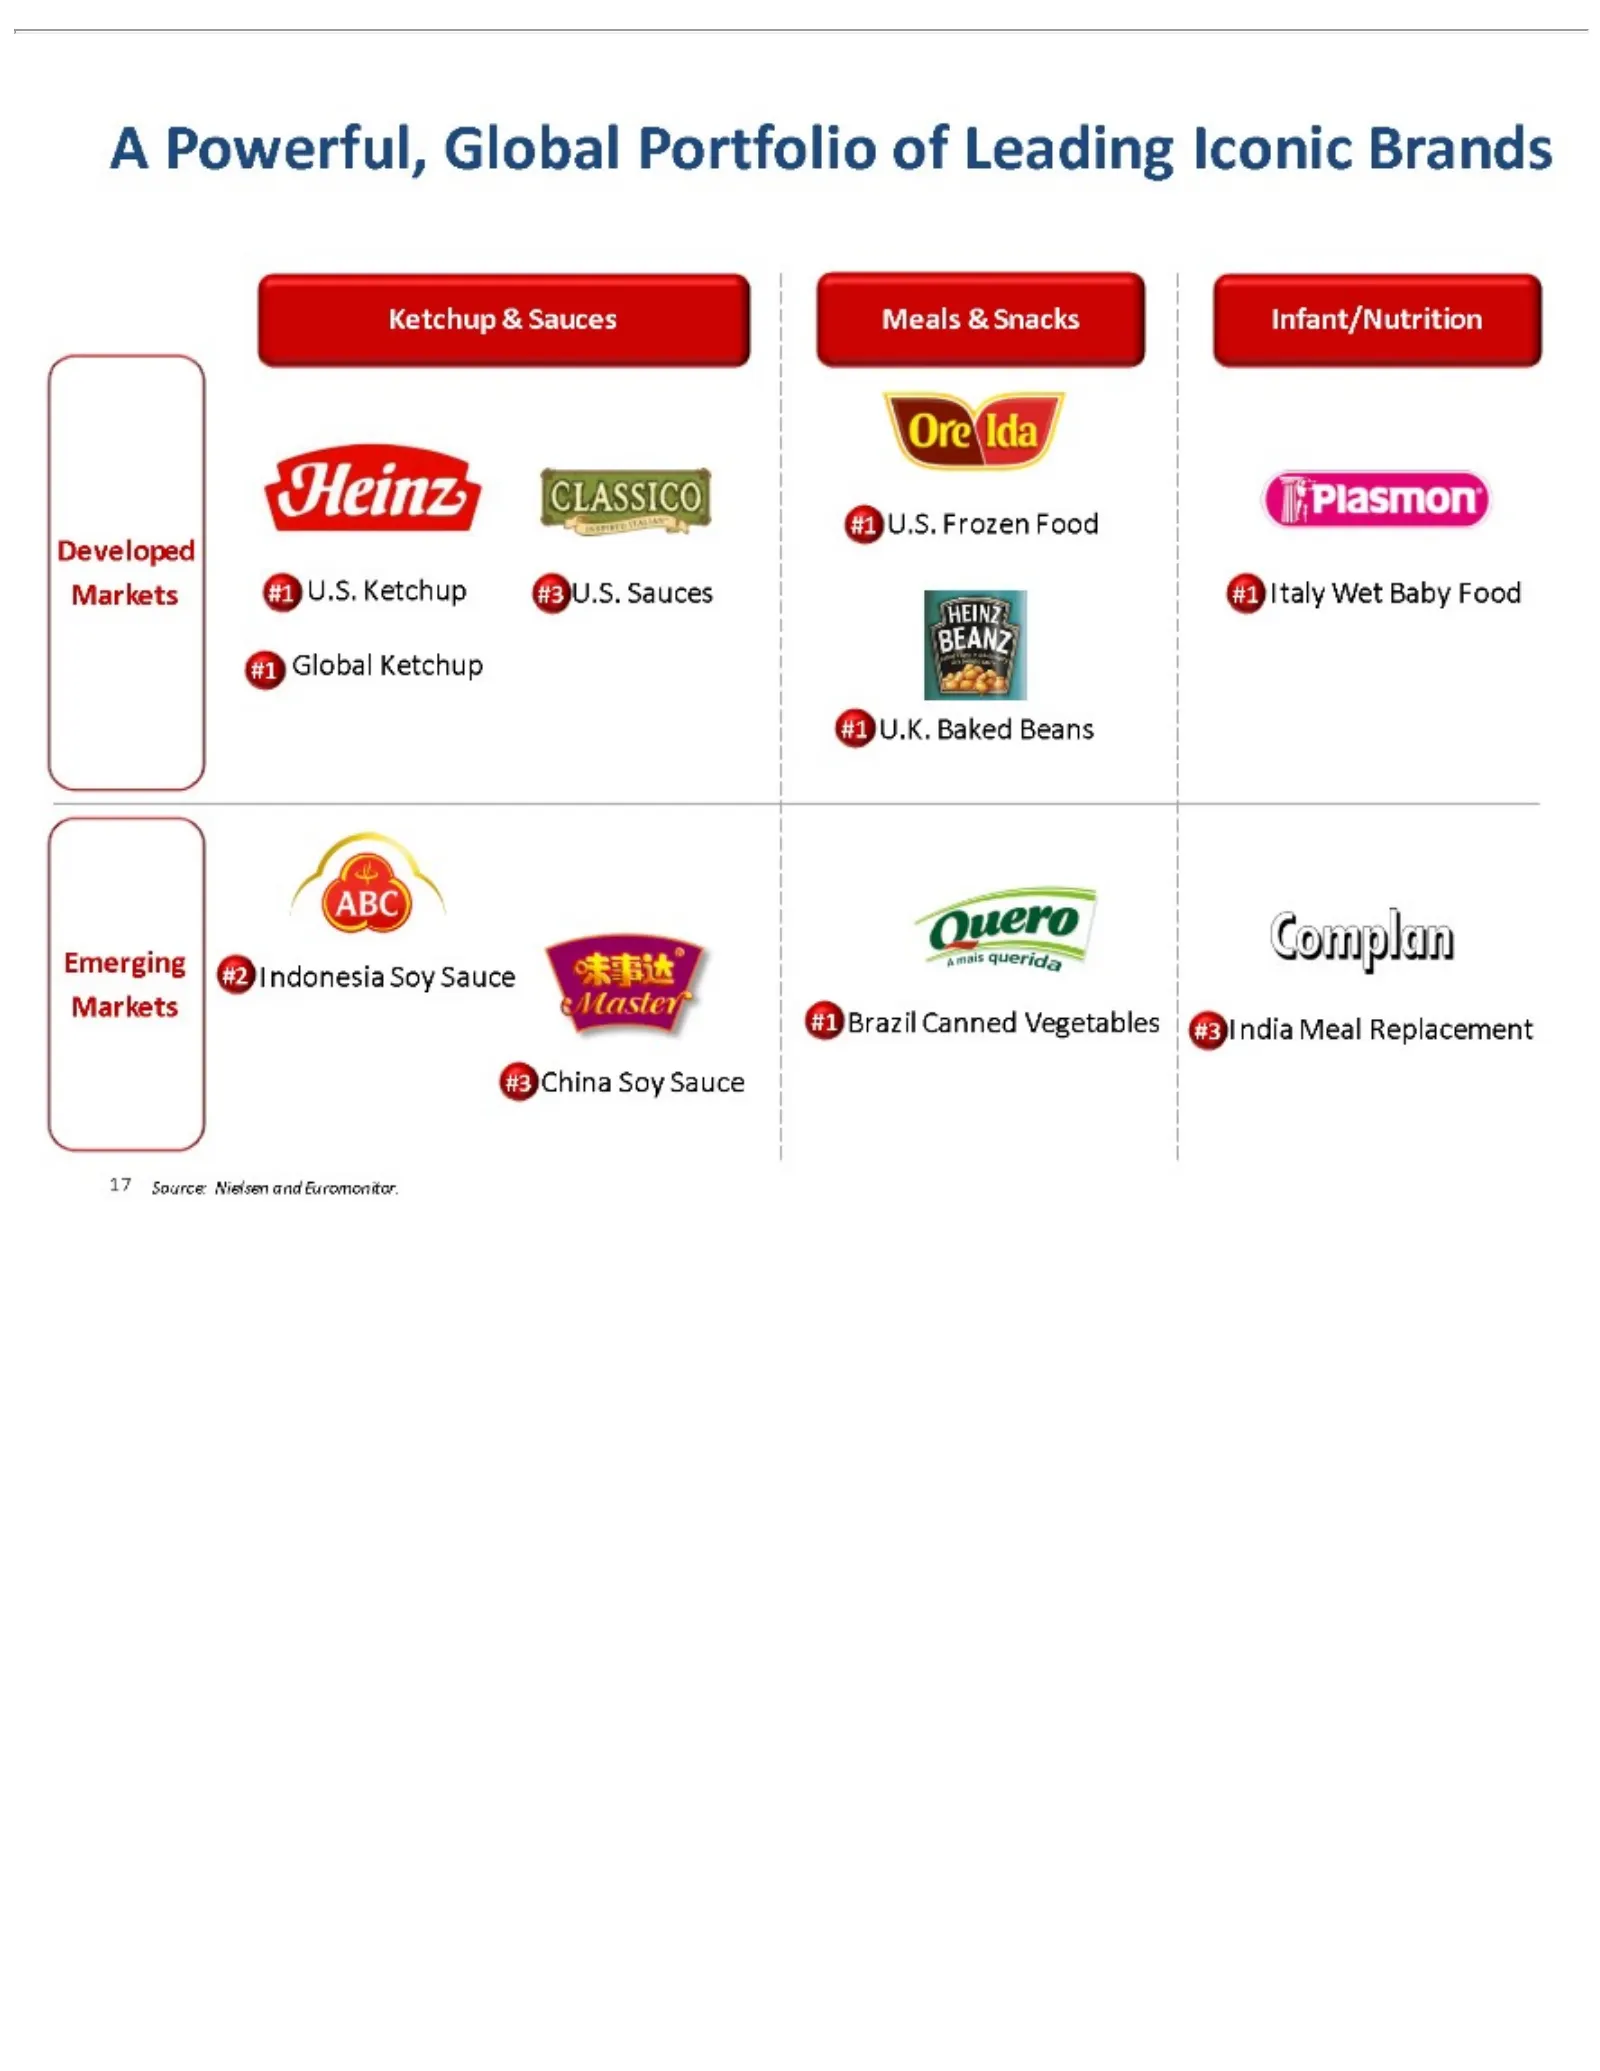
A Powerful, Ketchup Developed #1 Emerging Markets #3 17 U.S. Frozen Global U.K. China Source: Baked #1 & Soy #2 Ketchup Nielsen Sauces U.S. Brazil Global Indonesia Sauce Beans Food Ketchup Canned Meals and Portfolio Euromonitor. Soy & #3 Vegetables Sauce Snacks U.S. of Leading Sauces Infant/Nutritio
Slide 20: Strong Geographic Mix and Emerging Markets Exposure
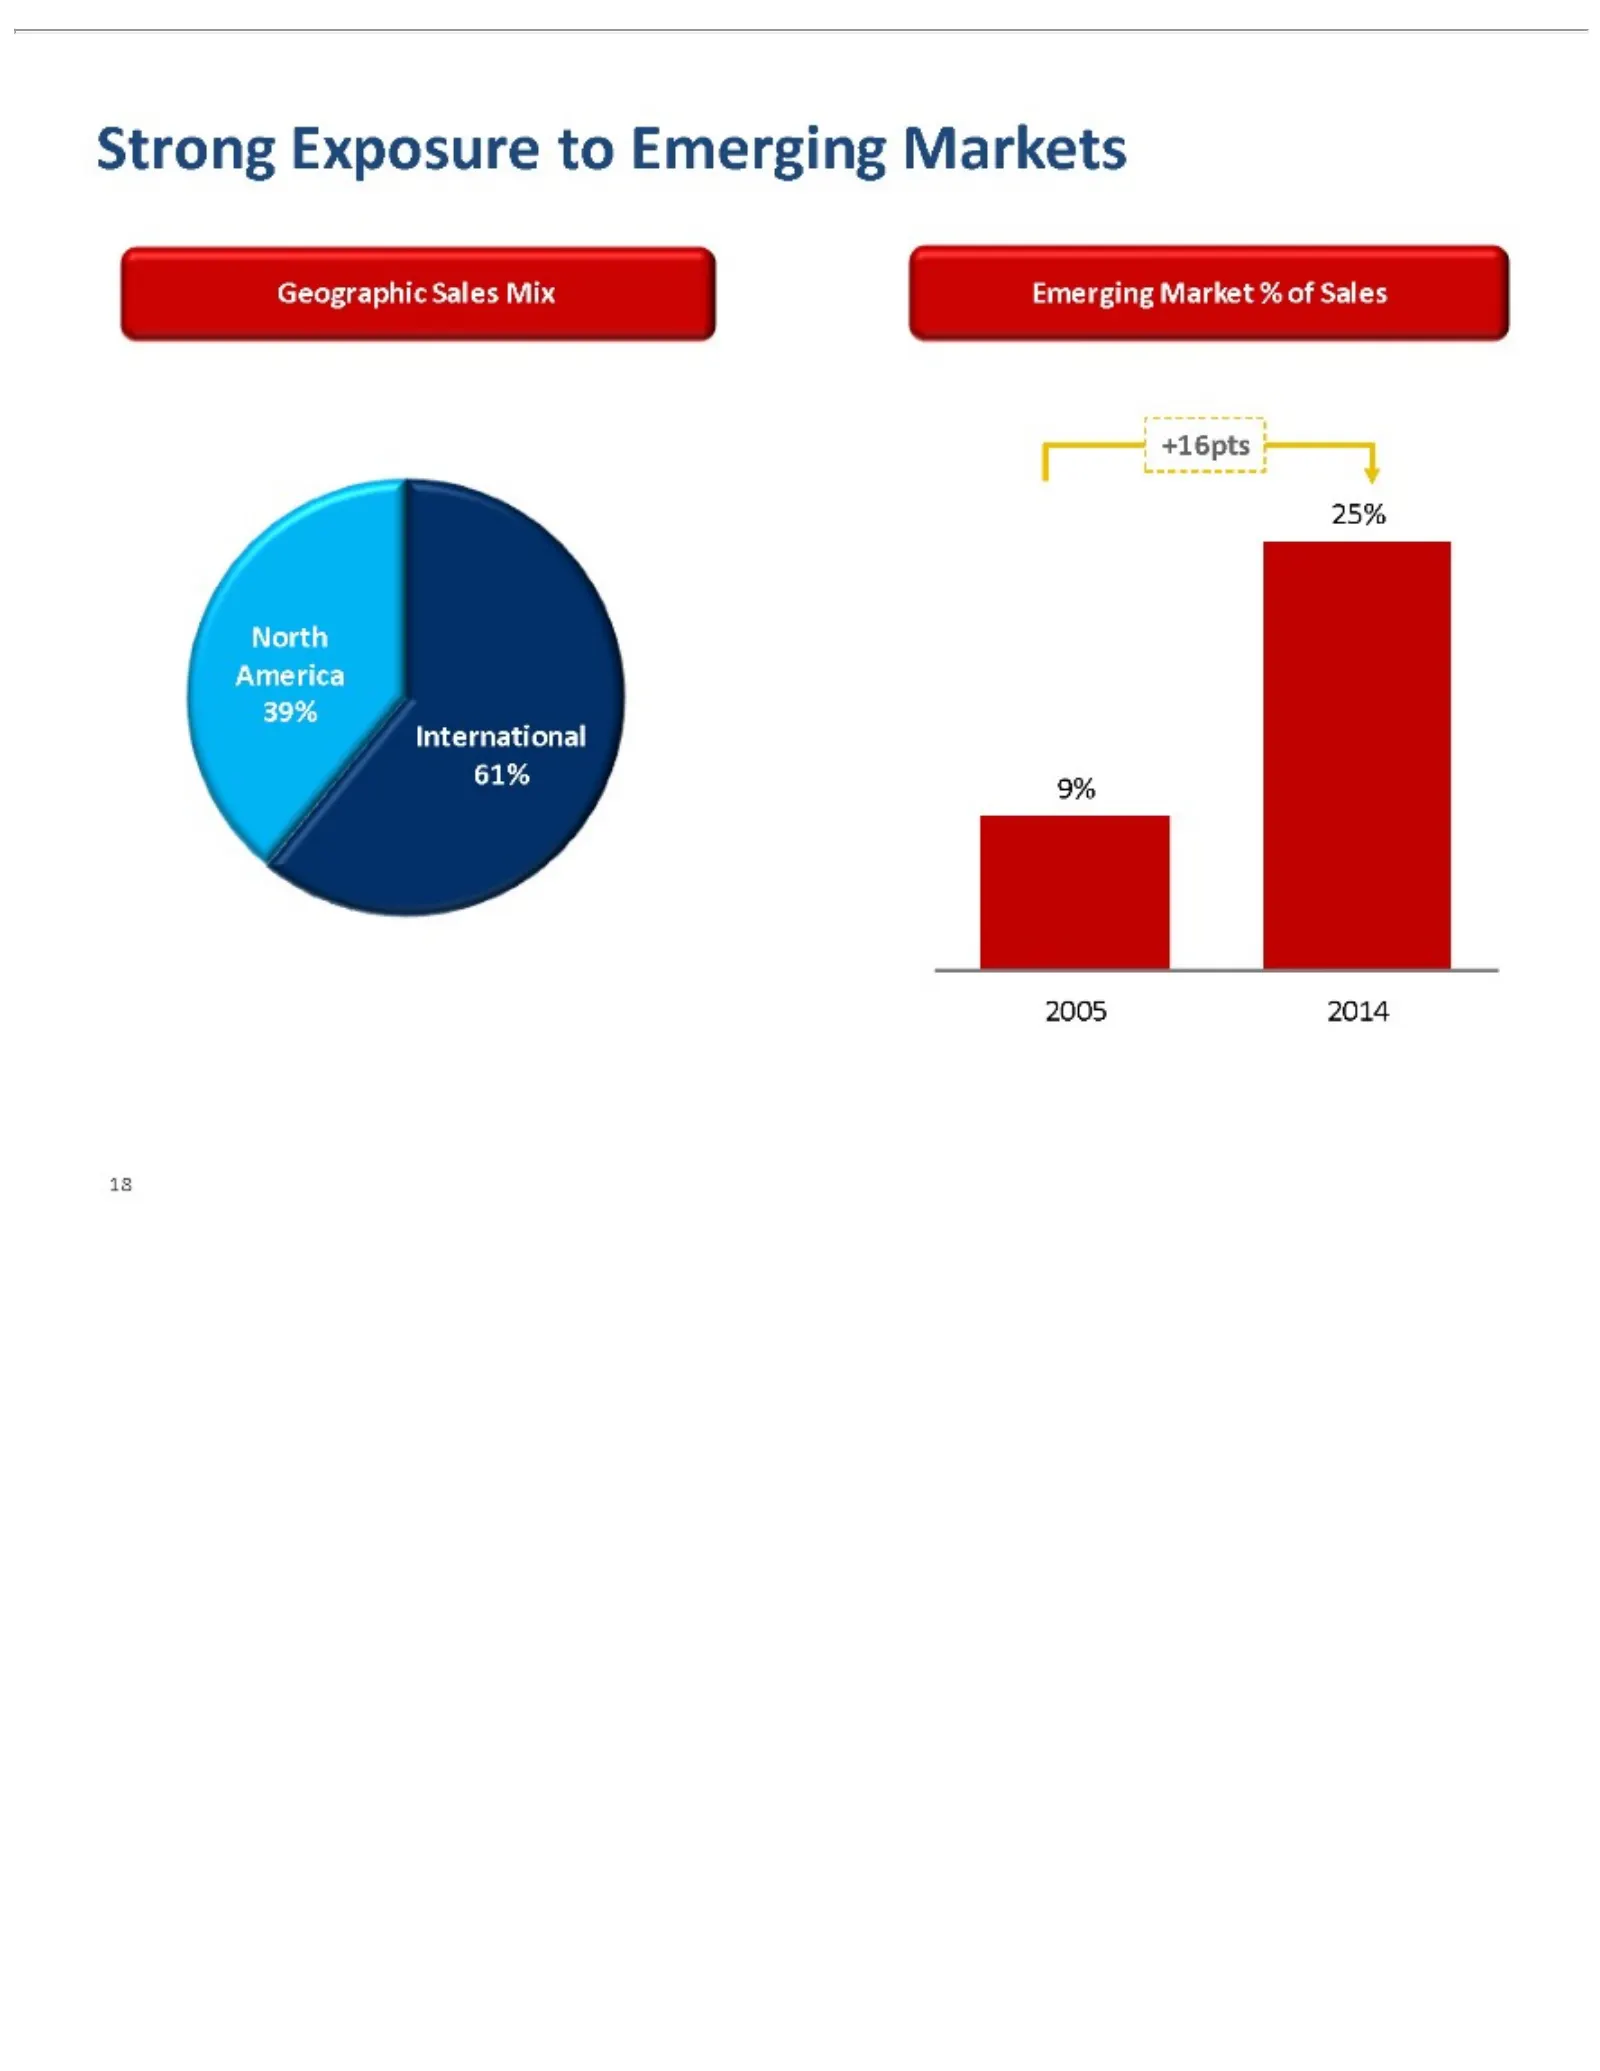
Strong Geographic Emerging 61% International 39% America North 25% +16pts 18 2014 2005 9%Exposure Market SalestoMix %Emerging of Sales Markets
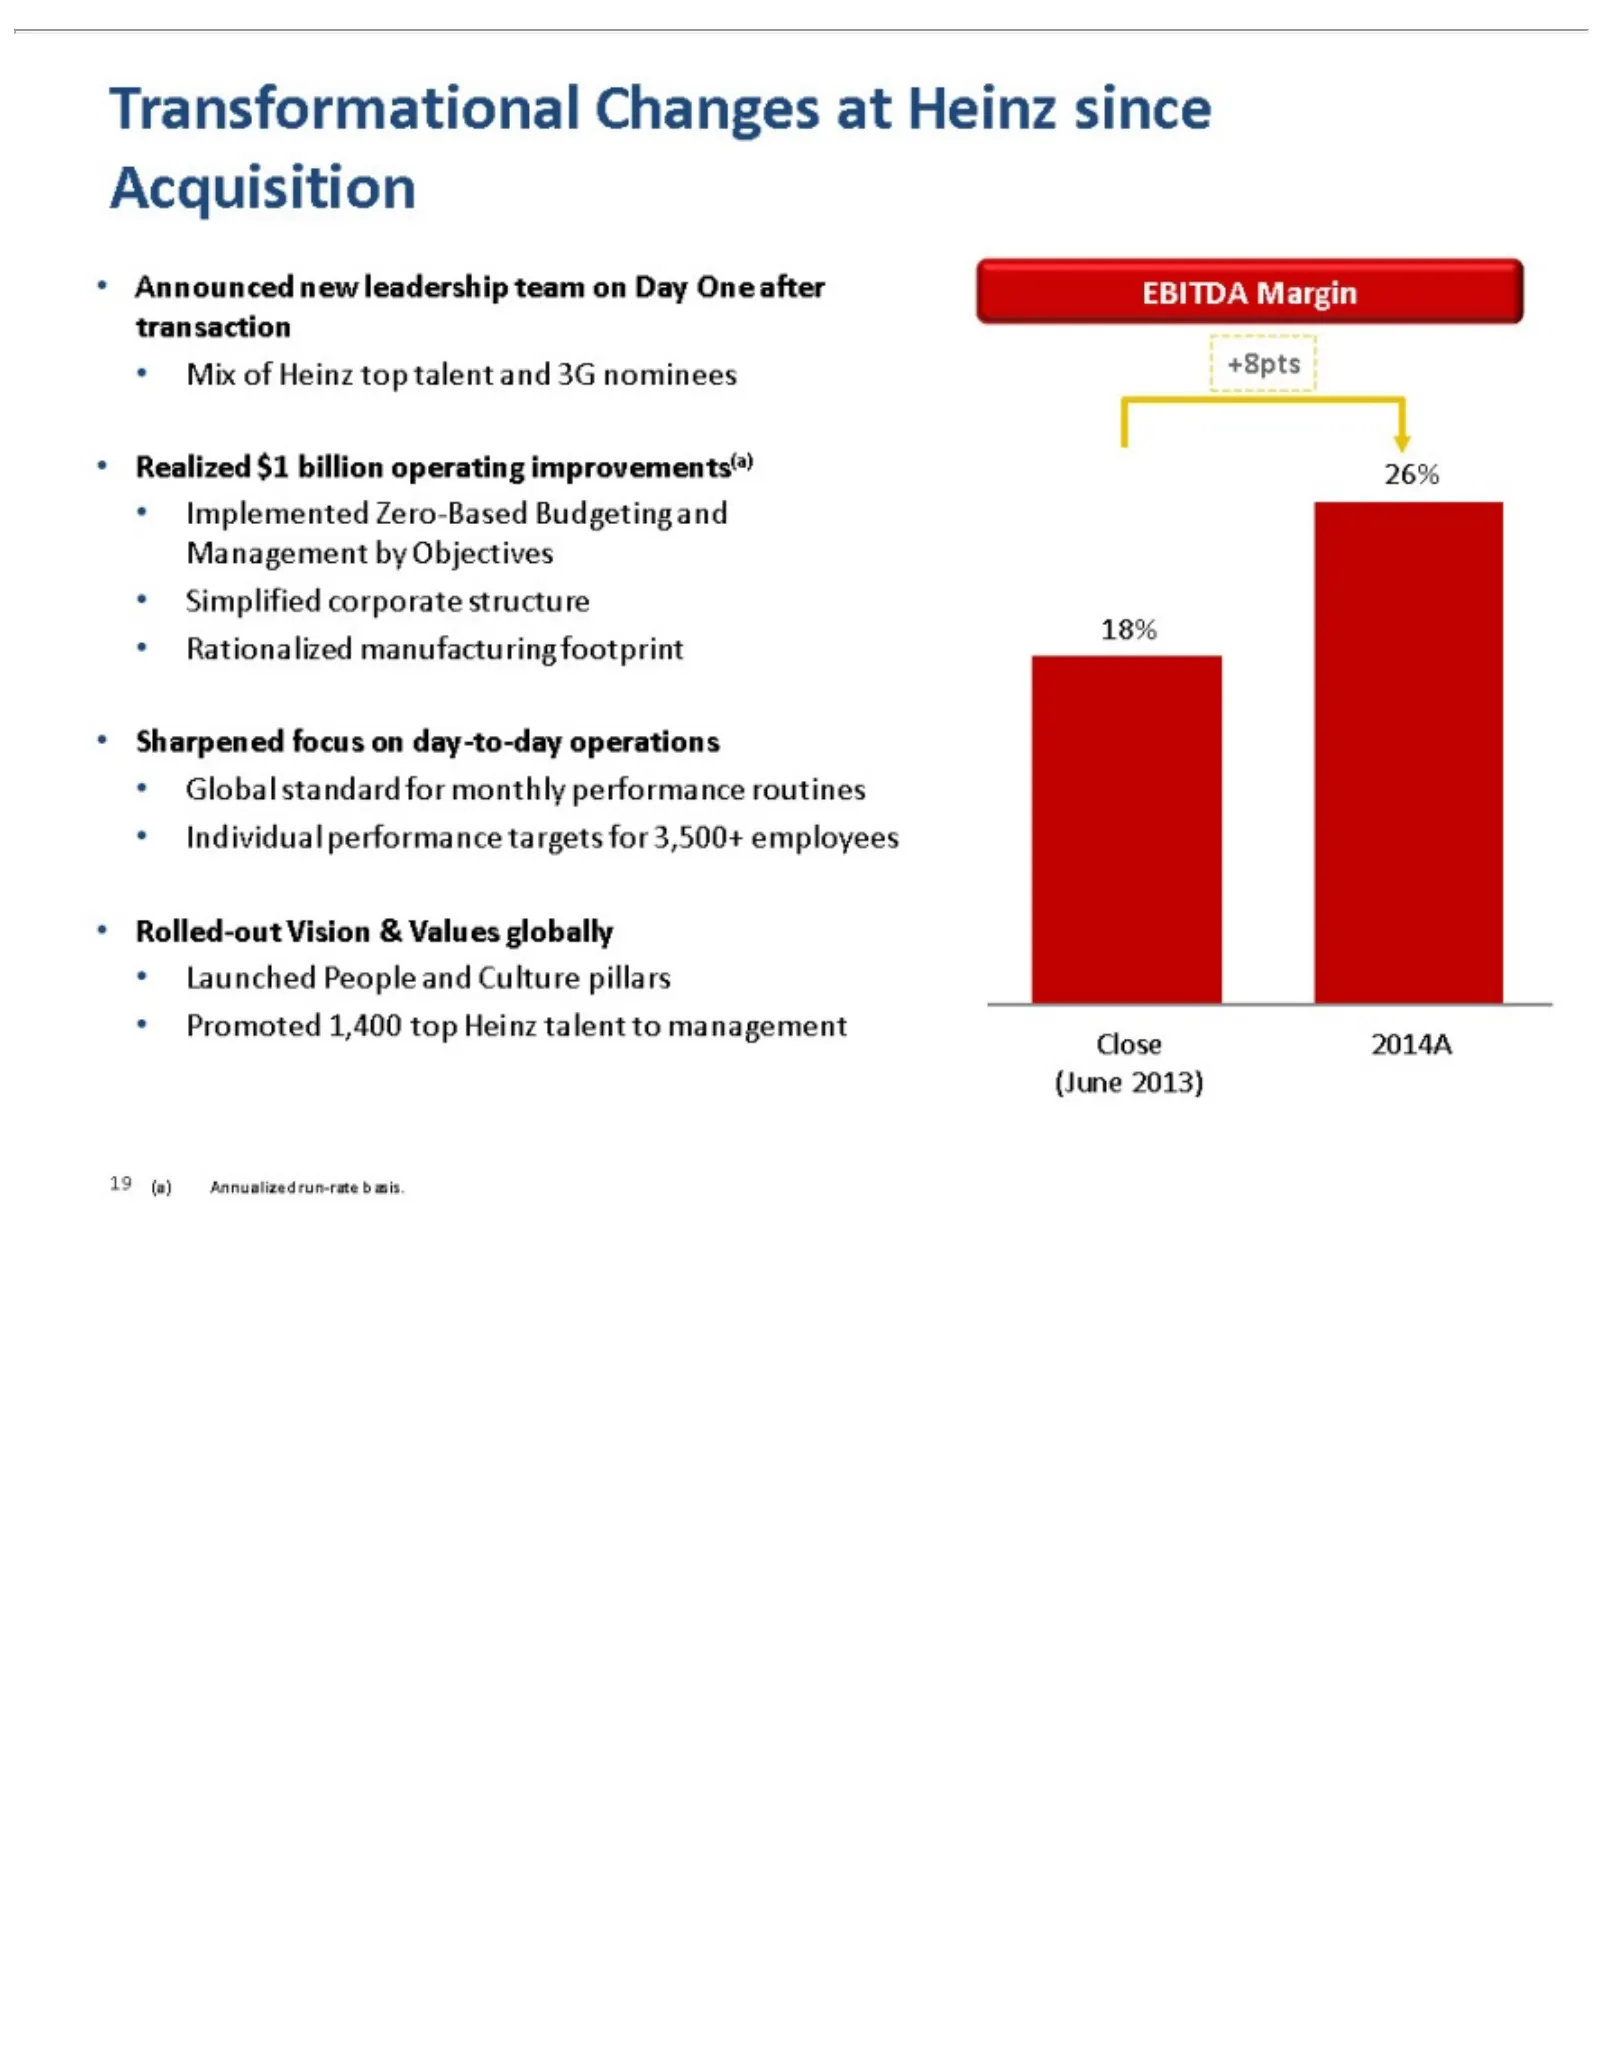
Slide 21: Transformational Changes Realized Since 3G Acquisition
Transformational Announced Mix Realized Implemented Simplified Sharpened Global Individual Rolled-out Launched Promoted EBITDA Close 18% 26% +8pts (June 19 (a)of2013) 2014A Annualized standard Heinz $1 Margin 1,400 People performance focus corporate Vision new billion Zero-Based topfor top leadershi
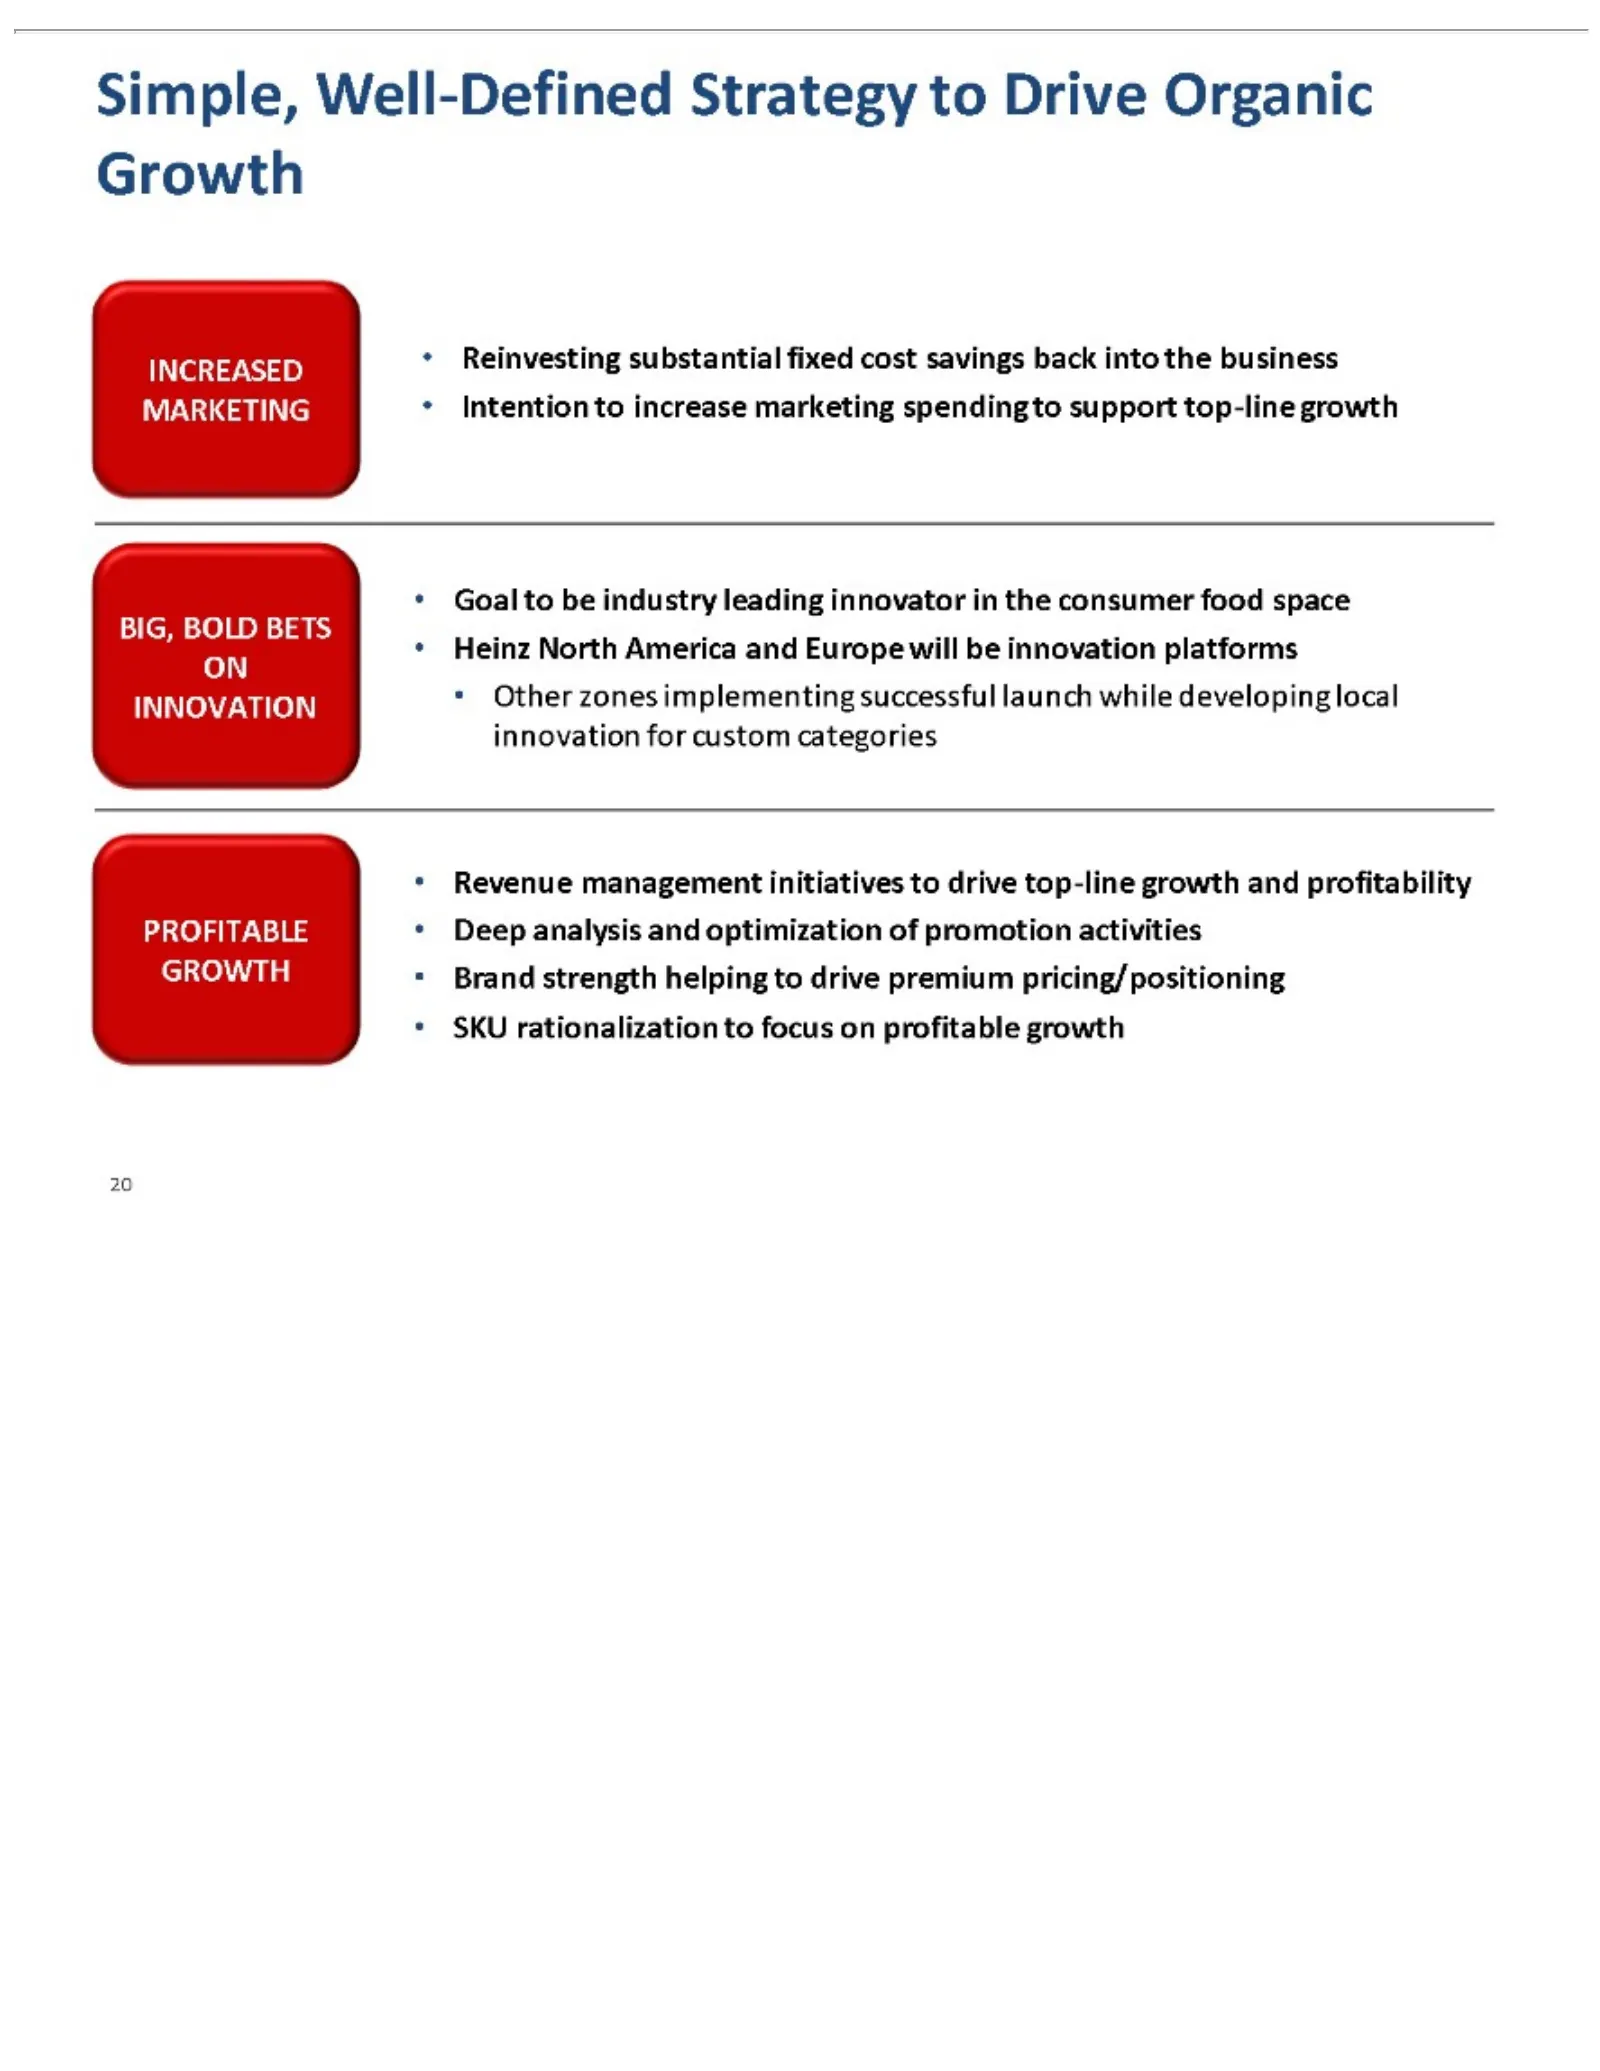
Slide 22: Well-Defined Strategy to Drive Profitable Growth
Simple, INCREASED MARKETING BIG, INNOVATION ON innovation PROFITABLE •GROWTH 20 GoalBOLD Revenue SKU to rationalization Well-Defined bemanagement for •industry BETS Brand •custom ••Reinvesting Deep Intention Other •strength Heinz leading to Strategy categories analysis zones initiatives focus toNort
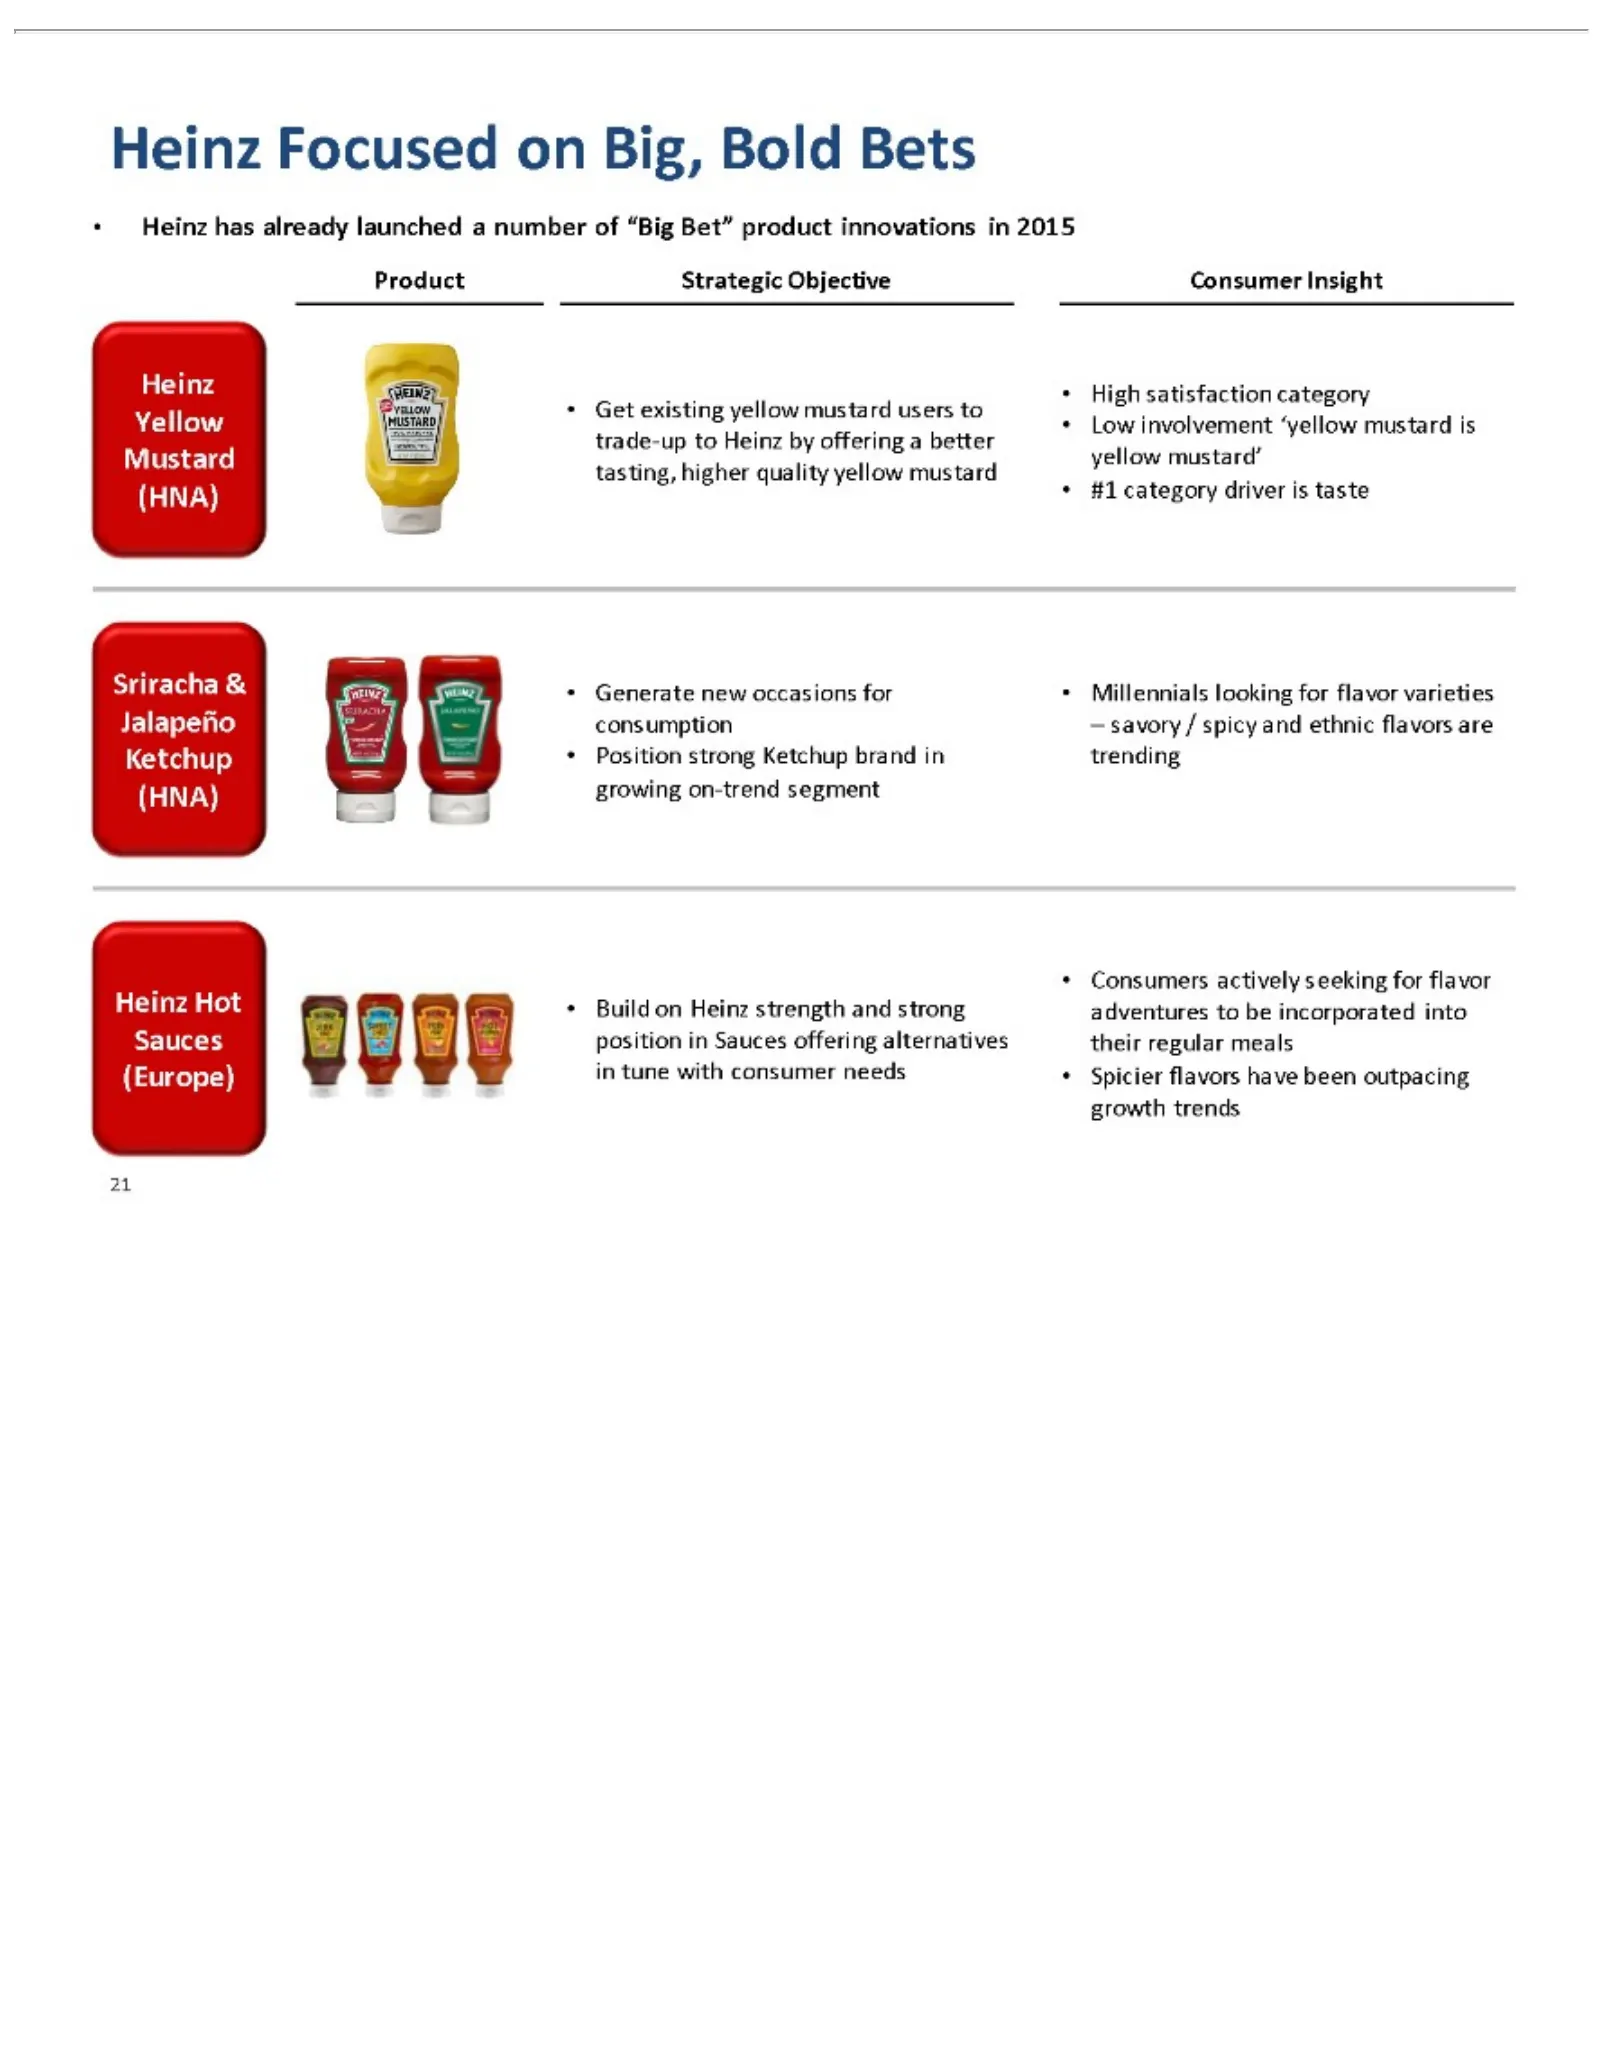
Slide 23: Big, Bold Bets: Yellow Mustard
•Product Yellow trade-up Mustard tasting, Sriracha Jalapeño Ketchup (HNA) Heinz Sauces (Europe) Consumers Spicier 21Heinz Get existing •Focused Hot position #1 growing flavors •higher has High Strategic to & yellow •Low consumption inPosition category ••Heinz actively already tune Build Generate sat
Slide 24: Transformational Combination Agenda
Transaction Agenda Kraft Heinz A 22Transformational Overview Overview Highlights Combination
Slide 25: Creating a Global Food & Beverage Powerhouse
Creating Substantially America Significant Opportunity International Through [Graphic Anchored With Investment Capital 23 Proven Structure A Retail Heinz Appears by Global Cost Grade of Track Expansion Long-Term Improved $1.5 and Platform Efficiency for Here] Company Powerhouse Records Foodservice b
Slide 26: #3 Food & Beverage Player in North America
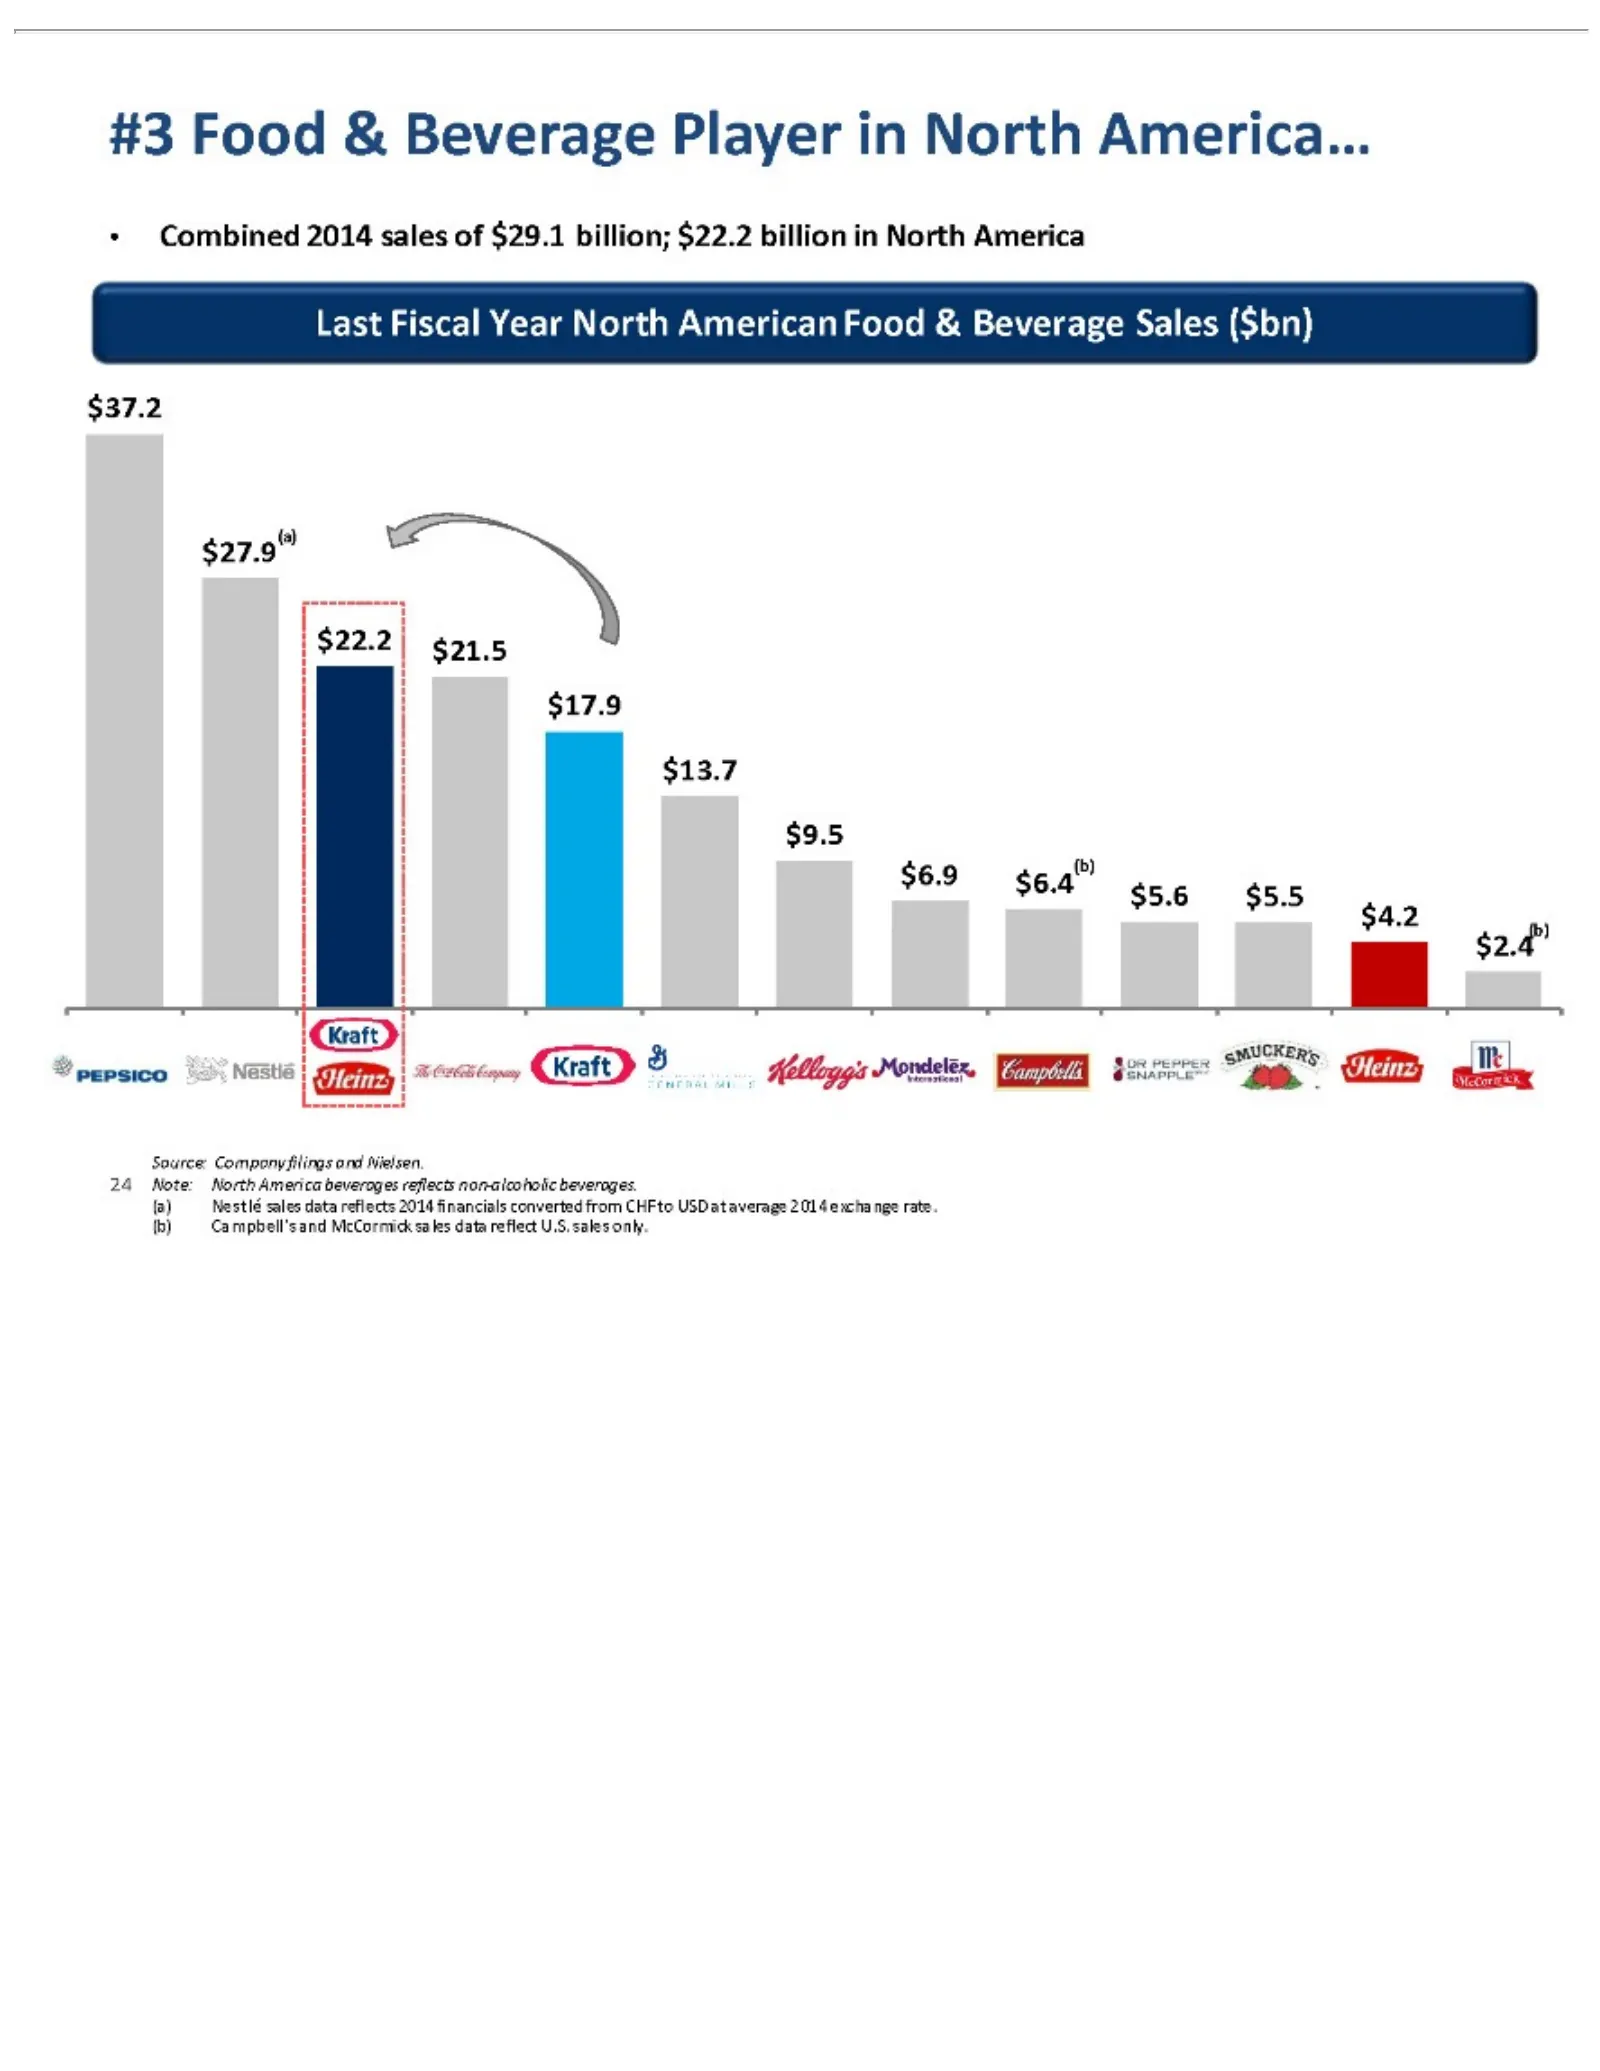
#3 Note: Combined Last $27.9 $37.2 $22.2 $6.9 $9.5 $13.7 $17.9 Source: $2.4 $4.2(b) 24 Food Fiscal $6.4(b) (a)Company $21.5 &North 2014 Year Beverage $5.6 America North sales $5.5 filings Player ofAmerican beverages $29.1 andinNielsen. North billion; Food reflects America… $22.2 & Beverage non-alcoh
Slide 27: Leading Scale in Foodservice
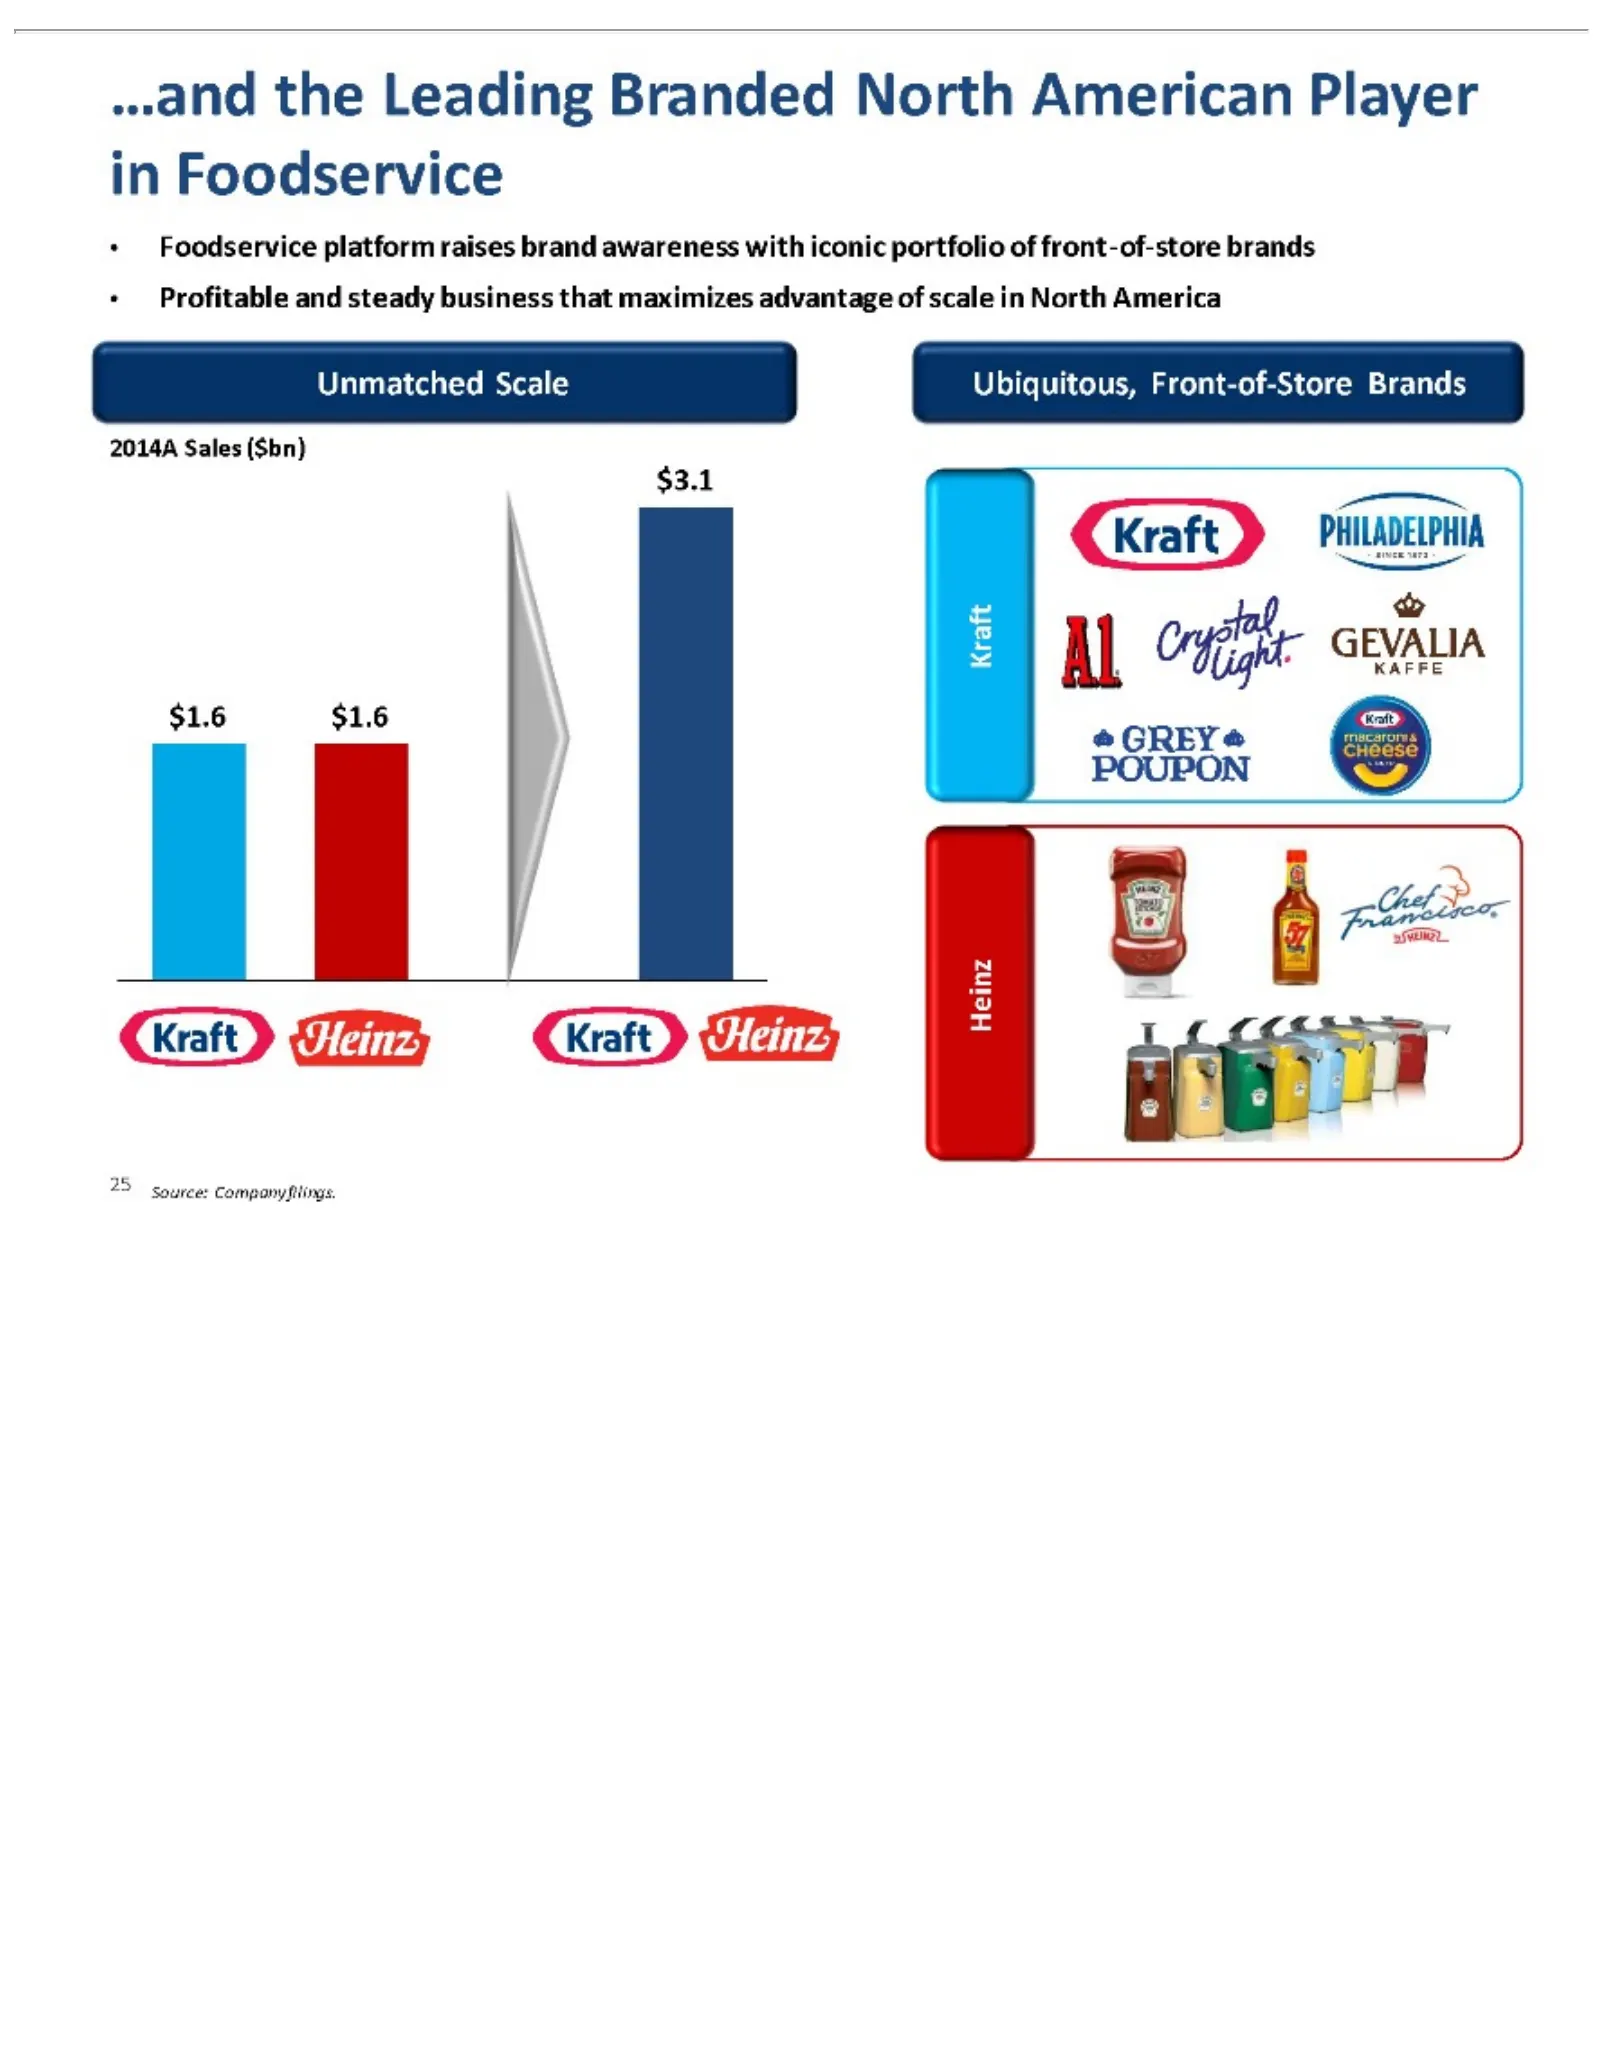
$3.1 Nestlé Campbell’s …and Foodservice Profitable Unmatched 2014A $1.6 Kraft Source:the 25 Heinz sales Sales $1.6 Leading and and Scale data platform ($bn) Companysteady McCormick reflects Ubiquitous, Branded business raises filings.2014 North brand sales Front-of-Store that financials data America
Slide 28: $1.5bn Cost Synergies
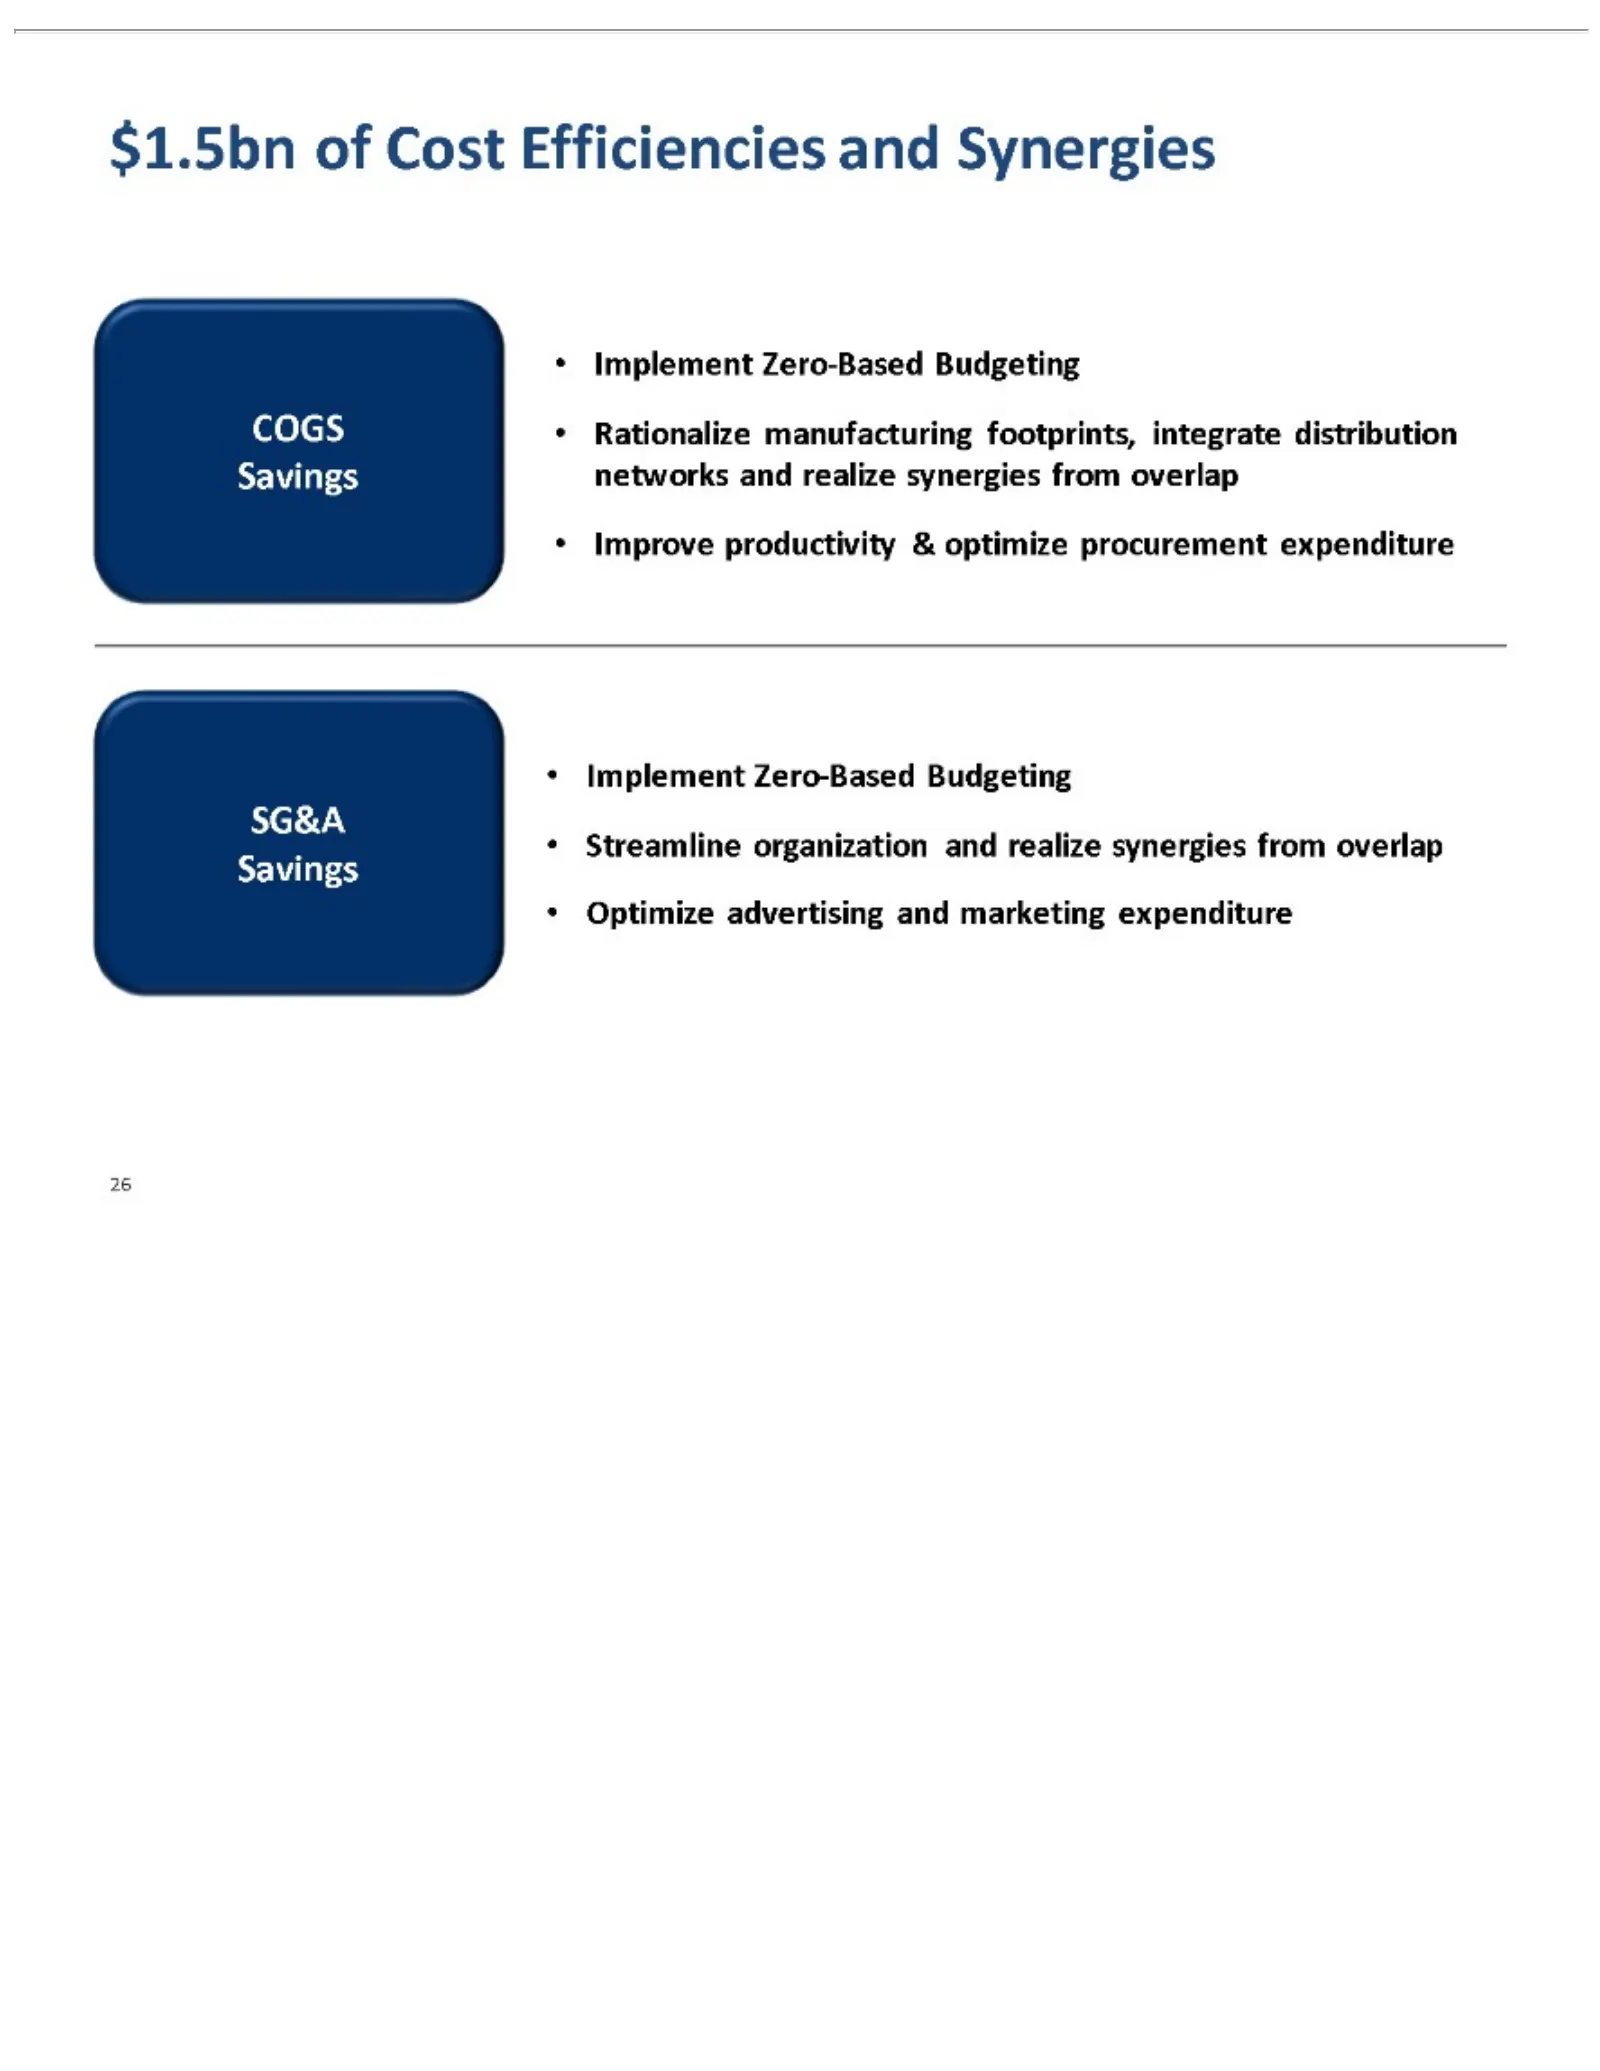
$1.5bn COGS •SG&A Savings 26 Improve Implement Streamline Optimize •ofnetworks Rationalize Cost productivity advertising Zero-Based organization Efficiencies andmanufacturing realize and &Budgeting optimize and marketing and synergies realize Synergies procurement footprints, synergies expenditure f
Slide 29: Unparalleled Portfolio of Leading Brands
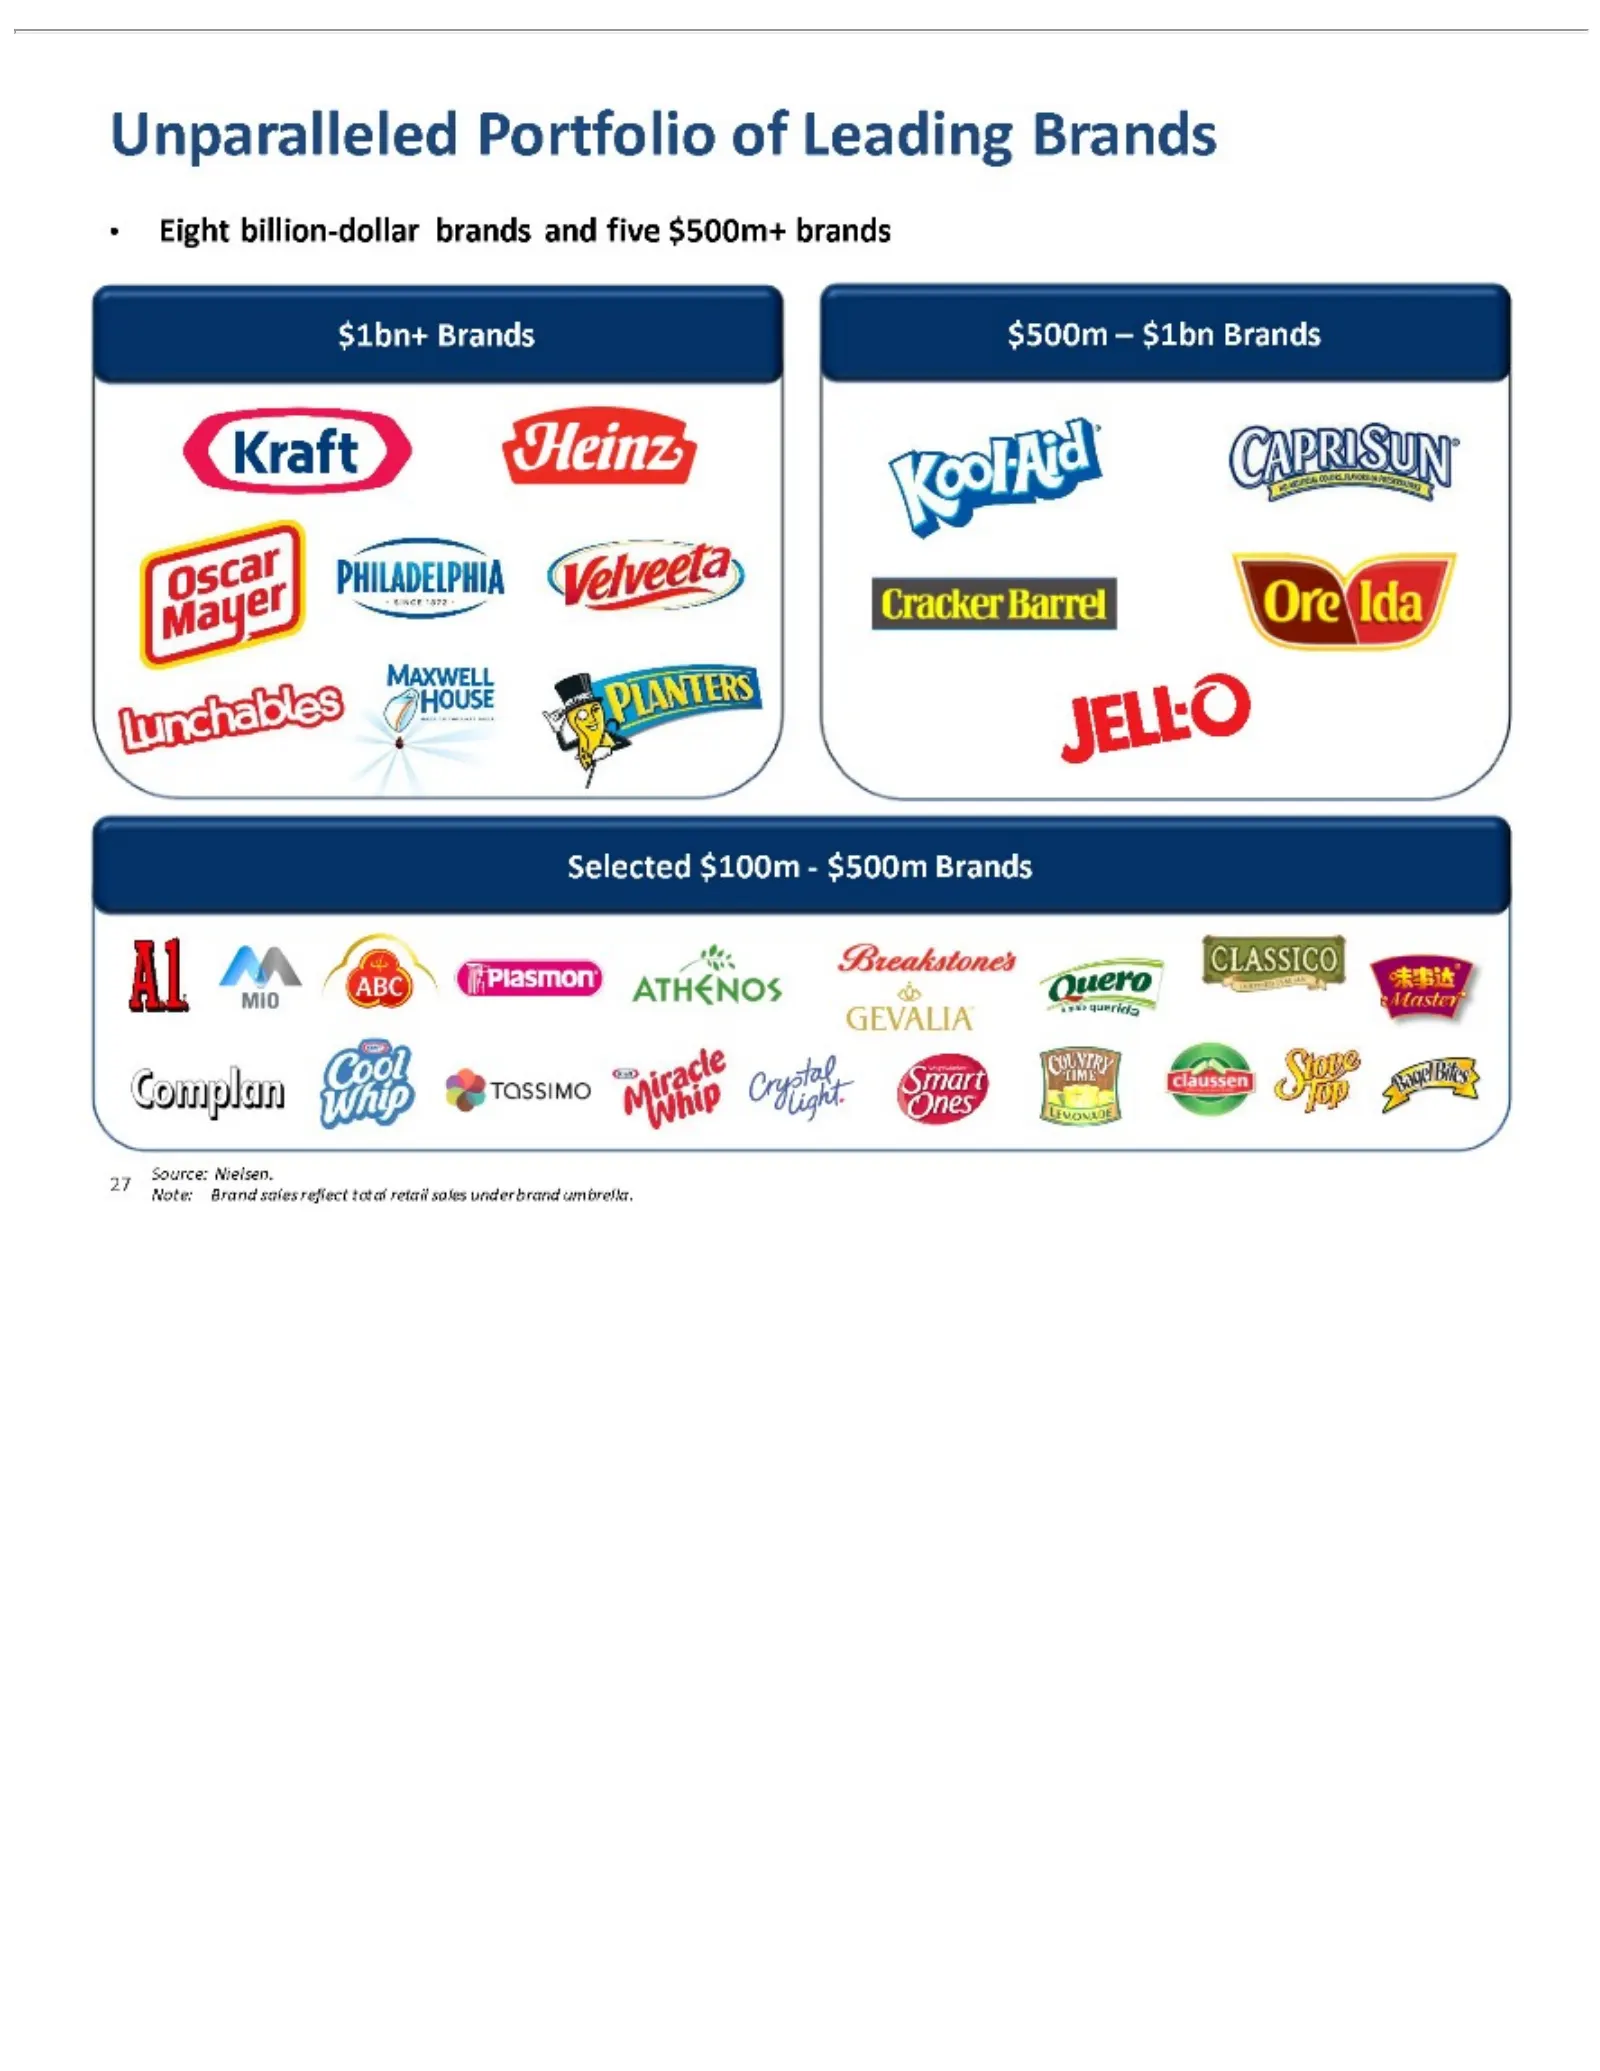
Unparalleled Eight $1bn+ Selected 27 Note: Source: billion-dollar Brand Brands $100m—$500m Nielsen. sales Portfolio $500m reflect brands –of$1bn total Leading Brands andBrands retail fiveBrands $500m+ sales under brands brand umbrella.
Slide 30: Clear Potential for Revenue Synergies and Increased Growth
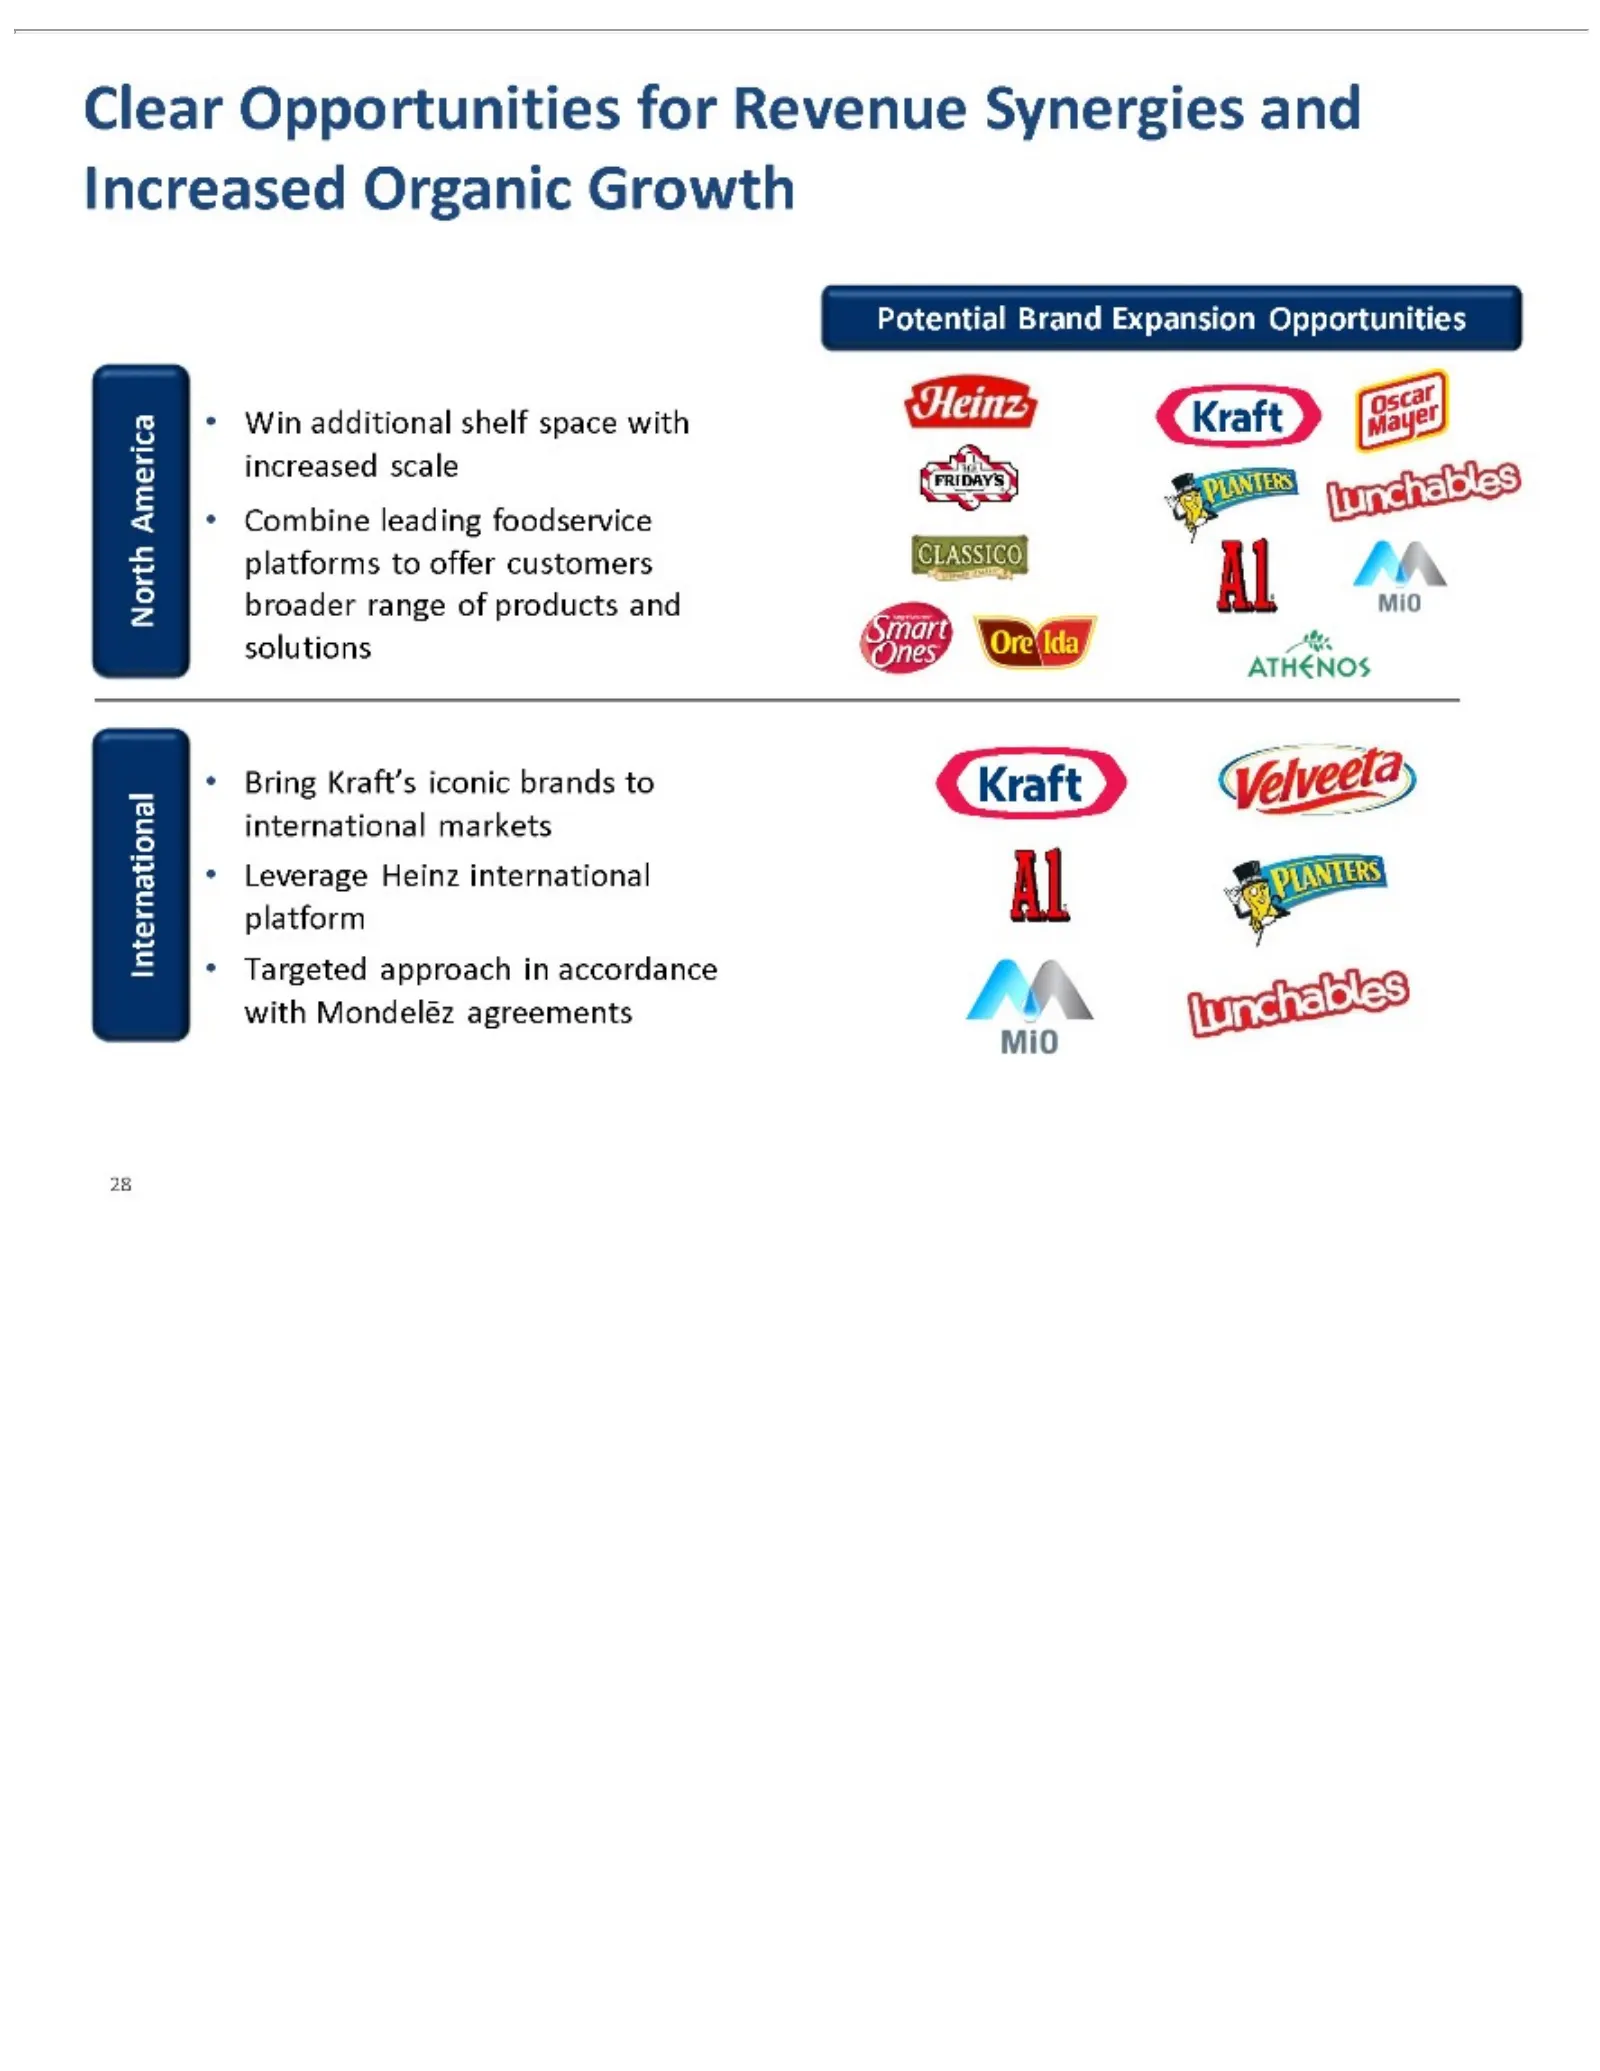
Clear Potential increased America platforms North solutions international •International with [Graphic 28 Win Targeted Bring Leverage Mondelēz Opportunities additional broader Kraft’s •Appears Brand scale to Combine approach Heinz offer markets platform range iconic agreements Expansion shelf intern
Slide 31: Existing Platform to Enable International Growth
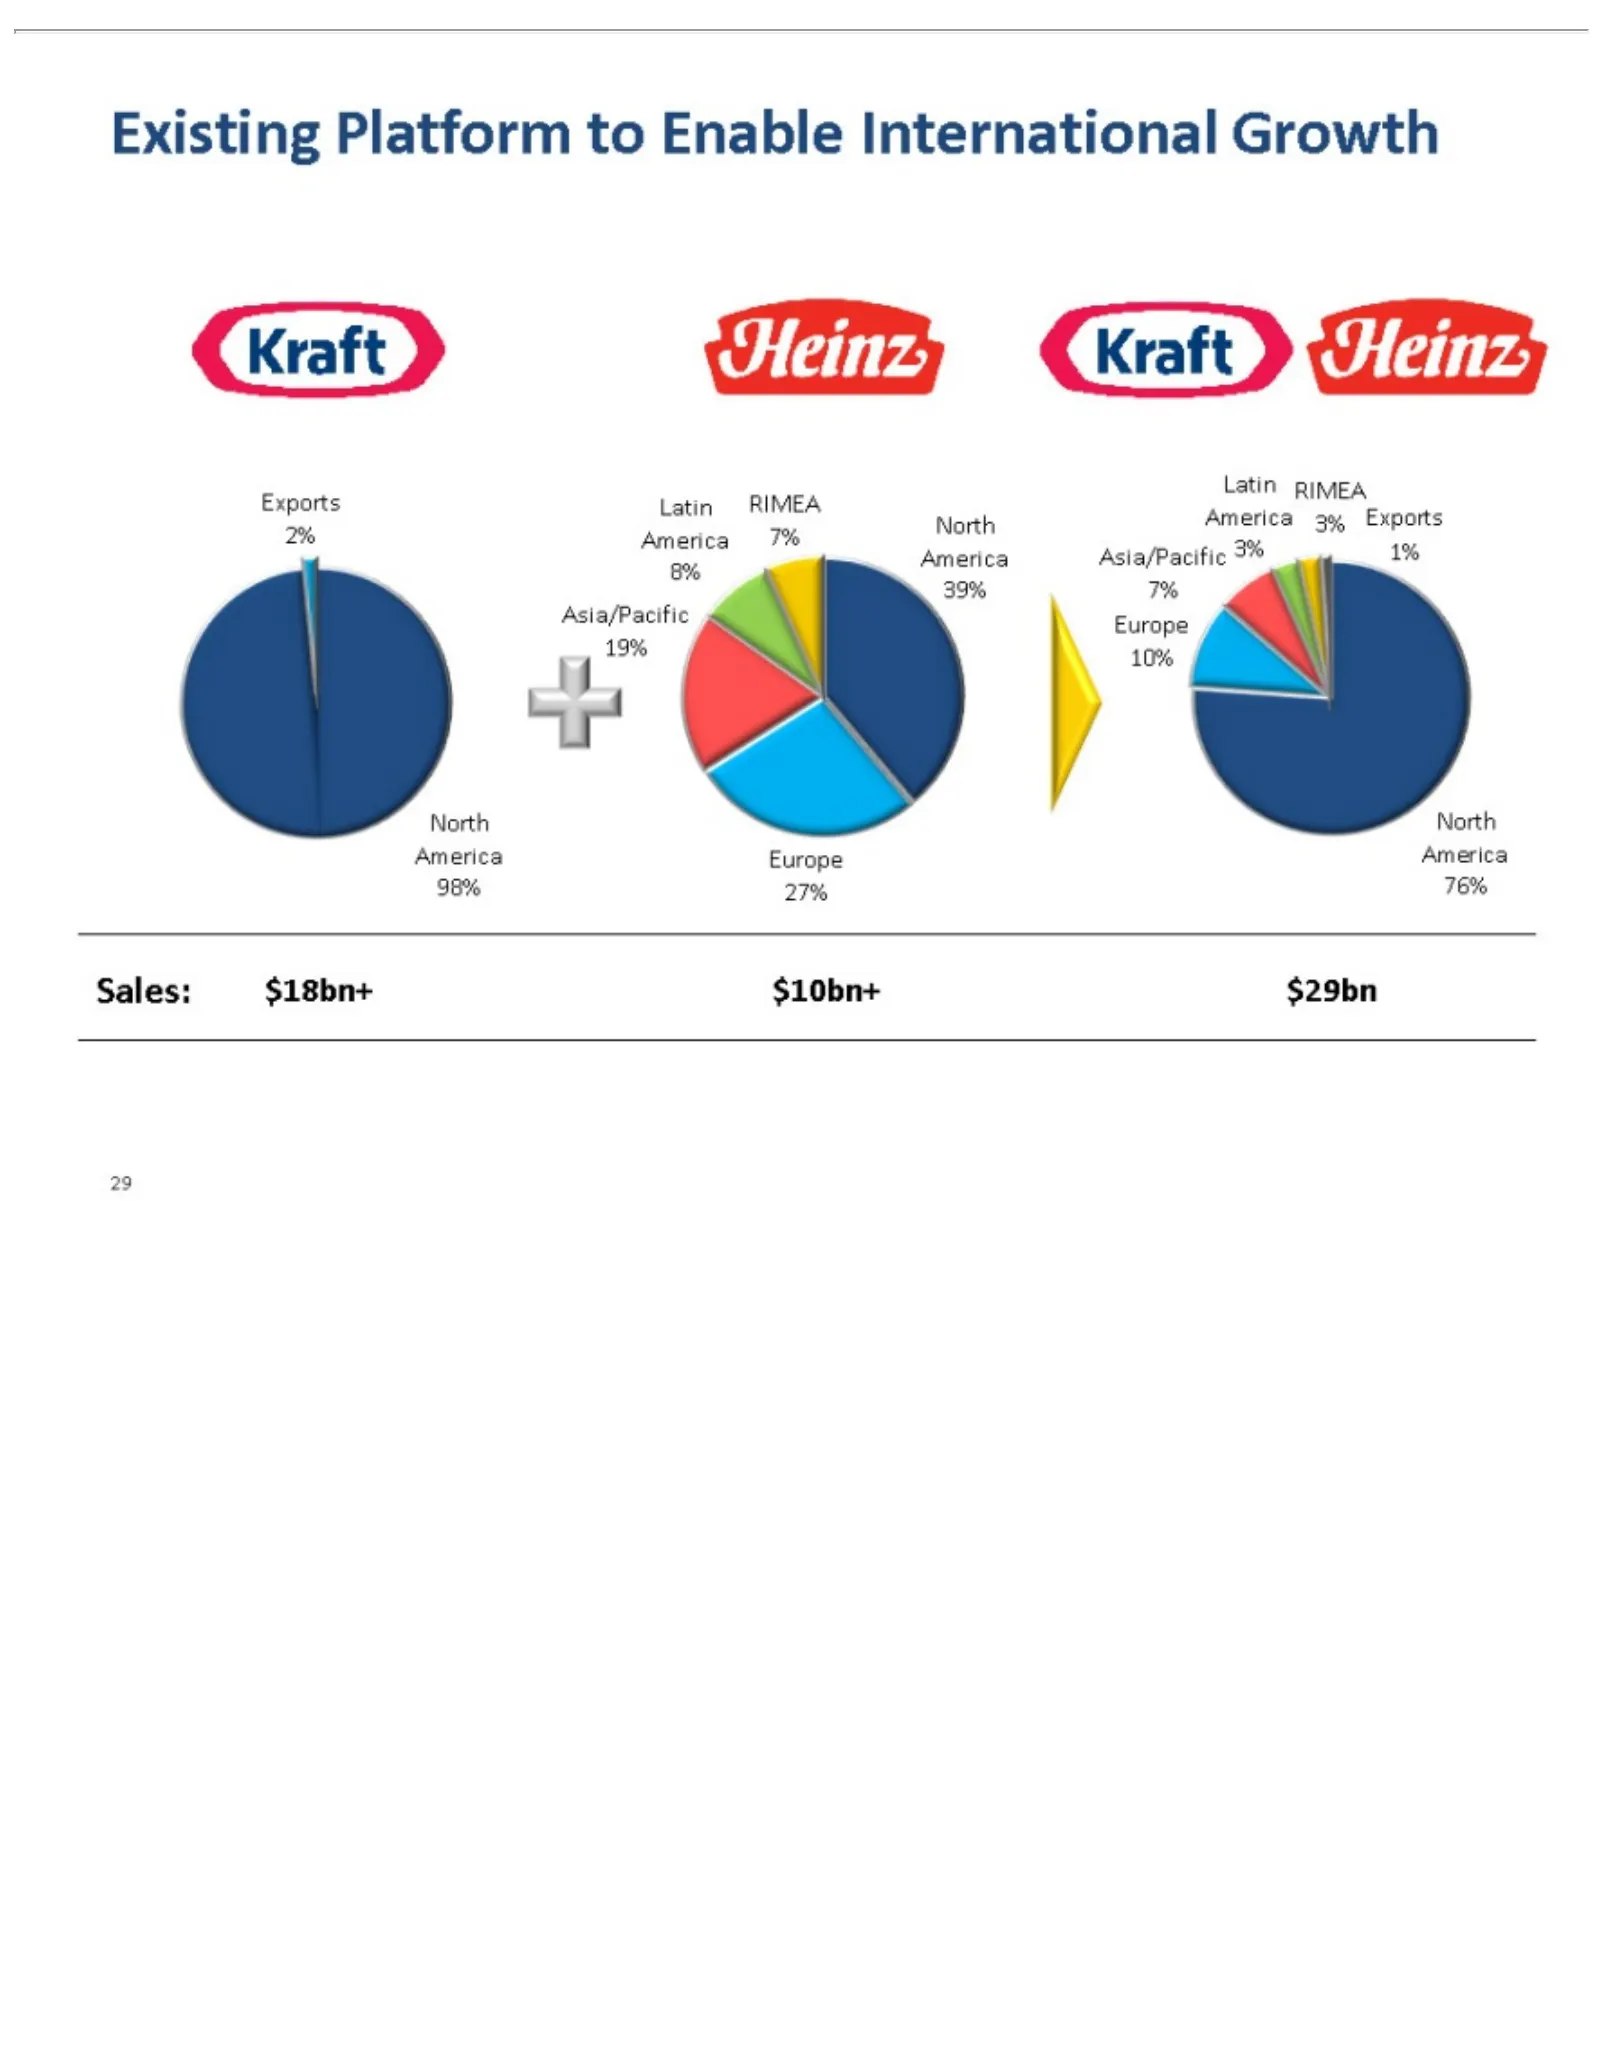
Existing Platform [Graphic 29 Appears Here] to Enable International Growth
Slide 32: Potential International Opportunity for Kraft Brands
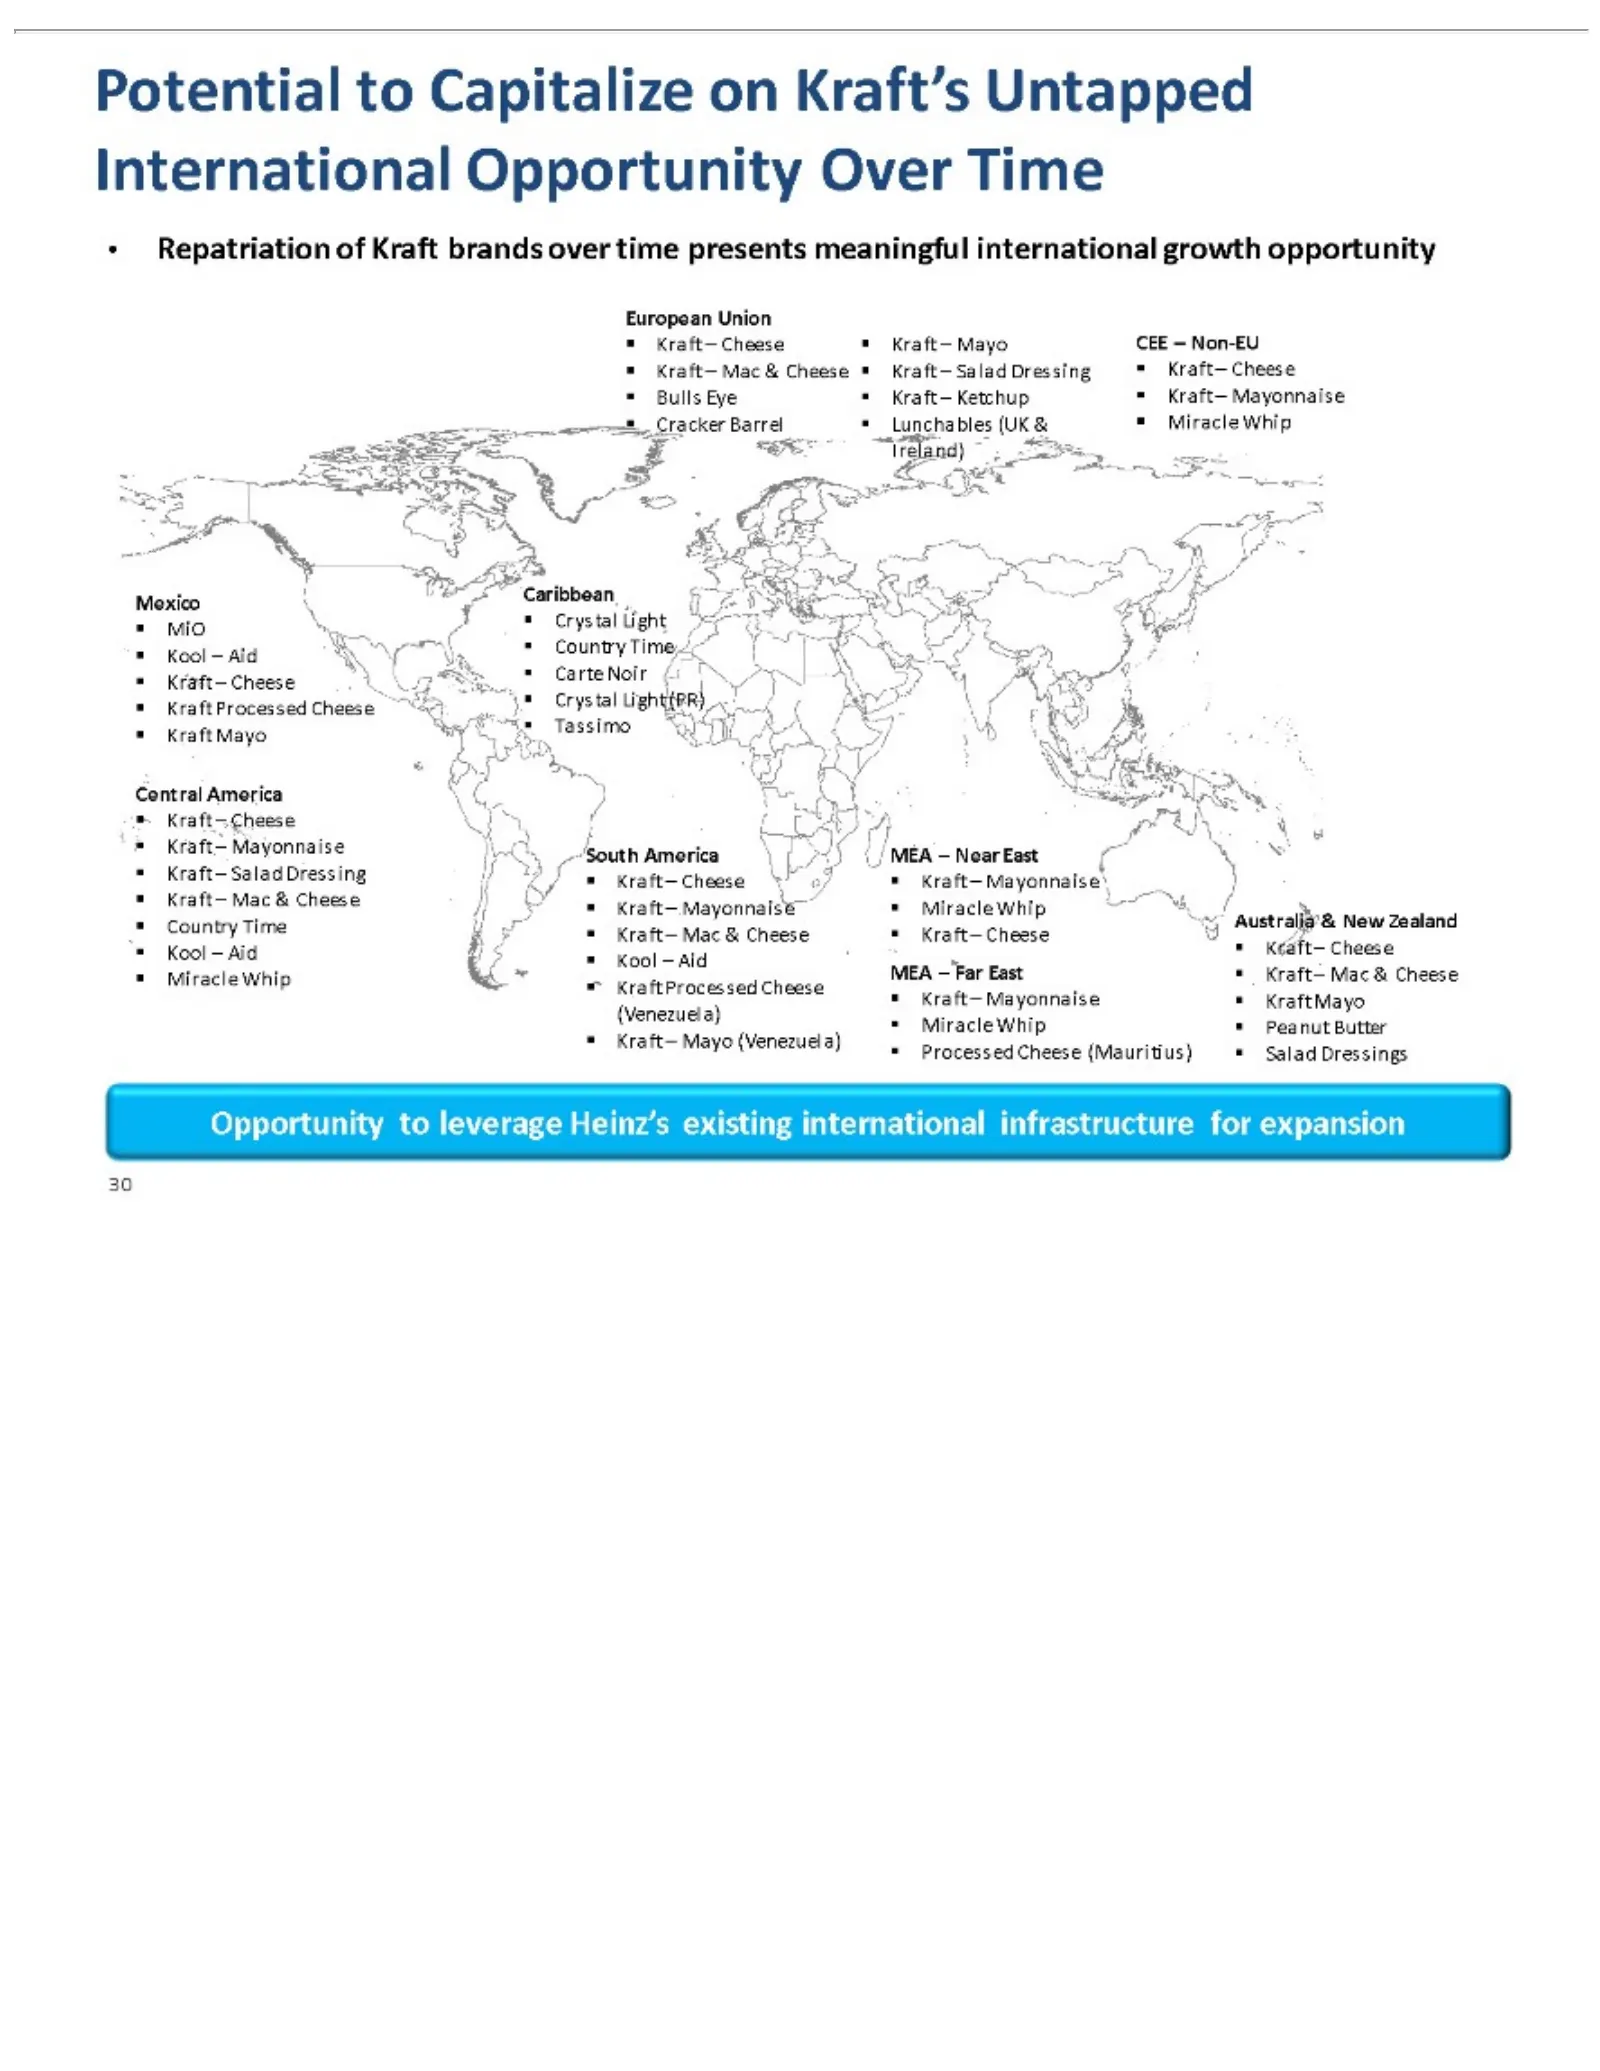
Potential International Repatriation MiO Mexico Central European Bulls Cracker Caribbean Country Carte Crystal South Tassimo Kool Lunchables CEE MEA Miracle Processed Australia Kraft Peanut Salad Opportunity 30 ––Mayo Processed – Eye Noir Dressings America Non-EU Aid Butter Mayo Salad Ketchup Mayonn
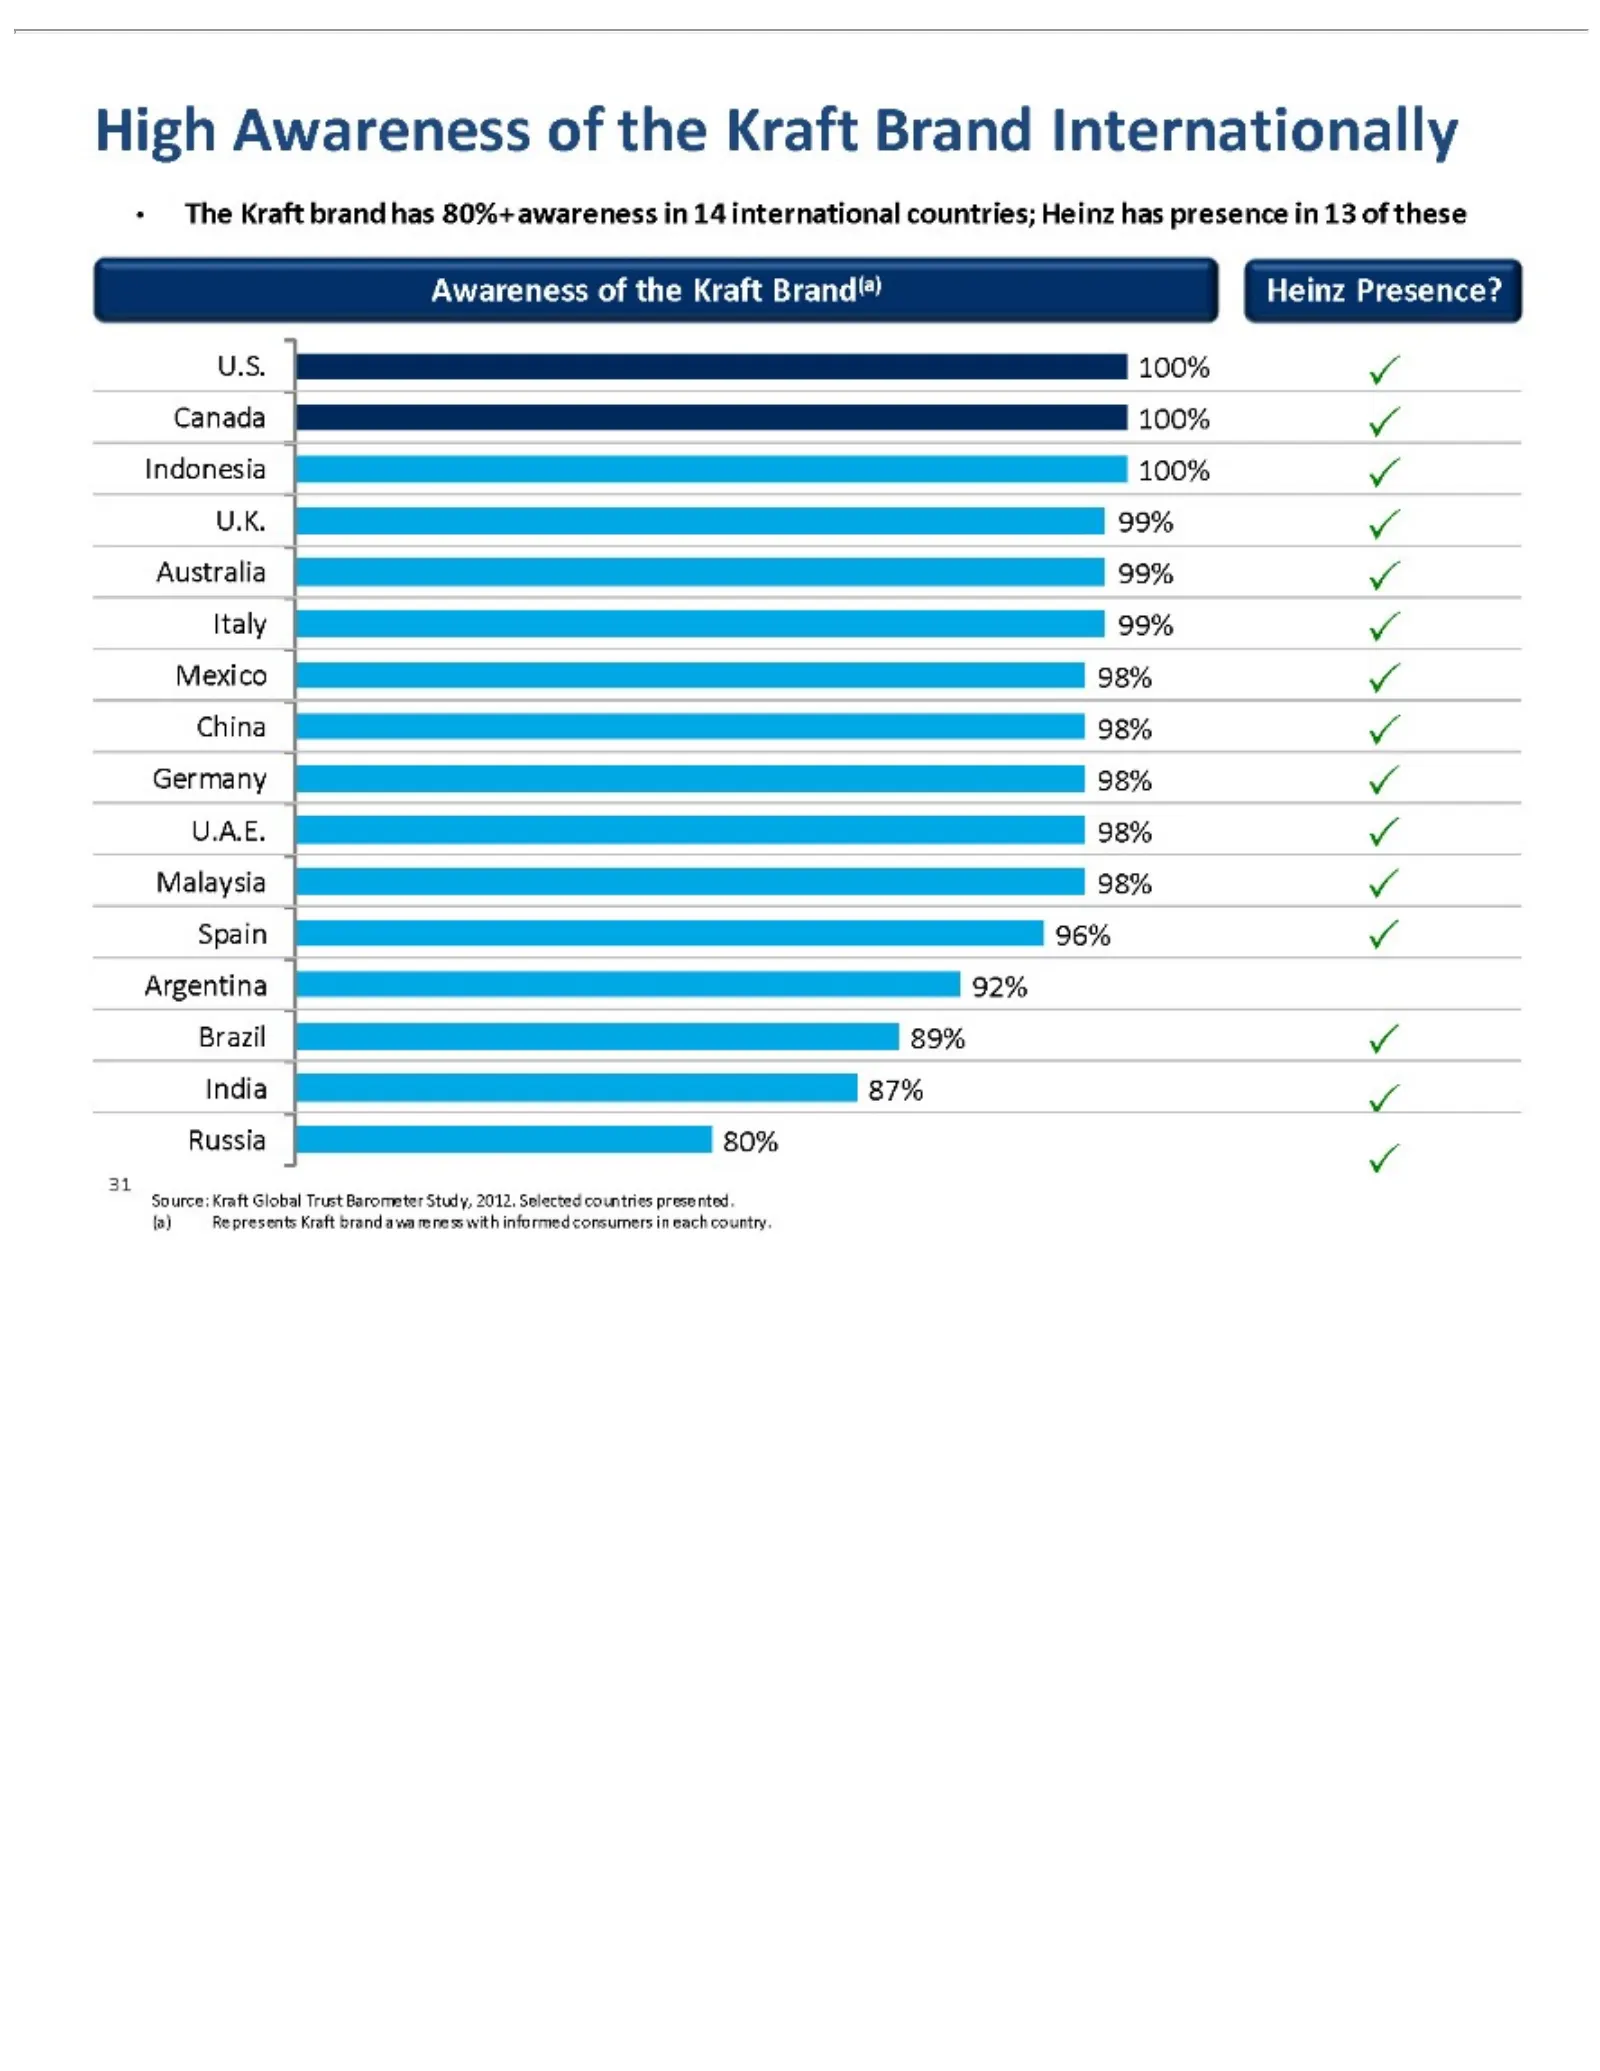
Slide 33: High Kraft Brand Awareness Internationally
31 High The Awareness U.S. Canada Indonesia U.K. Australia Italy Mexico China Germany U.A.E. Malaysia Spain Argentina Brazil India Russia Kraft 100% 99% 99% Awareness Source: (a) 87% 96% 98% 89% 80% 98% 100% 98% 99% 98% 100% brand ?92% ??of Kraft?????the Represents ?? has ?ofKraft Global the 80%+Kra
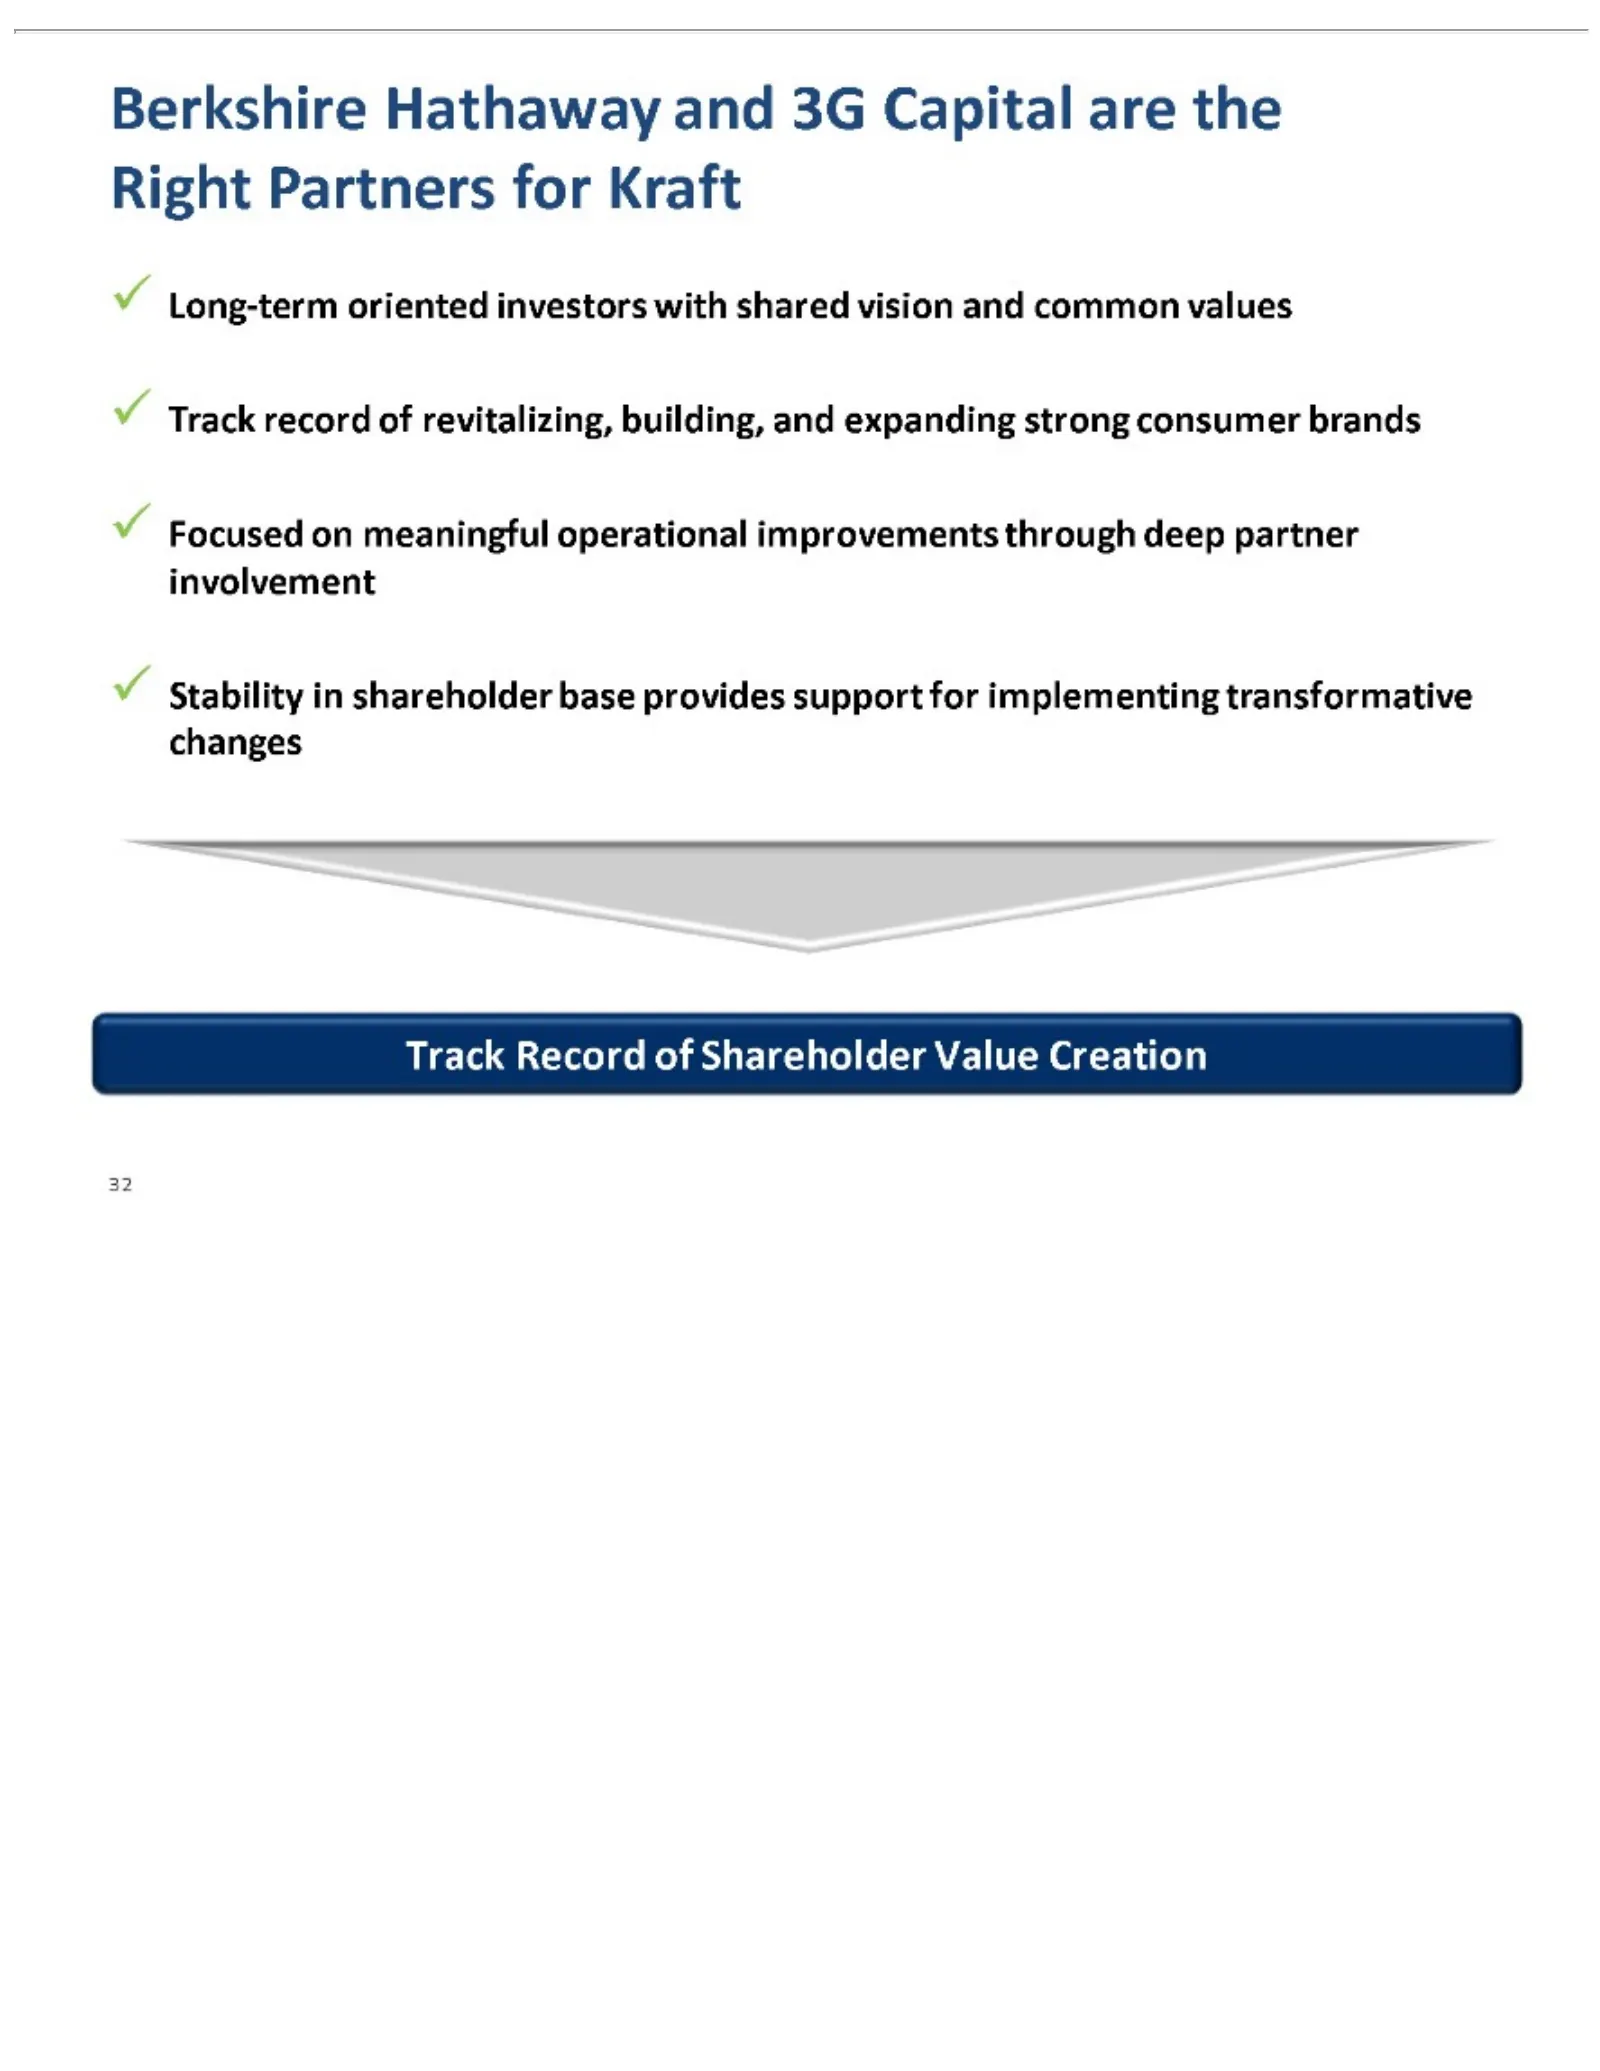
Slide 34: Berkshire Hathaway and 3G Capital: The Right Partners
Berkshire Long-term Focused Stability [Graphic Track 32 record Record on in Appears Hathaway oriented shareholder meaningful ofofrevitalizing, Shareholder Here] investors andbase operational 3G building, Capital provides Value with shared Creation improvements are support andthe vision expanding Rig
Slide 35: Q&A
Q&A
Source: SEC EDGAR · 425 filed Mar 25, 2015
More decks from Kraft Foods Group Inc
 Merger or Acquisition (March 2015)34 slides · Mar 25, 2015
 Kraft Foods Group Back-to-School Conference 201438 slides · Sep 3, 2014
 CAGE Conference 201436 slides · Mar 17, 2014
 CAGNY Conference 201438 slides · Feb 18, 2014
 Barclays Back-to-School Conference 201339 slides · Sep 4, 2013
 CAGNY Monthly Lunch Program (June 2013)21 slides · Jun 20, 2013