Endo International — Corporate Update (November 2023)
18 slides from Endo International's corporate update, Nov 6, 2023
Slide 1: Long Term Plan Update November 6, 2023
Long Term Plan Update November 6, 2023 Cleansing Material Preliminary and Subject to Material Change Exhibit 99.2
Slide 2: Disclaimer
Disclaimer This document has been prepared by Endo International plc (“Endo” or the “Company”) and its advisors from information provided by Company management and other sources, and is subject in all respects to the confidentiality agreement you have executed with the Company. All communications or
Slide 3: Table of Contents
Table of Contents Executive Summary Sep 2023 Long Term Plan Sep 2023 Segment Projections
Slide 4: Executive Summary
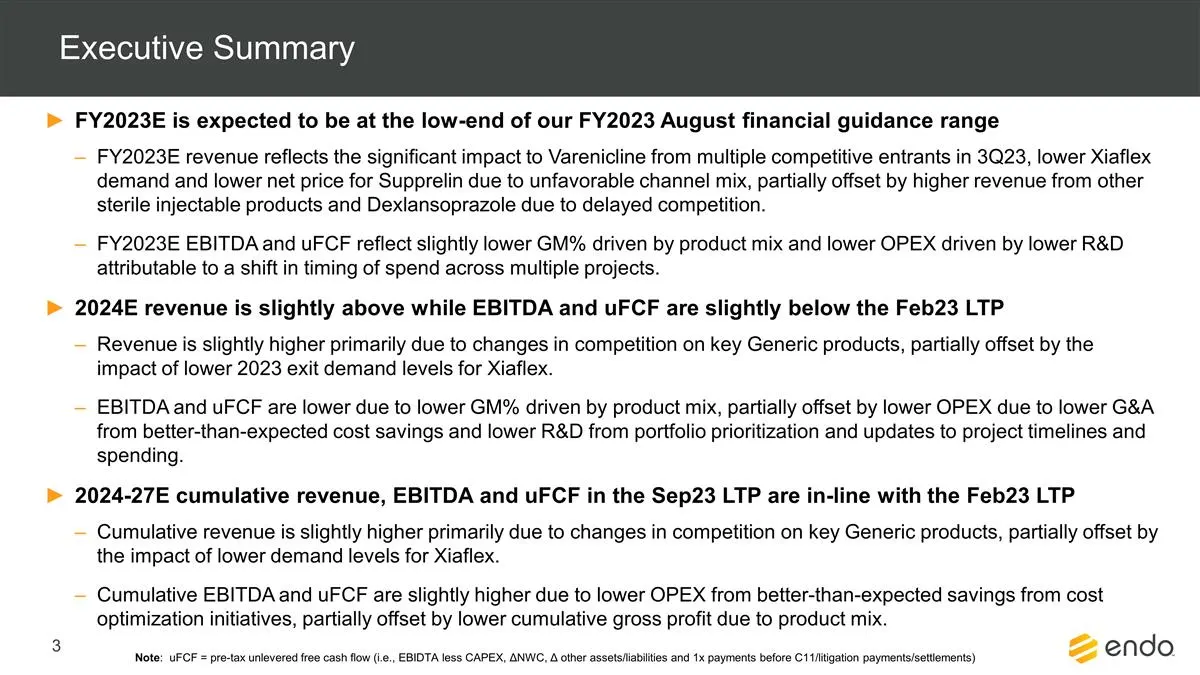
Executive Summary FY2023E is expected to be at the low-end of our FY2023 August financial guidance range FY2023E revenue reflects the significant impact to Varenicline from multiple competitive entrants in 3Q23, lower Xiaflex demand and lower net price for Supprelin due to unfavorable channel mix, p
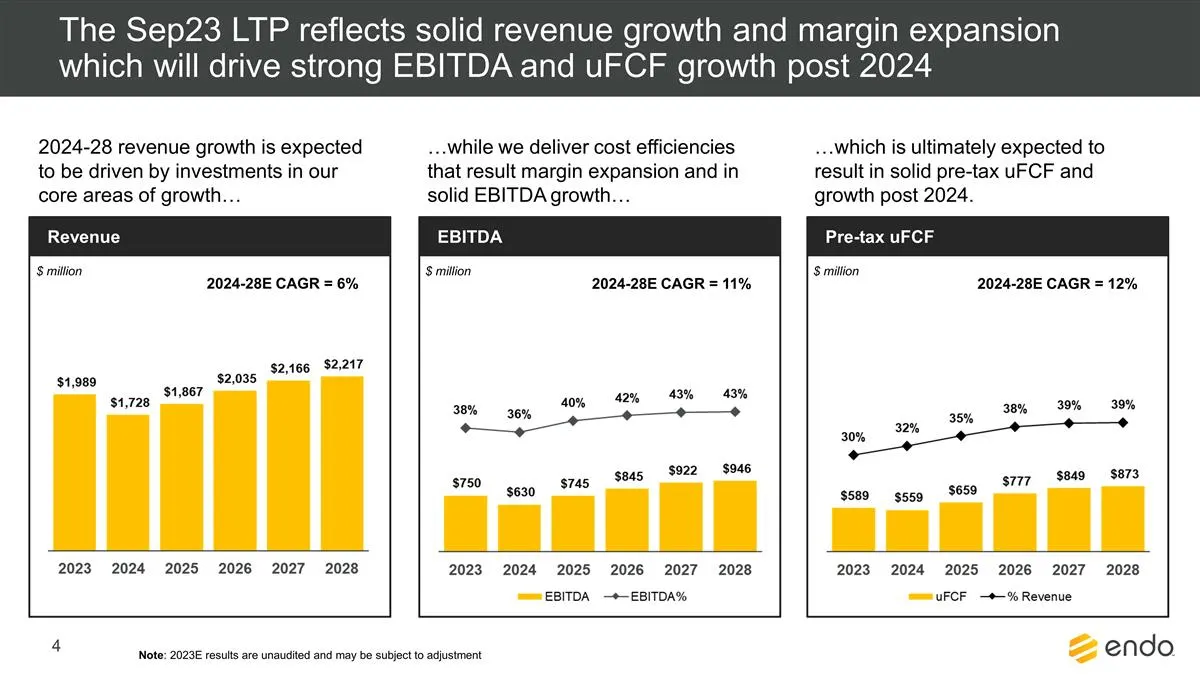
Slide 5: 2024-28 revenue, EBITDA and uFCF growth in Sep23 LTP
EBITDA Revenue Pre-tax uFCF 2024-28 revenue growth is expected to be driven by investments in our core areas of growth… …while we deliver cost efficiencies that result margin expansion and in solid EBITDA growth… …which is ultimately expected to result in solid pre-tax uFCF and growth post 2024. Not
Slide 6: Table of Contents
Table of Contents Executive Summary Sep 2023 Long Term Plan Sep 2023 Segment Projections
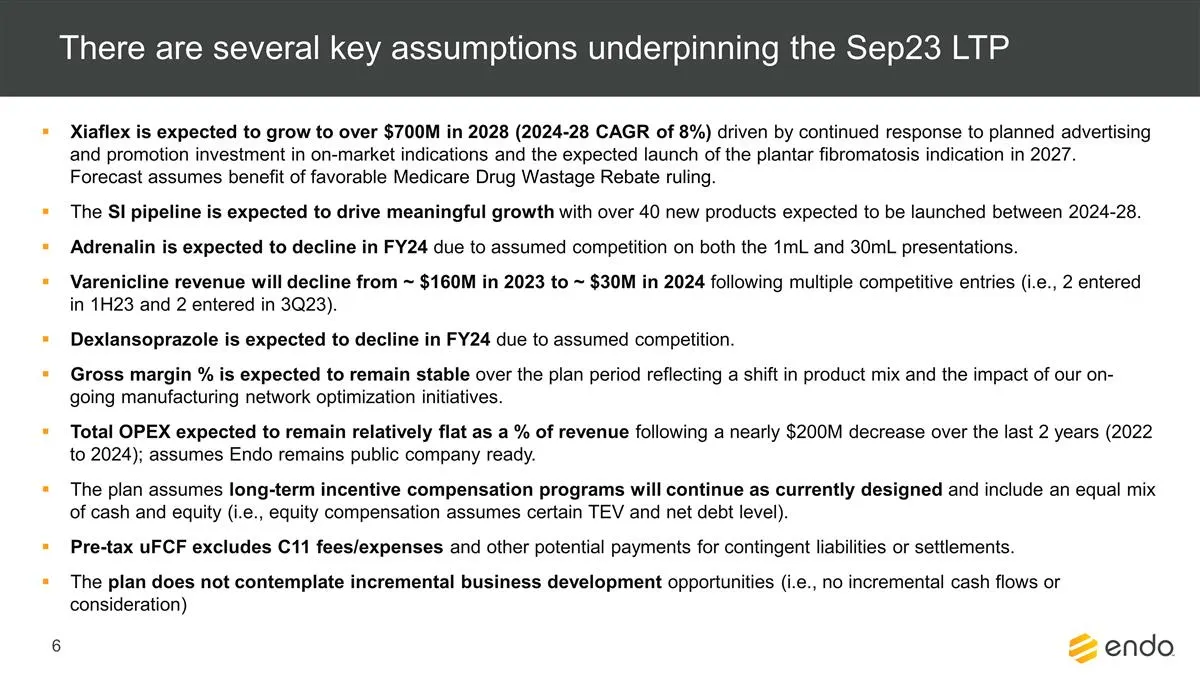
Slide 7: Key assumptions underpinning the Sep23 LTP
There are several key assumptions underpinning the Sep23 LTP Xiaflex is expected to grow to over $700M in 2028 (2024-28 CAGR of 8%) driven by continued response to planned advertising and promotion investment in on-market indications and the expected launch of the plantar fibromatosis indication in
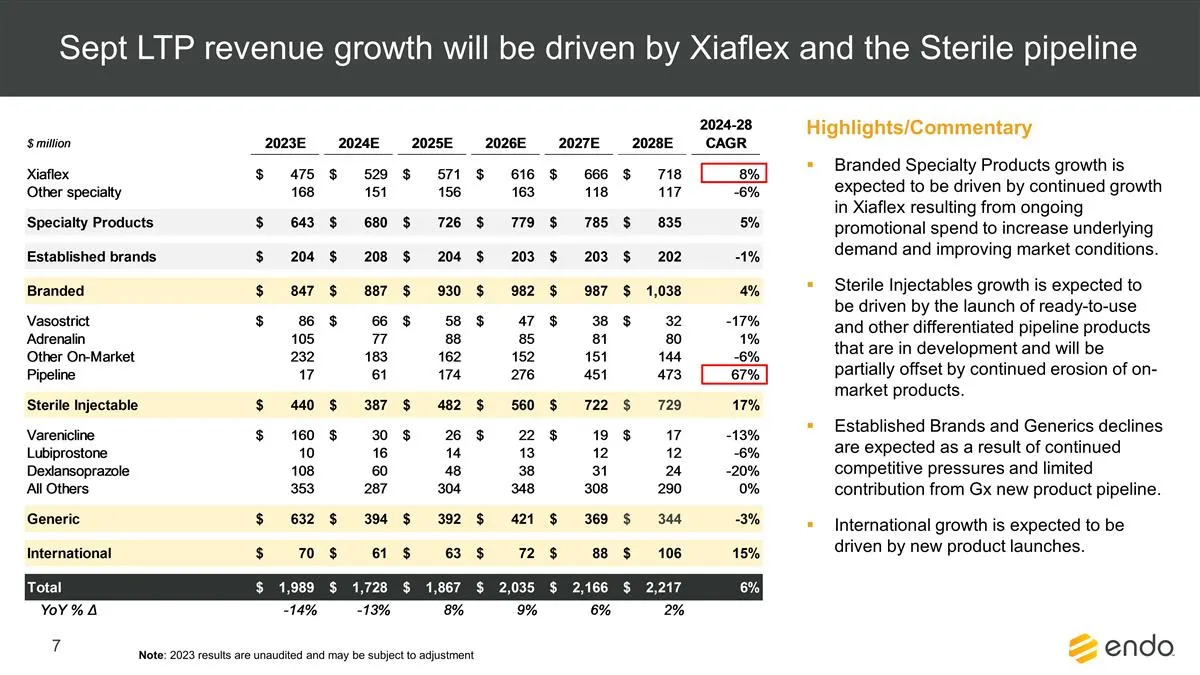
Slide 8: Sept LTP revenue growth driven by Xiaflex and the Sterile pipeline
Sept LTP revenue growth will be driven by Xiaflex and the Sterile pipeline Highlights/Commentary Branded Specialty Products growth is expected to be driven by continued growth in Xiaflex resulting from ongoing promotional spend to increase underlying demand and improving market conditions. Sterile I
Slide 9: Consistently high gross margins expected over the forecast horizon
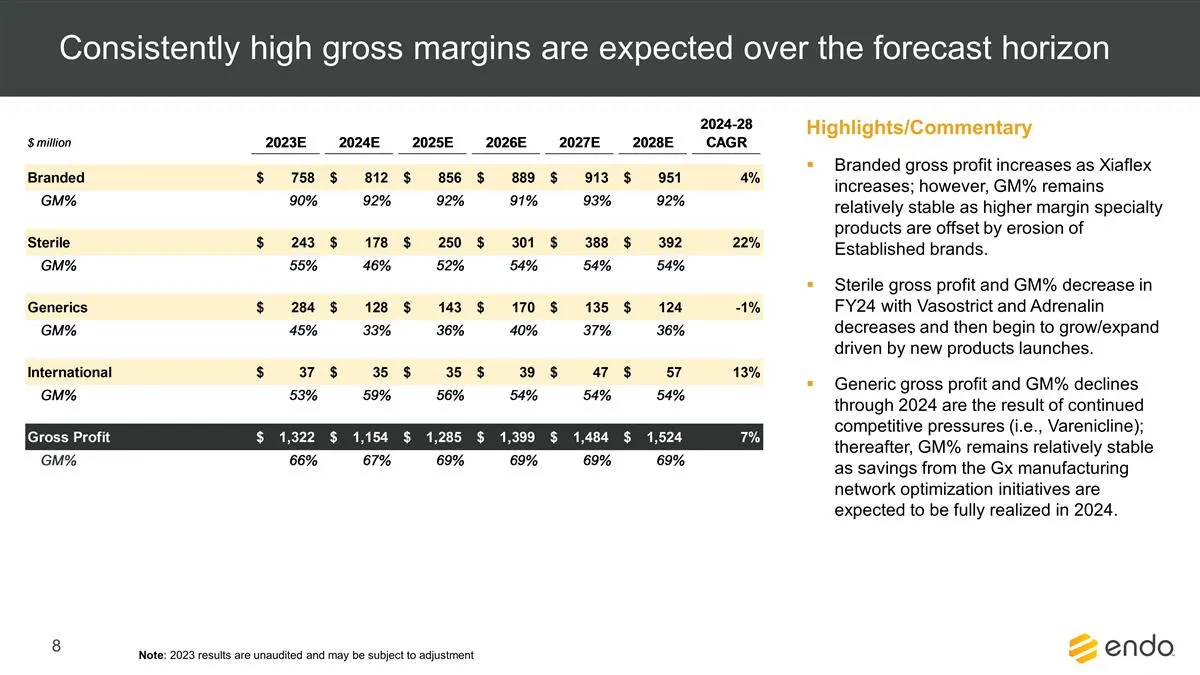
Consistently high gross margins are expected over the forecast horizon Highlights/Commentary Branded gross profit increases as Xiaflex increases; however, GM% remains relatively stable as higher margin specialty products are offset by erosion of Established brands. Sterile gross profit and GM% decre
Slide 10: EBITDA and unlevered FCF expected to grow faster than revenue
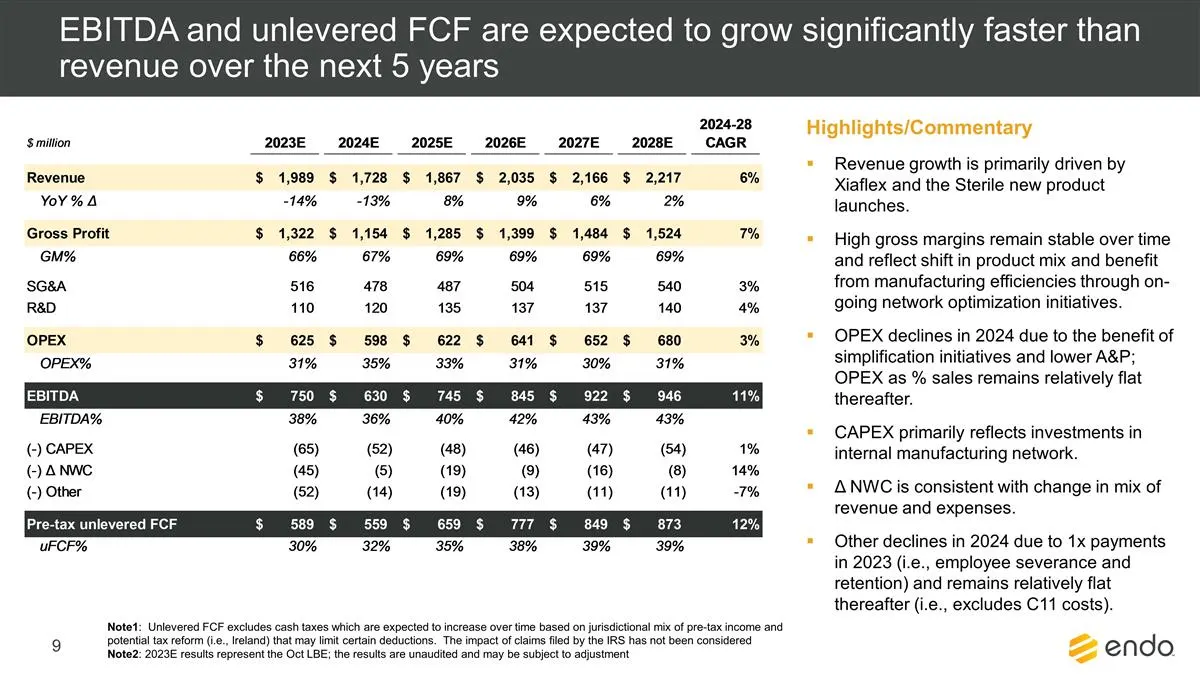
EBITDA and unlevered FCF are expected to grow significantly faster than revenue over the next 5 years Highlights/Commentary Revenue growth is primarily driven by Xiaflex and the Sterile new product launches. High gross margins remain stable over time and reflect shift in product mix and benefit from
Slide 11: Revenue and EBITDA growth driven by Branded and Sterile segments
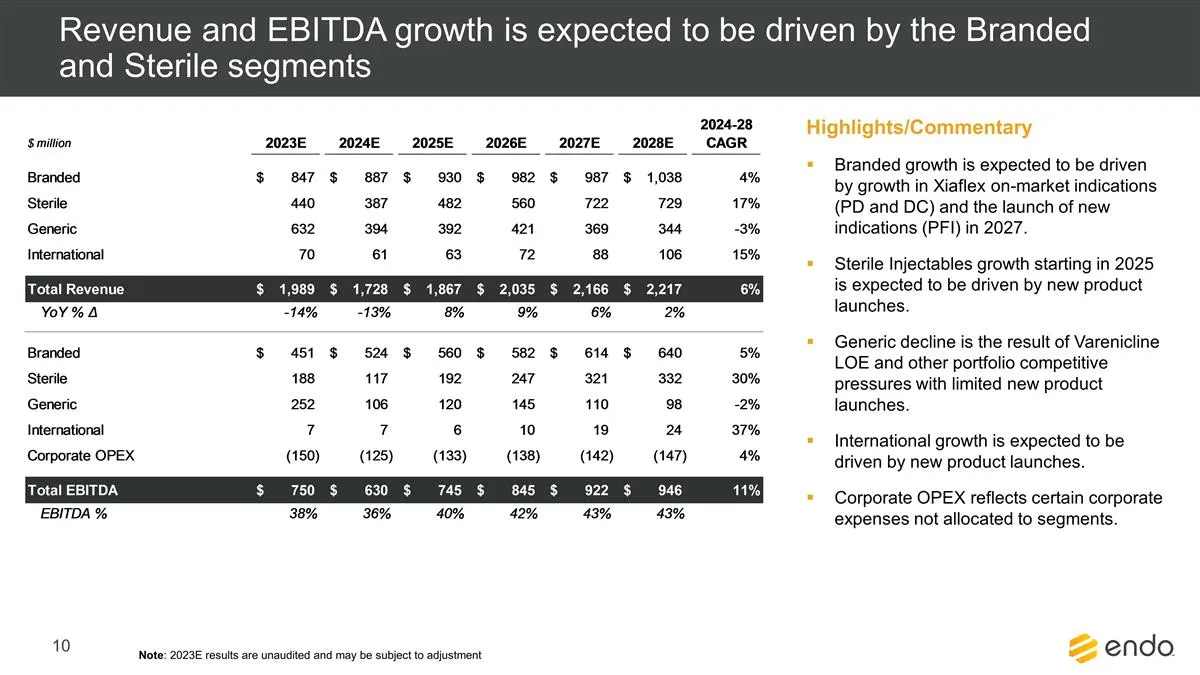
Revenue and EBITDA growth is expected to be driven by the Branded and Sterile segments Highlights/Commentary Branded growth is expected to be driven by growth in Xiaflex on-market indications (PD and DC) and the launch of new indications (PFI) in 2027. Sterile Injectables growth starting in 2025 is
Slide 12: LTP reflects uncertainties related to several opportunities and risks
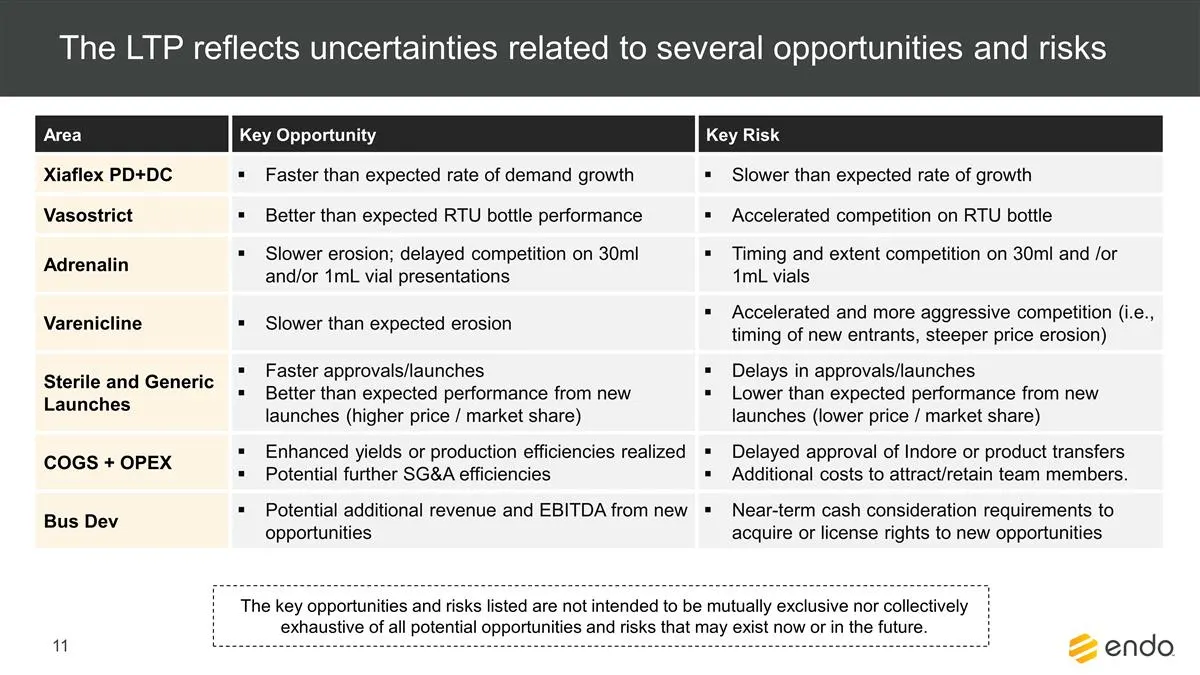
The LTP reflects uncertainties related to several opportunities and risks Area Key Opportunity Key Risk Xiaflex PD+DC Faster than expected rate of demand growth Slower than expected rate of growth Vasostrict Better than expected RTU bottle performance Accelerated competition on RTU bottle Adrenalin
Slide 13: Table of Contents
Table of Contents Executive Summary Sep 2023 Long Term Plan Sep 2023 Segment Projections
Slide 14: Branded portfolio to deliver solid and sustainable growth
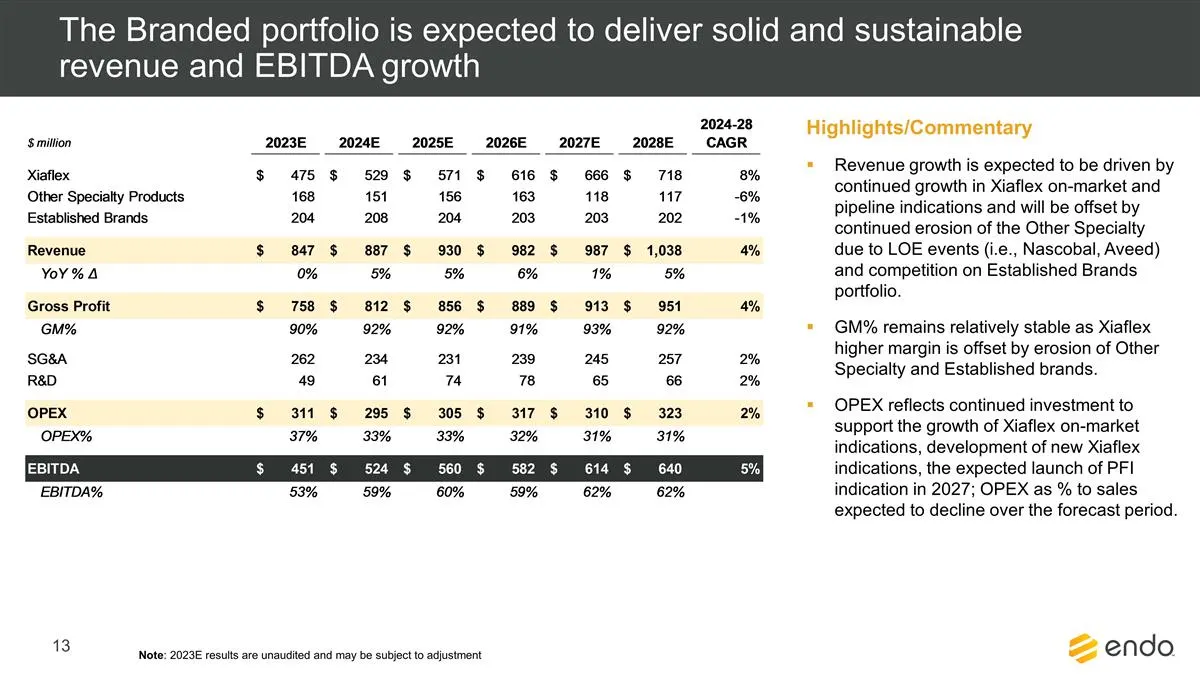
The Branded portfolio is expected to deliver solid and sustainable revenue and EBITDA growth Highlights/Commentary Revenue growth is expected to be driven by continued growth in Xiaflex on-market and pipeline indications and will be offset by continued erosion of the Other Specialty due to LOE event
Slide 15: Sterile Injectables pipeline has potential to deliver solid growth
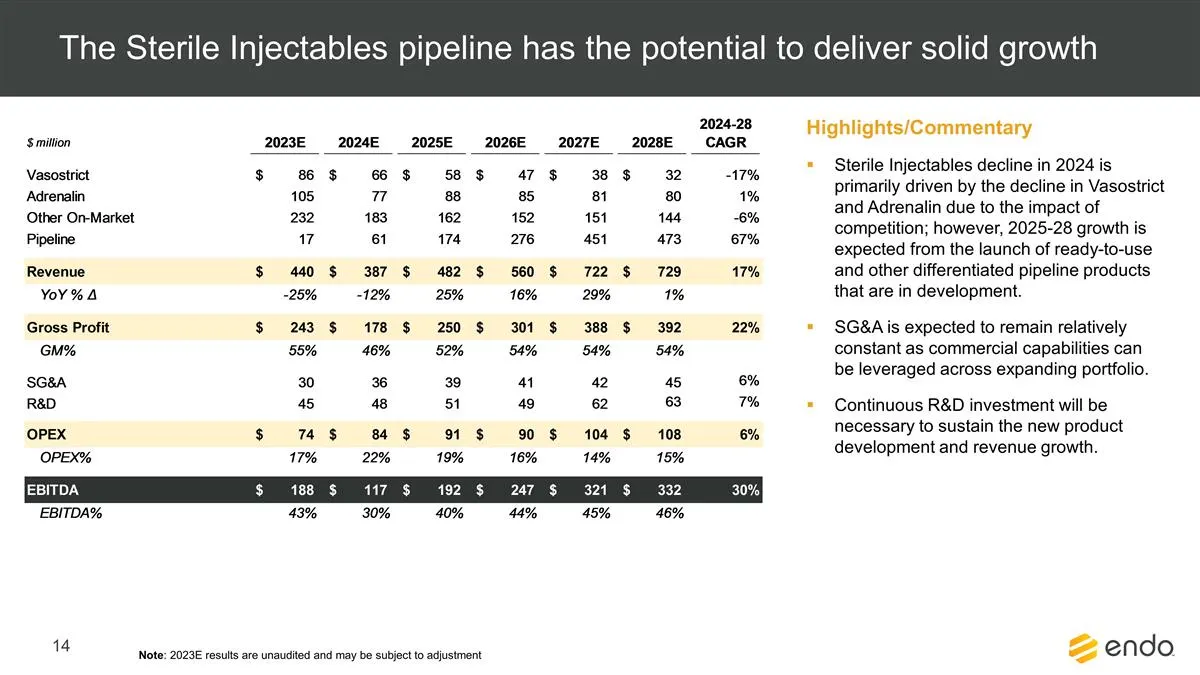
The Sterile Injectables pipeline has the potential to deliver solid growth Highlights/Commentary Sterile Injectables decline in 2024 is primarily driven by the decline in Vasostrict and Adrenalin due to the impact of competition; however, 2025-28 growth is expected from the launch of ready-to-use an
Slide 16: ~45 new Sterile product candidates in development
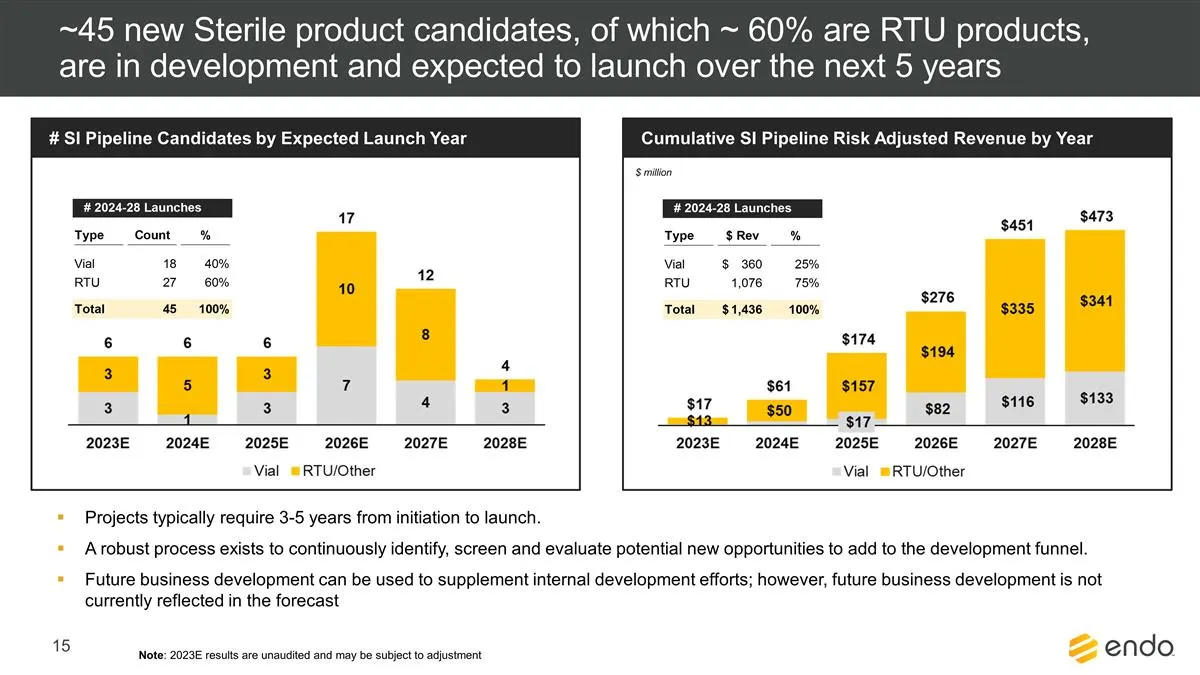
~45 new Sterile product candidates, of which ~ 60% are RTU products, are in development and expected to launch over the next 5 years Projects typically require 3-5 years from initiation to launch. A robust process exists to continuously identify, screen and evaluate potential new opportunities to ad
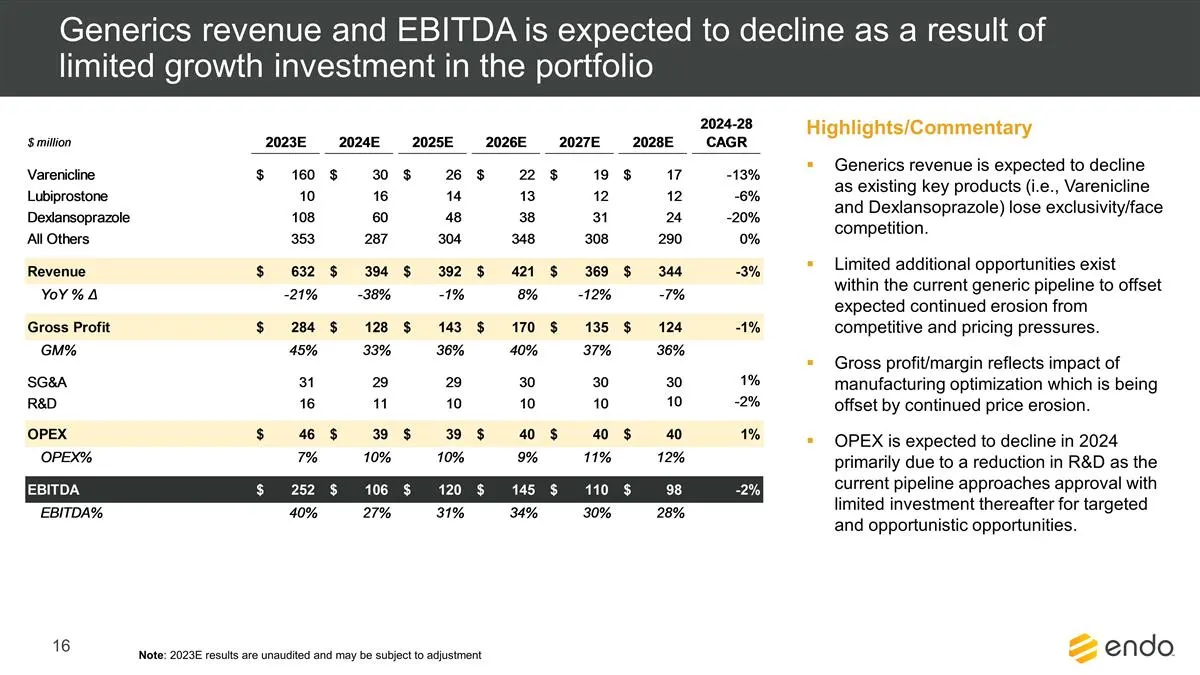
Slide 17: Generics revenue and EBITDA decline
Generics revenue and EBITDA is expected to decline as a result of limited growth investment in the portfolio Highlights/Commentary Generics revenue is expected to decline as existing key products (i.e., Varenicline and Dexlansoprazole) lose exclusivity/face competition. Limited additional opportunit
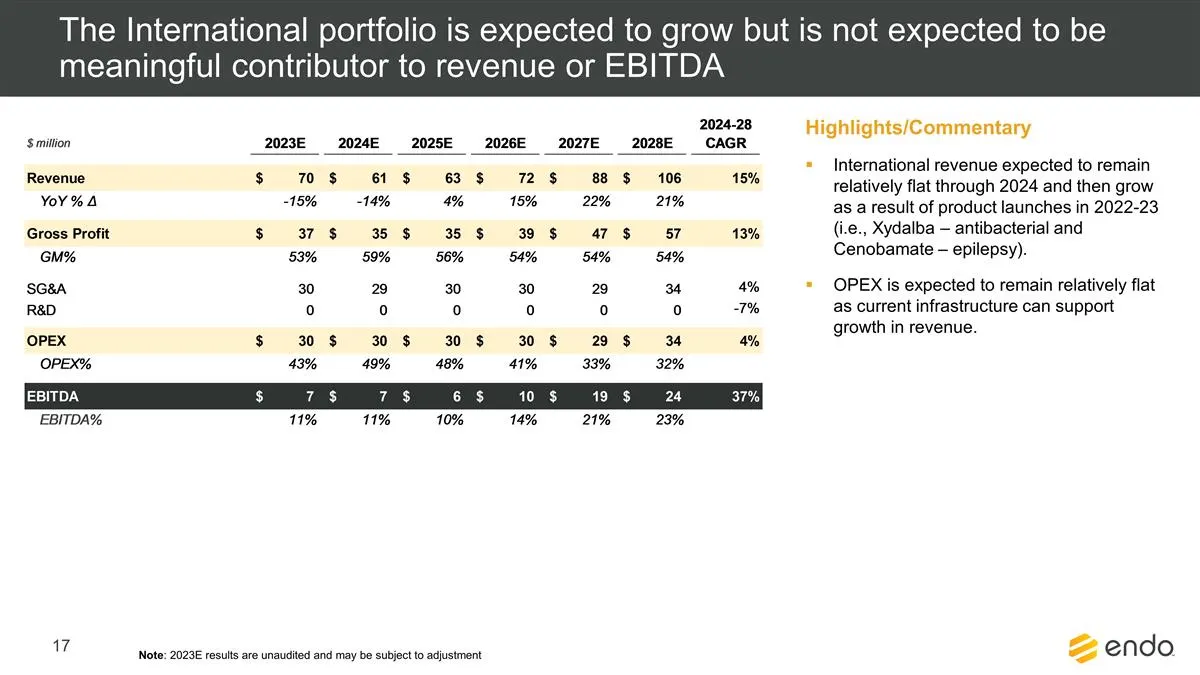
Slide 18: International portfolio to grow but not a meaningful contributor
The International portfolio is expected to grow but is not expected to be meaningful contributor to revenue or EBITDA Highlights/Commentary International revenue expected to remain relatively flat through 2024 and then grow as a result of product launches in 2022-23 (i.e., Xydalba – antibacterial an
Source: SEC EDGAR · 8-K filed Nov 6, 2023
More decks from Endo International PLC
 Corporate Update (February 2023)19 slides · Feb 14, 2023
 Corporate Update (December 2022)6 slides · Dec 6, 2022
 Investor Presentation (August 2022)72 slides · Aug 17, 2022
 Q4 2021 Earnings Presentation21 slides · Feb 28, 2022
 J.P. Morgan Healthcare Conference 202213 slides · Jan 11, 2022
 J.P. Morgan Healthcare Conference 202114 slides · Jan 12, 2021