Markwest Energy Partners LP — Platts Appalachian Gas Conference 2012
23 slides from Markwest Energy Partners LP's conference presentation, Oct 16, 2012
Slide 1: MarkWest Energy Partners Platts Appalachian Gas Conference
MarkWest Energy Partners Platts Appalachian Gas Conference October 16, 2012
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements and information. These forward-looking statements, which in many instances can be identified by words like “could,” “may,” “will,” “should,” “expects,” “plans,” “project,” “anticipates,” “believes,” “planned,” “proposed
Slide 3: MarkWest Operational Assets: Focused on the Shales
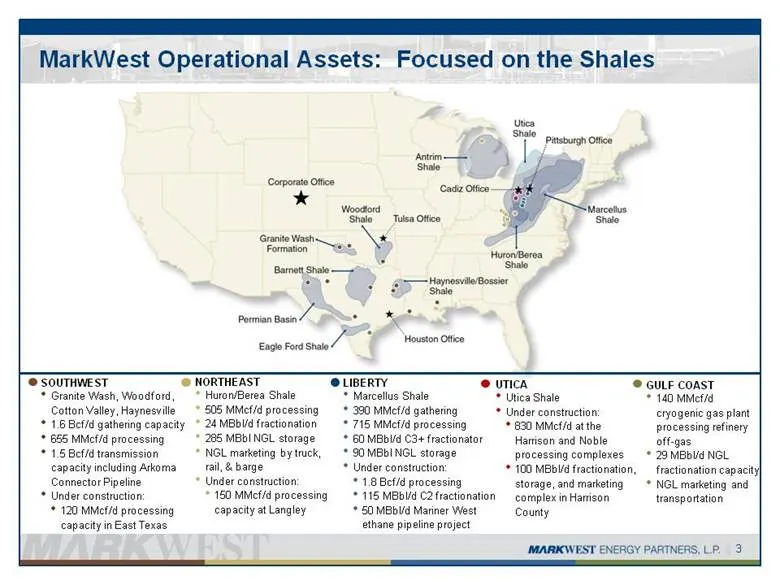
MarkWest Operational Assets: Focused on the Shales UTICA Utica Shale Under construction: 830 MMcf/d at the Harrison and Noble processing complexes 100 MBbl/d fractionation, storage, and marketing complex in Harrison County SOUTHWEST Granite Wash, Woodford, Cotton Valley, Haynesville 1.6 Bcf/d gather
Slide 4: Growth Driven by Customer Satisfaction
Growth Driven by Customer Satisfaction 4 Ranked #1 in Midstream Customer Satisfaction Survey for 2011 Since 2006, we have been ranked #1 or #2 by EnergyPoint Research
Slide 5: Contributions to Operating Income by Segment
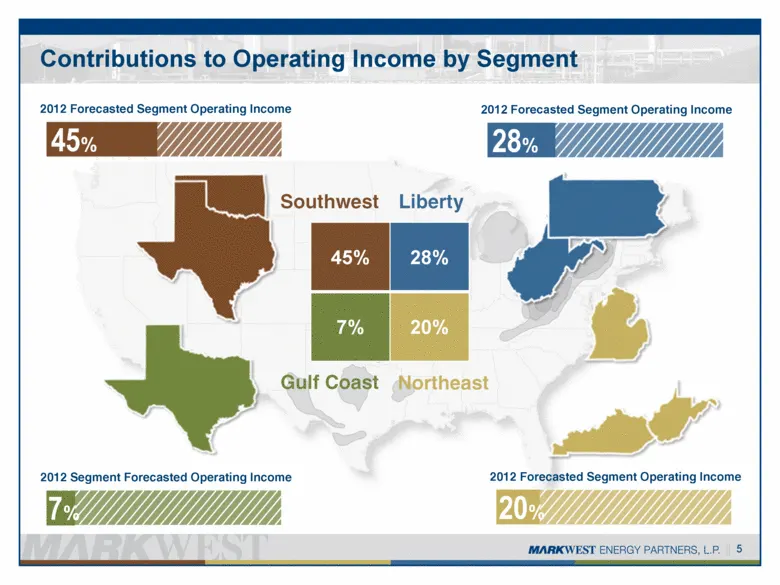
Contributions to Operating Income by Segment 5 45% 2012 Forecasted Segment Operating Income 28% 2012 Forecasted Segment Operating Income 7% 2012 Forecasted Segment Operating Income 20% 2012 Forecasted Segment Operating Income 45% 28% 7% 20% Southwest Gulf Coast Northeast Liberty
Slide 6: MarkWest: The Midstream Leader in the Northeast Shales
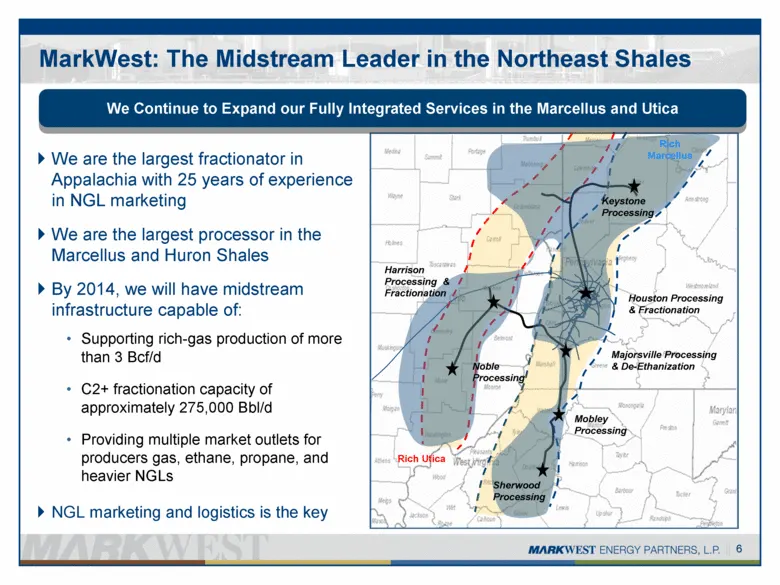
MarkWest: The Midstream Leader in the Northeast Shales We Continue to Expand our Fully Integrated Services in the Marcellus and Utica We are the largest fractionator in Appalachia with 25 years of experience in NGL marketing We are the largest processor in the Marcellus and Huron Shales By 2014, we
Slide 7: MarkWest Liberty: Growing to 2.5 Bcf/d of Processing Capacity
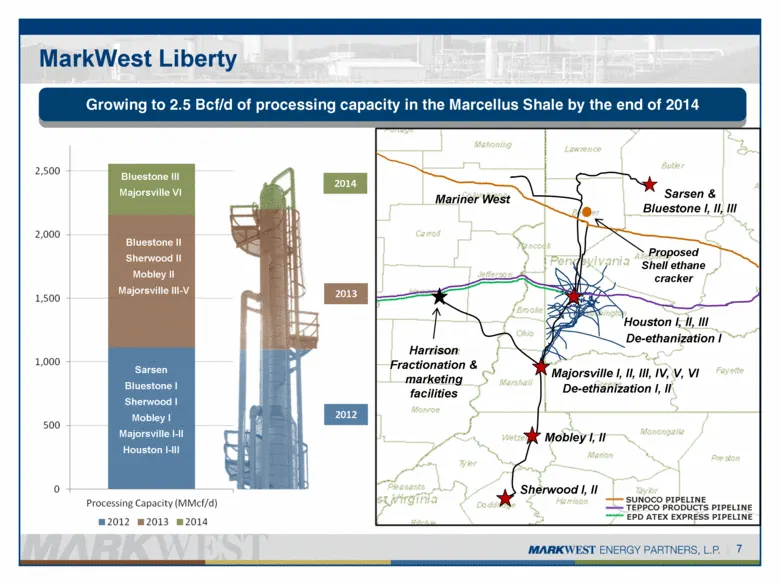
MarkWest Liberty 7 Growing to 2.5 Bcf/d of processing capacity in the Marcellus Shale by the end of 2014 TEPPCO PRODUCTS PIPELINE SUNOCO PIPELINE EPD ATEX EXPRESS PIPELINE Mariner West De-ethanization I Houston I, II, III De-ethanization I, II Majorsville I, II, III, IV, V, VI Sarsen & Bluestone I,
Slide 8: MarkWest Utica JV Processing Capacity Growth
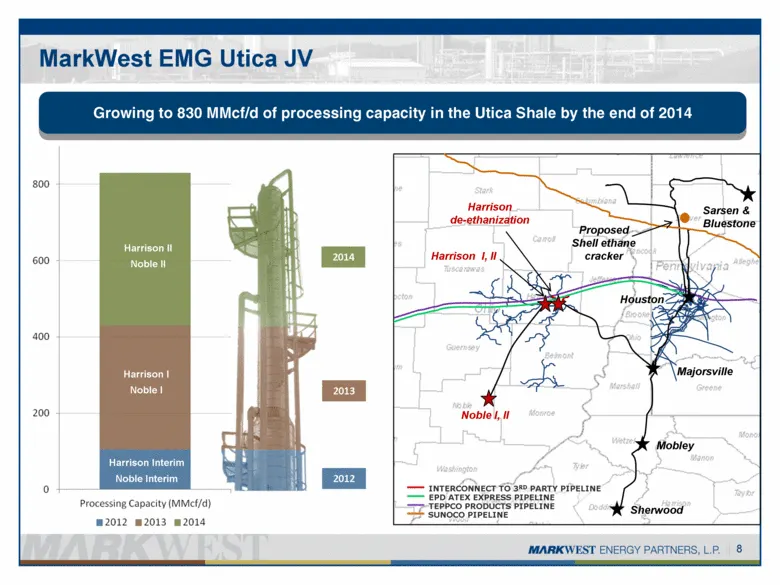
MarkWest Utica JV 8 Growing to 830 MMcf/d of processing capacity in the Utica Shale by the end of 2014 Mobley Sherwood Houston Majorsville Noble I, II Harrison de-ethanization Proposed Shell ethane cracker TEPPCO PRODUCTS PIPELINE EPD ATEX EXPRESS PIPELINE Sarsen & Bluestone INTERCONNECT TO 3RD PART
Slide 9: MarkWest Liberty & Utica Project Schedules
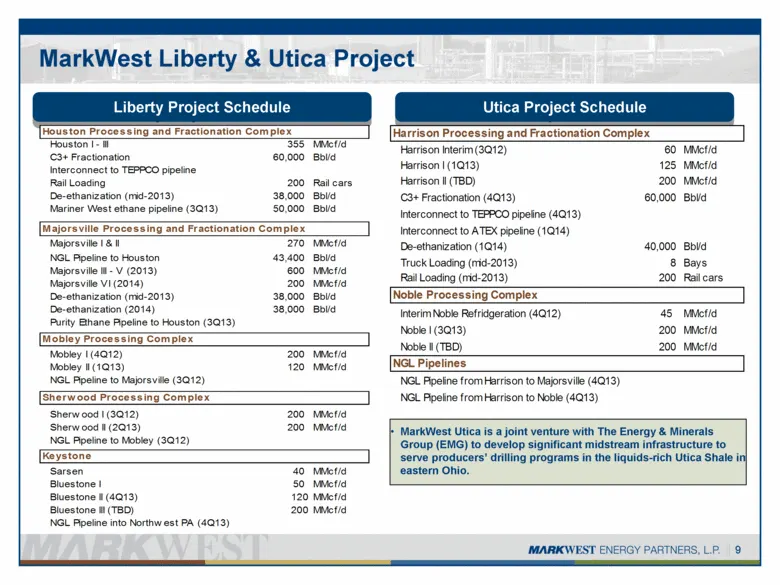
MarkWest Liberty & Utica Project 9 Liberty Project Schedule Utica Project Schedule MarkWest Utica is a joint venture with The Energy & Minerals Group (EMG) to develop significant midstream infrastructure to serve producers’ drilling programs in the liquids-rich Utica Shale in eastern Ohio. Houston P
Slide 10: MarkWest's Role in New Processing Expansions
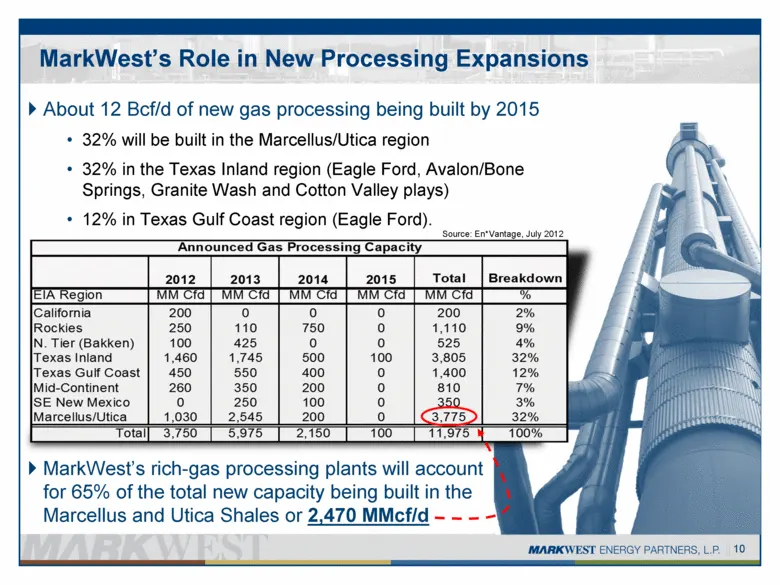
MarkWest’s Role in New Processing Expansions Source: En*Vantage, July 2012 10 About 12 Bcf/d of new gas processing being built by 2015 32% will be built in the Marcellus/Utica region 32% in the Texas Inland region (Eagle Ford, Avalon/Bone Springs, Granite Wash and Cotton Valley plays) 12% in Texas G
Slide 11: MarkWest's Growing Role in Processing – En*Vantage
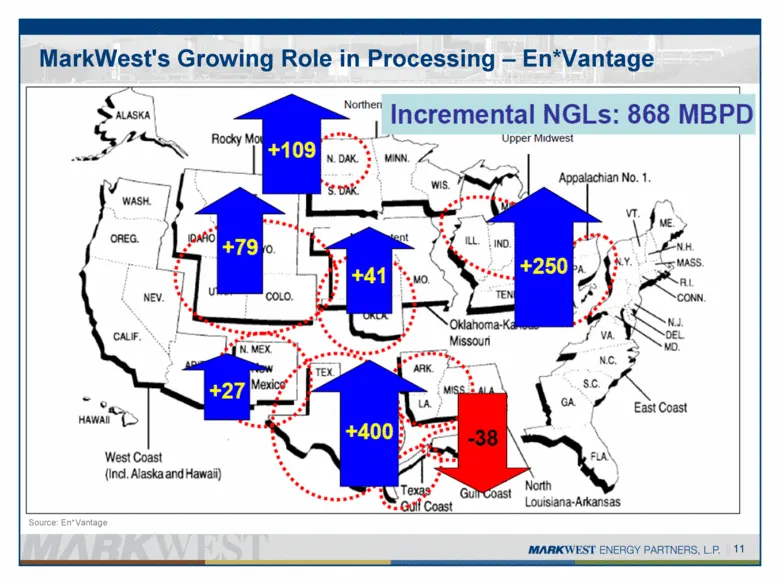
11 MarkWest's Growing Role in Processing – En*Vantage Source: En*Vantage
Slide 12: Announced Increases of Major Frac Capacity
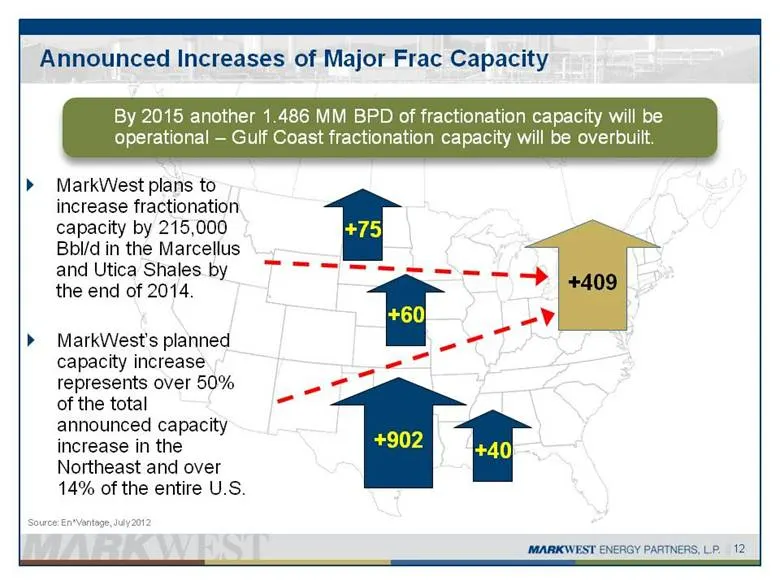
12 Announced Increases of Major Frac Capacity Source: En*Vantage, July 2012 +60 +902 +40 +409 +75 MarkWest plans to increase fractionation capacity by 215,000 Bbl/d in the Marcellus and Utica Shales by the end of 2014. MarkWest’s planned capacity increase represents over 50% of the total announced c
Slide 13: MarkWest Fractionation Capacity
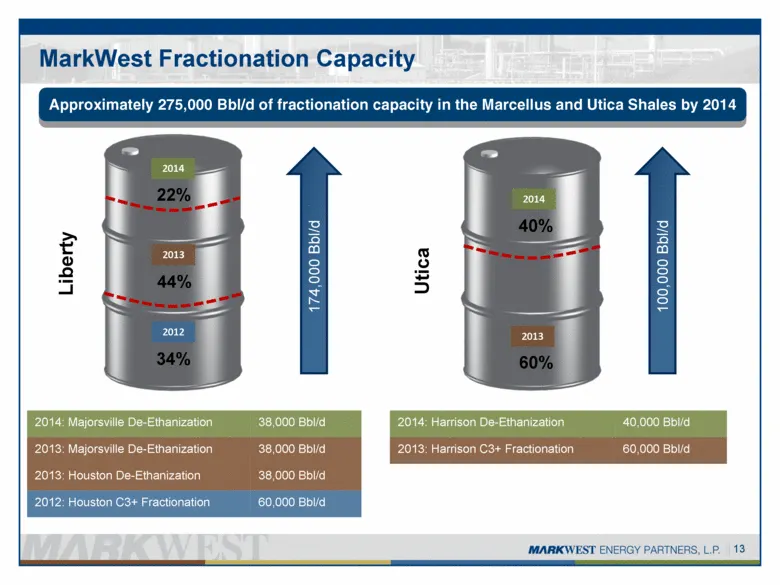
60% 40% MarkWest Fractionation Capacity 13 Approximately 275,000 Bbl/d of fractionation capacity in the Marcellus and Utica Shales by 2014 2014 2013 2012 2014: Majorsville De-Ethanization 38,000 Bbl/d 2013: Majorsville De-Ethanization 38,000 Bbl/d 2013: Houston De-Ethanization 38,000 Bbl/d 2012: Hou
Slide 14: Max US Ethane Supply vs. Max Ethane Cracking Capability
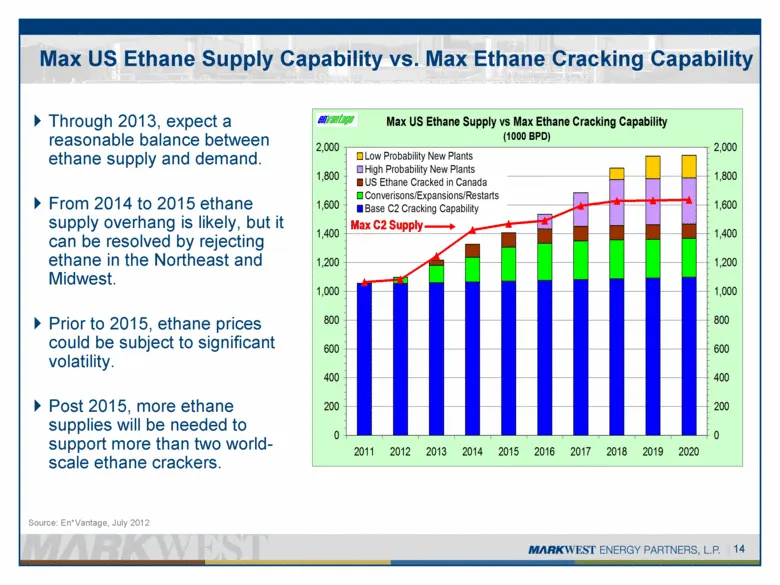
Max US Ethane Supply Capability vs. Max Ethane Cracking Capability Through 2013, expect a reasonable balance between ethane supply and demand. From 2014 to 2015 ethane supply overhang is likely, but it can be resolved by rejecting ethane in the Northeast and Midwest. Prior to 2015, ethane prices cou
Slide 15: Northeast Ethane has Multiple Markets
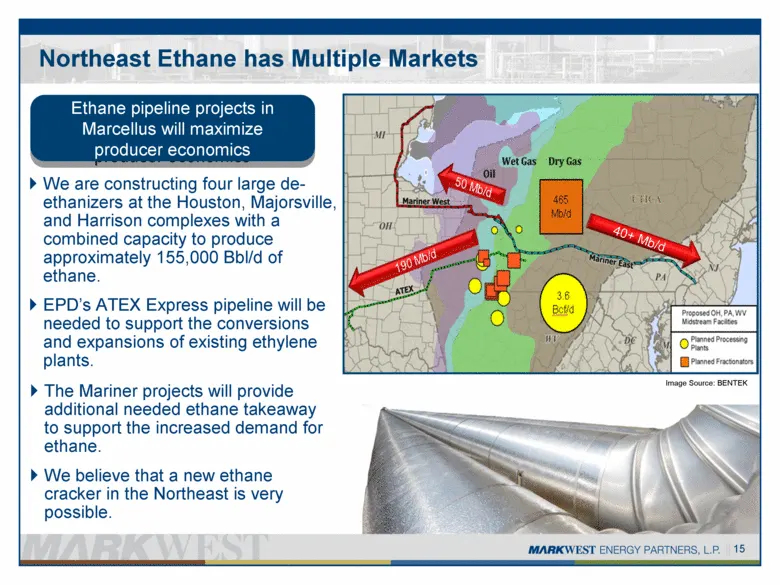
Northeast Ethane has Multiple Markets We are constructing four large de-ethanizers at the Houston, Majorsville, and Harrison complexes with a combined capacity to produce approximately 155,000 Bbl/d of ethane. EPD’s ATEX Express pipeline will be needed to support the conversions and expansions of ex
Slide 16: Outlook For US Propane Supply & Demand – En*Vantage
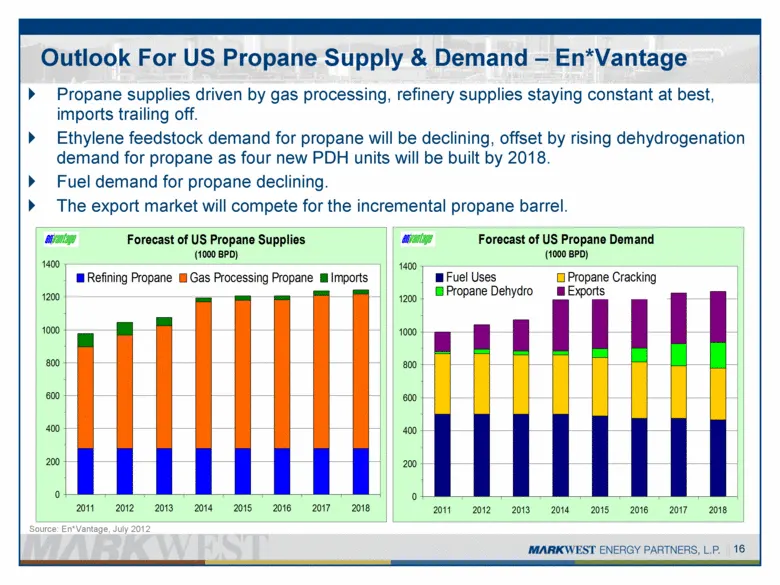
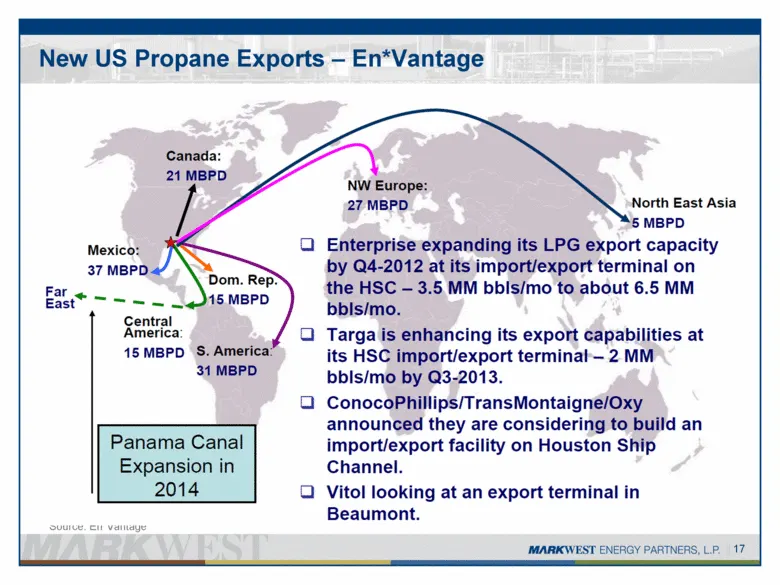
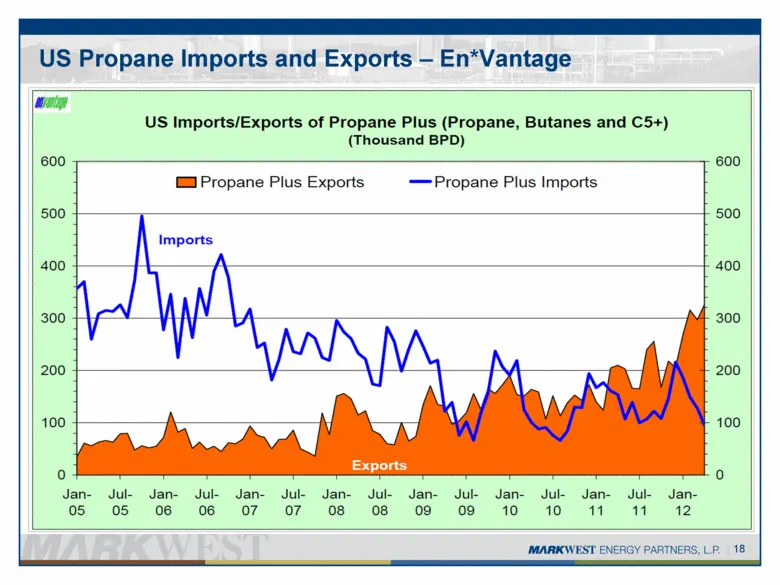
Outlook For US Propane Supply & Demand – En*Vantage Propane supplies driven by gas processing, refinery supplies staying constant at best, imports trailing off. Ethylene feedstock demand for propane will be declining, offset by rising dehydrogenation demand for propane as four new PDH units will be
Slide 17: New US Propane Exports – En*Vantage
17 New US Propane Exports – En*Vantage Source: En*Vantage
Slide 18: US Propane Imports and Exports – En*Vantage
18 US Propane Imports and Exports – En*Vantage Source: En*Vantage
Slide 19: Northeast Propane can Access International Markets
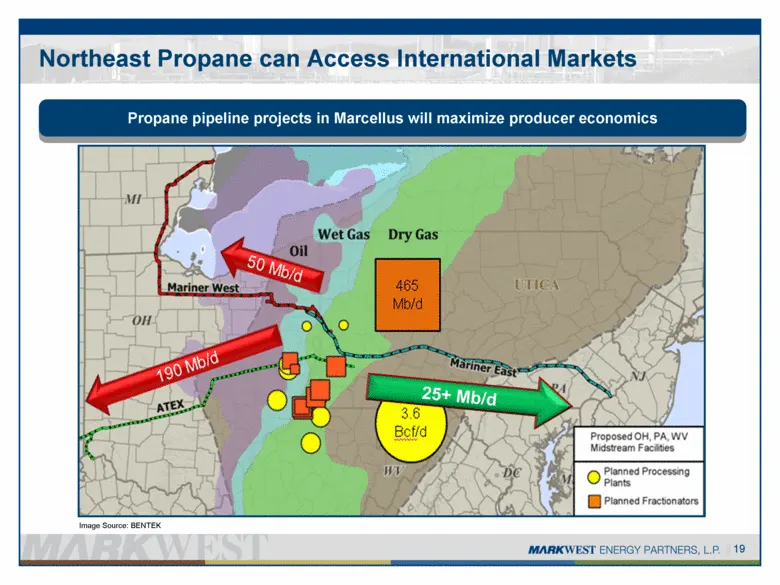
Northeast Propane can Access International Markets Propane pipeline projects in Marcellus will maximize producer economics Image Source: BENTEK 25+ Mb/d 19
Slide 20: Northeast Propane Supply & Demand – Wells Fargo Perspective
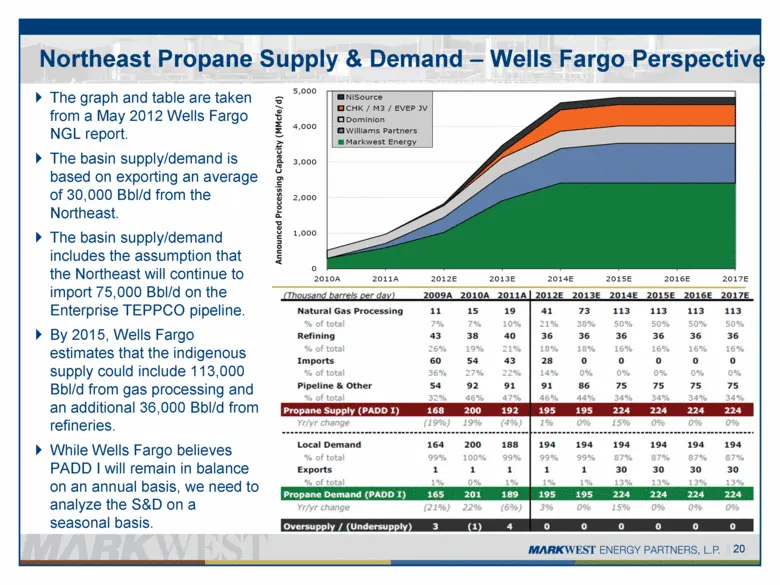
Northeast Propane Supply & Demand – Wells Fargo Perspective The graph and table are taken from a May 2012 Wells Fargo NGL report. The basin supply/demand is based on exporting an average of 30,000 Bbl/d from the Northeast. The basin supply/demand includes the assumption that the Northeast will conti
Slide 21: Northeast Propane Supply & Demand – MarkWest Perspective
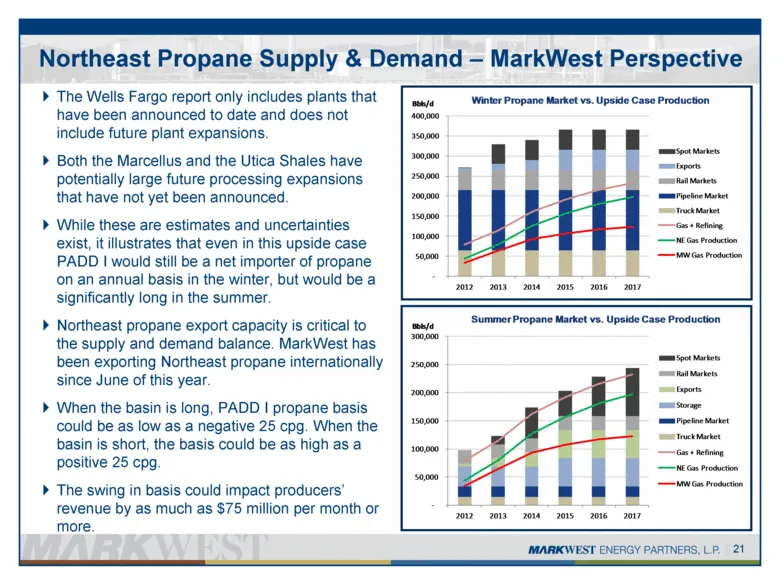
Northeast Propane Supply & Demand – MarkWest Perspective The Wells Fargo report only includes plants that have been announced to date and does not include future plant expansions. Both the Marcellus and the Utica Shales have potentially large future processing expansions that have not yet been annou
Slide 22: Growth By Design
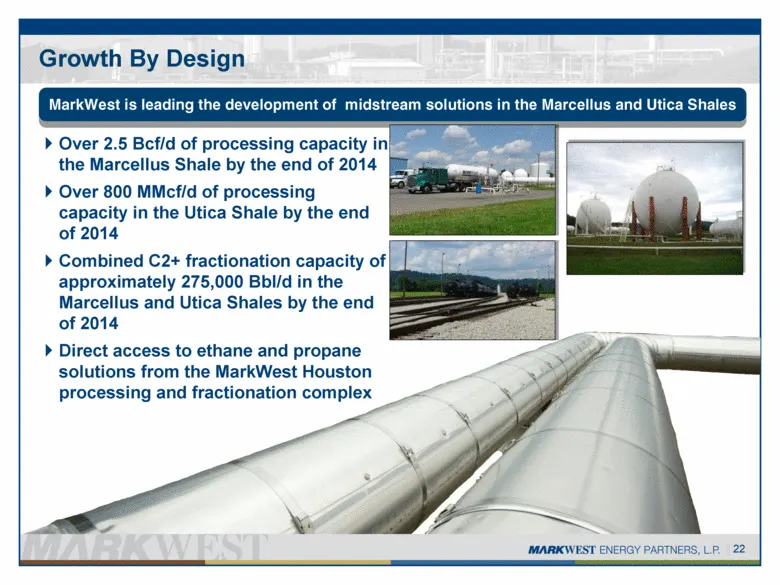
Growth By Design 22 MarkWest is leading the development of midstream solutions in the Marcellus and Utica Shales Over 2.5 Bcf/d of processing capacity in the Marcellus Shale by the end of 2014 Over 800 MMcf/d of processing capacity in the Utica Shale by the end of 2014 Combined C2+ fractionation cap
Slide 23: Contact and Investor Relations
1515 ARAPAHOE STREET TOWER 1, SUITE 1600 DENVER, COLORADO 80202 PHONE: 303-925-9200 INVESTOR RELATIONS: 866-858-0482 EMAIL: INVESTORRELATIONS@MARKWEST.COM WEBSITE: WWW.MARKWEST.COM
Source: SEC EDGAR · 8-K filed Oct 16, 2012
More decks from Markwest Energy Partners LP
 Fact Sheet (July 2017)1 slide · July 2017
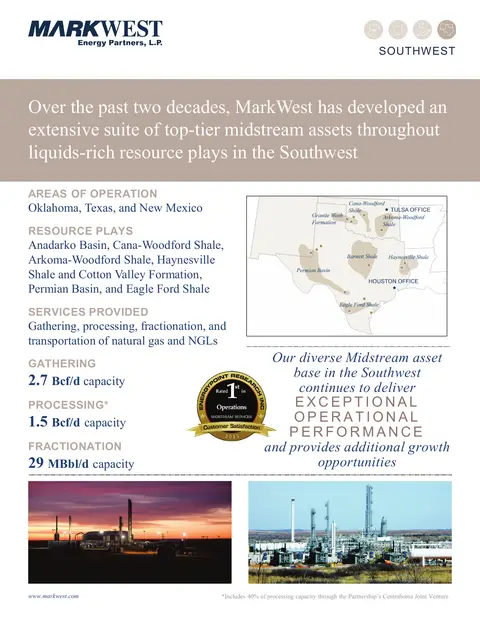 Fact Sheet (July 2017)1 slide · July 2017
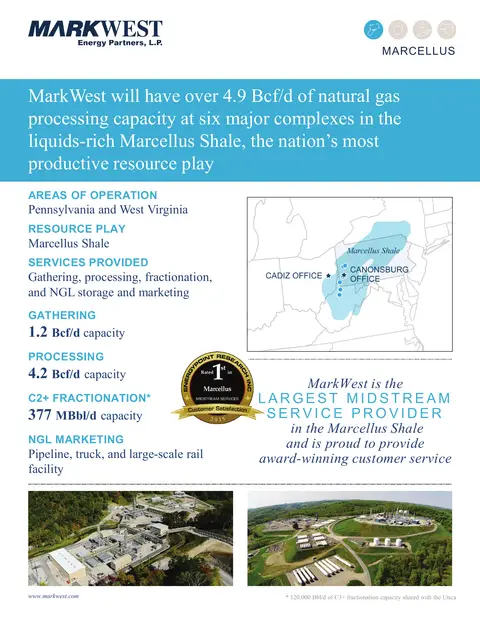 Fact Sheet (July 2017)1 slide · July 2017
 Markwest Energy Partners L P — Investor Day (December 2015)116 slides · Dec 3, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 13, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 12, 2015