Sappi Limited · JSE:SAP
Sappi — Investor Presentation (May 2017)
66 slides from Sappi's investor presentation, May 2017
Slide 1: Roadbook 2017 May
Roadbook 2017 May Sappi Limited
Slide 2: Forward-looking statements and Regulation G
Forward-looking statements and Regulation G Forward-looking statements Certain statements in this release that are neither reported financial results nor other historical information, are forward-looking statements, including but not limited to statements that are predictions of or indicate future e
Slide 3: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 3
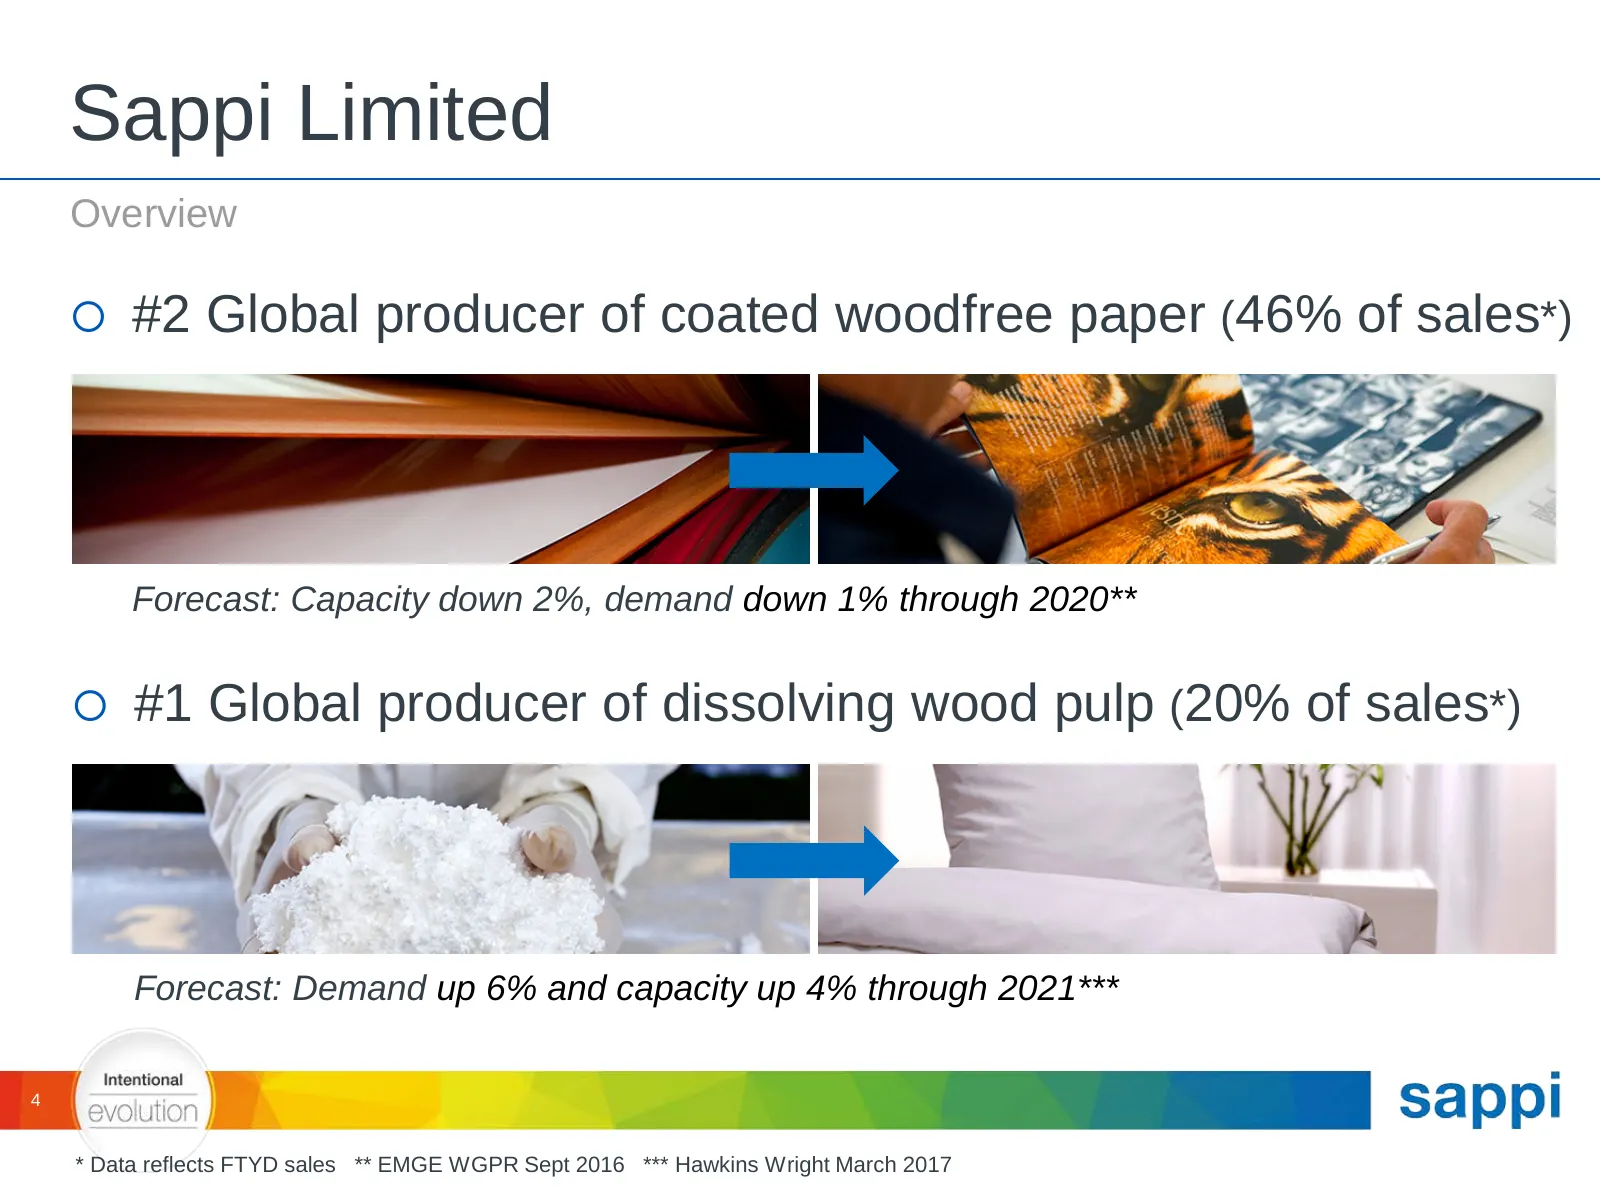
Slide 4: Sappi Limited Overview
Sappi Limited Overview #2 Global producer of coated woodfree paper (46% of sales*) Forecast: Capacity down 2%, demand down 1% through 2020** #1 Global producer of dissolving wood pulp (20% of sales*) Forecast: Demand up 6% and capacity up 4% through 2021*** 4 * Data reflects FTYD sales ** EMGE W
Slide 5: Sappi at a glance
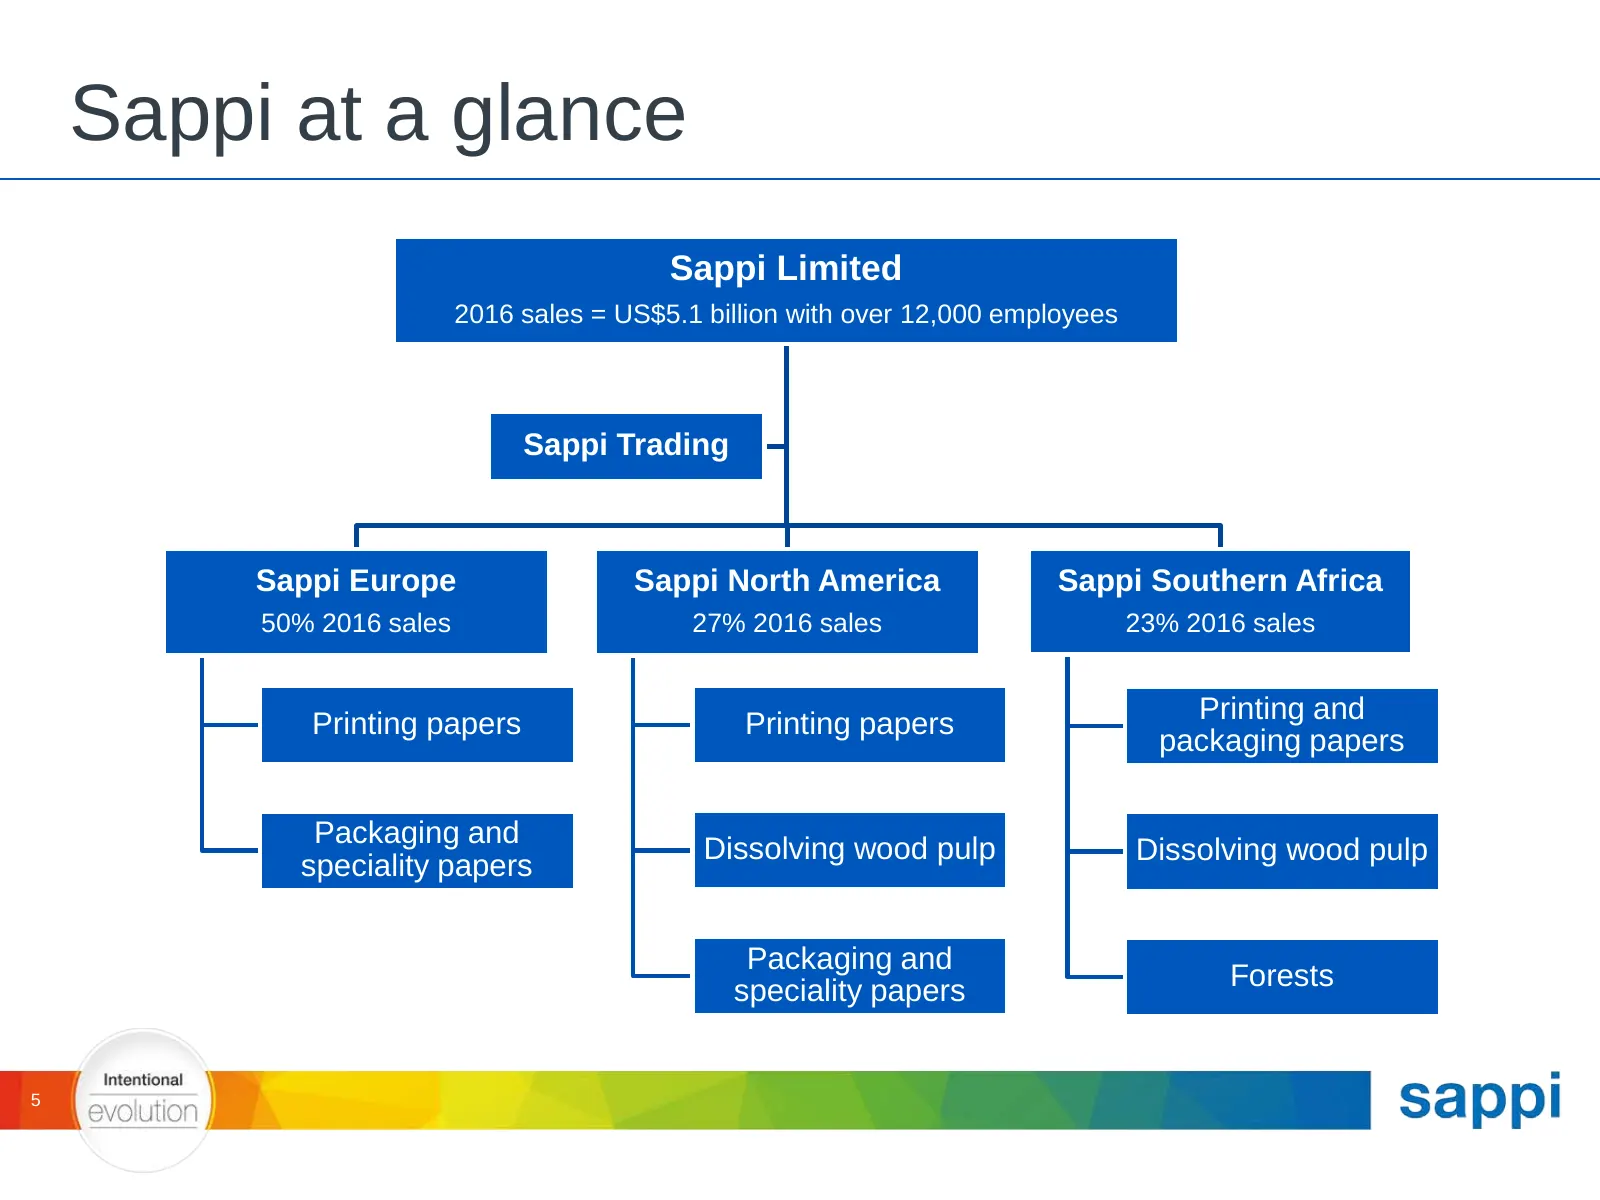
Sappi at a glance Sappi Limited 2016 sales = US$5.1 billion with over 12,000 employees Sappi Trading Sappi Europe Sappi North America Sappi Southern Africa 50% 2016 sales 27% 2016 sales 23% 2016 sales Printing papers Printing papers Printing and packaging papers Packaging and Dissolving wood pulp Di
Slide 6: Geographic diversification
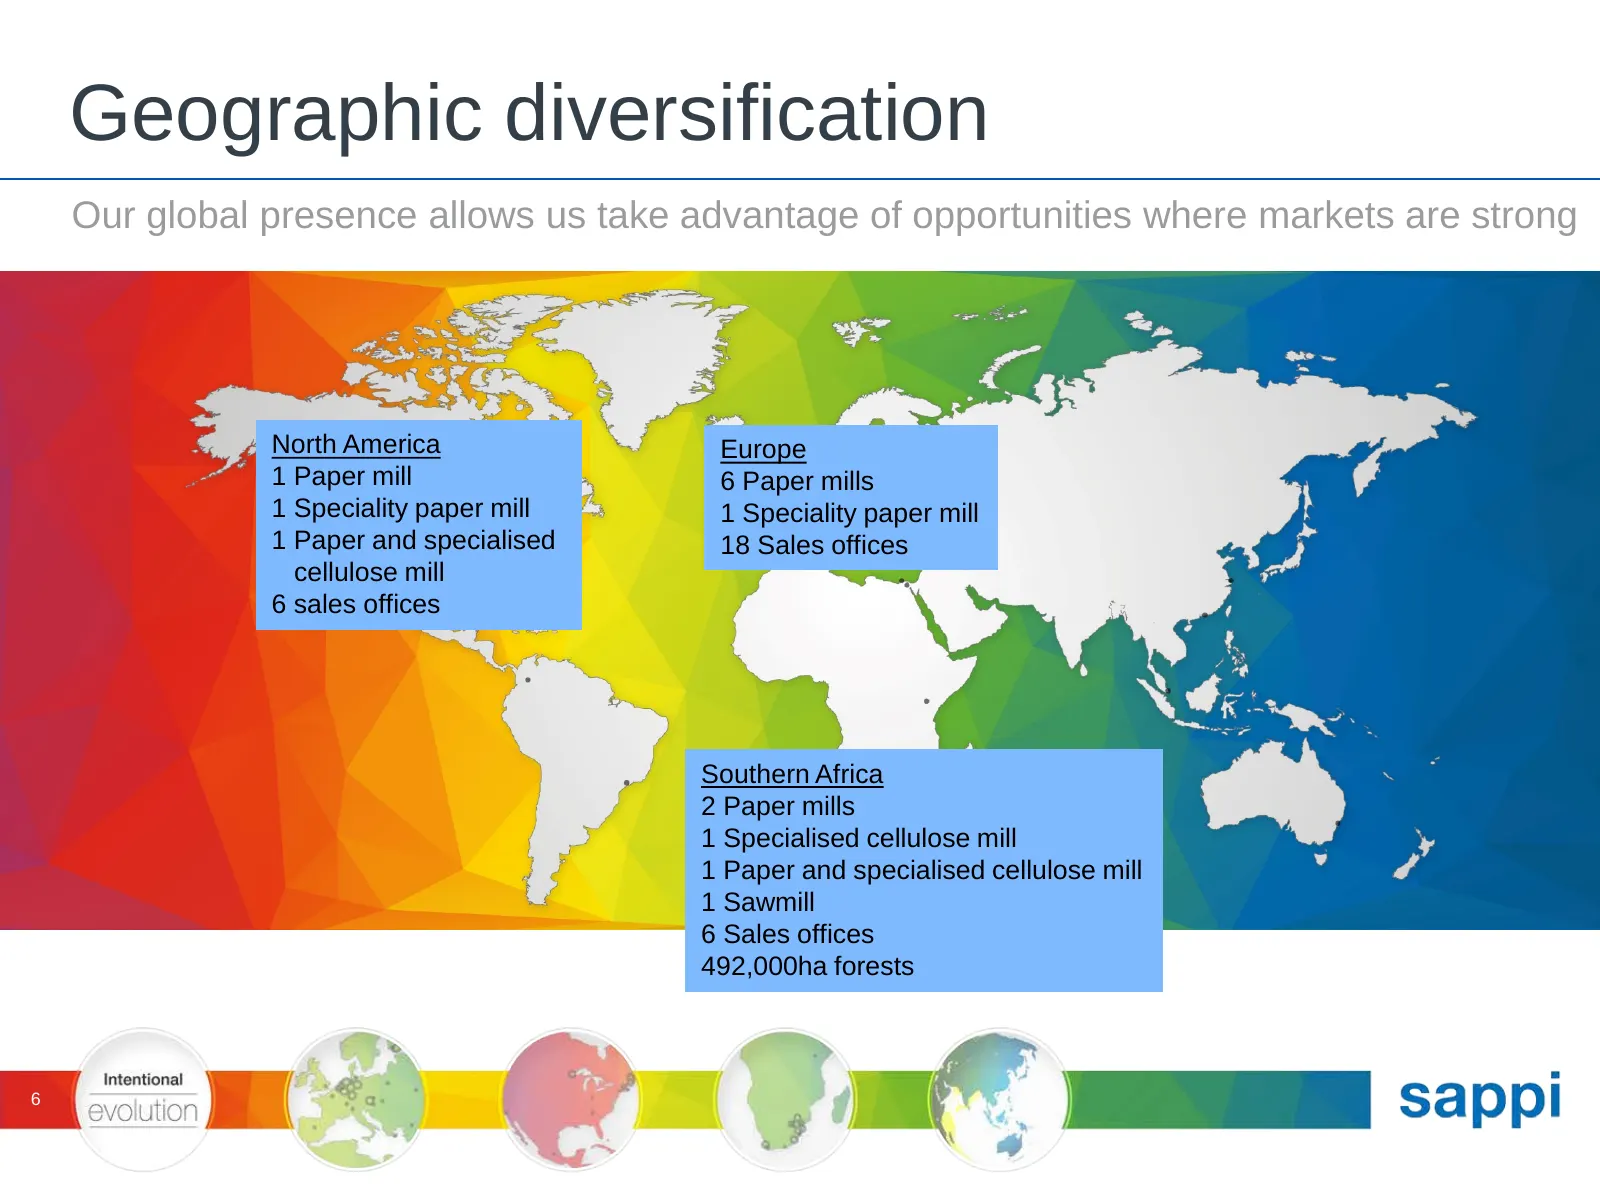
Geographic diversification Our global presence allows us take advantage of opportunities where markets are strong North America Europe 1 Paper mill 6 Paper mills 1 Speciality paper mill 1 Speciality paper mill 1 Paper and specialised 18 Sales offices cellulose mill 6 sales offices Southern Africa 2
Slide 7: Sales analysis
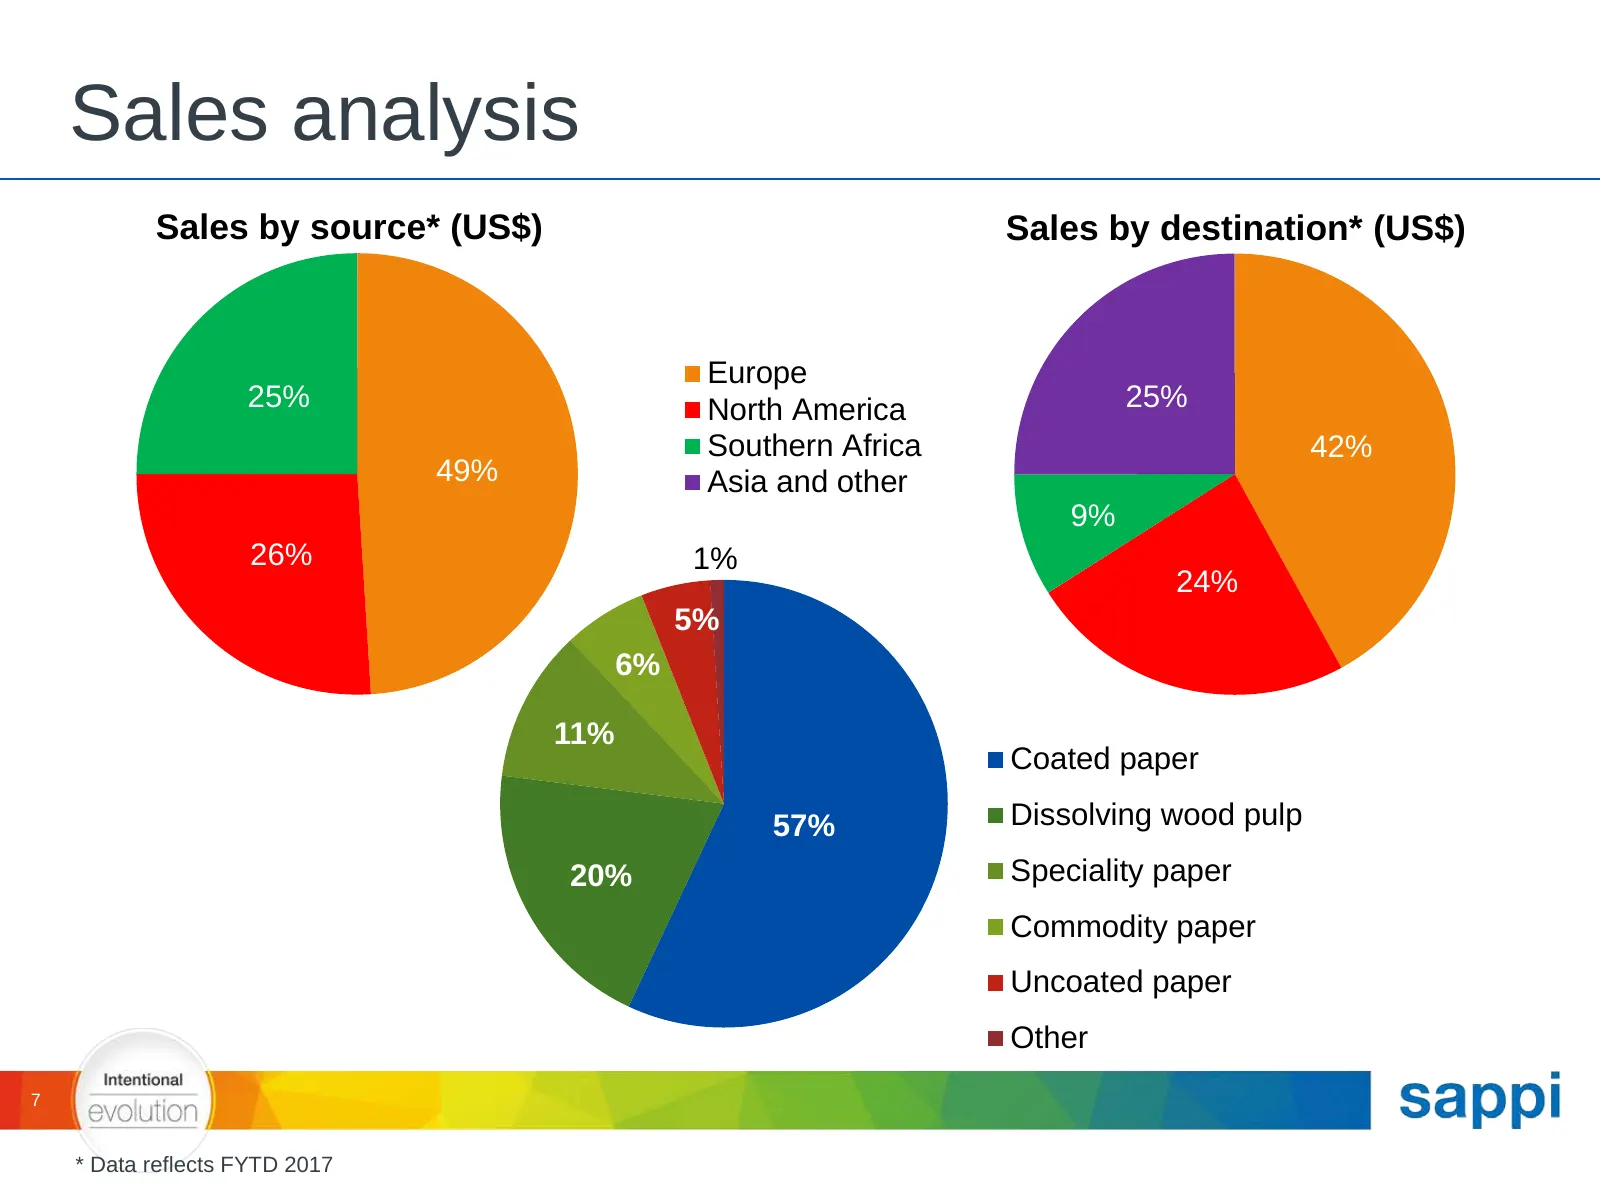
Sales analysis Sales by source* (US$) Sales by destination* (US$) Europe 25% North America 25% Southern Africa 42% 49% Asia and other 9% 26% 1% 24% 5% 6% 11% Coated paper 57% Dissolving wood pulp 20% Speciality paper Commodity paper Uncoated paper Other 7 * Data reflects FYTD 2017
Slide 8: Sales analysis
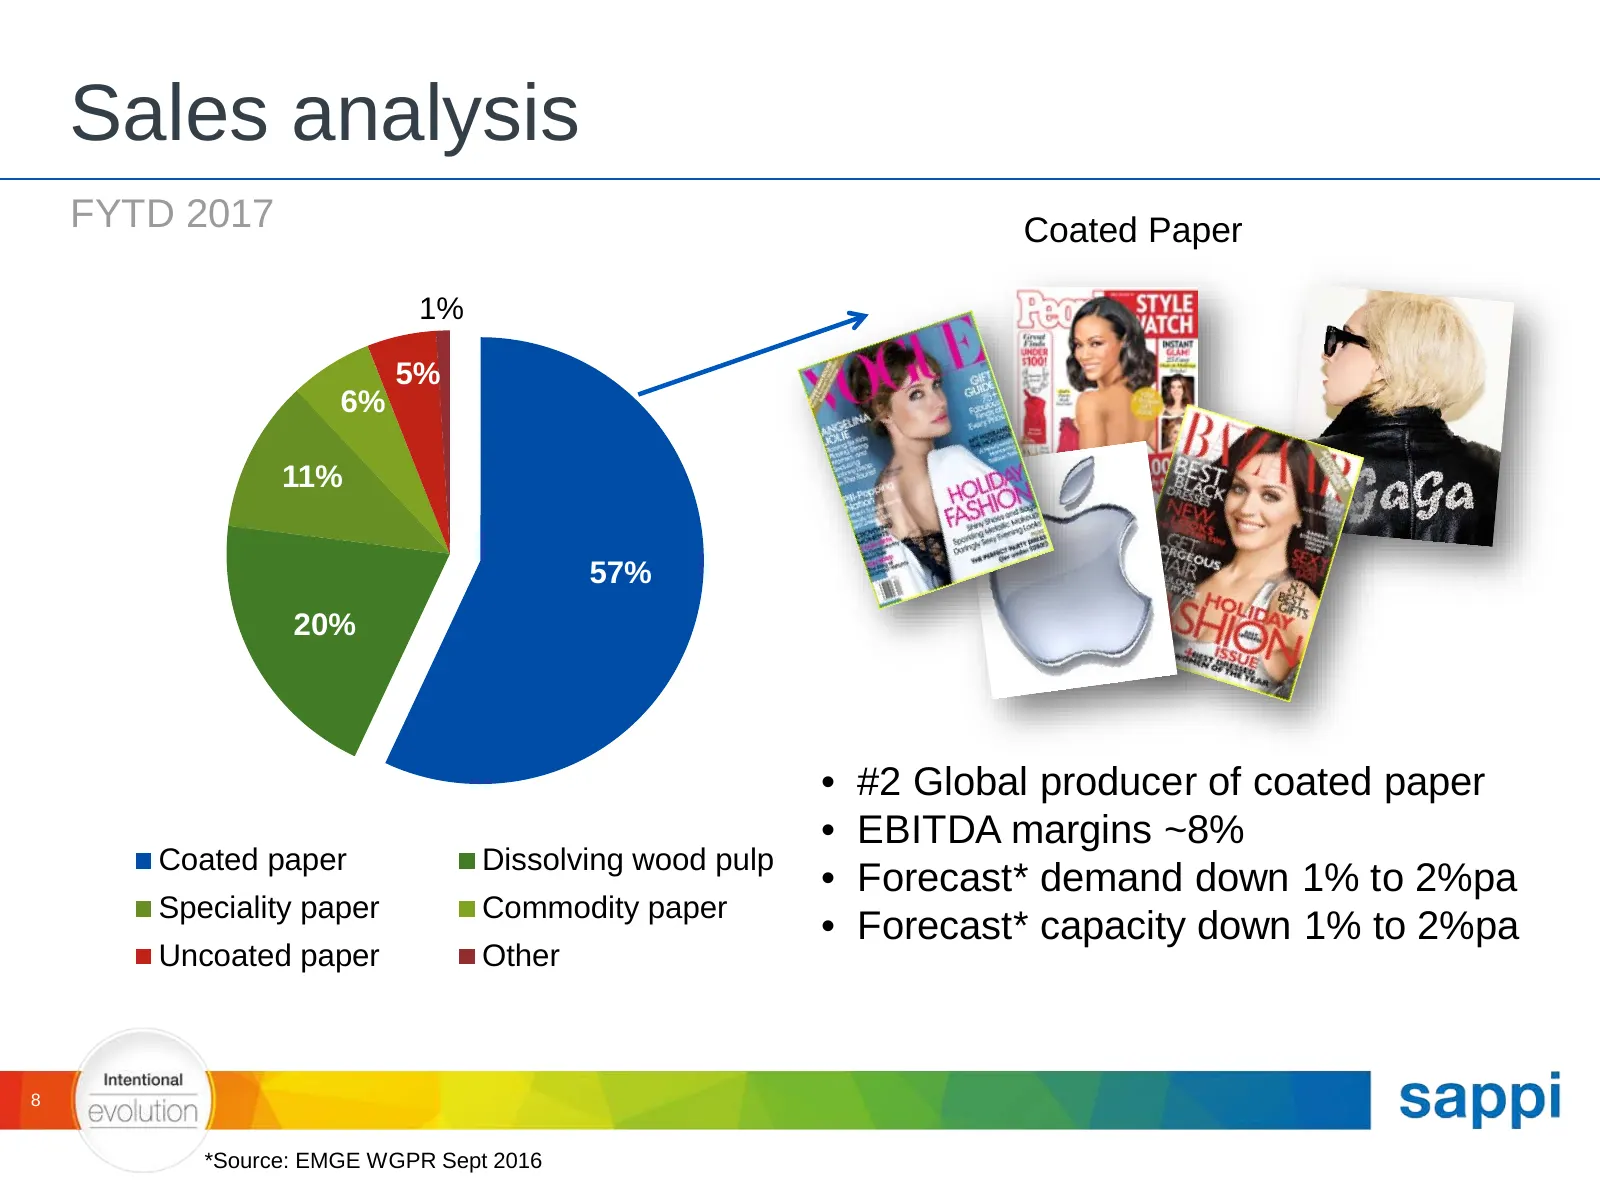
Sales analysis FYTD 2017 Coated Paper 1% 5% 6% 11% 57% 20% • #2 Global producer of coated paper • EBITDA margins ~8% Coated paper Dissolving wood pulp • Forecast* demand down 1% to 2%pa Speciality paper Commodity paper • Forecast* capacity down 1% to 2%pa Uncoated paper Other 8 *Source: EMGE WGPR Se
Slide 9: Sales analysis
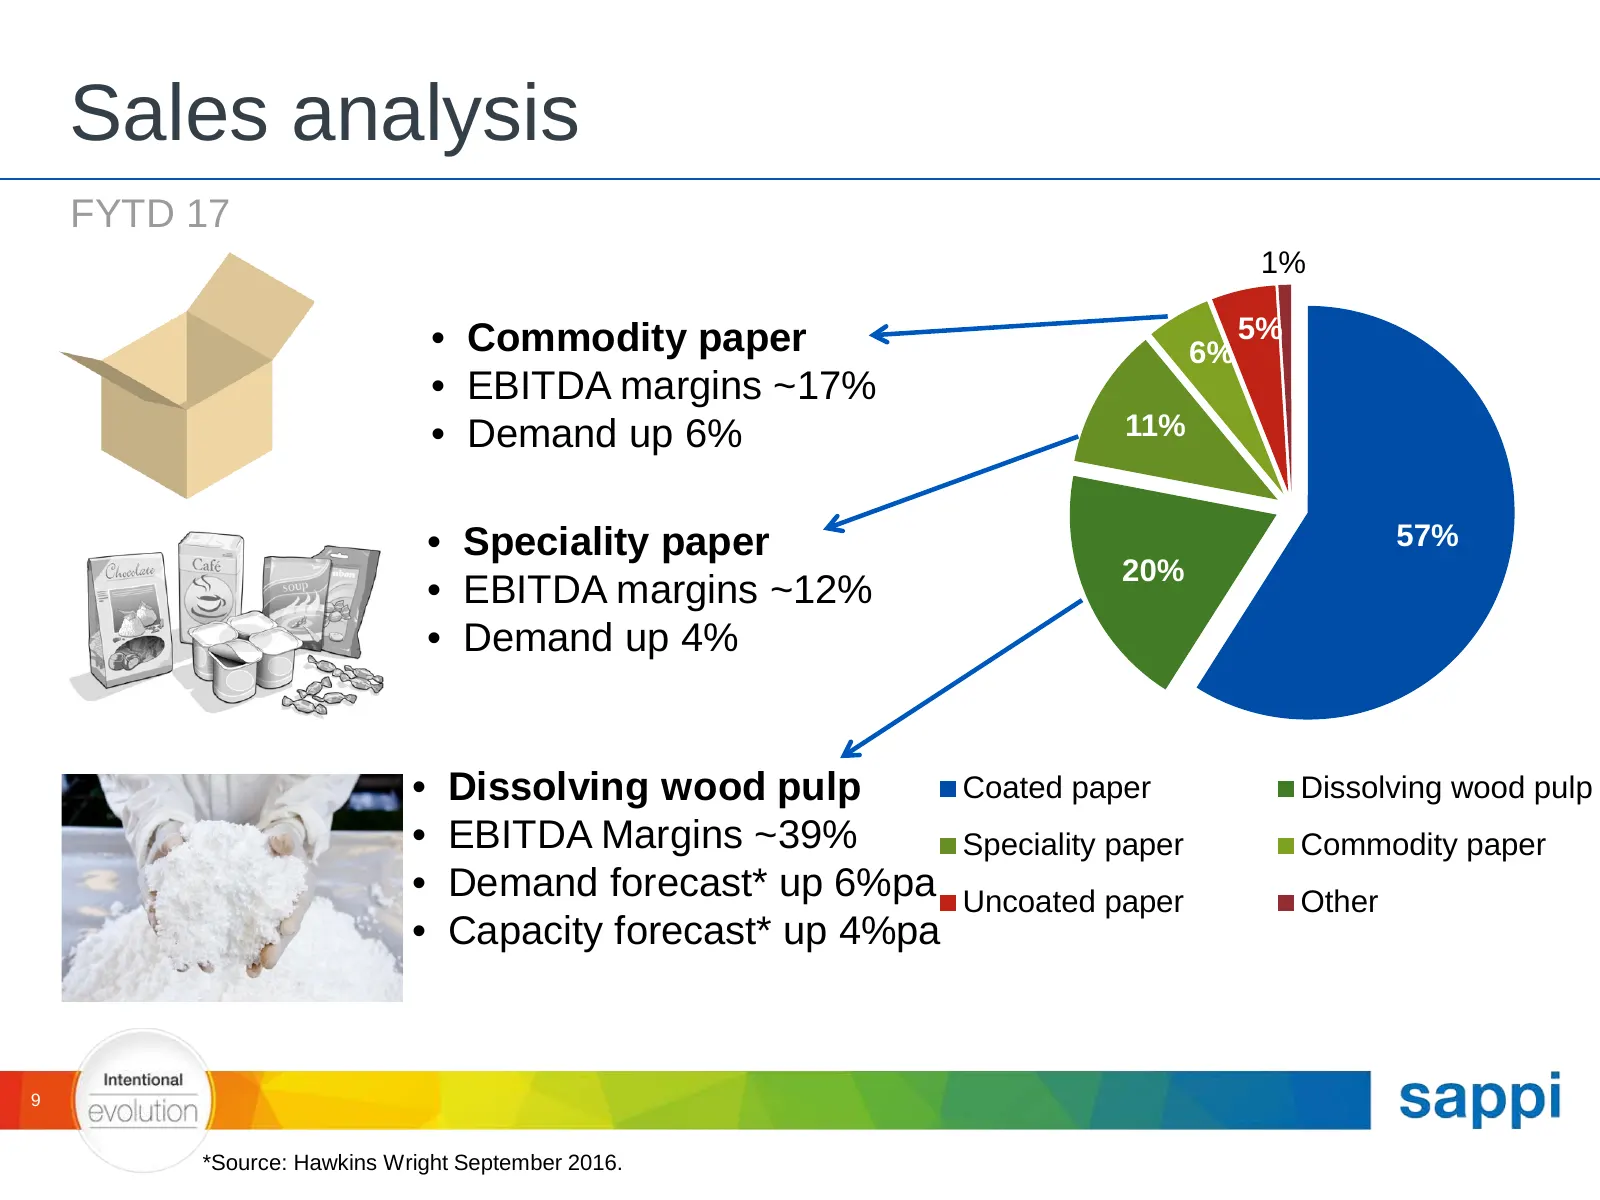
Sales analysis FYTD 17 1% • Commodity paper 5% 6% • EBITDA margins ~17% • Demand up 6% 11% • Speciality paper 57% 20% • EBITDA margins ~12% • Demand up 4% • Dissolving wood pulp Coated paper Dissolving wood pulp • EBITDA Margins ~39% Speciality paper Commodity paper • Demand forecast* up 6%pa Uncoat
Slide 10: Major Sensitivities
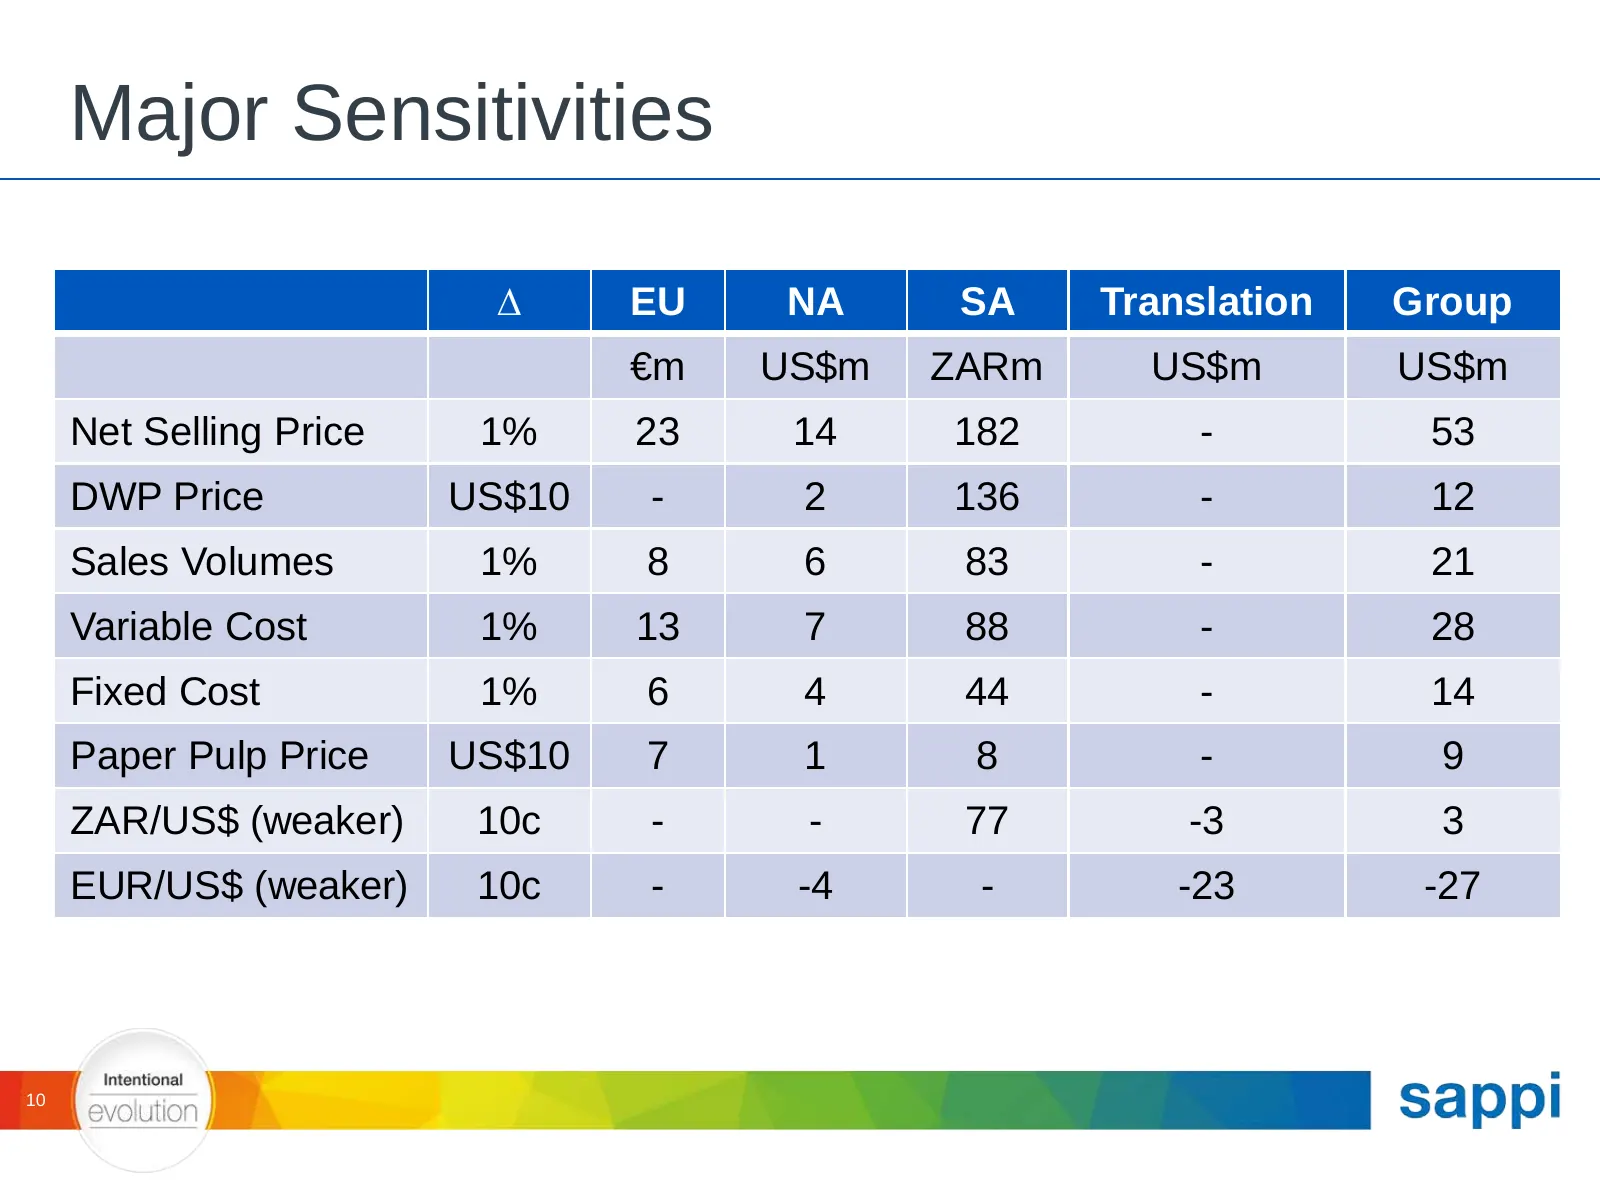
Major Sensitivities ∆ EU NA SA Translation Group €m US$m ZARm US$m US$m Net Selling Price 1% 23 14 182 - 53 DWP Price US$10 - 2 136 - 12 Sales Volumes 1% 8 6 83 - 21 Variable Cost 1% 13 7 88 - 28 Fixed Cost 1% 6 4 44 - 14 Paper Pulp Price US$10 7 1 8 - 9 ZAR/US$ (weaker) 10c - - 77 -3 3 EUR/US$ (wea
Slide 11: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 11
Slide 12: Graphic and printing papers grade structure
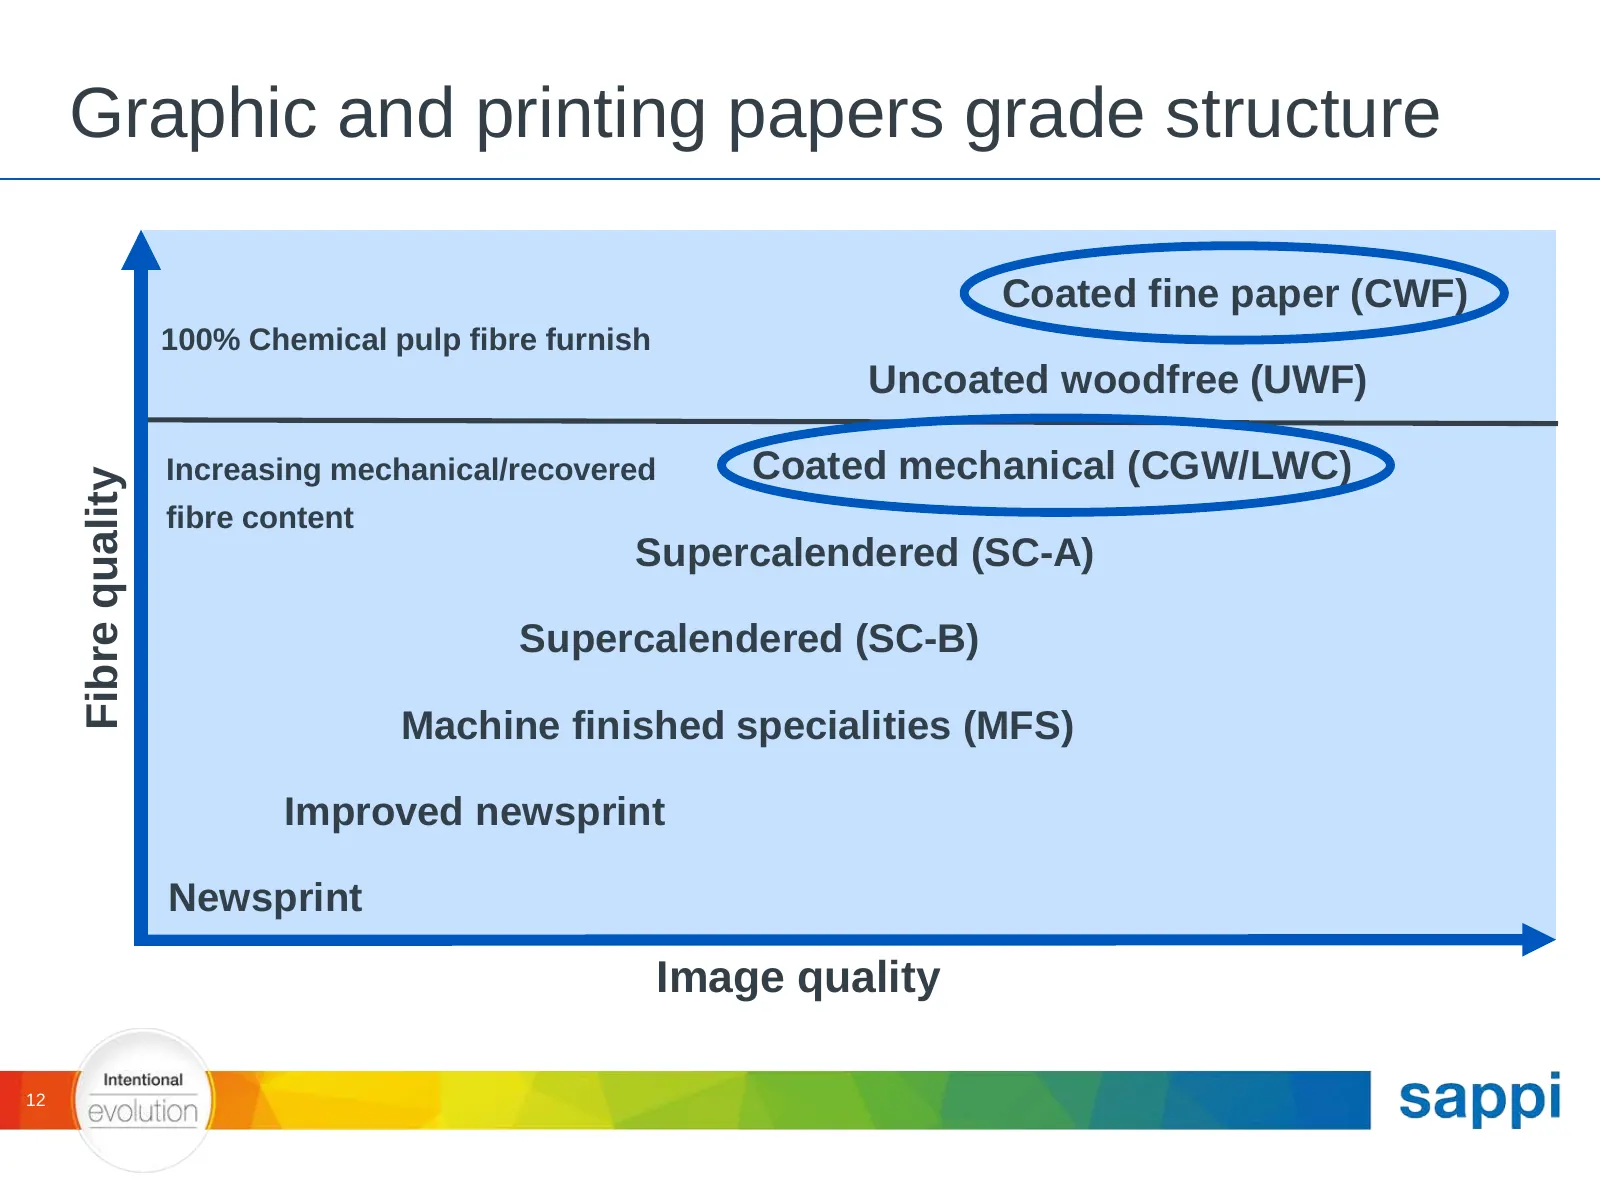
Graphic and printing papers grade structure Coated fine paper (CWF) 100% Chemical pulp fibre furnish Uncoated woodfree (UWF) Increasing mechanical/recovered Coated mechanical (CGW/LWC) Fibre quality fibre content Supercalendered (SC-A) Supercalendered (SC-B) Machine finished specialities (MFS) Impro
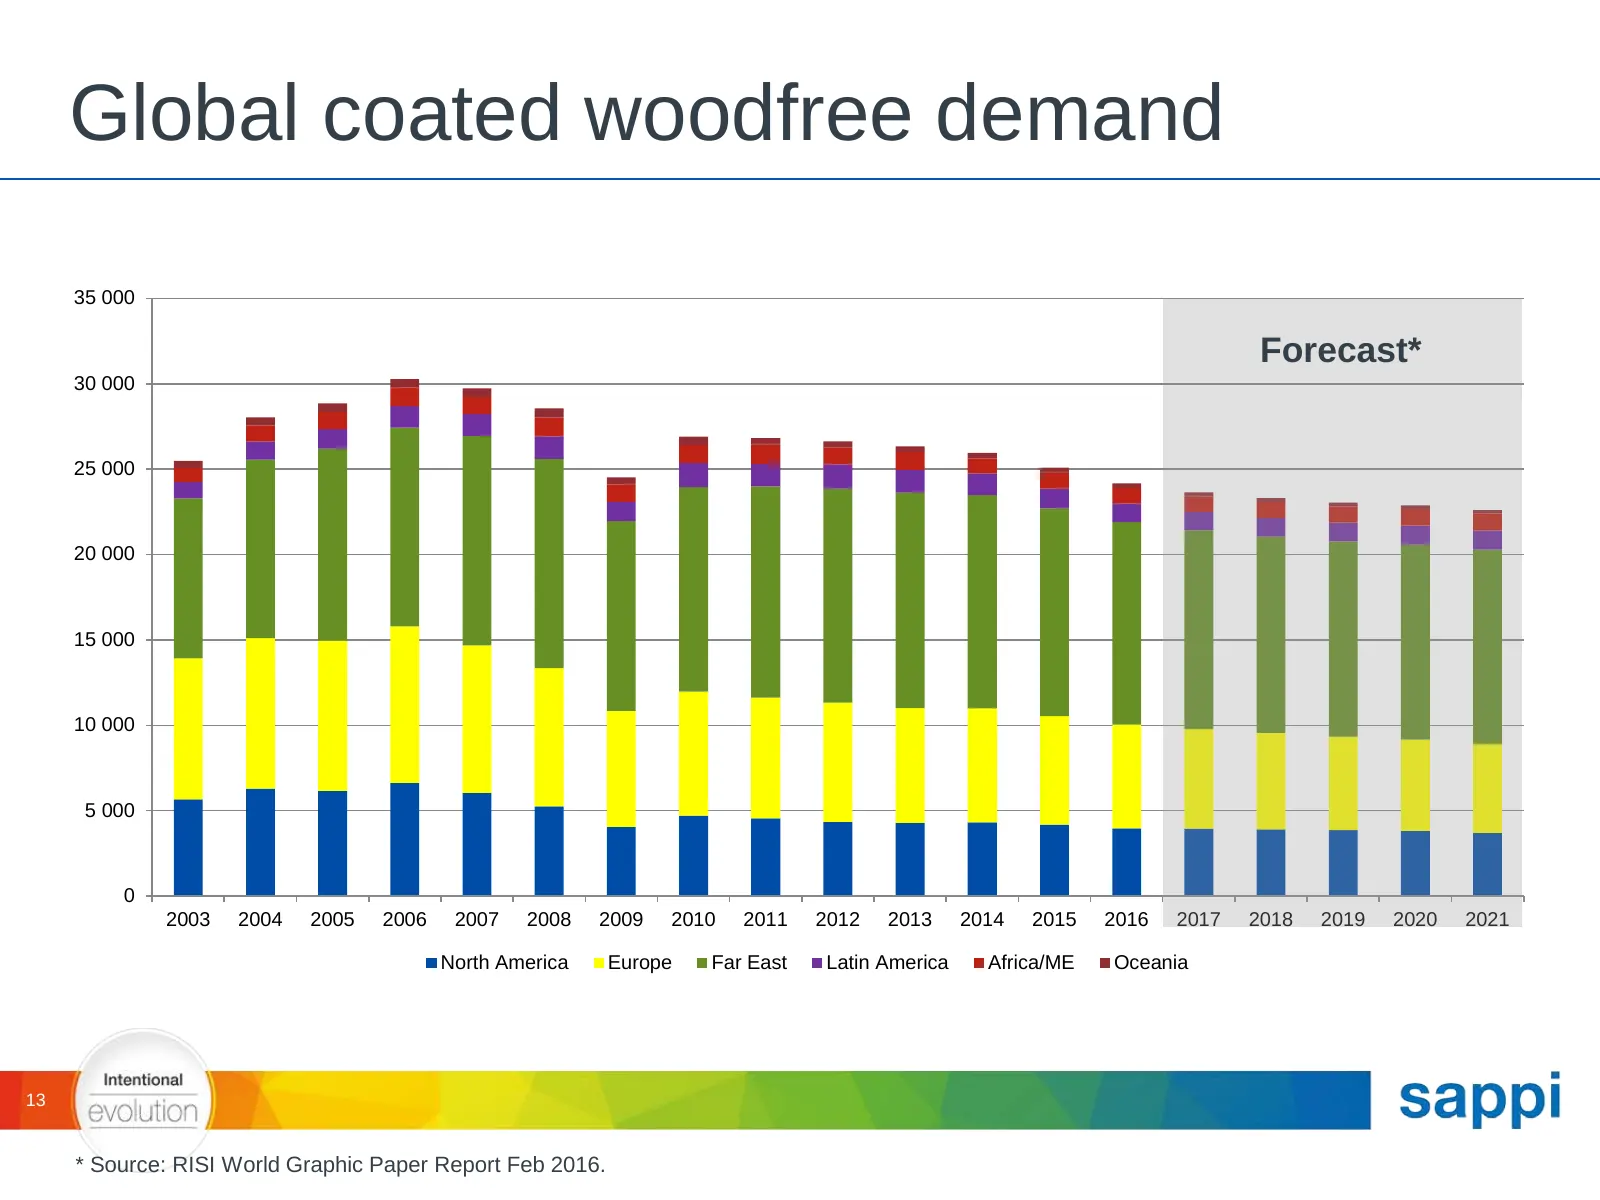
Slide 13: Global coated woodfree demand
Global coated woodfree demand 35 000 Forecast* 30 000 25 000 20 000 15 000 10 000 5 000 0 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 North America Europe Far East Latin America Africa/ME Oceania 13 * Source: RISI World Graphic Paper Report Feb 2016
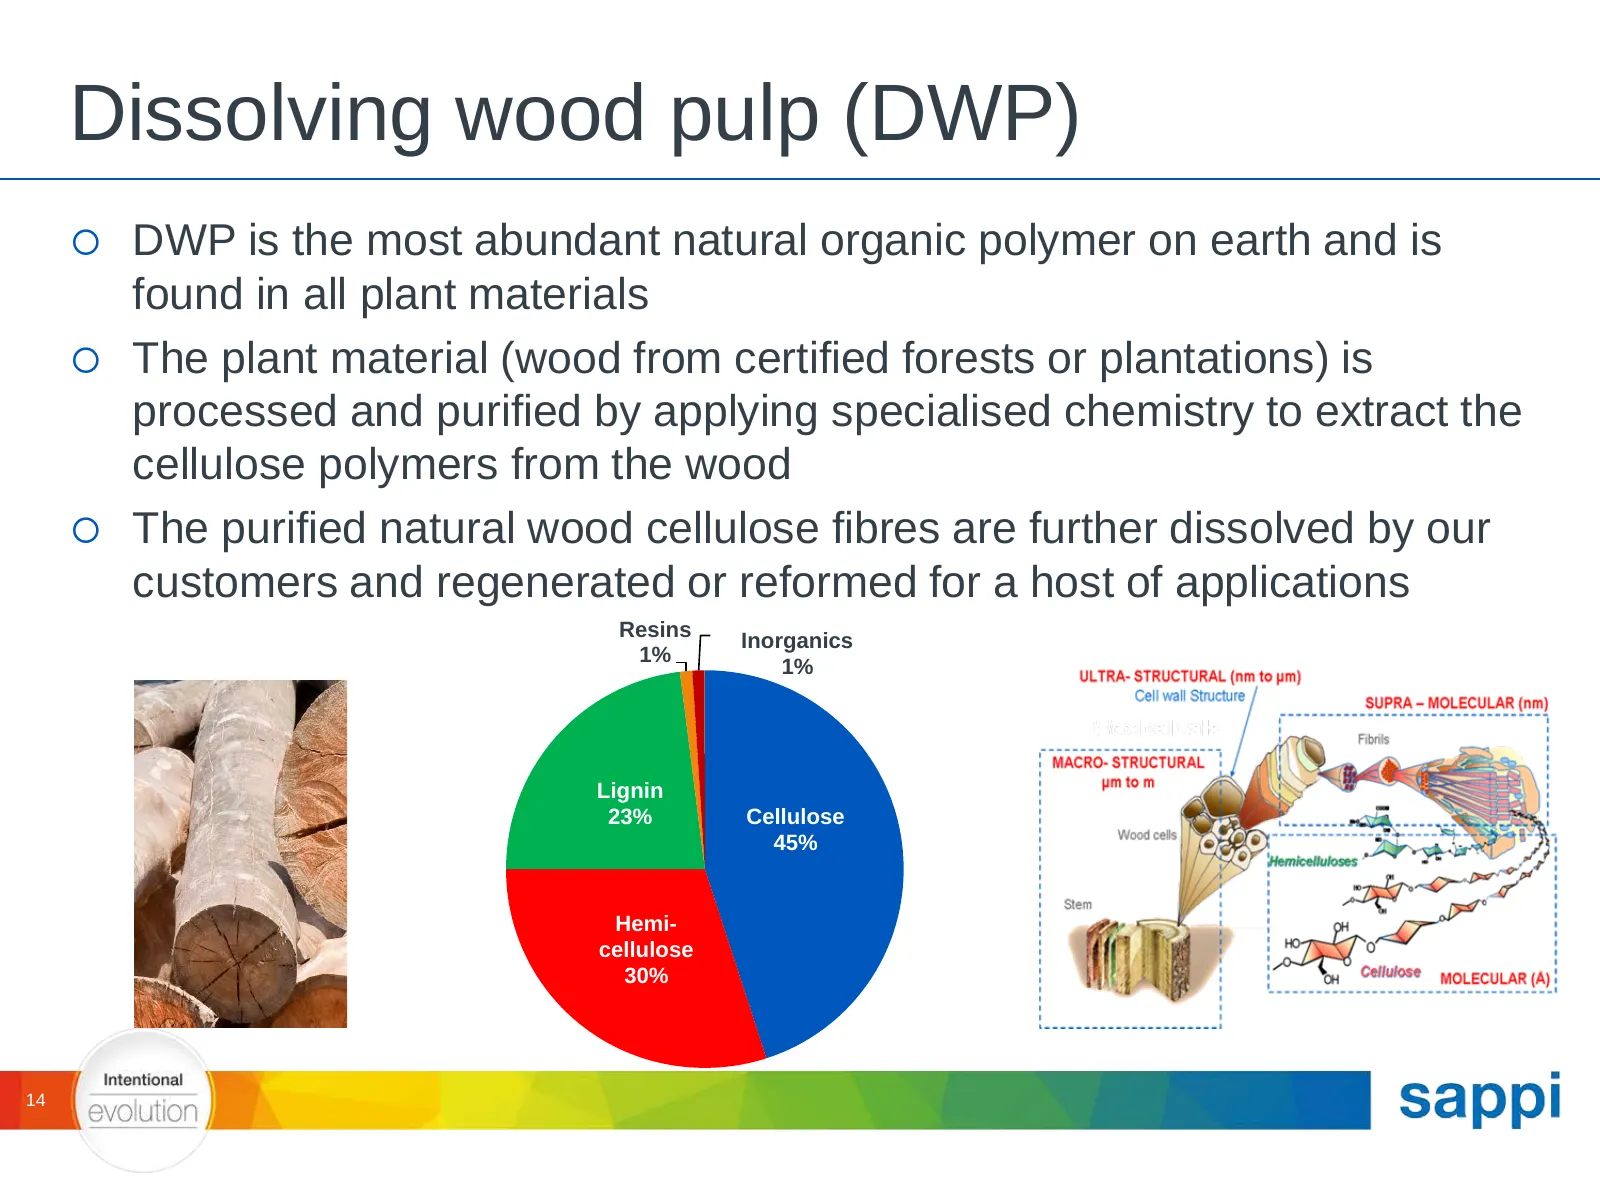
Slide 14: Dissolving wood pulp (DWP)
Dissolving wood pulp (DWP) DWP is the most abundant natural organic polymer on earth and is found in all plant materials The plant material (wood from certified forests or plantations) is processed and purified by applying specialised chemistry to extract the cellulose polymers from the wood T
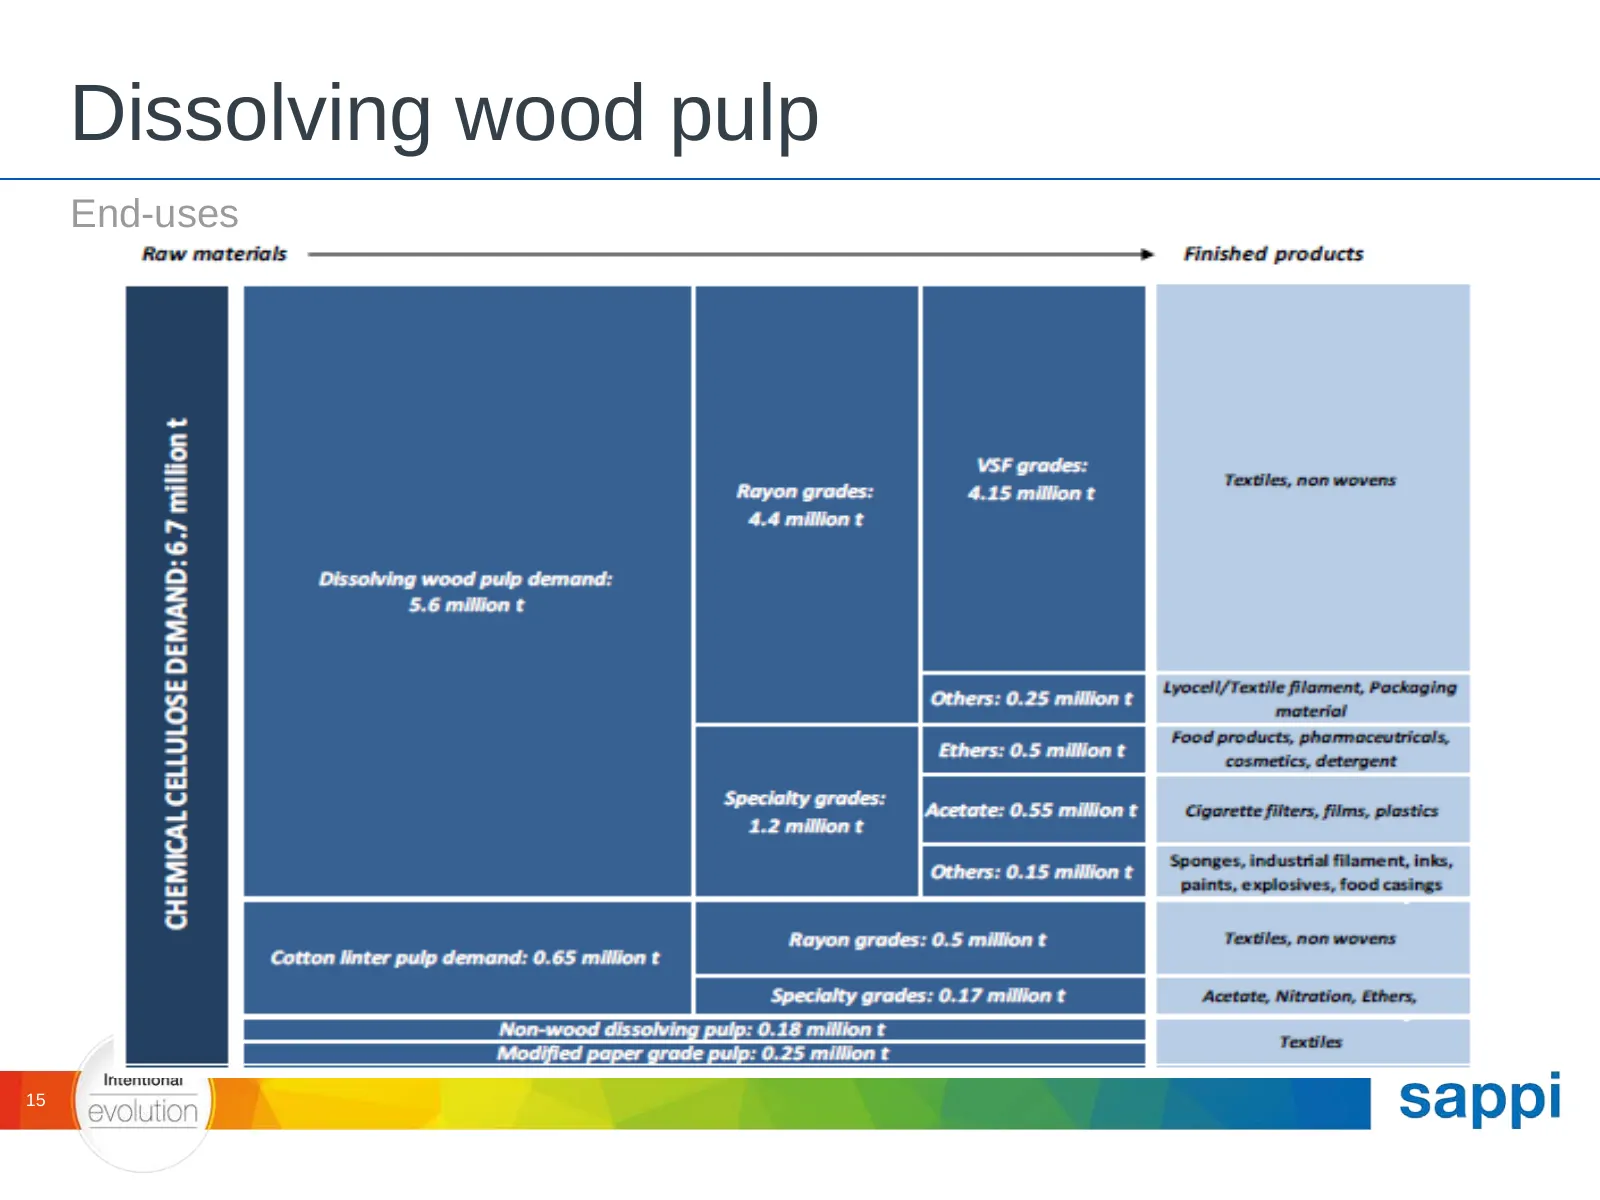
Slide 15: Dissolving wood pulp End-uses
Dissolving wood pulp End-uses 15
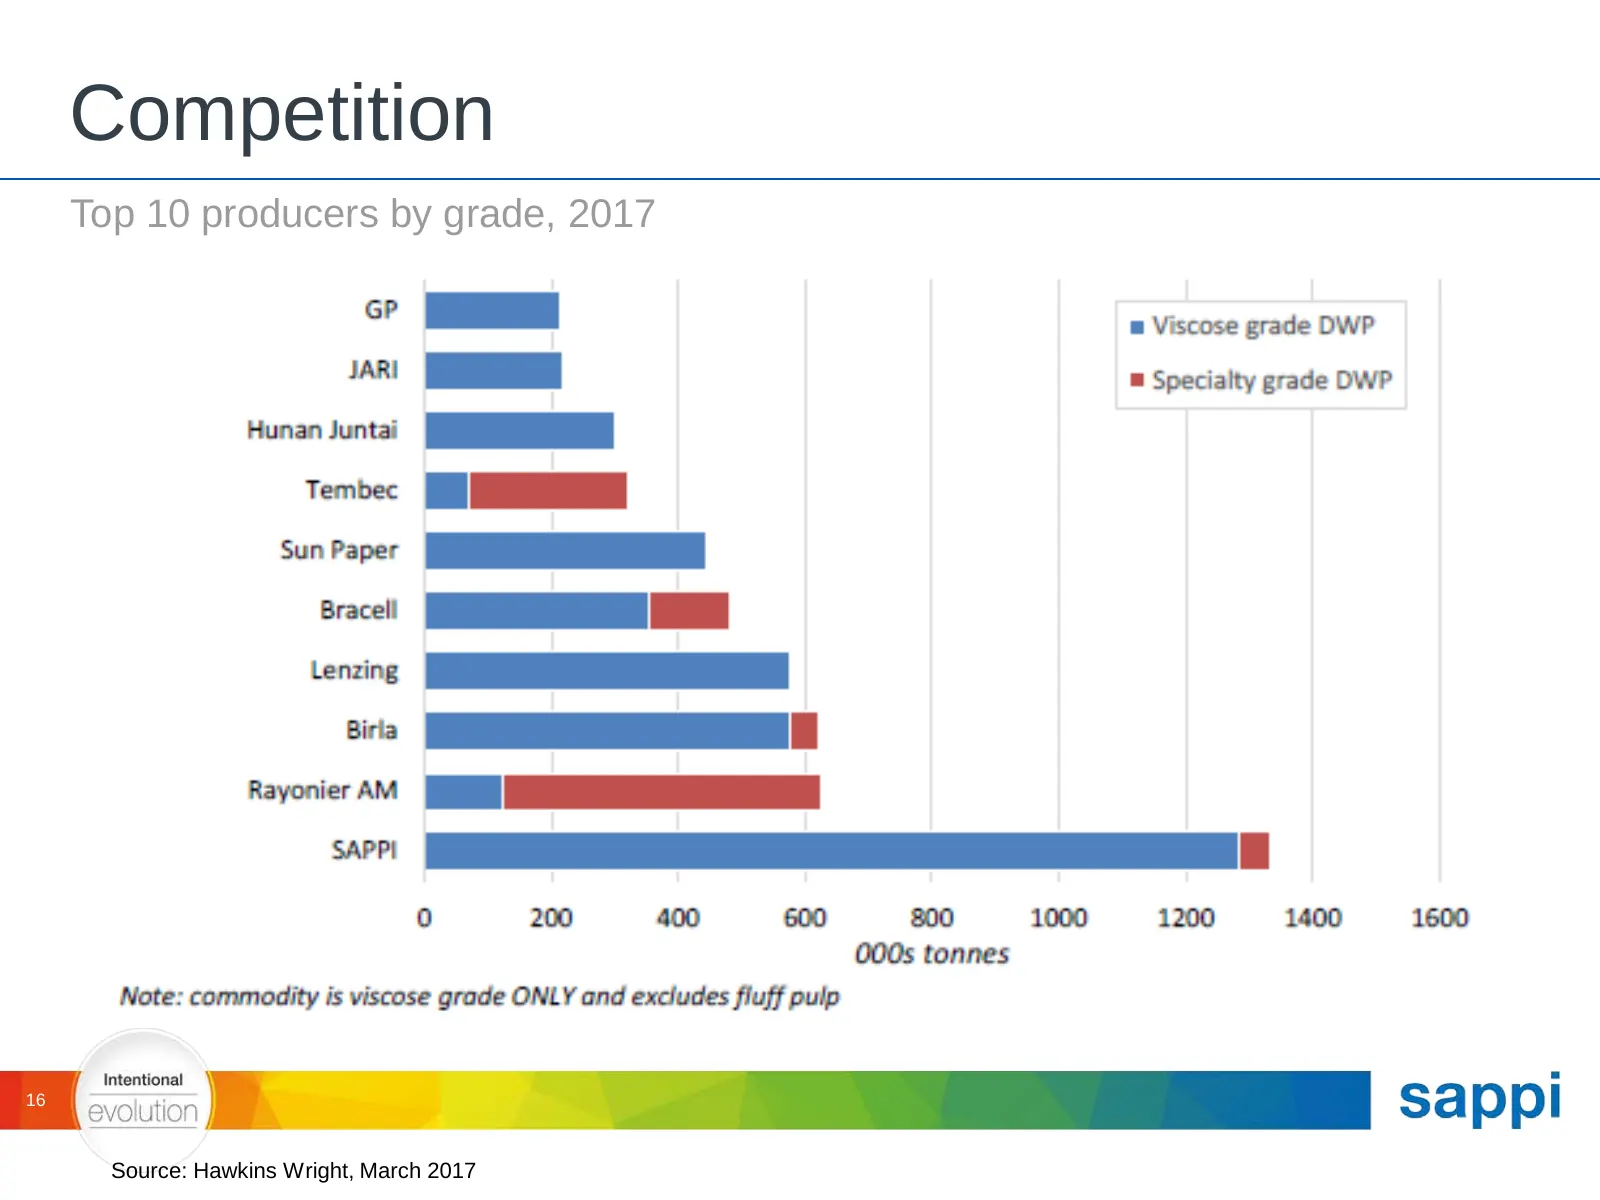
Slide 16: Competition
Competition Top 10 producers by grade, 2017 16 Source: Hawkins Wright, March 2017
Slide 17: Why dissolving wood pulp?
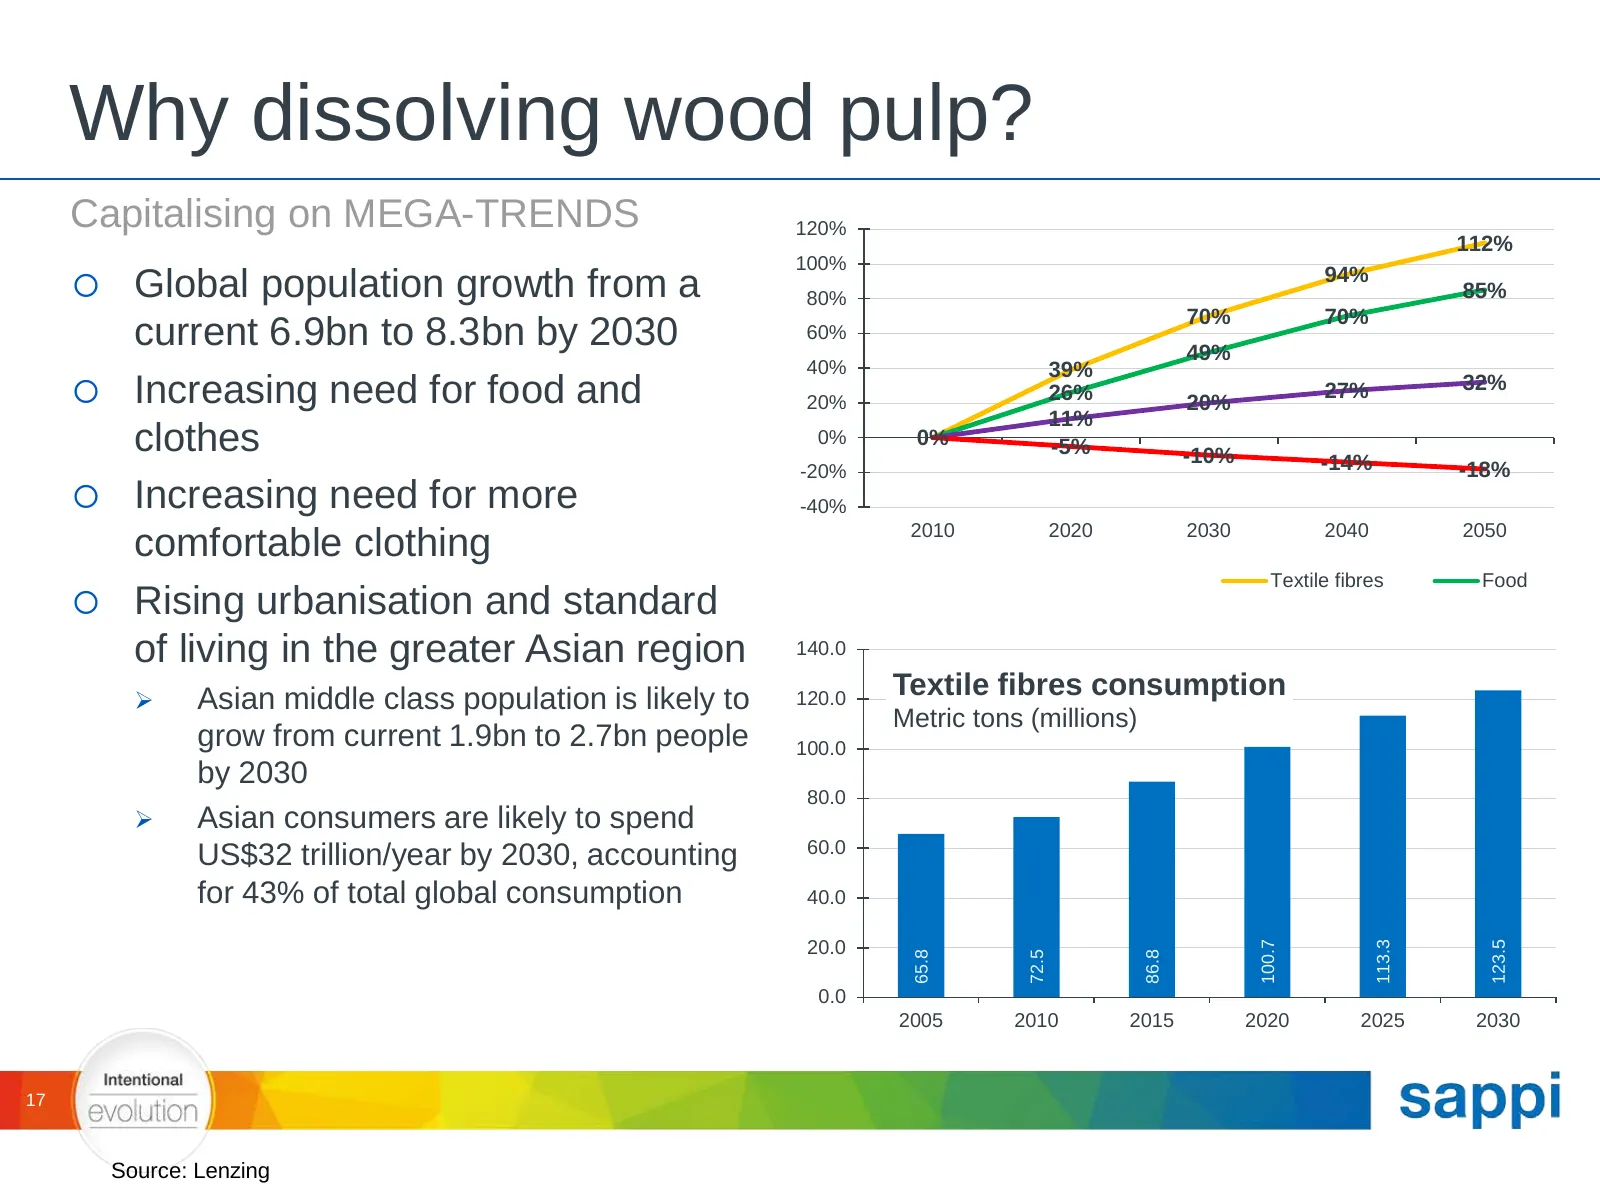
Why dissolving wood pulp? Capitalising on MEGA-TRENDS 120% 112% 100% 94% Global population growth from a 80% 85% 70% 70% current 6.9bn to 8.3bn by 2030 60% 49% 40% 39% 32% Increasing need for food and 20% 26% 20% 27% 11% clothes 0% 0% -5% -10% -14% -20% -18% Increasing need for more -40% 2010
Slide 18: Cellulose gap theory
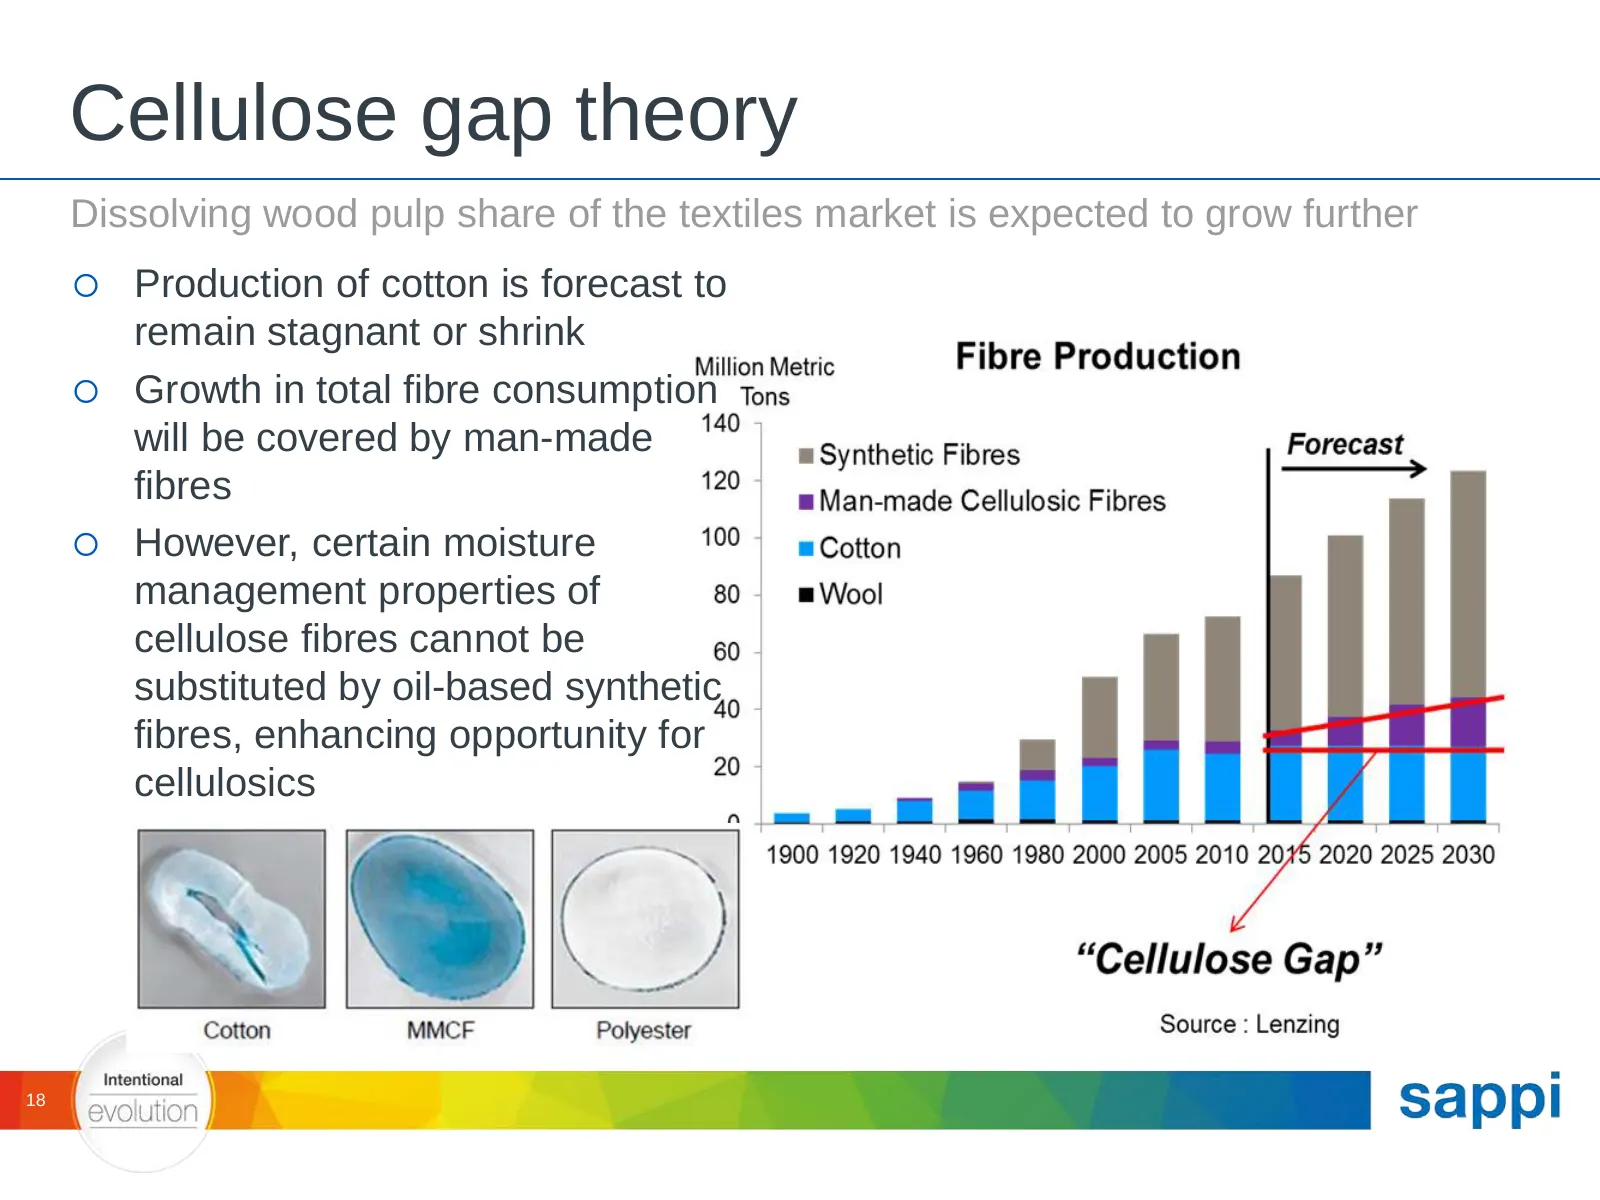
Cellulose gap theory Dissolving wood pulp share of the textiles market is expected to grow further Production of cotton is forecast to remain stagnant or shrink Growth in total fibre consumption will be covered by man-made fibres However, certain moisture management properties of cellulose fib
Slide 19: Textile Fibre Prices
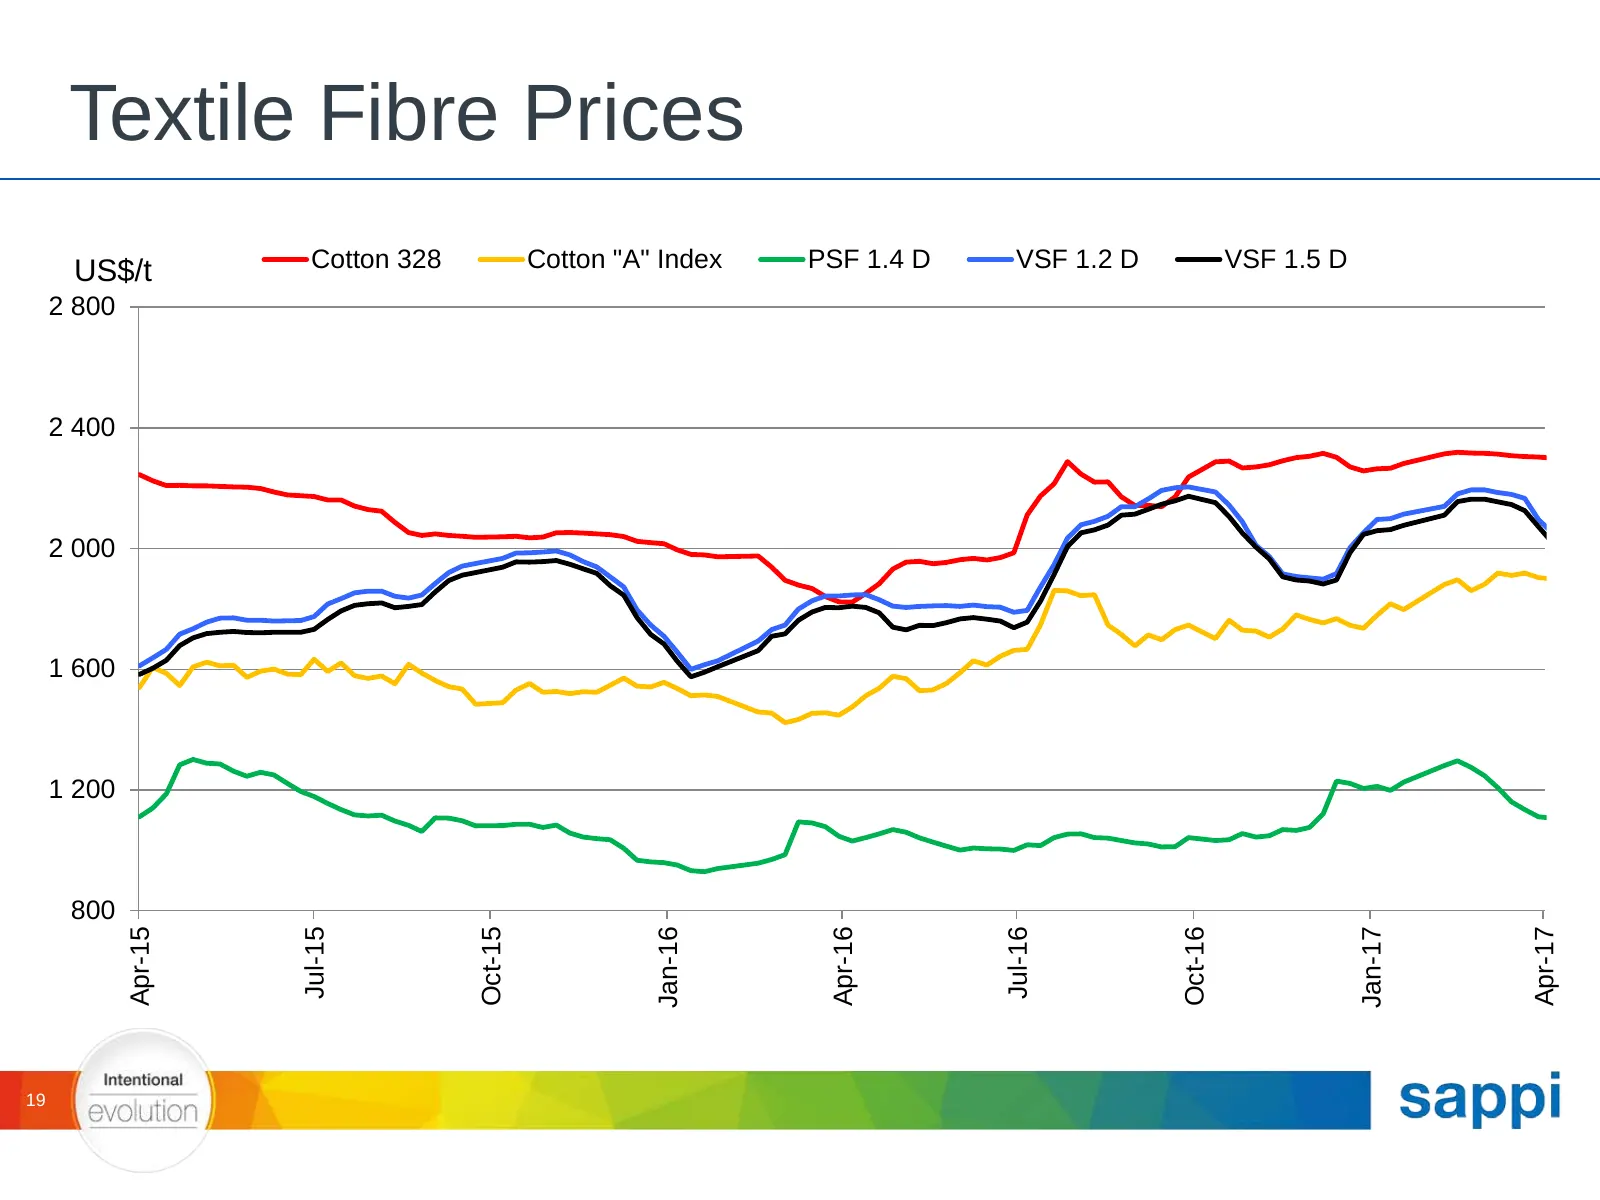
Textile Fibre Prices Cotton 328 Cotton "A" Index PSF 1.4 D VSF 1.2 D VSF 1.5 D US$/t 2 800 2 400 2 000 1 600 1 200 800 Apr-15 Oct-15 Apr-16 Oct-16 Apr-17 Jul-15 Jul-16 Jan-16 Jan-17 19
Slide 20: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 20
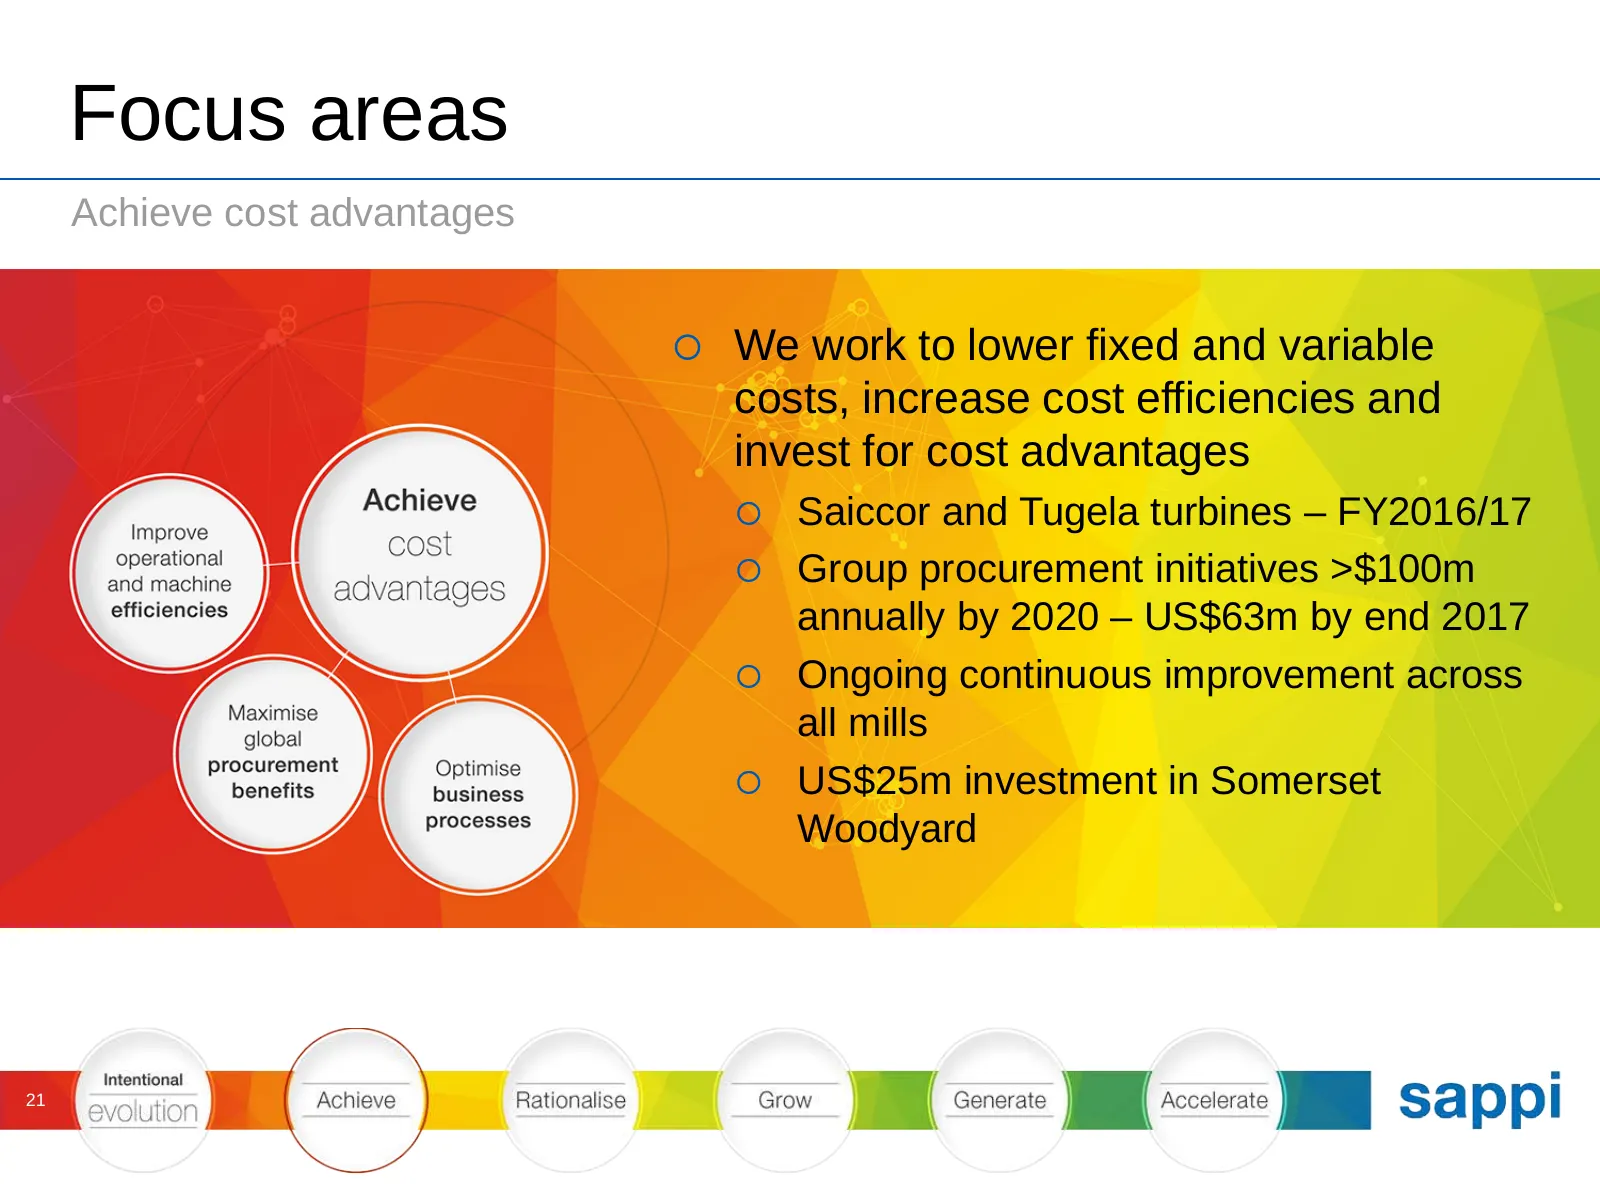
Slide 21: Focus areas: Achieve cost advantages
Focus areas Achieve cost advantages We work to lower fixed and variable costs, increase cost efficiencies and invest for cost advantages Saiccor and Tugela turbines – FY2016/17 Group procurement initiatives >$100m annually by 2020 – US$63m by end 2017 Ongoing continuous improvement across al
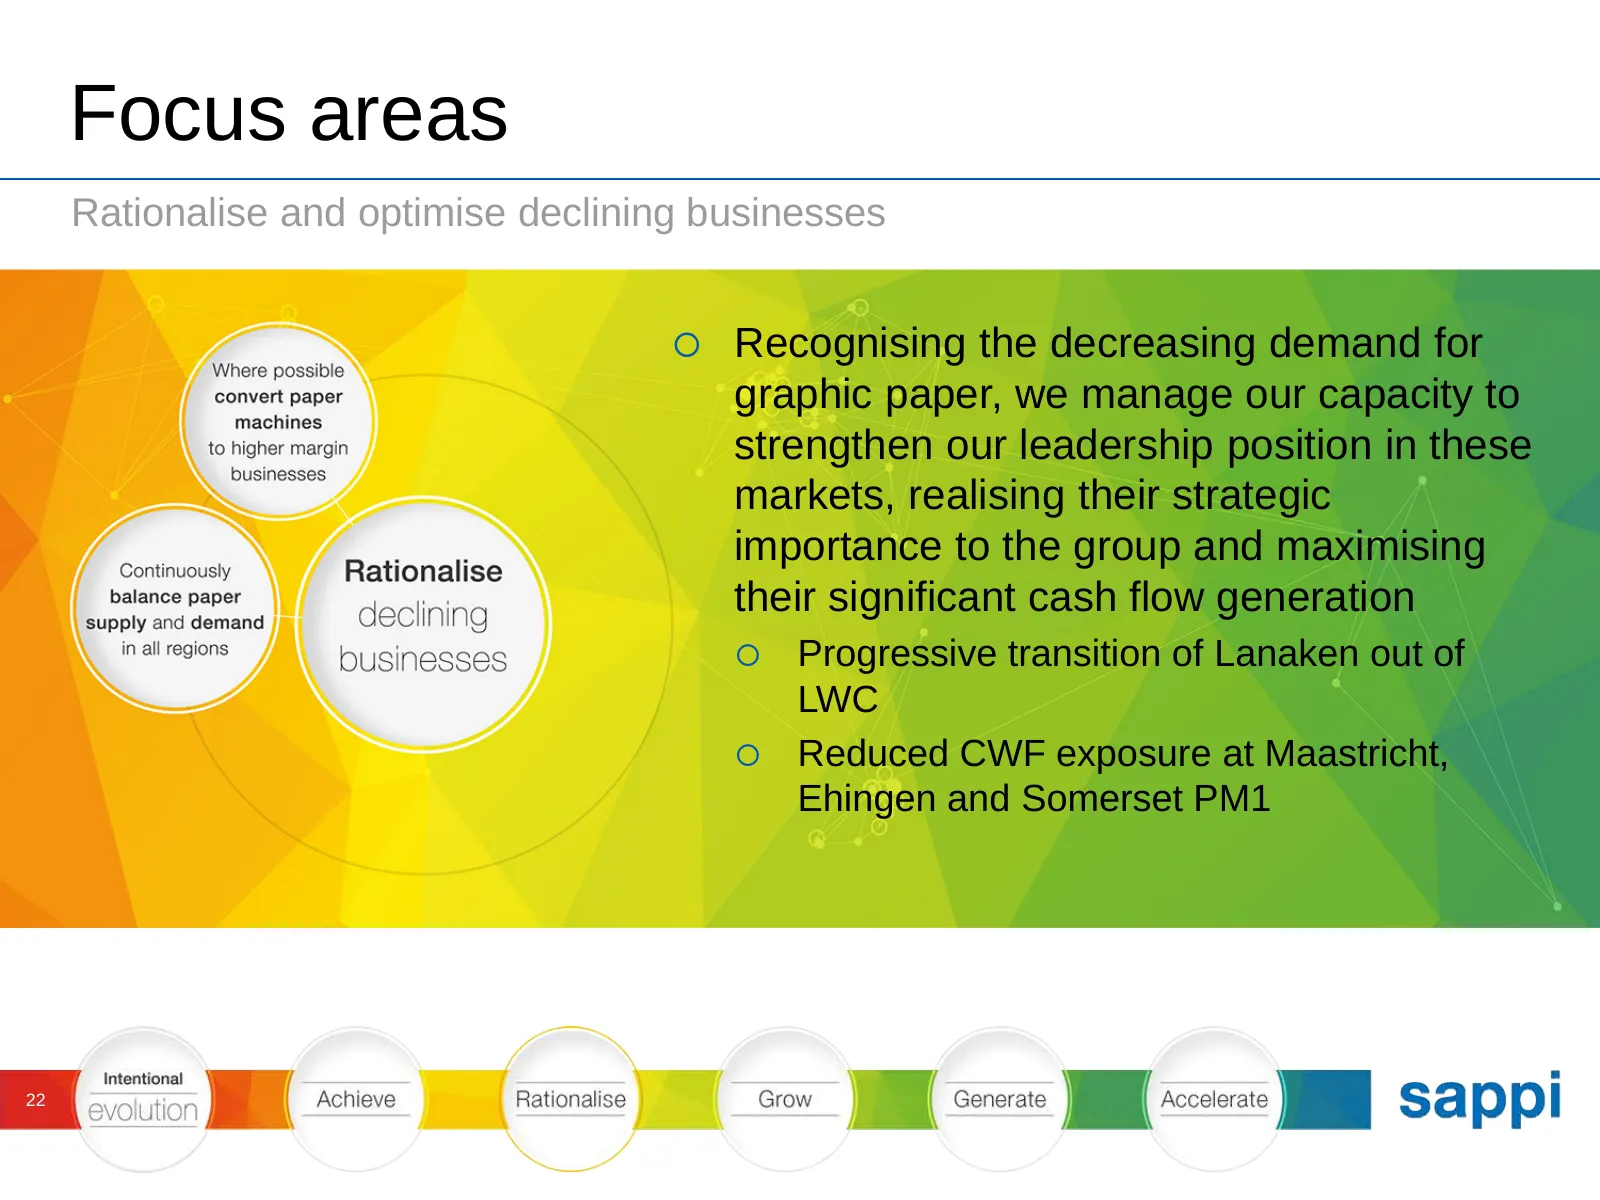
Slide 22: Focus areas: Rationalise and optimise declining businesses
Focus areas Rationalise and optimise declining businesses Recognising the decreasing demand for graphic paper, we manage our capacity to strengthen our leadership position in these markets, realising their strategic importance to the group and maximising their significant cash flow generation Pr
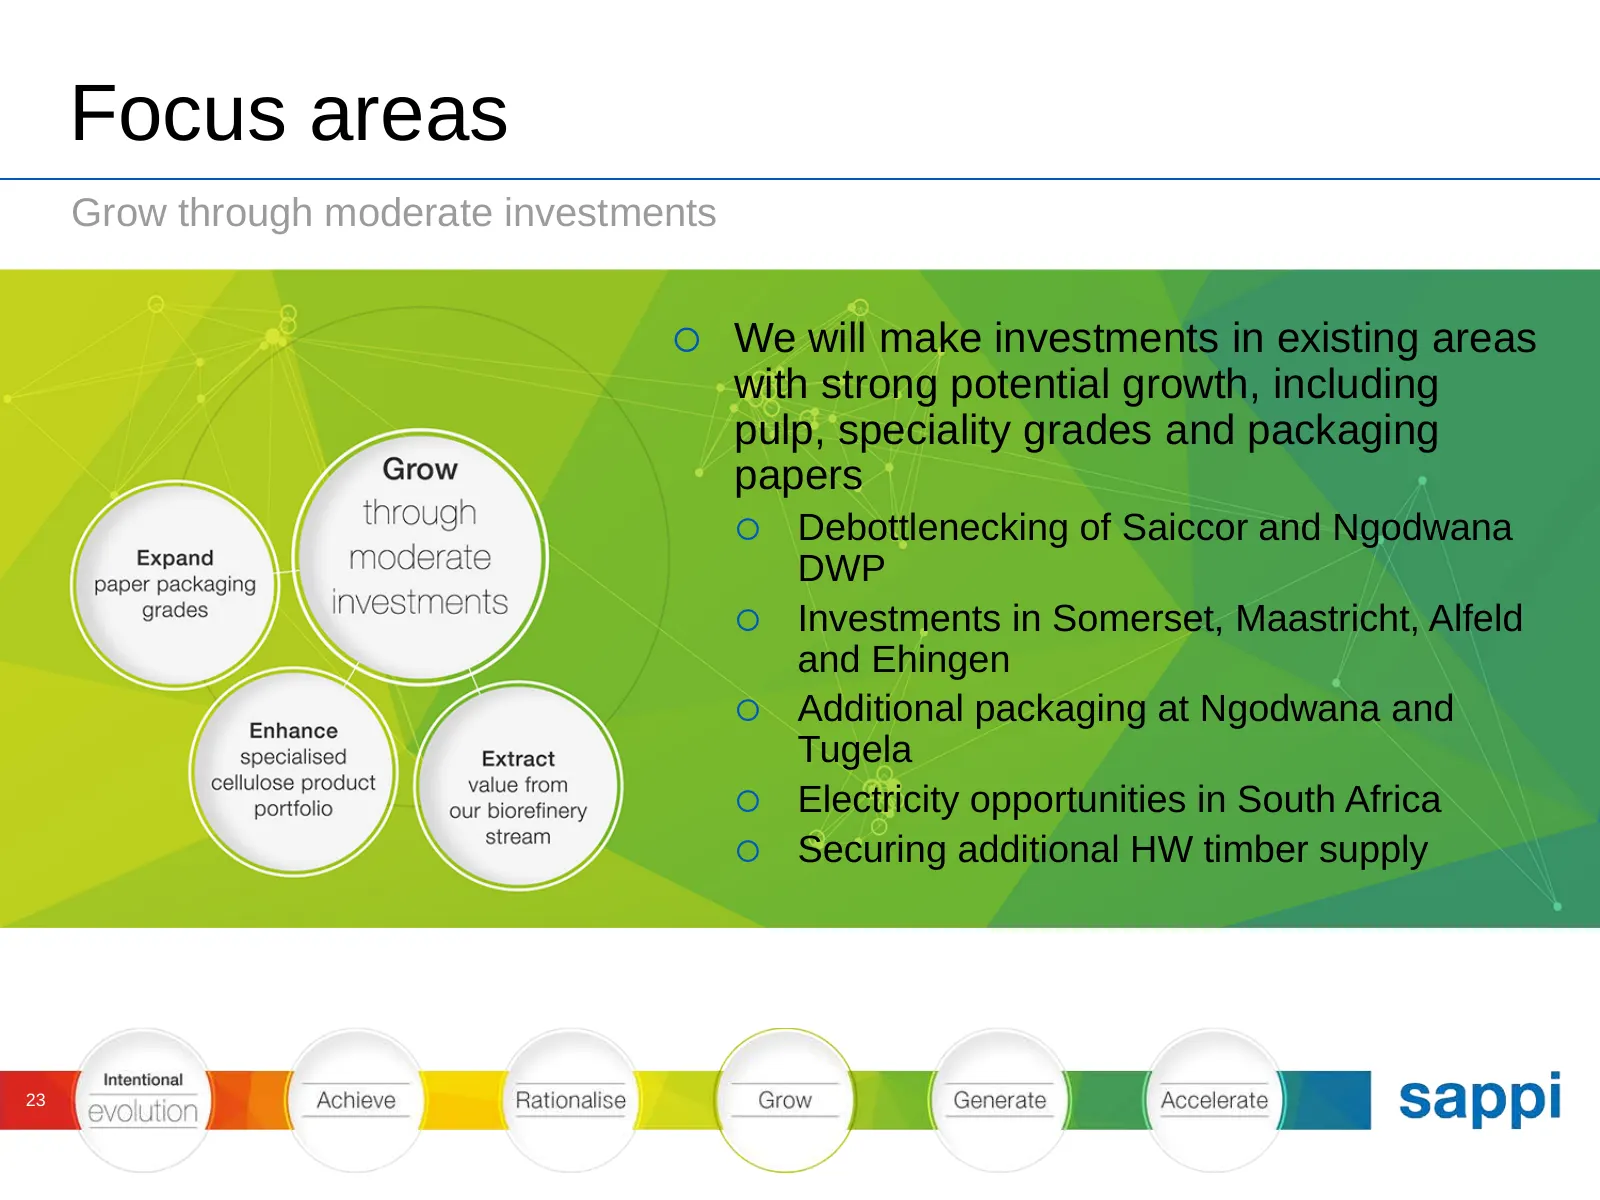
Slide 23: Focus areas: Grow through moderate investments
Focus areas Grow through moderate investments We will make investments in existing areas with strong potential growth, including pulp, speciality grades and packaging papers Debottlenecking of Saiccor and Ngodwana DWP Investments in Somerset, Maastricht, Alfeld and Ehingen Additional packagi
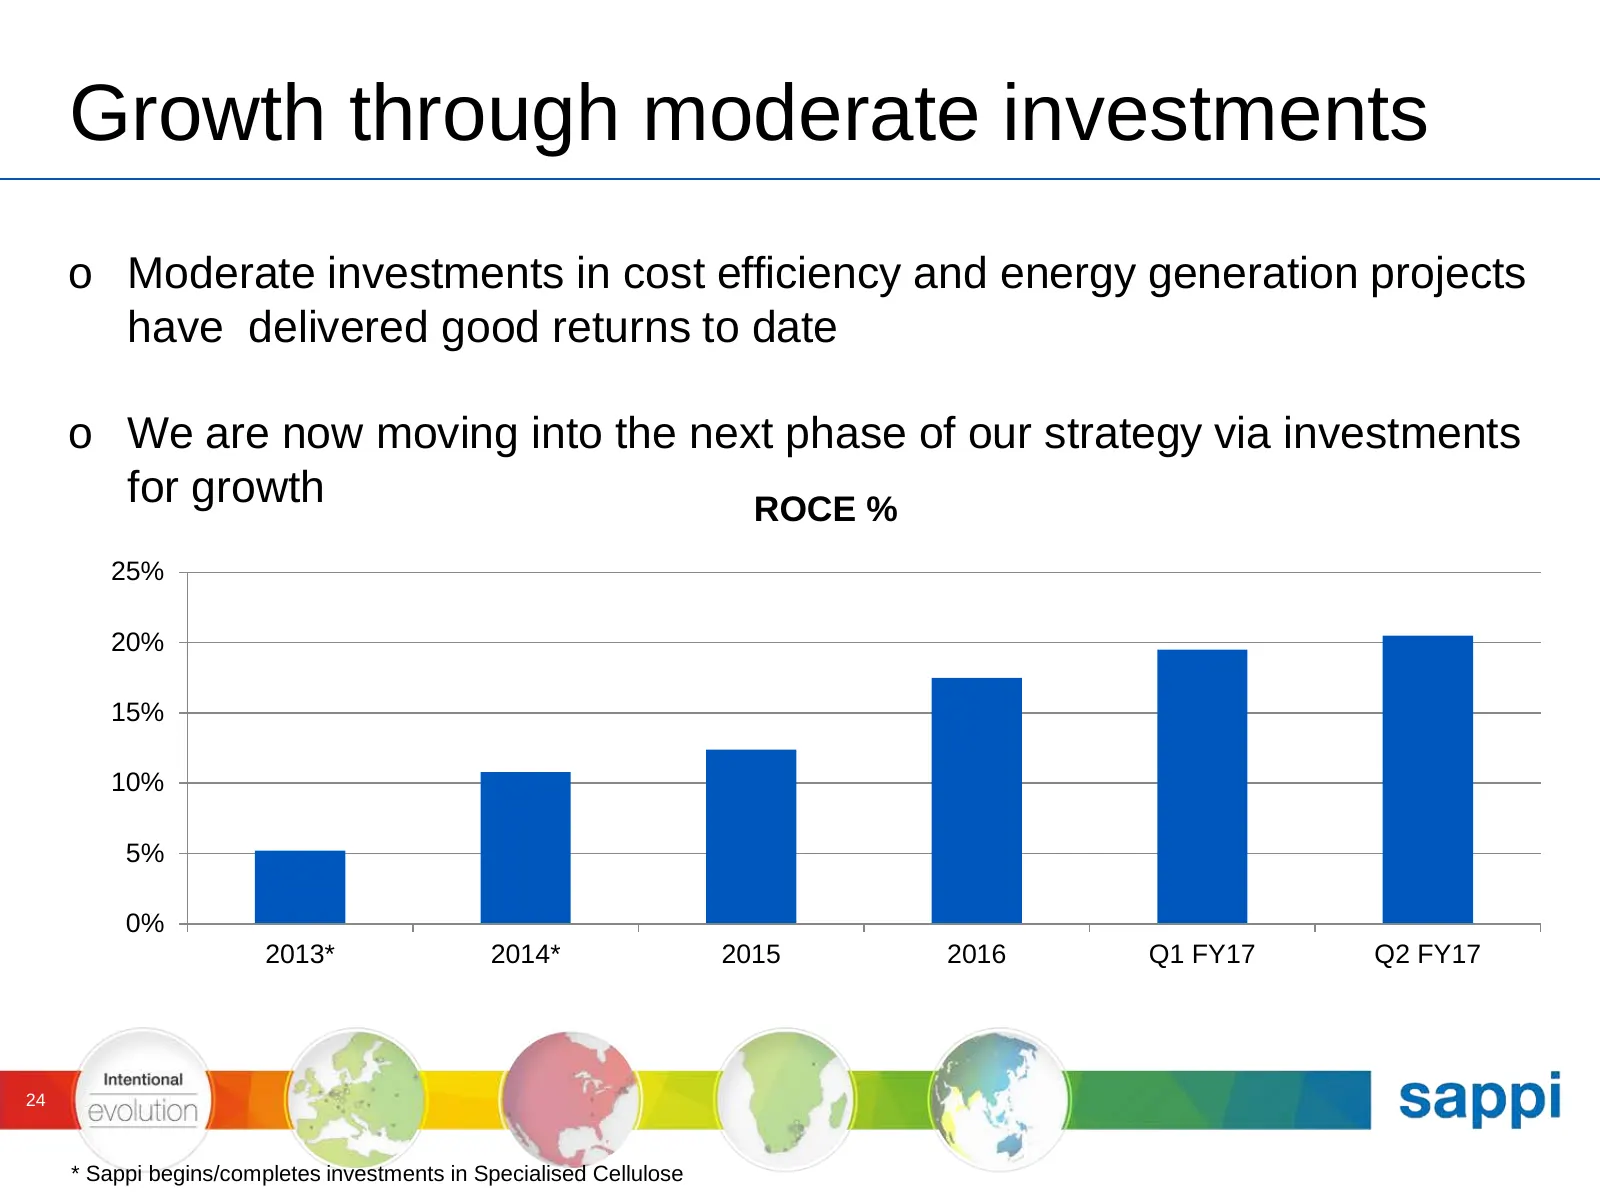
Slide 24: Growth through moderate investments
Growth through moderate investments o Moderate investments in cost efficiency and energy generation projects have delivered good returns to date o We are now moving into the next phase of our strategy via investments for growth ROCE % 25% 20% 15% 10% 5% 0% 2013* 2014* 2015 2016 Q1 FY17 Q2 FY17 24 *
Slide 25: Growth through moderate investments
Growth through moderate investments Investing in speciality packaging businesses in Europe and North America • US$140m at Maastricht, Ehingen, Alfeld and Lanaken • Maastricht, Ehingen and Alfeld to expand offering • Investments to be made over a 3-year period • Additional 200kt/annum of SBB,FBB and
Slide 26: Paperboard market
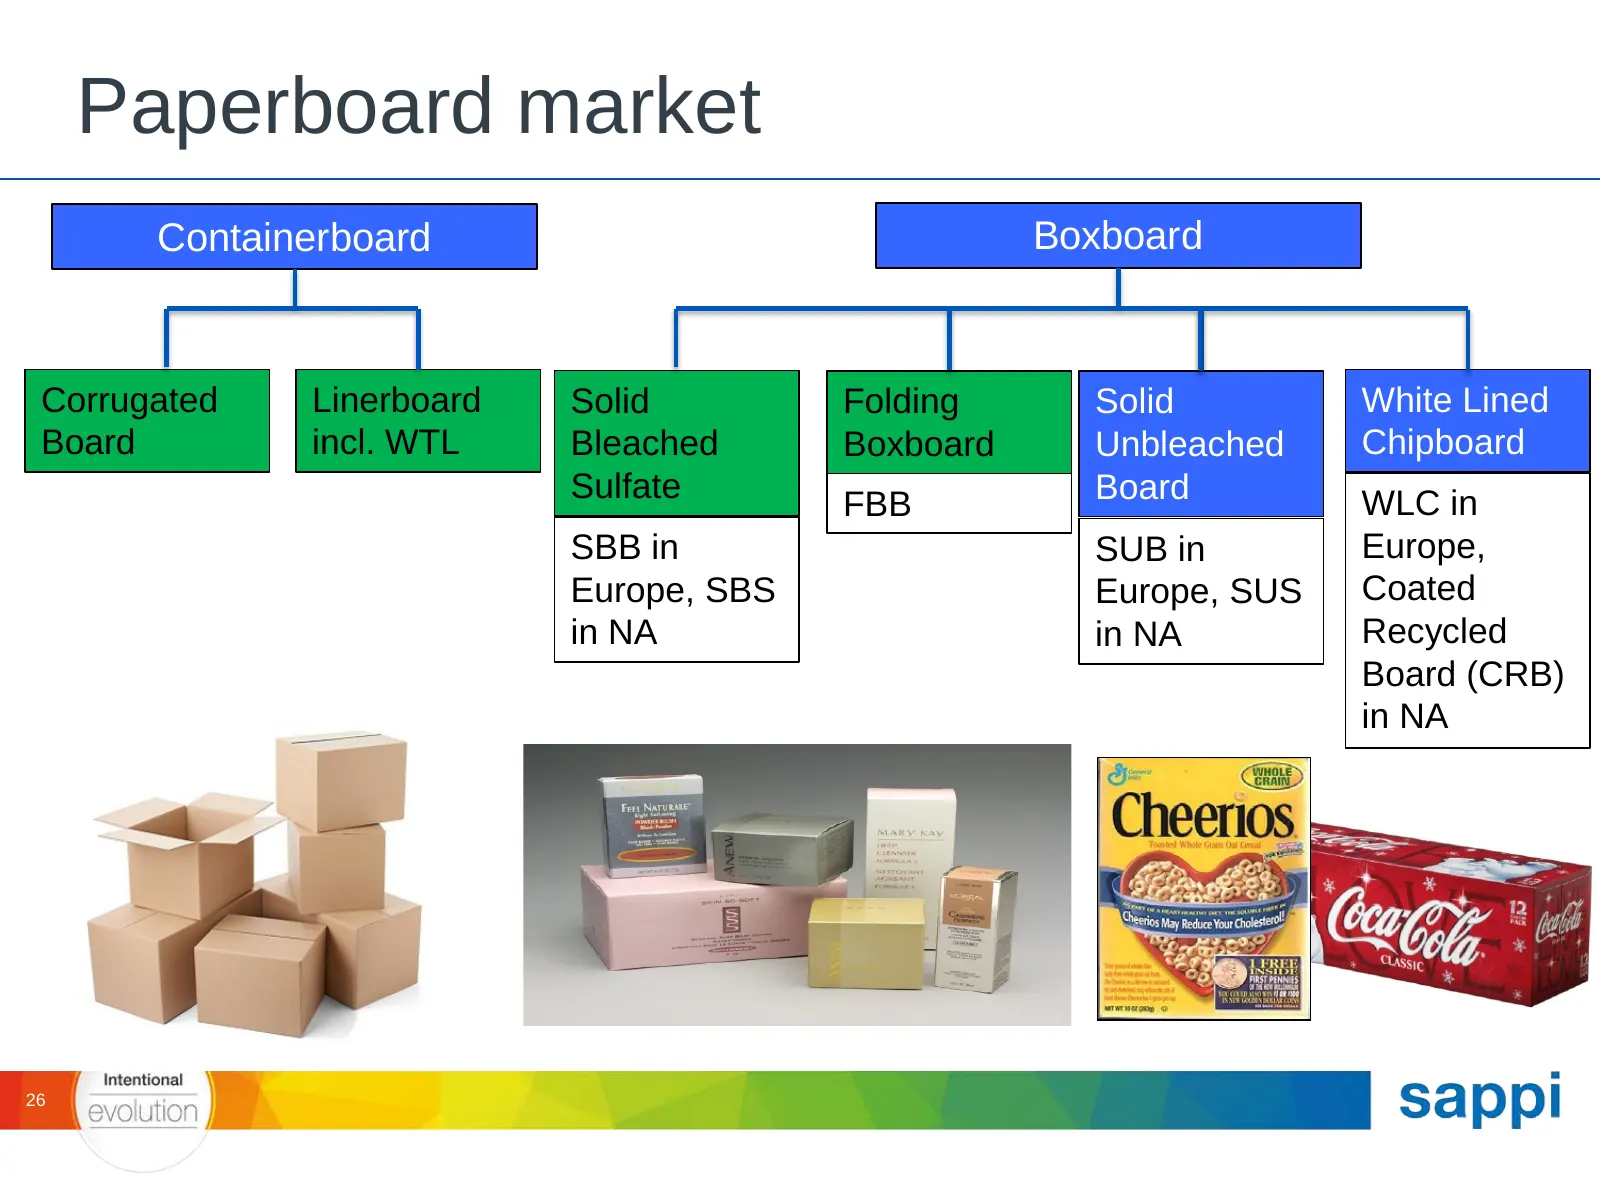
Paperboard market Containerboard Boxboard Corrugated Linerboard Solid Folding Solid White Lined Board incl. WTL Bleached Boxboard Unbleached Chipboard Sulfate Board WLC in FBB SBB in SUB in Europe, Europe, SBS Europe, SUS Coated in NA in NA Recycled Board (CRB) in NA 26
Slide 27: Mill summary – Sappi Europe
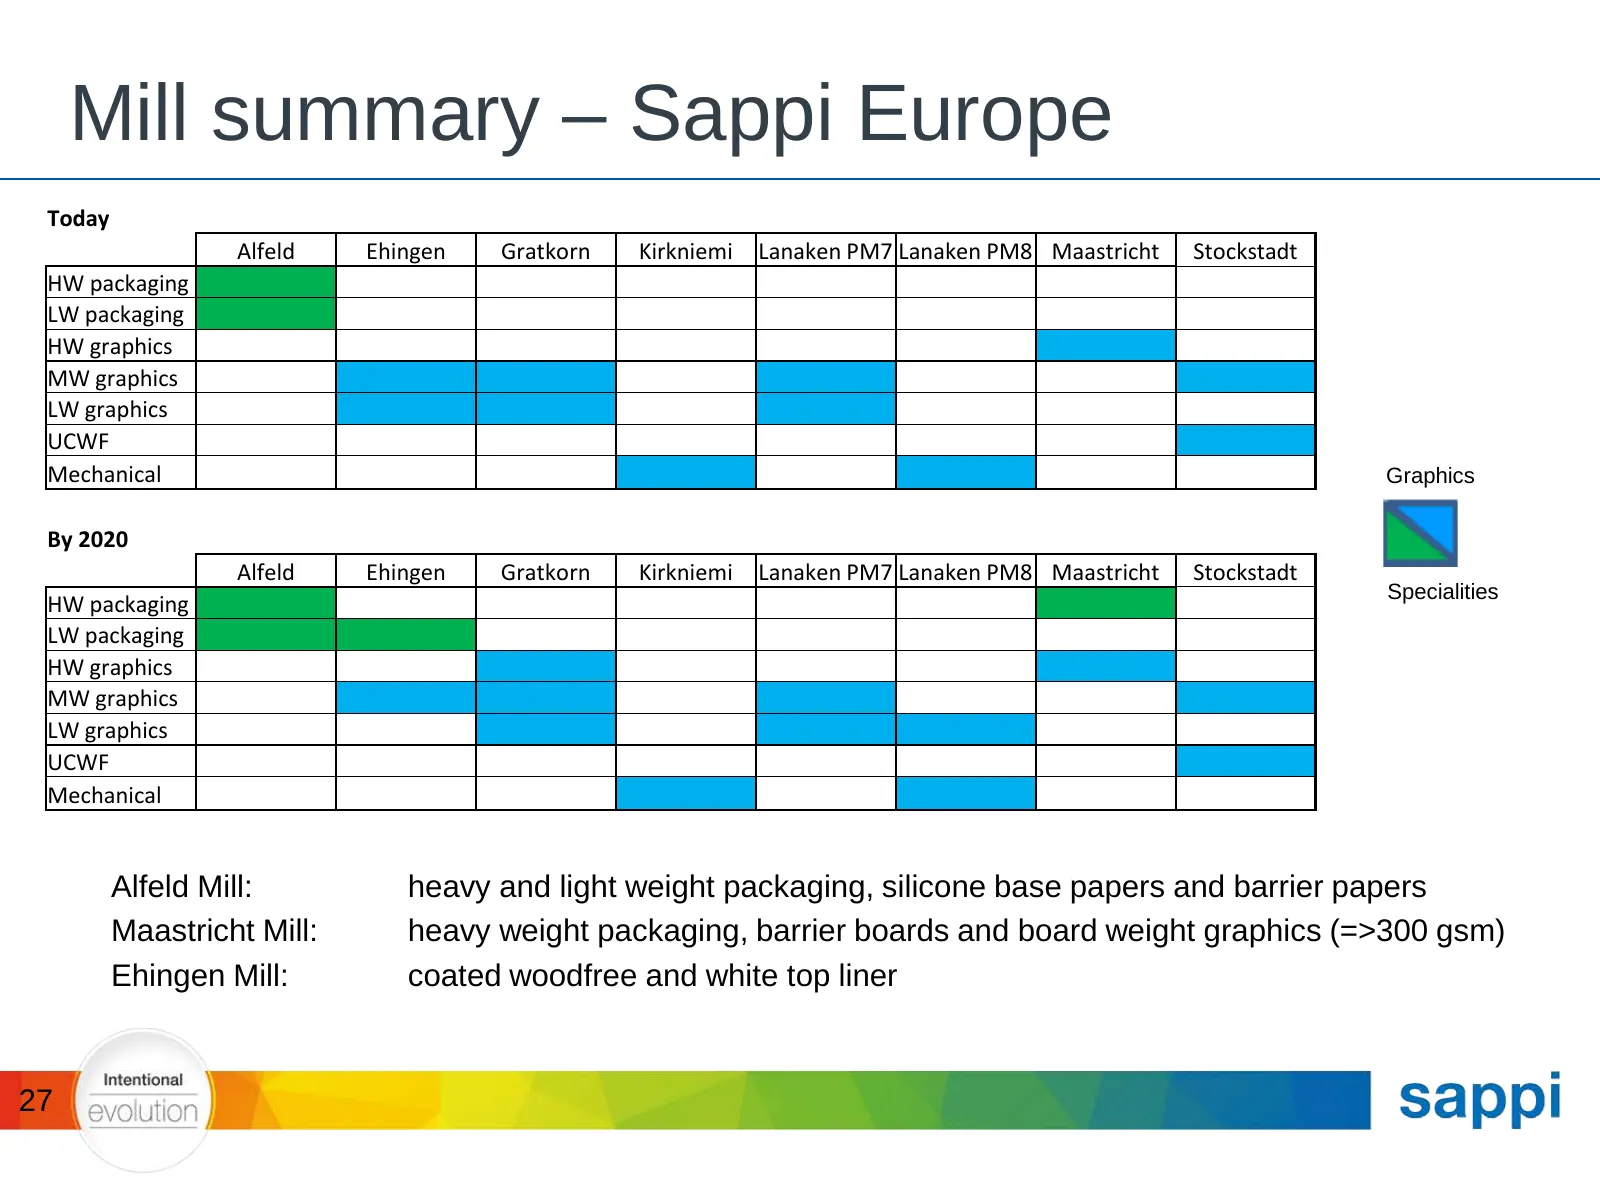
Mill summary – Sappi Europe Today Alfeld Ehingen Gratkorn Kirkniemi Lanaken PM7 Lanaken PM8 Maastricht Stockstadt HW packaging LW packaging HW graphics MW graphics LW graphics UCWF Mechanical Graphics By 2020 Alfeld Ehingen Gratkorn Kirkniemi Lanaken PM7 Lanaken PM8 Maastricht Stockstadt Specialitie
Slide 28: Focus areas: Generate cash to strengthen the balance sheet
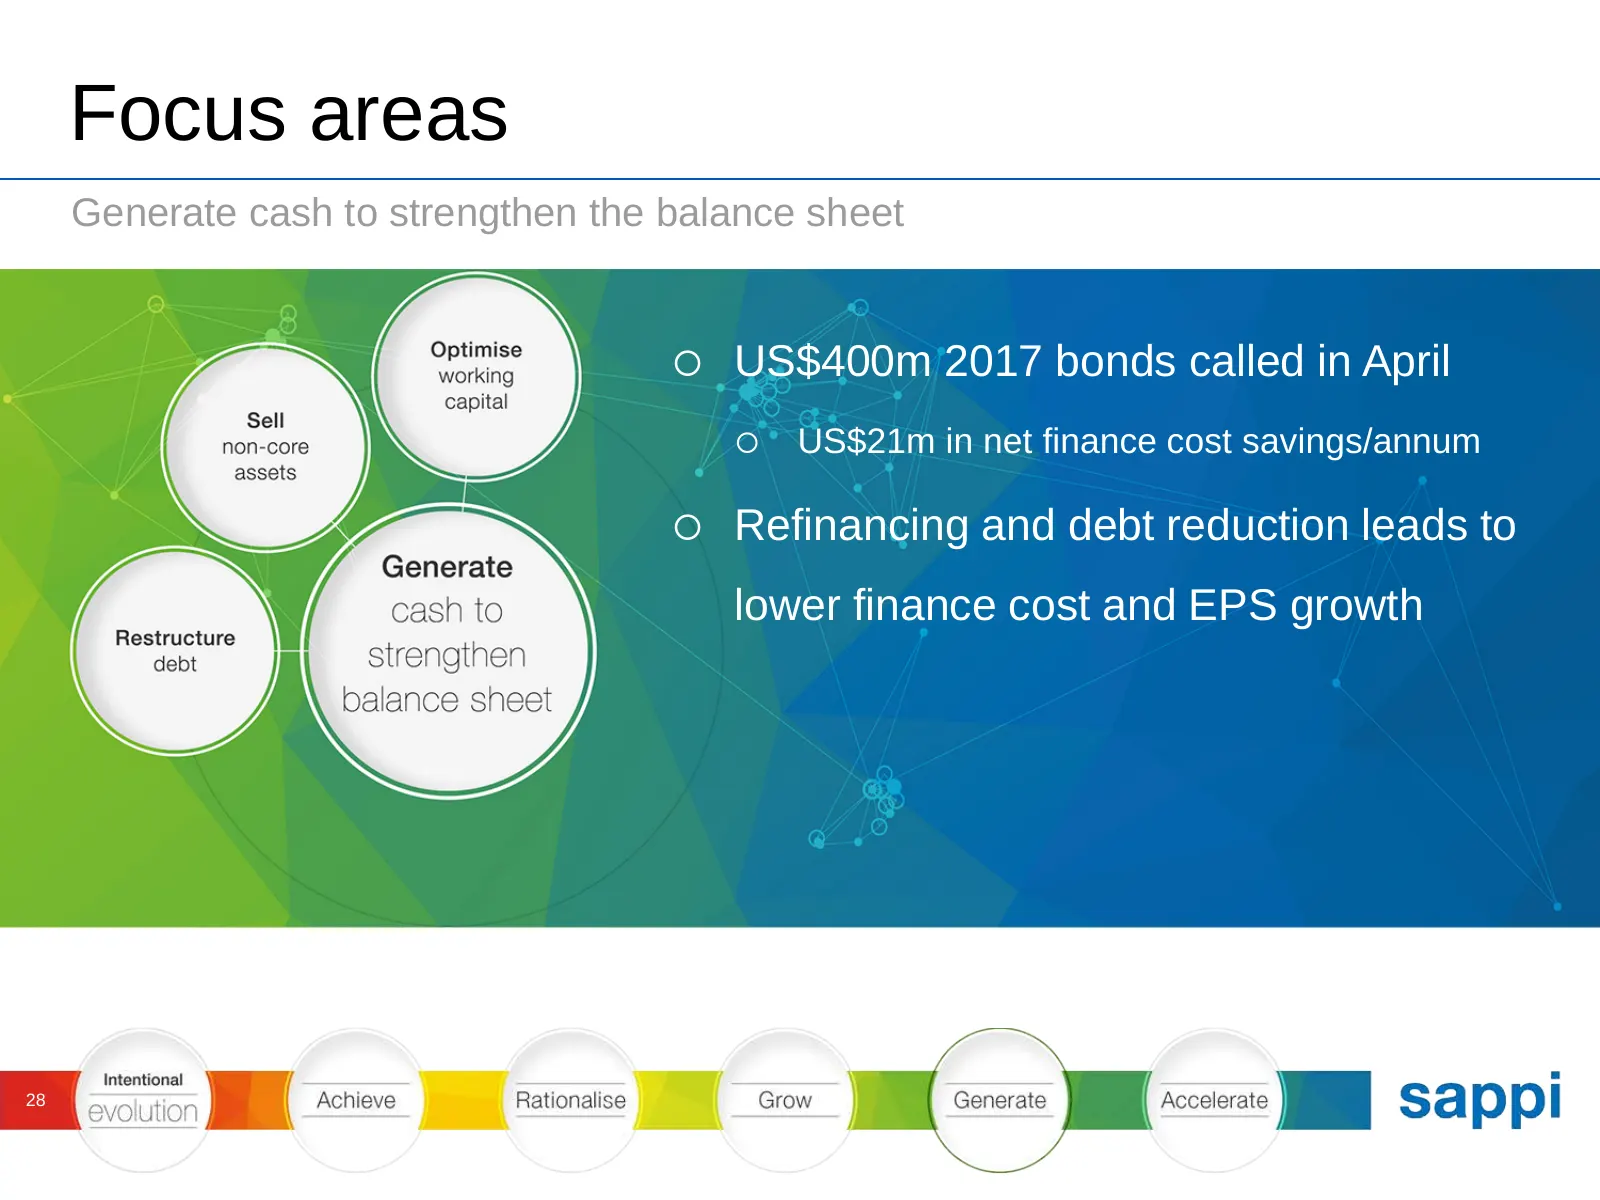
Focus areas Generate cash to strengthen the balance sheet US$400m 2017 bonds called in April US$21m in net finance cost savings/annum Refinancing and debt reduction leads to lower finance cost and EPS growth 28
Slide 29: Focus areas: Accelerate growth in adjacent businesses
Focus areas Accelerate growth in adjacent businesses from a strong base We will continue our focus on having a cleaner, stronger balance sheet so that we can then accelerate our growth in adjacent businesses o Speciality packaging paper o Biomaterials, biochemicals – lignins, sugars o Expanded DWP
Slide 30: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 30
Slide 31: EBITDA and operating profit
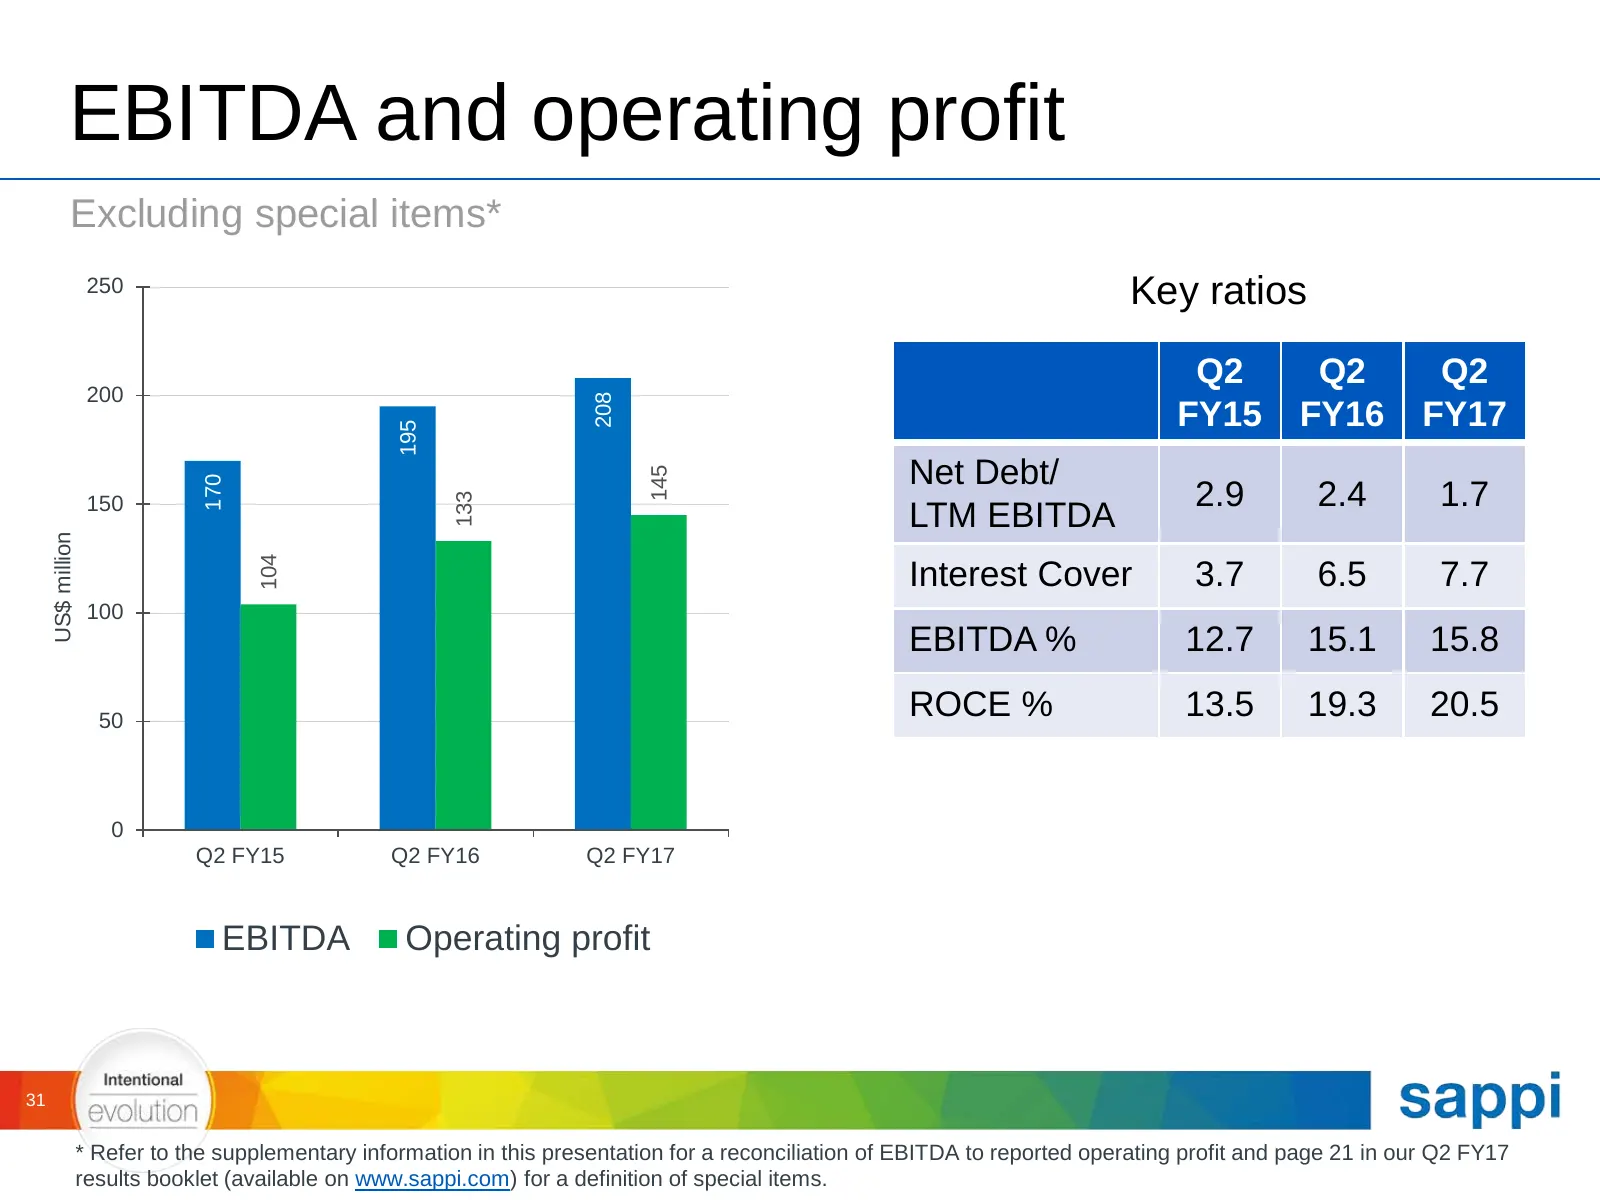
EBITDA and operating profit Excluding special items* 250 Key ratios Q2 Q2 Q2 200 208 195 FY15 FY16 FY17 Net Debt/ 145 170 2.9 2.4 1.7 133 150 LTM EBITDA US$ million 104 Interest Cover 3.7 6.5 7.7 100 EBITDA % 12.7 15.1 15.8 50 ROCE % 13.5 19.3 20.5 0 Q2 FY15 Q2 FY16 Q2 FY17 EBITDA Operating profit 3
Slide 32: Highlights – five year review
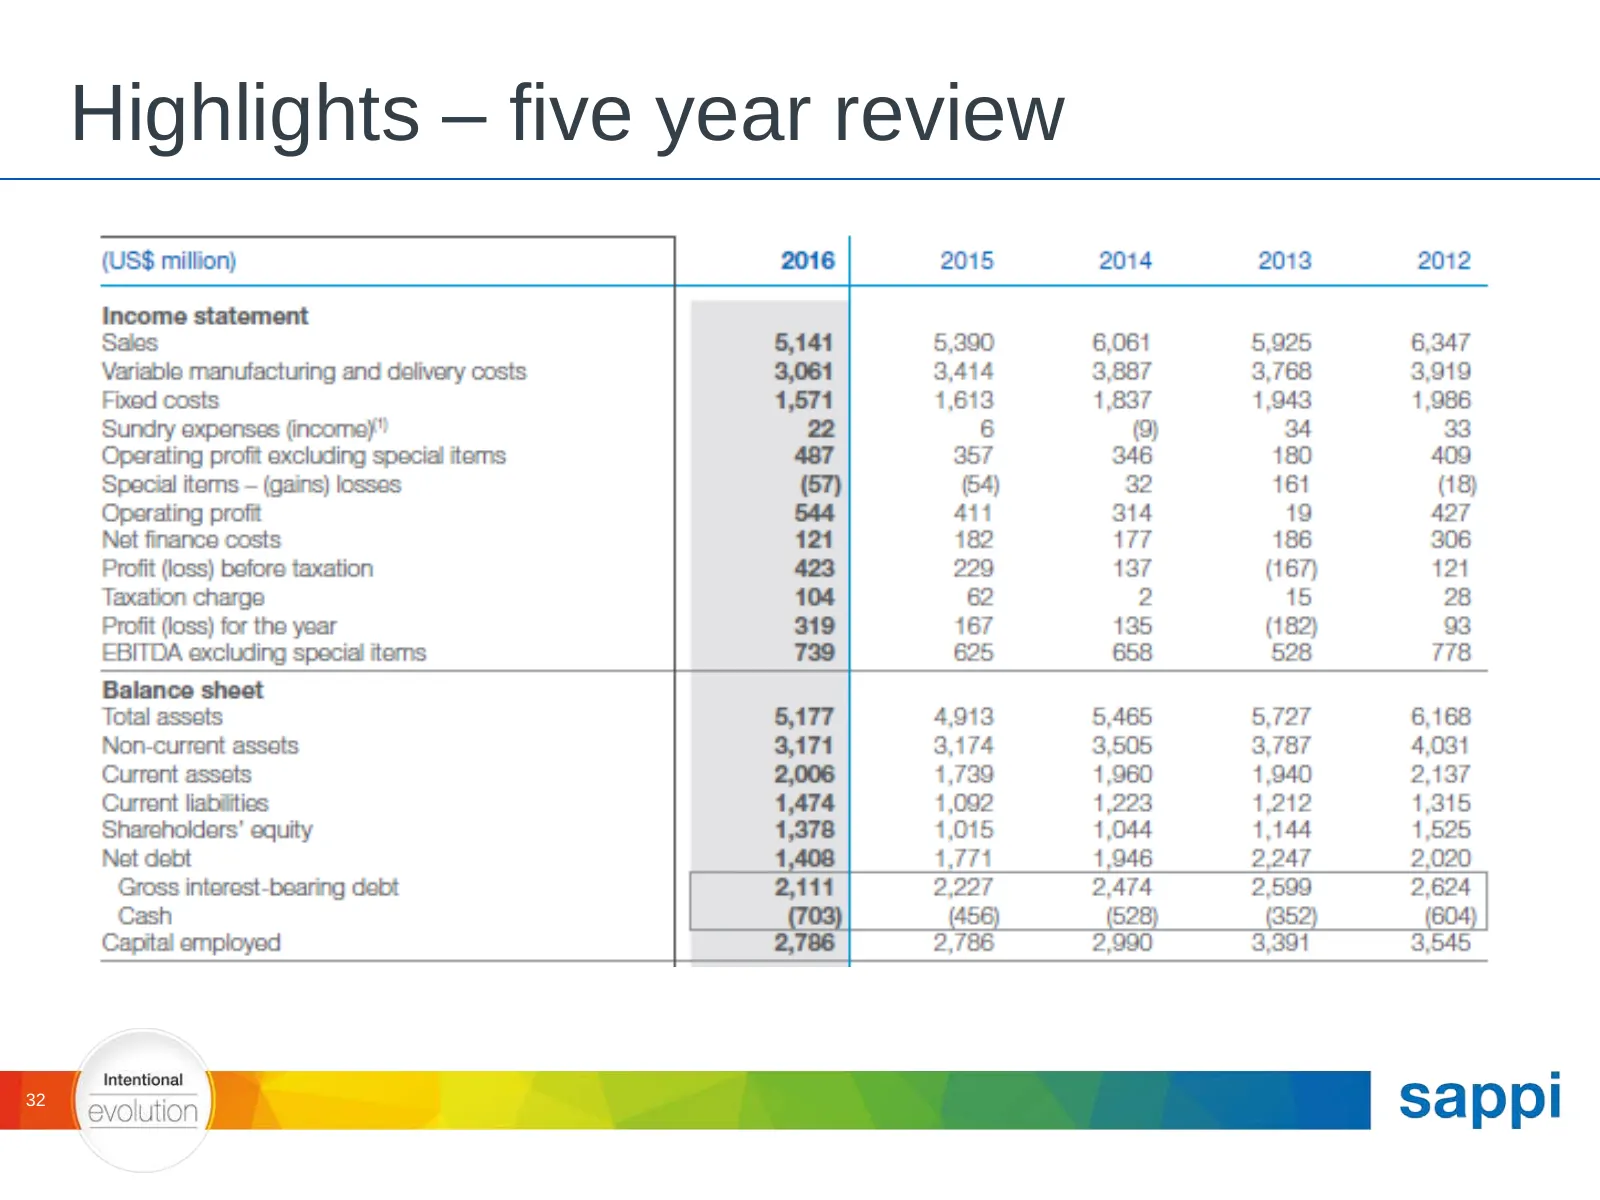
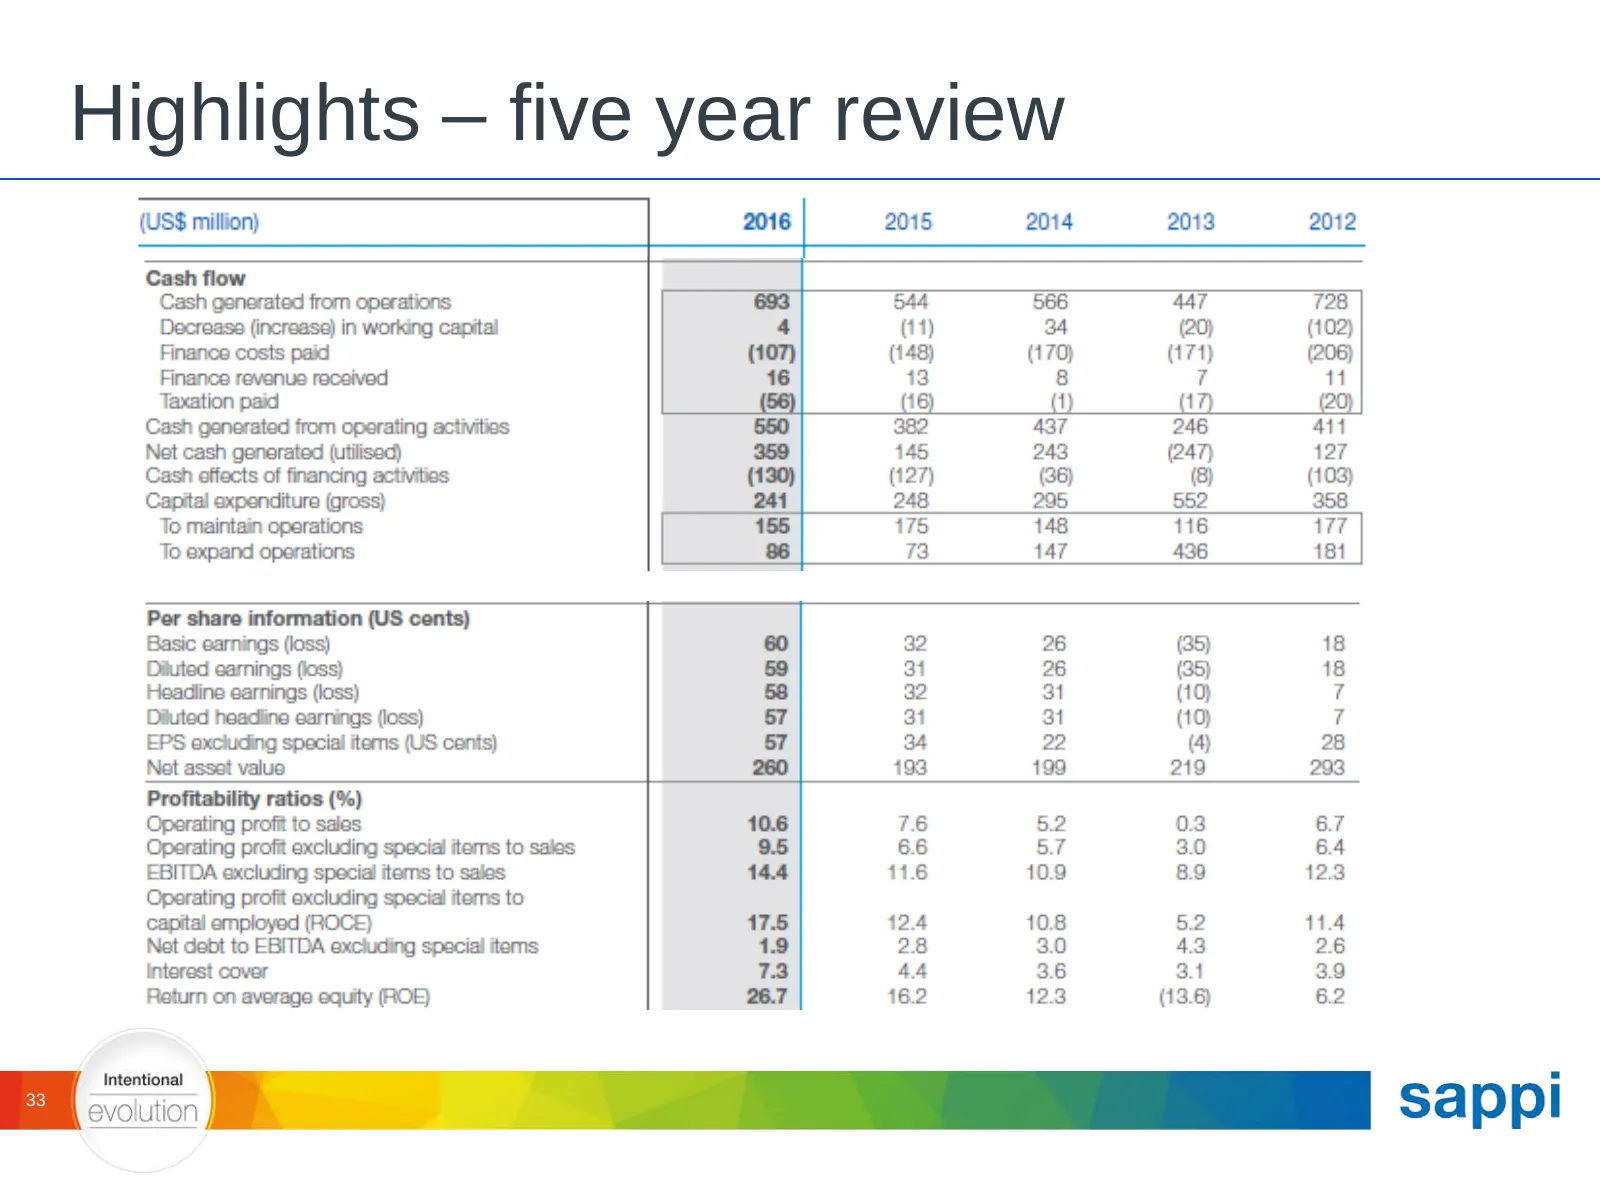
Highlights – five year review 32
Slide 33: Highlights – five year review
Highlights – five year review 33
Slide 34: Product contribution split - LTM
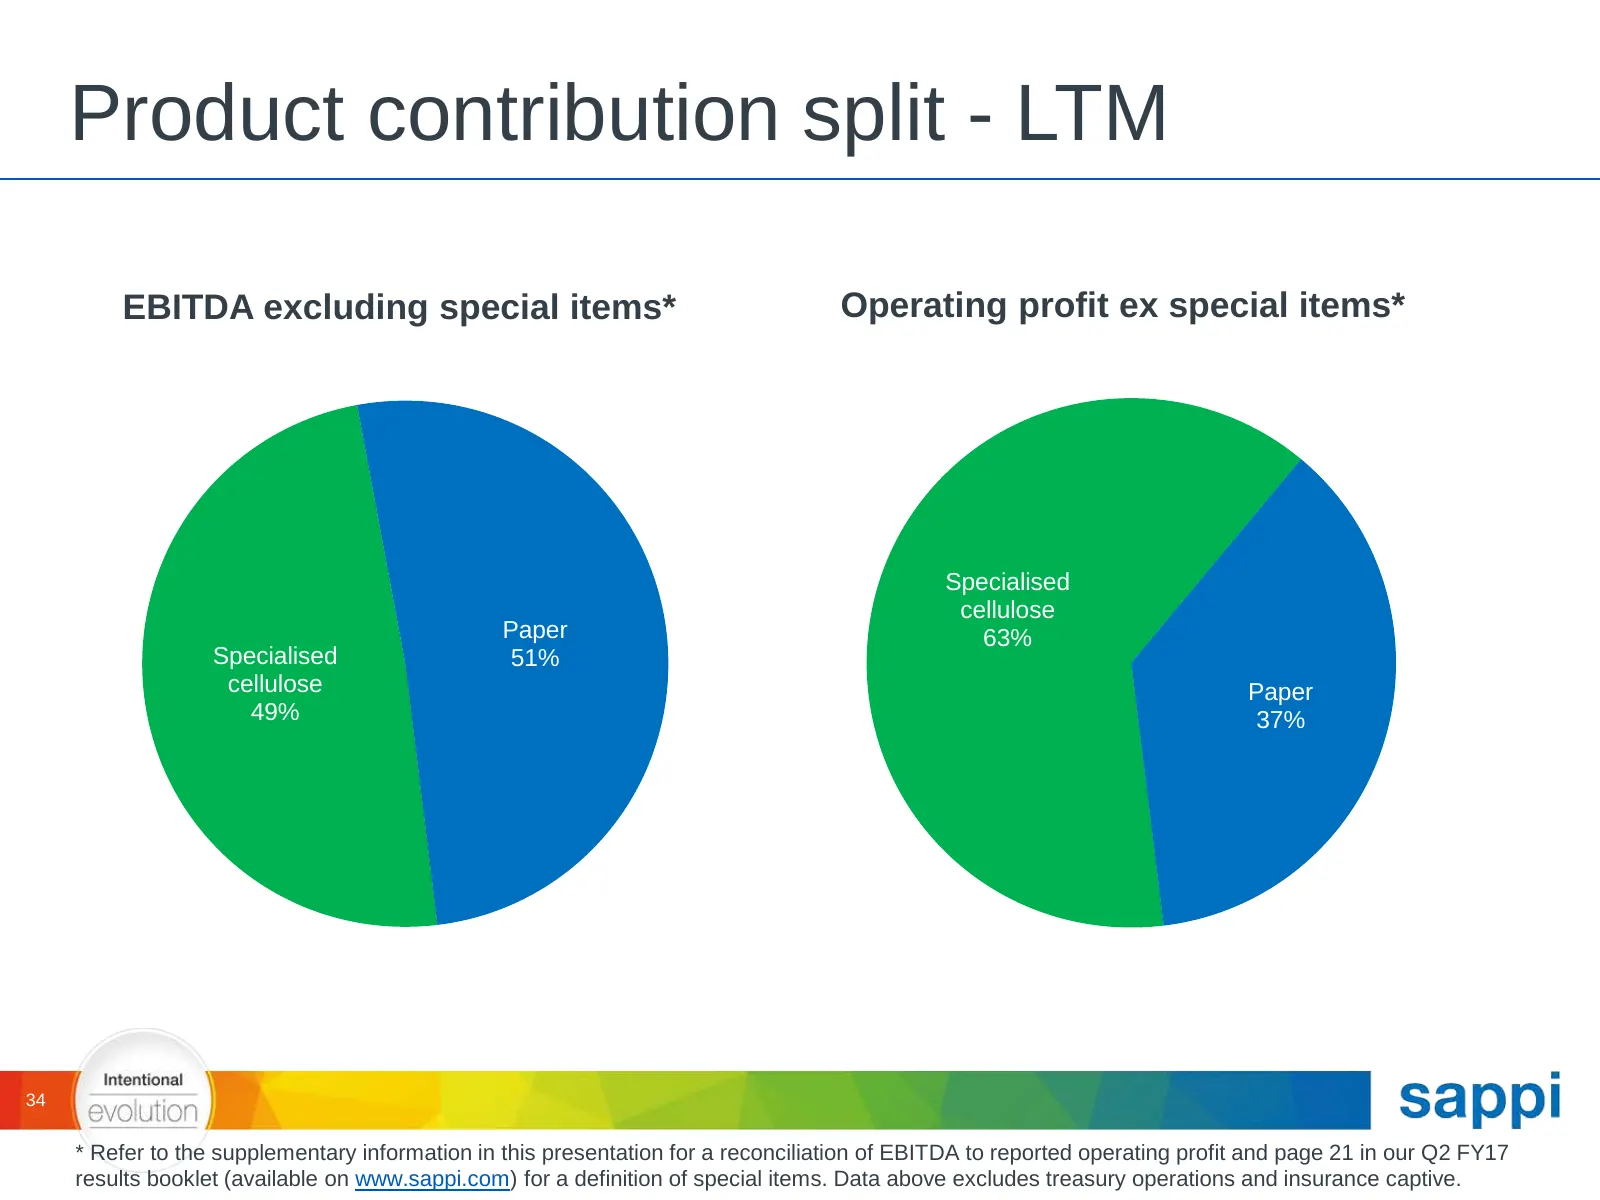
Product contribution split - LTM EBITDA excluding special items* Operating profit ex special items* Specialised cellulose Paper 63% Specialised 51% cellulose Paper 49% 37% 34 * Refer to the supplementary information in this presentation for a reconciliation of EBITDA to reported operating profit and
Slide 35: Net debt/EBITDA development
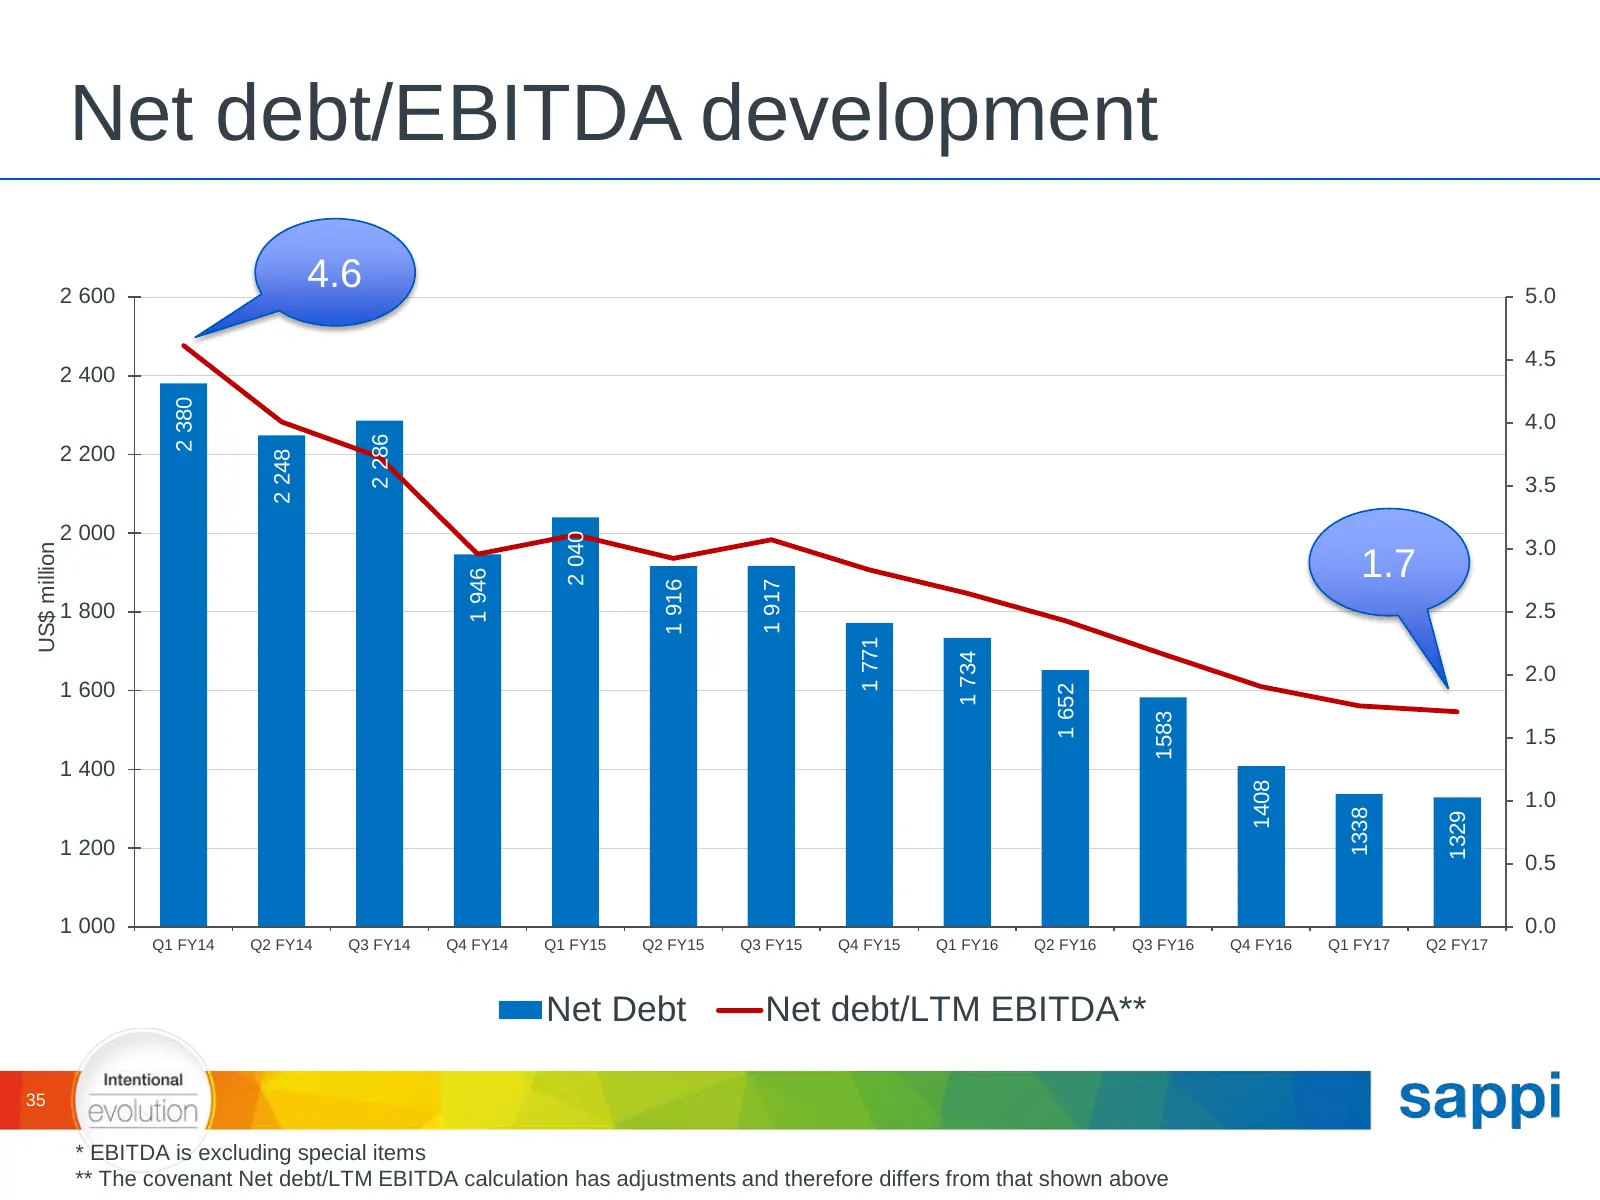
Net debt/EBITDA development 2 600 4.6 5.0 4.5 2 400 2 380 4.0 2 286 2 200 2 248 3.5 2 000 2 040 3.0 US$ million 1.7 1 946 1 917 1 916 1 800 2.5 1 771 1 734 2.0 1 600 1 652 1583 1.5 1 400 1408 1.0 1338 1329 1 200 0.5 1 000 0.0 Q1 FY14 Q2 FY14 Q3 FY14 Q4 FY14 Q1 FY15 Q2 FY15 Q3 FY15 Q4 FY15 Q1 FY16 Q2
Slide 36: Maturity profile
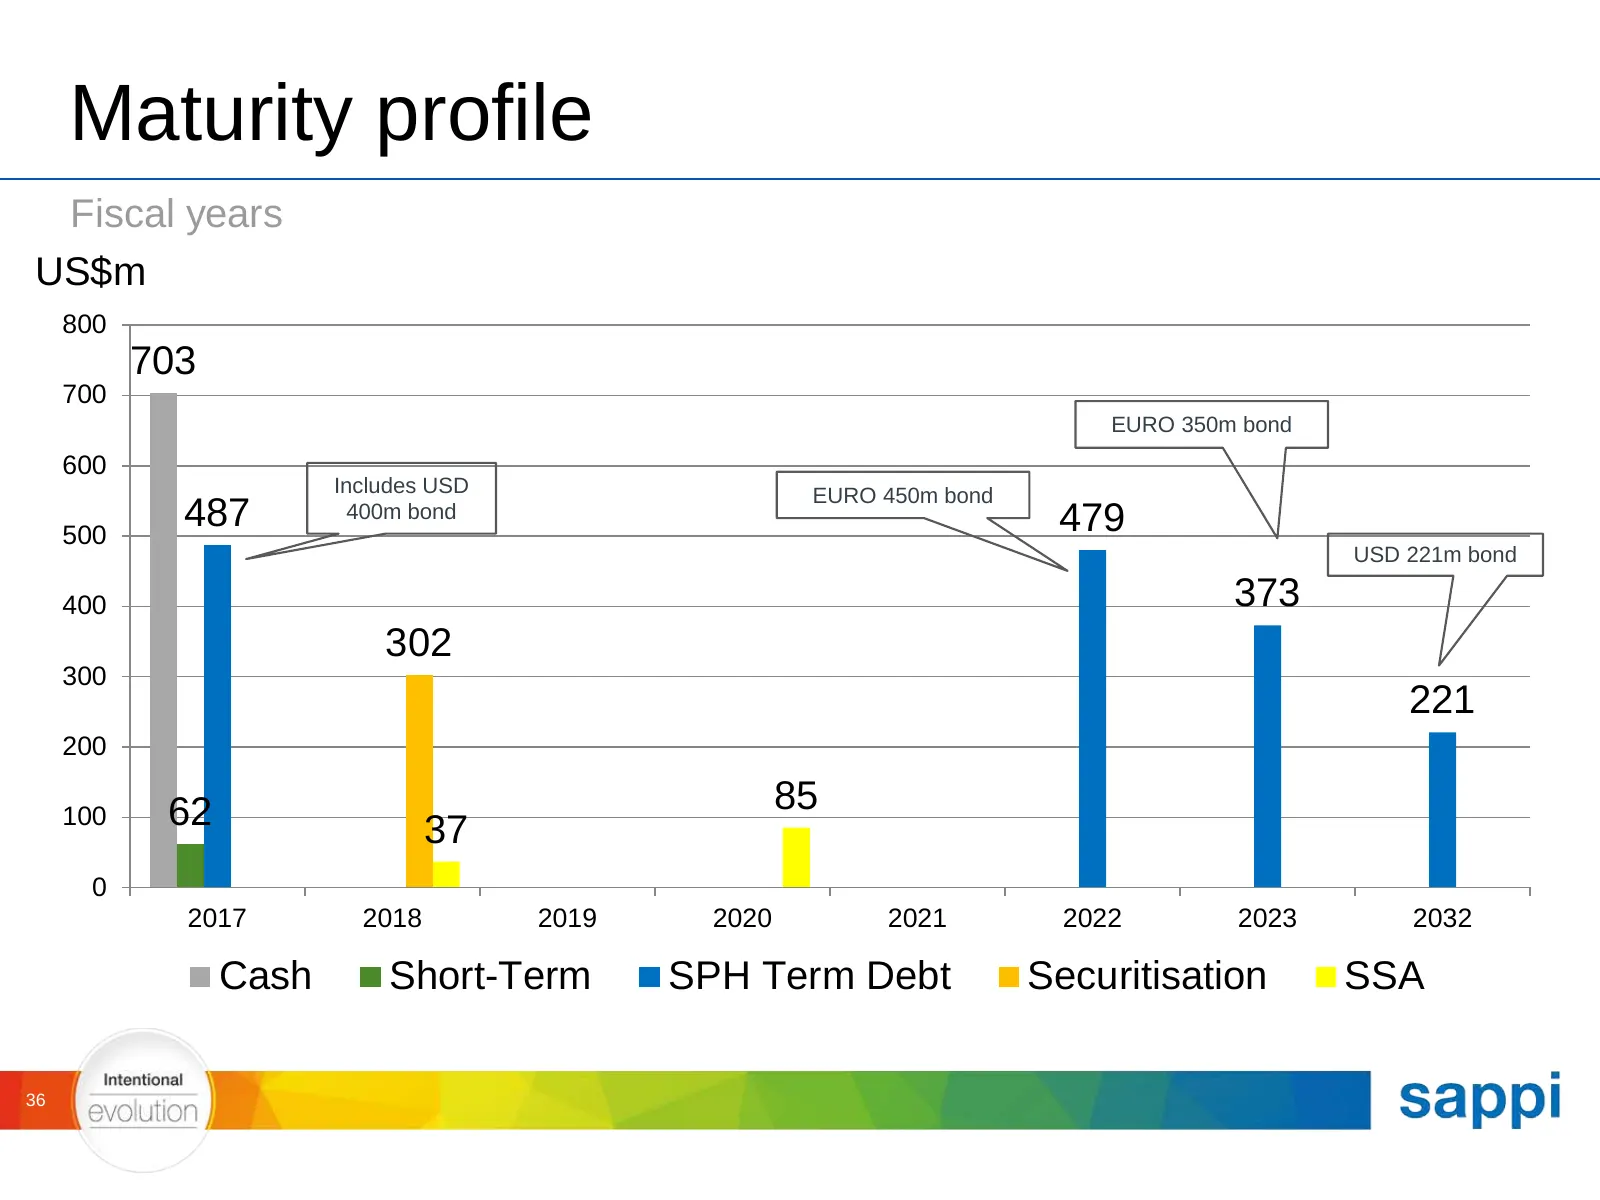
Maturity profile Fiscal years US$m 800 703 700 EURO 350m bond 600 Includes USD EURO 450m bond 500 487 400m bond 479 USD 221m bond 400 373 302 300 221 200 100 62 85 37 0 2017 2018 2019 2020 2021 2022 2023 2032 Cash Short-Term SPH Term Debt Securitisation SSA 36
Slide 37: Capex development
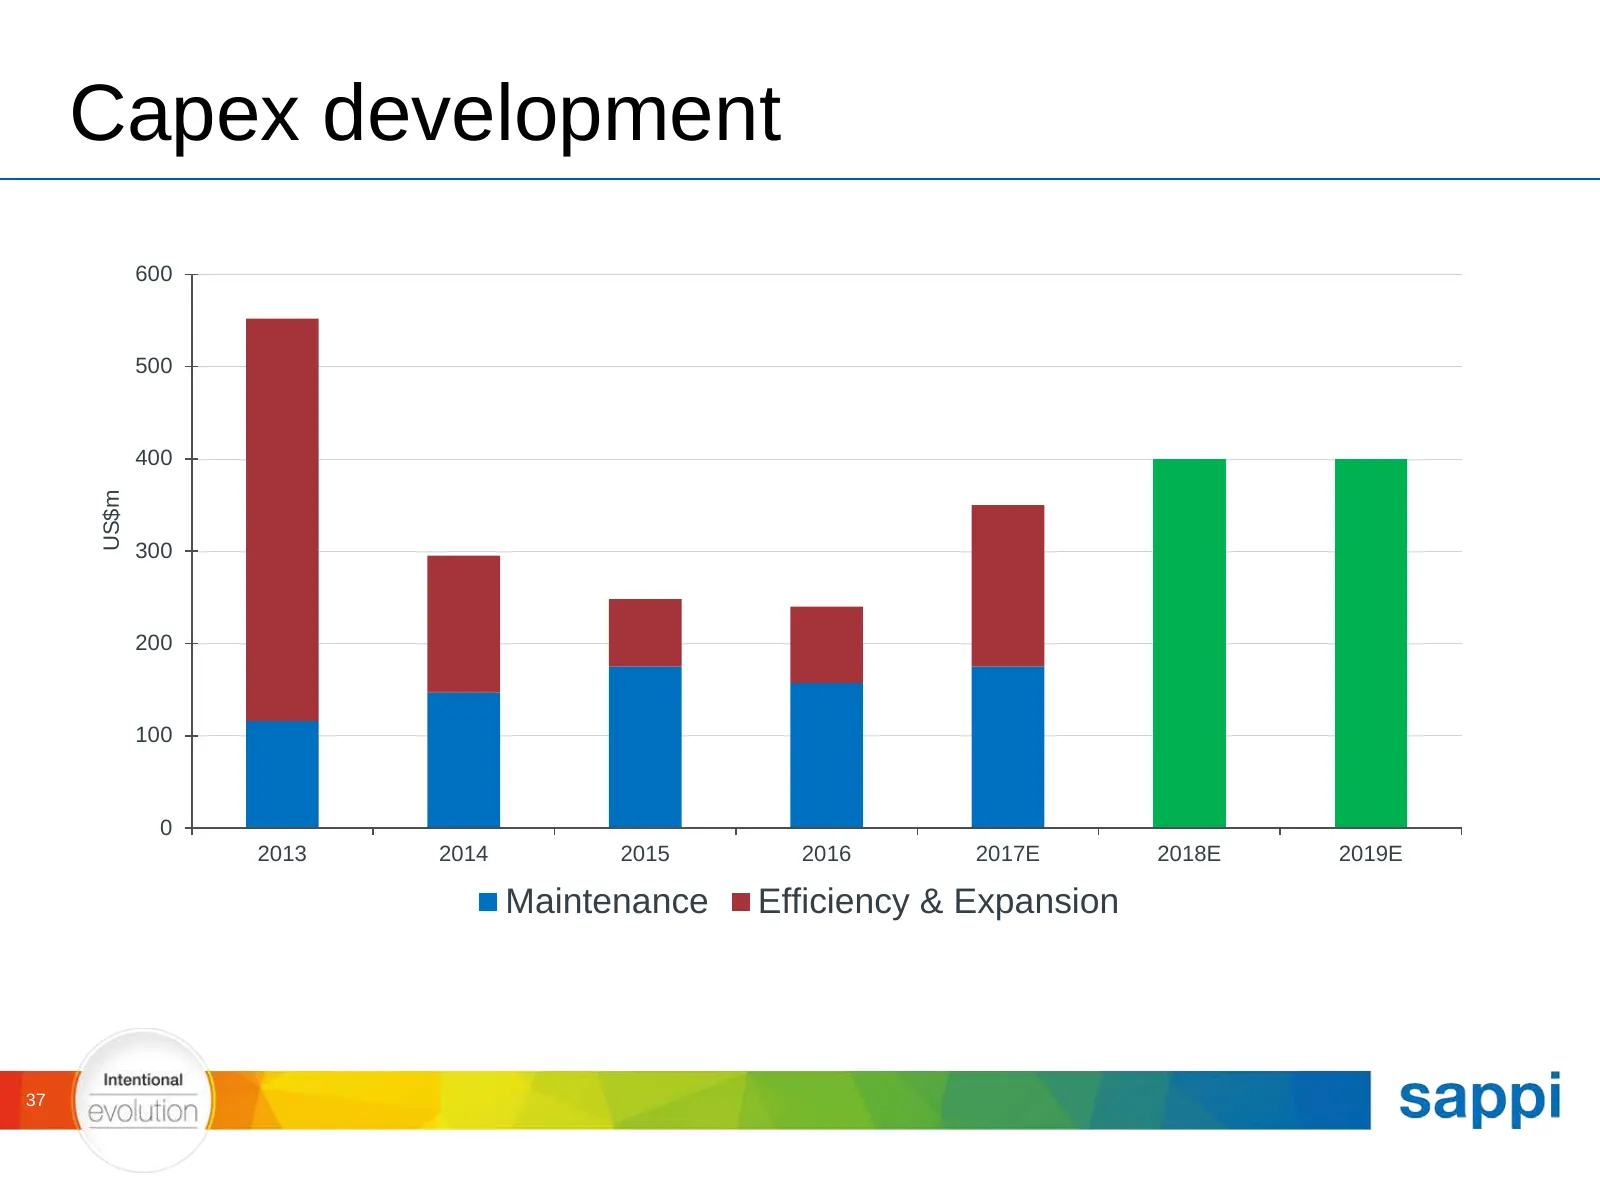
Capex development 600 500 400 US$m 300 200 100 0 2013 2014 2015 2016 2017E 2018E 2019E Maintenance Efficiency & Expansion 37
Slide 38: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 38
Slide 39: Divisional overview: Sappi Europe
Divisional overview Sappi Europe Leading European coated paper producer FY16 Net sales: US$2.6b FY16 EBITDA: US$261m 3.5m tons per annum of paper capacity 1.1m tons per annum of pulp capacity (integrated) Well-invested assets in the heart of the European market 39
Slide 40: Divisional overview: Sappi Europe
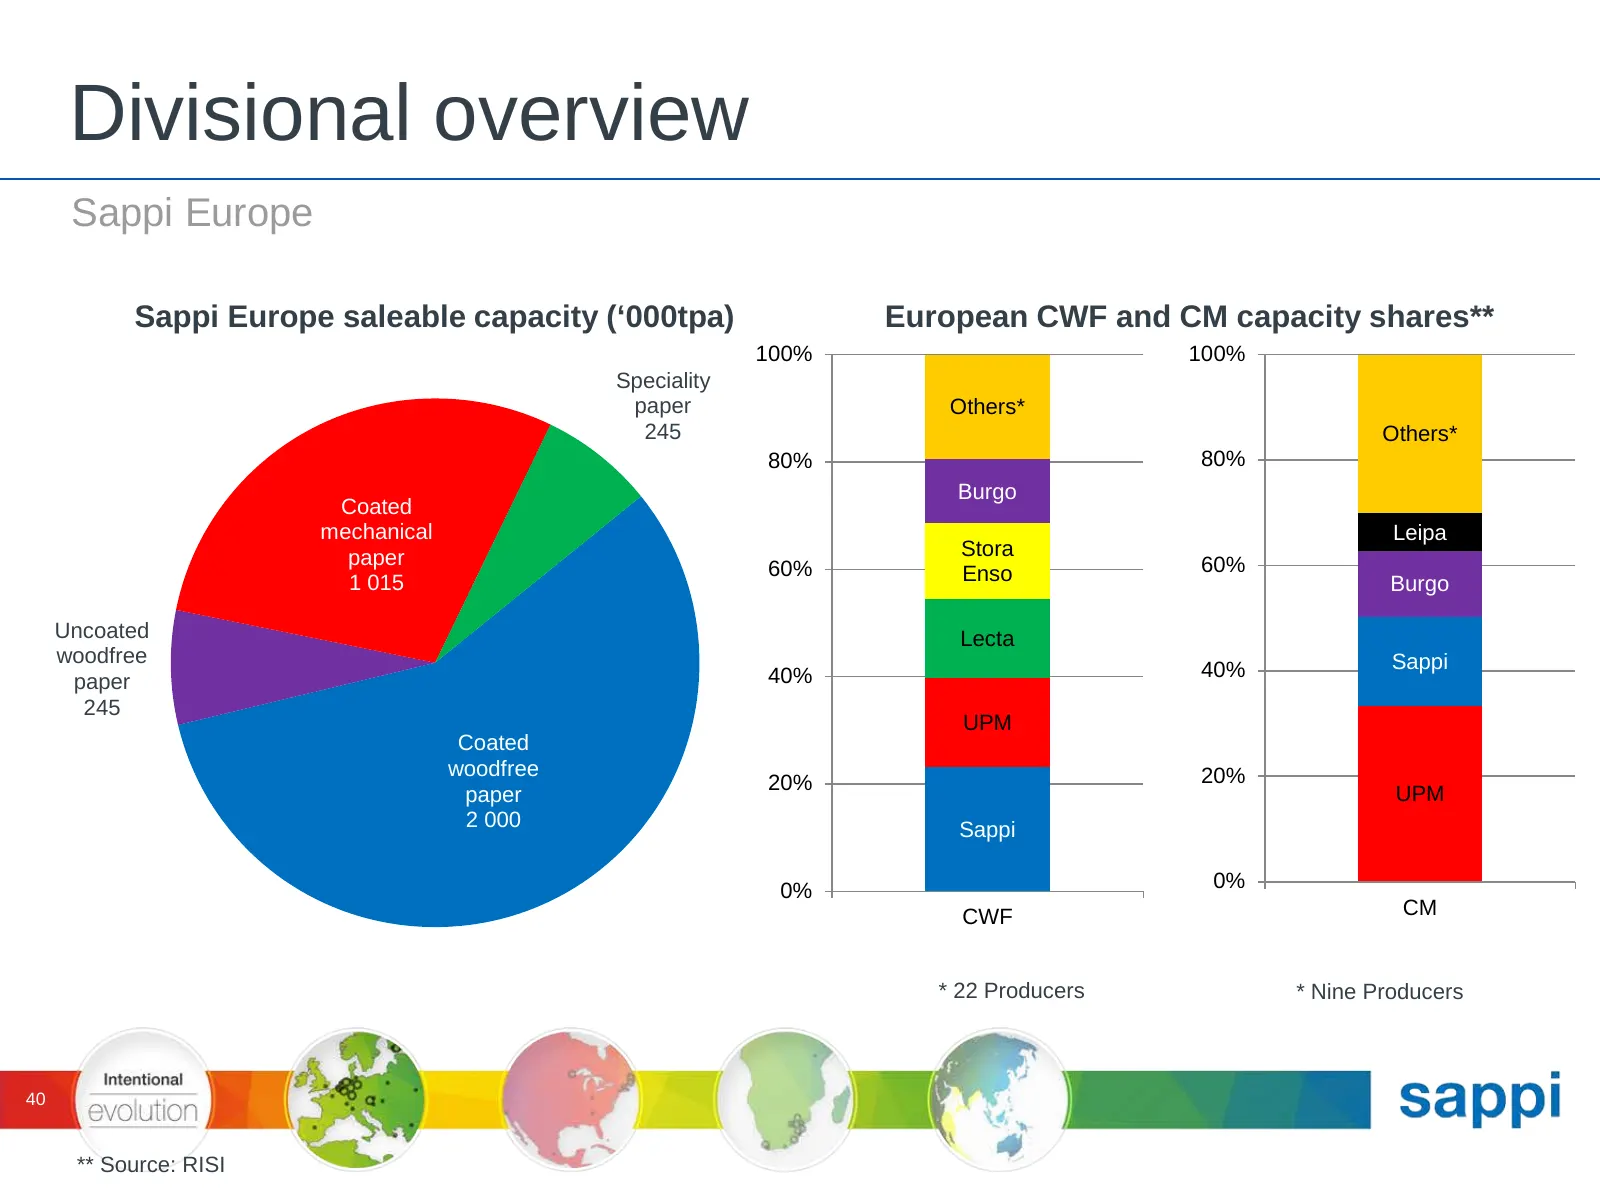
Divisional overview Sappi Europe Sappi Europe saleable capacity (‘000tpa) European CWF and CM capacity shares** 100% 100% Speciality paper Others* 245 Others* 80% 80% Burgo Coated mechanical Leipa paper Stora 60% Enso 60% 1 015 Burgo Uncoated Lecta woodfree Sappi 40% 40% paper 245 UPM Coated woodfre
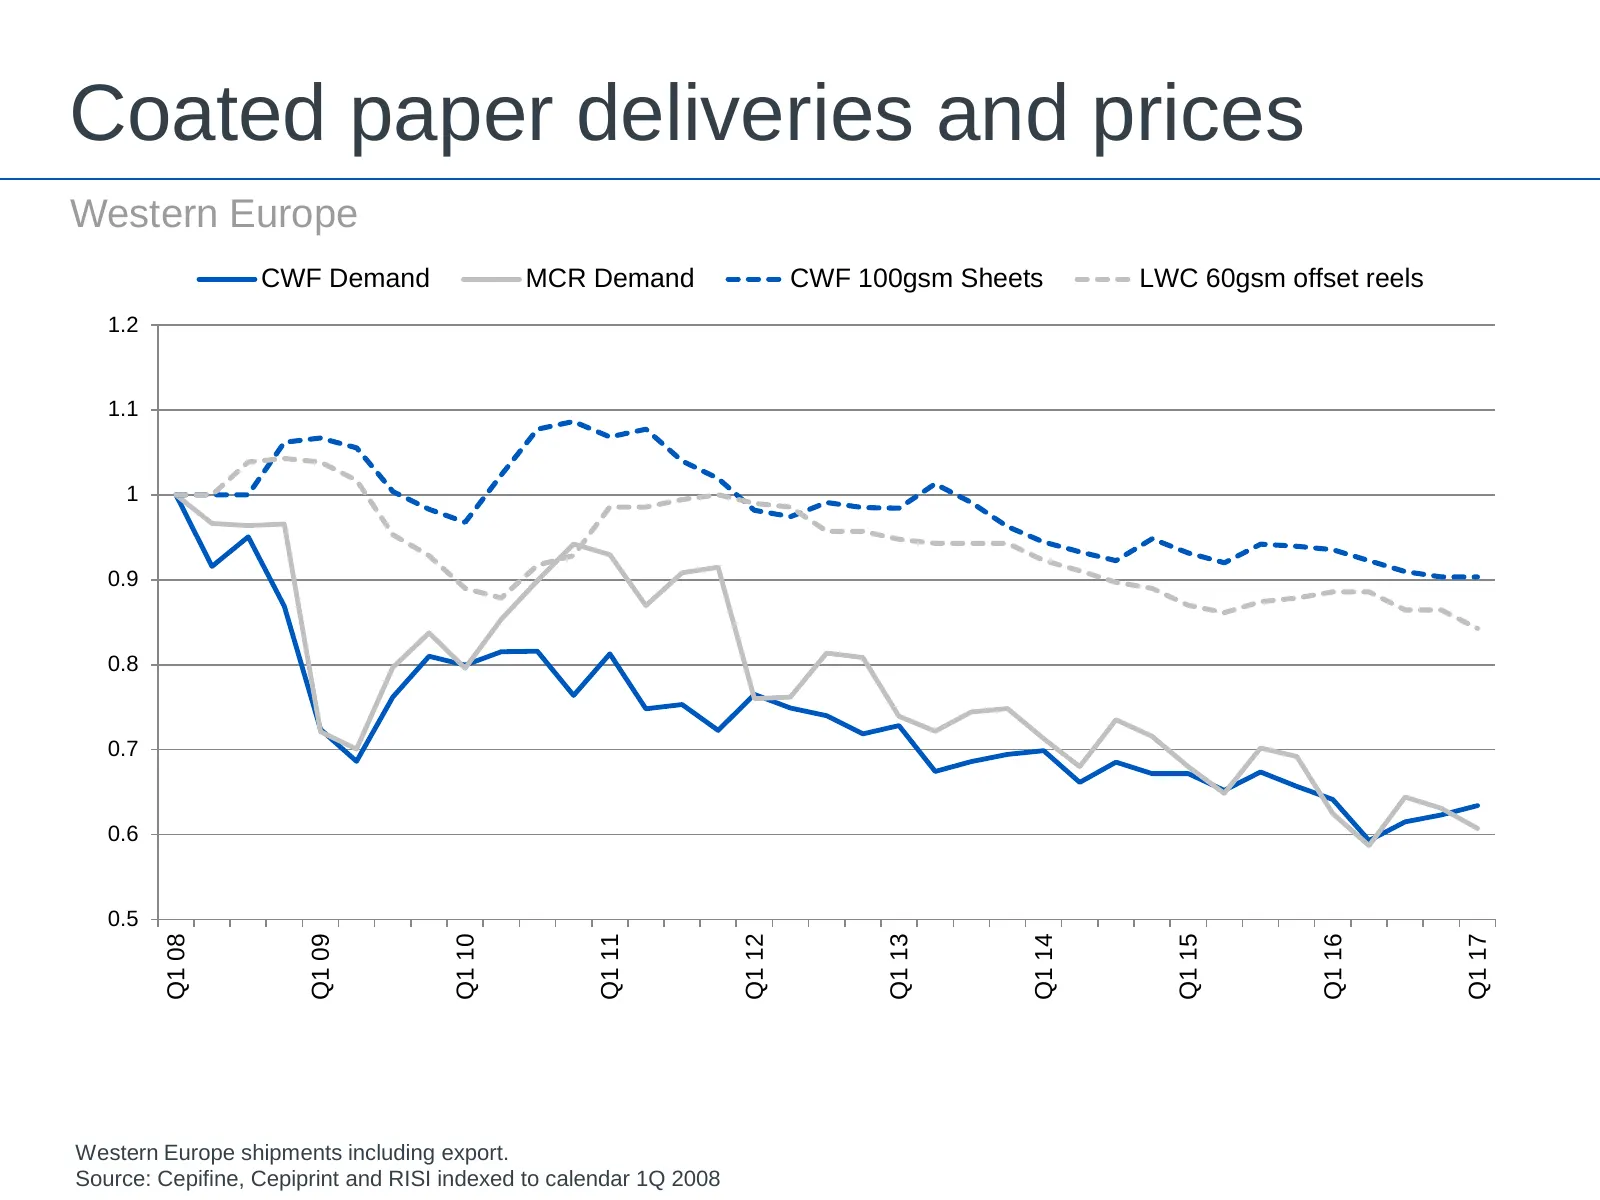
Slide 41: Coated paper deliveries and prices
Coated paper deliveries and prices Western Europe CWF Demand MCR Demand CWF 100gsm Sheets LWC 60gsm offset reels 1.2 1.1 1 0.9 0.8 0.7 0.6 0.5 Q1 08 Q1 09 Q1 10 Q1 11 Q1 12 Q1 13 Q1 14 Q1 15 Q1 16 Q1 17 41 Western Europe shipments including export. Source: Cepifine, Cepiprint and RISI indexed to cal
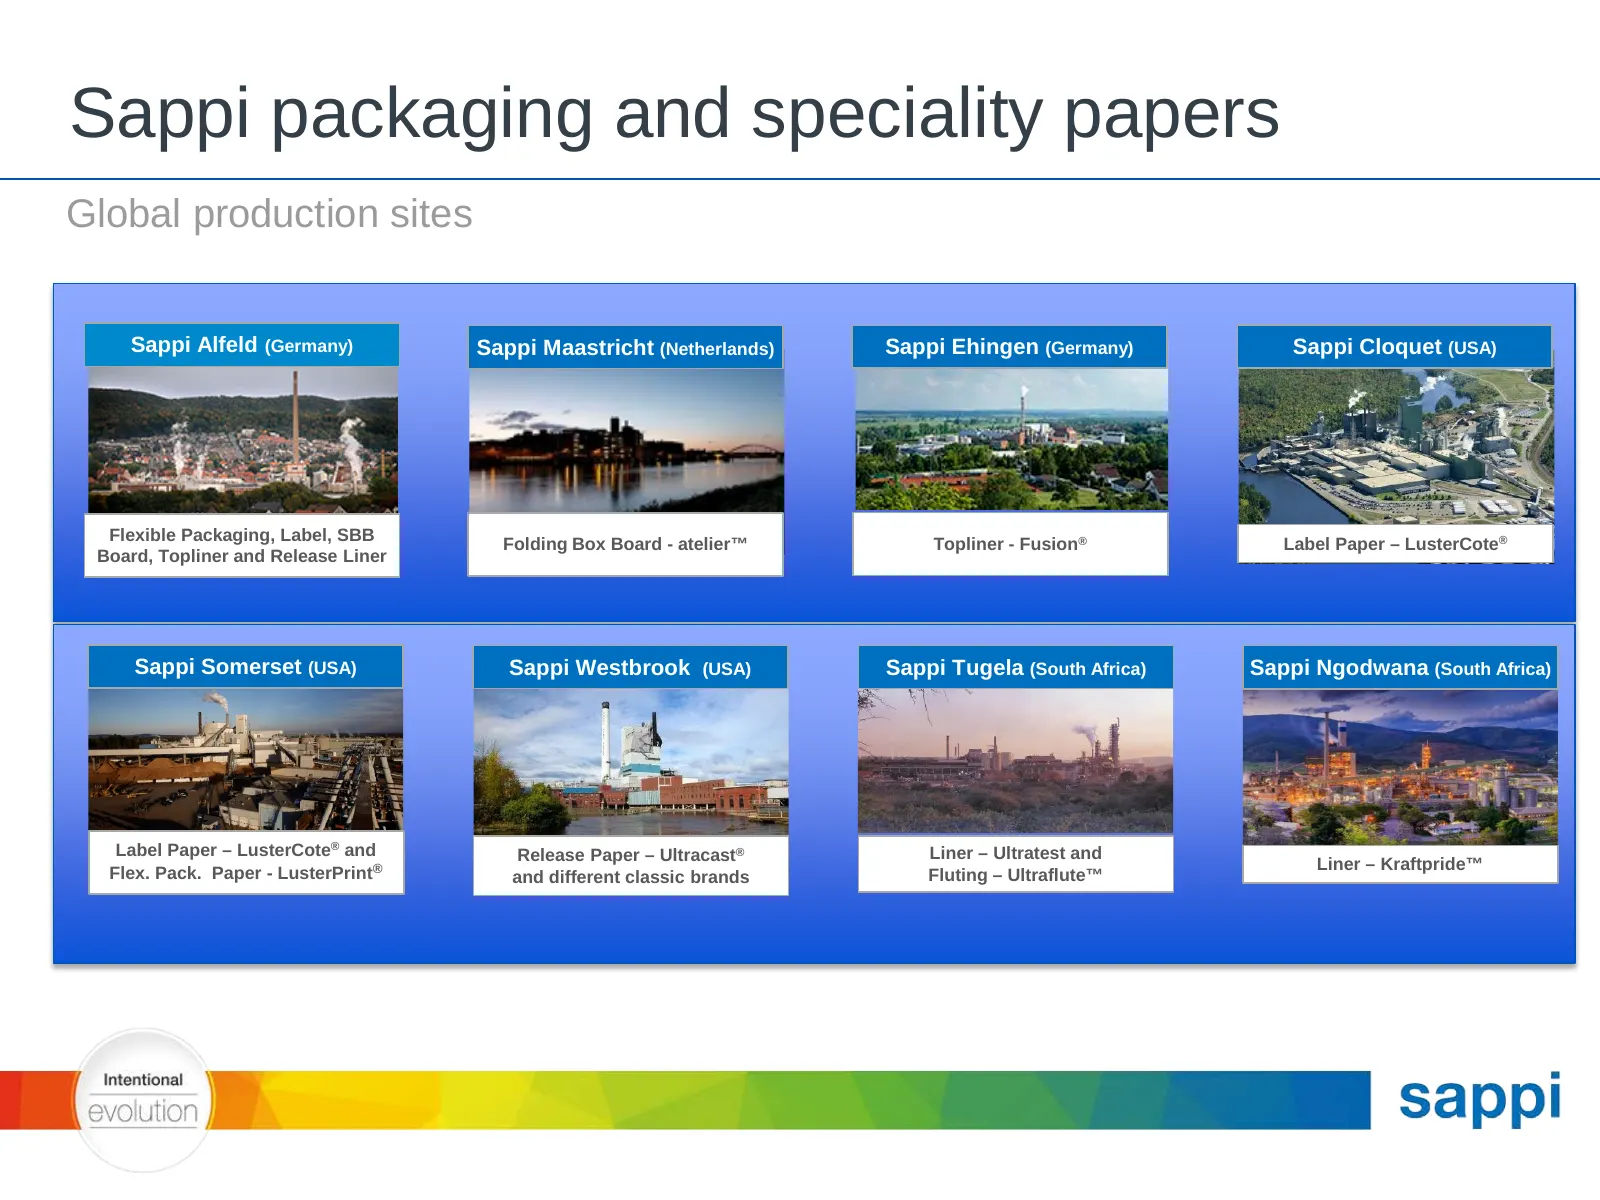
Slide 42: Sappi packaging and speciality papers
Sappi packaging and speciality papers Global production sites Sappi Alfeld (Germany) Sappi Maastricht (Netherlands) Sappi Ehingen (Germany) Sappi Cloquet (USA) Flexible Packaging, Label, SBB Label Paper – LusterCote® Folding Box Board - atelier™ Topliner - Fusion® Board, Topliner and Release Liner S
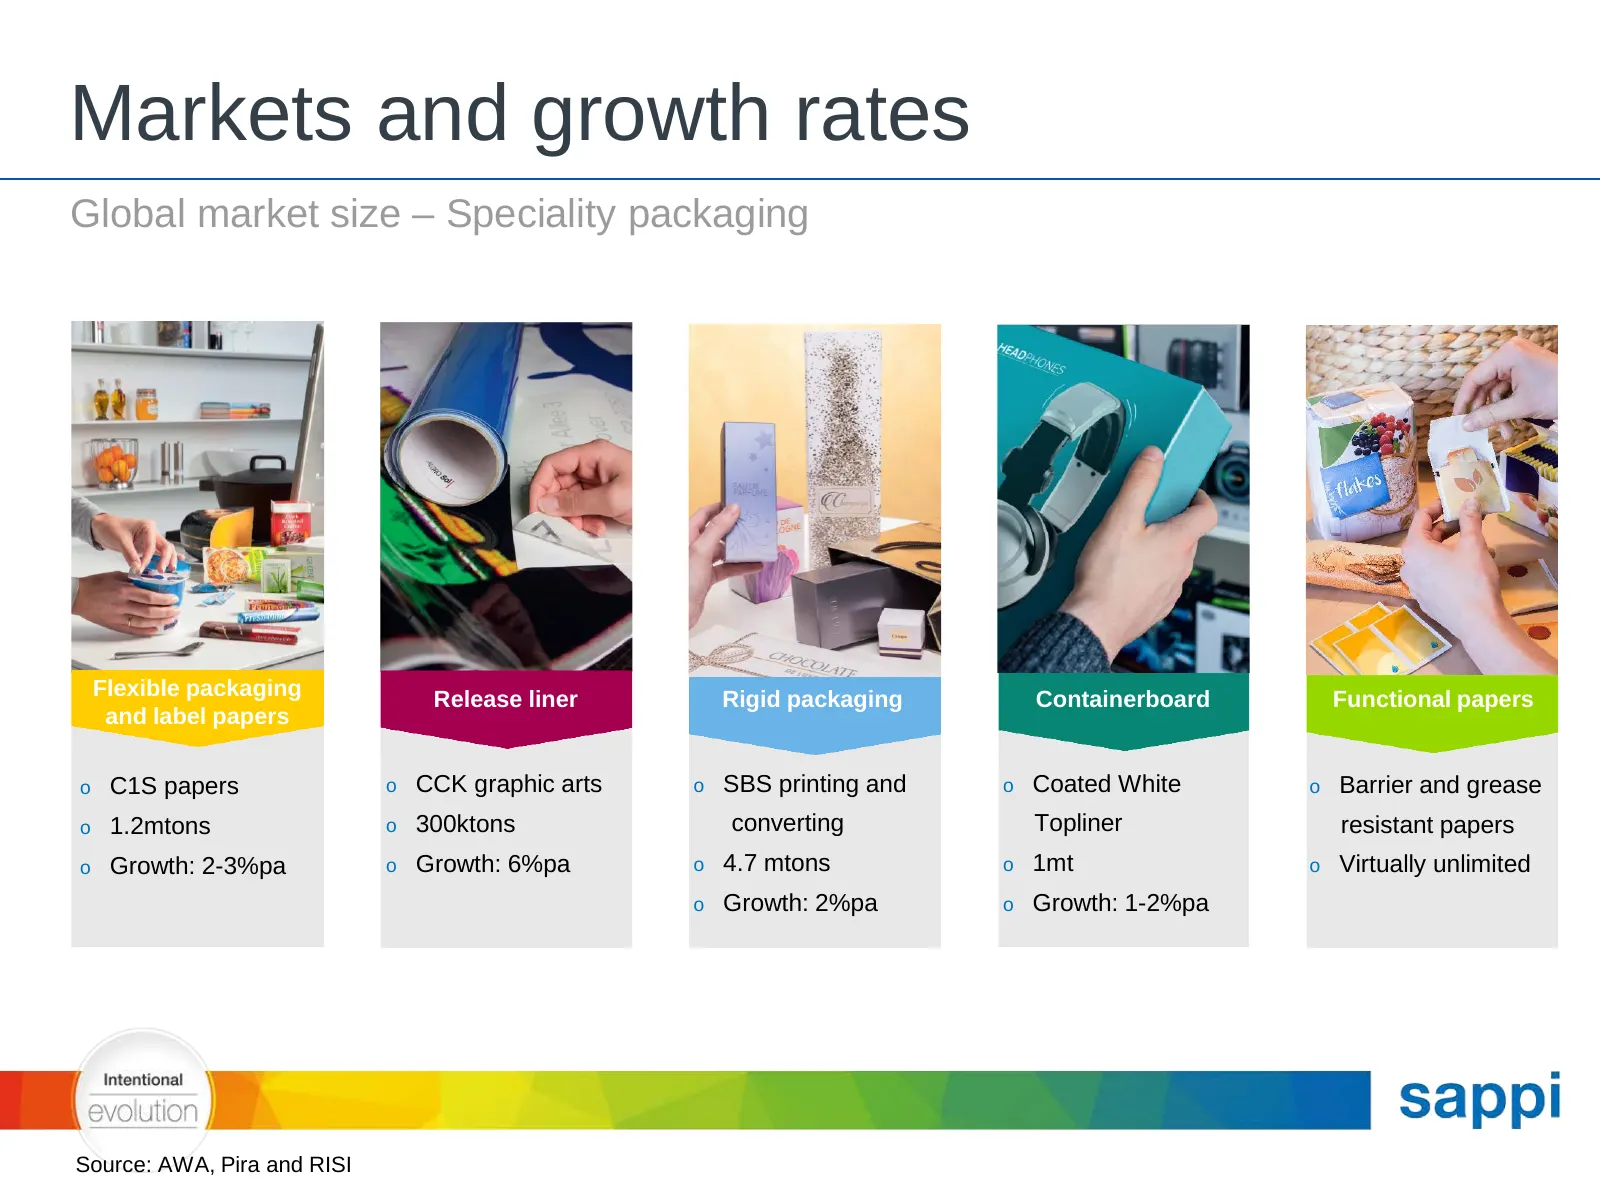
Slide 43: Markets and growth rates
Markets and growth rates Global market size – Speciality packaging Flexible packaging Release liner Rigid packaging Containerboard Functional papers and label papers o C1S papers o CCK graphic arts o SBS printing and o Coated White o Barrier and grease o 1.2mtons o 300ktons converting Topliner resis
Slide 44: Projects: Sappi Europe
Projects Sappi Europe Alfeld Mill Speciality conversion (December 2013) Gratkorn and Kirkniemi Mills Pulp mill and paper machine upgrades, power plant rebuild Nanocellulose pilot plant (The Netherlands) Trial runs Maastricht, Ehingen, Alfeld and Lanaken Mills Projects o Expanding our speciality
Slide 45: Summary: Sappi Europe
Summary Sappi Europe Highly competitive in service, quality and cost in Europe Strong cash flows Highly attractive and growing specialities business Flagship Alfeld Mill, plus Maastricht and Ehingen Mills Printing and writing paper market is in decline, capacity needs to be right-sized I
Slide 46: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 46
Slide 47: Divisional overview: Sappi North America
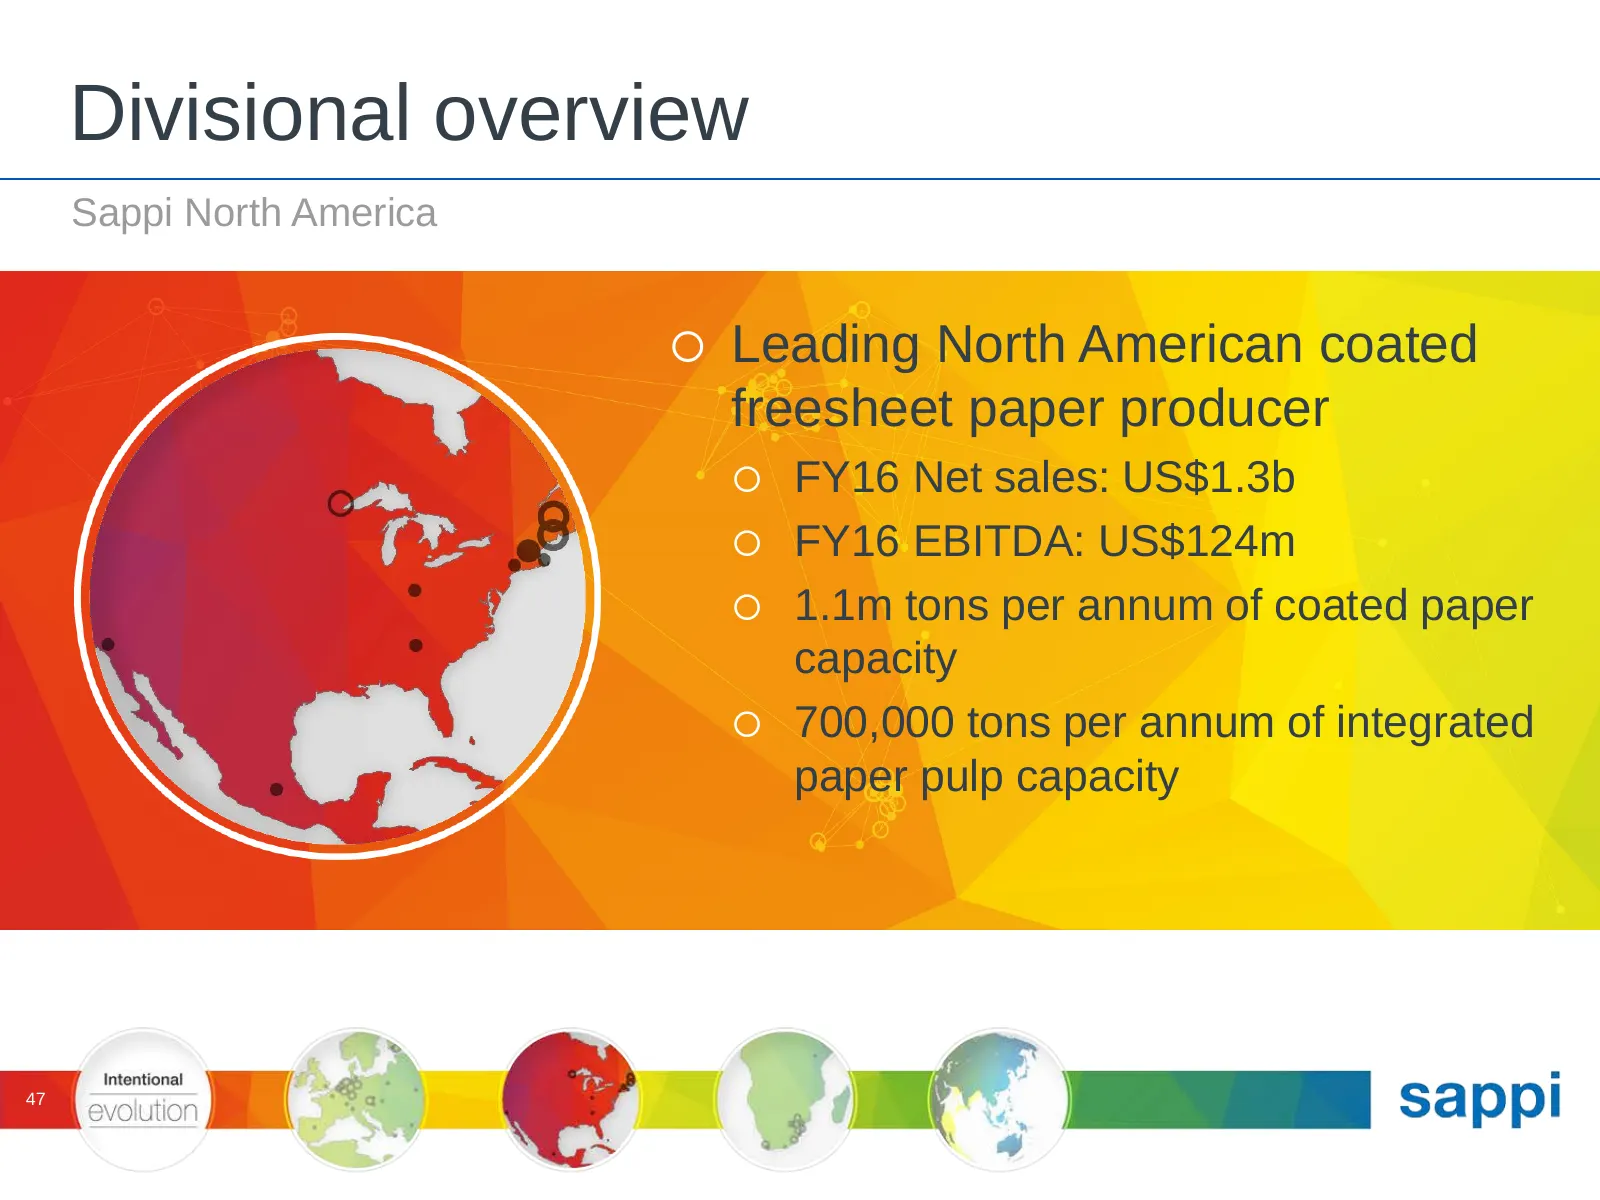
Divisional overview Sappi North America Leading North American coated freesheet paper producer FY16 Net sales: US$1.3b FY16 EBITDA: US$124m 1.1m tons per annum of coated paper capacity 700,000 tons per annum of integrated paper pulp capacity 47
Slide 48: Divisional overview: Sappi North America
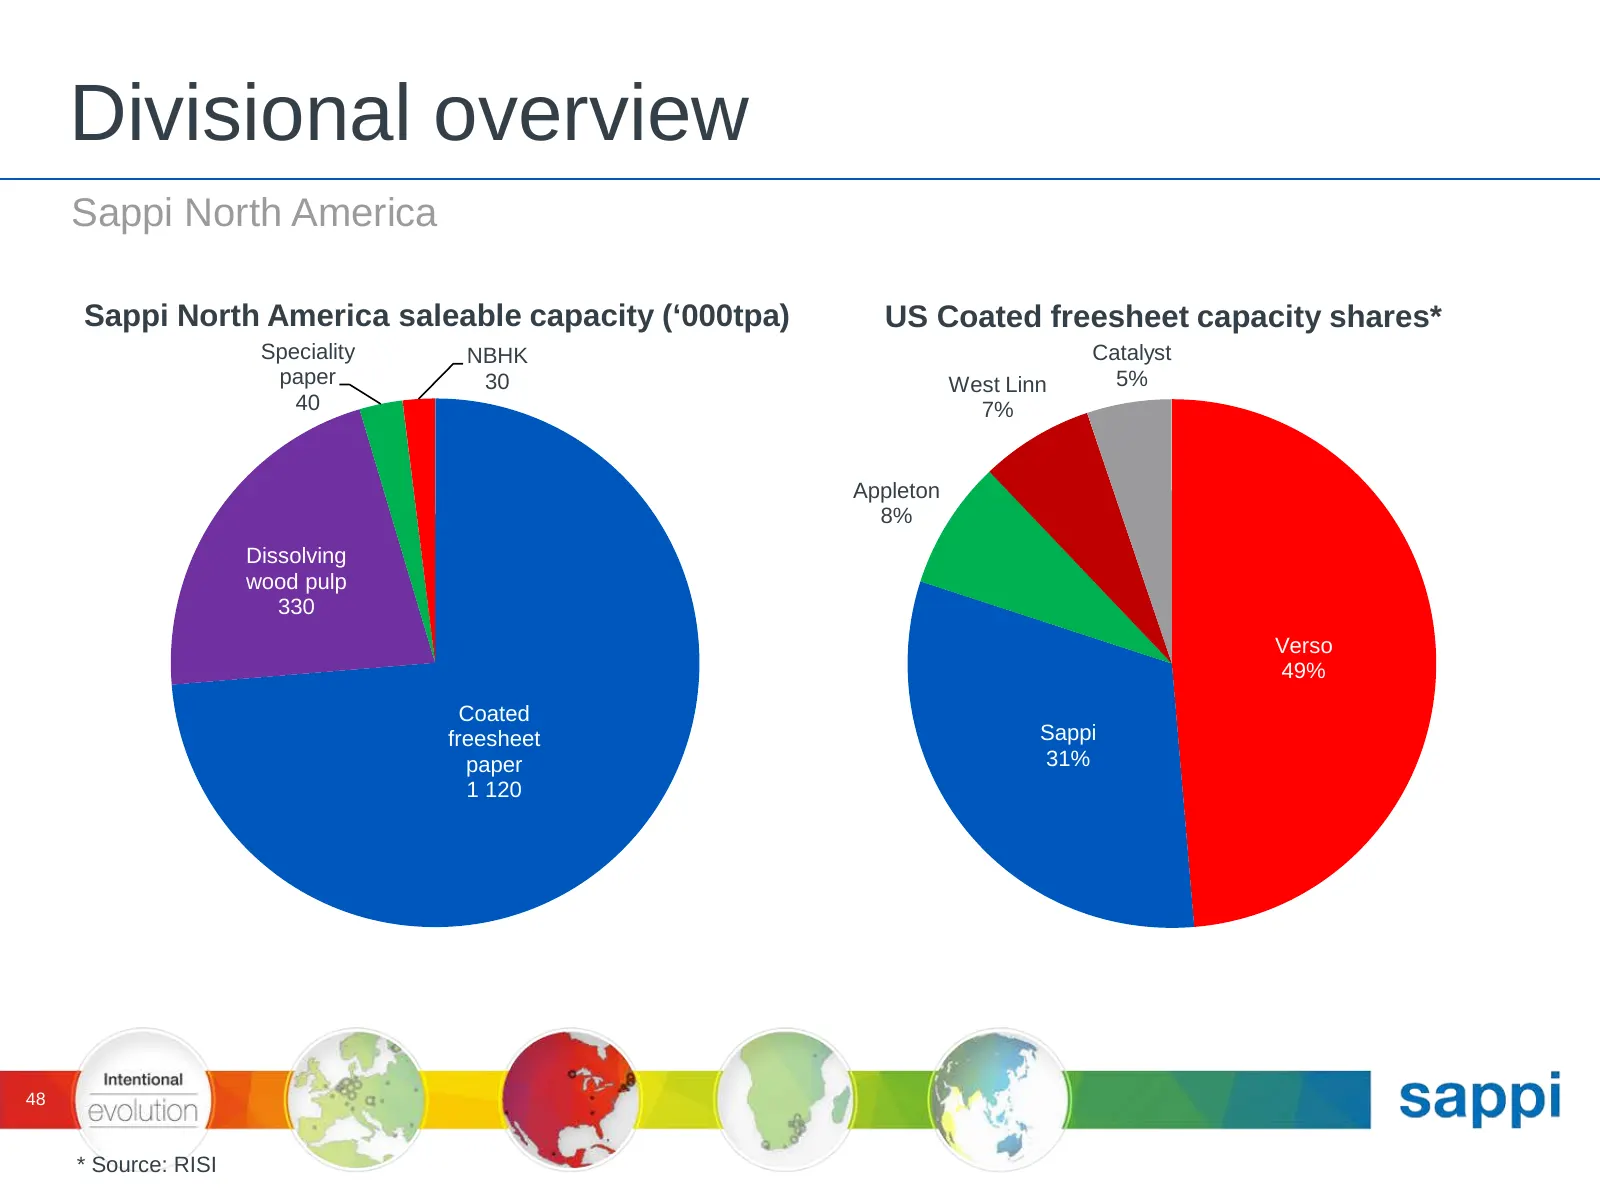
Divisional overview Sappi North America Sappi North America saleable capacity (‘000tpa) US Coated freesheet capacity shares* Speciality NBHK Catalyst paper 30 West Linn 5% 40 7% Appleton 8% Dissolving wood pulp 330 Verso 49% Coated freesheet Sappi paper 31% 1 120 48 * Source: RISI
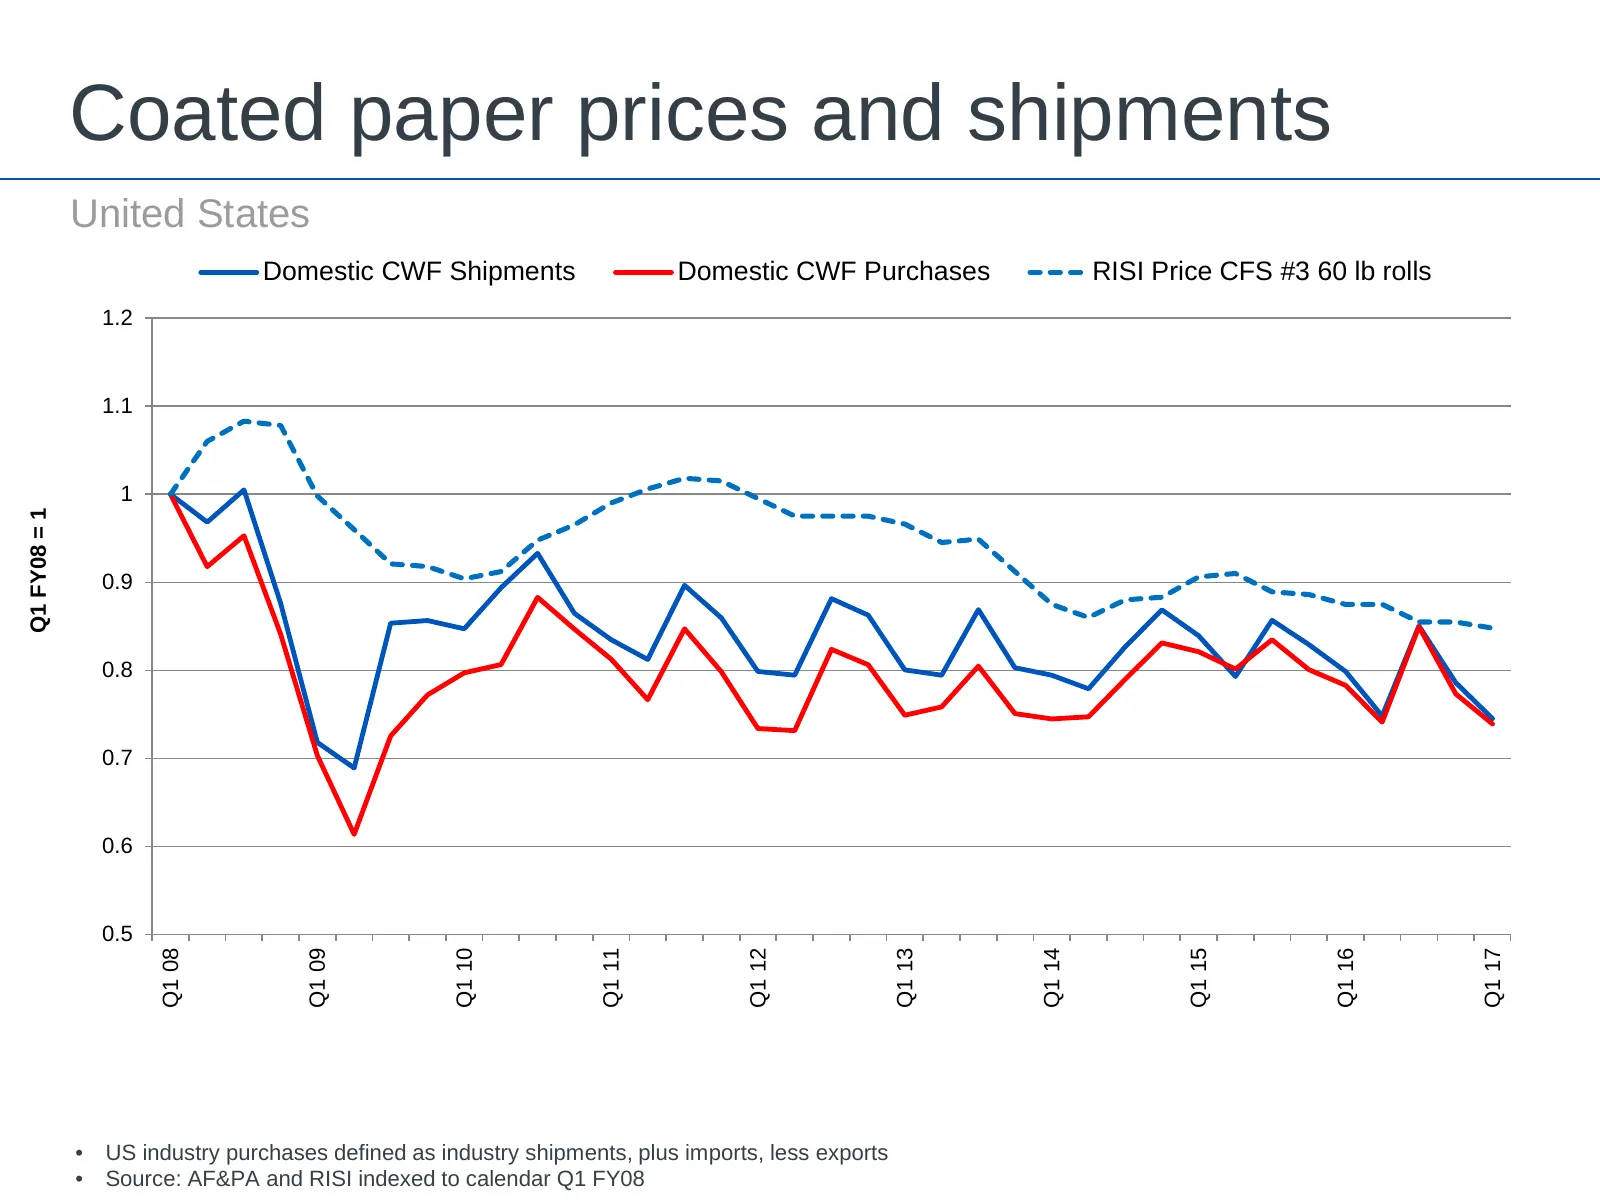
Slide 49: Coated paper prices and shipments
Coated paper prices and shipments United States Domestic CWF Shipments Domestic CWF Purchases RISI Price CFS #3 60 lb rolls 1.2 1.1 1 Q1 FY08 = 1 0.9 0.8 0.7 0.6 0.5 Q1 08 Q1 09 Q1 10 Q1 11 Q1 12 Q1 13 Q1 14 Q1 15 Q1 16 Q1 17 49 • US industry purchases defined as industry shipments, plus imports, le
Slide 50: Projects: Sappi North America
Projects Sappi North America Cloquet Mill Dissolving wood pulp conversion (2013), lime kiln rebuild Westbrook Mill Coater modernisation Somerset Mill Natural gas conversion Woodyard and chip processing investment PM1 Conversion to speciality packaging 50
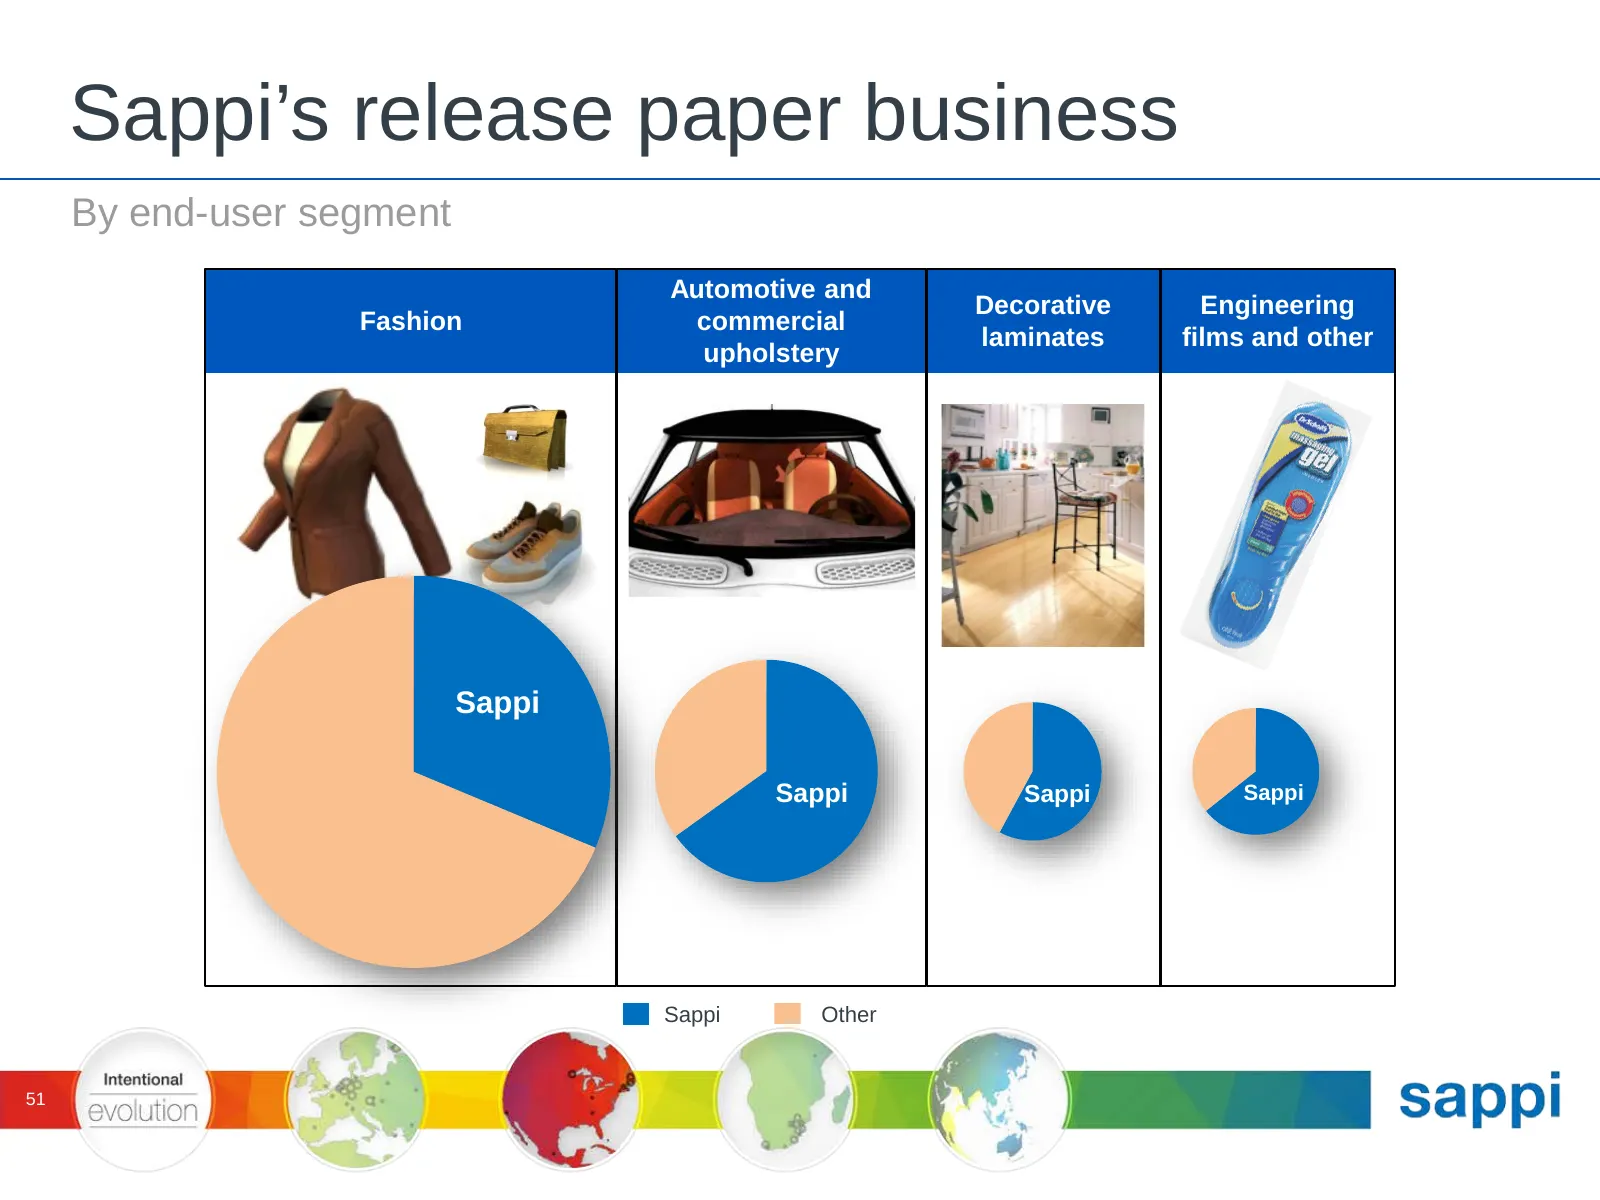
Slide 51: Sappi's release paper business
Sappi’s release paper business By end-user segment Automotive and Decorative Engineering Fashion commercial laminates films and other upholstery Sappi Sappi Sappi Sappi Sappi Other 51
Slide 52: Summary: Sappi North America
Summary Sappi North America Well-invested, premier asset portfolio Established brands with strong market position Exposure to most attractive end-market segment Unmatched reputation for product innovation and customer service A low-cost producer with strong free cash flow profile Defined
Slide 53: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 53
Slide 54: Divisional overview: Sappi Southern Africa
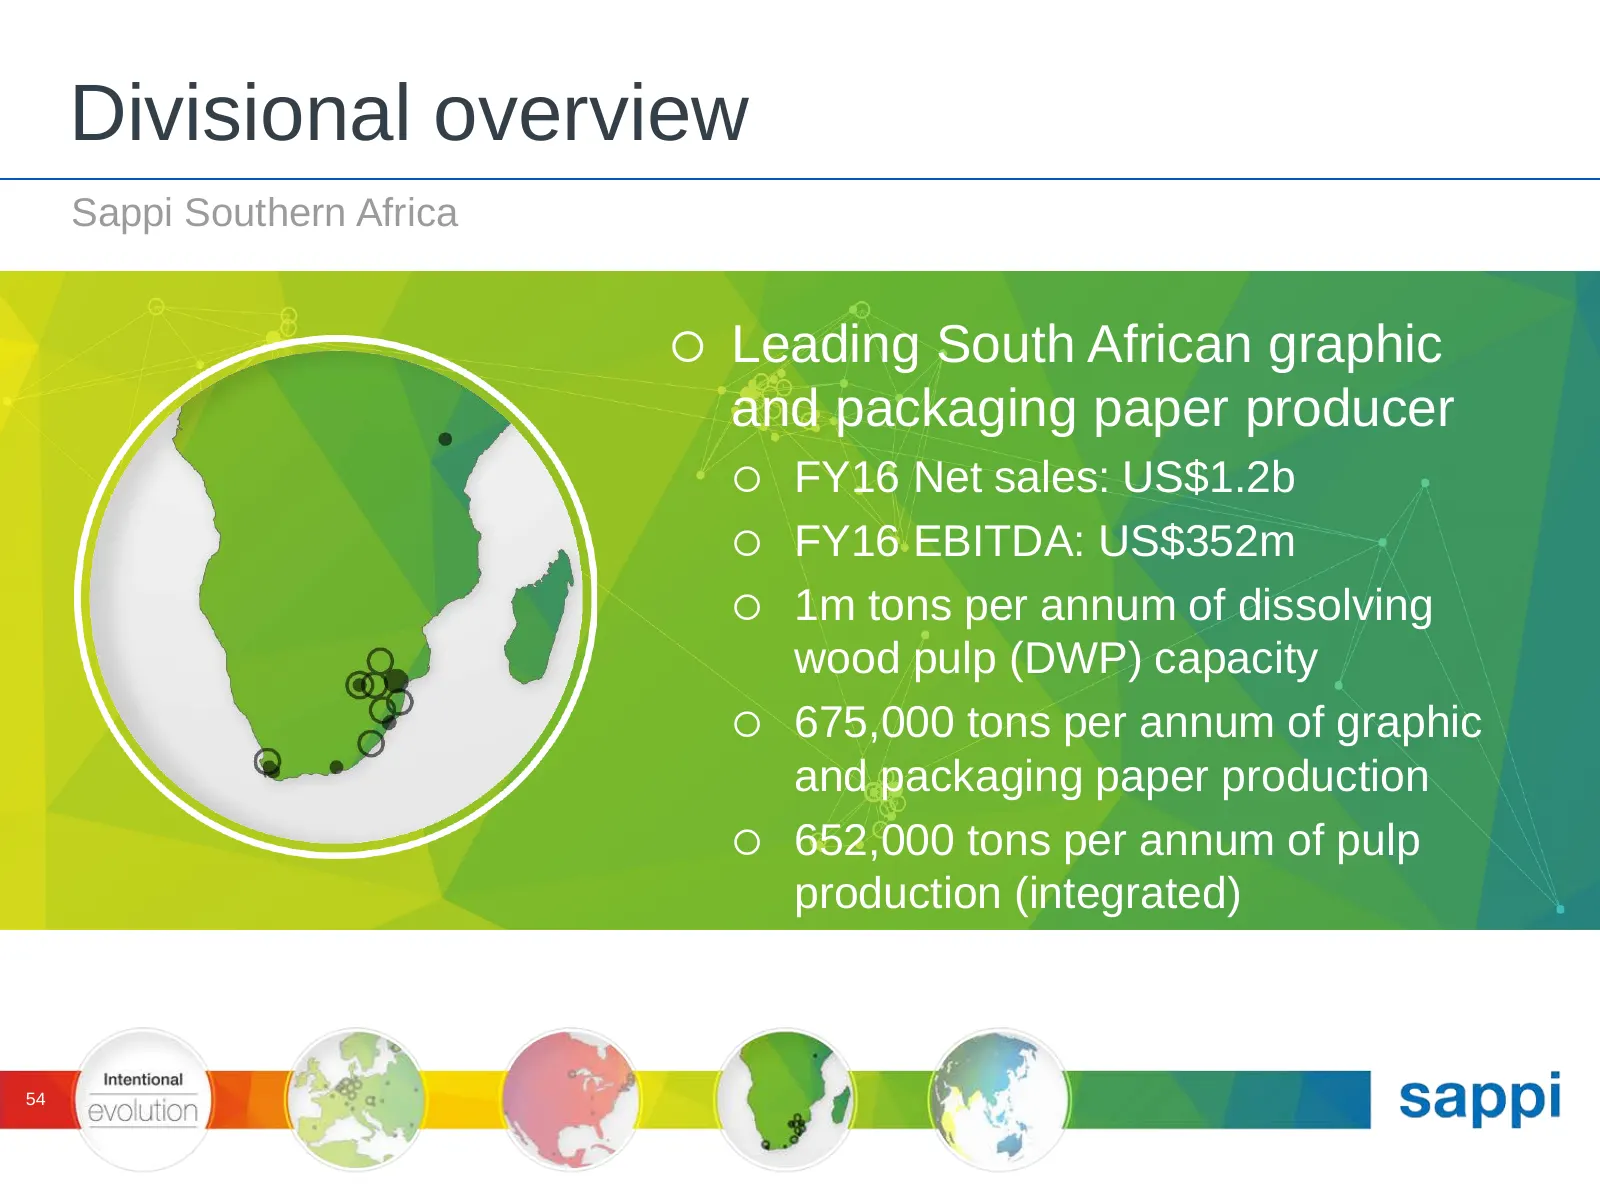
Divisional overview Sappi Southern Africa Leading South African graphic and packaging paper producer FY16 Net sales: US$1.2b FY16 EBITDA: US$352m 1m tons per annum of dissolving wood pulp (DWP) capacity 675,000 tons per annum of graphic and packaging paper production 652,000 tons per ann
Slide 55: Divisional overview: Sappi Southern Africa
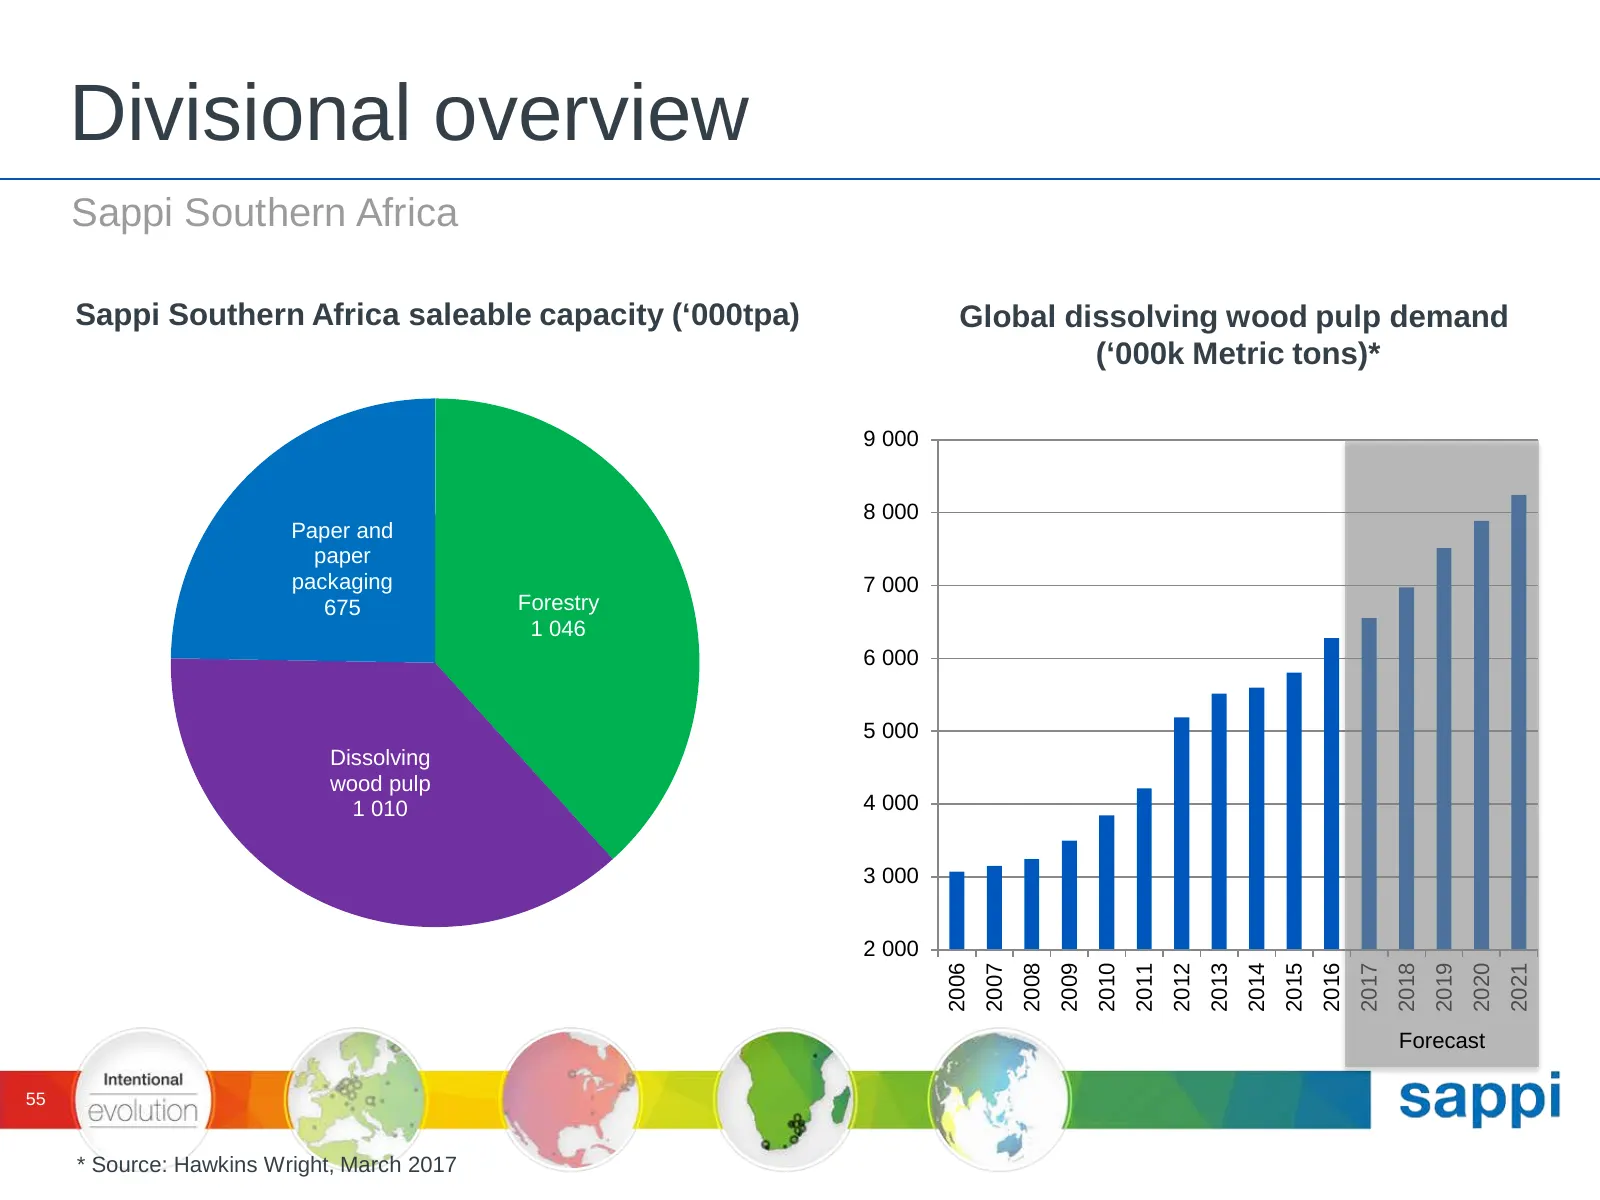
Divisional overview Sappi Southern Africa Sappi Southern Africa saleable capacity (‘000tpa) Global dissolving wood pulp demand (‘000k Metric tons)* 9 000 8 000 Paper and paper packaging 7 000 675 Forestry 1 046 6 000 5 000 Dissolving wood pulp 1 010 4 000 3 000 2 000 2006 2007 2008 2009 2010 2011 20
Slide 56: Projects: Sappi Southern Africa
Projects Sappi Southern Africa Ngodwana Mill Dissolving wood pulp (DWP) conversion Sale of Cape Kraft and Enstra Mills’ recycled packaging business Debottleneck Tugela, Saiccor and Ngodwana pulp mills ~ 10% increase in volumes in both packaging and dissolving wood pulp Increase access to mor
Slide 57: Our DWP competitive advantage
Our DWP competitive advantage Sappi Southern Africa Low-cost and fast-growing woodfibre from state-of-the-art plantations Large-scale, modern and well-invested assets Favourable currency trend Well-positioned in dynamic market 57
Slide 58: Summary: Sappi South Africa
Summary Sappi South Africa Improving paper business Better use of timber Improving cost position Product and asset optimisation – Printing and packaging papers Investing in dissolving wood pulp Low-cost producer Fast-growing market Excellent customer relationships 'Growing' our for
Slide 59: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 59
Slide 60: Sustainability – PPP + IIRC
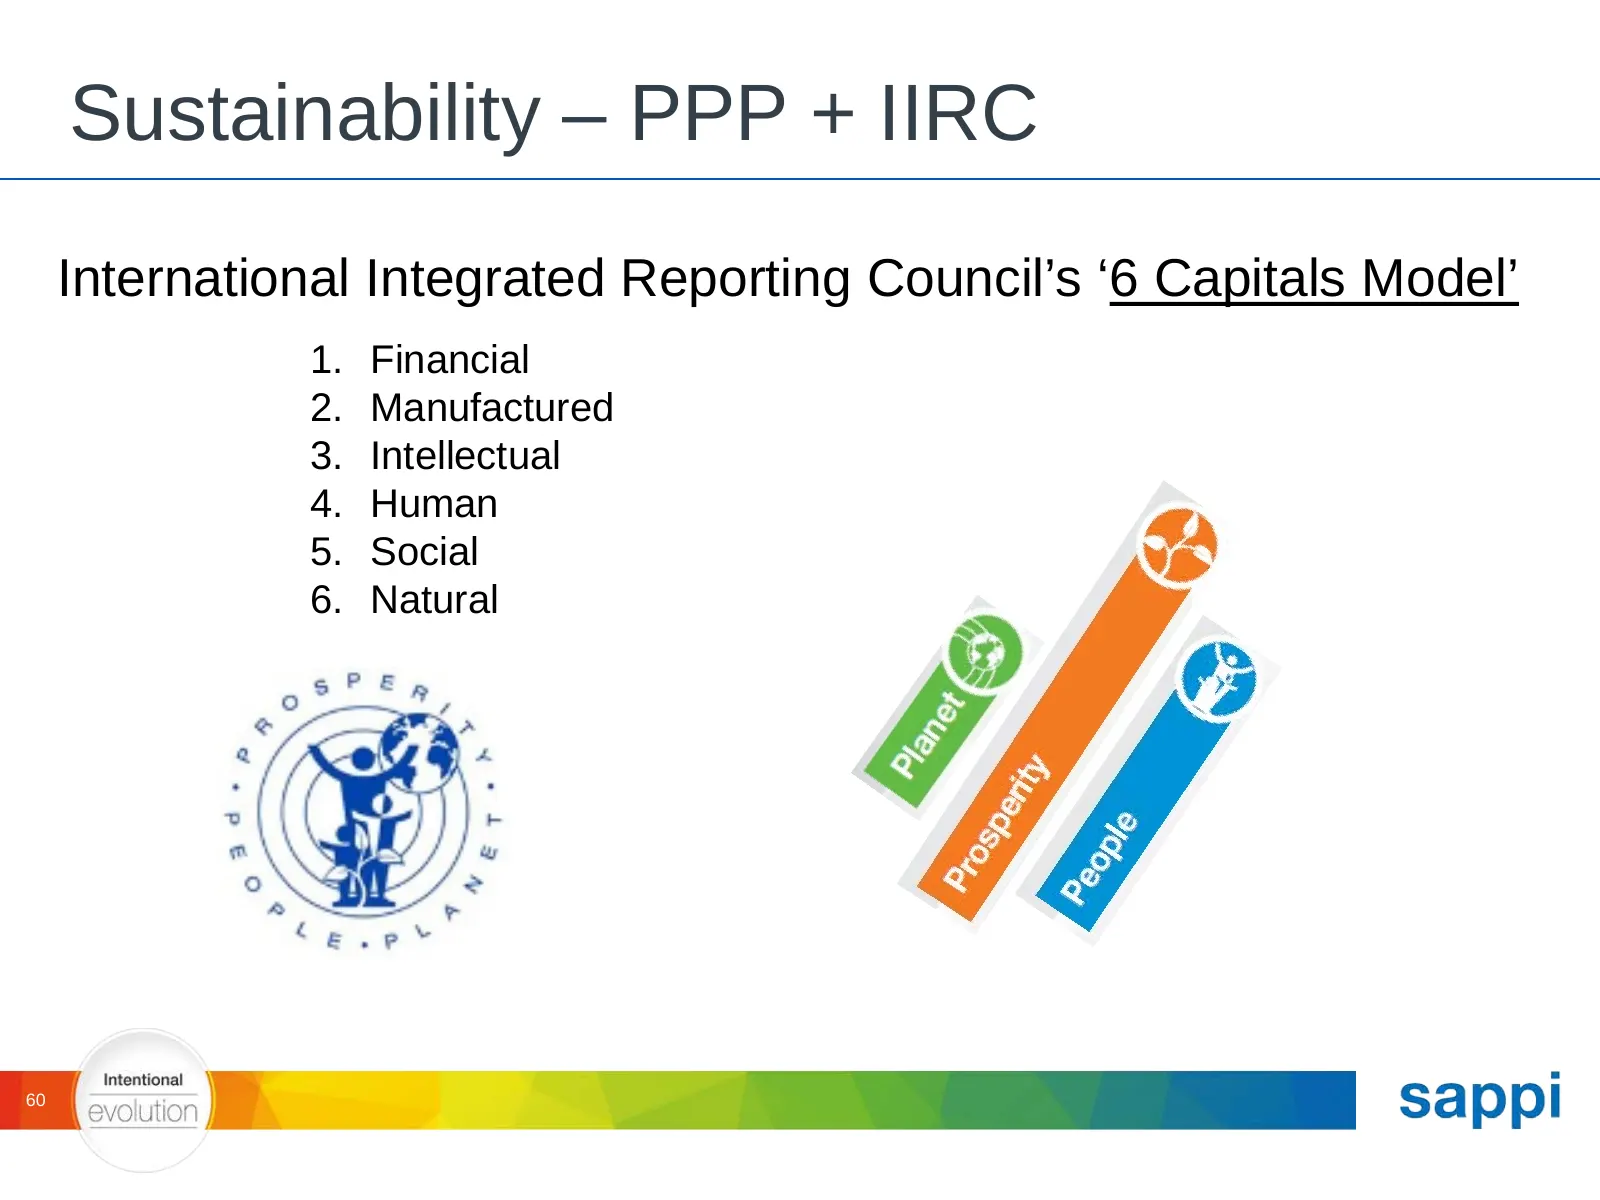
Sustainability – PPP + IIRC International Integrated Reporting Council’s ‘6 Capitals Model’ 1. Financial 2. Manufactured 3. Intellectual 4. Human 5. Social 6. Natural 60
Slide 61: Sustainability: financial, manufactured, intellectual capital
Sustainability #1 – Financial capital We manage our financial capital, including shareholder equity, debt and reinvested capital to maintain a solid balance between growth, profitability and liquidity. #2 – Manufactured Capital Investing in building, maintaining, operating, and improving this infras
Slide 62: Sustainability: human and social capital
Sustainability #4 – Human capital By creating a safe and healthy workplace for our people in which diversity is encouraged and valued, and providing them with ongoing development opportunities, we enhance productivity and our ability to service global markets. #5 – Social capital Building relationsh
Slide 63: Sustainability: natural capital
Sustainability #6 – Natural Capital Recognising our business depends on natural capital, we focus on managing and mitigating our impacts. Inputs: Outputs: • 2,798MW energy purchased, 1,911 • 92% of water drawn returned to the generated environment • Specific water process extracted • 48.8% renewable
Slide 64: Agenda
Agenda Overview Products Strategy Results Divisions Sappi Europe Sappi North America Sappi Southern Africa Sustainability Conclusions 64
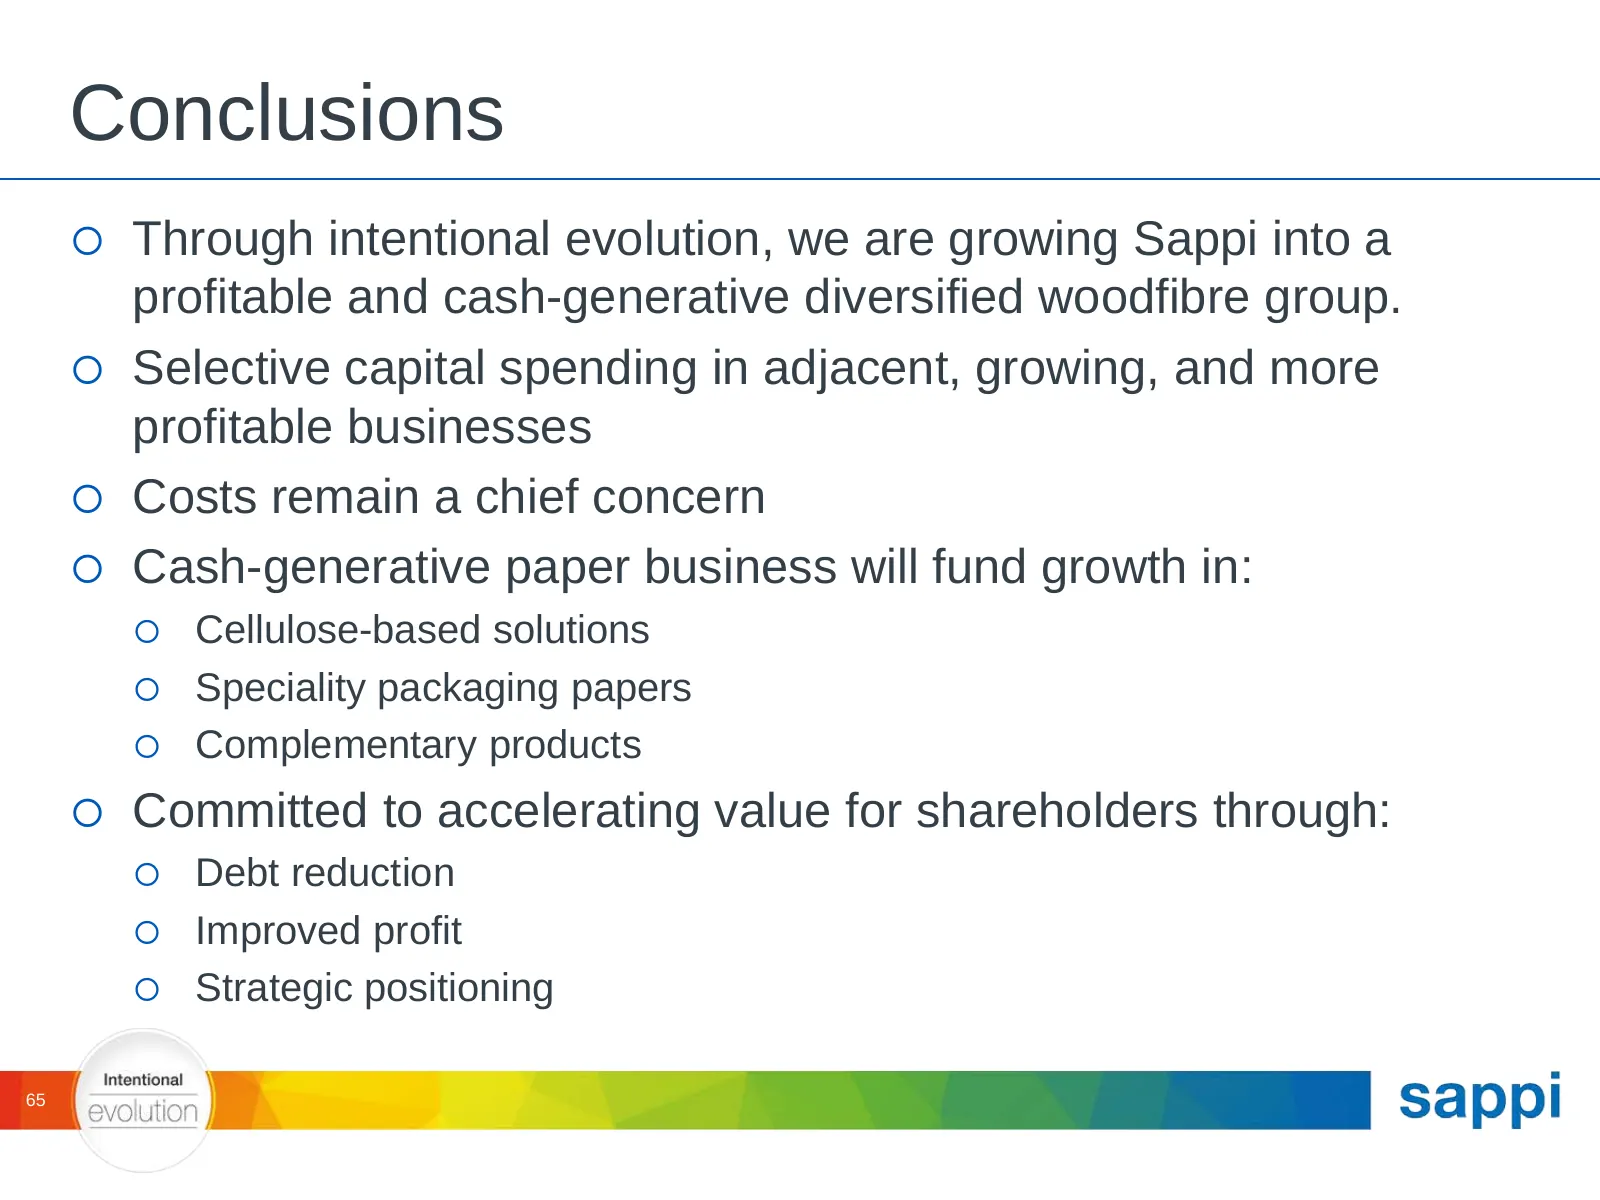
Slide 65: Conclusions
Conclusions Through intentional evolution, we are growing Sappi into a profitable and cash-generative diversified woodfibre group. Selective capital spending in adjacent, growing, and more profitable businesses Costs remain a chief concern Cash-generative paper business will fund growth in:
Slide 66: Thank you
Thank you 66
Source: company website
More decks from Sappi Limited
 Q3 FY26 Earnings Presentation47 slides · Aug 6, 2026
 Q2 2026 Earnings Presentation44 slides · May 7, 2026
 Q1 2026 Earnings Presentation43 slides · Feb 4, 2026
 Merger or Acquisition (December 2025)16 slides · Dec 4, 2025
 Q4 2025 Earnings Presentation61 slides · Nov 6, 2025
 Q3 FY25 Earnings Presentation59 slides · Aug 7, 2025