Air Transport Services Group Inc
Air Transport Services — Non-Deal Roadshow (March 2011)
12 slides from Air Transport Services's roadshow presentation, Mar 23, 2011
Slide 1: Investor Meetings
Investor Meetings March 2011 Joe Hete, President & CEO Quint Turner, CFO AISG Air Transport Services Group, Inc.
Slide 2: Safe Harbor Statement
Safe Harbor Statement Except for historical information contained herein, the matters discussed in this presentation contain forward-looking statements that involve risks and uncertainties. There are a numberof important factors that could cause Air Transport Services Group's ("ATSG's") actual resul
Slide 3: Unique Blend of Complementary Businesses
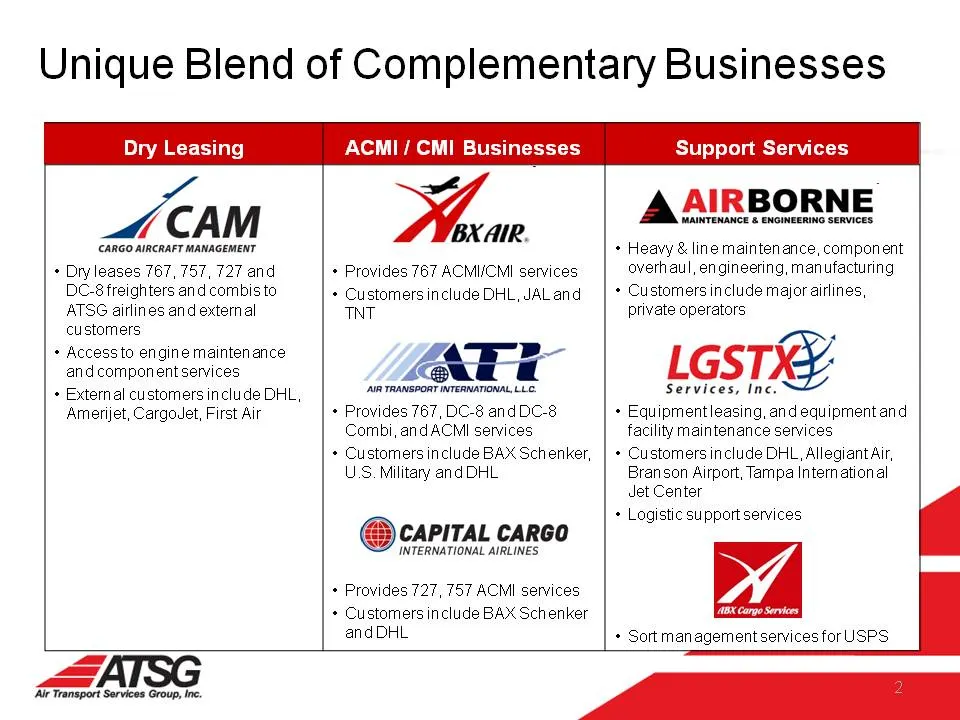
Unique Blend of Complementary Businesses A, AIRBORNE CAM Z_, | SAIRBORNE CARGO AIRCRAFT MANAGEMENT + Heavy & line maintenance, component + Dryleases 767, 757, 727 and + Provides 767 ACMI/CMI services overhaul, engineering, manufacturing DC-8 freighters and combis to + Customersinclude DHL, JALand |
Slide 4: Transformation Drives Earnings Growth
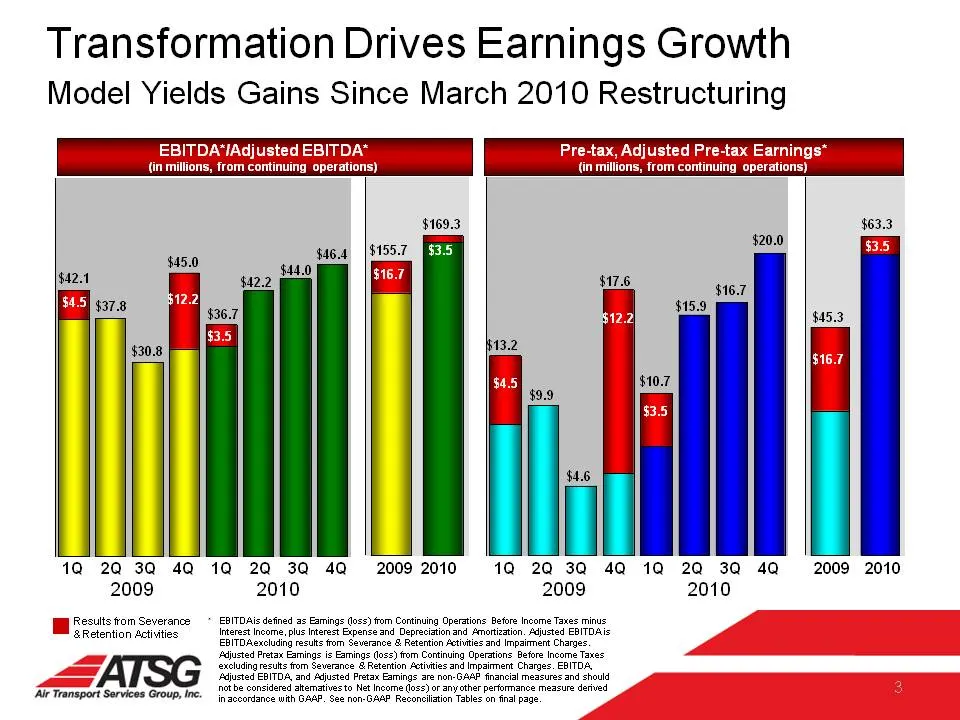
Transformation Drives Earnings Growth Model Yields Gains Since March 2010 Restructuring $169.3 $63.3 $20.0 etn $46.4 |$155.7 : $44.0 42.1 $ Ss By $42.2 $17.6 Aue $37.8 ae $15.9 ena $30.8 ae $10.7 $9.9 | [ ; 1Q 20 3Q 4Q 1Q 2Q 3Q 4Q 2009 2010 1Q 2Q 3Q 4Q 1Q 2Q 3Q 4Q 2009 2010 2009 2010 2009 2010 EBITD
Slide 5: De-levering Continues
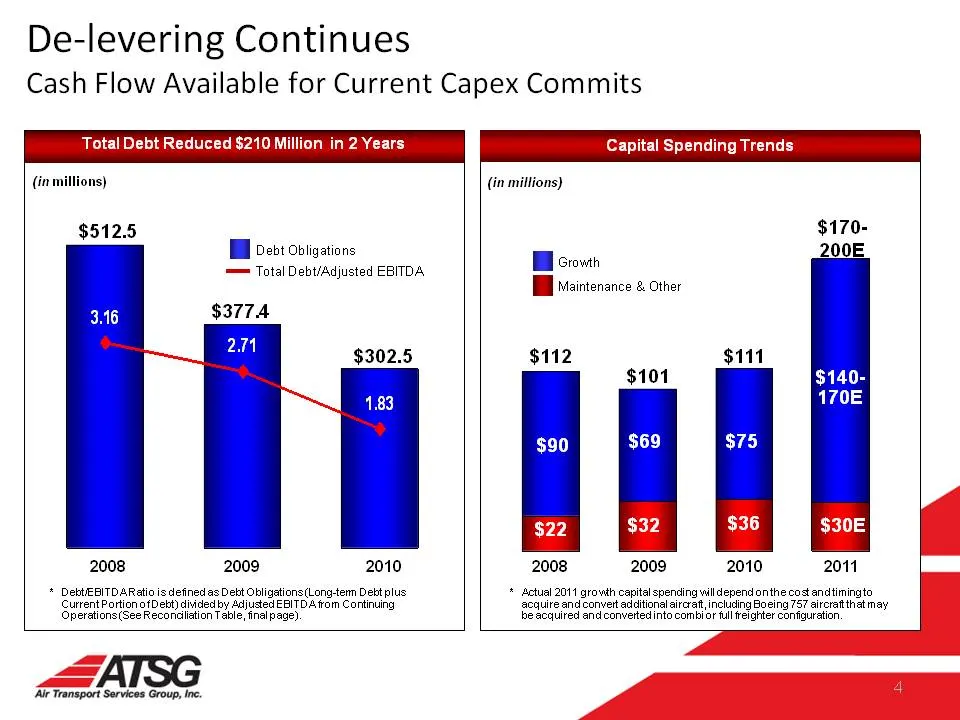
De-levering Continues Cash Flow Available for Current Capex Commits Bh bebt obligations — Total Debi/Adjusted EBITDA $3774 2008 2009 2010 * DebEBITD ARatia is defined as Debt Obligations (Long-term Debt plus CurrentPortion ofDebt) divided by Adjusted EBITDA om Continuing Operations (See Recondition
Slide 6: ATSG Business Model
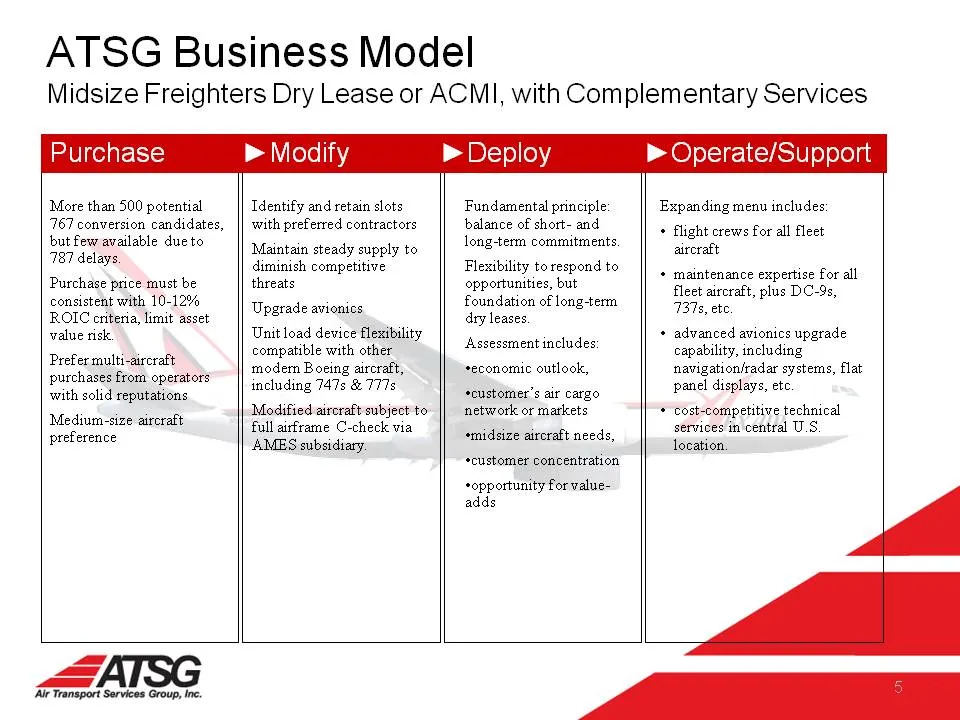
ATSG Business Model Midsize Freighters Dry Lease or ACMI, with Complementary Services Pur ase ‘More than 500 potential 767 conversion candidates, but Few available due to 787 delays Purchase price must be consistent with 10-12% ROIC criteria, limit asset value risk Prefer multi-aircraft purchases fr
Slide 7: ATSG Global Opportunities
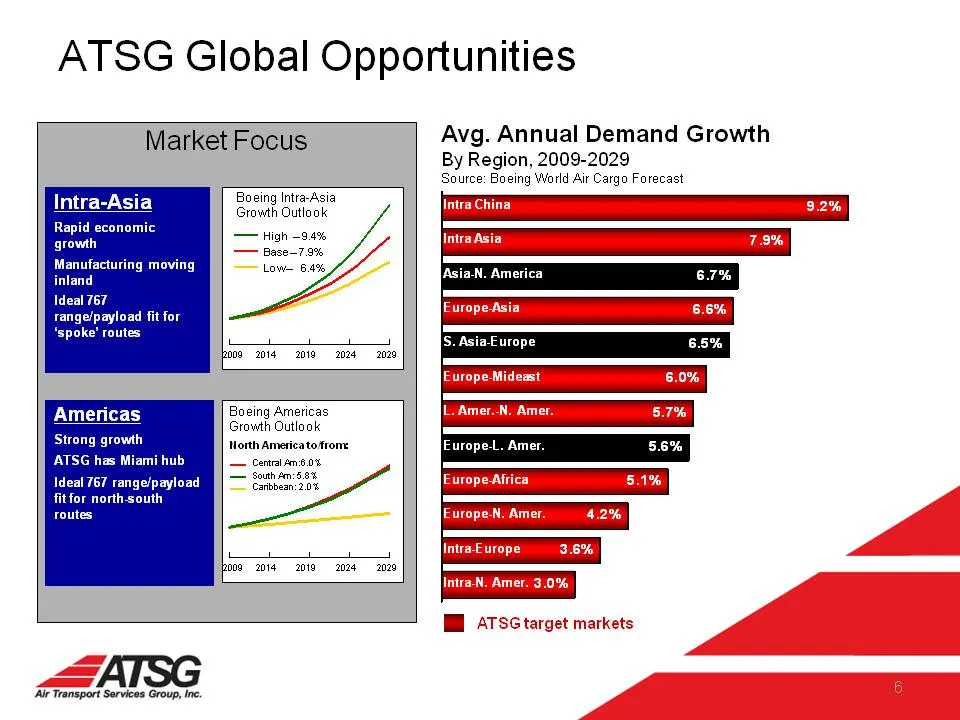
ATSG Global Opportunities a Boeing Intra-Asia Intra-Asia Growth Outlook Rapid economic — High -9.4% growth — Base-7.9% Manufacturing moving — Low- 6.4%, inland Ideal 767 range/payload fit for ‘spoke’ routes Europe-Asia noe ai 2018282020 IS. Asia-Europe Europe-Mideast i Boeing Americas Seal Growth Ou
Slide 8: 767s Serve Asia, Americas, Europe
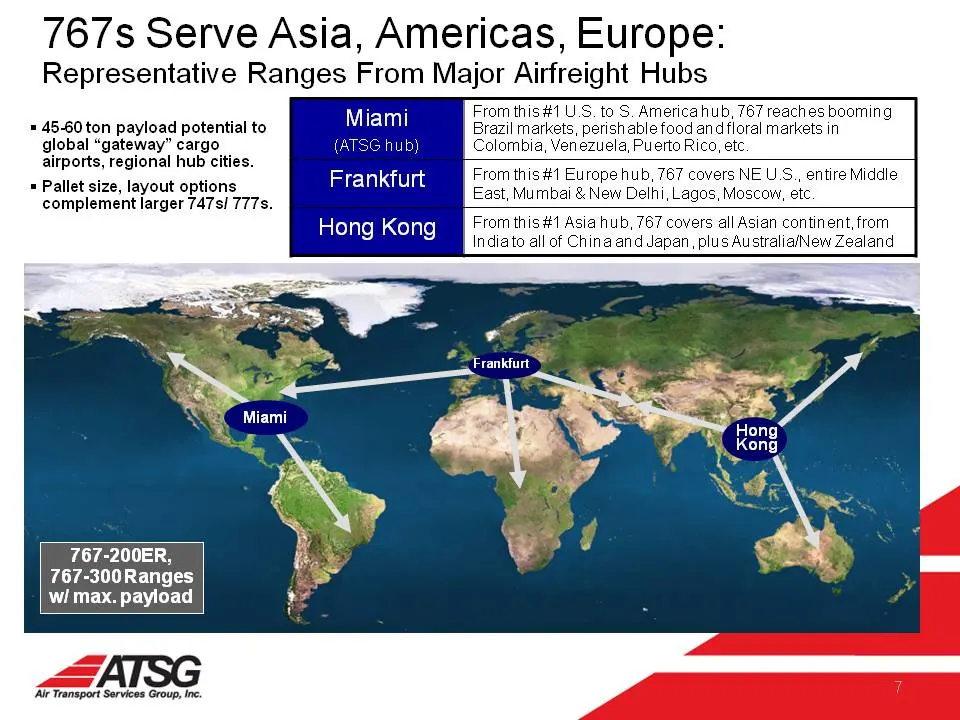
767s Serve Asia, Americas, Europe: Representative Ranges From Major Airfreight Hubs From this#1 U.S. to S. America hub, 767 reaches booming Brazil markets, perish able food and floral markets in Colombia, Venezuela, Puerto Rico, etc. From this #1 Europe hub, 767 covers NE U S., entire Middle East, M
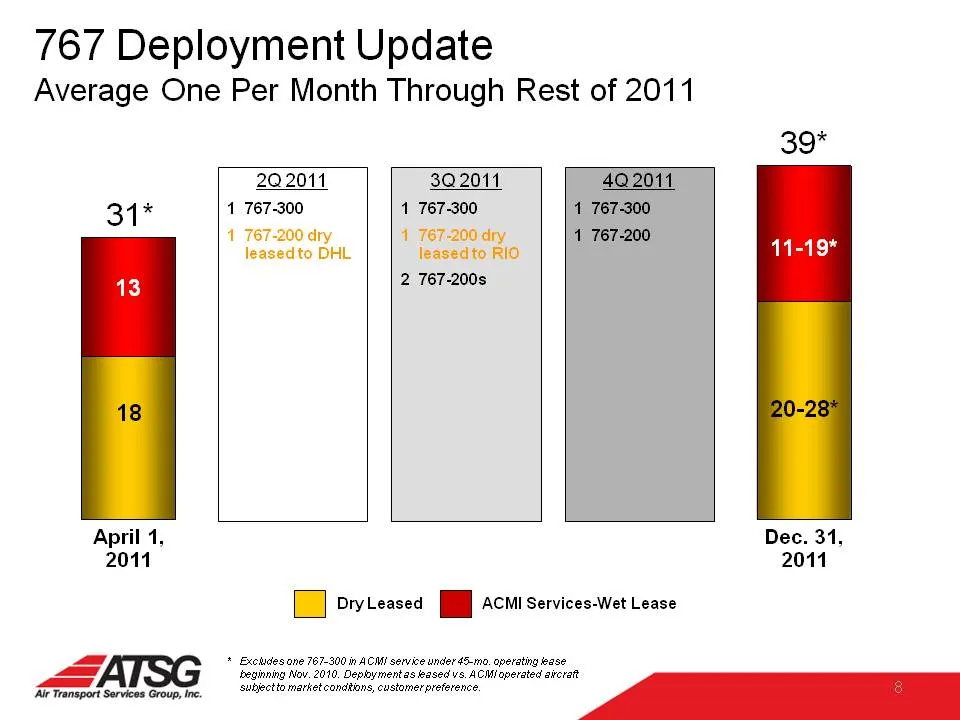
Slide 9: Deployment Update
767 Deployment Update Average One Per Month Through Rest of 2011 39* 202011 302011 402011 31* 1 767-300 1 767-300 1 767-300 1 767-200 dry 1 767-200 dry 1 767-200 leased to DHL leasedto RIO 2 767-200s April 1, Dec. 31, 2011 2011 B DryLeased i | ACMI Services-Wet Lease a + Excludes ane 767-200 in ACM!
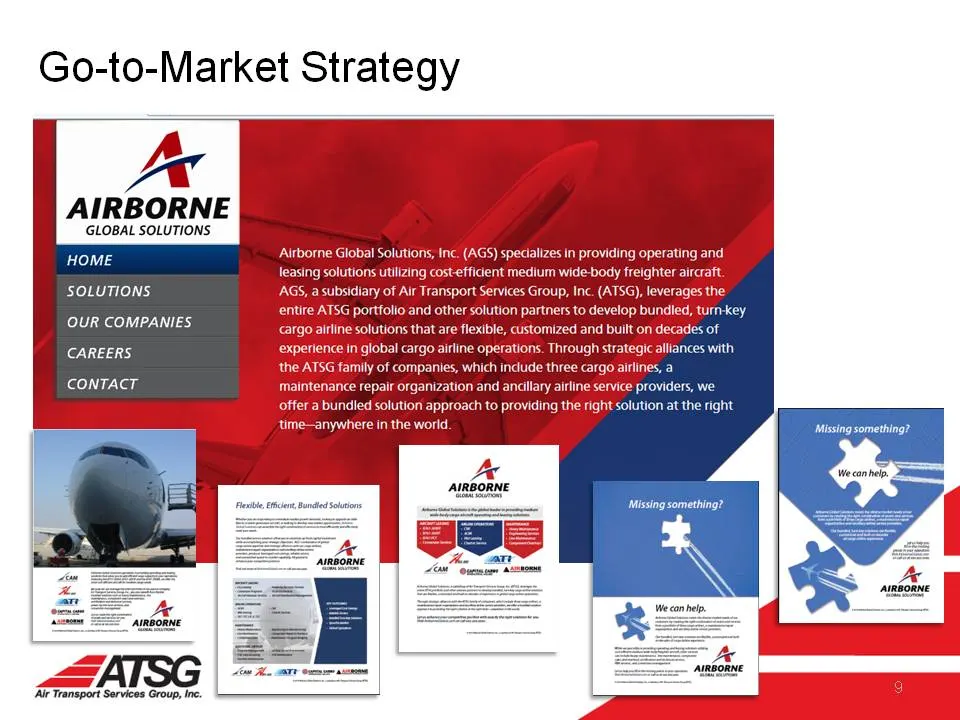
Slide 10: Go-to-Market Strategy
Go-to-Market Strategy AIRBORNE GLOBAL SOLUTIONS HOME SOLUTIONS OUR COMPANIES CAREERS CONTACT re Global Solution leasing solutions utiizin entire ATSG portfolio and other solution partners to. develop bu “cargo alti atthe right Missing something?
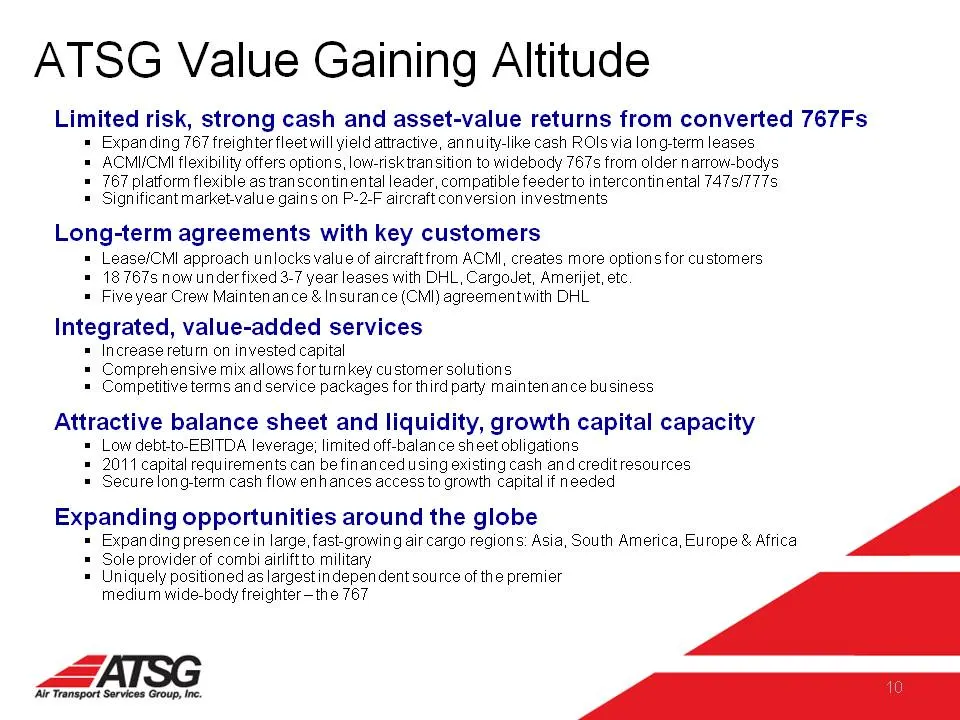
Slide 11: ATSG Value Gaining Altitude
ATSG Value Gaining Altitude Limited risk, strong cash and asset-value returns from converted 767Fs Expanding 767 freighter fleet will yield attractive, annuity-like cash ROIs via long-term leases ACMI/CMI flexibility offers options, low-risk tran sition to widebody 767s from older narrow-bodys 767 p
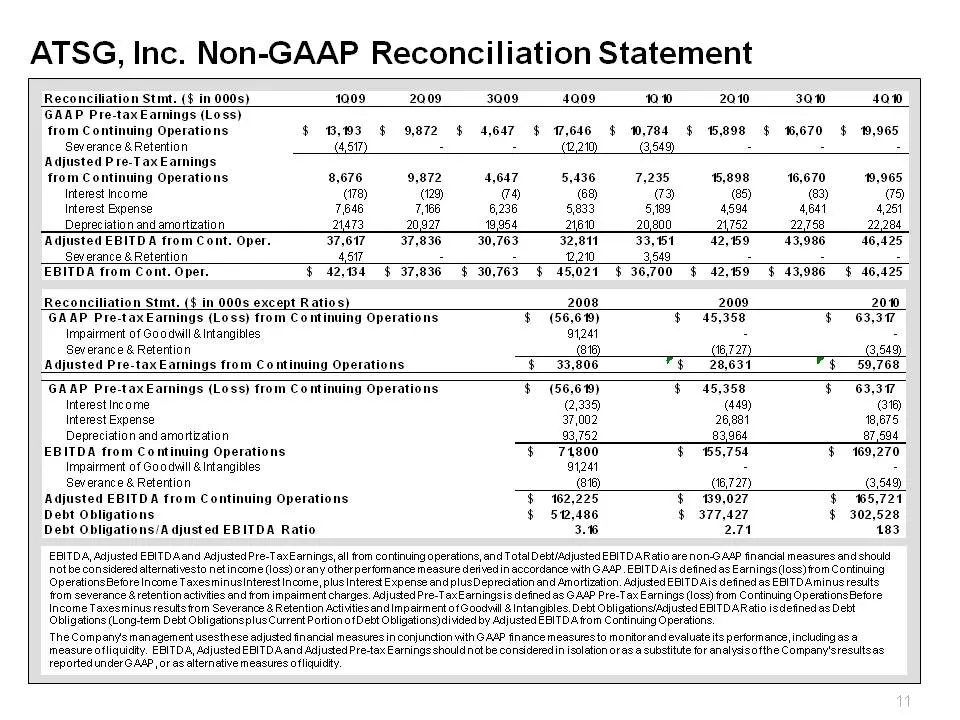
Slide 12: ATSG, Inc. Non-GAAP Reconciliation Statement
ATSG, Inc. Non-GAAP Reconciliation Statement Reconciliation Stmt. (§ in 000s) 1009 2009 3009 4009 100 2010 300 400 GAAP Pre-taxEamings (Loss) from Continuing Operations $ B93 $ 9872 $ 4.647 $ 17,646 $ 1,784 $ 898 $ O70 $ 19,965 Severance & Retention 457 E - (2.21) 3.549) a E Adjusted P re-Tax Earnin
Source: SEC EDGAR · 8-K filed Mar 23, 2011
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020