Strategic Hotels and Resorts Inc
Strategic Hotels and Resorts — Investor Day (October 2011)
58 slides from Strategic Hotels and Resorts's investor day presentation, Oct 4, 2011
Slide 1: Investor Day Presentation
Exhibit 99.1 fa Investor Day Presentation October 4th , 2011
Slide 2: Agenda
Agenda I. BEE’s Unique Value Proposition II. Macroeconomic and Industry Update III. Company Overview IV. Organic Growth and ROI Opportunities V. Balance Sheet Recapitalization VI. Financial Results and Guidance 2
Slide 3: BEE's Unique Value Proposition
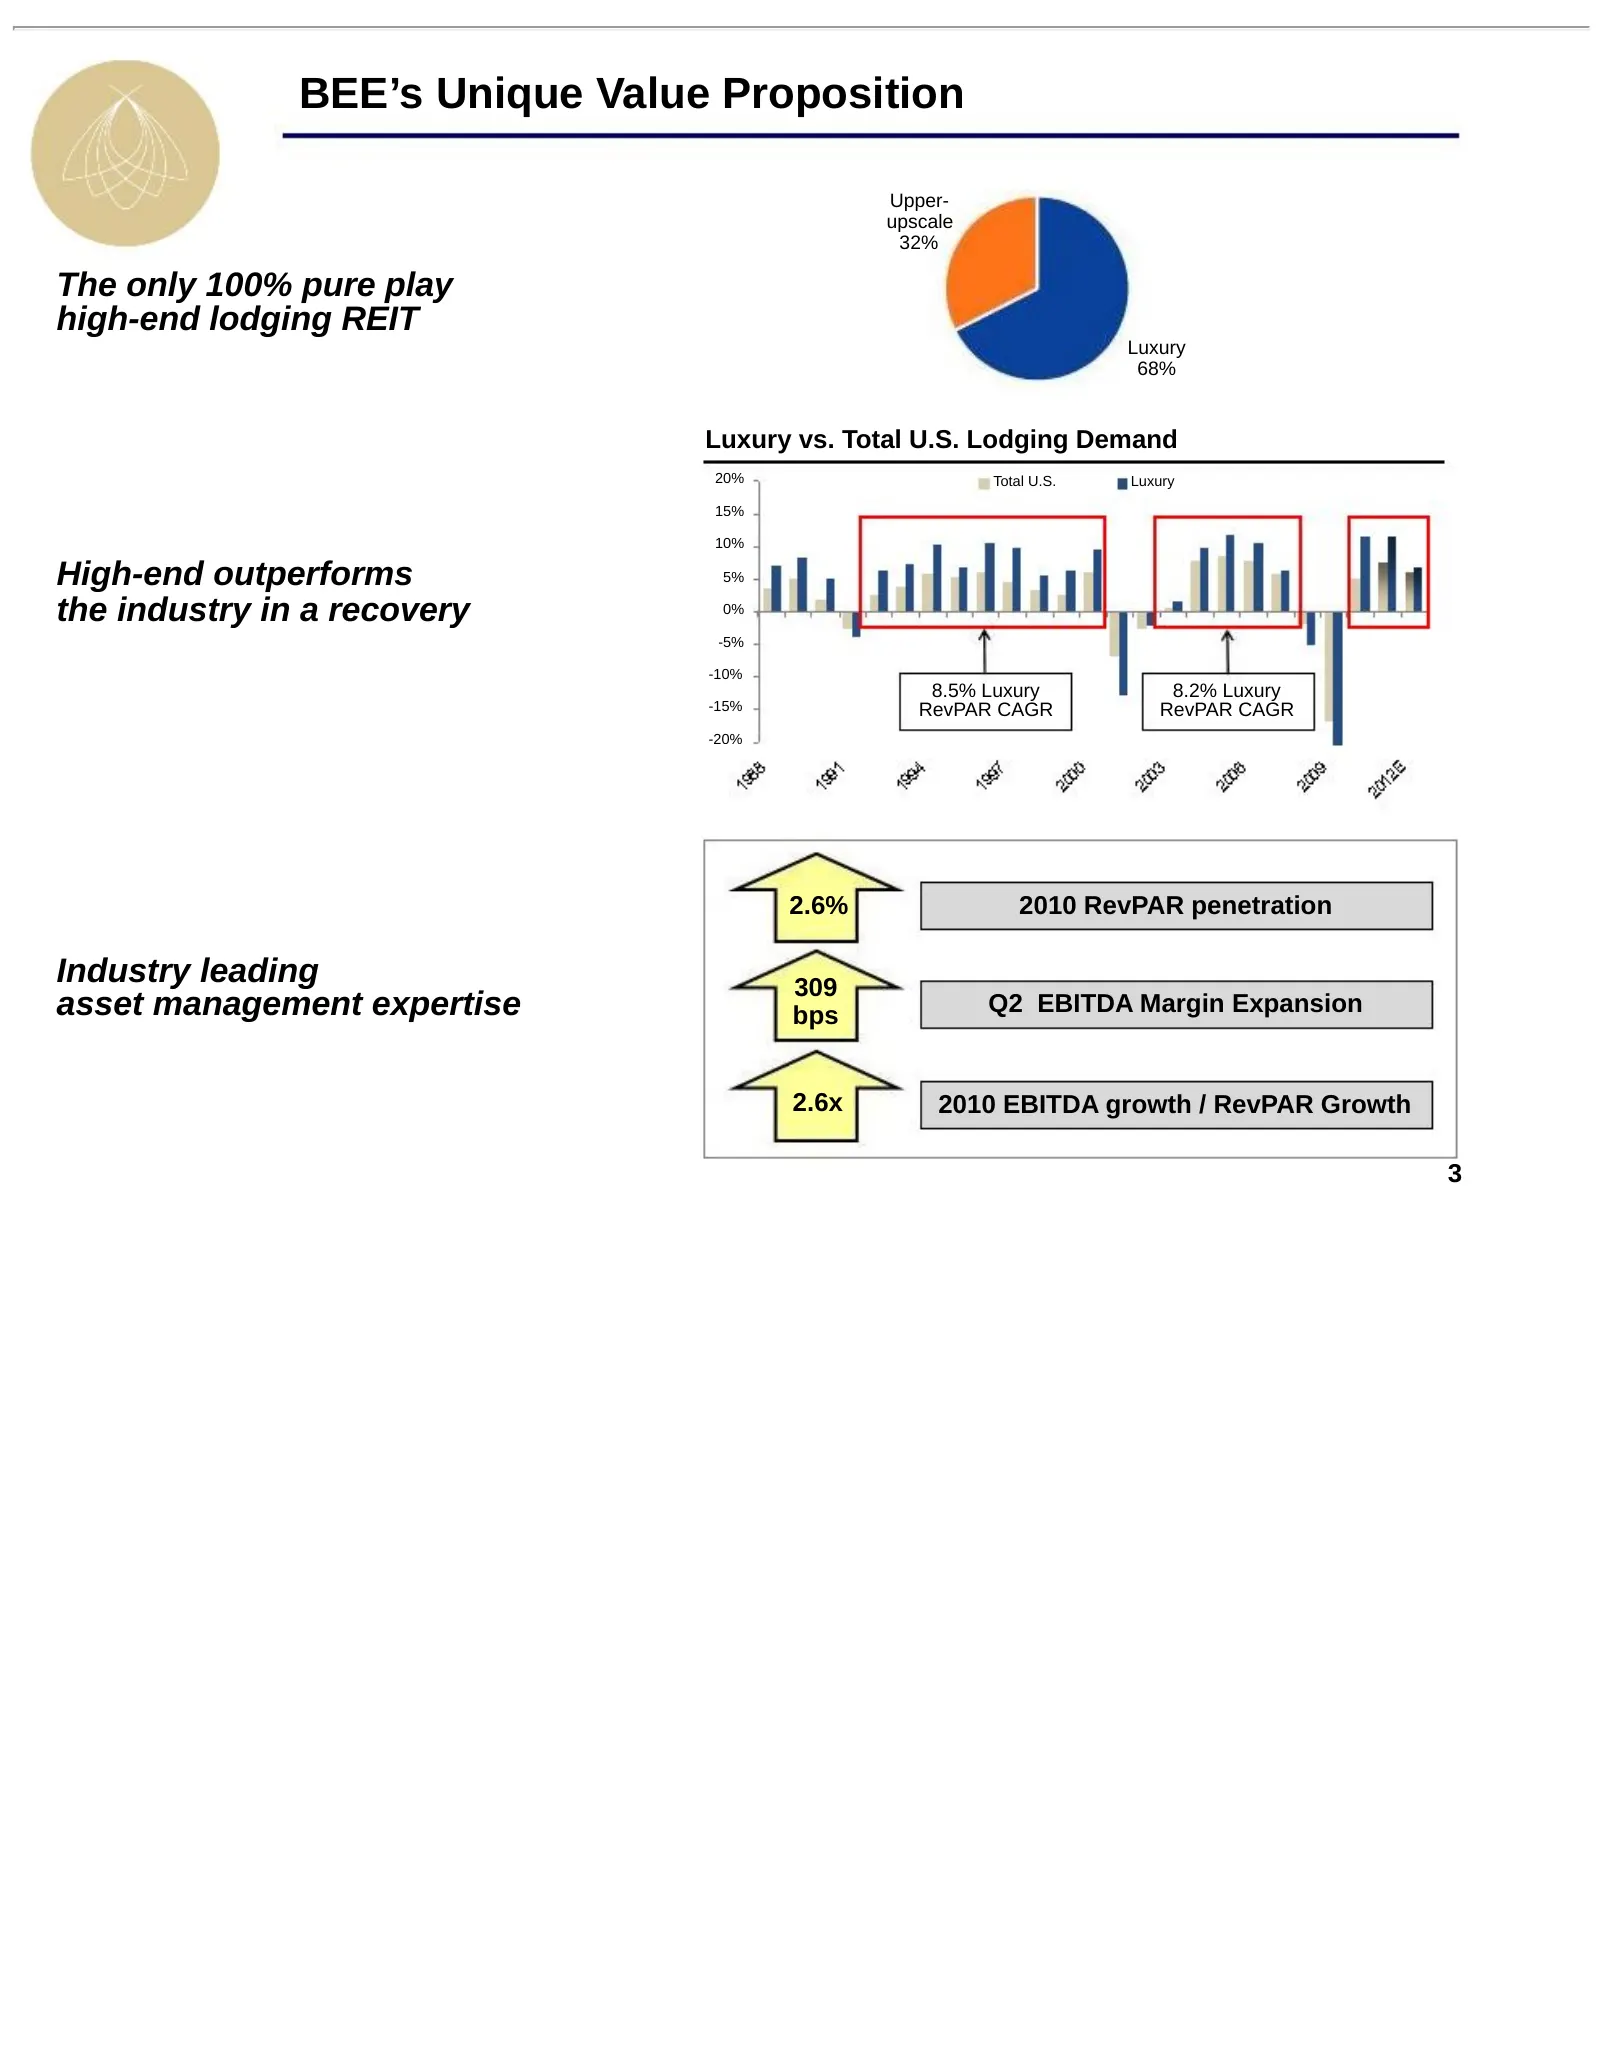
BEE’s Unique Value Proposition Upper- upscale 32% The only 100% pure play high-end lodging REIT Luxury 68% Luxury vs. Total U.S. Lodging Demand 20% Total U.S. Luxury 15% 10% High-end outperforms 5% the industry in a recovery 0% -5% -10% 8.5% Luxury 8.2% Luxury -15% RevPAR CAGR RevPAR CAGR -20% 2.6%
Slide 4: BEE's Unique Value Proposition
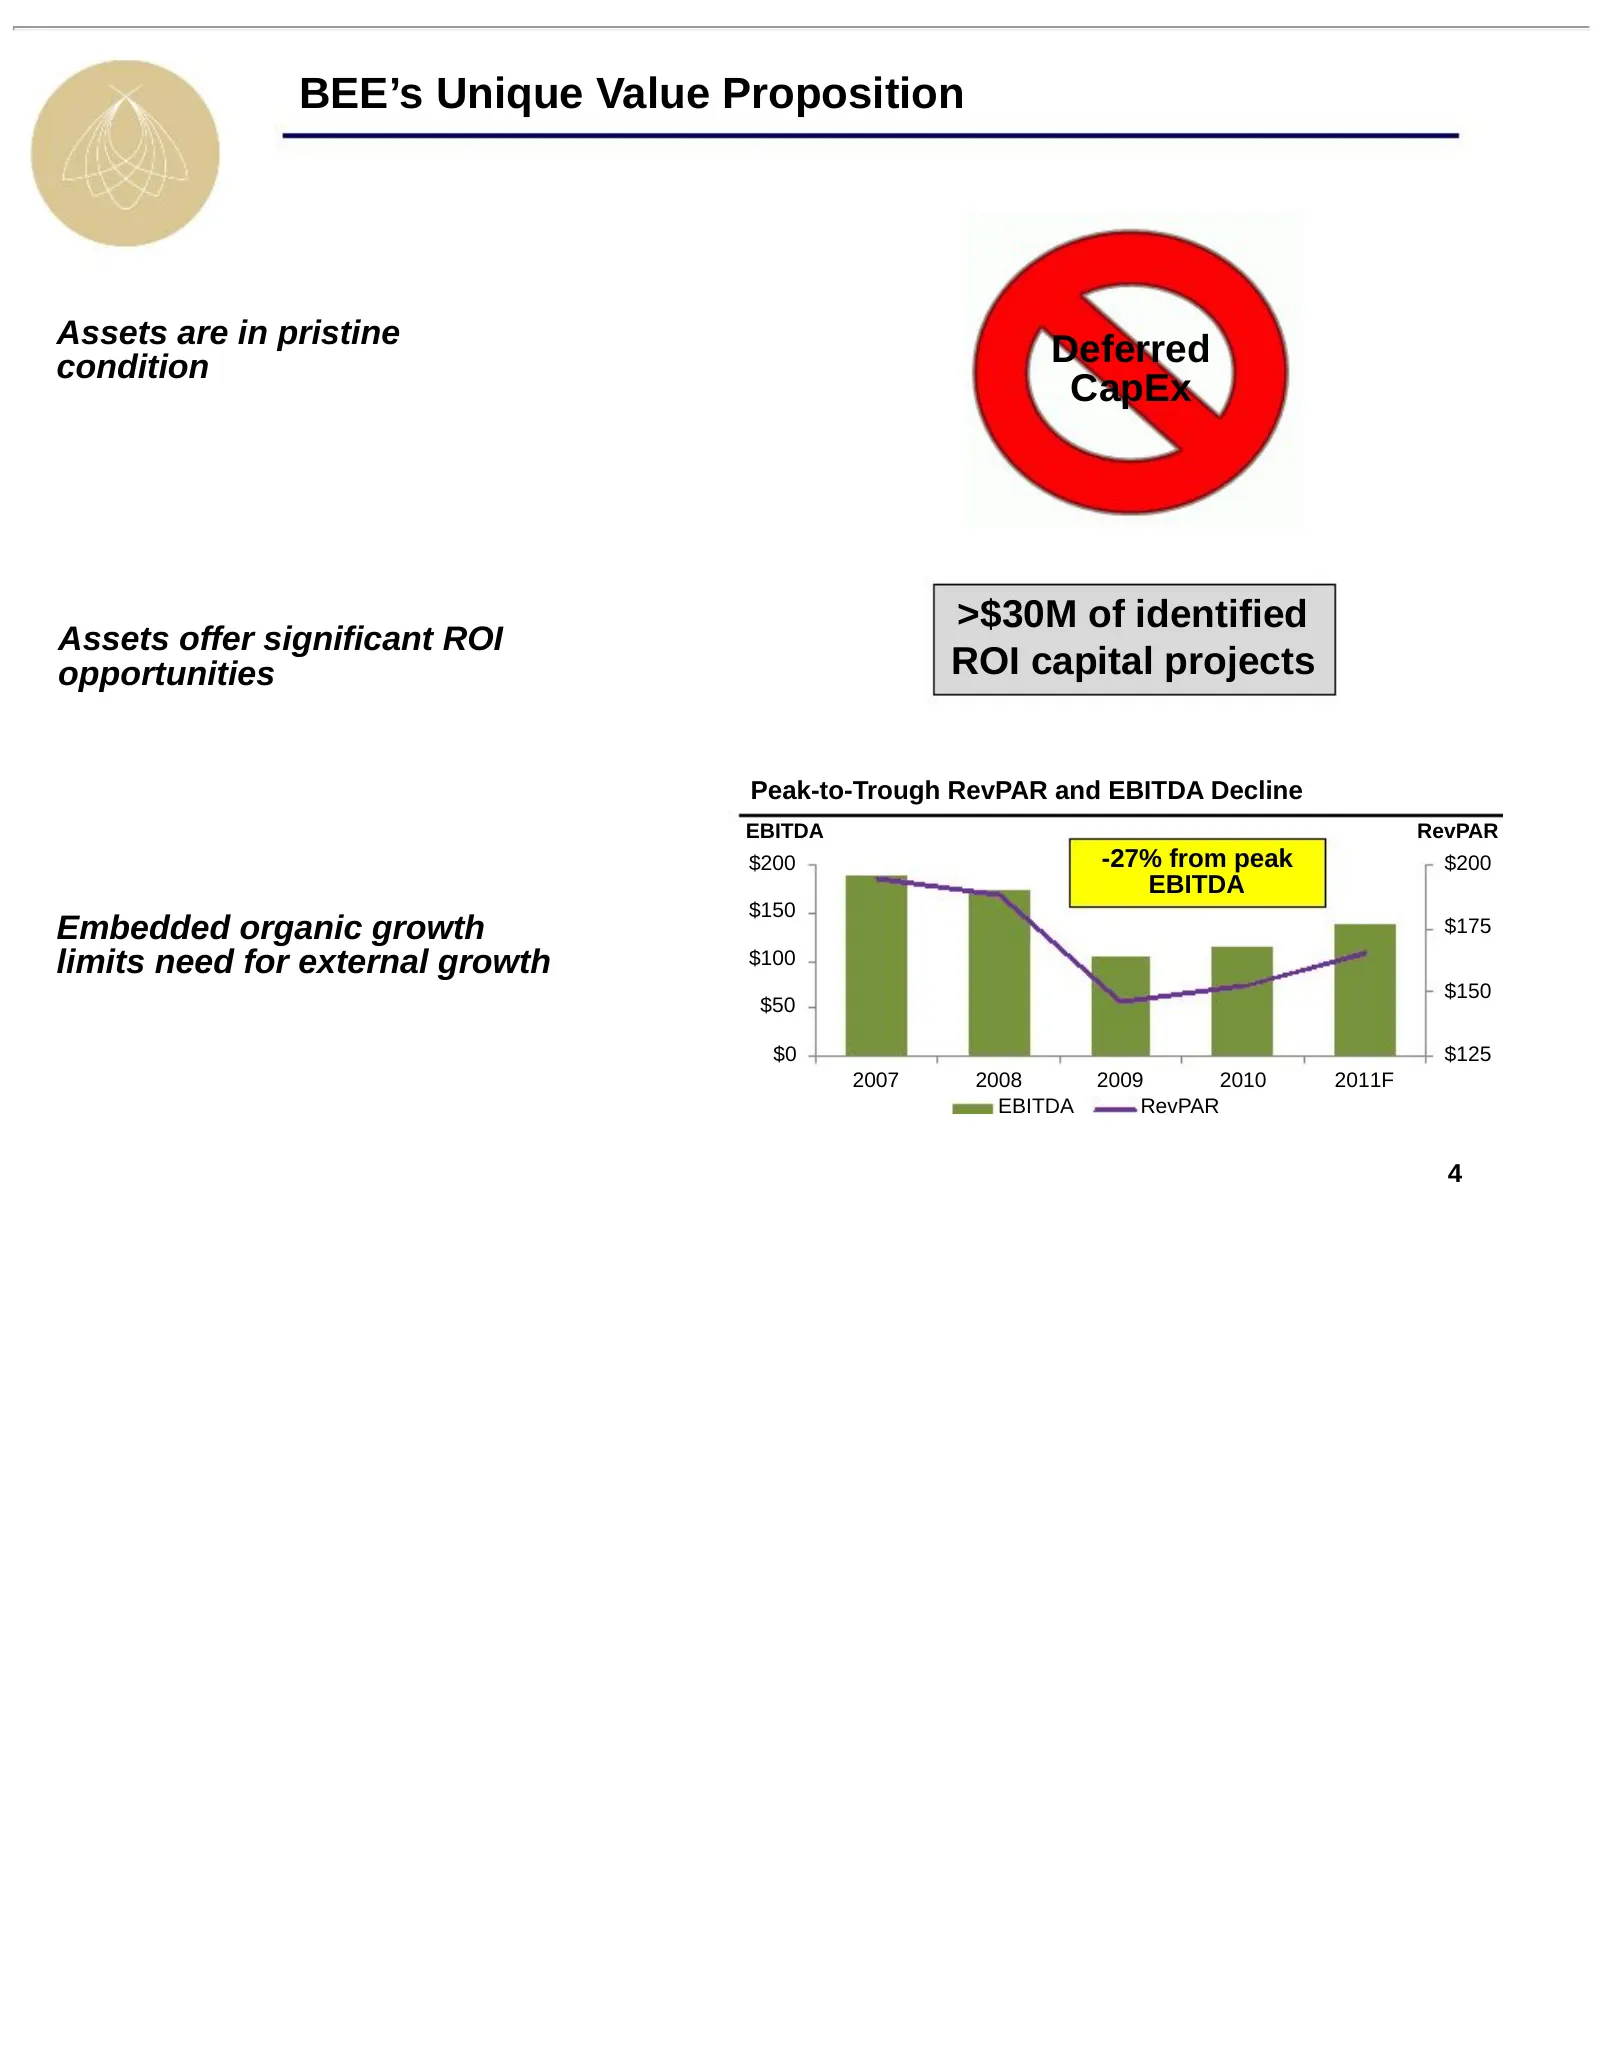
BEE’s Unique Value Proposition Assets are in pristine condition Deferred CapEx >$30M of identified Assets offer significant ROI opportunities ROI capital projects Peak-to-Trough RevPAR and EBITDA Decline EBITDA RevPAR $200 -27% from peak $200 EBITDA $150 Embedded organic growth $175 limits need for
Slide 5: BEE's Unique Value Proposition
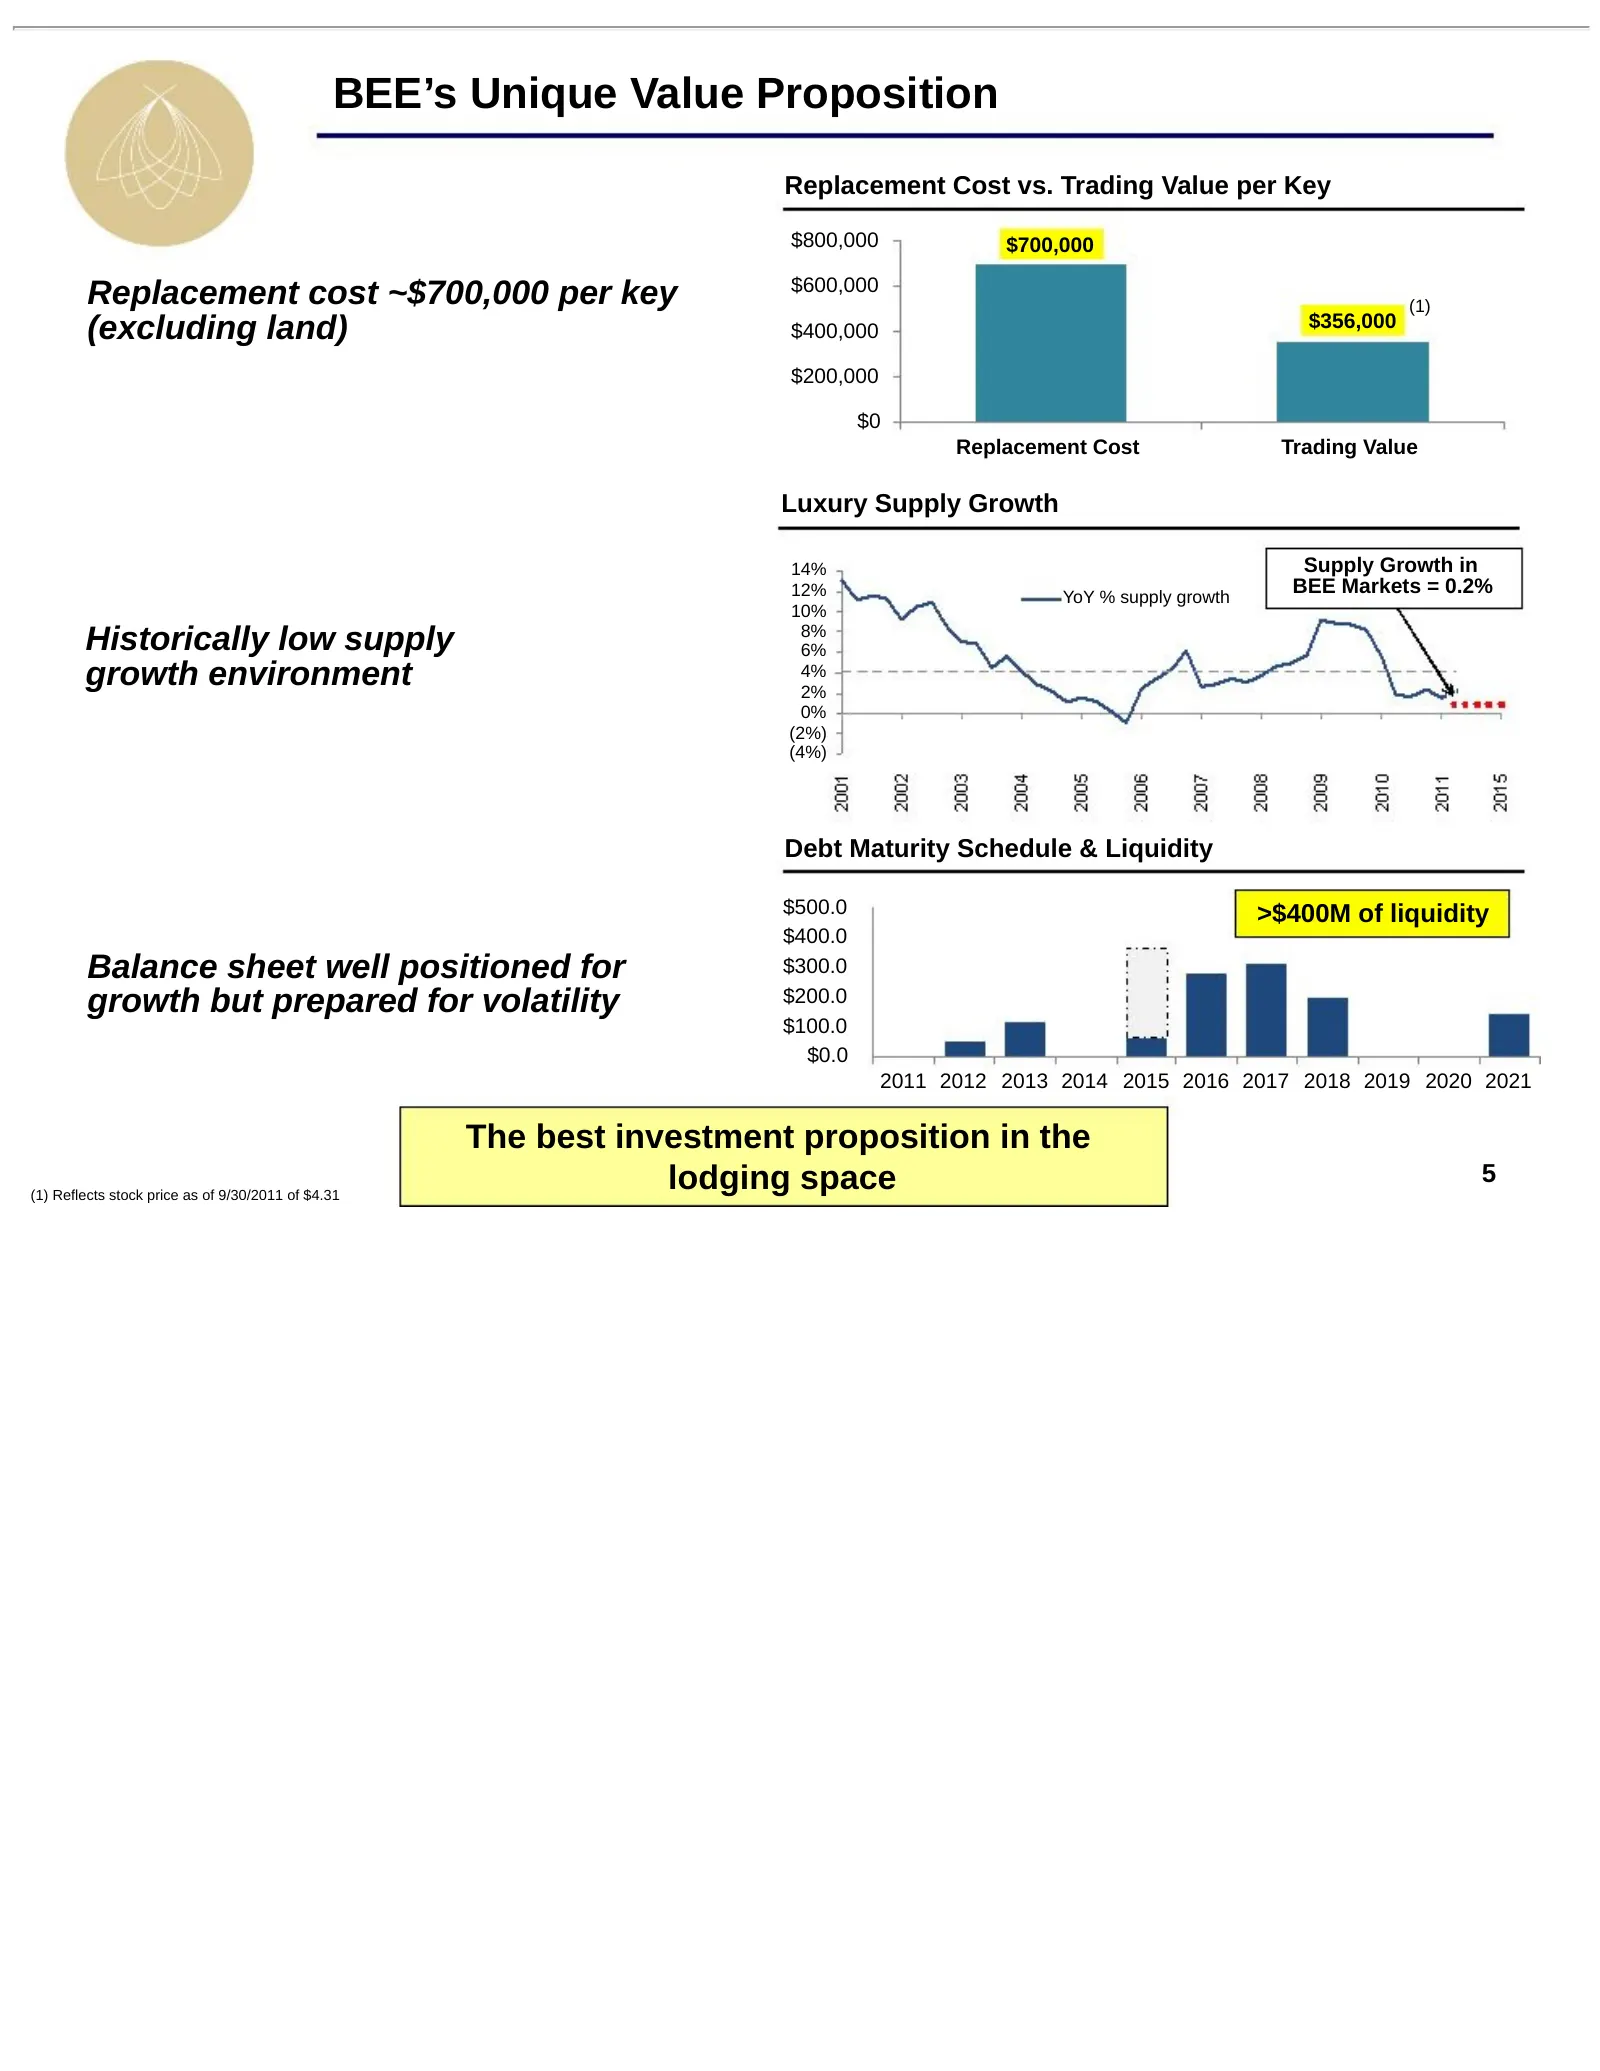
BEE’s Unique Value Proposition Replacement Cost vs. Trading Value per Key $800,000 $700,000 Replacement cost ~$700,000 per key $600,000 (1) (excluding land) $400,000 $356,000 $200,000 $0 Replacement Cost Trading Value Luxury Supply Growth 14% Supply Growth in 12% YoY % supply growth BEE Markets = 0.
Slide 6: Agenda
Agenda I. BEE’s Unique Value Proposition II. Macroeconomic and Industry Update 6
Slide 7: Macroeconomic Outlook
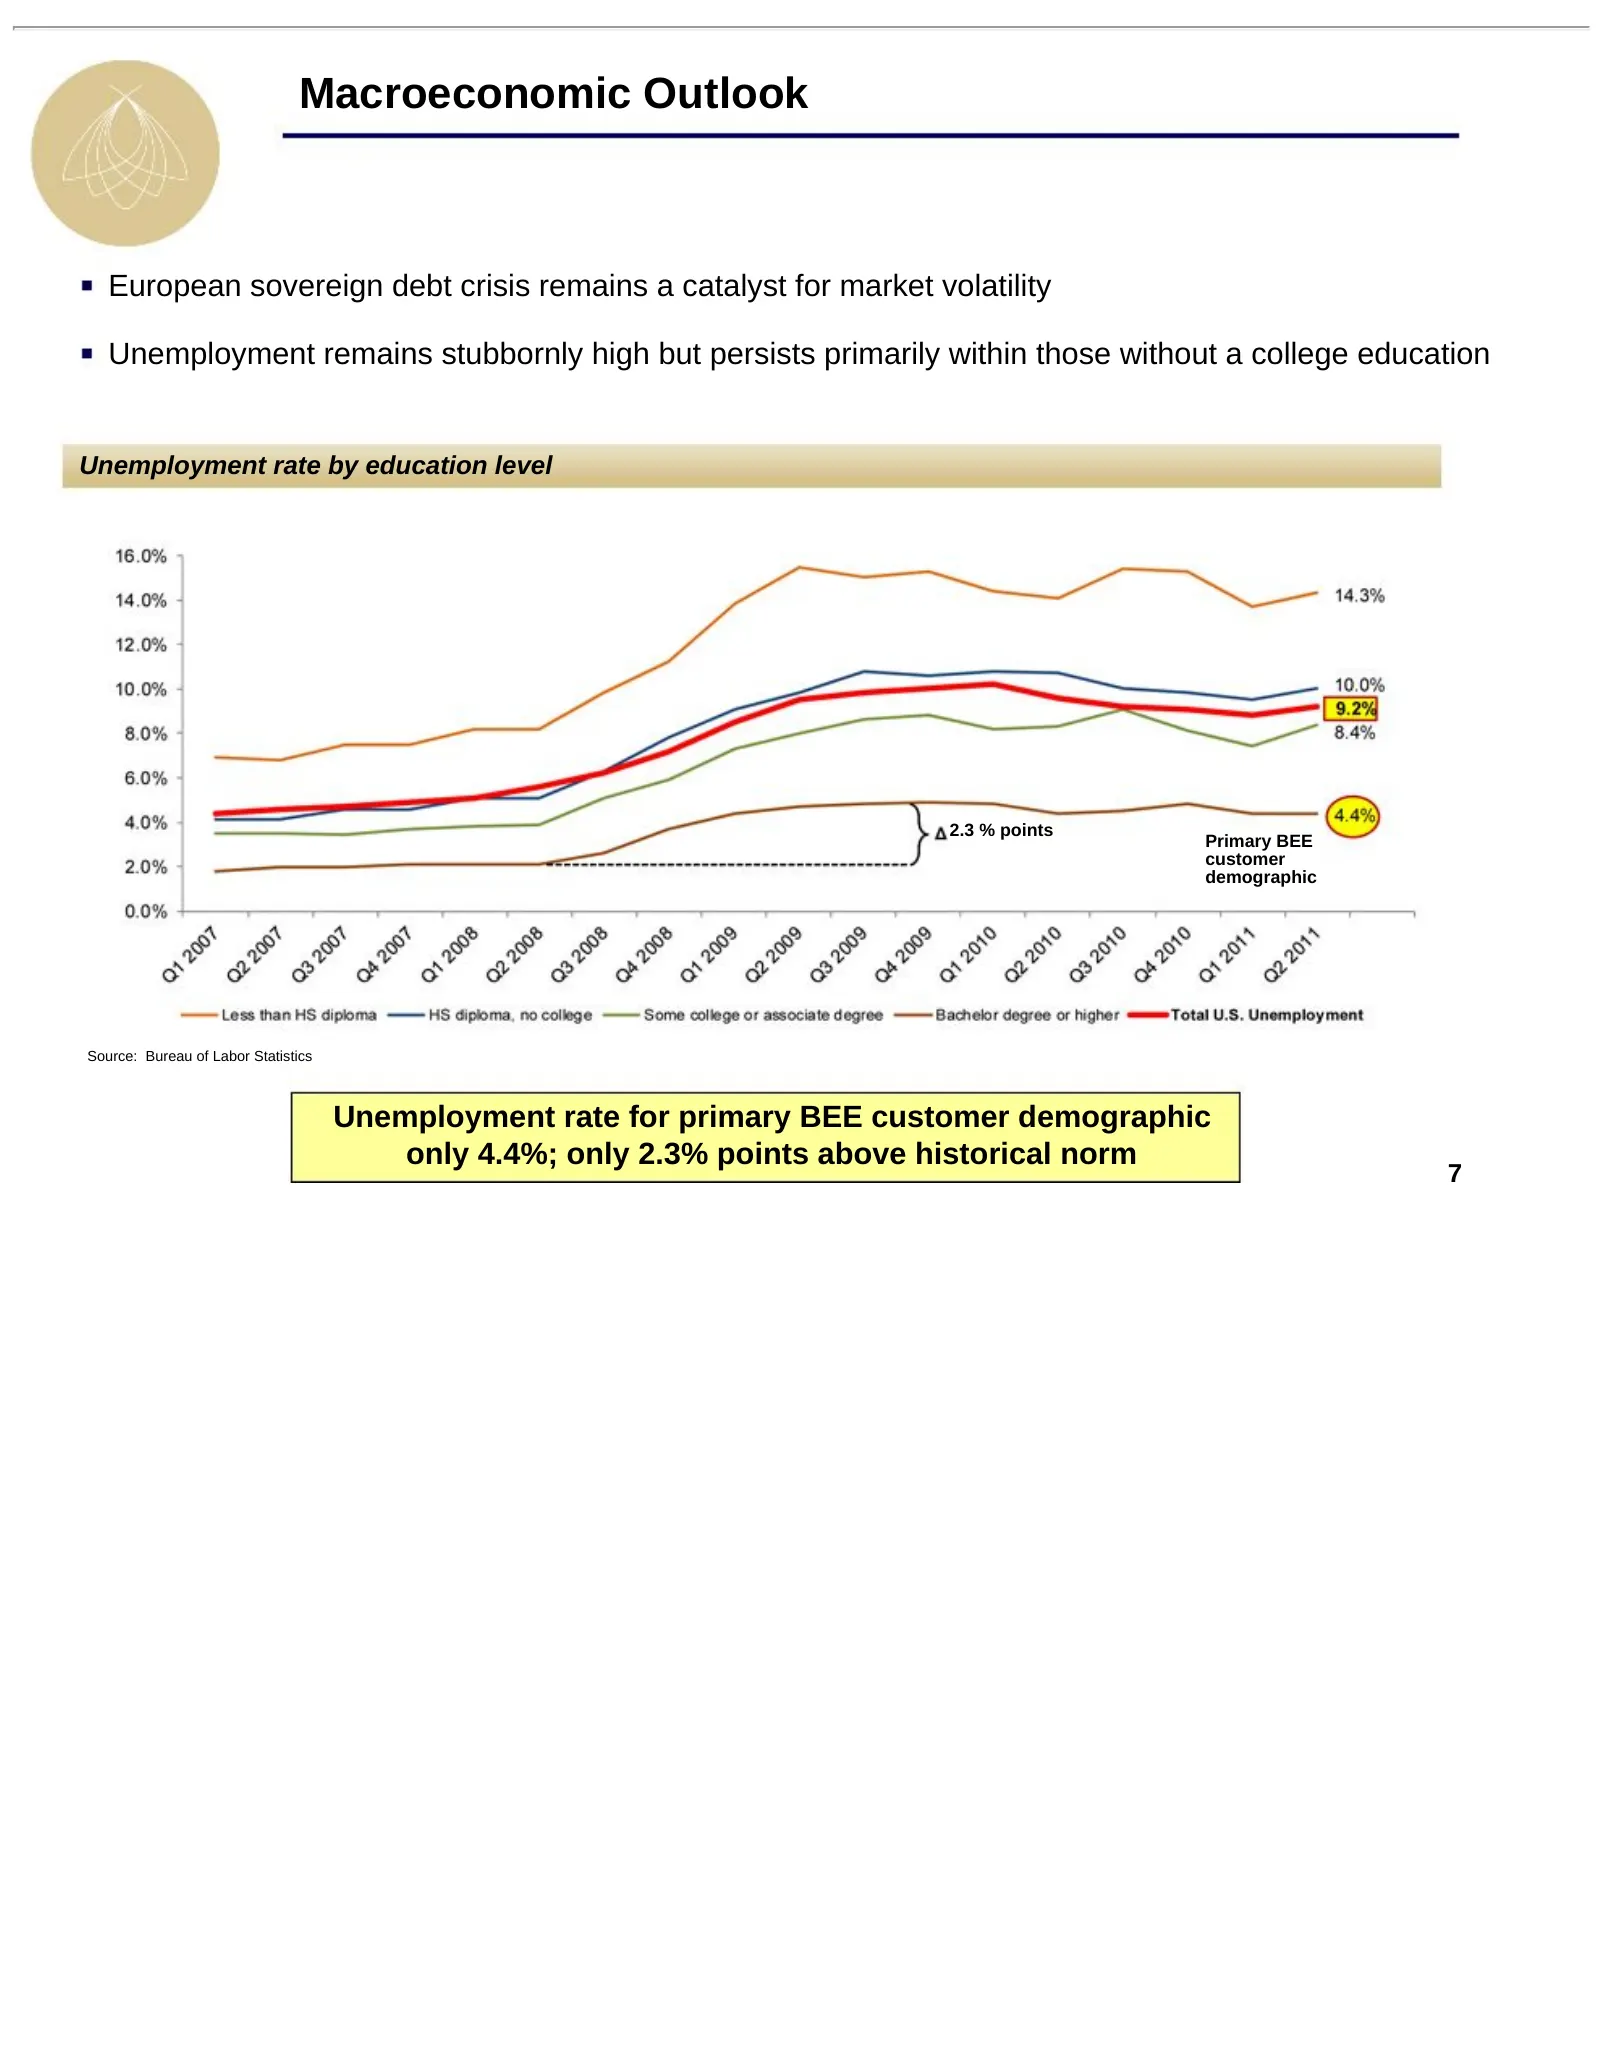
Macroeconomic Outlook European sovereign debt crisis remains a catalyst for market volatility Unemployment remains stubbornly high but persists primarily within those without a college education Unemployment rate by education level 2.3 % points Primary BEE customer demographic Source: Bureau of Labo
Slide 8: Macroeconomic Outlook
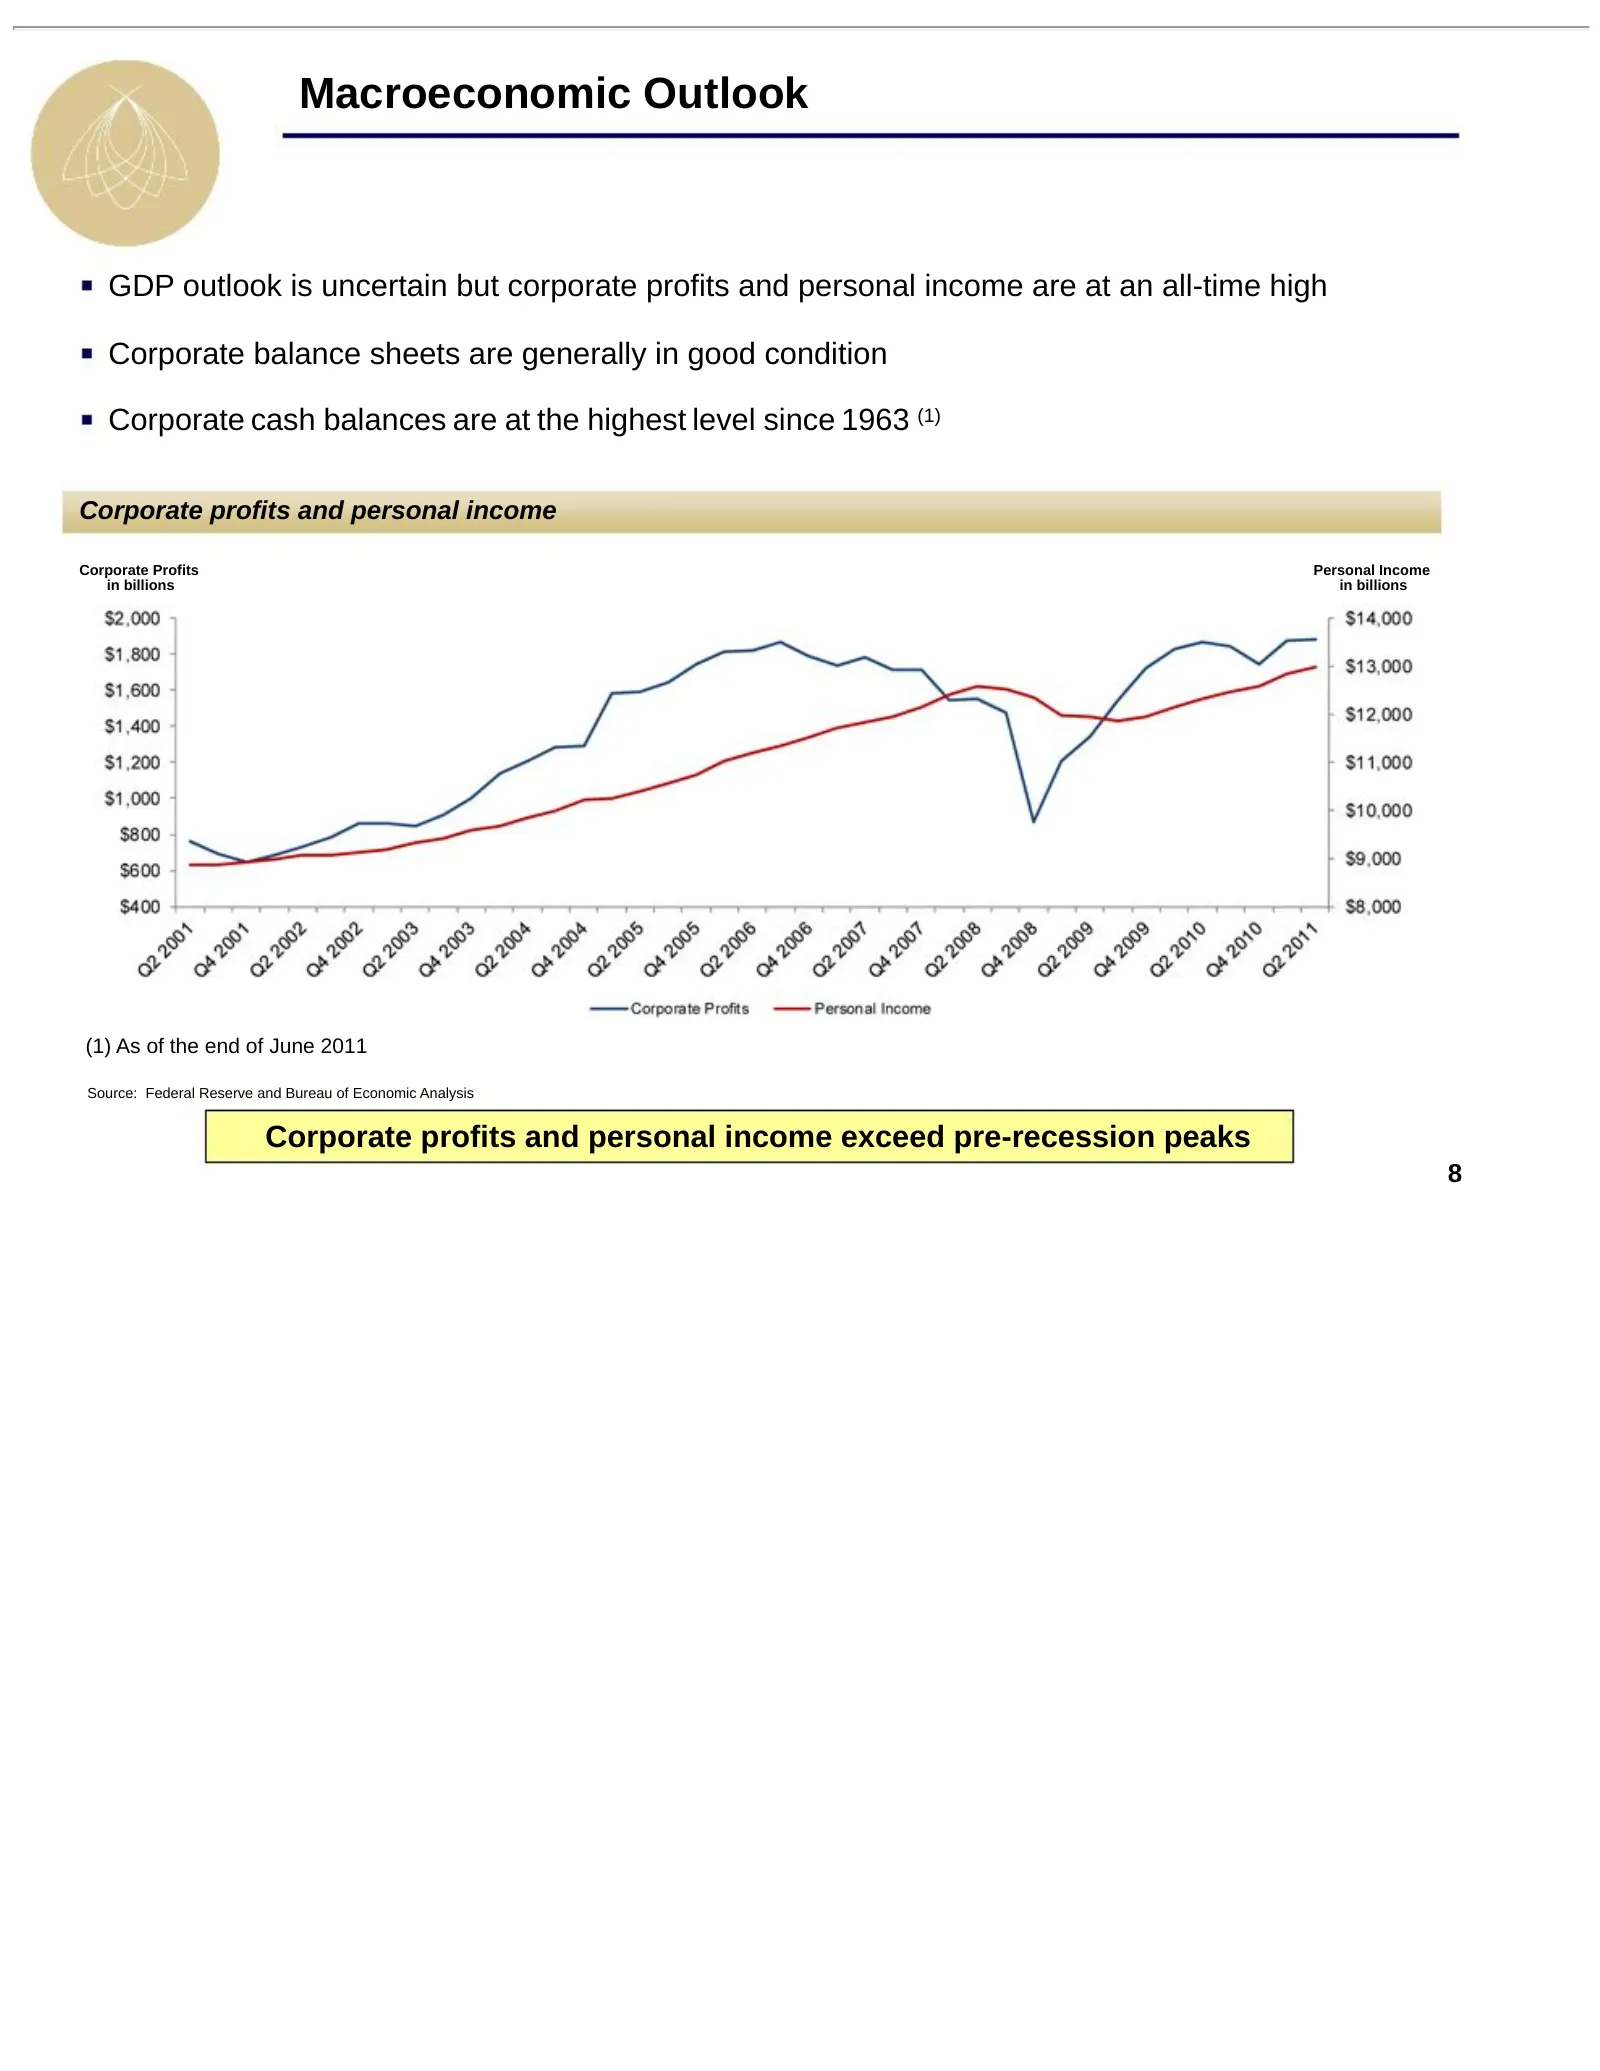
Macroeconomic Outlook GDP outlook is uncertain but corporate profits and personal income are at an all-time high Corporate balance sheets are generally in good condition Corporate cash balances are at the highest level since 1963 (1) Corporate profits and personal income Corporate Profits Personal I
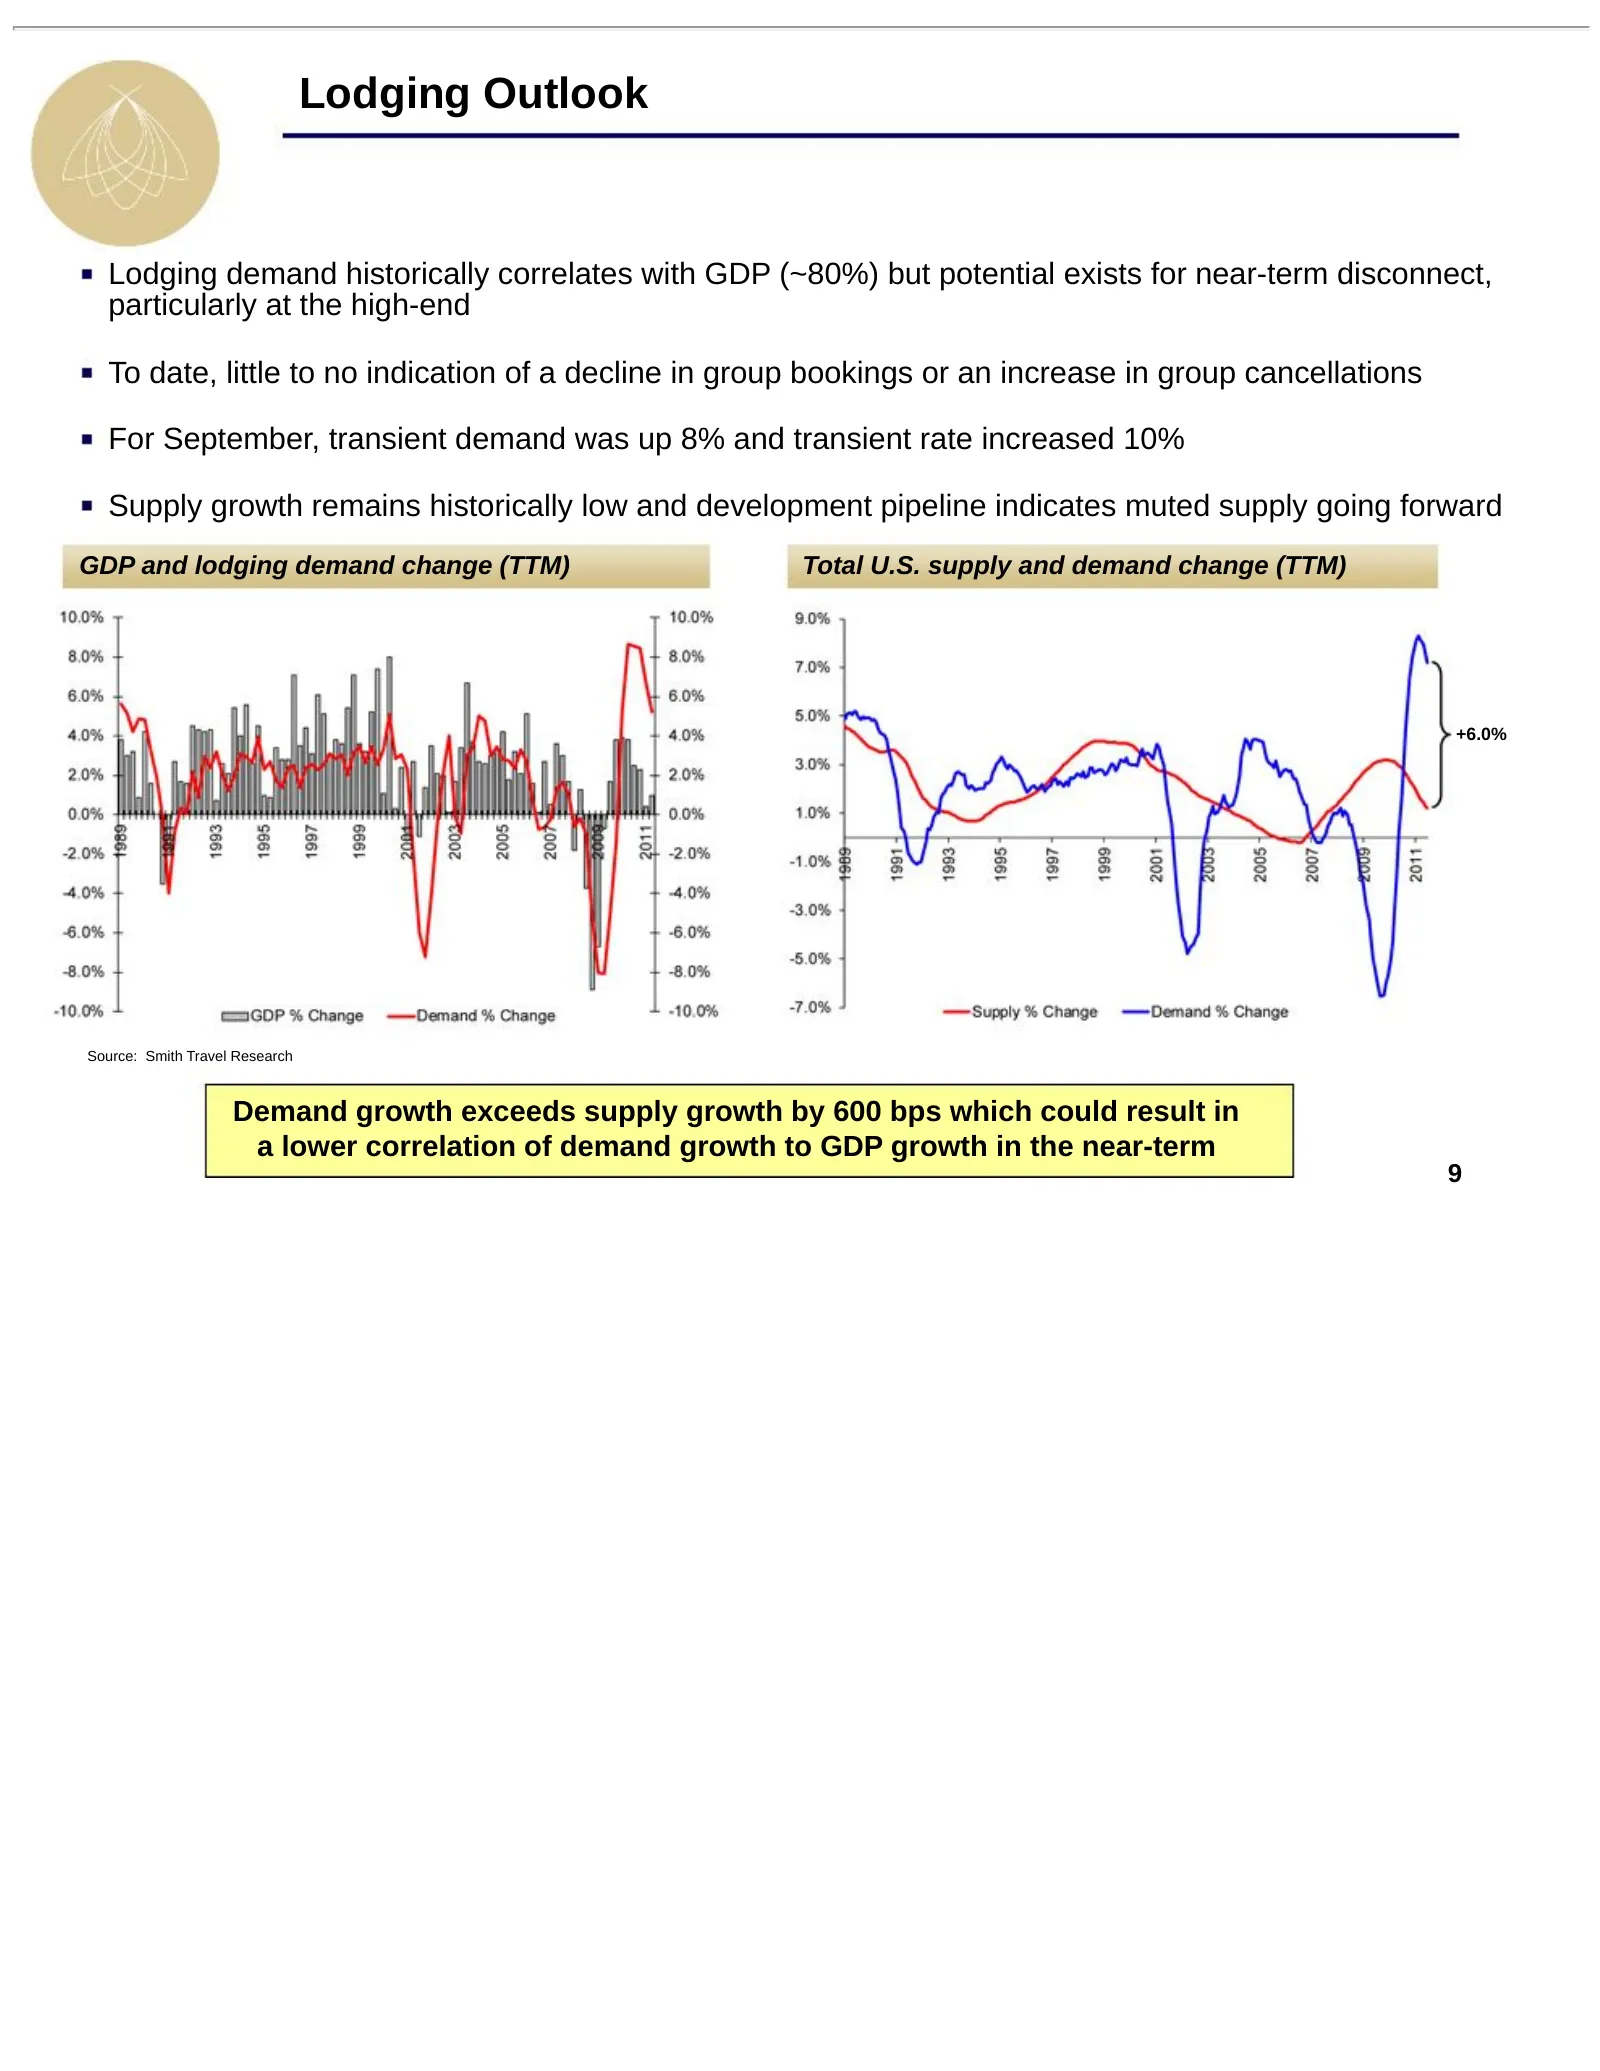
Slide 9: Lodging Outlook
Lodging Outlook Lodging demand historically correlates with GDP (~80%) but potential exists for near-term disconnect, particularly at the high-end To date, little to no indication of a decline in group bookings or an increase in group cancellations For September, transient demand was up 8% and trans
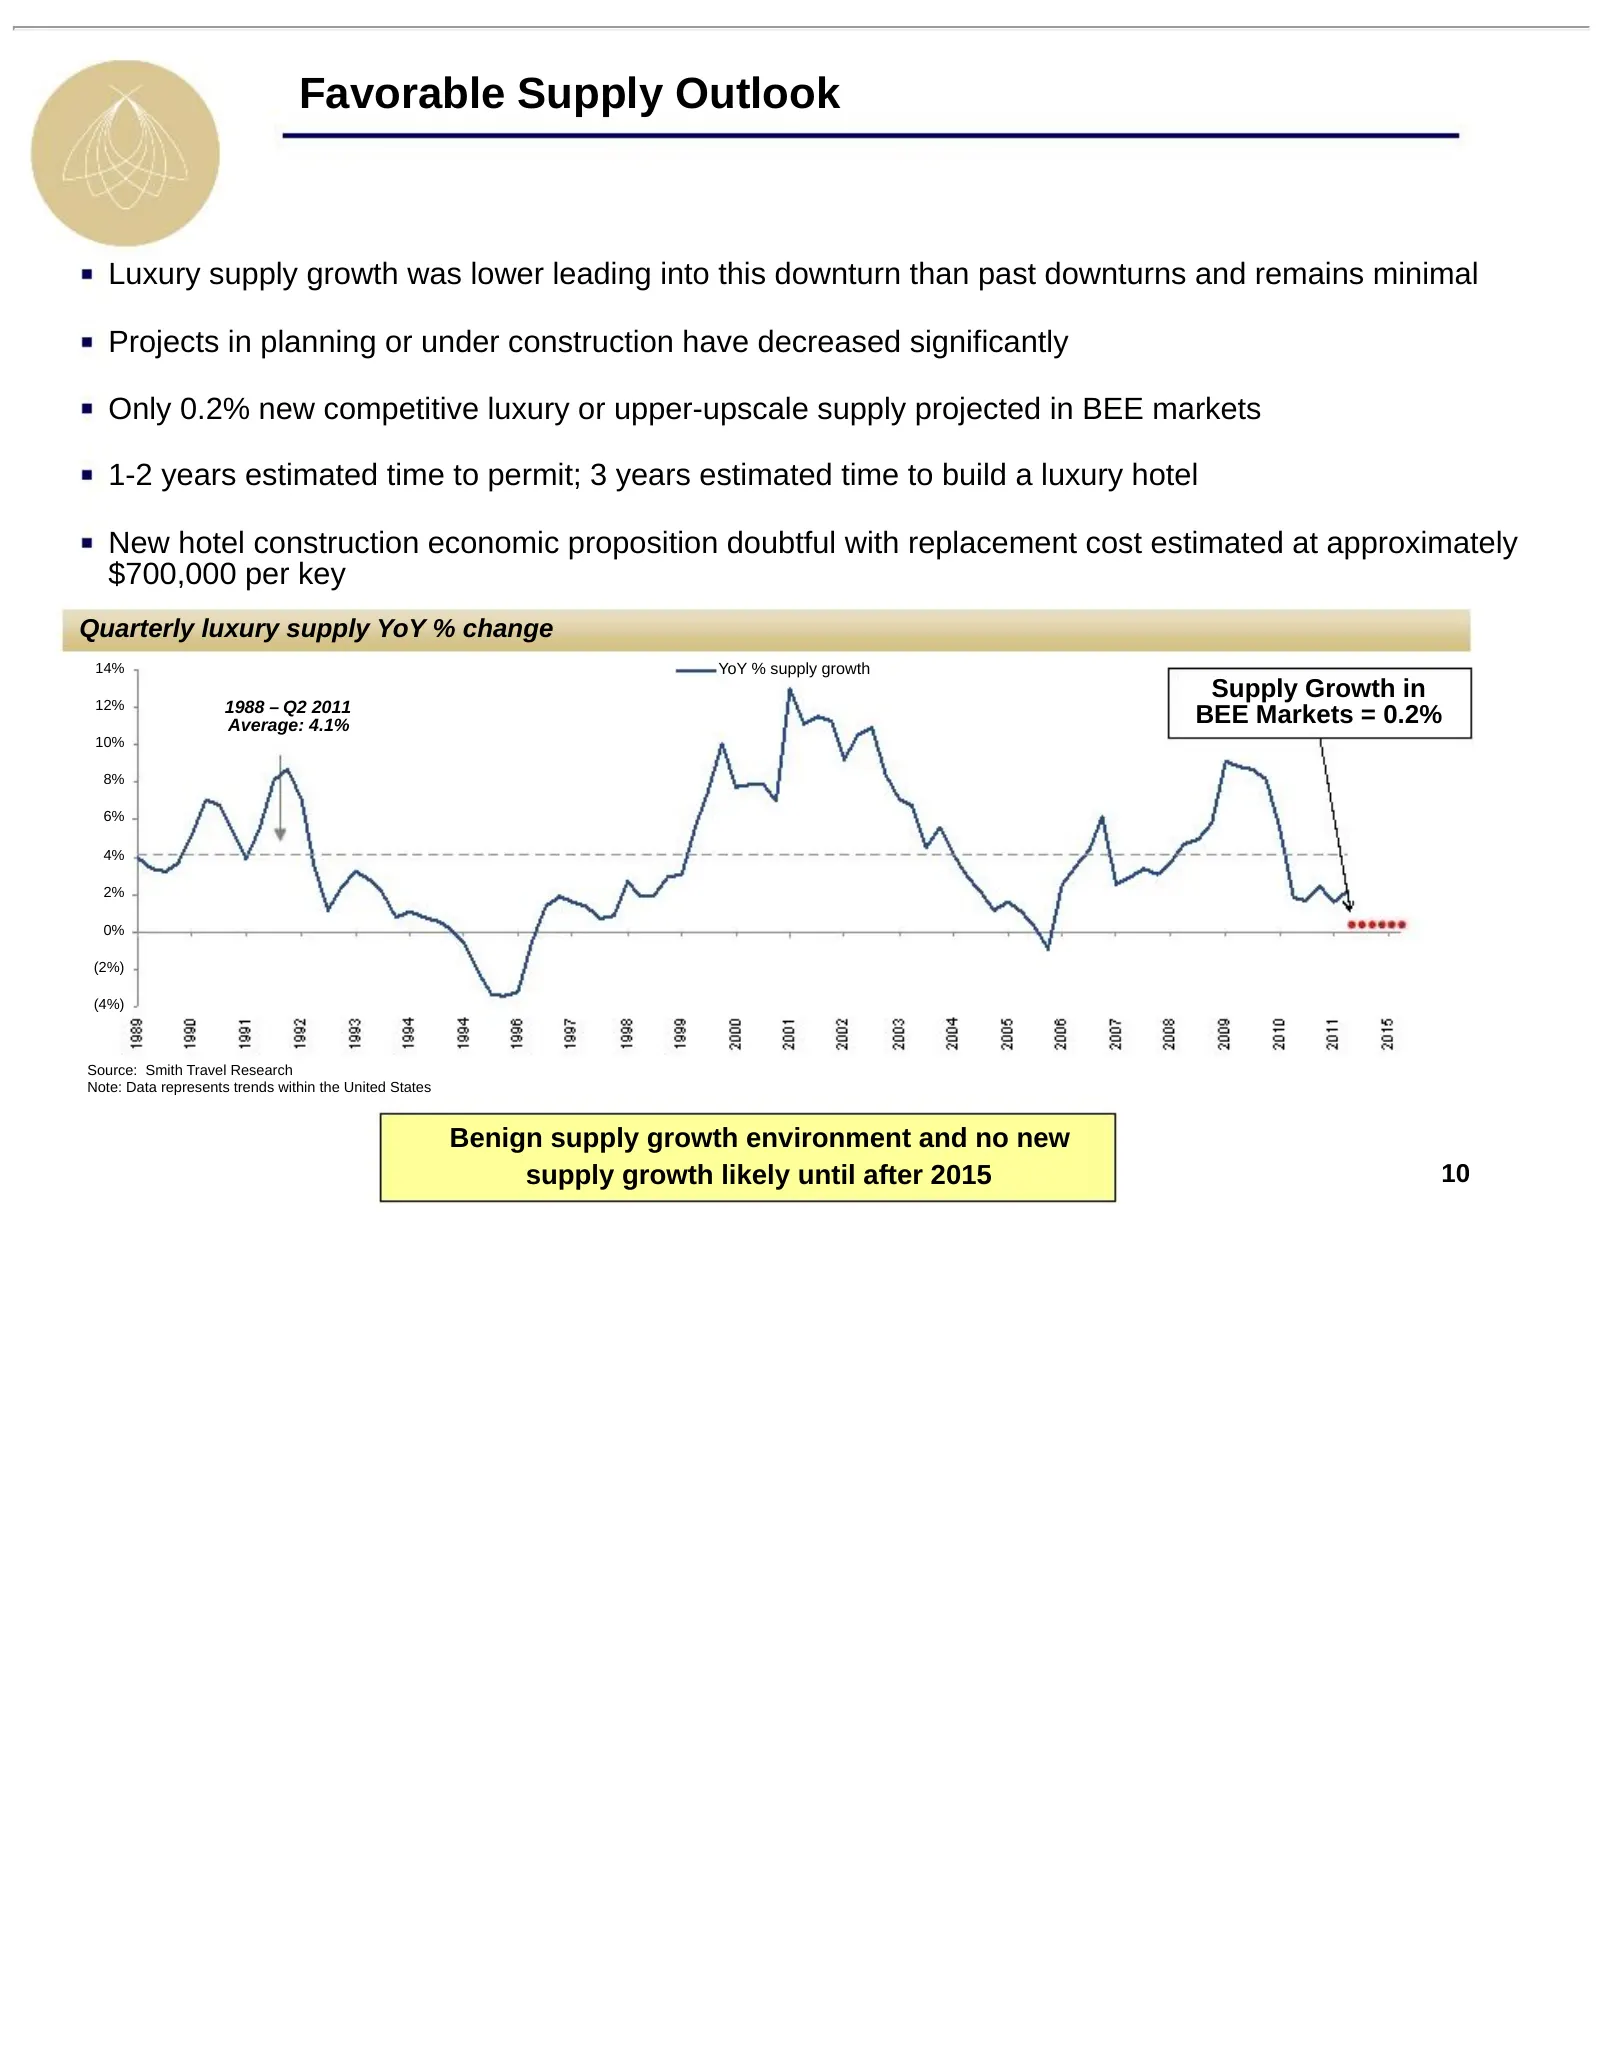
Slide 10: Favorable Supply Outlook
Favorable Supply Outlook Luxury supply growth was lower leading into this downturn than past downturns and remains minimal Projects in planning or under construction have decreased significantly Only 0.2% new competitive luxury or upper-upscale supply projected in BEE markets 1-2 years estimated tim
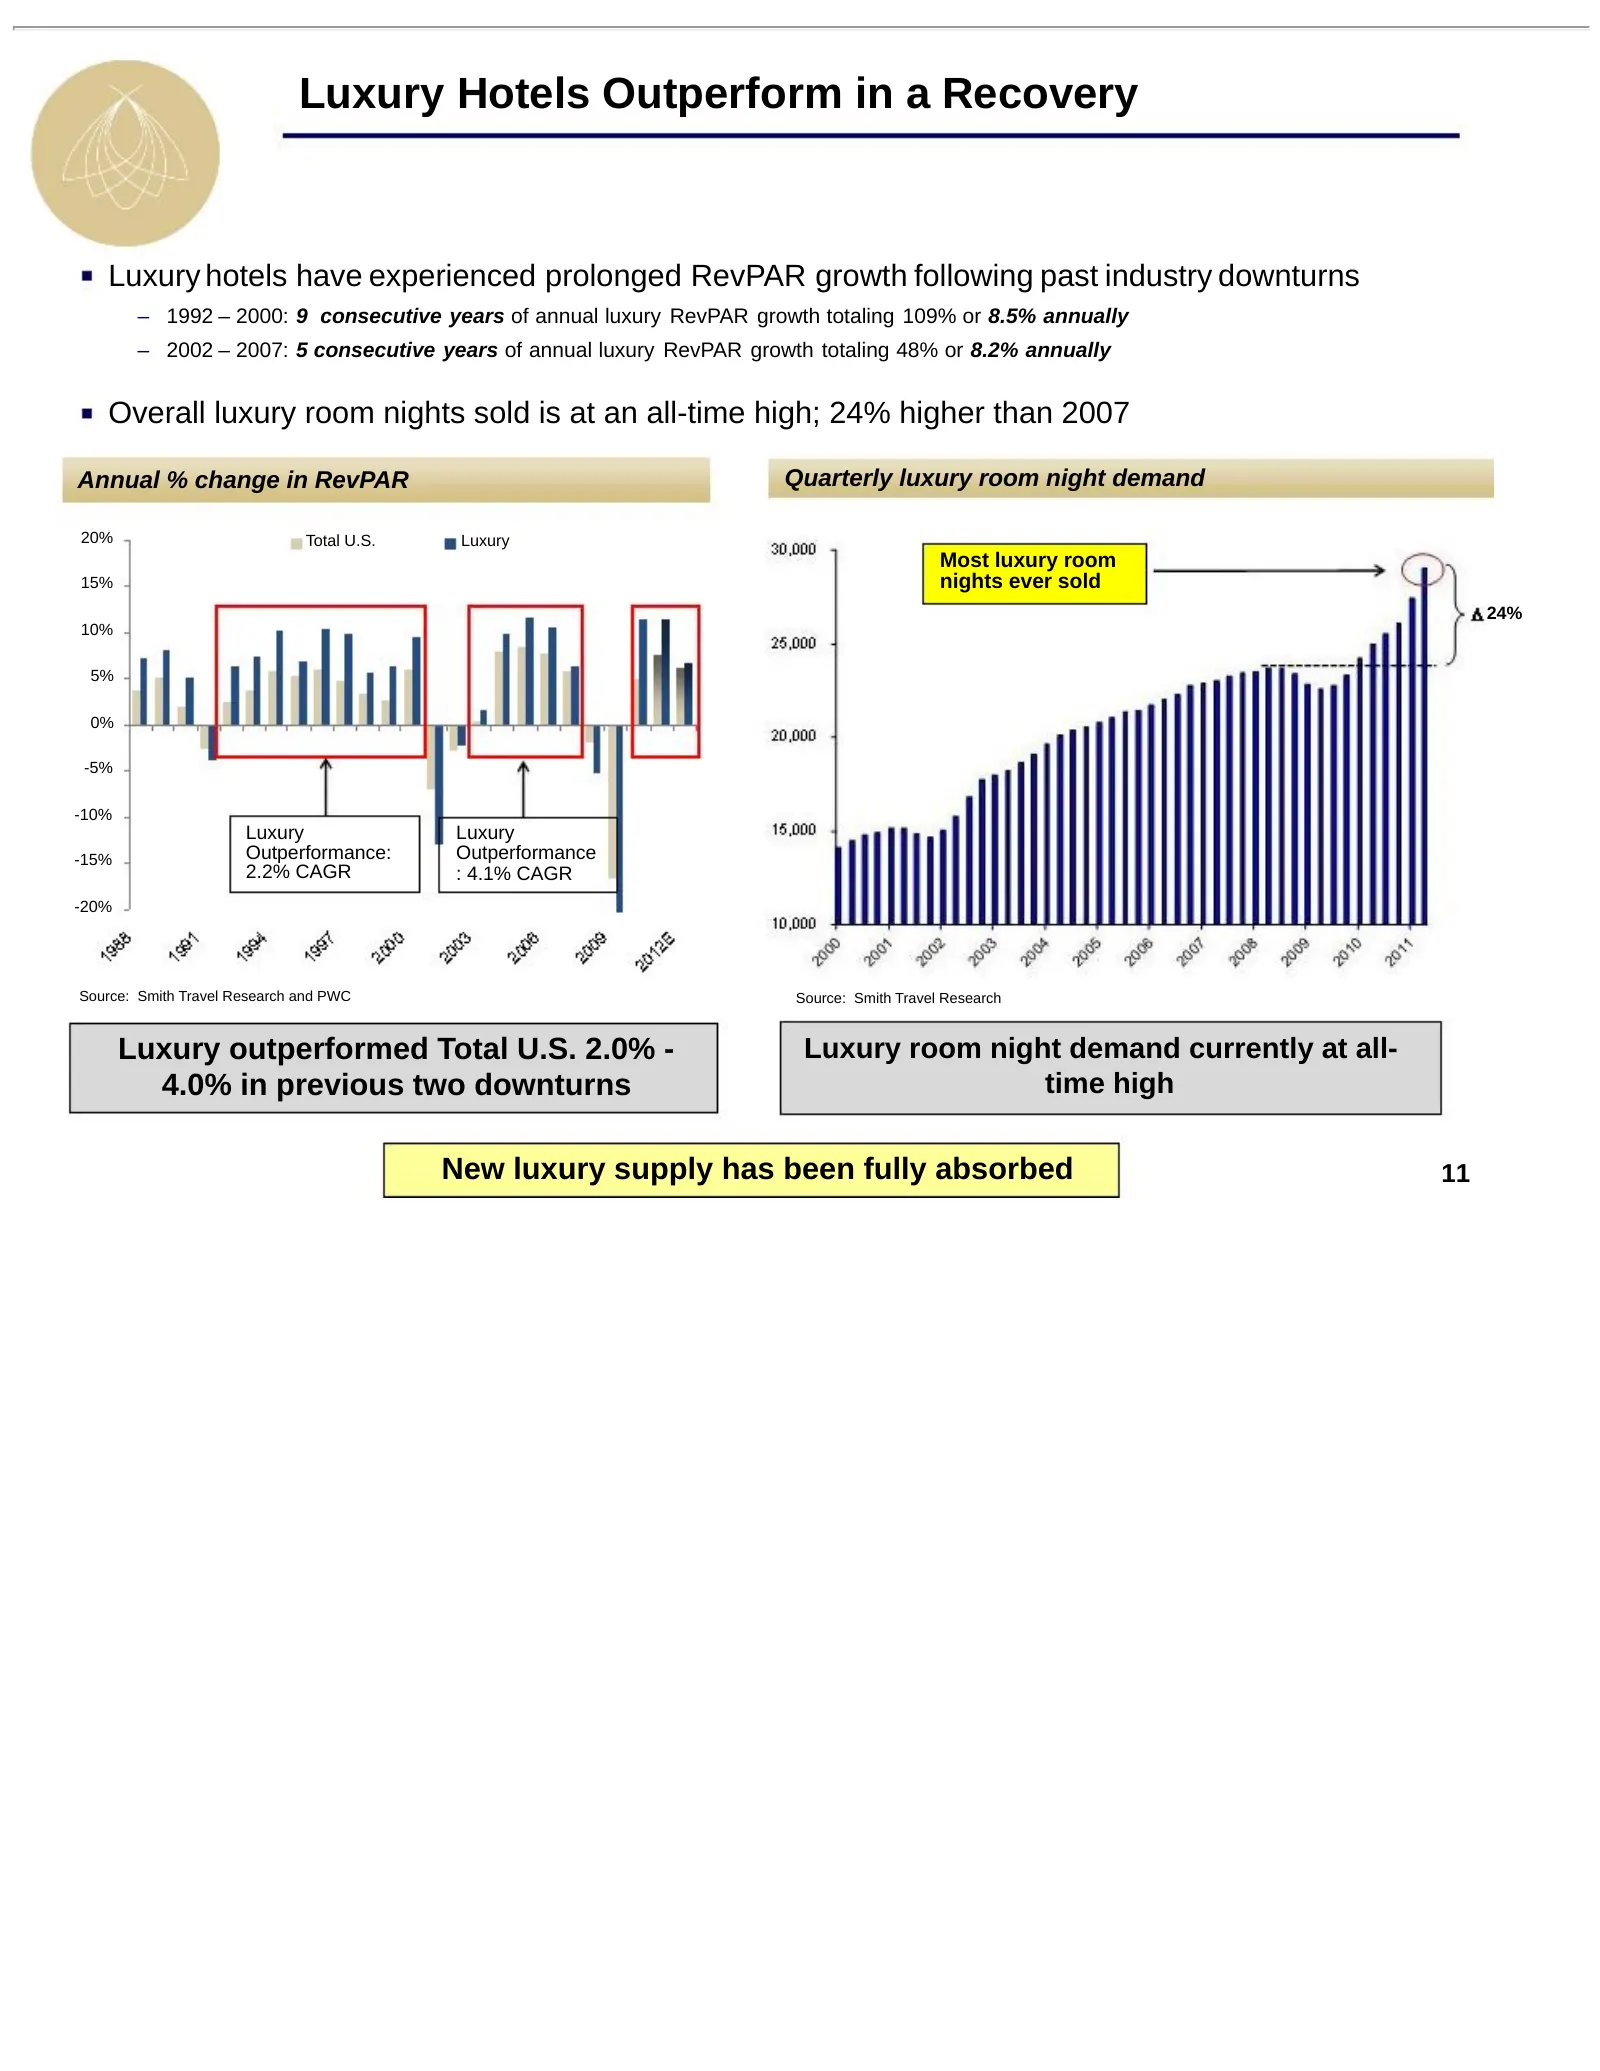
Slide 11: Luxury Hotels Outperform in a Recovery
Luxury Hotels Outperform in a Recovery Luxury hotels have experienced prolonged RevPAR growth following past industry downturns – 1992 – 2000: 9 consecutive years of annual luxury RevPAR growth totaling 109% or 8.5% annually – 2002 – 2007: 5 consecutive years of annual luxury RevPAR growth totaling
Slide 12: Agenda
Agenda I. BEE’s Unique Value Proposition II. Macroeconomic and Industry Update III. Company Overview 12
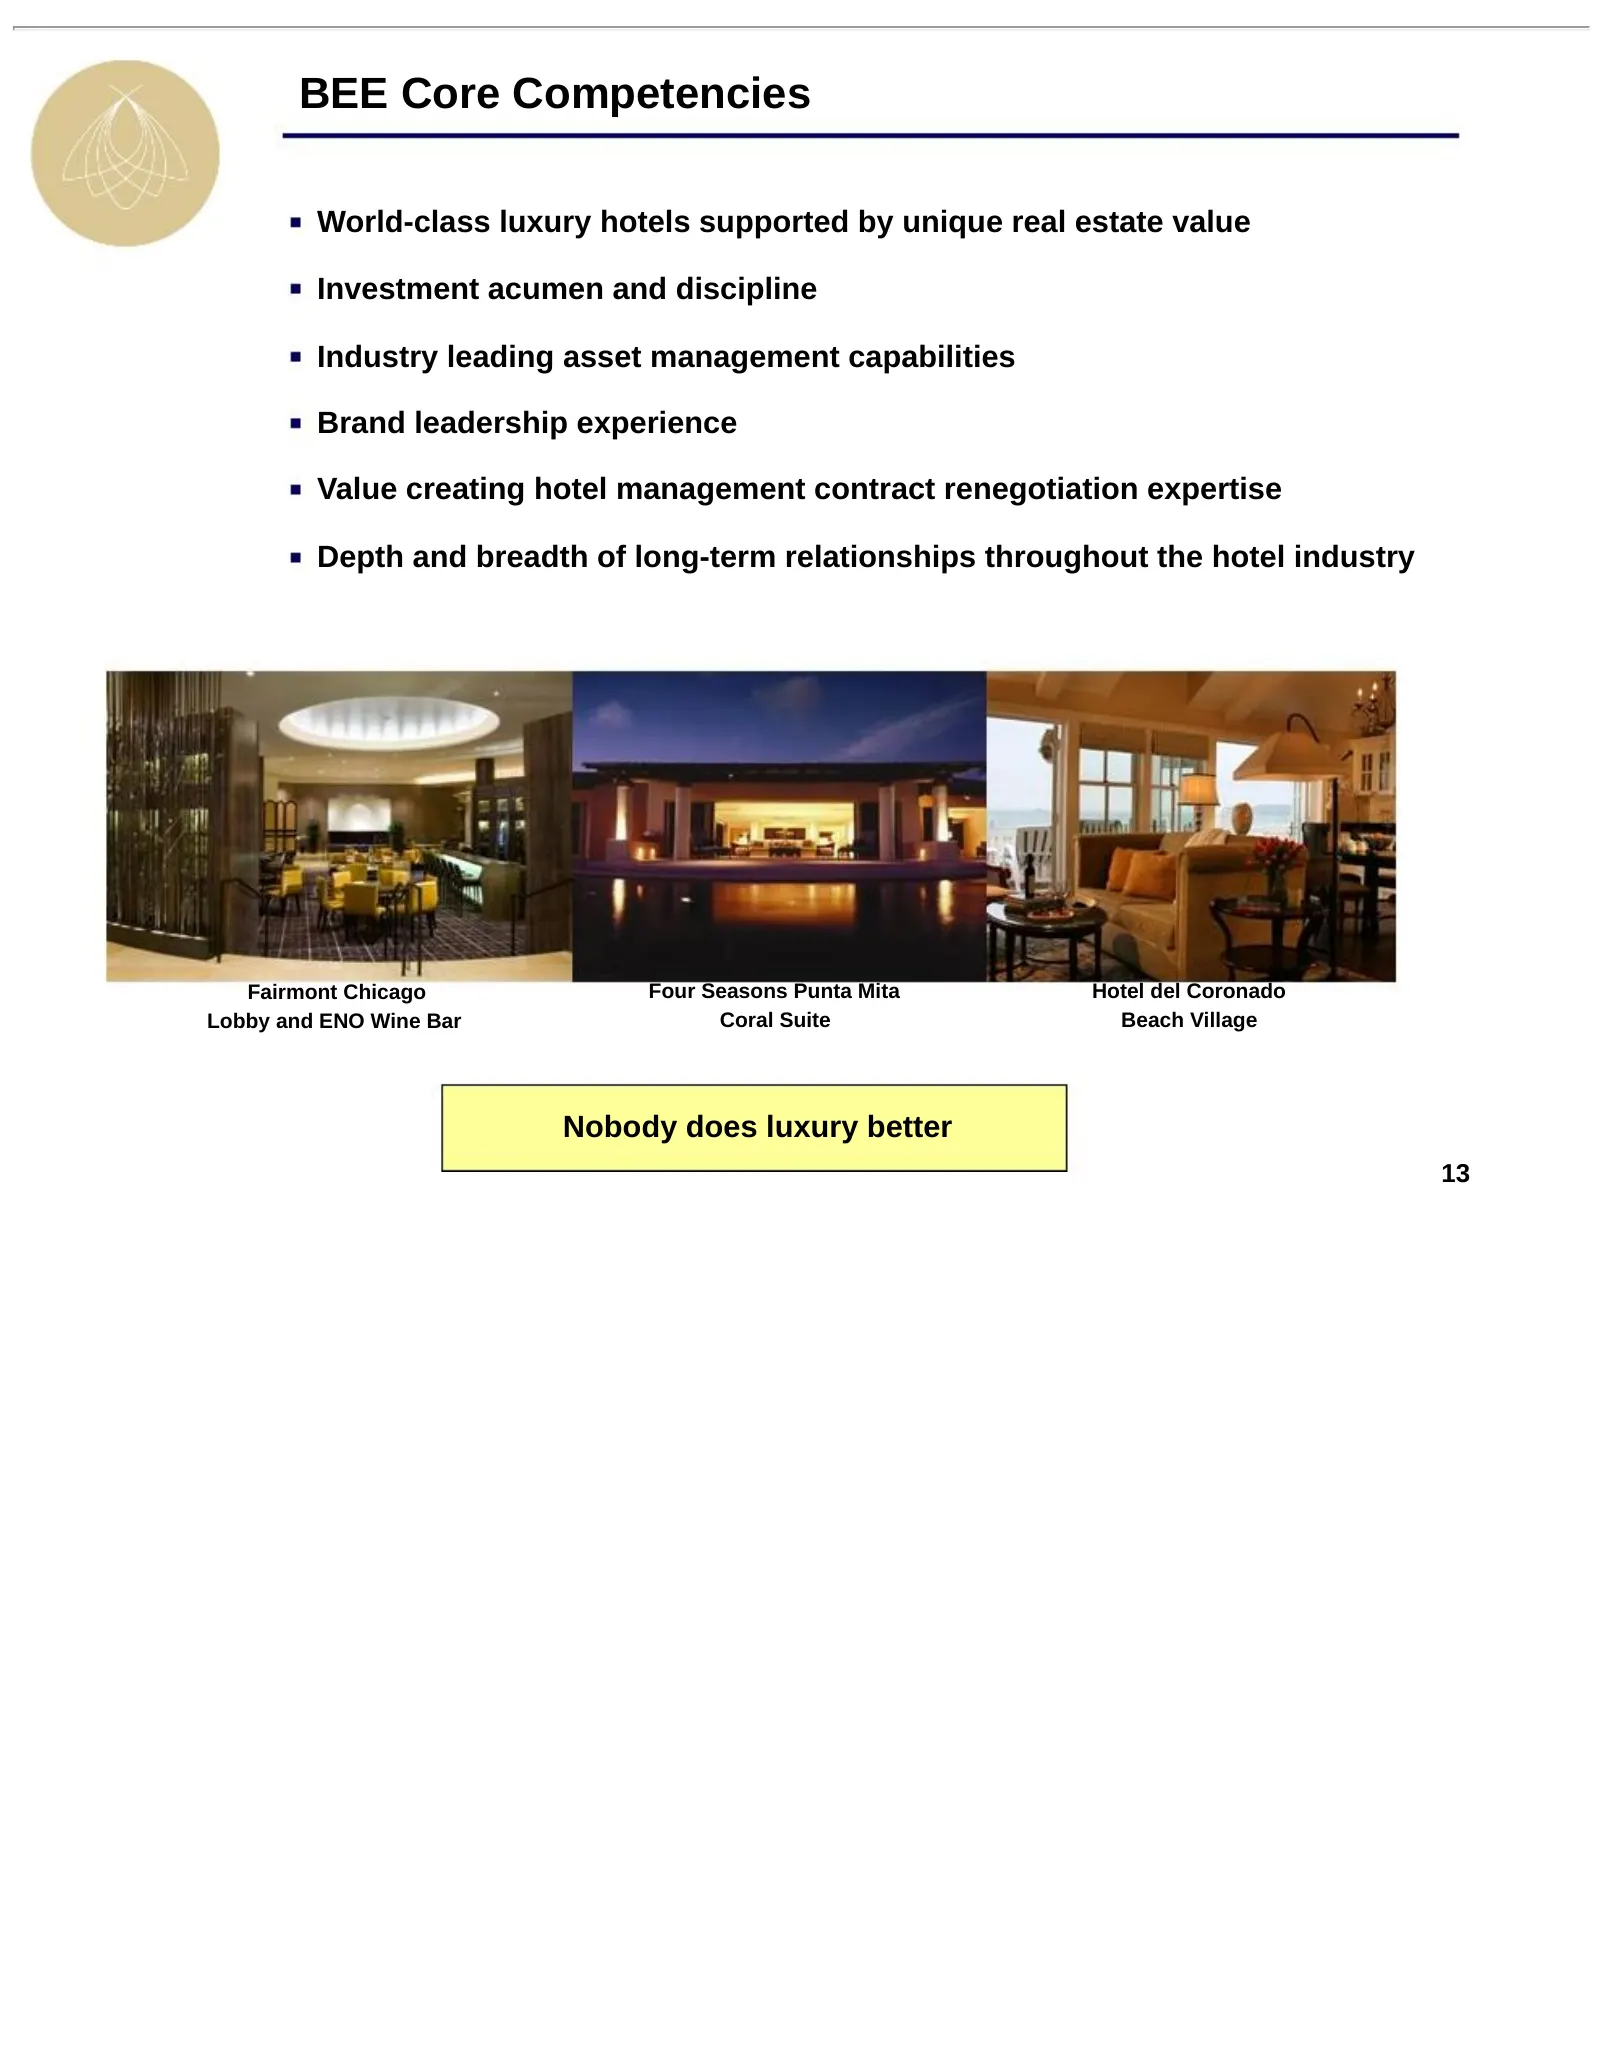
Slide 13: BEE Core Competencies
BEE Core Competencies World-class luxury hotels supported by unique real estate value Investment acumen and discipline Industry leading asset management capabilities Brand leadership experience Value creating hotel management contract renegotiation expertise Depth and breadth of long-term relationsh
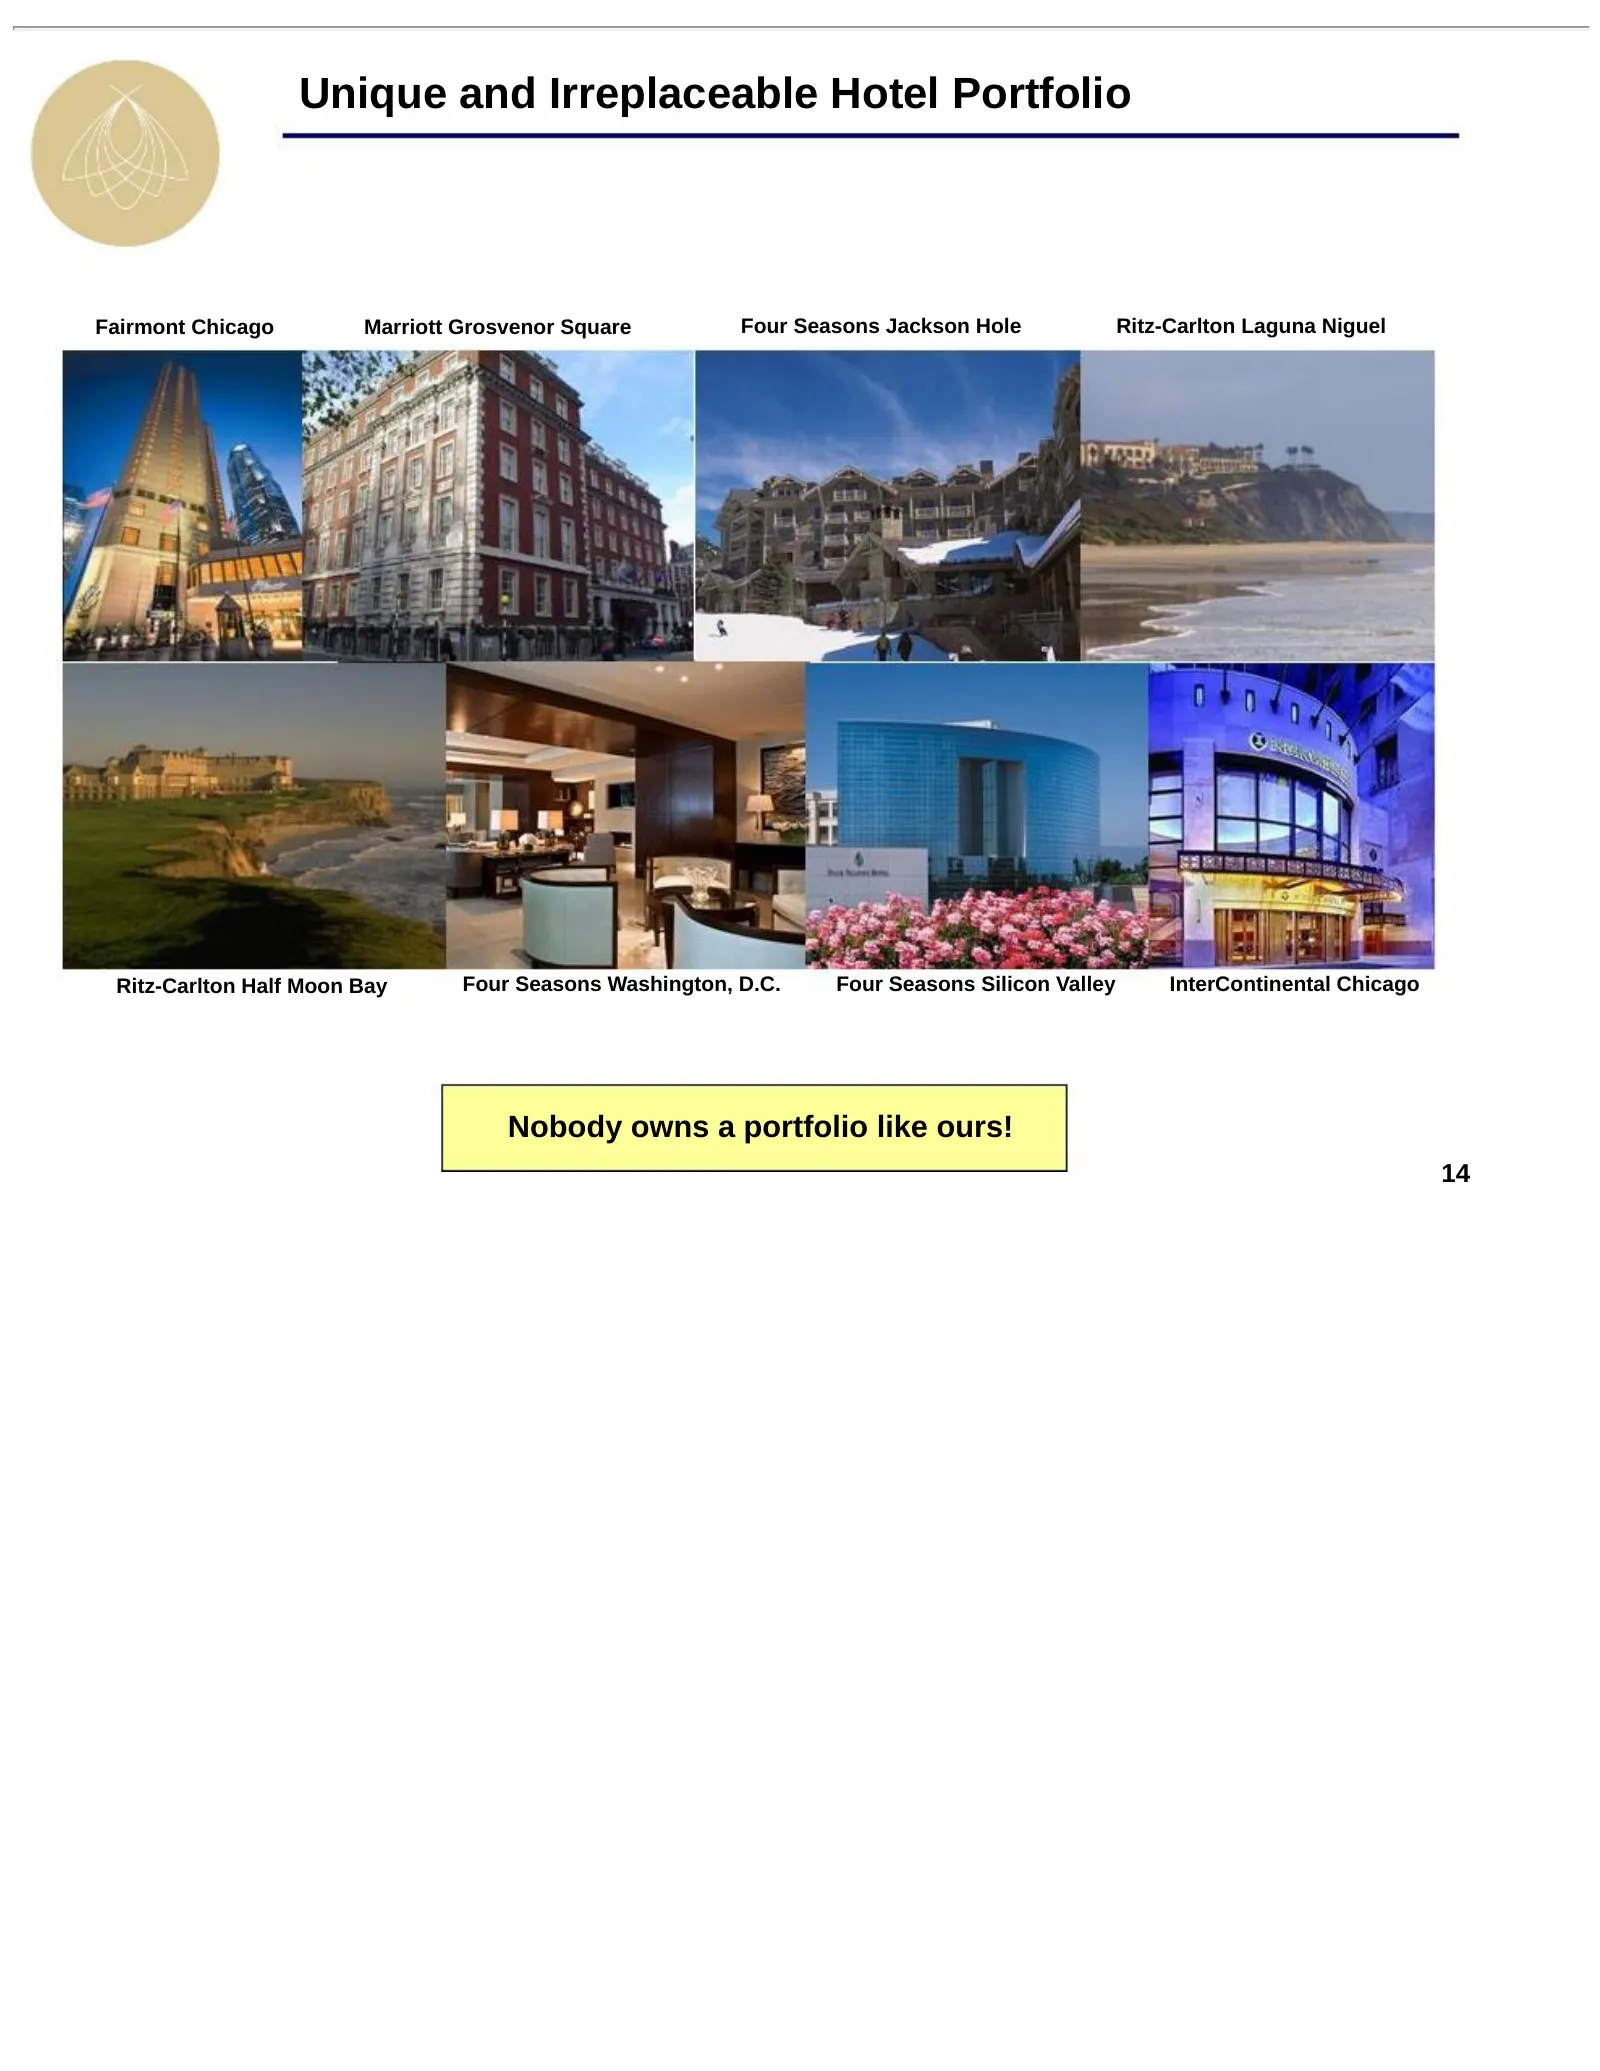
Slide 14: Unique and Irreplaceable Hotel Portfolio
Unique and Irreplaceable Hotel Portfolio Fairmont Chicago Marriott Grosvenor Square Four Seasons Jackson Hole Ritz-Carlton Laguna Niguel Ritz-Carlton Half Moon Bay Four Seasons Washington, D.C. Four Seasons Silicon Valley InterContinental Chicago Nobody owns a portfolio like ours! 14
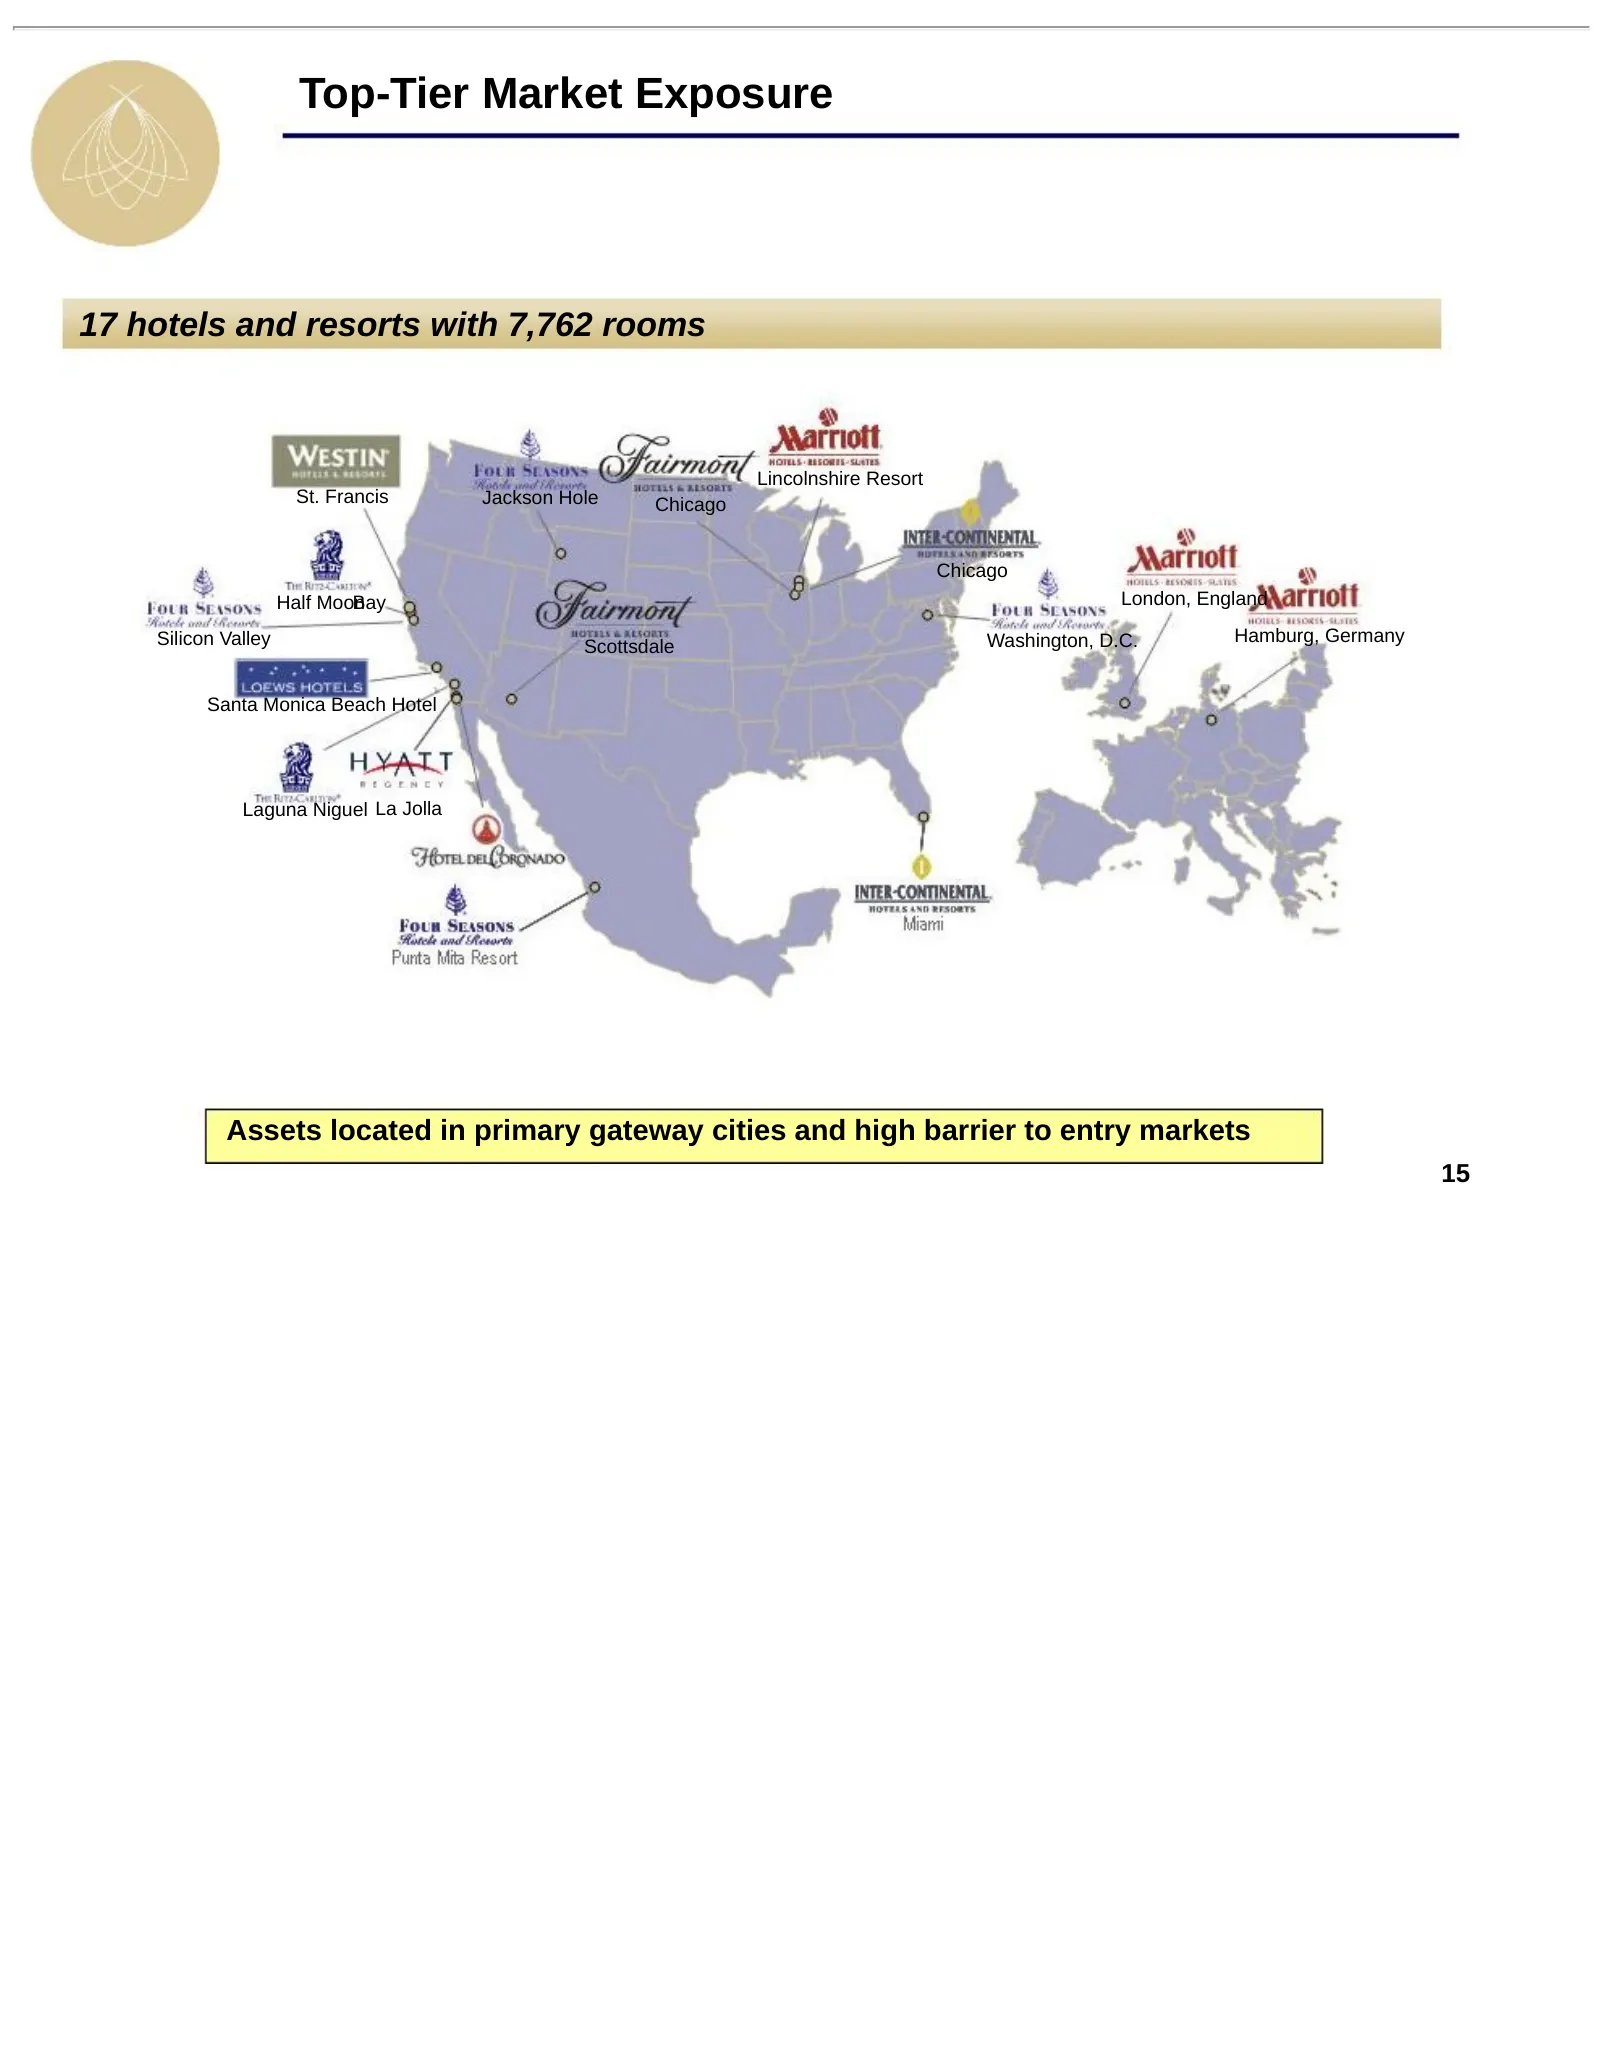
Slide 15: Top-Tier Market Exposure
Top-Tier Market Exposure 17 hotels and resorts with 7,762 rooms Lincolnshire Resort St. Francis Jackson Hole Chicago Chicago Half Moon Bay London, England Silicon Valley Washington, D.C. Hamburg, Germany Scottsdale Santa Monica Beach Hotel Laguna Niguel La Jolla Assets located in primary gateway cit
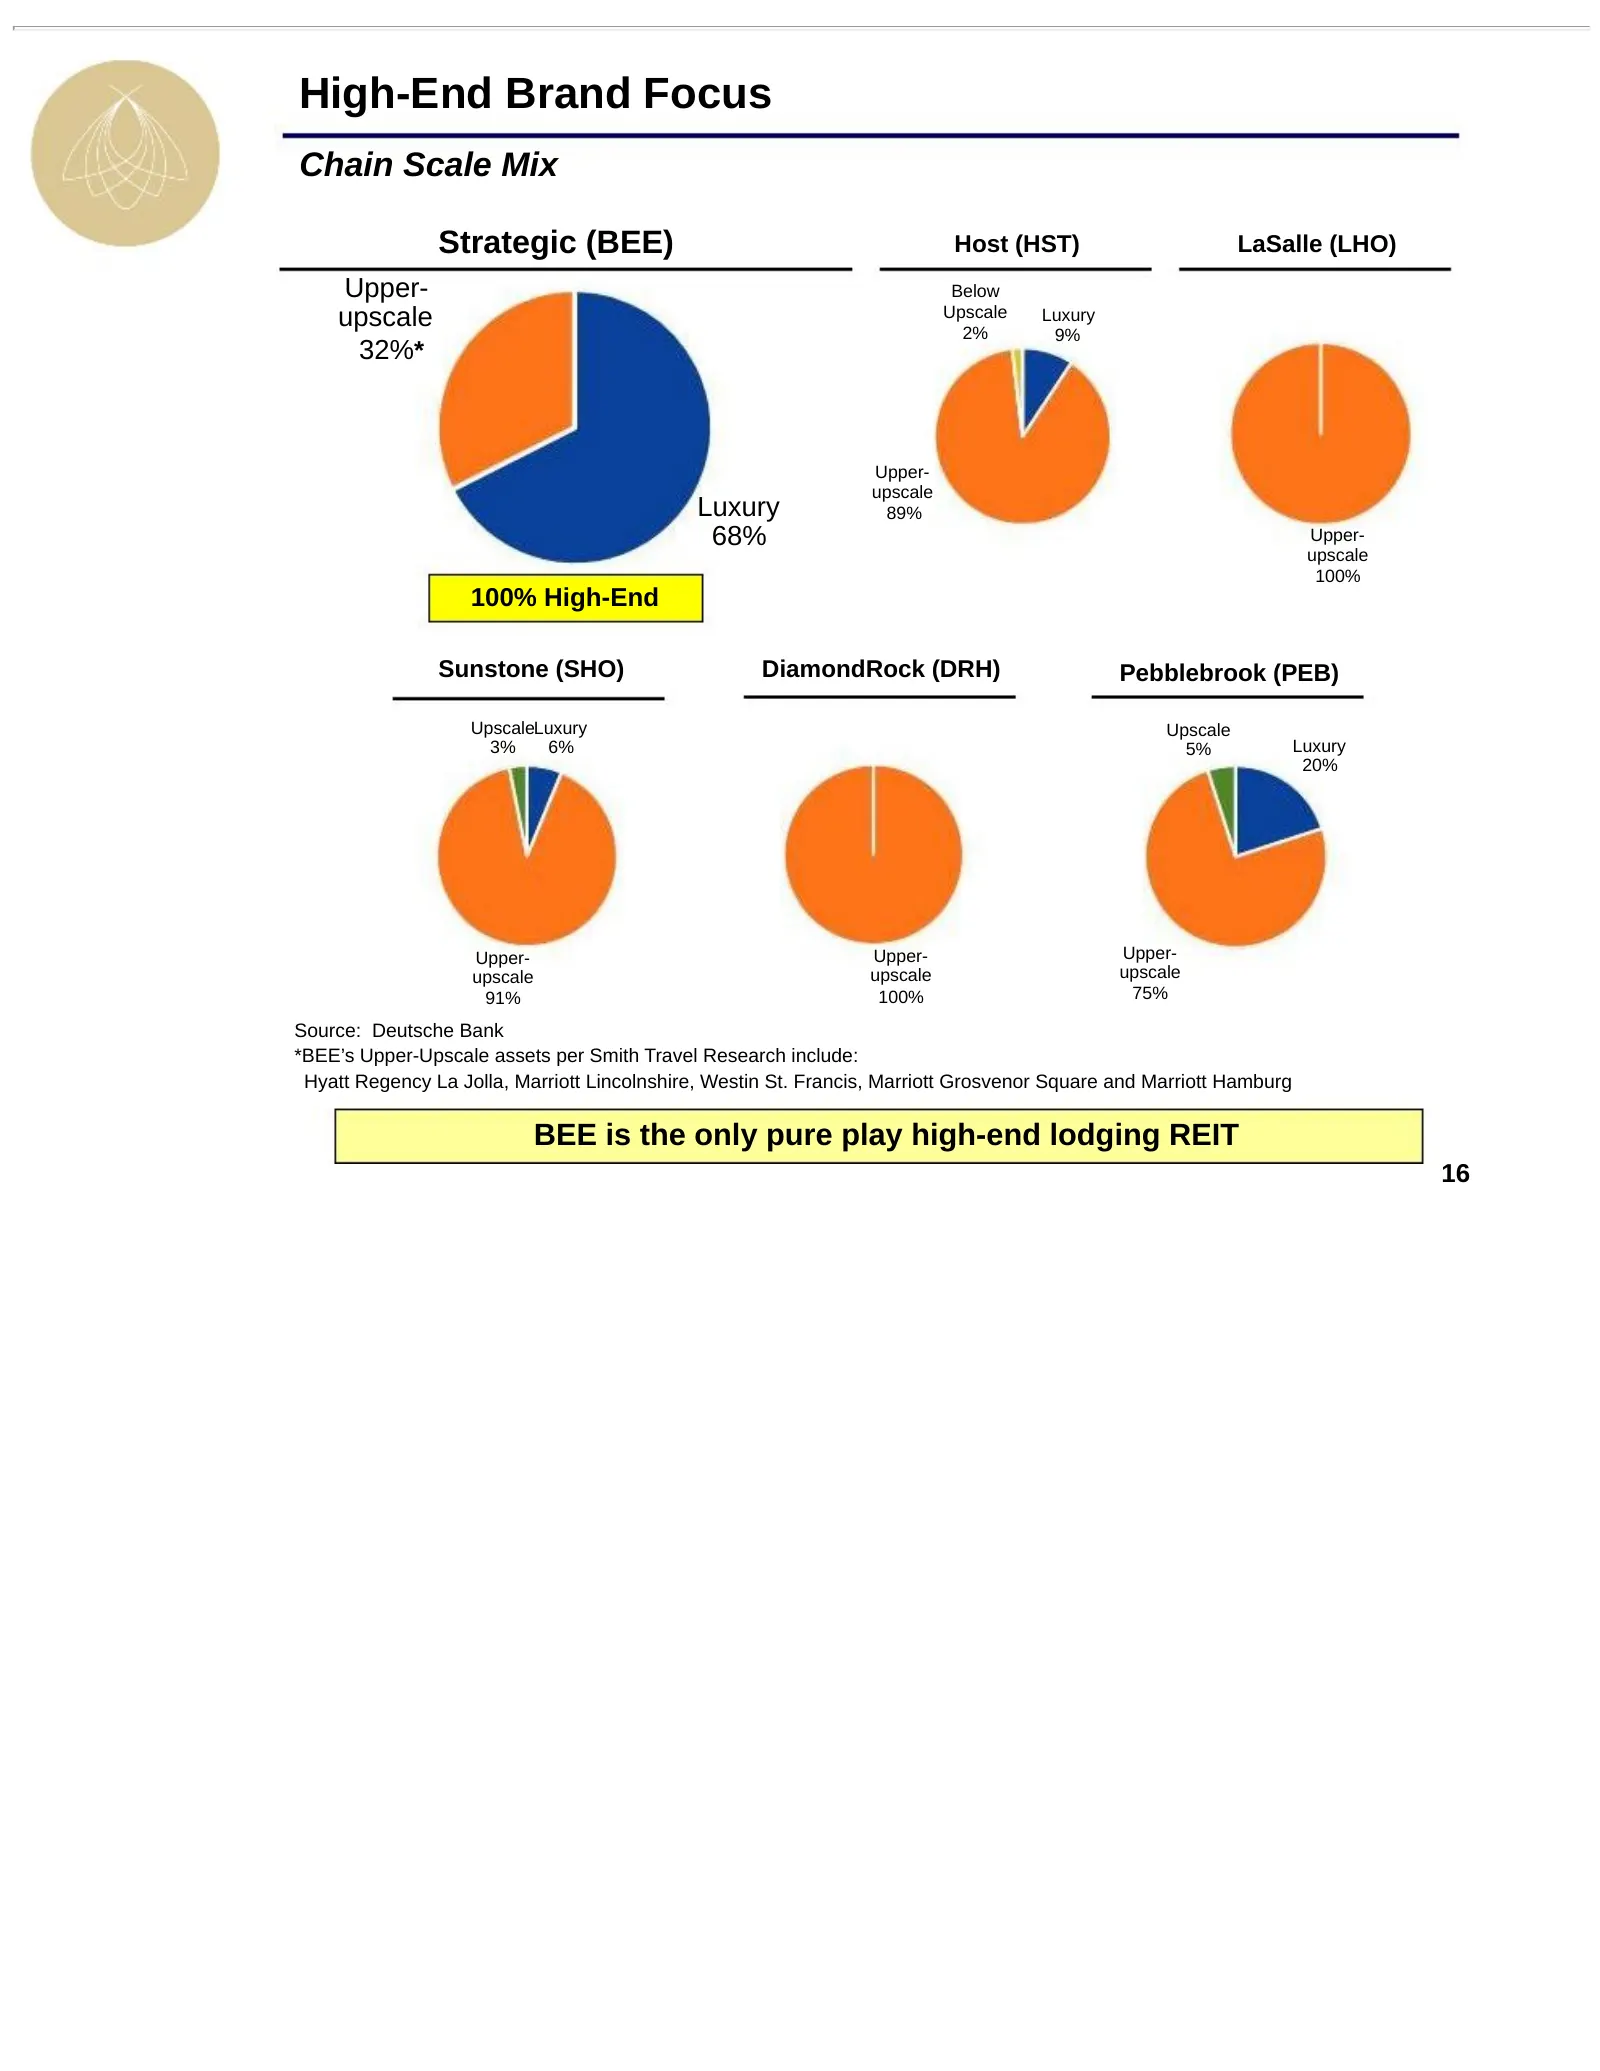
Slide 16: High-End Brand Focus
High-End Brand Focus Chain Scale Mix Strategic (BEE) Host (HST) LaSalle (LHO) Upper- Below upscale Upscale 2% Luxury 9% 32%* Upper- upscale Luxury 89% 68% Upper- upscale 100% 100% High-End Sunstone (SHO) DiamondRock (DRH) Pebblebrook (PEB) UpscaleLuxury Upscale 3% 6% 5% Luxury 20% Upper- Upper- Uppe
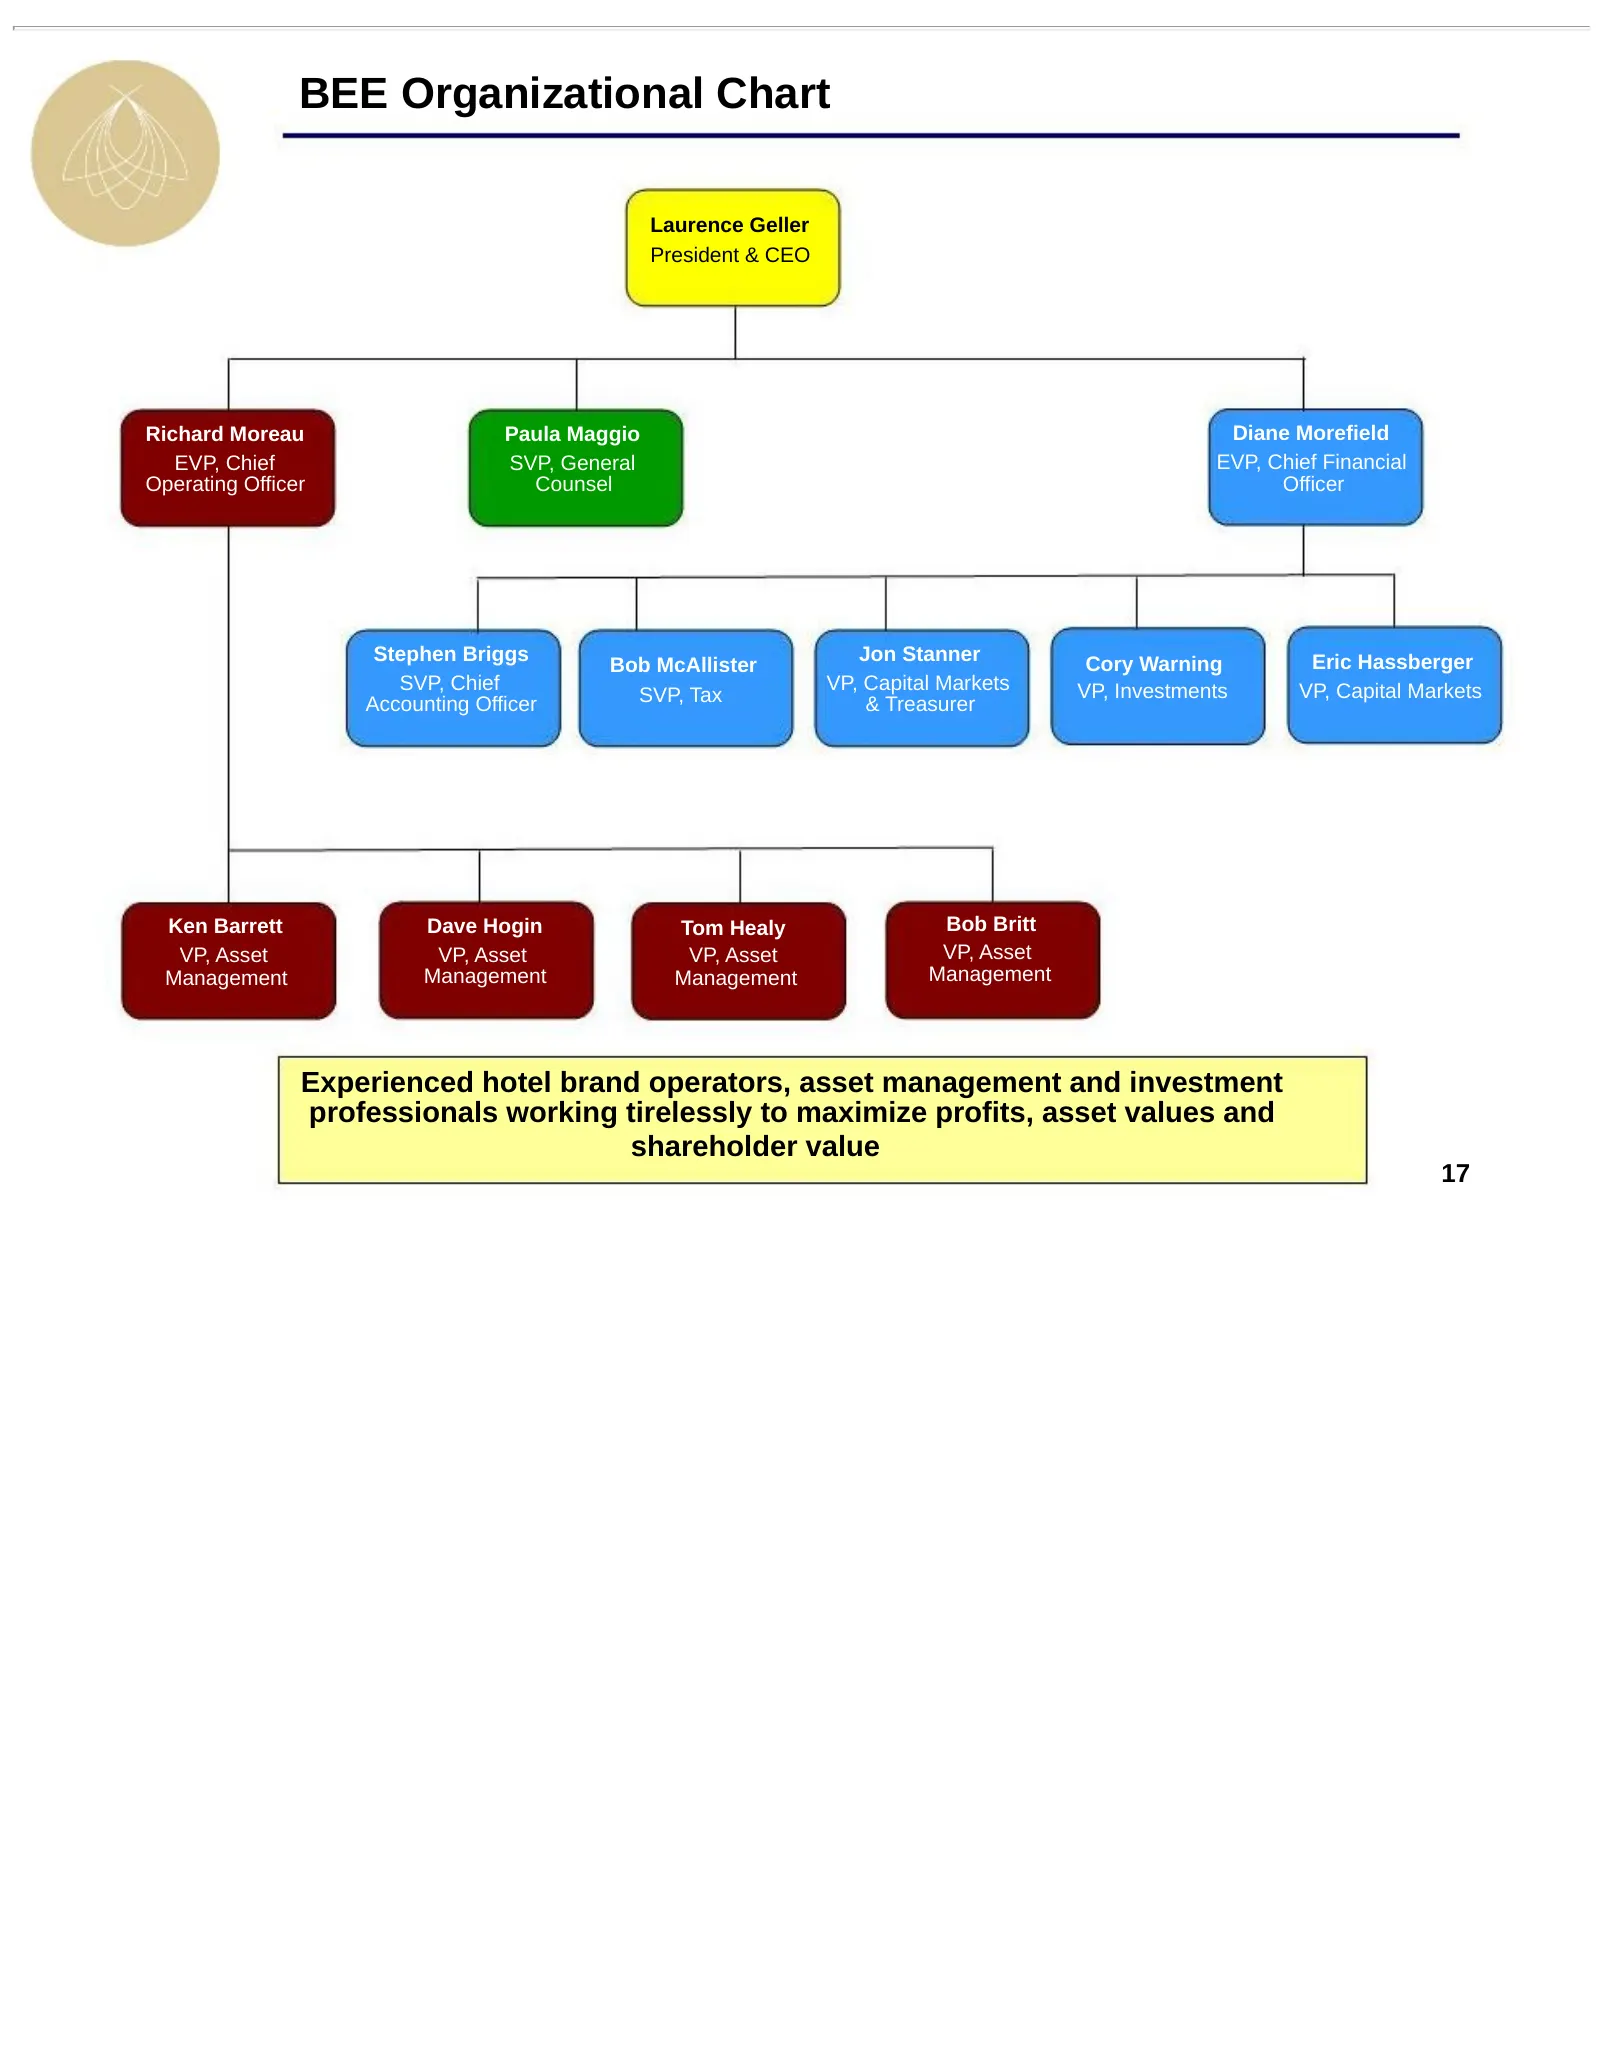
Slide 17: BEE Organizational Chart
BEE Organizational Chart Laurence Geller President & CEO Richard Moreau Paula Maggio Diane Morefield EVP, Chief SVP, General EVP, Chief Financial Operating Officer Counsel Officer Stephen Briggs Jon Stanner Cory Warning Eric Hassberger Bob McAllister SVP, Chief VP, Capital Markets VP, Investments VP
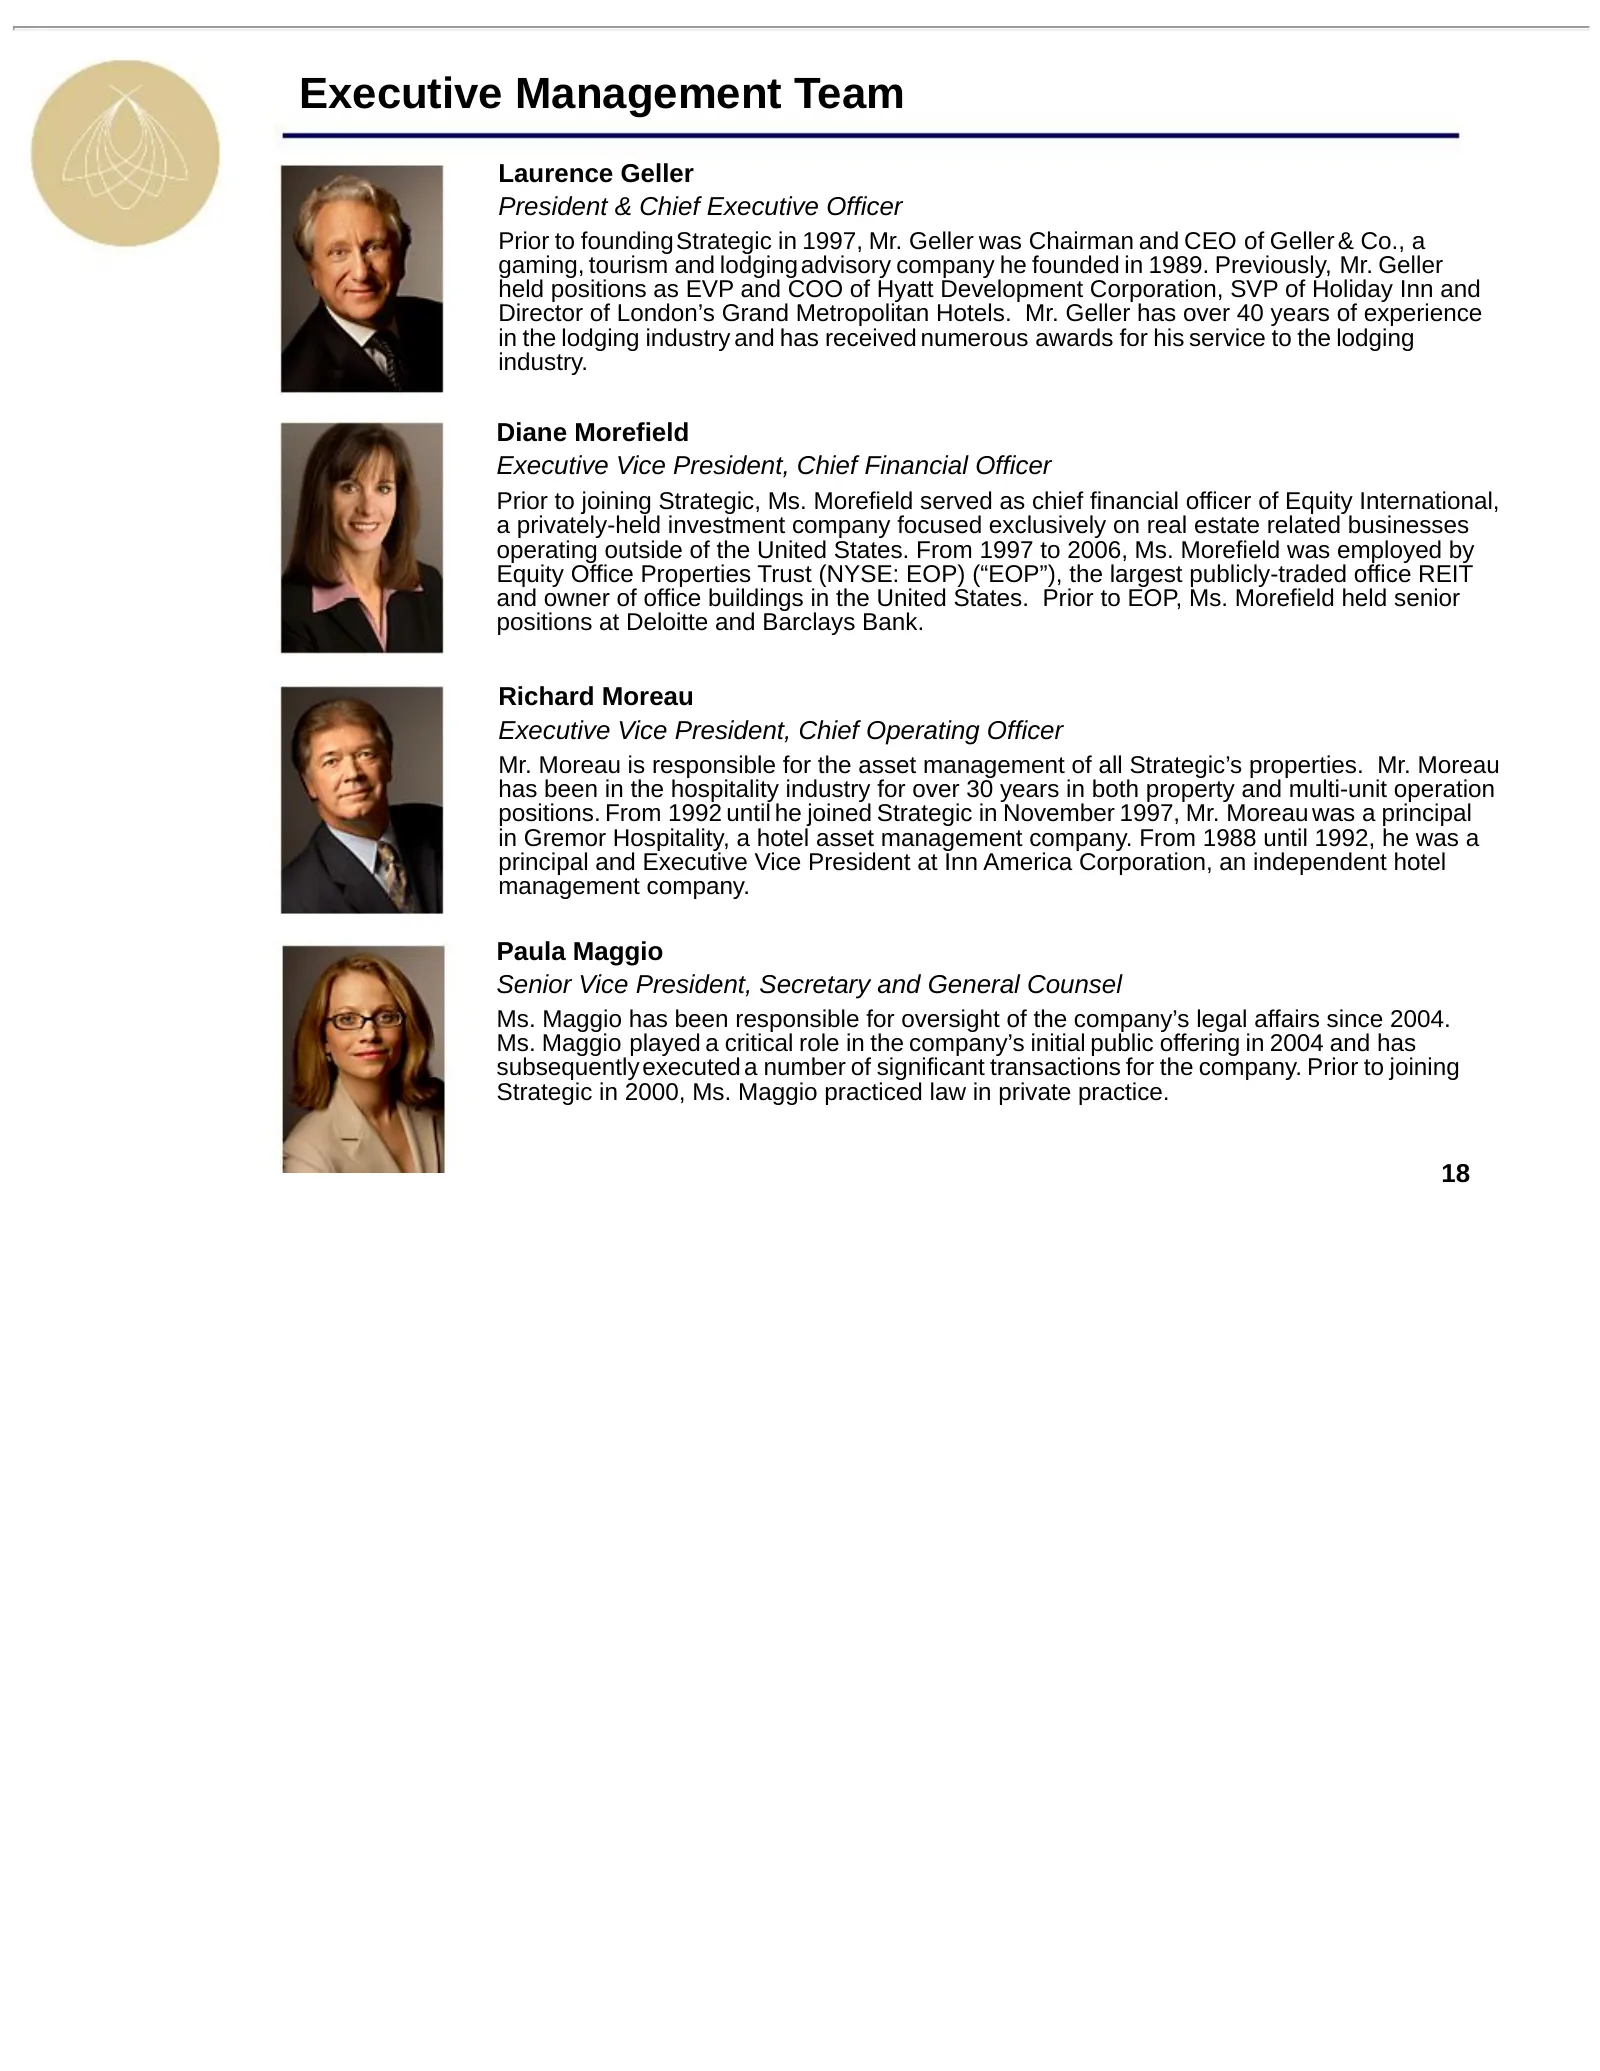
Slide 18: Executive Management Team
Executive Management Team Laurence Geller President & Chief Executive Officer Prior to foundingStrategic in 1997, Mr. Geller was Chairman and CEO of Geller & Co., a gaming, tourism and lodging advisory company he founded in 1989. Previously, Mr. Geller held positions as EVP and COO of Hyatt Developm
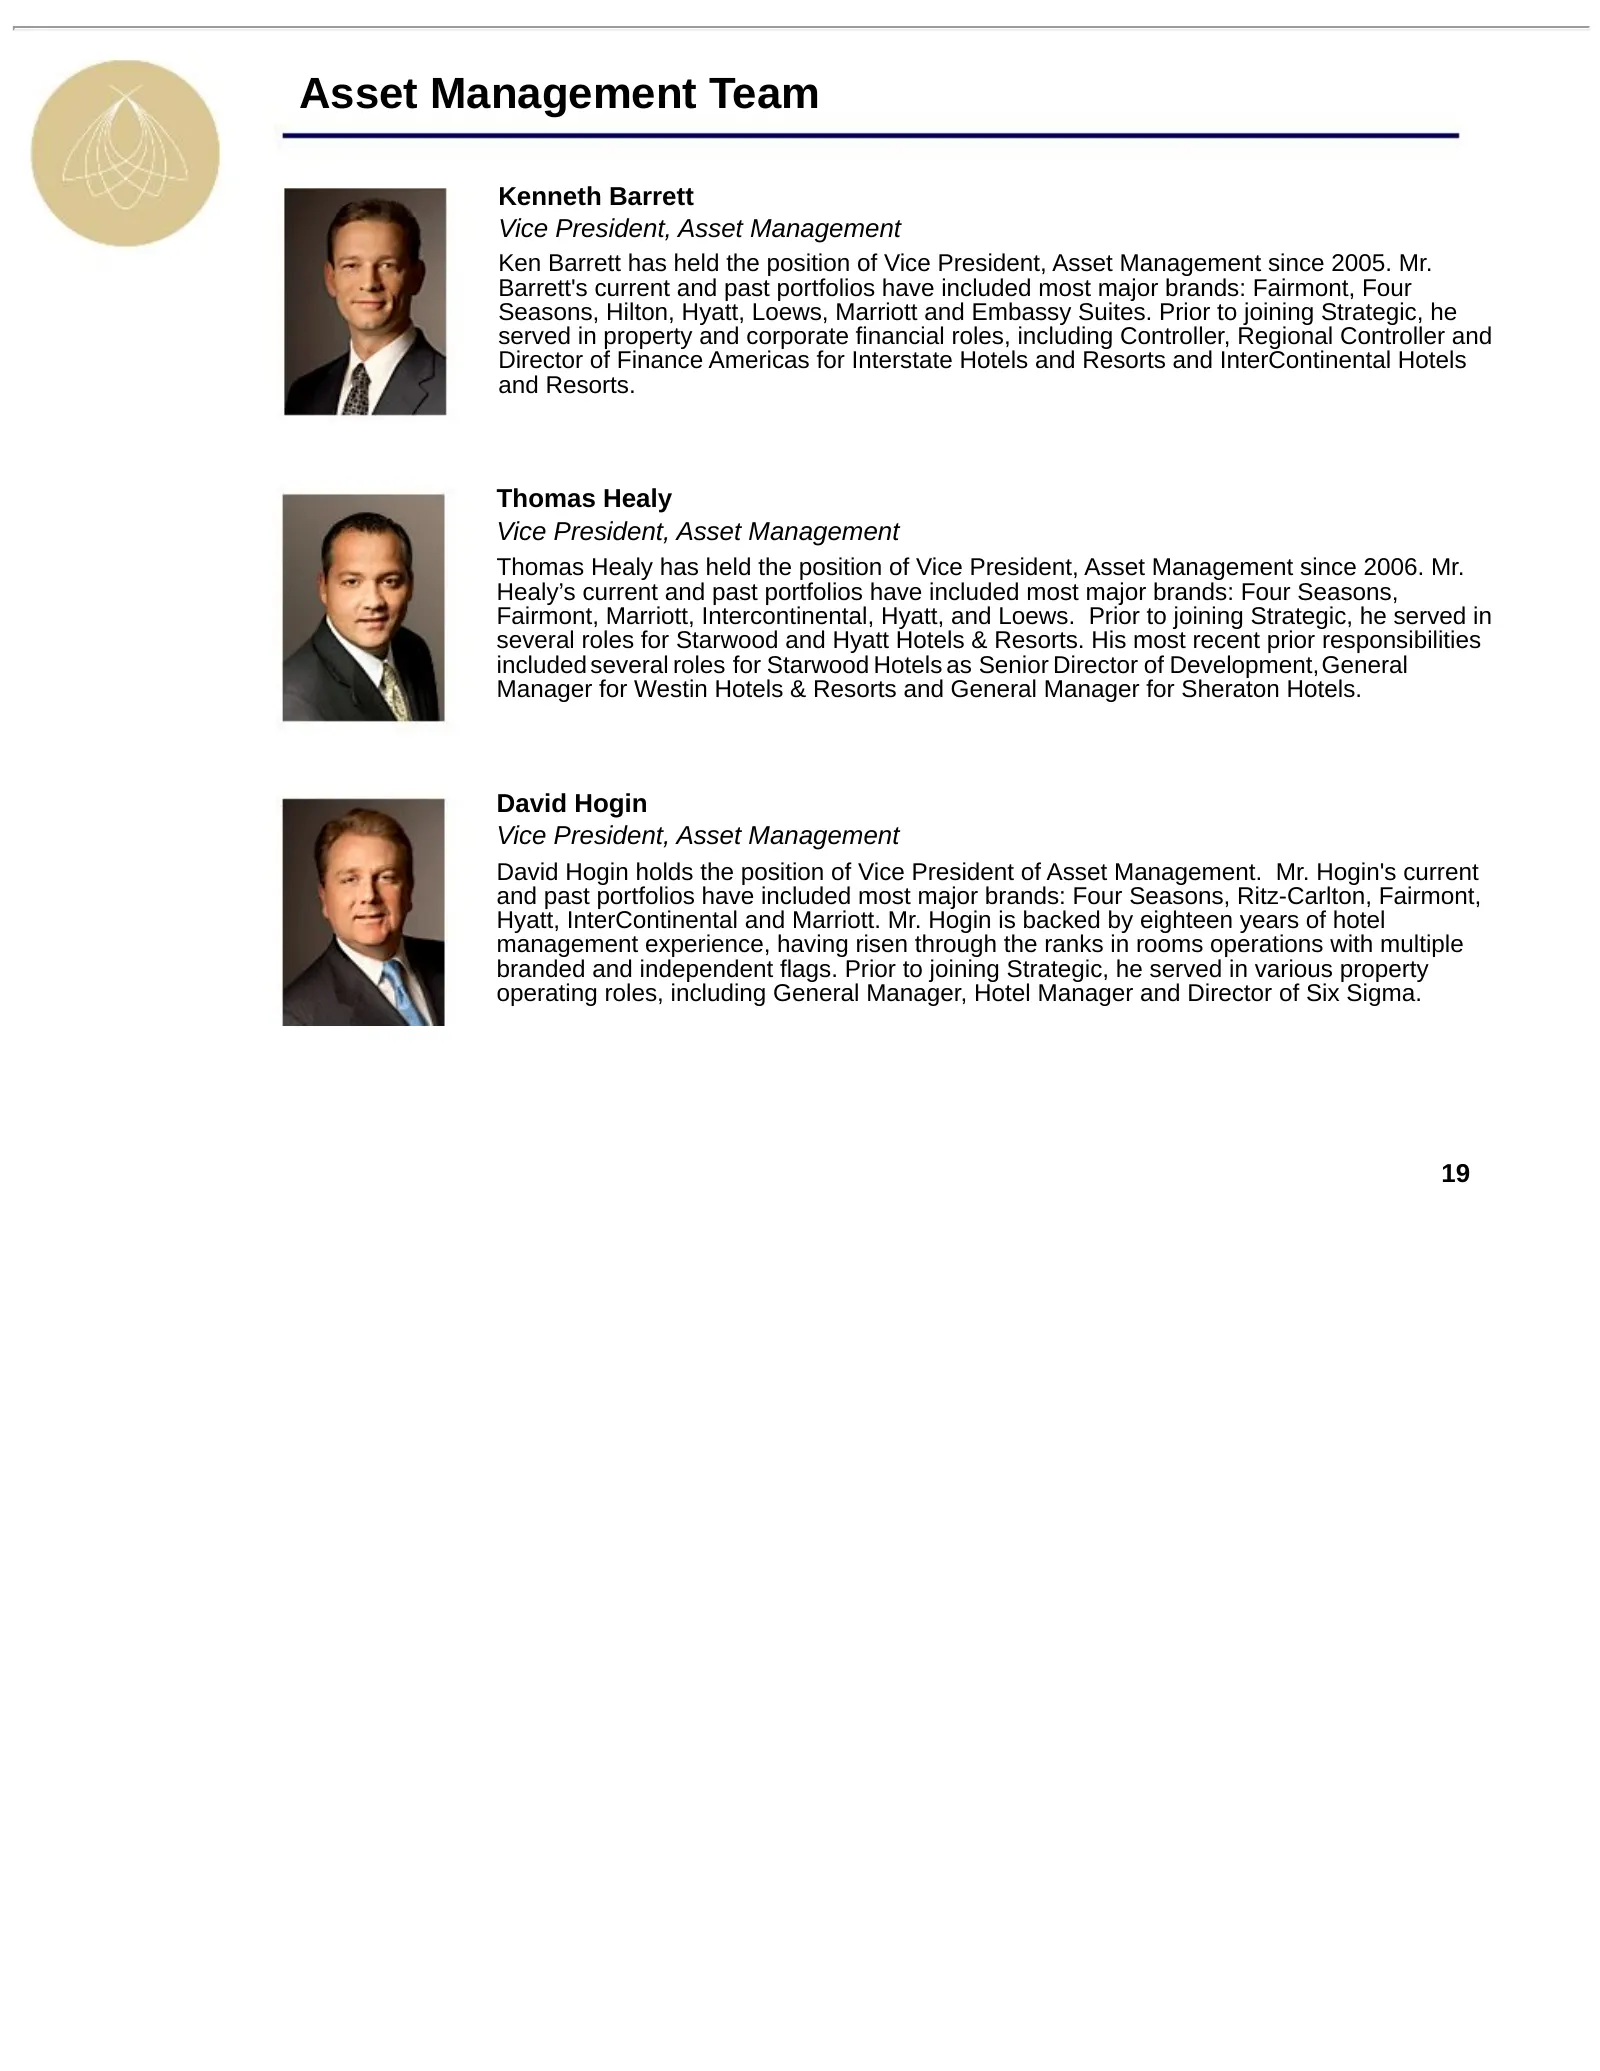
Slide 19: Asset Management Team
Asset Management Team Kenneth Barrett Vice President, Asset Management Ken Barrett has held the position of Vice President, Asset Management since 2005. Mr. Barrett's current and past portfolios have included most major brands: Fairmont, Four Seasons, Hilton, Hyatt, Loews, Marriott and Embassy Suite
Slide 20: Agenda
Agenda I. BEE’s Unique Value Proposition II. Macroeconomic and Industry Update III. Company Overview IV. Organic Growth and ROI Opportunities 20
Slide 21: Industry Leading Asset Management Capabilities
Industry Leading Asset Management Capabilities Market share growth and revenue enhancement through market research based programs Exceptional asset management supported by internally developed operating systems Aggressive and early cost cutting initiatives implemented in advance of the 2008 / 2009 r
Slide 22: BEE Positioning Compared to Peers
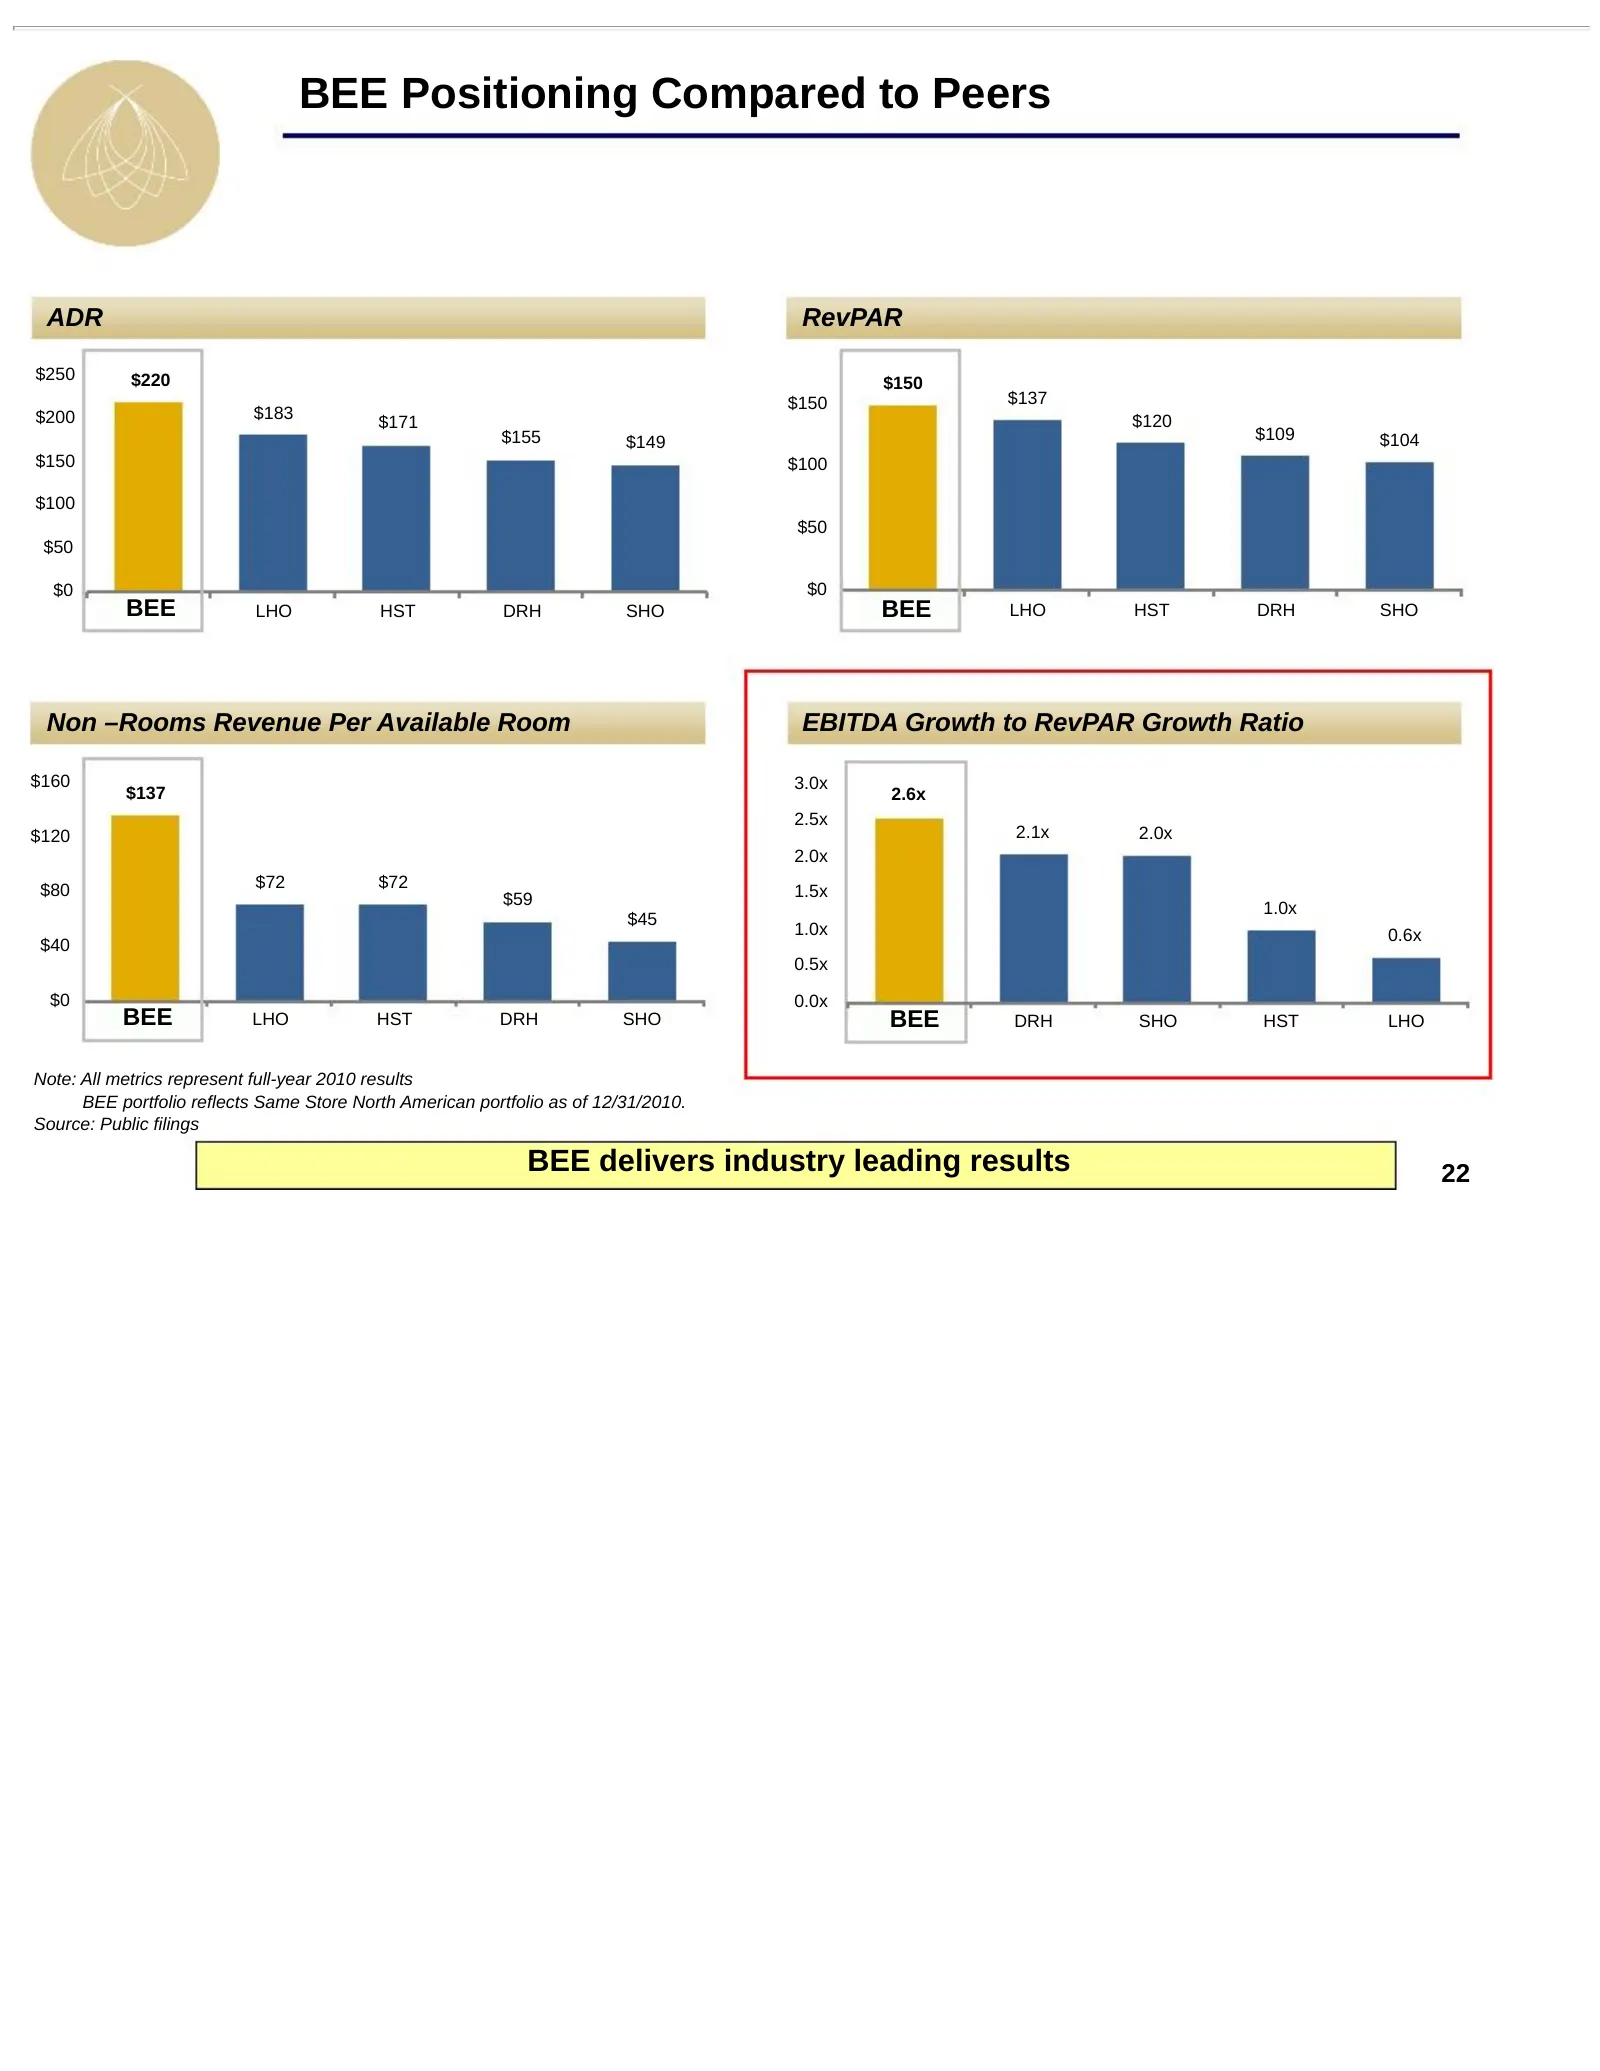
BEE Positioning Compared to Peers ADR RevPAR $250 $220 $150 $150 $137 $200 $183 $120 $171 $155 $149 $109 $104 $150 $100 $100 $50 $50 $0 $0 BEE LHO HST DRH SHO BEE LHO HST DRH SHO Non –Rooms Revenue Per Available Room EBITDA Growth to RevPAR Growth Ratio $160 3.0x $137 2.6x 2.5x $120 2.1x 2.0x 2.0x $
Slide 23: BEE Business Mix Compared to Peers
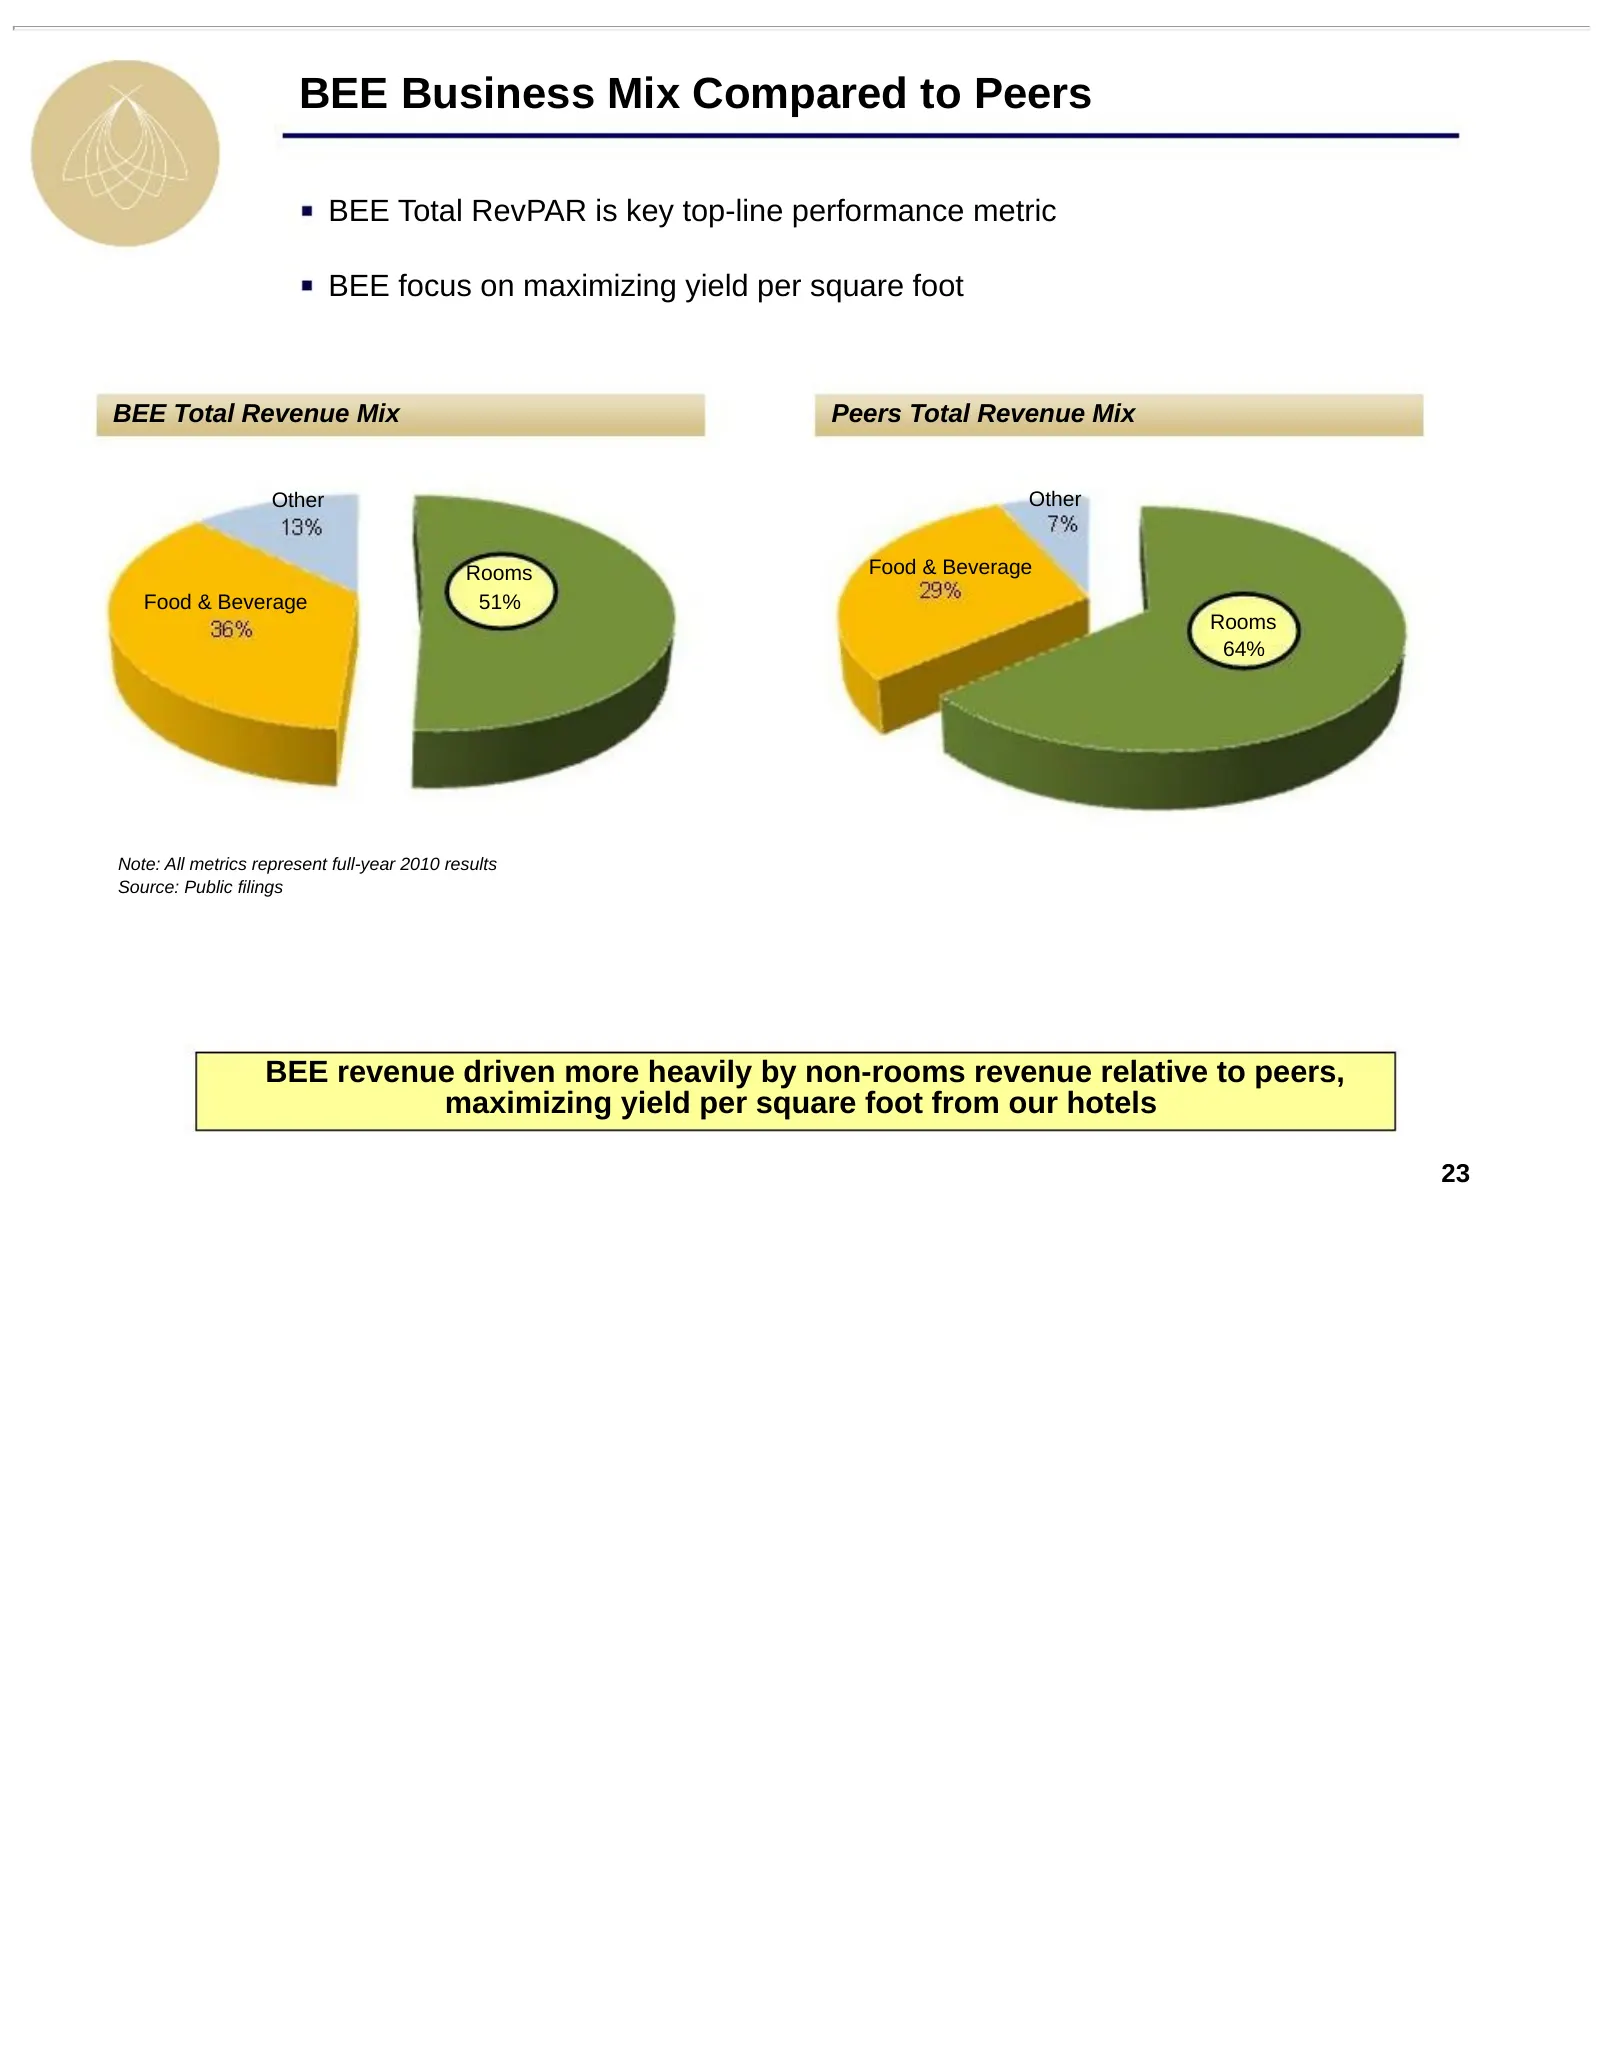
BEE Business Mix Compared to Peers BEE Total RevPAR is key top-line performance metric BEE focus on maximizing yield per square foot BEE Total Revenue Mix Peers Total Revenue Mix Other Other Rooms Food & Beverage Food & Beverage 51% Rooms 64% Note: All metrics represent full-year 2010 results Source
Slide 24: BEE Revenue Mix
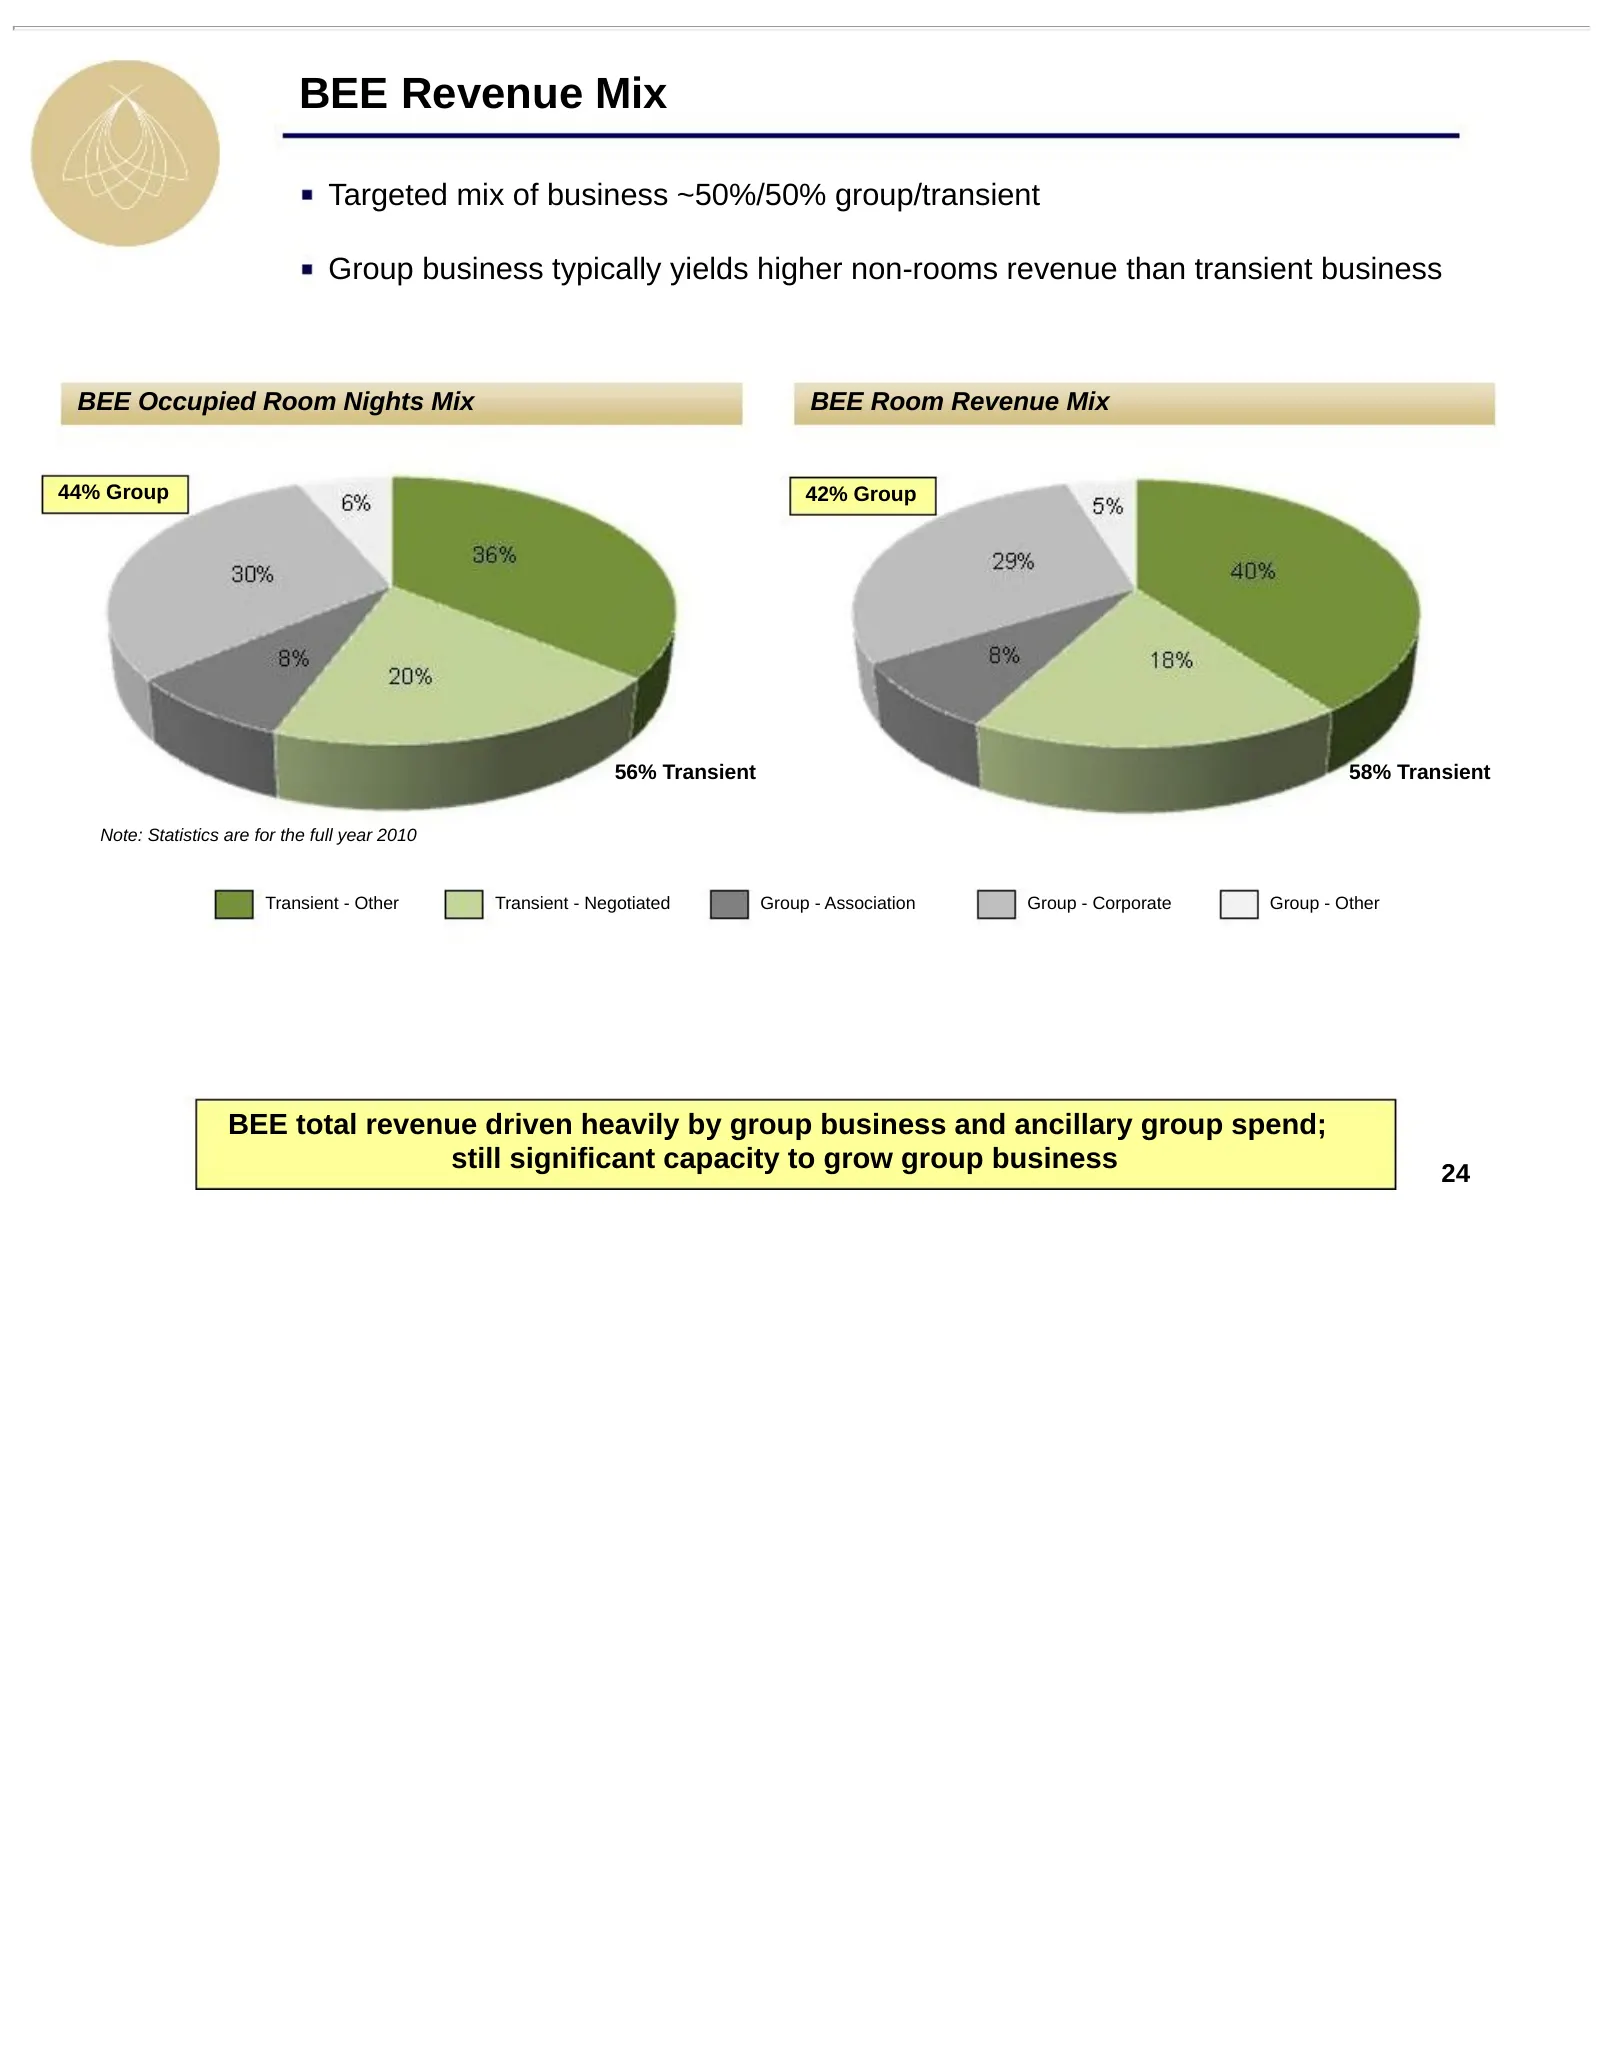
BEE Revenue Mix Targeted mix of business ~50%/50% group/transient Group business typically yields higher non-rooms revenue than transient business BEE Occupied Room Nights Mix BEE Room Revenue Mix 44% Group 42% Group 56% Transient 58% Transient Note: Statistics are for the full year 2010 Transient -
Slide 25: Industry Leading Operating Margins
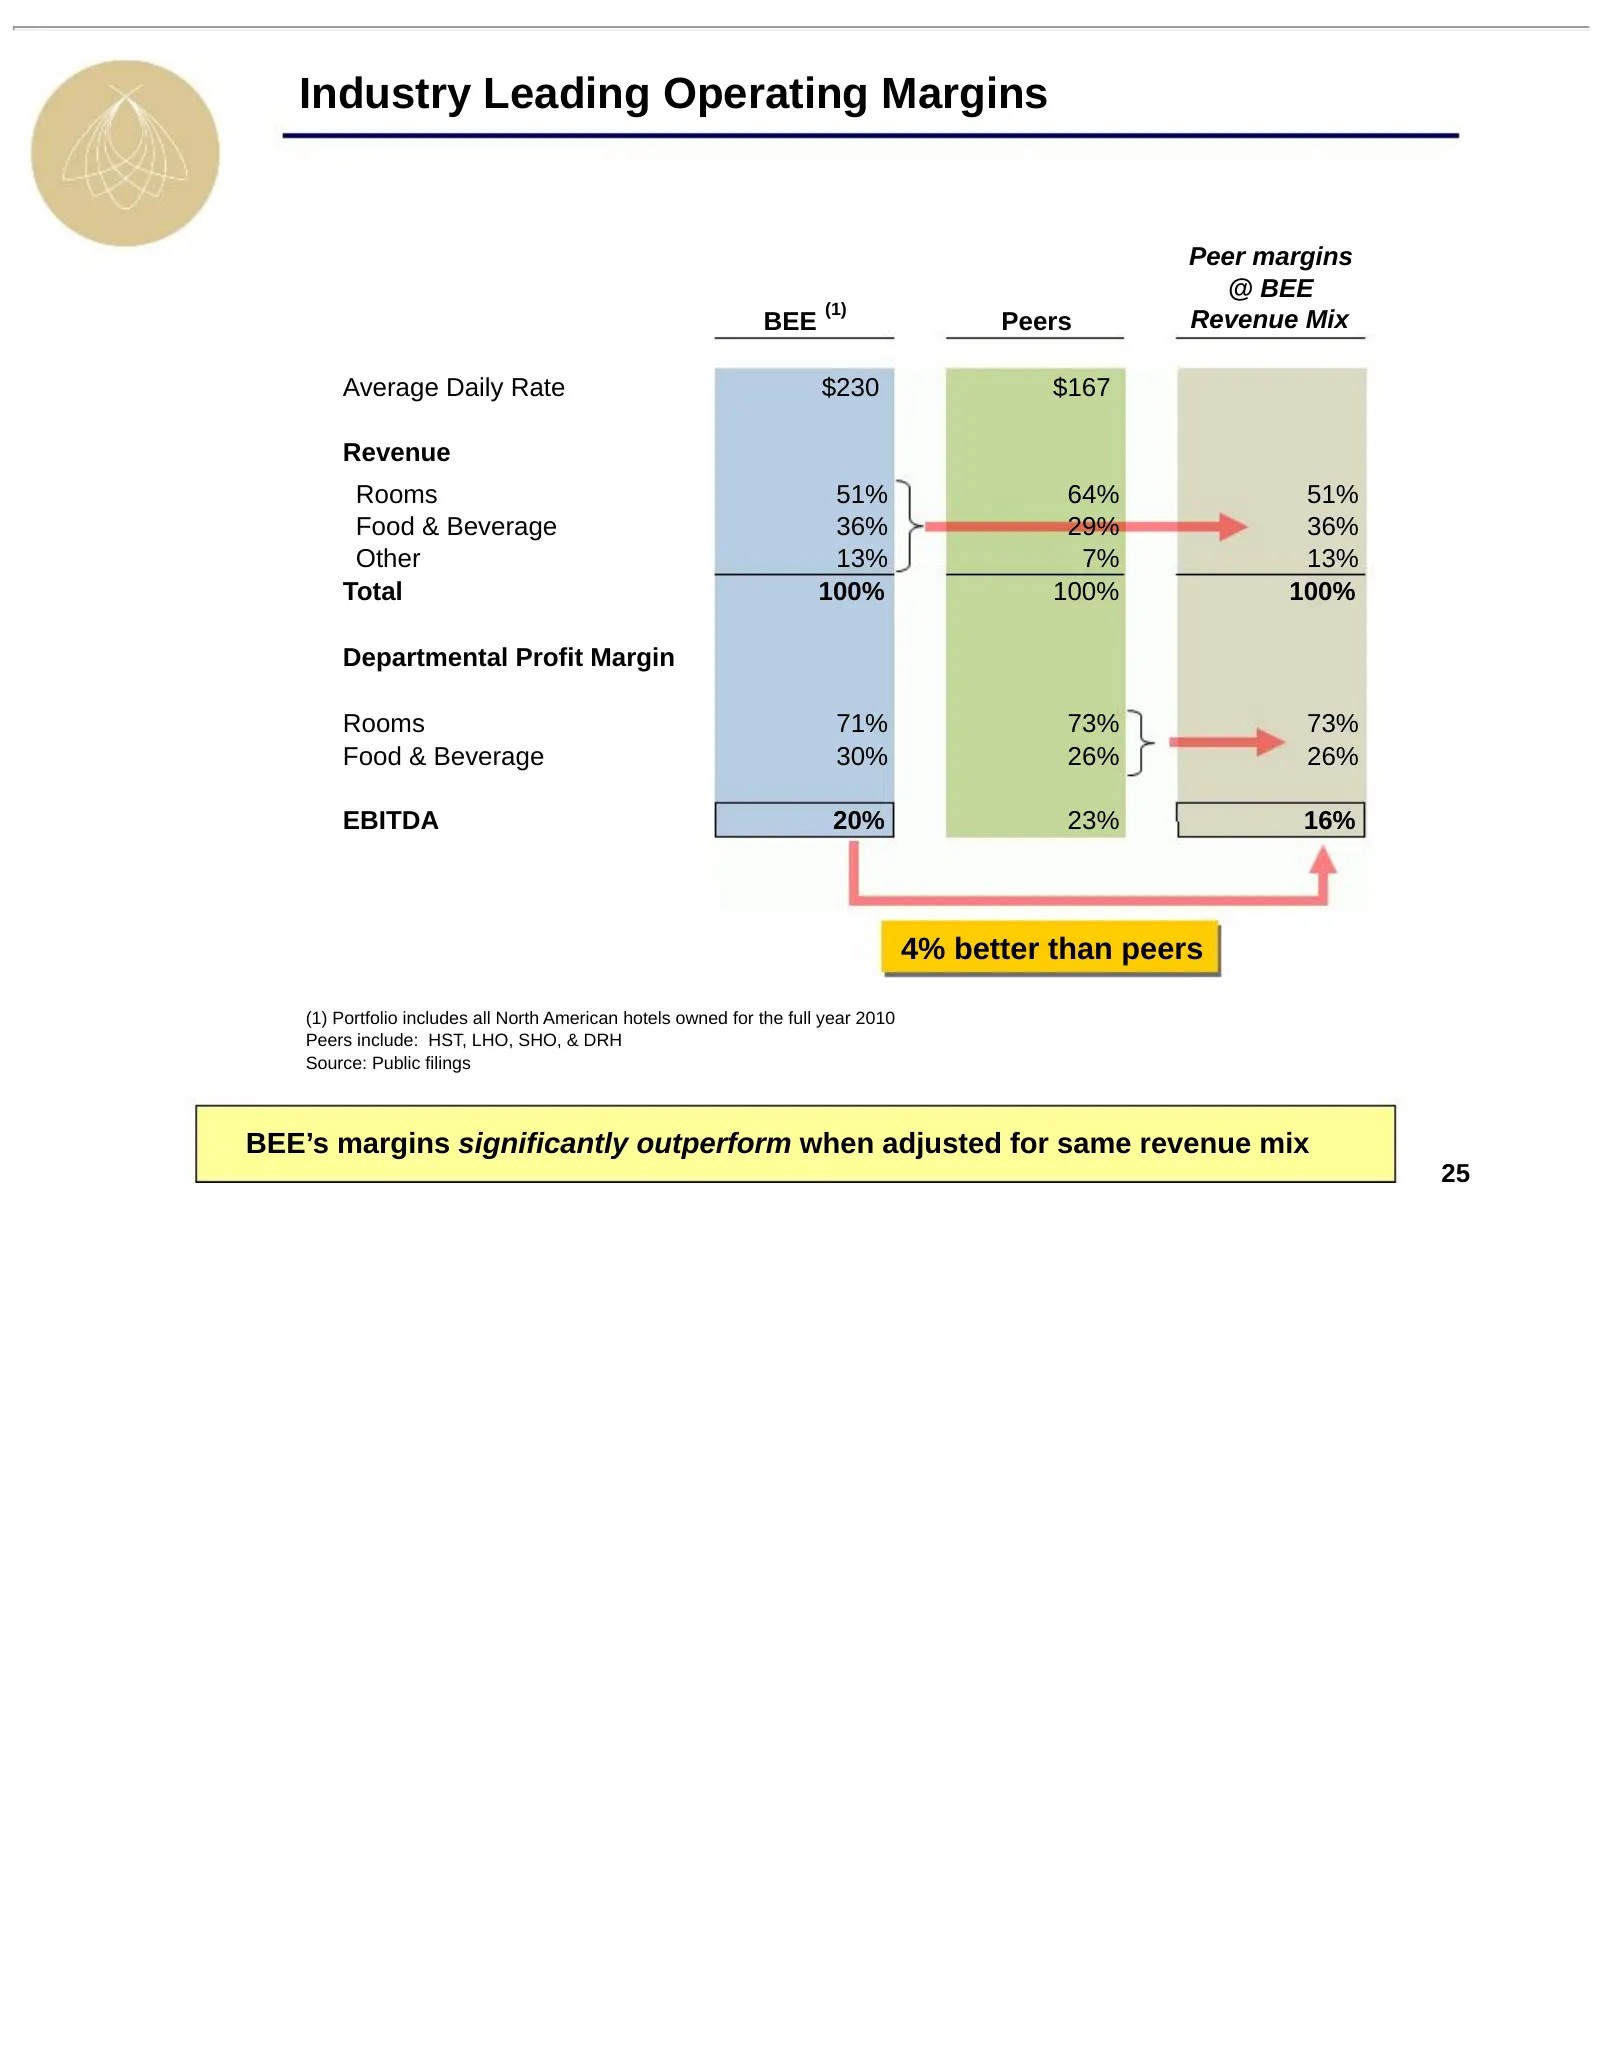
Industry Leading Operating Margins Peer margins @ BEE (1) BEE Peers Revenue Mix Average Daily Rate $230 $167 Revenue Rooms 51% 64% 51% Food & Beverage 36% 29% 36% Other 13% 7% 13% Total 100% 100% 100% Departmental Profit Margin Rooms 71% 73% 73% Food & Beverage 30% 26% 26% EBITDA 20% 23% 16% 4% bett
Slide 26: Group Booking Outlook
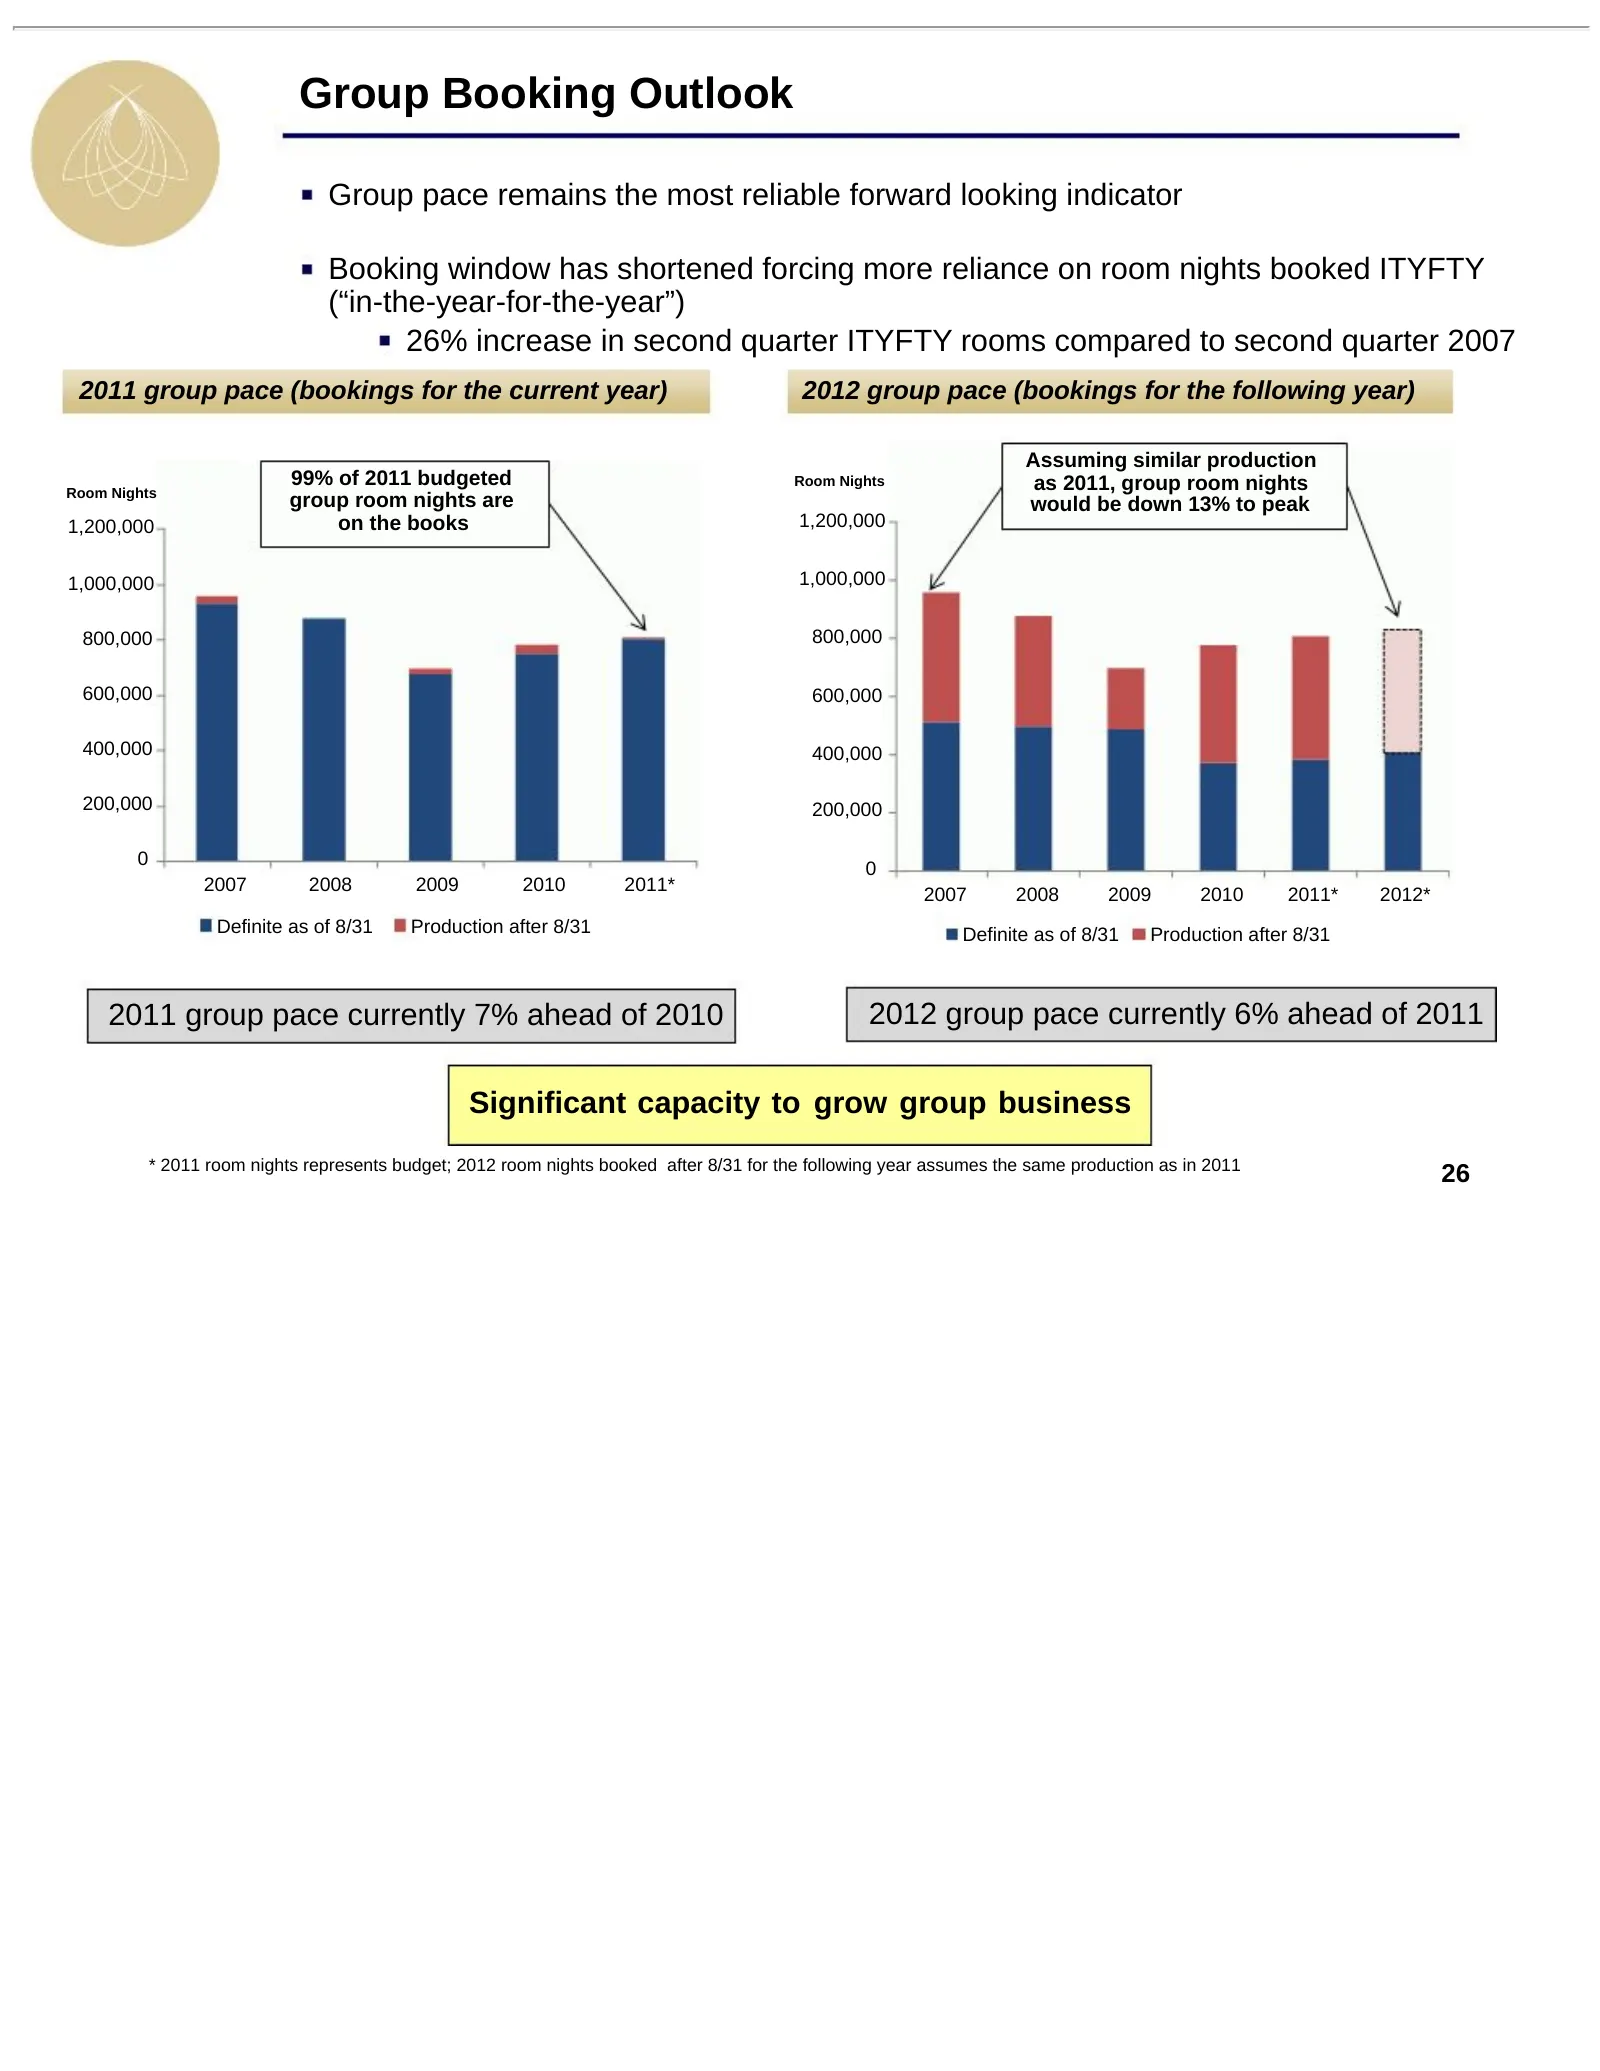
Group Booking Outlook Group pace remains the most reliable forward looking indicator Booking window has shortened forcing more reliance on room nights booked ITYFTY (“in-the-year-for-the-year”) 26% increase in second quarter ITYFTY rooms compared to second quarter 2007 2011 group pace (bookings for
Slide 27: Group Booking Outlook
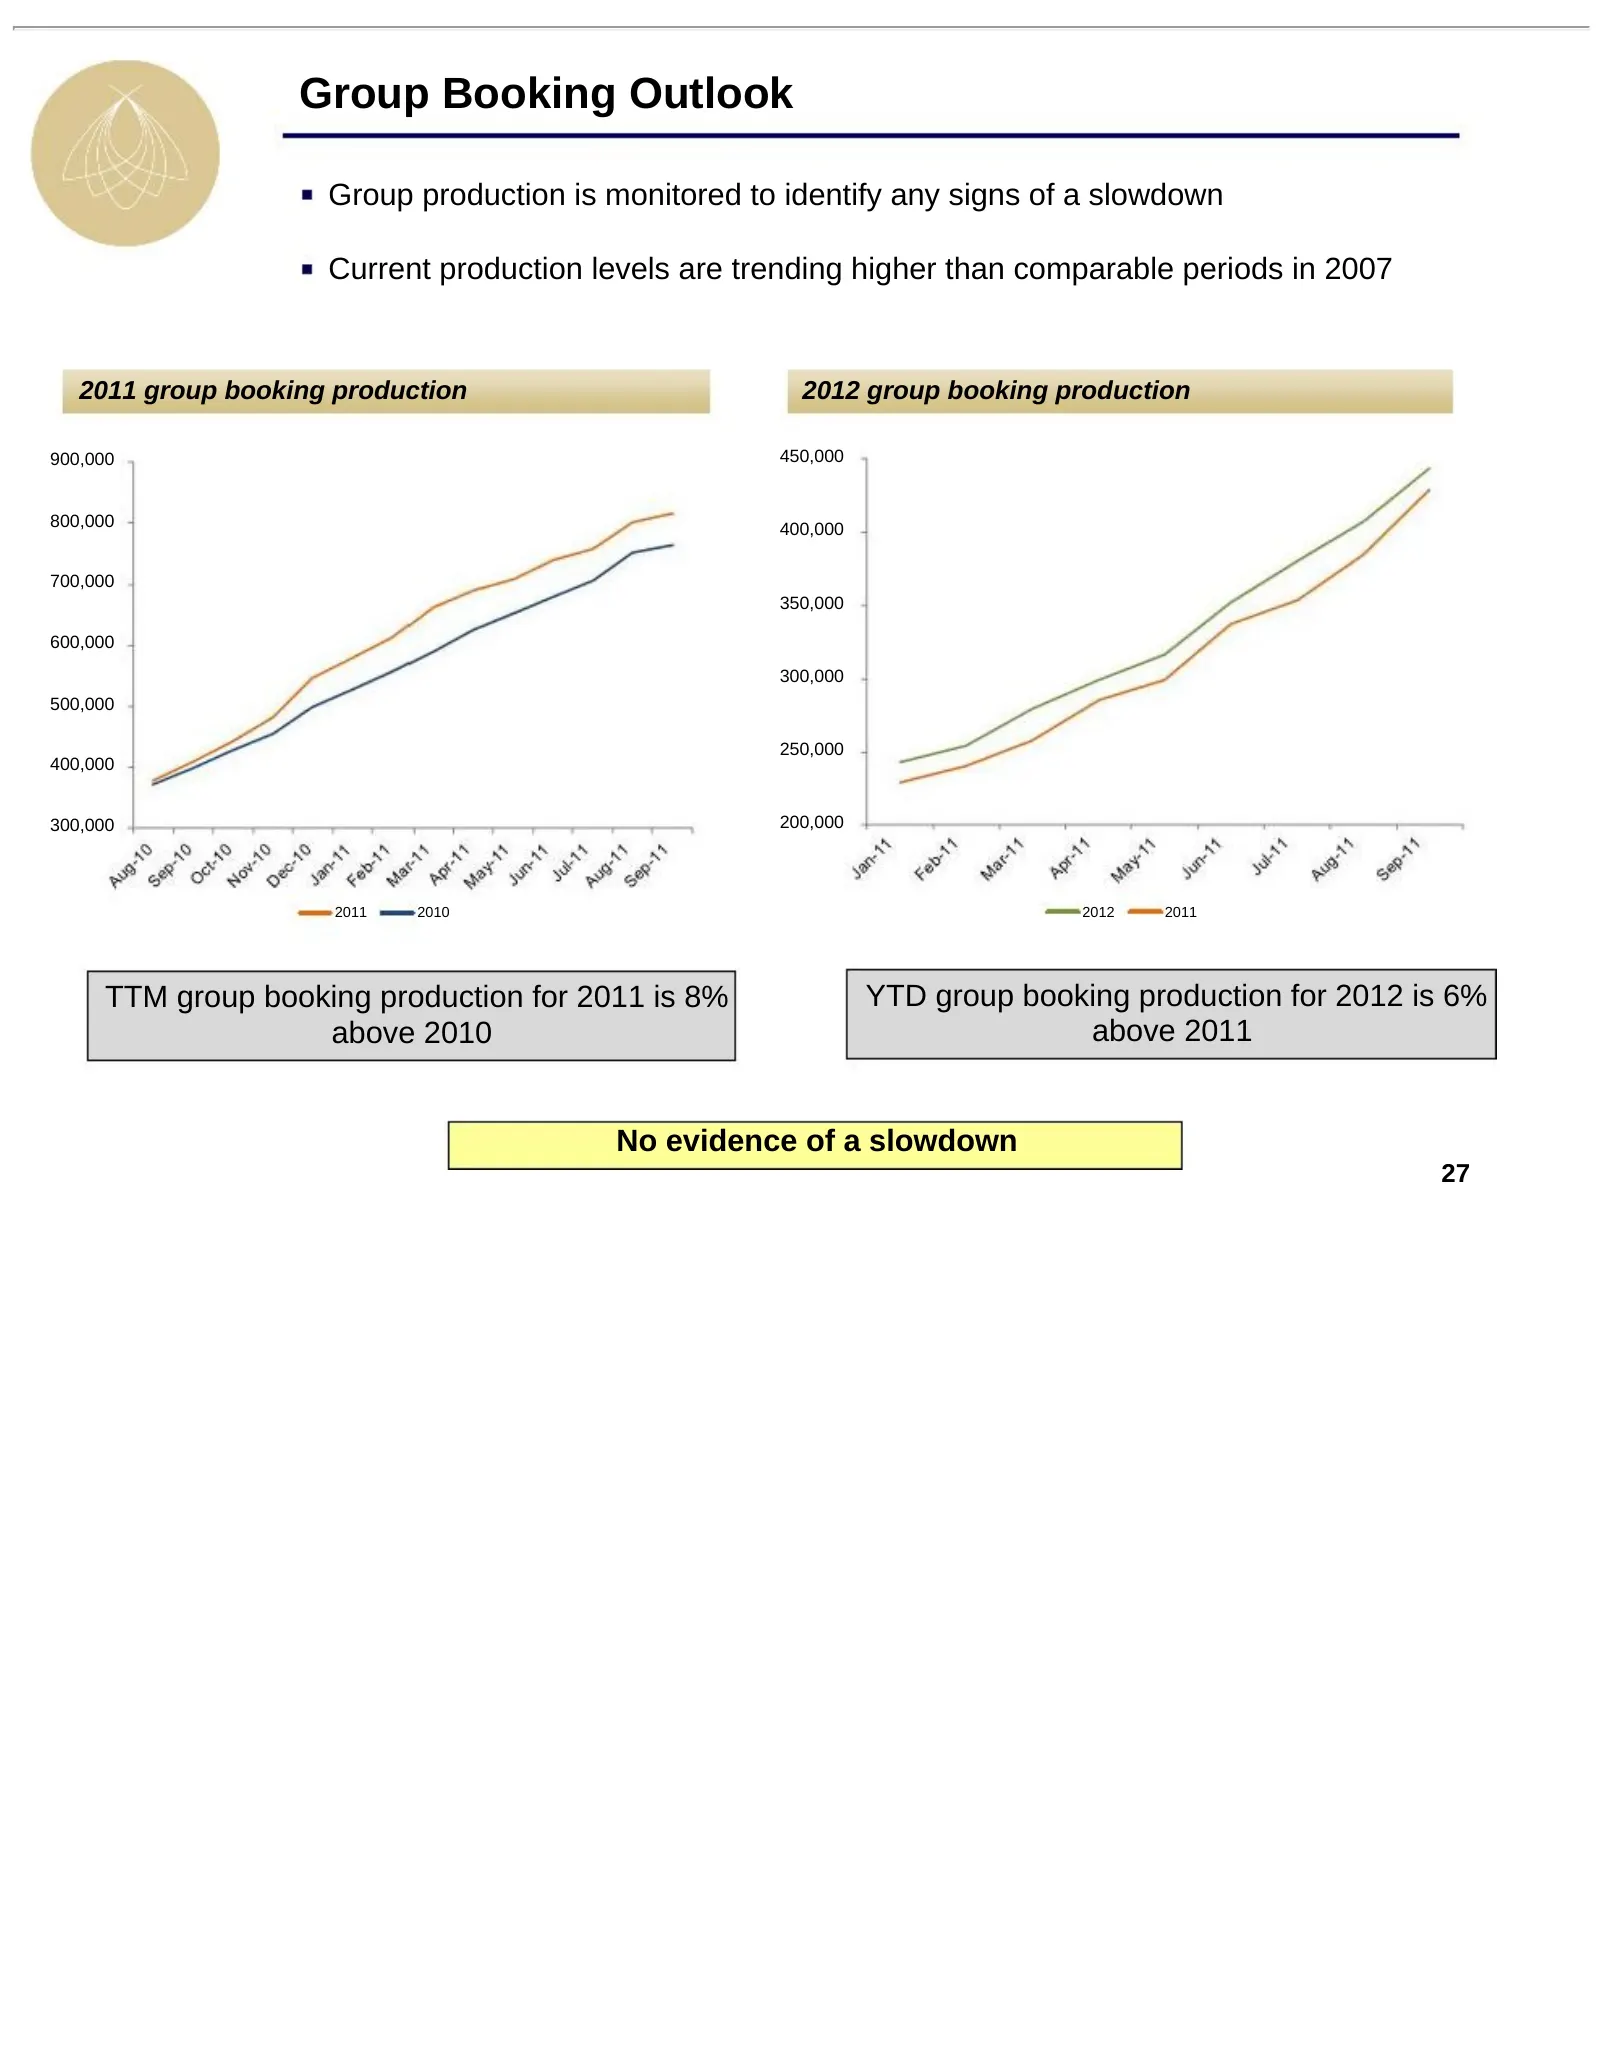
Group Booking Outlook Group production is monitored to identify any signs of a slowdown Current production levels are trending higher than comparable periods in 2007 2011 group booking production 2012 group booking production 900,000 450,000 800,000 400,000 700,000 350,000 600,000 300,000 500,000 25
Slide 28: Focus on ADR Growth Drives Margin Outperformance
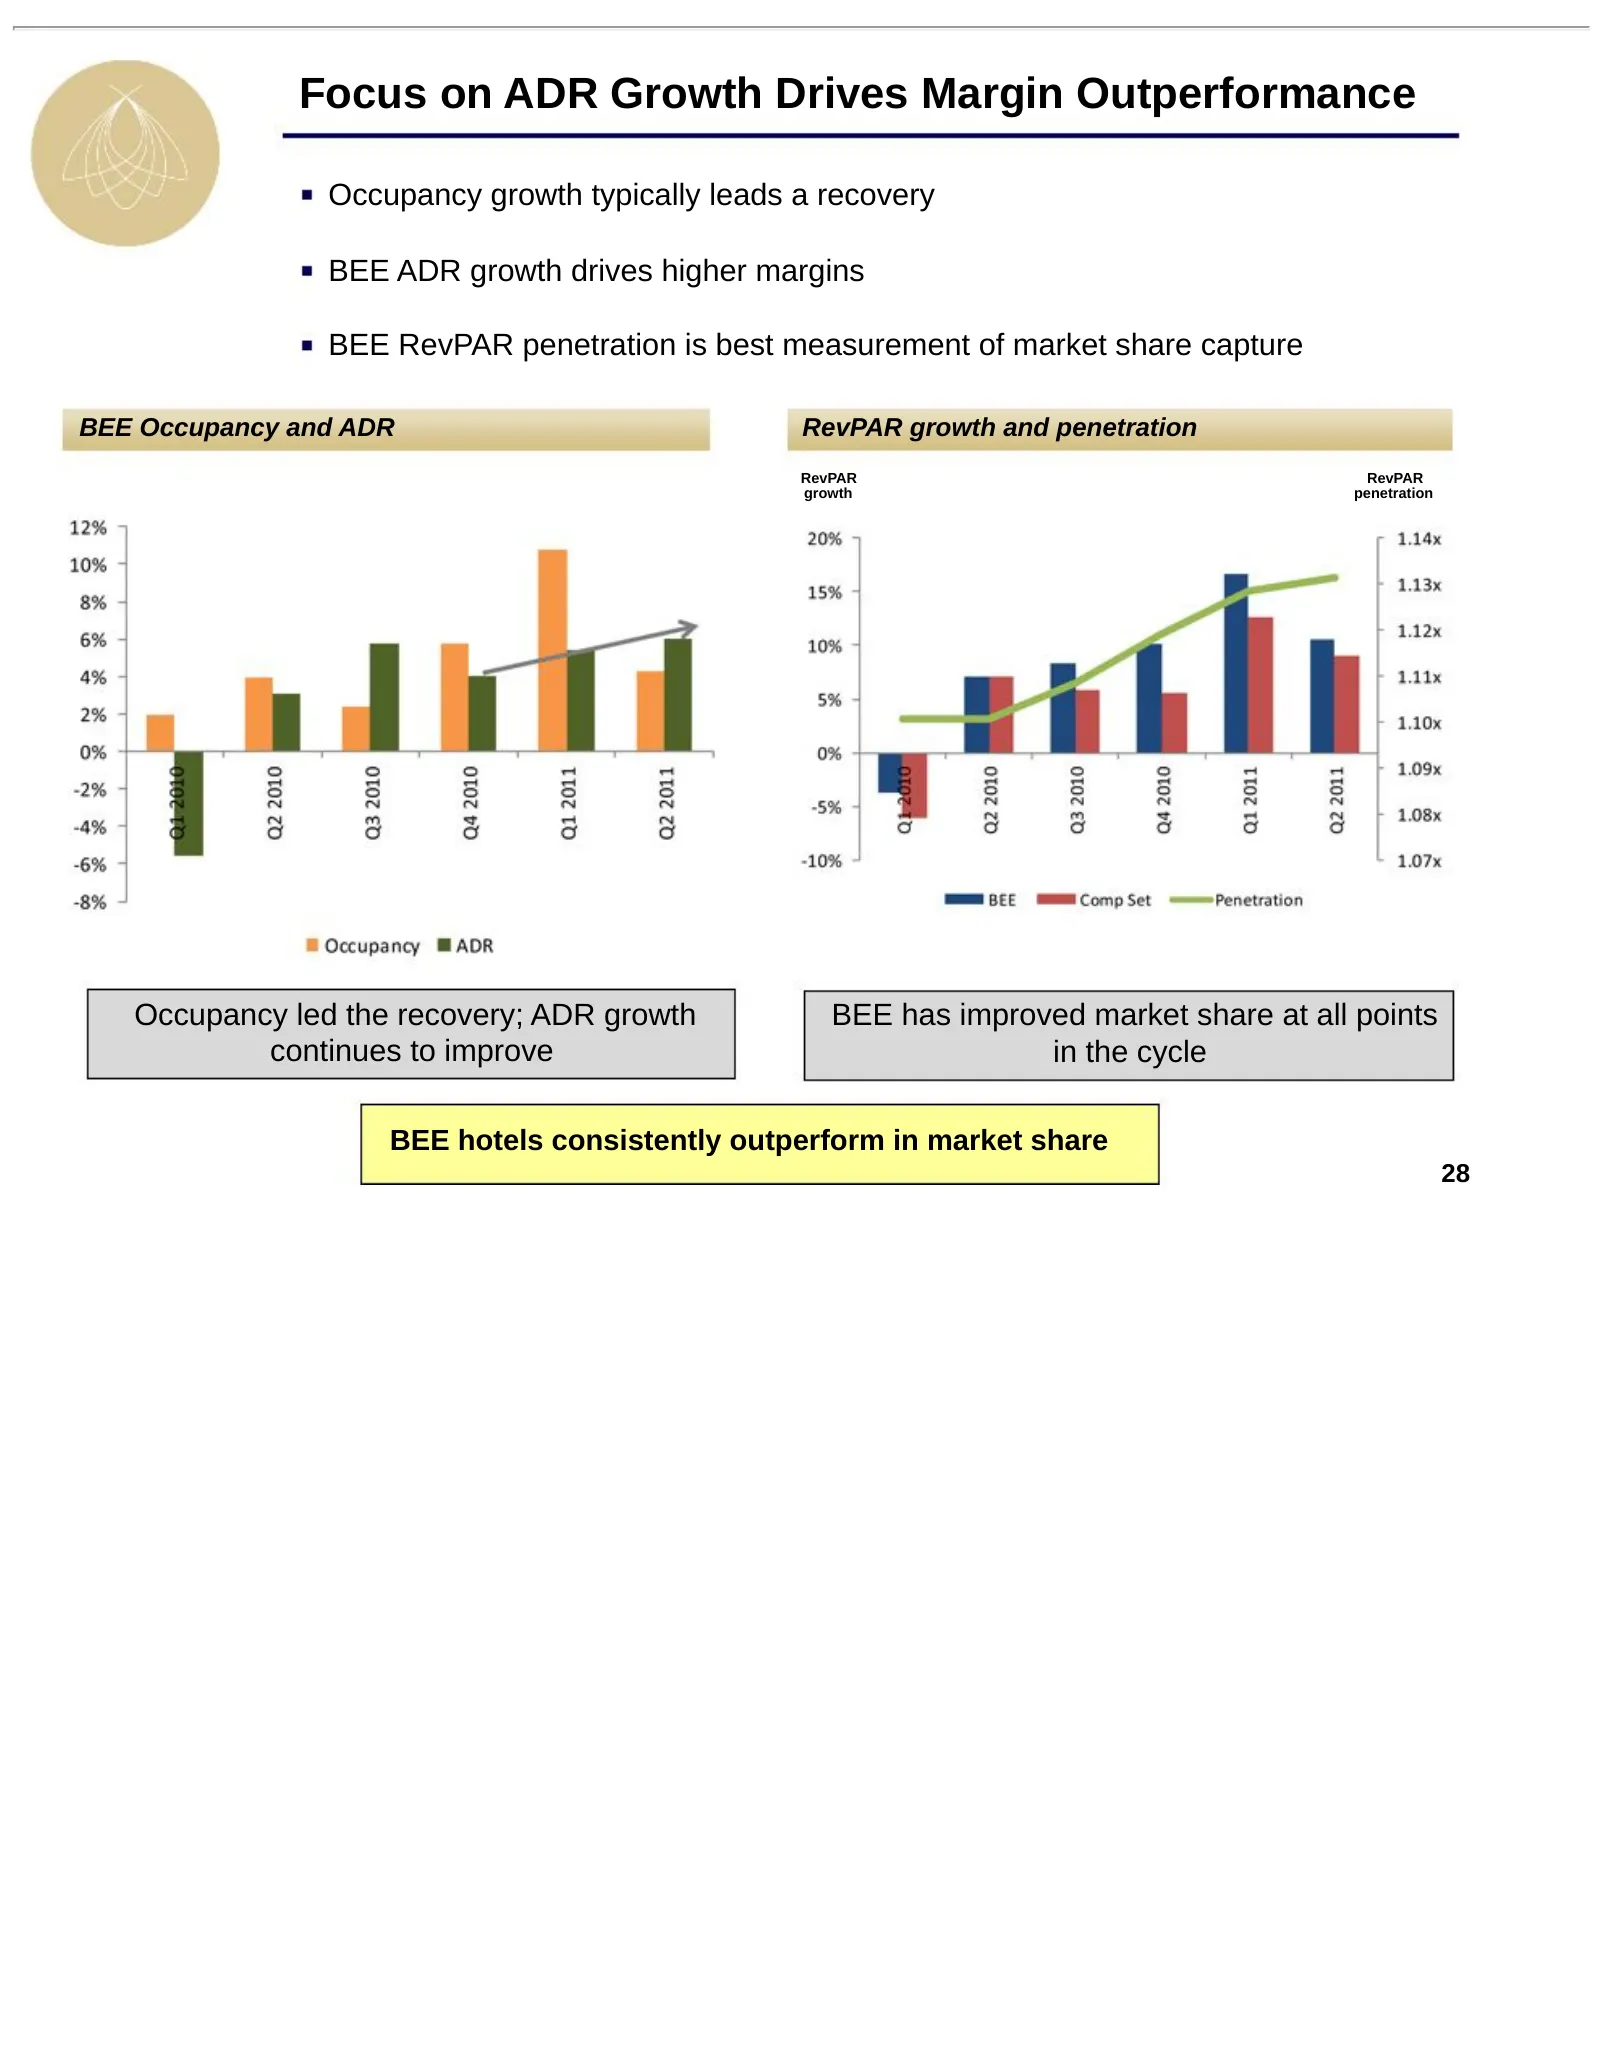
Focus on ADR Growth Drives Margin Outperformance Occupancy growth typically leads a recovery BEE ADR growth drives higher margins BEE RevPAR penetration is best measurement of market share capture BEE Occupancy and ADR RevPAR growth and penetration RevPAR RevPAR growth penetration Occupancy led the
Slide 29: Compression Room Nights
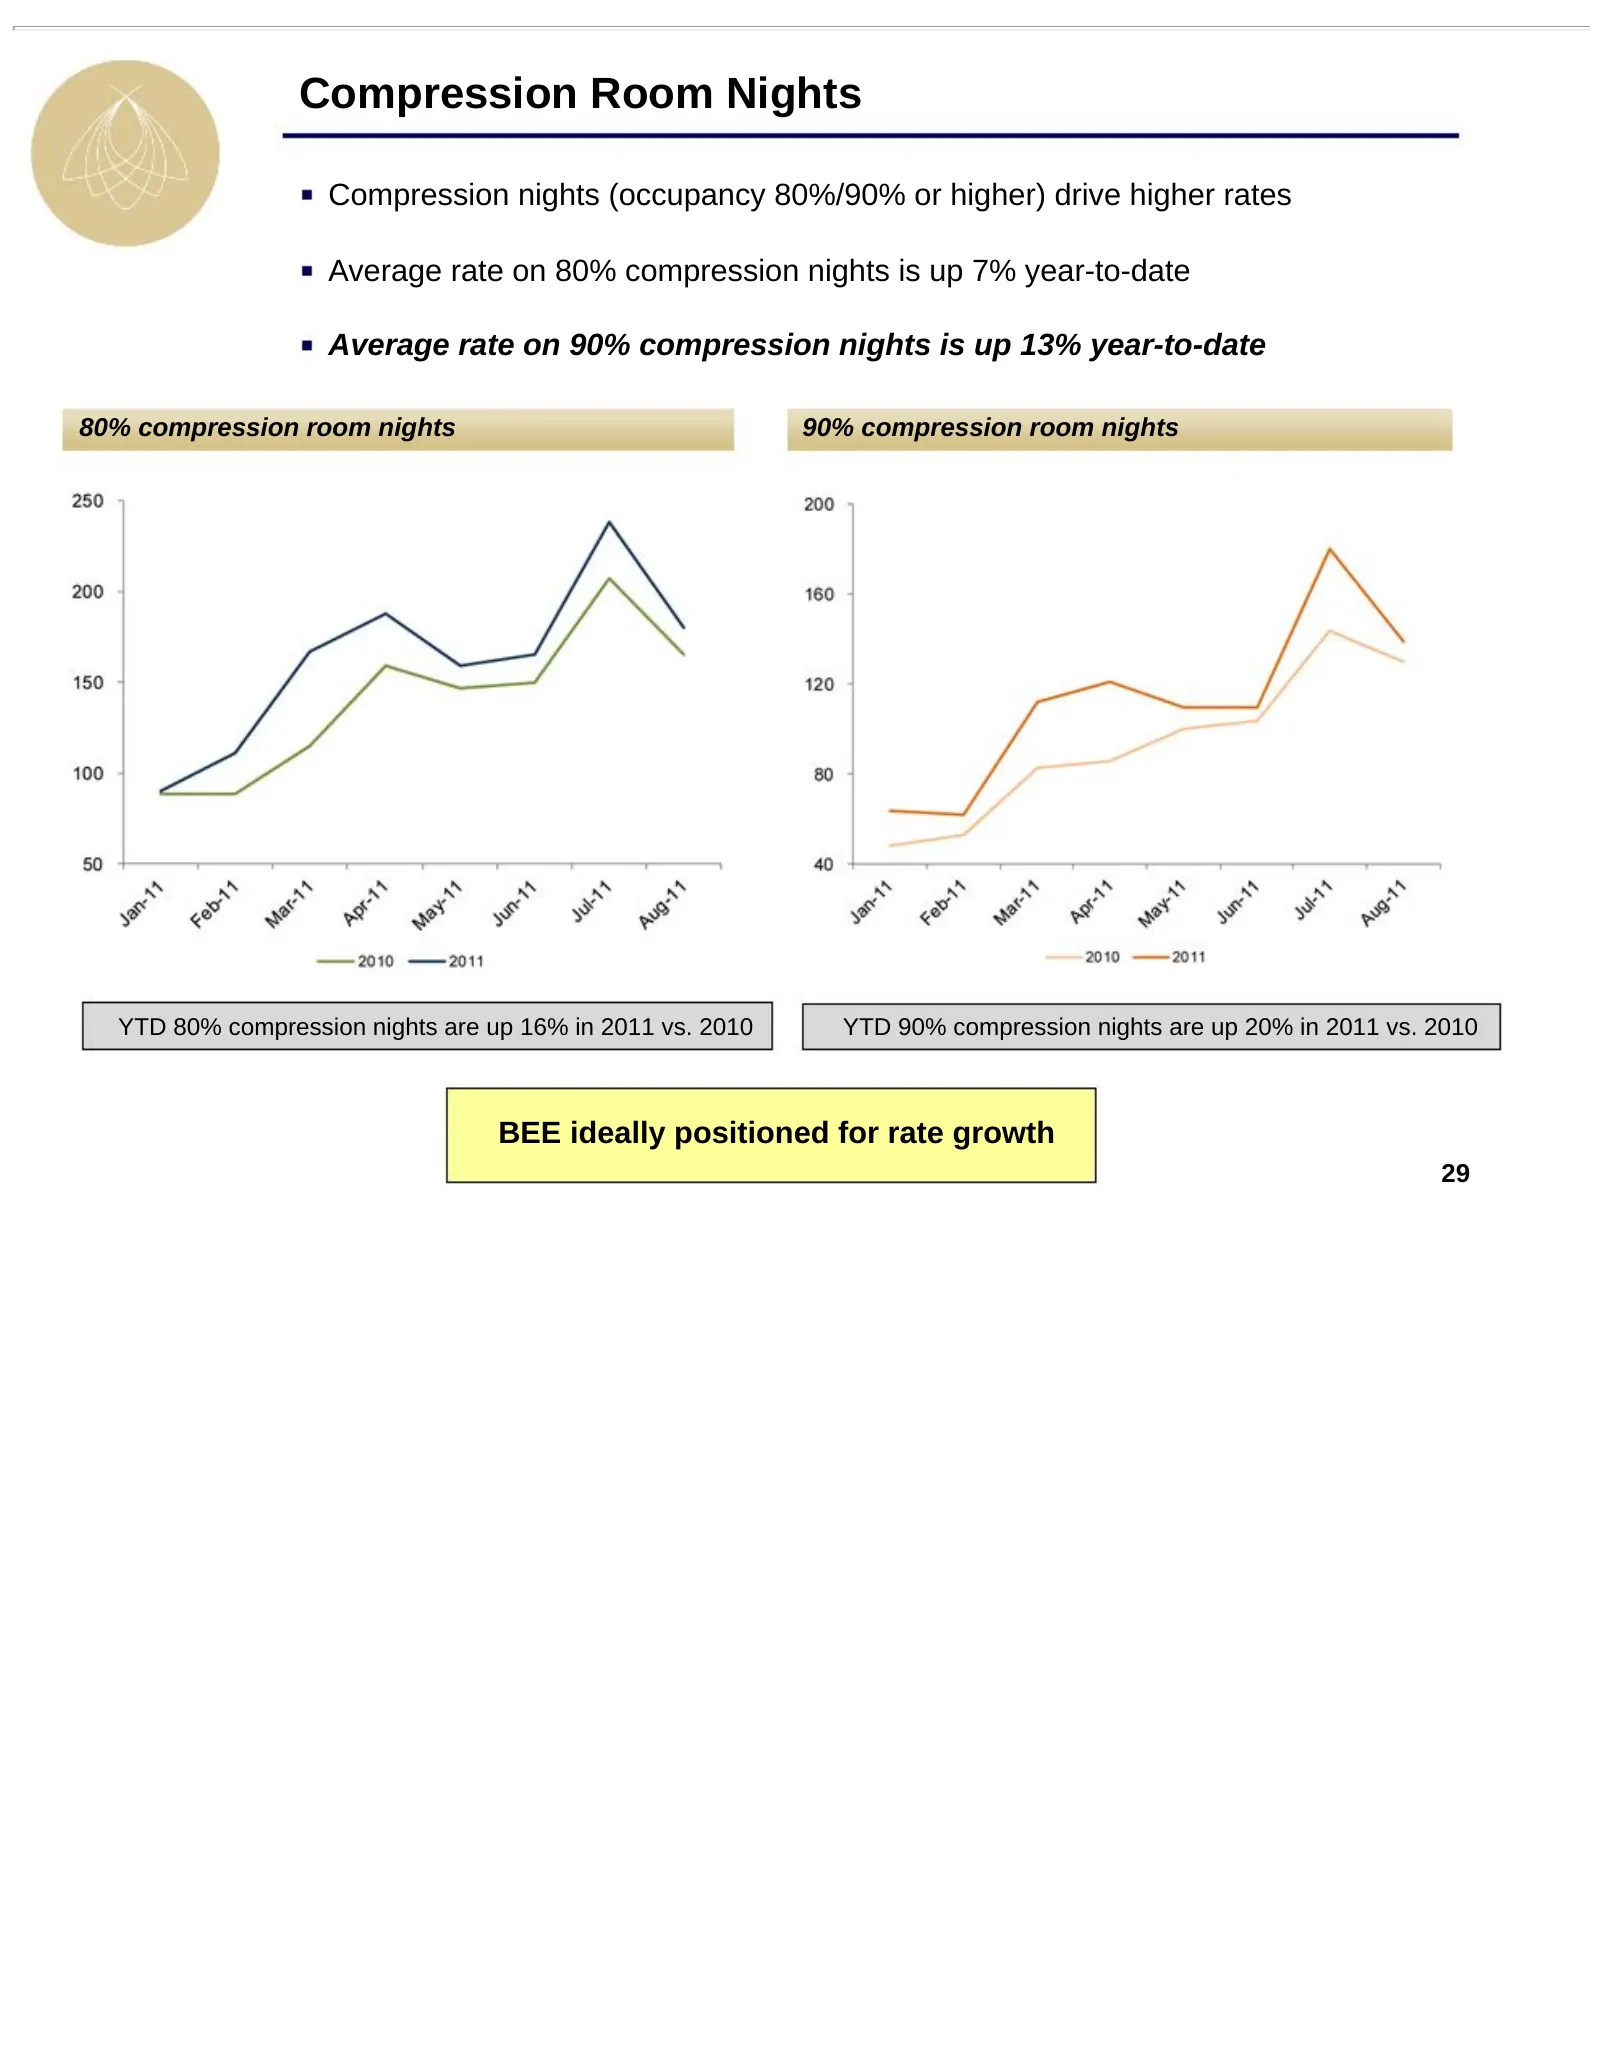
Compression Room Nights Compression nights (occupancy 80%/90% or higher) drive higher rates Average rate on 80% compression nights is up 7% year-to-date Average rate on 90% compression nights is up 13% year-to-date 80% compression room nights 90% compression room nights YTD 80% compression nights ar
Slide 30: Embedded Portfolio Growth
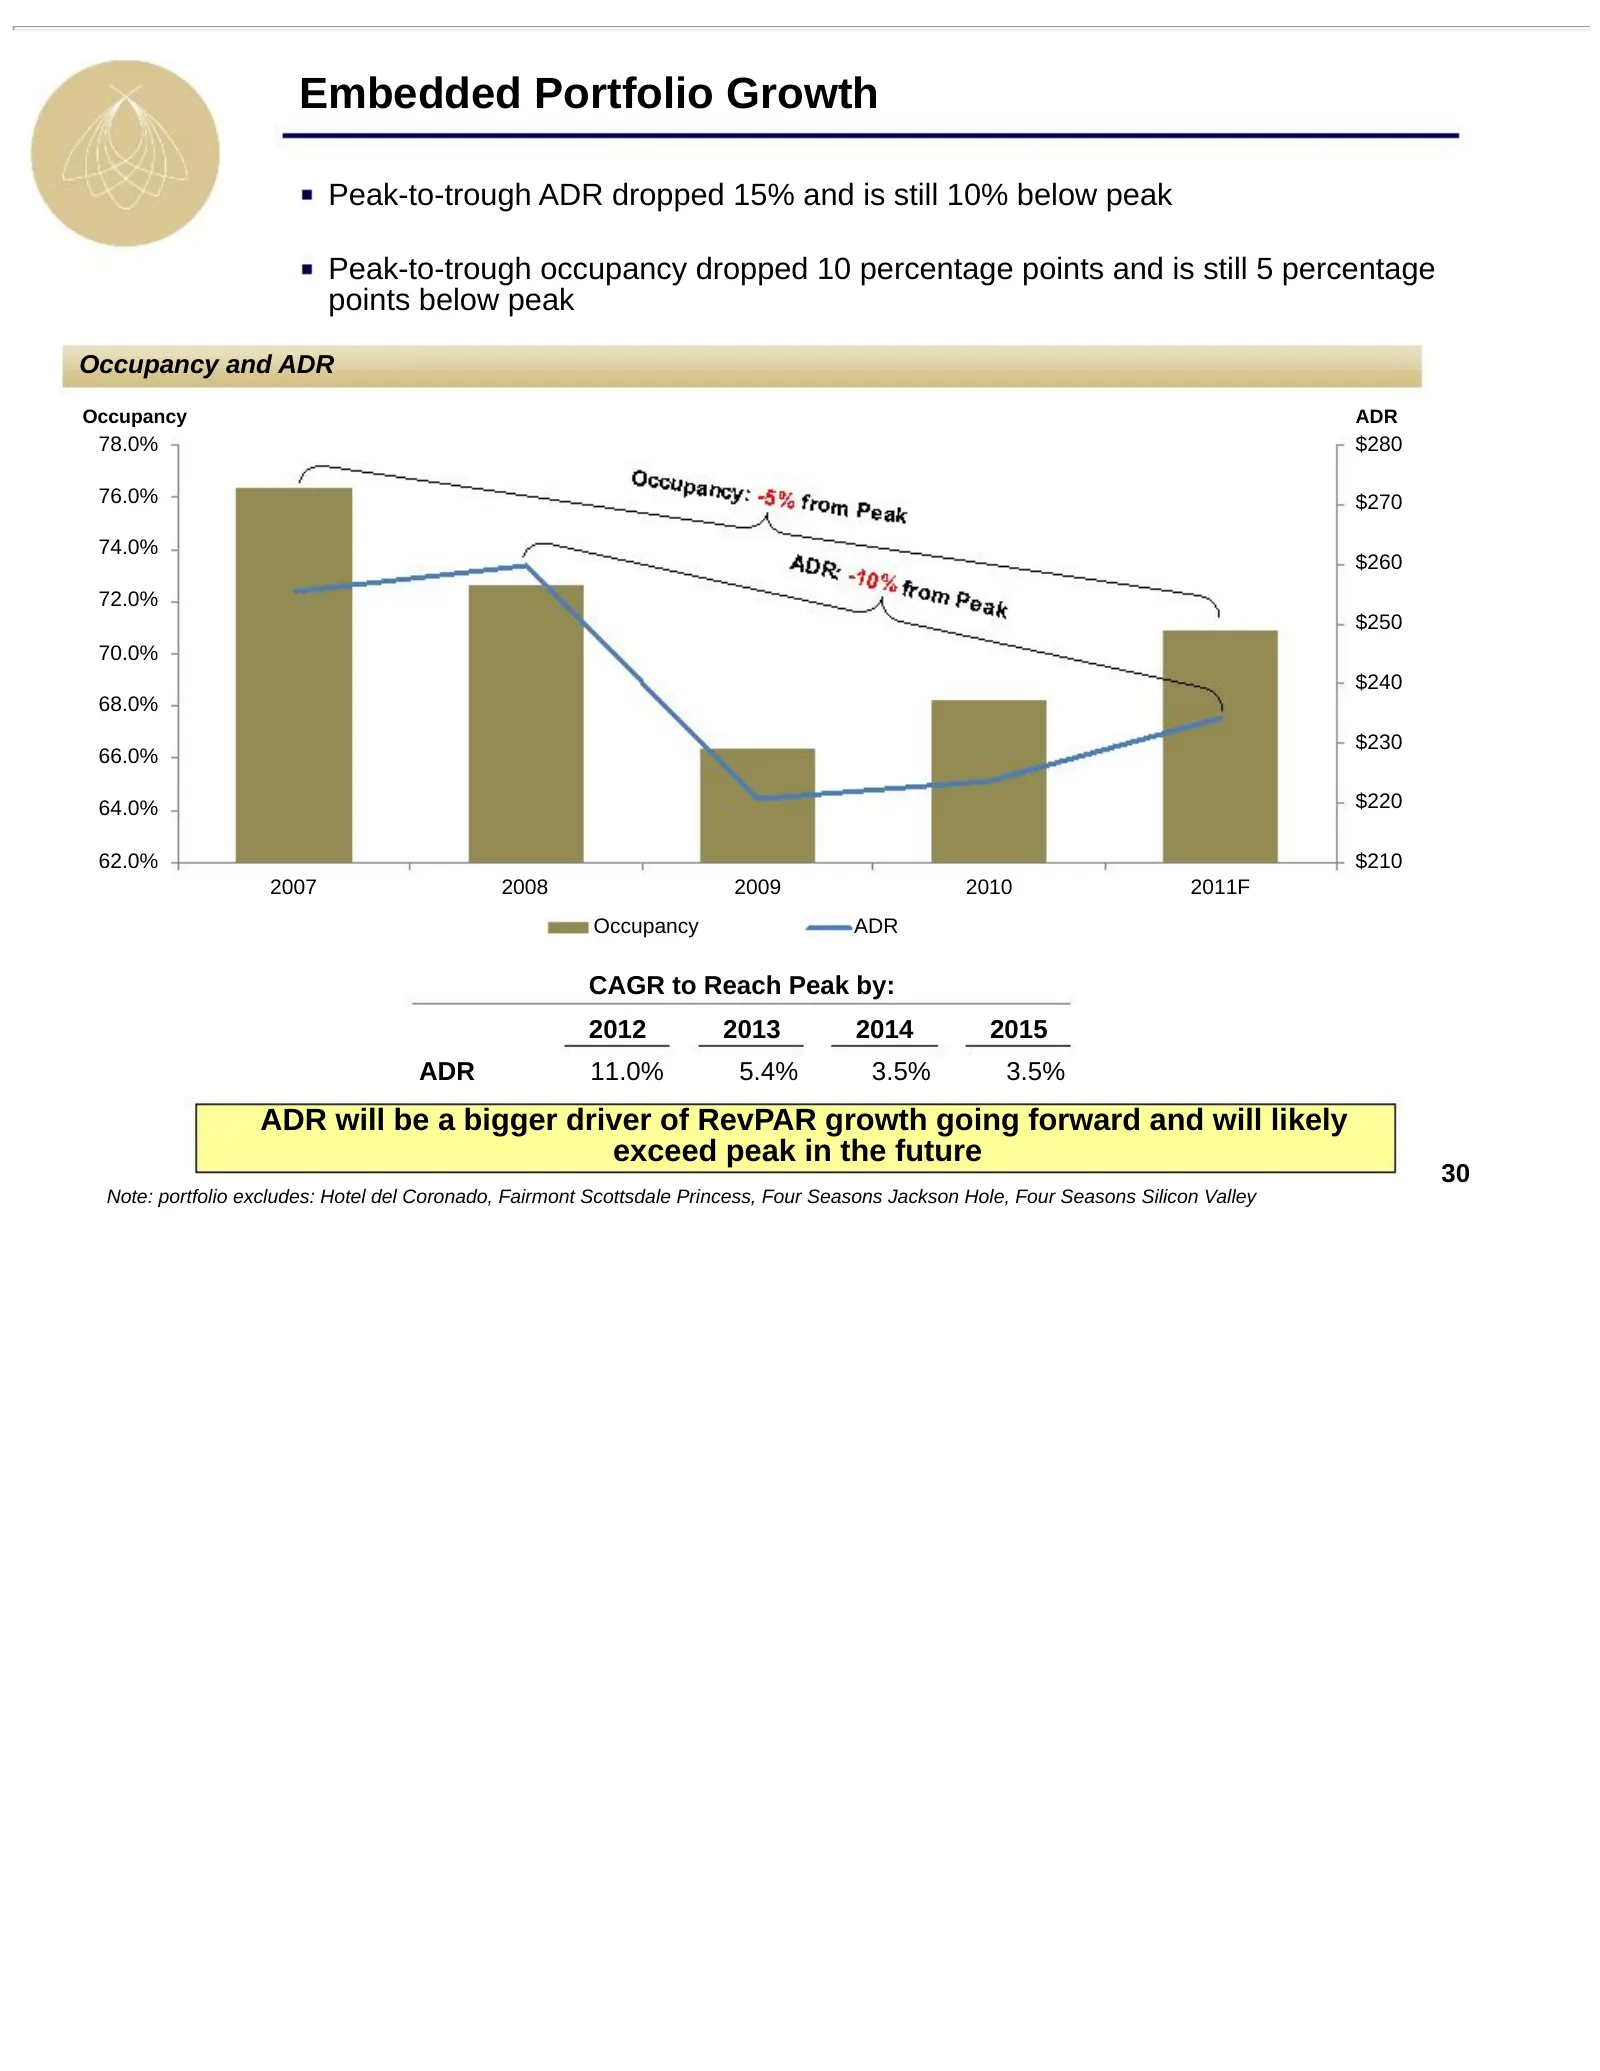
Embedded Portfolio Growth Peak-to-trough ADR dropped 15% and is still 10% below peak Peak-to-trough occupancy dropped 10 percentage points and is still 5 percentage points below peak Occupancy and ADR Occupancy ADR 78.0% $280 76.0% $270 74.0% $260 72.0% $250 70.0% $240 68.0% $230 66.0% 64.0% $220 62
Slide 31: Embedded Portfolio Growth
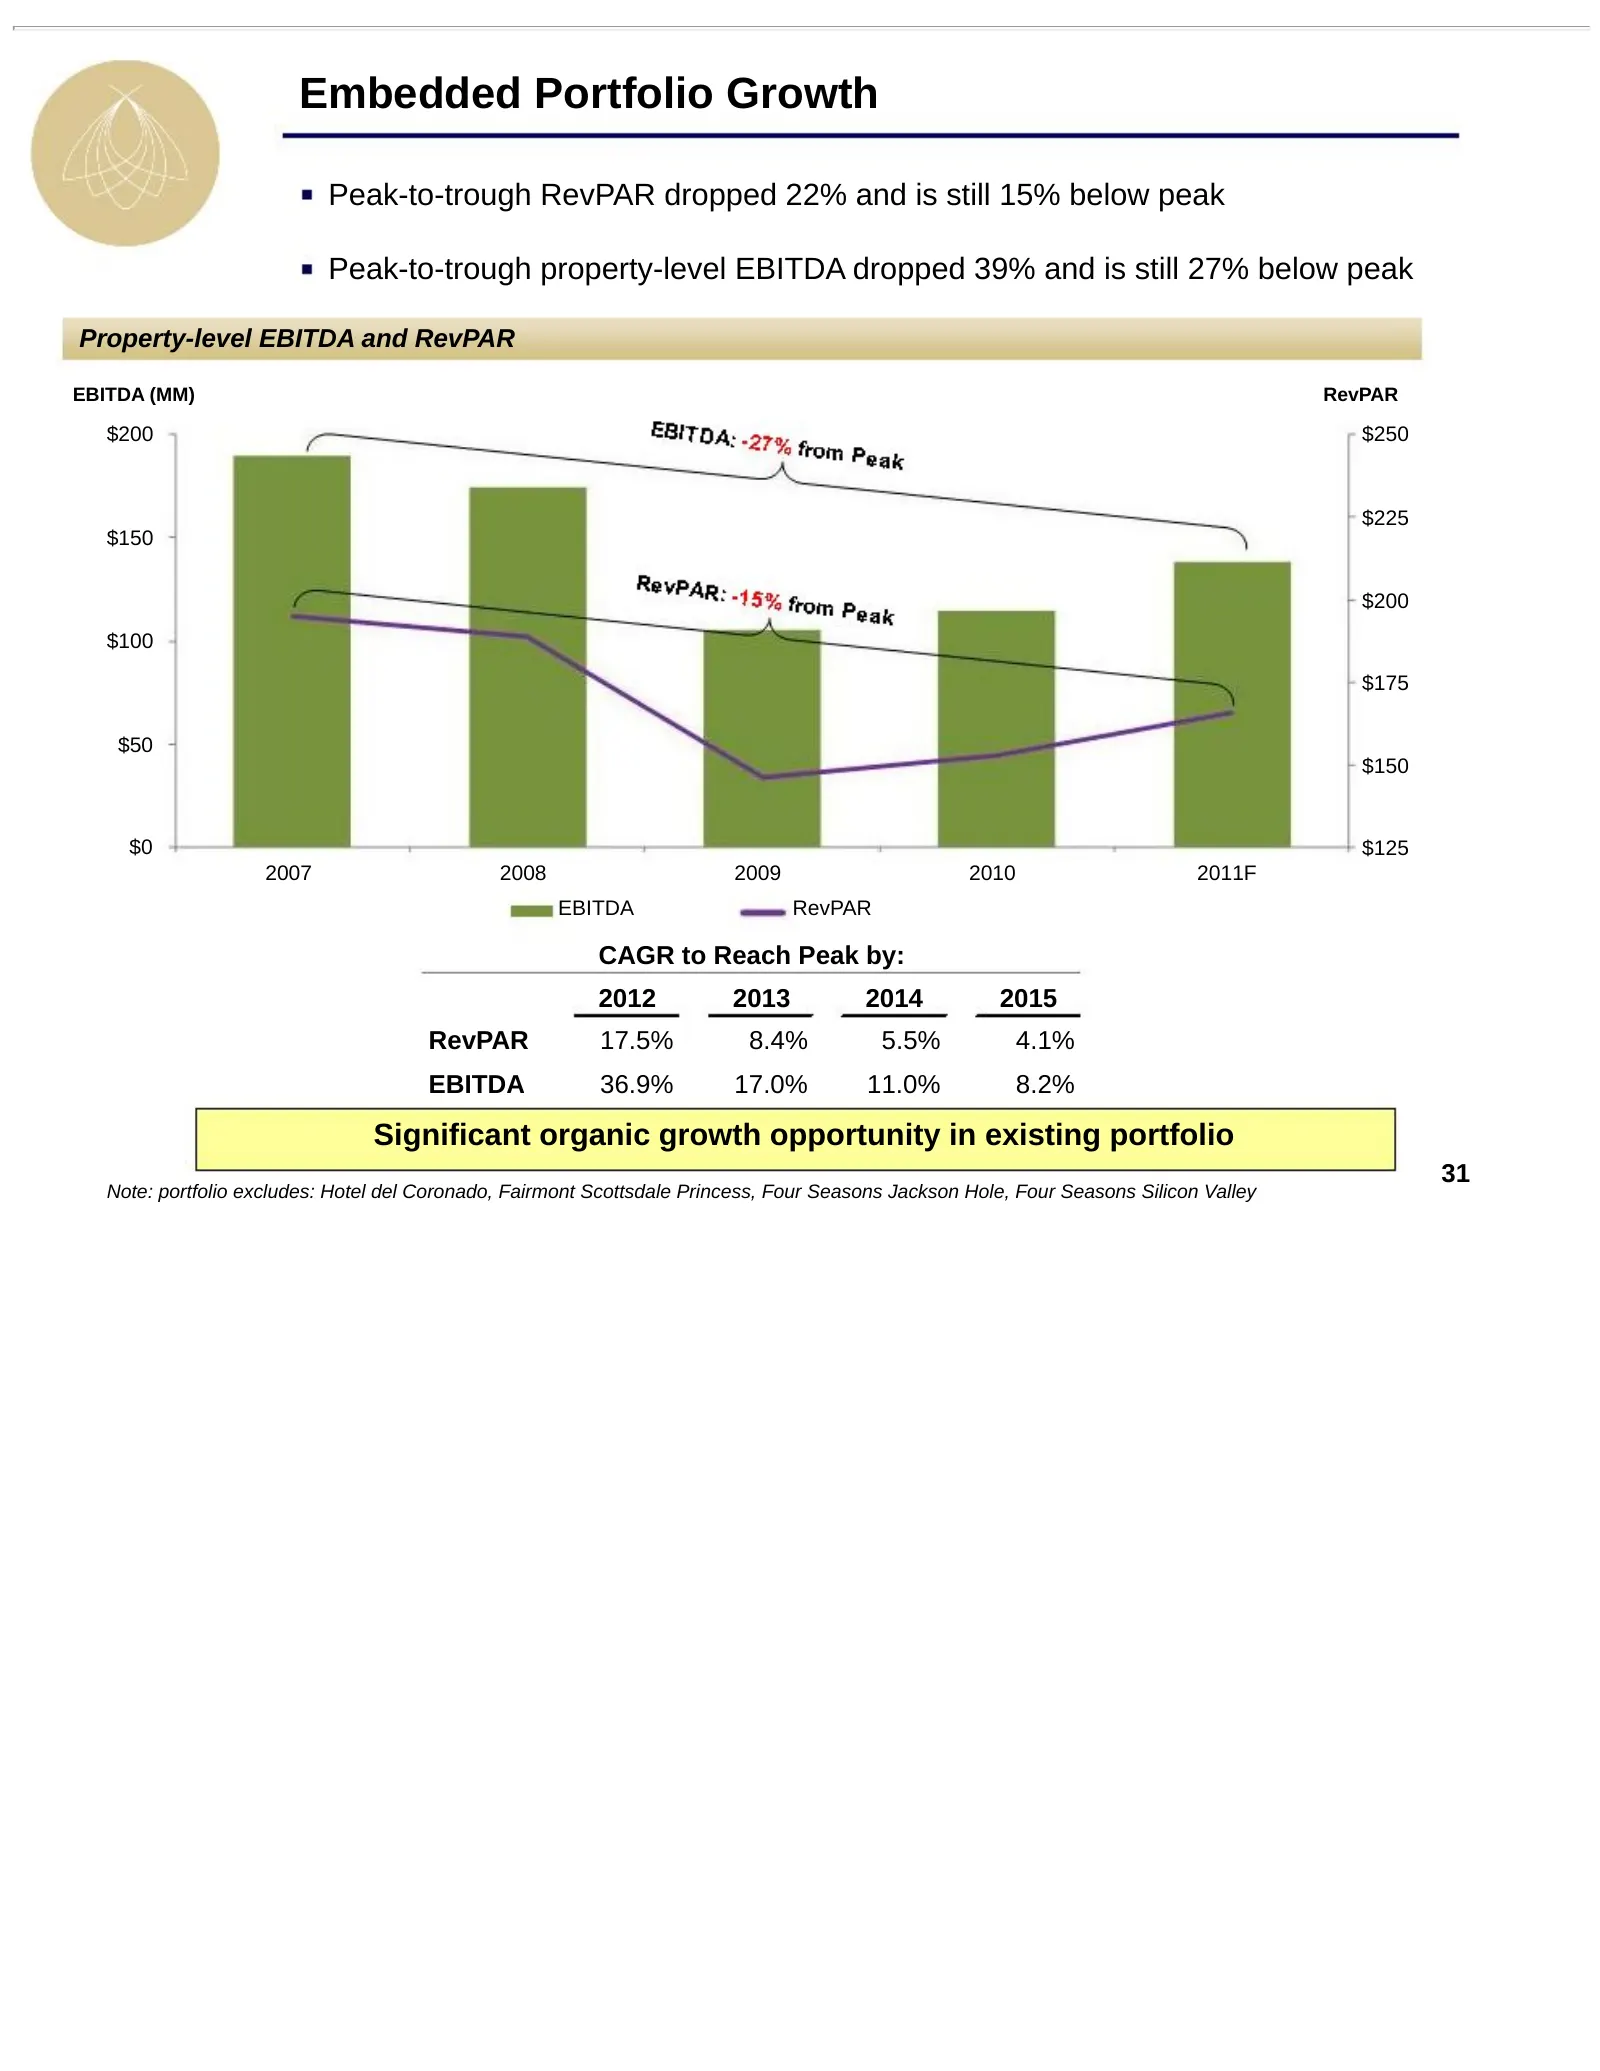
Embedded Portfolio Growth Peak-to-trough RevPAR dropped 22% and is still 15% below peak Peak-to-trough property-level EBITDA dropped 39% and is still 27% below peak Property-level EBITDA and RevPAR EBITDA (MM) RevPAR $200 $250 $225 $150 $200 $100 $175 $50 $150 $0 $125 2007 2008 2009 2010 2011F EBITD
Slide 32: Completed ROI Projects Enhance Future Growth
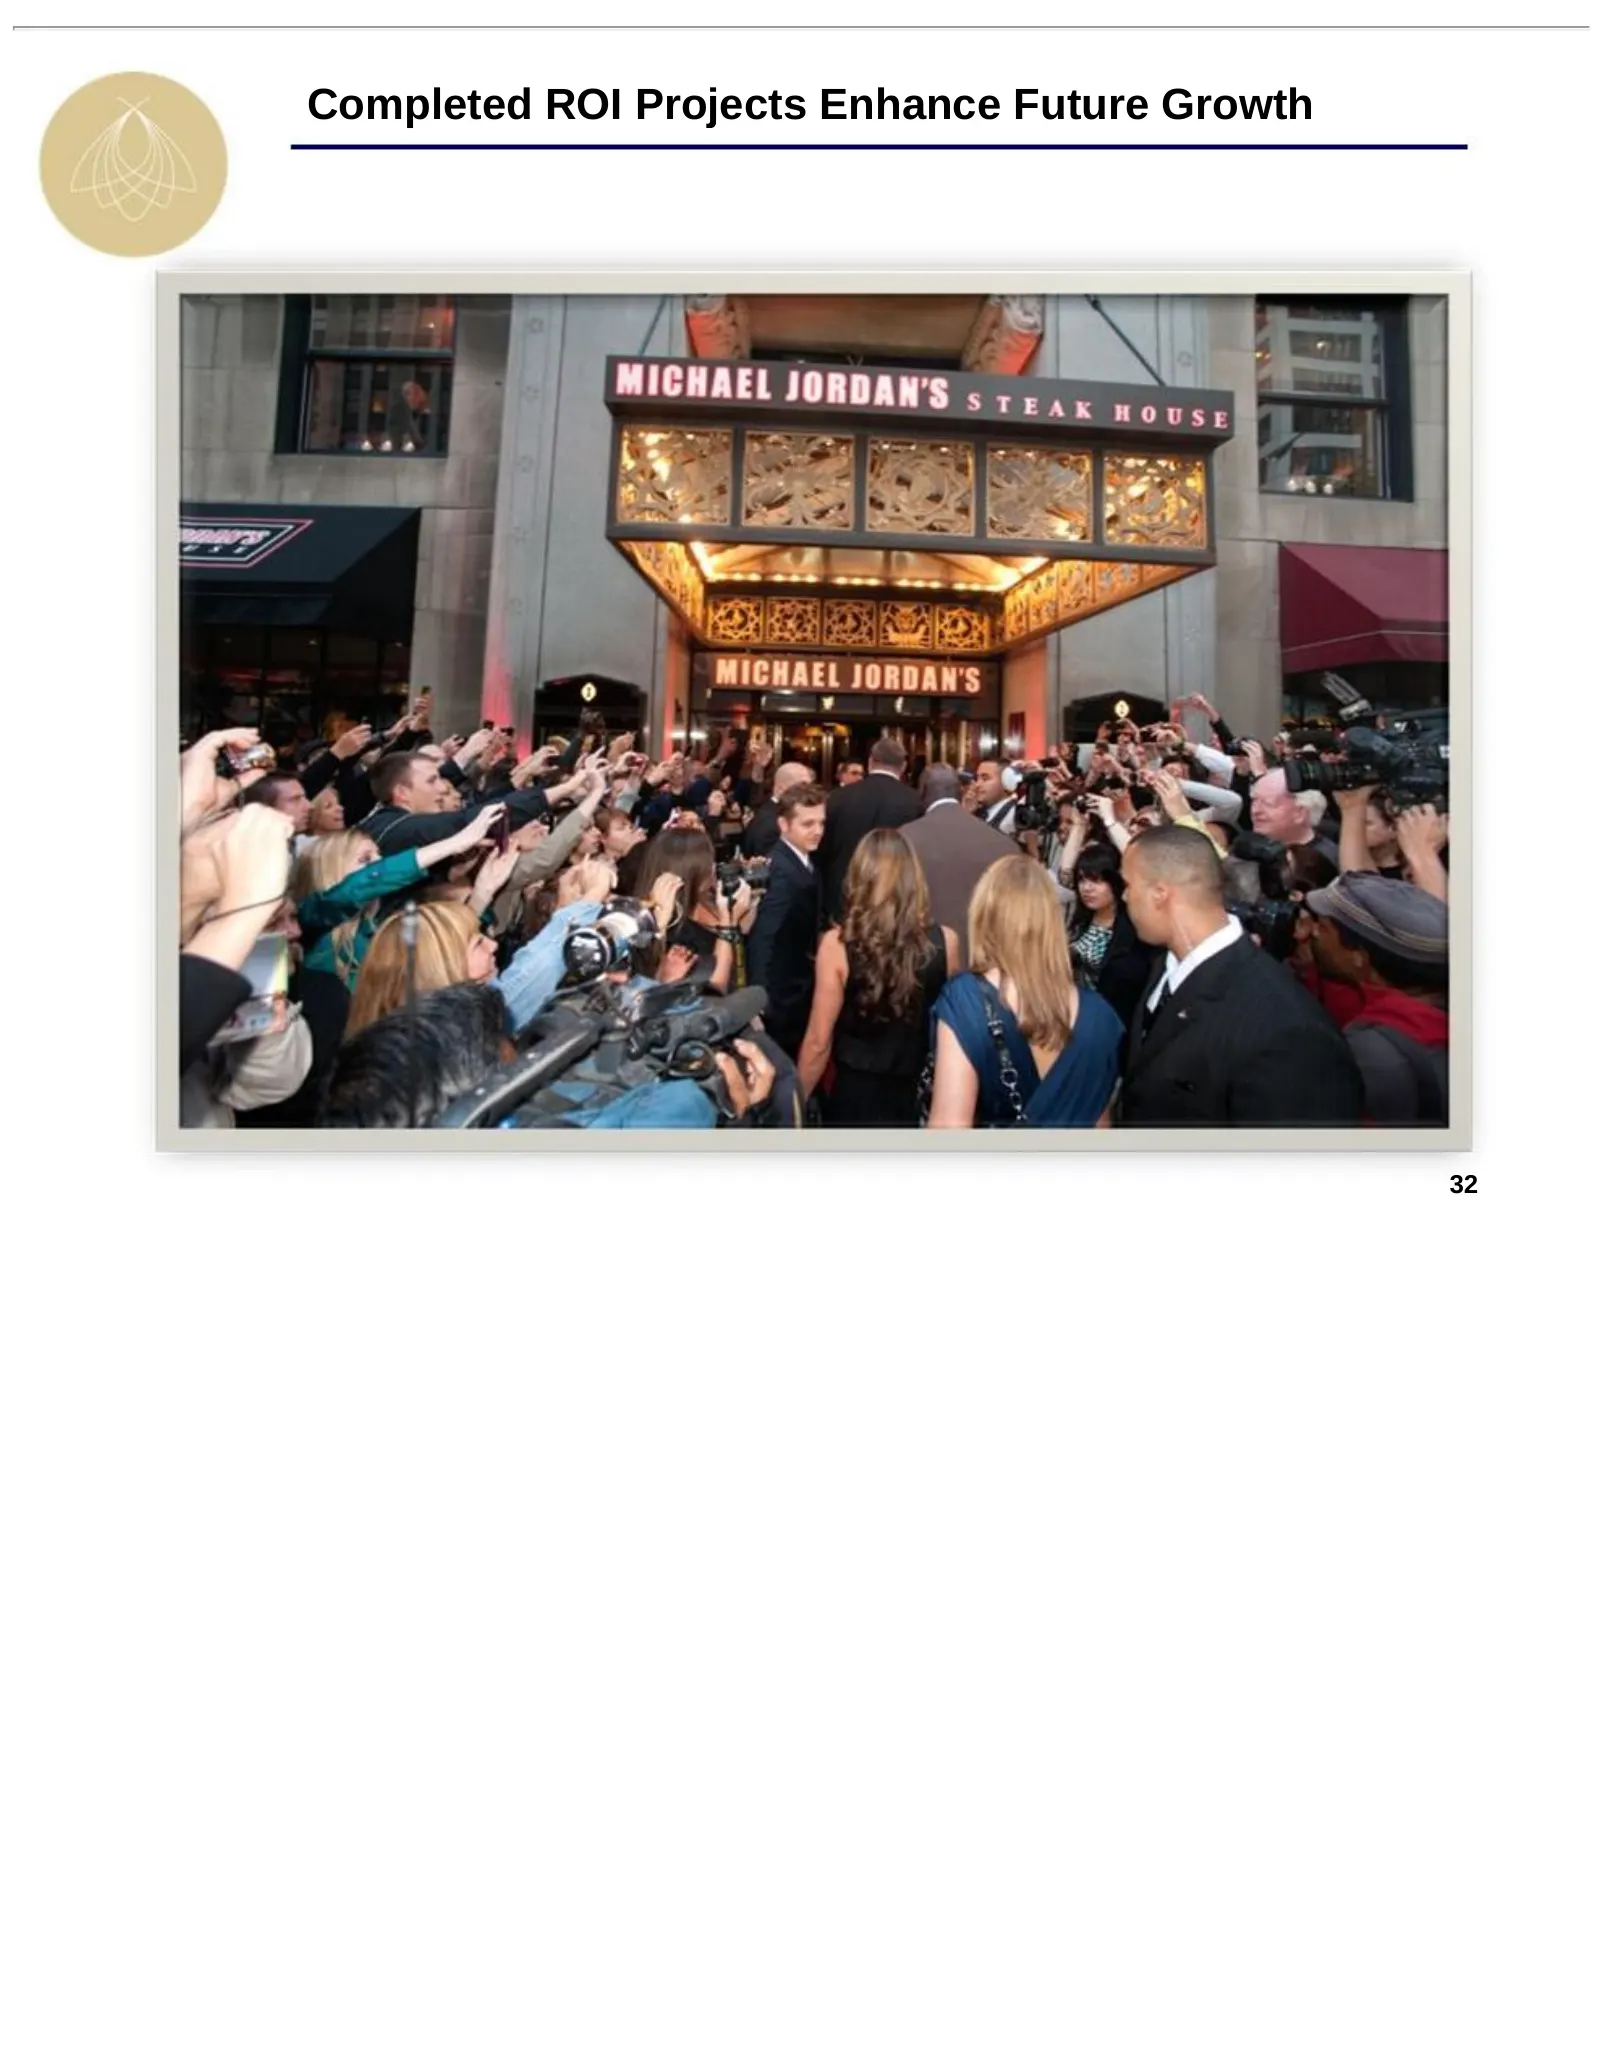
Completed ROI Projects Enhance Future Growth 32
Slide 33: Completed ROI Projects Enhance Future Growth
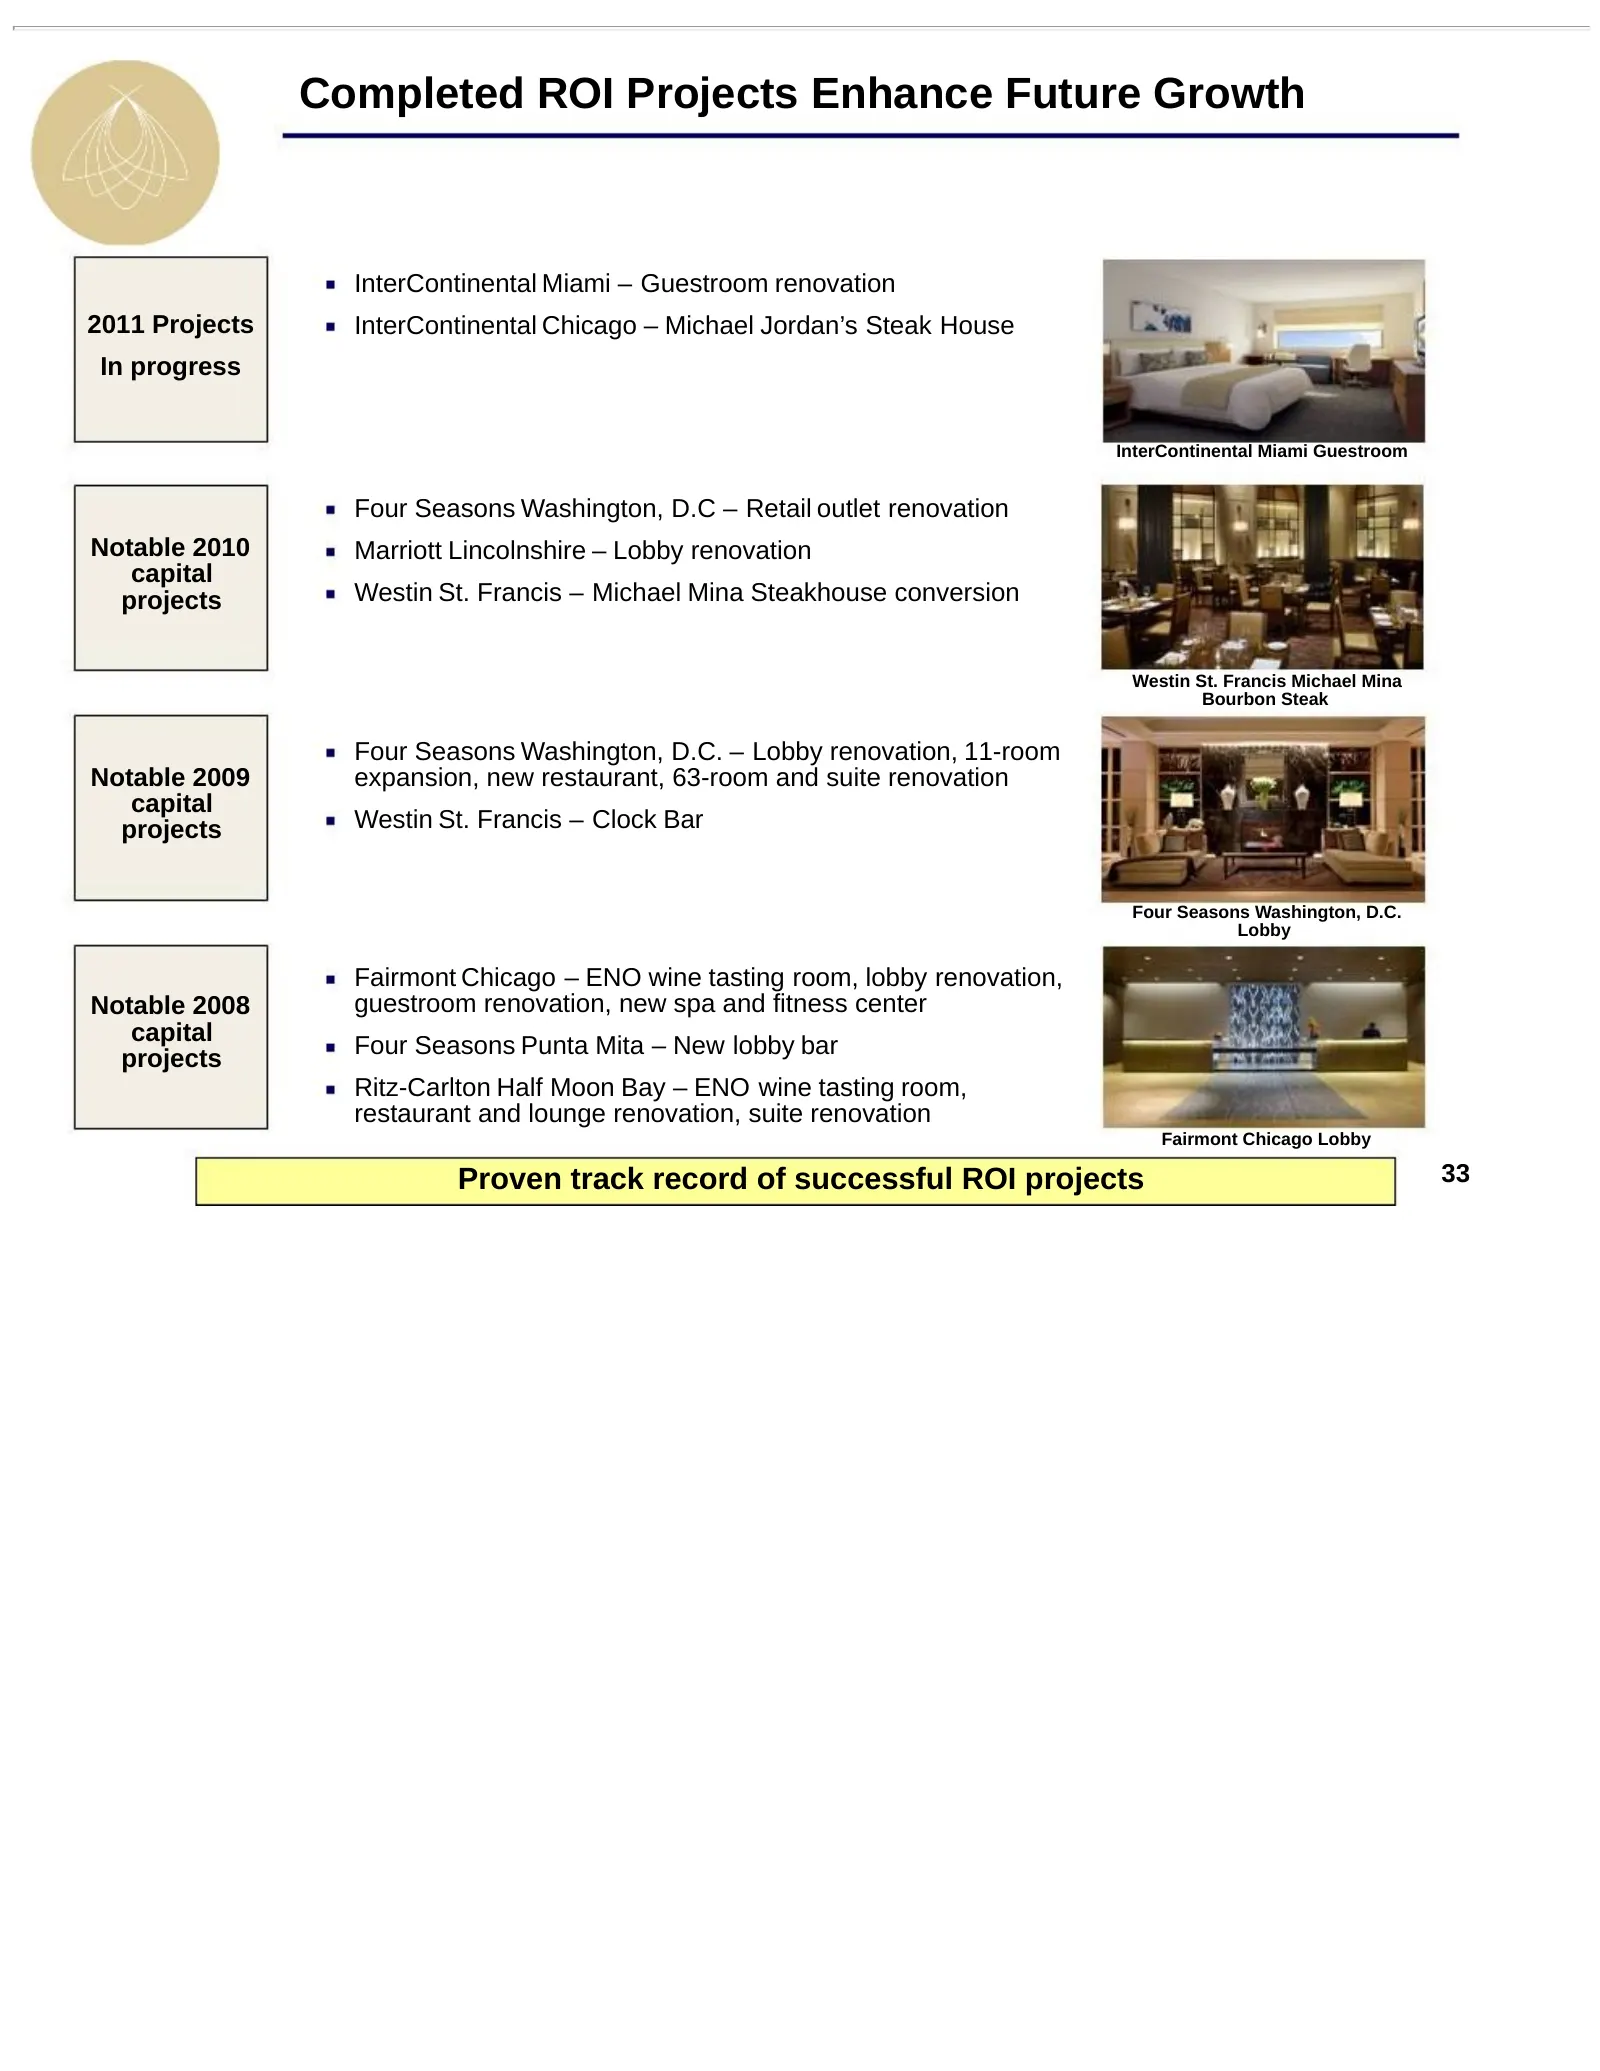
Completed ROI Projects Enhance Future Growth InterContinental Miami – Guestroom renovation 2011 Projects InterContinental Chicago – Michael Jordan’s Steak House In progress InterContinental Miami Guestroom Four Seasons Washington, D.C – Retail outlet renovation Notable 2010 Marriott Lincolnshire – L
Slide 34: ROI Capital Project Examples
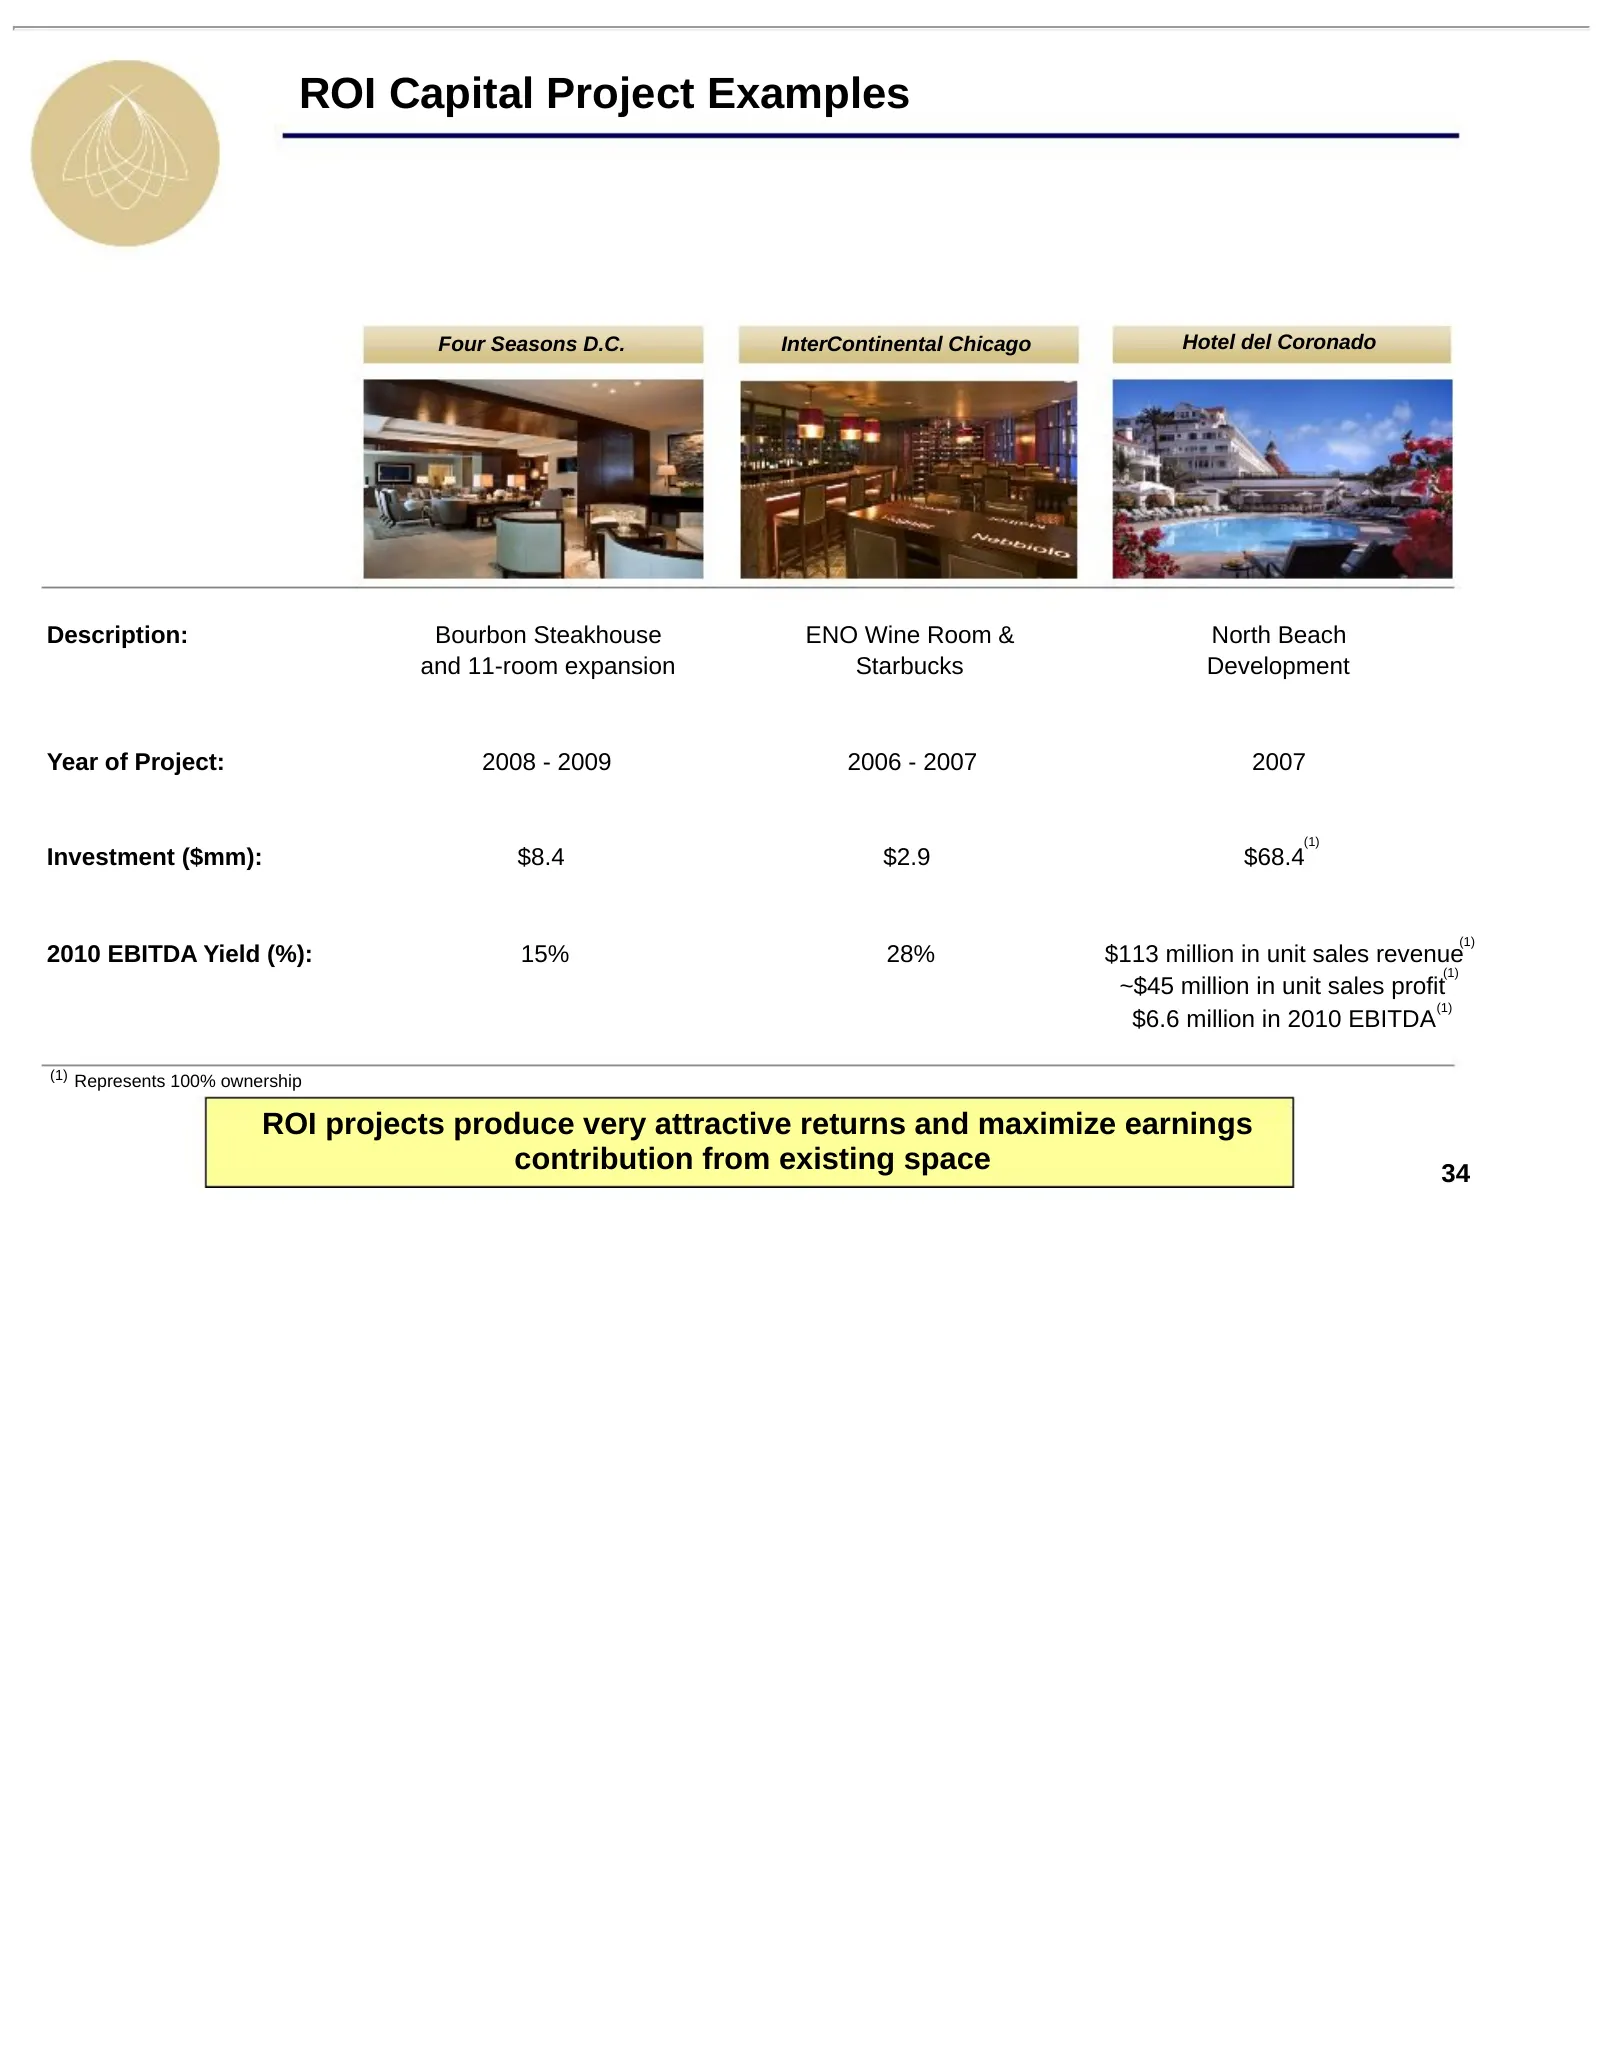
ROI Capital Project Examples Four Seasons D.C. InterContinental Chicago Hotel del Coronado Description: Bourbon Steakhouse ENO Wine Room & North Beach and 11-room expansion Starbucks Development Year of Project: 2008 - 2009 2006 - 2007 2007 (1) Investment ($mm): $8.4 $2.9 $68.4 (1) 2010 EBITDA Yield
Slide 35: 2011 Capital Projects
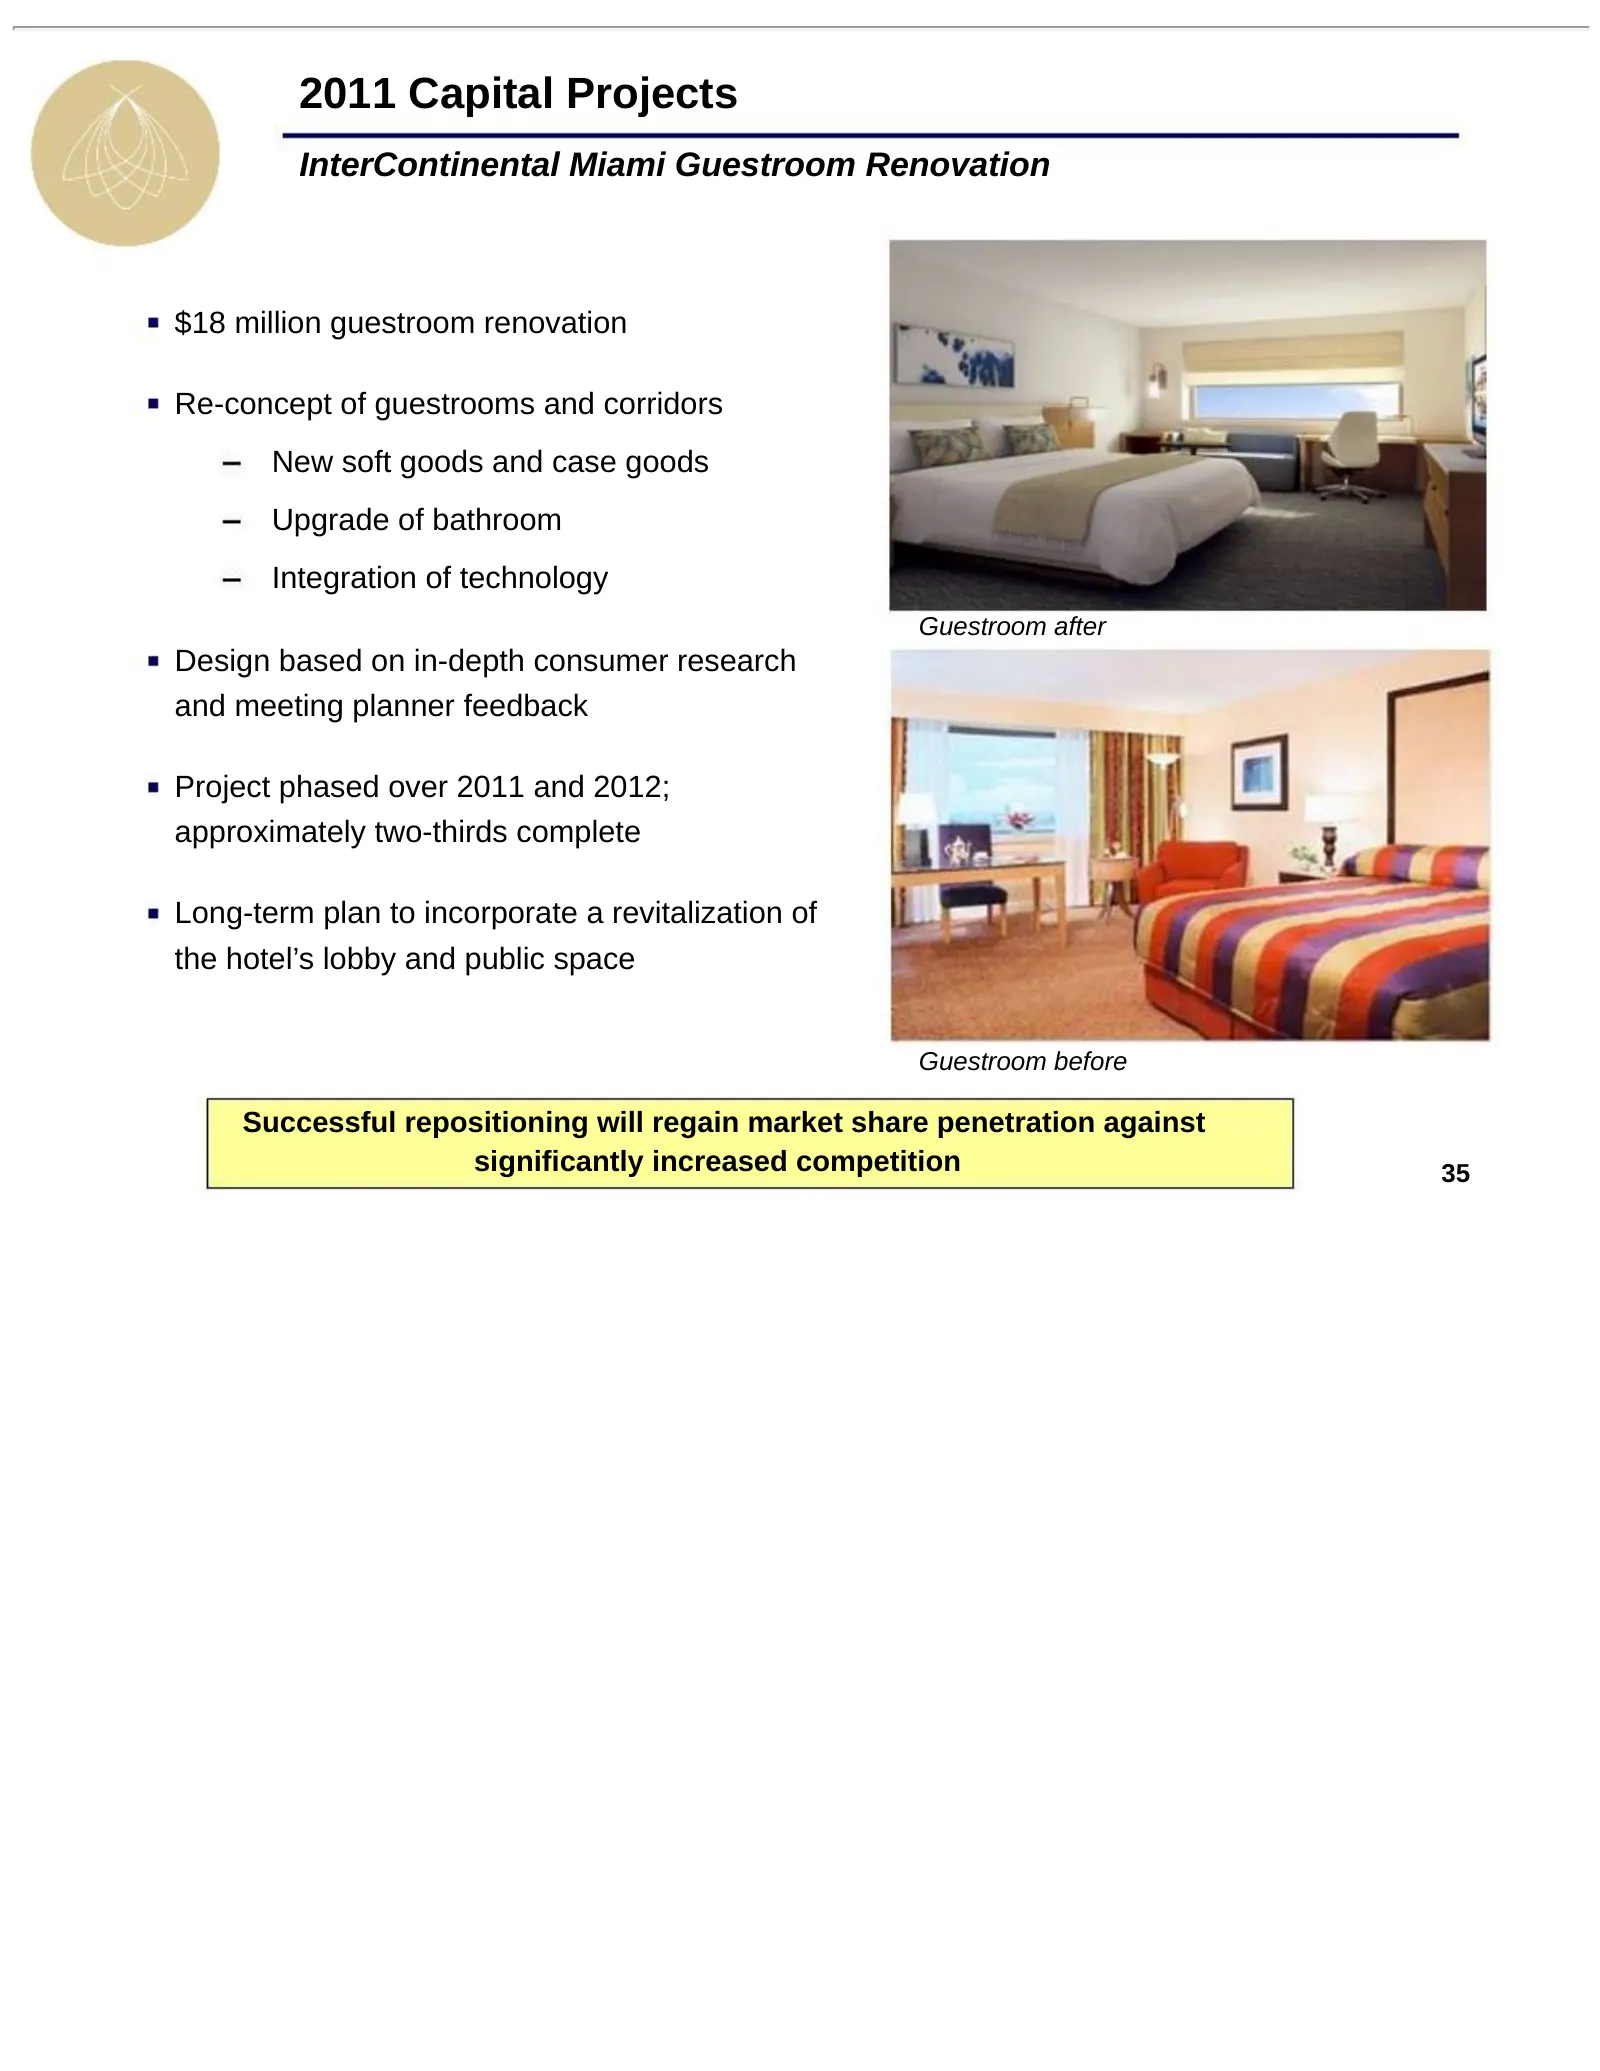
2011 Capital Projects InterContinental Miami Guestroom Renovation $18 million guestroom renovation Re-concept of guestrooms and corridors New soft goods and case goods Upgrade of bathroom Integration of technology Guestroom after Design based on in-depth consumer research and meeting planner feedbac
Slide 36: 2011 Capital Projects
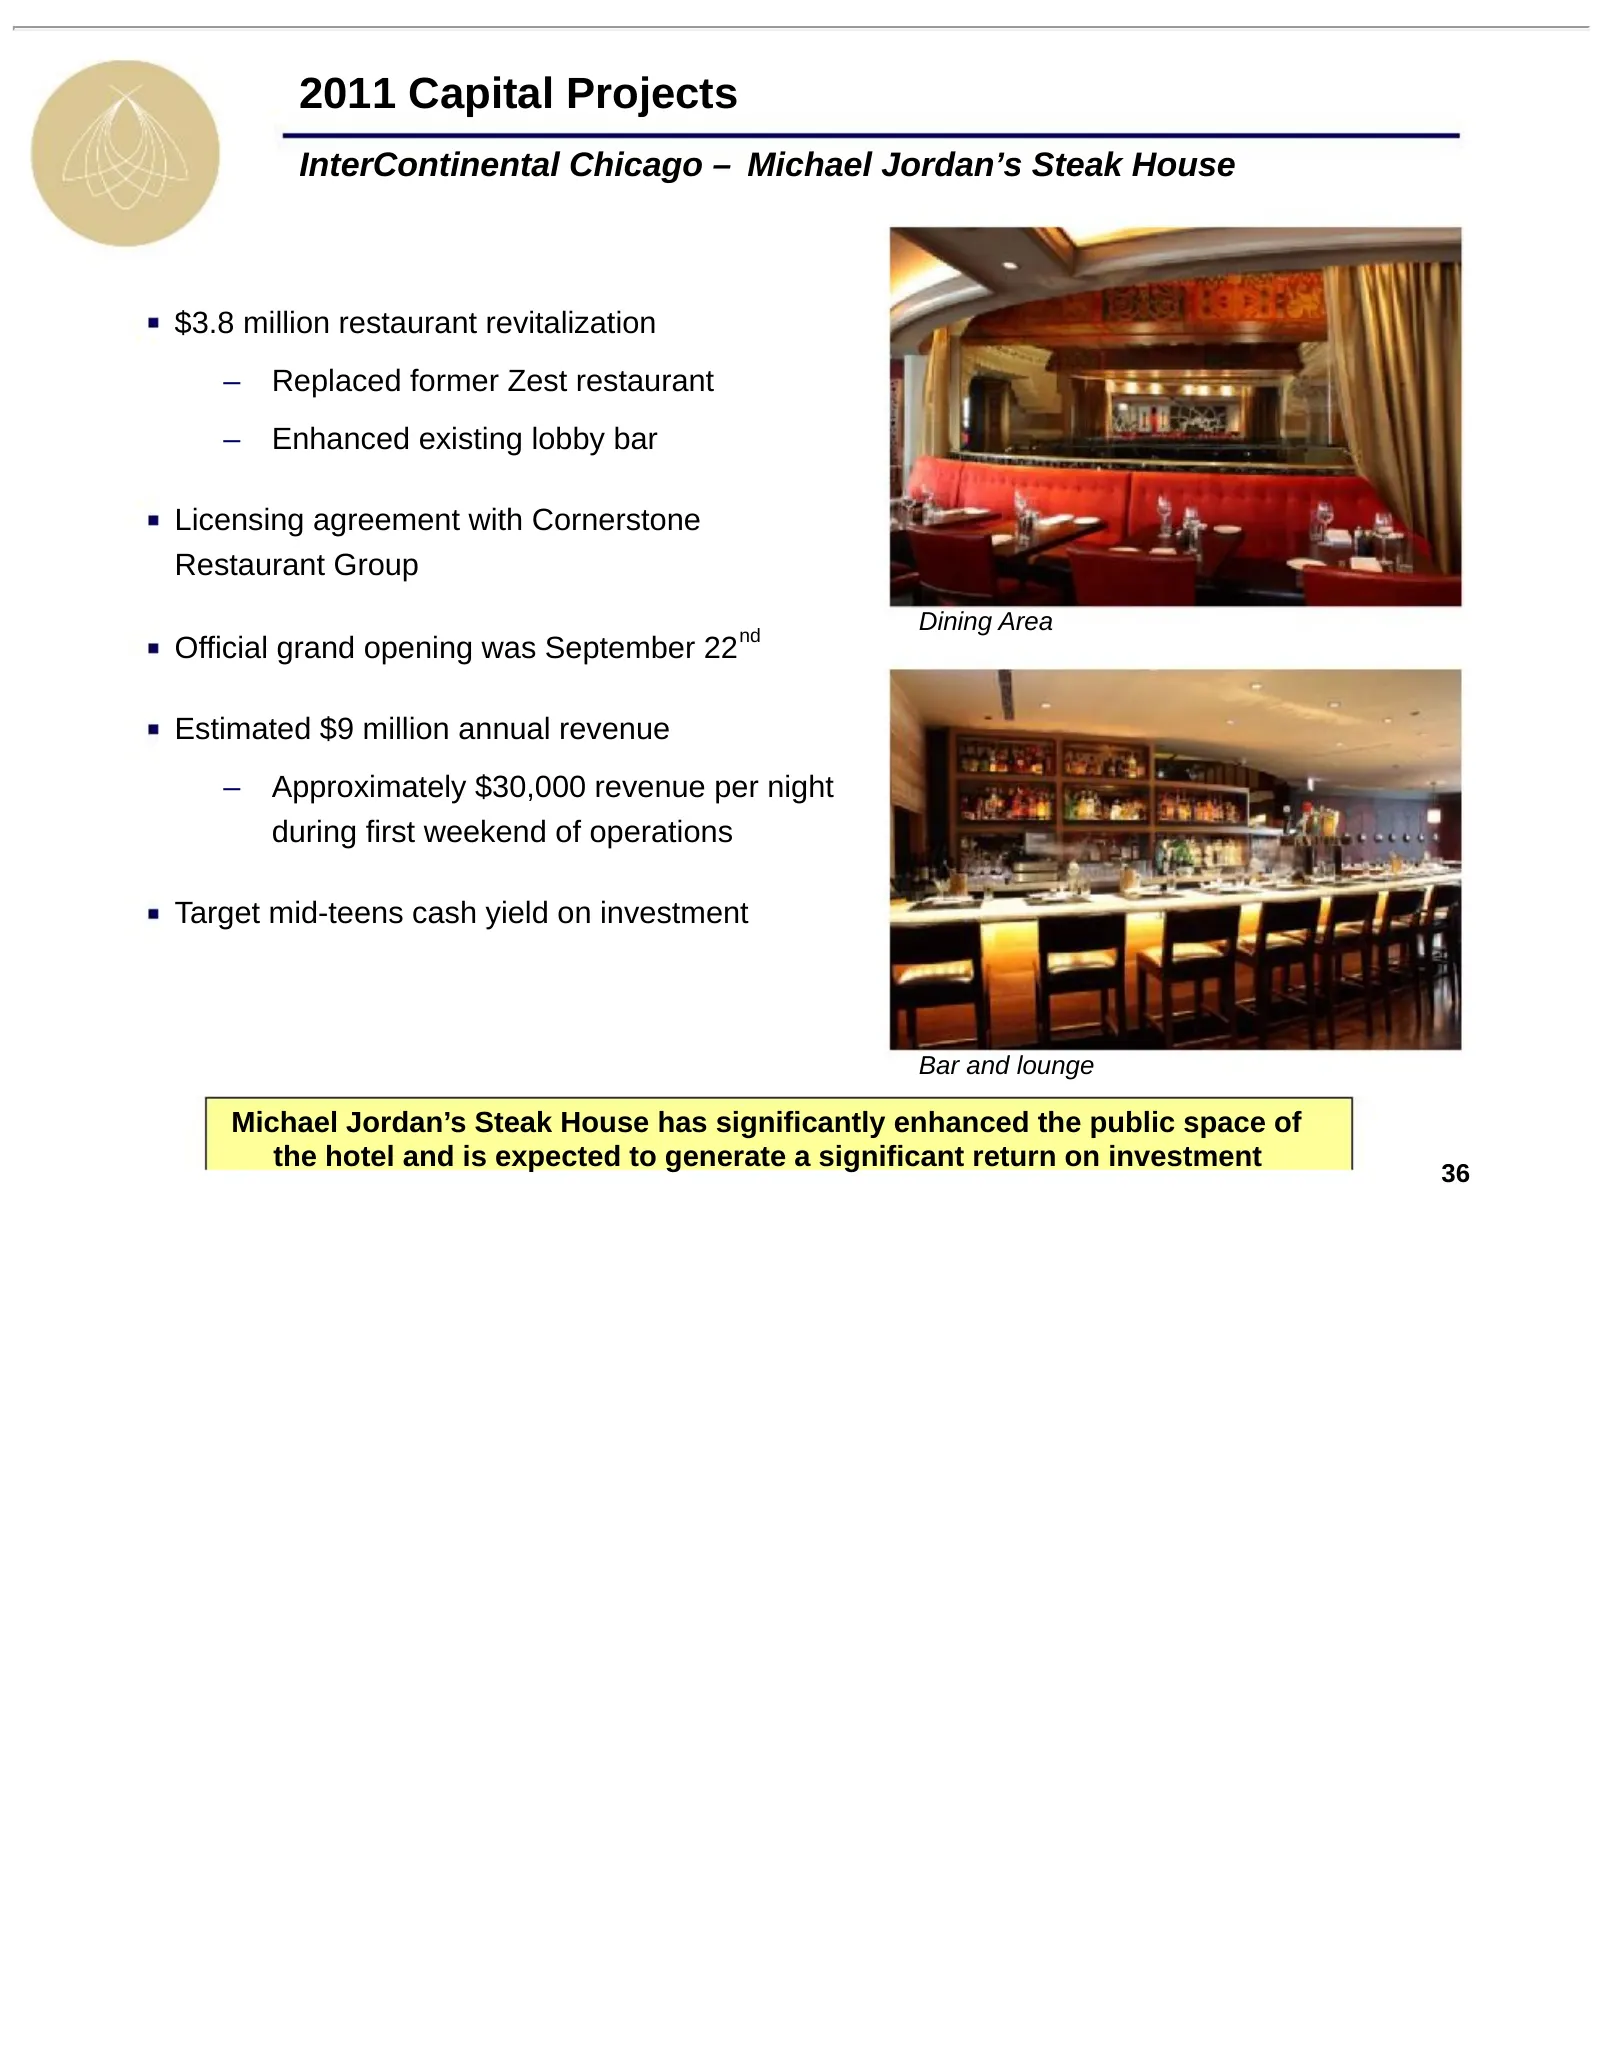
2011 Capital Projects InterContinental Chicago – Michael Jordan’s Steak House $3.8 million restaurant revitalization – Replaced former Zest restaurant – Enhanced existing lobby bar Licensing agreement with Cornerstone Restaurant Group nd Dining Area Official grand opening was September 22 Estimated
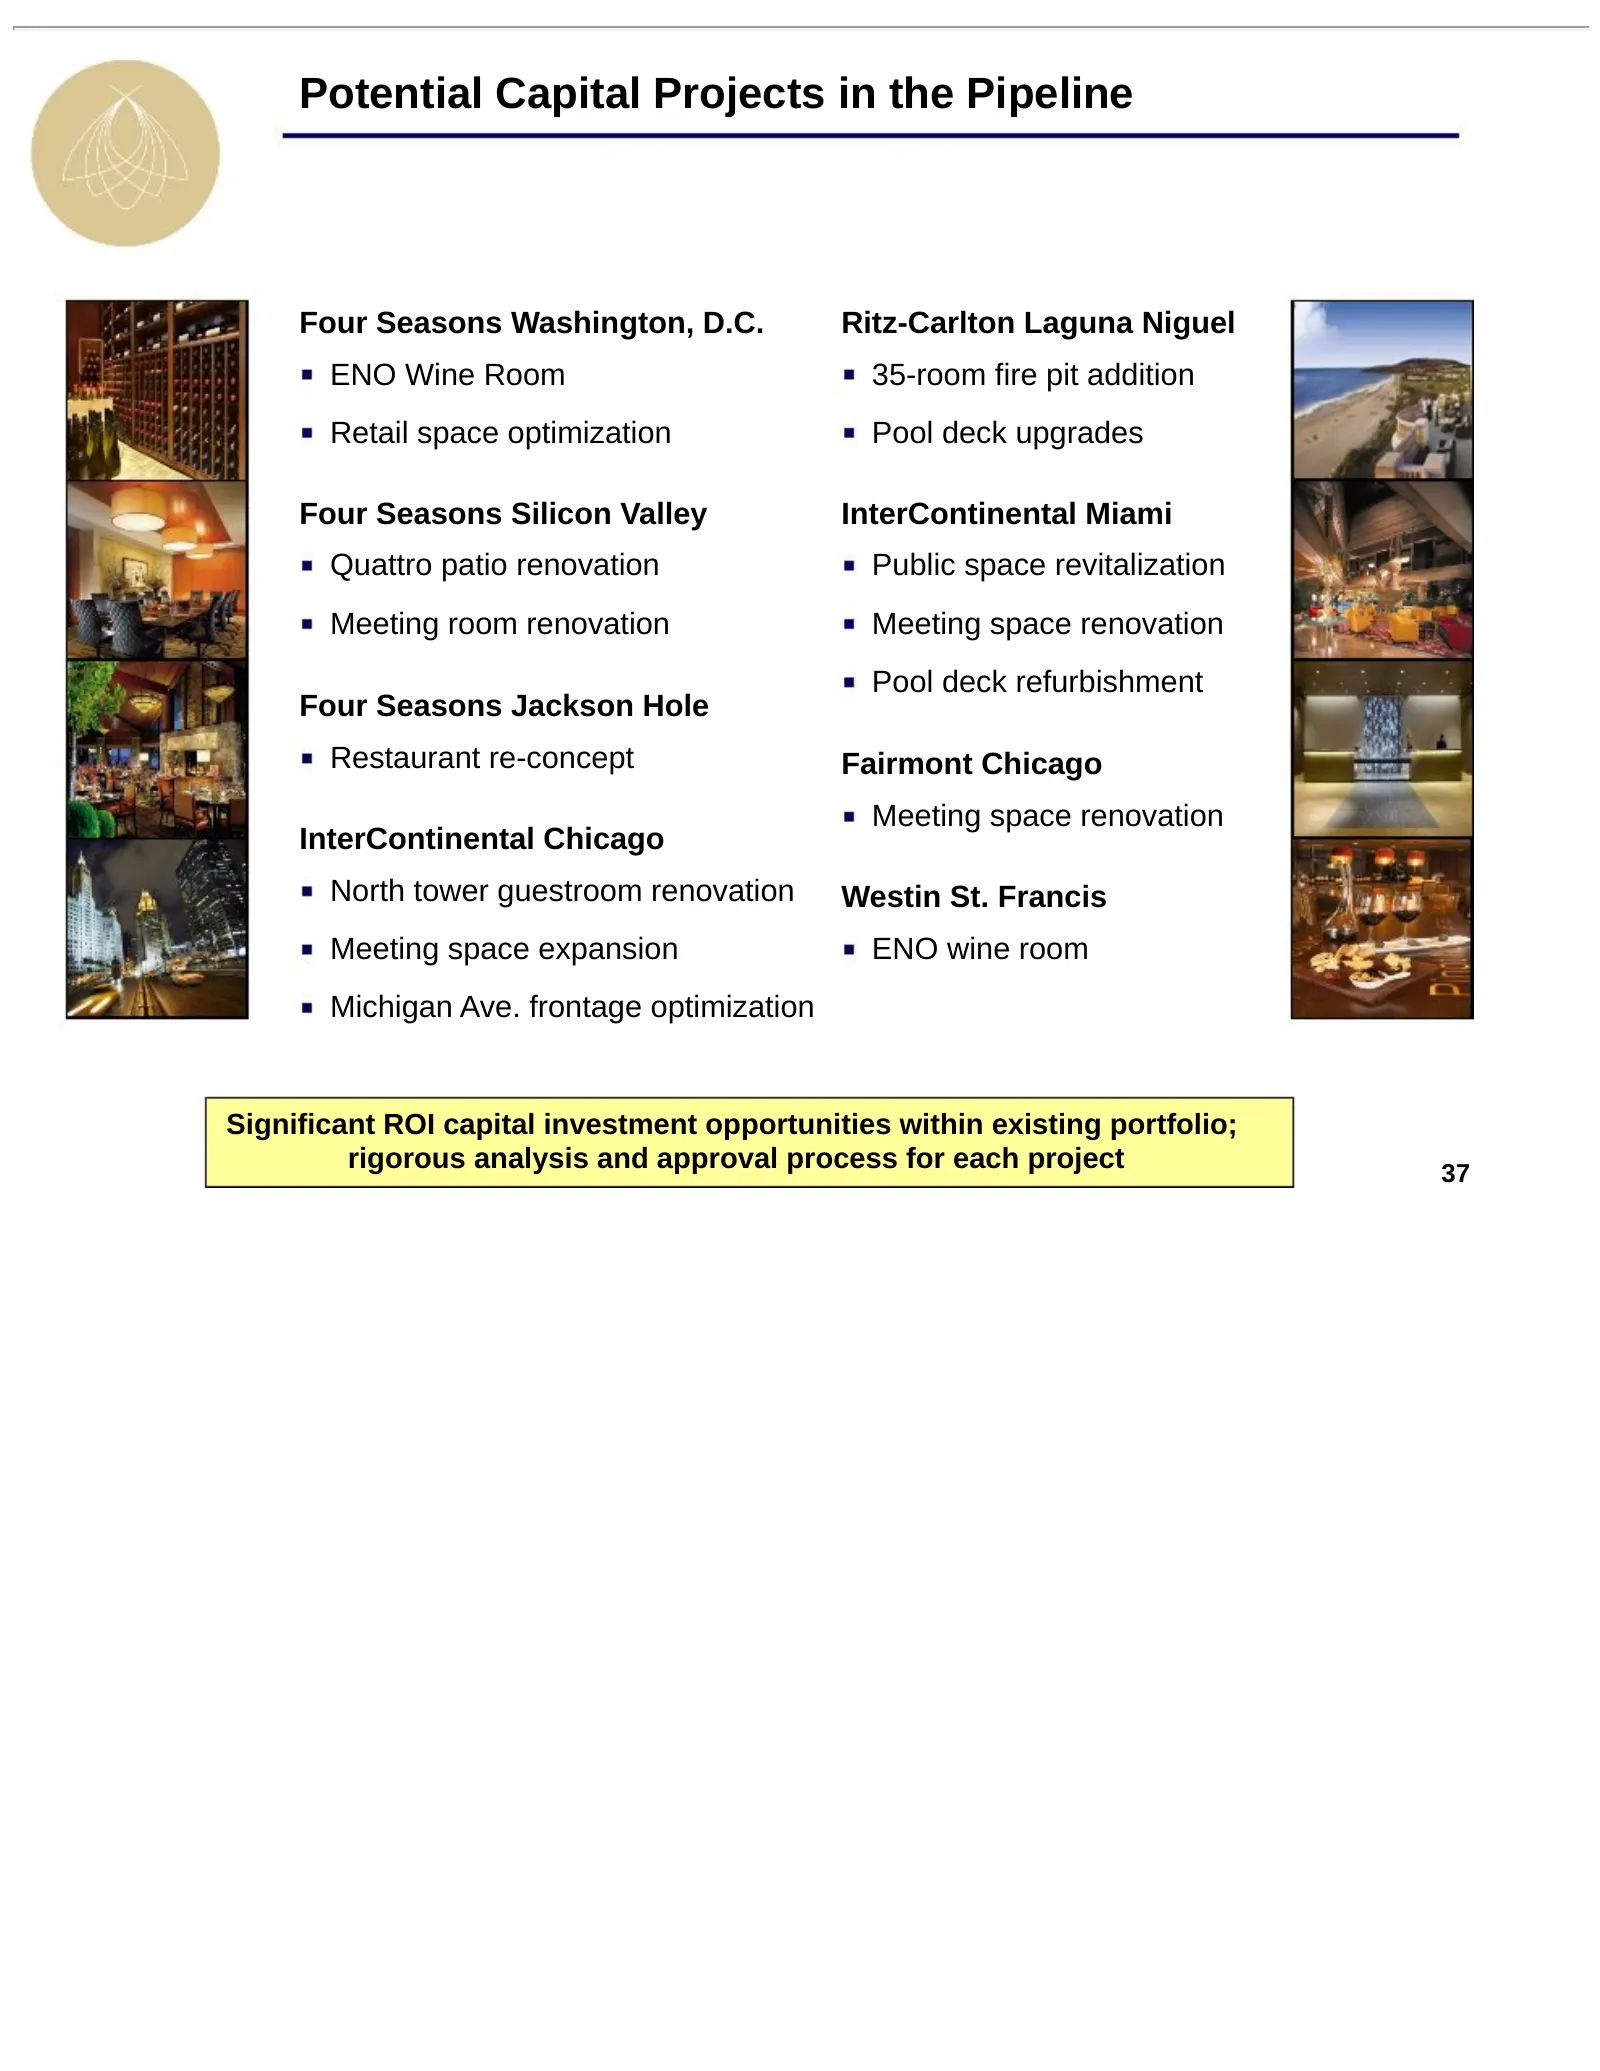
Slide 37: Potential Capital Projects in the Pipeline
Potential Capital Projects in the Pipeline Four Seasons Washington, D.C. Ritz-Carlton Laguna Niguel ENO Wine Room 35-room fire pit addition Retail space optimization Pool deck upgrades Four Seasons Silicon Valley InterContinental Miami Quattro patio renovation Public space revitalization Meeting roo
Slide 38: Agenda
Agenda I. BEE’s Unique Value Proposition II. Macroeconomic and Industry Update III. Company Overview IV. Organic Growth and ROI Opportunities V. Balance Sheet Recapitalization 38
Slide 39: 2011 Debt Refinancing Strategy Objectives
2011 Debt Refinancing Strategy Objectives Deliberate, focused decision made in January 2011 to accelerate the refinancing of all 2011 / 2012 debt maturities (1) Simultaneous negotiation of a new syndicated line of credit; substituting the Ritz-Carlton Half Moon Bay for the Four Seasons Washington, D
Slide 40: Strong Recapitalized Balance Sheet
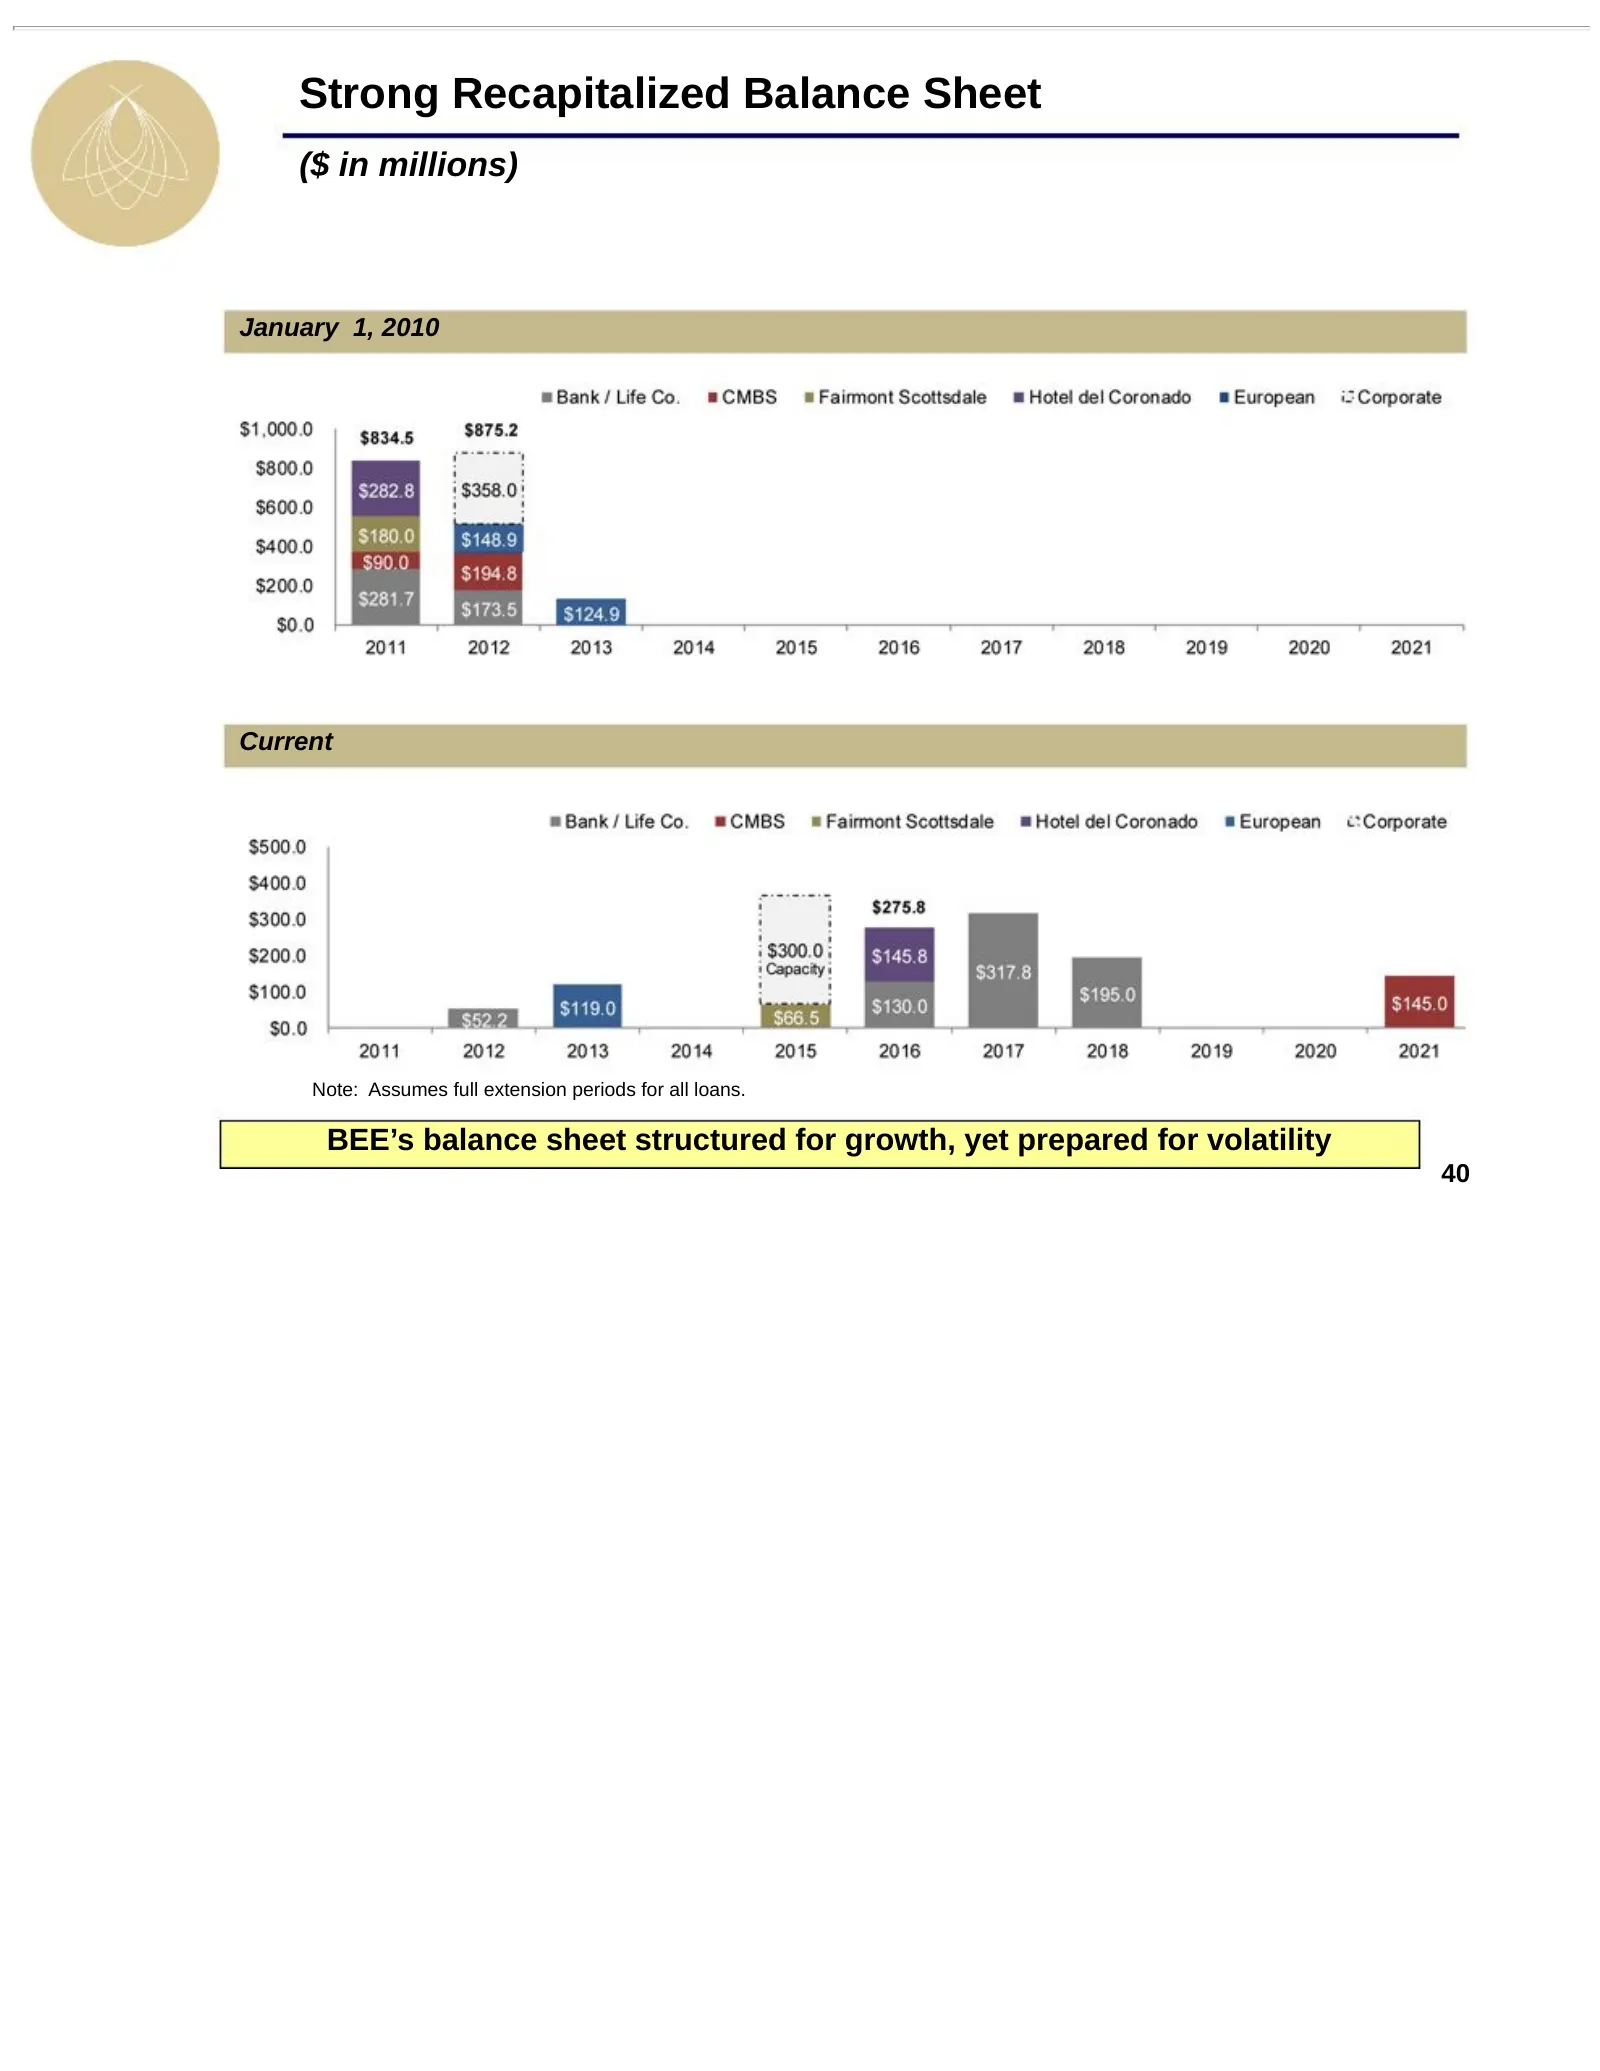
Strong Recapitalized Balance Sheet ($ in millions) January 1, 2010 Current Note: Assumes full extension periods for all loans. BEE’s balance sheet structured for growth, yet prepared for volatility 40
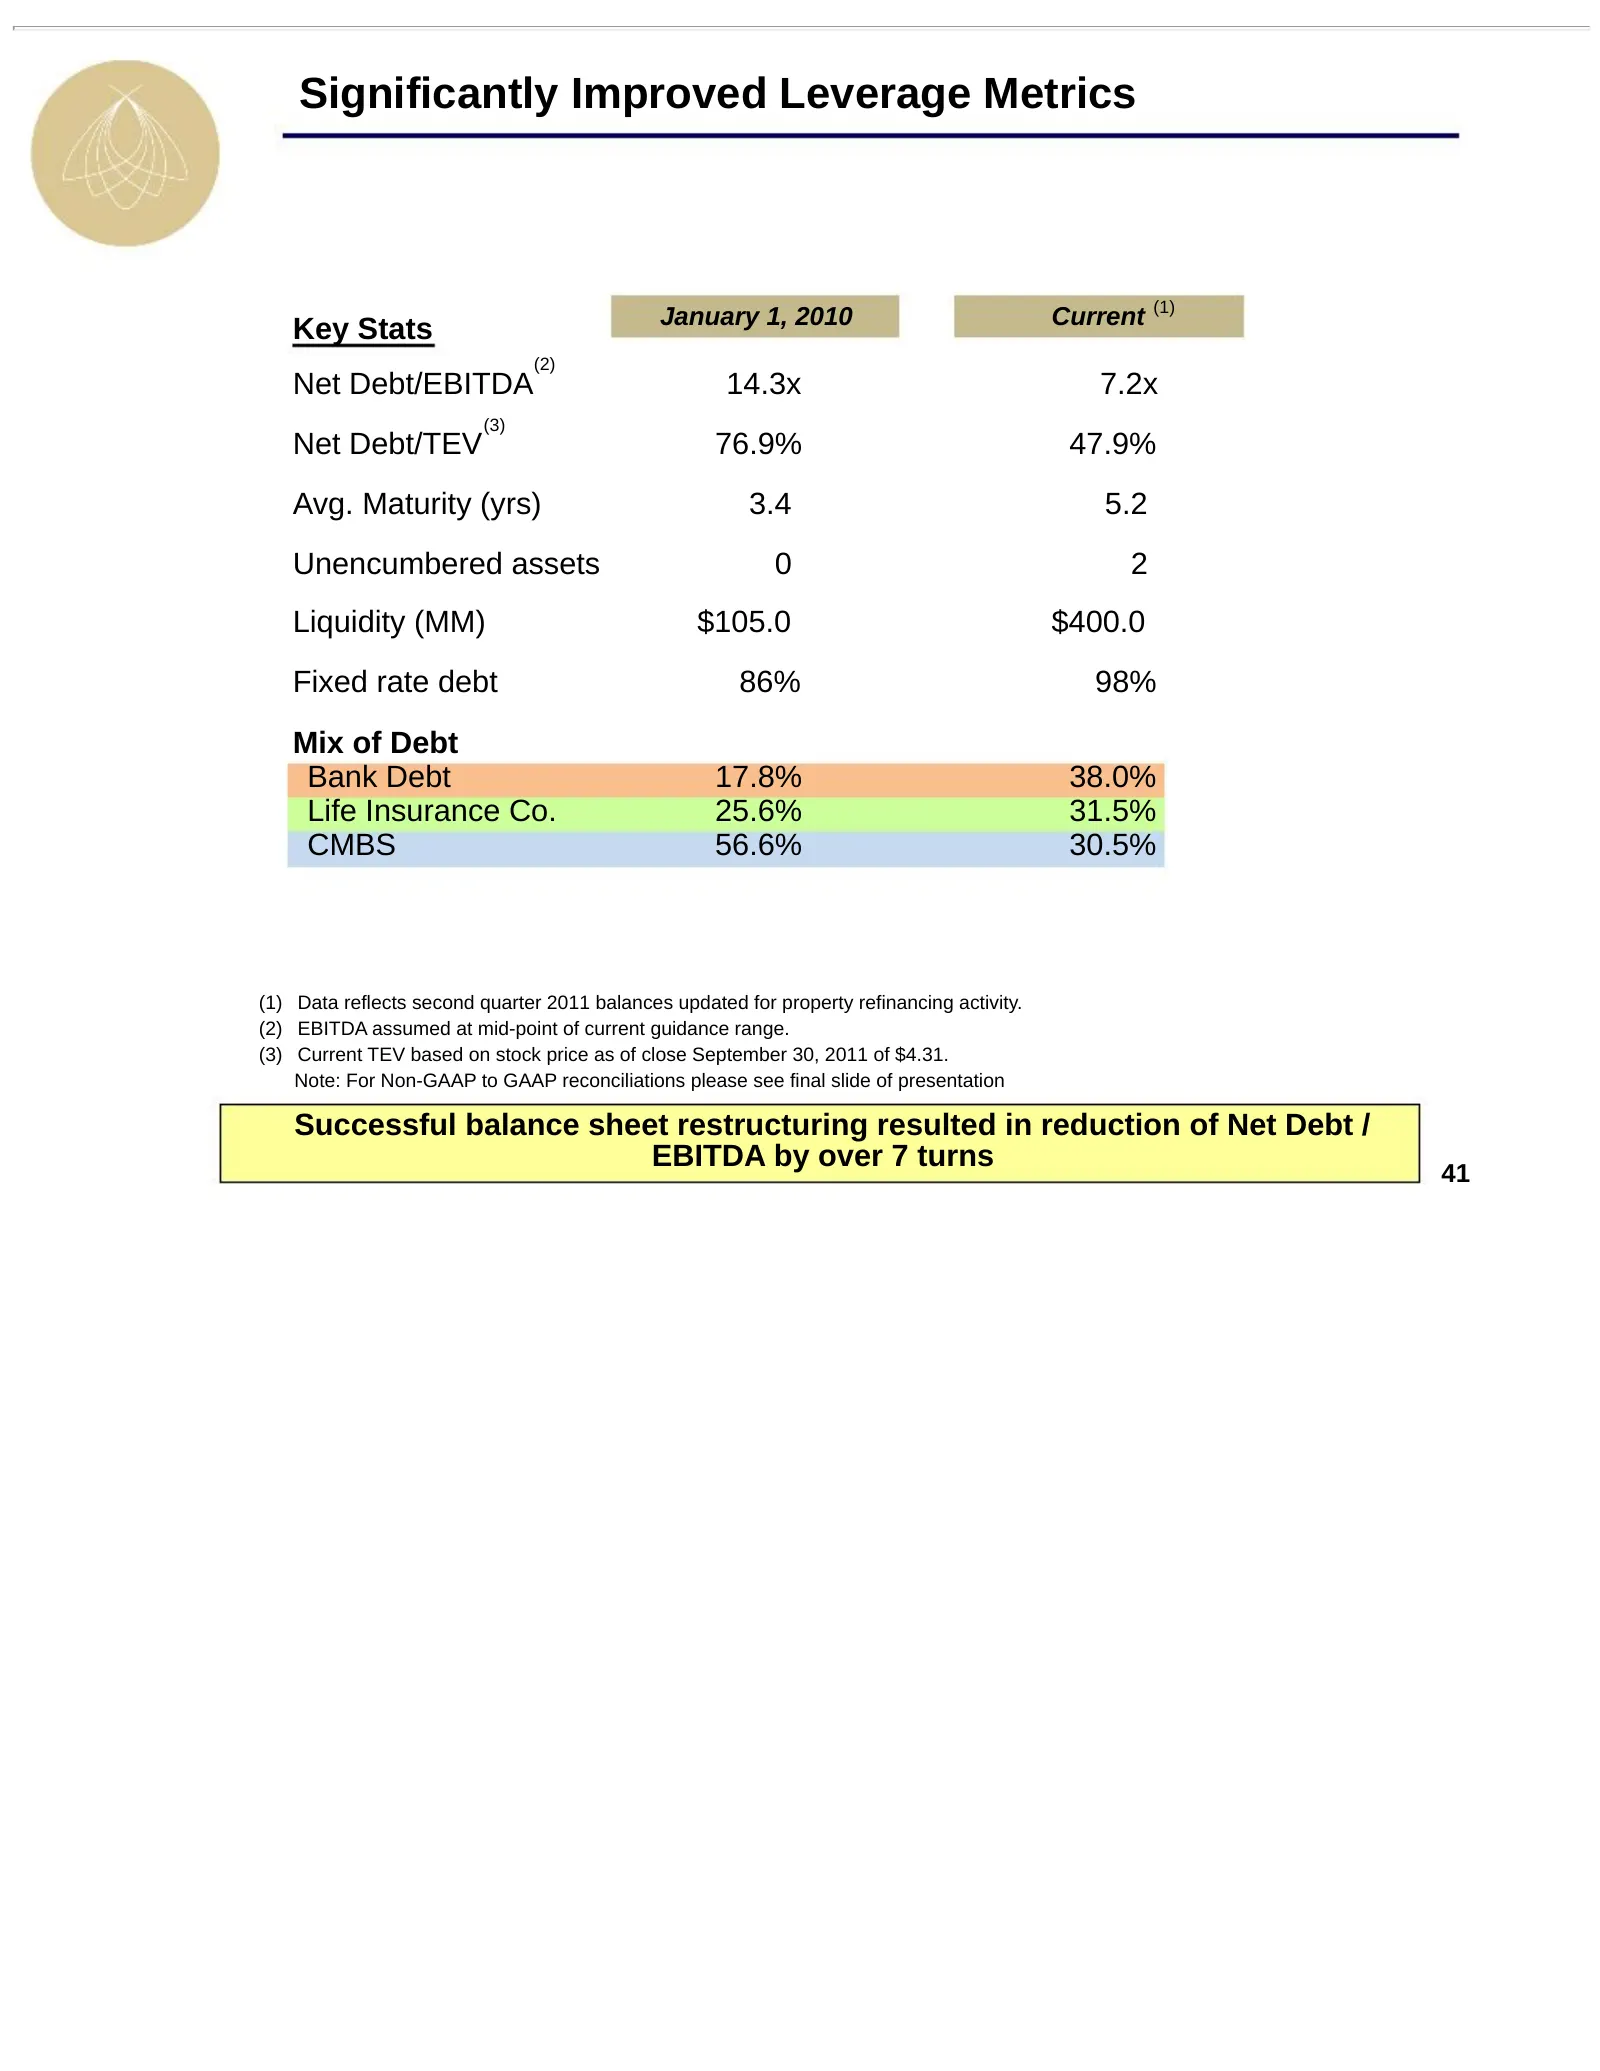
Slide 41: Significantly Improved Leverage Metrics
Significantly Improved Leverage Metrics January 1, 2010 Current (1) Key Stats (2) Net Debt/EBITDA 14.3x 7.2x (3) Net Debt/TEV 76.9% 47.9% Avg. Maturity (yrs) 3.4 5.2 Unencumbered assets 0 2 Liquidity (MM) $105.0 $400.0 Fixed rate debt 86% 98% Mix of Debt Bank Debt 17.8% 38.0% Life Insurance Co. 25.6
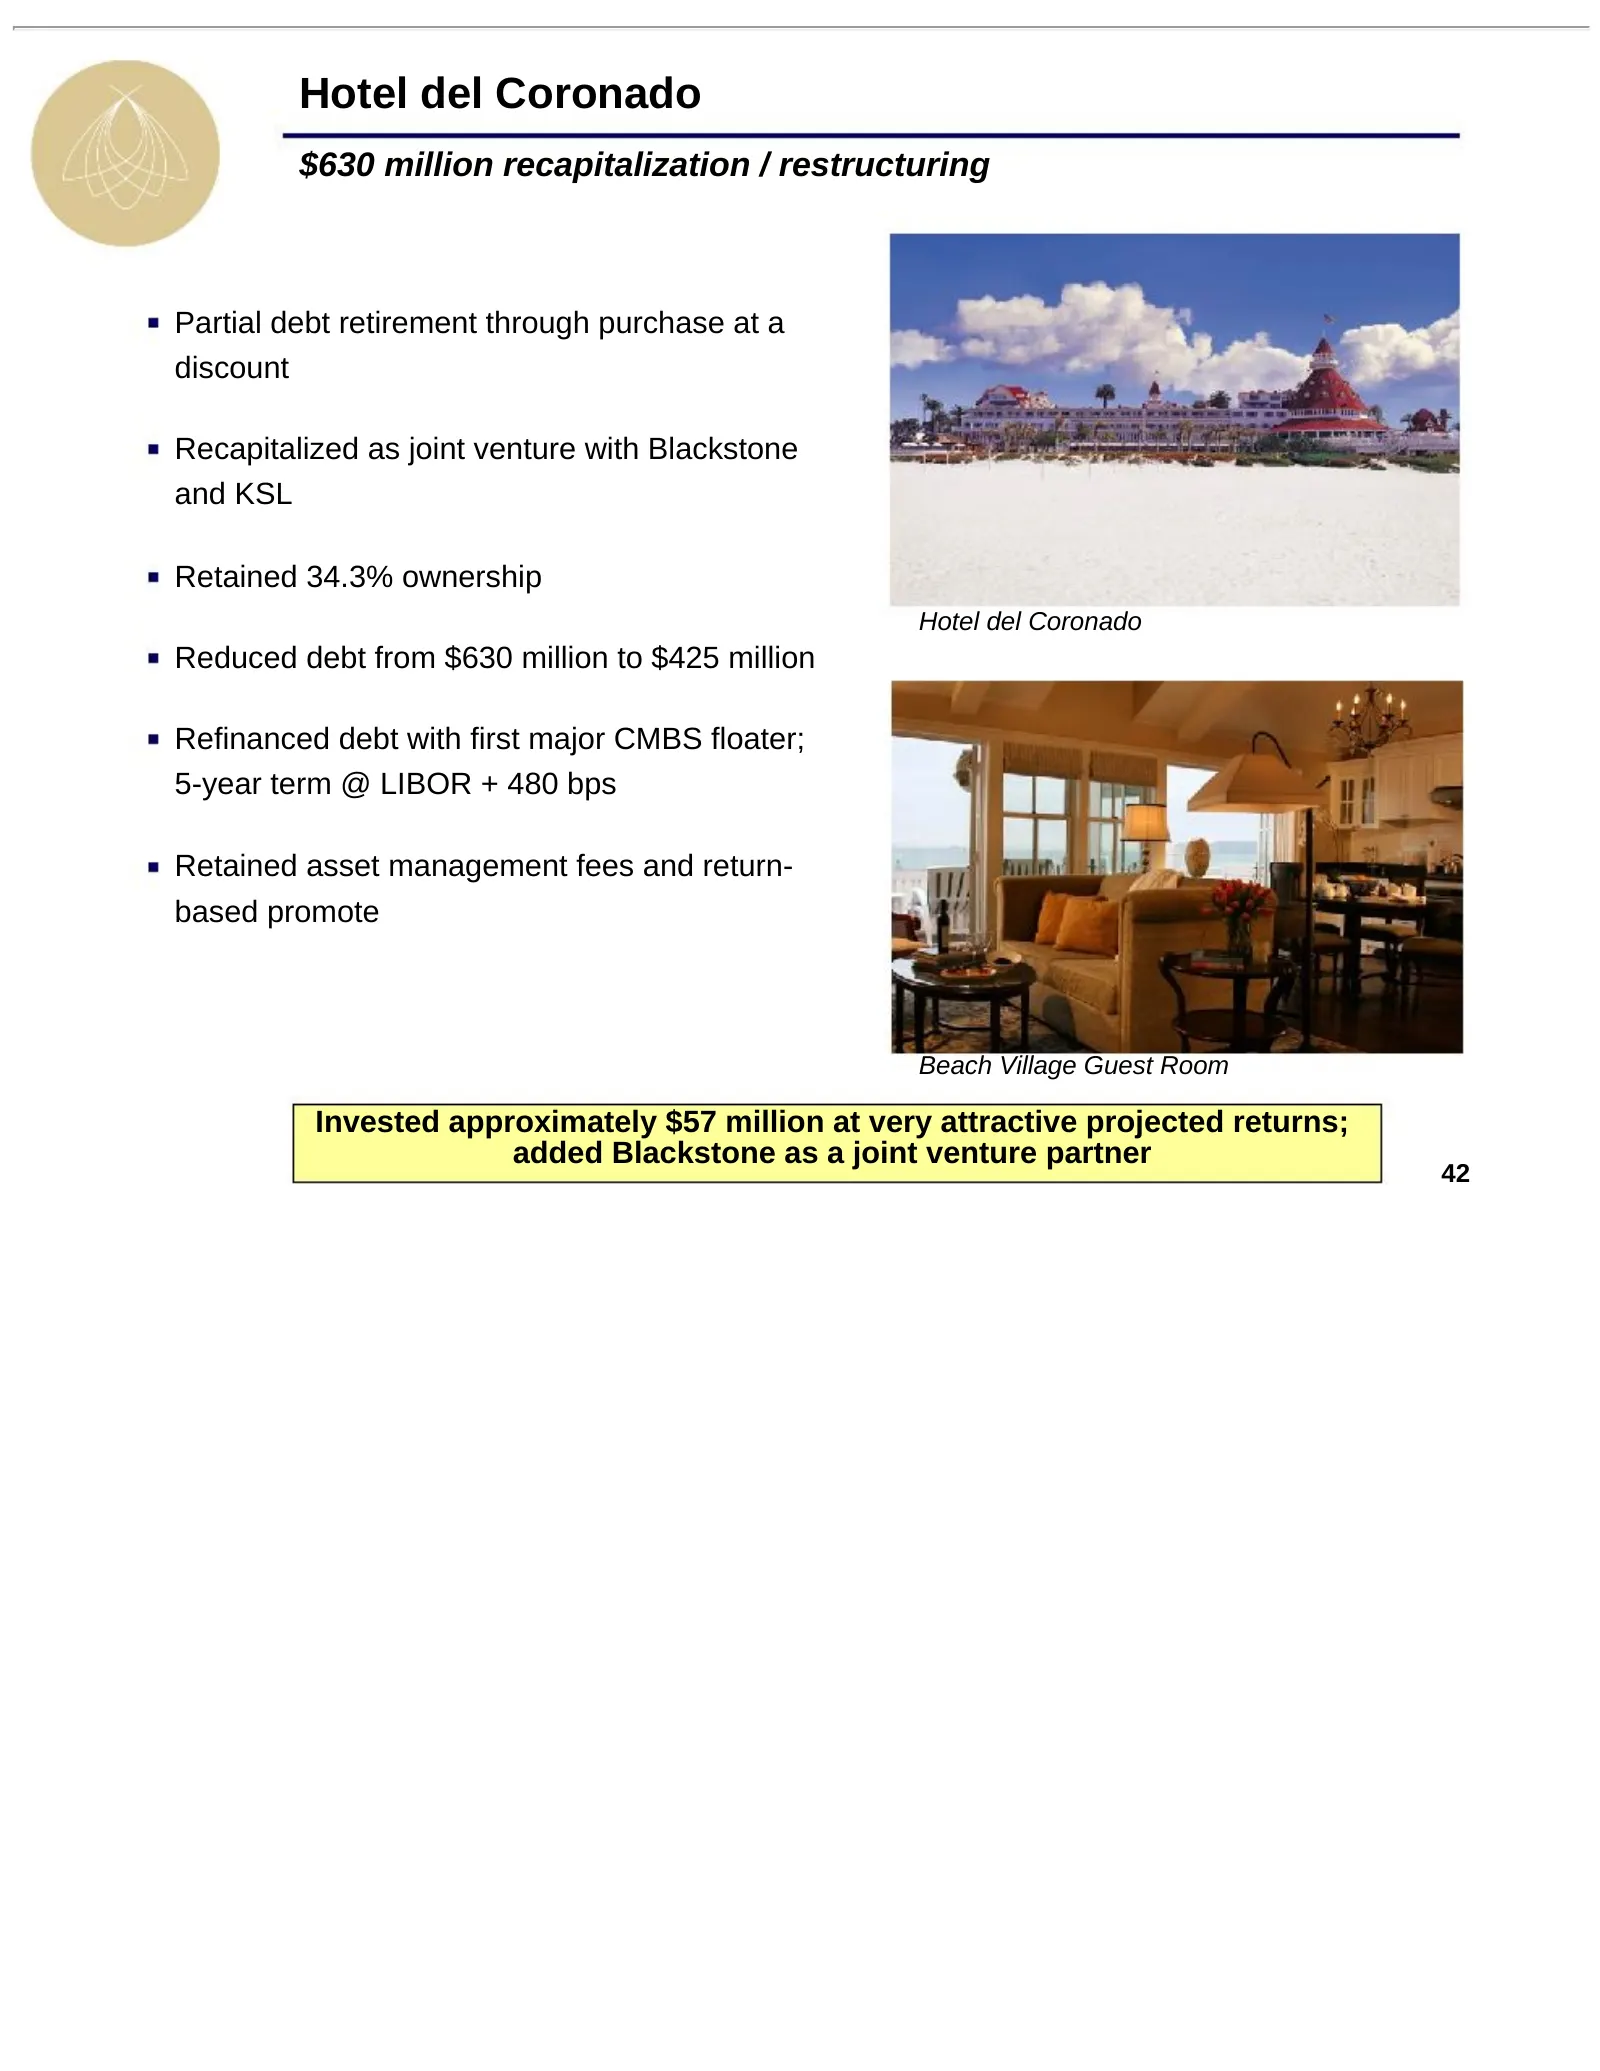
Slide 42: Hotel del Coronado
Hotel del Coronado $630 million recapitalization / restructuring Partial debt retirement through purchase at a discount Recapitalized as joint venture with Blackstone and KSL Retained 34.3% ownership Hotel del Coronado Reduced debt from $630 million to $425 million Refinanced debt with first major C
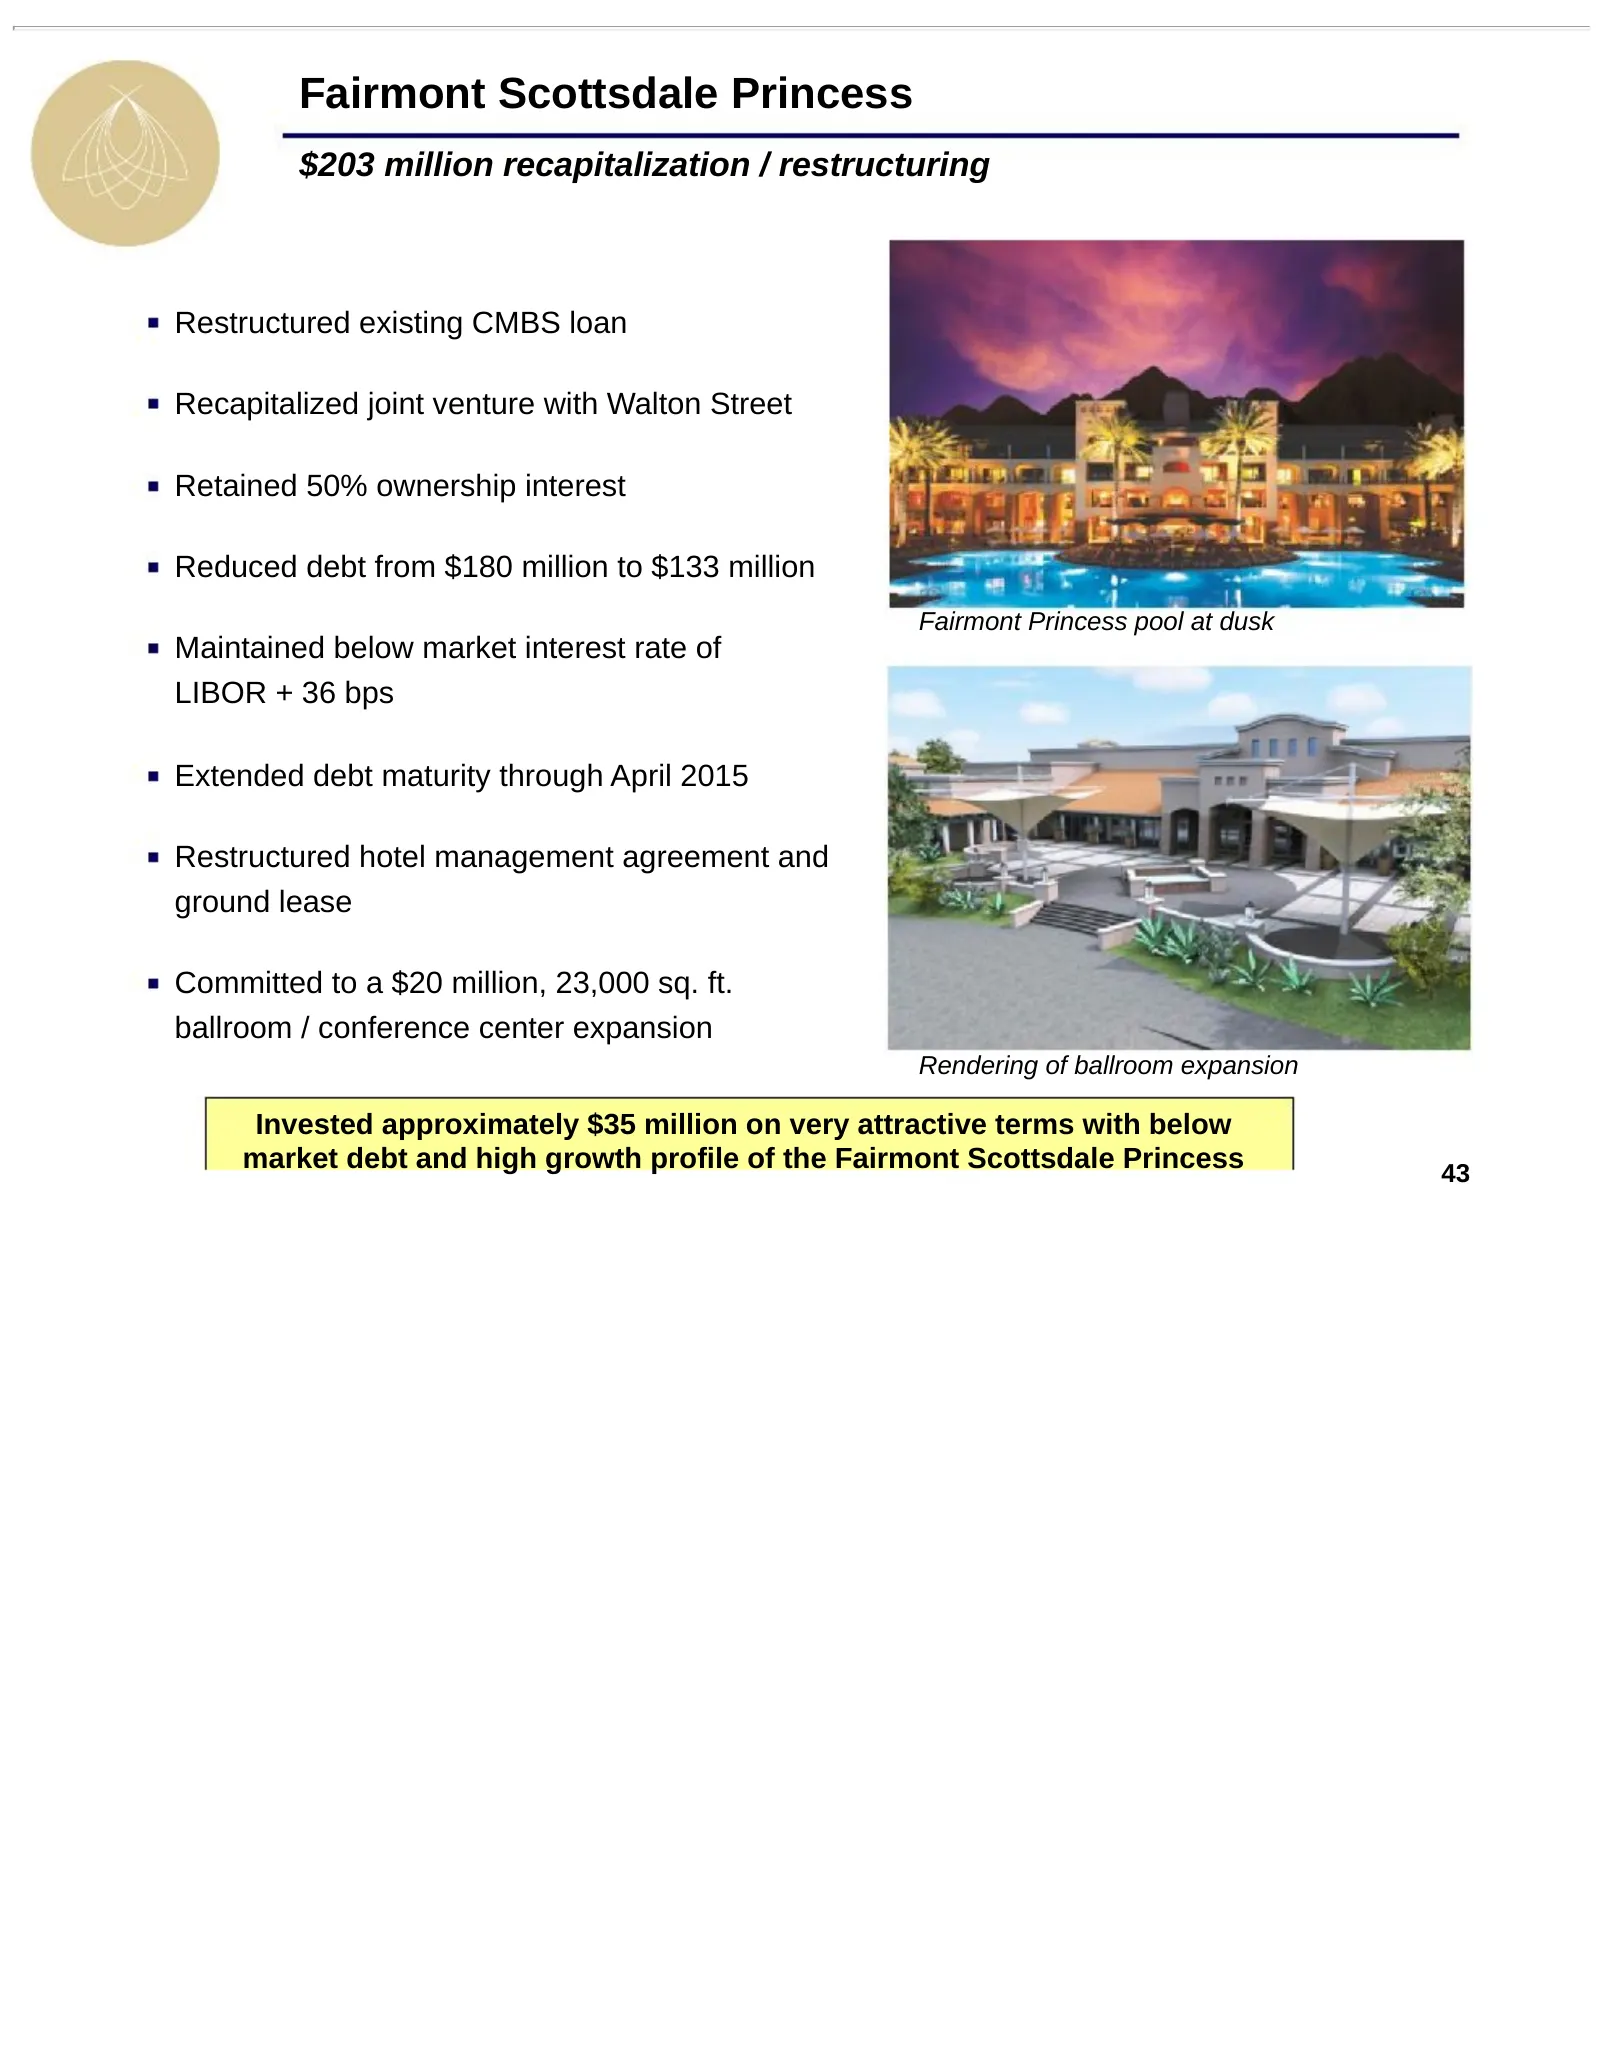
Slide 43: Fairmont Scottsdale Princess
Fairmont Scottsdale Princess $203 million recapitalization / restructuring Restructured existing CMBS loan Recapitalized joint venture with Walton Street Retained 50% ownership interest Reduced debt from $180 million to $133 million Fairmont Princess pool at dusk Maintained below market interest rat
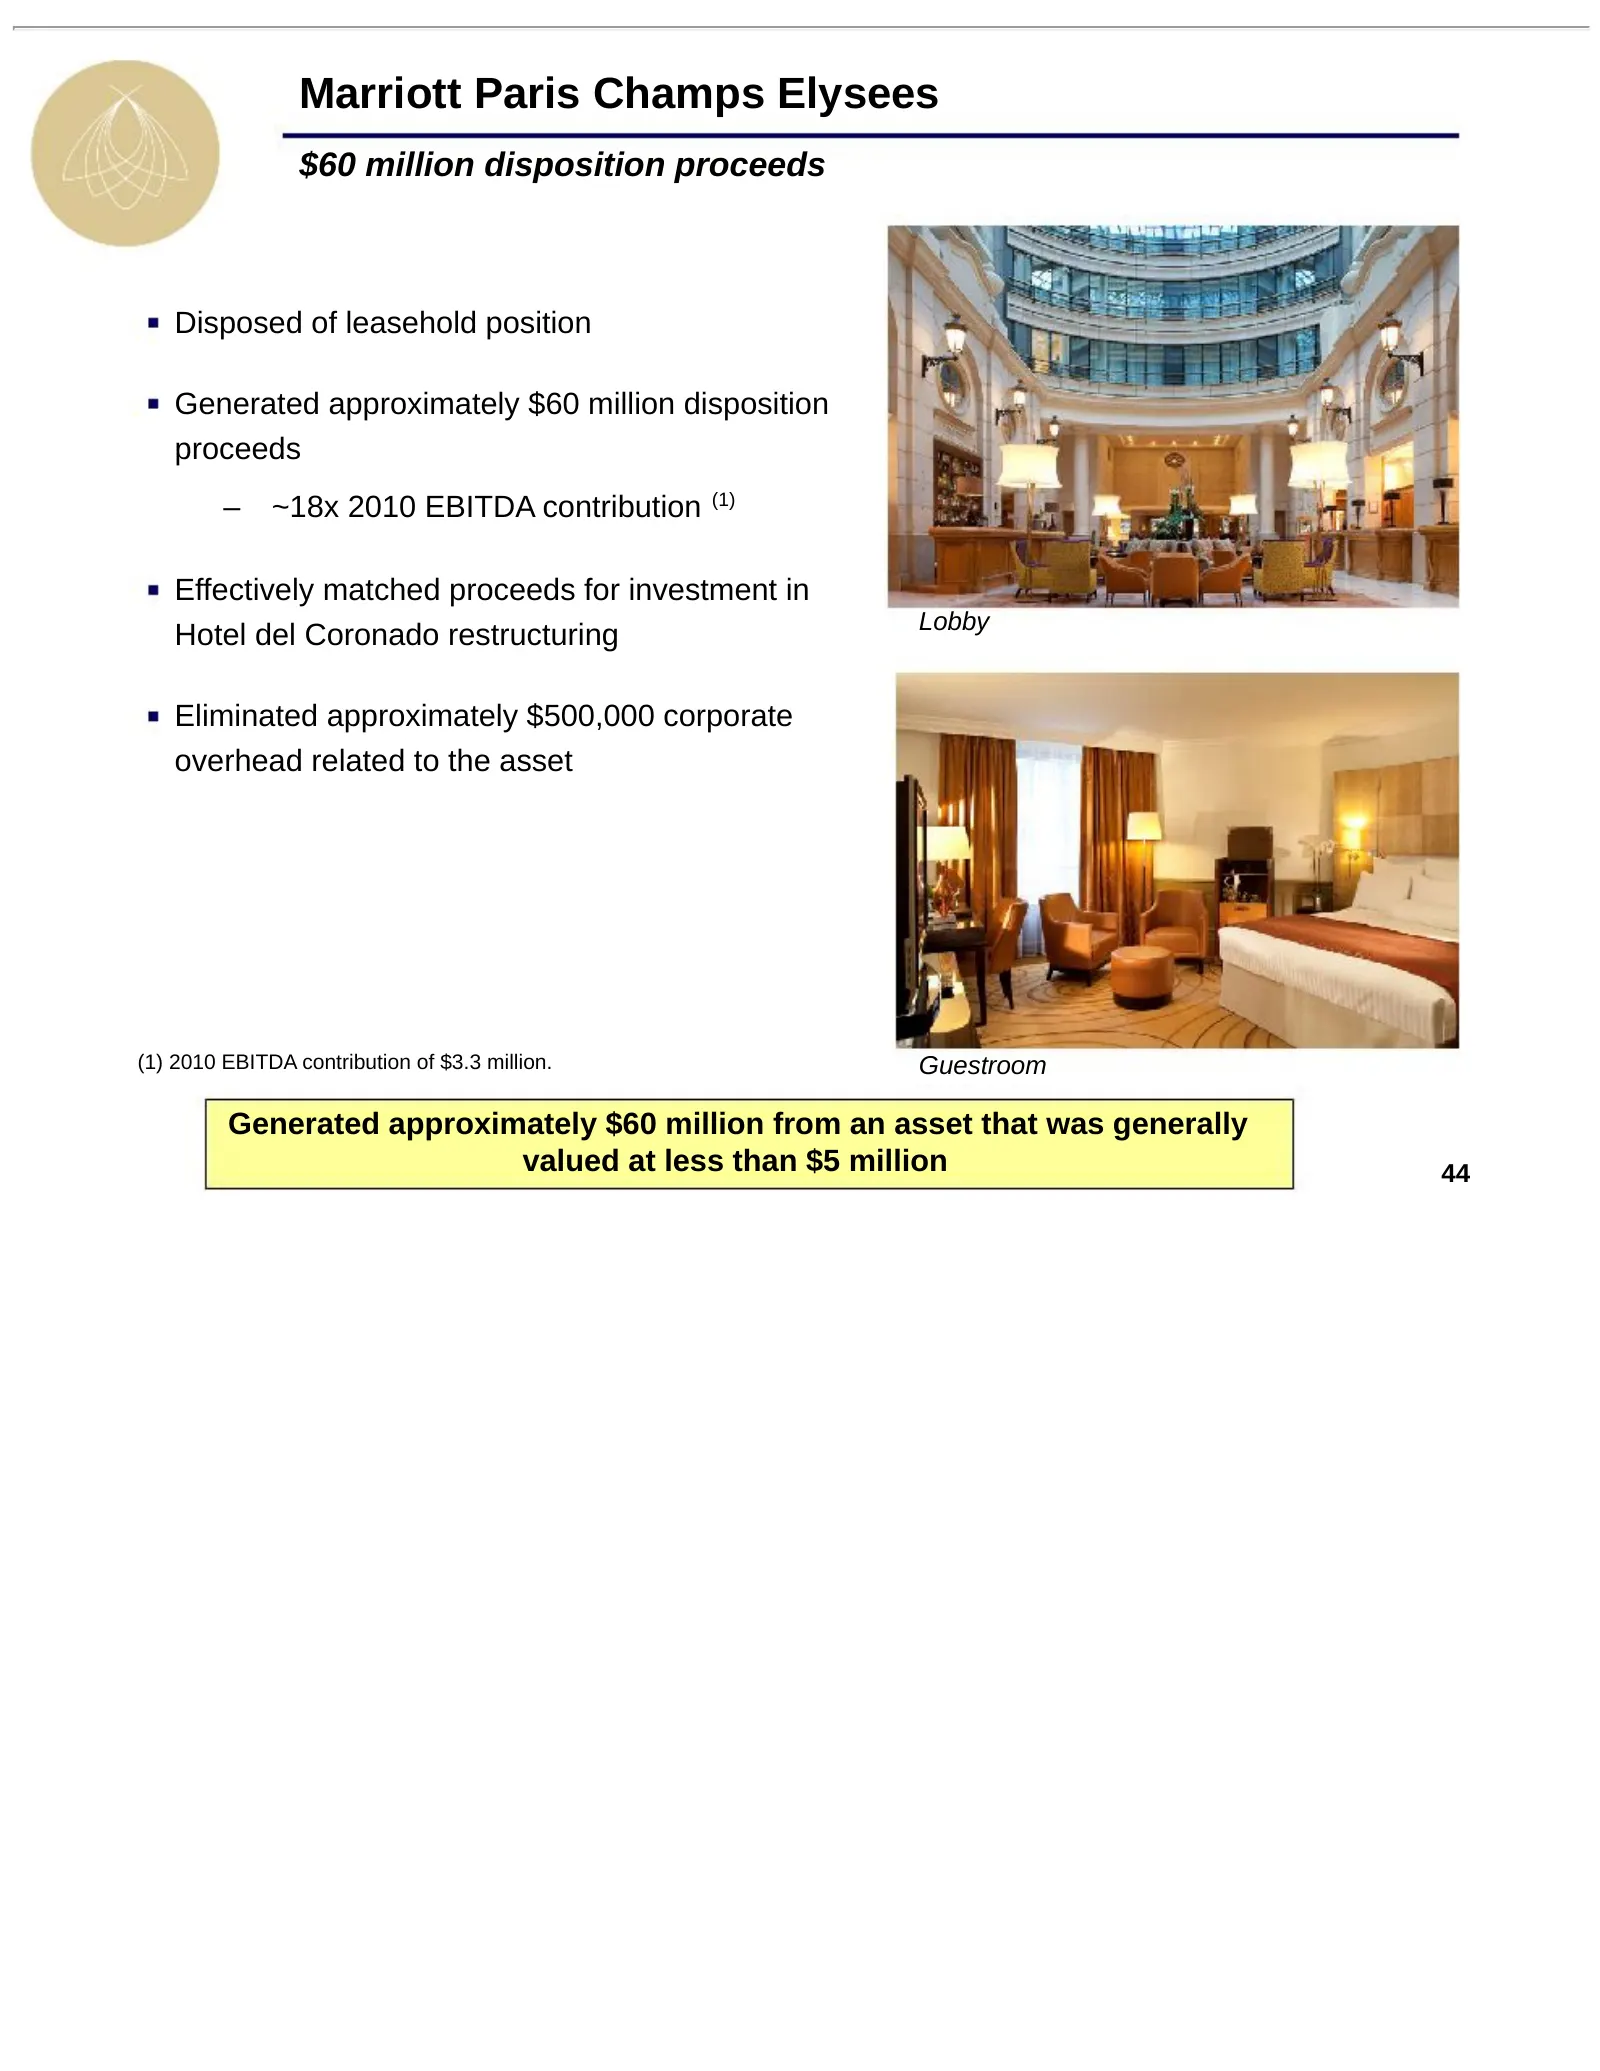
Slide 44: Marriott Paris Champs Elysees
Marriott Paris Champs Elysees $60 million disposition proceeds Disposed of leasehold position Generated approximately $60 million disposition proceeds – ~18x 2010 EBITDA contribution (1) Effectively matched proceeds for investment in Lobby Hotel del Coronado restructuring Eliminated approximately $5
Slide 45: Four Seasons / Woodbridge Transaction
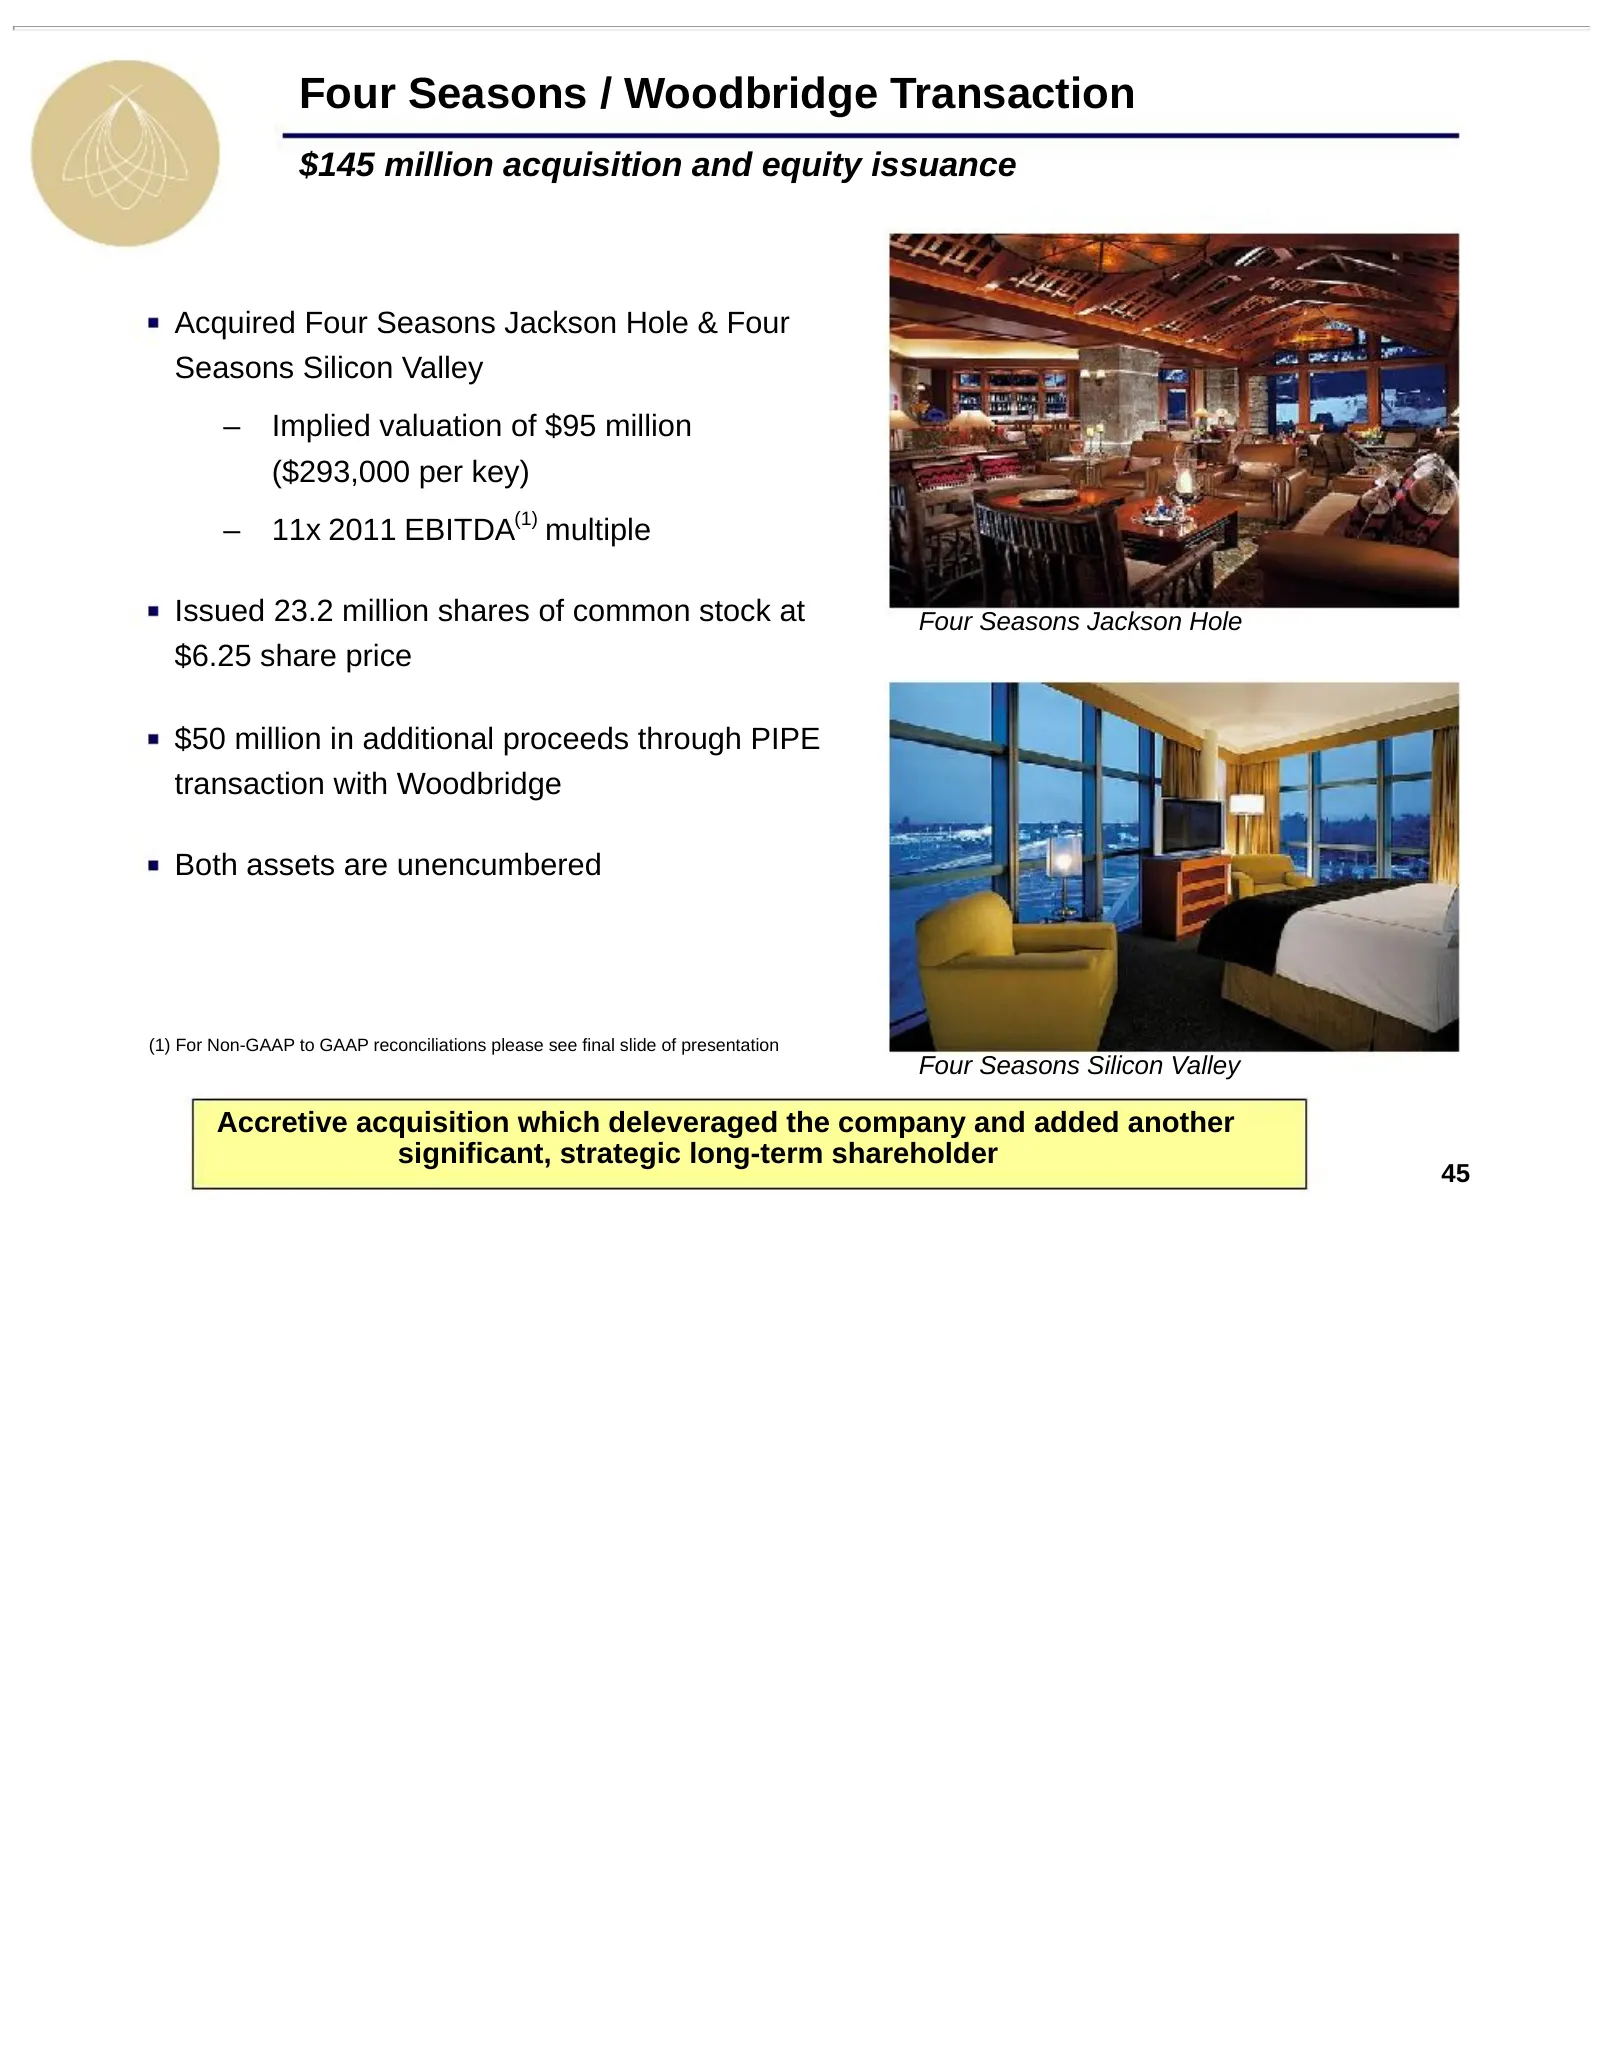
Four Seasons / Woodbridge Transaction $145 million acquisition and equity issuance Acquired Four Seasons Jackson Hole & Four Seasons Silicon Valley – Implied valuation of $95 million ($293,000 per key) – 11x 2011 EBITDA(1) multiple Issued 23.2 million shares of common stock at Four Seasons Jackson H
Slide 46: InterContinental Chicago / Government of Singapore
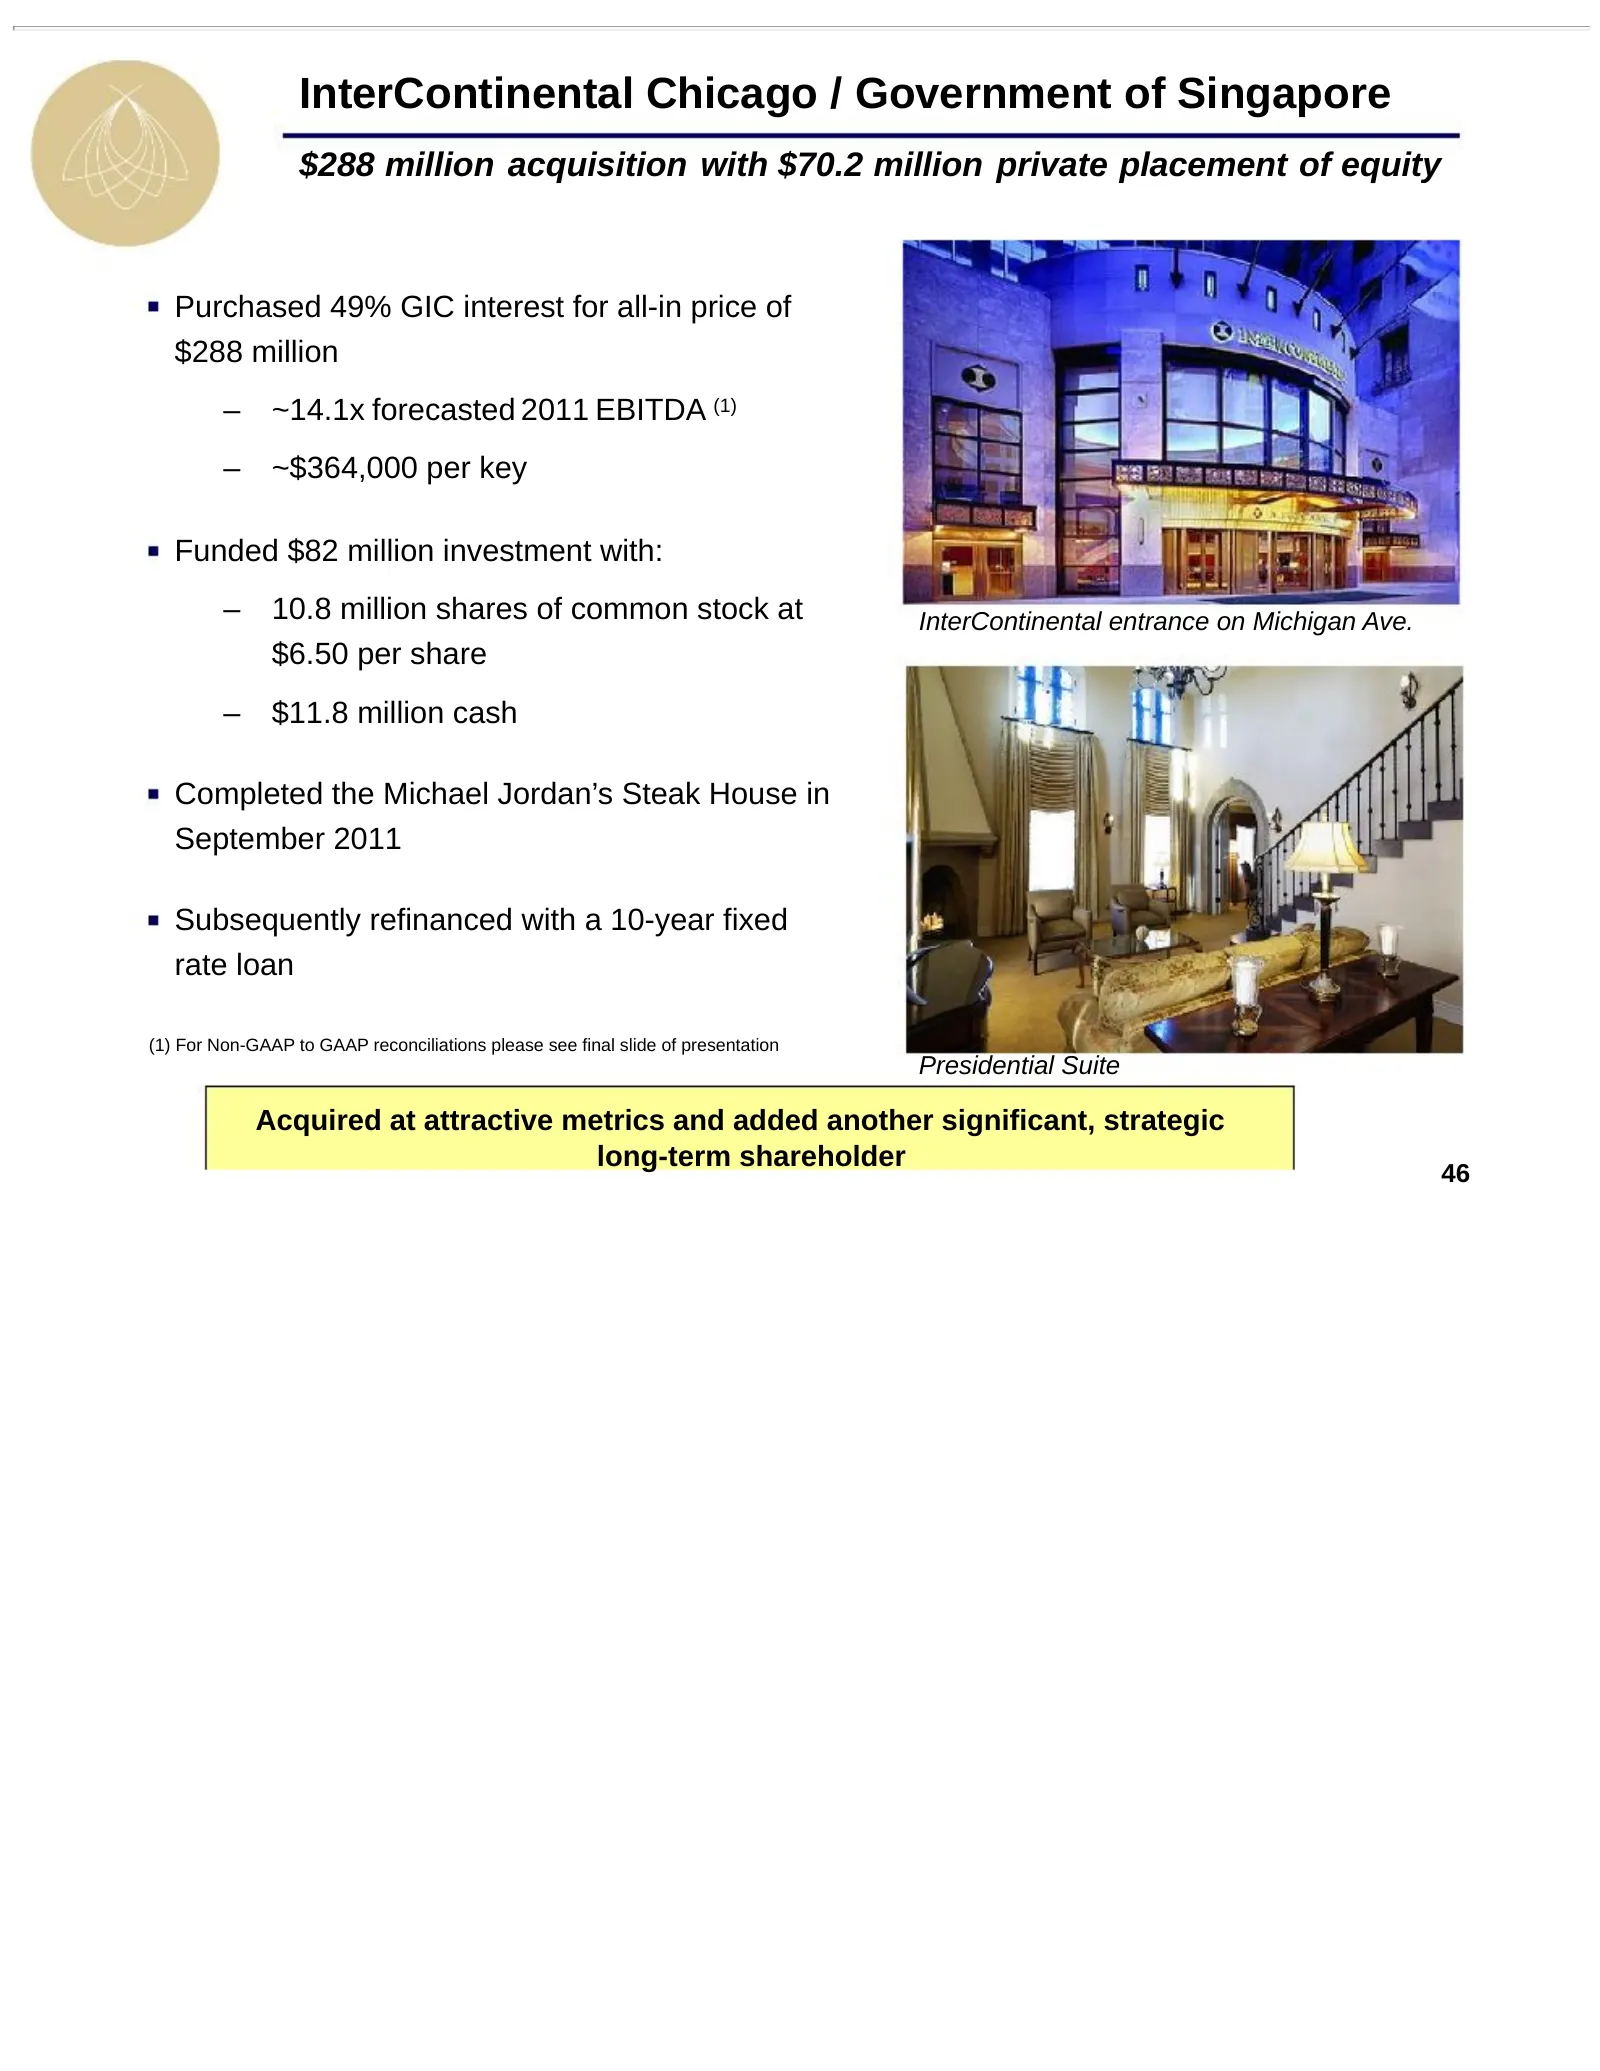
InterContinental Chicago / Government of Singapore $288 million acquisition with $70.2 million private placement of equity Purchased 49% GIC interest for all-in price of $288 million – ~14.1x forecasted 2011 EBITDA (1) – ~$364,000 per key Funded $82 million investment with: – 10.8 million shares of
Slide 47: Line of Credit Refinancing
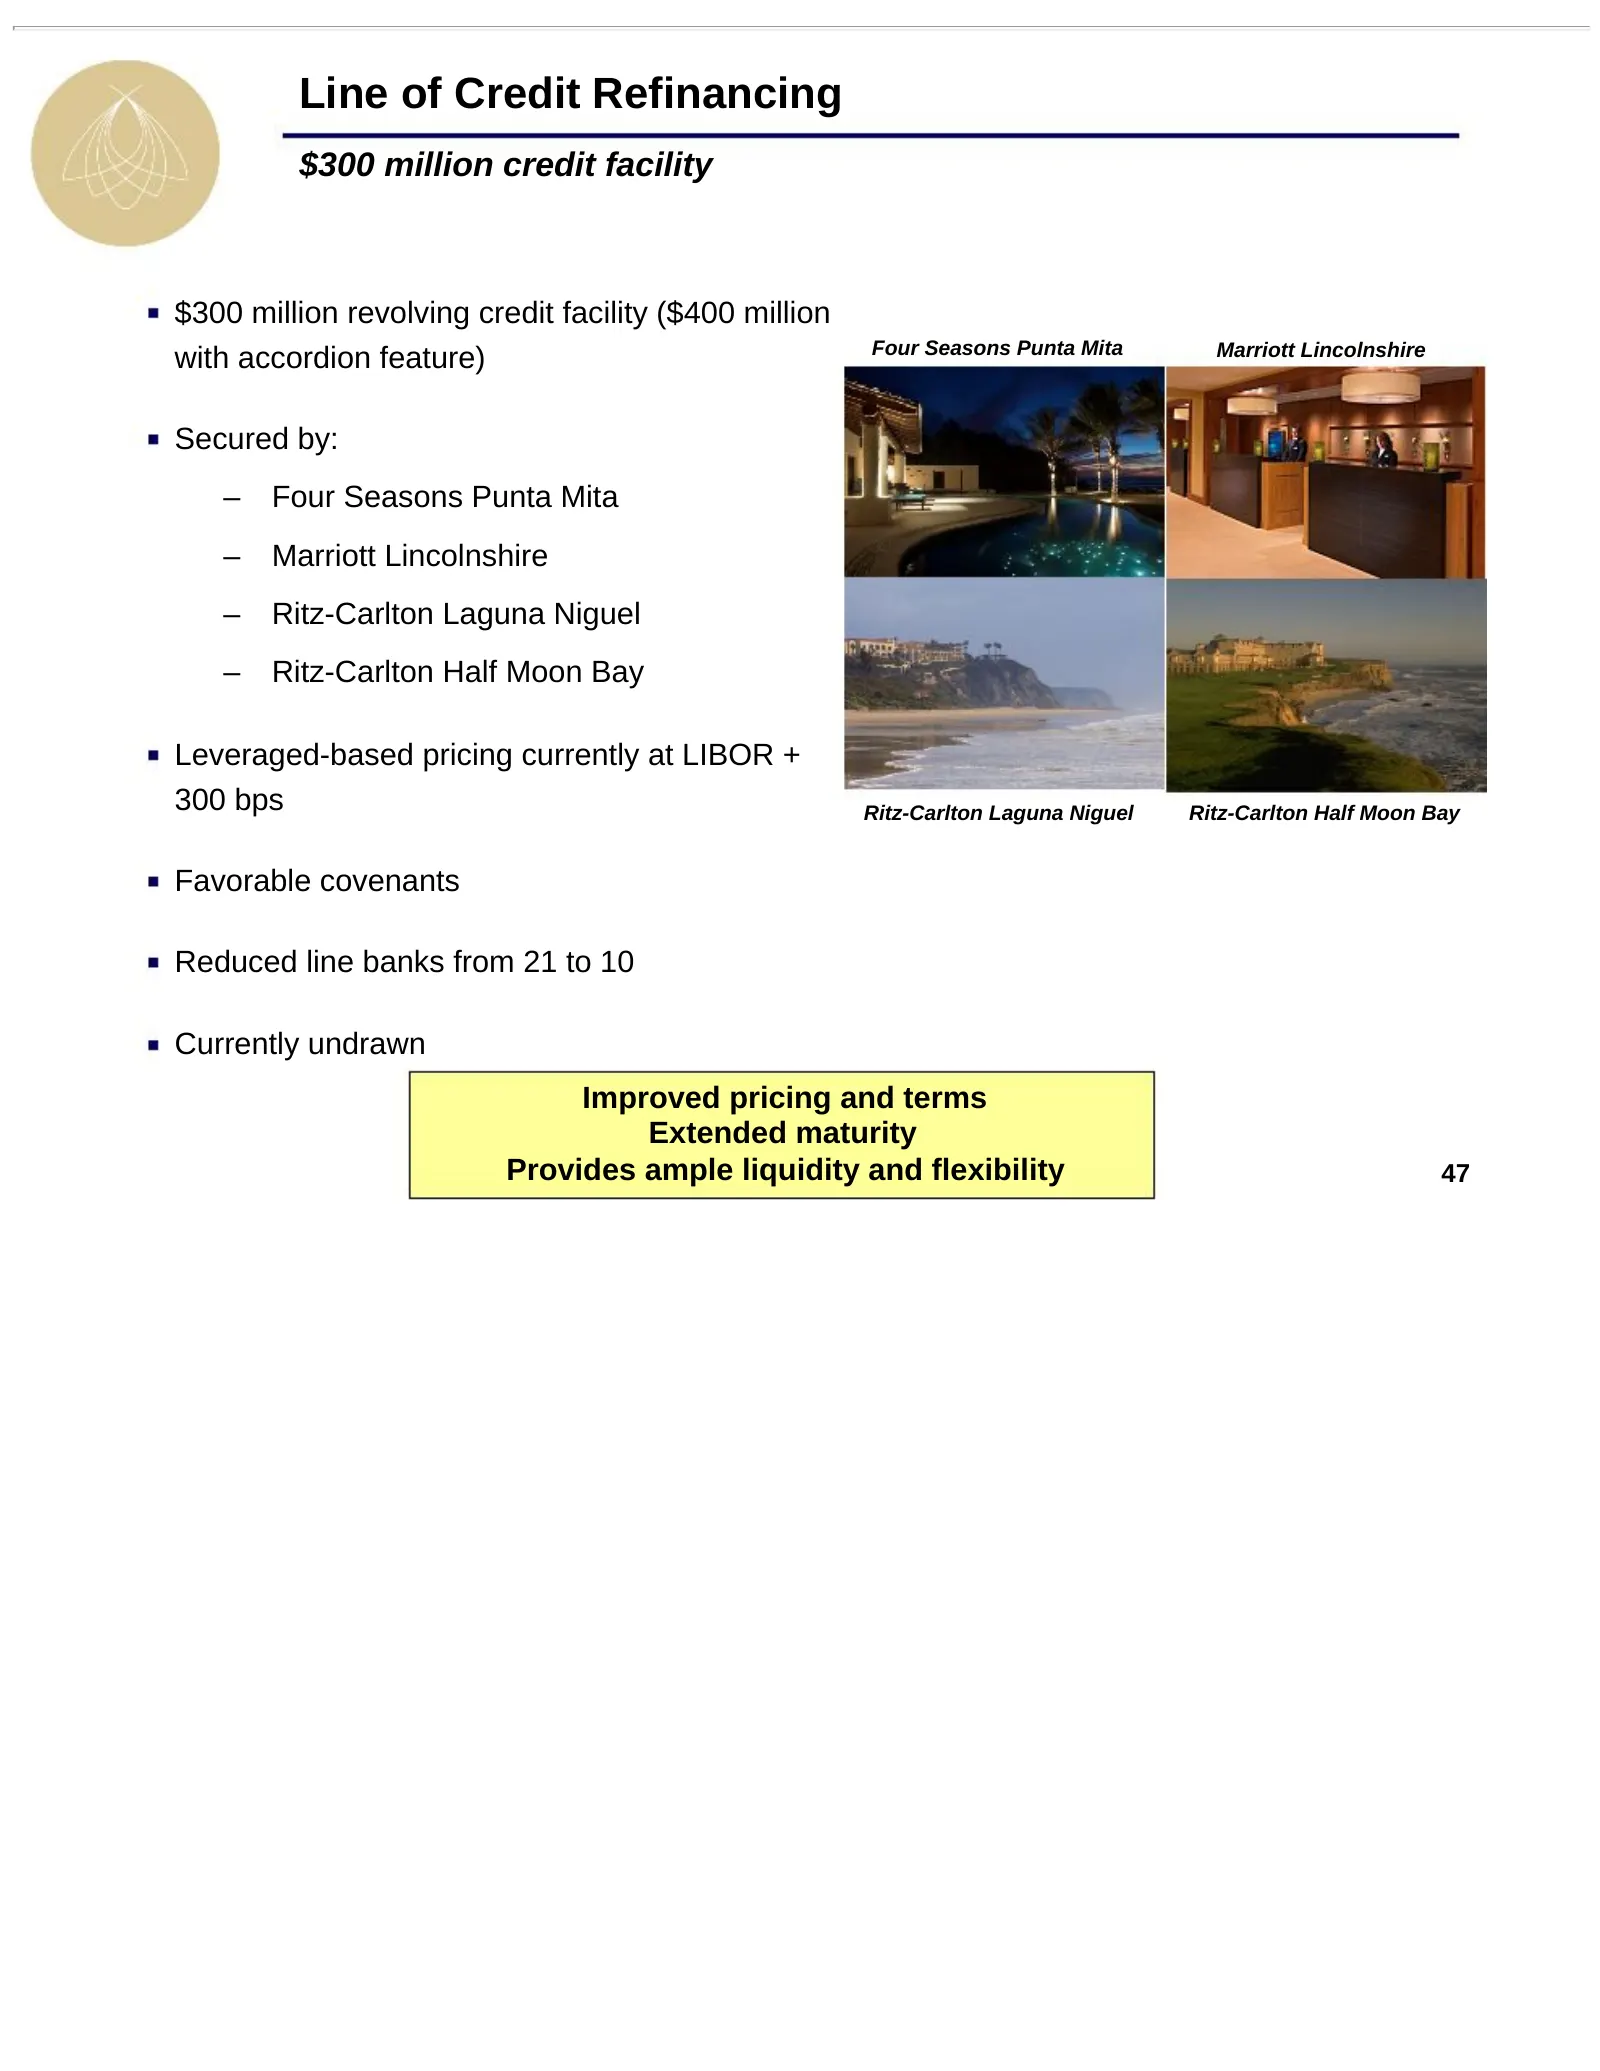
Line of Credit Refinancing $300 million credit facility $300 million revolving credit facility ($400 million Four Seasons Punta Mita Marriott Lincolnshire with accordion feature) Secured by: – Four Seasons Punta Mita – Marriott Lincolnshire – Ritz-Carlton Laguna Niguel – Ritz-Carlton Half Moon Bay L
Slide 48: Property Level Debt Financings
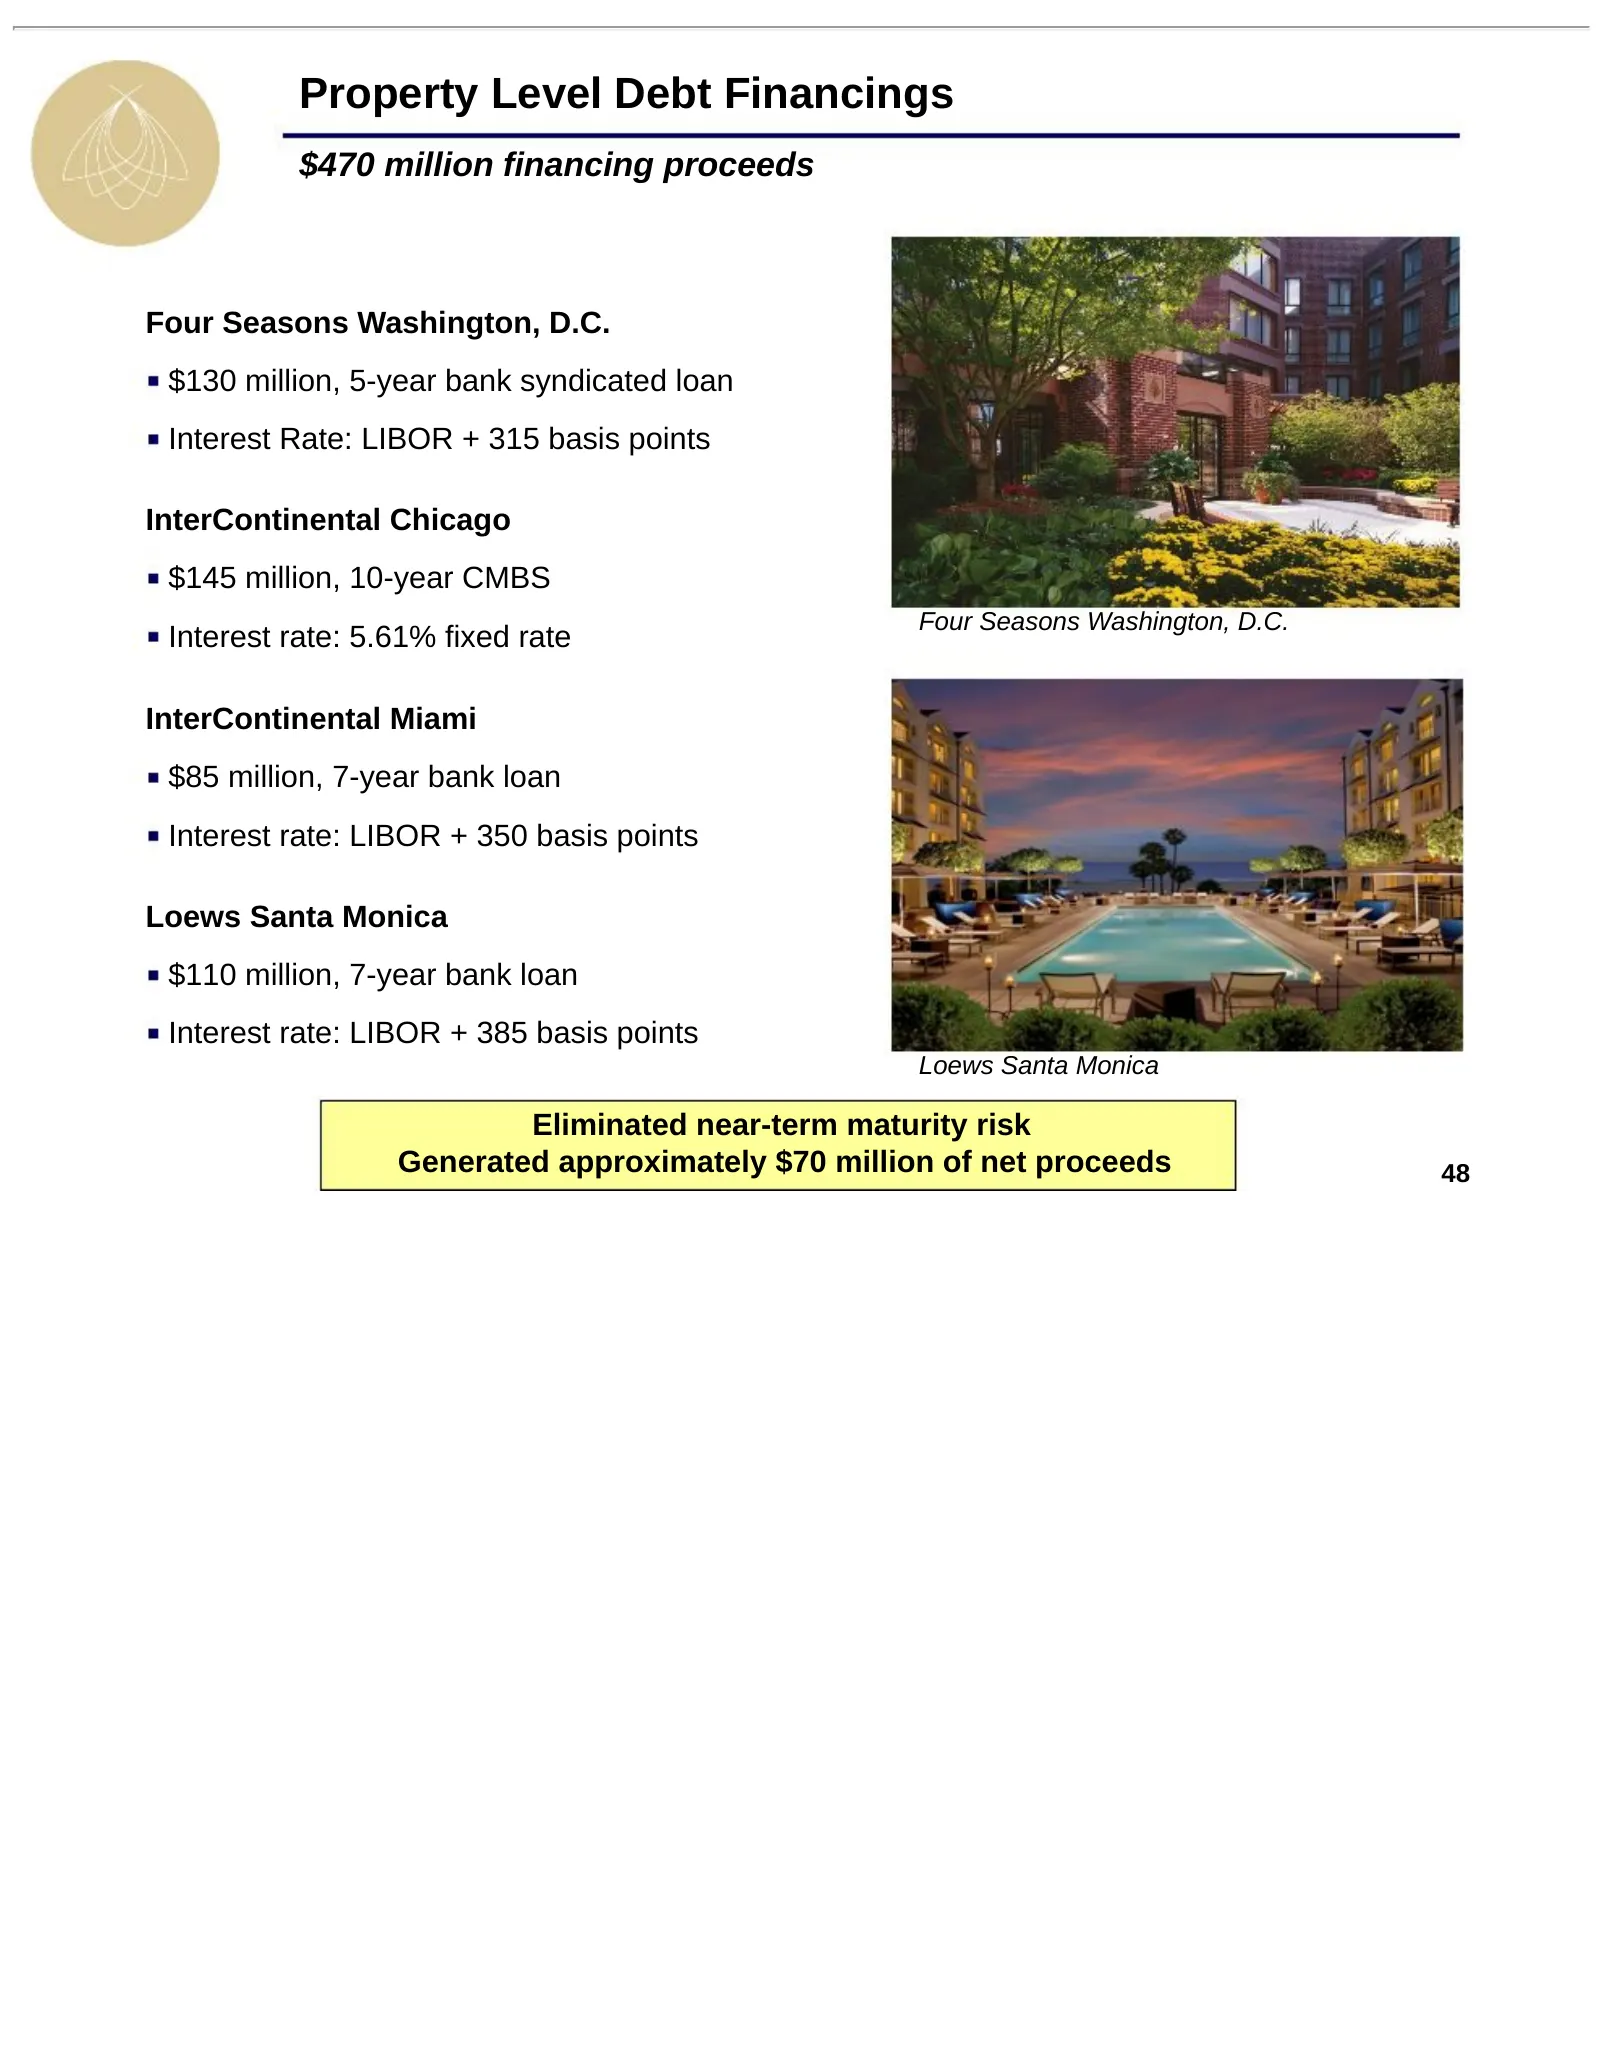
Property Level Debt Financings $470 million financing proceeds Four Seasons Washington, D.C. $130 million, 5-year bank syndicated loan Interest Rate: LIBOR + 315 basis points InterContinental Chicago $145 million, 10-year CMBS Four Seasons Washington, D.C. Interest rate: 5.61% fixed rate InterContin
Slide 49: Summary of Results – Debt Refinancing Strategy
Summary of Results – Debt Refinancing Strategy Completed accelerated refinancing of all 2011 and 2012 maturities Executed highly complicated CMBS restructurings for the Hotel del Coronado and Fairmont Scottsdale Princess Effectively staggered debt maturities; managed fixed rate vs. floating rate mix
Slide 50: Preferred Equity Dividend
Preferred Equity Dividend Accrued preferred dividend approximately $93 million by year-end 2011 Approximately $400 million corporate liquidity at year-end 2011 (excluding financeable unencumbered assets) Currently able to pay accrued preferred dividend under line of credit covenants Payment of accru
Slide 51: Agenda
Agenda I. BEE’s Unique Value Proposition II. Macroeconomic and Industry Update III. Company Overview IV. Organic Growth and ROI Opportunities V. Balance Sheet Recapitalization VI. Financial Results and Guidance 51
Slide 52: Strong First Half 2011 Results
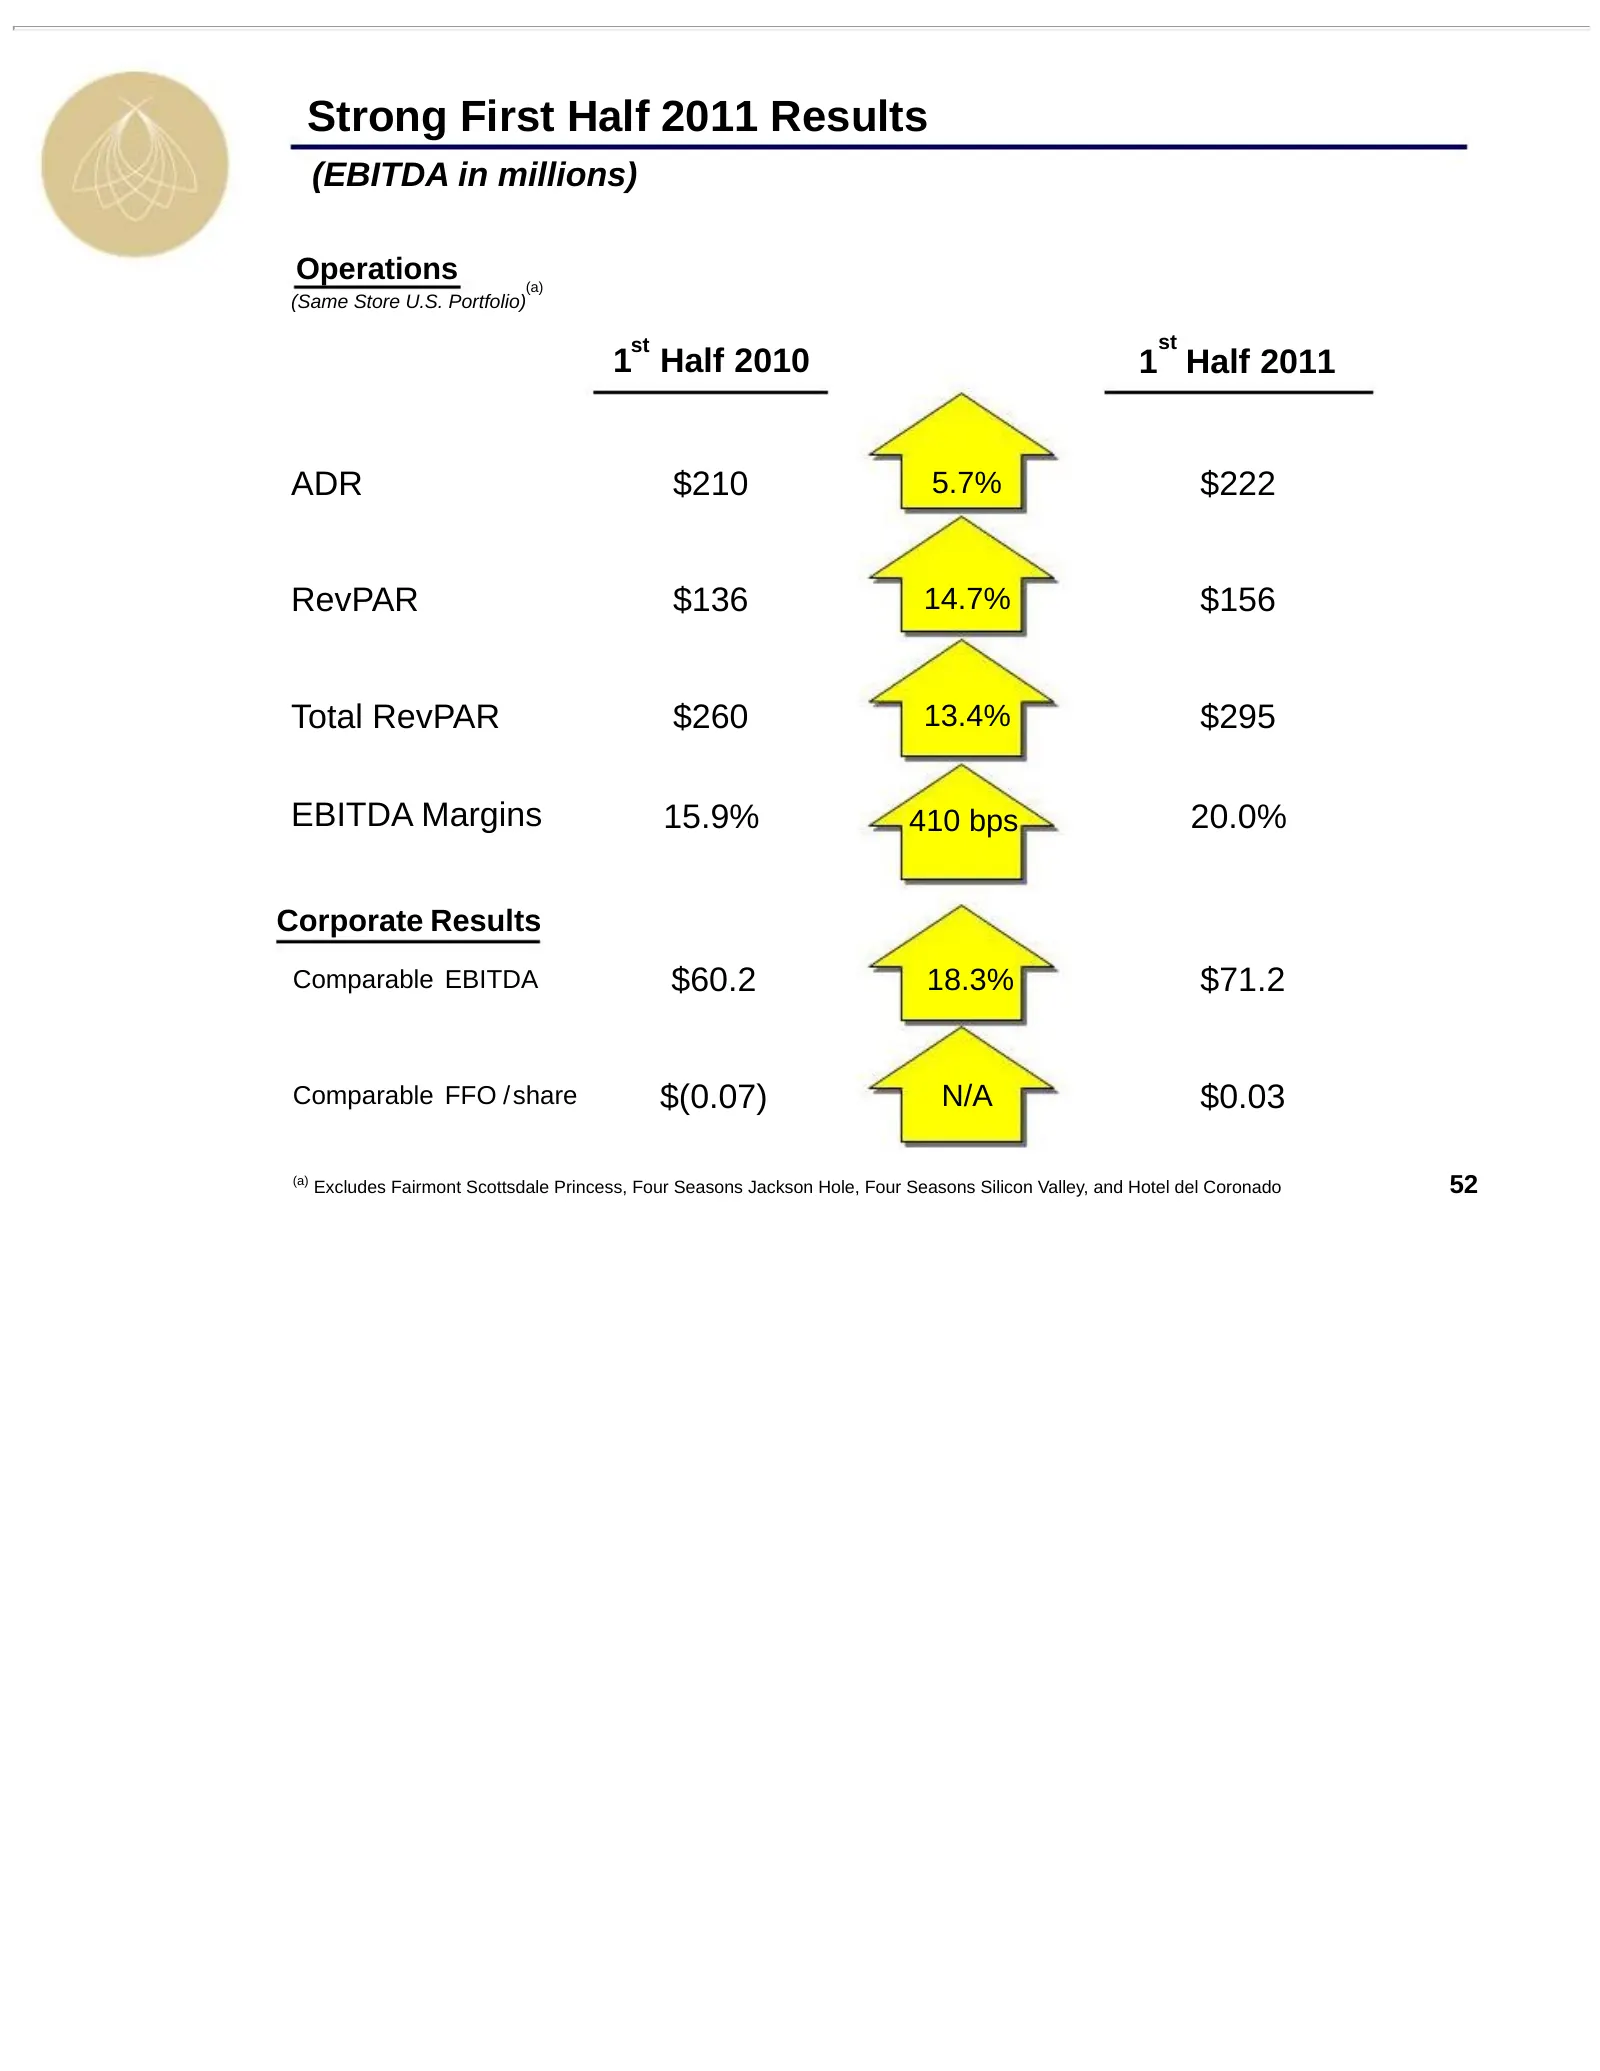
Strong First Half 2011 Results (EBITDA in millions) Operations (a) (Same Store U.S. Portfolio) st st 1 Half 2010 1 Half 2011 ADR $210 5.7% $222 RevPAR $136 14.7% $156 Total RevPAR $260 13.4% $295 EBITDA Margins 15.9% 410 bps 20.0% Corporate Results Comparable EBITDA $60.2 18.3% $71.2 Comparable FFO
Slide 53: 2011 Guidance
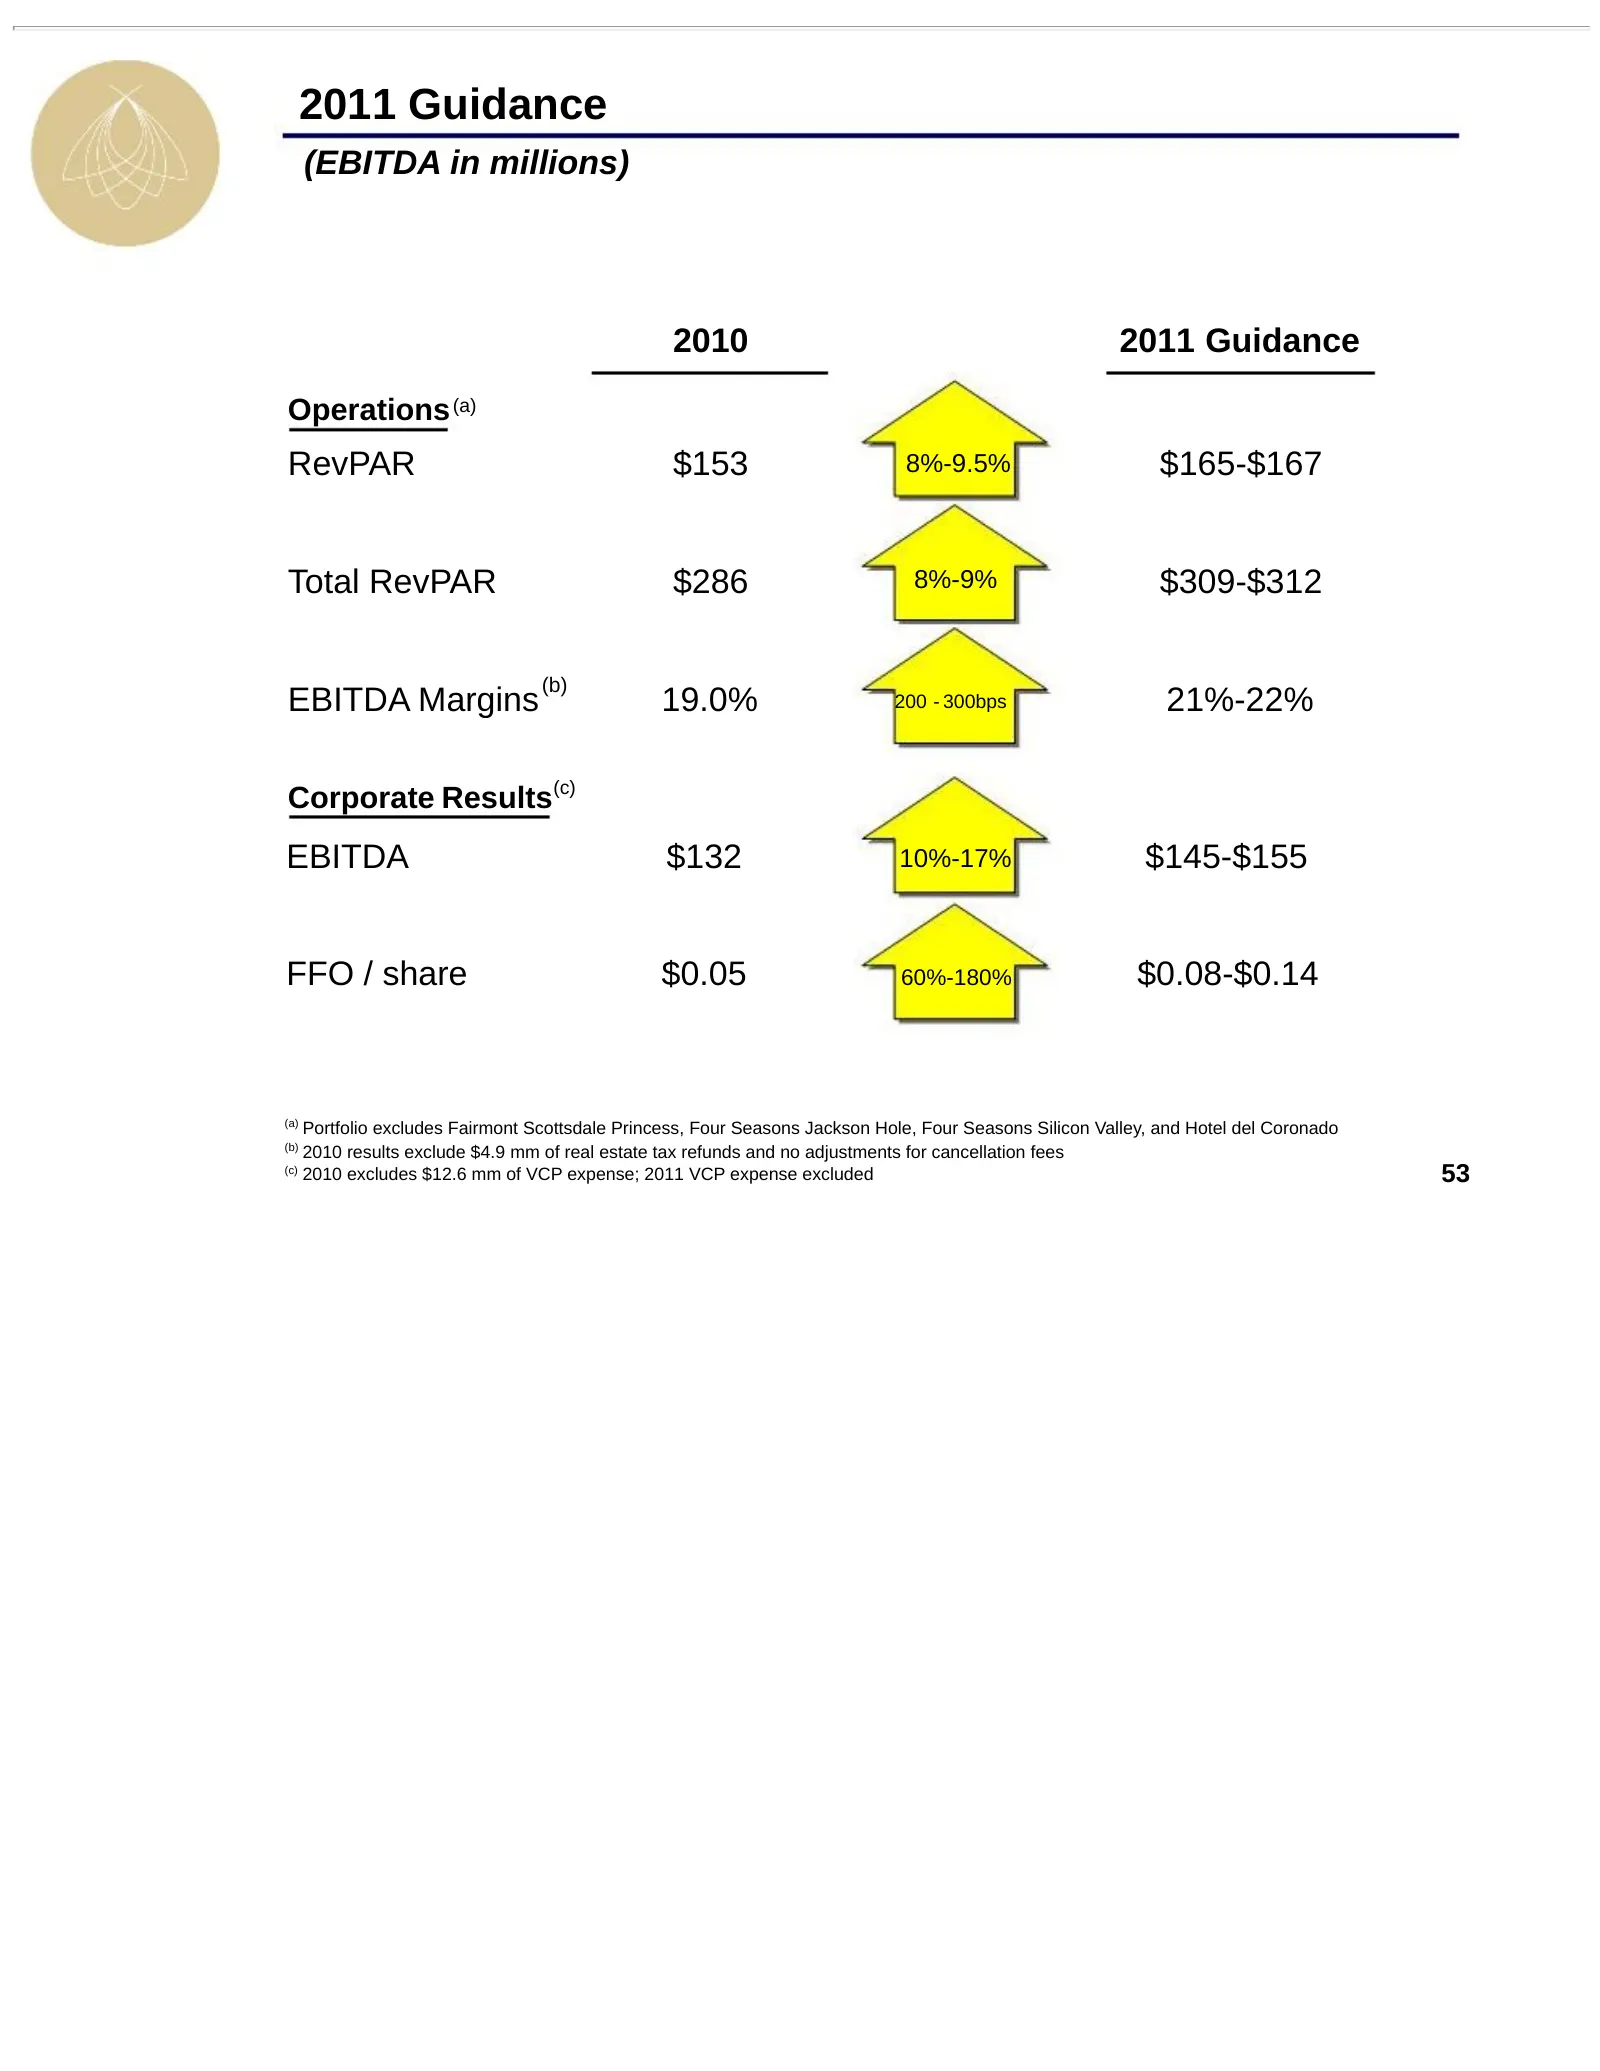
2011 Guidance (EBITDA in millions) 2010 2011 Guidance Operations (a) RevPAR $153 8%-9.5% $165-$167 Total RevPAR $286 8%-9% $309-$312 (b) EBITDA Margins 19.0% 200 - 300bps 21%-22% Corporate Results(c) EBITDA $132 10%-17% $145-$155 FFO / share $0.05 60%-180% $0.08-$0.14 (a) Portfolio excludes Fairmont
Slide 54: BEE's Unique Value Proposition
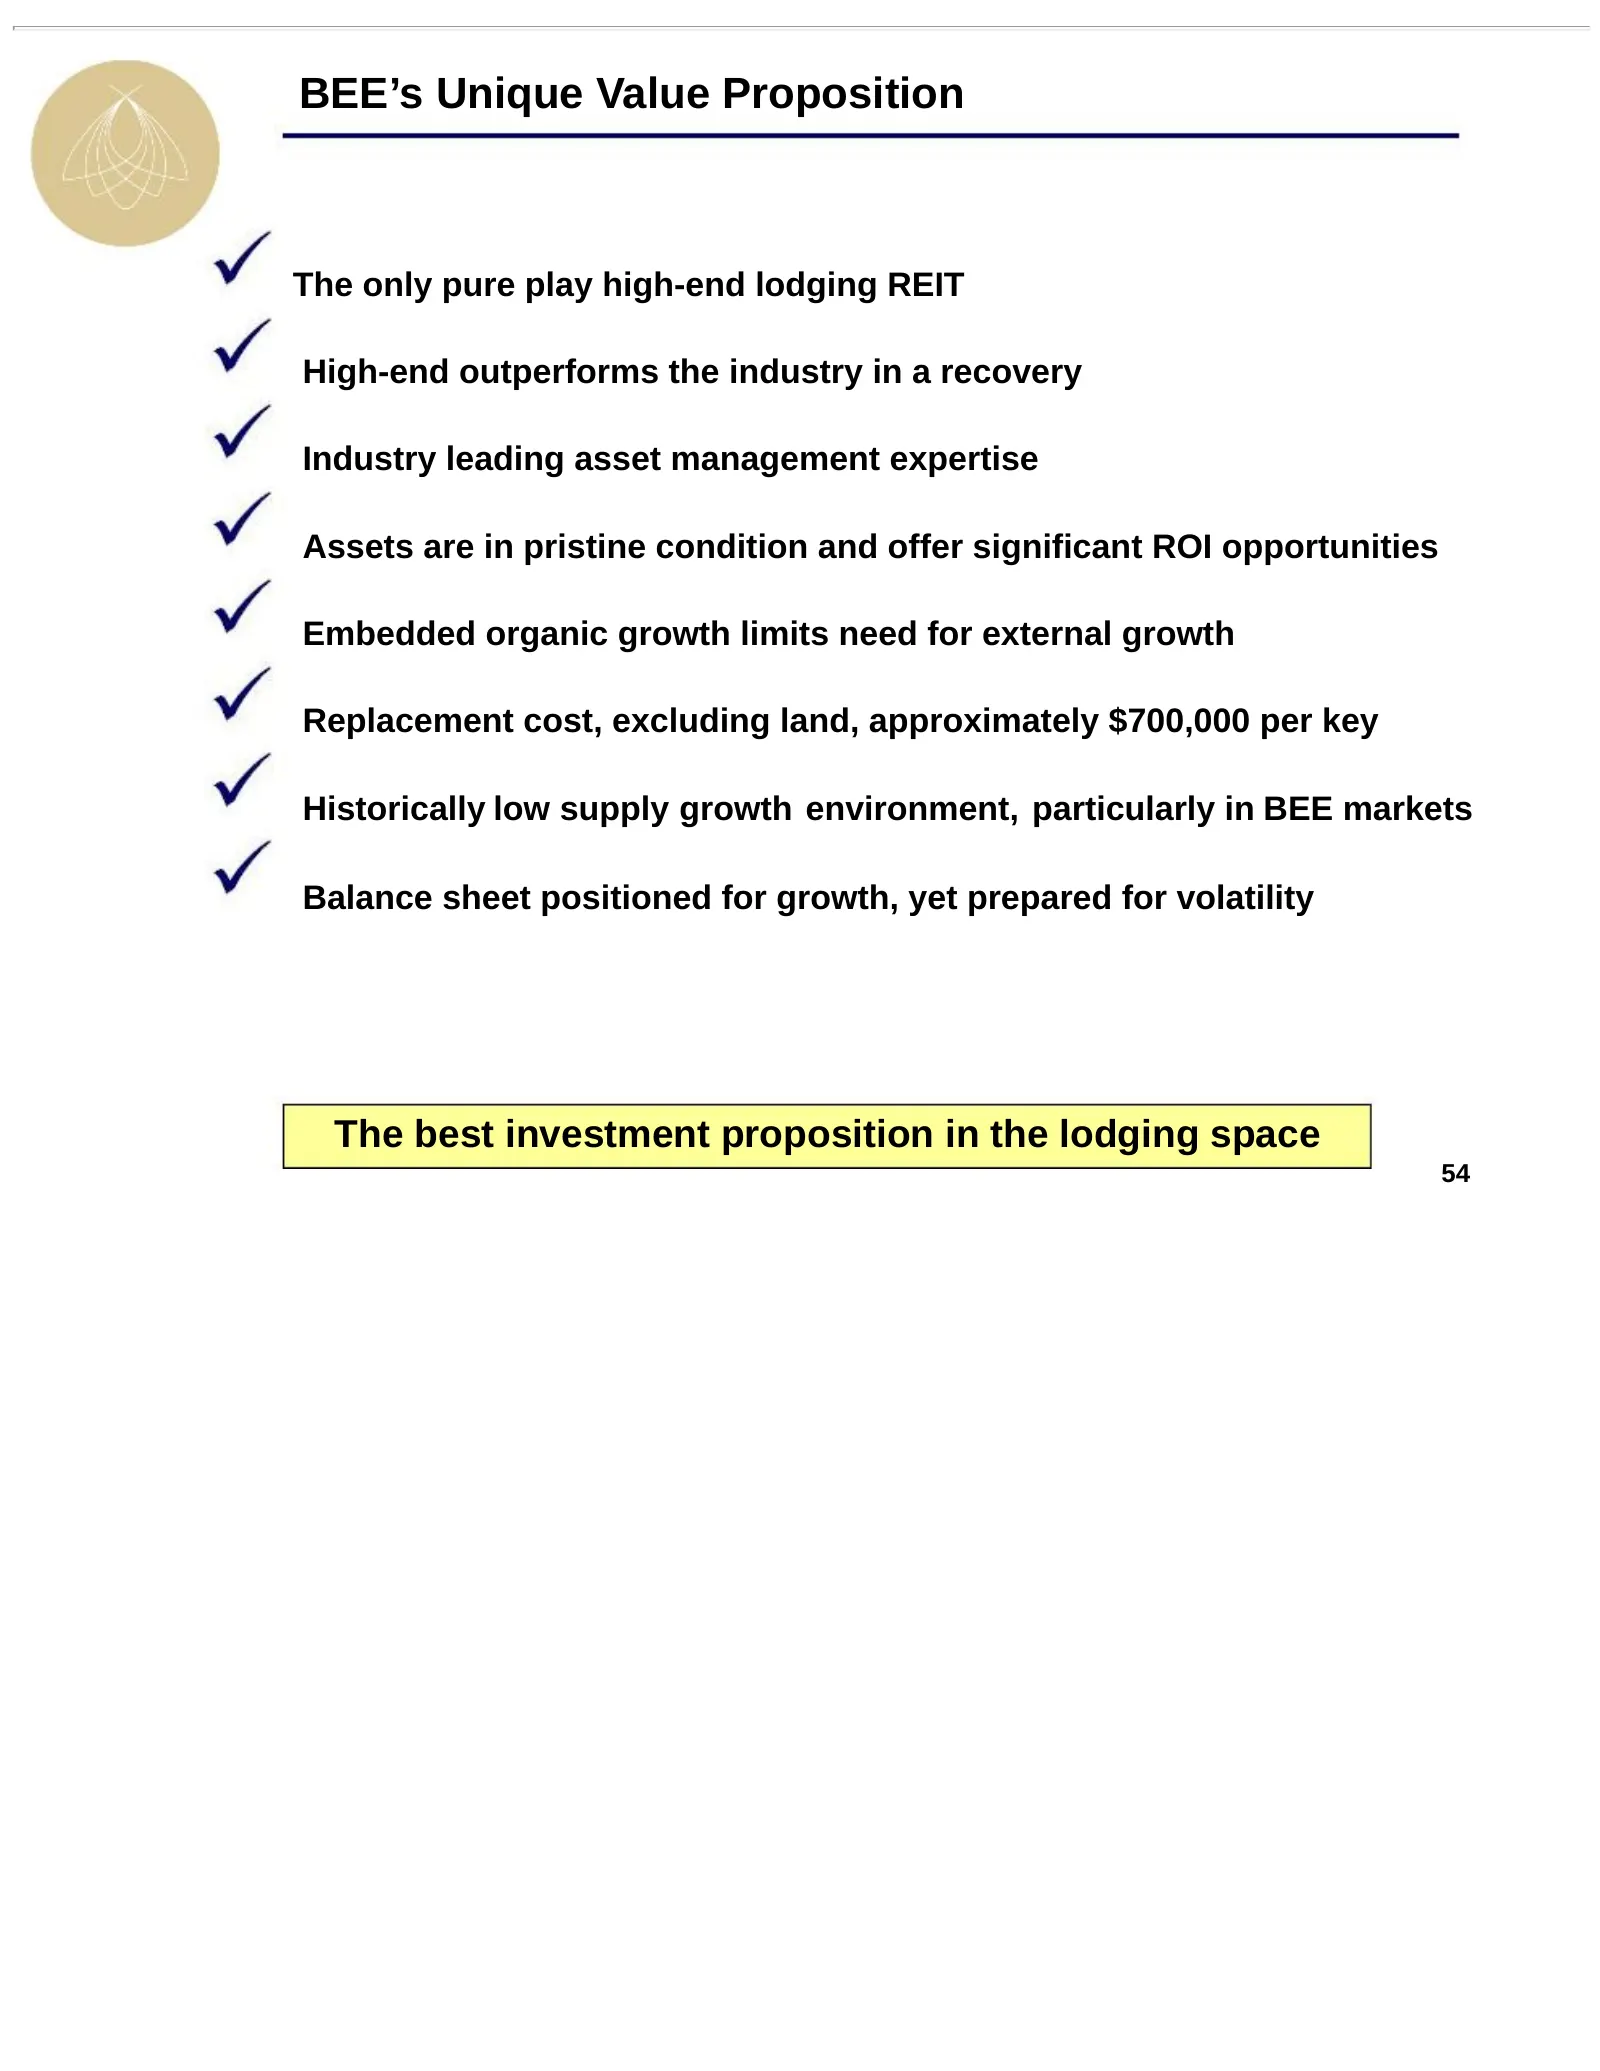
BEE’s Unique Value Proposition The only pure play high-end lodging REIT High-end outperforms the industry in a recovery Industry leading asset management expertise Assets are in pristine condition and offer significant ROI opportunities Embedded organic growth limits need for external growth Replace
Slide 55: Q&A
Q&A Q&A 55
Slide 56: Disclaimer
Disclaimer Except for historical information, the matters discussed in this press release are forward-looking statements subject to certain risks and uncertainties. Actual results could differ materially from the Company's projections and forward-looking statements are not guarantees of future perfo
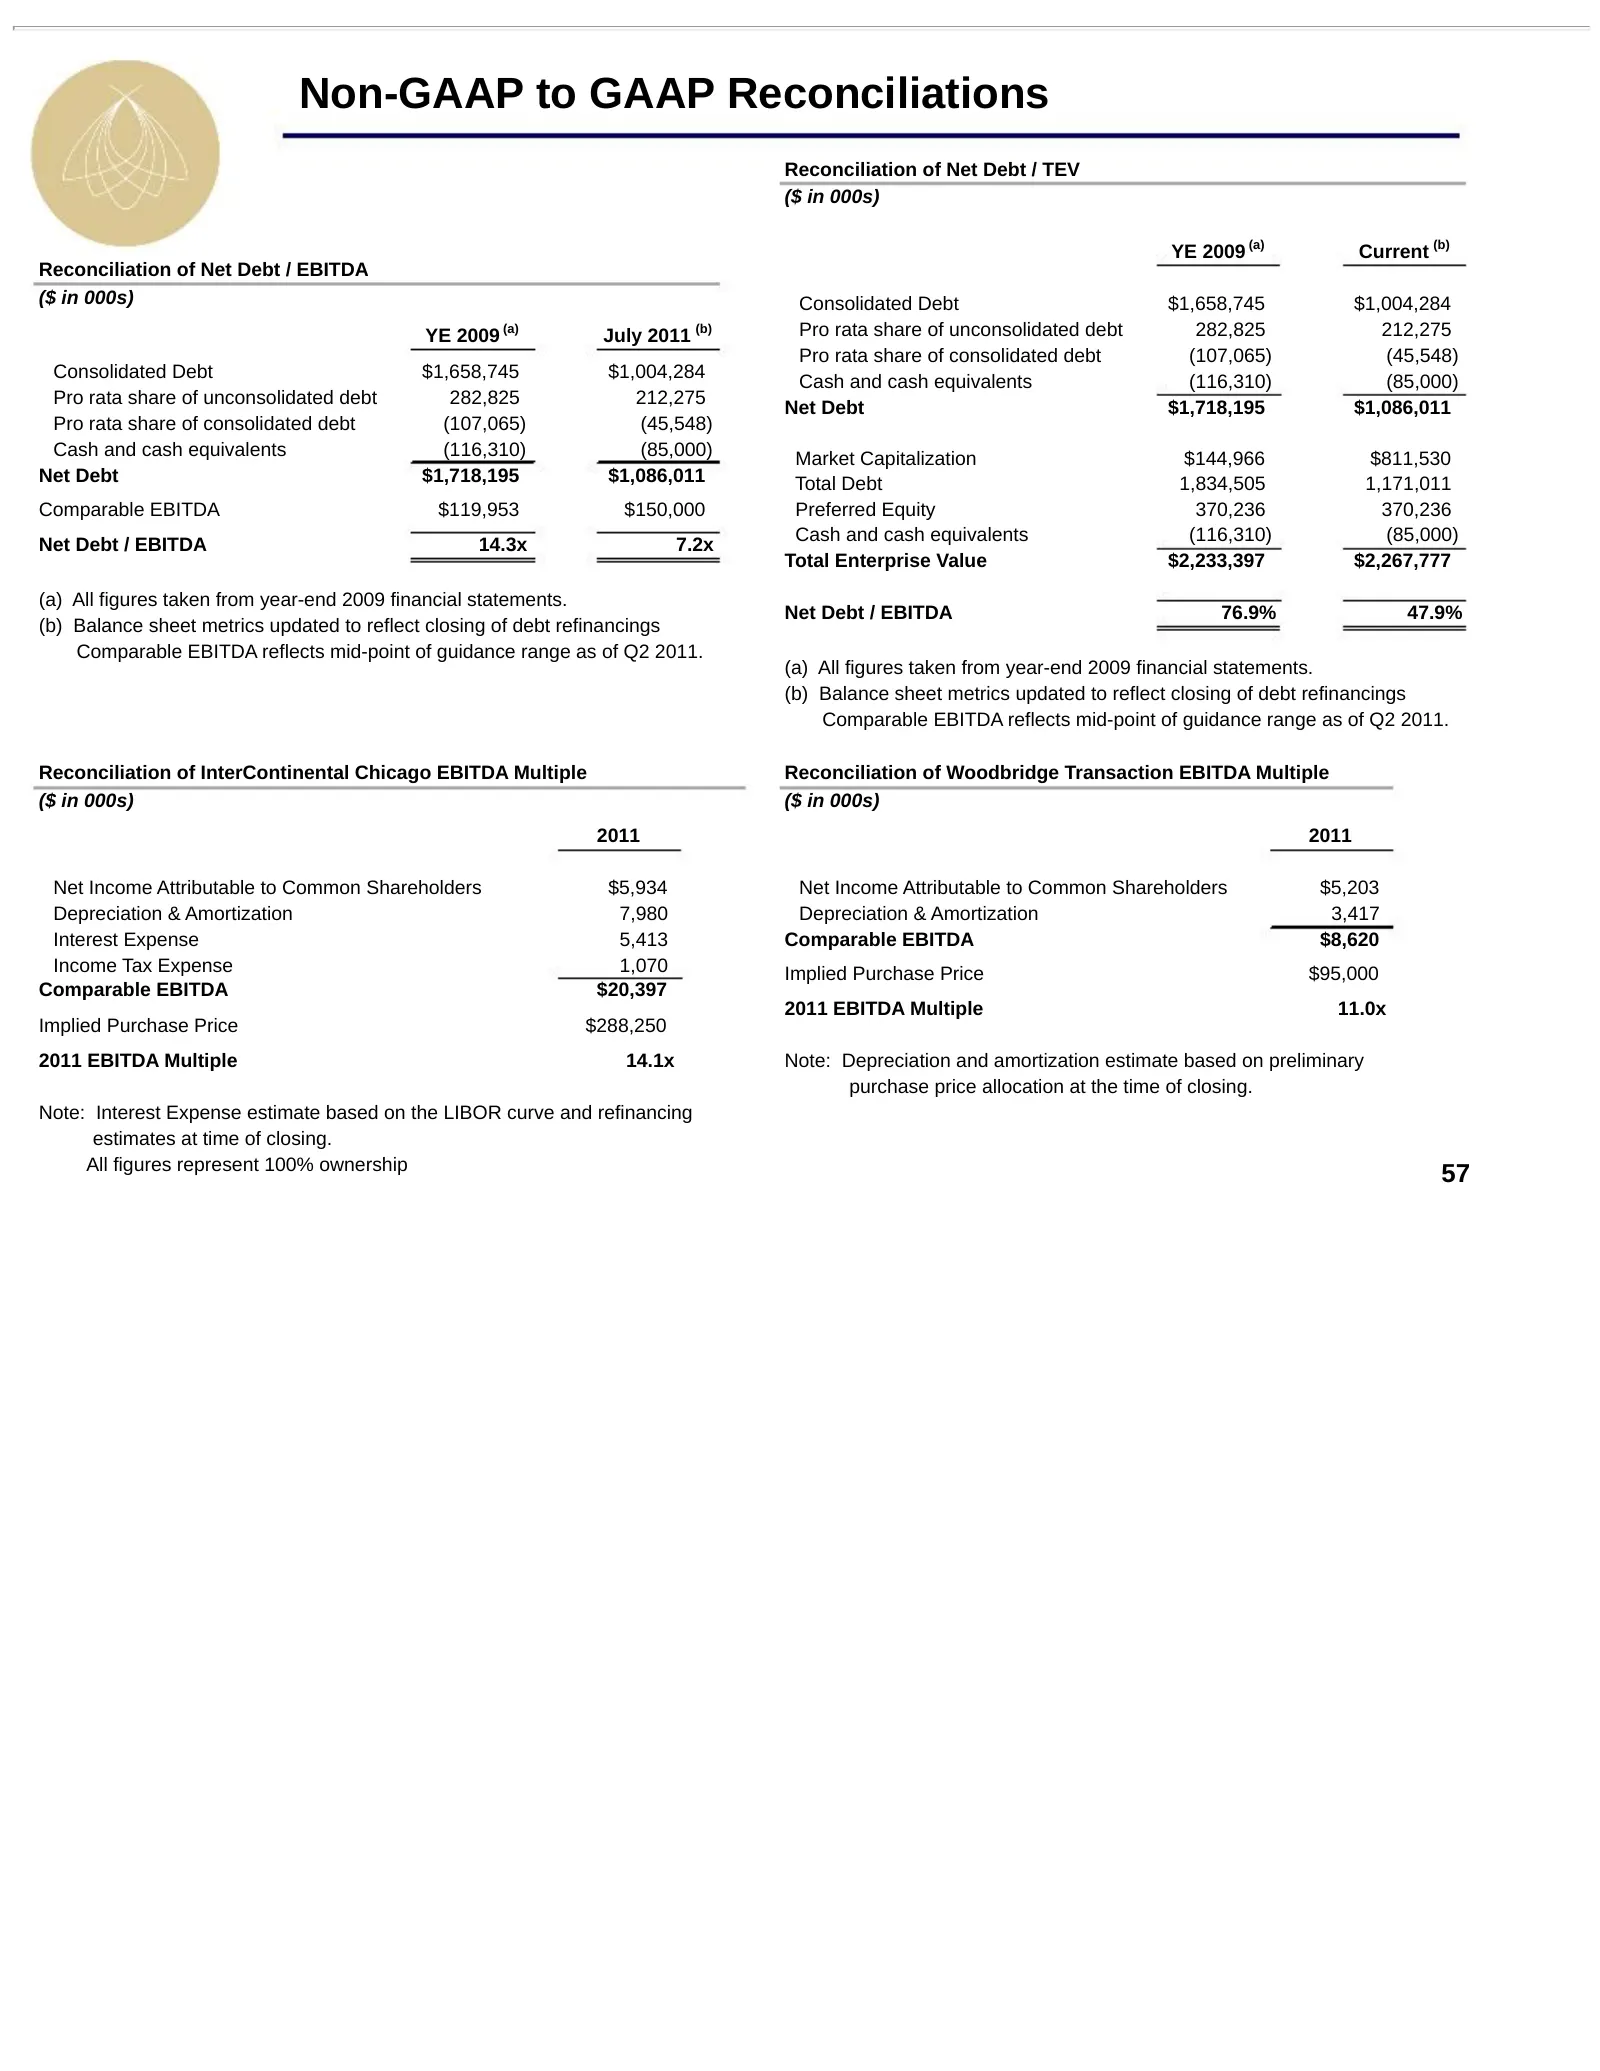
Slide 57: Non-GAAP to GAAP Reconciliations
Non-GAAP to GAAP Reconciliations Reconciliation of Net Debt / TEV ($ in 000s) (a) (b) YE 2009 Current Reconciliation of Net Debt / EBITDA ($ in 000s) Consolidated Debt $1,658,745 $1,004,284 YE 2009 (a) July 2011 (b) Pro rata share of unconsolidated debt 282,825 212,275 Pro rata share of consolidated
Slide 58: Strategic Hotels & Resorts
STRATEGIC Hlotels 5, Resorts
Source: SEC EDGAR · 8-K filed Oct 4, 2011
More decks from Strategic Hotels and Resorts Inc
 Investor Presentation (June 2015)43 slides · Jun 1, 2015
 Investor Presentation (February 2015)43 slides · Feb 24, 2015
 Investor Presentation (January 2015)44 slides · Jan 26, 2015
 Investor Presentation (November 2014)50 slides · Nov 5, 2014
 Investor Presentation (October 2014)50 slides · Oct 3, 2014
 Investor Day (September 2014)67 slides · Sep 22, 2014