Air Transport Services Group Inc
Air Transport Services — Cowen & Co. Global Transportation Conference 2017
18 slides from Air Transport Services's conference presentation, Sep 6, 2017
Slide 1: The global leader in midsize wide-body leasing and operating solutions
The global leader in midsize wide-body leasing and operating solutions Cowen & Co. Global Transportation Conference Boston September 6, 2017 Joe Hete President & CEO Quint Turner Chief Financial Officer
Slide 2: Safe Harbor Statement
Safe Harbor Statement 2 Except for historical information contained herein, the matters discussed in this presentation contain forward-looking statements that involve risks and uncertainties. There are a number of important factors that could cause Air Transport Services Group's ("ATSG's") actual re
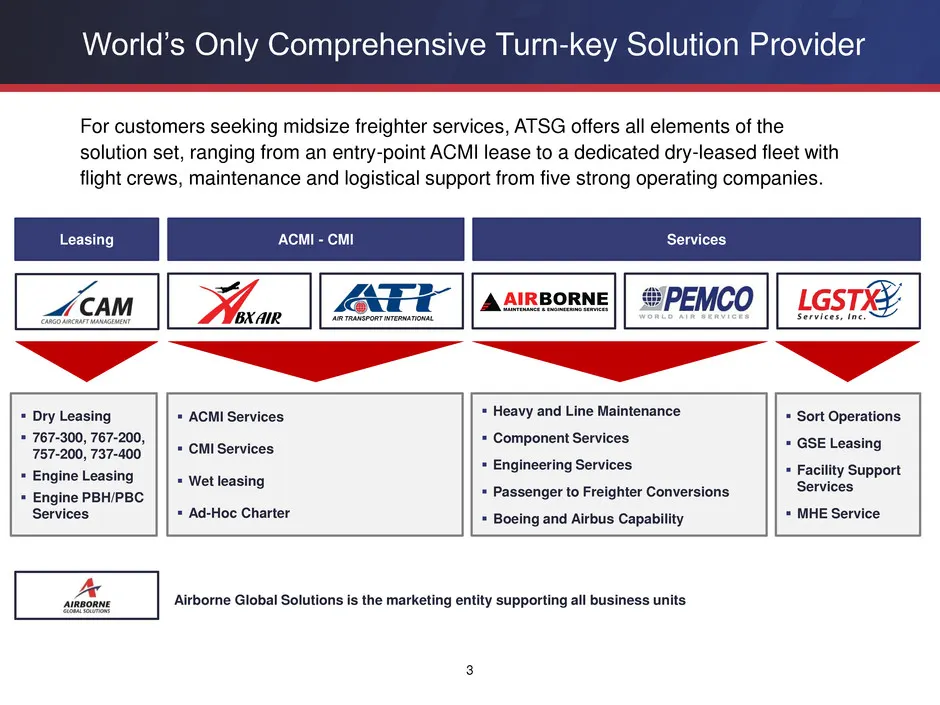
Slide 3: World's Only Comprehensive Turn-key Solution Provider
Dry Leasing 767-300, 767-200, 757-200, 737-400 Engine Leasing Engine PBH/PBC Services ACMI Services CMI Services Wet leasing Ad-Hoc Charter Heavy and Line Maintenance Component Services Engineering Services Passenger to Freighter Conversions Boeing and Airbus Capability S
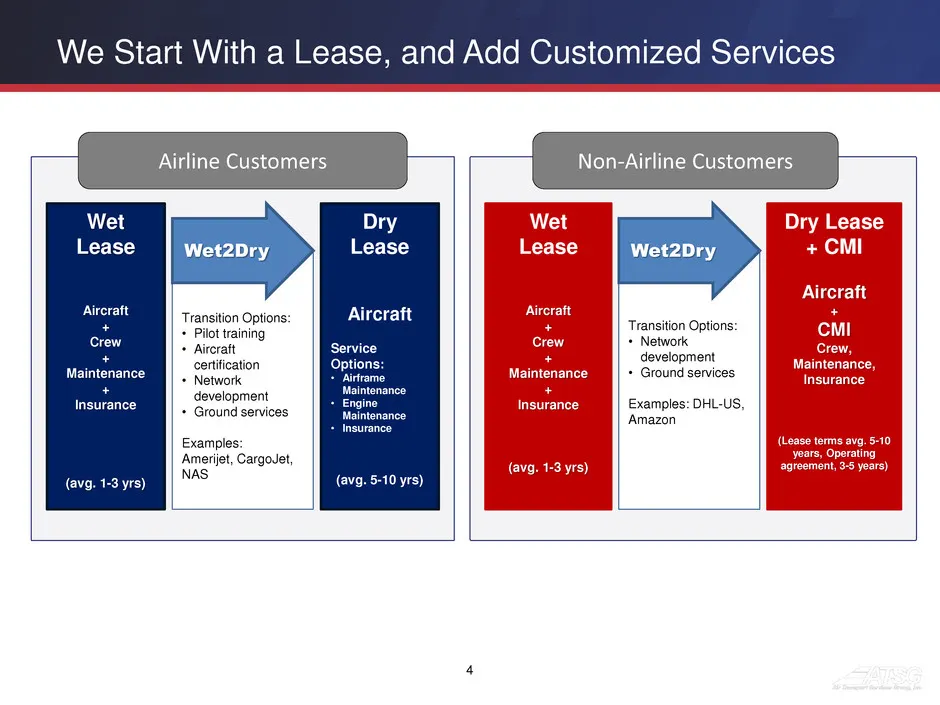
Slide 4: We Start With a Lease, and Add Customized Services
We Start With a Lease, and Add Customized Services 4 4 Wet Lease Aircraft + Crew + Maintenance + Insurance (avg. 1-3 yrs) Airline Customers Non-Airline Customers Dry Lease Aircraft Service Options: • Airframe Maintenance • Engine Maintenance • Insurance (avg. 5-10 yrs) Transition Options: • Pilot tr
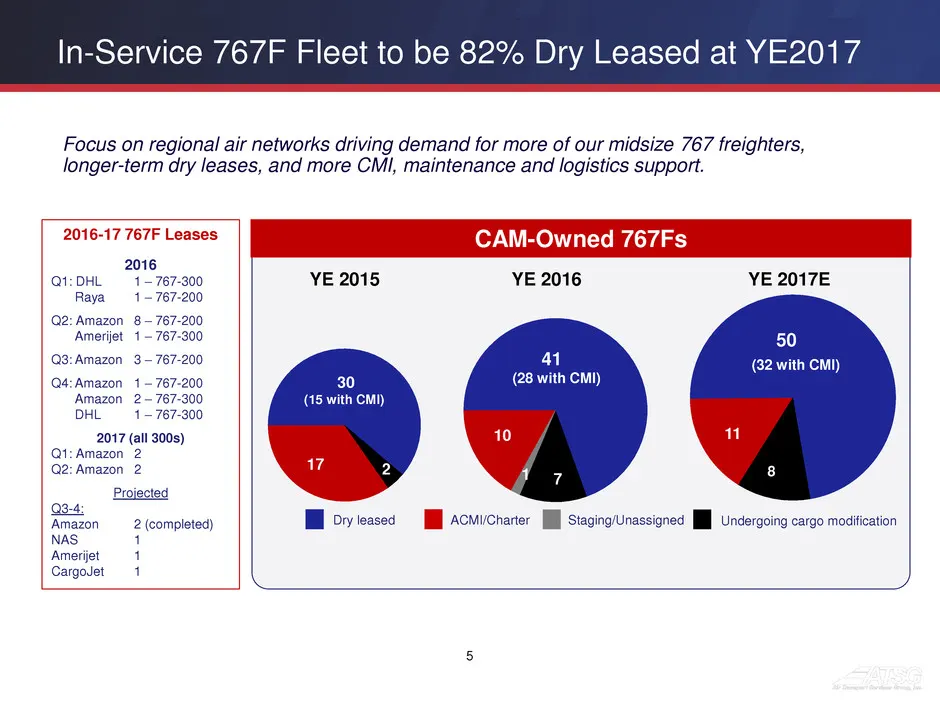
Slide 5: In-Service 767F Fleet to be 82% Dry Leased at YE2017
11 50 8 10 41 7 17 30 2 In-Service 767F Fleet to be 82% Dry Leased at YE2017 5 Focus on regional air networks driving demand for more of our midsize 767 freighters, longer-term dry leases, and more CMI, maintenance and logistics support. YE 2015 CAM-Owned 767Fs YE 2016 (15 with CMI) (28 with CMI) Dr
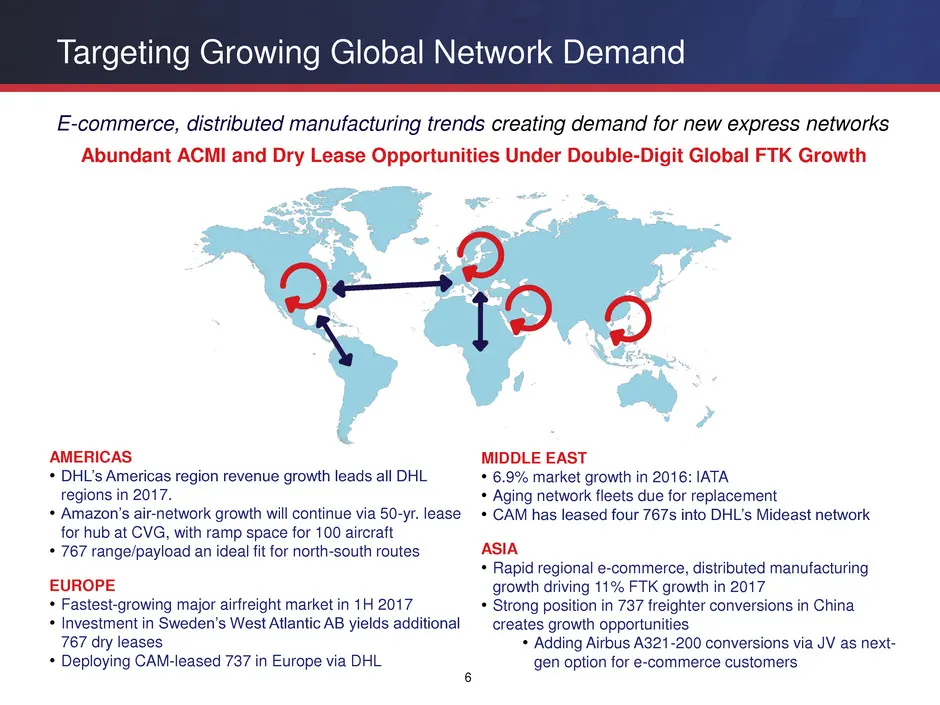
Slide 6: Targeting Growing Global Network Demand
Targeting Growing Global Network Demand 6 E-commerce, distributed manufacturing trends creating demand for new express networks Abundant ACMI and Dry Lease Opportunities Under Double-Digit Global FTK Growth MIDDLE EAST • 6.9% market growth in 2016: IATA • Aging network fleets due for replacement • C
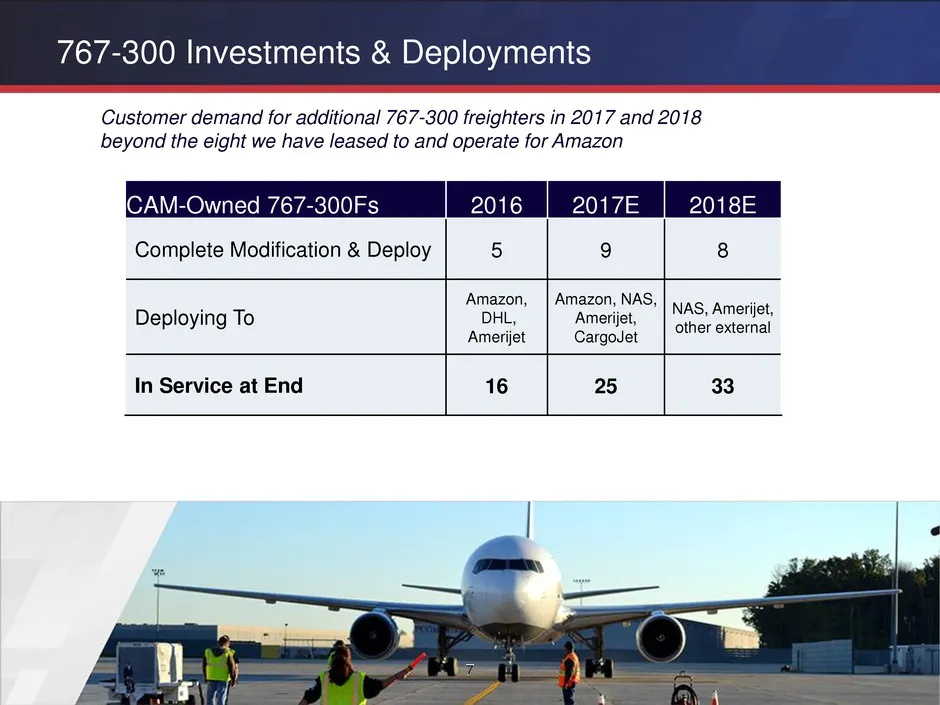
Slide 7: 767-300 Investments & Deployments
767-300 Investments & Deployments 7 CAM-Owned 767-300Fs 2016 2017E 2018E Complete Modification & Deploy 5 9 8 Deploying To Amazon, DHL, Amerijet Amazon, NAS, Amerijet, CargoJet NAS, Amerijet, other external In Service at End 16 25 33 Customer demand for additional 767-300 freighters in 2017 and 2018
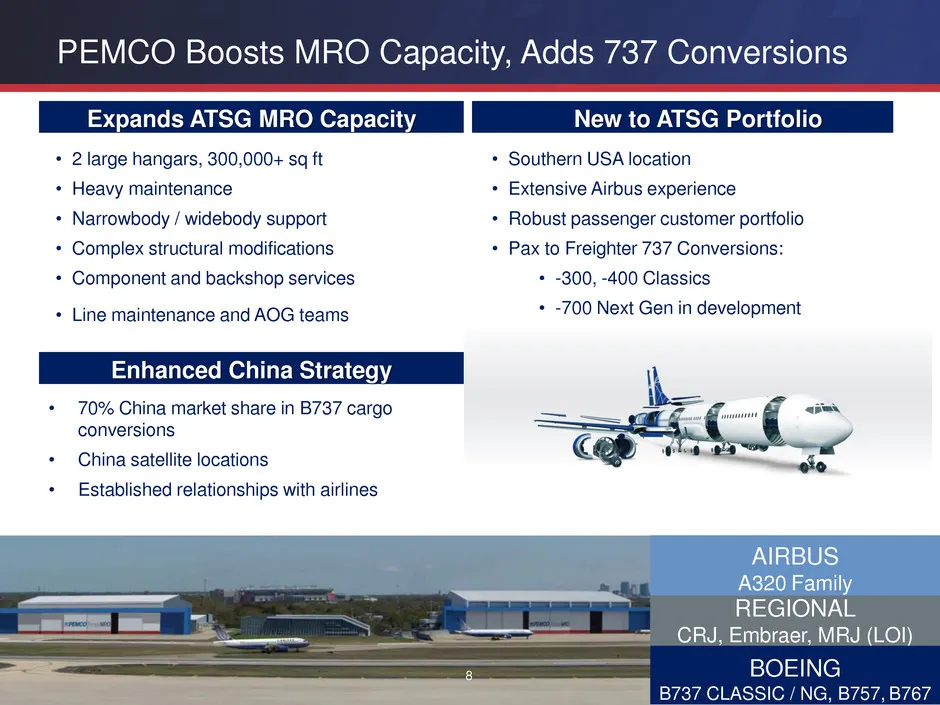
Slide 8: PEMCO Boosts MRO Capacity, Adds Conversions
PEMCO Boosts MRO Capacity, Adds 737 Conversions • 2 large hangars, 300,000+ sq ft • Heavy maintenance • Narrowbody / widebody support • Complex structural modifications • Component and backshop services • Line maintenance and AOG teams Expands ATSG MRO Capacity New to ATSG Portfolio REGIONAL CRJ, Em
Slide 9: New Joint Venture for A321 Freighter Conversion
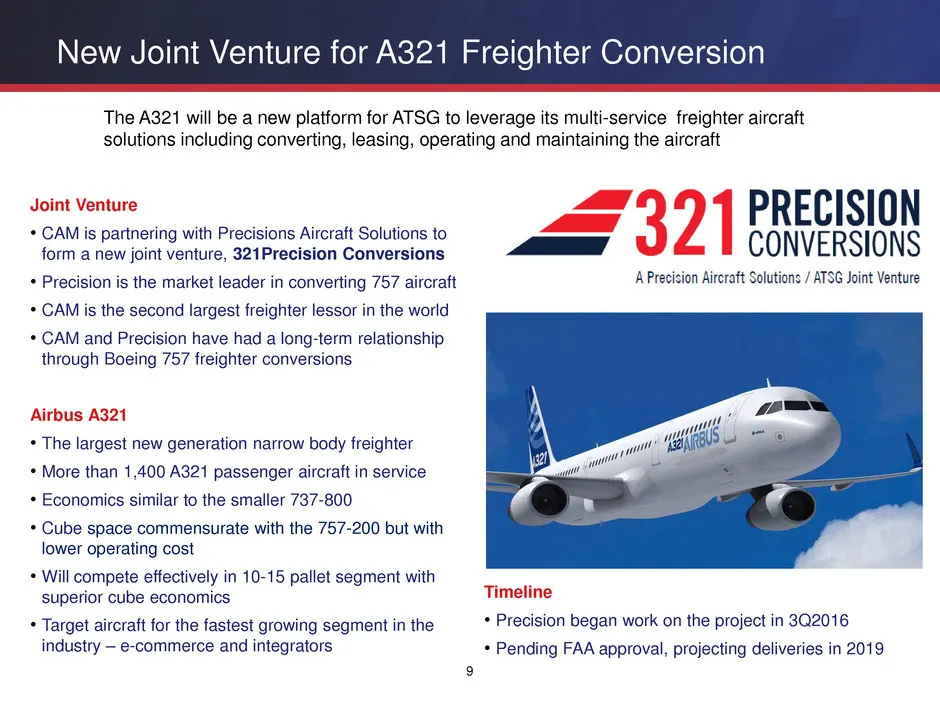
New Joint Venture for A321 Freighter Conversion Joint Venture • CAM is partnering with Precisions Aircraft Solutions to form a new joint venture, 321Precision Conversions • Precision is the market leader in converting 757 aircraft • CAM is the second largest freighter lessor in the world • CAM and P
Slide 10: All Amazon Freighters Leased and Deployed
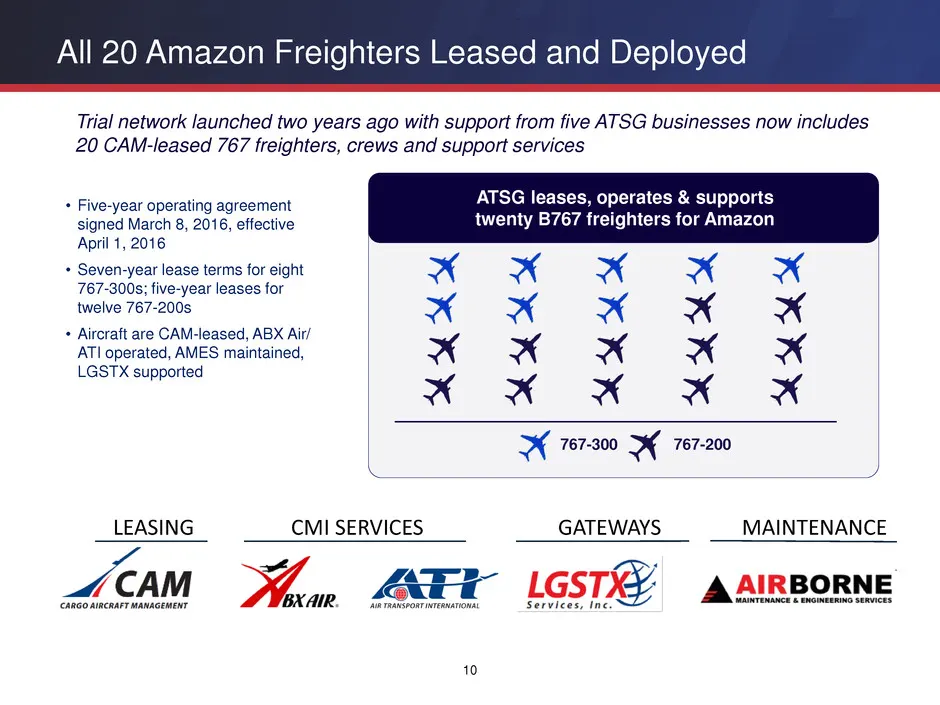
All 20 Amazon Freighters Leased and Deployed • Five-year operating agreement signed March 8, 2016, effective April 1, 2016 • Seven-year lease terms for eight 767-300s; five-year leases for twelve 767-200s • Aircraft are CAM-leased, ABX Air/ ATI operated, AMES maintained, LGSTX supported Trial networ
Slide 11: Amazon to receive ATSG warrants for up to 19.9% of common shares
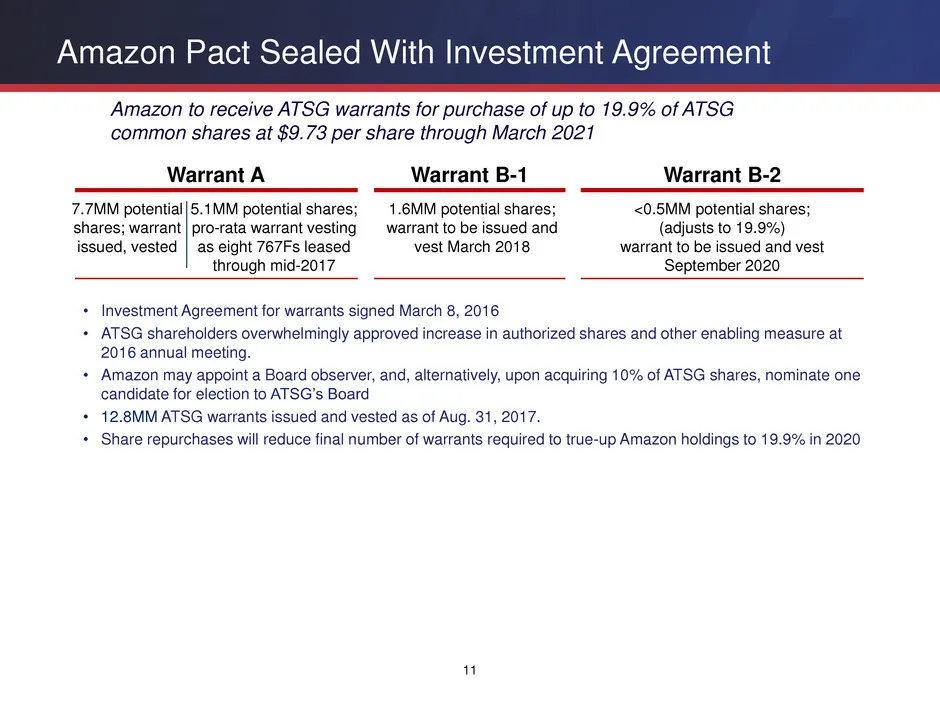
Amazon to receive ATSG warrants for purchase of up to 19.9% of ATSG common shares at $9.73 per share through March 2021 Warrant A Warrant B-1 7.7MM potential shares; warrant issued, vested 1.6MM potential shares; warrant to be issued and vest March 2018 Warrant B-2 <0.5MM potential shares; (adjusts
Slide 12: 2016 Results & 2017 Adjusted EBITDA Outlook
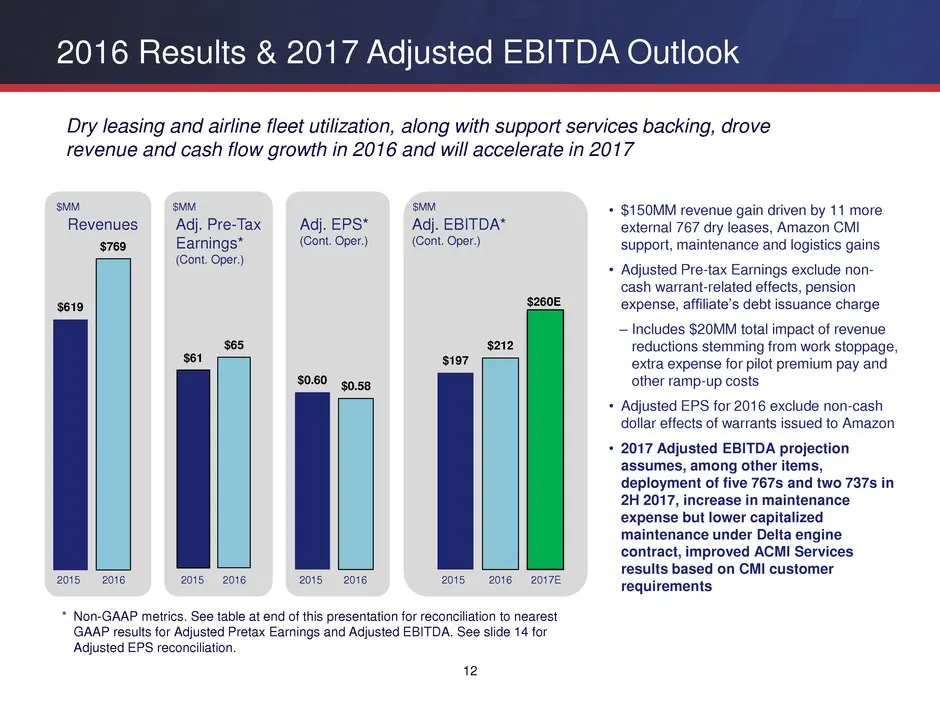
2016 Results & 2017 Adjusted EBITDA Outlook 12 • $150MM revenue gain driven by 11 more external 767 dry leases, Amazon CMI support, maintenance and logistics gains • Adjusted Pre-tax Earnings exclude non- cash warrant-related effects, pension expense, affiliate’s debt issuance charge – Includes $20M
Slide 13: 2017 First Half Results
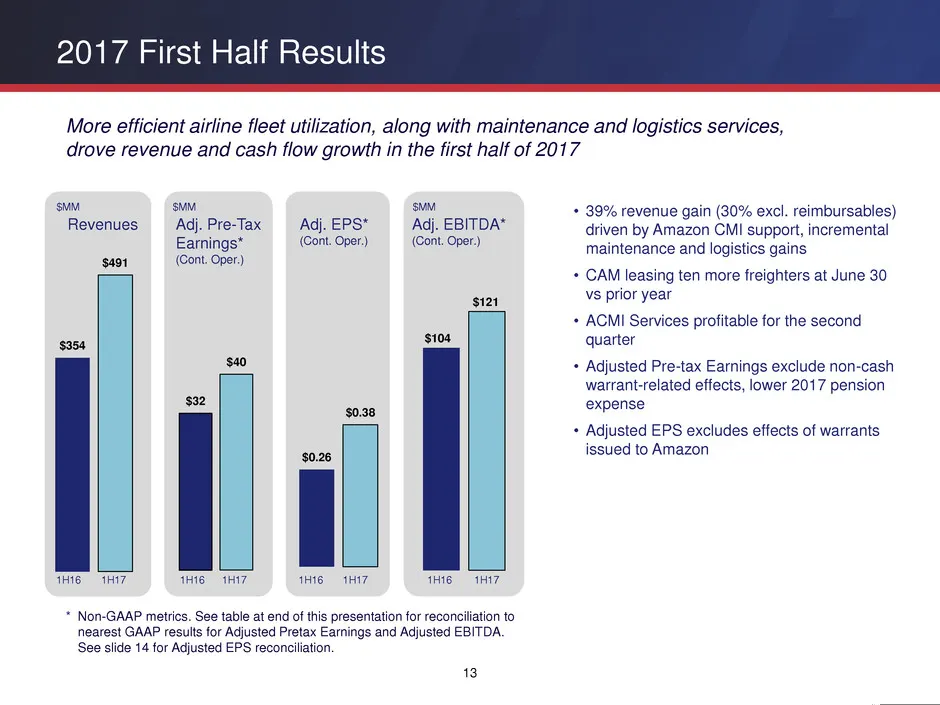
2017 First Half Results 13 • 39% revenue gain (30% excl. reimbursables) driven by Amazon CMI support, incremental maintenance and logistics gains • CAM leasing ten more freighters at June 30 vs prior year • ACMI Services profitable for the second quarter • Adjusted Pre-tax Earnings exclude non-cash
Slide 14: EPS Adjustments Reflect Warrant Valuation
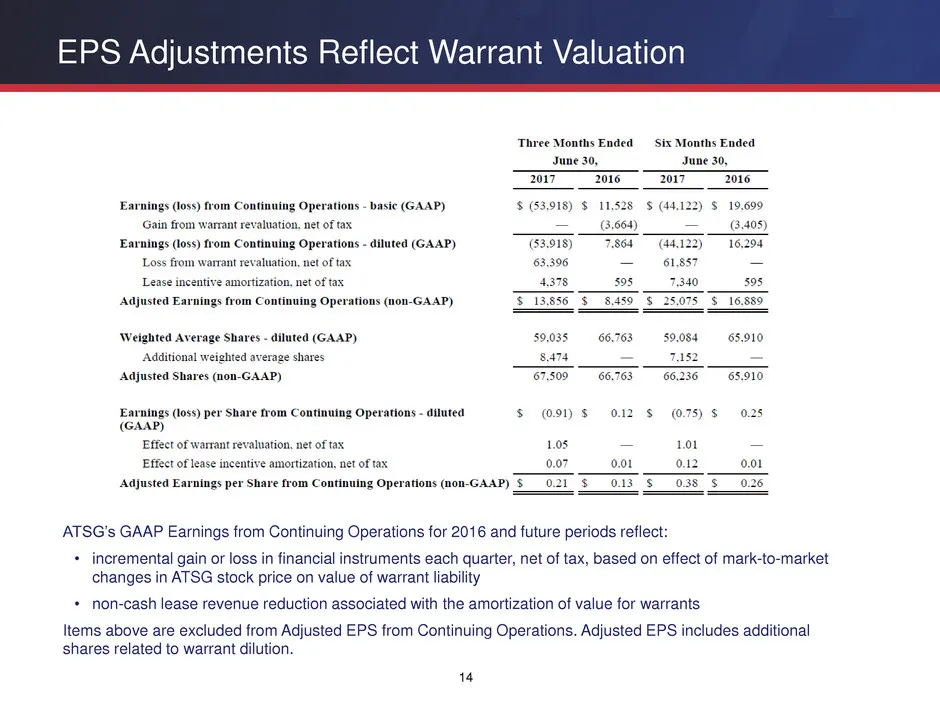
EPS Adjustments Reflect Warrant Valuation 14 ATSG’s GAAP Earnings from Continuing Operations for 2016 and future periods reflect: • incremental gain or loss in financial instruments each quarter, net of tax, based on effect of mark-to-market changes in ATSG stock price on value of warrant liability
Slide 15: Strong Capital Base to Support Fleet Growth
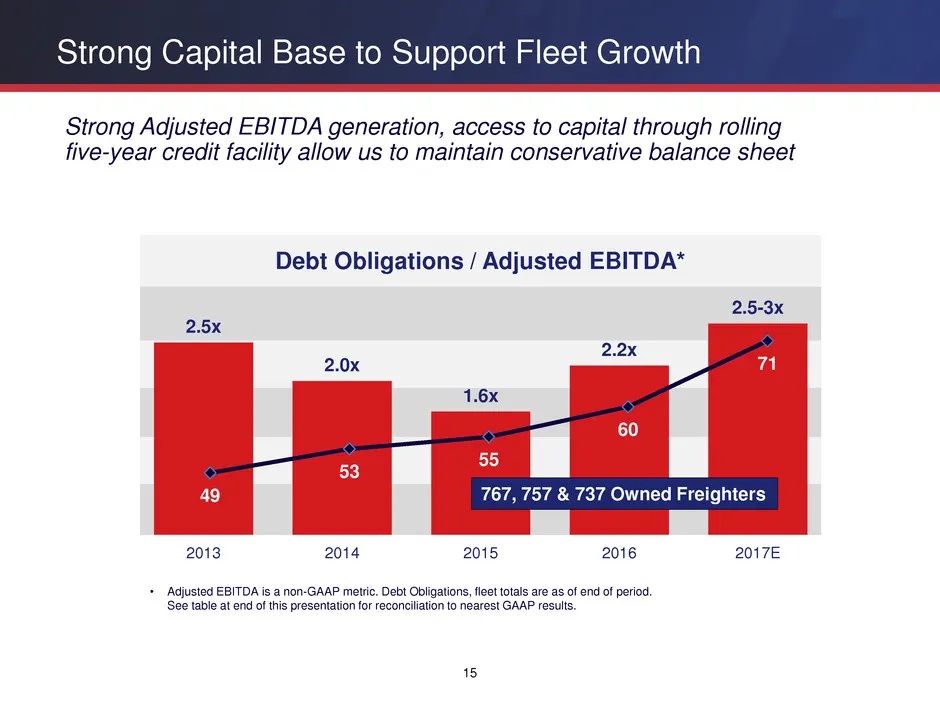
2.5x 2.0x 1.6x 2.2x 2.5-3x 2013 2014 2015 2016 2017E Debt Obligations / Adjusted EBITDA* 49 53 55 60 71 Strong Capital Base to Support Fleet Growth 15 Strong Adjusted EBITDA generation, access to capital through rolling five-year credit facility allow us to maintain conservative balance sheet • Adju
Slide 16: Seizing Opportunities for Balanced Capital Structure
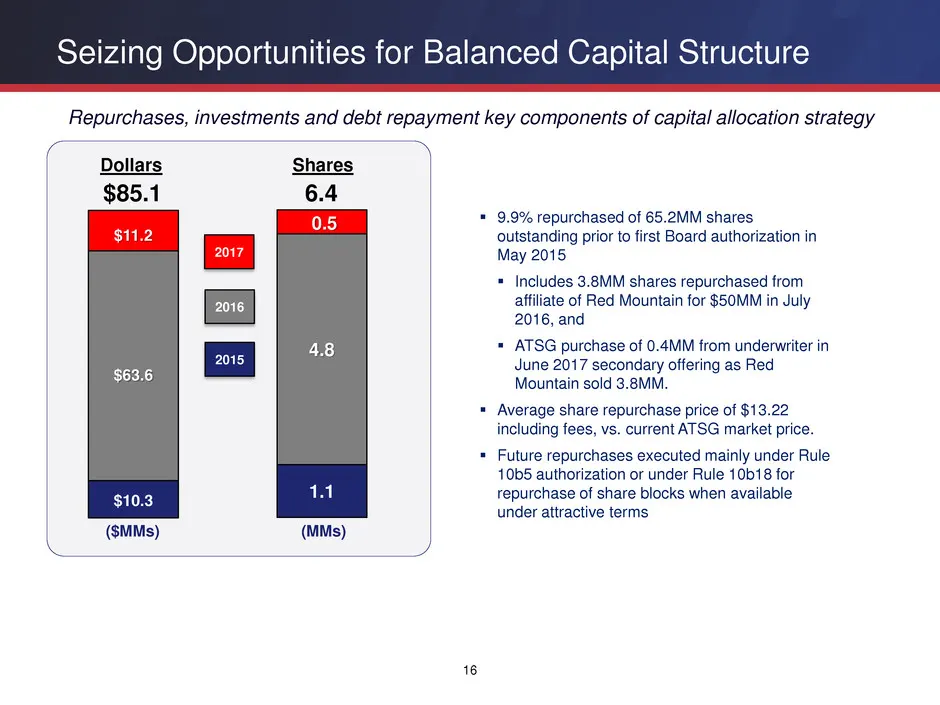
Seizing Opportunities for Balanced Capital Structure 16 Repurchases, investments and debt repayment key components of capital allocation strategy 1.1 4.8 0.5 6.4 (MMs) $10.3 $63.6 $11.2 $85.1 ($MMs) 2016 2015 9.9% repurchased of 65.2MM shares outstanding prior to first Board authorization in May 2
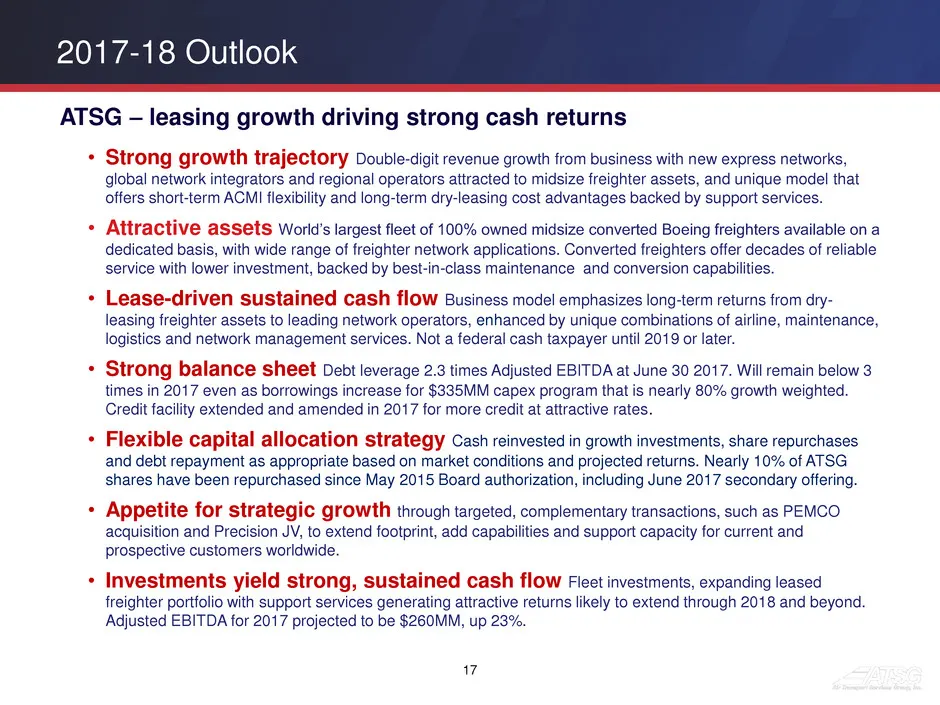
Slide 17: 2017-18 Outlook
2017-18 Outlook 17 • Strong growth trajectory Double-digit revenue growth from business with new express networks, global network integrators and regional operators attracted to midsize freighter assets, and unique model that offers short-term ACMI flexibility and long-term dry-leasing cost advantag
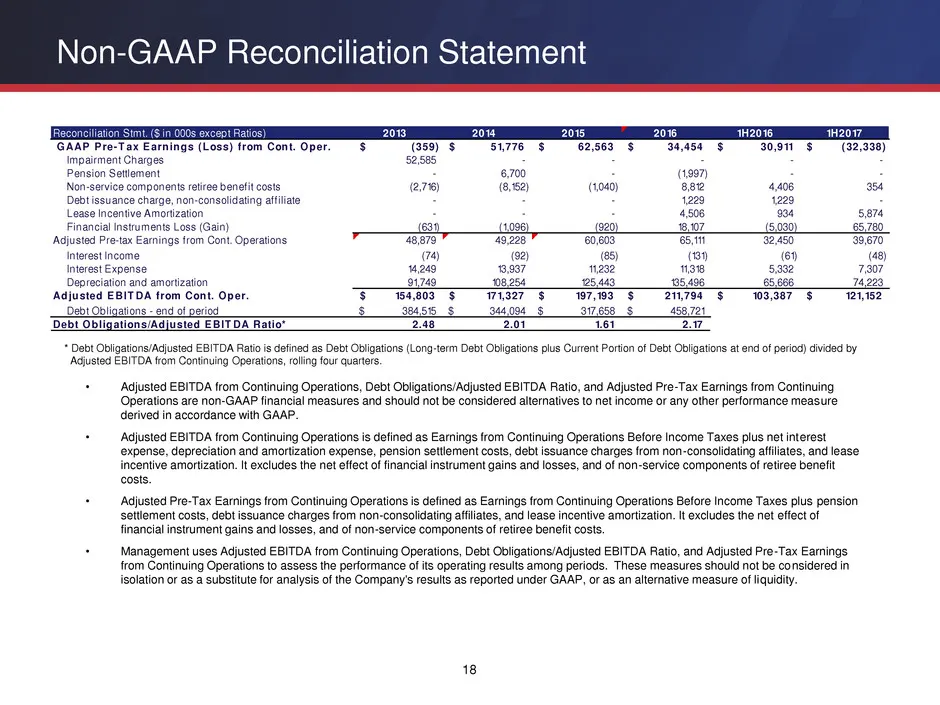
Slide 18: Non-GAAP Reconciliation Statement
Non-GAAP Reconciliation Statement 18 • Adjusted EBITDA from Continuing Operations, Debt Obligations/Adjusted EBITDA Ratio, and Adjusted Pre-Tax Earnings from Continuing Operations are non-GAAP financial measures and should not be considered alternatives to net income or any other performance measure
Source: SEC EDGAR · 8-K filed Sep 6, 2017
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020