SGL Carbon SE · XETR:SGL
SGL Carbon — Investor Day (March 2016)
34 slides from SGL Carbon's investor day presentation, Mar 23, 2016
Slide 1: Investor & Analyst Meeting & Conference Call
Investor & Analyst Meeting & Conference Call Frankfurt am Main March 23, 2016
Slide 2: Agenda
Agenda. 1. Review of the fiscal year 2015 – Jürgen Köhler 2. Financials 2015 3. Outlook 2016 4. Mid term strategy Page 2 | Investor and Analyst Conference | 23 March 2016
Slide 3: Review of the fiscal year 2015. Achievement of key milestones
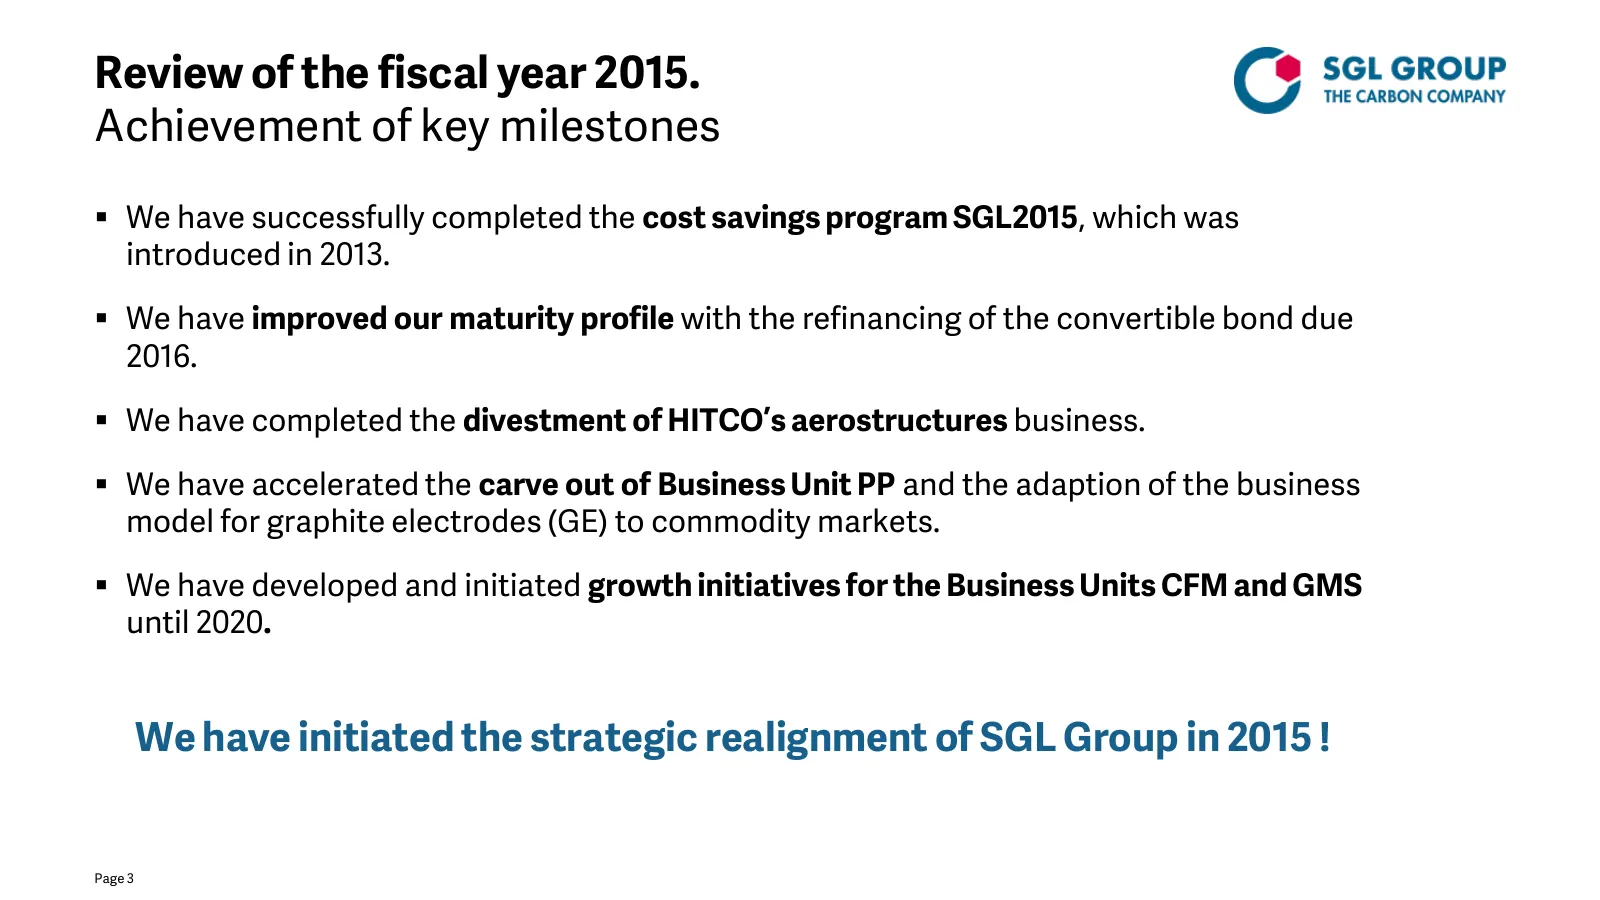
Review of the fiscal year 2015. Achievement of key milestones We have successfully completed the cost savings program SGL2015, which was introduced in 2013. We have improved our maturity profile with the refinancing of the convertible bond due 2016. We have completed the divestment of HITCO’s
Slide 4: Summary of key figures
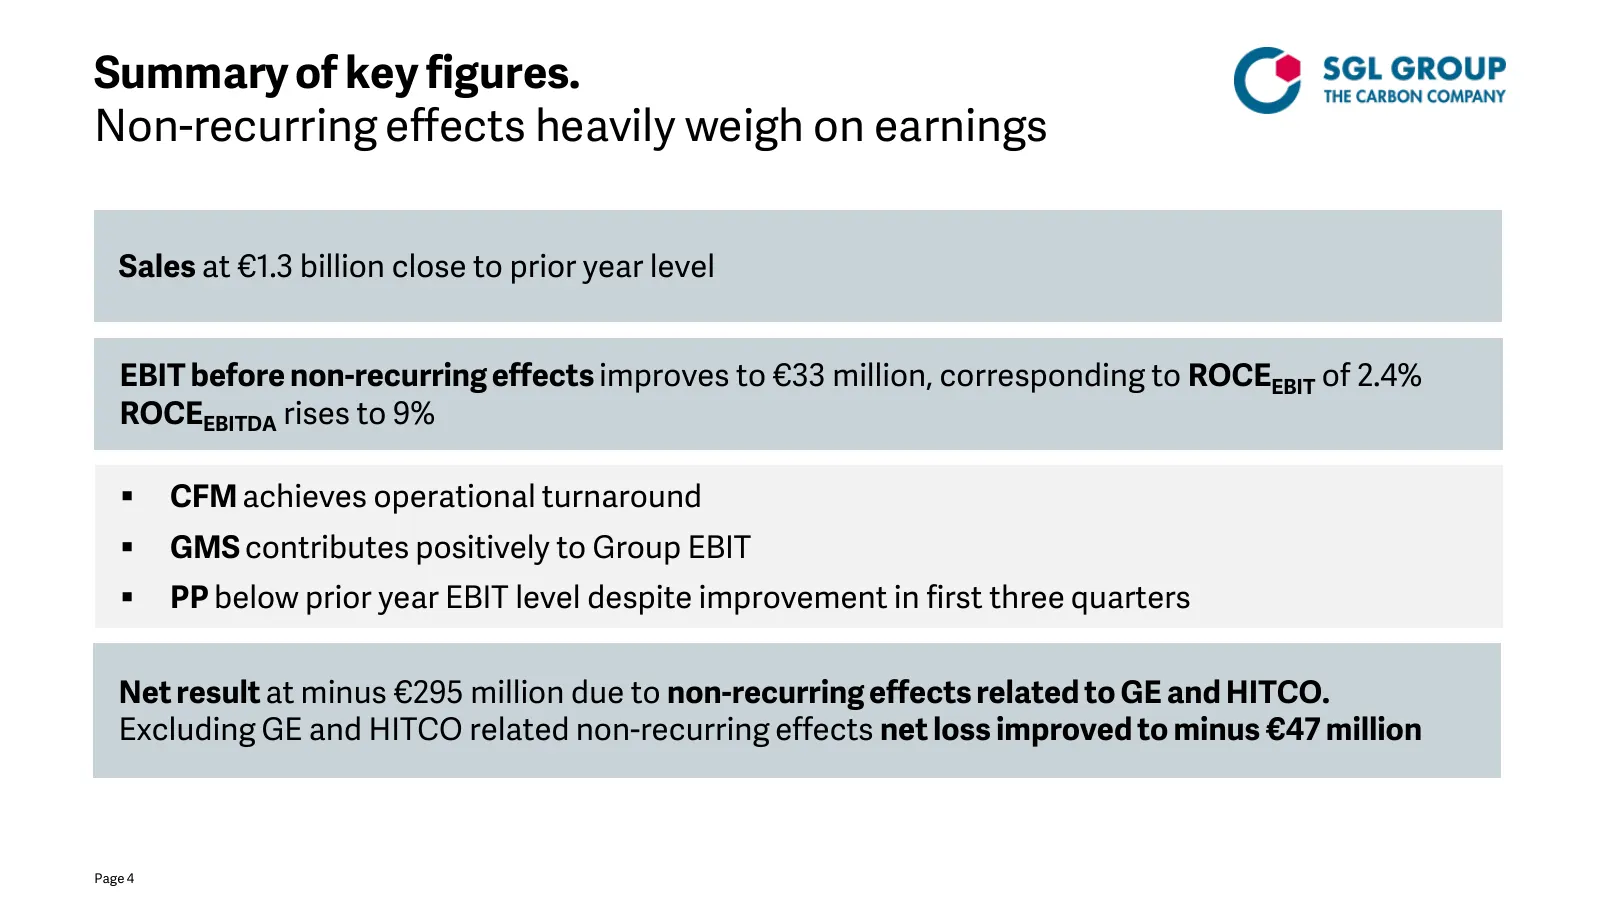
Summary of key figures. Non-recurring effects heavily weigh on earnings Sales at €1.3 billion close to prior year level EBIT before non-recurring effects improves to €33 million, corresponding to ROCEEBIT of 2.4% ROCEEBITDA rises to 9% CFM achieves operational turnaround GMS contributes positive
Slide 5: Agenda
Agenda. 1. Review of the fiscal year 2015 2. Financials 2015 – Michael Majerus 3. Outlook 2016 4. Mid term strategy Page 5 | Investor and Analyst Conference | 23 March 2016
Slide 6: Carbon Fibers & Materials. Positive earnings contribution for the first time
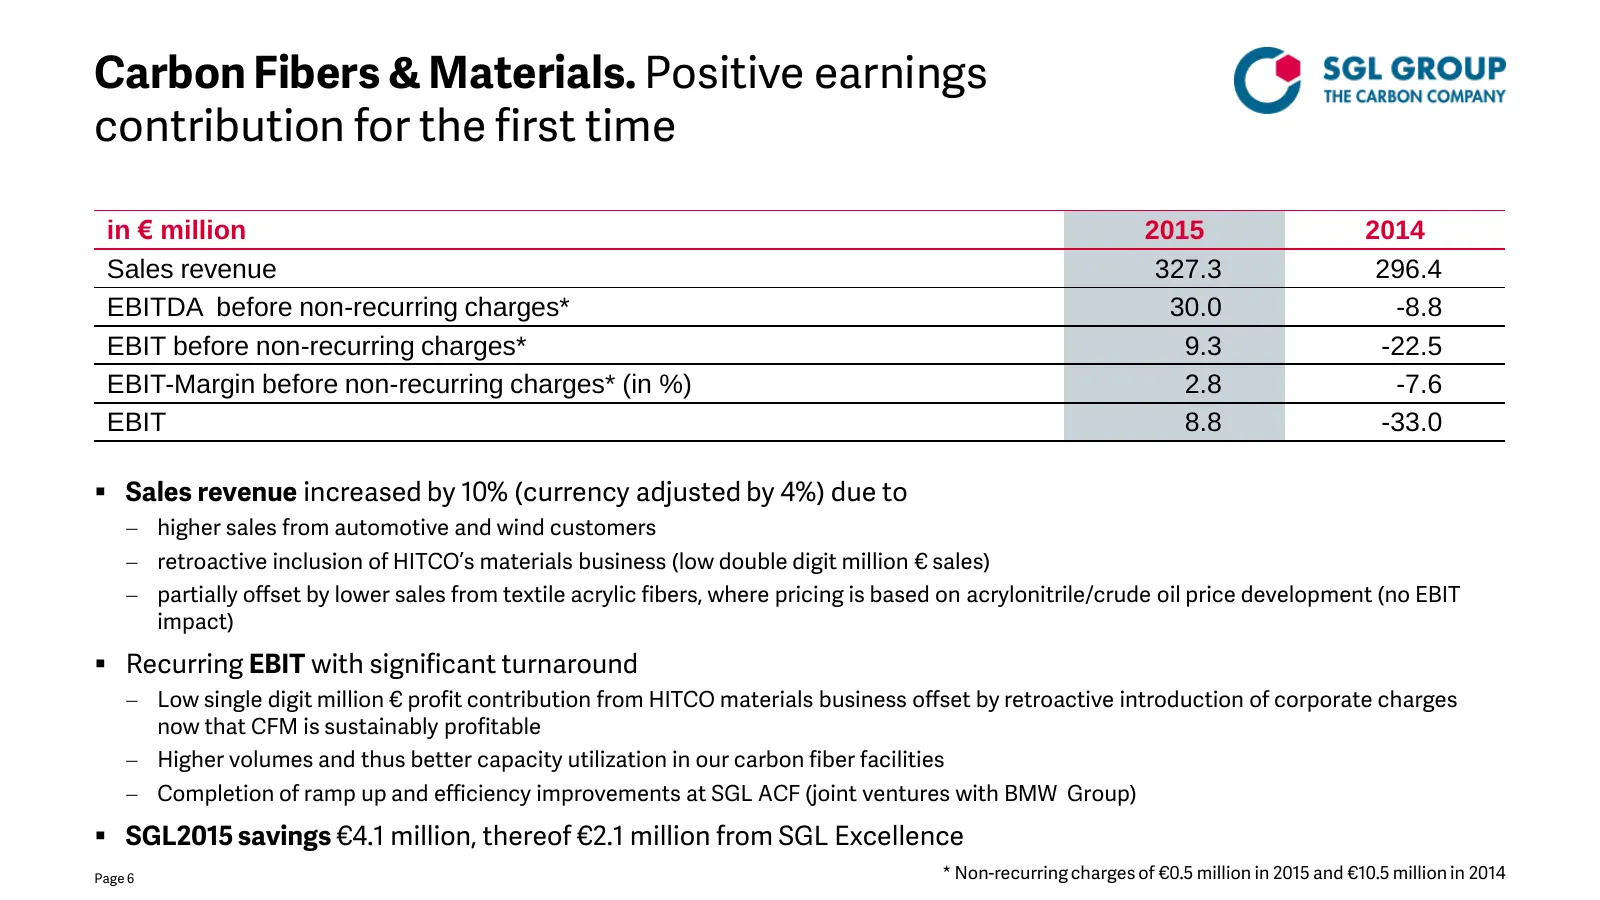
Carbon Fibers & Materials. Positive earnings contribution for the first time in € million 2015 2014 Sales revenue 327.3 296.4 EBITDA before non-recurring charges* 30.0 -8.8 EBIT before non-recurring charges* 9.3 -22.5 EBIT-Margin before non-recurring charges* (in %) 2.8 -7.6 EBIT 8.8 -33.0 Sales r
Slide 7: Graphite Materials & Systems
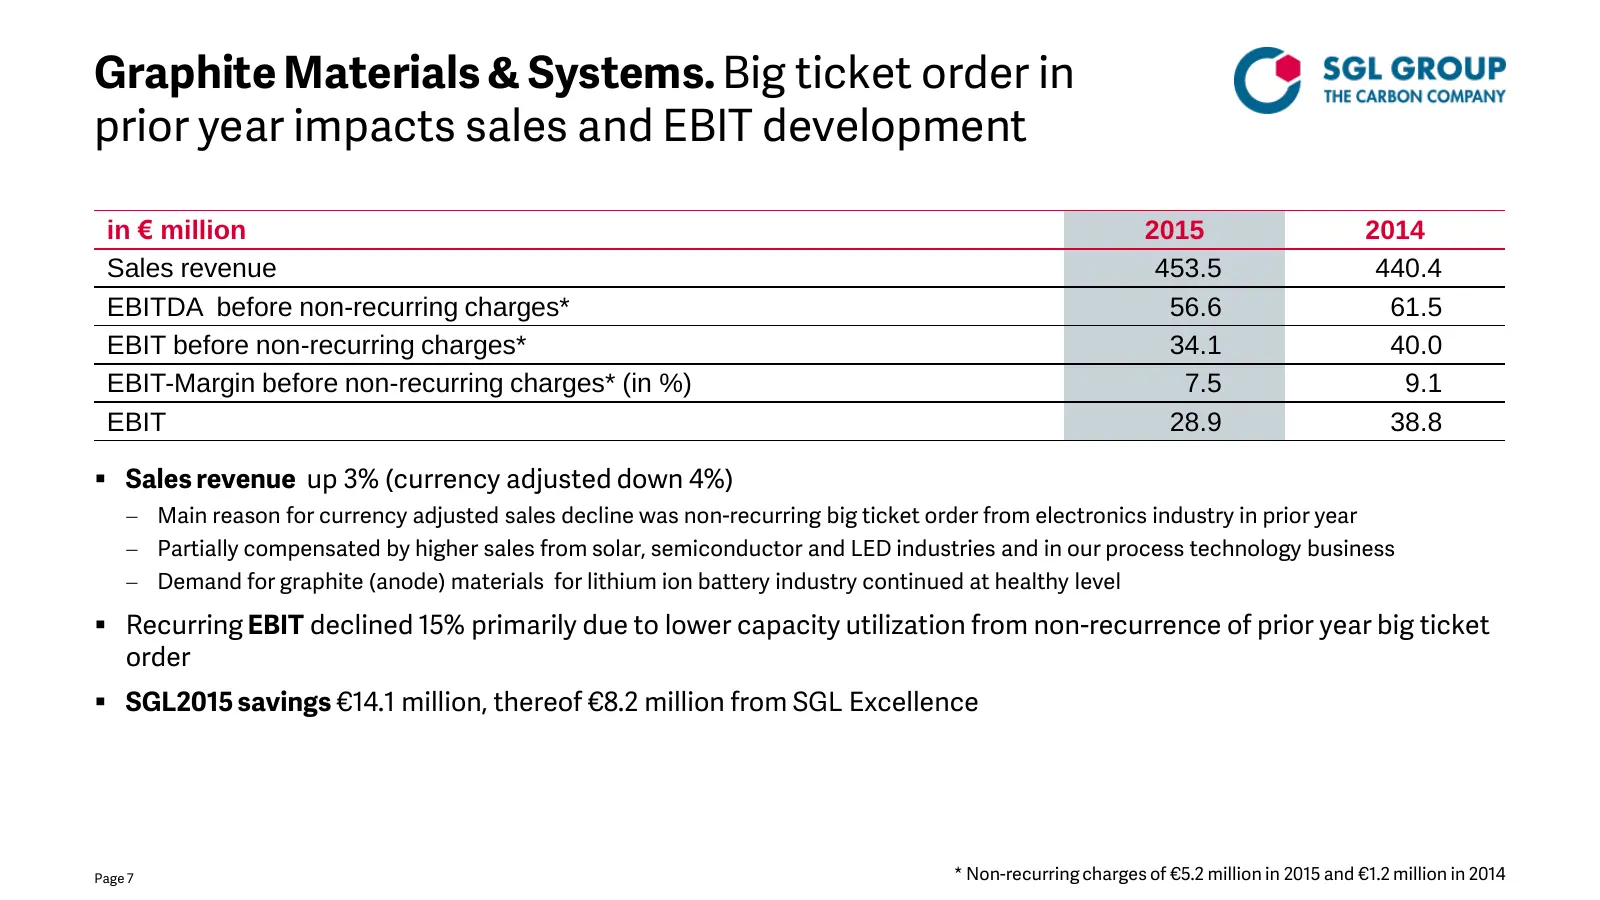
Graphite Materials & Systems. Big ticket order in prior year impacts sales and EBIT development in € million 2015 2014 Sales revenue 453.5 440.4 EBITDA before non-recurring charges* 56.6 61.5 EBIT before non-recurring charges* 34.1 40.0 EBIT-Margin before non-recurring charges* (in %) 7.5 9.1 EBIT 2
Slide 8: Performance Products
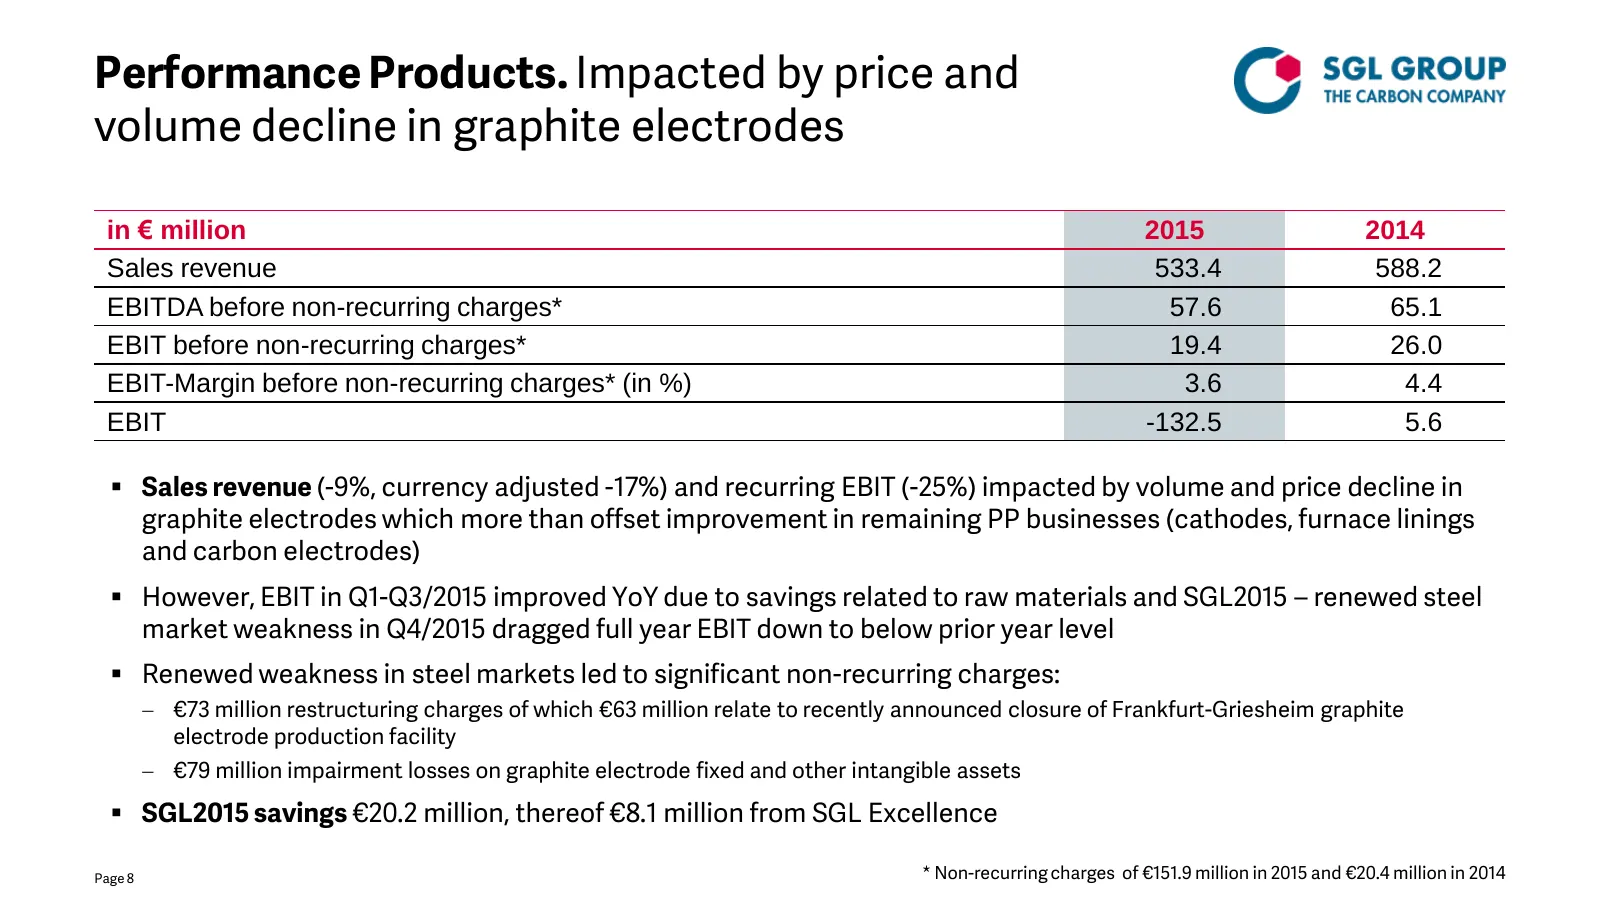
Performance Products. Impacted by price and volume decline in graphite electrodes in € million 2015 2014 Sales revenue 533.4 588.2 EBITDA before non-recurring charges* 57.6 65.1 EBIT before non-recurring charges* 19.4 26.0 EBIT-Margin before non-recurring charges* (in %) 3.6 4.4 EBIT -132.5 5.6 Sa
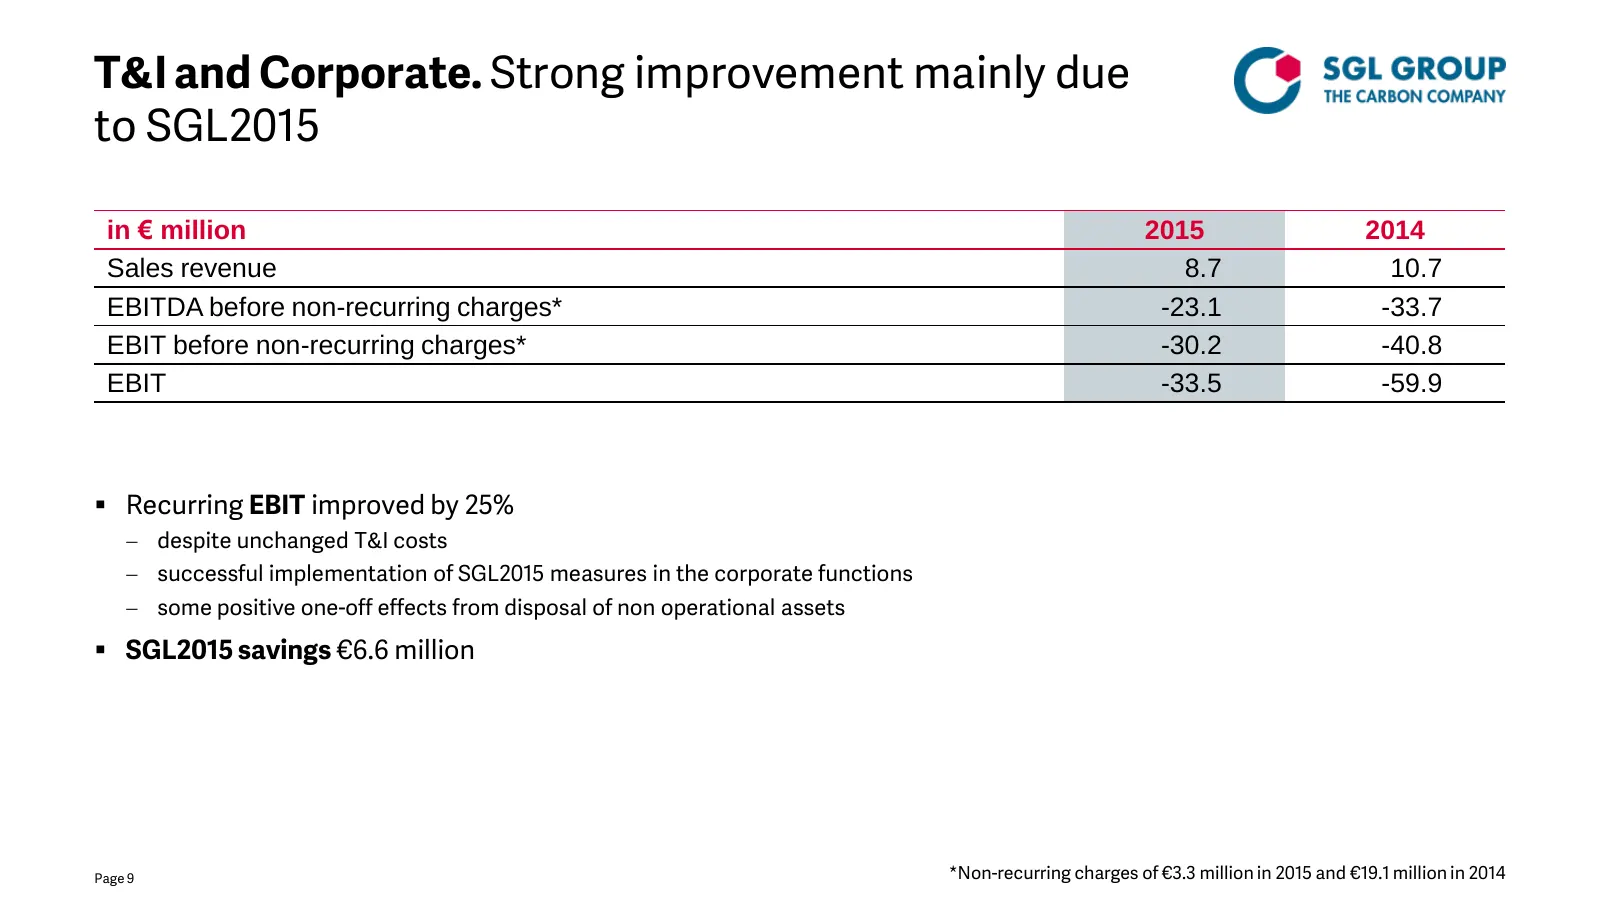
Slide 9: T&I and Corporate
T&I and Corporate. Strong improvement mainly due to SGL2015 in € million 2015 2014 Sales revenue 8.7 10.7 EBITDA before non-recurring charges* -23.1 -33.7 EBIT before non-recurring charges* -30.2 -40.8 EBIT -33.5 -59.9 Recurring EBIT improved by 25% despite unchanged T&I costs successful imple
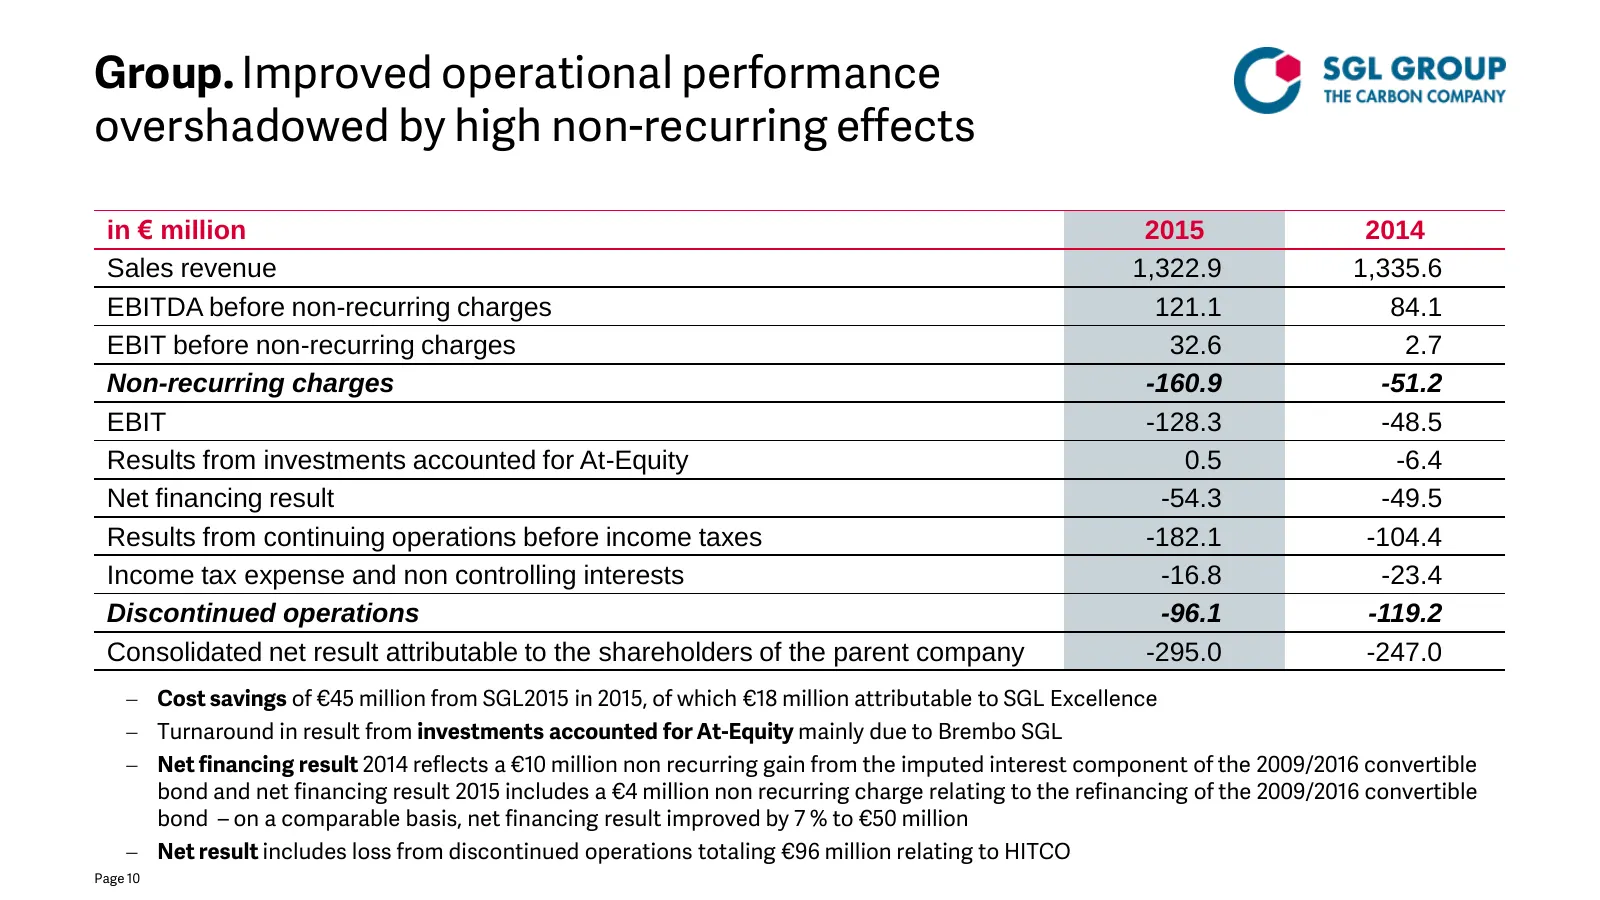
Slide 10: Group. Improved operational performance overshadowed by non-recurring effects
Group. Improved operational performance overshadowed by high non-recurring effects in € million 2015 2014 Sales revenue 1,322.9 1,335.6 EBITDA before non-recurring charges 121.1 84.1 EBIT before non-recurring charges 32.6 2.7 Non-recurring charges -160.9 -51.2 EBIT -128.3 -48.5 Results from investme
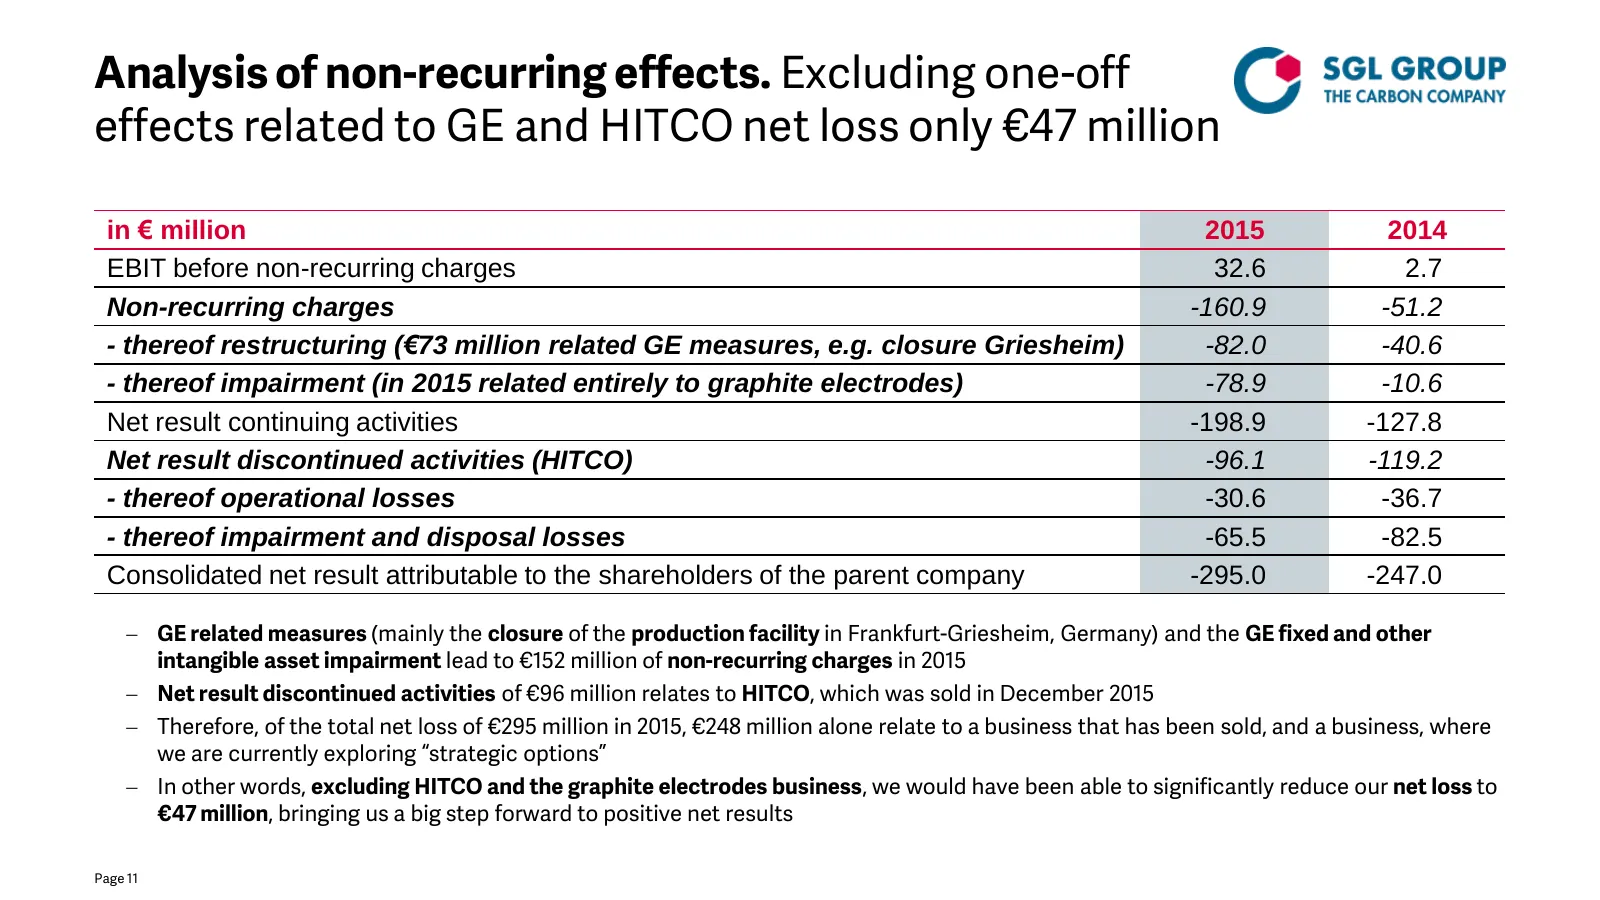
Slide 11: Analysis of non-recurring effects
Analysis of non-recurring effects. Excluding one-off effects related to GE and HITCO net loss only €47 million in € million 2015 2014 EBIT before non-recurring charges 32.6 2.7 Non-recurring charges -160.9 -51.2 - thereof restructuring (€73 million related GE measures, e.g. closure Griesheim) -82.0
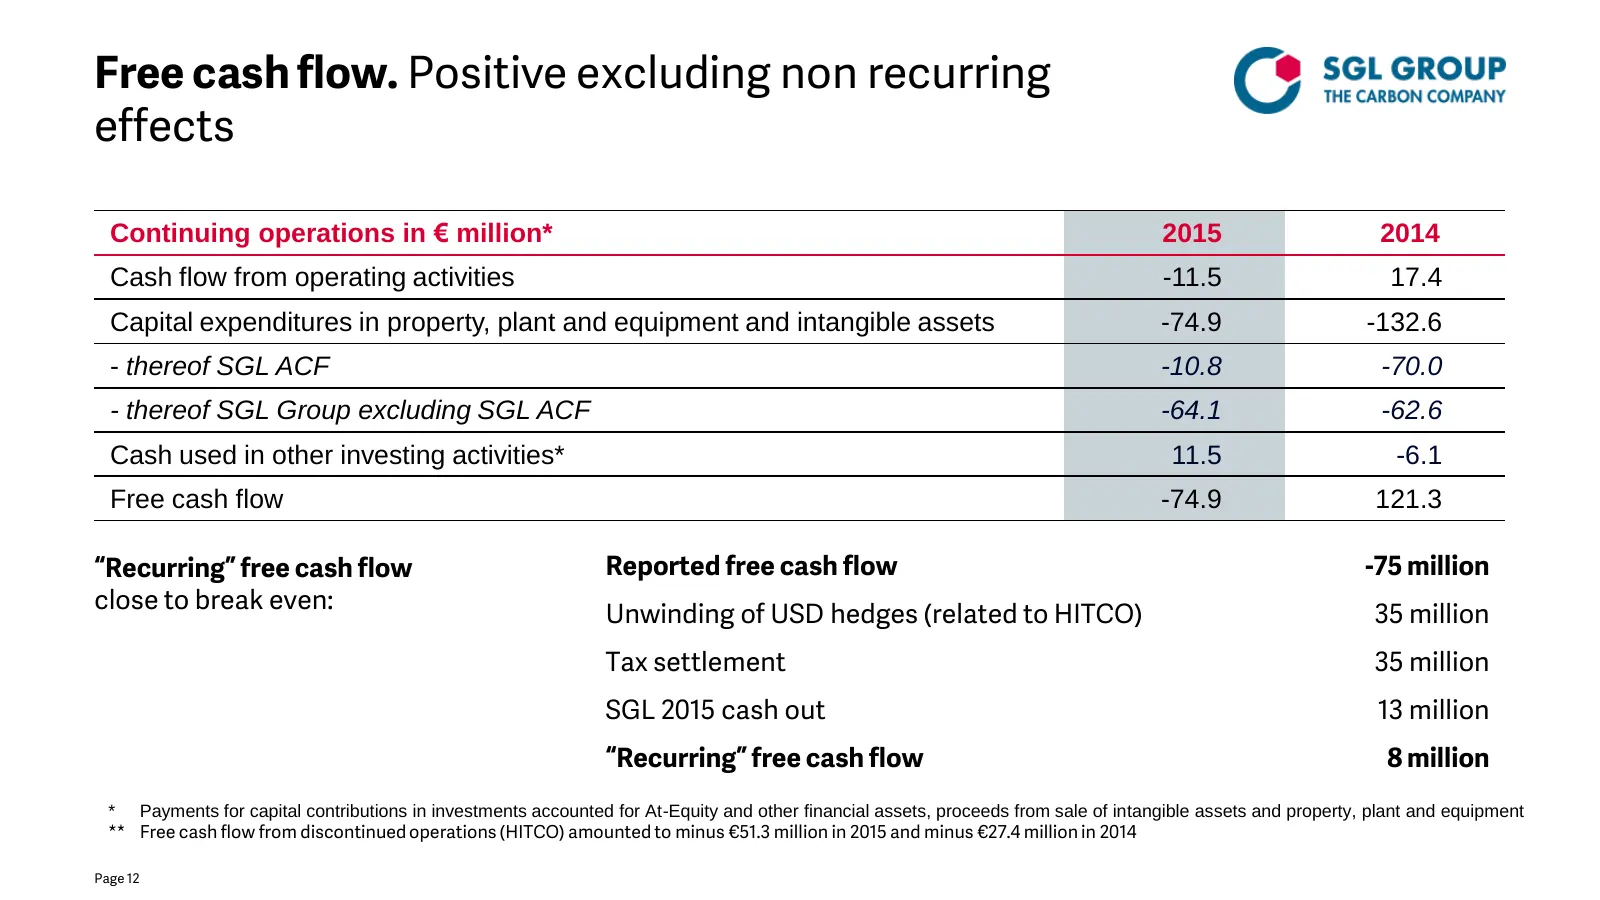
Slide 12: Free cash flow. Positive excluding non recurring effects
Free cash flow. Positive excluding non recurring effects Continuing operations in € million* 2015 2014 Cash flow from operating activities -11.5 17.4 Capital expenditures in property, plant and equipment and intangible assets -74.9 -132.6 - thereof SGL ACF -10.8 -70.0 - thereof SGL Group excluding S
Slide 13: Balance sheet. More than sufficient liquidity
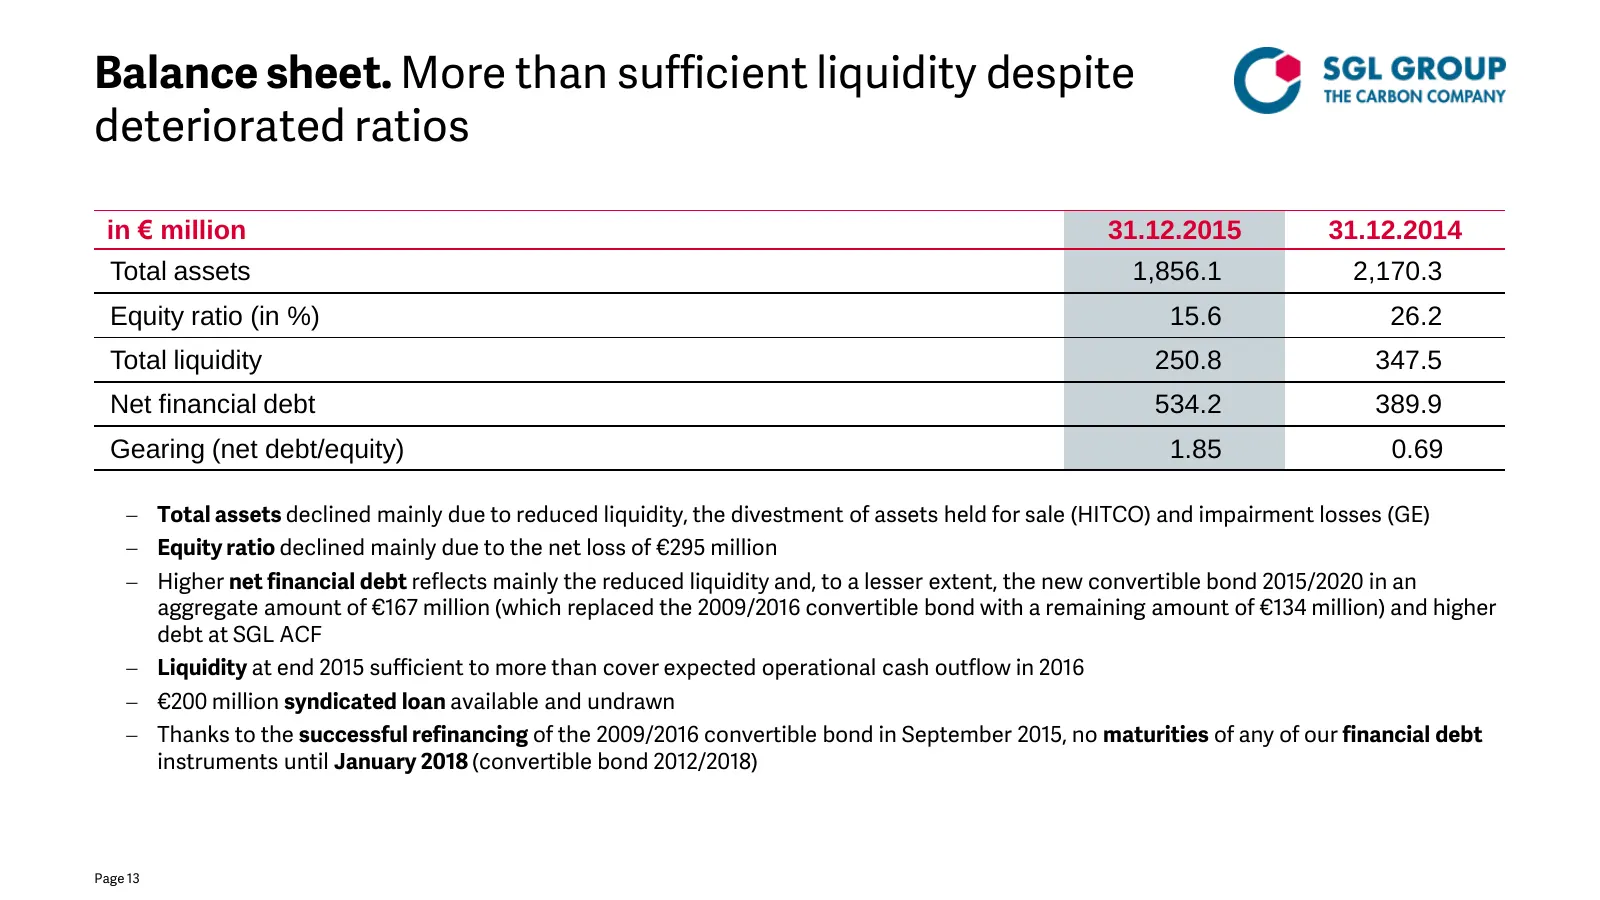
Balance sheet. More than sufficient liquidity despite deteriorated ratios in € million 31.12.2015 31.12.2014 Total assets 1,856.1 2,170.3 Equity ratio (in %) 15.6 26.2 Total liquidity 250.8 347.5 Net financial debt 534.2 389.9 Gearing (net debt/equity) 1.85 0.69 Total assets declined mainly due to
Slide 14: Agenda
Agenda. 1. Review of the fiscal year 2015 2. Financials 2015 3. Outlook 2016 – Jürgen Köhler 4. Mid term strategy Page 14 | Investor and Analyst Conference | 23 March 2016
Slide 15: Composites – Fibers & Materials. New name for a new, integrated strategy
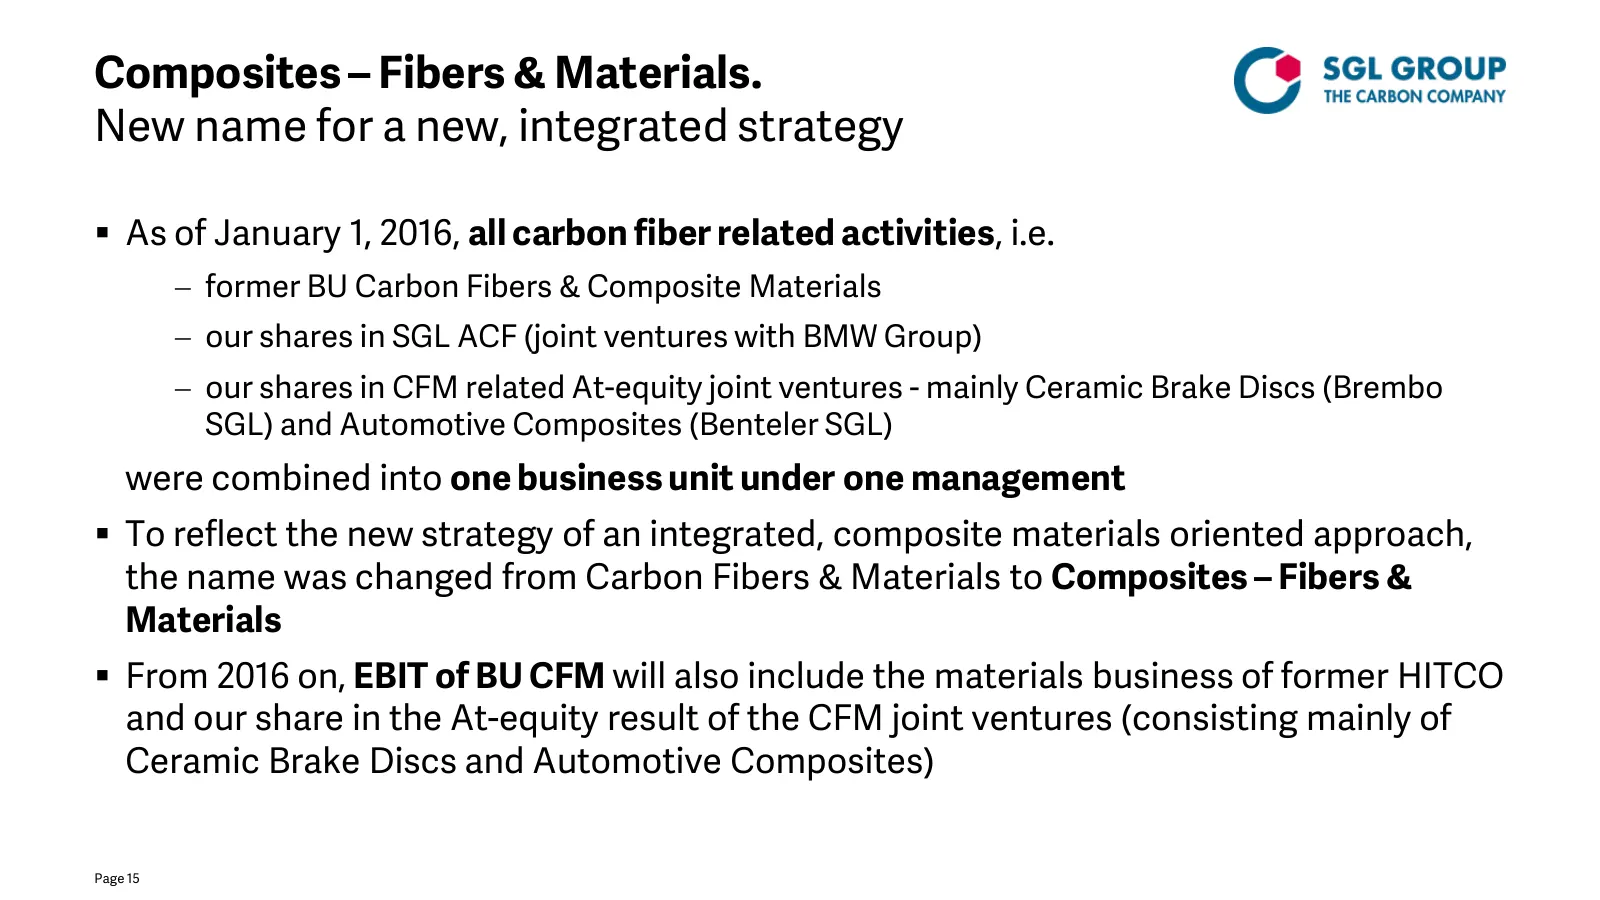
Composites – Fibers & Materials. New name for a new, integrated strategy As of January 1, 2016, all carbon fiber related activities, i.e. former BU Carbon Fibers & Composite Materials our shares in SGL ACF (joint ventures with BMW Group) our shares in CFM related At-equity joint ventures - m
Slide 16: Business unit outlook 2016
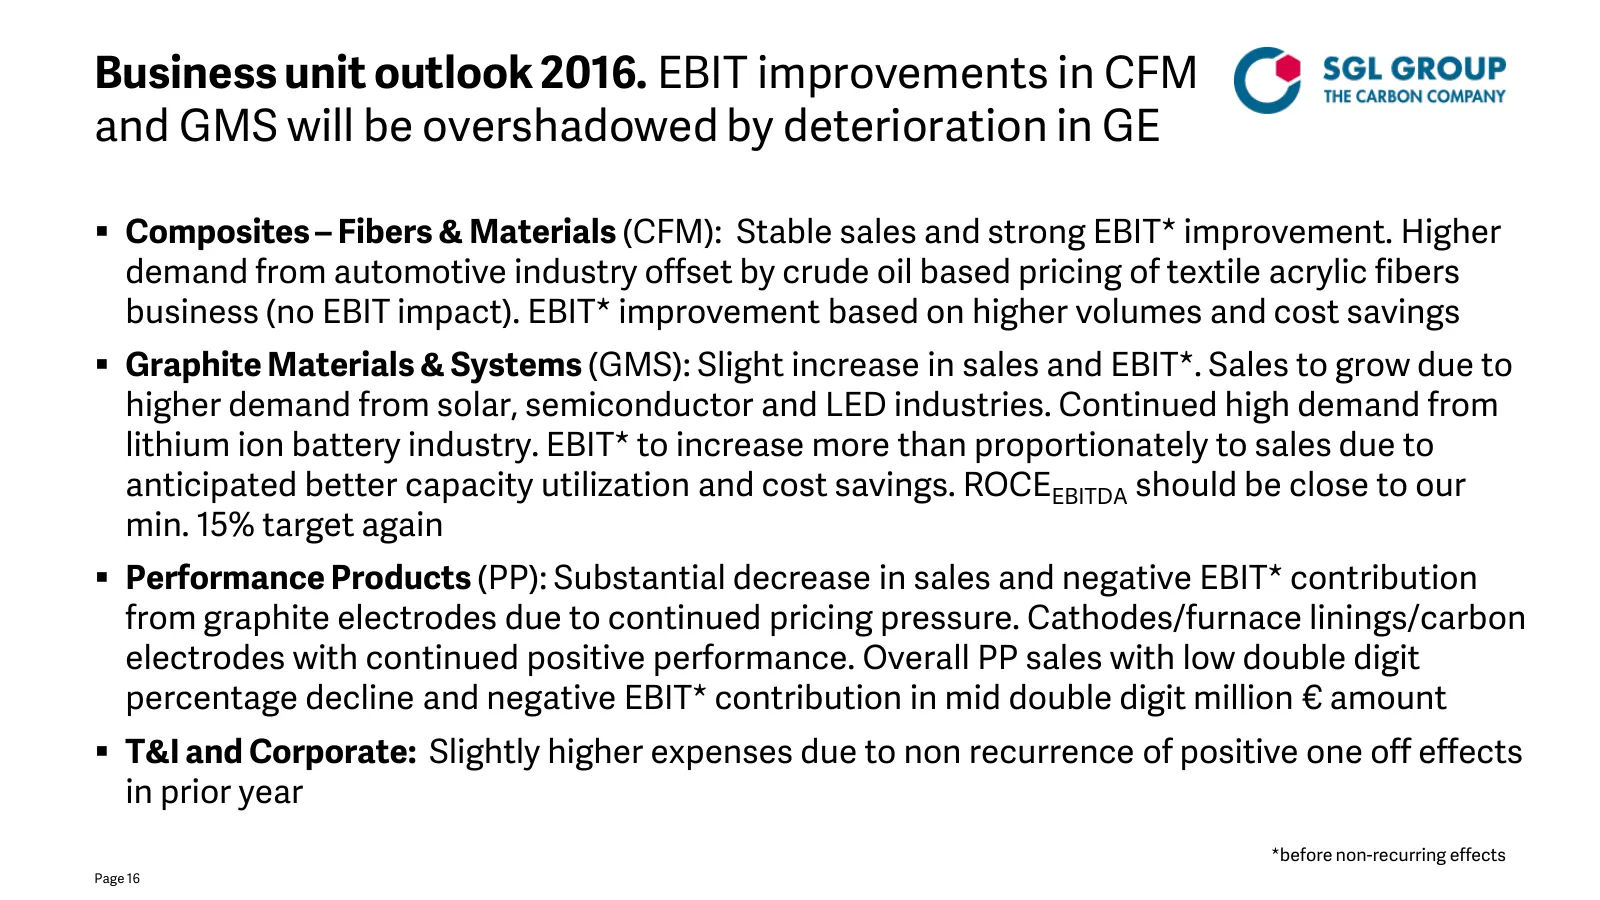
Business unit outlook 2016. EBIT improvements in CFM and GMS will be overshadowed by deterioration in GE Composites – Fibers & Materials (CFM): Stable sales and strong EBIT* improvement. Higher demand from automotive industry offset by crude oil based pricing of textile acrylic fibers business (no
Slide 17: Group outlook 2016
Group outlook 2016. Group KPIs will be heavily impacted by GE performance Full year Group sales slightly lower due to substantial decline in GE prices Group recurring EBITDA* and EBIT*: substantial decrease solely due to negative EBIT* contribution from GE Net result to improve due to lower re
Slide 18: 2016 negative free cash flow skewed to H1
2016 negative free cash flow more than proportionately skewed to H1 Q1 typically shows a high working capital buildup plus scheduled payment to Avcorp (buyer of HITCO’s aerostructure activities) in January 2016 Operationally, free cash flow will start improving from Q2 onwards – partially offset
Slide 19: Agenda
Agenda. 1. Review of the fiscal year 2015 2. Financials 2015 3. Outlook 2016 4. Mid term strategy – Jürgen Köhler Page 19 | Investor and Analyst Conference | 23 March 2016
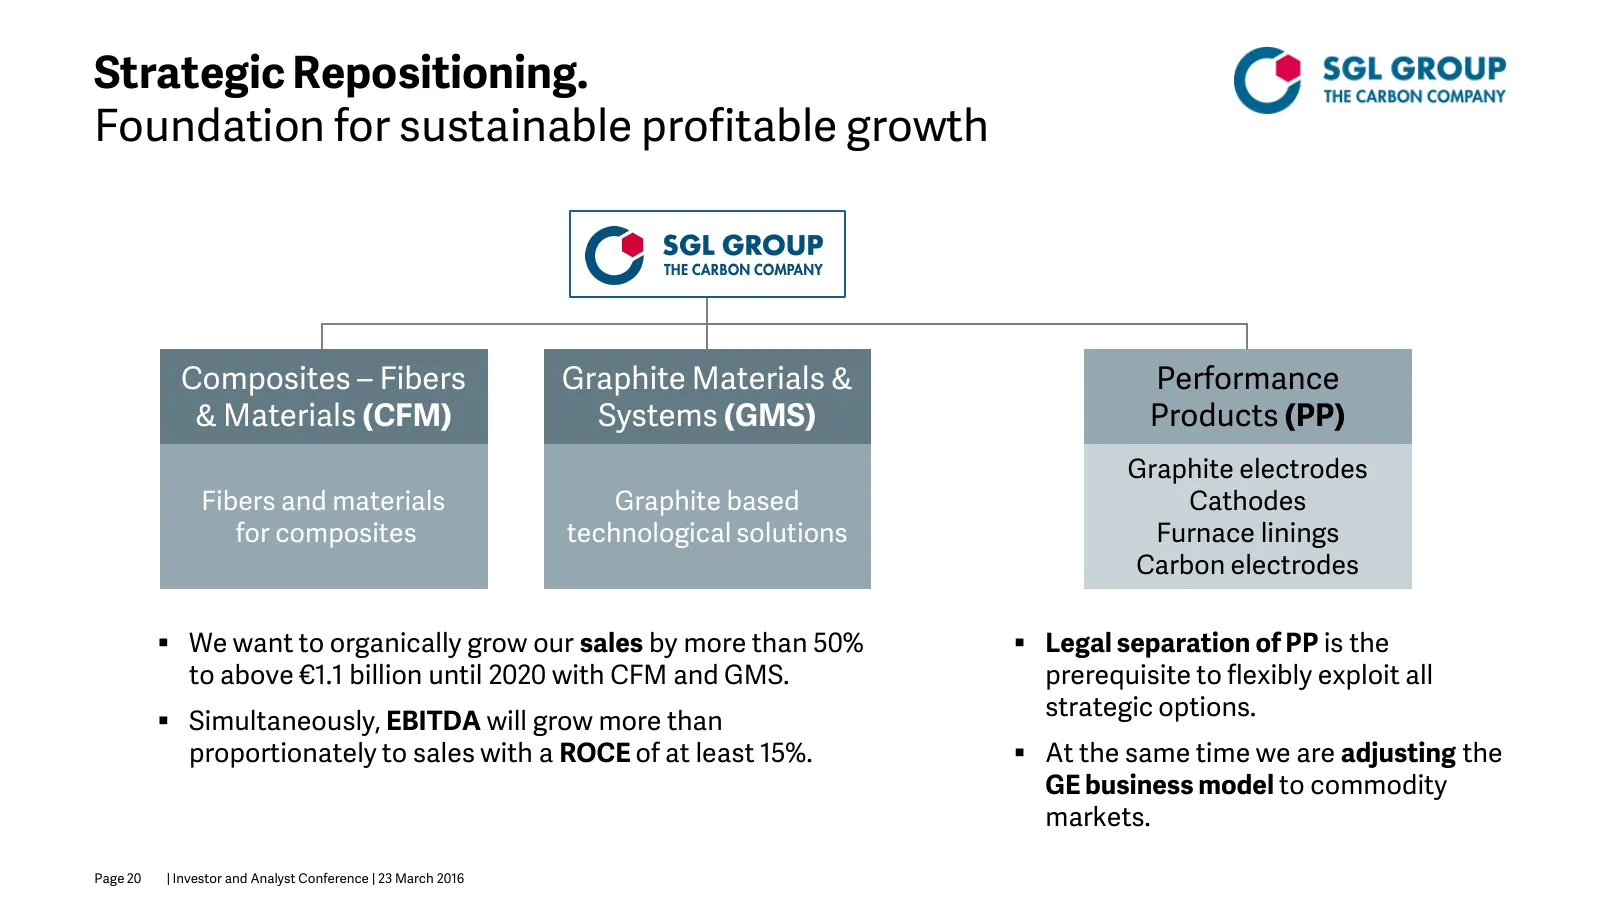
Slide 20: Strategic Repositioning. Foundation for sustainable profitable growth
Strategic Repositioning. Foundation for sustainable profitable growth Composites – Fibers Graphite Materials & Performance & Materials (CFM) Systems (GMS) Products (PP) Graphite electrodes Fibers and materials Graphite based Cathodes for composites technological solutions Furnace linings Carbon elec
Slide 21: PP: Steel environment continues to be difficult
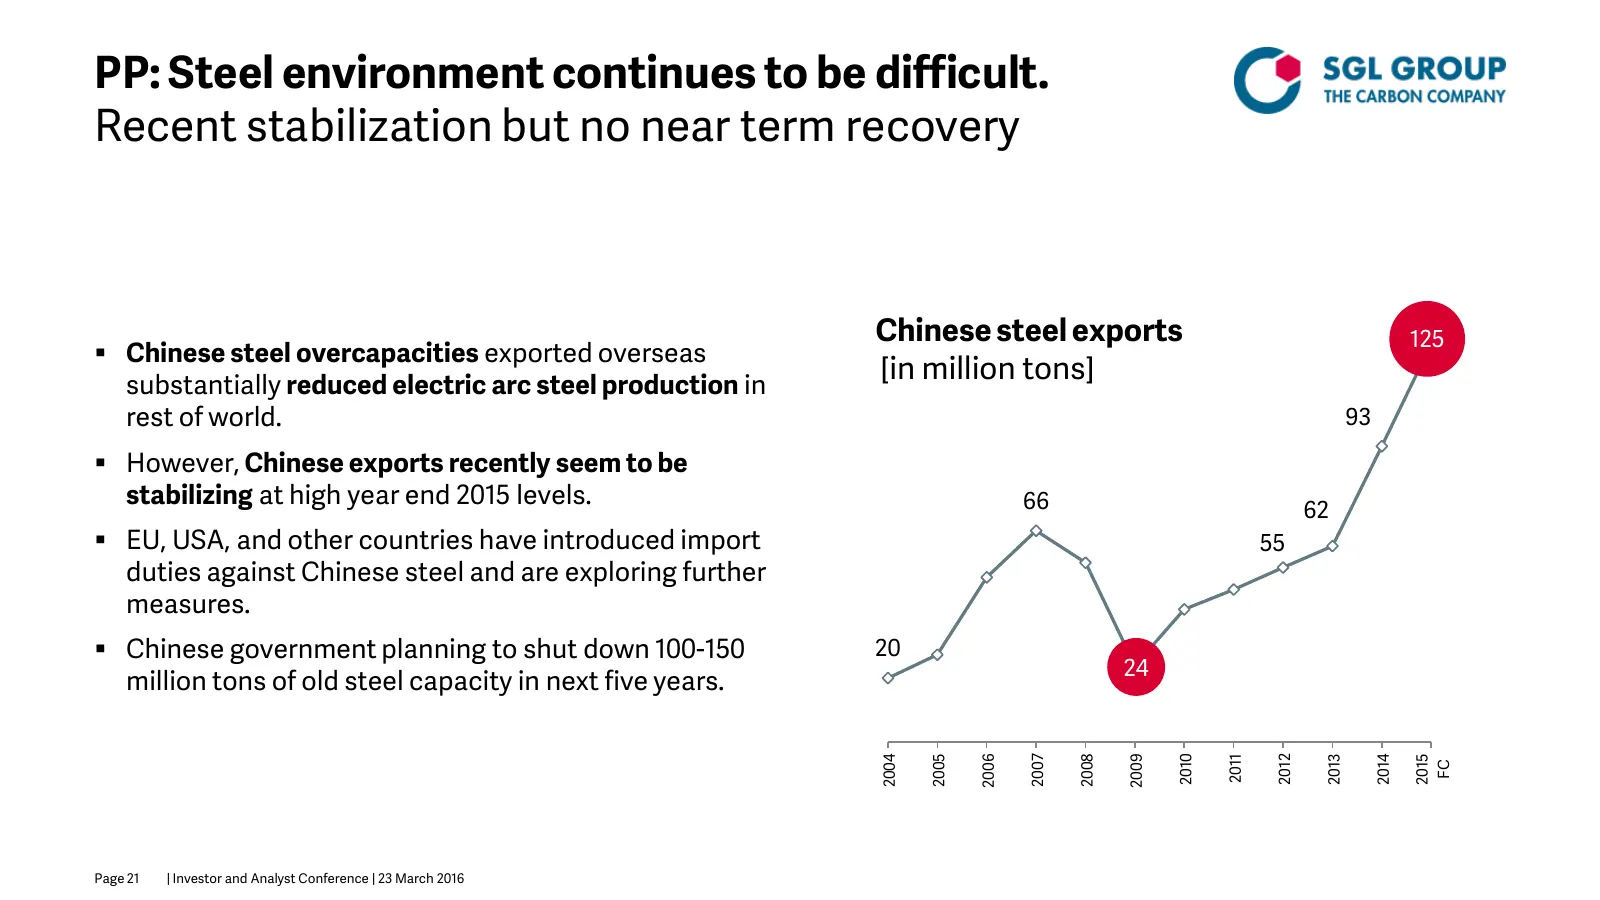
PP: Steel environment continues to be difficult. Recent stabilization but no near term recovery Chinese steel exports 125 Chinese steel overcapacities exported overseas substantially reduced electric arc steel production in [in million tons] rest of world. 93 However, Chinese exports recently se
Slide 22: PP: Current global steel situation problematic for GE
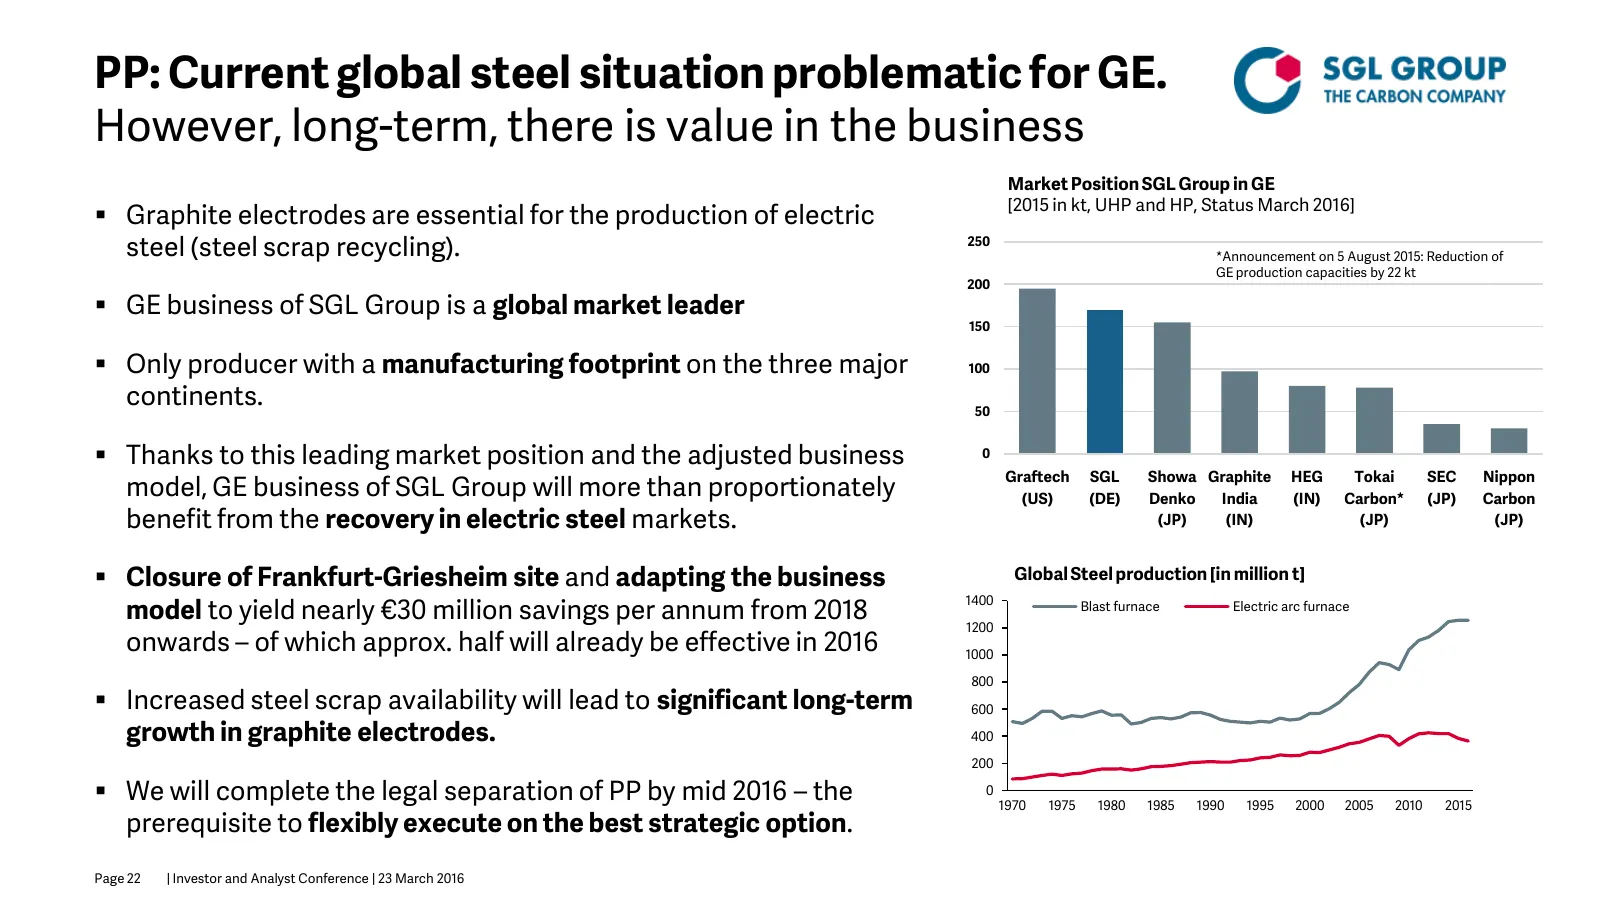
PP: Current global steel situation problematic for GE. However, long-term, there is value in the business Market Position SGL Group in GE [2015 in kt, UHP and HP, Status March 2016] Graphite electrodes are essential for the production of electric steel (steel scrap recycling). 250 *Announcement on
Slide 23: PP: Broad product portfolio. Carve out within PP
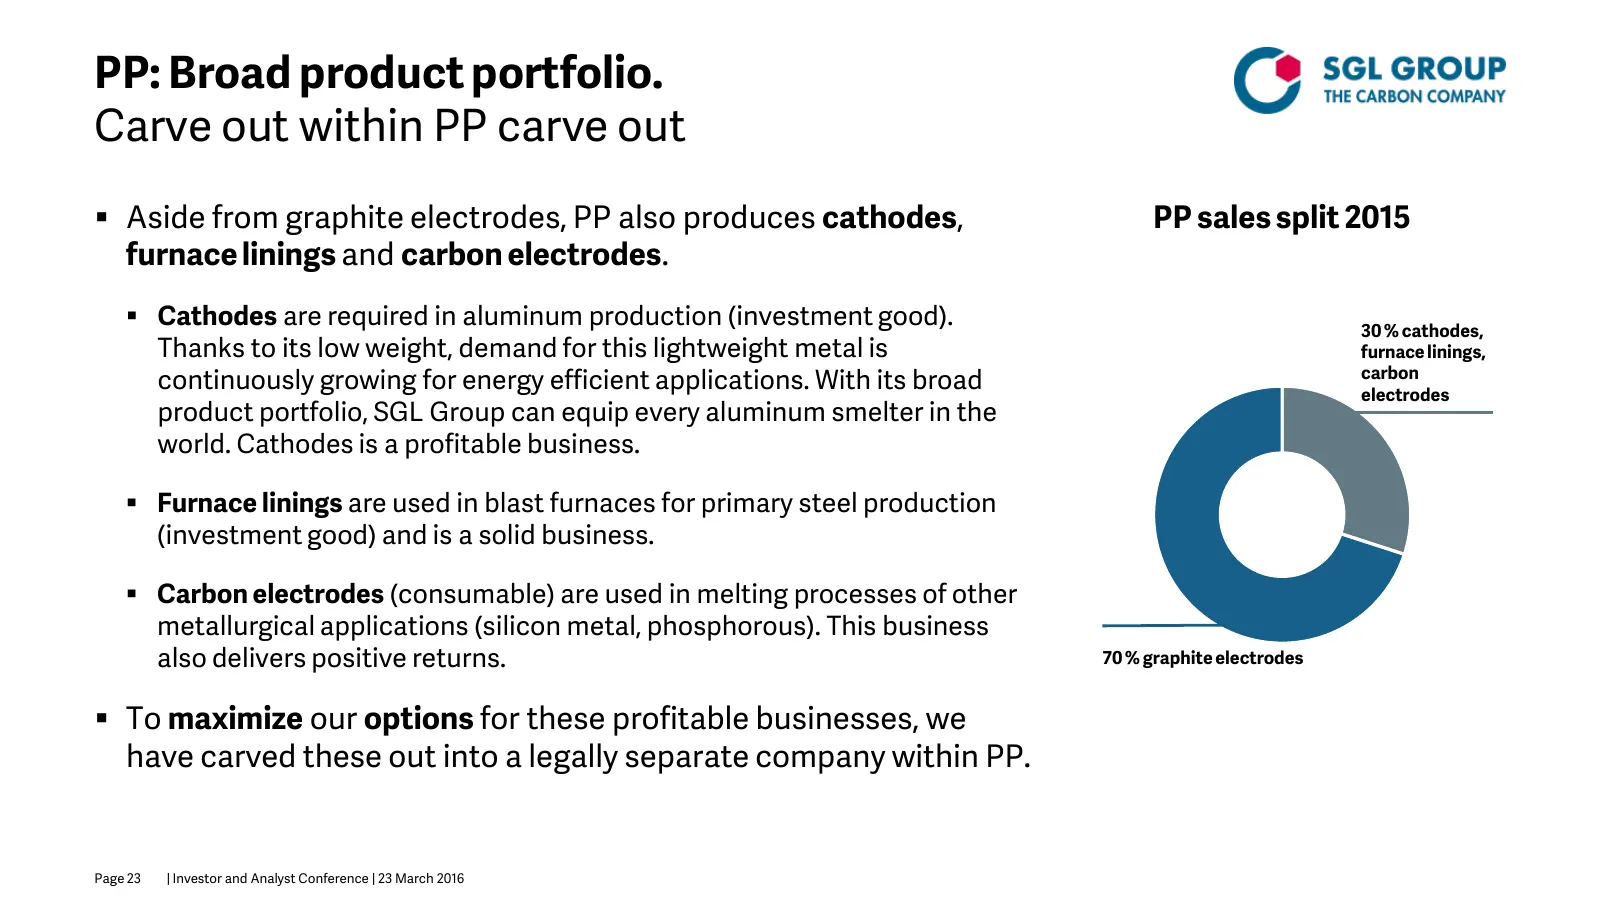
PP: Broad product portfolio. Carve out within PP carve out Aside from graphite electrodes, PP also produces cathodes, PP sales split 2015 furnace linings and carbon electrodes. Cathodes are required in aluminum production (investment good). 30 % cathodes, Thanks to its low weight, demand for thi
Slide 24: Status of the carve out project
Status of the carve out project. We are well within our accelerated schedule Last autumn we announced that we want to accelerate the PP carve out. Today, we already have the legal and organizational concepts for the new structure of PP. The agreement on the reconciliation of interests (“Intere
Slide 25: Growth strategy of SGL Group
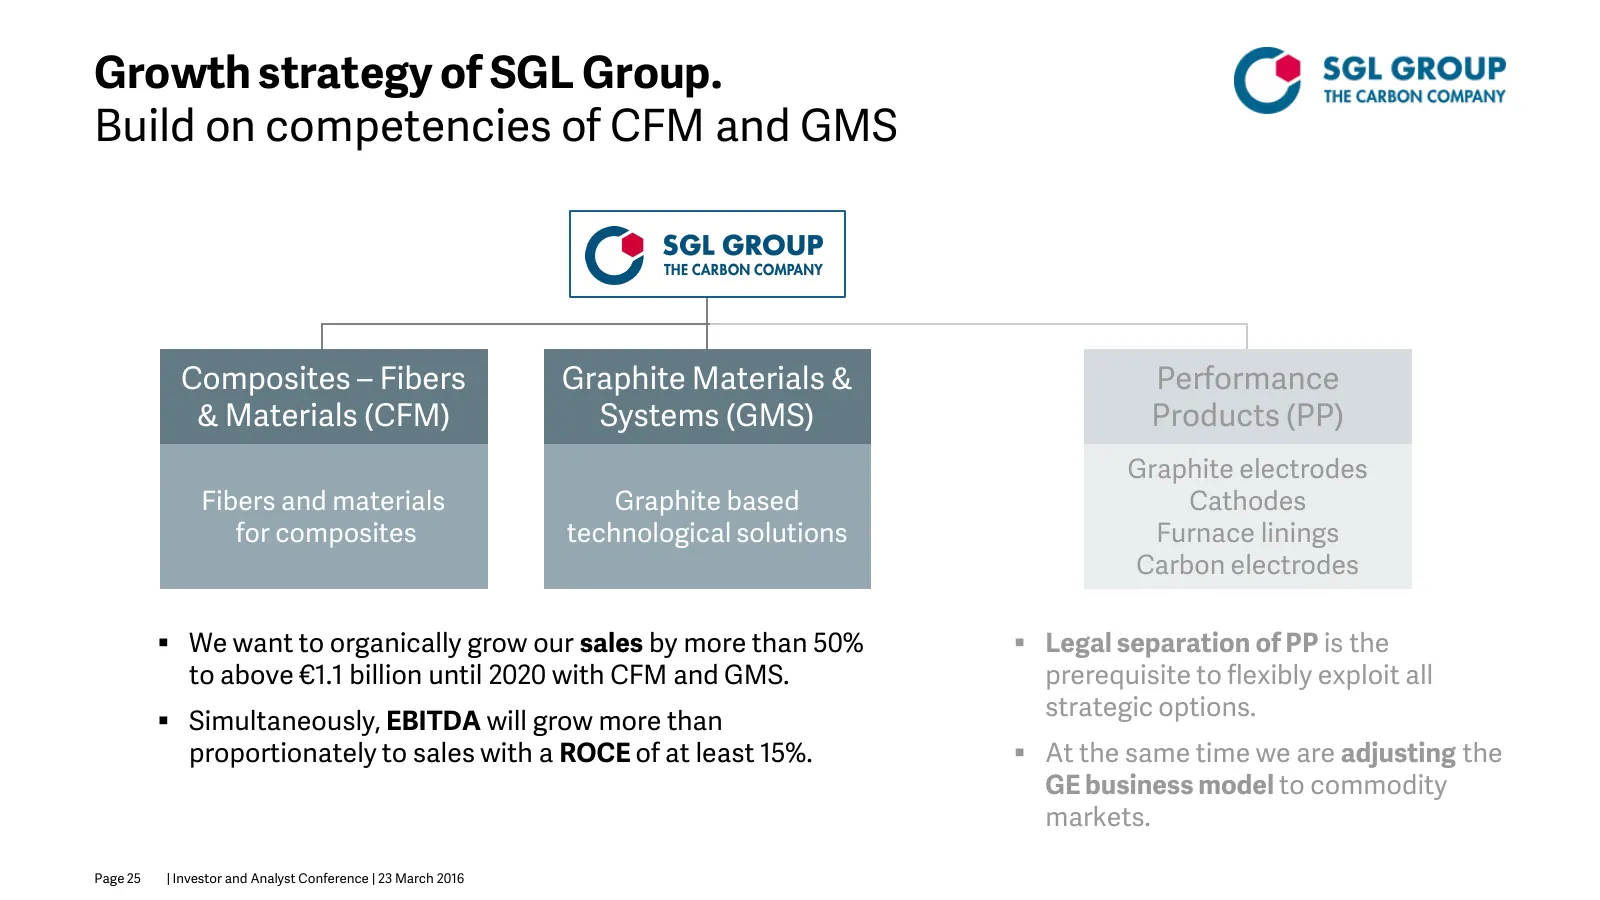
Growth strategy of SGL Group. Build on competencies of CFM and GMS Composites – Fibers Graphite Materials & Performance & Materials (CFM) Systems (GMS) Products (PP) Graphite electrodes Fibers and materials Graphite based Cathodes for composites technological solutions Furnace linings Carbon electro
Slide 26: CFM: Composite Specialist
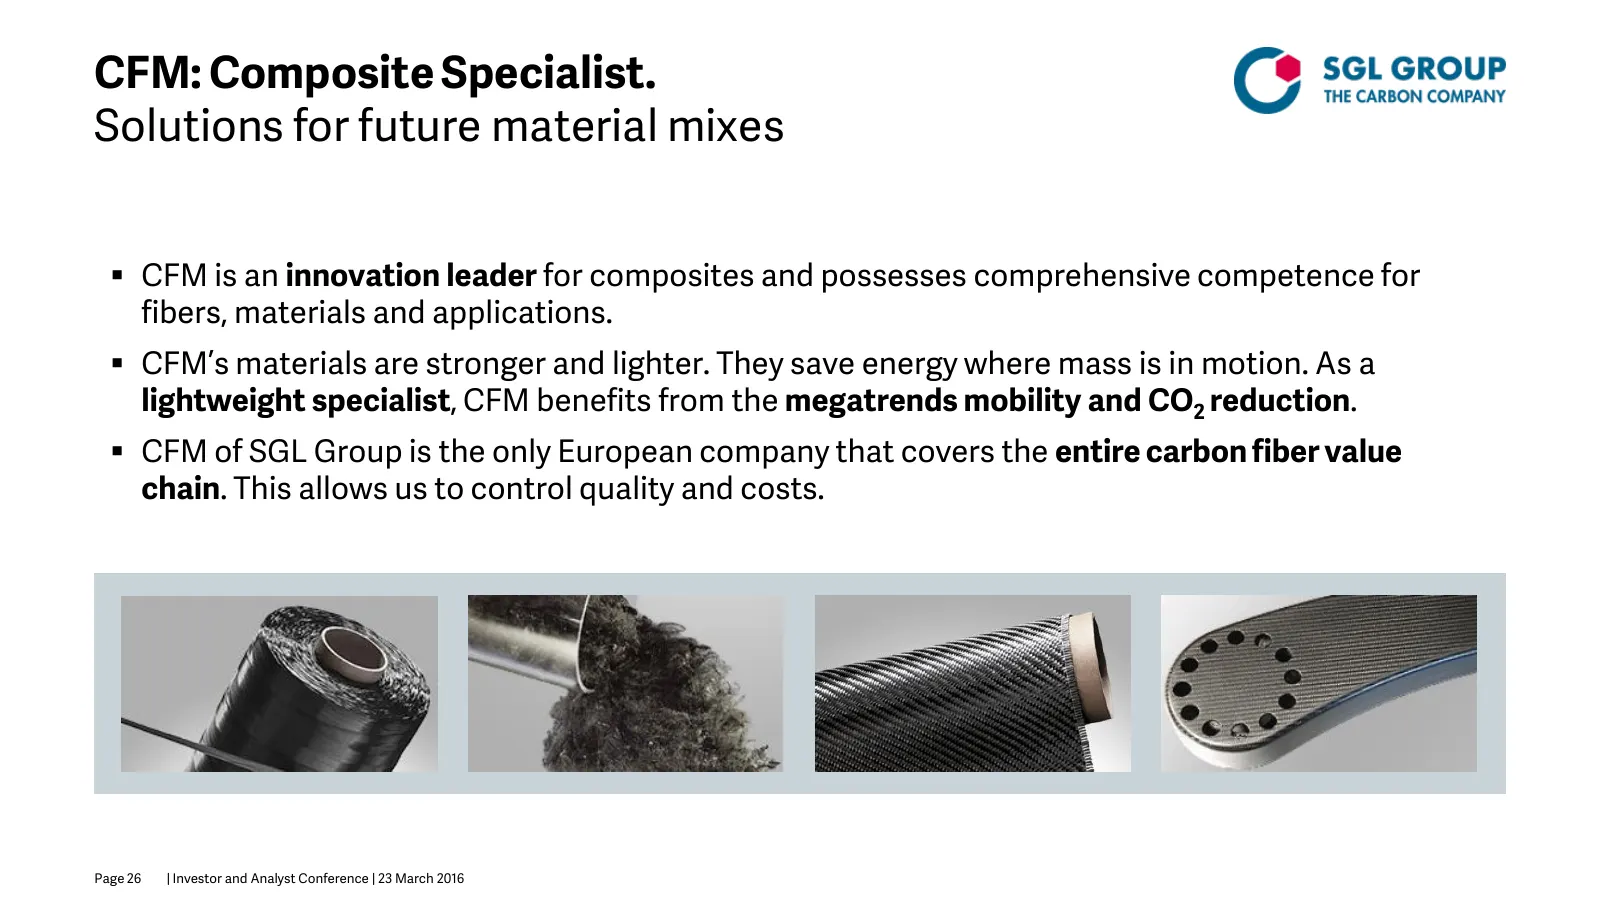
CFM: Composite Specialist. Solutions for future material mixes CFM is an innovation leader for composites and possesses comprehensive competence for fibers, materials and applications. CFM’s materials are stronger and lighter. They save energy where mass is in motion. As a lightweight specialist
Slide 27: CFM Example: Strong position in the automotive industry
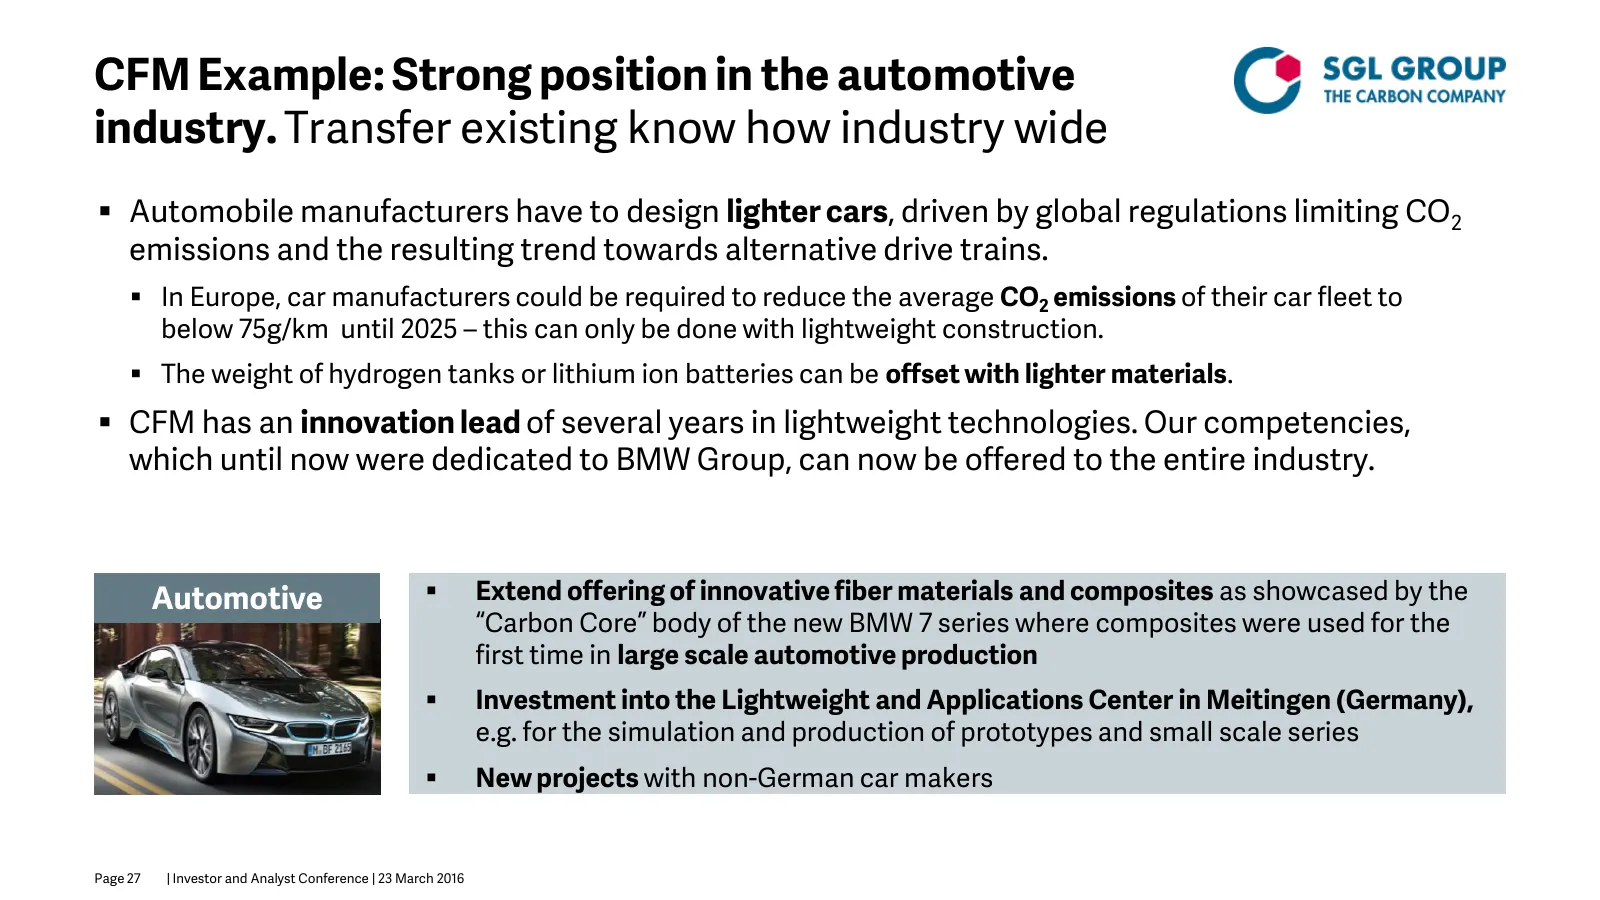
CFM Example: Strong position in the automotive industry. Transfer existing know how industry wide Automobile manufacturers have to design lighter cars, driven by global regulations limiting CO2 emissions and the resulting trend towards alternative drive trains. In Europe, car manufacturers could
Slide 28: CFM Example: Expansion into other industries
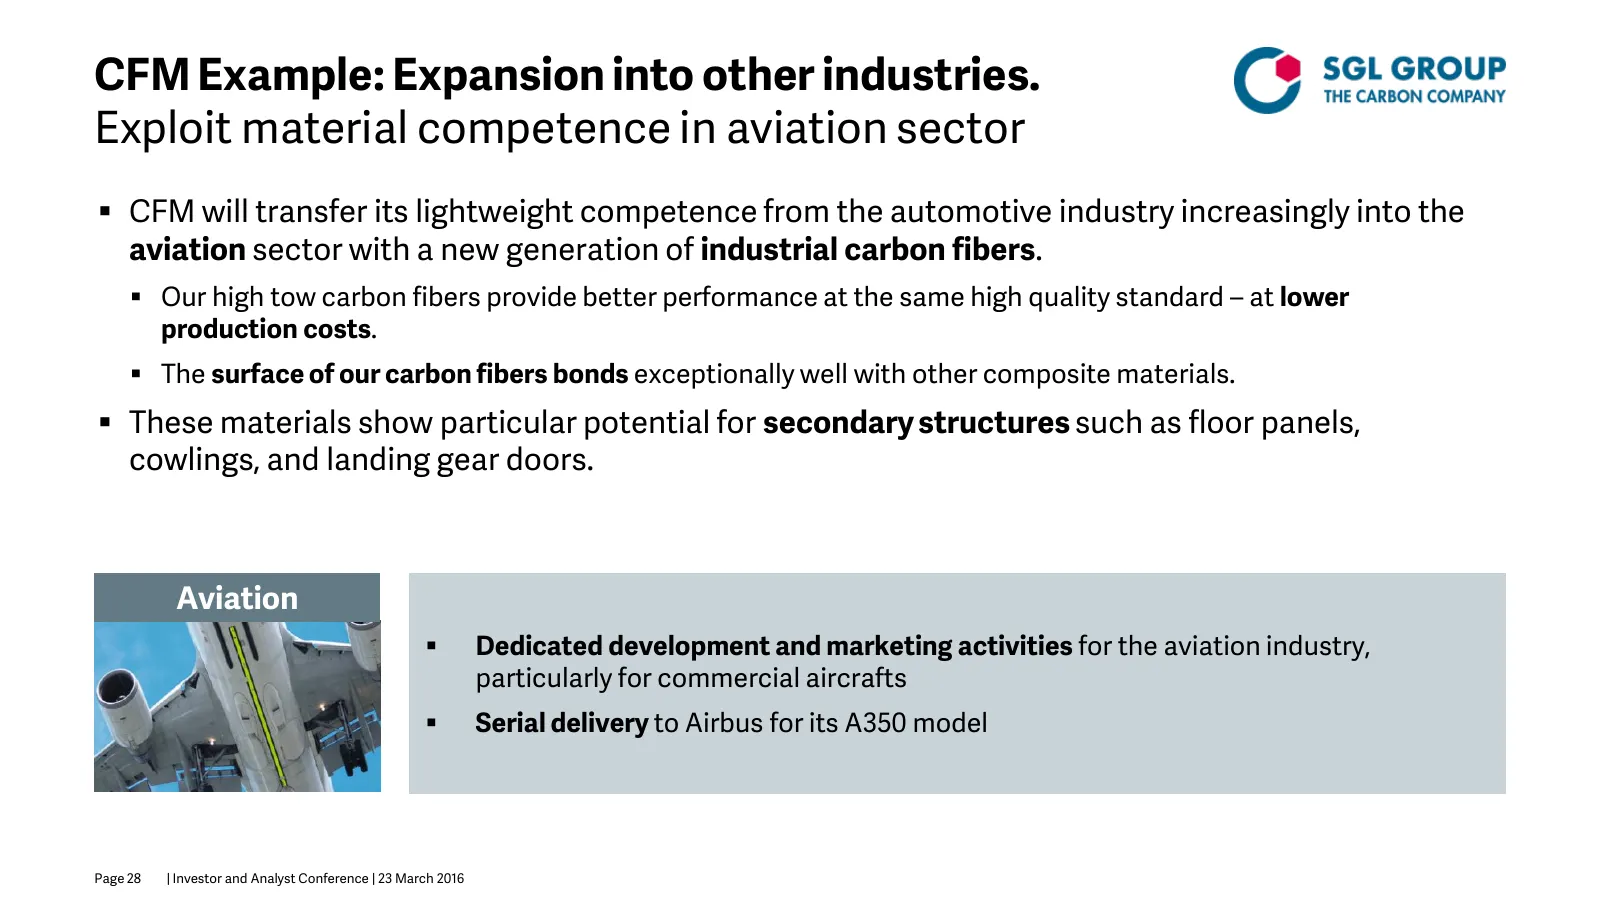
CFM Example: Expansion into other industries. Exploit material competence in aviation sector CFM will transfer its lightweight competence from the automotive industry increasingly into the aviation sector with a new generation of industrial carbon fibers. Our high tow carbon fibers provide bette
Slide 29: GMS: Development partner for our customers
GMS: Development partner for our customers. Graphite based solutions GMS is the development partner – “enabler” – of our customers for graphite based advanced technological solutions. Offering products and solutions to more than 35 industries, the business unit is grounded on a broad base. GMS h
Slide 30: GMS Example: Energy supply as growth driver
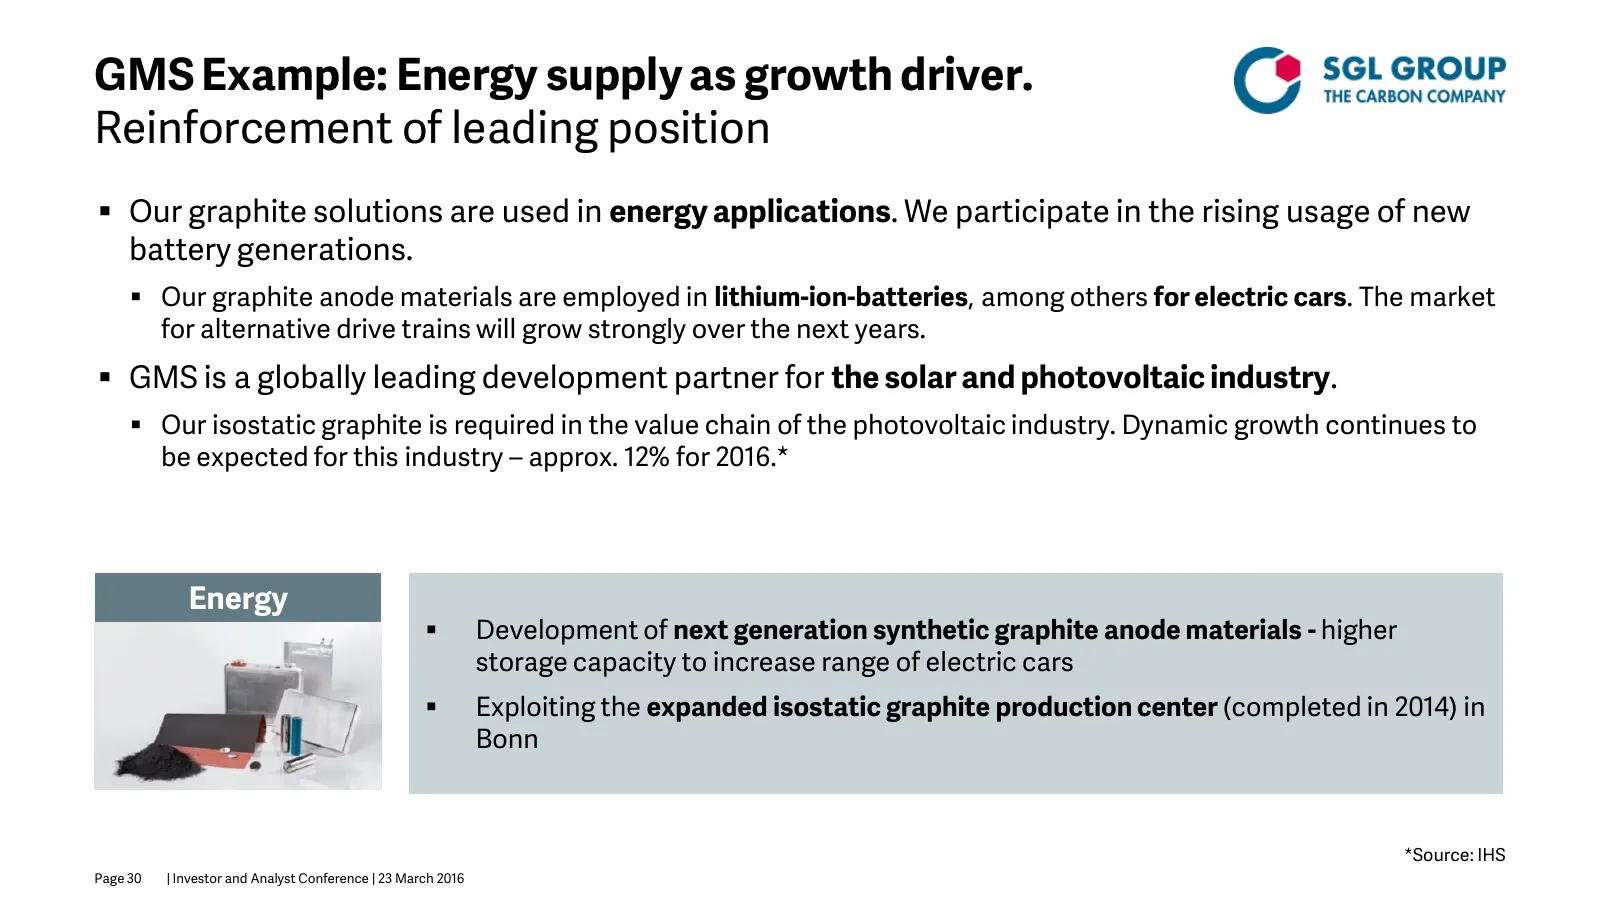
GMS Example: Energy supply as growth driver. Reinforcement of leading position Our graphite solutions are used in energy applications. We participate in the rising usage of new battery generations. Our graphite anode materials are employed in lithium-ion-batteries, among others for electric cars
Slide 31: GMS Example: Digitization and graphite
GMS Example: Digitization and graphite. LED and semiconductor industry drive demand GMS specializes in surface coating technologies. These are required in equipment for manufacturing polysilicon, LEDs, and semiconductors. Polysilicon demand for the semiconductor industry is expected to grow 11%
Slide 32: Summary: The course is set
Summary: The course is set. We are pursuing a clear strategy With the PP carve out we are creating the prerequisite for strategic options and a sustainable future for SGL Group and the business unit. The carve out of the profitable business with cathodes, furnace linings, and carbon electrodes i
Slide 33: Thank you for your attention!
Thank you for your attention! Page 33 | Investor and Analyst Conference | 23 March 2016
Slide 34: Important note
Important note: This presentation contains forward looking statements based on the information currently available to us and on our current projections and assumptions. By nature, forward looking statements are associated with known and unknown risks and uncertainties, as a consequence of which actu
Source: Internet Archive copy of sglgroup.com
More decks from SGL Carbon SE
 9M 2026 Earnings Presentation30 slides · Nov 5, 2026
 9M 2026 Earnings Presentation17 slides · Nov 5, 2026
 Q3 2024 Earnings Presentation28 slides · Nov 7, 2024
 H1 2024 Earnings Presentation18 slides · Aug 8, 2024
 Q1 2024 Earnings Presentation19 slides · May 8, 2024
 ESG Presentation (March 2024)7 slides · Mar 22, 2024