Evonik Industries AG · XETR:EVK
Evonik Industries — Investor Presentation (June 2017)
97 slides from Evonik Industries's investor presentation, June 2017
Slide 1: Evonik – Power to create. Company presentation June 2017
Evonik Power to create. Company presentation June 2017 1
Slide 2: Table of contents
Table of contents 1. Evonik at a glance 2. Strategy Update 3. Financials Q1 2017 4. Appendix 2
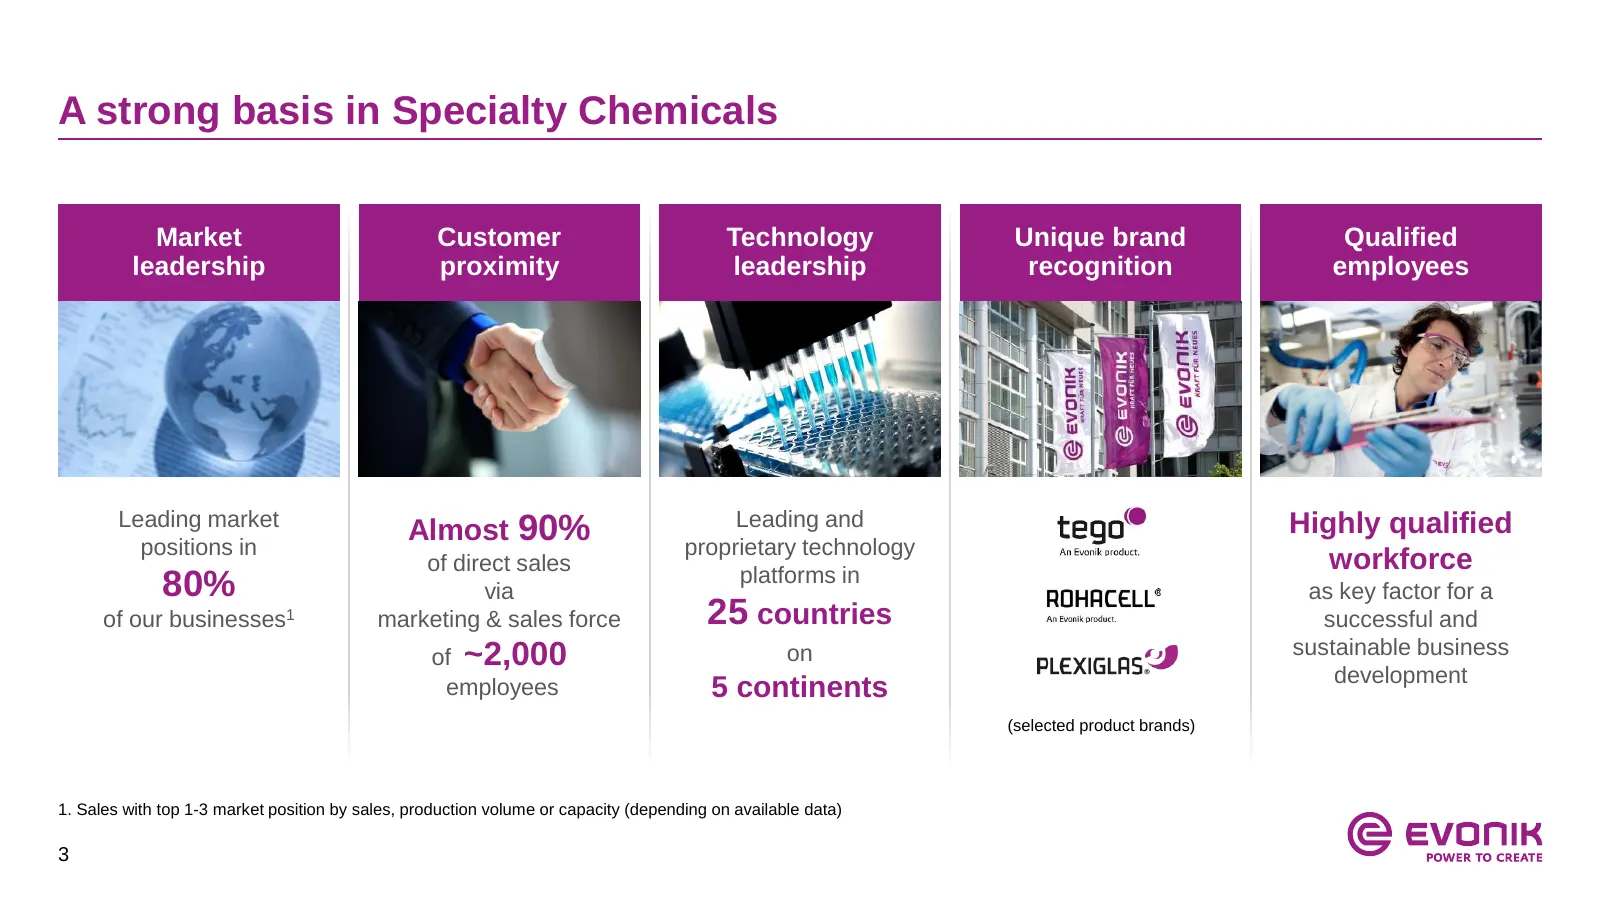
Slide 3: A strong basis in Specialty Chemicals
A strong basis in Specialty Chemicals Market Customer Technology Unique brand Qualified leadership proximity leadership recognition employees Leading market Leading and Highly qualified Almost 90% positions in proprietary technology of direct sales platforms in workforce 80% via as key factor for a
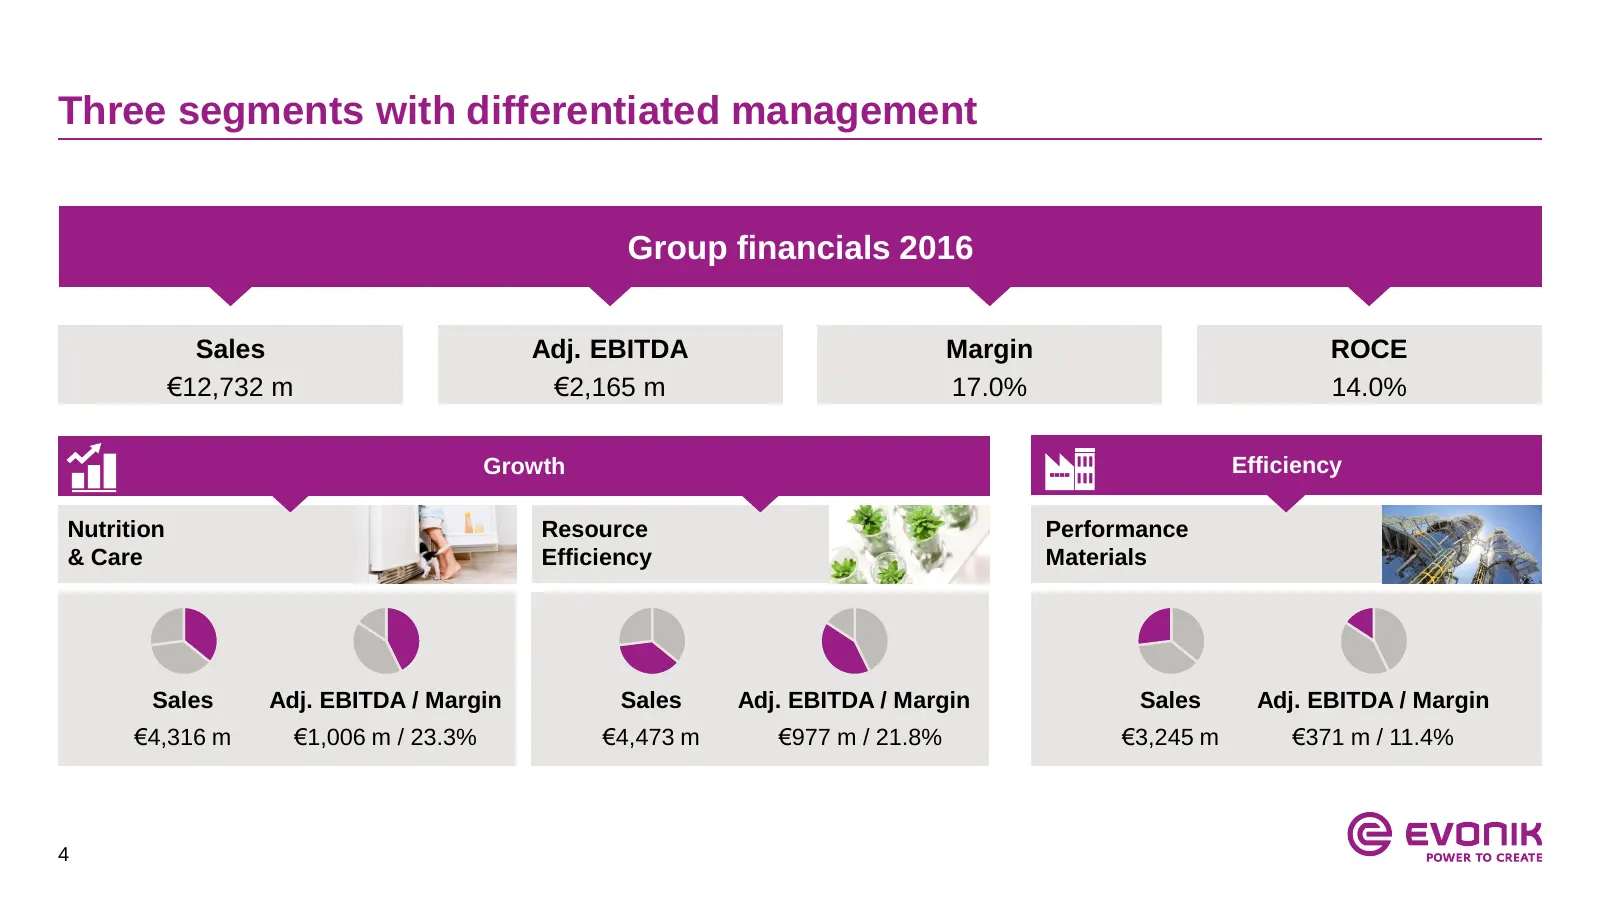
Slide 4: Three segments with differentiated management
Three segments with differentiated management Group financials 2016 Sales Adj. EBITDA Margin ROCE €12,732 m €2,165 m 17.0% 14.0% Growth Efficiency Nutrition Resource Performance & Care Efficiency Materials Sales Adj. EBITDA / Margin Sales Adj. EBITDA / Margin Sales Adj. EBITDA / Margin €4,316 m €1,0
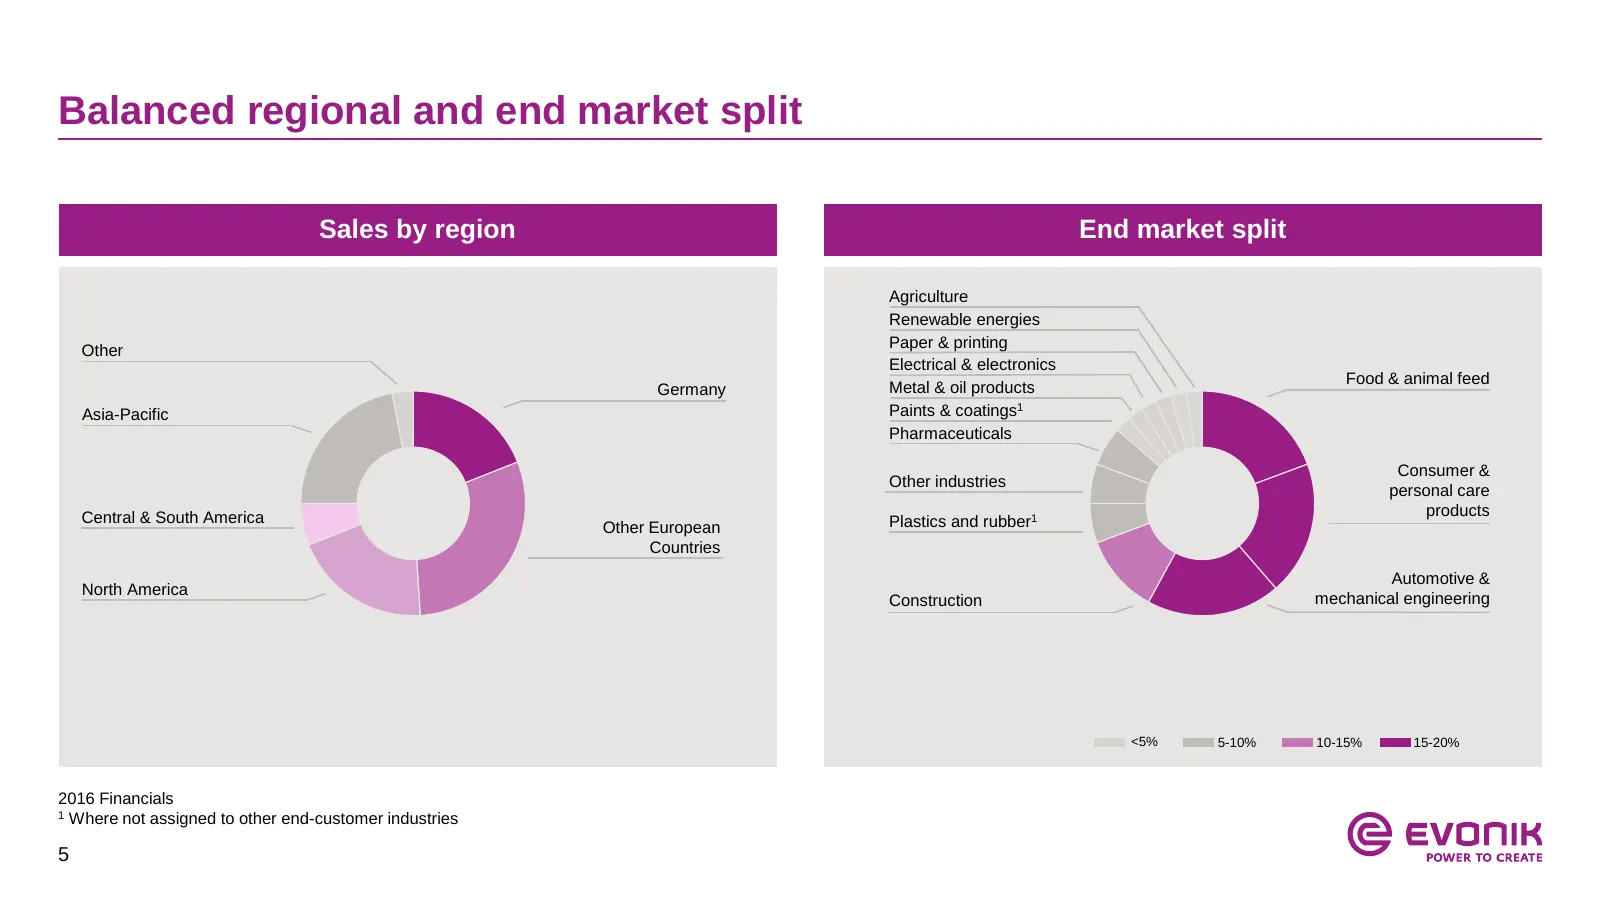
Slide 5: Balanced regional and end market split
Balanced regional and end market split Sales by region End market split Agriculture Renewable energies Paper & printing Other Electrical & electronics Food & animal feed Germany Metal & oil products Asia-Pacific Paints & coatings1 Pharmaceuticals Consumer & Other industries personal care Central & S
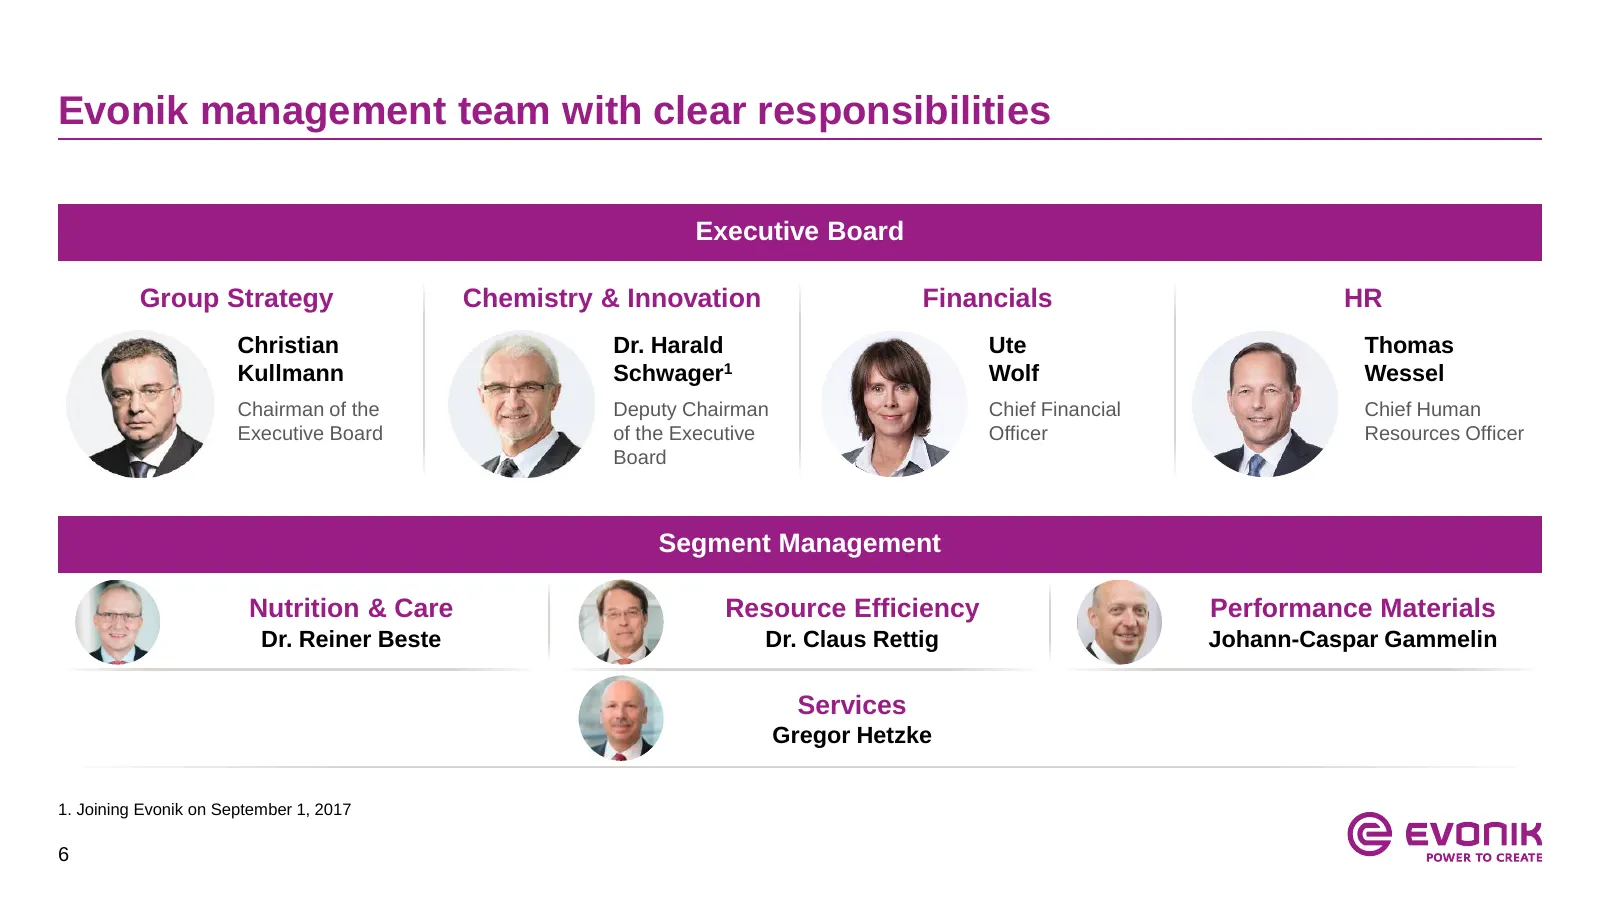
Slide 6: Evonik management team with clear responsibilities
Evonik management team with clear responsibilities Executive Board Group Strategy Chemistry & Innovation Financials HR Christian Dr. Harald Ute Thomas Kullmann Schwager1 Wolf Wessel Chairman of the Deputy Chairman Chief Financial Chief Human Executive Board of the Executive Officer Resources Officer
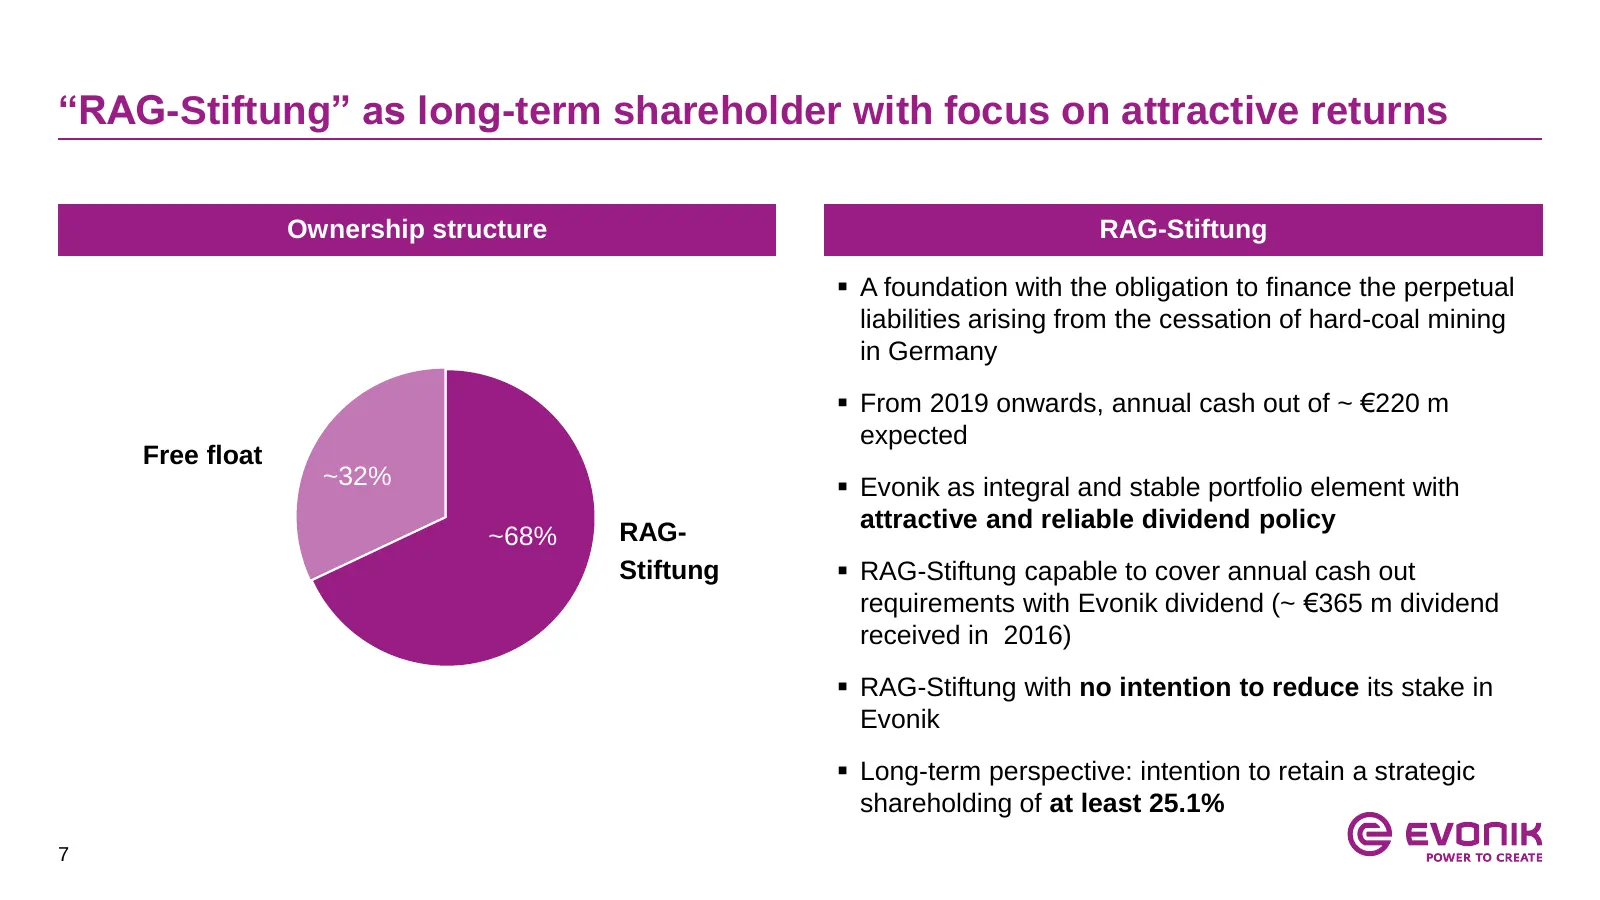
Slide 7: RAG-Stiftung as long-term shareholder with focus on attractive returns
“RAG-Stiftung” as long-term shareholder with focus on attractive returns Ownership structure RAG-Stiftung A foundation with the obligation to finance the perpetual liabilities arising from the cessation of hard-coal mining in Germany From 2019 onwards, annual cash out of ~ €220 m expected Free f
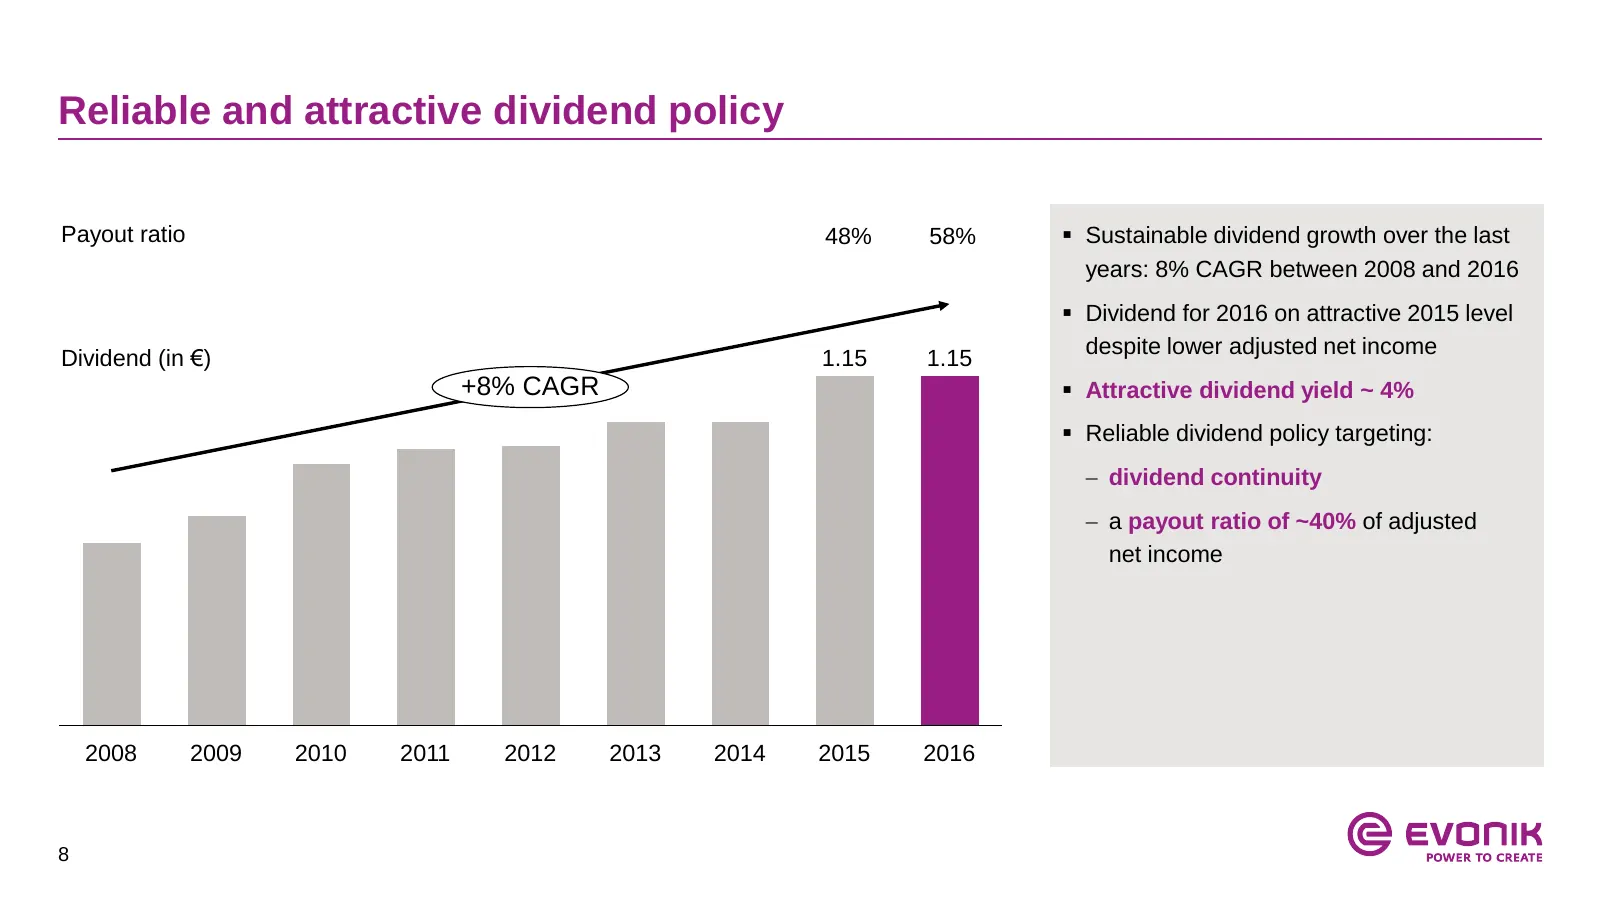
Slide 8: Reliable and attractive dividend policy
Reliable and attractive dividend policy Payout ratio 48% 58% Sustainable dividend growth over the last years: 8% CAGR between 2008 and 2016 Dividend for 2016 on attractive 2015 level Dividend (in €) despite lower adjusted net income 1.15 1.15 +8% CAGR Attractive dividend yield ~ 4% Reliable
Slide 9: Table of contents
Table of contents 1. Evonik at a glance 2. Strategy Update 3. Financials Q1 2017 4. Appendix 9
Slide 10: Significant progress achieved over last 3 years
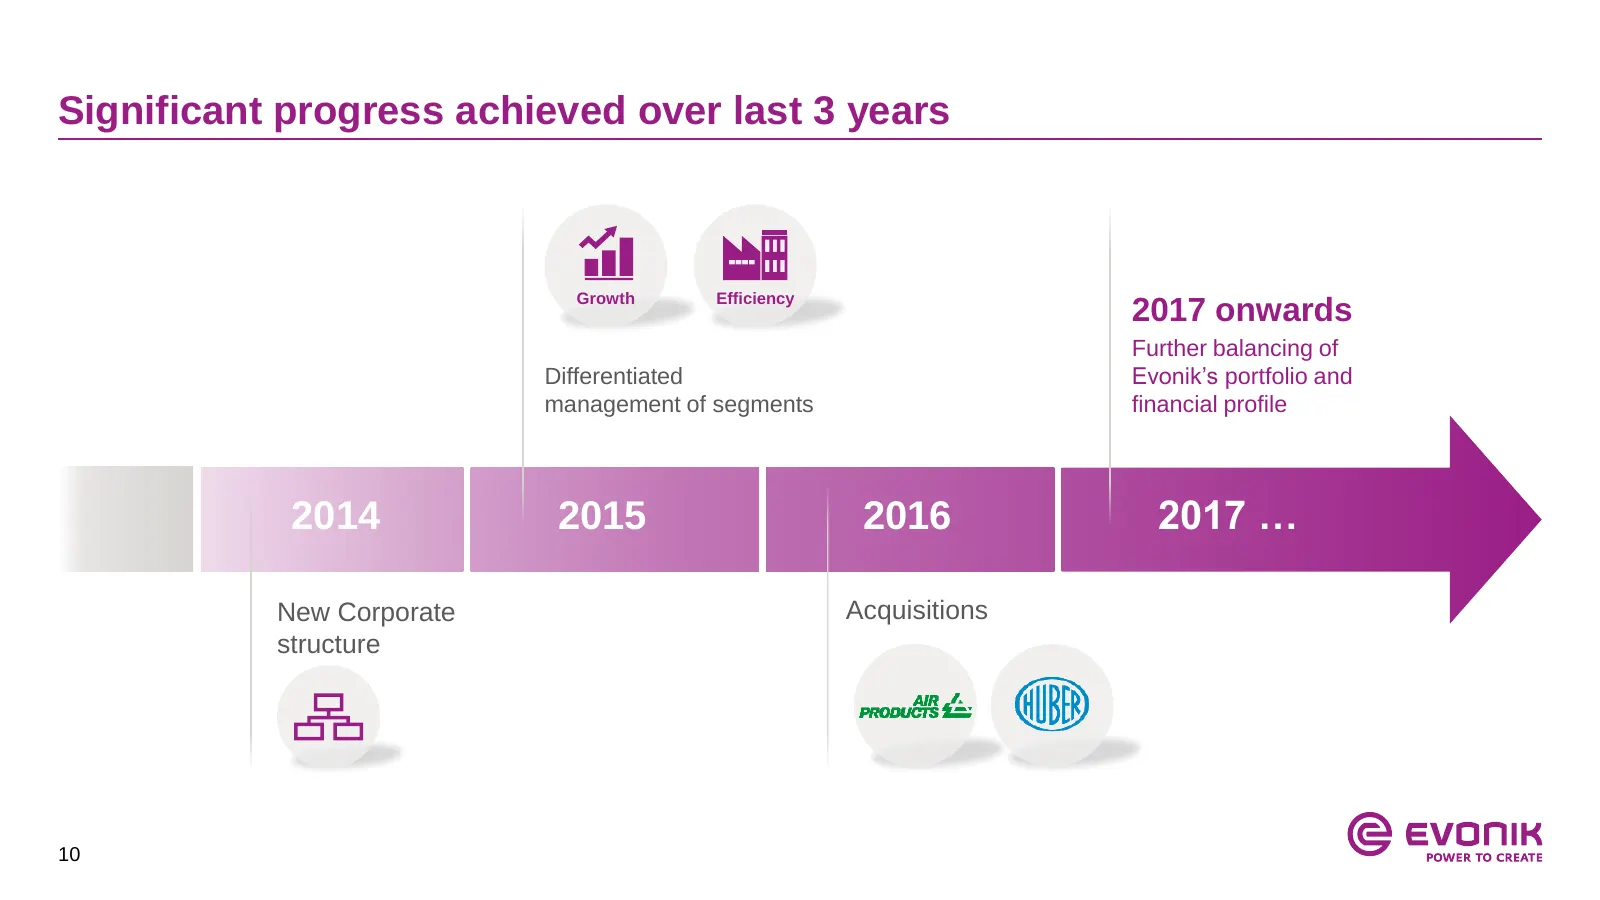
Significant progress achieved over last 3 years Growth Efficiency 2017 onwards Further balancing of Differentiated Evonik’s portfolio and management of segments financial profile 2014 2015 2016 2017 … New Corporate Acquisitions structure 10
Slide 11: Building a best-in-class specialty chemicals company
Building a best-in-class specialty chemicals company 11
Slide 12: Targeting excellence in three strategic focus areas
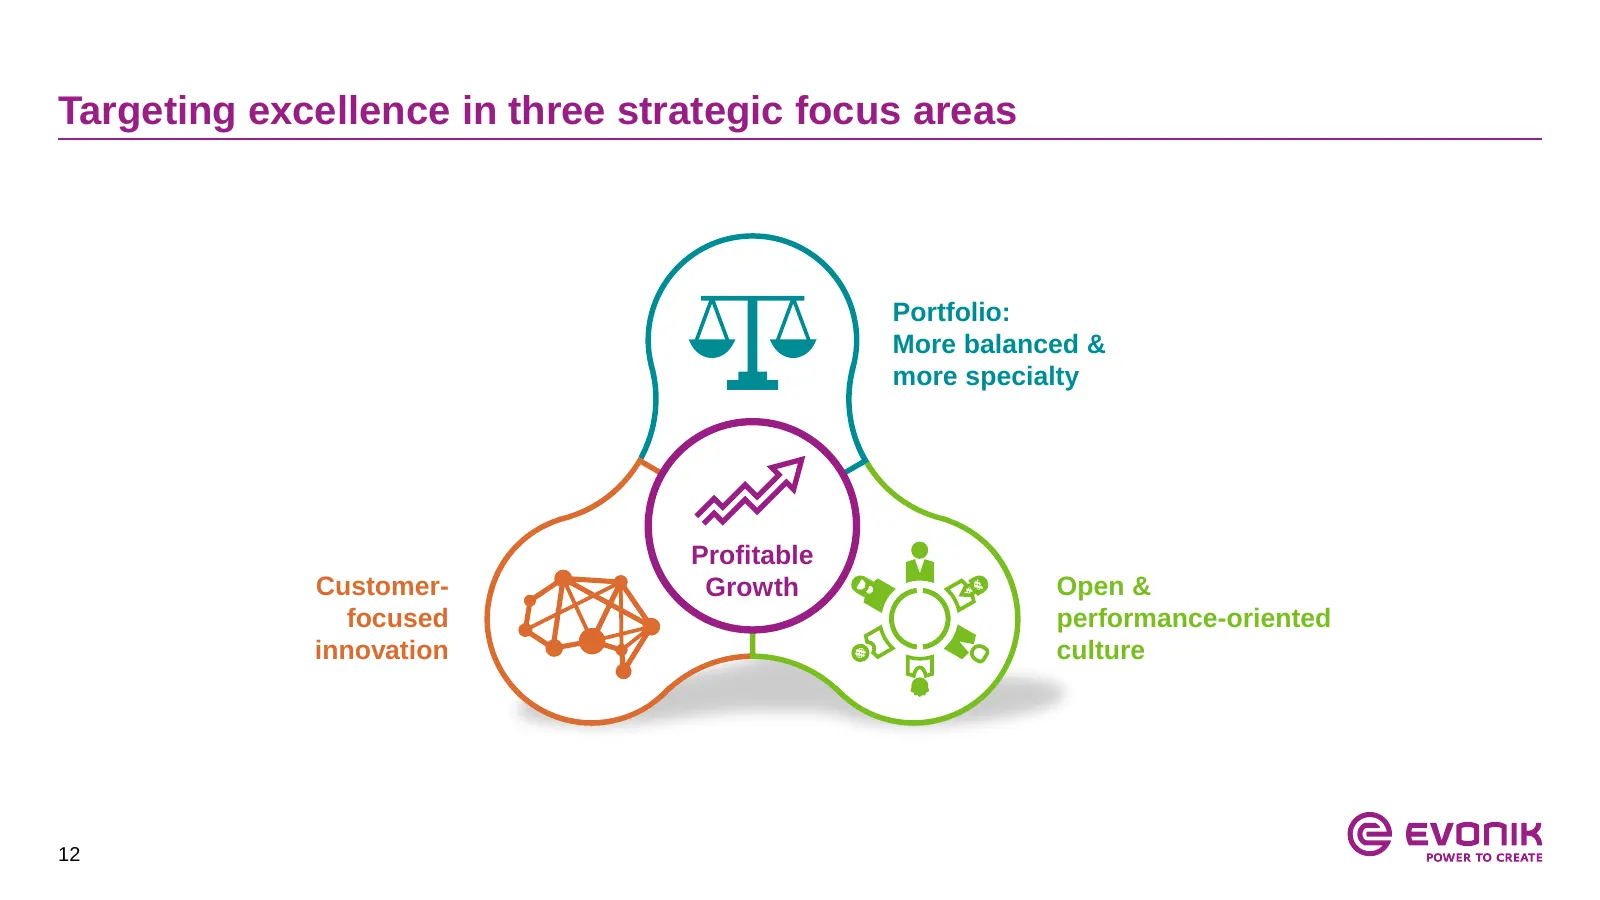
Targeting excellence in three strategic focus areas Portfolio: More balanced & more specialty Profitable Customer- Growth Open & focused performance-oriented innovation culture 12
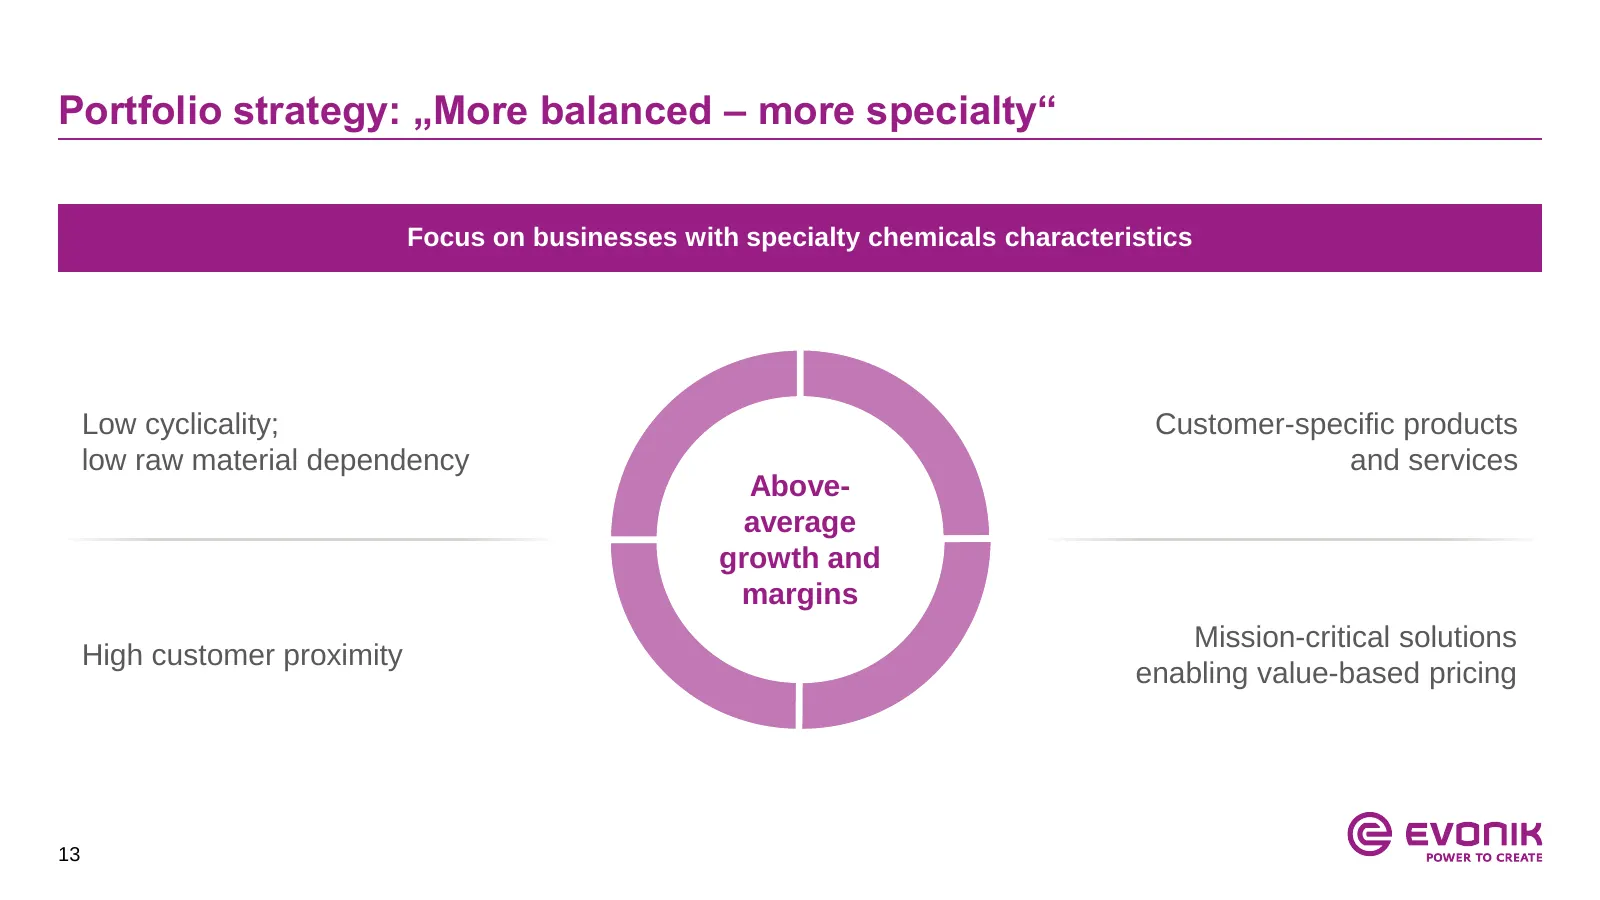
Slide 13: Portfolio strategy: More balanced – more specialty
Portfolio strategy: „More balanced – more specialty“ Focus on businesses with specialty chemicals characteristics Low cyclicality; Customer-specific products low raw material dependency and services Above- average growth and margins Mission-critical solutions High customer proximity enabling value-b
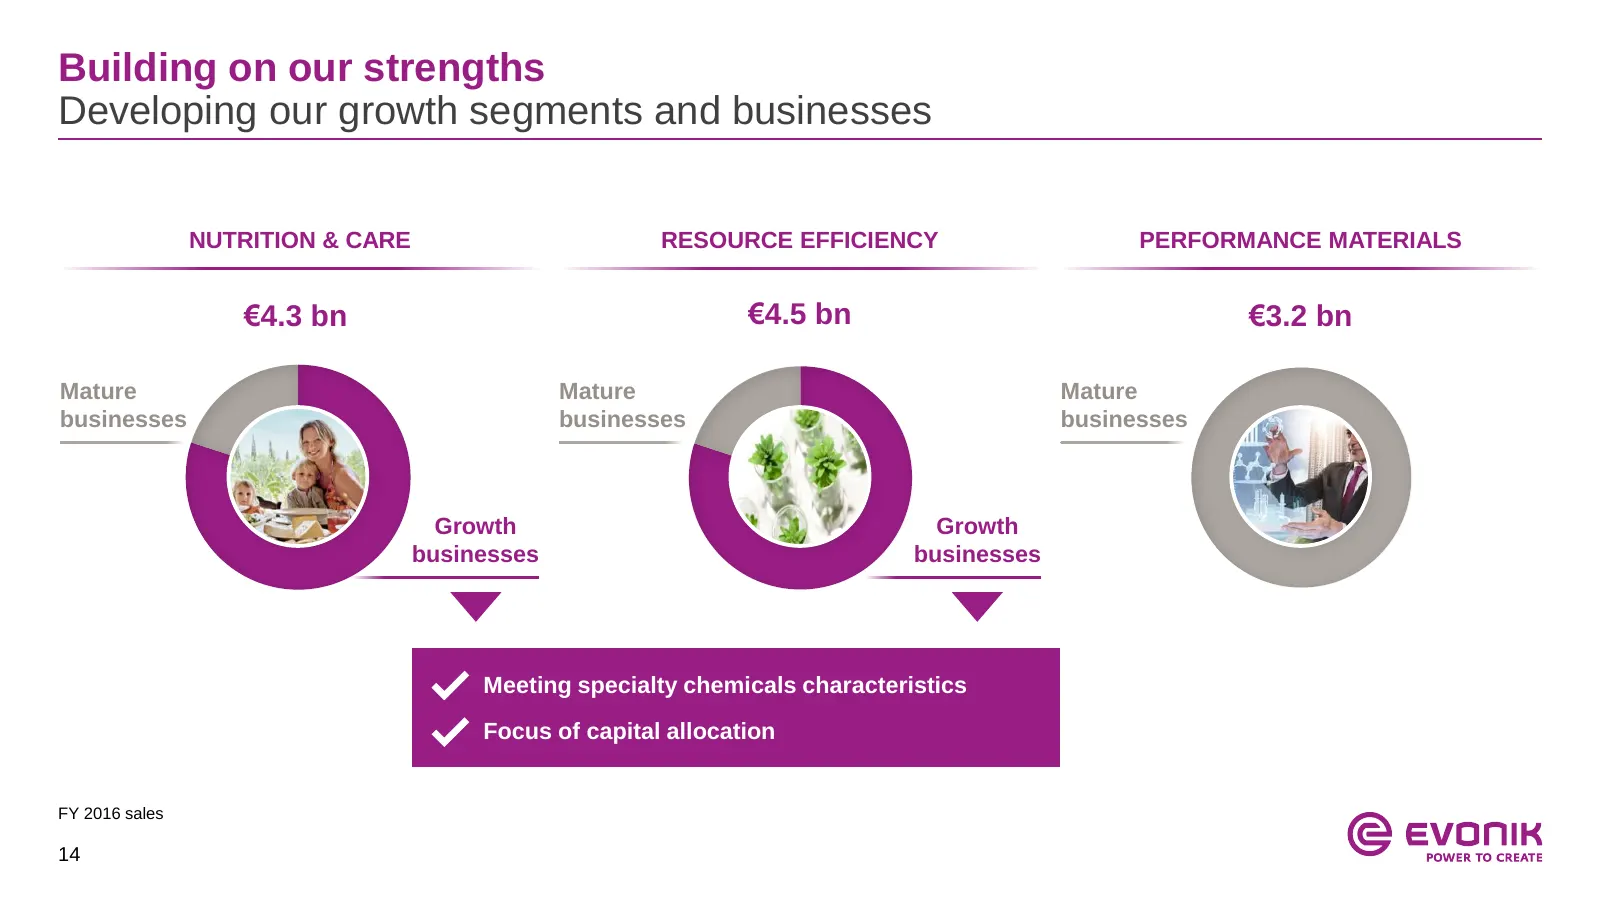
Slide 14: Building on our strengths: developing growth segments and businesses
Building on our strengths Developing our growth segments and businesses NUTRITION & CARE RESOURCE EFFICIENCY PERFORMANCE MATERIALS €4.3 bn €4.5 bn €3.2 bn Mature Mature Mature businesses businesses businesses Growth Growth businesses businesses Meeting specialty chemicals characteristics Focus of ca
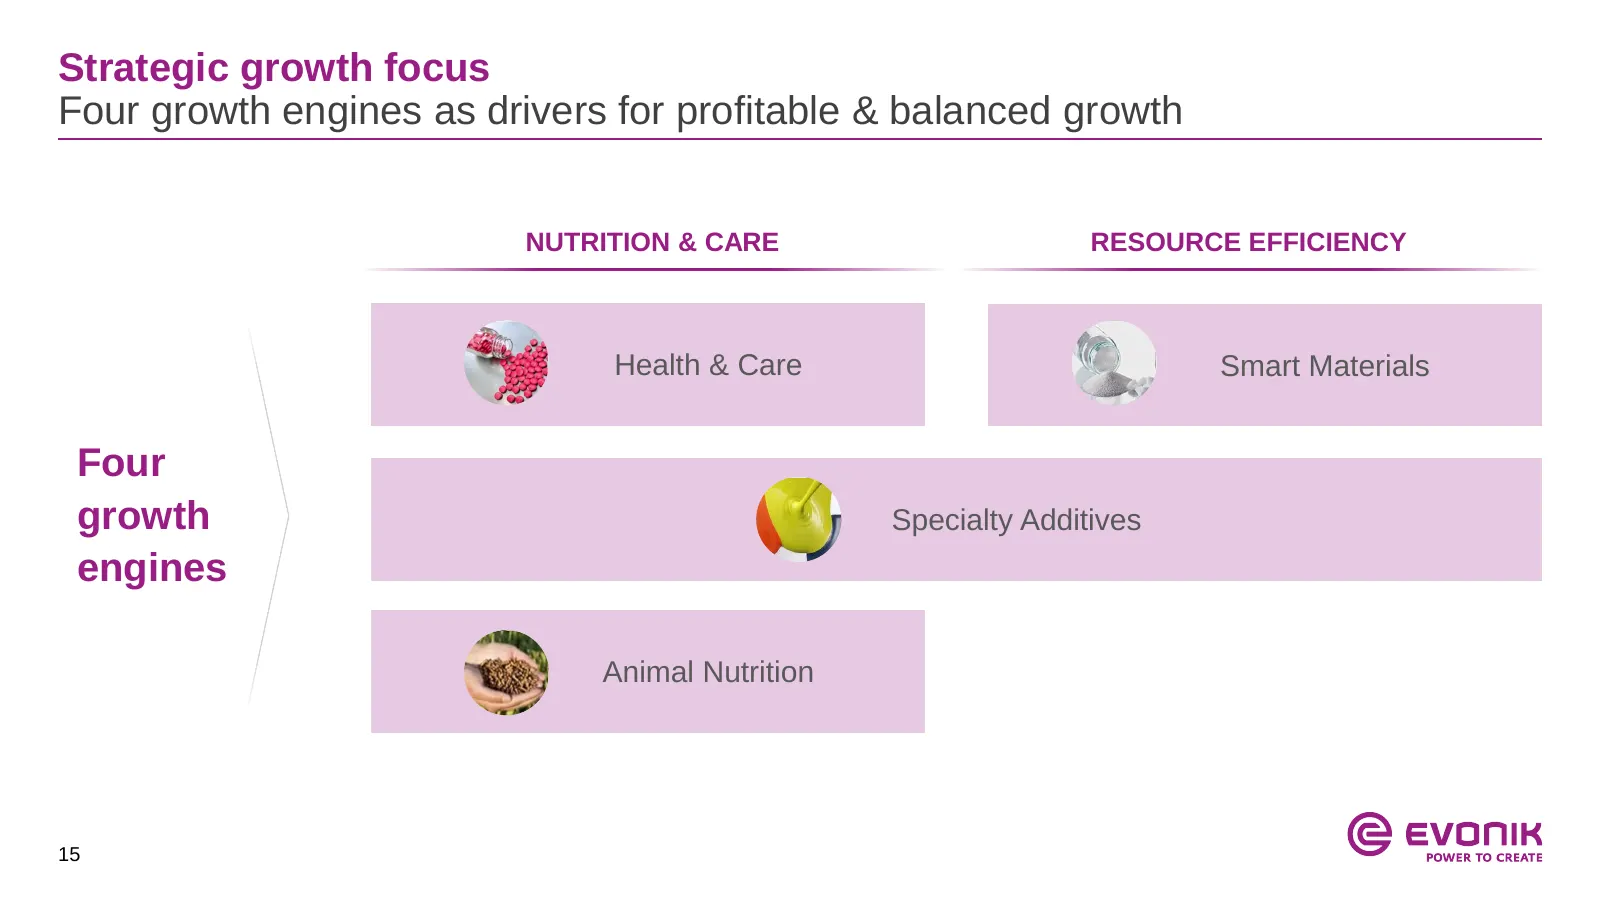
Slide 15: Strategic growth focus: four growth engines
Strategic growth focus Four growth engines as drivers for profitable & balanced growth NUTRITION & CARE RESOURCE EFFICIENCY Health & Care Smart Materials Four growth Specialty Additives engines Animal Nutrition 15
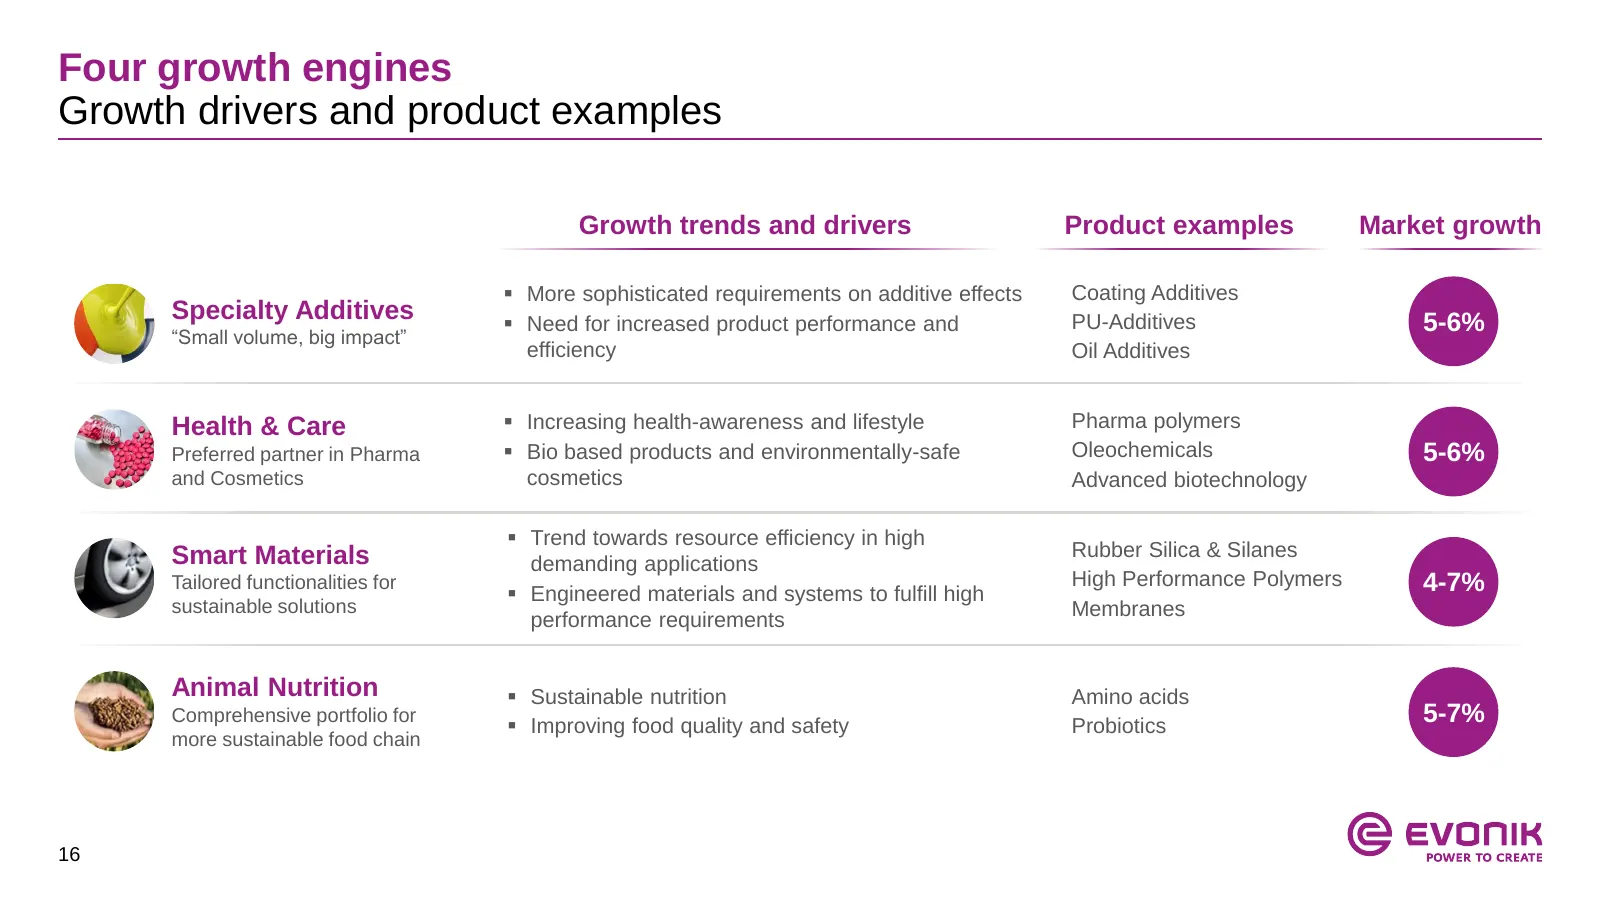
Slide 16: Four growth engines: growth drivers and product examples
Four growth engines Growth drivers and product examples Growth trends and drivers Product examples Market growth More sophisticated requirements on additive effects Coating Additives Specialty Additives Need for increased product performance and PU-Additives 5-6% “Small volume, big impact” effic
Slide 17: Thorough review process of key drivers for value creation
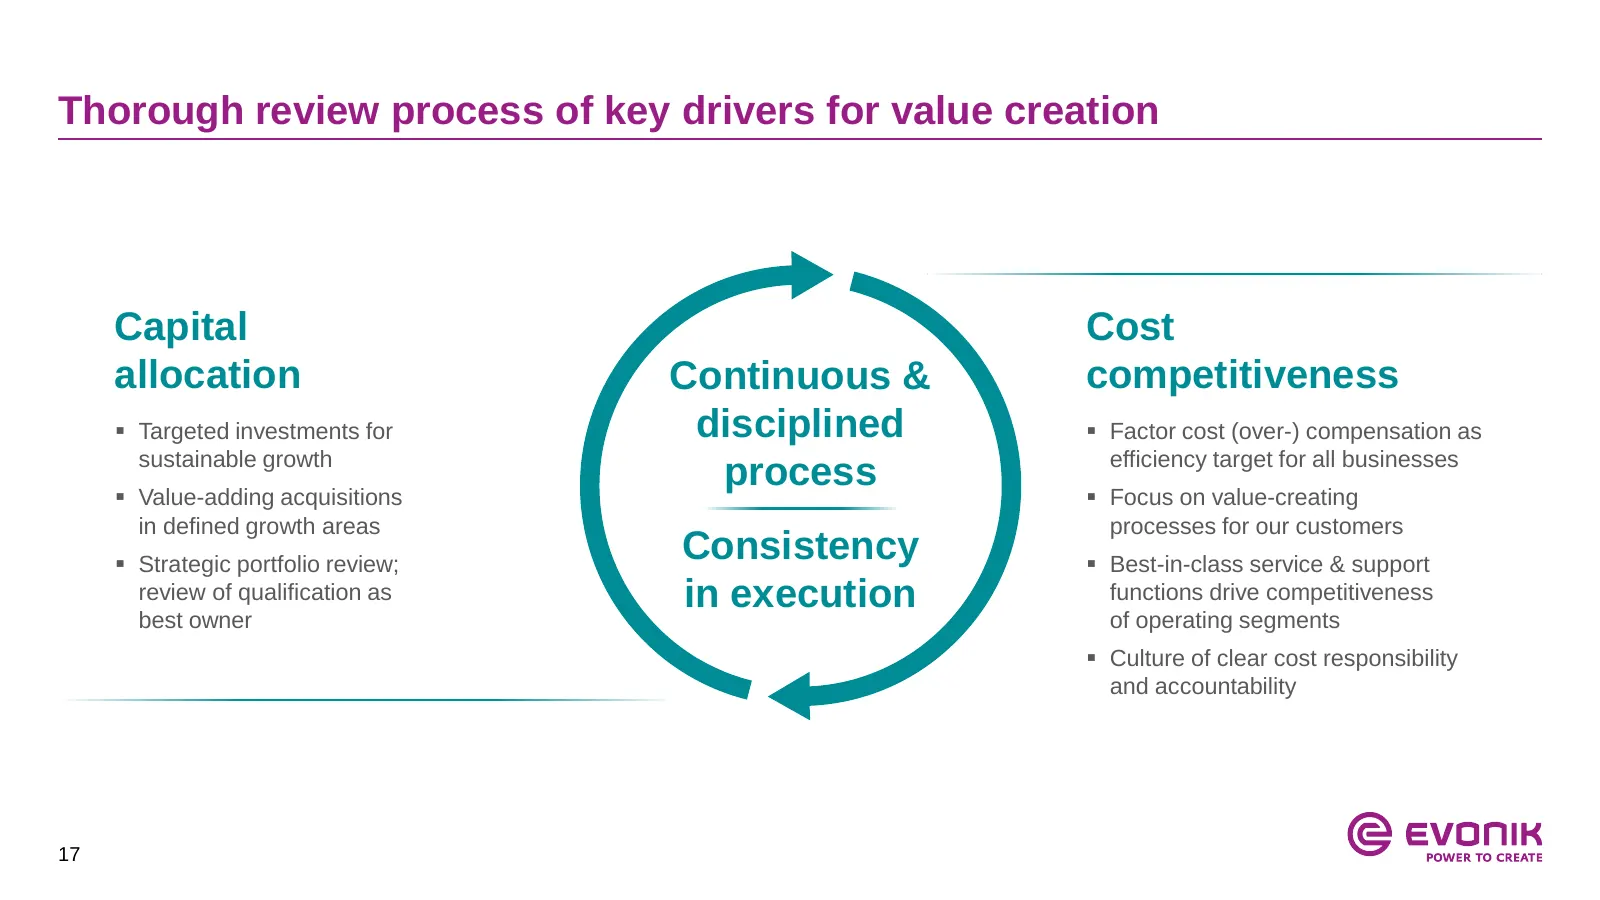
Thorough review process of key drivers for value creation Capital Cost allocation Continuous & competitiveness Targeted investments for disciplined Factor cost (over-) compensation as sustainable growth efficiency target for all businesses process Value-adding acquisitions Focus on value-cre
Slide 18: Targeted and disciplined M&A approach
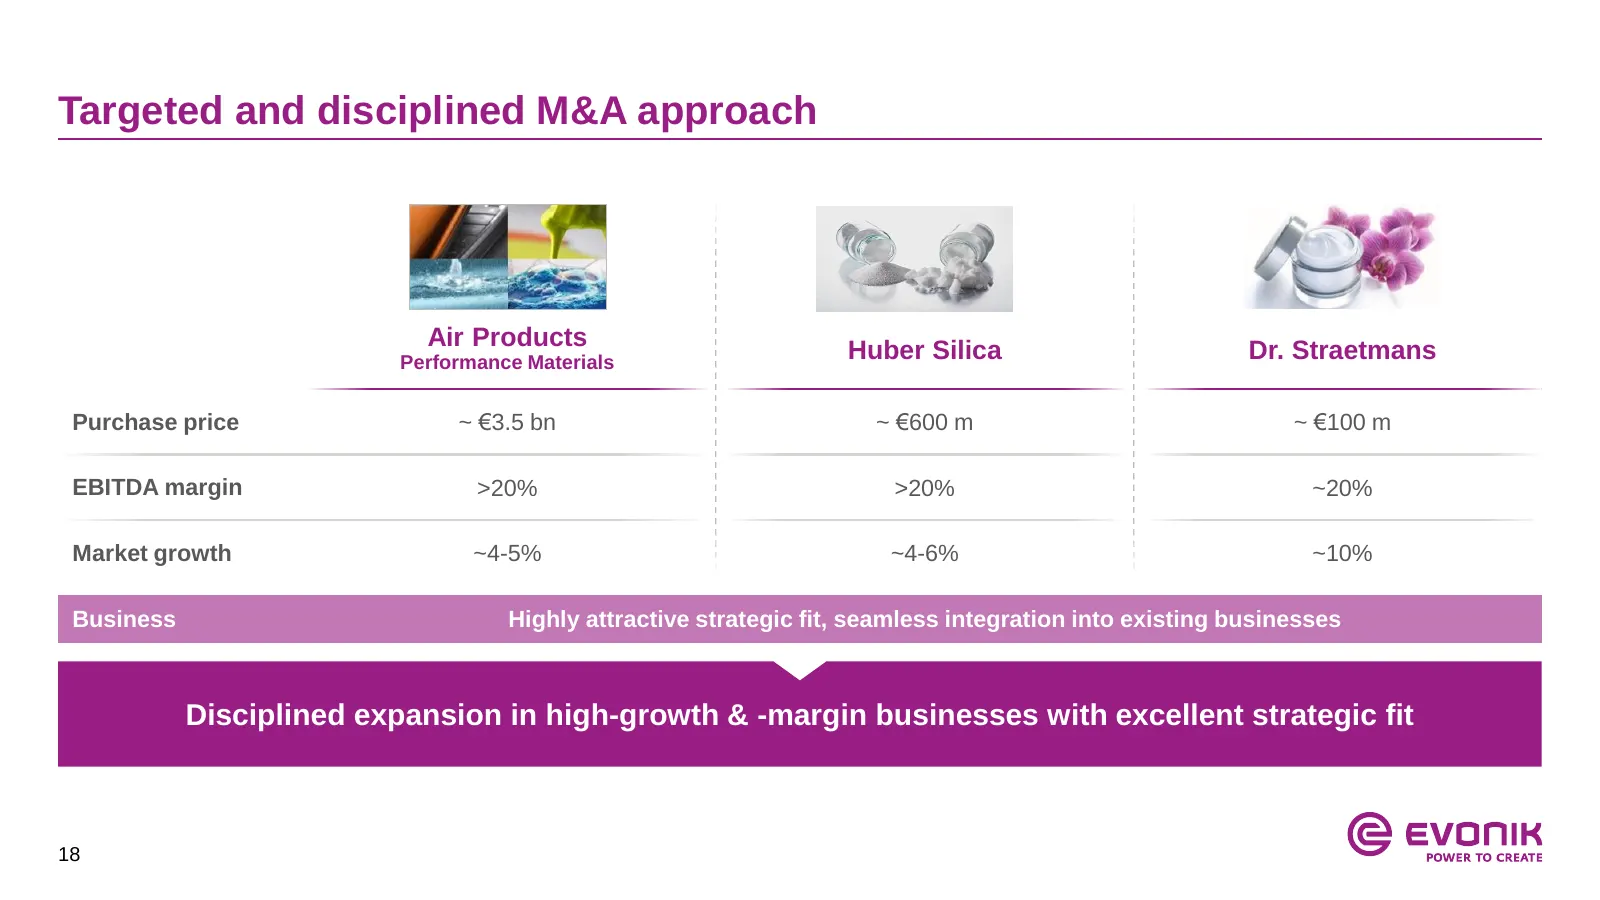
Targeted and disciplined M&A approach Air Products Huber Silica Dr. Straetmans Performance Materials Purchase price ~ €3.5 bn ~ €600 m ~ €100 m EBITDA margin >20% >20% ~20% Market growth ~4-5% ~4-6% ~10% Business Highly attractive strategic fit, seamless integration into existing businesses Discipli
Slide 19: Leading Innovation
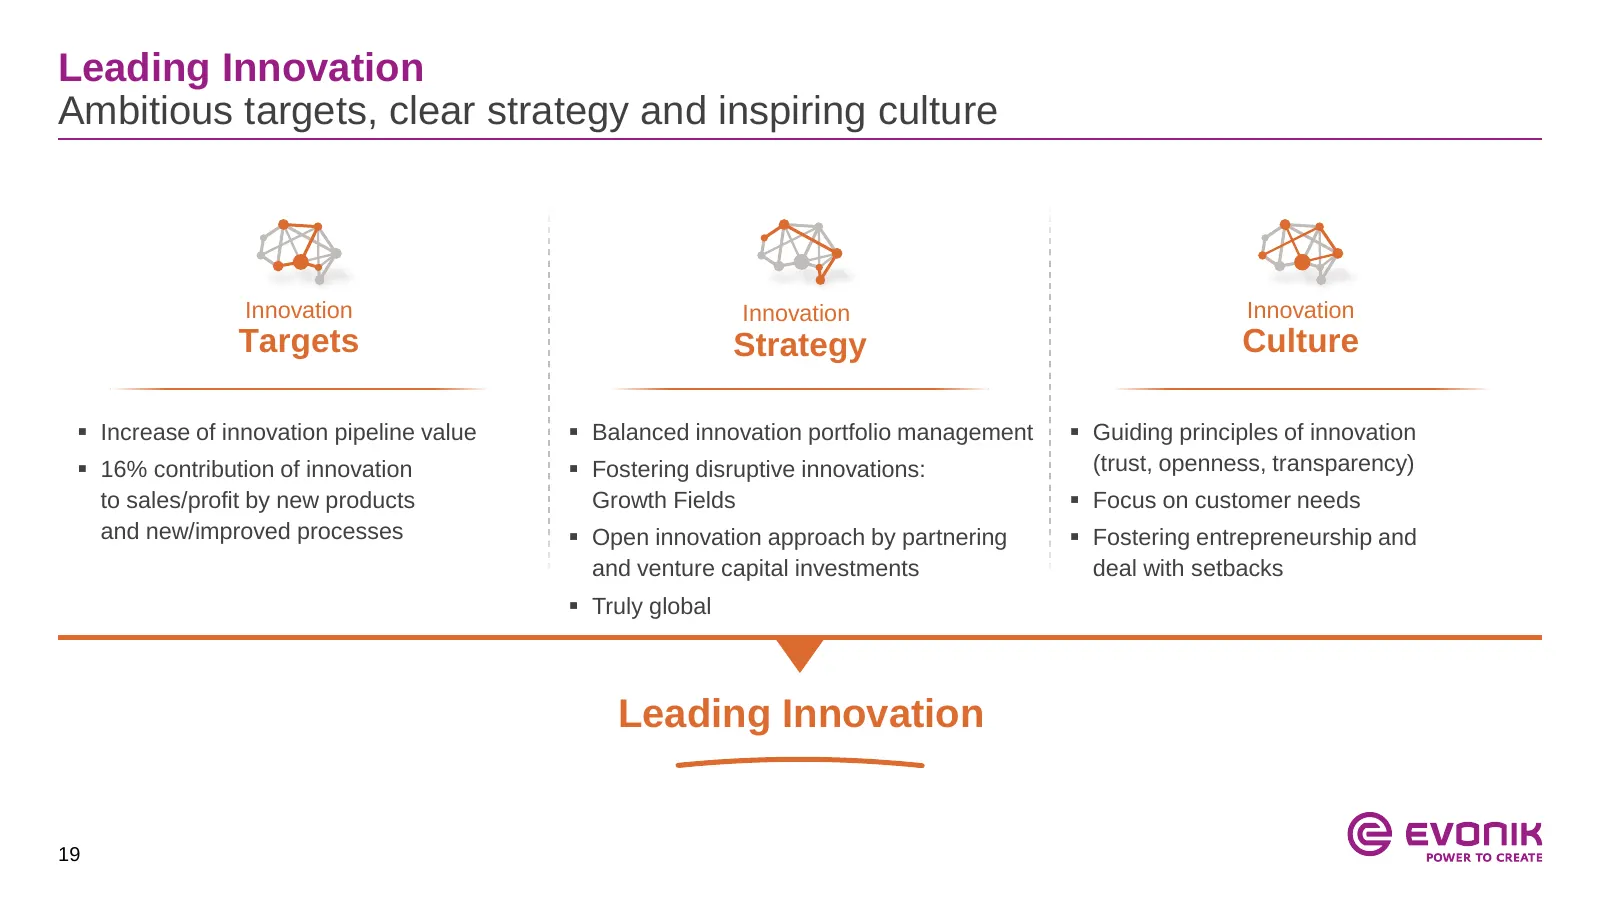
Leading Innovation Ambitious targets, clear strategy and inspiring culture Innovation Innovation Innovation Targets Strategy Culture Increase of innovation pipeline value Balanced innovation portfolio management Guiding principles of innovation 16% contribution of innovation Fostering disr
Slide 20: Innovation: Our goals
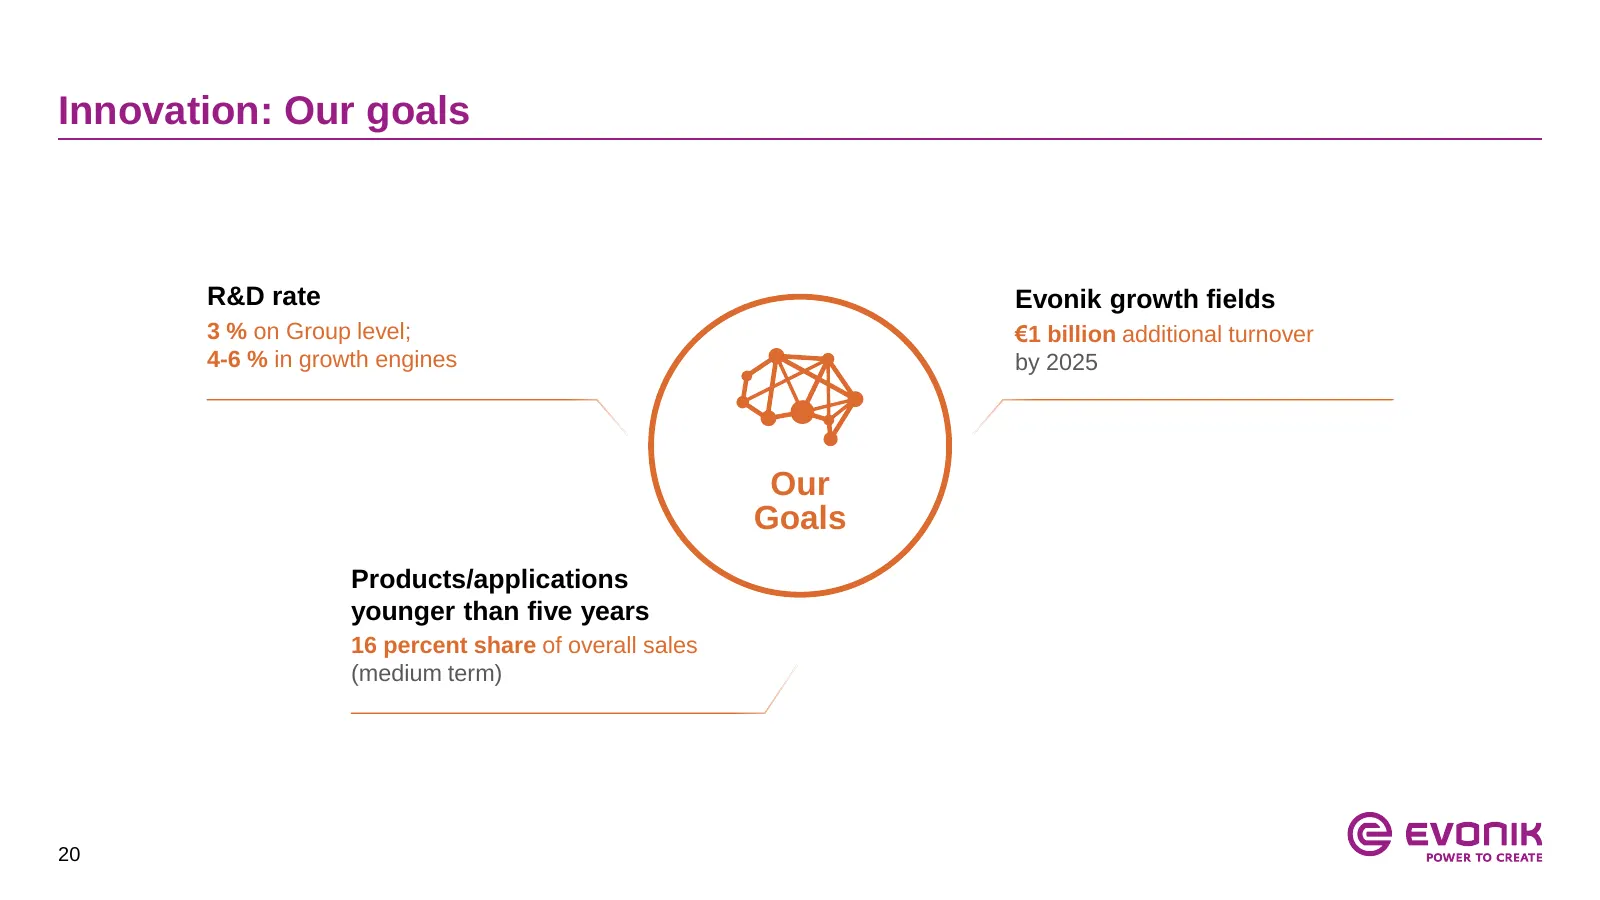
Innovation: Our goals R&D rate Evonik growth fields 3 % on Group level; €1 billion additional turnover 4-6 % in growth engines by 2025 Our Goals Products/applications younger than five years 16 percent share of overall sales (medium term) 20
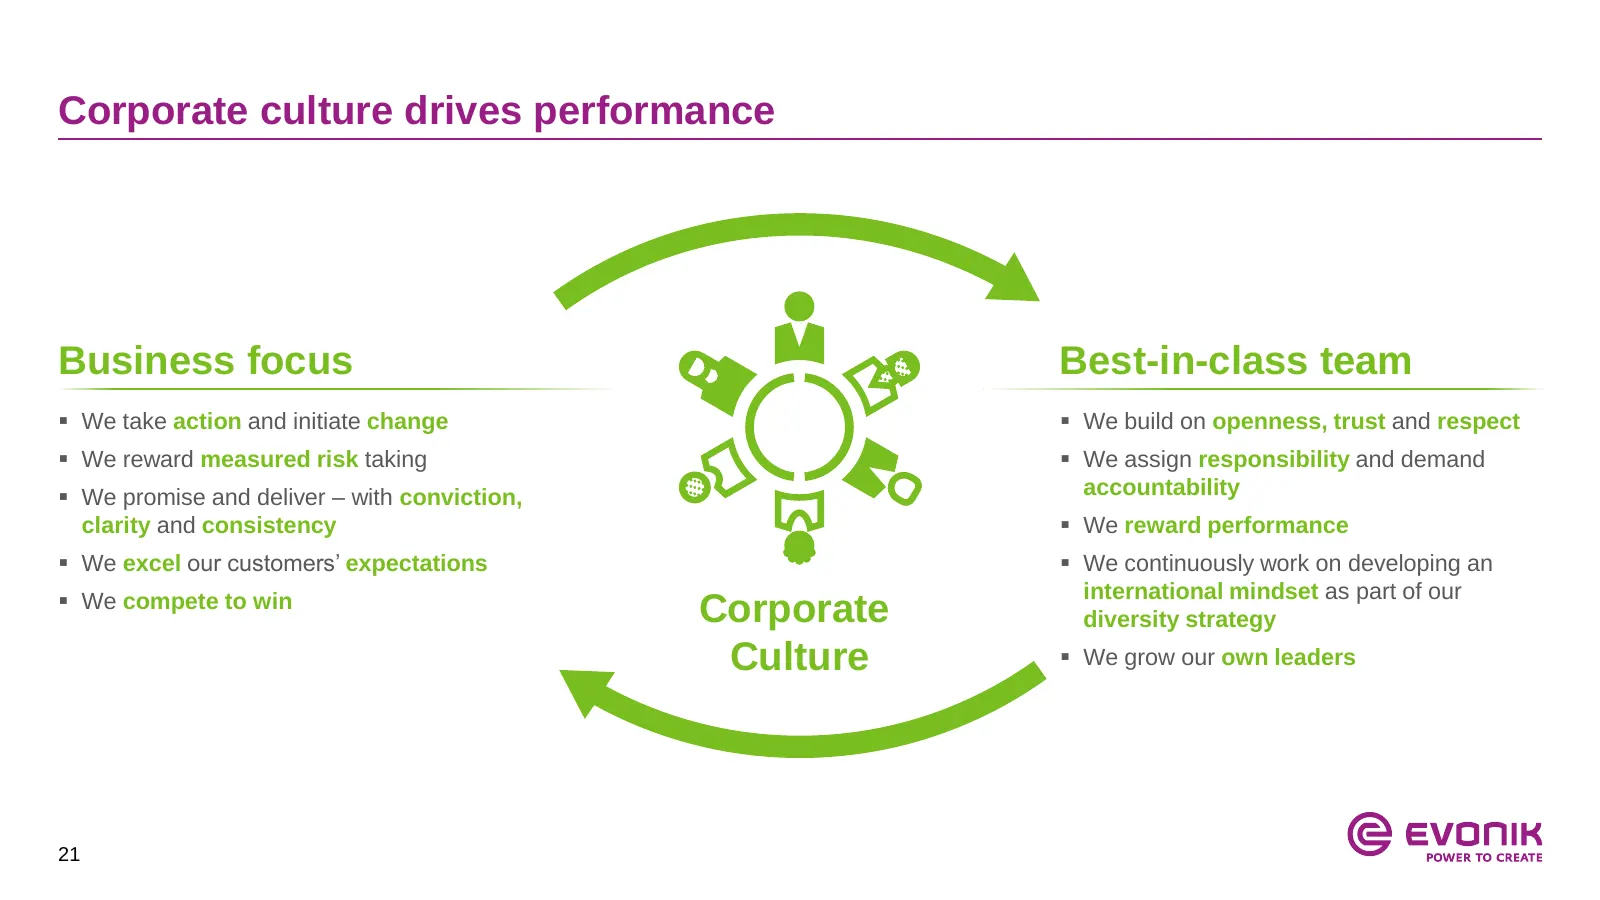
Slide 21: Corporate culture drives performance
Corporate culture drives performance Business focus Best-in-class team We take action and initiate change We build on openness, trust and respect We reward measured risk taking We assign responsibility and demand We promise and deliver – with conviction, accountability clarity and consiste
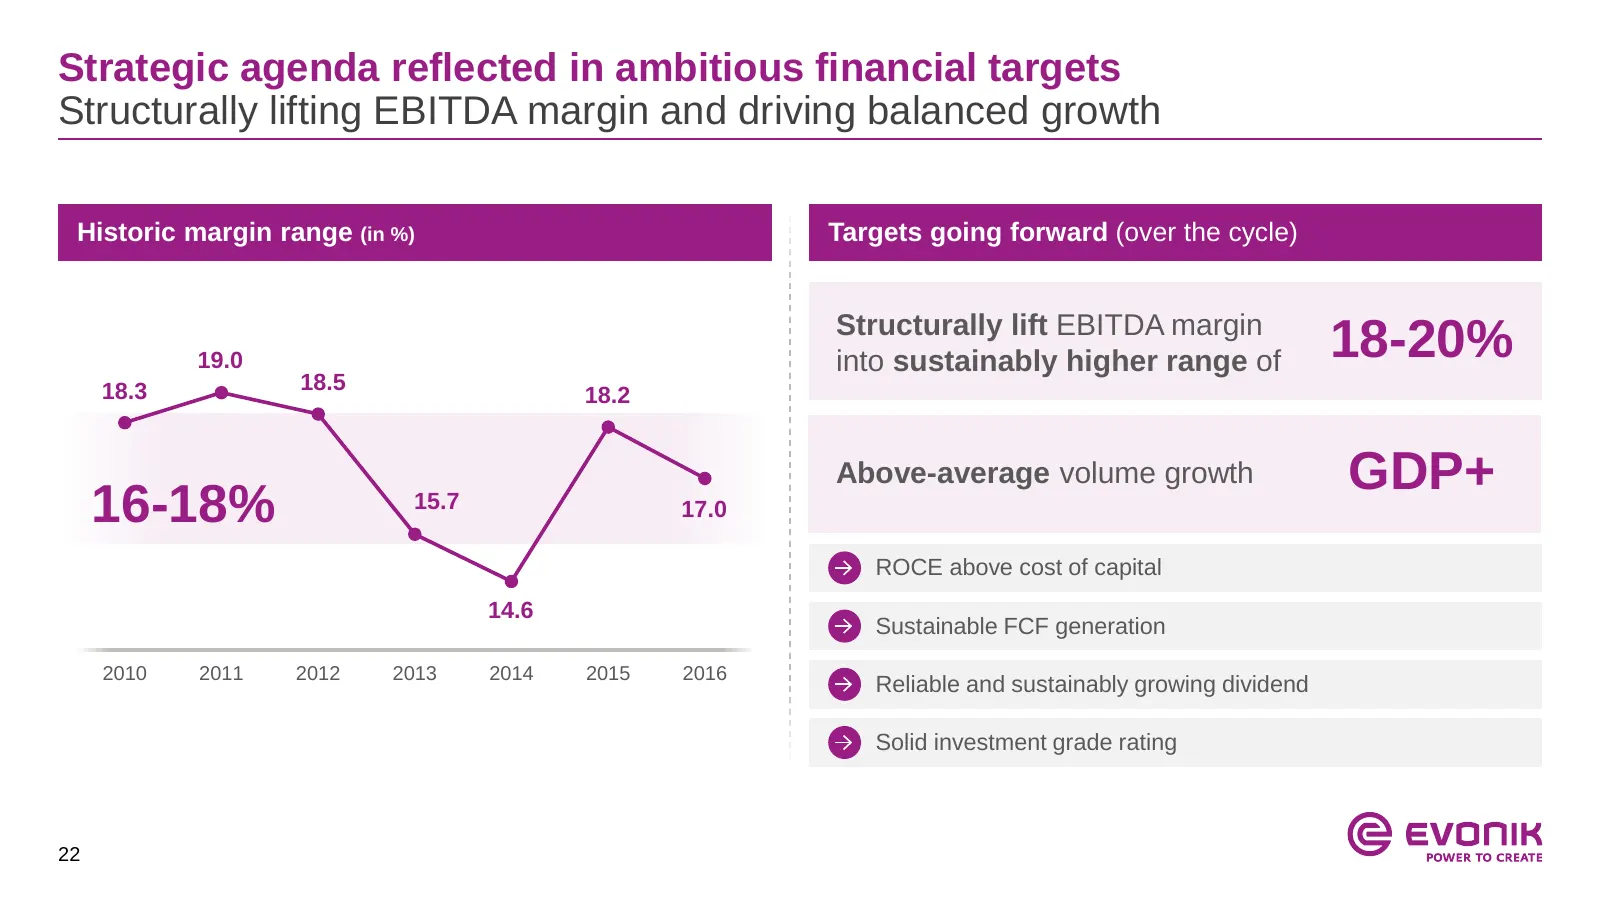
Slide 22: Strategic agenda reflected in ambitious financial targets
Strategic agenda reflected in ambitious financial targets Structurally lifting EBITDA margin and driving balanced growth Historic margin range (in %) Targets going forward (over the cycle) Structurally lift EBITDA margin 19.0 into sustainably higher range of 18-20% 18.3 18.5 18.2 Above-average volum
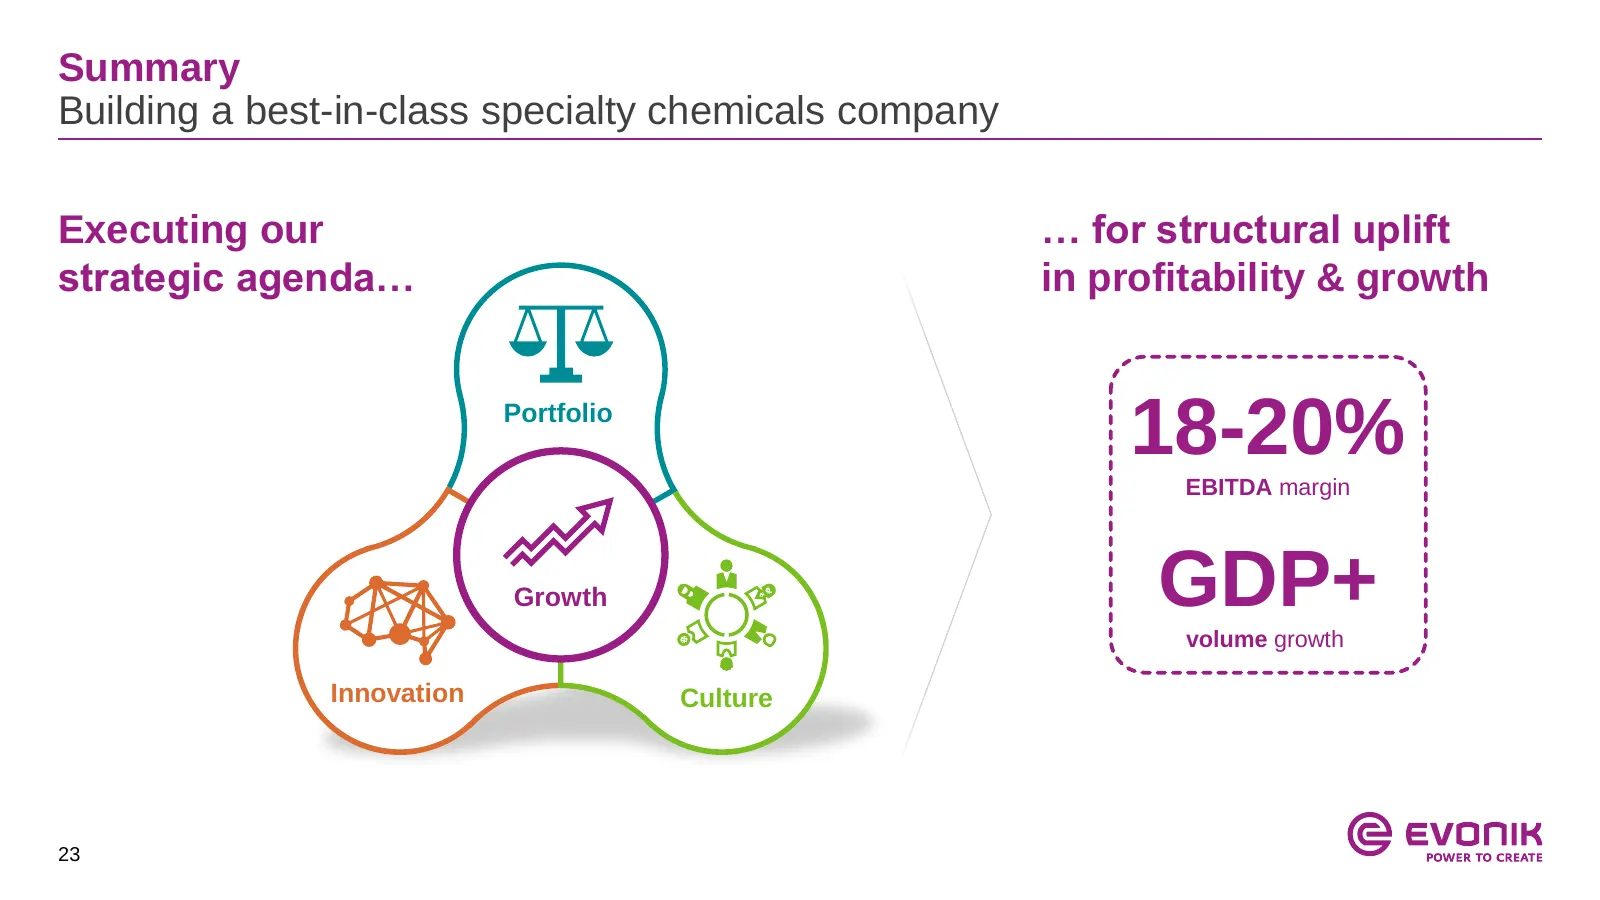
Slide 23: Summary: Building a best-in-class specialty chemicals company
Summary Building a best-in-class specialty chemicals company Executing our … for structural uplift strategic agenda… in profitability & growth Portfolio 18-20% EBITDA margin Growth GDP+ volume growth Innovation Culture 23
Slide 24: Table of contents
Table of contents 1. Evonik at a glance 2. Strategy Update 3. Financials Q1 2017 4. Appendix 24
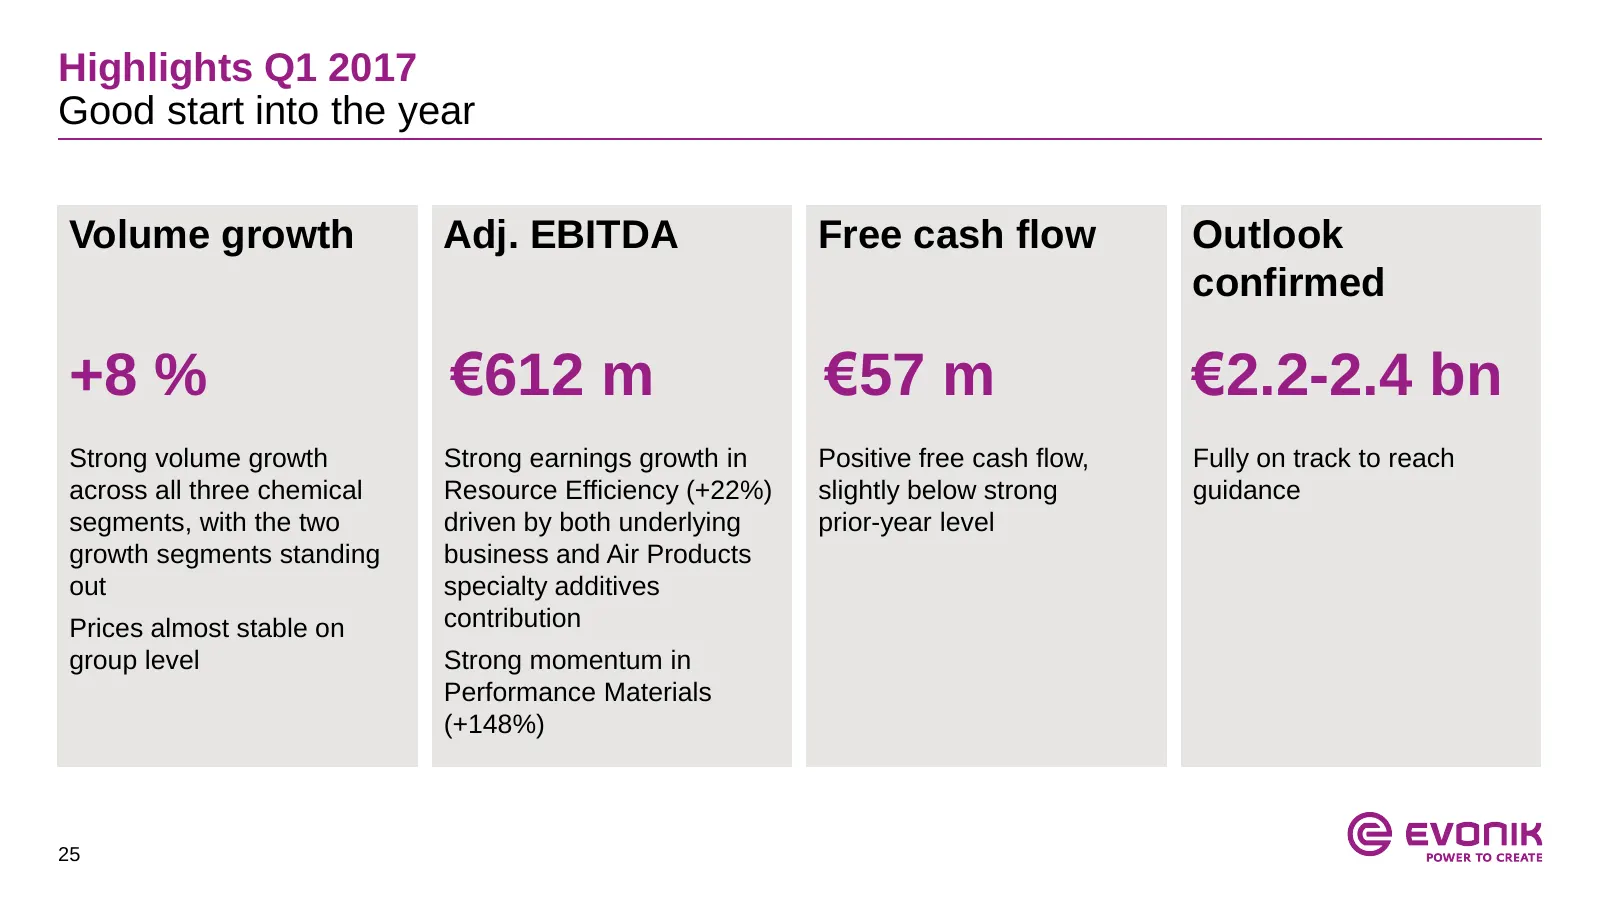
Slide 25: Highlights Q1 2017
Highlights Q1 2017 Good start into the year Volume growth Adj. EBITDA Free cash flow Outlook confirmed +8 % €612 m €57 m (vs. €2.2-2.4 bn (yoy) (vs. €653 m) €208 m in H1) (vs. €208 m in H1) Strong volume growth Strong earnings growth in Positive free cash flow, Fully on track to reach across all thr
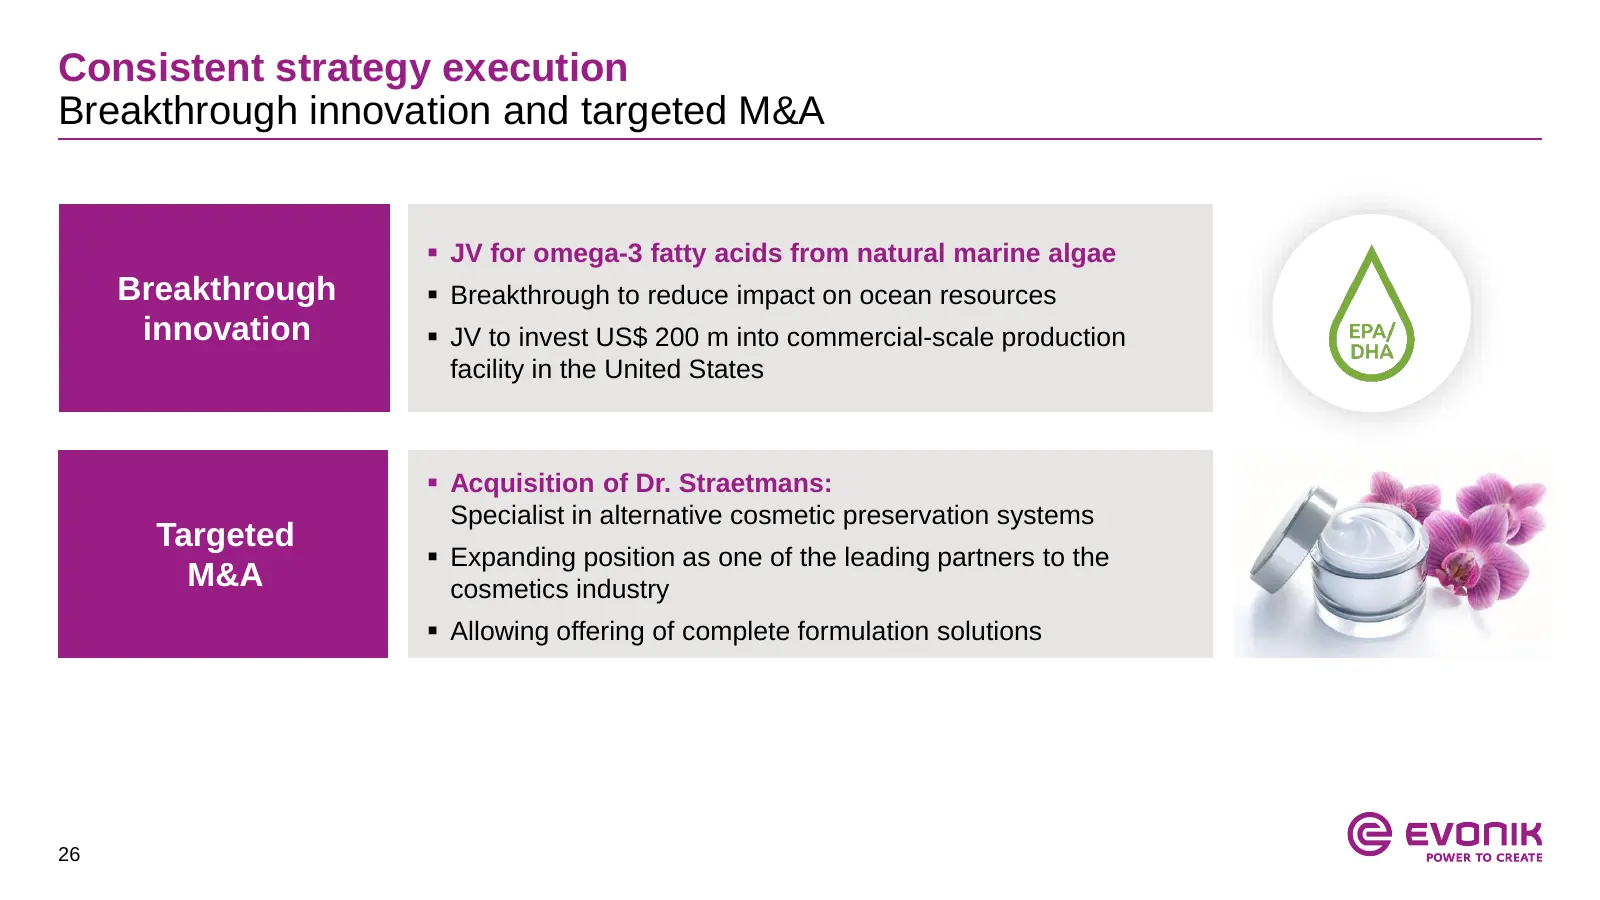
Slide 26: Consistent strategy execution
Consistent strategy execution Breakthrough innovation and targeted M&A JV for omega-3 fatty acids from natural marine algae Breakthrough Breakthrough to reduce impact on ocean resources innovation JV to invest US$ 200 m into commercial-scale production facility in the United States Acquisiti
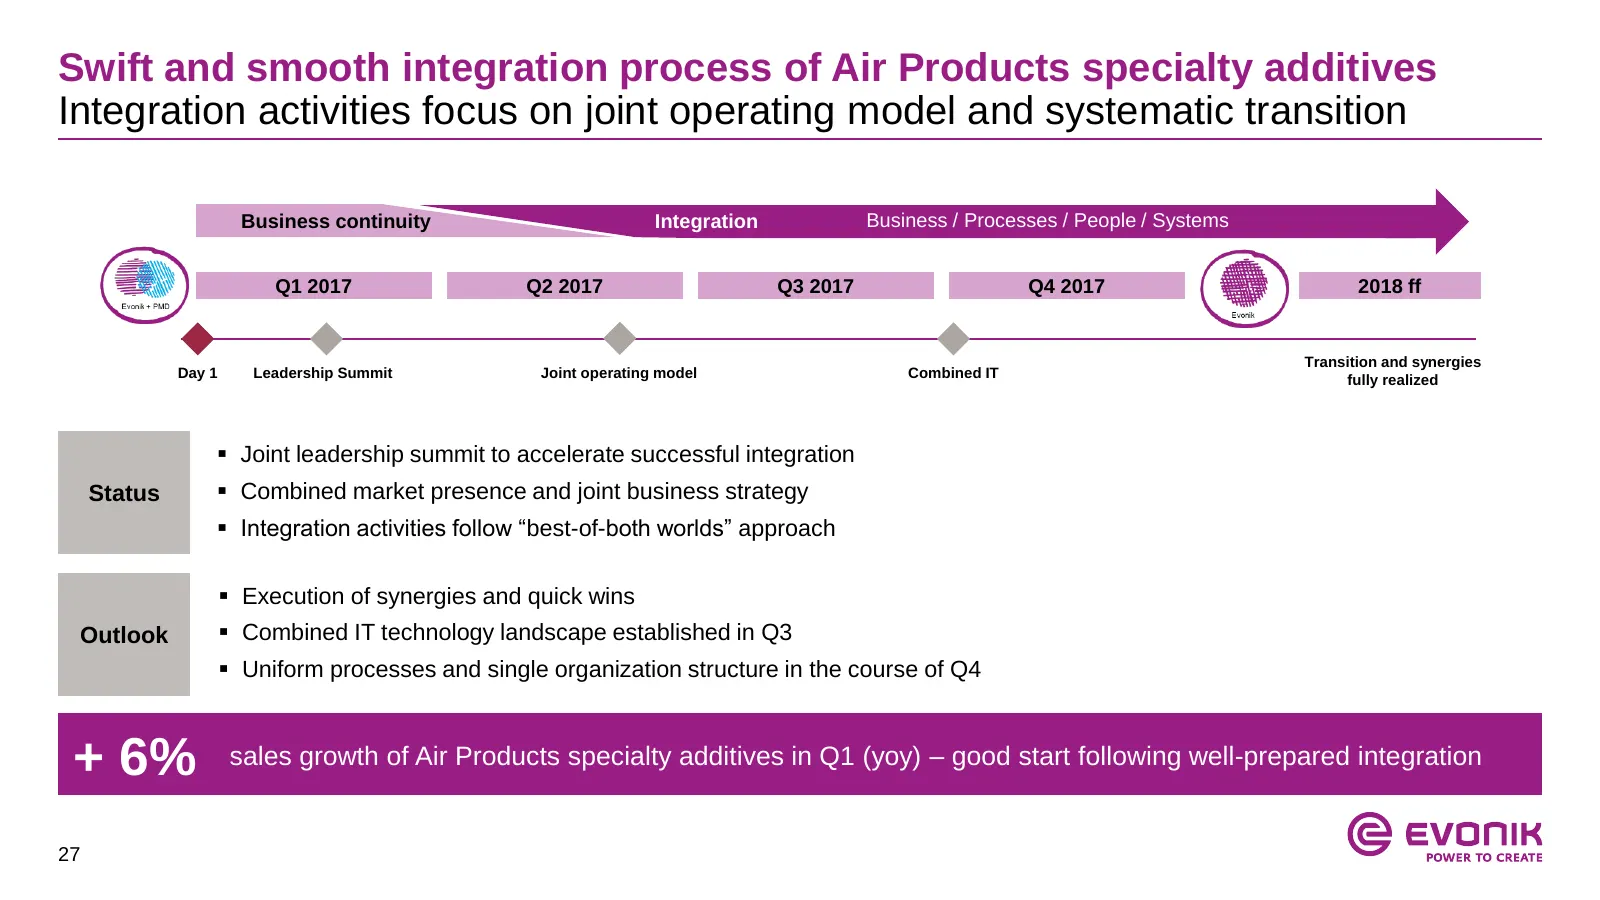
Slide 27: Swift and smooth integration of Air Products specialty additives
Swift and smooth integration process of Air Products specialty additives Integration activities focus on joint operating model and systematic transition Business continuity Integration Business / Processes / People / Systems Q1 2017 Q2 2017 Q3 2017 Q4 2017 2018 ff Transition and synergies Day 1 Lead
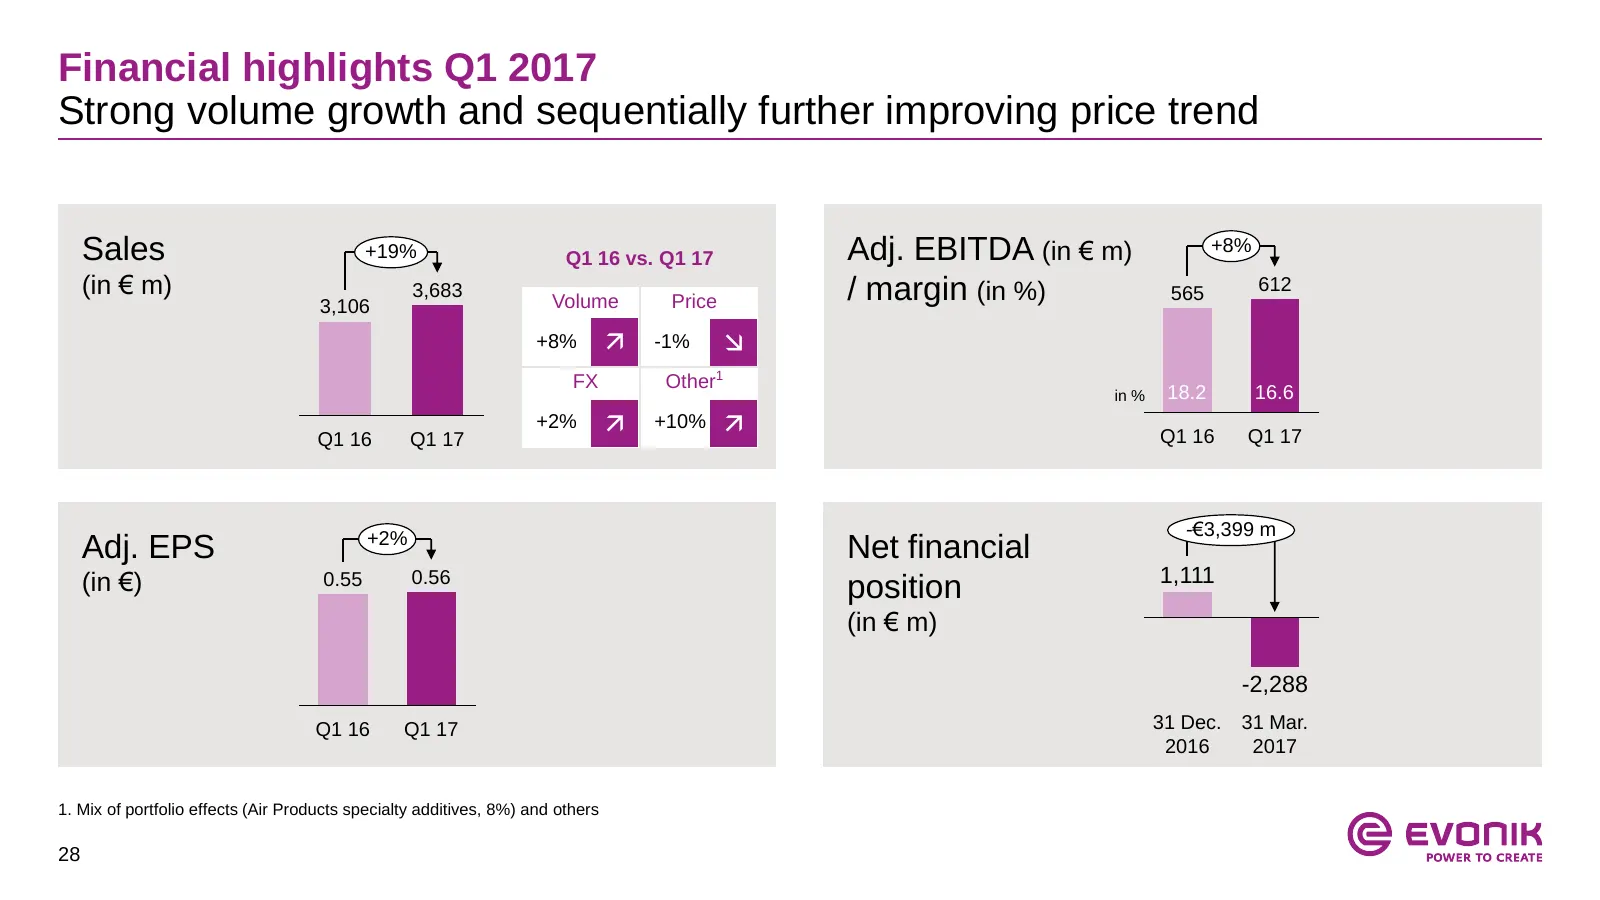
Slide 28: Financial highlights Q1 2017
Financial highlights Q1 2017 Strong volume growth and sequentially further improving price trend Sales +19% Q1 16 vs. Q1 17 Adj. EBITDA (in € m) +8% (in € m) 3,683 / margin (in %) 565 612 3,106 Volume Price +8% -1% FX Other1 in % 18.2 16.6 Q1 16 Q1 17 +2% +10% Q1 16 Q1 17 +2% -€3,399 m A
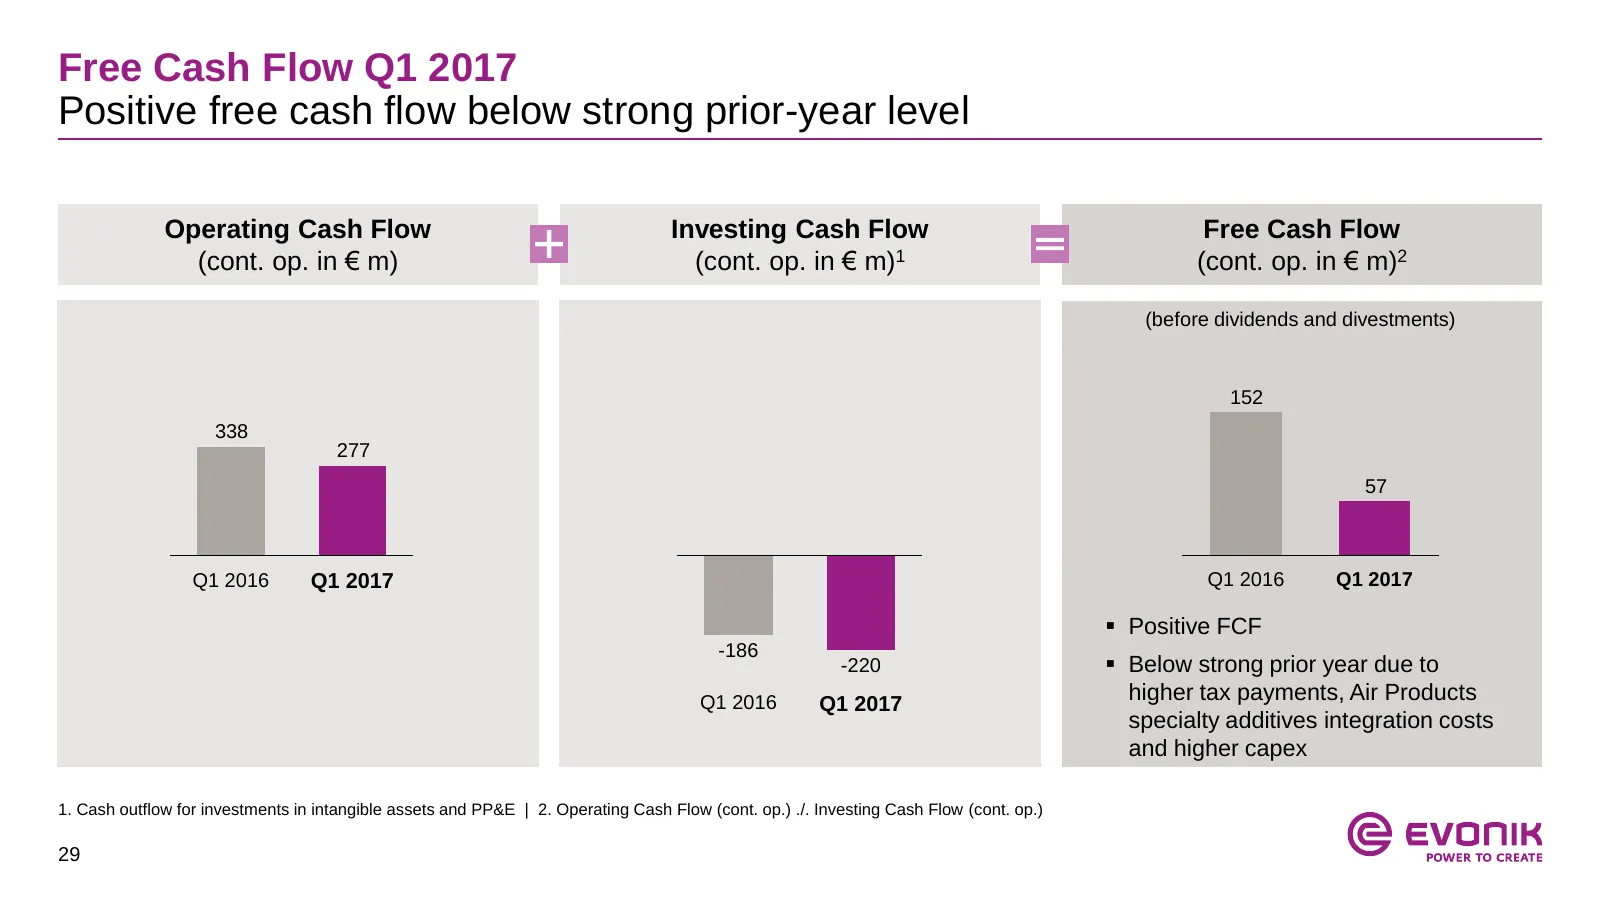
Slide 29: Free Cash Flow Q1 2017
Free Cash Flow Q1 2017 Positive free cash flow below strong prior-year level Operating Cash Flow Investing Cash Flow Free Cash Flow (cont. op. in € m) (cont. op. in € m)1 (cont. op. in € m)2 (before dividends and divestments) 152 338 277 57 Q1 2016 Q1 2017 Q1 2016 Q1 2017 Positive FCF -186 -220
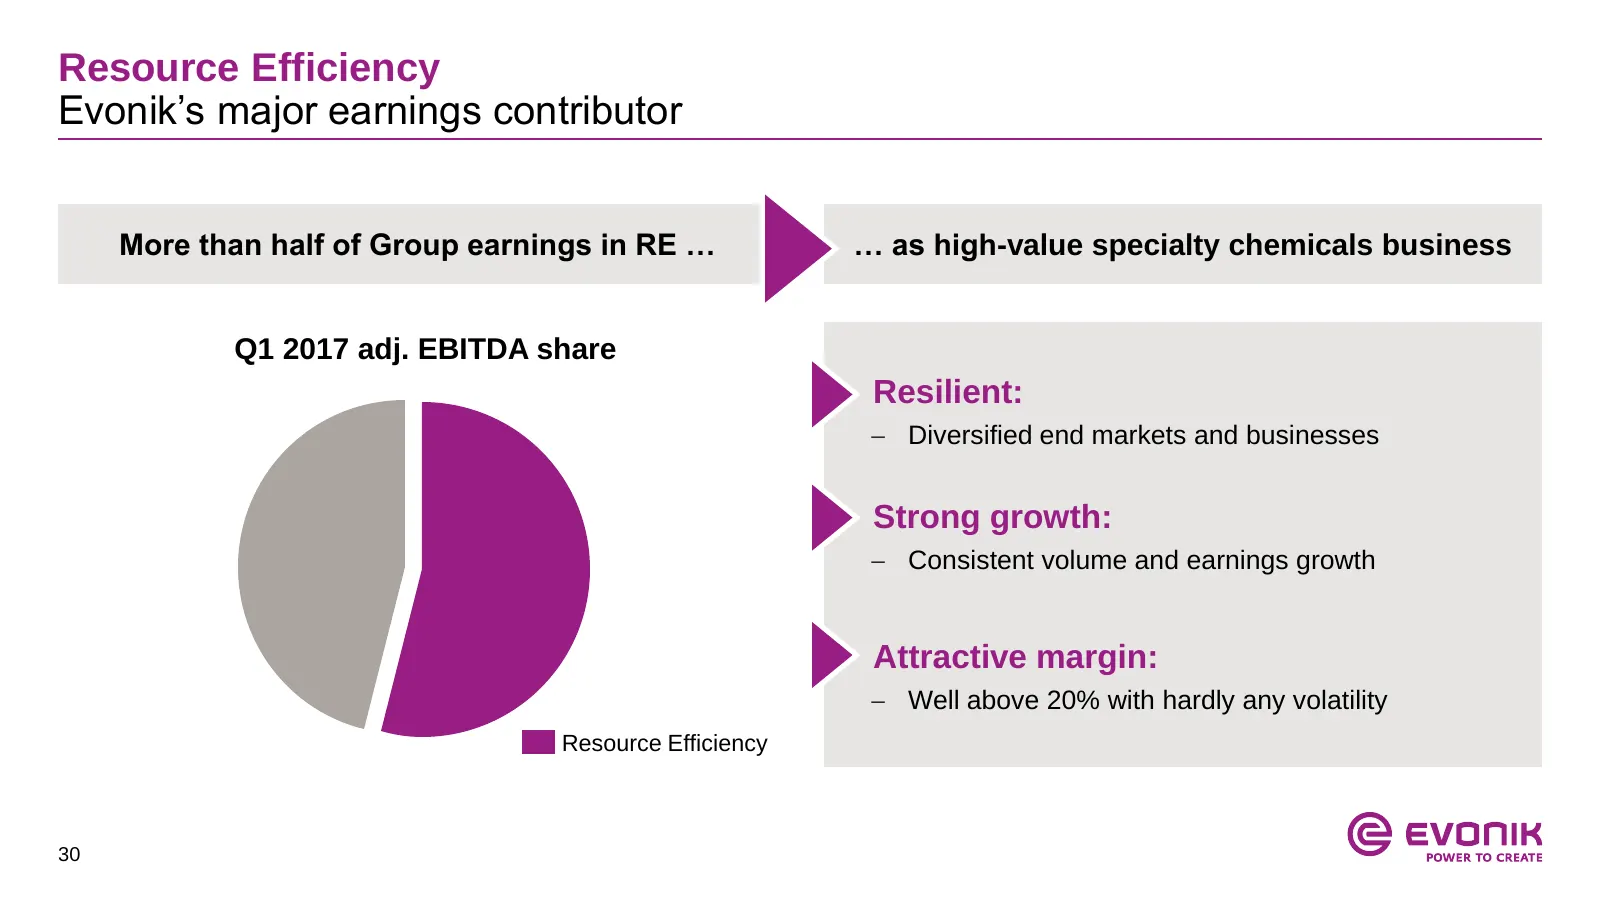
Slide 30: Resource Efficiency: Evonik's major earnings contributor
Resource Efficiency Evonik’s major earnings contributor More than half of Group earnings in RE … … as high-value specialty chemicals business Q1 2017 adj. EBITDA share Resilient: Diversified end markets and businesses Strong growth: Consistent volume and earnings growth Attractive margin: Well
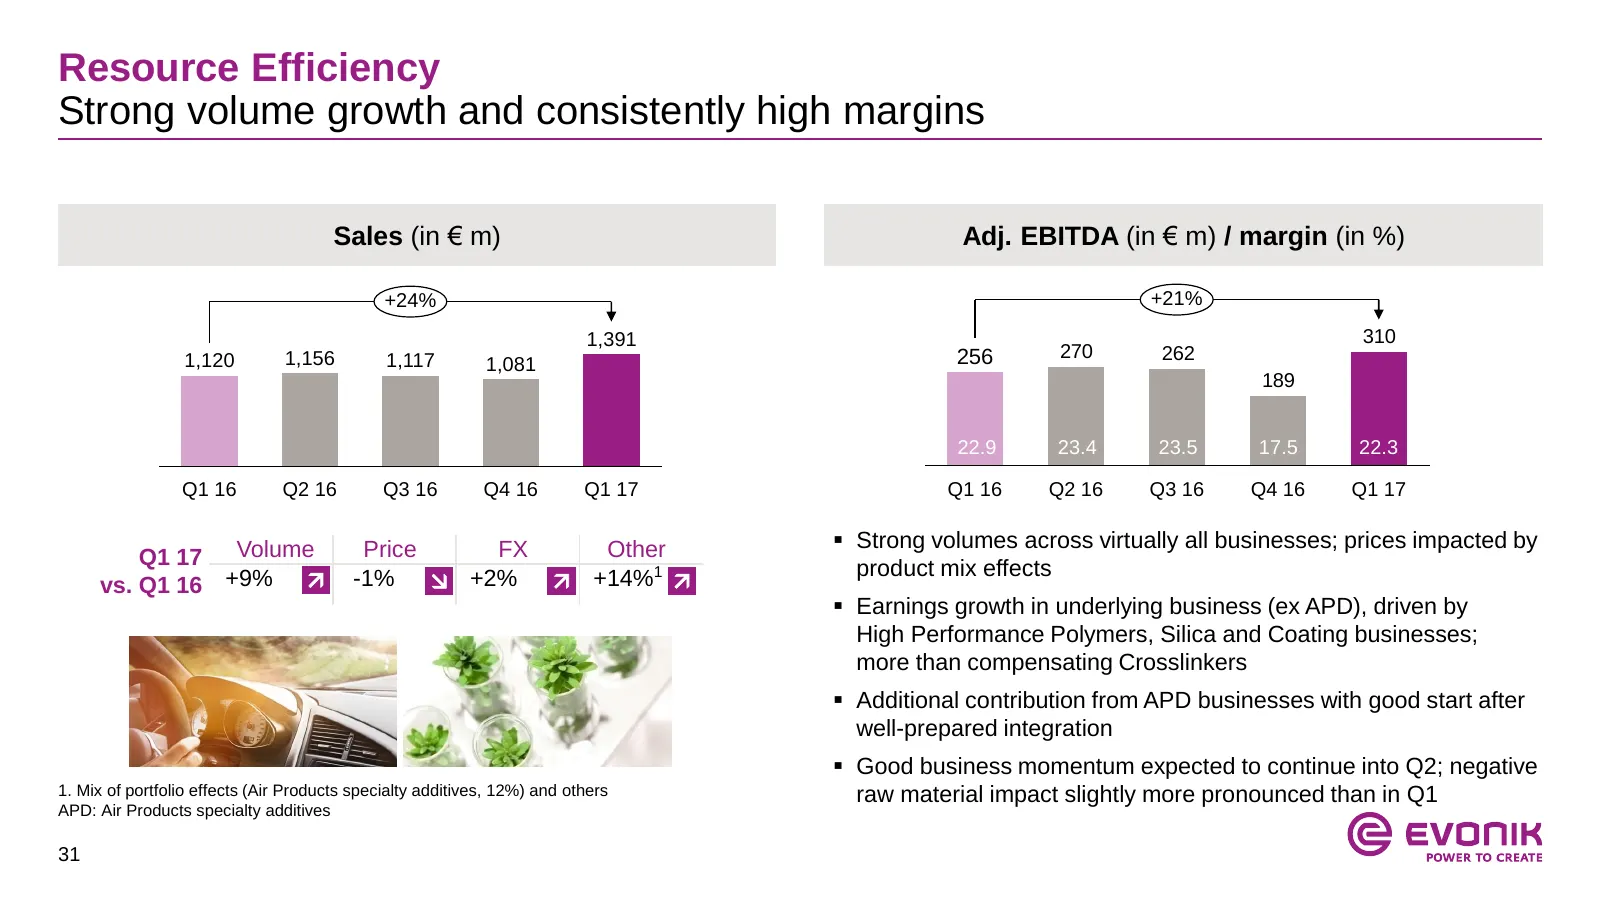
Slide 31: Resource Efficiency: strong volume growth and high margins
Resource Efficiency Strong volume growth and consistently high margins Sales (in € m) Adj. EBITDA (in € m) / margin (in %) +24% +21% 1,391 310 1,120 1,156 1,117 256 270 262 1,081 189 22.9 23.4 23.5 17.5 22.3 Q1 16 Q2 16 Q3 16 Q4 16 Q1 17 Q1 16 Q2 16 Q3 16 Q4 16 Q1 17 Strong volumes across virtuall
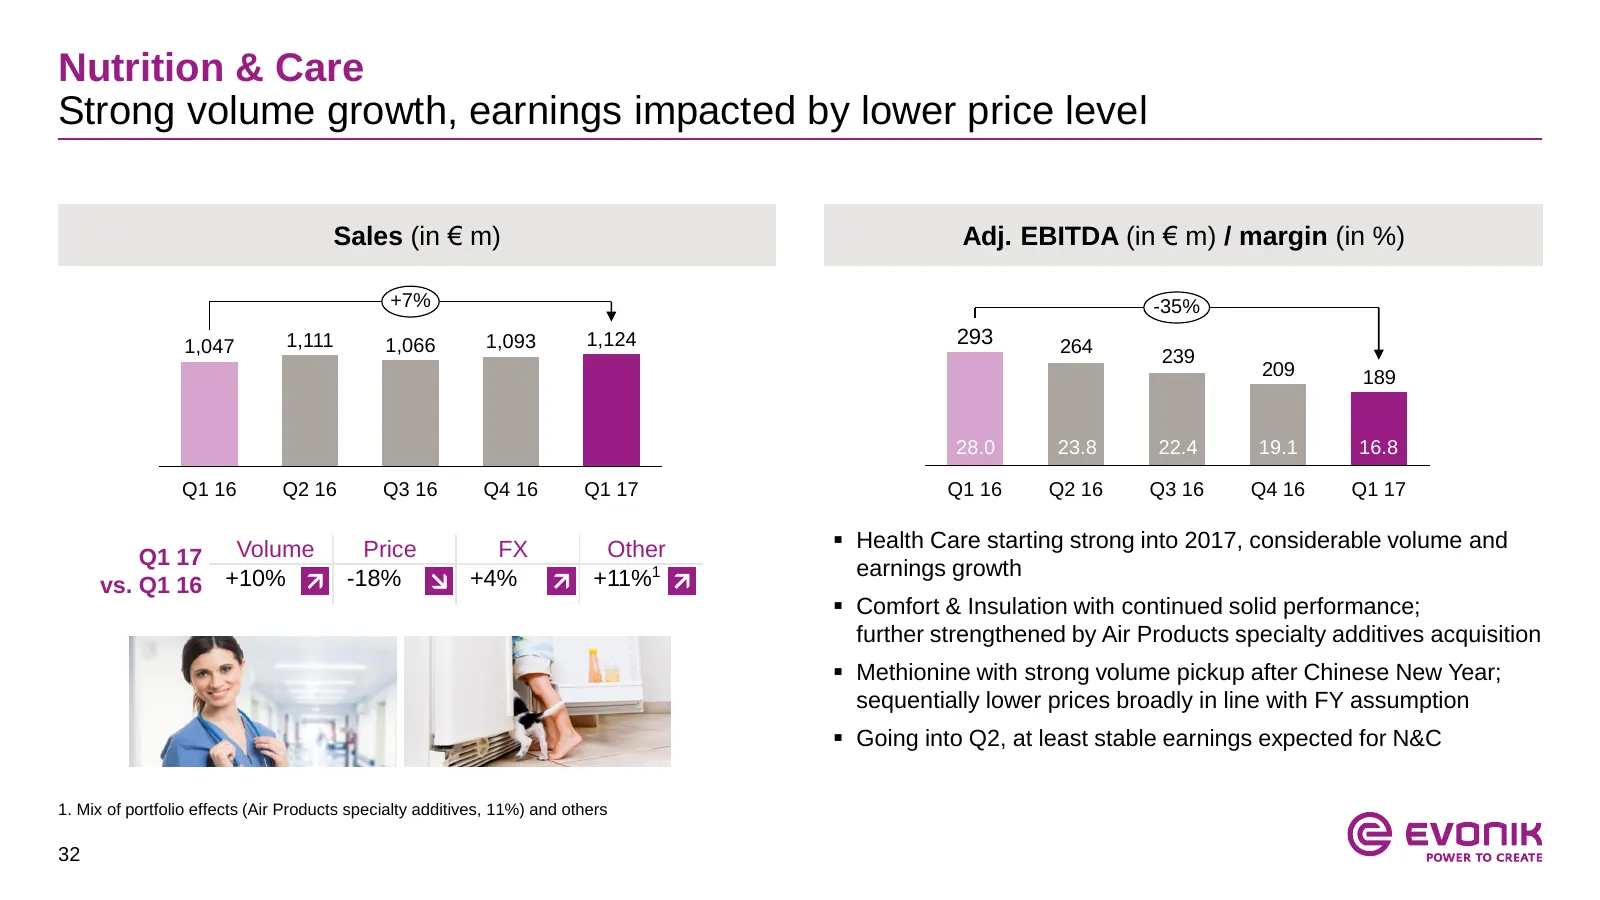
Slide 32: Nutrition & Care: strong volume growth, lower price level
Nutrition & Care Strong volume growth, earnings impacted by lower price level Sales (in € m) Adj. EBITDA (in € m) / margin (in %) +7% -35% 1,047 1,111 1,066 1,093 1,124 293 264 239 209 189 28.0 23.8 22.4 19.1 16.8 Q1 16 Q2 16 Q3 16 Q4 16 Q1 17 Q1 16 Q2 16 Q3 16 Q4 16 Q1 17 Health Care starting str
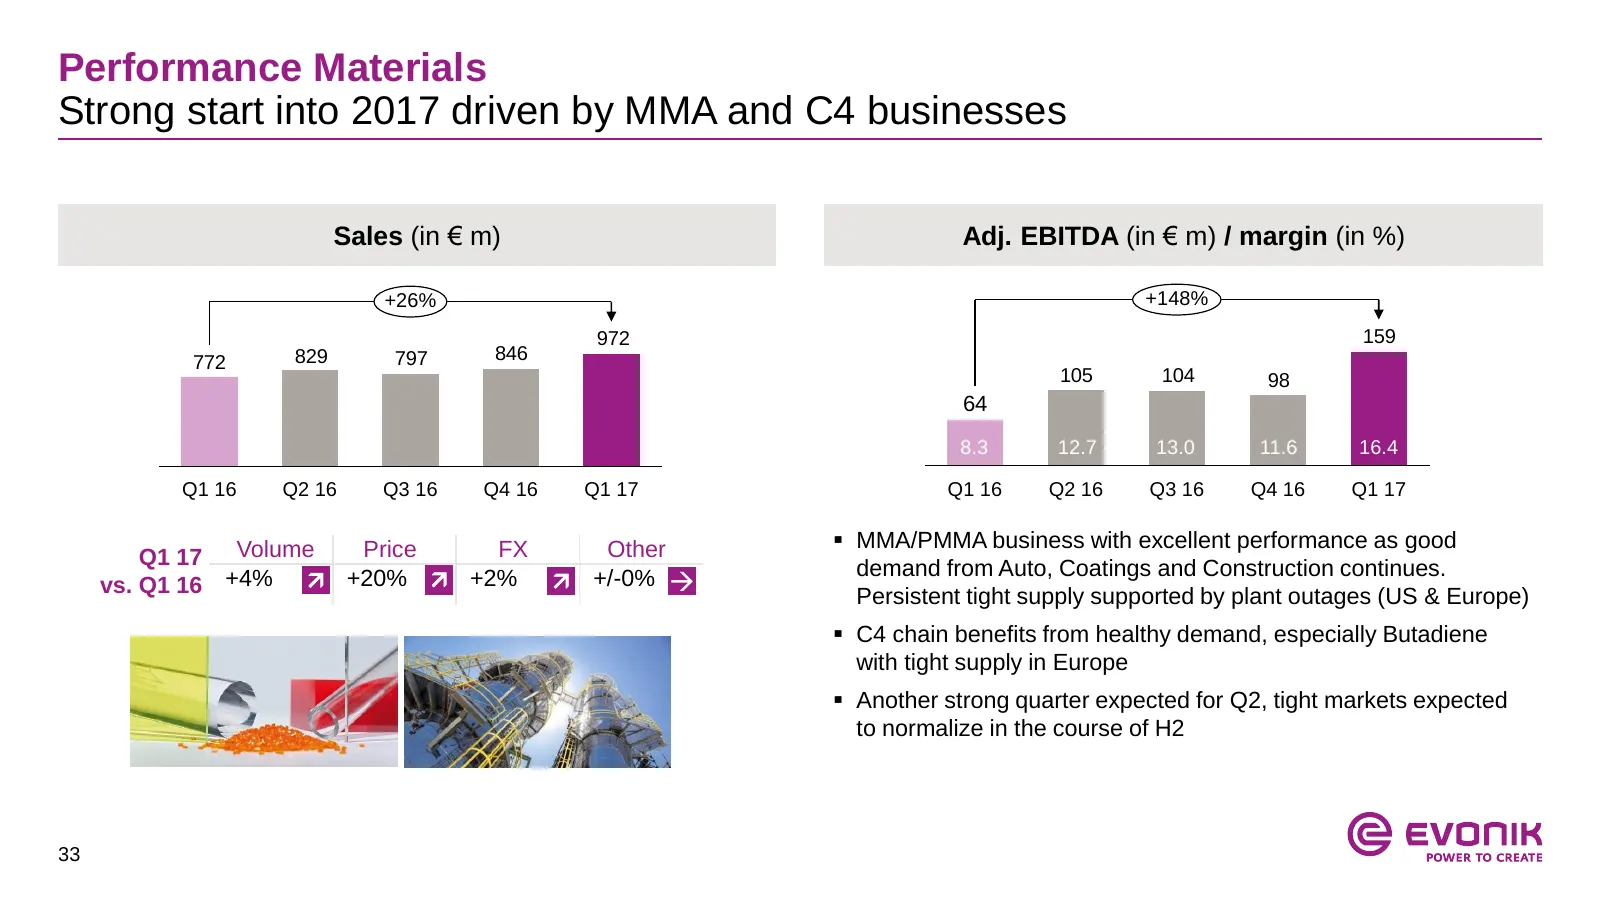
Slide 33: Performance Materials: strong start into 2017
Performance Materials Strong start into 2017 driven by MMA and C4 businesses Sales (in € m) Adj. EBITDA (in € m) / margin (in %) +26% +148% 972 159 772 829 797 846 105 104 98 64 8.3 12.7 13.0 11.6 16.4 Q1 16 Q2 16 Q3 16 Q4 16 Q1 17 Q1 16 Q2 16 Q3 16 Q4 16 Q1 17 MMA/PMMA business with excellent per
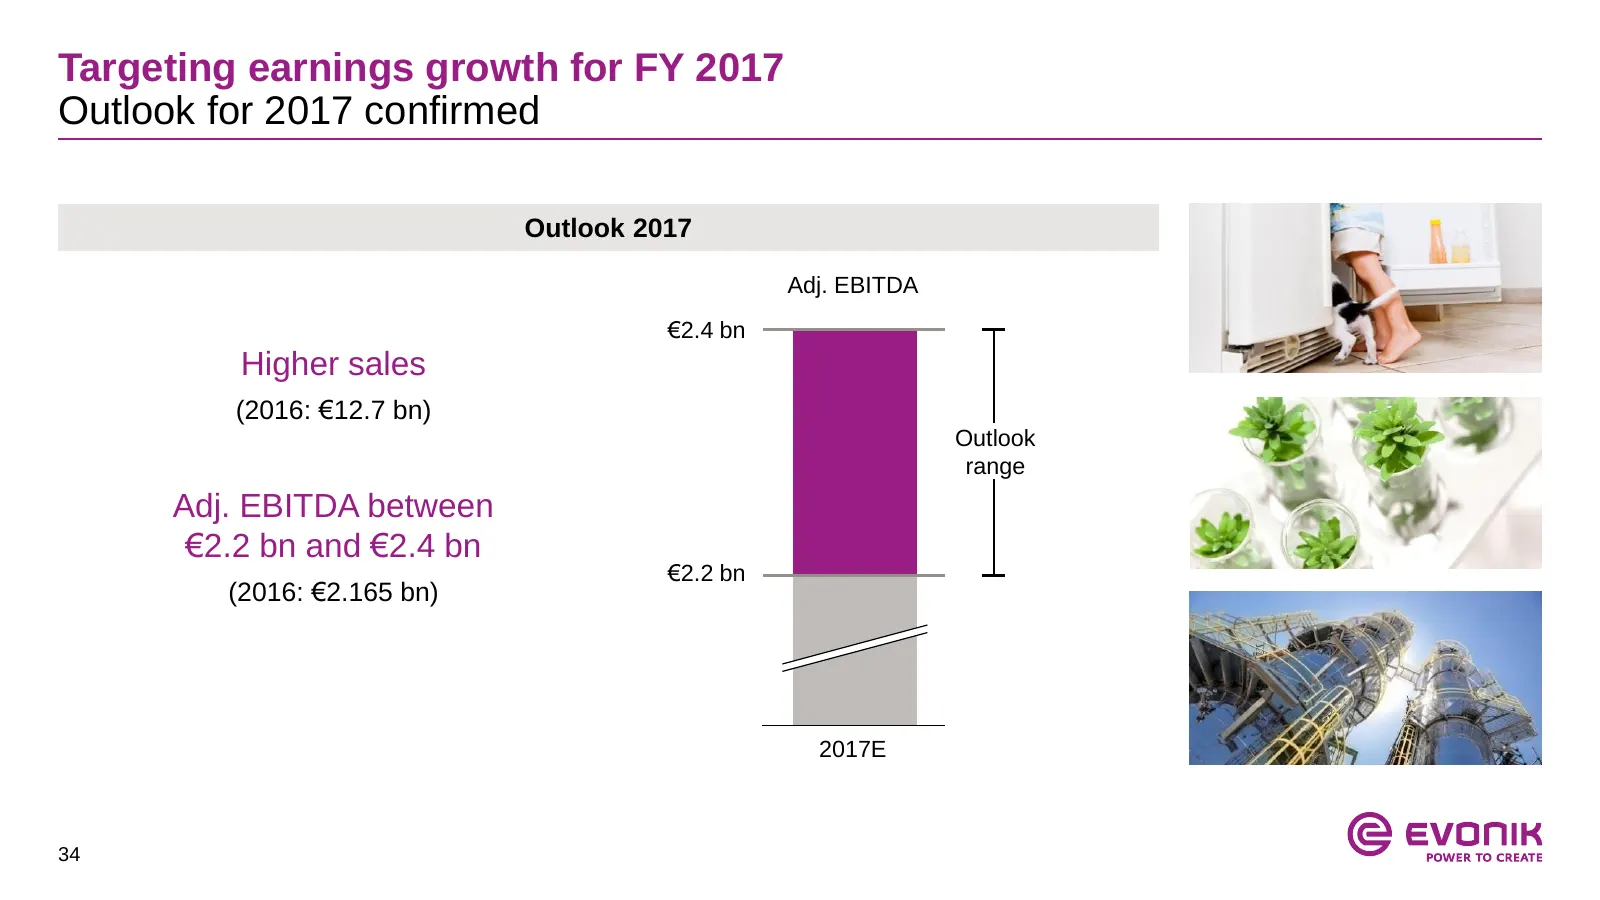
Slide 34: Targeting earnings growth for FY 2017
Targeting earnings growth for FY 2017 Outlook for 2017 confirmed Outlook 2017 Adj. EBITDA €2.4 bn Higher sales (2016: €12.7 bn) Outlook range Adj. EBITDA between €2.2 bn and €2.4 bn €2.2 bn (2016: €2.165 bn) 2017E 34
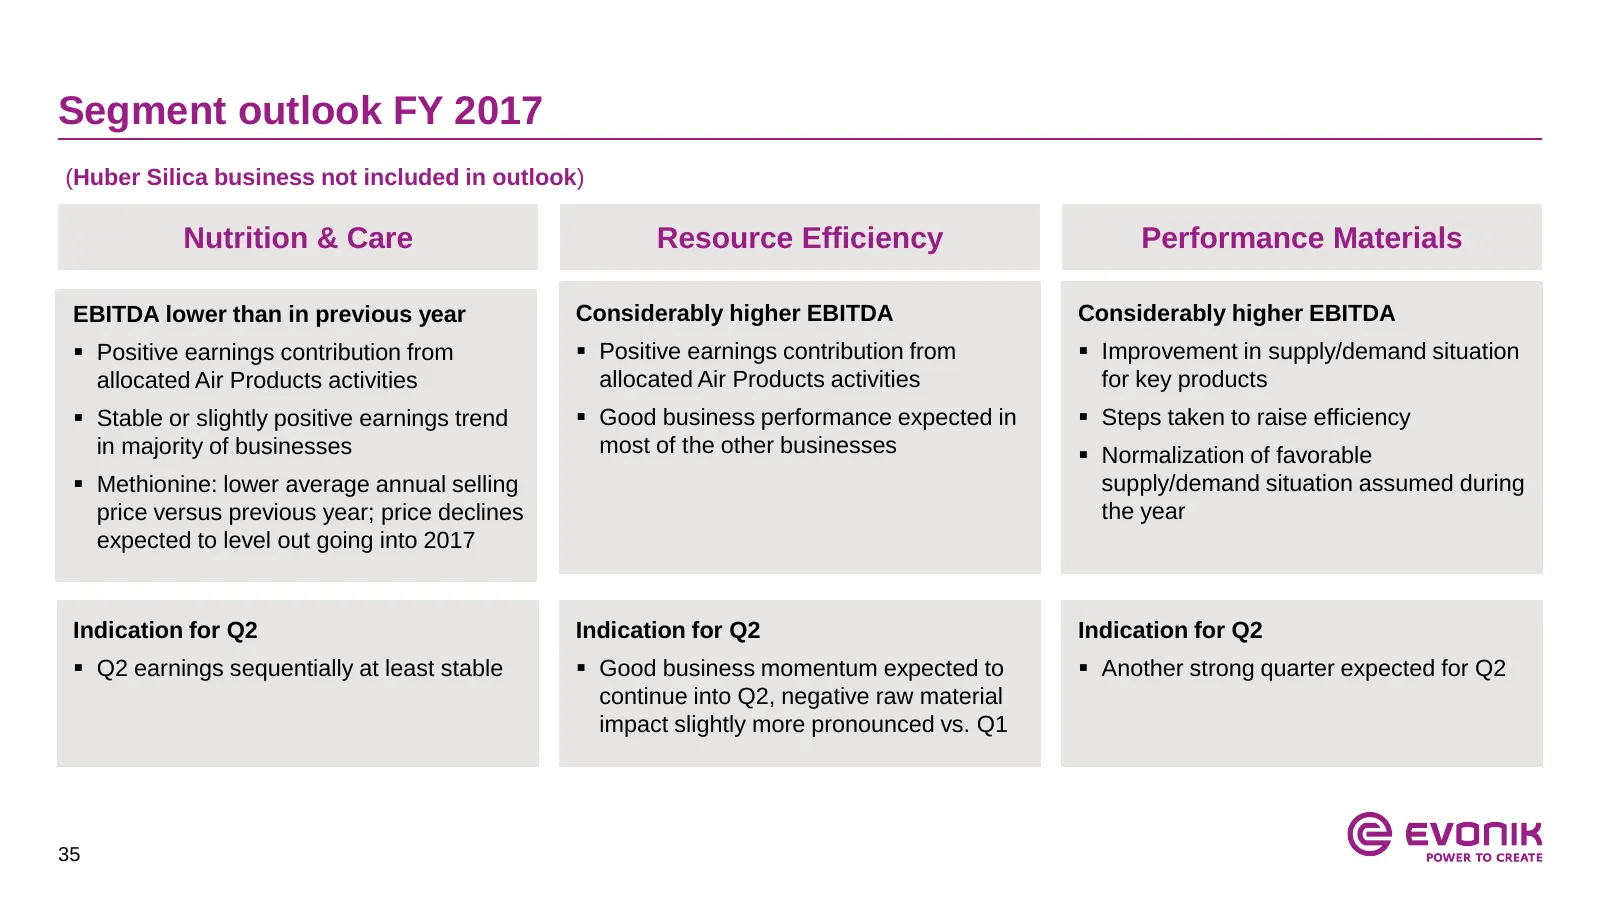
Slide 35: Segment outlook FY 2017
Segment outlook FY 2017 (Huber Silica business not included in outlook) Nutrition & Care Resource Efficiency Performance Materials EBITDA lower than in previous year Considerably higher EBITDA Considerably higher EBITDA Positive earnings contribution from Positive earnings contribution from Im
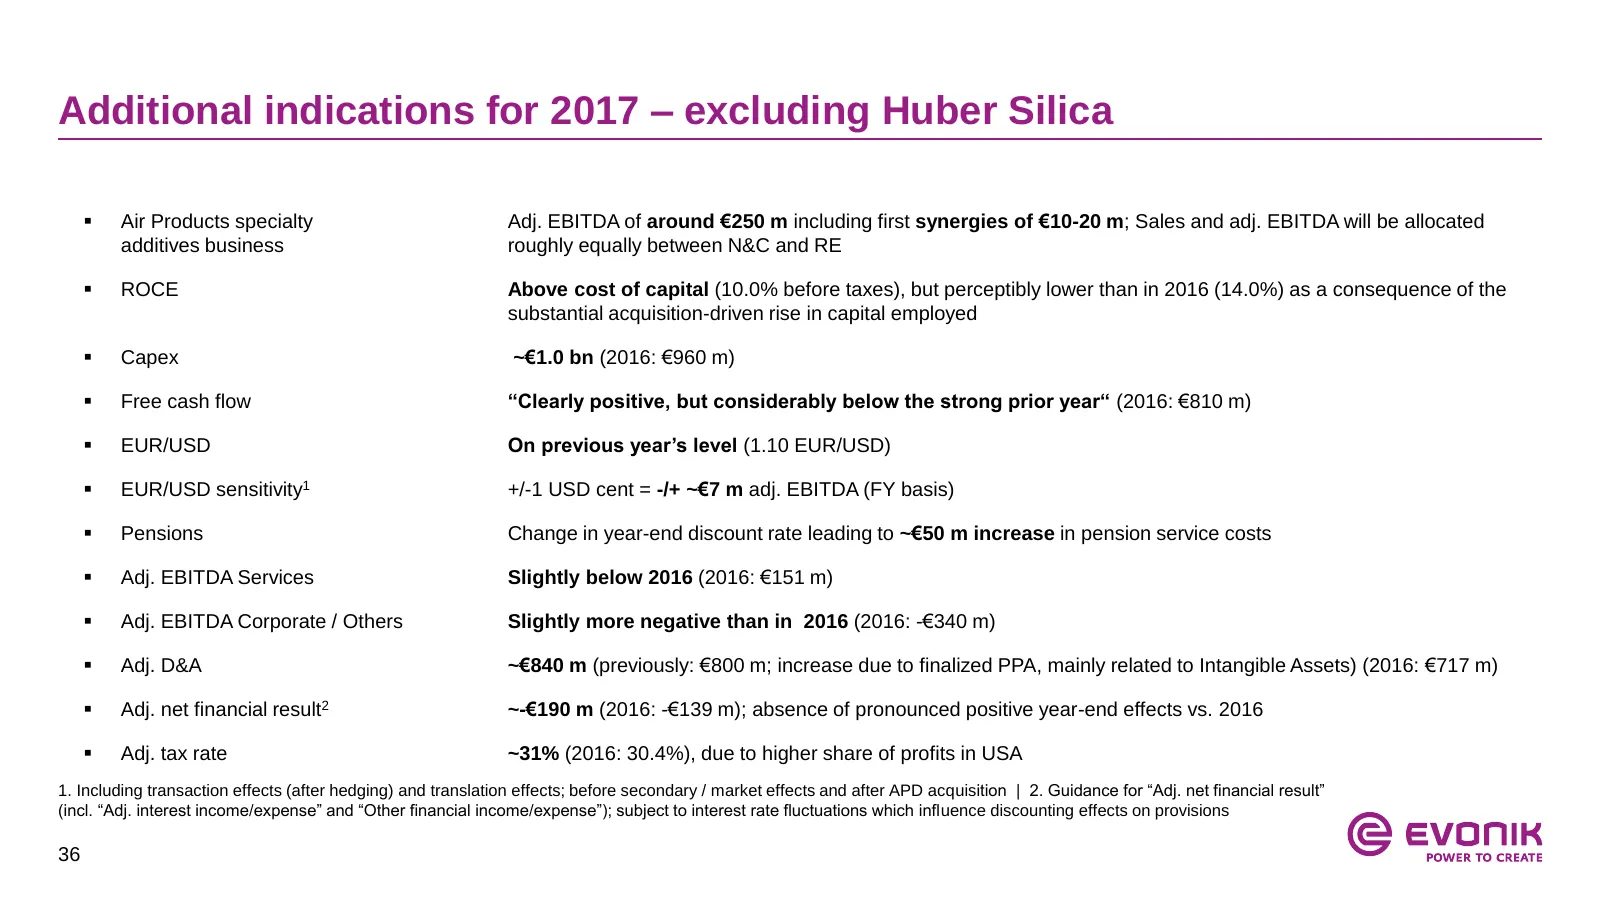
Slide 36: Additional indications for 2017 – excluding Huber Silica
Additional indications for 2017 – excluding Huber Silica Air Products specialty Adj. EBITDA of around €250 m including first synergies of €10-20 m; Sales and adj. EBITDA will be allocated additives business roughly equally between N&C and RE ROCE Above cost of capital (10.0% before taxes), but p
Slide 37: © evonik
© evonik
Slide 38: Appendix
Appendix 1. Acquisition of Air Products specialty additives business 2. Acquisition of Huber Silica 3. Segment overview 4. Financials 5. Upcoming events 38
Slide 39: Acquisition of Air Products Performance Materials activities
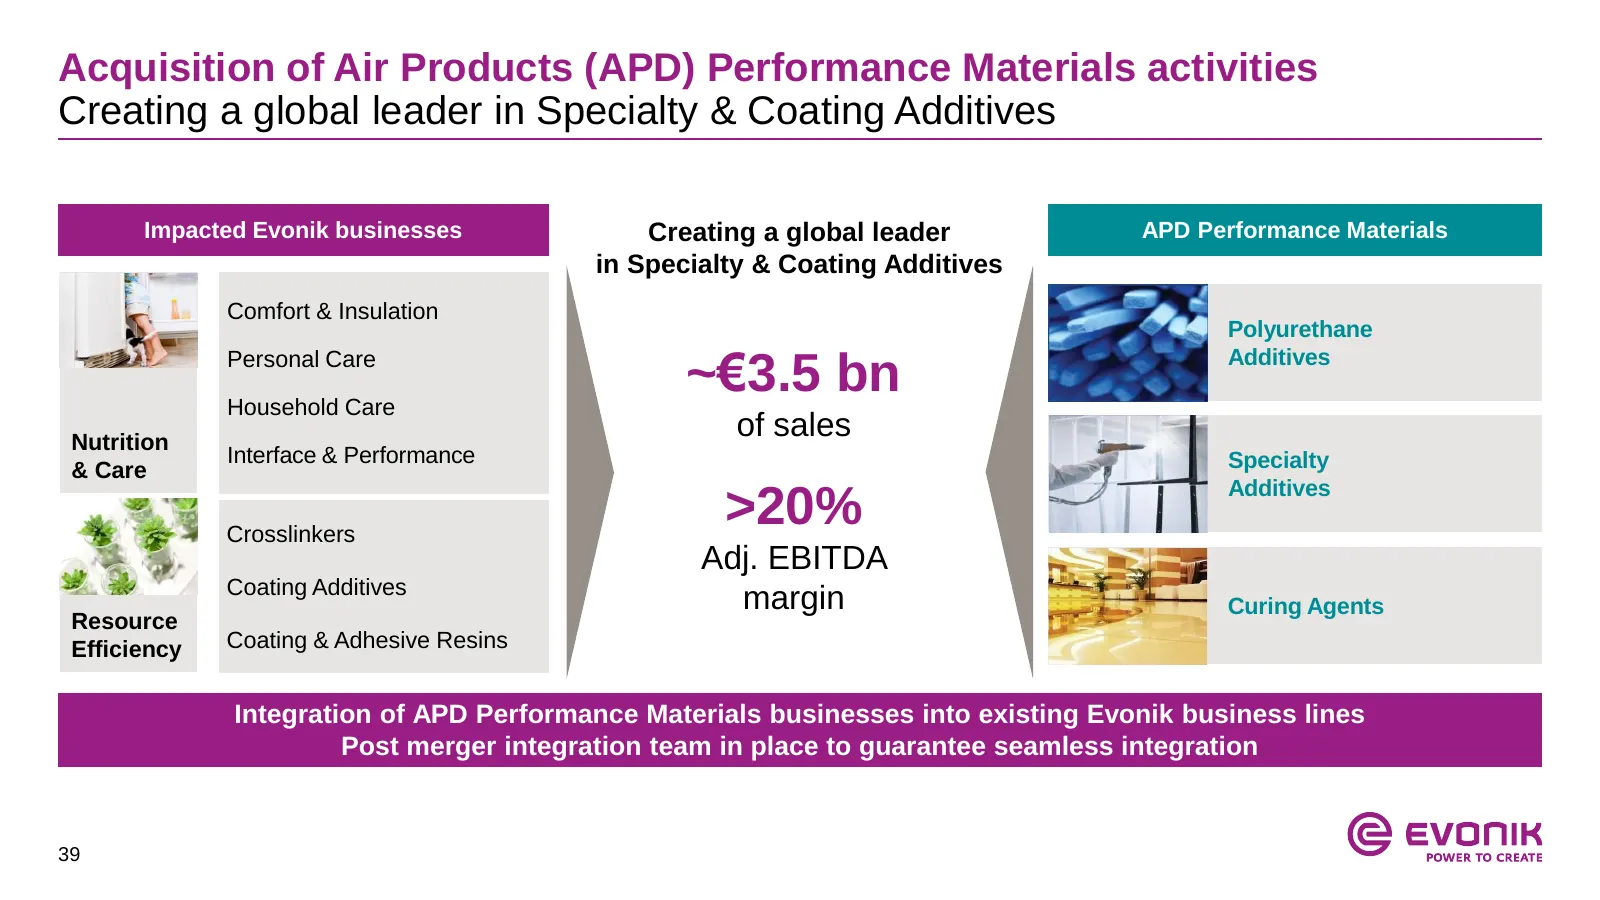
Acquisition of Air Products (APD) Performance Materials activities Creating a global leader in Specialty & Coating Additives Impacted Evonik businesses Creating a global leader APD Performance Materials in Specialty & Coating Additives Comfort & Insulation Polyurethane Personal Care Additives Househ
Slide 40: Complementary fit of Evonik and Air Products specialty additives
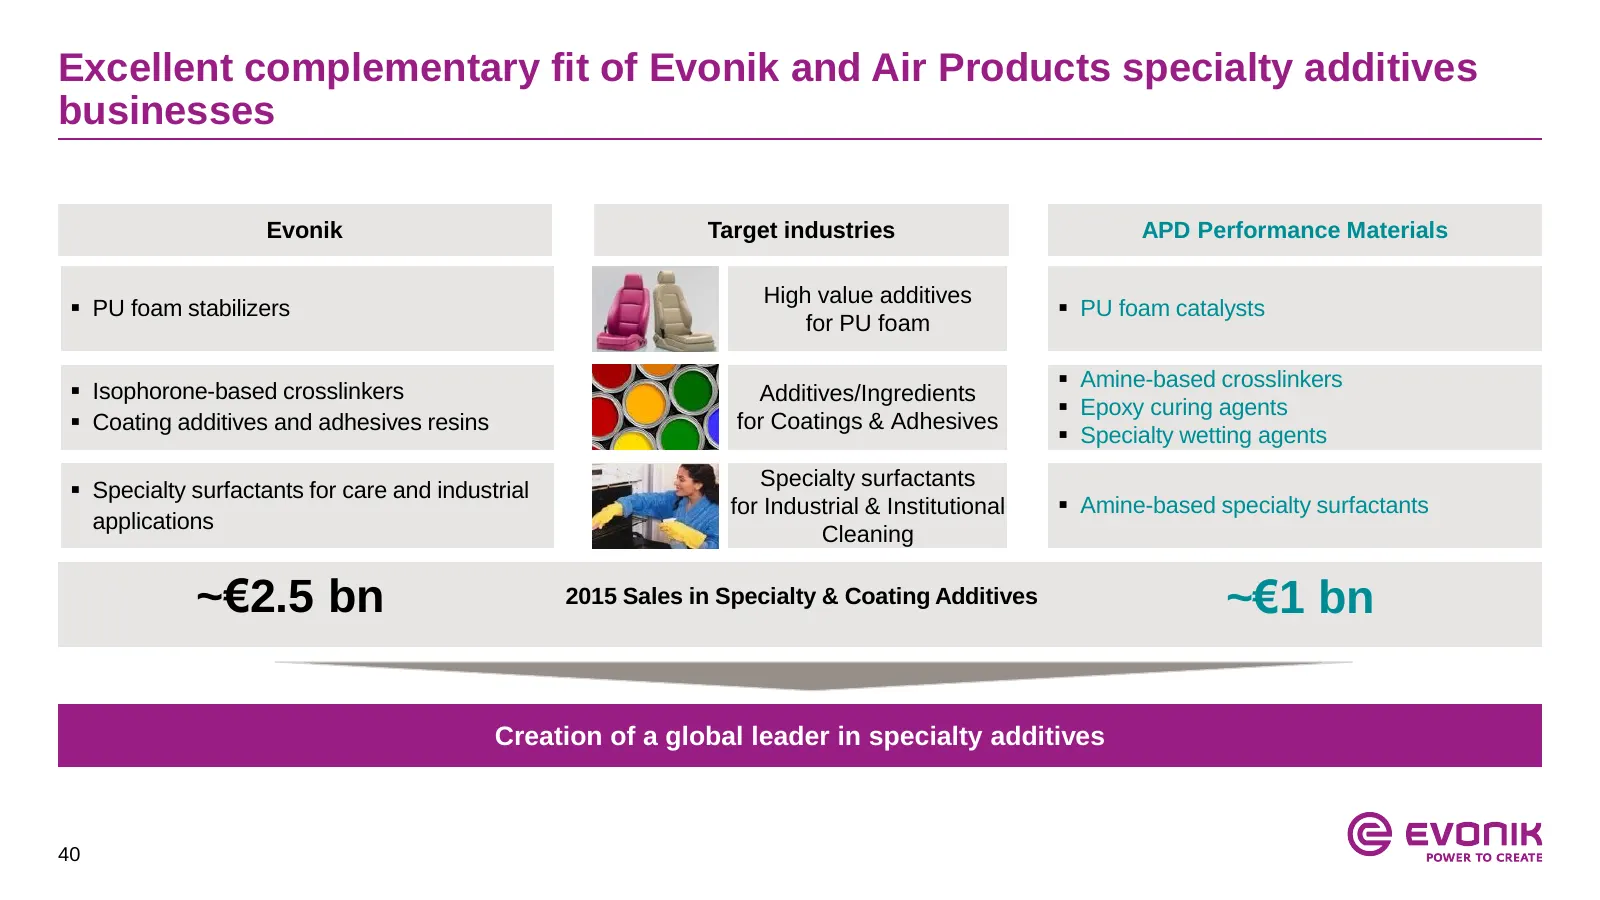
Excellent complementary fit of Evonik and Air Products specialty additives businesses Evonik Target industries APD Performance Materials High value additives PU foam stabilizers PU foam catalysts for PU foam Amine-based crosslinkers Isophorone-based crosslinkers Additives/Ingredients Epoxy
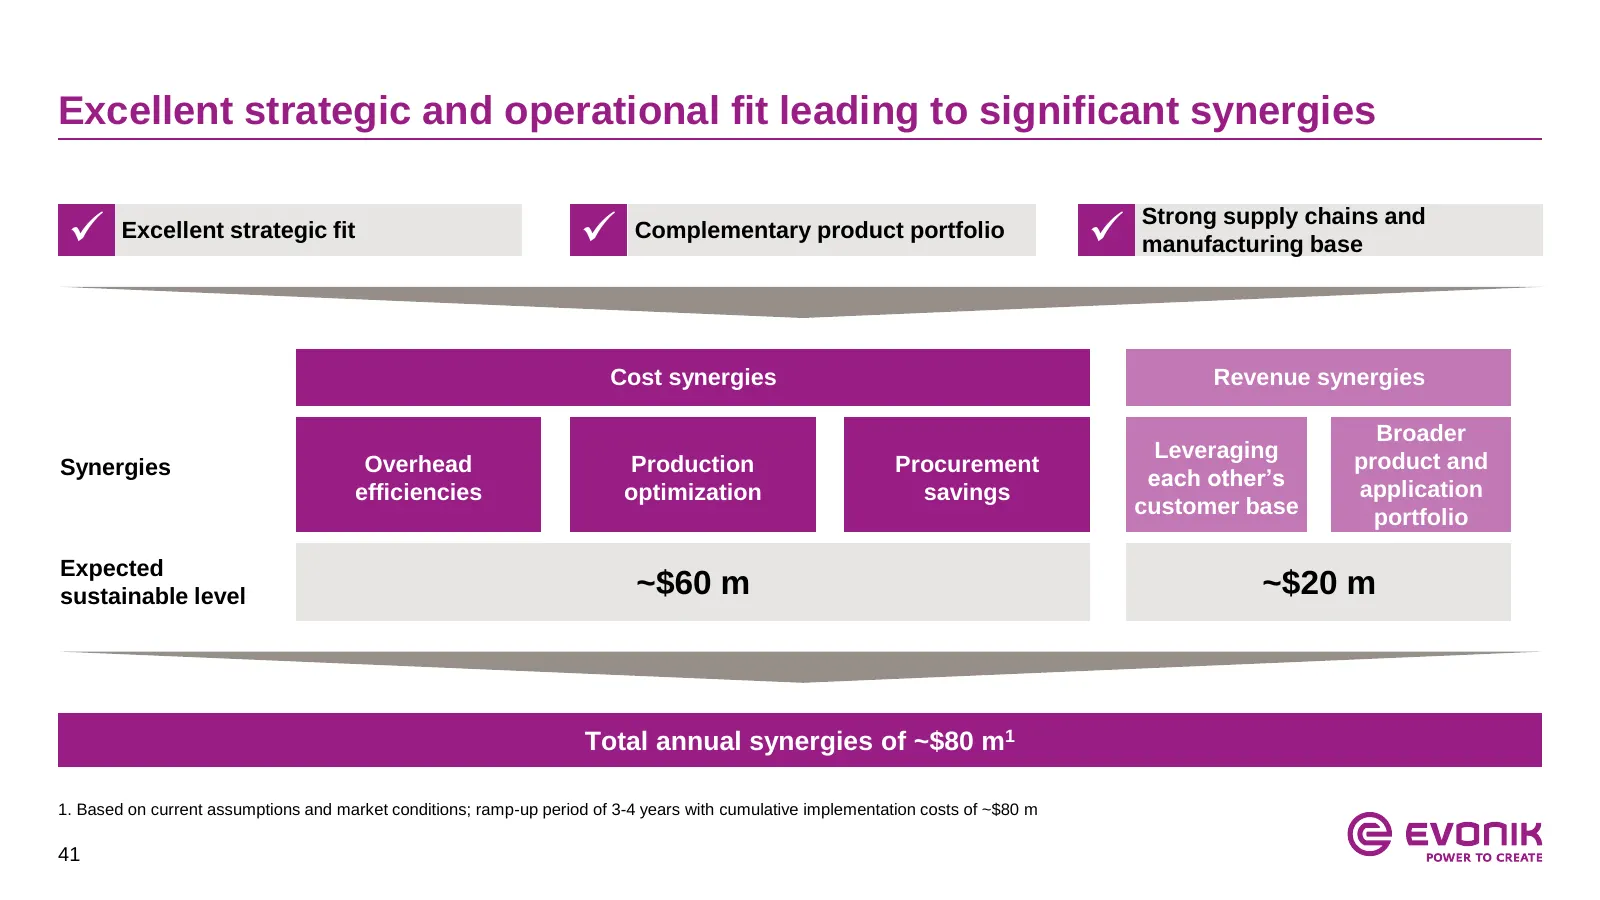
Slide 41: Strategic and operational fit leading to significant synergies
Excellent strategic and operational fit leading to significant synergies Excellent strategic fit Complementary product portfolio Strong supply chains and manufacturing base Cost synergies Revenue synergies Broader Leveraging product and Synergies Overhead Production Procurement each other’s ap
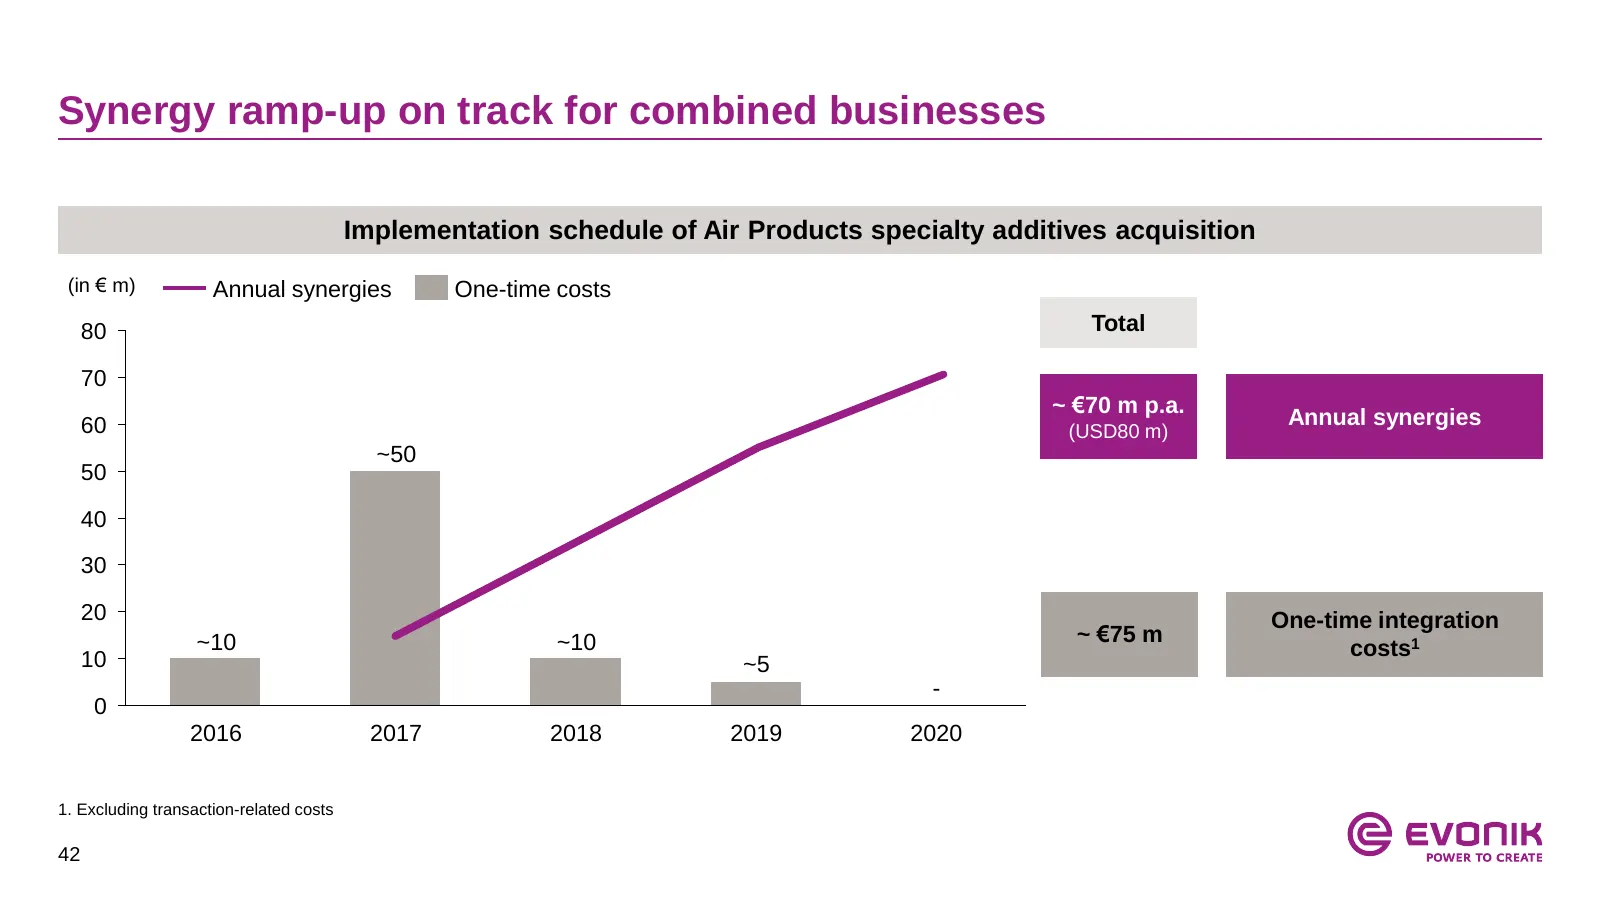
Slide 42: Synergy ramp-up on track for combined businesses
Synergy ramp-up on track for combined businesses Implementation schedule of Air Products specialty additives acquisition (in € m) Annual synergies One-time costs 80 Total 70 ~ €70 m p.a. 60 Annual synergies (USD80 m) ~50 50 40 30 20 One-time integration ~10 ~10 ~ €75 m 10 costs1 ~5 - 0 2016 2017 201
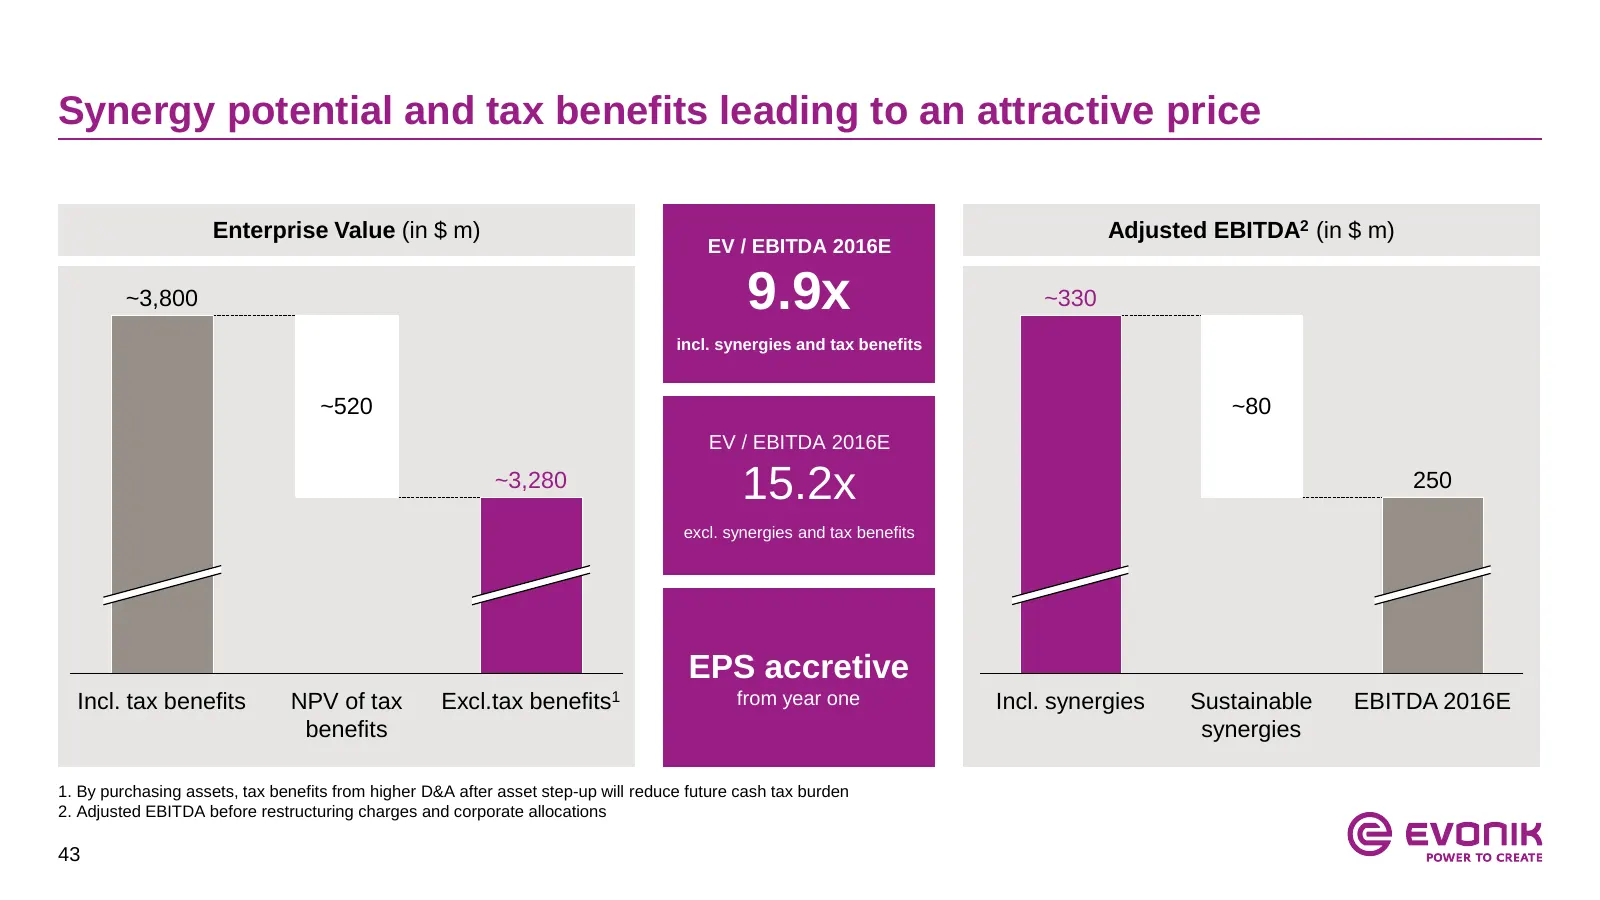
Slide 43: Synergy potential and tax benefits leading to an attractive price
Synergy potential and tax benefits leading to an attractive price Enterprise Value (in $ m) Adjusted EBITDA2 (in $ m) EV / EBITDA 2016E ~3,800 9.9x ~330 incl. synergies and tax benefits ~520 ~80 EV / EBITDA 2016E ~3,280 15.2x 250 excl. synergies and tax benefits EPS accretive Incl. tax benefits NPV
Slide 44: Appendix
Appendix 1. Acquisition of Air Products specialty additives business 2. Acquisition of Huber Silica 3. Segment overview 4. Financials 5. Upcoming events 44
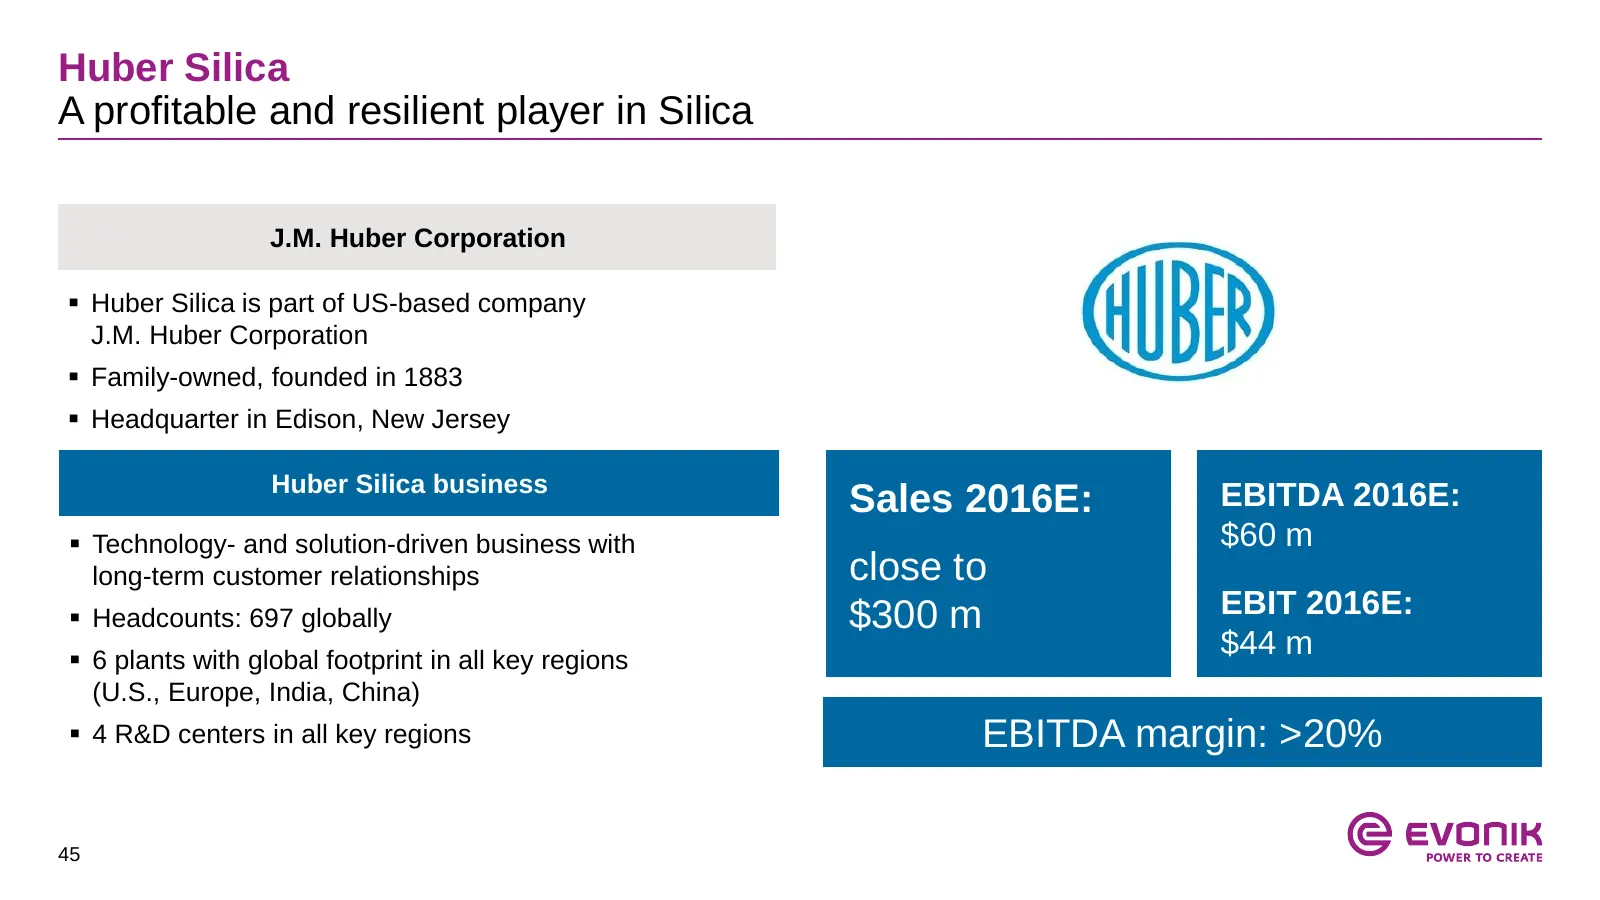
Slide 45: Huber Silica: a profitable and resilient player in Silica
Huber Silica A profitable and resilient player in Silica J.M. Huber Corporation Huber Silica is part of US-based company J.M. Huber Corporation Family-owned, founded in 1883 Headquarter in Edison, New Jersey Huber Silica business EBITDA 2016E: Sales 2016E: Technology- and solution-driven bus
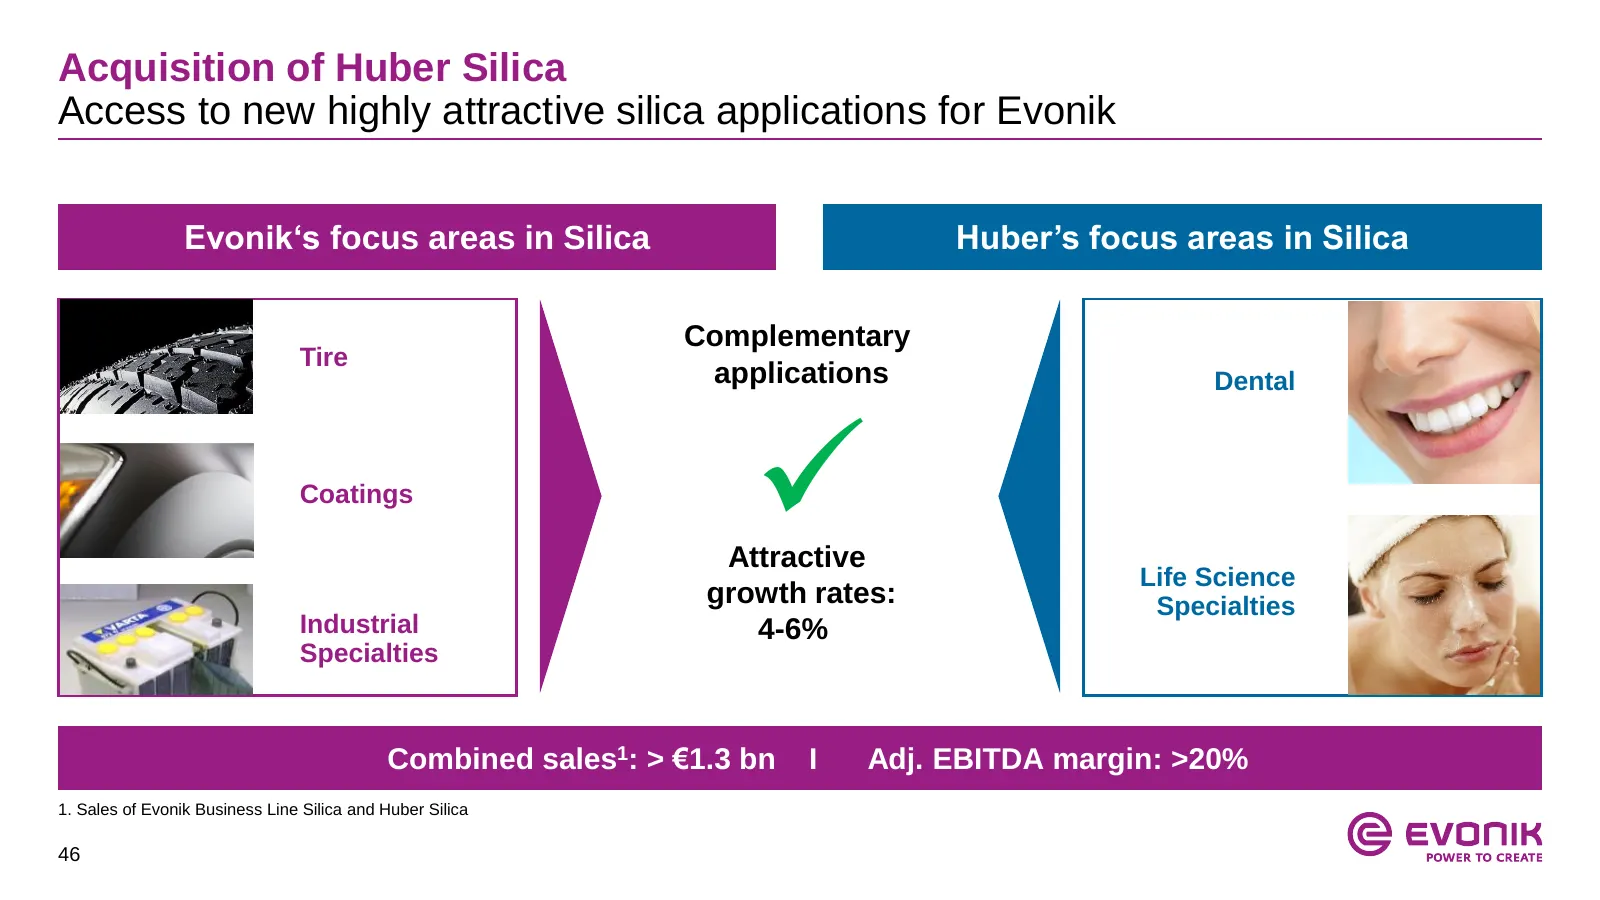
Slide 46: Acquisition of Huber Silica
Acquisition of Huber Silica Access to new highly attractive silica applications for Evonik Evonik‘s focus areas in Silica Huber’s focus areas in Silica Complementary Tire applications Dental Coatings Attractive growth rates: Life Science Specialties Industrial 4-6% Specialties Combined sales1: > €
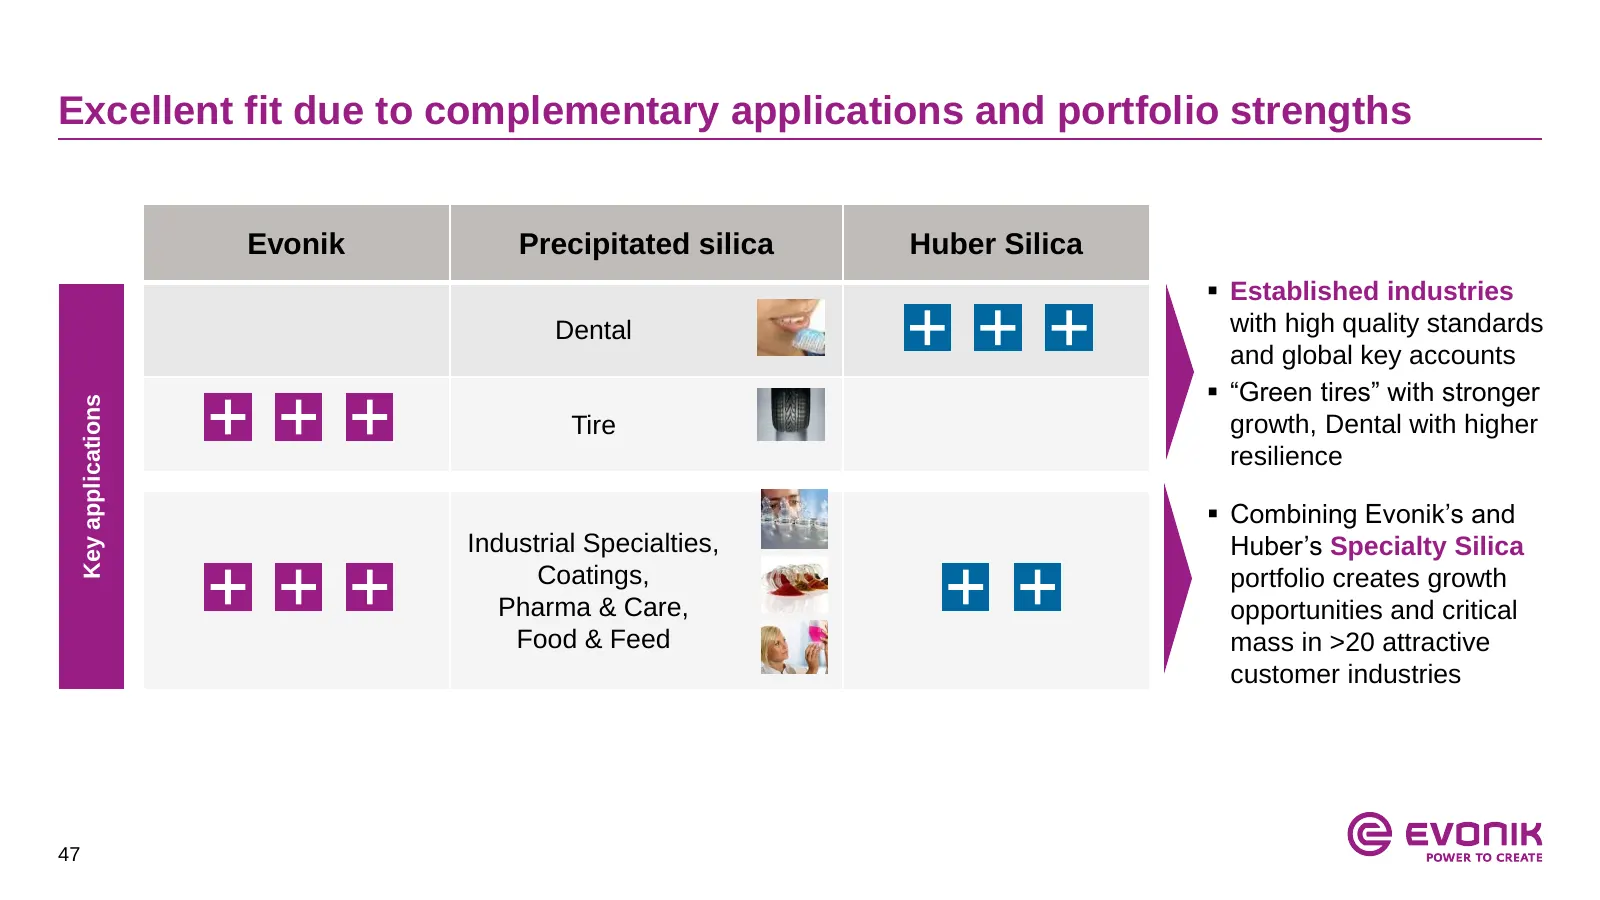
Slide 47: Key applications
Excellent fit due to complementary applications and portfolio strengths Evonik Precipitated silica Huber Silica Established industries Dental with high quality standards and global key accounts “Green tires” with stronger Key applications Tire growth, Dental with higher resilience Combining Ev
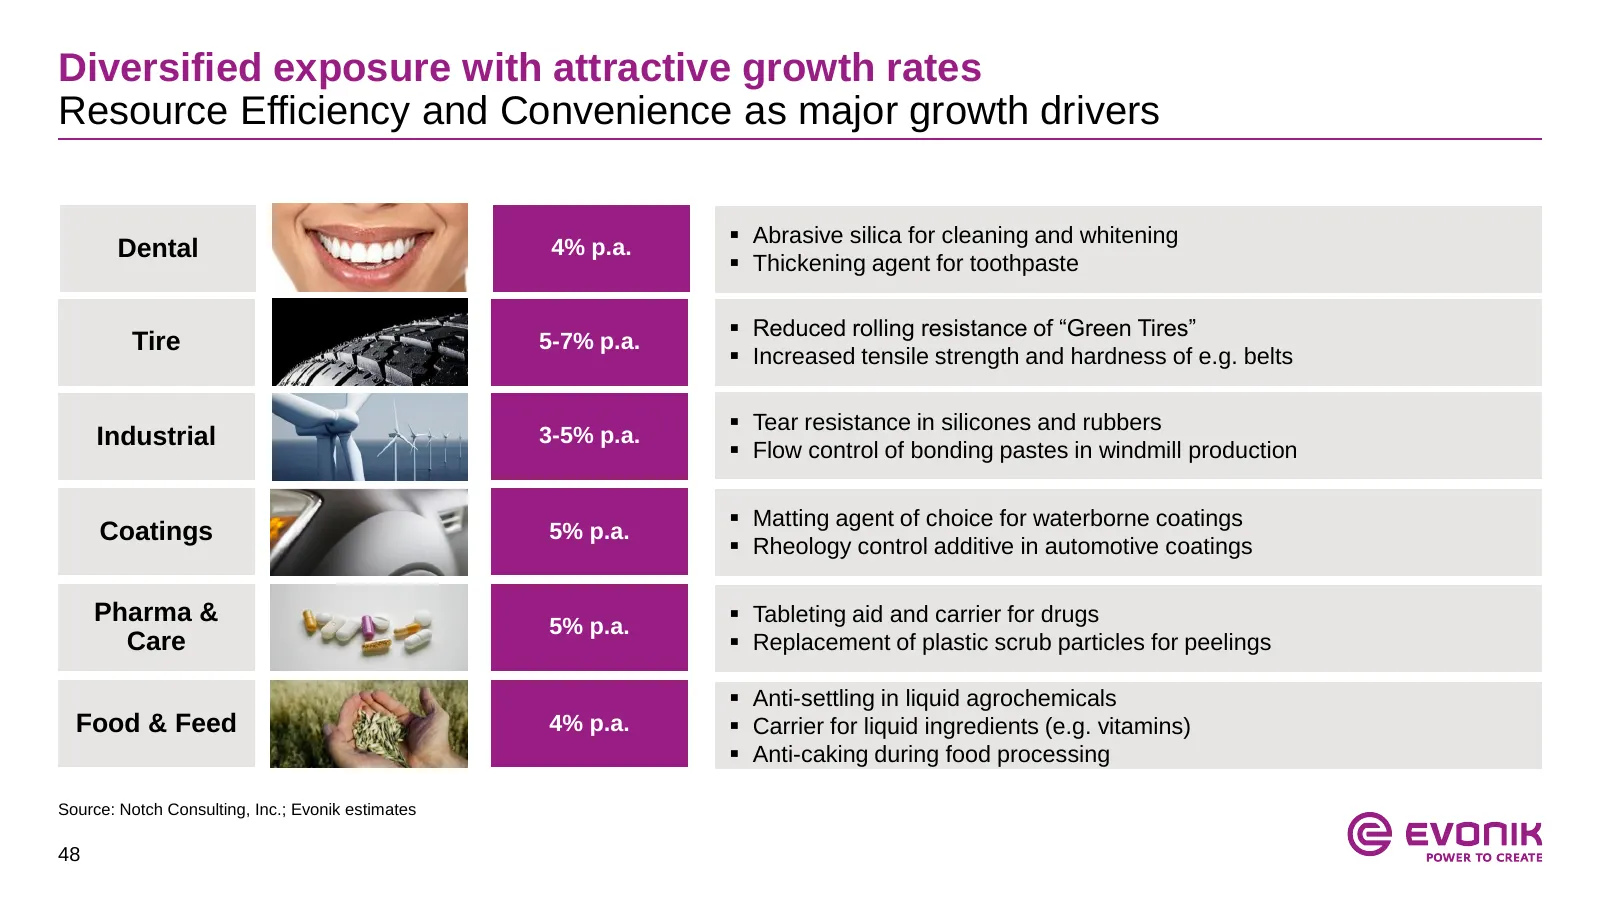
Slide 48: Diversified exposure with attractive growth rates
Diversified exposure with attractive growth rates Resource Efficiency and Convenience as major growth drivers Abrasive silica for cleaning and whitening Dental 4% p.a. Thickening agent for toothpaste Reduced rolling resistance of “Green Tires” Tire 5-7% p.a. Increased tensile strength and ha
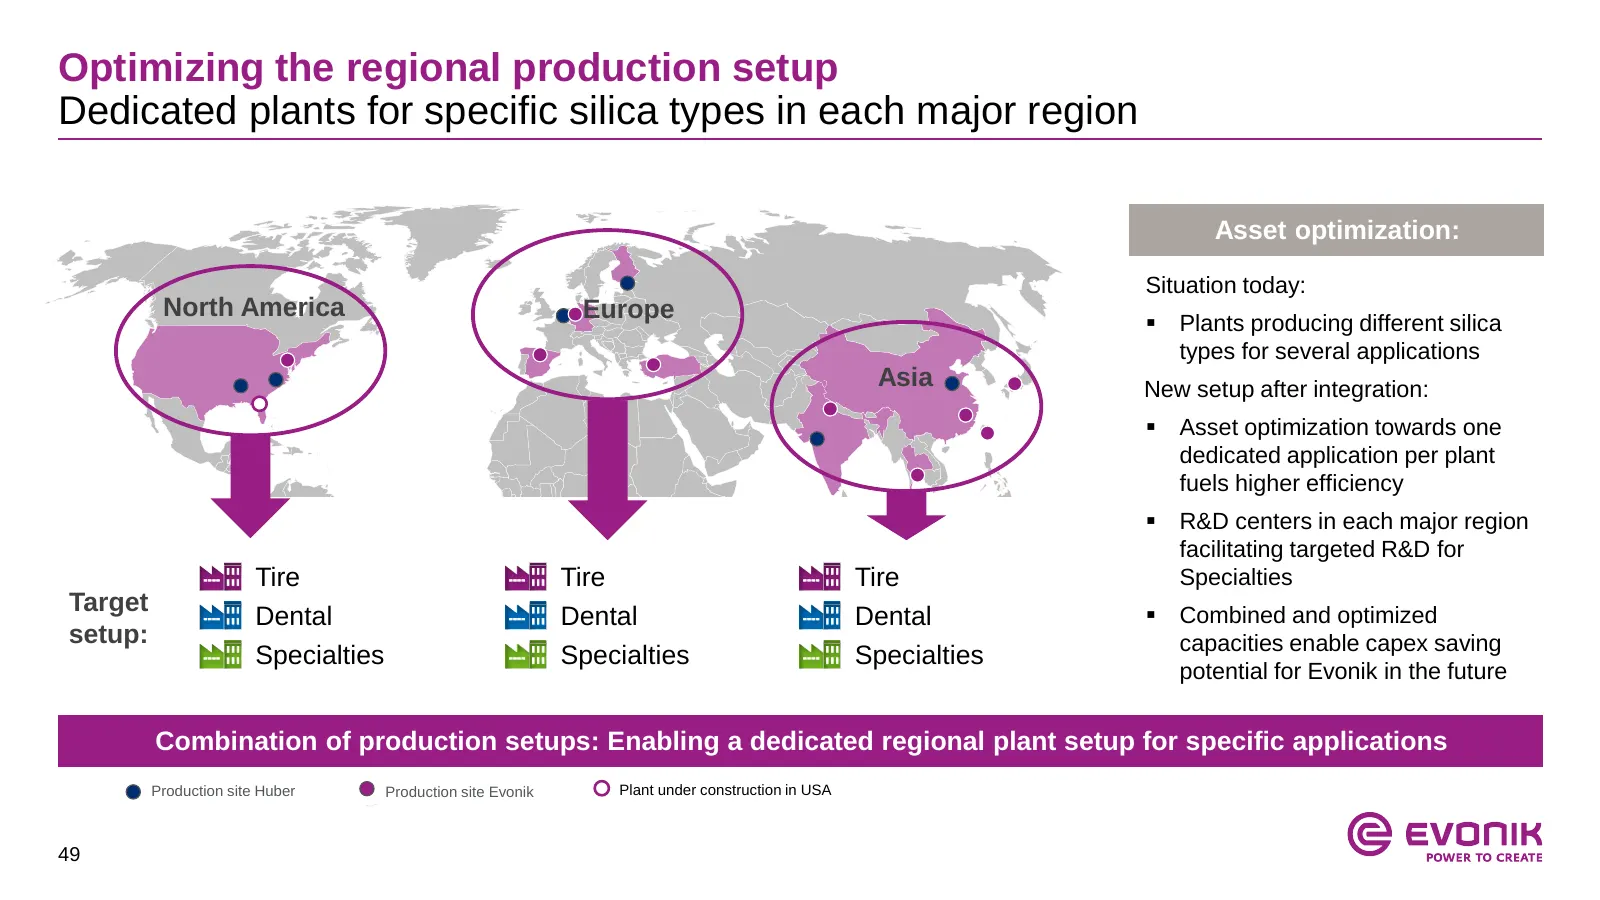
Slide 49: Optimizing the regional production setup
Optimizing the regional production setup Dedicated plants for specific silica types in each major region Asset optimization: Situation today: North America Europe Plants producing different silica types for several applications Asia New setup after integration: Asset optimization towards one ded
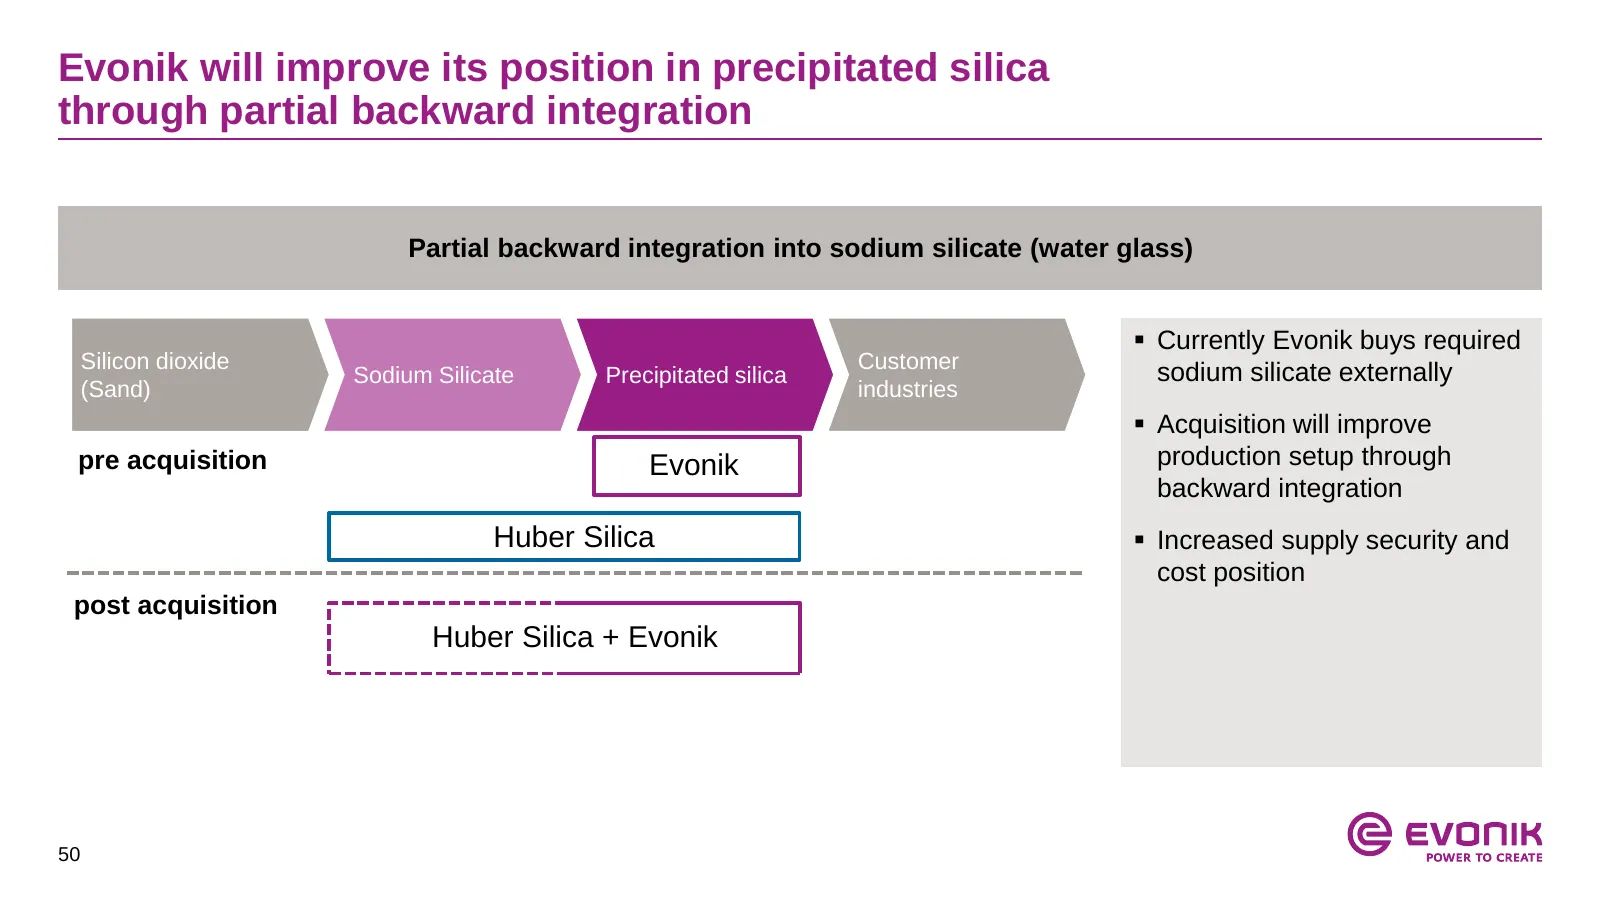
Slide 50: Partial backward integration in precipitated silica
Evonik will improve its position in precipitated silica through partial backward integration Partial backward integration into sodium silicate (water glass) Currently Evonik buys required Silicon dioxide Customer Sodium Silicate Precipitated silica sodium silicate externally (Sand) industries Ac
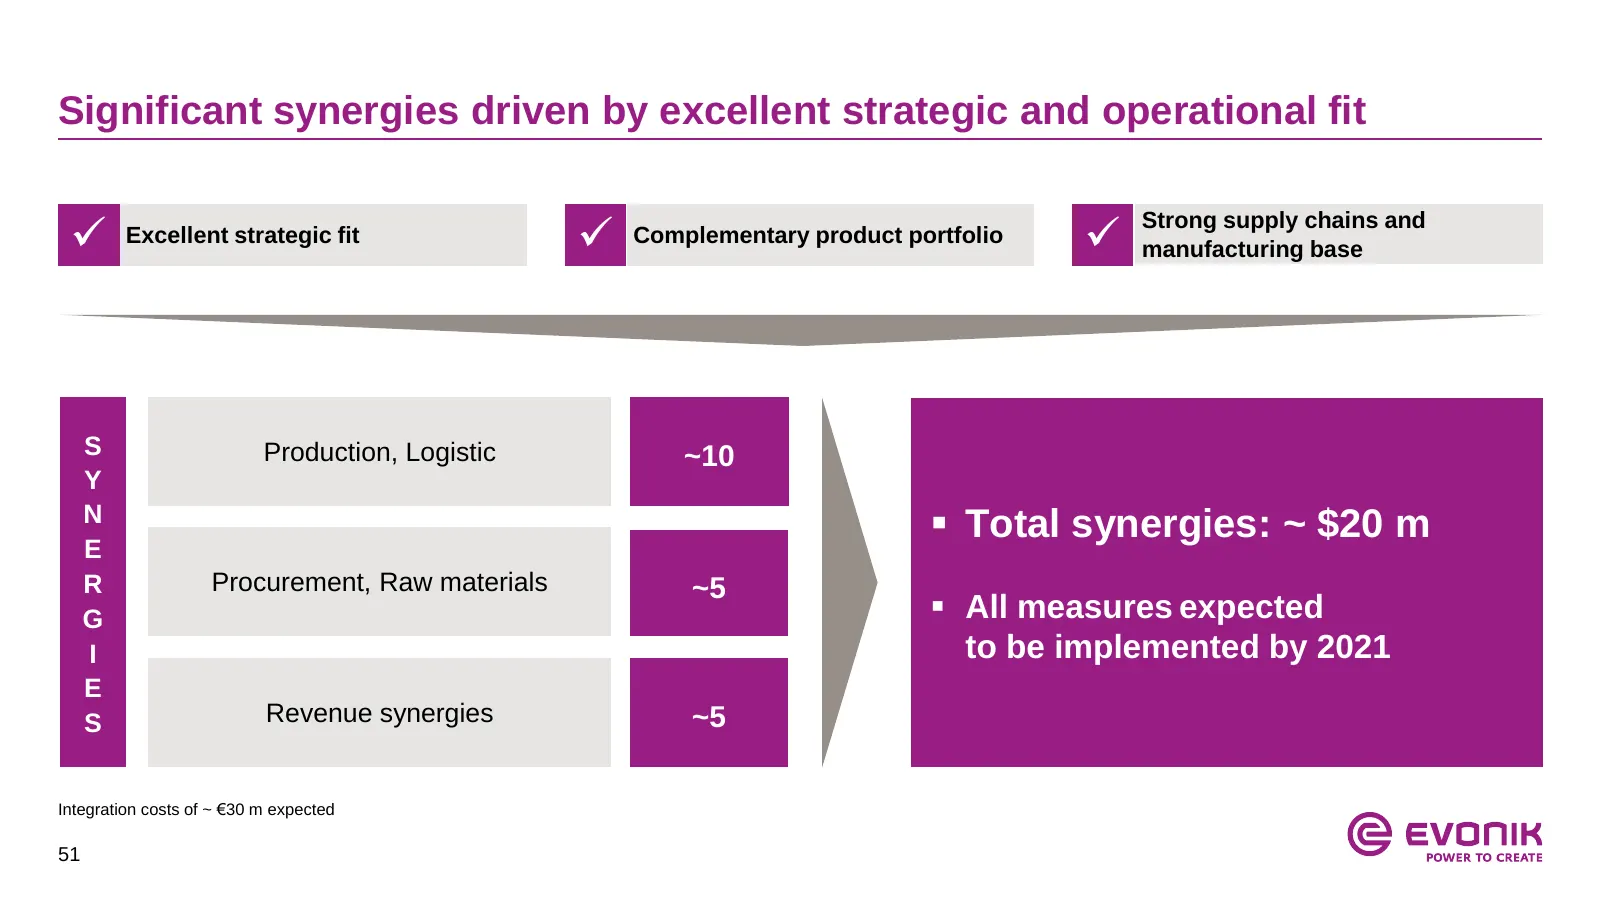
Slide 51: Significant synergies from strategic and operational fit
Significant synergies driven by excellent strategic and operational fit Excellent strategic fit Complementary product portfolio manufacturing base Strong supply chains and S Production, Logistic ~10 Y N Total synergies: ~ $20 m E R Procurement, Raw materials ~5 G All measures expected I to
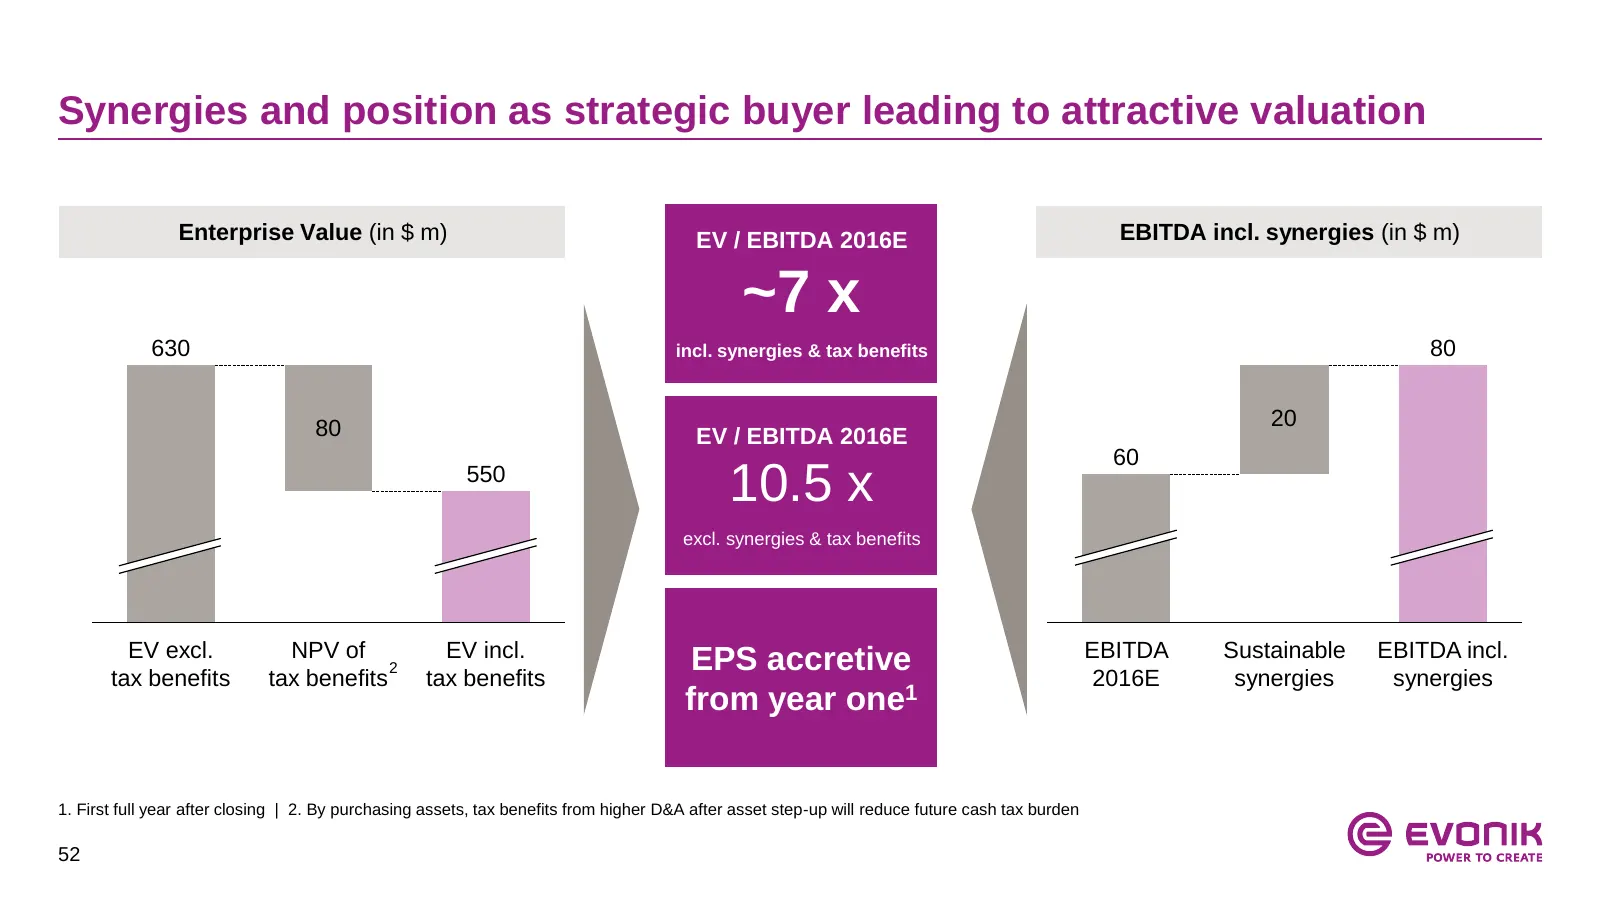
Slide 52: Synergies and strategic buyer position leading to attractive valuation
Synergies and position as strategic buyer leading to attractive valuation Enterprise Value (in $ m) EV / EBITDA 2016E EBITDA incl. synergies (in $ m) ~7 x 630 incl. synergies & tax benefits 80 80 20 EV / EBITDA 2016E 60 550 10.5 x excl. synergies & tax benefits EV excl. NPV of EV incl. EBITDA Sustai
Slide 53: Target market example: dental silica
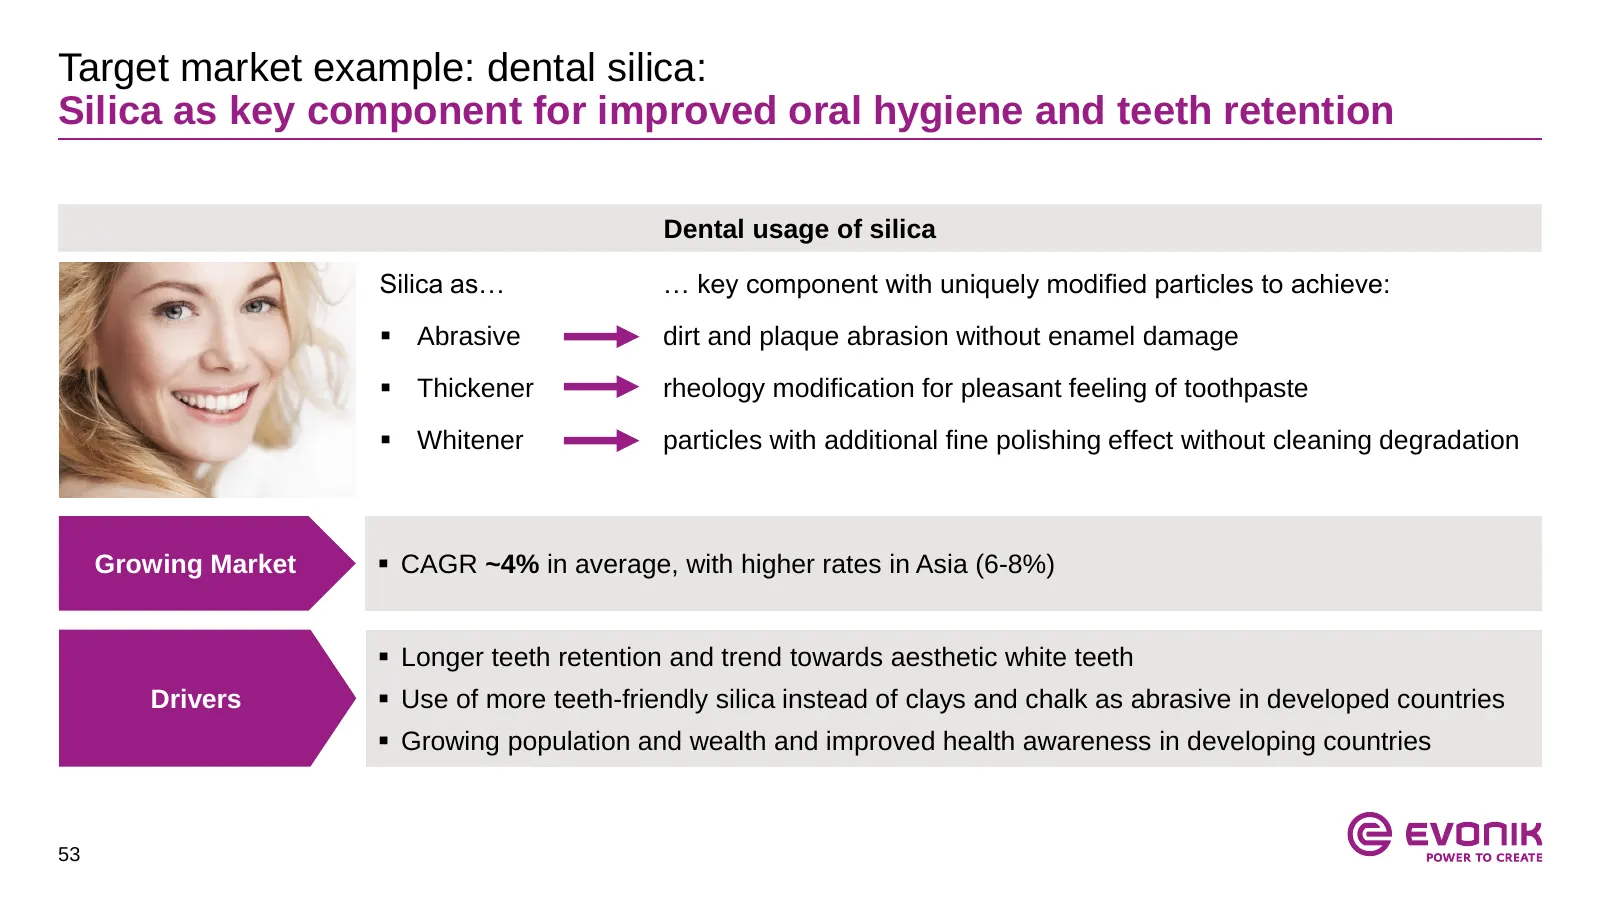
Target market example: dental silica: Silica as key component for improved oral hygiene and teeth retention Dental usage of silica Silica as… … key component with uniquely modified particles to achieve: Abrasive dirt and plaque abrasion without enamel damage Thickener rheology modification for p
Slide 54: Appendix
Appendix 1. Acquisition of Air Products specialty additives business 2. Acquisition of Huber Silica 3. Segment overview 4. Financials 5. Upcoming events 54
Slide 55: Evonik Group: 22 Business Lines grouped in 3 segments
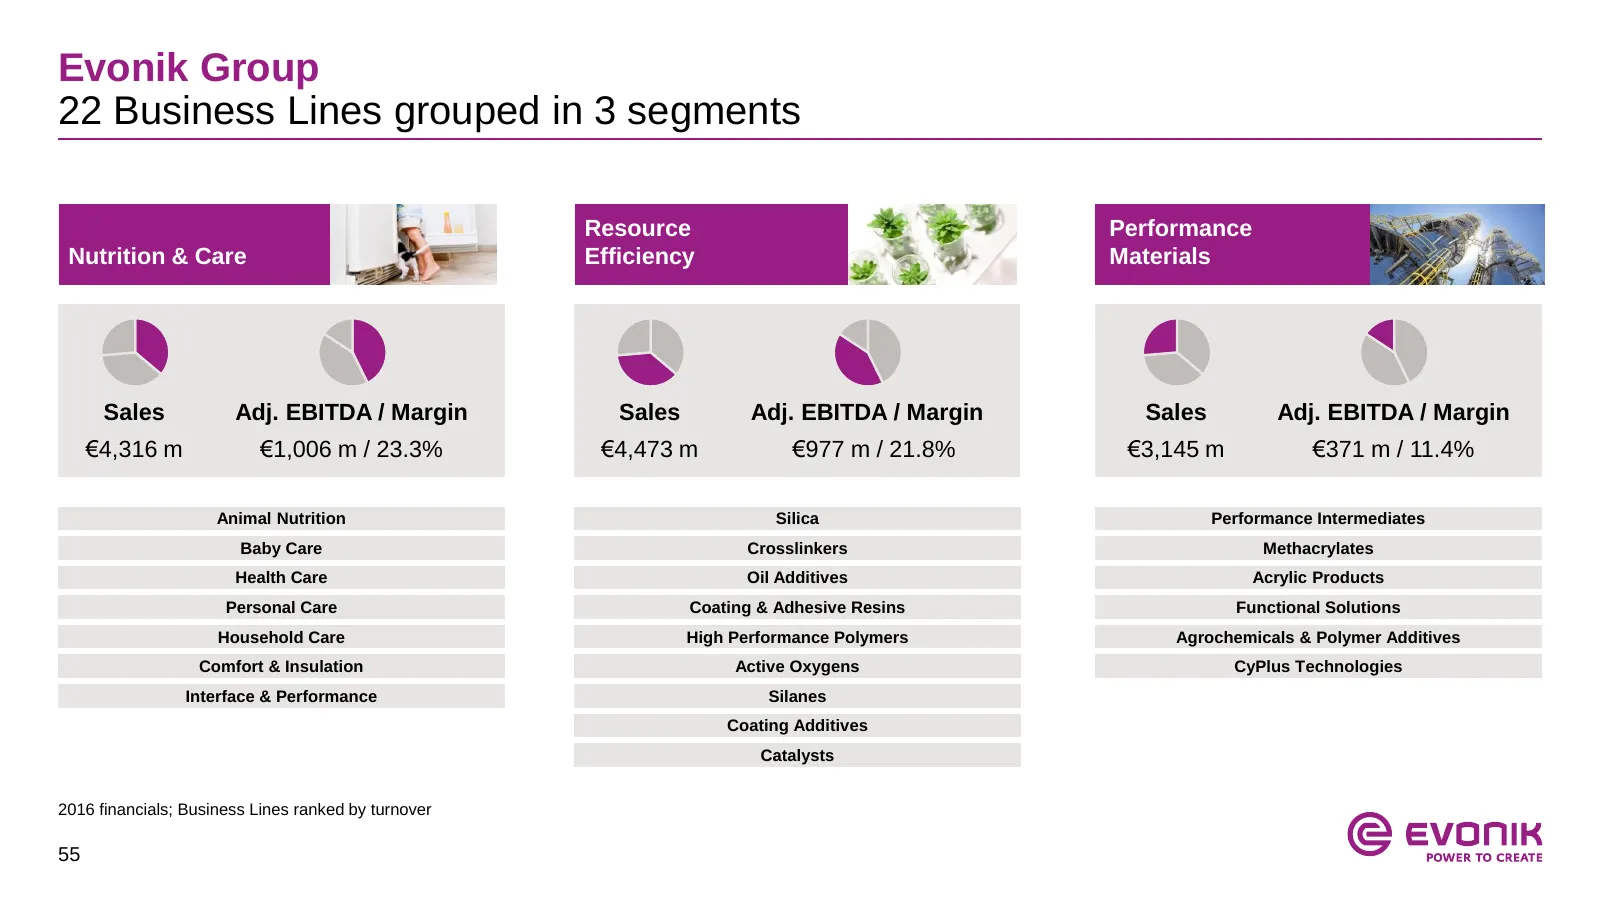
Evonik Group 22 Business Lines grouped in 3 segments Resource Performance Nutrition & Care Efficiency Materials Sales Adj. EBITDA / Margin Sales Adj. EBITDA / Margin Sales Adj. EBITDA / Margin €4,316 m €1,006 m / 23.3% €4,473 m €977 m / 21.8% €3,145 m €371 m / 11.4% Animal Nutrition Silica Performan
Slide 56: Nutrition & Care: fulfilling human needs
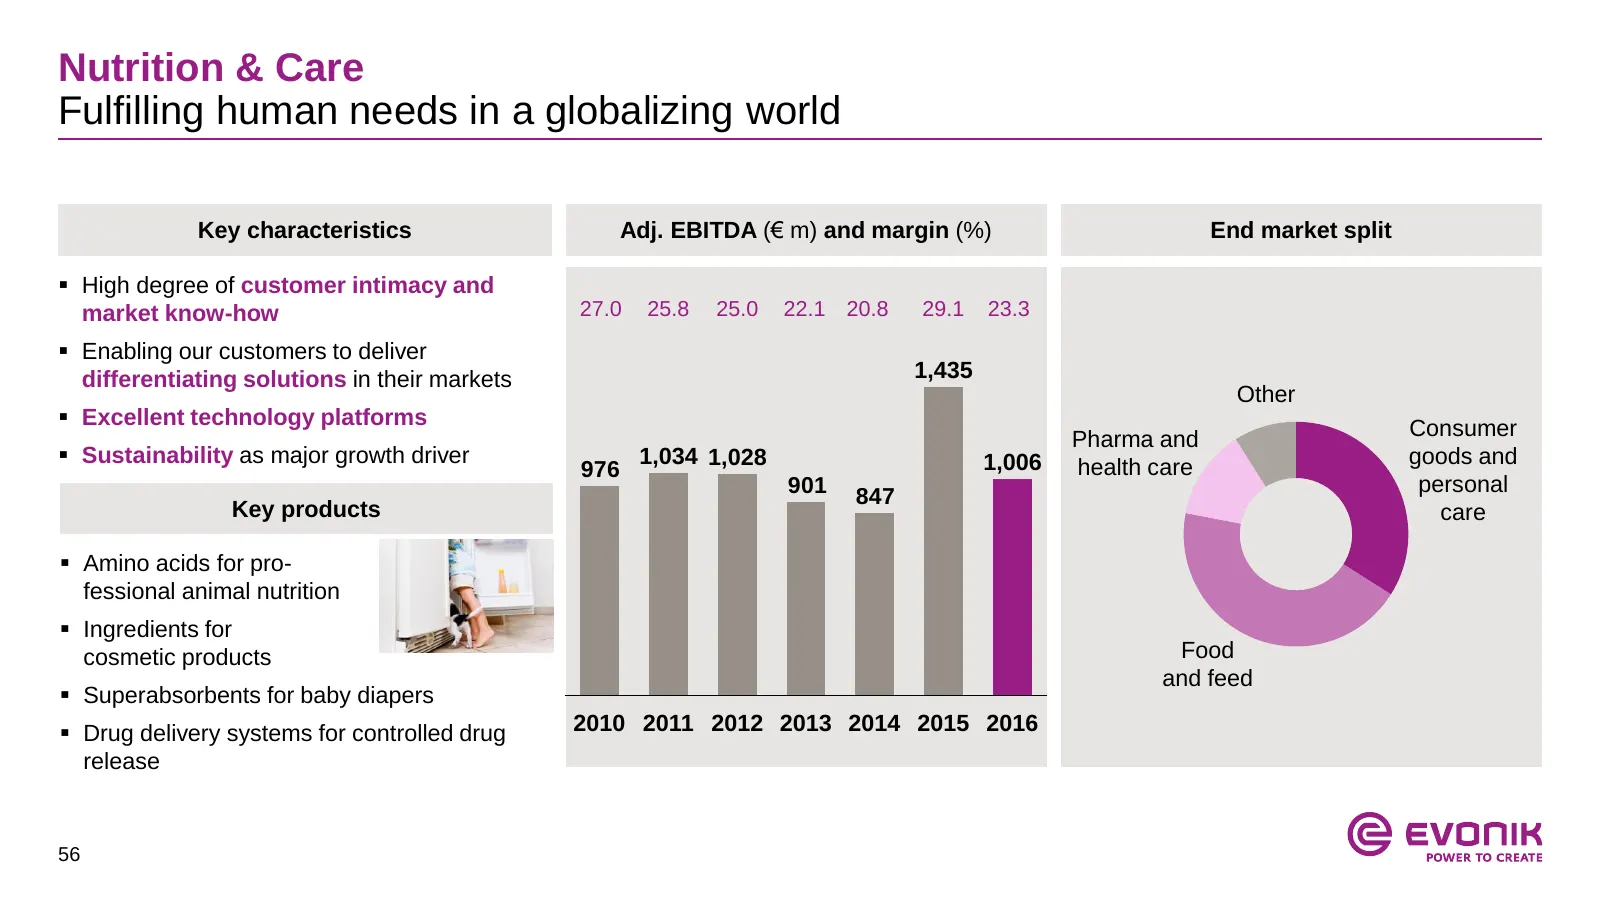
Nutrition & Care Fulfilling human needs in a globalizing world Key characteristics Adj. EBITDA (€ m) and margin (%) End market split High degree of customer intimacy and market know-how 27.0 25.8 25.0 22.1 20.8 29.1 23.3 Enabling our customers to deliver differentiating solutions in their market
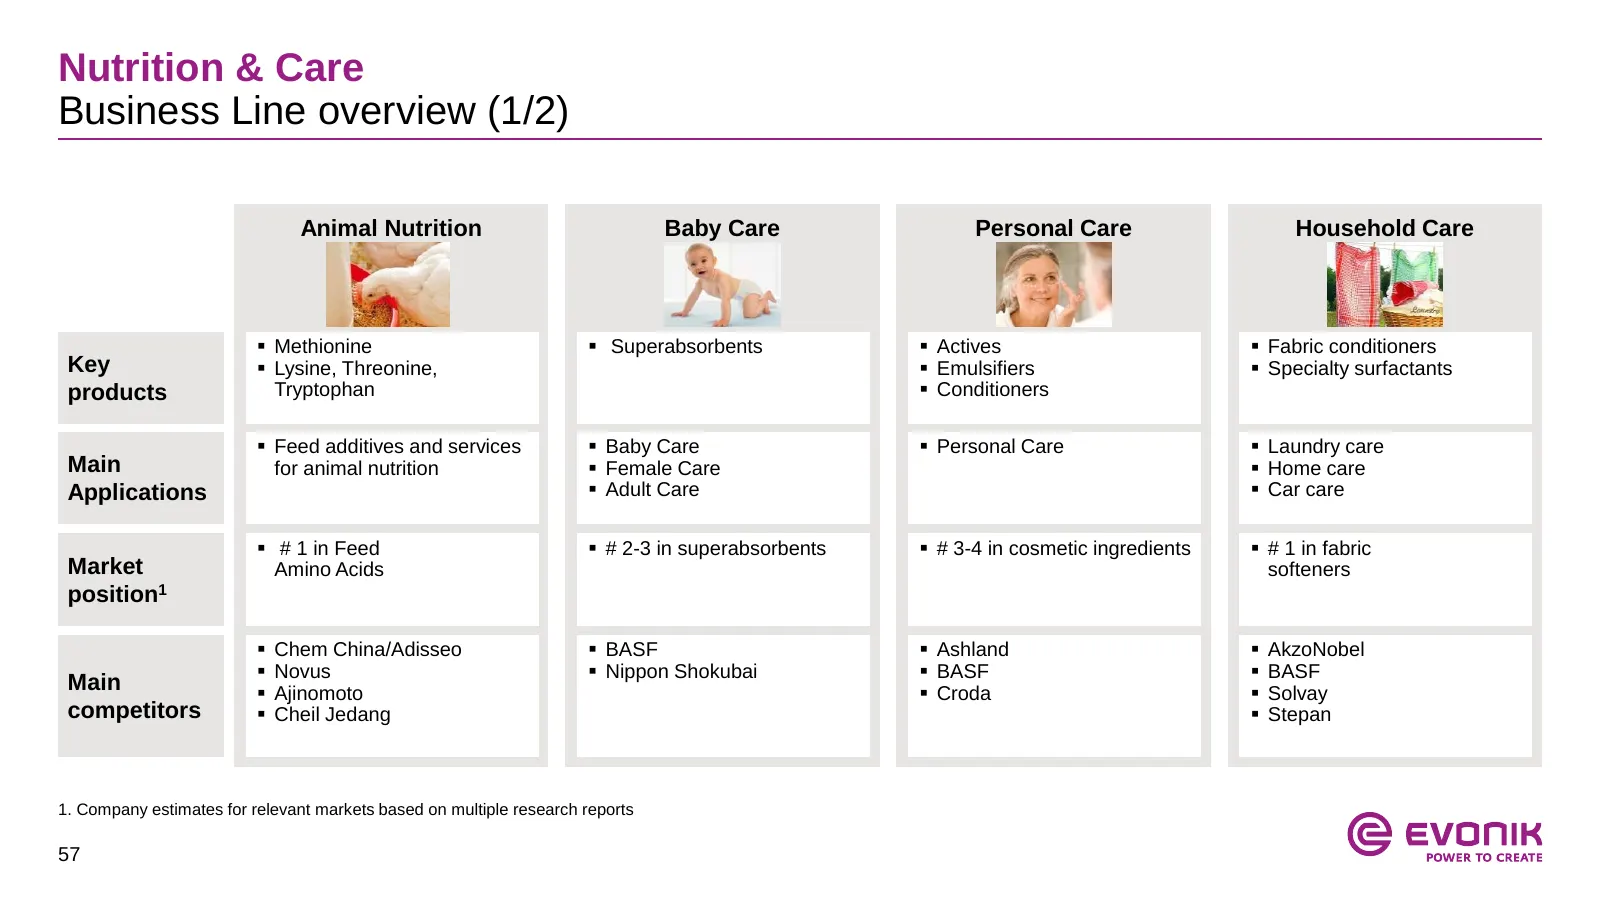
Slide 57: Nutrition & Care Business Line overview (1/2)
Nutrition & Care Business Line overview (1/2) Animal Nutrition Baby Care Personal Care Household Care Methionine Superabsorbents Actives Fabric conditioners Key Lysine, Threonine, Emulsifiers Specialty surfactants products Tryptophan Conditioners Feed additives and services Baby
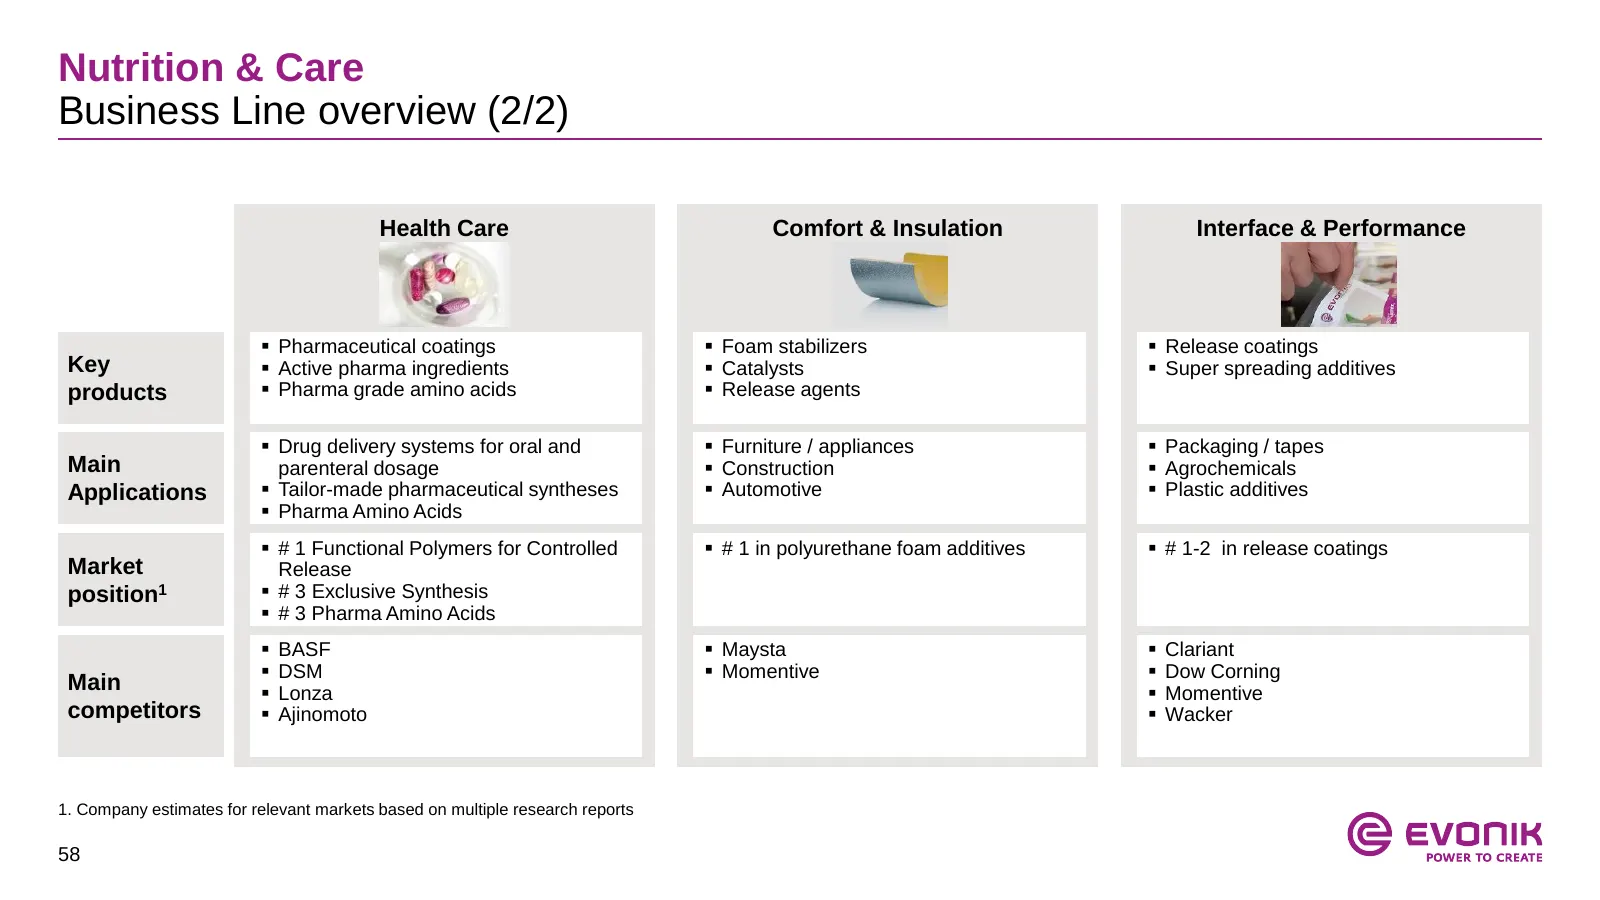
Slide 58: Nutrition & Care Business Line overview (2/2)
Nutrition & Care Business Line overview (2/2) Health Care Comfort & Insulation Interface & Performance Pharmaceutical coatings Foam stabilizers Release coatings Key Active pharma ingredients Catalysts Super spreading additives products Pharma grade amino acids Release agents Drug d
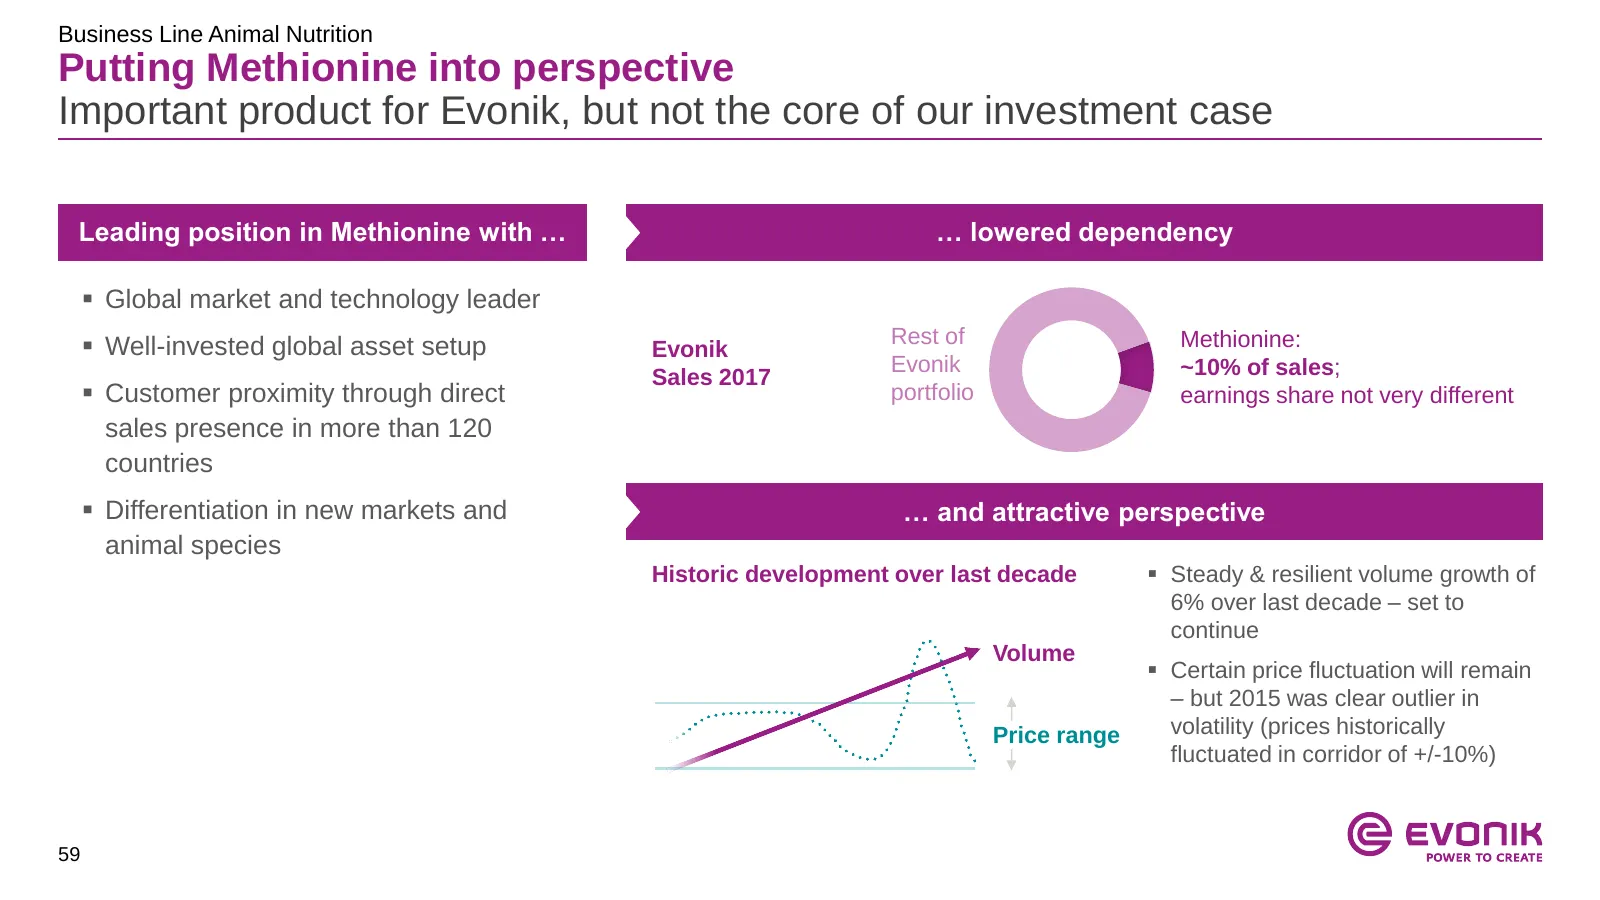
Slide 59: Putting Methionine into perspective
Business Line Animal Nutrition Putting Methionine into perspective Important product for Evonik, but not the core of our investment case Leading position in Methionine with … … lowered dependency Global market and technology leader Well-invested global asset setup Rest of Methionine: Evonik Evon
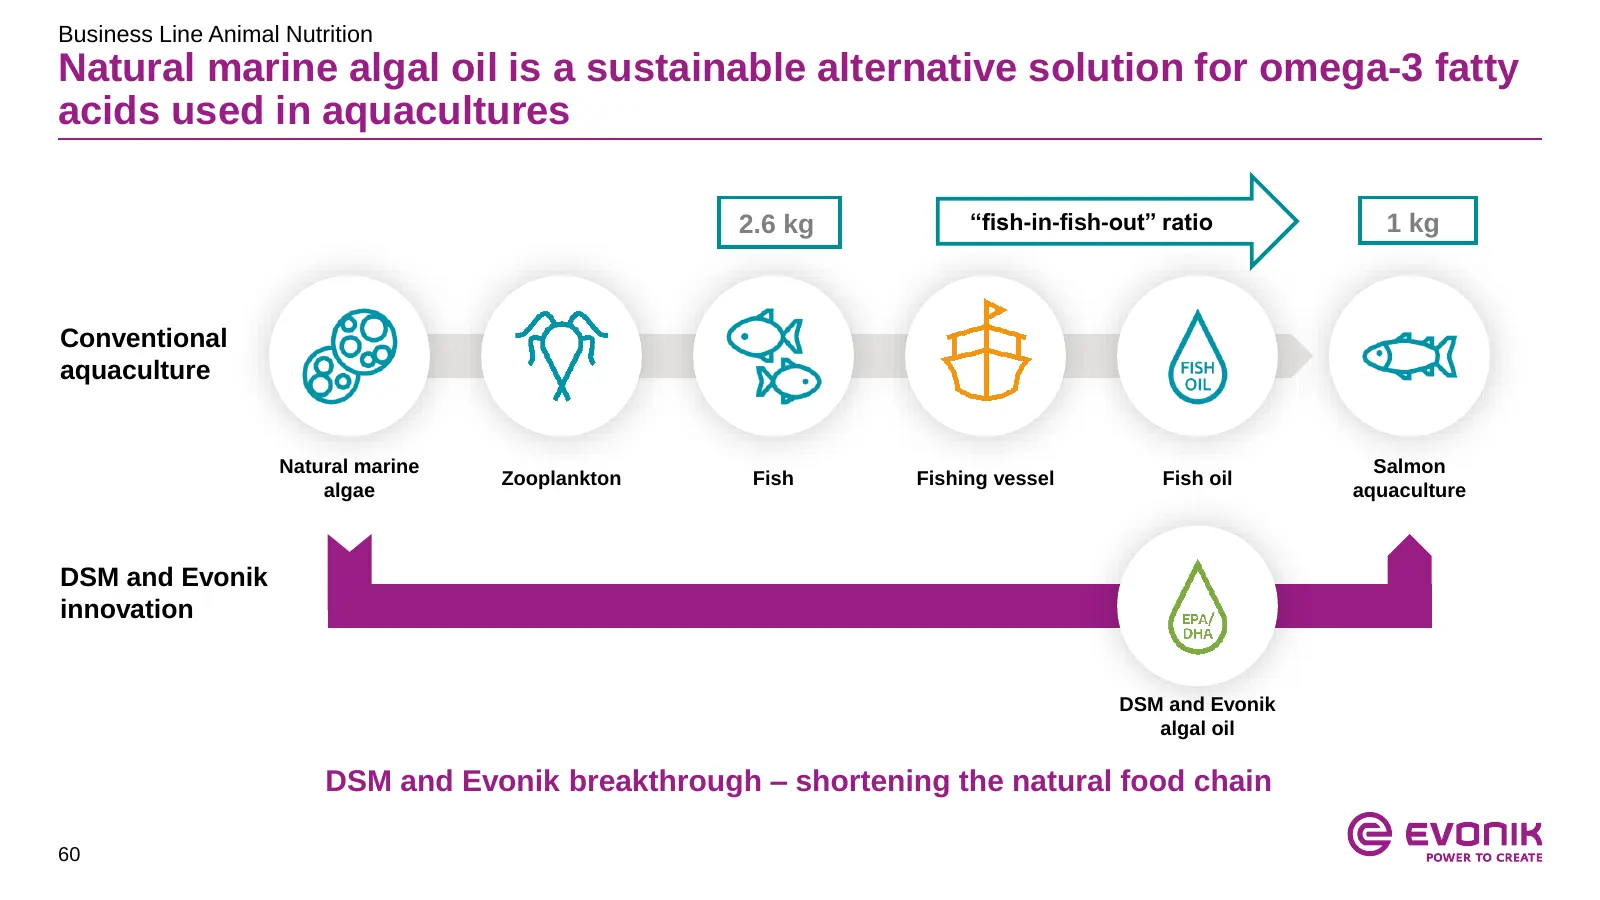
Slide 60: Natural marine algal oil as sustainable omega-3 alternative
Business Line Animal Nutrition Natural marine algal oil is a sustainable alternative solution for omega-3 fatty acids used in aquacultures 2.6 kg “fish-in-fish-out” ratio 1 kg Conventional aquaculture Natural marine Salmon Zooplankton Fish Fishing vessel Fish oil algae aquaculture DSM and Evonik inn
Slide 61: Algal oil advantages versus other omega-3 sources
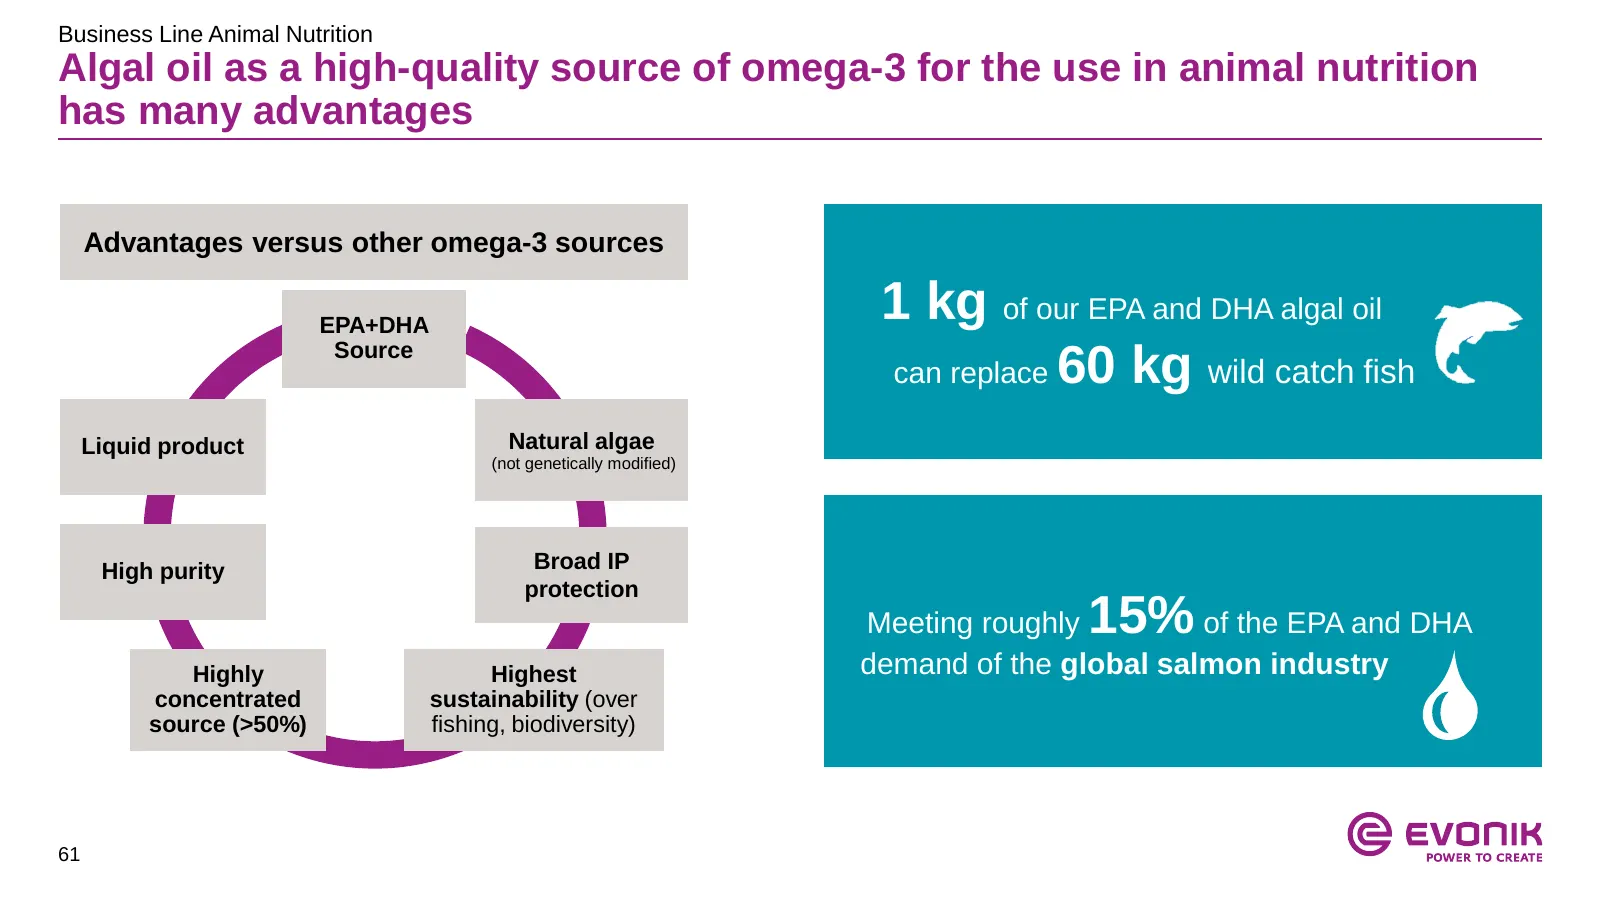
Business Line Animal Nutrition Algal oil as a high-quality source of omega-3 for the use in animal nutrition has many advantages Advantages versus other omega-3 sources EPA+DHA 1 kg of our EPA and DHA algal oil Source can replace 60 kg wild catch fish 3 Liquid product Natural algae (not genetically
Slide 62: DSM and Evonik joint venture for omega-3 from algae
Business Line Animal Nutrition DSM and Evonik establish joint venture for omega-3 fatty acids from natural marine algae for animal nutrition DSM and Evonik to found a 50:50 joint venture to be named VeramarisTM, headquartered in The Netherlands Joint venture for high value omega-3 fatty acid pro
Slide 63: Key components for sustainable aquacultures
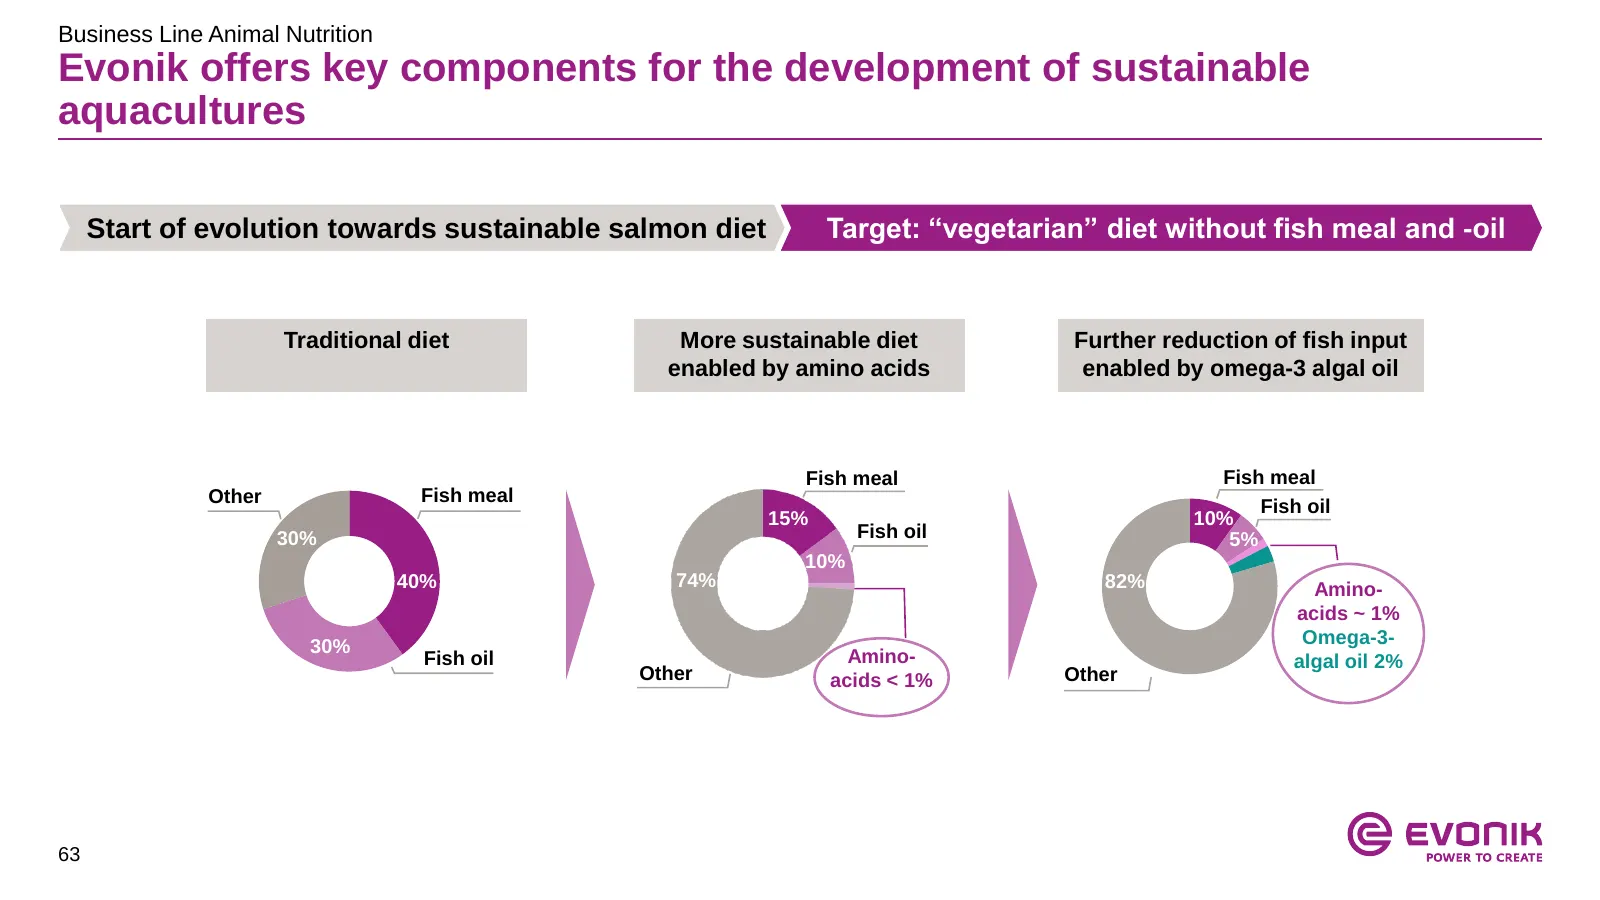
Business Line Animal Nutrition Evonik offers key components for the development of sustainable aquacultures Start of evolution towards sustainable salmon diet Target: “vegetarian” diet without fish meal and -oil Traditional diet More sustainable diet Further reduction of fish input enabled by amino
Slide 64: Acquisition of Dr. Straetmans
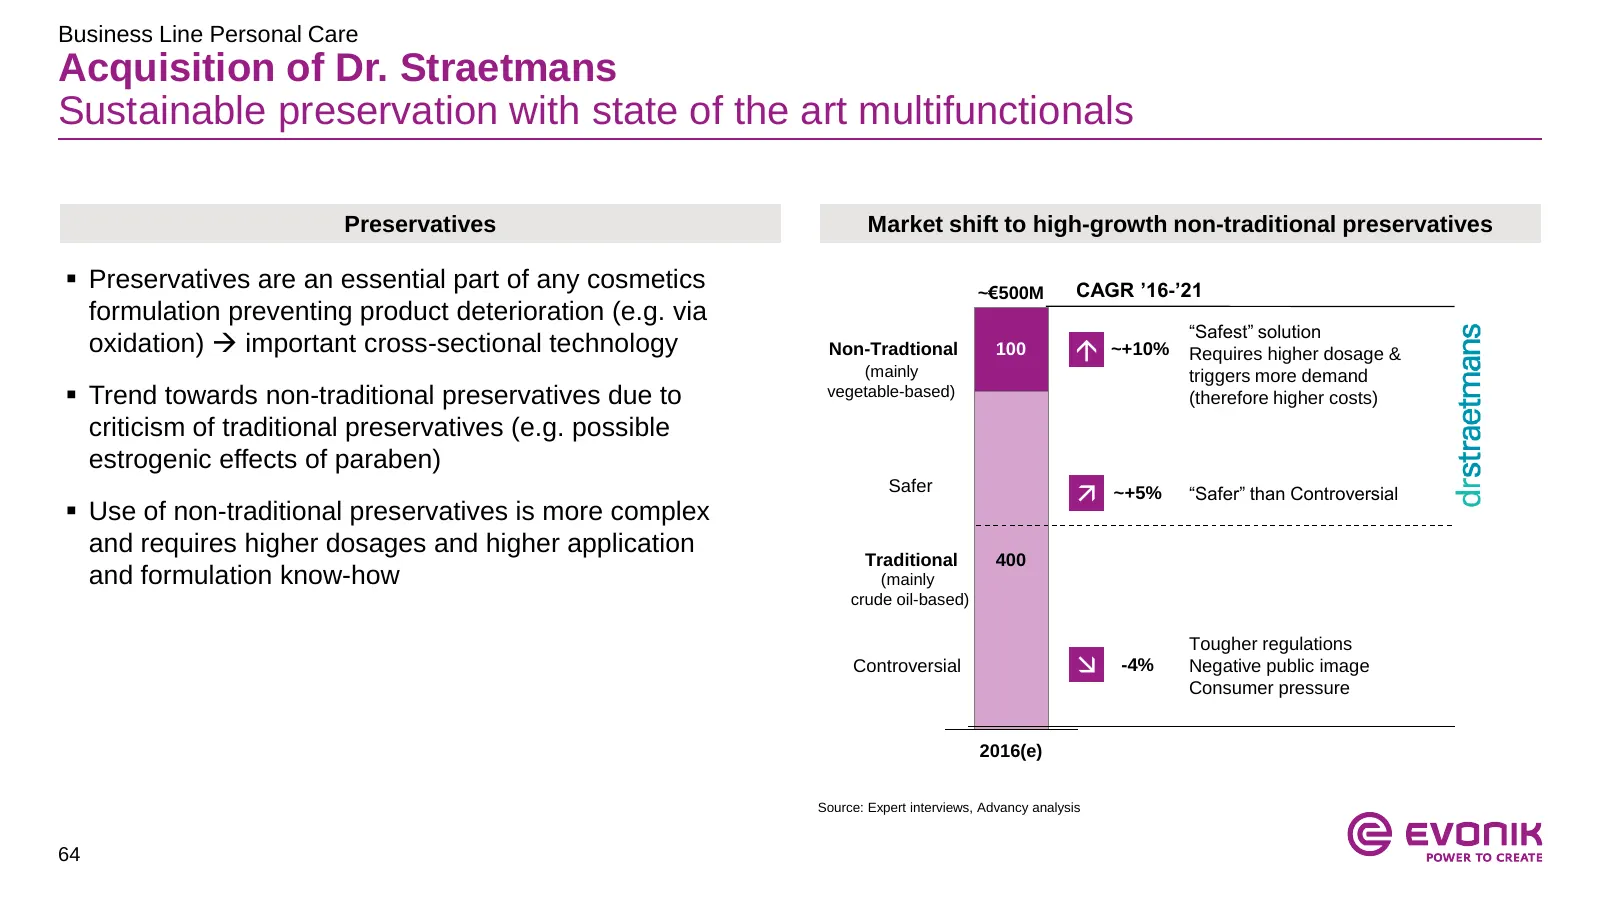
Business Line Personal Care Acquisition of Dr. Straetmans Sustainable preservation with state of the art multifunctionals Preservatives Market shift to high-growth non-traditional preservatives Preservatives are an essential part of any cosmetics ~€500M CAGR ’16-’21 formulation preventing product
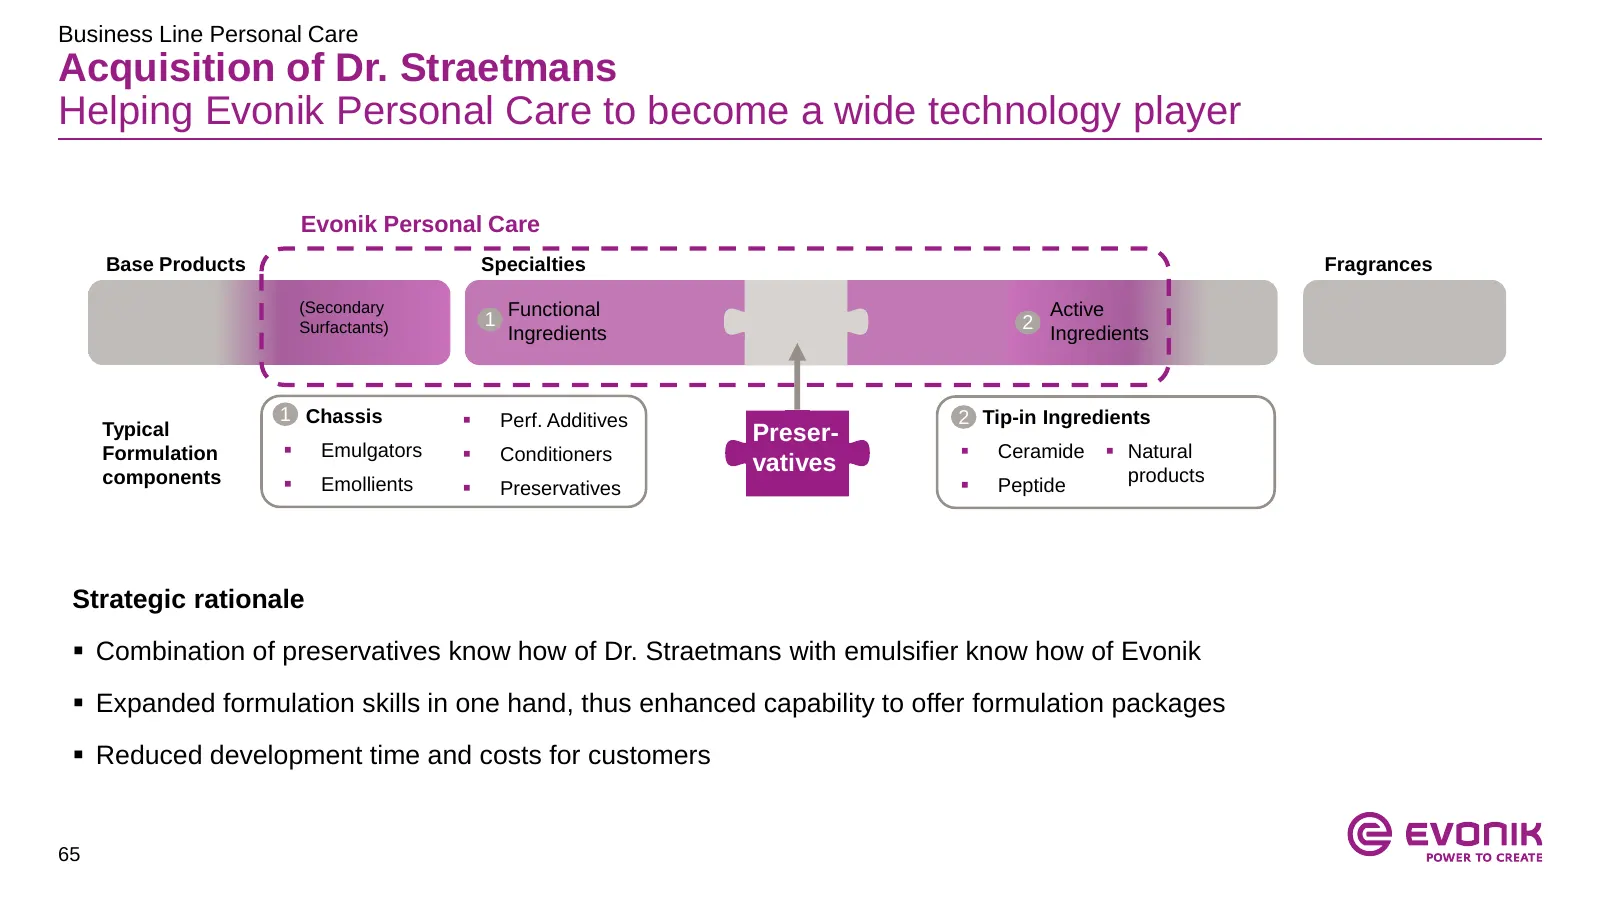
Slide 65: Dr. Straetmans helping Personal Care become wide technology player
Business Line Personal Care Acquisition of Dr. Straetmans Helping Evonik Personal Care to become a wide technology player Evonik Personal Care Base Products Specialties Fragrances (Secondary Functional Active Surfactants) 1 2 Ingredients Ingredients 1 Chassis Perf. Additives 2 Tip-in Ingredients T
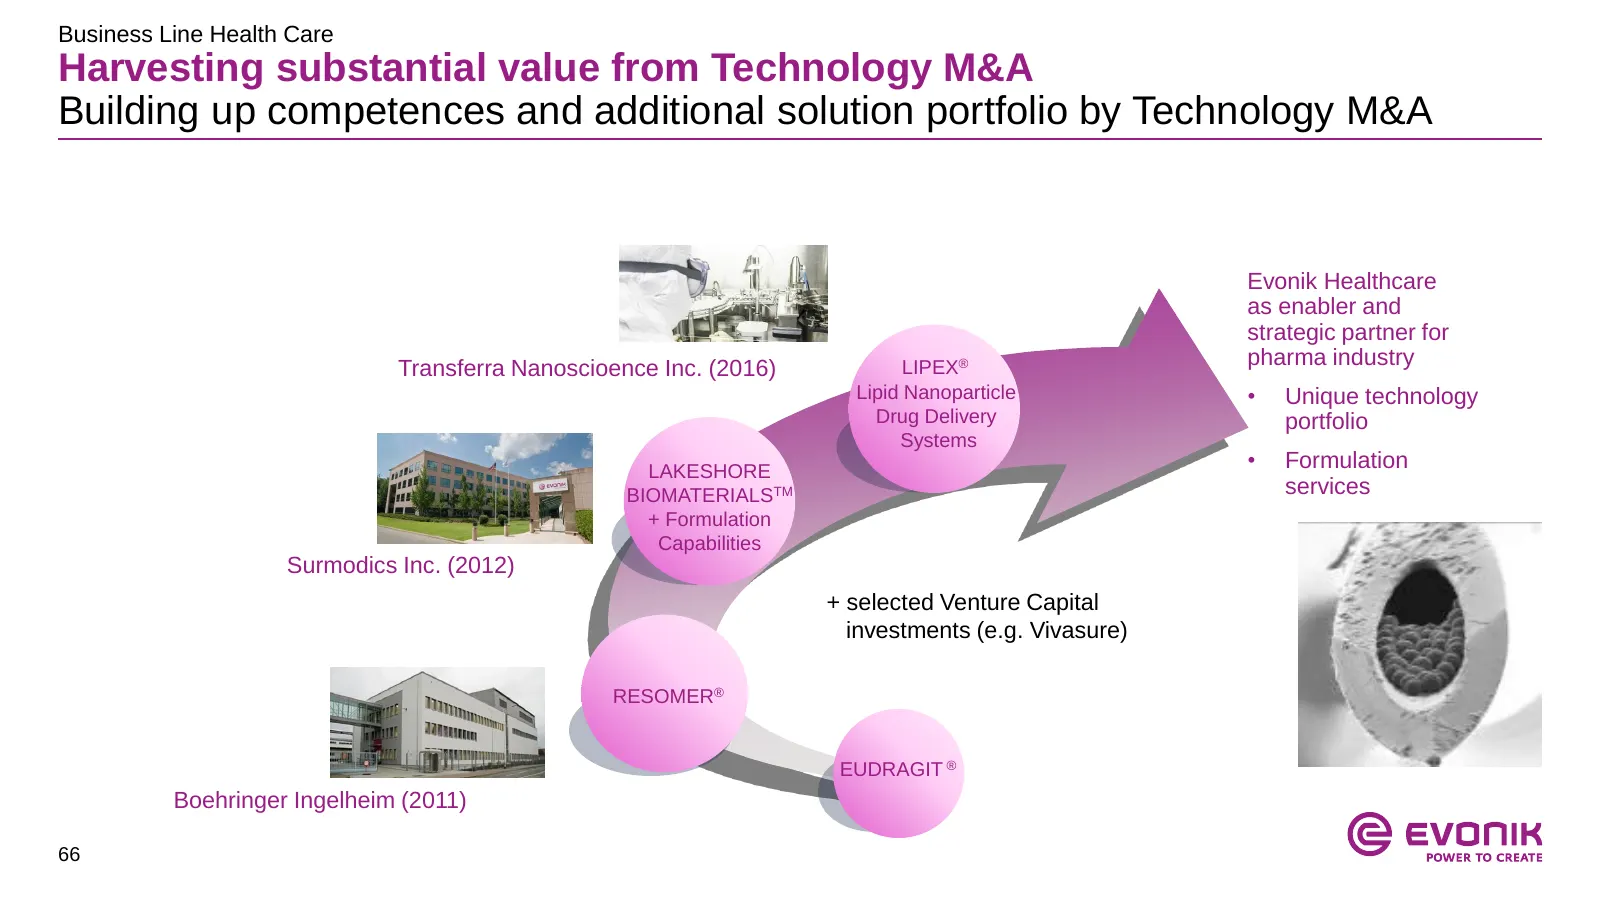
Slide 66: Harvesting substantial value from Technology M&A
Business Line Health Care Harvesting substantial value from Technology M&A Building up competences and additional solution portfolio by Technology M&A Evonik Healthcare as enabler and strategic partner for Transferra Nanoscioence Inc. (2016) LIPEX® pharma industry Lipid Nanoparticle • Unique technol
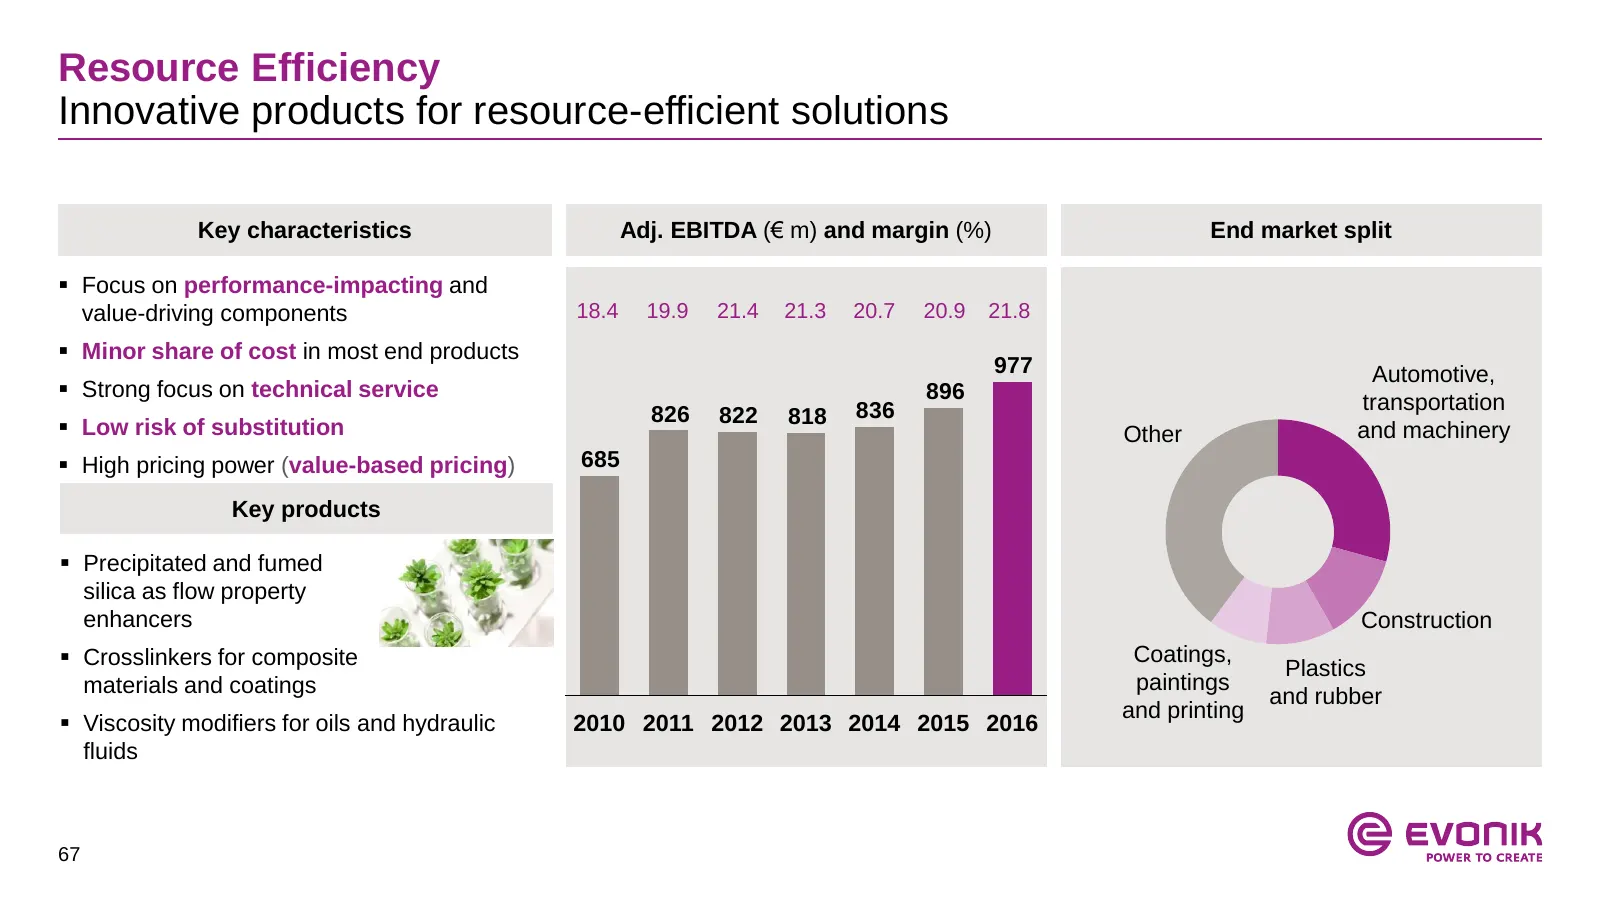
Slide 67: Resource Efficiency: innovative products for resource-efficient solutions
Resource Efficiency Innovative products for resource-efficient solutions Key characteristics Adj. EBITDA (€ m) and margin (%) End market split Focus on performance-impacting and value-driving components 18.4 19.9 21.4 21.3 20.7 20.9 21.8 Minor share of cost in most end products 977 Automotive,
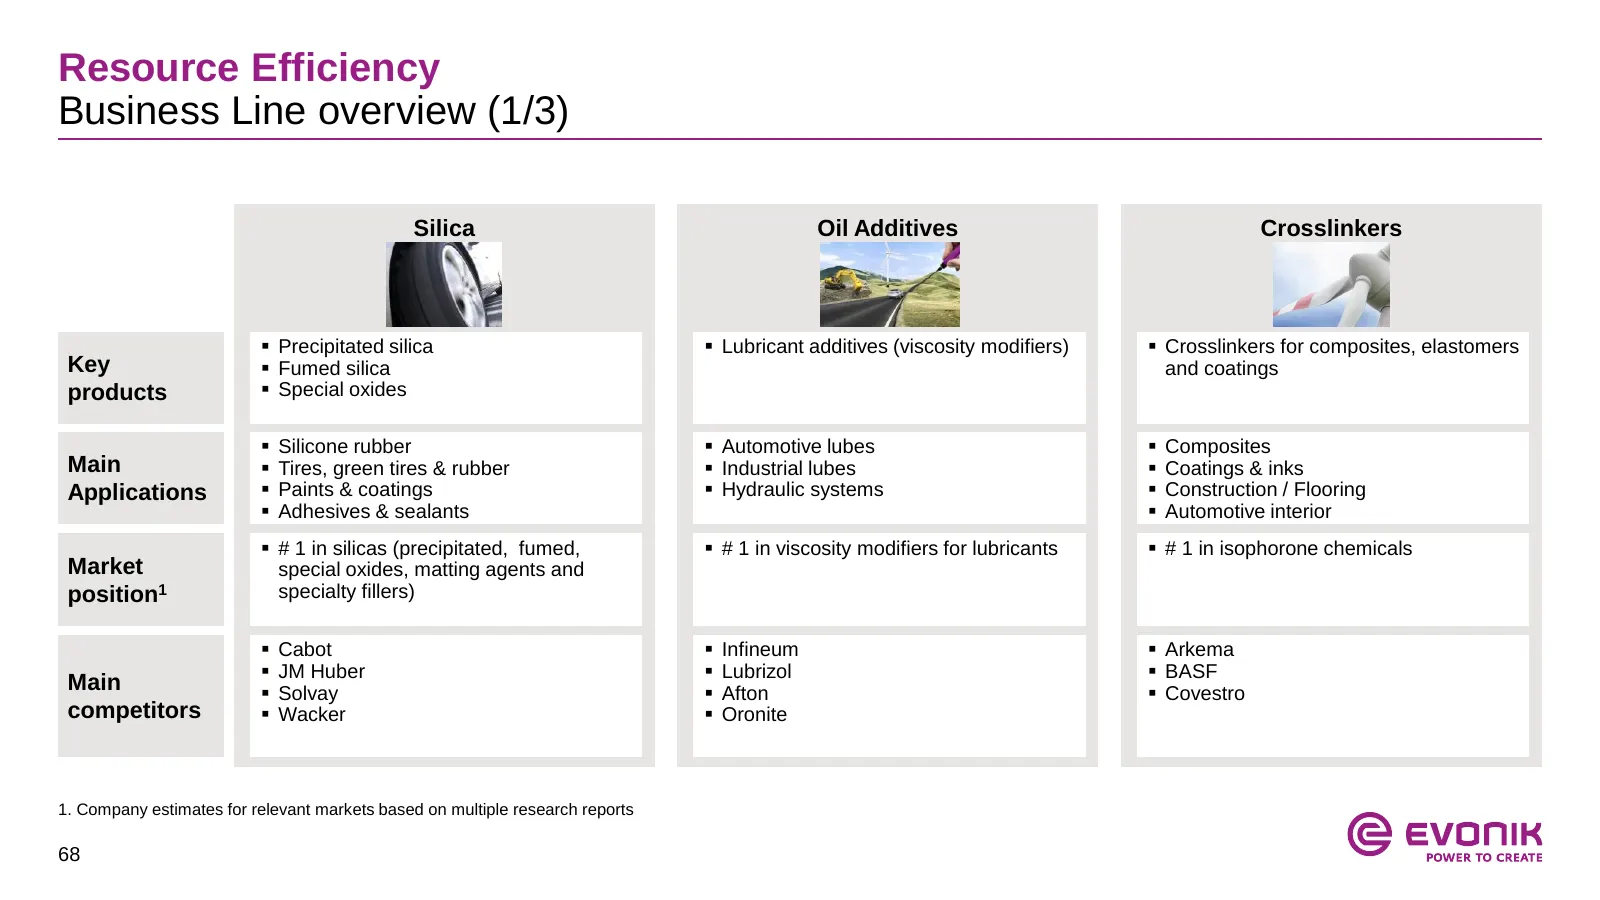
Slide 68: Resource Efficiency Business Line overview (1/3)
Resource Efficiency Business Line overview (1/3) Silica Oil Additives Crosslinkers Precipitated silica Lubricant additives (viscosity modifiers) Crosslinkers for composites, elastomers Key Fumed silica and coatings products Special oxides Silicone rubber Automotive lubes Composites M
Slide 69: Resource Efficiency Business Line overview (2/3)
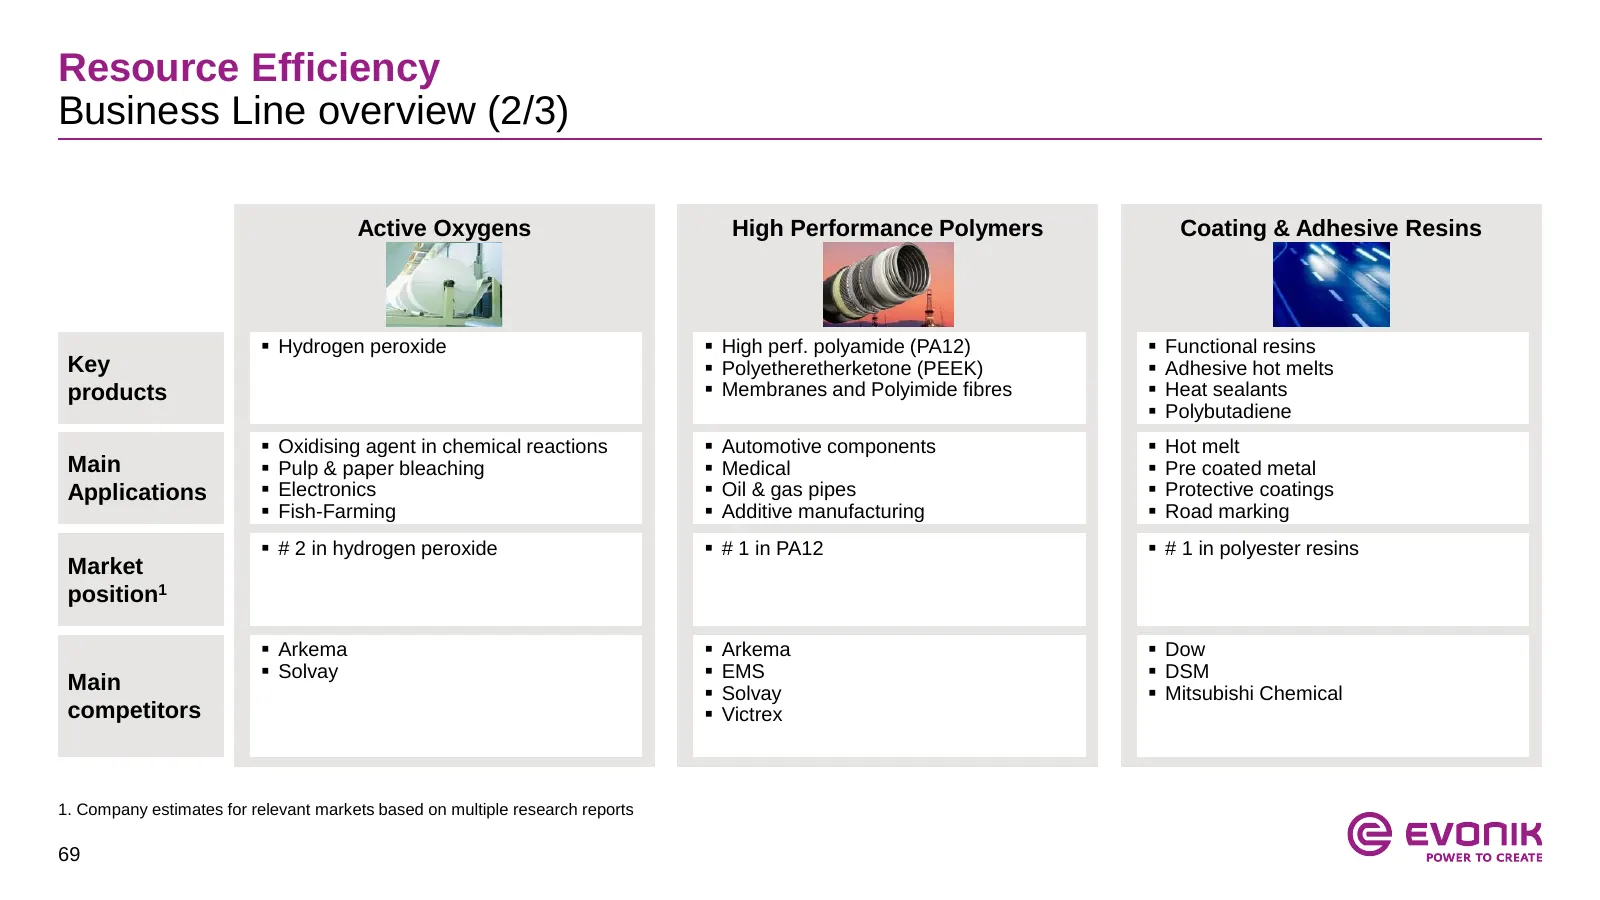
Resource Efficiency Business Line overview (2/3) Active Oxygens High Performance Polymers Coating & Adhesive Resins Hydrogen peroxide High perf. polyamide (PA12) Functional resins Key Polyetheretherketone (PEEK) Adhesive hot melts products Membranes and Polyimide fibres Heat sealants
Slide 70: Resource Efficiency Business Line overview (3/3)
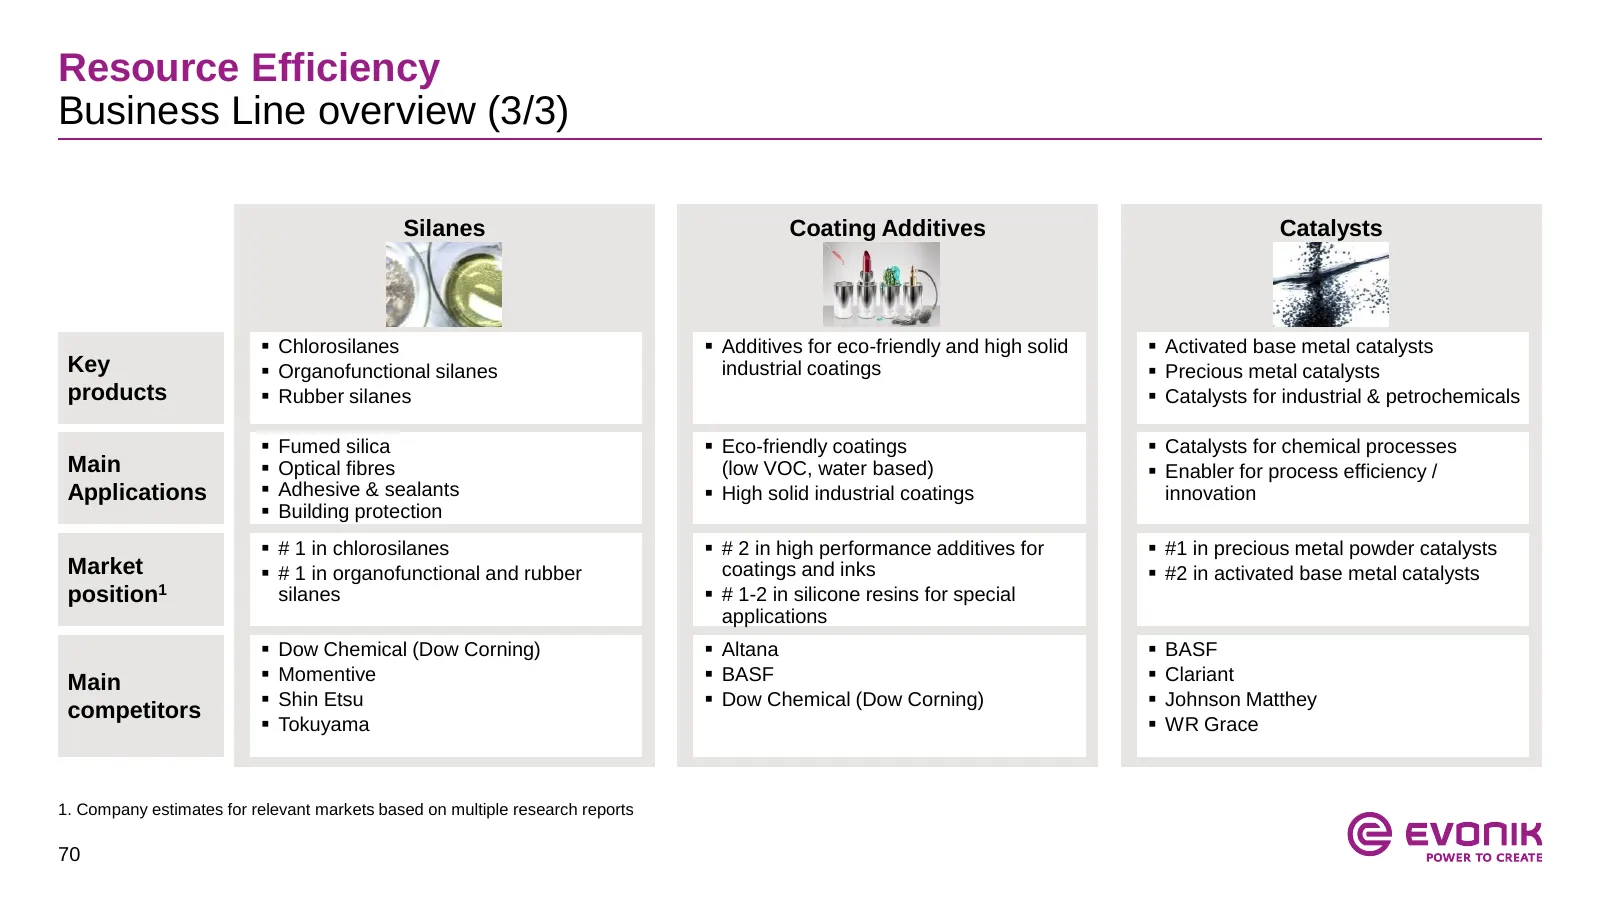
Resource Efficiency Business Line overview (3/3) Silanes Coating Additives Catalysts Chlorosilanes Additives for eco-friendly and high solid Activated base metal catalysts Key Organofunctional silanes industrial coatings Precious metal catalysts products Rubber silanes Catalysts for in
Slide 71: Performance Materials: integrated production platforms
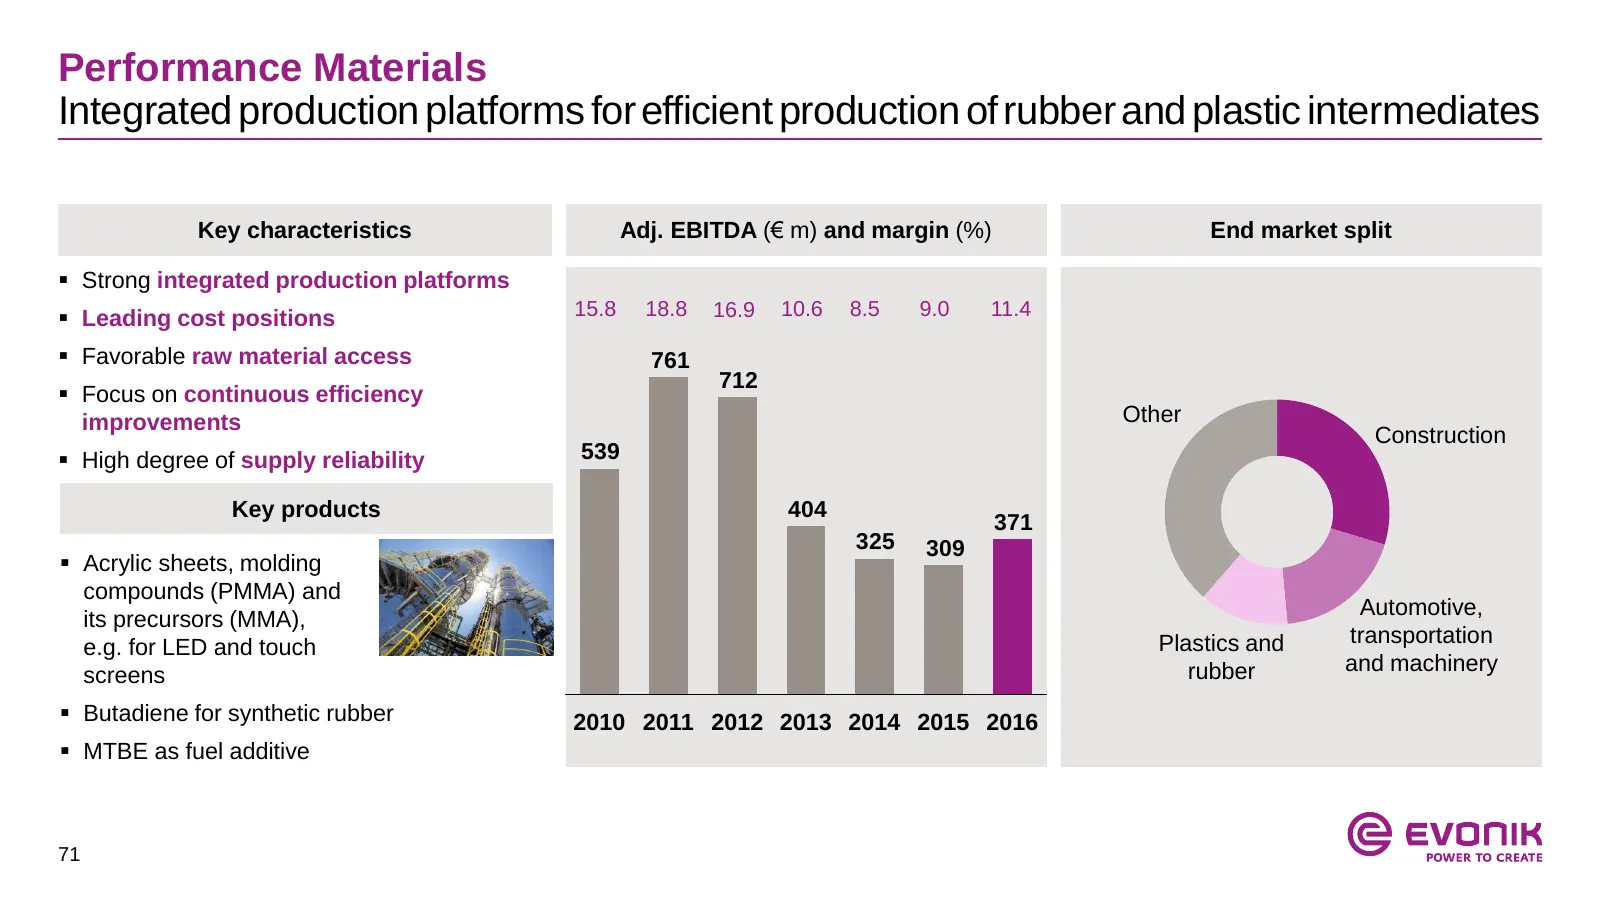
Performance Materials Integrated production platforms for efficient production of rubber and plastic intermediates Key characteristics Adj. EBITDA (€ m) and margin (%) End market split Strong integrated production platforms Leading cost positions 15.8 18.8 16.9 10.6 8.5 9.0 11.4 Favorable raw
Slide 72: Performance Materials Business Line overview (1/2)
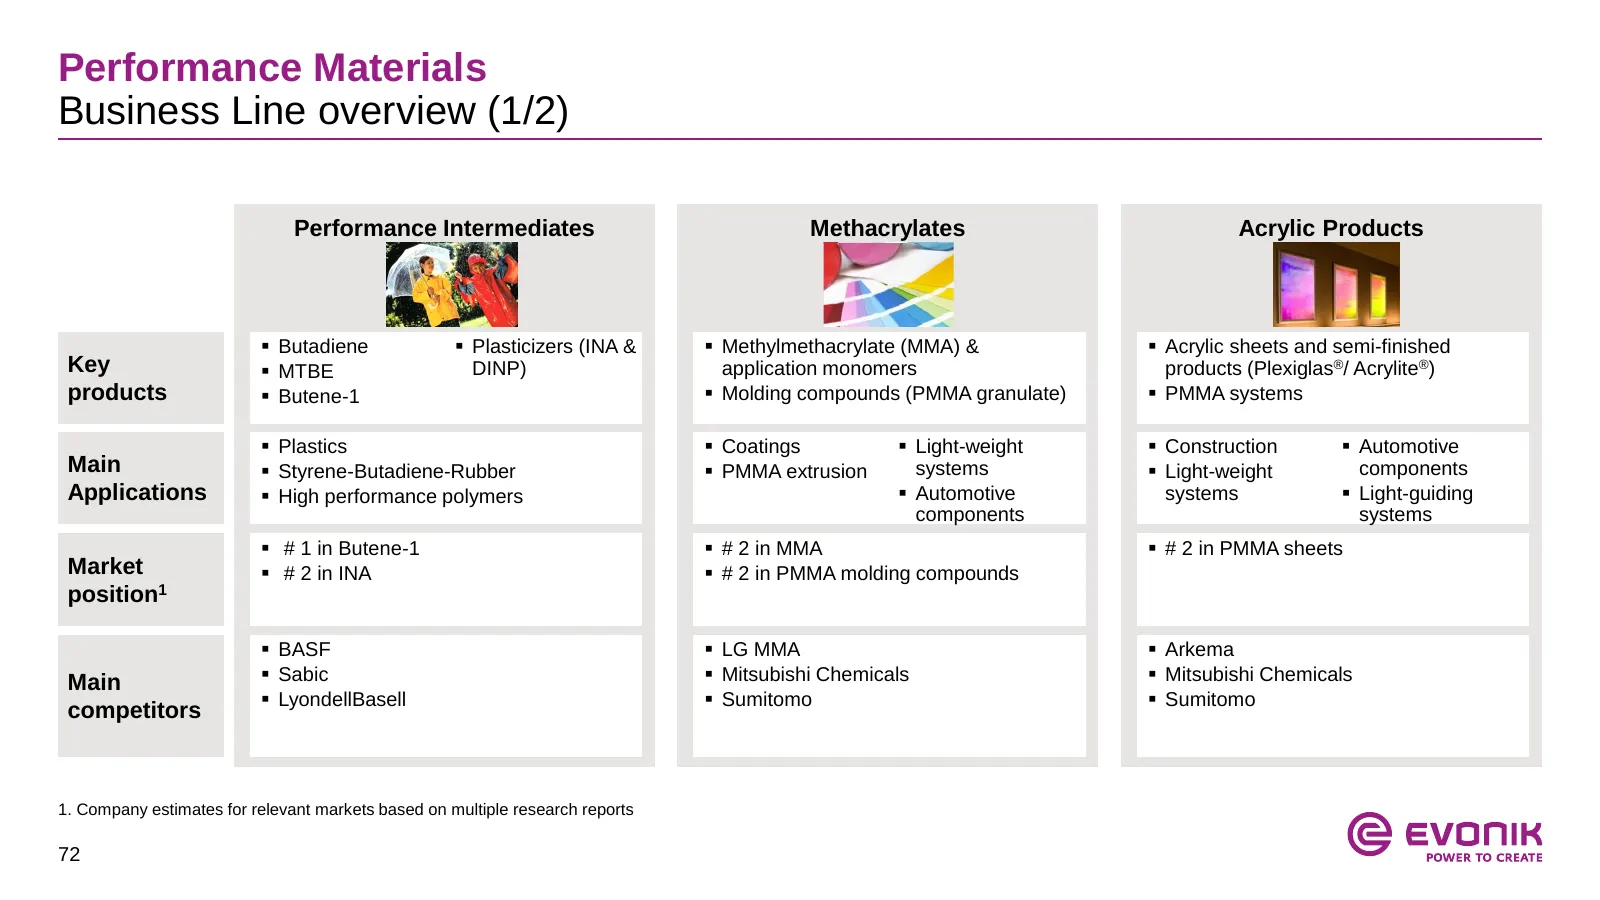
Performance Materials Business Line overview (1/2) Performance Intermediates Methacrylates Acrylic Products Butadiene Plasticizers (INA & Methylmethacrylate (MMA) & Acrylic sheets and semi-finished Key MTBE DINP) application monomers products (Plexiglas®/ Acrylite®) products Butene-1 M
Slide 73: Performance Materials Business Line overview (2/2)
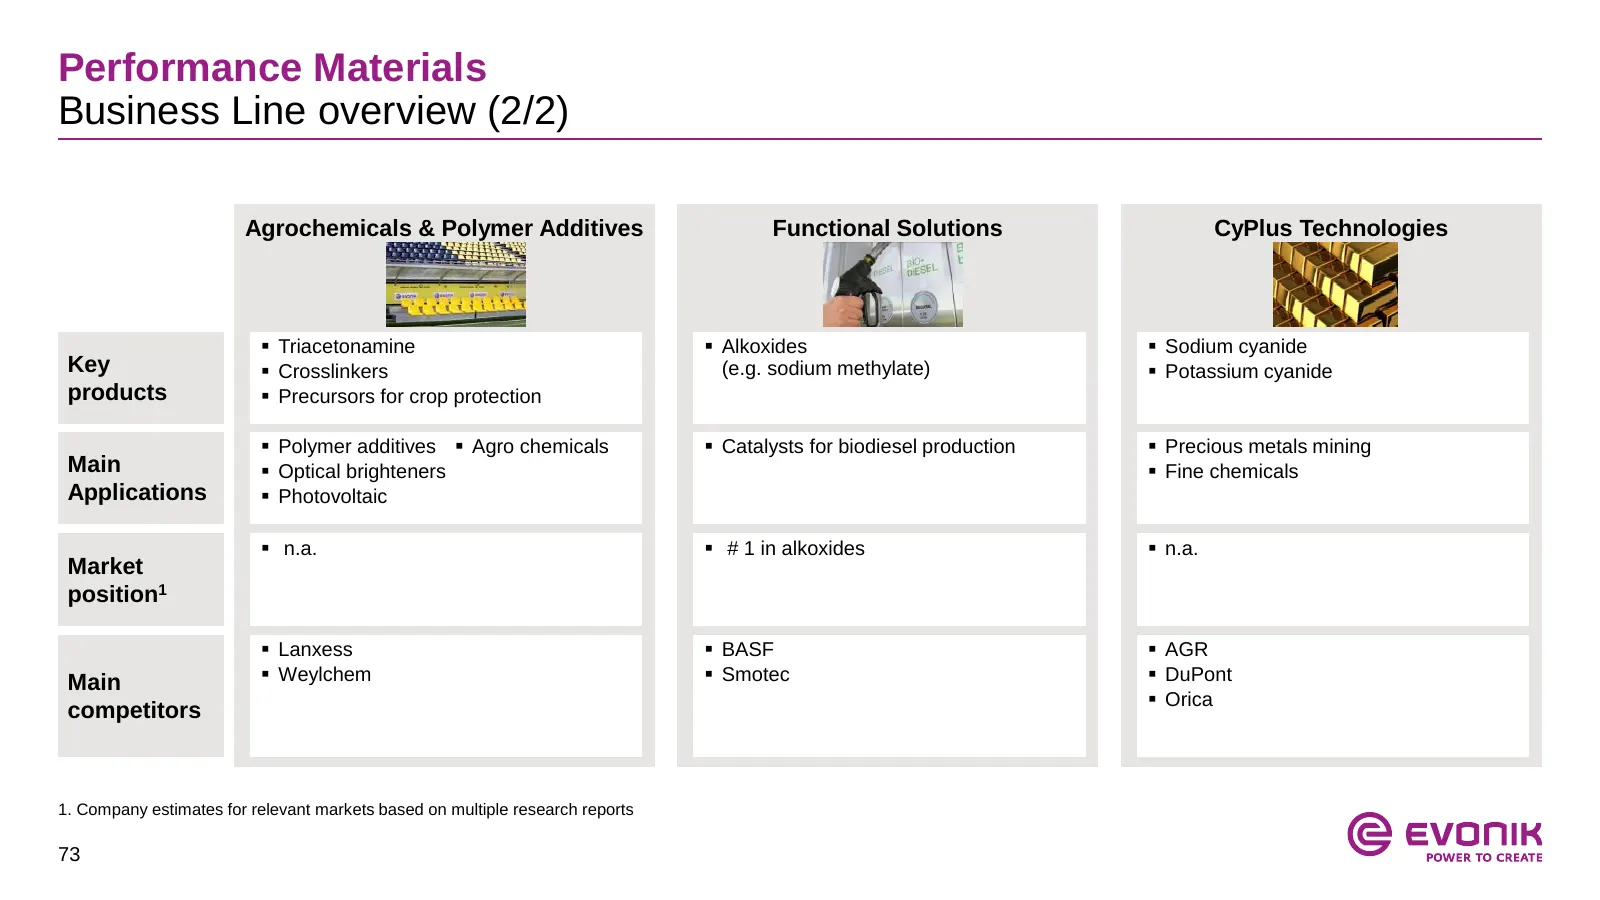
Performance Materials Business Line overview (2/2) Agrochemicals & Polymer Additives Functional Solutions CyPlus Technologies Triacetonamine Alkoxides Sodium cyanide Key Crosslinkers (e.g. sodium methylate) Potassium cyanide products Precursors for crop protection Polymer additives A
Slide 74: Performance Intermediates (C4 chain)
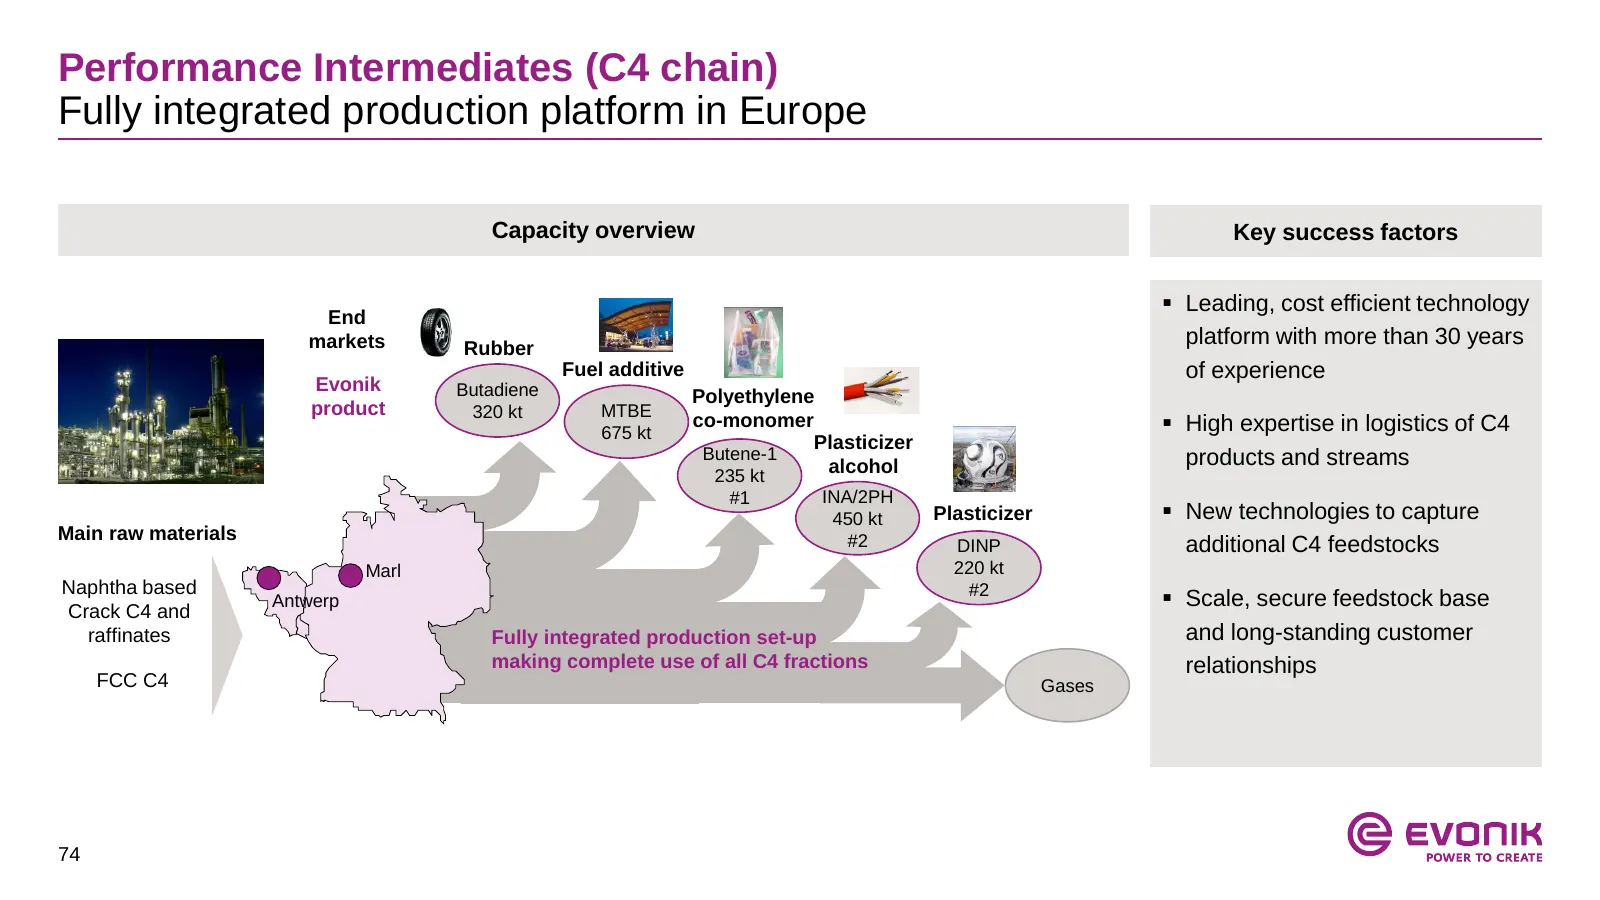
Performance Intermediates (C4 chain) Fully integrated production platform in Europe Capacity overview Key success factors Leading, cost efficient technology End markets Rubber platform with more than 30 years Fuel additive of experience Evonik Butadiene Polyethylene product 320 kt MTBE 675 kt co-m
Slide 75: Appendix
Appendix 1. Acquisition of Air Products specialty additives business 2. Acquisition of Huber Silica 3. Segment overview 4. Financials 5. Upcoming events 75
Slide 76: Segment performance FY 2016
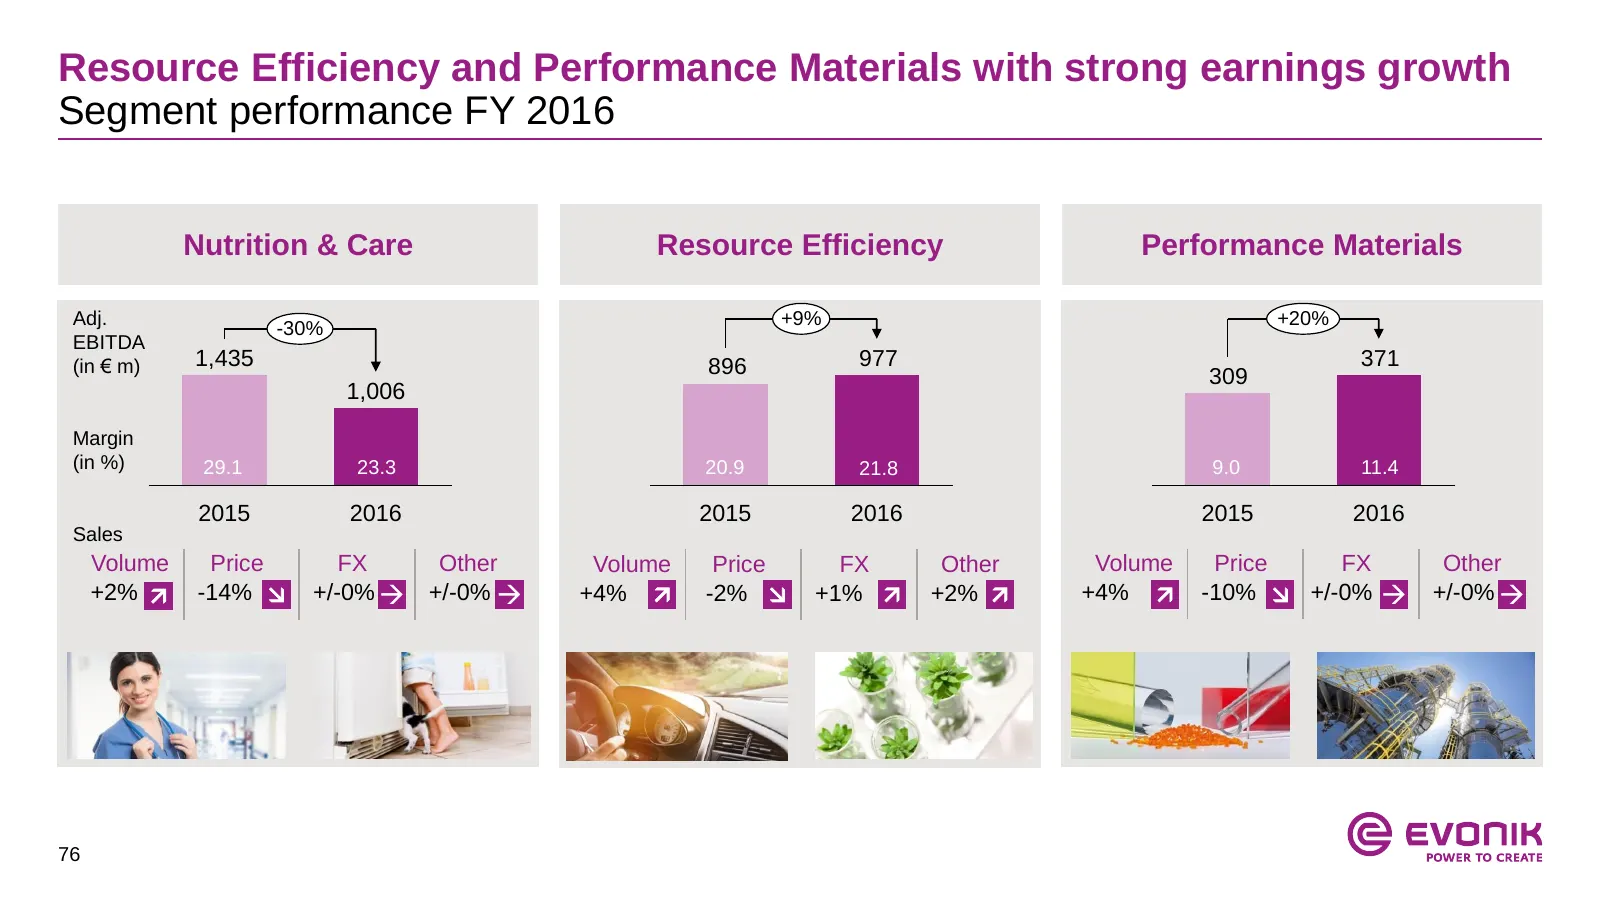
Resource Efficiency and Performance Materials with strong earnings growth Segment performance FY 2016 Nutrition & Care Resource Efficiency Performance Materials Adj. -30% +9% +20% EBITDA (in € m) 1,435 896 977 371 309 1,006 Margin (in %) 29.1 23.3 20.9 21.8 9.0 11.4 2015 2016 2015 2016 2015 2016 Sal
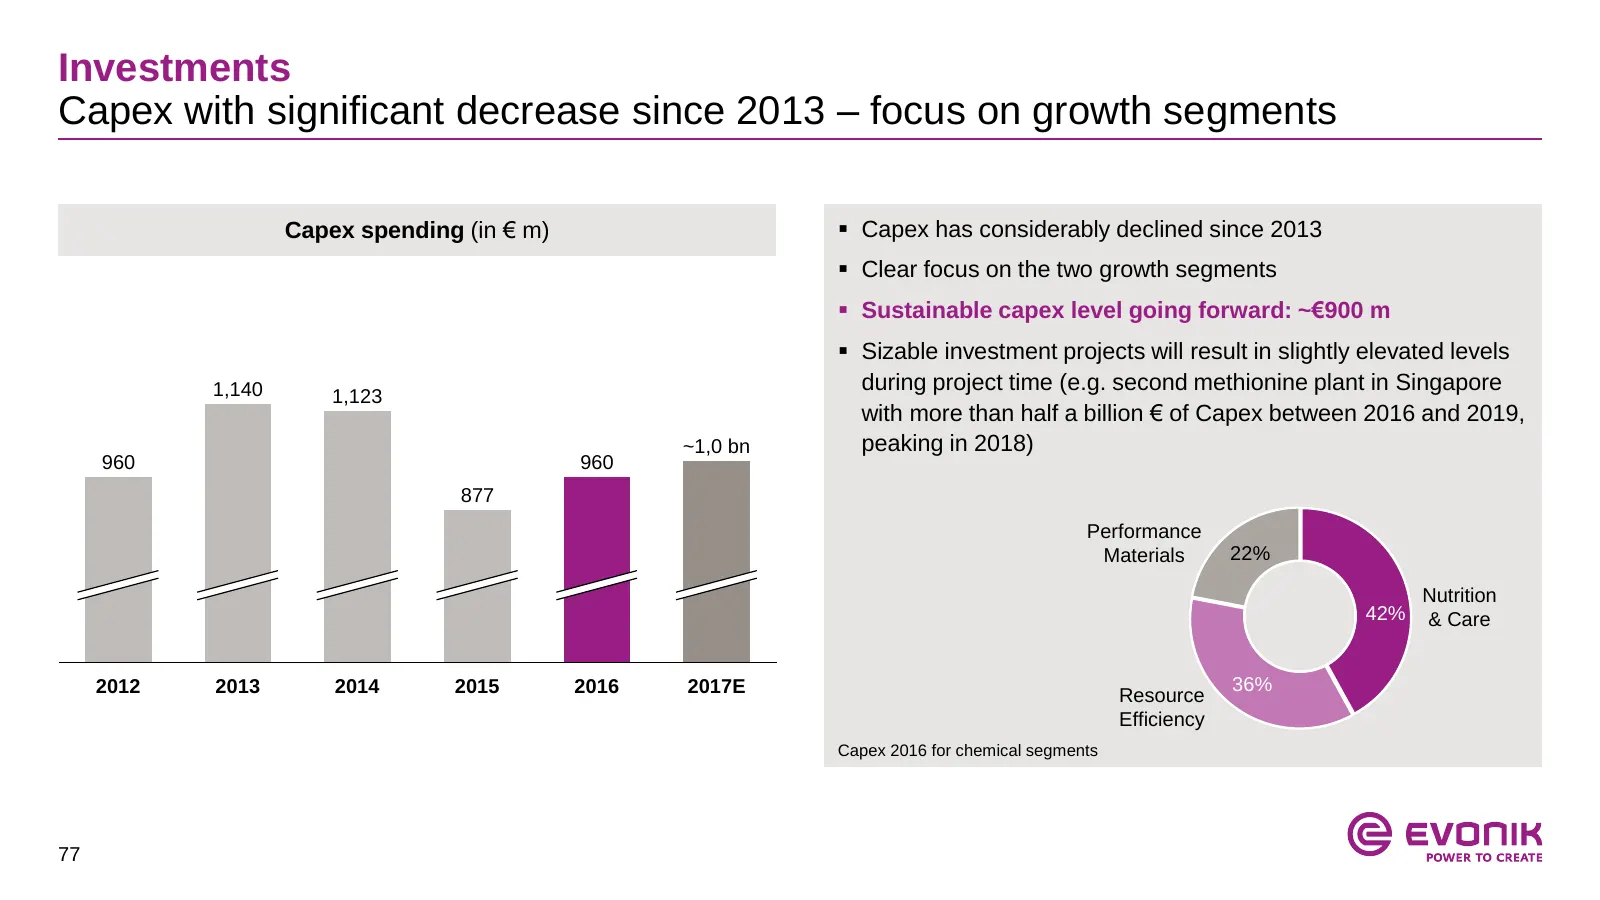
Slide 77: Capex with significant decrease since 2013
Investments Capex with significant decrease since 2013 – focus on growth segments Capex spending (in € m) Capex has considerably declined since 2013 Clear focus on the two growth segments Sustainable capex level going forward: ~€900 m Sizable investment projects will result in slightly eleva
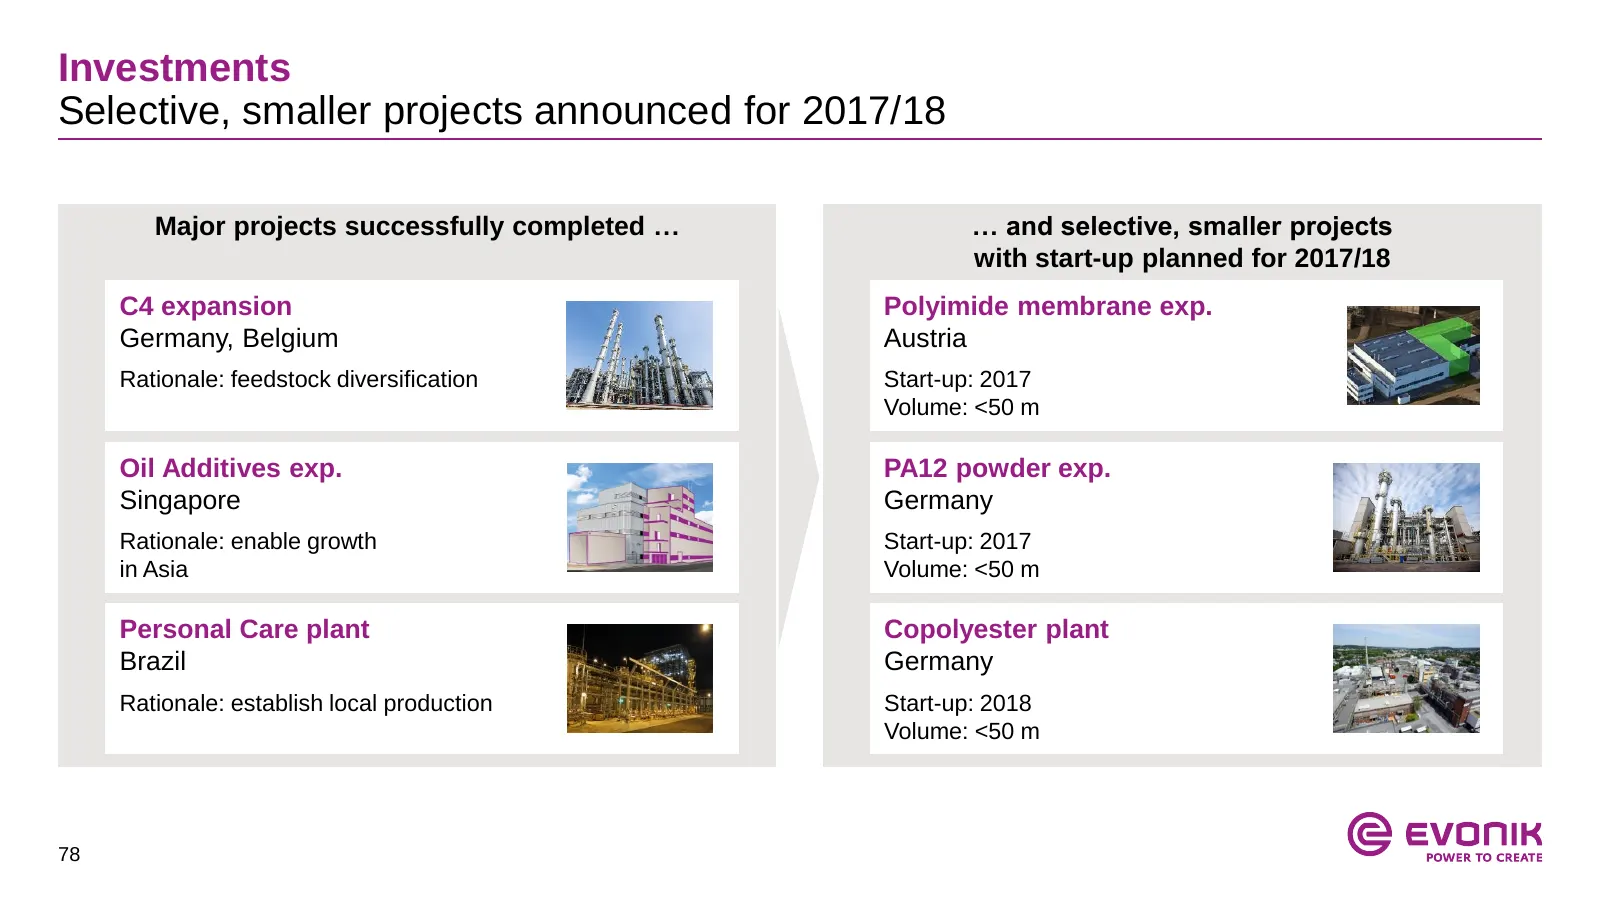
Slide 78: Investments: selective, smaller projects announced for 2017/18
Investments Selective, smaller projects announced for 2017/18 Major projects successfully completed … … and selective, smaller projects with start-up planned for 2017/18 C4 expansion Polyimide membrane exp. Germany, Belgium Austria Rationale: feedstock diversification Start-up: 2017 Volume: <50 m Oi
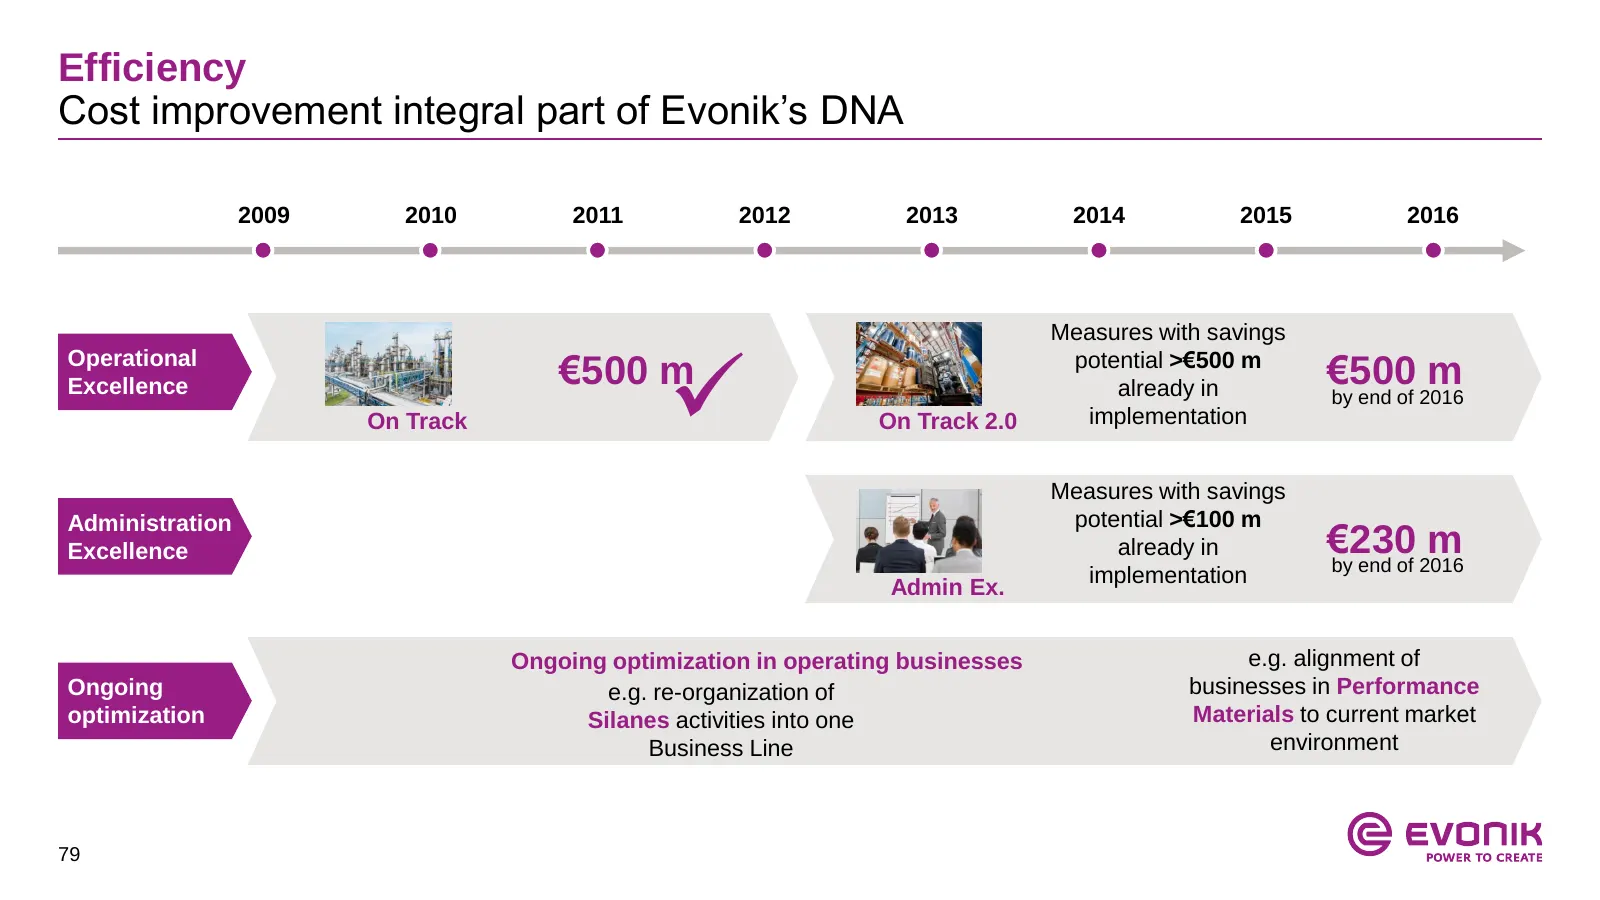
Slide 79: Cost improvement integral part of Evonik's DNA
Efficiency Cost improvement integral part of Evonik’s DNA 2009 2010 2011 2012 2013 2014 2015 2016 Measures with savings €500 m €500 Operational potential >€500 m Excellence already in m by end of 2016 On Track On Track 2.0 implementation Measures with savings Administration potential >€100 m Excel
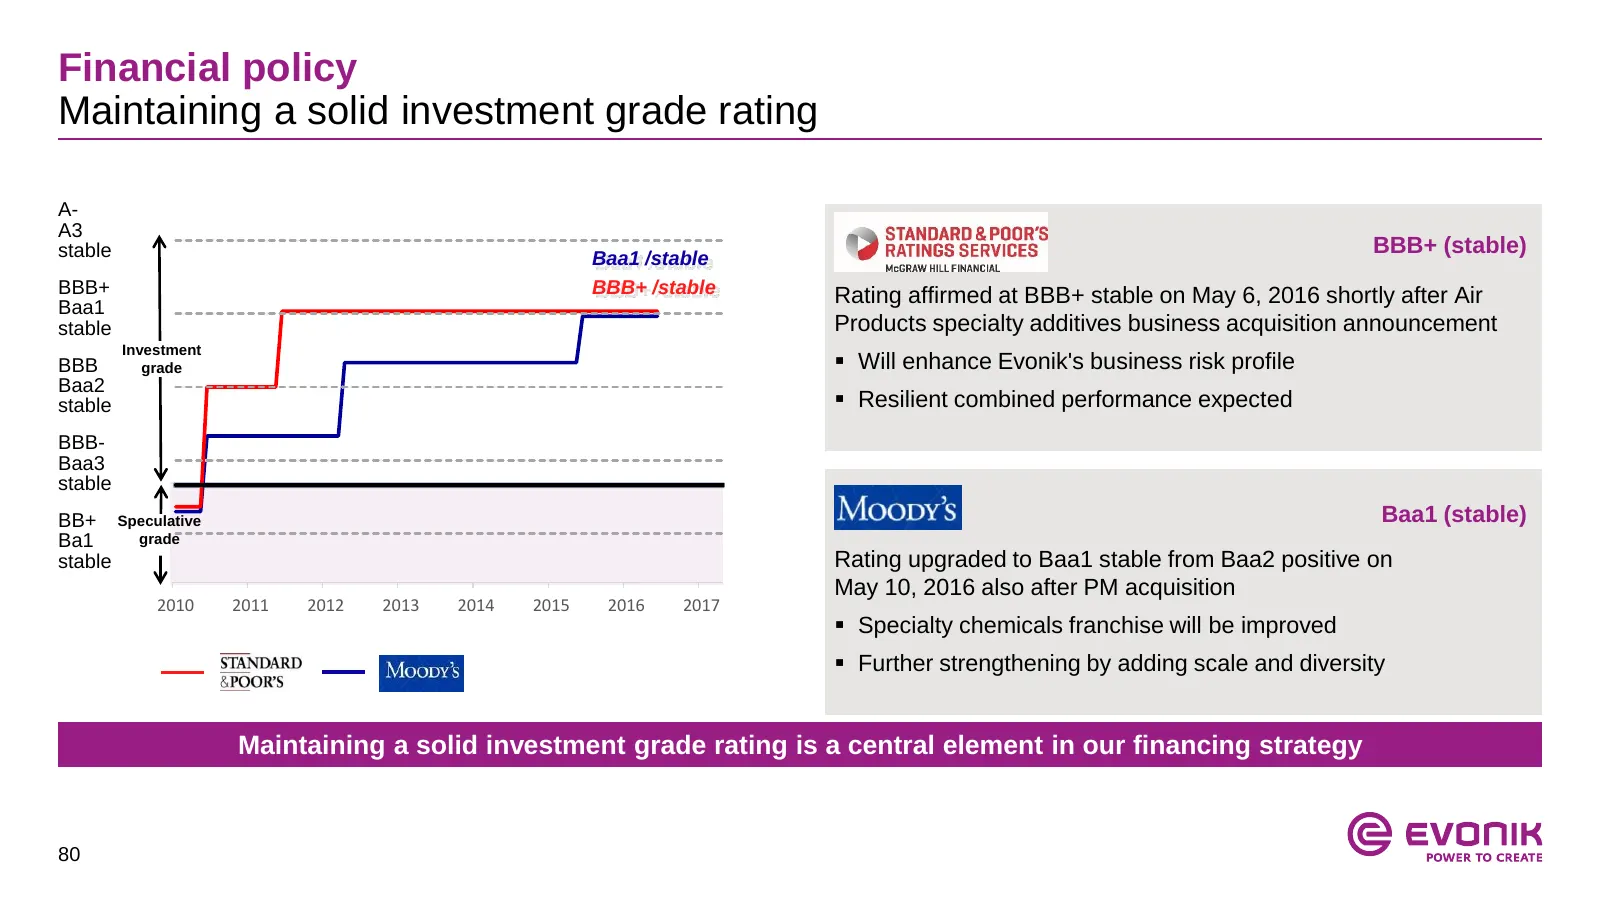
Slide 80: Financial policy: maintaining solid investment grade rating
Financial policy Maintaining a solid investment grade rating A- A3 stable BBB+ (stable) Baa1 /stable BBB+ BBB+ /stable Rating affirmed at BBB+ stable on May 6, 2016 shortly after Air Baa1 stable Products specialty additives business acquisition announcement Investment BBB grade Will enhance Evonik
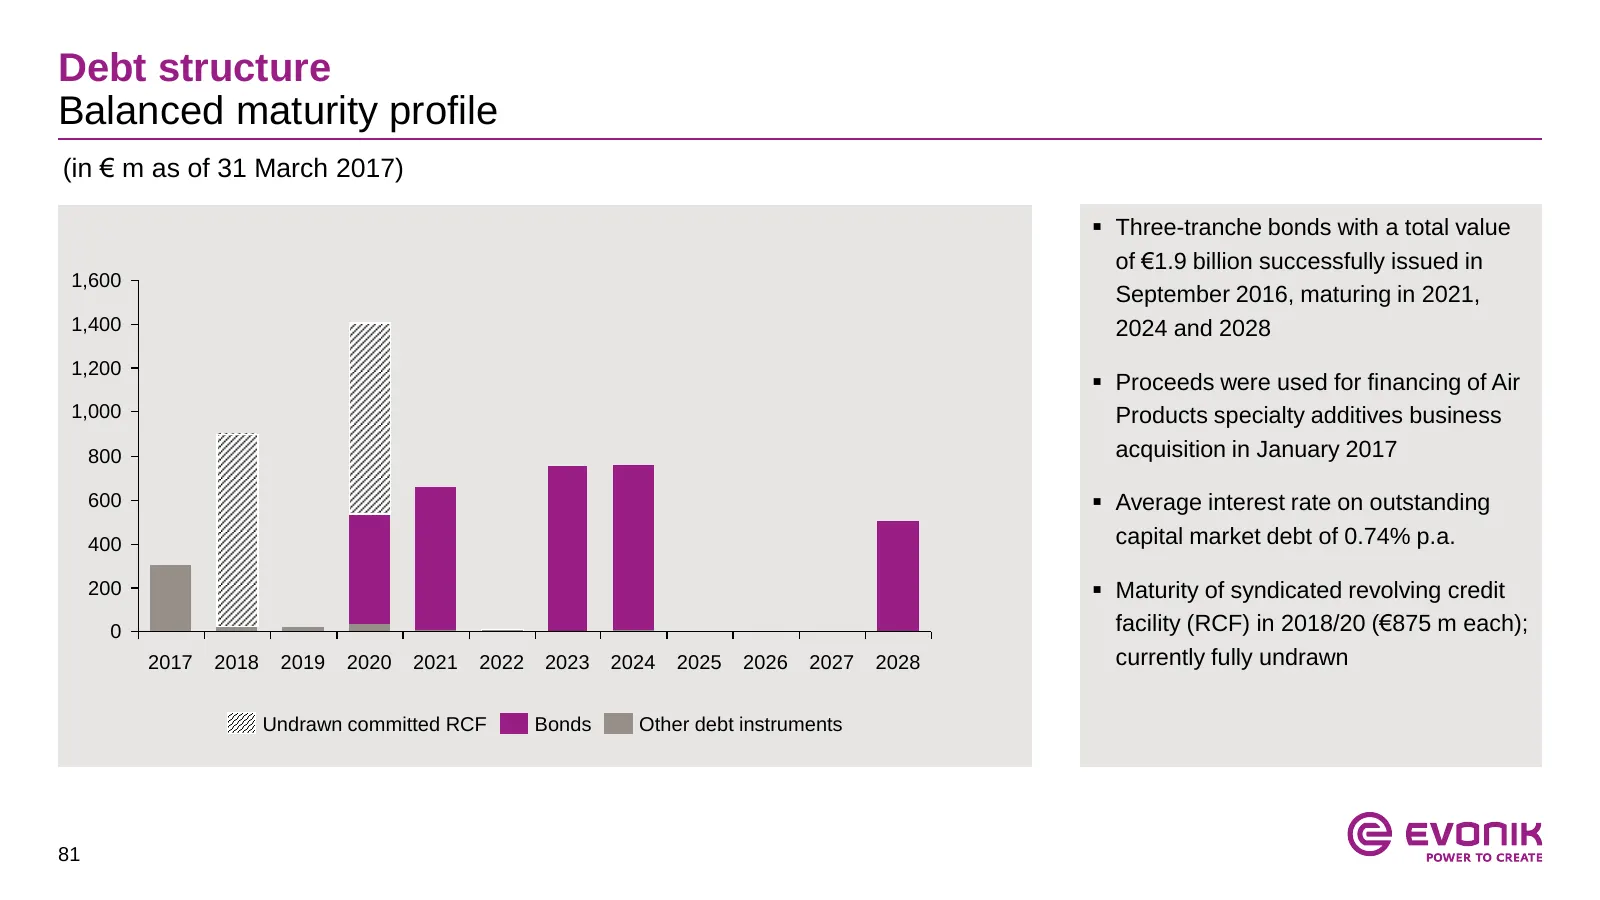
Slide 81: Debt structure: balanced maturity profile
Debt structure Balanced maturity profile (in € m as of 31 March 2017) Three-tranche bonds with a total value of €1.9 billion successfully issued in 1,600 September 2016, maturing in 2021, 1,400 2024 and 2028 1,200 Proceeds were used for financing of Air 1,000 Products specialty additives busines
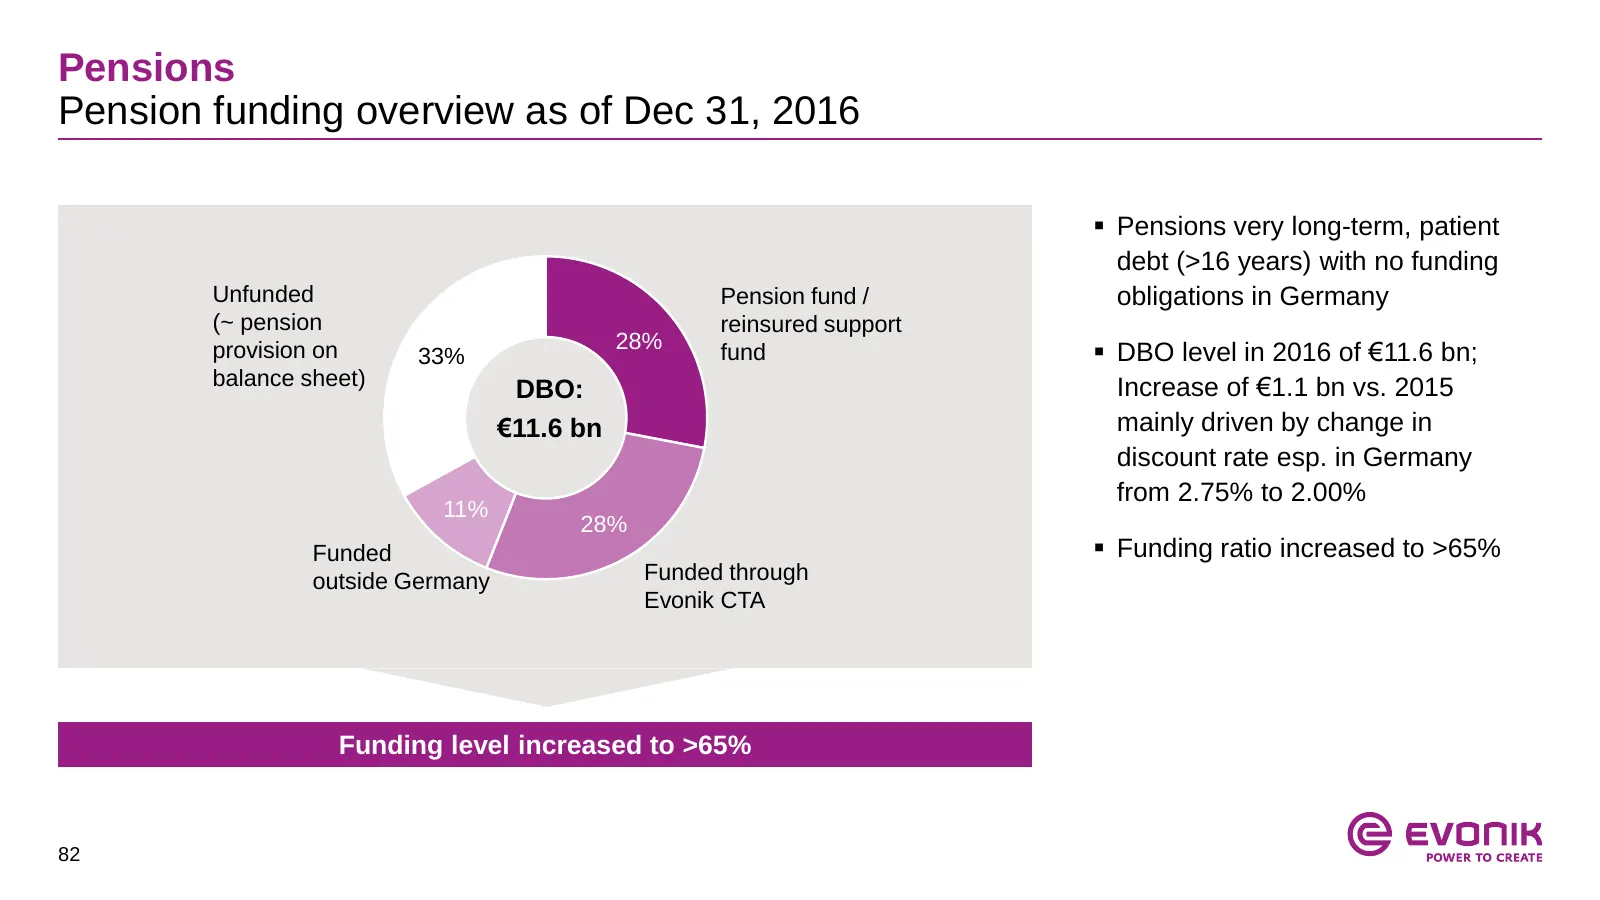
Slide 82: Pensions: funding overview
Pensions Pension funding overview as of Dec 31, 2016 Pensions very long-term, patient debt (>16 years) with no funding Unfunded Pension fund / obligations in Germany (~ pension reinsured support 28% provision on 33% fund DBO level in 2016 of €11.6 bn; balance sheet) Increase of €1.1 bn vs. 2015
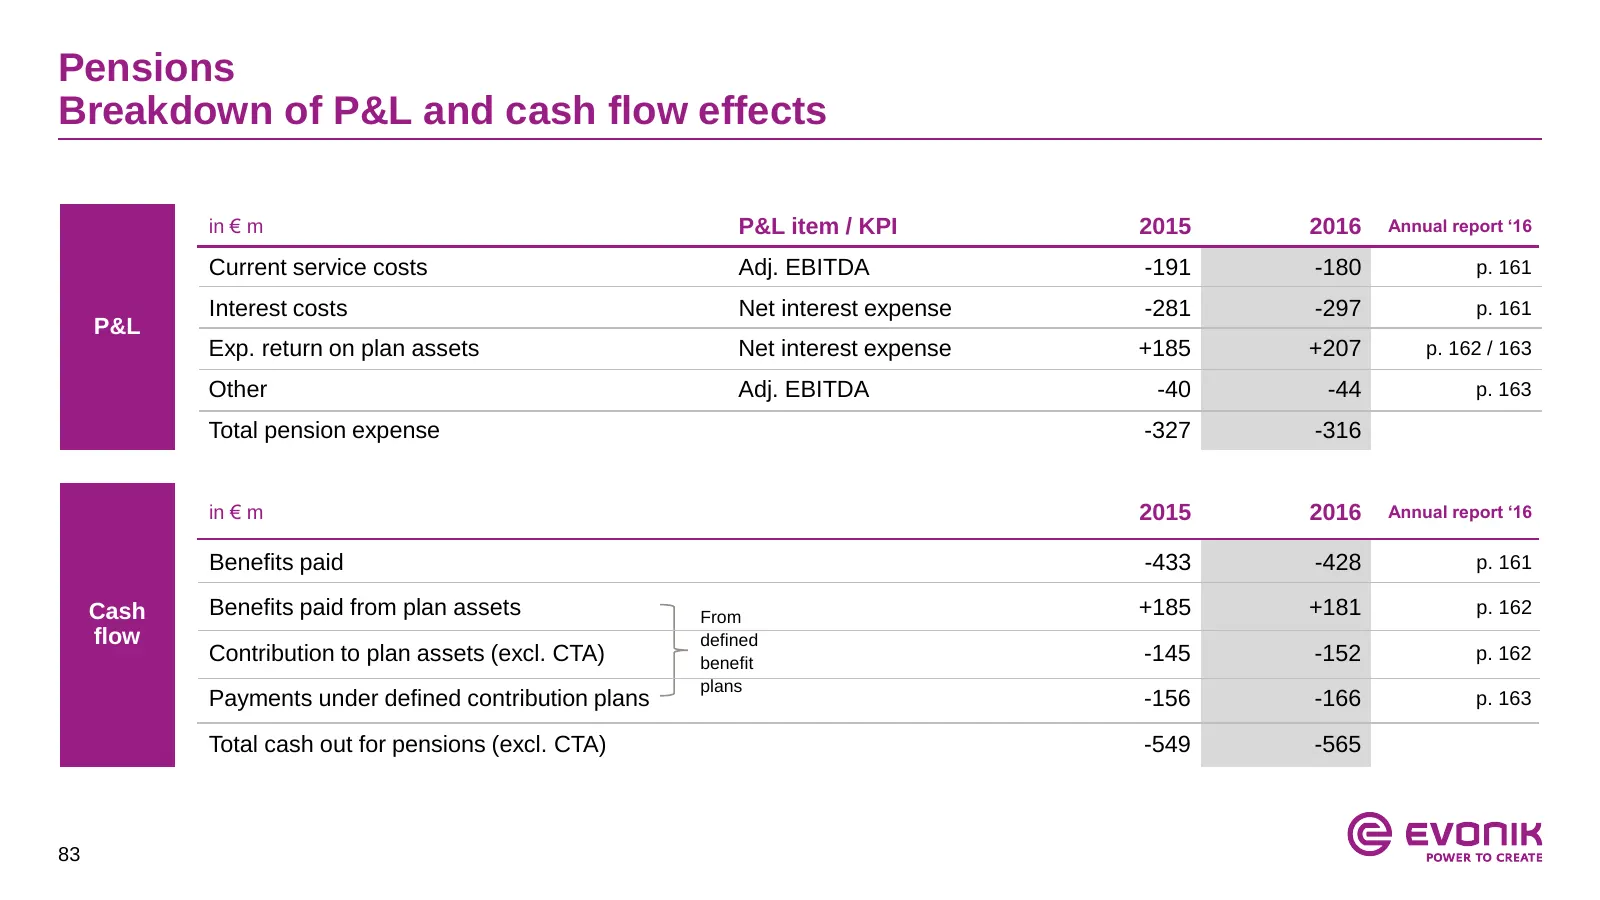
Slide 83: Pensions: breakdown of P&L and cash flow effects
Pensions Breakdown of P&L and cash flow effects in € m P&L item / KPI 2015 2016 Annual report ‘16 Current service costs Adj. EBITDA -191 -180 p. 161 Interest costs Net interest expense -281 -297 p. 161 P&L Exp. return on plan assets Net interest expense +185 +207 p. 162 / 163 Other Adj. EBITDA -40 -
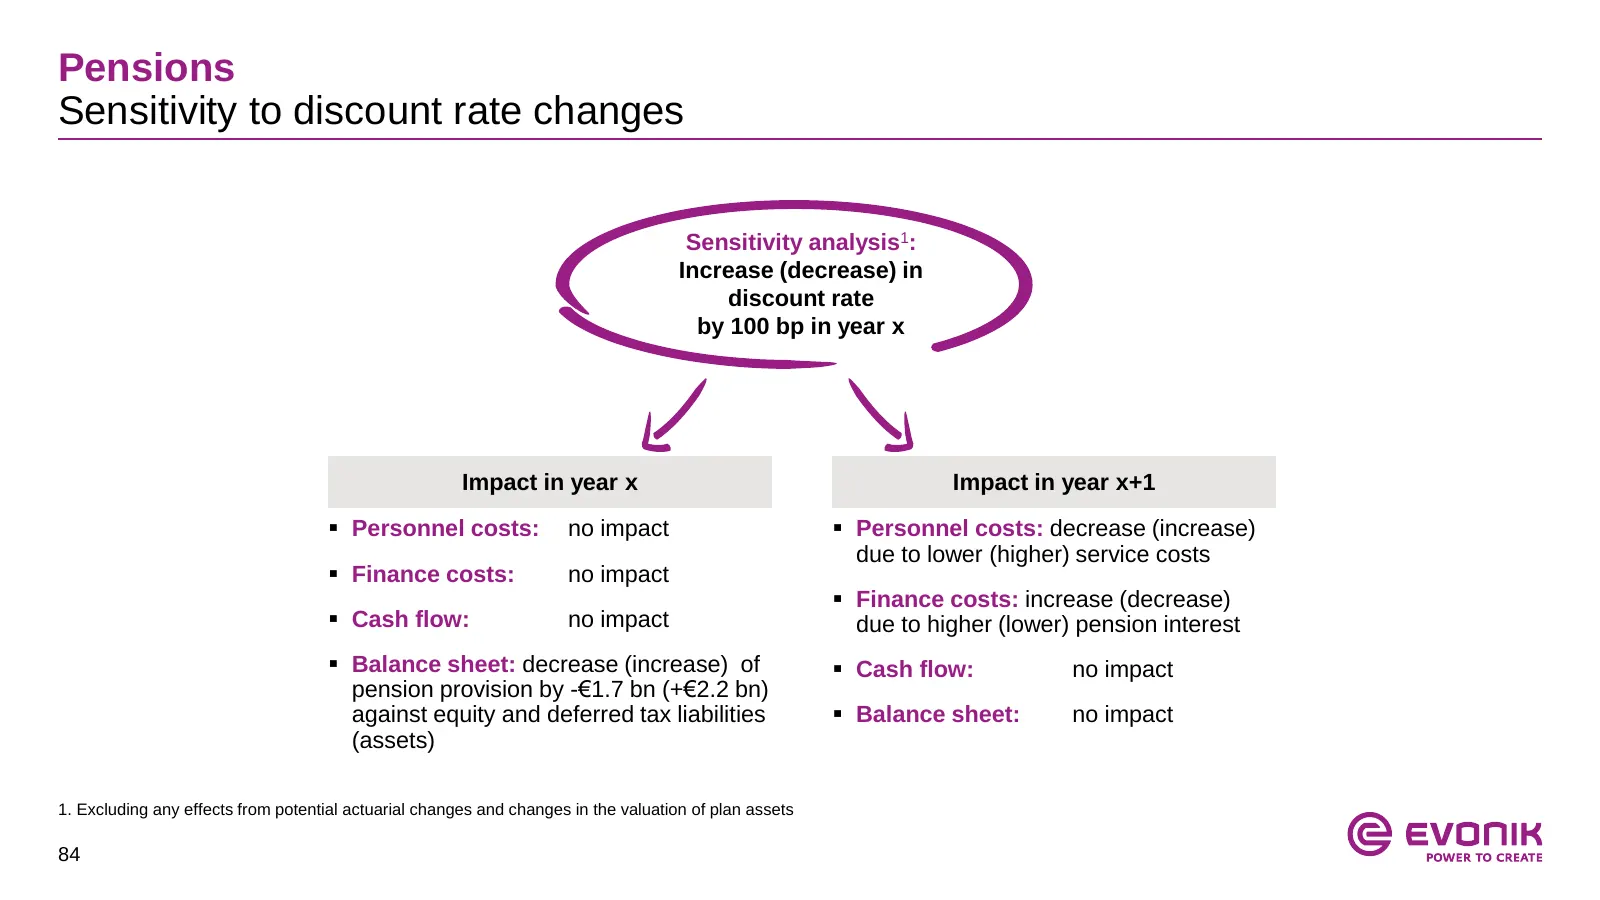
Slide 84: Pensions: sensitivity to discount rate changes
Pensions Sensitivity to discount rate changes Sensitivity analysis1: Increase (decrease) in discount rate by 100 bp in year x Impact in year x Impact in year x+1 Personnel costs: no impact Personnel costs: decrease (increase) due to lower (higher) service costs Finance costs: no impact Finan
Slide 85: Net debt development
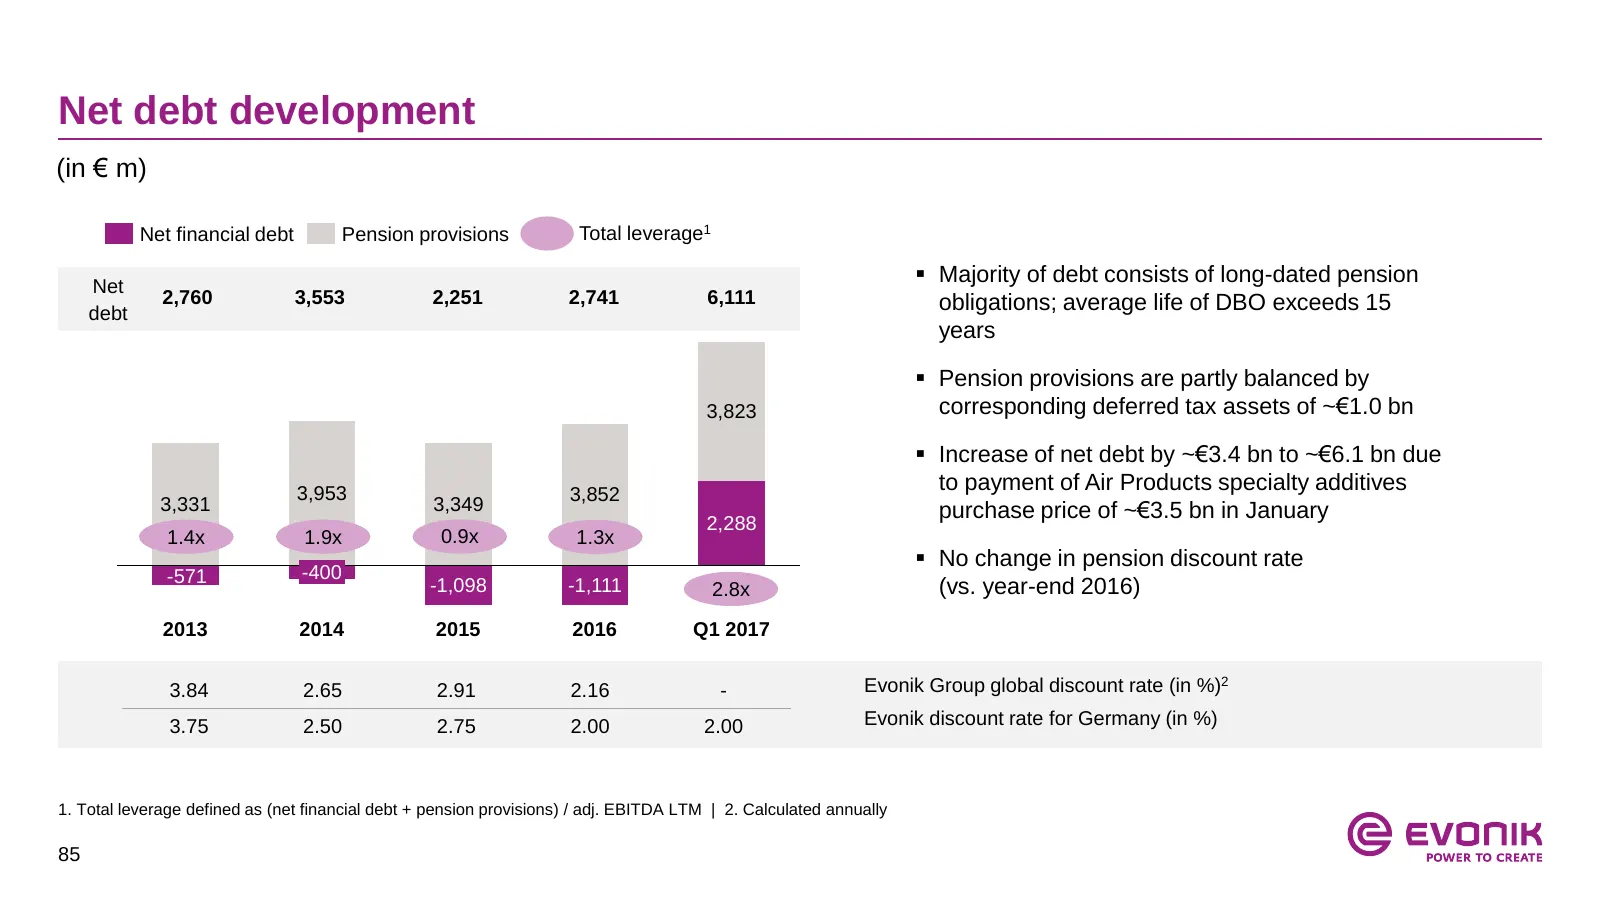
Net debt development (in € m) Net financial debt Pension provisions Total leverage1 Net Majority of debt consists of long-dated pension 2,760 3,553 2,251 2,741 6,111 obligations; average life of DBO exceeds 15 debt years Pension provisions are partly balanced by 3,823 corresponding deferred tax
Slide 86: Financial track record
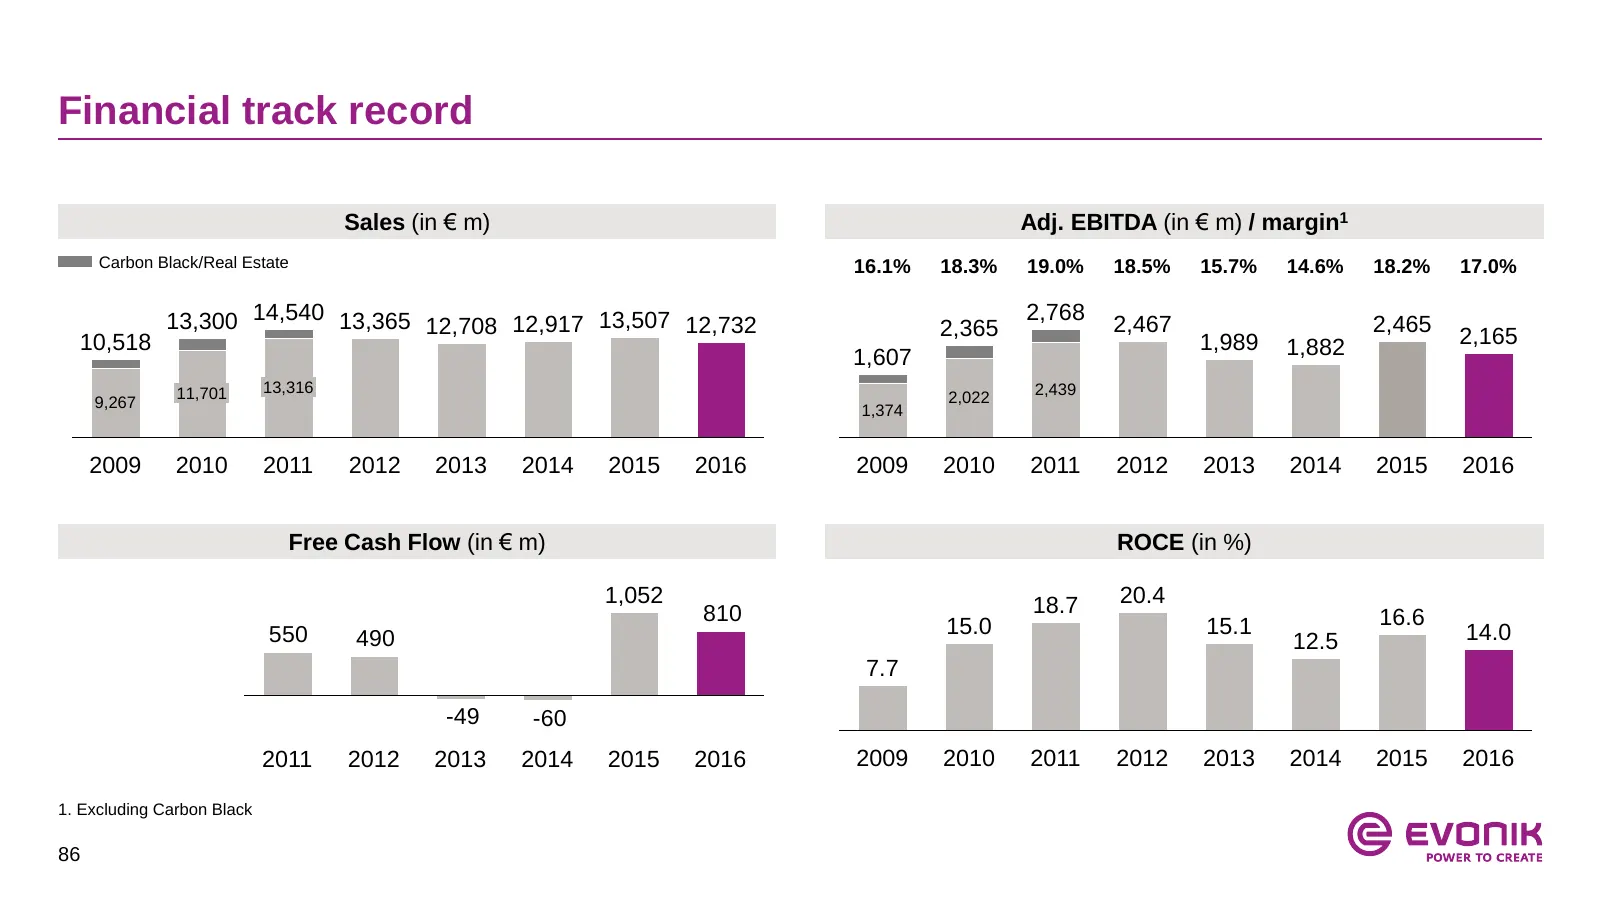
Financial track record Sales (in € m) Adj. EBITDA (in € m) / margin1 Carbon Black/Real Estate 16.1% 18.3% 19.0% 18.5% 15.7% 14.6% 18.2% 17.0% 13,300 14,540 13,365 12,708 12,917 13,507 12,732 2,365 2,768 2,467 2,465 10,518 1,989 1,882 2,165 1,607 11,701 13,316 2,439 9,267 2,022 1,374 2009 2010 2011 2
Slide 87: Segment overview by quarter
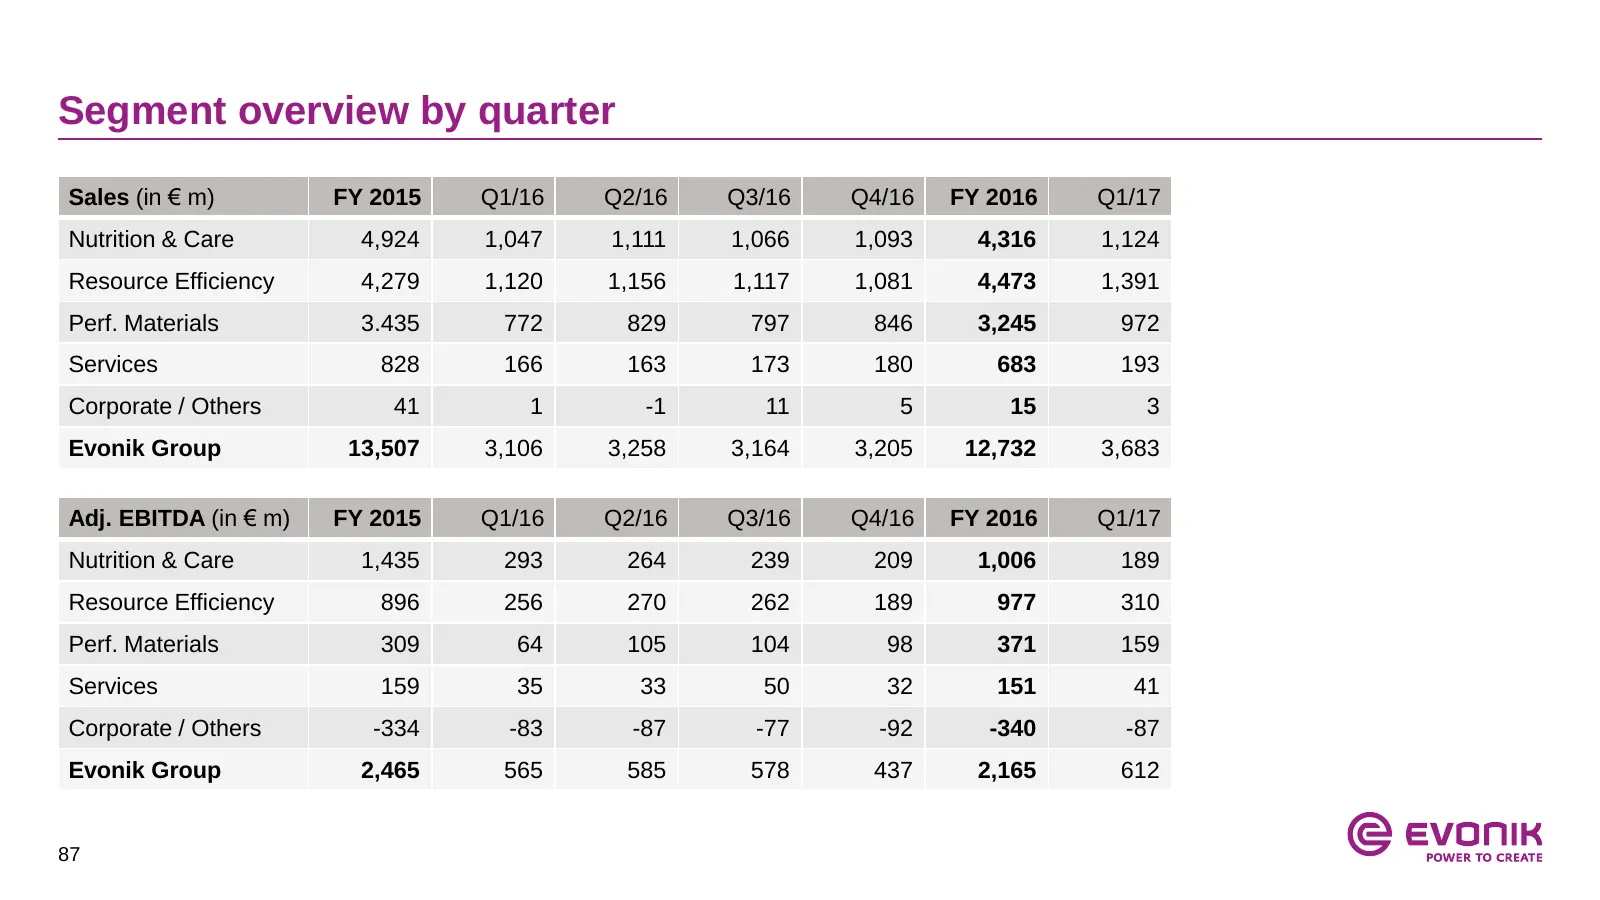
Segment overview by quarter Sales (in € m) FY 2015 Q1/16 Q2/16 Q3/16 Q4/16 FY 2016 Q1/17 Nutrition & Care 4,924 1,047 1,111 1,066 1,093 4,316 1,124 Resource Efficiency 4,279 1,120 1,156 1,117 1,081 4,473 1,391 Perf. Materials 3.435 772 829 797 846 3,245 972 Services 828 166 163 173 180 683 193 Corpo
Slide 88: Balanced regional and end market split
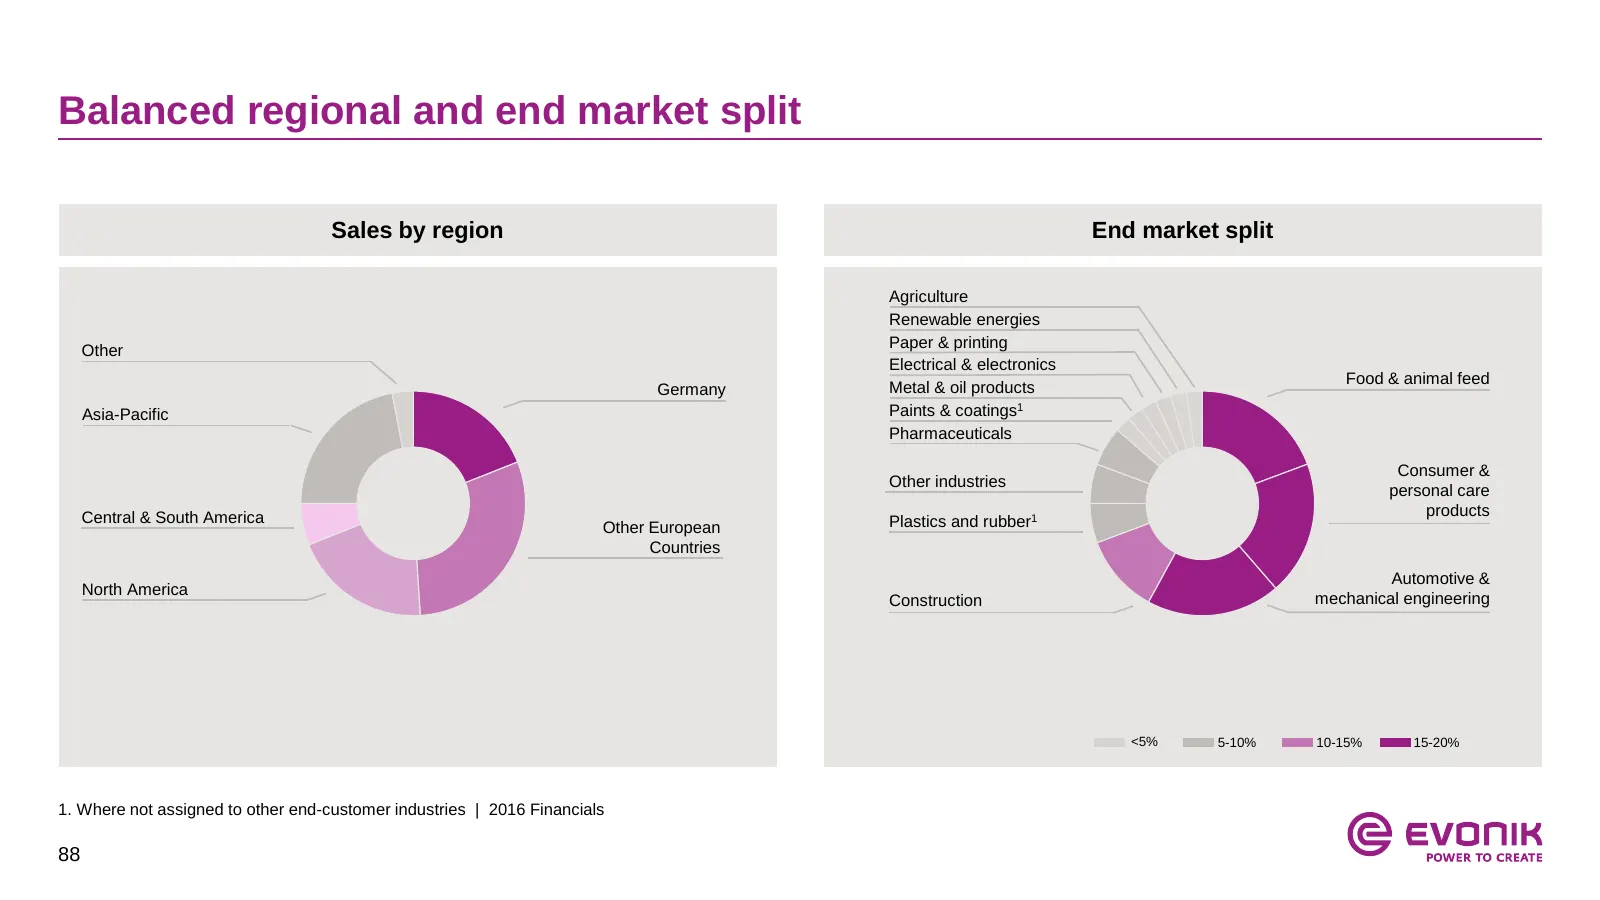
Balanced regional and end market split Sales by region End market split Agriculture Renewable energies Paper & printing Other Electrical & electronics Food & animal feed Germany Metal & oil products Asia-Pacific Paints & coatings1 Pharmaceuticals Consumer & Other industries personal care Central & S
Slide 89: Raw material split
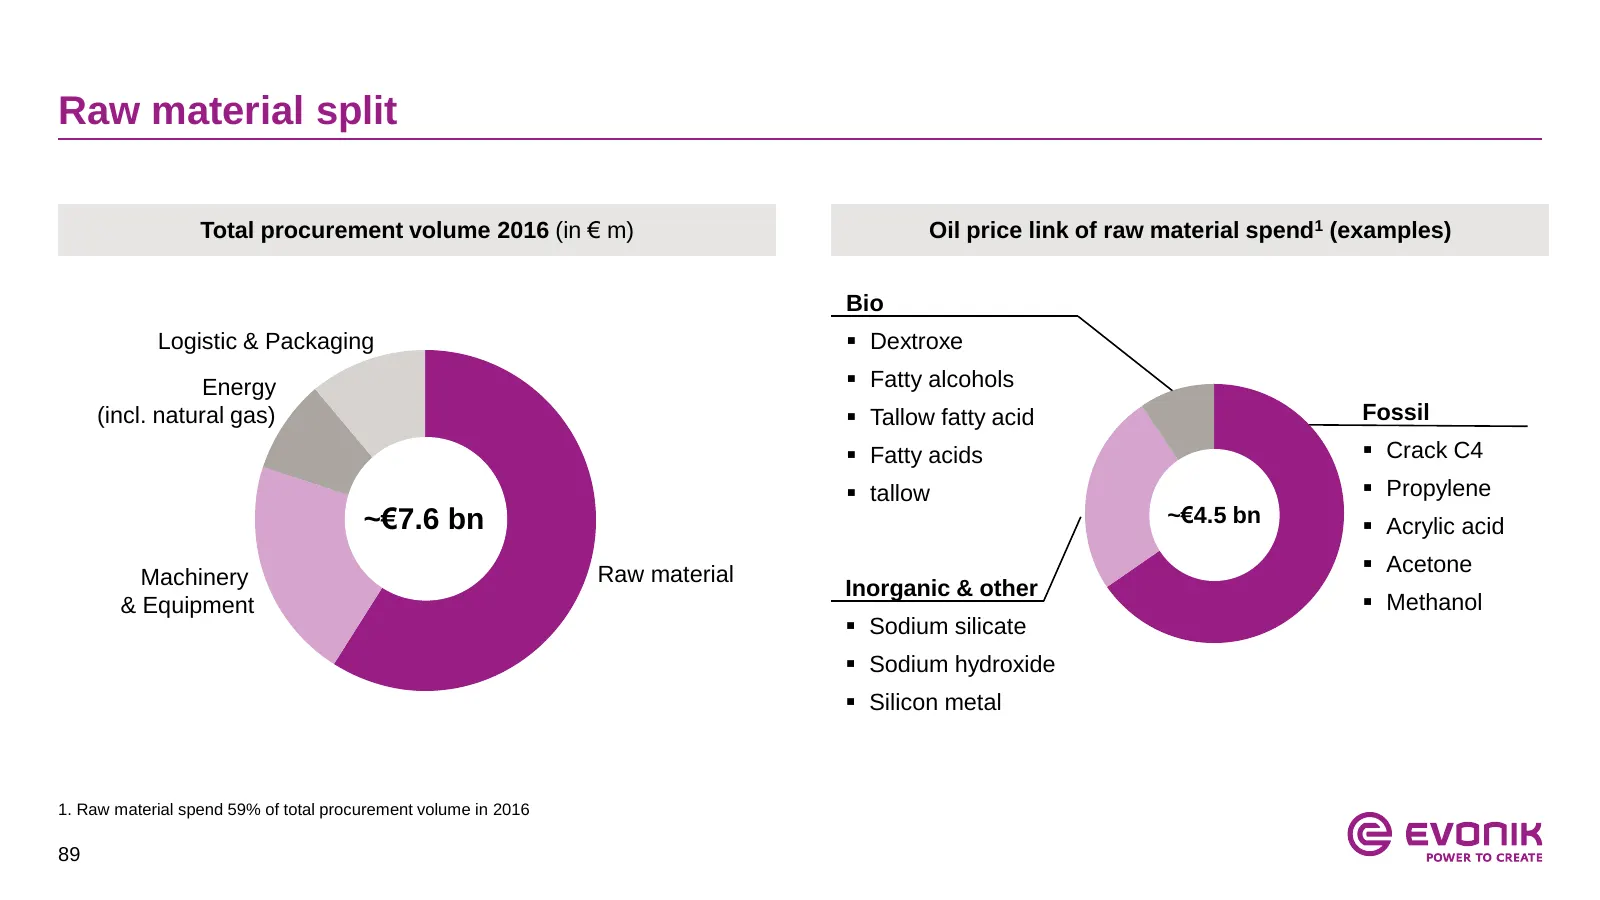
Raw material split Total procurement volume 2016 (in € m) Oil price link of raw material spend1 (examples) Bio Logistic & Packaging Dextroxe Energy Fatty alcohols (incl. natural gas) Tallow fatty acid Fossil Fatty acids Crack C4 tallow Propylene ~€7.6 bn ~€4.5 bn Acrylic acid Raw mat
Slide 90: Management compensation
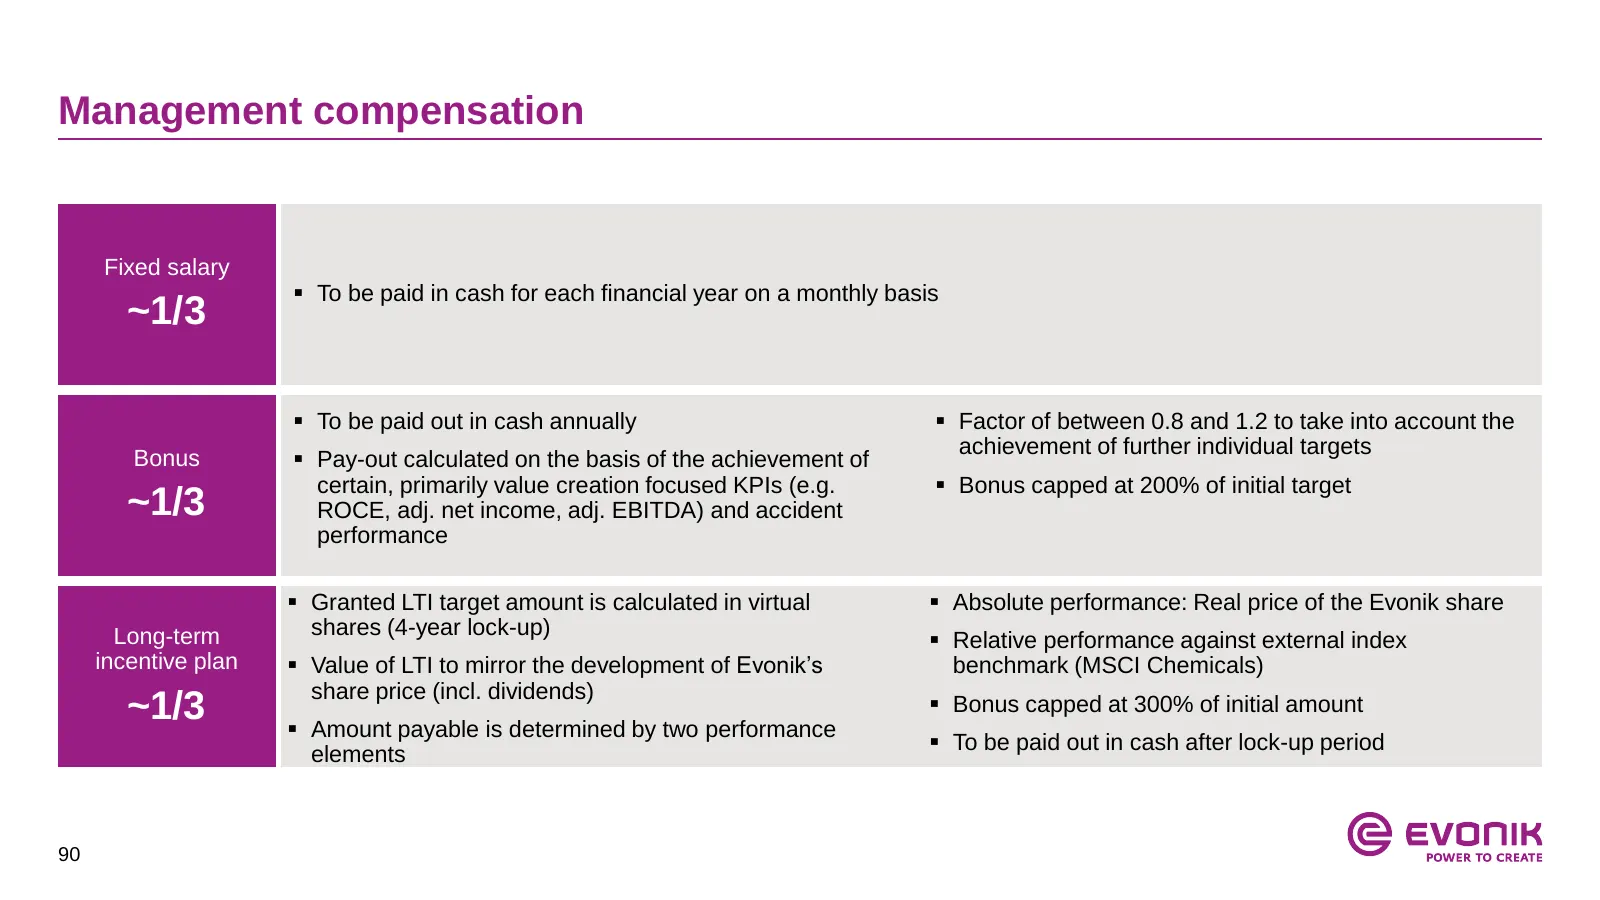
Management compensation Fixed salary To be paid in cash for each financial year on a monthly basis ~1/3 To be paid out in cash annually Factor of between 0.8 and 1.2 to take into account the achievement of further individual targets Bonus Pay-out calculated on the basis of the achievement of
Slide 91: Innovation excellence: Evonik growth fields
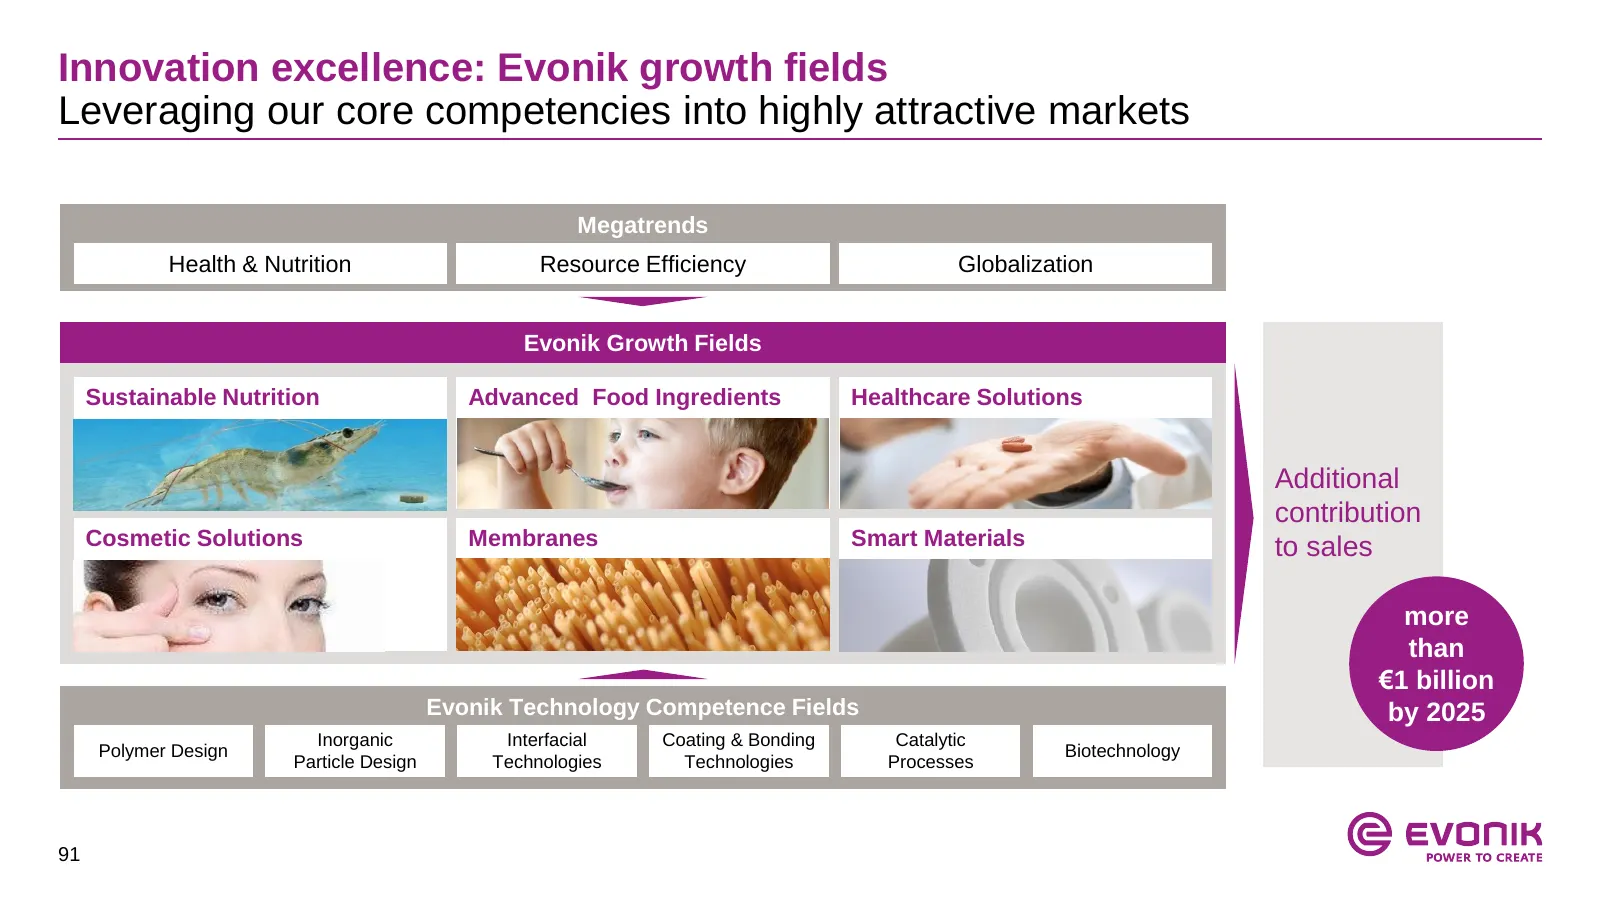
Innovation excellence: Evonik growth fields Leveraging our core competencies into highly attractive markets Megatrends Health & Nutrition Resource Efficiency Globalization Evonik Growth Fields Sustainable Nutrition Advanced Food Ingredients Healthcare Solutions Additional contribution Cosmetic Solut
Slide 92: Evonik's sustainability performance publicly recognized
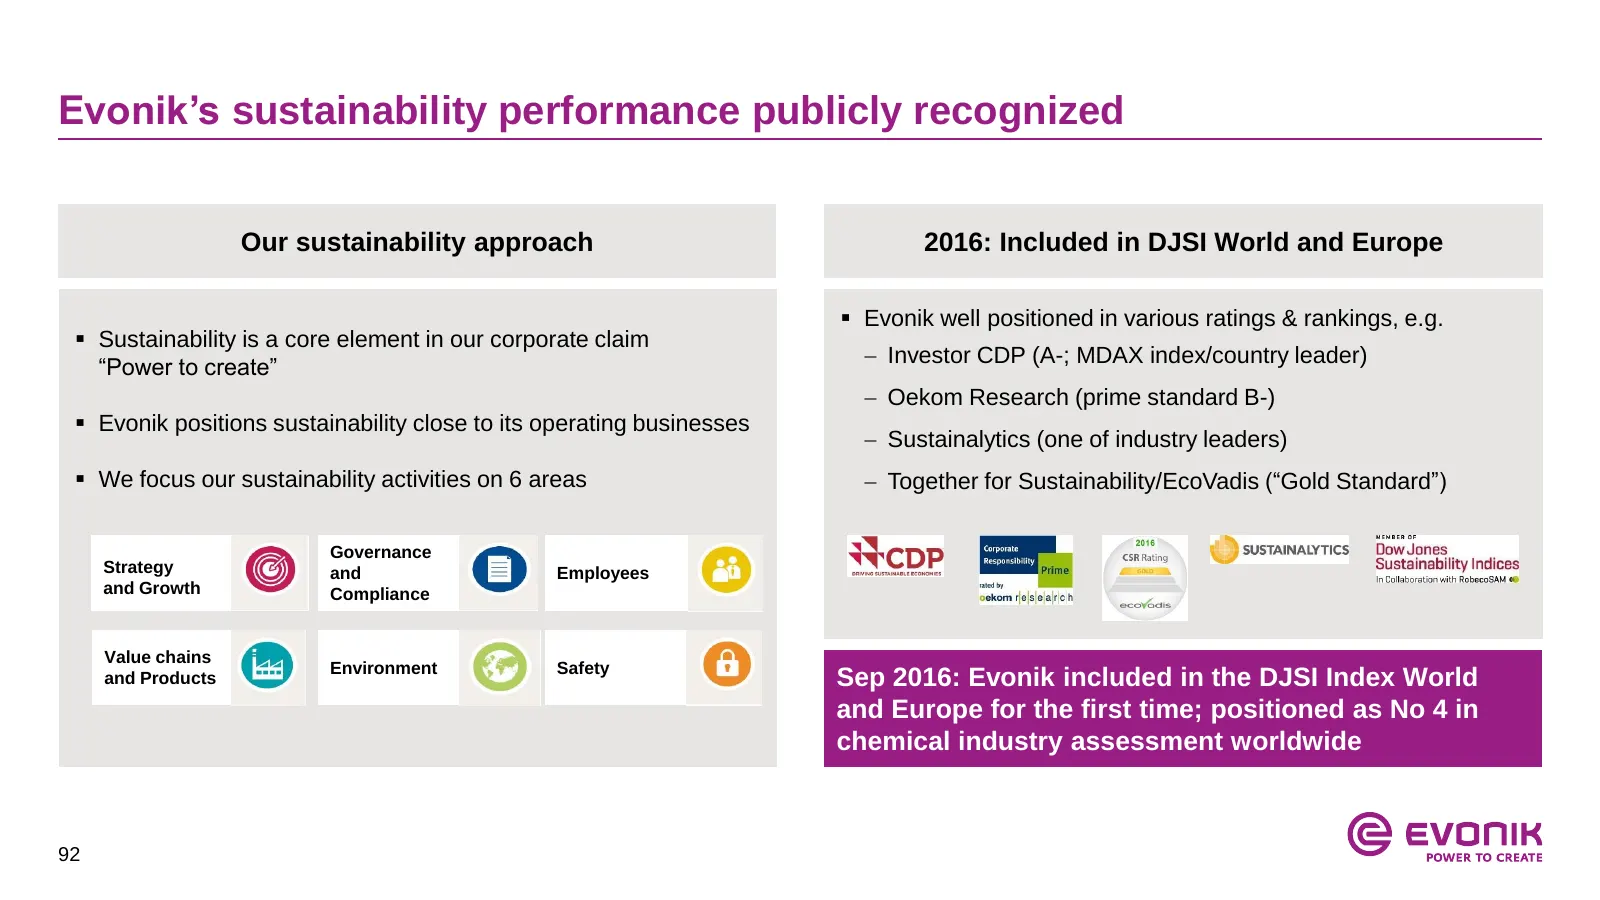
Evonik’s sustainability performance publicly recognized Our sustainability approach 2016: Included in DJSI World and Europe Evonik well positioned in various ratings & rankings, e.g. Sustainability is a core element in our corporate claim Investor CDP (A-; MDAX index/country leader) “Power to
Slide 93: Appendix
Appendix 1. Acquisition of Air Products specialty additives business 2. Acquisition of Huber Silica 3. Segment overview 4. Financials 5. Upcoming events 93
Slide 94: Upcoming IR events
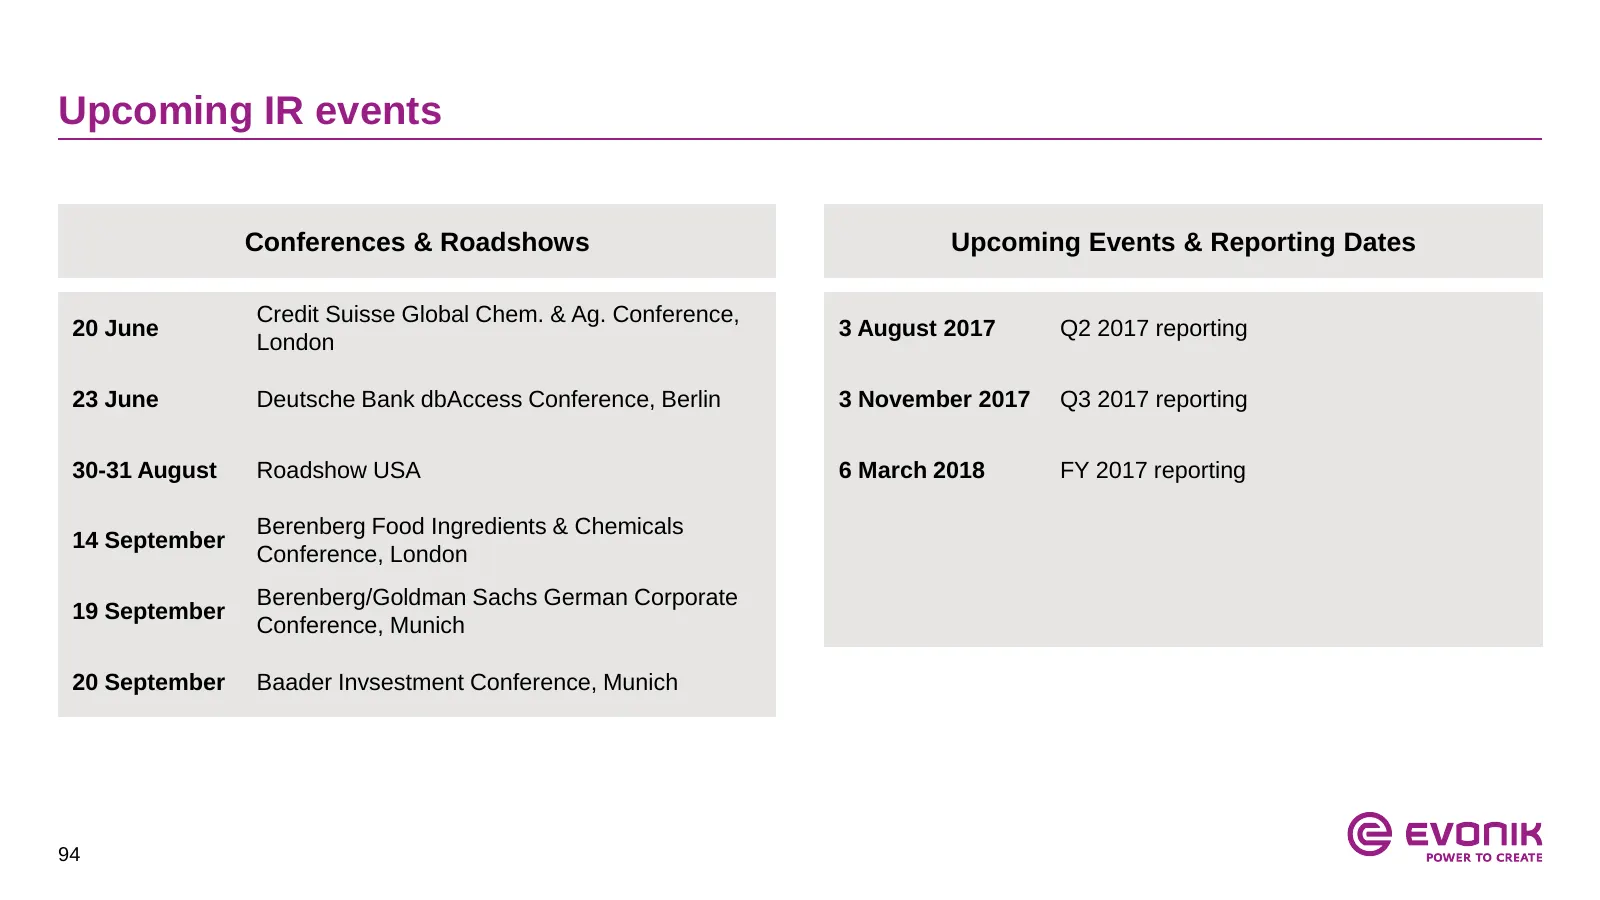
Upcoming IR events Conferences & Roadshows Upcoming Events & Reporting Dates Credit Suisse Global Chem. & Ag. Conference, 20 June 3 August 2017 Q2 2017 reporting London 23 June Deutsche Bank dbAccess Conference, Berlin 3 November 2017 Q3 2017 reporting 30-31 August Roadshow USA 6 March 2018 FY 2017
Slide 95: Evonik Investor Relations team
Evonik Investor Relations team Tim Lange Janine Kanotowsky Head of Investor Relations Team Assistant +49 201 177 3150 +49 201 177 3146 tim.lange@evonik.com janine.kanotowsky@evonik.com Daniel Györy Kai Kirchhoff Investor Relations Manager Investor Relations Manager +49 201 177 3147 +49 201 177 3145
Slide 96: Disclaimer
Disclaimer In so far as forecasts or expectations are expressed in this presentation or where our statements concern the future, these forecasts, expectations or statements may involve known or unknown risks and uncertainties. Actual results or developments may vary, depending on changes in the oper
Slide 97: © evonik
© evonik
Source: Internet Archive copy of corporate.evonik.de
More decks from Evonik Industries AG
 Q3 2026 Earnings Presentation34 slides · Nov 3, 2026
 Q2 2026 Earnings Presentation27 slides · Aug 4, 2026
 Q2 2026 Earnings Presentation39 slides · August 2026
 Q1 2026 Earnings Presentation26 slides · May 8, 2026
 Q4 2025 Earnings Presentation44 slides · Feb 5, 2026
 Q3 2025 Earnings Presentation35 slides · Nov 4, 2025