Rudolph Technologies — Shareholder Meeting (May 2015)
32 slides from Rudolph Technologies's shareholder meeting presentation, May 22, 2015
Slide 1: 2015 Annual Shareholders Meeting
Paul F McLaughlin Chairman and CEO 2015 Annual Shareholders Meeting Flanders, New Jersey May 20, 2015
Slide 2: Safe Harbor Statement
Safe Harbor Statement This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 (the “Act”) which include the benefits to customers of Rudolph’s products, Rudolph’s business momentum and future growth, Rudolph’s existing market
Slide 3: Highlights To Look for Today
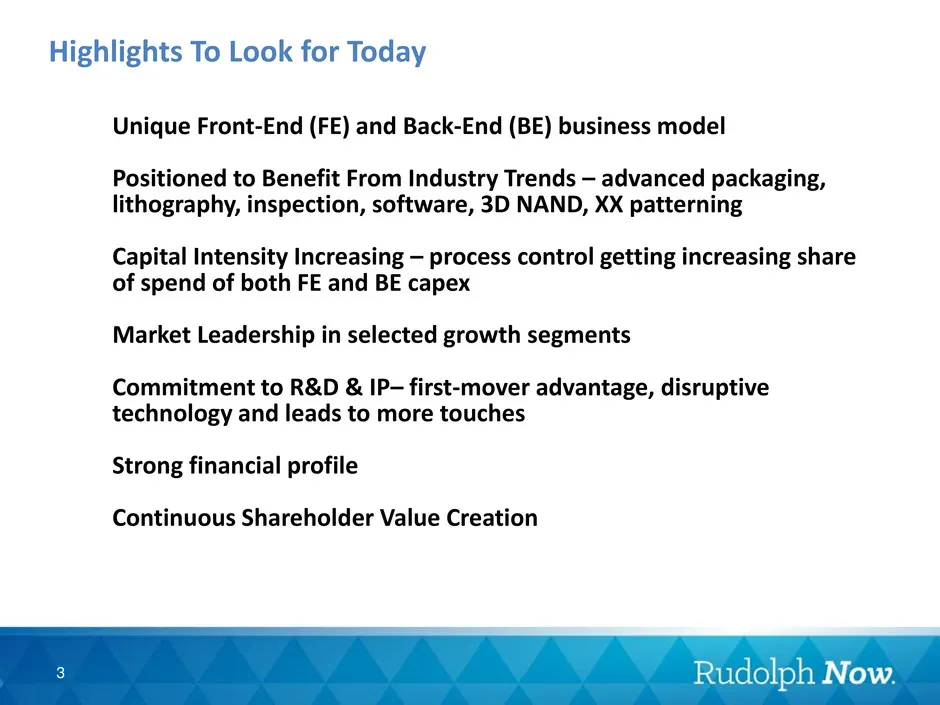
Highlights To Look for Today Unique Front-End (FE) and Back-End (BE) business model Positioned to Benefit From Industry Trends – advanced packaging, lithography, inspection, software, 3D NAND, XX patterning Capital Intensity Increasing – process control getting increasing share of spend of both F
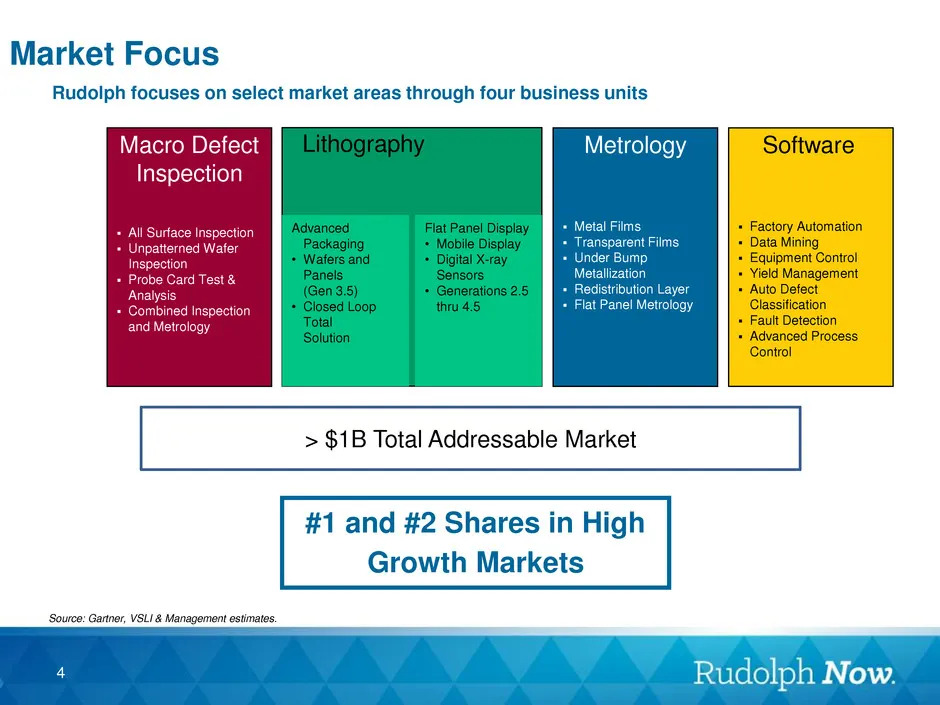
Slide 4: Rudolph focuses on select market areas through four business units
All Surface Inspection Unpatterned Wafer Inspection Probe Card Test & Analysis Combined Inspection and Metrology Macro Defect Inspection $223M Metal Films Transparent Films Under Bump Metallization Redistribution Layer Flat Panel Metrology Metrology $226M Factory Automation Dat
Slide 5: Uniquely Balanced Between Front- and Back-End
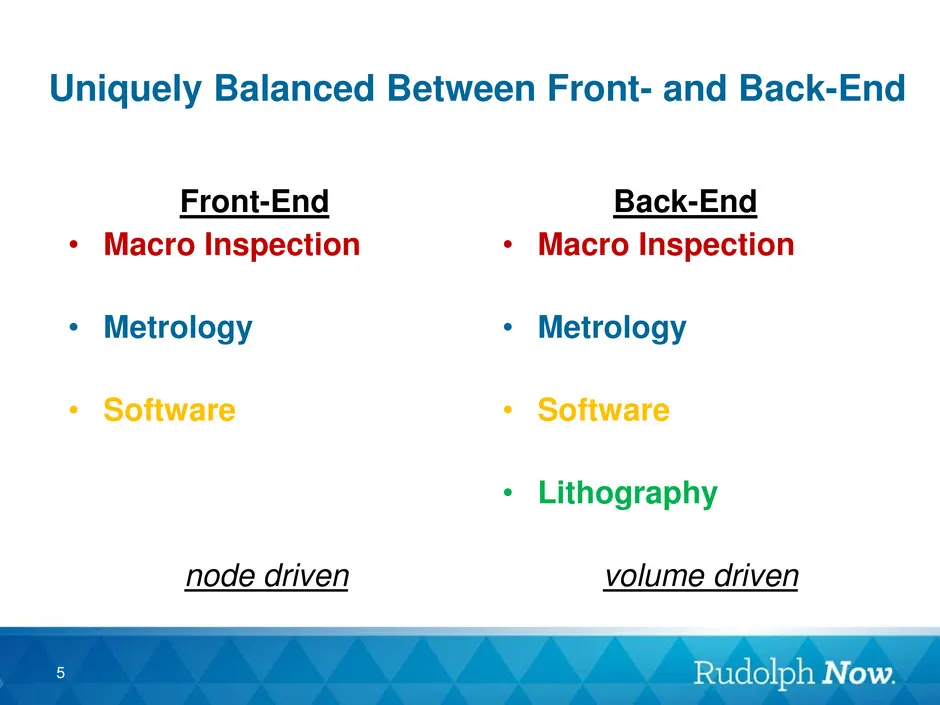
Uniquely Balanced Between Front- and Back-End Front-End • Macro Inspection • Metrology • Software node driven Back-End • Macro Inspection • Metrology • Software • Lithography volume driven 5
Slide 6: 2014 Revenue Percentage by Customer
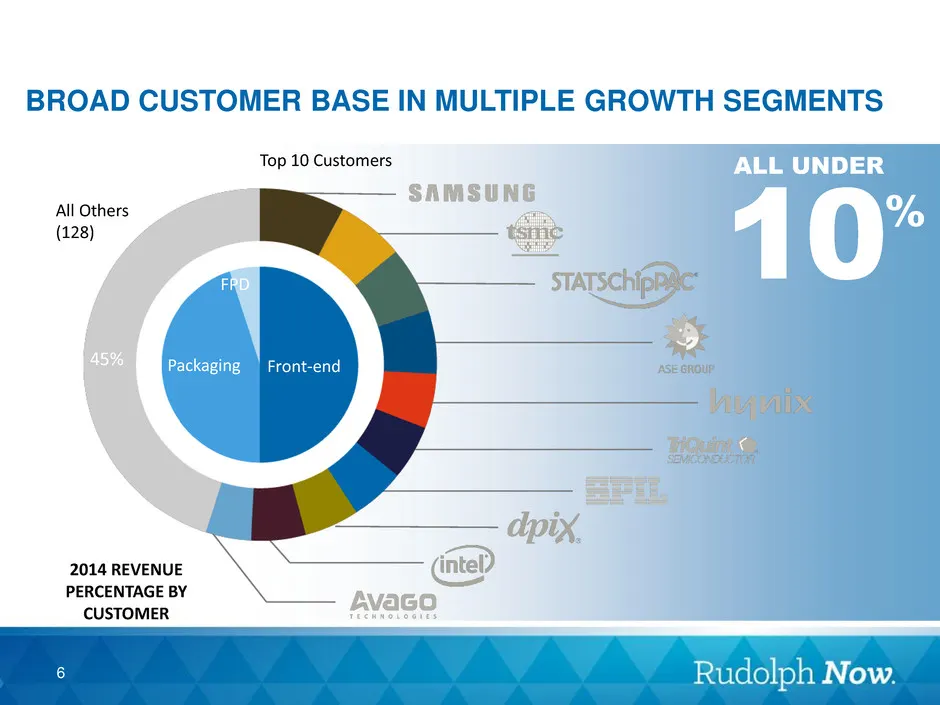
2014 REVENUE PERCENTAGE BY CUSTOMER Top 10 Customers All Others (128) BROAD CUSTOMER BASE IN MULTIPLE GROWTH SEGMENTS Packaging Front-end FPD 45% 10% ALL UNDER 6
Slide 7: Where We Play in the Semiconductor Process
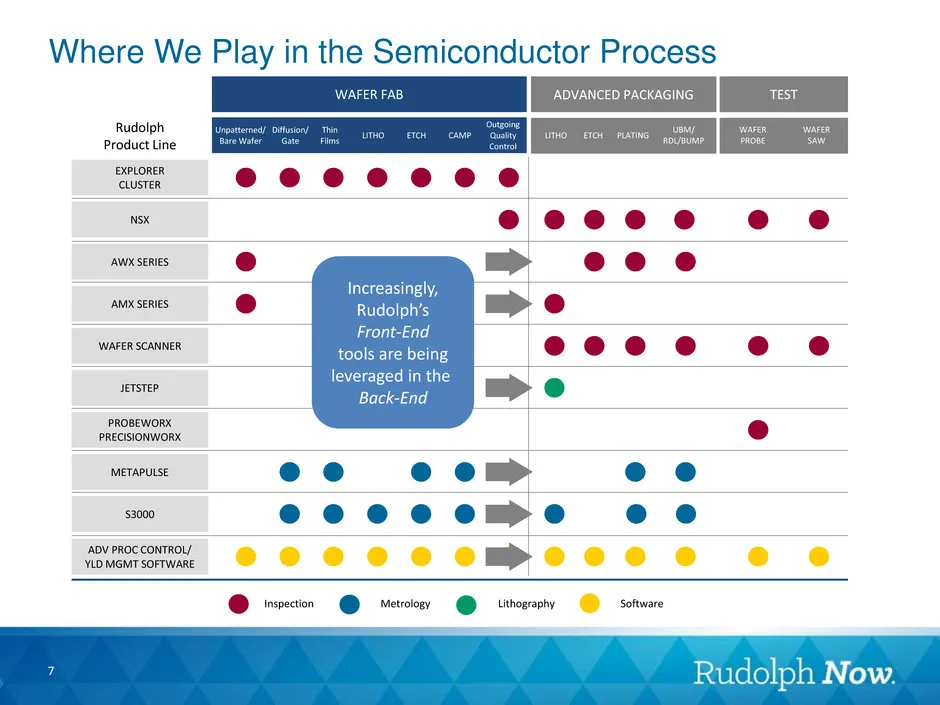
WAFER FAB ADVANCED PACKAGING TEST EXPLORER CLUSTER NSX AWX SERIES AMX SERIES WAFER SCANNER JETSTEP PROBEWORX PRECISIONWORX METAPULSE S3000 Rudolph Product Line ADV PROC CONTROL/ YLD MGMT SOFTWARE Unpatterned/ Bare Wafer Diffusion/ Gate Thin Films LITHO ETCH CAMP Outgoing Quality Control LITHO ETCH P
Slide 8: Positioned to Benefit From Industry Trends
Positioned to Benefit From Industry Trends 8
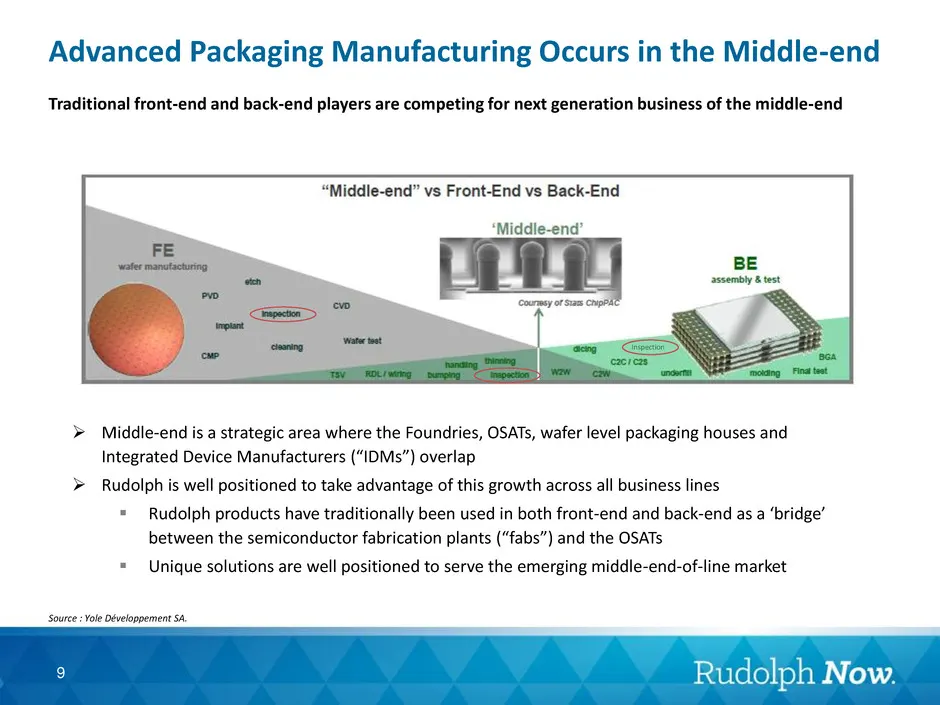
Slide 9: Advanced Packaging Manufacturing Occurs in the Middle-end
Middle-end is a strategic area where the Foundries, OSATs, wafer level packaging houses and Integrated Device Manufacturers (“IDMs”) overlap Rudolph is well positioned to take advantage of this growth across all business lines Rudolph products have traditionally been used in both front-end and
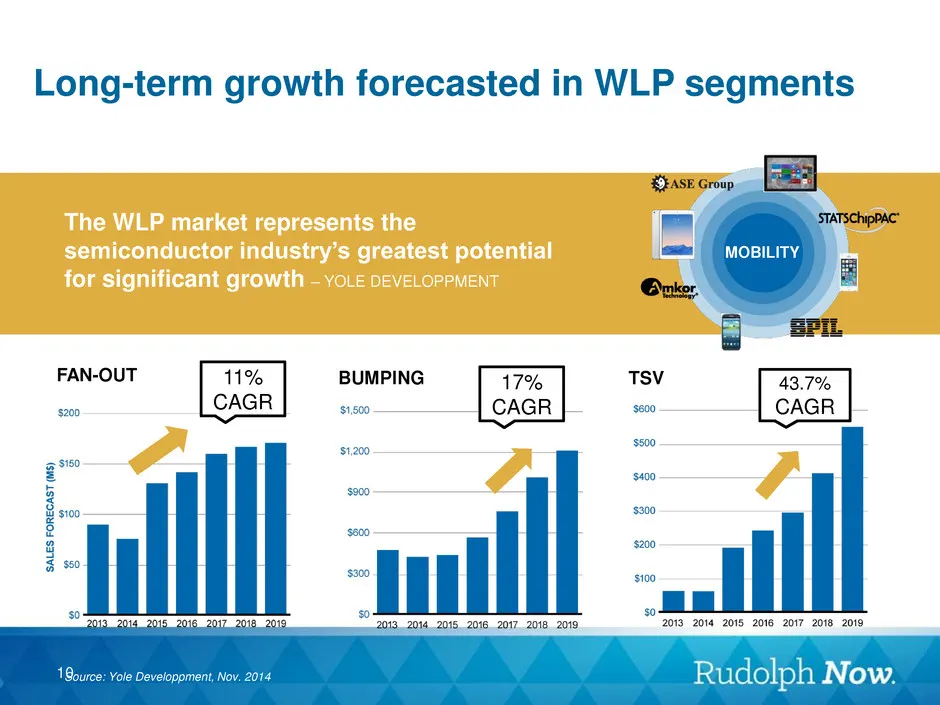
Slide 10: Long-term growth forecasted in WLP segments
Long-term growth forecasted in WLP segments BUMPING MOBILITY TSV FAN-OUT The WLP market represents the semiconductor industry’s greatest potential for significant growth – YOLE DEVELOPPMENT 17% CAGR 43.7% CAGR Source: Yole Developpment, Nov. 2014 11% CAGR 10
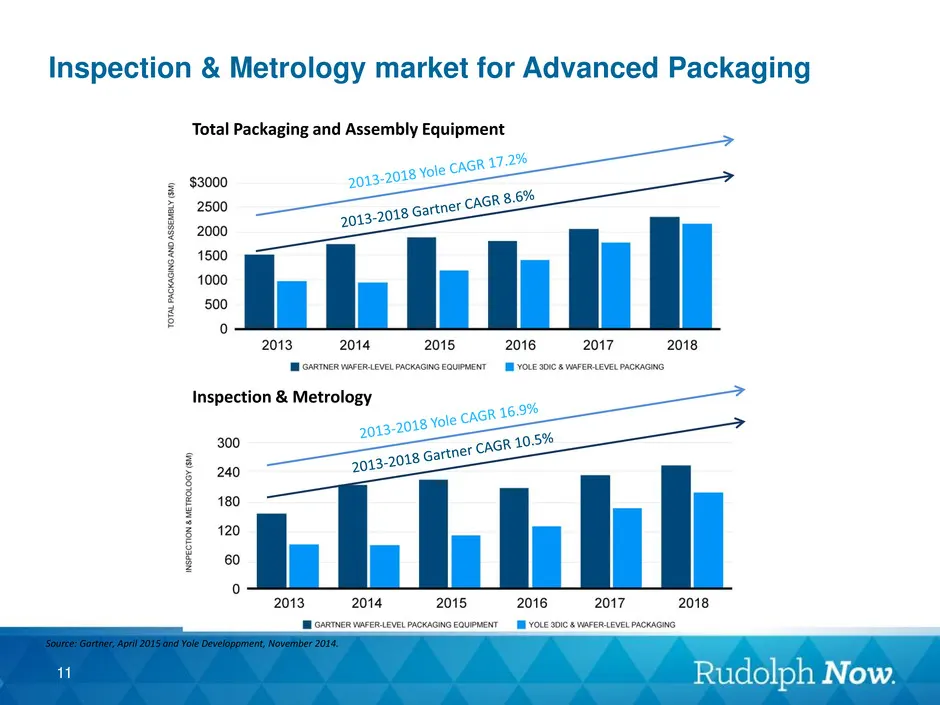
Slide 11: Inspection & Metrology market for Advanced Packaging
Inspection & Metrology market for Advanced Packaging Total Packaging and Assembly Equipment Inspection & Metrology Source: Gartner, April 2015 and Yole Developpment, November 2014. 11
Slide 12: Commitment to R&D & IP
Commitment to R&D & IP– first-mover advantage, disruptive technology and leads to more touches 12
Slide 13: Expanded advanced packaging portfolio
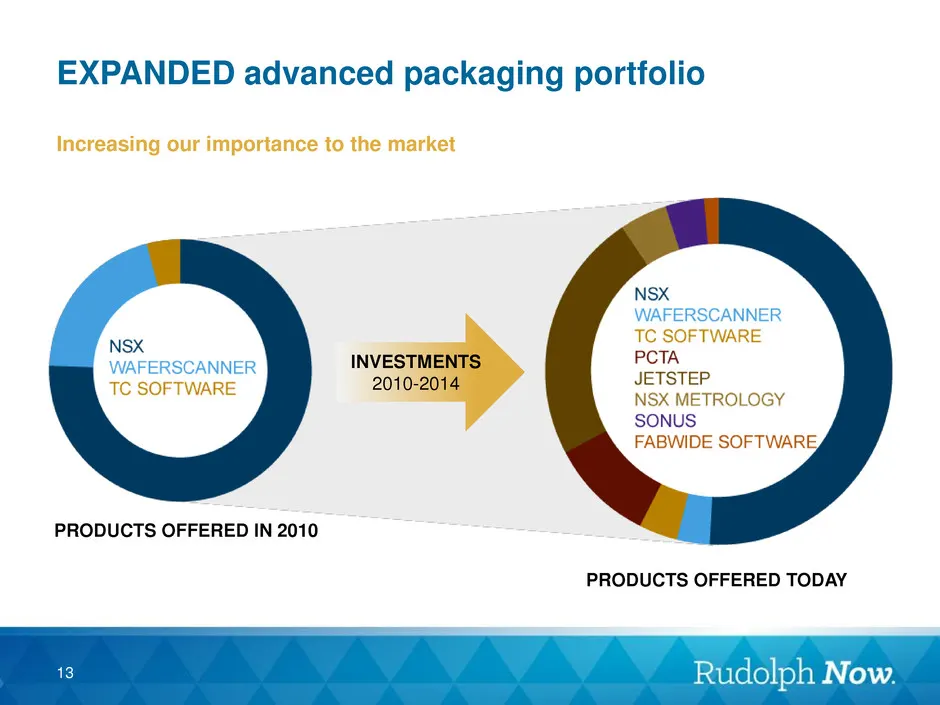
EXPANDED advanced packaging portfolio Increasing our importance to the market INVESTMENTS 2010-2014 PRODUCTS OFFERED IN 2010 PRODUCTS OFFERED TODAY 13
Slide 14: Rudolph Surrounds Advanced Packaging
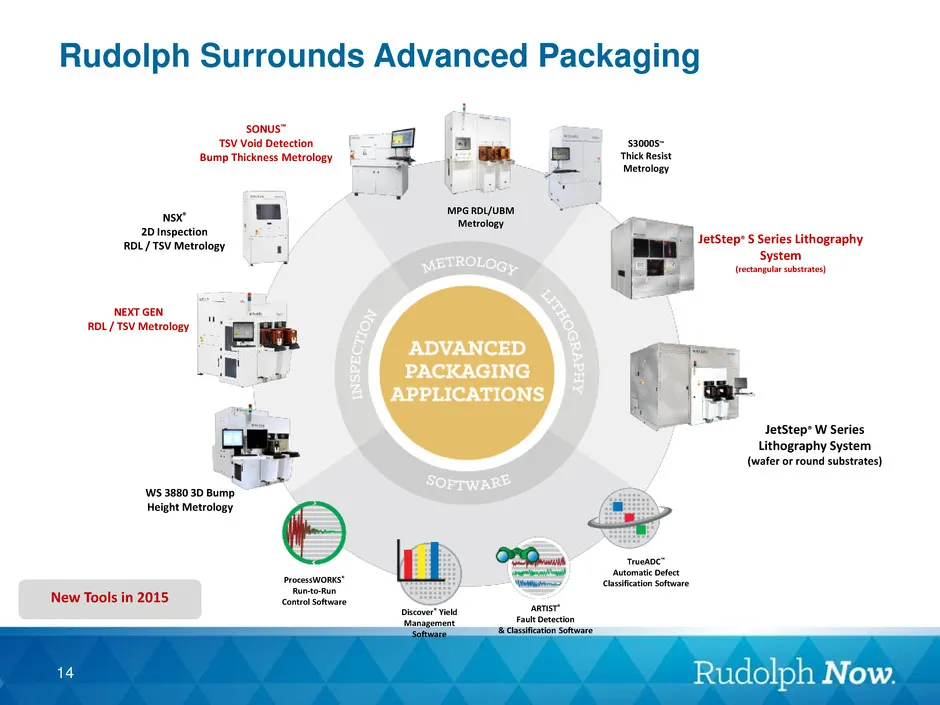
Rudolph Surrounds Advanced Packaging Discover® Yield Management Software JetStep® W Series Lithography System (wafer or round substrates) ProcessWORKS® Run-to-Run Control Software ARTIST® Fault Detection & Classification Software TrueADC™ Automatic Defect Classification Software WS 3880 3D Bump Heig
Slide 15: Rudolph Product Suite Enabling Advanced Packaging
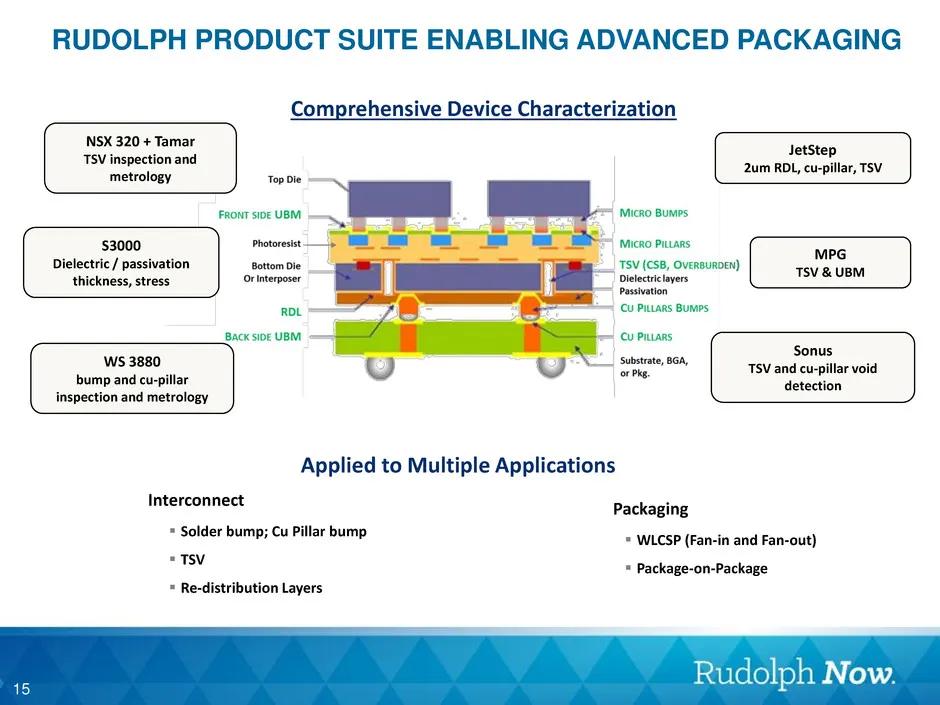
Interconnect Solder bump; Cu Pillar bump TSV Re-distribution Layers Packaging WLCSP (Fan-in and Fan-out) Package-on-Package MPG TSV & UBM NSX 320 + Tamar TSV inspection and metrology WS 3880 bump and cu-pillar inspection and metrology 15 RUDOLPH PRODUCT SUITE ENABLING ADVANCED PACKAGING
Slide 16: Rudolph Advantage: System Configurability
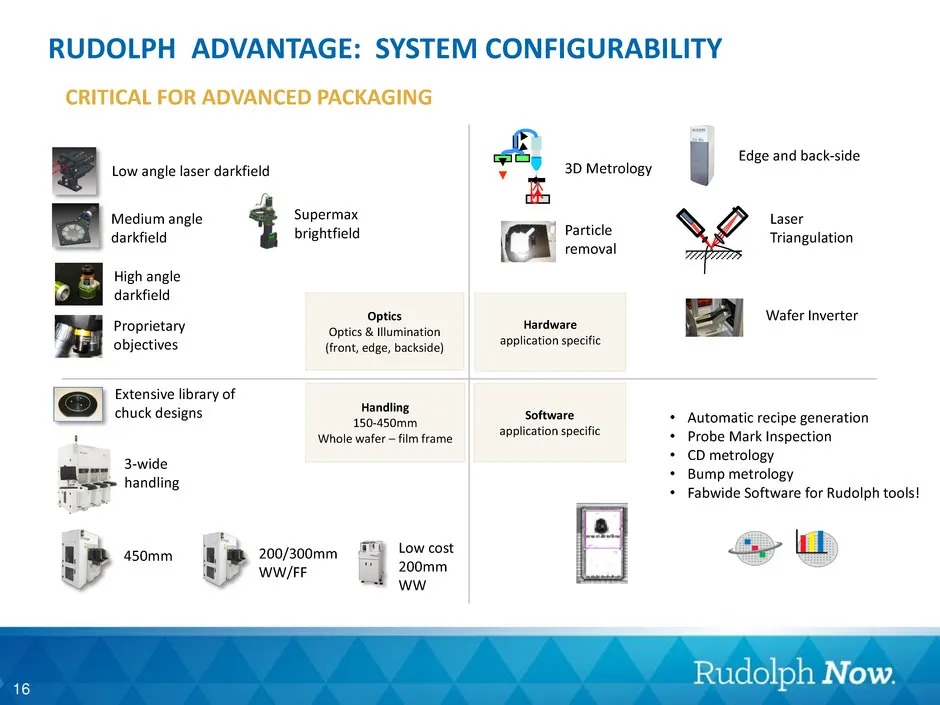
Supermax brightfield High angle darkfield Low angle laser darkfield Medium angle darkfield Proprietary objectives 200/300mm WW/FF Low cost 200mm WW Extensive library of chuck designs 450mm Edge and back-side Particle removal Laser Triangulation Wafer Inverter 3D Metrology • Automatic recipe generati
Slide 17: Changing Dynamics in Process Control Software
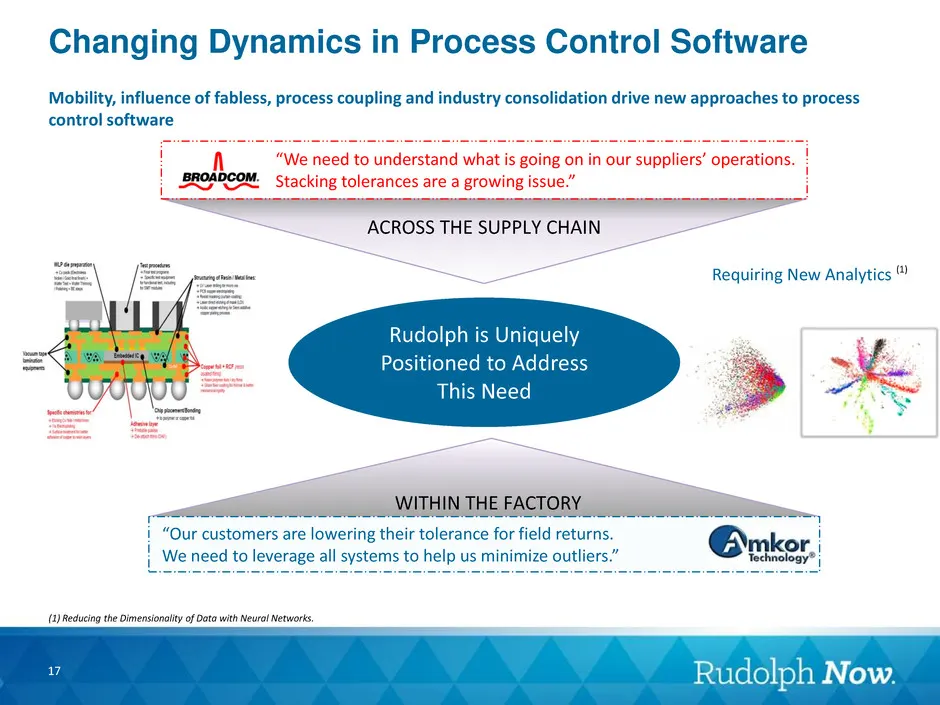
ACROSS THE SUPPLY CHAIN “We need to understand what is going on in our suppliers’ operations. Stacking tolerances are a growing issue.” WITHIN THE FACTORY “Our customers are lowering their tolerance for field returns. We need to leverage all systems to help us minimize outliers.” Changing Dynamics i
Slide 18: The Strategic Value of Rudolph's Software Solution
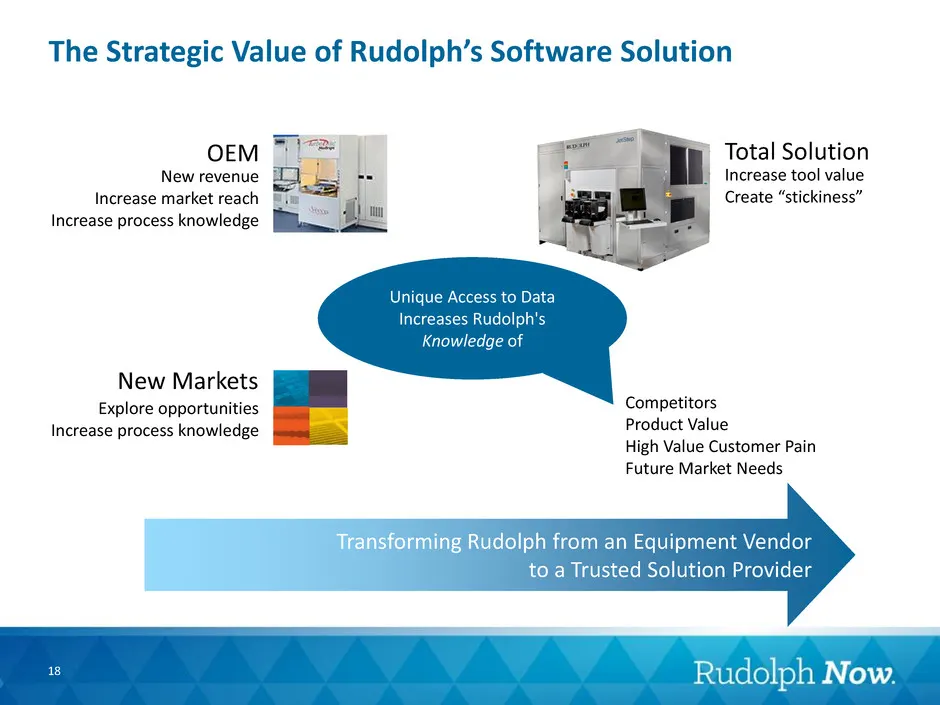
Total Solution Increase tool value Create “stickiness” OEM New revenue Increase market reach Increase process knowledge New Markets Explore opportunities Increase process knowledge Unique Access to Data Increases Rudolph’s Knowledge of Competitors Product Value High Value Customer Pain Future Market
Slide 19: JetStep Lithography Enables Advances in WLP
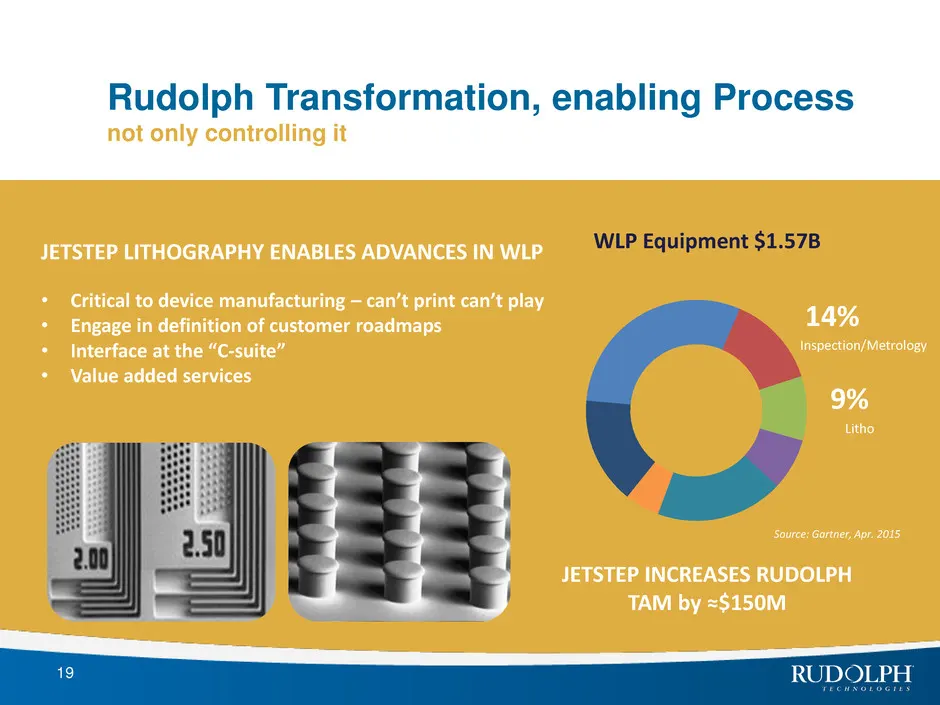
Rudolph Transformation, enabling Process not only controlling it JETSTEP LITHOGRAPHY ENABLES ADVANCES IN WLP • Critical to device manufacturing – can’t print can’t play • Engage in definition of customer roadmaps • Interface at the “C-suite” • Value added services Inspection/Metrology Litho WLP Equi
Slide 20: Lithography raises Rudolph's importance in Advanced Packaging
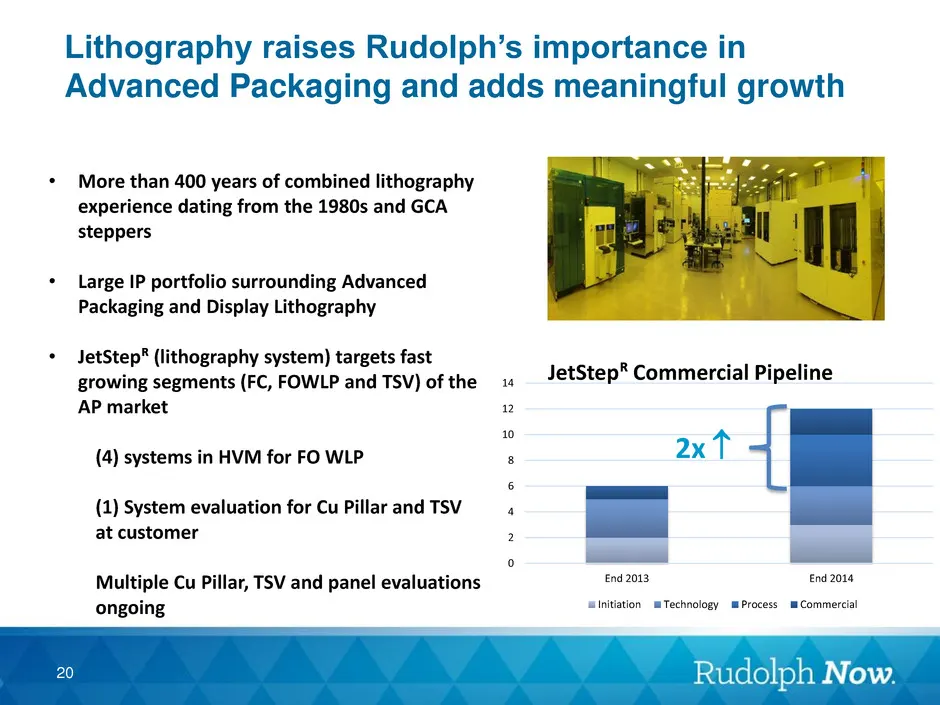
Lithography raises Rudolph’s importance in Advanced Packaging and adds meaningful growth 0 2 4 6 8 10 12 14 End 2013 End 2014 Initiation Technology Process Commercial 2x • More than 400 years of combined lithography experience dating from the 1980s and GCA steppers • Large IP portfolio surrounding
Slide 21: Lithography Market
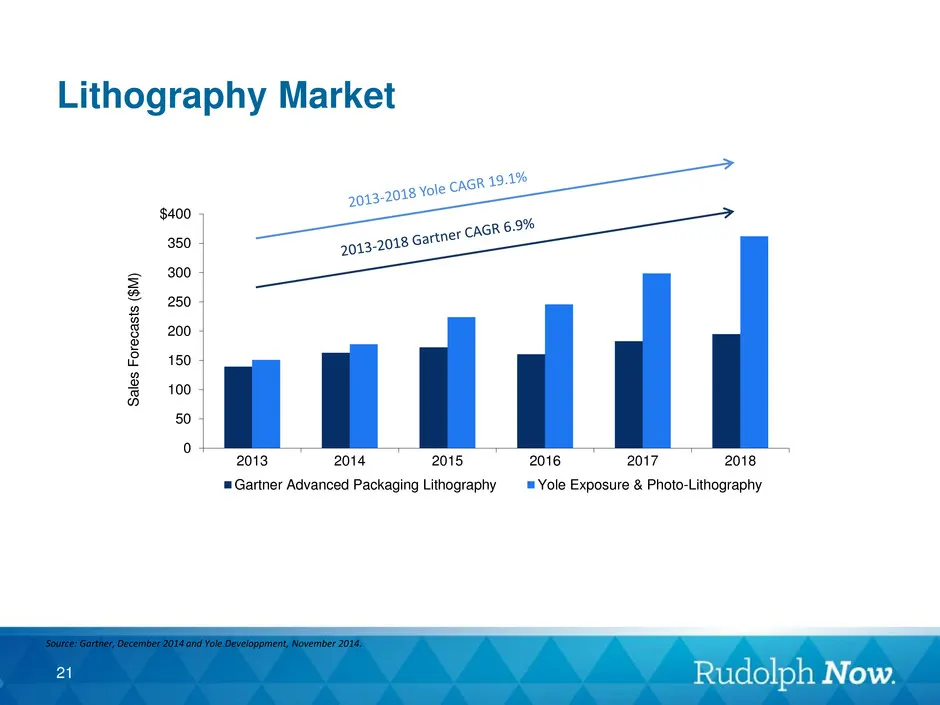
Lithography Market 0 50 100 150 200 250 300 350 $400 2013 2014 2015 2016 2017 2018 Sa les Fore ca sts ($ M) Gartner Advanced Packaging Lithography Yole Exposure & Photo-Lithography Source: Gartner, December 2014 and Yole Developpment, November 2014. 21
Slide 22: JetStep System the Complete Advanced Packaging System
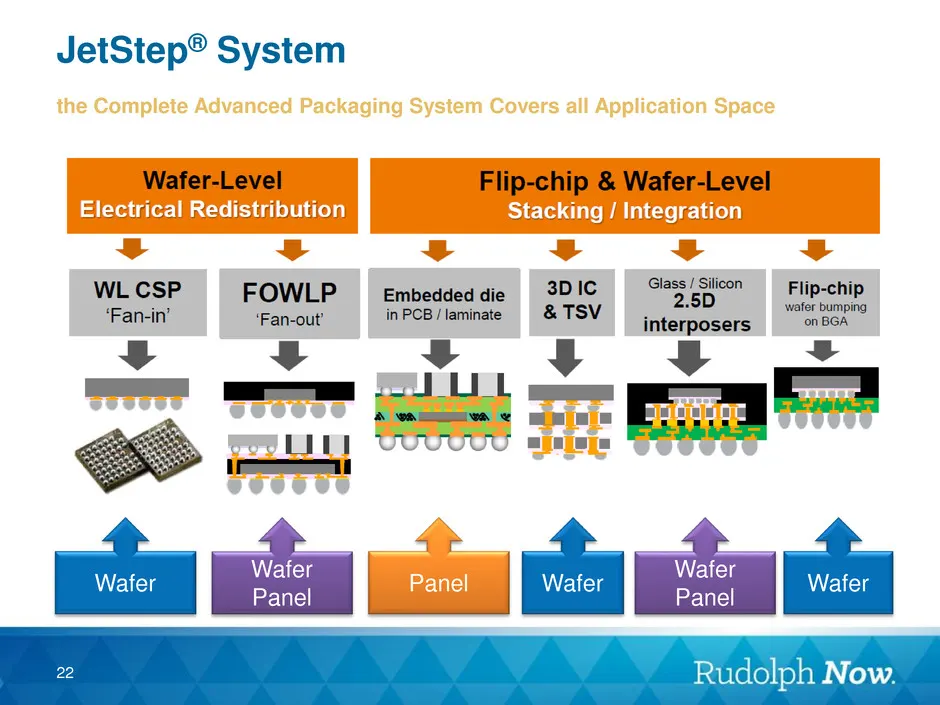
JetStep® System the Complete Advanced Packaging System Covers all Application Space Wafer Wafer Panel Panel Wafer Wafer Panel Wafer 22
Slide 23: Product Offering Evolution Since 1999 IPO
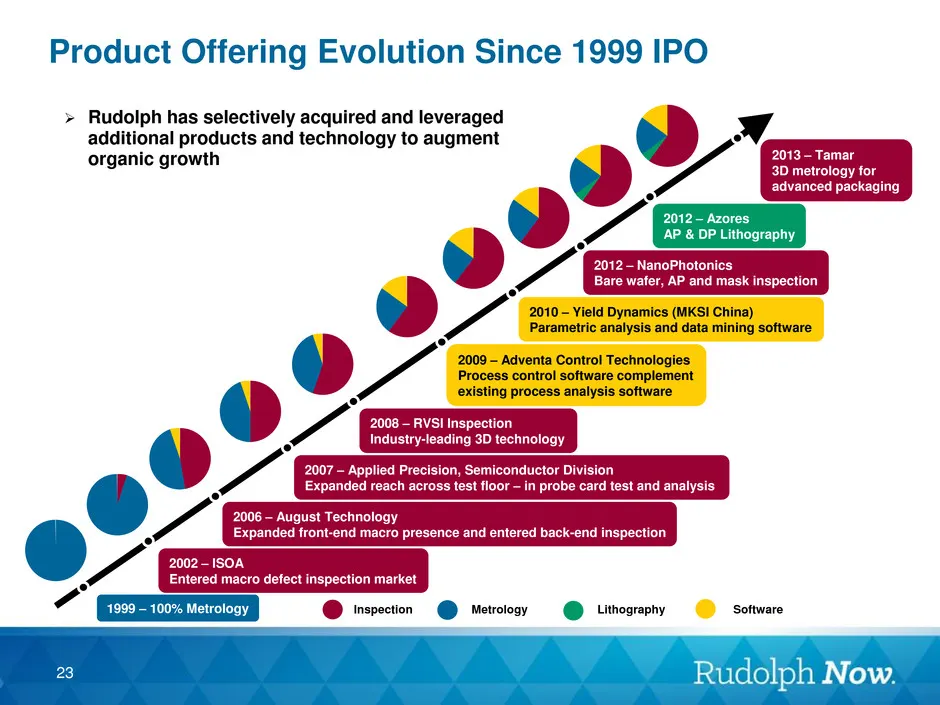
1999 – 100% Metrology 2002 – ISOA Entered macro defect inspection market 2006 – August Technology Expanded front-end macro presence and entered back-end inspection 2007 – Applied Precision, Semiconductor Division Expanded reach across test floor – in probe card test and analysis 2008 – RVSI Inspecti
Slide 24: Customer Centric Focus
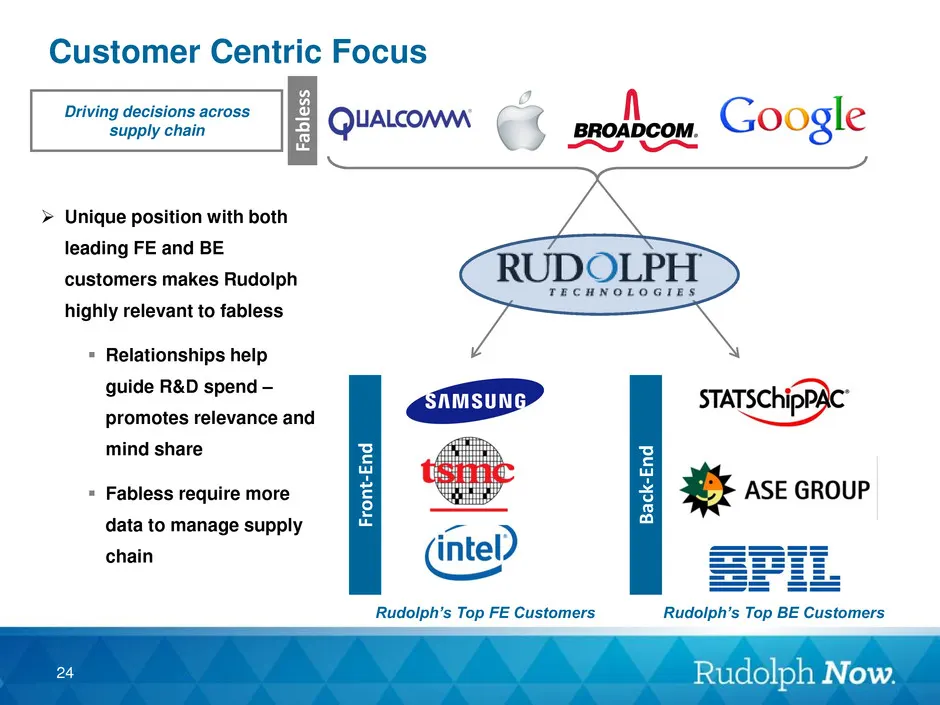
Customer Centric Focus Driving decisions across supply chain Unique position with both leading FE and BE customers makes Rudolph highly relevant to fabless Relationships help guide R&D spend – promotes relevance and mind share Fabless require more data to manage supply chain Fr o n t- En d B a
Slide 25: Financials
Financials 25
Slide 26: Balance Sheet – Highlights
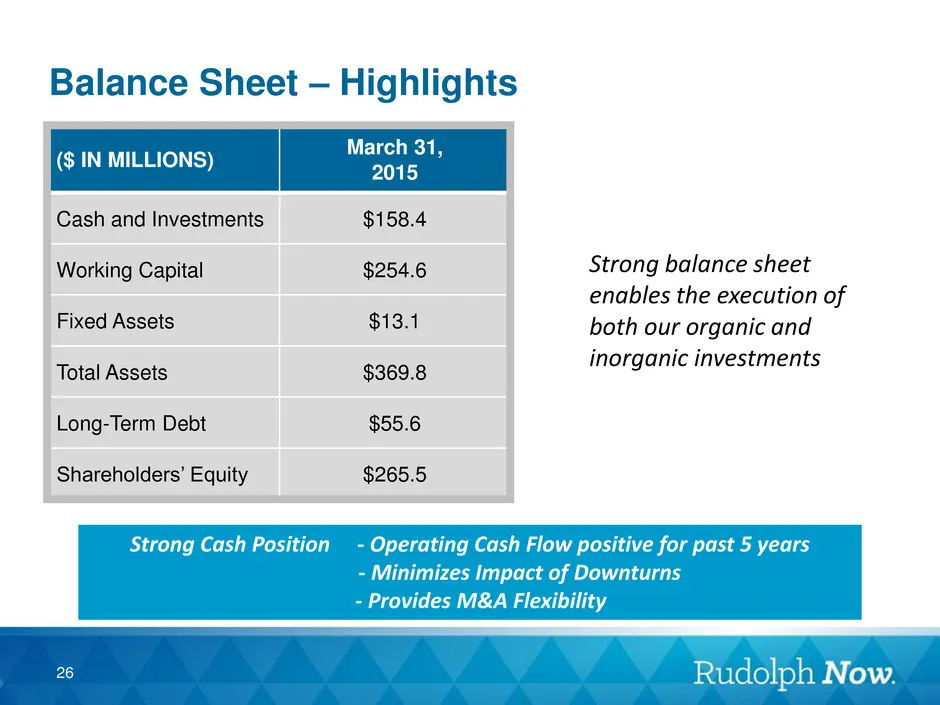
Balance Sheet – Highlights ($ IN MILLIONS) March 31, 2015 Cash and Investments $158.4 Working Capital $254.6 Fixed Assets $13.1 Total Assets $369.8 Long-Term Debt $55.6 Shareholders’ Equity $265.5 Strong Cash Position - Operating Cash Flow positive for past 5 years - Minimizes Impact of Downturns -
Slide 27: 2015 Q1 Results Non-GAAP
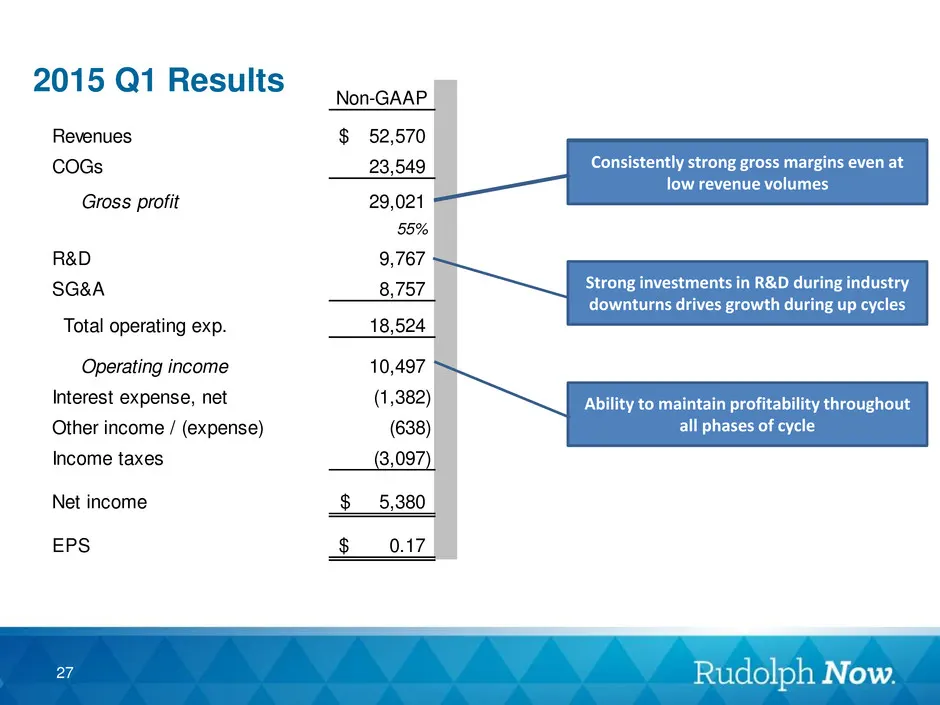
2015 Q1 Results Non-GAAP Revenues 52,570$ COGs 23,549 Gross profit 29,021 55% R&D 9,767 SG&A 8,757 Total operating exp. 18,524 Operating income 10,497 Interest expense, net (1,382) Other income / (expense) (638) Income taxes (3,097) Net income 5,380$ EPS 0.17$ Strong investments in R&D during indust
Slide 28: Operating performance 2Q15 Guidance
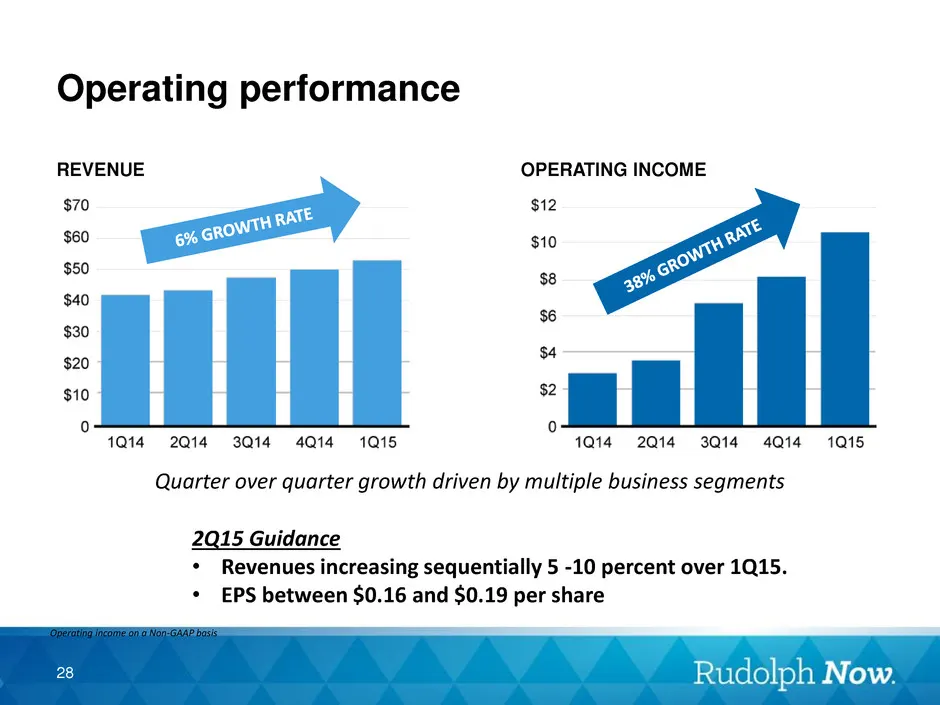
Operating performance 2Q15 Guidance • Revenues increasing sequentially 5 -10 percent over 1Q15. • EPS between $0.16 and $0.19 per share Operating income on a Non-GAAP basis Quarter over quarter growth driven by multiple business segments REVENUE OPERATING INCOME 28
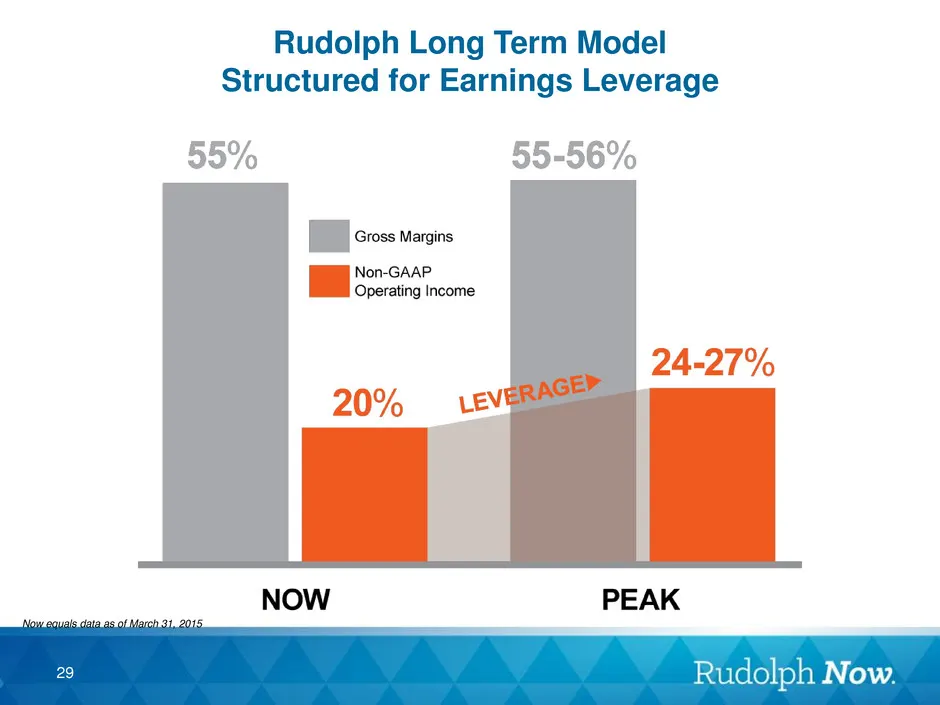
Slide 29: Rudolph Long Term Model
Rudolph Long Term Model Structured for Earnings Leverage Now equals data as of March 31, 2015 29
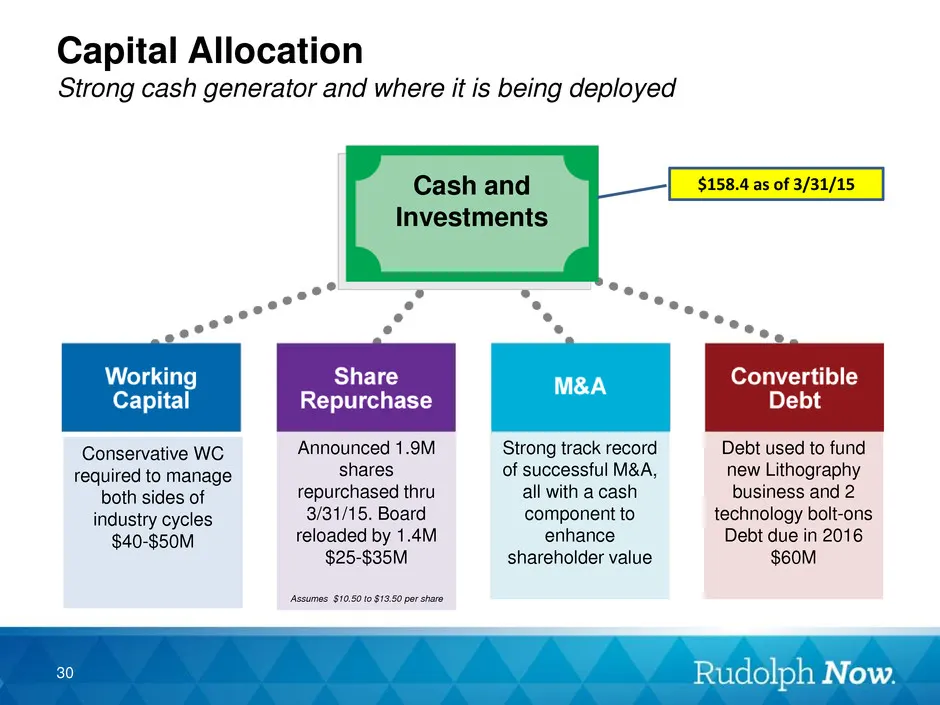
Slide 30: Capital Allocation
Capital Allocation Strong cash generator and where it is being deployed Conservative WC required to manage both sides of industry cycles $40-$50M Announced 1.9M shares repurchased thru 3/31/15. Board reloaded by 1.4M $25-$35M Assumes $10.50 to $13.50 per share Strong track record of successful M&A,
Slide 31: Summary
SUMMARY Your Company is driving growth and shareholder value 31
Slide 32: Thank You
Thank You 22 Rudolph Now.
Source: SEC EDGAR · 8-K filed May 22, 2015
More decks from Rudolph Technologies Inc
 Merger or Acquisition (June 2019)12 slides · Jun 24, 2019
 Merger or Acquisition (June 2019)18 slides · Jun 24, 2019
 Investor Day (September 2017)79 slides · Sep 14, 2017
 Investor Presentation (February 2015)13 slides · Feb 4, 2015
 Investor Day (February 2015)13 slides · Feb 4, 2015
 Investor Day (February 2015)15 slides · Feb 4, 2015