Limestone Bancorp — Porter Bancorp — Investor Presentation (February 2009)
38 slides from Limestone Bancorp's investor presentation, Feb 9, 2009
Slide 1: Porter Bancorp February 2009
Slide: 1 Title: NASDAQ: PBIB February 2009
Slide 2: Disclaimer
Slide: 2 Disclaimer This presentation contains forward-looking statements that involve risks and uncertainties. These forward-looking statements are based on management’s current expectations. Porter Bancorp’s actual results in future periods may differ materially from those currently expected due t
Slide 3: Company Overview
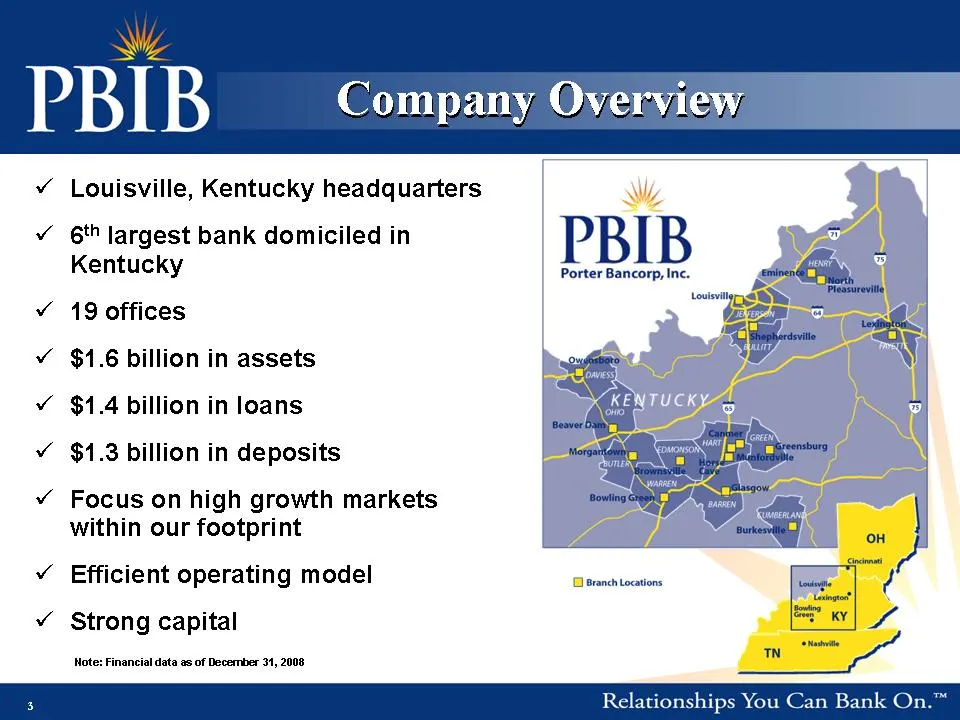
Slide: 3 Louisville, Kentucky headquarters 6th largest bank domiciled in Kentucky 19 offices $1.6 billion in assets $1.4 billion in loans $1.3 billion in deposits Focus on high growth markets within our footprint Efficient operating model Strong capital Note: Financial data as of December 31, 2008 C
Slide 4: Market Overview
Slide: 4 Title: Market Overview Body: Louisville and Bullitt County 16th largest city in U.S. and largest city in Kentucky Above average growth rates for economy and jobs Large employers include UPS, GE, Humana, YUM! Brands, Ford New UPS hub attracting distribution companies – Best Buy (“Geek Squad”
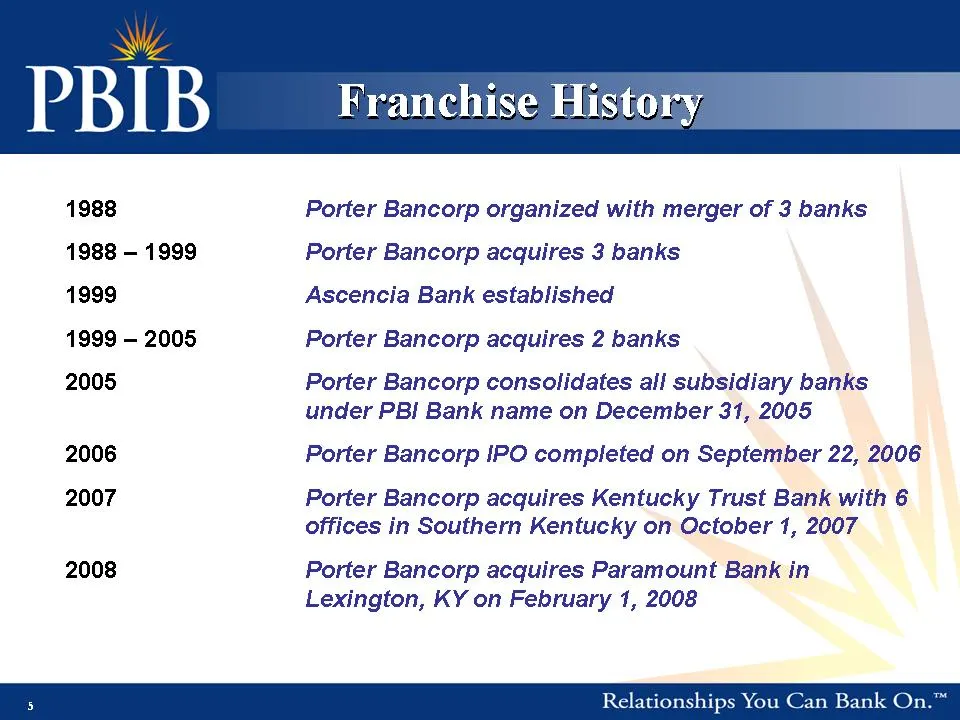
Slide 5: Franchise History
Slide: 5 Franchise History Porter Bancorp organized with merger of 3 banks 1988 – 1999 Porter Bancorp acquires 3 banks Ascencia Bank established 1999 – 2005 Porter Bancorp acquires 2 banks Porter Bancorp consolidates all subsidiary banks under PBI Bank name on December 31, 2005 Porter Bancorp IPO co
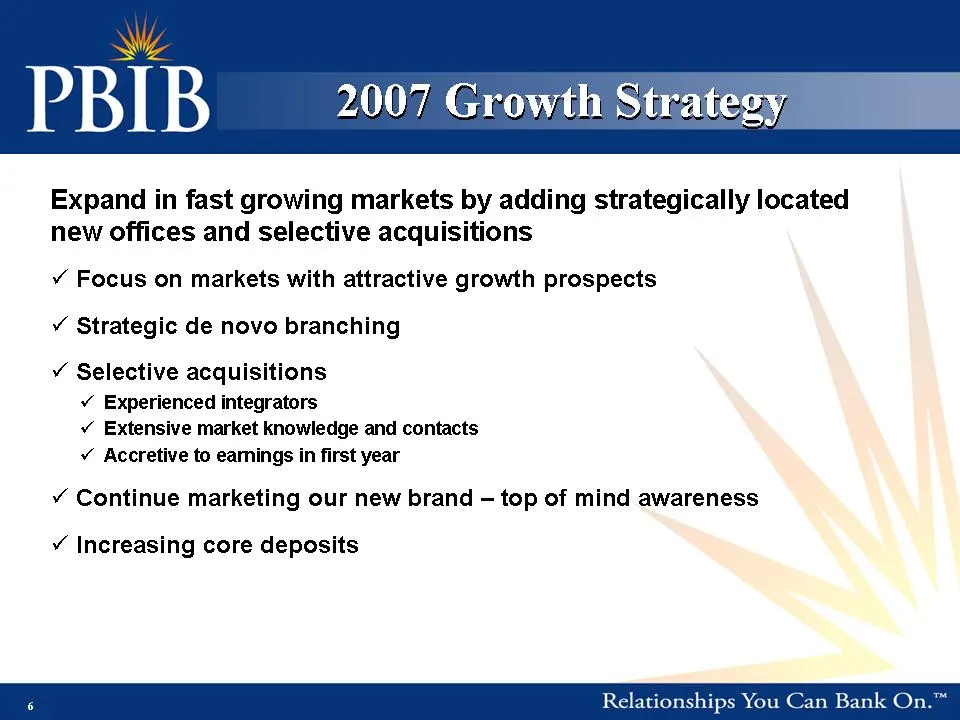
Slide 6: 2007 Growth Strategy
Slide: 6 Expand in fast growing markets by adding strategically located new offices and selective acquisitions Focus on markets with attractive growth prospects Strategic de novo branching Selective acquisitions Experienced integrators Extensive market knowledge and contacts Accretive to earnings in
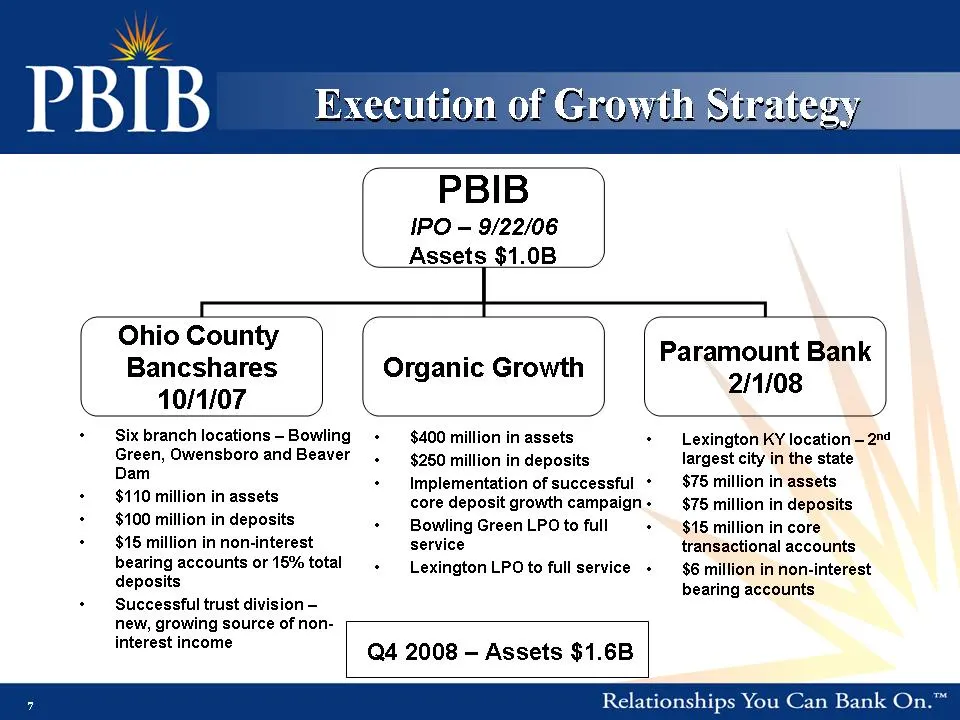
Slide 7: Execution of Growth Strategy
Slide: 7 Execution of Growth Strategy Body: Six branch locations – Bowling Green, Owensboro and Beaver Dam $110 million in assets $100 million in deposits $15 million in non-interest bearing accounts or 15% total deposits Successful trust division – new, growing source of non-interest income Body: L
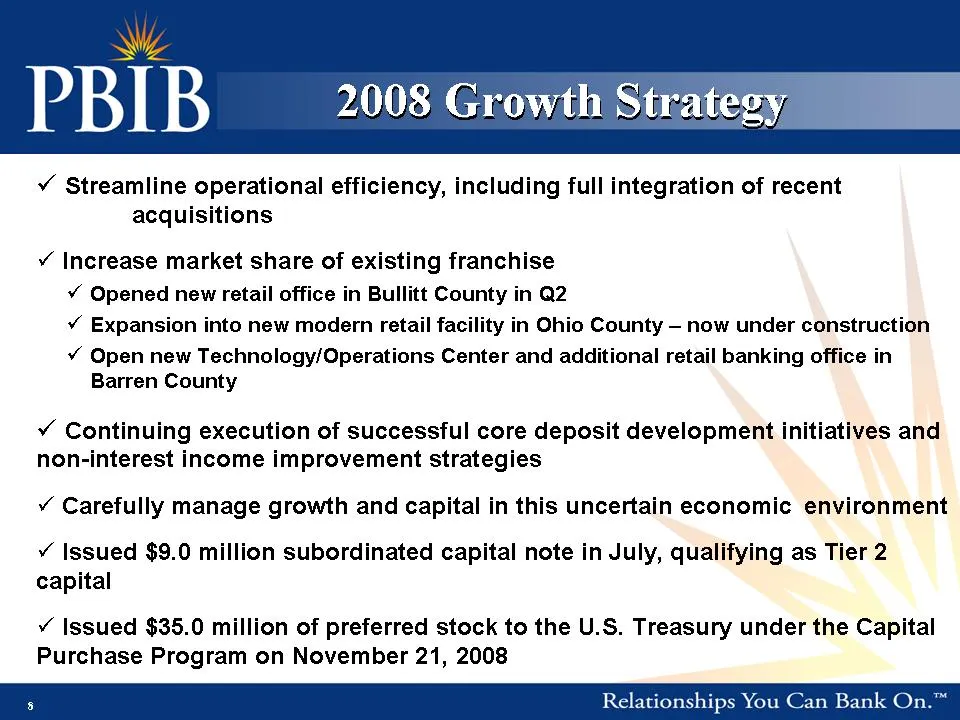
Slide 8: 2008 Growth Strategy
Slide: 8 Streamline operational efficiency, including full integration of recent acquisitions Increase market share of existing franchise Opened new retail office in Bullitt County in Q2 Expansion into new modern retail facility in Ohio County – now under construction Open new Technology/Operations
Slide 9: Financial Highlights
Slide: 9 Financial Highlights
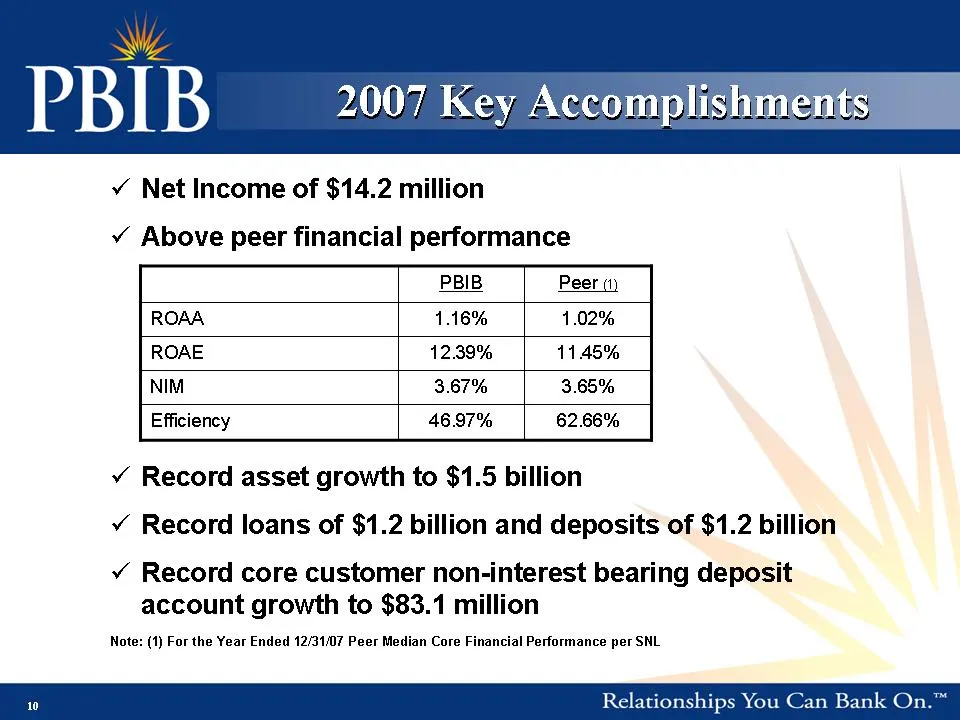
Slide 10: 2007 Key Accomplishments
Slide: 10 2007 Key Accomplishments Net Income of $14.2 million Above peer financial performance Record asset growth to $1.5 billion Record loans of $1.2 billion and deposits of $1.2 billion Record core customer non-interest bearing deposit account growth to $83.1 million Note: (1) For the Year Ended
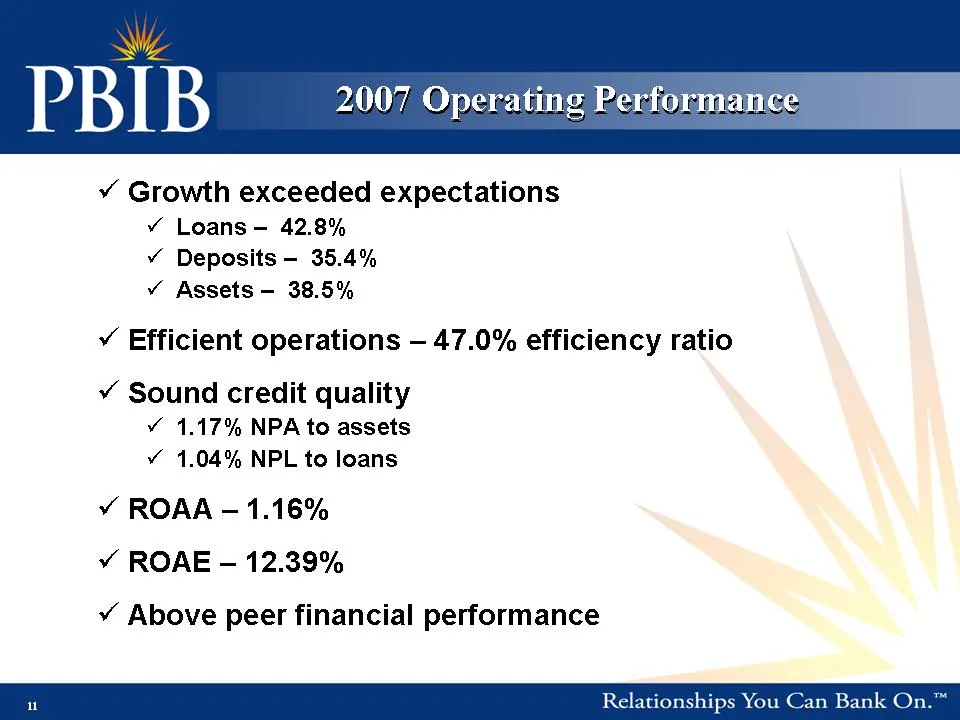
Slide 11: 2007 Operating Performance
Slide: 11 2007 Operating Performance Growth exceeded expectations Loans – 42.8% Deposits – 35.4% Assets – 38.5% Efficient operations – 47.0% efficiency ratio Sound credit quality 1.17% NPA to assets 1.04% NPL to loans ROAA – 1.16% ROAE – 12.39% Above peer financial performance
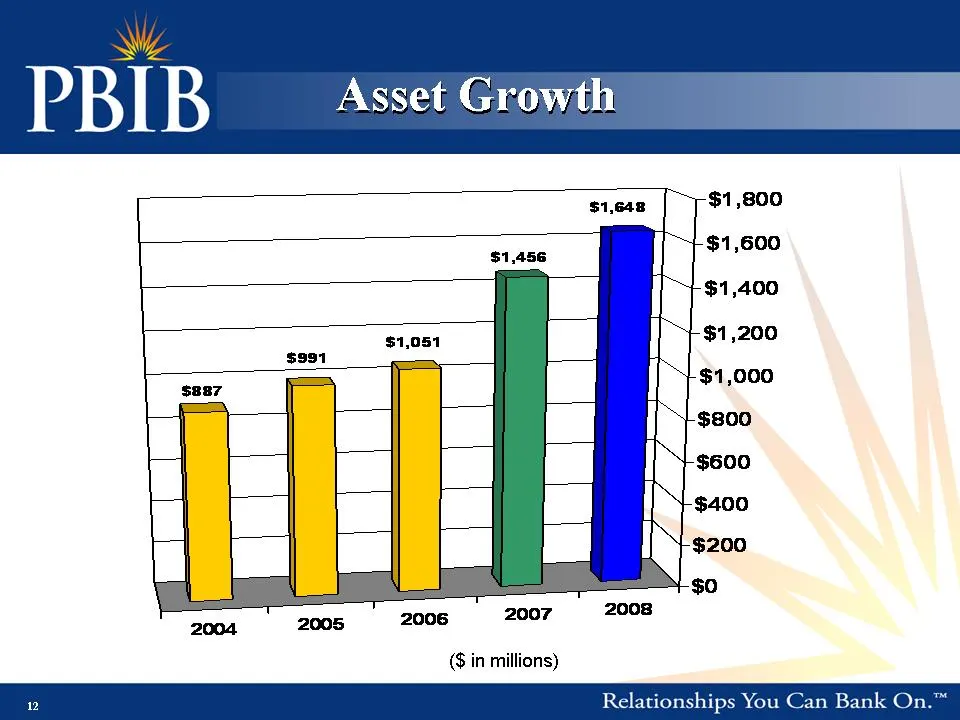
Slide 12: Asset Growth
Slide: 12 Asset Growth ($ in millions) 2004 2005 2006 2007 2008 $887 $991 $1,051 $1,456 $1,648
Slide 13: Loan Growth
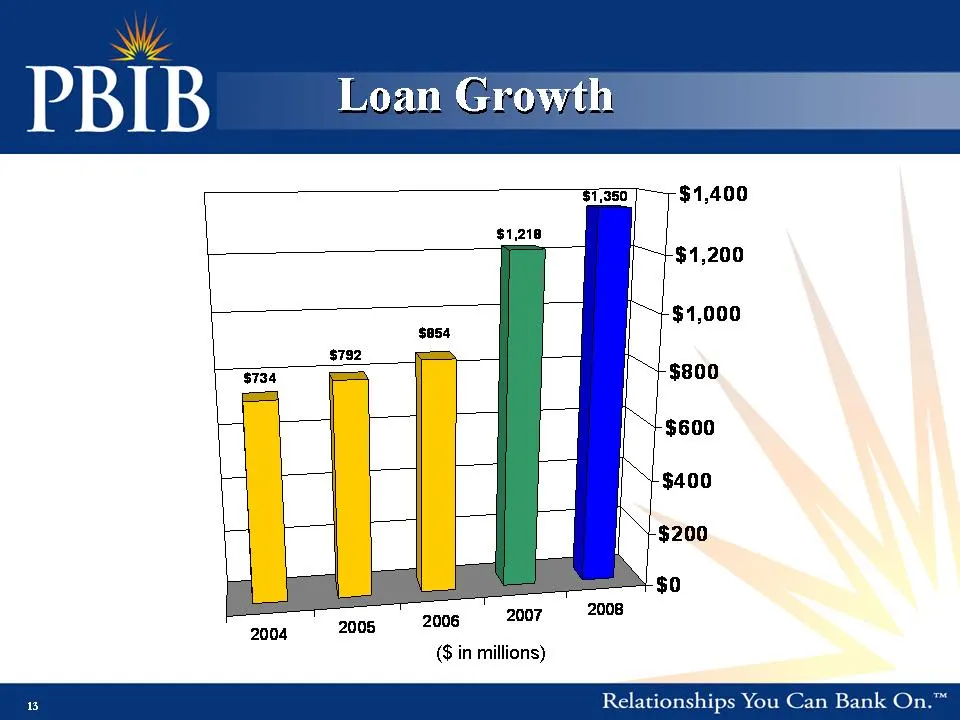
Slide: 13 Loan Growth ($ in millions) 2004 2005 2006 2007 2008 $734 $792 $854 $1,218 $1,350
Slide 14: Deposit Growth
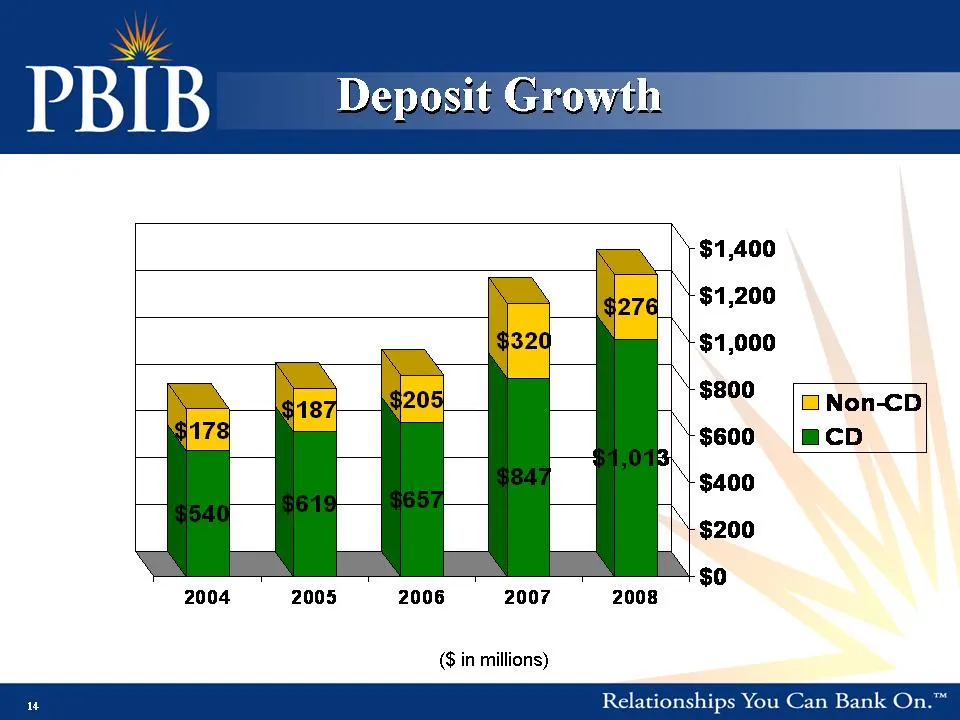
Slide: 14 Deposit Growth ($ in millions) 2004 2005 2006 2007 2008 CD $540 $619 $657 $847 $1,013 Non-CD $178 $187 $205 $320 $276
Slide 15: Transactional Account Growth
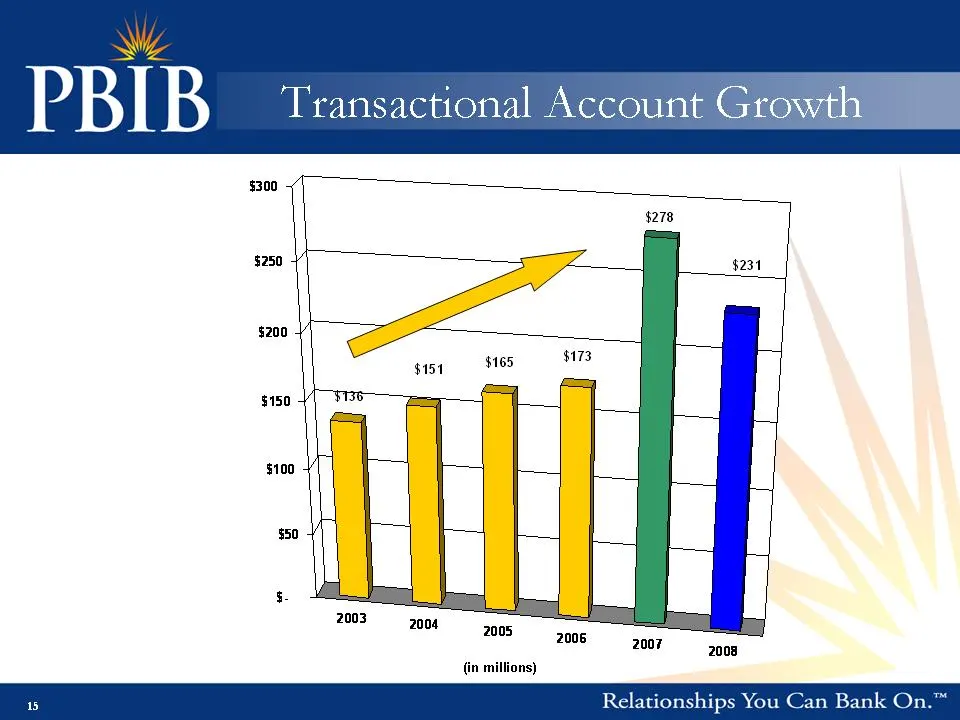
Slide: 15 Title: Transactional Account Growth (in millions)
Slide 16: Strong Net Income
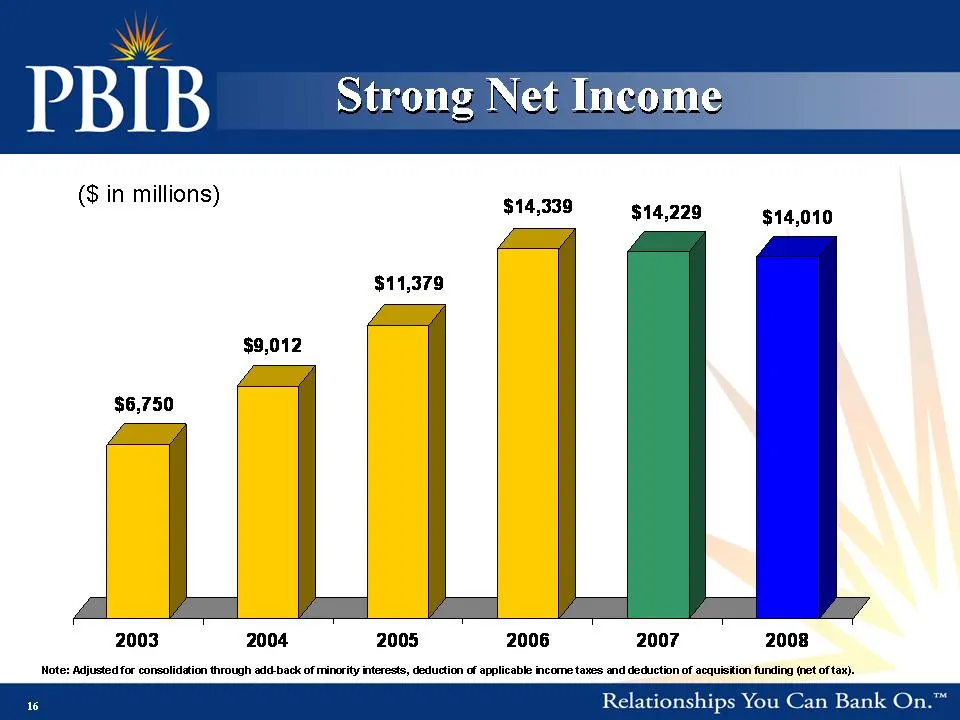
Slide: 16 Strong Net Income ($ in millions) Note: Adjusted for consolidation through add-back of minority interests, deduction of applicable income taxes and deduction of acquisition funding (net of tax). 2003 2004 2005 2006 2007 2008 $6,750 $9,012 $11,379 $14,339 $14,229 $14,010
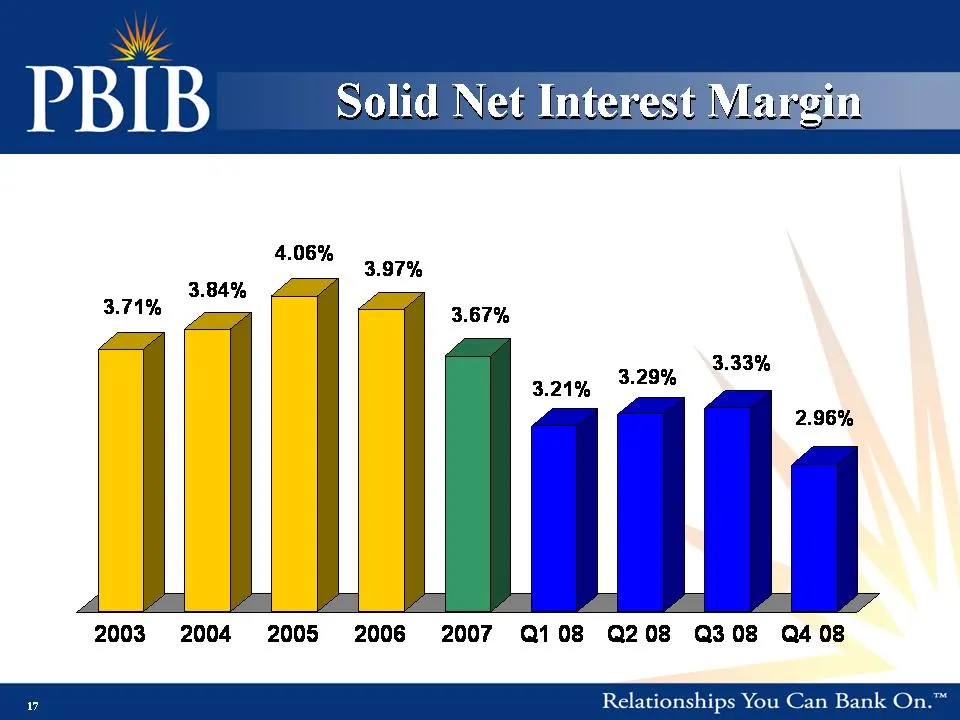
Slide 17: Solid Net Interest Margin
Slide: 17 Solid Net Interest Margin 2003 2004 2005 2006 2007 Q1 08 Q2 08 Q3 08 Q4 08 3.71% 3.84% 4.06% 3.97% 3.67% 3.21% 3.29% 3.33% 2.96%
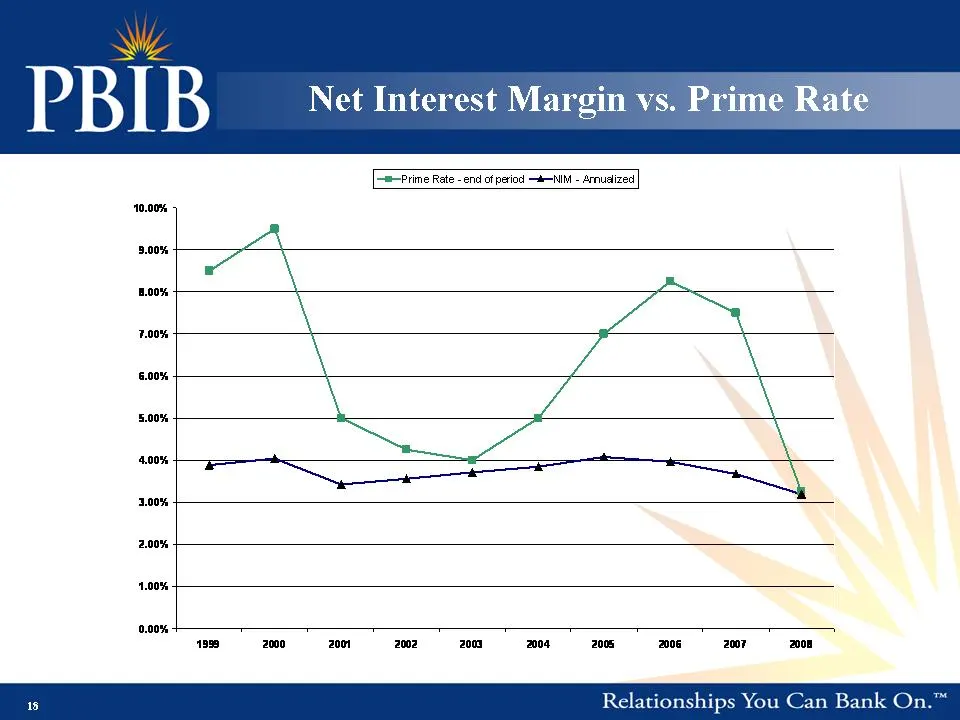
Slide 18: Net Interest Margin vs. Prime Rate
Slide: 18 Net Interest Margin vs. Prime Rate 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 Prime Rate - end of period 8.50% 9.50% 5.00% 4.25% 4.00% 5.00% 7.00% 8.25% 7.50% 3.25% NIM 3.89% 4.03% 3.42% 3.56% 3.71% 3.85% 4.07% 3.97% 3.67% 3.20%
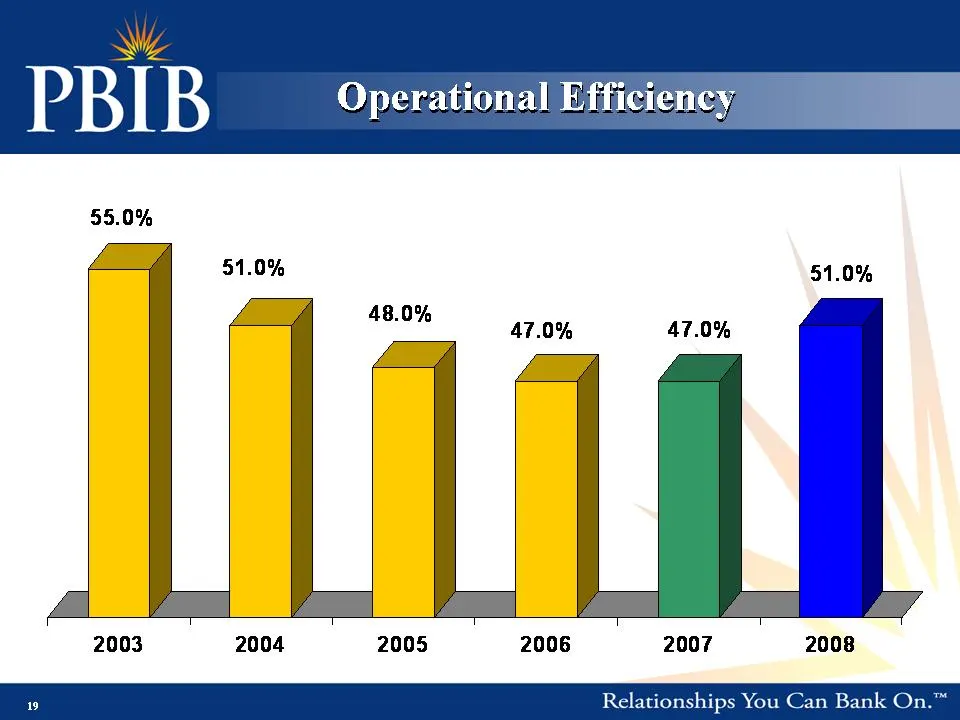
Slide 19: Operational Efficiency
Slide: 19 Operational Efficiency 2003 2004 2005 2006 2007 2008 TNCC 55.0% 51.0% 48.0% 47.0% 47.0% 51.0%
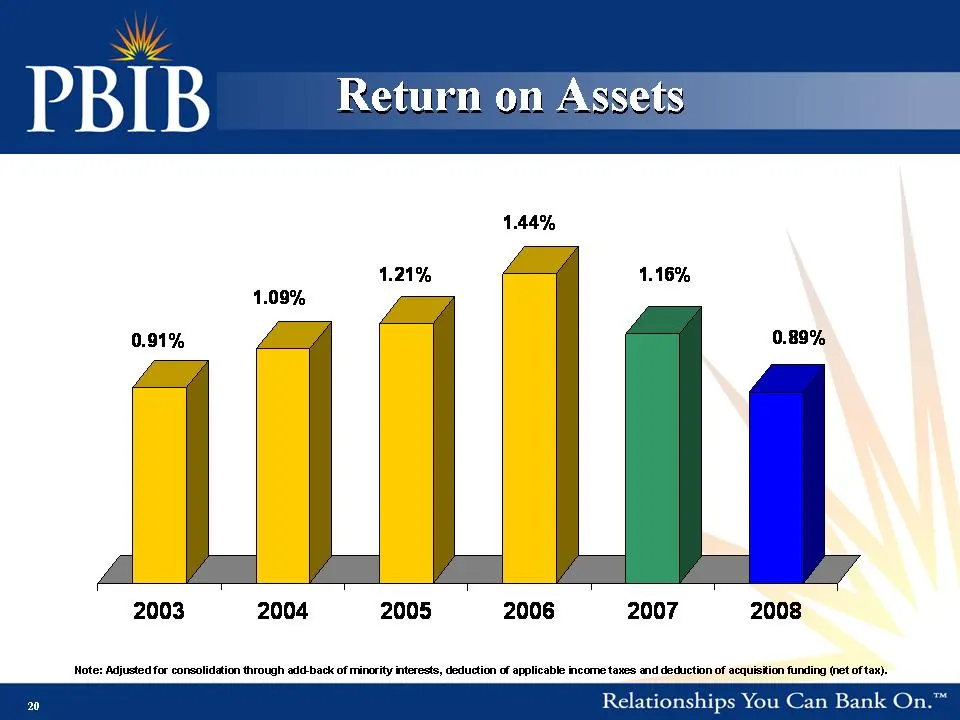
Slide 20: Return on Assets
Slide: 20 Return on Assets Note: Adjusted for consolidation through add-back of minority interests, deduction of applicable income taxes and deduction of acquisition funding (net of tax). 2003 2004 2005 2006 2007 2008 ROA 0.91% 1.09% 1.21% 1.44% 1.16% 0.89%
Slide 21: Return on Equity
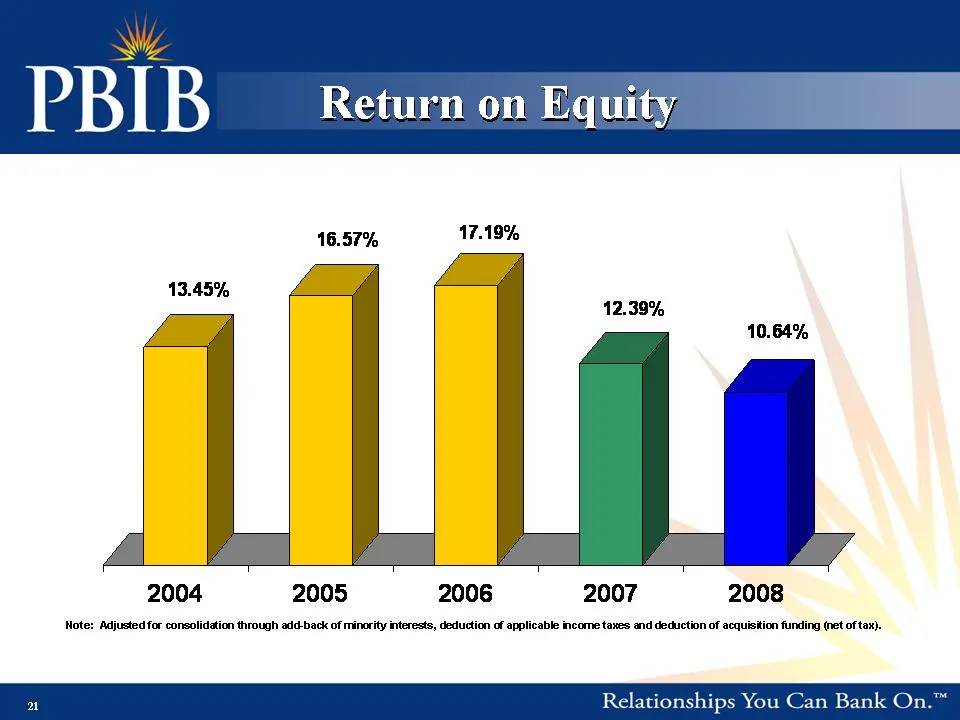
Slide: 21 Return on Equity Note: Adjusted for consolidation through add-back of minority interests, deduction of applicable income taxes and deduction of acquisition funding (net of tax). 2004 2005 2006 2007 2008 13.45% 16.57% 17.19% 12.39% 10.64%
Slide 22: 2008 Operating Performance
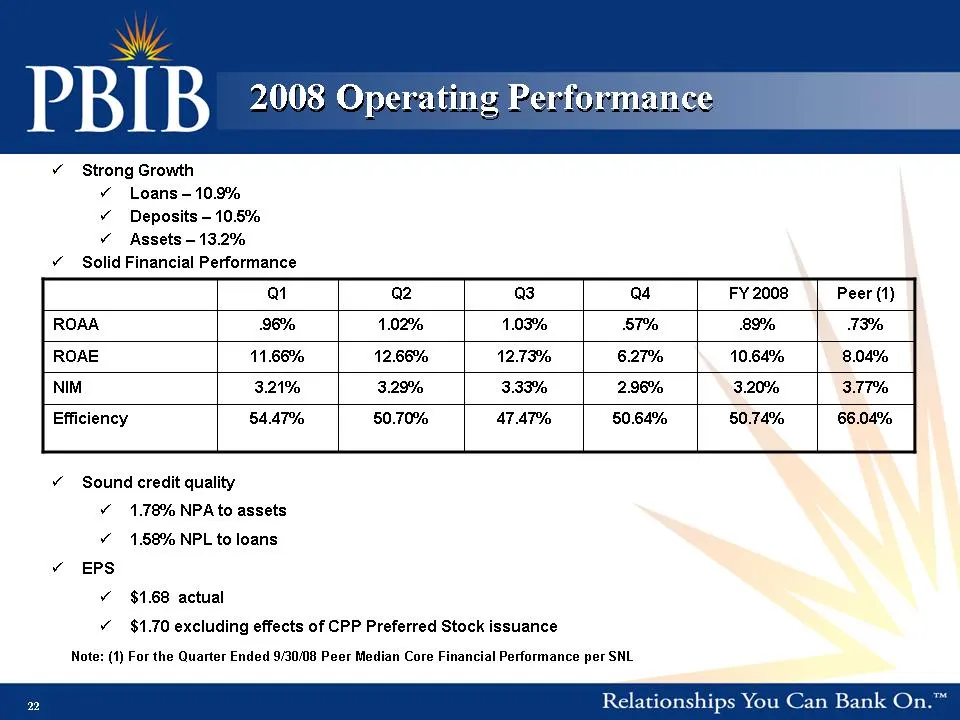
Slide: 22 2008 Operating Performance Strong Growth Loans – 10.9% Deposits – 10.5% Assets – 13.2% Solid Financial Performance Sound credit quality 1.78% NPA to assets 1.58% NPL to loans EPS $1.68 actual $1.70 excluding effects of CPP Preferred Stock issuance Note: (1) For the Quarter Ended 9/30/08 Pe
Slide 23: Loan Portfolio
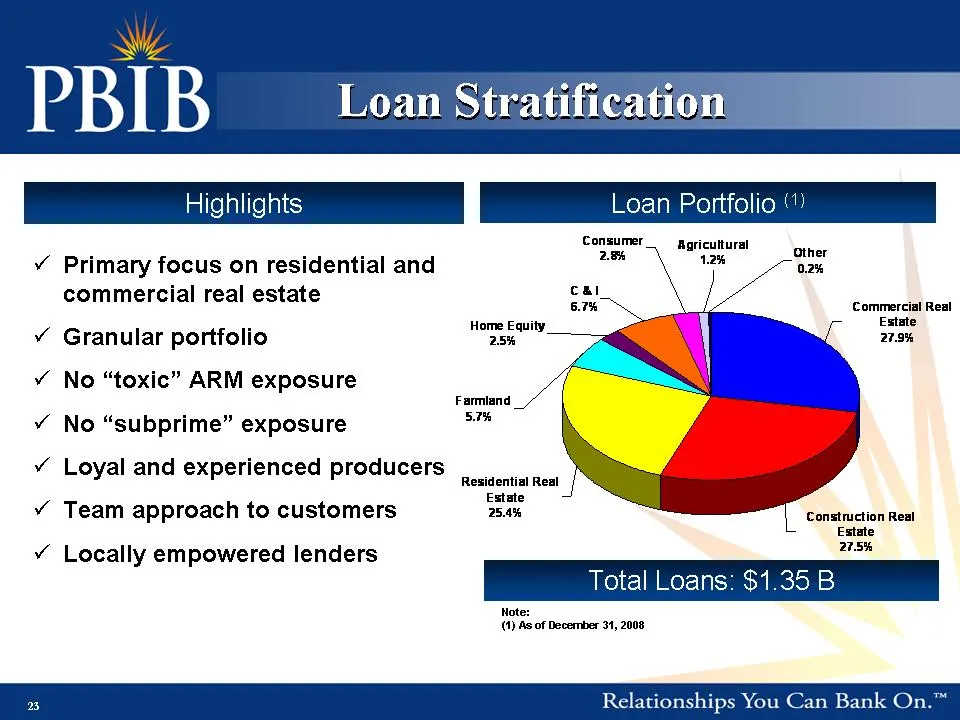
Slide: 23 Note: (1) As of December 31, 2008 Primary focus on residential and commercial real estate Granular portfolio No “toxic” ARM exposure No “subprime” exposure Loyal and experienced producers Team approach to customers Locally empowered lenders Loan Portfolio (1) Total Loans: $1.35 B Loan Stra
Slide 24: Construction Real Estate Composition
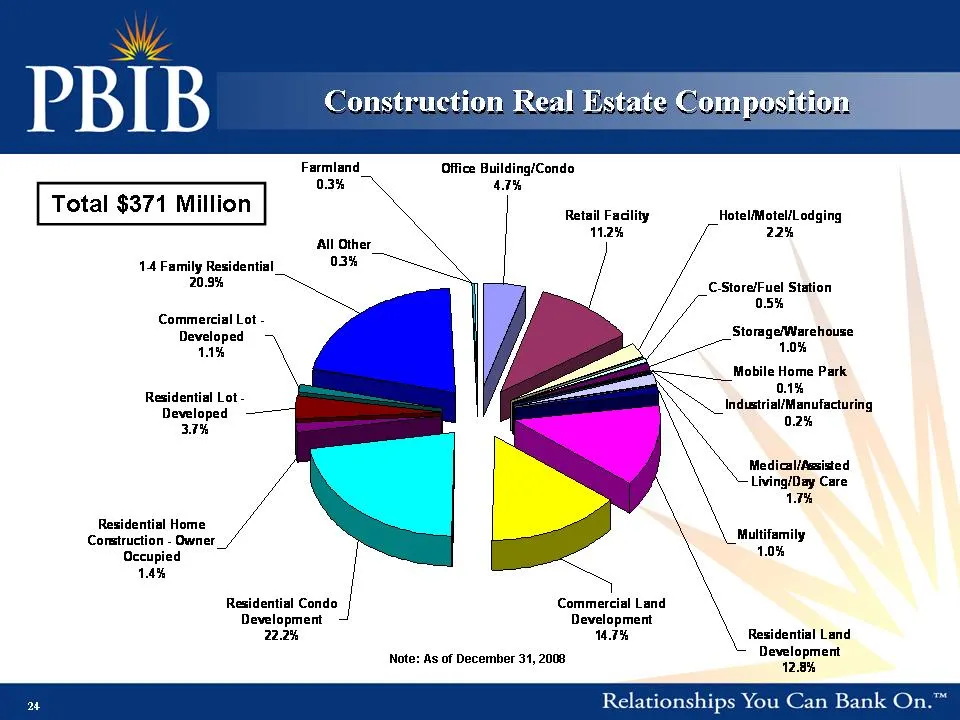
Slide: 24 Construction Real Estate Composition Note: As of December 31, 2008 Total $371 Million Total $371 Million Farmland 0.3% Storage/Warehouse 1.0% Office Building/Condo 4.7% Retail Facility 11.2% Hotel/Motel/Lodging 2.2% C-Store/Fuel Station 0.5%Mobile Home Park 0.1% Industrial/Manufacturing 0.
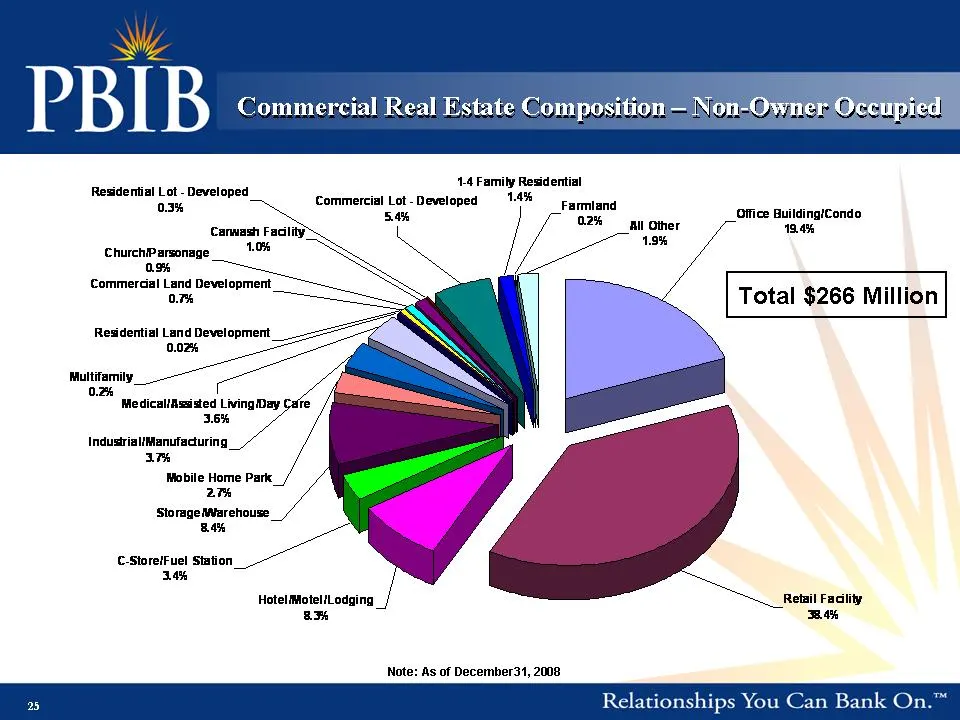
Slide 25: Commercial Real Estate Composition – Non-Owner Occupied
Slide: 25 Commercial Real Estate Composition – Non-Owner Occupied Note: As of December31, 2008 Total $266 Million Total $266 Million Office Building/Condo 19.4% All Other 1.9% Farmland 0.2% 1-4 Family Residential 1.4% Commercial Lot - Developed 5.4% Residential Lot - Developed 0.3% Carwash Facility
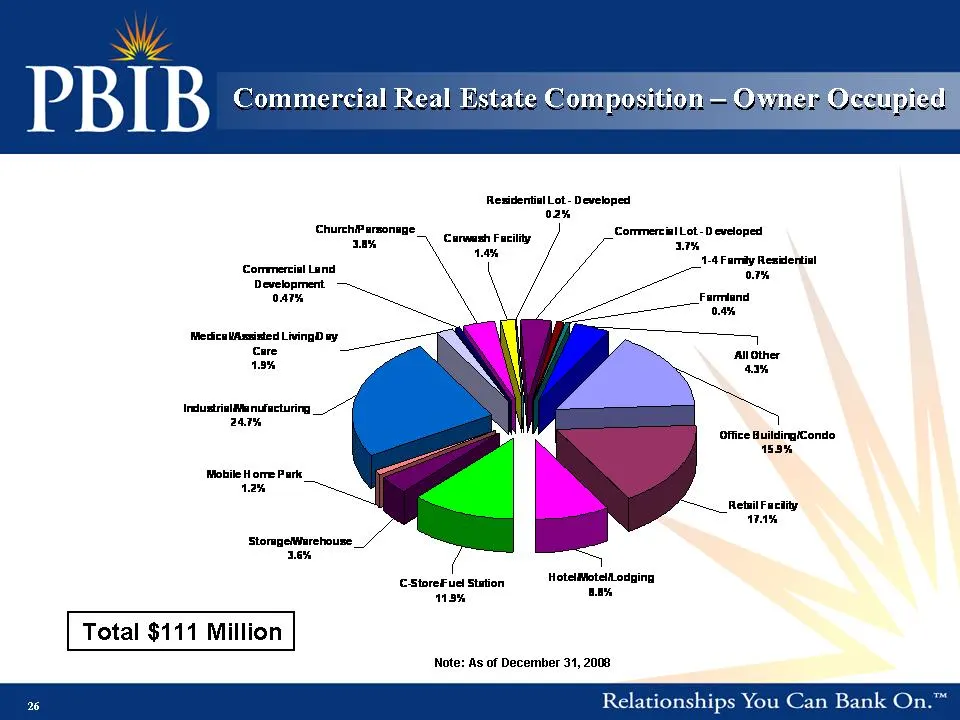
Slide 26: Commercial Real Estate Composition – Owner Occupied
Slide: 26 Commercial Real Estate Composition – Owner Occupied Note: As of December 31, 2008 Total $111 Million Total $111 Million Hotel/Motel/Lodging 8.8% C-Store/Fuel Station 11.9% Storage/Warehouse 3.6% Mobile Home Park 1.2% Industrial/Manufacturing 24.7% Medical/Assisted Living/Day Care 1.9% Comm
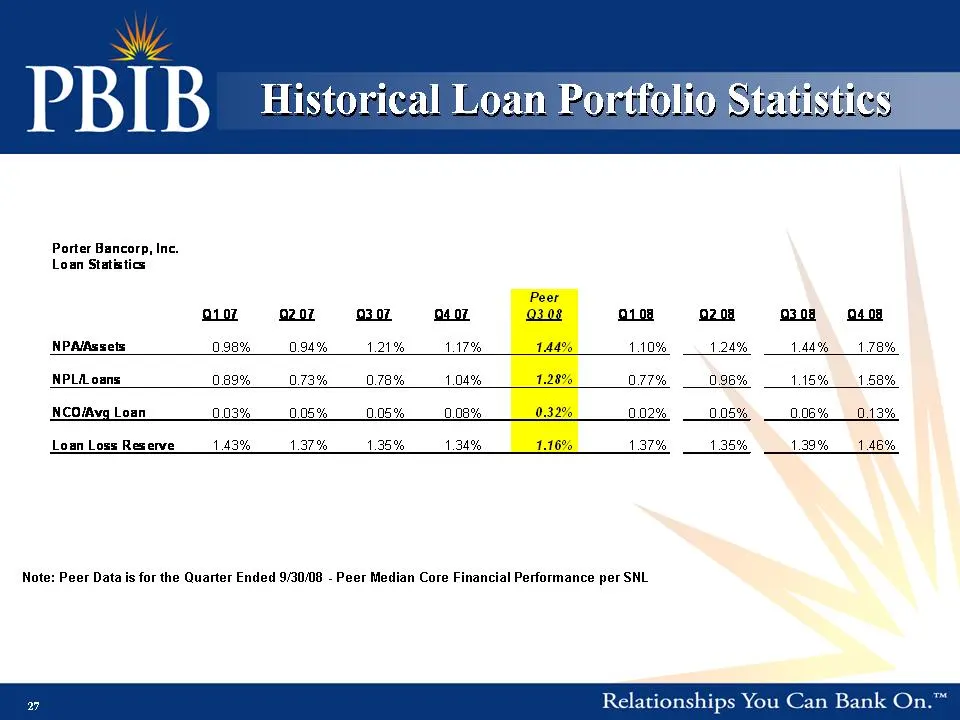
Slide 27: Historical Loan Portfolio Statistics
Slide: 27 Historical Loan Portfolio Statistics Note: Peer Data is for the Quarter Ended 9/30/08 - Peer Median Core Financial Performance per SNL Porter Bancorp, Inc. Loan Statistics Peer Q1 07 Q2 07 Q3 07 Q4 07 Q3 08 Q1 08 Q2 08 Q3 08 Q4 08 NPA/Assets 0.98% 0.94% 1.21% 1.17% 1.44% 1.10% 1.24% 1.44%
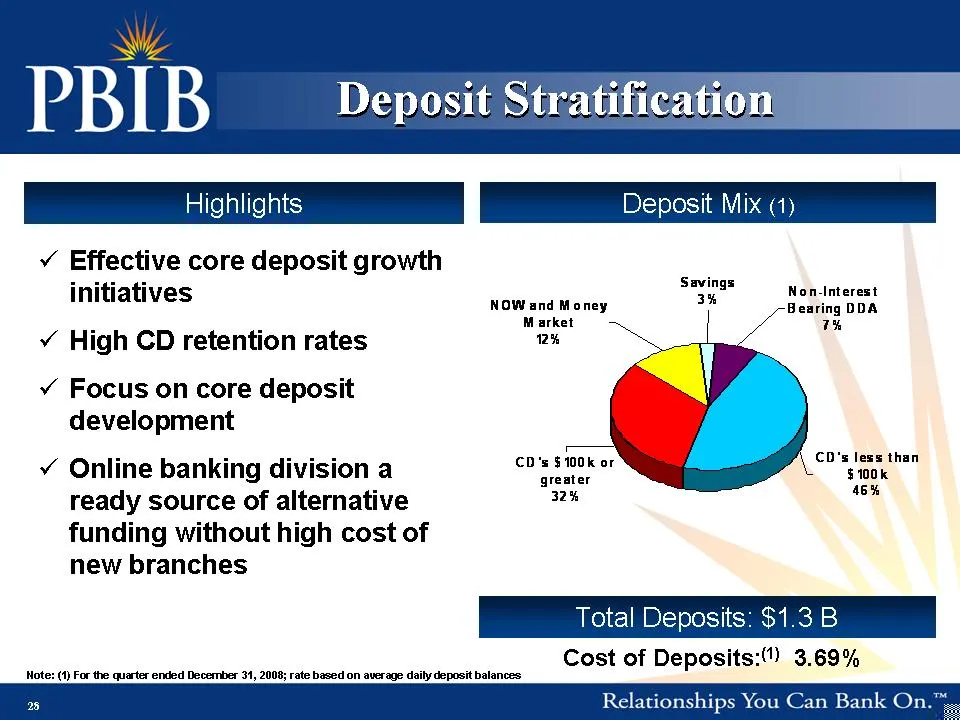
Slide 28: Deposit Mix
Slide: 28 Note: (1) For the quarter ended December 31, 2008; rate based on average daily deposit balances Deposit Mix (1) Total Deposits: $1.3 B Cost of Deposits:(1) 3.69% Effective core deposit growth initiatives High CD retention rates Focus on core deposit development Online banking division a re
Slide 29: Investment Highlights
Slide: 29 Investment Highlights
Slide 30: Operating Strengths
Slide: 30 Experienced management team Extensive market knowledge and community relationships Acquisition and integration capabilities Scalable operating platform Highly efficient organizational structure Diversified funding sources Highly focused on profits Strong capital Operating Strengths
Slide 31: Investment Highlights
Slide: 31 Attractive, diversified growth markets Successful history of executing growth strategy Scalable platform for expansion Efficient operating model Solid operating performance Undervalued investment opportunity Investment Highlights
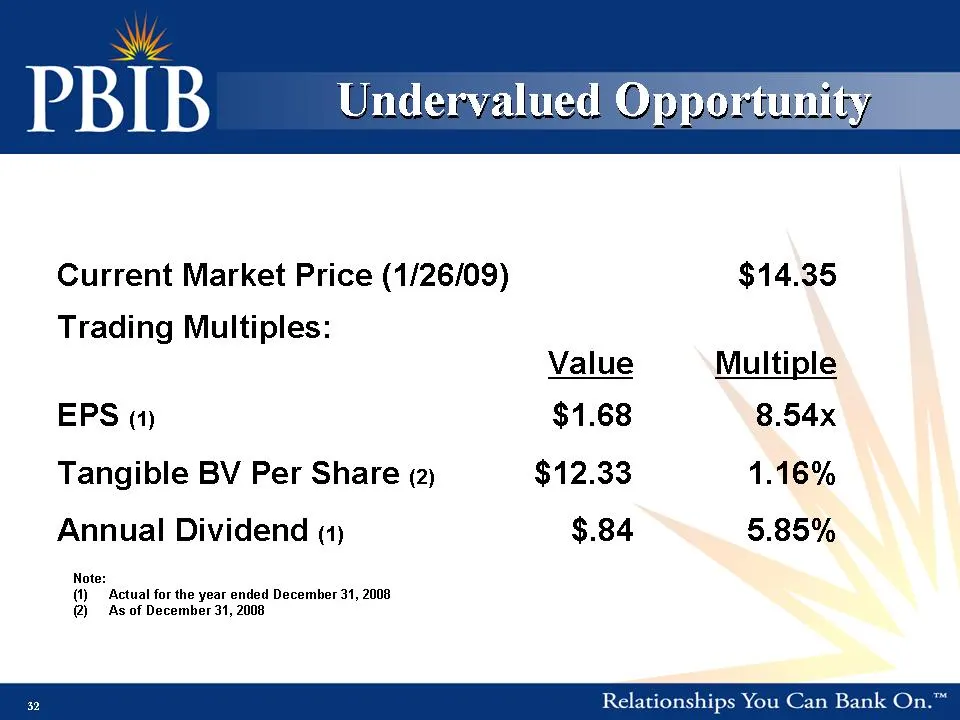
Slide 32: Undervalued Opportunity
Slide: 32 Undervalued Opportunity Current Market Price (1/26/09) $14.35 Trading Multiples: Value Multiple EPS (1) $1.68 8.54x Tangible BV Per Share (2) $12.33 1.16% Annual Dividend (1) $.84 5.85% Note: (1) Actual for the year ended December 31, 2008 As of December 31, 2008
Slide 33: Addendum
Slide: 33 Addendum
Slide 34: Experienced Management Team
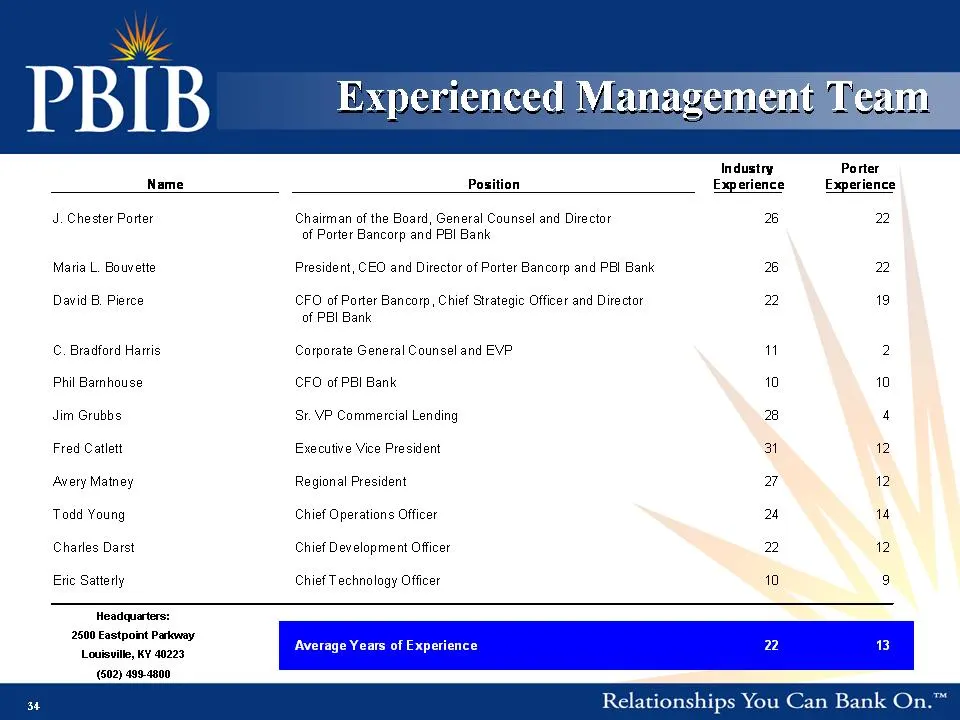
Slide: 34 Experienced Management Team Headquarters: 2500 Eastpoint Parkway Louisville, KY 40223 (502) 499-4800 Industry Porter Name Position Experience Experience J. Chester Porter Chairman of the Board, General Counsel and Director 26 22 of Porter Bancorp and PBI Bank Maria L. Bouvette President, C
Slide 35: Peer Metrics
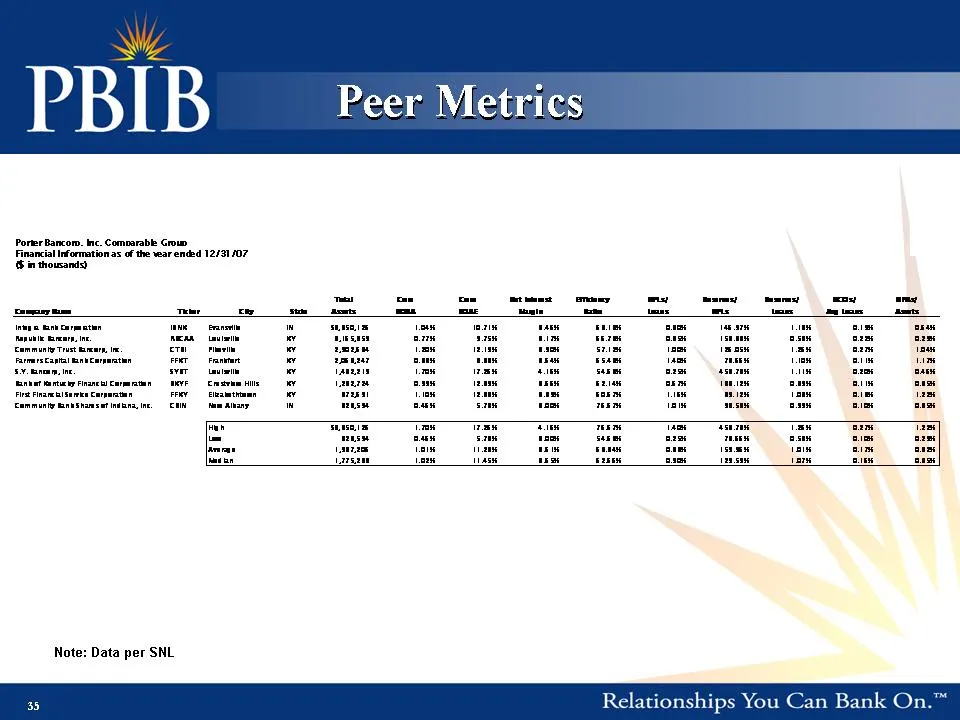
Slide: 35 Peer Metrics Note: Data per SNL Porter Bancorp, Inc. Comparable Group Financial Information as of the year ended 12/31/07 ($ in thousands) Total Core Core Net Interest Efficiency NPLs/ Reserves/ Reserves/ NCOs/ NPAs/ Company Name Ticker City State Assets ROAA ROAE Margin Ratio Loans NPLs L
Slide 36: Peer Metrics
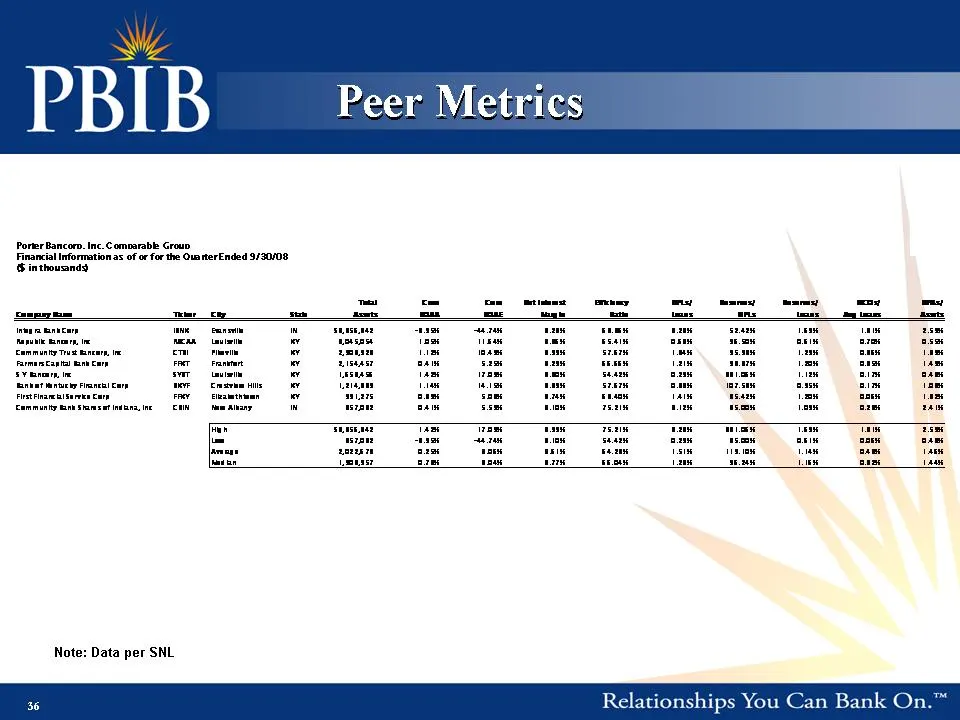
Slide: 36 Peer Metrics Note: Data per SNL Porter Bancorp, Inc. Comparable Group Financial Information as of or for the Quarter Ended 9/30/08 ($ in thousands) Total Core Core Net Interest Efficiency NPLs/ Reserves/ Reserves/ NCOs/ NPAs/ Expense/ Company Name Ticker City State Assets ROAA ROAE Margin
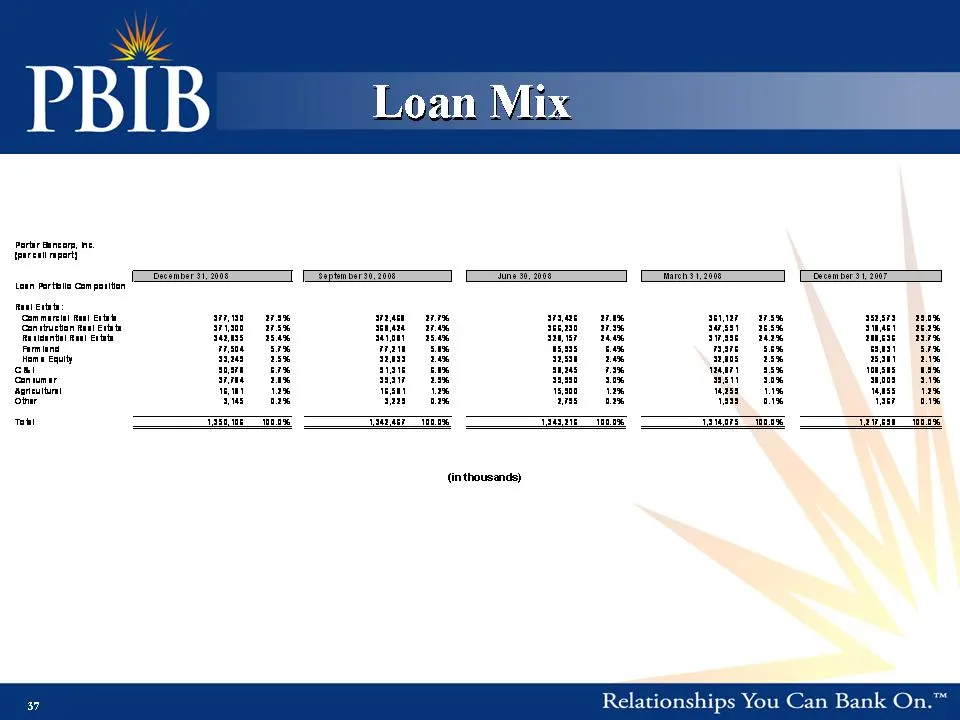
Slide 37: Loan Mix
Slide: 37 Loan Mix (in thousands) Porter Bancorp, Inc. (per call report) December 31, 2008 September 30, 2008 June 30, 2008 March 31, 2008 December 31, 2007 Loan Portfolio Composition Real Estate: Commercial Real Estate 377,130 27.9% 372,468 27.7% 373,426 27.8% 361,127 27.5% 352,573 29.0% Constructi
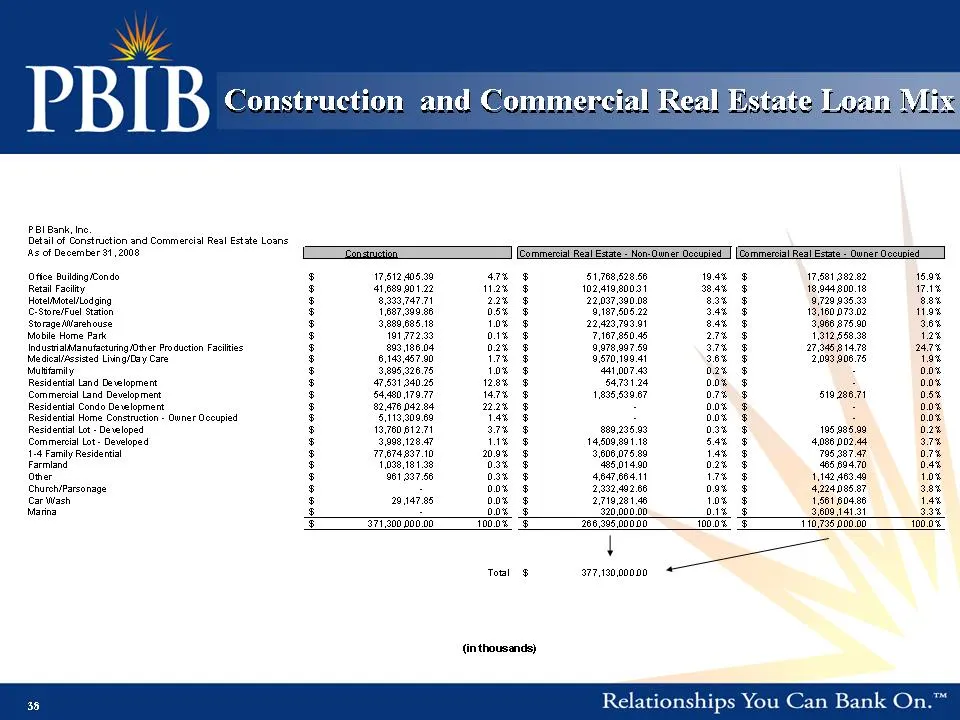
Slide 38: Construction and Commercial Real Estate Loan Mix
Slide: 38 Construction and Commercial Real Estate Loan Mix (in thousands) PBI Bank, Inc. Detail of Construction and Commercial Real Estate Loans As of December 31, 2008 Construction Commercial Real Estate - Non-Owner OcCommercial Real Estate - Owner Occupied Office Building/Condo $ 17,512,405.39 4.7
Source: SEC EDGAR · 8-K filed Feb 9, 2009
More decks from Limestone Bancorp Inc
 Q4 2022 Earnings Presentation44 slides · Feb 10, 2023
 Q3 2022 Earnings Presentation44 slides · Nov 1, 2022
 Merger or Acquisition (October 2022)15 slides · Oct 25, 2022
 Q2 2022 Earnings Presentation20 slides · Jul 29, 2022
 Q1 2022 Earnings Presentation20 slides · Apr 29, 2022
 Q2 2021 Earnings Presentation20 slides · Jul 21, 2021