Whitehaven Coal Limited · ASX:WHC
Whitehaven Coal — Shareholder Meeting (October 2022)
26 slides from Whitehaven Coal's shareholder meeting presentation, Oct 26, 2022
Slide 1: Whitehaven Coal 2022 AGM Presentation
Whitehaven Coal 2022 AGM Presentation 26 October 2022 Authorised for release by the Board of Whitehaven Coal Limited Whitehaven Coal Limited ABN 68 124 425 396 Level 28, 259 George Street, Sydney NSW 2000 P 02 8222 1100 | F 02 8222 1101 PO Box R1113, Royal Exchange NSW 1225 whitehavencoal.com.au
Slide 2: Disclosure
Disclosure FORWARD LOOKING STATEMENTS Statements contained in this material, particularly those regarding the possible or assumed future performance, costs, dividends, returns, production levels or rates, prices, reserves, potential growth of Whitehaven Coal Limited, industry growth or other trend p
Slide 3: Exceptionally strong demand
Exceptionally strong demand
Slide 4: Premium products delivered into premium markets
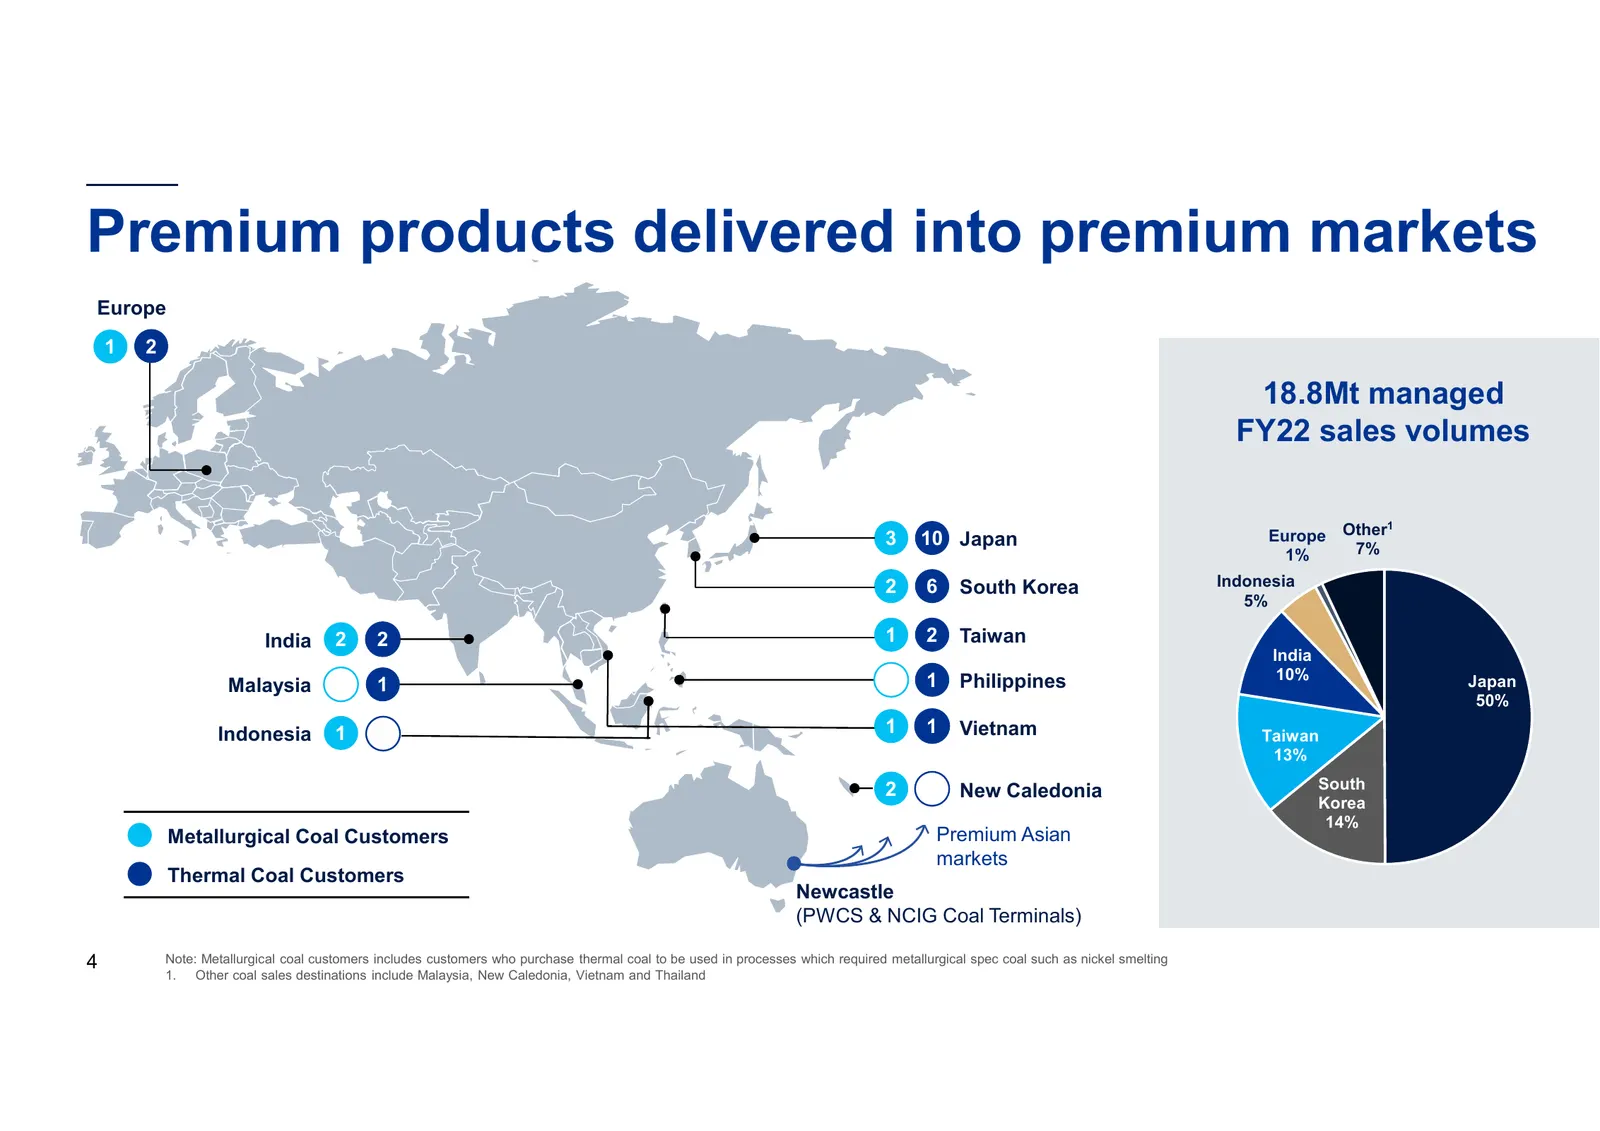
Premium products delivered into premium markets Europe 1 2 18.8Mt managed FY22 sales volumes 1 3 10 Japan Europe Other 1% 7% 2 6 South Korea Indonesia 5% India 2 2 1 2 Taiwan India - 1 Philippines 10% Japan Malaysia - 1 50% Indonesia 1 1 1 Vietnam Taiwan 13% 2 2 New Caledonia South 2 Korea 14% Metal
Slide 5: Providing energy security for customers
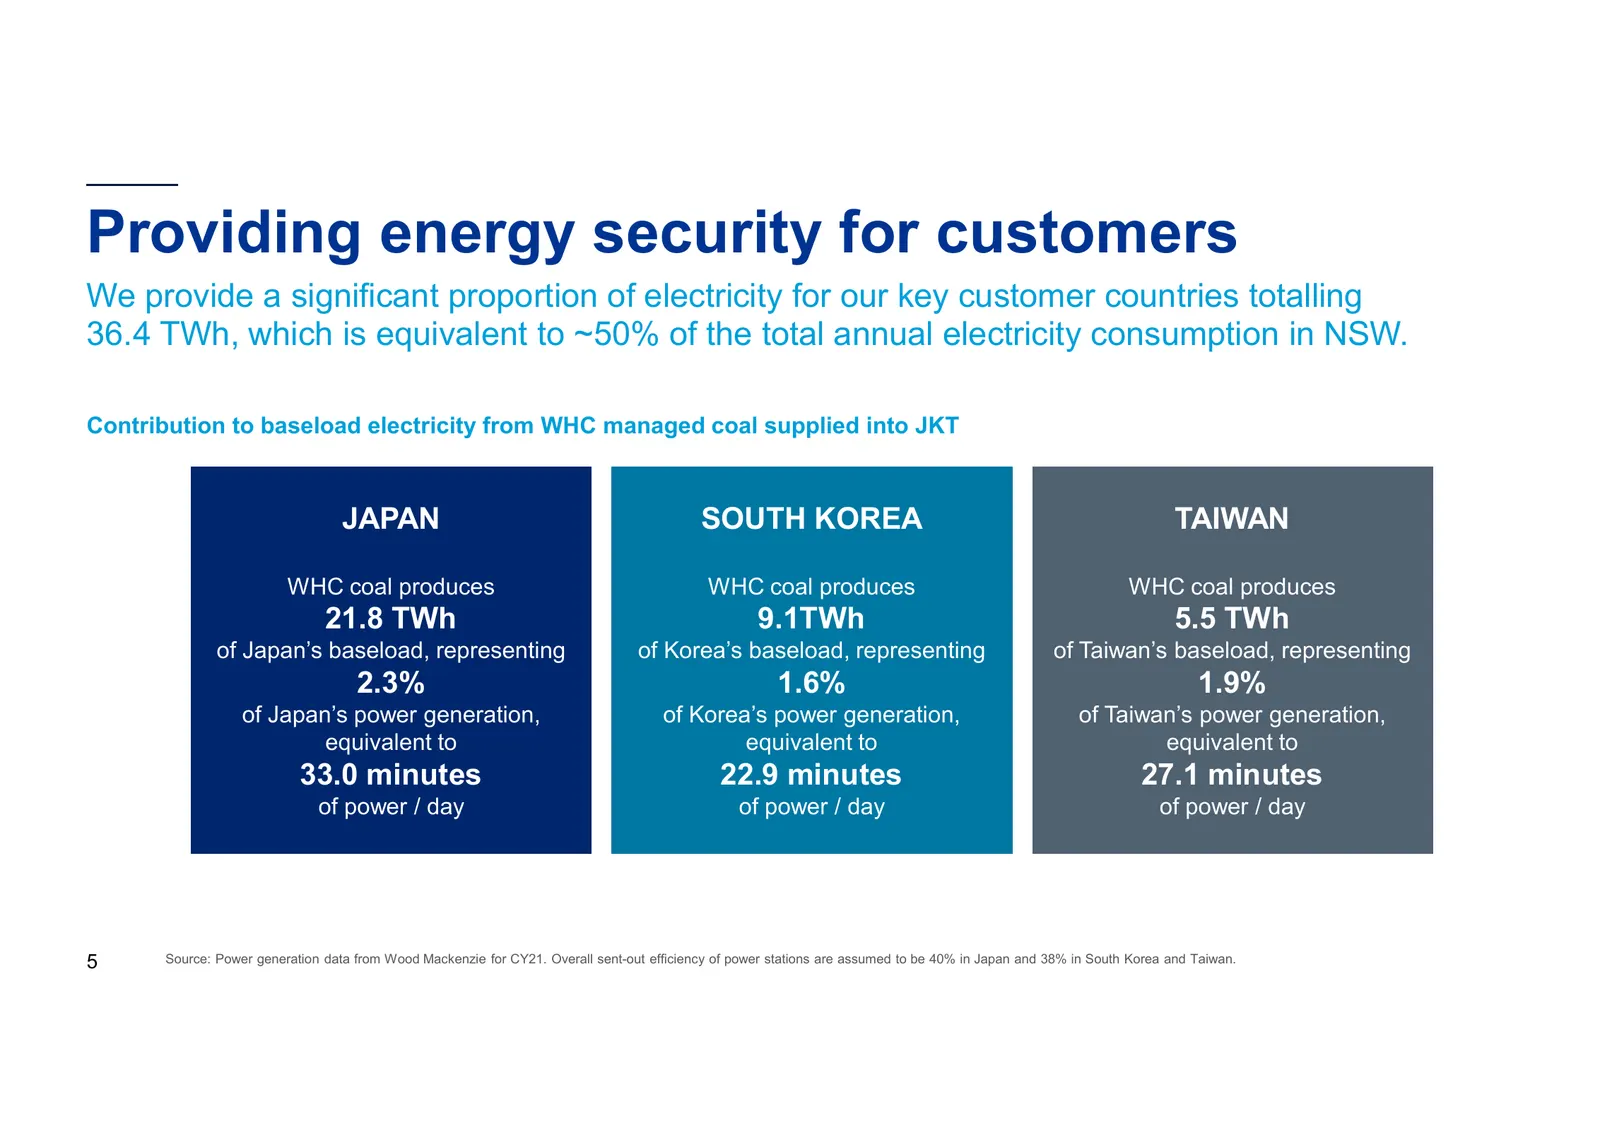
Providing energy security for customers We provide a significant proportion of electricity for our key customer countries totalling 36.4 TWh, which is equivalent to ~50% of the total annual electricity consumption in NSW. Contribution to baseload electricity from WHC managed coal supplied into JKT J
Slide 6: Thermal coal prices (US$/t)
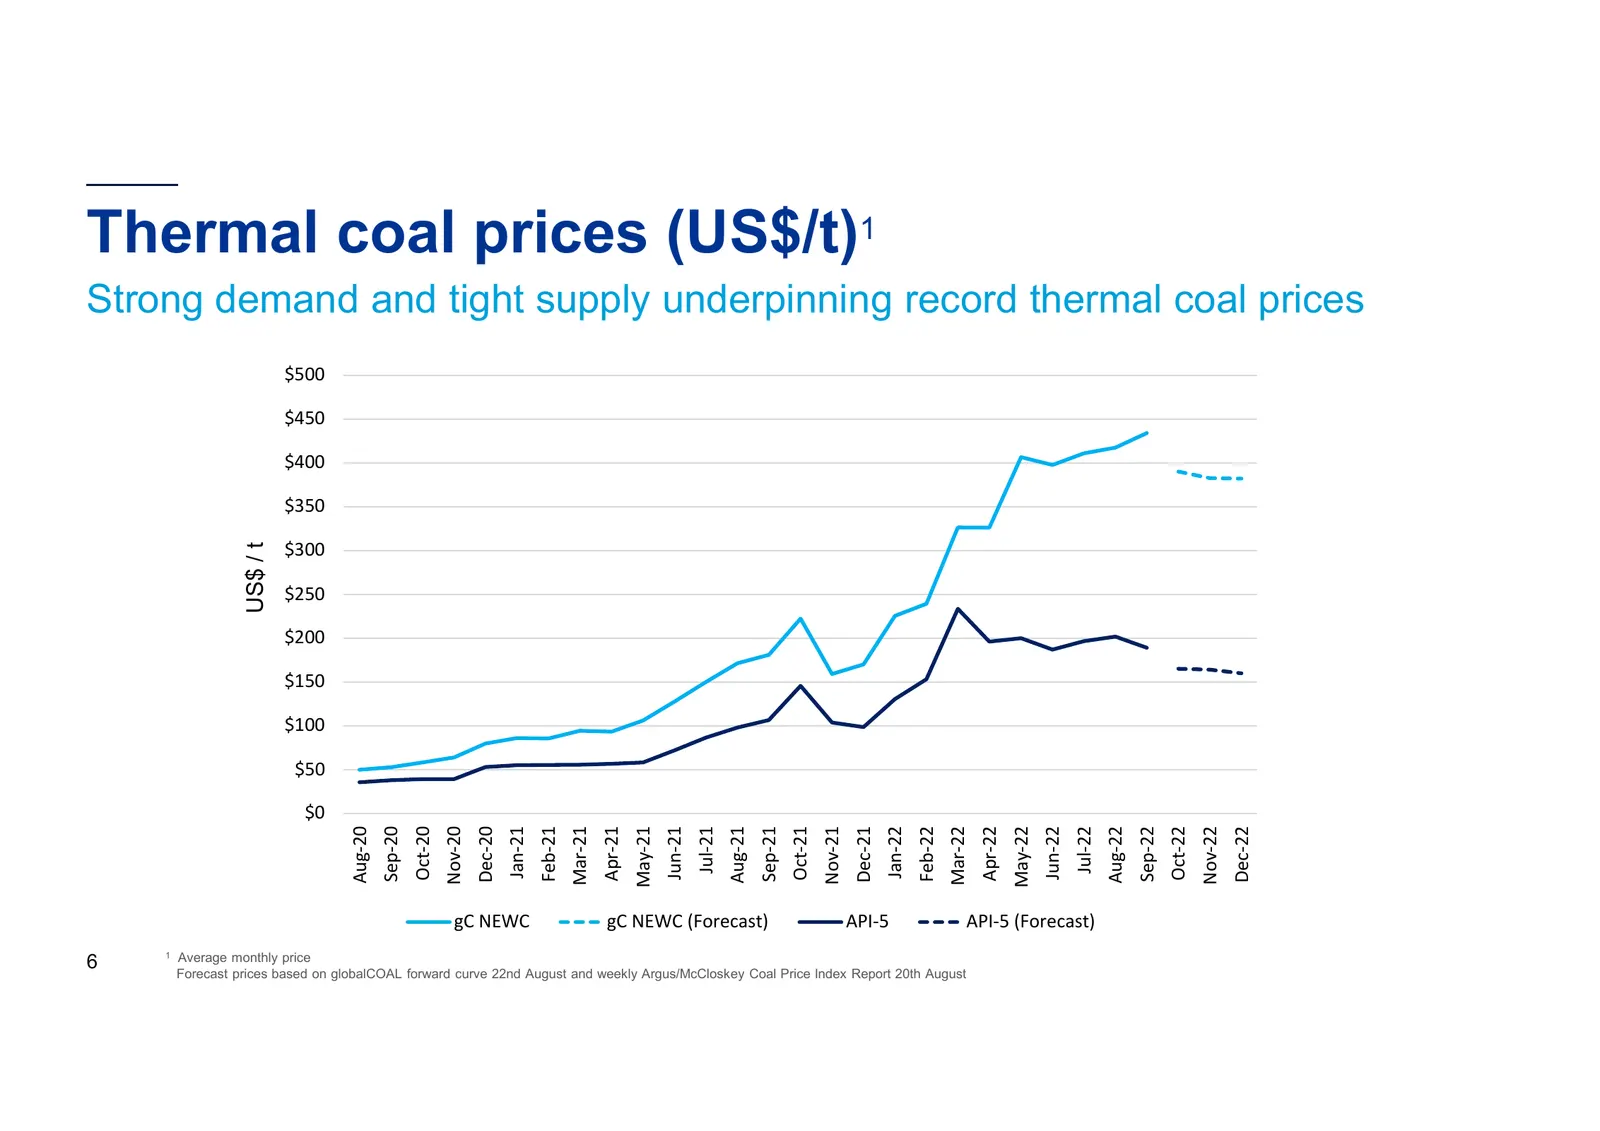
Thermal coal prices (US$/t)1 Strong demand and tight supply underpinning record thermal coal prices $500 $450 $400 $350 $300 US$ / t $250 $200 $150 $100 $50 $0 Oct-20 Nov-20 Dec-20 Mar-21 Apr-21 May-21 Oct-21 Nov-21 Dec-21 Mar-22 Apr-22 May-22 Oct-22 Nov-22 Dec-22 Aug-20 Sep-20 Jan-21 Feb-21 Jun-21
Slide 7: Metallurgical coal prices (US$/t)
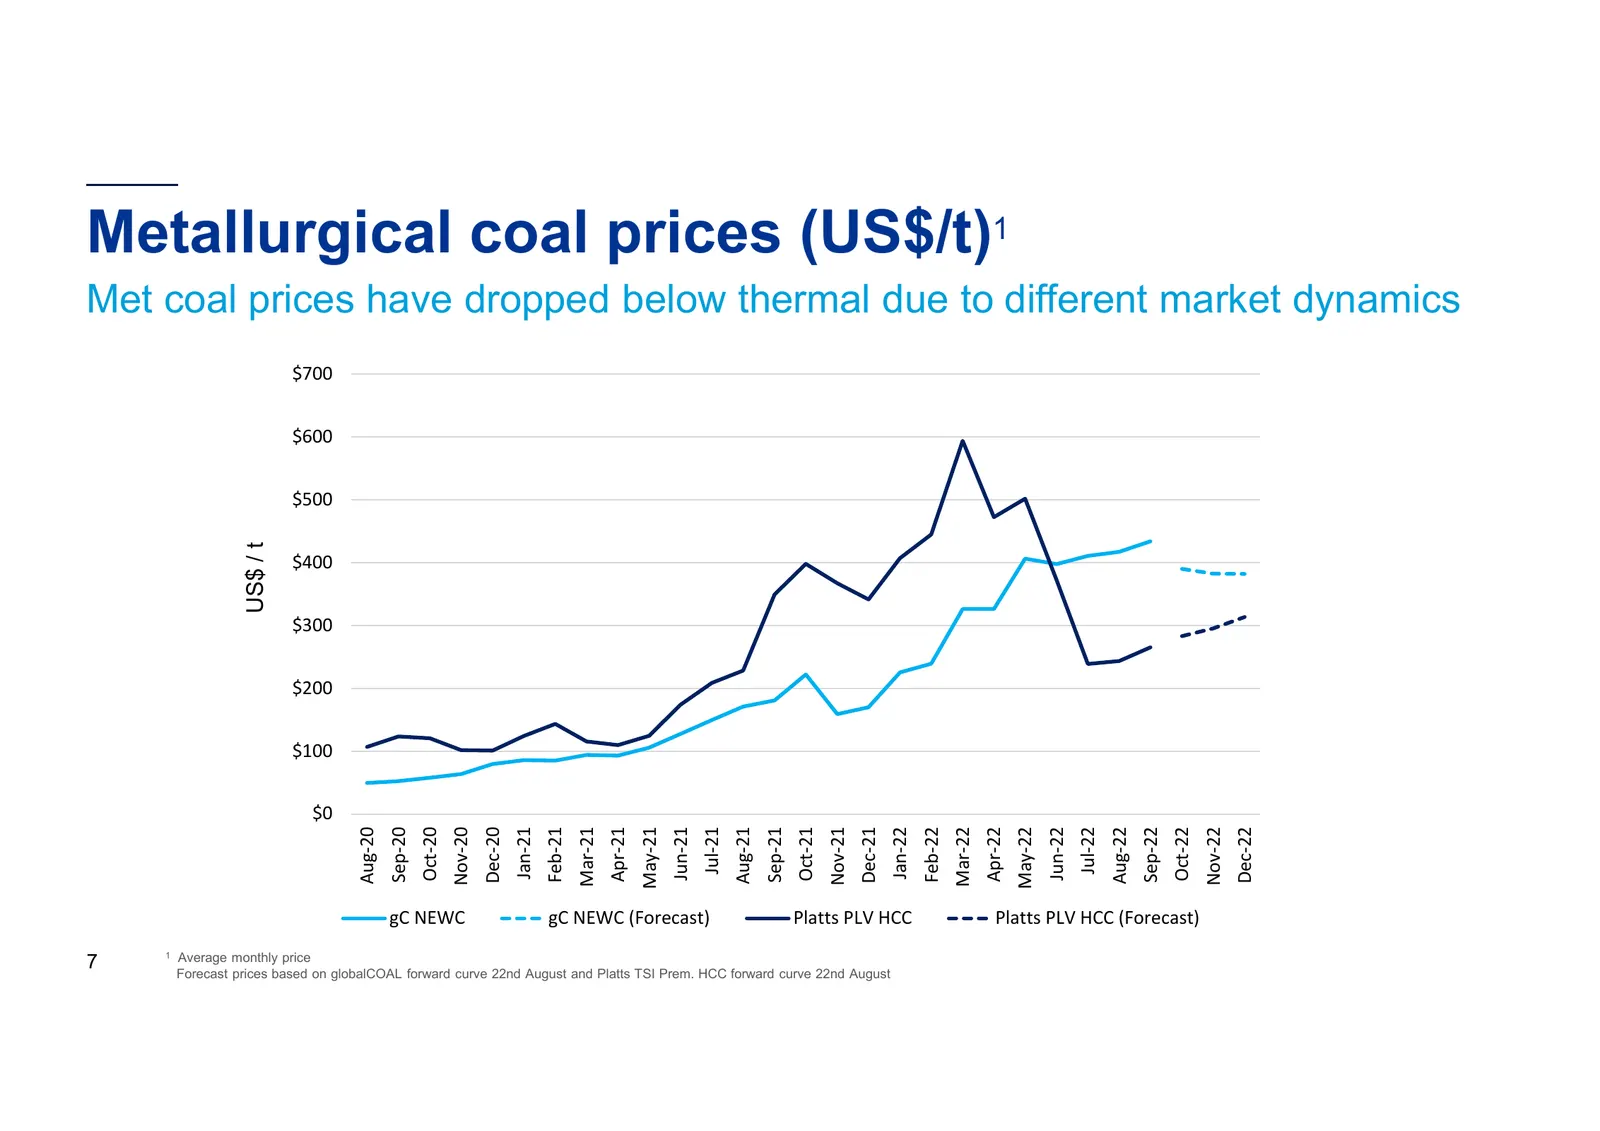
Metallurgical coal prices (US$/t)1 Met coal prices have dropped below thermal due to different market dynamics $700 $600 $500 US$ / t $400 $300 $200 $100 $0 Aug-20 Sep-20 Oct-20 Nov-20 Dec-20 Jan-21 Feb-21 Mar-21 Apr-21 May-21 Jun-21 Jul-21 Aug-21 Sep-21 Oct-21 Nov-21 Dec-21 Jan-22 Feb-22 Mar-22 Apr
Slide 8: FY22 impact of coal market dynamics on WHC
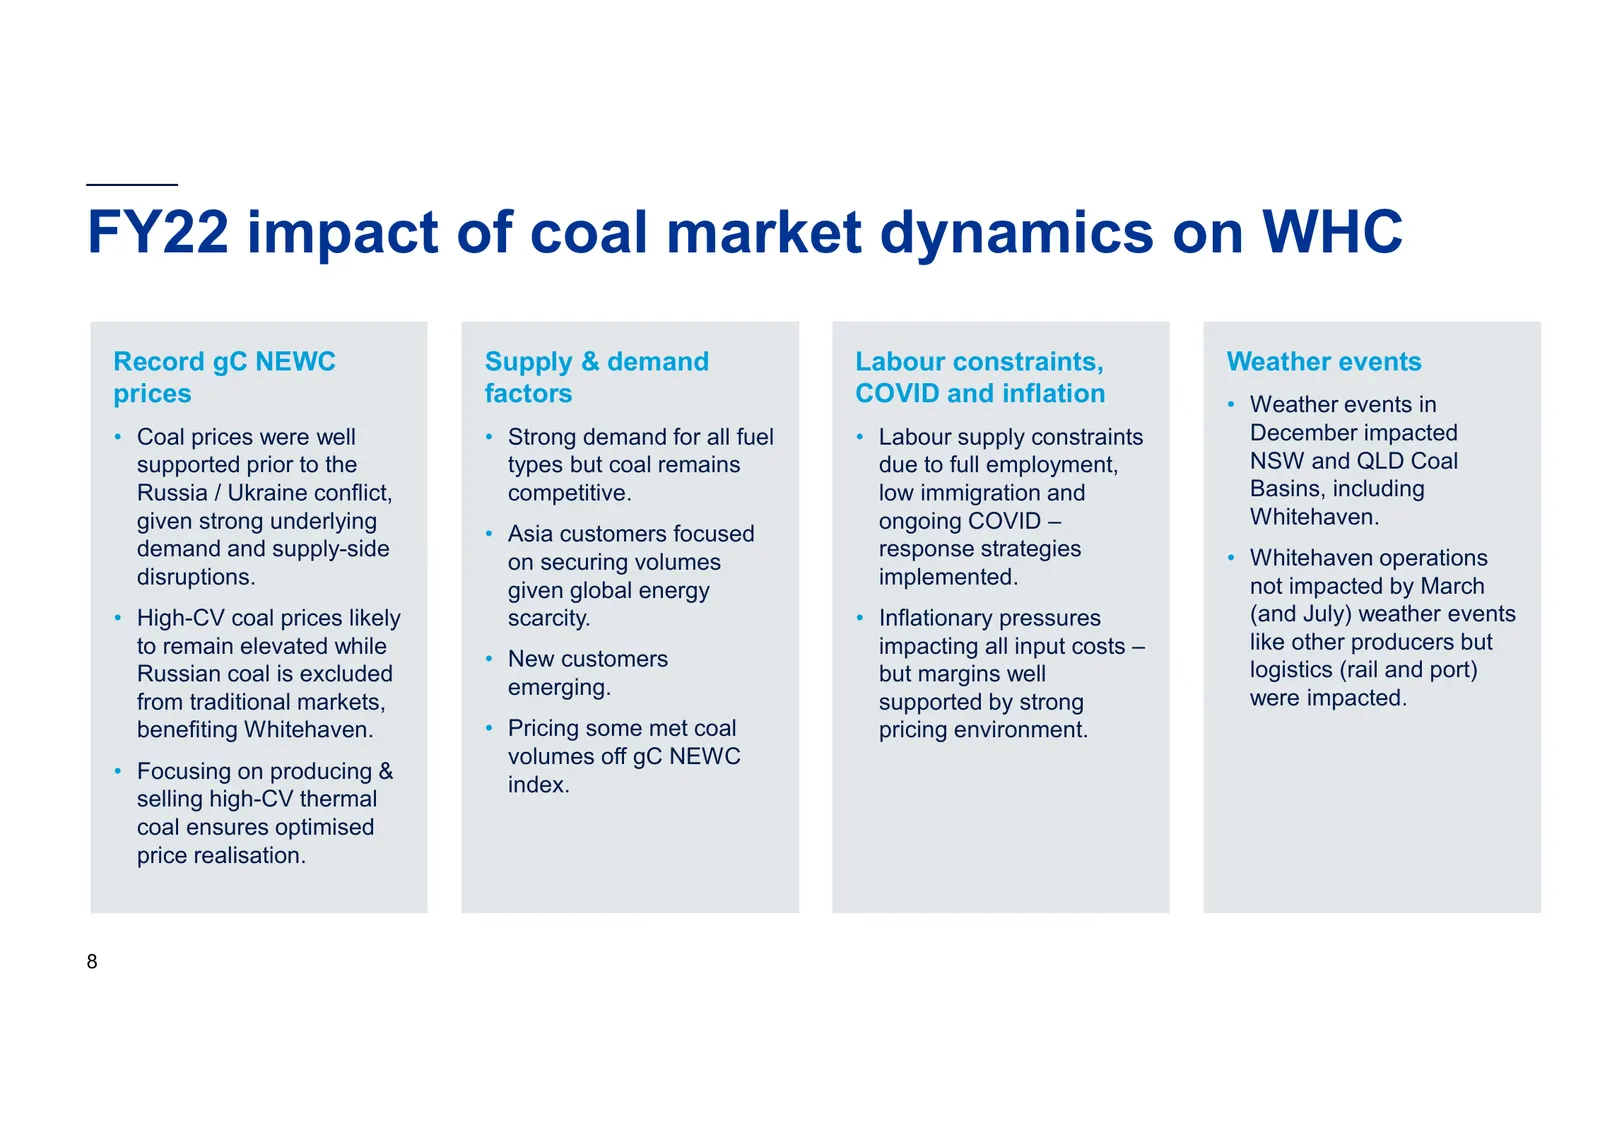
FY22 impact of coal market dynamics on WHC Record gC NEWC Supply & demand Labour constraints, Weather events prices factors COVID and inflation • Weather events in • Coal prices were well • Strong demand for all fuel • Labour supply constraints December impacted supported prior to the types but coal
Slide 9: Record financial results
Record financial results
Slide 10: FY22 ROM coal production and sales
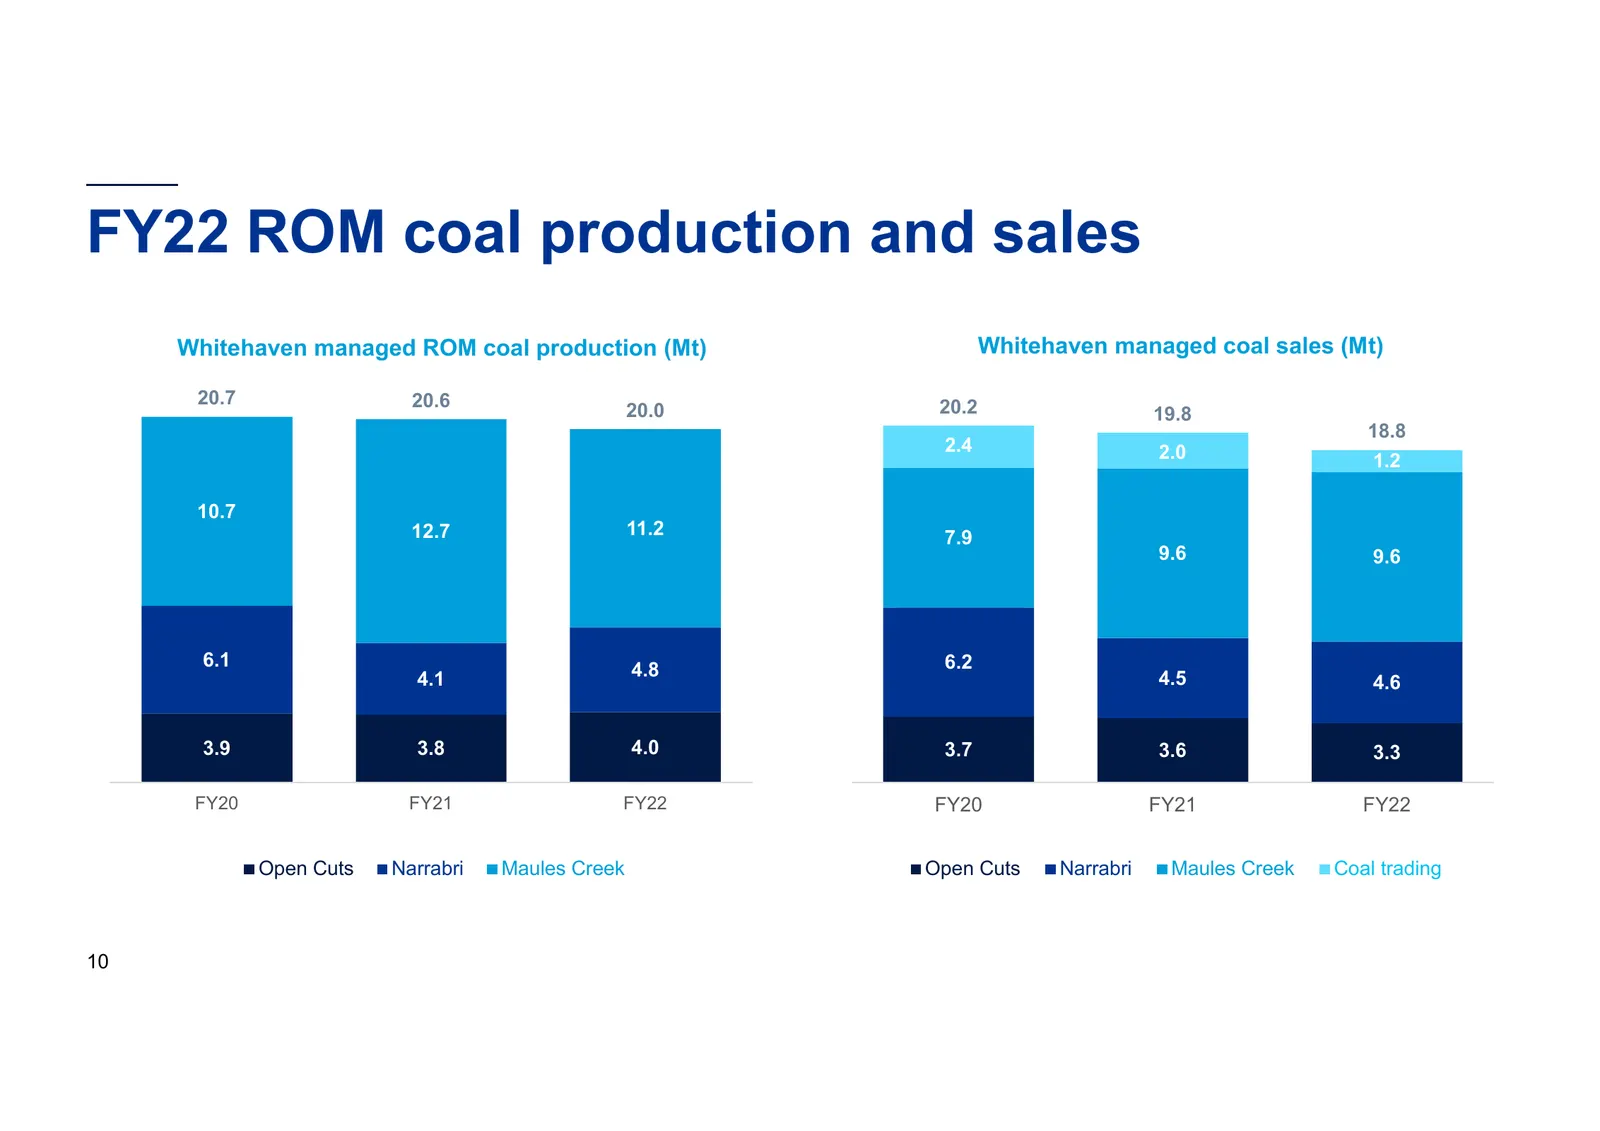
FY22 ROM coal production and sales Whitehaven managed ROM coal production (Mt) Whitehaven managed coal sales (Mt) 20.7 20.6 20.2 20.0 19.8 18.8 2.4 2.0 1.2 10.7 12.7 11.2 7.9 9.6 9.6 6.1 4.8 6.2 4.1 4.5 4.6 3.9 3.8 4.0 3.7 3.6 3.3 FY20 FY21 FY22 FY20 FY21 FY22 Open Cuts Narrabri Maules Creek Open Cu
Slide 11: FY22 financial highlights – a record year
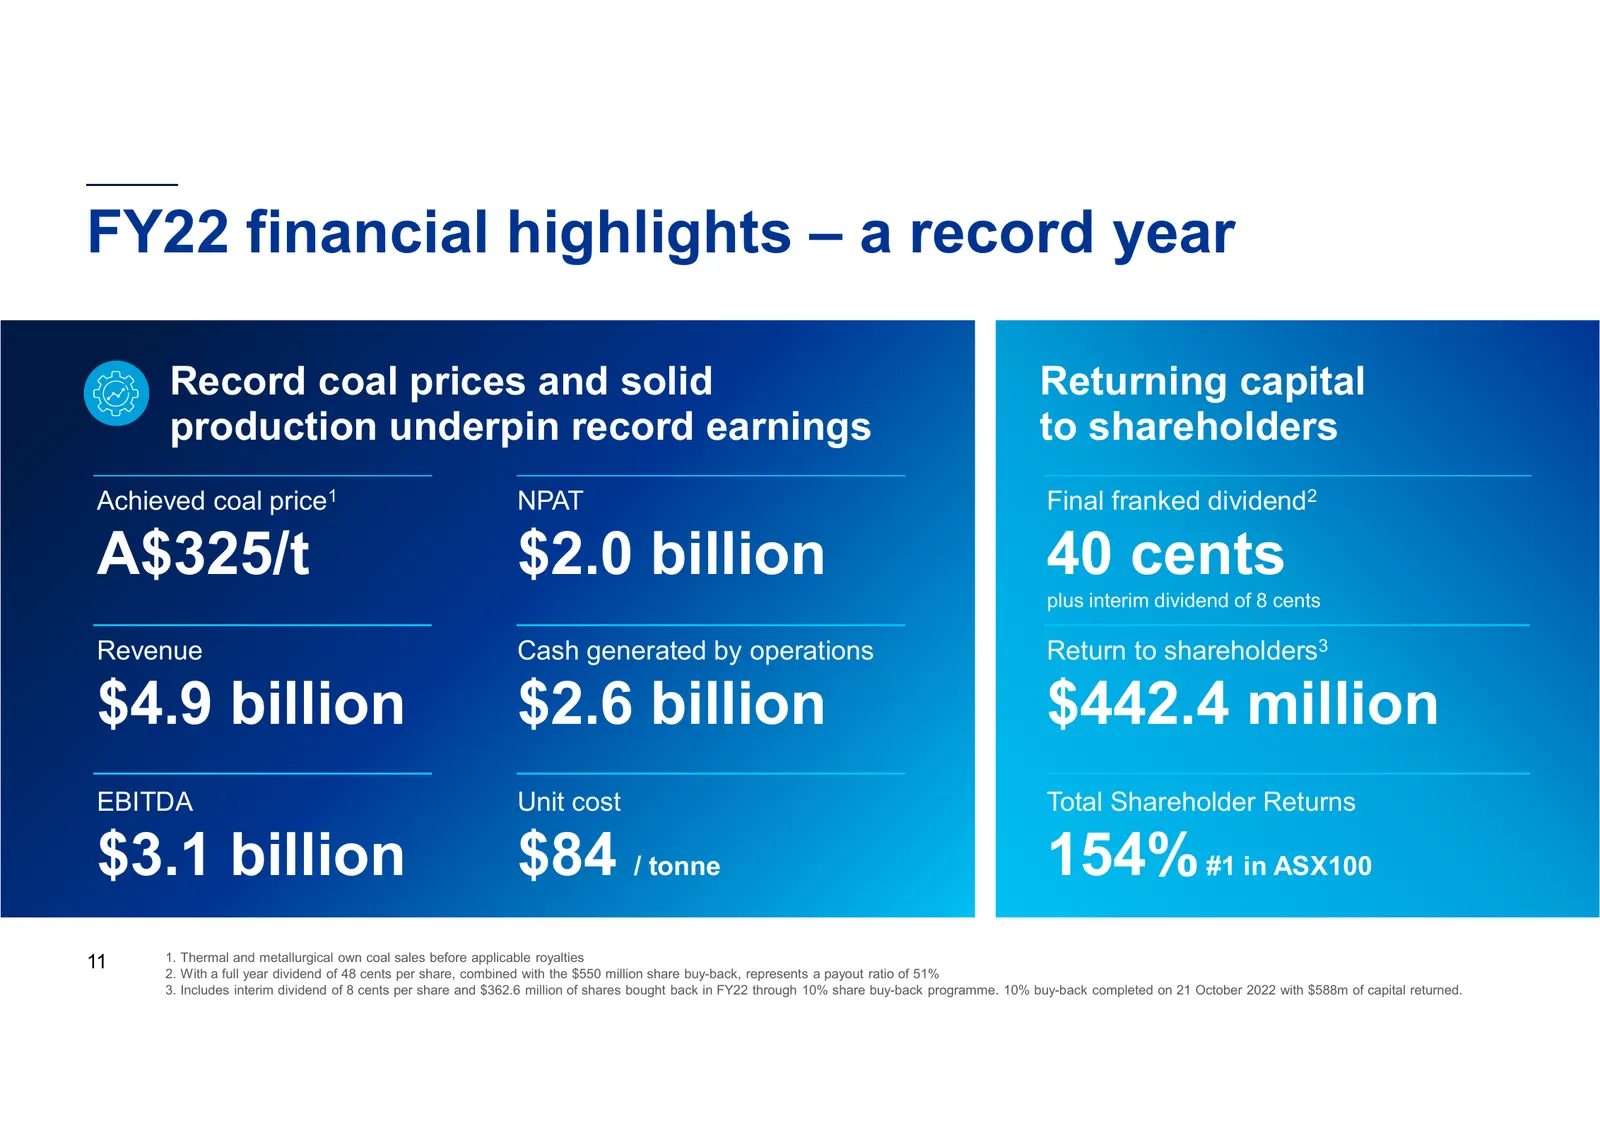
FY22 financial highlights – a record year Record coal prices and solid Returning capital production underpin record earnings to shareholders Achieved coal price1 NPAT Final franked dividend2 A$325/t $2.0 billion 40 cents plus interim dividend of 8 cents Revenue Cash generated by operations Return to
Slide 12: Disciplined approach to capital management
Disciplined approach to capital management
Slide 13: Capital allocation framework
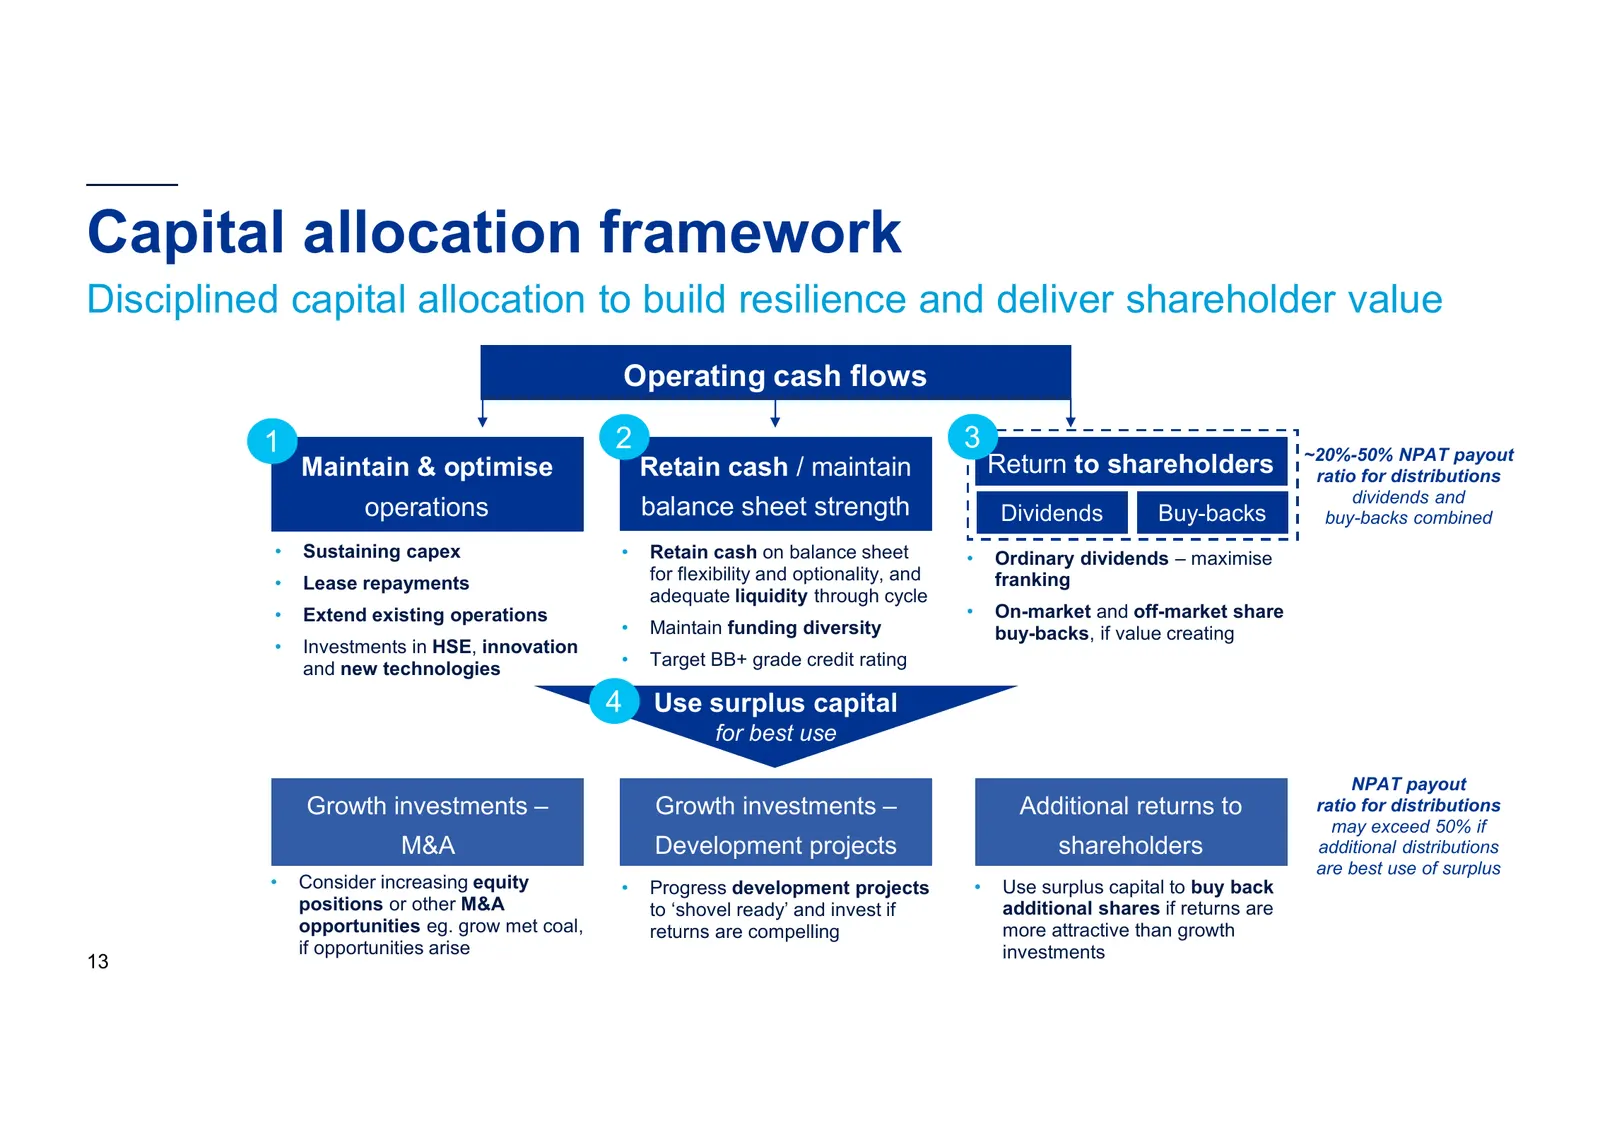
Capital allocation framework Disciplined capital allocation to build resilience and deliver shareholder value Operating cash flows 1 2 3 ~20%-50% NPAT payout Maintain & optimise Retain cash / maintain Return to shareholders ratio for distributions dividends and operations balance sheet strength Divi
Slide 14: Disconnect in long-term coal price to share price relationship
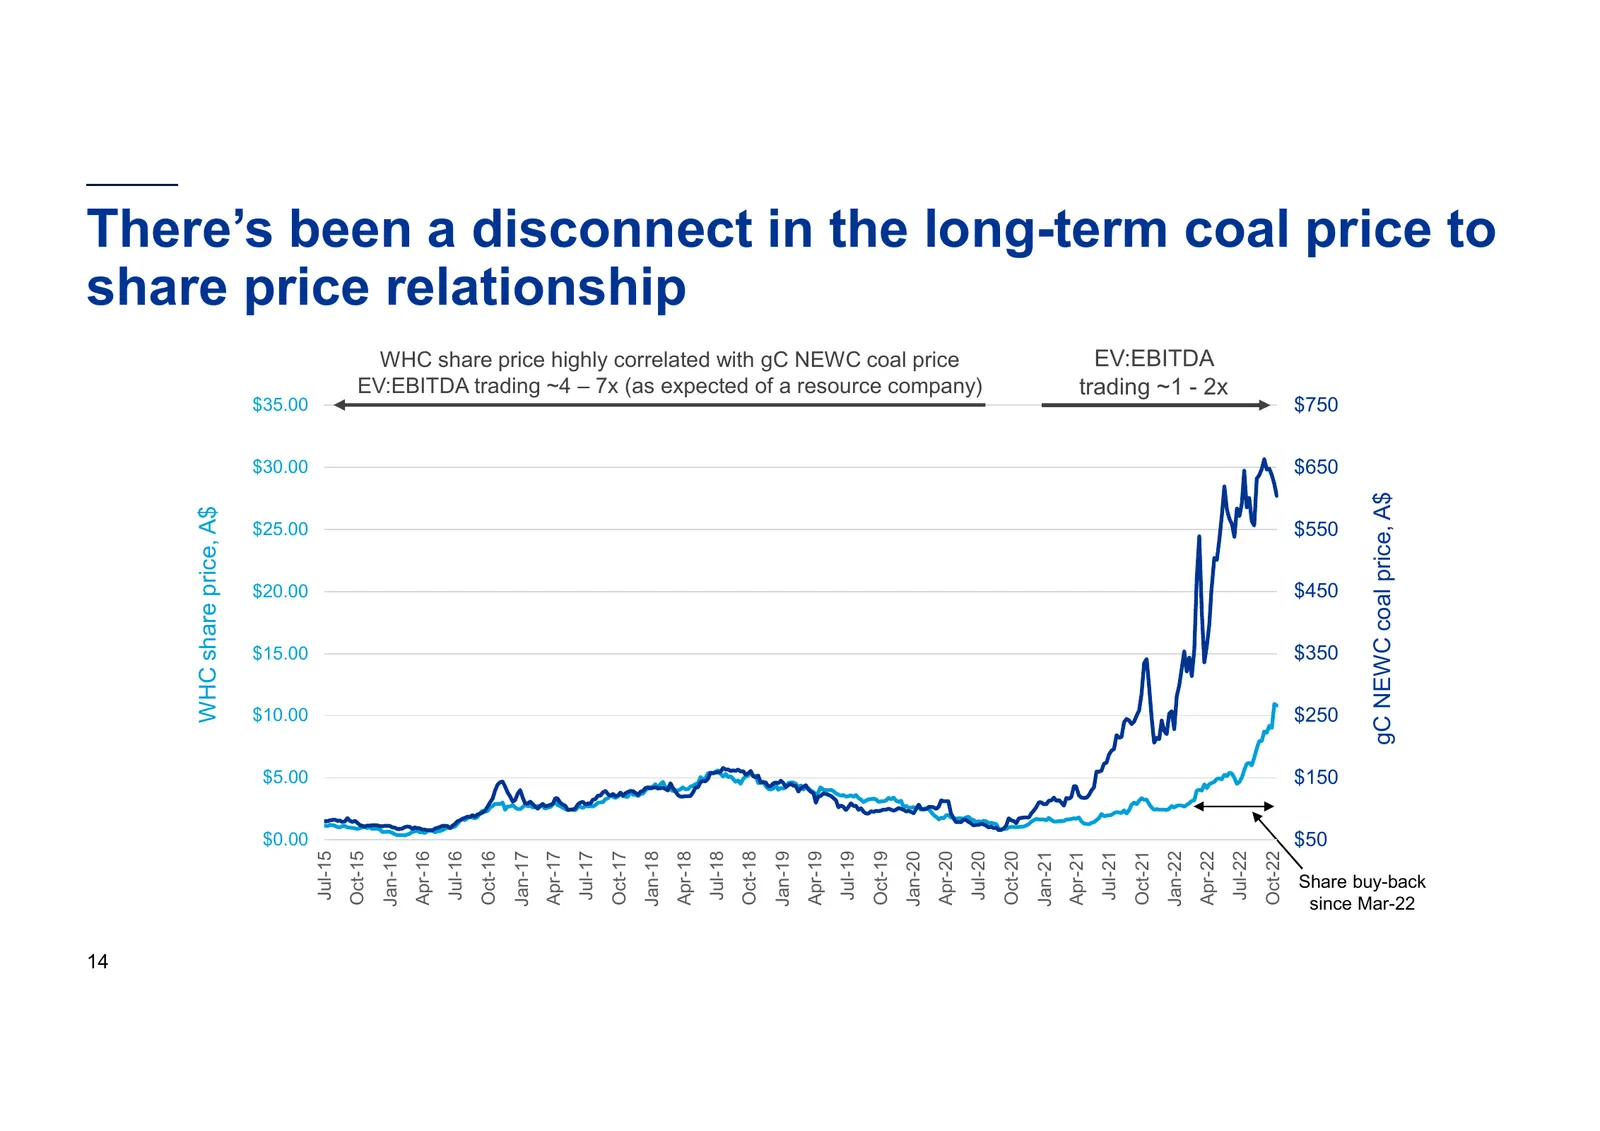
There’s been a disconnect in the long-term coal price to share price relationship WHC share price highly correlated with gC NEWC coal price EV:EBITDA EV:EBITDA trading ~4 – 7x (as expected of a resource company) trading ~1 - 2x $35.00 $750 $30.00 $650 gC NEWC coal price, A$ WHC share price, A$ $25.0
Slide 15: Safe, efficient and sustainable operations
Safe, efficient and sustainable operations
Slide 16: Safe, efficient and sustainable operations
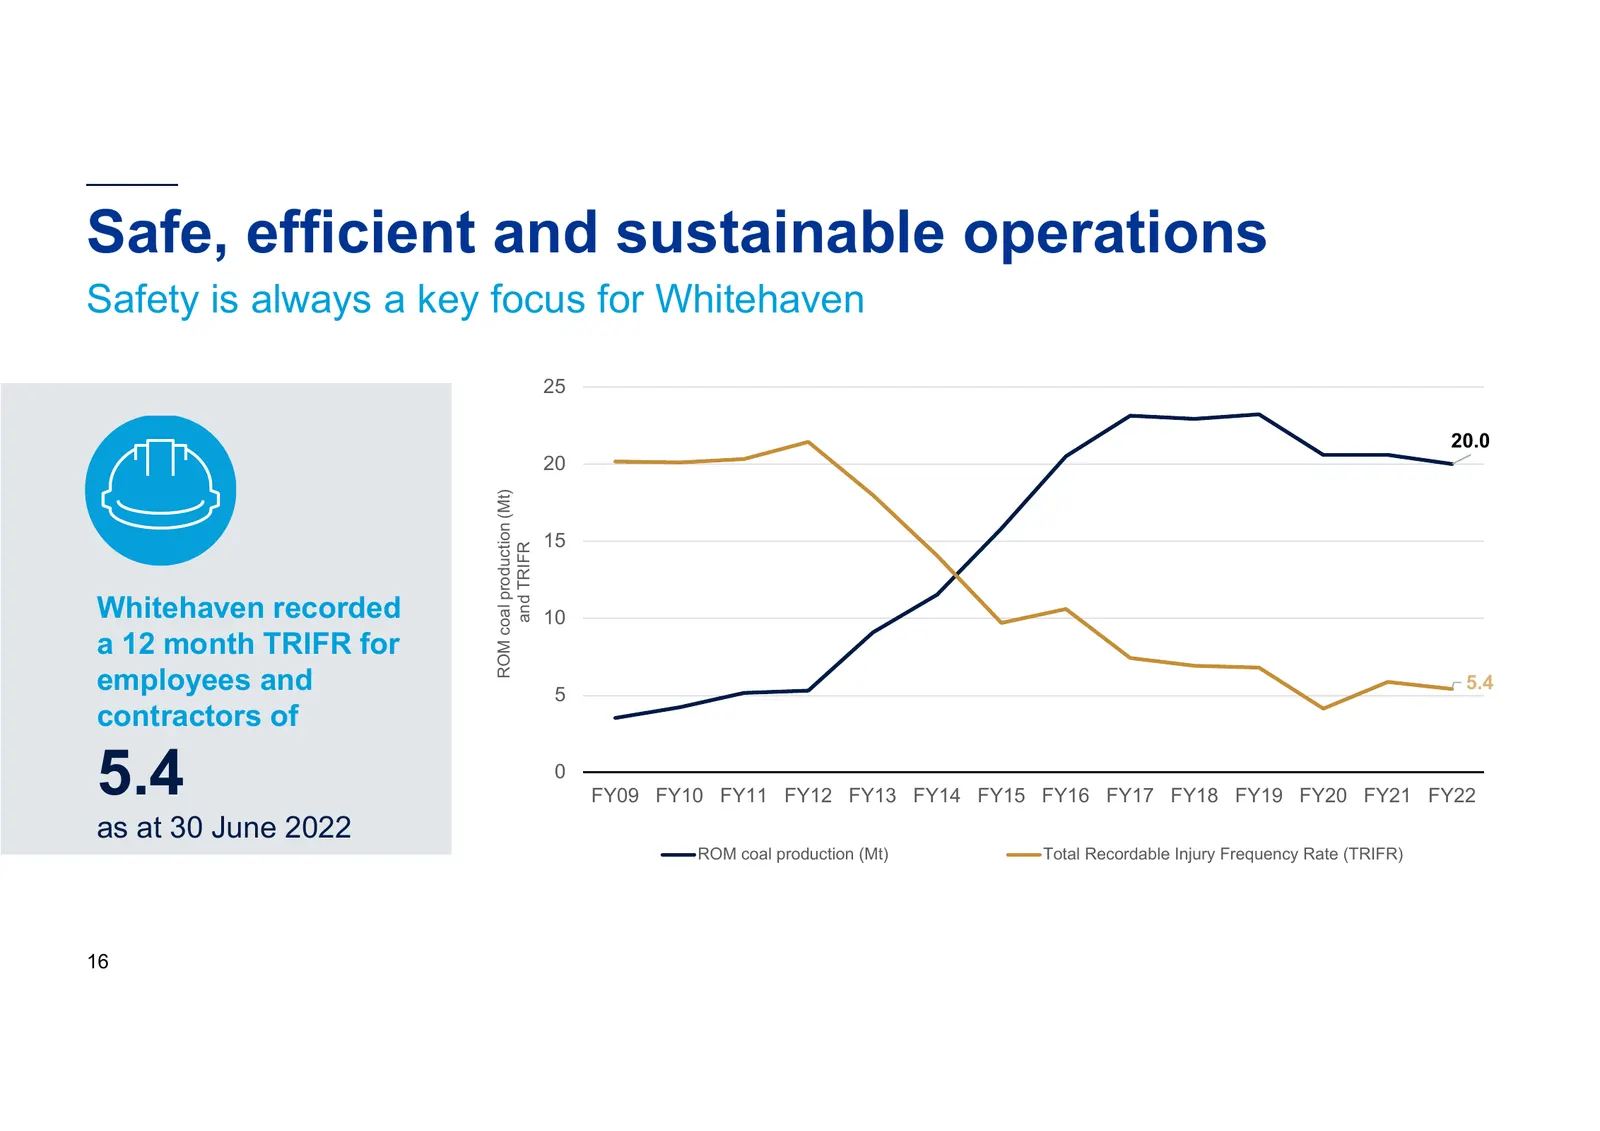
Safe, efficient and sustainable operations Safety is always a key focus for Whitehaven 25 20.0 20 ROM coal production (Mt) 15 and TRIFR Whitehaven recorded 10 a 12 month TRIFR for employees and 5 5.4 contractors of 5.4 0 FY09 FY10 FY11 FY12 FY13 FY14 FY15 FY16 FY17 FY18 FY19 FY20 FY21 FY22 as at 30
Slide 17: Highly engaged people and communities
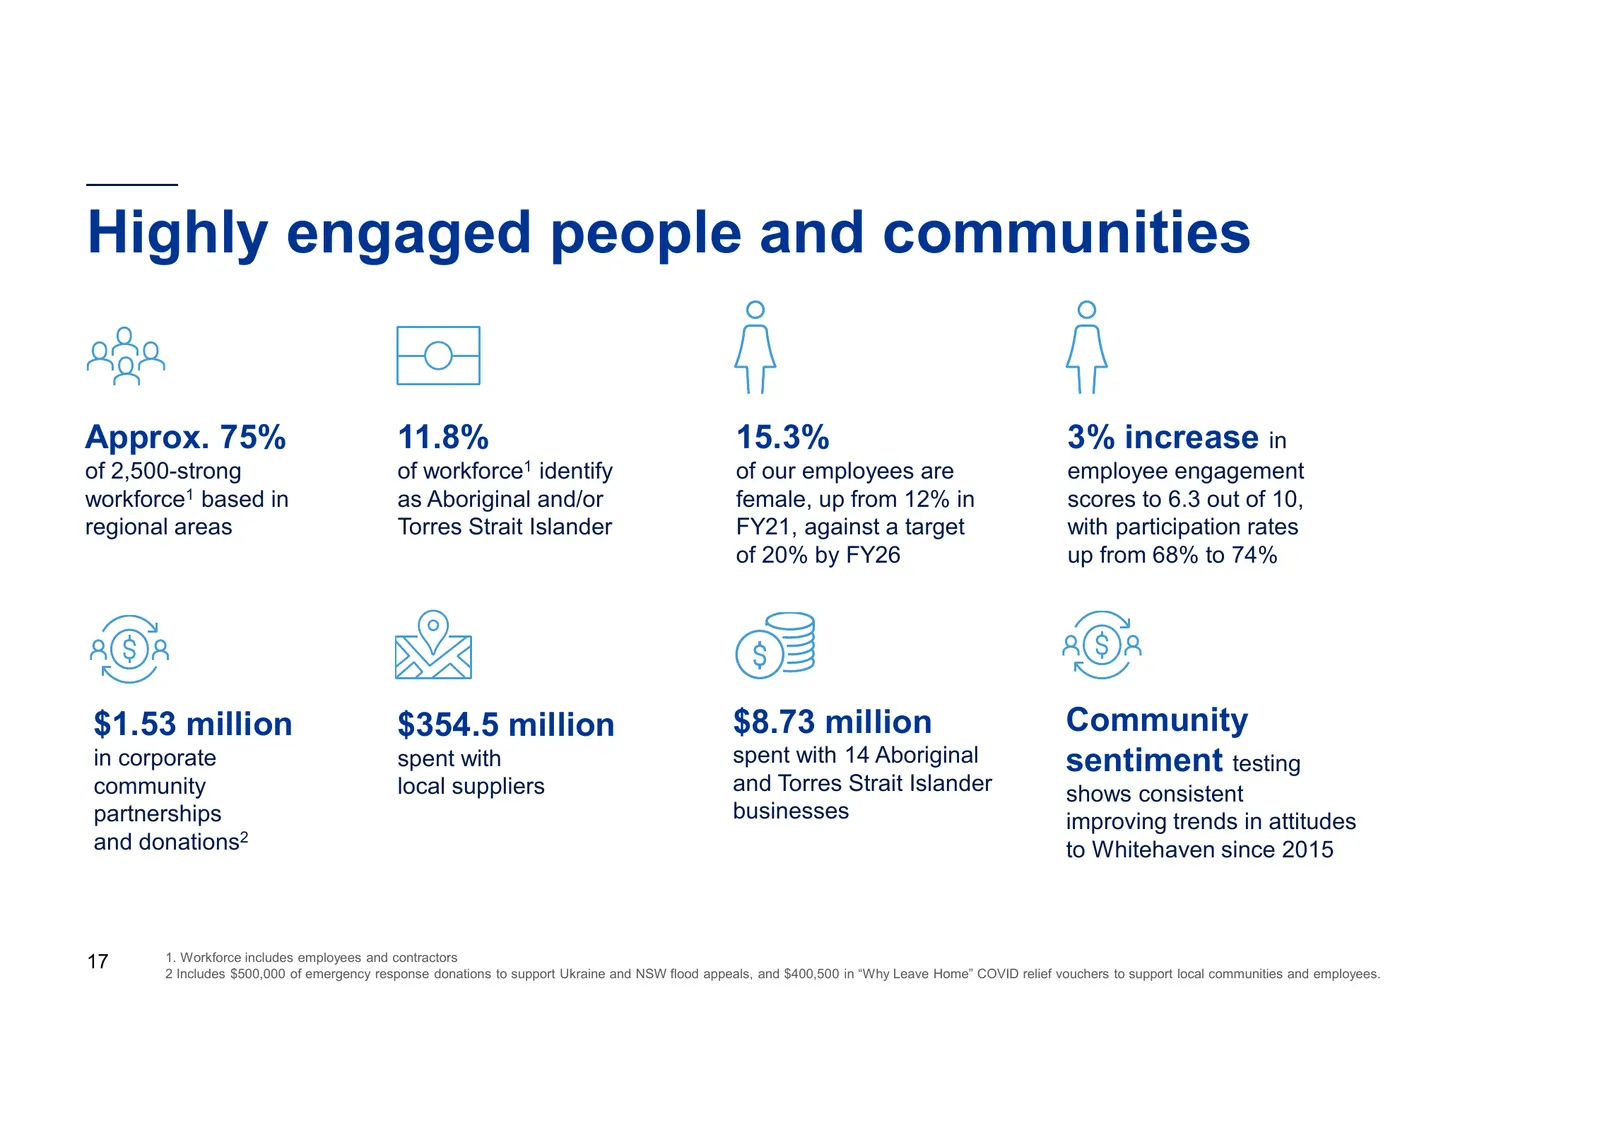
Highly engaged people and communities Approx. 75% 11.8% 15.3% 3% increase in of 2,500-strong of workforce1 identify of our employees are employee engagement workforce1 based in as Aboriginal and/or female, up from 12% in scores to 6.3 out of 10, regional areas Torres Strait Islander FY21, against a
Slide 18: Focused on Scope 1 and 2 emissions and TCFD reporting
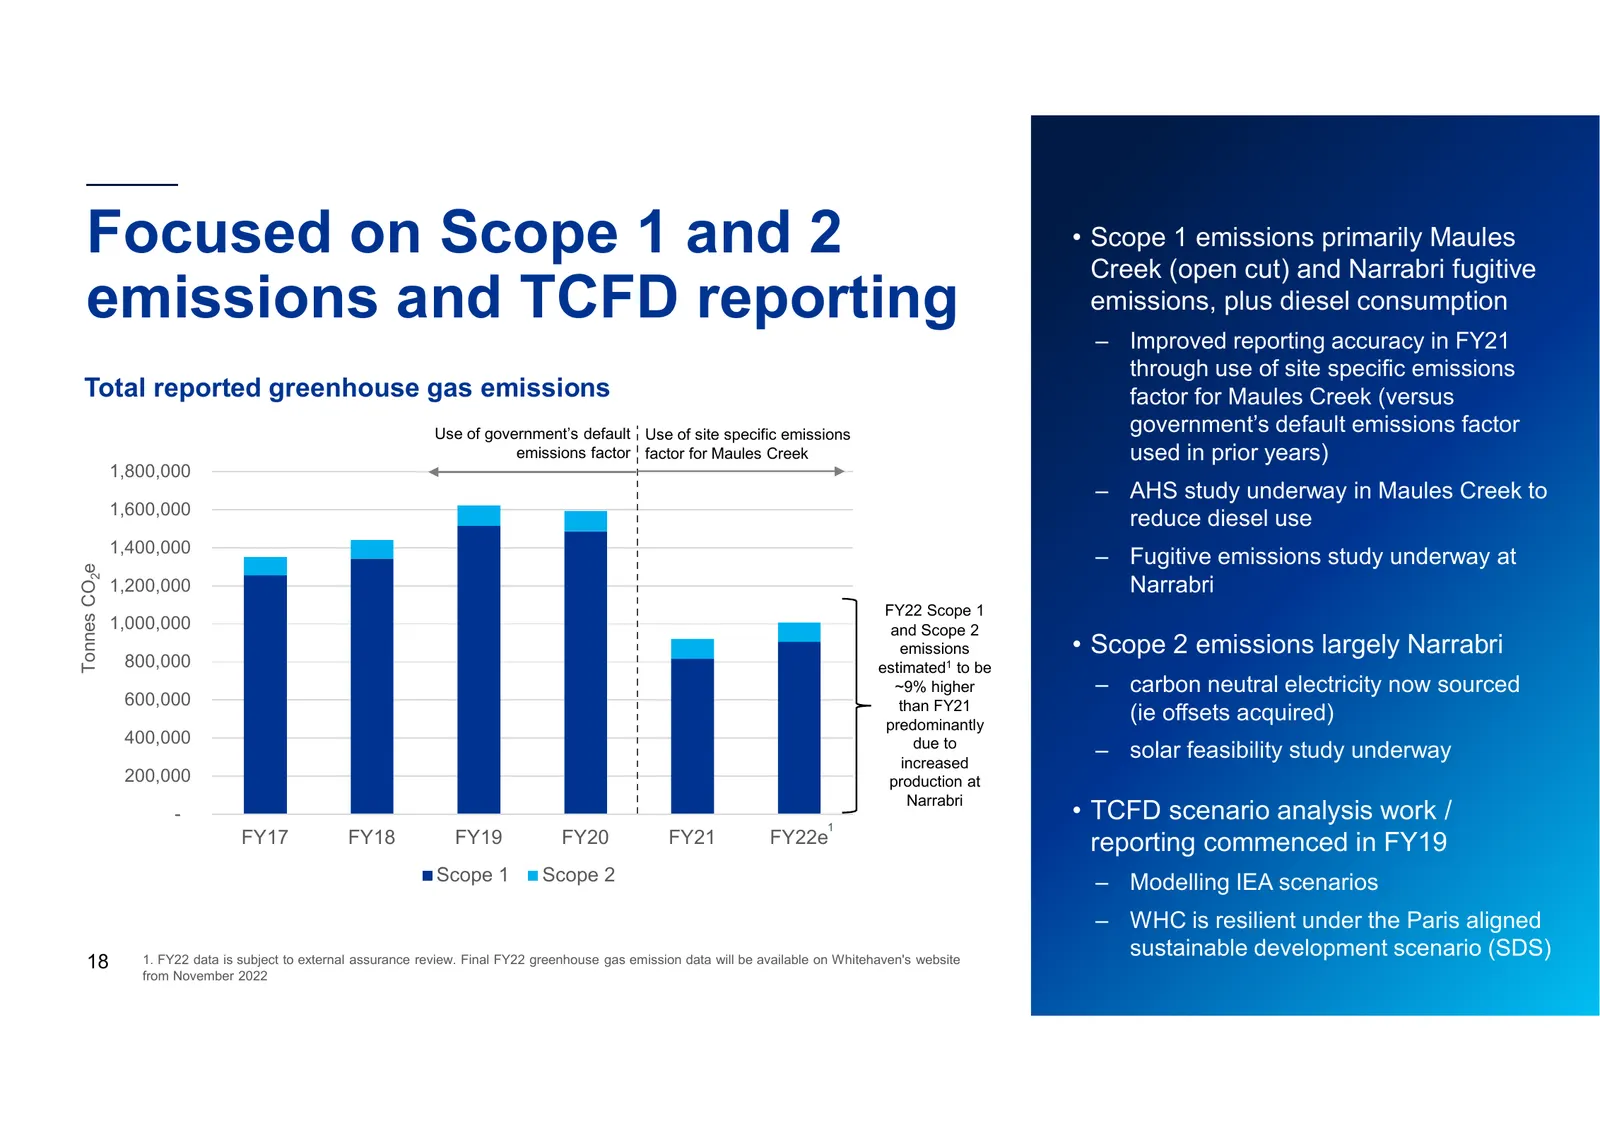
Focused on Scope 1 and 2 • Scope 1 emissions primarily Maules Creek (open cut) and Narrabri fugitive emissions and TCFD reporting emissions, plus diesel consumption – Improved reporting accuracy in FY21 through use of site specific emissions Total reported greenhouse gas emissions factor for Maules
Slide 19: Our high-CV thermal coal supports emissions reduction
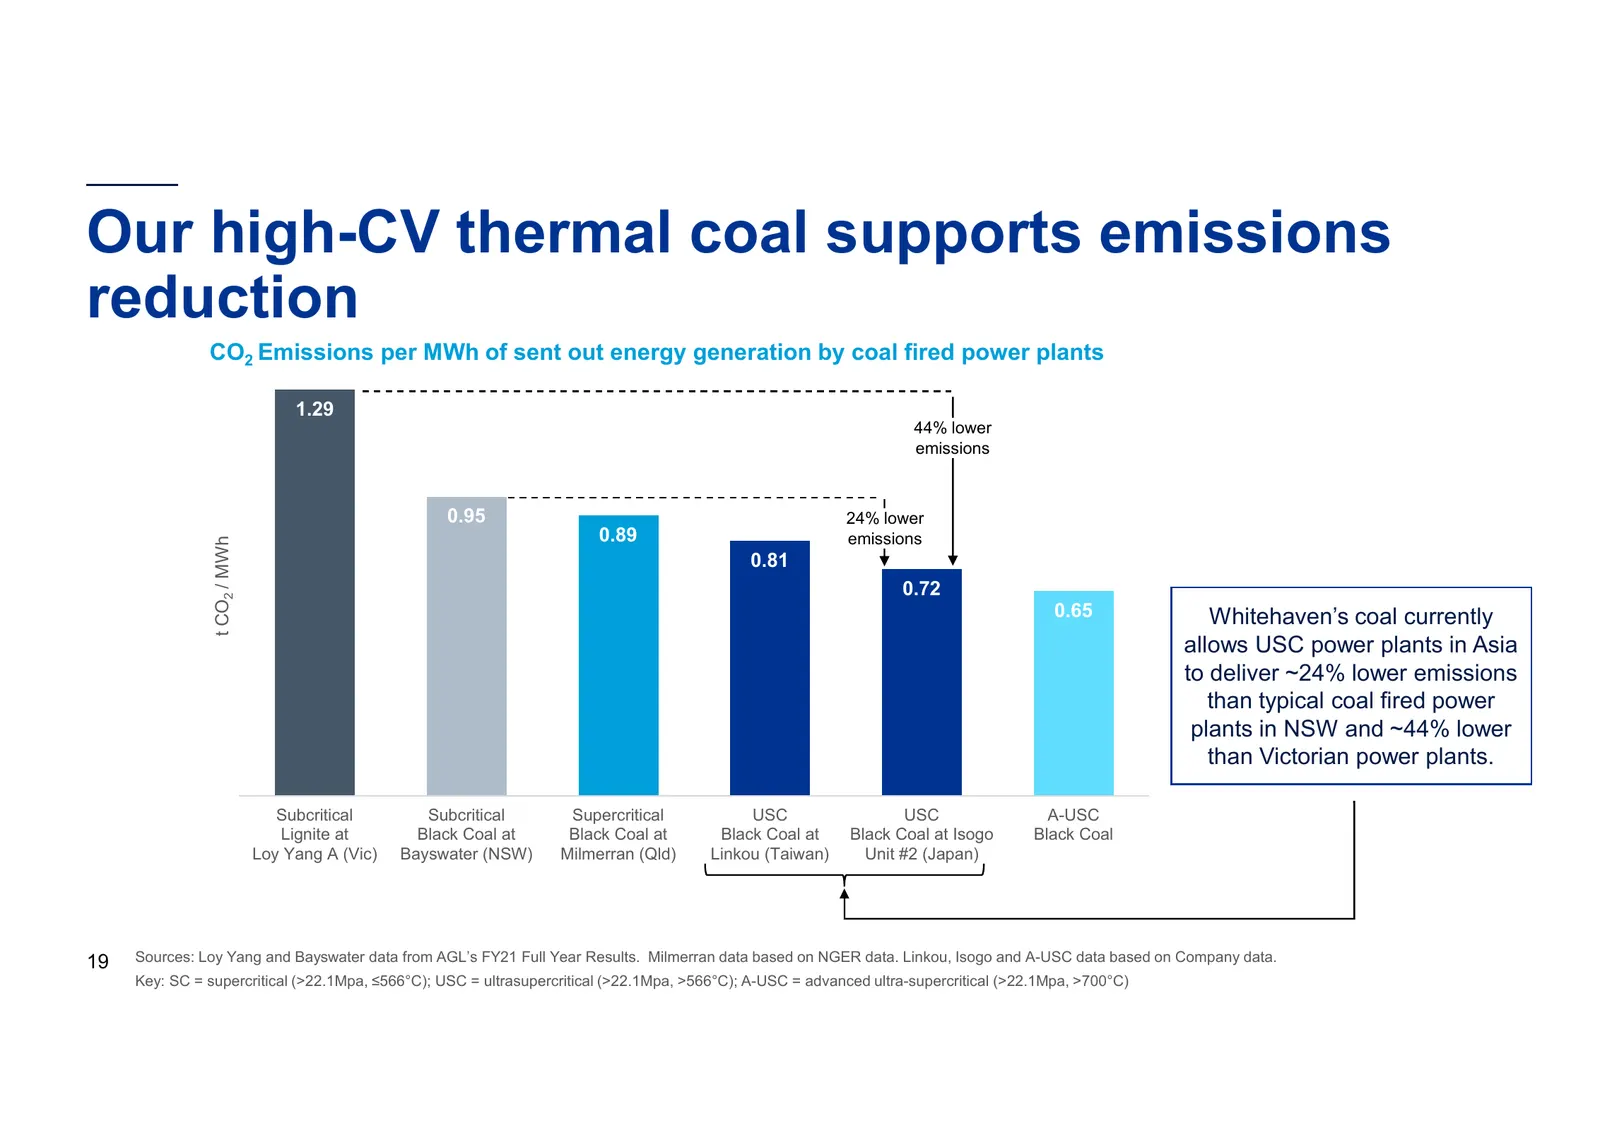
Our high-CV thermal coal supports emissions reduction CO2 Emissions per MWh of sent out energy generation by coal fired power plants 1.29 44% lower emissions 0.95 24% lower 0.89 emissions t CO2 / MWh 0.81 0.72 0.65 Whitehaven’s coal currently allows USC power plants in Asia to deliver ~24% lower emi
Slide 20: We produce the highest quality seaborne coal
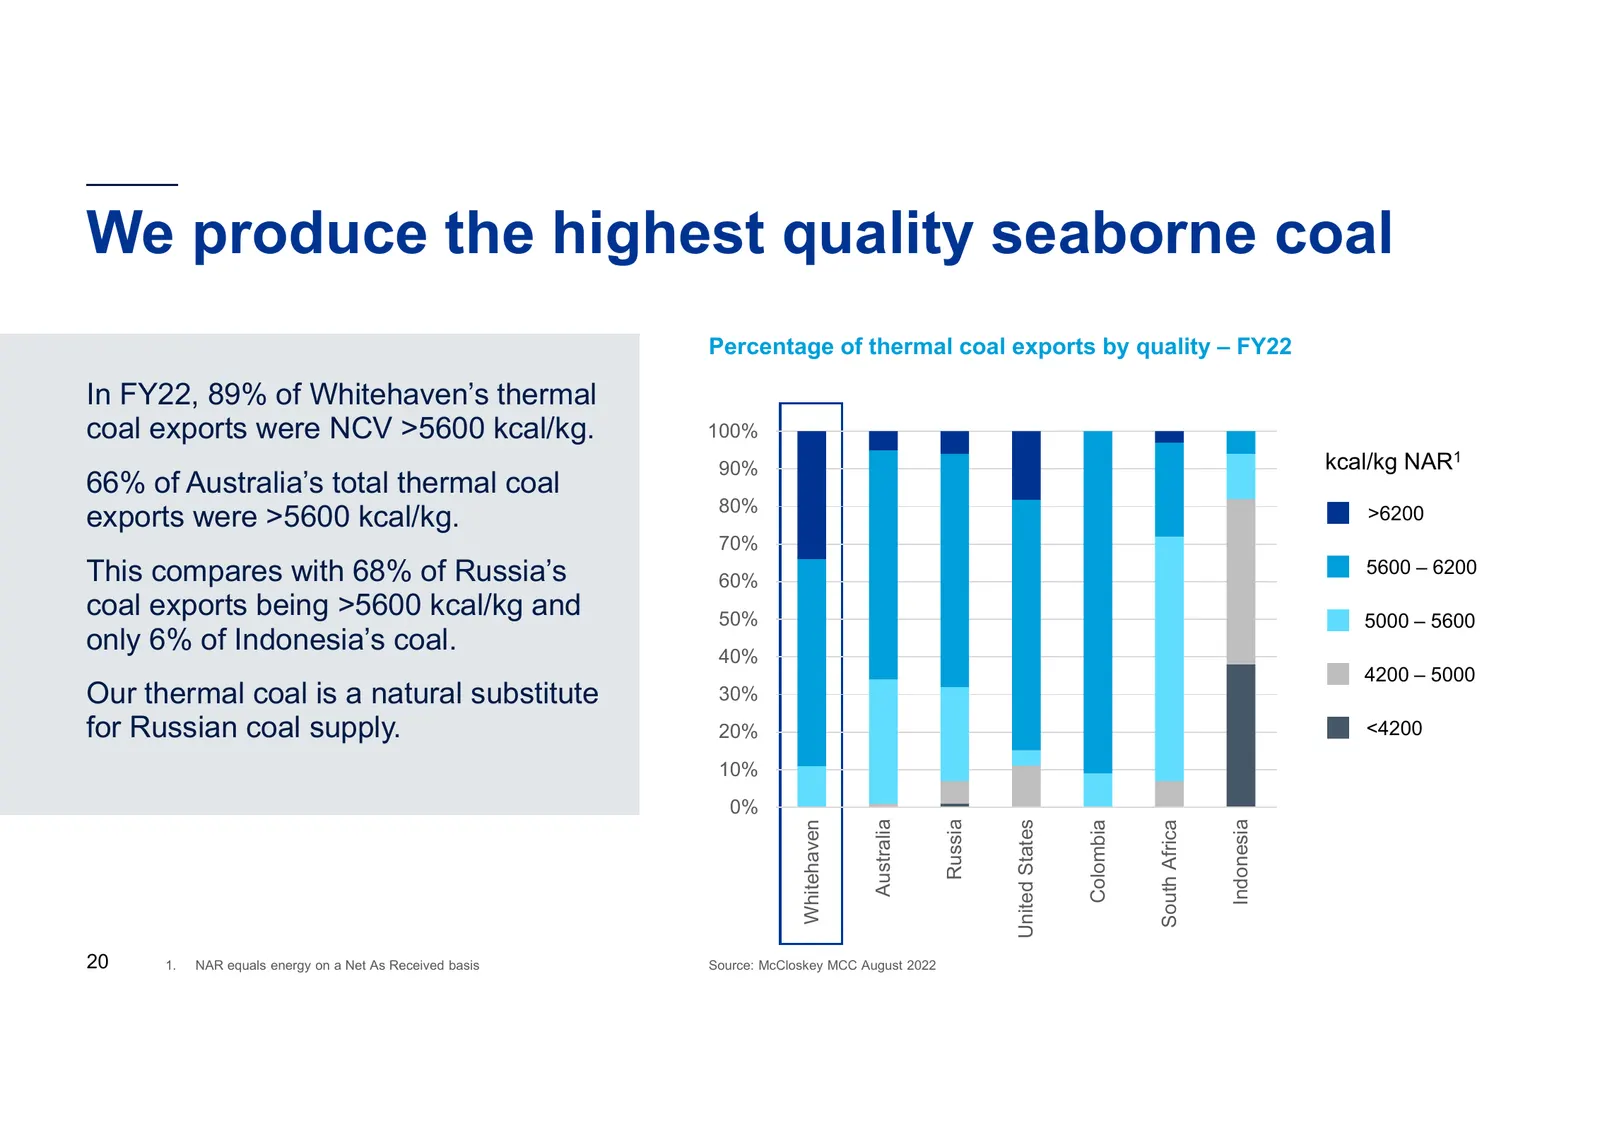
We produce the highest quality seaborne coal Percentage of thermal coal exports by quality – FY22 In FY22, 89% of Whitehaven’s thermal coal exports were NCV >5600 kcal/kg. 100% 90% kcal/kg NAR1 66% of Australia’s total thermal coal 80% exports were >5600 kcal/kg. >6200 70% This compares with 68% of
Slide 21: Our future
Our future
Slide 22: Reliable energy is required for the energy transition but the supply gap continues
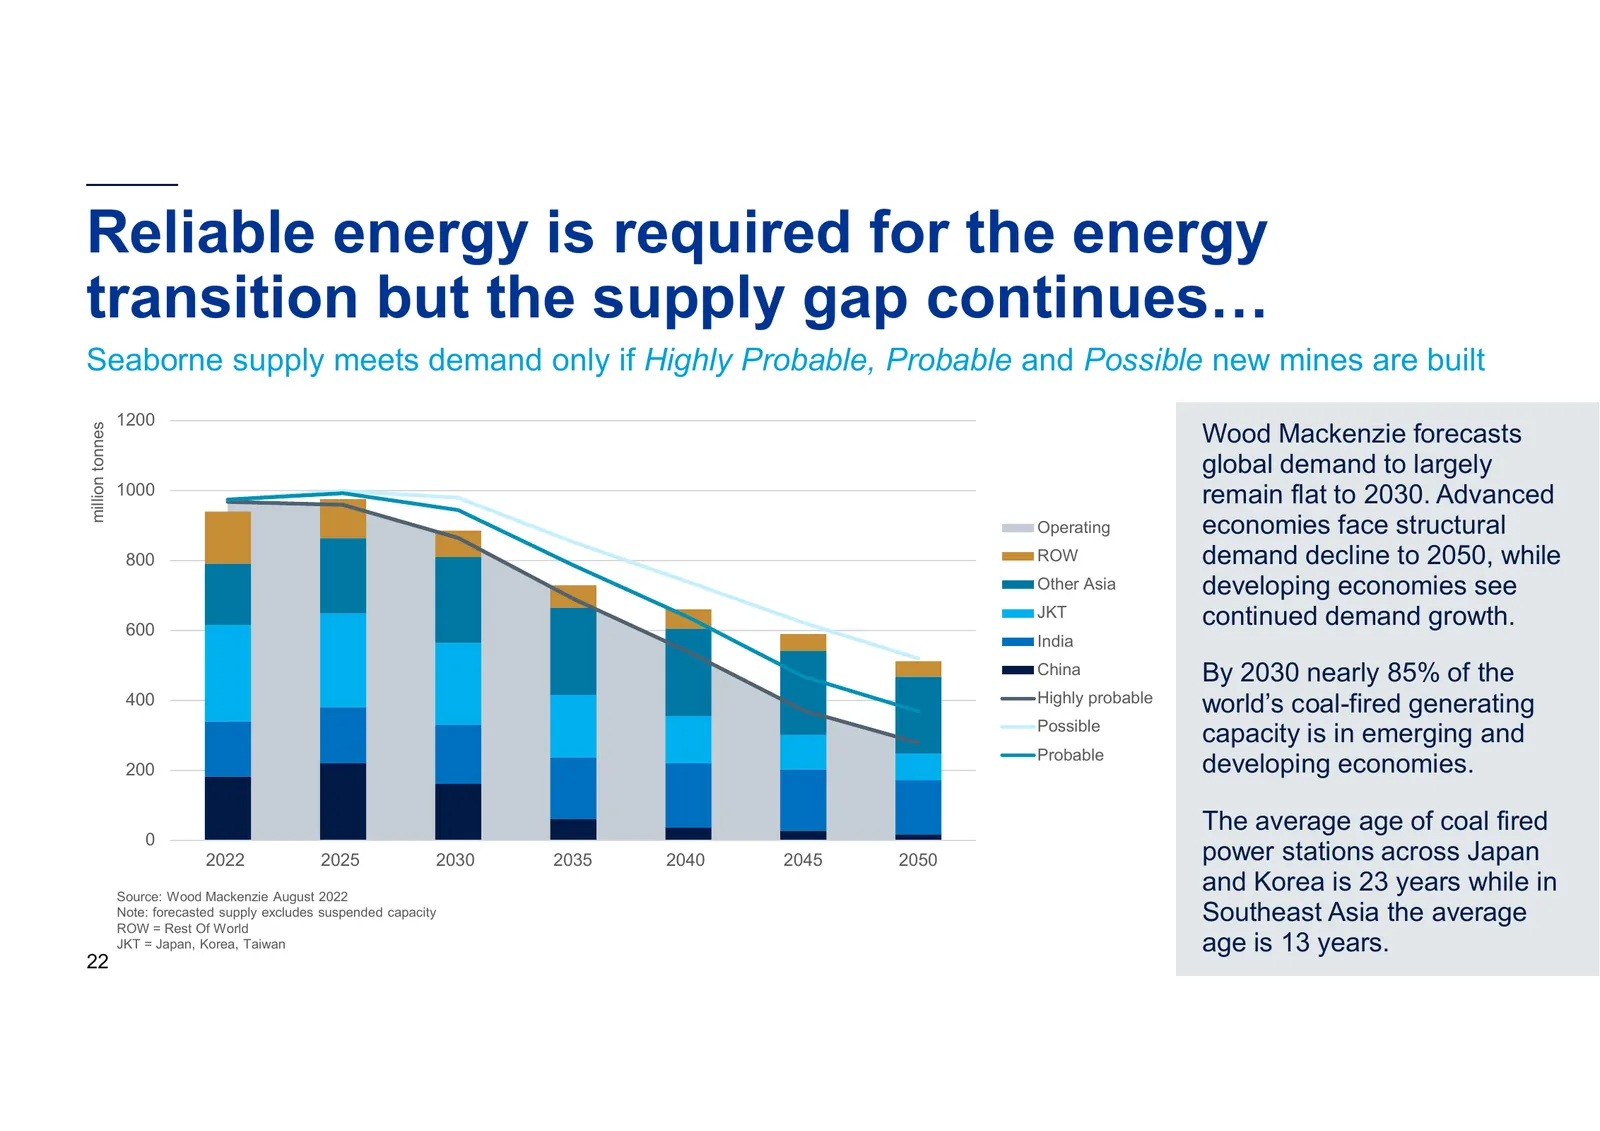
Reliable energy is required for the energy transition but the supply gap continues… Seaborne supply meets demand only if Highly Probable, Probable and Possible new mines are built 1200 million tonnes Wood Mackenzie forecasts global demand to largely 1000 remain flat to 2030. Advanced Operating econo
Slide 23: Our portfolio of assets presents options to grow
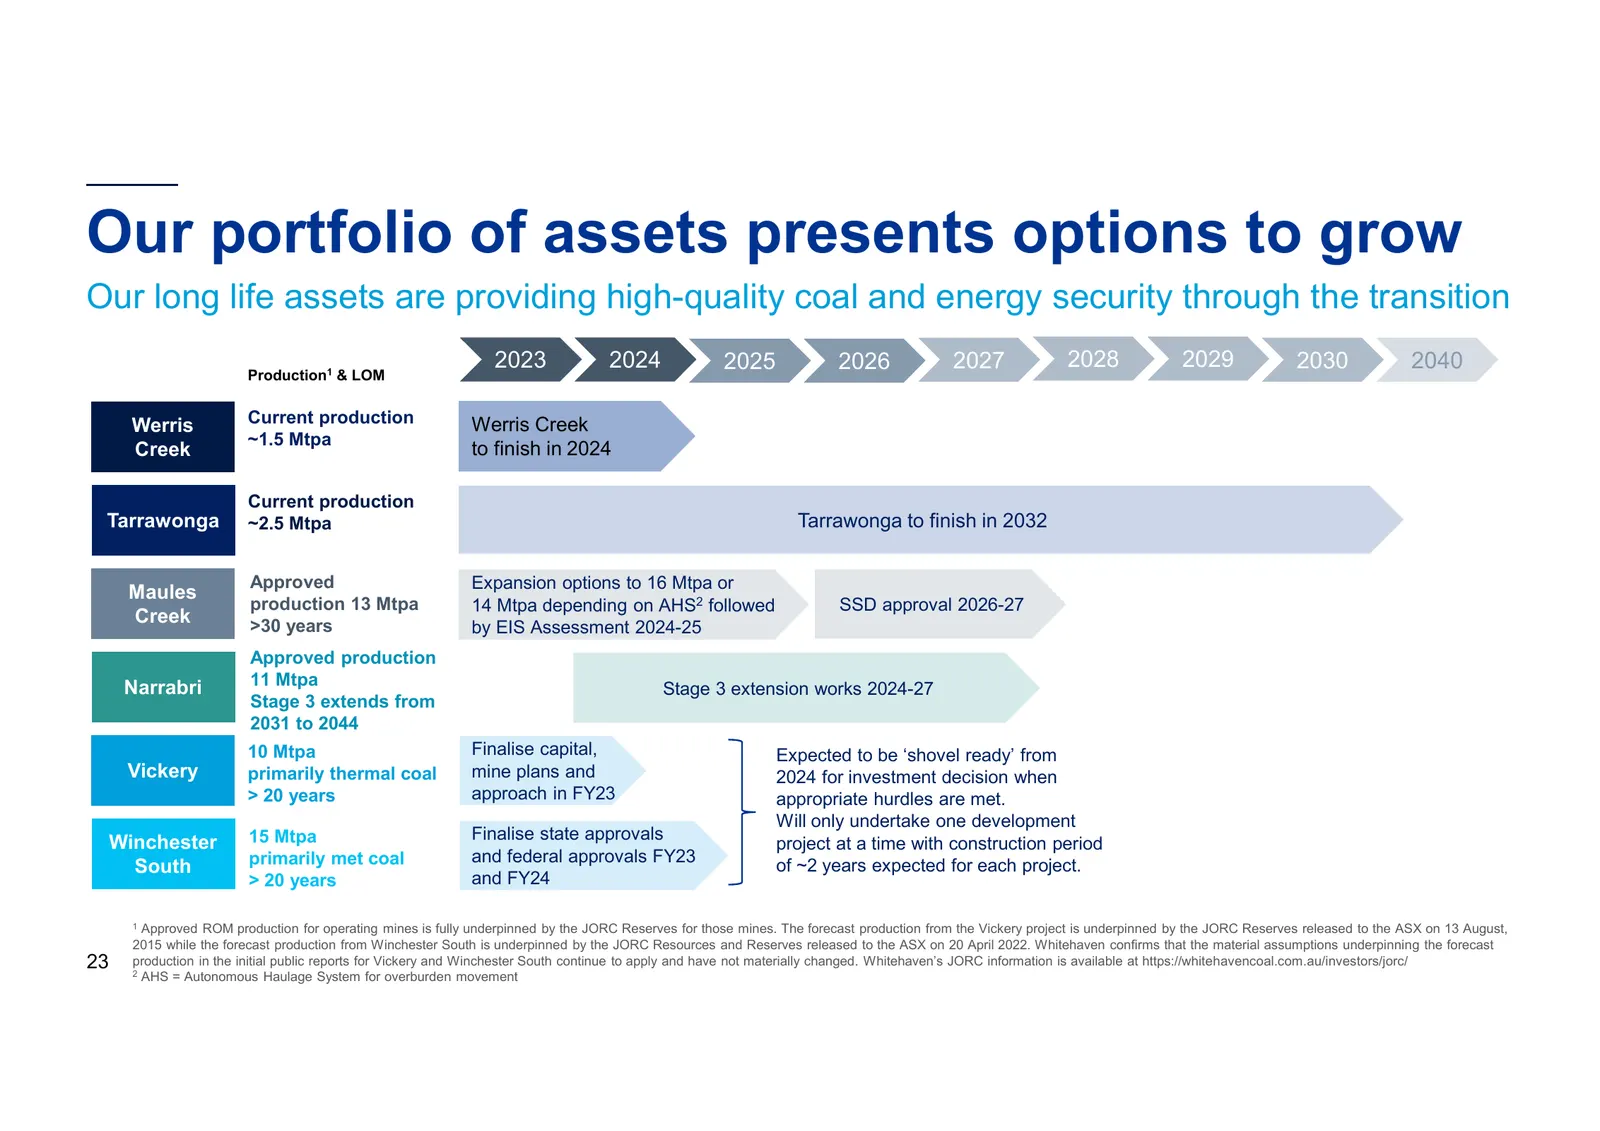
Our portfolio of assets presents options to grow Our long life assets are providing high-quality coal and energy security through the transition 2023 2024 2025 2026 2027 2028 2029 2030 2040 Production1 & LOM Werris Current production Werris Creek ~1.5 Mtpa Creek to finish in 2024 Current production
Slide 24: Asian demand for metallurgical coal remains robust over the next three decades
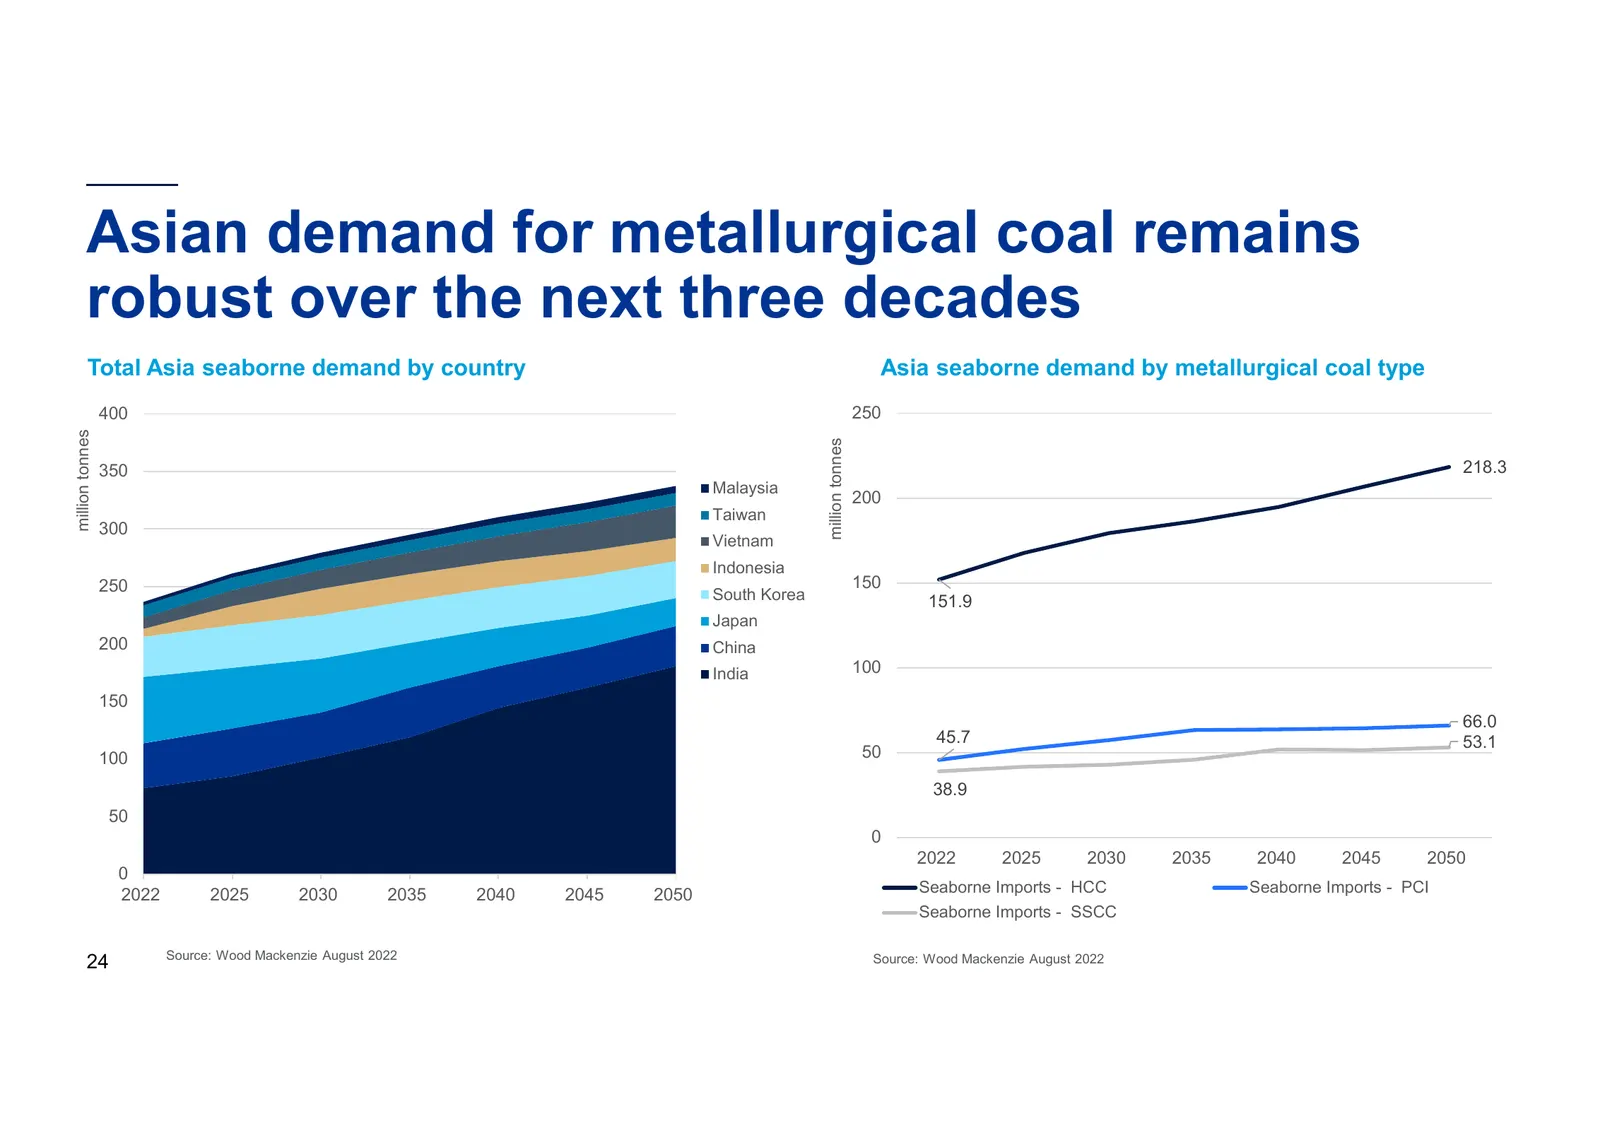
Asian demand for metallurgical coal remains robust over the next three decades Total Asia seaborne demand by country Asia seaborne demand by metallurgical coal type 400 250 million tonnes million tonnes 350 218.3 Malaysia 200 Taiwan 300 Vietnam Indonesia 250 150 South Korea 151.9 Japan 200 China Ind
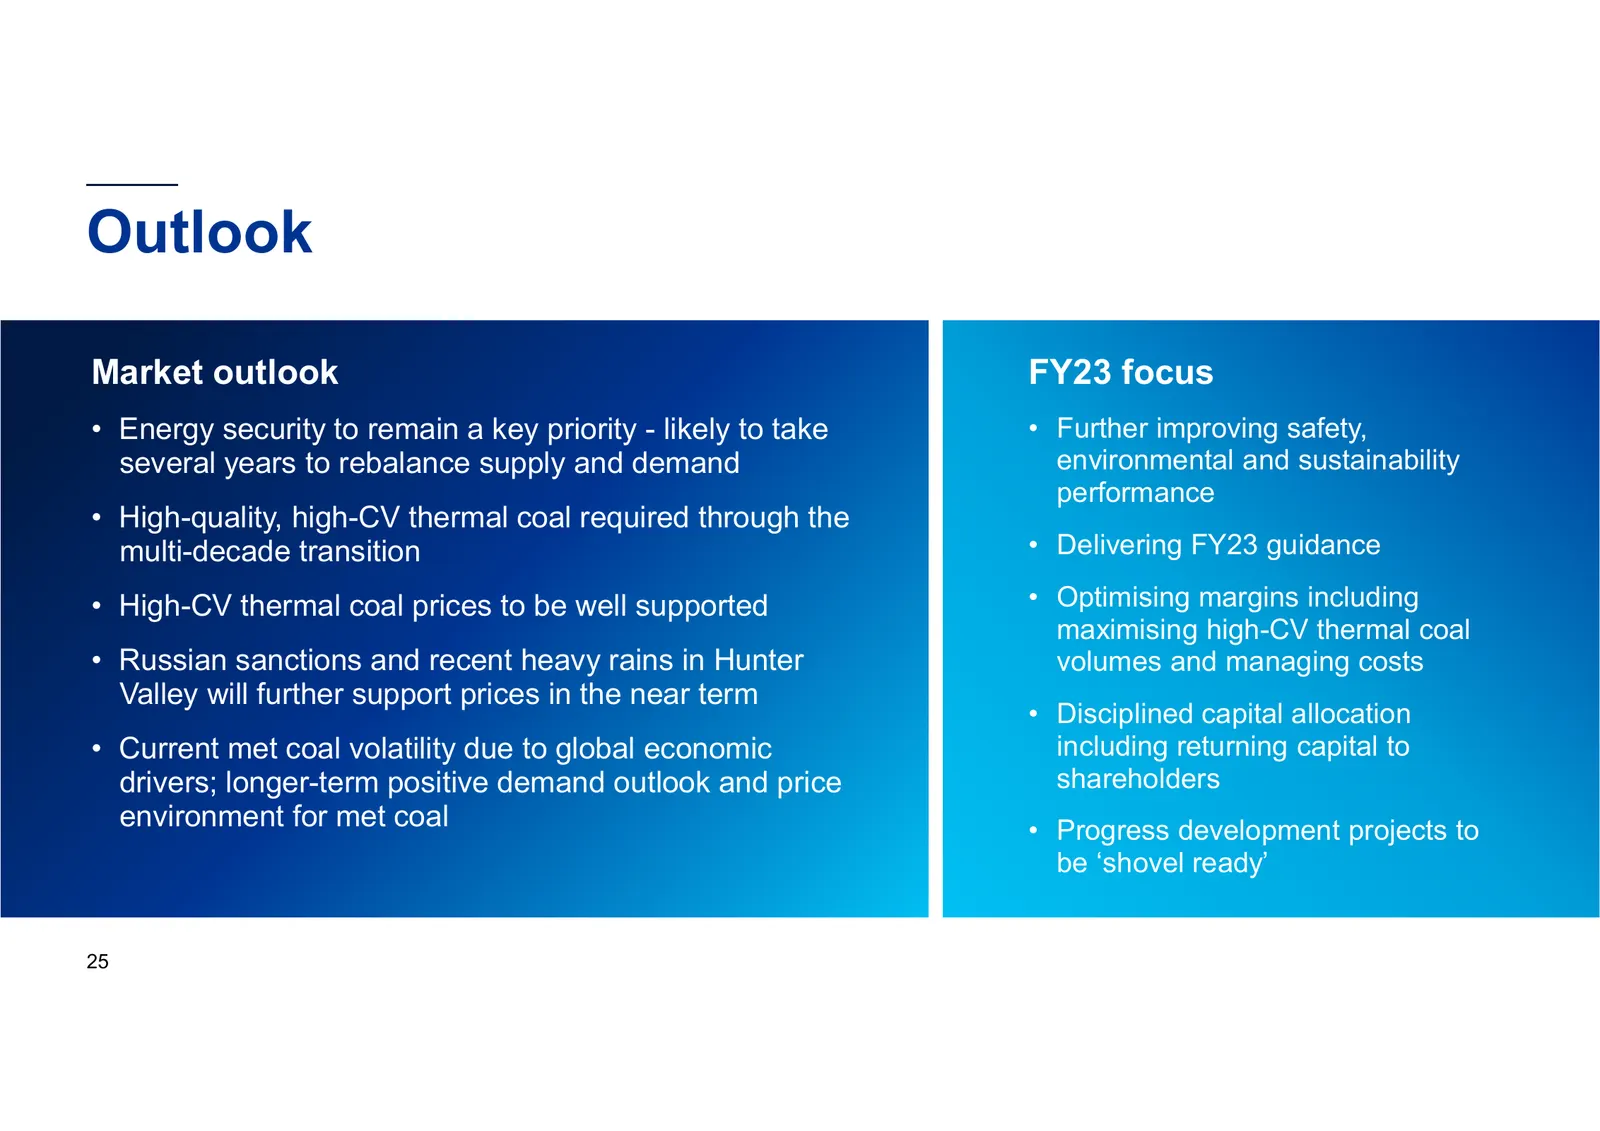
Slide 25: Outlook
Outlook Market outlook FY23 focus • Energy security to remain a key priority - likely to take • Further improving safety, several years to rebalance supply and demand environmental and sustainability performance • High-quality, high-CV thermal coal required through the multi-decade transition • Deli
Slide 26
Source: Internet Archive copy of whitehavencoal.com.au
More decks from Whitehaven Coal Limited
 Shareholder Meeting (November 2026)20 slides · Nov 5, 2026
 FY2026 Earnings Presentation46 slides · Aug 19, 2026
 H1 FY26 Earnings Presentation48 slides · Feb 19, 2026
 Shareholder Meeting (October 2025)16 slides · Oct 30, 2025
 Shareholder Meeting (October 2025)25 slides · Oct 30, 2025
 FY25 Earnings Presentation50 slides · Aug 21, 2025