Grenergy Renovables S.A · BME:GRE
Grenergy Renovables — Q1 2024 Earnings Presentation
28 slides from Grenergy Renovables's earnings presentation, May 23, 2024
Slide 1: 1Q24 Results Presentation
The sky is the limit RESULTS PRESENTATION 1Q24 RESULTS Madrid, 23rd May 2024 Gran Teno Solar PV - Chile
Slide 2: Disclaimer
DISCLAIMER By attending this presentation and/or by accepting this presentation you will be cial condition or results of operations by the Company and should not be relied upon taken to have represented, warranted and undertaken that you have read and when making an investment decision. Certain finan
Slide 3: Highlights: Business, Financial, Sustainability
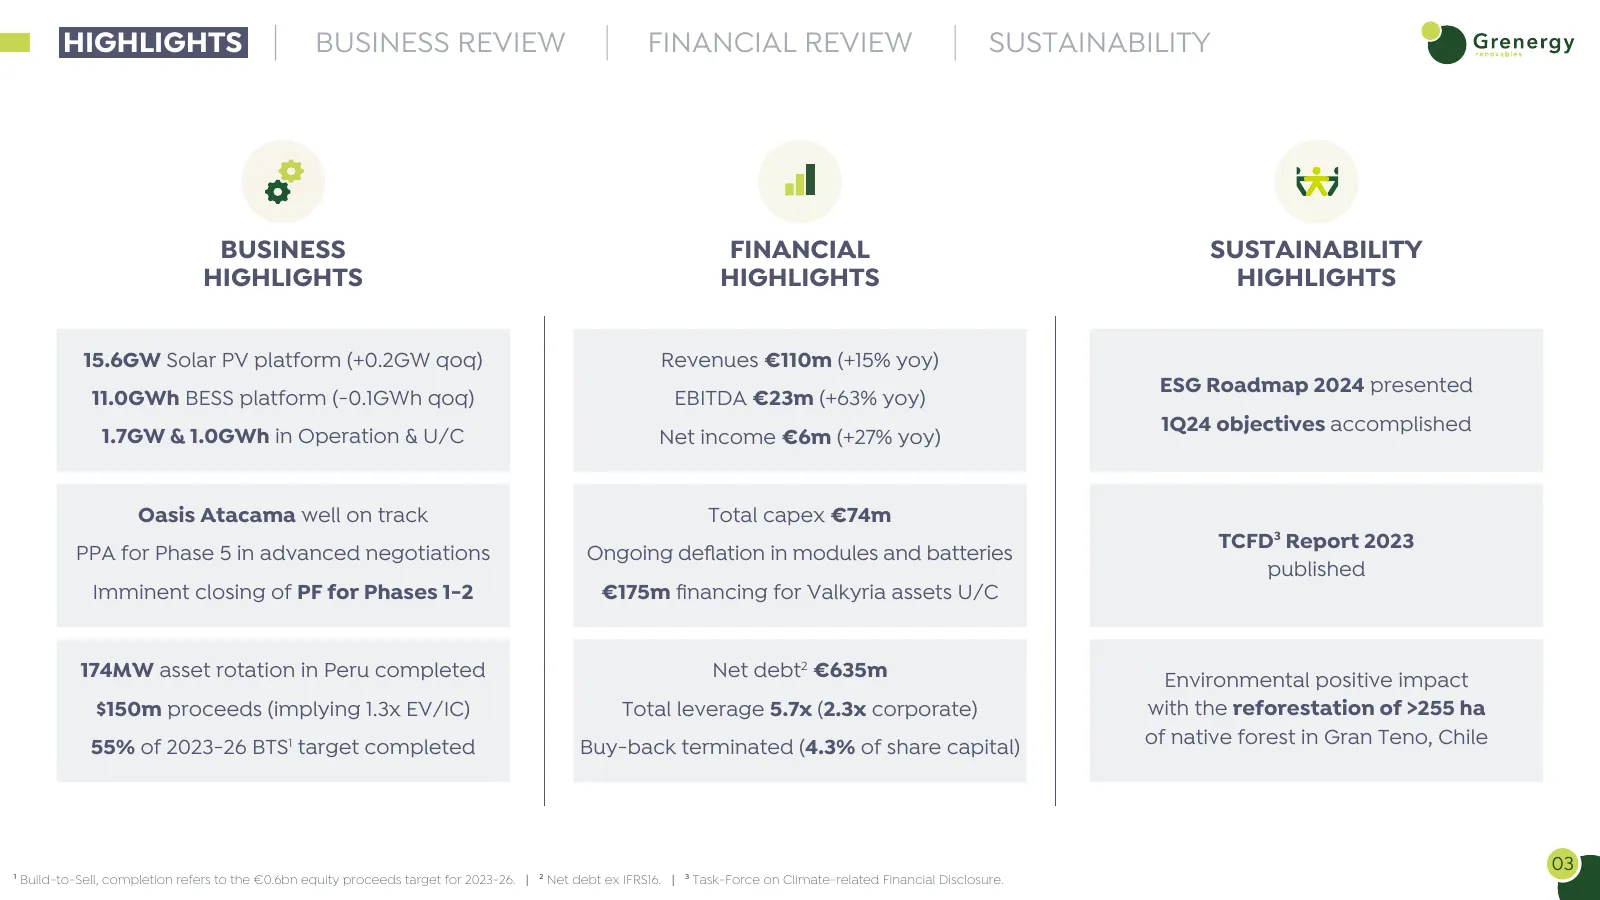
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY BUSINESS FINANCIAL SUSTAINABILITY HIGHLIGHTS HIGHLIGHTS HIGHLIGHTS 15.6GW Solar PV platform (+0.2GW qoq) Revenues €110m (+15% yoy) ESG Roadmap 2024 presented 11.0GWh BESS platform (-0.1GWh qoq) EBITDA €23m (+63% yoy) 1Q24 objectives accompli
Slide 4: Platform Overview – Solar PV & BESS
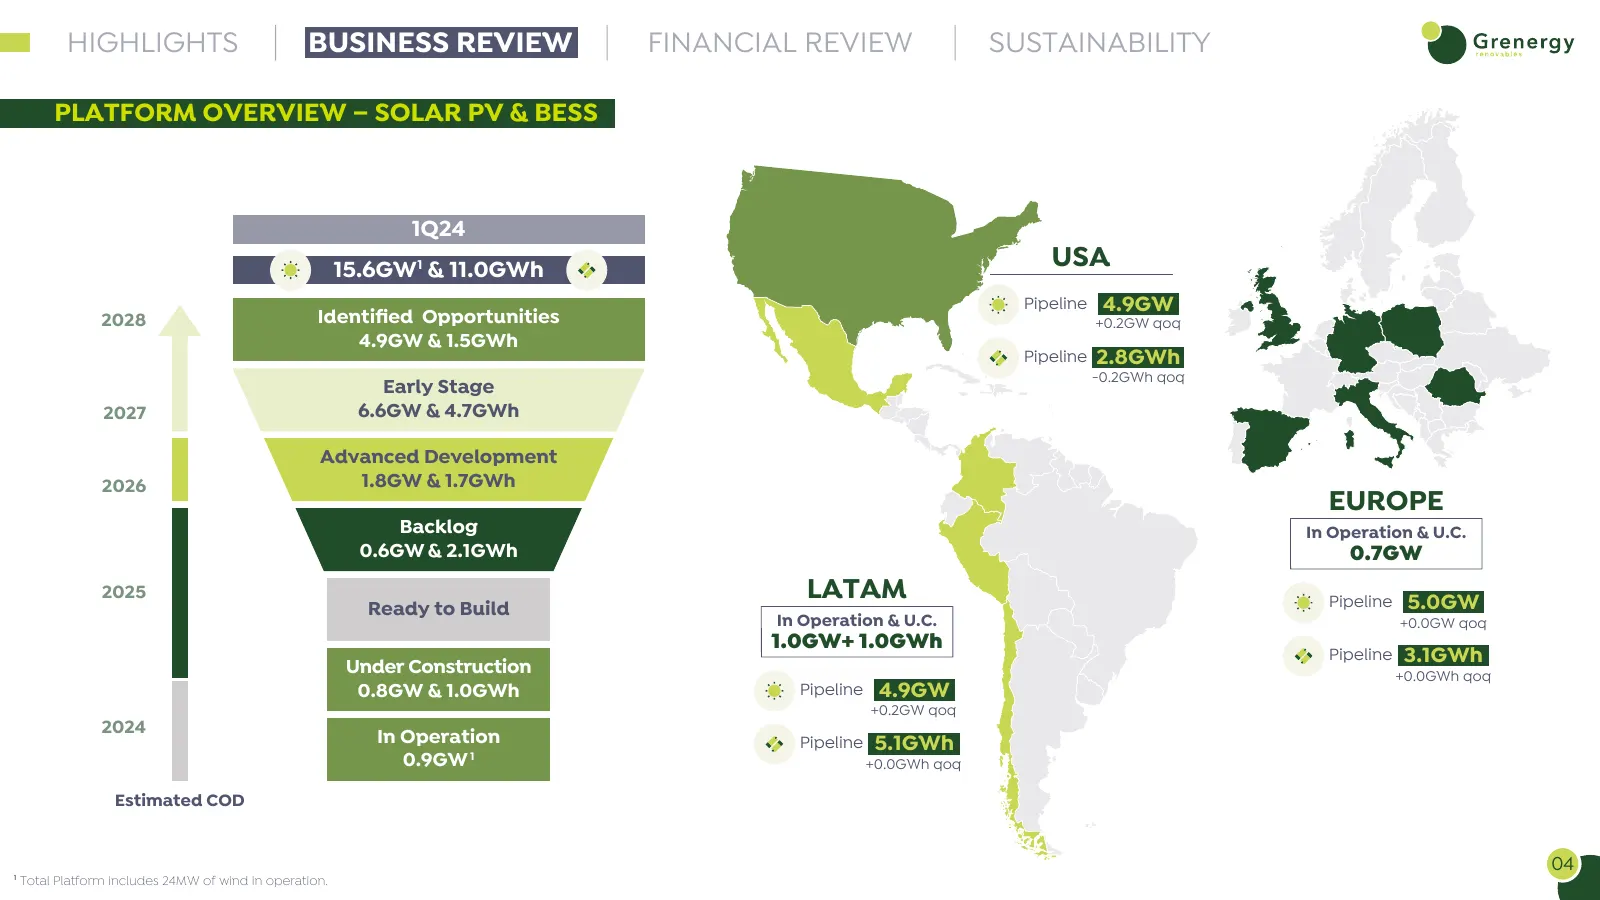
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY PLATFORM OVERVIEW – SOLAR PV & BESS 1Q24 15.6GW1 & 11.0GWh USA Pipeline 4.9GW 2028 Identified Opportunities +0.2GW qoq 4.9GW & 1.5GWh Pipeline 2.8GWh -0.2GWh qoq Early Stage 2027 6.6GW & 4.7GWh Advanced Development 2026 1.8GW & 1.7GWh EUROPE
Slide 5: Solar PV & BESS Pipeline Update
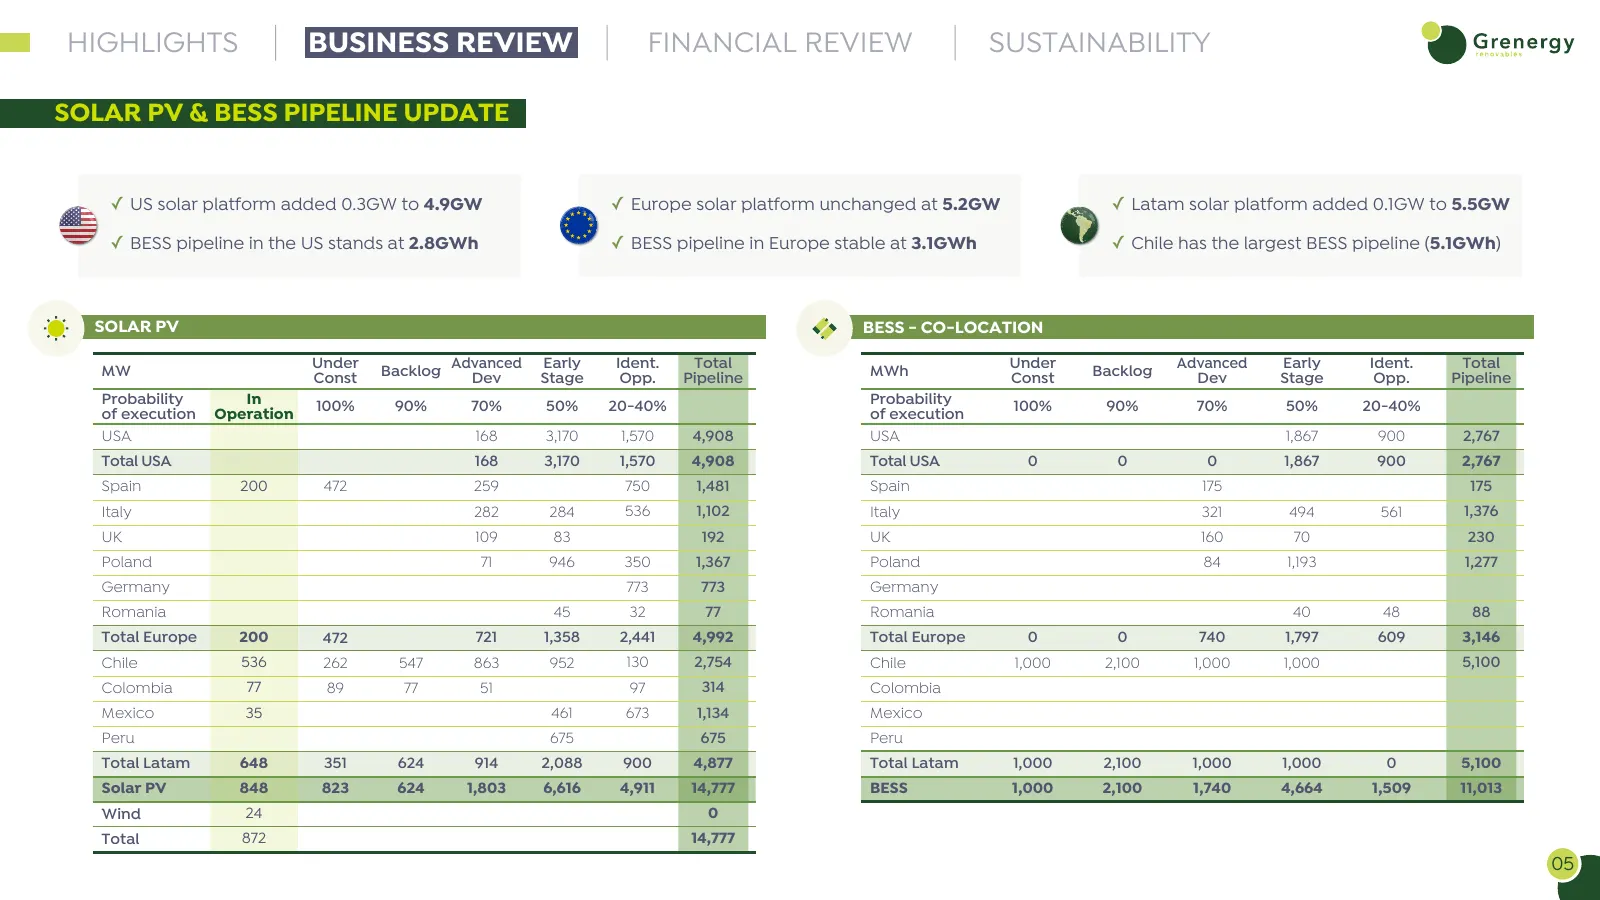
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY SOLAR PV & BESS PIPELINE UPDATE ✓ US solar platform added 0.3GW to 4.9GW ✓ Europe solar platform unchanged at 5.2GW ✓ Latam solar platform added 0.1GW to 5.5GW ✓ BESS pipeline in the US stands at 2.8GWh ✓ BESS pipeline in Europe stable at 3.
Slide 6: Highly Contracted Output & Revenues
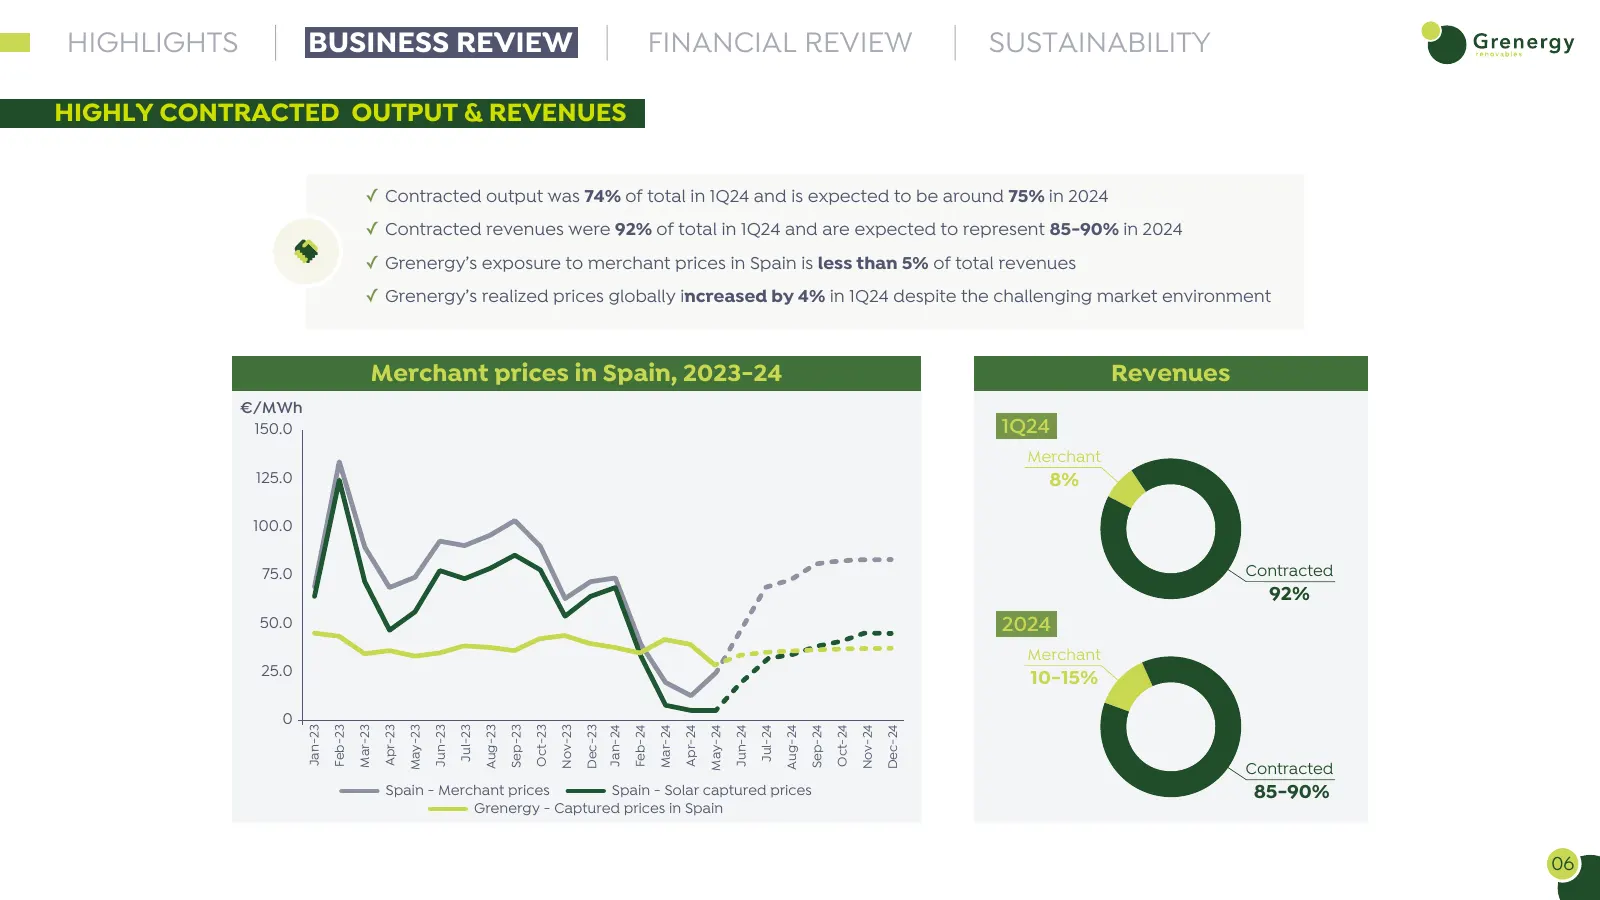
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY HIGHLY CONTRACTED OUTPUT & REVENUES ✓ Contracted output was 74% of total in 1Q24 and is expected to be around 75% in 2024 ✓ Contracted revenues were 92% of total in 1Q24 and are expected to represent 85-90% in 2024 ✓ Grenergy’s exposure to m
Slide 7: Largest BESS Project in LatAm with 4.1GWh
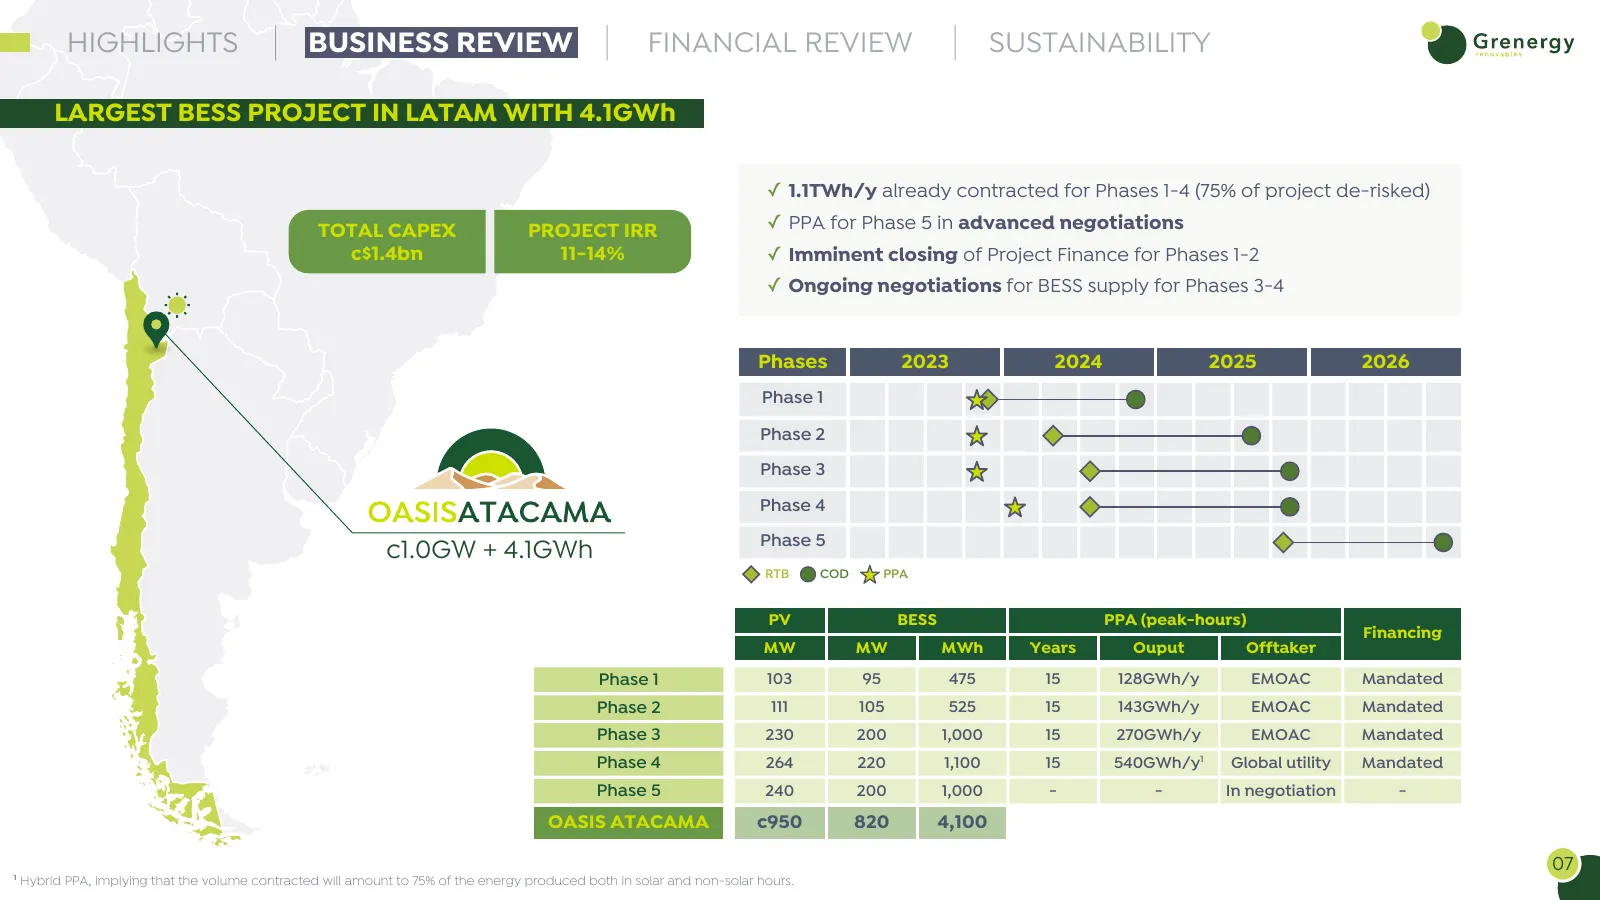
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY LARGEST BESS PROJECT IN LATAM WITH 4.1GWh ✓ 1.1TWh/y already contracted for Phases 1-4 (75% of project de-risked) TOTAL CAPEX PROJECT IRR ✓ PPA for Phase 5 in advanced negotiations c$1.4bn 11-14% ✓ Imminent closing of Project Finance for Pha
Slide 8: Atacama's Execution Well on Track
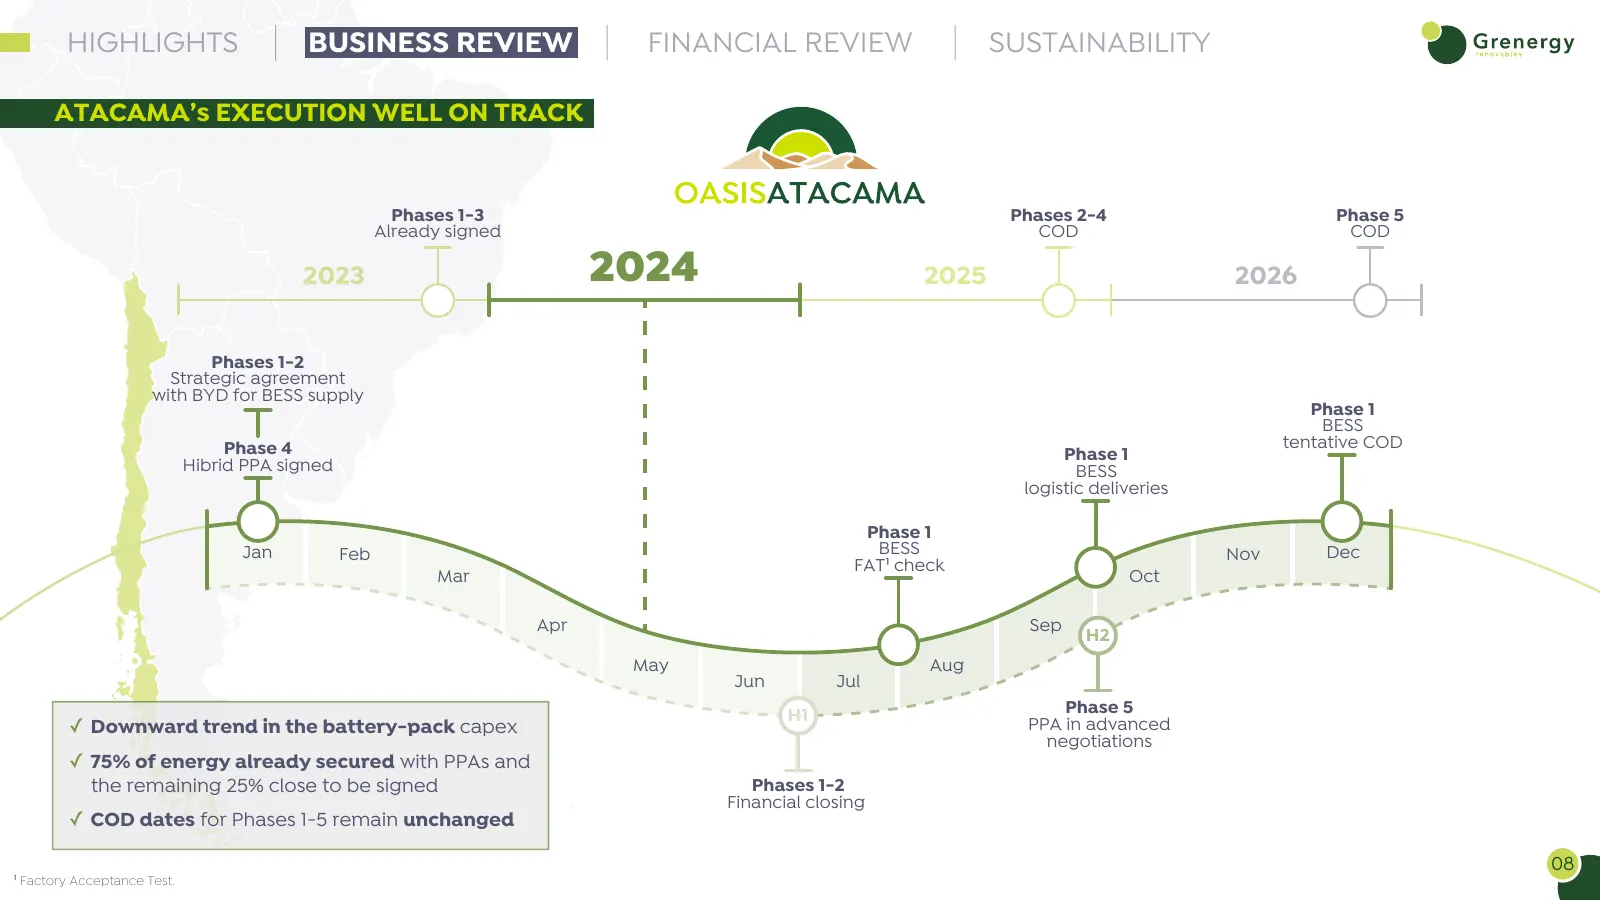
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY ATACAMA’s EXECUTION WELL ON TRACK Phases 1-3 Phases 2-4 Phase 5 Already signed COD COD 2023 2024 2025 2026 Phases 1-2 Strategic agreement with BYD for BESS supply Phase 1 BESS Phase 4 tentative COD Phase 1 Hibrid PPA signed BESS logistic del
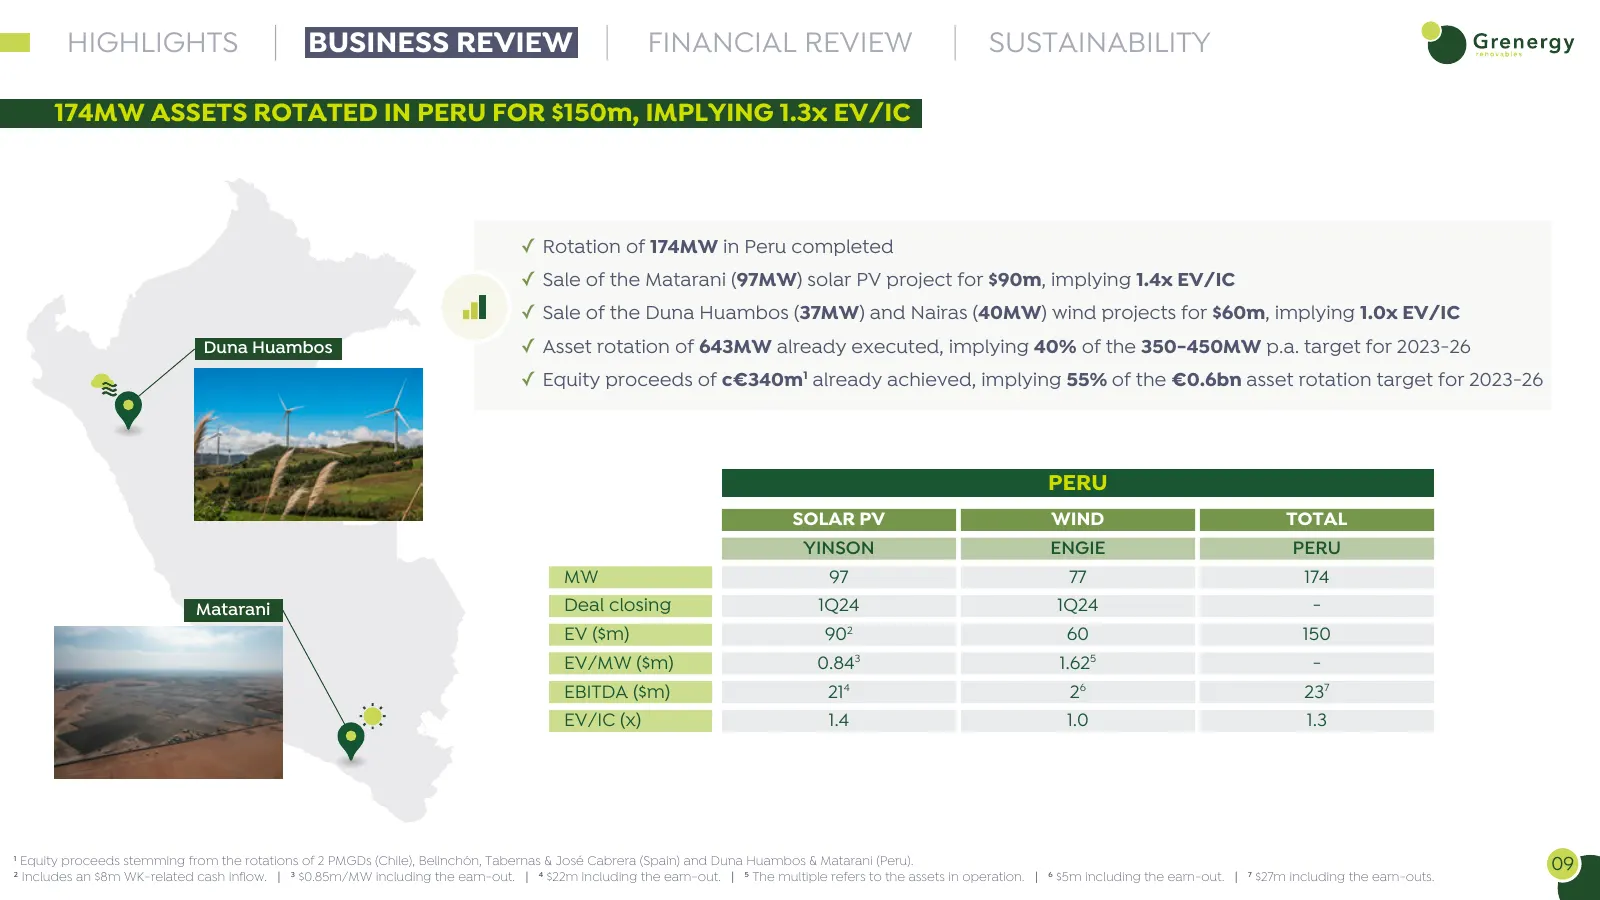
Slide 9: 174MW Assets Rotated in Peru for $150m
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY 174MW ASSETS ROTATED IN PERU FOR $150m, IMPLYING 1.3x EV/IC ✓ Rotation of 174MW in Peru completed ✓ Sale of the Matarani (97MW) solar PV project for $90m, implying 1.4x EV/IC ✓ Sale of the Duna Huambos (37MW) and Nairas (40MW) wind projects
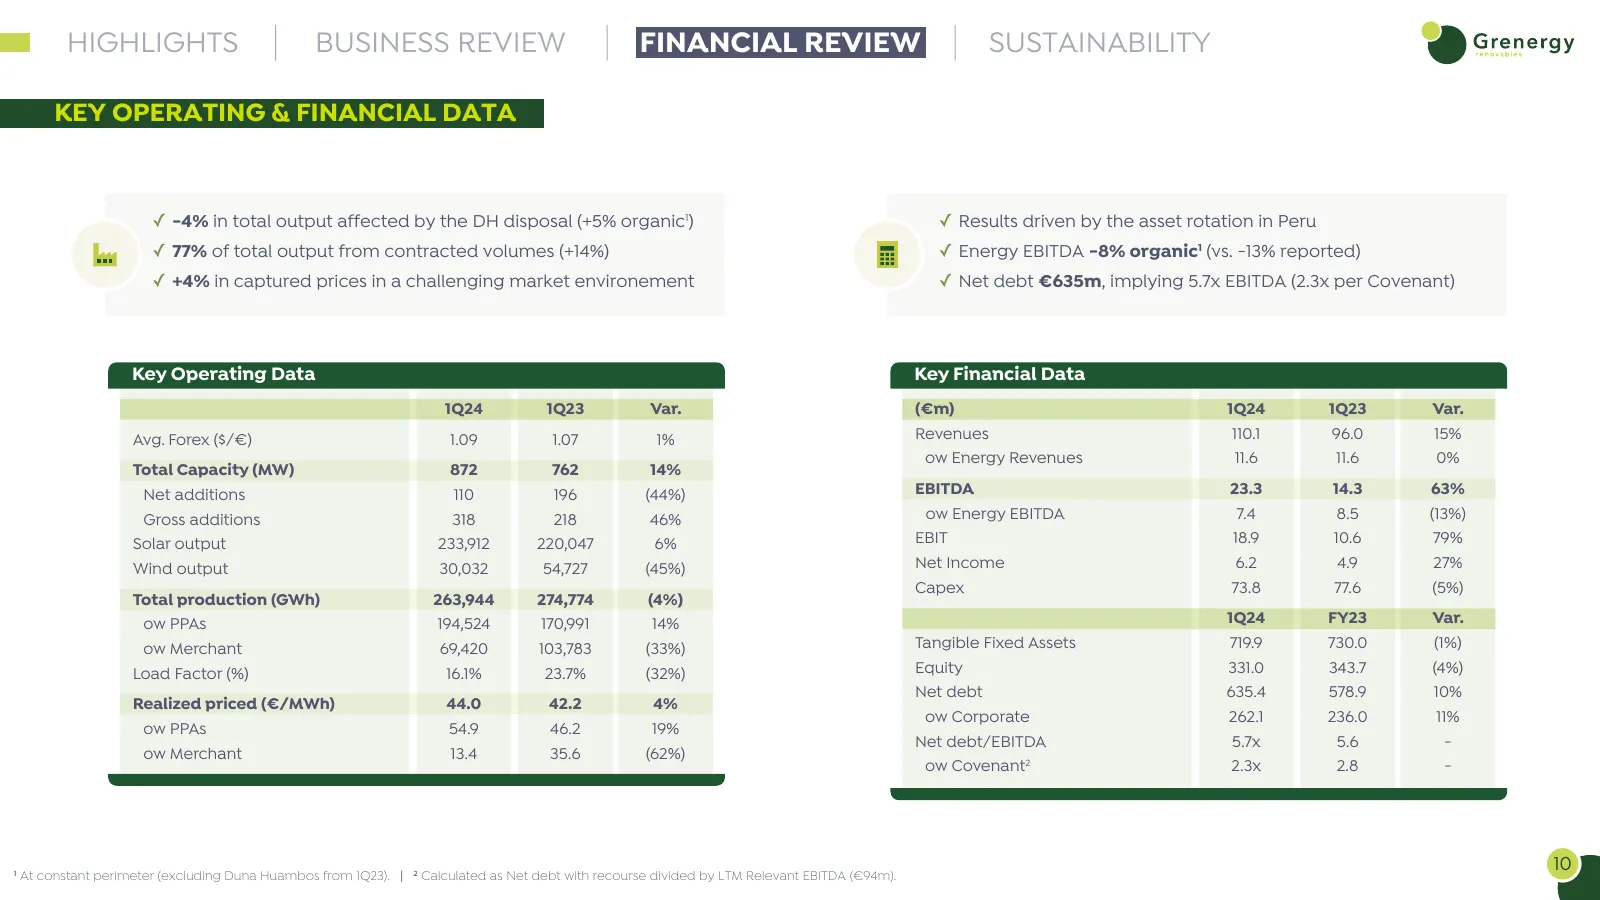
Slide 10: Key Operating & Financial Data
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY KEY OPERATING & FINANCIAL DATA ✓ -4% in total output affected by the DH disposal (+5% organic1) ✓ Results driven by the asset rotation in Peru ✓ 77% of total output from contracted volumes (+14%) ✓ Energy EBITDA -8% organic1 (vs. -13% report
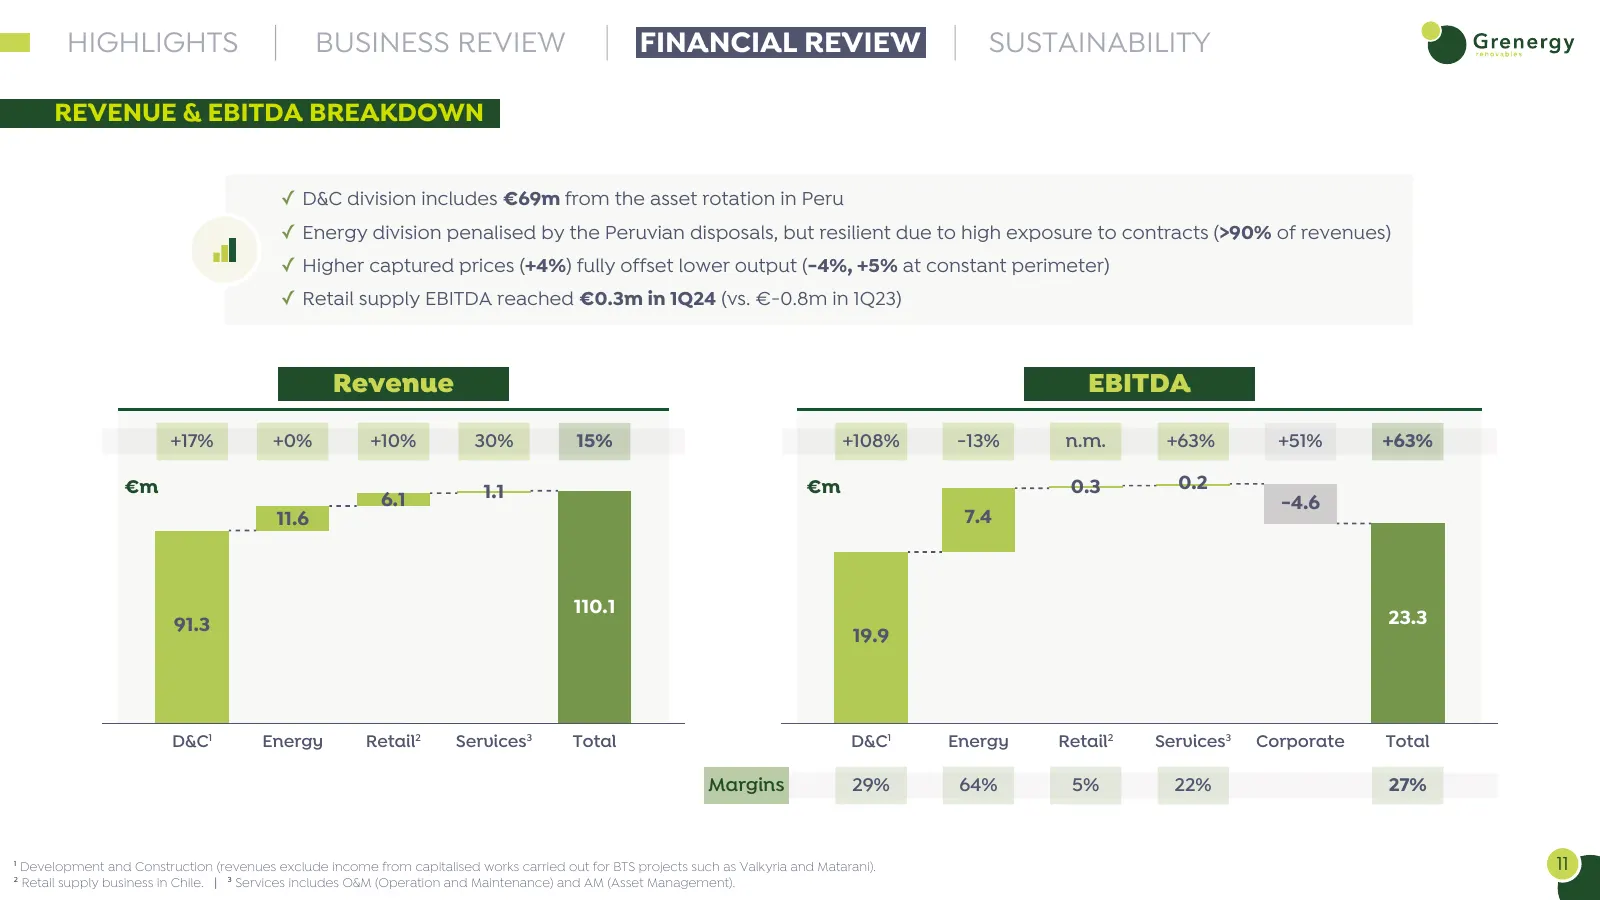
Slide 11: Revenue & EBITDA Breakdown
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY REVENUE & EBITDA BREAKDOWN ✓ D&C division includes €69m from the asset rotation in Peru ✓ Energy division penalised by the Peruvian disposals, but resilient due to high exposure to contracts (>90% of revenues) ✓ Higher captured prices (+4%)
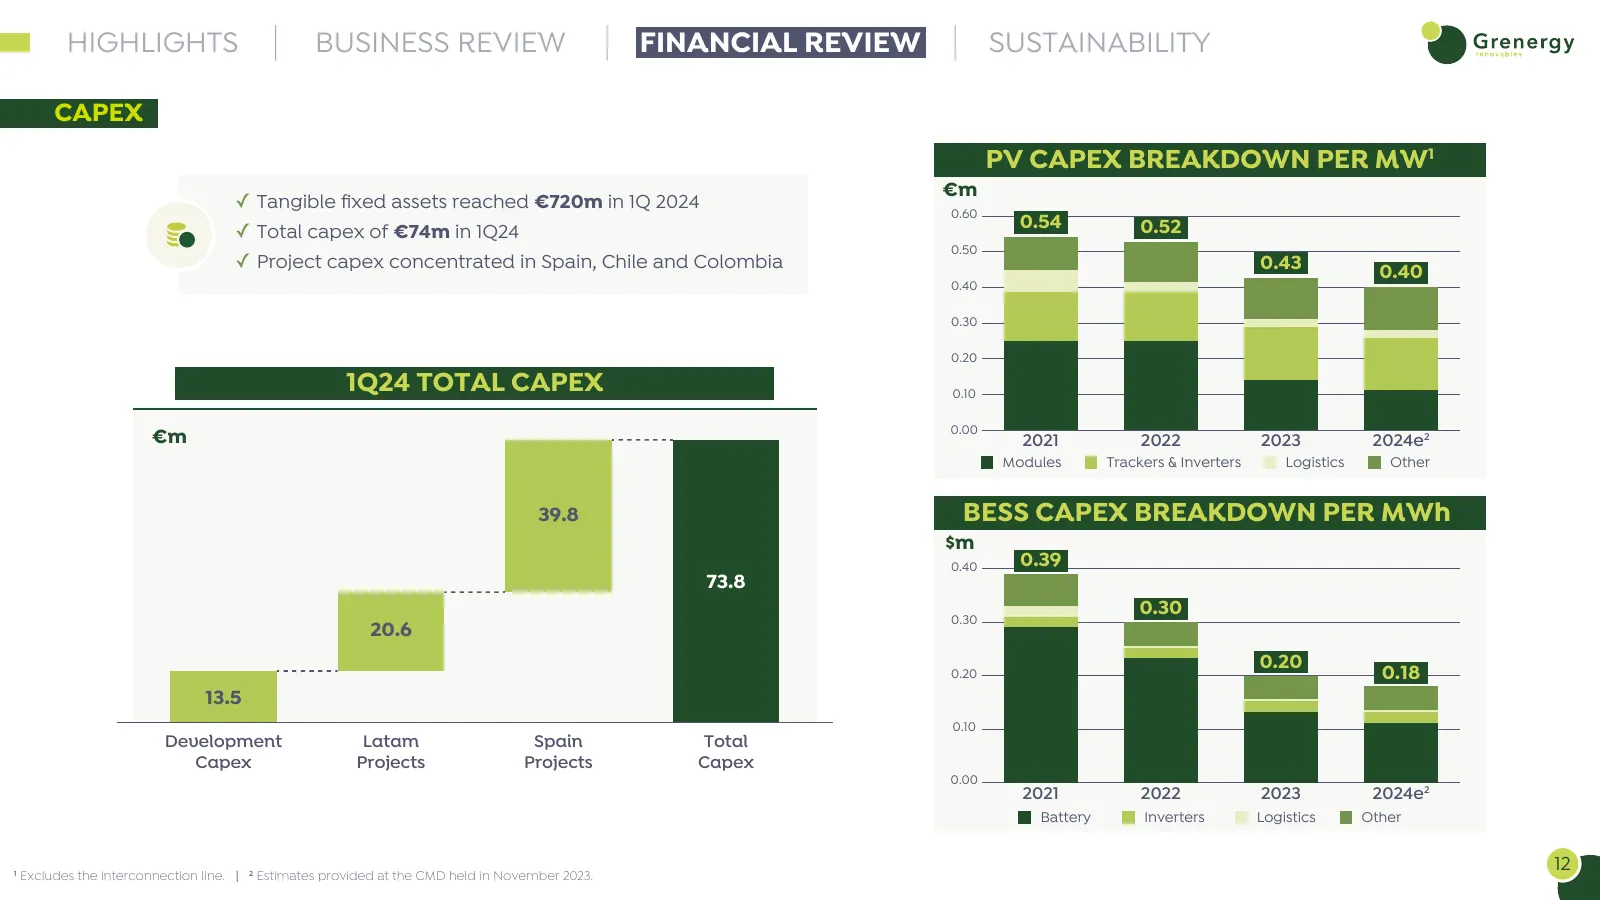
Slide 12: Capex
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY CAPEX PV CAPEX BREAKDOWN PER MW1 €m ✓ Tangible fixed assets reached €720m in 1Q 2024 0.60 0.54 0.52 ✓ Total capex of €74m in 1Q24 0.50 ✓ Project capex concentrated in Spain, Chile and Colombia 0.43 0.40 0.40 0.30 0.20 1Q24 TOTAL CAPEX 0.10 0
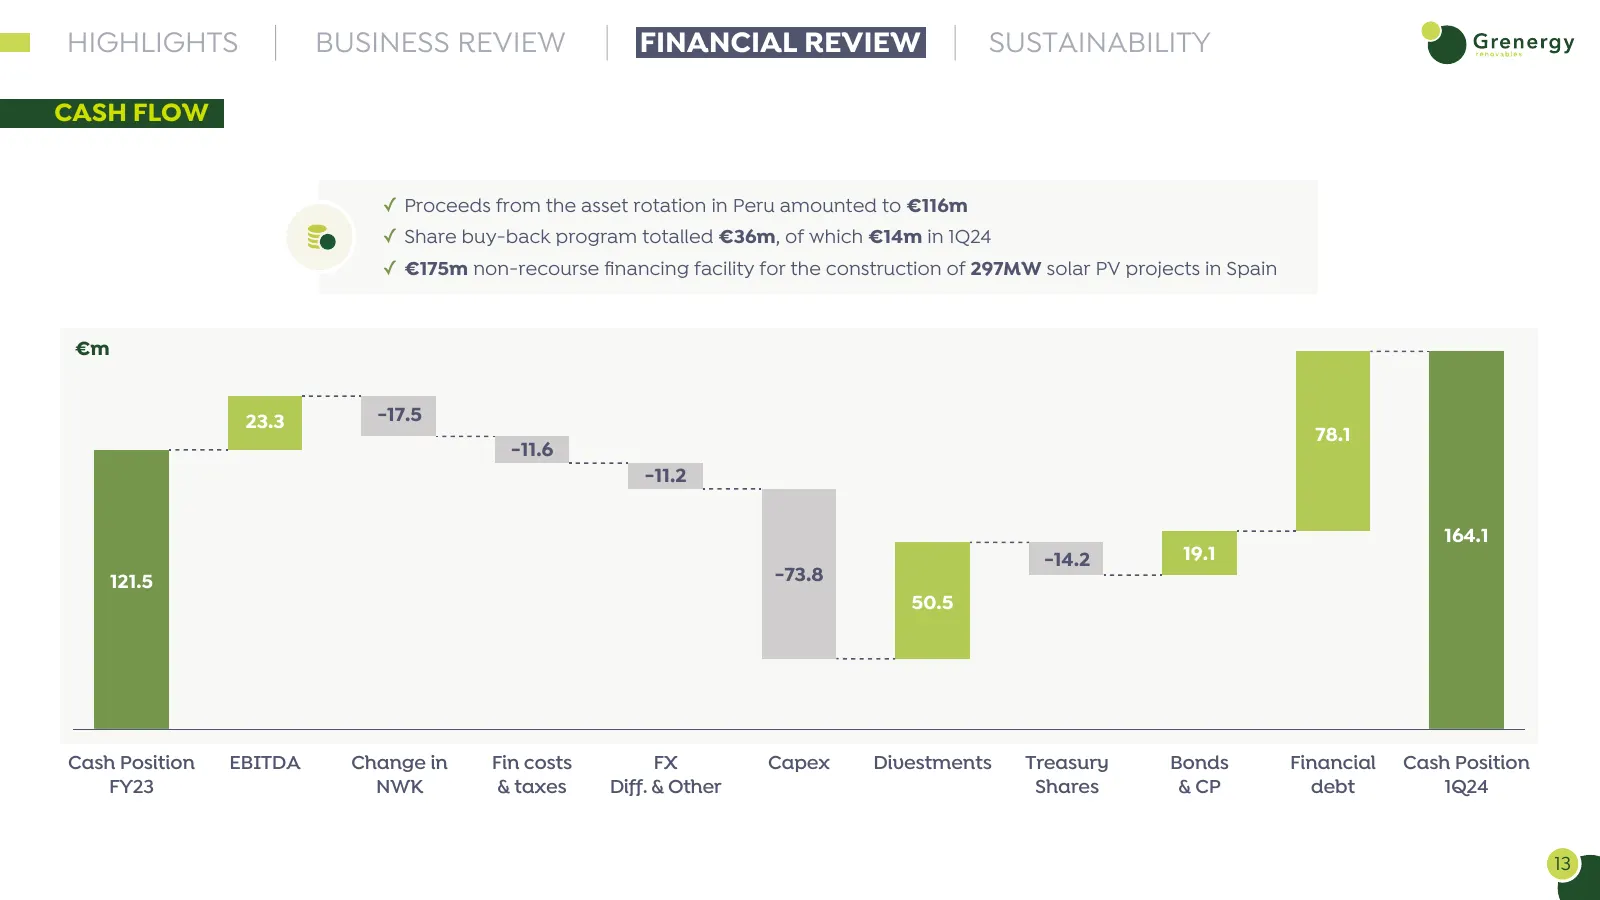
Slide 13: Cash Flow
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY CASH FLOW ✓ Proceeds from the asset rotation in Peru amounted to €116m ✓ Share buy-back program totalled €36m, of which €14m in 1Q24 ✓ €175m non-recourse financing facility for the construction of 297MW solar PV projects in Spain €m 23.3 -17
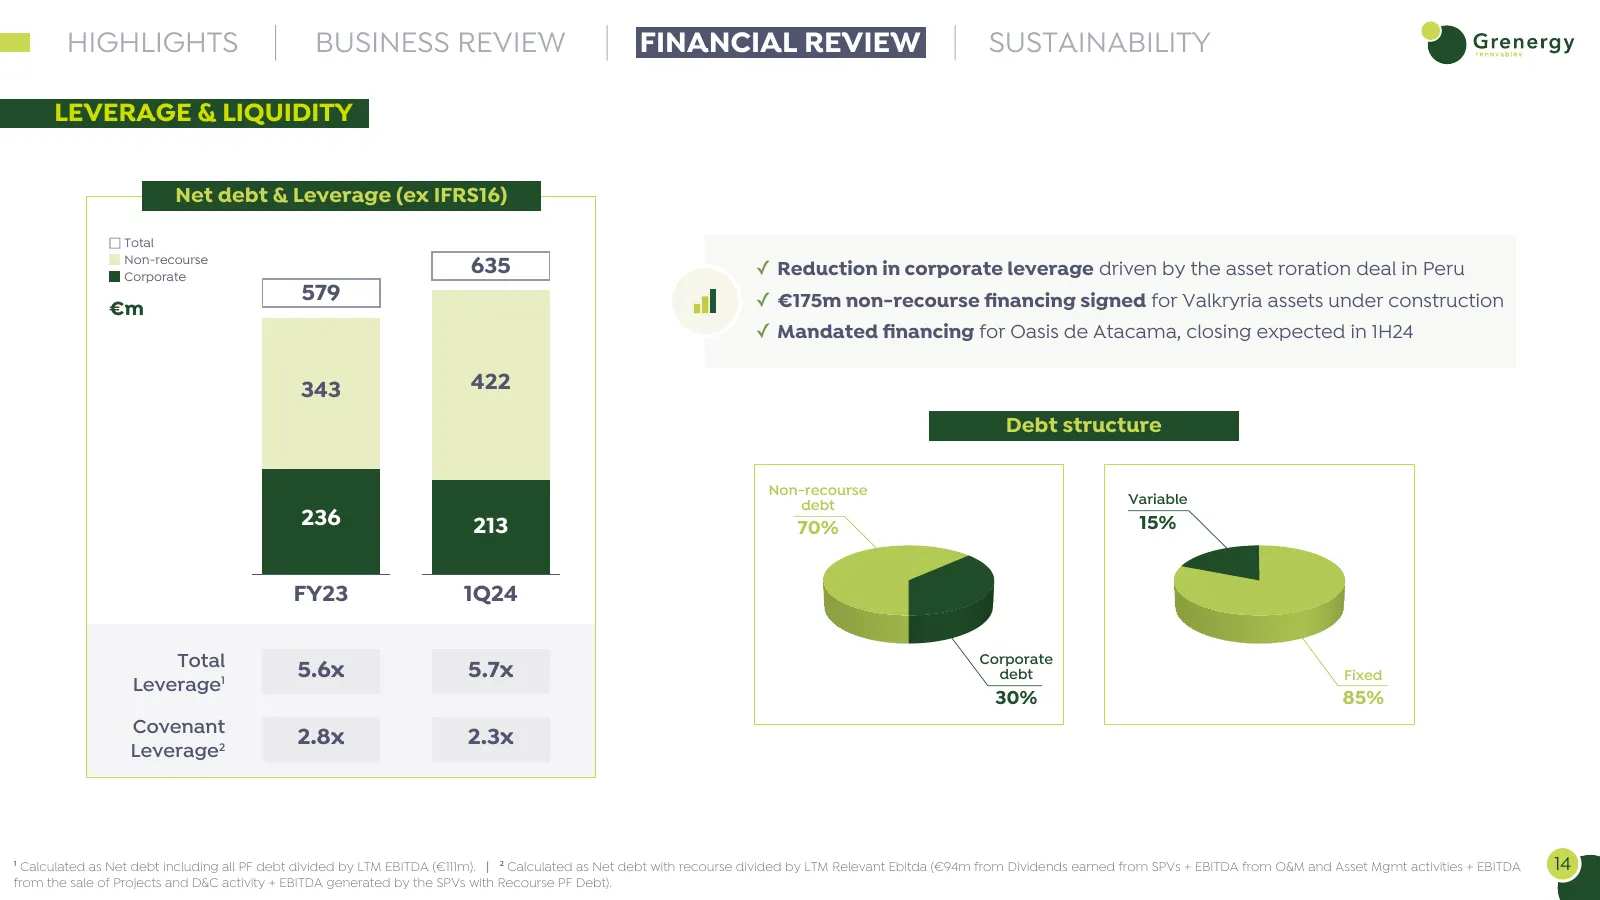
Slide 14: Leverage & Liquidity
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY LEVERAGE & LIQUIDITY Net debt & Leverage (ex IFRS16) Total Non-recourse Corporate 635 ✓ Reduction in corporate leverage driven by the asset roration deal in Peru 579 ✓ €175m non-recourse financing signed for Valkryria assets under constructi
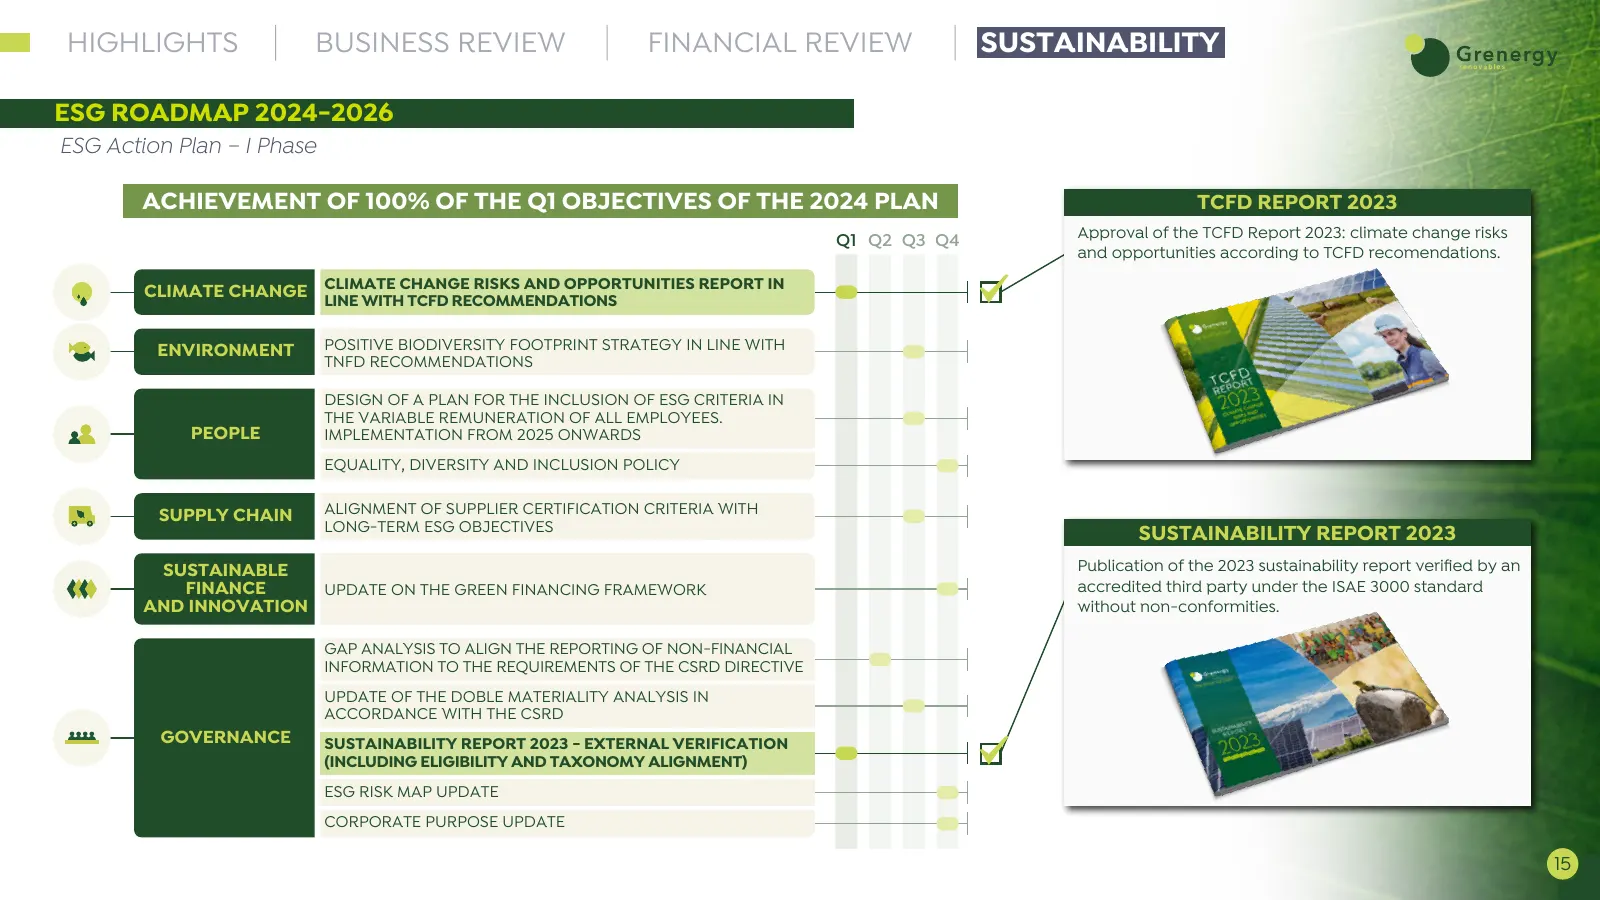
Slide 15: ESG Roadmap 2024-2026
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY ESG ROADMAP 2024-2026 ESG Action Plan – I Phase ACHIEVEMENT OF 100% OF THE Q1 OBJECTIVES OF THE 2024 PLAN TCFD REPORT 2023 Q1 Q2 Q3 Q4 Approval of the TCFD Report 2023: climate change risks and opportunities according to TCFD recomendations.
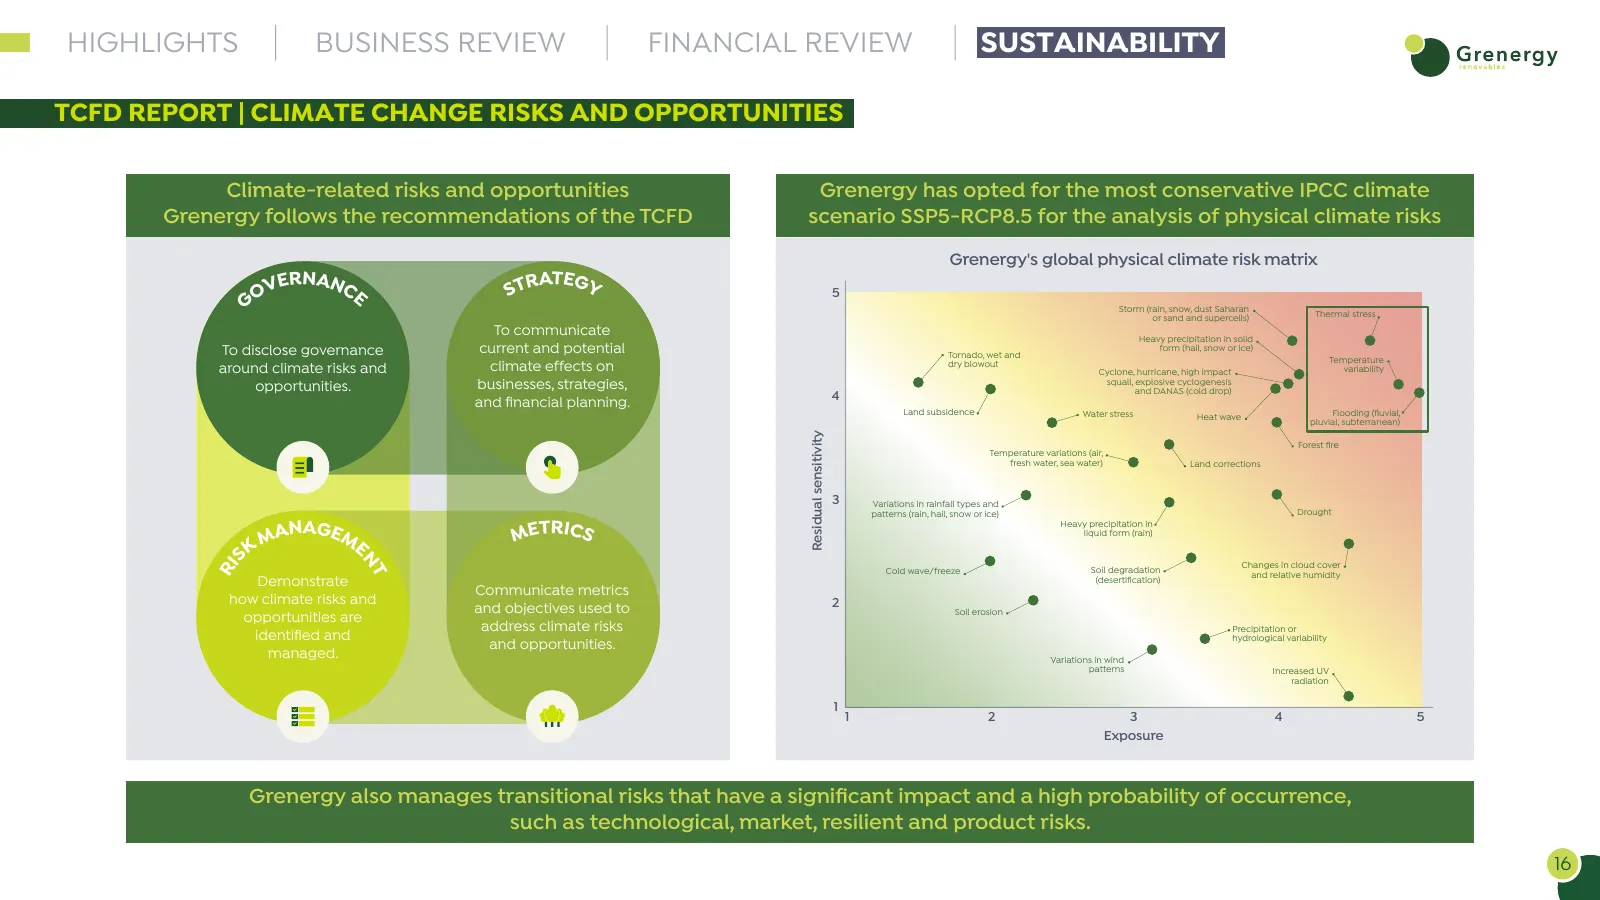
Slide 16: TCFD Report | Climate Change Risks and Opportunities
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY TCFD REPORT | CLIMATE CHANGE RISKS AND OPPORTUNITIES Climate-related risks and opportunities Grenergy has opted for the most conservative IPCC climate Grenergy follows the recommendations of the TCFD scenario SSP5-RCP8.5 for the analysis of
Slide 17: Environmental Positive Impact
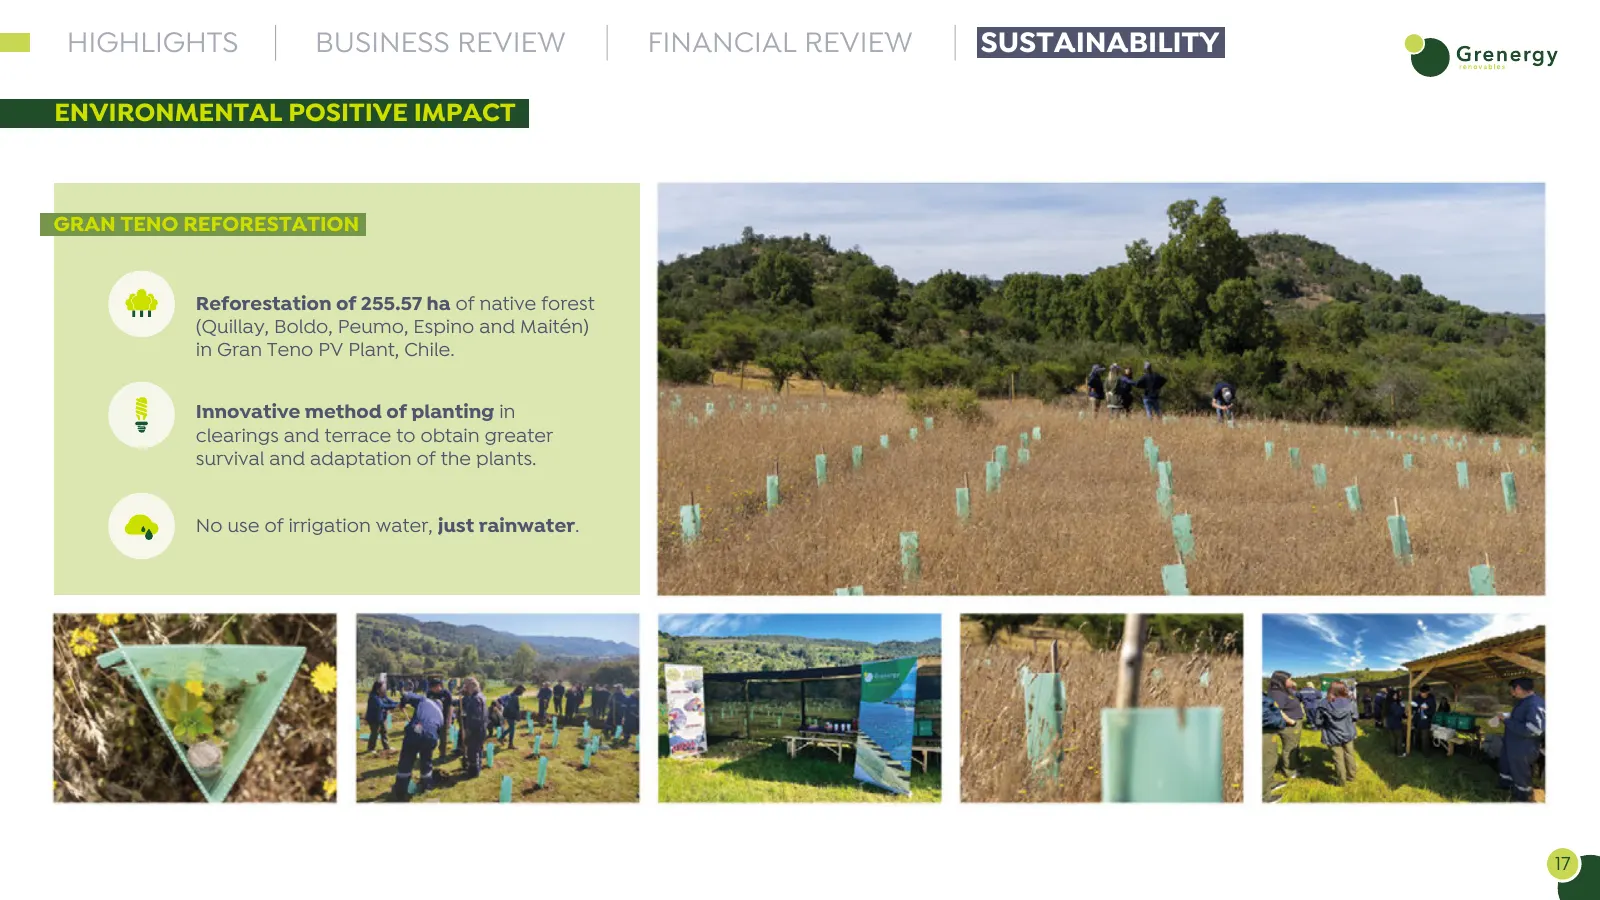
HIGHLIGHTS BUSINESS REVIEW FINANCIAL REVIEW SUSTAINABILITY ENVIRONMENTAL POSITIVE IMPACT GRAN TENO REFORESTATION Reforestation of 255.57 ha of native forest (Quillay, Boldo, Peumo, Espino and Maitén) in Gran Teno PV Plant, Chile. Innovative method of planting in clearings and terrace to obtain great
Slide 18: Appendices
APPENDICES
Slide 19: Platform Update: Projects In Operation, Under Construction & Backlog
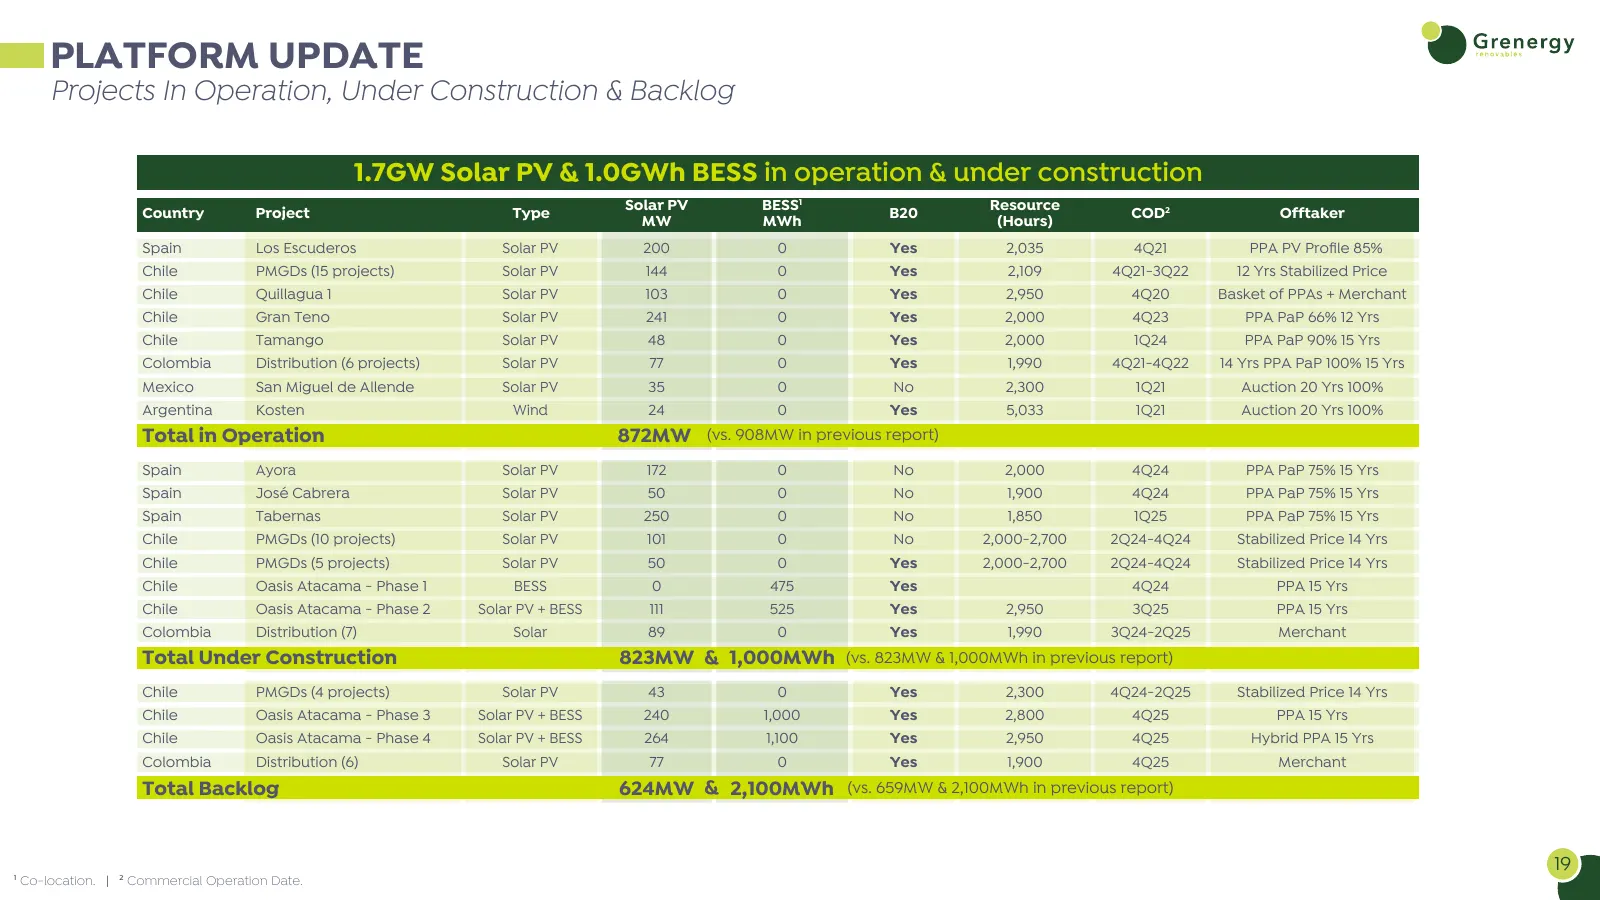
PLATFORM UPDATE Projects In Operation, Under Construction & Backlog 1.7GW Solar PV & 1.0GWh BESS in operation & under construction Country Project Type Solar PV BESS1 B20 Resource COD2 Offtaker MW MWh (Hours) Spain Los Escuderos Solar PV 200 0 Yes 2,035 4Q21 PPA PV Profile 85% Chile PMGDs (15 project
Slide 20: Platform Update: Projects in Advanced Development
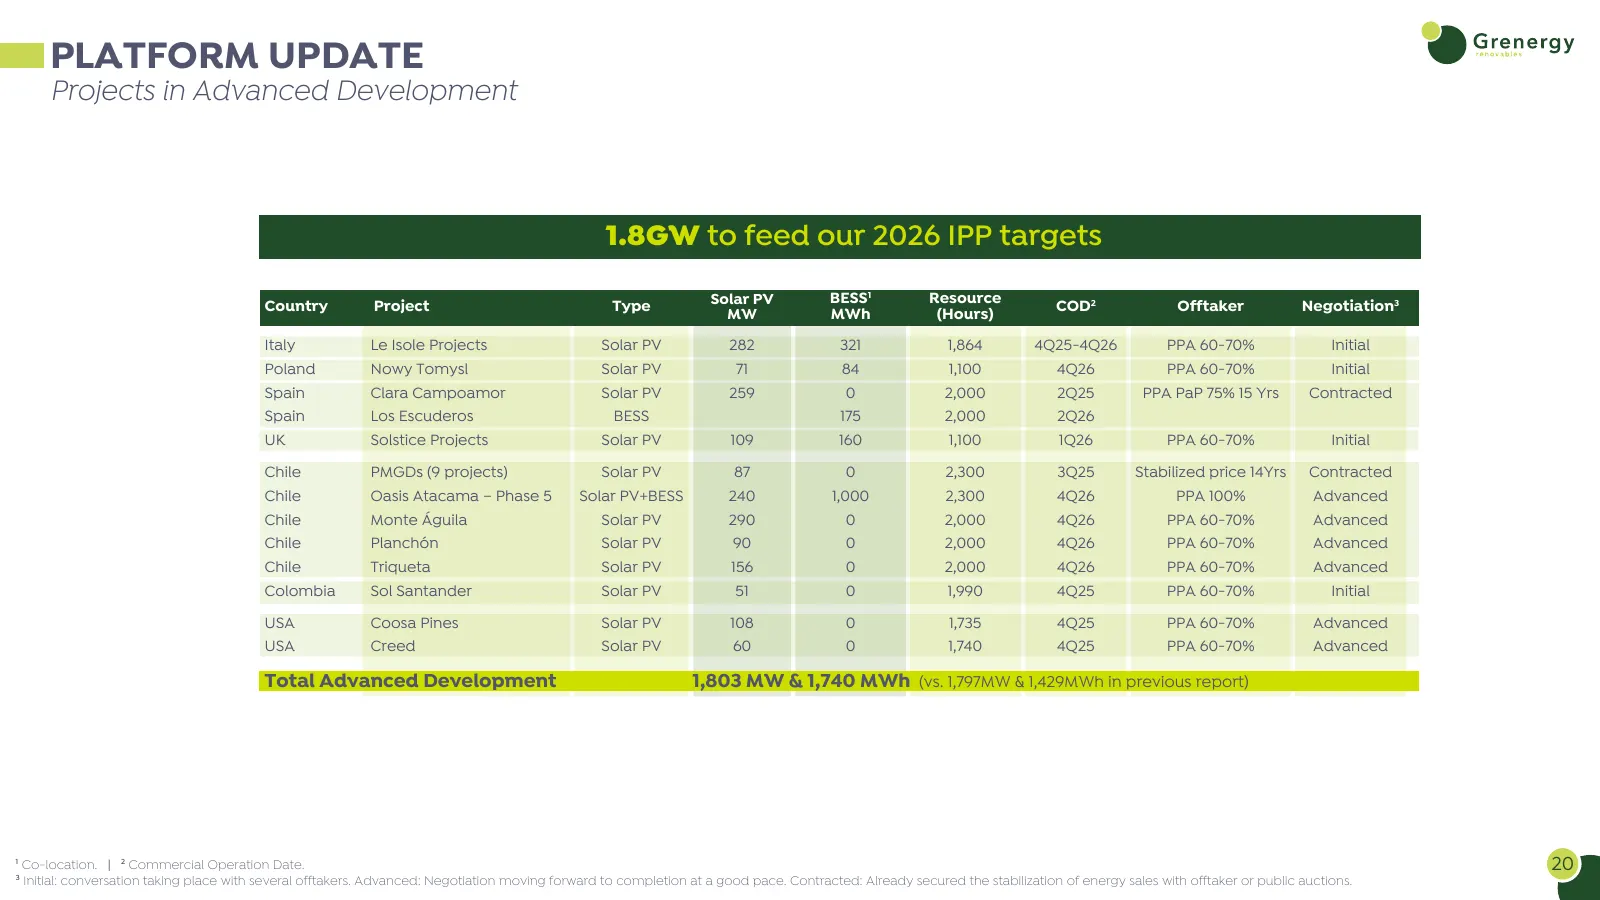
PLATFORM UPDATE Projects in Advanced Development 1.8GW to feed our 2026 IPP targets Country Project Type Solar PV BESS1 Resource COD2 Offtaker Negotiation3 MW MWh (Hours) Italy Le Isole Projects Solar PV 282 321 1,864 4Q25-4Q26 PPA 60-70% Initial Poland Nowy Tomysl Solar PV 71 84 1,100 4Q26 PPA 60-7
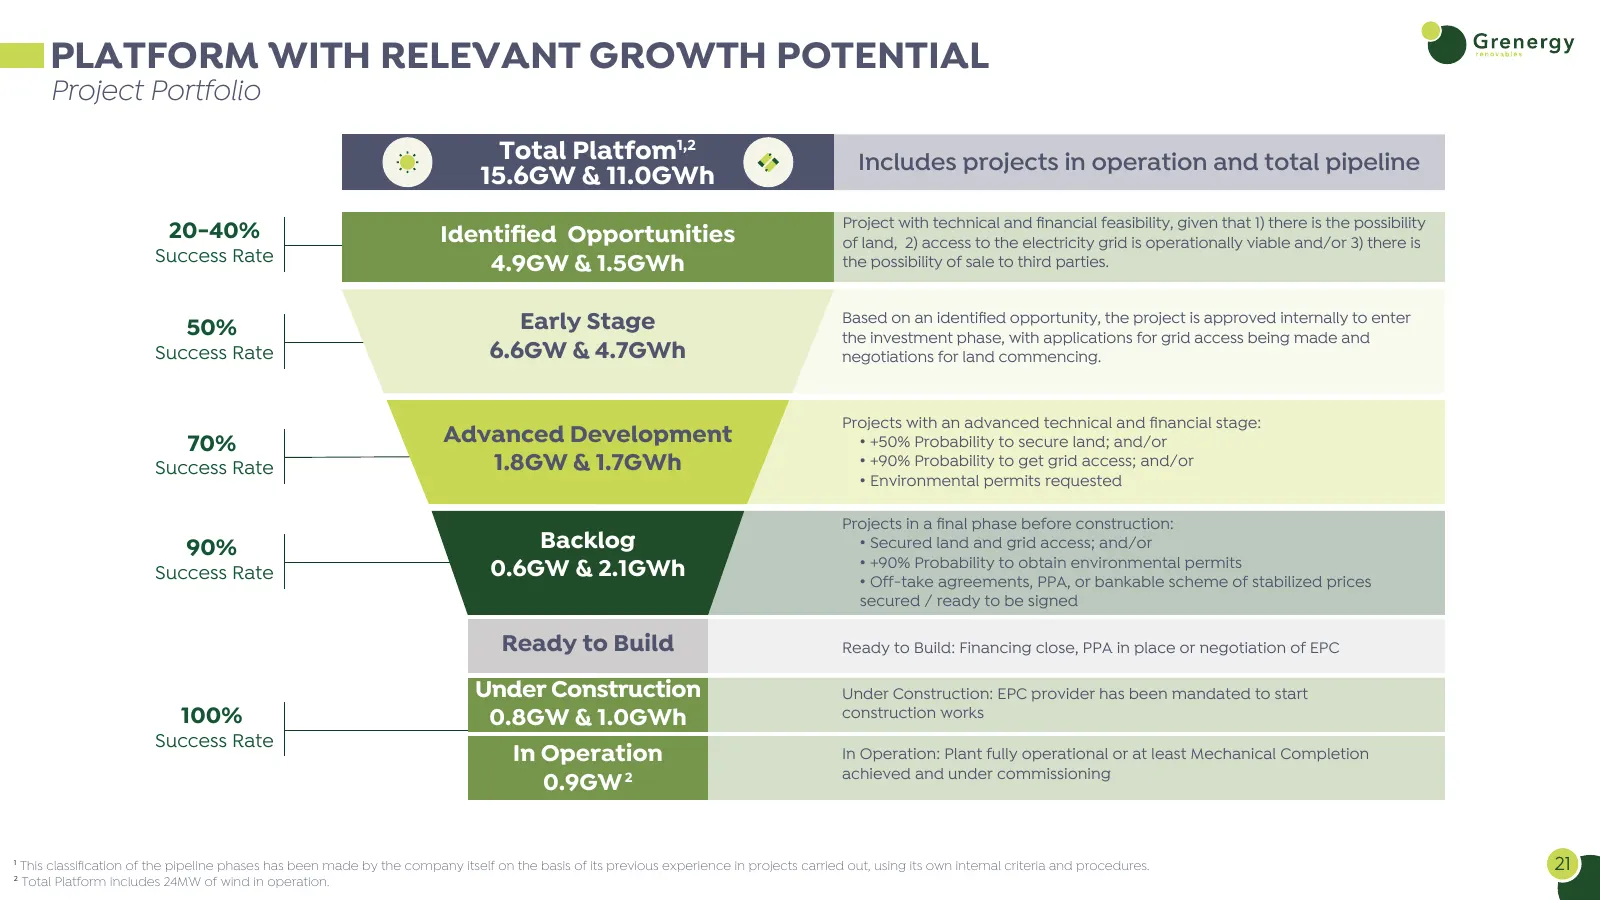
Slide 21: Platform with Relevant Growth Potential
PLATFORM WITH RELEVANT GROWTH POTENTIAL Project Portfolio Total Platfom1,2 Includes projects in operation and total pipeline 15.6GW & 11.0GWh Project with technical and financial feasibility, given that 1) there is the possibility 20-40% Identified Opportunities of land, 2) access to the electricity g
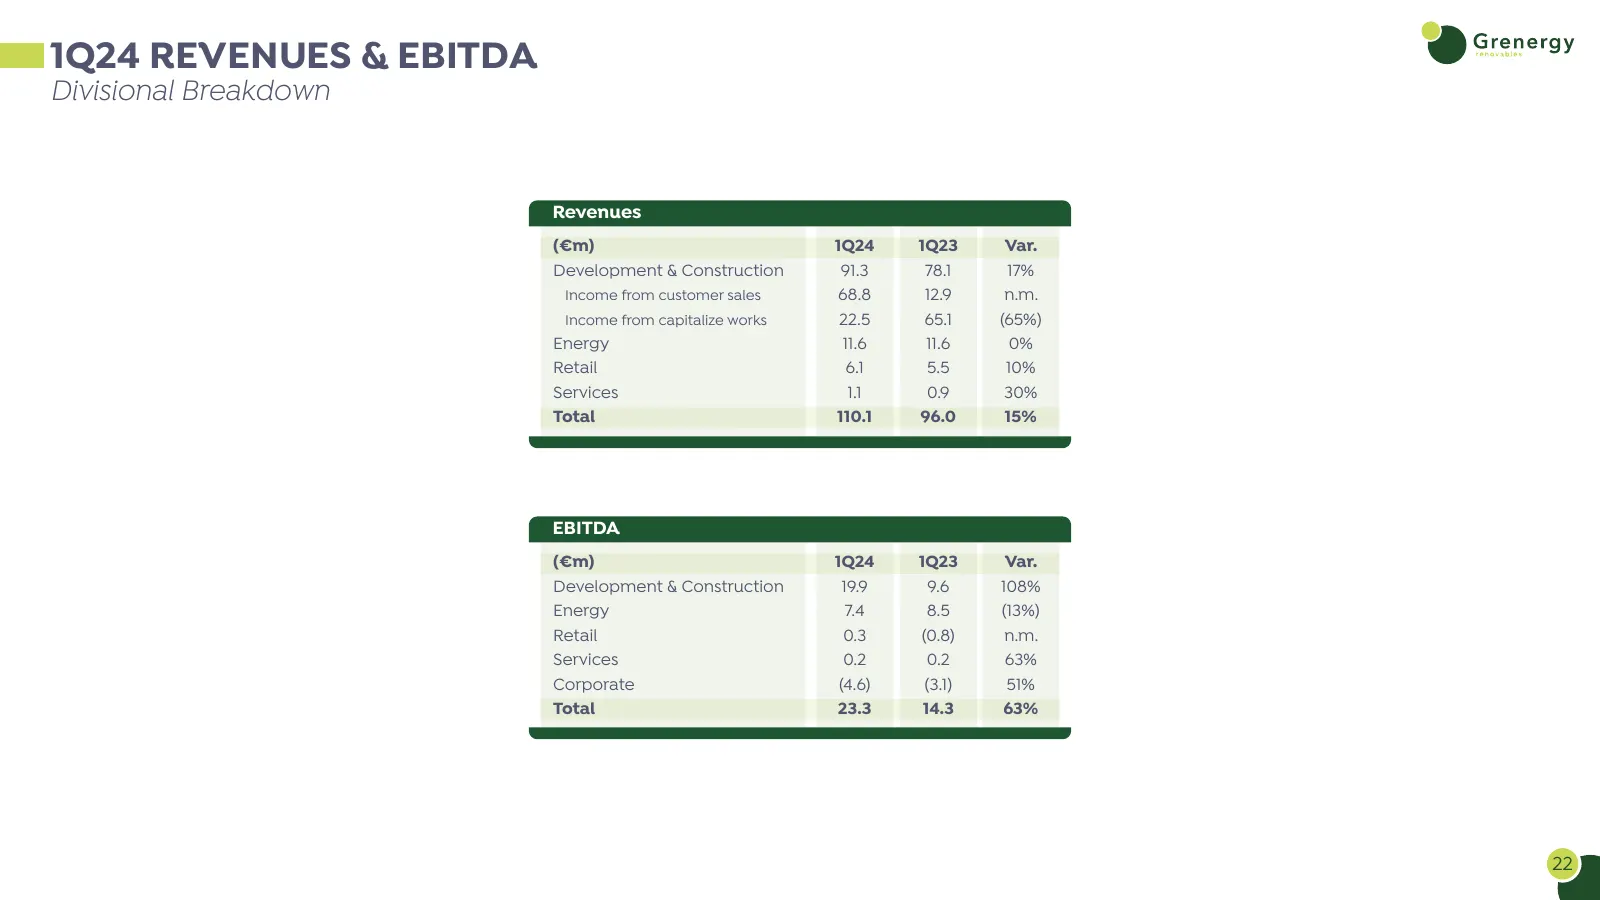
Slide 22: 1Q24 Revenues & EBITDA
1Q24 REVENUES & EBITDA Divisional Breakdown Revenues (€m) 1Q24 1Q23 Var. Development & Construction 91.3 78.1 17% Income from customer sales 68.8 12.9 n.m. Income from capitalize works 22.5 65.1 (65%) Energy 11.6 11.6 0% Retail 6.1 5.5 10% Services 1.1 0.9 30% Total 110.1 96.0 15% EBITDA (€m) 1Q24 1
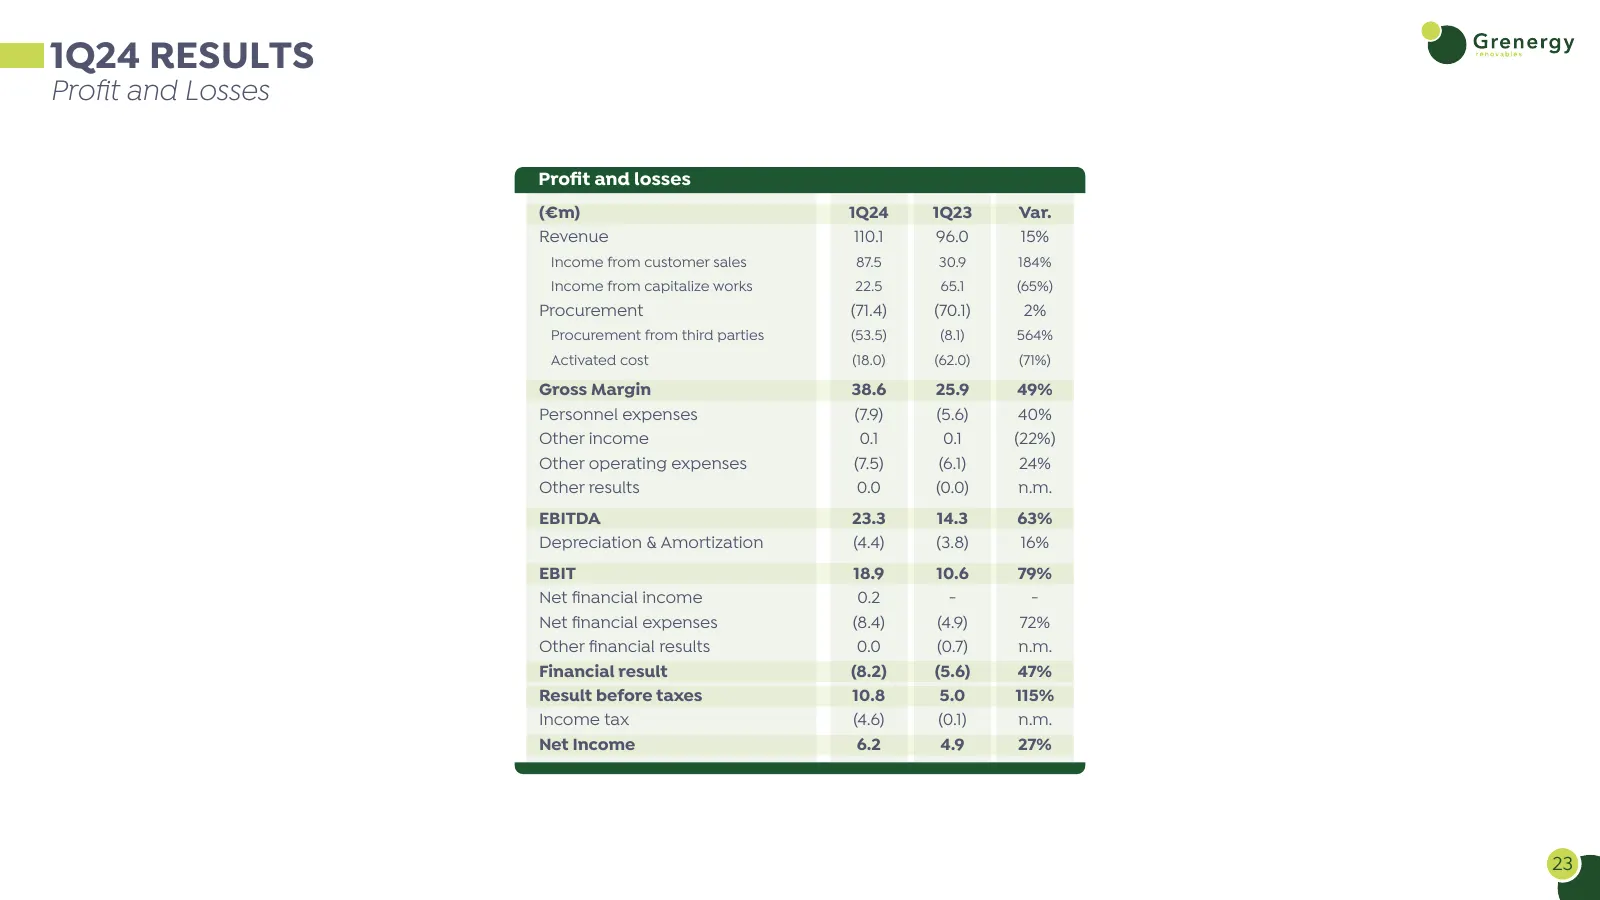
Slide 23: Profit and Losses
1Q24 RESULTS Profit and Losses Profit and losses (€m) 1Q24 1Q23 Var. Revenue 110.1 96.0 15% Income from customer sales 87.5 30.9 184% Income from capitalize works 22.5 65.1 (65%) Procurement (71.4) (70.1) 2% Procurement from third parties (53.5) (8.1) 564% Activated cost (18.0) (62.0) (71%) Gross Mar
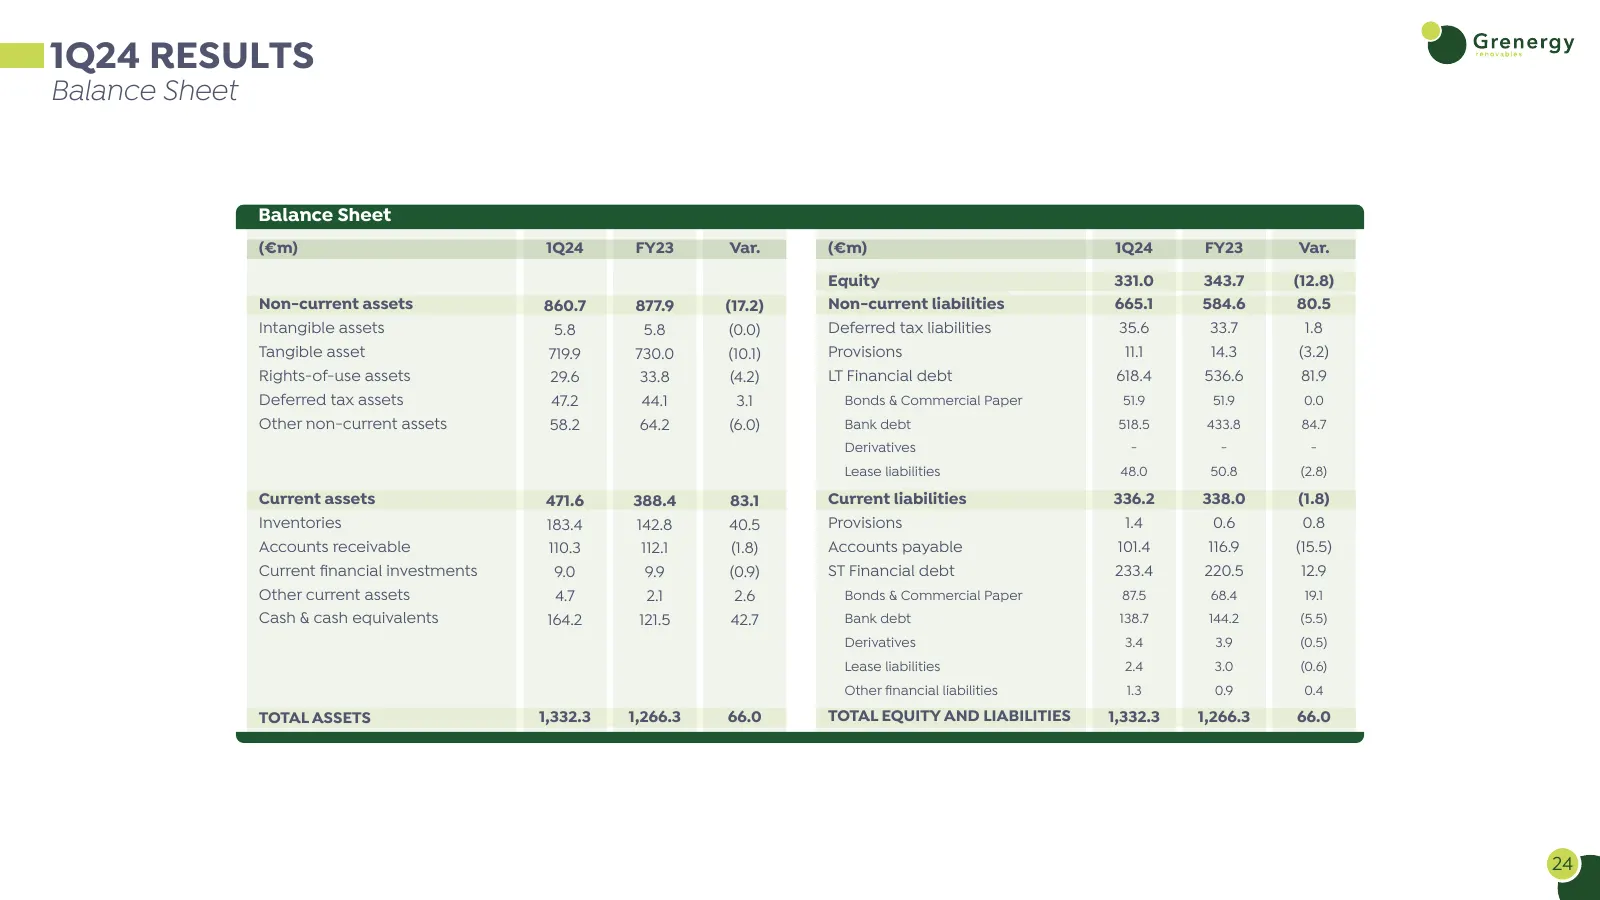
Slide 24: Balance Sheet
1Q24 RESULTS Balance Sheet Balance Sheet (€m) 1Q24 FY23 Var. (€m) 1Q24 FY23 Var. Equity 331.0 343.7 (12.8) Non-current assets 860.7 877.9 (17.2) Non-current liabilities 665.1 584.6 80.5 Intangible assets 5.8 5.8 (0.0) Deferred tax liabilities 35.6 33.7 1.8 Tangible asset 719.9 730.0 (10.1) Provision
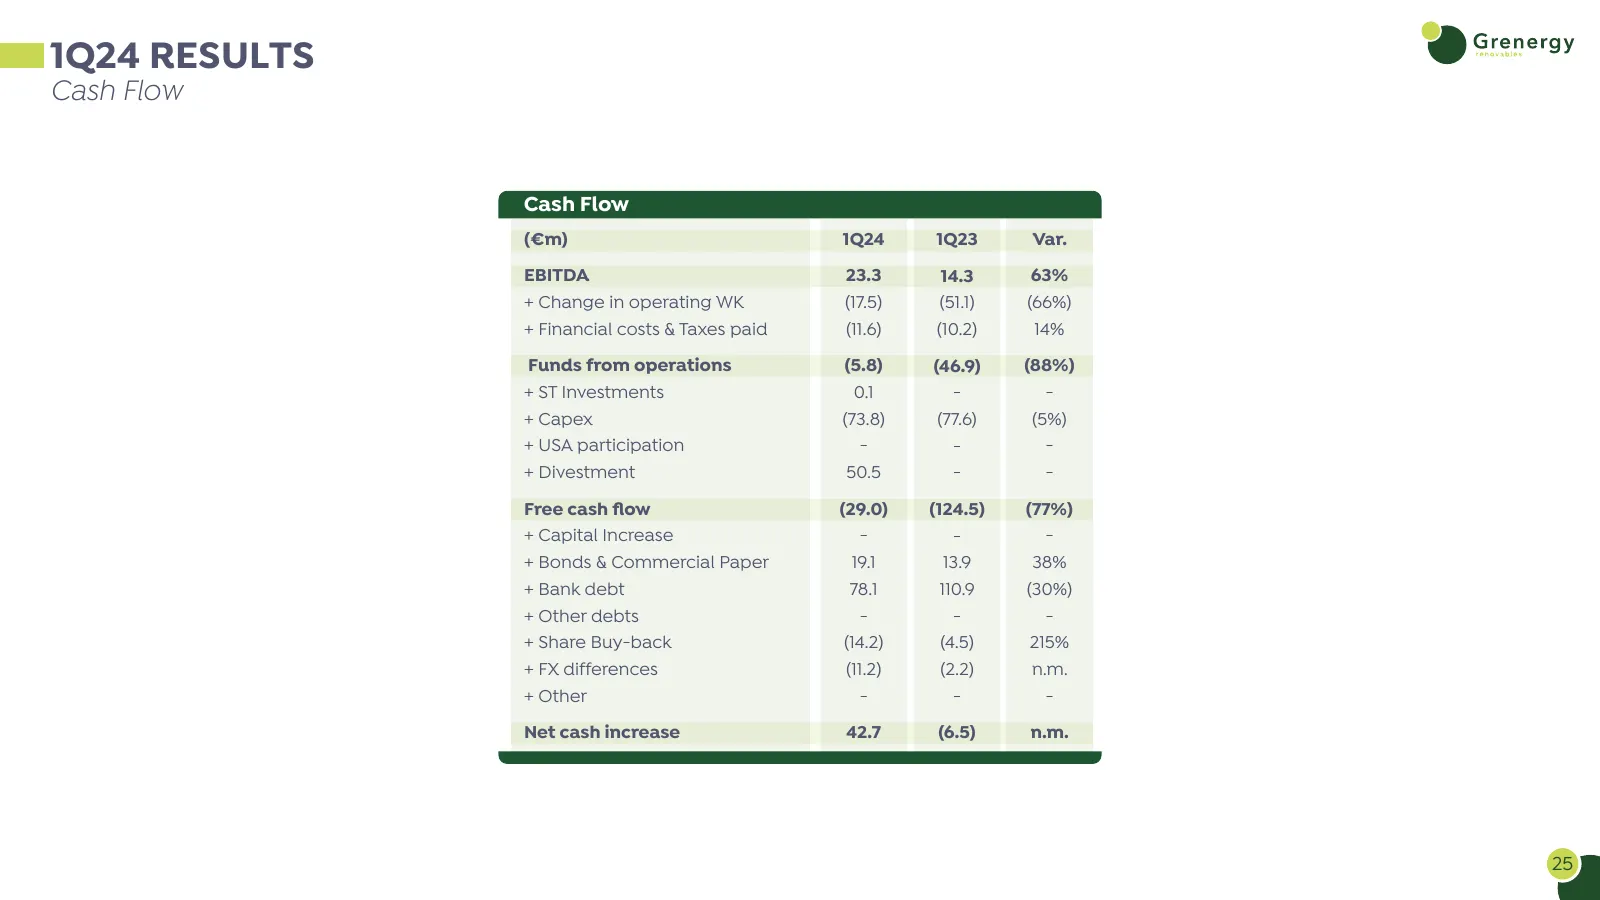
Slide 25: Cash Flow
1Q24 RESULTS Cash Flow Cash Flow (€m) 1Q24 1Q23 Var. EBITDA 23.3 14.3 63% + Change in operating WK (17.5) (51.1) (66%) + Financial costs & Taxes paid (11.6) (10.2) 14% Funds from operations (5.8) (46.9) (88%) + ST Investments 0.1 - - + Capex (73.8) (77.6) (5%) + USA participation - - - + Divestment
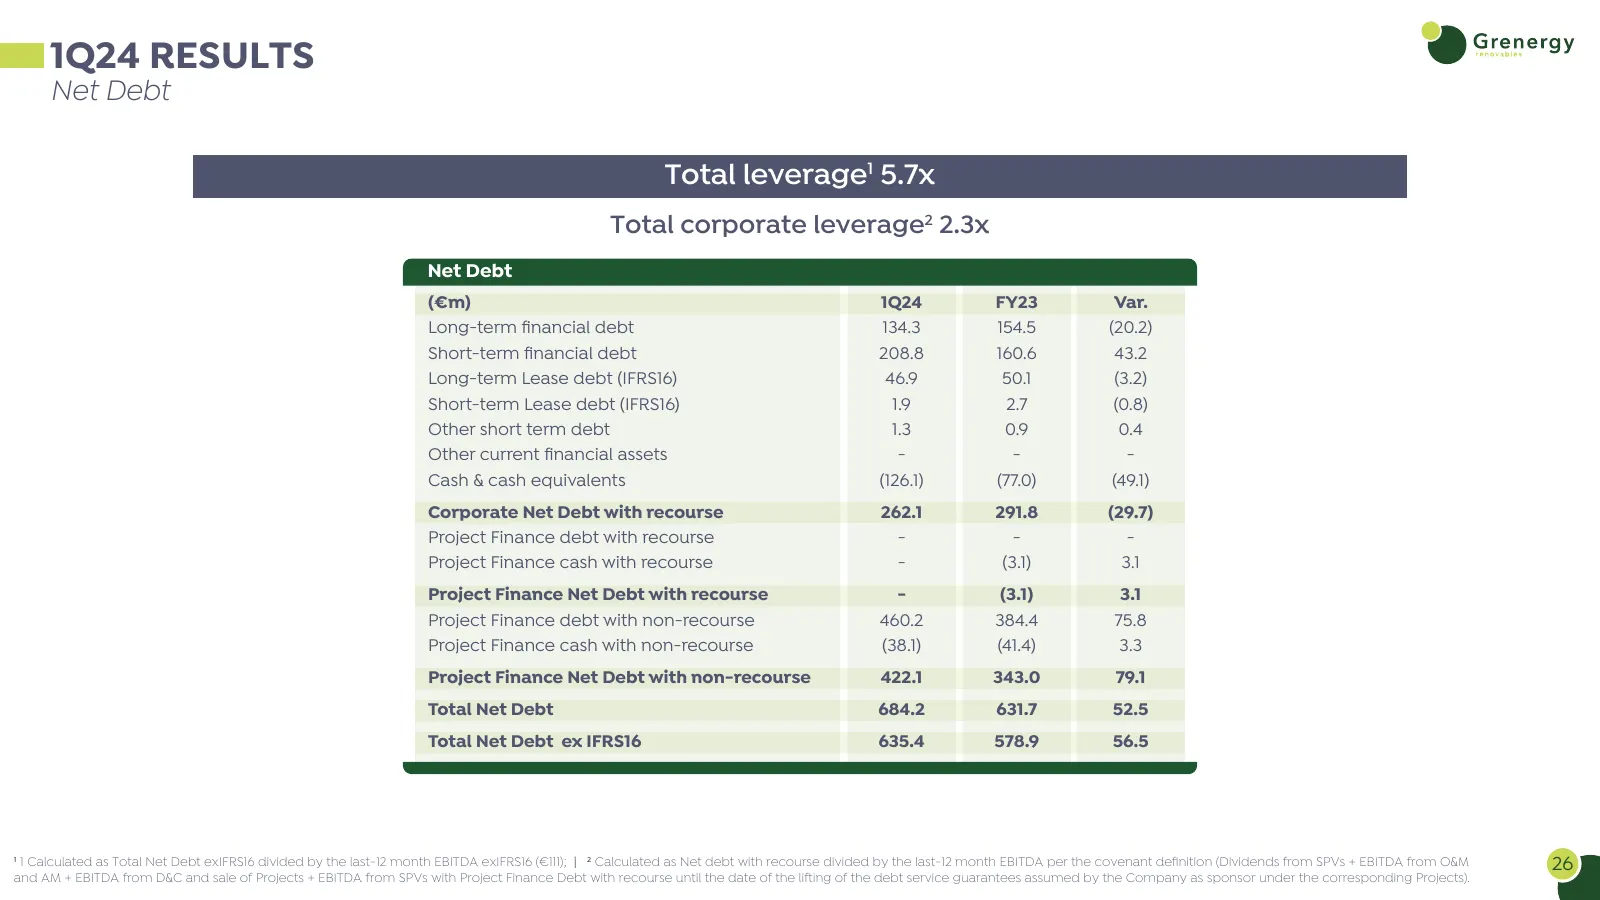
Slide 26: Net Debt
1Q24 RESULTS Net Debt Total leverage1 5.7x Total corporate leverage2 2.3x Net Debt (€m) 1Q24 FY23 Var. Long-term financial debt 134.3 154.5 (20.2) Short-term financial debt 208.8 160.6 43.2 Long-term Lease debt (IFRS16) 46.9 50.1 (3.2) Short-term Lease debt (IFRS16) 1.9 2.7 (0.8) Other short term de
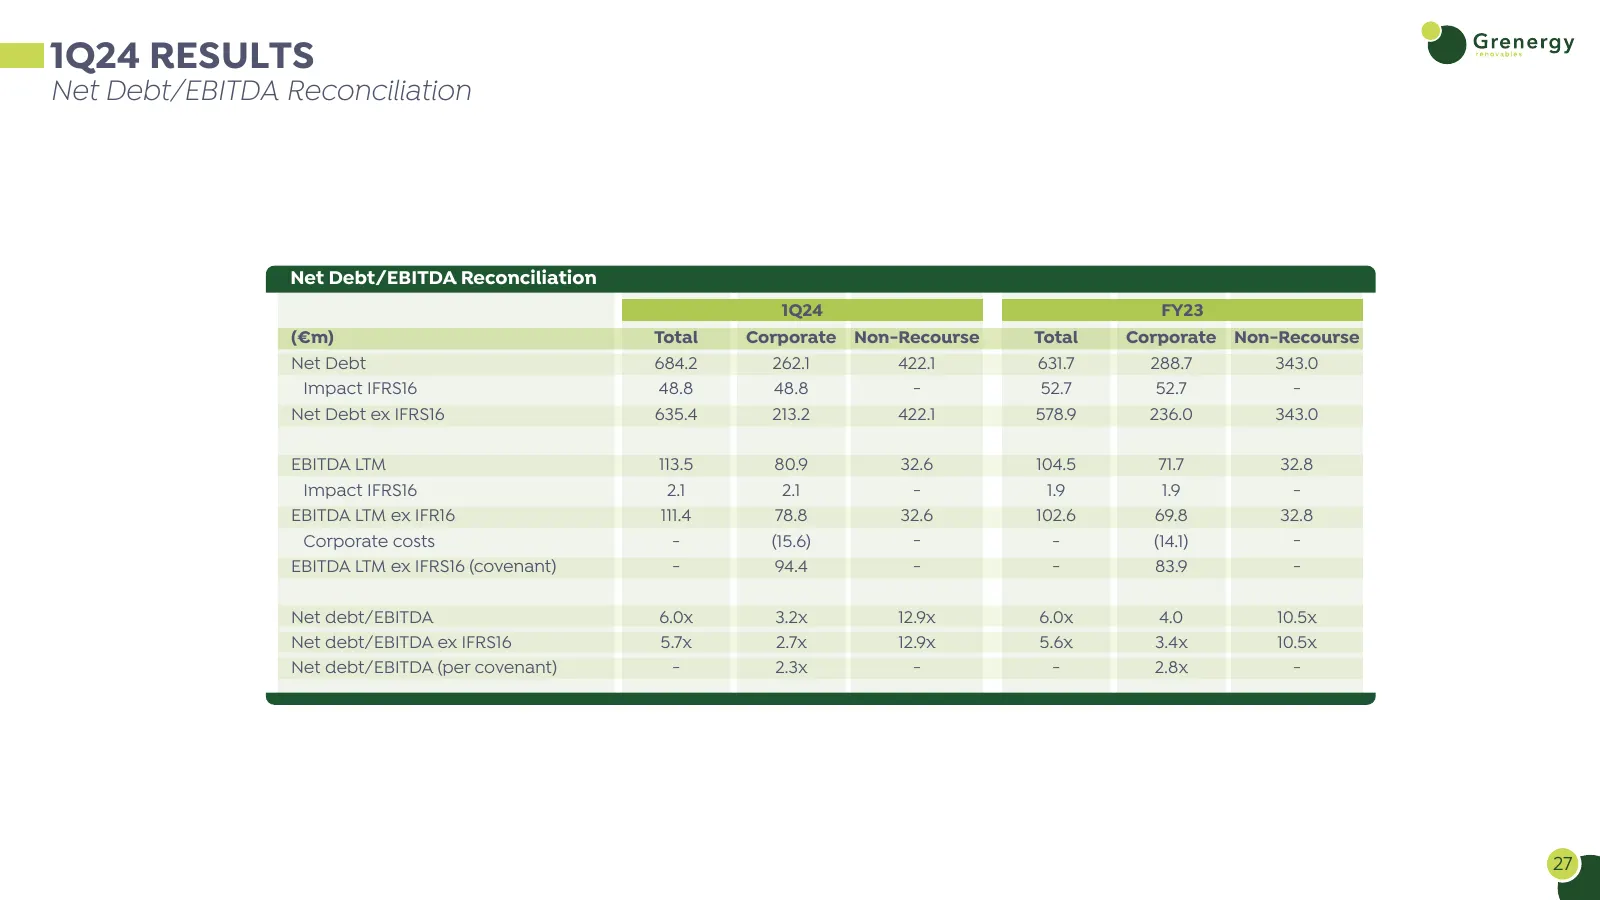
Slide 27: Net Debt/EBITDA Reconciliation
1Q24 RESULTS Net Debt/EBITDA Reconciliation Net Debt/EBITDA Reconciliation 1Q24 FY23 (€m) Total Corporate Non-Recourse Total Corporate Non-Recourse Net Debt 684.2 262.1 422.1 631.7 288.7 343.0 Impact IFRS16 48.8 48.8 - 52.7 52.7 - Net Debt ex IFRS16 635.4 213.2 422.1 578.9 236.0 343.0 EBITDA LTM 113
Slide 28: Solar PV + Storage
SOLAR PV + STORAGE EUROPE - USA - LATAM
Source: Internet Archive copy of grenergy.eu
More decks from Grenergy Renovables S.A
 H1 2026 Earnings Presentation38 slides · Sep 16, 2026
 Investor Presentation (September 2026)55 slides · September 2026
 Investor Presentation (July 2026)46 slides · July 2026
 Q1 2026 Earnings Presentation50 slides · May 27, 2026
 9M 2025 Earnings Presentation36 slides · Nov 27, 2025
 Investor Day (May 2025)50 slides · May 28, 2025