Verso — Verso Paper Holdings — Debt Investor Presentation (June 2016)
54 slides from Verso's debt investor presentation, Jun 6, 2016
Slide 1: Lenders Presentation June 6th, 2016
Exhibit 99.1 Lenders June 6th,Presentation 2016 - Public
Slide 2: Disclaimer
Disclaimer proposed information you information, express financial, document. as recipient. construed This of results Forward-Looking Exchange “estimate,” views Company. risks and Non-GAAP In supplement CONFIDENTIAL any this anExchange all are document and agent of such presentation, and liability n
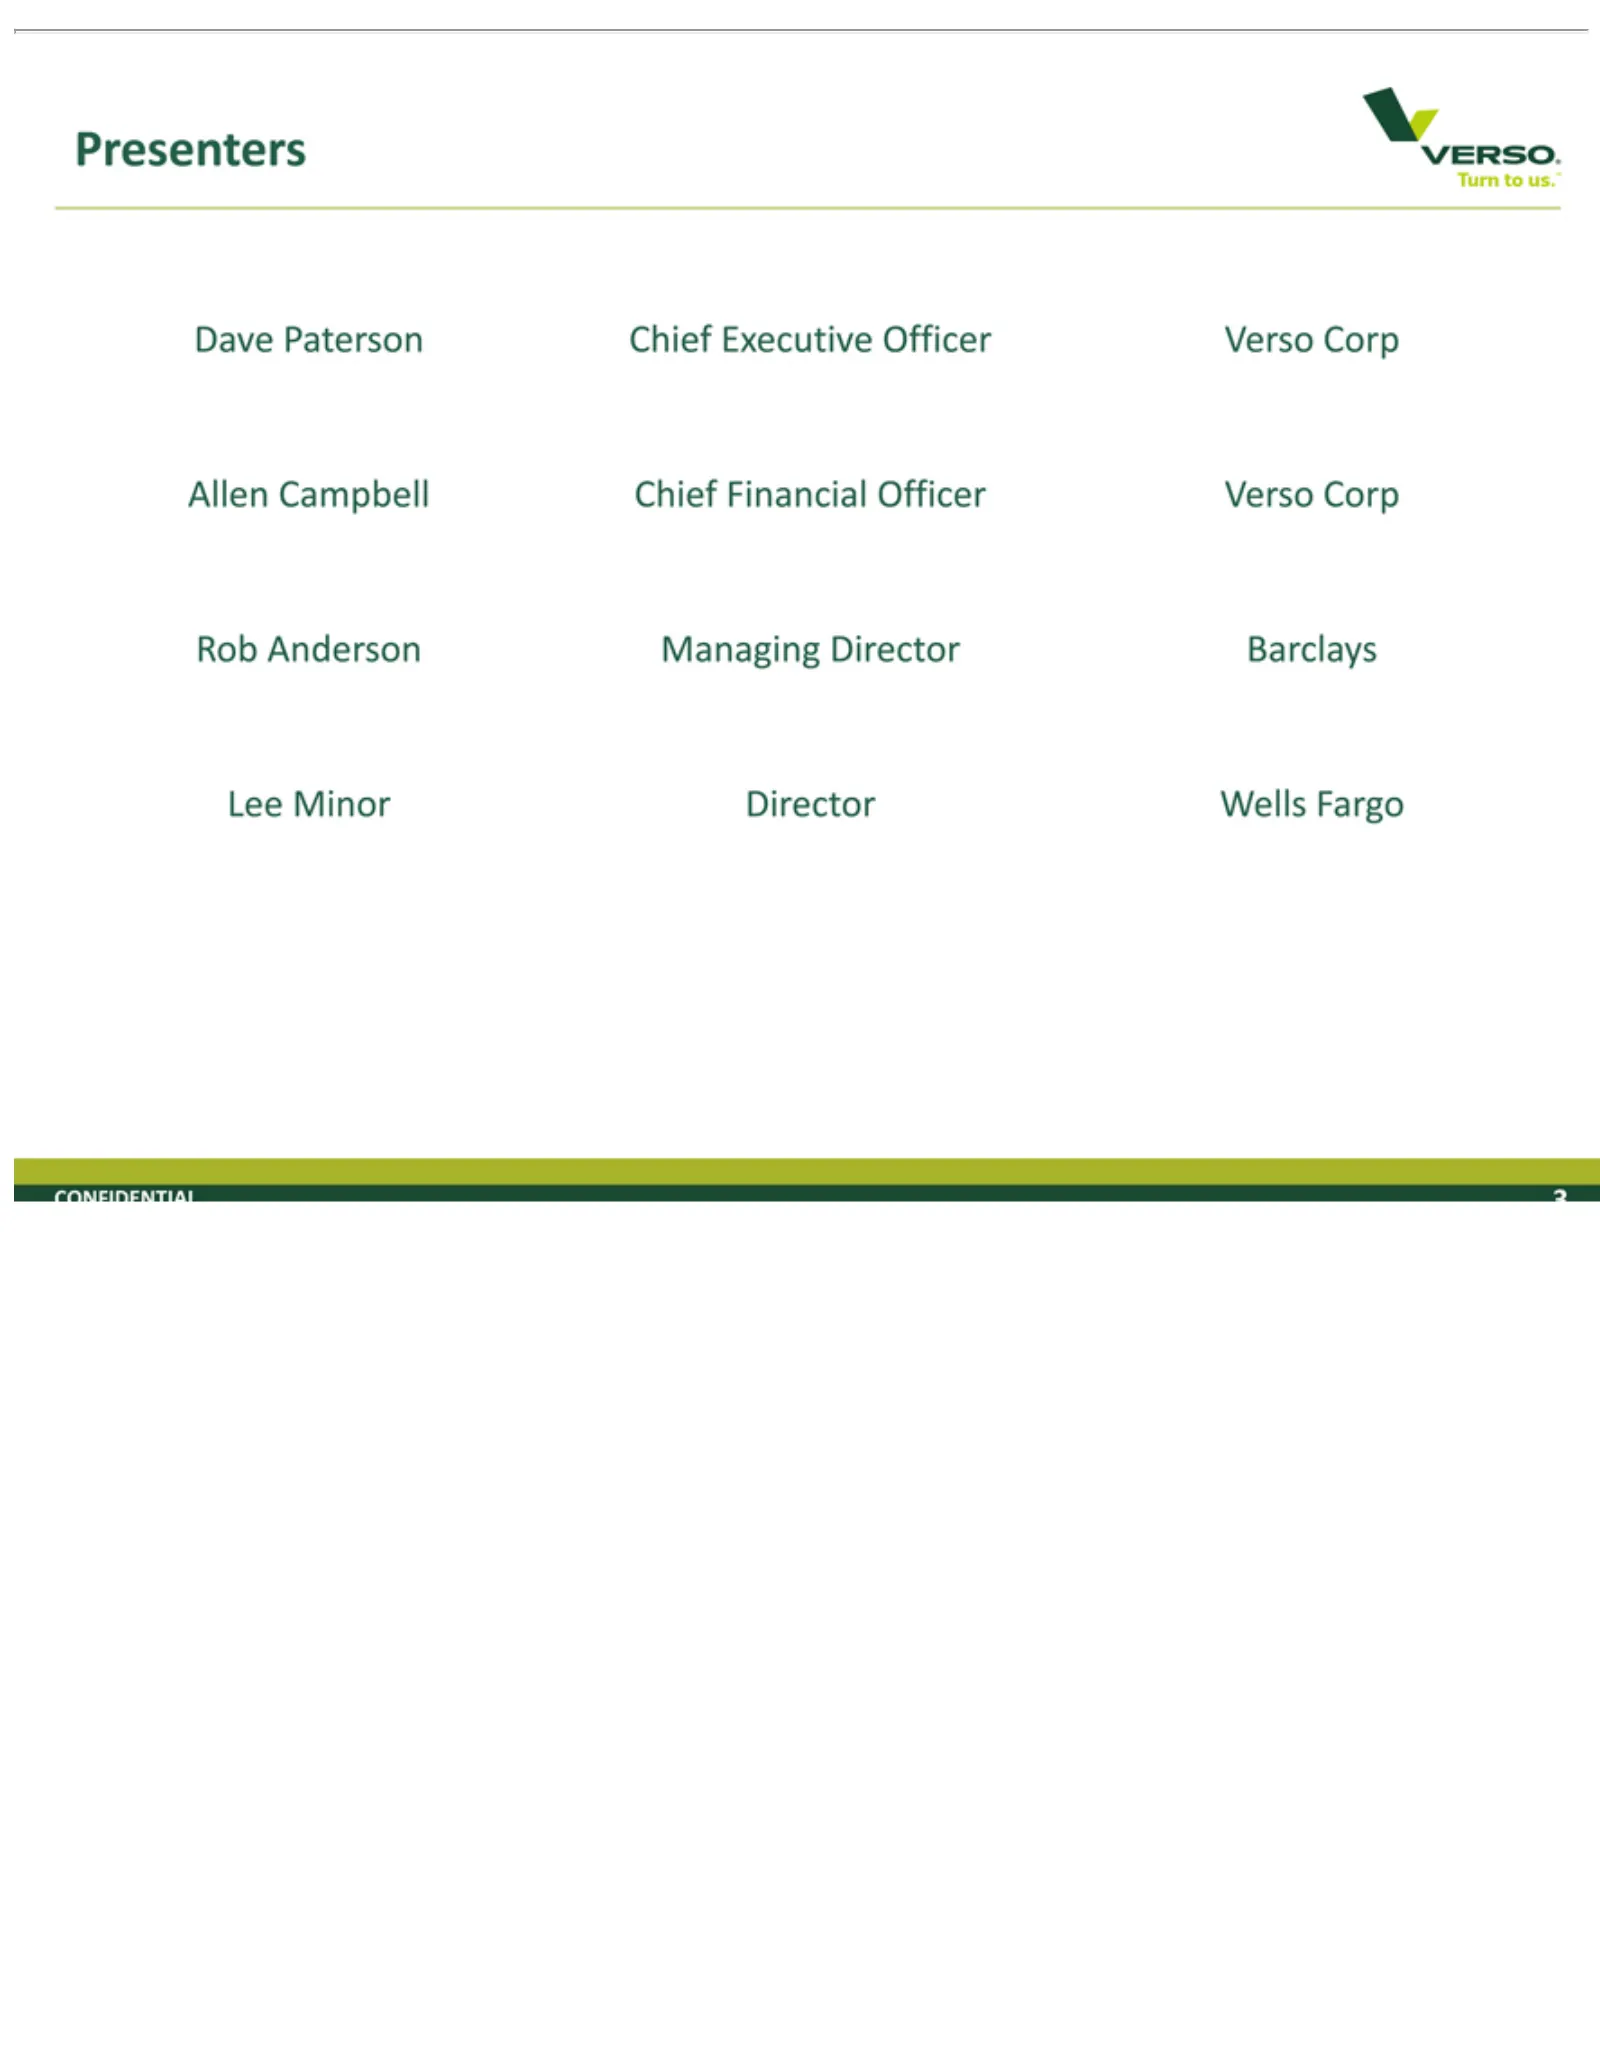
Slide 3: Presenters
DaveMinor Presenters Lee CONFIDENTIAL Paterson Director Chief 3Wells Executive FargoOfficer Verso Corp Allen Campbell Chief Financial Officer Verso Corp Rob Anderson Managing Director Barclays
Slide 4: Table of Contents
Table 1. 2. 3. 4. 5. 6. CONFIDENTIAL Appendices Transaction Introduction Company Industry Recent Financial of Contents Financial Update Projections Overview Overview and Performance and Outlook Overview Credit Highlights
Slide 5: Introduction
CONFIDENTIAL Introduction
Slide 6: Executive Summary
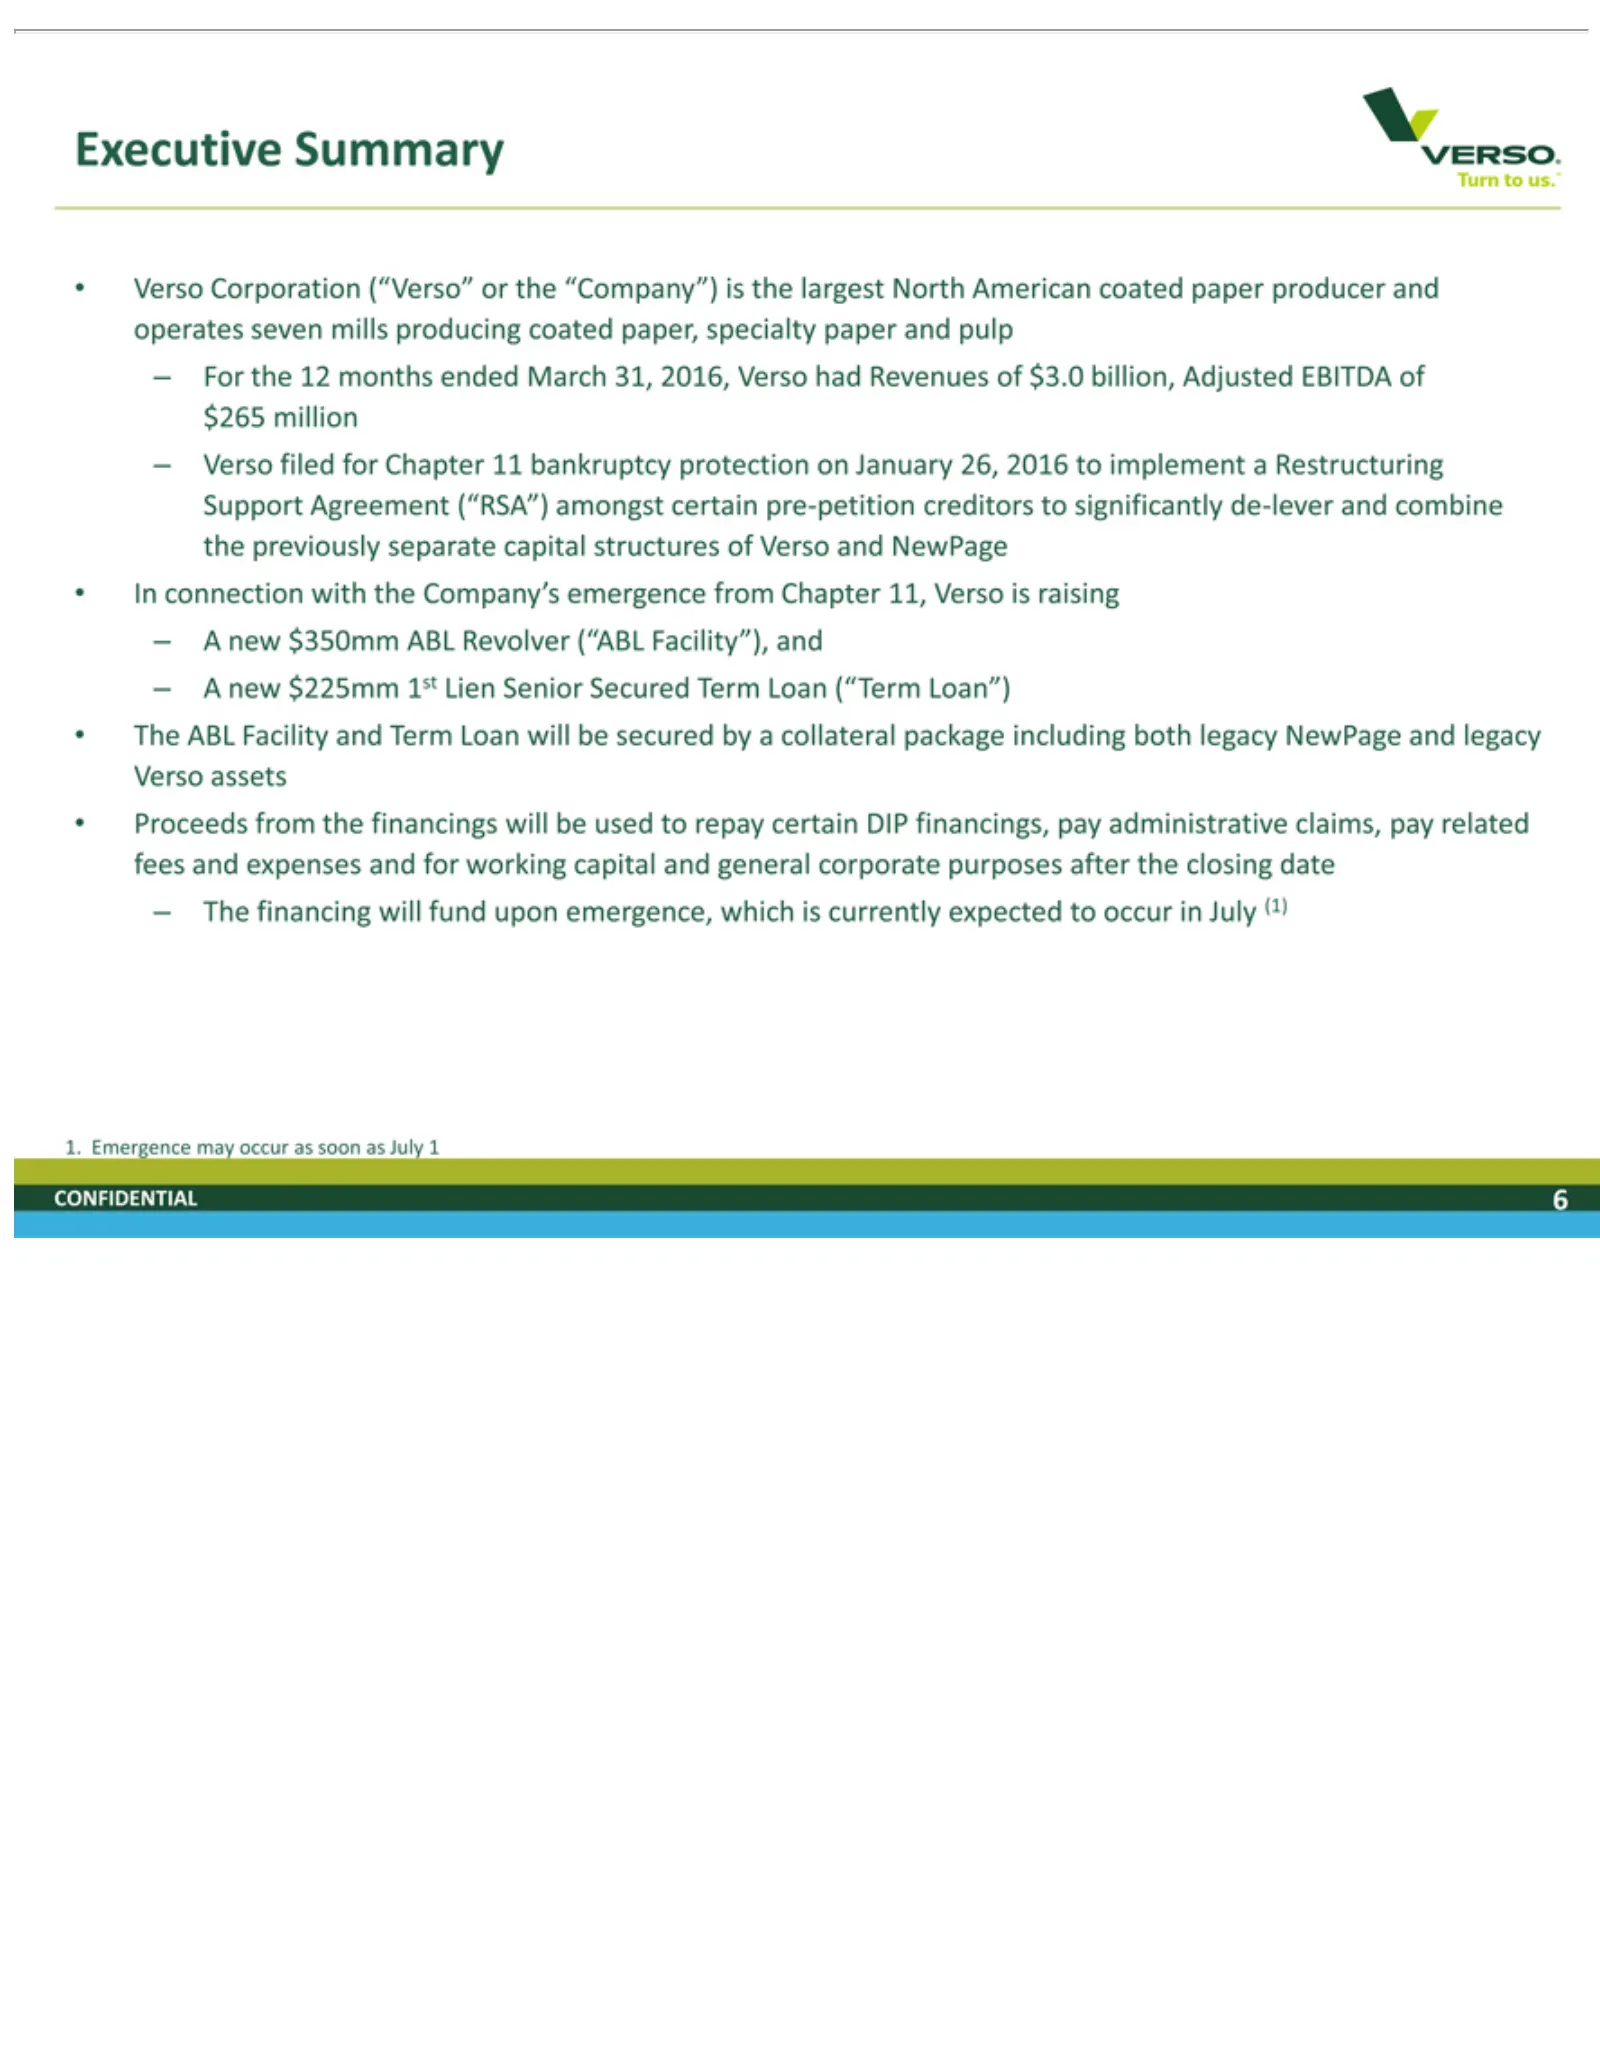
Executive Verso Support In The –Proceeds 1. CONFIDENTIAL A Verso The For Emergence connection new ABL the Corporation financing filed Agreement $350mm $225mm from 12 Facility Summary months for with may the will Chapter and ABL 1st financings 6(“Verso” occur the (“RSA”) ended fund Lien Term Company’
Slide 7: Transaction Overview: Sources and Uses
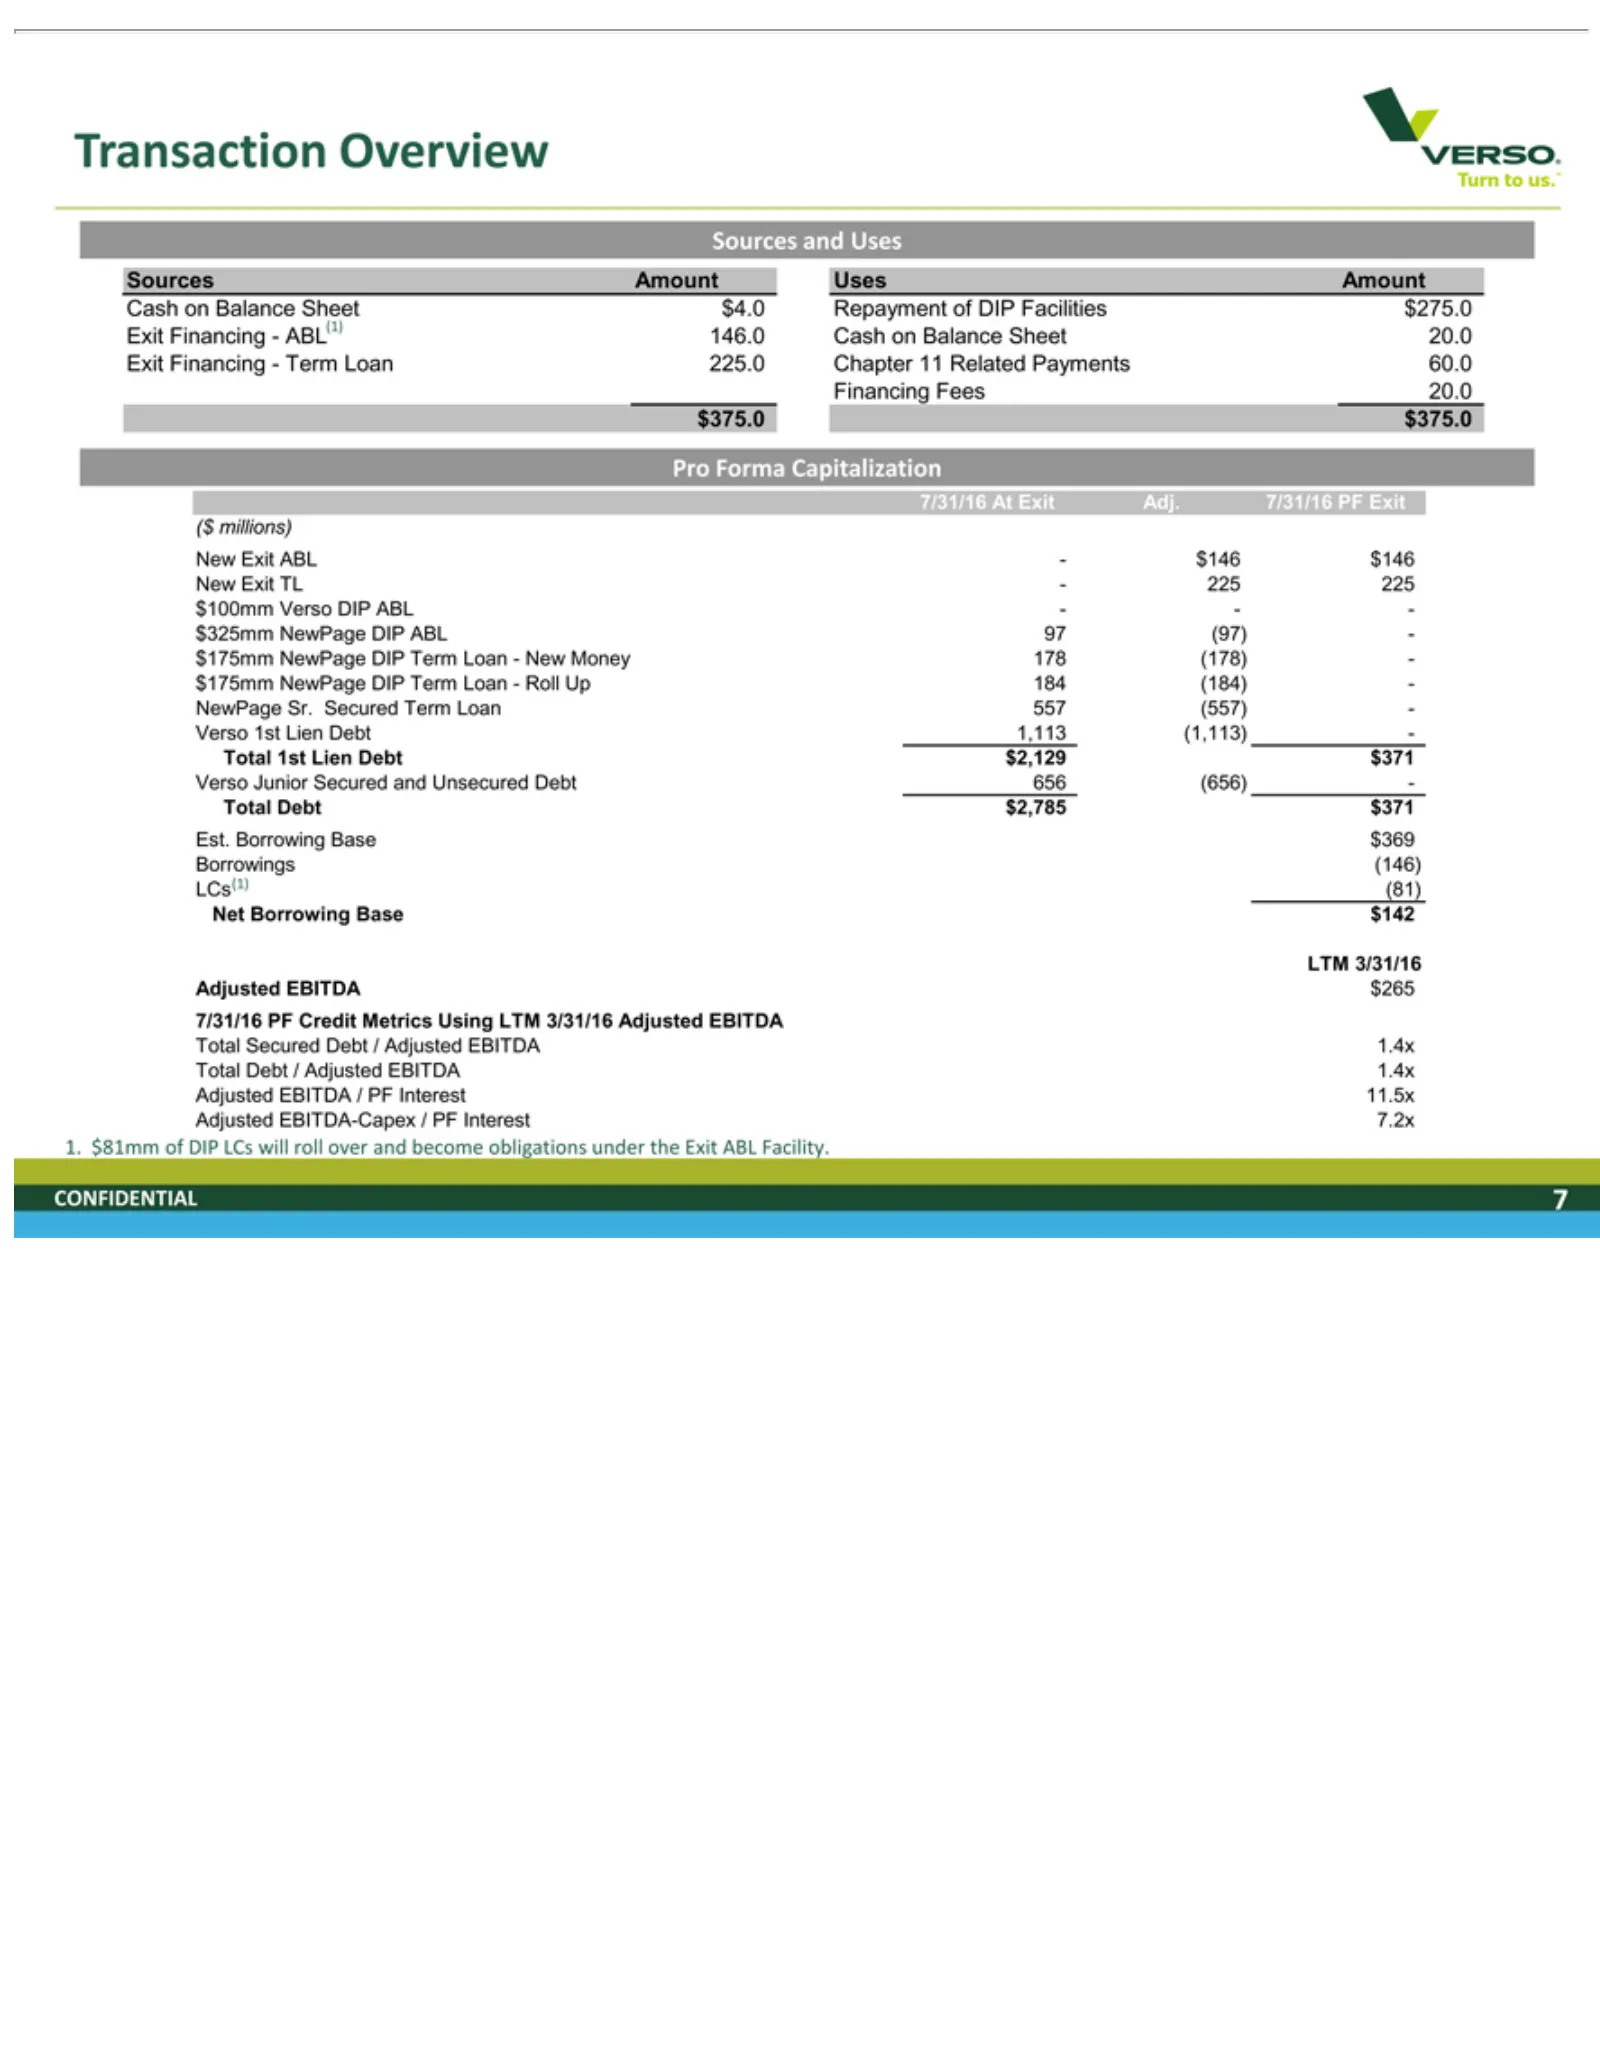
Transaction Sources Cash Exit Financing $375.0 Pro ($ New $100mm $325mm $175mm NewPage Verso Est. Net LCs(1)(81) Borrowings(146) LTM 7/31/16 Total Adjusted 1. CONFIDENTIAL $81mm millions) Forma Borrowing Financing—ABL(1) Financing—Term Exit on 3/31/16 1st Secured Debt 1st Junior $375.0 At PF Amount
Slide 8: Restructuring Overview
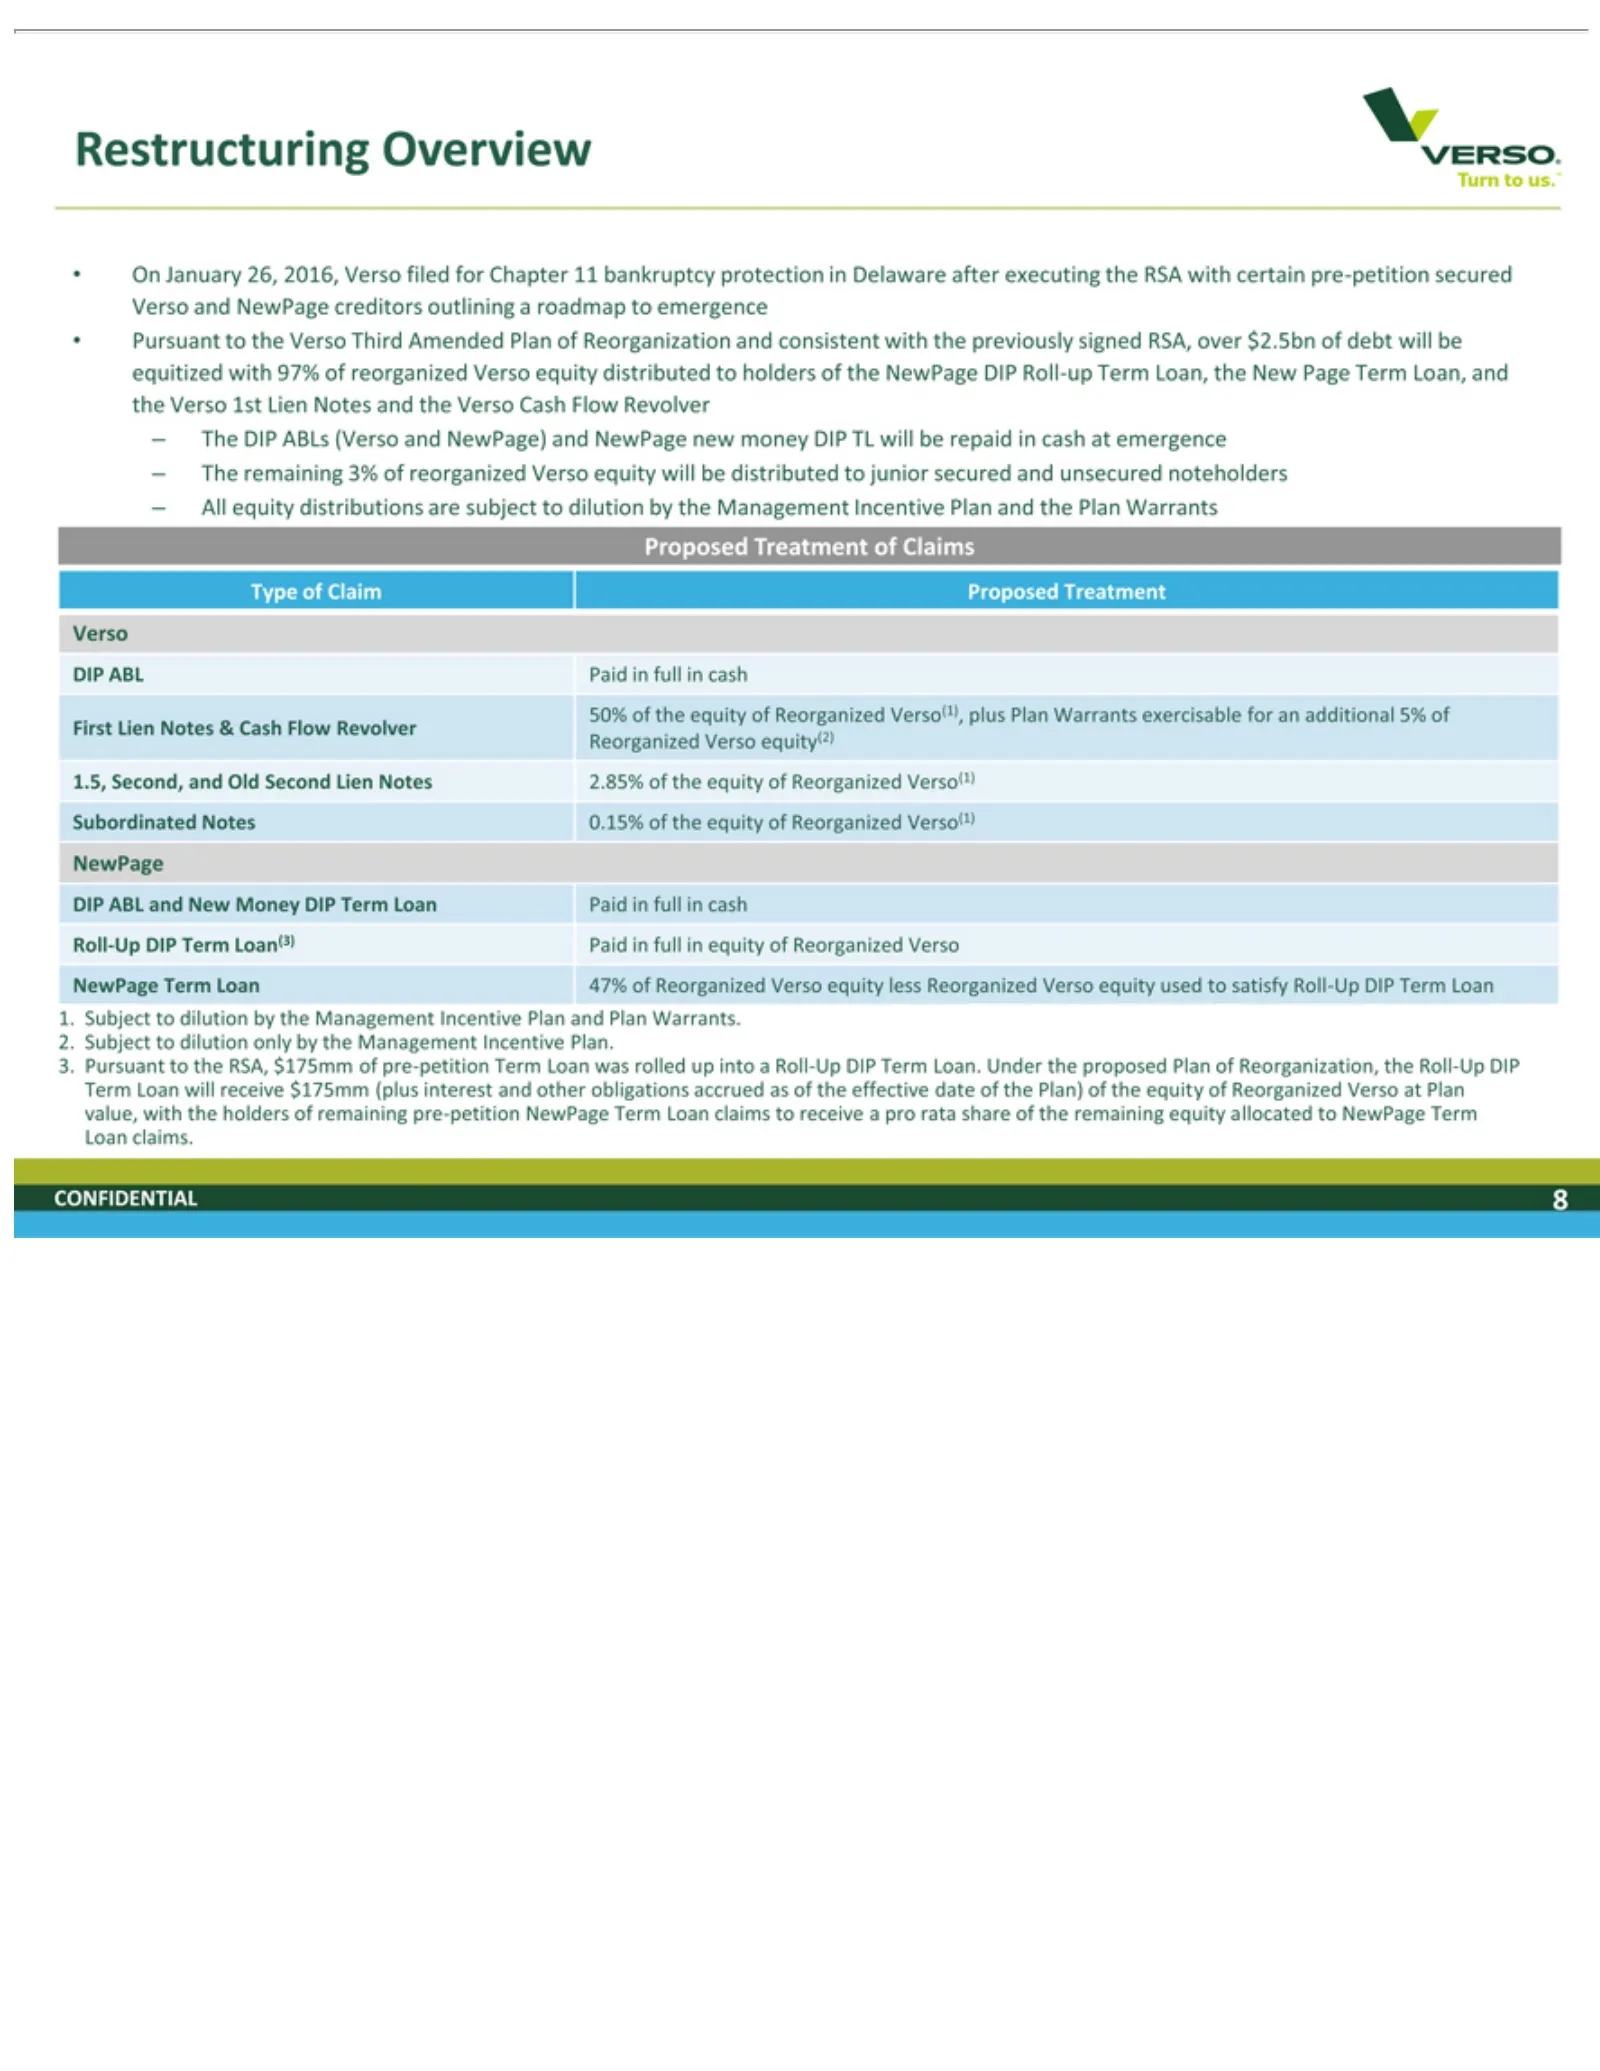
Restructuring On –Pursuant Proposed Type Verso 50% First Reorganized 1.5, Subordinated DIP Roll-Up NewPage 1. 2. 3. and the CONFIDENTIAL All The Subject Pursuant remaining January other Second, ABL of Lien equity of DIP remaining the Claim DIP to Treatment Paid and obligations Term DIP Notes to ABLs
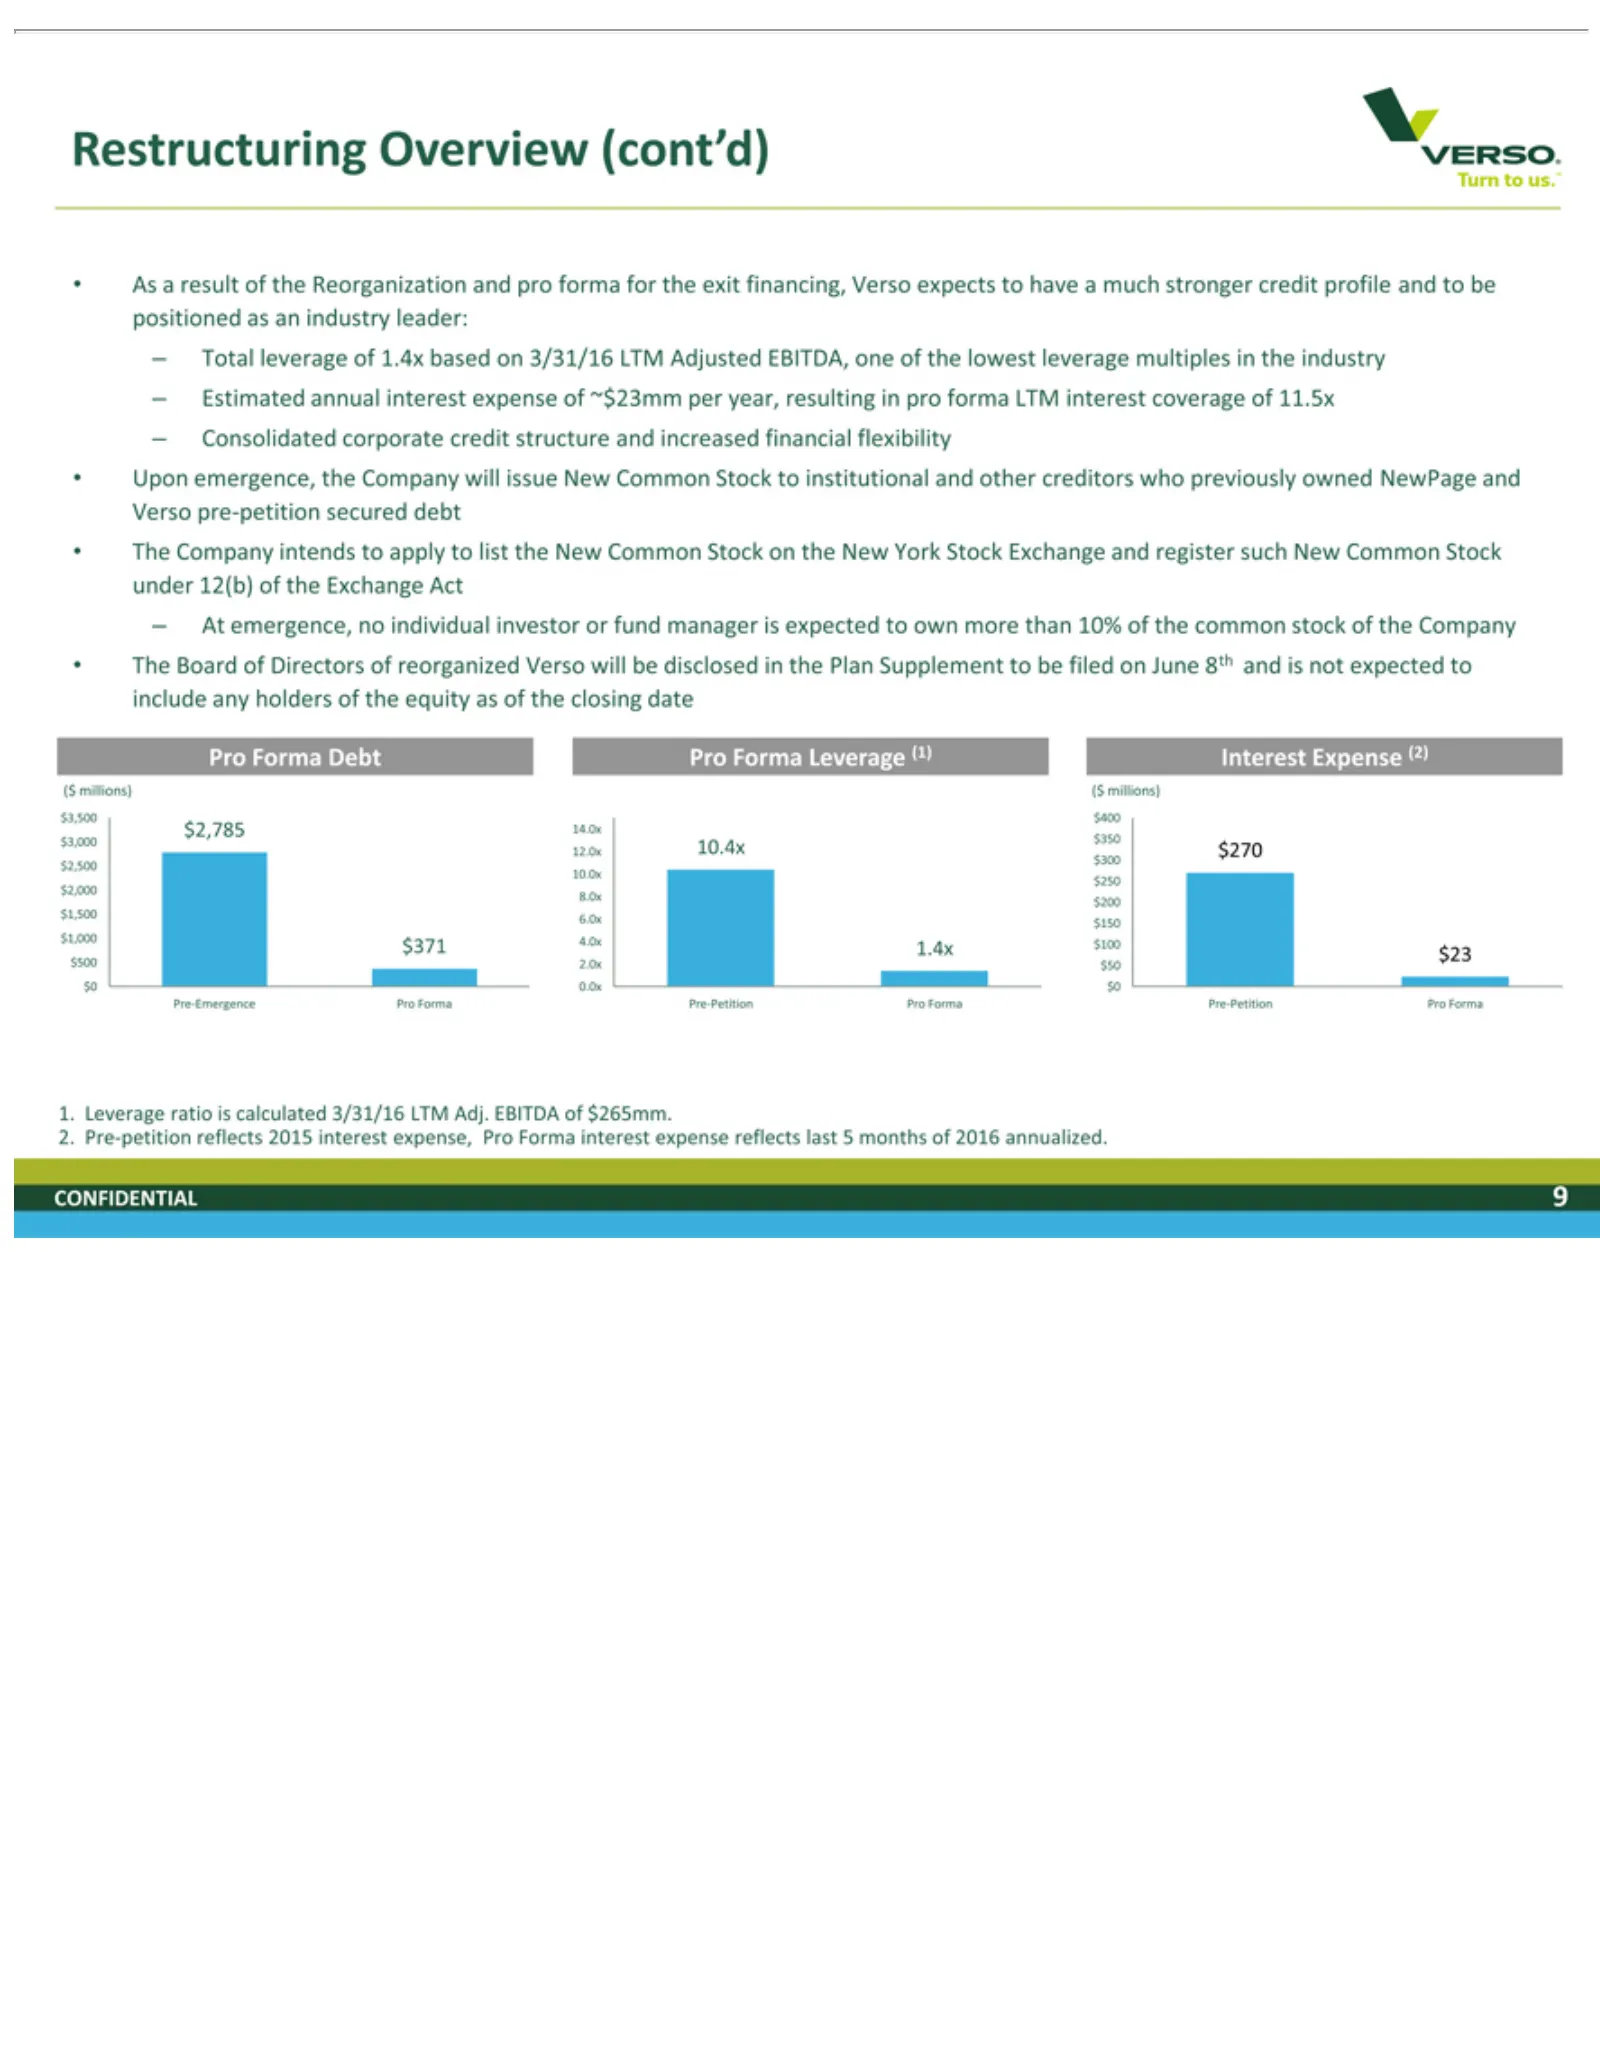
Slide 9: Restructuring Overview: Pro Forma Capitalization
Restructuring As –Upon The Pro ($ $3,500 $2,785 $3,000 $2,500 10.0x 8.0x $2,000 6.0x $1,500 $371 $1,000 $500 $0 Pre-Emergence 1. 2. CONFIDENTIAL At Total Estimated Consolidated Leverage Pre-petition millions)($ 0.0x aForma Company Board emergence, $200 $150 result 4.0x 2.0x emergence, $250 $400 14.0
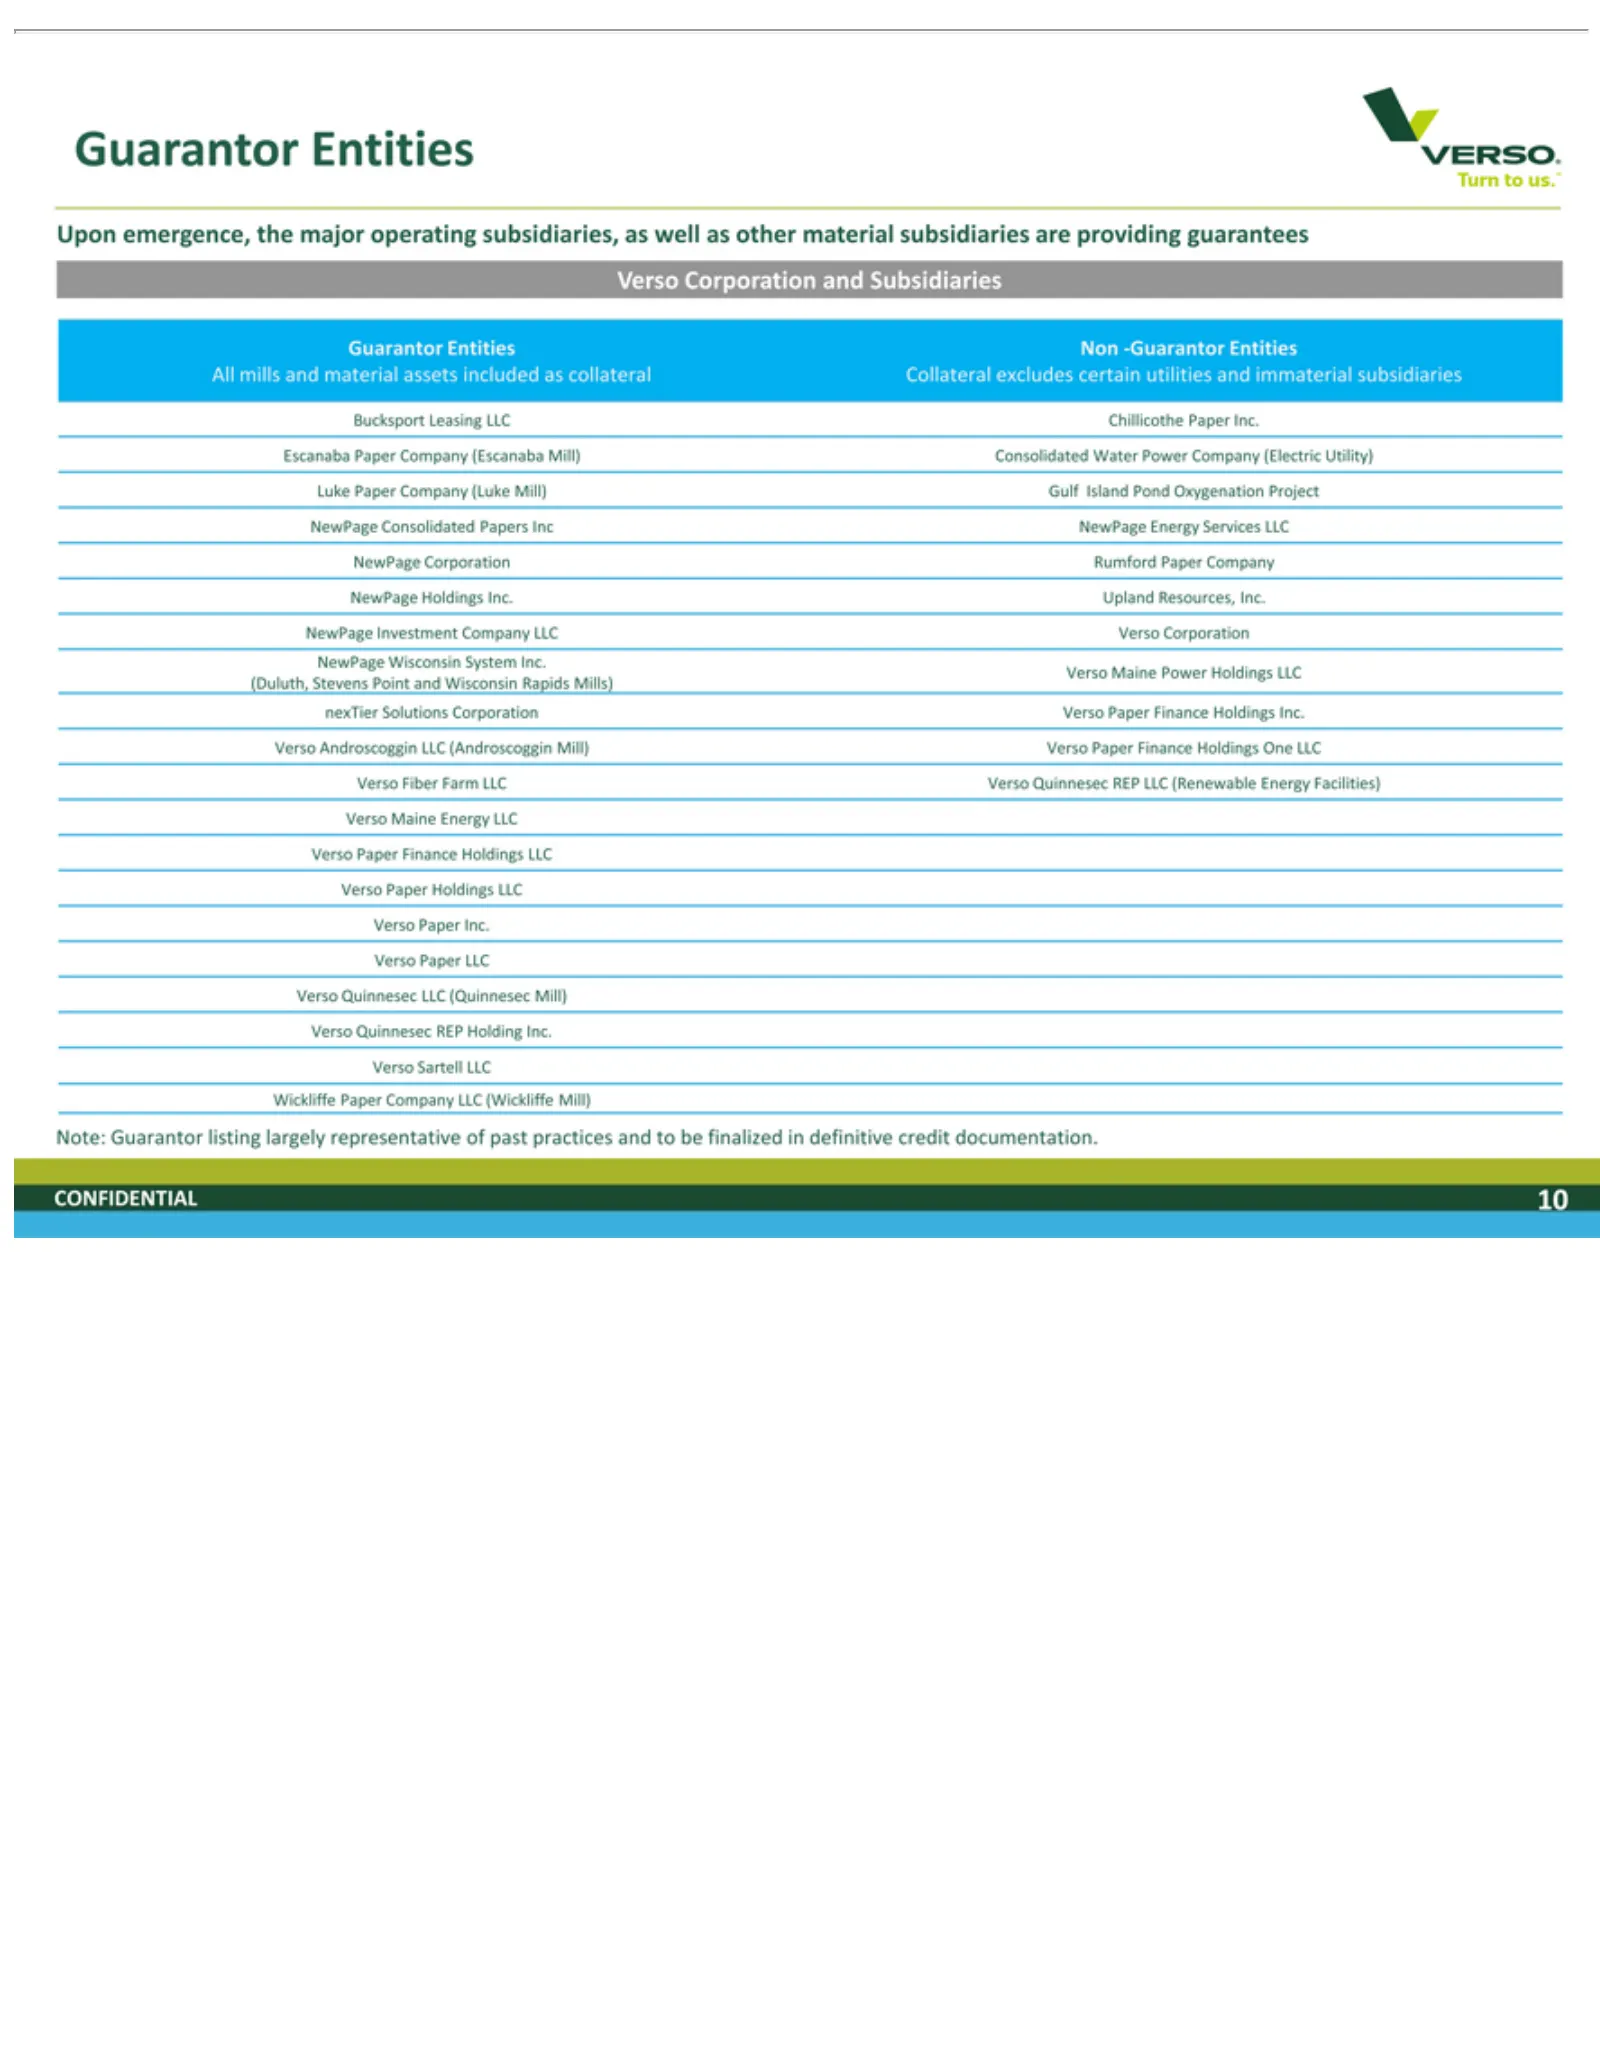
Slide 10: Guarantor and Non-Guarantor Entities
Upon Guarantor All Bucksport Escanaba Luke NewPage (Duluth, nexTier Verso Wickliffe Note: CONFIDENTIAL mills Paper Guarantor Androscoggin emergence, Corporation Fiber Maine Paper Quinnesec Sartell Solutions Stevens and Paper Wisconsin Consolidated Corporation Holdings Investment Entities Leasing Com
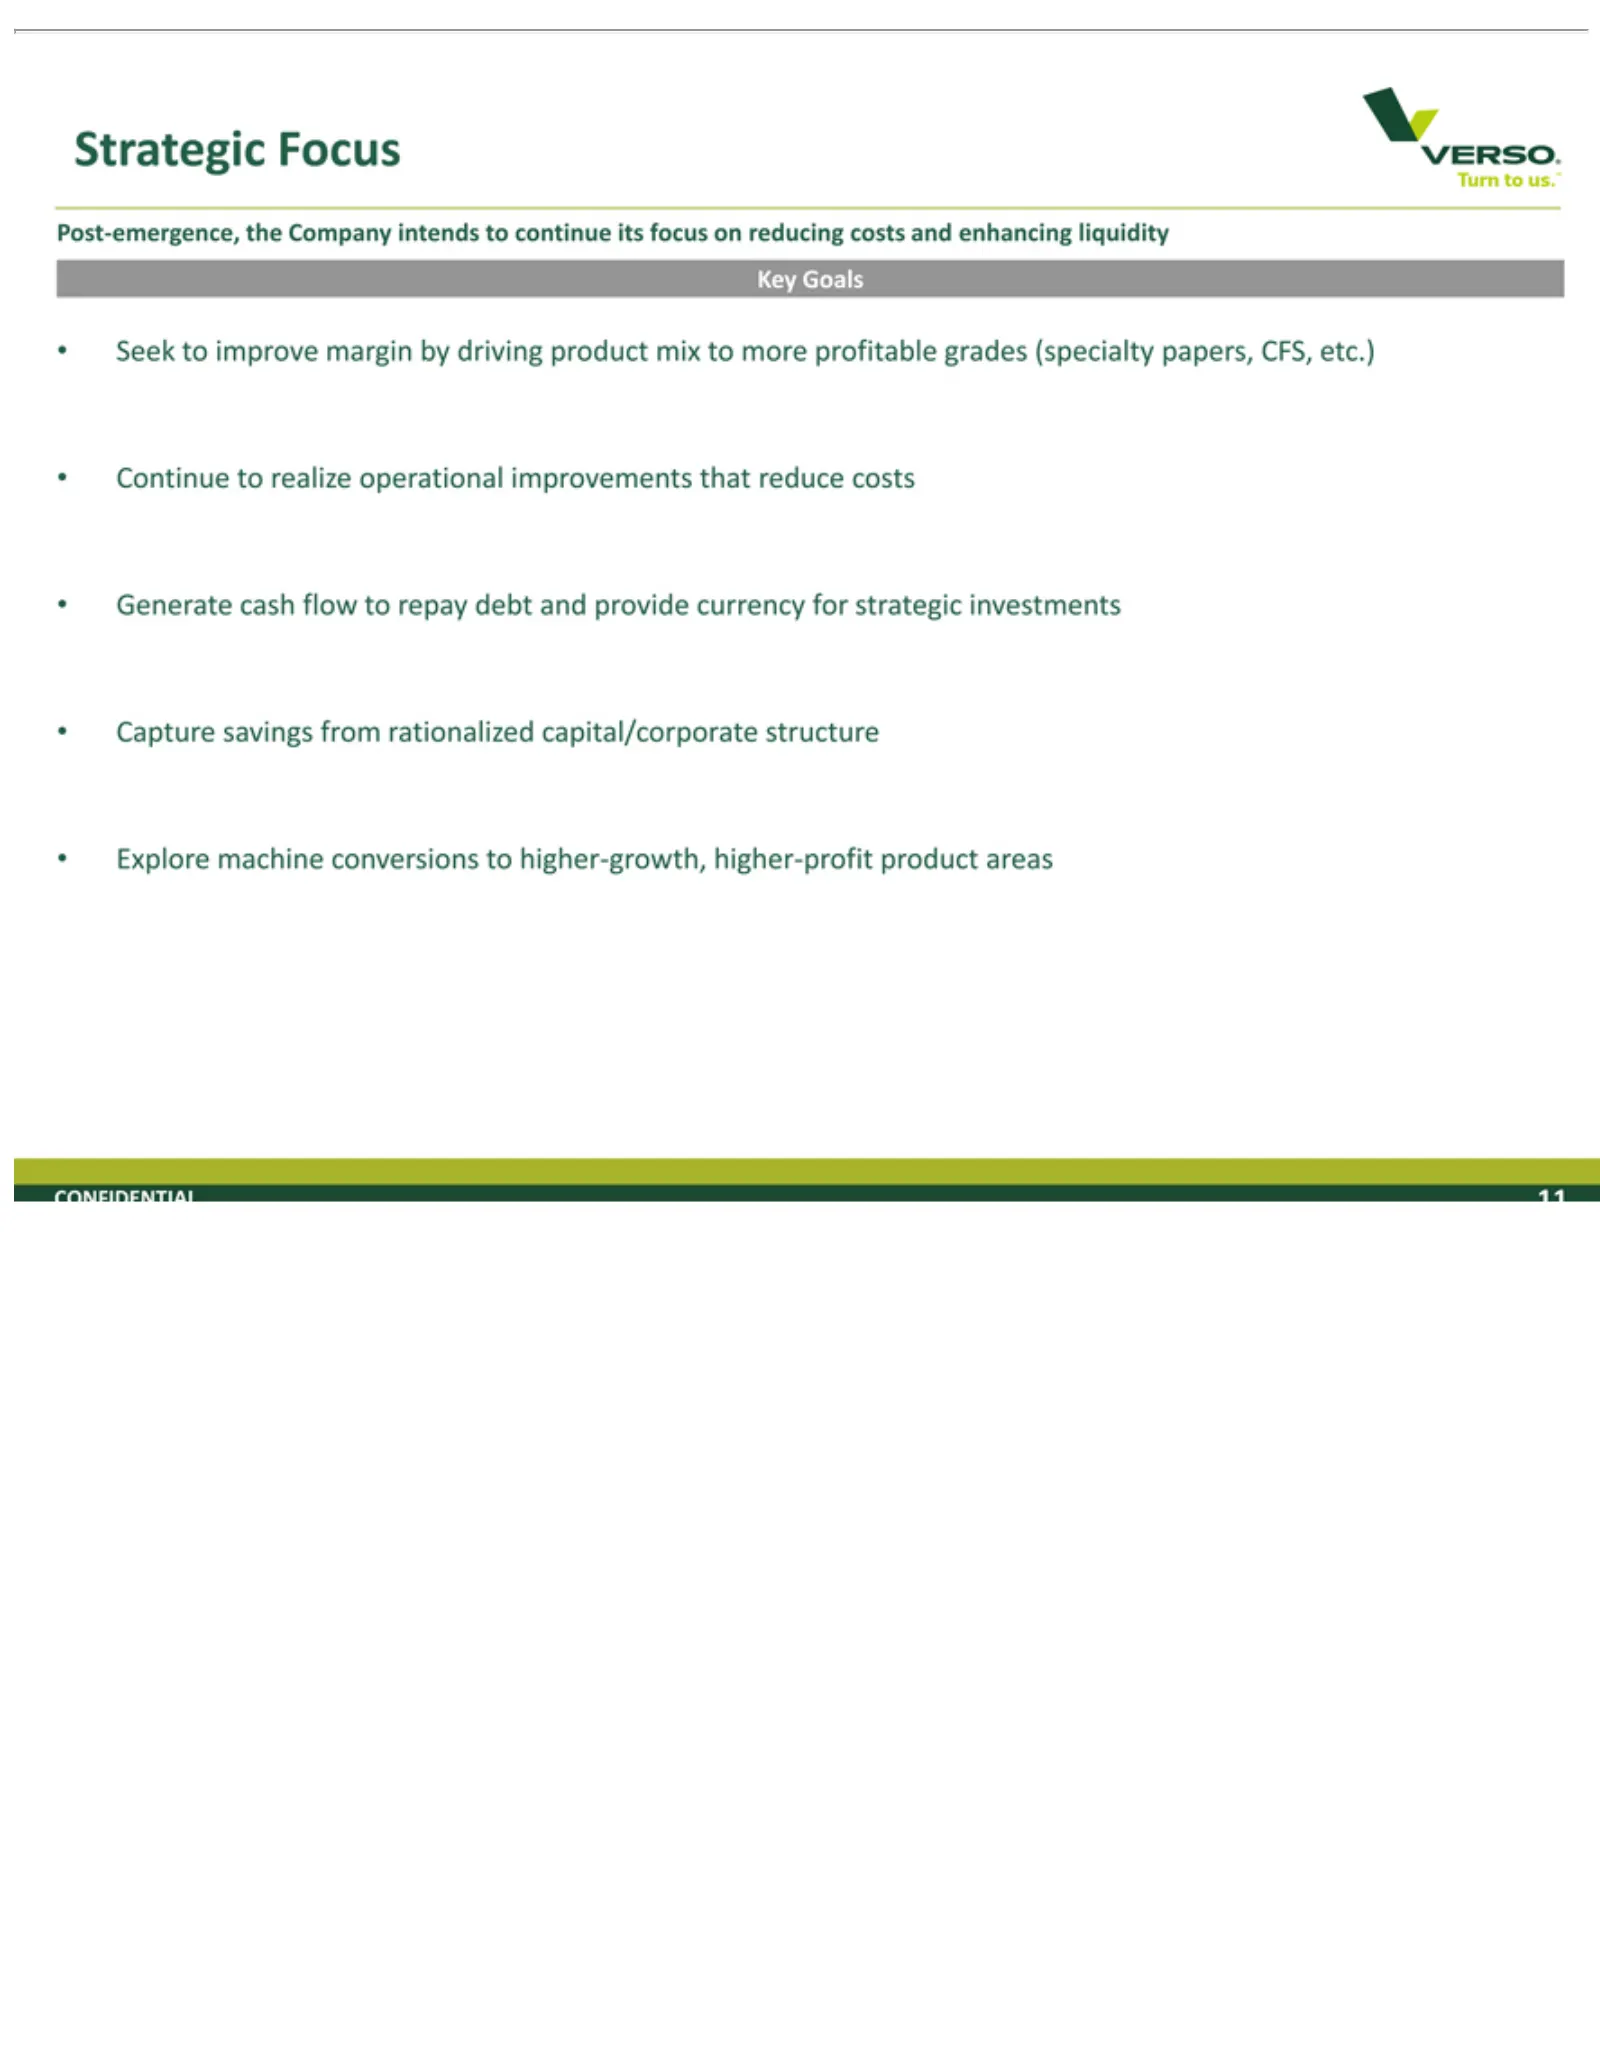
Slide 11: Key Strategic Goals
Strategic Post-emergence, Key Seek Continue Generate Capture Explore CONFIDENTIAL Goals to improve machine savings Focus cash to realize flow from margin the conversions 11 operational toCompany rationalized repay by driving debt tointends improvements higher-growth, and capital/corporate product pr
Slide 12: Company Overview and Credit Highlights
Company Overview and Credit Highlights CONFIDENTIAL
Slide 13: Key Credit Highlights
Key Credit Leading Broad Profitable Exposure Substantial Significant CONFIDENTIAL Product Producer to Low Collateral Highlights Cost Growing Offering Cost Savings with 13Mill Coverage Specialty Significant Achieved Portfolio Paper Share Grades of Manufacturing Capacity
Slide 14: Company Overview
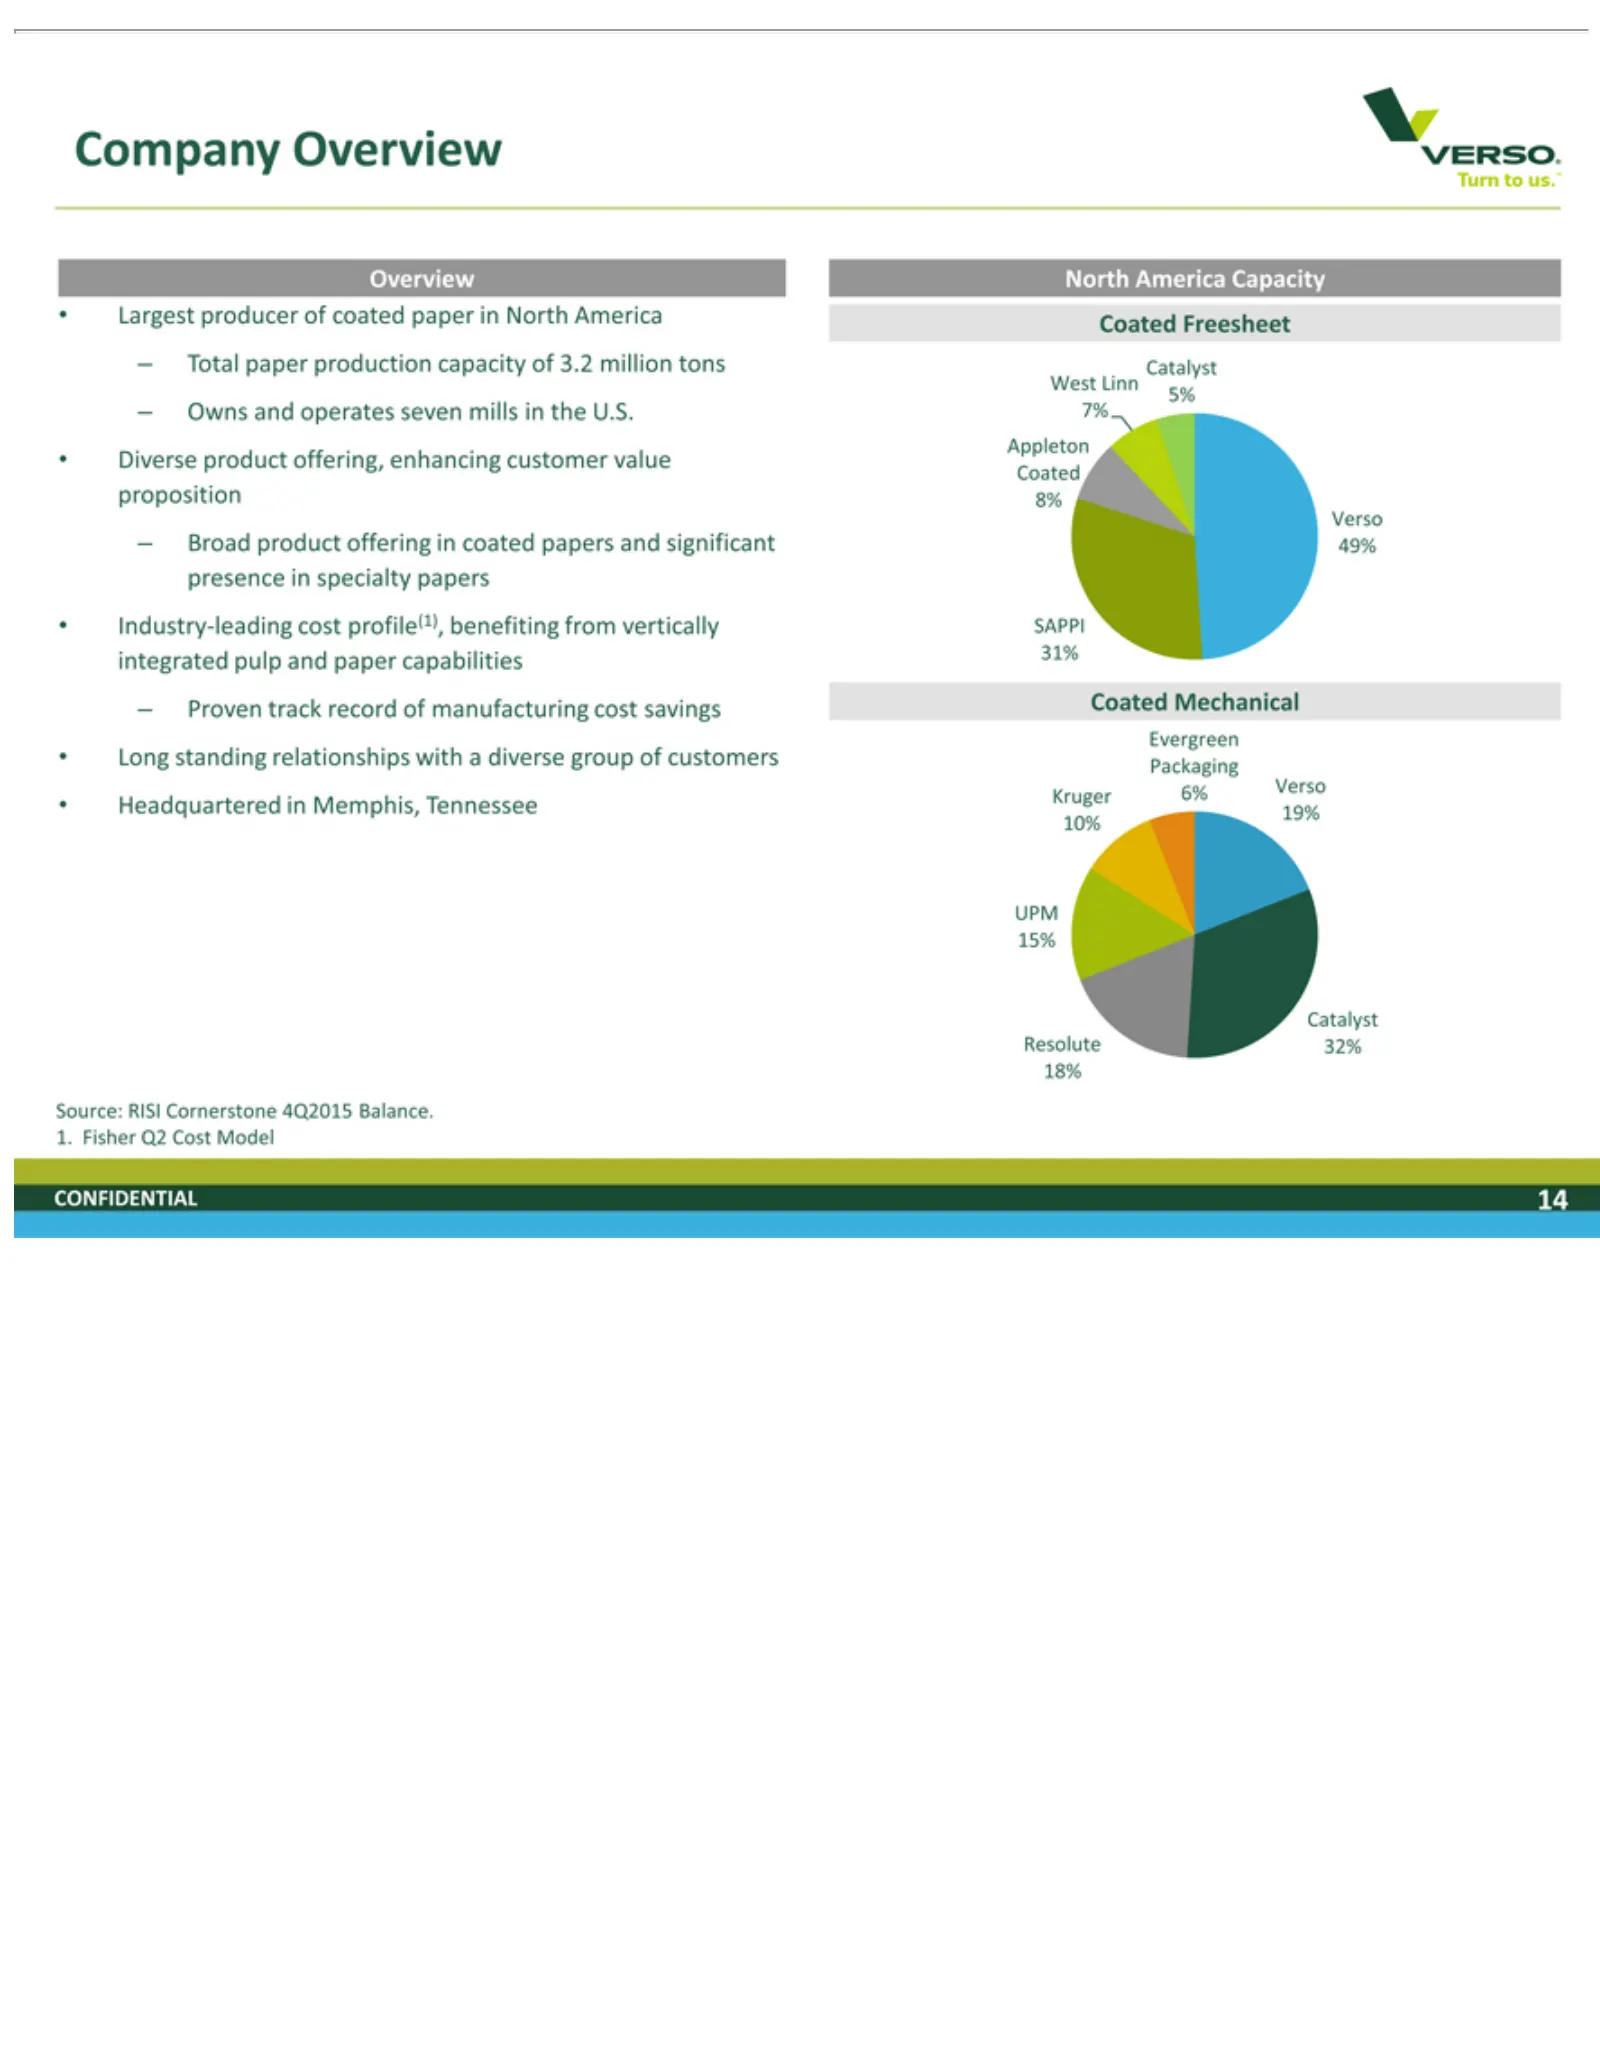
Company Overview Largest West Diverse proposition Coated presence Industry-leading –integrated Long Evergreen Headquartered Verso Resolute Catalyst 15% UPM 10% Source: 18% 1. CONFIDENTIAL Total Owns Broad Proven Fisher Linn standing paper producer RISI and product in 32% Q2 track Overview North pulp
Slide 15: Seven Mills Strategically Located
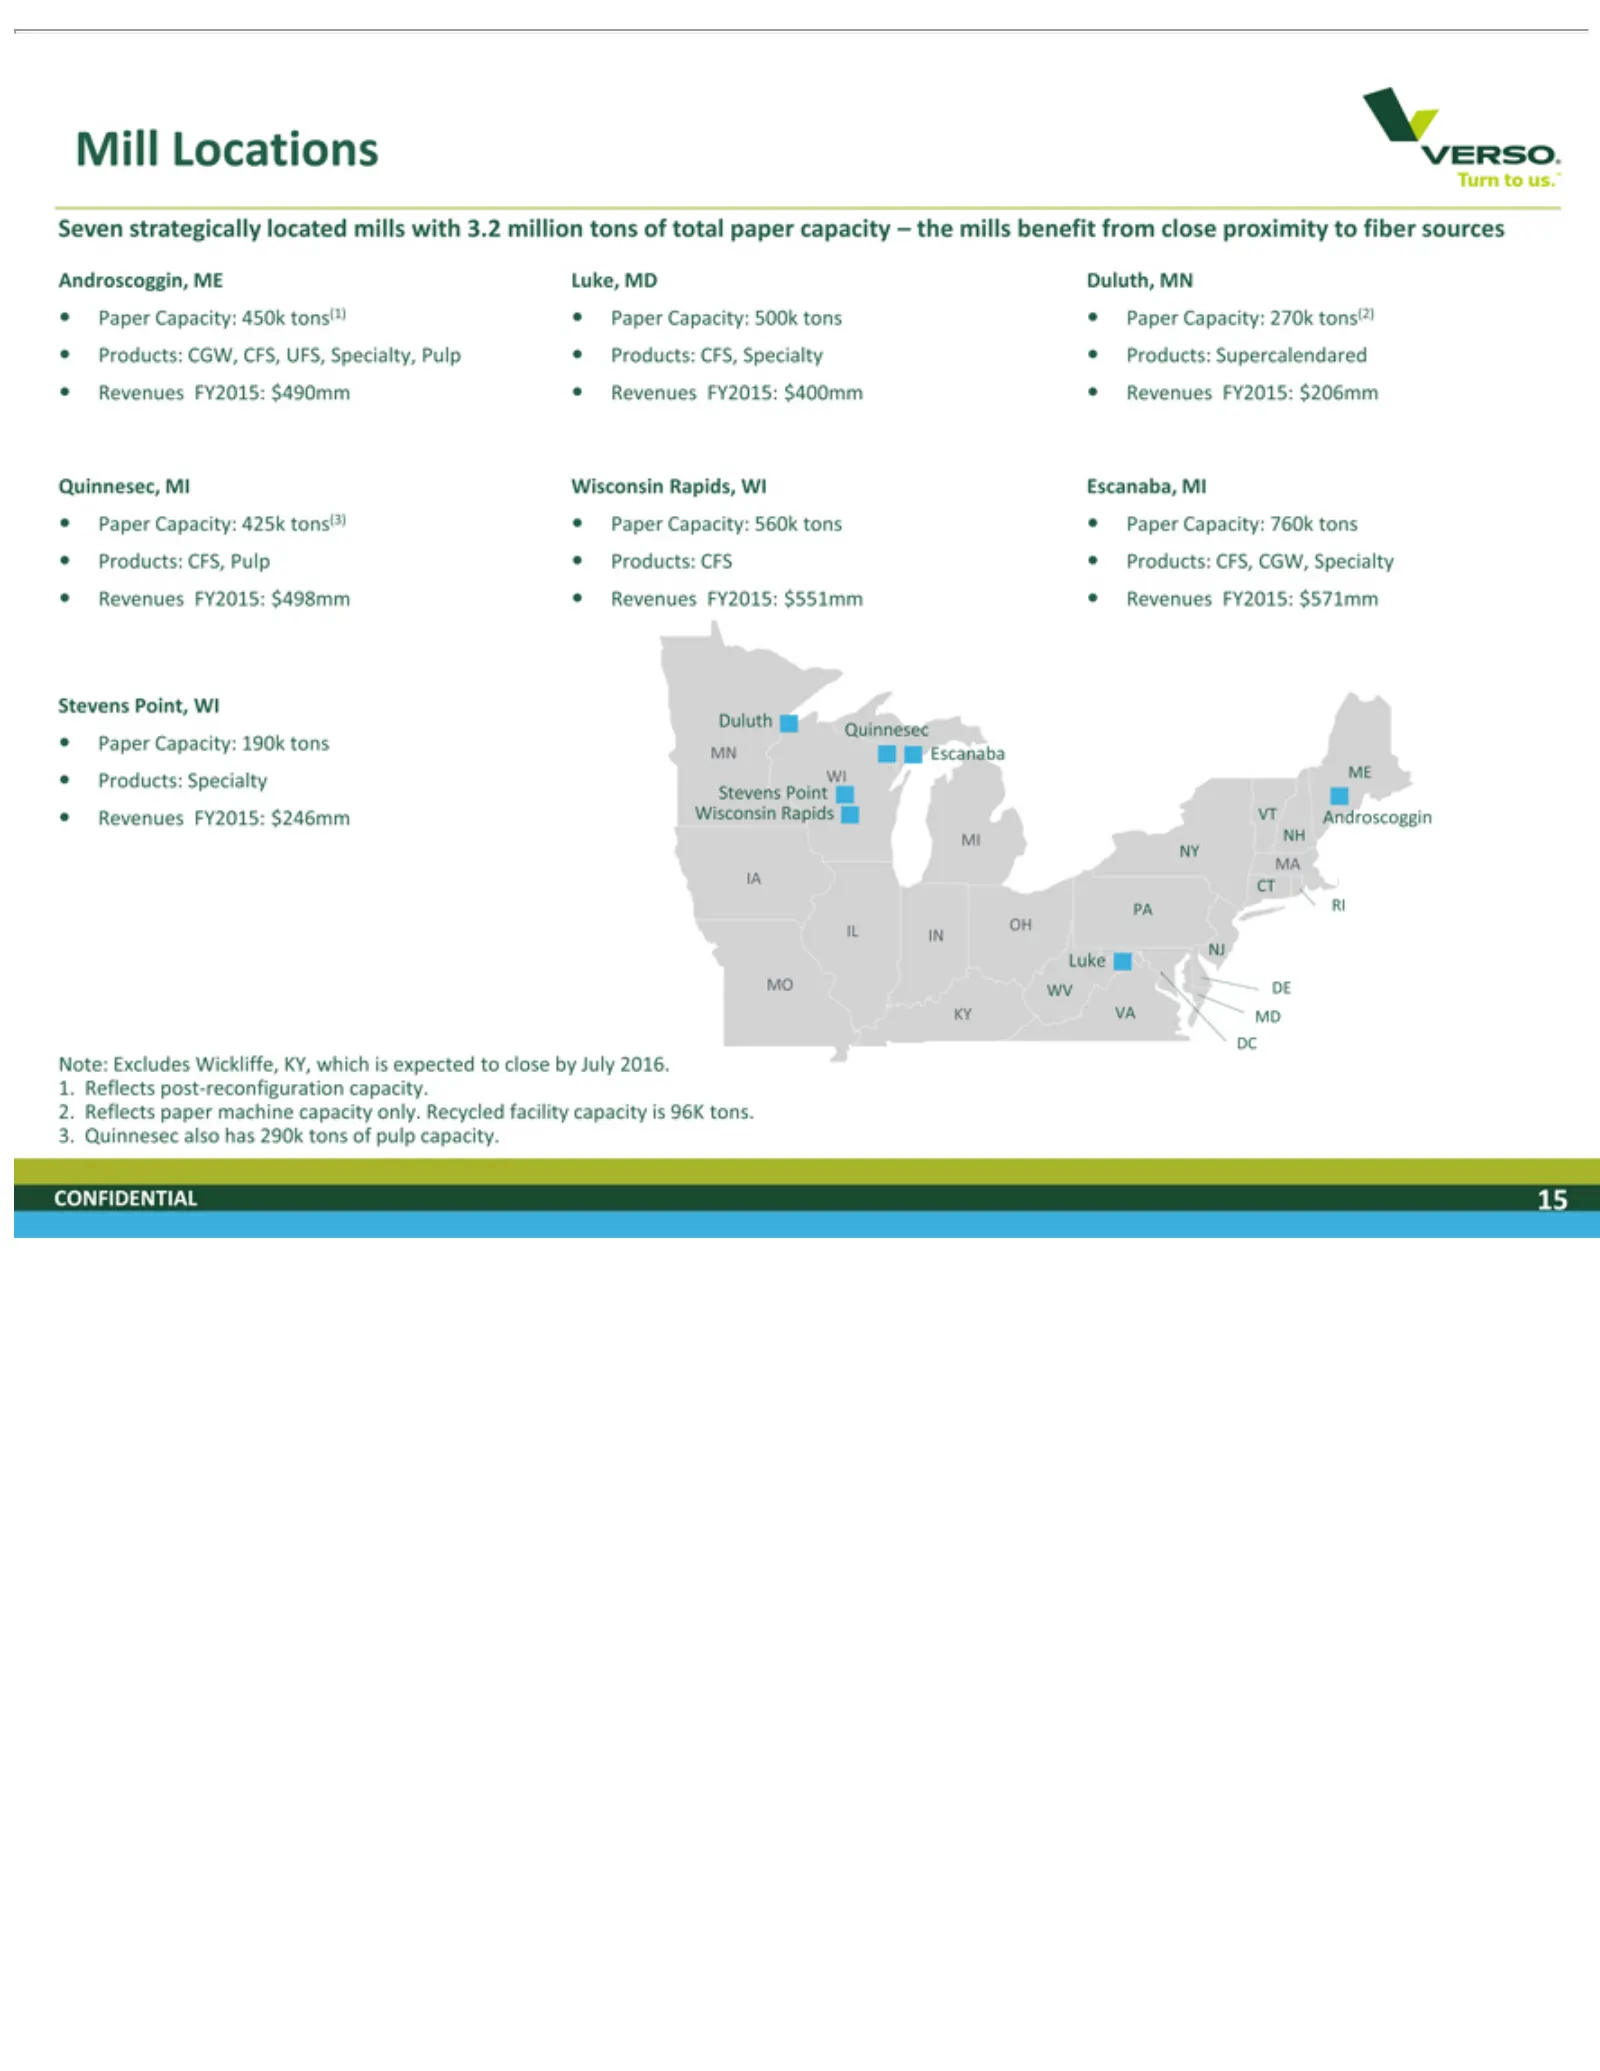
Mill Seven Androscoggin, Quinnesec, Duluth Paper Products: Stevens Revenues MI IA MA NY PA IL MO Luke NJ KY Note: DC 1. 2. 3. CONFIDENTIAL Reflects Quinnesec IN CT RI NH VA WV Locations OH Excludes Capacity: strategically Quinnesec MD Point, Point DE CGW, CFS, Specialty FY2015: post-reconfiguration
Slide 16: Broad Product Offering
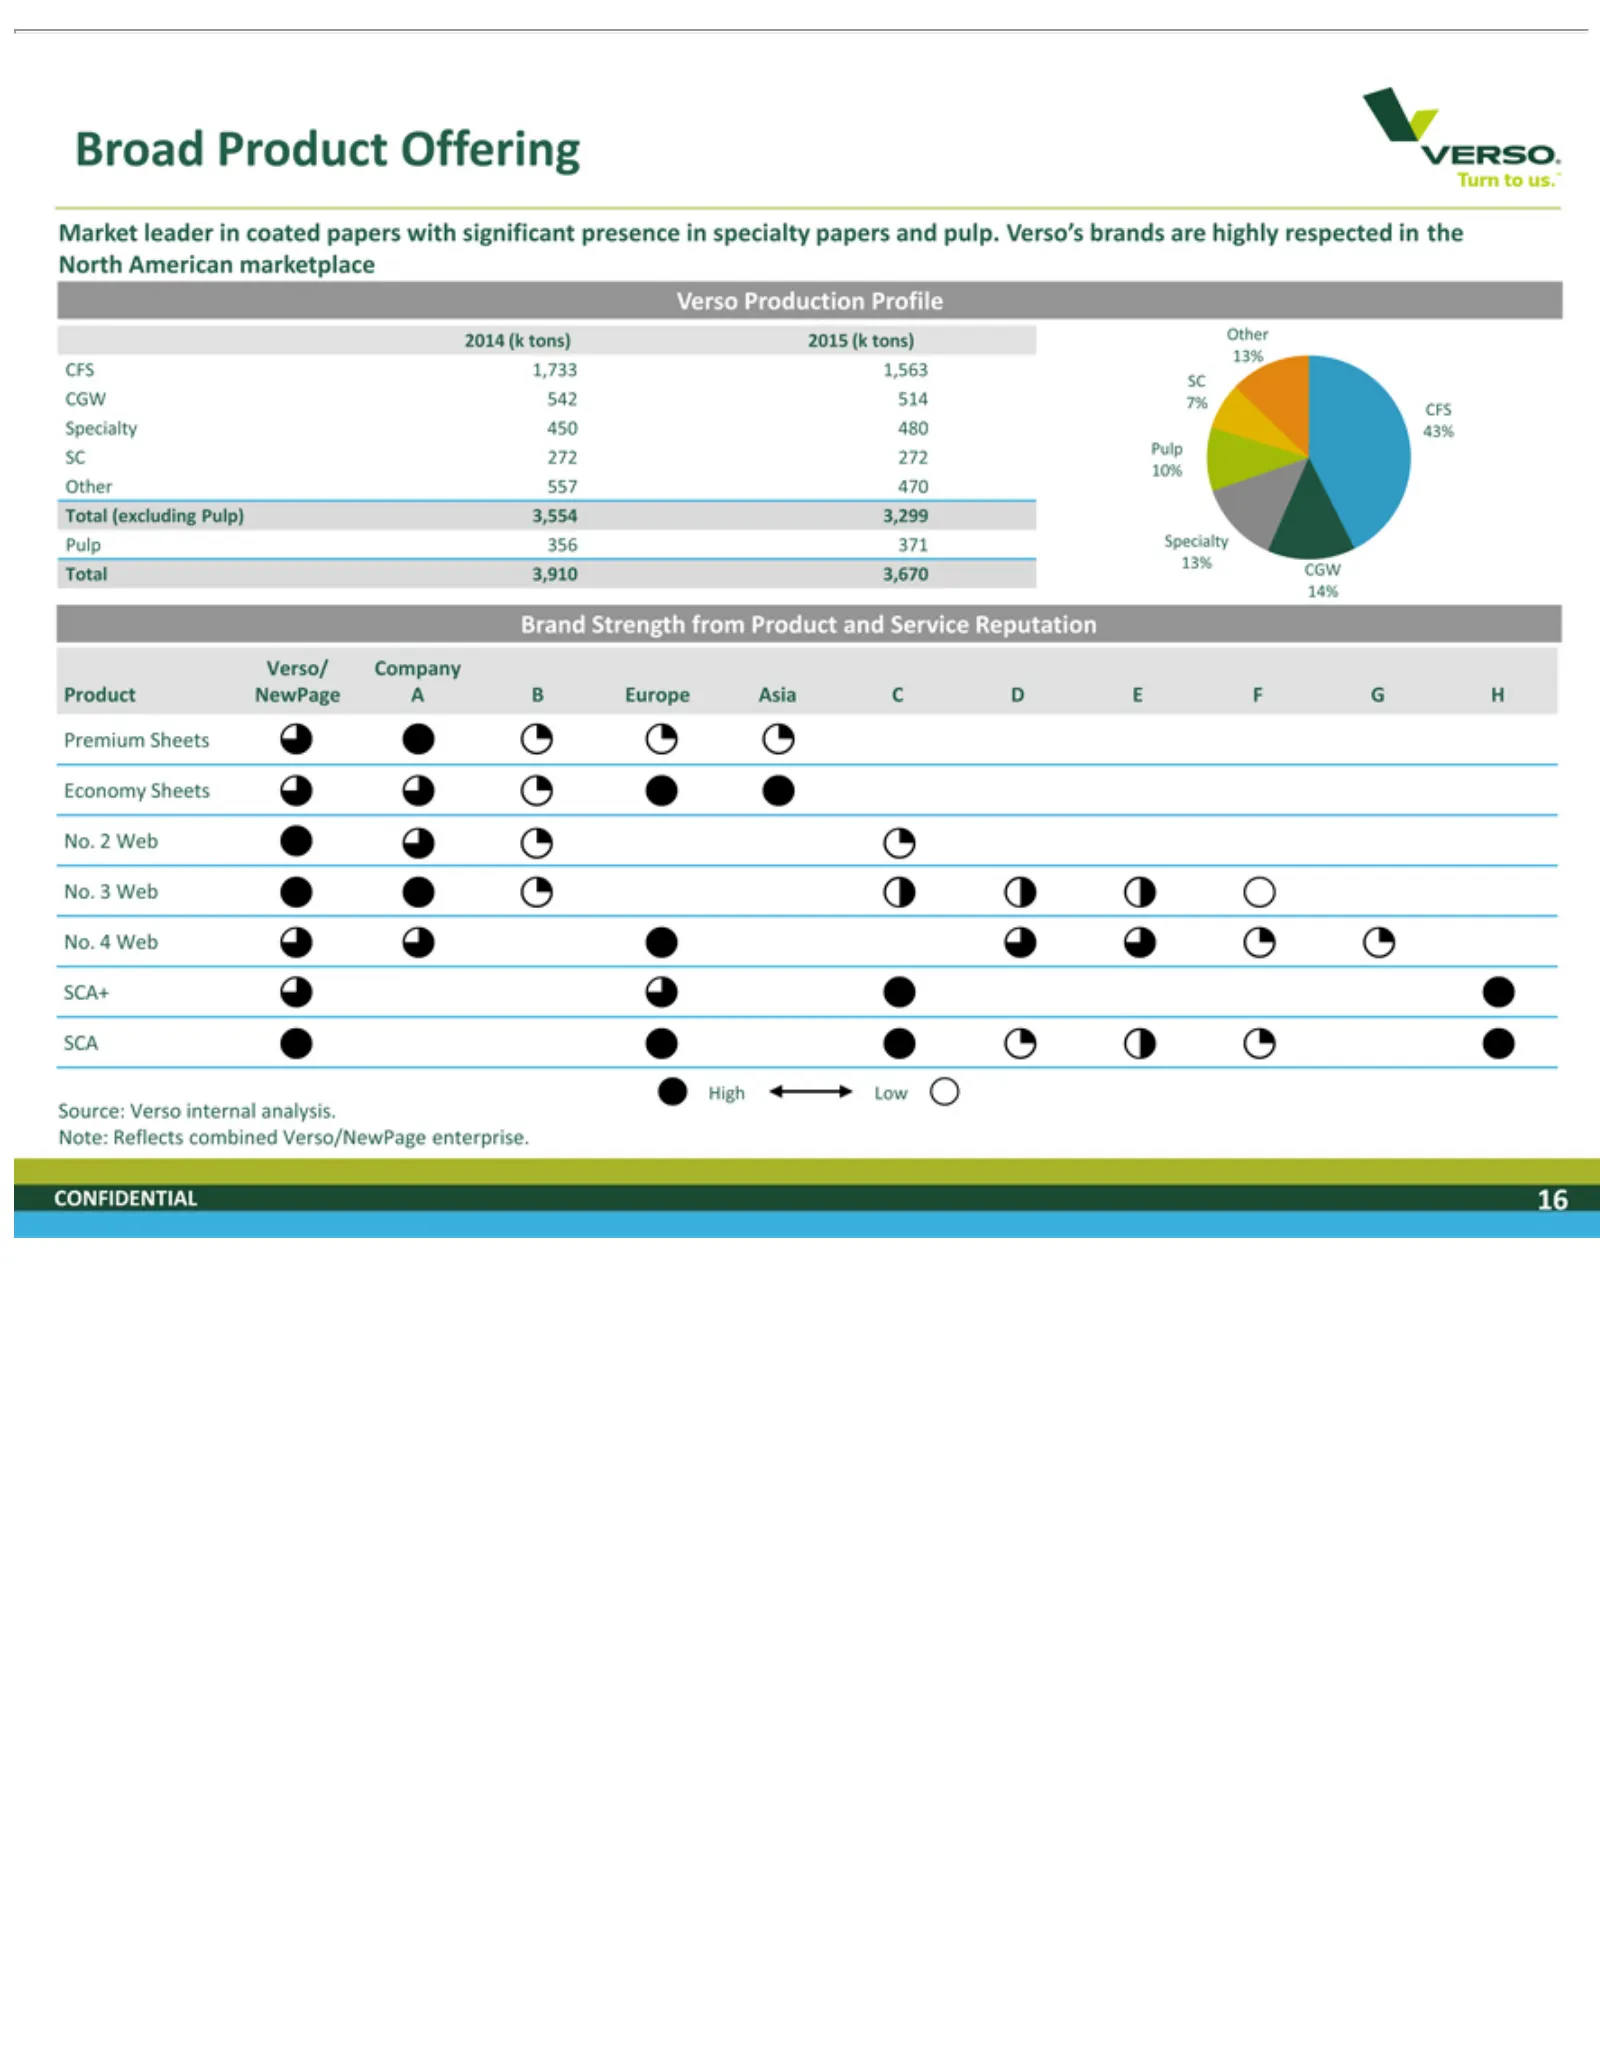
Broad Market North Verso 2014 CFS CGW Specialty SC Other 10% Pulp Total 13% Brand 14% Verso/ Product Premium Economy No. High SCA SCA+ Source: Note: CONFIDENTIAL 272 21,733 3 4 356 (k Low (excluding 3,910 Web Reflects 557 Production American 542 Product Strength Company leader 272 Verso tons) NewPag
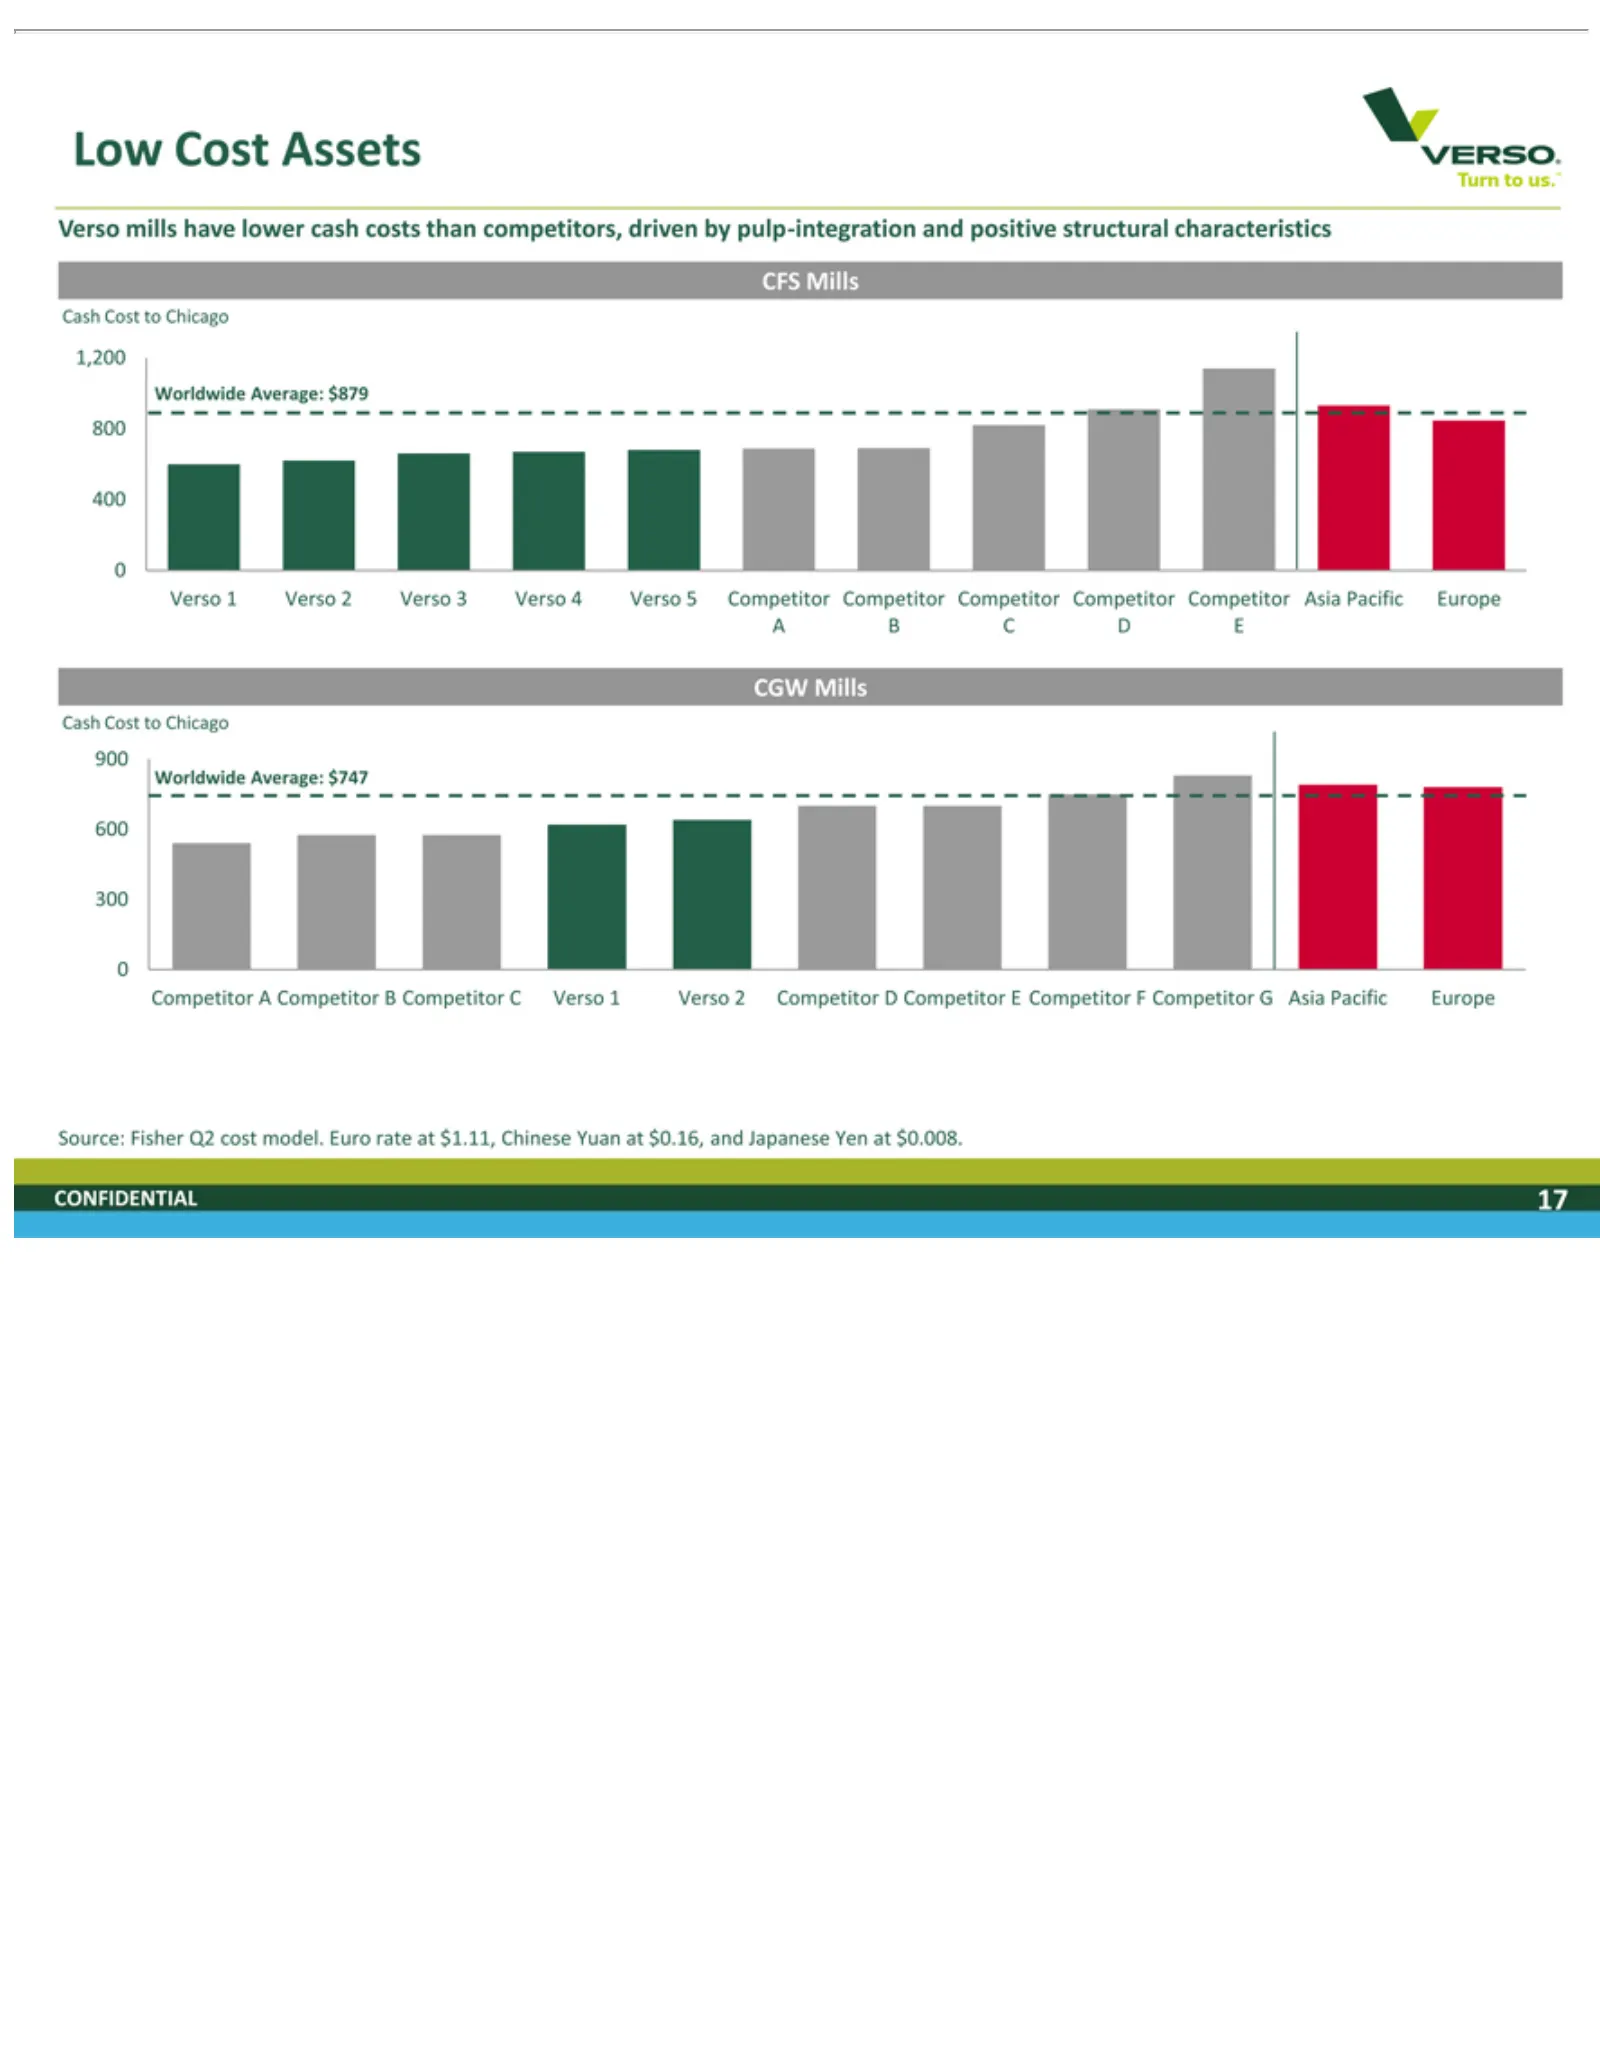
Slide 17: Low Cost Producer
Low Verso CFS 1,200 V 400 800 CGW Cash Worldwide 900 0C 300 600 Source: CONFIDENTIAL erso ompetitor Mills Cost Cost mills 1 Mills Verso Fisher Assets toAverage: A have Chicago Competitor 2Q2 Verso lower cost 17$747 $879 3model. cash Verso B Competitor costs 4Euro Verso than rate 5competitors, C Comp
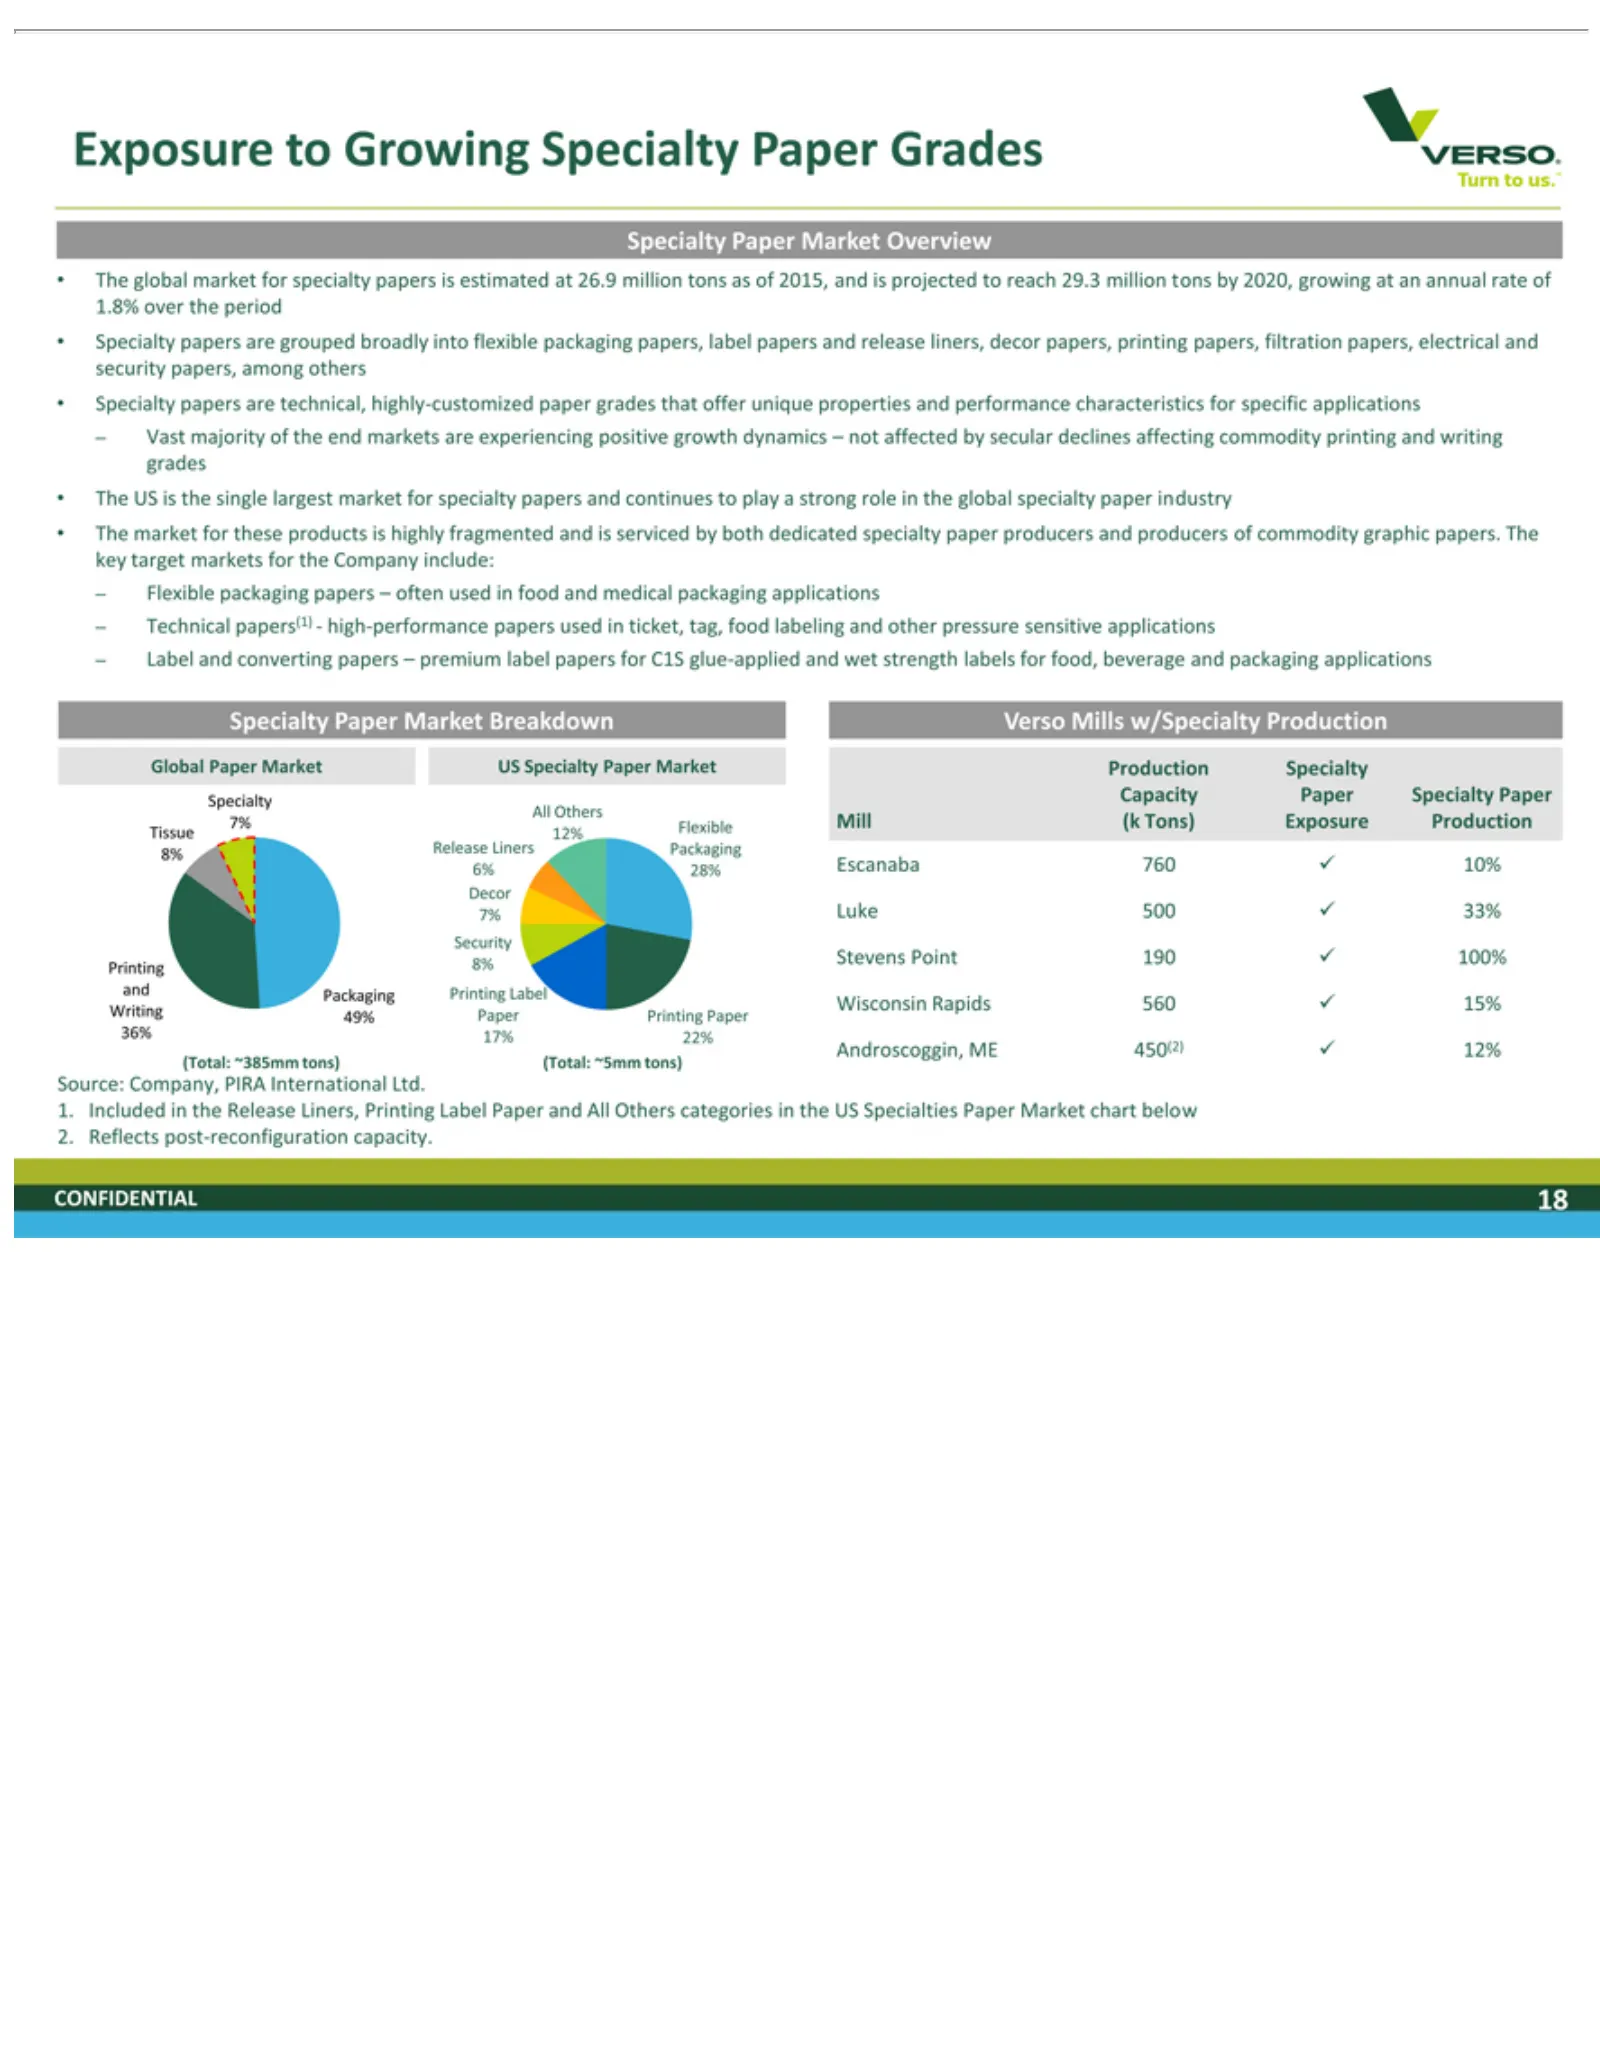
Slide 18: Exposure to Growing Specialty Paper Grades
Exposure 1.8% security grades The –key Global Specialty All Tissue 8% 6% 7% Decor Printing Security and Writing 36% (Total: Source: 1. 2. CONFIDENTIAL Vast Technical Flexible Label Included Reflects Others Release 28% Luke target Packaging global US market 17% over majority 7% ~385mm Paper and Compa
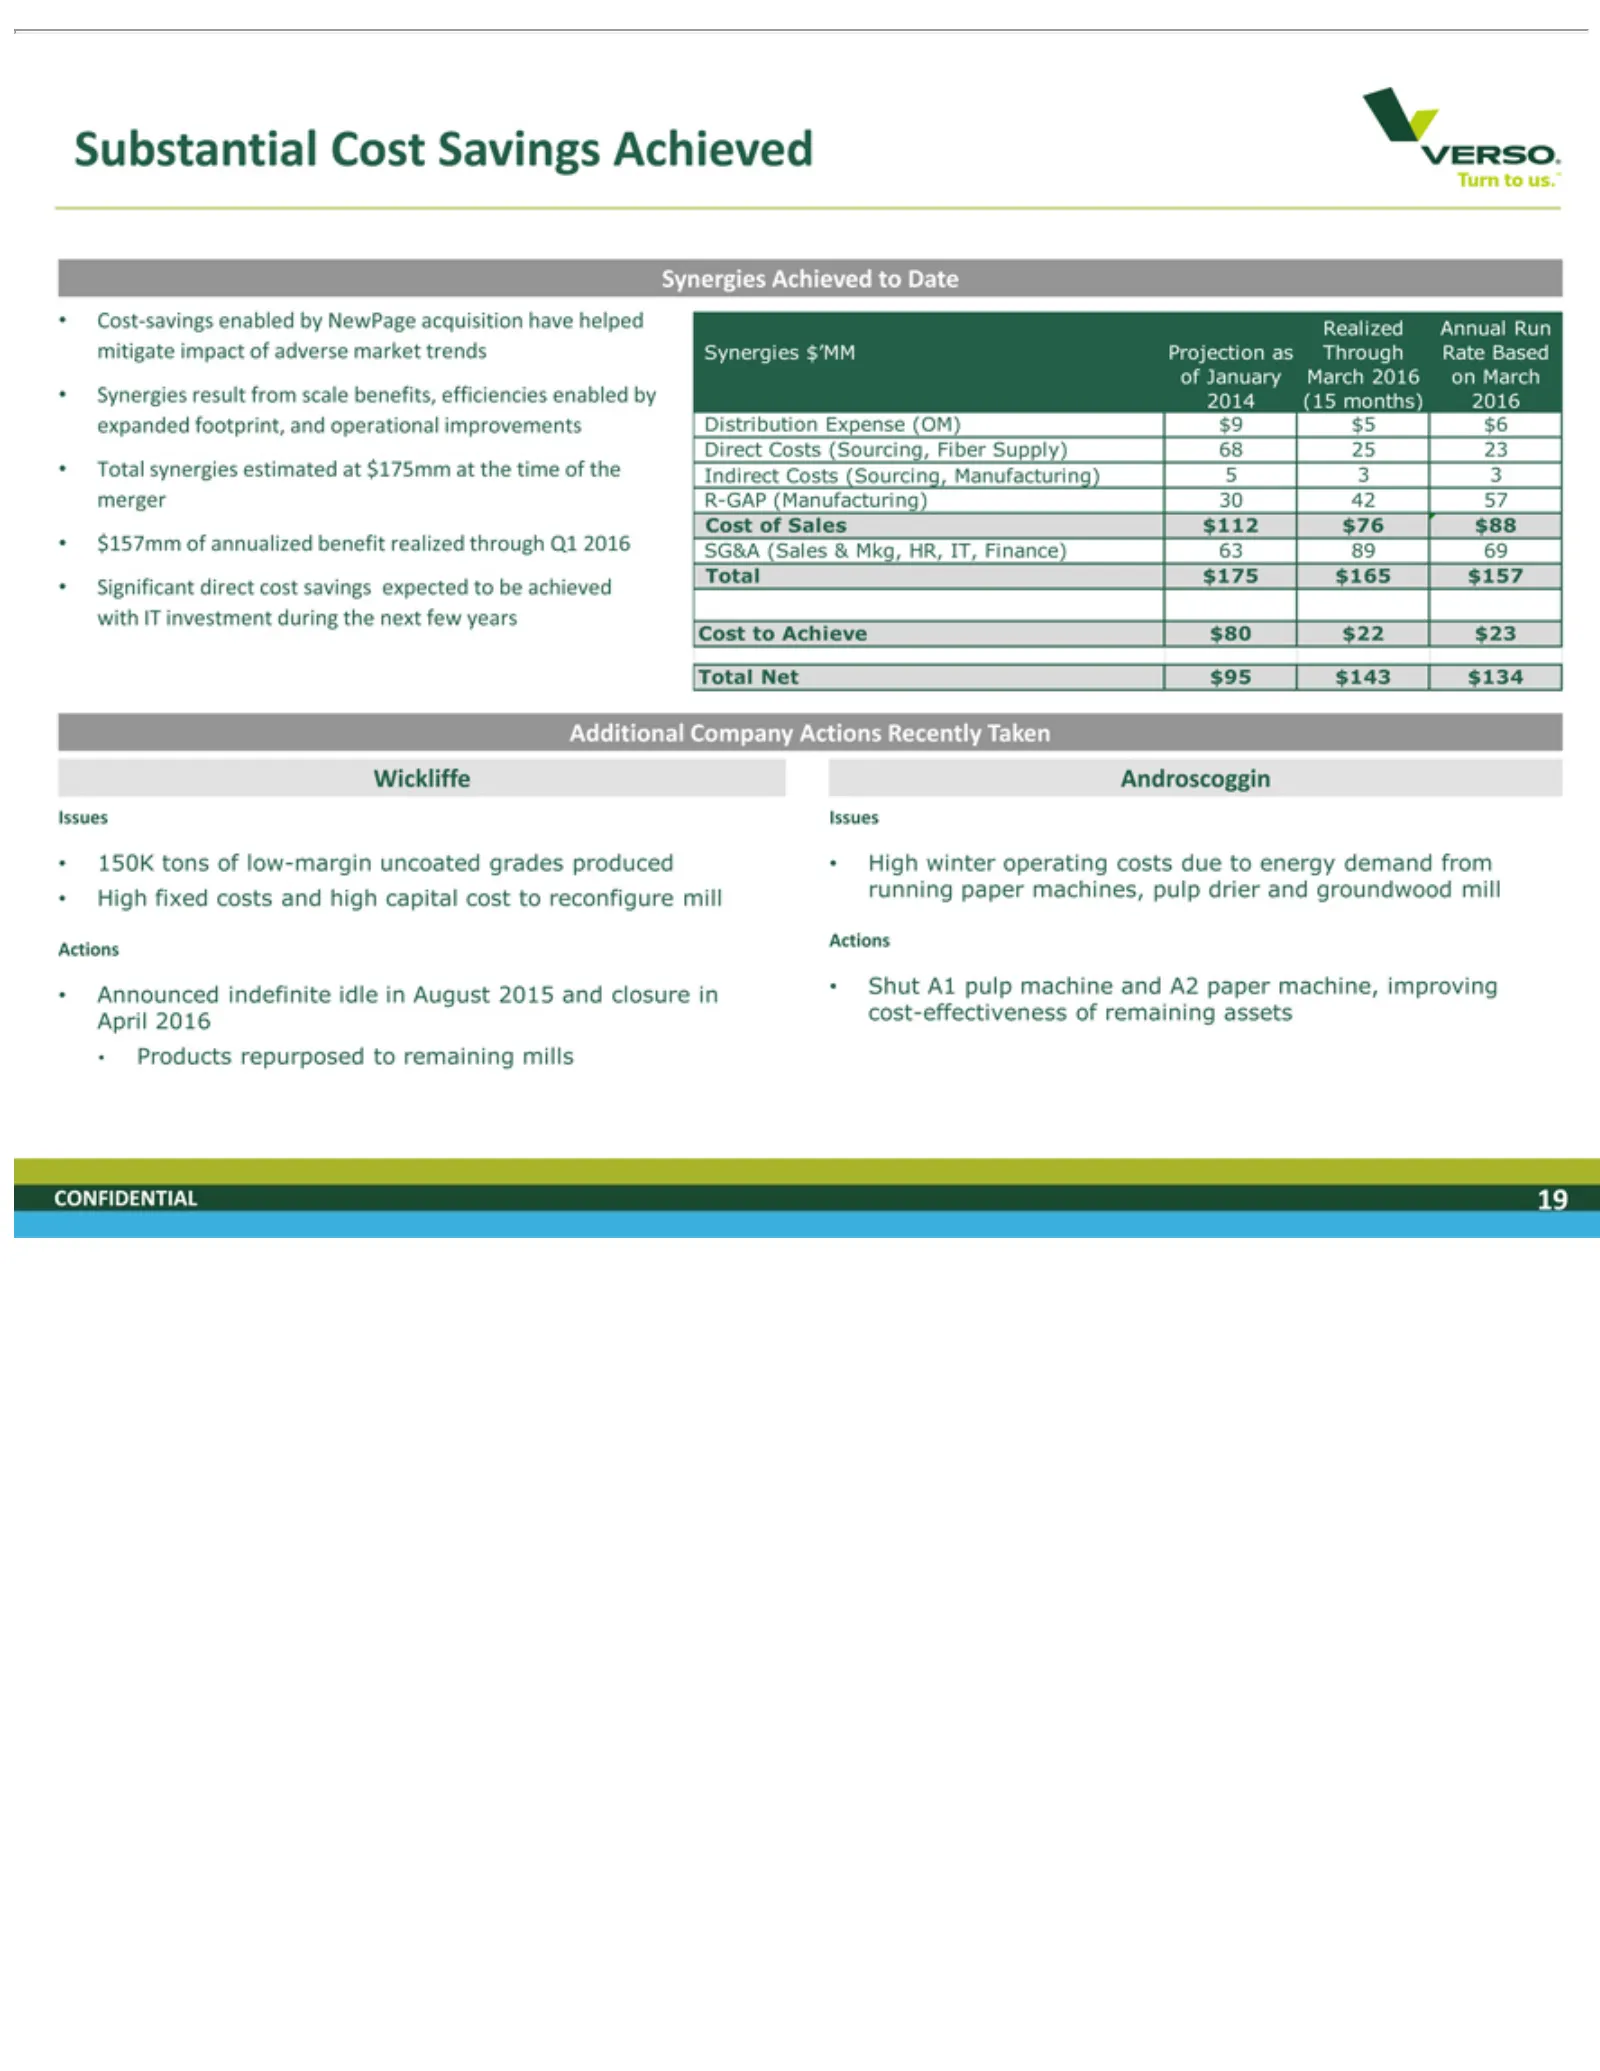
Slide 19: Substantial Cost Savings Achieved
Substantial Cost-savings mitigate of Synergies expanded Direct merger $157mm Significant with Cost Total Additional Wickliffe Issues 150K High Actions Announced April Products CONFIDENTIAL January IT of to fixed synergies Net 2016 tons Issues Costs Achieve R-GAP Sales investment Actions impact repur
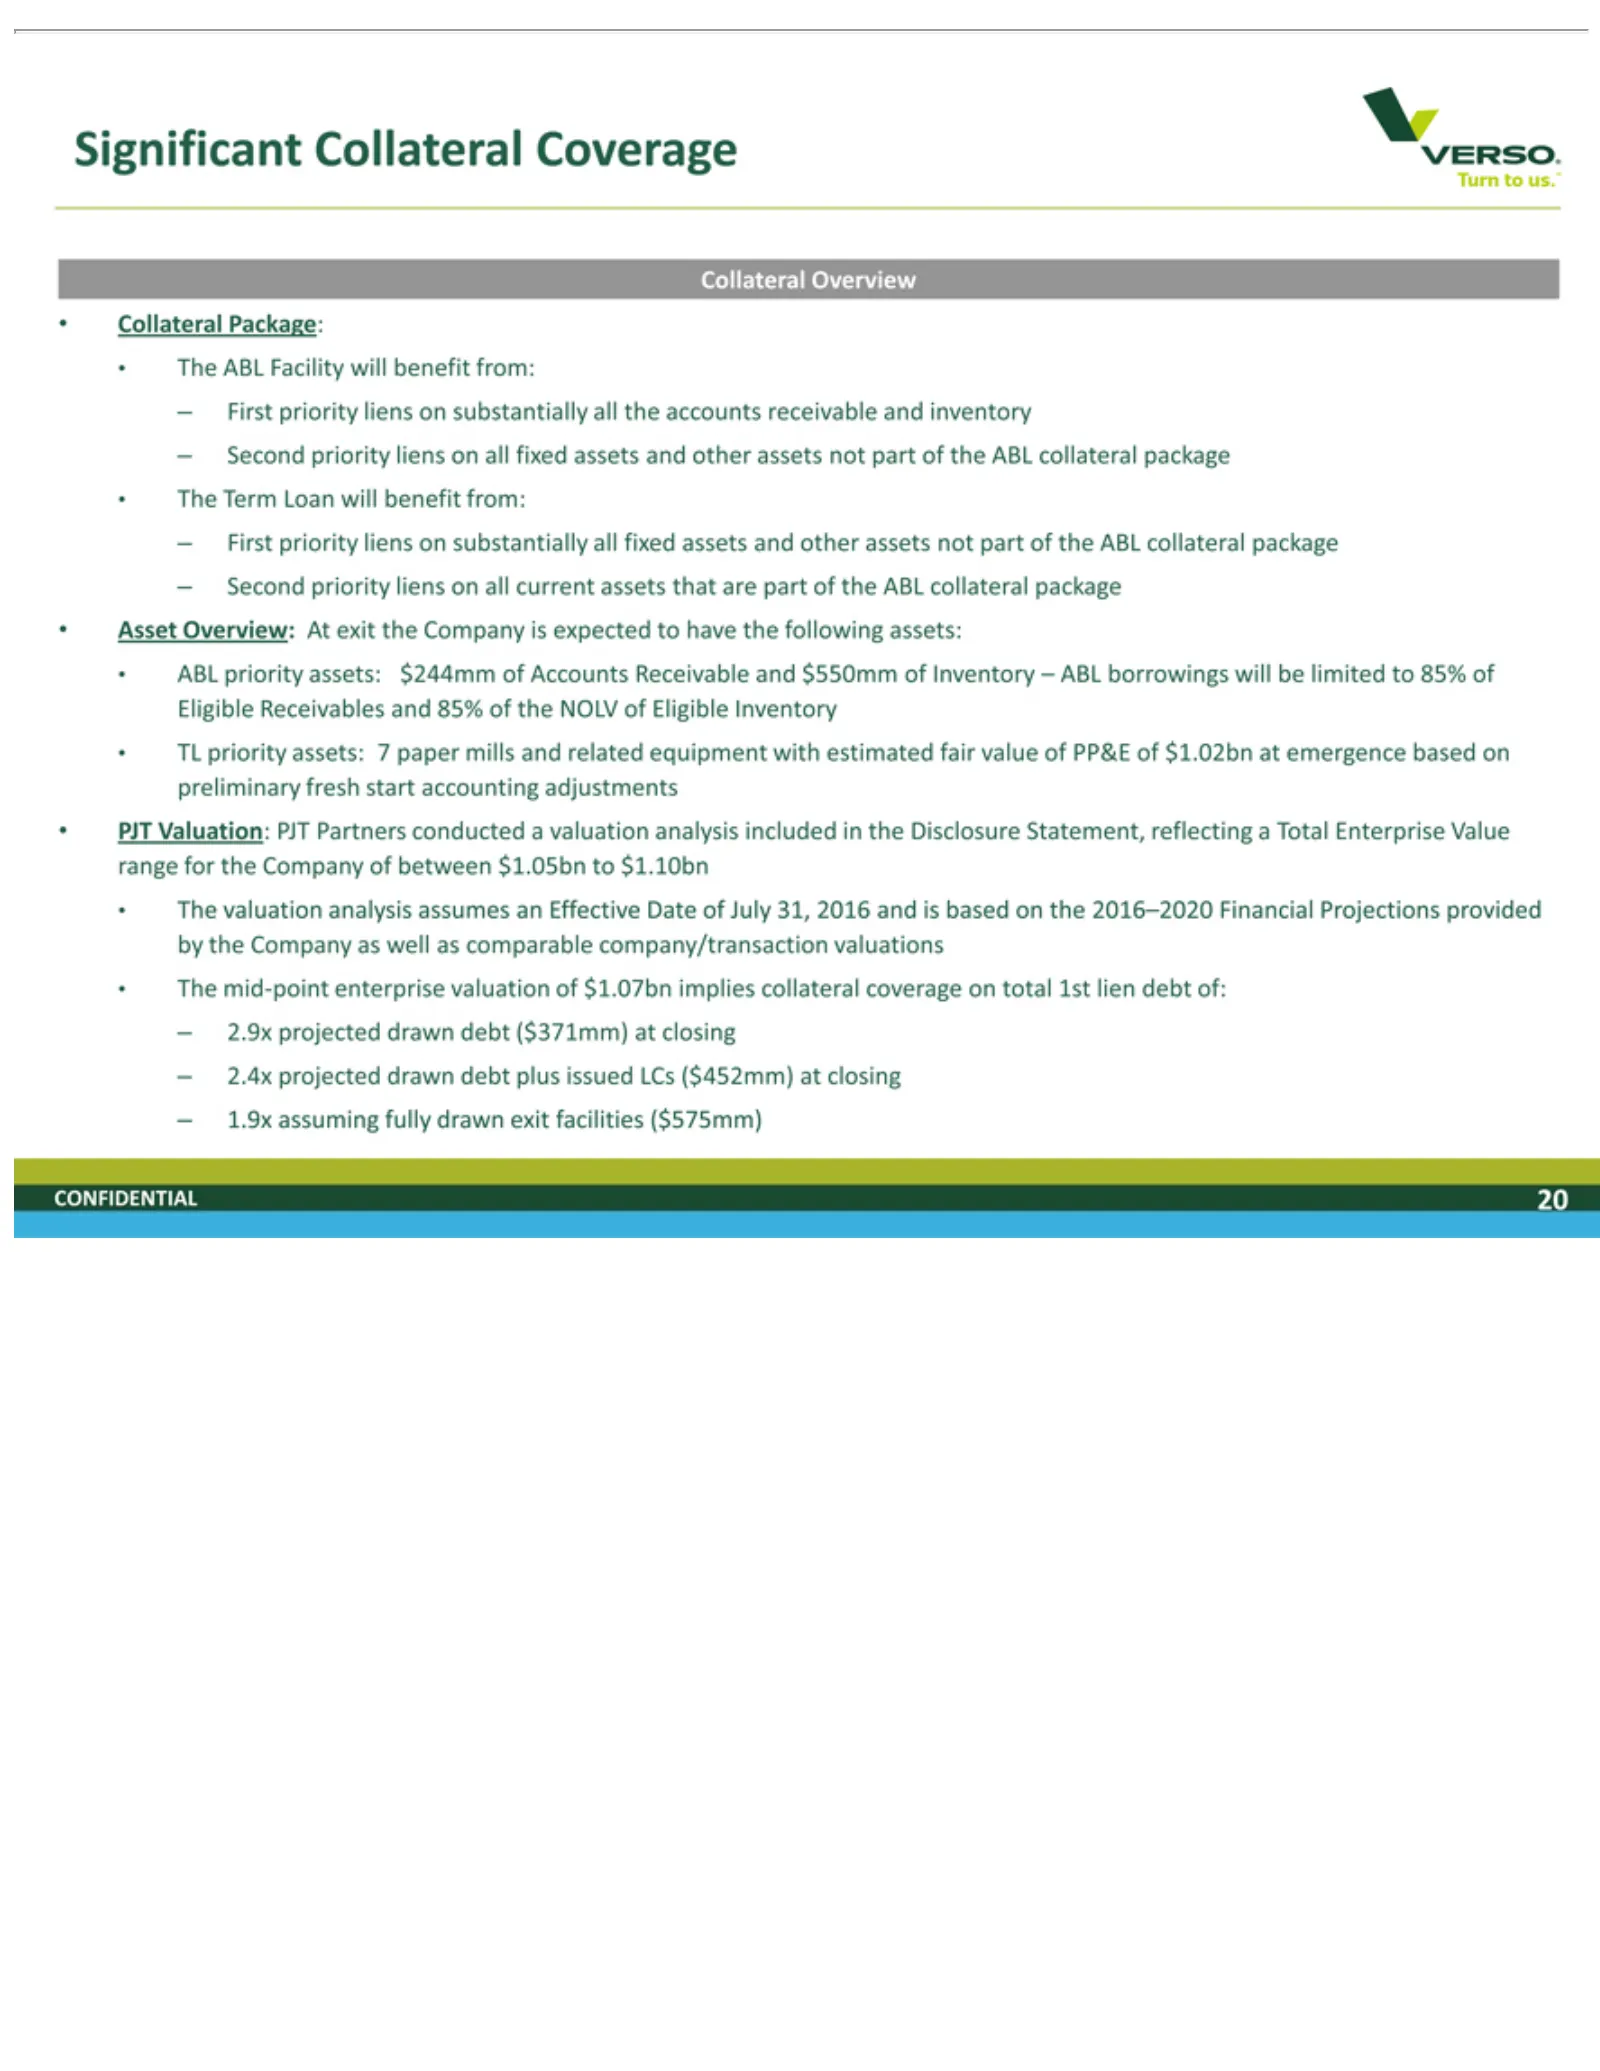
Slide 20: Significant Collateral Coverage
Significant Collateral Asset ABL Eligible TL preliminary PJT range by –The CONFIDENTIAL First Second 2.9x 2.4x 1.9x the priority ABL Valuation: Term valuation mid-point priority for Overview: Company projected assuming priority Receivables the priority Facility Loan Overview Package: Collateral asse
Slide 21: Industry Update and Outlook
Industry Update and Outlook CONFIDENTIAL
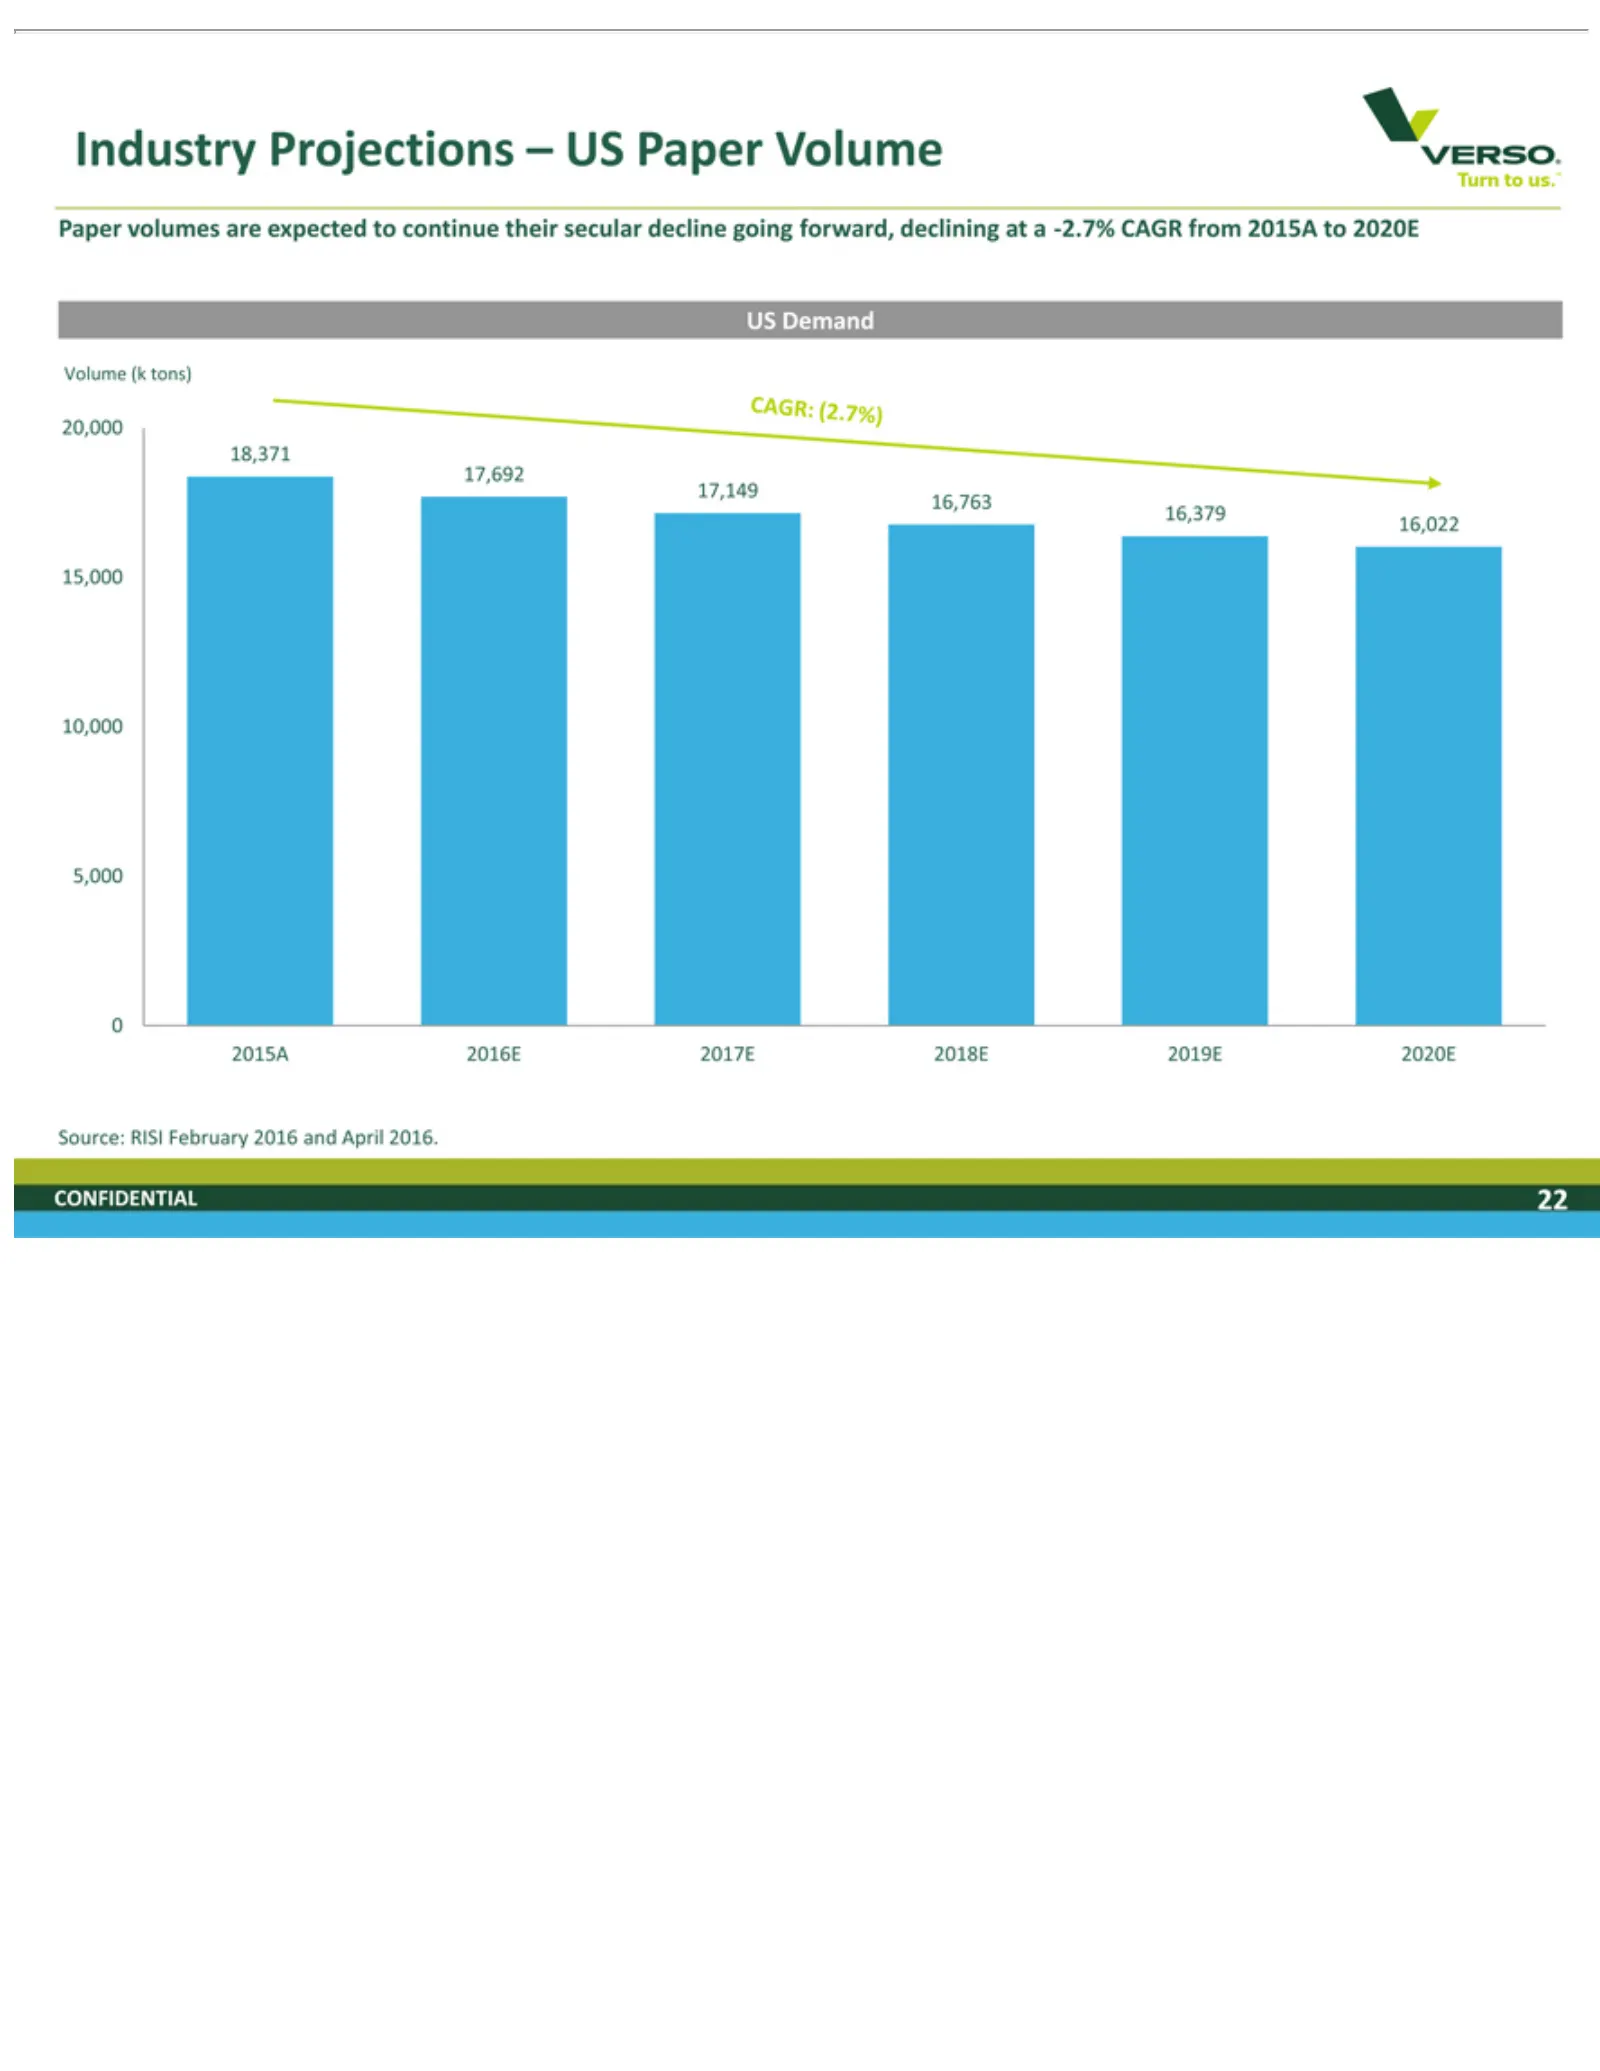
Slide 22: Industry US Paper Volume
Industry Paper US Volume 17,692 18,371 0220,000 5,000 10,000 15,000 16,022 16,379 16,763 Source: CONFIDENTIAL 015A Demand volumes 2016E 17,149 RISI (k Projections tons) February 2017E are 22 expected –2018E US 2016 Paper to 2019E andcontinue Volume April 2020E 2016. their secular decline going forwa
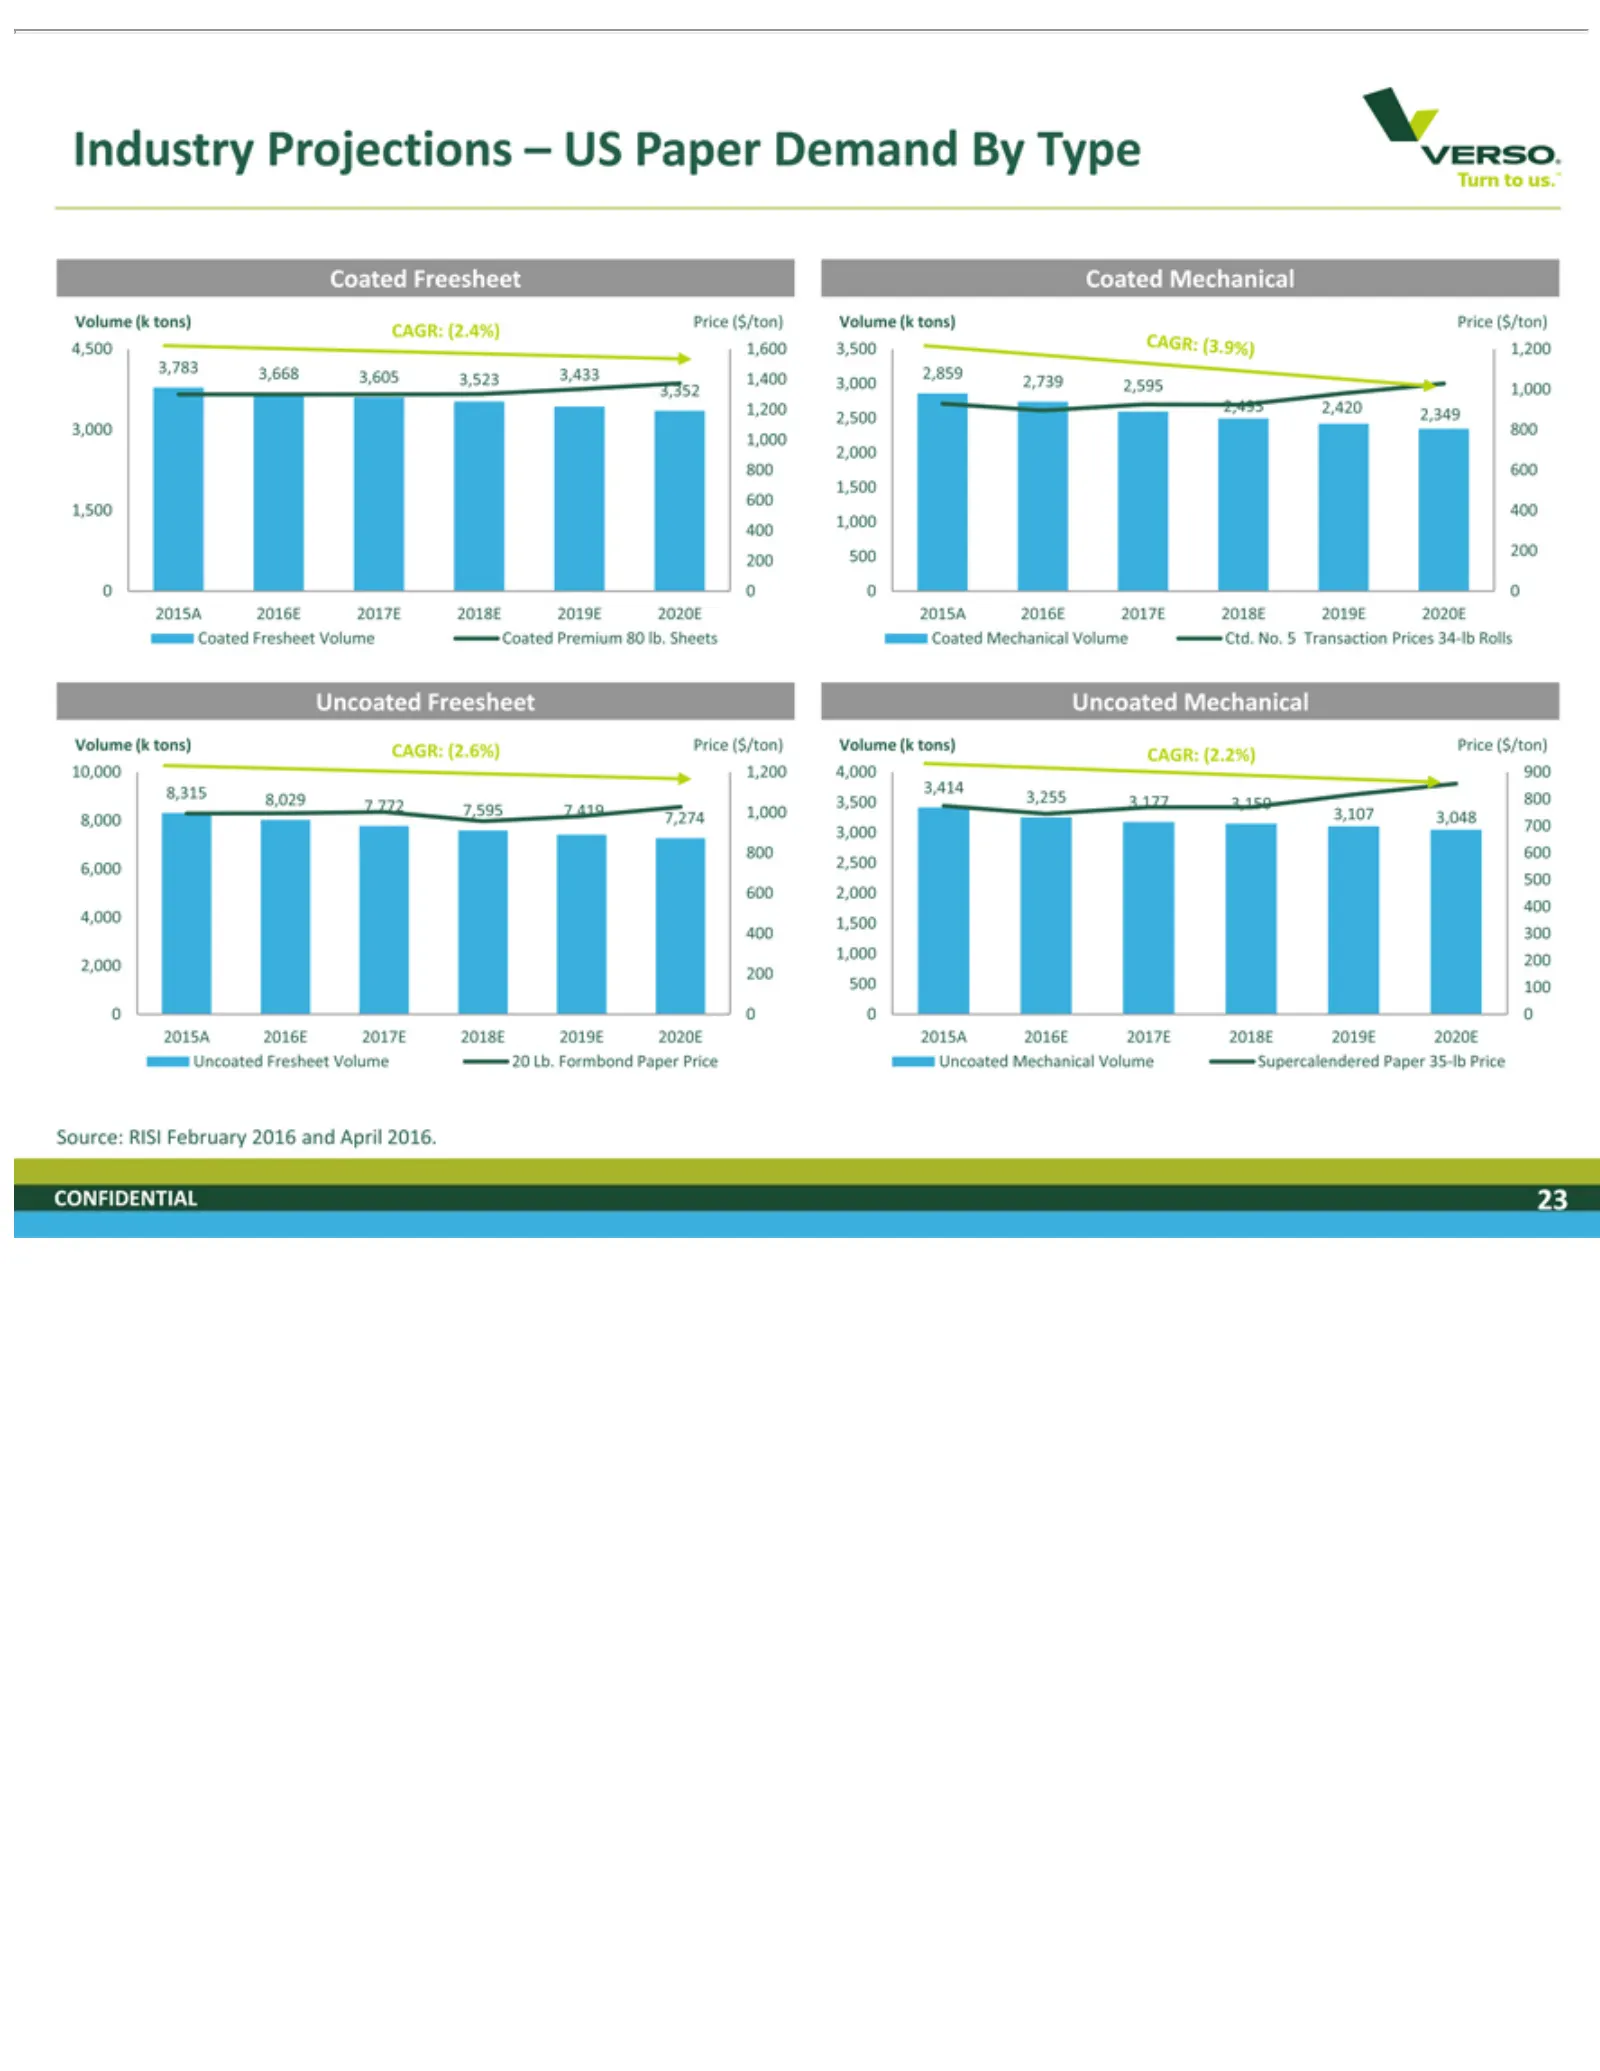
Slide 23: Industry Coated Volume and Price
Industry 4,500 Coated Volume CAGR: 10,000 0500 Uncoated Source: CONFIDENTIAL 0 0100 01,600 1,200 2015A Freesheet Fresheet RISI (2.4%) (2.2%) (k Projections Freesheet Fresheet tons) 3,500 February 4,000 2016E Price CAGR: Volume Coated 1,200 23 Volume 900 Uncoated –2017E ($/ton) US 2016 8,315 (2.6%) 3
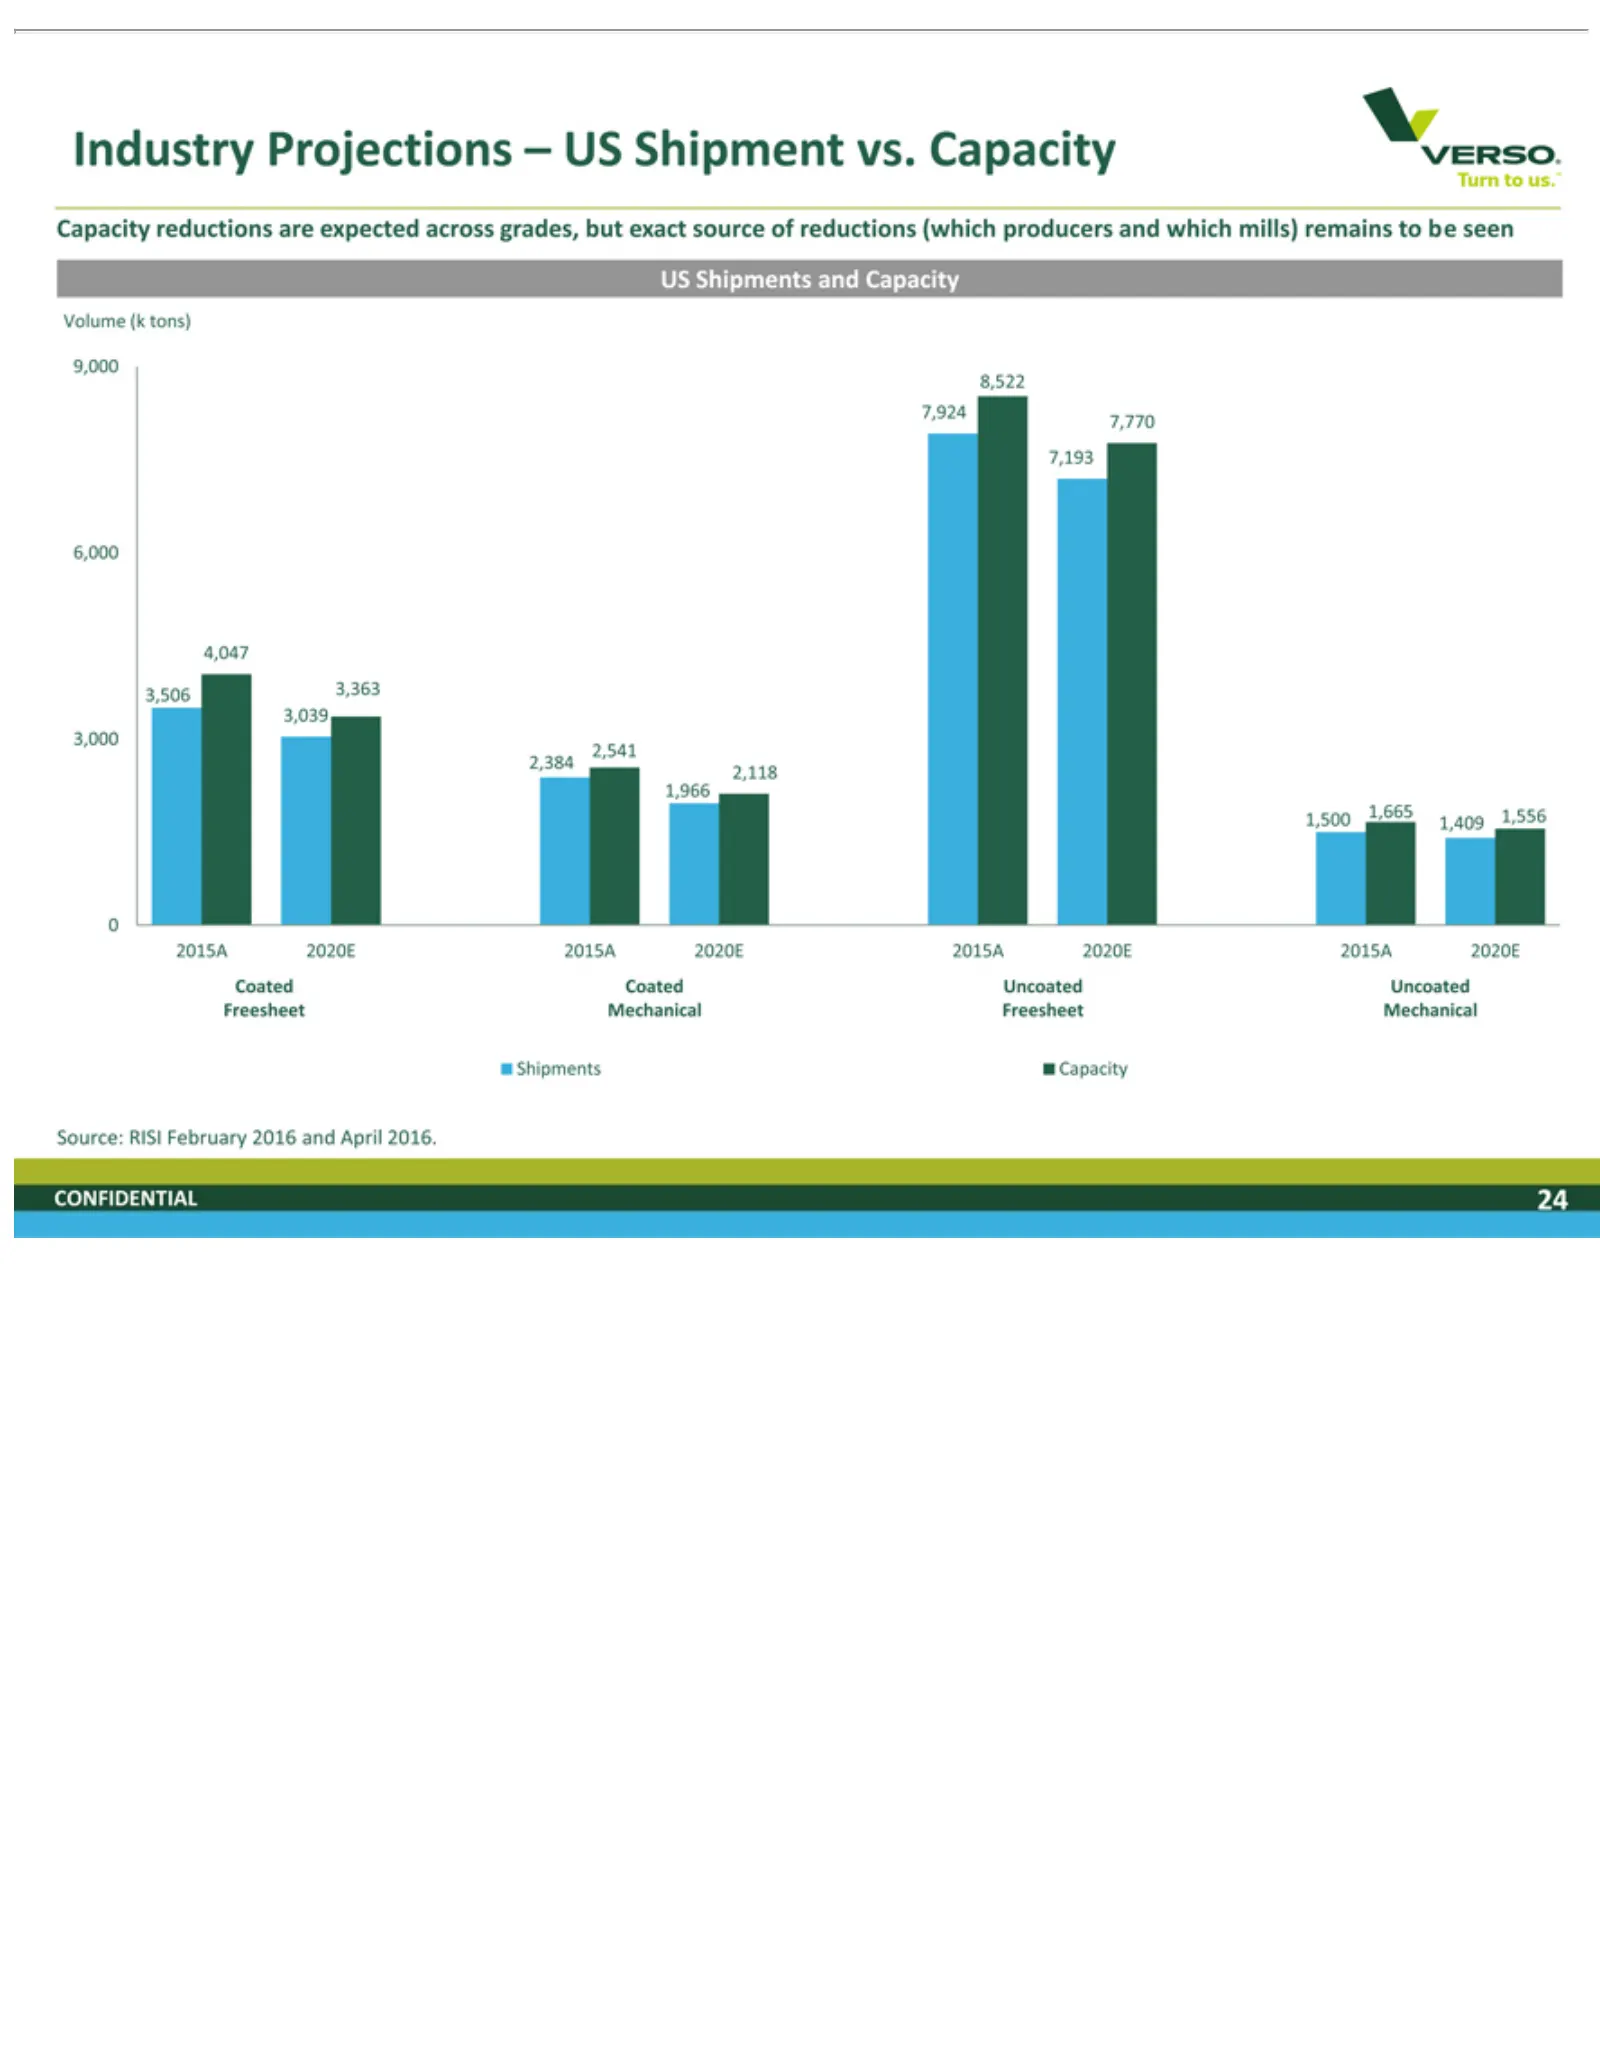
Slide 24: Industry Capacity
Industry Capacity US Volume 9,000 3,506 4,047 6,000 7,193 7,770 2,541 2,118 021,665 Coated Shipments Source: CONFIDENTIAL 015A Shipments 1,966 8,522 3,363 2,384 1,556 2020E Coated RISI (k Projections reductions tons) Capacity 7,924 3,039 1,500 February 2015A and Uncoated 3,000 1,409 24 Capacity are
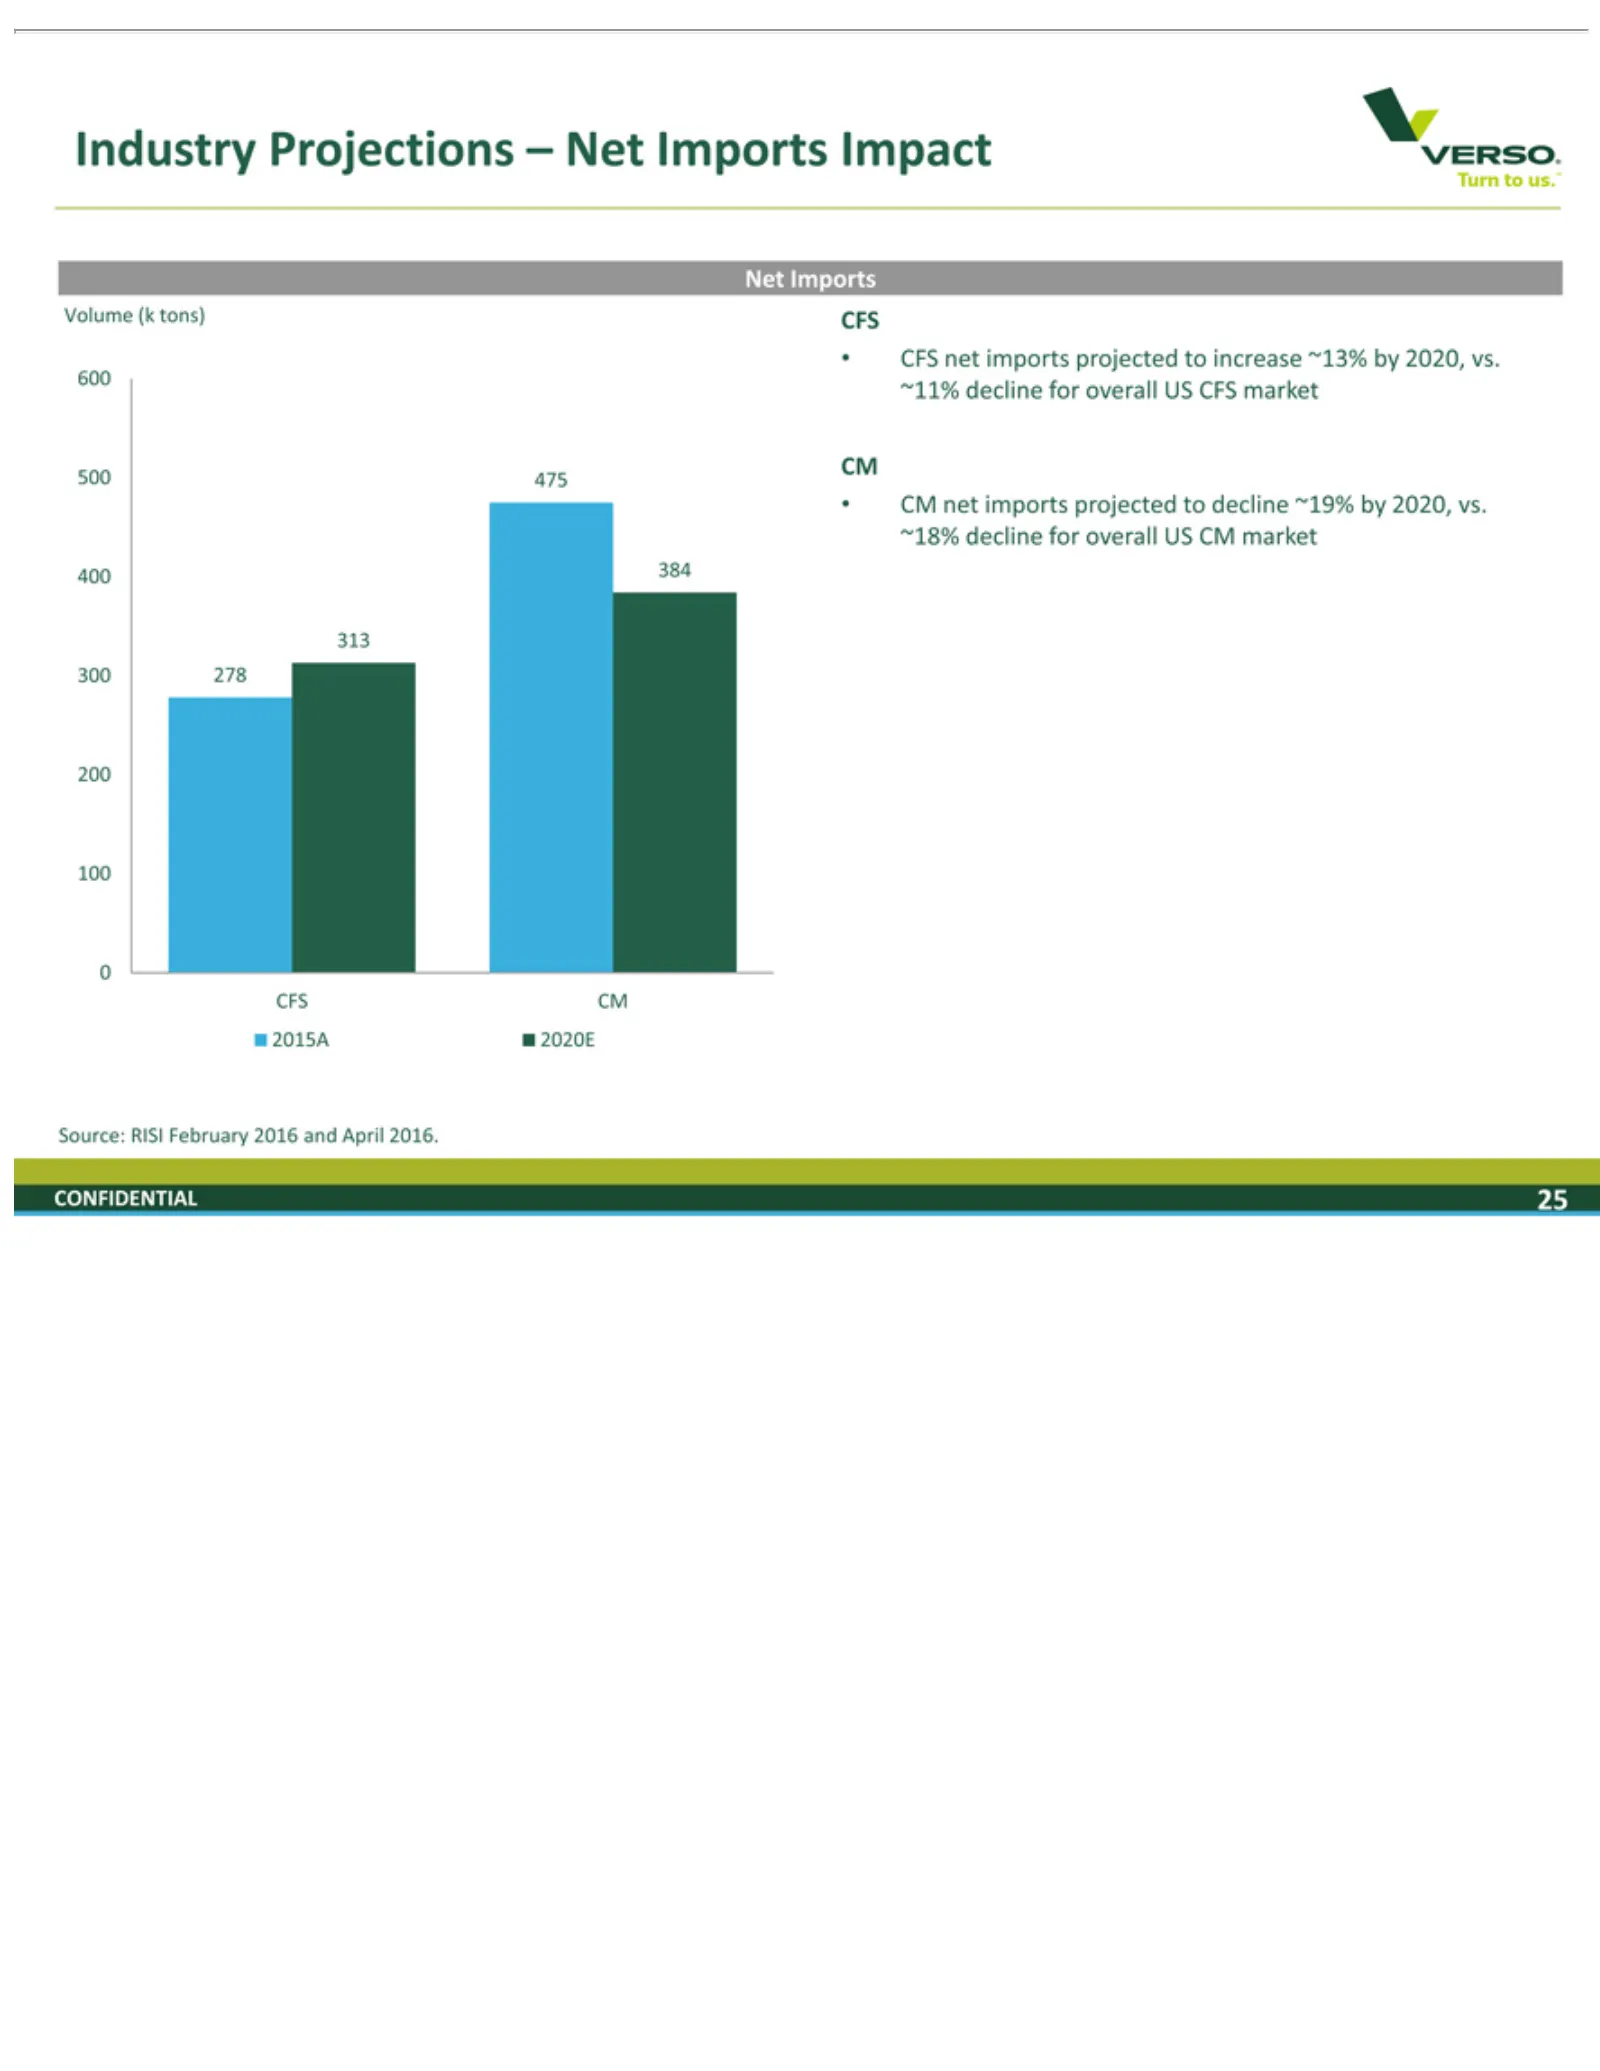
Slide 25: Industry Net Imports
Industry Net Volume CFS ~11% 600 500 CM 400 313 0C 100 200 2015A Source: CONFIDENTIAL FSImports 475 384 300 net net CM decline 2020E imports RISI (k 278 imports Projections tons) February forprojected CFS projected overall 25– Net 2016 US to Imports toand decline CFS increase April market Impact ~19
Slide 26: Recent Financial Performance
Recent Financial Performance CONFIDENTIAL
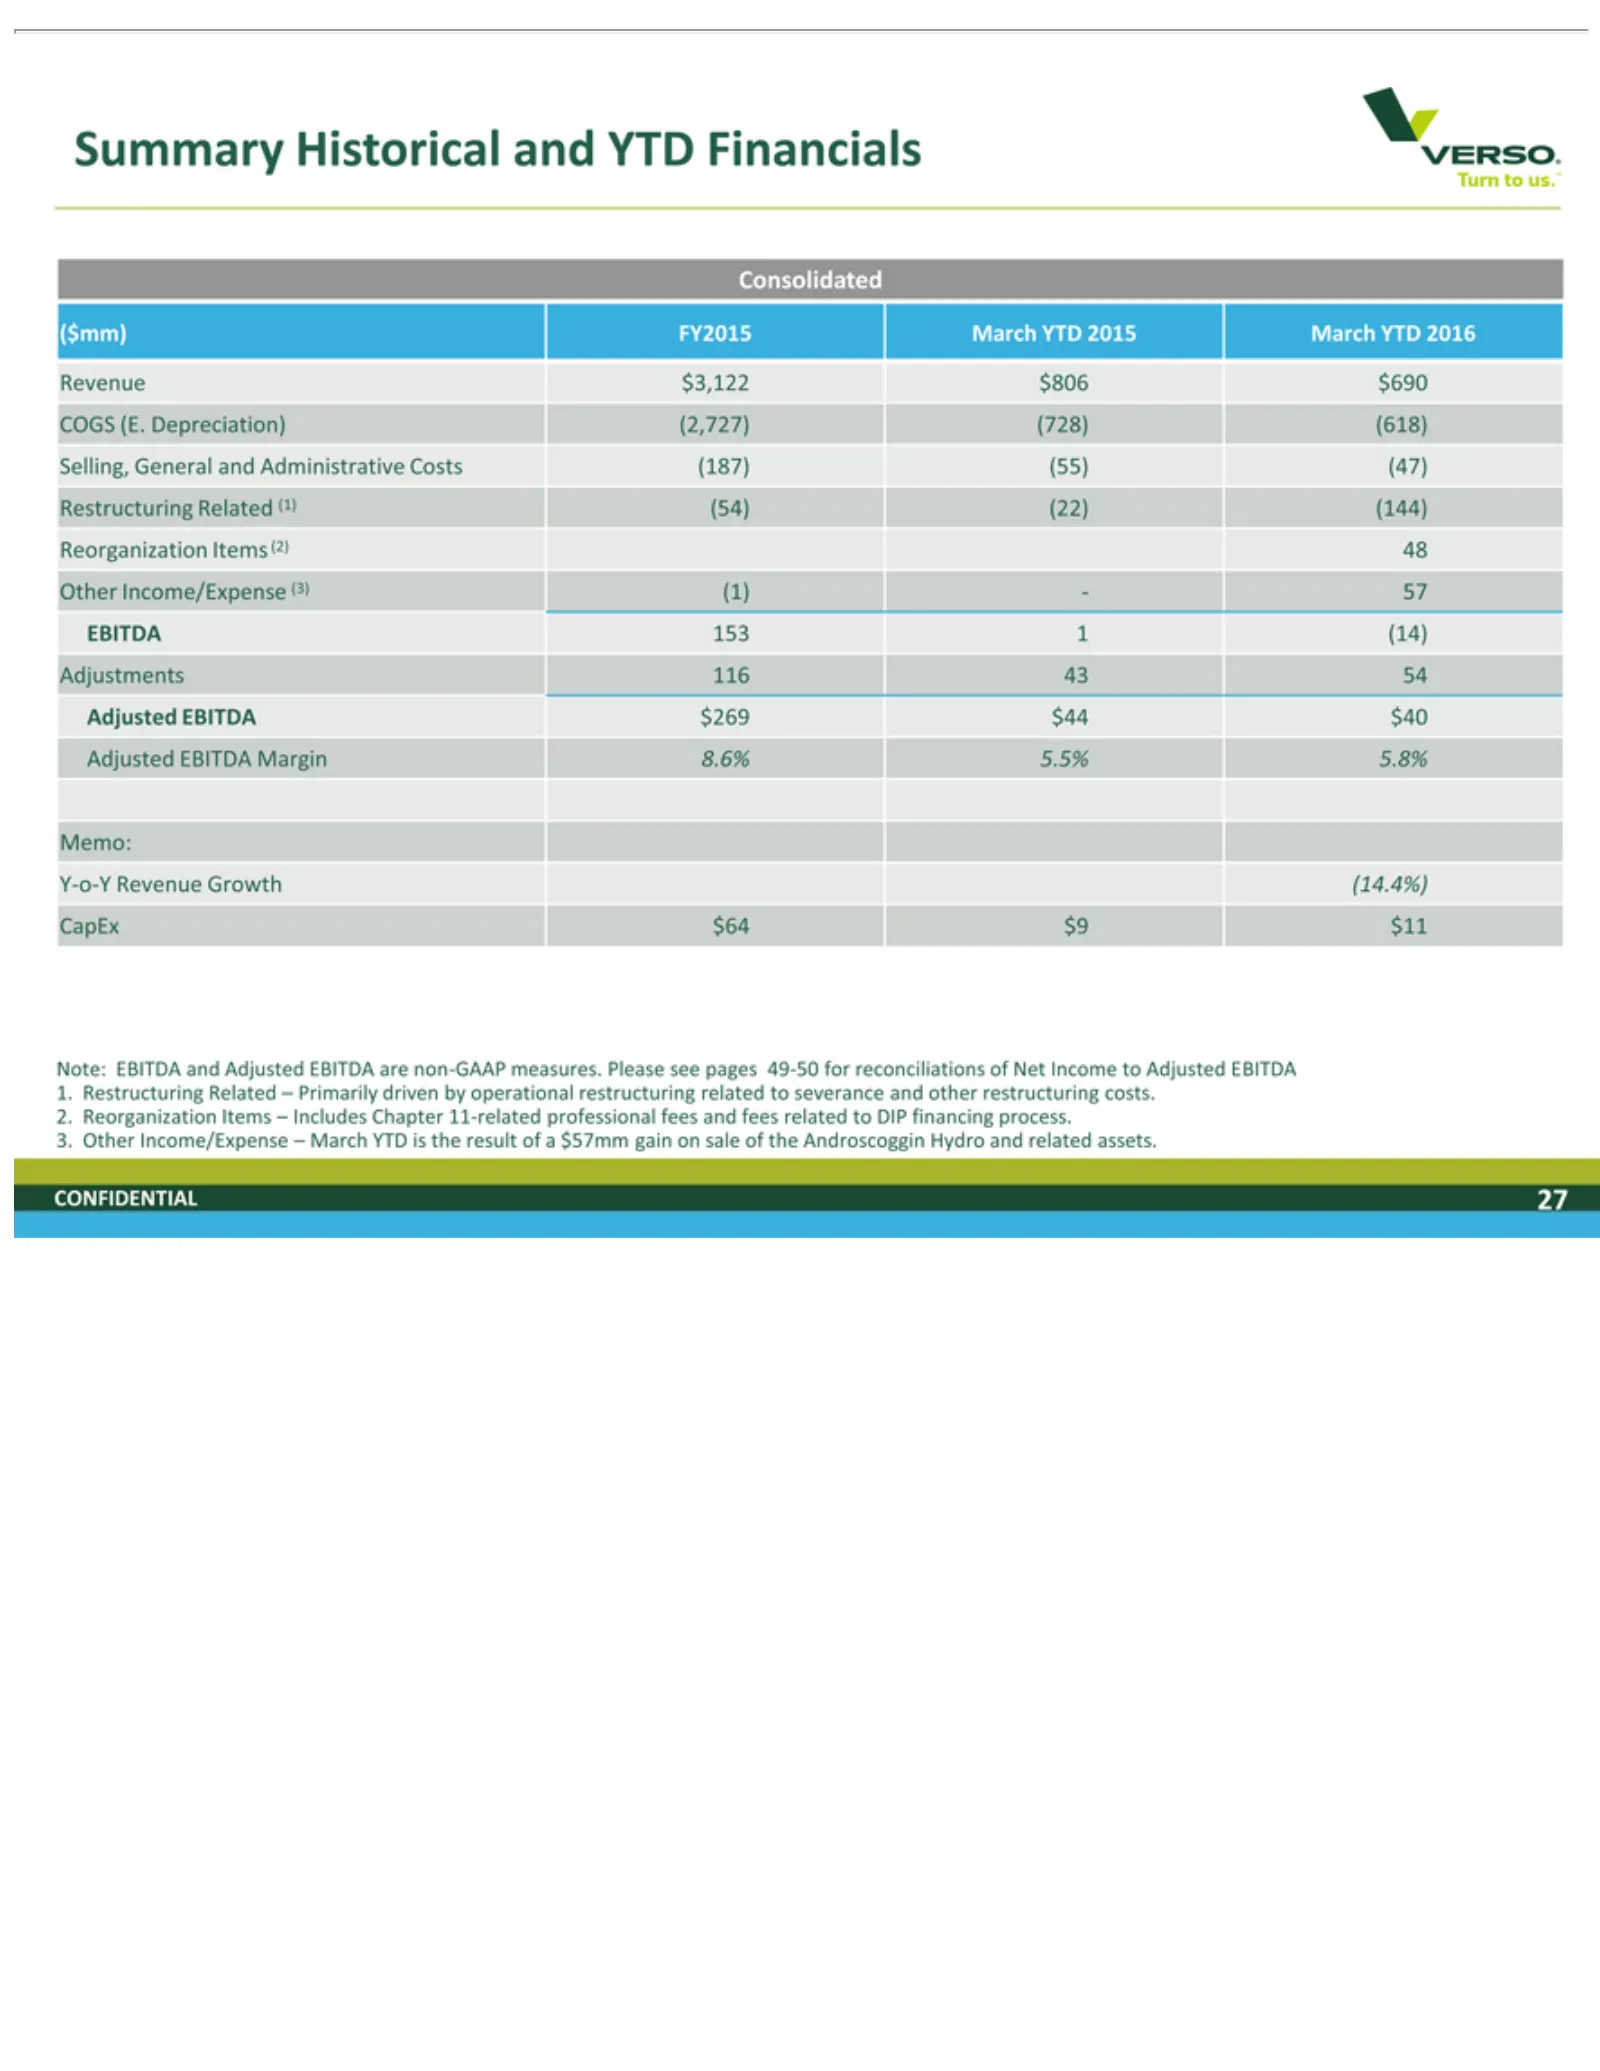
Slide 27: Consolidated Summary Financials
Summary ($mm) Consolidated Revenue Income/Expense Adjusted Y-o-Y Memo: CapEx Note: 1. 2. 3. CONFIDENTIAL Restructuring Reorganization Other EBITDA Revenue FY2015 $64 Income/Expense $3,122 EBITDA Historical $9 $11 and Growth March Related $806 (3) Items 27 $269 Margin Adjusted (1)—57 and $690 YTD (14
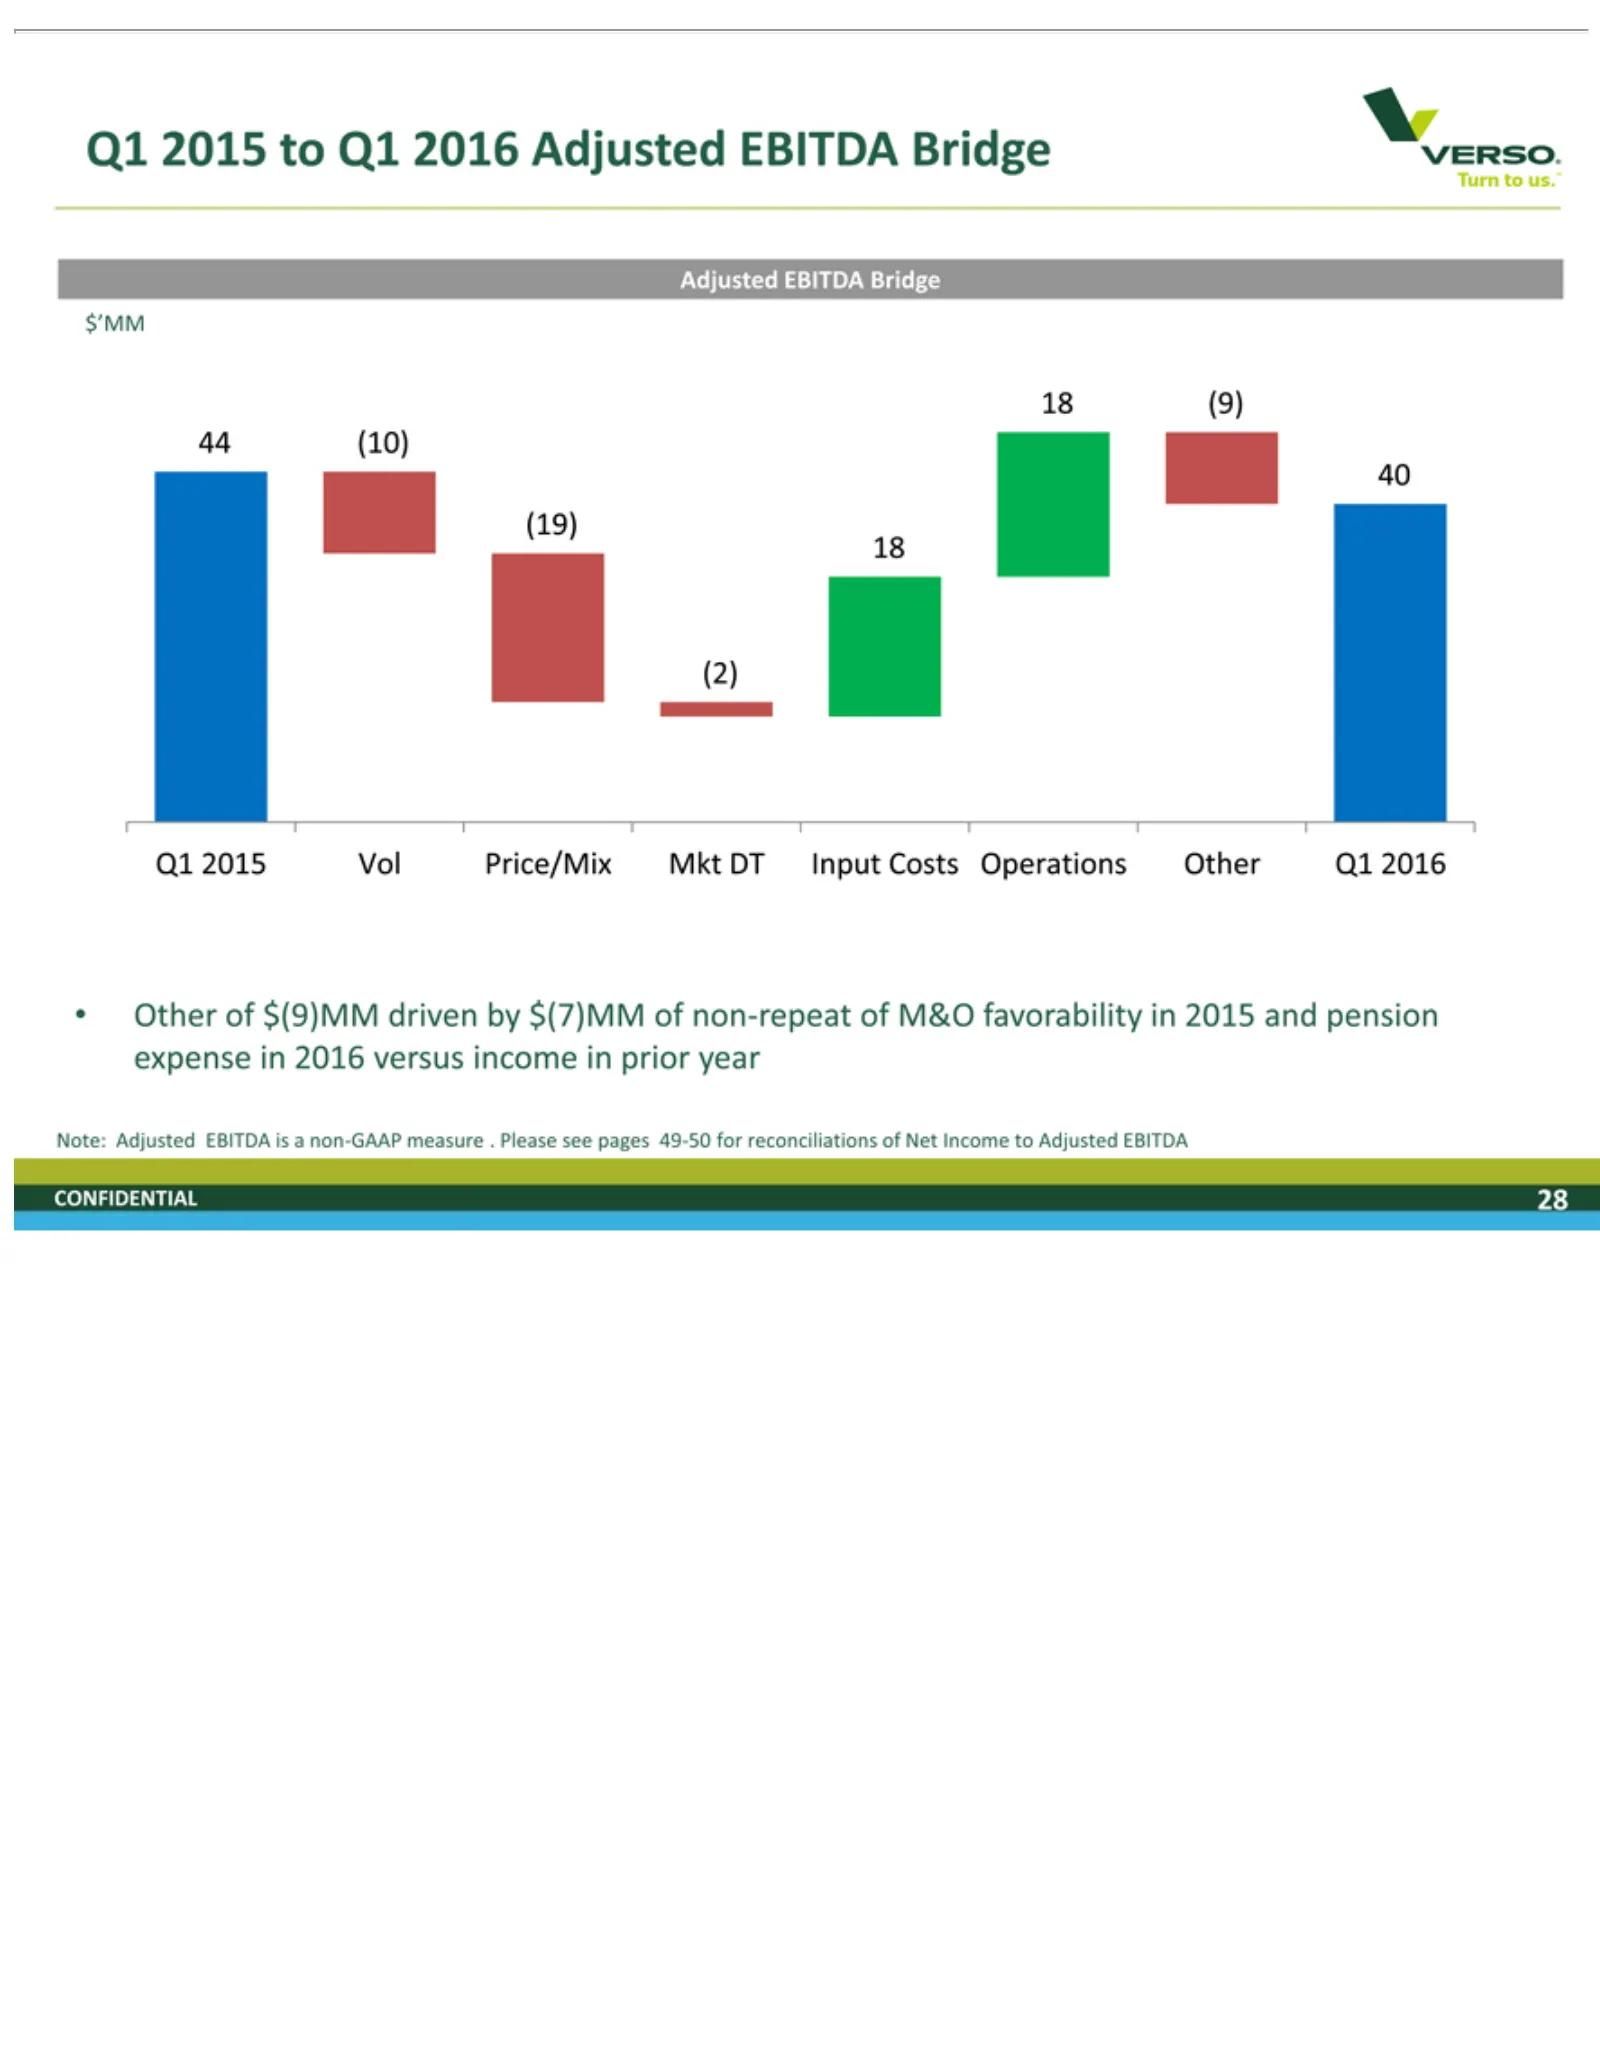
Slide 28: Q1 Adjusted EBITDA Bridge
Adjusted 18 44 40 Q1 (2) Other Note: CONFIDENTIAL (9) (10) (19) 2015 Adjusted of18 $(9)MM Vol to EBITDA Q1 Price/Mix 2016 EBITDA driven 28 Bridge Adjusted Mkt by is$’MM a$(7)MM DT non-GAAP EBITDA InputofCosts non-repeat Bridge measure Operations . Please of M&O Other seefavorability pages Q1 2016 49
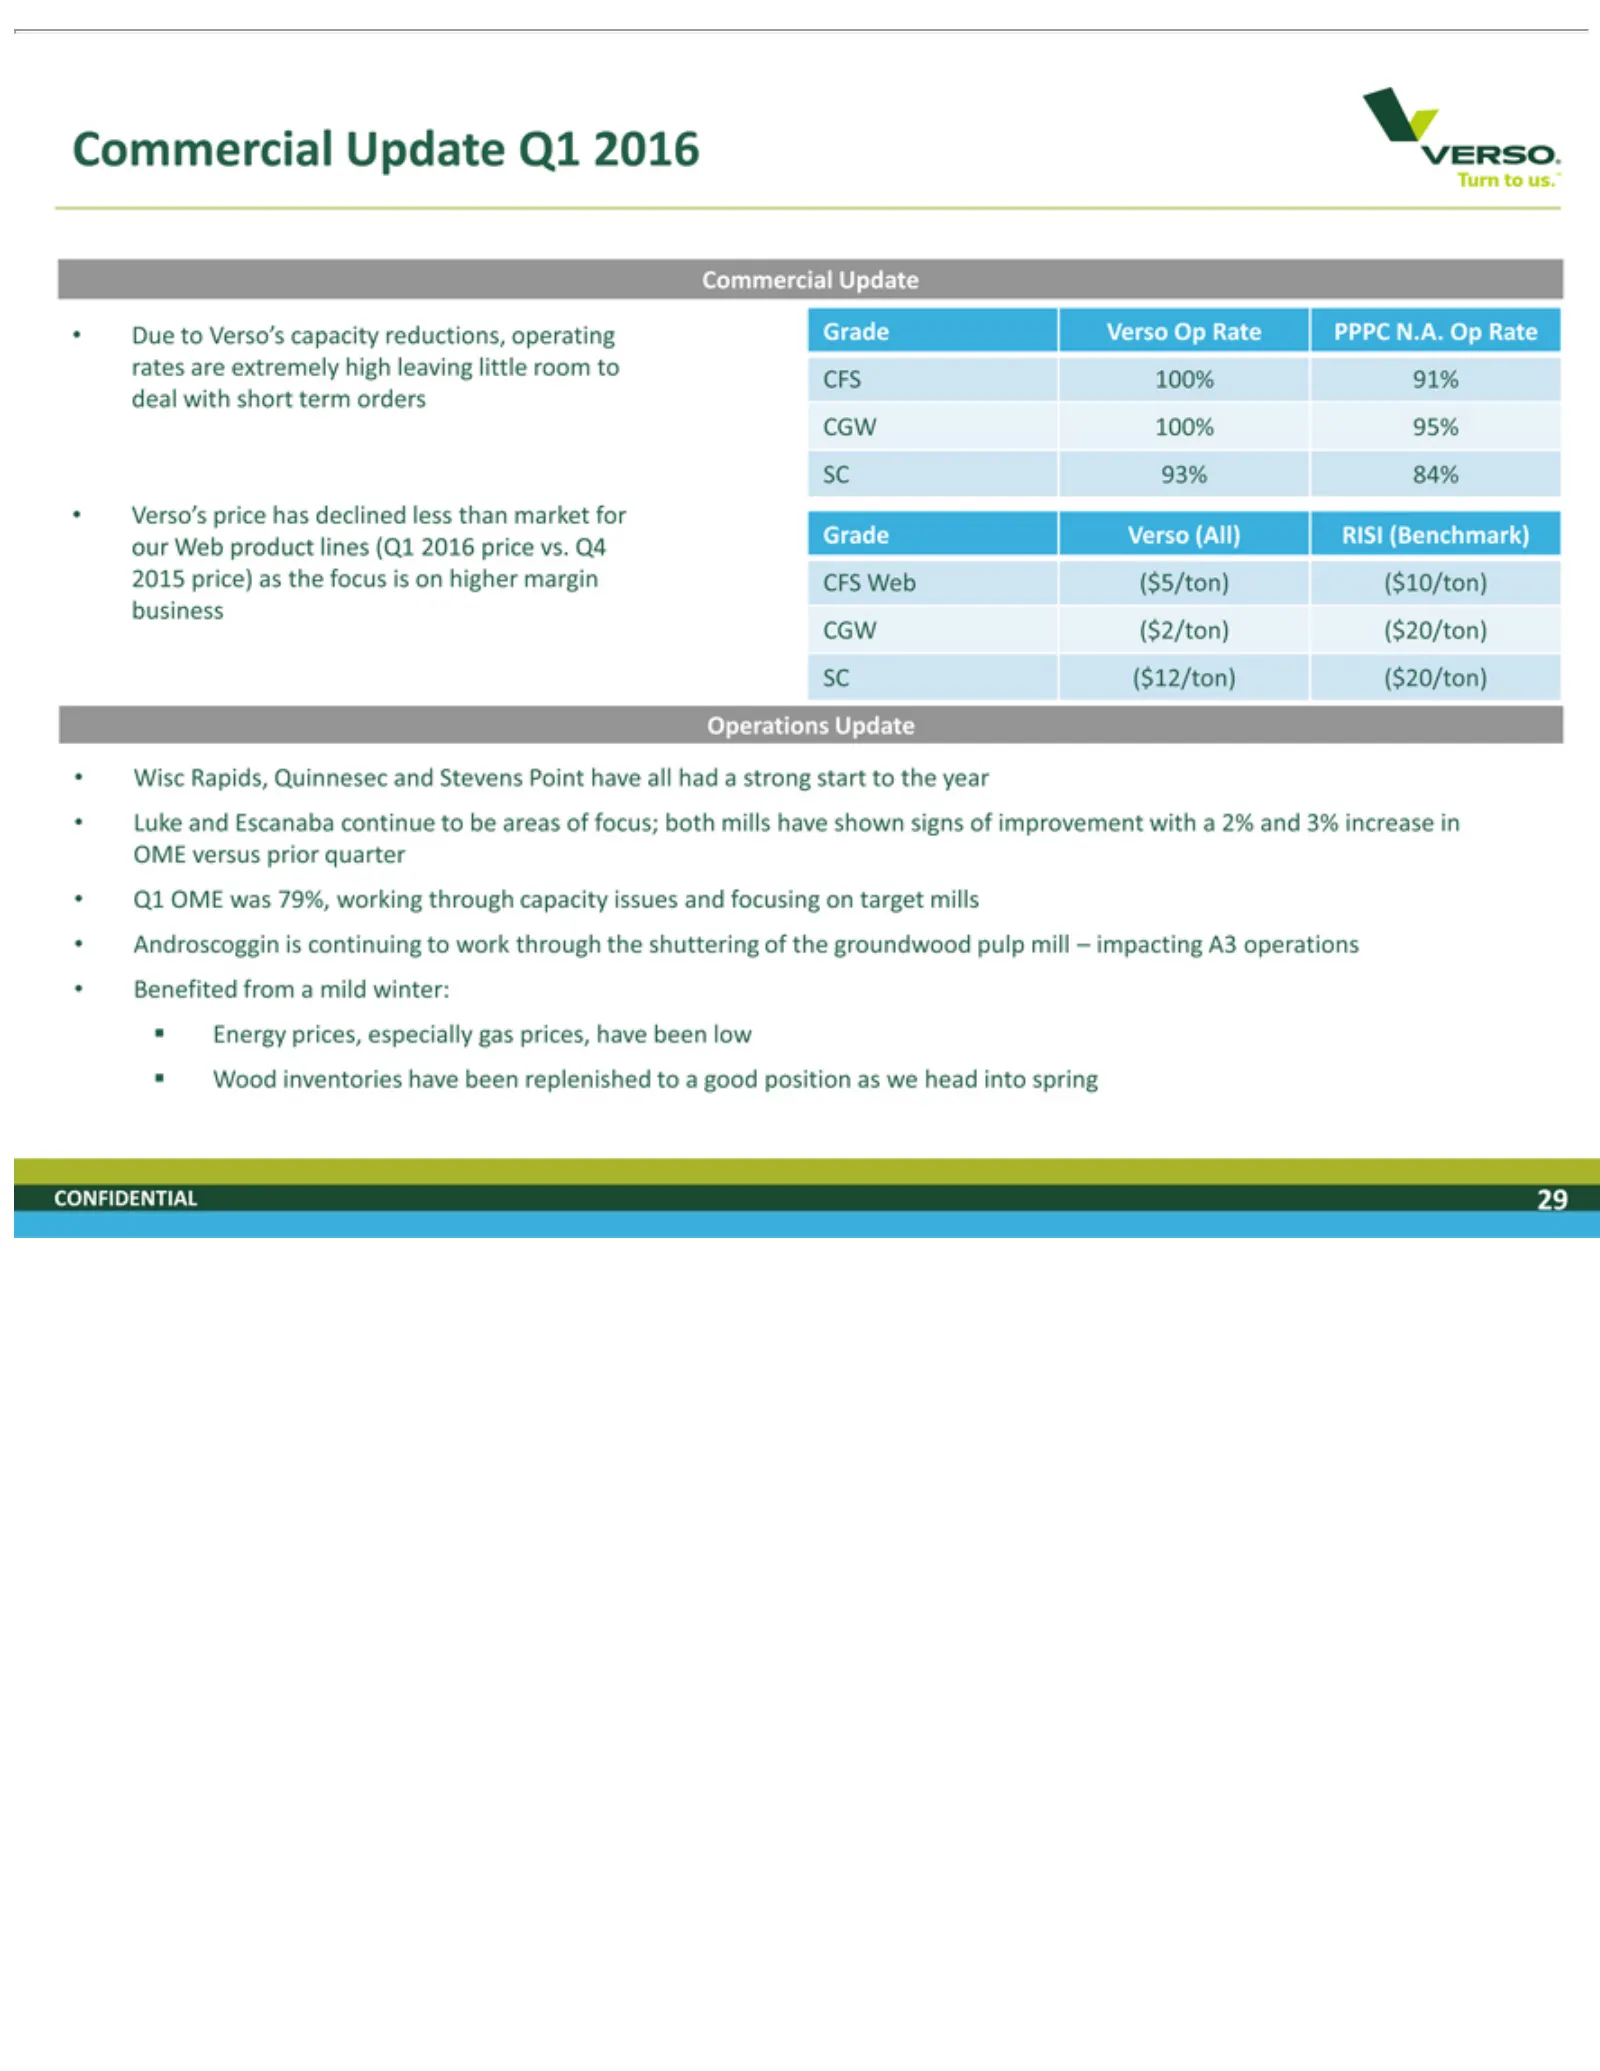
Slide 29: Commercial and Operations Update
Commercial Due SC Verso’s 2015 Operations Wisc Luke Q1 Androscoggin Benefited Energy Wood CONFIDENTIAL OME 93% toprice) Rapids, and inventories Verso’s prices, price 84% was Escanaba from Update asUpdate has Quinnesec 79%, the is especially capacity a continuing mild declined have focus 29 continue
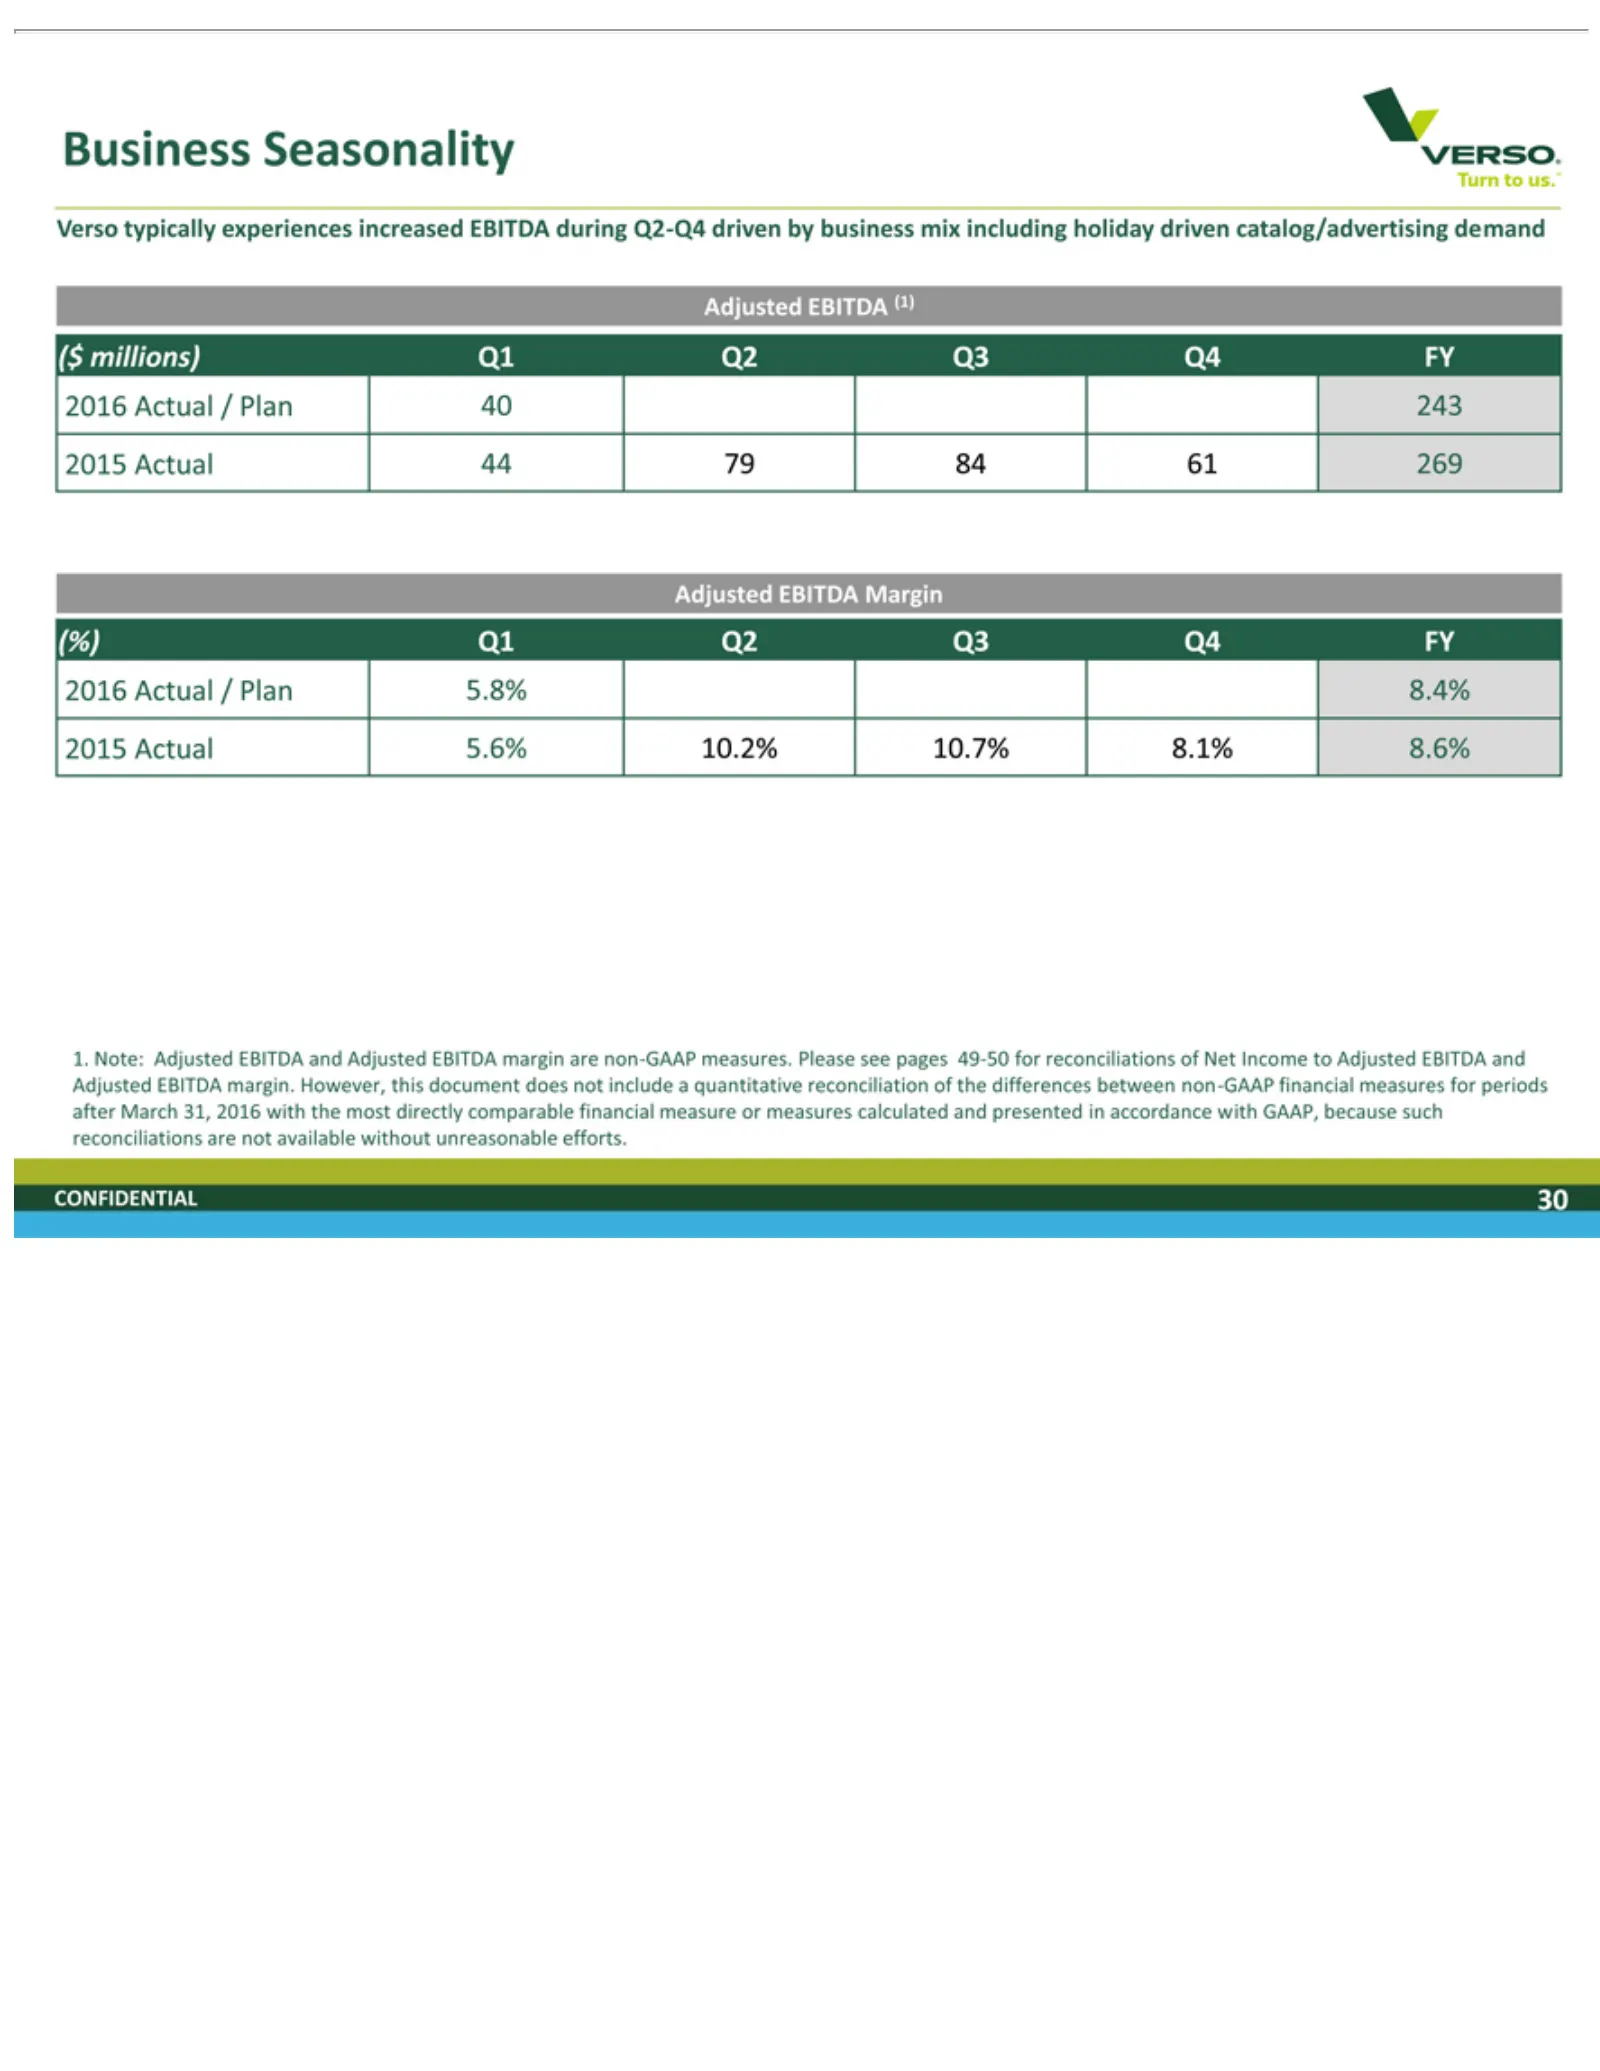
Slide 30: Business Seasonality
Business Verso ($ Adjusted (%) 2016 2015 1. document calculated CONFIDENTIAL Note: millions) Q1 Actual typically Q2 Adjusted Seasonality EBITDA does and Q3 Q1 /44Plan 5.6% presented Q4 experiences not 79 Q2EBITDA 10.2% 30 84 FY 40 5.8% (1) Margin include Q361 243 Q4 8.4% in 269 10.7% FY aaccordance
Slide 31: Financial Projections Overview
Financial Projections Overview CONFIDENTIAL
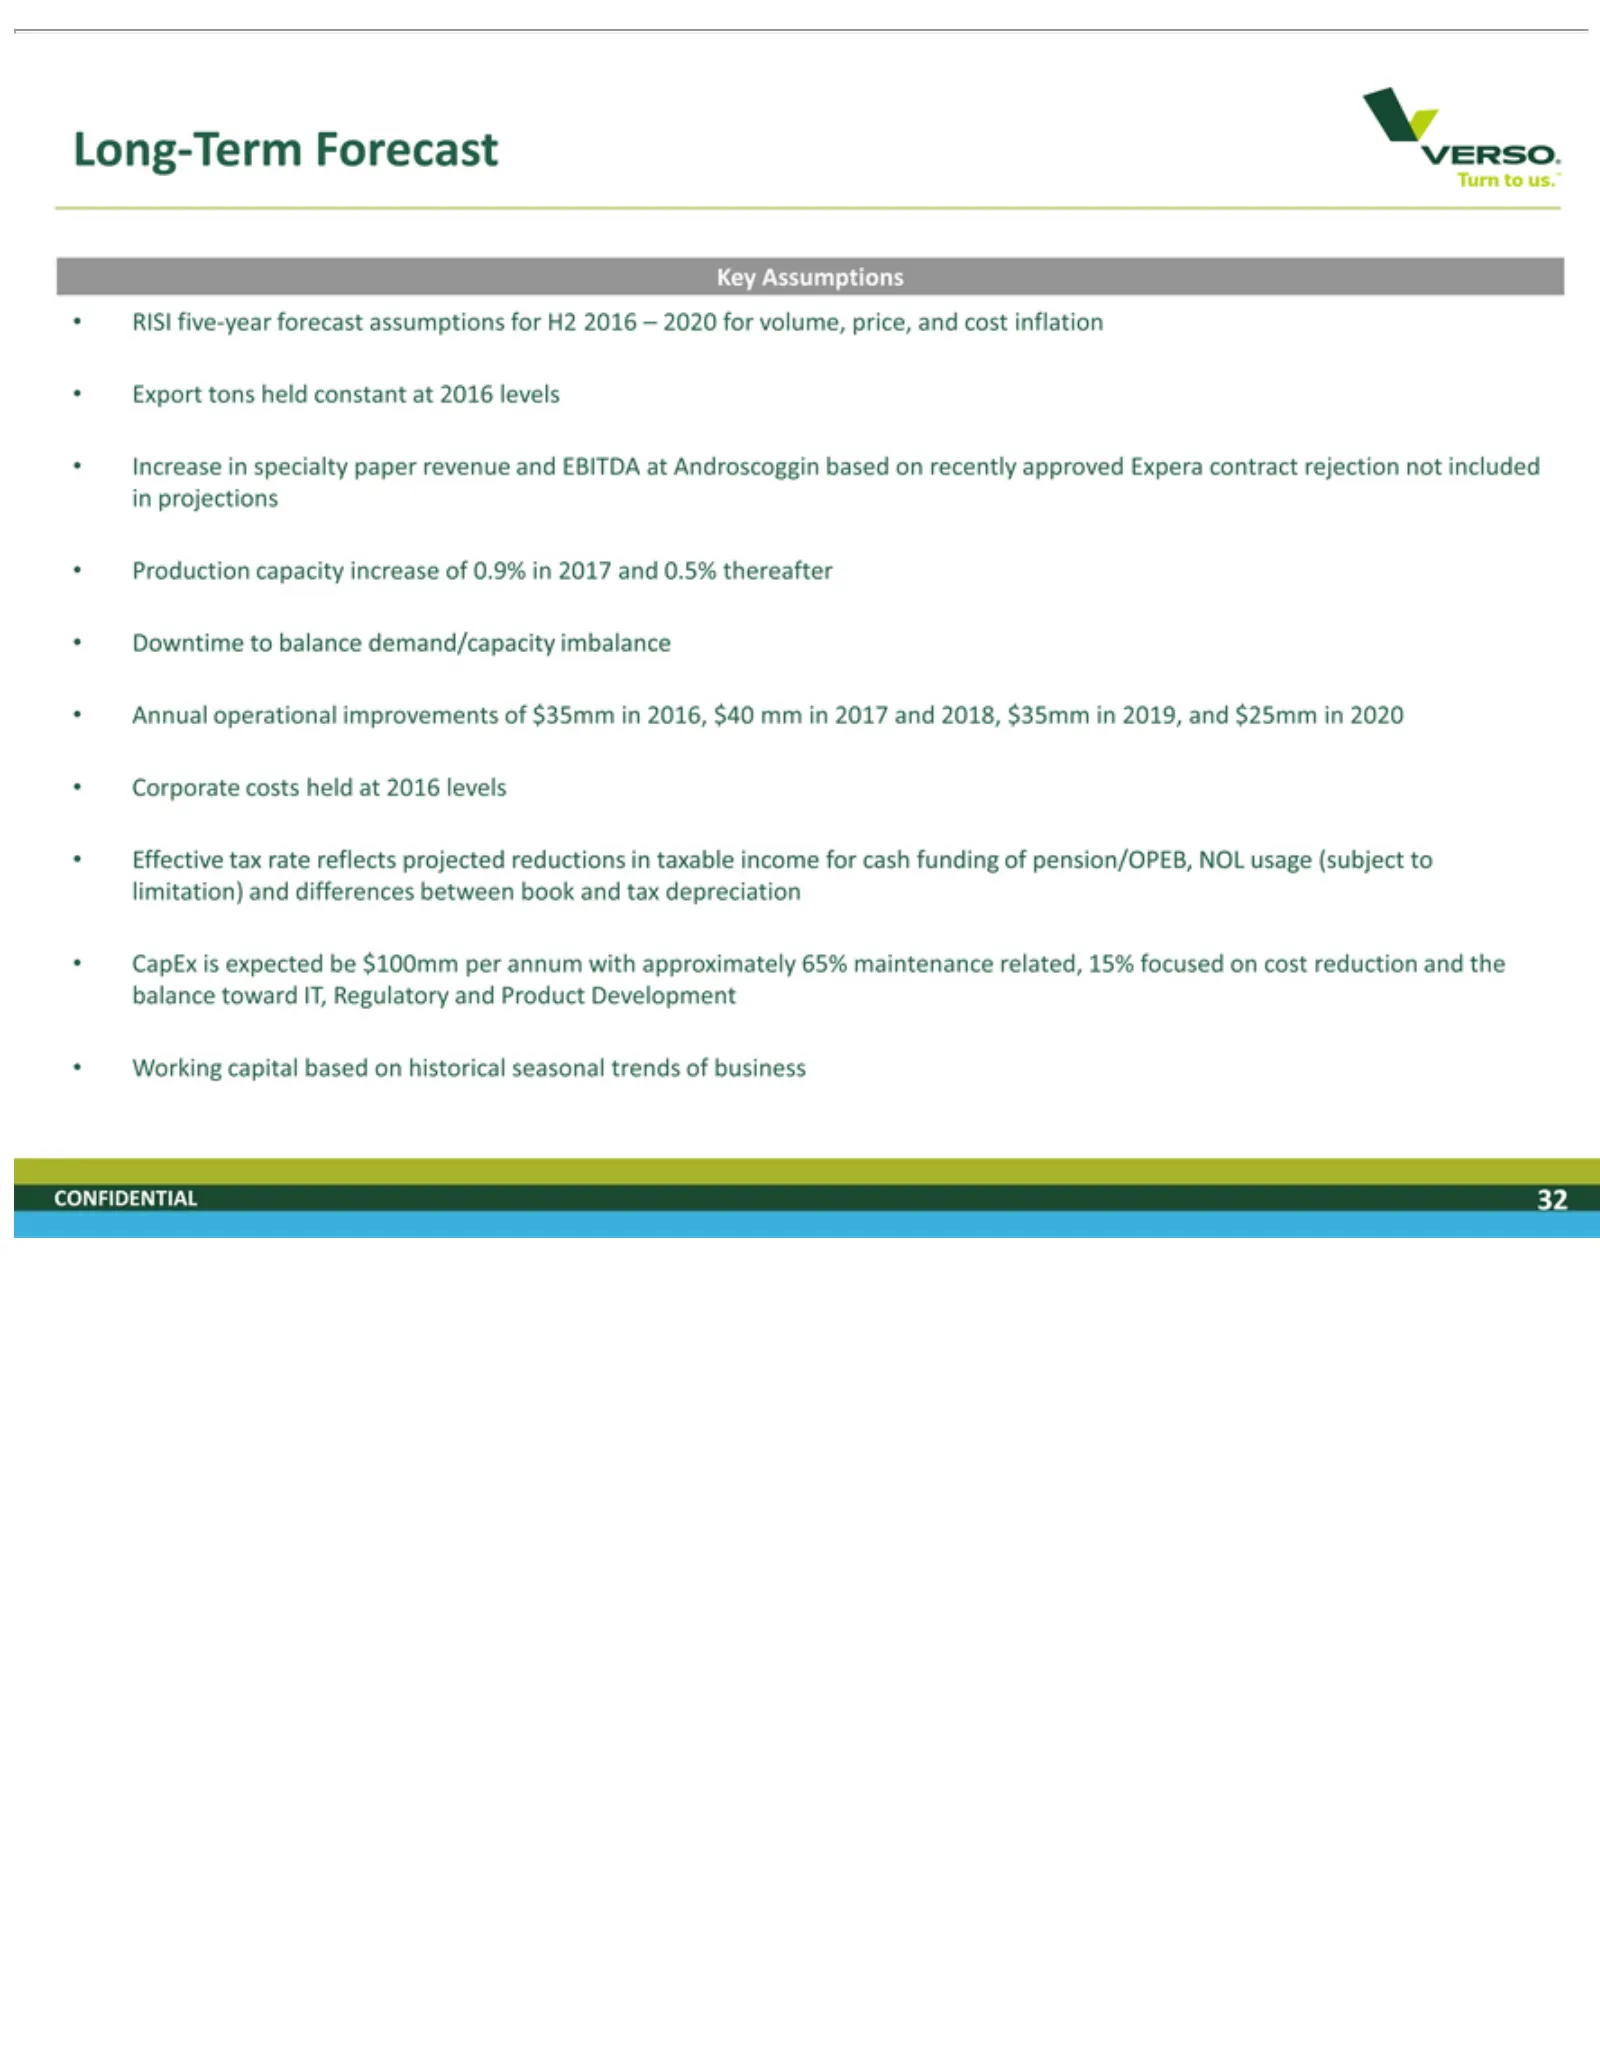
Slide 32: Key Long-Term Assumptions
Long-Term Key RISI Export Increase Production Downtime Annual Corporate Effective CapEx Working CONFIDENTIAL Assumptions five-year tons isoperational in capital expected tax costs to specialty capacity Forecast held rate balance forecast held based constant reflects 32 be improvements increase paper
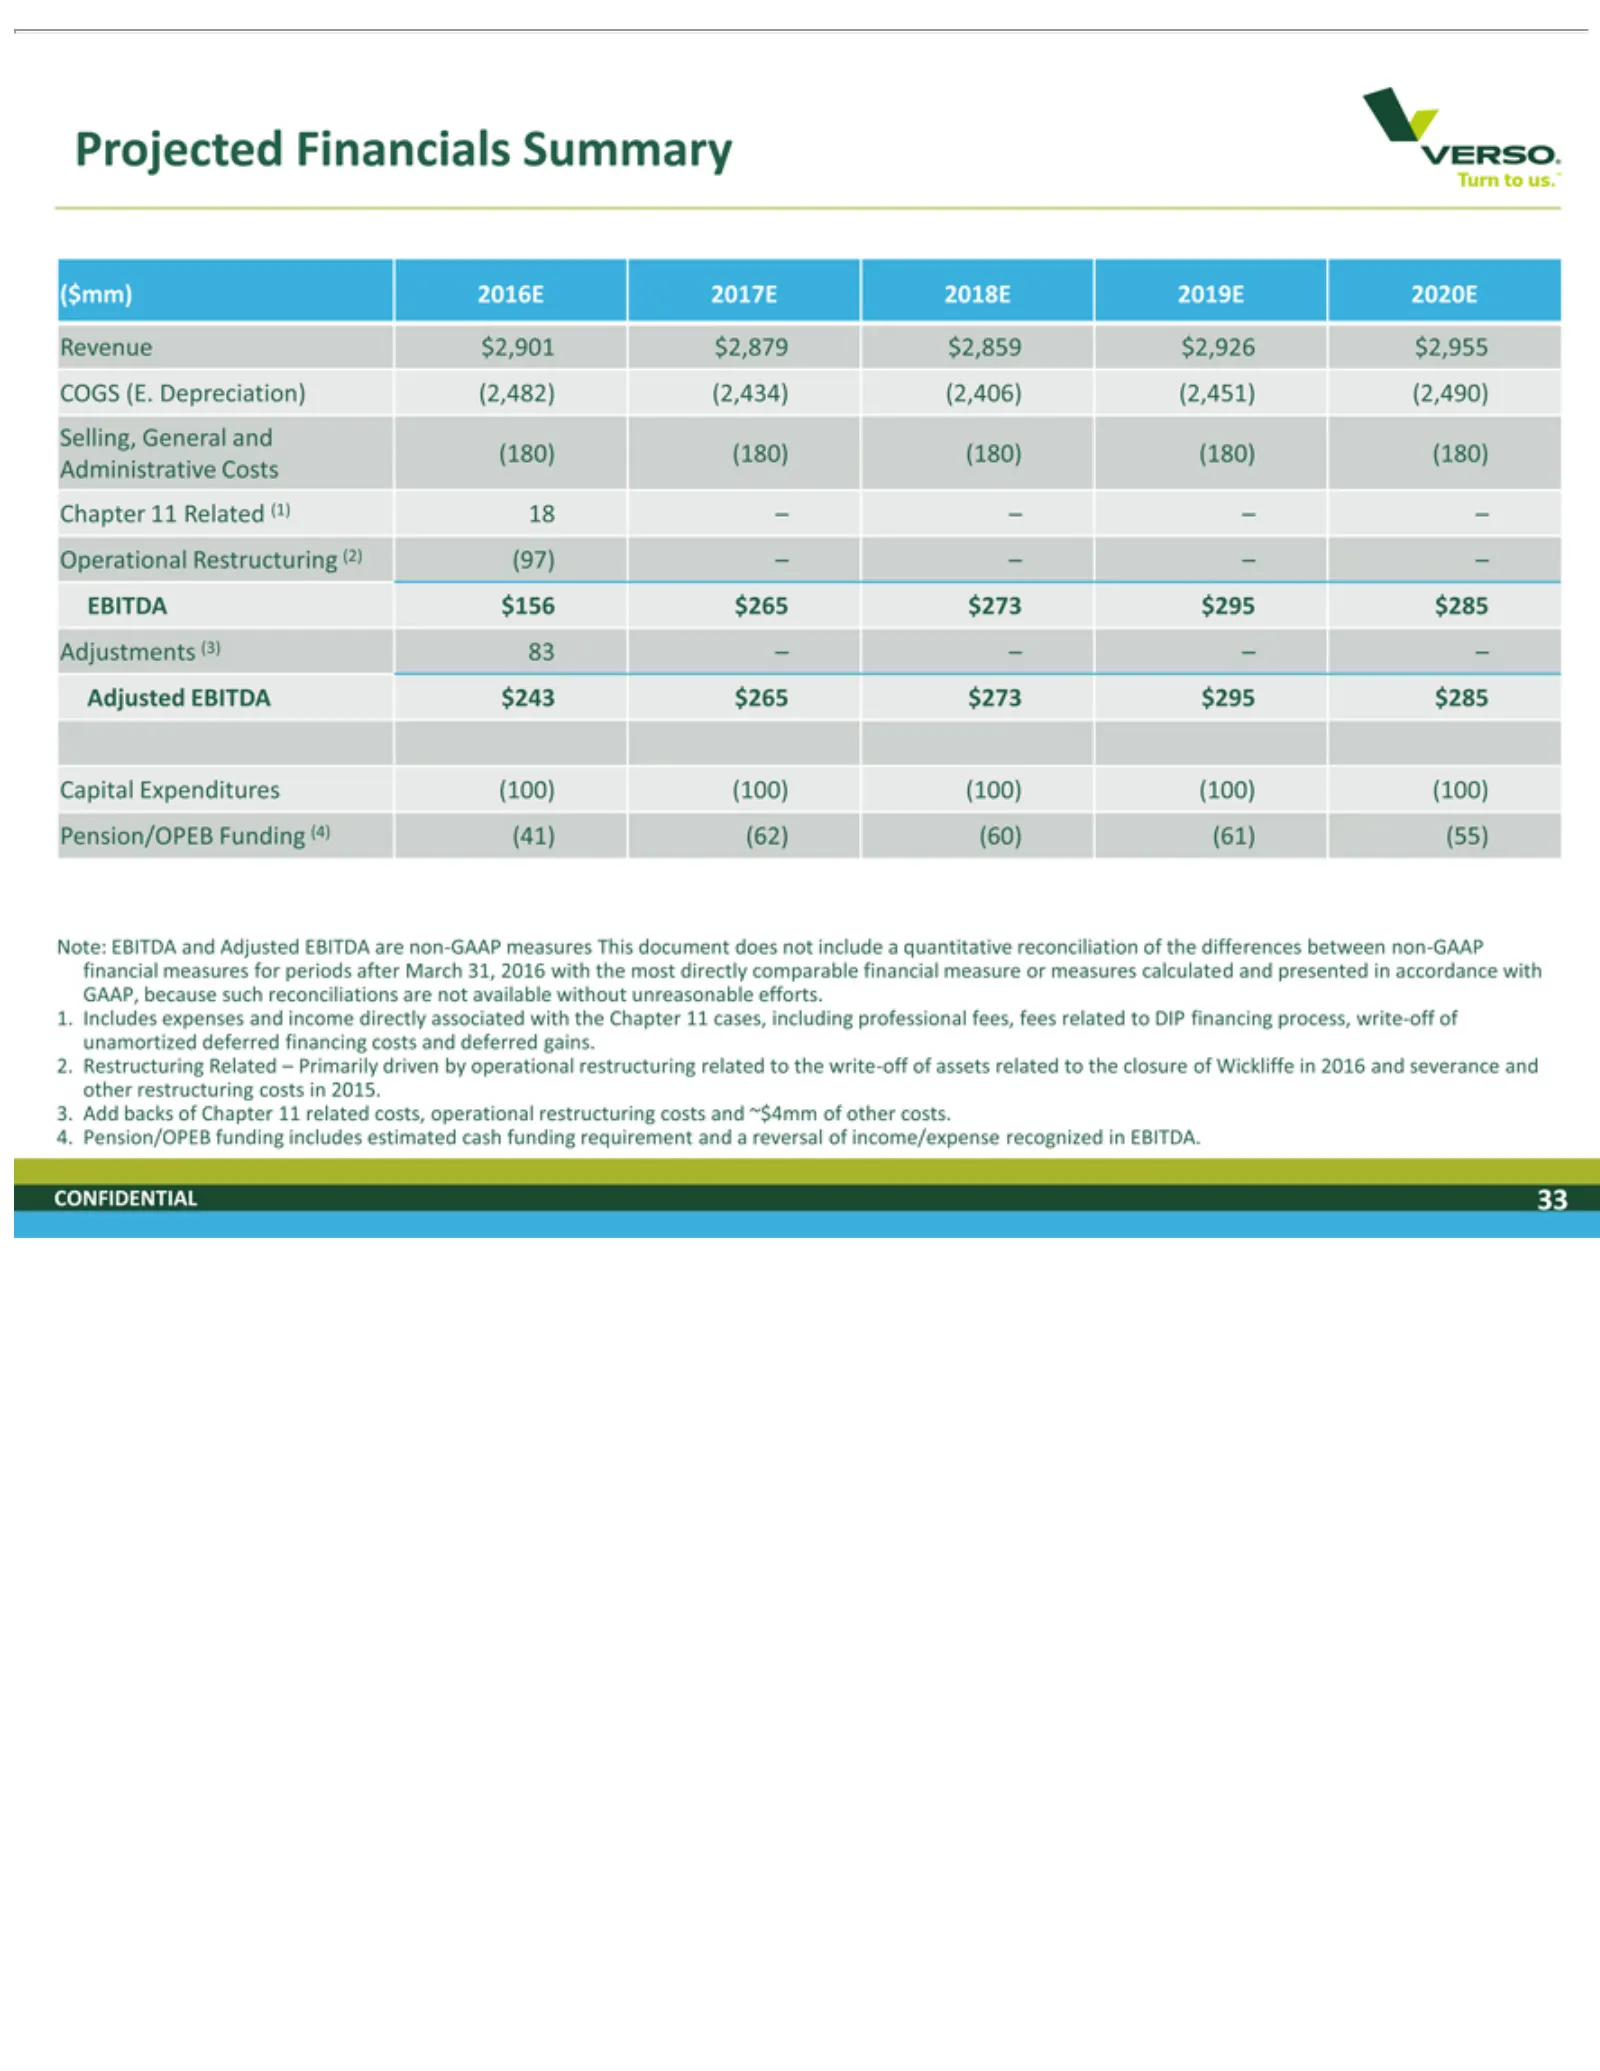
Slide 33: Projected Financial Summary
Projected ($mm) Revenue COGS $265 Adjustments Adjusted Capital Pension/OPEB Note: with 1. 2. 3. 4. CONFIDENTIAL Add Includes Restructuring Pension/OPEB the $273 EBITDA backs (E. 2016E Expenditures most $2,901 EBITDA Financials Depreciation) $295 expenses (3) of directly 2017E Funding and Chapter Rel
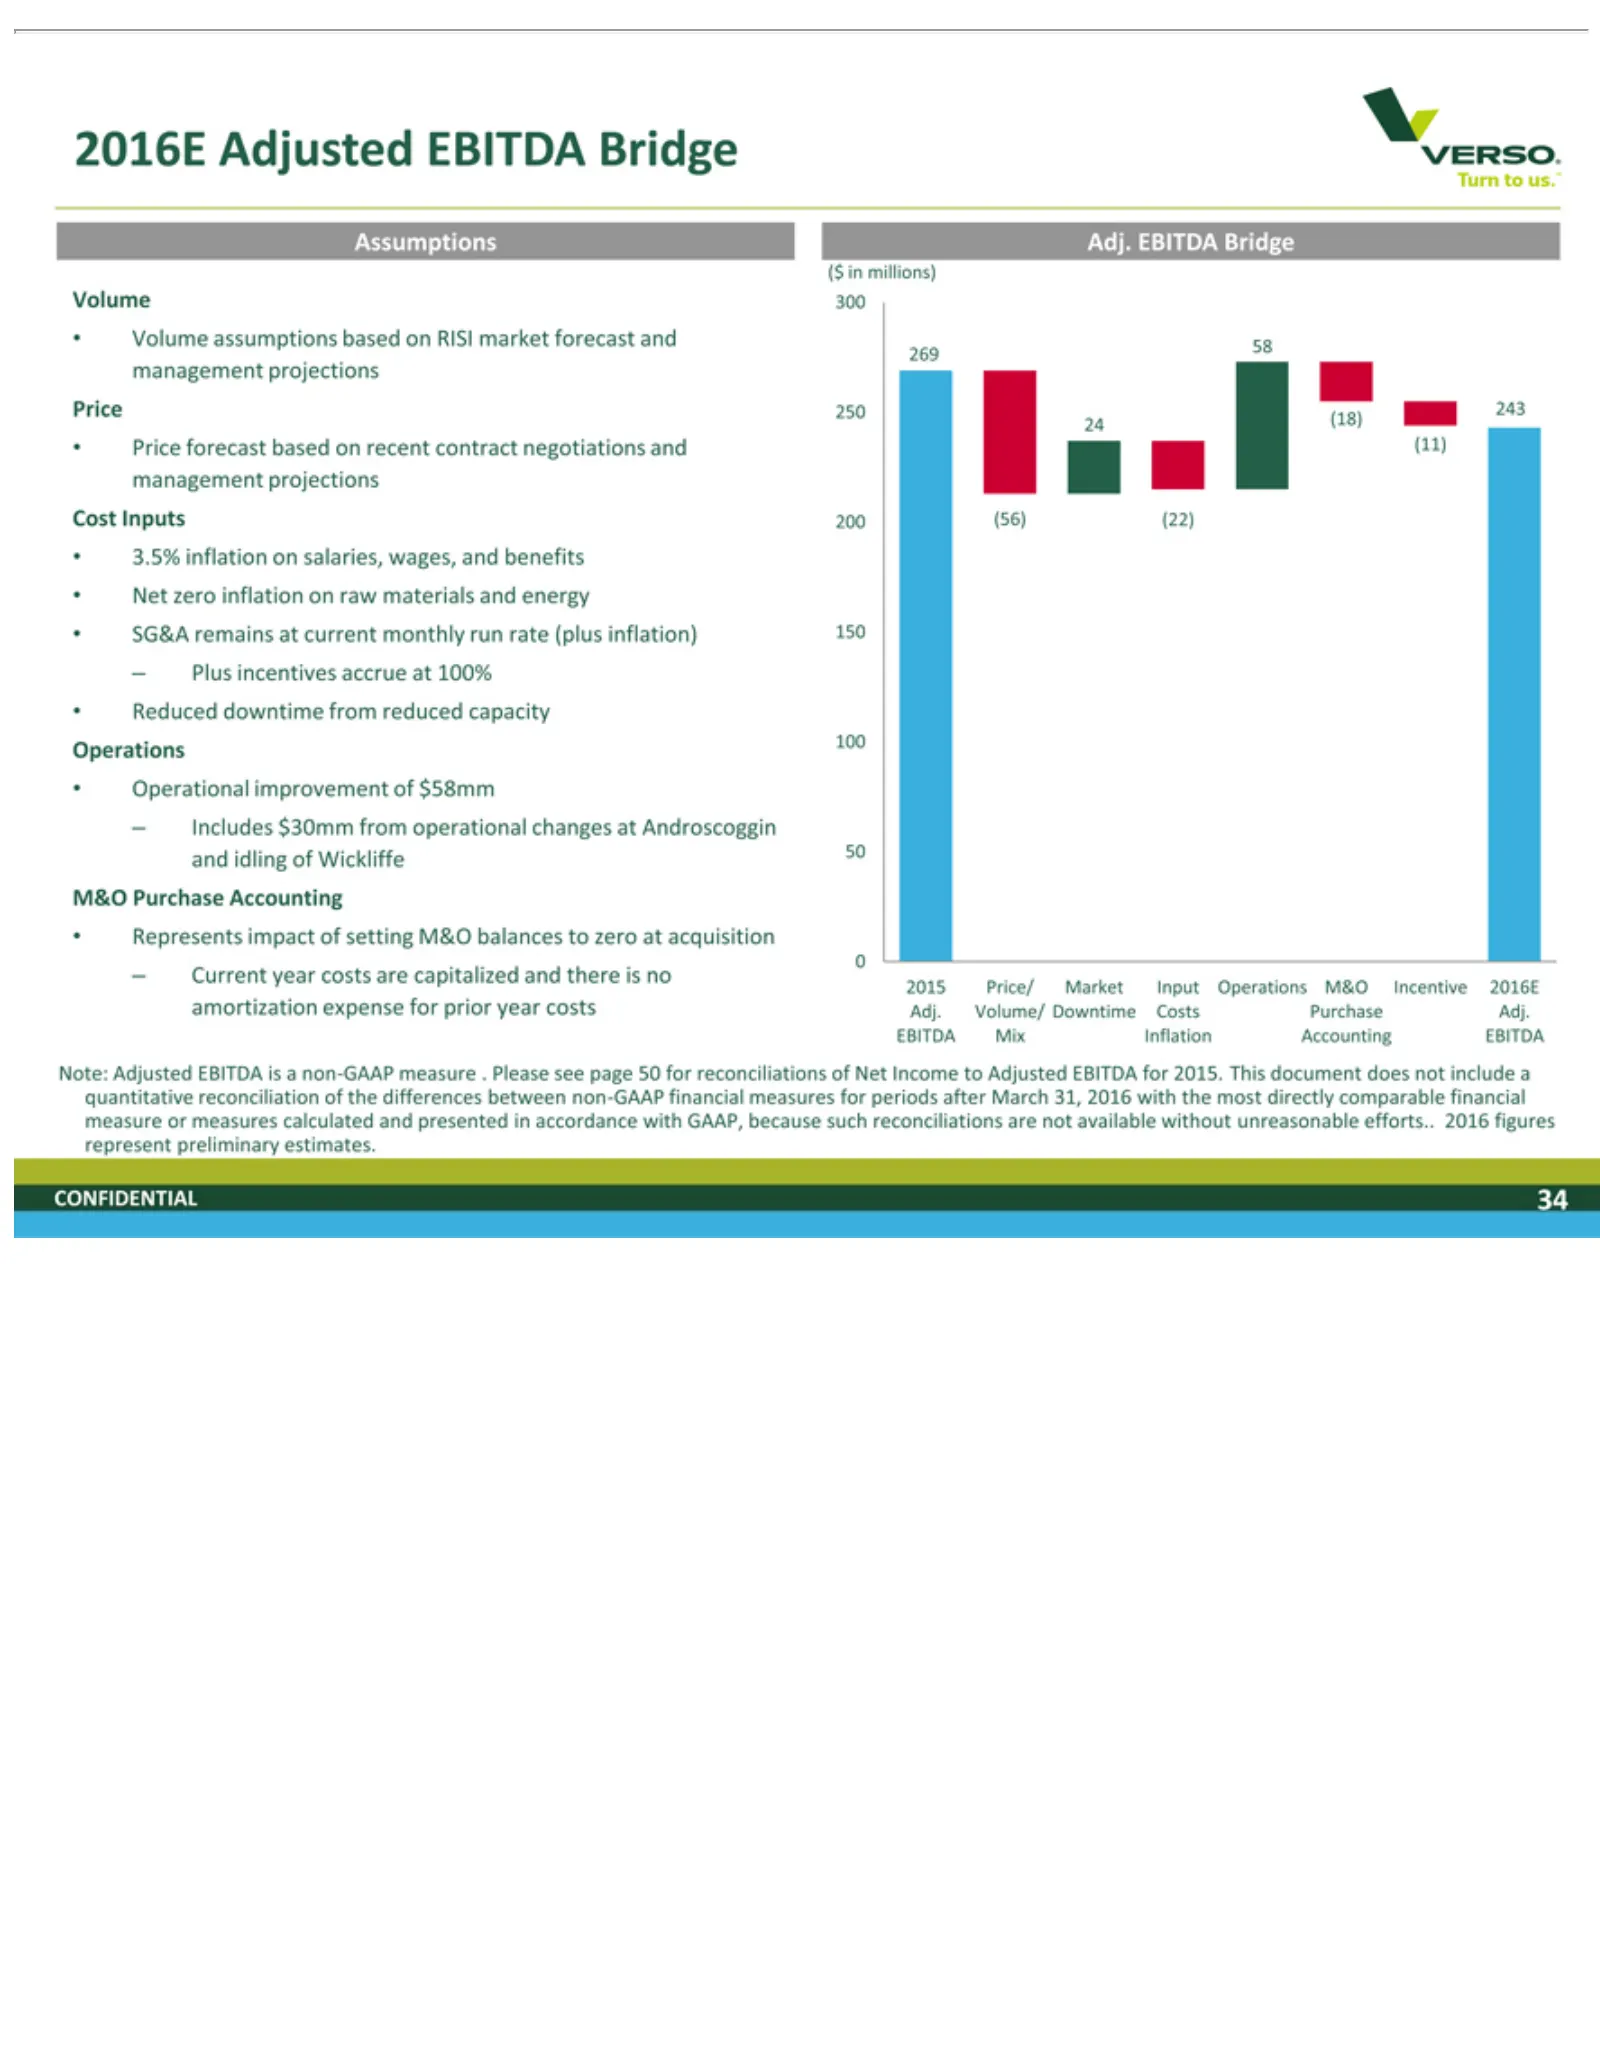
Slide 34: 2016E Assumptions and EBITDA Bridge
2016E Assumptions ($ Volume 24 Price Cost 3.5% Net SG&A Reduced Operations Operational M&O 0–Represents 2015 amortization EBITDA Note: between reconciliations CONFIDENTIAL Plus Includes Current in (18) zero Inputs millions) Price/ 250 forecast inflation Adjusted Purchase incentives Adjusted remains
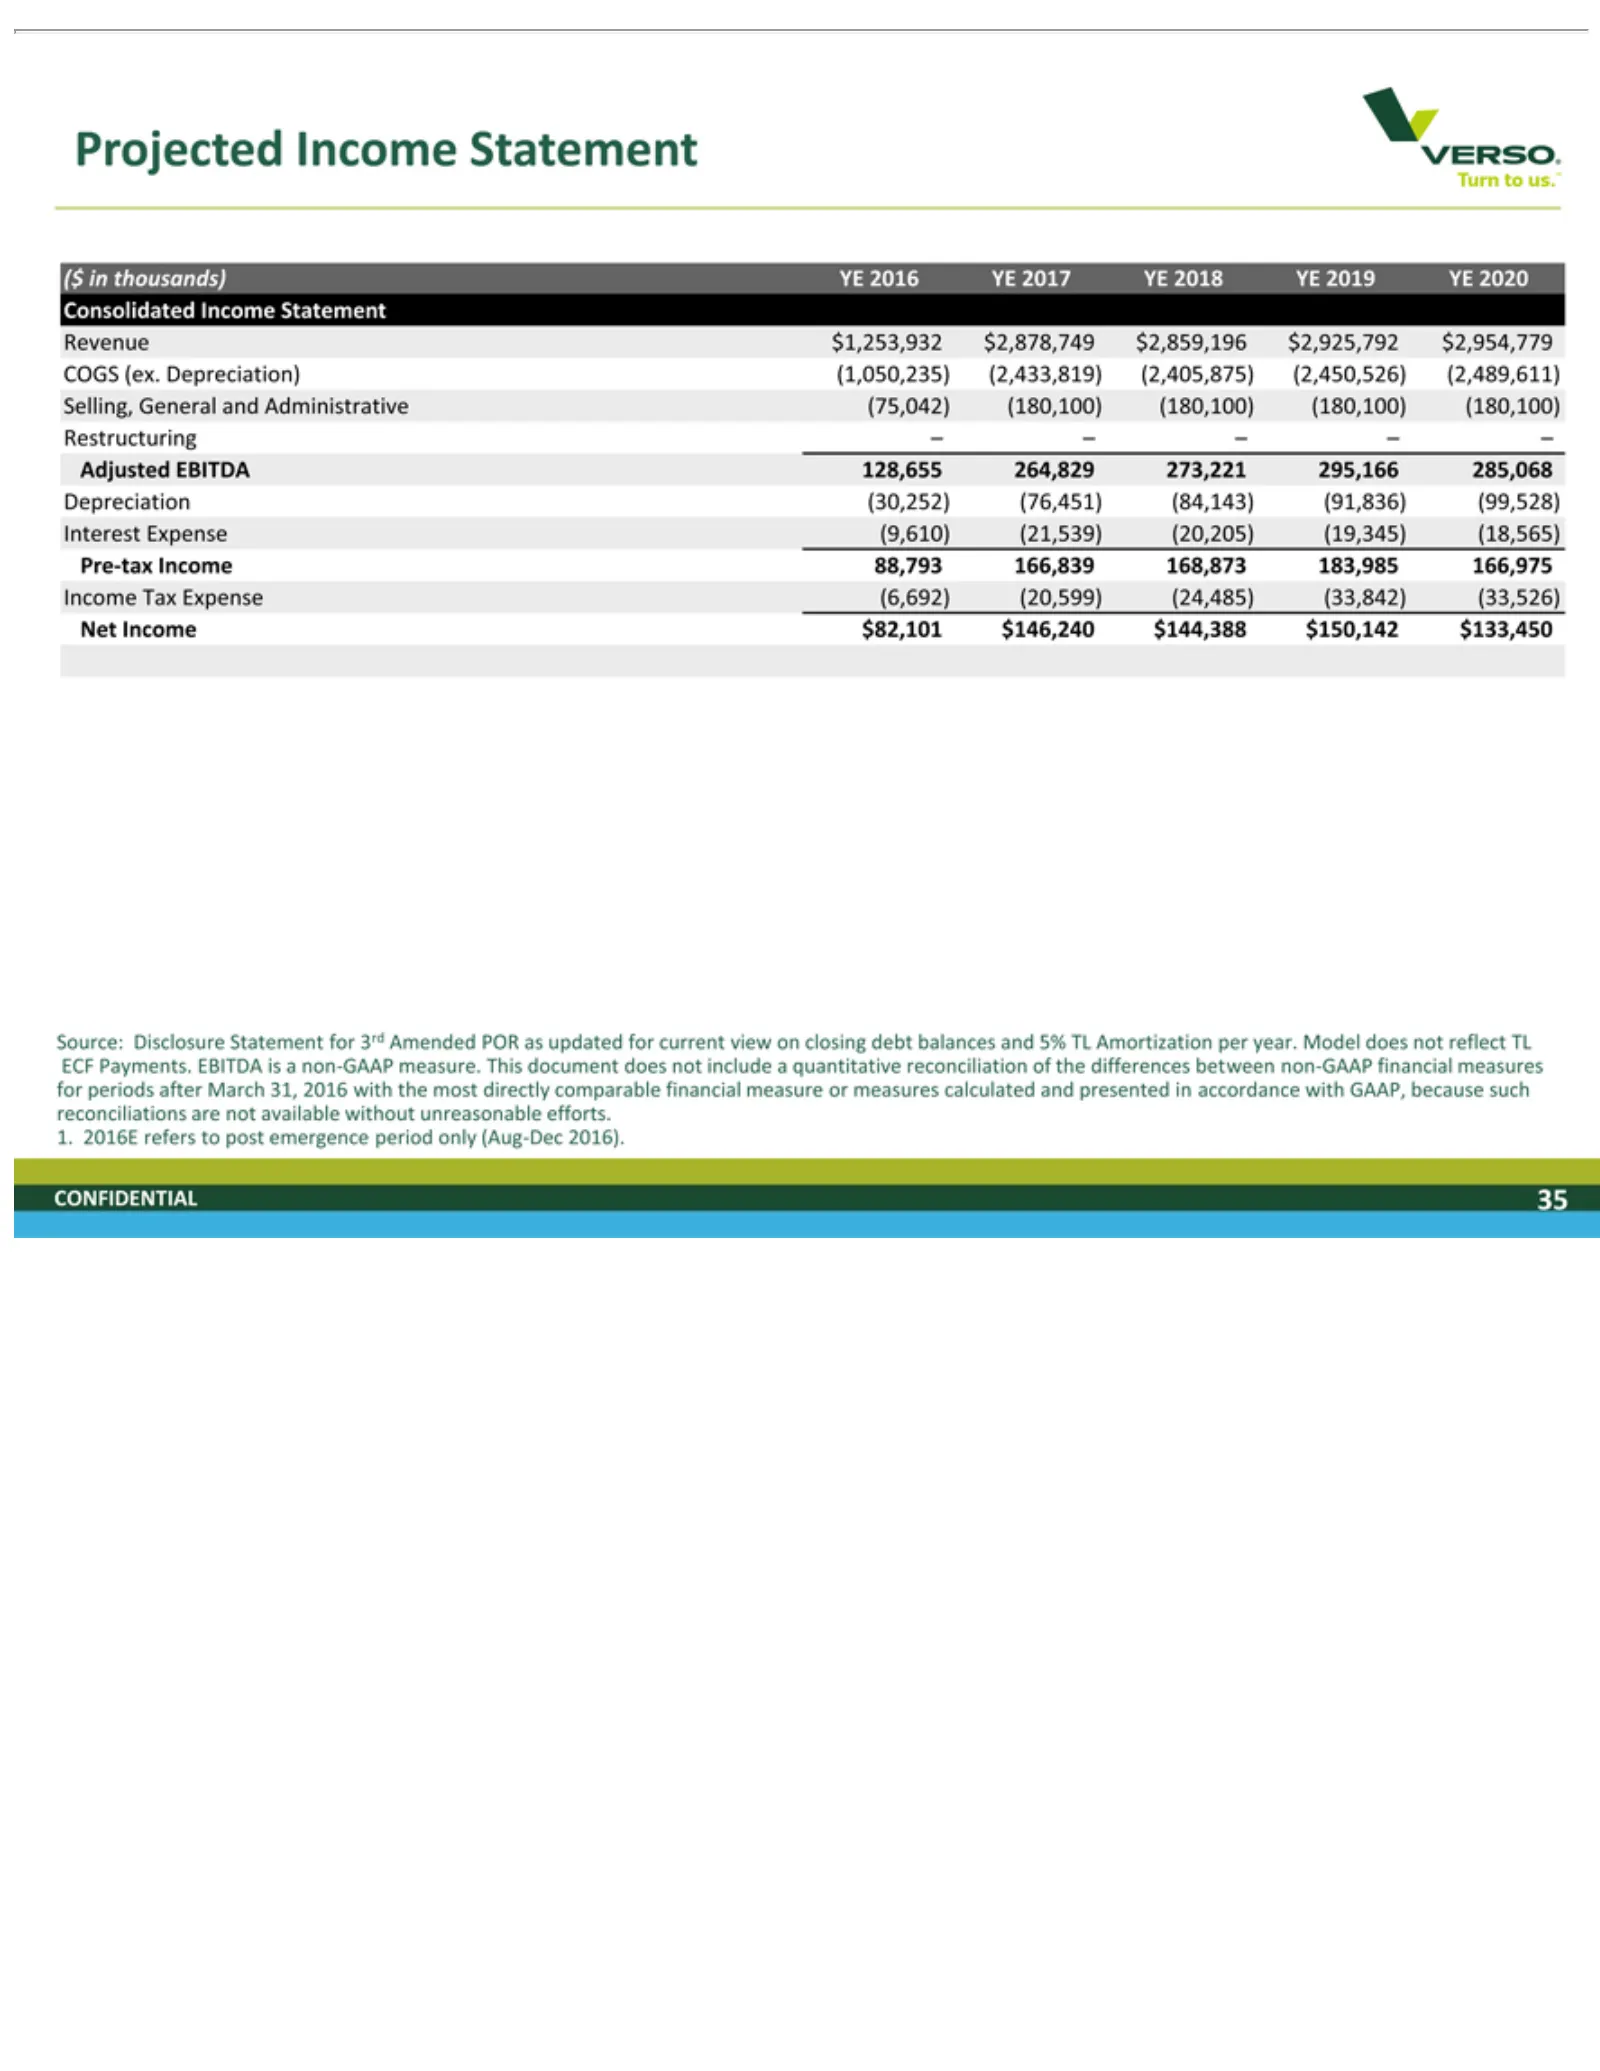
Slide 35: Projected Income Statement
Projected ($ Revenue (75,042) Depreciation Pre-tax Income Net Source: measure. measures 1. CONFIDENTIAL 2016E inIncome thousands) Income Tax Disclosure (180,100) $1,253,932 This refers calculated Income $82,101 Expense (30,252) document 88,793 to YEStatement post 35 Statement (180,100) 2016 and $146
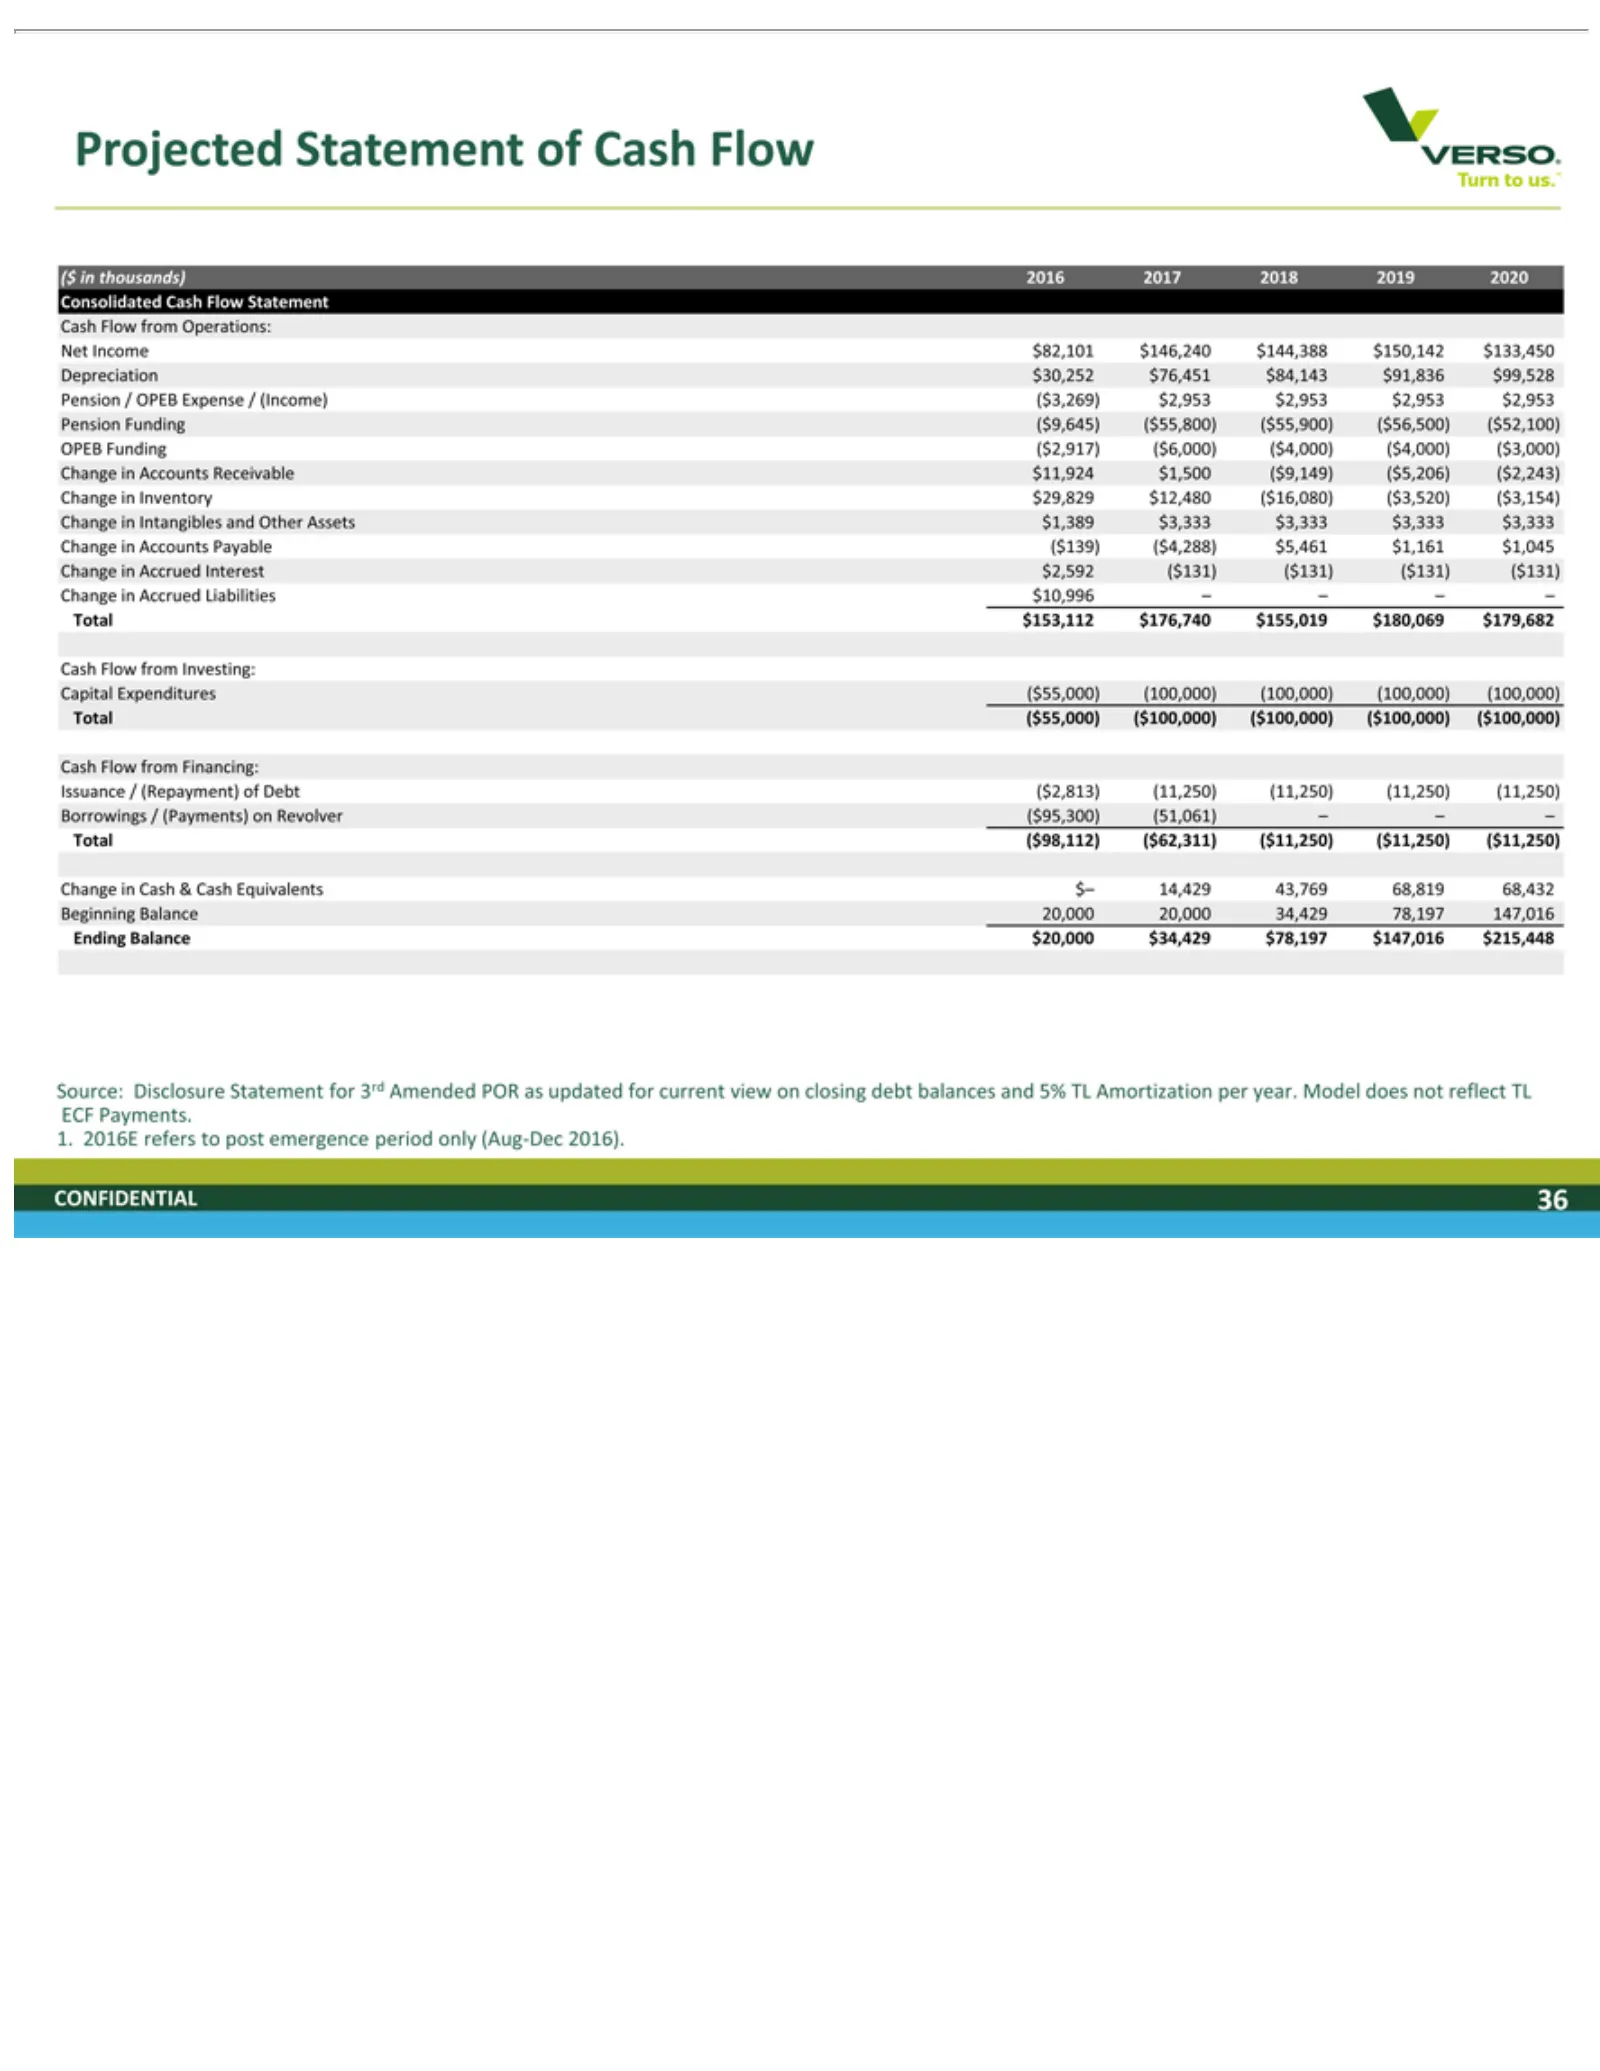
Slide 36: Projected Cash Flow Statement
Projected ($ Net ($9,645) $29,829 Interest Capital Total Cash Issuance Change Ending Source: 1. CONFIDENTIAL 2016E inIncome thousands) Flow ($55,000) Expenditures Balance $2,592 Disclosure in $12,480 ($55,800) /refers Statement (Repayment) Cash from $82,101 ($131) to ($100,000) & $20,000 2016 Operat
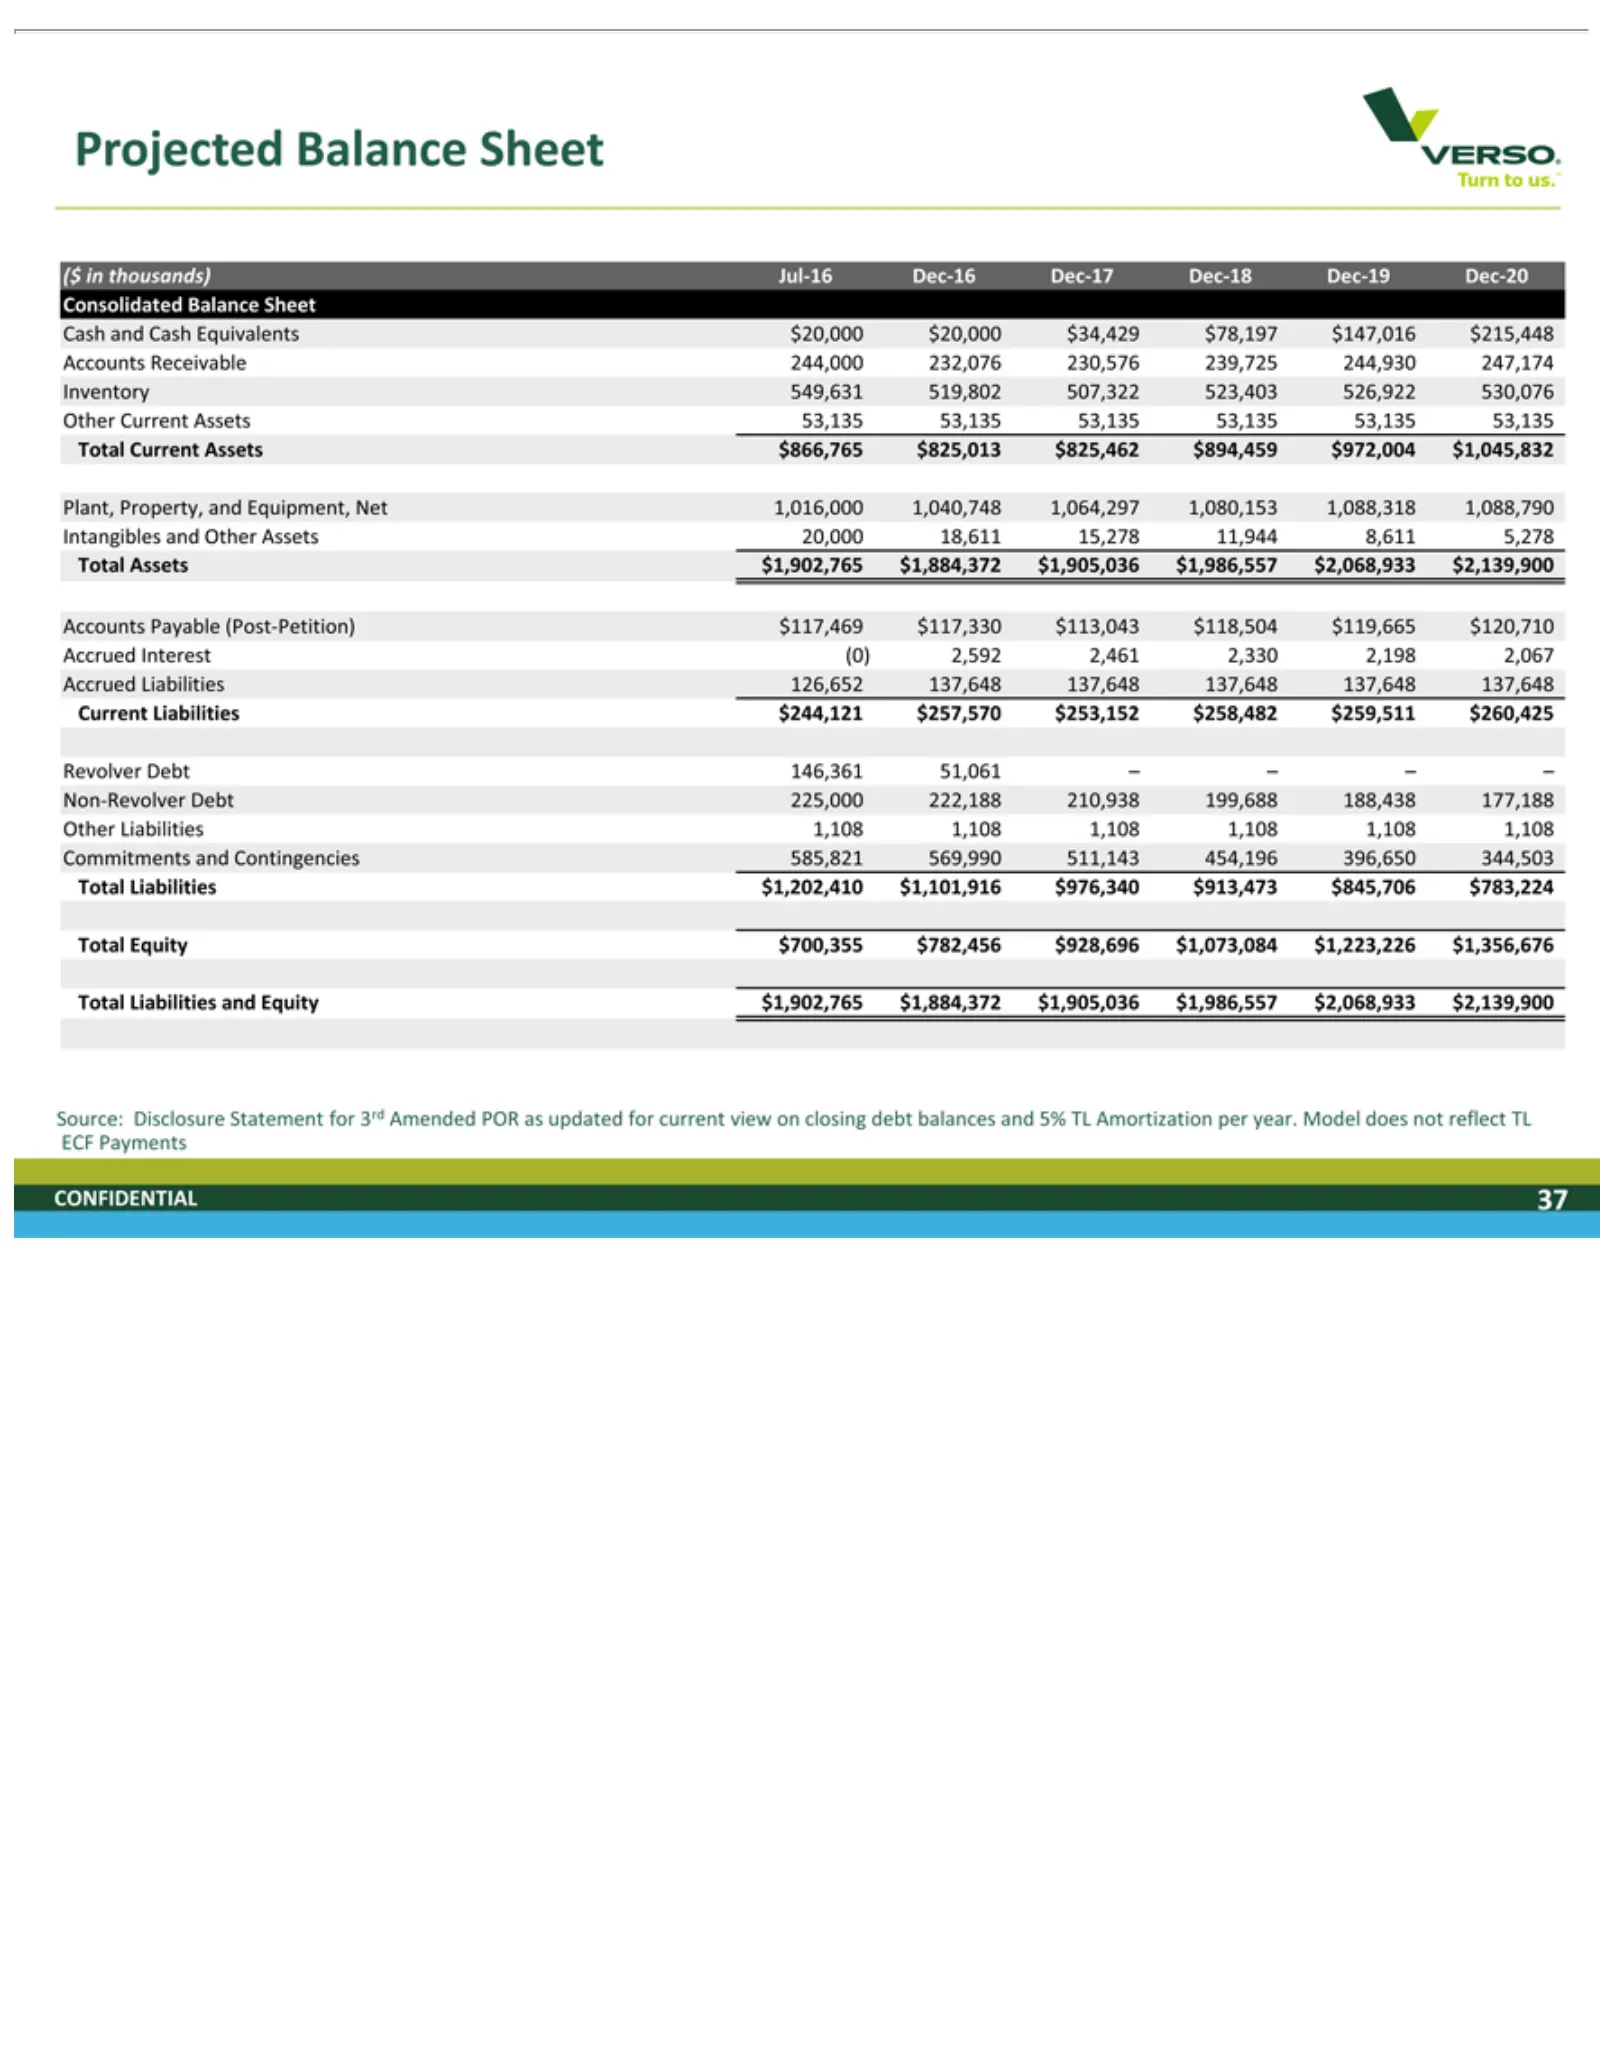
Slide 37: Projected Balance Sheet
Projected ($ Cash 530,076 Plant, Accounts Current Revolver 511,143 Total $1,905,036 Source: CONFIDENTIAL in thousands) Assets and Current Liabilities Property, Liabilities Disclosure 454,196 Other Debt Cash Balance Payable $1,986,557 $1,902,765 Assets Current 146,361 Equivalents and $1,202,410 Jul-1
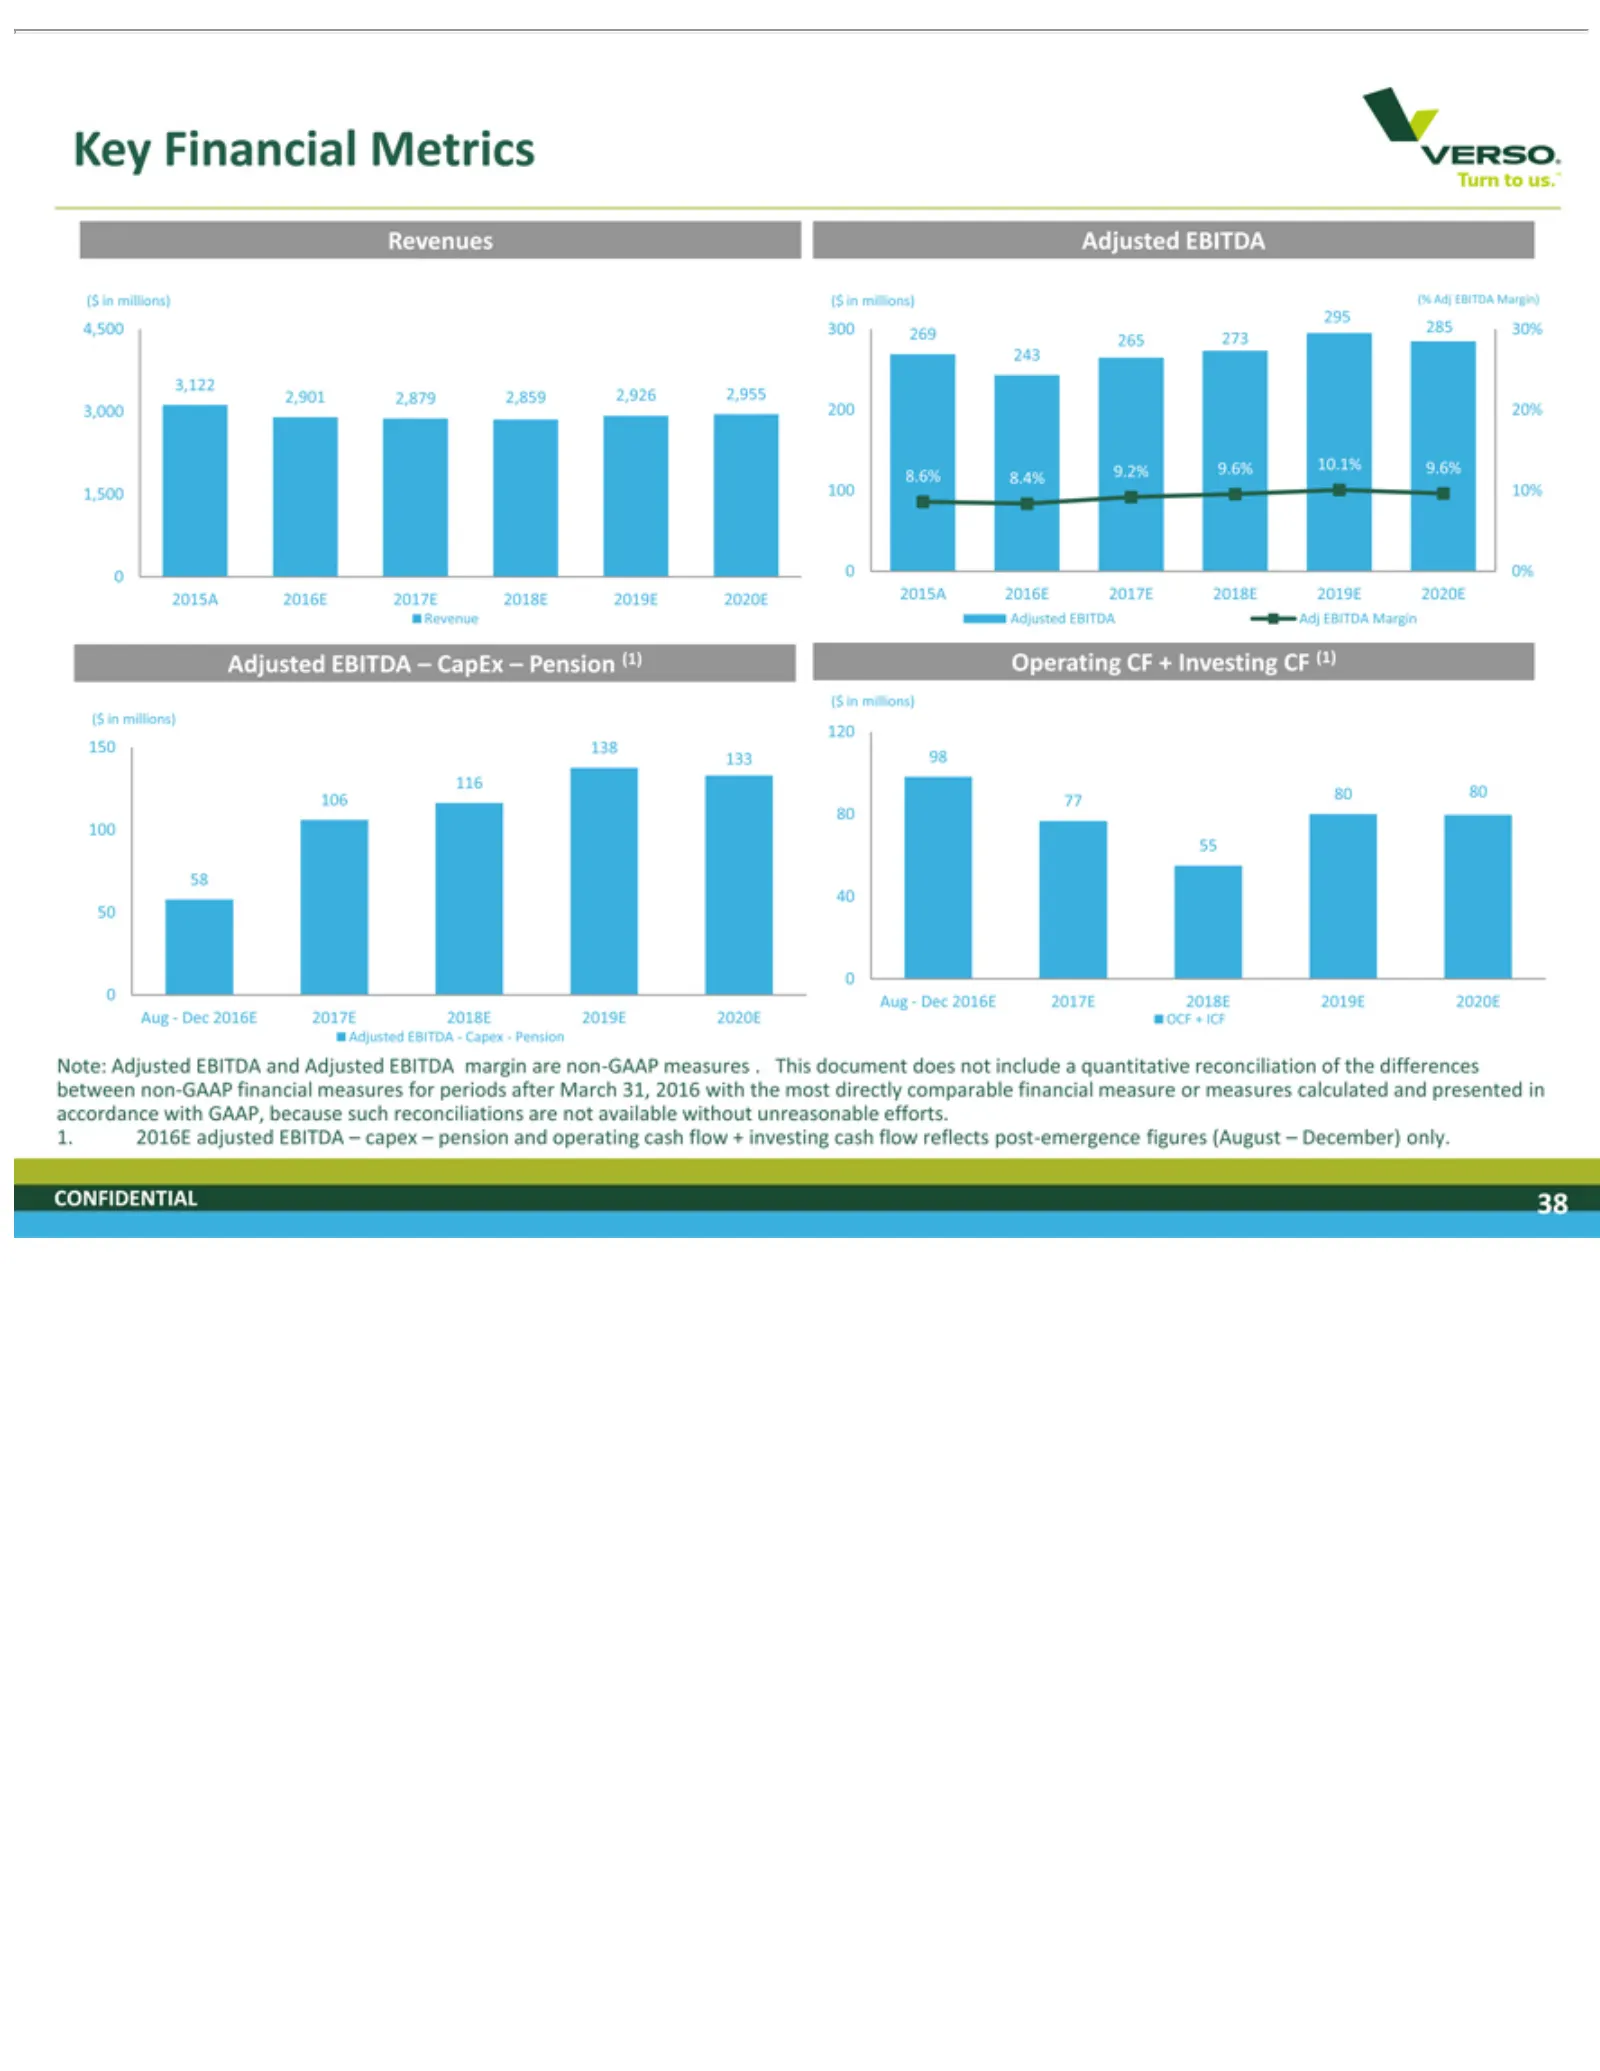
Slide 38: Key Financial Metrics
Key Revenues 4,500 295 9.6% 8.6% 1,500 8.4% Revenue ($ 150 133 80 40 058 Aug—Dec Adjusted Note: after 1. CONFIDENTIAL 02016E in 80 50 0% 138 98 Financial March millions) 10.1% 9.2% Adjusted 300 100 106 116 2015A Adjusted adjusted EBITDA EBITDA—Capex—Pension Adjusted 285 10% 80 2016E 31, 9.6% 77 Metr
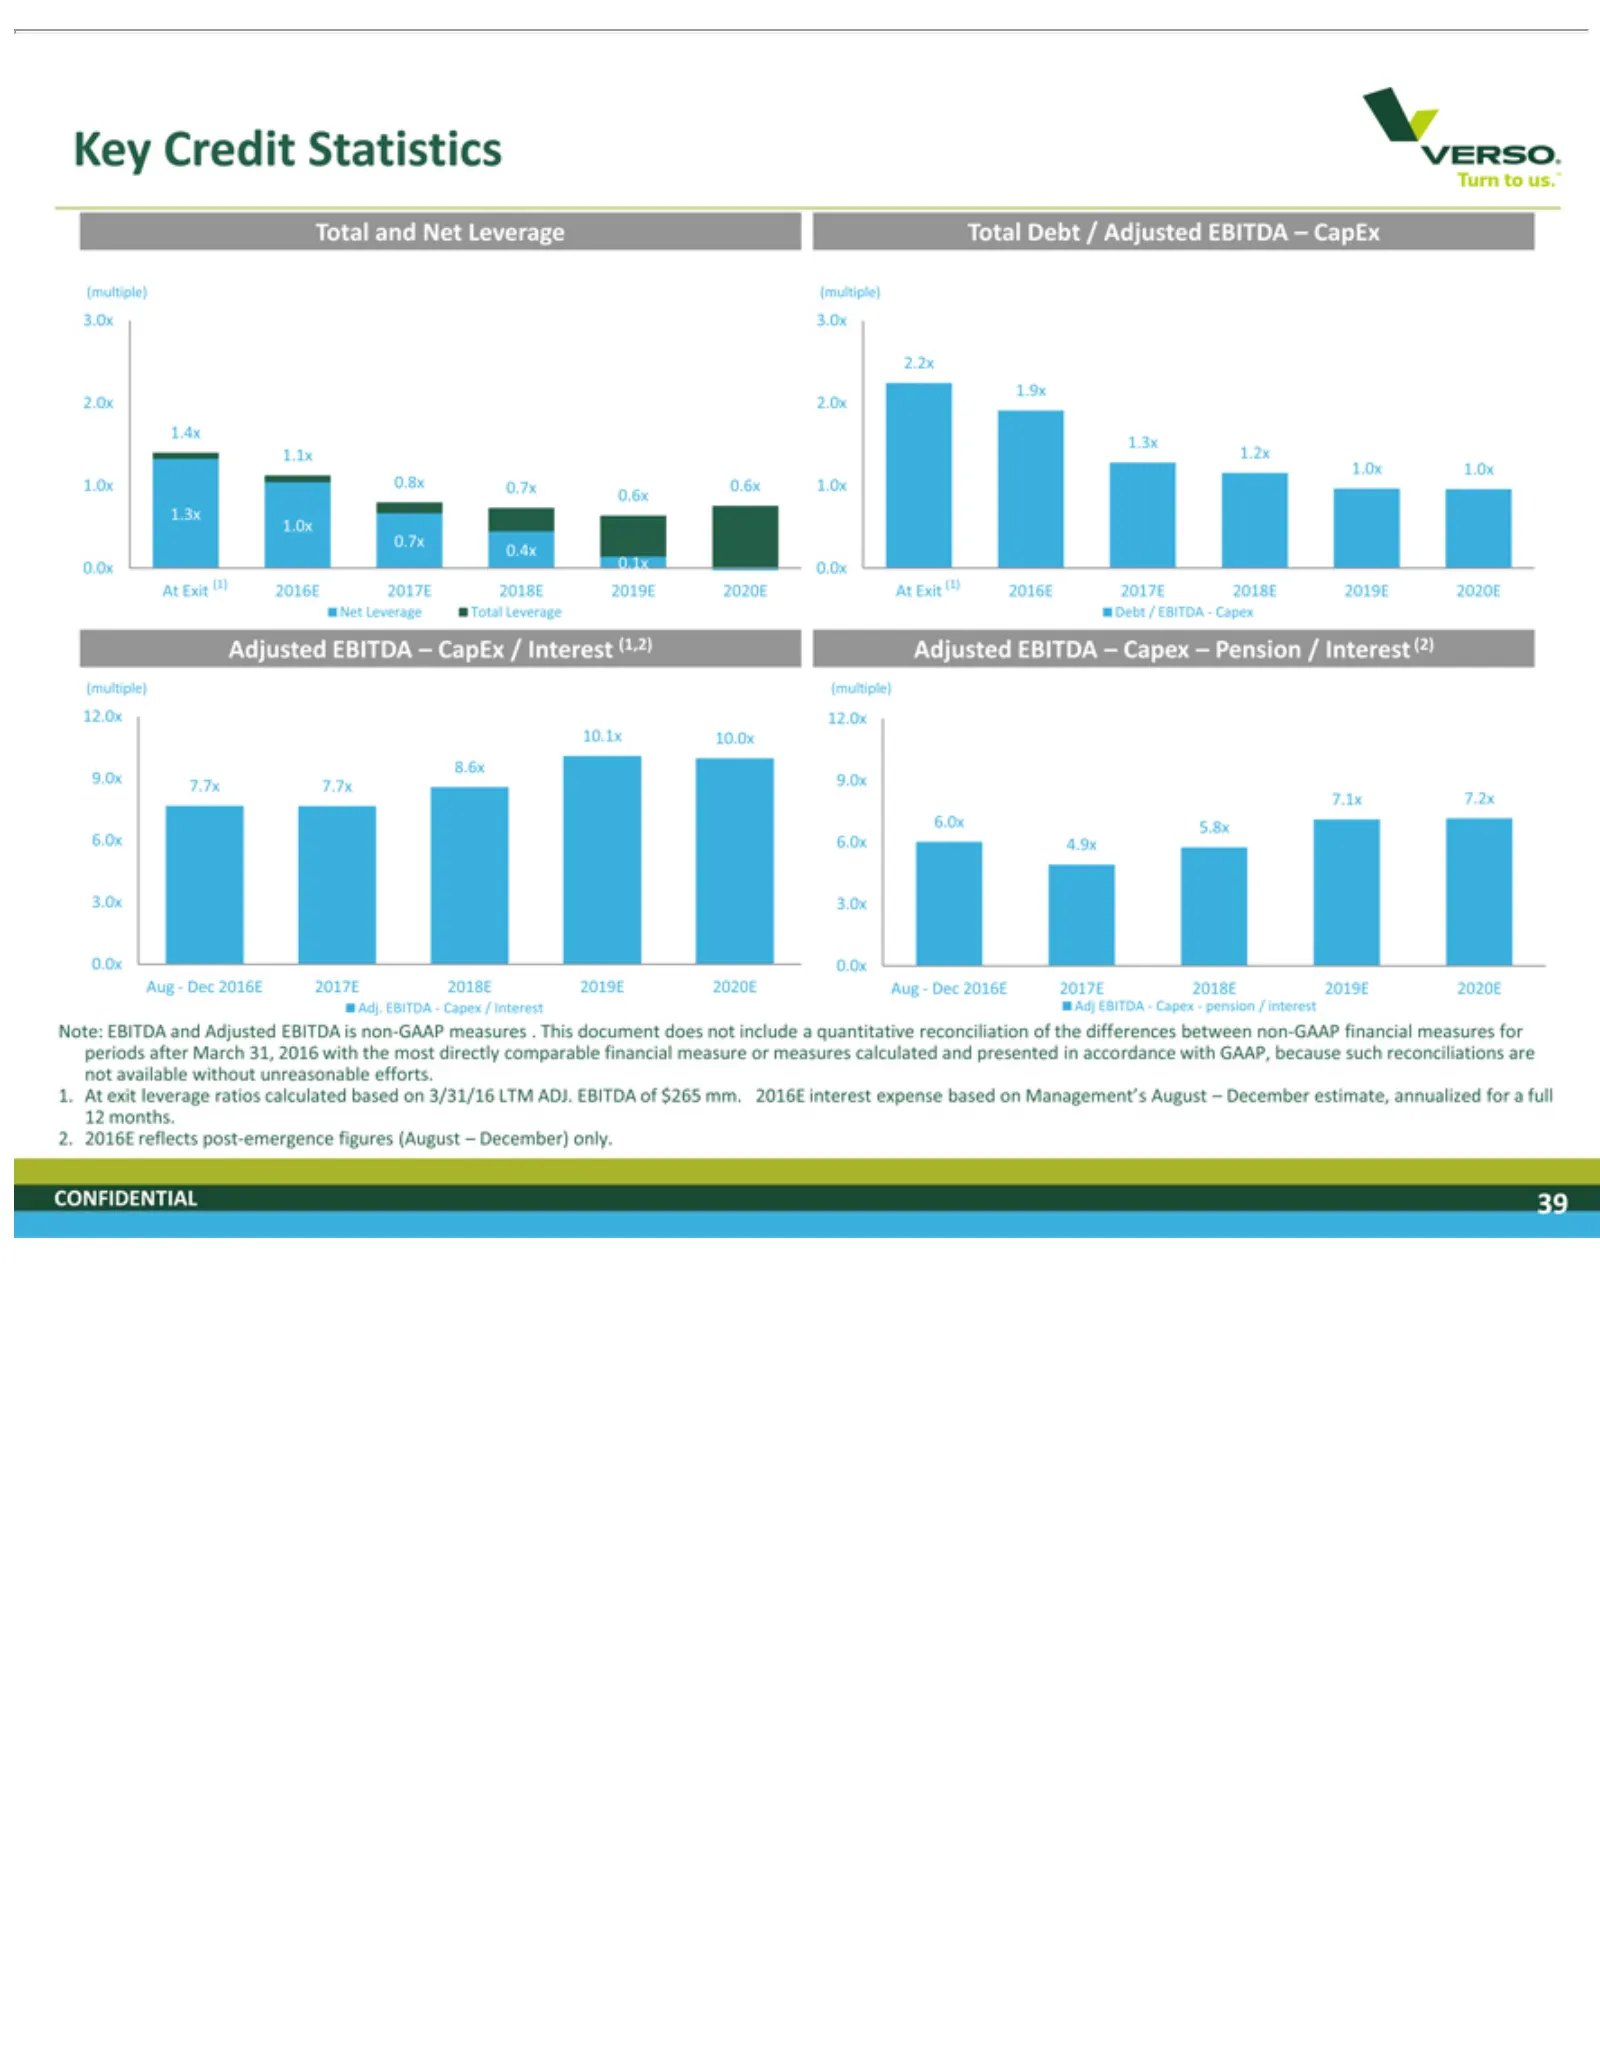
Slide 39: Key Credit Statistics
Key Total 3.0x 10.7x 2.0x 1.4x 1.1x 0.8x 1.0x 1.3x 0.6x 0.7x At Net Adjusted (multiple) 9.0x 7.7x 6.0x 0.0x Aug—Dec Adj. Note: with 1. 12 2. CONFIDENTIAL At 2016E Exit months. Leverage Credit 3.0x 2.0x 1.3x 1.2x 0.7x 1.0x 0.4x 9.0x 7.7x 6.0x 0.0x EBITDA—Capex the exit and EBITDA 14. (1) most reflect
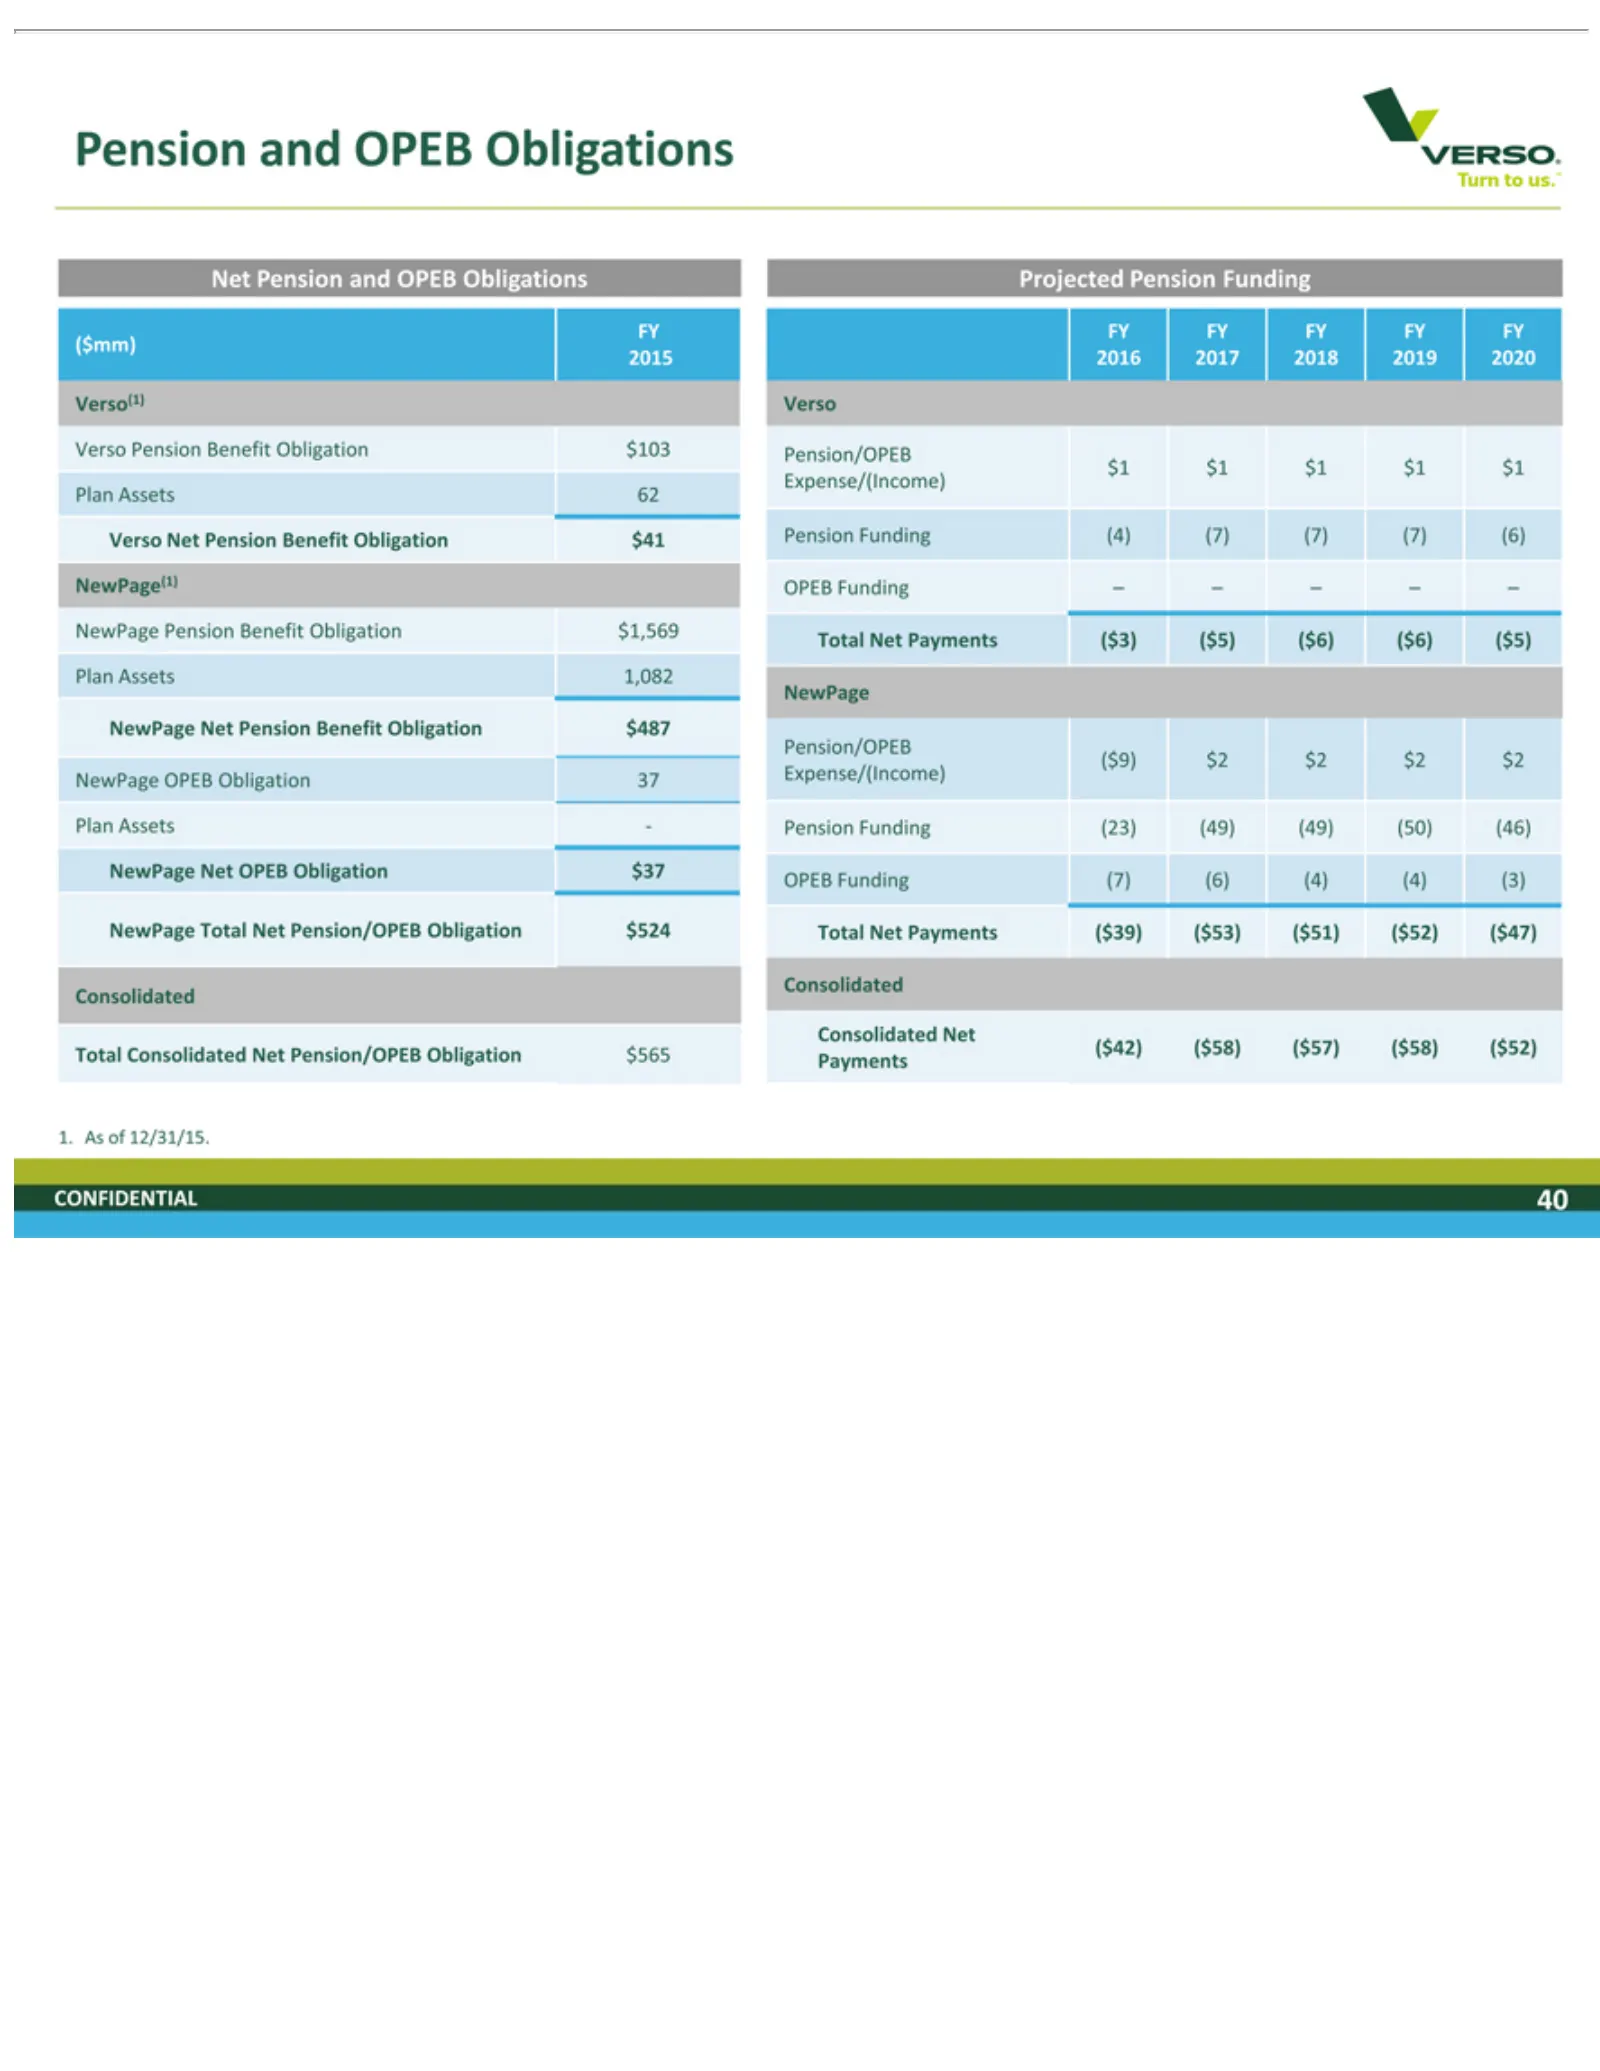
Slide 40: Pension and OPEB
Pension Net FY Verso(1) $1 Verso NewPage(1) Plan ($9) Pension/OPEB OPEB NewPage Consolidated Total 1. CONFIDENTIAL As $1 FY Pension $2 Assets Net Consolidated of $1 Pension Net Funding FY $2 12/31/15. and Verso $1 Payments Total Pension NewPage Net Pension $2 FY 1,082 $1 and OPEB OPEB Consolidated N
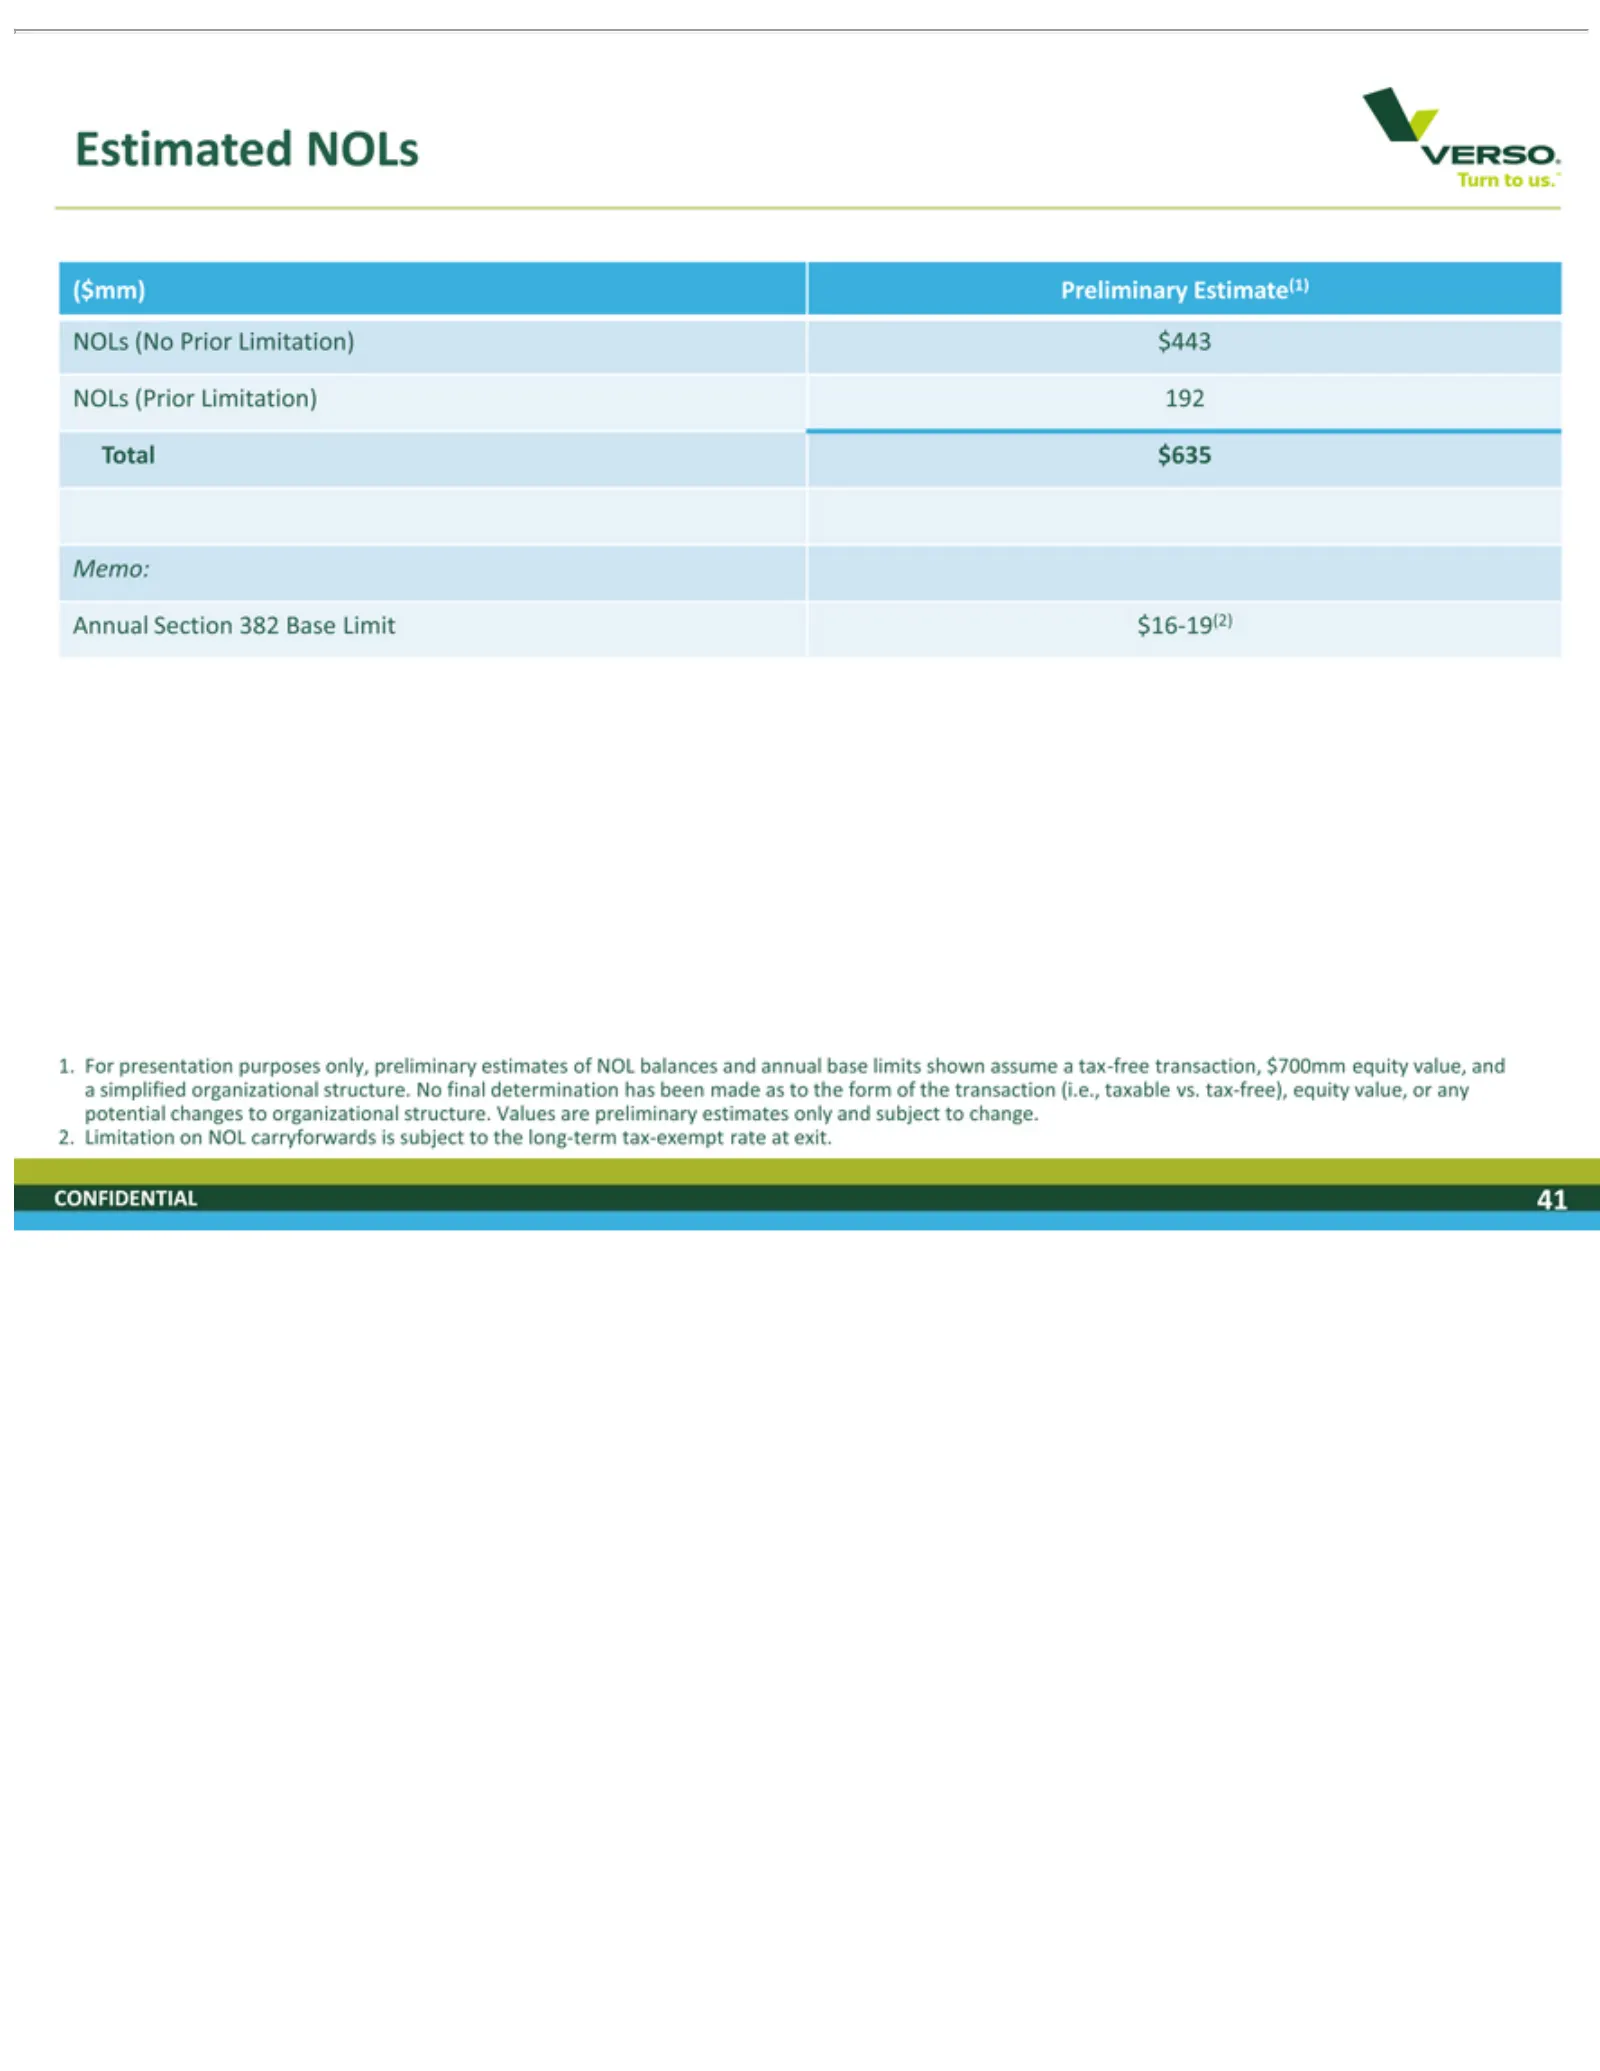
Slide 41: Estimated NOLs
Estimated VERSO ($mm) NOLs Total Annual Memo: 1. determination 2. CONFIDENTIAL For$635 Limitation presentation (No (Prior Preliminary Section Turn NOLs Prior Limitation) on to has 382 us. NOL Limitation) been 41 purposes Estimate(1) Base carryforwards made 192 Limit $443 only, as $16-19(2) toprelimi
Slide 42: Transaction Overview
VERSO TurnOverview Transaction CONFIDENTIALto us.
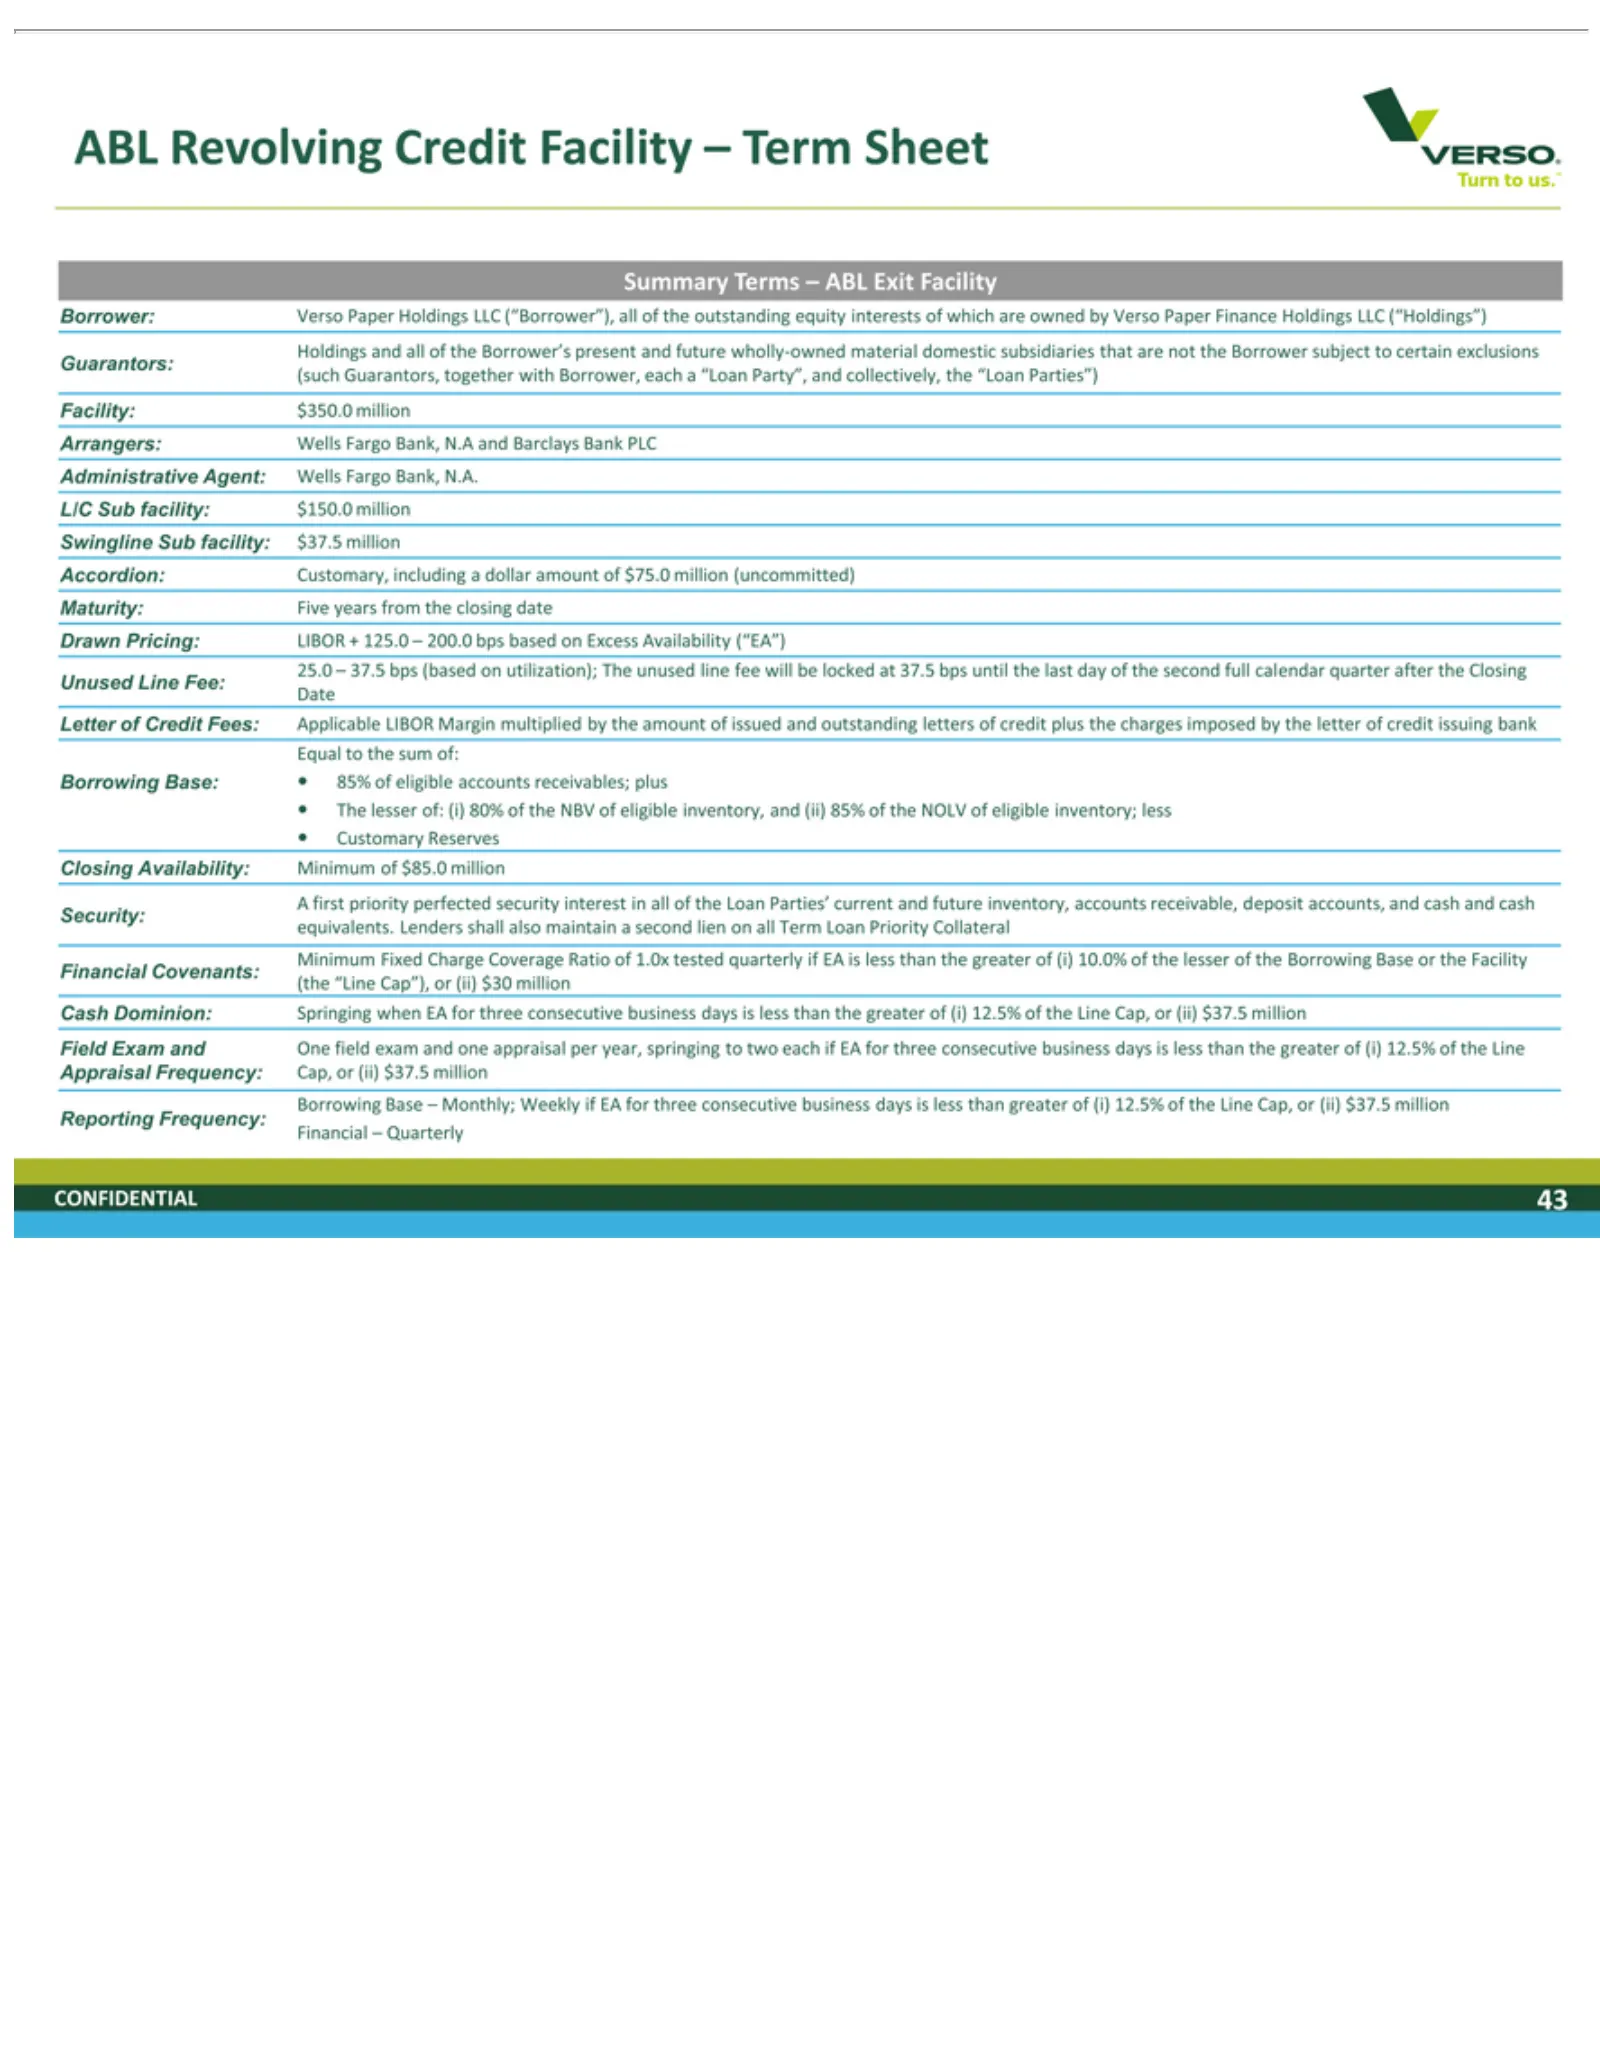
Slide 43: Exit ABL Summary
ABL VERSO Summary Borrower: Guarantors: (such Arrangers: Administrative L/C Swingline Accordion: Maturity: Drawn Unused Letter Equal The Customary Closing Security: on Cash Field Appraisal Borrowing Reporting Financial CONFIDENTIAL alllesser Sub Revolving Dominion: Exam Guarantors, Term to ofPricing
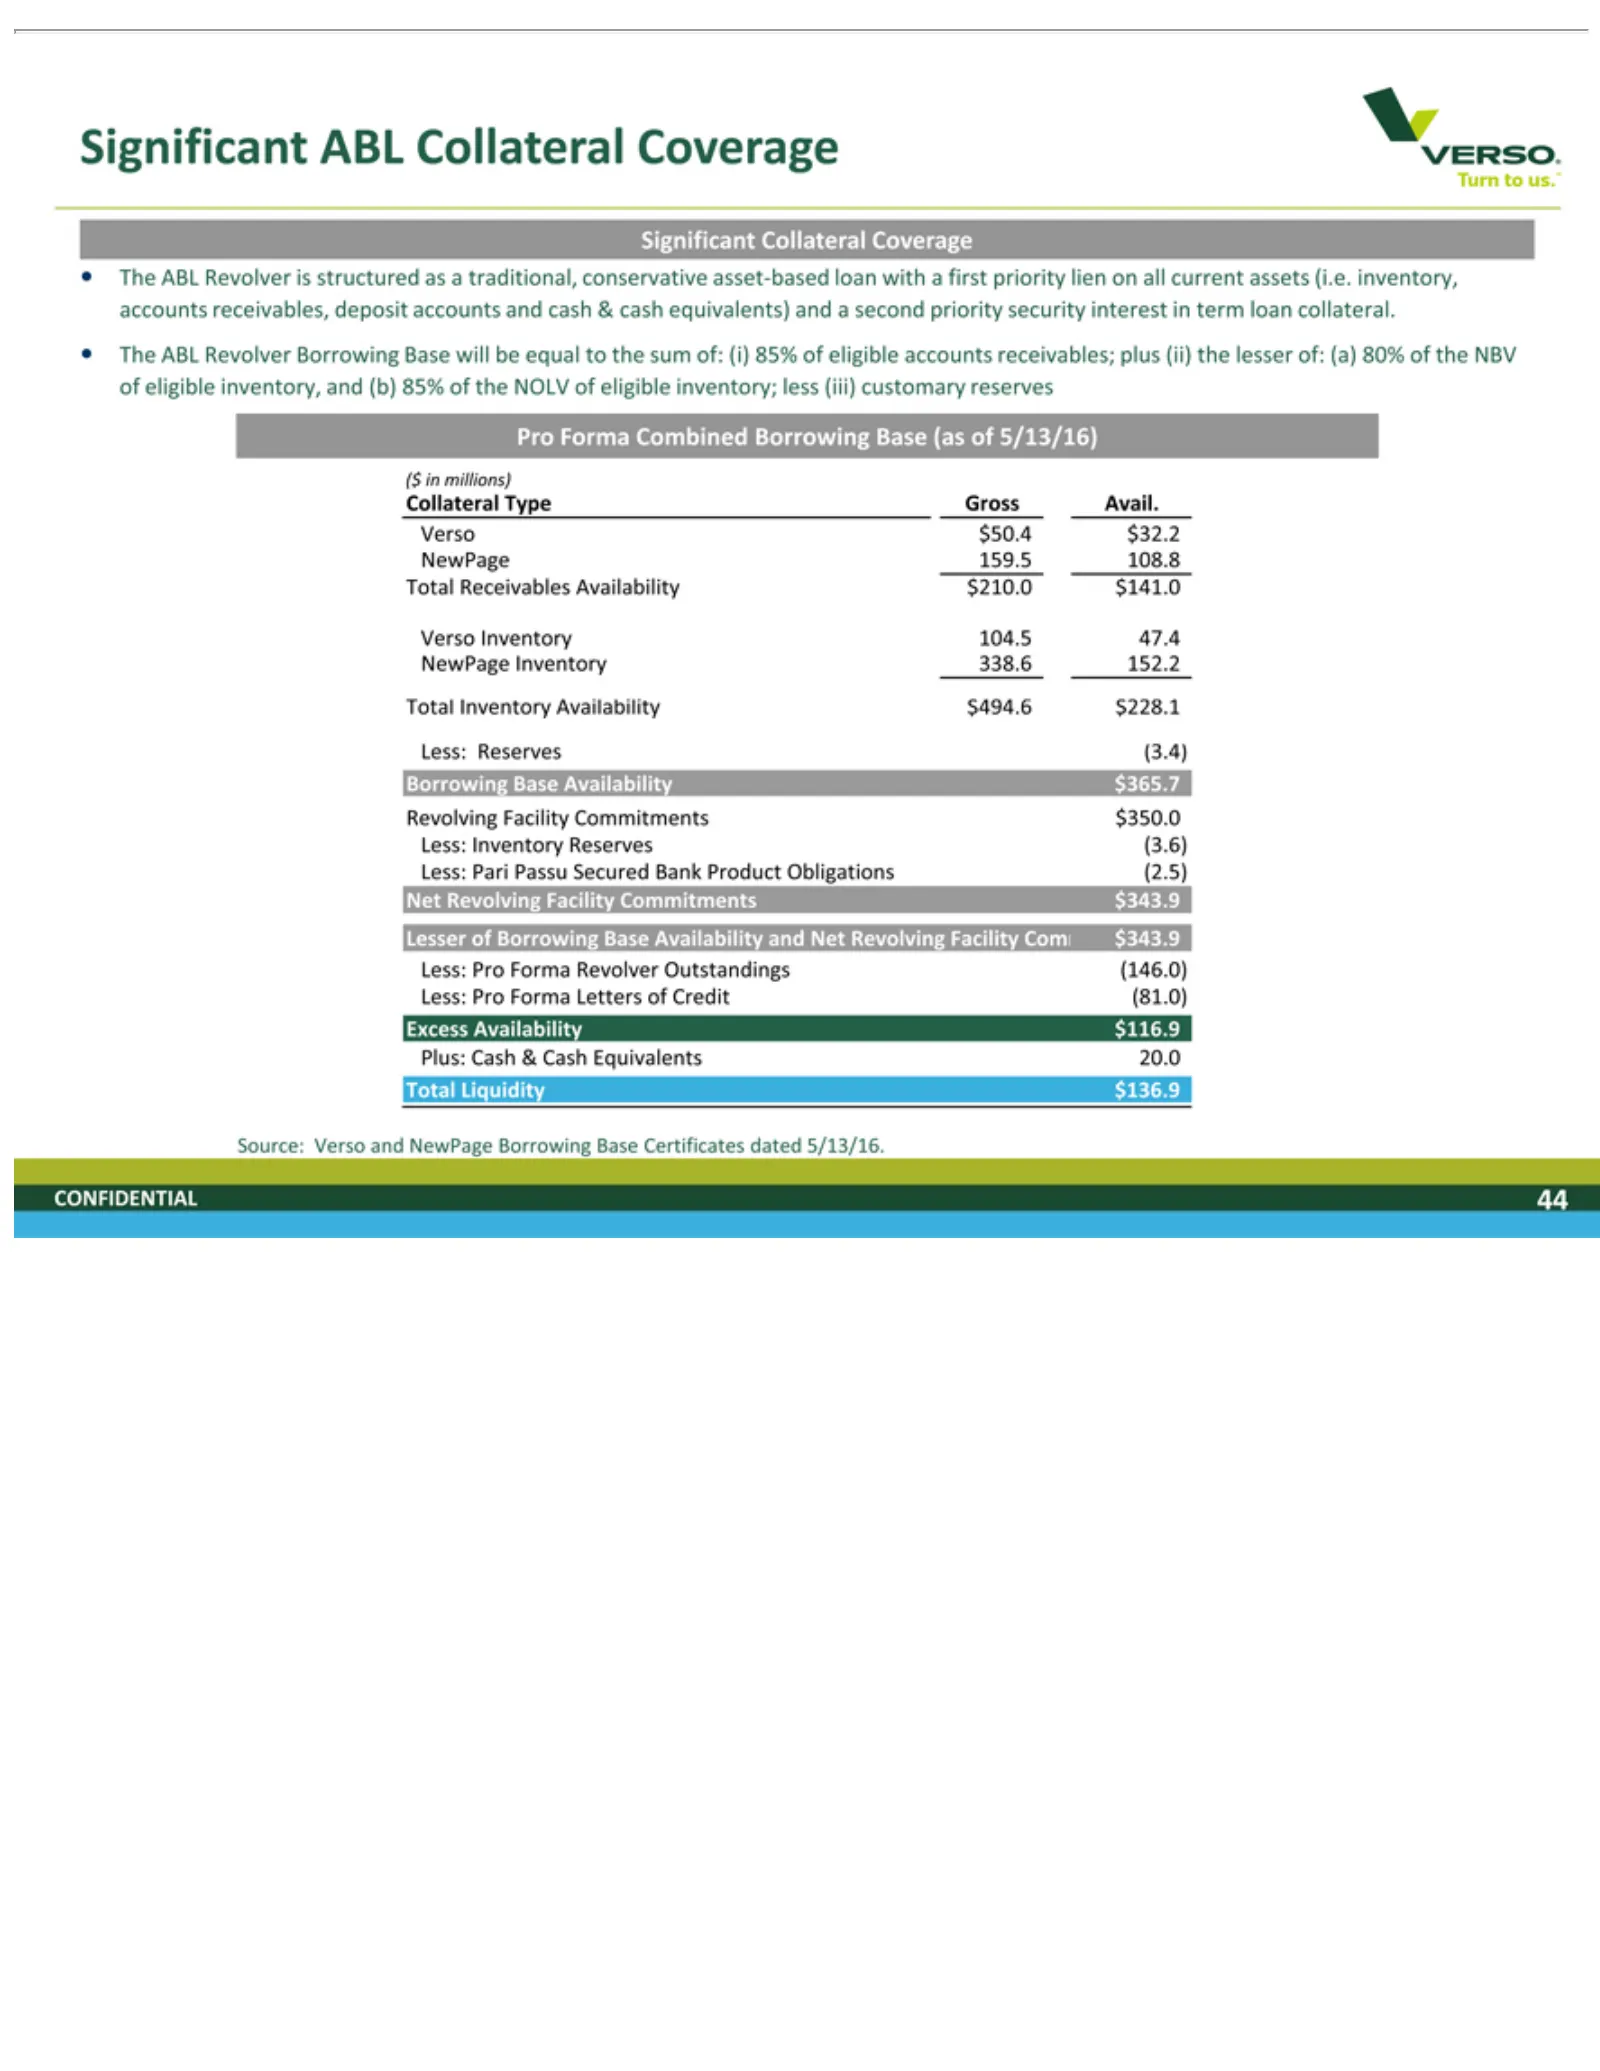
Slide 44: ABL Borrowing Base and Liquidity
VERSO Significant second The less Pro ($ Collateral Verso NewPage Borrowing Revolving Net Lesser Less: Excess Plus: Total Source: CONFIDENTIAL inForma Revolving ABL (iii) millions) Cash Receivables Inventory Liquidity Reserves Pari Pro $50.4 Inventory of Availability priority Verso customary Turn Bo
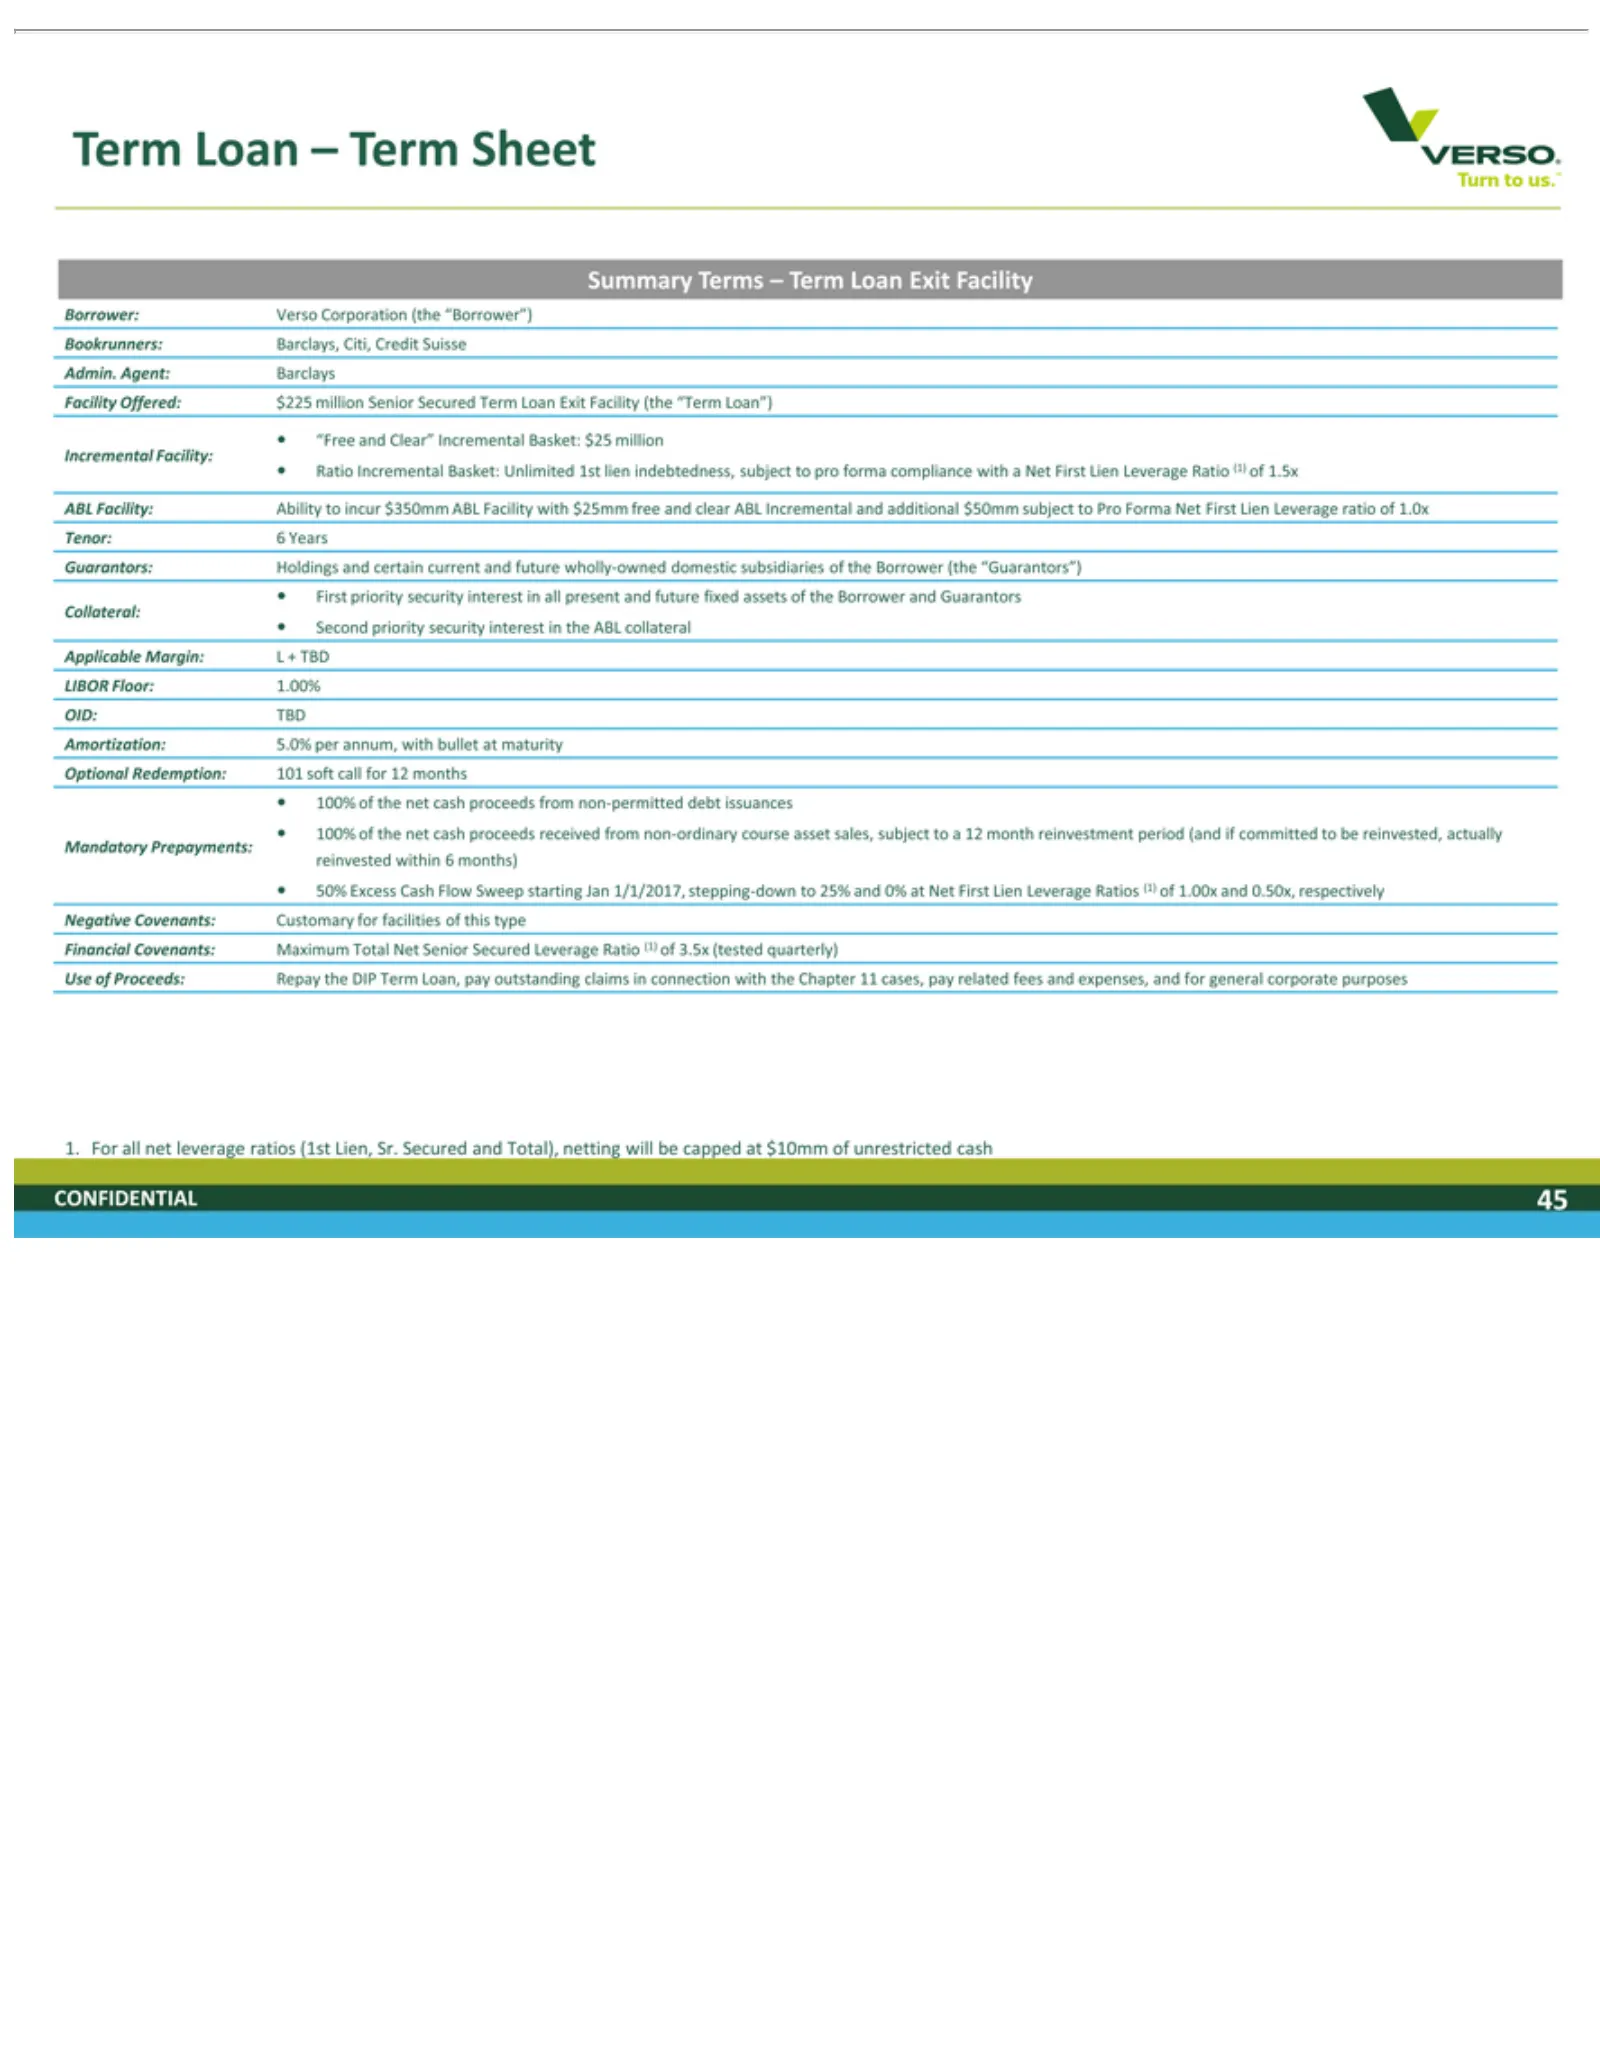
Slide 45: Term Loan Summary
Term VERSO Summary Borrower: Bookrunners: Admin. Facility “Free Incremental Ratio ABL Tenor: Guarantors: First Second Collateral: Applicable LIBOR OID: Amortization: Optional 100% Mandatory 50% Negative Financial Use 1. CONFIDENTIAL For of Excess priority Facility: TBD Loan Incremental and of all 6P
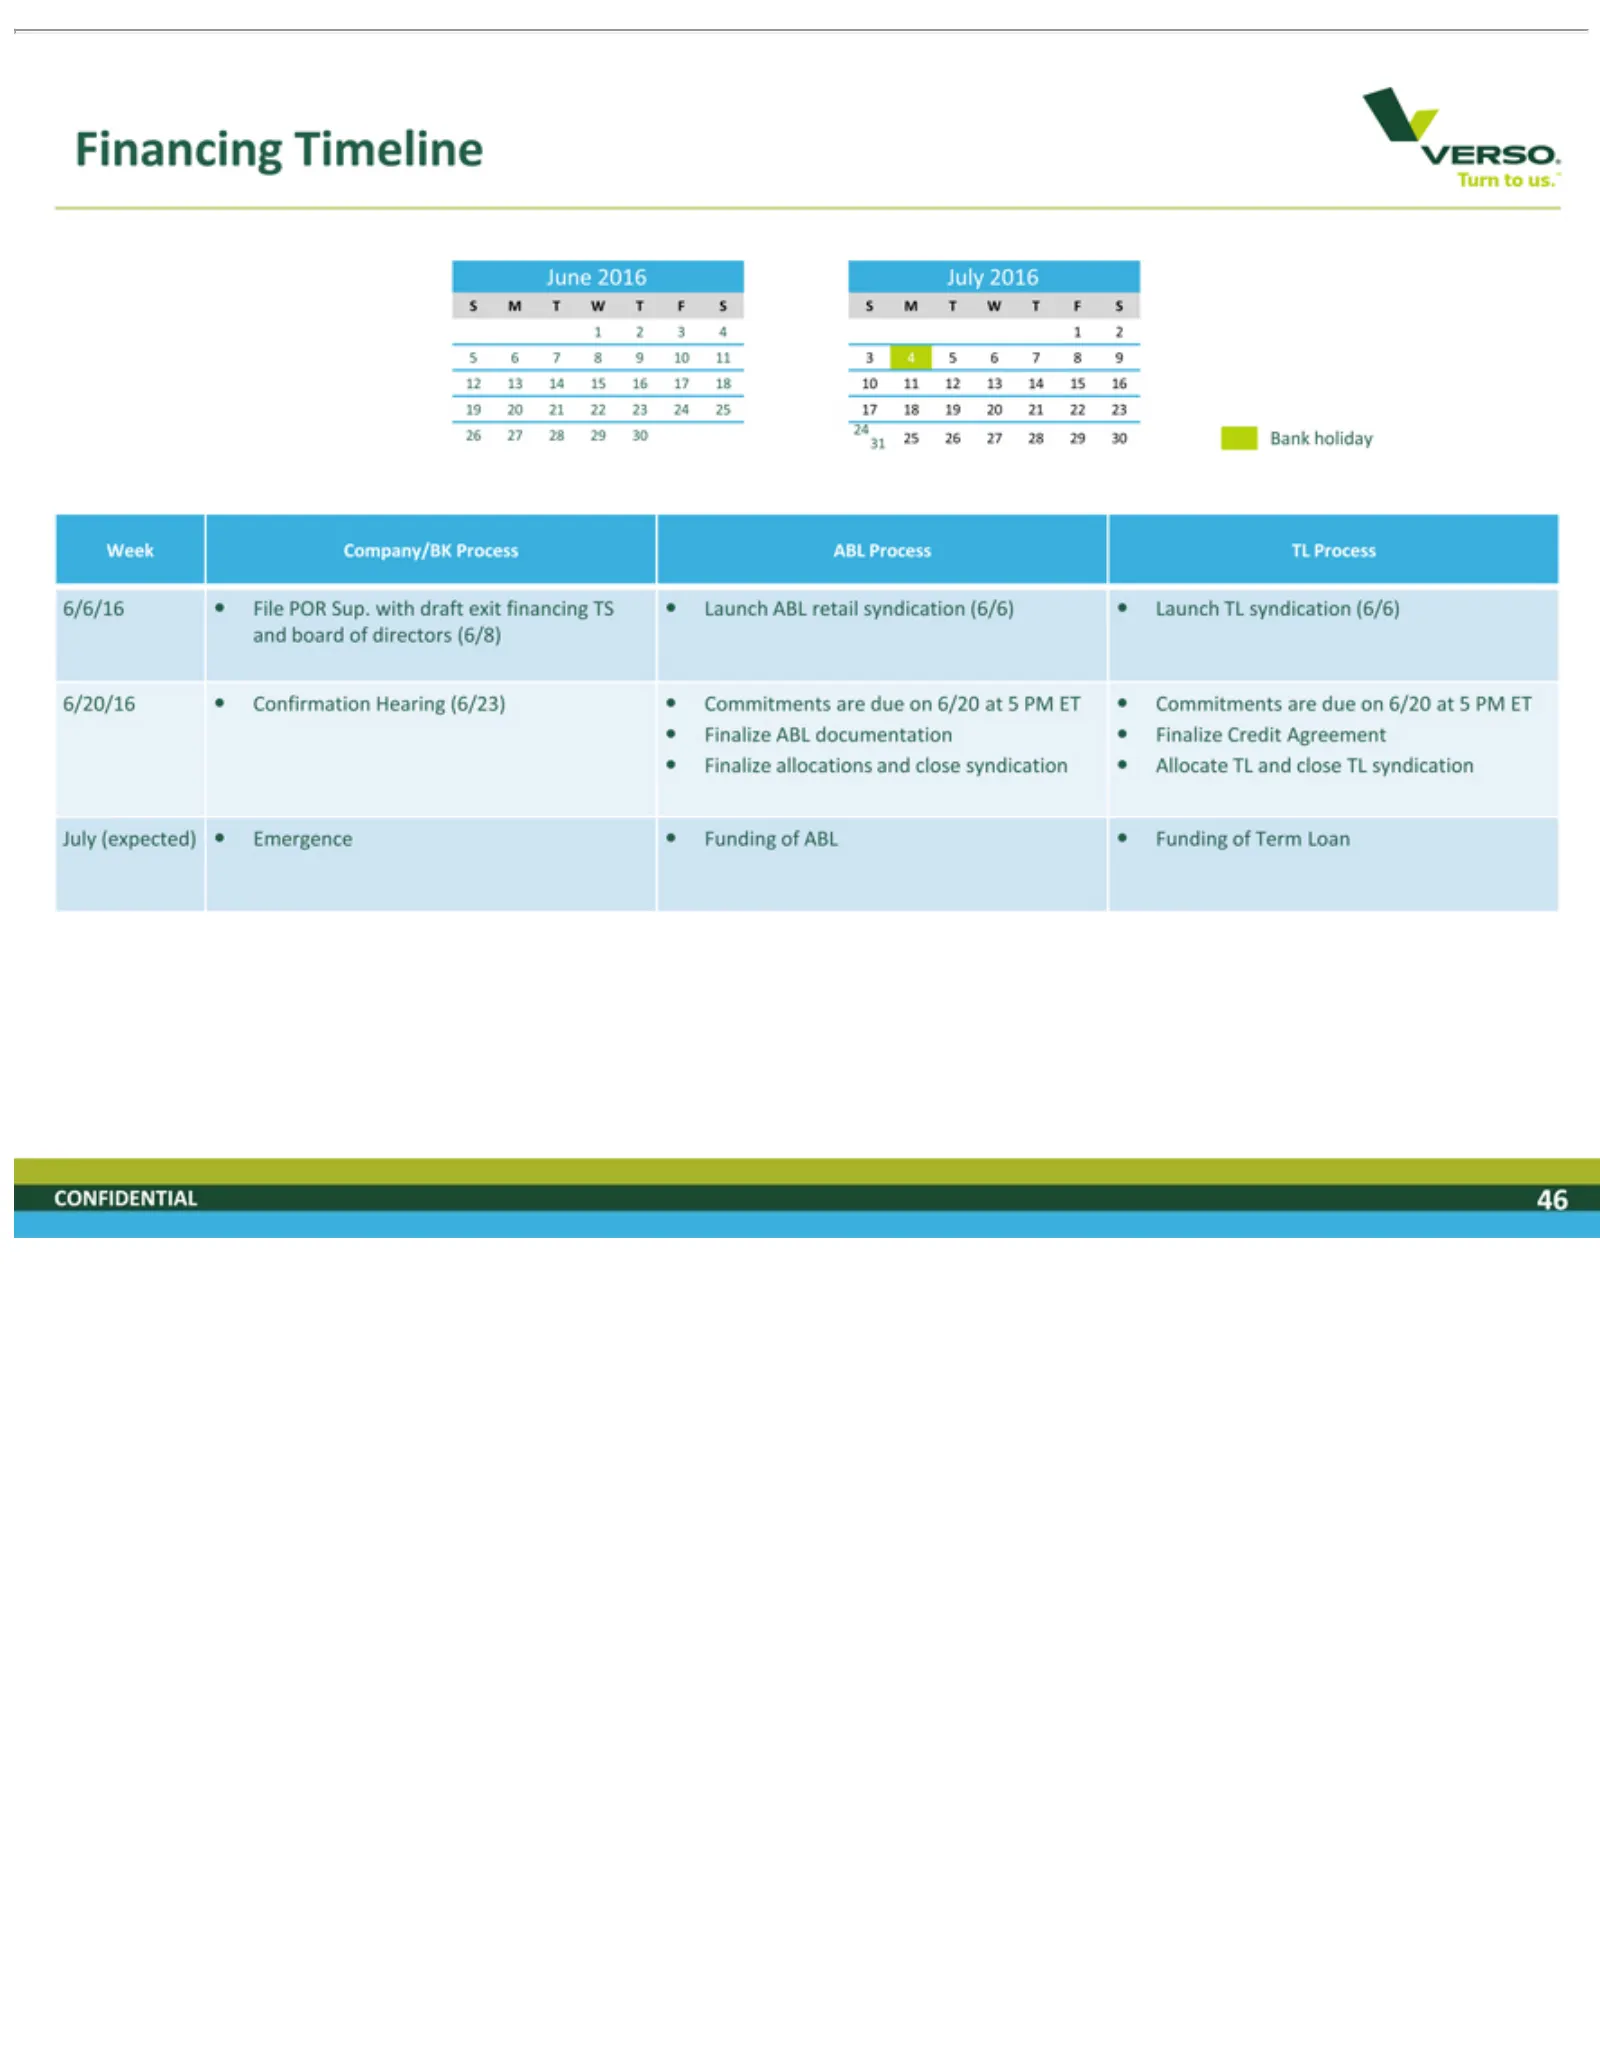
Slide 46: Financing Timeline
Financing VERSO June 51S 12 19 26 Week 6/6/16 6/20/16 Finalize July CONFIDENTIAL 62M27 13 20 3(expected) 7T2016 428 814 21 Company/BK W File 1Confirmation 9ABL allocations Turn 2TTimeline 10 15 22 29July POR F30 11Sdocumentation 16 23 to325 17 24 2016 S Emergence us. Sup. 4M 18 25 26 46 5and T Proce
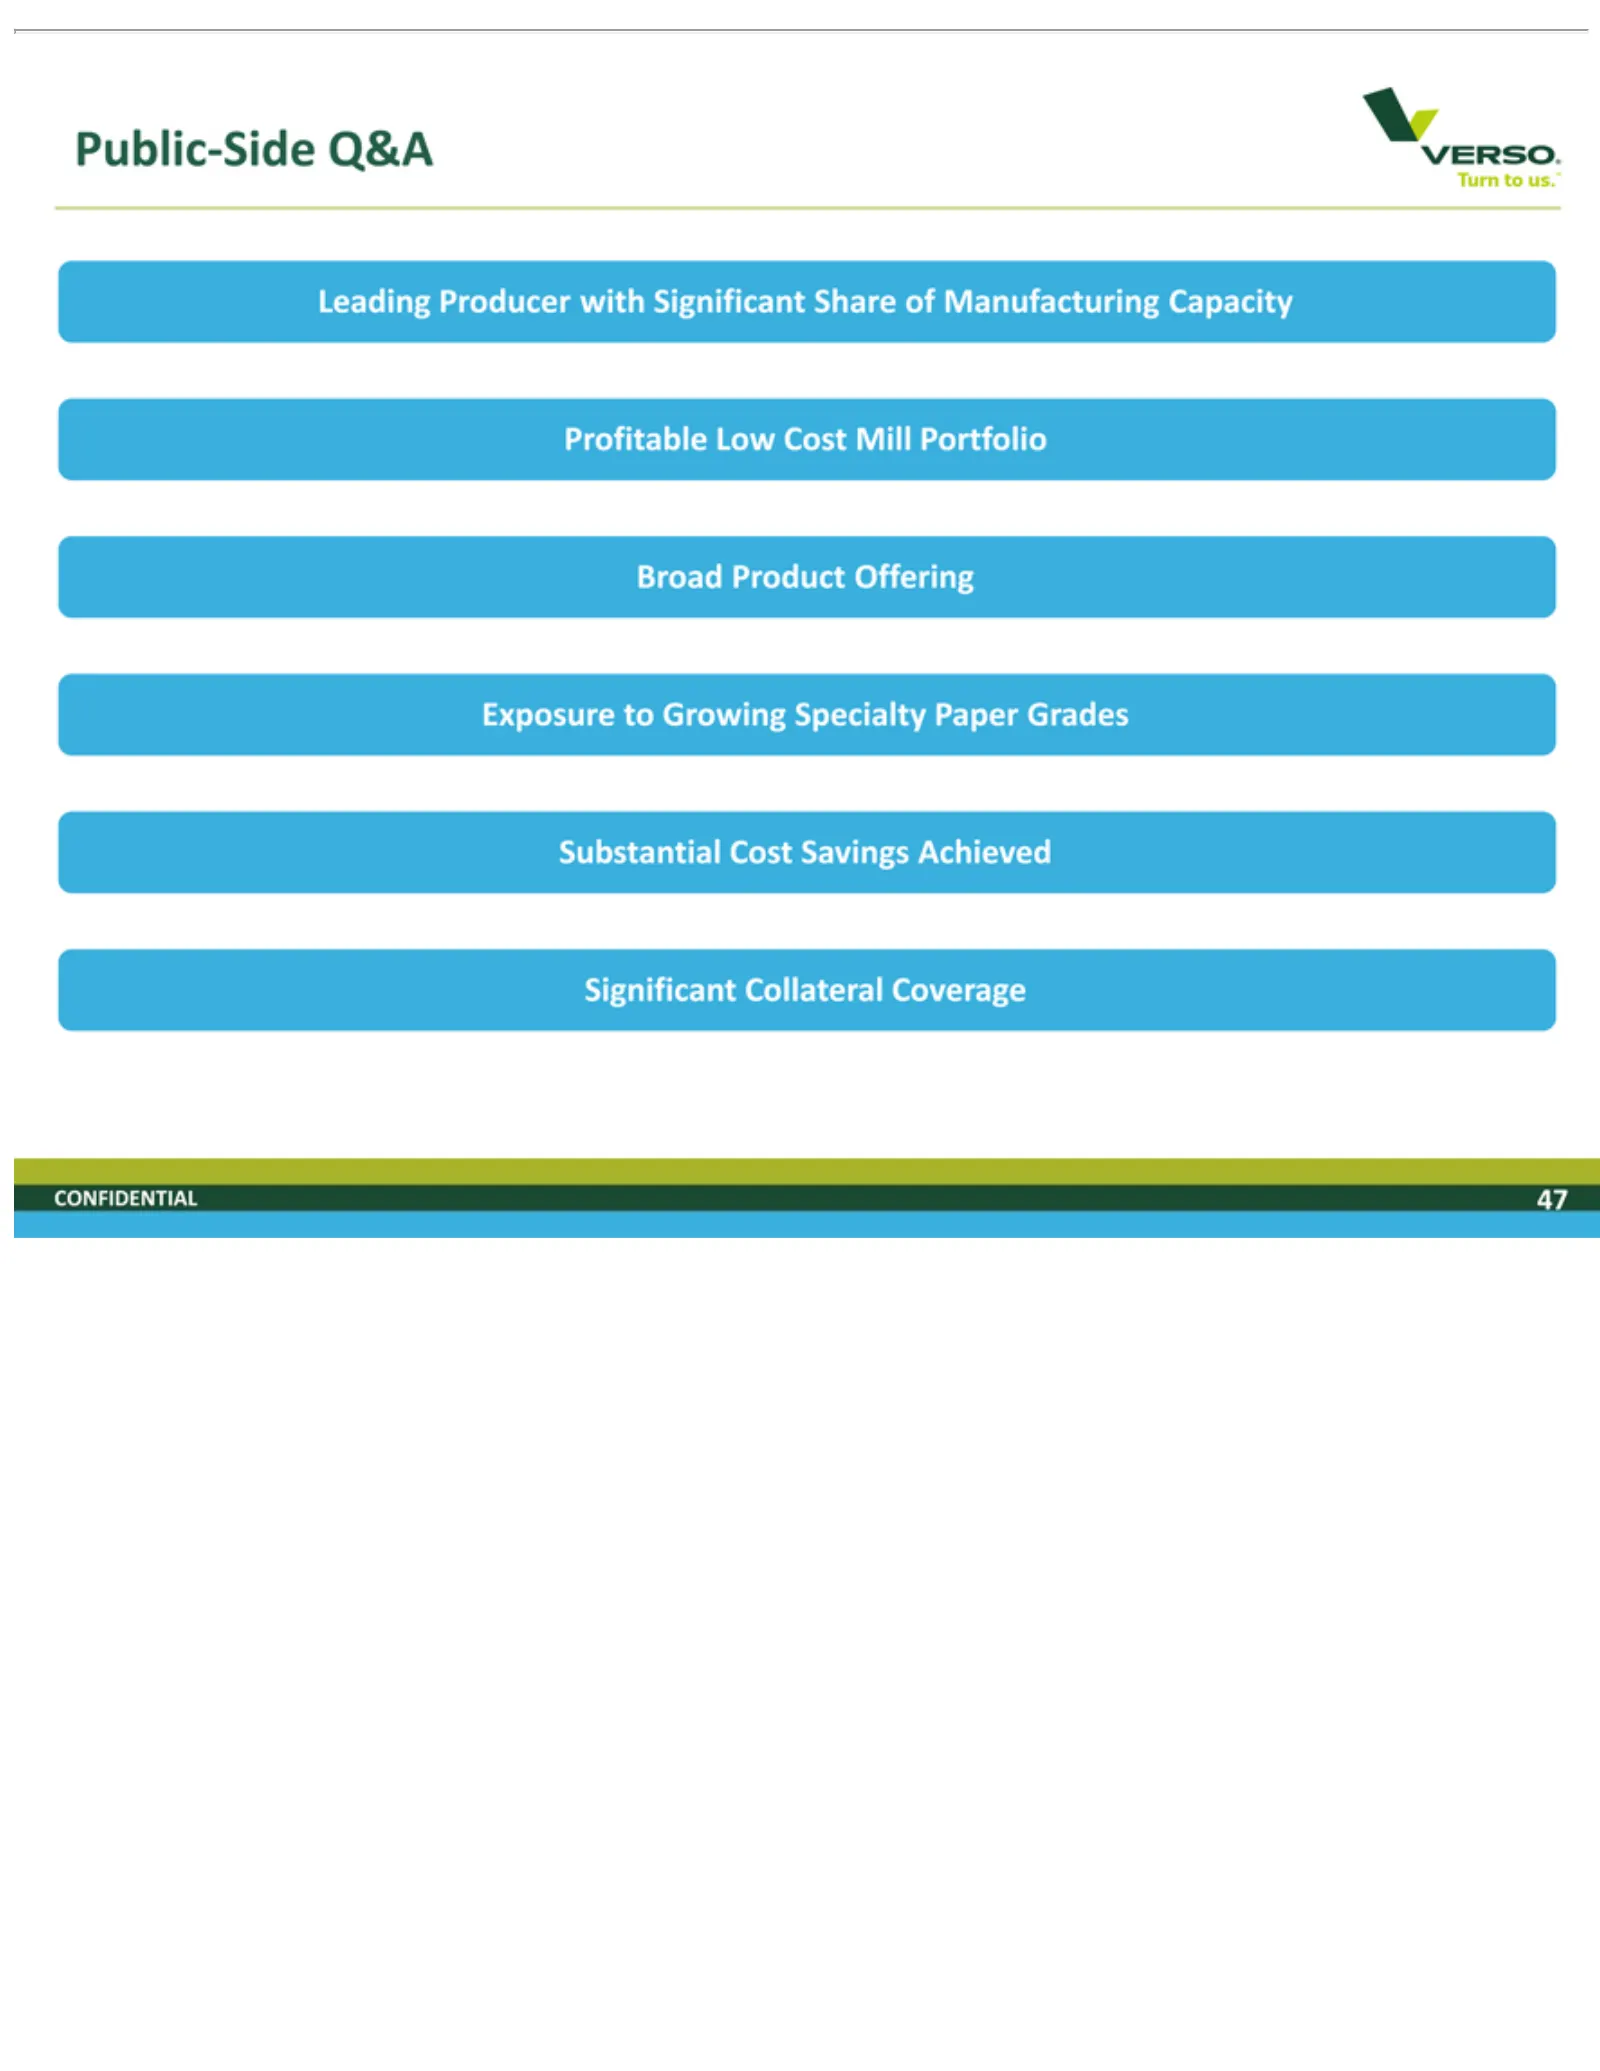
Slide 47: Public-Side Q&A: Key Credit Highlights
Public-Side VERSO Leading Profitable Broad Exposure Substantial Significant CONFIDENTIAL Product Turn Producer to Low Collateral Cost Q&A Growing toOffering Cost us. Savings with 47Mill Coverage Specialty Significant Achieved Portfolio Paper Share Grades of Manufacturing Capacity
Slide 48: Appendices
VERSO Turn to us. Appendices CONFIDENTIAL
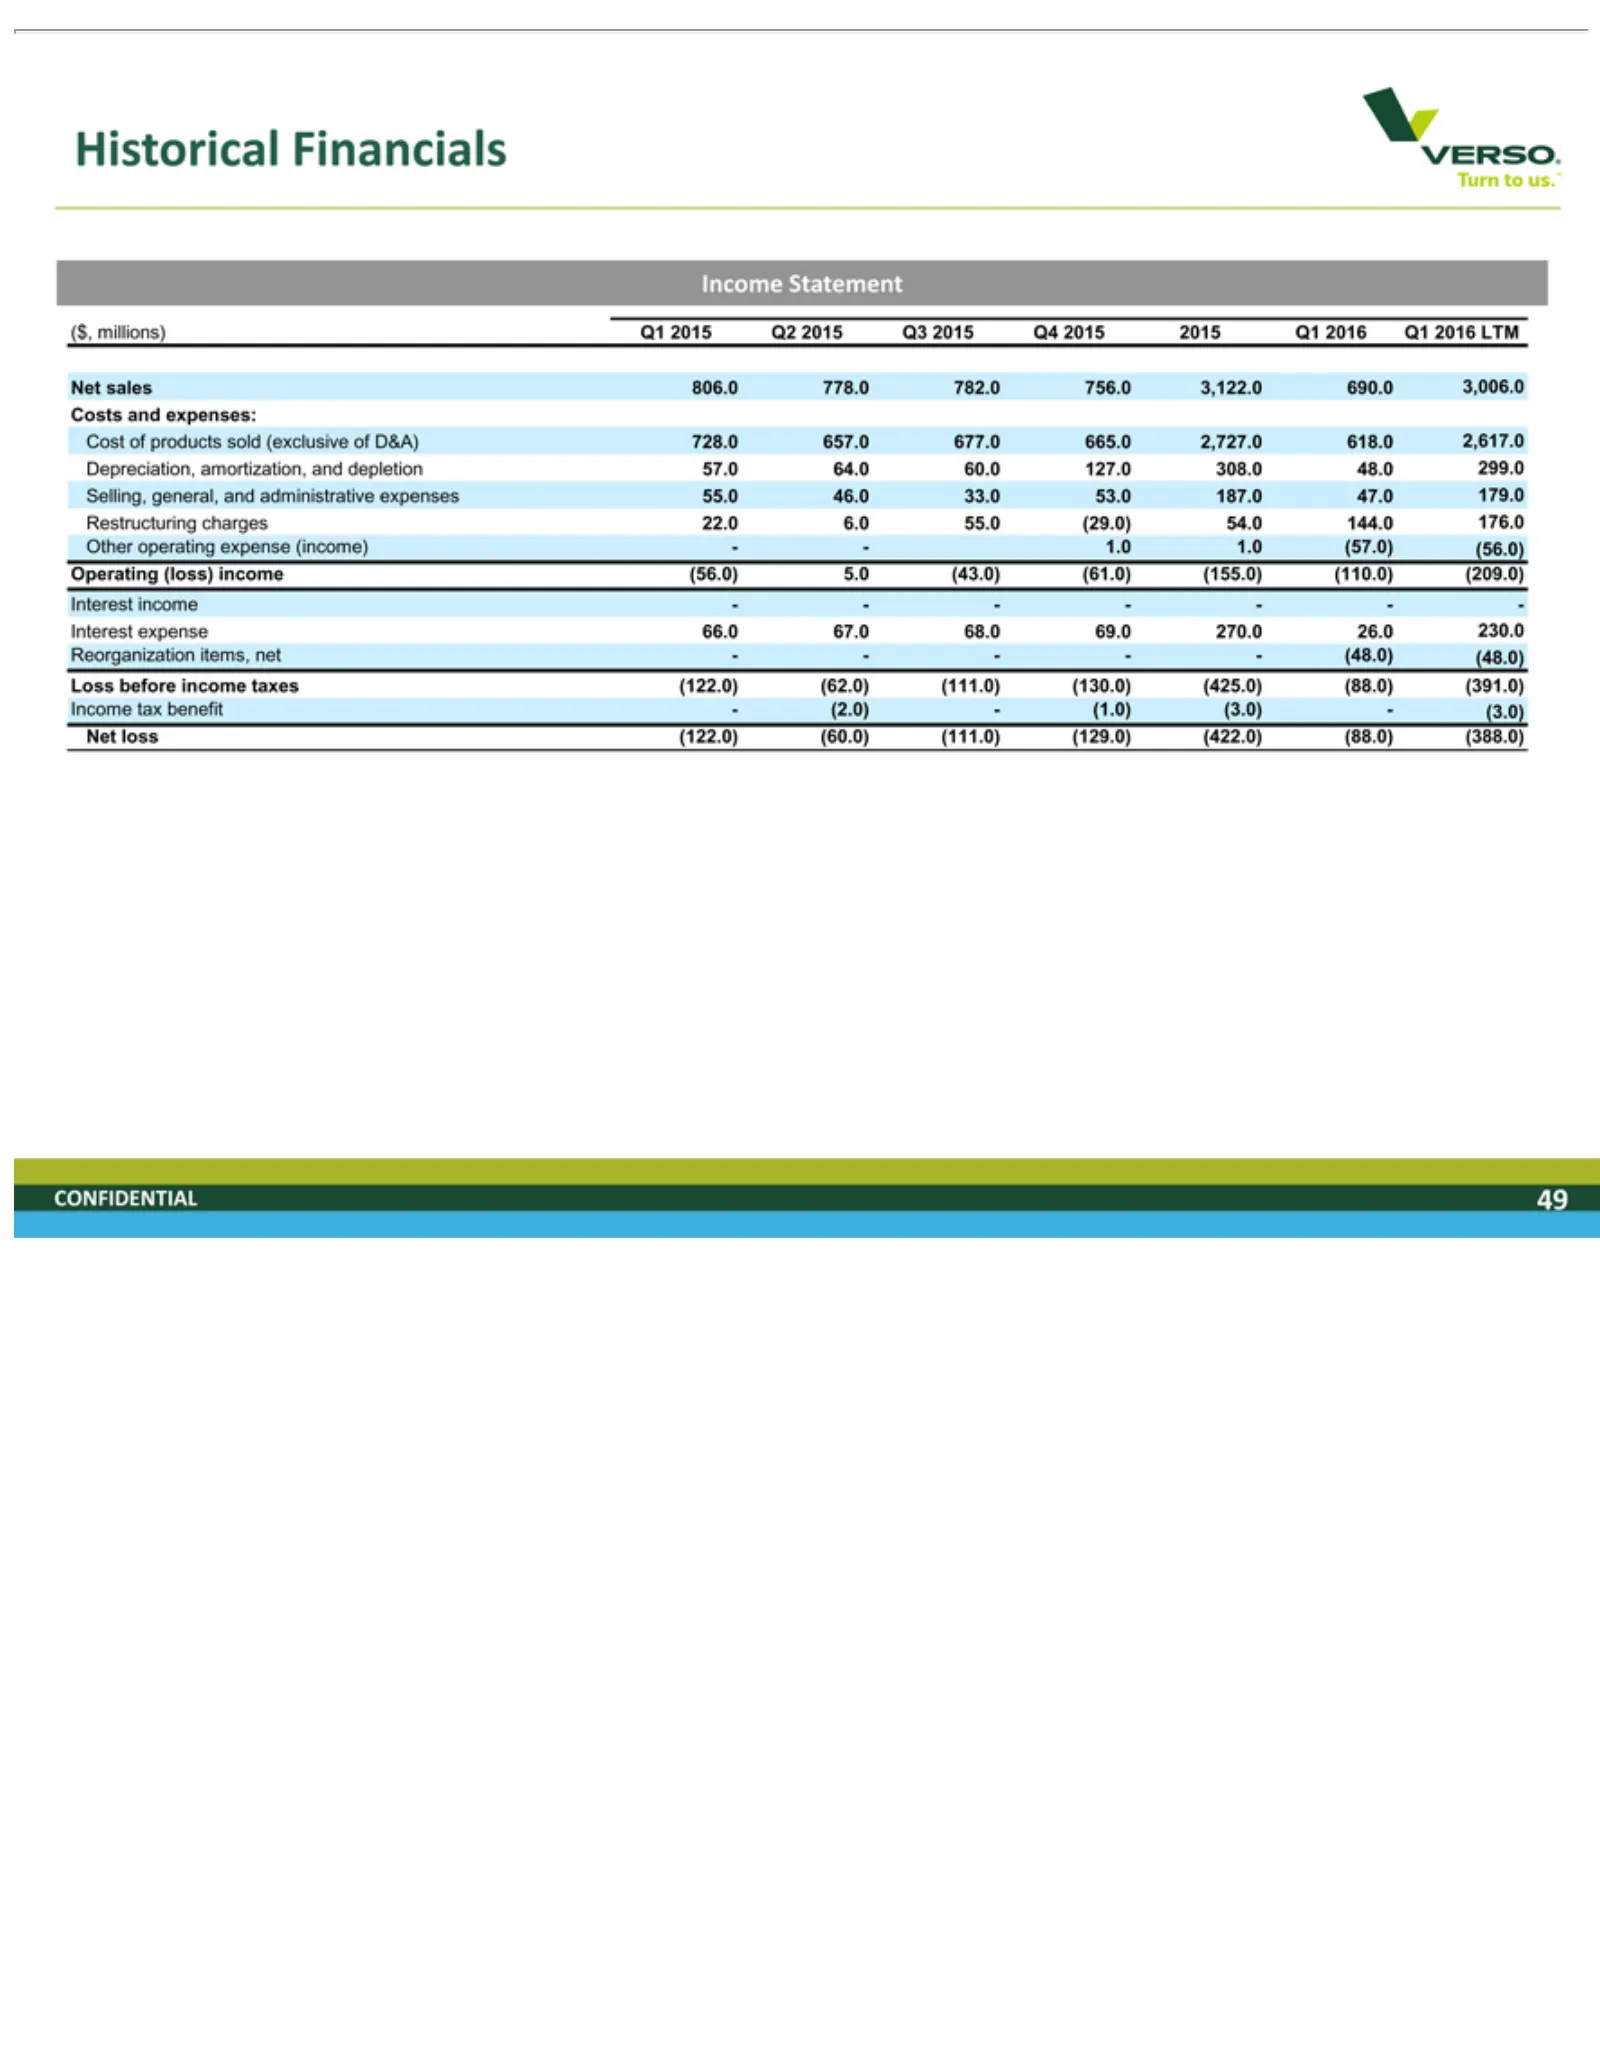
Slide 49: Historical Financials
Historical VERSO ($, Costs Cost Depreciation, Selling, Restructuring Other Operating Interest Reorganization Loss Income Net CONFIDENTIAL millions) sales loss of before and operating products Statement income expense tax general, (122.0) Turn 806.0 expenses: Financials (loss) benefit—(2.0)—(1.0) inc
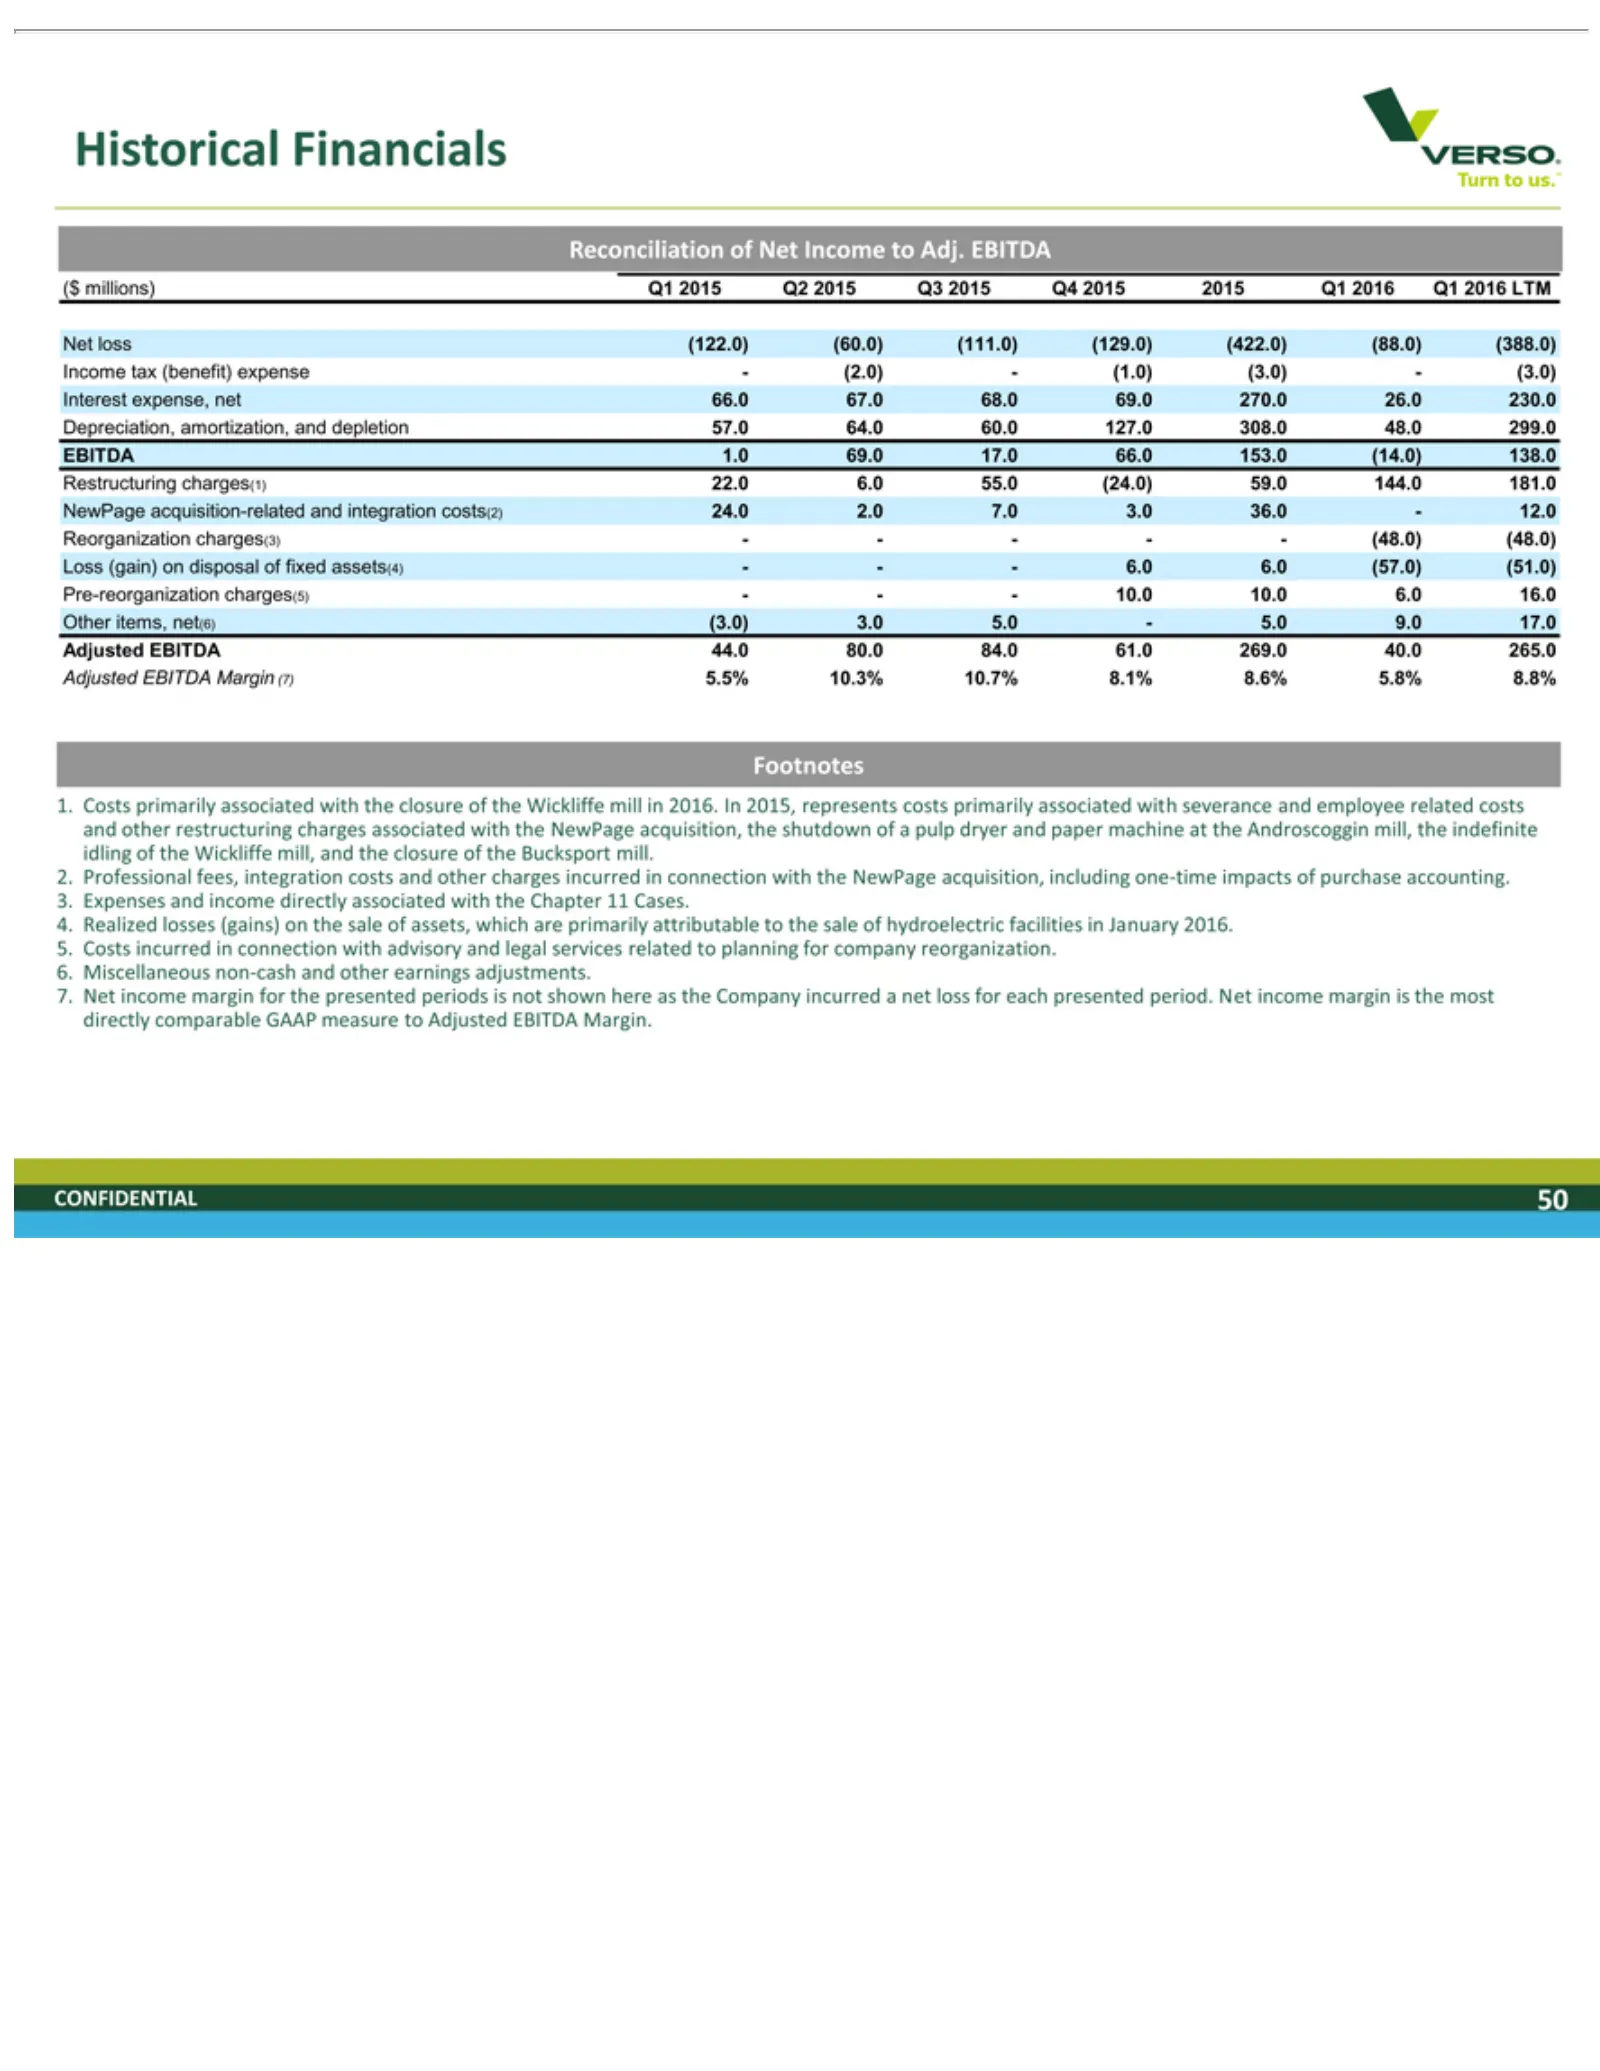
Slide 50: Historical Adjusted EBITDA Reconciliation
Historical VERSO Reconciliation ($ Net Income Interest Depreciation, EBITDA Restructuring Reorganization Loss Pre-reorganization Other Adjusted 1. Footnotes NewPage 2. 3. 4. 5. 6. 7. CONFIDENTIAL Margin. Professional Expenses Realized Costs Miscellaneous Net millions) loss (gain) items, income tax e
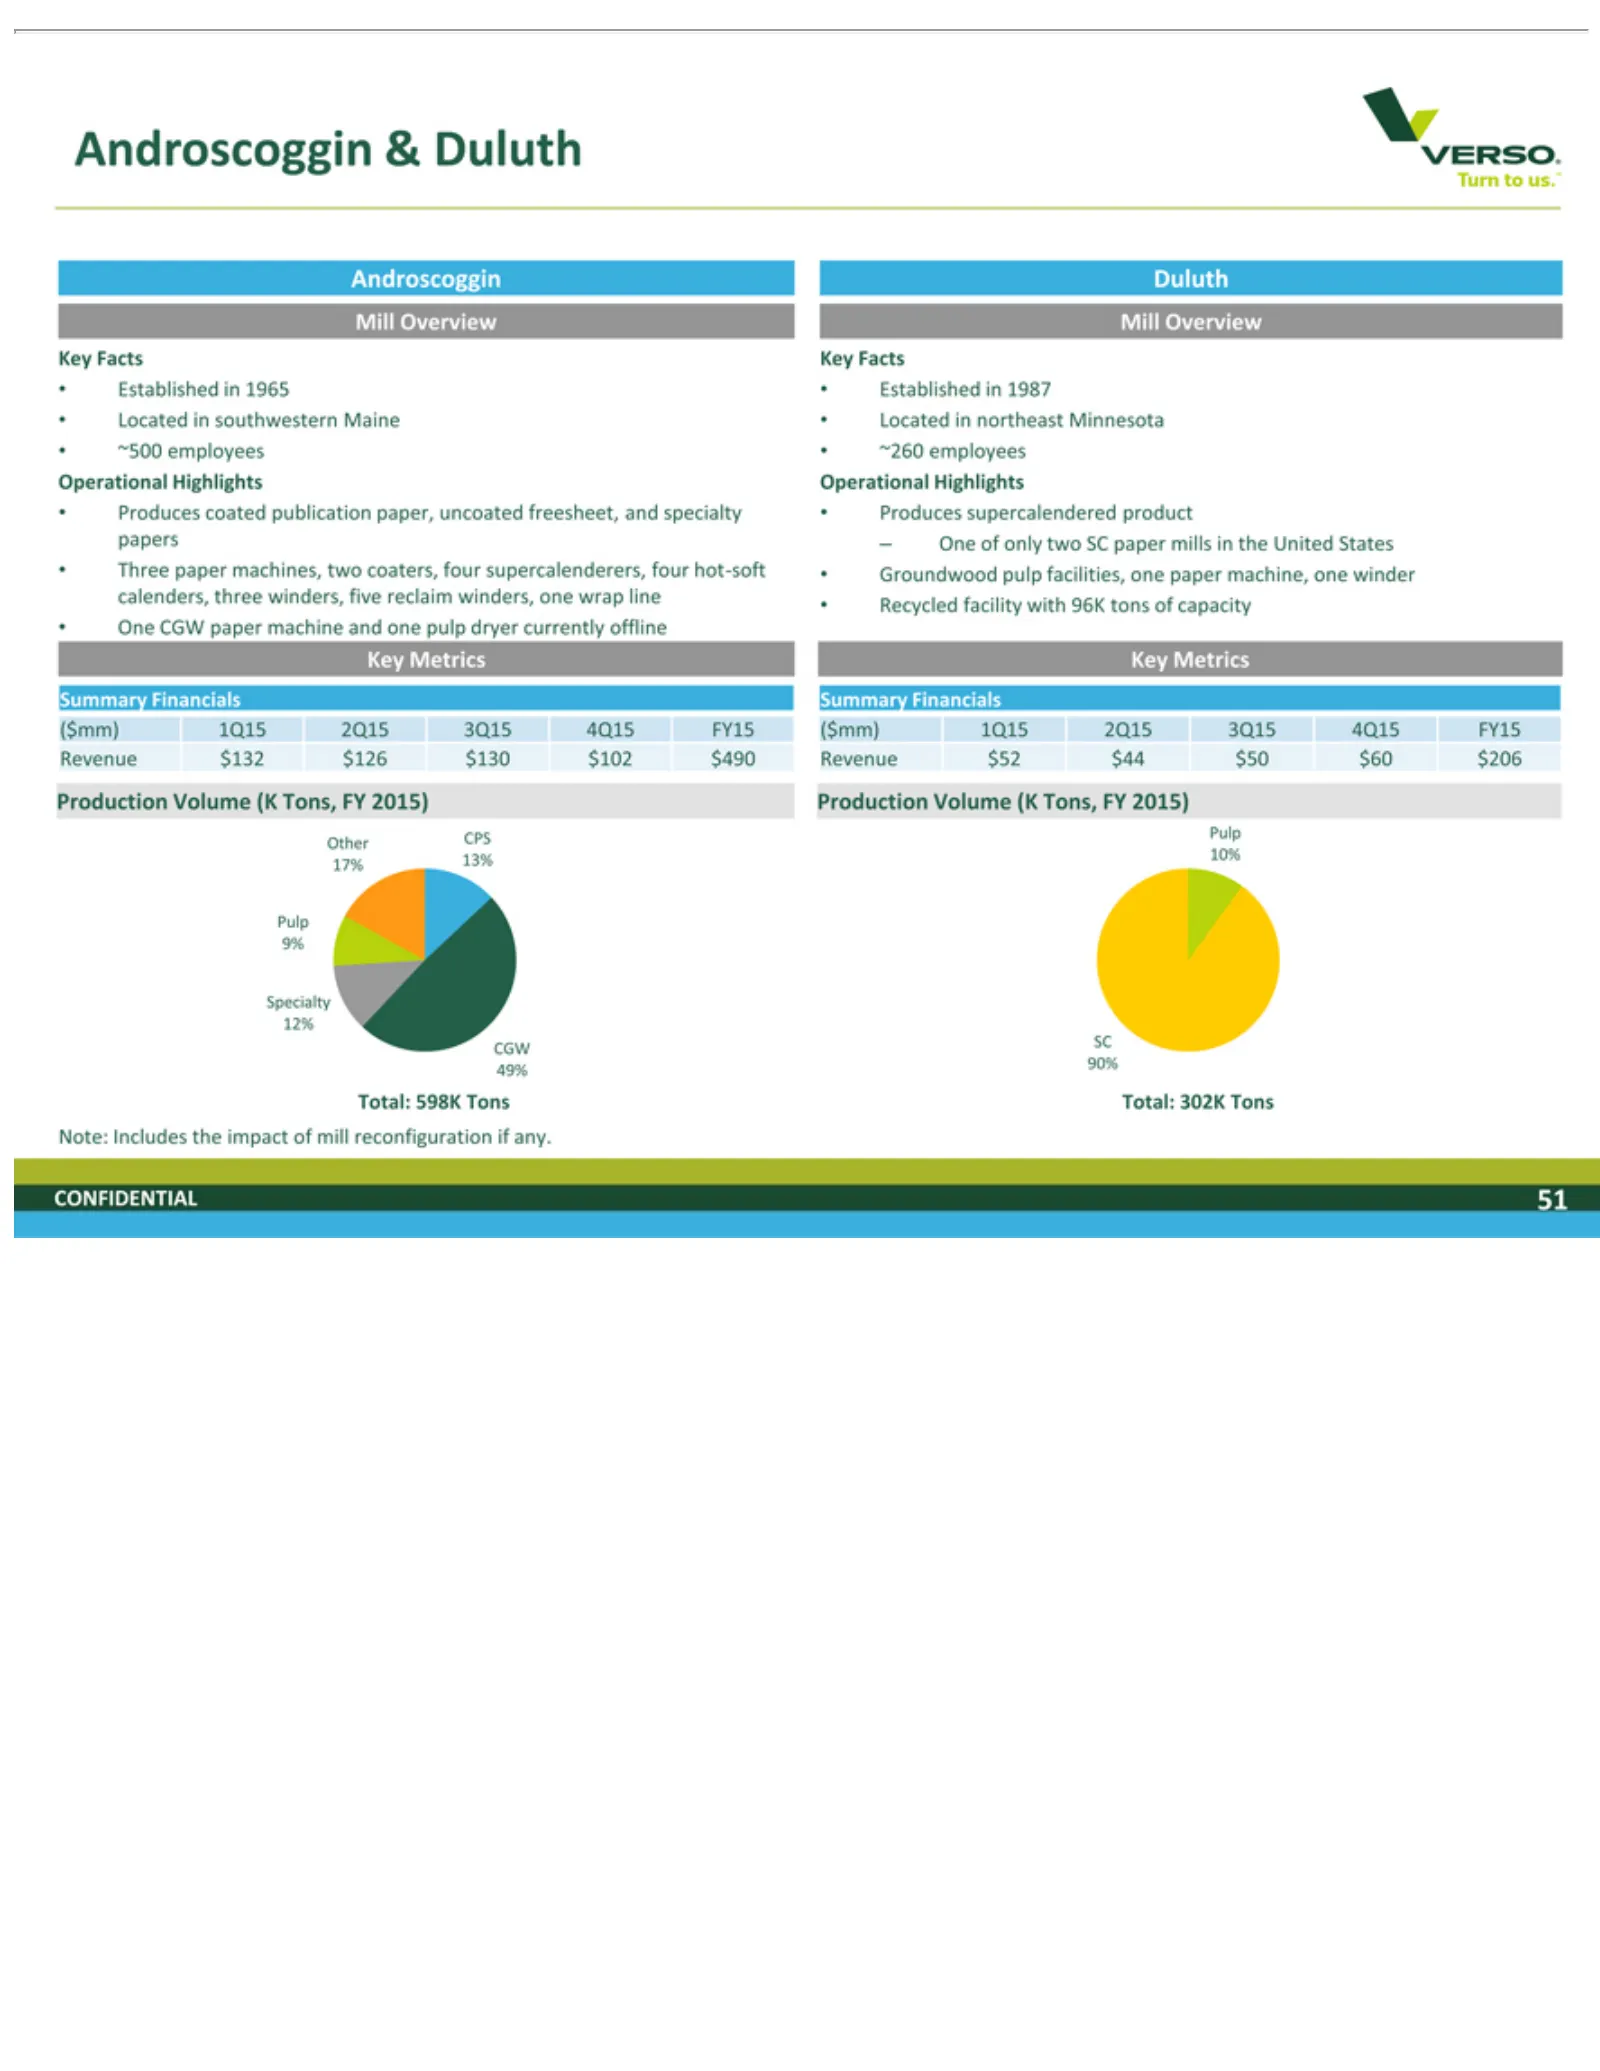
Slide 51: Androscoggin and Duluth Mill Summary
VERSO Androscoggin ~500 Three One Other Specialty CGW Note: Mill Duluth Established Located ~260 Operational –Produces Groundwood Recycled Key Summary ($mm) Production Pulp SC Total: CONFIDENTIAL One 90% CGW Facts Metrics Overview 9% 10% employees Includes CPS 49% 598K 302K paper of 1Q15 in Turn onl
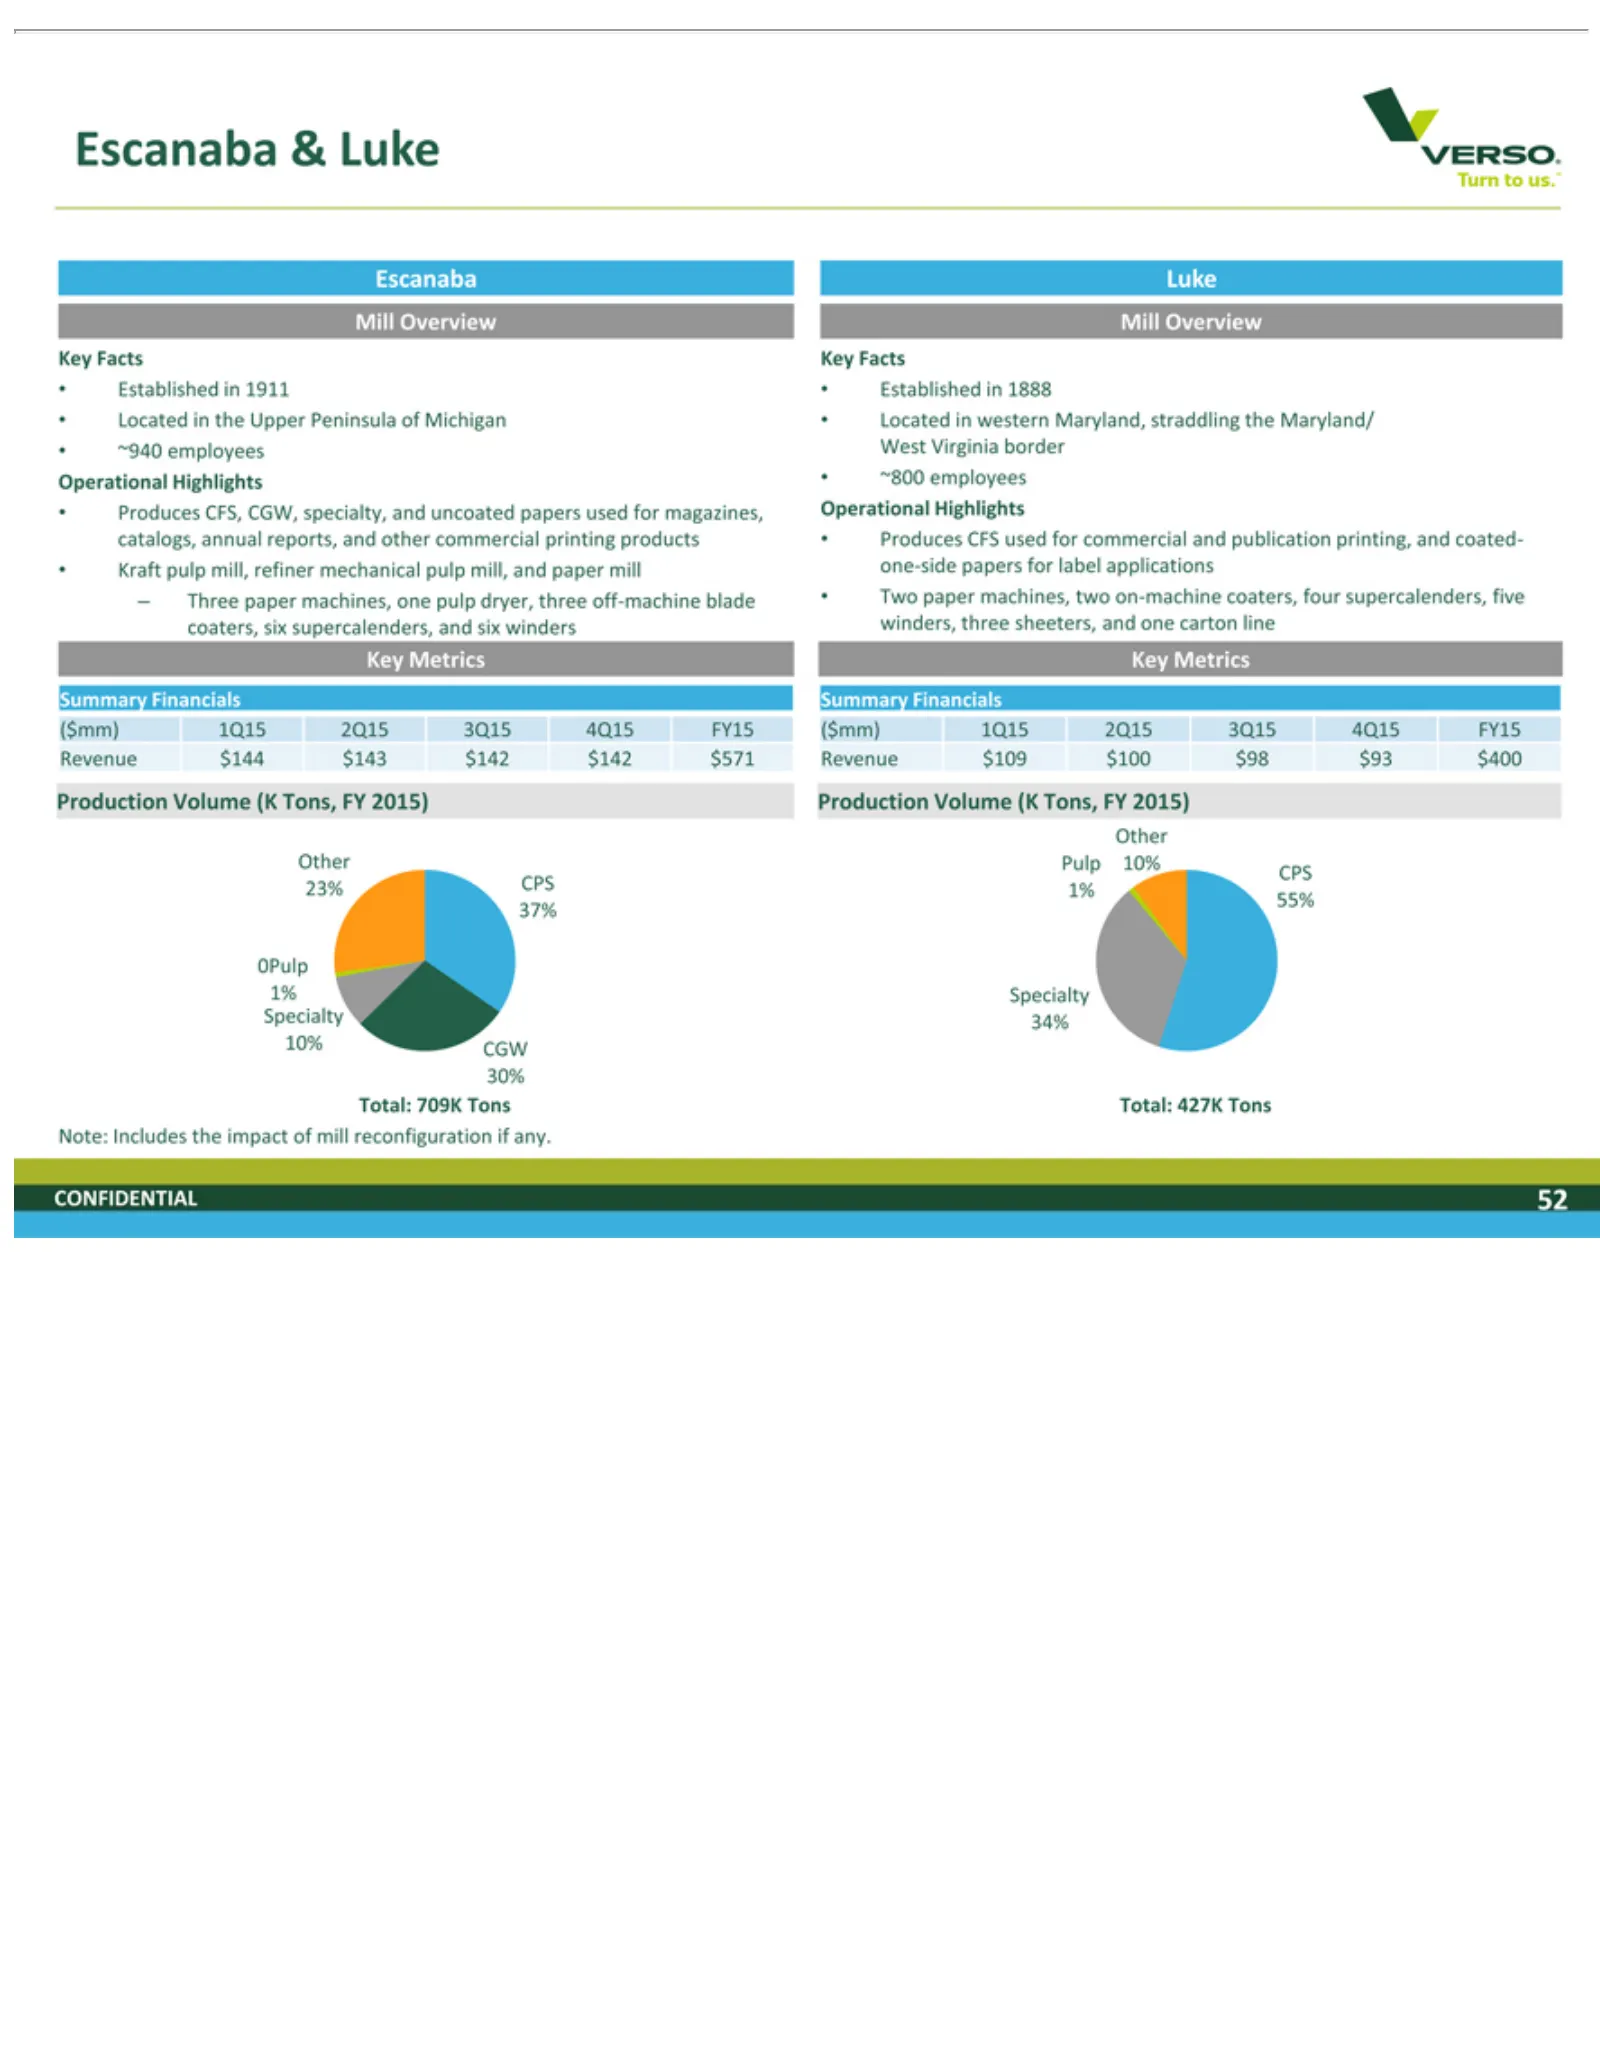
Slide 52: Escanaba Mill Summary
VERSO Escanaba ~940 –Kraft 23% 0Pulp 10% Note: Mill Established Located ~800 Operational Produces Two Key Summary ($mm) Production Other 1% Specialty Total: CONFIDENTIAL Three CPS Facts Metrics Overview paper CPS CGW employees pulp Includes Pulp 709K 427K 1% 1Q15 paper in Turn 55% CFS, CFS 34% & 37%
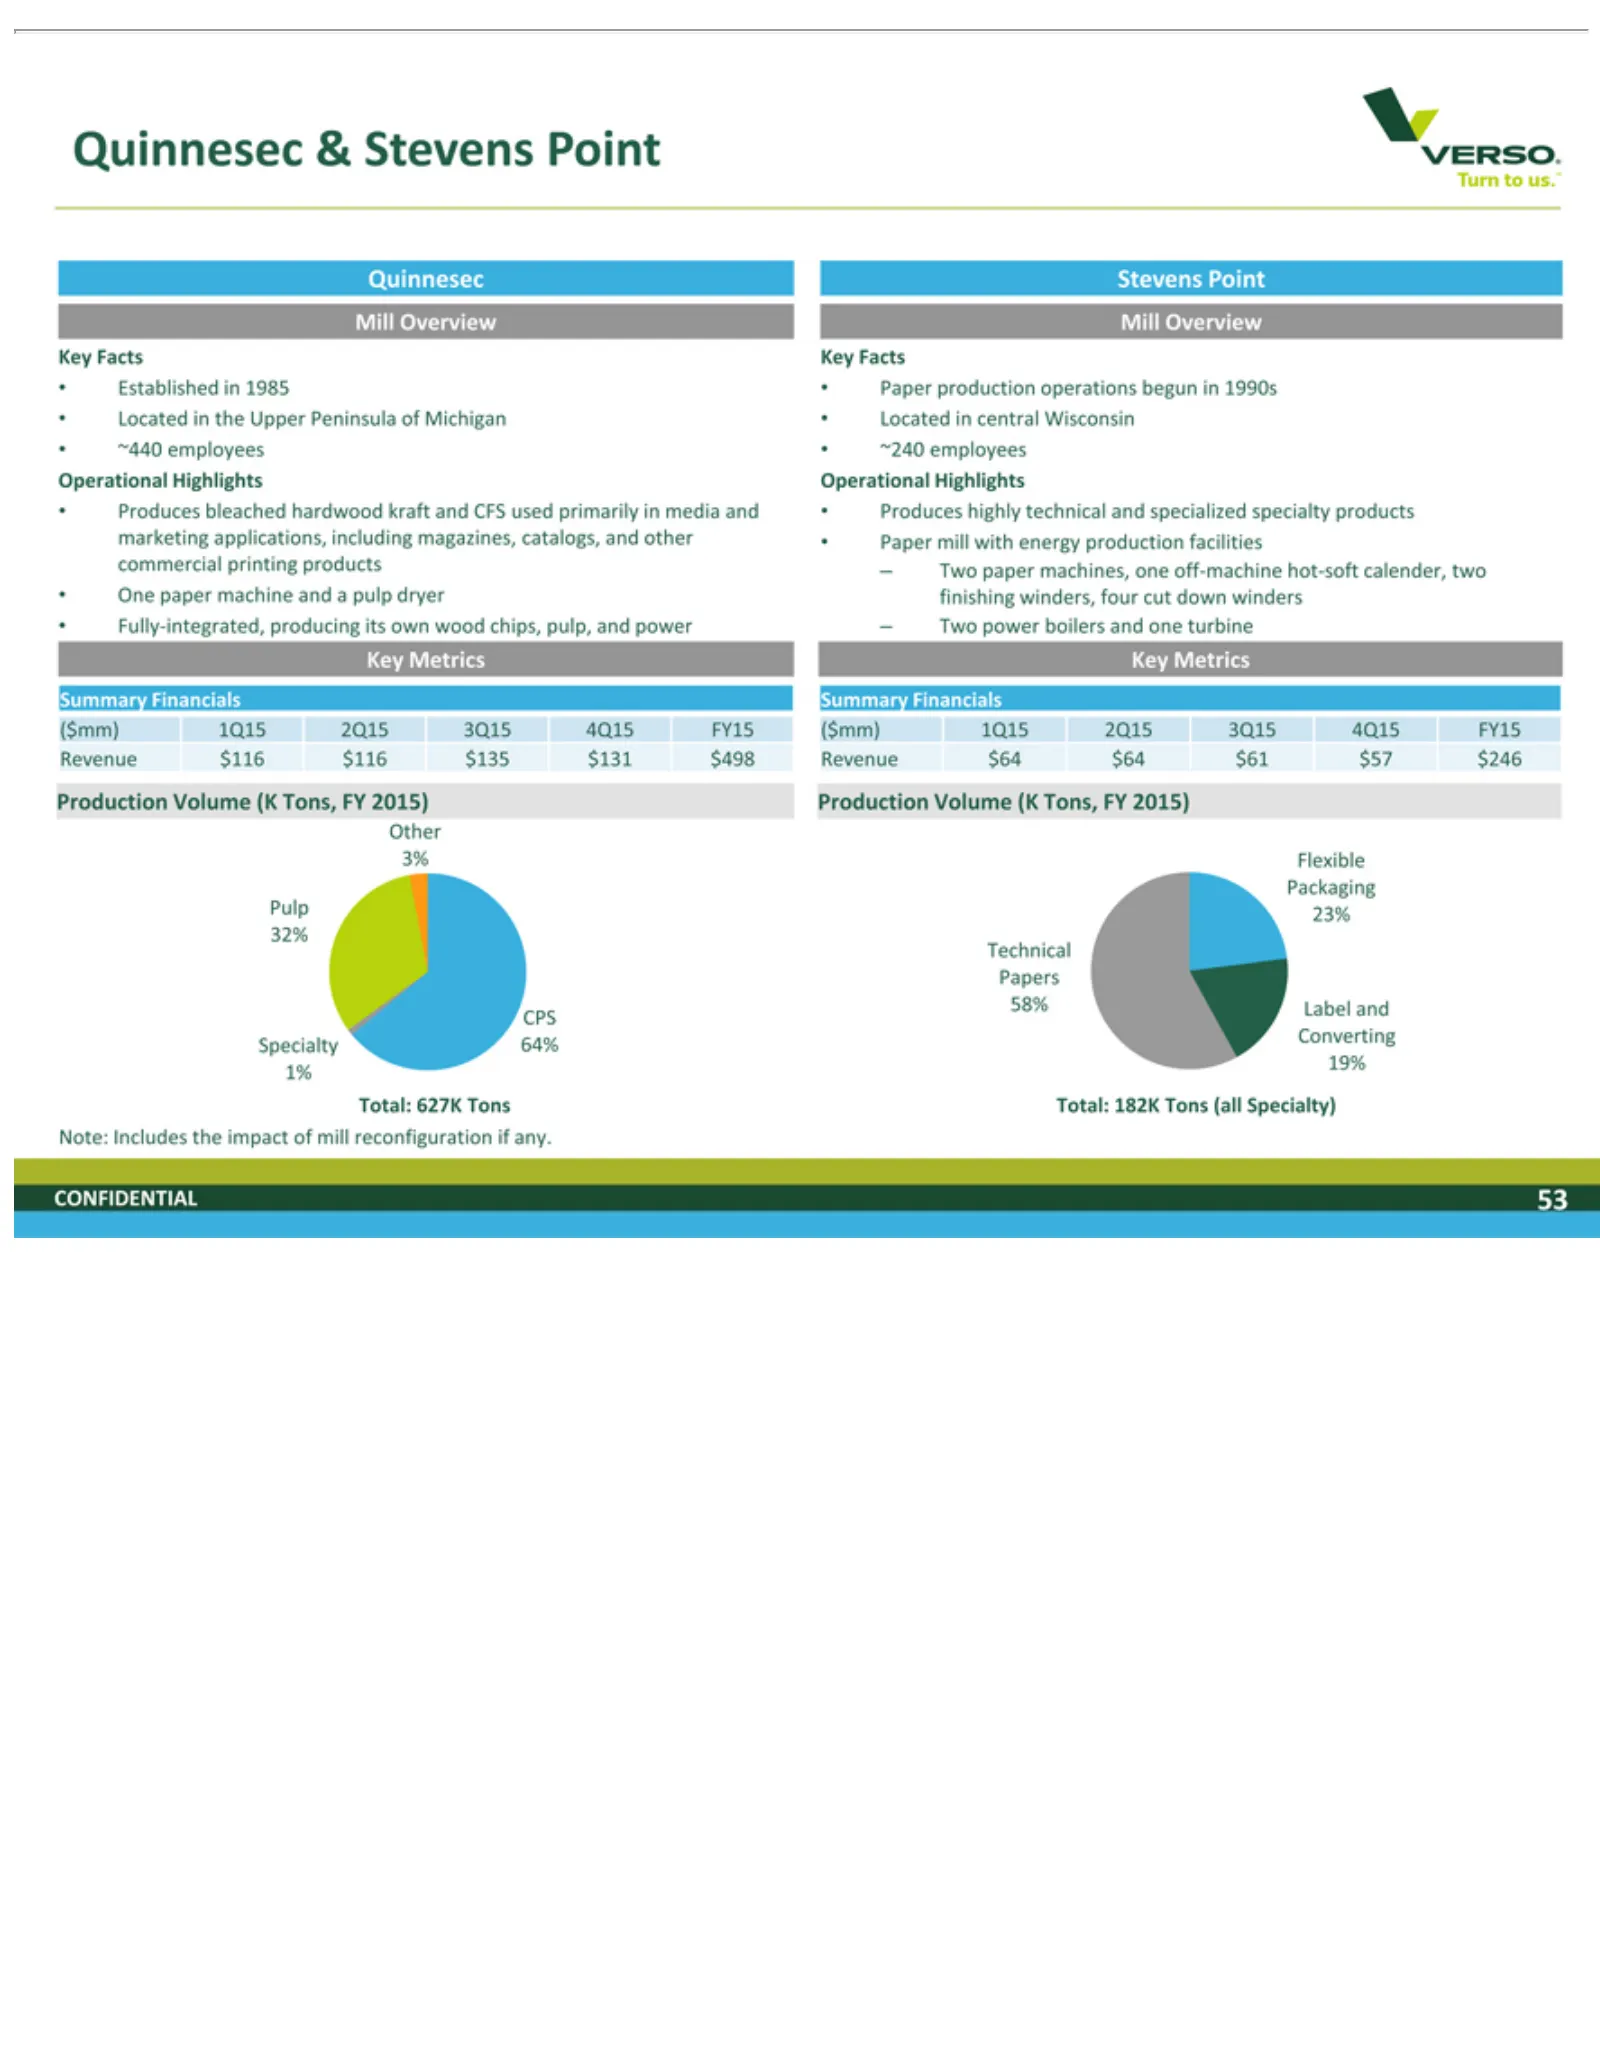
Slide 53: Quinnesec and Stevens Point Mill Summary
VERSO Quinnesec Established ~440 One Fully-integrated, Other Pulp CPS Note: Stevens Mill Located ~240 Operational Produces –Paper Key Summary ($mm) Production Flexible Total: CONFIDENTIAL Twopaper Facts Metrics Overview Specialty 32% employees Includes 3% production mill 627K 182K paper power 1Q15 P
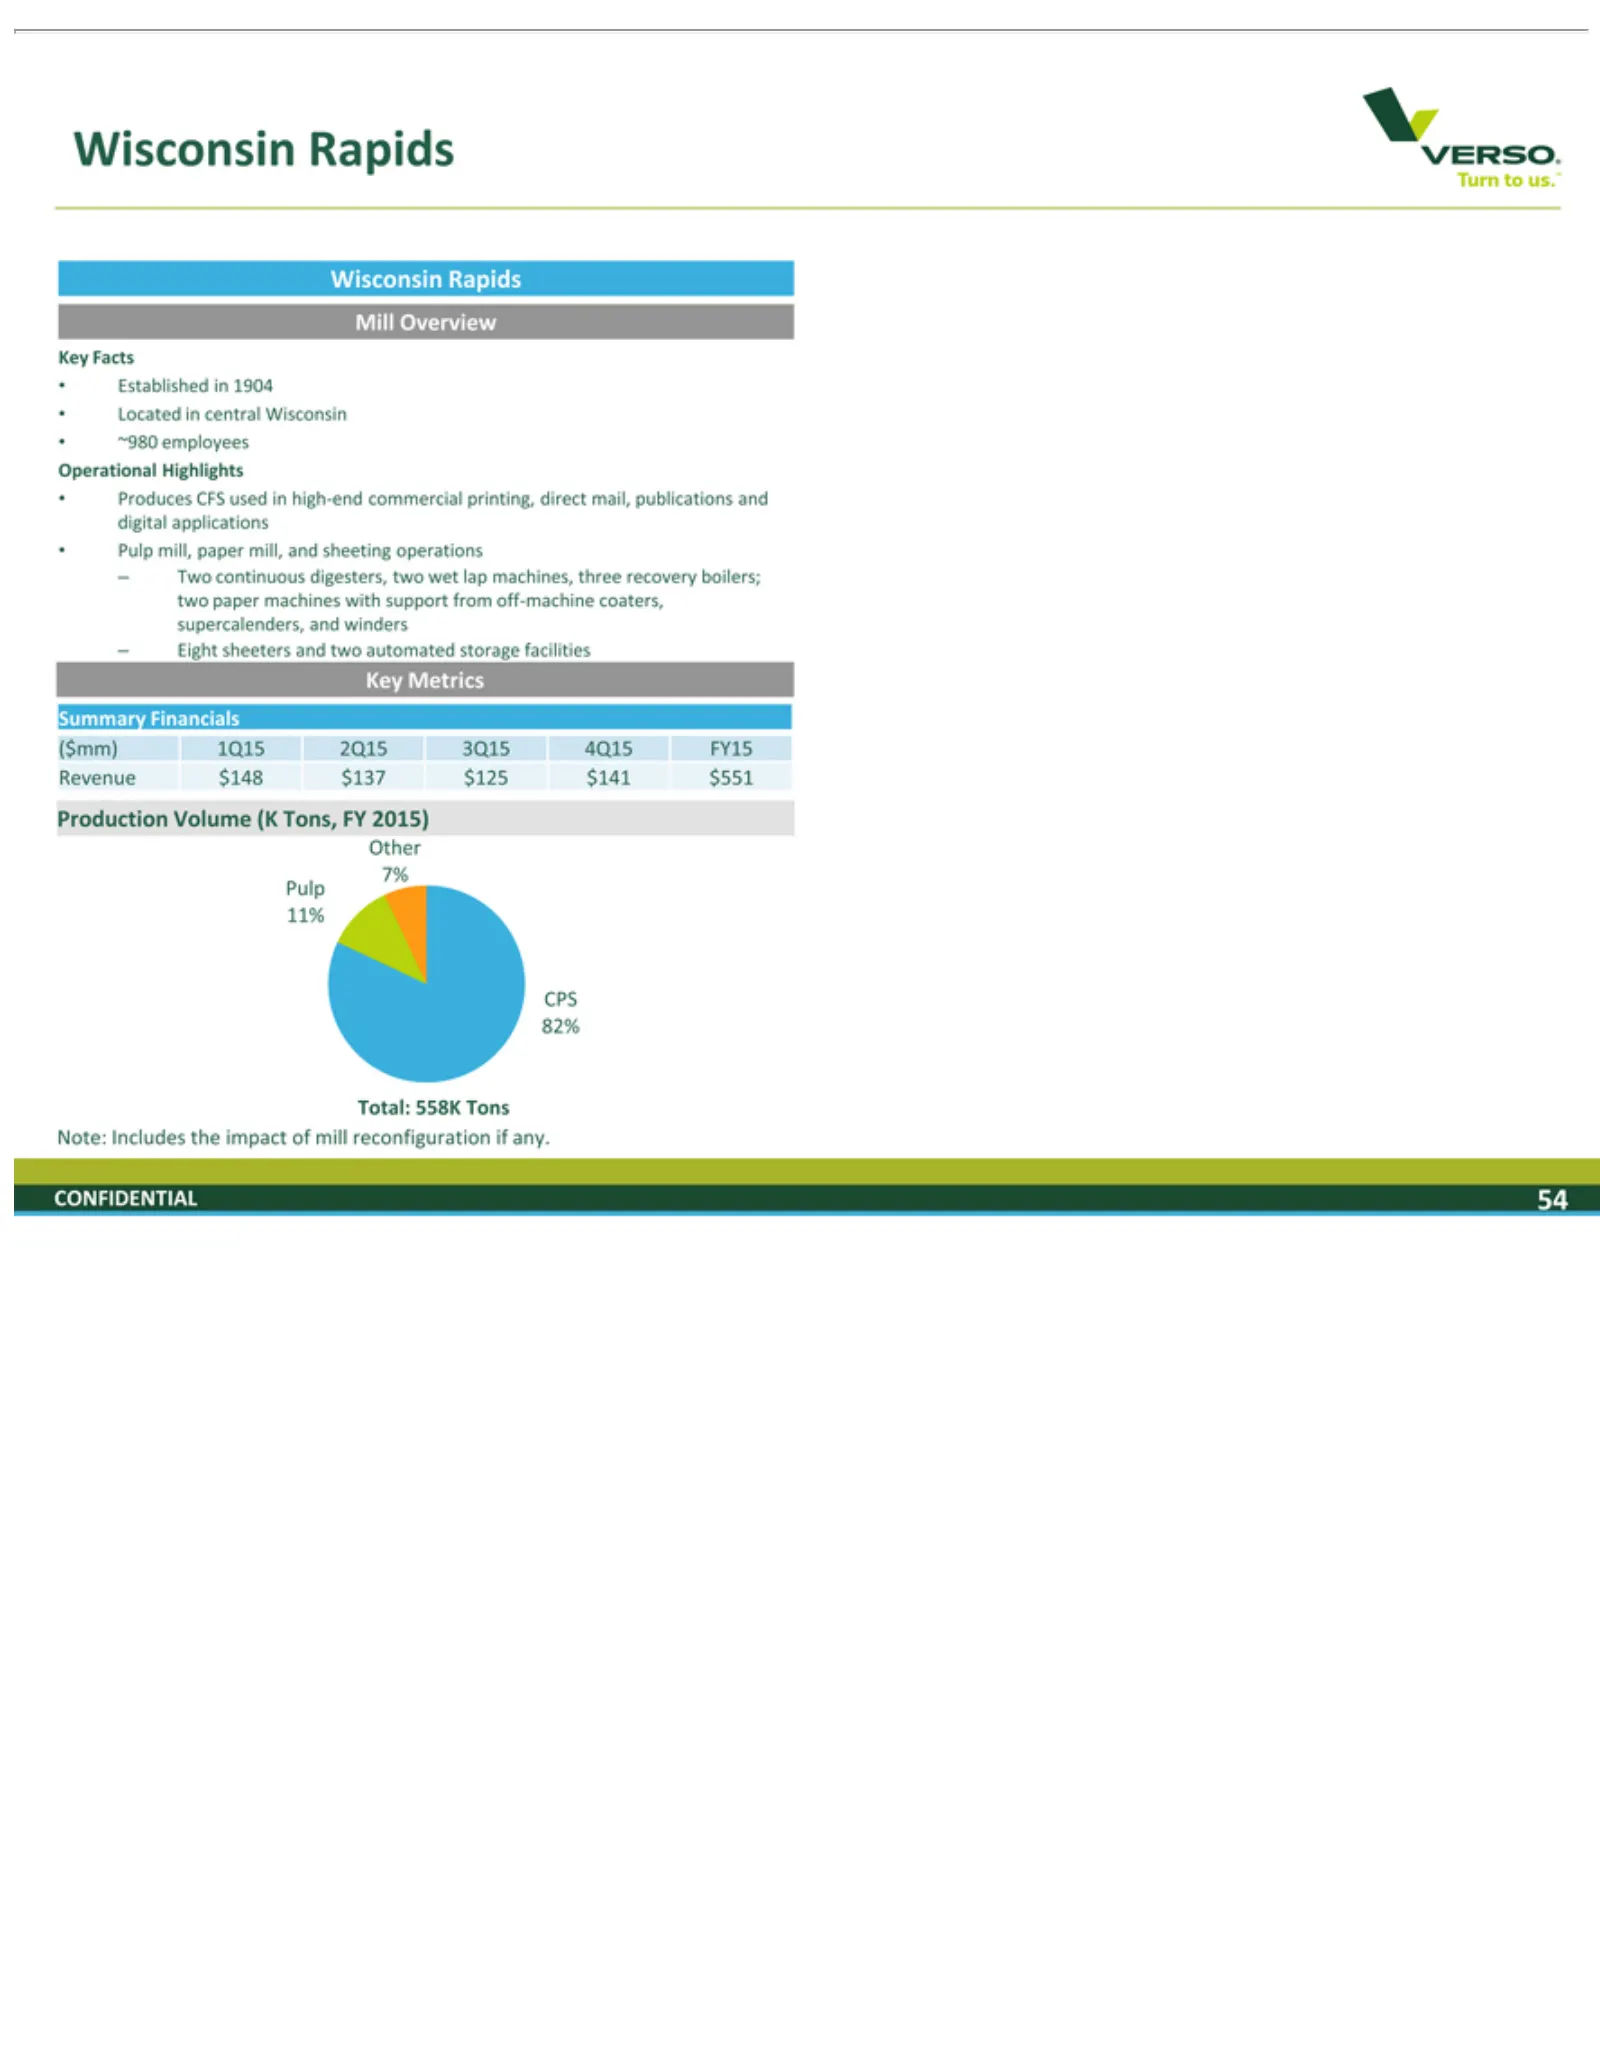
Slide 54: Wisconsin Rapids Mill Summary
VERSO Wisconsin Mill Established Located ~980 Operational Produces –Pulp Key Summary ($mm) Production Other CPS Total: Note: CONFIDENTIAL Two Eight Facts Metrics Overview 82% mill, employees Includes 7% 558K continuous 1Q15 sheeters in Turn CFS Pulp Financials paper Rapids central Volume in Highligh
Source: SEC EDGAR · 8-K filed Jun 6, 2016
More decks from Verso Corporation
 Merger or Acquisition (December 2021)21 slides · Dec 22, 2021
 Merger or Acquisition (December 2021)14 slides · Dec 20, 2021
 Merger or Acquisition (December 2021)15 slides · Dec 20, 2021
 Q3 2020 Earnings Presentation26 slides · Nov 9, 2020
 Q2 2020 Earnings Presentation28 slides · Aug 6, 2020
 Q1 2020 Earnings Presentation22 slides · May 11, 2020