Almirall SA · BME:ALM
Almirall SA — UBS Global Specialty and Generic Pharmaceuticals Conference 2008
26 slides from Almirall SA's conference presentation, May 29, 2008
Slide 1: Almirall Corporate Presentation
Almirall Corporate Presentation UBS Global Specialty and Generic Pharmaceuticals Conference London, 28th-29th May 2008
Slide 2: Disclaimer
Disclaimer This document includes only summary information and does not intend to be comprehensive. Facts, figures and opinions contained herein, other than historical, are "forward-looking statements". These statements are based on currently available information and on best estimates and assumptio
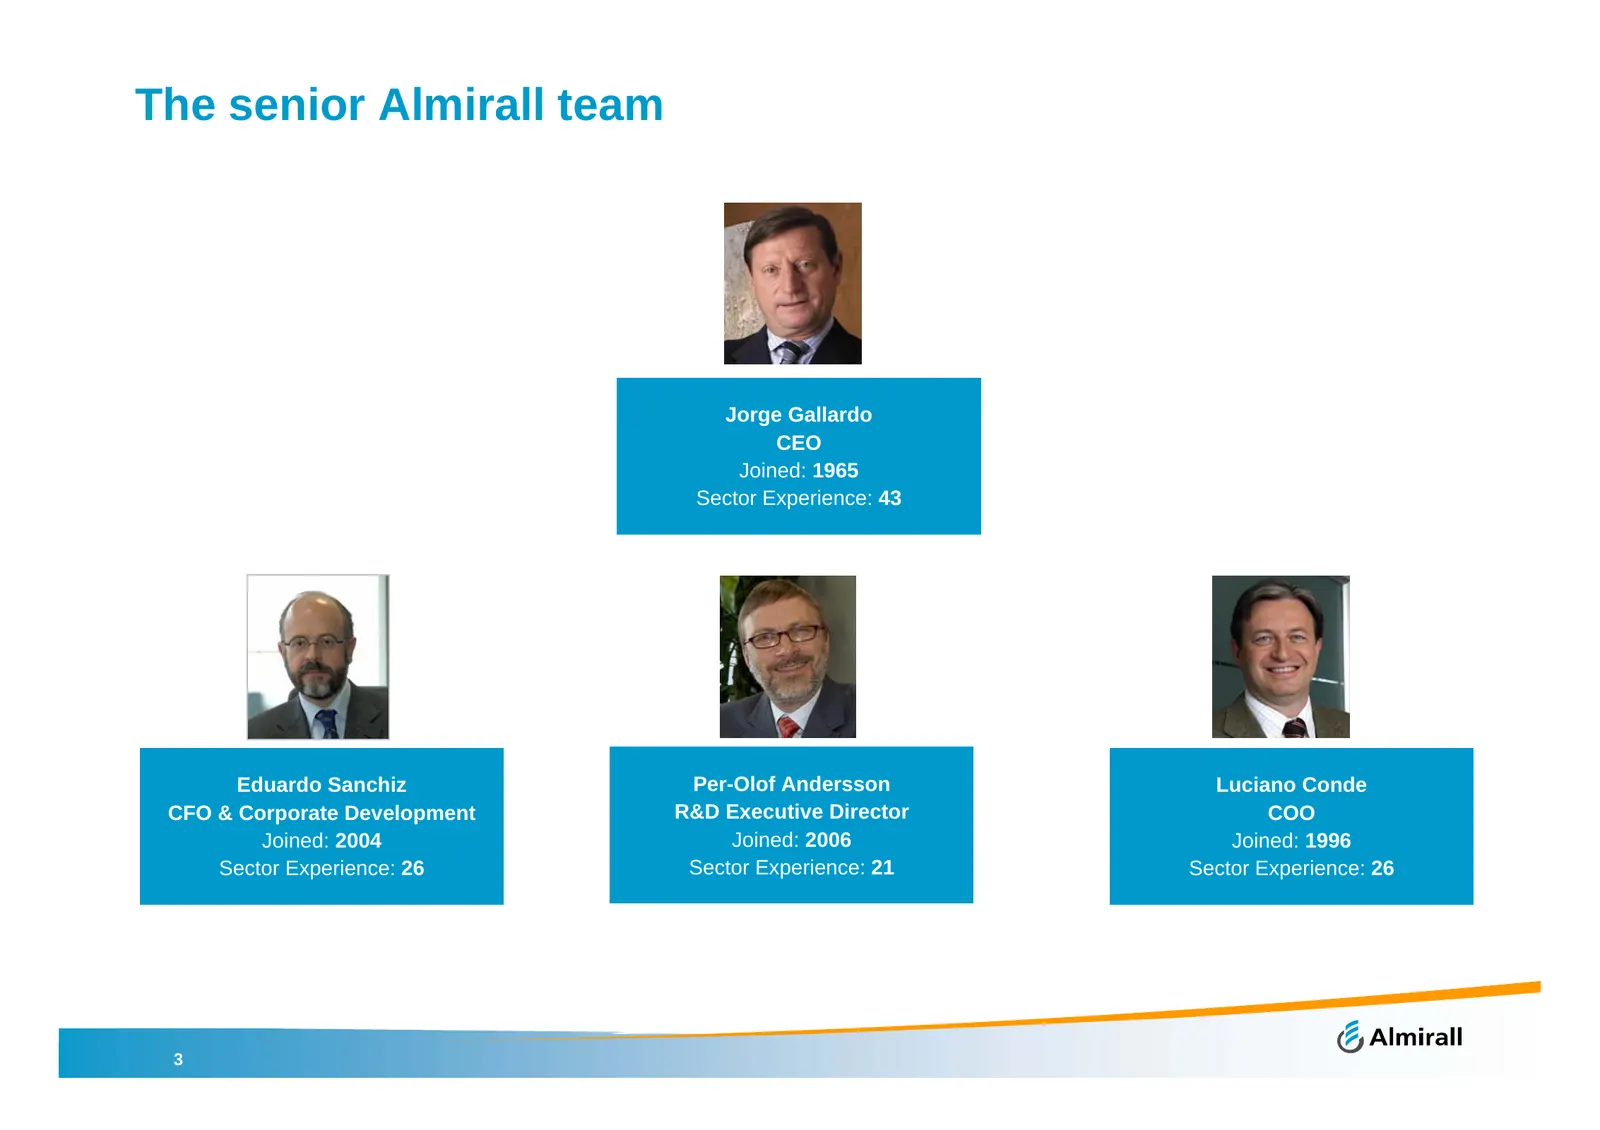
Slide 3: The senior Almirall team
The senior Almirall team Jorge Gallardo CEO Joined: 1965 Sector Experience: 43 Eduardo Sanchiz Per-Olof Andersson Luciano Conde CFO & Corporate Development R&D Executive Director COO Joined: 2004 Joined: 2006 Joined: 1996 Sector Experience: 26 Sector Experience: 21 Sector Experience: 26 3
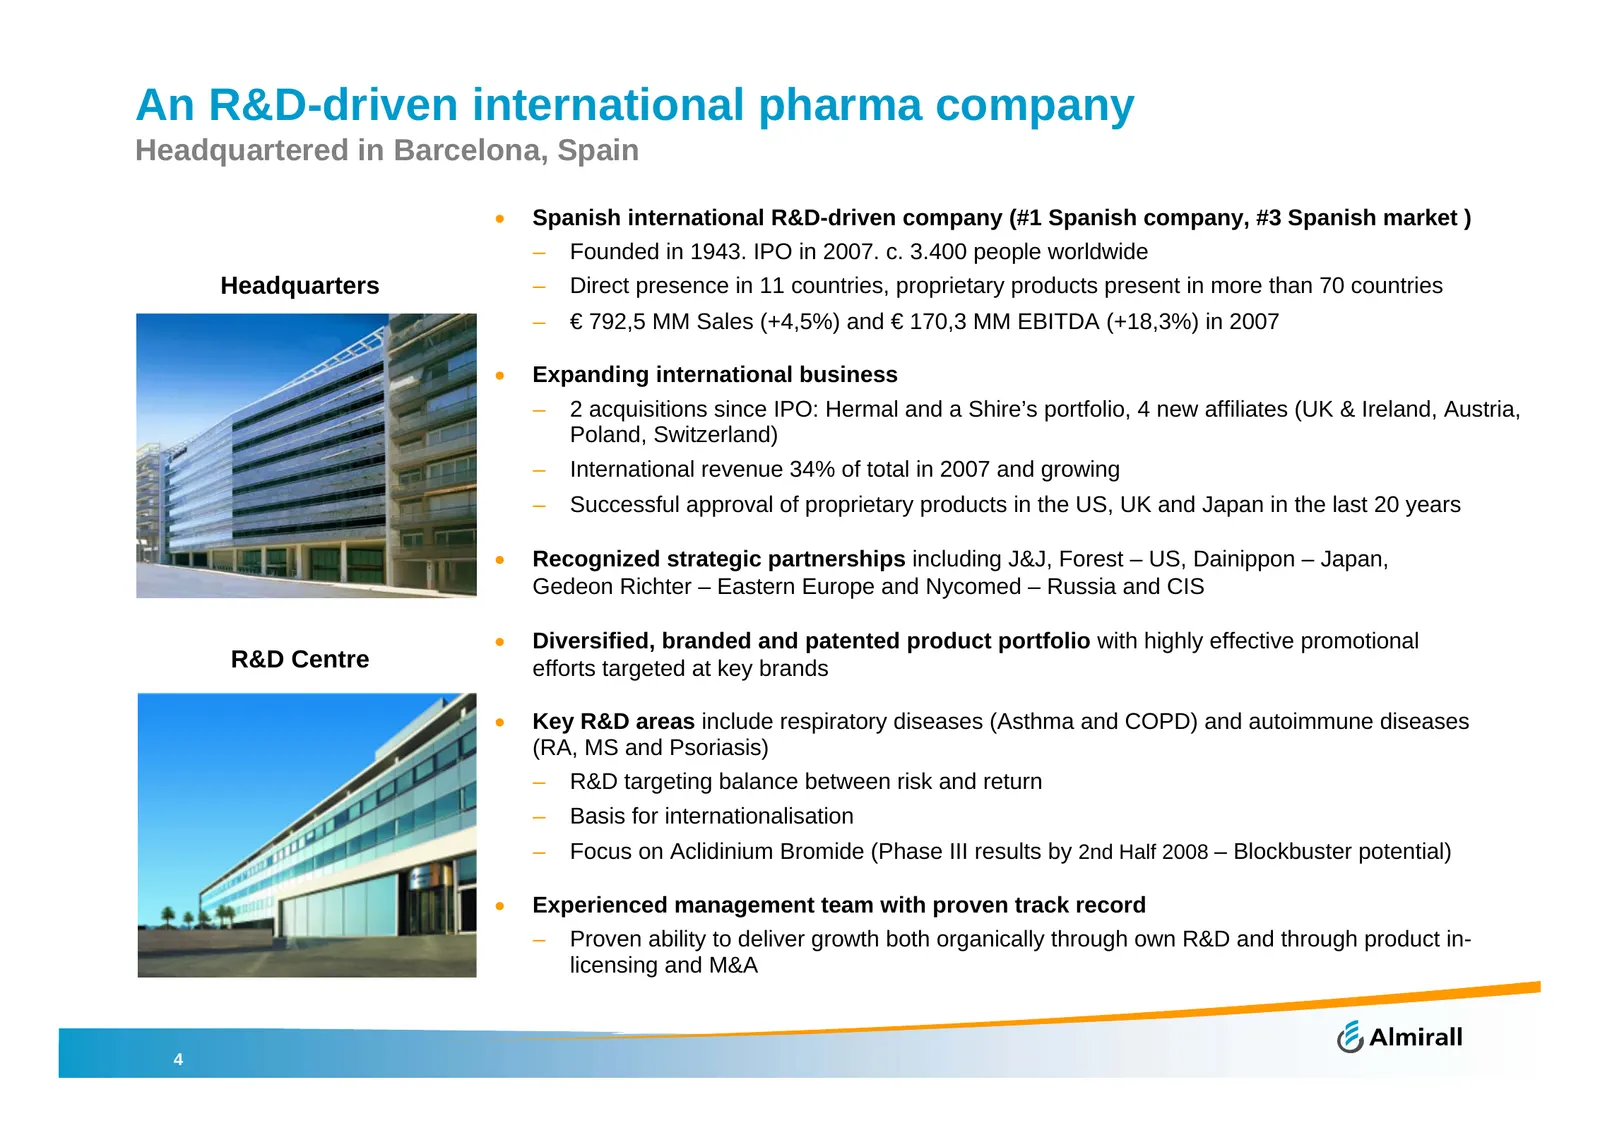
Slide 4: An R&D-driven international pharma company
An R&D-driven international pharma company Headquartered in Barcelona, Spain • Spanish international R&D-driven company (#1 Spanish company, #3 Spanish market ) – Founded in 1943. IPO in 2007. c. 3.400 people worldwide Headquarters – Direct presence in 11 countries, proprietary products present in m
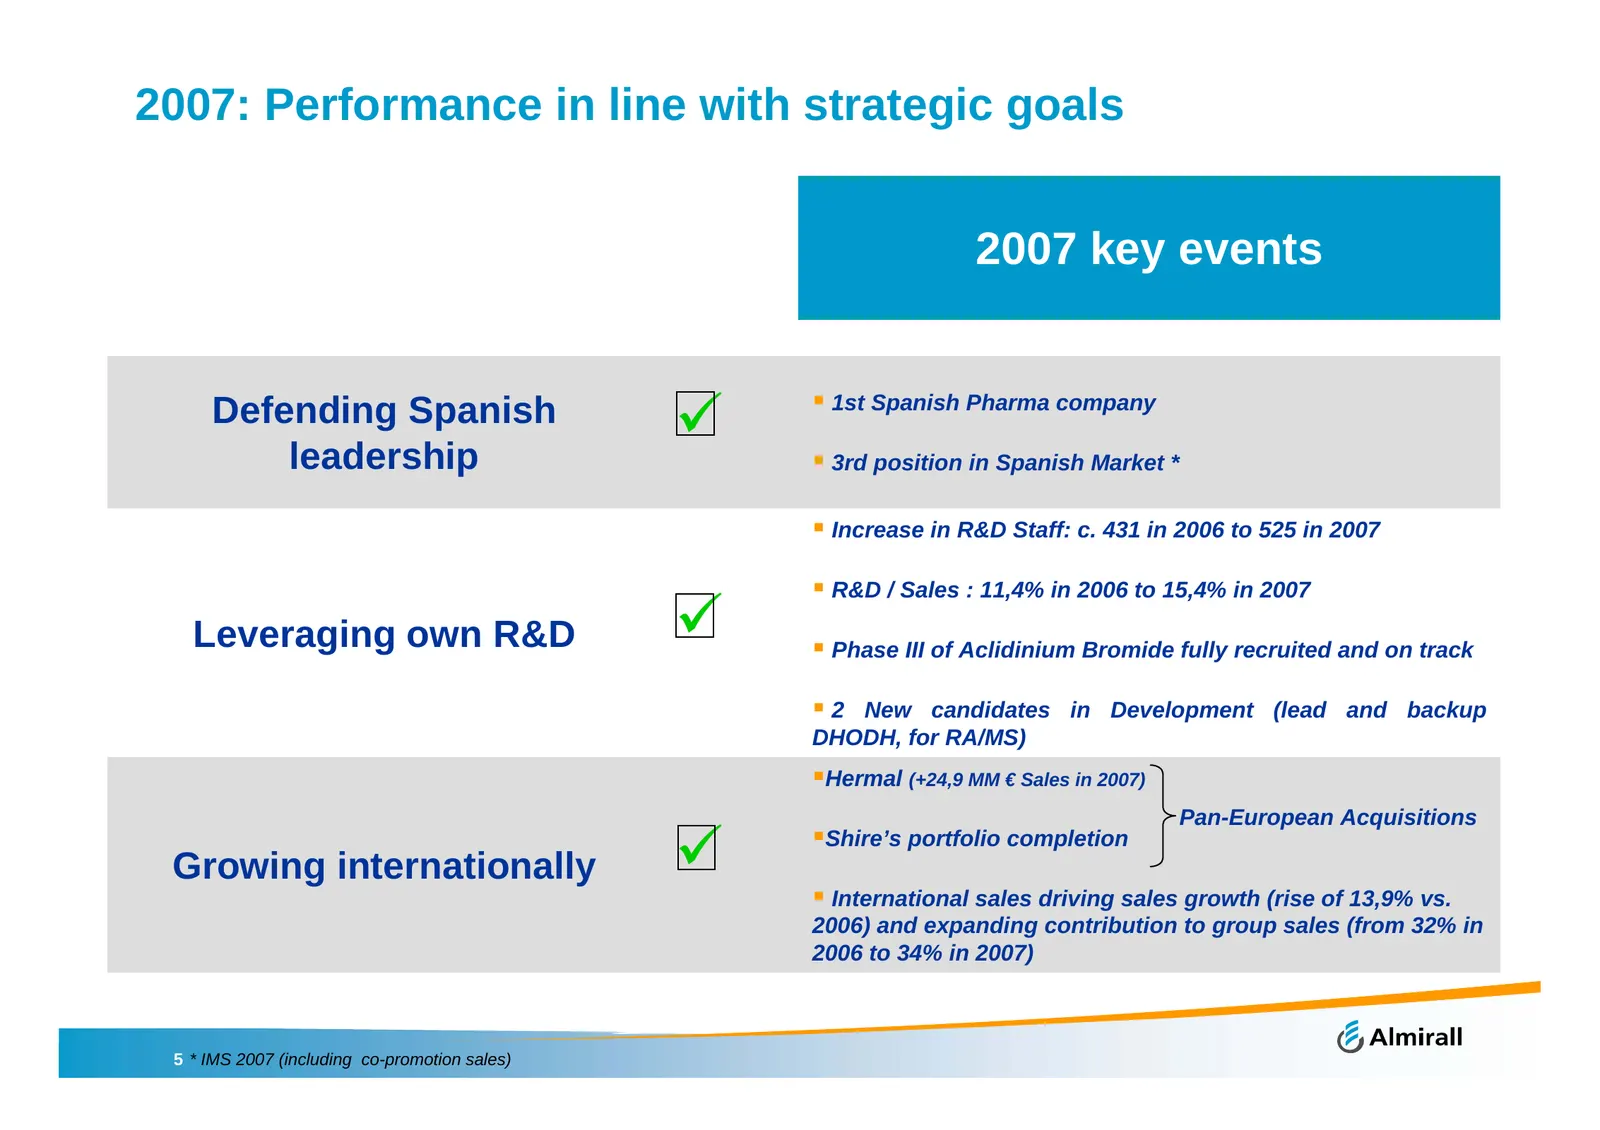
Slide 5: 2007: Performance in line with strategic goals
2007: Performance in line with strategic goals 2007 key events 1st Spanish Pharma company Defending Spanish leadership 3rd position in Spanish Market * Increase in R&D Staff: c. 431 in 2006 to 525 in 2007 R&D / Sales : 11,4% in 2006 to 15,4% in 2007 Leveraging own R&D Phase III of Aclidinium Bromide
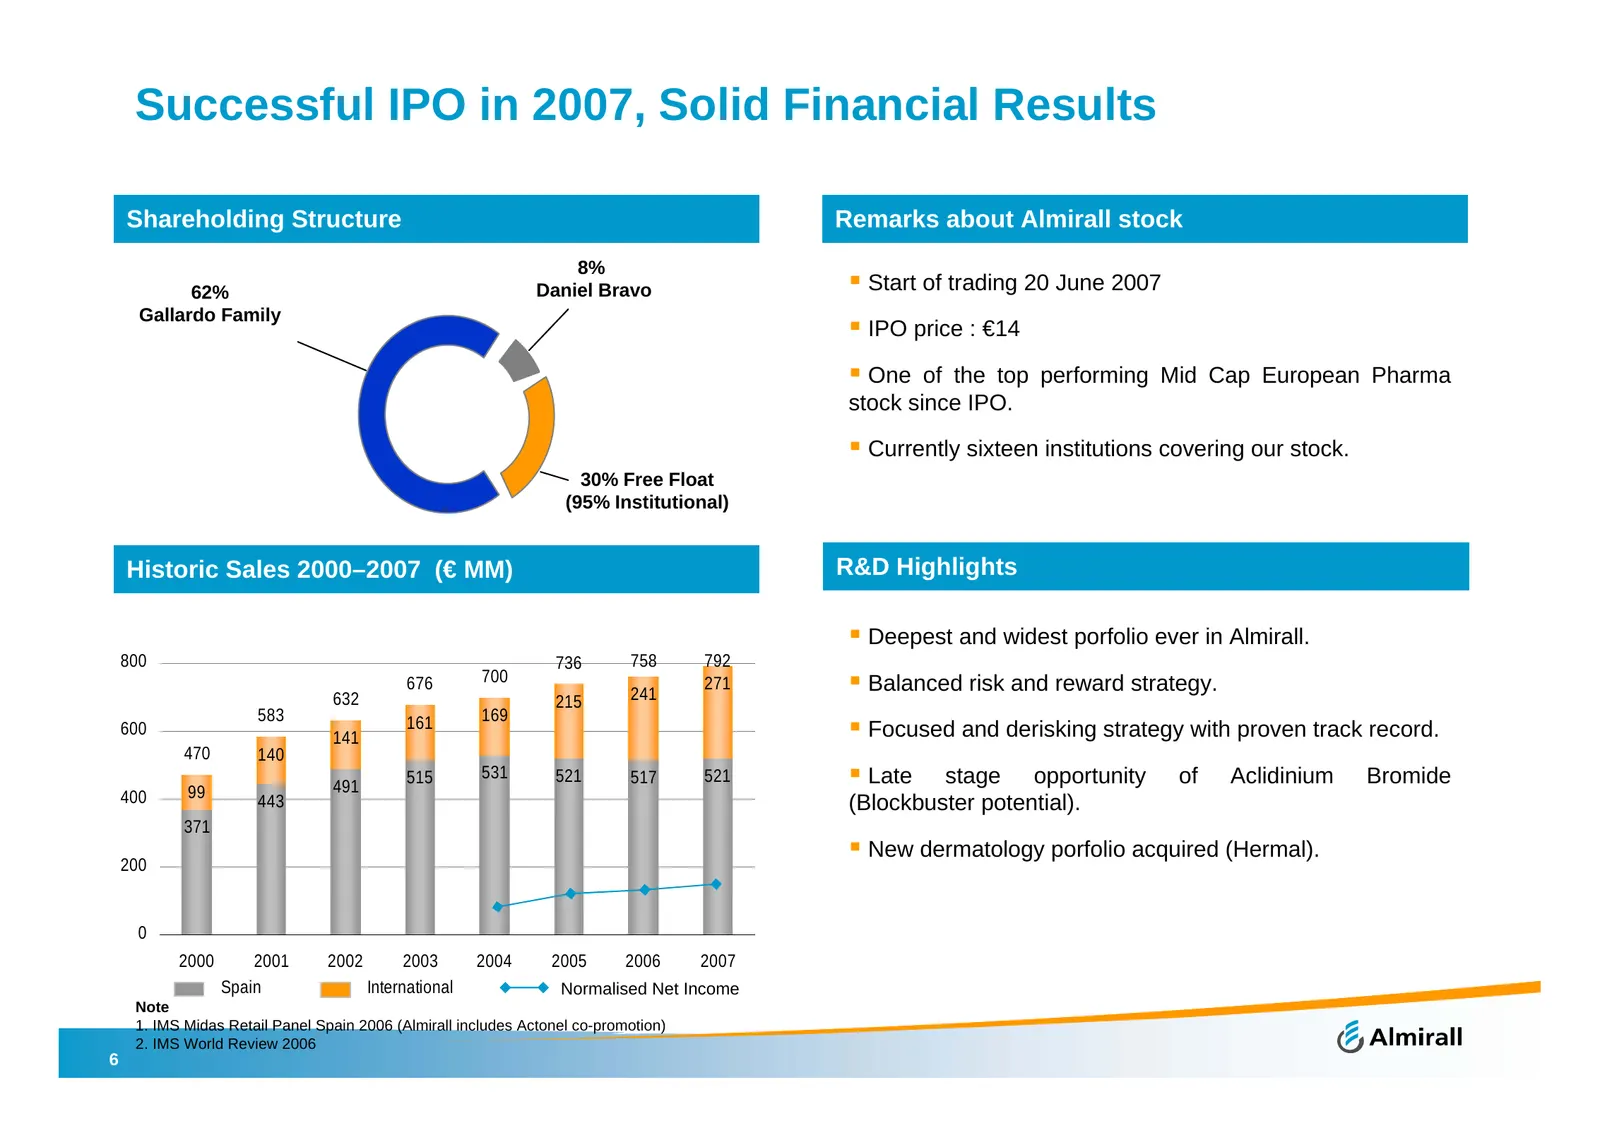
Slide 6: Successful IPO in 2007, Solid Financial Results
Successful IPO in 2007, Solid Financial Results Shareholding Structure Remarks about Almirall stock 8% 62% Daniel Bravo Start of trading 20 June 2007 Gallardo Family IPO price : €14 One of the top performing Mid Cap European Pharma stock since IPO. Currently sixteen institutions covering our stock.
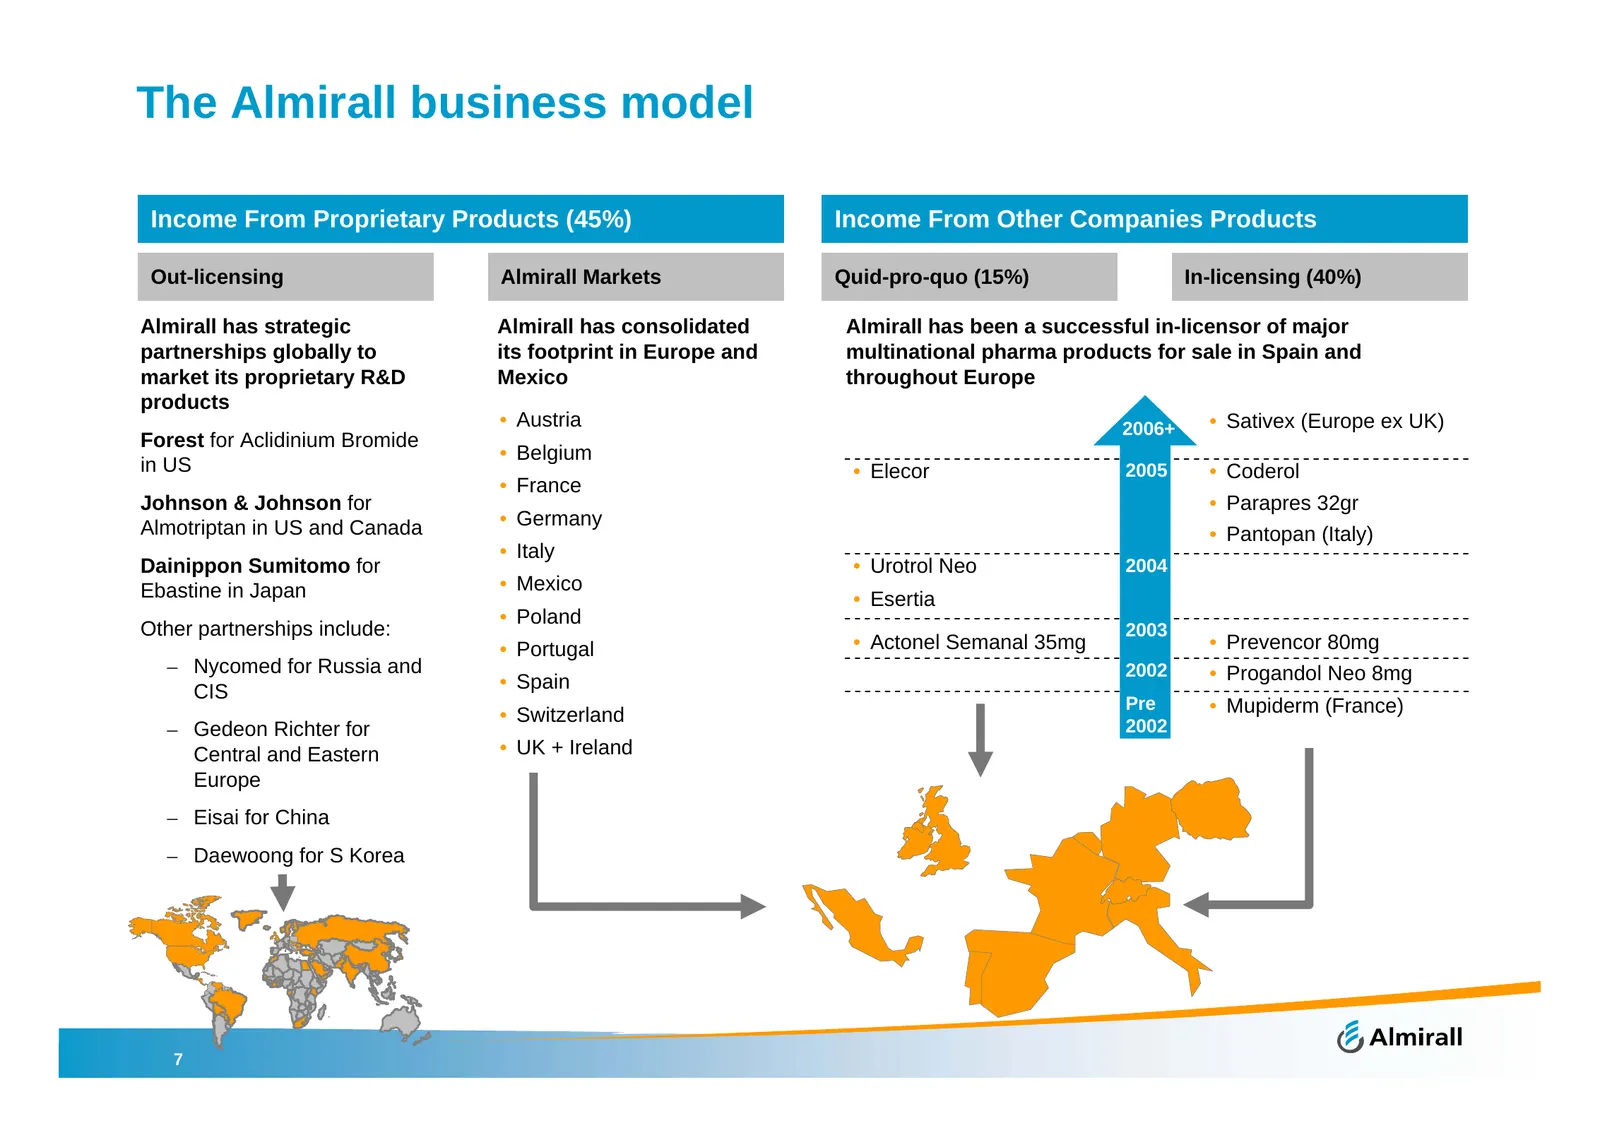
Slide 7: The Almirall business model
The Almirall business model Income From Proprietary Products (45%) Income From Other Companies Products Out-licensing Almirall Markets Quid-pro-quo (15%) In-licensing (40%) Almirall has strategic Almirall has consolidated Almirall has been a successful in-licensor of major partnerships globally to i
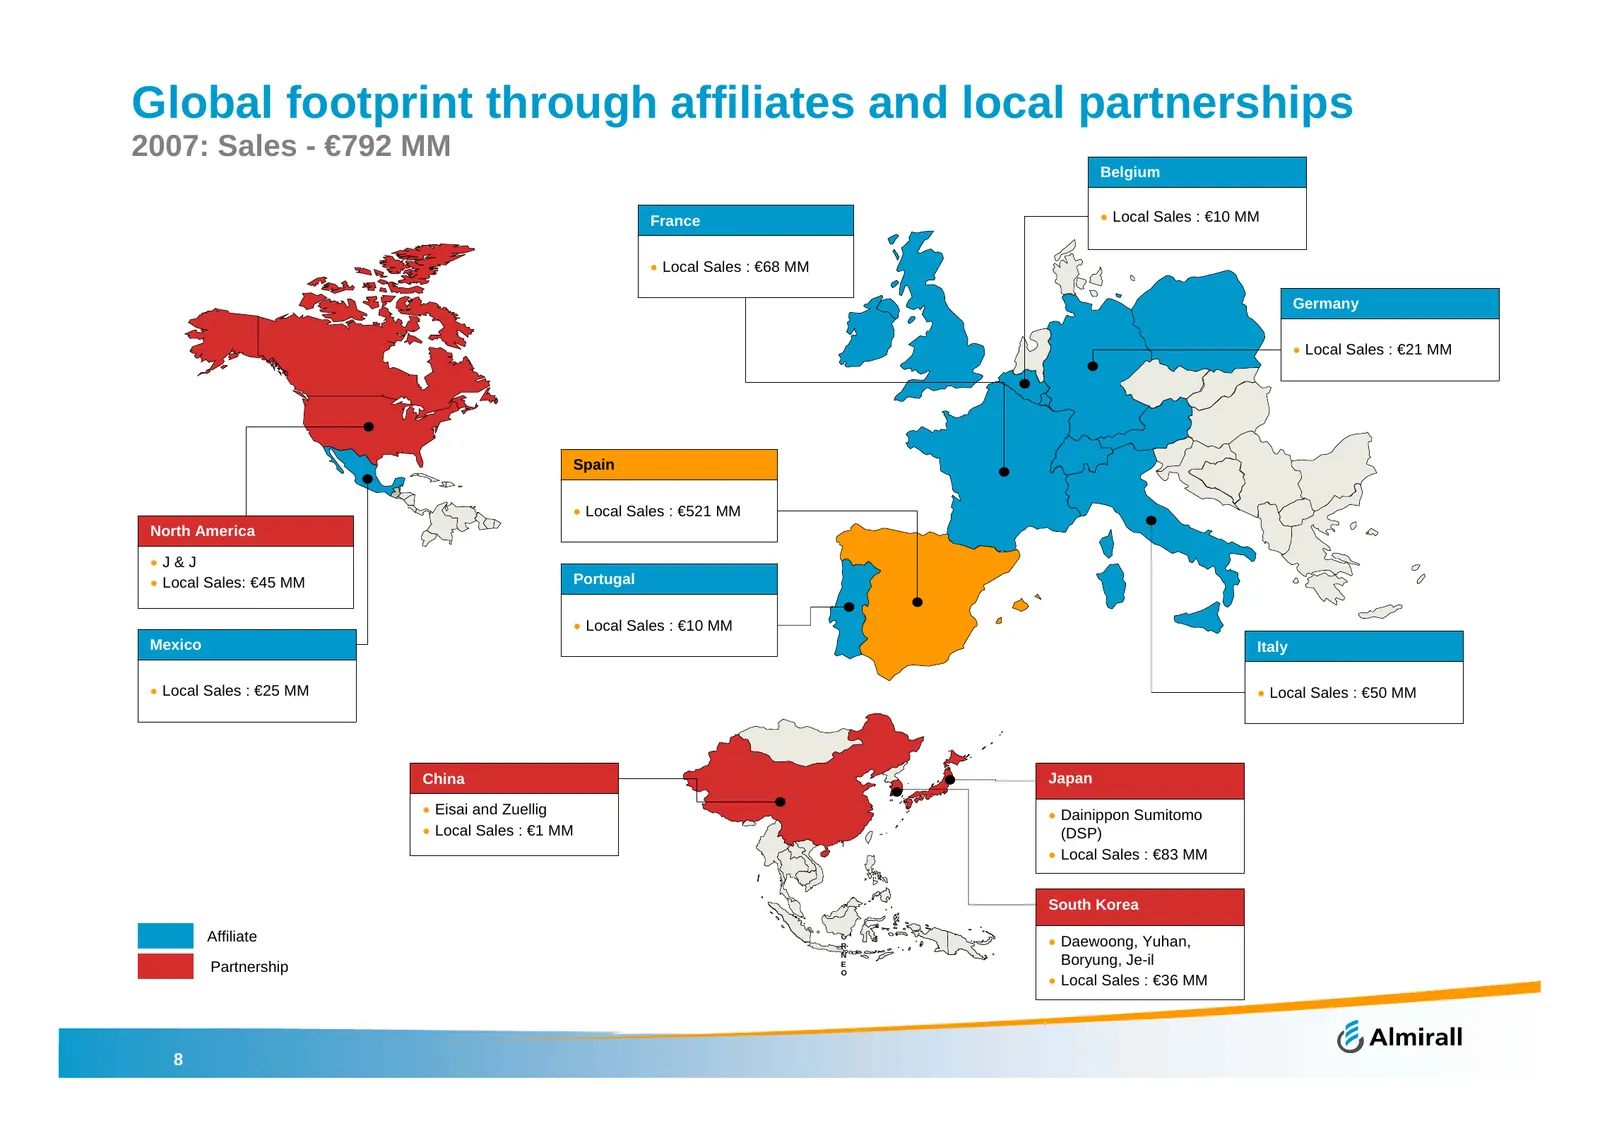
Slide 8: Global footprint through affiliates and local partnerships
Global footprint through affiliates and local partnerships 2007: Sales - €792 MM Belgium France • Local Sales : €10 MM • Local Sales : €68 MM Germany • Local Sales : €21 MM Spain • Local Sales : €521 MM North America •J&J • Local Sales: €45 MM Portugal • Local Sales : €10 MM Mexico Italy • Local Sal
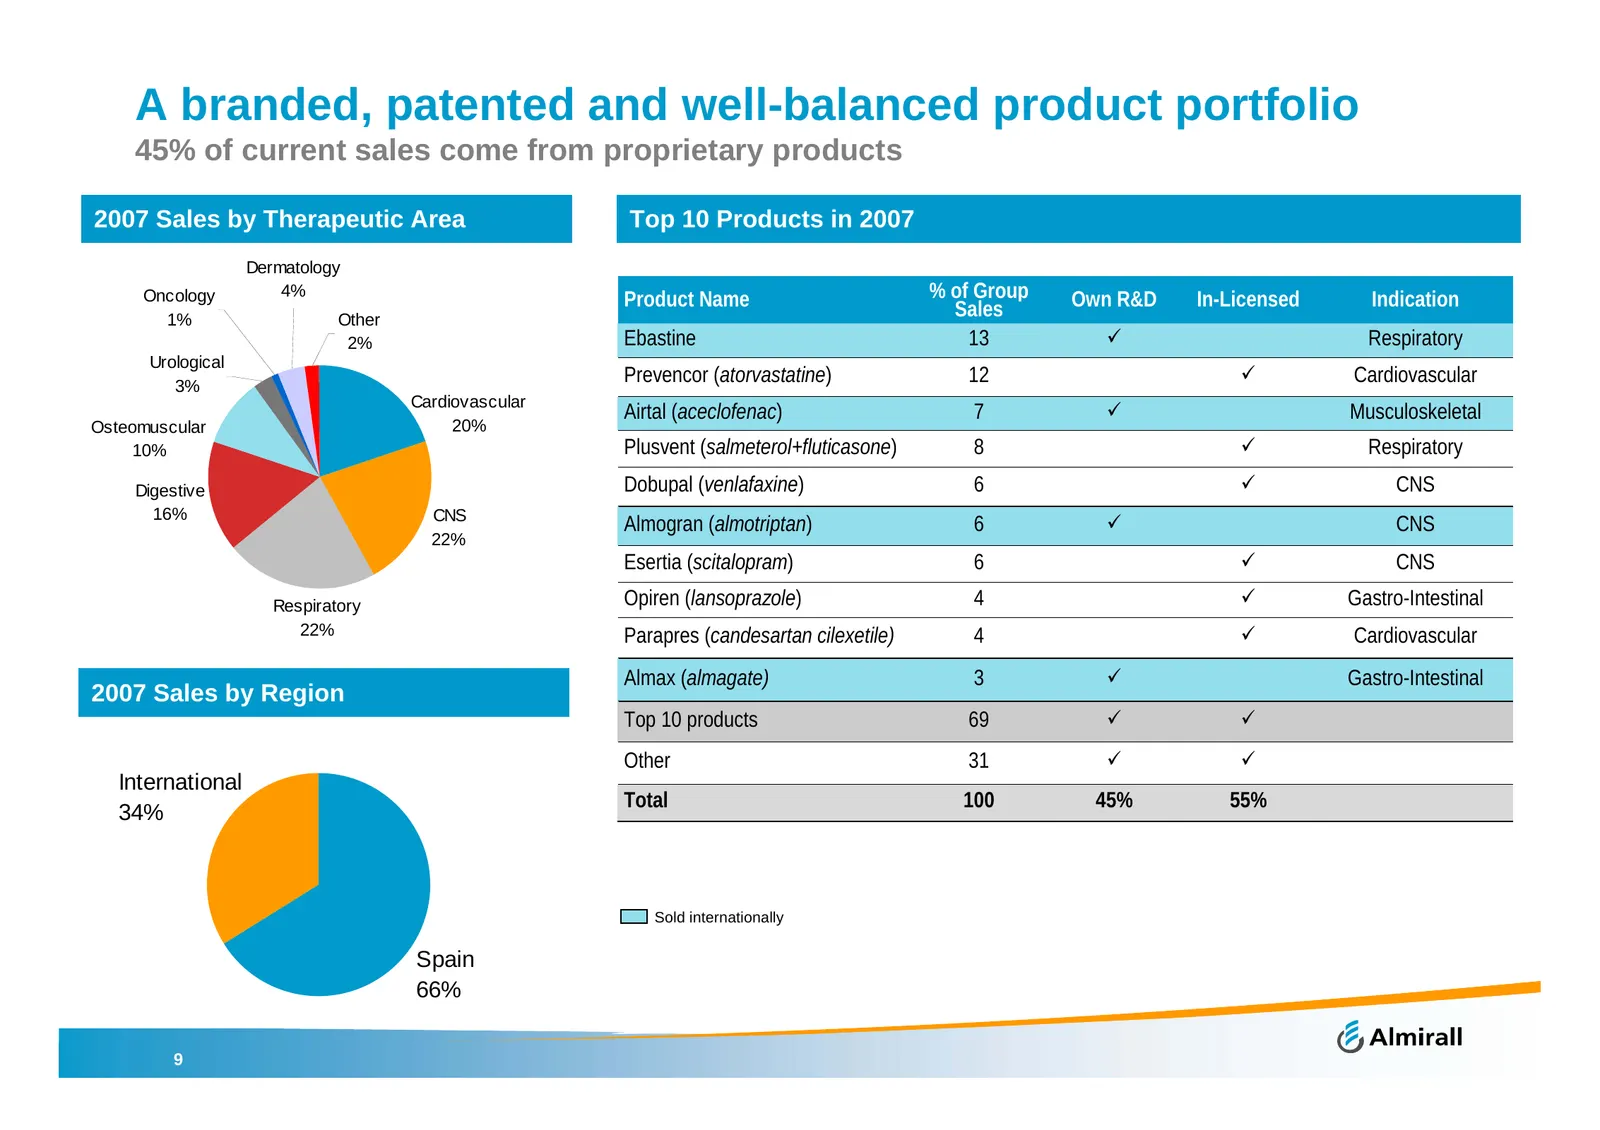
Slide 9: A branded, patented and well-balanced product portfolio
A branded, patented and well-balanced product portfolio 45% of current sales come from proprietary products 2007 Sales by Therapeutic Area Top 10 Products in 2007 Dermatology Oncology 4% Product Name % of Group Own R&D In-Licensed Indication 1% Other Sales 2% Ebastine 13 Respiratory Urological 3% Pr
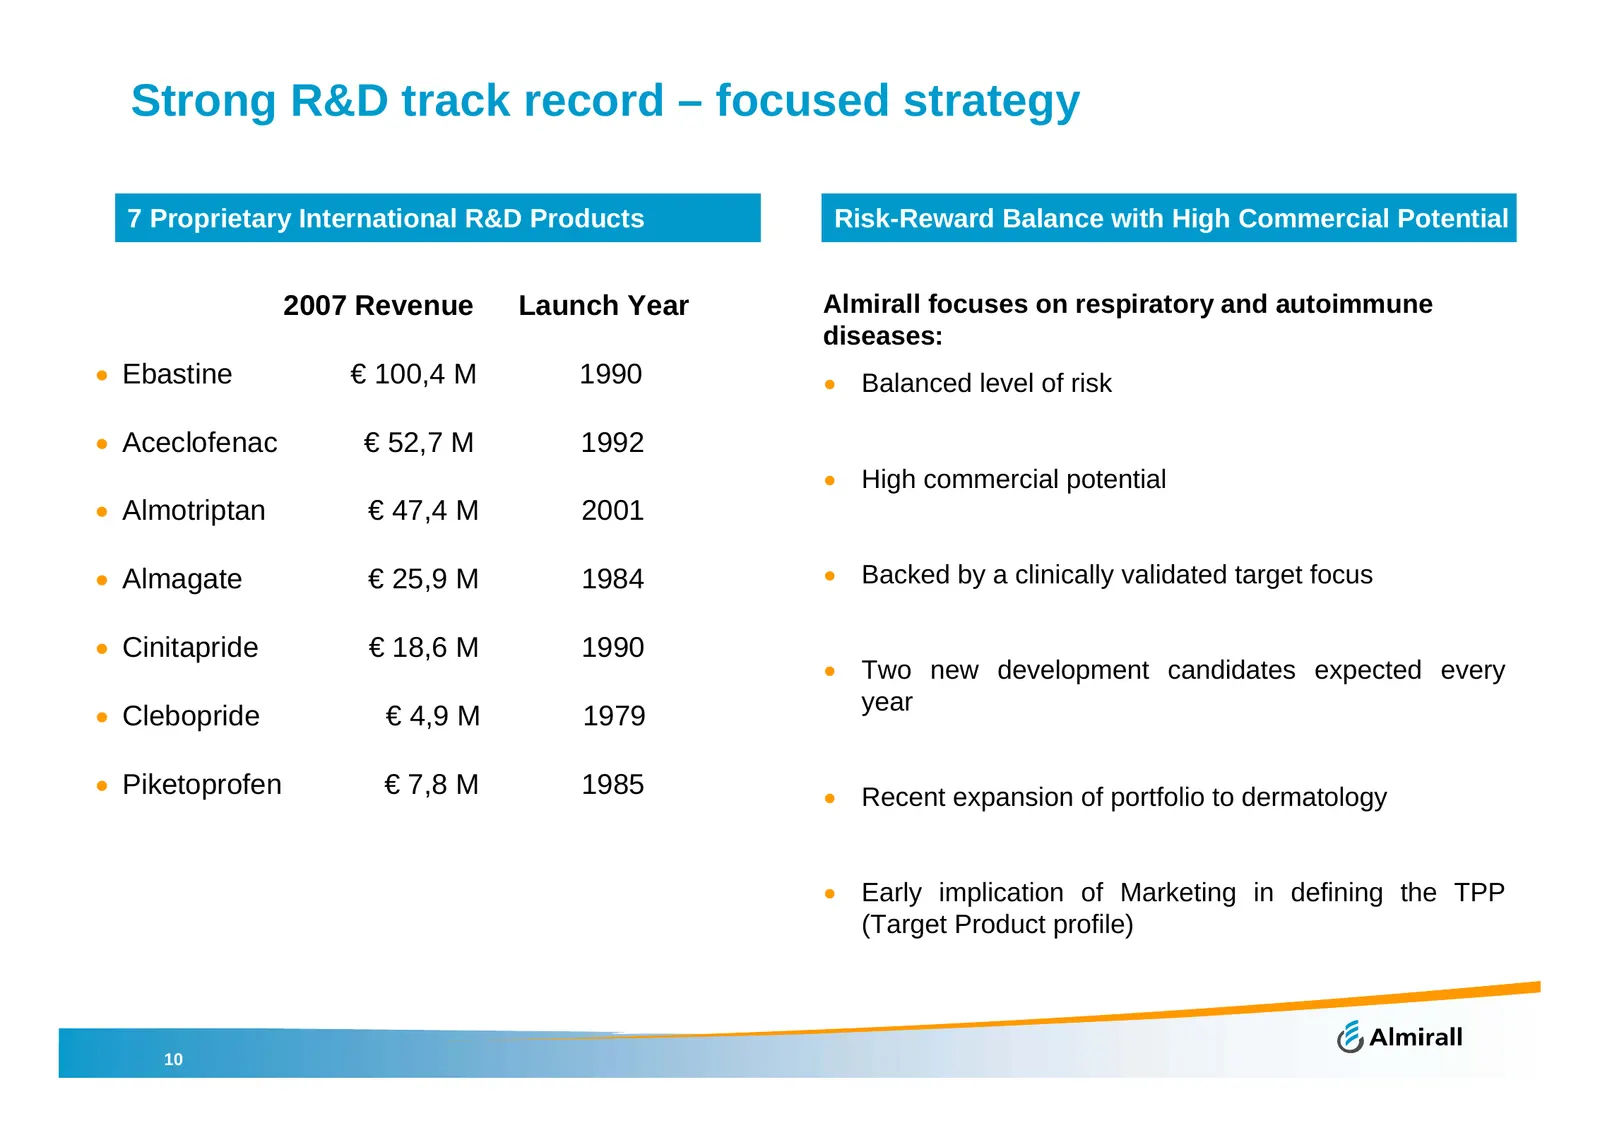
Slide 10: Strong R&D track record – focused strategy
Strong R&D track record – focused strategy 7 Proprietary International R&D Products Risk-Reward Balance with High Commercial Potential 2007 Revenue Launch Year Almirall focuses on respiratory and autoimmune diseases: • Ebastine € 100,4 M 1990 • Balanced level of risk • Aceclofenac € 52,7 M 1992 • Hi
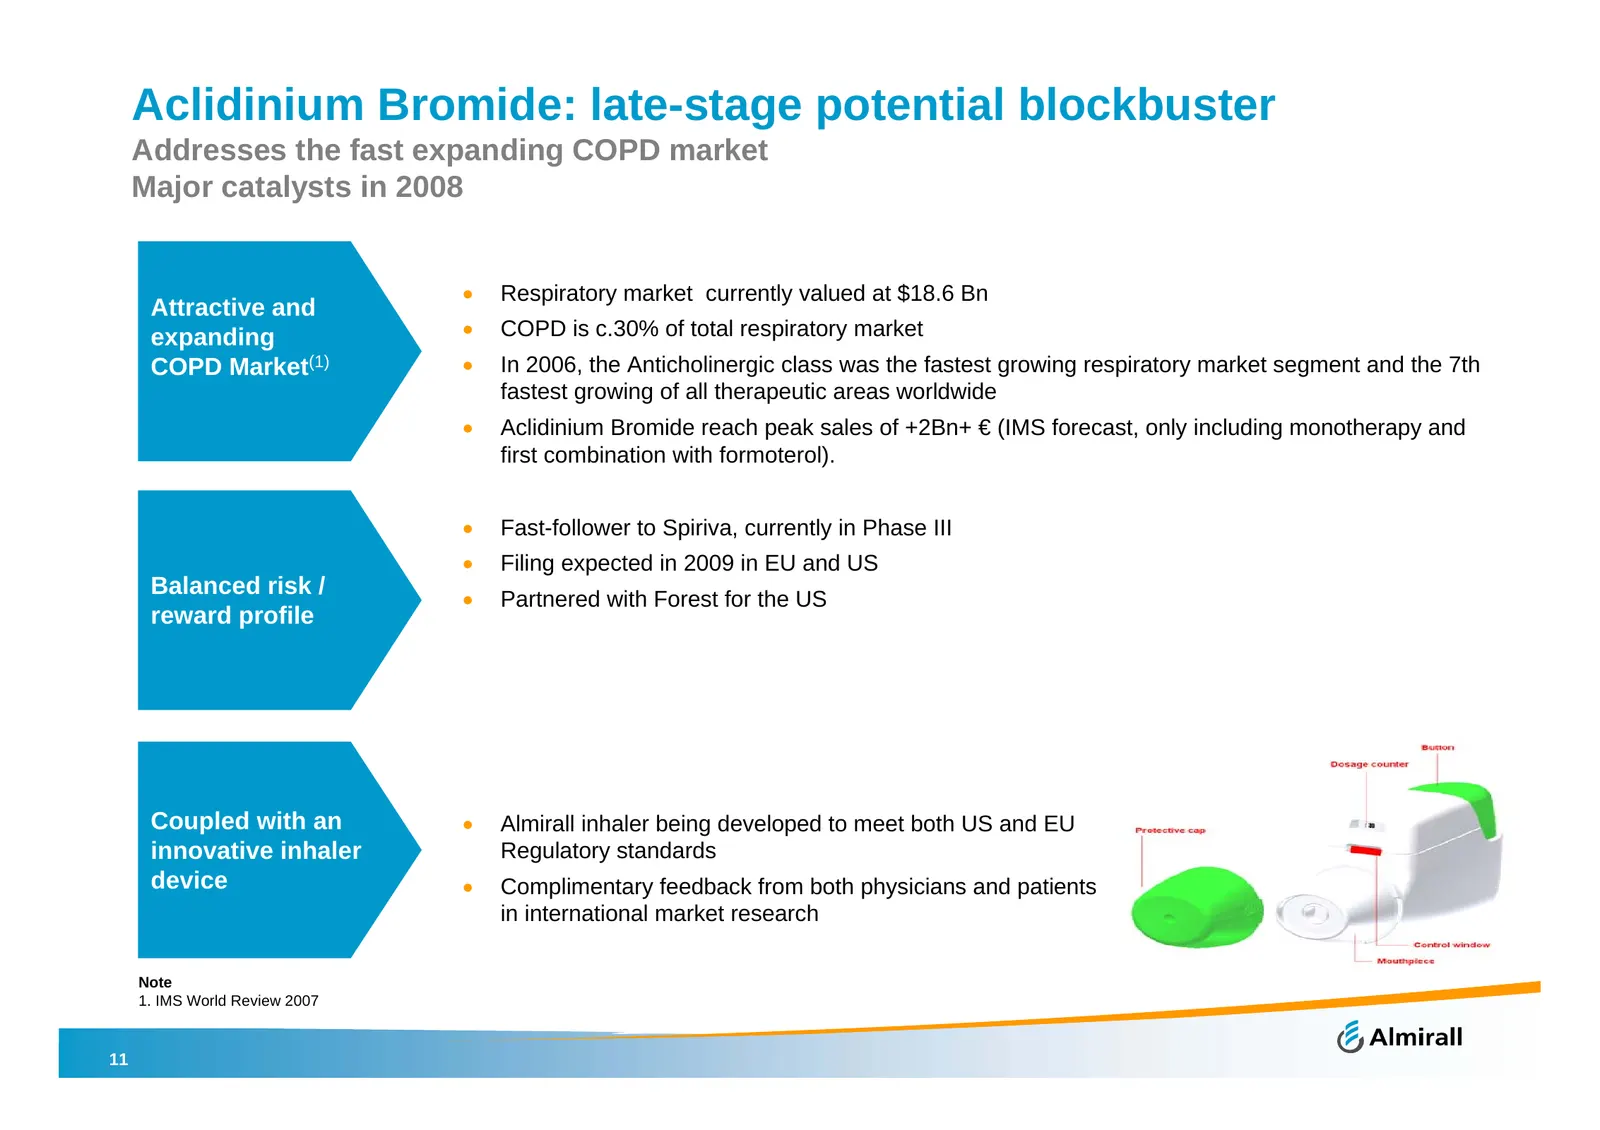
Slide 11: Aclidinium Bromide: late-stage potential blockbuster
Aclidinium Bromide: late-stage potential blockbuster Addresses the fast expanding COPD market Major catalysts in 2008 • Respiratory market currently valued at $18.6 Bn Attractive and expanding • COPD is c.30% of total respiratory market COPD Market(1) • In 2006, the Anticholinergic class was the fas
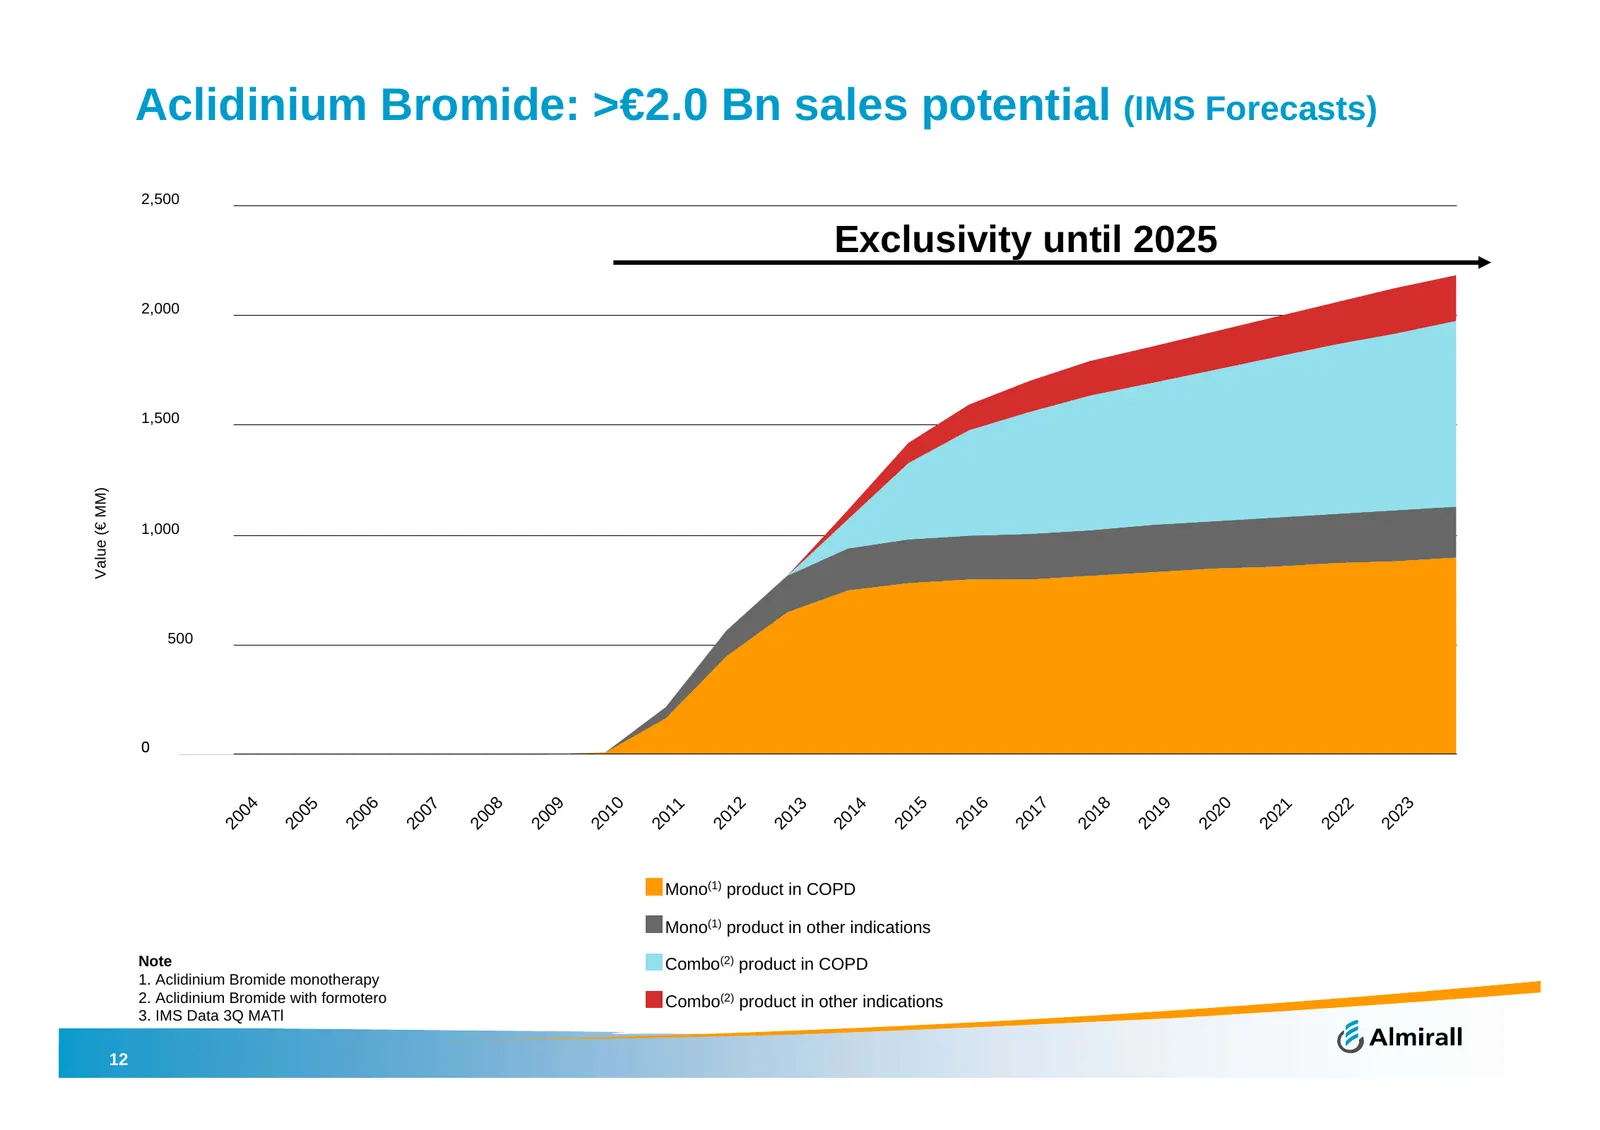
Slide 12: Aclidinium Bromide: >€2.0 Bn sales potential (IMS Forecasts)
Aclidinium Bromide: >€2.0 Bn sales potential (IMS Forecasts) 2,500 Exclusivity until 2025 2,000 1,500 Value (€ MM) 1,000 500 0 04 06 08 09 10 12 15 16 17 18 19 20 23 11 21 22 05 07 13 14 20 20 20 20 20 20 20 20 20 20 20 20 20 20 20 20 20 20 20 20 Mono(1) product in COPD Mono(1) product in other indi
Slide 13: Aclidinium Bromide: strong pre-clinical and early clinical data
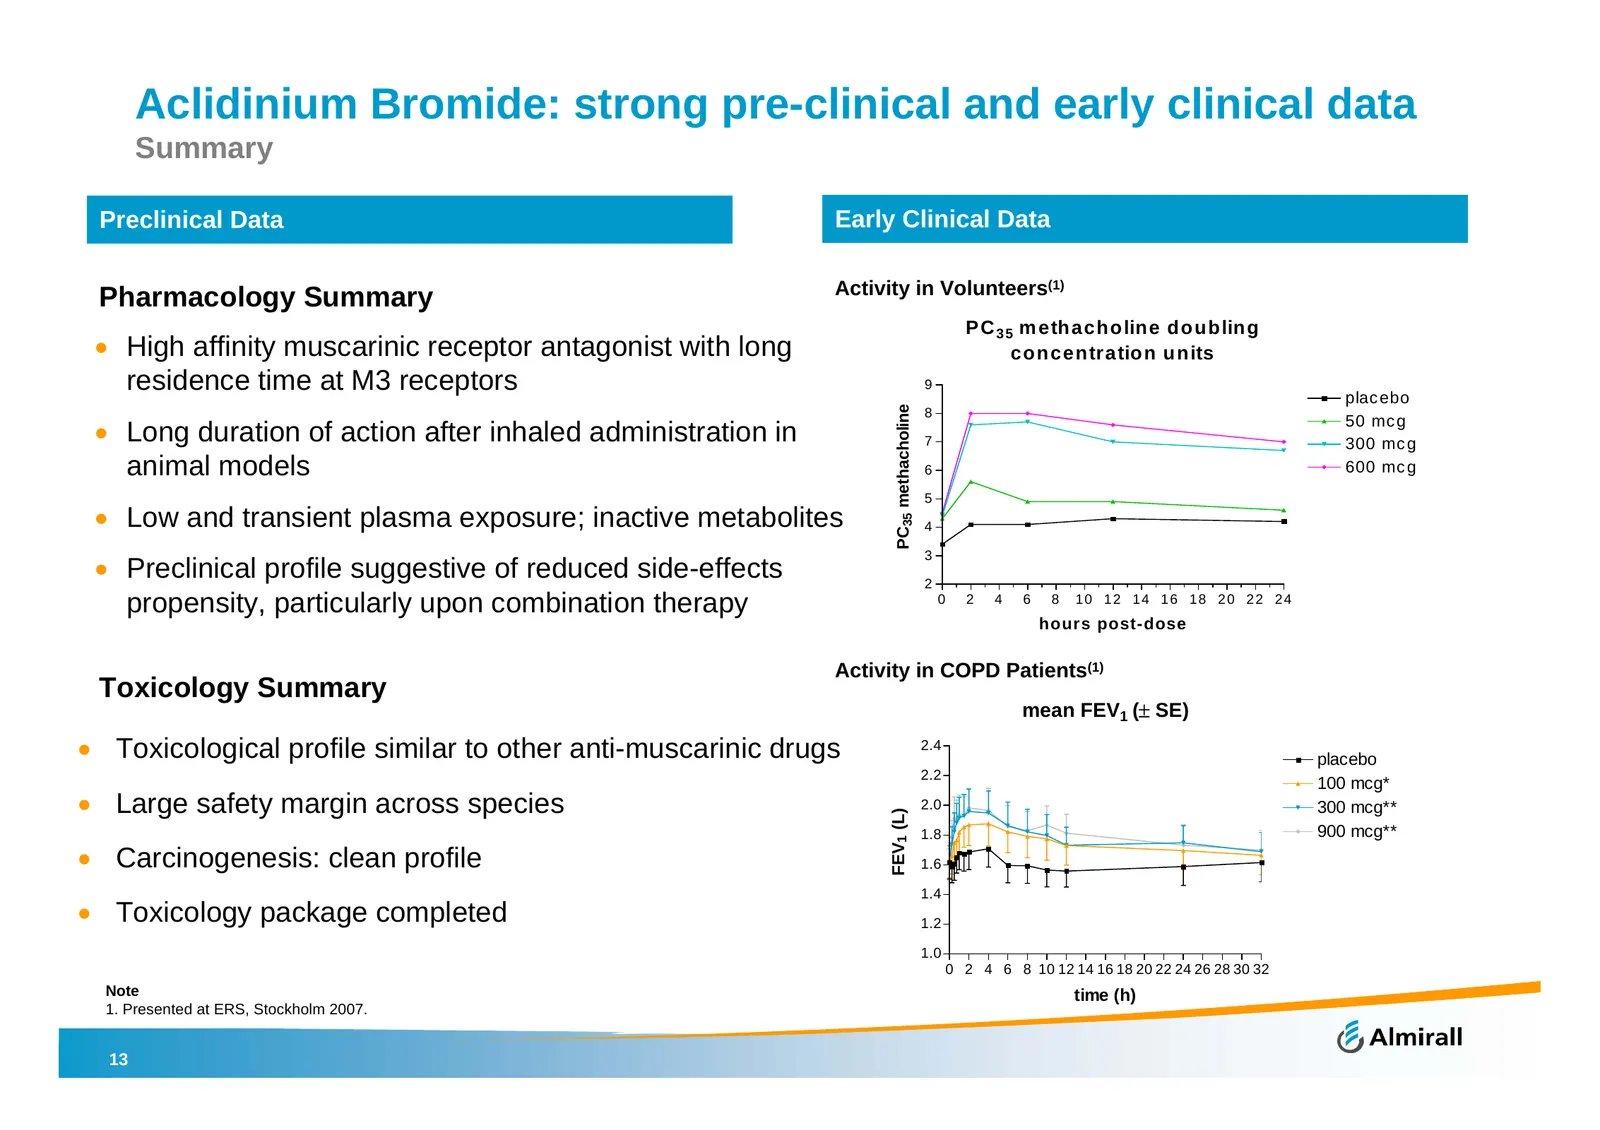
Aclidinium Bromide: strong pre-clinical and early clinical data Summary Preclinical Data Early Clinical Data Activity in Volunteers(1) Pharmacology Summary P C 3 5 m ethacholine doubling • High affinity muscarinic receptor antagonist with long concentration units residence time at M3 receptors 9 pla
Slide 14: Aclidinium Bromide: ongoing clinical programme
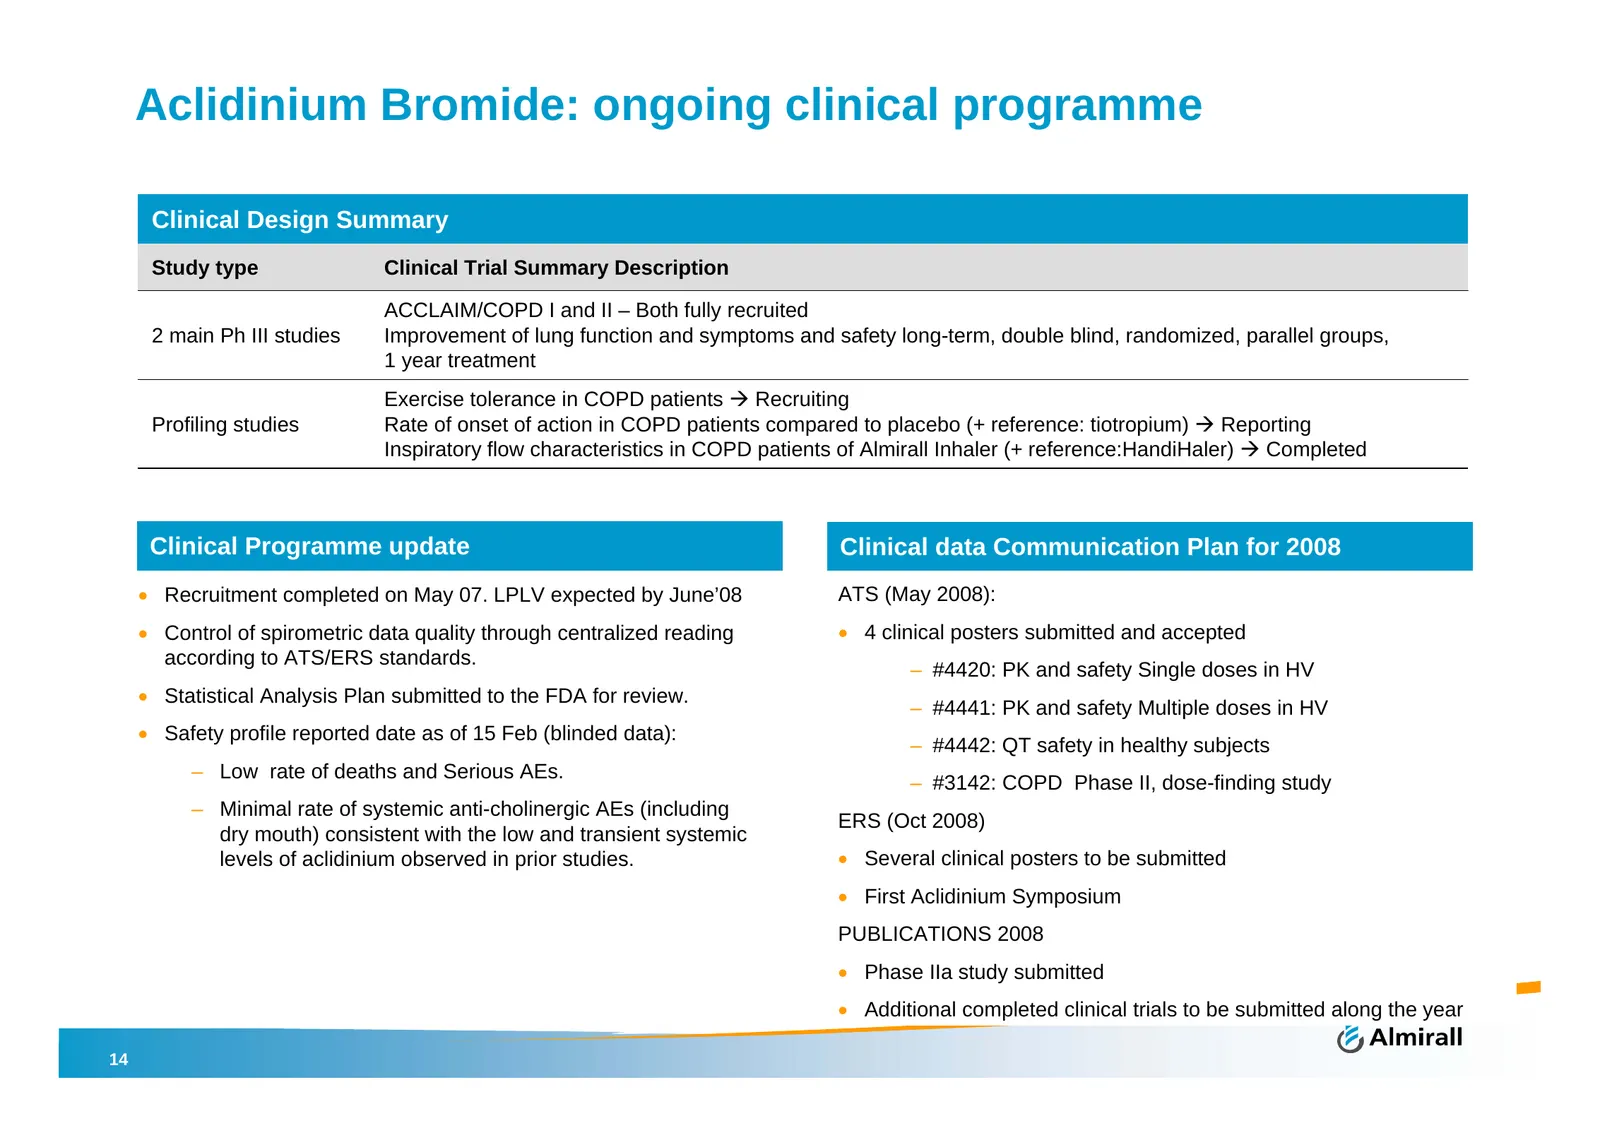
Aclidinium Bromide: ongoing clinical programme Clinical Design Summary Study type Clinical Trial Summary Description ACCLAIM/COPD I and II – Both fully recruited 2 main Ph III studies Improvement of lung function and symptoms and safety long-term, double blind, randomized, parallel groups, 1 year tr
Slide 15: Aclidinium Bromide: superior inhalation device
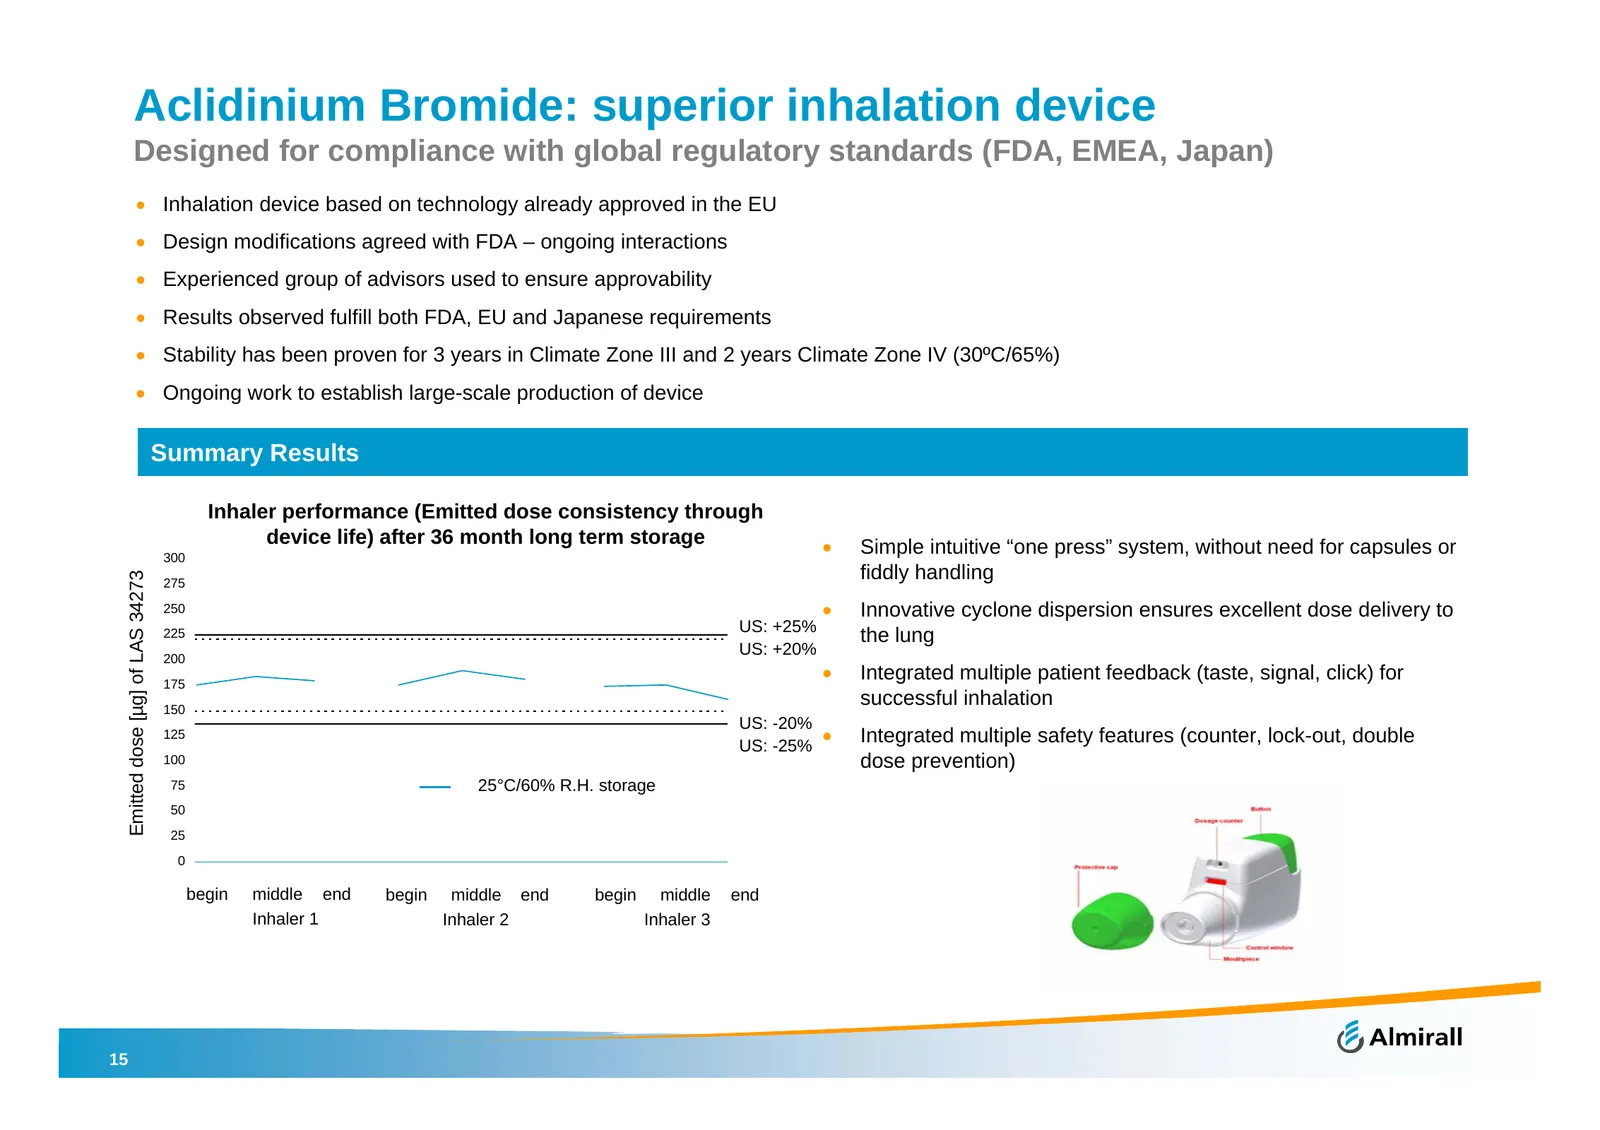
Aclidinium Bromide: superior inhalation device Designed for compliance with global regulatory standards (FDA, EMEA, Japan) • Inhalation device based on technology already approved in the EU • Design modifications agreed with FDA – ongoing interactions • Experienced group of advisors used to ensure a
Slide 16: A pipeline with transformational potential
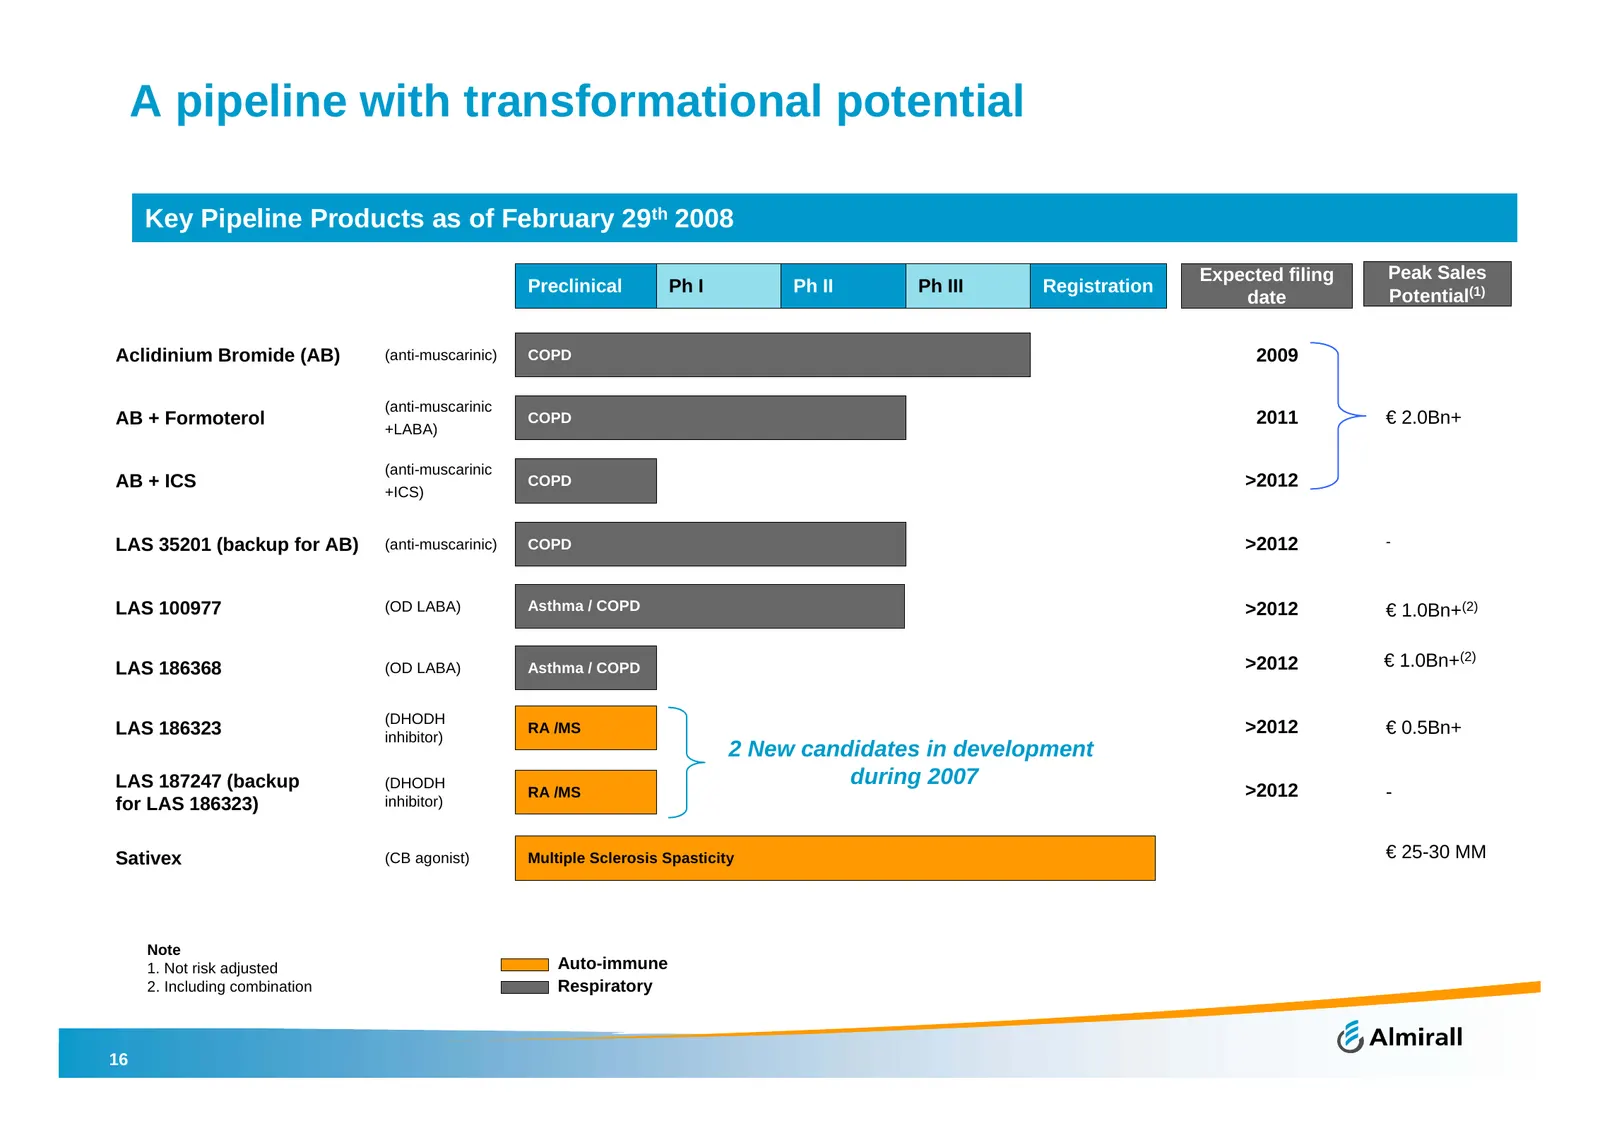
A pipeline with transformational potential Key Pipeline Products as of February 29th 2008 Expected filing Peak Sales Preclinical Ph I Ph II Ph III Registration Potential(1) date Aclidinium Bromide (AB) (anti-muscarinic) COPD 2009 (anti-muscarinic AB + Formoterol COPD 2011 € 2.0Bn+ +LABA) (anti-musca
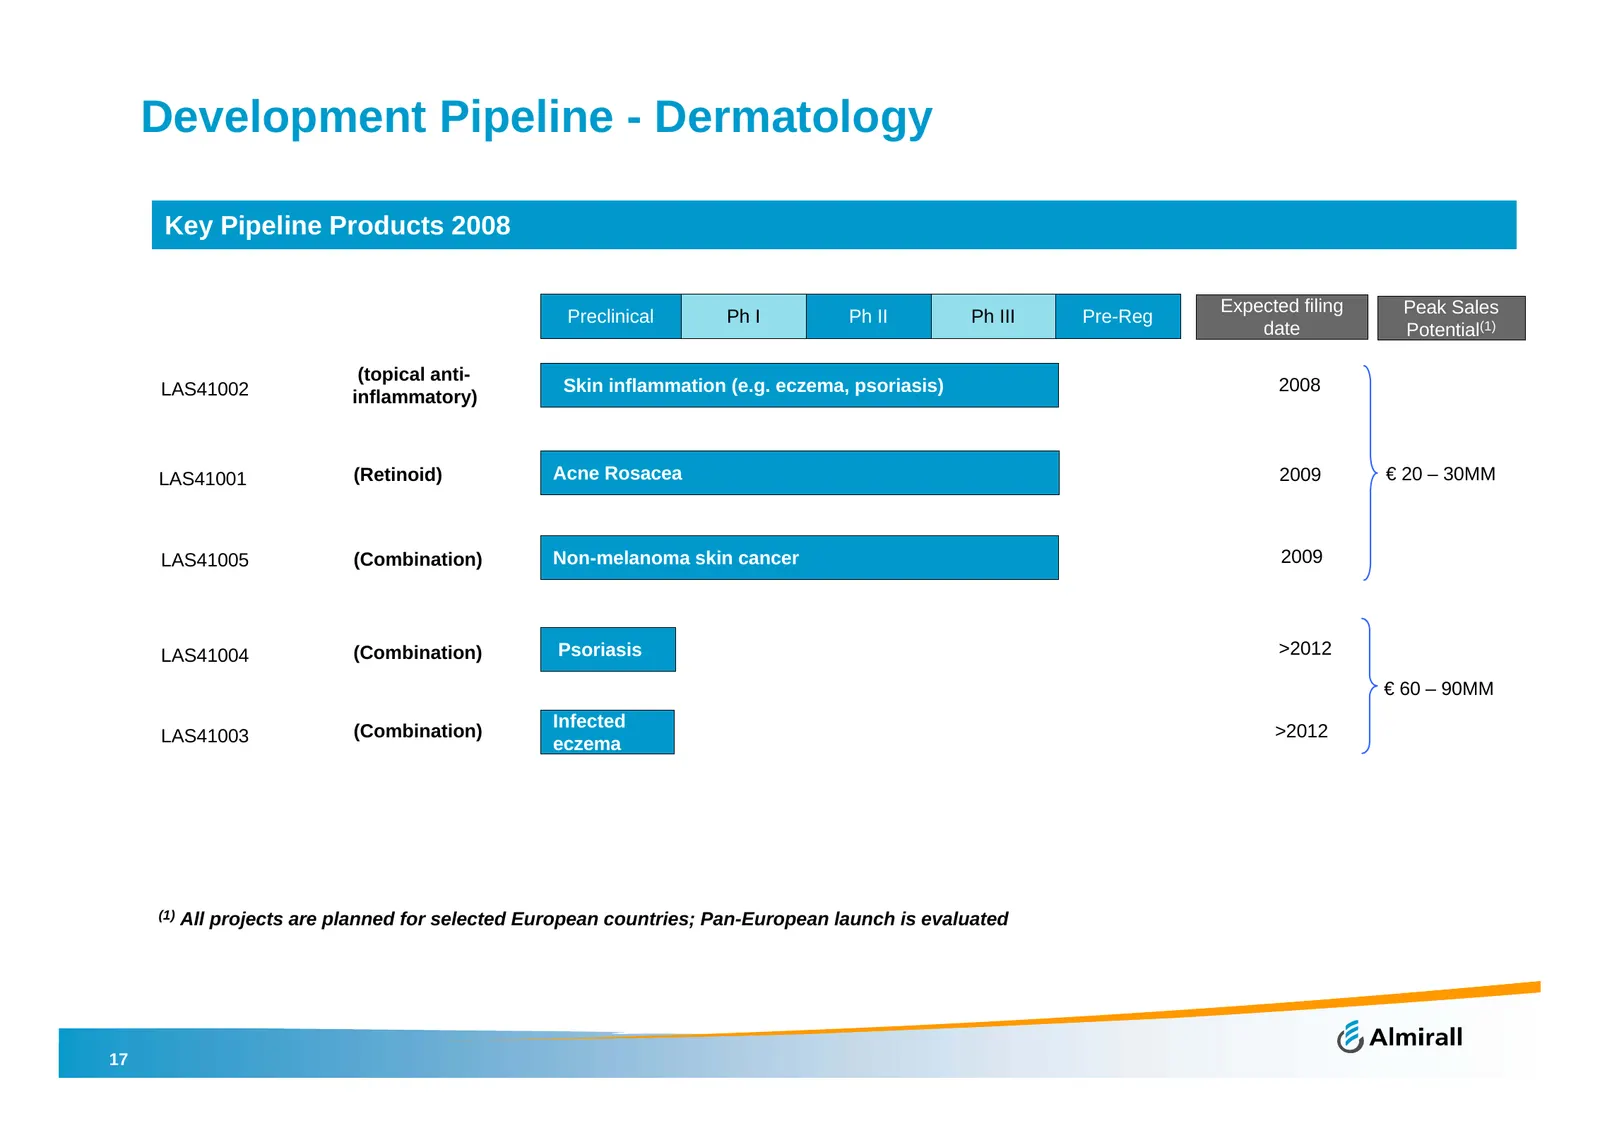
Slide 17: Development Pipeline - Dermatology
Development Pipeline - Dermatology Key Pipeline Products 2008 Expected filing Peak Sales Preclinical Ph I Ph II Ph III Pre-Reg date Potential(1) (topical anti- LAS41002 Skin inflammation (e.g. eczema, psoriasis) 2008 inflammatory) LAS41001 (Retinoid) Acne Rosacea 2009 € 20 – 30MM LAS41005 (Combinati
Slide 18: Financials
Financials 18
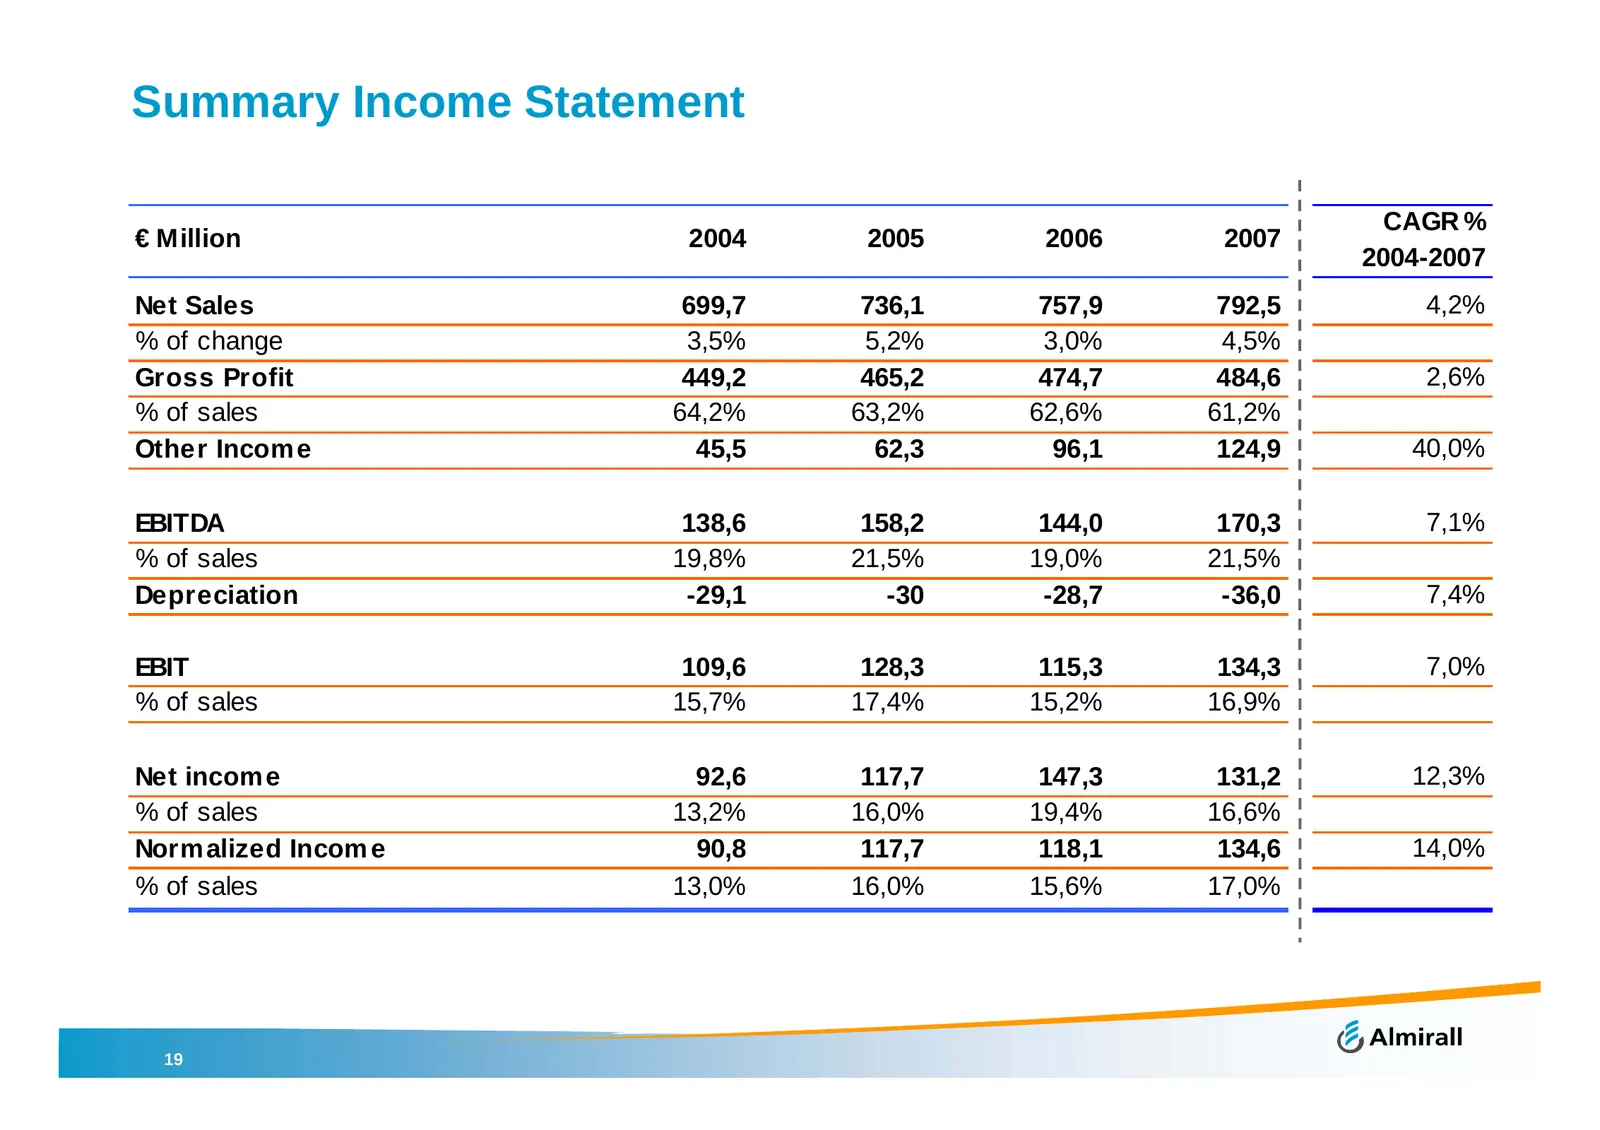
Slide 19: Summary Income Statement
Summary Income Statement CAGR % € Million 2004 2005 2006 2007 2004-2007 Net Sales 699,7 736,1 757,9 792,5 4,2% % of change 3,5% 5,2% 3,0% 4,5% Gross Profit 449,2 465,2 474,7 484,6 2,6% % of sales 64,2% 63,2% 62,6% 61,2% Other Incom e 45,5 62,3 96,1 124,9 40,0% EBITDA 138,6 158,2 144,0 170,3 7,1% % o
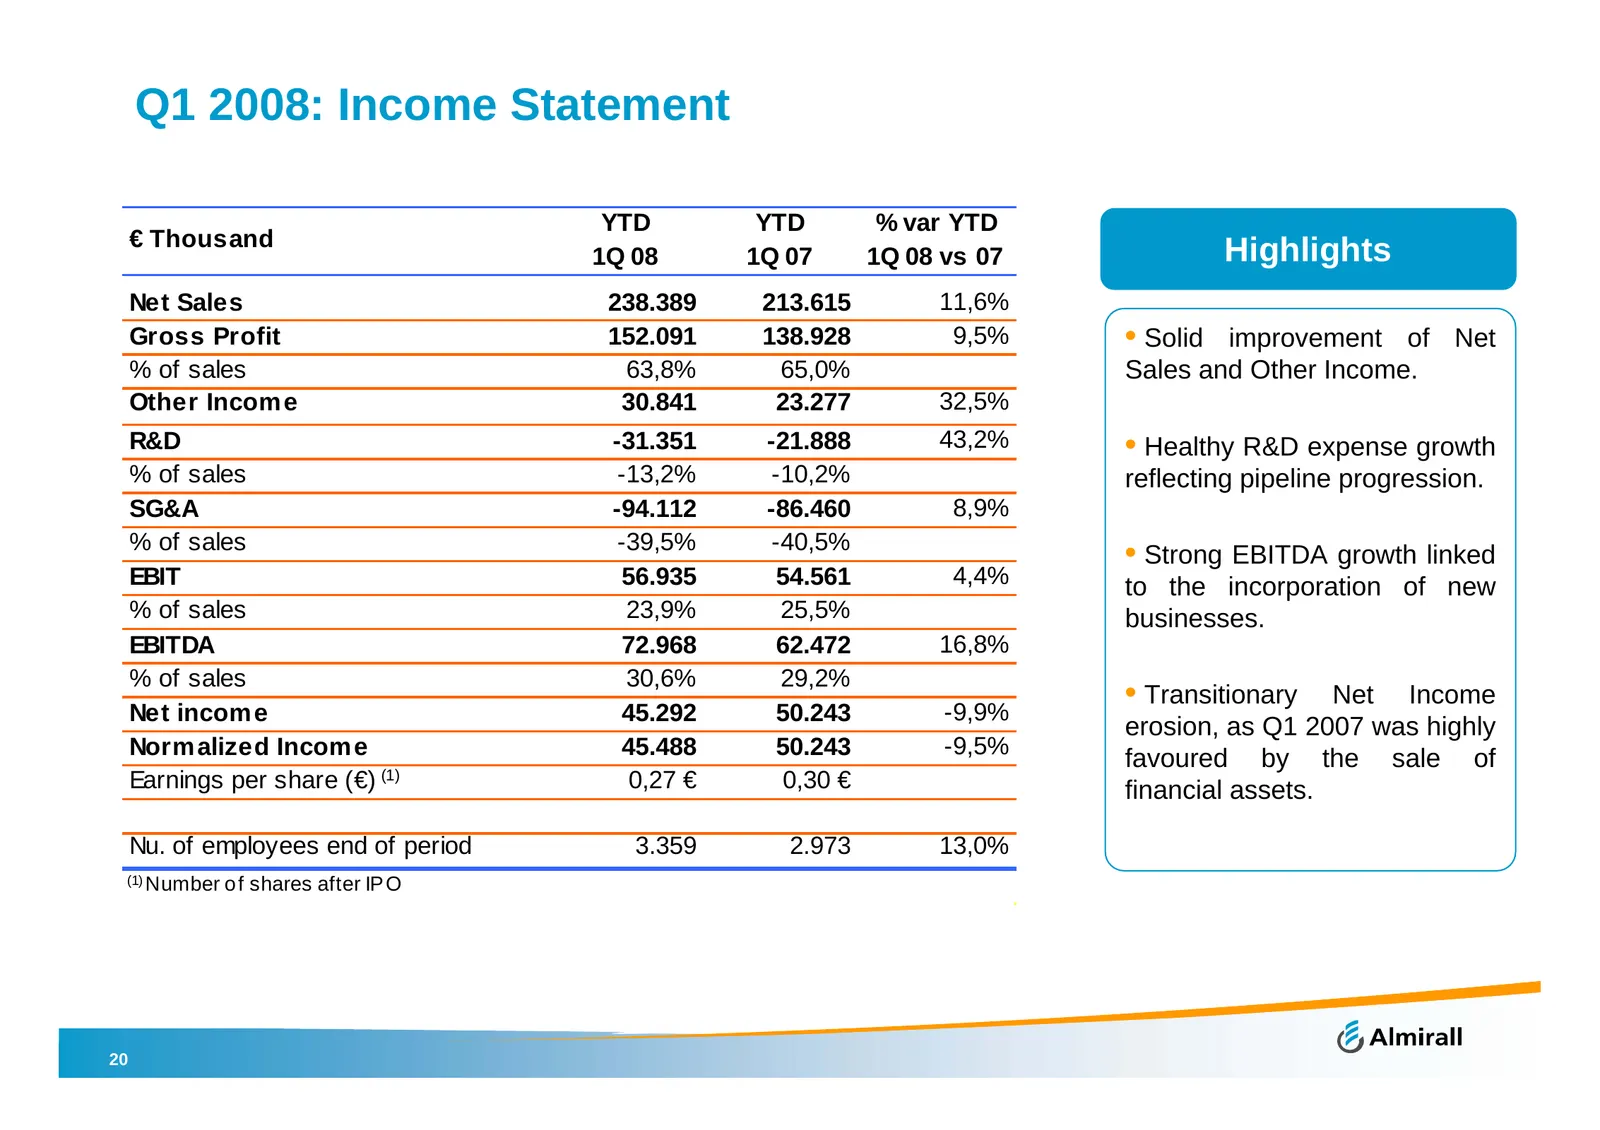
Slide 20: Q1 2008: Income Statement
Q1 2008: Income Statement YTD YTD % var YTD € Thousand 1Q 08 1Q 07 1Q 08 vs 07 Highlights Net Sales 238.389 213.615 11,6% Gross Profit 152.091 138.928 9,5% • Solid improvement of Net % of sales 63,8% 65,0% Sales and Other Income. Other Incom e 30.841 23.277 32,5% R&D -31.351 -21.888 43,2% • Healthy
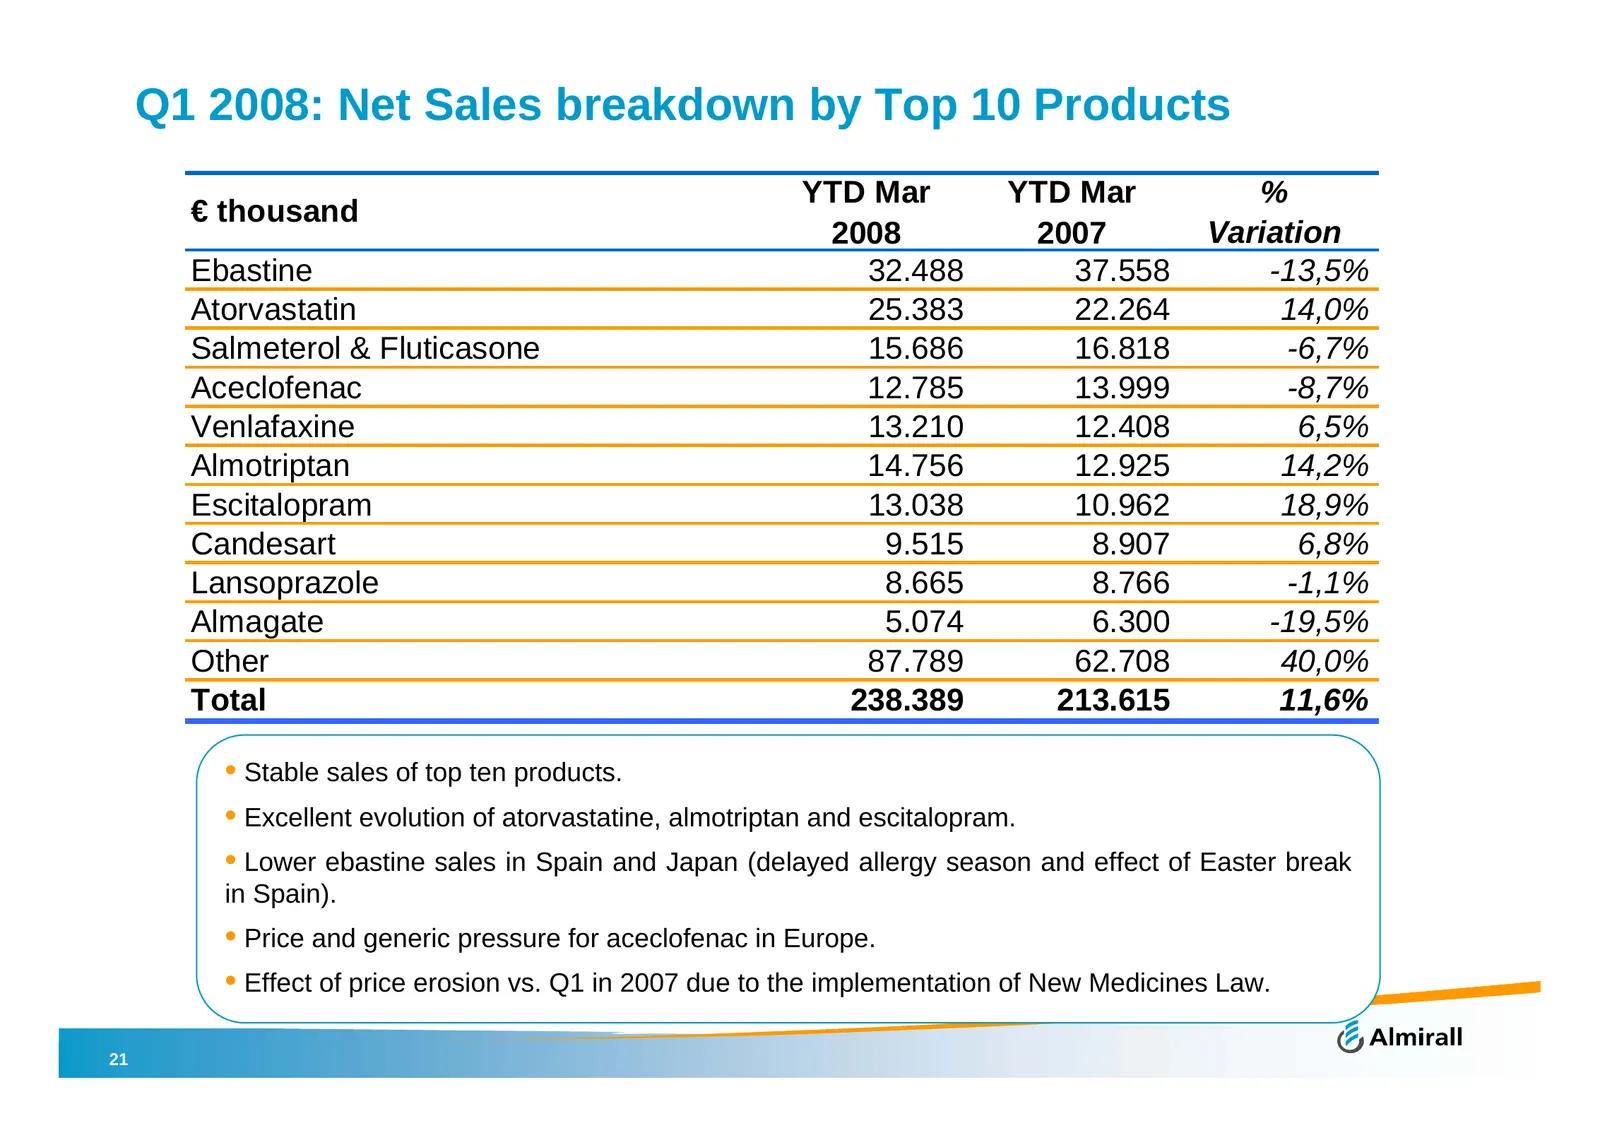
Slide 21: Q1 2008: Net Sales breakdown by Top 10 Products
Q1 2008: Net Sales breakdown by Top 10 Products YTD Mar YTD Mar % € thousand 2008 2007 Variation Ebastine 32.488 37.558 -13,5% Atorvastatin 25.383 22.264 14,0% Salmeterol & Fluticasone 15.686 16.818 -6,7% Aceclofenac 12.785 13.999 -8,7% Venlafaxine 13.210 12.408 6,5% Almotriptan 14.756 12.925 14,2%
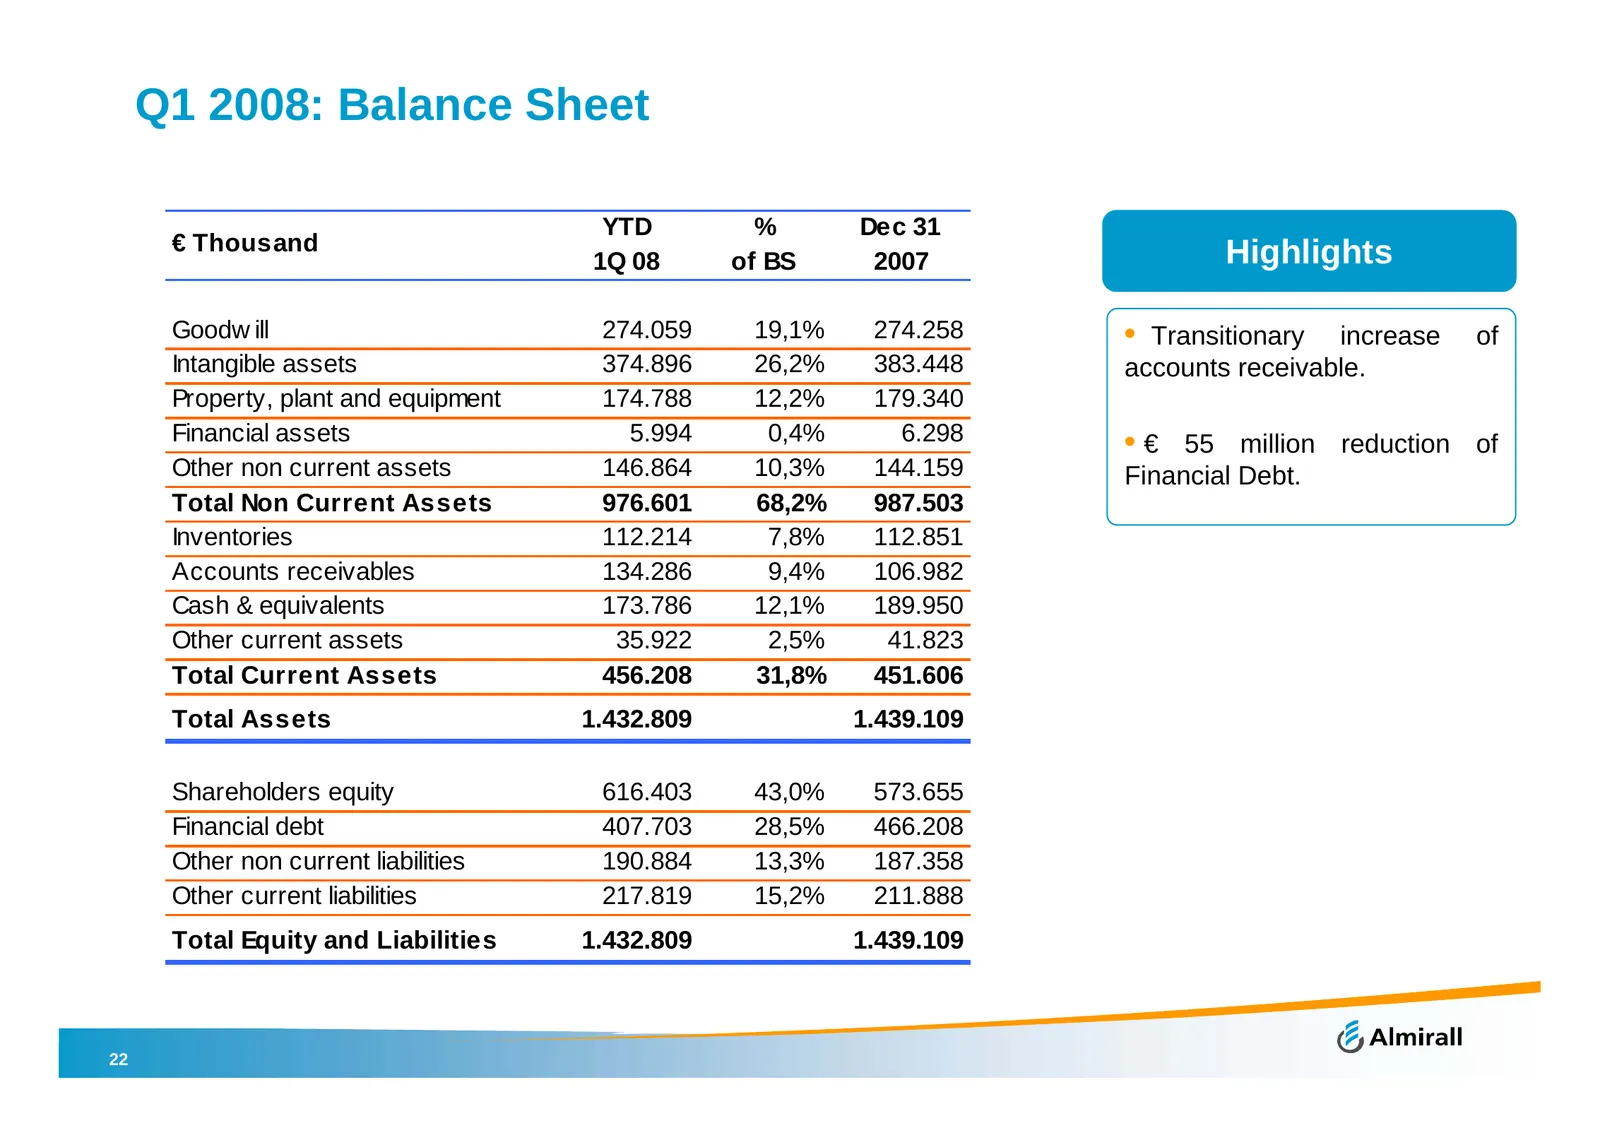
Slide 22: Q1 2008: Balance Sheet
Q1 2008: Balance Sheet YTD % Dec 31 € Thousand Highlights 1Q 08 of BS 2007 Goodw ill 274.059 19,1% 274.258 • Transitionary increase of Intangible assets 374.896 26,2% 383.448 accounts receivable. Property, plant and equipment 174.788 12,2% 179.340 Financial assets 5.994 0,4% 6.298 •€ 55 million redu
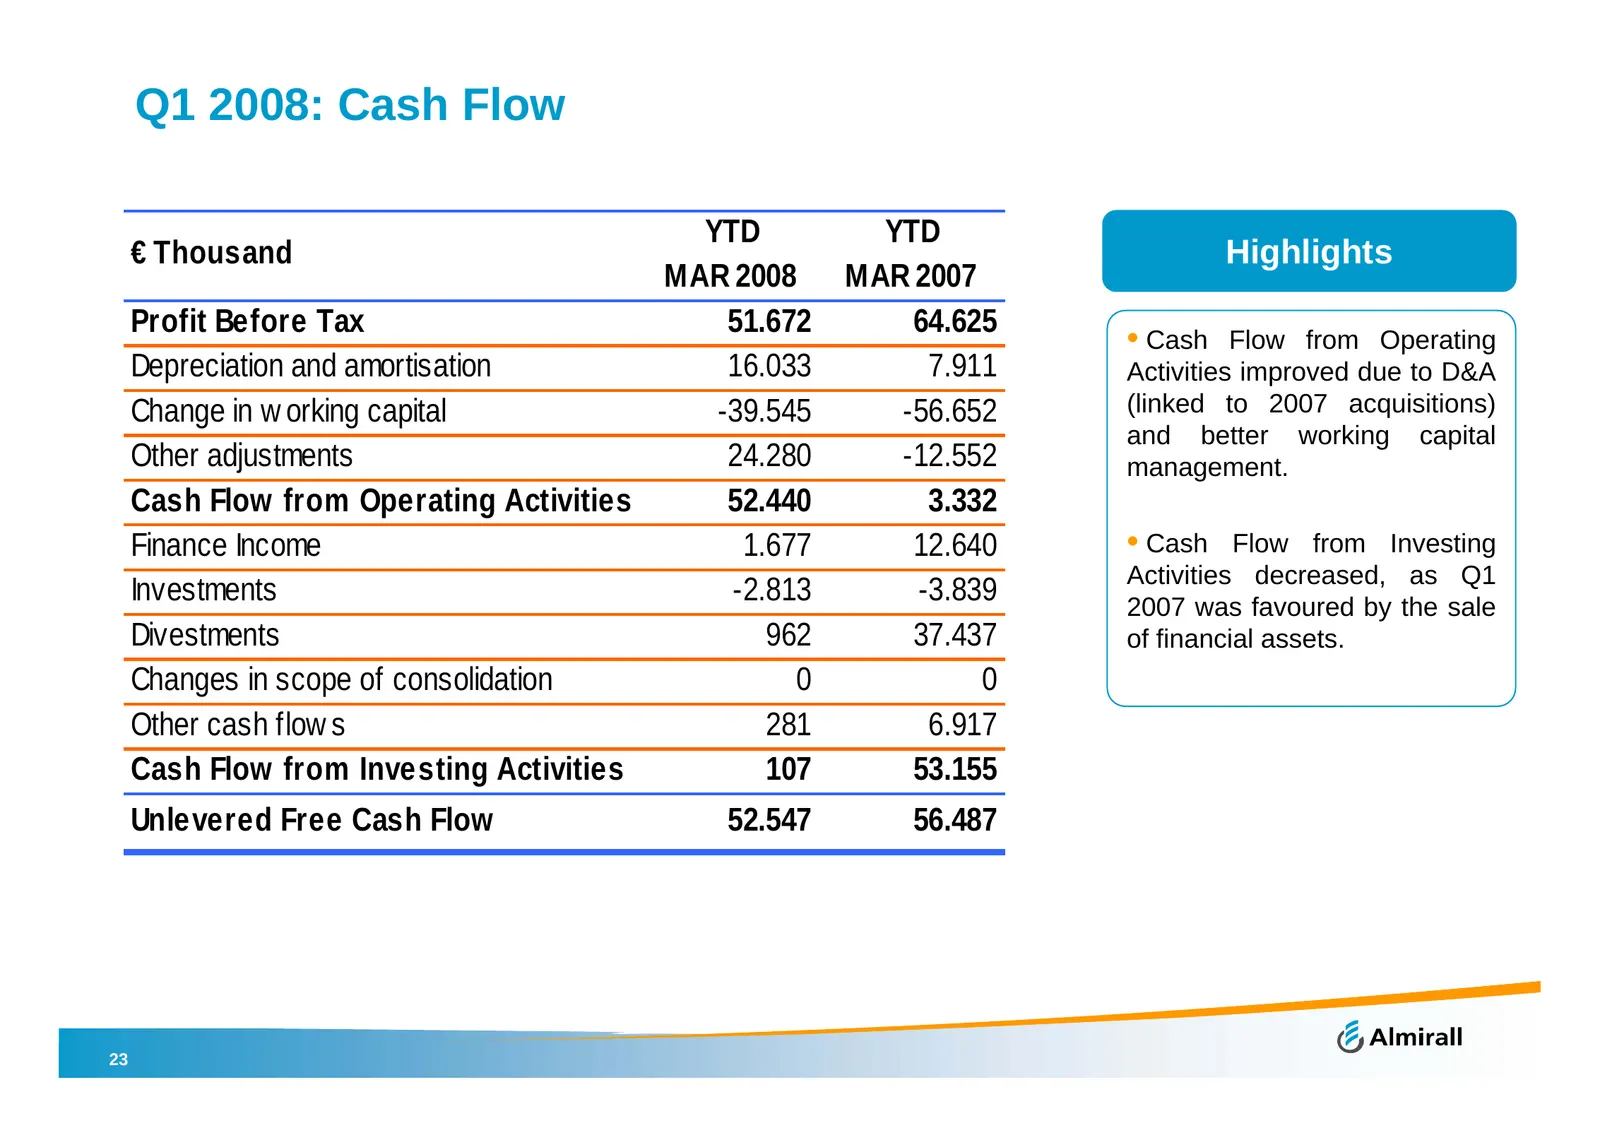
Slide 23: Q1 2008: Cash Flow
Q1 2008: Cash Flow YTD YTD € Thousand Highlights MAR 2008 MAR 2007 Profit Before Tax 51.672 64.625 • Cash Flow from Operating Depreciation and amortisation 16.033 7.911 Activities improved due to D&A Change in w orking capital -39.545 -56.652 (linked to 2007 acquisitions) and better working capital
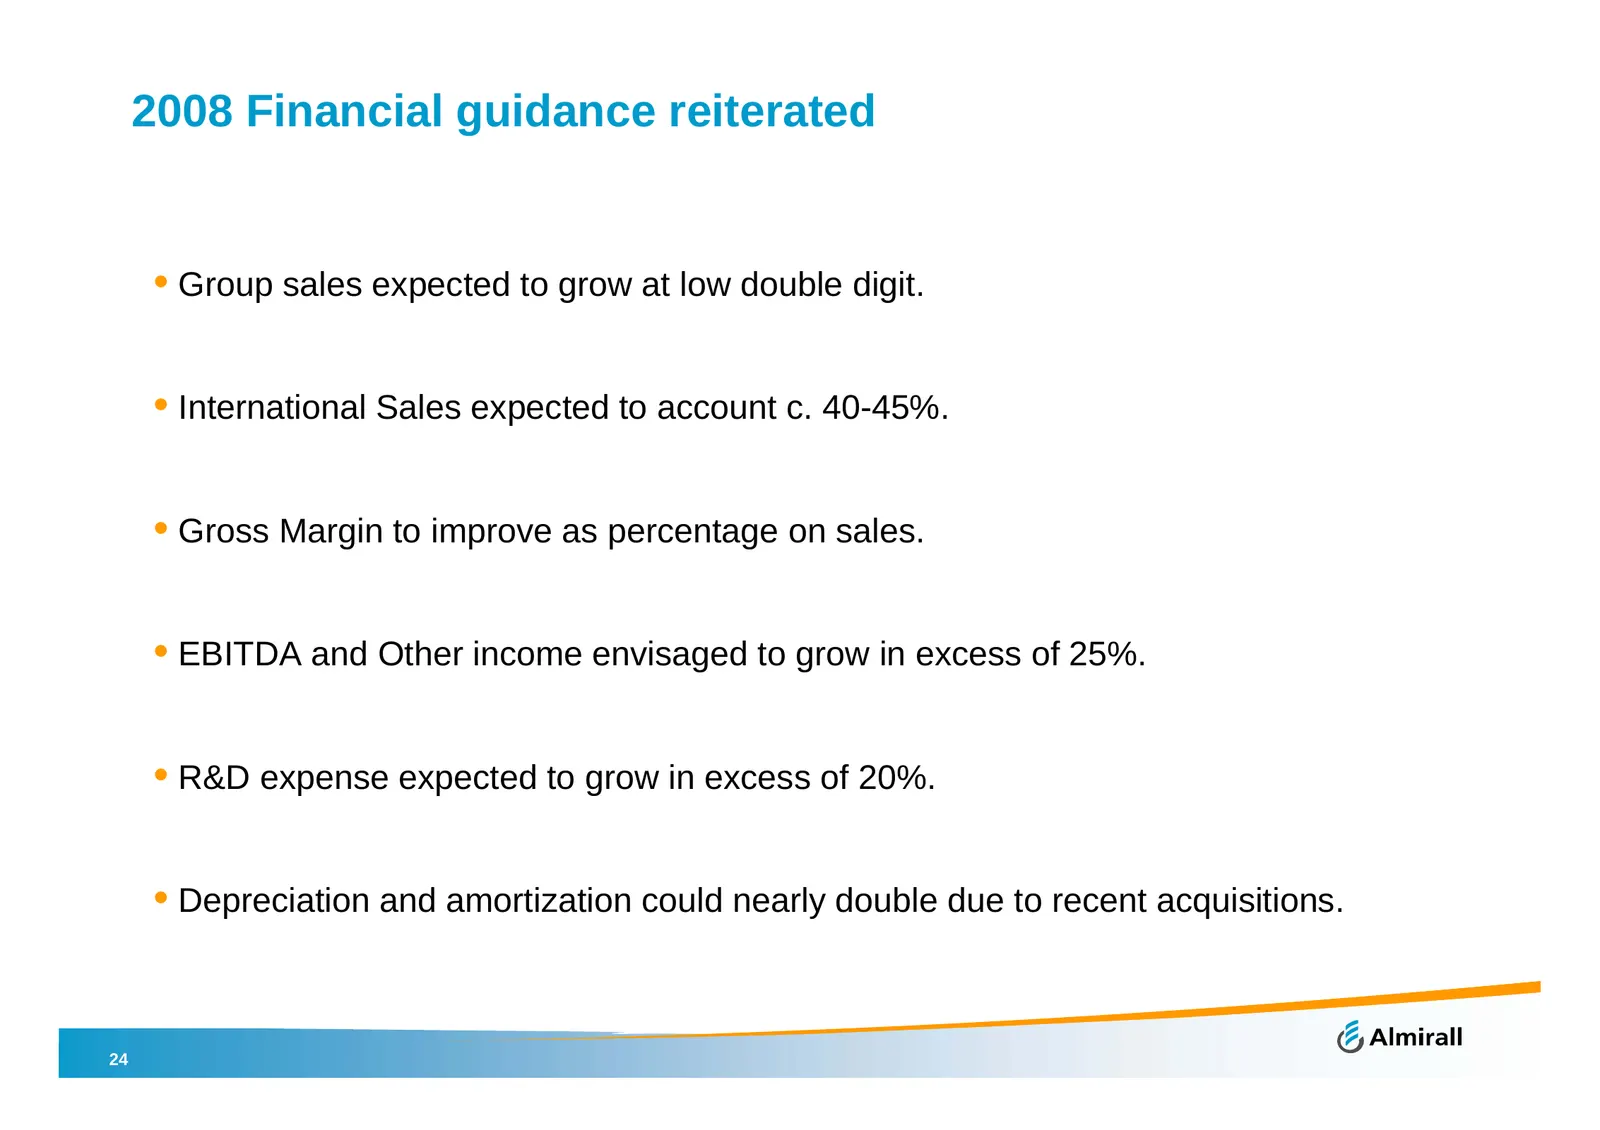
Slide 24: 2008 Financial guidance reiterated
2008 Financial guidance reiterated • Group sales expected to grow at low double digit. • International Sales expected to account c. 40-45%. • Gross Margin to improve as percentage on sales. • EBITDA and Other income envisaged to grow in excess of 25%. • R&D expense expected to grow in excess of 20%.
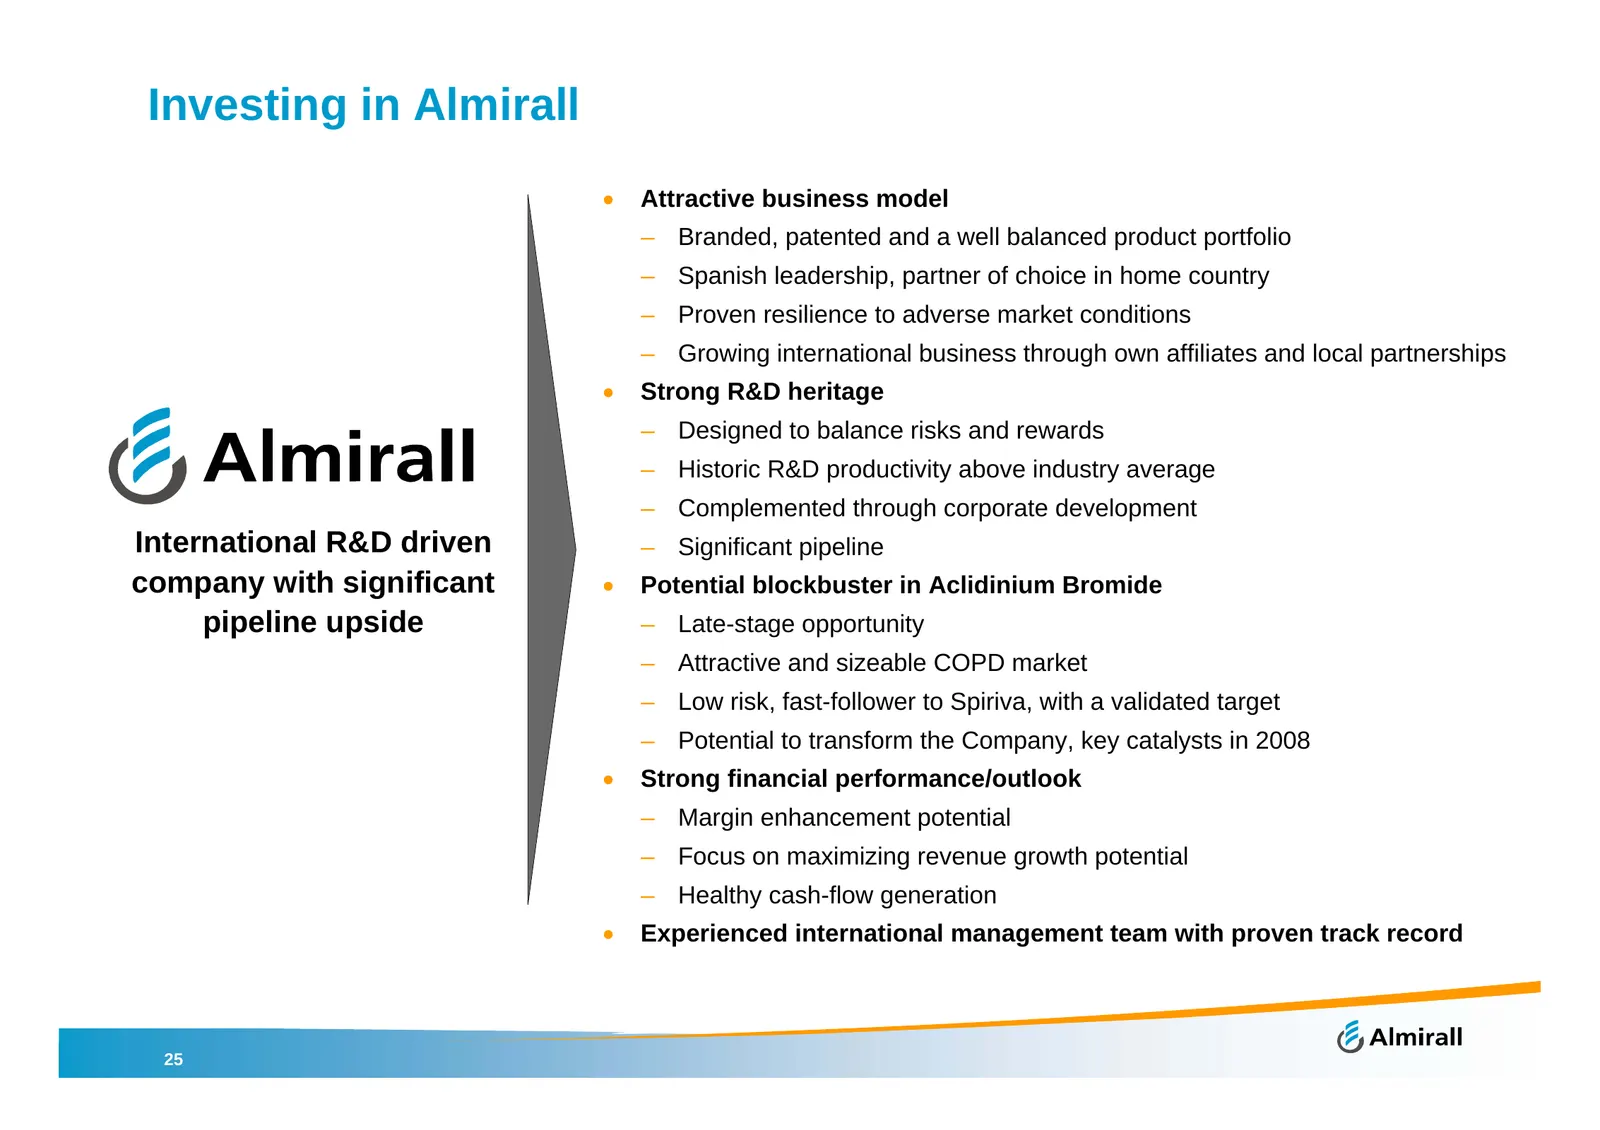
Slide 25: Investing in Almirall
Investing in Almirall • Attractive business model – Branded, patented and a well balanced product portfolio – Spanish leadership, partner of choice in home country – Proven resilience to adverse market conditions – Growing international business through own affiliates and local partnerships • Strong
Slide 26: (% Almirall
Zé . (% Almirall Solutions with you in mind
Source: Internet Archive copy of almirall.com
More decks from Almirall SA
 H1 2026 Earnings Presentation30 slides · Jul 24, 2026
 Q1 2026 Earnings Presentation29 slides · May 11, 2026
 FY 2025 Earnings Presentation34 slides · Feb 23, 2026
 Q1 2025 Earnings Presentation28 slides · May 12, 2025
 FY2024 Earnings Presentation41 slides · Feb 24, 2025
 H1 2024 Earnings Presentation33 slides · Jul 22, 2024