SVB Financial — JMP Securities Research Conference 2011
43 slides from SVB Financial's conference presentation, May 9, 2011
Slide 1: JMP Securities Research Conference
JMP Securities Research Conference May 9, 2011 Exhibit 99.1
Slide 2: Overview
SVB’s Unique Model Strong Performance Growth Initiatives Outlook for 2011 Appendix Overview Overview
Slide 3: A Unique Financial Services Company
A Unique Financial Services Company Differentiated business model • Focus on “innovation” markets • Balance sheet lender • Low cost funds from highly liquid clients • Diversified revenue streams Leader • Leading market share • More than 550 venture firm clients • The bank for high-growth innovation
Slide 4: Complete Financial Services Platform
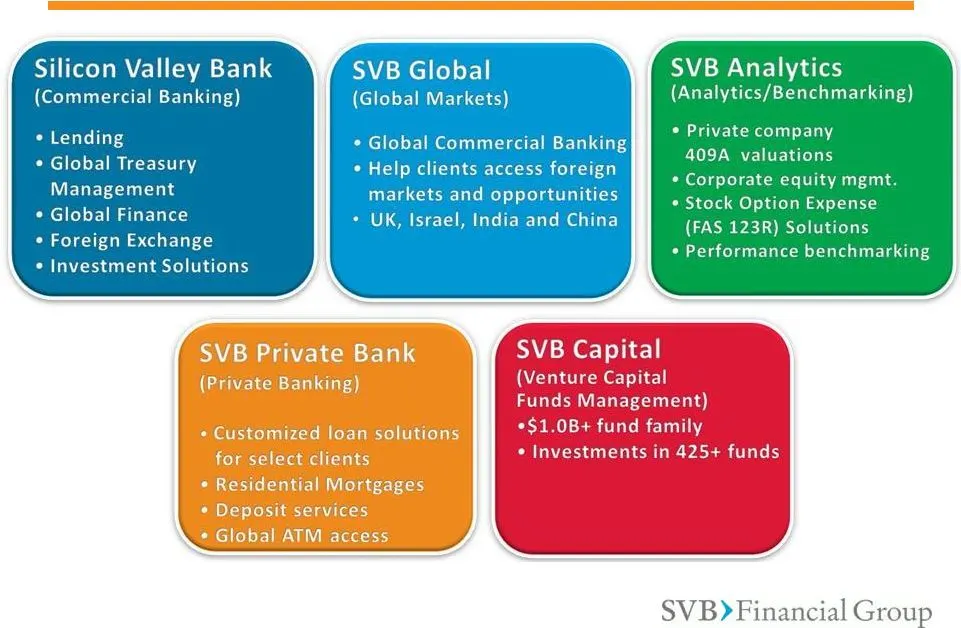
Complete Financial Services Platform SVB’s Unique Model
Slide 5: Solid Q111 Performance
Third straight quarter of loan growth Fifth straight quarter of credit quality improvement Improving net interest margin Strong warrant and VC gains Net interest income at record highs Strong loan pipeline Outstanding deposit growth Improving markets for our clients Solid Q111 Performance Strong Per
Slide 6: Strong Organic Growth in Q111
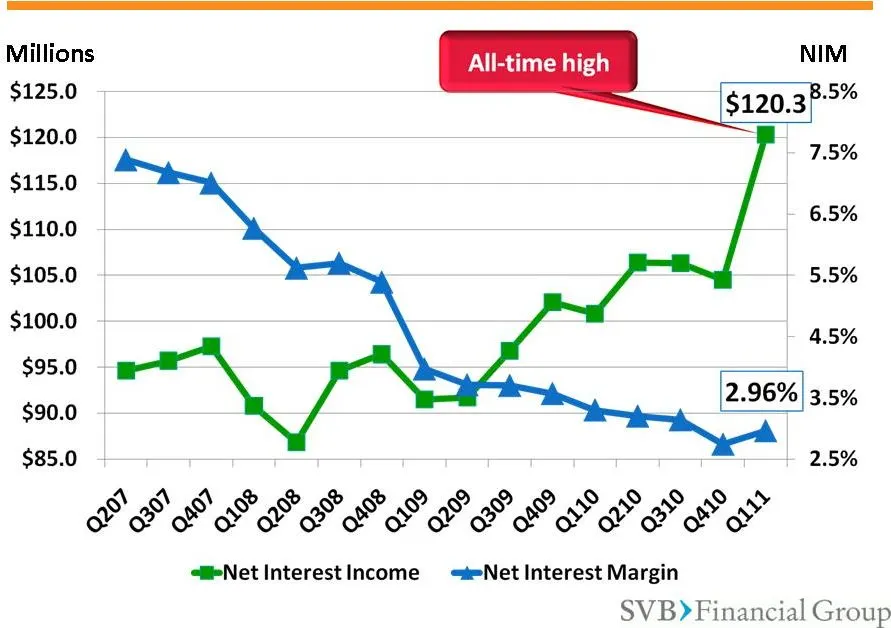
Strong Organic Growth in Q111 Strong Performance * From prior quarter • Diluted earnings per share of $0.76 vs. street consensus of $0.48 • Net income of $33 million • Average loan growth of $305 million (6.1%)* • Average deposit growth of $1.4 billion (10.3%)* • Record net interest income of $120 m
Slide 7: Net Interest Income Remains Strong
Net Interest Income Remains Strong Strong Performance
Slide 8: An Expanded Balance Sheet
An Expanded Balance Sheet DRIVERS • Low interest rate environment • Solid client liquidity • New client acquisition • High-quality balance sheet WE REMAIN FOCUSED ON MANAGING OUR BALANCE SHEET • Ensuring clients are in the right deposit and investment products • New client investment products • Rece
Slide 9: Our Growth Initiatives
UK Branch Application India Branch Application China JV Application Israel Office Correspondent Banking Network Debit & Credit Cards New Products & Services Custom Credit Products & Programs GLOBAL MARKETS & REACH Global Core Banking System IT Backbone Upgrade Global Payment Systems Enhanced On- lin
Slide 10: Our 2011 Outlook Has Improved
Metric 2011 Outlook (1) Prior Outlook (1/20/11) Our 2011 Outlook Has Improved 1) See latest quarterly press release for more information 2) Excluding expenses related to non-controlling interests. Non-GAAP number. Please see non-GAAP disclosures at end of presentation and our most recent financial r
Slide 11: Outlook for 2011 vs. Street Estimates: EPS and ROE
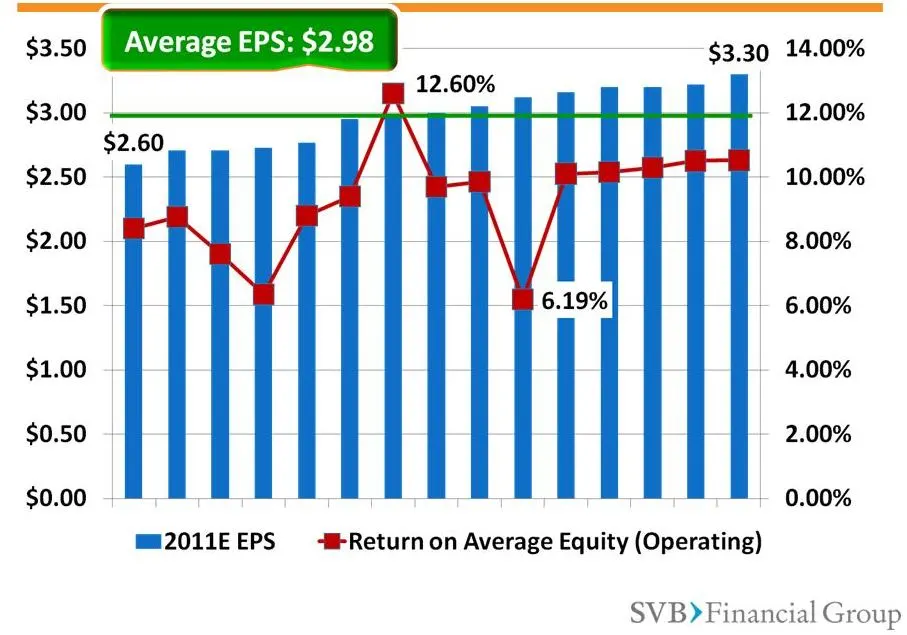
Street Estimates: 2011 EPS and ROE* * Based on published reports as of 05/08/11. Certain estimates and adjustments have been made where necessary. Please refer to analyst reports before forming any conclusions. Outlook for – vs. Street Estimates
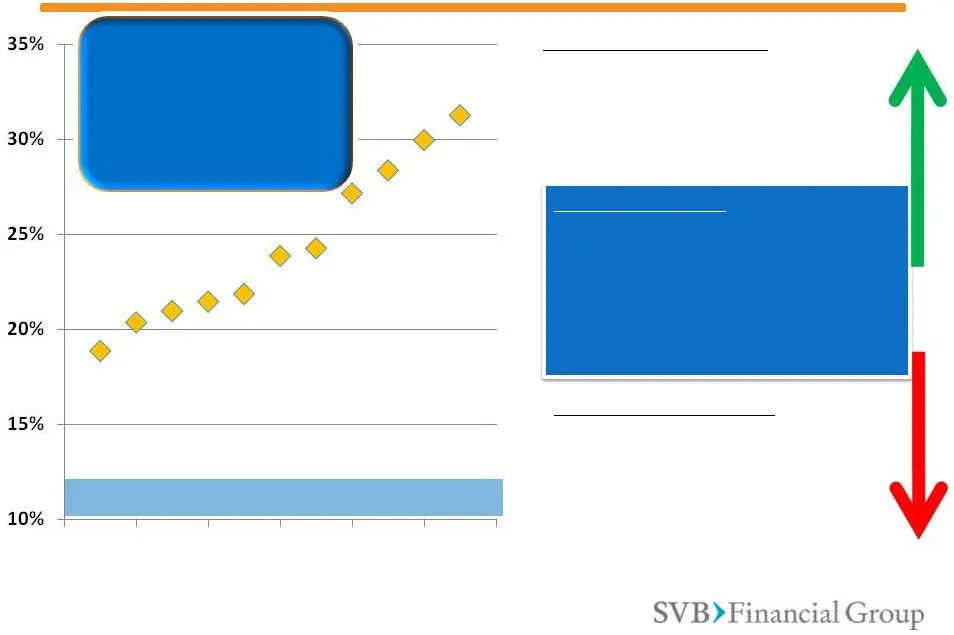
Slide 12: SVB 2011 Outlook: Mid-20s % Growth
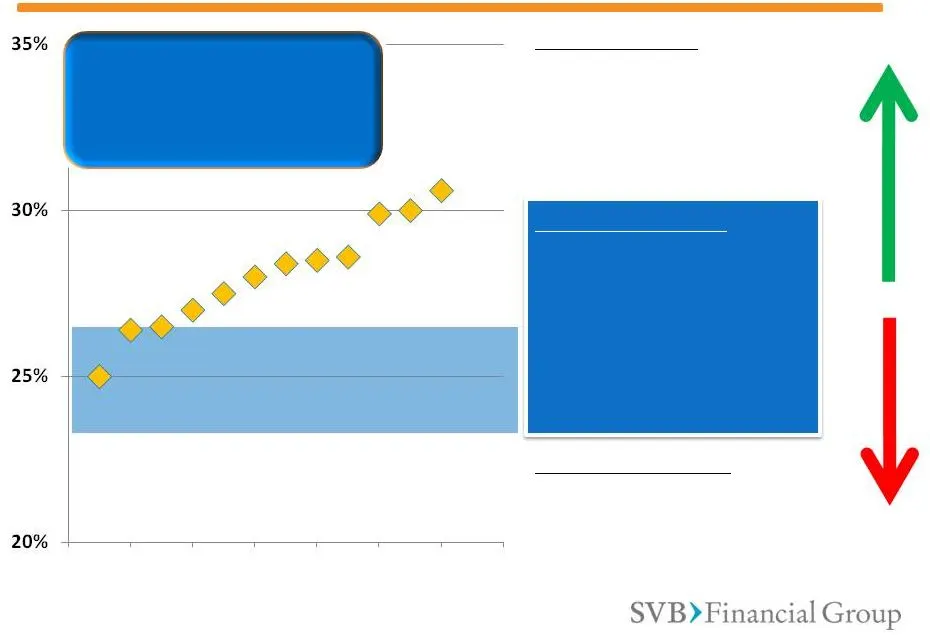
SVB 2011 Outlook: Mid-20s % Growth Our Assumptions • Modest economic growth in 2011 • Stabilizing IPO/M&A markets • Stabilizing VC investment * Based on published providing estimates for average loan growth as of 05/08/11. Certain estimates and adjustments have been made where necessary. Please refe
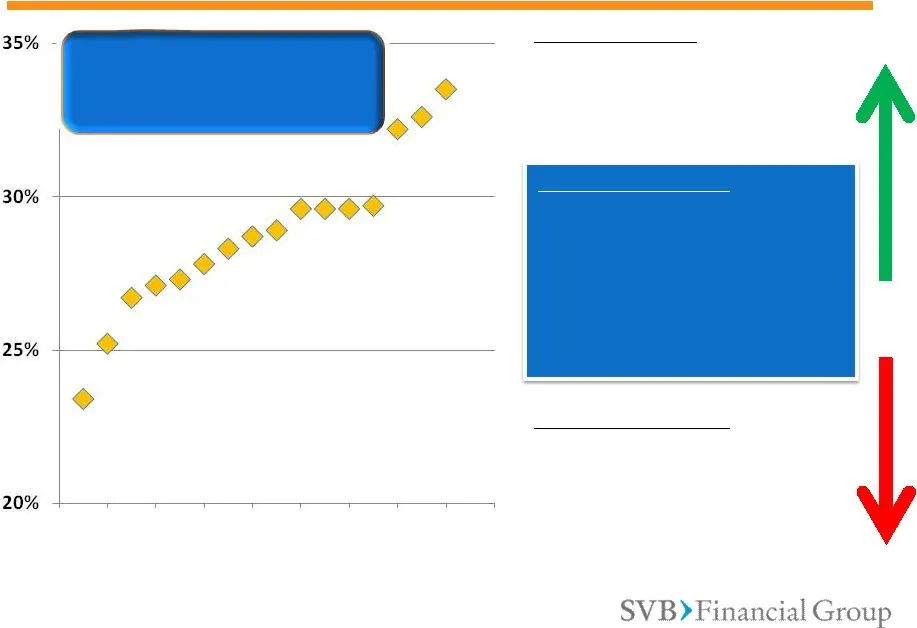
Slide 13: SVB 2011 Outlook: Low Double Digit % Growth
Our Assumptions • Modest economic growth • VC Investment improves but remains low • Strong tech spending • Success of target initiatives to increase off-balance sheet funds SVB 2011 Outlook: Low Double Digit % Growth Street Estimates: Average Deposits* Outlook for 2011 – vs. Street Estimates Higher
Slide 14: SVB> Financial Group
35% - 30% 25% 20% SVB> Financial Group
Slide 15: Solid Momentum For Growth in 2011
Solid Momentum For Growth in 2011 • Improving business environment • Growing client revenues due to increasing technology spending • Improving venture-backed exit markets • Beginning to see results from growth initiatives Outlook for 2011
Slide 16: SVB> Financial Group
SVB> Financial Group

Slide 17: Appendix
Appendix 1) First Quarter 2011 Review • Highlights • Loans & Credit Quality 21-24 • Assets and Client Liquidity 25-26 • Balance Sheet • Sensitivity Charts 28-29 • Capital Ratios • 2011 Outlook 2) Annual Metrics 32-33 3) Growth Initiatives 34-37 4) Venture Capital Markets 38-39 6) Non-GAAP Reconcilia
Slide 18: First Quarter 2011 Review
First Quarter 2011 Review Appendix – First Quarter Review
Slide 19: Quarterly Financial Highlights
Q111 Q410 Q310 Q210 Q110 Quarterly Financial Highlights Diluted Earnings Per Share $0.76 $0.41 $0.89 (1) $0.50 $0.44 Net Income Available to Common Stockholders $33.0M $17.5M $37.8M (1) $21.1M $18.6M Average Loans (Change) $5.3B (+6.1%) $5.0B (+11.3%) $4.5B (+9.4%) $4.1B (-0.1%) $4.1B (-5.8%) Averag
Slide 20: Loans Are At an All-Time High
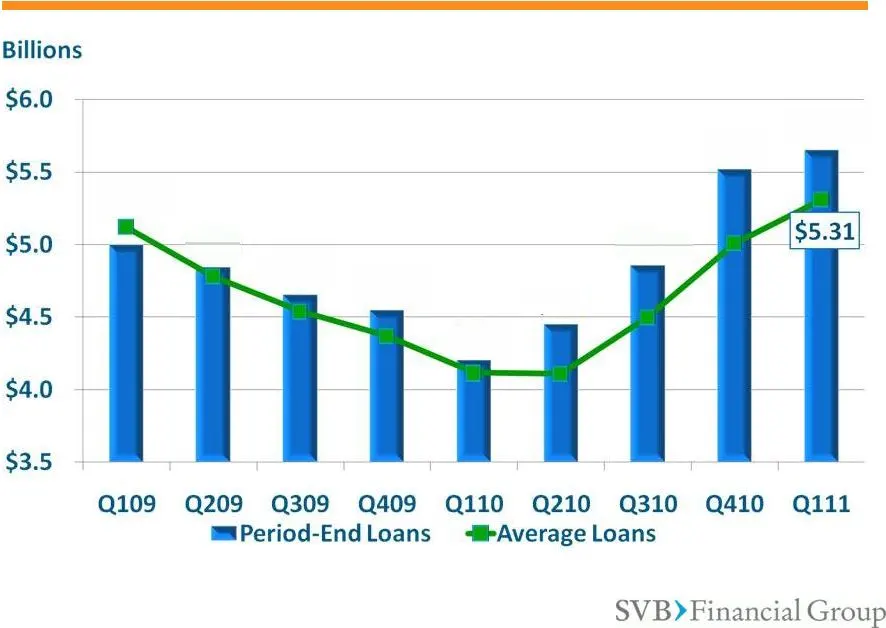
Loans Are At an All-Time High Appendix – First Quarter Review $5.65
Slide 21: A Focused, High-Quality Loan Portfolio
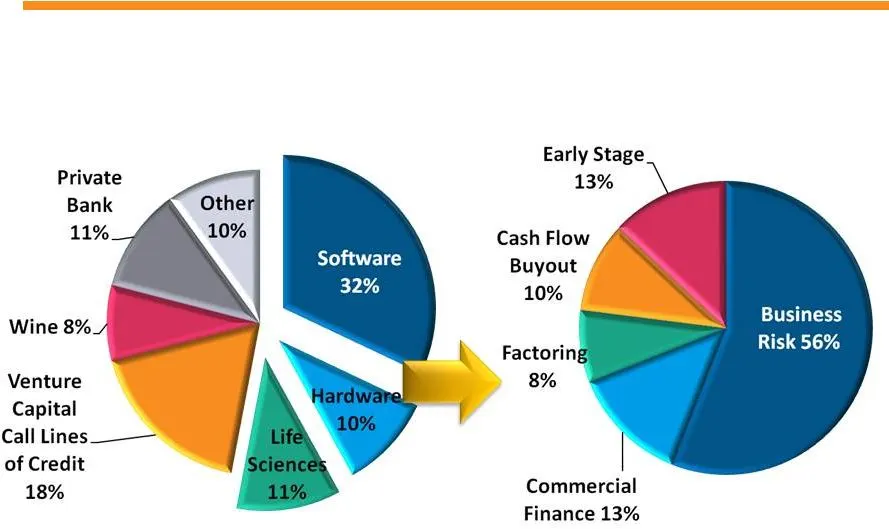
A Focused, High-Quality Loan Portfolio Risk Composition of Technology and Life Science Lending Total Loan Portfolio (3/31/11) $5.7 Billion Appendix – First Quarter Review
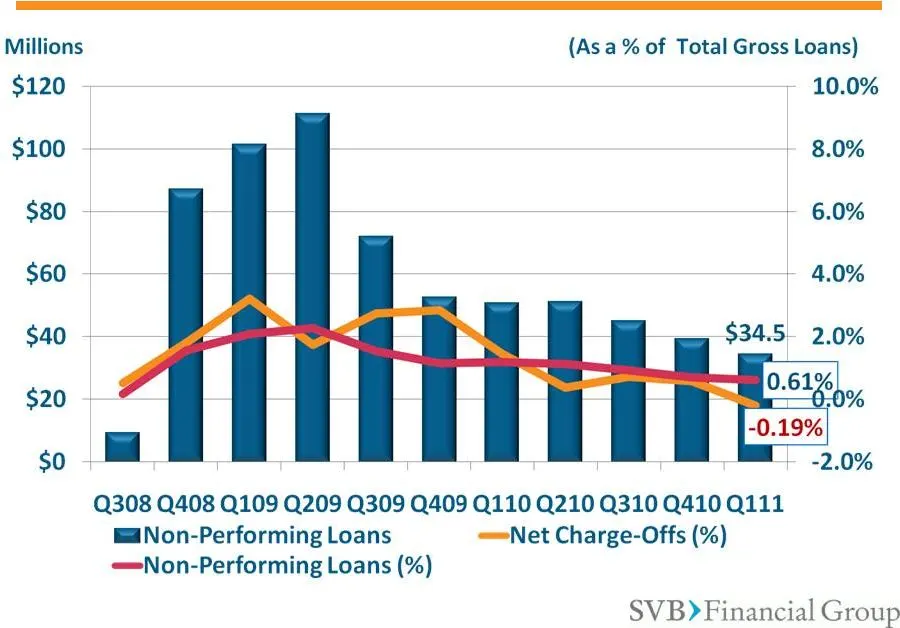
Slide 22: Credit Quality Has Improved
Credit Quality Has Improved Appendix – First Quarter Review
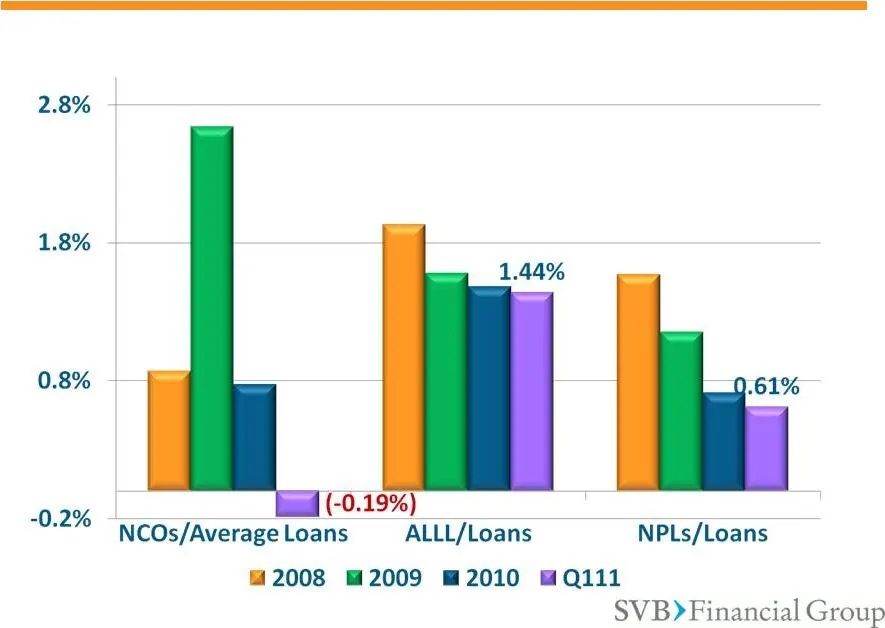
Slide 23: Credit Quality Has Improved
Credit Quality Has Improved Appendix – First Quarter Review
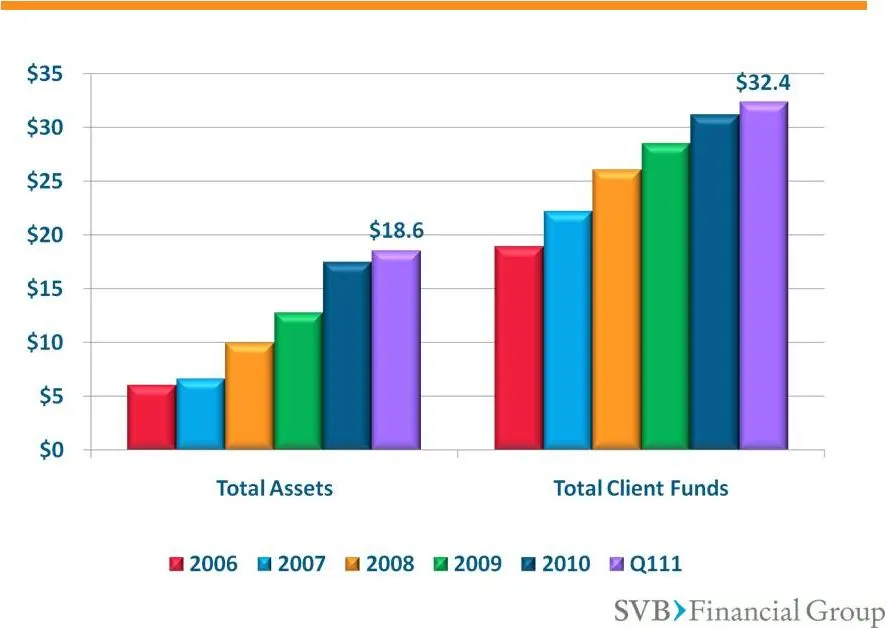
Slide 24: Solid Franchise With Consistent Growth
Solid Franchise With Consistent Growth Billions Appendix – First Quarter Review
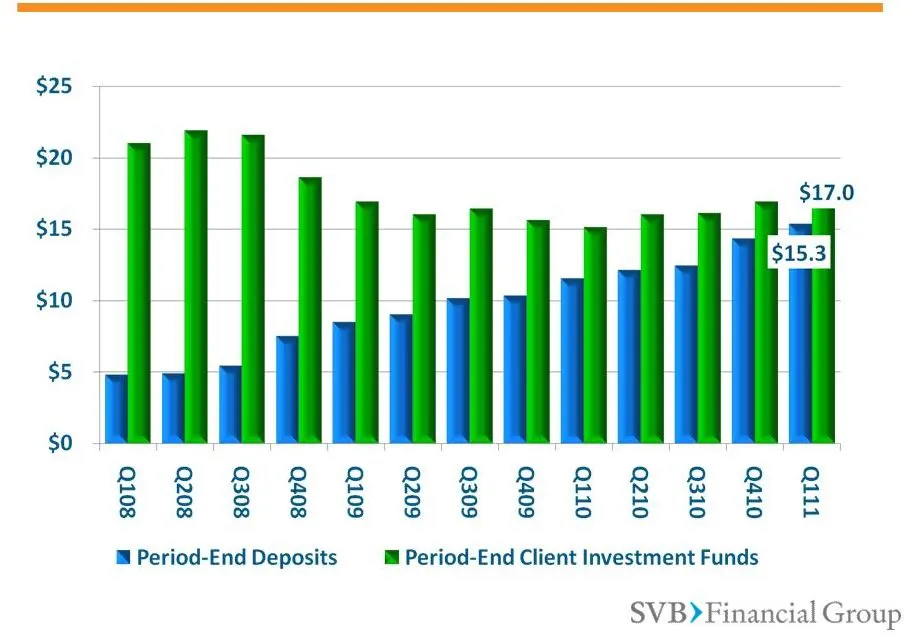
Slide 25: Our Clients Have Ample Liquidity
Our Clients Have Ample Liquidity Billions Appendix – First Quarter 2011 Review
Slide 26: A Liquid Balance Sheet
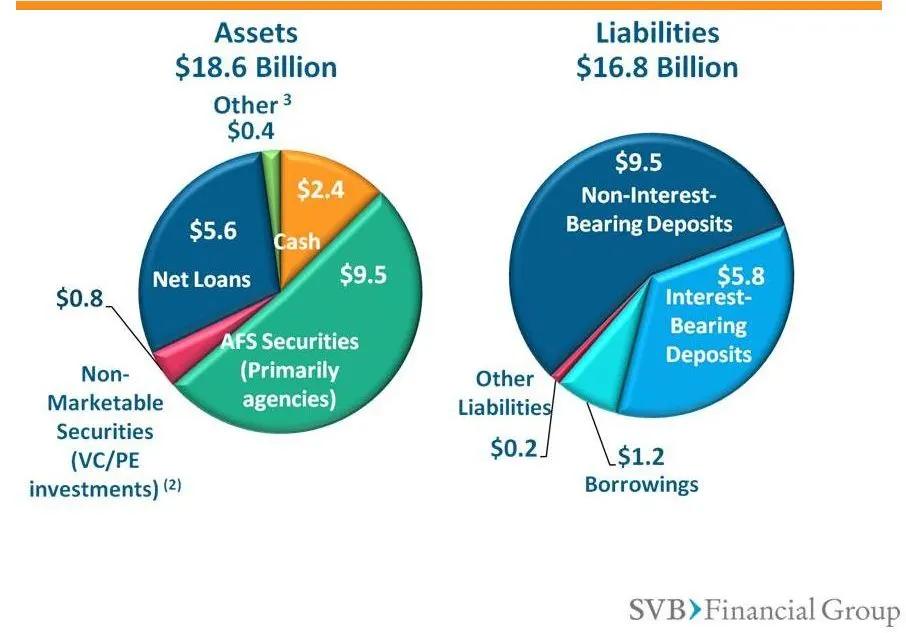
A Liquid Balance Sheet (1) 1) At 3/31/11 2) Net of non-controlling interests, non-marketable securities were $310.1 million. Non-GAAP number. Please see non-GAAP reconciliation at end of presentation and our most recent financial releases for more information. 3) Includes A) Premises and Equipment N
Slide 27: Rising Rates Will Benefit Us Significantly
Changes in Fed Funds Rate (basis points) Changes in Net Interest Income (tax effected) Incremental EPS Effect Incremental ROE Effect Net Interest Margin Effect Rising Rates Will Benefit Us Significantly Each 25 bps increase in the Fed Funds rate contributes approximately $4 – $8 million to Net Inter
Slide 28: Higher Loan Balances Will Benefit Us
Growth in Overall Loan Balances ($$) Changes in Net Interest Income (tax effected) Incremental EPS Effect Incremental ROE Effect Net Interest Margin Effect Higher Loan Balances Will Benefit Us **Estimates are based on static balance sheet and assumptions as of 3/31/11 Each $250 million increase in l
Slide 29: We Are Well Capitalized
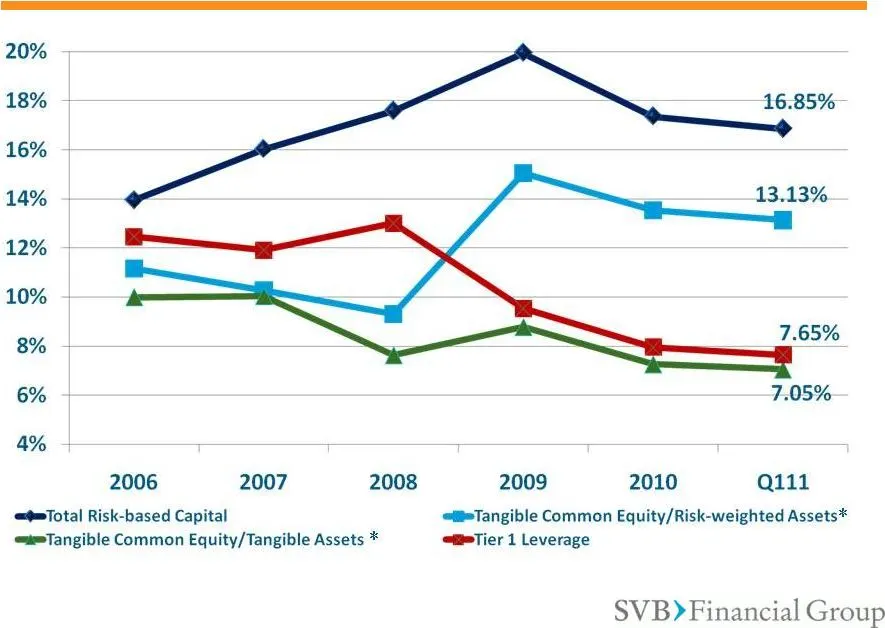
We Are Well Capitalized *TCE/TA and TCE/RWA are non-GAAP Numbers; please Refer to Non-GAAP reconciliations at end of presentation for more information. Appendix – First Quarter Review
Slide 30: Full Year Outlook: 2011 vs. 2010
Metric 2010 Actual 2011 Outlook (3) as of 4/21/11 Full Year Outlook: 2011 vs. 2010 Loans (average) $4.4 Billion Mid-20s % growth Deposits (average) $12.0 Billion Low double-digit % growth Net Interest Income $418.1 Million Mid-twenties % growth Net Interest Margin 3.08% Between 3.30% and 3.40% Allow
Slide 31: Annual Metrics
Annual Metrics Appendix – Annual Metrics
Slide 32: Financial Highlights: 2008-2010
2008 2009 2010 Financial Highlights: 2008 -2010 Diluted Earnings Per Share $2.16 $0.66 $2.24 Net Income Available to Common Stockholders $73.6M $22.7M $95.0M Average Loans (Change) $4.6B (+31.5%) $4.7B (+1.4%) $4.4B (-5.6%) Average Deposits (Change) $4.9B (+23.6%) $8.8B (+79.6%) $12.0B (+36.8%) Aver
Slide 33: Growth Initiatives
Growth Initiatives Appendix – Growth Initiatives
Slide 34: We're Supporting Clients At All Stages
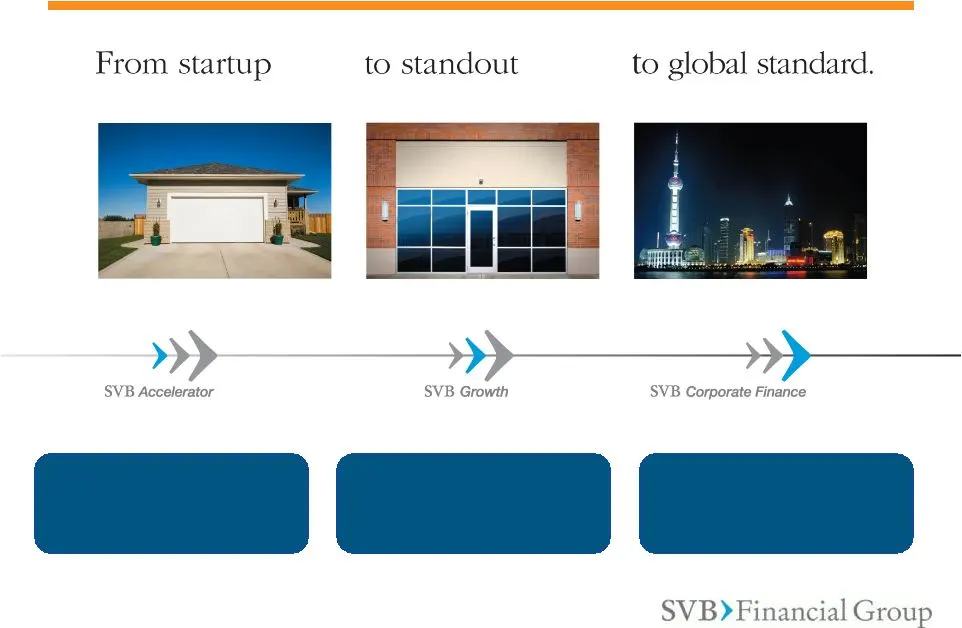
50% Market Share 10% – 12% Market Share < 10% Market Share We’re Supporting Clients At All Stages Appendix – Growth Initiatives
Slide 35: We Are Extending Our Platform Globally
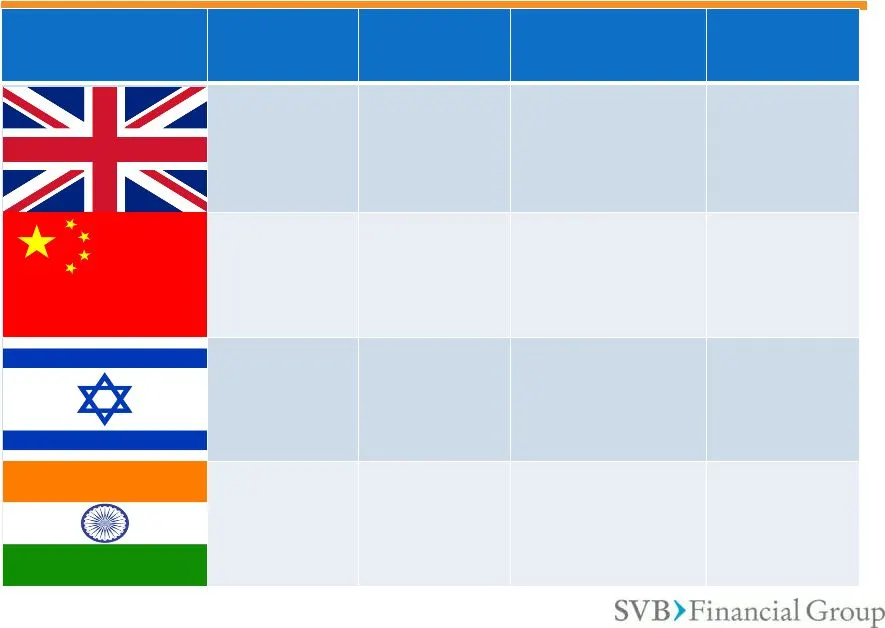
Prior to 2011 2011 - 2012 Long Term Financial Impact - Rep office - LPO Branch and full product set Subsidiary bank + Europe; expansion and growth 0-2 years - Rep Office - Funds JV Bank and related activities Subsidiary Branch; expansion and growth 3-5 years - Rep Office - LPO Expansion and growth 0
Slide 36: Private Bank
Private Bank • Expanded private banking services • Tailored lending for influencers in the SVB ecosystem • An advanced, easy-to-use, online platform • Support for clients’ success in all arenas: business, family, life Appendix – Growth Initiatives
Slide 37: Venture Capital Markets
Venture Capital Markets Appendix – Venture Capital Markets
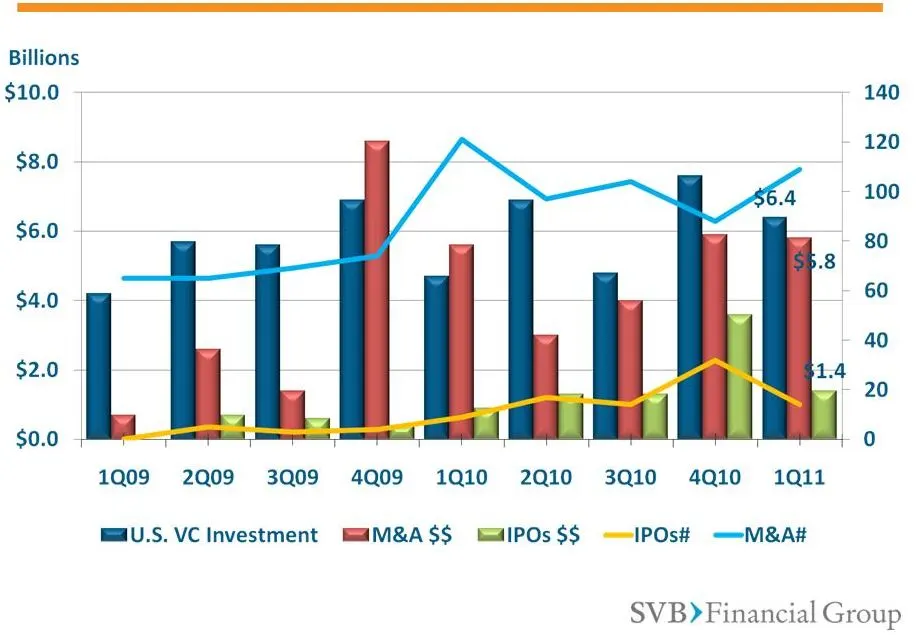
Slide 38: VC Markets Are Stabilizing
VC Markets Are Stabilizing Source: Thomson Reuters, National Venture Capital Association, Dow Jones Appendix – Venture Capital Markets
Slide 39: Non-GAAP Reconciliations
Non-GAAP Reconciliations Appendix – Non-GAAP Reconciliations
Slide 40: Non-GAAP TCE/TA and TCE/RWA Reconciliation
Non-GAAP tangible common equity and tangible assets (dollars in thousands, except ratios) March 31, December 31, March 31, 2011 2010 2010 Non-GAAP TCE/TA and TCE/RWA Reconciliation GAAP SVBFG stockholders' equity $ 1,313,574 $ 1,274,350 $ 1,173,480 Less: intangible assets Tangible common equity $ 1,
Slide 41: Non-GAAP Non-Interest Income Reconciliation
Three months ended Year ended Non-GAAP noninterest income, net of noncontrolling interests (dollars in thousands) March 31, December 31, March 31, December 31, December 31, 2011 2010 2010 2010 2009 Non-GAAP Non-Interest Income Reconciliation GAAP noninterest income $ 89,954 $ 71,864 $ 49,273 $ 247,5
Slide 42: Non-GAAP Non-Interest Expense Reconciliation
Three months ended Year ended Non-GAAP operating efficiency ratio, net of noncontrolling interests (dollars in thousands, except ratios) March 31, December 31, March 31, December 31, December 31, 2011 2010 2010 2010 2009 Non-GAAP Non-Interest Expense Reconciliation Appendix – Non-GAAP Reconciliation
Slide 43: Non-GAAP Non-Marketable Securities Reconciliation
Non-GAAP non-marketable securities, net of noncontrolling interests (dollars in thousands) March 31, December 31, March 31, 2011 2010 2010 Non-GAAP Non-Marketable Securities Reconciliation For additional GAAP to Non-GAAP reconciliation information, please refer to our regularly filed forms 10-Q and
Source: SEC EDGAR · 8-K filed May 9, 2011
More decks from SVB Financial Group
 Investor Presentation (February 2024)8 slides · Feb 9, 2024
 Presentation (January 2024)35 slides · Jan 10, 2024
 IPO Roadshow (March 2023)30 slides · Mar 9, 2023
 Merger or Acquisition (January 2021)15 slides · Jan 4, 2021
 Q1 2020 Earnings Presentation54 slides · May 4, 2020
 Q1 2020 Earnings Presentation37 slides · Apr 23, 2020