MFA Financial, Inc. · NYSE:MFA
MFA Financial — Q4 2019 Earnings Presentation
29 slides from MFA Financial's earnings presentation, 2020
Slide 1: Fourth Quarter 2019 Earnings Presentation
Fourth Quarter 2019 Earnings Presentation
Slide 2: Forward Looking Statements
Forward Looking Statements When used in this presentation or other written or oral communications, statements which are not historical in nature, including those containing words such as “will,” “believe,” “expect,” “anticipate,” “estimate,” “plan,” “continue,” “intend,” “should,” “could,” “would,”
Slide 3: Executive summary
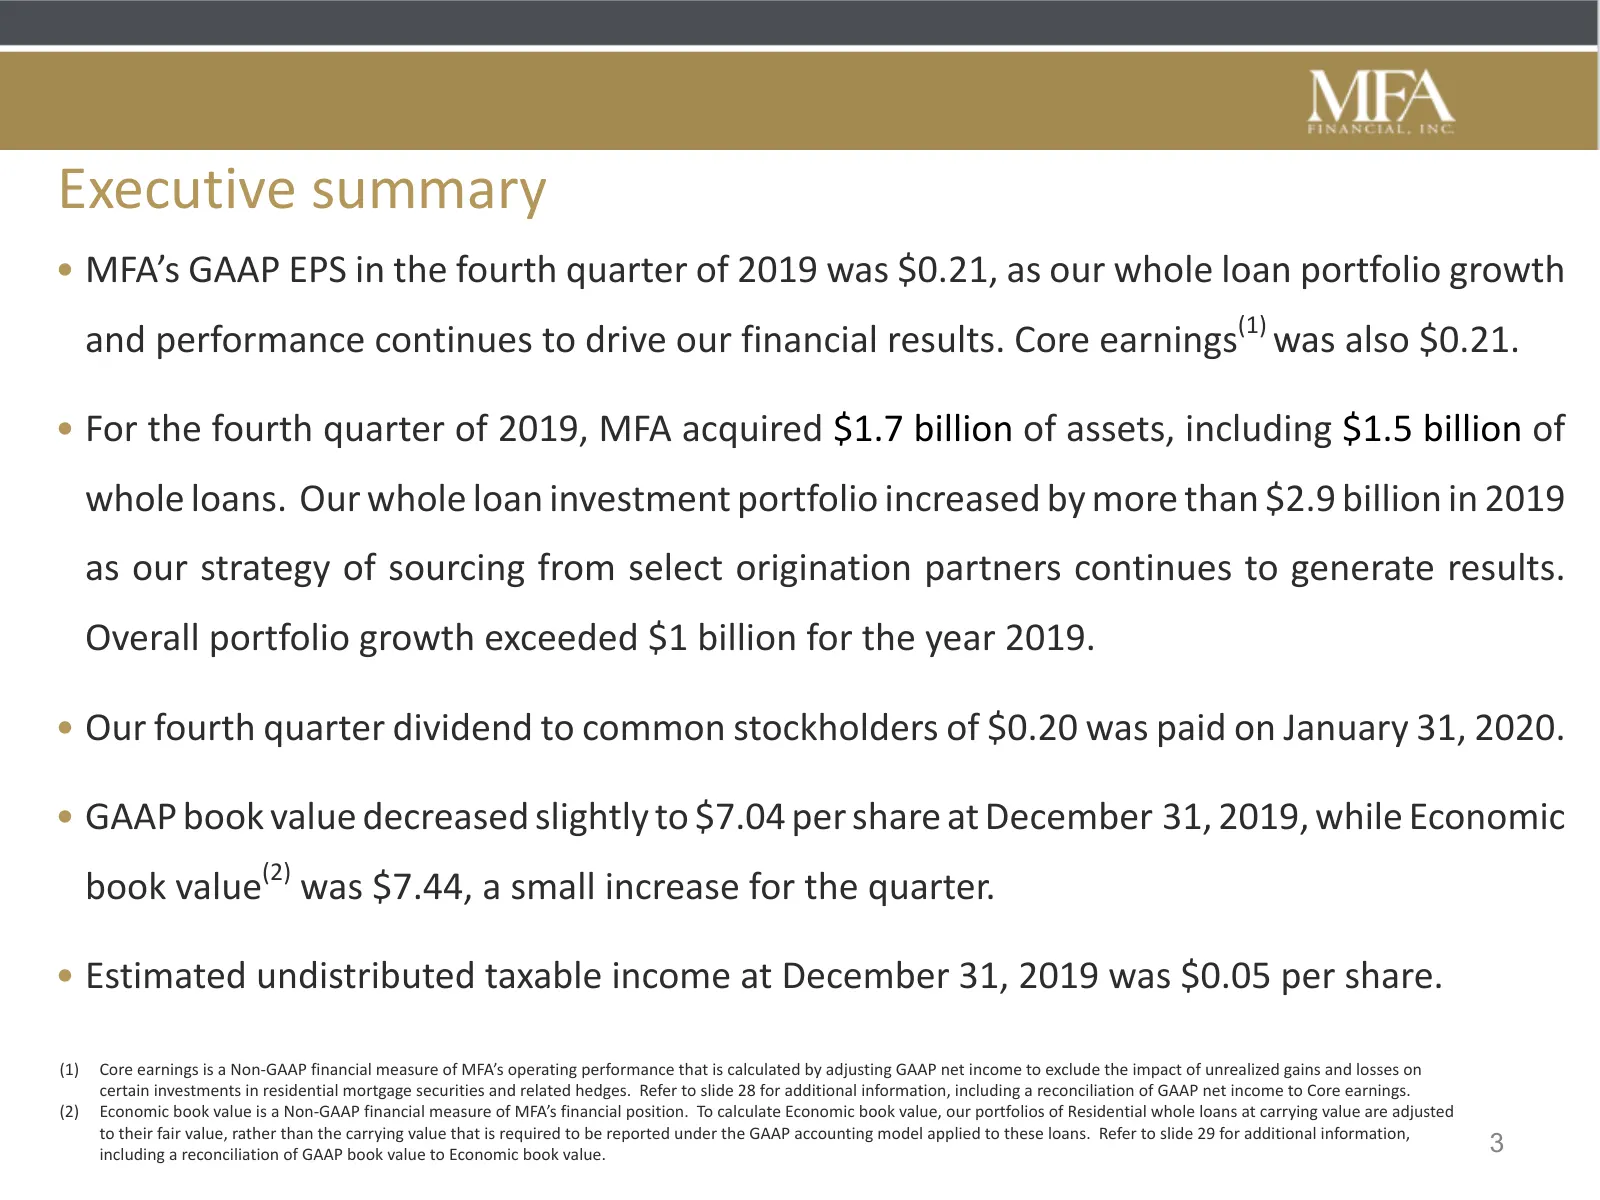
Executive summary • MFA’s GAAP EPS in the fourth quarter of 2019 was $0.21, as our whole loan portfolio growth and performance continues to drive our financial results. Core earnings(1) was also $0.21. • For the fourth quarter of 2019, MFA acquired $1.7 billion of assets, including $1.5 billion of w
Slide 4: Executive summary (cont'd.)
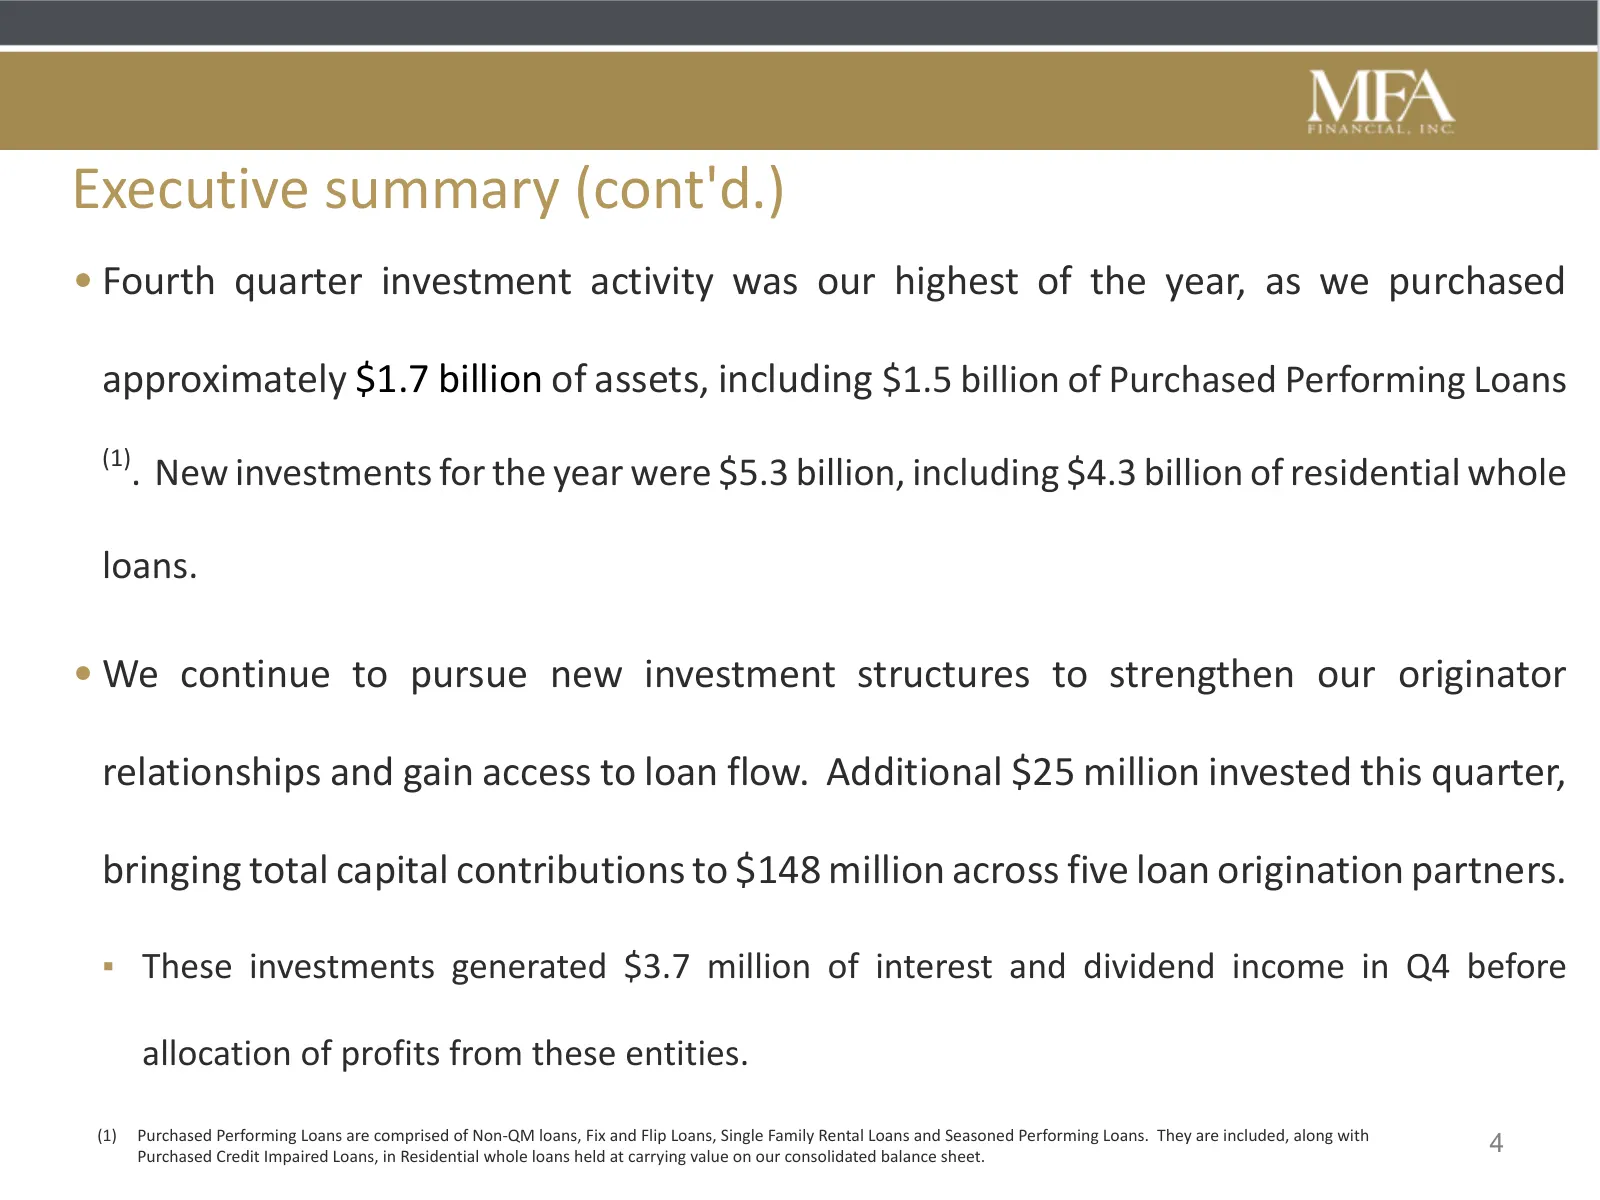
Executive summary (cont'd.) • Fourth quarter investment activity was our highest of the year, as we purchased approximately $1.7 billion of assets, including $1.5 billion of Purchased Performing Loans (1) . New investments for the year were $5.3 billion, including $4.3 billion of residential whole l
Slide 5: Executive summary (cont'd.)
Executive summary (cont'd.) • Growth of Purchased Performing Loans continues to drive interest income: ▪ Loans held at carrying value produced $72.3 million of interest income in the fourth quarter of 2019 (versus $64.2 million in Q3 2019 and $100.9 million for all of 2018). ▪ Interest income from r
Slide 6: Executive summary (cont'd.)
Executive summary (cont'd.) • Our asset management team maintains very active oversight of the servicing of delinquent and credit sensitive loans to improve outcomes and expected returns. This team also manages our REO properties, some of which we have converted to rental properties. • Technology in
Slide 7: Investment strategy
Investment strategy • Continue to grow investment assets ▪ Purchased Performing Loans are providing recurring (and increasing) portfolio growth ▪ Opportunistic growth in other asset classes if/when available • Optimize Balance Sheet/Capital Structure ▪ Modest increase in leverage (including securiti
Slide 8: Market conditions and investment activity
Market conditions and investment activity • Expand investment opportunities in the form of newly originated whole loans. ▪ Benign rate environment often leads to higher origination volume of non-conventional loan products such as Non-QM mortgages. ▪ Creative approach to partnering with originators g
Slide 9: Higher net interest income drives earnings
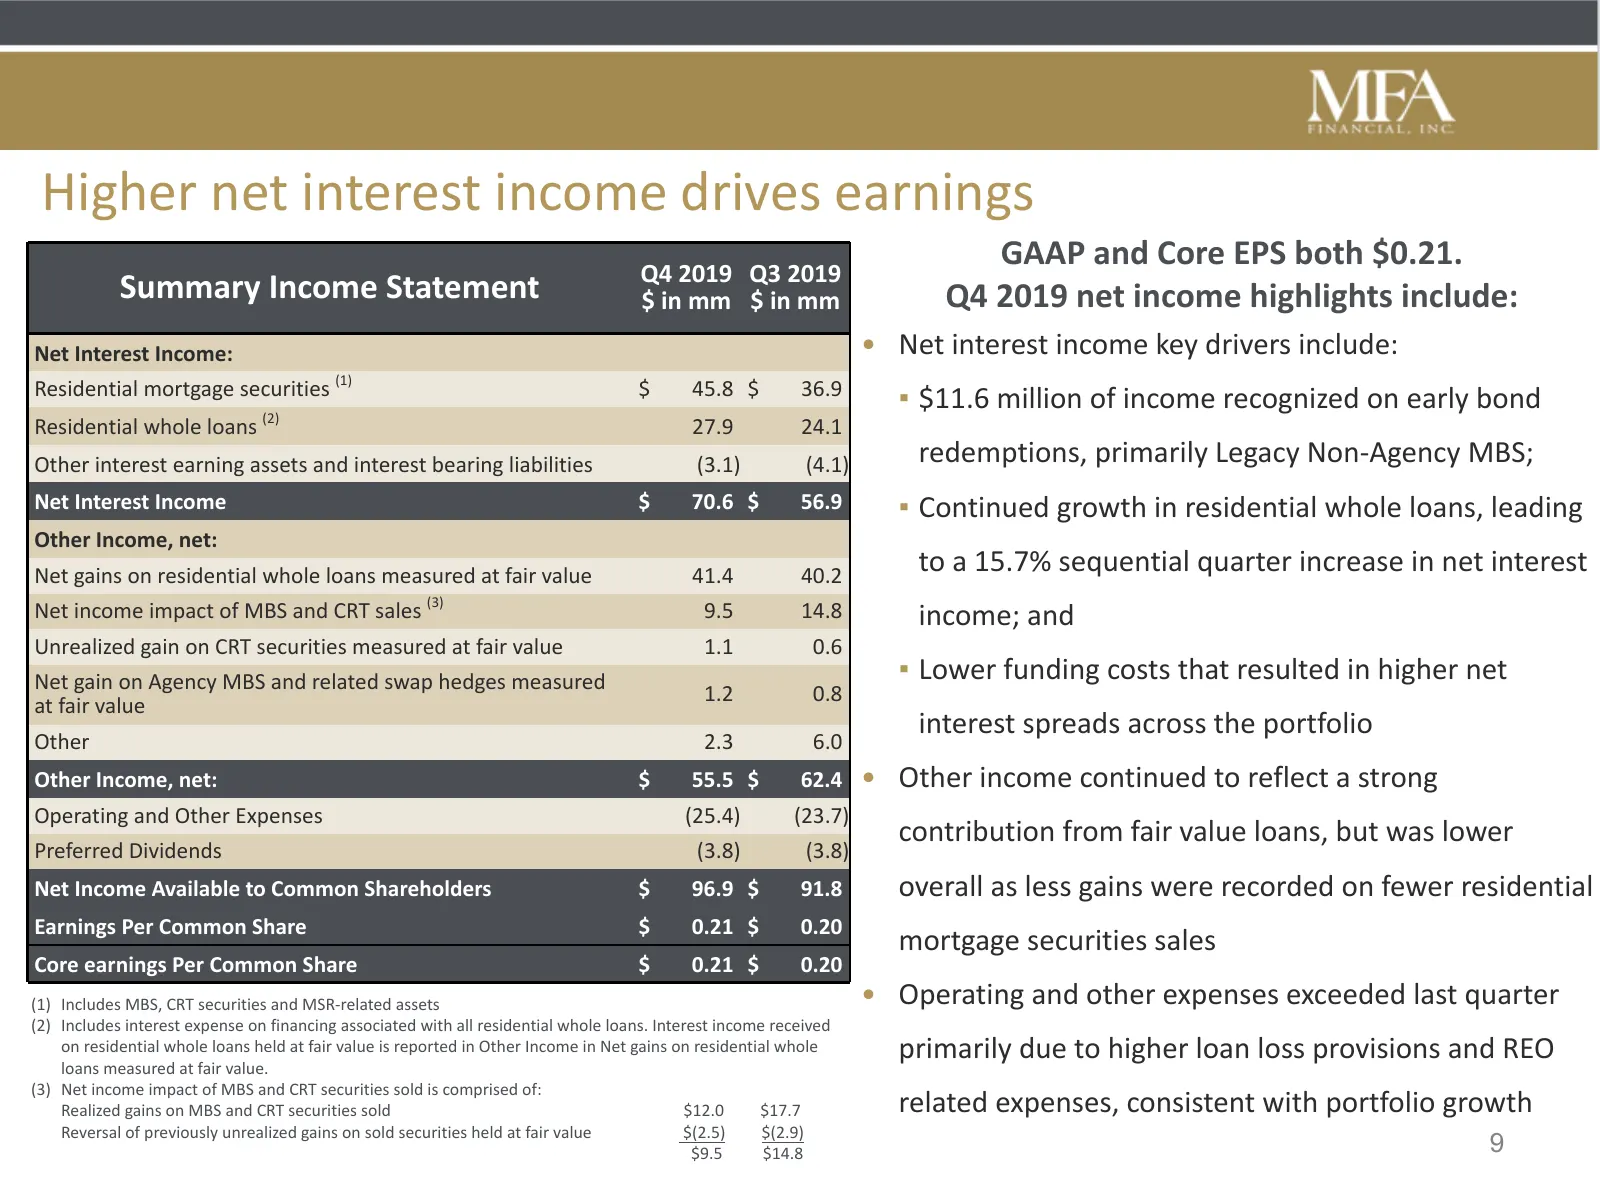
Higher net interest income drives earnings GAAP and Core EPS both $0.21. Q4 2019 Q3 2019 Summary Income Statement $ in mm $ in mm Q4 2019 net income highlights include: Net Interest Income: • Net interest income key drivers include: Residential mortgage securities (1) $ 45.8 $ 36.9 (2) ▪ $11.6 milli
Slide 10: FY 2019 reflects lower market volatility and loan portfolio growth
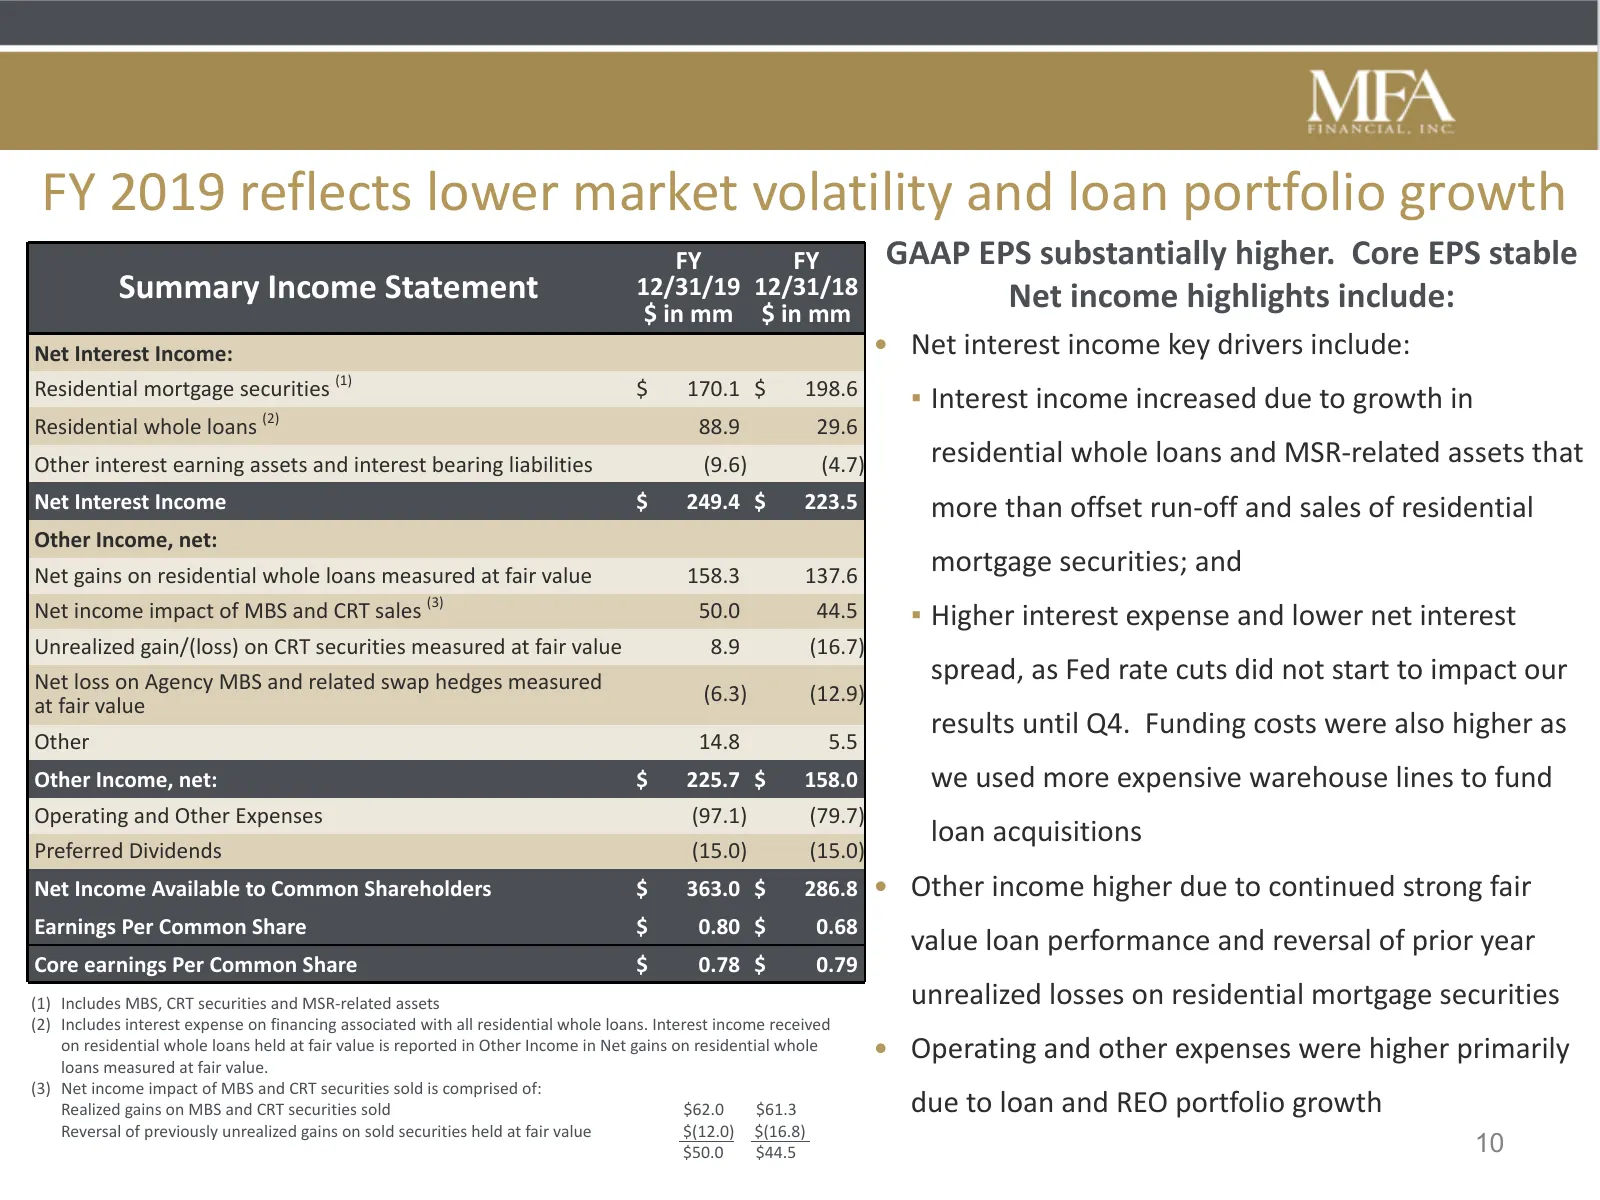
FY 2019 reflects lower market volatility and loan portfolio growth FY FY GAAP EPS substantially higher. Core EPS stable Summary Income Statement 12/31/19 12/31/18 Net income highlights include: $ in mm $ in mm Net Interest Income: • Net interest income key drivers include: Residential mortgage secur
Slide 11: Impact of Credit Impairment standard (CECL) adoption
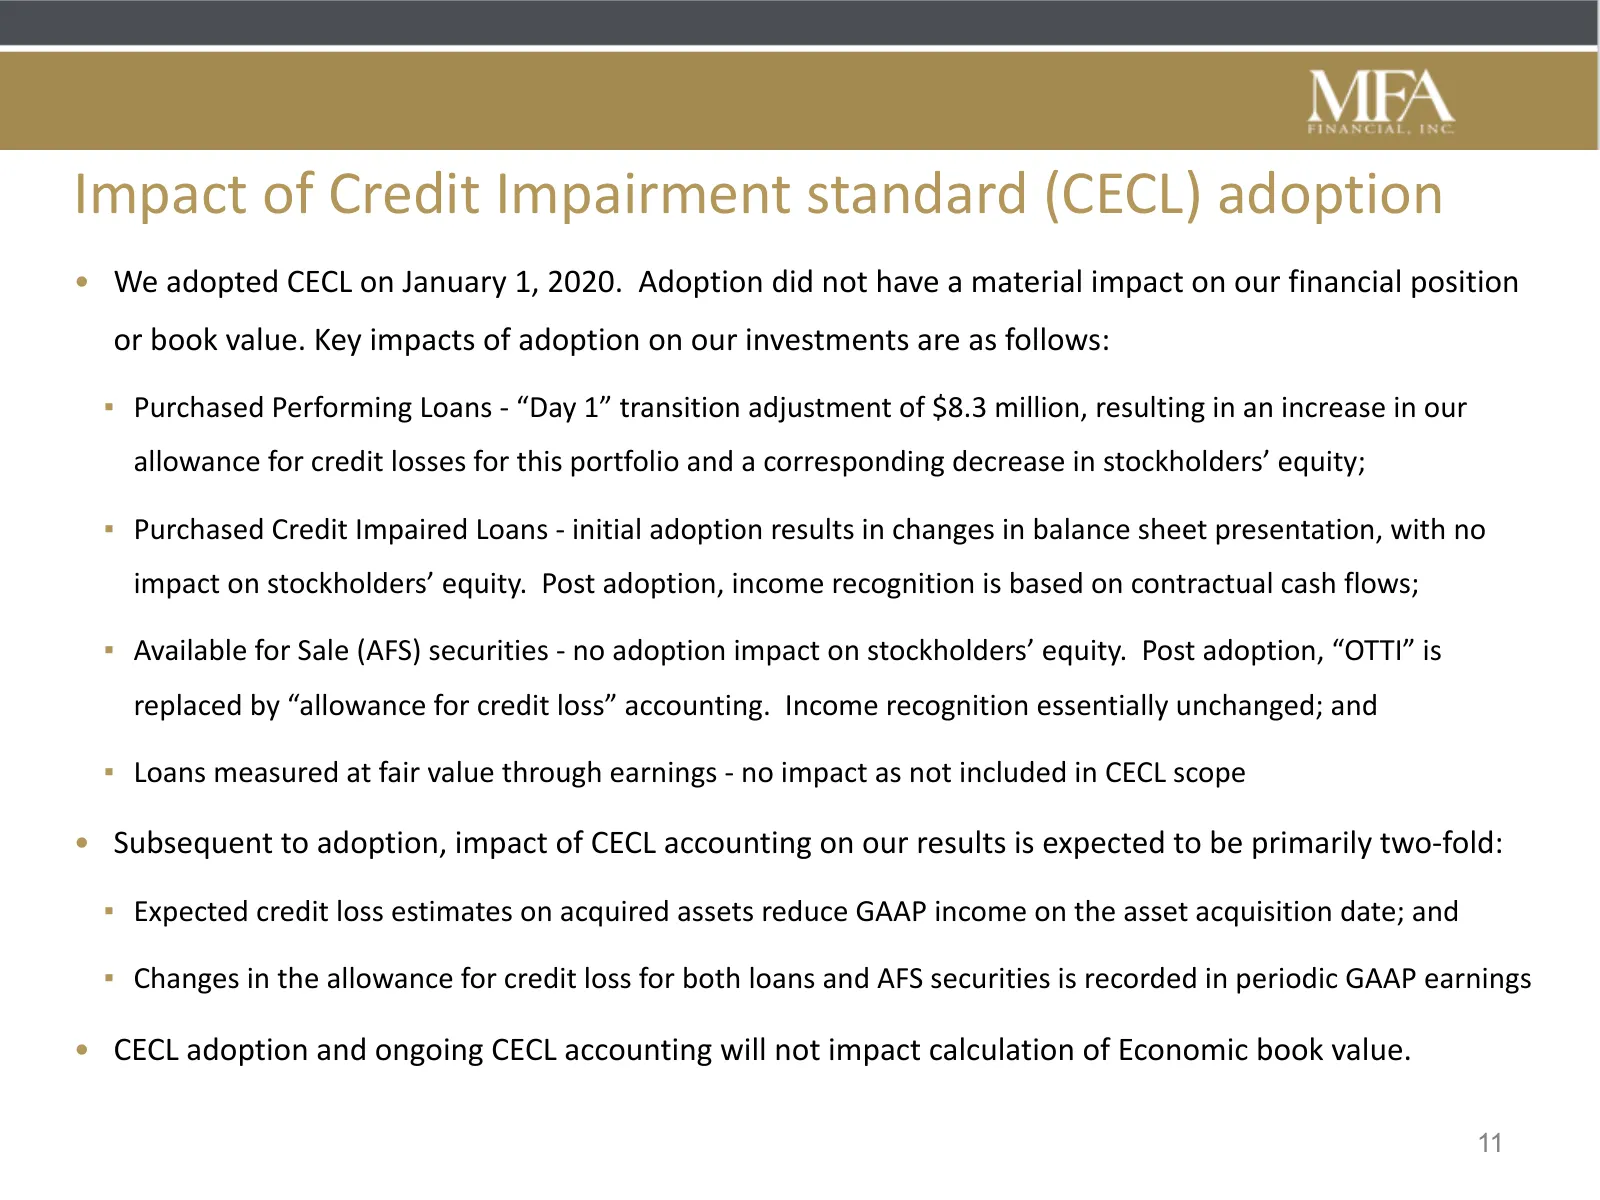
Impact of Credit Impairment standard (CECL) adoption • We adopted CECL on January 1, 2020. Adoption did not have a material impact on our financial position or book value. Key impacts of adoption on our investments are as follows: ▪ Purchased Performing Loans - “Day 1” transition adjustment of $8.3
Slide 12: Fourth quarter 2019 investment flows
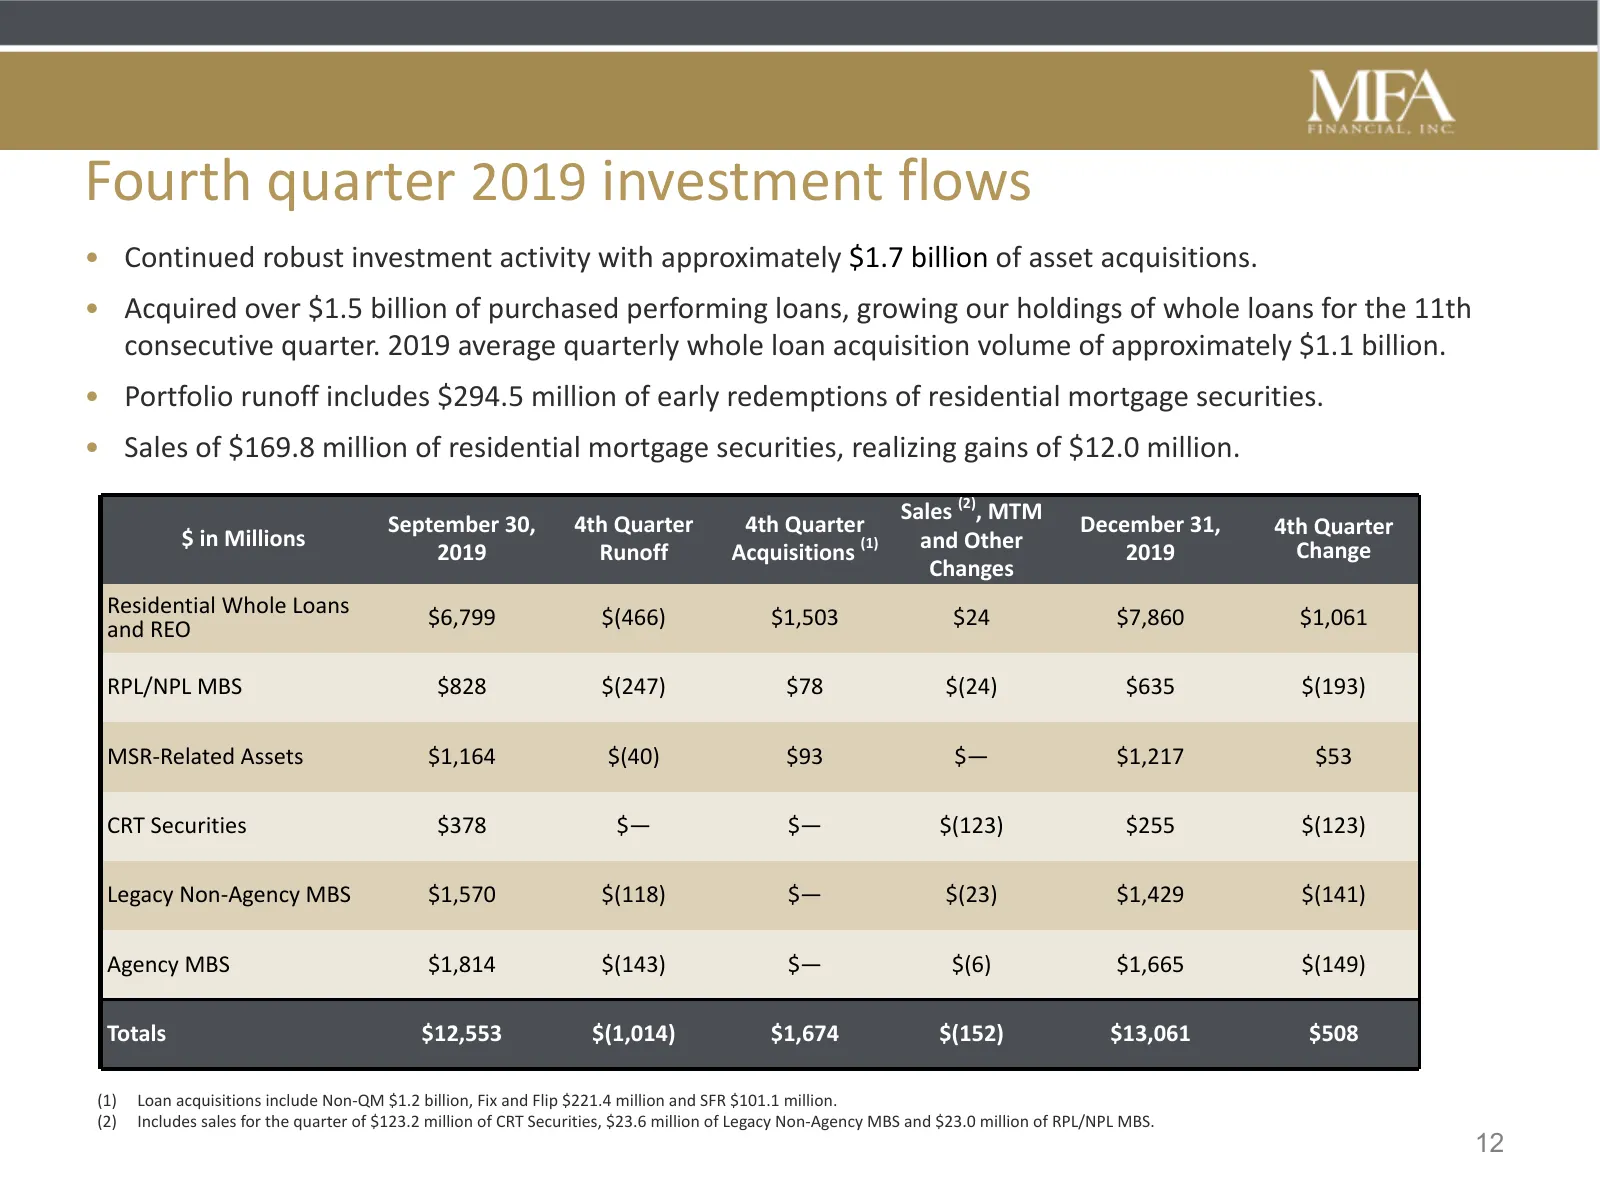
Fourth quarter 2019 investment flows • Continued robust investment activity with approximately $1.7 billion of asset acquisitions. • Acquired over $1.5 billion of purchased performing loans, growing our holdings of whole loans for the 11th consecutive quarter. 2019 average quarterly whole loan acqui
Slide 13: 2019 Investment Flows
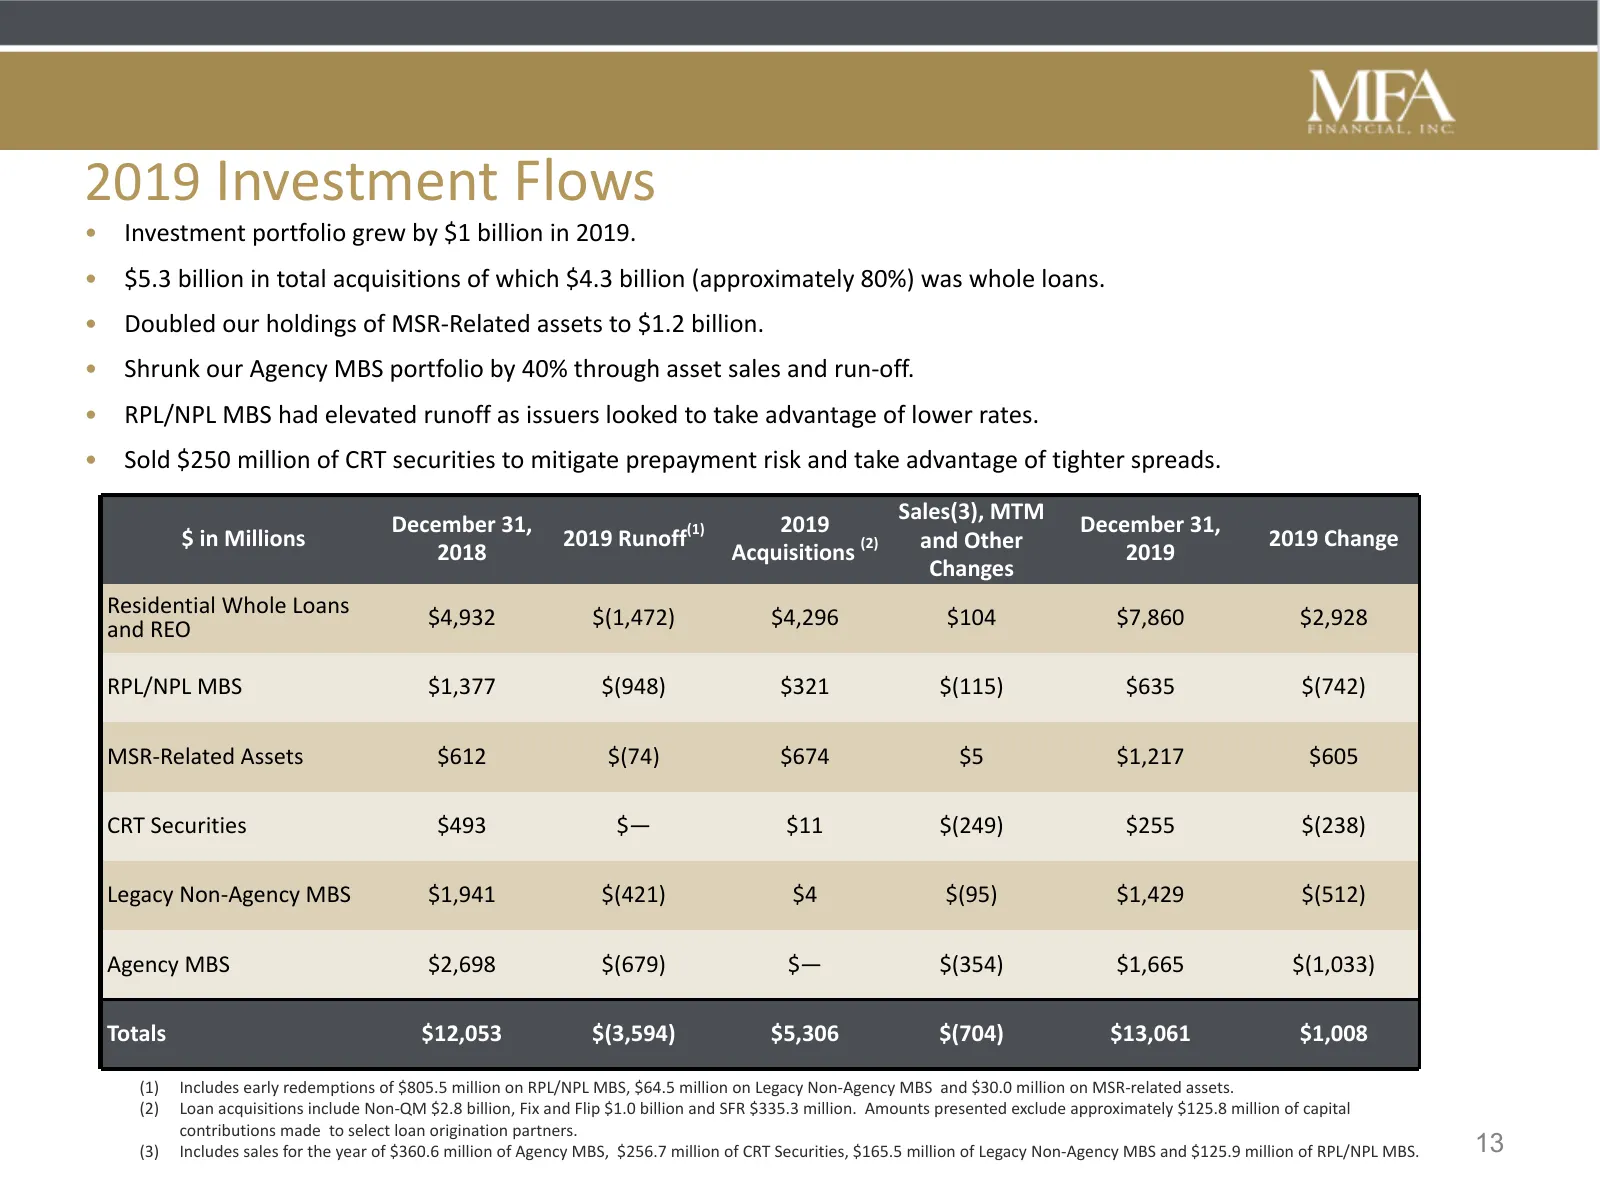
2019 Investment Flows • Investment portfolio grew by $1 billion in 2019. • $5.3 billion in total acquisitions of which $4.3 billion (approximately 80%) was whole loans. • Doubled our holdings of MSR-Related assets to $1.2 billion. • Shrunk our Agency MBS portfolio by 40% through asset sales and run-
Slide 14: Strong portfolio growth since expanding investment strategy to include Non-QM, Fix and Flip and SFR Loans
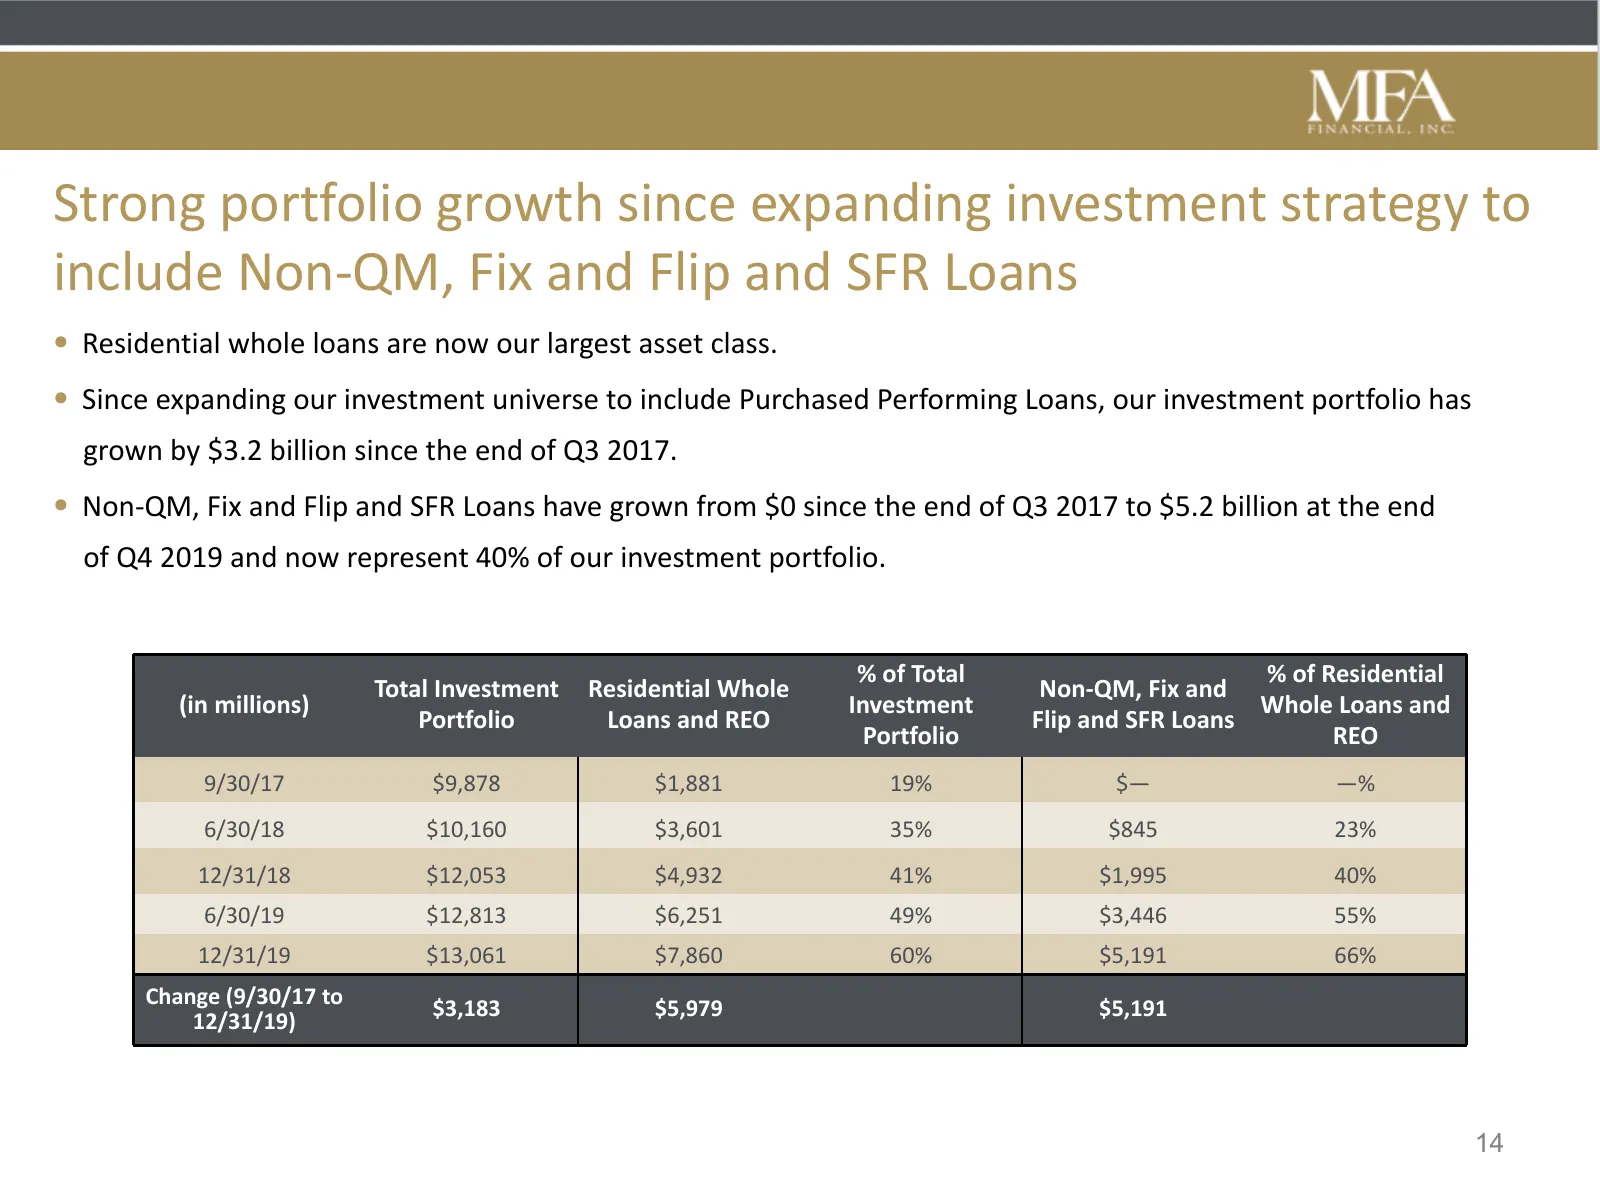
Strong portfolio growth since expanding investment strategy to include Non-QM, Fix and Flip and SFR Loans • Residential whole loans are now our largest asset class. • Since expanding our investment universe to include Purchased Performing Loans, our investment portfolio has grown by $3.2 billion sin
Slide 15: MFA's yields and spreads remain attractive
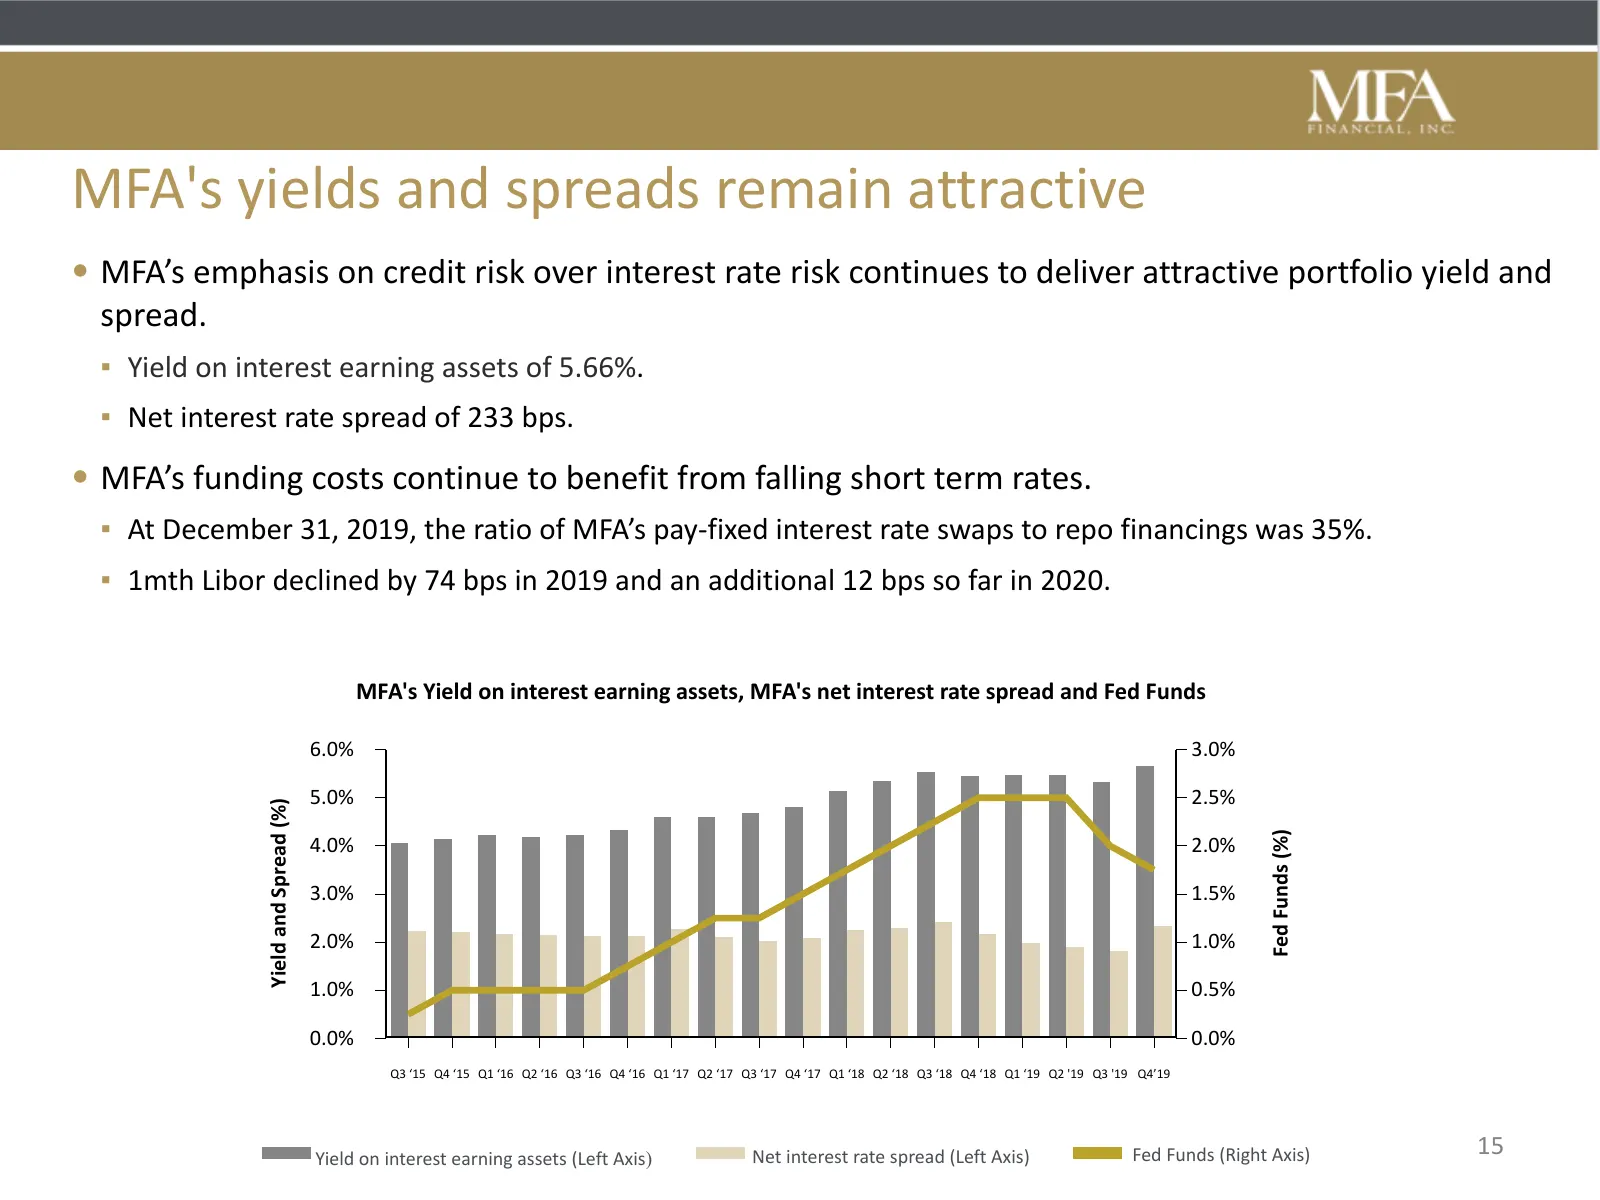
MFA's yields and spreads remain attractive • MFA’s emphasis on credit risk over interest rate risk continues to deliver attractive portfolio yield and spread. ▪ Yield on interest earning assets of 5.66%. ▪ Net interest rate spread of 233 bps. • MFA’s funding costs continue to benefit from falling sh
Slide 16: Fourth quarter 2019 yields and spreads by asset type
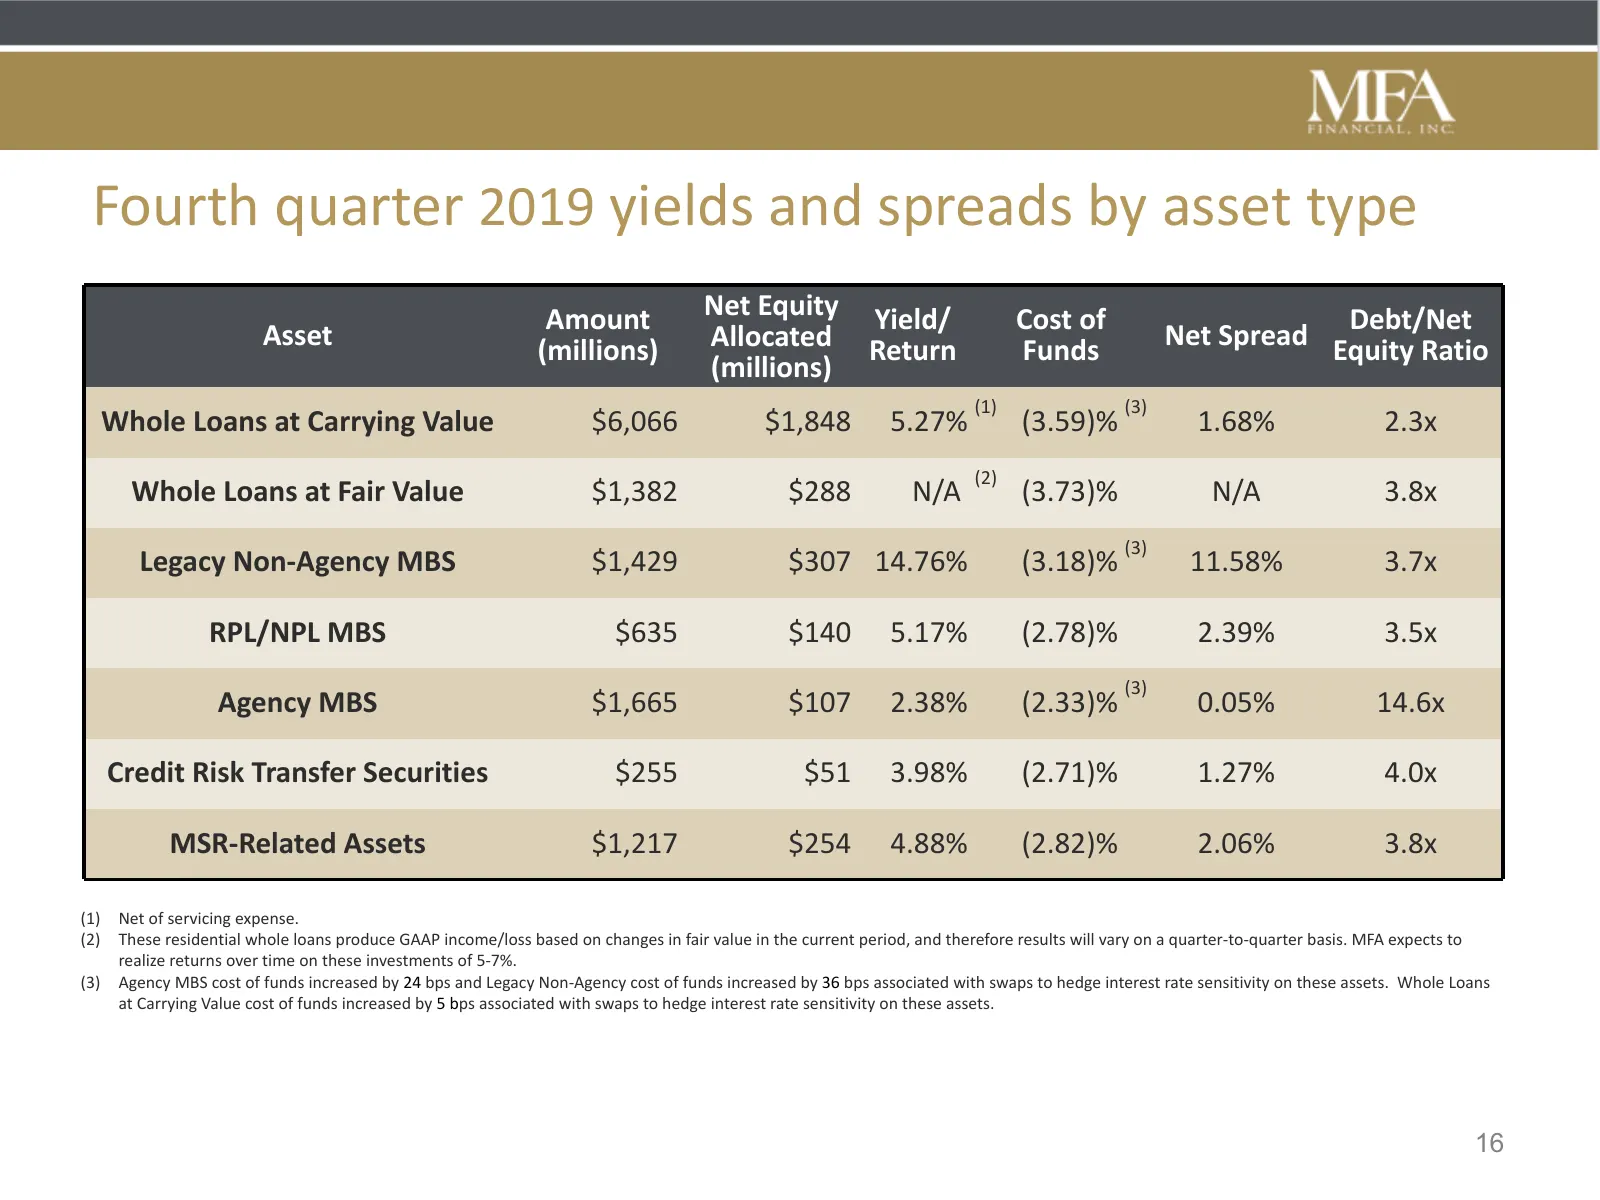
Fourth quarter 2019 yields and spreads by asset type Amount Net Equity Yield/ Cost of Debt/Net Asset Allocated Return Net Spread Equity (millions) Funds Ratio (millions) (1) (3) Whole Loans at Carrying Value $6,066 $1,848 5.27% (3.59)% 1.68% 2.3x (2) Whole Loans at Fair Value $1,382 $288 N/A (3.73)%
Slide 17: MFA's net interest rate sensitivity remains low at 1.36
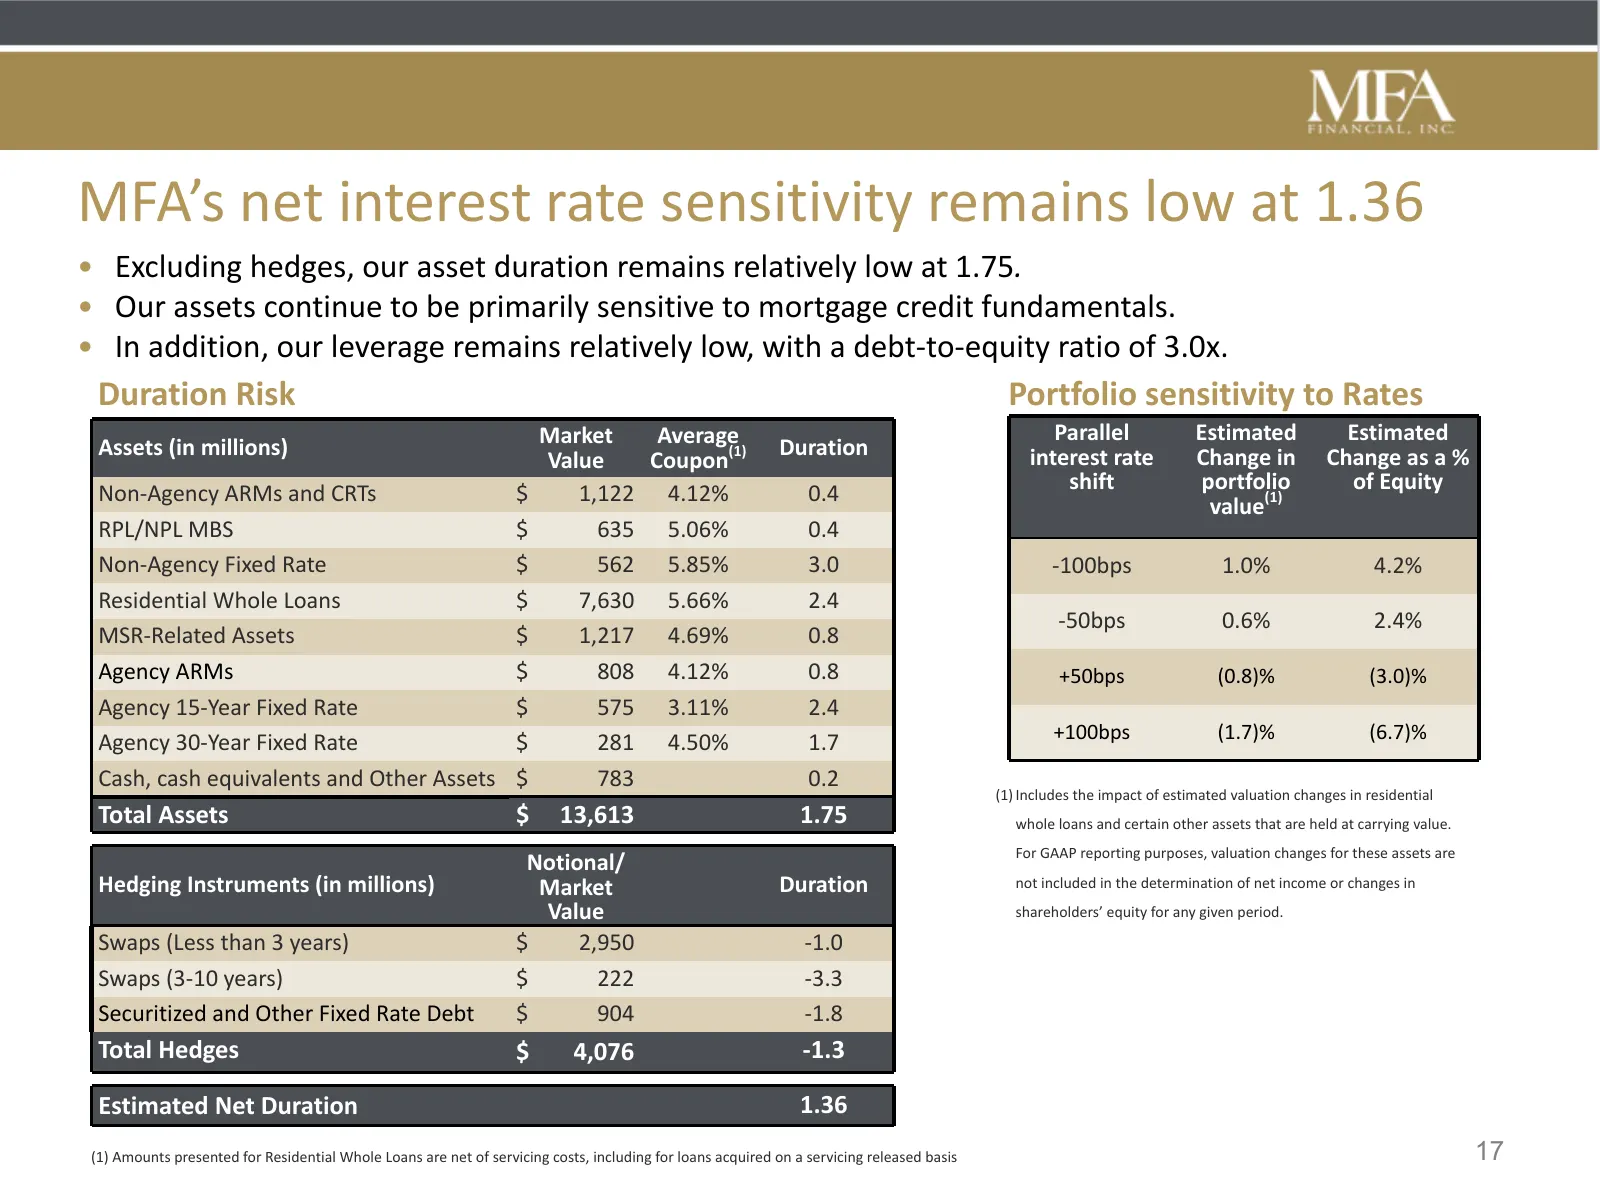
MFA’s net interest rate sensitivity remains low at 1.36 • Excluding hedges, our asset duration remains relatively low at 1.75. • Our assets continue to be primarily sensitive to mortgage credit fundamentals. • In addition, our leverage remains relatively low, with a debt-to-equity ratio of 3.0x. Dur
Slide 18: MFA's strategy continued to limit quarterly book value fluctuations
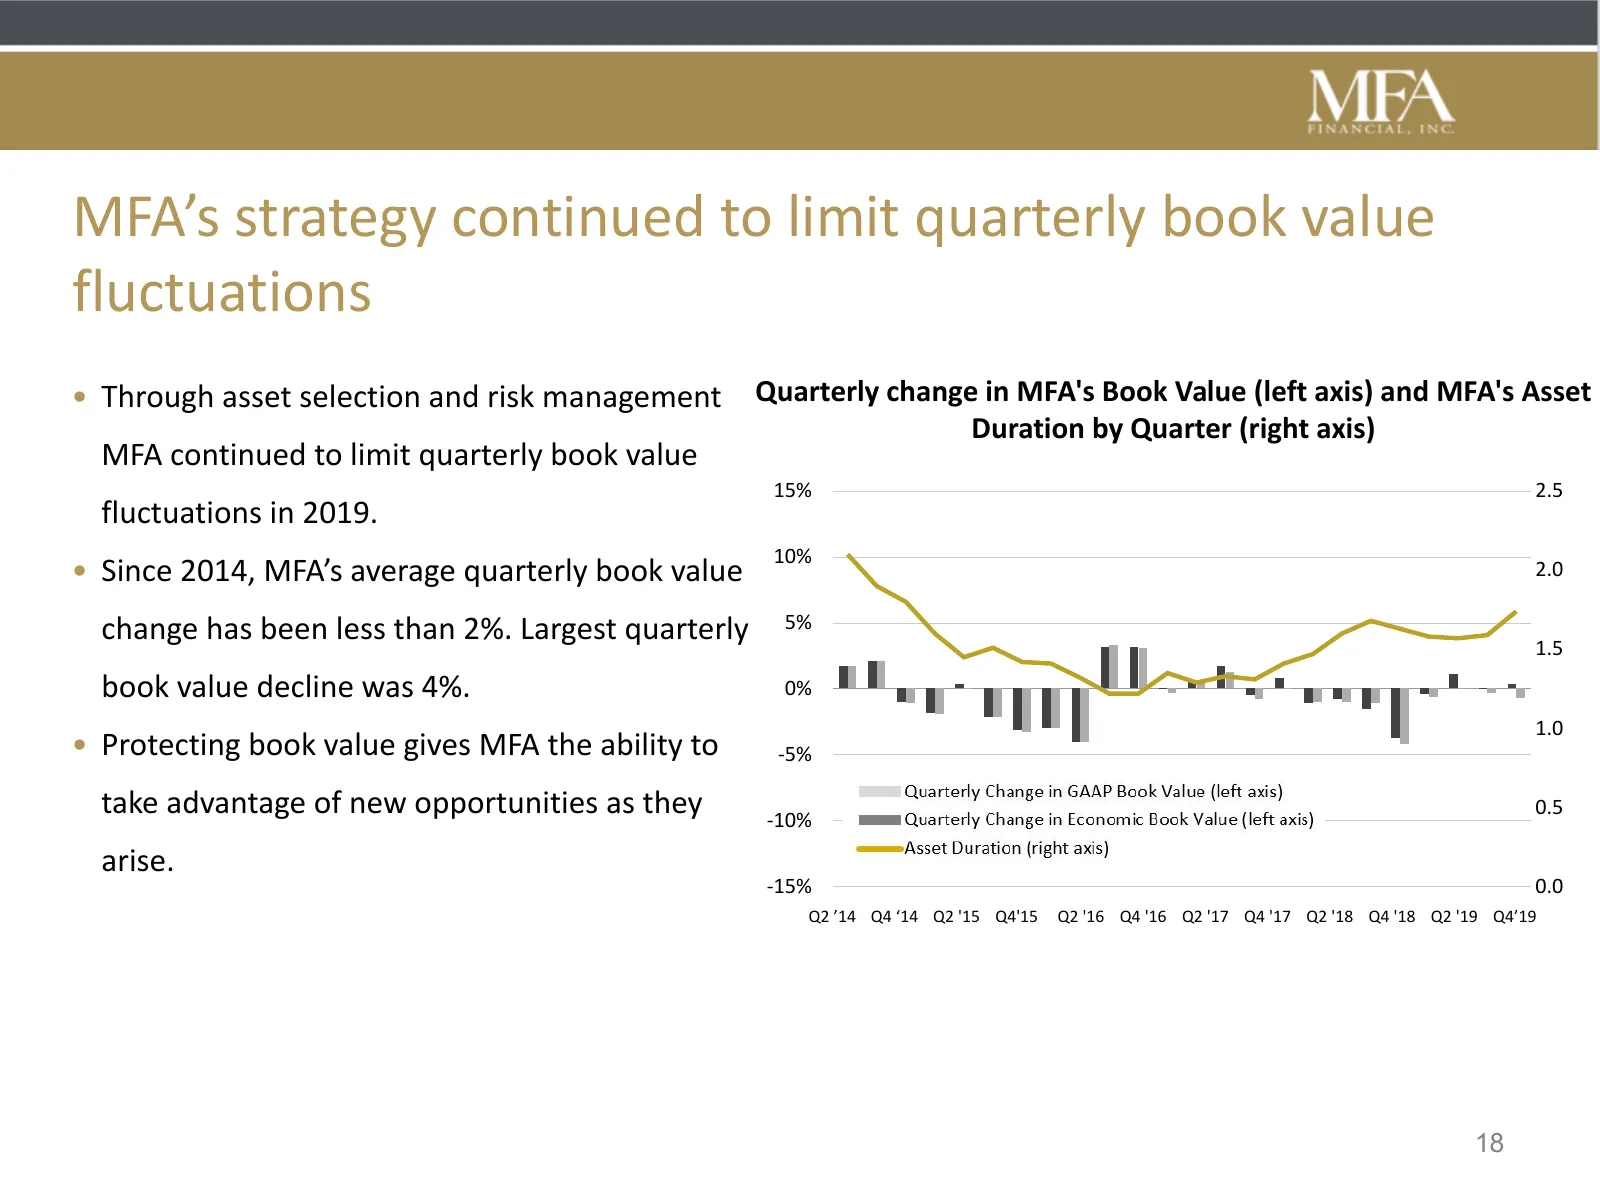
MFA’s strategy continued to limit quarterly book value fluctuations • Through asset selection and risk management Quarterly change in MFA's Book Value (left axis) and MFA's Asset Duration by Quarter (right axis) MFA continued to limit quarterly book value 15% 2.5 fluctuations in 2019. 10% • Since 20
Slide 19: Jul-2019 # of Units (millions)
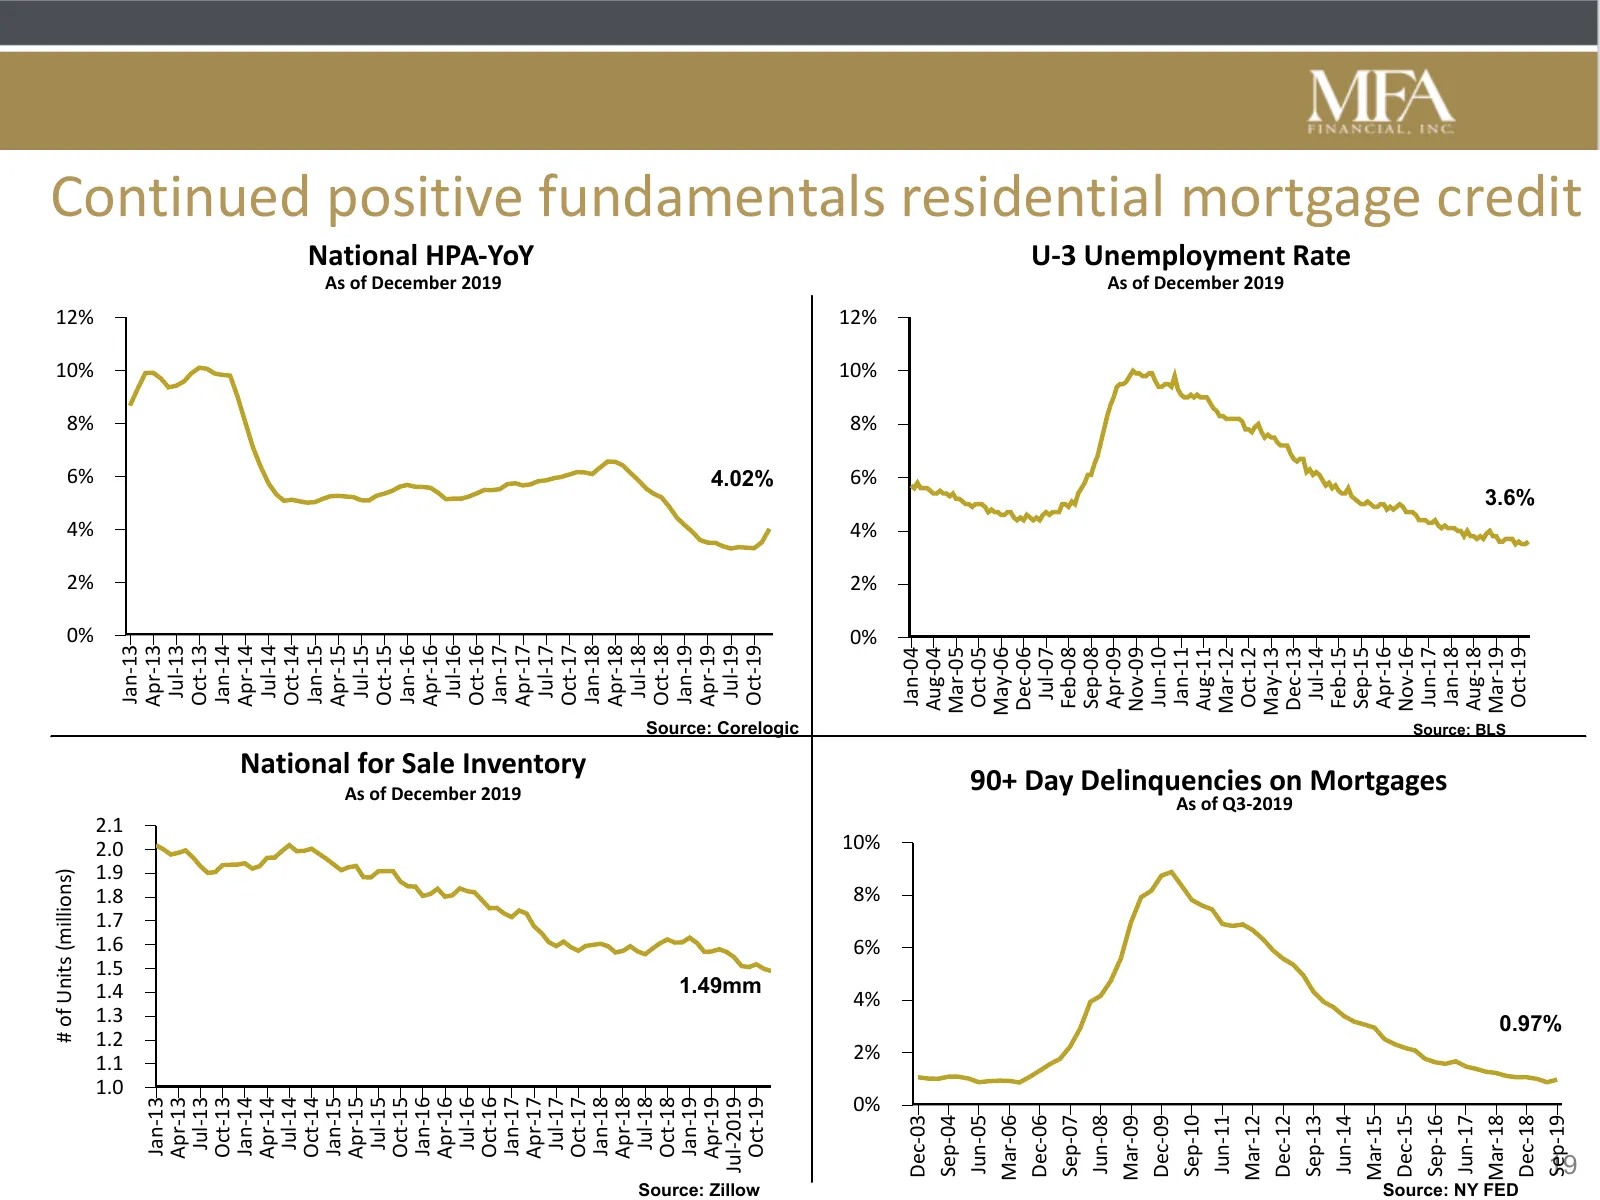
# of Units (millions) 0% 2% 4% 6% 8% 10% 12% 1.0 1.1 1.2 1.3 1.4 1.5 1.6 1.7 1.8 1.9 2.0 2.1 Jan-13 Jan-13 Apr-13 Apr-13 Jul-13 Jul-13 Oct-13 Oct-13 Jan-14 Jan-14 Apr-14 Apr-14 Jul-14 Jul-14 Oct-14 Oct-14 Jan-15 Jan-15 Apr-15 Apr-15 Jul-15 Jul-15 Oct-15 Oct-15 Jan-16 Jan-16 Apr-16 Apr-16 Jul-16 Jul-
Slide 20: Residential whole loan portfolio
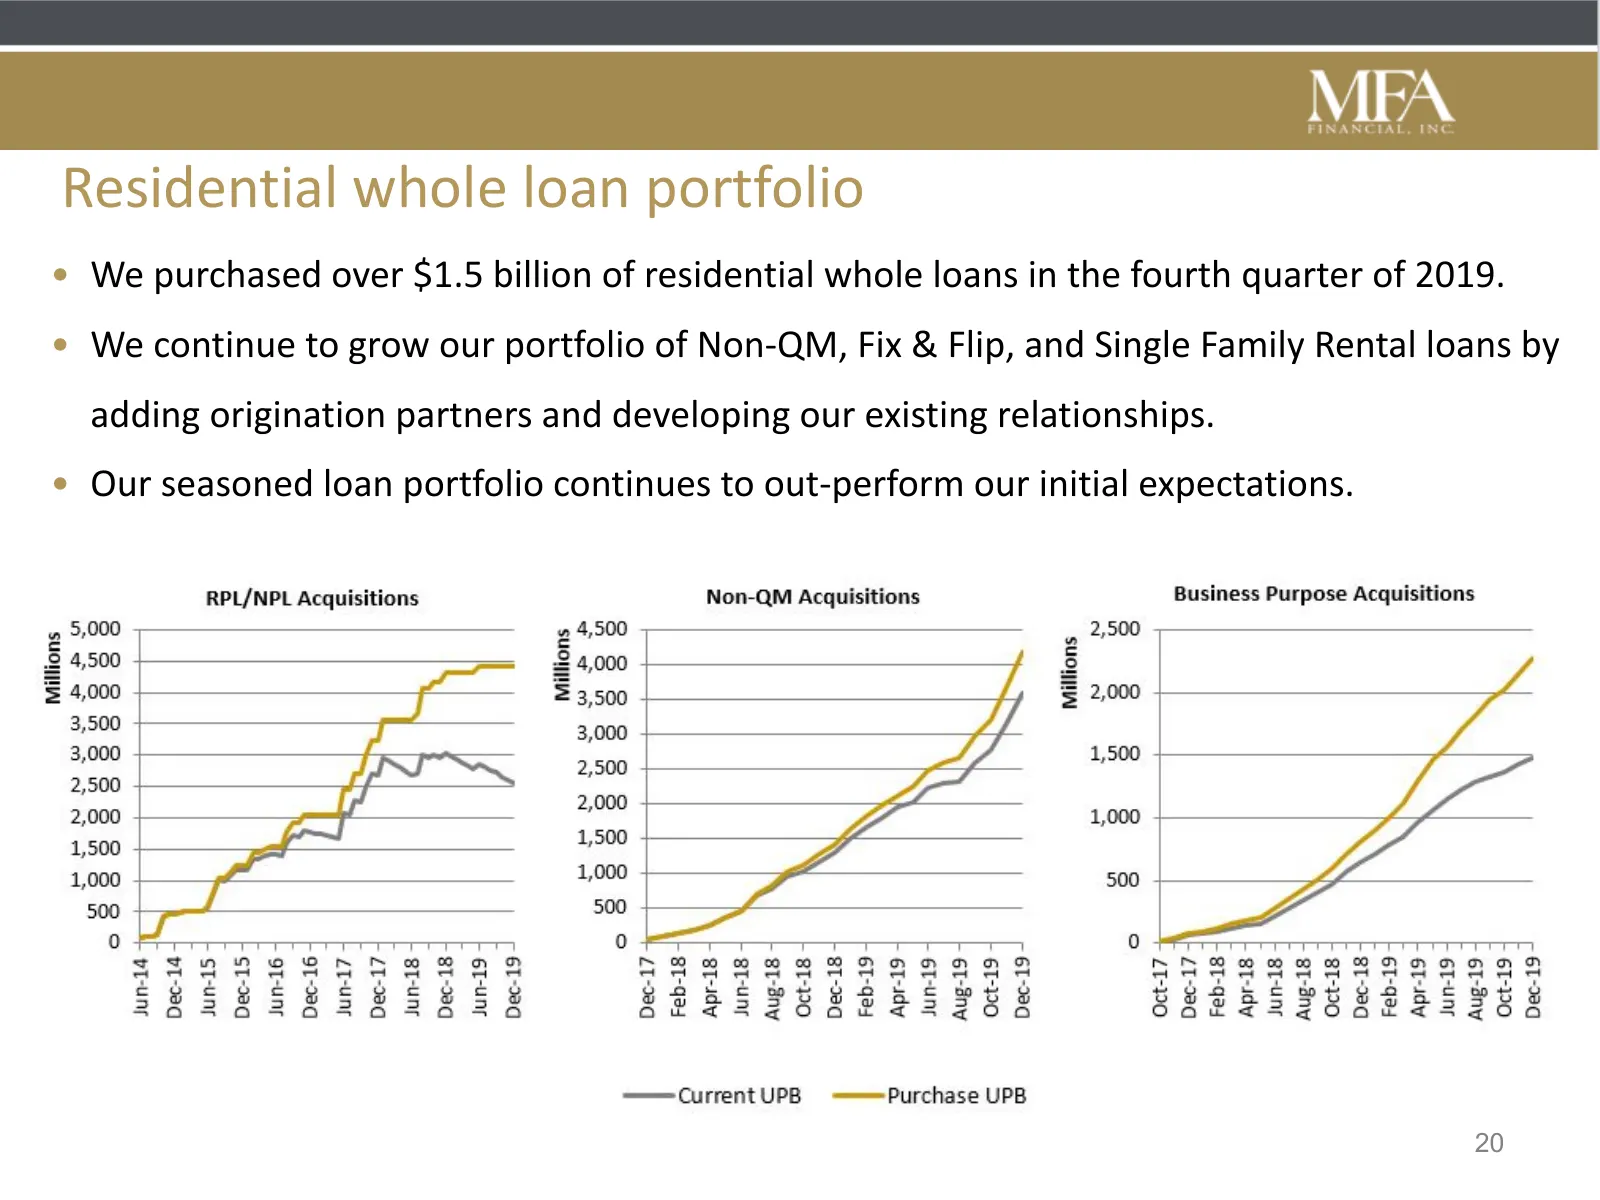
Residential whole loan portfolio • We purchased over $1.5 billion of residential whole loans in the fourth quarter of 2019. • We continue to grow our portfolio of Non-QM, Fix & Flip, and Single Family Rental loans by adding origination partners and developing our existing relationships. • Our season
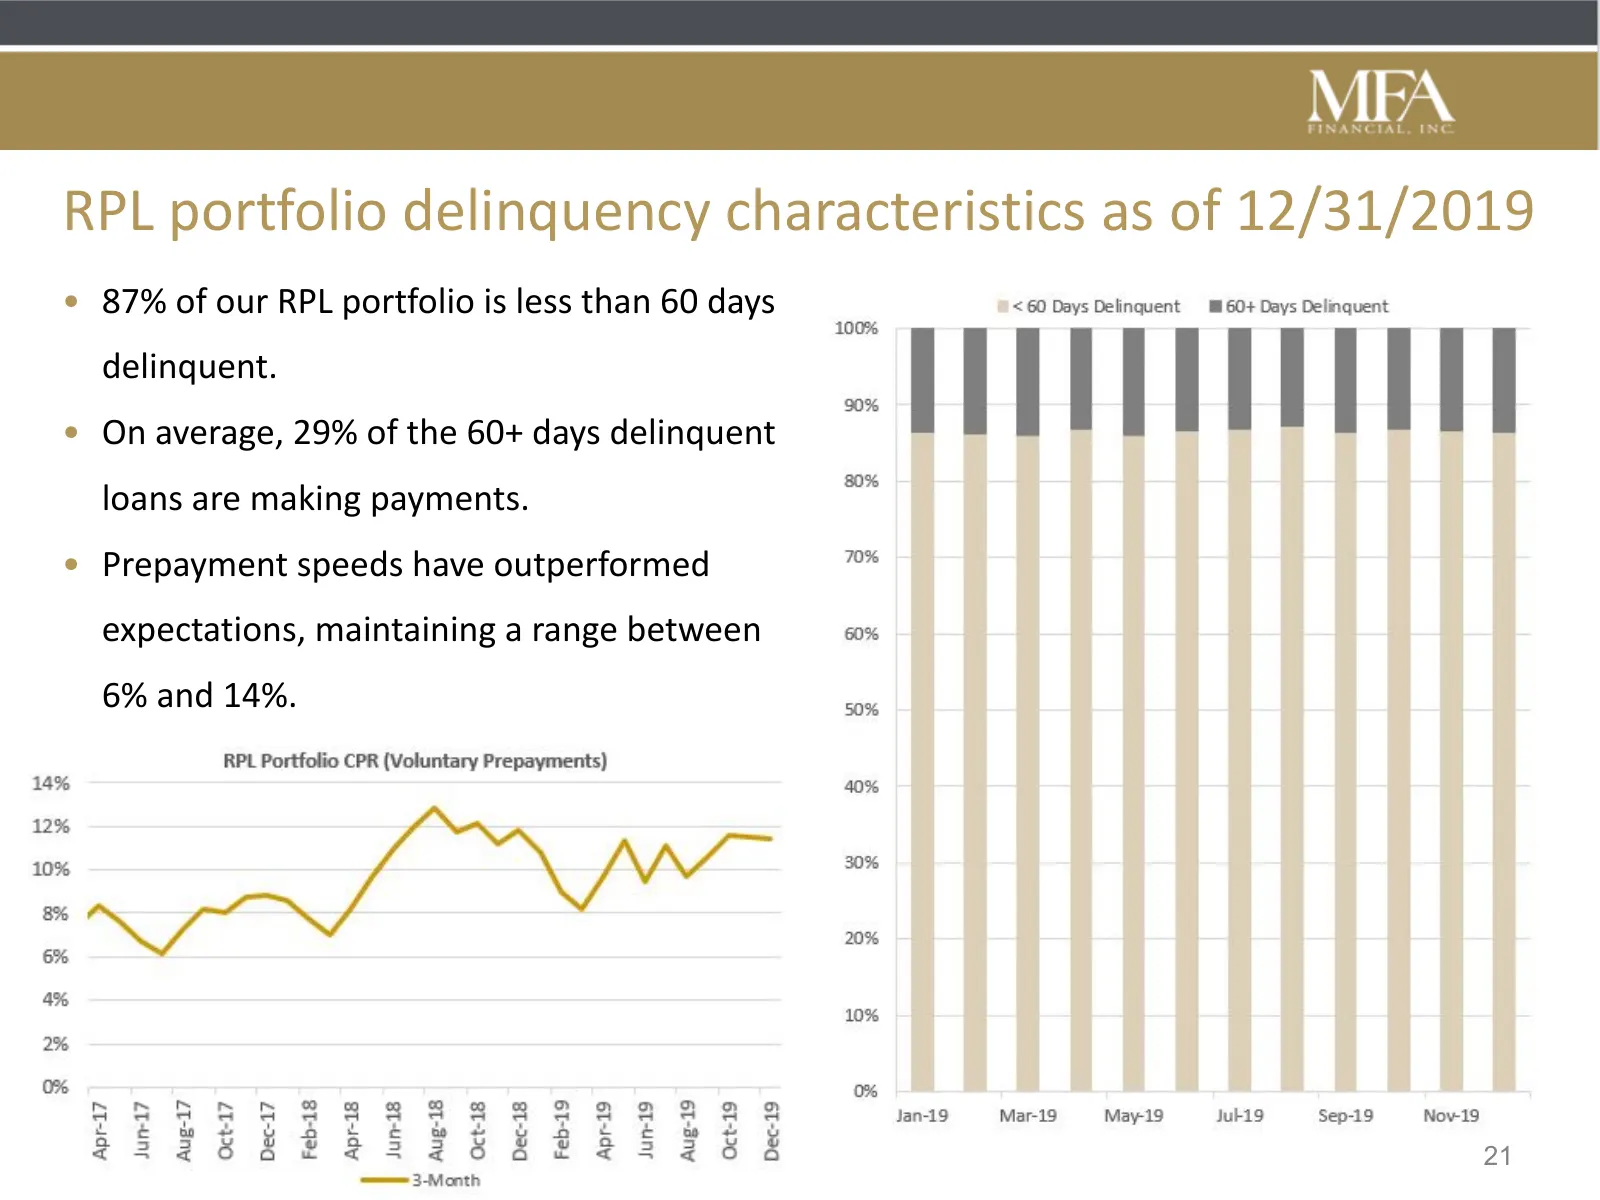
Slide 21: RPL portfolio delinquency characteristics as of 12/31/2019
RPL portfolio delinquency characteristics as of 12/31/2019 • 87% of our RPL portfolio is less than 60 days delinquent. • On average, 29% of the 60+ days delinquent loans are making payments. • Prepayment speeds have outperformed expectations, maintaining a range between 6% and 14%. 21
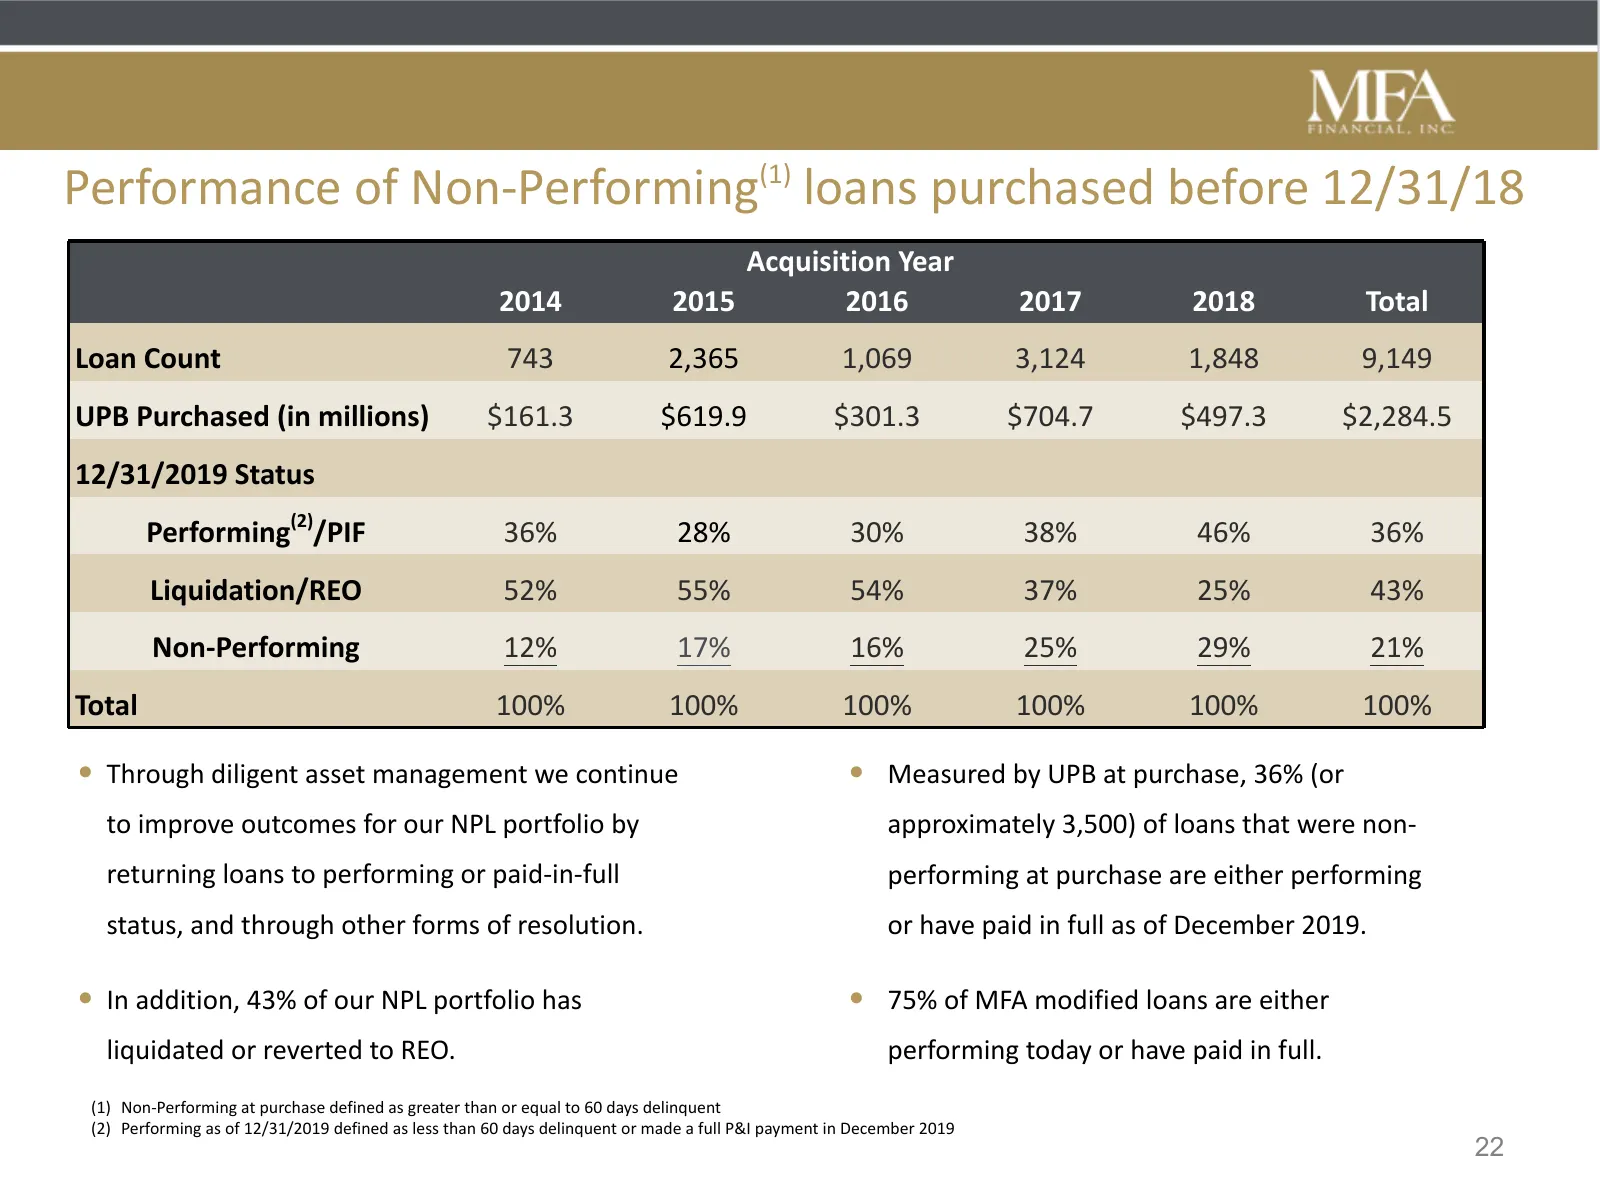
Slide 22: Performance of Non-Performing loans purchased before 12/31/18
Performance of Non-Performing(1) loans purchased before 12/31/18 Acquisition Year 2014 2015 2016 2017 2018 Total Loan Count 743 2,365 1,069 3,124 1,848 9,149 UPB Purchased (in millions) $161.3 $619.9 $301.3 $704.7 $497.3 $2,284.5 12/31/2019 Status Performing(2)/PIF 36% 28% 30% 38% 46% 36% Liquidatio
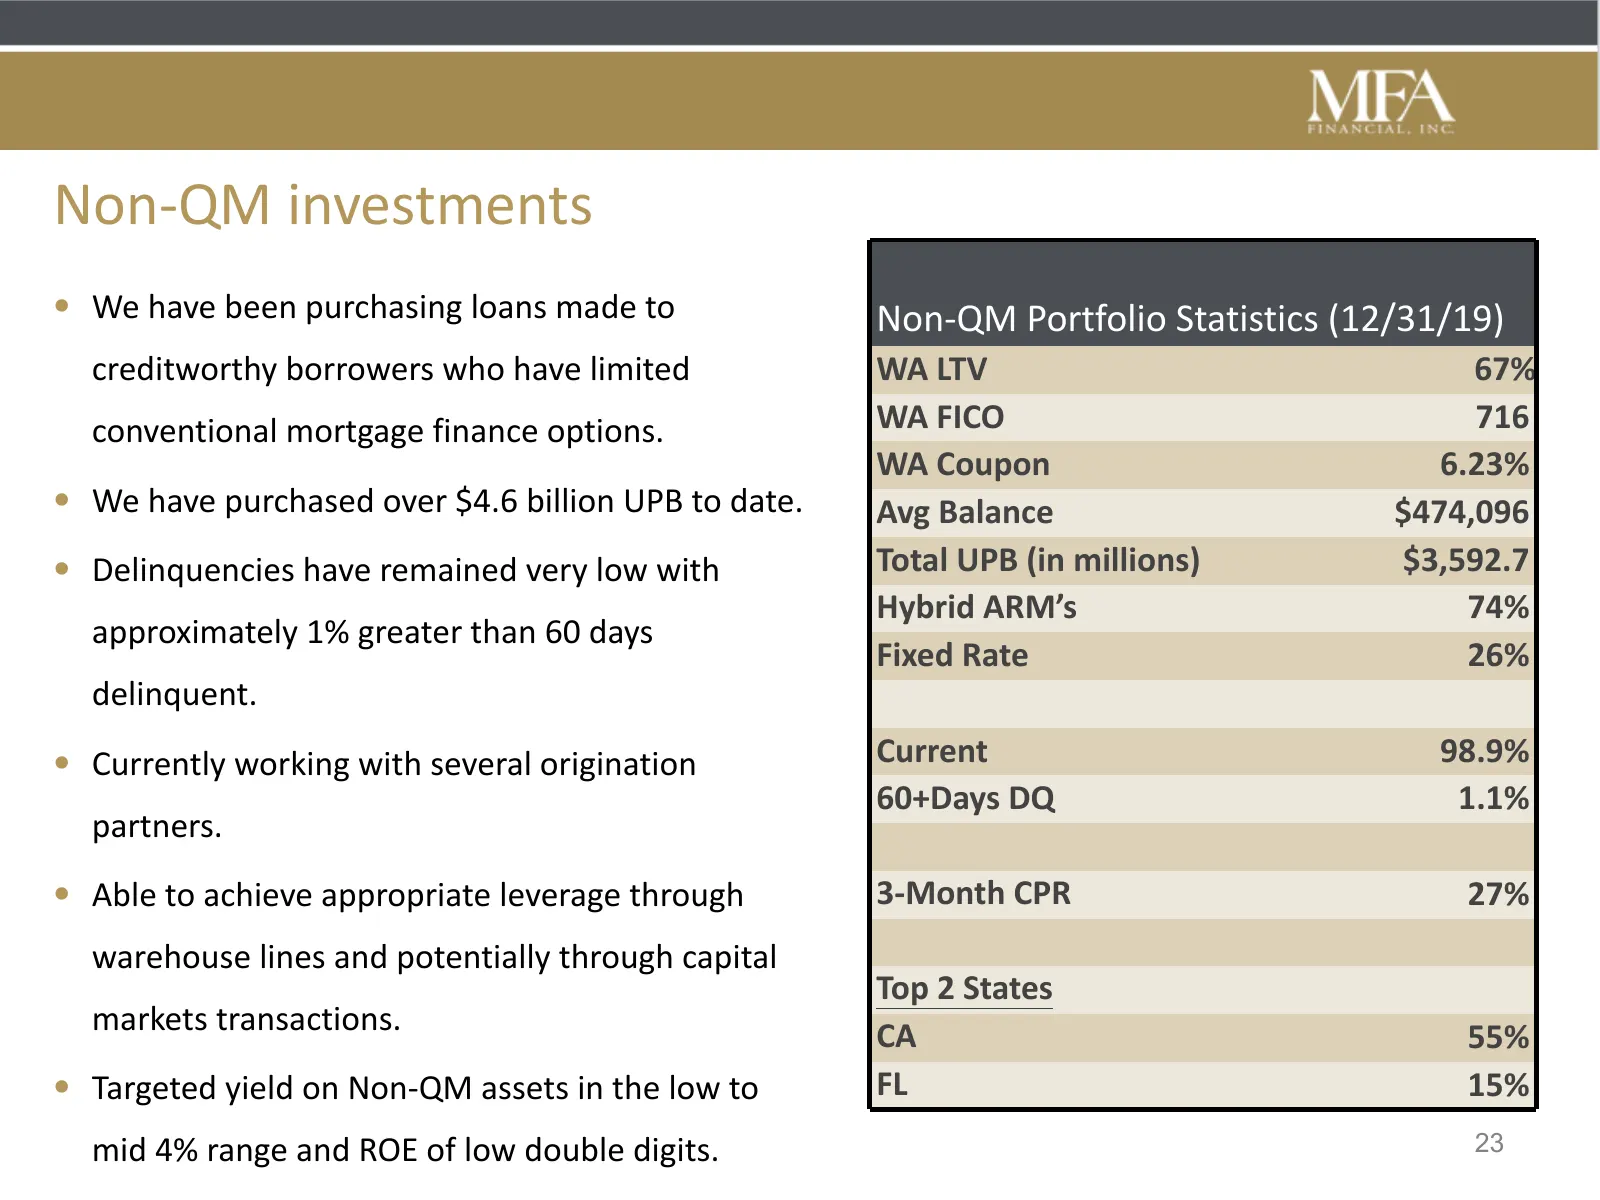
Slide 23: Non-QM investments
Non-QM investments • We have been purchasing loans made to Non-QM Portfolio Statistics (12/31/19) creditworthy borrowers who have limited WA LTV 67% conventional mortgage finance options. WA FICO 716 WA Coupon 6.23% • We have purchased over $4.6 billion UPB to date. Avg Balance $474,096 • Delinquenc
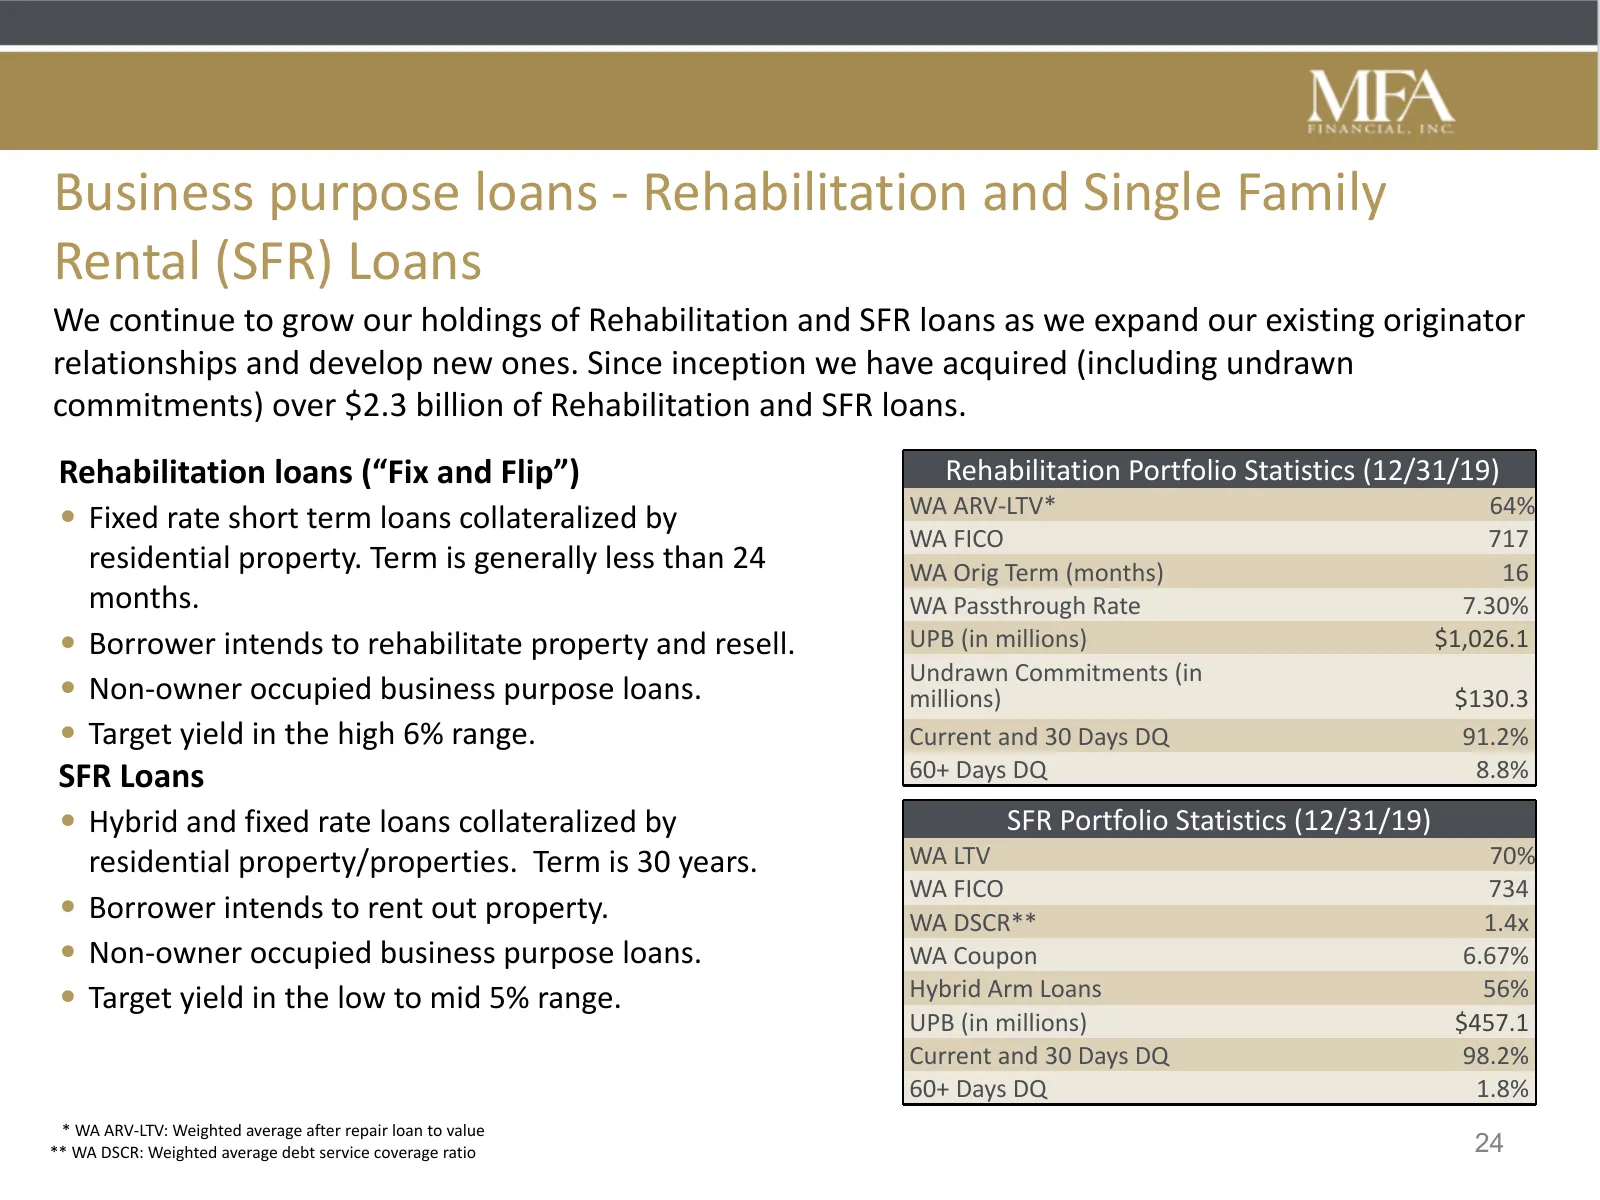
Slide 24: Business purpose loans - Rehabilitation and Single Family Rental (SFR) Loans
Business purpose loans - Rehabilitation and Single Family Rental (SFR) Loans We continue to grow our holdings of Rehabilitation and SFR loans as we expand our existing originator relationships and develop new ones. Since inception we have acquired (including undrawn commitments) over $2.3 billion of
Slide 25: Summary
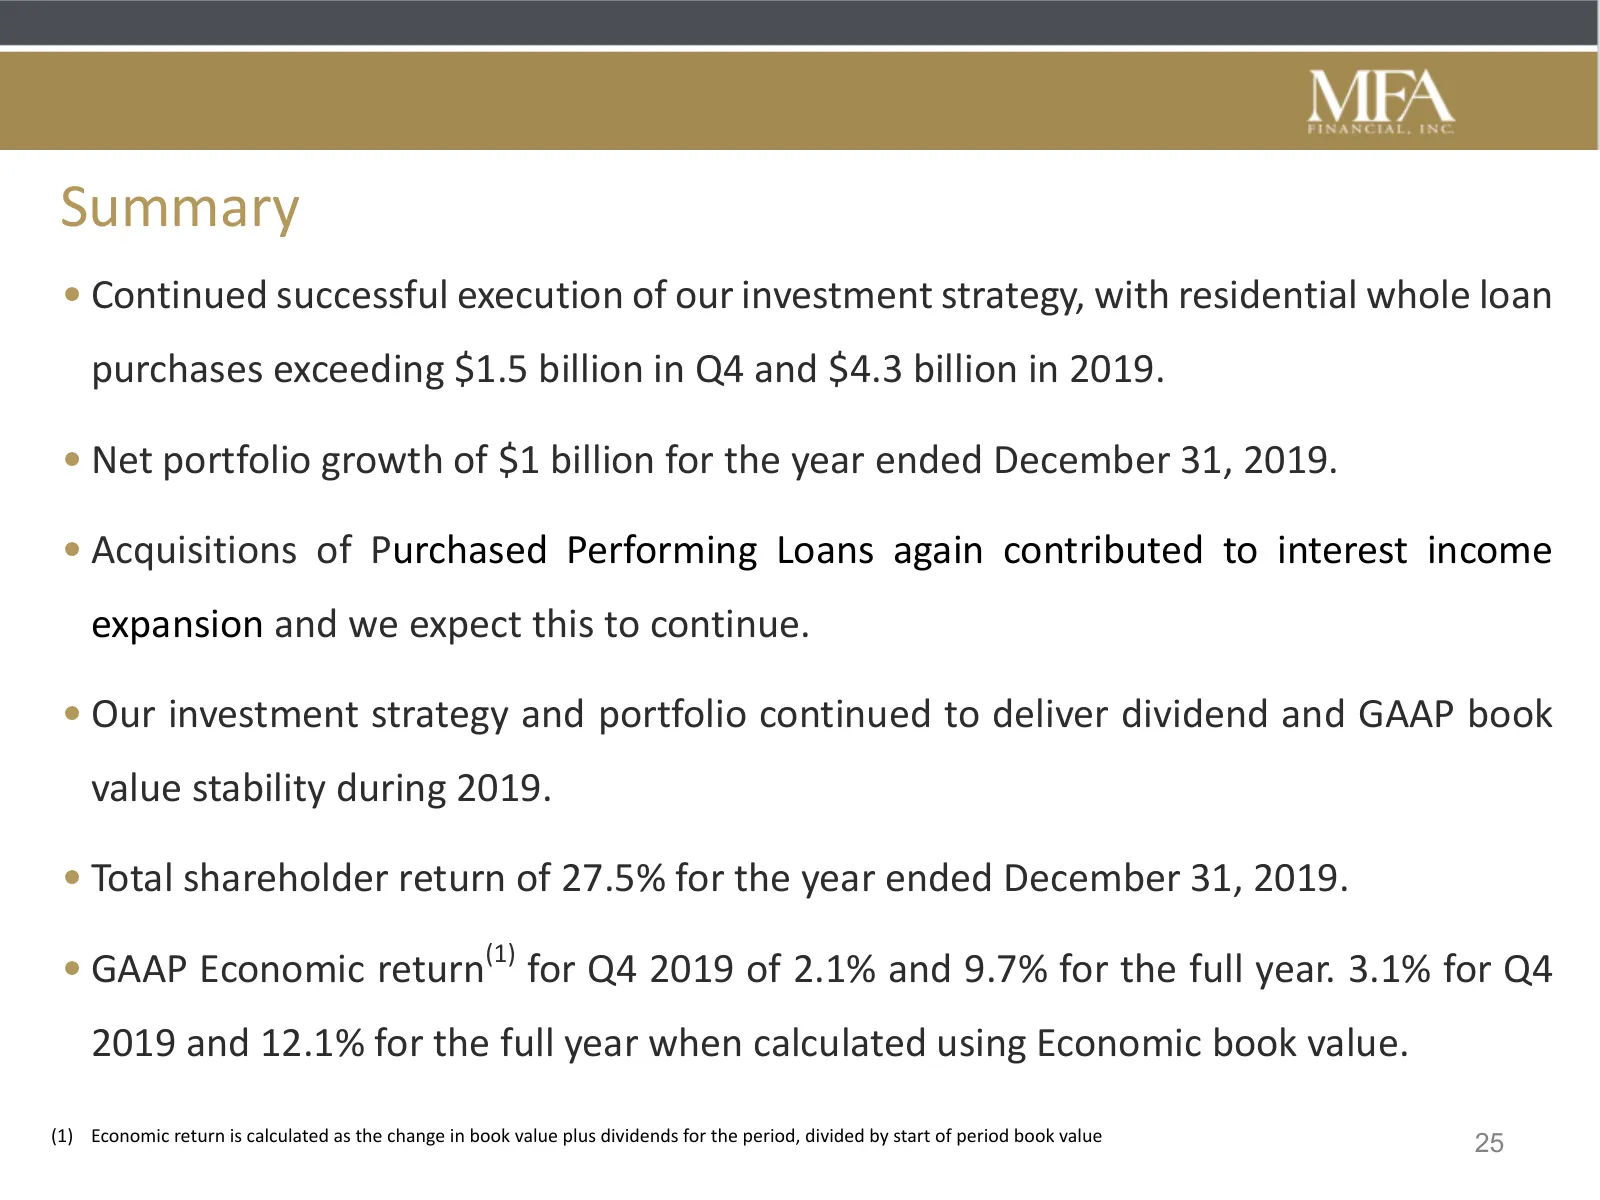
Summary • Continued successful execution of our investment strategy, with residential whole loan purchases exceeding $1.5 billion in Q4 and $4.3 billion in 2019. • Net portfolio growth of $1 billion for the year ended December 31, 2019. • Acquisitions of Purchased Performing Loans again contributed
Slide 26: Additional Information
SSS Additional Information
Slide 27: Economic book value increased 1% during 2019
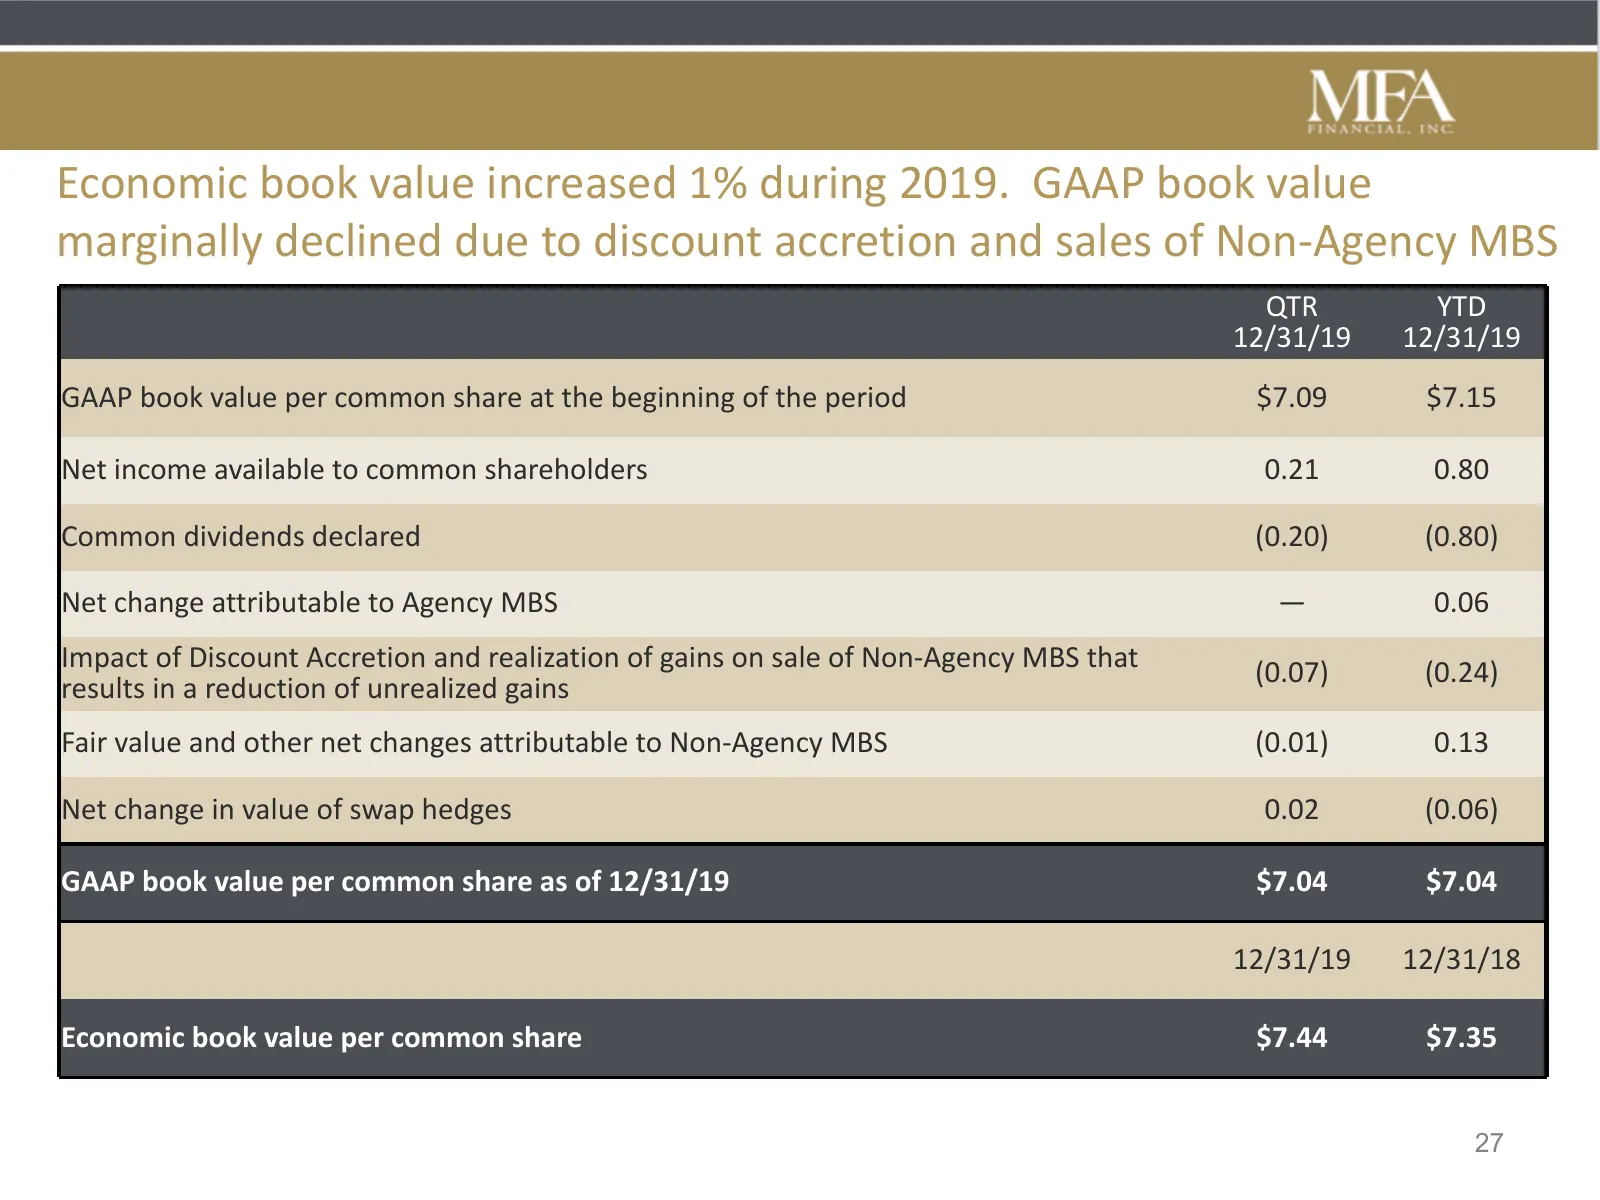
Economic book value increased 1% during 2019. GAAP book value marginally declined due to discount accretion and sales of Non-Agency MBS QTR YTD 12/31/19 12/31/19 GAAP book value per common share at the beginning of the period $7.09 $7.15 Net income available to common shareholders 0.21 0.80 Common d
Slide 28: Reconciliation of GAAP earnings to Core earnings
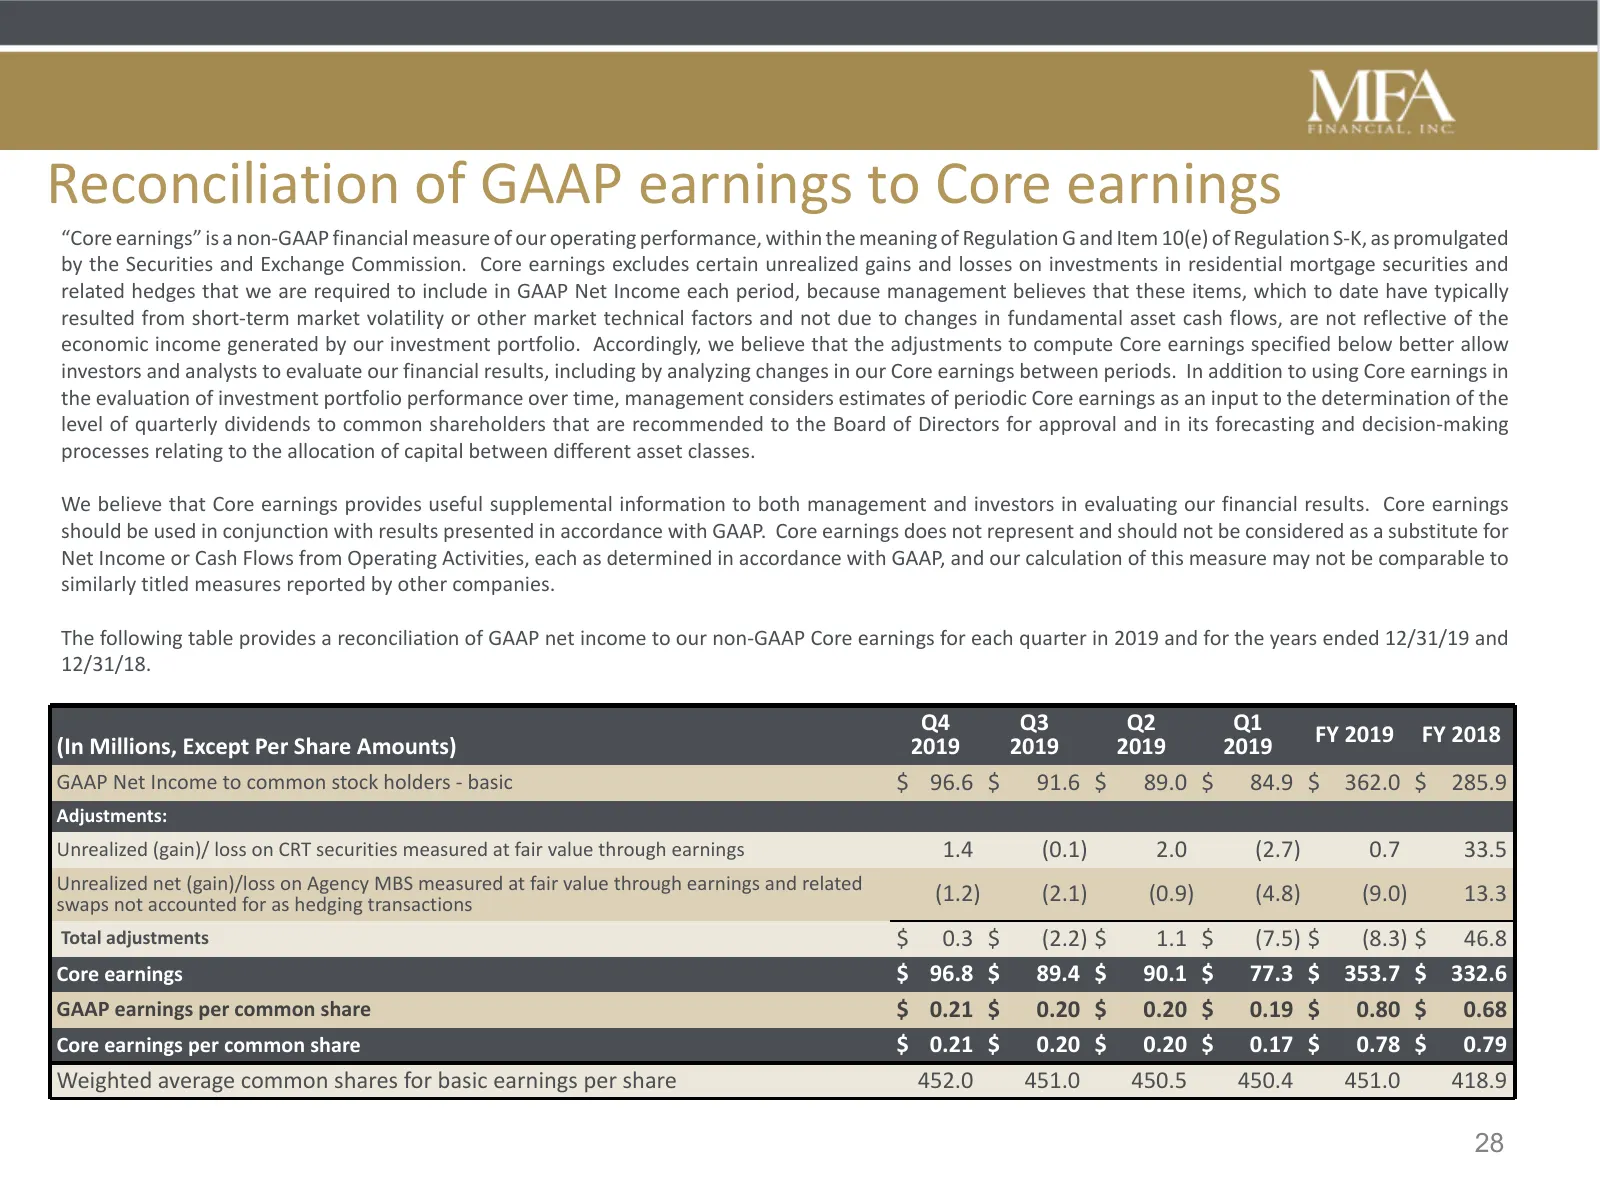
Reconciliation of GAAP earnings to Core earnings “Core earnings” is a non-GAAP financial measure of our operating performance, within the meaning of Regulation G and Item 10(e) of Regulation S-K, as promulgated by the Securities and Exchange Commission. Core earnings excludes certain unrealized gain
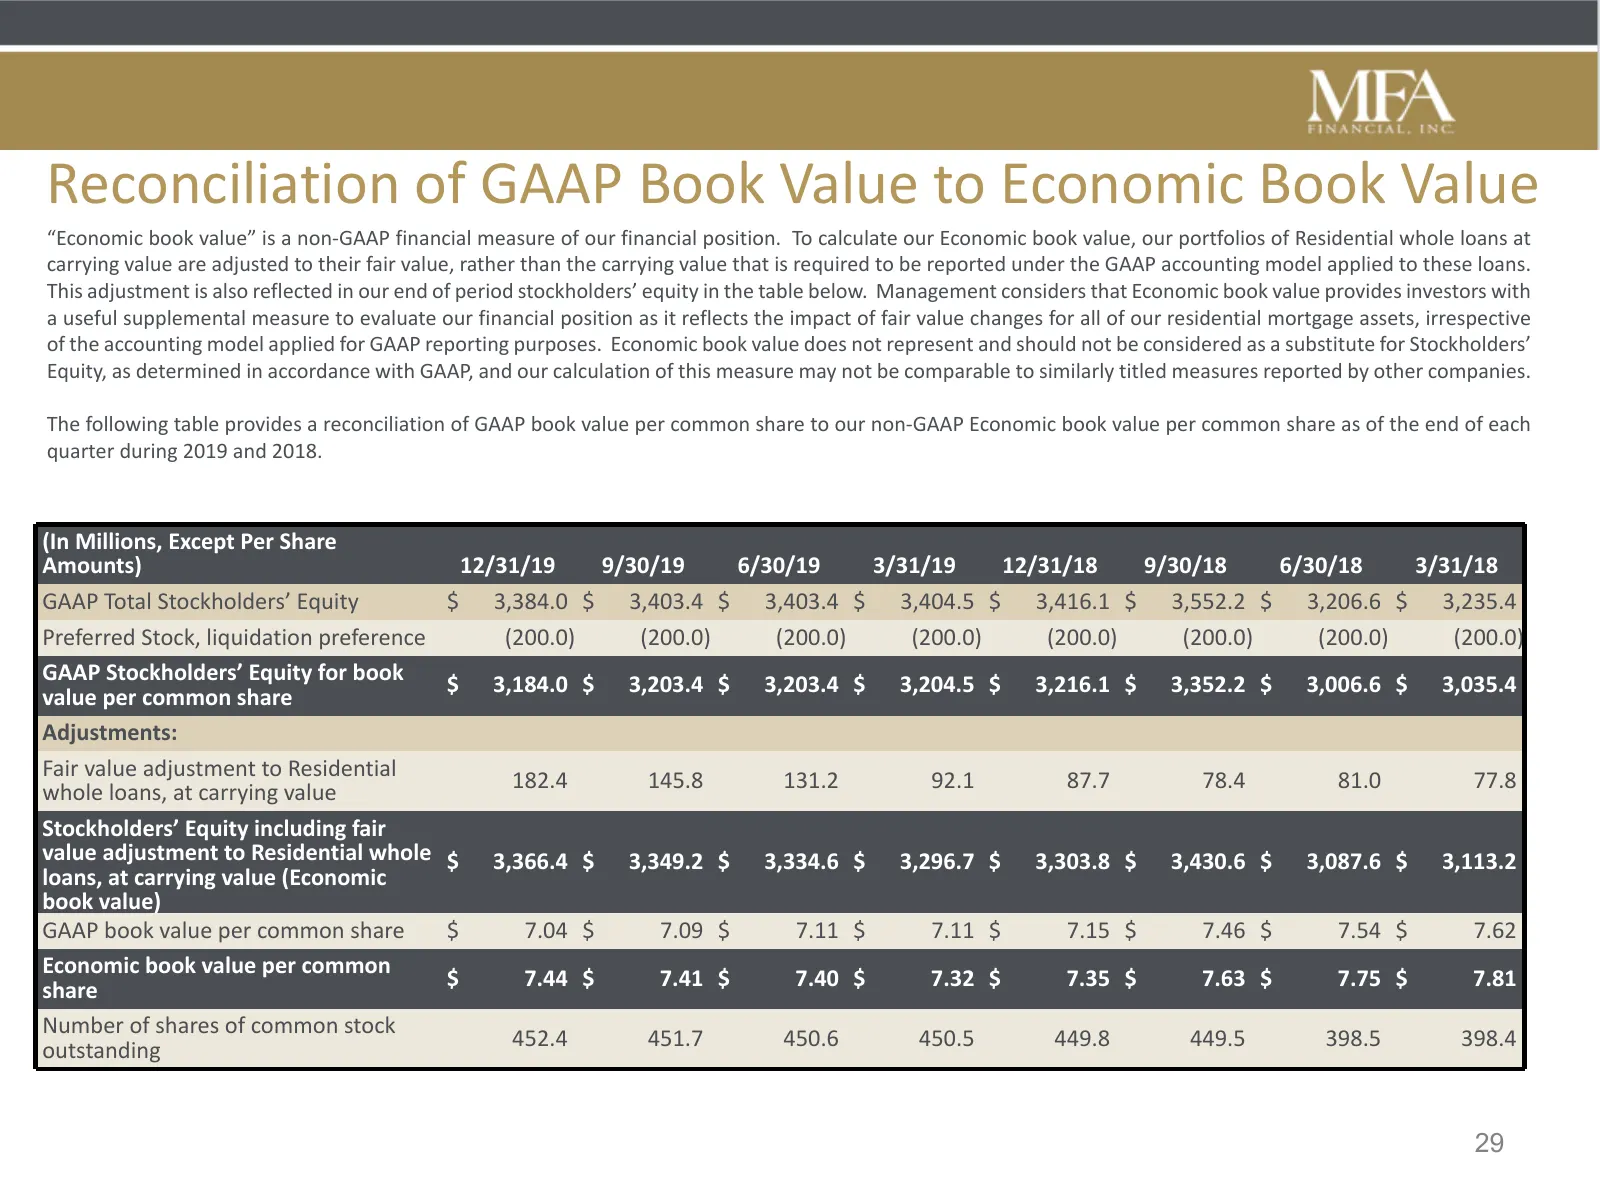
Slide 29: Reconciliation of GAAP Book Value to Economic Book Value
Reconciliation of GAAP Book Value to Economic Book Value “Economic book value” is a non-GAAP financial measure of our financial position. To calculate our Economic book value, our portfolios of Residential whole loans at carrying value are adjusted to their fair value, rather than the carrying value
Source: company website
More decks from MFA Financial, Inc.
 Q3 2026 Earnings Presentation22 slides · November 2026
 Q2 2026 Earnings Presentation22 slides · Aug 5, 2026
 Q1 2026 Earnings Presentation21 slides · May 5, 2026
 Q4 2025 Earnings Presentation21 slides · Feb 18, 2026
 Q3 2025 Earnings Presentation21 slides · Nov 6, 2025
 Q2 2025 Earnings Presentation20 slides · Aug 6, 2025