Airtran — Next Generation Equity Research Airlines Conference (December 2009)
26 slides from Airtran's conference presentation, Dec 10, 2009
Slide 1: December 2009 Investor Update
December 2009 Investor Update December 2009 Investor Update
Slide 2: Safe Harbor
2 Safe Harbor Certain of the statements contained herein should be considered “forward-looking statements,” including within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements may be identified by words such as “may”, “will”, “expect,” “intend,” “in
Slide 3: AirTran Investment Highlights
3 AirTran Investment Highlights n Great combination of low costs, diversified network, and high quality ― Lowest cost major airline in the U.S. ― Ranked #1 in the Airline Quality Rating n Company has been successfully repositioned for good times and bad ― Acted quickly to mitigate record high oil in
Slide 4: AirTran Product: Low Fares and Major Airline Amenities
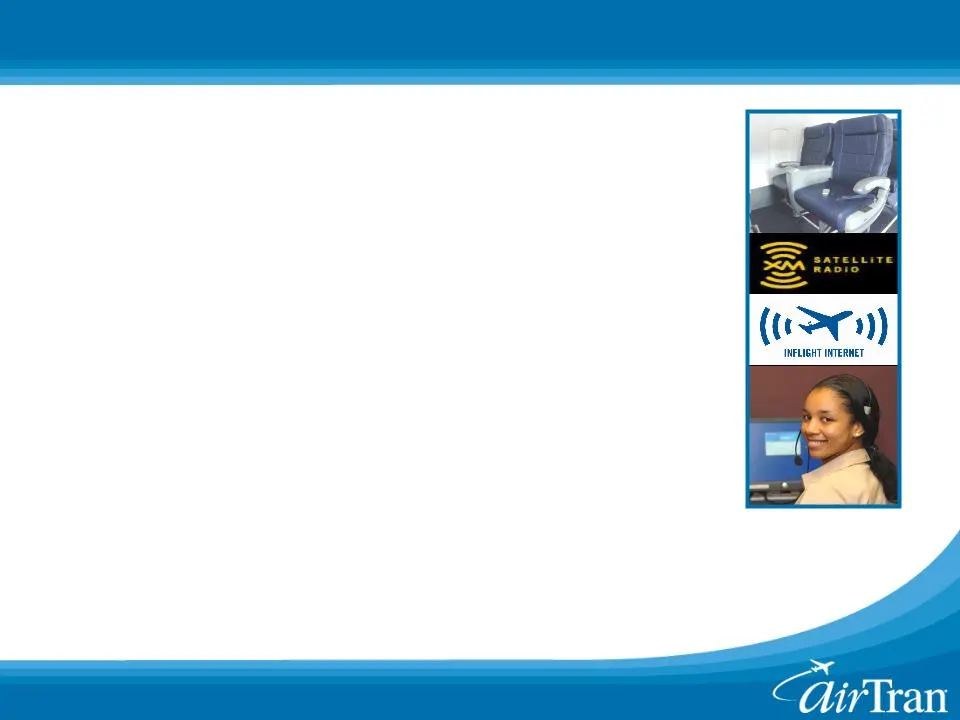
4 AirTran Product: Low Fares and Major Airline Amenities n Business Class on every flight n Assigned seating n Wi-Fi on every flight n Over 100 channels of free XM Satellite Radio n Oversized luggage bins n Friendly Crew Members n Broad distribution network n New aircraft - average age is 6 years
Slide 5: AirTran is Well Prepared for Economic Uncertainty
5 AirTran is Well Prepared for Economic Uncertainty n Industry leading low costs n Conservative fleet plan and modest growth n Strong ancillary revenues ― Less dependent on initial sale to passenger n Better diversified network ― Fewer price sensitive connections, less exposure to any single competi
Slide 6: AirTran's Cost Advantage Remains Strong
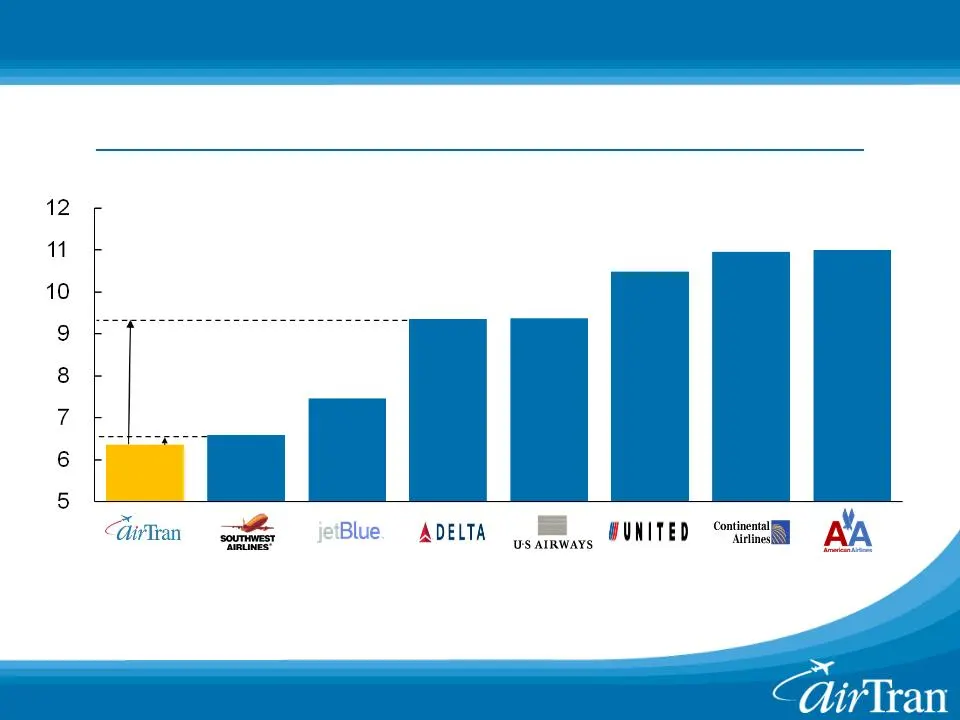
6 AirTran’s Cost Advantage Remains Strong (Cents) Note: Excludes fuel and special items Industry Cost Comparison Non-Fuel Unit Costs at 740 Miles for First Nine Months 2009 47% Higher 4% Higher
Slide 7: What Creates AirTran's Low Cost Advantage?
7 What Creates AirTran’s Low Cost Advantage? n Productive workforce at all levels n Young, simplified fleet ― Fuel efficient ― Attractive ownership costs n Efficient use of facilities n Competition for heavy maintenance contracts n Low cost distribution ― Over 70% of sales are directly with AirTran
Slide 8: AirTran Has High Quality & Industry Leading Low Costs
AirTran AirTran AirTran AirTran AirTran 8 2007 2006 2005 2008 2009 AirTran Has High Quality & Industry Leading Low Costs JetBlue Independence Southwest United America West Northwest Continental Alaska American JetBlue Southwest United Alaska America West Northwest American Continental ATA JetBlue No
Slide 9: Fleet Plan Well-Suited for Economic Uncertainty
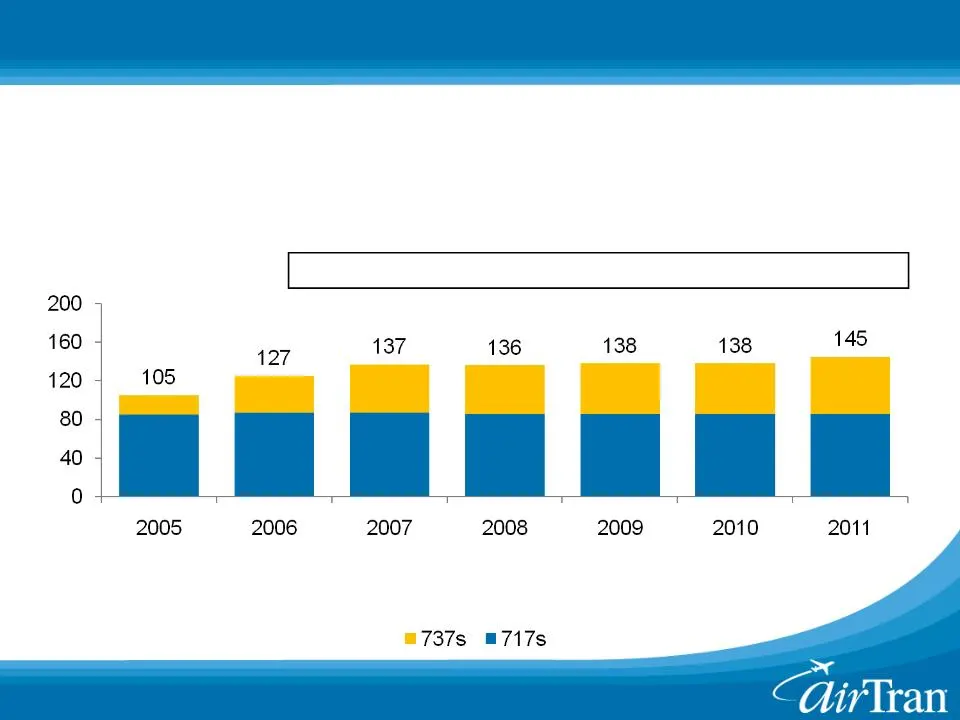
9 Fleet Plan Well-Suited for Economic Uncertainty 28% 24% 20% 5% (2-3)% 3-4% 2-3% (Aircraft) Previous Plan: n Currently 138 aircraft: 86 717s / 52 737-700s ― Deferred / sold 47 aircraft from 2008-2011 fleet plan ― Reduced capital requirements by nearly $1 billion through 2010 ― No permanent aircraft
Slide 10: Strong Ancillary Revenue Growth
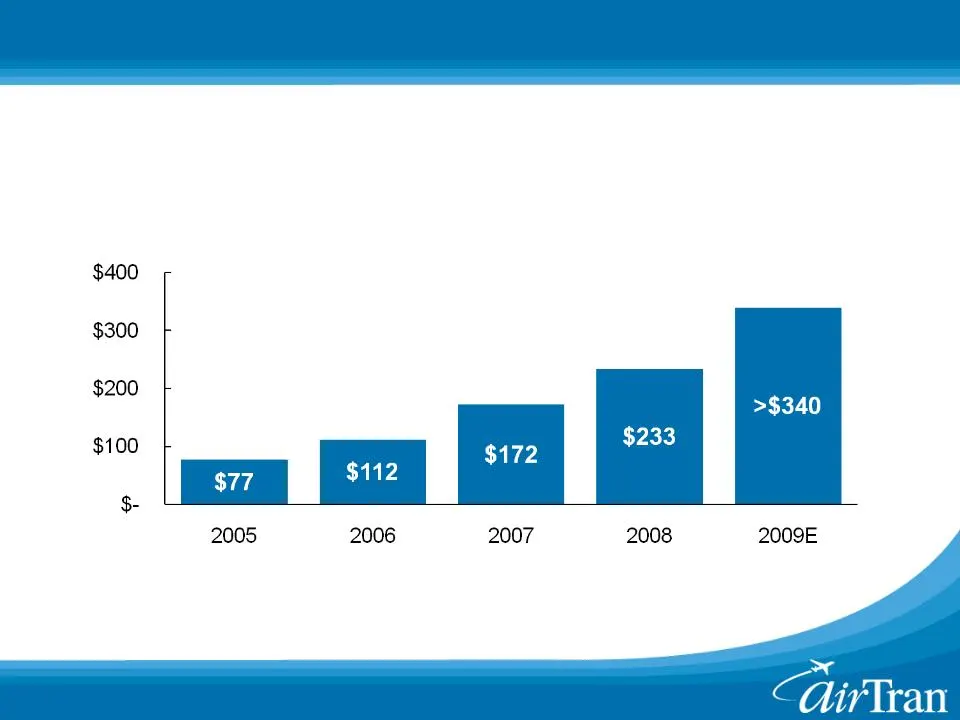
10 Strong Ancillary Revenue Growth 28% 24% 20% 5% (2-3)% (Millions) 43% 45% 54% 36% >45% Yr/Yr Growth * Select ancillary revenues are recorded in passenger revenues ASM Growth AirTran Ancillary Revenue n Well-suited for low cost carriers n High net margins
Slide 11: AirTran Has Successfully Diversified Its Network
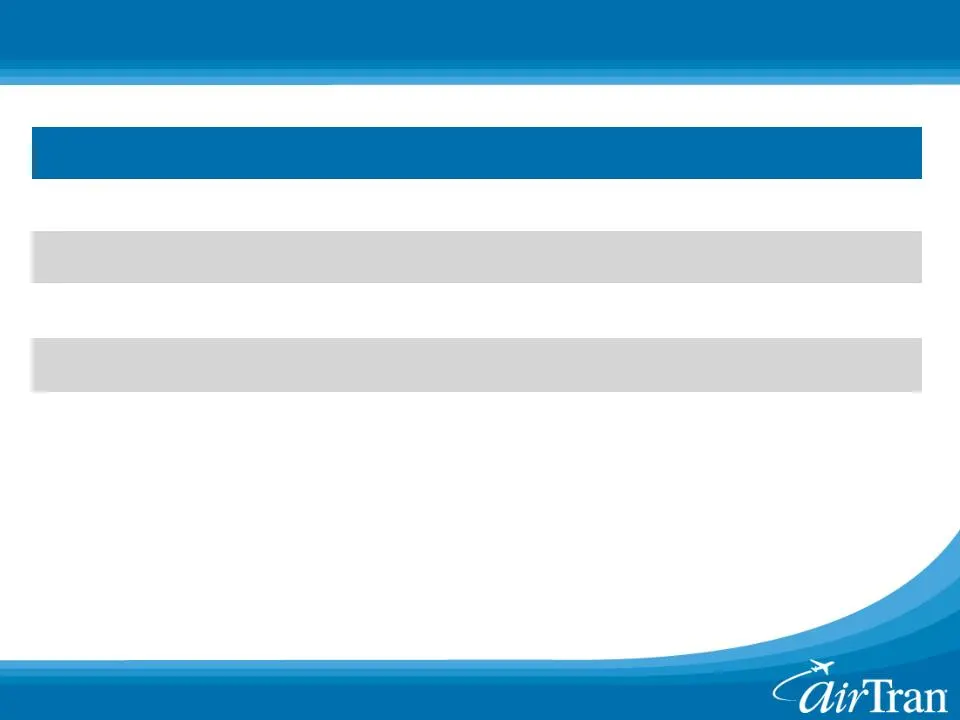
11 AirTran Has Successfully Diversified Its Network % ASMs 2000 2002 2004 2006 2008 2010E Atlanta 91% 76% 67% 64% 58% 48% Florida 29% 35% 34% 38% 45% 43% Baltimore 0% 13% 13% 9% 11% 14% Milwaukee 0% 3% 3% 2% 7% 13% Caribbean 0% 1% 1% 0% 3% 7% Daily Flights 278 362 492 650 713 713 Note: Totals >100%
Slide 12: AirTran Had a Regional Route Network in 2000
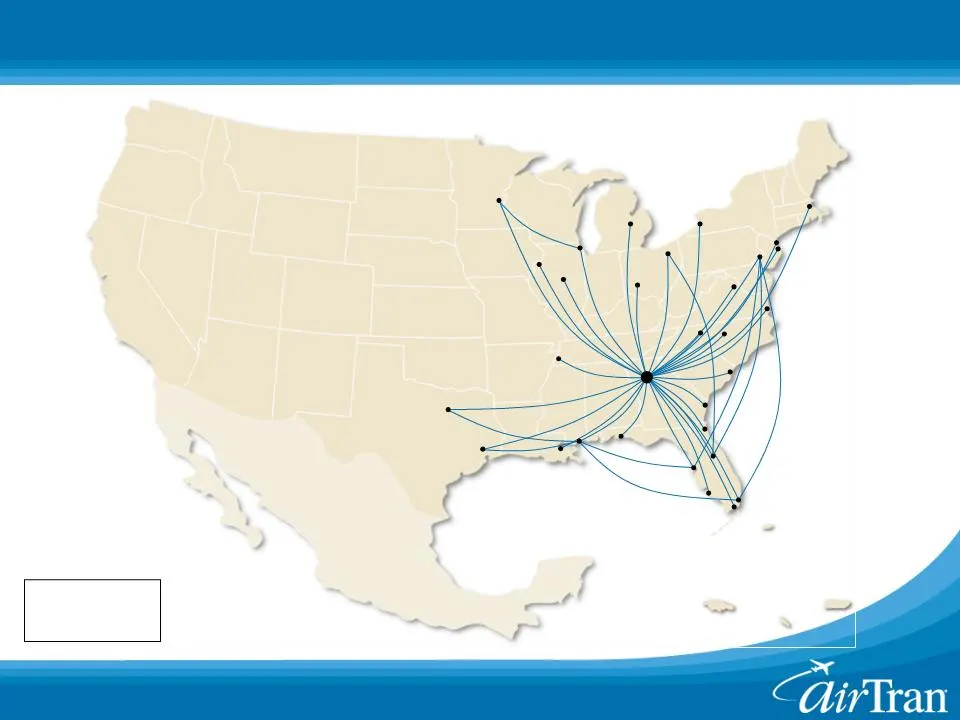
12 AirTran Had a Regional Route Network in 2000 Boston Flint Moline Buffalo Dayton Dallas/Ft. Worth Houston New Orleans Memphis Bloomington Minneapolis Akron/ Canton Newport News New York (LGA) Ft. Lauderdale Gulfport/Biloxi Fort Walton Beach Miami Ft. Myers Orlando Jacksonville Savannah Myrtle Beac
Slide 13: AirTran's 2009 Atlanta Network Has Grown
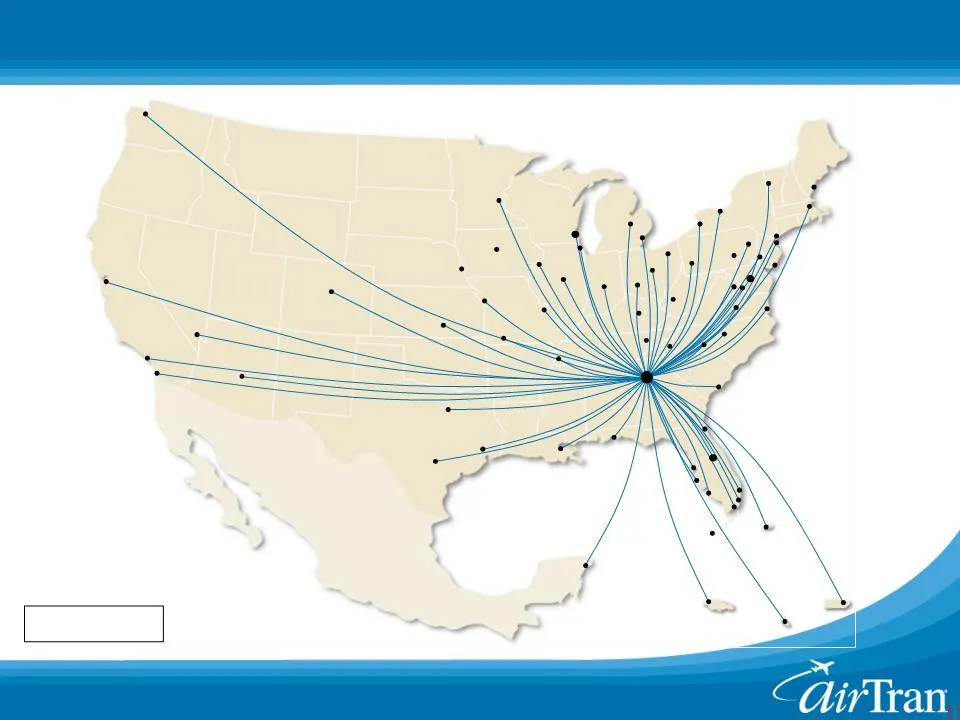
13 AirTran’s 2009 Atlanta Network Has Grown to 59 Cities Portland Boston Las Vegas Burlington Flint San Juan Cancun Montego Bay Aruba Moline Pittsburgh Buffalo Rochester Dayton San Diego Los Angeles Phoenix Seattle San Francisco Dallas/Ft. Worth Houston San Antonio New Orleans Atlanta Pensacola Memp
Slide 14: AirTran Now Serves the Most Destinations from Orlando
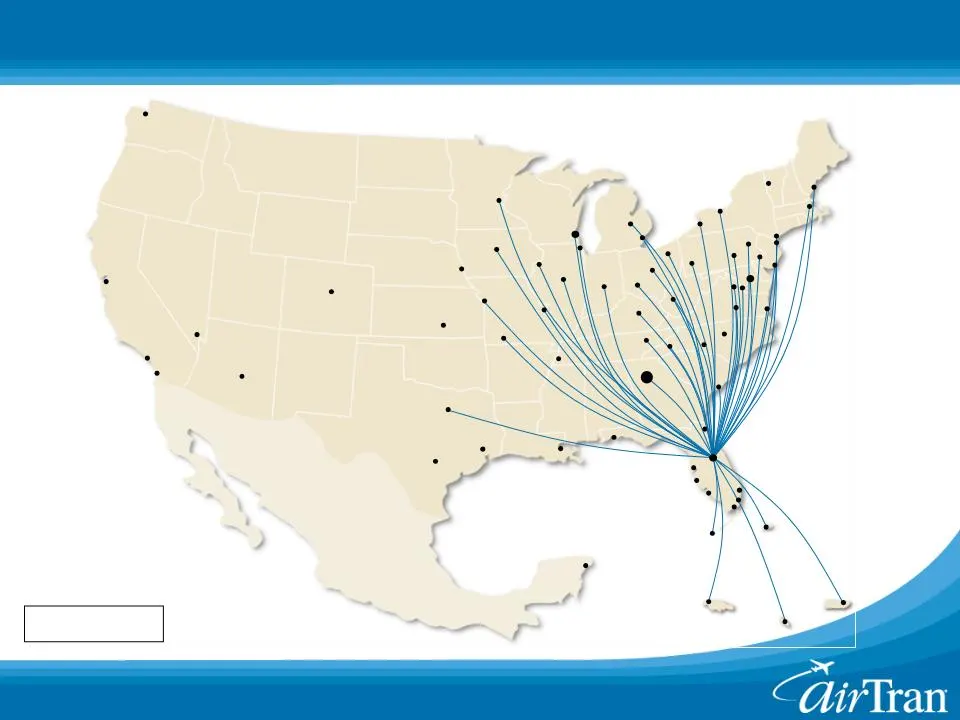
14 AirTran Now Serves the Most Destinations from Orlando Portland Boston Las Vegas Burlington Flint San Juan Cancun Montego Bay Aruba Pittsburgh Buffalo Rochester Dayton San Diego Los Angeles Phoenix Seattle San Francisco Dallas/Ft. Worth Houston San Antonio New Orleans Branson Wichita Kansas City S
Slide 15: AirTran Has Replaced US Airways' Baltimore Network
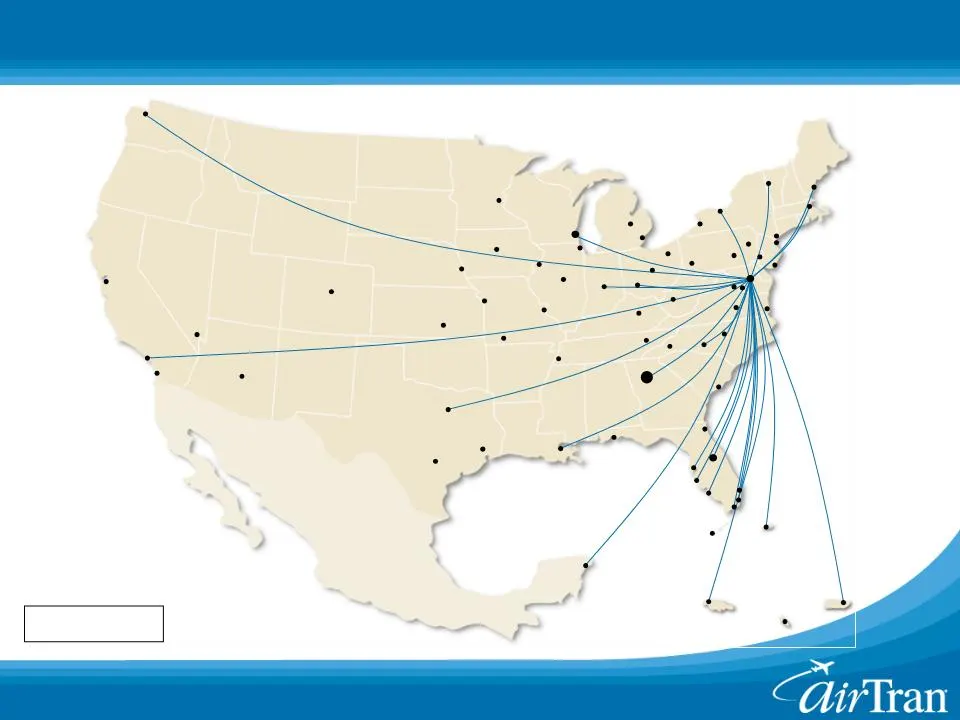
15 AirTran Has Replaced US Airways’ Baltimore Network Portland Boston Las Vegas Burlington Flint San Juan Cancun Montego Bay Aruba Moline Pittsburgh Buffalo Rochester Dayton San Diego Los Angeles Phoenix Seattle San Francisco Dallas/Ft. Worth Houston San Antonio New Orleans Atlanta Pensacola Memphis
Slide 16: AirTran is Now Milwaukee's Largest Mainline Carrier
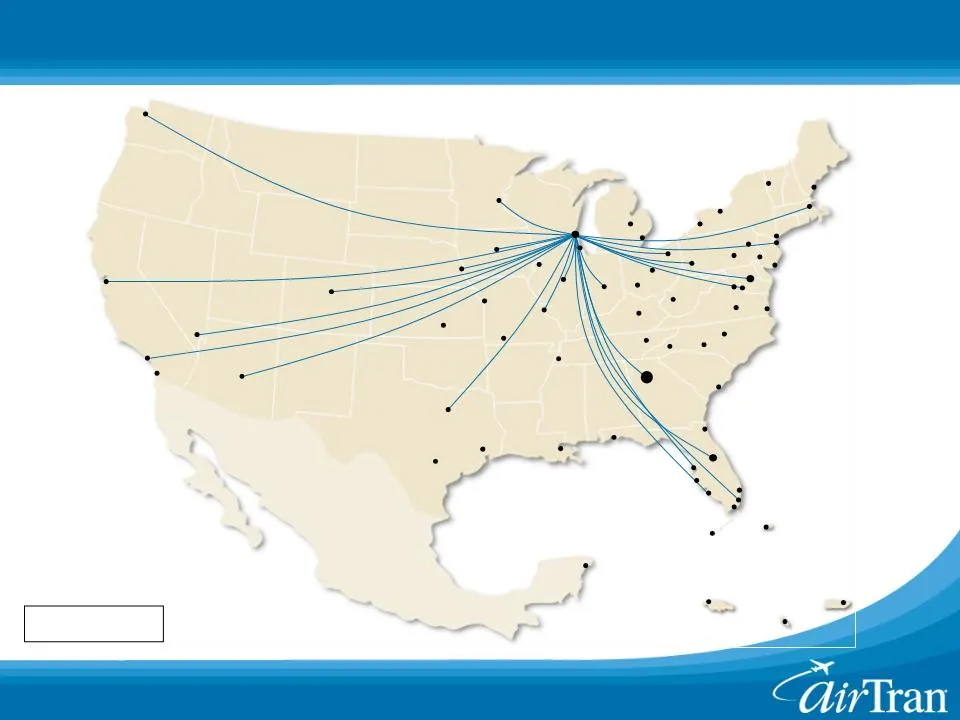
16 AirTran is Now Milwaukee’s Largest Mainline Carrier Portland Boston Las Vegas Burlington Flint San Juan Cancun Montego Bay Aruba Moline Pittsburgh Buffalo Rochester Dayton San Diego Los Angeles Phoenix Seattle San Francisco Dallas/Ft. Worth Houston San Antonio New Orleans Atlanta Pensacola Memphi
Slide 17: AirTran's 2009 Network is Nationwide and Diversified
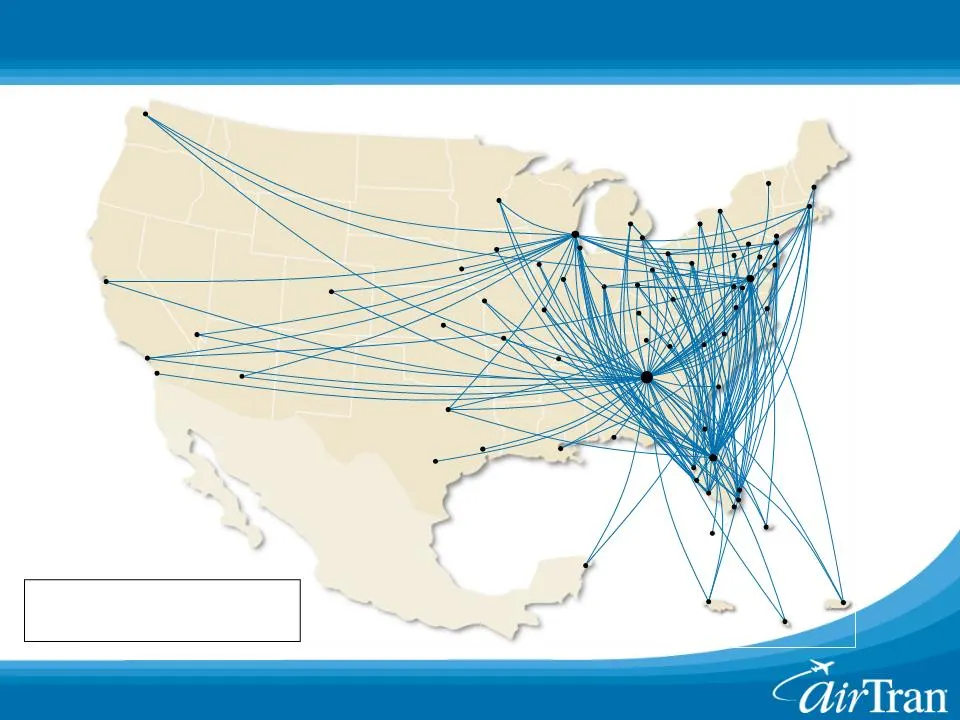
17 AirTran’s 2009 Network is Nationwide and Diversified Portland Boston Dallas/Ft. Worth Las Vegas Denver Minneapolis Burlington San Antonio Flint Houston San Juan Cancun Montego Bay Aruba Ft. Myers Tampa Charleston Knoxville Charlotte Raleigh/Durham Detroit Allentown Pittsburgh Newport News Washing
Slide 18: AirTran is Committed to Reducing Fuel Cost Volatility
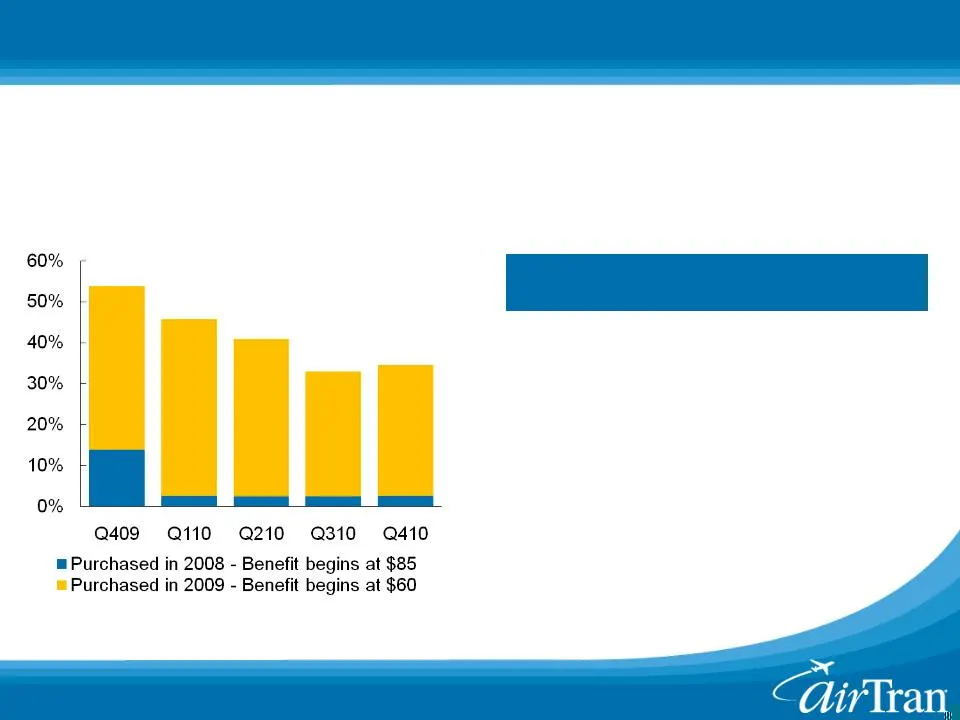
18 18 Crude Price Period Hedge % $50 $70 $90 Q409 54% $62 $69 $70 Q110 46% $61 $73 $79 Q210 41% $62 $75 $81 Q310 33% $63 $77 $85 Q410 35% $63 $77 $85 2010 38% $62 $75 $82 AirTran is Committed to Reducing Fuel Cost Volatility n Hedge portfolio was restructured in 2008 n One of few airlines to activel
Slide 19: Legacy Airline's Domestic Networks Remain Unprofitable
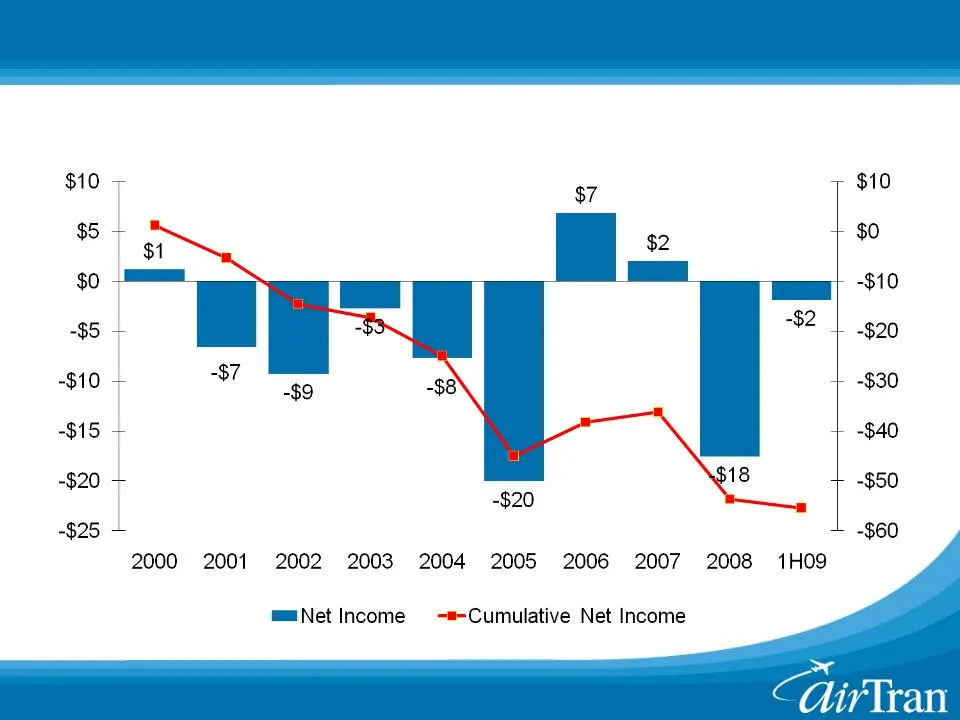
19 Legacy Airline’s Domestic Networks Remain Unprofitable (Billions) (Billions) Legacy Airline Domestic Net Income Source: DOT Form 41 Filings Annual Cumulative
Slide 20: Industry Losses Results in Disciplined Domestic Capacity
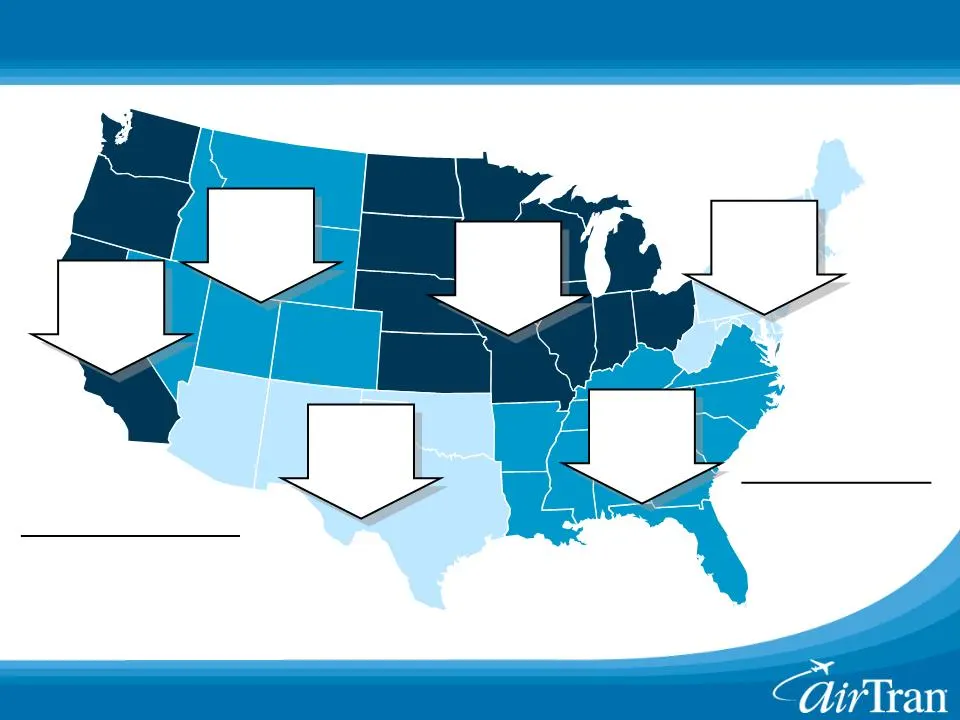
20 Industry Losses Results in Disciplined Domestic Capacity AirTran: Delta: Southwest: -2% to - -3% -7% to - -9% -5% to - -6% 2009 Planned Domestic Capacity Note: Domestic capacity change for 2009 Northeast -6% Midwest -8% Southwest -5% Mountain -6% West -8% South -8% Las Vegas: St. Louis: Cincinnat
Slide 21: Domestic Capacity Now at Lowest Level In Over a Decade
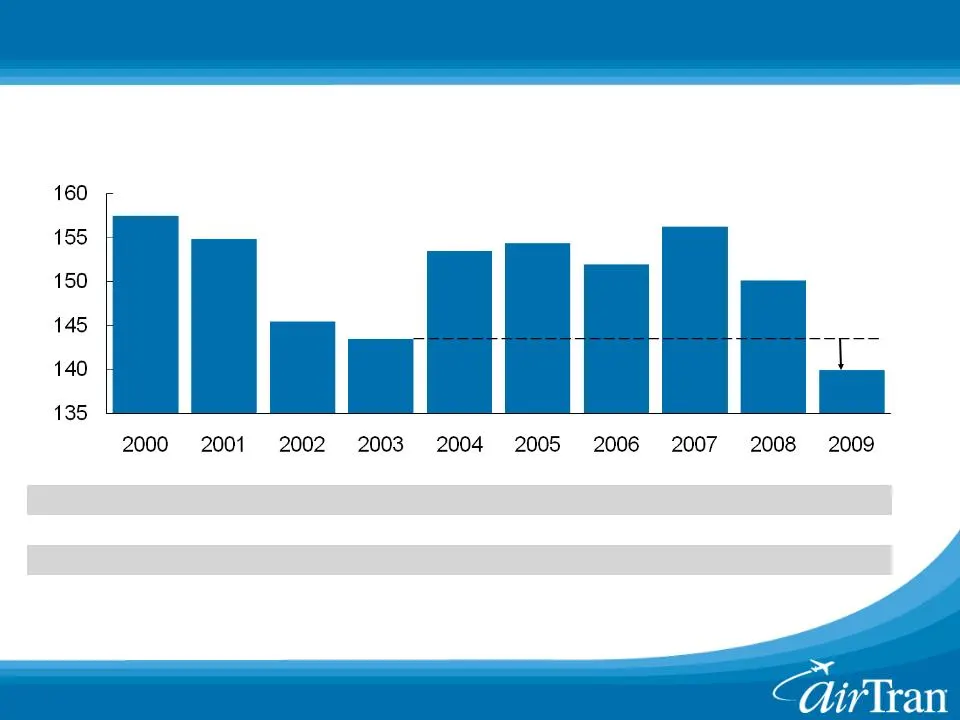
21 21 82% 79% 76% 72% 69% 64% 61% 59% 57% 56% 6% 7% 8% 10% 12% 14% 14% 14% 14% 15% 12% 14% 16% 18% 19% 22% 25% 27% 29% 29% Domestic Capacity Now at Lowest Level In Over a Decade Source: DOT Form 41 Filings (Trillions) Continental U.S. Available Seat Miles Legacy Regional LCC (2-3%)
Slide 22: AirTran Yr/Yr Growth Largely Focused in Milwaukee
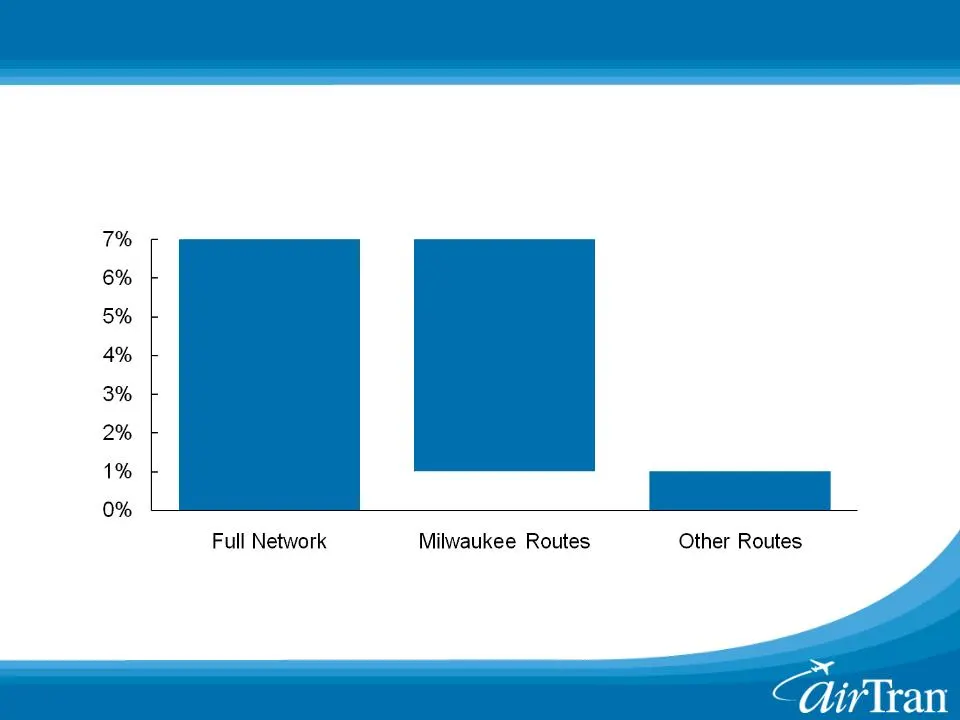
22 AirTran Yr/Yr Growth Largely Focused in Milwaukee 7% 6% 1% (ASM Growth) AirTran Q409 Available Seat Mile Growth
Slide 23: AirTran's Milwaukee Network Has Matured
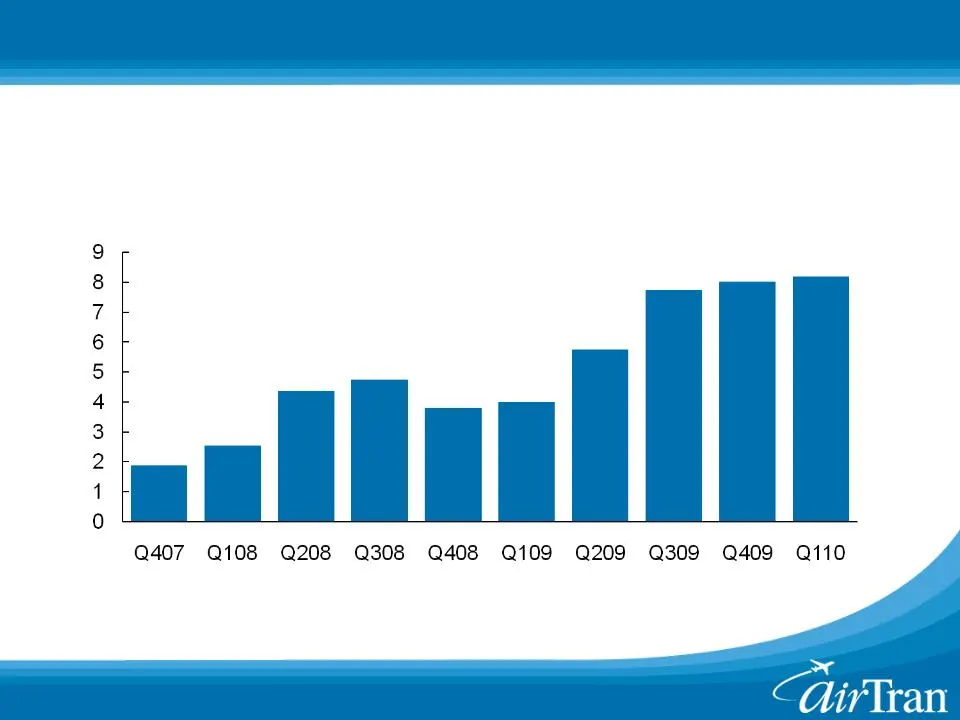
23 AirTran’s Milwaukee Network Has Matured (ASMs in Millions) AirTran Milwaukee Daily ASMs n AirTran now serves 18 of the top 20 markets
Slide 24: Outlook for AirTran Remains Positive
24 Outlook for AirTran Remains Positive n Track record of profitability was restored in 2009 ― Record net income in 2009 ― Consumers are increasingly value-oriented ― Softening consumer demand has been offset by lower fuel, capacity reductions, and strong growth in ancillary revenues n Significant n
Slide 25: AirTran Investment Summary
25 AirTran Investment Summary n Industry leading low costs and a high quality product drives strong 2009 profitability across multiple market segments n Significant cost advantage resulting in share shift in leisure markets ― Business Class / Wi-Fi / assigned seats appeal to high-yielding travelers
Slide 26
Source: SEC EDGAR · 8-K filed Dec 10, 2009
More decks from Airtran Holdings Inc
 Merger or Acquisition (September 2010)21 slides · Sep 27, 2010
 Bank of America - Merrill Lynch Global Transportation Conference 201025 slides · Jun 15, 2010
 Shareholder Meeting (May 2010)33 slides · May 18, 2010
 Investor Presentation (May 2010)26 slides · May 13, 2010
 JP Morgan Aviation, Transportation and Defense Conference 201025 slides · Mar 9, 2010
 Raymond James 2010 Growth Airline Conference25 slides · Feb 4, 2010