Scentre Group · ASX:SCG
Scentre — FY2016 Earnings Presentation
29 slides from Scentre's earnings presentation, Feb 21, 2017
Slide 1: Scentre Group reports full year 2016 results above guidance
ASX Announcement 21 February 2017 For personal use only SCENTRE GROUP REPORTS FULL YEAR 2016 RESULTS ABOVE GUIDANCE WITH 3.2% GROWTH IN FFO EARNINGS Scentre Group (ASX: SCG) today announced results for the 12 months to 31 December 2016, with Funds From Operations (“FFO”) of $1.238 billion representi
Slide 2: Creating extraordinary places connecting and enriching communities
Creating extraordinary places connecting and enriching communities In 2016 the Group completed and opened $665 million (SCG share: $410 million) of redevelopments including For personal use only Westfield Warringah Mall and Westfield North Lakes, with yields in excess of 7.5%. Both centres are tradi
Slide 3: Portfolio and capital management; outlook
Ticketless parking and parking guidance systems continue to be implemented across the portfolio to improve the customer car park experience. For personal use only The Group has commenced the implementation of a net promoter system facilitating customer feedback. This direct communication enables cus
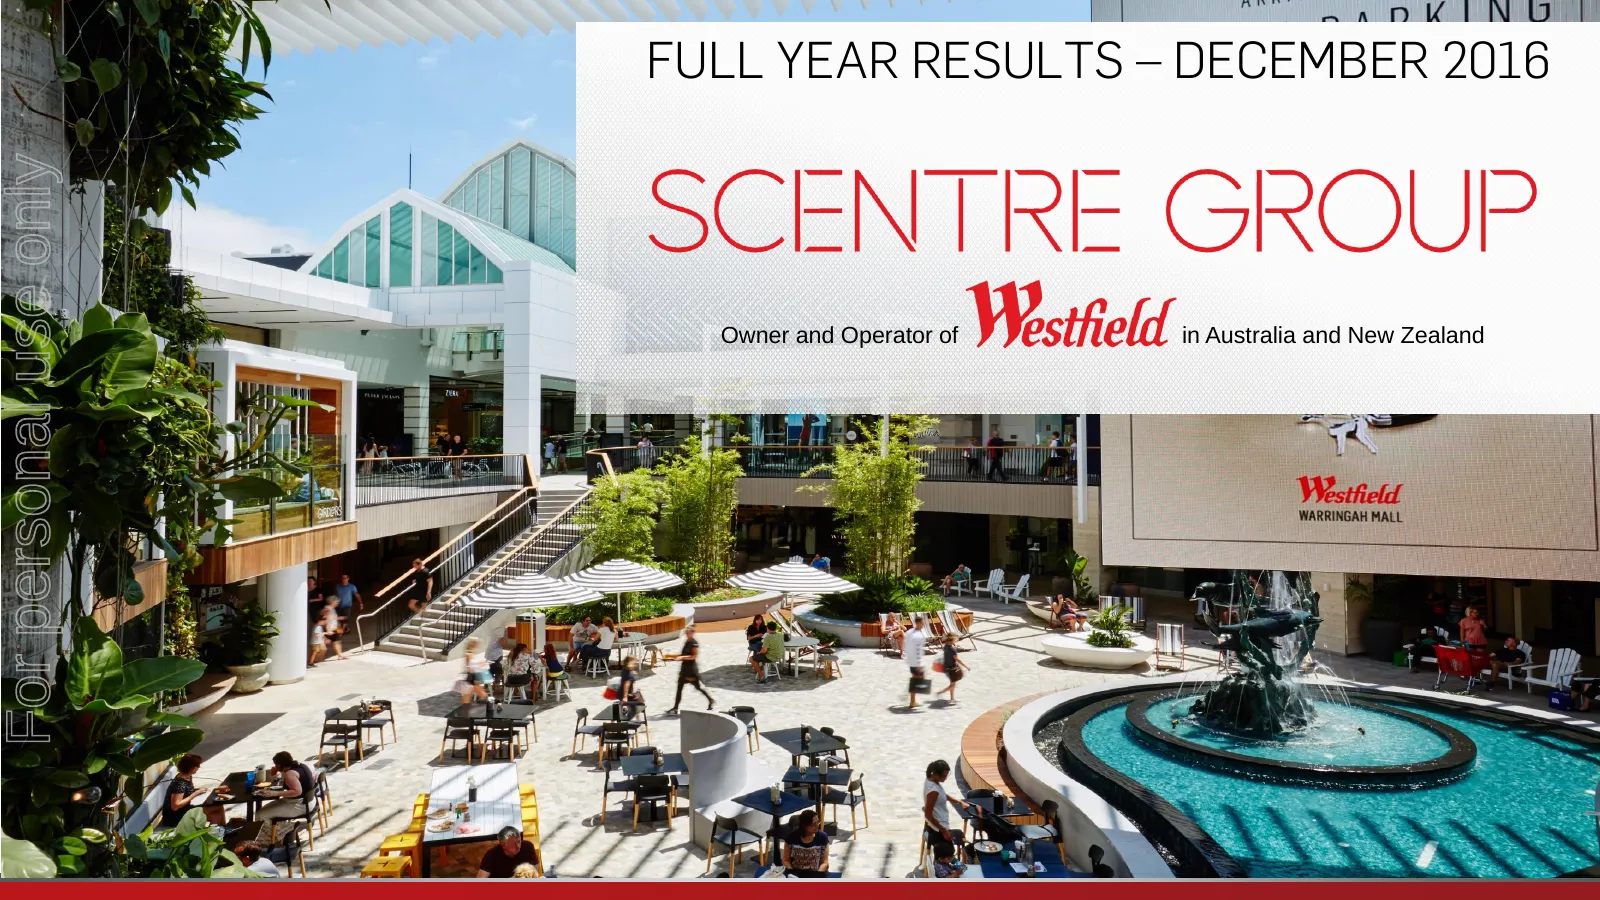
Slide 4: Full Year Results – December 2016
FULL YEAR RESULTS – DECEMBER 2016 For personal use only Owner and Operator of in Australia and New Zealand Westfield Newmarket
Slide 5: Scentre Group delivers strong results
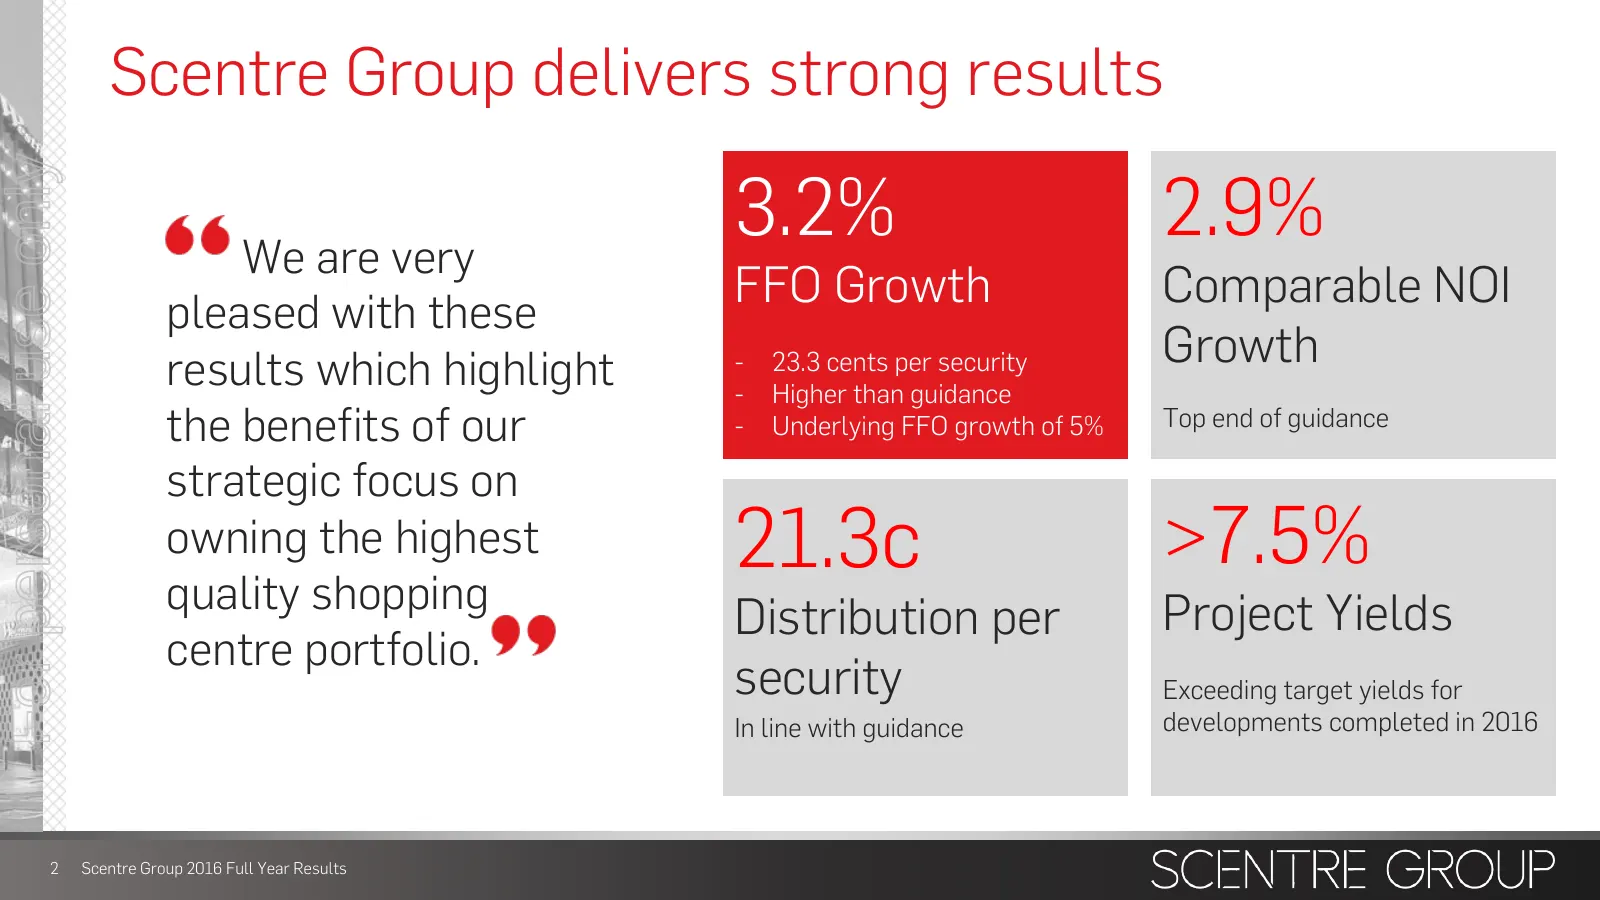
Scentre Group delivers strong results For personal use only We are very 3.2% 2.9% FFO Growth Comparable NOI pleased with these results which highlight - 23.3 cents per security Growth - Higher than guidance the benefits of our - Underlying FFO growth of 5% Top end of guidance strategic focus on owni
Slide 6: Our purpose and strategy
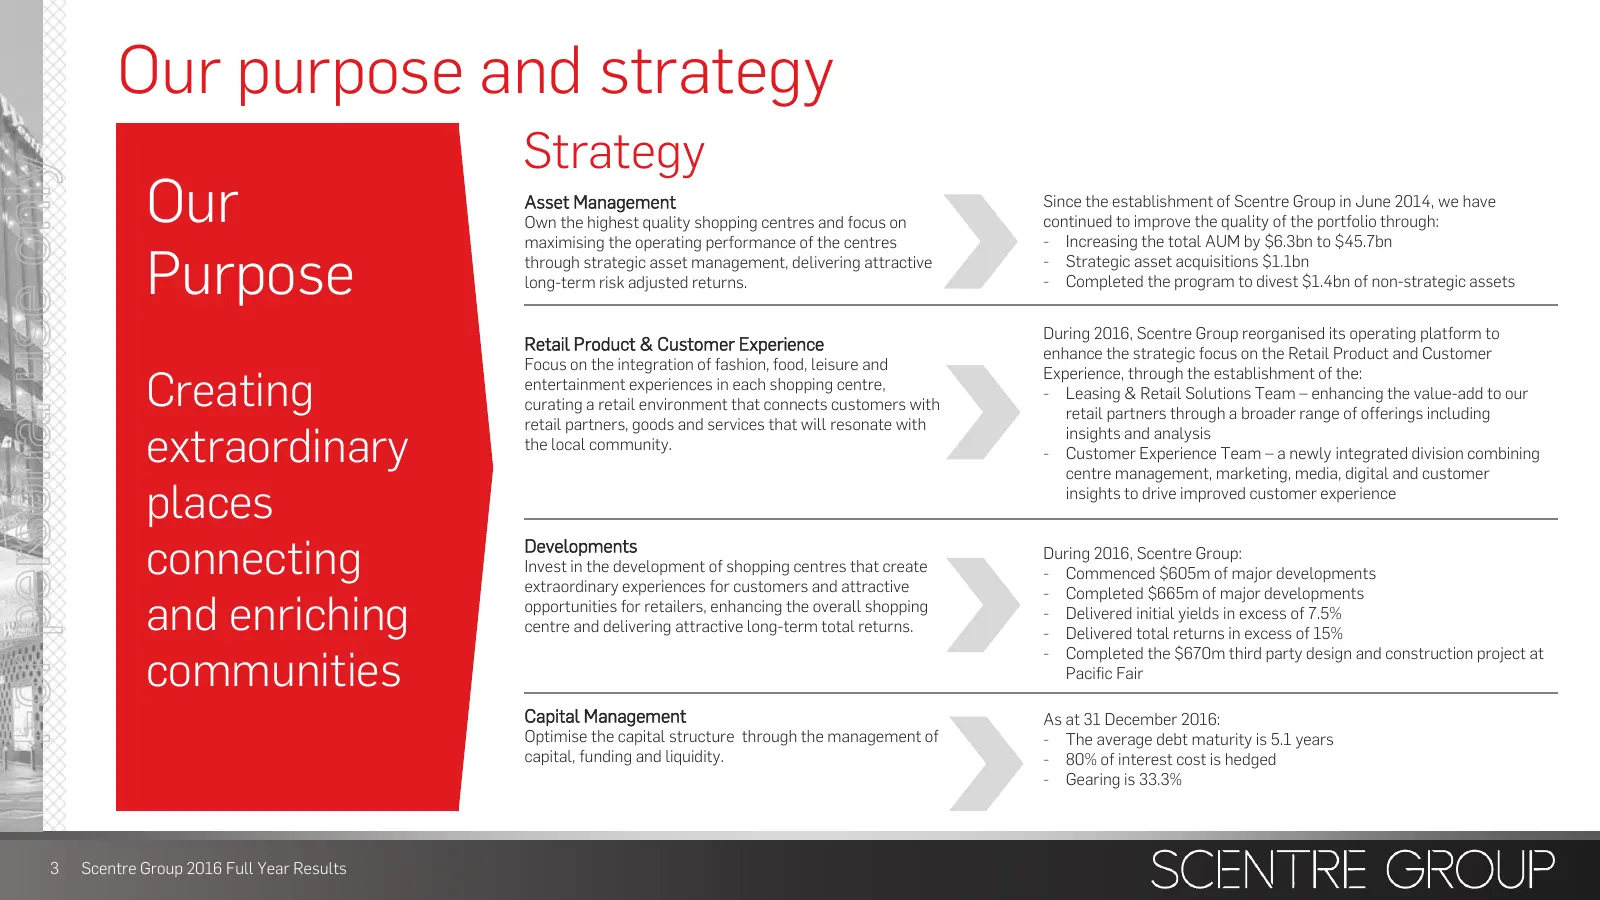
Our purpose and strategy Strategy For personal use only Our Asset Management Own the highest quality shopping centres and focus on maximising the operating performance of the centres Since the establishment of Scentre Group in June 2014, we have continued to improve the quality of the portfolio thro
Slide 7: The highest quality shopping centre portfolio
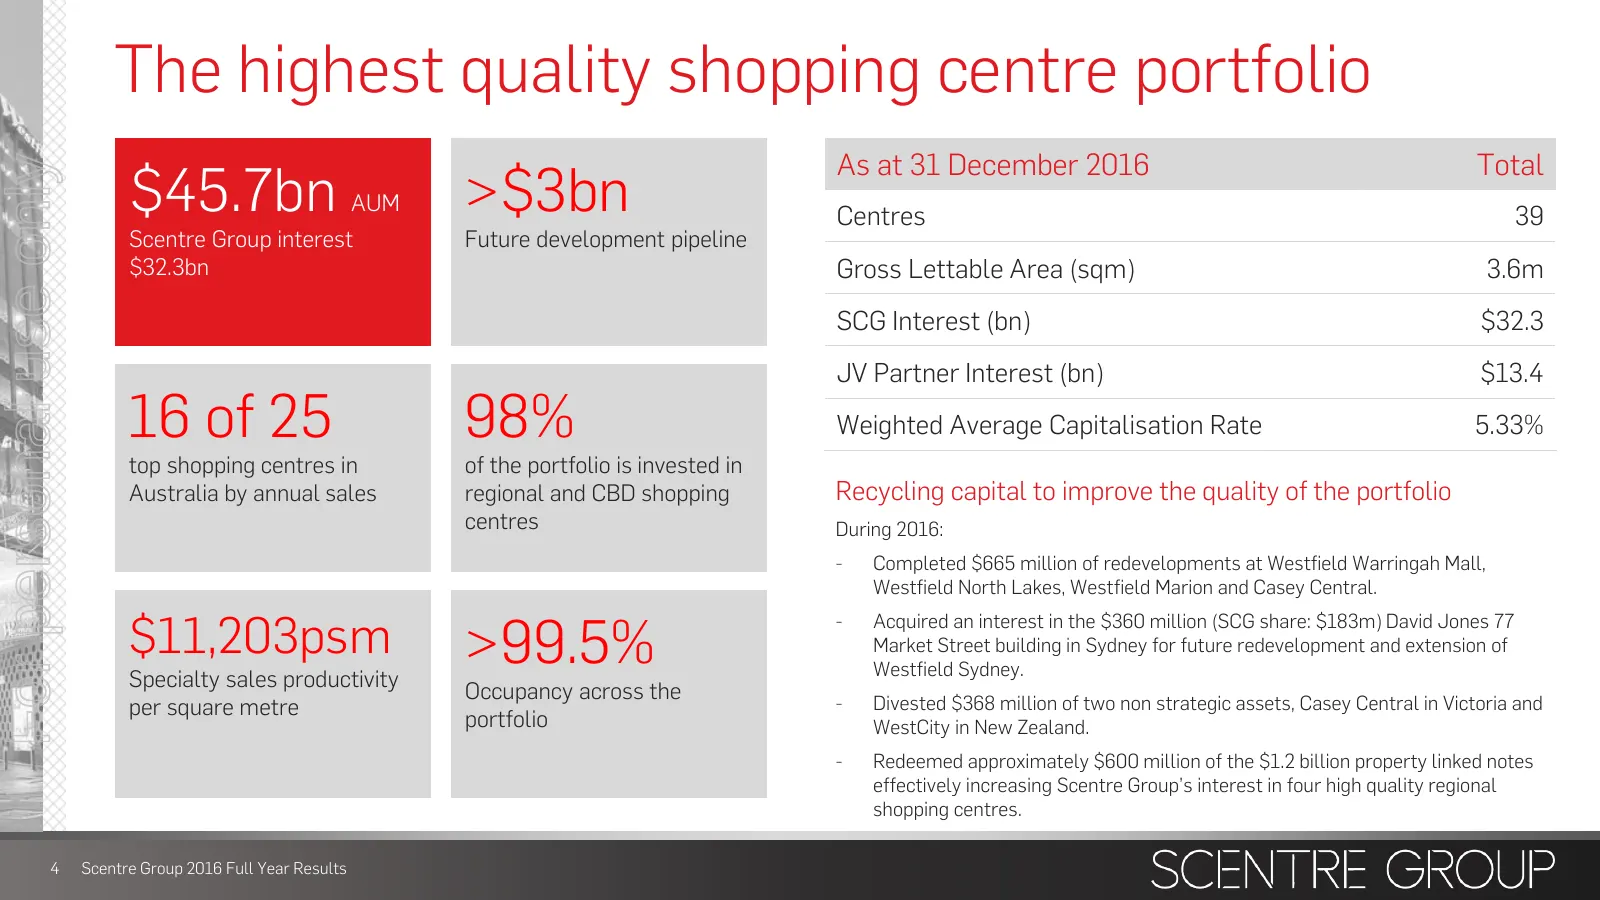
The highest quality shopping centre portfolio As at 31 December 2016 Total $45.7bn >$3bn For personal use only AUM Centres 39 Scentre Group interest Future development pipeline $32.3bn Gross Lettable Area (sqm) 3.6m SCG Interest (bn) $32.3 JV Partner Interest (bn) $13.4 16 of 25 98% Weighted Average
Slide 8: In the best locations
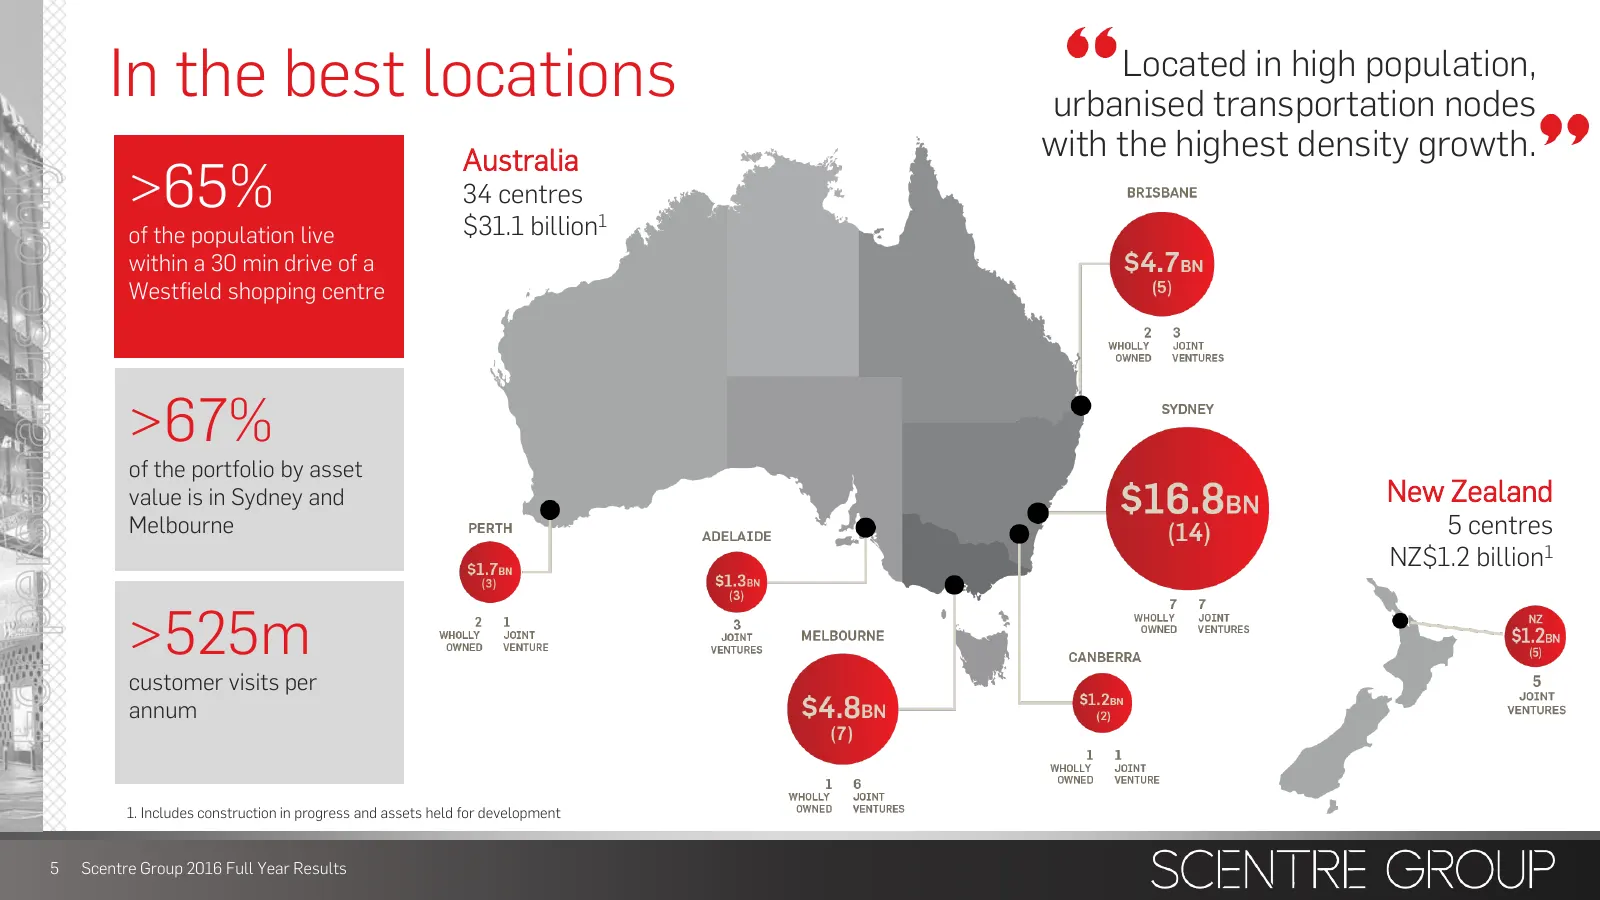
In the best locations Located in high population, urbanised transportation nodes Australia with the highest density growth. >65% For personal use only 34 centres of the population live $31.1 billion1 within a 30 min drive of a Westfield shopping centre >67% of the portfolio by asset value is in Sydn
Slide 9: Strong underlying operating performance
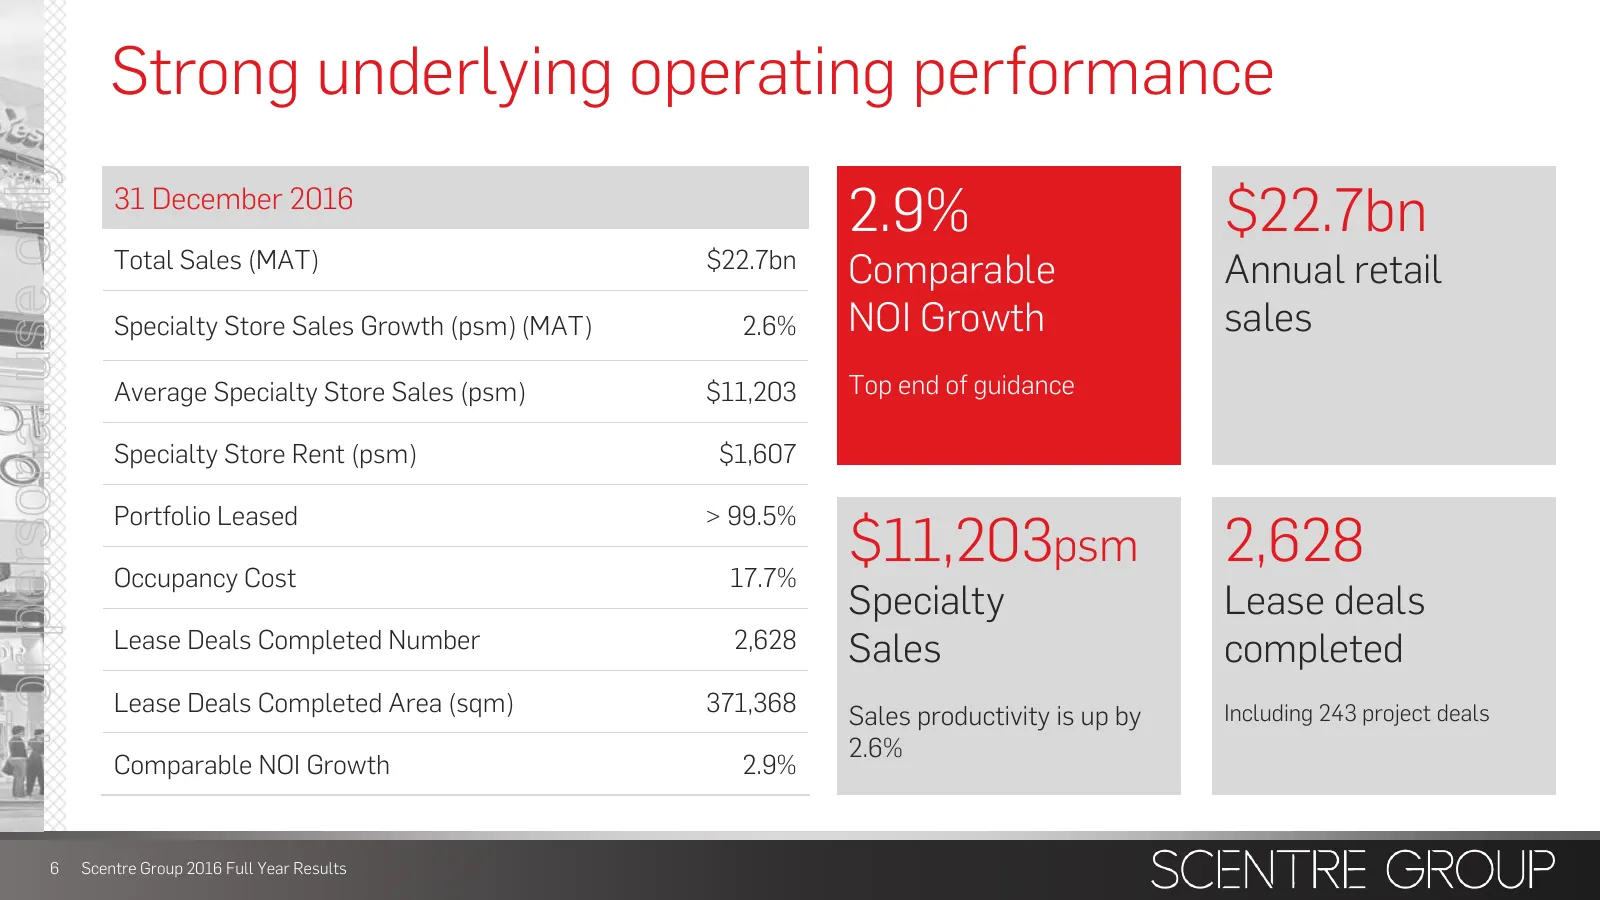
Strong underlying operating performance For personal use only 31 December 2016 2.9% $22.7bn Total Sales (MAT) $22.7bn Comparable Annual retail Specialty Store Sales Growth (psm) (MAT) 2.6% NOI Growth sales Average Specialty Store Sales (psm) $11,203 Top end of guidance Specialty Store Rent (psm) $1,
Slide 10: Continued growth in retail sales
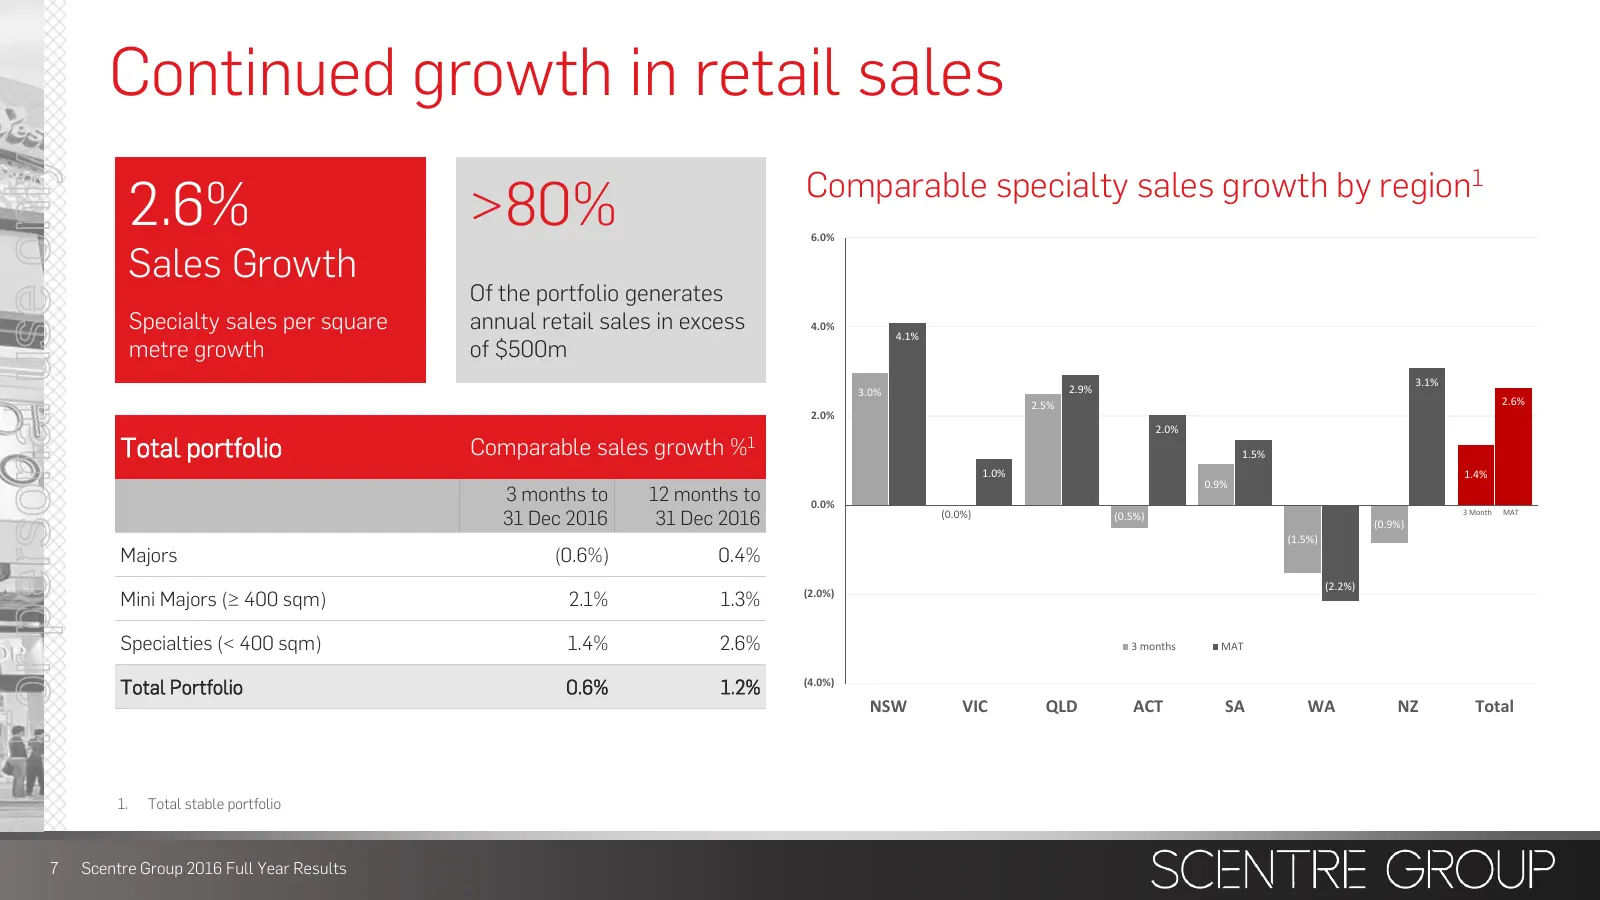
Continued growth in retail sales For personal use only Comparable specialty sales growth by region1 2.6% >80% 6.0% Sales Growth Of the portfolio generates Specialty sales per square annual retail sales in excess 4.0% 4.1% metre growth of $500m 3.1% 3.0% 2.9% 2.5% 2.6% 2.0% 2.0% Total portfolio Compa
Slide 11: Continued growth in retail sales by category
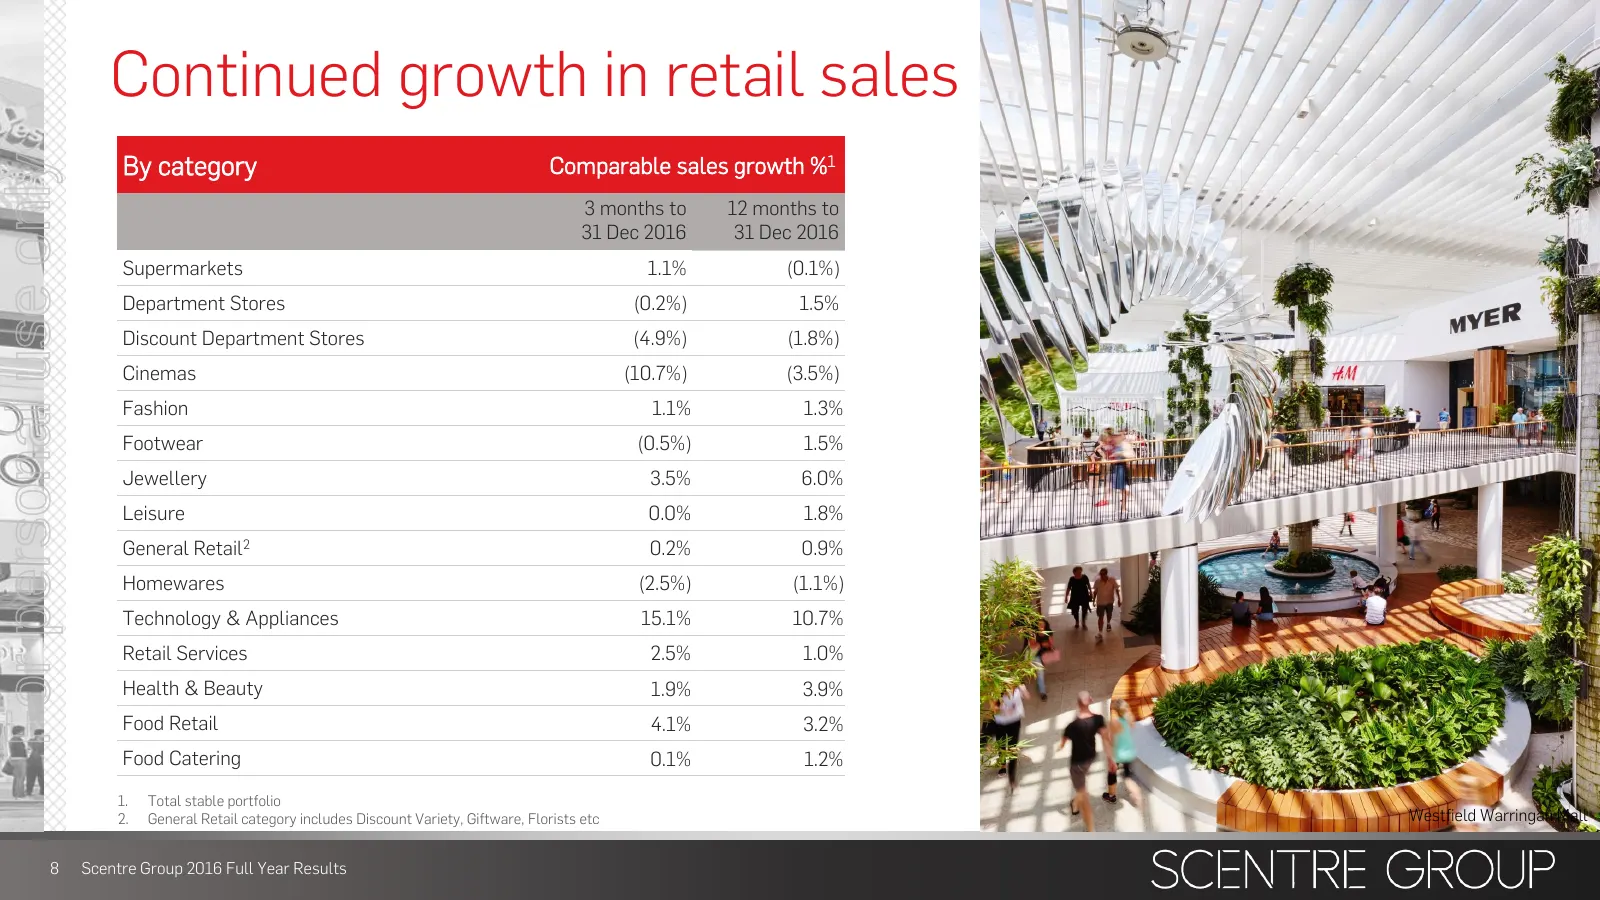
Continued growth in retail sales By category Comparable sales growth %1 For personal use only 3 months to 12 months to 31 Dec 2016 31 Dec 2016 Supermarkets 1.1% (0.1%) Department Stores (0.2%) 1.5% Discount Department Stores (4.9%) (1.8%) Cinemas (10.7%) (3.5%) Fashion 1.1% 1.3% Footwear (0.5%) 1.5%
Slide 12: Creating the best retail product offering
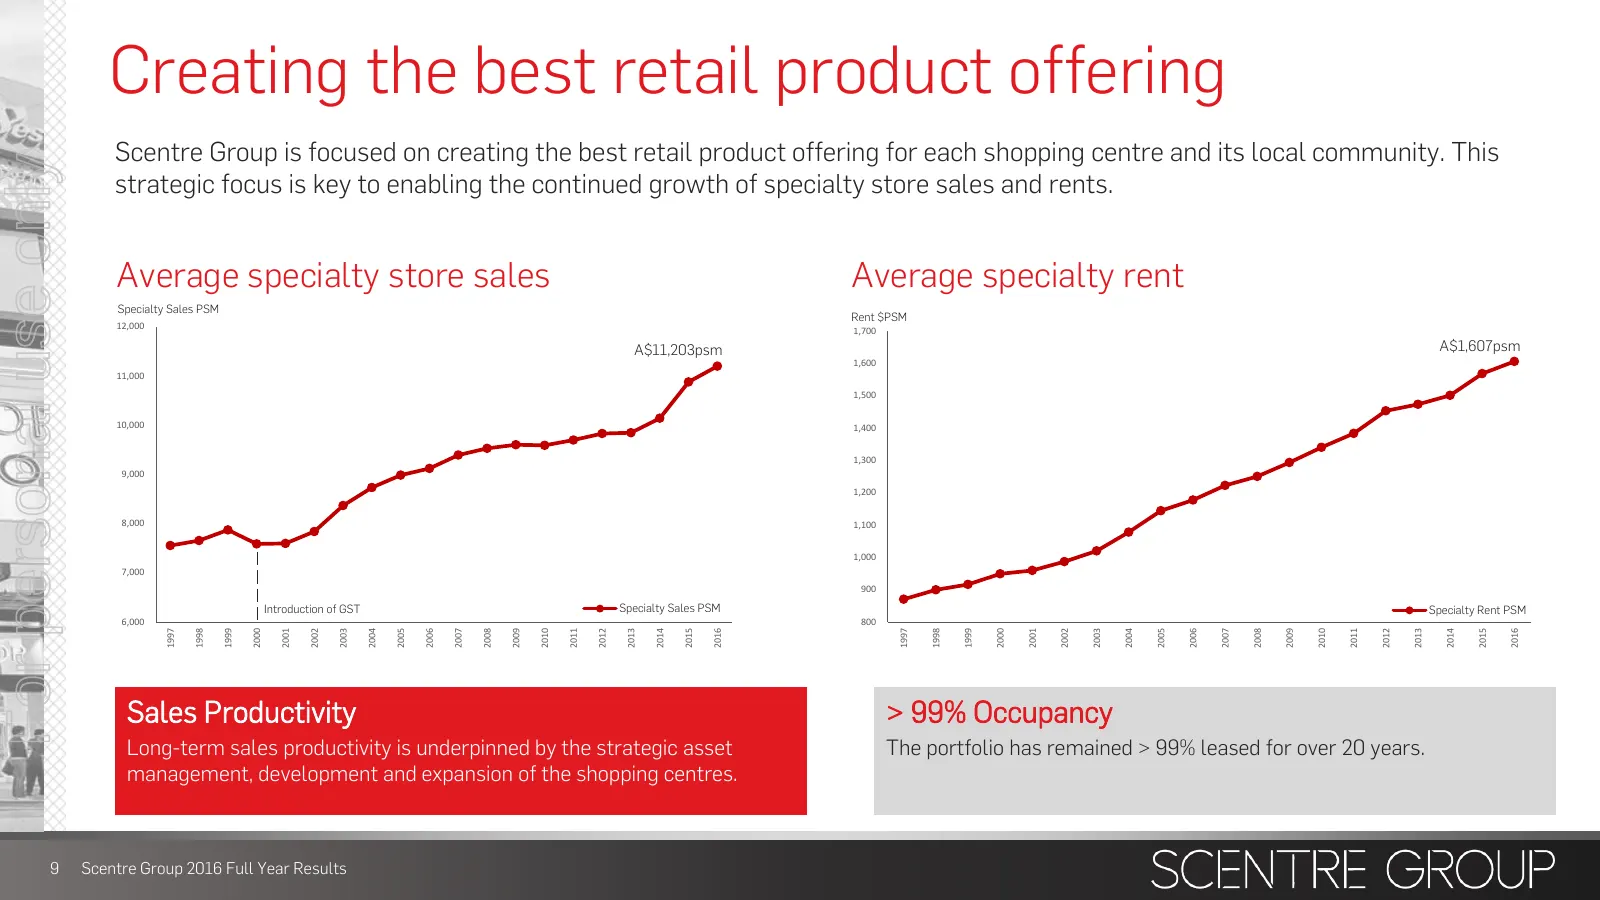
Creating the best retail product offering Scentre Group is focused on creating the best retail product offering for each shopping centre and its local community. This For personal use only strategic focus is key to enabling the continued growth of specialty store sales and rents. Average specialty s
Slide 13: Developing extraordinary places with exceptional returns
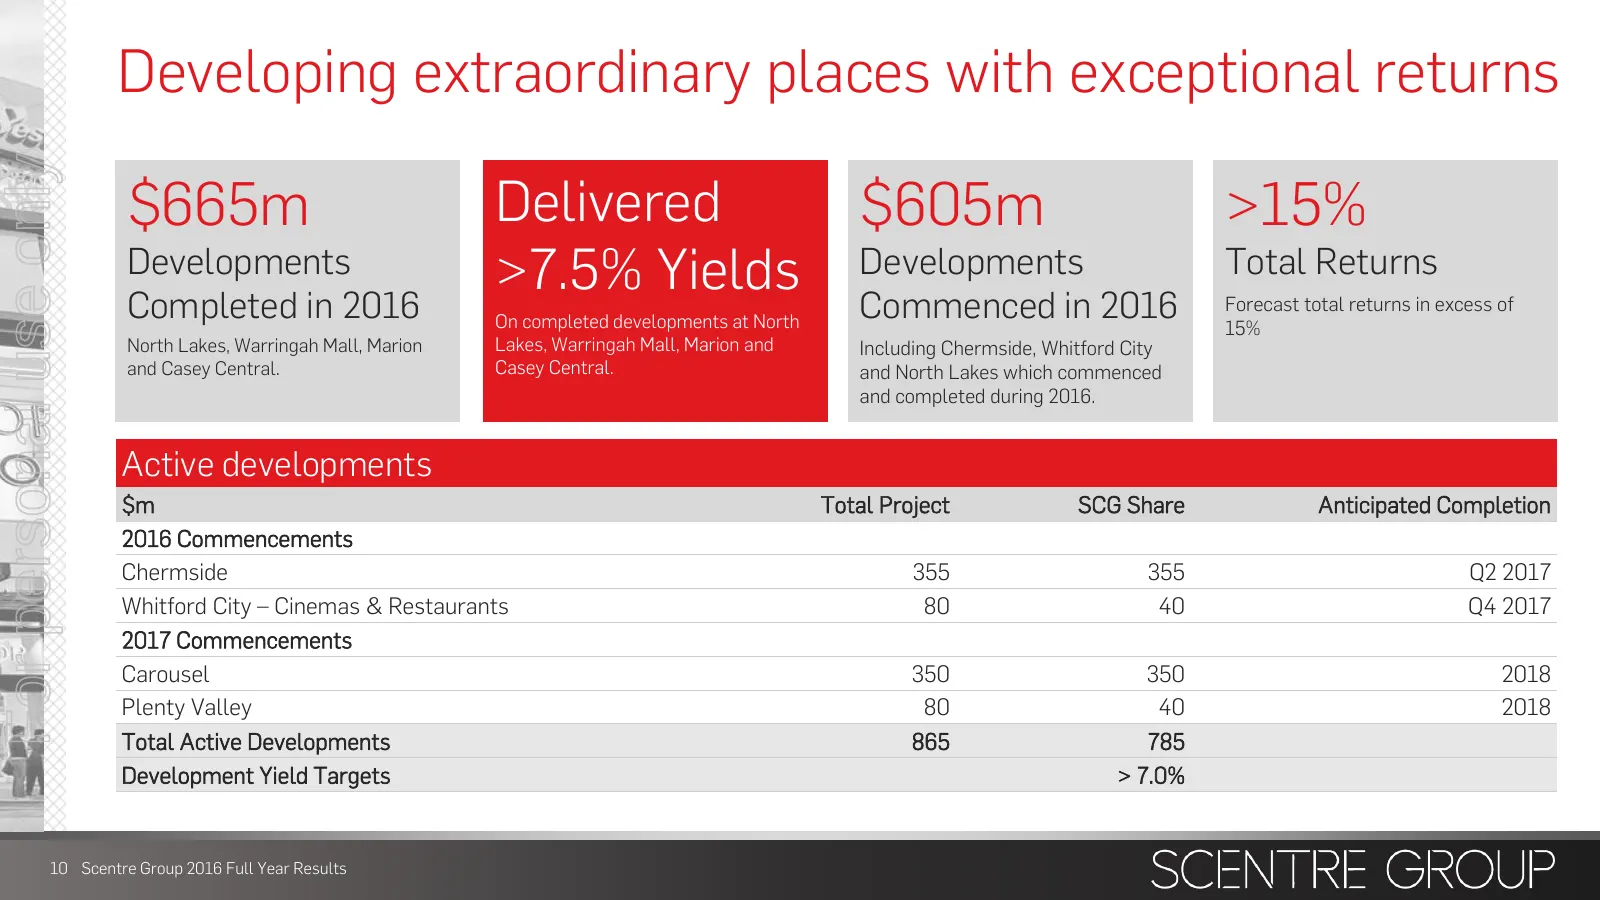
Developing extraordinary places with exceptional returns For personal use only $665m Delivered $605m >15% Developments Completed in 2016 >7.5% Yields Developments Commenced in 2016 Total Returns Forecast total returns in excess of On completed developments at North 15% North Lakes, Warringah Mall, M
Slide 14: Deliverable development pipeline for future growth
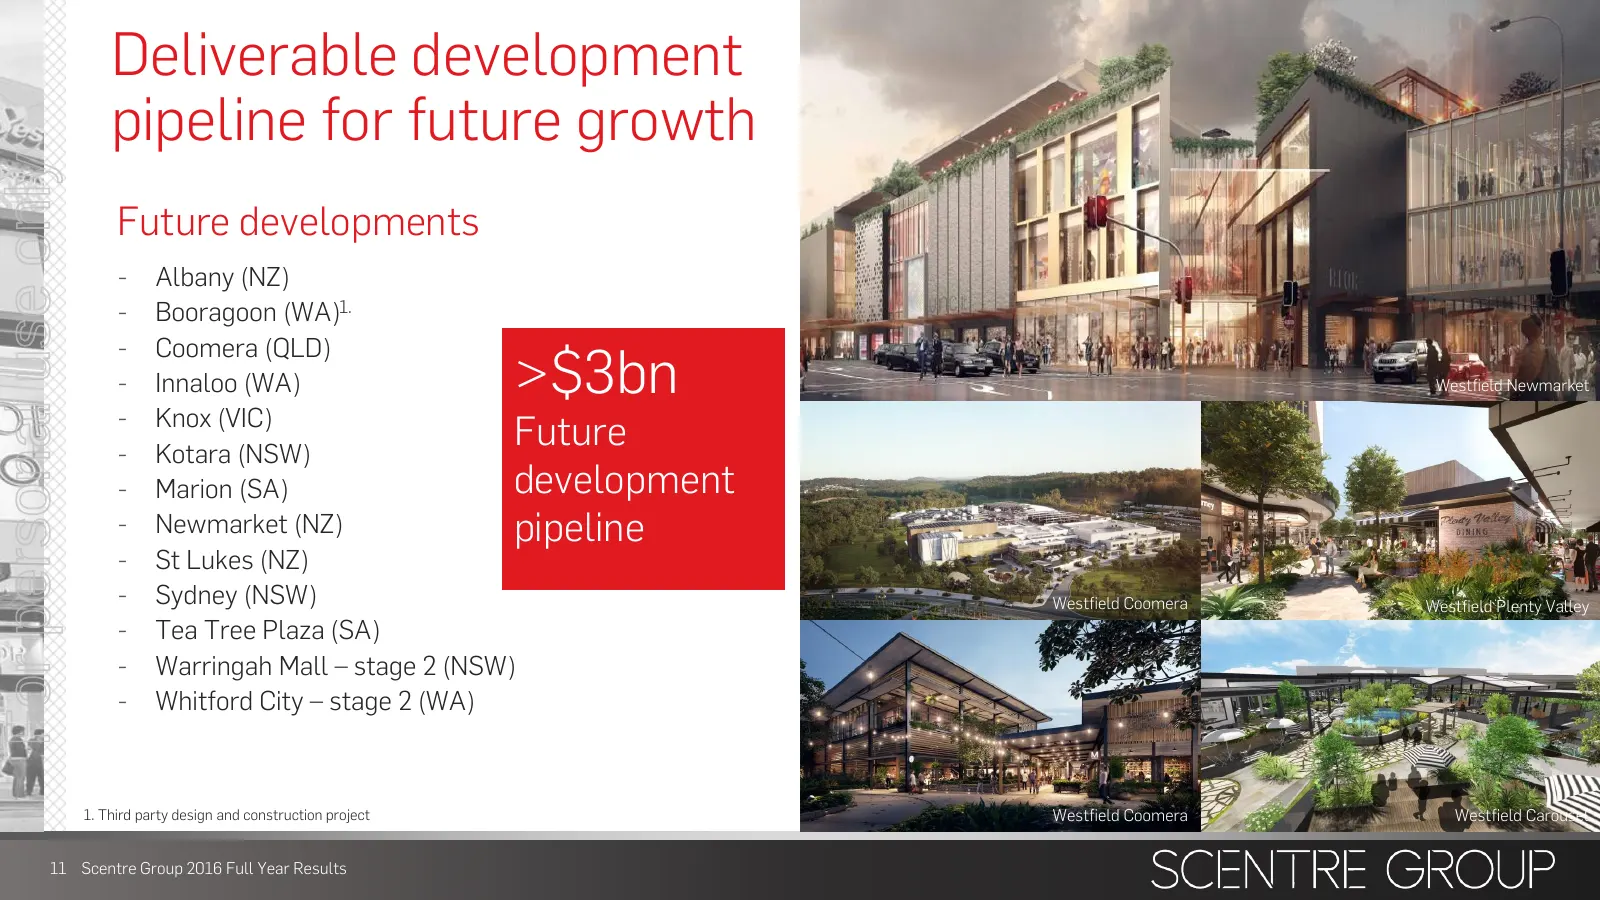
Deliverable development pipeline for future growth For personal use only Future developments - Albany (NZ) - Booragoon (WA)1. - Coomera (QLD) - Innaloo (WA) >$3bn Westfield Newmarket - Knox (VIC) - Kotara (NSW) Future - Marion (SA) development - Newmarket (NZ) pipeline - St Lukes (NZ) - Sydney (NSW)
Slide 15: Delivering outstanding development returns
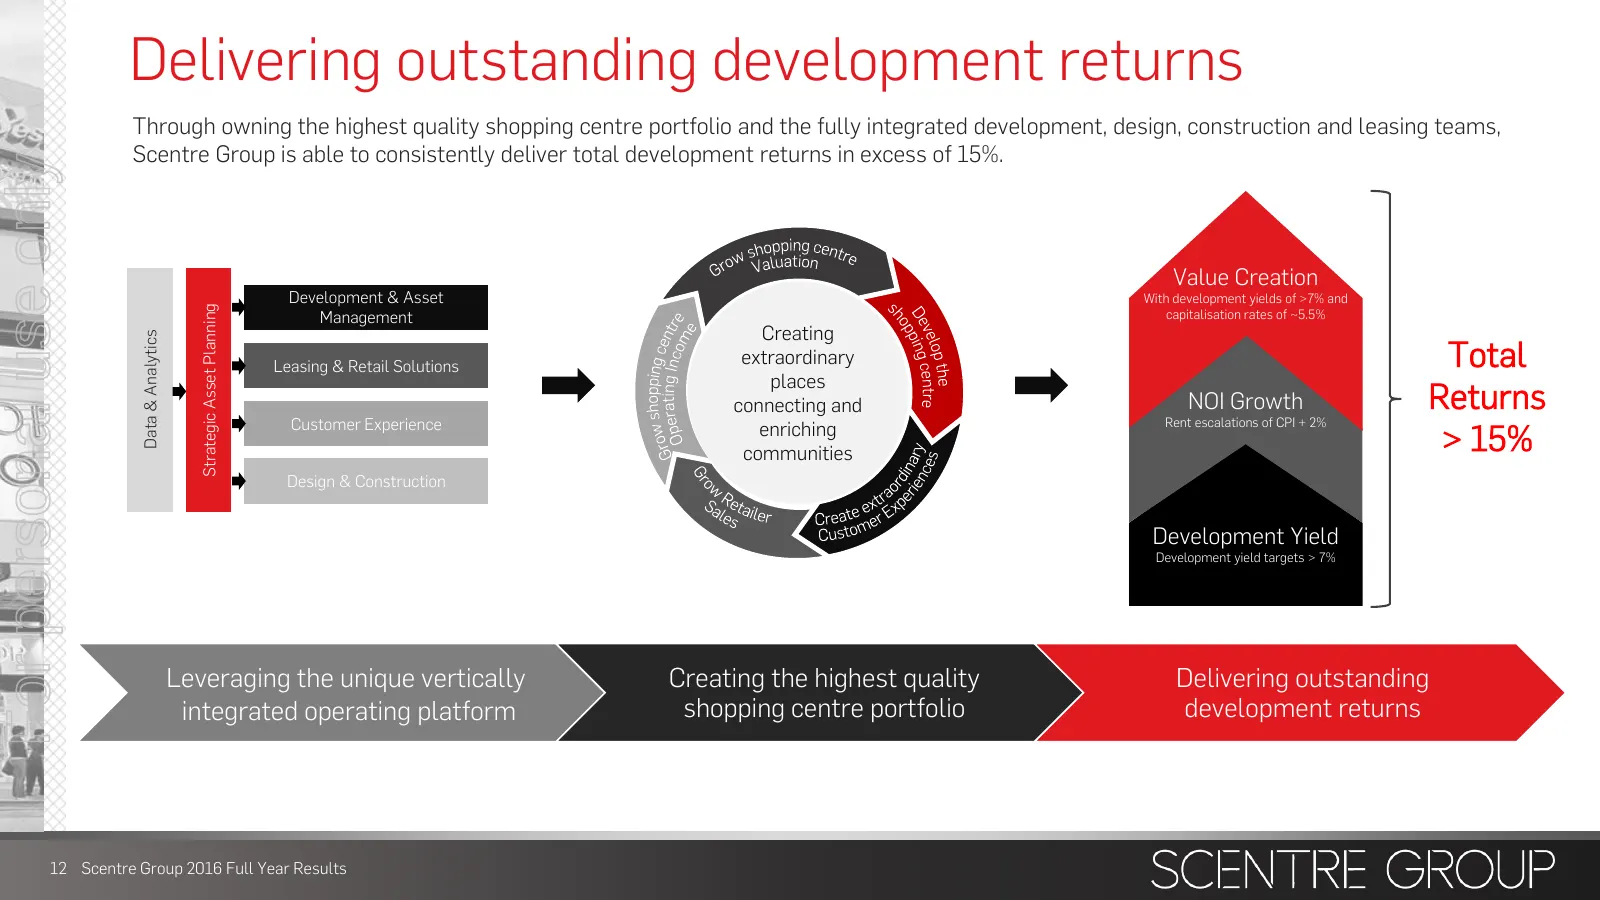
Delivering outstanding development returns Through owning the highest quality shopping centre portfolio and the fully integrated development, design, construction and leasing teams, Scentre Group is able to consistently deliver total development returns in excess of 15%. For personal use only Value
Slide 16: Strong financial performance
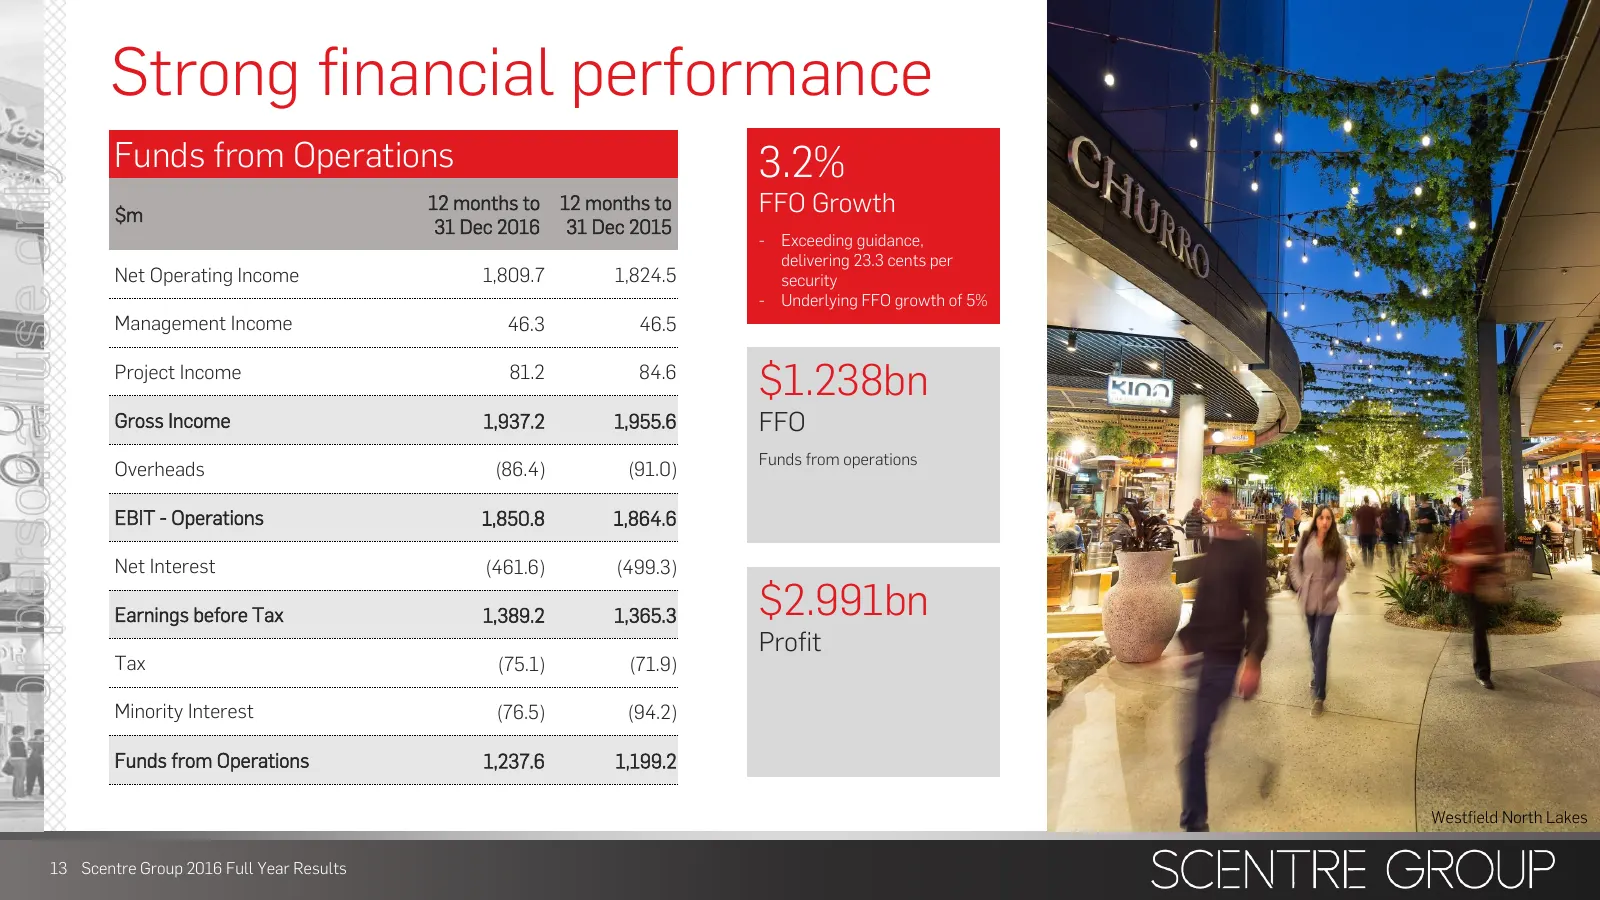
Strong financial performance Funds from Operations 3.2% For personal use only $m 12 months to 12 months to FFO Growth 31 Dec 2016 31 Dec 2015 - Exceeding guidance, delivering 23.3 cents per Net Operating Income 1,809.7 1,824.5 security - Underlying FFO growth of 5% Management Income 46.3 46.5 Projec
Slide 17: Stable financial position
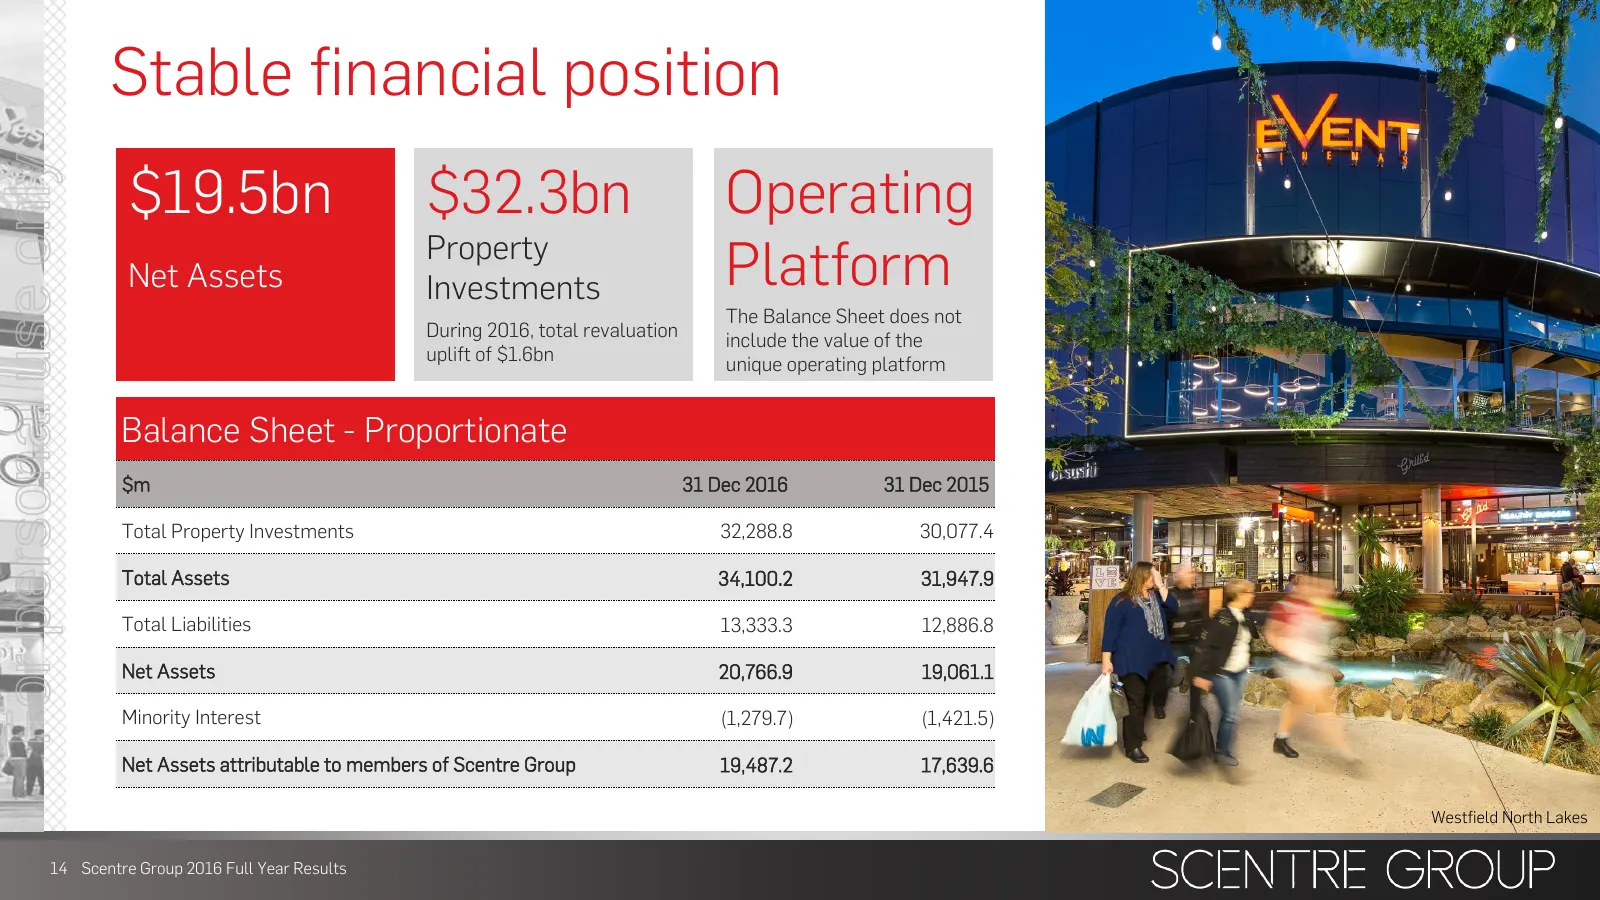
Stable financial position $19.5bn $32.3bn Operating For personal use only Net Assets Property Investments Platform The Balance Sheet does not During 2016, total revaluation include the value of the uplift of $1.6bn unique operating platform Balance Sheet - Proportionate $m 31 Dec 2016 31 Dec 2015 To
Slide 18: Strong capital structure
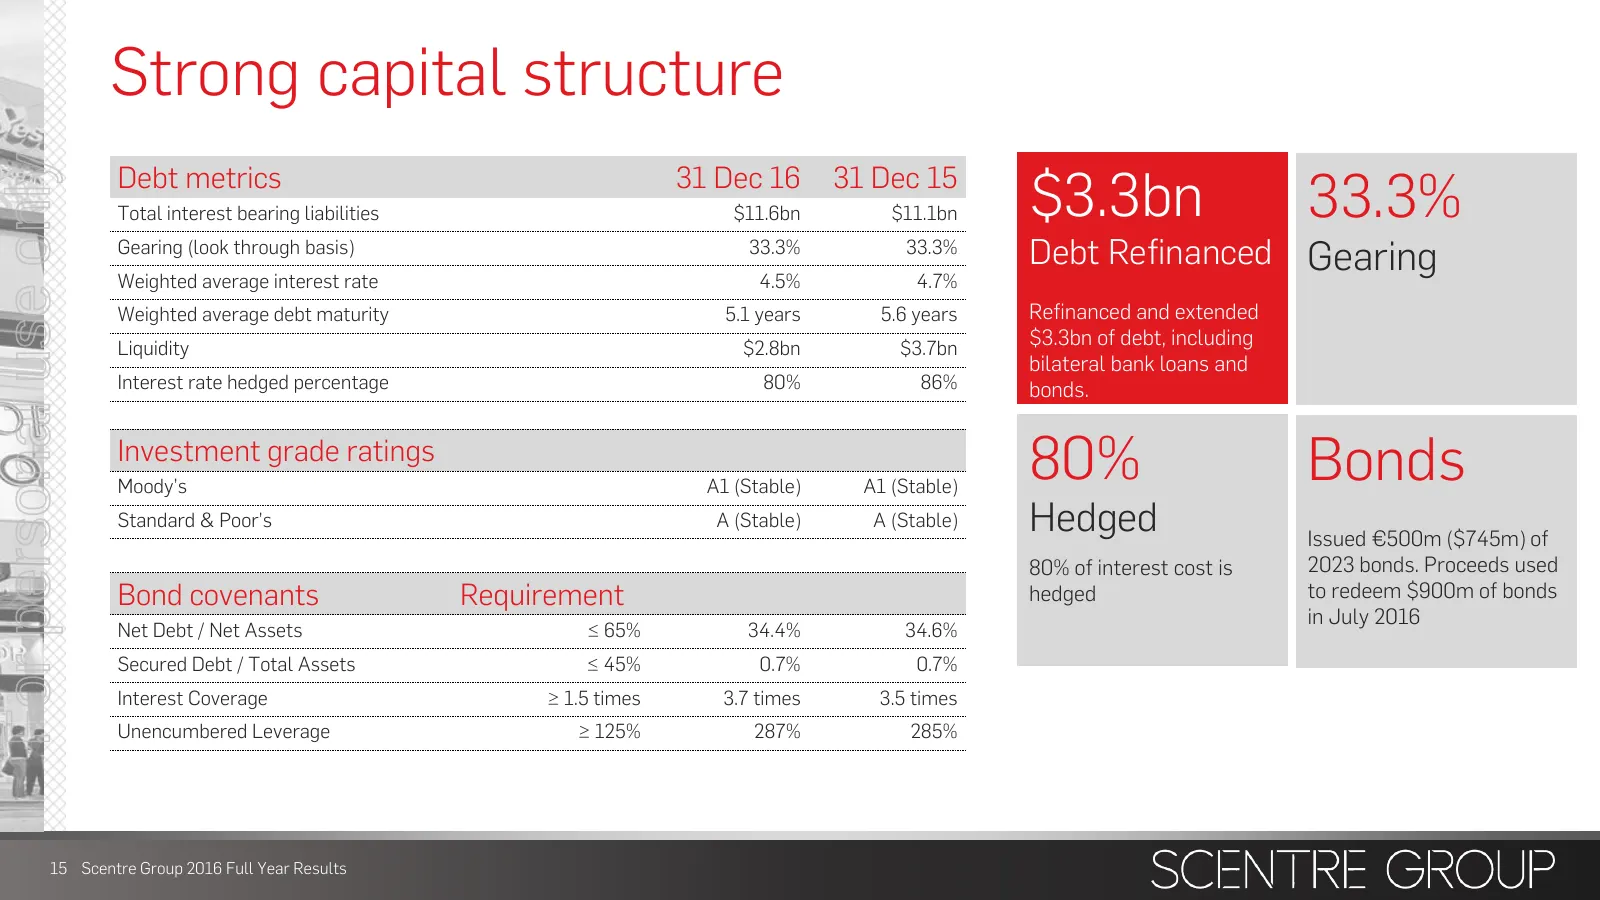
Strong capital structure For personal use only Debt metrics Total interest bearing liabilities 31 Dec 16 $11.6bn 31 Dec 15 $11.1bn $3.3bn 33.3% Gearing (look through basis) 33.3% 33.3% Debt Refinanced Gearing Weighted average interest rate 4.5% 4.7% Weighted average debt maturity 5.1 years 5.6 years
Slide 19: Disciplined capital management
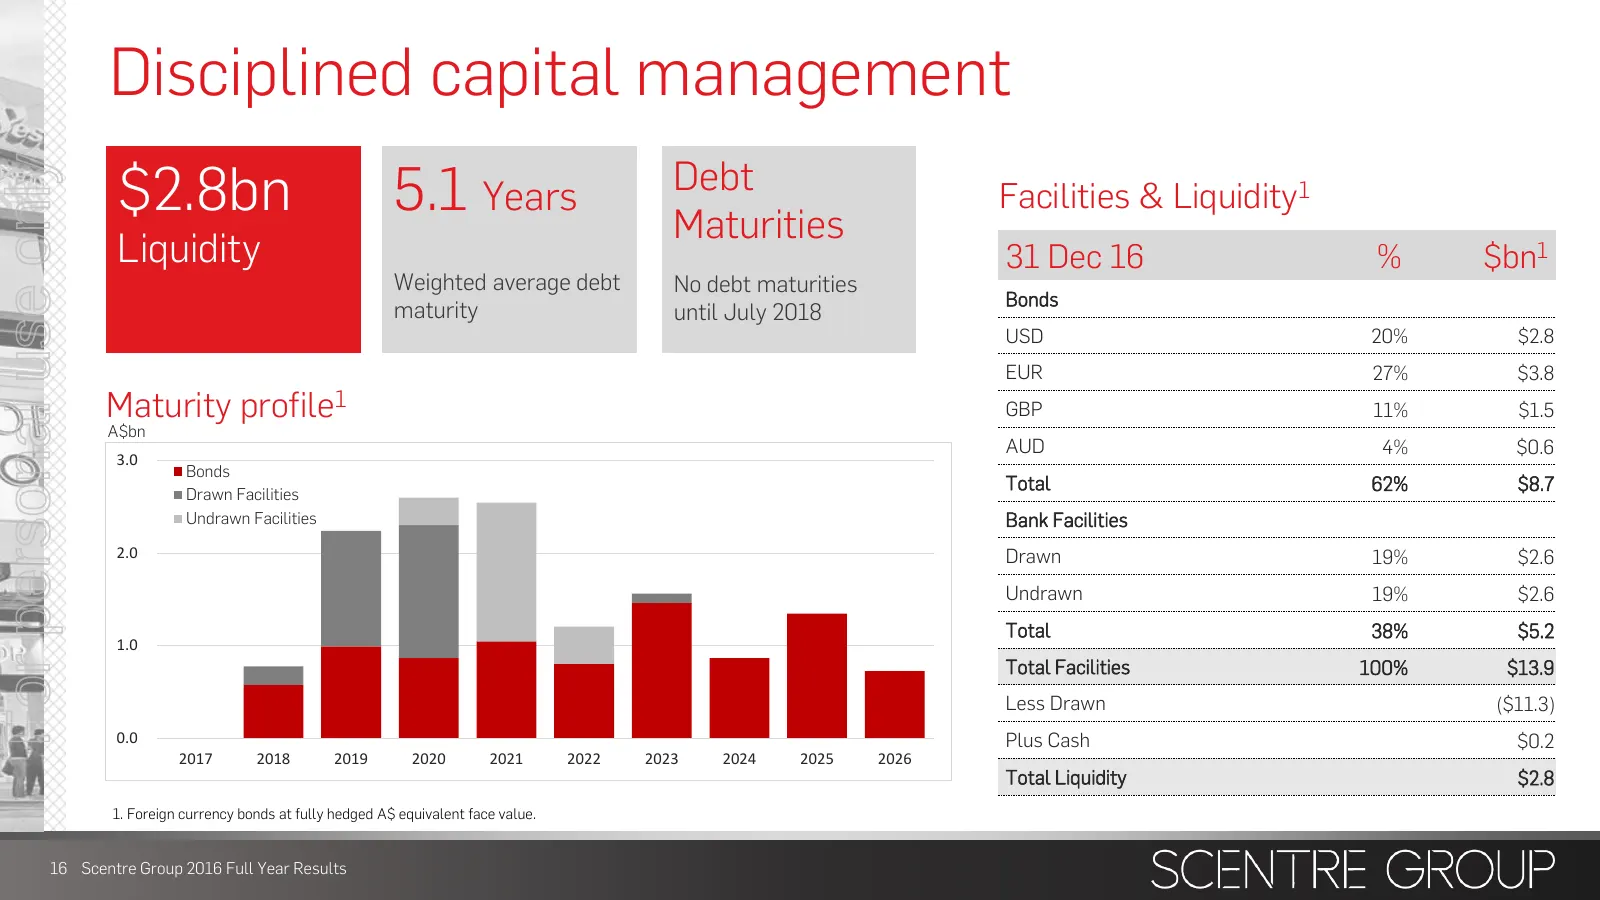
Disciplined capital management $2.8bn 5.1 Years Debt For personal use only Facilities & Liquidity1 Maturities Liquidity 31 Dec 16 % $bn1 Weighted average debt No debt maturities Bonds maturity until July 2018 USD 20% $2.8 EUR 27% $3.8 Maturity profile1 GBP 11% $1.5 A$bn AUD 4% $0.6 3.0 Bonds Total 6
Slide 20: 2017 Outlook – Continued strong growth
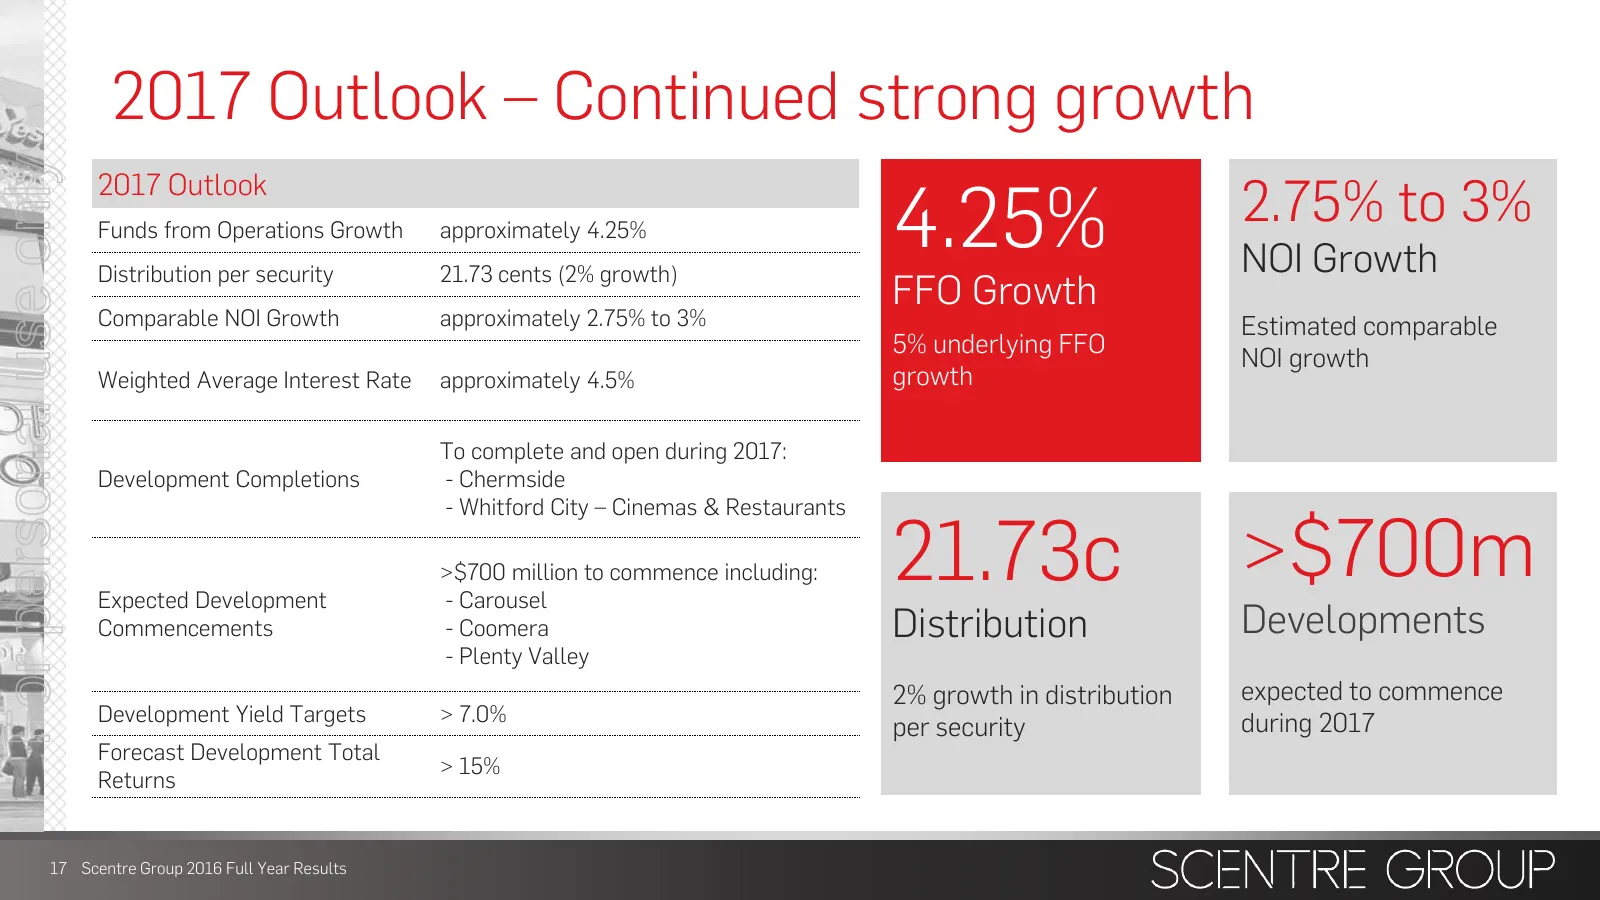
2017 Outlook – Continued strong growth For personal use only 4.25% 2.75% to 3% 2017 Outlook Funds from Operations Growth approximately 4.25% Distribution per security 21.73 cents (2% growth) NOI Growth FFO Growth Comparable NOI Growth approximately 2.75% to 3% Estimated comparable 5% underlying FFO
Slide 21: Appendices
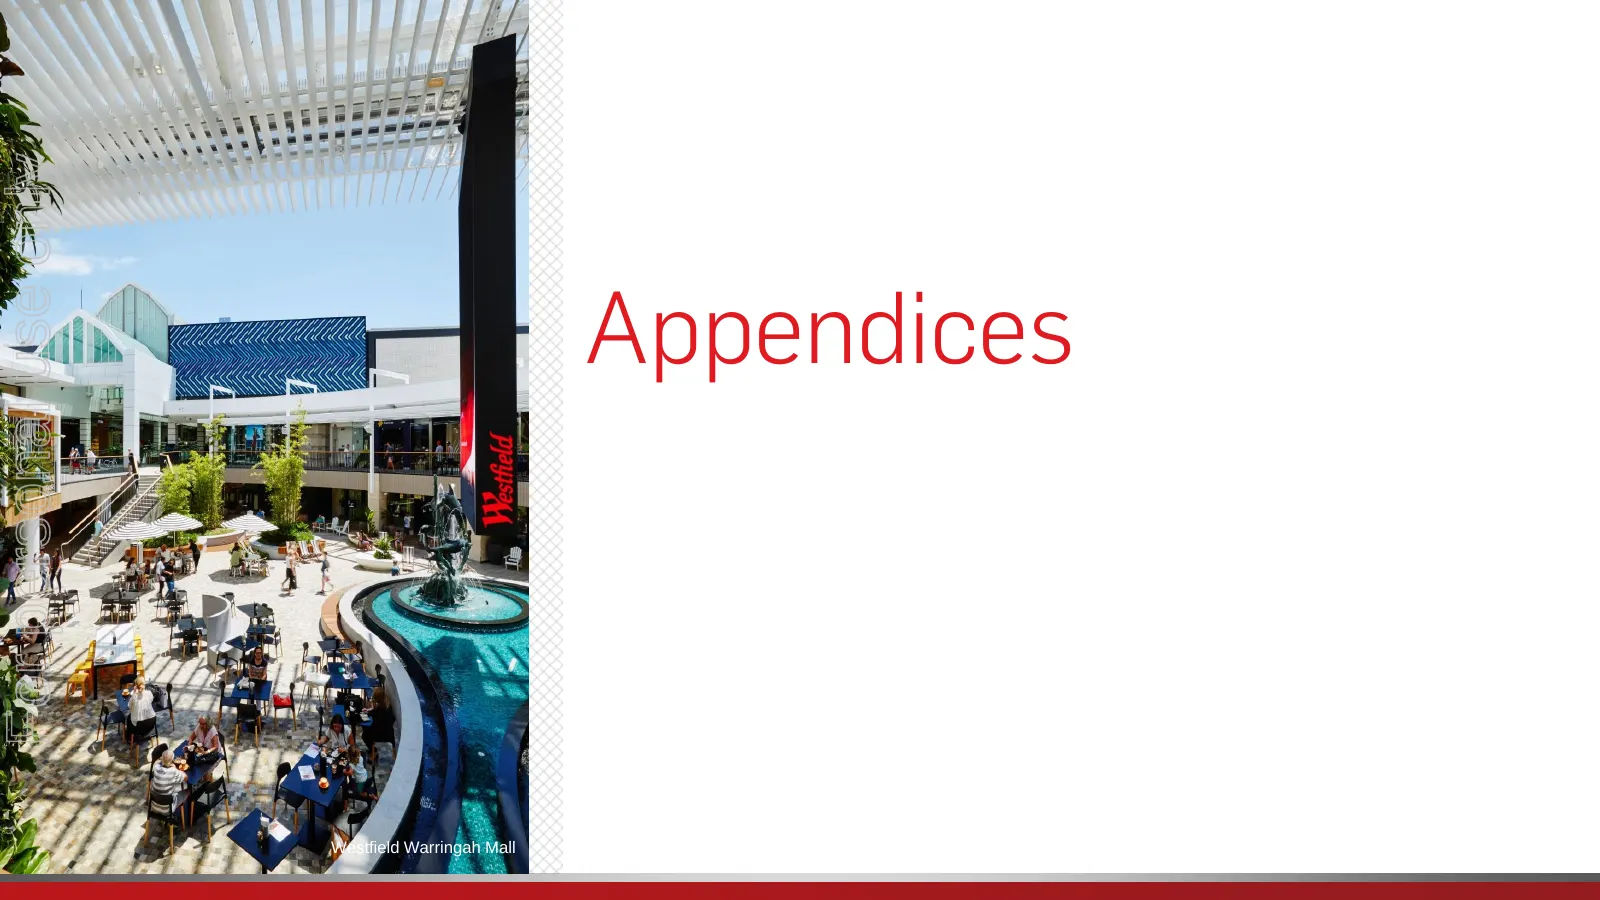
For personal use only Appendices Westfield Warringah Mall
Slide 22: Developments: Westfield Carousel
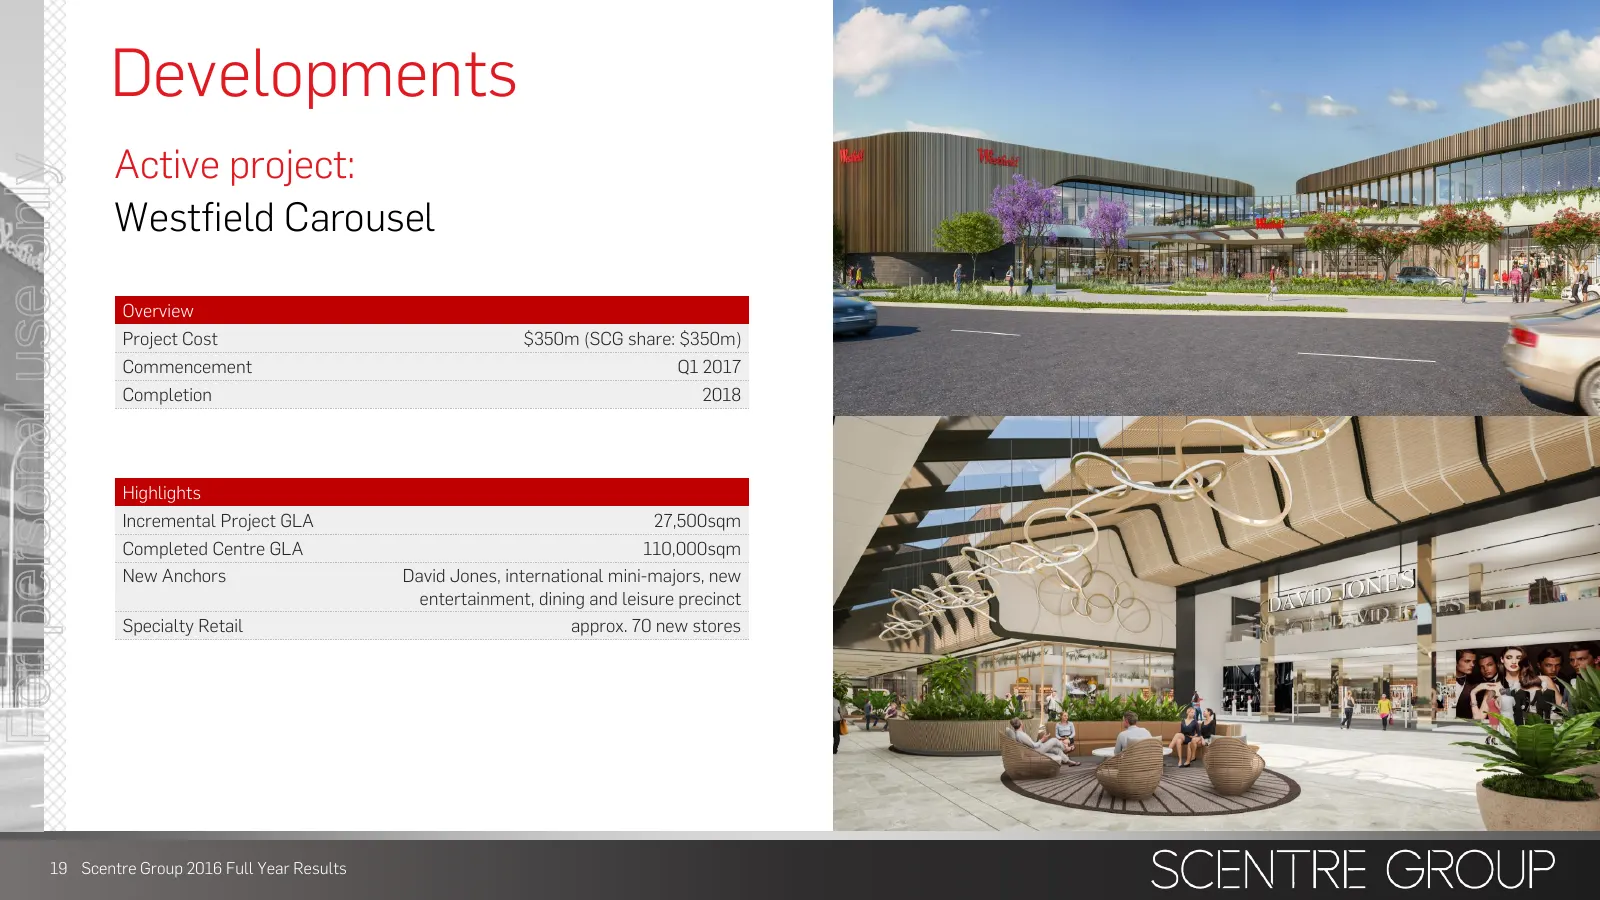
Developments Active project: For personal use only Westfield Carousel Overview Project Cost $350m (SCG share: $350m) Commencement Q1 2017 Completion 2018 Highlights Incremental Project GLA 27,500sqm Completed Centre GLA 110,000sqm New Anchors David Jones, international mini-majors, new entertainment
Slide 23: Developments: Westfield Chermside
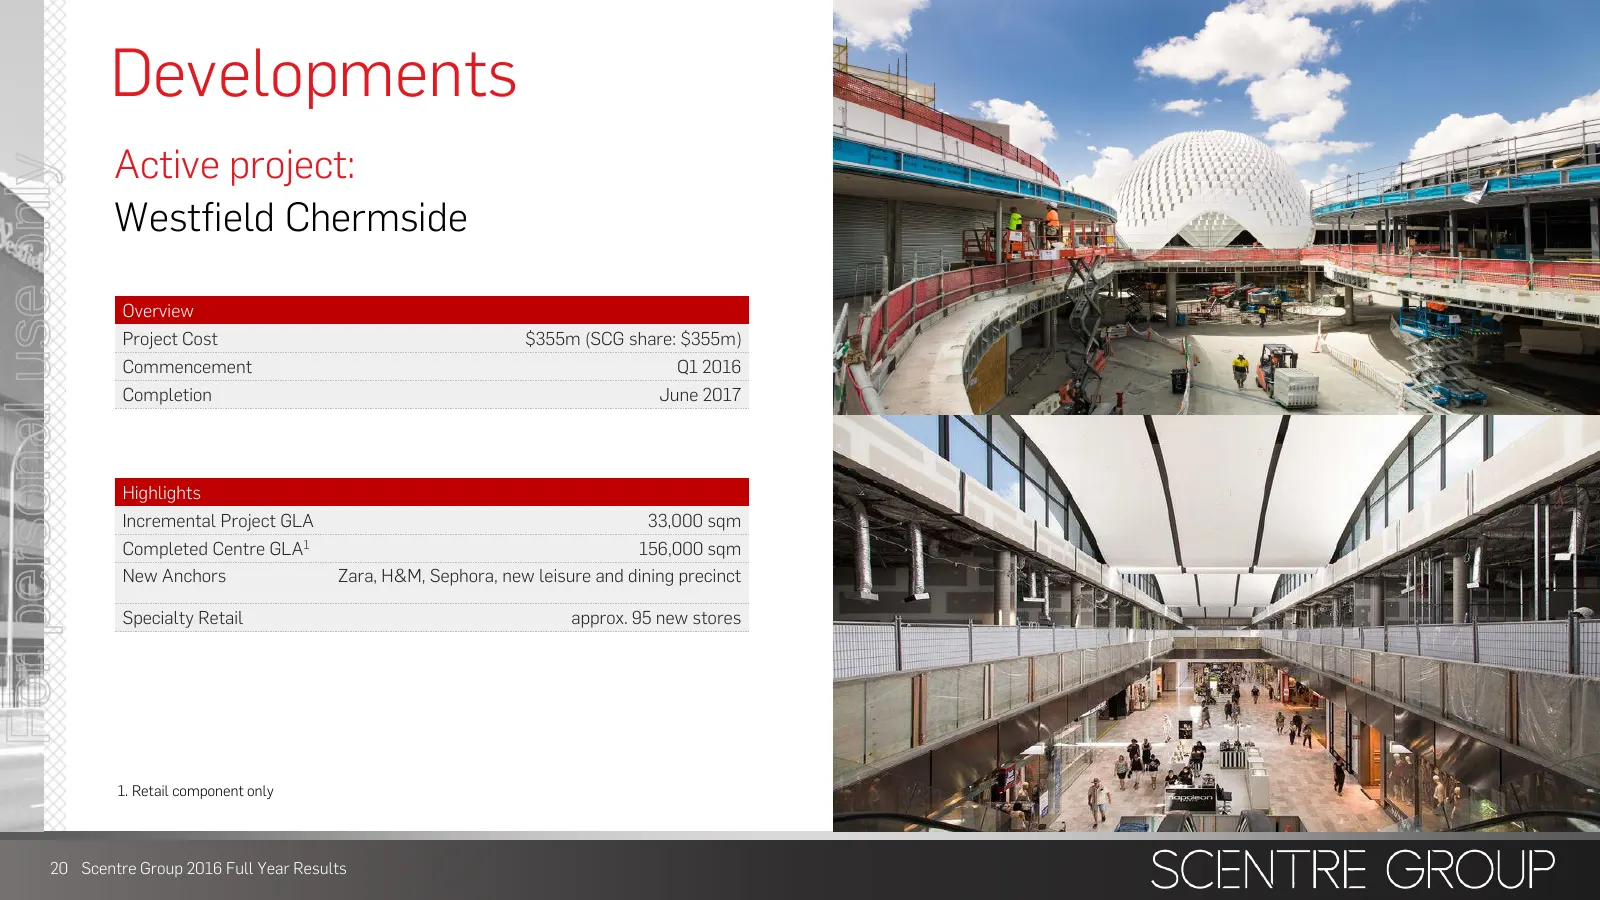
Developments Active project: For personal use only Westfield Chermside Overview Project Cost $355m (SCG share: $355m) Commencement Q1 2016 Completion June 2017 Highlights Incremental Project GLA 33,000 sqm Completed Centre GLA1 156,000 sqm New Anchors Zara, H&M, Sephora, new leisure and dining preci
Slide 24: Developments: Westfield Plenty Valley
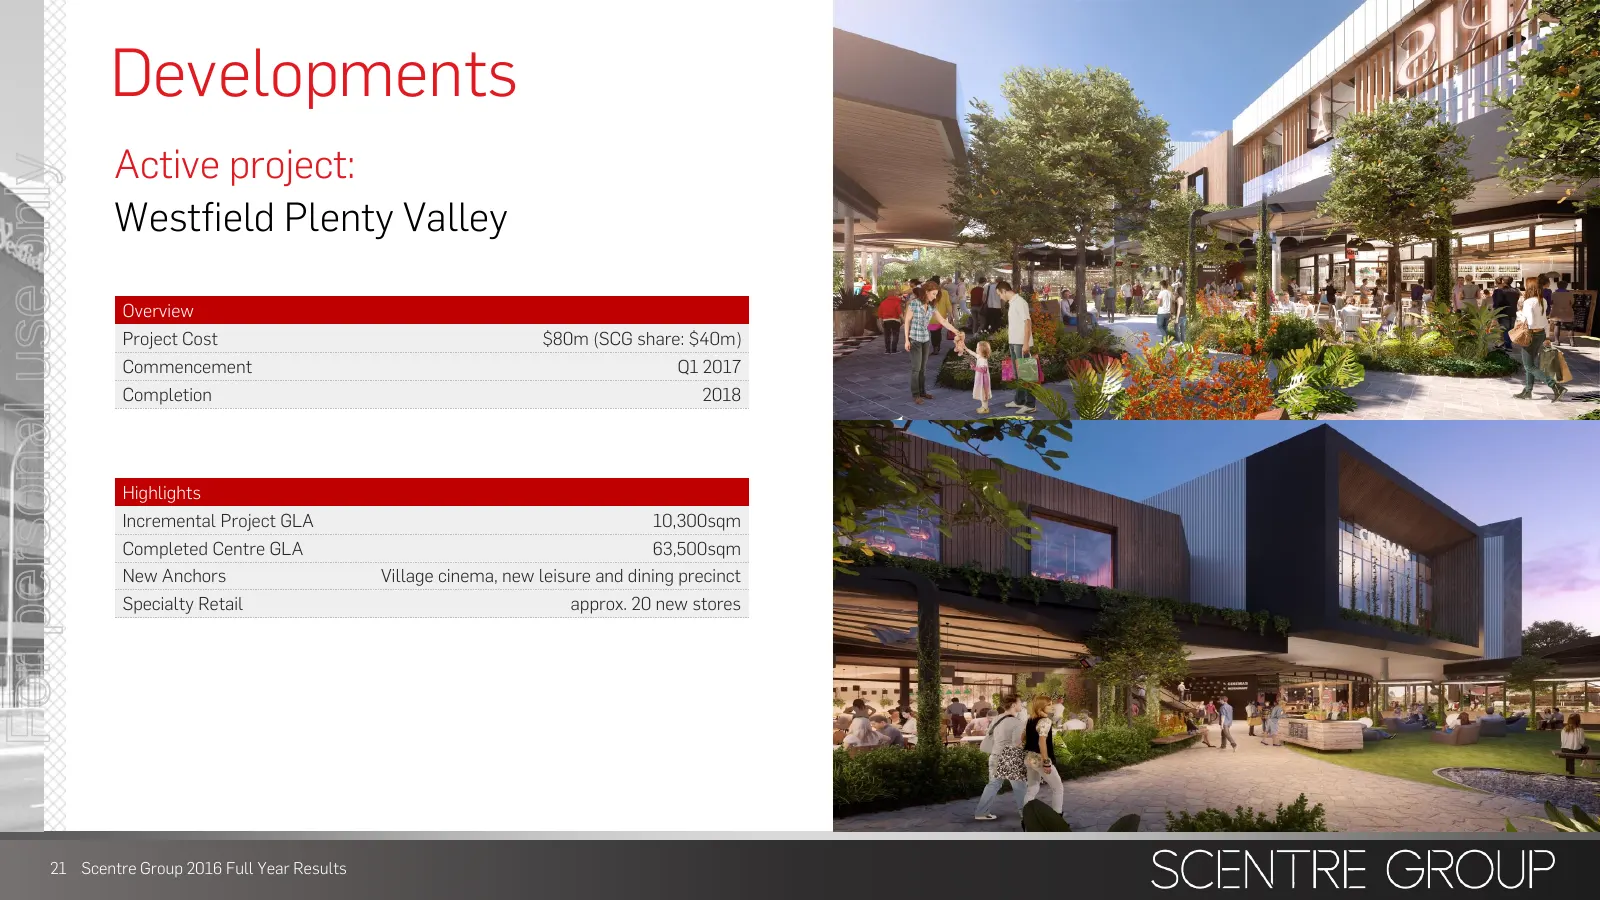
Developments Active project: For personal use only Westfield Plenty Valley Overview Project Cost $80m (SCG share: $40m) Commencement Q1 2017 Completion 2018 Highlights Incremental Project GLA 10,300sqm Completed Centre GLA 63,500sqm New Anchors Village cinema, new leisure and dining precinct Special
Slide 25: Profit and FFO
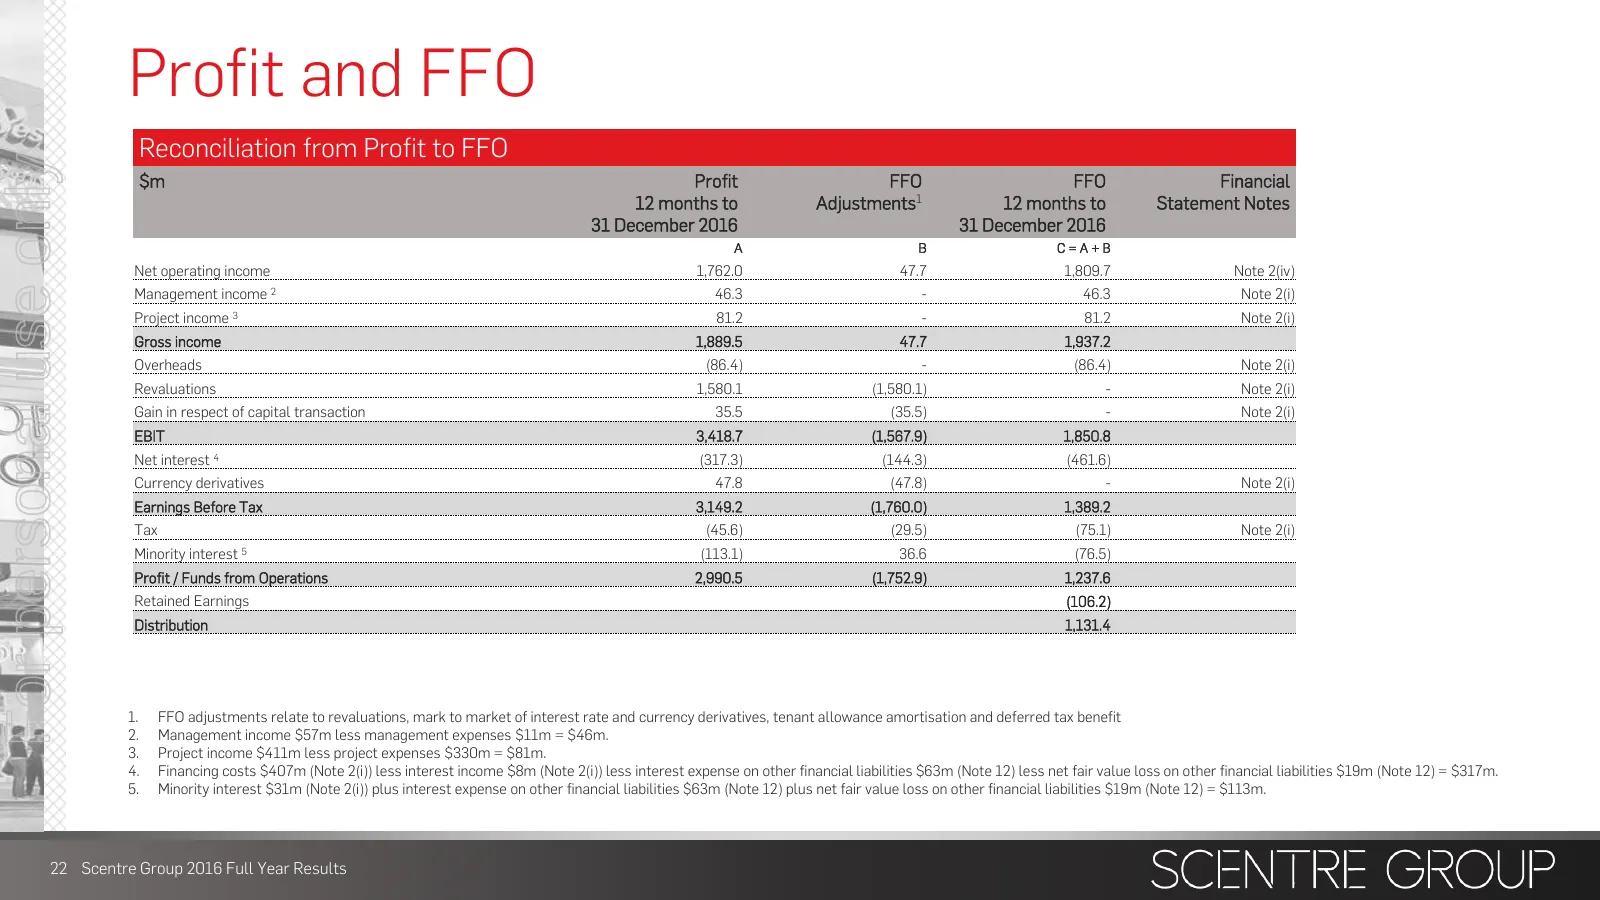
Profit and FFO Reconciliation from Profit to FFO For personal use only $m Profit FFO FFO Financial 12 months to Adjustments1 12 months to Statement Notes 31 December 2016 31 December 2016 A B C=A+B Net operating income 1,762.0 47.7 1,809.7 Note 2(iv) Management income 2 46.3 - 46.3 Note 2(i) Project
Slide 26: Balance Sheet
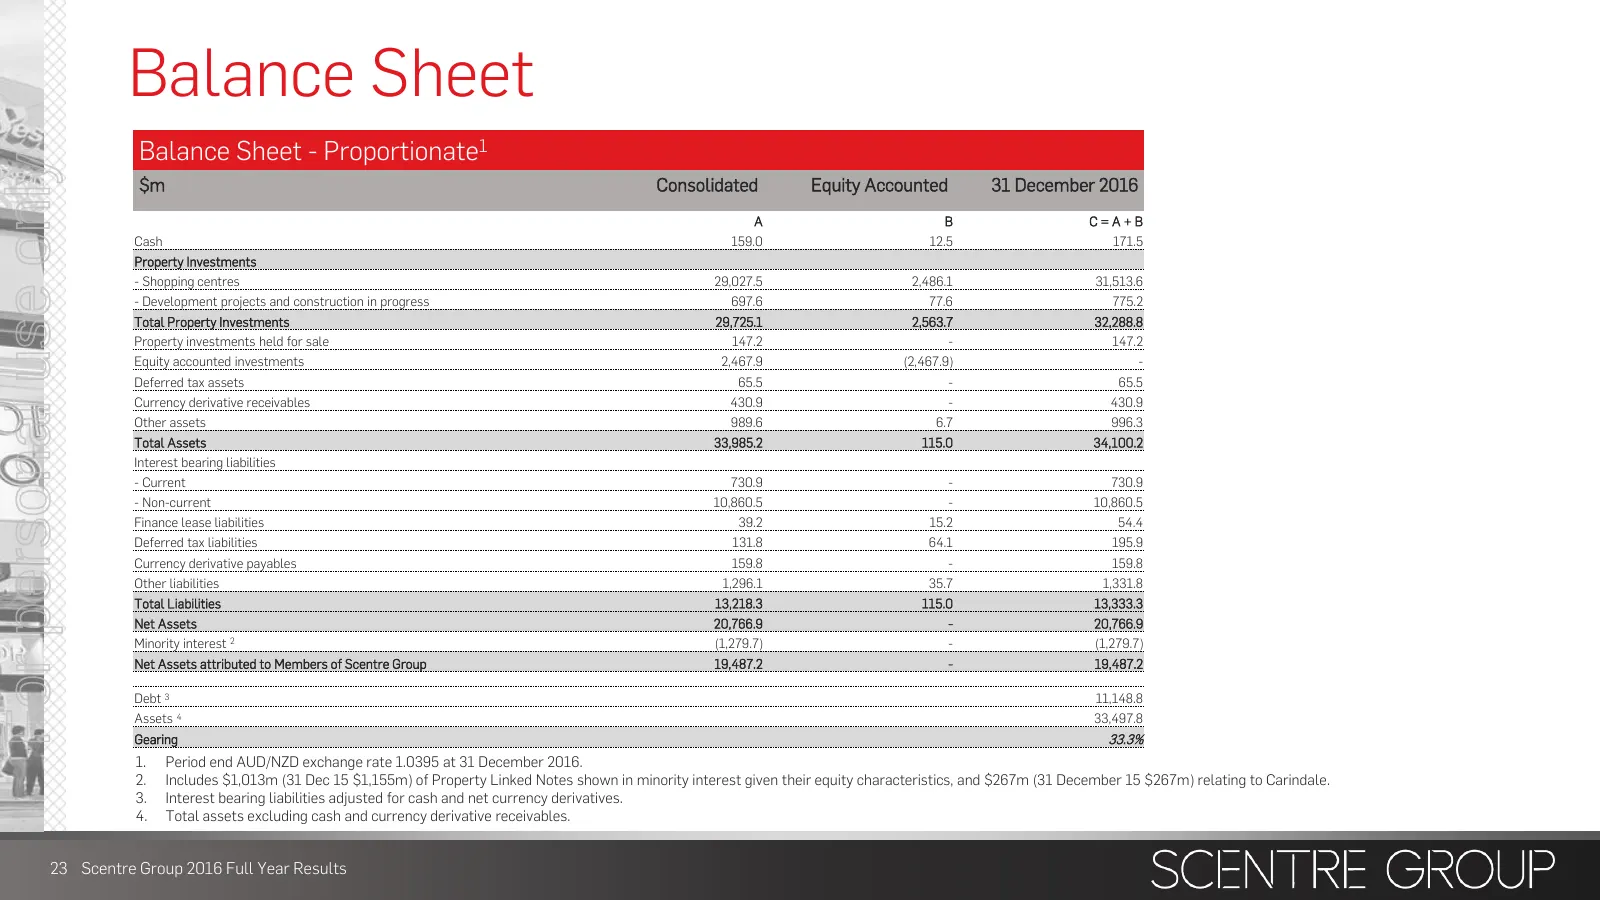
Balance Sheet Balance Sheet - Proportionate1 For personal use only $m Consolidated Equity Accounted 31 December 2016 A B C=A+B Cash 159.0 12.5 171.5 Property Investments - Shopping centres 29,027.5 2,486.1 31,513.6 - Development projects and construction in progress 697.6 77.6 775.2 Total Property I
Slide 27: Cashflow
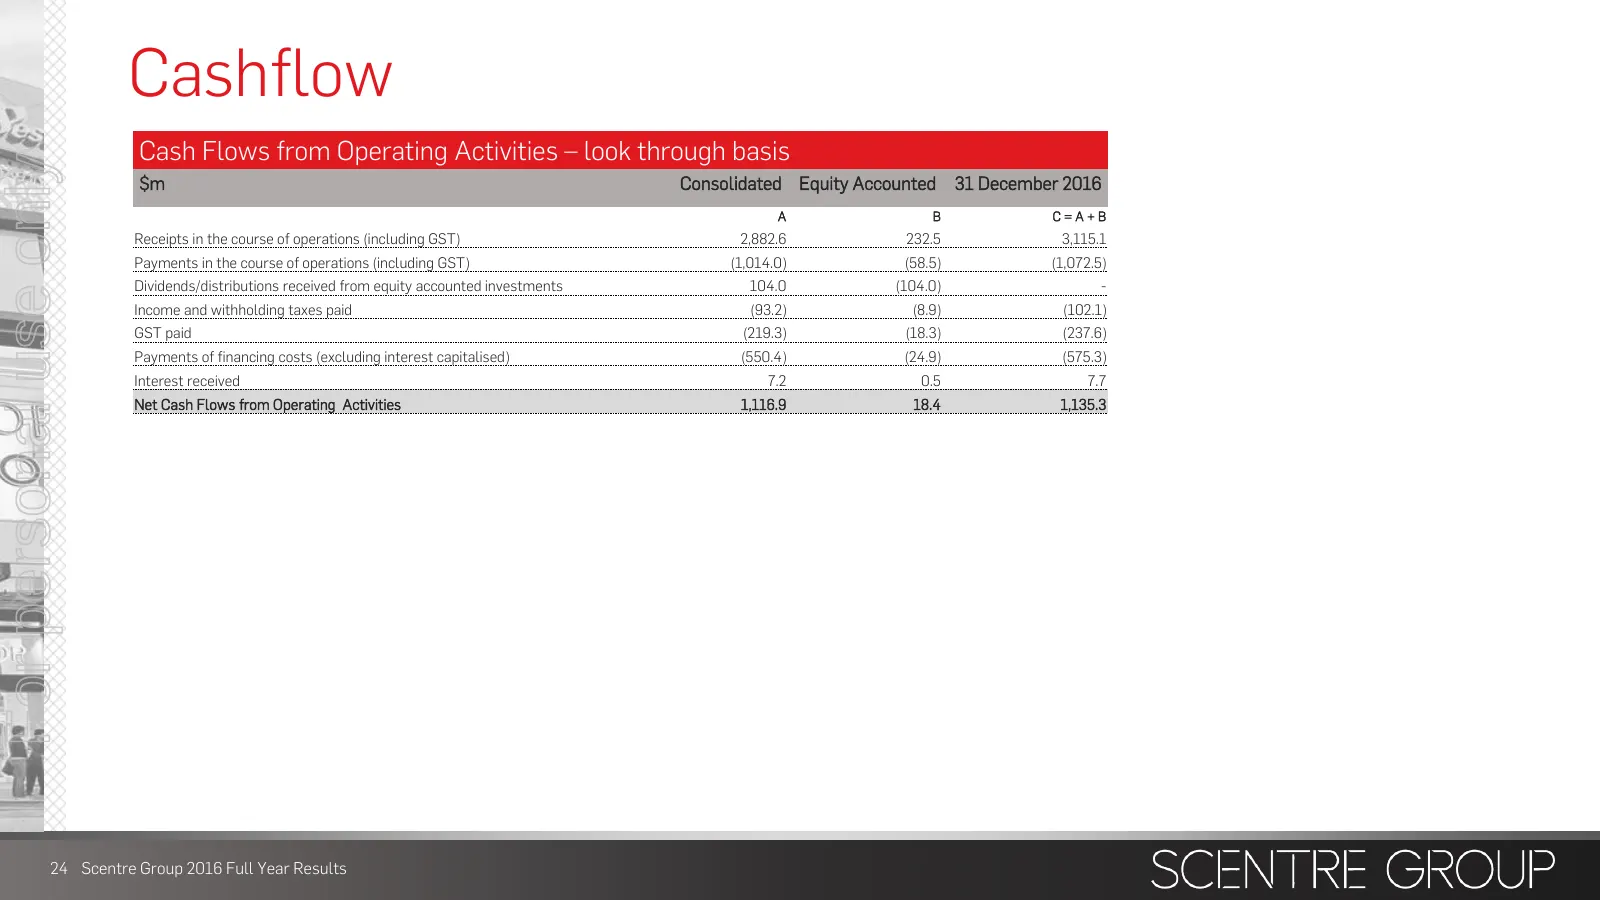
Cashflow Cash Flows from Operating Activities – look through basis For personal use only $m Consolidated Equity Accounted 31 December 2016 A B C=A+B Receipts in the course of operations (including GST) 2,882.6 232.5 3,115.1 Payments in the course of operations (including GST) (1,014.0) (58.5) (1,072
Slide 28: Interest hedging profile
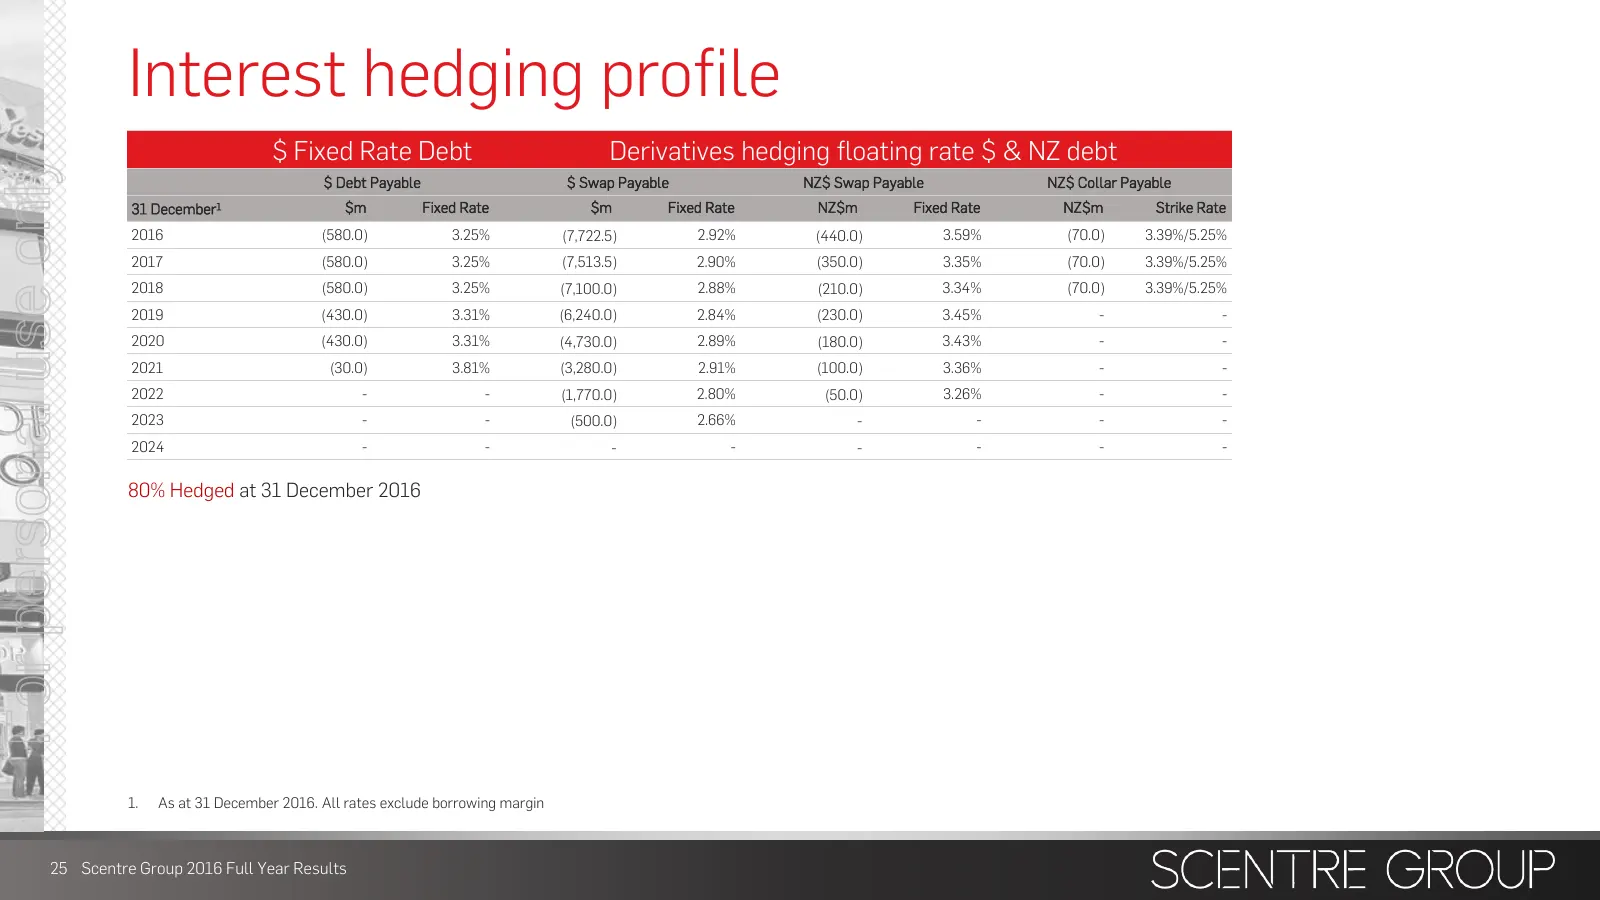
Interest hedging profile $ Fixed Rate Debt Derivatives hedging floating rate $ & NZ debt For personal use only $ Debt Payable $ Swap Payable NZ$ Swap Payable NZ$ Collar Payable 31 December1 $m Fixed Rate $m Fixed Rate NZ$m Fixed Rate NZ$m Strike Rate 2016 (580.0) 3.25% (7,722.5) 2.92% (440.0) 3.59%
Slide 29: Important Notice
For personal use only IMPORTANT NOTICE All amounts in Australian dollars unless otherwise specified. The financial information included in this document is based on the Scentre Group’s IFRS financial statements. Non IFRS financial information included in this document has not been audited or reviewe
Source: ASX announcement, Feb 21, 2017
More decks from Scentre Group
 Q3 2026 Earnings Presentation6 slides · Nov 4, 2026
 H1 2026 Earnings Presentation27 slides · Aug 25, 2026
 Q1 2026 Earnings Presentation6 slides · Apr 22, 2026
 FY2025 Earnings Presentation26 slides · Feb 24, 2026
 Q3 2025 Earnings Presentation6 slides · Nov 11, 2025
 H1 2025 Earnings Presentation27 slides · Aug 26, 2025