Air Transport Services Group Inc
Air Transport Services — Shareholder Meeting (May 2013)
20 slides from Air Transport Services's shareholder meeting presentation, May 14, 2013
Slide 1: Annual Meeting of Shareholders / Investor Meetings May 2013
0 Air Transport Services Group, Inc. Annual Meeting of Shareholders May XX, 2013 Investor Meetings May 2013
Slide 2: Safe Harbor Statement
Safe Harbor Statement Except for historical information contained herein, the matters discussed in this presentation contain forward-looking statements that involve risks and uncertainties. There are a number of important factors that could cause Air Transport Services Group's ("ATSG's") actual resu
Slide 3: Business Units
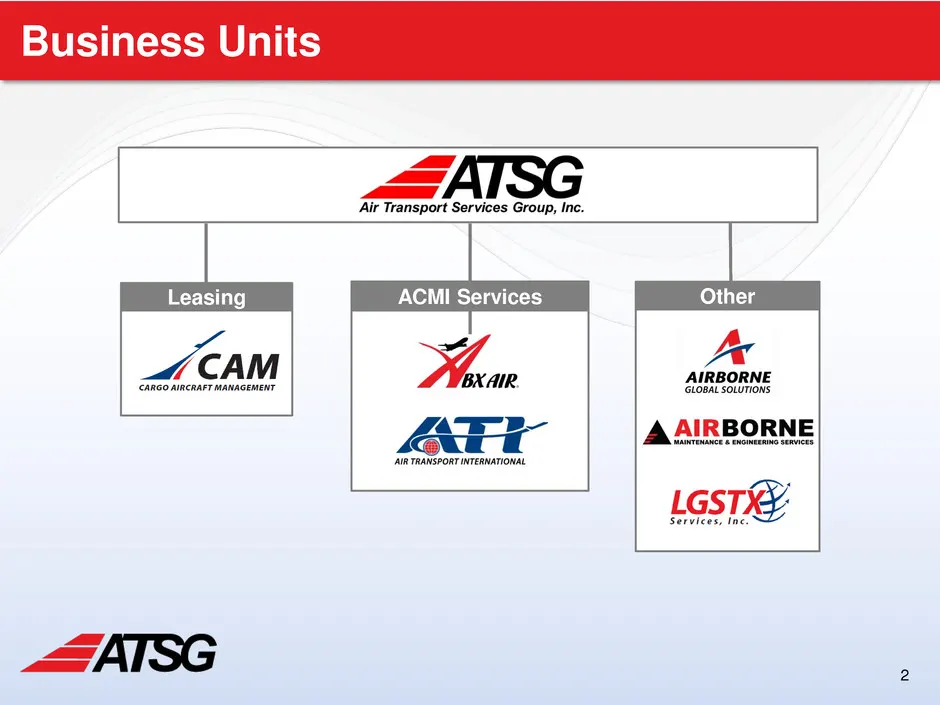
2 Business Units Leasing ACMI Services Other
Slide 4: 2012 Accomplishments
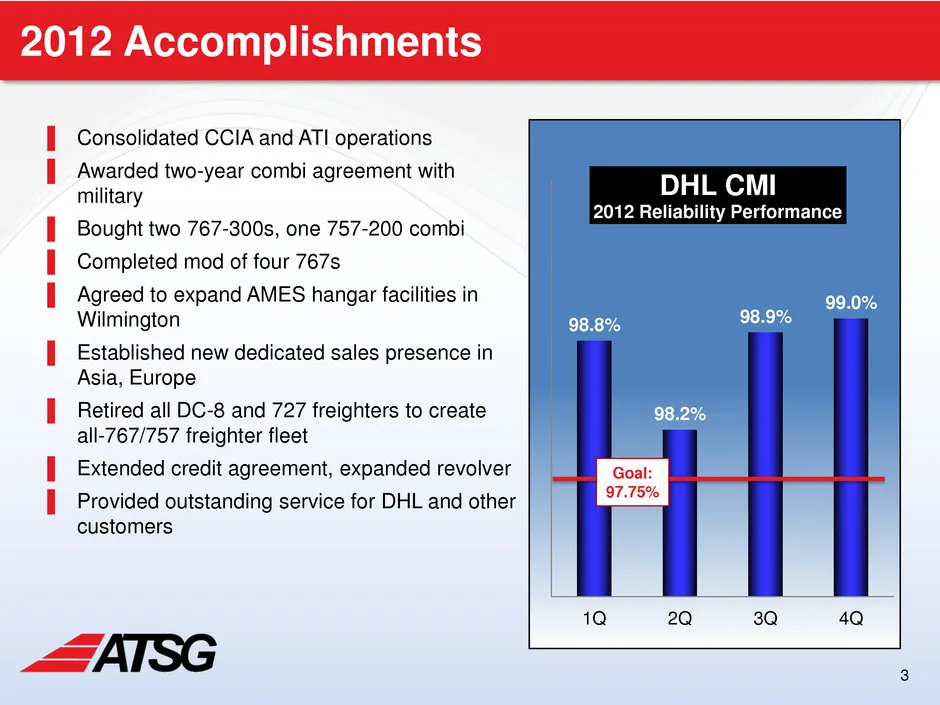
3 2012 Accomplishments ▌ Consolidated CCIA and ATI operations ▌ Awarded two-year combi agreement with military ▌ Bought two 767-300s, one 757-200 combi ▌ Completed mod of four 767s ▌ Agreed to expand AMES hangar facilities in Wilmington ▌ Established new dedicated sales presence in Asia, Europe ▌ Re
Slide 5: First Quarter 2013 Accomplishments
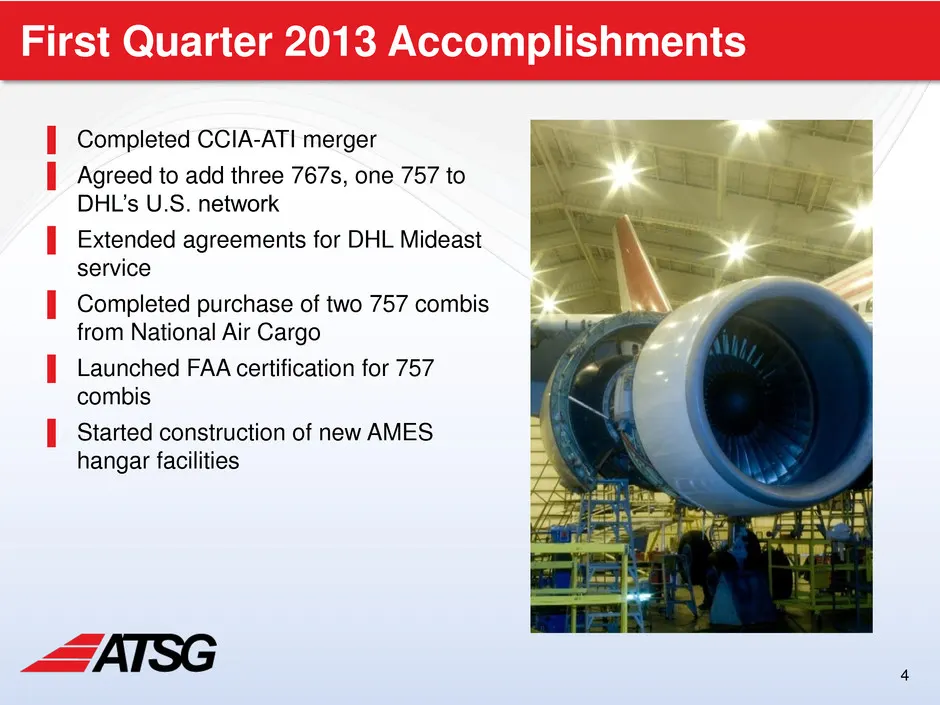
4 First Quarter 2013 Accomplishments ▌ Completed CCIA-ATI merger ▌ Agreed to add three 767s, one 757 to DHL’s U.S. network ▌ Extended agreements for DHL Mideast service ▌ Completed purchase of two 757 combis from National Air Cargo ▌ Launched FAA certification for 757 combis ▌ Started construction o
Slide 6: ATSG Strategy – It Starts With The Lease
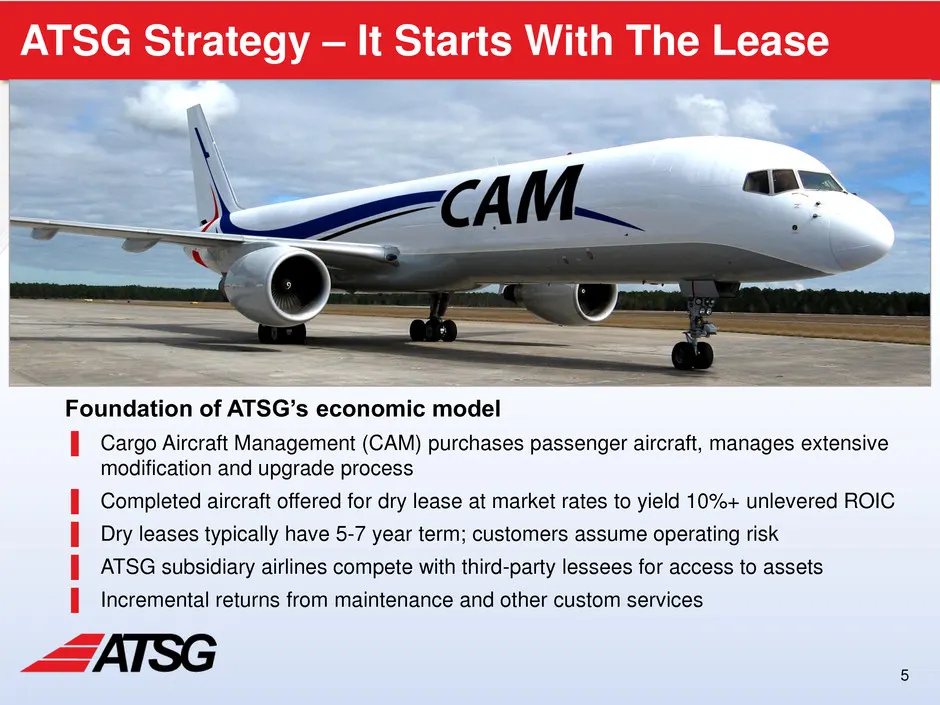
5 ATSG Strategy – It Starts With The Lease 767 and 757 freighter dry leases, plus airline operations and other complementary services generating incremental returns Foundation of ATSG’s economic model ▌ Cargo Aircraft Management (CAM) purchases passenger aircraft, manages extensive modification and
Slide 7: ATSG Strategy – ACMI or CMI Operations
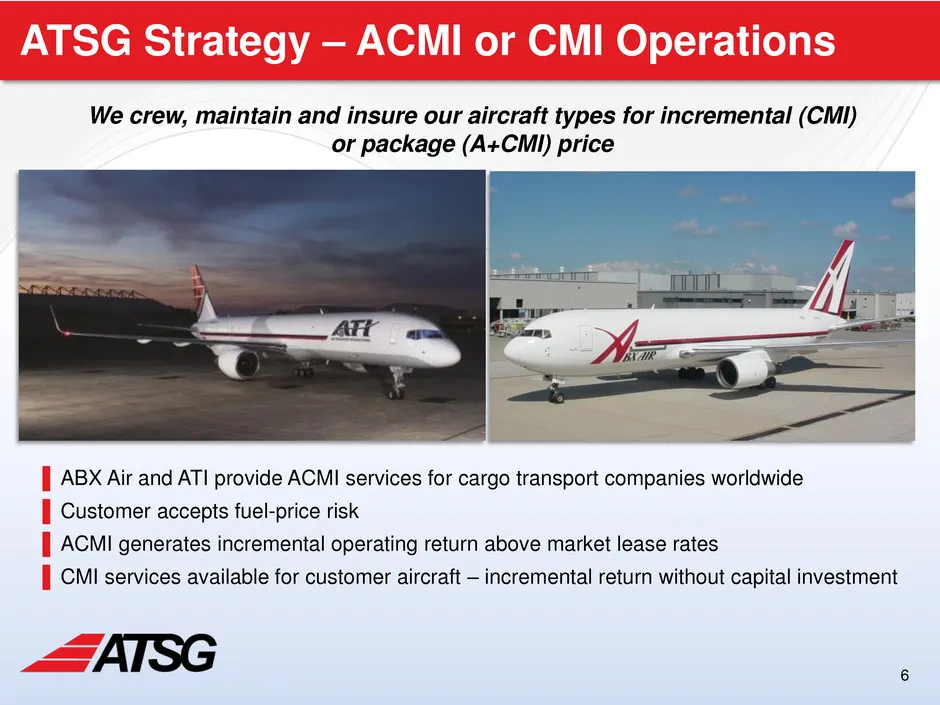
6 ATSG Strategy – ACMI or CMI Operations We crew, maintain and insure our aircraft types for incremental (CMI) or package (A+CMI) price ▌ABX Air and ATI provide ACMI services for cargo transport companies worldwide ▌Customer accepts fuel-price risk ▌ACMI generates incremental operating return above
Slide 8: ATSG Strategy – Customized Support
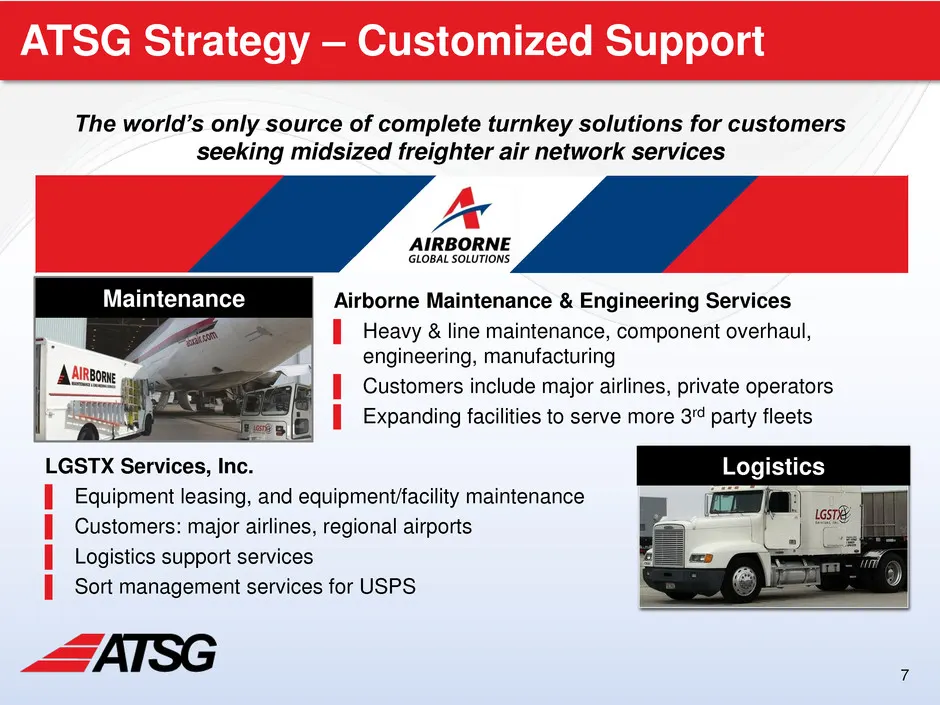
7 ATSG Strategy – Customized Support The world’s only source of complete turnkey solutions for customers seeking midsized freighter air network services Airborne Maintenance & Engineering Services ▌ Heavy & line maintenance, component overhaul, engineering, manufacturing ▌ Customers include major ai
Slide 9: ATSG Investment Strategy
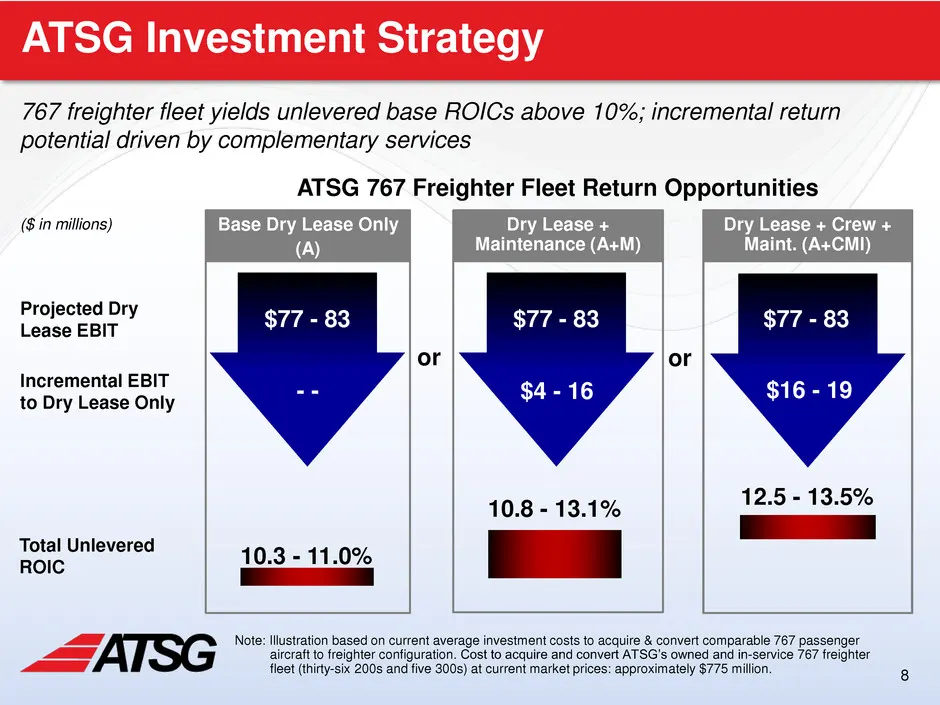
8 ATSG Investment Strategy 767 freighter fleet yields unlevered base ROICs above 10%; incremental return potential driven by complementary services Base Dry Lease Only (A) Dry Lease + Crew + Maint. (A+CMI) Dry Lease + Maintenance (A+M) Projected Dry Lease EBIT Incremental EBIT to Dry Lease Only Tota
Slide 10: 2012 Results
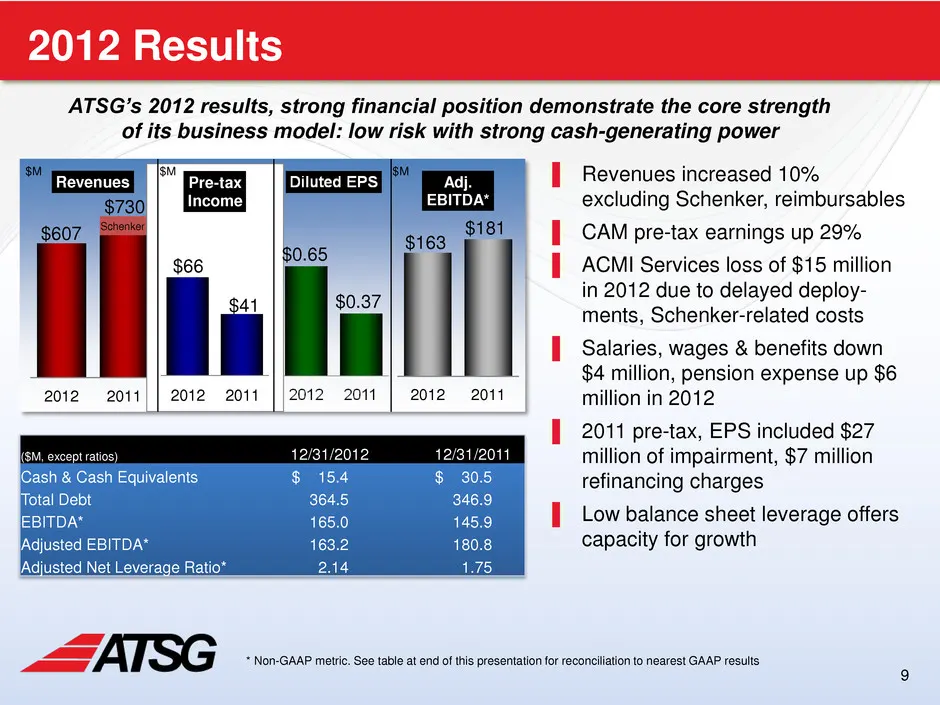
9 2012 Results 2012 2011 Revenues ▌ Revenues increased 10% excluding Schenker, reimbursables ▌ CAM pre-tax earnings up 29% ▌ ACMI Services loss of $15 million in 2012 due to delayed deploy- ments, Schenker-related costs ▌ Salaries, wages & benefits down $4 million, pension expense up $6 million in 2
Slide 11: First Quarter 2013 Results
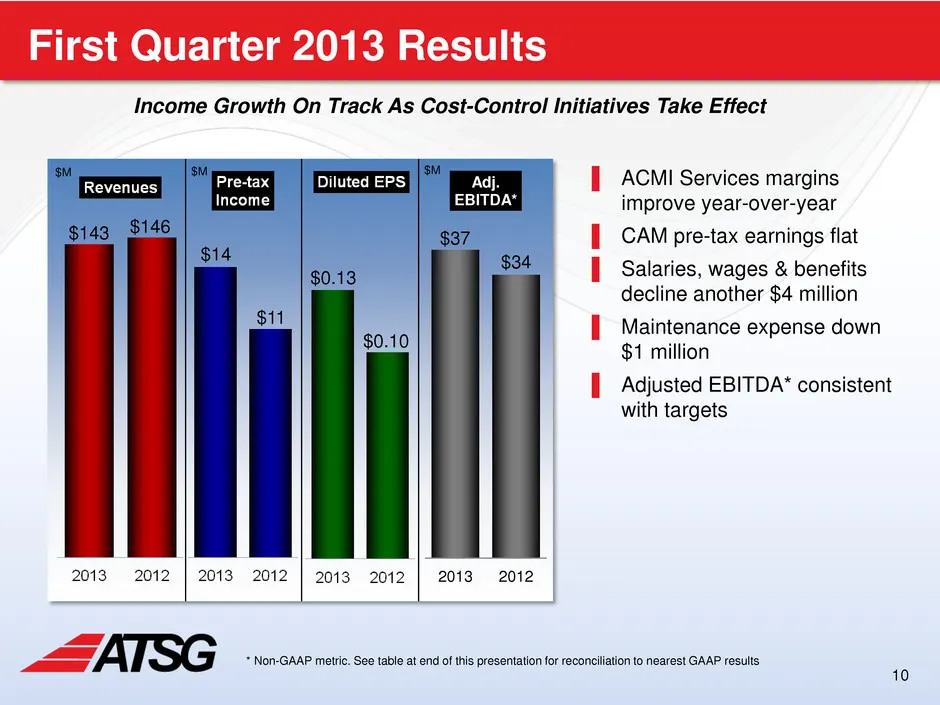
10 First Quarter 2013 Results ▌ ACMI Services margins improve year-over-year ▌ CAM pre-tax earnings flat ▌ Salaries, wages & benefits decline another $4 million ▌ Maintenance expense down $1 million ▌ Adjusted EBITDA* consistent with targets 2013 2012 Adj. EBITDA* $143 $146 $14 $11 $0.13 $0.10 $37 $
Slide 12: Merger Complete – Savings Accruing
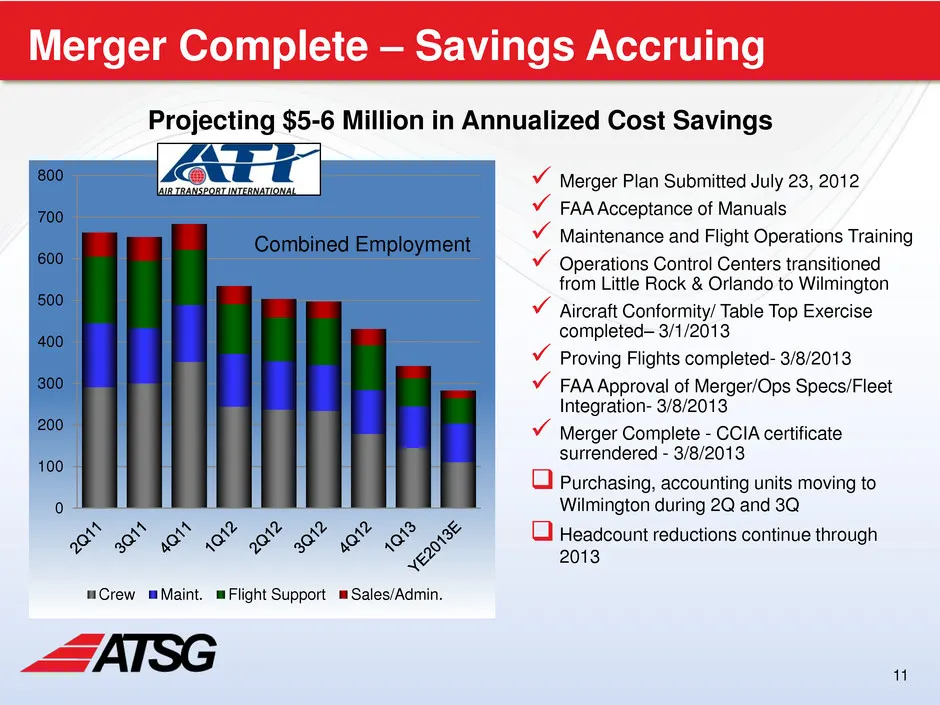
11 Merger Complete – Savings Accruing Merger Plan Submitted July 23, 2012 FAA Acceptance of Manuals Maintenance and Flight Operations Training Operations Control Centers transitioned from Little Rock & Orlando to Wilmington Aircraft Conformity/ Table Top Exercise completed– 3/1/2013 Prov
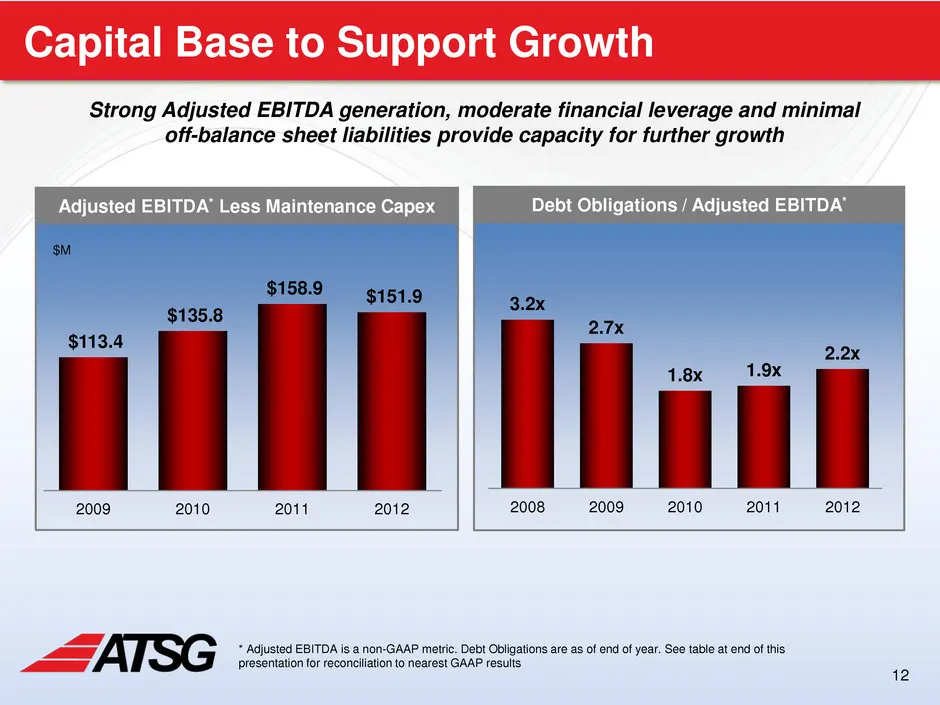
Slide 13: Capital Base to Support Growth
12 3.2x 2.7x 1.8x 1.9x 2.2x 2008 2009 2010 2011 2012 Capital Base to Support Growth Strong Adjusted EBITDA generation, moderate financial leverage and minimal off-balance sheet liabilities provide capacity for further growth $113.4 $135.8 $158.9 $151.9 2009 2010 2011 2012 Debt Obligations / Adjusted
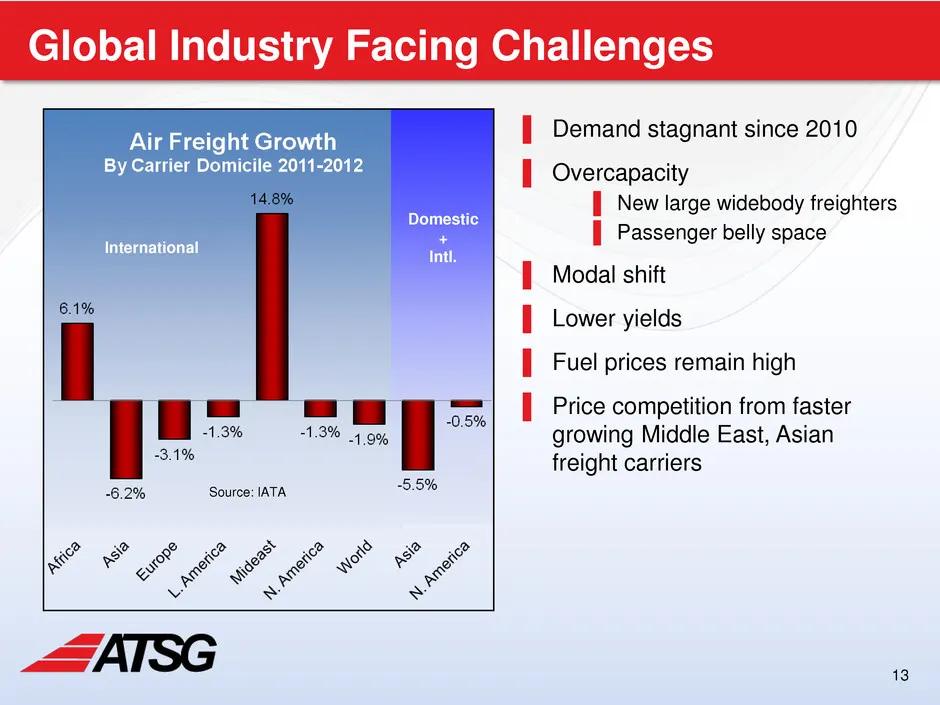
Slide 14: Global Industry Facing Challenges
13 Global Industry Facing Challenges ▌ Demand stagnant since 2010 ▌ Overcapacity ▌ New large widebody freighters ▌ Passenger belly space ▌ Modal shift ▌ Lower yields ▌ Fuel prices remain high ▌ Price competition from faster growing Middle East, Asian freight carriers International Domestic + Intl. S
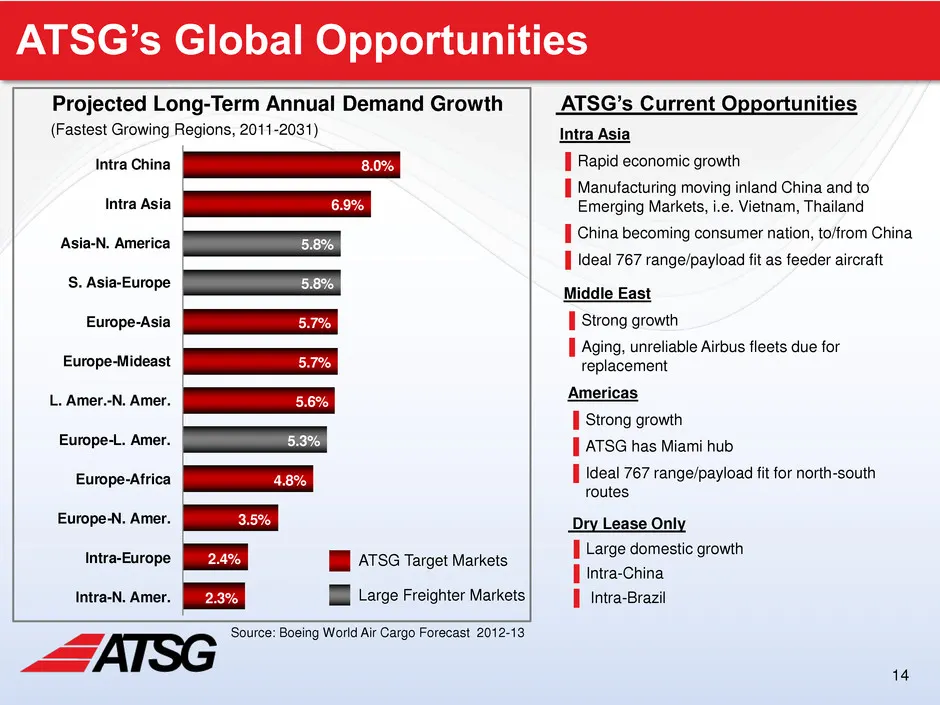
Slide 15: ATSG's Global Opportunities
14 (Fastest Growing Regions, 2011-2031) ATSG’s Global Opportunities Projected Long-Term Annual Demand Growth Source: Boeing World Air Cargo Forecast 2012-13 Large Freighter Markets ATSG Target Markets Americas ▐ Strong growth ▐ ATSG has Miami hub ▐ Ideal 767 range/payload fit for north-south routes
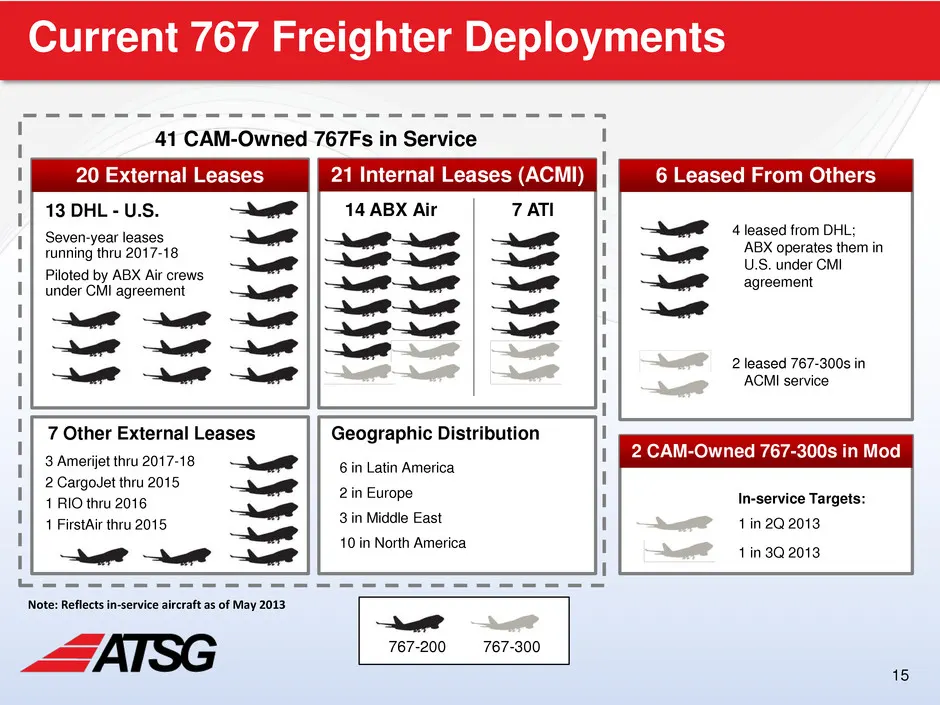
Slide 16: Current Freighter Deployments
15 Current 767 Freighter Deployments 20 External Leases 21 Internal Leases (ACMI) 13 DHL - U.S. Seven-year leases running thru 2017-18 Piloted by ABX Air crews under CMI agreement 7 ATI Geographic Distribution 14 ABX Air 7 Other External Leases 3 Amerijet thru 2017-18 2 CargoJet thru 2015 1 RIO thru
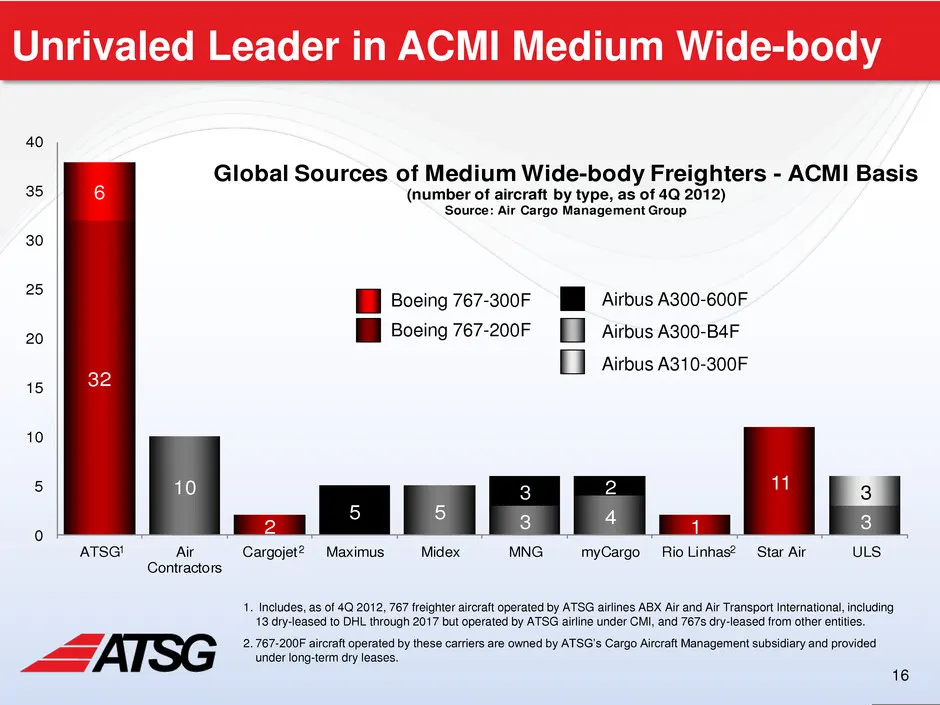
Slide 17: Unrivaled Leader in ACMI Medium Wide-body
16 32 2 1 11 6 10 5 3 4 3 5 3 2 3 0 5 10 15 20 25 30 35 40 ATSG Air Contractors Cargojet Maximus Midex MNG myCargo Rio Linhas Star Air ULS Global Sources of Medium Wide-body Freighters - ACMI Basis (number of aircraft by type, as of 4Q 2012) Source: Air Cargo Management Group Unrivaled Leader in ACM
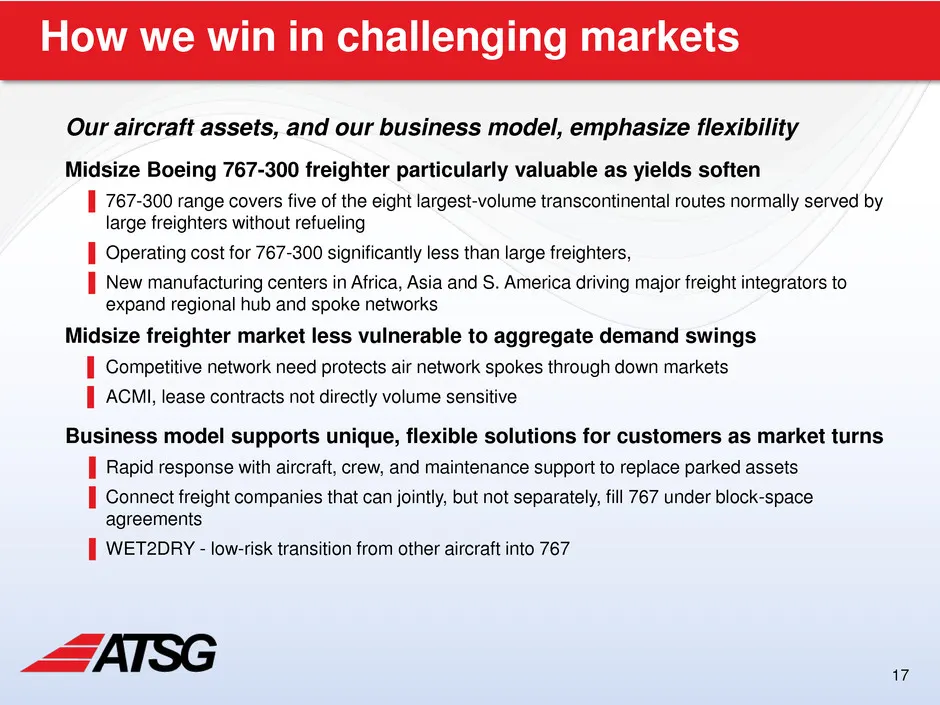
Slide 18: How we win in challenging markets
17 How we win in challenging markets Our aircraft assets, and our business model, emphasize flexibility Midsize Boeing 767-300 freighter particularly valuable as yields soften ▌ 767-300 range covers five of the eight largest-volume transcontinental routes normally served by large freighters without
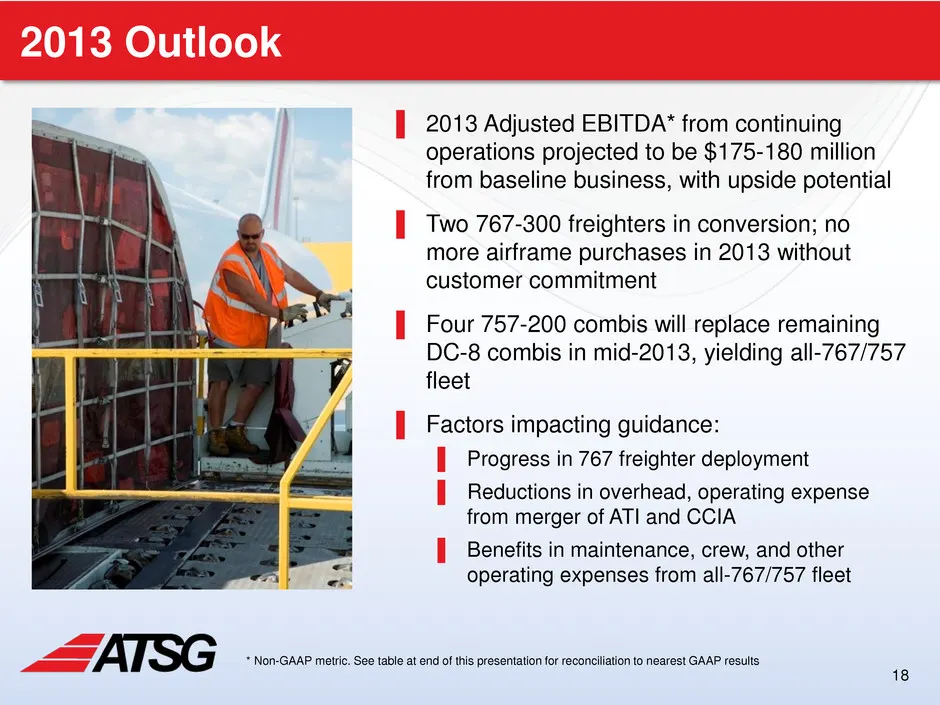
Slide 19: 2013 Outlook
18 2013 Outlook ▌ 2013 Adjusted EBITDA* from continuing operations projected to be $175-180 million from baseline business, with upside potential ▌ Two 767-300 freighters in conversion; no more airframe purchases in 2013 without customer commitment ▌ Four 757-200 combis will replace remaining DC-8 c
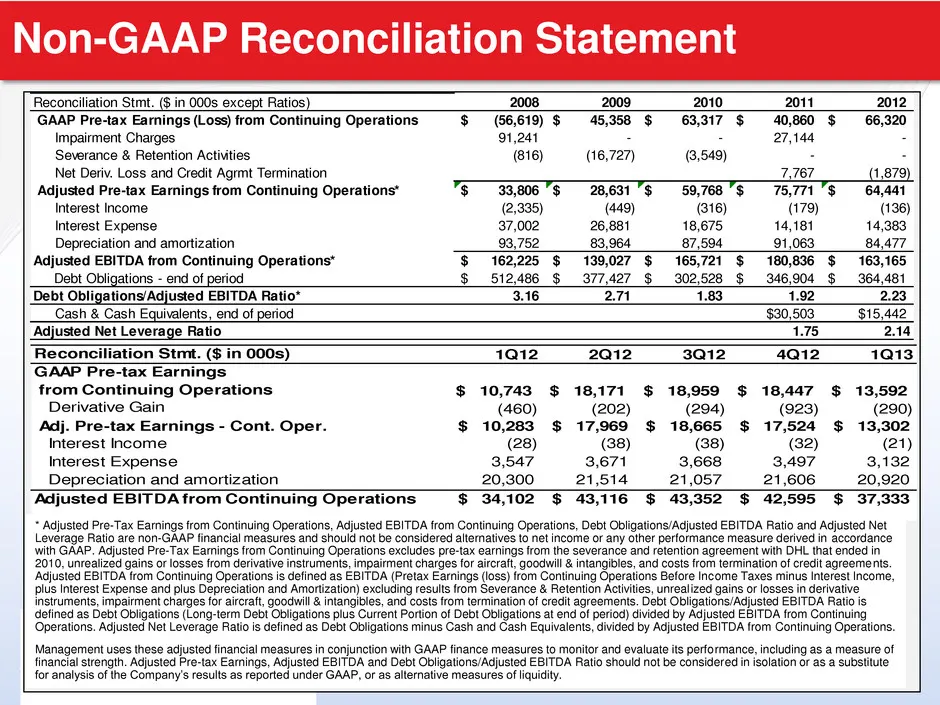
Slide 20: Non-GAAP Reconciliation Statement
19 Non-GAAP Reconciliation Statement * Adjusted Pre-Tax Earnings from Continuing Operations, Adjusted EBITDA from Continuing Operations, Debt Obligations/Adjusted EBITDA Ratio and Adjusted Net Leverage Ratio are non-GAAP financial measures and should not be considered alternatives to net income or a
Source: SEC EDGAR · 8-K filed May 14, 2013
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020