Tiger Brands Limited · JSE:TBS
Tiger Brands — Investor Day (March 2013)
59 slides from Tiger Brands's investor day presentation, Mar 7, 2013
Slide 1: Grains – Investor Day, 7 March 2013
Overview Baked Goods Milling Breakfast Grains – Investor Day 7 March 2013
Slide 2: Agenda
Overview Baked Goods Milling Breakfast Agenda Overview Baked Goods Milling Breakfast Bakery Tour 2
Slide 3: Overview
Overview Group Baked Goods Milling Breakfast Overview Noel Doyle Business Execu?ve
Slide 4: Operating environment remains even more challenging
Overview Baked Goods Milling Breakfast Opera>ng environment remains even more challenging • Overall upward trend in commodity prices • Significant vola?lity con?nues to prevail • DOB penetra?on inves?ng in a value economy • Relentless pressure on consumer spend • Compe??ve environment less predictabl
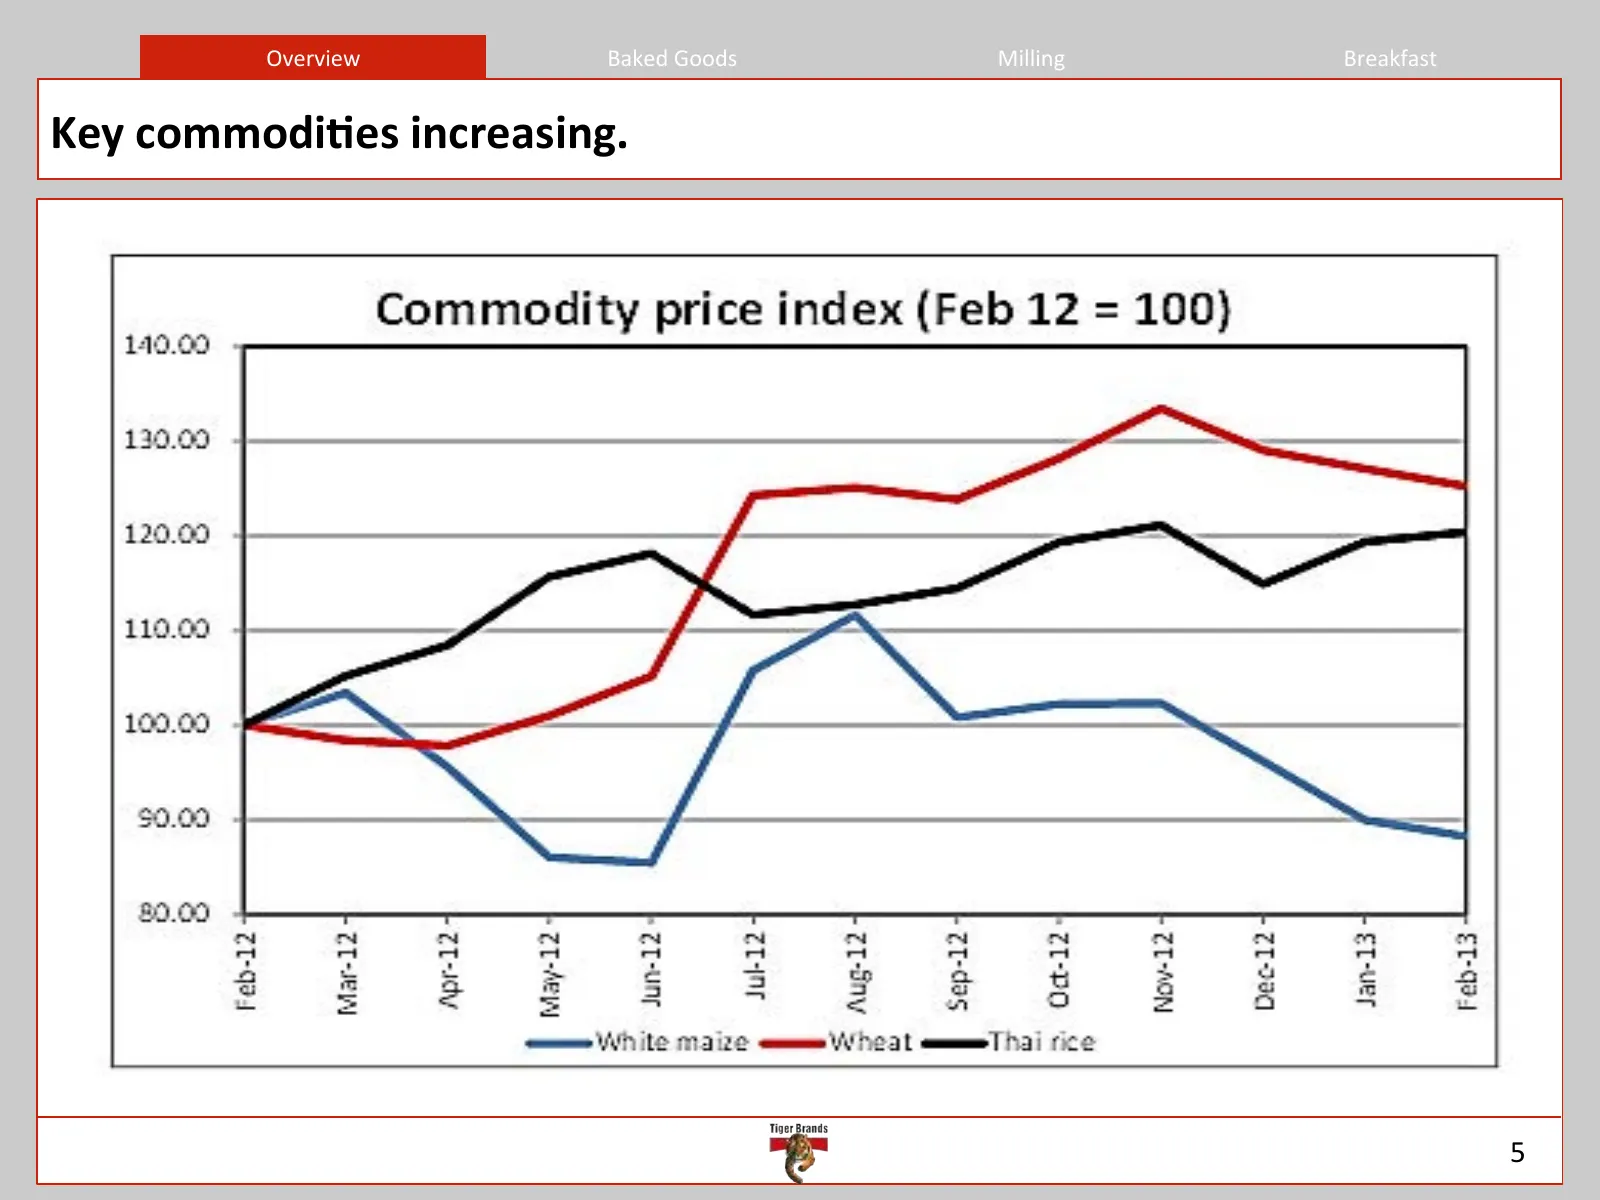
Slide 5: Key commodities increasing
Overview Baked Goods Milling Breakfast Key commodi>es increasing. 5
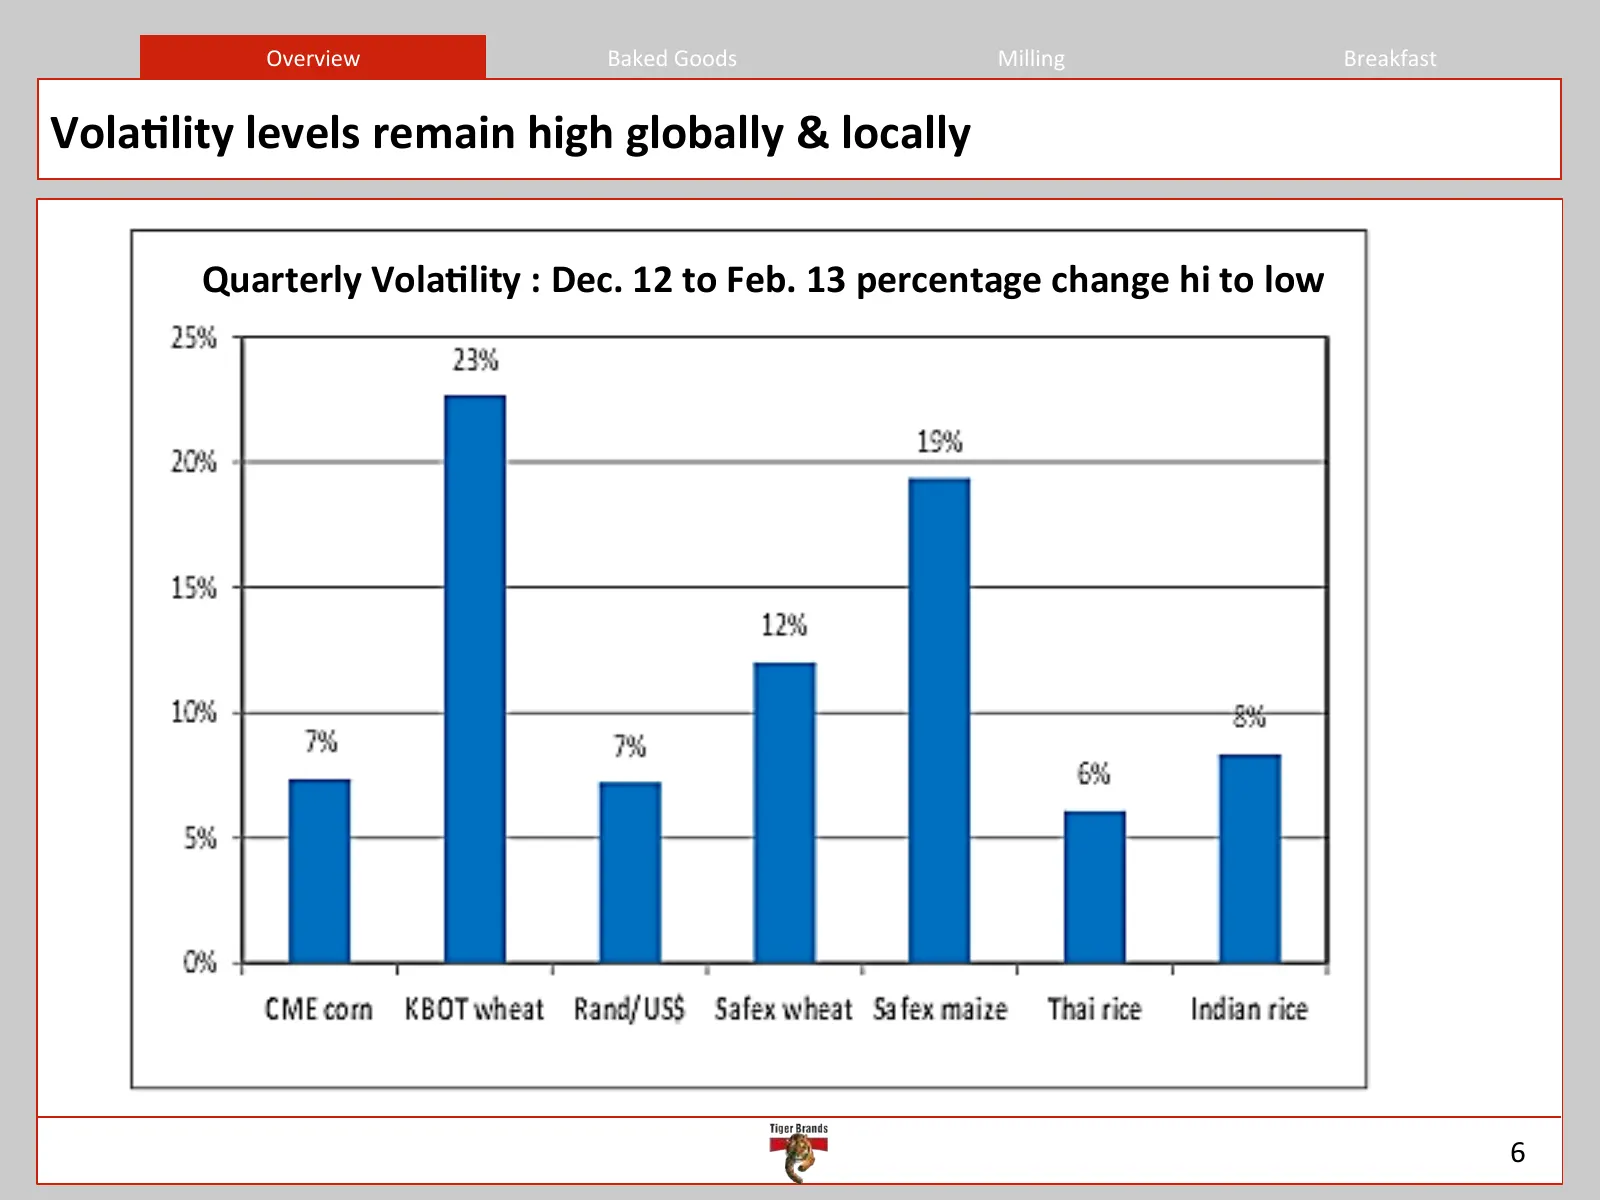
Slide 6: Volatility levels remain high globally & locally
Overview Baked Goods Milling Breakfast Vola>lity levels remain high globally & locally Quarterly Vola>lity : Dec. 12 to Feb. 13 percentage change hi to low 6
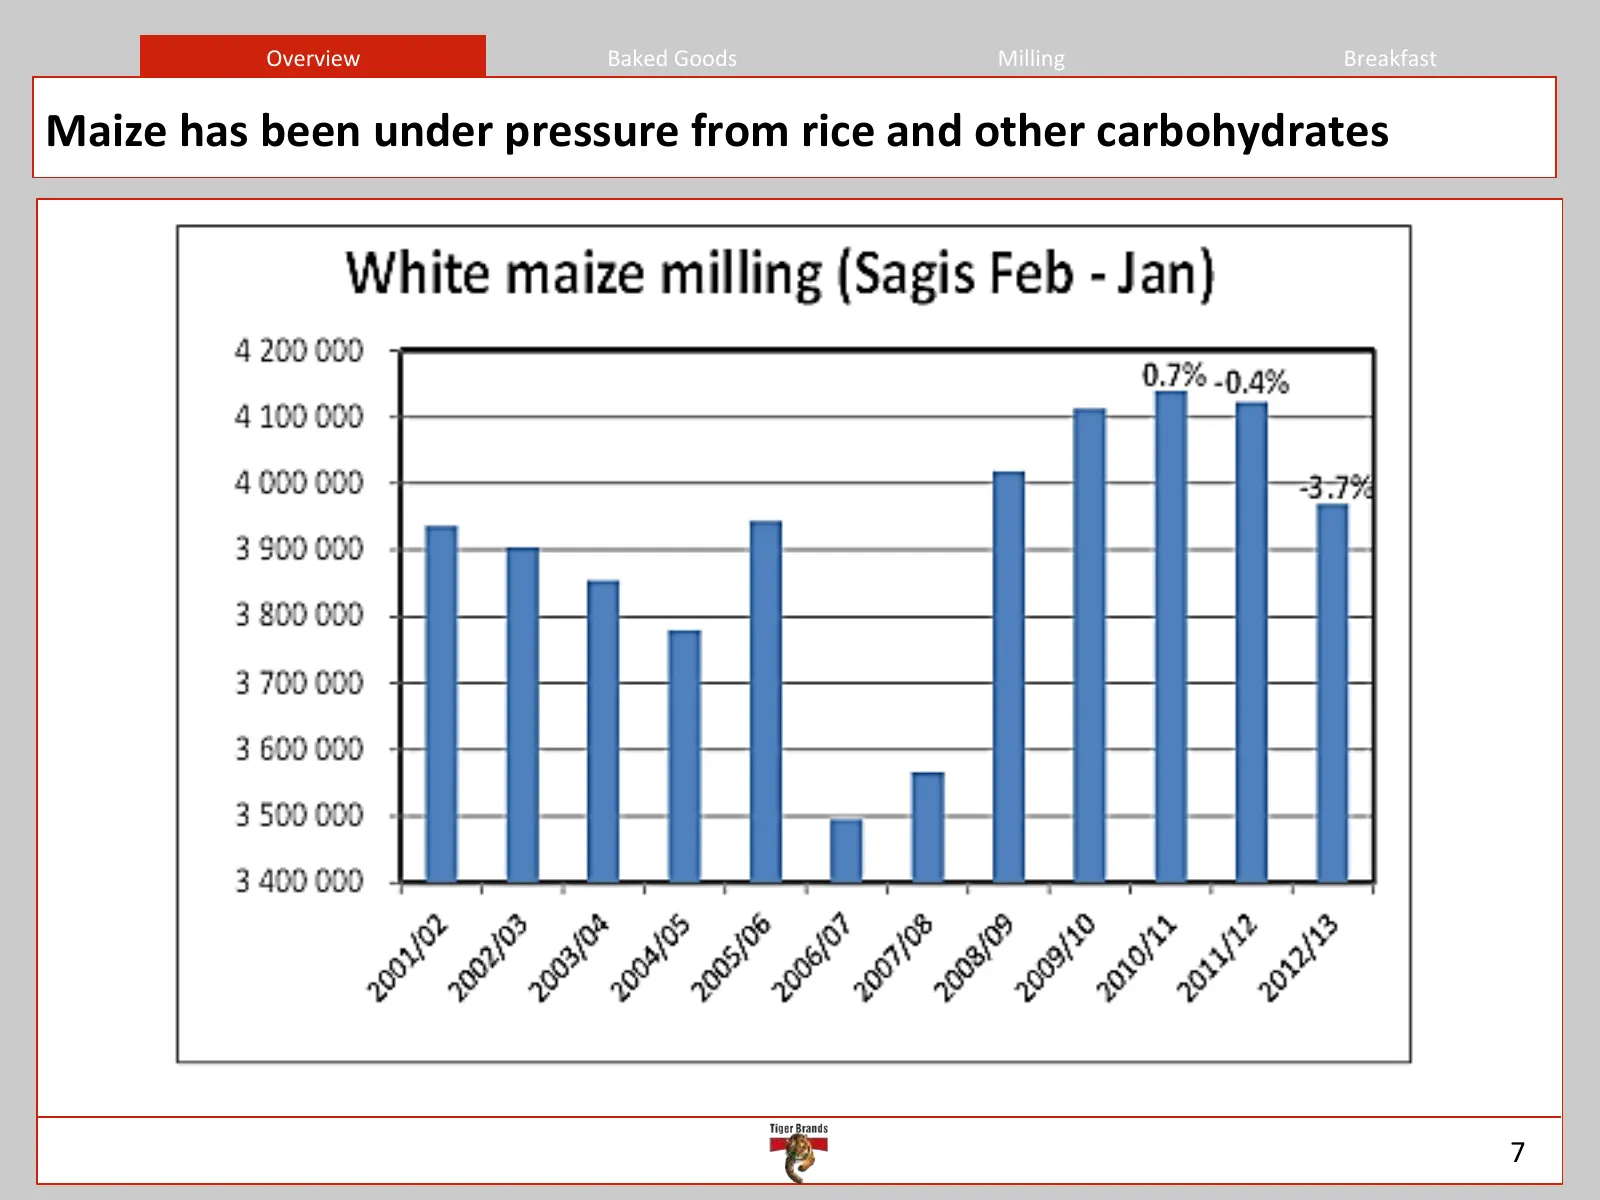
Slide 7: Maize has been under pressure from rice and other carbohydrates
Overview Baked Goods Milling Breakfast Maize has been under pressure from rice and other carbohydrates 7
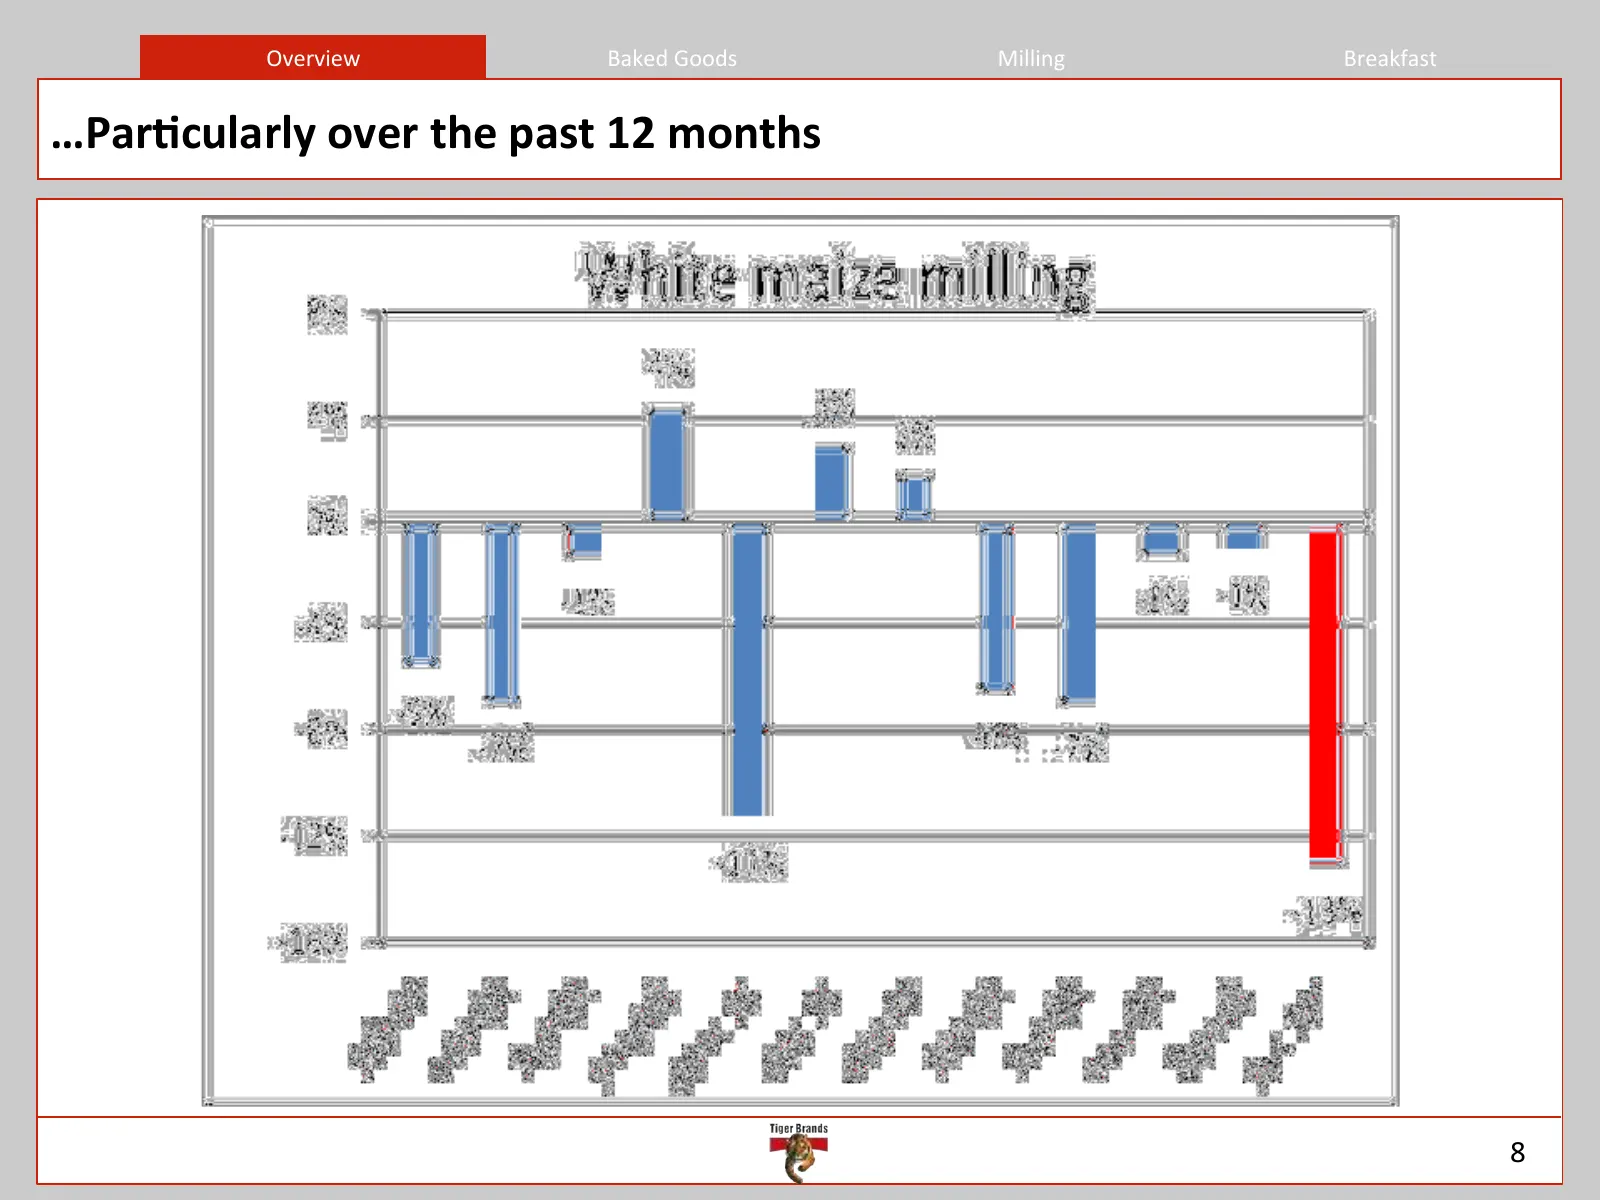
Slide 8: Particularly over the past 12 months
Overview Baked Goods Milling Breakfast …Par>cularly over the past 12 months 8
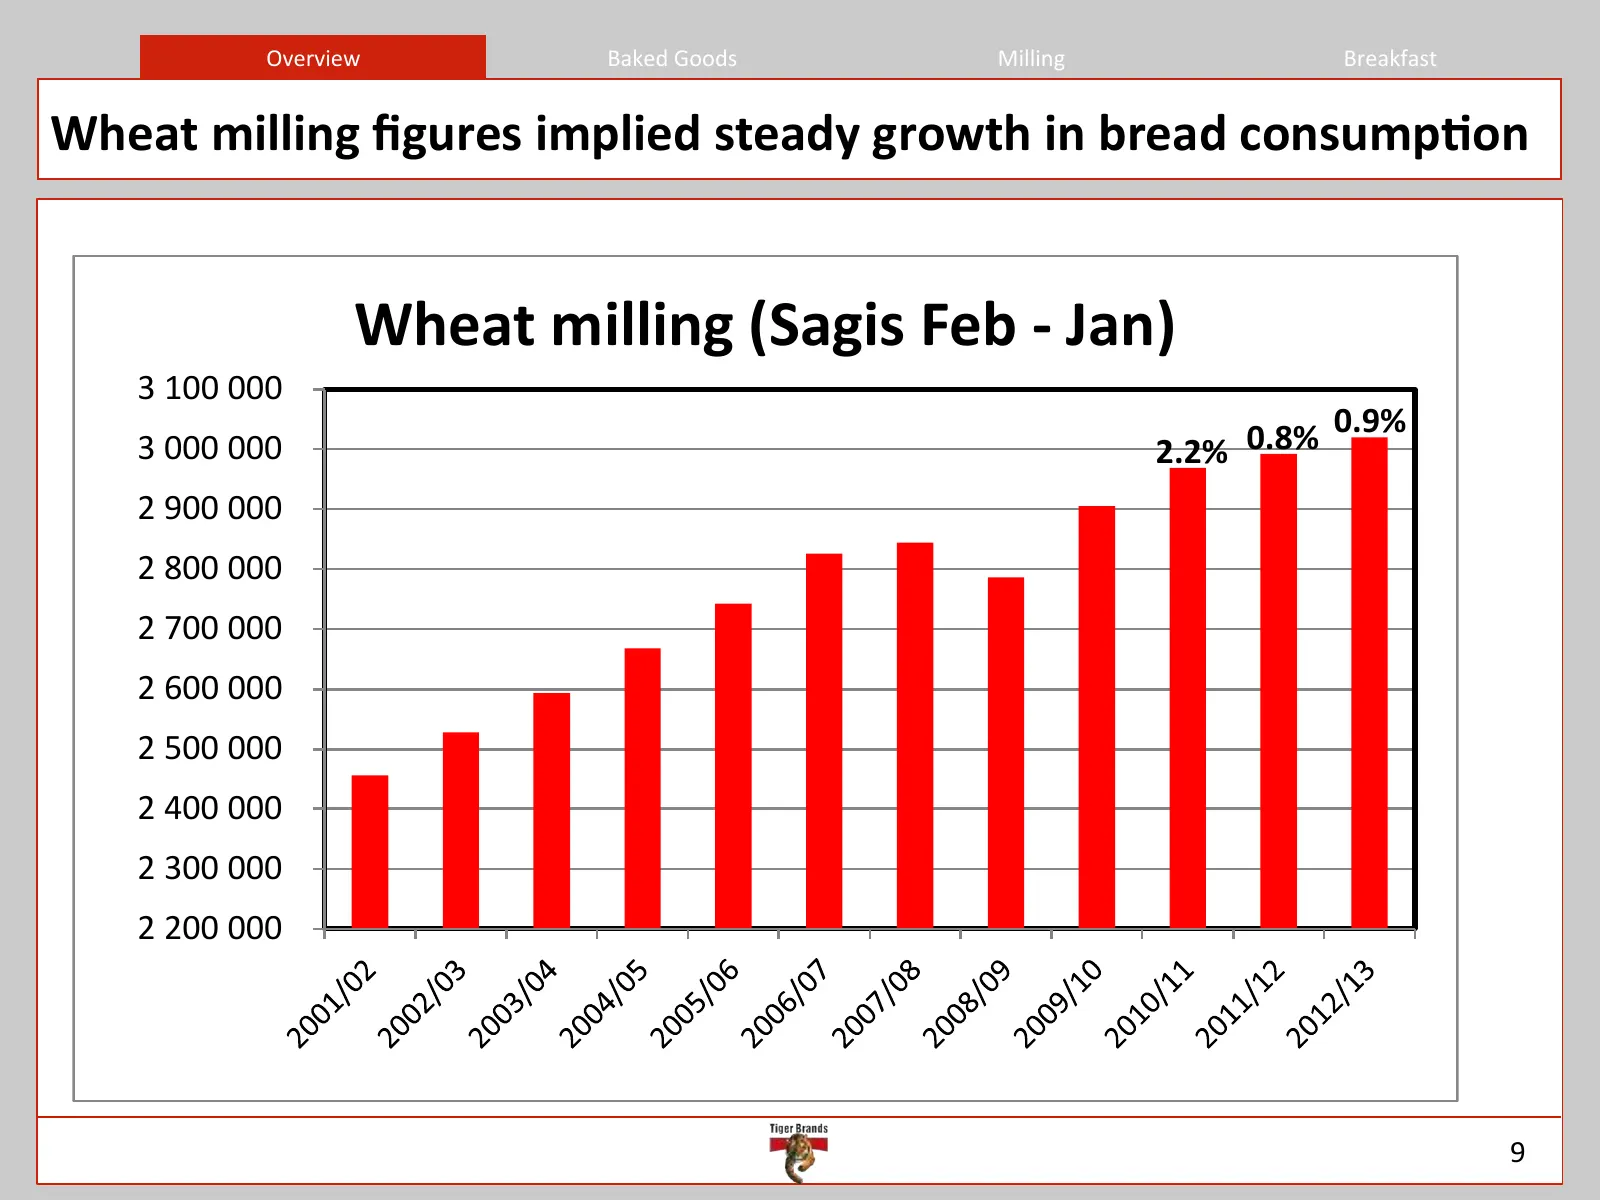
Slide 9: Wheat milling figures implied steady growth in bread consumption
Overview Baked Goods Milling Breakfast Wheat milling figures implied steady growth in bread consump>on Wheat milling (Sagis Feb -‐ Jan) 3 100 000 0.8% 0.9% 3 000 000 2.2% 2 900 000 2 800 000 2 700 000 2 600 000 2 500 000 2 400 000 2 300 000 2 200 000 9
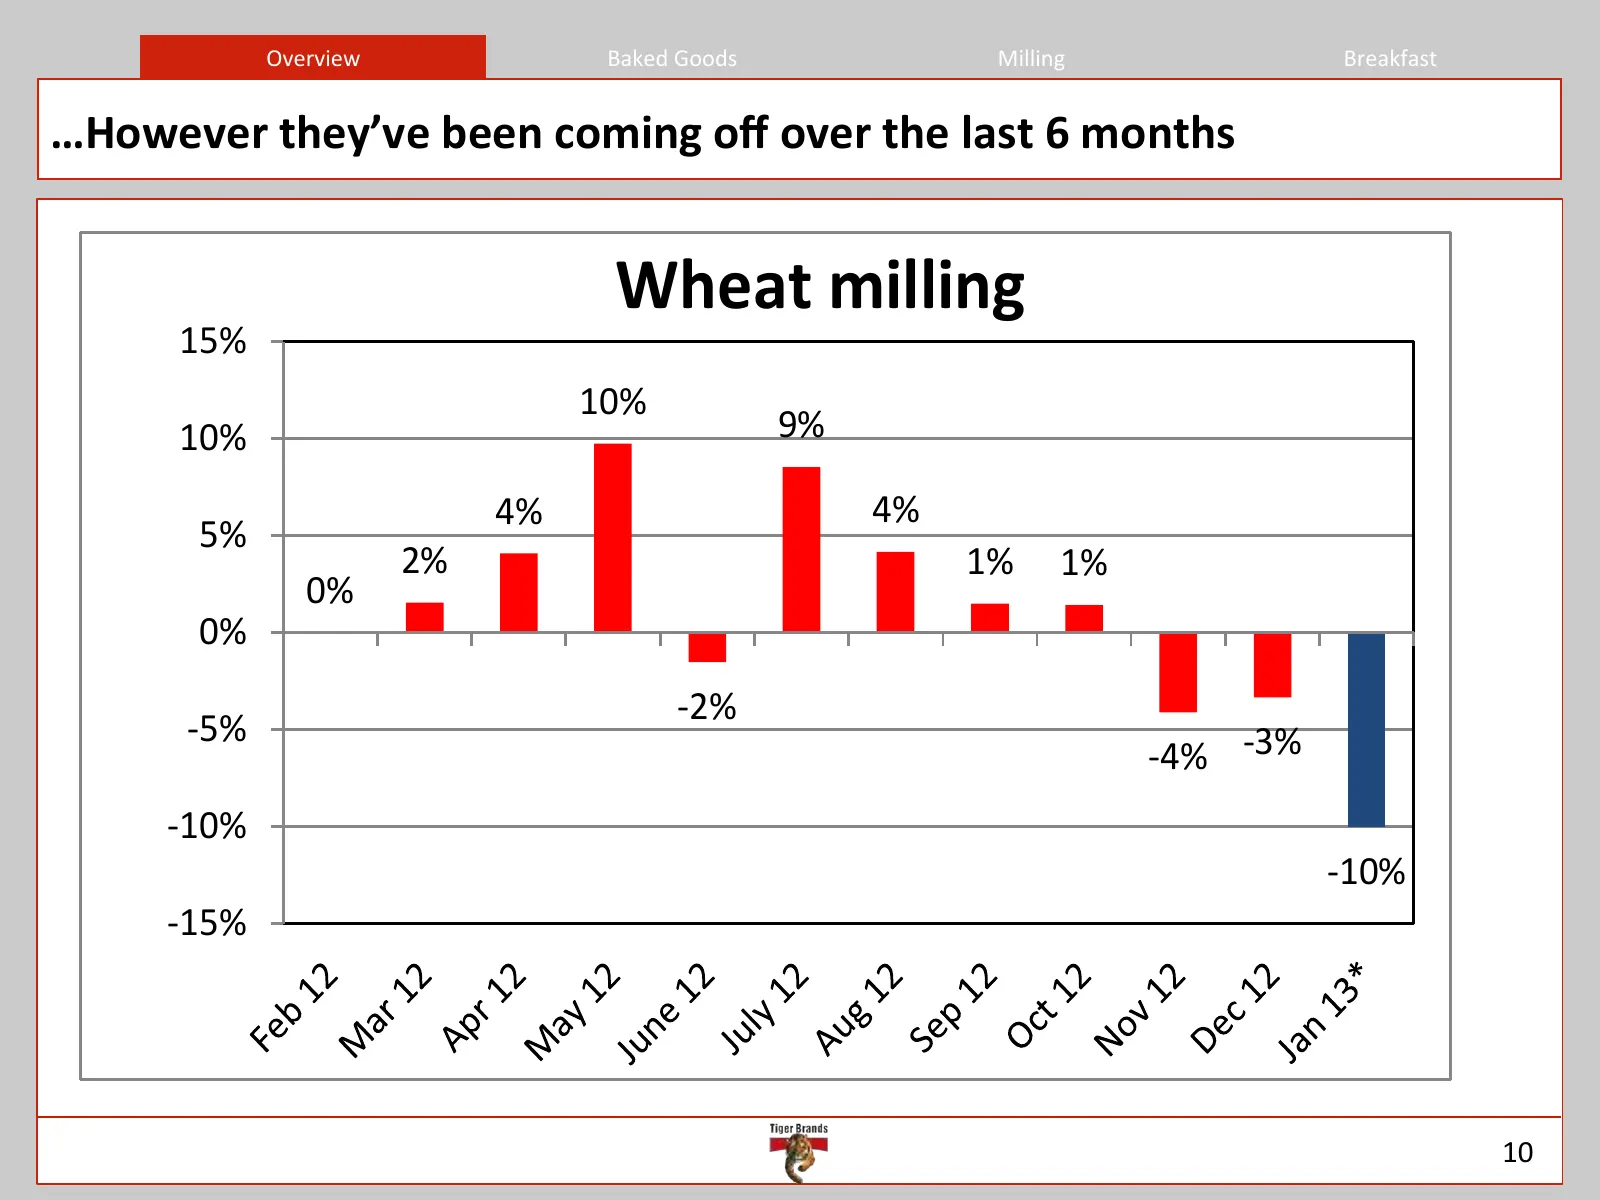
Slide 10: However they've been coming off over the last months
Overview Baked Goods Milling Breakfast …However they’ve been coming off over the last 6 months Wheat milling 15% 10% 10% 9% 4% 4% 5% 2% 1% 1% 0% 0% -‐2% -‐5% -‐4% -‐3% -‐10% -‐10% -‐15% 10
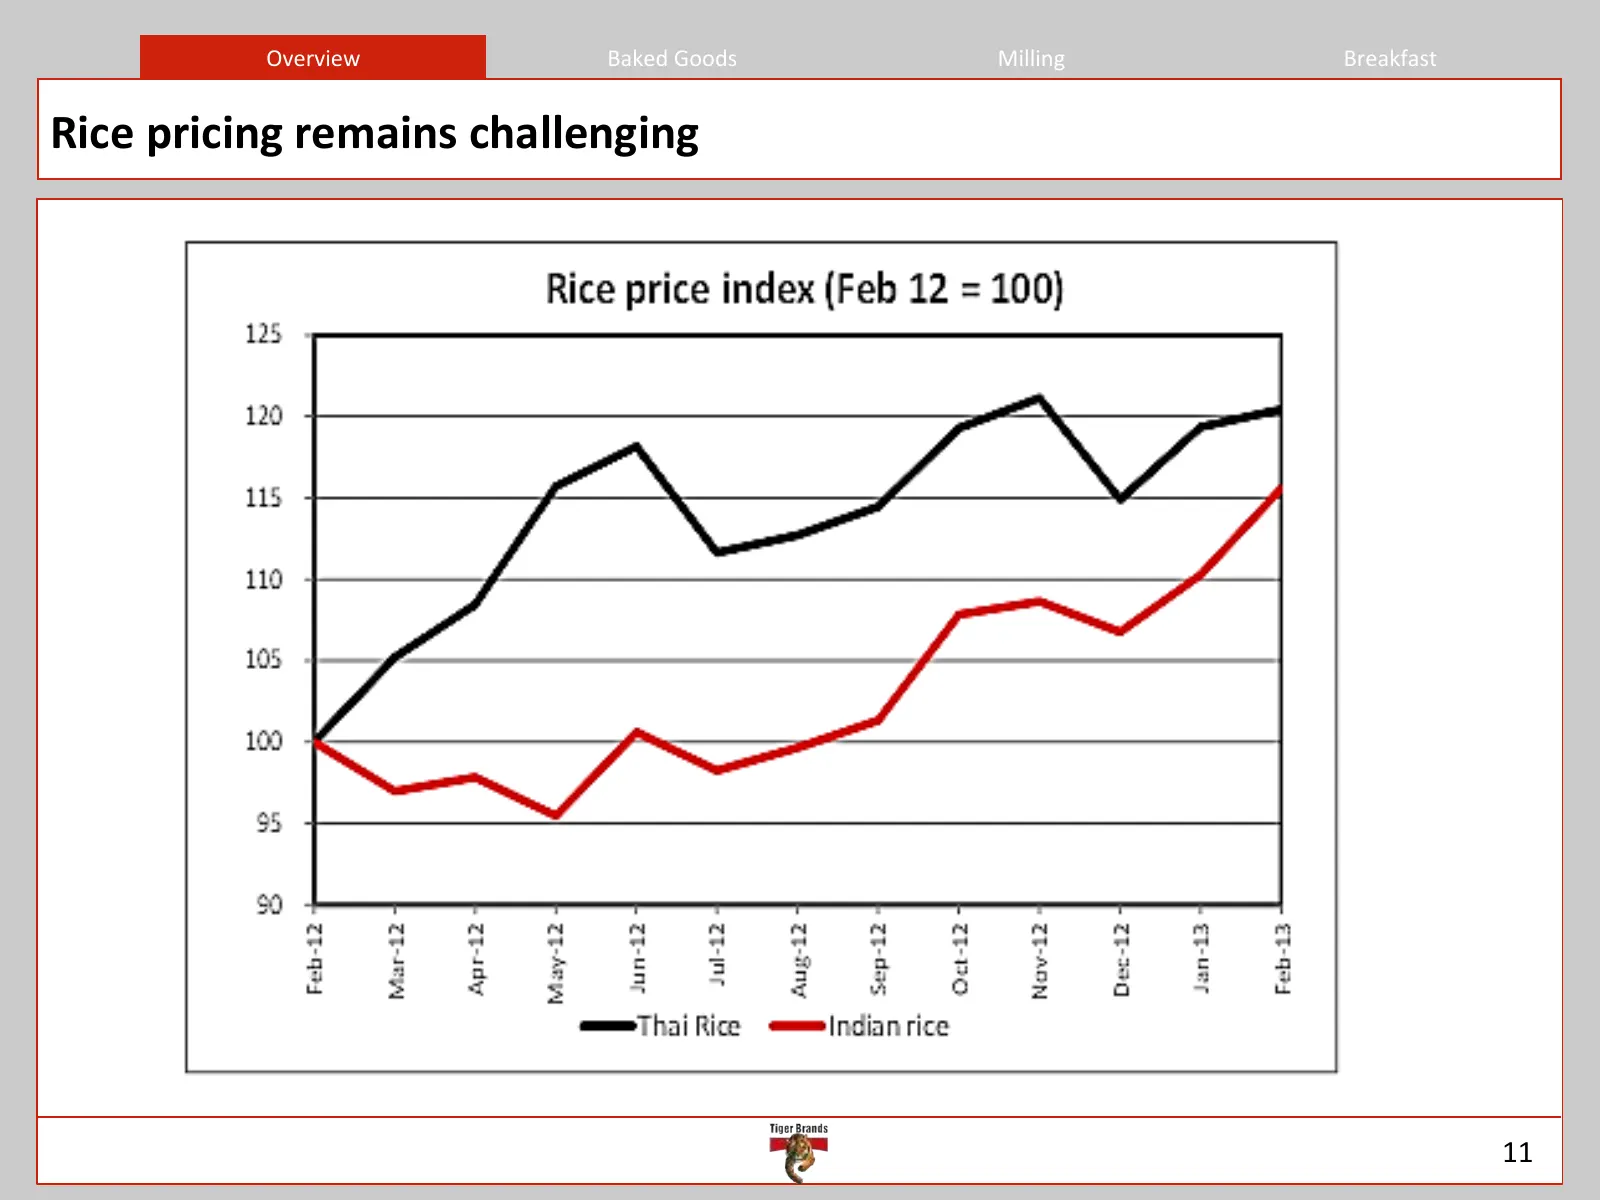
Slide 11: Rice pricing remains challenging
Overview Baked Goods Milling Breakfast Rice pricing remains challenging 11
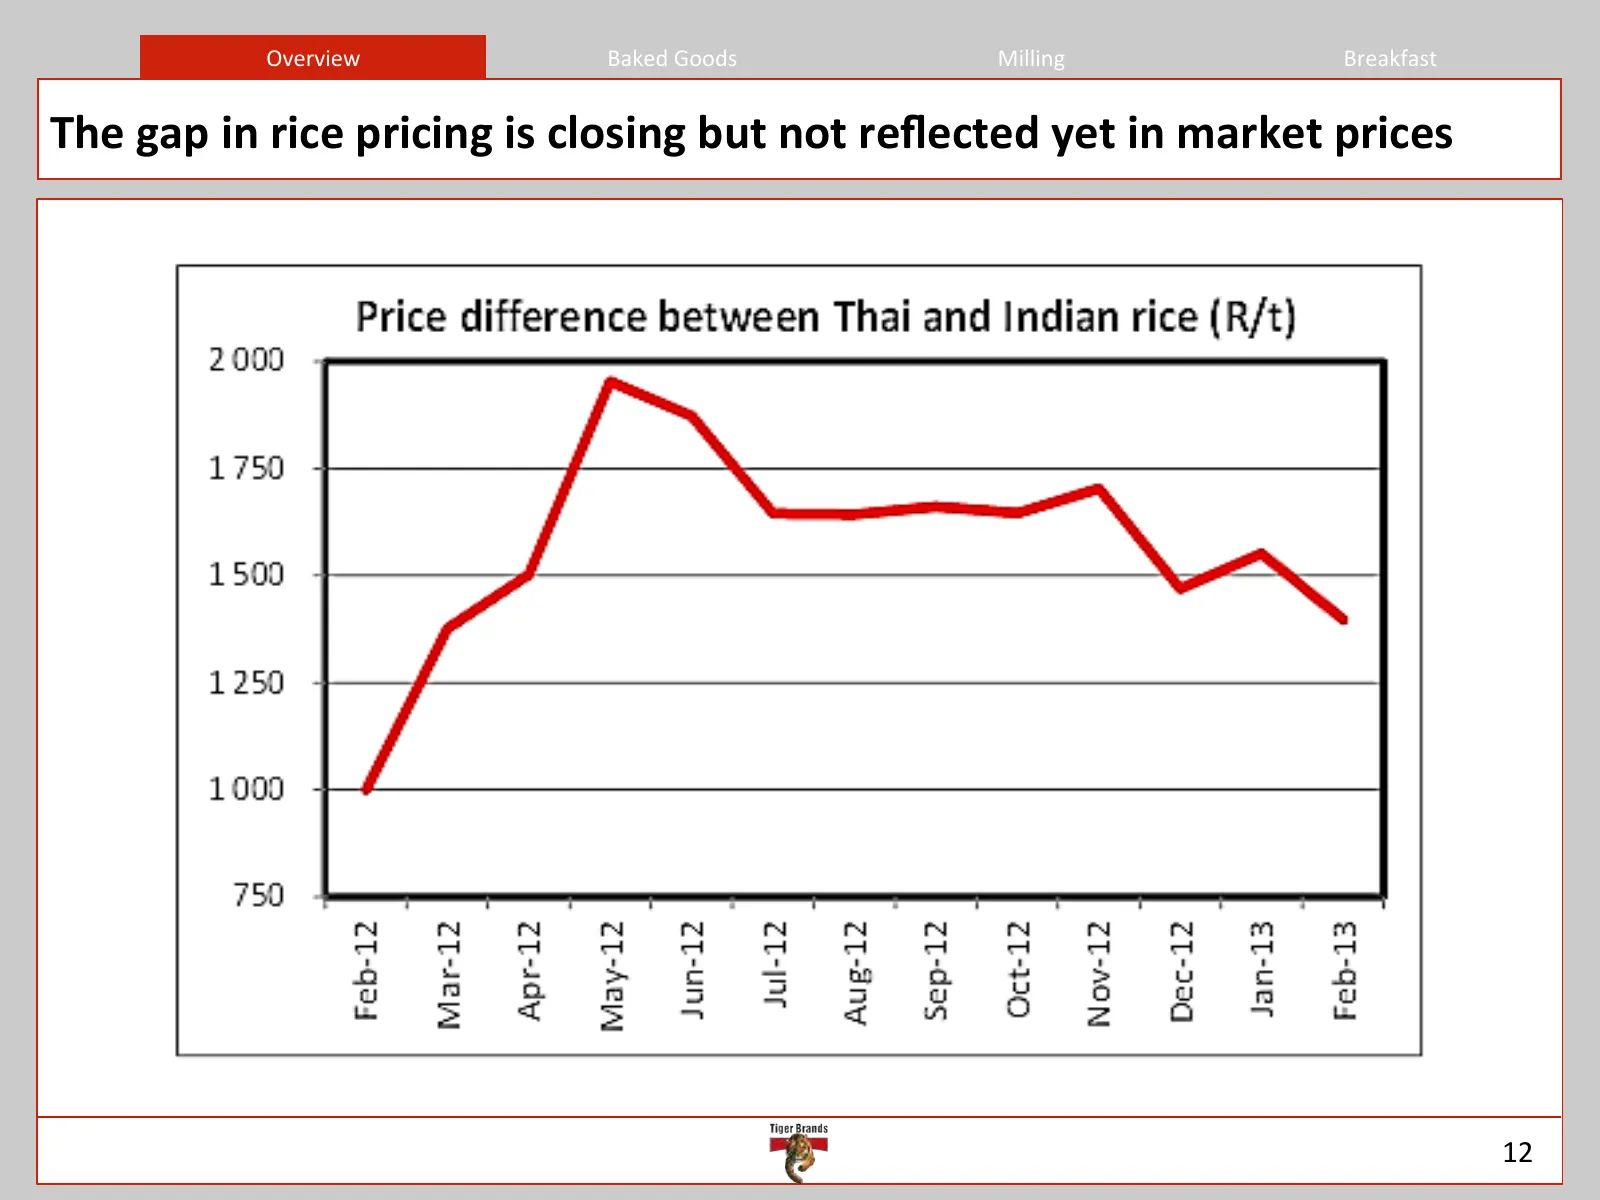
Slide 12: The gap in rice pricing is closing but not reflected yet in market prices
Overview Baked Goods Milling Breakfast The gap in rice pricing is closing but not reflected yet in market prices 12
Slide 13: How do we mitigate against a challenging environment
Overview Baked Goods Milling Breakfast How do we mi>gate against a challenging environment The progress and future intent on key ini?a?ves – Keeping the Albany locomo?ve fuelled − Enabling/Enhancement Capex − Brand Investment − Innova?on – Milling − Innova?on − Procurement efficiency – Breakfast − Inn
Slide 14: Baked Goods
Overview Baked Goods Milling Breakfast Baked Goods Gerrit le Grange Managing Execu?ve
Slide 15: Baked Goods
Baked Goods
Slide 16: Evolving into a diverse baked goods company
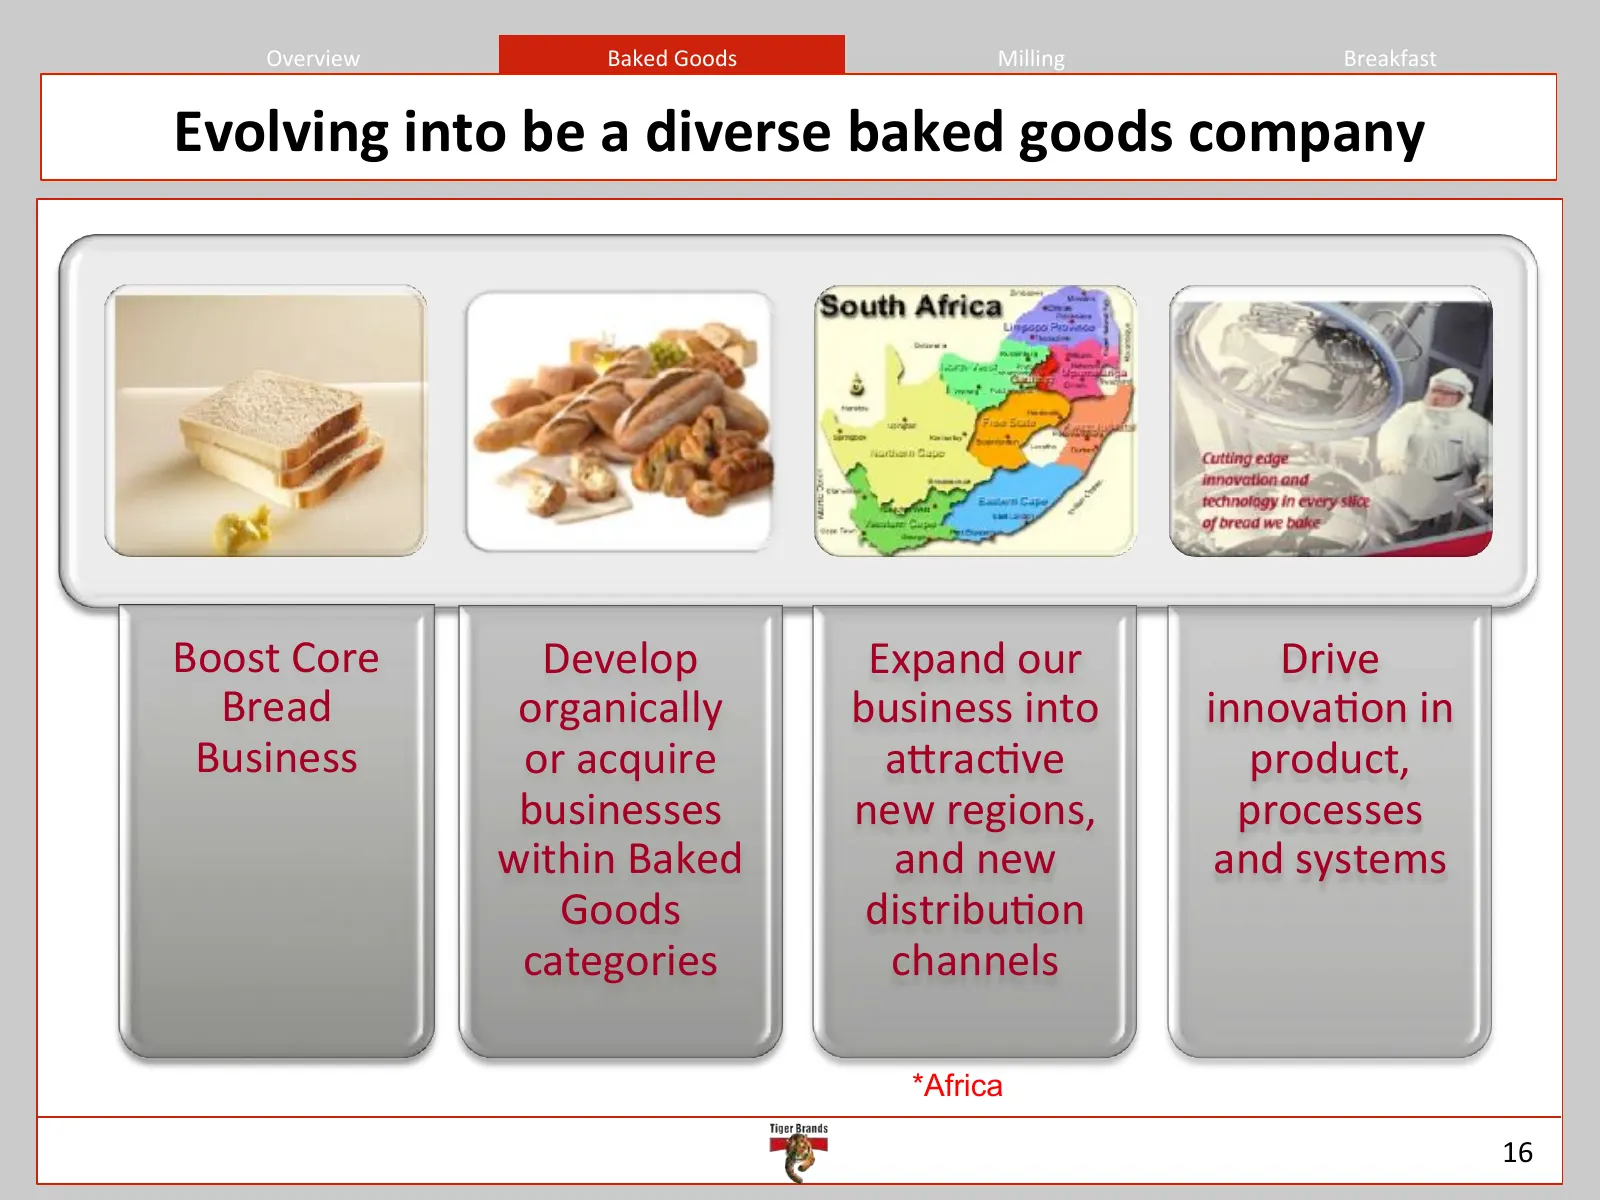
Overview Baked Goods Milling Breakfast Evolving into be a diverse baked goods company Boost Core Develop Expand our Drive Bread organically business into innova?on in Business or acquire aZrac?ve product, businesses new regions, processes within Baked and new and systems Goods distribu?on categories
Slide 17: Baked Goods market
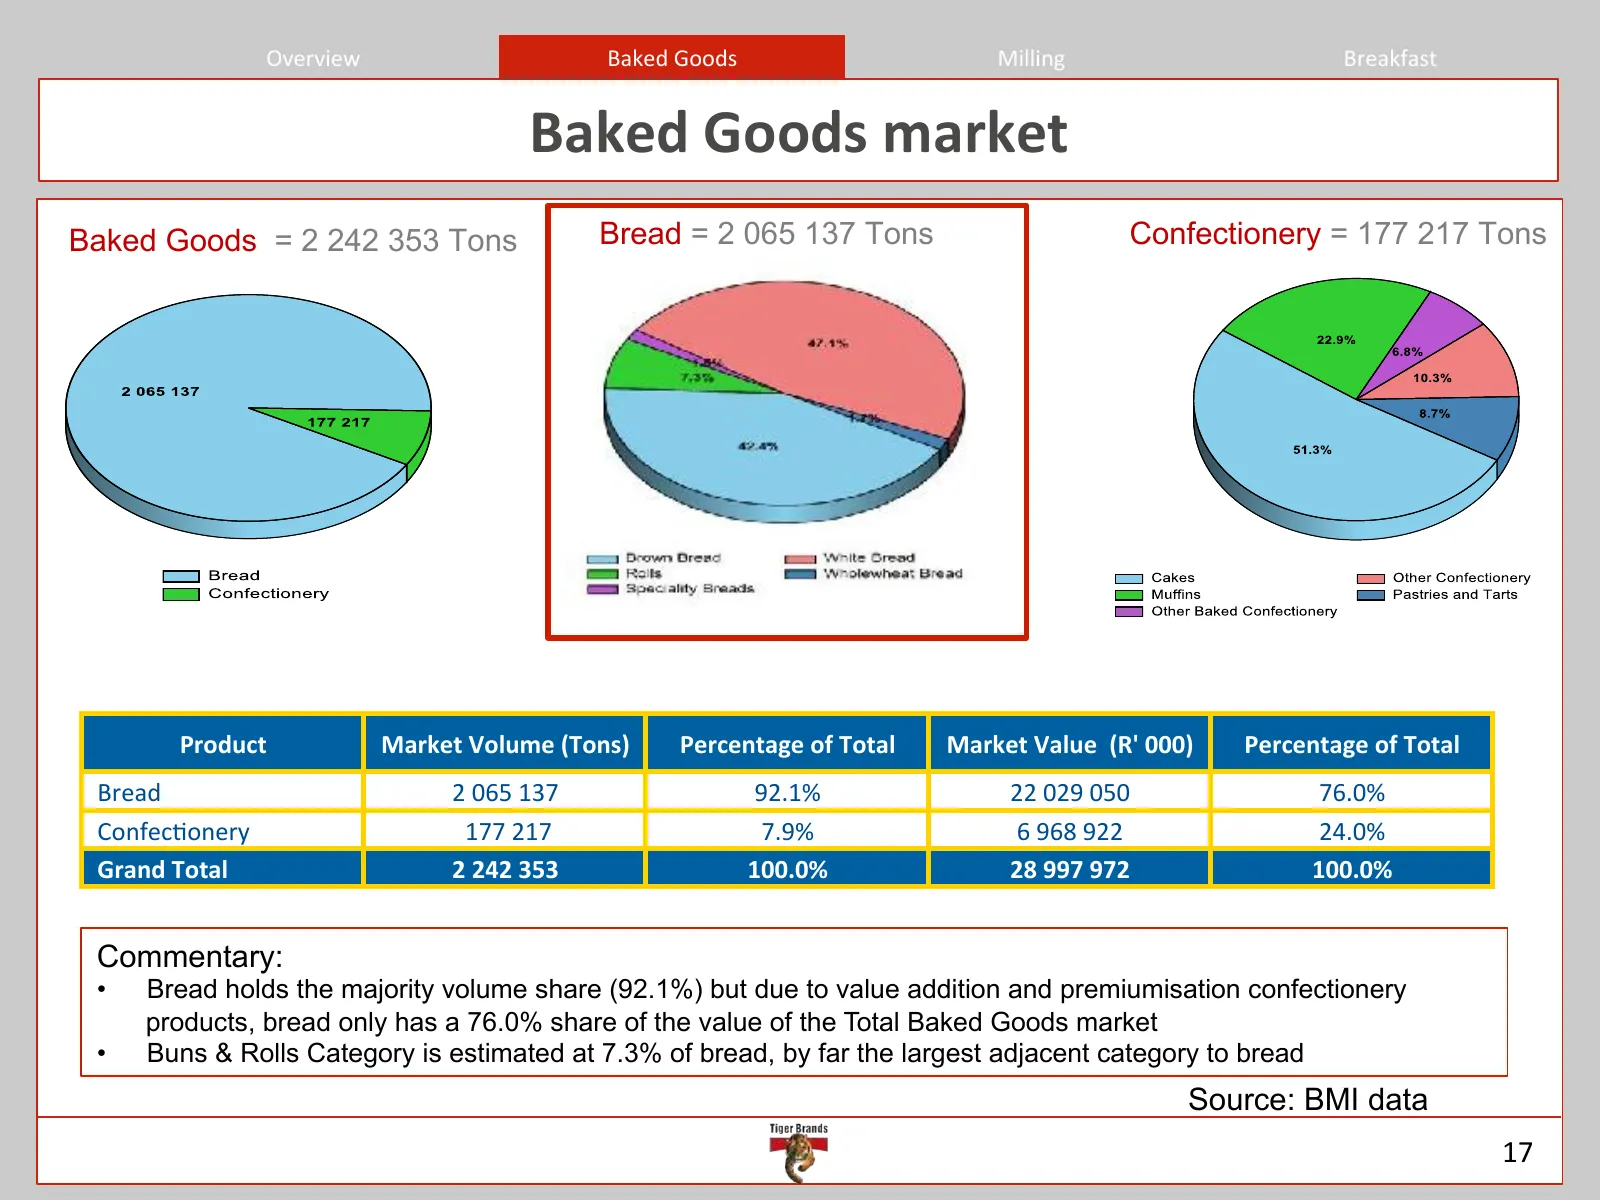
Overview Baked Goods Milling Breakfast Baked Goods market Baked Goods = 2 242 353 Tons Bread = 2 065 137 Tons Confectionery = 177 217 Tons Product Market Volume (Tons) Percentage of Total Market Value (R' 000) Percentage of Total Bread 2 065 137 92.1% 22 029 050 76.0% Confec?onery 177 217 7.9% 6 968
Slide 18: Core bread business remains healthy
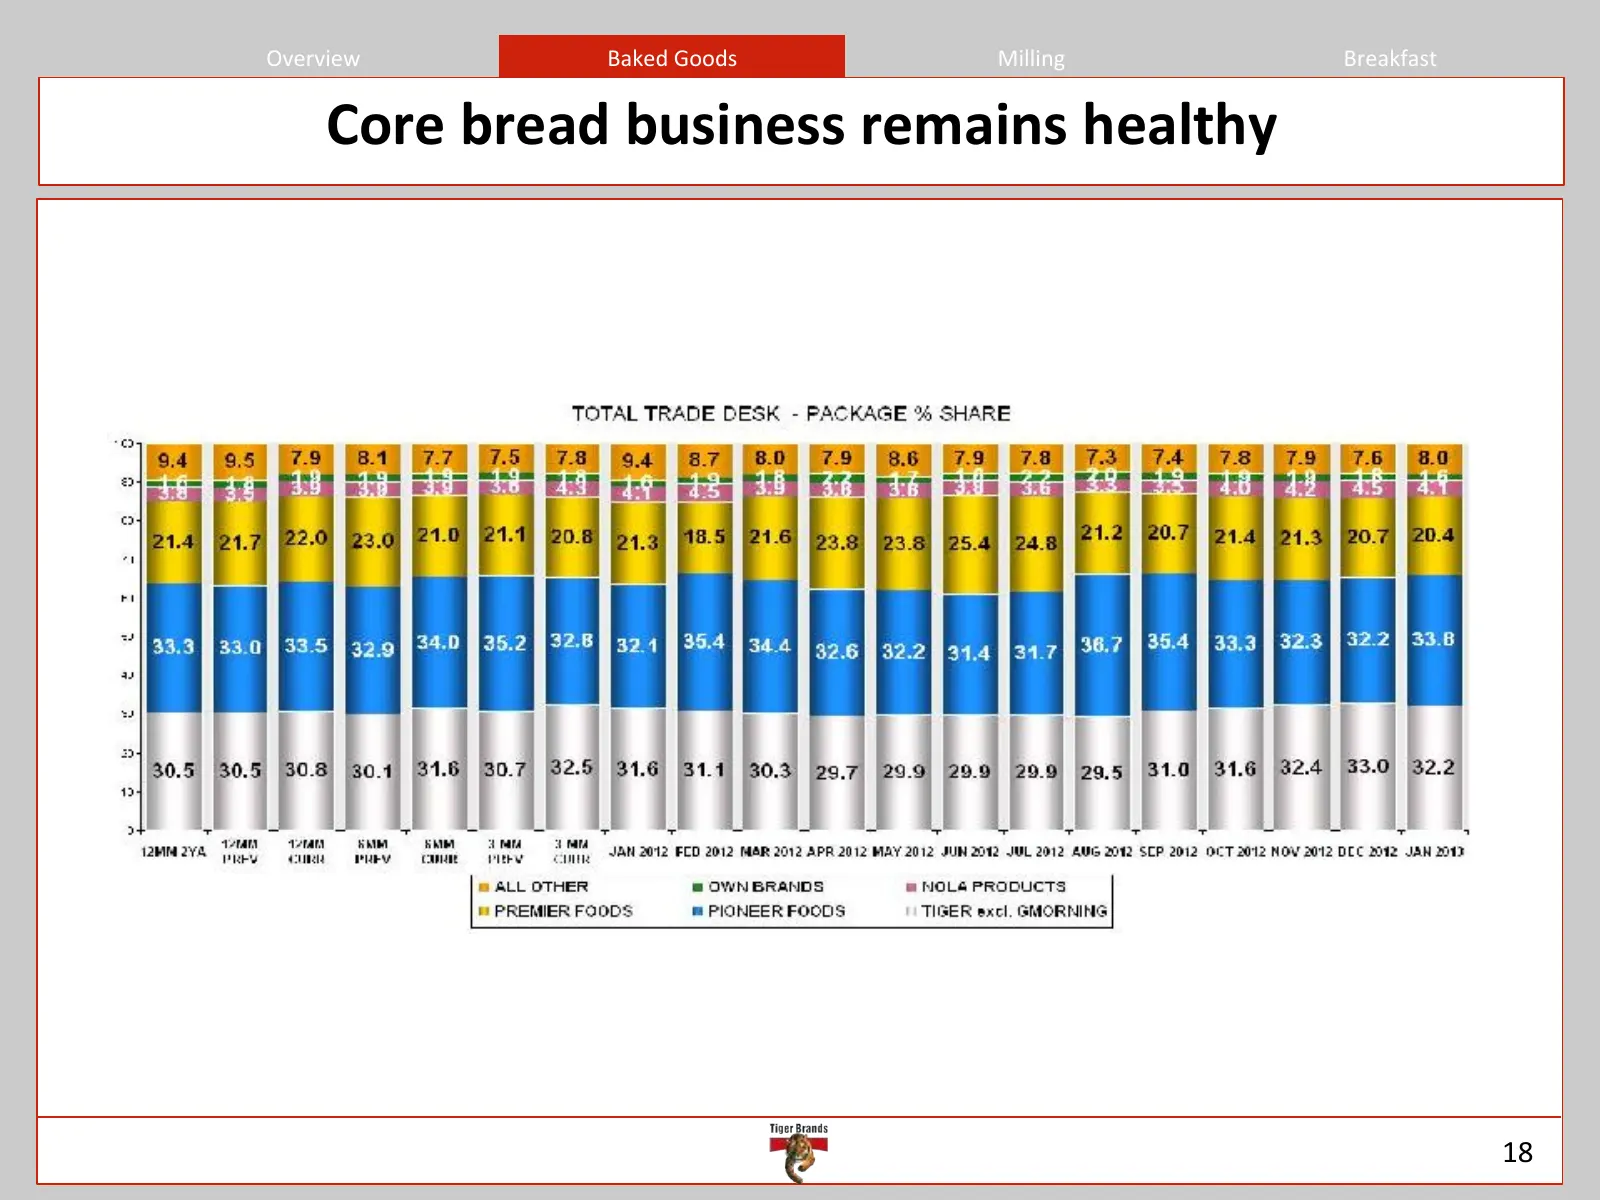
Overview Baked Goods Milling Breakfast Core bread business remains healthy 18
Slide 19: What drives core health
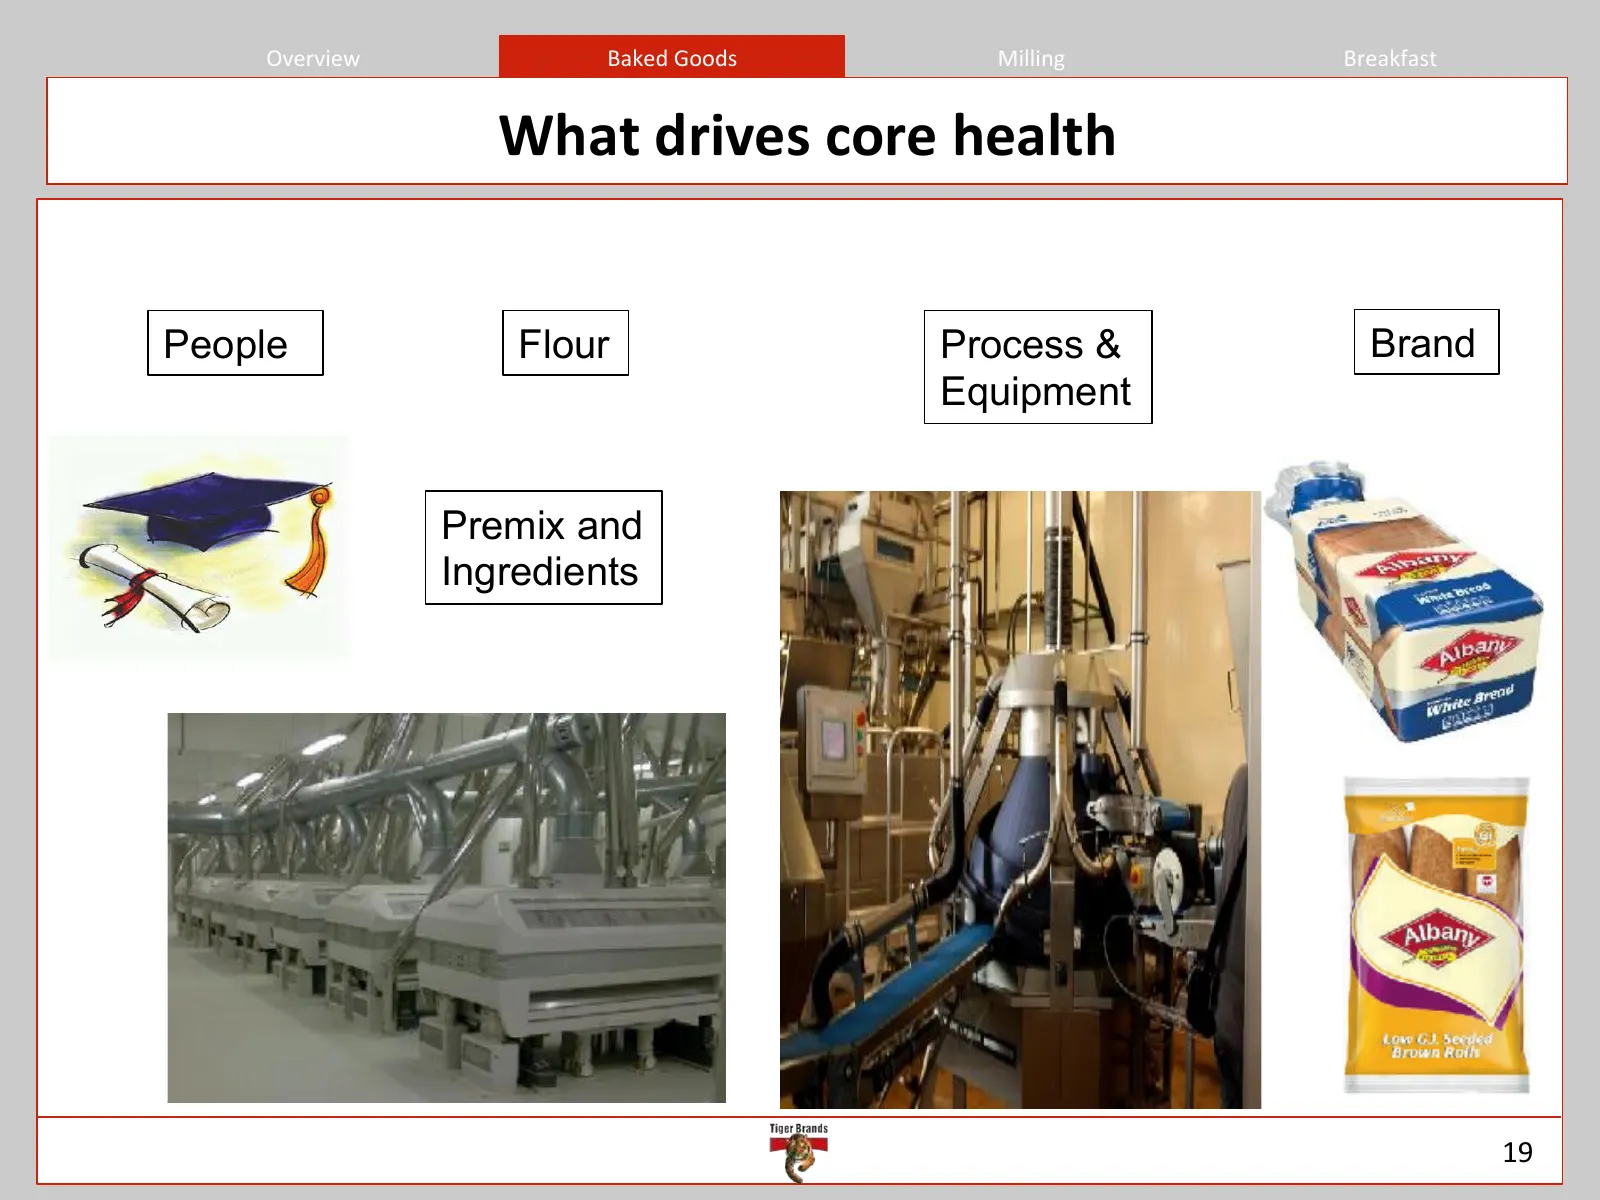
Overview Baked Goods Milling Breakfast What drives core health People Flour Process & Brand Equipment Premix and Ingredients 19
Slide 20: Investment in people
Overview Baked Goods Milling Breakfast Investment in people • Tiger Graduate Program • Tiger Manufacturing Academy • Tiger Supply Chain Academy • Customer Academy • School of Magic 20
Slide 21: Continued investment in equipment and technology
Overview Baked Goods Milling Breakfast Con>nued investment in equipment and technology • Reinvestment in manufacturing facili?es • Enhancement of baking capacity in KZN to enable growth – Hence PMB facility • Interna?onal Enzyme and Ingredients partnerships 21
Slide 22: World class manufacturing – PMB Bakery
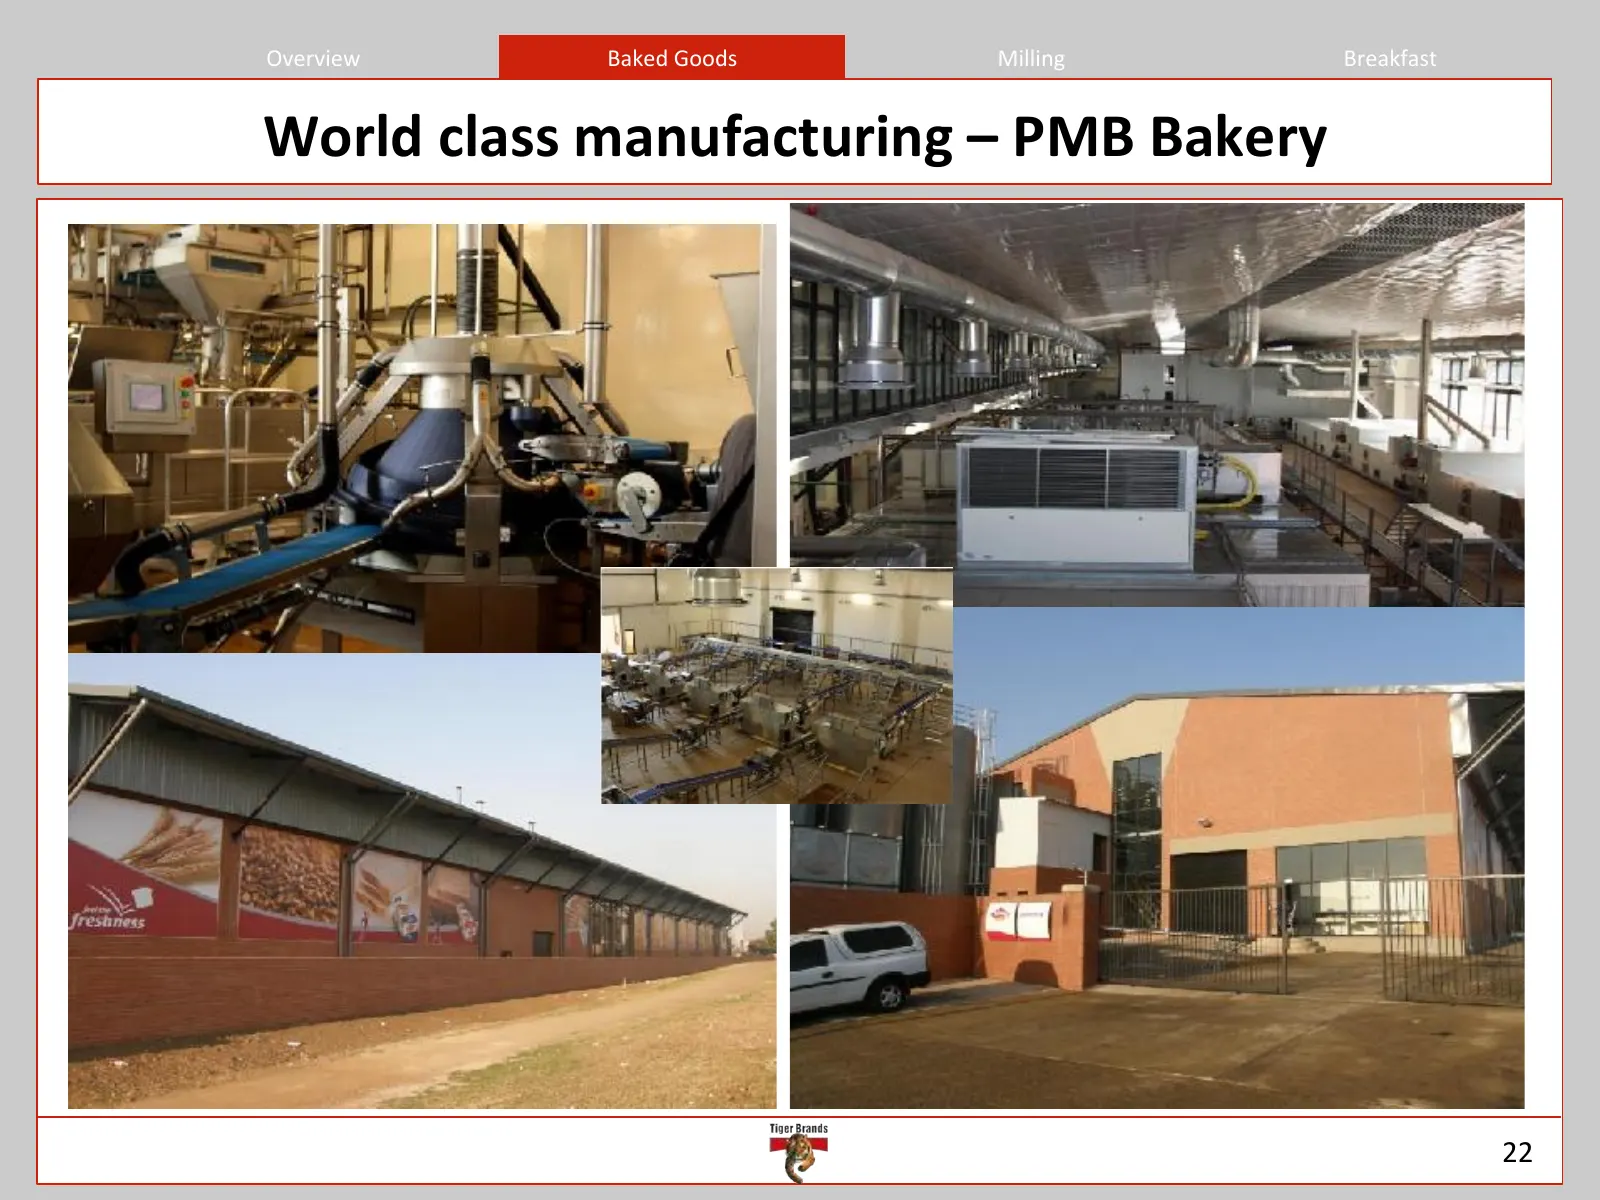
Overview Baked Goods Milling Breakfast World class manufacturing – PMB Bakery 22
Slide 23: Brand investment
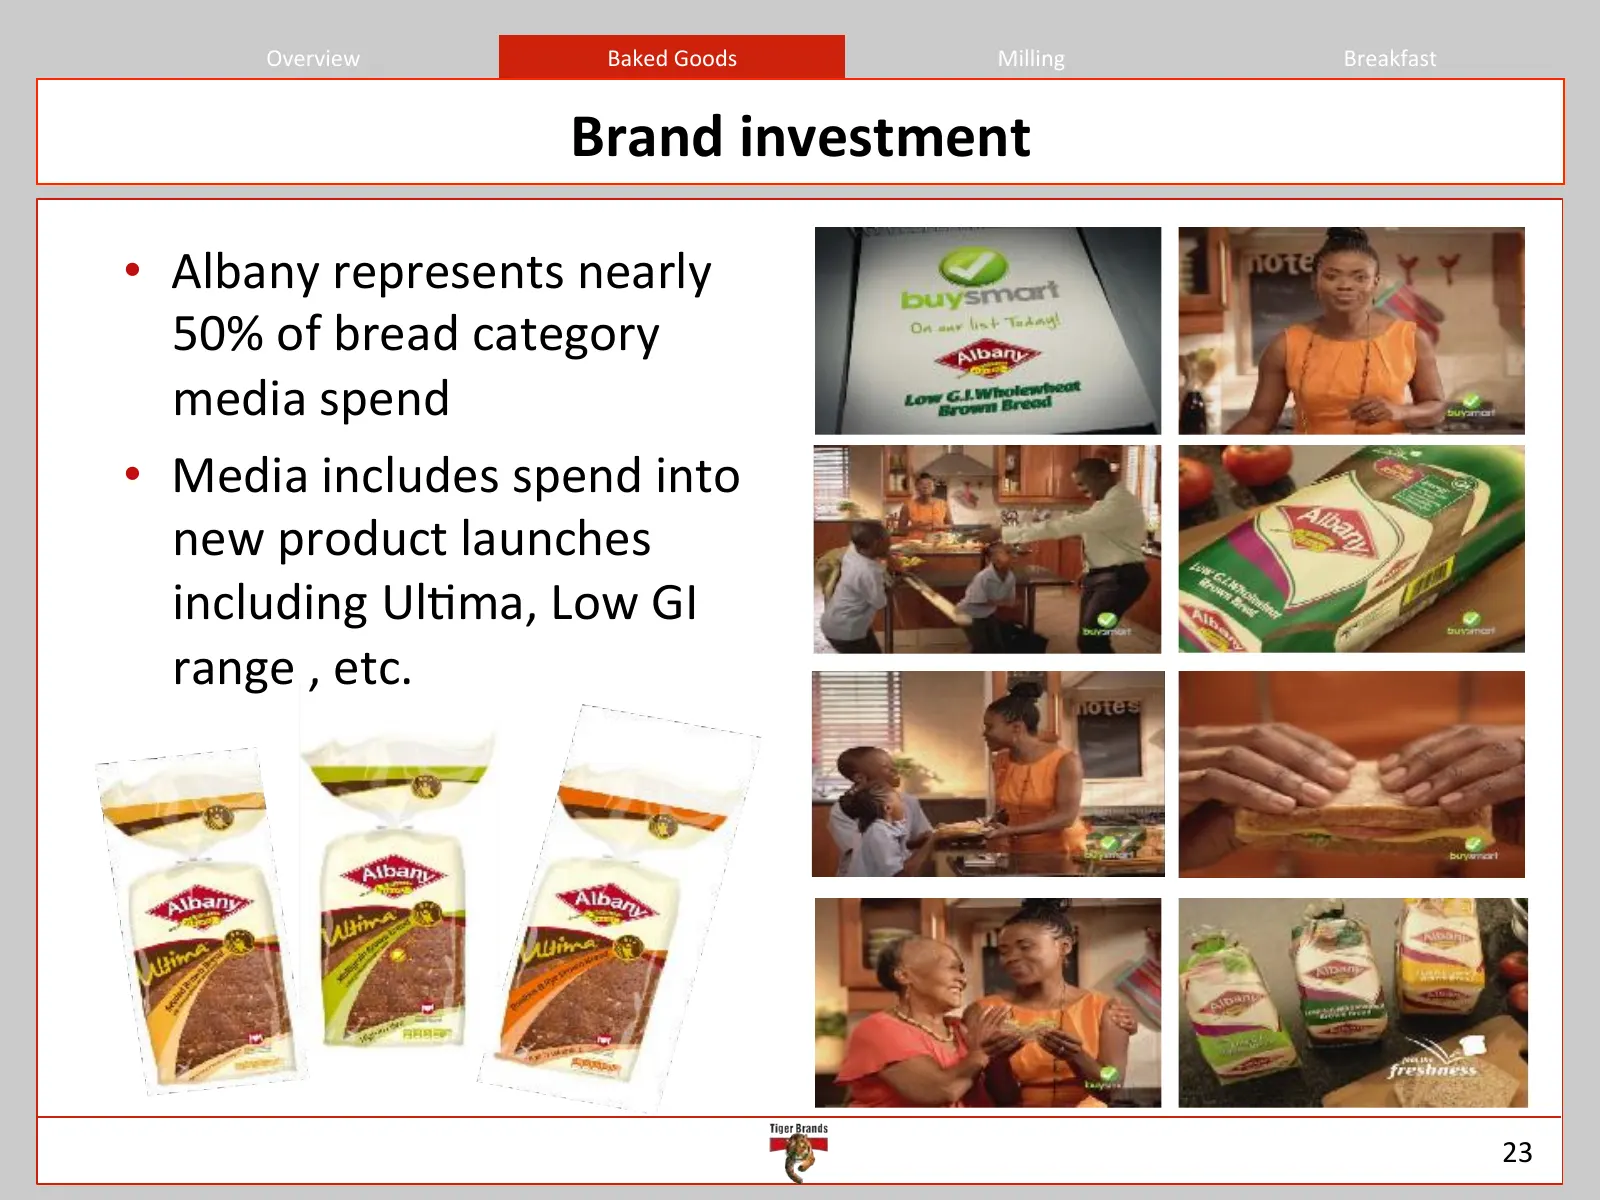
Overview Baked Goods Milling Breakfast Brand investment • Albany represents nearly 50% of bread category media spend • Media includes spend into new product launches including Ul?ma, Low GI range , etc. 23
Slide 24: Expansion into adjacent categories Buns and Rolls
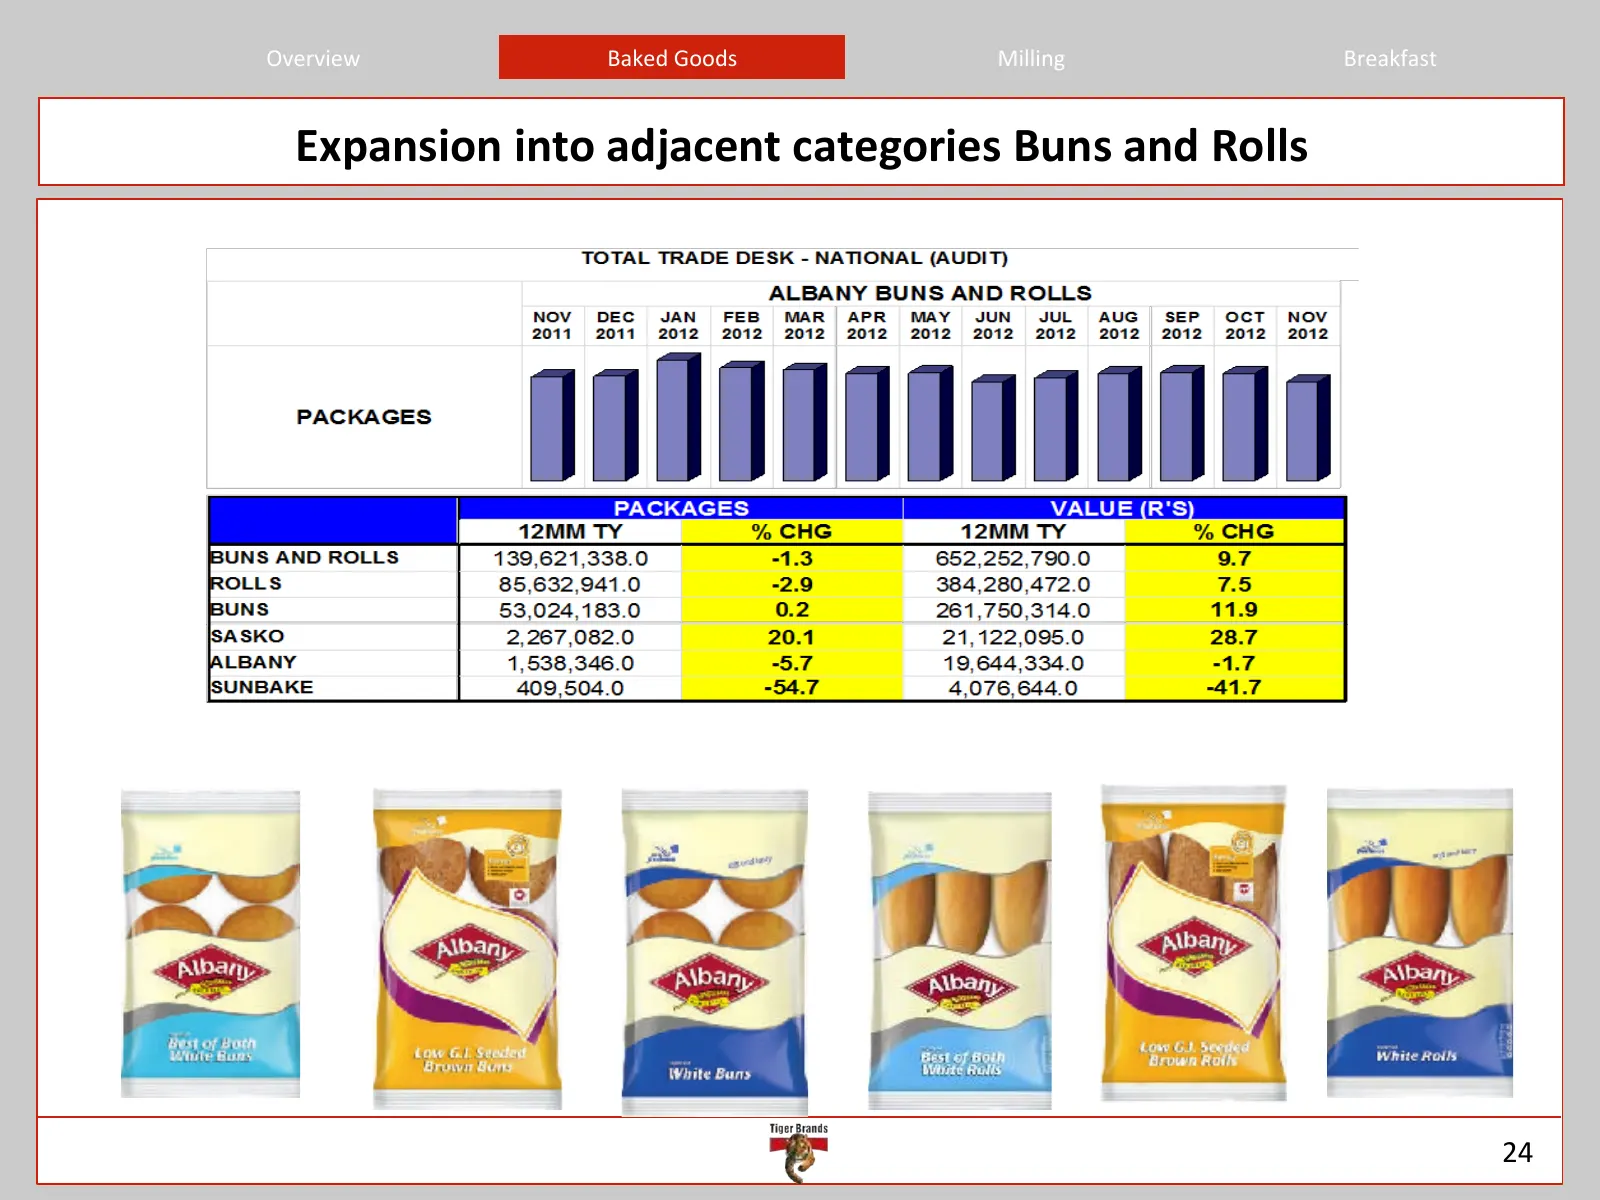
Overview Baked Goods Milling Breakfast Expansion into adjacent categories Buns and Rolls 24
Slide 25: Transforming Baking into a diversified Baked Goods business
Overview Baked Goods Milling Breakfast Ul?mately the strategy is to transform Tiger’s current Baking Business into a diversified Baked Goods business. 25
Slide 26: Milling
Overview Baked Goods Milling Breakfast Milling Craig Manning Managing Execu?ve
Slide 27: Ace Leading Maize Innovation
Ace Leading Maize Innova>on
Slide 28: Ace has a history of leading innovation in the maize category
Ace has a History of Leading Innova>on in the Maize Category • Played a leading role in the migra?on from Special Maize in the urban areas to Super post deregula?on in the 1990’s • Differen>ated branded product proposi?on to a consistent finer and whiter product based on consumer insight into the top
Slide 29: Ace has a history of leading innovation in the maize category
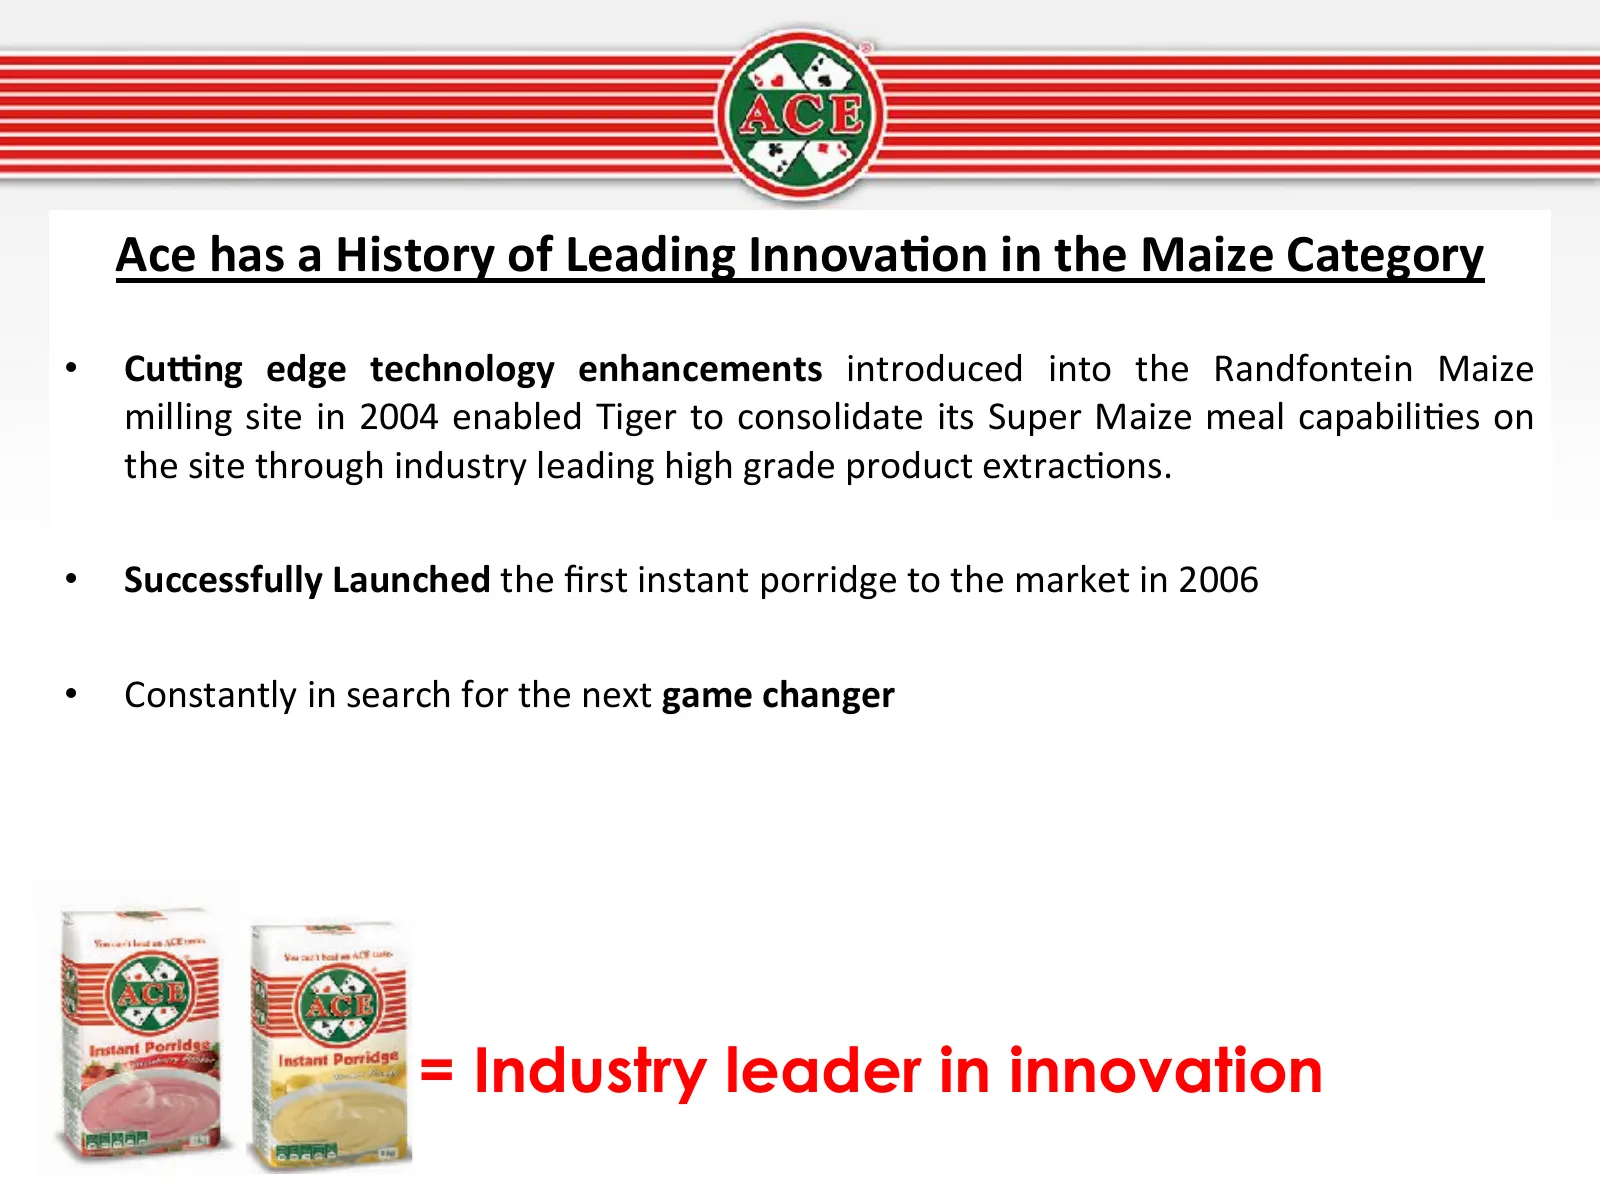
Ace has a History of Leading Innova>on in the Maize Category • Cuhng edge technology enhancements introduced into the Randfontein Maize milling site in 2004 enabled Tiger to consolidate its Super Maize meal capabili?es on the site through industry leading high grade product extrac?ons. • Successfull
Slide 30: Industry leader in consumer understanding
Ace Super Maize • Currently working with our technology partners to: – Further enhance our product consistency – Enable our core product proposi>on to bejer meet specific geographic preferences – Defend against commodi>sa>on through quality enhancements based on superior consumer insights =Industry l
Slide 31: Ace Super Maize about to launch the next generation
Ace Super Maize about to launch the next genera>on • Through constant scanning we uncovered a major revival in maize consump?on in the Venezuelan and Columbian markets: – Human consump?on in the area ager many years of decline has risen from 28kg per capita to over 44 kg per capita – The significant
Slide 32: Ace launch: Functional differentiation to broaden usage and appeal
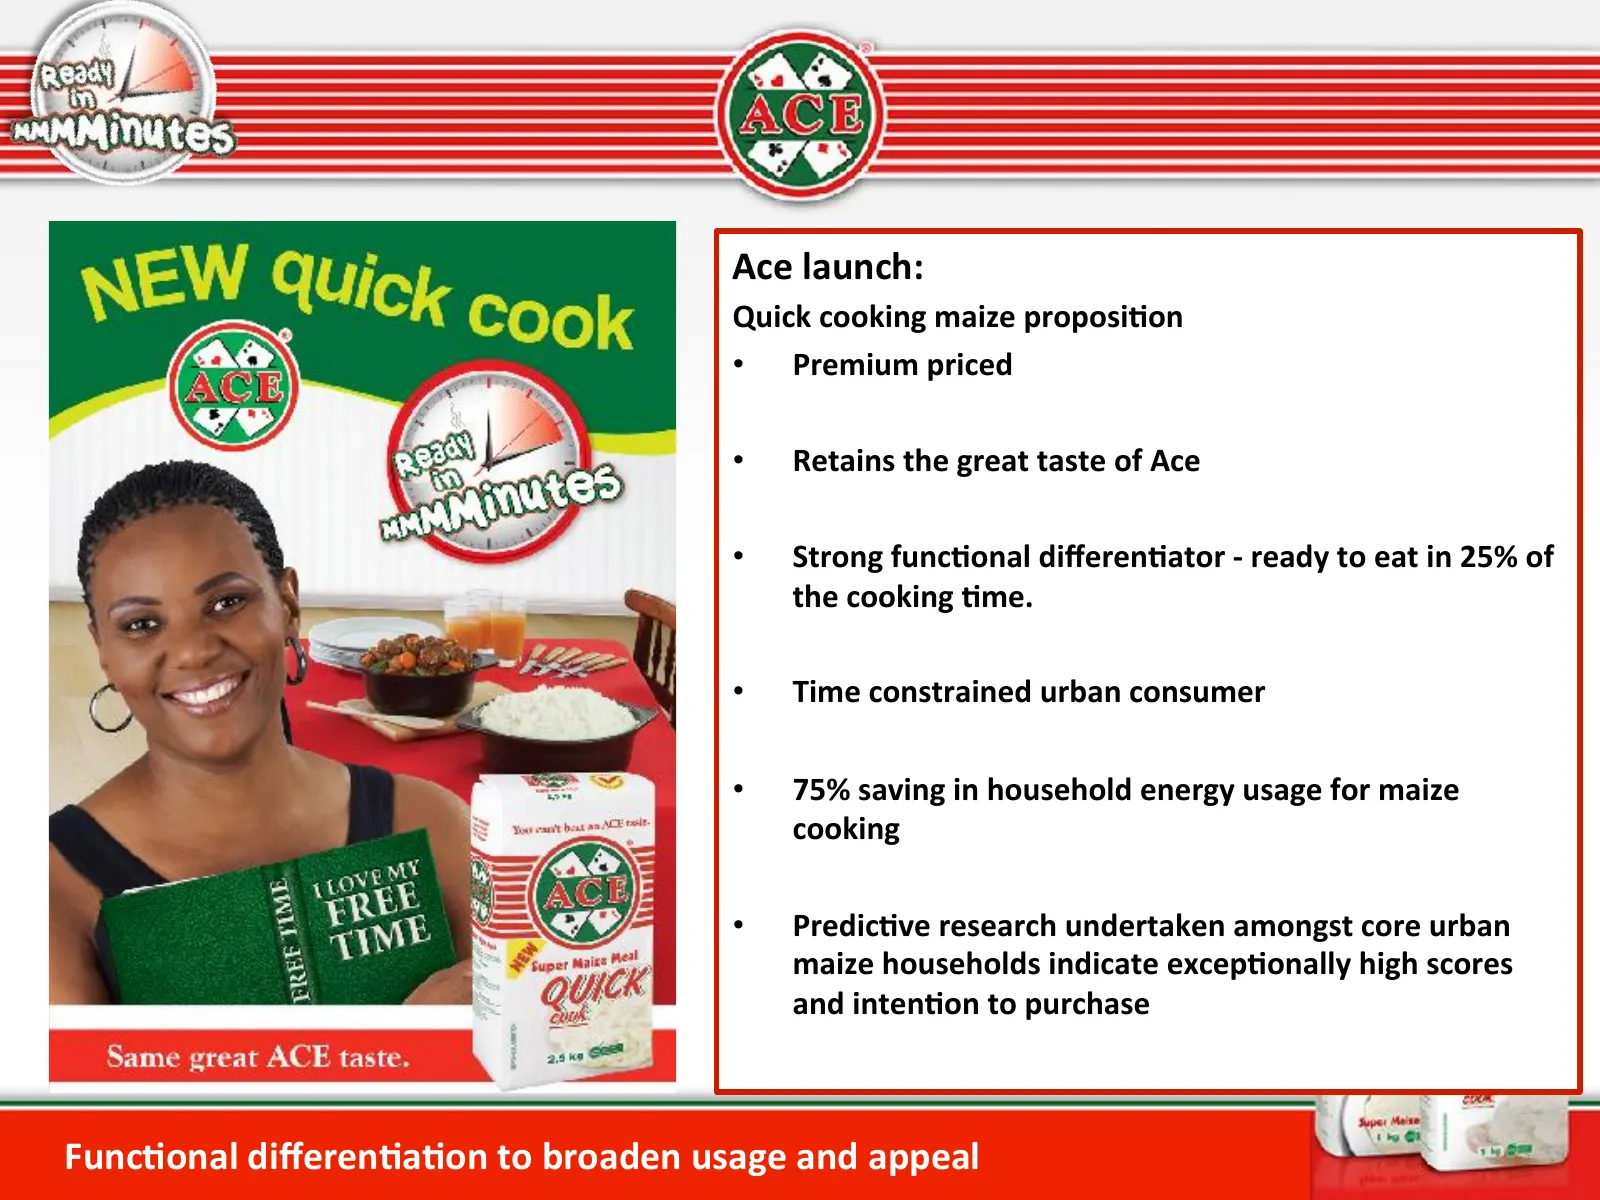
Ace launch: Quick cooking maize proposi>on • Premium priced • Retains the great taste of Ace • Strong func>onal differen>ator -‐ ready to eat in 25% of the cooking >me. • Time constrained urban consumer • 75% saving in household energy usage for maize cooking • Predic>ve research undertaken amongst
Slide 33: Investment in pilot plant capability at maize facility
• Investment of over R50 million in developing pilot plant capability at our maize facility • A world first for Buhler, our milling technology partner. • An integrated but adjacent process to our exis>ng milling capabili>es at our Randfontein maize unit. • Increases versa>lity of the base maize produ
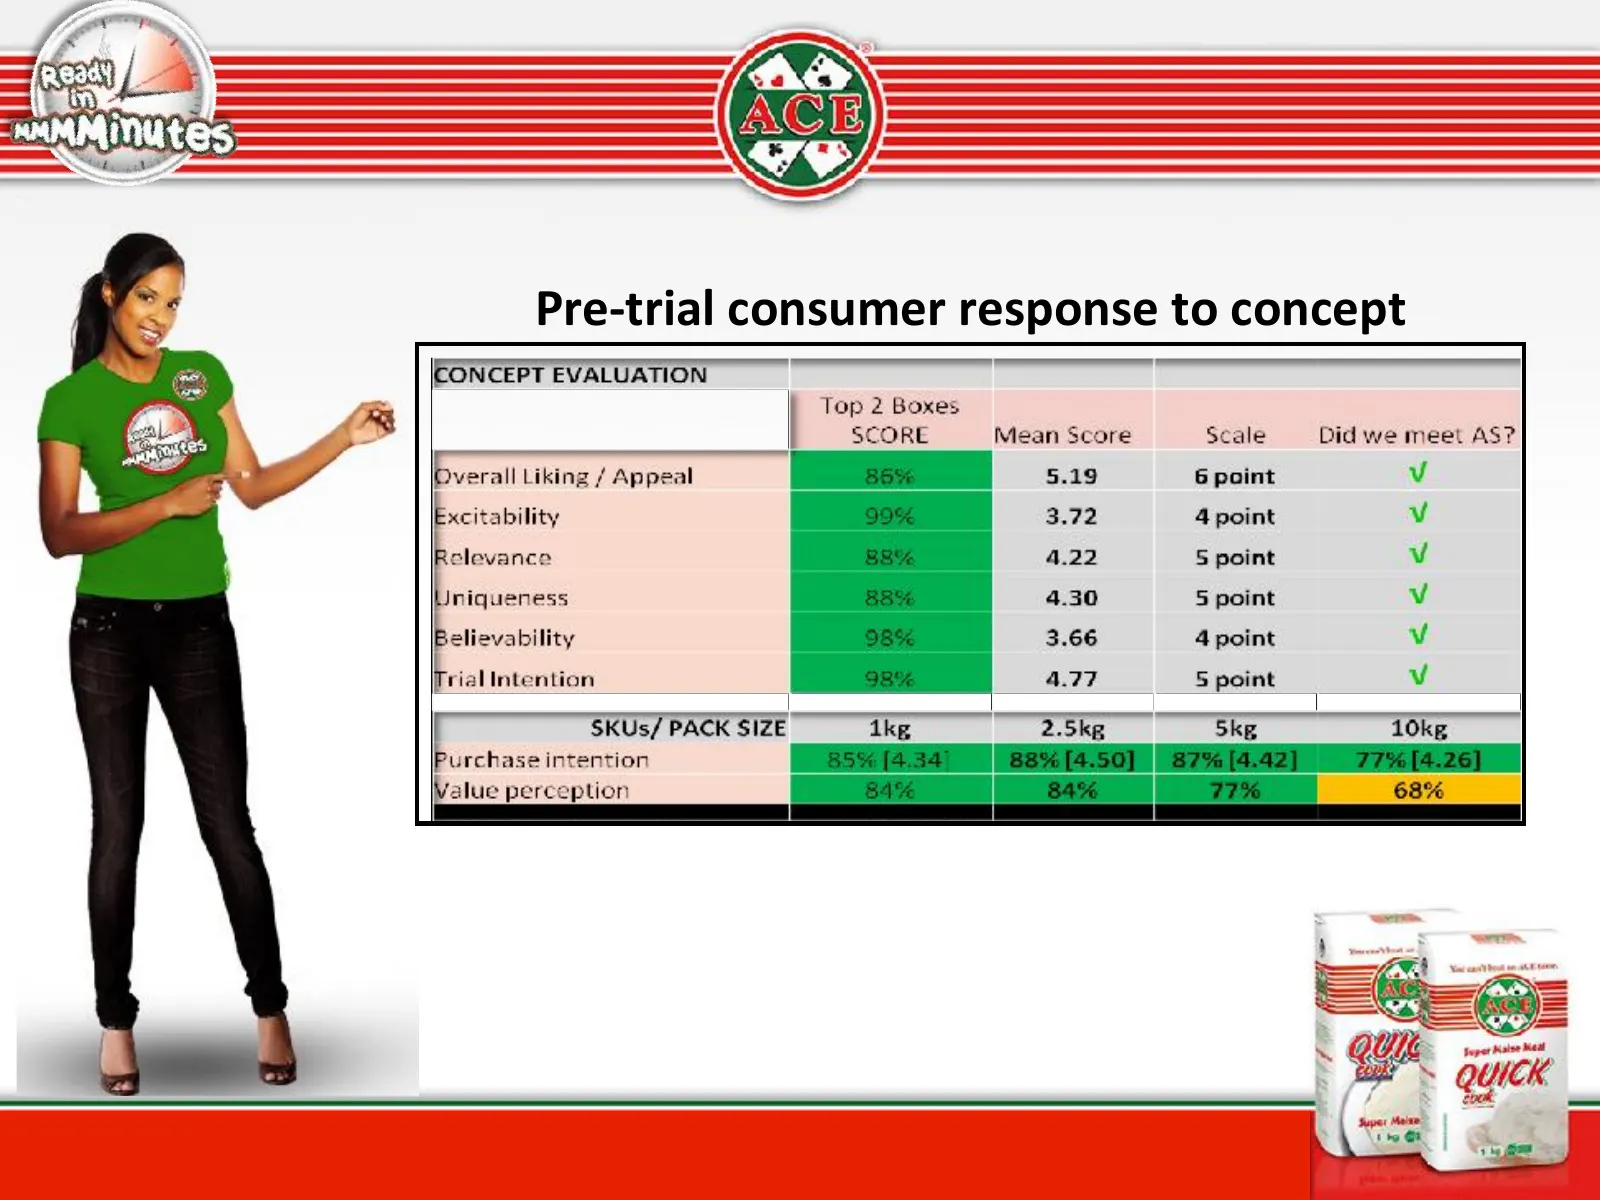
Slide 34: Pre-trial consumer response to concept
Pre-‐trial consumer response to concept
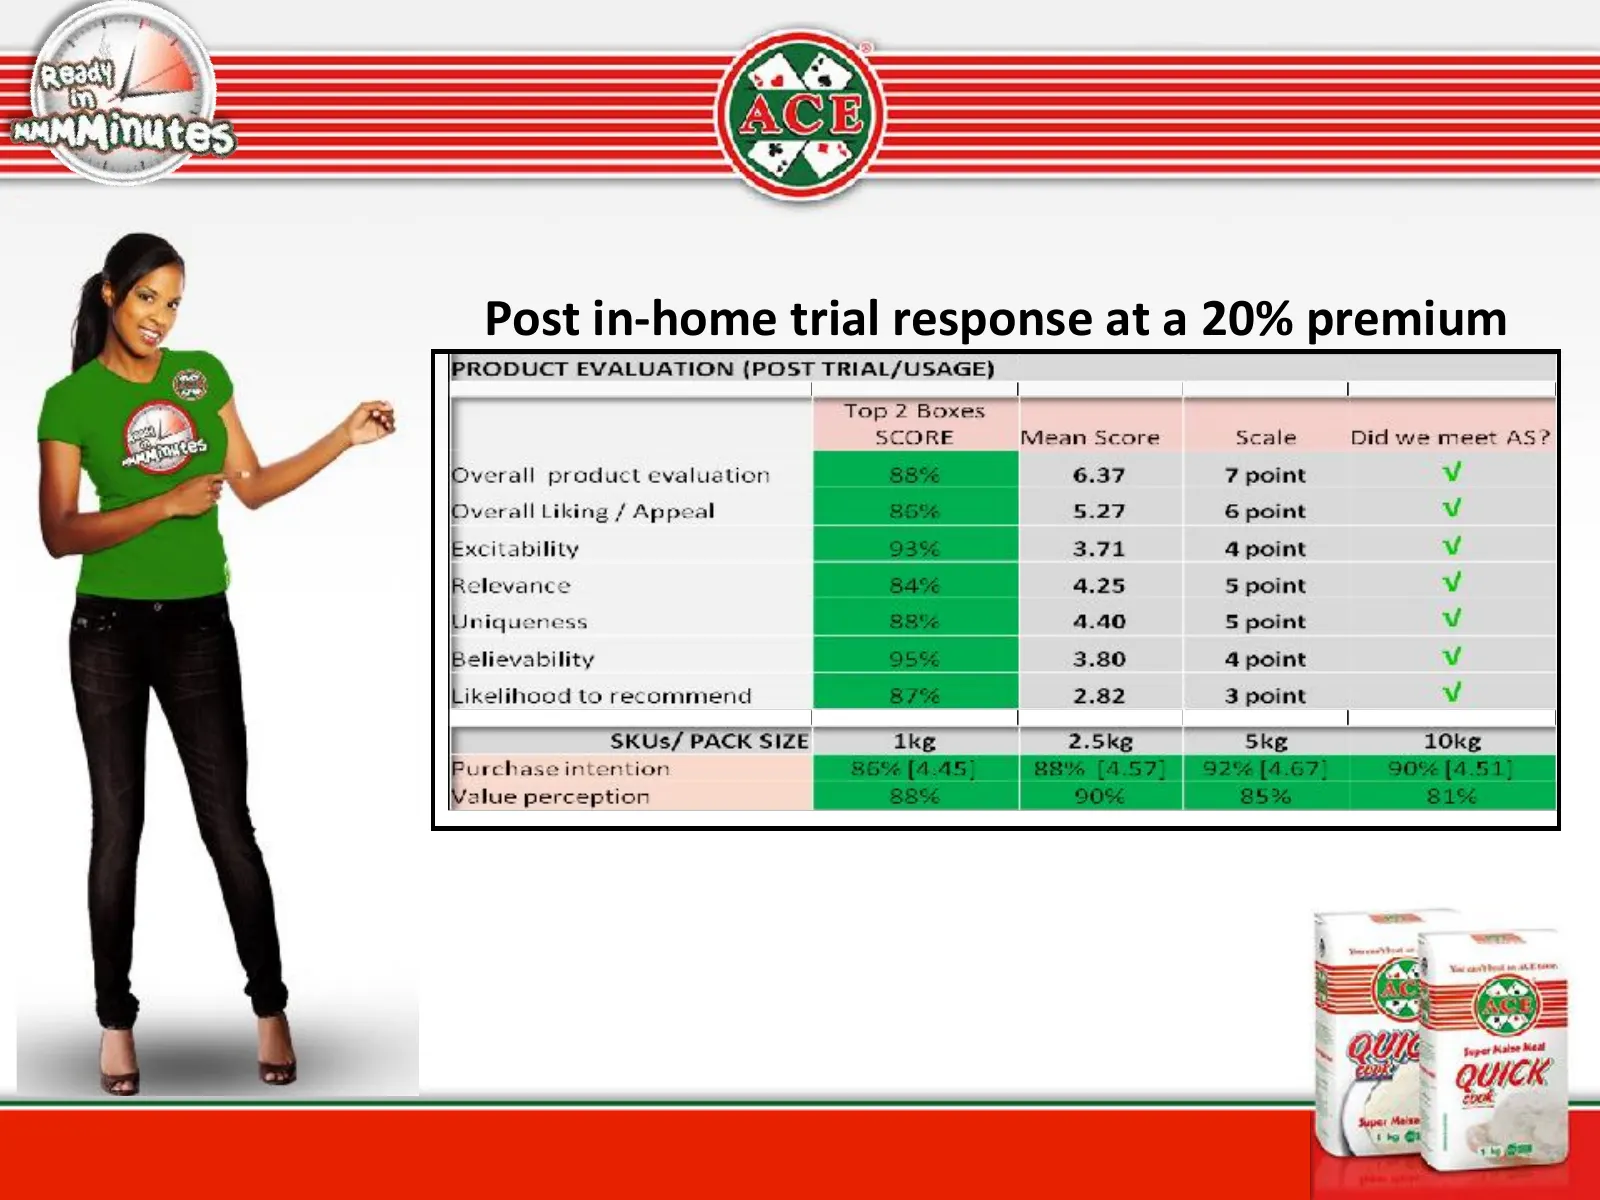
Slide 35: Post in-home trial response at a 20% premium
Post in-‐home trial response at a 20% premium
Slide 36: Golden Cloud
Slide 37: Flour Volume Contribution
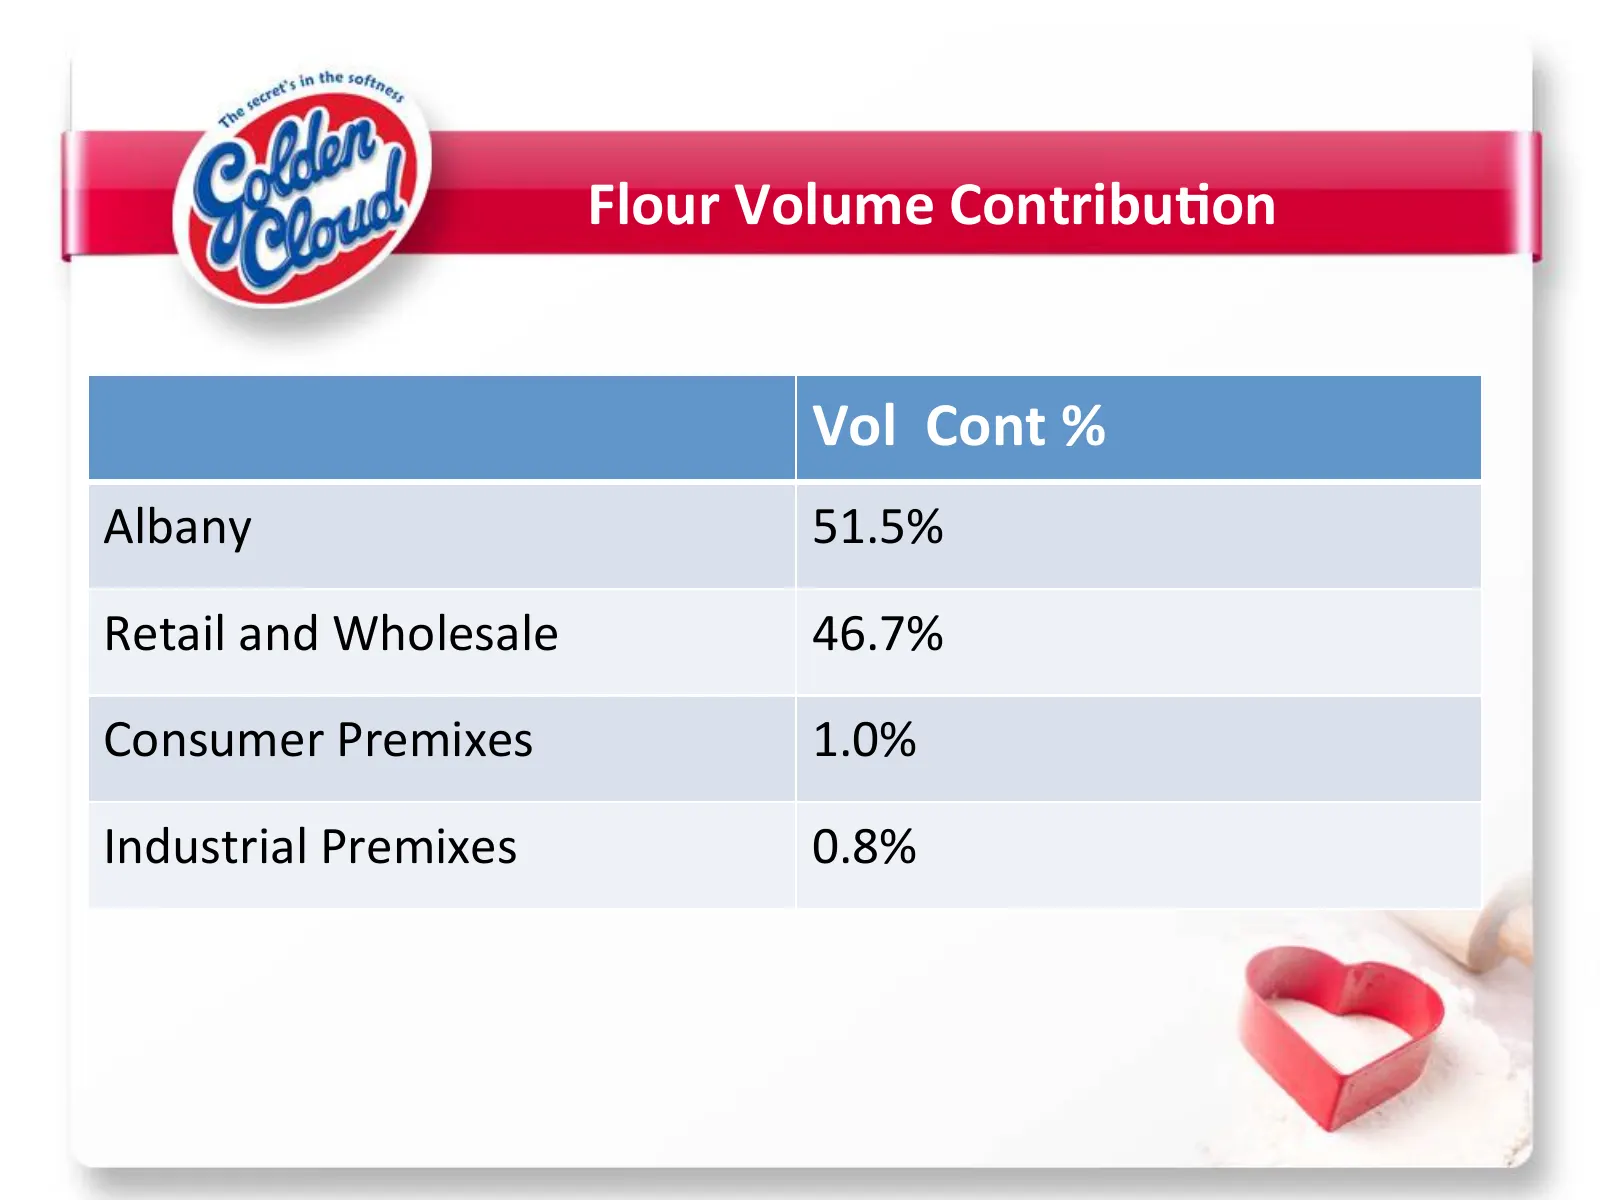
Flour Volume Contribu>on Vol Cont % Albany 51.5% Retail and Wholesale 46.7% Consumer Premixes 1.0% Industrial Premixes 0.8%
Slide 38: Realisations
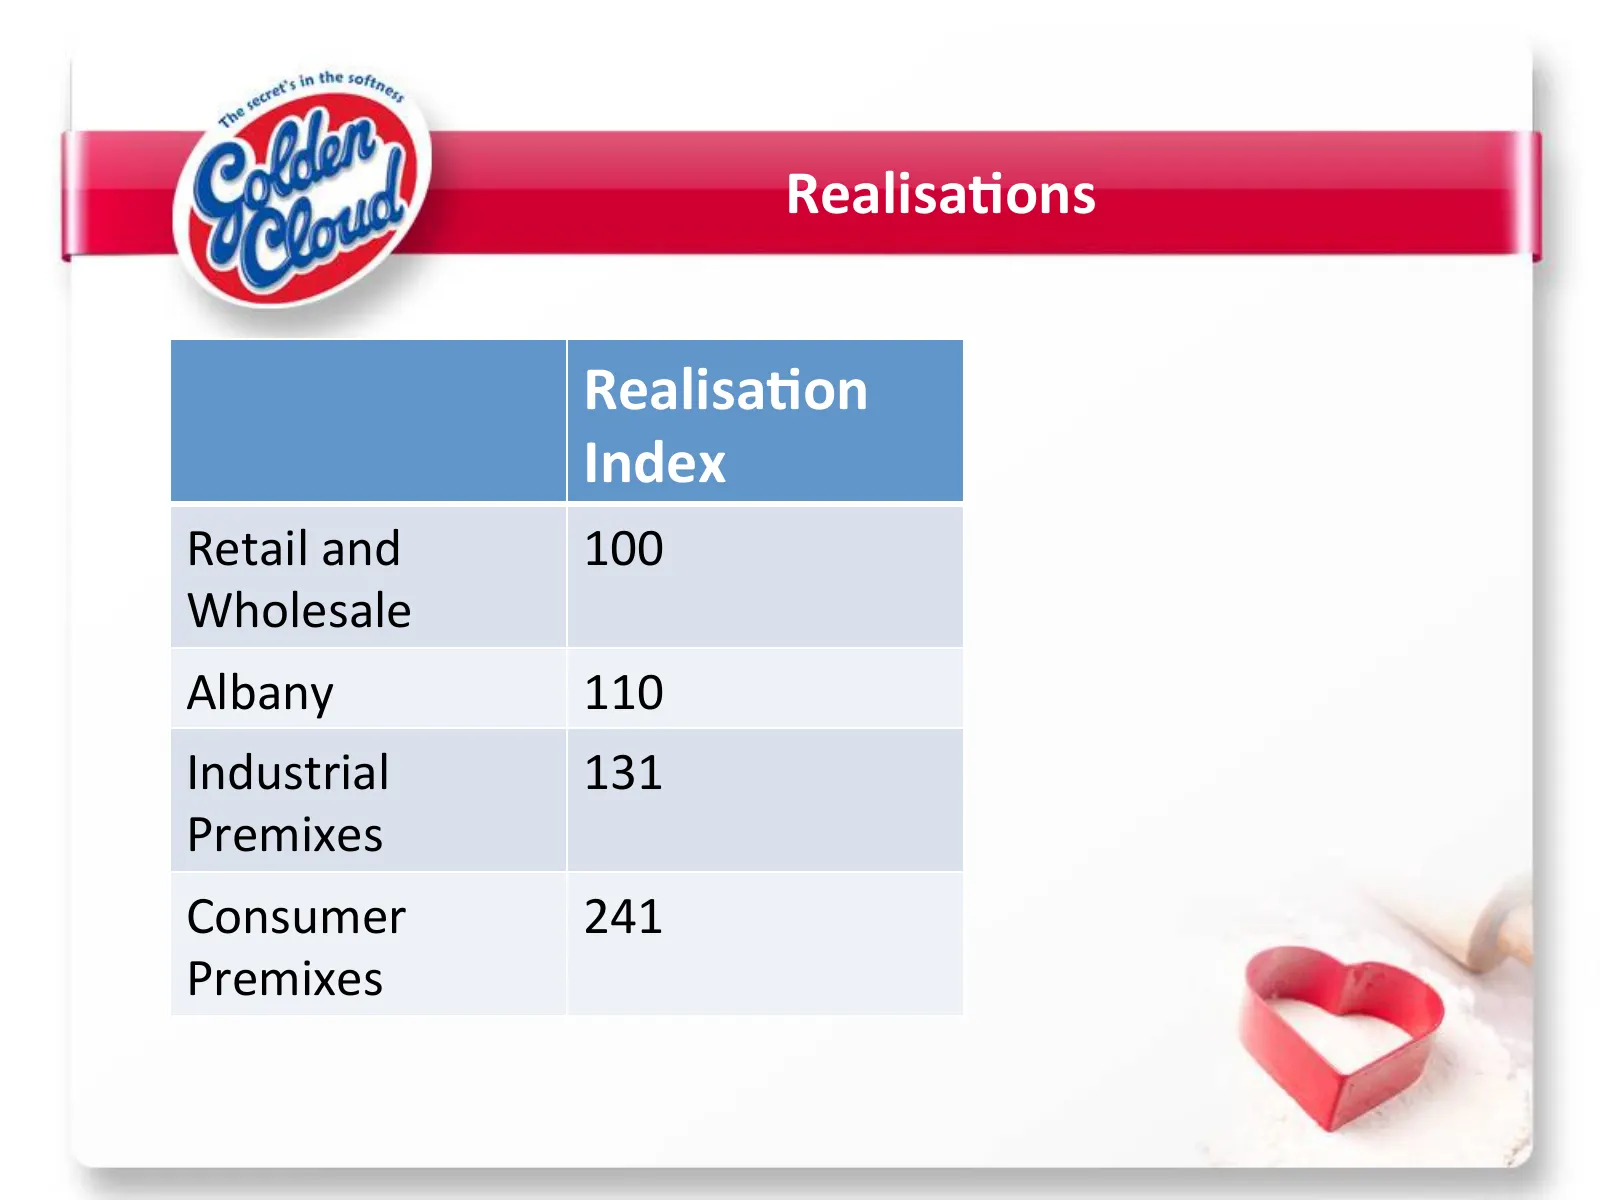
Realisa>ons Realisa>on Index Retail and 100 Wholesale Albany 110 Industrial 131 Premixes Consumer 241 Premixes
Slide 39: Grist/Import Origins
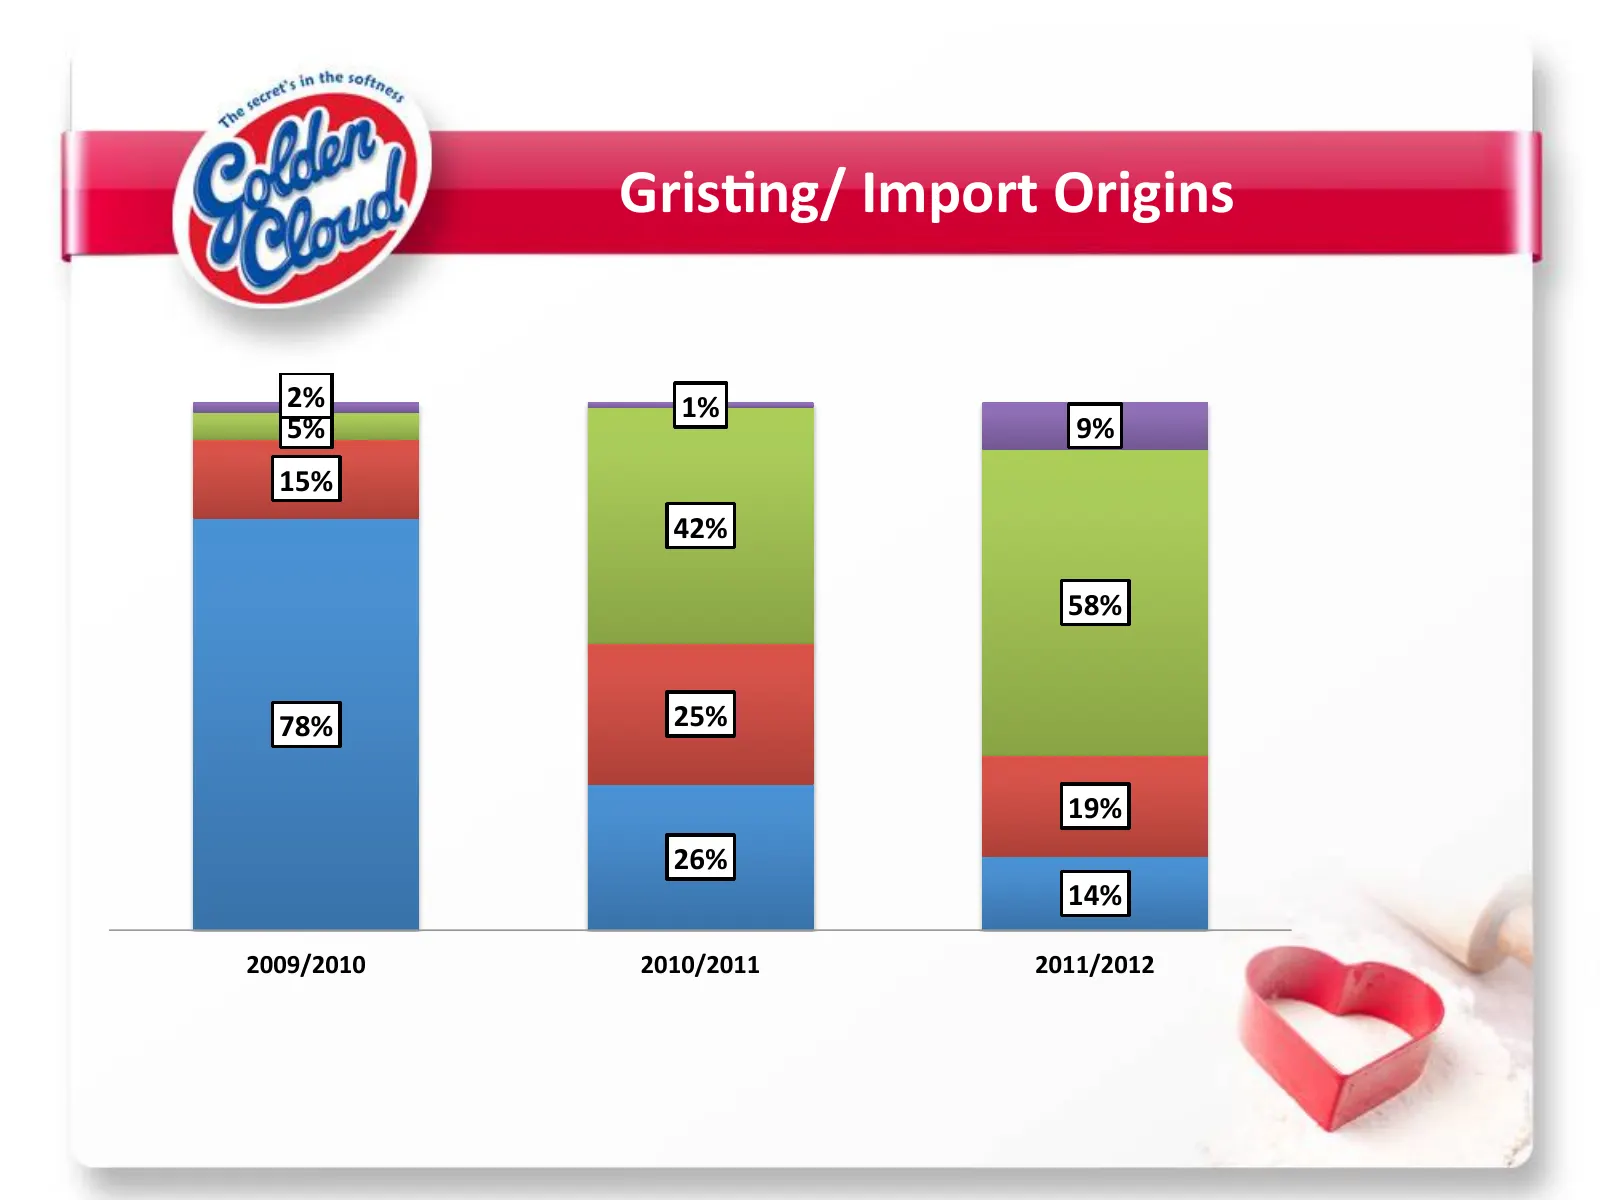
Gris>ng/ Import Origins 2% 1% 5% 9% 15% 42% 58% 78% 25% 19% 26% 14% 2009/2010 2010/2011 2011/2012
Slide 40: Hennenman Project
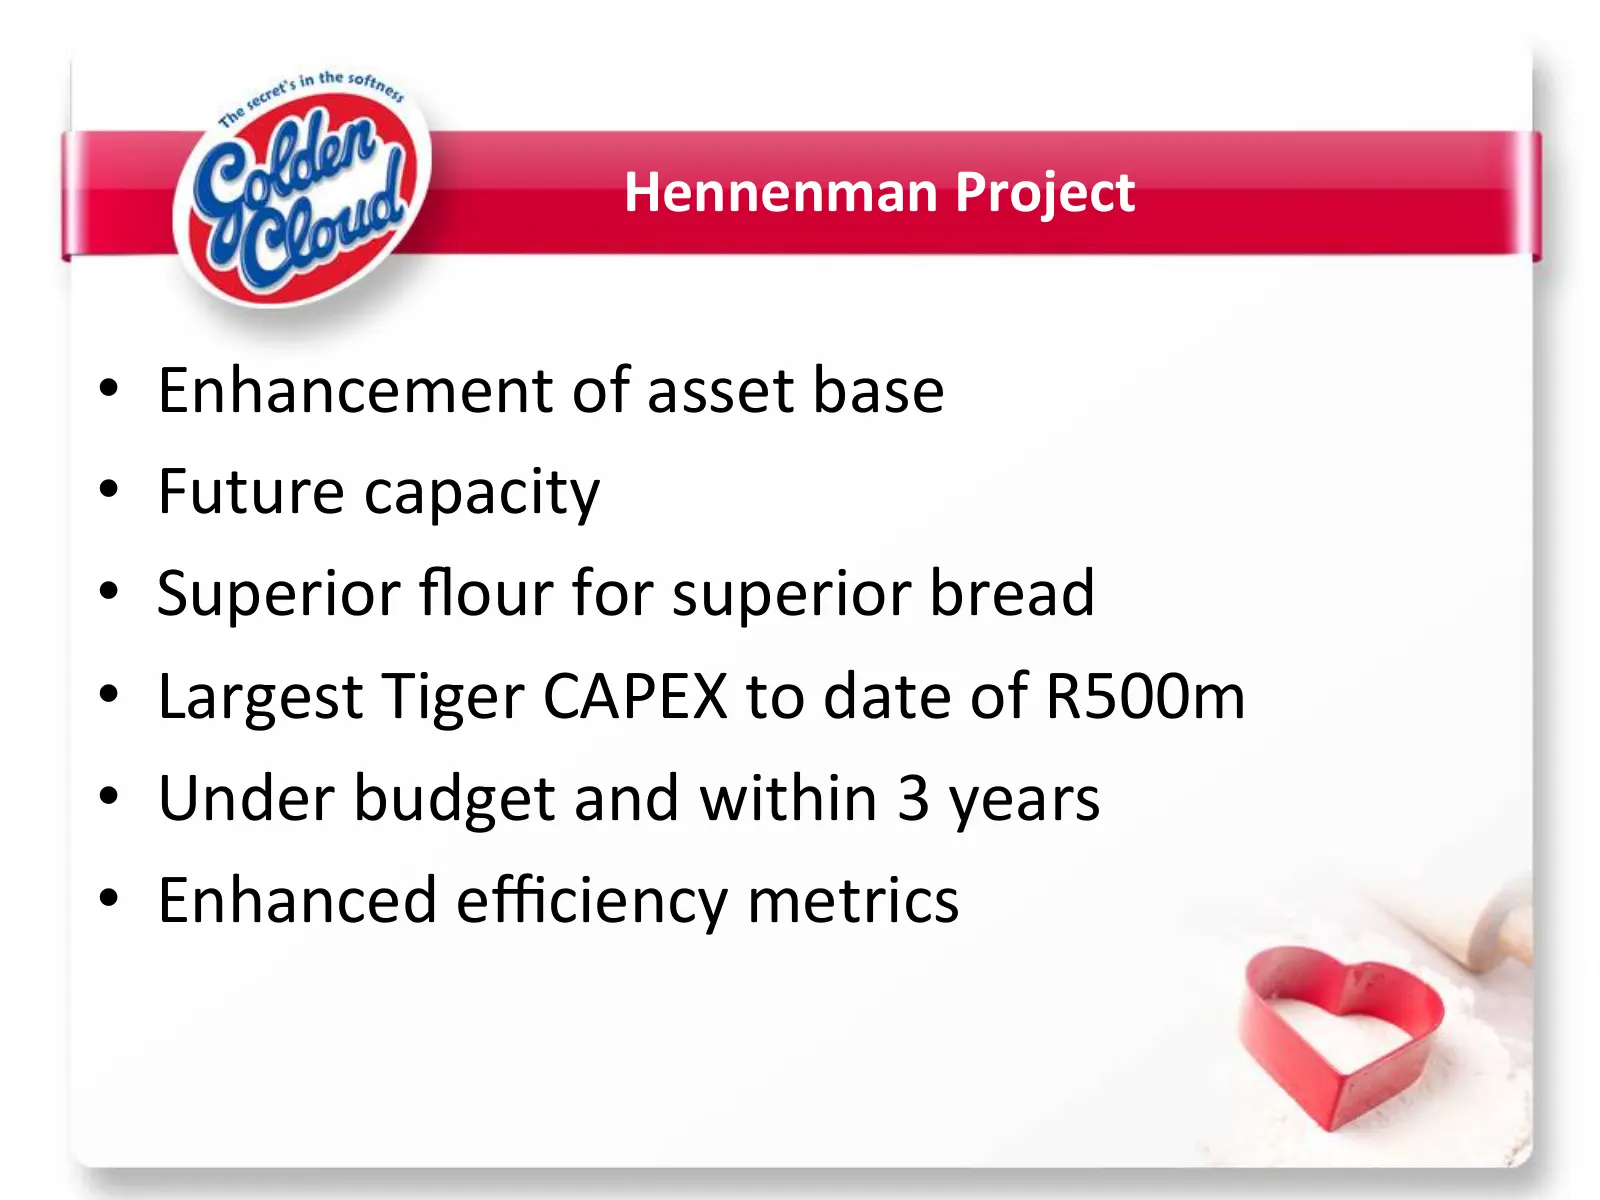
Hennenman Project • Enhancement of asset base • Future capacity • Superior flour for superior bread • Largest Tiger CAPEX to date of R500m • Under budget and within 3 years • Enhanced efficiency metrics
Slide 41: Hennenman Video
Hennenman Video VTS_01_1.VOB
Slide 42: Industrial Premixes: Industry Challenges
Industrial Premixes • Industry Challenges – Weakly differen?ated/highly commodi?sed base flour proposi?ons • Independent Industrial • In-‐store baking arena – Poor skills levels outside of the major branded bakeries – High qualified labour turnover in industrial and in-‐store bakery environment – Hig
Slide 43: Industrial Premixes: Golden Cloud Solutions
Industrial Premixes • Golden Cloud Solu>ons – Development of product solu?ons to enable reduc?on of required labour on the bakery floor – Manage full core product solu?ons in partnership with iden?fied key customers – Minimise recipe inclusions and adjustments required on the bakery floor – Ul?mately u
Slide 44: Consumer Premixes
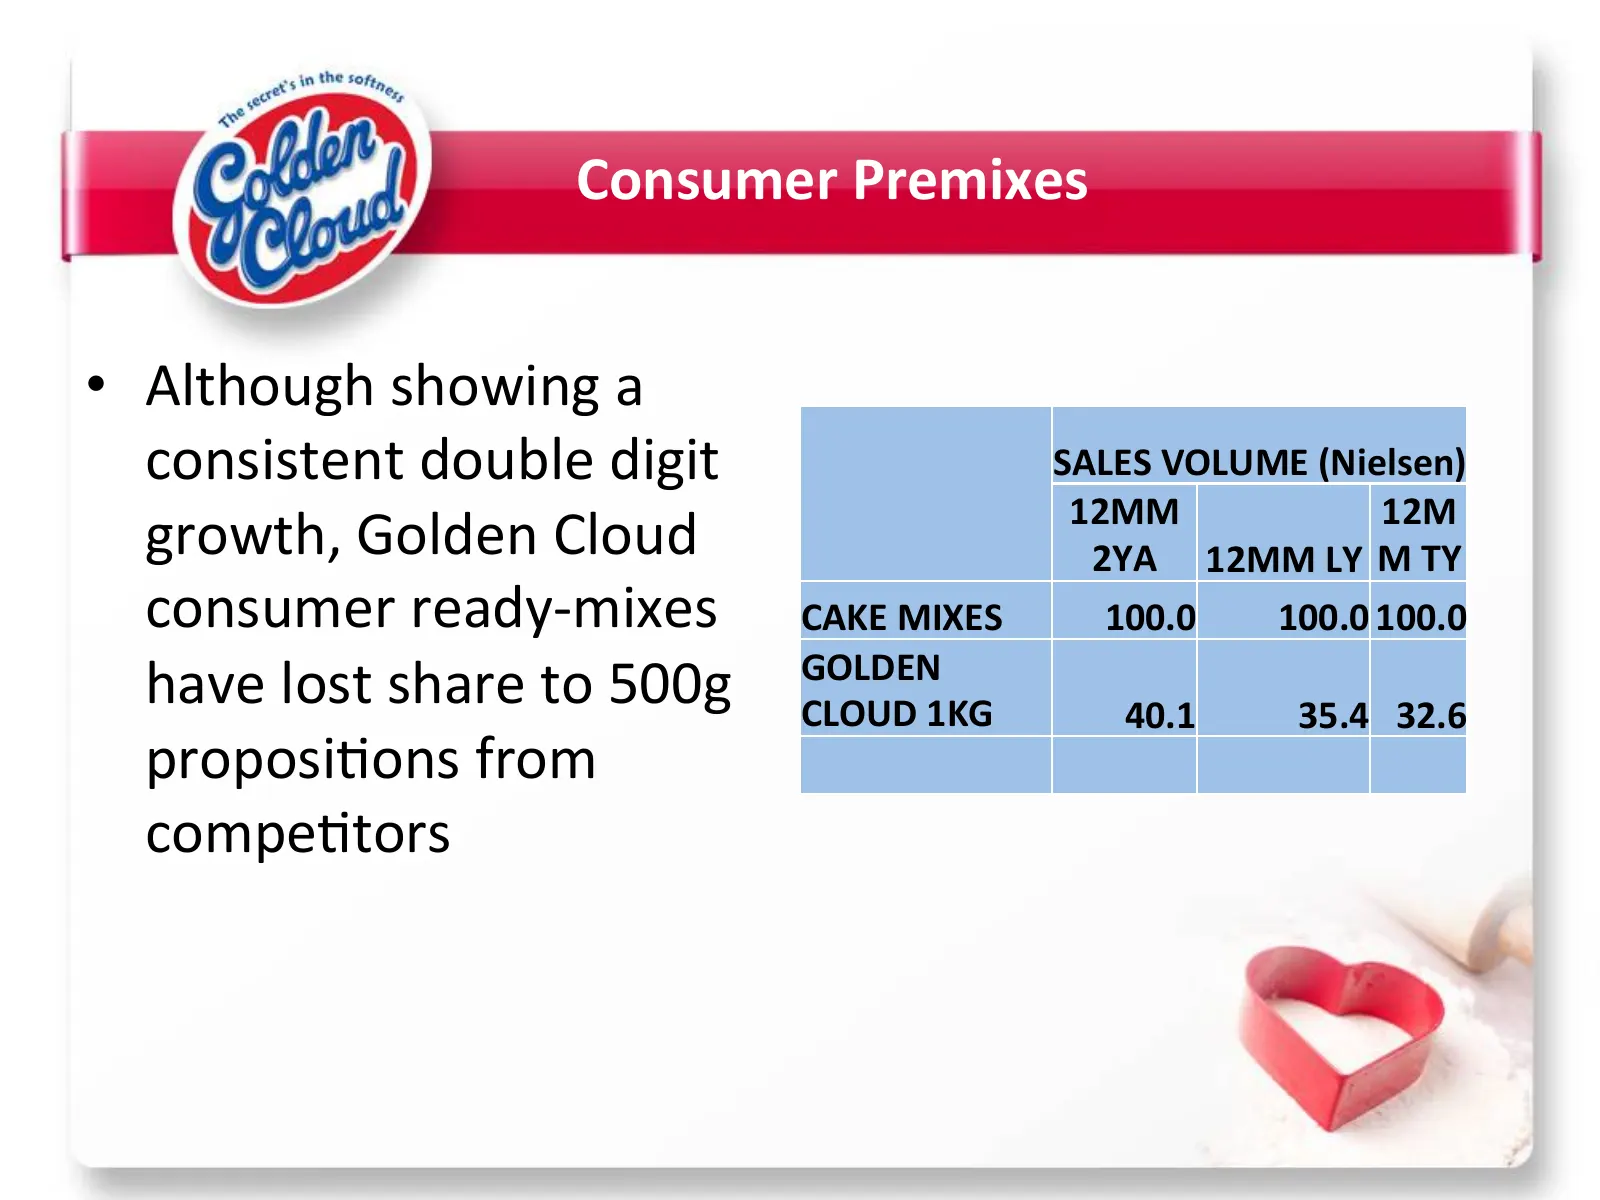
Consumer Premixes • Although showing a consistent double digit SALES VOLUME (Nielsen) 12MM 12M growth, Golden Cloud 2YA 12MM LY M TY consumer ready-‐mixes CAKE MIXES 100.0 100.0 100.0 GOLDEN have lost share to 500g CLOUD 1KG 40.1 35.4 32.6 proposi?ons from compe?tors
Slide 45: Consumer Premixes
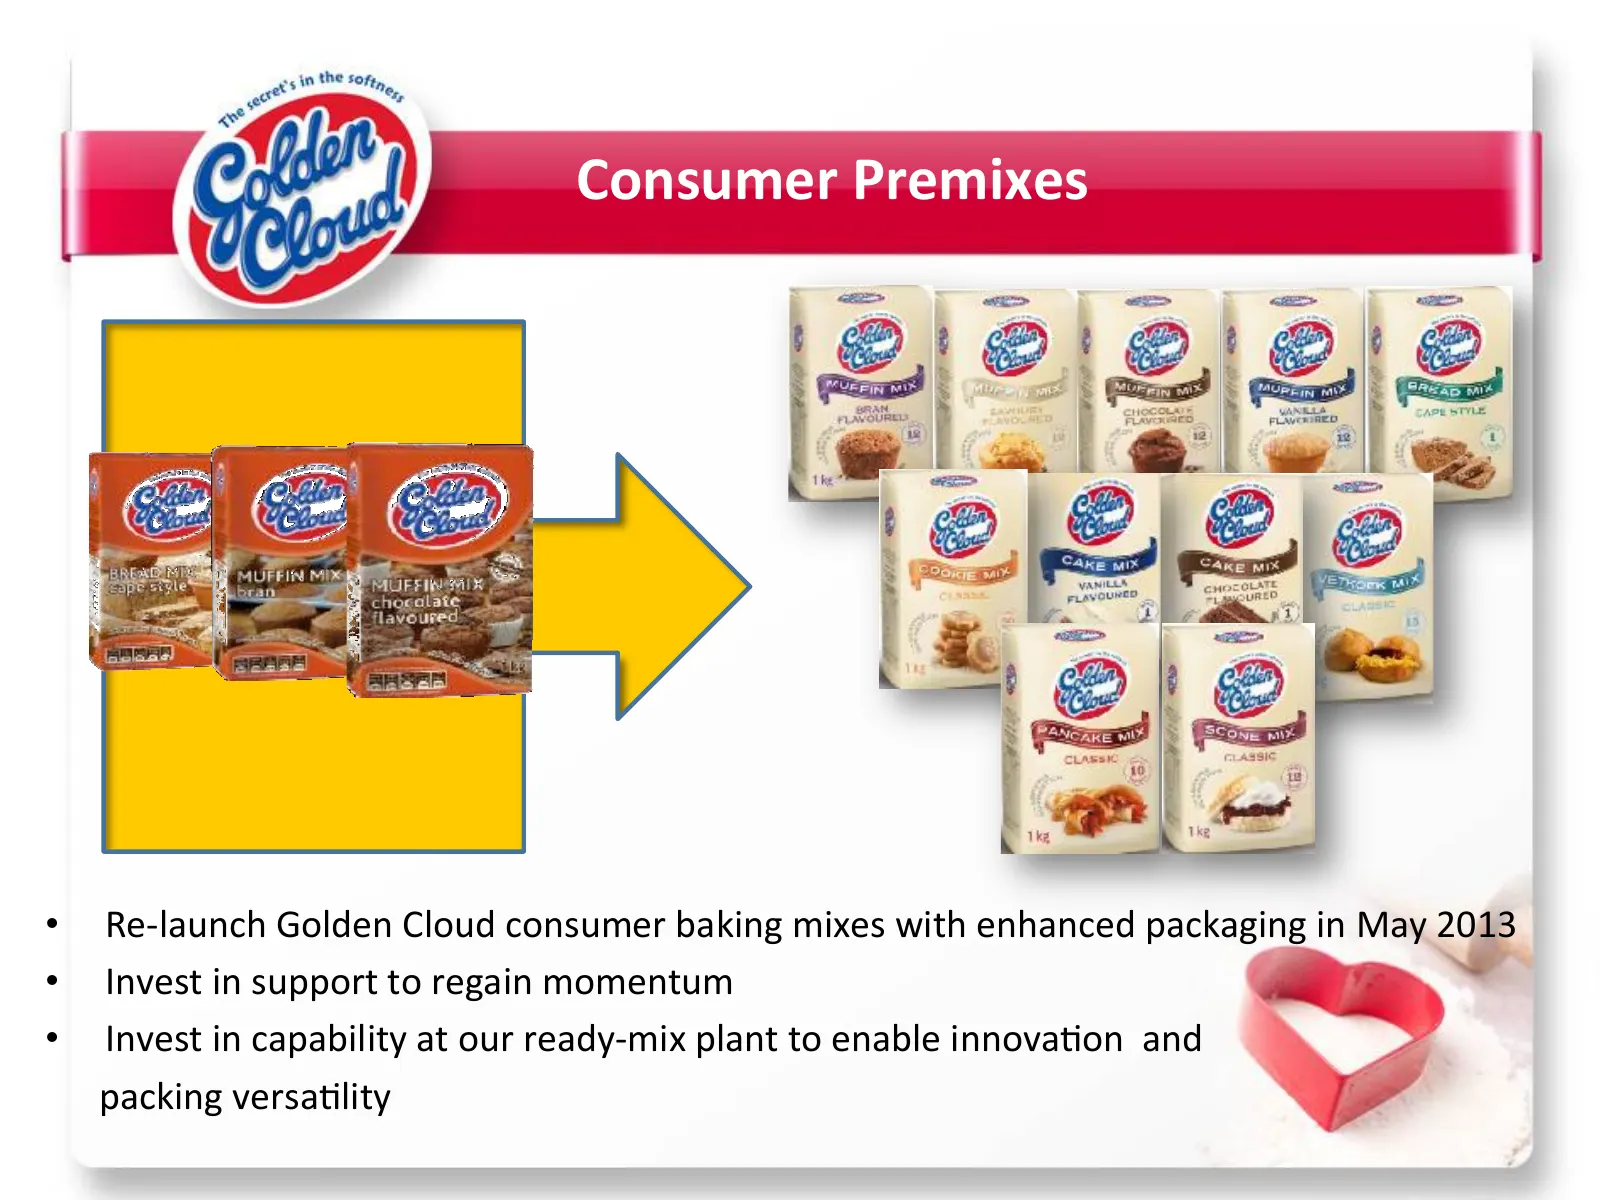
Consumer Premixes • Re-‐launch Golden Cloud consumer baking mixes with enhanced packaging in May 2013 • Invest in support to regain momentum • Invest in capability at our ready-‐mix plant to enable innova?on and packing versa?lity
Slide 46: Breakfast
Overview Baked Goods Milling Breakfast Breakfast Naresh Singh Managing Execu?ve
Slide 47: Agenda
Overview Baked Goods Milling Breakfast Agenda § Breakfast Market Overview § Breakfast Strategy § Brand & Product Porrolio AGENDA § Brand Investment § Innova>on § Current Performance & Inhibitors 47
Slide 48: Breakfast market overview
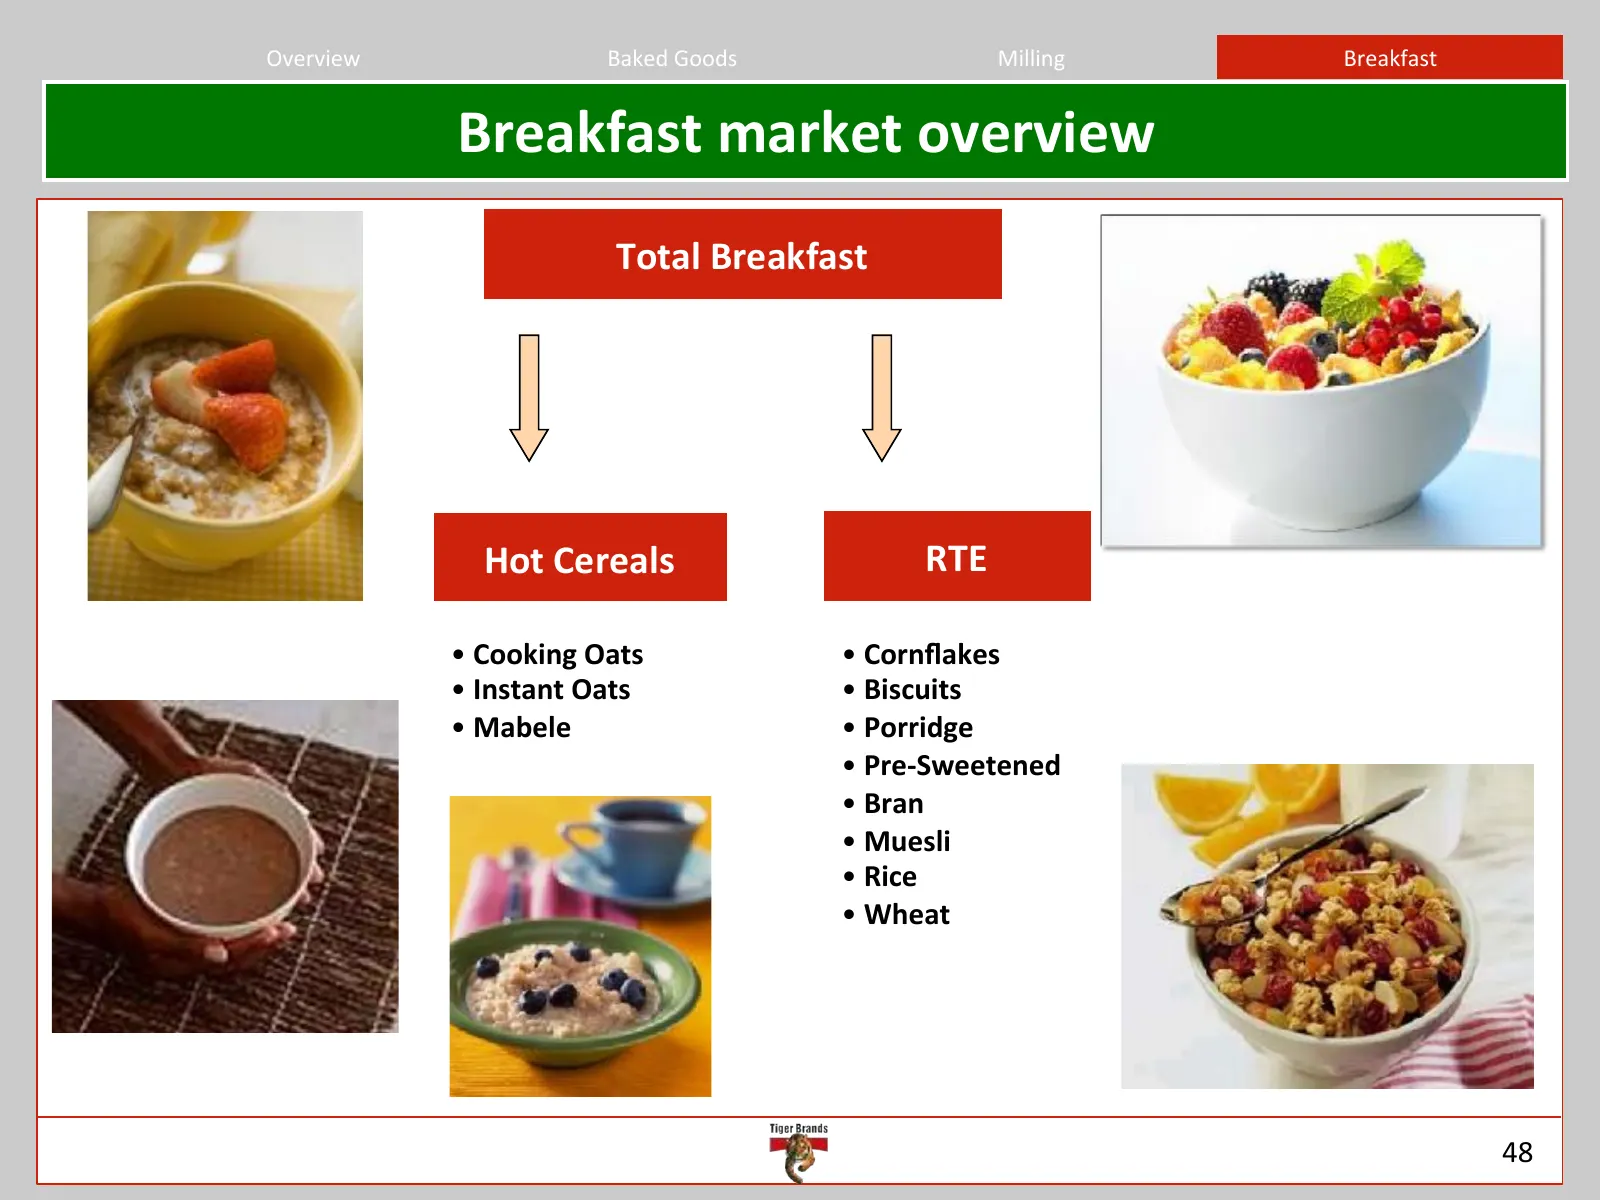
Overview Baked Goods Milling Breakfast Breakfast market overview Total Breakfast Hot Cereals RTE AGENDA • Cooking Oats • Cornflakes • Instant Oats • Biscuits • Mabele • Porridge • Pre-‐Sweetened • Bran • Muesli • Rice • Wheat 48
Slide 49: Breakfast market overview
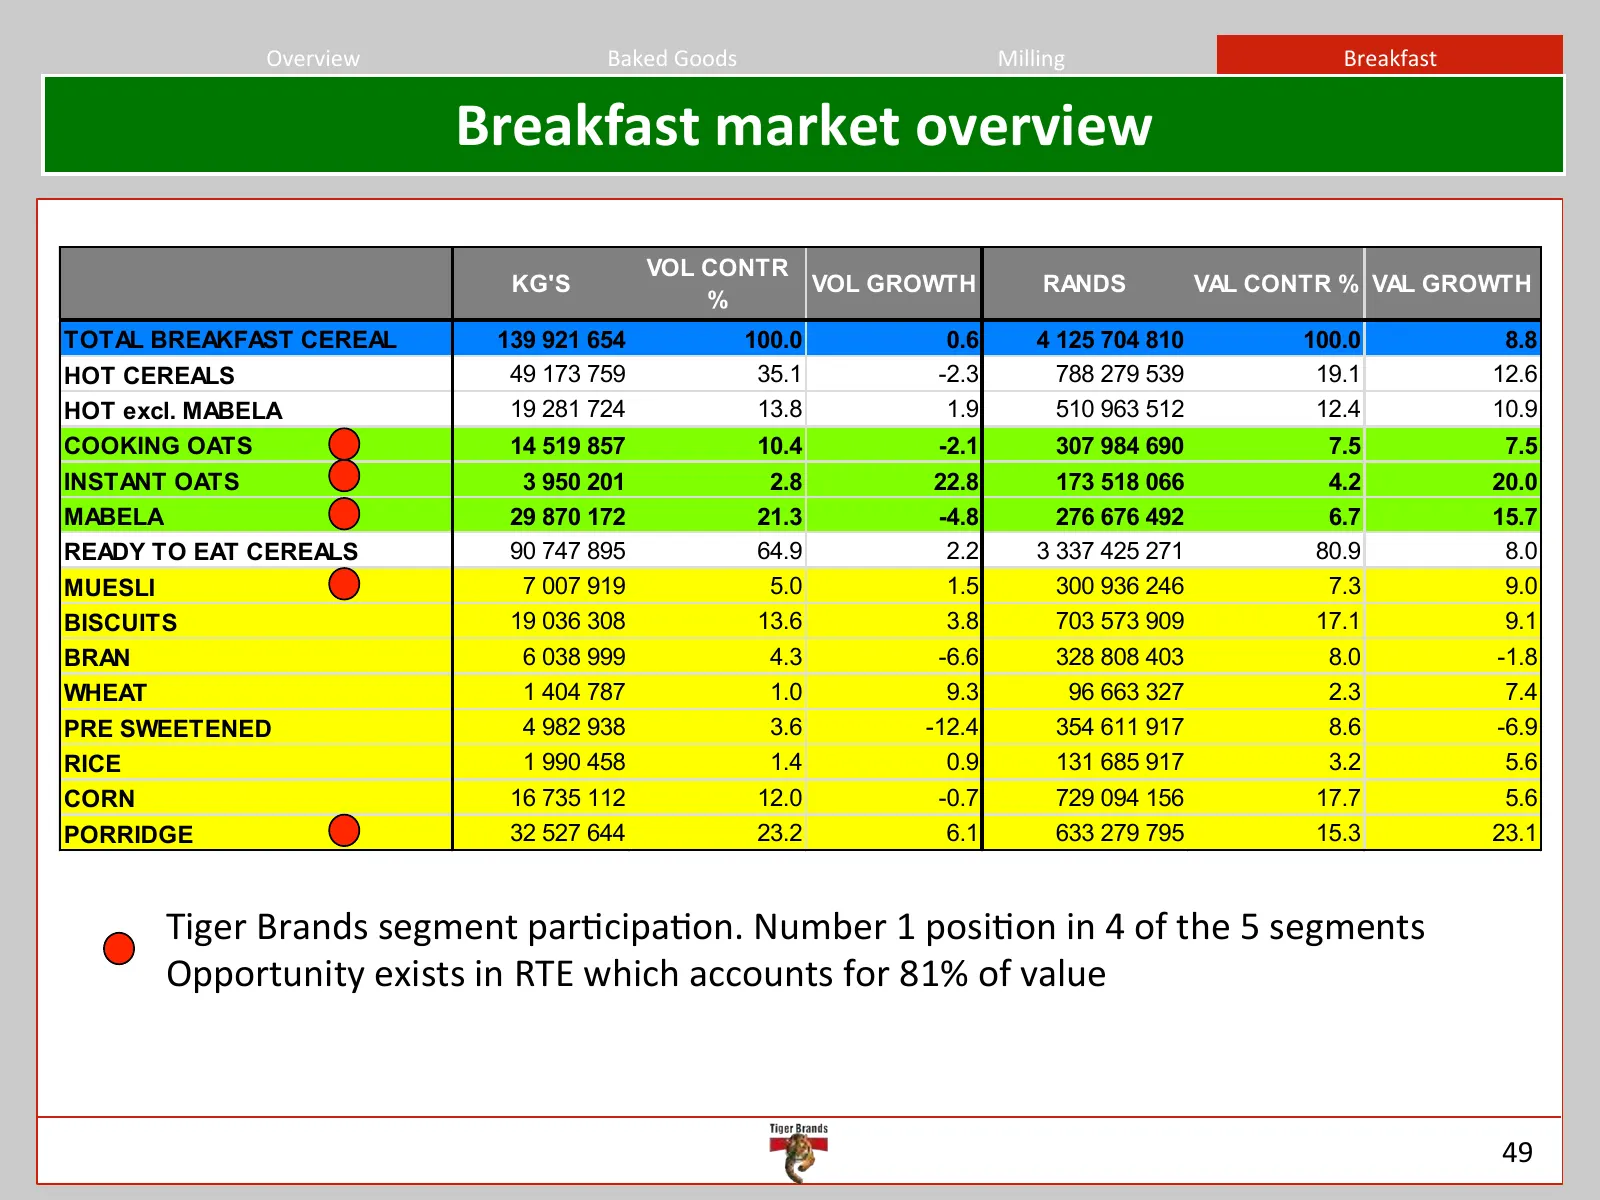
Overview Baked Goods Milling Breakfast Breakfast market overview VOL CONTR KG'S VOL GROWTH RANDS VAL CONTR % VAL GROWTH % TOTAL BREAKFAST CEREAL 139 921 654 100.0 0.6 4 125 704 810 100.0 8.8 HOT CEREALS 49 173 759 35.1 -2.3 788 279 539 19.1 12.6 HOT excl. MABELA 19 281 724 13.8 1.9 510 963 512 12.4
Slide 50: Breakfast market overview
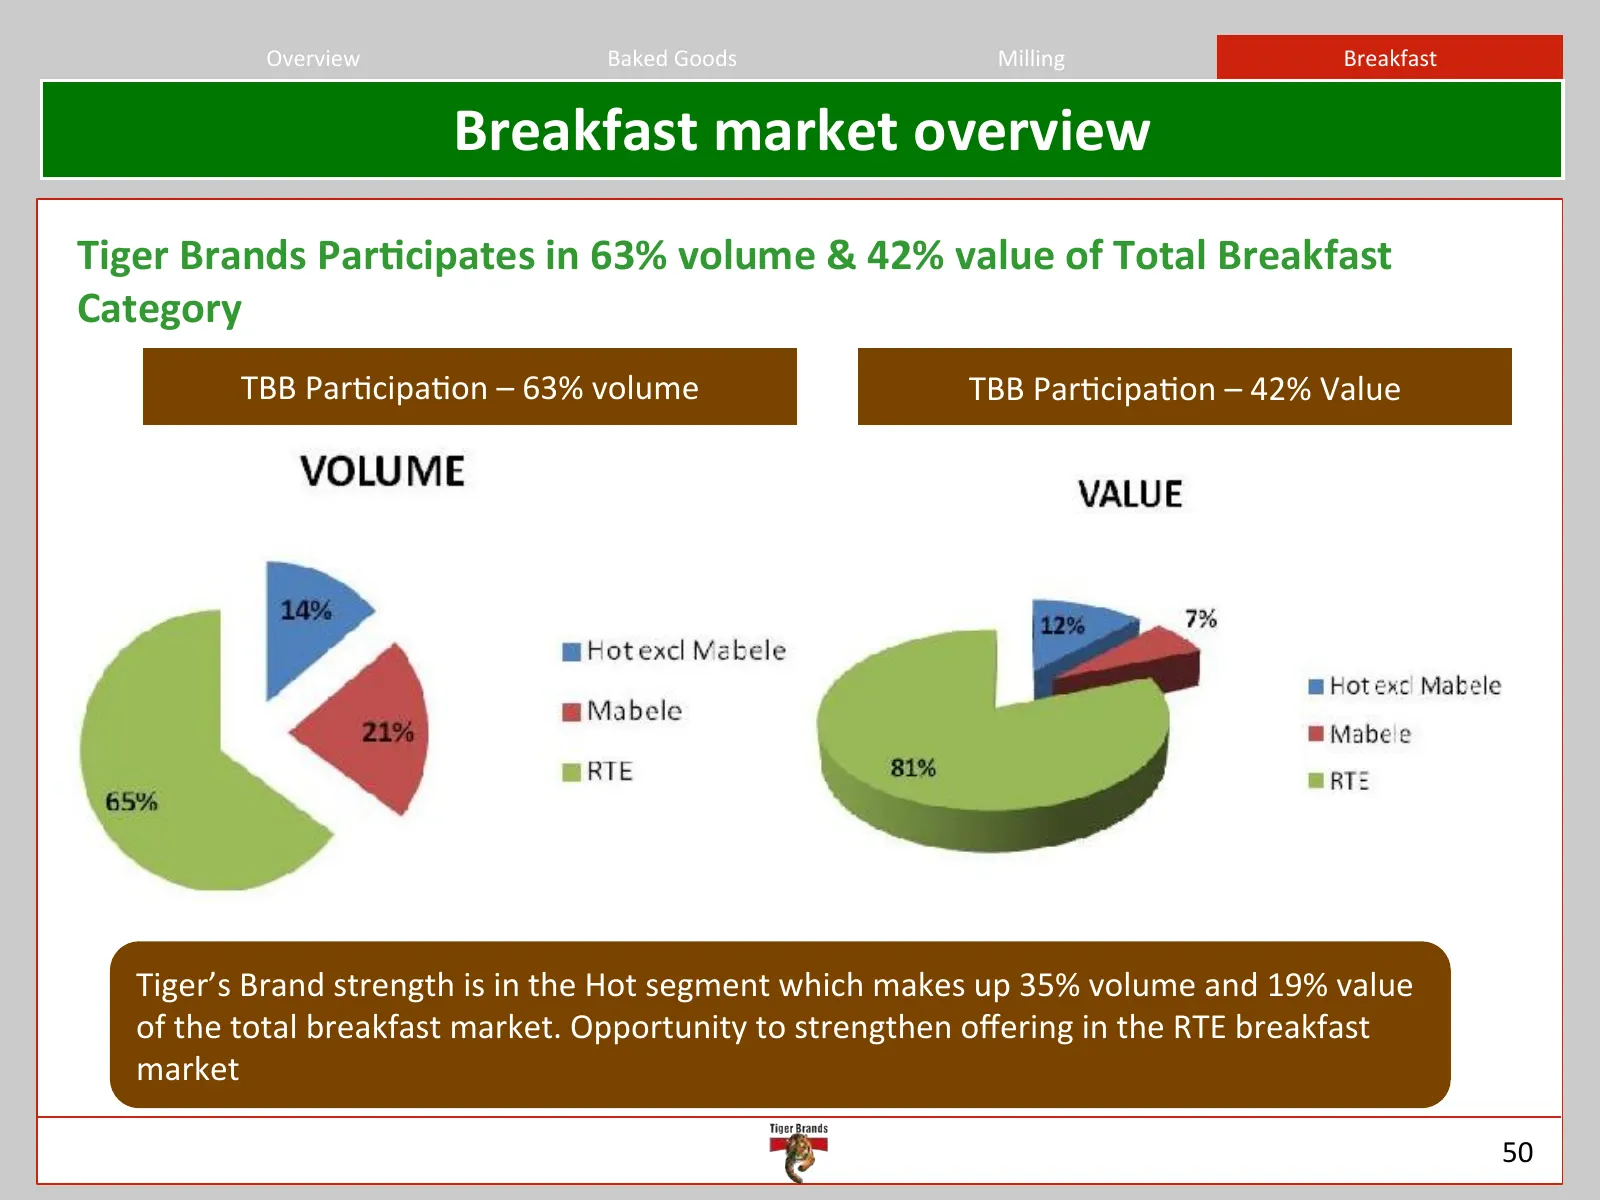
Overview Baked Goods Milling Breakfast Breakfast market overview Tiger Brands Par>cipates in 63% volume & 42% value of Total Breakfast Category TBB Par?cipa?on – 63% volume TBB Par?cipa?on – 42% Value Tiger’s Brand strength is in the Hot segment which makes up 35% volume and 19% value of the total b
Slide 51: Breakfast market overview: Tiger Brands Participation
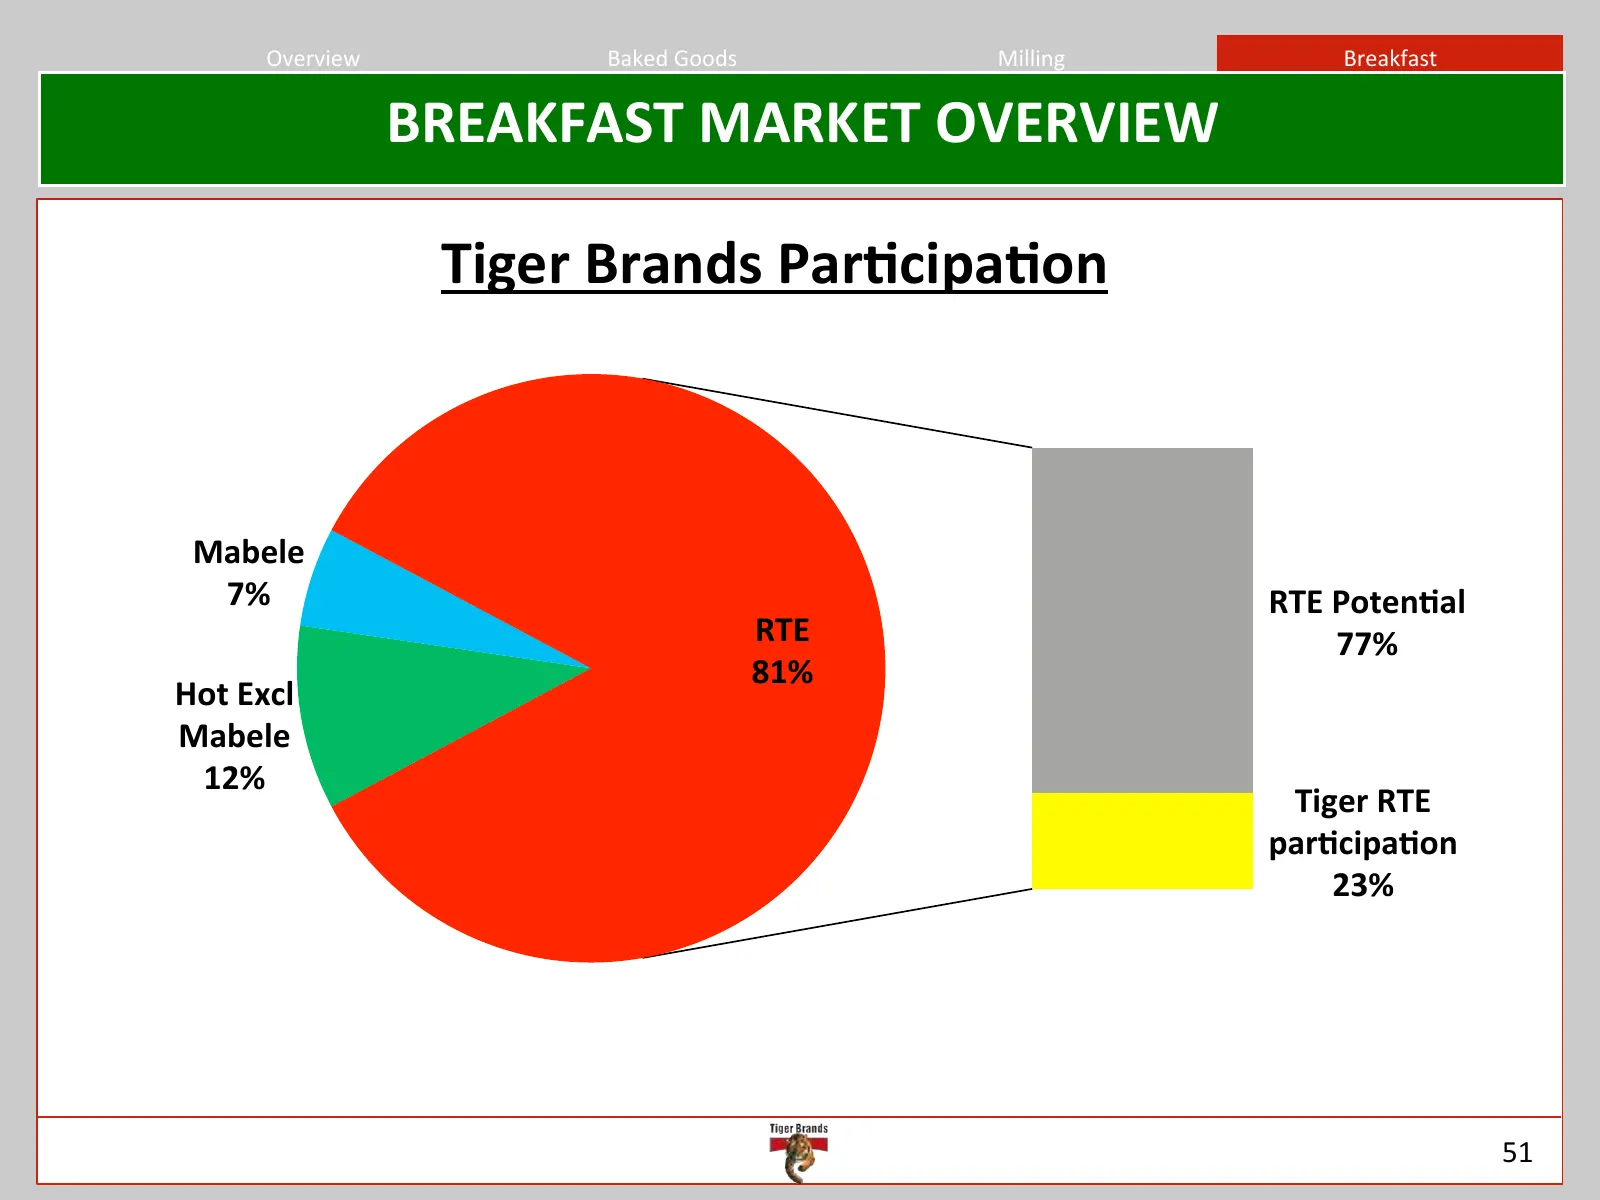
Overview Baked Goods Milling Breakfast BREAKFAST MARKET OVERVIEW Tiger Brands Par>cipa>on Mabele 7% RTE Poten>al RTE 77% 81% Hot Excl Mabele 12% Tiger RTE par>cipa>on 23% 51
Slide 52: Breakfast strategy
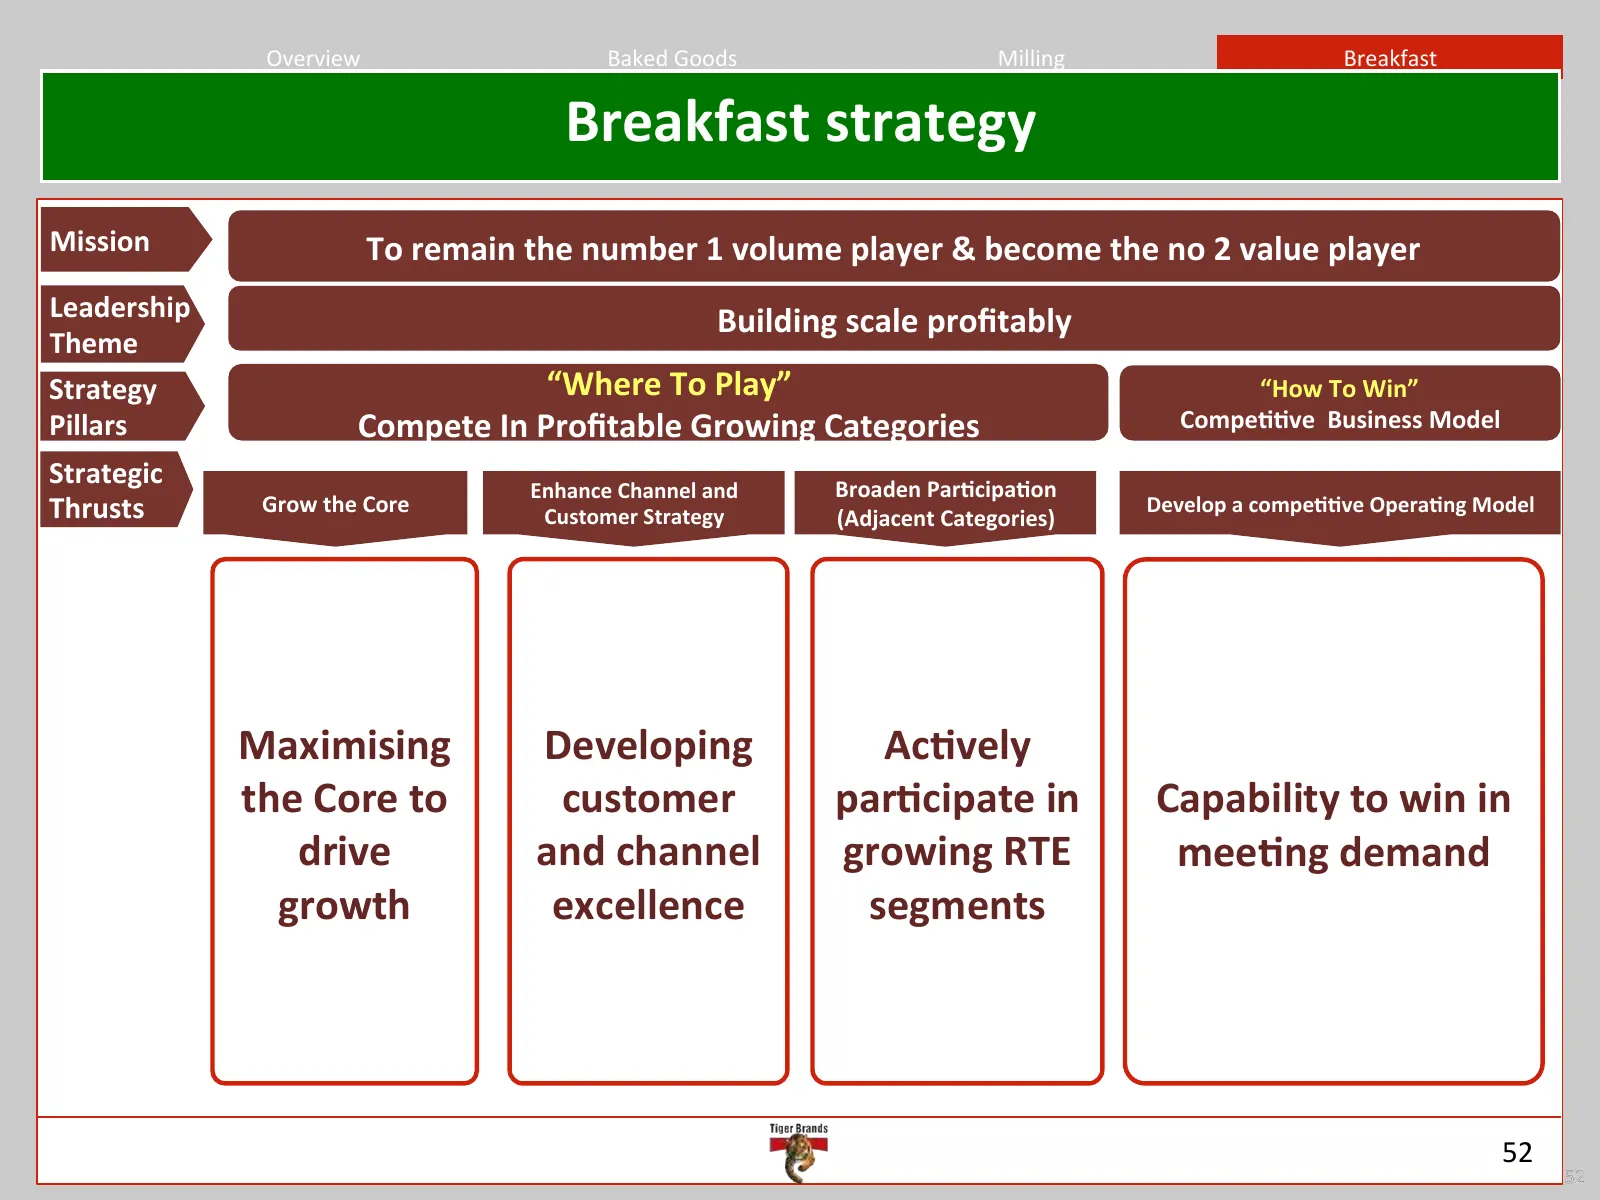
Overview Baked Goods Milling Breakfast Breakfast strategy Mission To remain the number 1 volume player & become the no 2 value player Leadership Building scale profitably Theme Strategy “Where To Play” “How To Win” Pillars Compete In Profitable Growing Categories Compe>>ve Business Model Strategic Enh
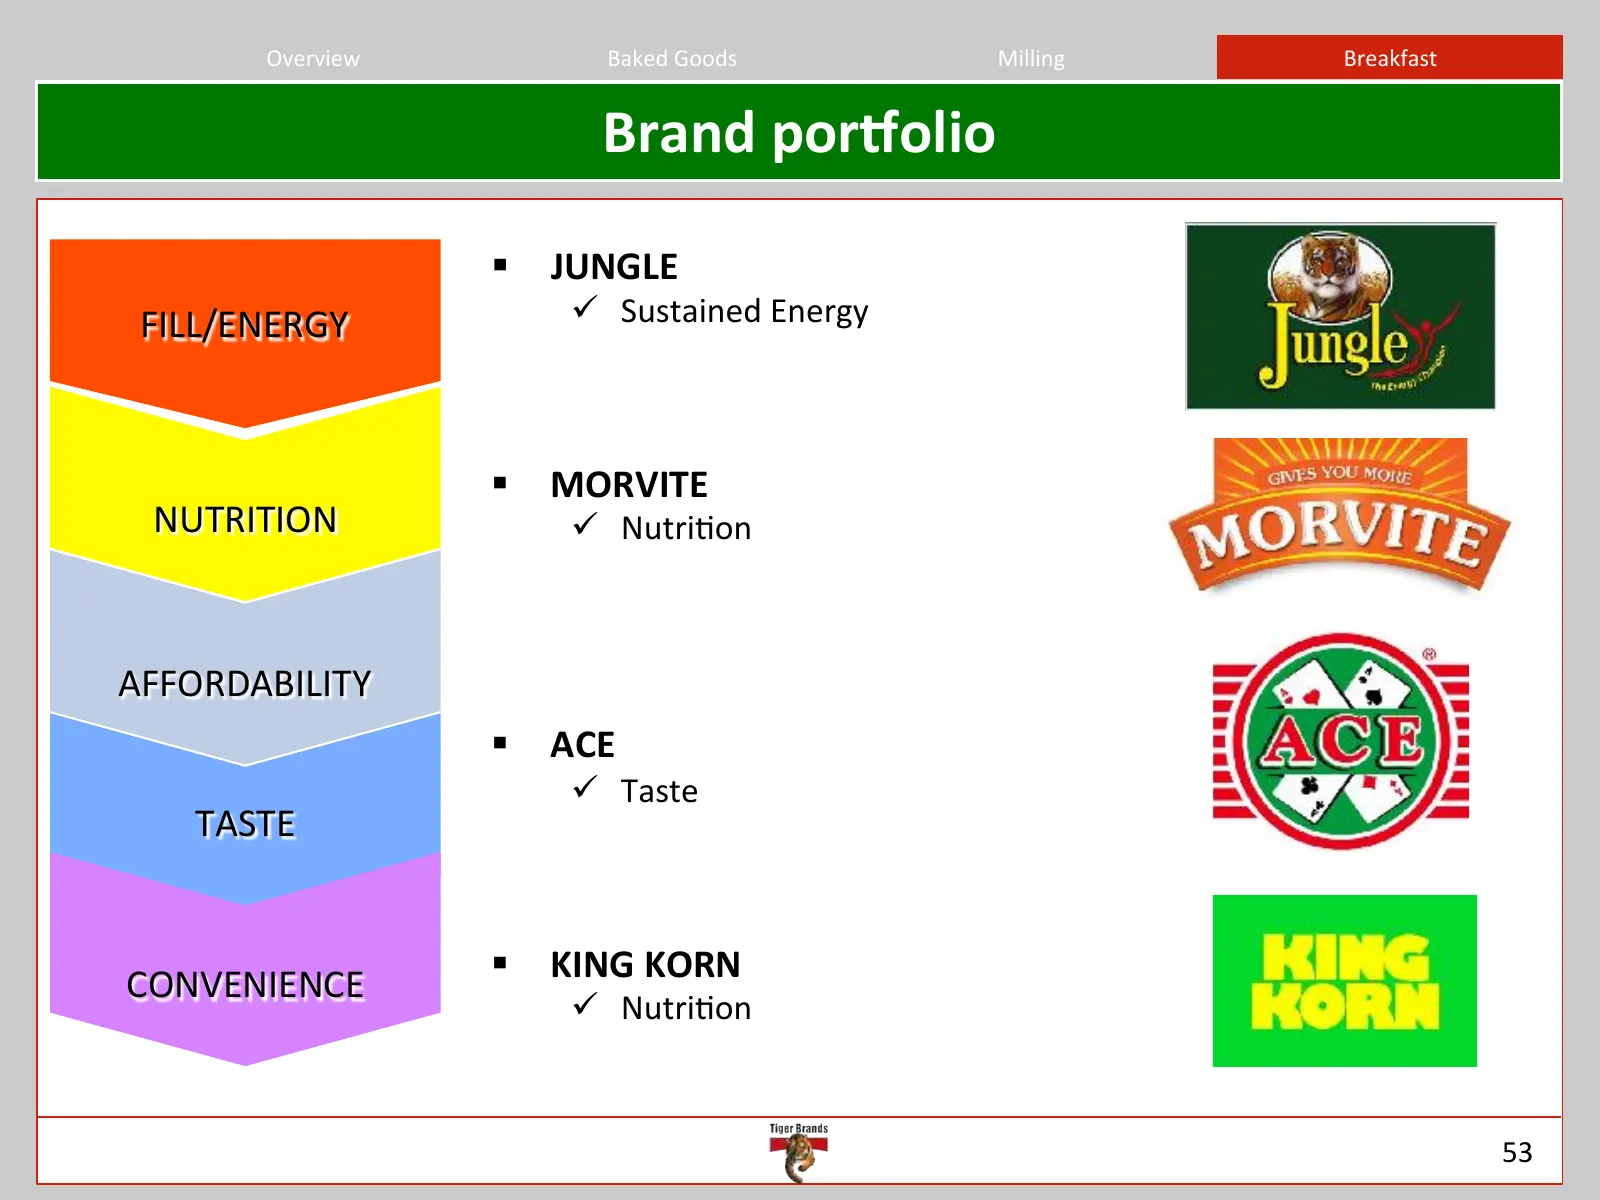
Slide 53: Brand portfolio
Overview Baked Goods Milling Breakfast Brand porrolio § JUNGLE FILL/ENERGY ü Sustained Energy § MORVITE NUTRITION ü Nutri?on AFFORDABILITY § ACE ü Taste TASTE CONVENIENCE § KING KORN ü Nutri?on 53
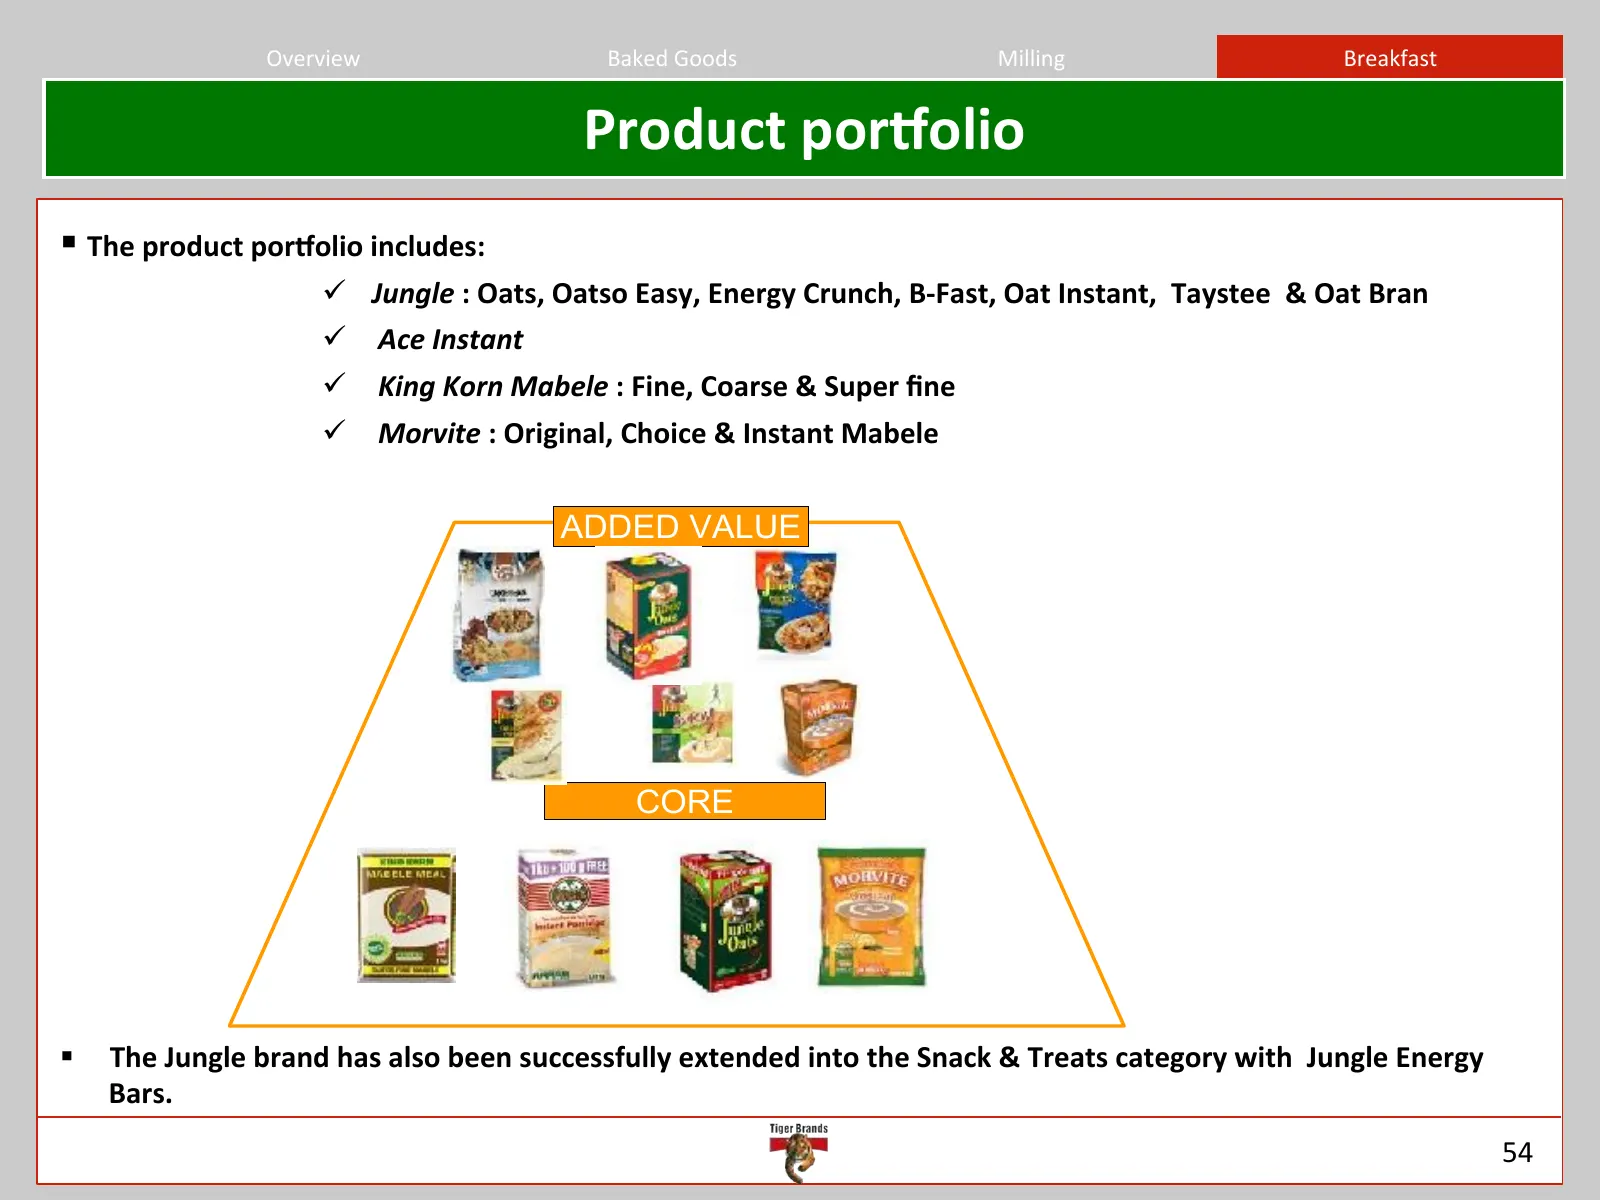
Slide 54: Product portfolio
Overview Baked Goods Milling Breakfast Product porrolio § The product porrolio includes: ü Jungle : Oats, Oatso Easy, Energy Crunch, B-‐Fast, Oat Instant, Taystee & Oat Bran ü Ace Instant ü King Korn Mabele : Fine, Coarse & Super fine ü Morvite : Original, Choice & Instant Mabele ADDED VALUE AG
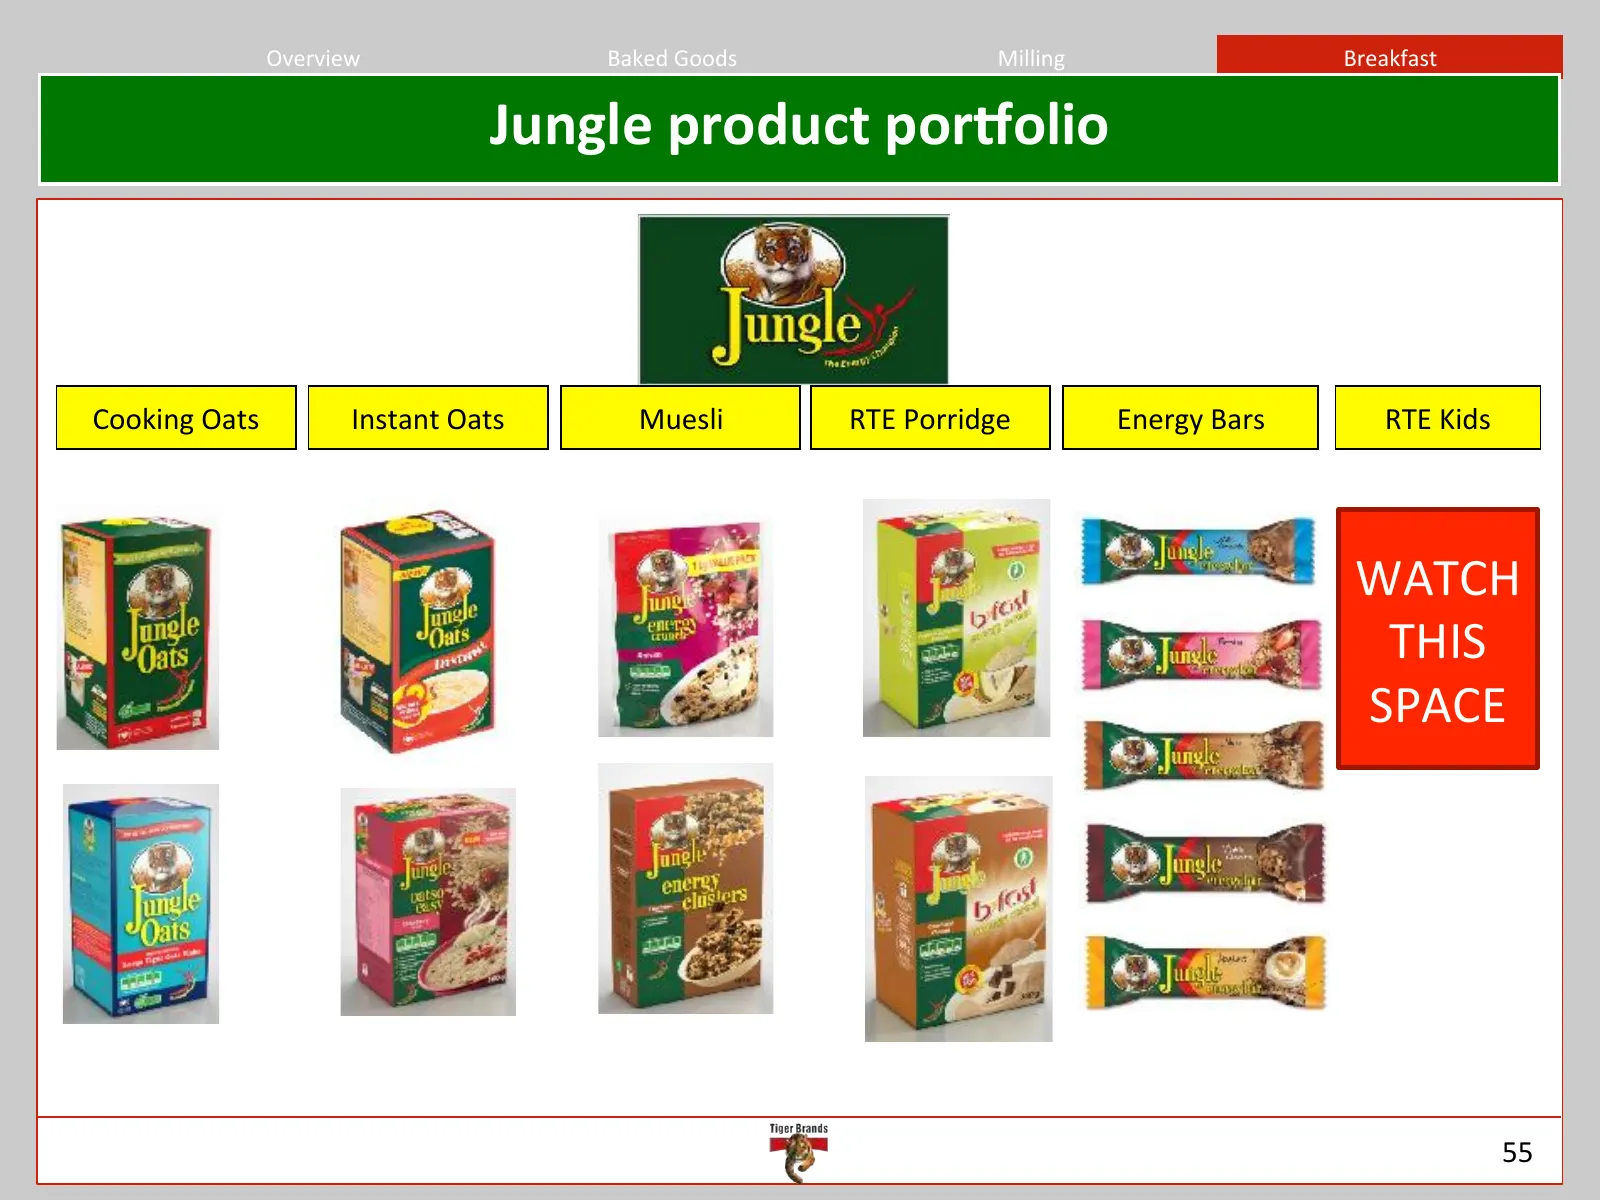
Slide 55: Jungle product portfolio
Overview Baked Goods Milling Breakfast Jungle product porrolio Cooking Oats Instant Oats Muesli RTE Porridge Energy Bars RTE Kids AGENDA WATCH THIS SPACE 55
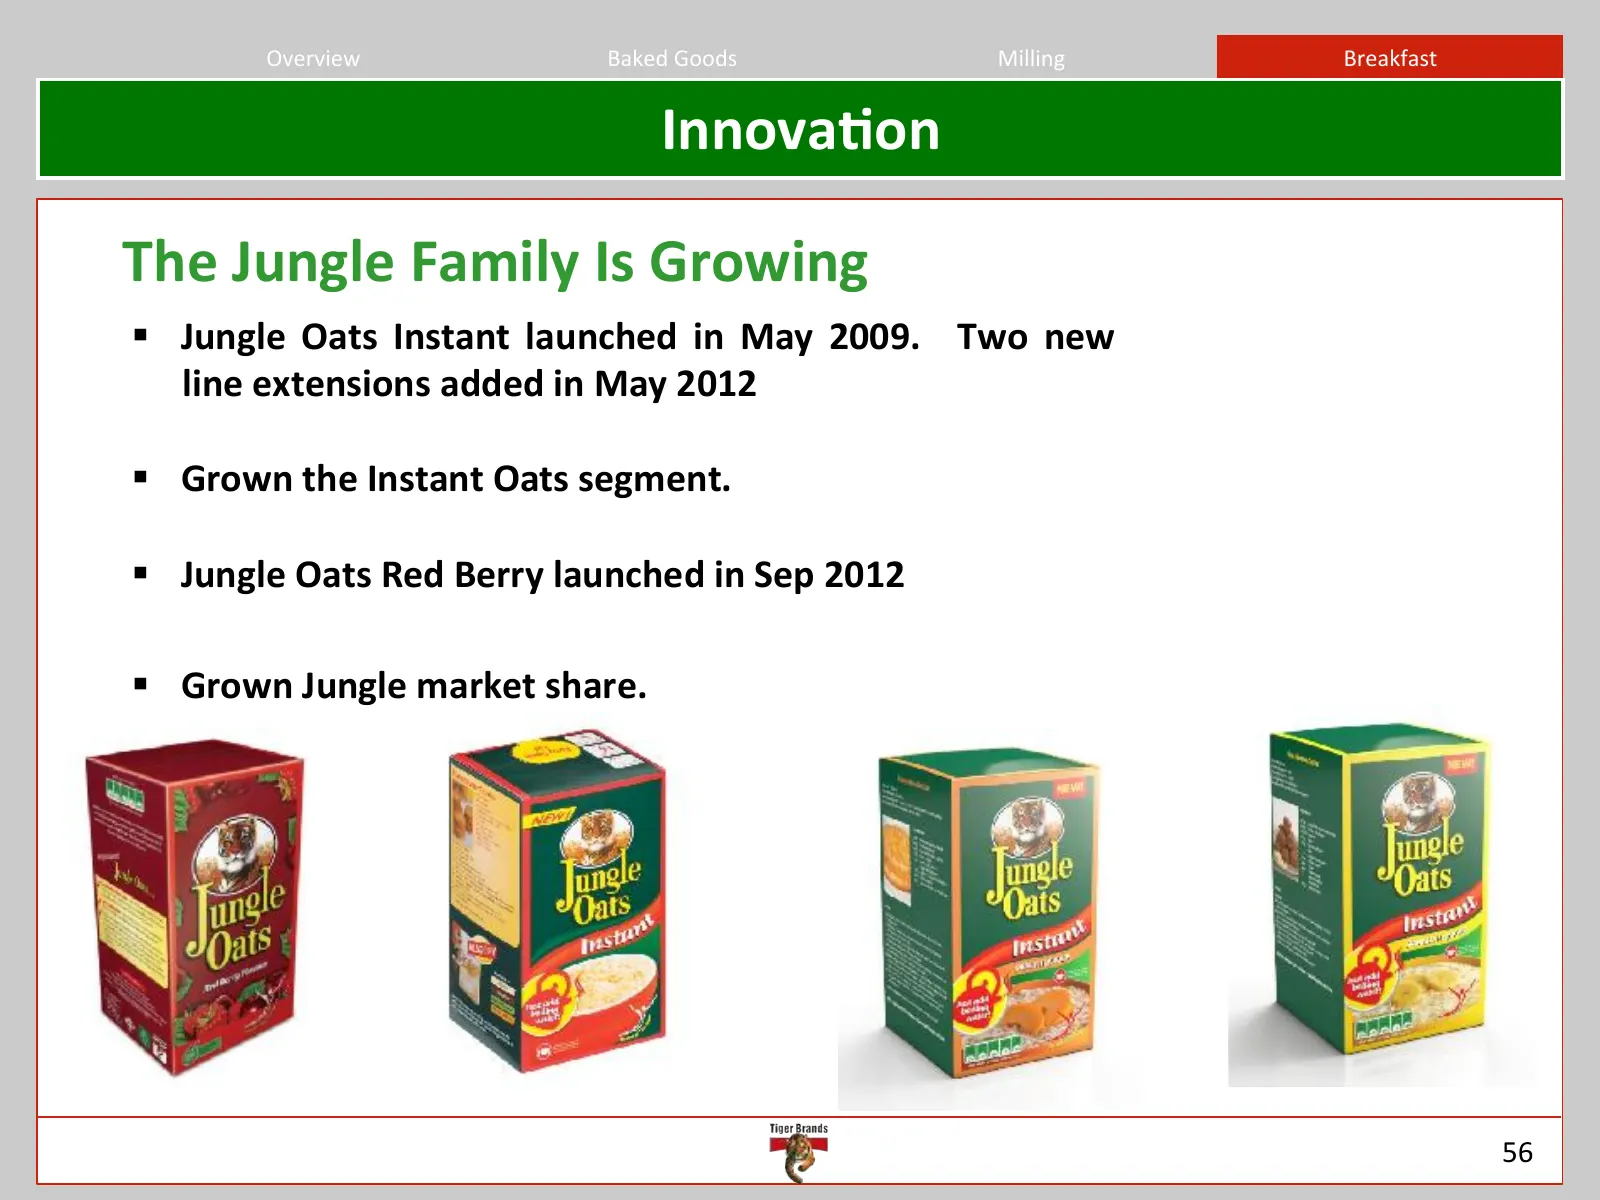
Slide 56: Innovation: The Jungle Family Is Growing
Overview Baked Goods Milling Breakfast Innova>on The Jungle Family Is Growing § Jungle Oats Instant launched in May 2009. Two new line extensions added in May 2012 § Grown the Instant Oats segment. § Jungle Oats Red Berry launched in Sep 2012 AGENDA § Grown Jungle market share. 56
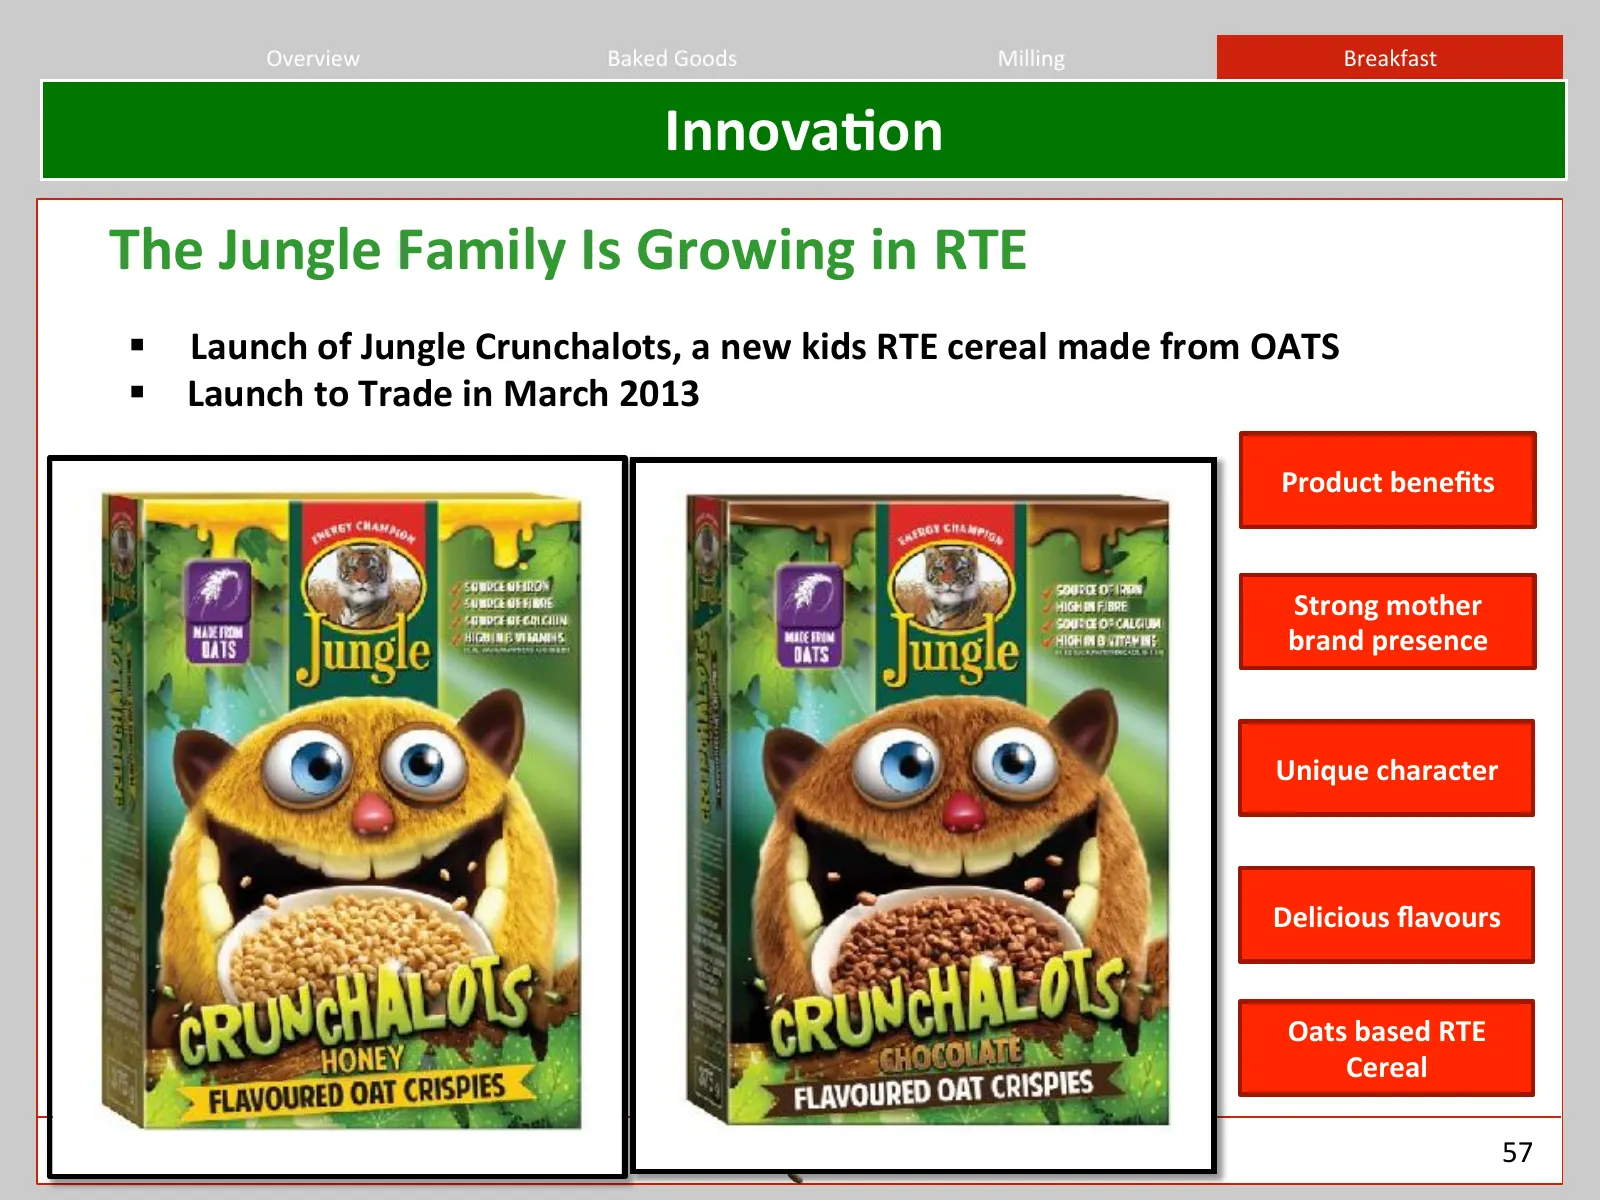
Slide 57: Innovation: The Jungle Family Is Growing in RTE
Overview Baked Goods Milling Breakfast Innova>on The Jungle Family Is Growing in RTE § Launch of Jungle Crunchalots, a new kids RTE cereal made from OATS § Launch to Trade in March 2013 Product benefits AGENDA Strong mother brand presence Unique character Delicious flavours Oats based RTE Cereal 57
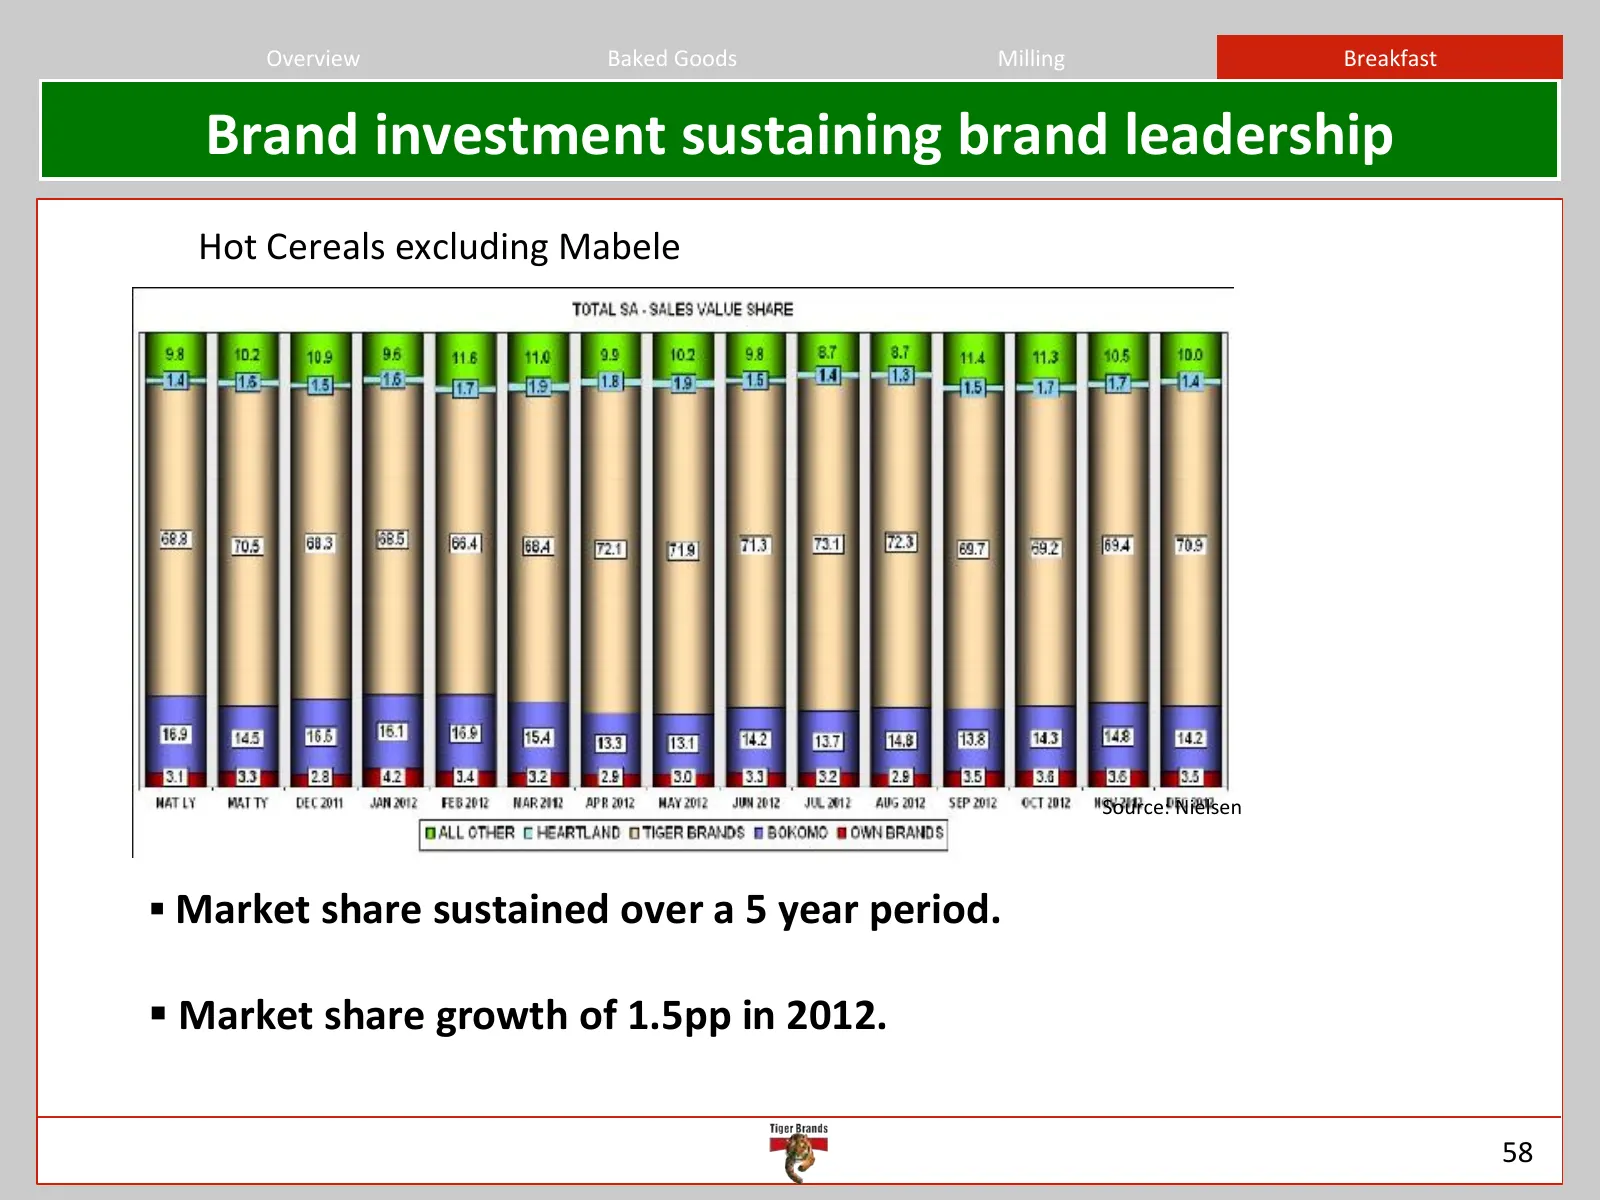
Slide 58: Brand investment sustaining brand leadership
Overview Baked Goods Milling Breakfast Brand investment sustaining brand leadership Hot Cereals excluding Mabele AGENDA Source: Nielsen § Market share sustained over a 5 year period. § Market share growth of 1.5pp in 2012. 58
Slide 59: Current performance & inhibitors
Overview Baked Goods Milling Breakfast Current performance & inhibitors § Tiger Brands Breakfast porrolio con>nues to deliver good volume & EBIT growth. § Consistent investment behind the brands has sustained its market leadership in segments where we compete. AGENDA § Innova>on remains a key foc
Source: Internet Archive copy of tigerbrands.com
More decks from Tiger Brands Limited
 H1 2026 Earnings Presentation37 slides · Jun 1, 2026
 H1 2026 Earnings Presentation38 slides · Jun 1, 2026
 FY2025 Earnings Presentation38 slides · Nov 26, 2025
 H1 2025 Earnings Presentation43 slides · May 28, 2025
 H1 FY2024 Earnings Presentation38 slides · May 27, 2024
 FY2023 Earnings Presentation45 slides · Dec 1, 2023