Argo Group International Holdings Ltd
Argo Group International — Proxy Contest (April 2019)
131 slides from Argo Group International's proxy contest presentation, Apr 30, 2019
Slide 1: Voce Capital: A voice for value
© Voce Capital Management LLC; April 30,2019 voce capital A voice for value
Slide 2: Discussion Materials: Righting The Ship
voce capital Discussion Materials April 30, 2019 Righting The Ship
Slide 3: Disclaimer
2 voce capital The views expressed herein represent the subjective opinions of Voce Capital Management LLC and certain of its affiliates and controlling persons (collectively, “Voce”), who beneficially own shares of Argo Group International Holdings, Ltd . (the “Company”) . These views are based on
Slide 4: Table of Contents
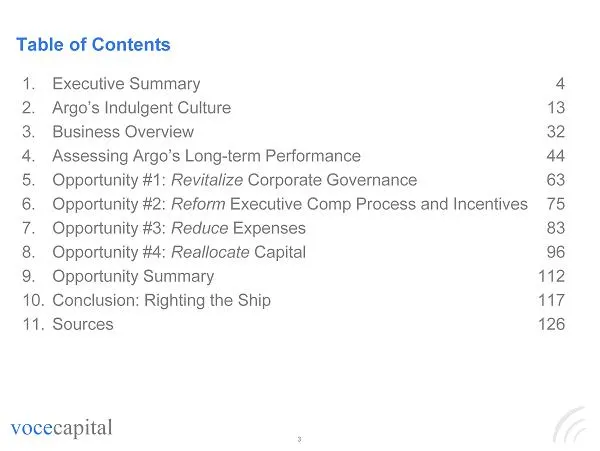
3 voce capital Table of Contents 1. Executive Summary 2. Argo’s Indulgent Culture 3. Business Overview 4. Assessing Argo’s Long - term Performance 5. Opportunity #1: Revitalize Corporate Governance 6. Opportunity #2: Reform Executive Comp Process and Incentives 7. Opportunity #3: Reduce Expenses 8.
Slide 5: Executive Summary
Executive Summary “I commend your shareholder letter and efforts regarding Argo . You are dead on in your conclusions . ” ‒ Former Argo Senior Executive email to Voce, February 26 , 2019
Slide 6: Argo: Interrelated Issues and Opportunities
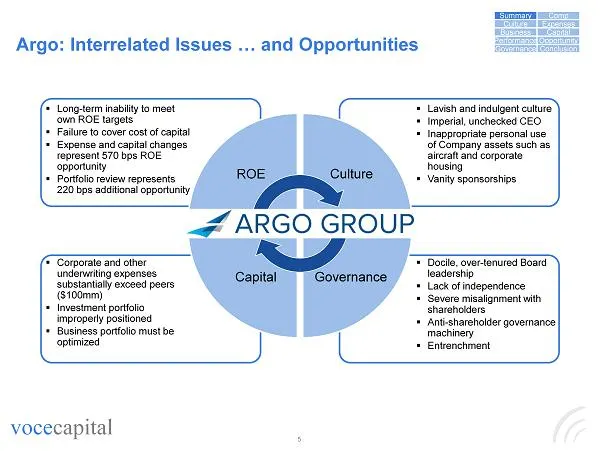
5 voce capital ▪ Docile, over - tenured Board leadership ▪ Lack of independence ▪ Severe misalignment with shareholders ▪ Anti - shareholder governance machinery ▪ Entrenchment ▪ Lavish and indulgent culture ▪ Imperial, unchecked CEO ▪ Inappropriate personal use of Company assets such as aircraft an
Slide 7: voce capital ▪ Argo Group International Holdings, Ltd. (“Argo” or the “Company”) is an
6 voce capital ▪ Argo Group International Holdings, Ltd. (“Argo” or the “Company”) is an international underwriter of specialty and reinsurance products in property and casualty insurance ▪ We believe Argo’s corporate governance is shockingly deficient – Significant misuse use of corporate employees
Slide 8: voce capital ▪ Argo’s expenses significantly exceed those of its peers – Argo’s purported
7 voce capital ▪ Argo’s expenses significantly exceed those of its peers – Argo’s purported expense reductions are illusory; it has simply transferred costs from its underwriting business and buried them in its investment portfolio ▪ As a result of its profligacy, Argo has failed over a long period
Slide 9: voce capital ▪ We believe a top - to - bottom investigation is urgently
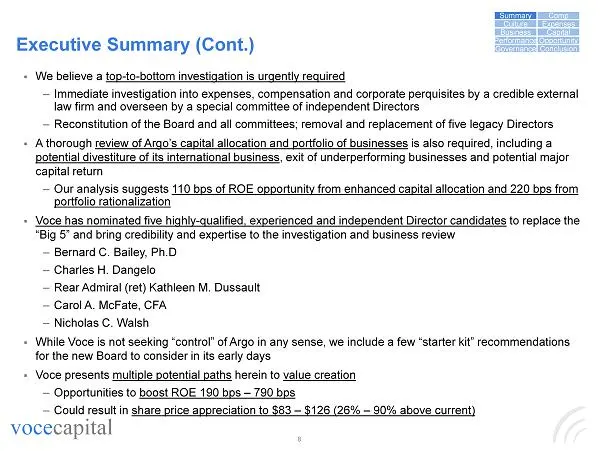
8 voce capital ▪ We believe a top - to - bottom investigation is urgently required – Immediate investigation into expenses, compensation and corporate perquisites by a credible external law firm and overseen by a special committee of independent Directors – Reconstitution of the Board and all commit
Slide 10: ROE Opportunity Summary
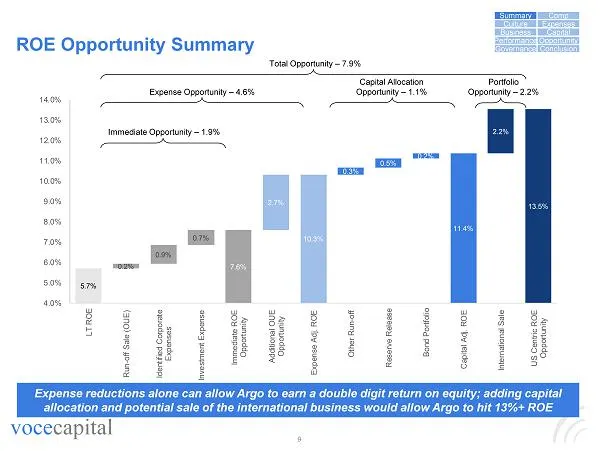
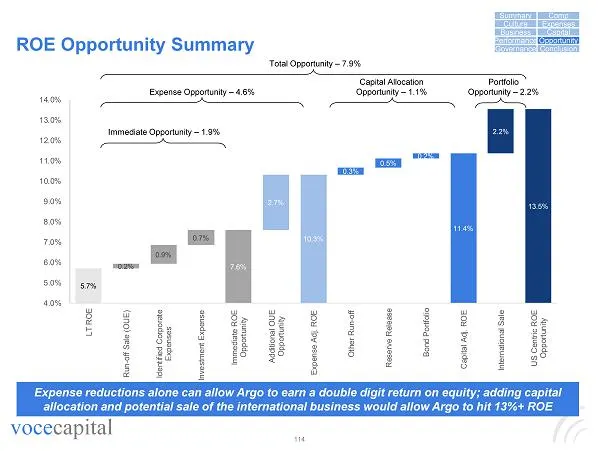
9 voce capital 5.7% 7.6% 10.3% 11.4% 13.5% 0.2% 0.9% 0.7% 2.7% 0.3% 0.5% 0.2% 2.2% 4.0% 5.0% 6.0% 7.0% 8.0% 9.0% 10.0% 11.0% 12.0% 13.0% 14.0% LT ROE Run-off Sale (OUE) Identified Corporate Expenses Investment Expense Immediate ROE Opportunity Additional OUE Opportunity Expense Adj. ROE Other Run-of
Slide 11: Our Nominees: Highly experienced, fully independent
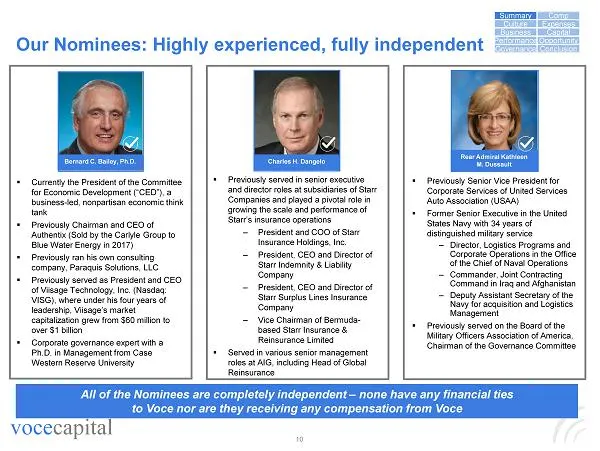
10 voce capital All of the Nominees are completely independent – none have any financial ties to Voce nor are they receiving any compensation from Voce Our Nominees: Highly experienced, fully independent ▪ Currently the President of the Committee for Economic Development (“CED”), a business - led, n
Slide 12: Our Nominees: Highly experienced, fully independent
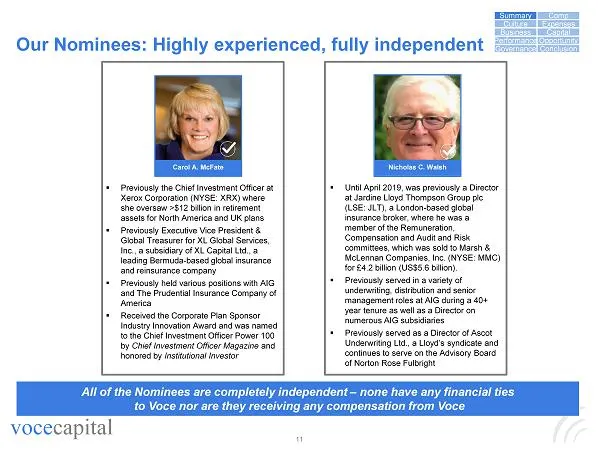
11 voce capital All of the Nominees are completely independent – none have any financial ties to Voce nor are they receiving any compensation from Voce Our Nominees: Highly experienced, fully independent ▪ Previously the Chief Investment Officer at Xerox Corporation (NYSE: XRX) where she oversaw >$1
Slide 13: About Voce
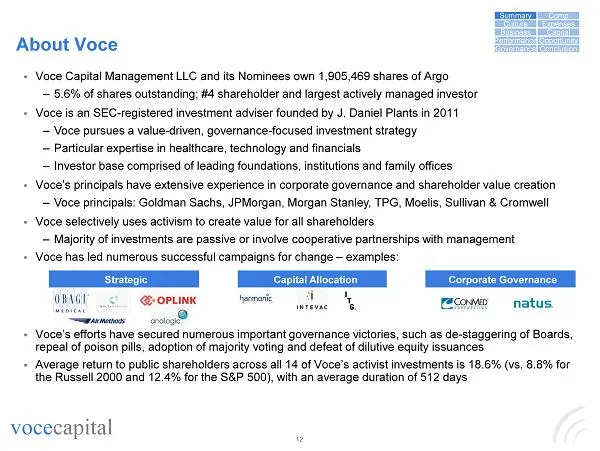
12 voce capital About Voce ▪ Voce Capital Management LLC and its Nominees own 1,905,469 shares of Argo – 5.6% of shares outstanding; #4 shareholder and largest actively managed investor ▪ Voce is an SEC - registered investment adviser founded by J. Daniel Plants in 2011 – Voce pursues a value - driv
Slide 14: Argo's Indulgent Culture
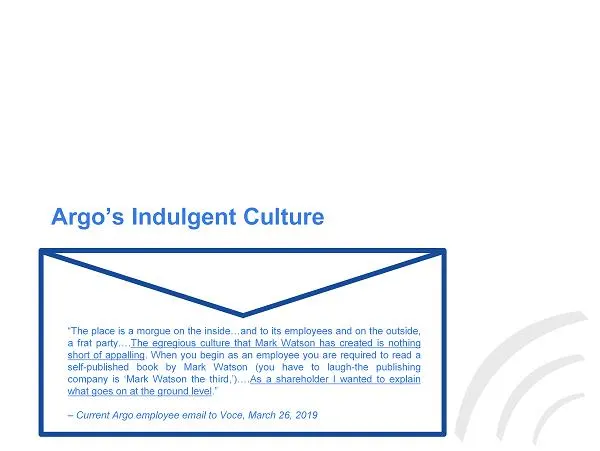
Argo’s Indulgent Culture “The place is a morgue on the inside … and to its employees and on the outside, a frat party … . The egregious culture that Mark Watson has created is nothing short of appalling . When you begin as an employee you are required to read a self - published book by Mark Watson (
Slide 15: Argo's Indulgent Culture: Summary
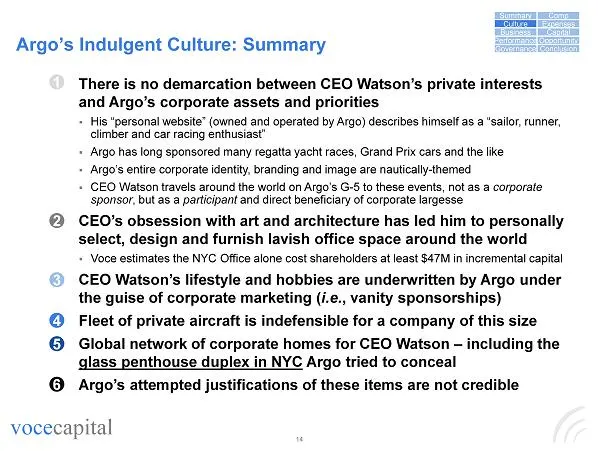
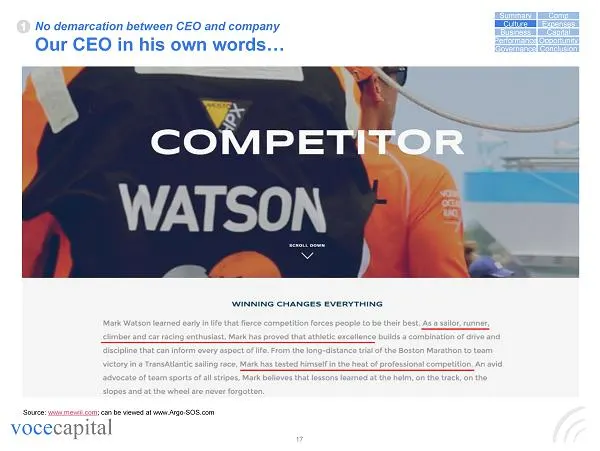
14 voce capital Argo’s Indulgent Culture: Summary ▪ There is no demarcation between CEO Watson’s private interests and Argo’s corporate assets and priorities ▪ His “personal website” (owned and operated by Argo) describes himself as a “sailor, runner, climber and car racing enthusiast” ▪ Argo has lo
Slide 16: Argo's Code of Conduct & Business Ethics
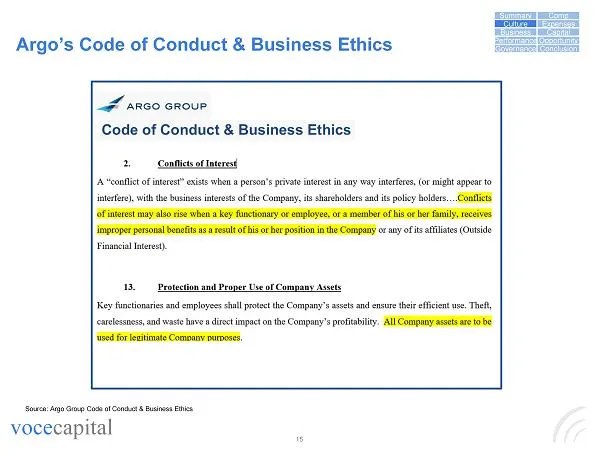
15 voce capital Argo’s Code of Conduct & Business Ethics Source: Argo Group Code of Conduct & Business Ethics Capital Expenses Comp Business Culture Summary Opportunity Performance Governance Conclusion
Slide 17: No demarcation between CEO and company
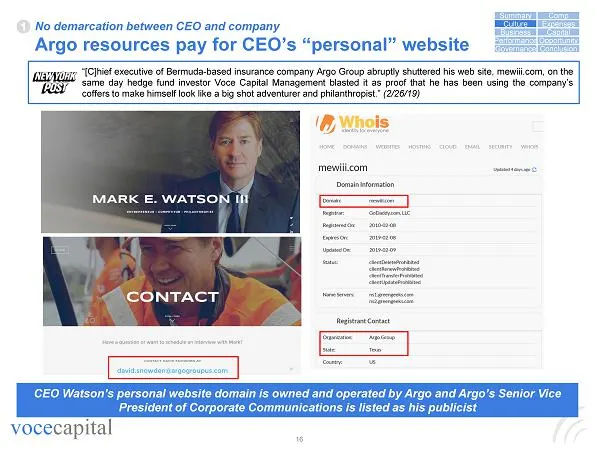
16 voce capital CEO Watson’s personal website domain is owned and operated by Argo and Argo’s Senior Vice President of Corporate Communications is listed as his publicist No demarcation between CEO and company Argo resources pay for CEO’s “personal” website 1 “[C] hief executive of Bermuda - based i
Slide 18: No demarcation between CEO and company
17 voce capital No demarcation between CEO and company Our CEO in his own words… Source: www.mewiii.com ; can be viewed at www.Argo - SOS.com 1 Capital Expenses Comp Business Culture Summary Opportunity Performance Governance Conclusion
Slide 19: CEO Watson: You should never confuse social and business objectives
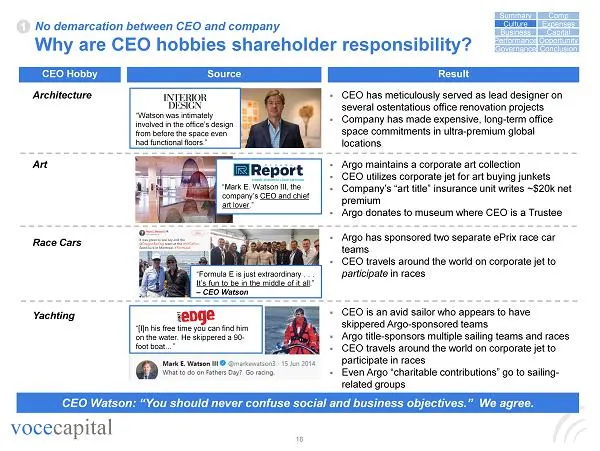
18 voce capital CEO Watson: “You should never confuse social and business objectives.” We agree. CEO Hobby Result Source ▪ CEO has meticulously served as lead designer on several ostentatious office renovation projects ▪ Company has made expensive, long - term office space commitments in ultra - pre
Slide 20: Lavish, award-winning office designs and locations
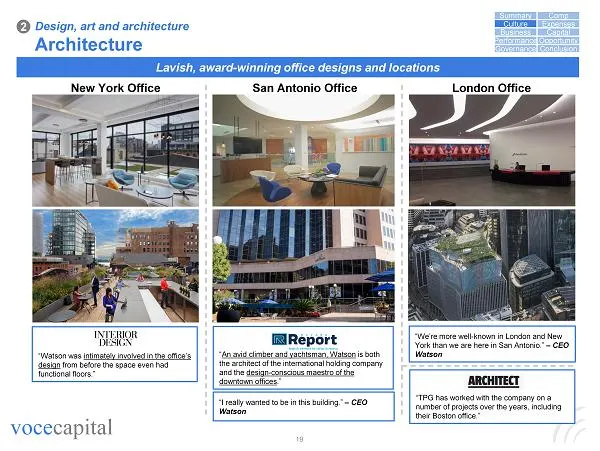
19 voce capital New York Office London Office San Antonio Office Lavish, award - winning office designs and locations Design, art and architecture Architecture 2 “ An avid climber and yachtsman, Watson is both the architect of the international holding company and the design - conscious maestro of t
Slide 21: Design, art and architecture: NYC Office
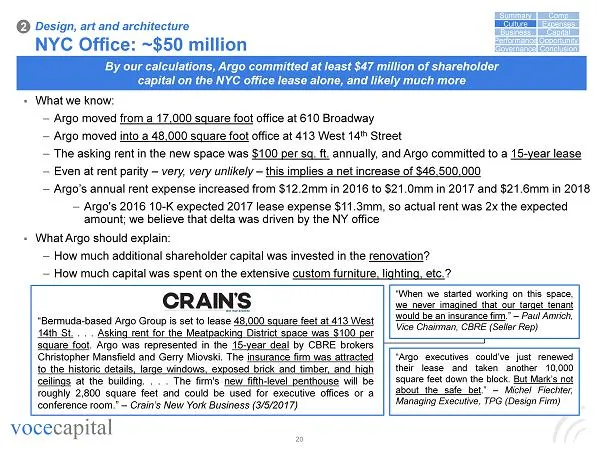
20 voce capital Design, art and architecture NYC Office: ~$50 million 2 By our calculations, Argo committed at least $47 million of shareholder capital on the NYC office lease alone, and likely much more “Bermuda - based Argo Group is set to lease 48 , 000 square feet at 413 West 14 th St . . . . As
Slide 22: NYC Office: No expenses spared
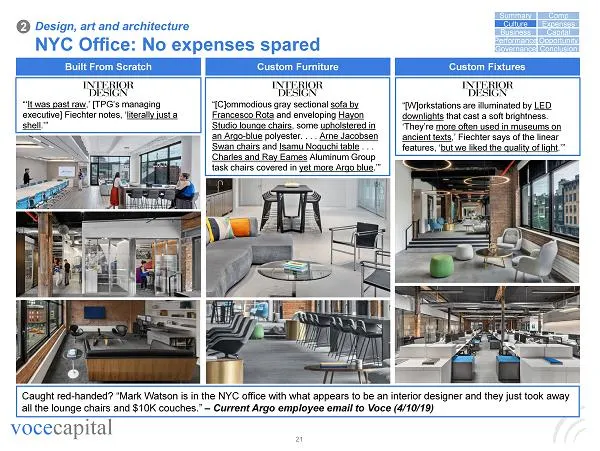
21 voce capital Design, art and architecture NYC Office: No expenses spared 2 “‘ It was past raw ,’ [TPG’s managing executive] Fiechter notes, ‘ literally just a shell .’” “[W] orkstations are illuminated by LED downlights that cast a soft brightness. ‘They’re more often used in museums on ancient t
Slide 23: Corporate art collection
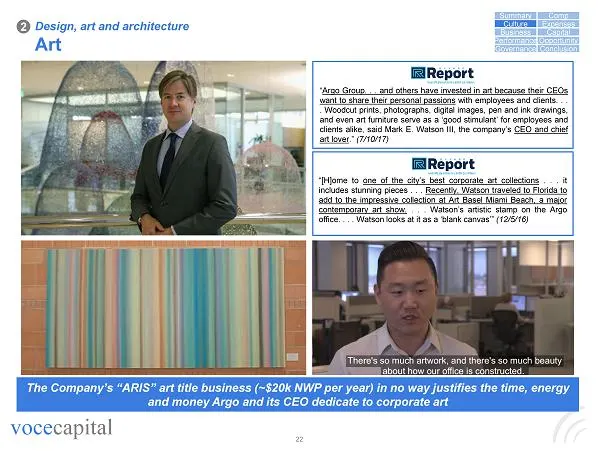
22 voce capital The Company’s “ARIS” art title business (~$20k NWP per year) in no way justifies the time, energy and money Argo and its CEO dedicate to corporate art Design, art and architecture Art 2 “ Argo Group . . . and others have invested in art because their CEOs want to share their personal
Slide 24: Vanity sponsorships: Race Cars
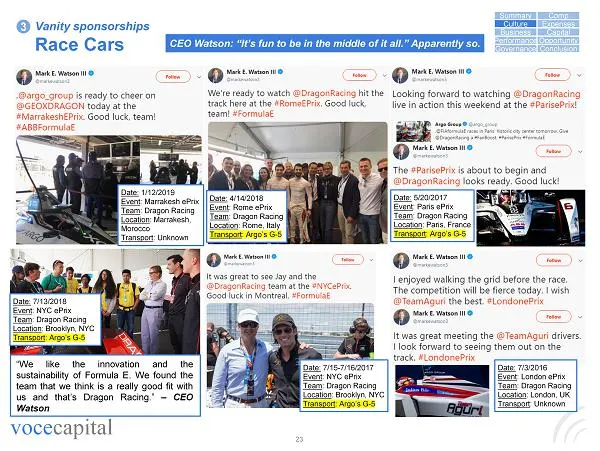
23 voce capital Vanity sponsorships Race Cars 3 Date: 1/12/2019 Event : Marrakesh ePrix Team : Dragon Racing Location : Marrakesh, Morocco Transport : Unknown Date: 7/13/2018 Event : NYC ePrix Team : Dragon Racing Location : Brooklyn, NYC Transport : Argo’s G - 5 Date: 4/14/2018 Event : Rome ePrix T
Slide 25: Vanity sponsorships: Yachting
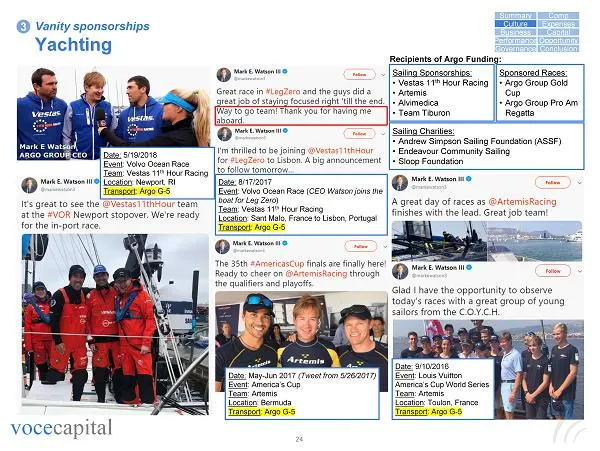
24 voce capital Vanity sponsorships Yachting 3 Sailing Sponsorships: • Vestas 11 th Hour Racing • Artemis • Alvimedica • Team Tiburon Sailing Charities: • Andrew Simpson Sailing Foundation (ASSF) • Endeavour Community Sailing • Sloop Foundation Sponsored Races: • Argo Group Gold Cup • Argo Group Pro
Slide 26: Vanity sponsorships: Yachting (Cont.)
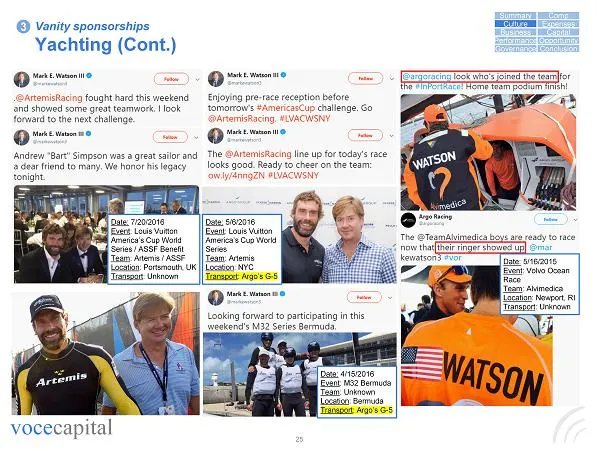
25 voce capital Vanity sponsorships Yachting (Cont.) 3 Date: 7/20/2016 Event : Louis Vuitton America’s Cup World Series / ASSF Benefit Team : Artemis / ASSF Location : Portsmouth, UK Transport : Unknown Date: 5/6/2016 Event : Louis Vuitton America’s Cup World Series Team : Artemis Location : NYC Tra
Slide 27: Illustrative America's Cup Team Costs
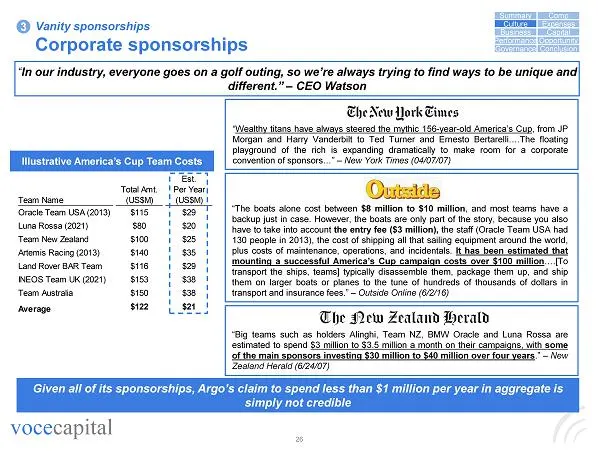
26 voce capital “ In our industry, everyone goes on a golf outing, so we’re always trying to find ways to be unique and different.” ‒ CEO Watson Illustrative America’s Cup Team Costs Given all of its sponsorships, Argo’s claim to spend less than $1 million per year in aggregate is simply not credibl
Slide 28: Argo's Recent G-5 Destinations
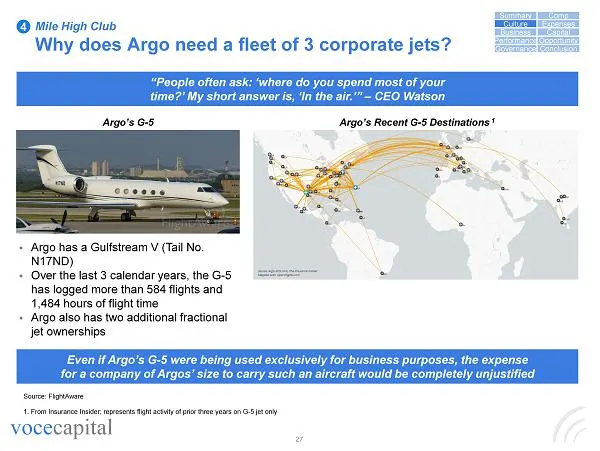
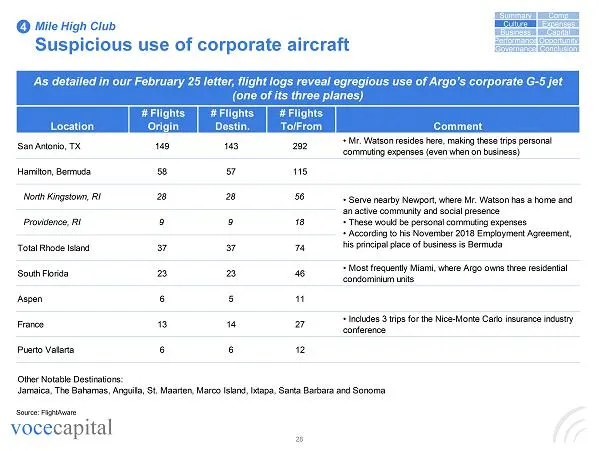
27 voce capital Argo’s Recent G - 5 Destinations 1 Source: FlightAware “People often ask: ‘where do you spend most of your time?’ My short answer is, ‘In the air.’” – CEO Watson Even if Argo’s G - 5 were being used exclusively for business purposes, the expense for a company of Argos’ size to carry
Slide 29: Suspicious use of corporate aircraft
28 voce capital As detailed in our February 25 letter, flight logs reveal egregious use of Argo’s corporate G - 5 jet (one of its three planes) Mile High Club Suspicious use of corporate aircraft 4 Source: FlightAware Location # Flights Origin # Flights Destin. # Flights To/From Comment San Antonio,
Slide 30: Business or pleasure?
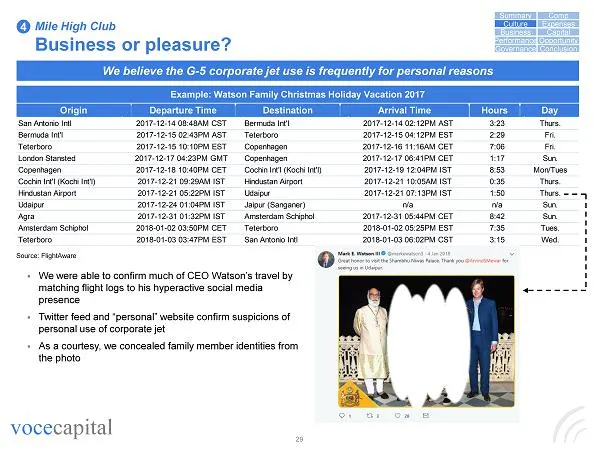
29 voce capital We believe the G - 5 corporate jet use is frequently for personal reasons Mile High Club Business or pleasure? 4 Example: Watson Family Christmas Holiday Vacation 2017 Origin Departure Time Destination Arrival Time Hours Day San Antonio Intl 2017-12-14 08:48AM CST Bermuda Int'l 2017-
Slide 31: Argo's global network of corporate housing
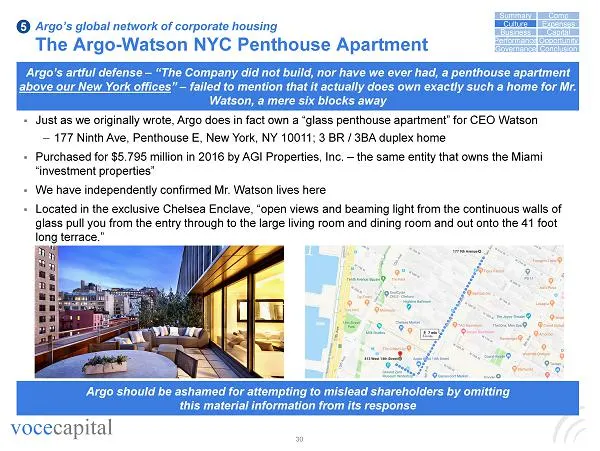
30 voce capital ▪ Just as we originally wrote, Argo does in fact own a “glass penthouse apartment” for CEO Watson – 177 Ninth Ave, Penthouse E, New York, NY 10011; 3 BR / 3BA duplex home ▪ Purchased for $5.795 million in 2016 by AGI Properties, Inc. – the same entity that owns the Miami “investment
Slide 32: Argo's Justification vs Reality
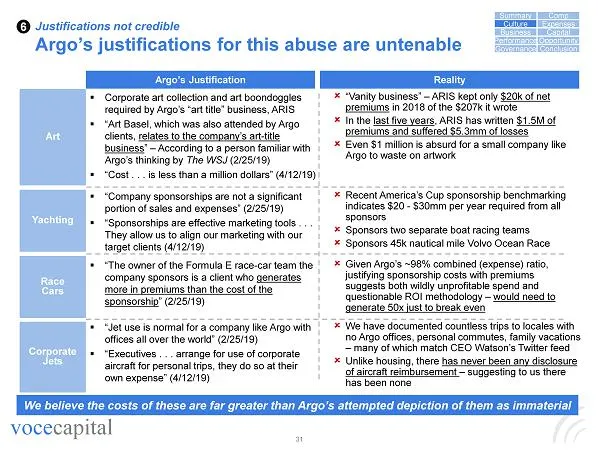
31 voce capital Argo’s Justification Reality “Vanity business” – ARIS kept only $20k of net premiums in 2018 of the $207k it wrote In the last five years , ARIS has written $1.5M of premiums and suffered $5.3mm of losses Even $1 million is absurd for a small company like Argo to waste on artwo
Slide 33: Business Overview
Business Overview
Slide 34: Argo snapshot
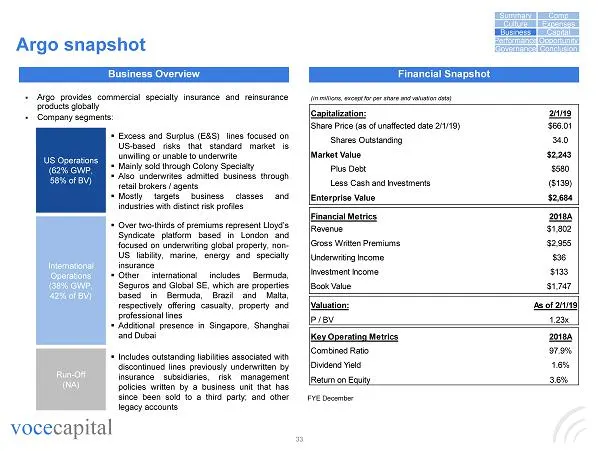
33 voce capital Argo snapshot Business Overview Financial Snapshot ▪ Argo provides commercial specialty insurance and reinsurance products globally ▪ Company segments: US Operations (62% GWP, 58% of BV) International Operations (38% GWP, 42% of BV) ▪ Excess and Surplus (E&S) lines focused on US - ba
Slide 35: Argo business overview
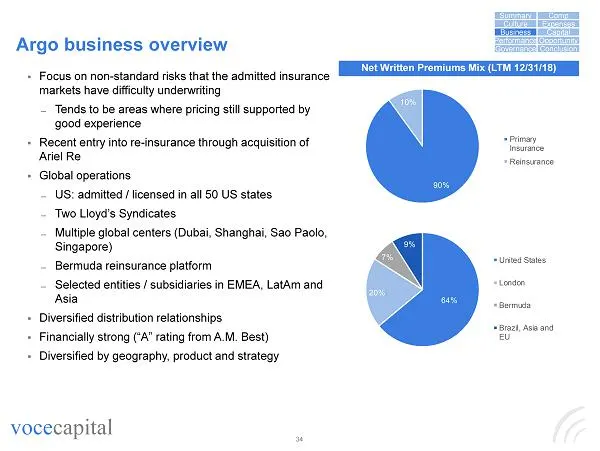
34 voce capital Argo business overview ▪ Focus on non - standard risks that the admitted insurance markets have difficulty underwriting ̶ Tends to be areas where pricing still supported by good experience ▪ Recent entry into re - insurance through acquisition of Ariel Re ▪ Global operations ̶ US: ad
Slide 36: US Operations Segment overview
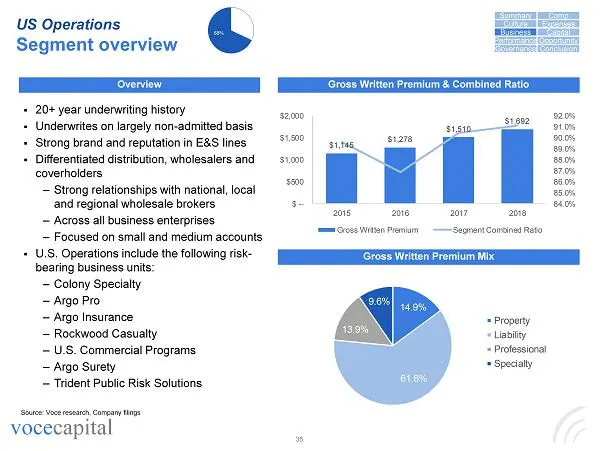
35 voce capital US Operations Segment overview 68% Overview Gross Written Premium & Combined Ratio Source: Voce research, Company filings Gross Written Premium Mix ▪ 20+ year underwriting history ▪ Underwrites on largely non - admitted basis ▪ Strong brand and reputation in E&S lines ▪ Differentiate
Slide 37: Colony Specialty
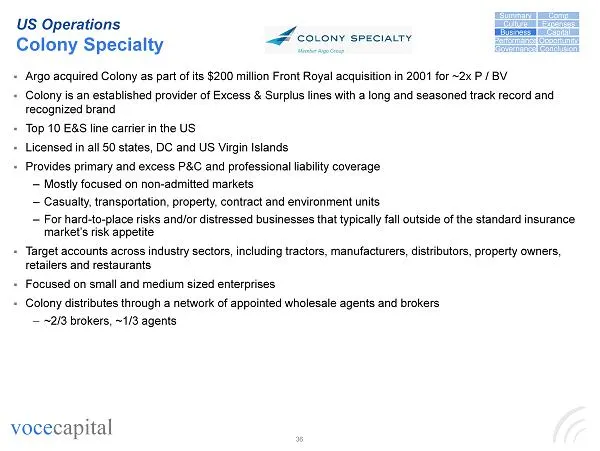
36 voce capital ▪ Argo acquired Colony as part of its $200 million Front Royal acquisition in 2001 for ~2x P / BV ▪ Colony is an established provider of Excess & Surplus lines with a long and seasoned track record and recognized brand ▪ Top 10 E&S line carrier in the US ▪ Licensed in all 50 states,
Slide 38: Argo Pro and other US units
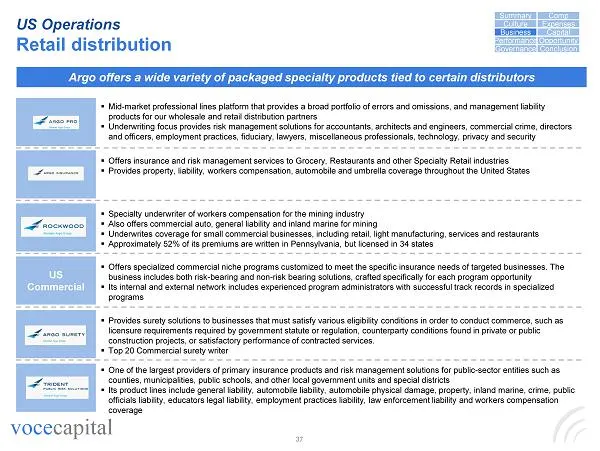
37 voce capital Argo Pro US Operations Retail distribution ▪ Mid - market professional lines platform that provides a broad portfolio of errors and omissions, and management liability products for our wholesale and retail distribution partners ▪ Underwriting focus provides risk management solutions
Slide 39: International Operations Segment overview
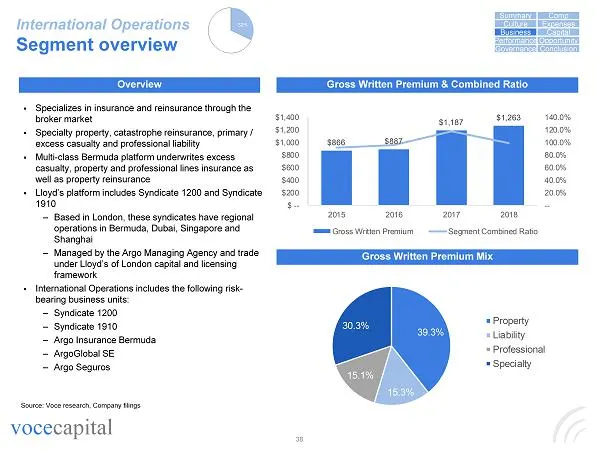
38 voce capital International Operations Segment overview 32% Overview Gross Written Premium & Combined Ratio Source: Voce research, Company filings Gross Written Premium Mix ▪ Specializes in insurance and reinsurance through the broker market ▪ Specialty property, catastrophe reinsurance, primary /
Slide 40: International Operations business units
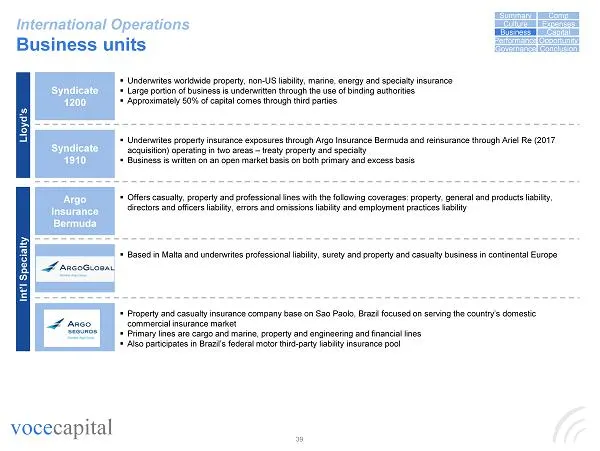
39 voce capital Syndicate 1200 International Operations Business units ▪ Underwrites worldwide property, non - US liability, marine, energy and specialty insurance ▪ Large portion of business is underwritten through the use of binding authorities ▪ Approximately 50% of capital comes through third pa
Slide 41: Investment portfolio
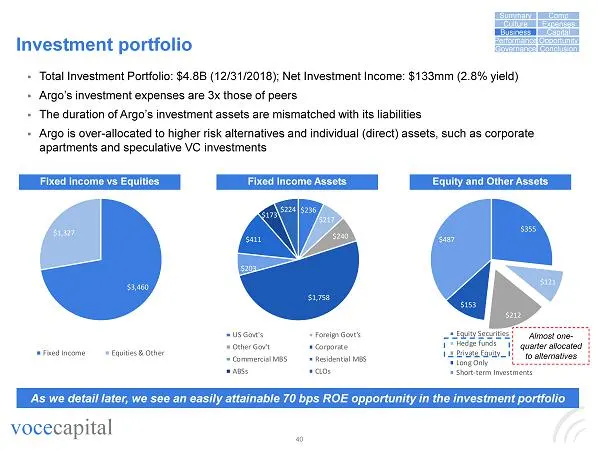
40 voce capital Investment portfolio ▪ Total Investment Portfolio: $4.8B (12/31/2018); Net Investment Income: $133mm (2.8% yield) ▪ Argo’s investment expenses are 3x those of peers ▪ The duration of Argo’s investment assets are mismatched with its liabilities ▪ Argo is over - allocated to higher ris
Slide 42: Decentralized Management Structure
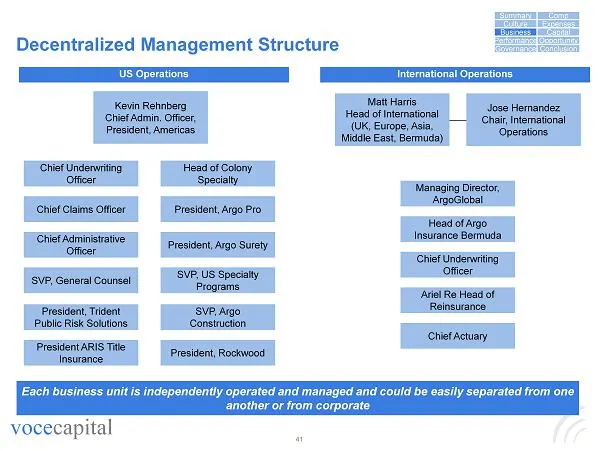
41 voce capital Decentralized Management Structure Kevin Rehnberg Chief Admin. Officer, President, Americas Matt Harris Head of International (UK, Europe, Asia, Middle East, Bermuda) Jose Hernandez Chair, International Operations Chief Underwriting Officer Chief Claims Officer Chief Administrative O
Slide 43: Underwriting Income Contribution
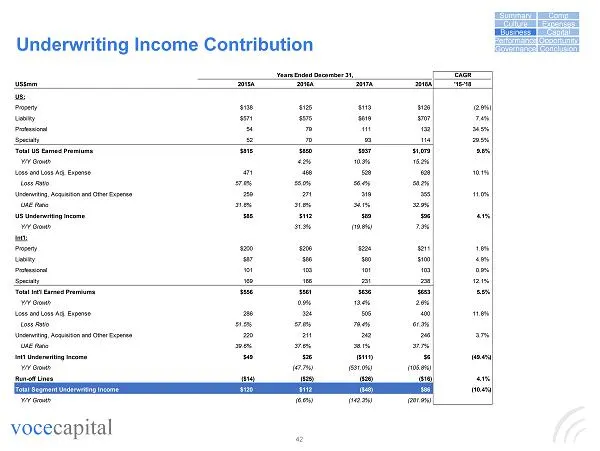
42 voce capital Underwriting Income Contribution Years Ended December 31, CAGR US$mm 2015A 2016A 2017A 2018A '15-'18 US: Property $138 $125 $113 $126 (2.9%) Liability $571 $575 $619 $707 7.4% Professional 54 79 111 132 34.5% Specialty 52 70 93 114 29.5% Total US Earned Premiums $815 $850 $937 $1,079
Slide 44: Income Statement
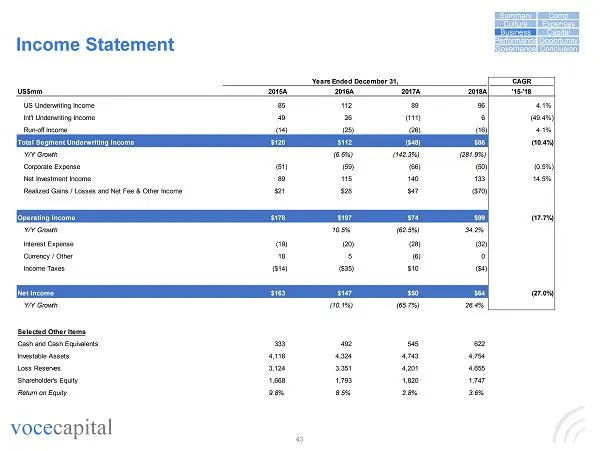
43 voce capital Income Statement Years Ended December 31, CAGR US$mm 2015A 2016A 2017A 2018A '15-'18 US Underwriting Income 85 112 89 96 4.1% Int'l Underwriting Income 49 26 (111) 6 (49.4%) Run-off Income (14) (25) (26) (16) 4.1% Total Segment Underwriting Income $120 $112 ($48) $86 (10.4%) Y/Y Grow
Slide 45: Assessing Argo's Long-Term Performance
Assessing Argo’s Long - Term Performance 1. Total Shareholder Return 2. Return on Equity 3. Argo’s Peers
Slide 46: Annotated Stock Price Chart
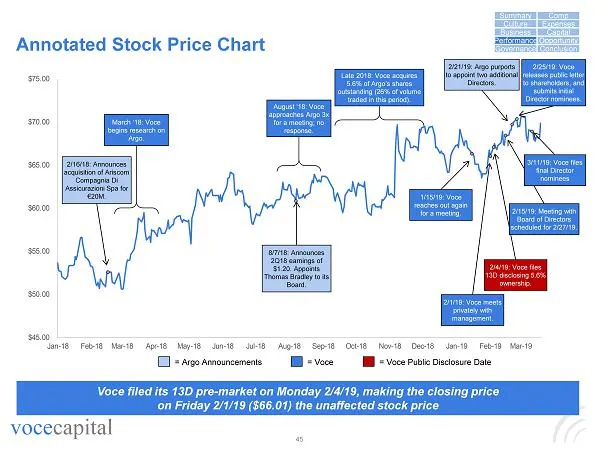
45 voce capital $45.00 $50.00 $55.00 $60.00 $65.00 $70.00 $75.00 Jan-18 Feb-18 Mar-18 Apr-18 May-18 Jun-18 Jul-18 Aug-18 Sep-18 Oct-18 Nov-18 Dec-18 Jan-19 Feb-19 Mar-19 Annotated Stock Price Chart 2/16/18: Announces acquisition of Ariscom Compagnia Di Assicurazioni Spa for €20M. 8/7/18: Announces 2
Slide 47: Argo's TSR is not materially different from its peers
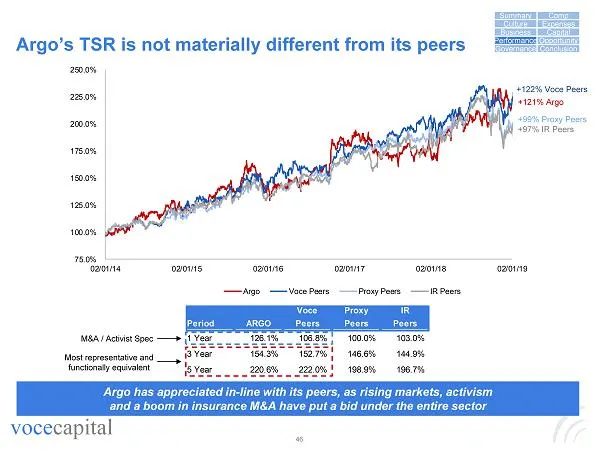
46 voce capital 75.0% 100.0% 125.0% 150.0% 175.0% 200.0% 225.0% 250.0% 02/01/14 02/01/15 02/01/16 02/01/17 02/01/18 02/01/19 Argo Voce Peers Proxy Peers IR Peers Voce Proxy IR Period ARGO Peers Peers Peers 1 Year 126.1% 106.8% 100.0% 103.0% 3 Year 154.3% 152.7% 146.6% 144.9% 5 Year 220.6% 222.0% 198
Slide 48: 5-Year TSR Bridge
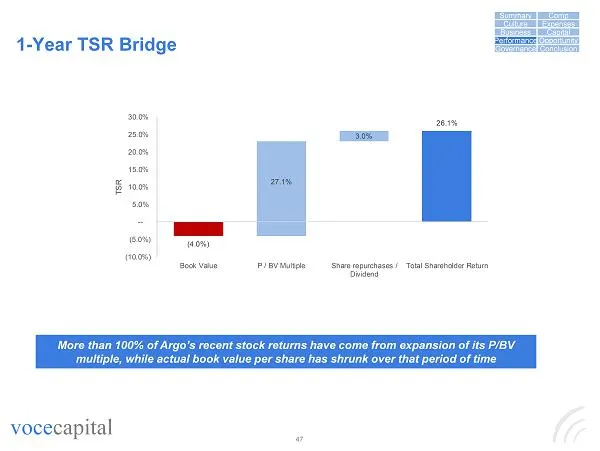
47 voce capital 1 - Year TSR Bridge More than 100% of Argo’s recent stock returns have come from expansion of its P/BV multiple, while actual book value per share has shrunk over that period of time 27.1% 3.0% (4.0%) 26.1% (10.0%) (5.0%) -- 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% Book Value P / BV Multip
Slide 49: Argo Historical BV Multiples
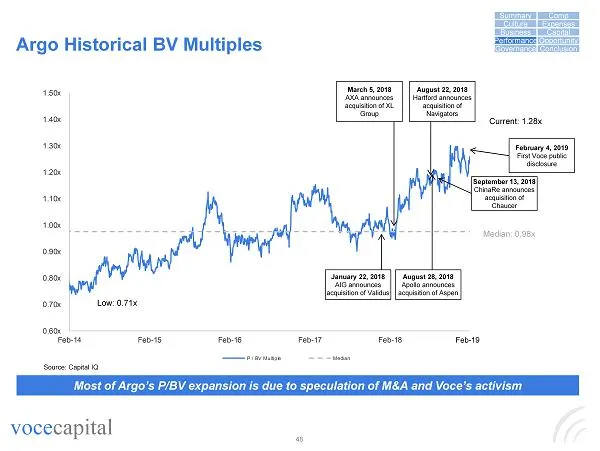
48 voce capital 0.60x 0.70x 0.80x 0.90x 1.00x 1.10x 1.20x 1.30x 1.40x 1.50x Feb-14 Feb-15 Feb-16 Feb-17 Feb-18 P / BV Multiple Median Argo Historical BV Multiples Median: 0.98x Low: 0.71x Current: 1.28x Source: Capital IQ Most of Argo’s P/BV expansion is due to speculation of M&A and Voce’s activism
Slide 50: Historical Discount to Peers
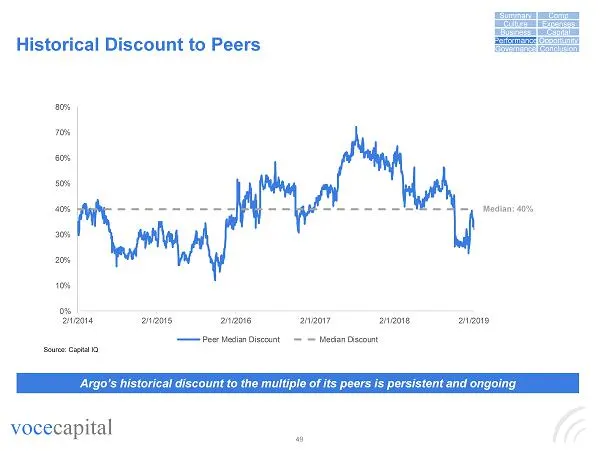
49 voce capital Historical Discount to Peers Argo’s historical discount to the multiple of its peers is persistent and ongoing Median: 40% 0% 10% 20% 30% 40% 50% 60% 70% 80% 2/1/2014 2/1/2015 2/1/2016 2/1/2017 2/1/2018 2/1/2019 Peer Median Discount Median Discount Capital Expenses Comp Business Cult
Slide 51: Argo bemoaned its valuation discount
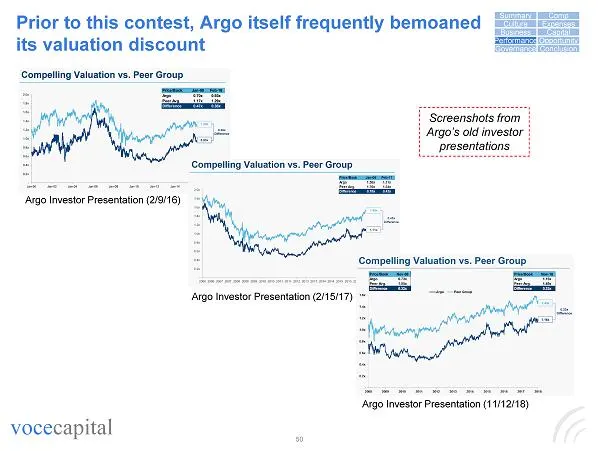
50 voce capital Prior to this contest, Argo itself frequently bemoaned its valuation discount Argo Investor Presentation (2/15/17) Argo Investor Presentation (11/12/18) Argo Investor Presentation (2/9/16) Screenshots from Argo’s old investor presentations Capital Expenses Comp Business Culture Summa
Slide 52: Peer comparison table
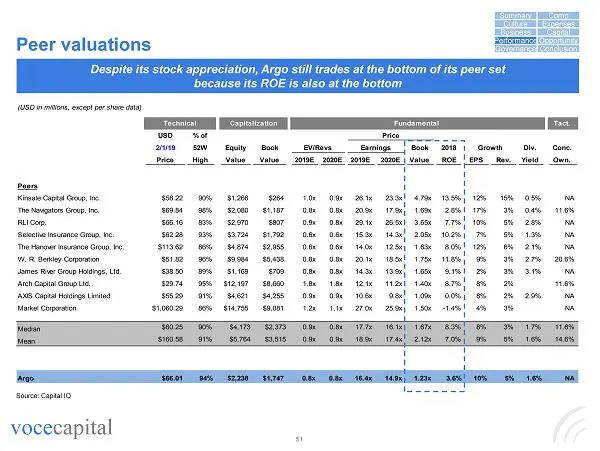
51 voce capital (USD in millions, except per share data) Technical Capitalization Fundamental Tact. USD % of Price 2/1/19 52W Equity Book EV/Revs Earnings Book 2018 Growth Div. Conc. Price High Value Value 2019E 2020E 2019E 2020E Value ROE EPS Rev. Yield Own. Peers Kinsale Capital Group, Inc. $58.22
Slide 53: TSR isn't everything
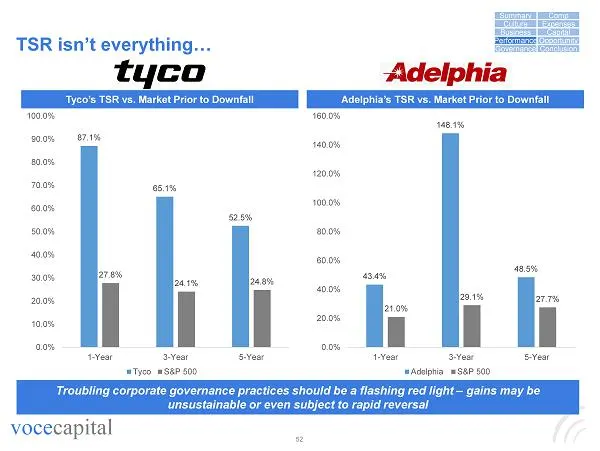
52 voce capital 43.4% 148.1% 48.5% 21.0% 29.1% 27.7% 0.0% 20.0% 40.0% 60.0% 80.0% 100.0% 120.0% 140.0% 160.0% 1-Year 3-Year 5-Year Adelphia S&P 500 TSR isn’t everything… 87.1% 65.1% 52.5% 27.8% 24.1% 24.8% 0.0% 10.0% 20.0% 30.0% 40.0% 50.0% 60.0% 70.0% 80.0% 90.0% 100.0% 1-Year 3-Year 5-Year Tyco S&
Slide 54: Assessing Argo's Long-Term Performance
Assessing Argo’s Long - Term Performance 1. Total Shareholder Return 2. Return on Equity 3. Argo’s Peers
Slide 55: Argo's inferior Return on Equity
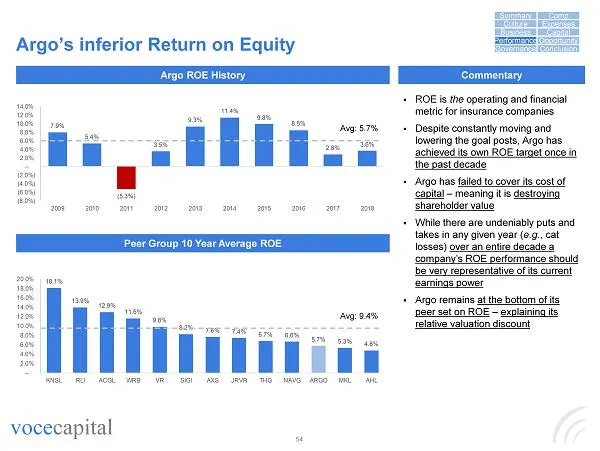
54 voce capital 18.1% 13.9% 12.9% 11.6% 9.8% 8.2% 7.6% 7.4% 6.7% 6.6% 5.7% 5.3% 4.8% -- 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% 18.0% 20.0% KNSL RLI ACGL WRB VR SIGI AXS JRVR THG NAVG ARGO MKL AHL Argo’s inferior Return on Equity Argo ROE History Peer Group 10 Year Average ROE Commentary ▪ ROE i
Slide 56: Long-term failure to meet own ROE targets
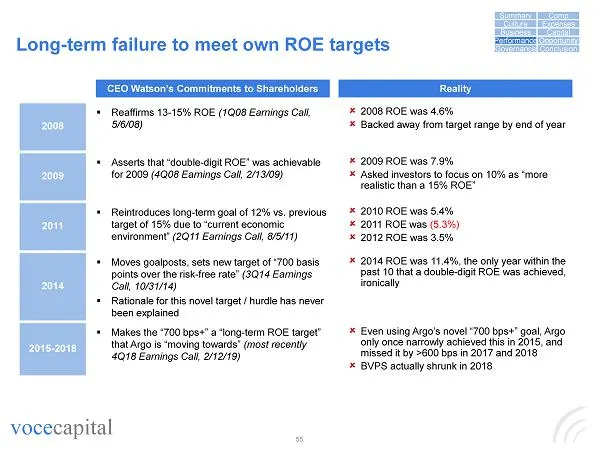
55 voce capital Long - term failure to meet own ROE targets CEO Watson’s Commitments to Shareholders Reality 2008 ROE was 4.6% Backed away from target range by end of year 2008 ▪ Reaffirms 13 - 15% ROE (1Q08 Earnings Call, 5/6/08) 2009 ROE was 7.9% Asked investors to focus on 10% as “more re
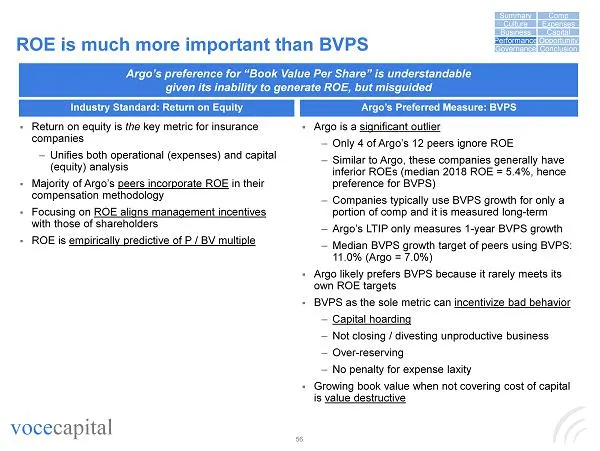
Slide 57: ROE is much more important than BVPS
56 voce capital ROE is much more important than BVPS Argo’s preference for “Book Value Per Share” is understandable given its inability to generate ROE, but misguided Industry Standard: Return on Equity Argo’s Preferred Measure: BVPS ▪ Return on equity is the key metric for insurance companies – Uni
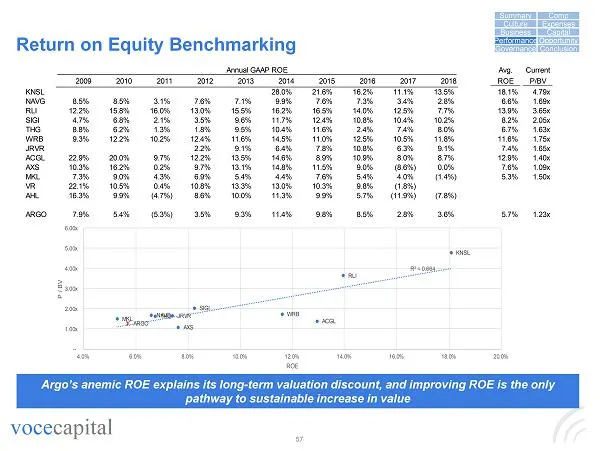
Slide 58: Return on Equity Benchmarking
57 voce capital Return on Equity Benchmarking Argo’s anemic ROE explains its long - term valuation discount, and improving ROE is the only pathway to sustainable increase in value KNSL NAVG RLI SIGI THG WRB JRVR ACGL AXS MKL ARGO R² = 0.664 -- 1.00x 2.00x 3.00x 4.00x 5.00x 6.00x 4.0% 6.0% 8.0% 10.0%
Slide 59: Assessing Argo's Long-Term Performance
Assessing Argo’s Long - Term Performance 1. Total Shareholder Return 2. Return on Equity 3. Argo’s Peers
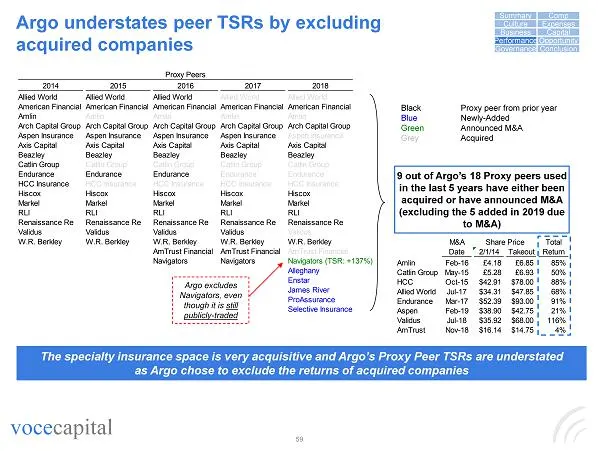
Slide 60: Argo understates peer TSRs
59 voce capital M&A Share Price Total Date 2/1/14 Takeout Return Amlin Feb-16 £4.18 £6.85 85% Catlin Group May-15 £5.28 £6.93 50% HCC Oct-15 $42.91 $78.00 88% Allied World Jul-17 $34.31 $47.85 68% Endurance Mar-17 $52.39 $93.00 91% Aspen Feb-19 $38.90 $42.75 21% Validus Jul-18 $35.92 $68.00 116% AmT
Slide 61: Argo's selective peering
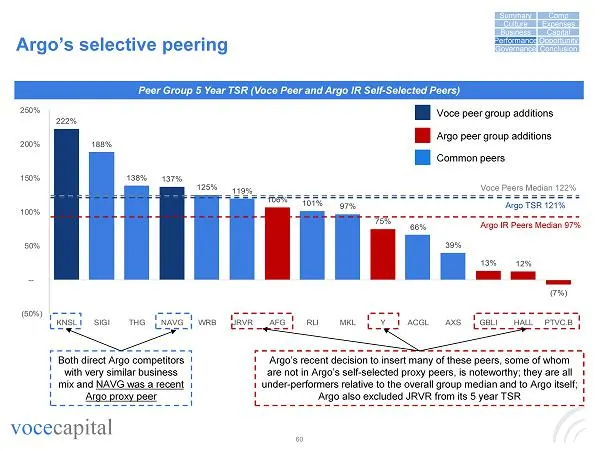
60 voce capital 222% 188% 138% 137% 125% 119% 106% 101% 97% 75% 66% 39% 13% 12% (7%) (50%) -- 50% 100% 150% 200% 250% KNSL SIGI THG NAVG WRB JRVR AFG RLI MKL Y ACGL AXS GBLI HALL PTVC.B Argo’s selective peering Peer Group 5 Year TSR (Voce Peer and Argo IR Self - Selected Peers) Voce Peers Median 122
Slide 62: Musical peers
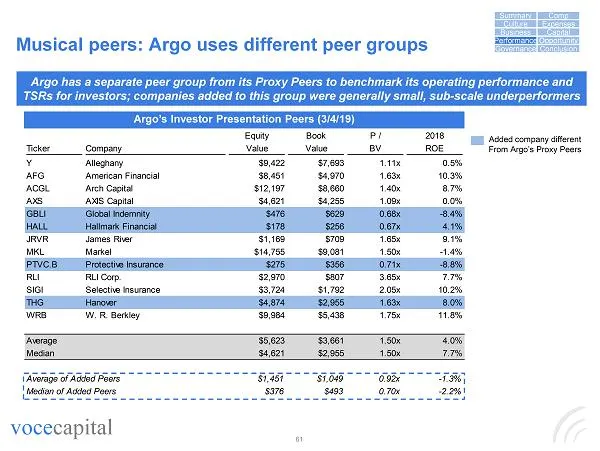
61 voce capital Musical peers: Argo uses different peer groups Argo has a separate peer group from its Proxy Peers to benchmark its operating performance and TSRs for investors; companies added to this group were generally small, sub - scale underperformers Argo’s Investor Presentation Peers (3/4/19
Slide 63: Why would Argo include these companies?
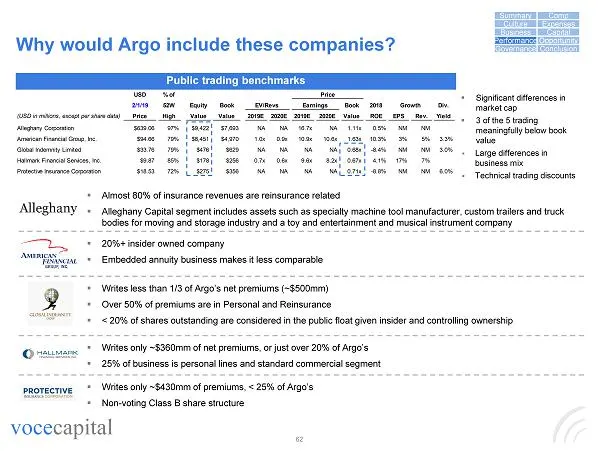
62 voce capital Why would Argo include these companies? ▪ Almost 80% of insurance revenues are reinsurance related ▪ Alleghany Capital segment includes assets such as specialty machine tool manufacturer, custom trailers and truck bodies for moving and storage industry and a toy and entertainment and
Slide 64: Opportunity #1: Revitalize Corporate Governance
Opportunity #1: Revitalize Corporate Governance
Slide 65: Revitalize Corporate Governance: Summary
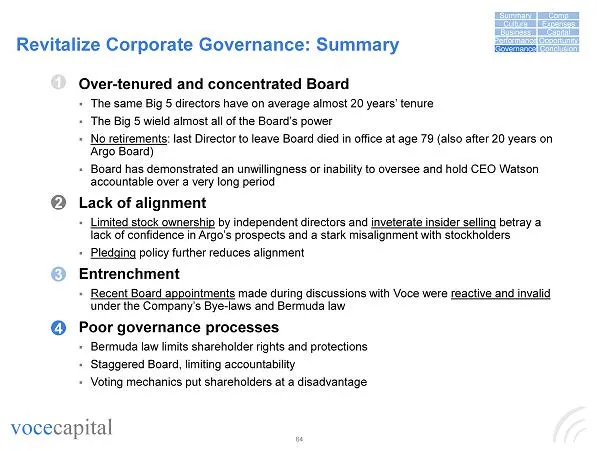
64 voce capital Revitalize Corporate Governance: Summary ▪ Over - tenured and concentrated Board ▪ The same Big 5 directors have on average almost 20 years’ tenure ▪ The Big 5 wield almost all of the Board’s power ▪ No retirements : last Director to leave Board died in office at age 79 (also after 2
Slide 66: Director tenure on Argo Board
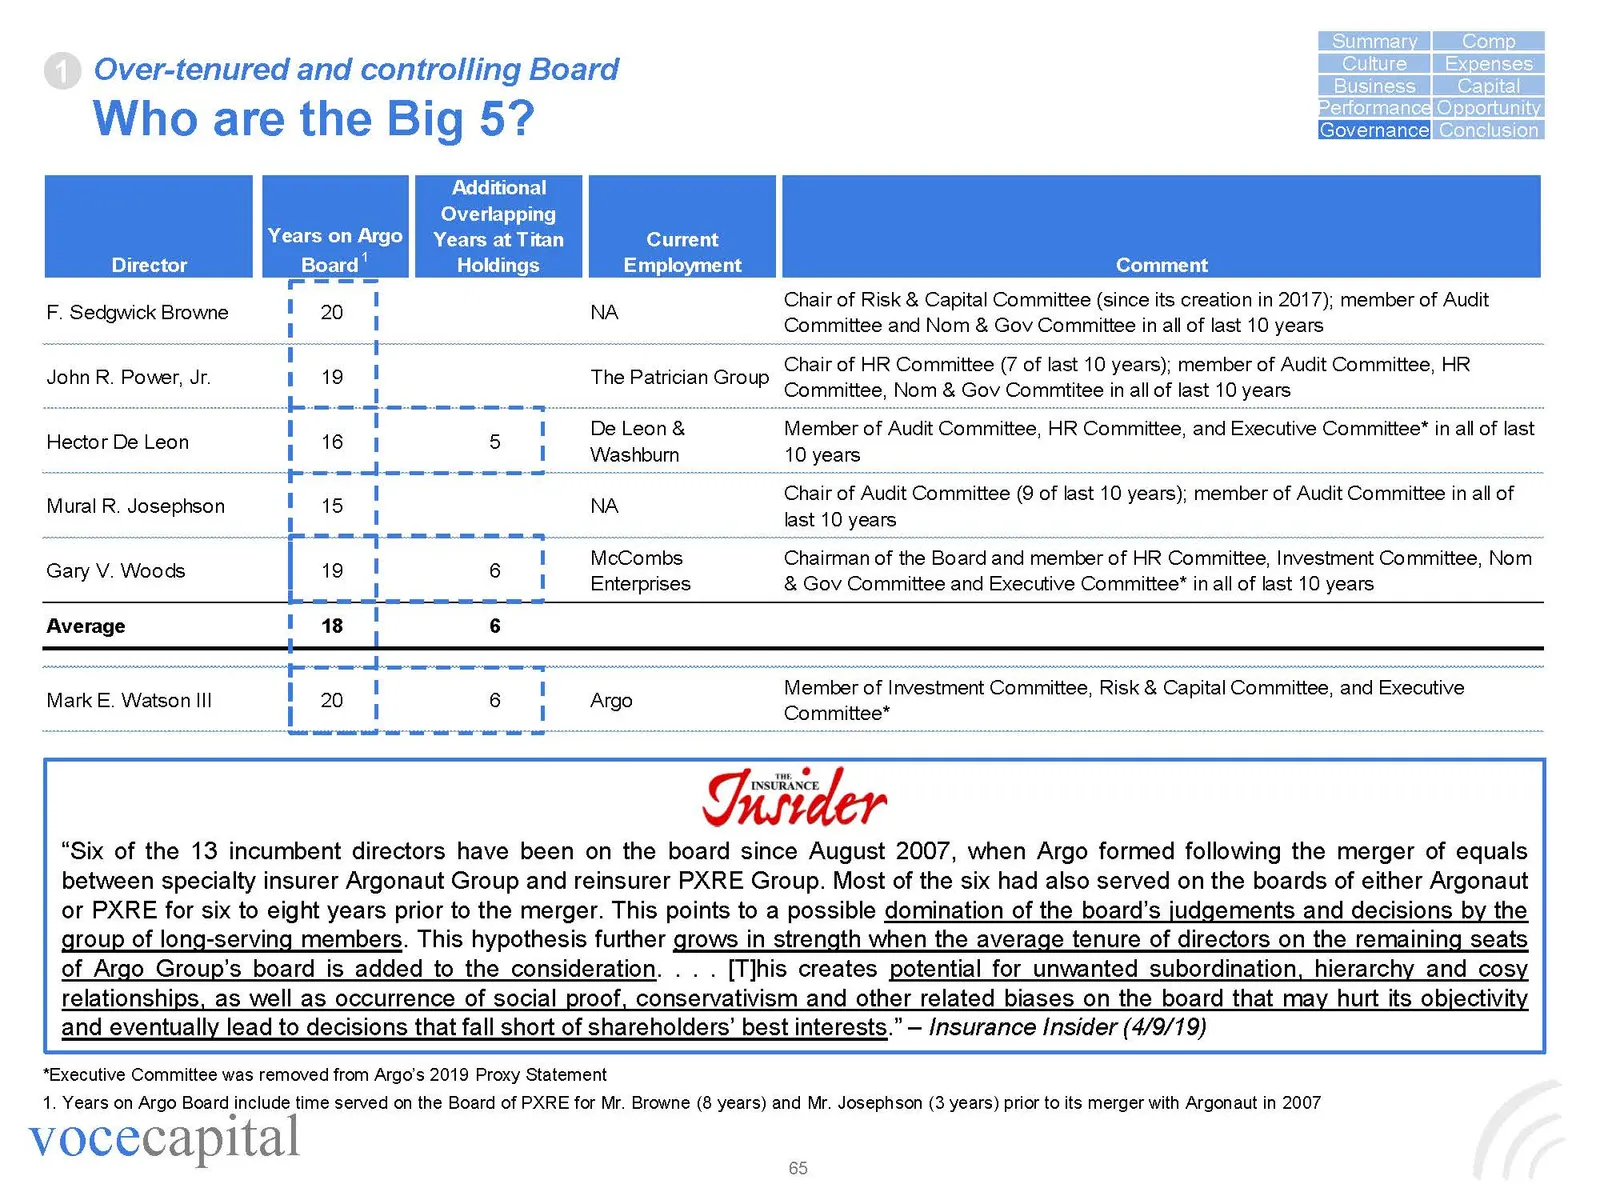
65 voce capital Director Years on Argo Board 1 Additional Overlapping Years at Titan Holdings Current Employment Comment F. Sedgwick Browne 20 NA Chair of Risk & Capital Committee (since its creation in 2017); member of Audit Committee and Nom & Gov Committee in all of last 10 years John R. Power, J
Slide 67: Window dressing of Board committees
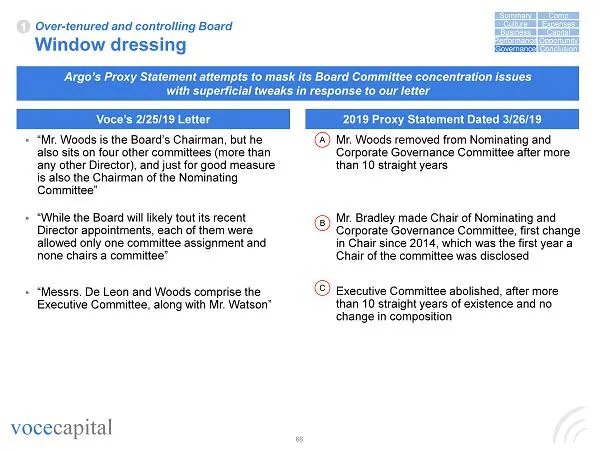
66 voce capital ▪ Mr. Woods removed from Nominating and Corporate Governance Committee after more than 10 straight years ▪ Mr. Bradley made Chair of Nominating and Corporate Governance Committee, first change in Chair since 2014, which was the first year a Chair of the committee was disclosed ▪ Exec
Slide 68: Committee membership history
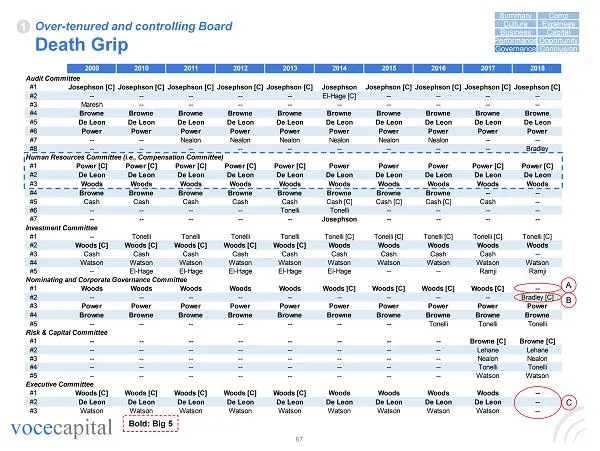
67 voce capital 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 Audit Committee #1 Josephson [C]Josephson [C]Josephson [C]Josephson [C]Josephson [C] Josephson Josephson [C]Josephson [C]Josephson [C]Josephson [C] #2 -- -- -- -- -- El-Hage [C] -- -- -- -- #3 Maresh -- -- -- -- -- -- -- -- -- #4 Brow
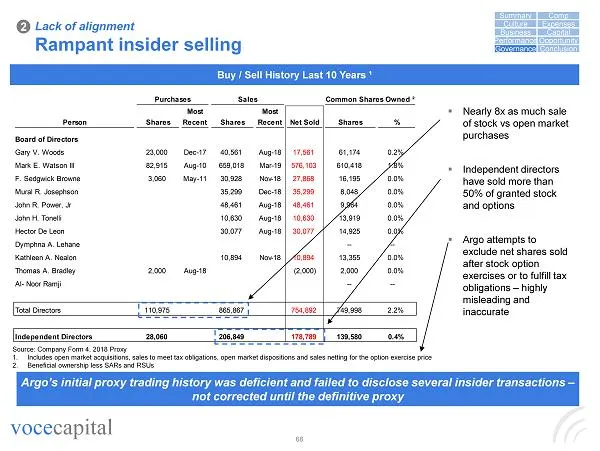
Slide 69: Lack of alignment: insider selling
68 voce capital Purchases Sales Common Shares Owned ² Person Shares Most Recent Shares Most Recent Net Sold Shares % Board of Directors Gary V. Woods 23,000 Dec-17 40,561 Aug-18 17,561 61,174 0.2% Mark E. Watson III 82,915 Aug-10 659,018 Mar-19 576,103 610,418 1.8% F. Sedgwick Browne 3,060 May-11 30
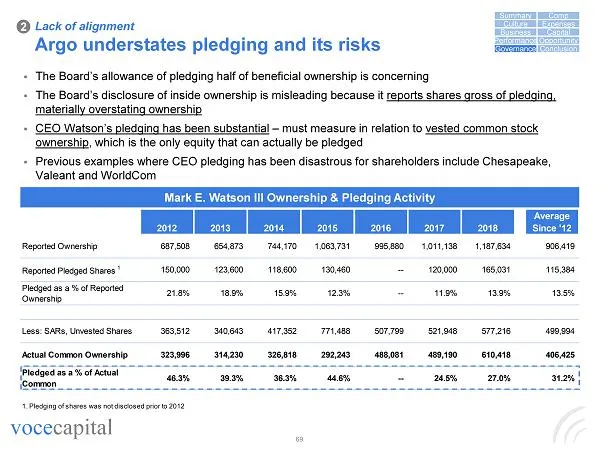
Slide 70: Mark E. Watson III Ownership & Pledging Activity
69 voce capital Mark E. Watson III Ownership & Pledging Activity Lack of alignment Argo understates pledging and its risks ▪ The Board’s allowance of pledging half of beneficial ownership is concerning ▪ The Board’s disclosure of inside ownership is misleading because it reports shares gross of pled
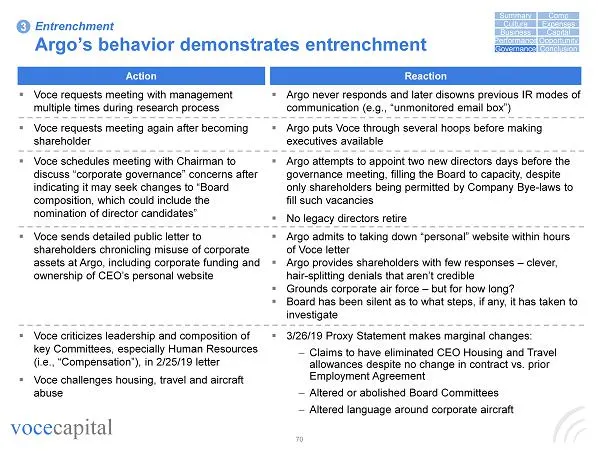
Slide 71: Entrenchment
70 voce capital Entrenchment Argo’s behavior demonstrates entrenchment Action Reaction ▪ Voce requests meeting with management multiple times during research process ▪ Argo never responds and later disowns previous IR modes of communication (e.g., “unmonitored email box”) ▪ Voce requests meeting aga
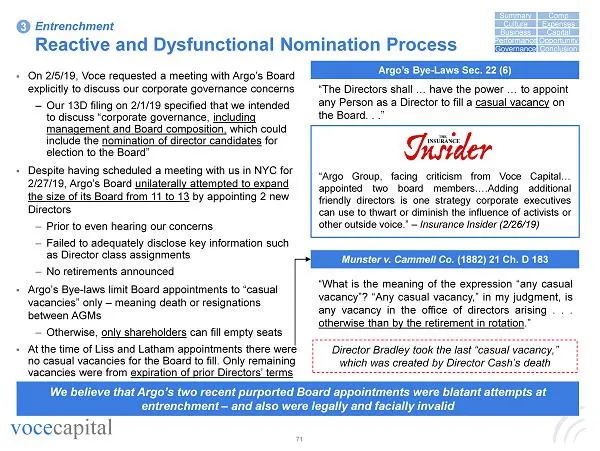
Slide 72: Entrenchment: Board appointments
71 voce capital ▪ On 2/5/19, Voce requested a meeting with Argo’s Board explicitly to discuss our corporate governance concerns – Our 13D filing on 2/1/19 specified that we intended to discuss “corporate governance, including management and Board composition, which could include the nomination of di
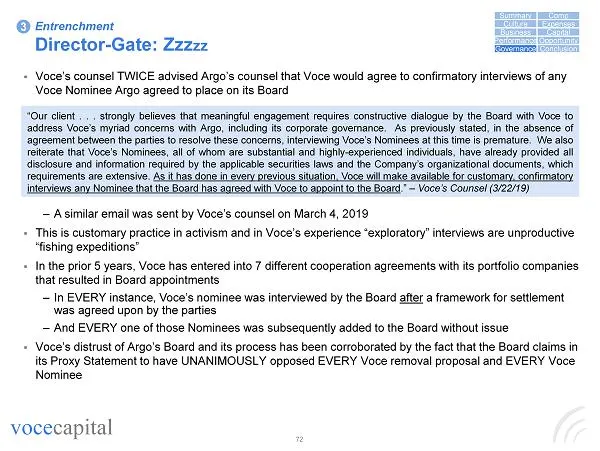
Slide 73: Entrenchment: Director-Gate
72 voce capital Entrenchment Director - Gate: Zzz zz ▪ Voce’s counsel TWICE advised Argo’s counsel that Voce would agree to confirmatory interviews of any Voce Nominee Argo agreed to place on its Board – A similar email was sent by Voce’s counsel on March 4, 2019 ▪ This is customary practice in acti
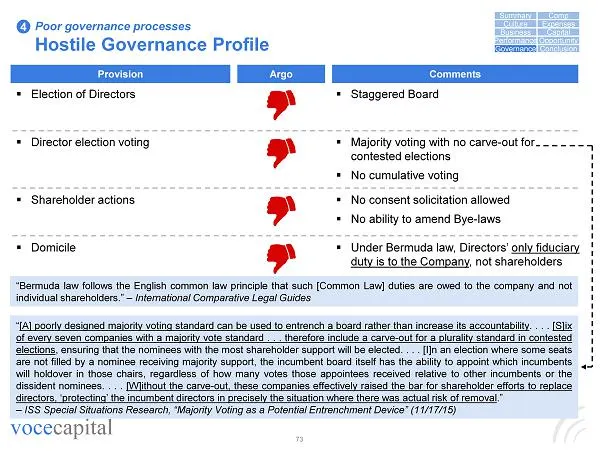
Slide 74: Anti-shareholder governance provisions
73 voce capital Provision Comments Argo ▪ Election of Directors ▪ Staggered Board ▪ Director election voting ▪ Majority voting with no carve - out for contested elections ▪ No cumulative voting ▪ Shareholder actions ▪ No consent solicitation allowed ▪ No ability to amend Bye - laws ▪ Domicile ▪ Unde
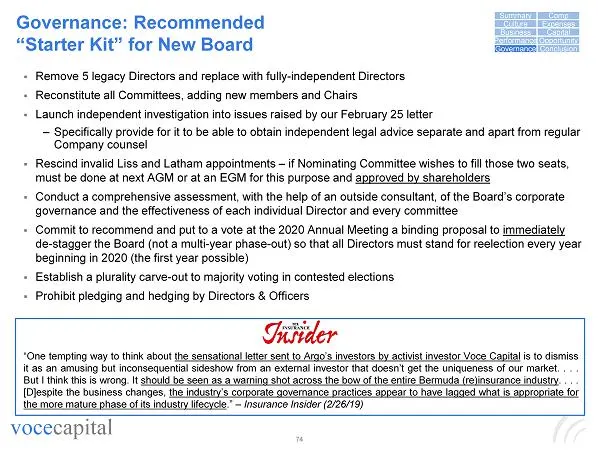
Slide 75: Governance: Recommended Starter Kit for New Board
74 voce capital Governance: Recommended “Starter Kit” for New Board ▪ Remove 5 legacy Directors and replace with fully - independent Directors ▪ Reconstitute all Committees, adding new members and Chairs ▪ Launch independent investigation into issues raised by our February 25 letter – Specifically p
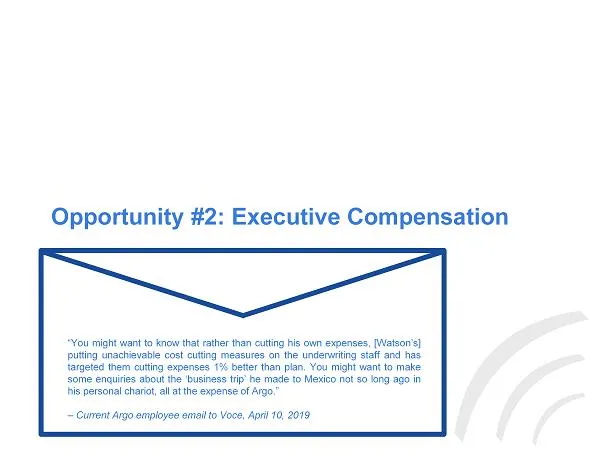
Slide 76: Opportunity #2: Executive Compensation
Opportunity #2: Executive Compensation “You might want to know that rather than cutting his own expenses, [Watson’s] putting unachievable cost cutting measures on the underwriting staff and has targeted them cutting expenses 1 % better than plan . You might want to make some enquiries about the ‘bus
Slide 77: Executive Compensation: Summary
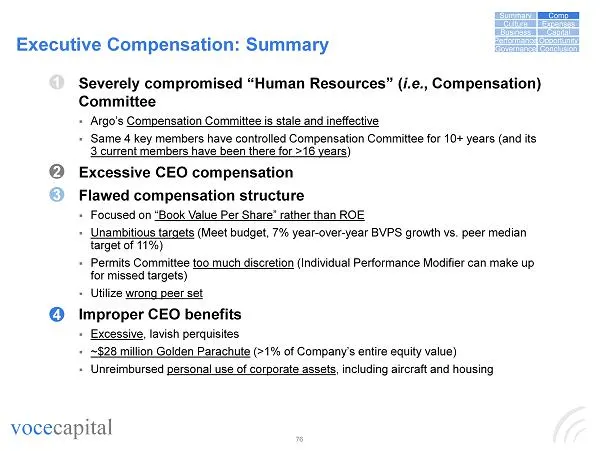
76 voce capital Executive Compensation: Summary ▪ Severely compromised “Human Resources” ( i.e. , Compensation) Committee ▪ Argo’s Compensation Committee is stale and ineffective ▪ Same 4 key members have controlled Compensation Committee for 10+ years (and its 3 current members have been there for
Slide 78: CEO Employment Agreement of November 2018
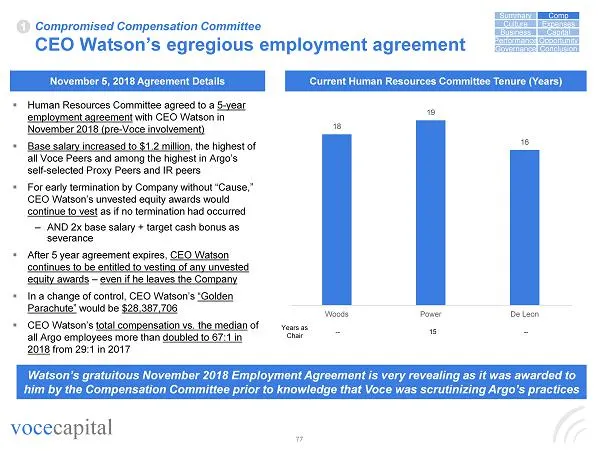
77 voce capital Watson’s gratuitous November 2018 Employment Agreement is very revealing as it was awarded to him by the Compensation Committee prior to knowledge that Voce was scrutinizing Argo’s practices November 5, 2018 Agreement Details Current Human Resources Committee Tenure (Years) ▪ Human R
Slide 79: Compromised Compensation Committee
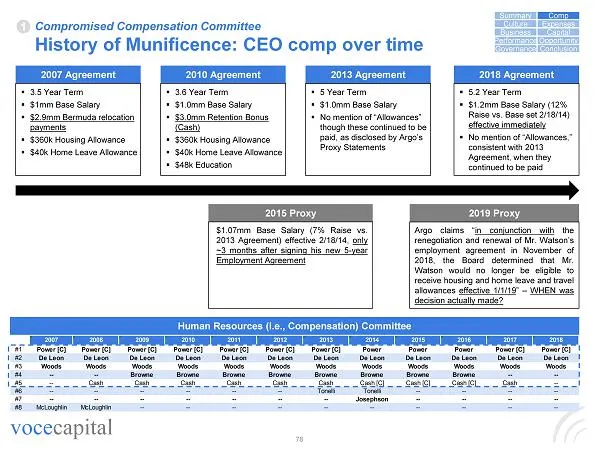
78 voce capital Compromised Compensation Committee History of Munificence: CEO comp over time 1 2007 Agreement ▪ 3.5 Year Term ▪ $1mm Base Salary ▪ $2.9mm Bermuda relocation payments ▪ $360k Housing Allowance ▪ $40k Home Leave Allowance 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 #1
Slide 80: CEO compensation is excessive
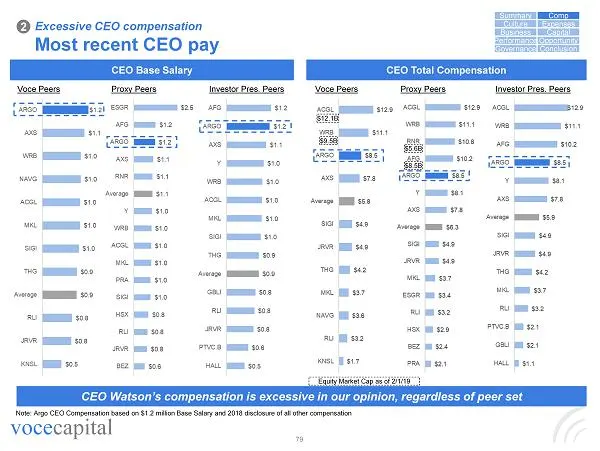
79 voce capital CEO Base Salary CEO Total Compensation CEO Watson’s compensation is excessive in our opinion, regardless of peer set Excessive CEO compensation Most recent CEO pay Voce Peers Proxy Peers Investor Pres. Peers Voce Peers Proxy Peers Investor Pres. Peers $12.1B $9.5B $5.6B Equity Market
Slide 81: Flawed compensation structure
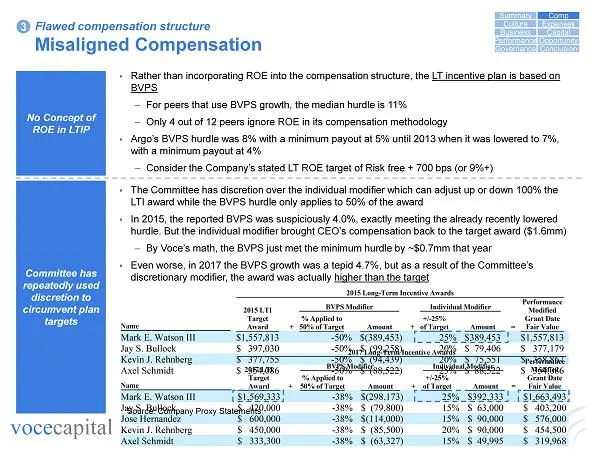
80 voce capital 2015 Long-Term Incentive Awards 2015 LTI Target Award BVPS Modifier Individual Modifier Performance Modified Grant Date Fair Value Name + % Applied to 50% of Target Amount + +/-25% of Target Amount = Mark E. Watson III $ 1,557,813 -50 % $ (389,453 ) 25 % $ 389,453 $ 1,557,813 Jay S.
Slide 82: Improper CEO benefits: Housing and Travel
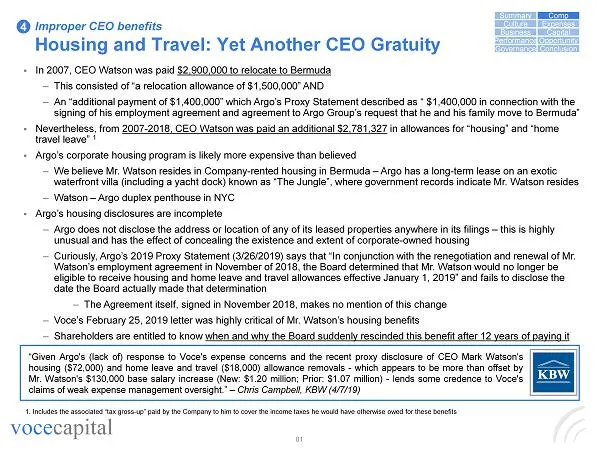
81 voce capital Improper CEO benefits Housing and Travel: Yet Another CEO Gratuity ▪ In 2007, CEO Watson was paid $2,900,000 to relocate to Bermuda – This consisted of “a relocation allowance of $1,500,000” AND – An “additional payment of $1,400,000” which Argo’s Proxy Statement described as “ $1,40
Slide 83: Compensation: Recommended Starter Kit
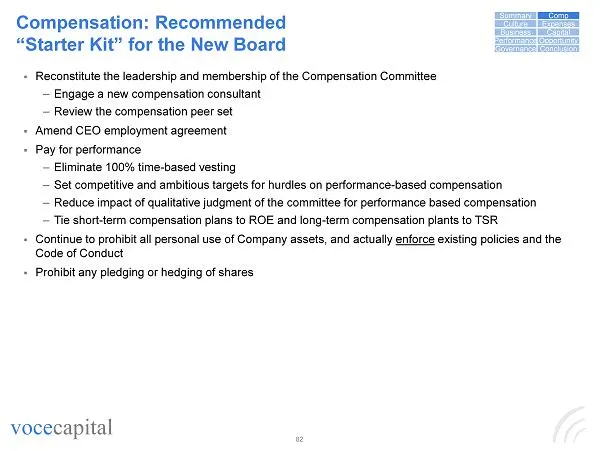
82 voce capital Compensation: Recommended “Starter Kit” for the New Board ▪ Reconstitute the leadership and membership of the Compensation Committee – Engage a new compensation consultant – Review the compensation peer set ▪ Amend CEO employment agreement ▪ Pay for performance – Eliminate 100% time
Slide 84: Opportunity #3: Reduce Expenses
Opportunity #3: Reduce Expenses “Dear Voce, Been watching your Argo battle with interest . Your detailed review of the expense pattern of Argo and the Board Composition (all friends of his dad), has been right on point . His abuse of expenses has been going on for 15 years, thank you for finally poi
Slide 85: Expense Reductions: Summary
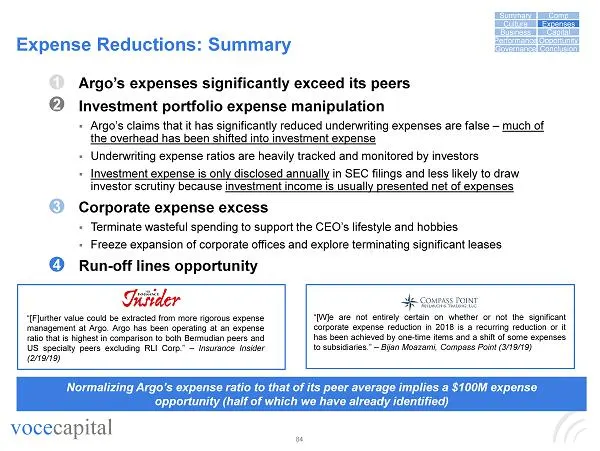
84 voce capital Expense Reductions: Summary ▪ Argo’s expenses significantly exceed its peers ▪ Investment portfolio expense manipulation ▪ Argo’s claims that it has significantly reduced underwriting expenses are false – much of the overhead has been shifted into investment expense ▪ Underwriting ex
Slide 86: Expenses exceed peers
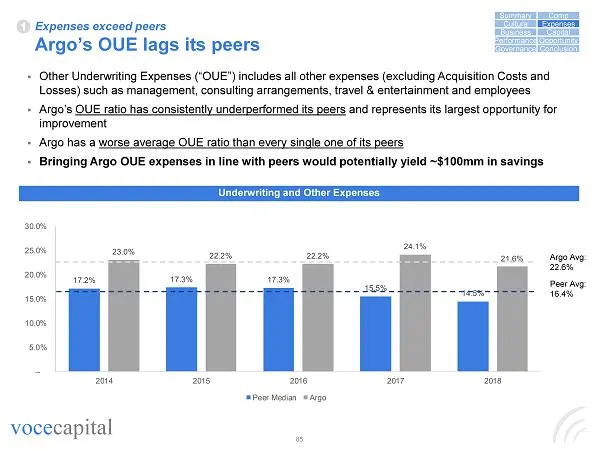
85 voce capital Expenses exceed peers Argo’s OUE lags its peers 17.2% 17.3% 17.3% 15.5% 14.5% 23.0% 22.2% 22.2% 24.1% 21.6% -- 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% 2014 2015 2016 2017 2018 Peer Median Argo ▪ Other Underwriting Expenses (“OUE”) includes all other expenses (excluding Acquisition Costs a
Slide 87: $100mm Expense Opportunity
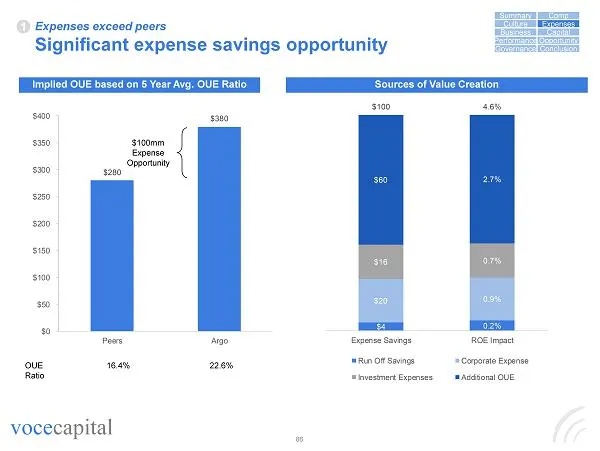
86 voce capital $280 $380 $0 $50 $100 $150 $200 $250 $300 $350 $400 Peers Argo Implied OUE based on 5 Year Avg. OUE Ratio Sources of Value Creation $100mm Expense Opportunity OUE Ratio 16.4% 22.6% Expenses exceed peers Significant expense savings opportunity $4 0.2% $20 0.9% $16 0.7% $60 2.7% $100 4
Slide 88: Reasonable other expense opportunity
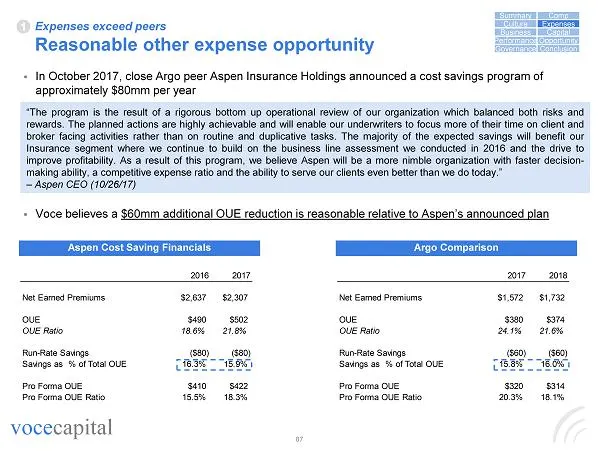
87 voce capital Expenses exceed peers Reasonable other expense opportunity Aspen Cost Saving Financials ▪ In October 2017, close Argo peer Aspen Insurance Holdings announced a cost savings program of approximately $80mm per year ▪ Voce believes a $60mm additional OUE reduction is reasonable relative
Slide 89: Investment expense growth
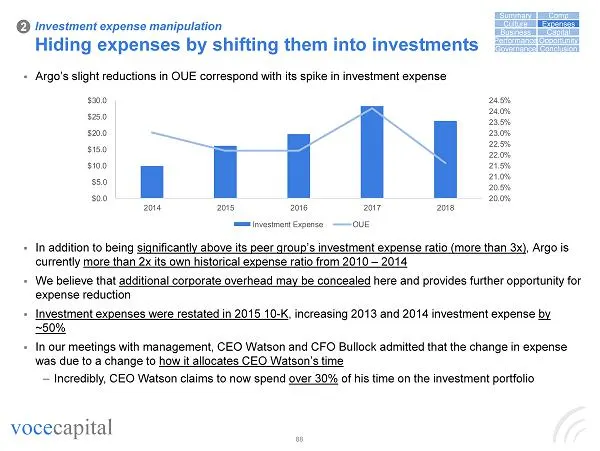
88 voce capital ▪ Argo’s slight reductions in OUE correspond with its spike in investment expense ▪ In addition to being significantly above its peer group’s investment expense ratio (more than 3x) , Argo is currently more than 2x its own historical expense ratio from 2010 – 2014 ▪ We believe that a
Slide 90: Investment expenses as % of portfolio
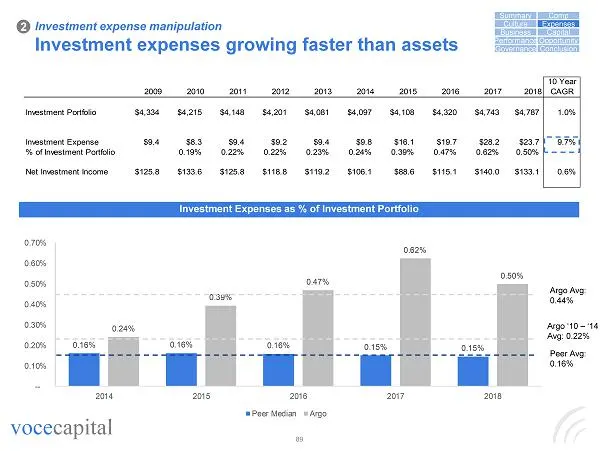
89 voce capital 0.16% 0.16% 0.16% 0.15% 0.15% 0.24% 0.39% 0.47% 0.62% 0.50% -- 0.10% 0.20% 0.30% 0.40% 0.50% 0.60% 0.70% 2014 2015 2016 2017 2018 Peer Median Argo Peer Avg: 0.16% Argo Avg: 0.44% Argo ‘10 – ‘14 Avg: 0.22% Investment Expenses as % of Investment Portfolio Investment expense manipulatio
Slide 91: $16 million immediate expense opportunity
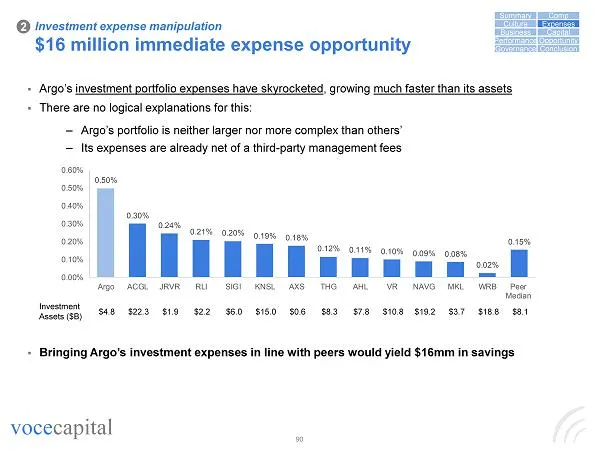
90 voce capital ▪ Argo’s investment portfolio expenses have skyrocketed , growing much faster than its assets ▪ There are no logical explanations for this: – Argo’s portfolio is neither larger nor more complex than others’ – Its expenses are already net of a third - party management fees ▪ Bringing
Slide 92: Corporate expense opportunities
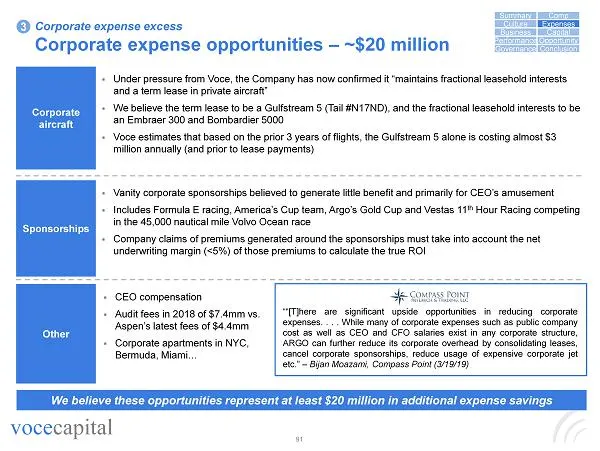
91 voce capital Corporate expense excess Corporate expense opportunities – ~$20 million Corporate aircraft Other Sponsorships We believe these opportunities represent at least $20 million in additional expense savings ▪ Vanity corporate sponsorships believed to generate little benefit and primarily
Slide 93: Run-off lines: historical drag on earnings
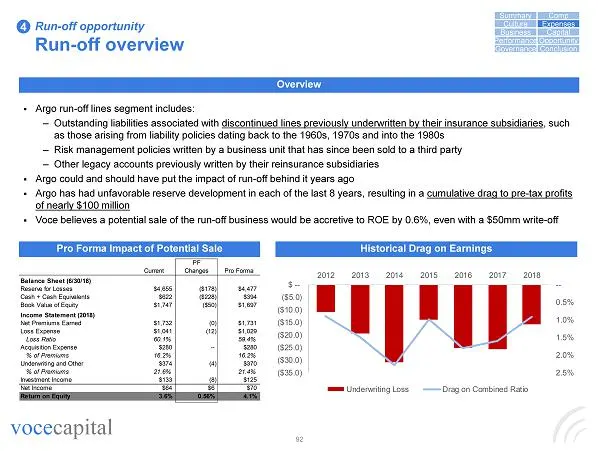
92 voce capital Overview Historical Drag on Earnings ▪ Argo run - off lines segment includes: – Outstanding liabilities associated with discontinued lines previously underwritten by their insurance subsidiaries , such as those arising from liability policies dating back to the 1960s, 1970s and into
Slide 94: Run-off loss portfolio transfer
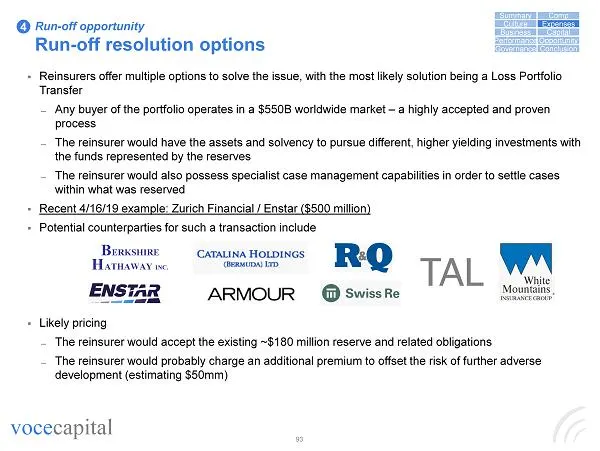
93 voce capital ▪ Reinsurers offer multiple options to solve the issue, with the most likely solution being a Loss Portfolio Transfer ̶ Any buyer of the portfolio operates in a $550B worldwide market – a highly accepted and proven process ̶ The reinsurer would have the assets and solvency to pursue
Slide 95: Expense ROE Opportunity Summary
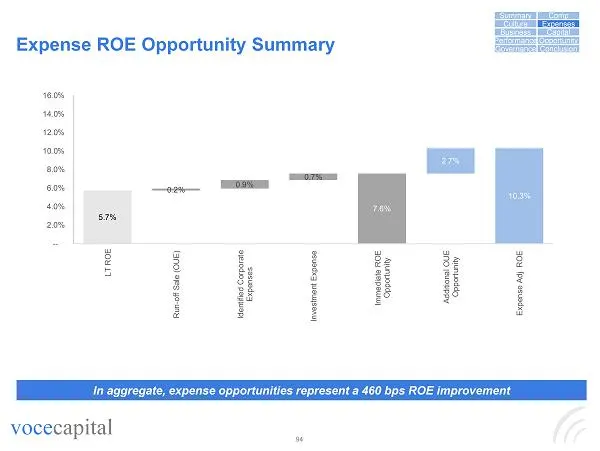
94 voce capital Expense ROE Opportunity Summary In aggregate, expense opportunities represent a 460 bps ROE improvement 5.7% 7.6% 10.3% 0.2% 0.9% 0.7% 2.7% -- 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% LT ROE Run-off Sale (OUE) Identified Corporate Expenses Investment Expense Immediate ROE Opportun
Slide 96: Expenses: Recommended Starter Kit
95 voce capital Expenses: Recommended “Starter Kit” for the New Board ▪ Immediately announce intention to pursue “low - hanging expense fruit” – $40 million of identified savings – Terminate all yachting, racing and similar sponsorships – Align investment portfolio expenses with those of peers – Div
Slide 97: Opportunity #4: Reallocate Capital
Opportunity #4: Reallocate Capital “Thank you for exposing the excessive waste at the CEO level at Argo . As a long - time Argo employee I have been disgusted by the total disregard for the hard - working employees on the front lines . Inspired by your open letter to shareholders, I wanted to make s
Slide 98: Capital Allocation: Summary
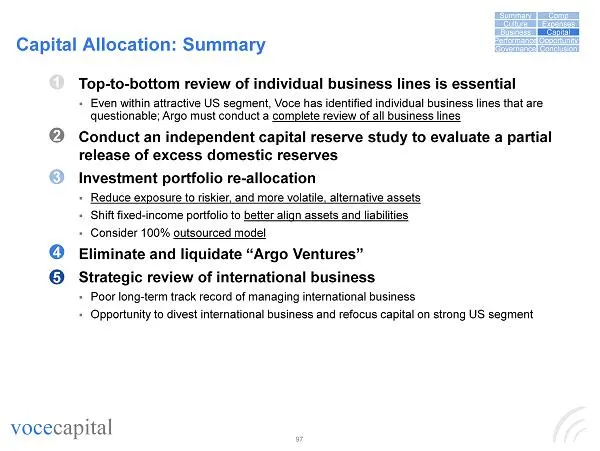
97 voce capital Capital Allocation: Summary ▪ Top - to - bottom review of individual business lines is essential ▪ Even within attractive US segment, Voce has identified individual business lines that are questionable; Argo must conduct a complete review of all business lines ▪ Conduct an independen
Slide 99: Corporate Structure: ARIS Title Insurance
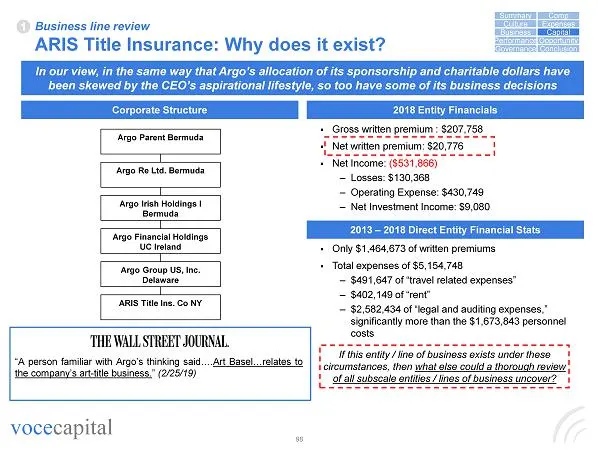
98 voce capital Corporate Structure In our view, in the same way that Argo’s allocation of its sponsorship and charitable dollars have been skewed by the CEO’s aspirational lifestyle, so too have some of its business decisions Business line review ARIS Title Insurance: Why does it exist? Argo Parent
Slide 100: US reserves: excess reserve opportunity
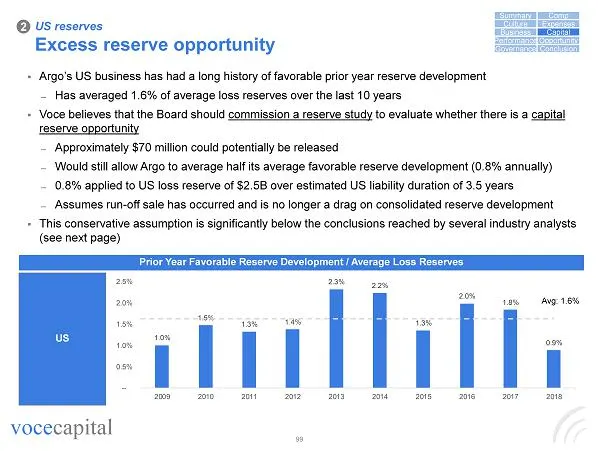
99 voce capital US reserves Excess reserve opportunity Prior Year Favorable Reserve Development / Average Loss Reserves US 1.0% 1.5% 1.3% 1.4% 2.3% 2.2% 1.3% 2.0% 1.8% 0.9% -- 0.5% 1.0% 1.5% 2.0% 2.5% 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 Avg: 1.6% ▪ Argo’s US business has had a long his
Slide 101: Others also view Argo as over-reserved
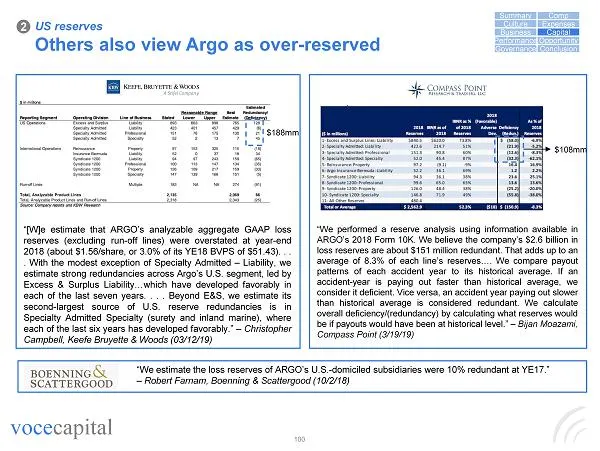
100 voce capital US reserves Others also view Argo as over - reserved 2 “We performed a reserve analysis using information available in ARGO’s 2018 Form 10 K . We believe the company’s $ 2 . 6 billion in loss reserves are about $ 151 million redundant . That adds up to an average of 8 . 3 % of each
Slide 102: Investment portfolio re-allocation
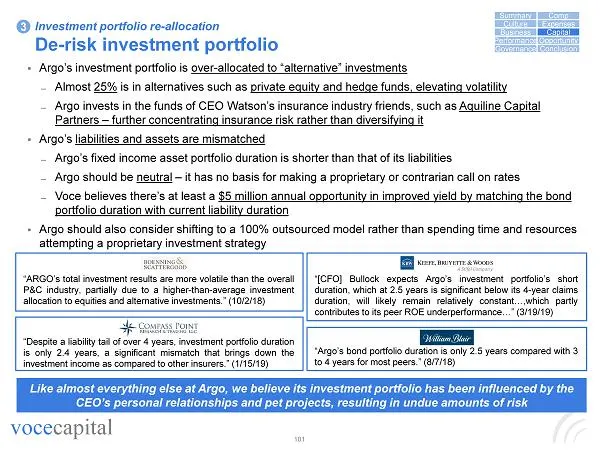
101 voce capital Like almost everything else at Argo, we believe its investment portfolio has been influenced by the CEO’s personal relationships and pet projects, resulting in undue amounts of risk Investment portfolio re - allocation De - risk investment portfolio ▪ Argo’s investment portfolio is
Slide 103: Miami condo investment properties
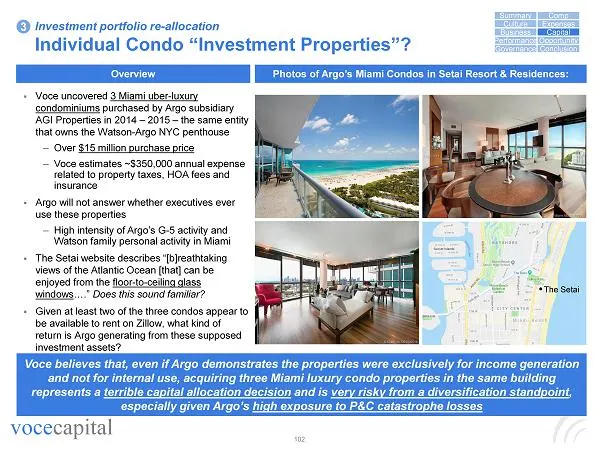
102 voce capital Investment portfolio re - allocation Individual Condo “Investment Properties”? 3 Capital Expenses Comp Business Culture Summary Opportunity Performance Governance Conclusion Voce believes that, even if Argo demonstrates the properties were exclusively for income generation and not f
Slide 104: Eliminate Argo Ventures
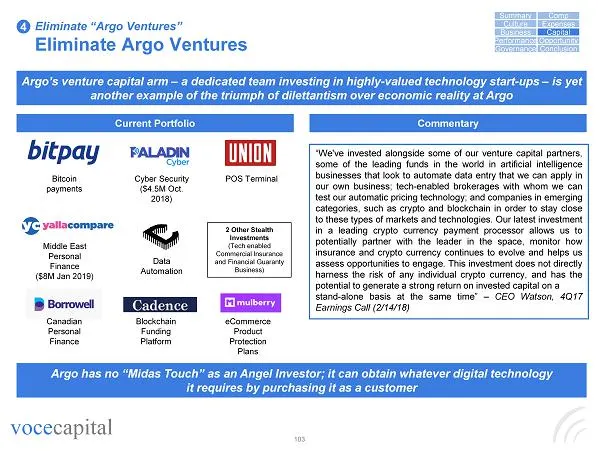
103 voce capital Eliminate “Argo Ventures” Eliminate Argo Ventures Argo’s venture capital arm – a dedicated team investing in highly - valued technology start - ups – is yet another example of the triumph of dilettantism over economic reality at Argo Argo has no “Midas Touch” as an Angel Investor; i
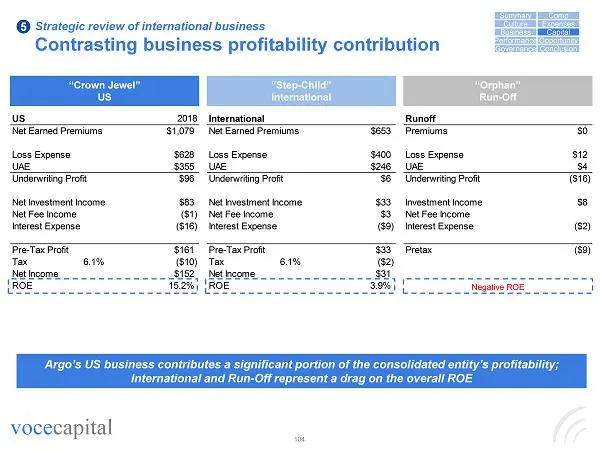
Slide 105: Strategic review of international business
104 voce capital Strategic review of international business Contrasting business profitability contribution Argo’s US business contributes a significant portion of the consolidated entity’s profitability; International and Run - Off represent a drag on the overall ROE “Crown Jewel” US “Step - Child”
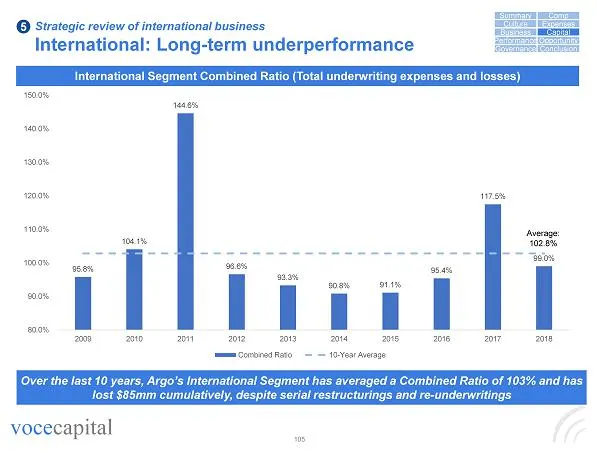
Slide 106: International: Long-term underperformance
105 voce capital Strategic review of international business International: Long - term underperformance International Segment Combined Ratio (Total underwriting expenses and losses) 95.8% 104.1% 144.6% 96.6% 93.3% 90.8% 91.1% 95.4% 117.5% 99.0% 80.0% 90.0% 100.0% 110.0% 120.0% 130.0% 140.0% 150.0% 2
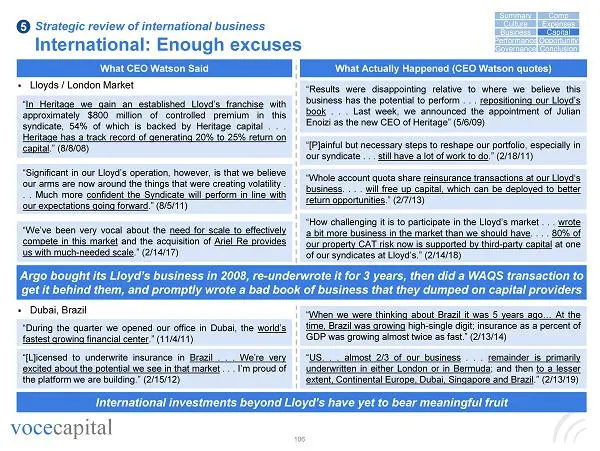
Slide 107: International: Enough excuses
106 voce capital Strategic review of international business International: Enough excuses What CEO Watson Said What Actually Happened (CEO Watson quotes) “Results were disappointing relative to where we believe this business has the potential to perform . . . repositioning our Lloyd’s book . . . Las
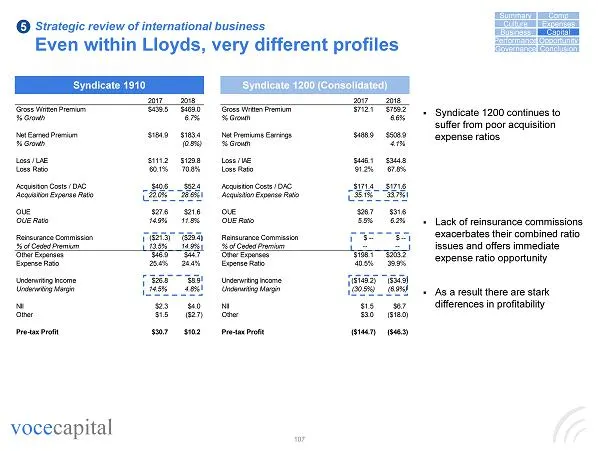
Slide 108: Even within Lloyds, very different profiles
107 voce capital Strategic review of international business Even within Lloyds, very different profiles Syndicate 1910 Syndicate 1200 (Consolidated) ▪ Syndicate 1200 continues to suffer from poor acquisition expense ratios ▪ Lack of reinsurance commissions exacerbates their combined ratio issues and
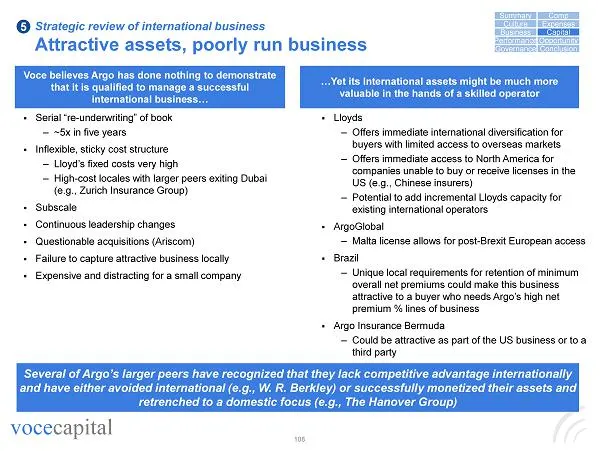
Slide 109: Attractive assets, poorly run business
108 voce capital Strategic review of international business Attractive assets, poorly run business Several of Argo’s larger peers have recognized that they lack competitive advantage internationally and have either avoided international (e.g., W. R. Berkley) or successfully monetized their assets an
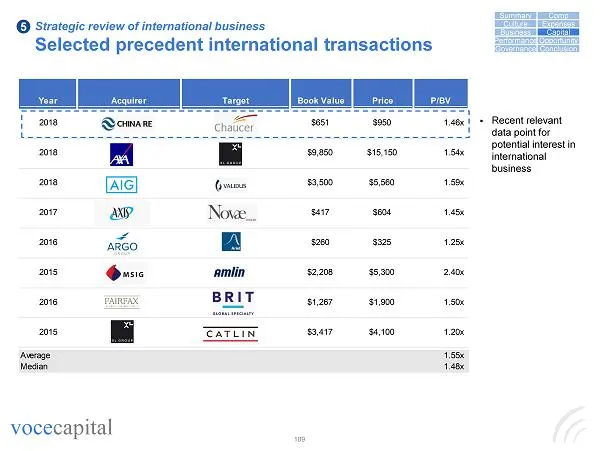
Slide 110: Selected precedent international transactions
109 voce capital Strategic review of international business Selected precedent international transactions ▪ Recent relevant data point for potential interest in international business Year Acquirer Target Book Value Price P/BV 2018 $651 $950 1.46x 2018 $9,850 $15,150 1.54x 2018 $3,500 $5,560 1.59x 2
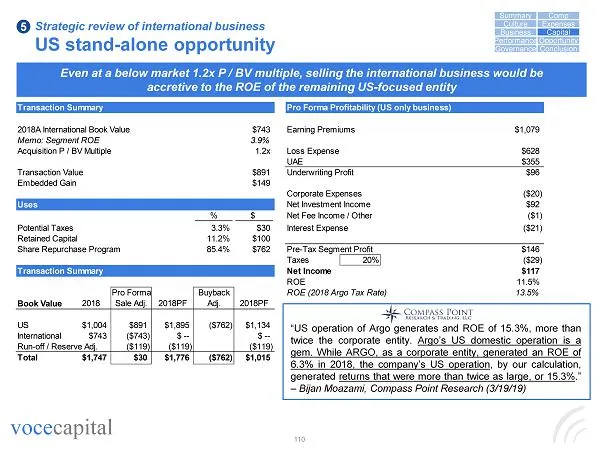
Slide 111: US stand-alone opportunity
110 voce capital Strategic review of international business US stand - alone opportunity Even at a below market 1.2x P / BV multiple, selling the international business would be accretive to the ROE of the remaining US - focused entity Transaction Summary 2018A International Book Value $743 Memo: Se
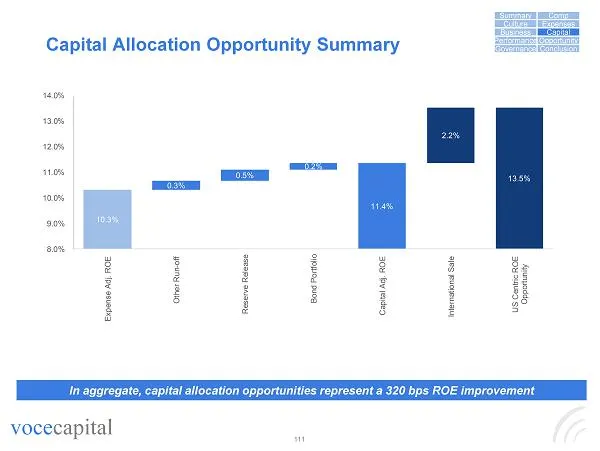
Slide 112: Capital Allocation Opportunity Summary
111 voce capital Capital Allocation Opportunity Summary In aggregate, capital allocation opportunities represent a 320 bps ROE improvement 10.3% 11.4% 13.5% 0.3% 0.5% 0.2% 2.2% 8.0% 9.0% 10.0% 11.0% 12.0% 13.0% 14.0% Expense Adj. ROE Other Run-off Reserve Release Bond Portfolio Capital Adj. ROE Inte
Slide 113: Opportunity Summary
Opportunity Summary
Slide 114: Improving ROE is a prerequisite to re-rating
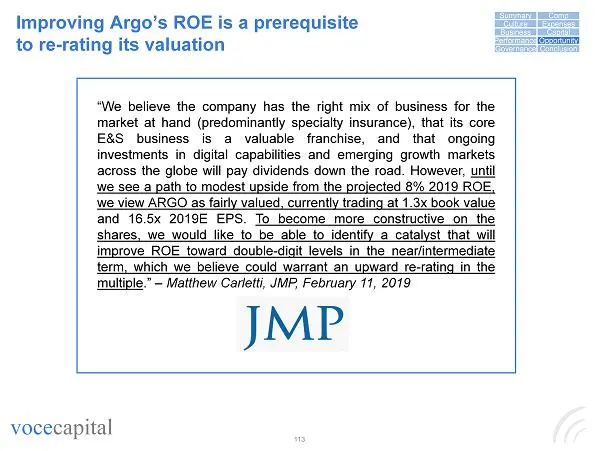
113 voce capital Improving Argo’s ROE is a prerequisite to re - rating its valuation “We believe the company has the right mix of business for the market at hand (predominantly specialty insurance), that its core E&S business is a valuable franchise, and that ongoing investments in digital capabilit
Slide 115: ROE Opportunity Summary
114 voce capital ROE Opportunity Summary Expense reductions alone can allow Argo to earn a double digit return on equity; adding capital allocation and potential sale of the international business would allow Argo to hit 13%+ ROE Capital Expenses Comp Business Culture Summary Opportunity Performance
Slide 116: How might the US business be valued stand-alone?
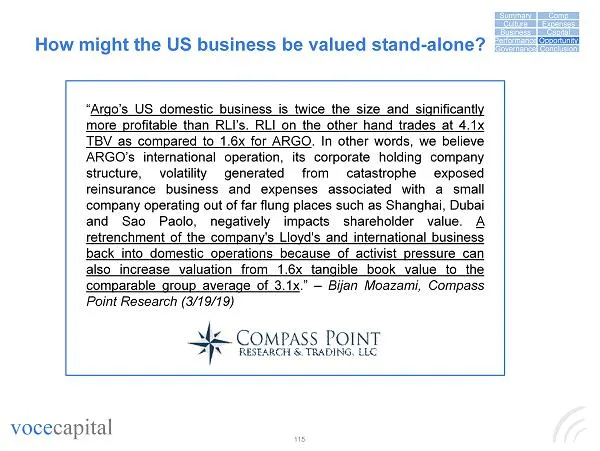
115 voce capital How might the US business be valued stand - alone? “ Argo’s US domestic business is twice the size and significantly more profitable than RLI’s . RLI on the other hand trades at 4 . 1 x TBV as compared to 1 . 6 x for ARGO . In other words, we believe ARGO’s international operation,
Slide 117: Value creation potential
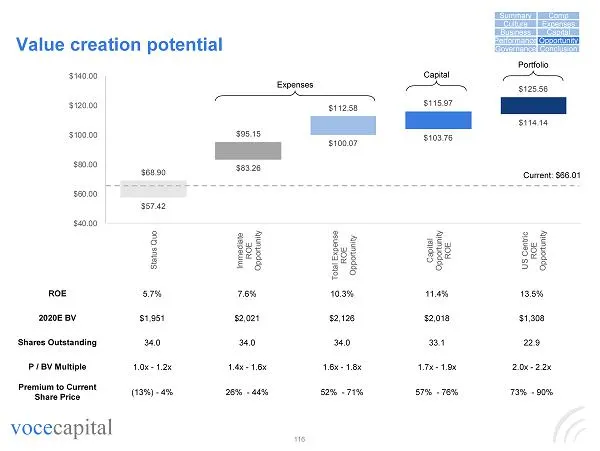
116 voce capital Value creation potential $57.42 $83.26 $100.07 $103.76 $114.14 $68.90 $95.15 $112.58 $115.97 $125.56 $40.00 $60.00 $80.00 $100.00 $120.00 $140.00 Status Quo Immediate ROE Opportunity Total Expense ROE Opportunity Capital Opportunity ROE US Centric ROE Opportunity ROE 5.7% 7.6% 10.3%
Slide 118: Conclusion: Righting the Ship
Conclusion: Righting the Ship ““[W]hat happens at Argo may have significant consequences for the industry . Though once seen as too complicated due to regulation and capital requirements, the sector is now seeing a surge of activist interest that is likely only to increase if a successful model of c
Slide 119: New Board Can Make an Immediate Impact
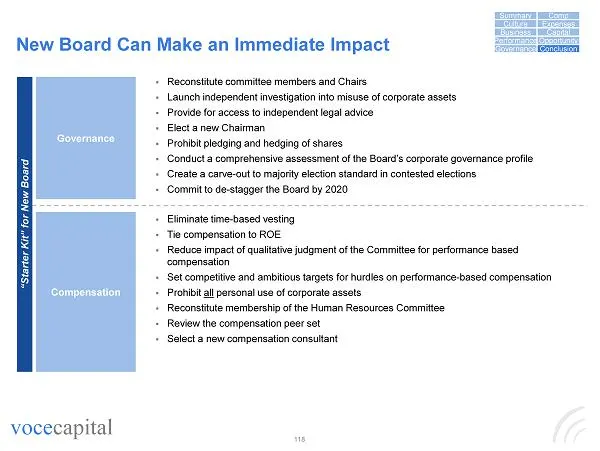
118 voce capital New Board Can Make an Immediate Impact Governance Compensation “Starter Kit” for New Board ▪ Eliminate time - based vesting ▪ Tie compensation to ROE ▪ Reduce impact of qualitative judgment of the Committee for performance based compensation ▪ Set competitive and ambitious targets f
Slide 120: New Board Can Make an Immediate Impact (cont.)
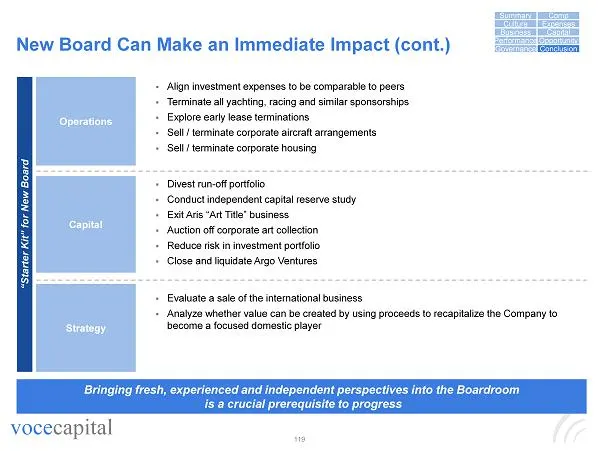
119 voce capital New Board Can Make an Immediate Impact (cont.) Operations Capital Strategy “Starter Kit” for New Board ▪ Evaluate a sale of the international business ▪ Analyze whether value can be created by using proceeds to recapitalize the Company to become a focused domestic player ▪ Align inv
Slide 121: Bernard C. Bailey, Ph.D
120 voce capital Bernard C. Bailey, Ph.D “During my tenure as CEO of two public companies, and as a Director or Chairman of ten others, I’m absolutely certain that sound corporate governance is a non - negotiable prerequisite for sustainable shareholder value . While Argo appears to have assembled s
Slide 122: Charles H. Dangelo
121 voce capital Charles H. Dangelo “The insurance industry is a highly competitive industry around the world . In my 47 years in the business I have helped lead companies that have successfully outperformed their competition, and seen competitors underperform or fail . One important key, especially
Slide 123: Rear Admiral (ret.) Kathleen M. Dussault
122 voce capital Rear Admiral (ret.) Kathleen M. Dussault “Honor . Service . Accountability . Many of the same essential characteristics that I drew upon in my 34 years in the US Navy are the same ones that I believe effective governance requires of corporate directors . I see a multitude of operati
Slide 124: Carol A. McFate, CFA
123 voce capital Carol A. McFate, CFA “My career has concentrated in finance and investment management, with much of this experience in the insurance industry . This experience developed the skills to efficiently and productively allocate capital . In insurance, effective capital allocation is criti
Slide 125: Nicholas C. Walsh
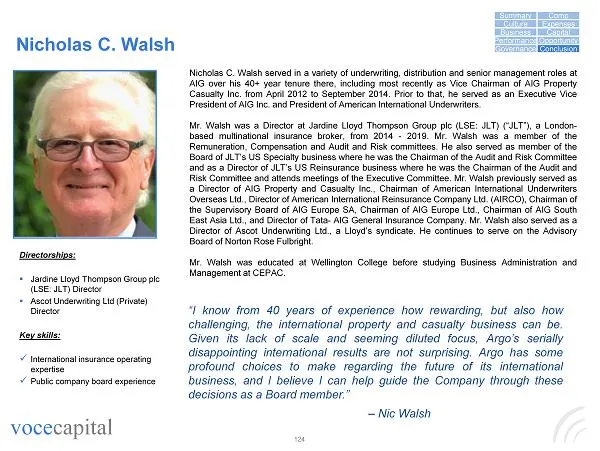
124 voce capital Nicholas C. Walsh “I know from 40 years of experience how rewarding, but also how challenging, the international property and casualty business can be . Given its lack of scale and seeming diluted focus, Argo’s serially disappointing international results are not surprising . Argo h
Slide 126: Contact Information
125 voce capital Contact Information Shareholders Media Sloane & Company Dan Zacchei / Joe Germani, 212 - 486 - 9500 Dzacchei@sloanepr.com / JGermani@sloanepr.com If you have any questions, or need assistance voting your BLUE proxy card, please contact: 1212 Avenue of the Americas, 24th Floor New Yo
Slide 127: Sources
126 voce capital Sources ▪ Page 5: Returns calculated through 12/31/18 ▪ Page 6: SEC filings; Voce research ▪ Page 7: Capital IQ; SEC filings; Voce research ▪ Page 8: Voce research ▪ Page 9: Voce research ▪ Page 10: Voce research ▪ Page 11: Voce research ▪ Page 12: Capital IQ; Voce research ▪ Page 1
Slide 128: Sources (cont.)
127 voce capital Sources (cont.) ▪ Page 23: Voce research; New York Daily News; Company website; Twitter ▪ Page 26: Voce research; FlightAware; New York Times; Outside Magazine; The New Zealand Herald ▪ Page 27: Voce research; FlightAware; Leader's Edge Magazine ▪ Page 28: Voce research; FlightAware
Slide 129: Sources (cont.)
128 voce capital Sources (cont.) ▪ Page 46: Capital IQ ▪ Page 47: Capital IQ; Voce research ▪ Page 48: Capital IQ; Voce research ▪ Page 49: Capital IQ ▪ Page 50: Company presentation ▪ Page 51: Capital IQ ▪ Page 52: Capital IQ ▪ Page 54: Capital IQ; SEC filings; Voce research ▪ Page 55: Capital IQ;
Slide 130: Sources (cont.)
129 voce capital Sources (cont.) ▪ Page 70: Voce research ▪ Page 71: Voce researchCompany Bye - Laws; Insurance Insider; Munster v. Cammell Co. (1882) 21 Ch. D 183 ▪ Page 72: Voce research ▪ Page 73: Company Bye - Laws; ISS; International Comparative Legal Guides ▪ Page 74: Insurance Insider ▪ Page
Slide 131: Sources (cont.)
130 voce capital Sources (cont.) ▪ Page 93: Voce research ▪ Page 95: Insurance Insider ▪ Page 98: The WSJ; State regulatory filings ▪ Page 99: SEC filings; Voce research ▪ Page 100: Wall Street research ▪ Page 101: SEC filings; Voce research; Wall Street research ▪ Page 102: www.Zillow.com ▪ Page 10
Source: SEC EDGAR · DFAN14A filed Apr 30, 2019
More decks from Argo Group International Holdings Ltd
 Proxy Contest (November 2022)39 slides · Nov 18, 2022
 Corporate Update (September 2022)23 slides · Sep 8, 2022
 Investor Presentation (February 2022)24 slides · Feb 23, 2022
 Q3 2021 Earnings Presentation7 slides · Nov 3, 2021
 Investor Day (March 2021)59 slides · Mar 12, 2021
 Investor Presentation (November 2020)17 slides · Nov 10, 2020