Foster Wheeler — Citi Global Energy & Utilities Conference 2014
21 slides from Foster Wheeler's conference presentation, May 13, 2014
Slide 1: AMEC plc Citi Global Energy & Utilities conference
AMEC plc Citi Global Energy & Utilities conference 13 May 2014
Slide 2: Important information and offer disclaimer
2 This presentation is for informational purposes only and does not constitute or form part of an offer to sell or the solicitation of an offer to buy or subscribe to any securities, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unla
Slide 3: AMEC today
AMEC today 3 Diversified model minimises risk and maximises opportunity Long term track record of growth Focused on creating shareholder value
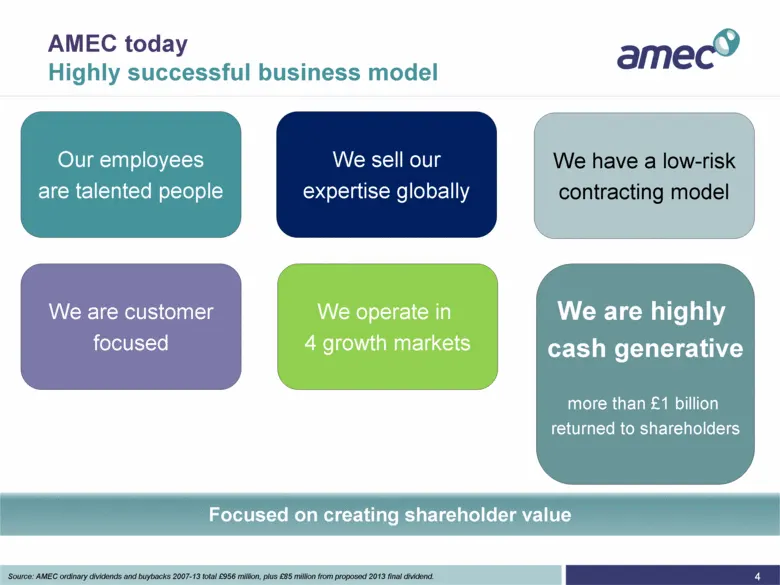
Slide 4: Highly successful business model
AMEC today Highly successful business model We are customer focused Our employees are talented people Focused on creating shareholder value Source: AMEC ordinary dividends and buybacks 2007-13 total £956 million, plus £85 million from proposed 2013 final dividend. We are highly cash generative more
Slide 5: Successful track record of delivery
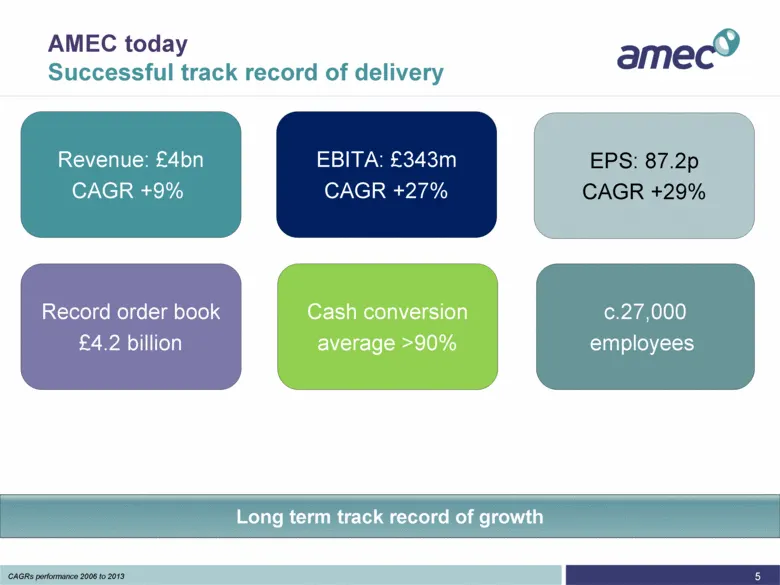
AMEC today Successful track record of delivery 5 Long term track record of growth Record order book £4.2 billion Revenue: £4bn CAGR +9% c.27,000 employees EBITA: £343m CAGR +27% Cash conversion average >90% EPS: 87.2p CAGR +29% CAGRs performance 2006 to 2013
Slide 6: Our approach to growth and returns
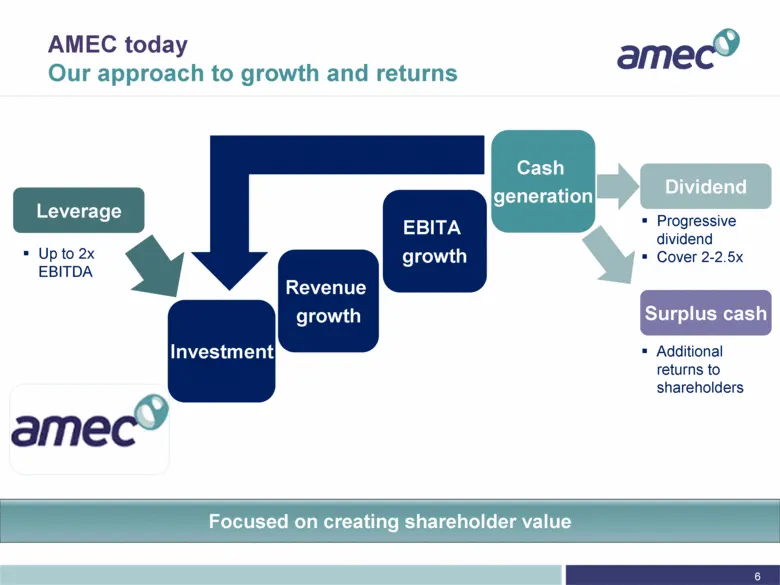
AMEC today Our approach to growth and returns 6 Focused on creating shareholder value Cash generation Investment Revenue growth EBITA growth Dividend Progressive dividend Cover 2-2.5x Surplus cash Additional returns to shareholders Leverage Up to 2x EBITDA
Slide 7: Balanced portfolio
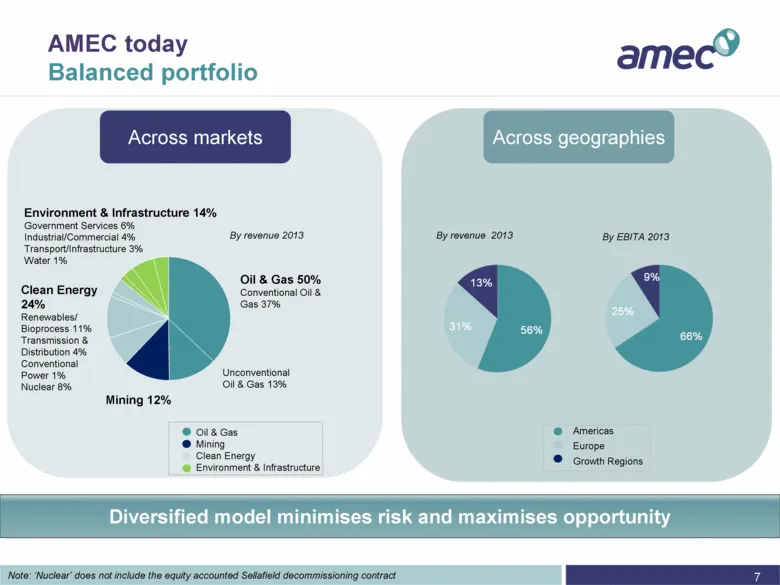
AMEC today Balanced portfolio 7 Diversified model minimises risk and maximises opportunity Note: ‘Nuclear’ does not include the equity accounted Sellafield decommissioning contract 7 By EBITA 2012 Oil & Gas Mining Clean Energy Environment & Infrastructure Mining 12% Oil & Gas 50% Conventional Oil &
Slide 8: Strong customer relationships
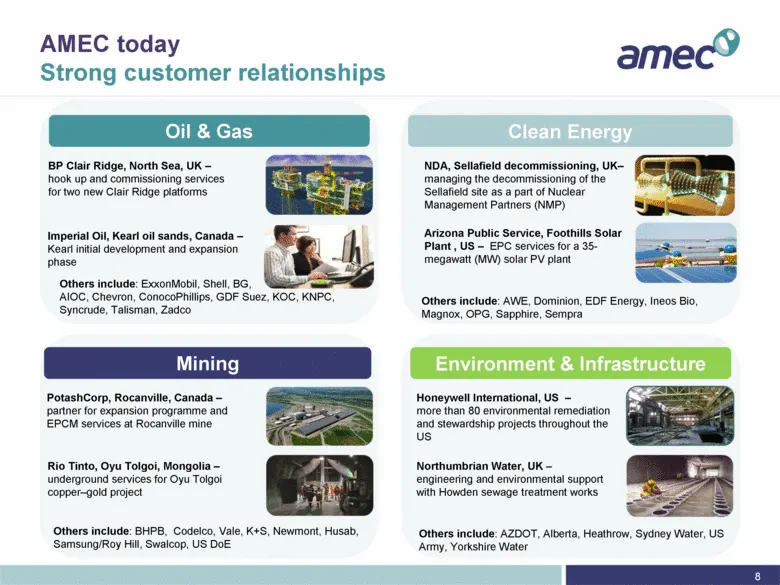
8 AMEC today Strong customer relationships Oil & Gas Mining Environment & Infrastructure Clean Energy BP Clair Ridge, North Sea, UK – hook up and commissioning services for two new Clair Ridge platforms Honeywell International, US – more than 80 environmental remediation and stewardship projects thr
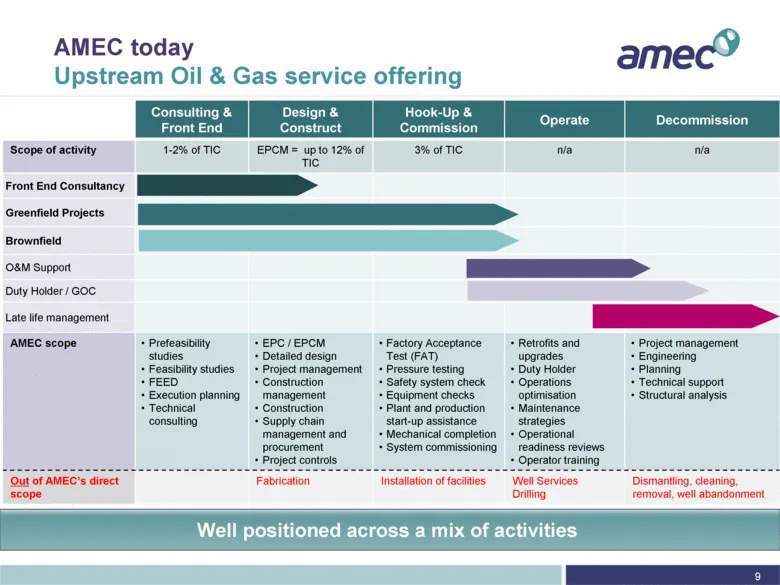
Slide 9: Scope of activity across project lifecycle
Consulting & Front End Design & Construct Hook-Up & Commission Operate Decommission Scope of activity 1-2% of TIC EPCM = up to 12% of TIC 3% of TIC n/a n/a Front End Consultancy Greenfield Projects Brownfield O&M Support Duty Holder / GOC Late life management AMEC scope Prefeasibility studies Feasib
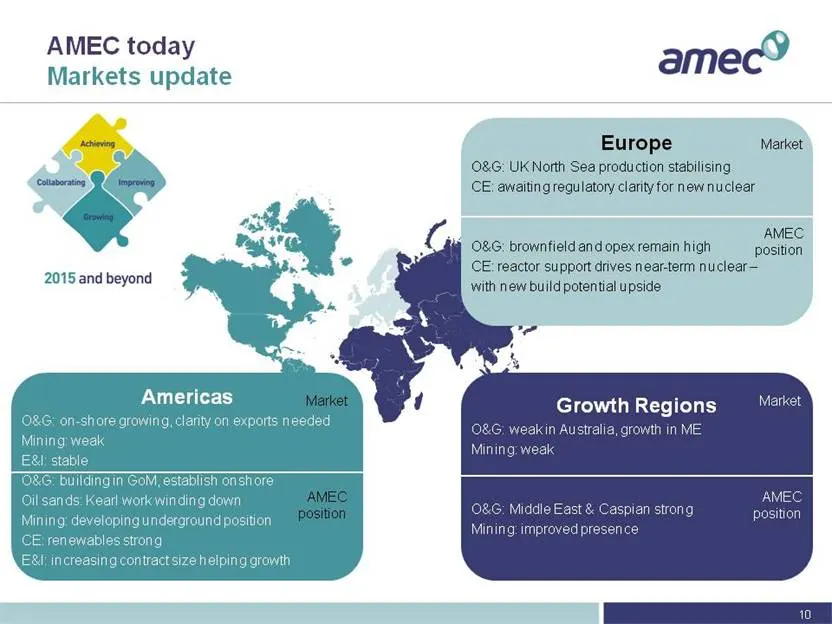
Slide 10: Markets update
AMEC today Markets update 10 Americas O&G: on-shore growing, clarity on exports needed Mining: weak E&I: stable O&G: building in GoM, establish onshore Oil sands: Kearl work winding down Mining: developing underground position CE: renewables strong E&I: increasing contract size helping growth Growth
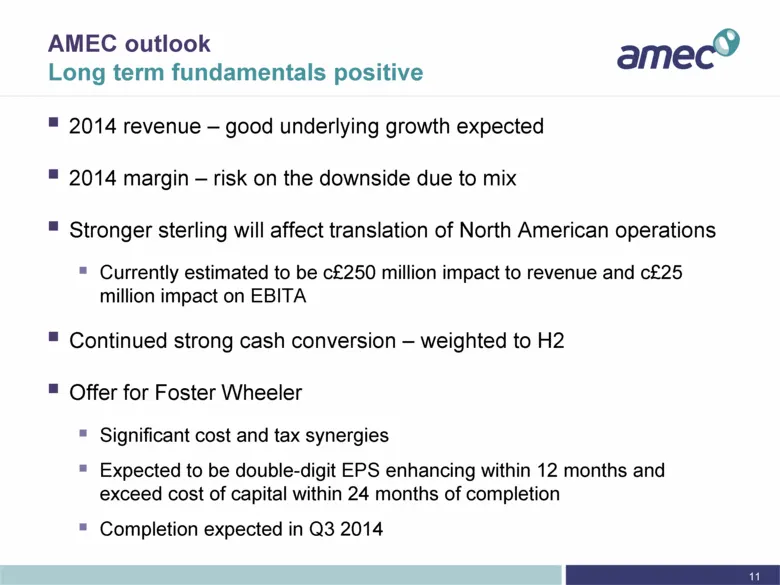
Slide 11: Outlook
AMEC outlook Long term fundamentals positive 11 2014 revenue – good underlying growth expected 2014 margin – risk on the downside due to mix Stronger sterling will affect translation of North American operations Currently estimated to be c£250 million impact to revenue and c£25 million impact on EBI
Slide 12: Foster Wheeler acquisition
AMEC plc Foster Wheeler acquisition
Slide 13: Offer for Foster Wheeler: key benefits
Offer for Foster Wheeler Key benefits Significantly enhances oil & gas position and improves geographic footprint Brings together two highly-skilled workforces Retention of low-risk and cash generative business model Financially attractive Significant cost and tax synergies Expected to be double-dig
Slide 14: Offer for Foster Wheeler: headline terms
Offer for Foster Wheeler Headline terms For each Foster Wheeler share: 0.8998 new AMEC shares/ADRs and $16.00 in cash Represents c.$3.3 billion for whole of Foster Wheeler(1) Two Foster Wheeler non-executive directors are expected to join AMEC board on completion Financing AMEC to issue c.90 million
Slide 15: Cost and tax synergies
Cost synergies 15 Identified cost synergies of at least US$75 million per annum Full annualised run-rate by year three Approximate cost of $75-90 million to achieve Predominantly removal of duplicated corporate overhead and SG&A costs Tax synergies Meaningful benefits of utilising tax losses more ef
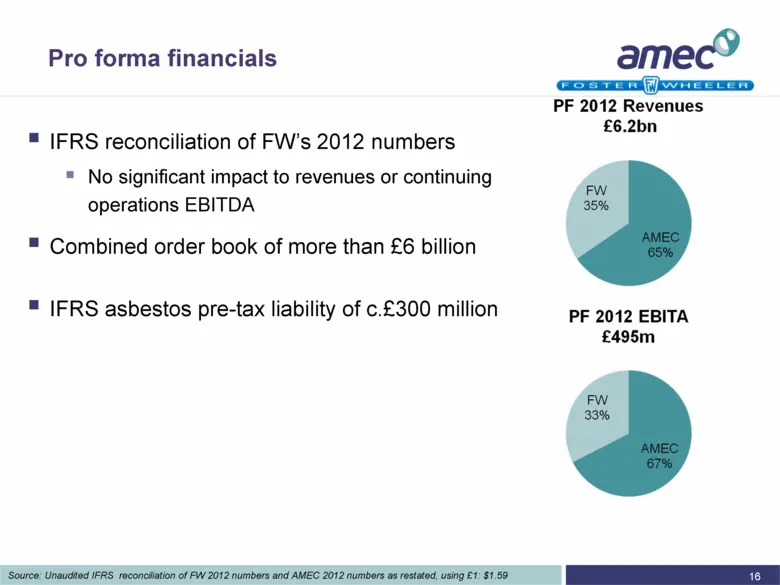
Slide 16: Pro forma financials
Pro forma financials IFRS reconciliation of FW’s 2012 numbers No significant impact to revenues or continuing operations EBITDA Combined order book of more than £6 billion IFRS asbestos pre-tax liability of c.£300 million 16 Source: Unaudited IFRS reconciliation of FW 2012 numbers and AMEC 2012 numb
Slide 17: Anticipated timetable
Anticipated timetable Q1 Announce firm offer (13 February 2014) Progress AMEC’s US registration and listing AMEC makes anti-trust filings Q2/3 AMEC shareholder documents published and shareholder meetings Offer document posted to FW shareholders Anticipated completion 17 Targeting close in H2
Slide 18: Strategic rationale for the acquisition
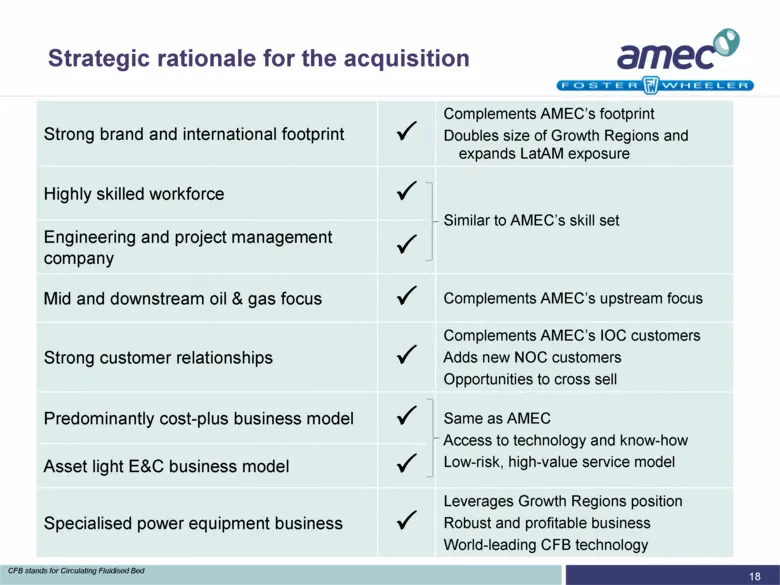
Strategic rationale for the acquisition Strong brand and international footprint P Complements AMEC’s footprint Doubles size of Growth Regions and expands LatAM exposure Highly skilled workforce P Similar to AMEC’s skill set Engineering and project management company P Mid and downstream oil & gas f
Slide 19: Enhanced O&G competitive positioning
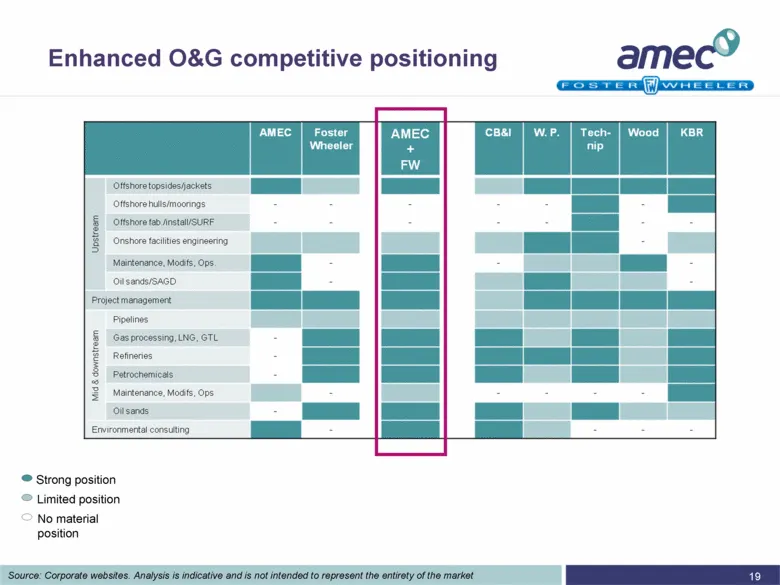
Enhanced O&G competitive positioning 19 Source: Corporate websites. Analysis is indicative and is not intended to represent the entirety of the market Strong position Limited position No material position
Slide 20: Enhanced opportunities with Foster Wheeler
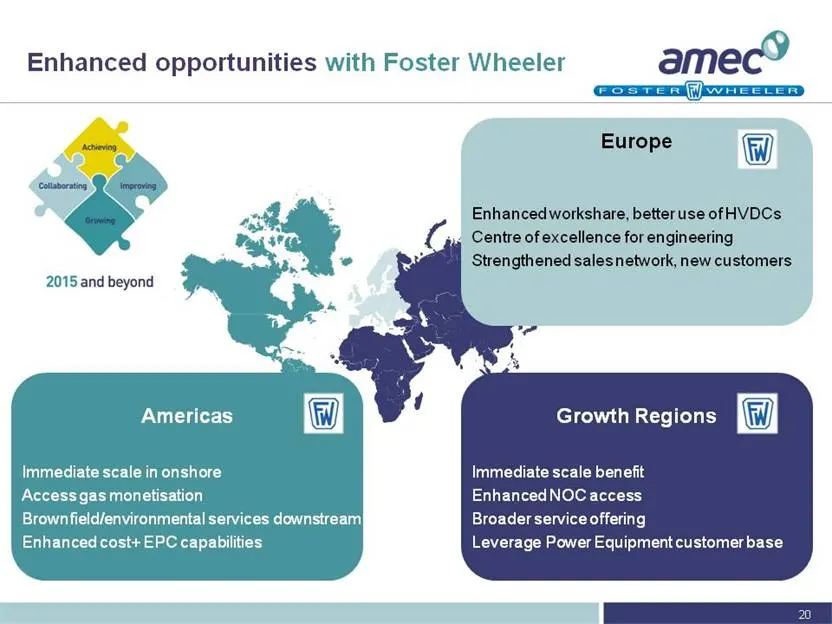
Enhanced opportunities with Foster Wheeler 20 Americas Immediate scale in onshore Access gas monetisation Brownfield/environmental services downstream Enhanced cost+ EPC capabilities Growth Regions Immediate scale benefit Enhanced NOC access Broader service offering Leverage Power Equipment customer
Slide 21: AMEC + Foster Wheeler: a compelling combination
AMEC + Foster Wheeler: a compelling combination Enhances oil and gas position across the whole value chain: on and offshore Expands geographic footprint Brings together two highly-skilled workforces Retains low-risk, cash generative, business model Financially attractive Accelerates AMEC’s growth st
Source: SEC EDGAR · 425 filed May 13, 2014
More decks from Foster Wheeler AG
 Merger or Acquisition (August 2014)28 slides · Aug 27, 2014
 Merger or Acquisition (August 2014)19 slides · Aug 7, 2014
 Merger or Acquisition (May 2014)39 slides · May 2, 2014
 Merger or Acquisition (February 2014)39 slides · Feb 28, 2014
 Merger or Acquisition (February 2014)49 slides · Feb 13, 2014
 Merger or Acquisition (February 2014)11 slides · Feb 13, 2014