Arlington Asset Investment Corp
Arlington Asset Investment — Q1 2019 Earnings Presentation
25 slides from Arlington Asset Investment's earnings presentation, May 2, 2019
Slide 1: Investor Presentation First Quarter 2019
Investor Presentation First Quarter 2019 Exhibit 99.2
Slide 2: Information Related to Forward-Looking Statements
Information Related to Forward-Looking Statements Statements concerning interest rates, portfolio allocation, financing costs, portfolio hedging, prepayments, dividends, book value, utilization of loss carryforwards, any change in long-term tax structures (including any REIT election) and any other
Slide 3: Contents
Contents First Quarter of 2019 Financial Results and Portfolio Update…………………….Slide 4 Appendix – Additional Financial Data…………………………………………………Slide 17
Slide 4: First Quarter of 2019 Financial Results and Portfolio Update
First Quarter of 2019 Financial Results and Portfolio Update
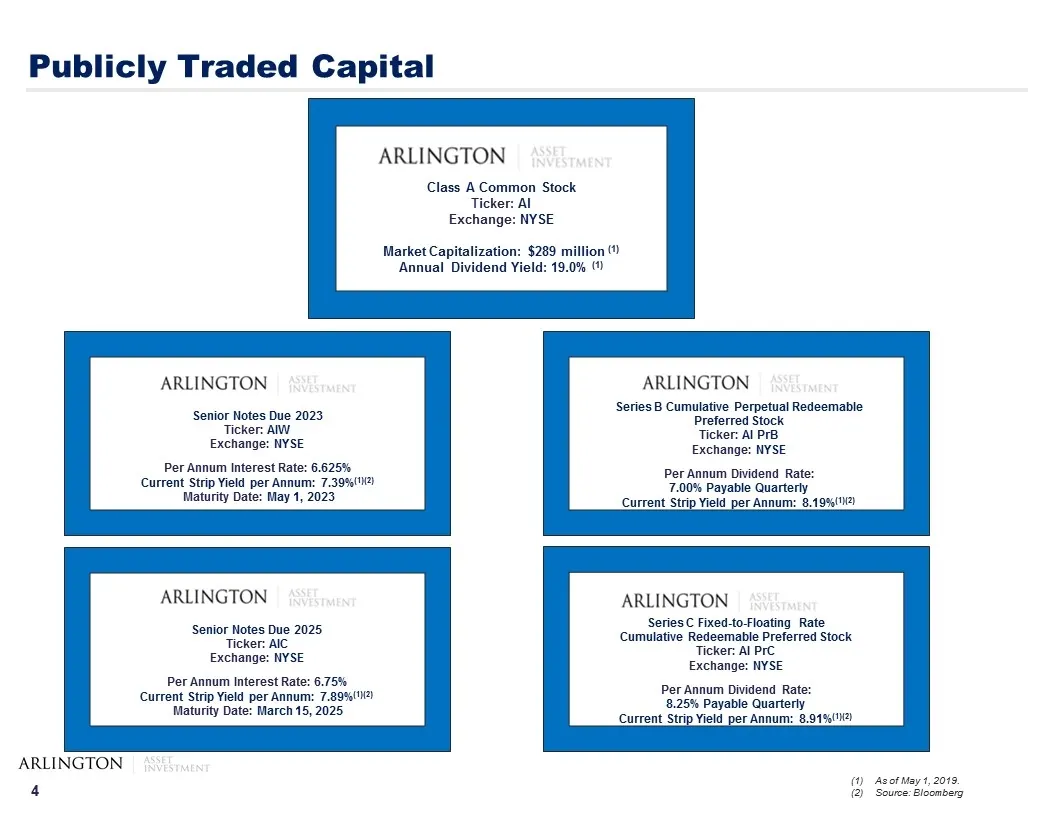
Slide 5: Publicly Traded Capital
Publicly Traded Capital Class A Common Stock Ticker: AI Exchange: NYSE Market Capitalization: $289 million (1) Annual Dividend Yield: 19.0% (1) Senior Notes Due 2023 Ticker: AIW Exchange: NYSE Per Annum Interest Rate: 6.625% Current Strip Yield per Annum: 7.39%(1)(2) Maturity Date: May 1, 2023 Senio
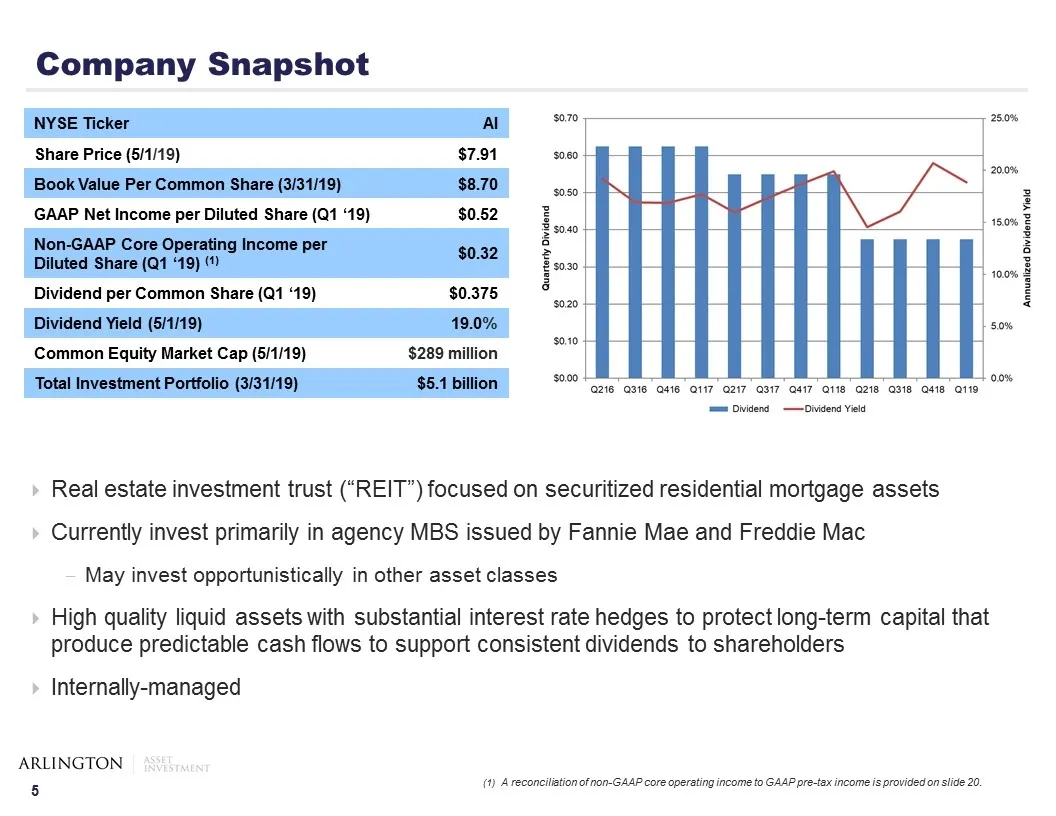
Slide 6: Company Snapshot
Company Snapshot Real estate investment trust (“REIT”) focused on securitized residential mortgage assets Currently invest primarily in agency MBS issued by Fannie Mae and Freddie Mac May invest opportunistically in other asset classes High quality liquid assets with substantial interest rate hedges
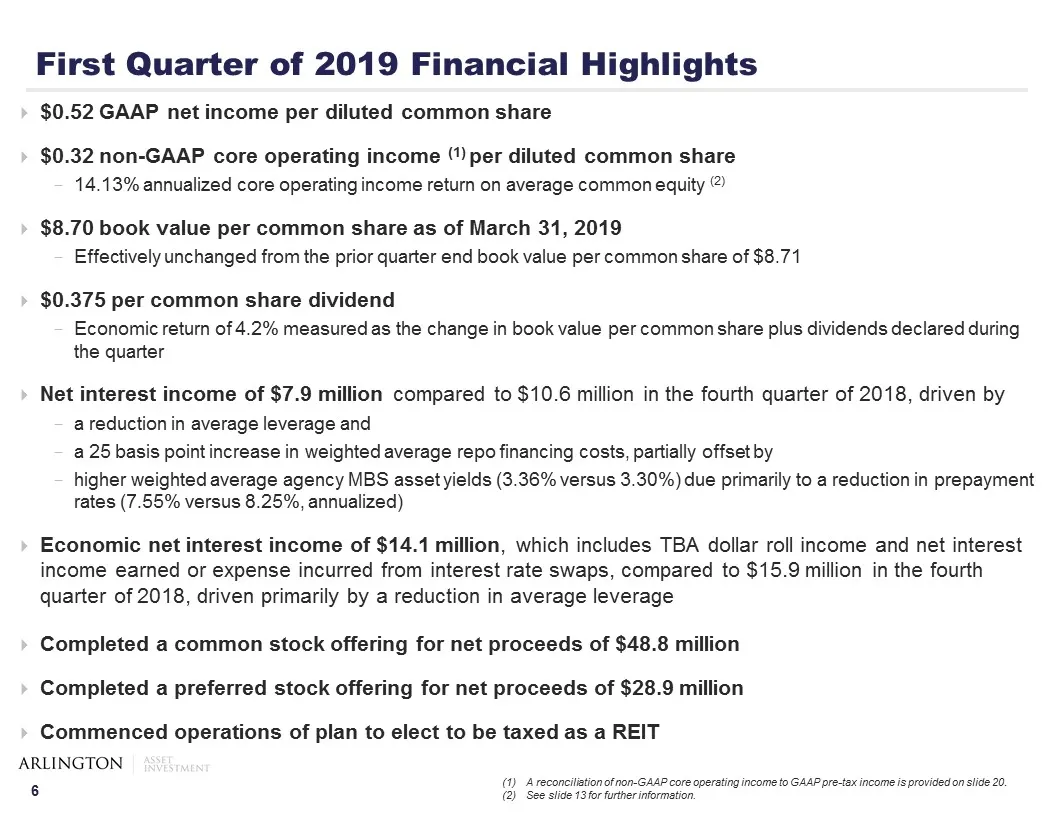
Slide 7: First Quarter of 2019 Financial Highlights
First Quarter of 2019 Financial Highlights $0.52 GAAP net income per diluted common share $0.32 non-GAAP core operating income (1) per diluted common share 14.13% annualized core operating income return on average common equity (2) $8.70 book value per common share as of March 31, 2019 Effectively u
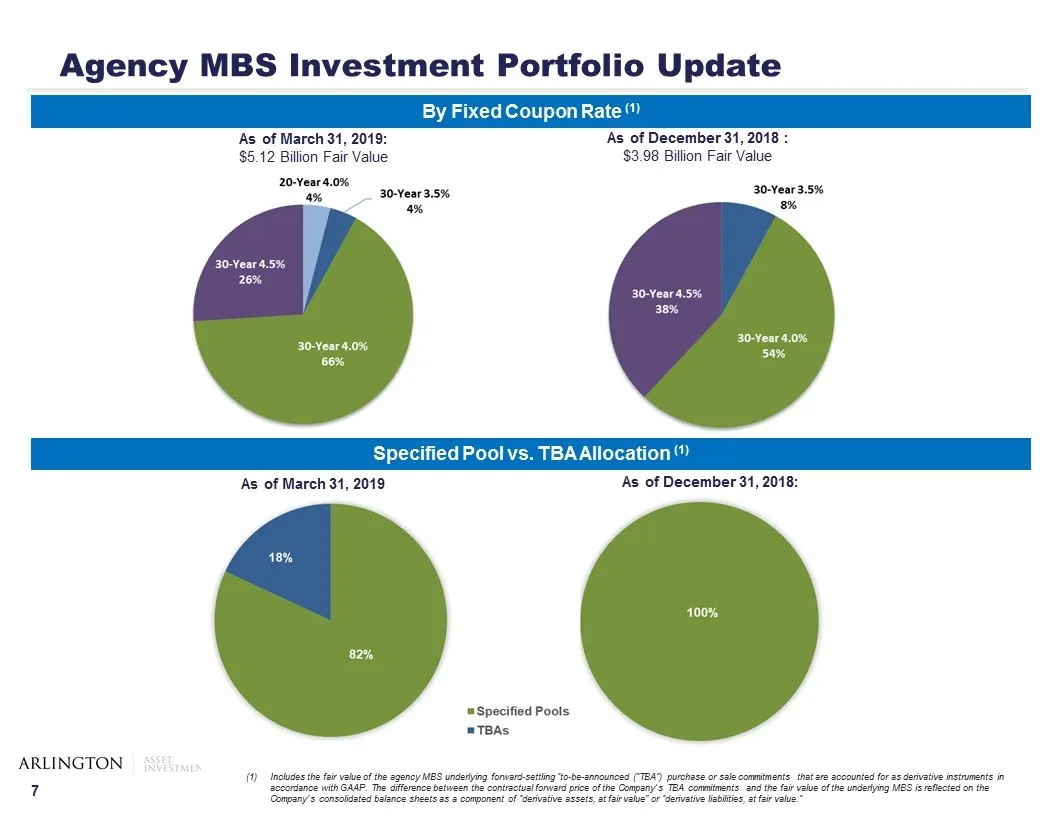
Slide 8: Agency MBS Investment Portfolio Update
As of March 31, 2019: $5.12 Billion Fair Value As of December 31, 2018 : $3.98 Billion Fair Value Agency MBS Investment Portfolio Update Specified Pool vs. TBA Allocation (1) Includes the fair value of the agency MBS underlying forward-settling “to-be-announced (“TBA”) purchase or sale commitments t
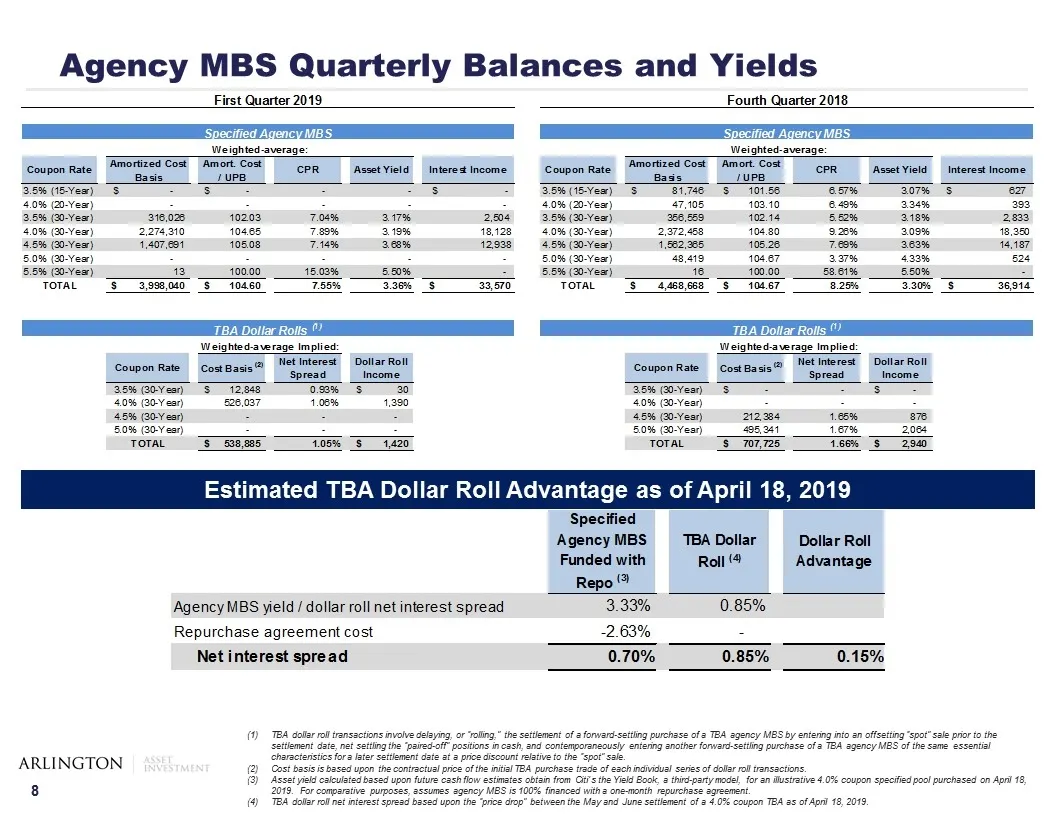
Slide 9: Agency MBS Quarterly Balances and Yields
Agency MBS Quarterly Balances and Yields TBA dollar roll transactions involve delaying, or “rolling,” the settlement of a forward-settling purchase of a TBA agency MBS by entering into an offsetting “spot” sale prior to the settlement date, net settling the “paired-off” positions in cash, and contem
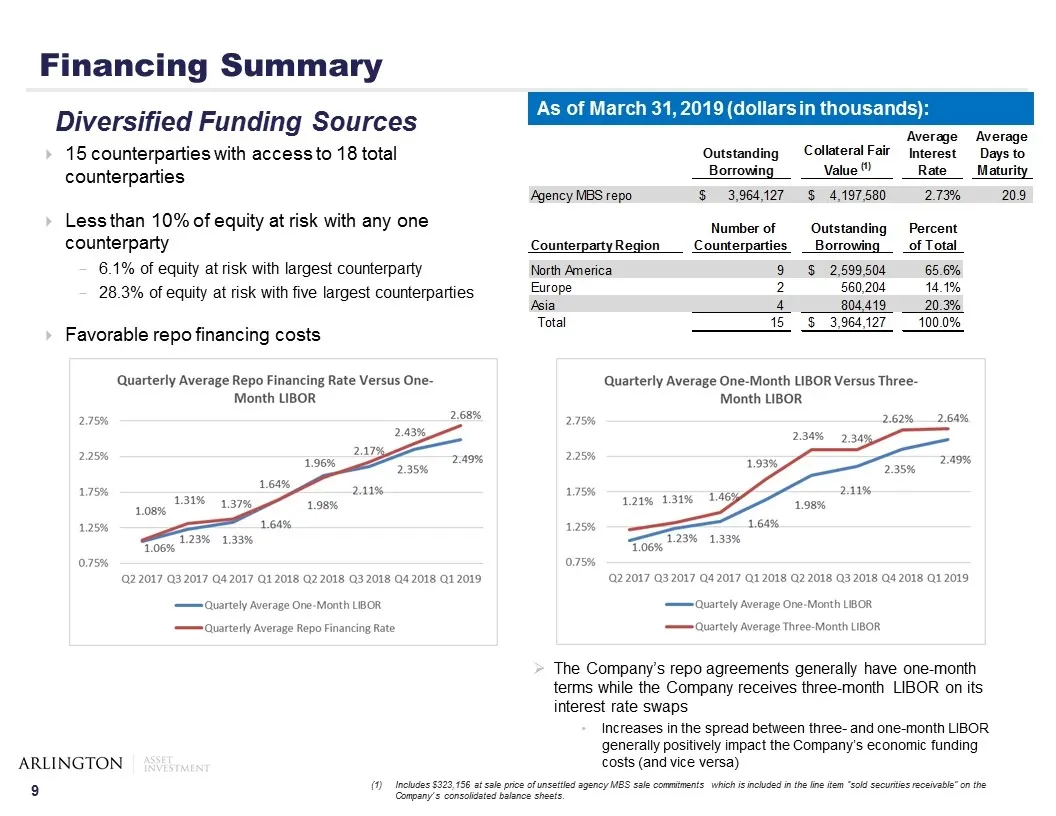
Slide 10: Financing Summary
Financing Summary 15 counterparties with access to 18 total counterparties Less than 10% of equity at risk with any one counterparty 6.1% of equity at risk with largest counterparty 28.3% of equity at risk with five largest counterparties Favorable repo financing costs Diversified Funding Sources As
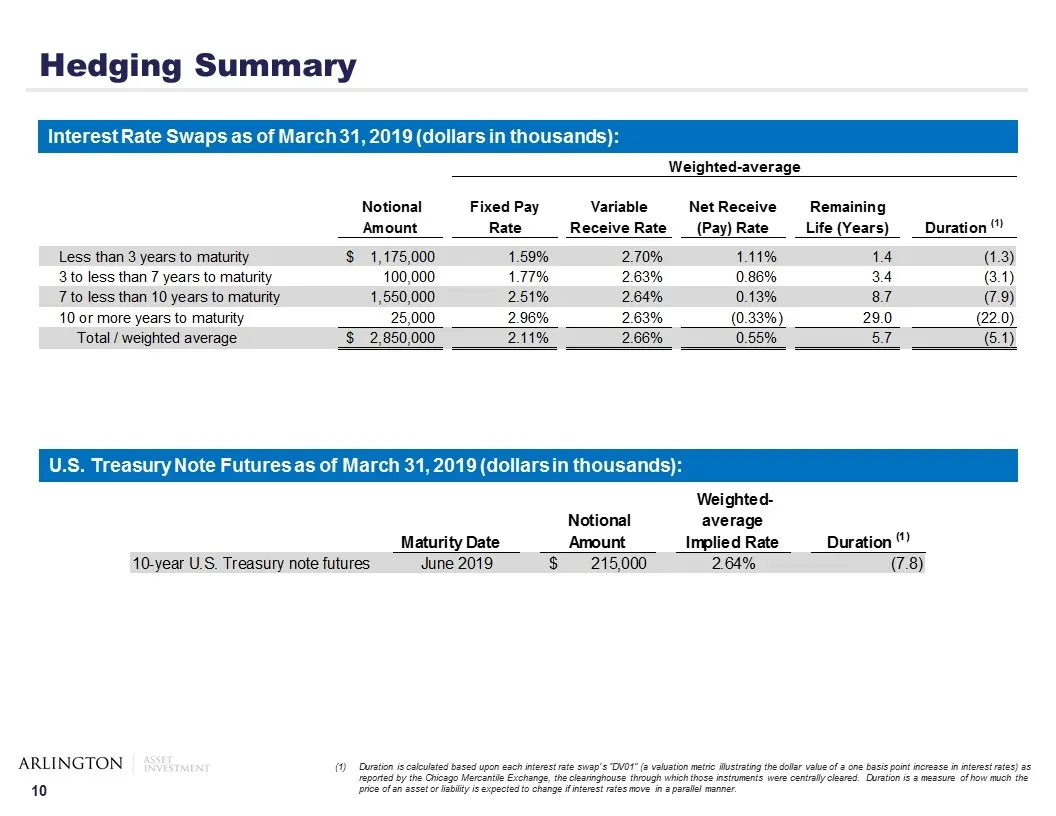
Slide 11: Hedging Summary
Hedging Summary Duration is calculated based upon each interest rate swap’s “DV01” (a valuation metric illustrating the dollar value of a one basis point increase in interest rates) as reported by the Chicago Mercantile Exchange, the clearinghouse through which those instruments were centrally clear
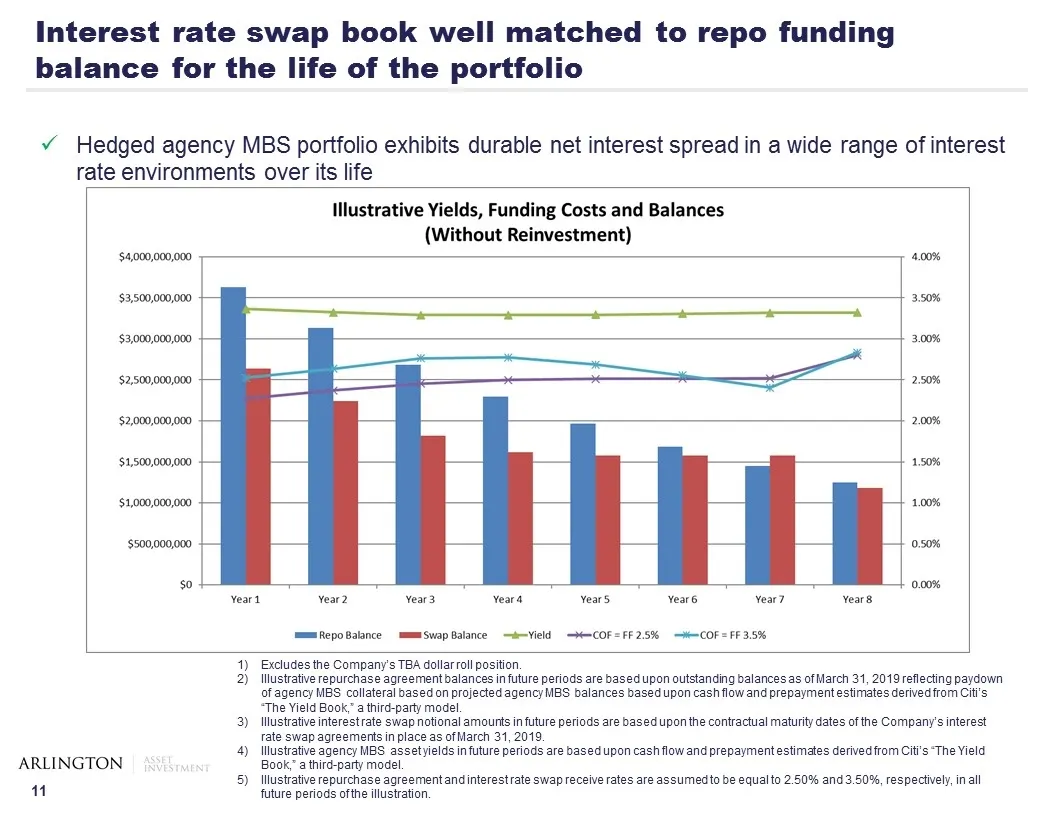
Slide 12: Interest rate swap book well matched to repo funding balance
Interest rate swap book well matched to repo funding balance for the life of the portfolio Hedged agency MBS portfolio exhibits durable net interest spread in a wide range of interest rate environments over its life Excludes the Company’s TBA dollar roll position. Illustrative repurchase agreement b
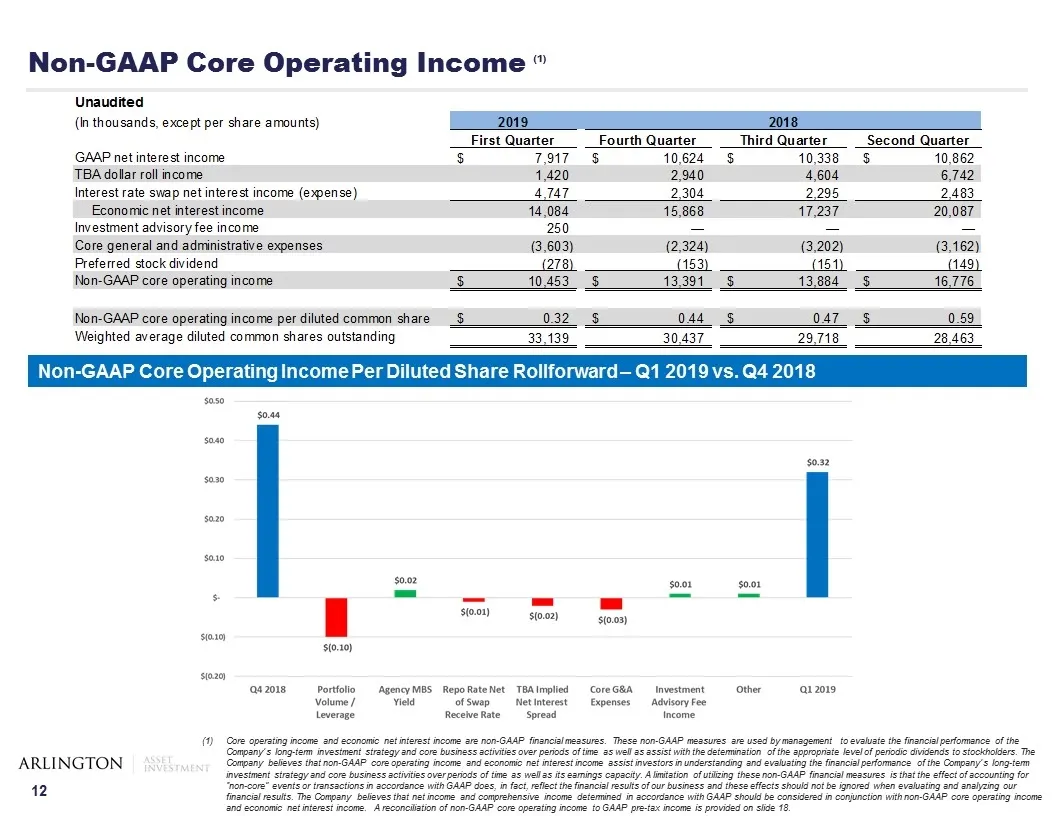
Slide 13: Non-GAAP Core Operating Income
Non-GAAP Core Operating Income (1) Core operating income and economic net interest income are non-GAAP financial measures. These non-GAAP measures are used by management to evaluate the financial performance of the Company’s long-term investment strategy and core business activities over periods of
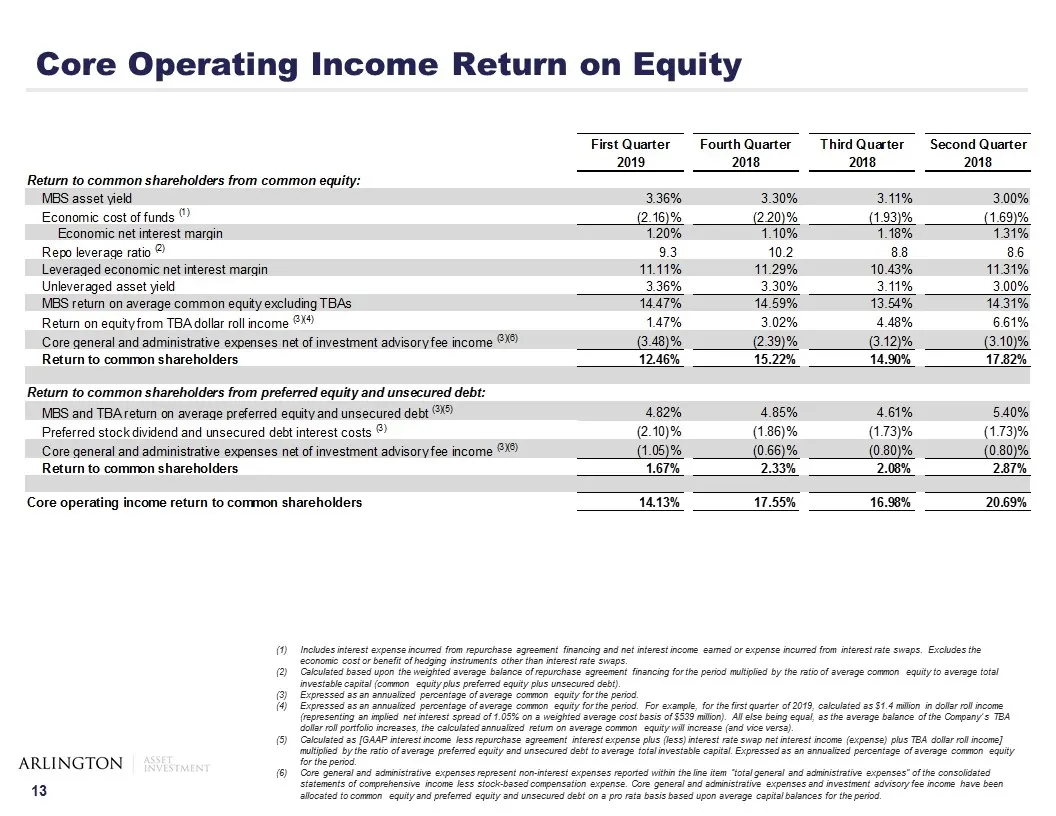
Slide 14: Core Operating Income Return on Equity
Core Operating Income Return on Equity Includes interest expense incurred from repurchase agreement financing and net interest income earned or expense incurred from interest rate swaps. Excludes the economic cost or benefit of hedging instruments other than interest rate swaps. Calculated based upo
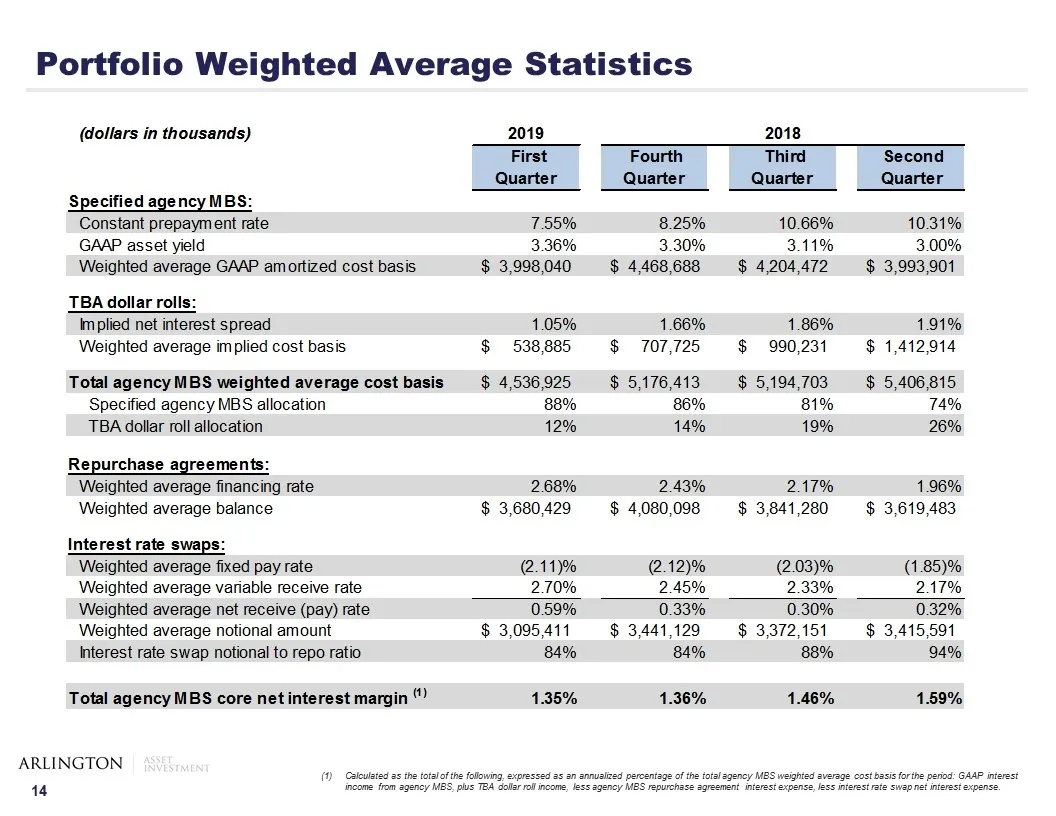
Slide 15: Portfolio Weighted Average Statistics
Portfolio Weighted Average Statistics Calculated as the total of the following, expressed as an annualized percentage of the total agency MBS weighted average cost basis for the period: GAAP interest income from agency MBS, plus TBA dollar roll income, less agency MBS repurchase agreement interest e
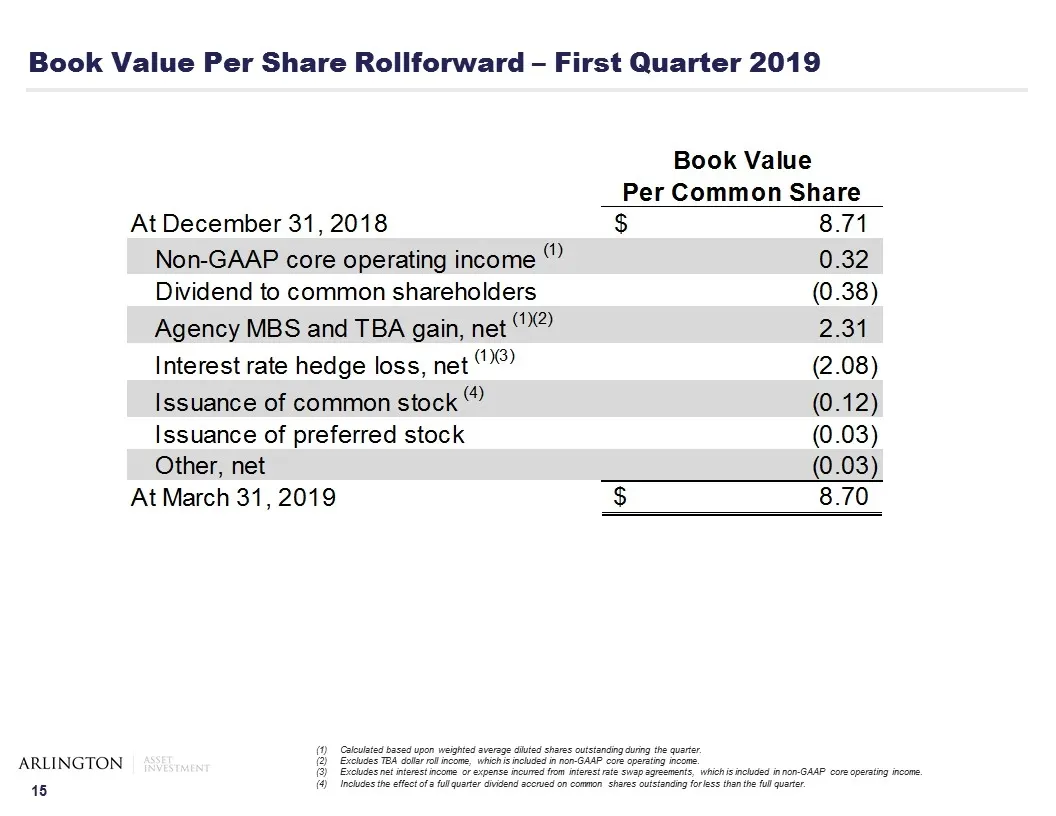
Slide 16: Book Value Per Share Rollforward – First Quarter 2019
Book Value Per Share Rollforward – First Quarter 2019 Calculated based upon weighted average diluted shares outstanding during the quarter. Excludes TBA dollar roll income, which is included in non-GAAP core operating income. Excludes net interest income or expense incurred from interest rate swap a
Slide 17: Appendix – Additional Financial Data
Appendix – Additional Financial Data
Slide 18: Market Data
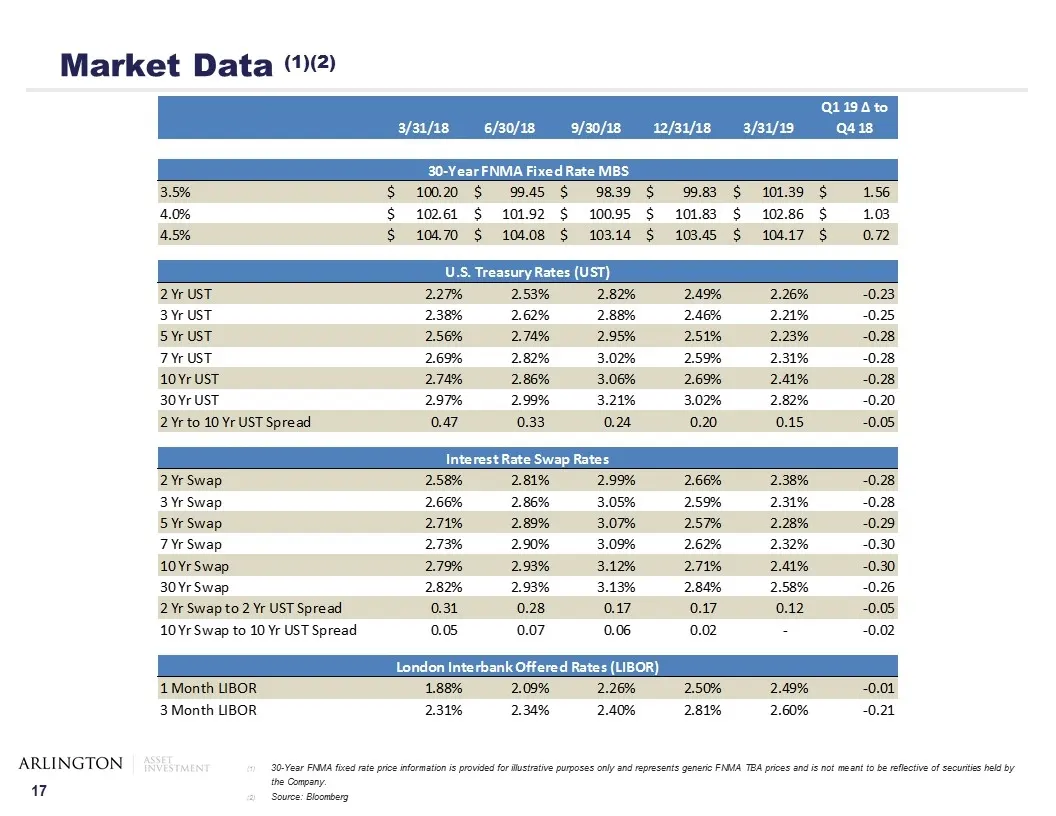
Market Data (1)(2) 30-Year FNMA fixed rate price information is provided for illustrative purposes only and represents generic FNMA TBA prices and is not meant to be reflective of securities held by the Company. Source: Bloomberg
Slide 19: Balance Sheet
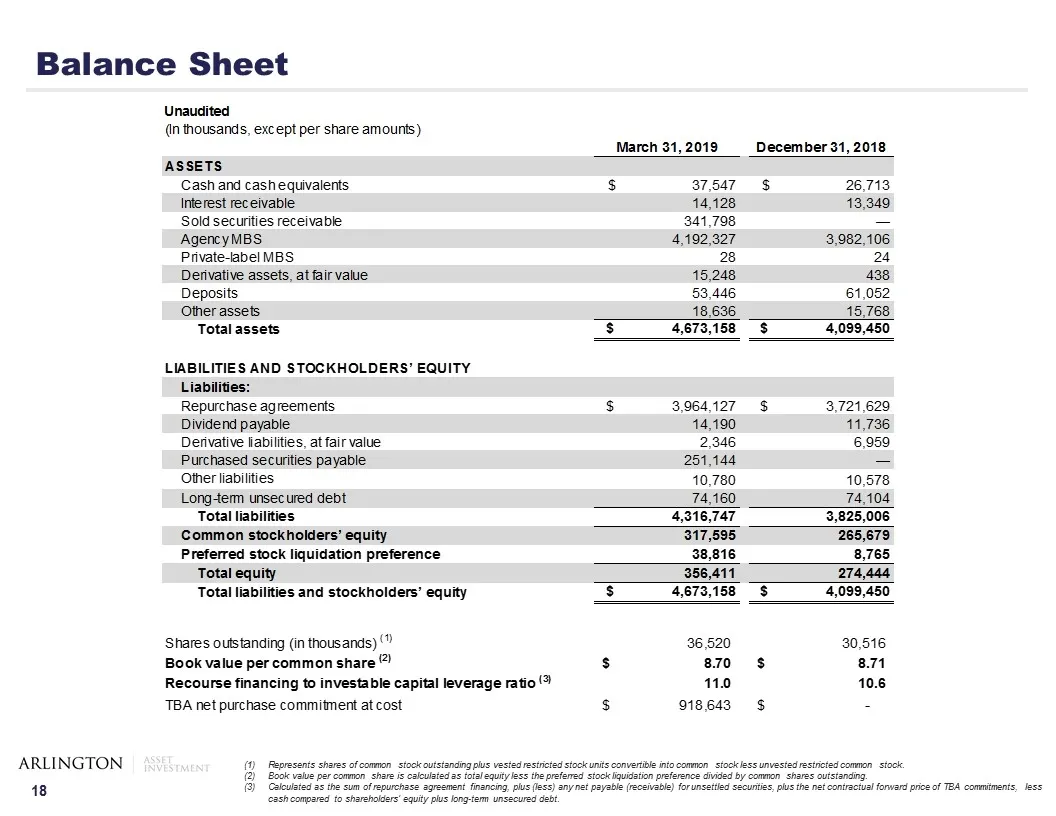
Balance Sheet Represents shares of common stock outstanding plus vested restricted stock units convertible into common stock less unvested restricted common stock. Book value per common share is calculated as total equity less the preferred stock liquidation preference divided by common shares outst
Slide 20: Statement of Comprehensive Income
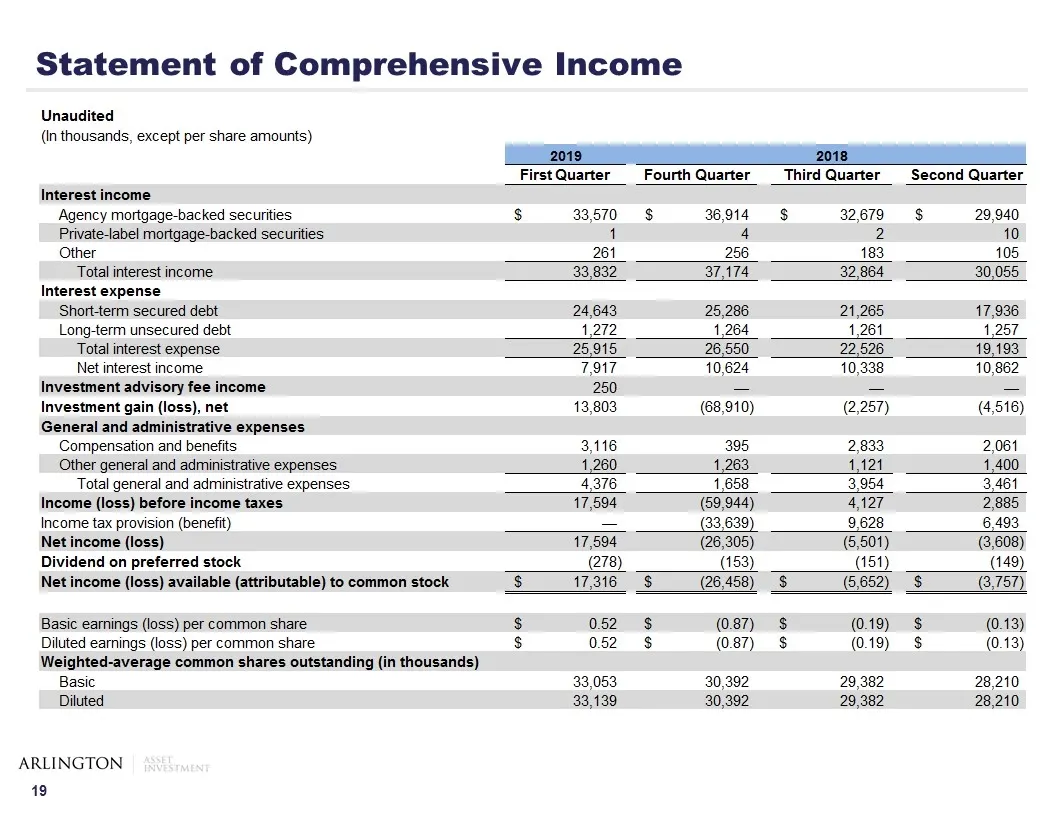
Statement of Comprehensive Income
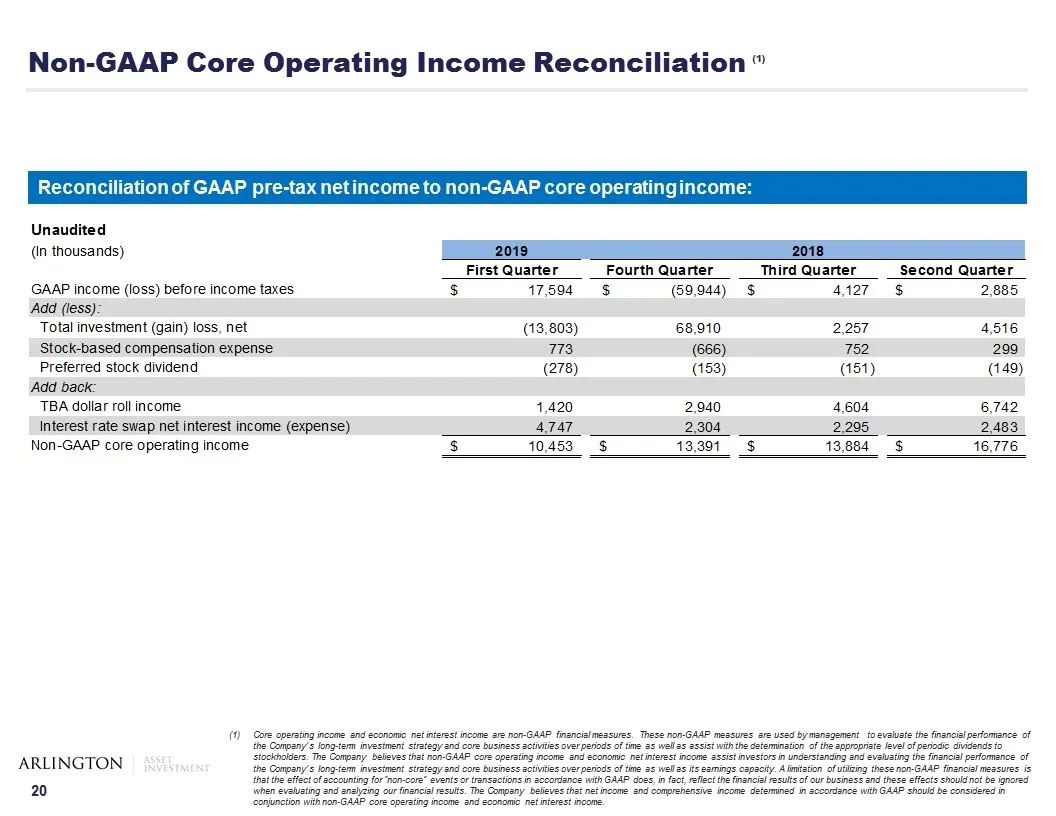
Slide 21: Non-GAAP Core Operating Income Reconciliation
Non-GAAP Core Operating Income Reconciliation (1) Core operating income and economic net interest income are non-GAAP financial measures. These non-GAAP measures are used by management to evaluate the financial performance of the Company’s long-term investment strategy and core business activities o
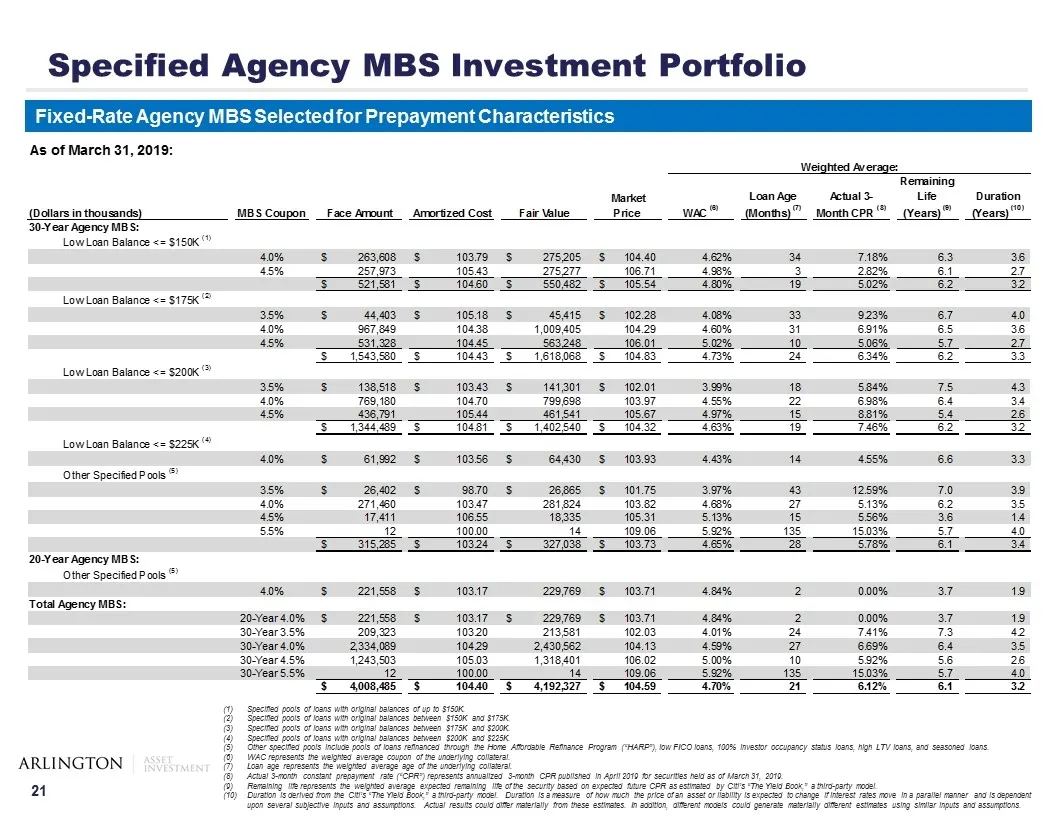
Slide 22: Specified Agency MBS Investment Portfolio
Specified Agency MBS Investment Portfolio Specified pools of loans with original balances of up to $150K. Specified pools of loans with original balances between $150K and $175K. Specified pools of loans with original balances between $175K and $200K. Specified pools of loans with original balances
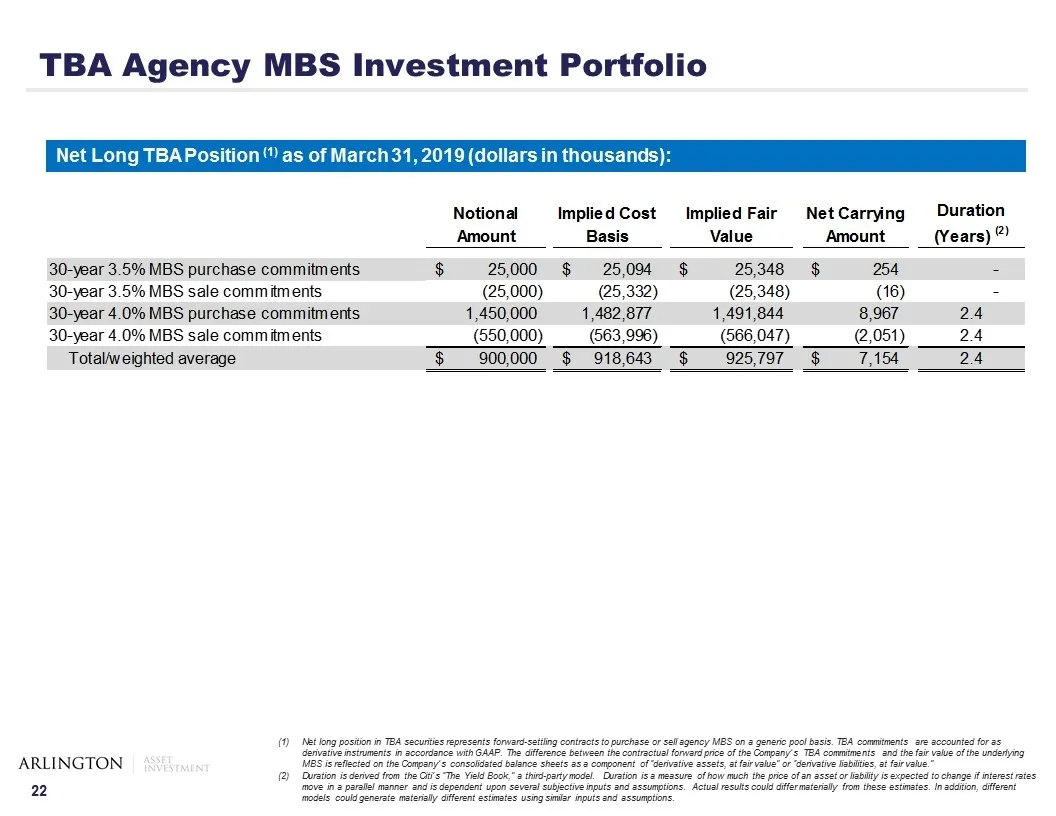
Slide 23: TBA Agency MBS Investment Portfolio
TBA Agency MBS Investment Portfolio Net Long TBA Position (1) as of March 31, 2019 (dollars in thousands): Net long position in TBA securities represents forward-settling contracts to purchase or sell agency MBS on a generic pool basis. TBA commitments are accounted for as derivative instruments in
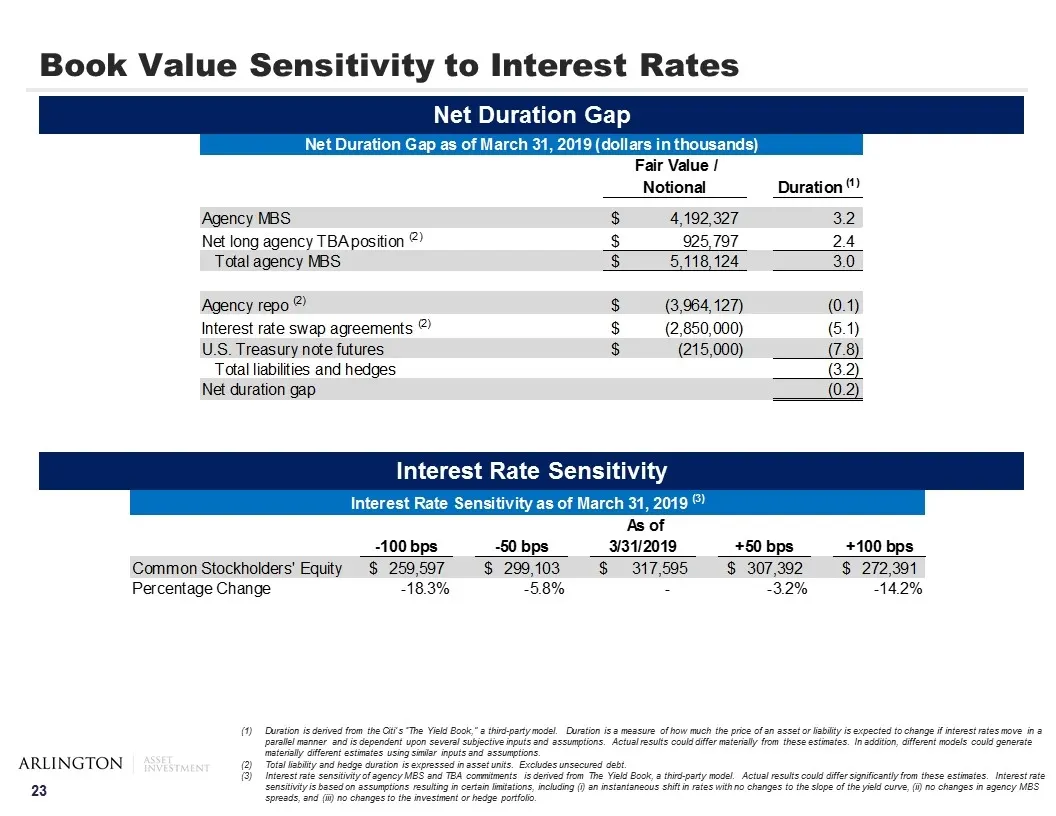
Slide 24: Book Value Sensitivity to Interest Rates
Book Value Sensitivity to Interest Rates Duration is derived from the Citi’s “The Yield Book,” a third-party model. Duration is a measure of how much the price of an asset or liability is expected to change if interest rates move in a parallel manner and is dependent upon several subjective inputs a
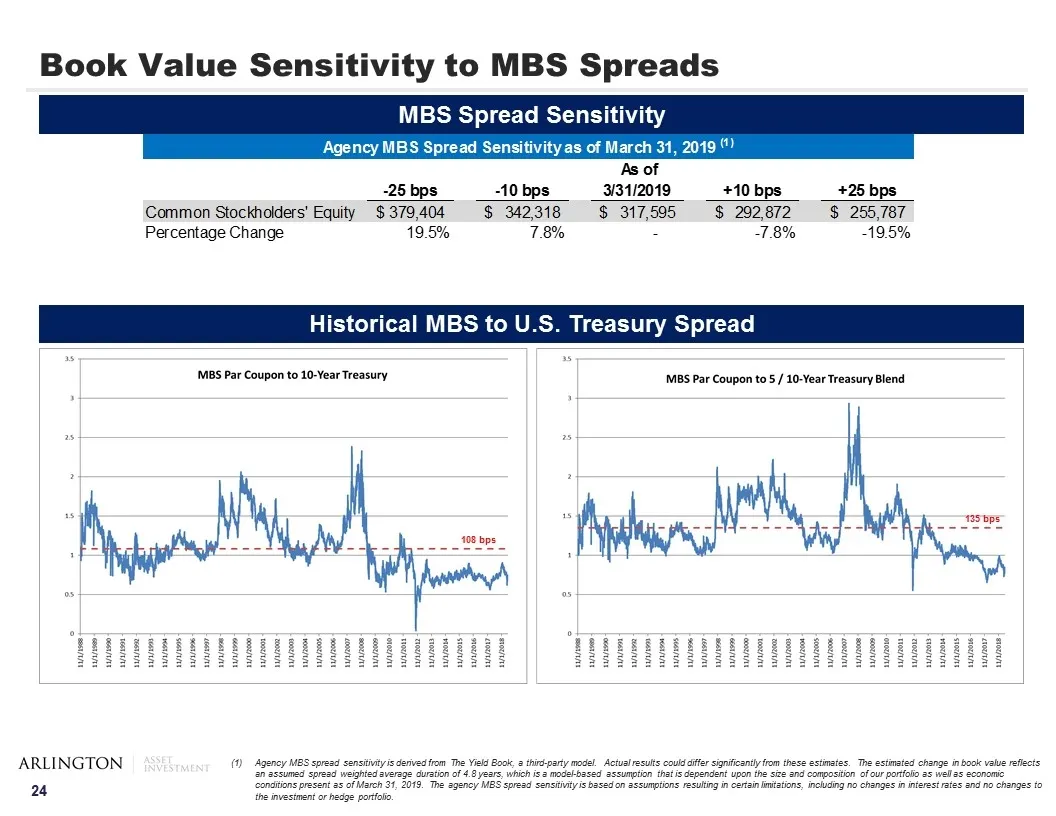
Slide 25: Book Value Sensitivity to MBS Spreads
Book Value Sensitivity to MBS Spreads Agency MBS spread sensitivity is derived from The Yield Book, a third-party model. Actual results could differ significantly from these estimates. The estimated change in book value reflects an assumed spread weighted average duration of 4.8 years, which is a mo
Source: SEC EDGAR · 8-K filed May 2, 2019
More decks from Arlington Asset Investment Corp
 Q3 2023 Earnings Presentation12 slides · Nov 13, 2023
 Q2 2023 Earnings Presentation12 slides · Aug 14, 2023
 Q1 2023 Earnings Presentation16 slides · May 15, 2023
 Q4 2022 Earnings Presentation20 slides · Mar 31, 2023
 Q3 2022 Earnings Presentation29 slides · Nov 15, 2022
 Q2 2022 Earnings Presentation31 slides · Aug 10, 2022