Ucb S.A. · EURONEXT:UCB
Ucb — Investor Presentation (November 2008)
42 slides from Ucb's investor presentation, November 2008
Slide 1: The next generation biopharma leader
The next generation biopharma leader UCB GROUP Company Presentation Lloyd and Alexander, living with epilepsy November 2008
Slide 2: Disclaimer and safe harbour
Disclaimer and safe harbour 2 the next generation biopharma leader November 2008 Forward-looking statements: This presentation includes “forward-looking statements” relating to UCB and Schwarz Pharma that are subject to known and unknown risks and uncertainties, many of which are outside of UCB’s an
Slide 3: New UCB
New UCB 3 the next generation biopharma leader November 2008 Vision: to build a global biopharmaceutical leader, based on unique blending of innovation, entrepreneurship and proven experience, bringing to specialists first, new medicines to treat patients suffering from severe diseases. Focus: centr
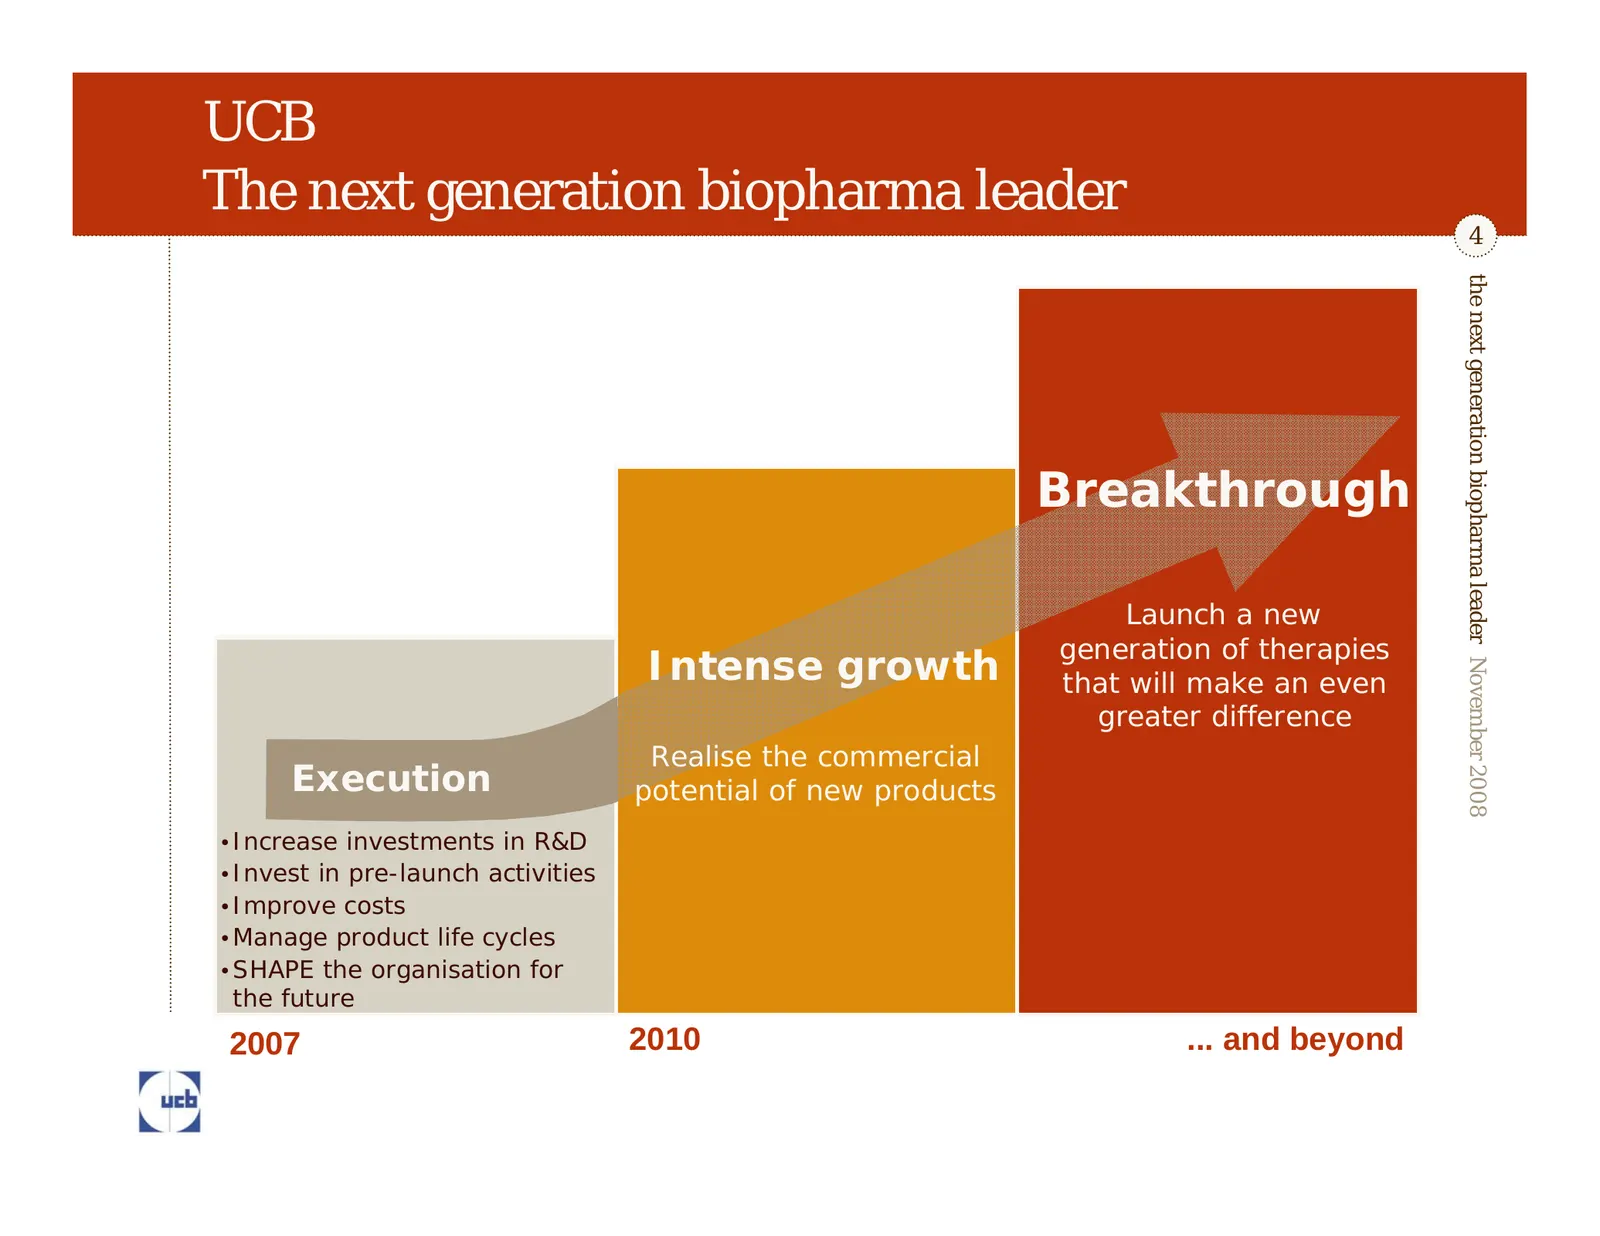
Slide 4: The next generation biopharma leader
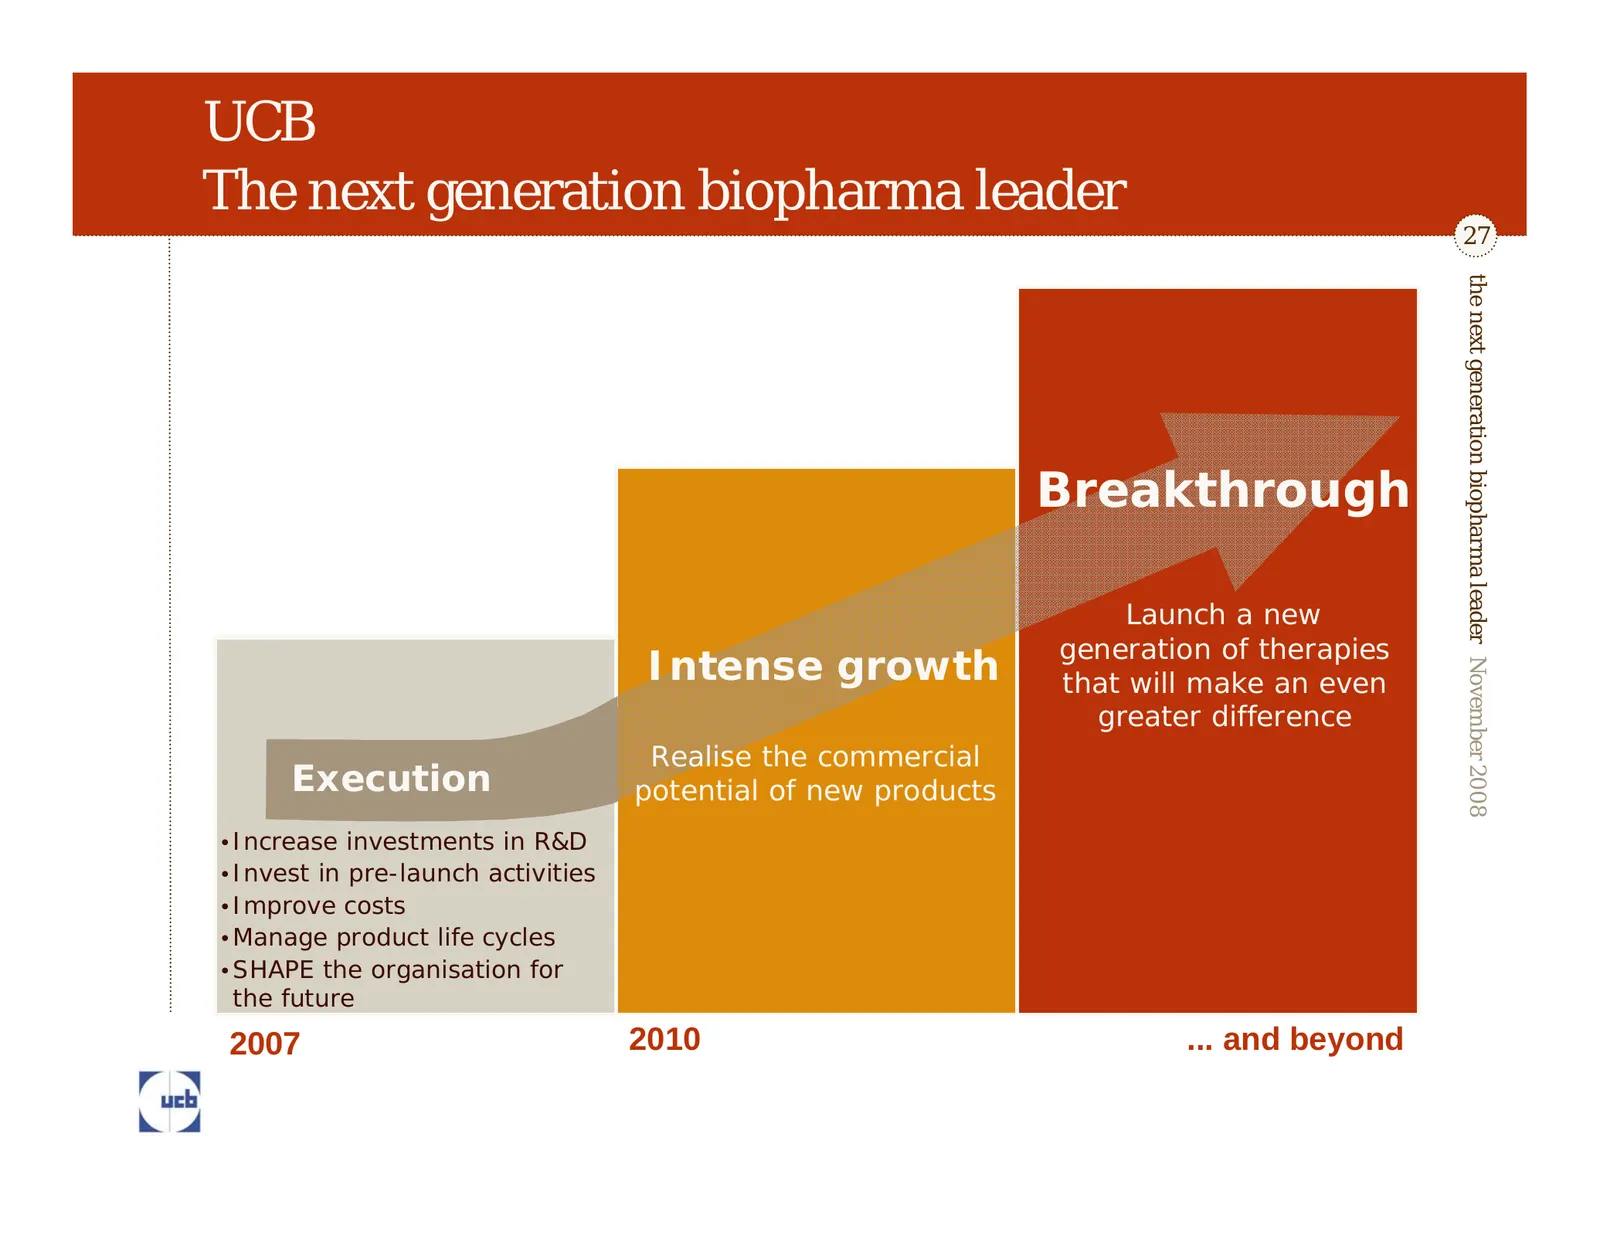
UCB The next generation biopharma leader 4 the next generation biopharma leader November 2008 Breakthrough Launch a new generation of therapies Intense growth that will make an even greater difference Realise the commercial Execution potential of new products • Increase investments in R&D • Invest i
Slide 5: Execution phase: 2007-2010
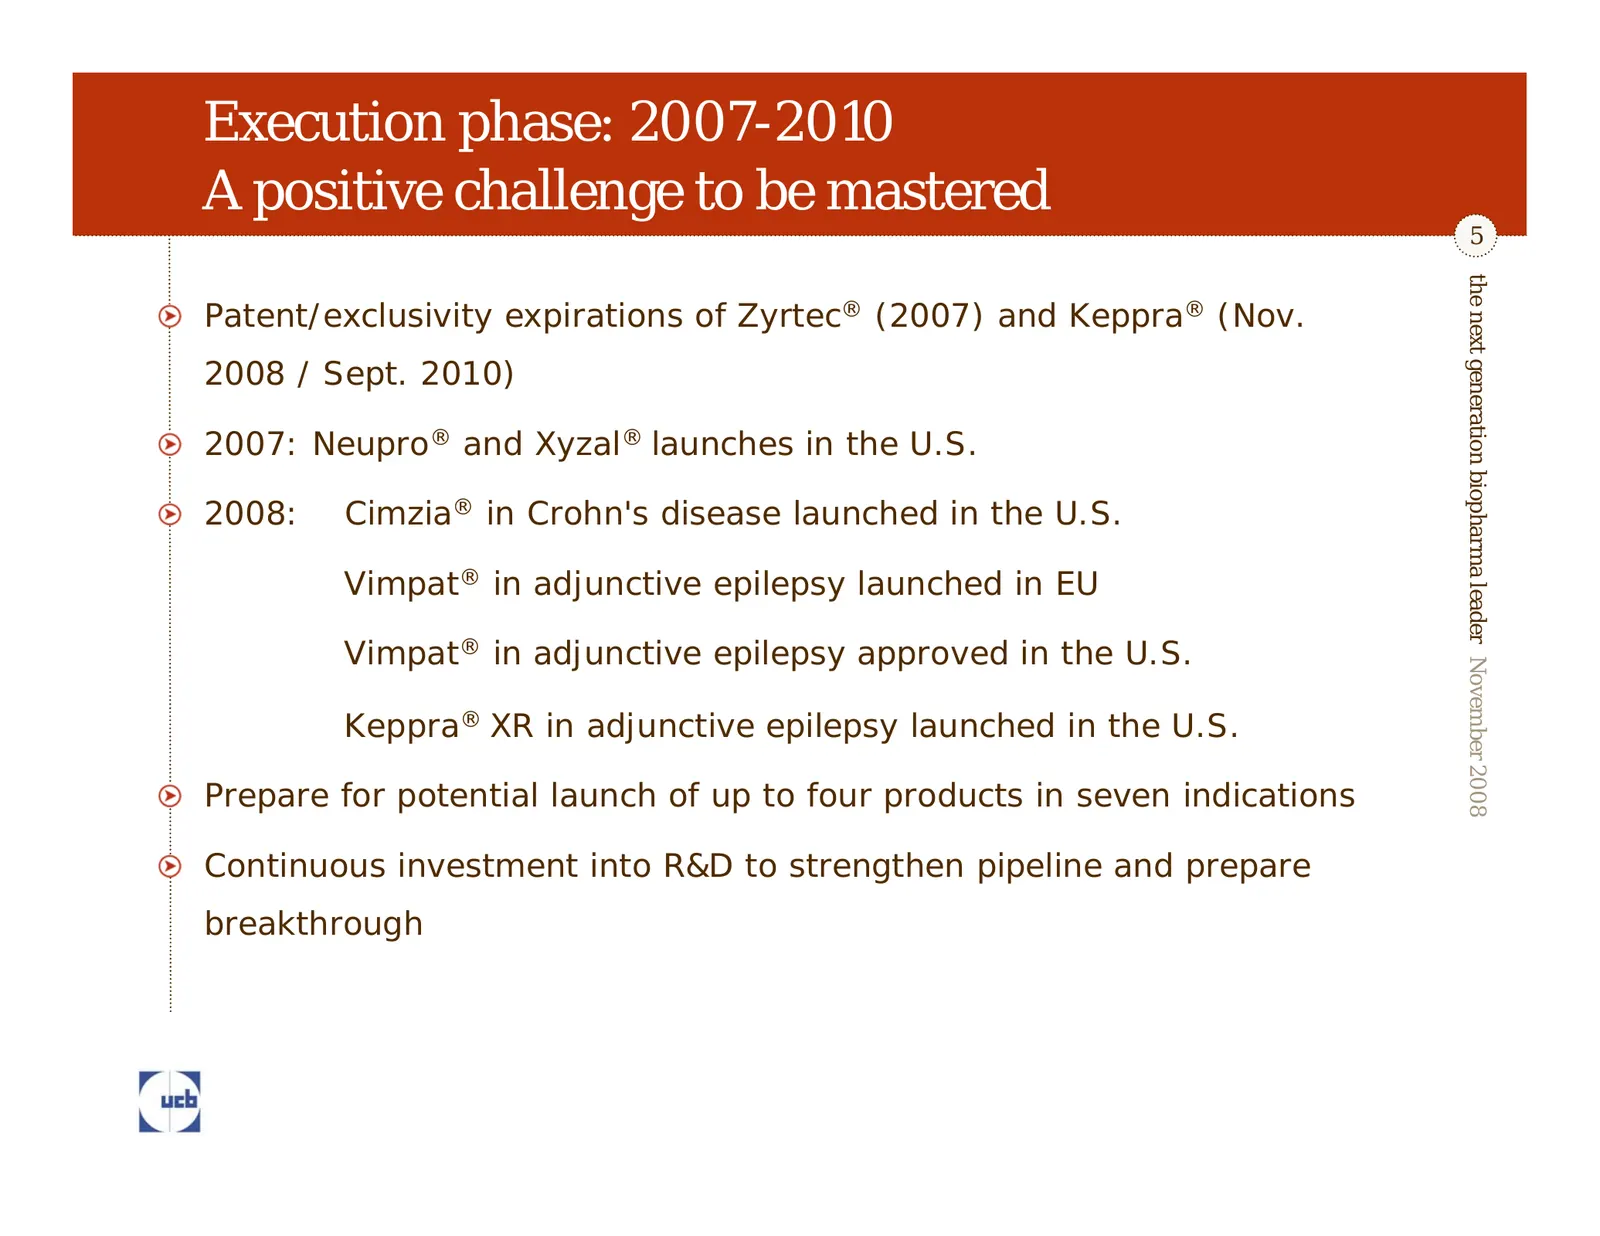
Execution phase: 2007-2010 A positive challenge to be mastered 5 the next generation biopharma leader November 2008 Patent/exclusivity expirations of Zyrtec® (2007) and Keppra® (Nov. 2008 / Sept. 2010) 2007: Neupro® and Xyzal® launches in the U.S. 2008: Cimzia® in Crohn's disease launched in the U.S
Slide 6: Multiple regulatory milestones and first approvals
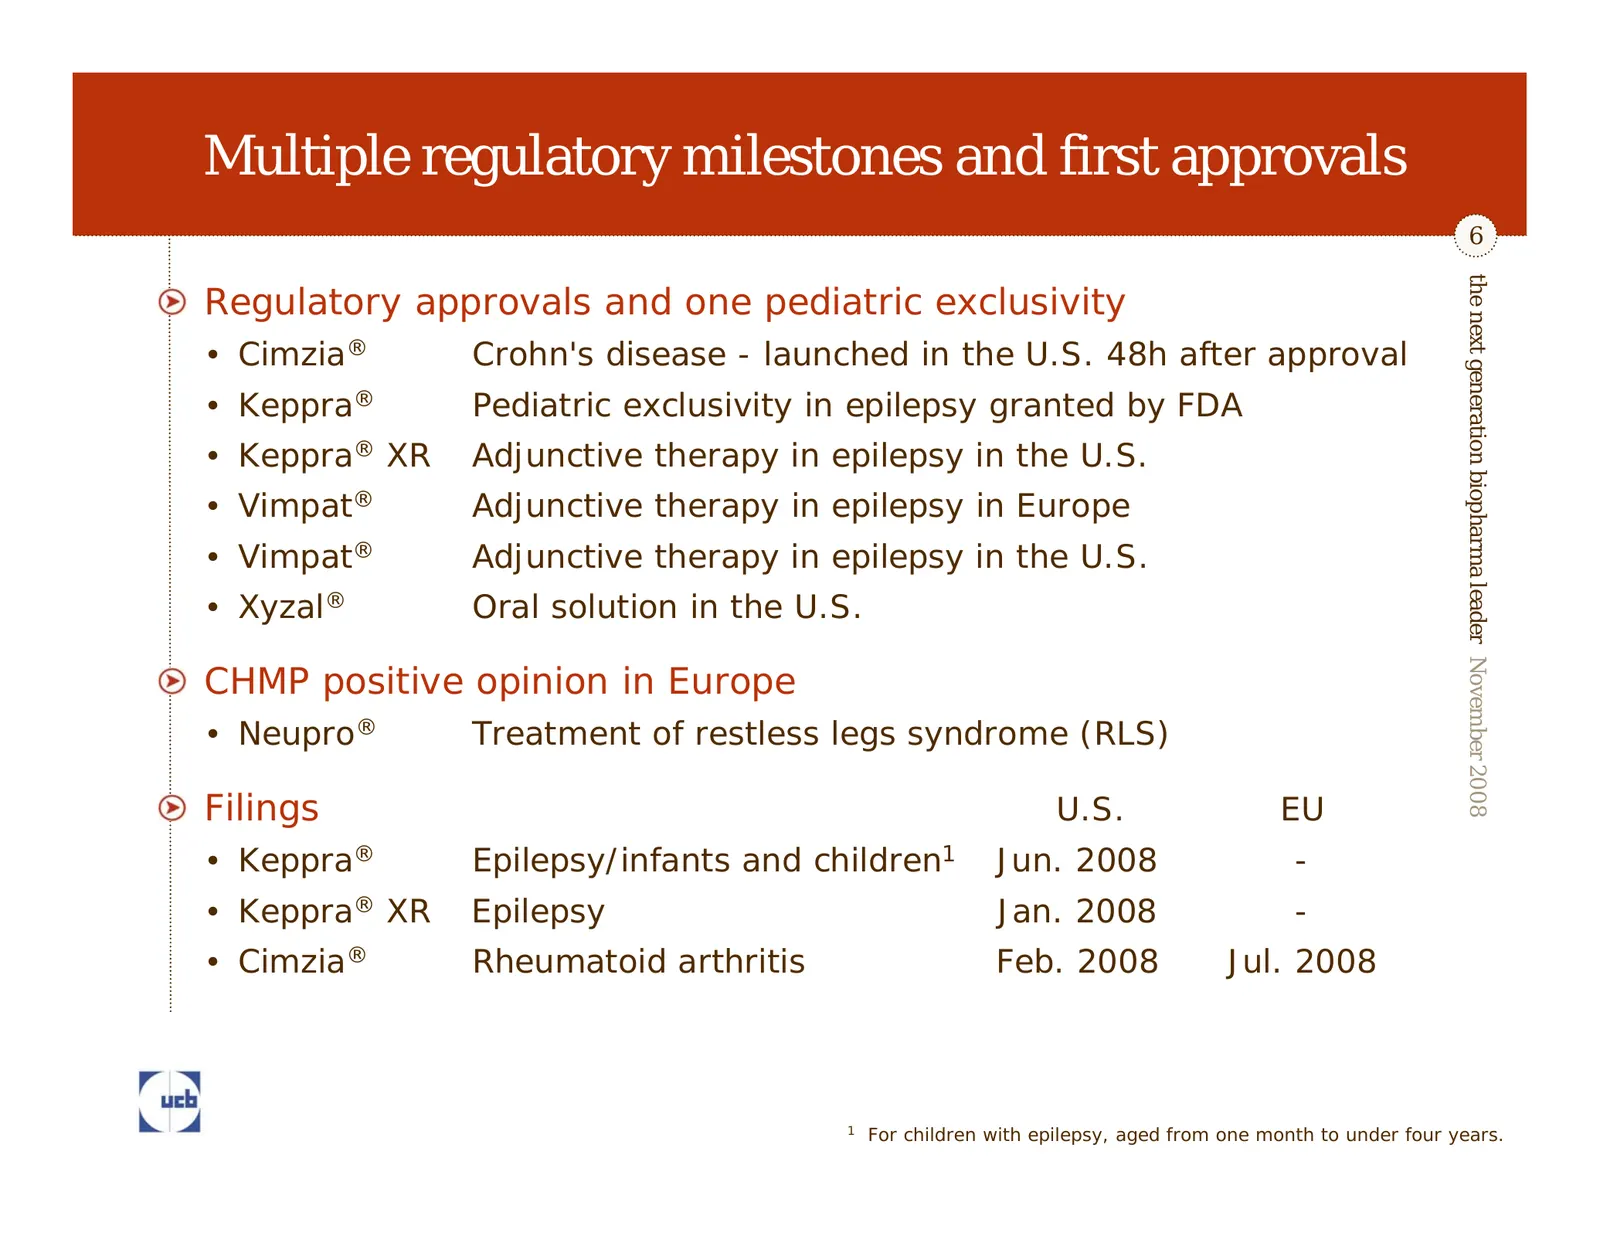
Multiple regulatory milestones and first approvals 6 the next generation biopharma leader November 2008 Regulatory approvals and one pediatric exclusivity • Cimzia® Crohn's disease - launched in the U.S. 48h after approval • Keppra® Pediatric exclusivity in epilepsy granted by FDA • Keppra® XR Adjun
Slide 7: Outlook 2008 and beyond
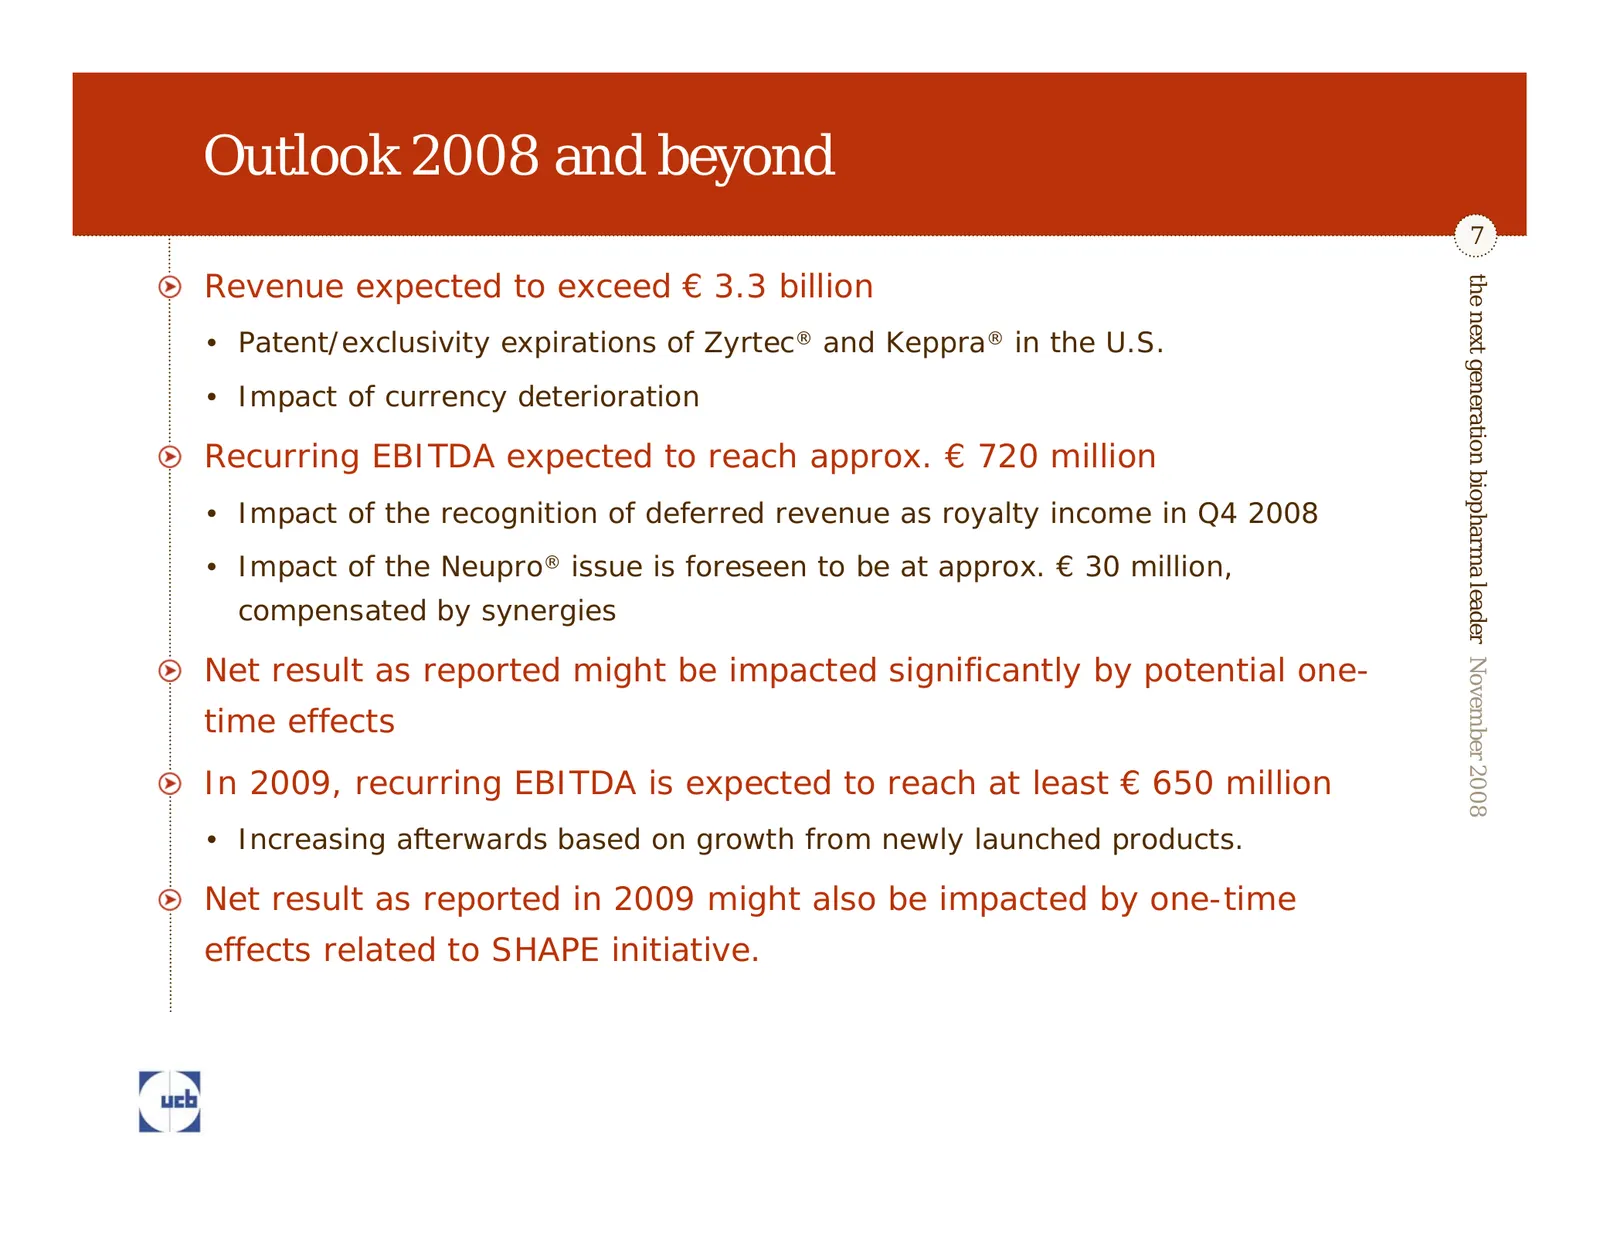
Outlook 2008 and beyond 7 Revenue expected to exceed € 3.3 billion the next generation biopharma leader November 2008 • Patent/exclusivity expirations of Zyrtec® and Keppra® in the U.S. • Impact of currency deterioration Recurring EBITDA expected to reach approx. € 720 million • Impact of the recogn
Slide 8: Rich R&D pipeline
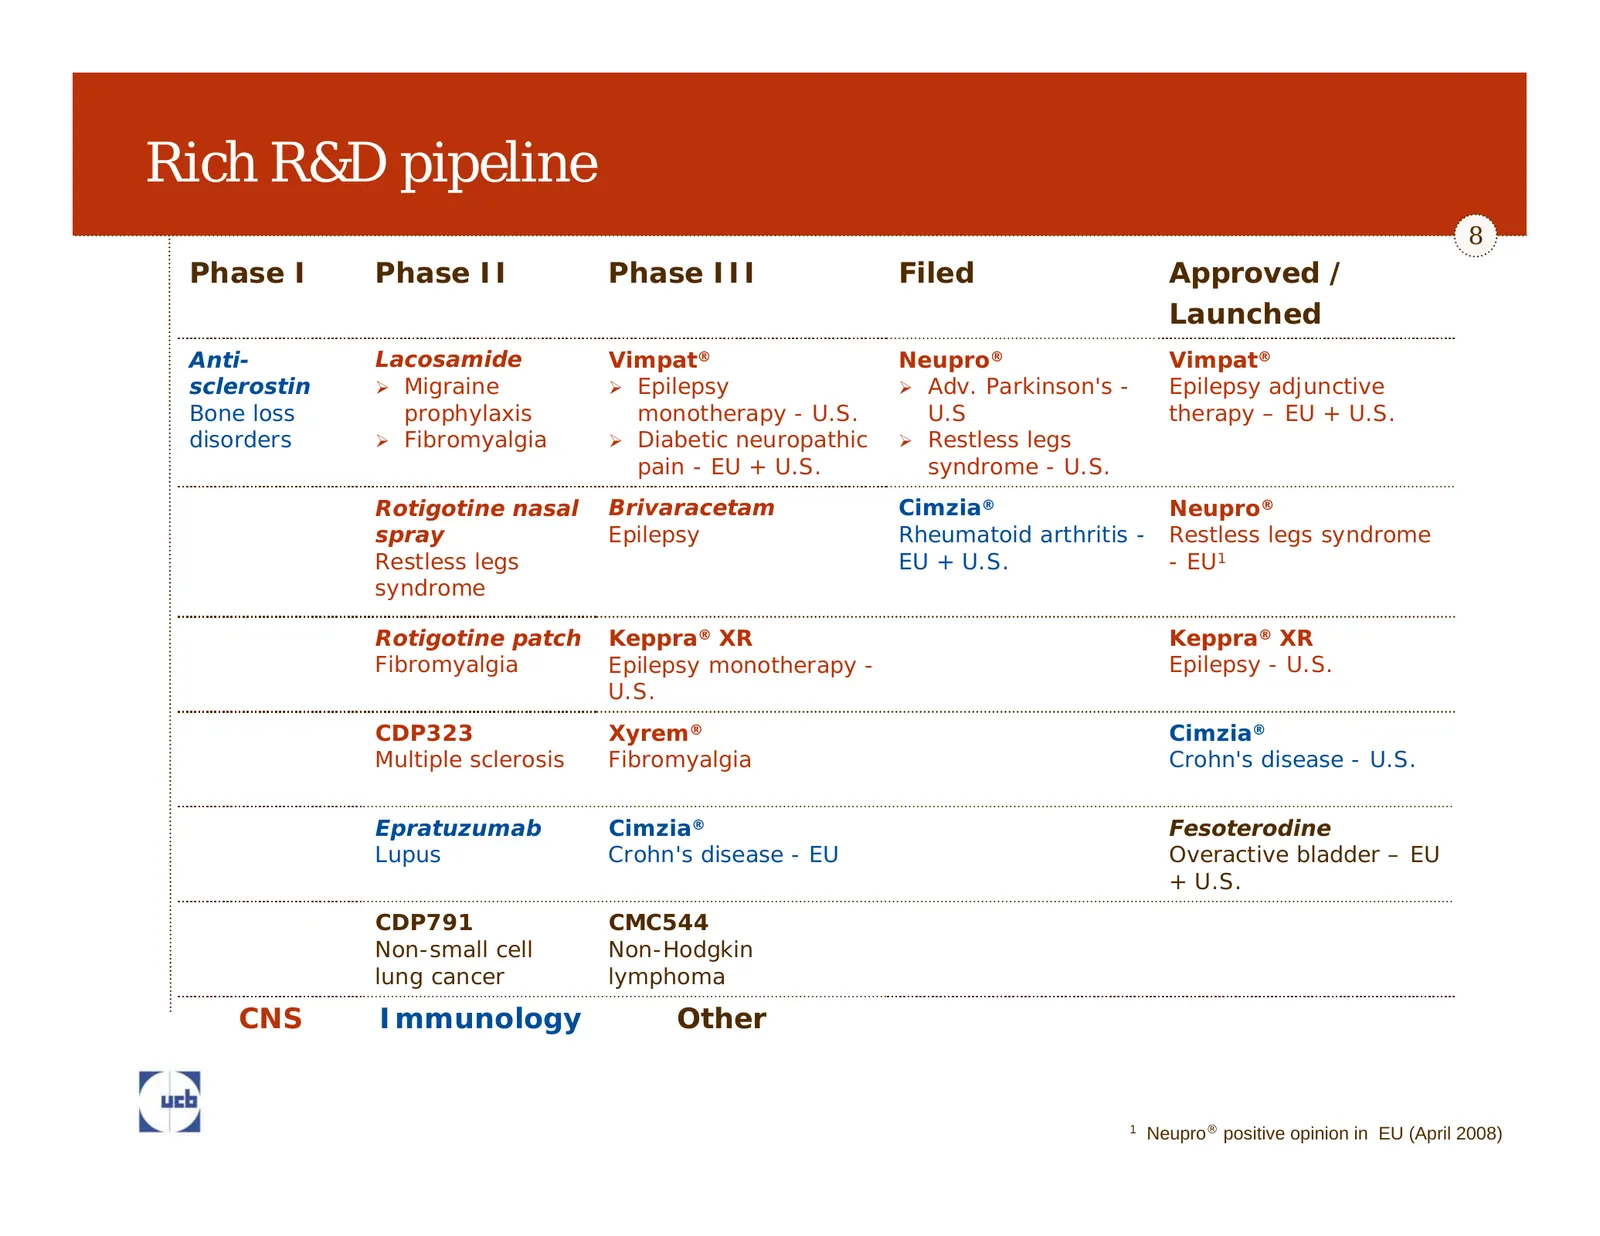
Rich R&D pipeline 8 Phase I Phase II Phase III Filed Approved / Launched Anti- Lacosamide Vimpat® Neupro® Vimpat® sclerostin ¾ Migraine ¾ Epilepsy ¾ Adv. Parkinson's - Epilepsy adjunctive Bone loss prophylaxis monotherapy - U.S. U.S therapy – EU + U.S. disorders ¾ Fibromyalgia ¾ Diabetic neuropathic
Slide 9: CNS: Expansion in our core area
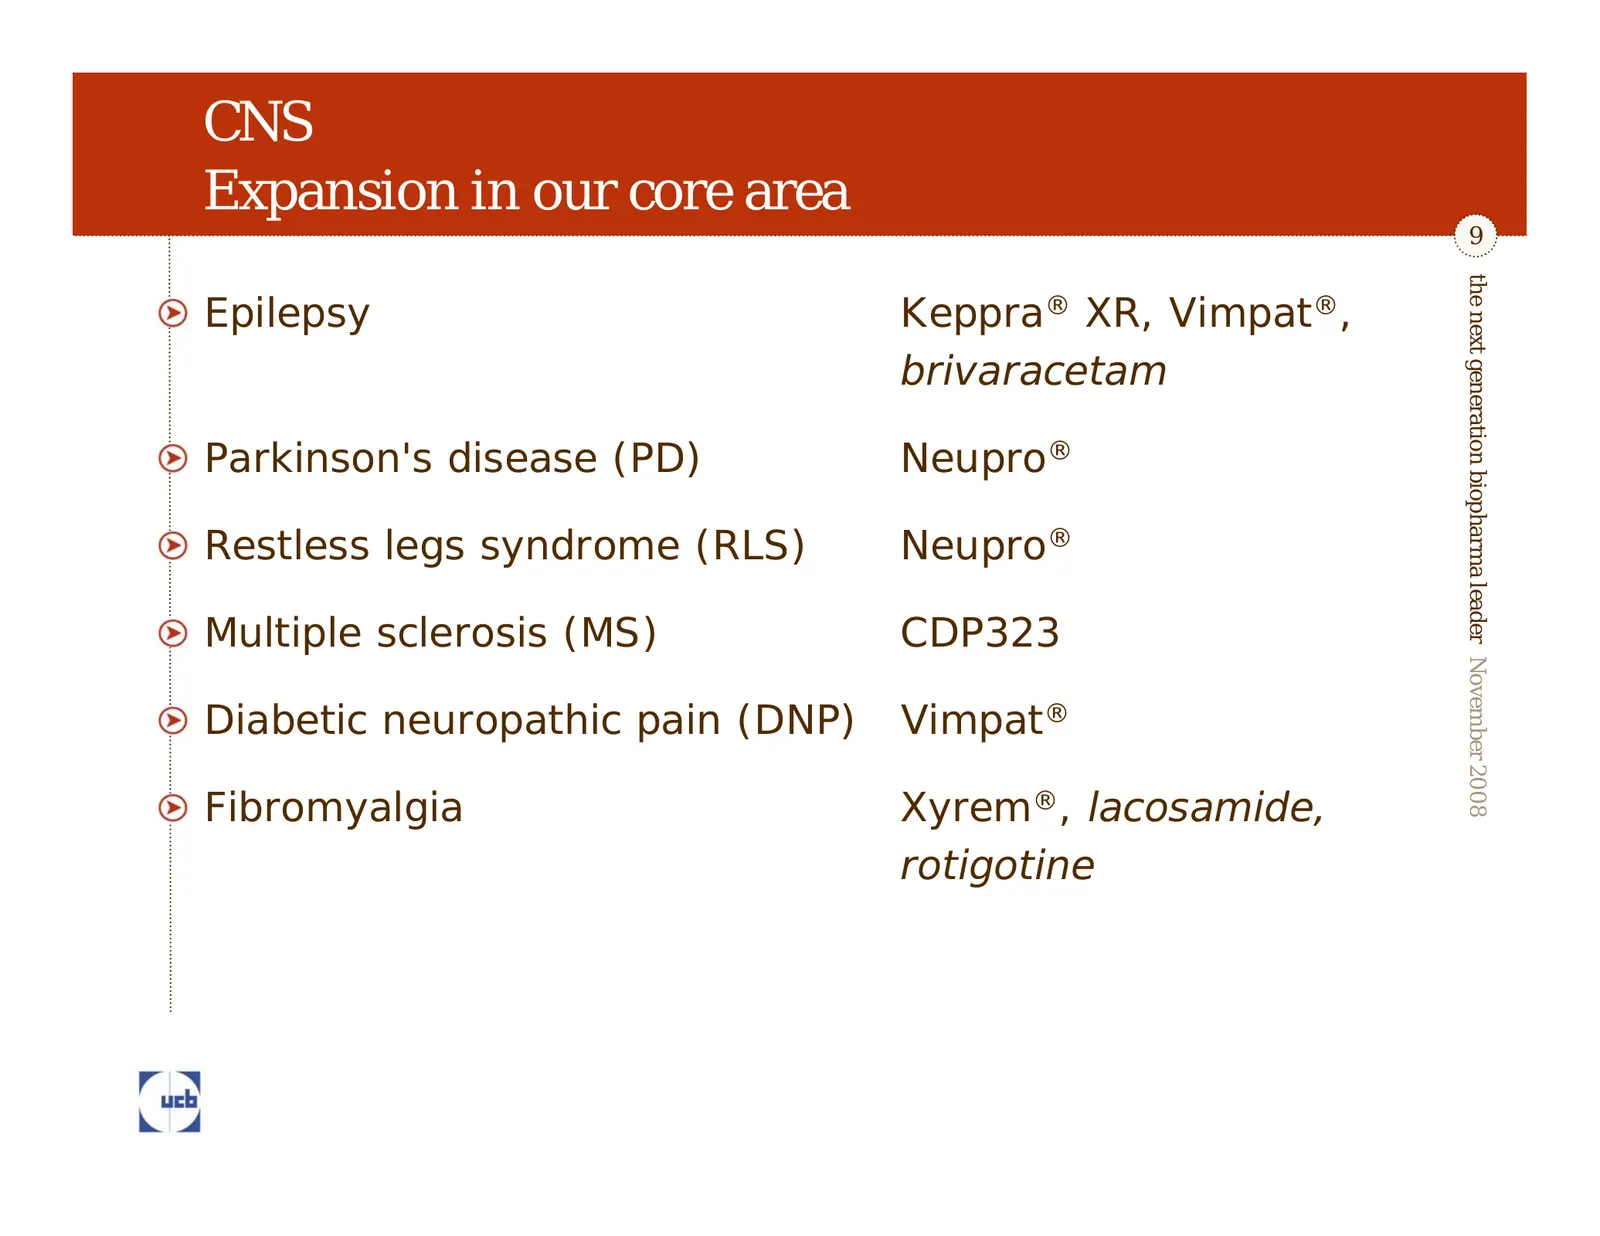
CNS Expansion in our core area 9 the next generation biopharma leader November 2008 Epilepsy Keppra® XR, Vimpat®, brivaracetam Parkinson's disease (PD) Neupro® Restless legs syndrome (RLS) Neupro® Multiple sclerosis (MS) CDP323 Diabetic neuropathic pain (DNP) Vimpat® Fibromyalgia Xyrem®, lacosamide,
Slide 10: Major unmet medical need
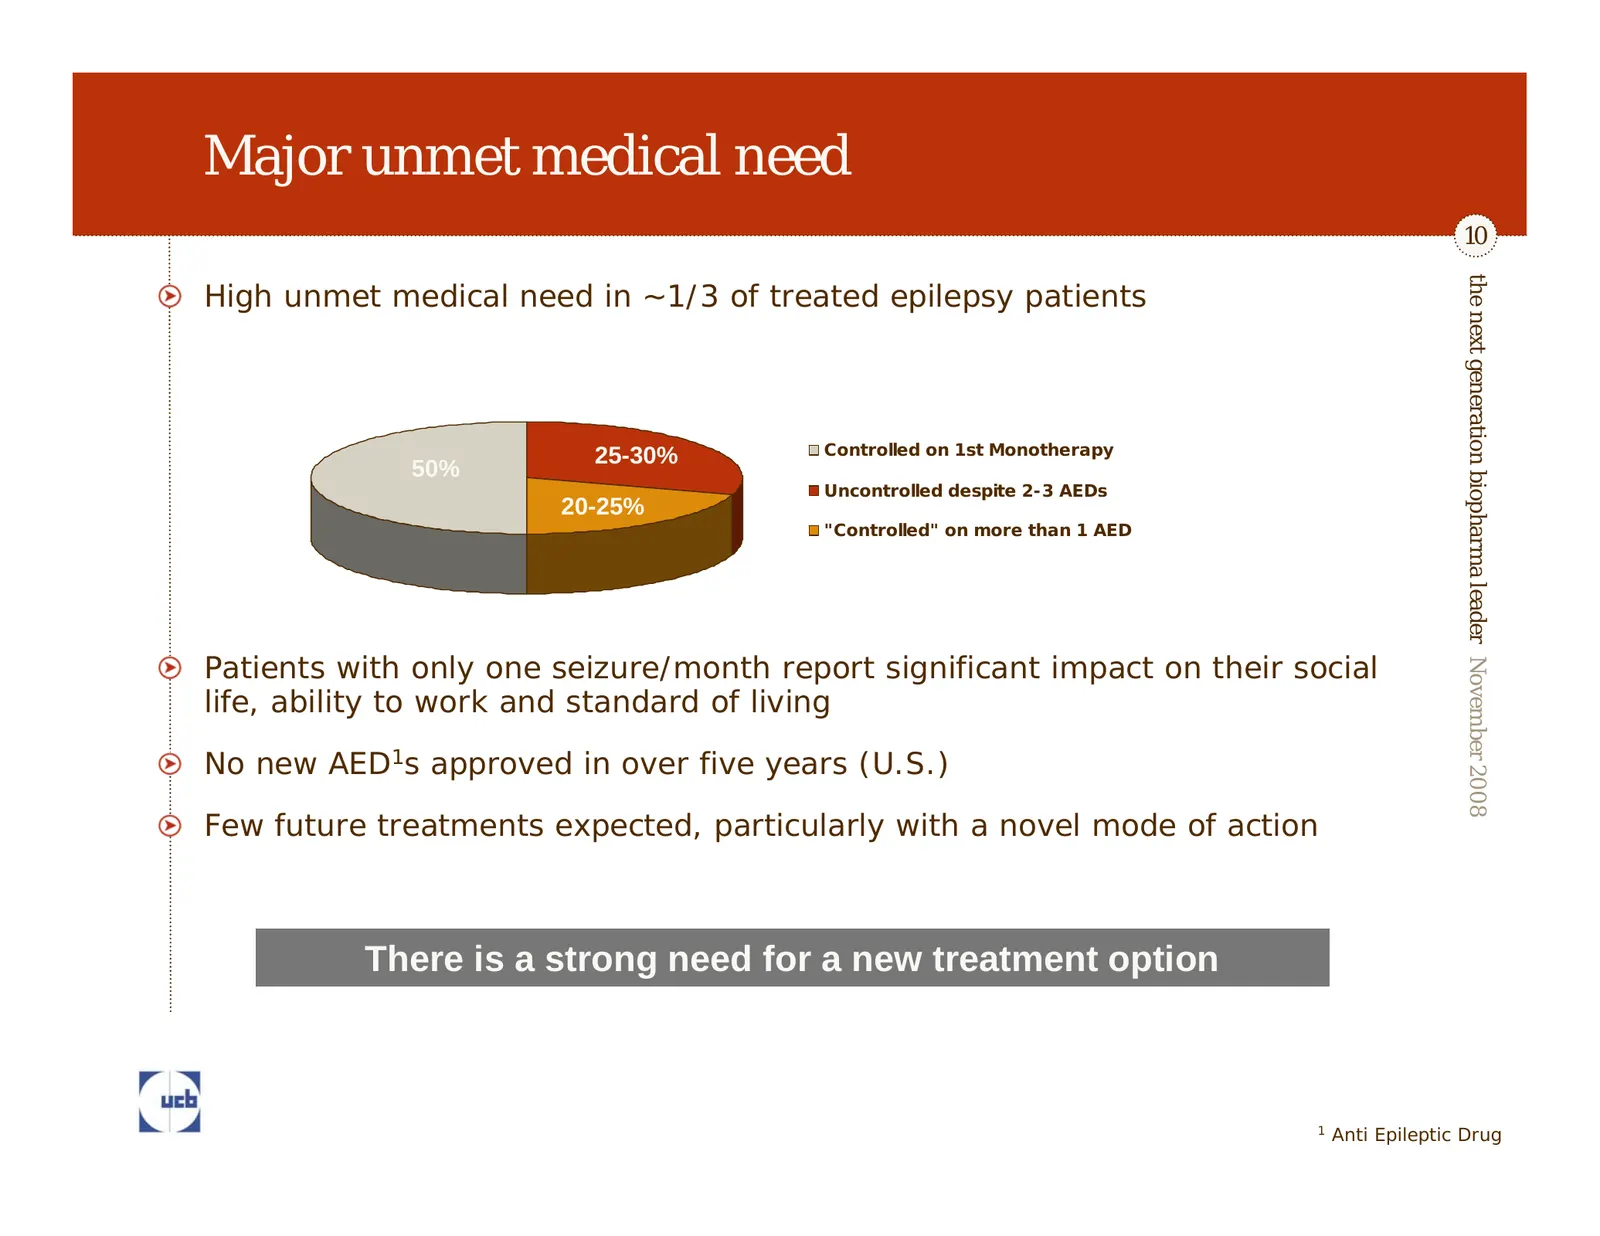
Major unmet medical need 10 the next generation biopharma leader November 2008 High unmet medical need in ~1/3 of treated epilepsy patients 25-30% Controlled on 1st Monotherapy 50% Uncontrolled despite 2-3 AEDs 20-25% "Controlled" on more than 1 AED Patients with only one seizure/month report signif
Slide 11: Keppra XR: Once daily convenience
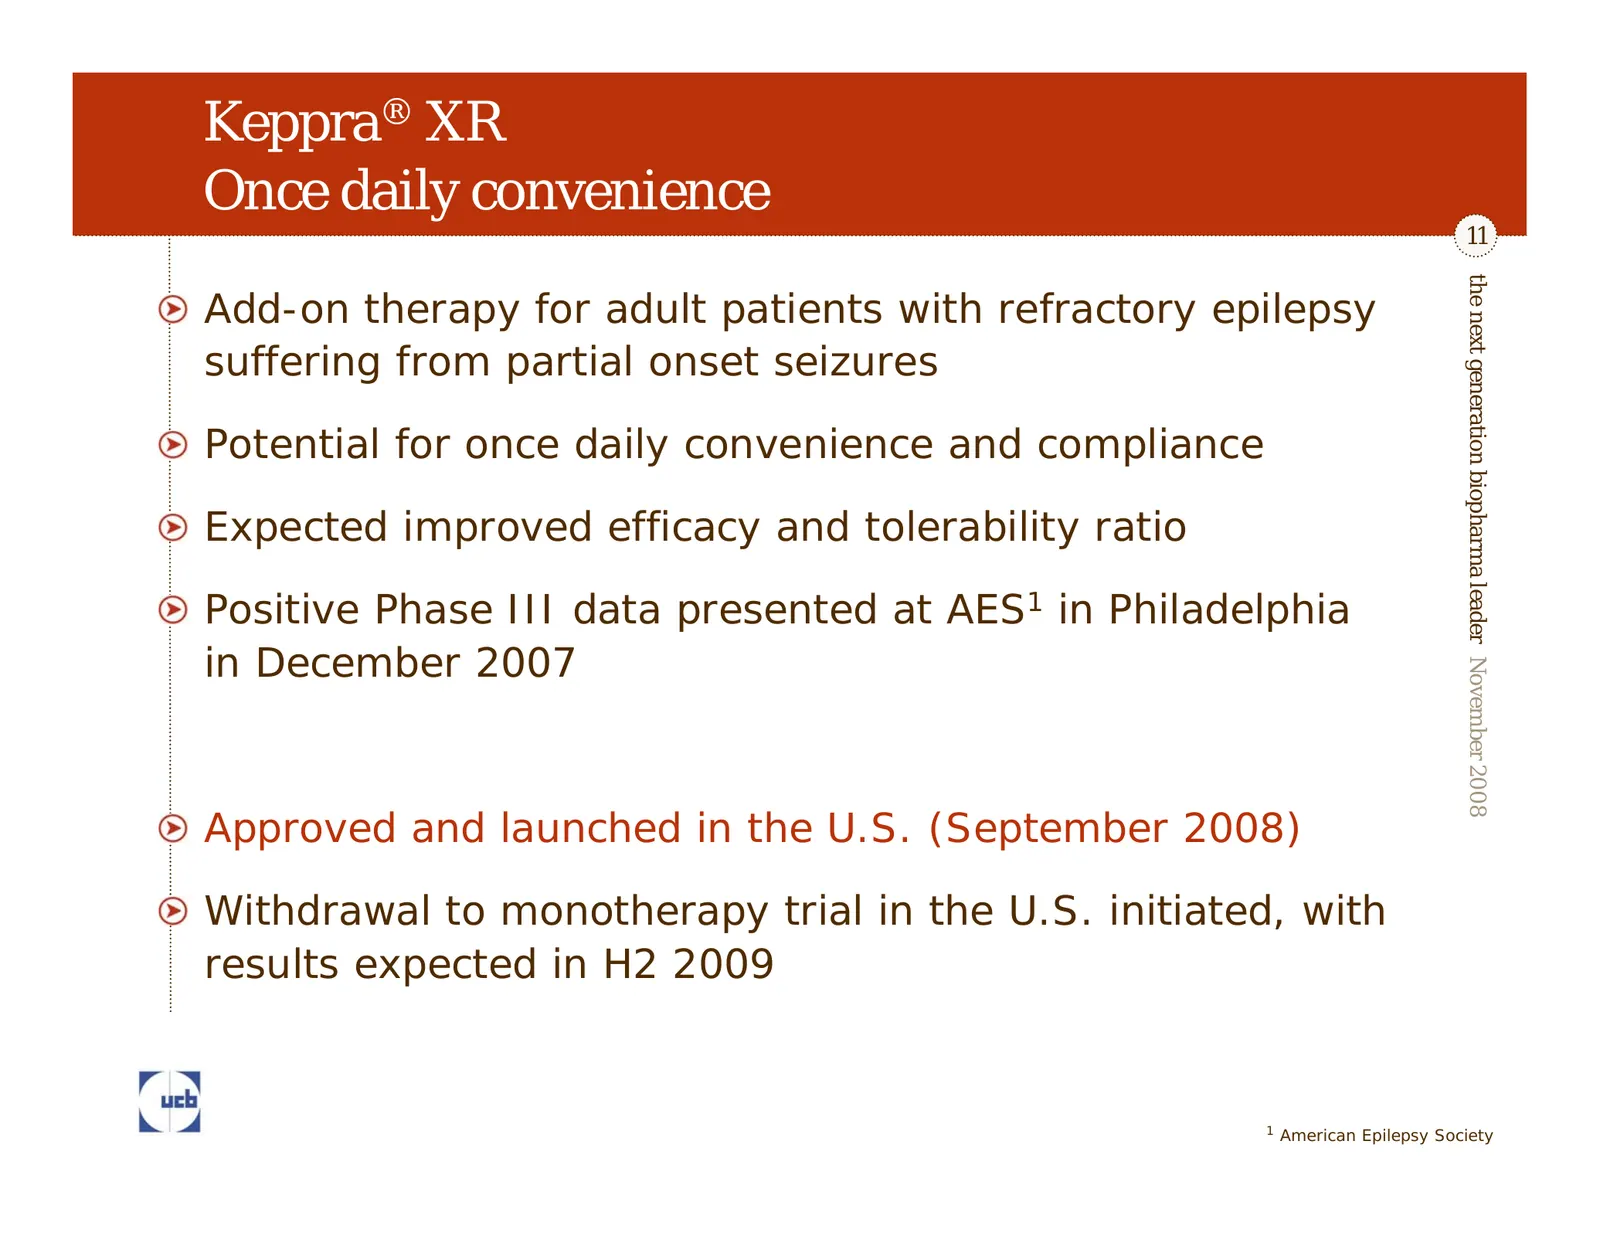
Keppra® XR Once daily convenience 11 the next generation biopharma leader November 2008 Add-on therapy for adult patients with refractory epilepsy suffering from partial onset seizures Potential for once daily convenience and compliance Expected improved efficacy and tolerability ratio Positive Phas
Slide 12: Vimpat in epilepsy
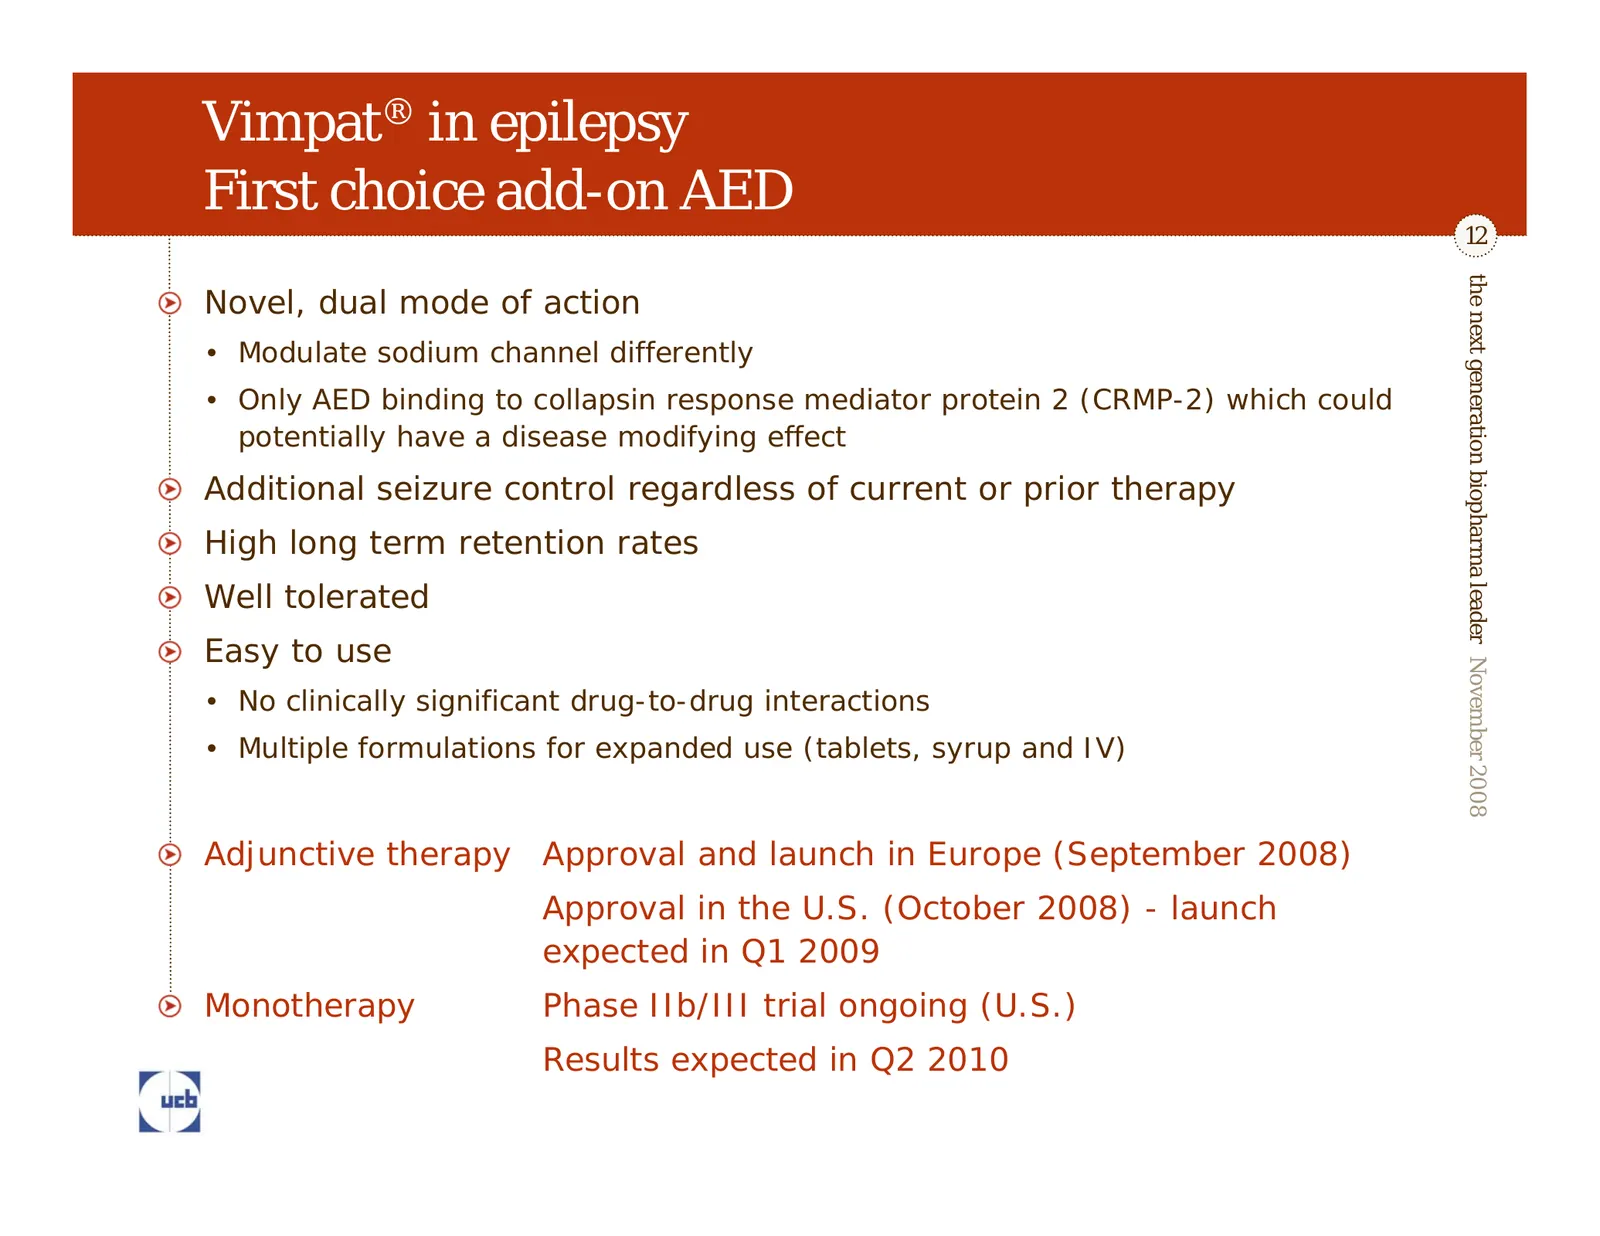
Vimpat® in epilepsy First choice add-on AED 12 the next generation biopharma leader November 2008 Novel, dual mode of action • Modulate sodium channel differently • Only AED binding to collapsin response mediator protein 2 (CRMP-2) which could potentially have a disease modifying effect Additional s
Slide 13: Brivaracetam in epilepsy
Brivaracetam in epilepsy Start of Phase III programme 13 the next generation biopharma leader November 2008 Different pharmacology than Keppra®, broader mechanism of action Population includes patients not controlled with Keppra® Phase III development programme started in October 2007 Results expect
Slide 14: Neupro: A new Parkinson's therapy is taking shape
Neupro® A new Parkinson's therapy is taking shape 14 the next generation biopharma leader November 2008 First once a day non-ergolinic dopamine agonist First transdermal patch for treatment of Parkinson’s disease 24-hour coverage for signs and symptoms of Parkinson’s disease Early stage Parkinson la
Slide 15: Neupro in Parkinson's disease: Update
Neupro® in Parkinson's disease Update 15 the next generation biopharma leader November 2008 Successful implementation of the full cold- chain in Europe achieved in September 08 • Target: to make Neupro® available again to all patients (including new patients) in Europe by first half 2009 To resolve
Slide 16: Neupro in restless legs syndrome (RLS)
Neupro® in restless legs syndrome (RLS) Increased awareness of an unrecognised disease 16 the next generation biopharma leader November 2008 Demonstrated efficacy Well tolerated Consistent results within comprehensive clinical program Evidence of improved sleep and reduced daytime tiredness Excellen
Slide 17: Vimpat in diabetic neuropathic pain
Vimpat® in diabetic neuropathic pain Promising drug for a large unmet medical need 17 the next generation biopharma leader November 2008 Demonstrated sustained efficacy in reducing diabetic neuropathy Good tolerability profile No drug-drug or food interactions or weight gain New mode of action Filed
Slide 18: Immunology and other diseases
Immunology and other diseases 18 the next generation biopharma leader November 2008 Crohn's disease (CD) Cimzia® Rheumatoid arthritis (RA) Cimzia® Systemic lupus erythematosus (SLE) epratuzumab Bone loss disorders anti-sclerostin
Slide 19: Cimzia in Crohn's disease
Cimzia® in Crohn’s disease A new generation 19 the next generation biopharma leader November 2008 The First and Only PEGylated anti-TNF Sustainable Results Every 4 weeks stable dosing "CIMplicity™ Service Center" • Health insurance verification • Free trial and co-pay assistance • Home health nurse
Slide 20: Cimzia in rheumatoid arthritis
Cimzia® in rheumatoid arthritis Only PEGylated Fc-free anti-TNF 20 the next generation biopharma leader November 2008 Positive results from three Phase III studies presented at EULAR1 and ACR2 in 2007 Primary endpoints met with statistical significance • Significant and rapid improvement in signs an
Slide 21: Rich R&D pipeline
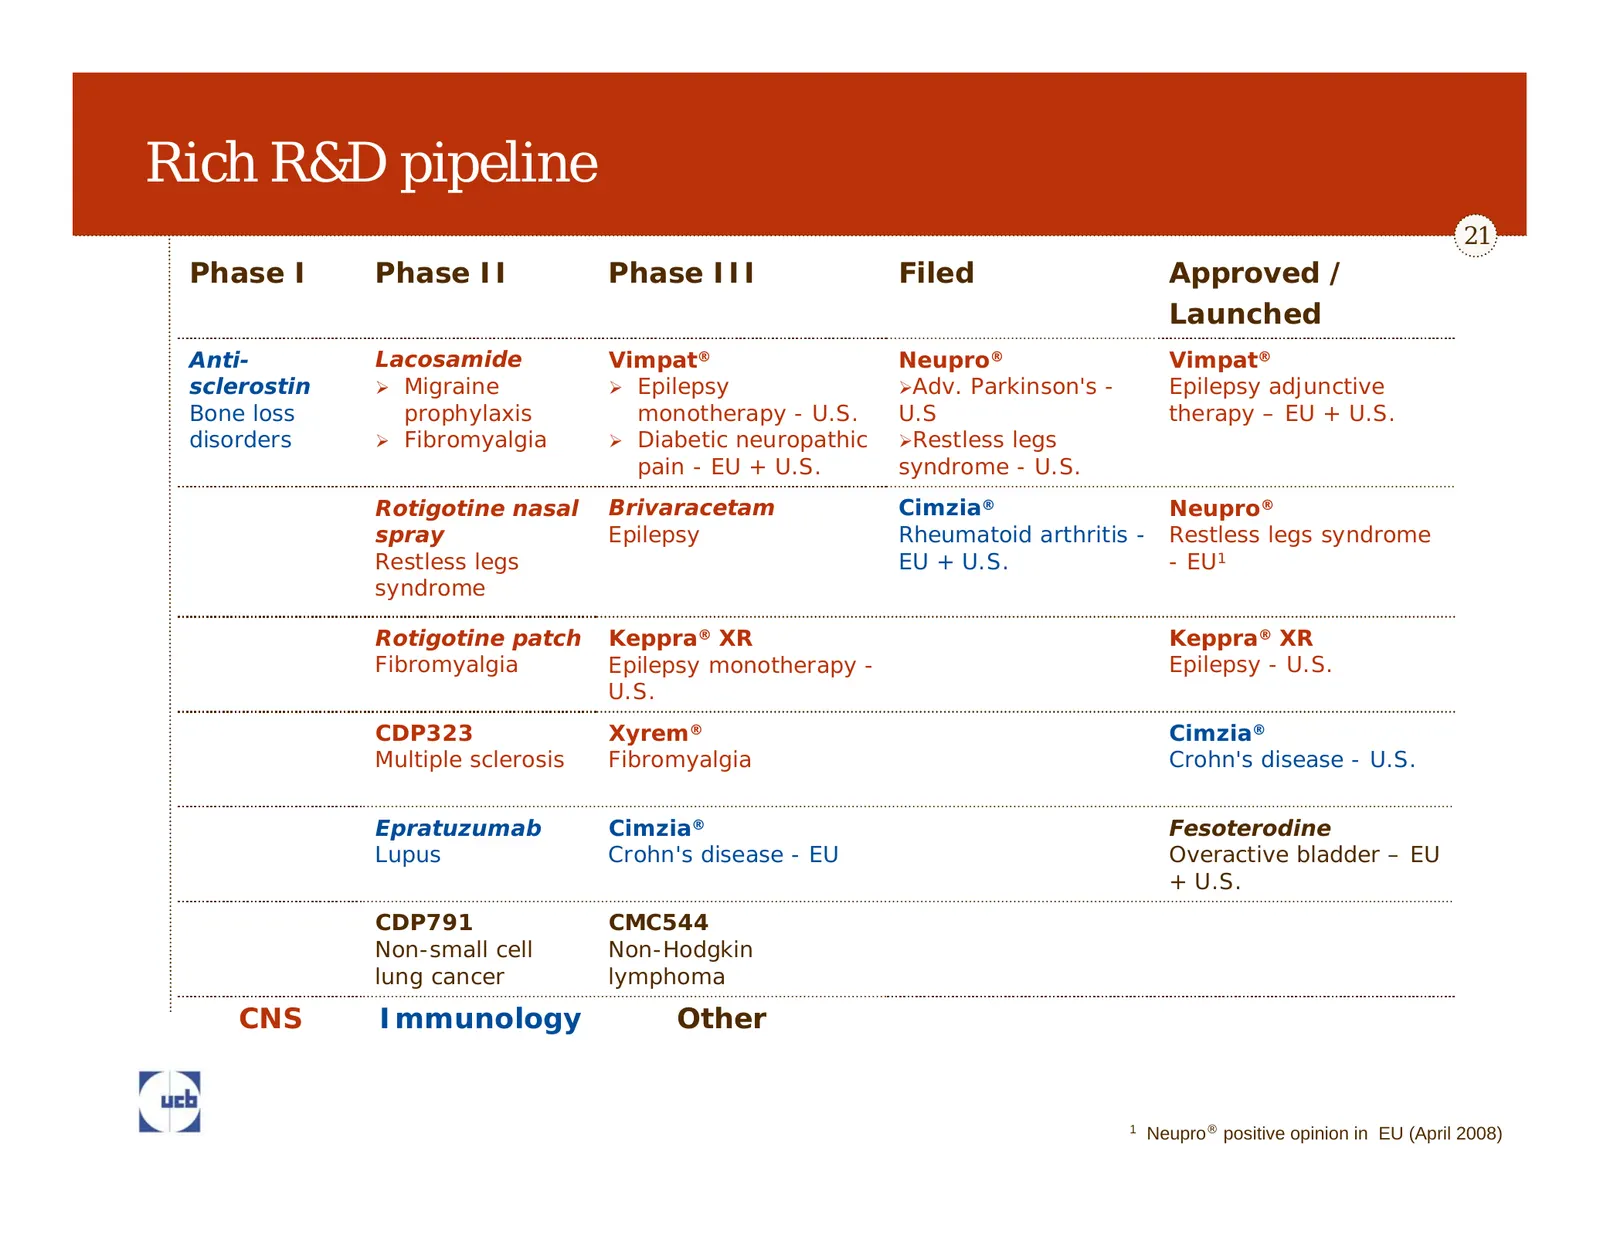
Rich R&D pipeline 21 Phase I Phase II Phase III Filed Approved / Launched Anti- Lacosamide Vimpat® Neupro® Vimpat® sclerostin ¾ Migraine ¾ Epilepsy ¾Adv. Parkinson's - Epilepsy adjunctive Bone loss prophylaxis monotherapy - U.S. U.S therapy – EU + U.S. disorders ¾ Fibromyalgia ¾ Diabetic neuropathic
Slide 22: SHAPE!
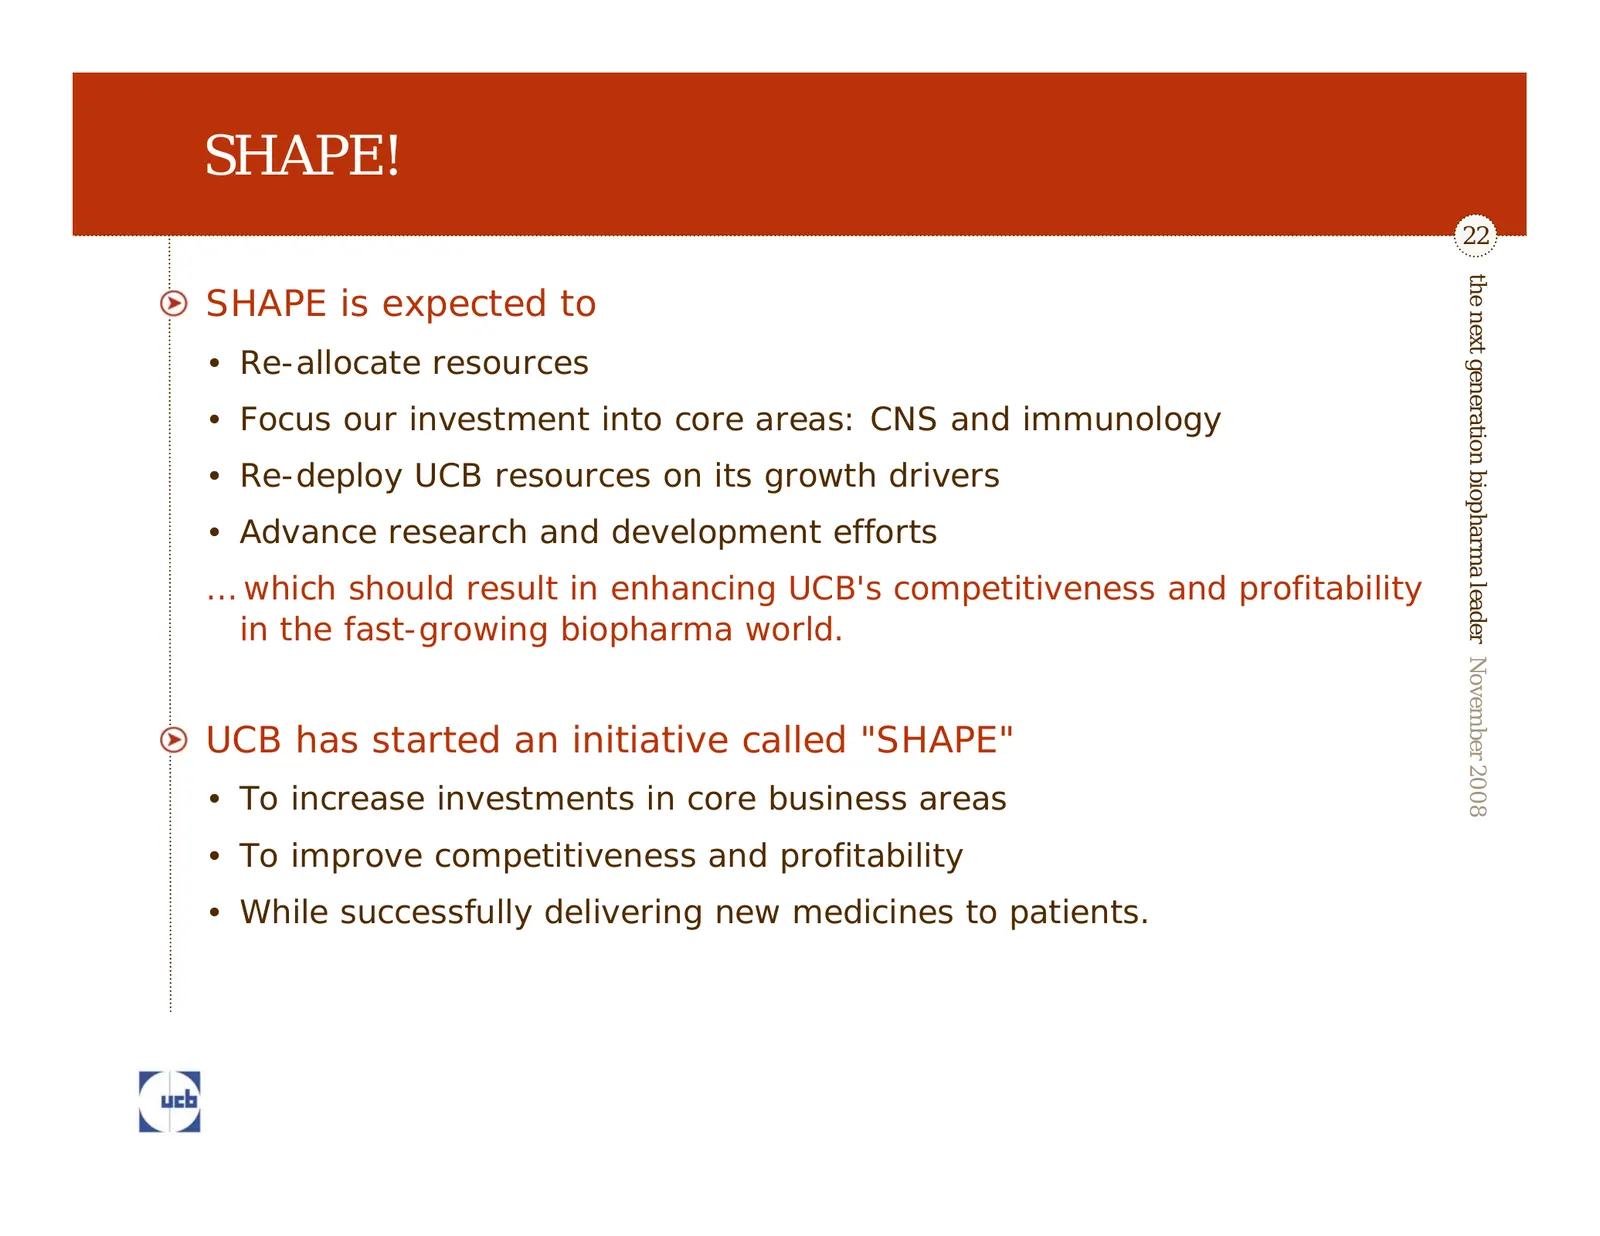
SHAPE! 22 the next generation biopharma leader November 2008 SHAPE is expected to • Re-allocate resources • Focus our investment into core areas: CNS and immunology • Re-deploy UCB resources on its growth drivers • Advance research and development efforts … which should result in enhancing UCB's com
Slide 23: UCB to SHAPE the organisation for the future
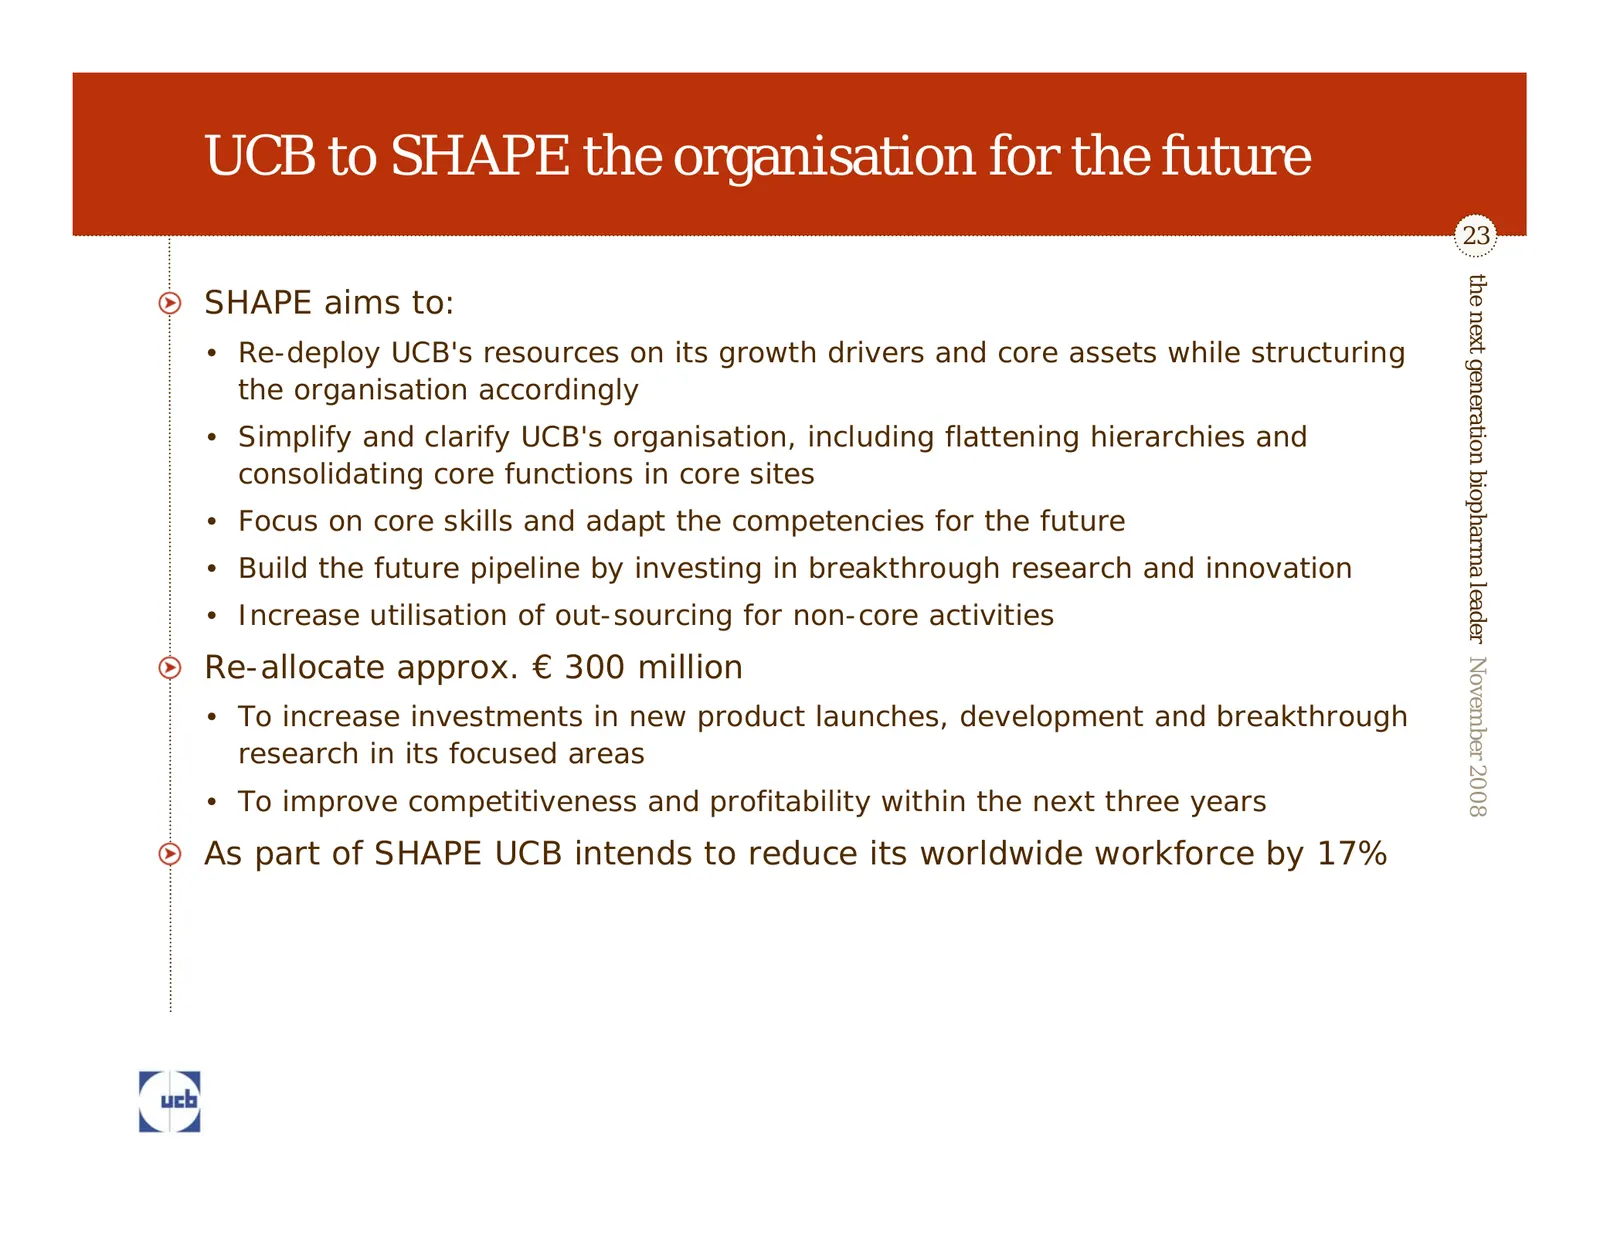
UCB to SHAPE the organisation for the future 23 the next generation biopharma leader November 2008 SHAPE aims to: • Re-deploy UCB's resources on its growth drivers and core assets while structuring the organisation accordingly • Simplify and clarify UCB's organisation, including flattening hierarchi
Slide 24: 2008, another year of execution: Regulatory milestones
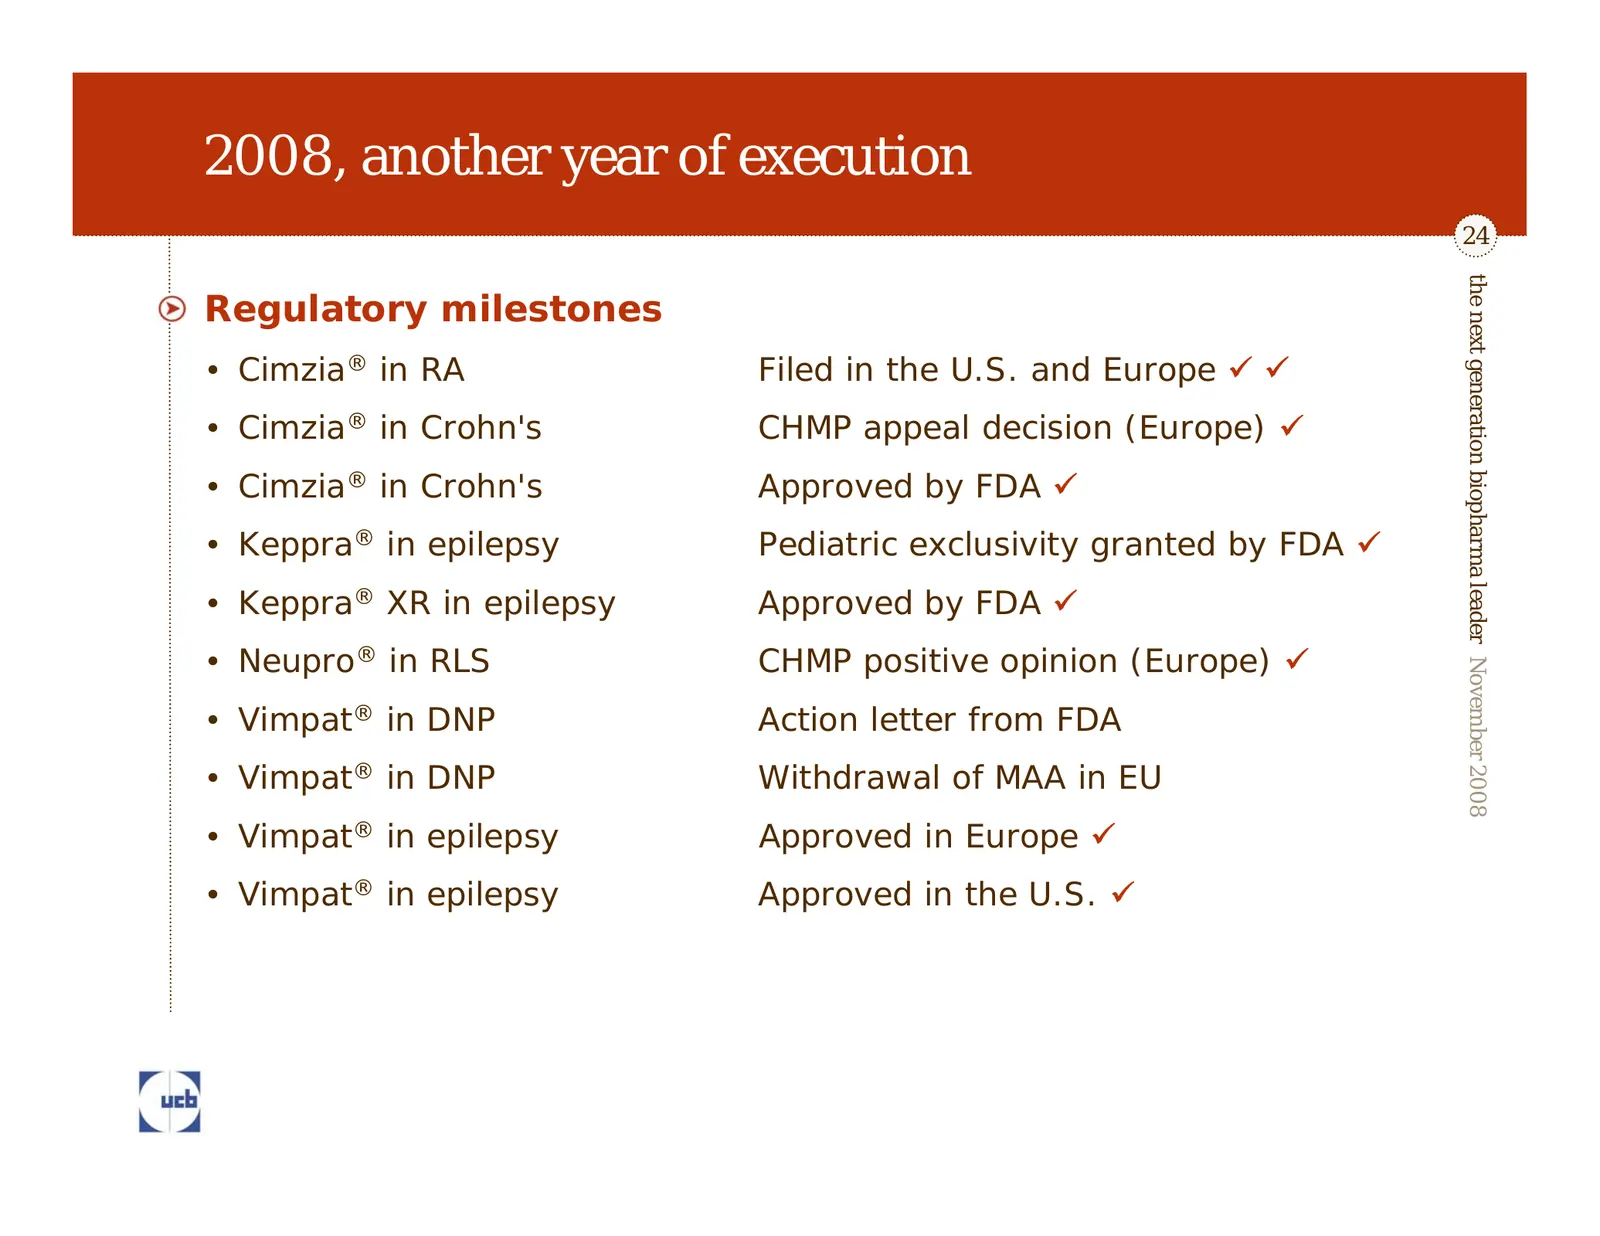
2008, another year of execution 24 the next generation biopharma leader November 2008 Regulatory milestones • Cimzia® in RA Filed in the U.S. and Europe 9 9 • Cimzia® in Crohn's CHMP appeal decision (Europe) 9 • Cimzia® in Crohn's Approved by FDA 9 • Keppra® in epilepsy Pediatric exclusivity granted
Slide 25: 2008, another year of execution: Marketing milestones
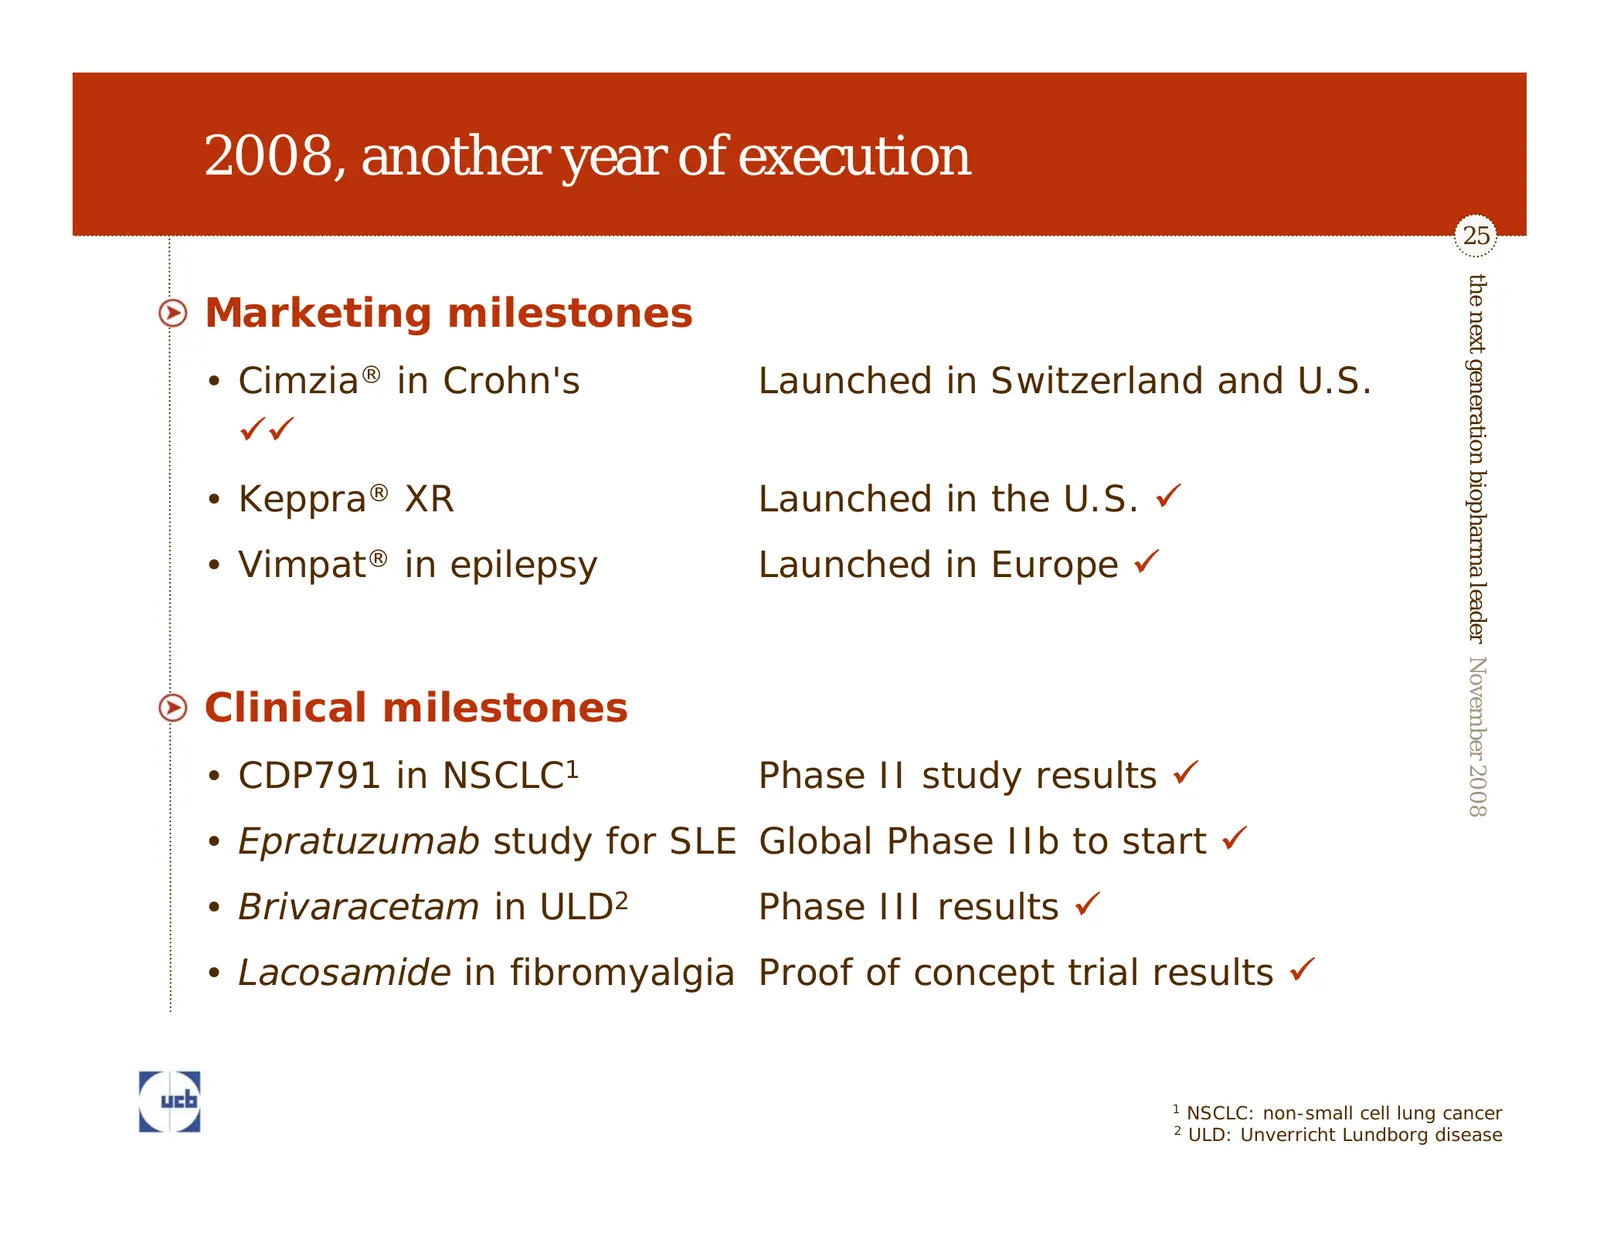
2008, another year of execution 25 the next generation biopharma leader November 2008 Marketing milestones • Cimzia® in Crohn's Launched in Switzerland and U.S. 99 • Keppra® XR Launched in the U.S. 9 • Vimpat® in epilepsy Launched in Europe 9 Clinical milestones • CDP791 in NSCLC1 Phase II study res
Slide 26: 2008 – 2009 upcoming milestones
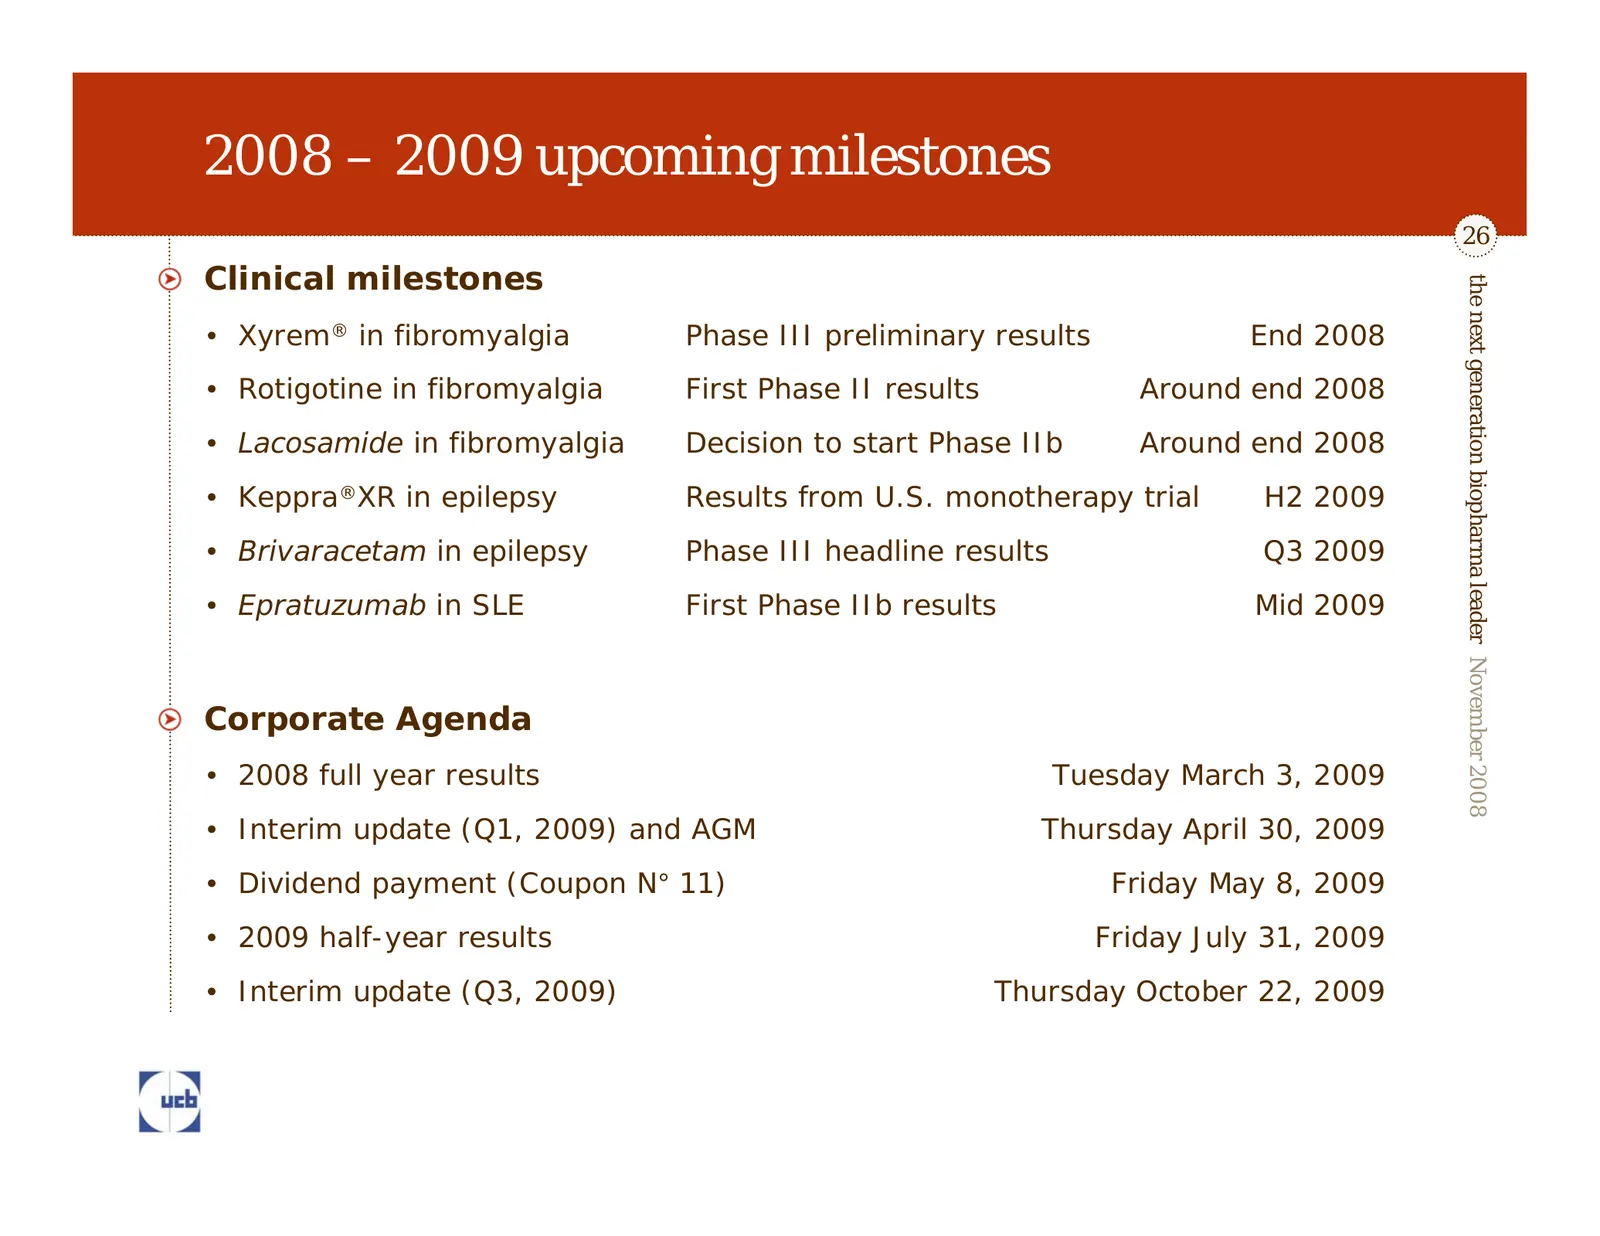
2008 – 2009 upcoming milestones 26 Clinical milestones the next generation biopharma leader November 2008 • Xyrem® in fibromyalgia Phase III preliminary results End 2008 • Rotigotine in fibromyalgia First Phase II results Around end 2008 • Lacosamide in fibromyalgia Decision to start Phase IIb Aroun
Slide 27: The next generation biopharma leader
UCB The next generation biopharma leader 27 the next generation biopharma leader November 2008 Breakthrough Launch a new generation of therapies Intense growth that will make an even greater difference Realise the commercial Execution potential of new products • Increase investments in R&D • Invest
Slide 28: Appendix
the next generation biopharma leader November 2008 28 Appendix
Slide 29: CDP323 in multiple sclerosis
CDP323 in multiple sclerosis Oral administration 29 the next generation biopharma leader November 2008 Potent and orally active small molecule antagonist of alpha 4-integrin Phase I data were presented at ECTRIMS1 in 2006 • Well tolerated Successful collaboration with Biogen IDEC Phase II program on
Slide 30: Xyrem, lacosamide and rotigotine in fibromyalgia
Xyrem®, lacosamide and rotigotine in fibromyalgia A wide range of potential treatment options 30 the next generation biopharma leader November 2008 Lacosamide • Inconclusive Phase IIa reported in June 2008 • Decision to start Phase IIb will be made around the end of the year Rotigotine • Proof of co
Slide 31: Epratuzumab in systemic lupus erythematosus
Epratuzumab in systemic lupus erythematosus Phase IIb study has started 31 the next generation biopharma leader November 2008 Analyses of recently closed clinical trials suggest a favorable efficacy and tolerability profile A Phase IIb dose ranging study has started • Number of randomized patients:
Slide 32: Anti-sclerostin in bone loss disorders
Anti-sclerostin in bone loss disorders Novel therapy with strong potential 32 the next generation biopharma leader November 2008 Development of novel Study of naturally occurring human disorder leads to a potential new drug therapy anabolic therapy • Antibody to sclerostin potentially treating bone
Slide 33: CMC544 in non-Hodgkin's lymphoma (NHL)
CMC544 in non-Hodgkin's lymphoma (NHL) Entered Phase III with encouraging data 33 the next generation biopharma leader November 2008 Project partnered with Wyeth A Phase I/II trial with CMC544 in combination with rituximab is continuing and preliminary data are encouraging. Further analysis is ongoi
Slide 34: CDP791 in non-small cell lung cancer
CDP791 in non-small cell lung cancer Novel antibody with unique selective mechanism 34 the next generation biopharma leader November 2008 Humanised di-Fab fragment conjugated to PEG1 Specific and potent inhibitor of VEGFR-22 Phase II trial in advanced non-small-cell lung cancer • Headline results pr
Slide 35: Top selling products & new launches
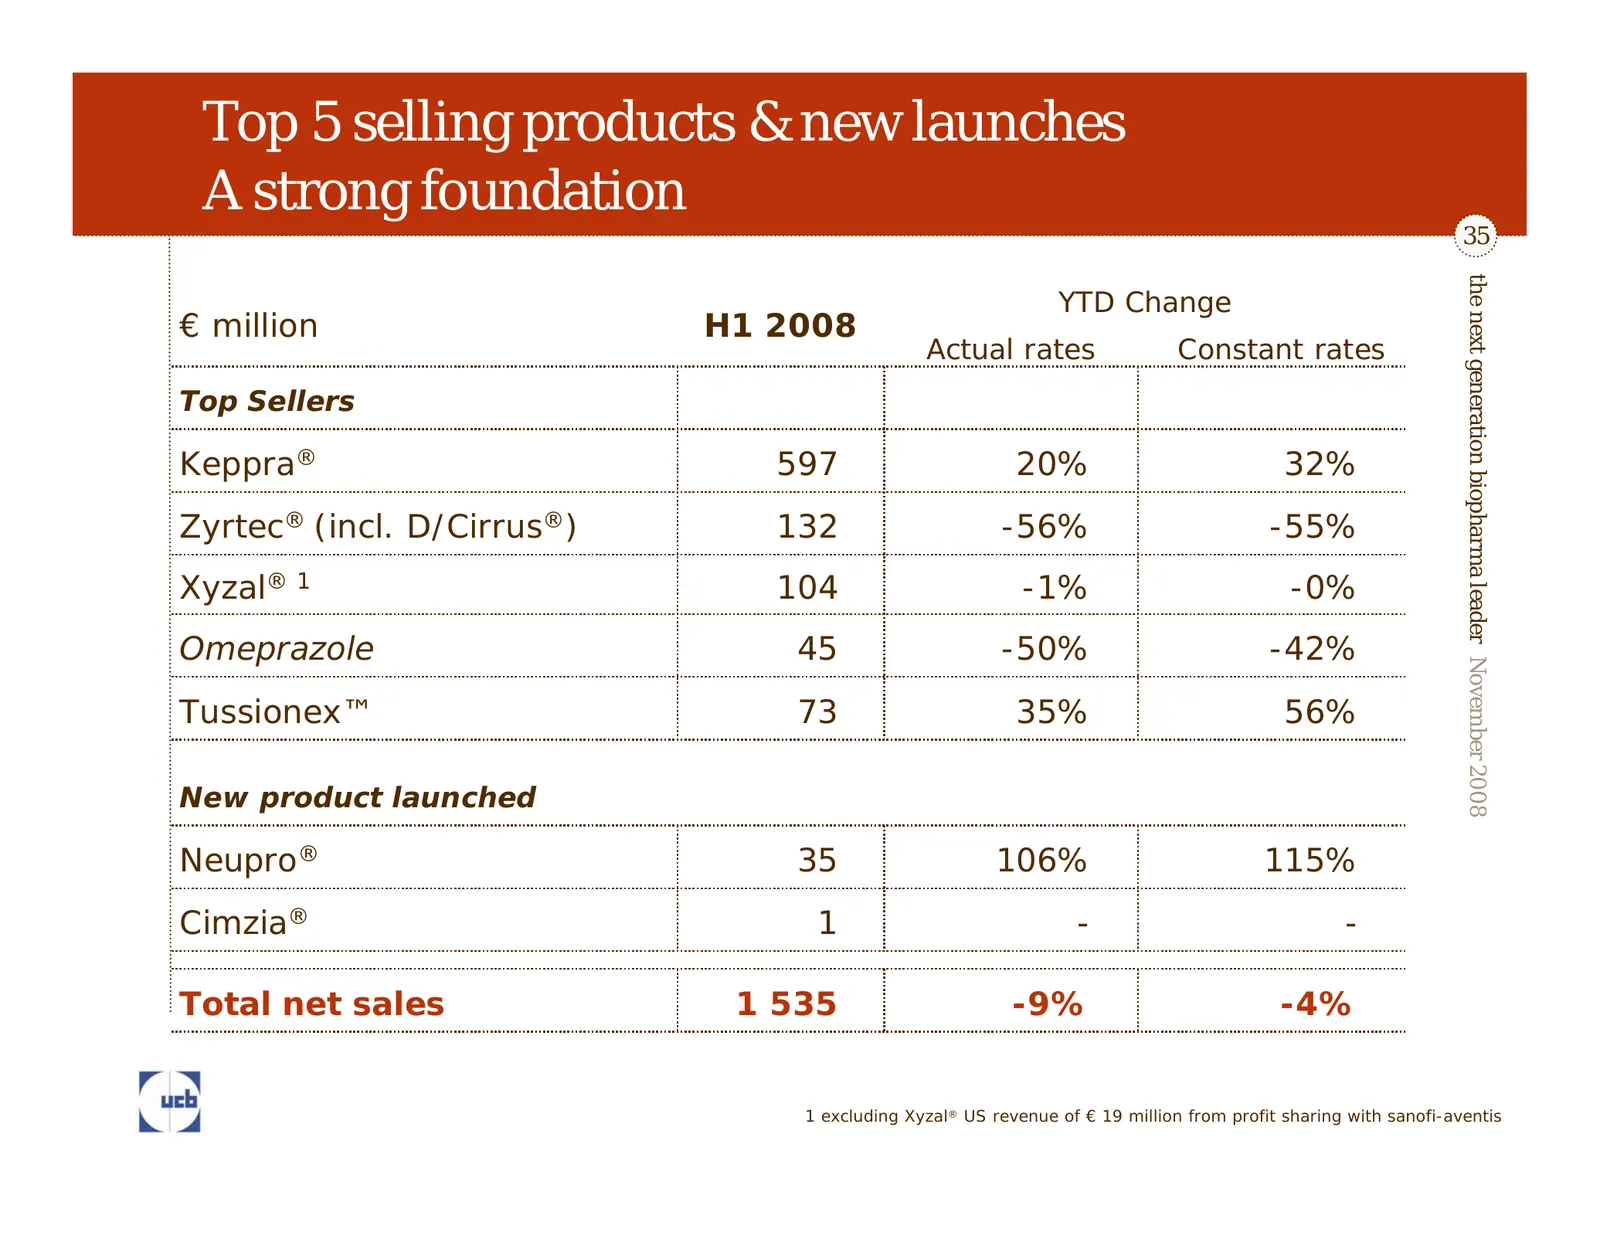
Top 5 selling products & new launches A strong foundation 35 the next generation biopharma leader November 2008 YTD Change € million H1 2008 Actual rates Constant rates Top Sellers Keppra® 597 20% 32% Zyrtec® (incl. D/Cirrus®) 132 -56% -55% Xyzal® 1 104 -1% -0% Omeprazole 45 -50% -42% Tussionex™ 73
Slide 36: HY 2008 net sales: Therapeutic areas
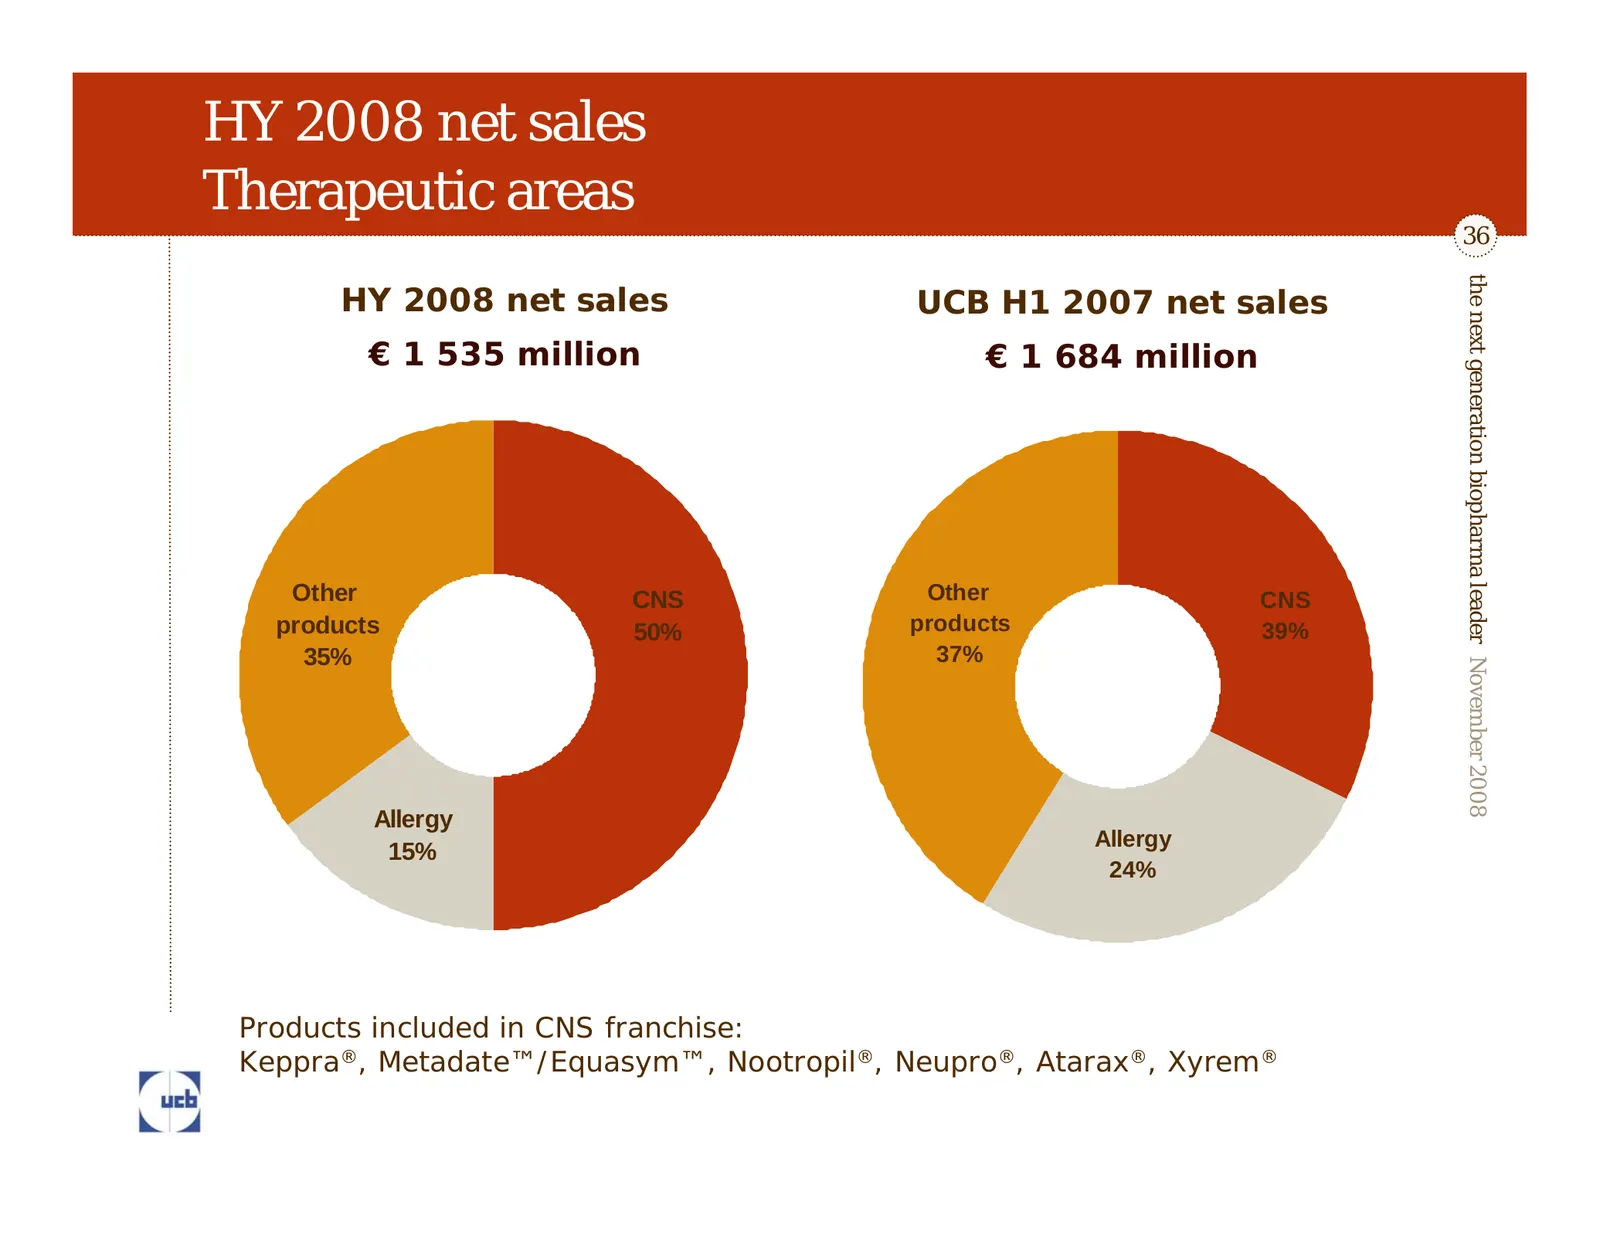
HY 2008 net sales Therapeutic areas 36 the next generation biopharma leader November 2008 HY 2008 net sales UCB H1 2007 net sales € 1 535 million € 1 684 million Other CNS Other CNS products 50% products 39% 35% 37% Allergy Allergy 15% 24% Products included in CNS franchise: Keppra®, Metadate™/Equas
Slide 37: HY 2008 net sales: Geographic diversification
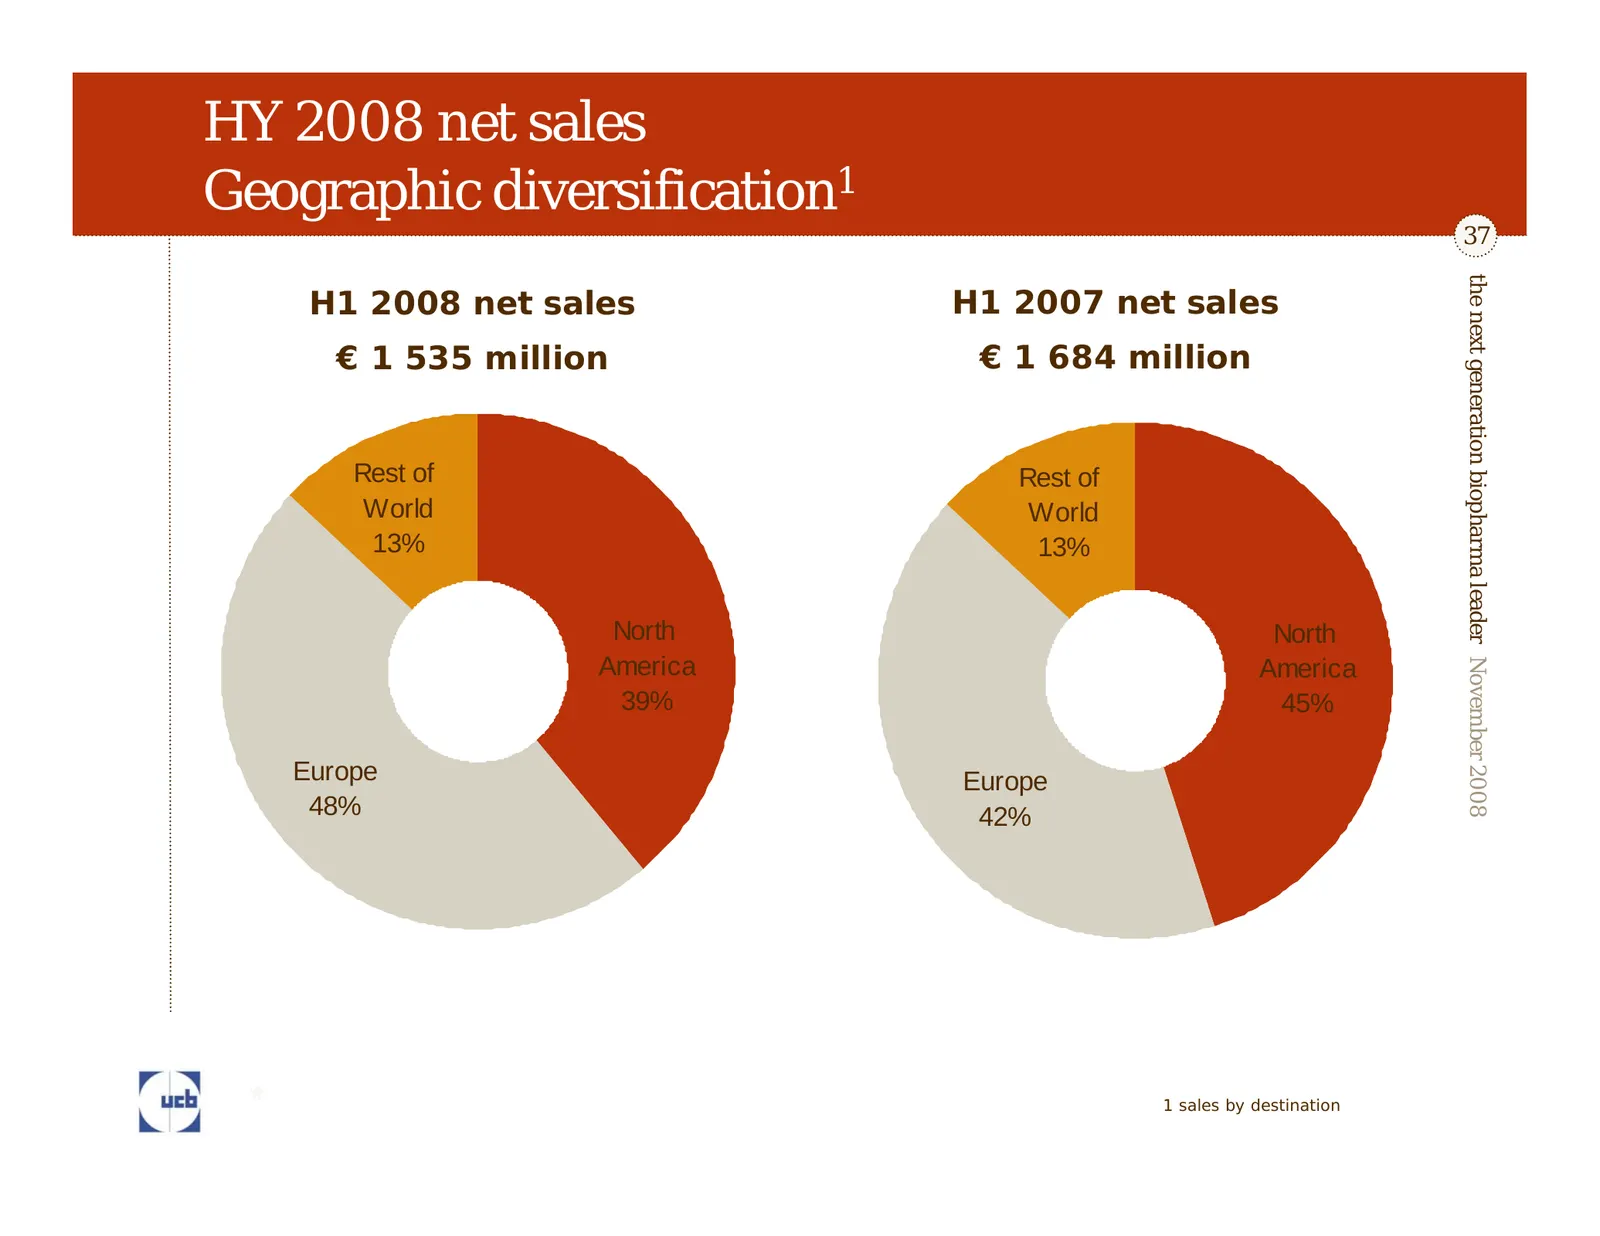
HY 2008 net sales Geographic diversification1 37 the next generation biopharma leader November 2008 H1 2008 net sales H1 2007 net sales € 1 535 million € 1 684 million Rest of Rest of World World 13% 13% North North America America 39% 45% Europe Europe 48% 42% * 1 sales by destination
Slide 38: Commercial highlights HY 2008
Commercial highlights HY 2008 38 the next generation biopharma leader November 2008 Keppra® dynamic growth: +20% to € 597 million • U.S. sales of € 371 million up 16%, with 34.9% market share1 • EU sales of € 202 million up 26%, with 31.7% market share1 • Pediatric exclusivity granted by the FDA Sus
Slide 39: SHAPE UCB: NewMedicines
SHAPE UCB: NewMedicines Delivering the breakthrough 39 the next generation biopharma leader November 2008 In February 2008 UCB announced a two-fold focus for ‘R’ and ‘D’ • Recognising the need for different environments and skill sets • Strategic reorganisation to ‘beat the odds’ in biopharma R&D, b
Slide 40: What is different in UCB NewMedicines?
What is different in UCB NewMedicines? 40 the next generation biopharma leader November 2008 Networked R&D with a disseminated discovery organisation • Two principal research ‘hubs’, one CNS, one immunology • External incubators • Open, collaborative research with strengthened external focus • Discr
Slide 41: Mid-term Action Plan for UCB NewMedicines
Mid-term Action Plan for UCB NewMedicines 41 the next generation biopharma leader November 2008 Advance the internal portfolio • Deliver late pre-clinical projects rapidly to proof of concept Partnering and licensing activity • In-license pre-clinical/clinical phase I products to boost mid-term pipe
Slide 42: Your Investor Relations Team
Your Investor Relations Team 42 the next generation biopharma leader November 2008 Antje Witte, Vice President Corporate Communications & Investor Relations • Phone +32 2 559 9414 • E-mail: antje.witte@ucb-group.com Richard Simpson, Senior Director Investor Relations • Phone: +32 2 559 9494 • E-mail
Source: Internet Archive copy of ucb.com
More decks from Ucb S.A.
 H1 2026 Earnings Presentation22 slides · Jul 30, 2026
 FY2025 Earnings Presentation22 slides · Feb 26, 2026
 44th Annual J.P. Morgan Healthcare Conference 202616 slides · Jan 14, 2026
 H1 2025 Earnings Presentation21 slides · Jul 31, 2025
 FY2024 Earnings Presentation18 slides · Feb 27, 2025
 43rd Annual J.P. Morgan Healthcare Conference (January 2025)13 slides · Jan 15, 2025