Southwest Bancorp — SunTrust Robinson Humphrey Financial Services UnConference 2007
35 slides from Southwest Bancorp's conference presentation, May 21, 2007
Slide 1: SunTrust Robinson Humphrey Financial Services UnConference May 23, 2007
SunTrust Robinson Humphrey Financial Services UnConference May 23, 2007
Slide 2: Forward-looking Statements
Forward-looking Statements This presentation includes forward-looking statements such as: statements of Southwest's goals, intentions, and expectations; estimates of risks and of future costs and benefits; expectations regarding future financial performance of Southwest and its operating segments; a
Slide 3: A Different Kind of Financial Holding Company
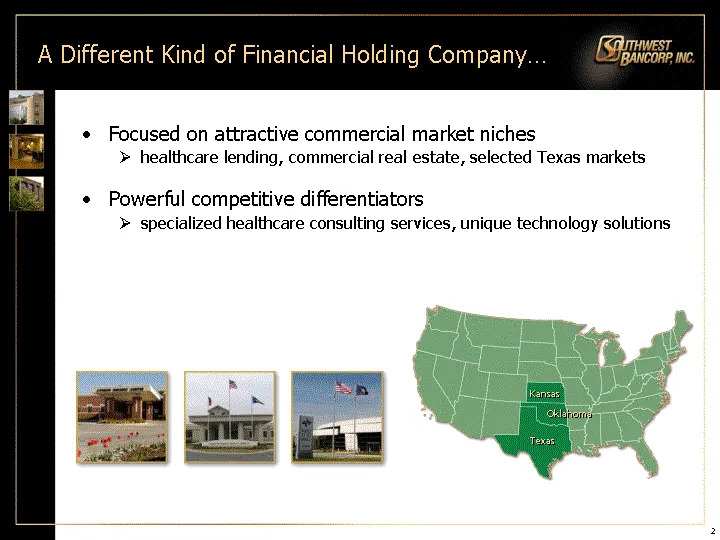
A Different Kind of Financial Holding Company... Focused on attractive commercial market niches healthcare lending, commercial real estate, selected Texas markets Powerful competitive differentiators specialized healthcare consulting services, unique technology solutions Kansas Oklahoma Texas
Slide 4: With an Impressive Performance Record
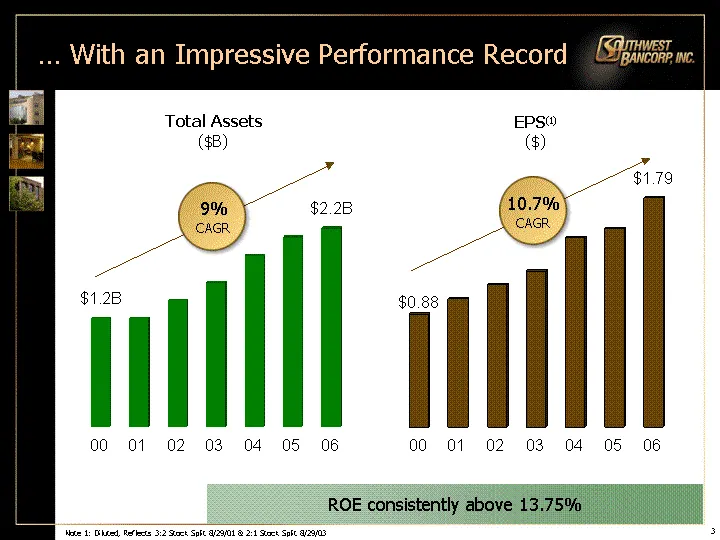
.... With an Impressive Performance Record 00 01 02 03 04 05 06 East 1.2 1.2 1.4 1.6 1.9 2.1 2.2 9% CAGR Total Assets ($B) Note 1: Diluted, Reflects 3:2 Stock Split 8/29/01 & 2:1 Stock Split 8/29/03 00 01 02 03 04 05 06 East 0.88 1 1.11 1.22 1.48 1.55 1.79 EPS(1) ($) ROE consistently above 13.75% 10
Slide 5: The Southwest Bancorp Story
The Southwest Bancorp Story On the move Strong performance record Powerful differentiators Executing focused growth strategy
Slide 6: At a Glance
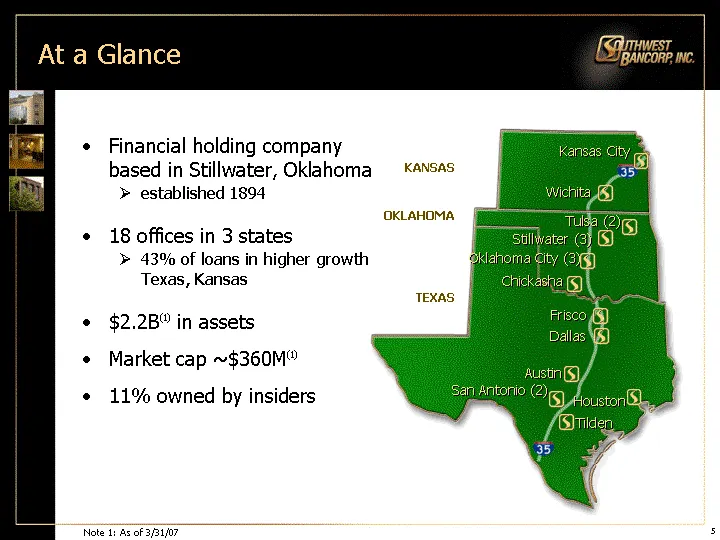
At a Glance Financial holding company based in Stillwater, Oklahoma established 1894 18 offices in 3 states 43% of loans in higher growth Texas, Kansas $2.2B(1) in assets Market cap ~$360M(1) 11% owned by insiders KANSAS OKLAHOMA TEXAS Kansas City Wichita Tulsa (2) Stillwater (3) Oklahoma City (3) C
Slide 7: More Than Just a Bank
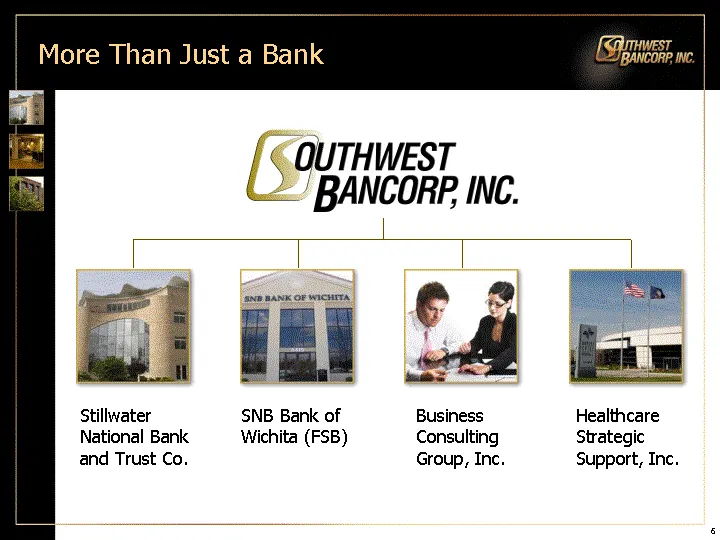
More Than Just a Bank Stillwater National Bank and Trust Co. SNB Bank of Wichita (FSB) Business Consulting Group, Inc. Healthcare Strategic Support, Inc.
Slide 8: Successful Growth Record
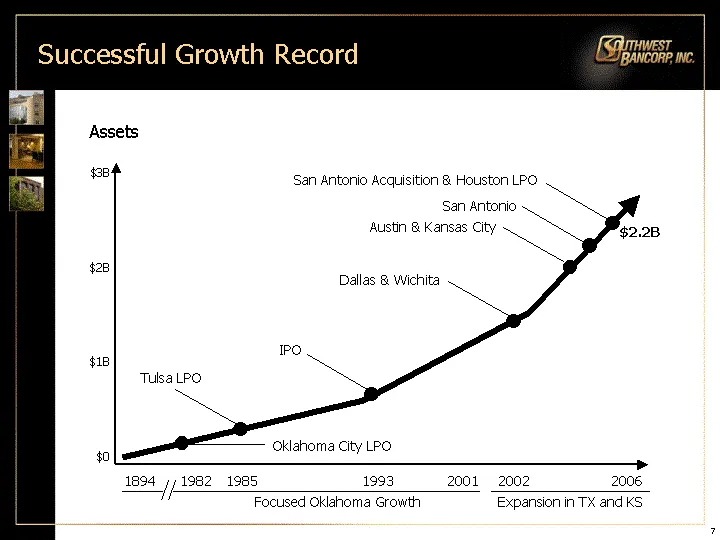
Successful Growth Record Assets $3B 1894 1982 1993 Focused Oklahoma Growth Expansion in TX and KS $0 $1B $2.2B San Antonio Acquisition & Houston LPO San Antonio Austin & Kansas City Dallas & Wichita IPO Oklahoma City LPO Tulsa LPO 2002 1985 2006 2001 $2B
Slide 9: Our Focus is Commercial
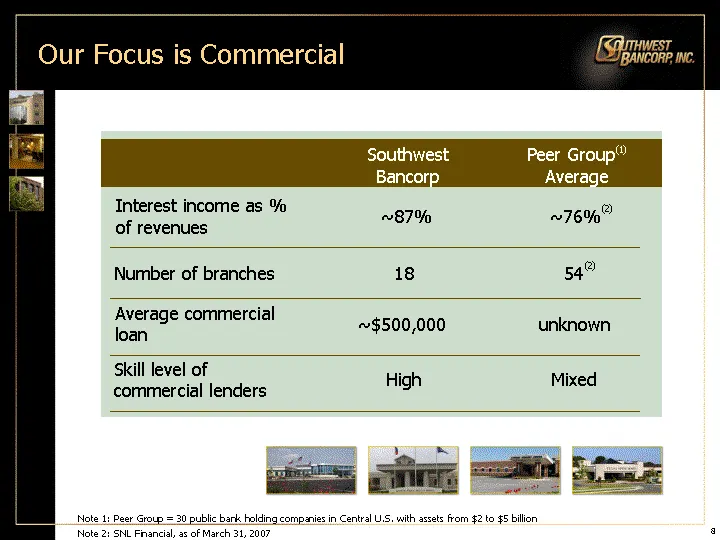
Our Focus is Commercial Southwest Bancorp Peer Group(1) Average Interest income as % of revenues ~87% ~76% Average commercial loan ~$500,000 unknown Skill level of commercial lenders High Mixed Number of branches 18 Note 1: Peer Group = 30 public bank holding companies in Central U.S. with assets fr
Slide 10: The Southwest Bancorp Story
The Southwest Bancorp Story On the move Strong performance record Powerful differentiators Executing focused growth strategy
Slide 11: Strong Growth in Loans
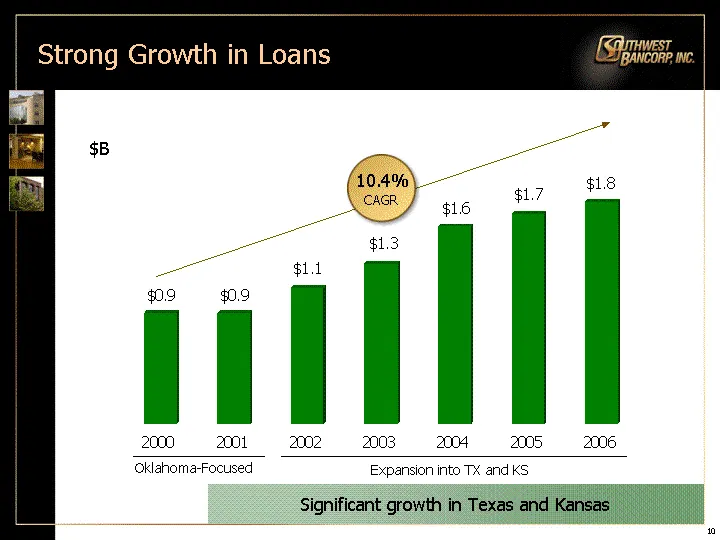
2000 2001 2002 2003 2004 2005 2006 0.9 0.9 1.1 1.3 1.6 1.7 1.8 $B Significant growth in Texas and Kansas 10.4% CAGR Strong Growth in Loans Oklahoma-Focused Expansion into TX and KS
Slide 12: Diversified Loan Portfolio
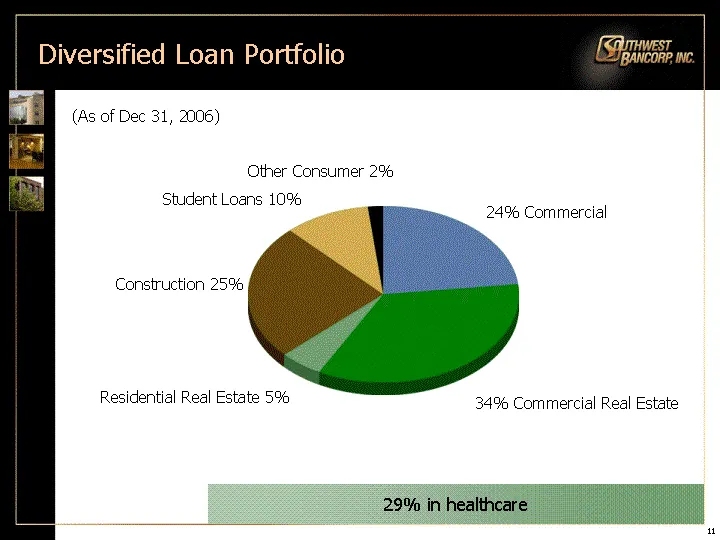
29% in healthcare Diversified Loan Portfolio (As of Dec 31, 2006) 24% Commercial 34% Commercial Real Estate Residential Real Estate 5% Construction 25% Student Loans 10% Other Consumer 2%
Slide 13: Solid Capital Ratios
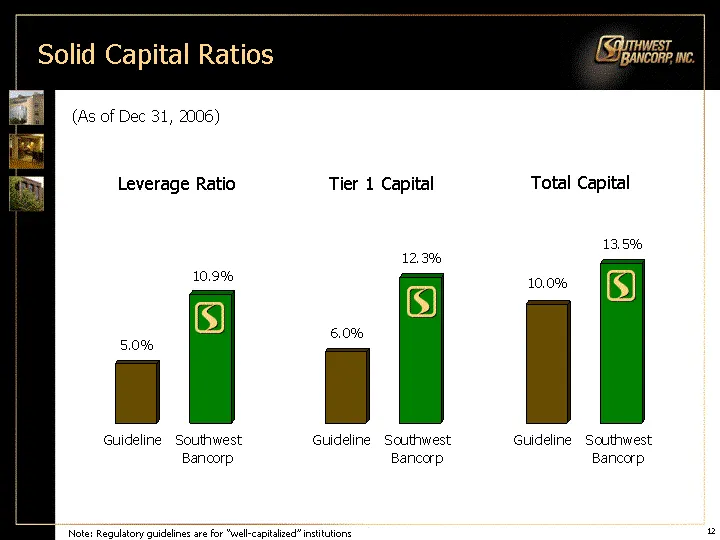
Solid Capital Ratios Guideline Southwest Bancorp East 0.05 0.109 Leverage Ratio Guideline Southwest Bancorp East 0.06 0.123 Tier 1 Capital Guideline Southwest Bancorp East 0.1 0.135 Total Capital Note: Regulatory guidelines are for "well-capitalized" institutions (As of Dec 31, 2006)
Slide 14: Non-Performing Loans to Total Loans
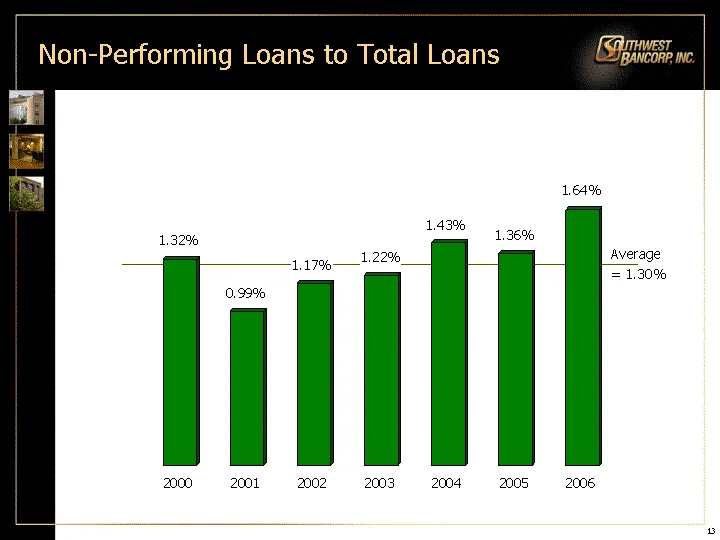
Average = 1.30% Non-Performing Loans to Total Loans 2000 2001 2002 2003 2004 2005 2006 0.0132 0.0099 0.0117 0.0122 0.0143 0.0136 0.0164
Slide 15: Improved Efficiency Ratio
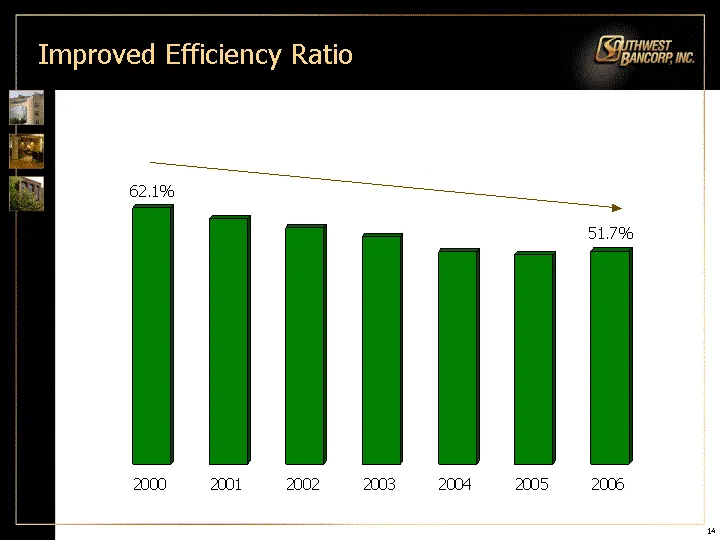
2000 2001 2002 2003 2004 2005 2006 0.6214 0.5948 0.5728 0.5511 0.5144 0.506 0.5167 Improved Efficiency Ratio
Slide 16: Q1, 2007 Highlights
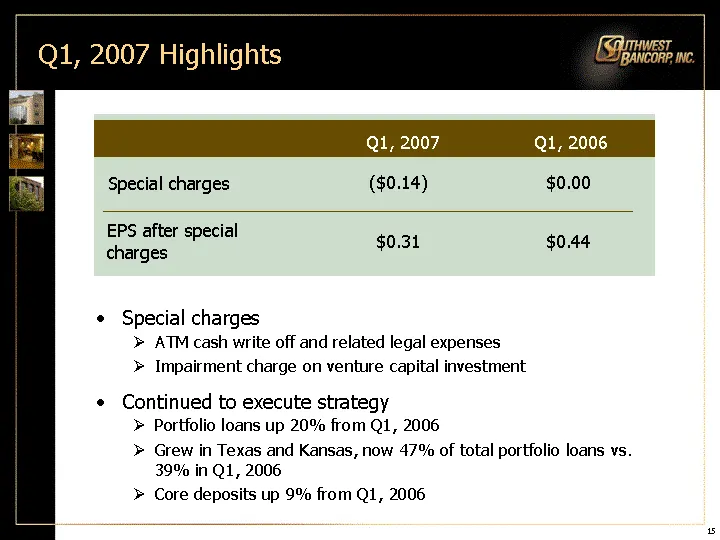
Q1, 2007 Highlights Q1, 2007 Q1, 2006 Special charges ($0.14) $0.00 EPS after special charges $0.31 $0.44 Special charges ATM cash write off and related legal expenses Impairment charge on venture capital investment Continued to execute strategy Portfolio loans up 20% from Q1, 2006 Grew in Texas and
Slide 17: The Southwest Bancorp Story
The Southwest Bancorp Story On the move Strong performance record Powerful differentiators Executing focused growth strategy
Slide 18: As We Have Grown... Developed and Refined our Business Models
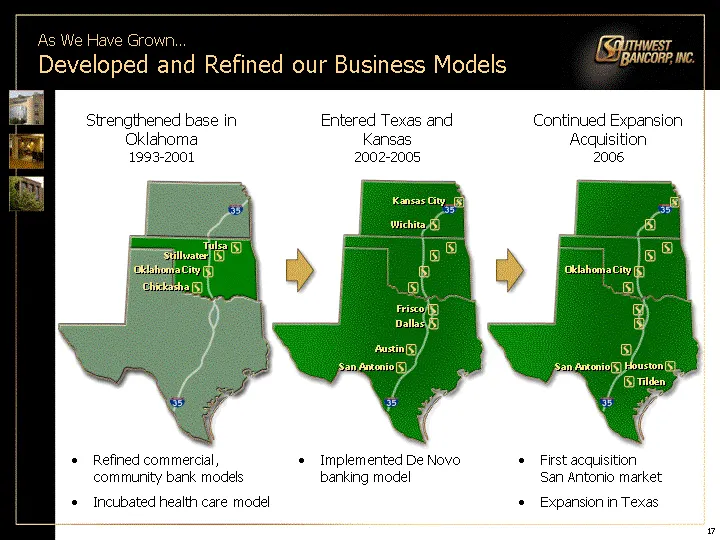
As We Have Grown... Developed and Refined our Business Models Strengthened base in Oklahoma 1993-2001 Entered Texas and Kansas 2002-2005 Continued Expansion Acquisition 2006 Refined commercial, community bank models Incubated health care model Implemented De Novo banking model First acquisition San
Slide 19: Today: Four Key Differentiators
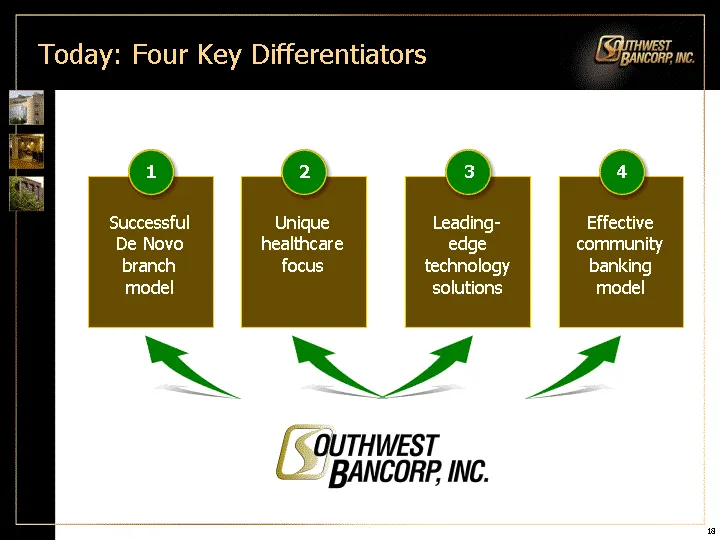
Today: Four Key Differentiators Effective community banking model 4 Successful De Novo branch model 1 Unique healthcare focus 2 Leading- edge technology solutions 3
Slide 20: Differentiator #1 Successful De Novo Branch Model
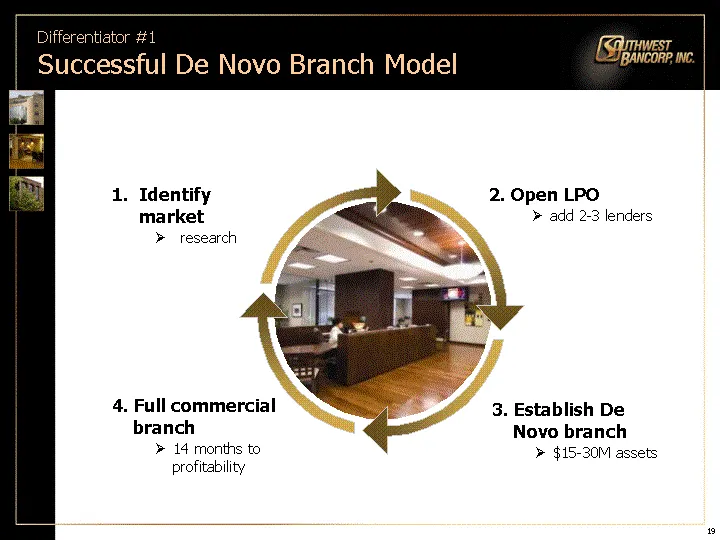
Differentiator #1 Successful De Novo Branch Model 2. Open LPO add 2-3 lenders 3. Establish De Novo branch $15-30M assets 4. Full commercial branch 14 months to profitability Identify market research
Slide 21: Differentiator #1 Branch Model at Work
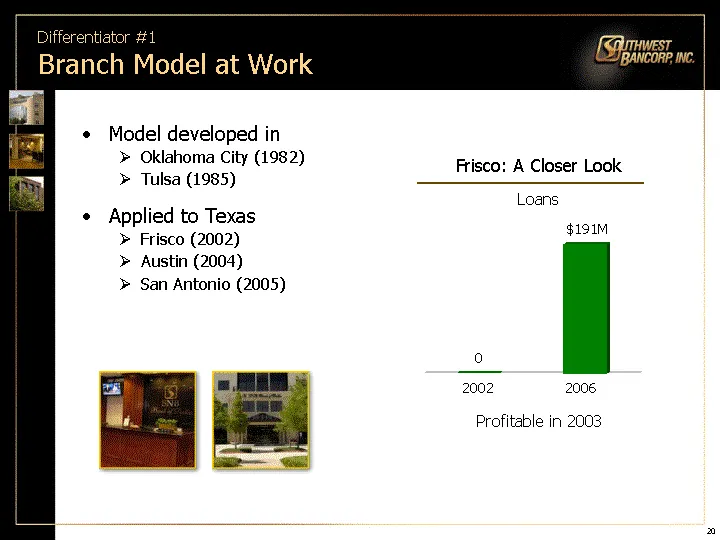
0 $191M 2002 2006 Differentiator #1 Branch Model at Work Model developed in Oklahoma City (1982) Tulsa (1985) Applied to Texas Frisco (2002) Austin (2004) San Antonio (2005) Frisco: A Closer Look Loans Profitable in 2003
Slide 22: Differentiator #2 Unique Healthcare Focus
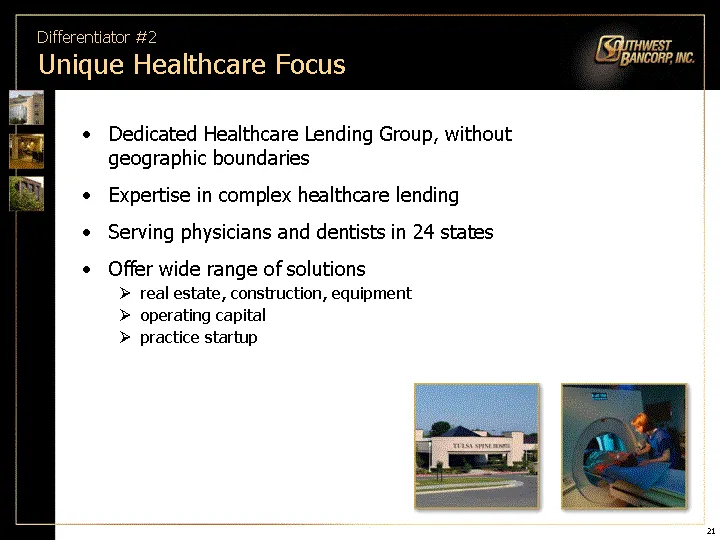
Differentiator #2 Unique Healthcare Focus Dedicated Healthcare Lending Group, without geographic boundaries Expertise in complex healthcare lending Serving physicians and dentists in 24 states Offer wide range of solutions real estate, construction, equipment operating capital practice startup
Slide 23: Differentiator #2 Healthcare Model at Work
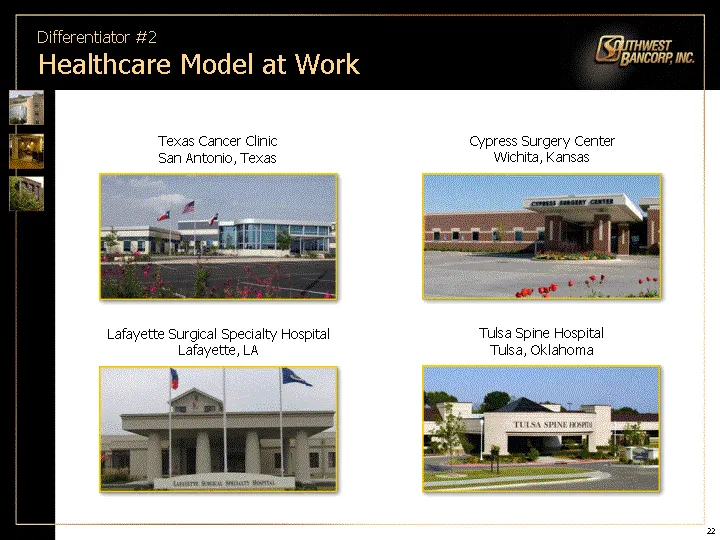
Differentiator #2 Healthcare Model at Work Texas Cancer Clinic San Antonio, Texas Cypress Surgery Center Wichita, Kansas Lafayette Surgical Specialty Hospital Lafayette, LA Tulsa Spine Hospital Tulsa, Oklahoma
Slide 24: Differentiator #2 Unique Healthcare Services = Loyal Customers
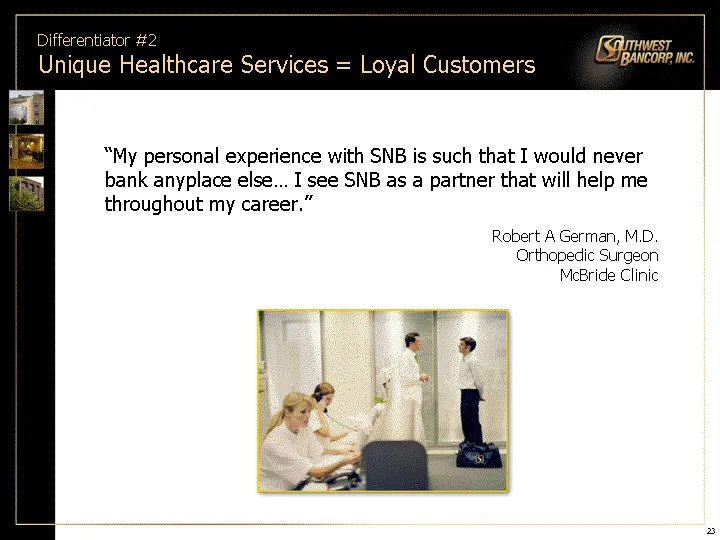
Differentiator #2 Unique Healthcare Services = Loyal Customers "My personal experience with SNB is such that I would never bank anyplace else... I see SNB as a partner that will help me throughout my career." Robert A German, M.D. Orthopedic Surgeon McBride Clinic
Slide 25: Differentiator #3 Leading Edge Technology Solutions
Differentiator #3 Leading Edge Technology Solutions Allow us to compete without boundaries cutting edge delivery solutions Digital Lockbox accelerates cash flow, minimize paper documents, improve service, reduce overhead Check Capture allows clients to make deposits at their location - in cities out
Slide 26: Differentiator #3 A Closer Look at Digital Lockbox Services
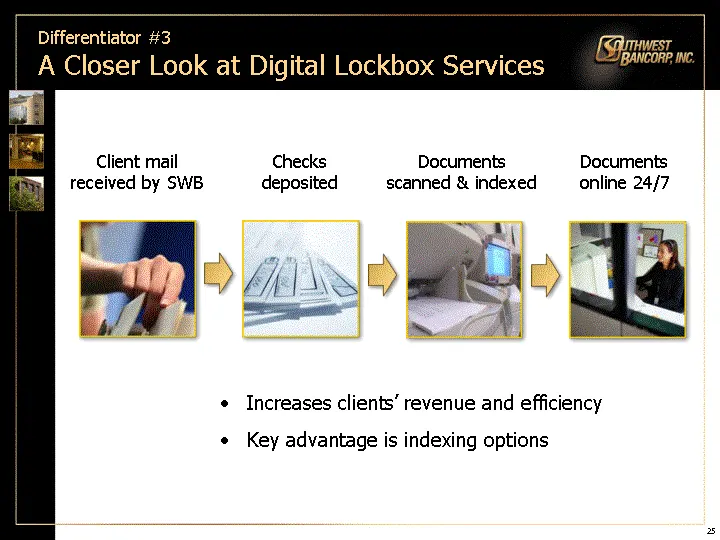
Differentiator #3 A Closer Look at Digital Lockbox Services Increases clients' revenue and efficiency Key advantage is indexing options Client mail received by SWB Checks deposited Documents scanned & indexed Documents online 24/7
Slide 27: Differentiator #3 Digital Lockbox Model at Work
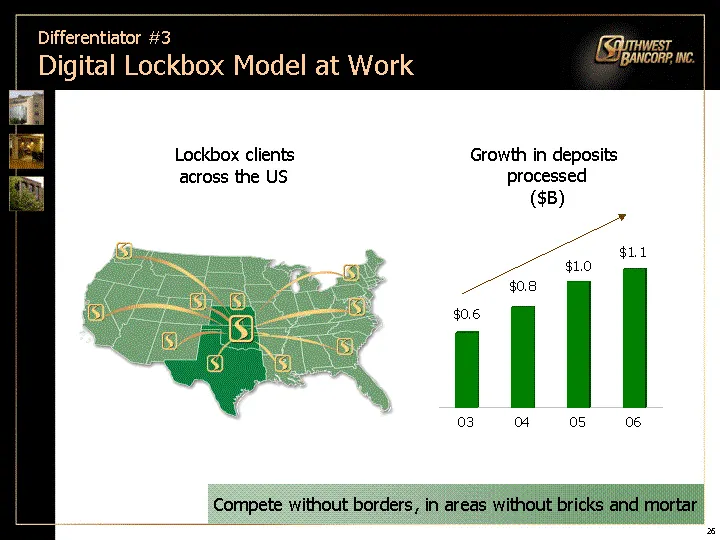
Compete without borders, in areas without bricks and mortar Differentiator #3 Digital Lockbox Model at Work 03 04 05 06 East 0.6 0.8 1 1.1 Growth in deposits processed ($B) Lockbox clients across the US
Slide 28: Differentiator #4 Effective Community Banking Model
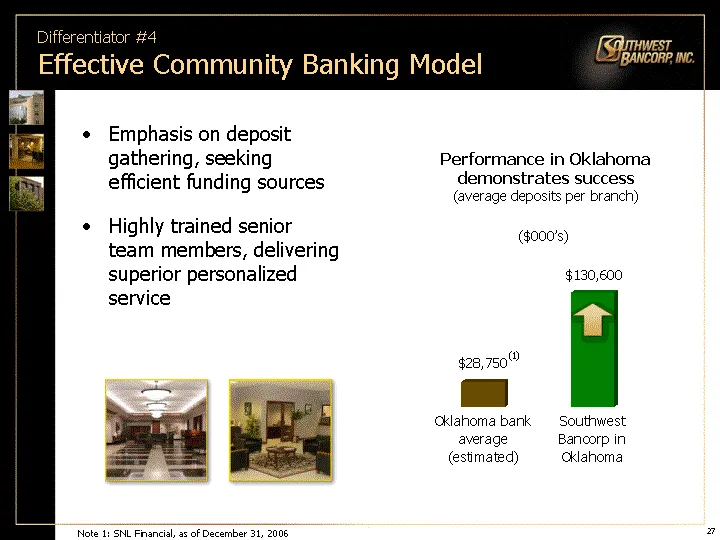
Differentiator #4 Effective Community Banking Model Emphasis on deposit gathering, seeking efficient funding sources Highly trained senior team members, delivering superior personalized service Oklahoma bank average (estimated) Southwest Bancorp in Oklahoma East 28750 130600 Performance in Oklahoma
Slide 29: The Southwest Bancorp Story
The Southwest Bancorp Story On the move Strong performance record Powerful differentiators Executing focused growth strategy
Slide 30: Growth Strategy
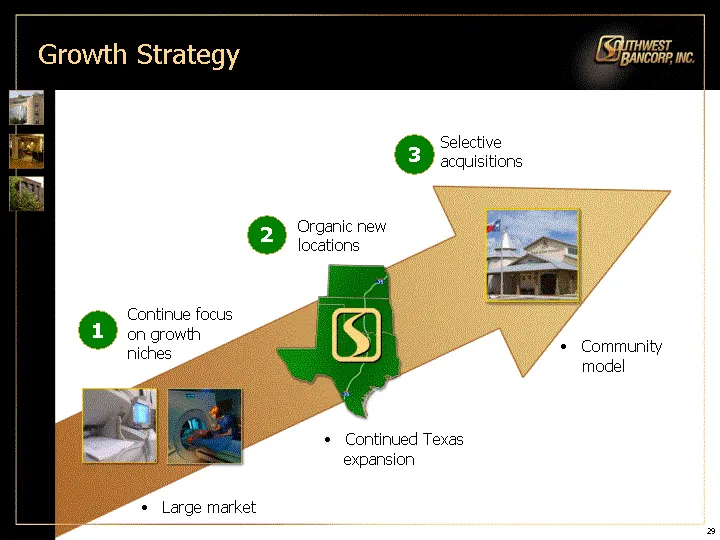
Growth Strategy Continue focus on growth niches Large market 1 Selective acquisitions Community model 3
Slide 31: A Closer Look at Our Acquisition Criteria
A Closer Look at Our Acquisition Criteria Locations in Texas and other select geographies, where market is supportive Characteristics: bank size ^ $200M community population ^ 500,000 mature ownership and management
Slide 32: Leveraging Success: Large Growth Opportunity in Texas
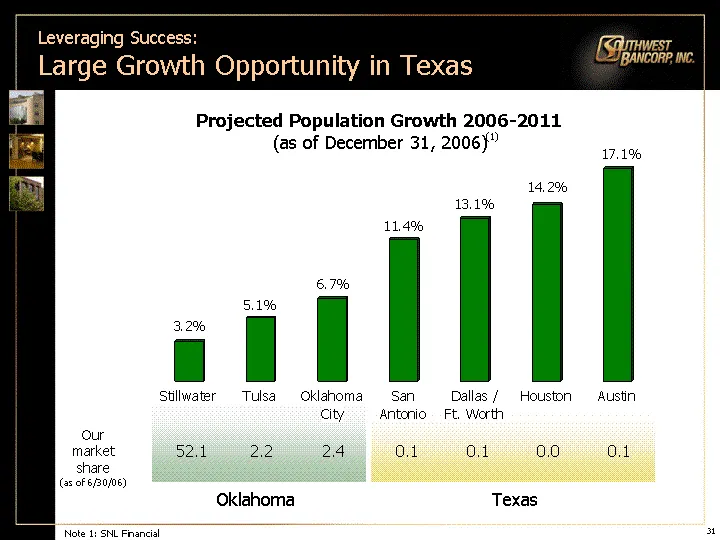
Oklahoma Leveraging Success: Large Growth Opportunity in Texas Note 1: SNL Financial Texas 0.1 Stillwater Tulsa Oklahoma City San Antonio Dallas / Ft. Worth Houston Austin East 0.032 0.051 0.067 0.114 0.131 0.142 0.171 Projected Population Growth 2006-2011 (as of December 31, 2006) (1)
Slide 33: Current Low Valuation: Price / LTM Earnings
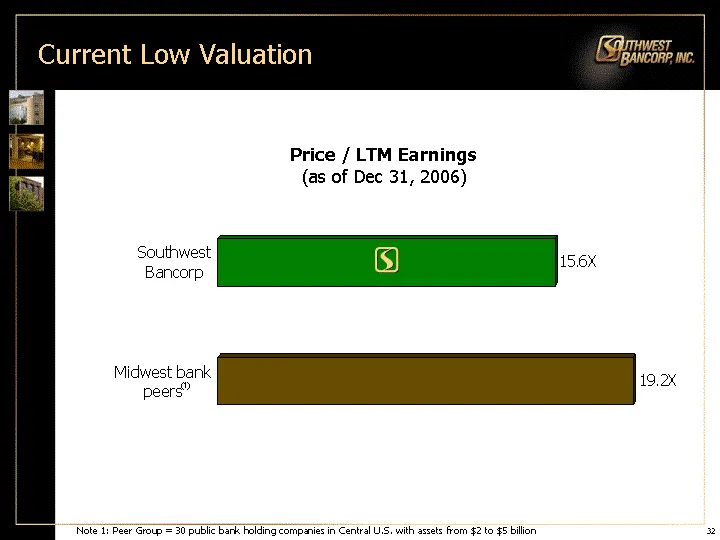
Midwest bank peers Southwest Bancorp 3rd Qtr 4th Qtr East 19.2 15.6 90 20.4 West North Current Low Valuation Price / LTM Earnings (as of Dec 31, 2006) Note 1: Peer Group = 30 public bank holding companies in Central U.S. with assets from $2 to $5 billion
Slide 34: Why Invest in Southwest Bancorp
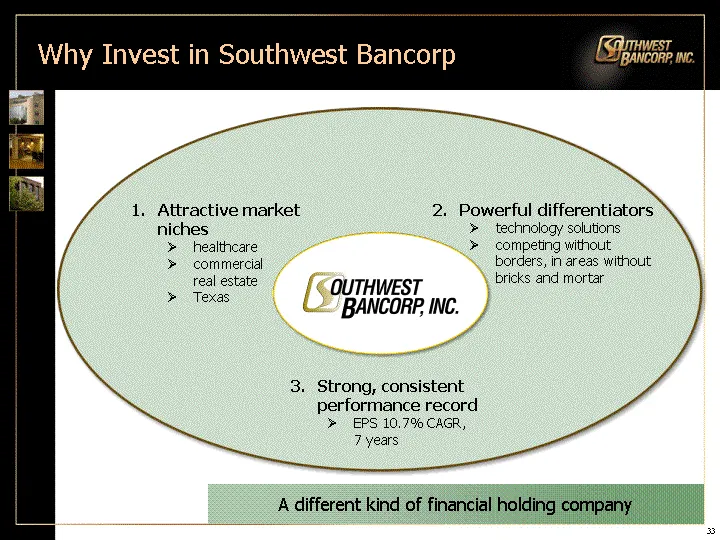
A different kind of financial holding company Why Invest in Southwest Bancorp Attractive market niches healthcare commercial real estate Texas Powerful differentiators technology solutions competing without borders, in areas without bricks and mortar Strong, consistent performance record EPS 10.7% C
Slide 35: SunTrust Robinson Humphrey Financial Services UnConference May 23, 2007
SunTrust Robinson Humphrey Financial Services UnConference May 23, 2007
Source: SEC EDGAR · 8-K filed May 21, 2007
More decks from Southwest Bancorp Inc
 Merger or Acquisition (September 2017)41 slides · Sep 5, 2017
 Q2 2017 Earnings Presentation31 slides · Jul 25, 2017
 Merger or Acquisition (May 2017)43 slides · May 15, 2017
 Q1 2017 Earnings Presentation31 slides · Apr 25, 2017
 Merger or Acquisition (February 2017)45 slides · Feb 8, 2017
 Q4 2016 Earnings Presentation32 slides · Jan 24, 2017