SGL Carbon SE · XETR:SGL
SGL Carbon — Investor Presentation (June 2017)
90 slides from SGL Carbon's investor presentation, June 2017
Slide 1: Investor Relations Presentation June 2017
Investor Relations Presentation June 2017
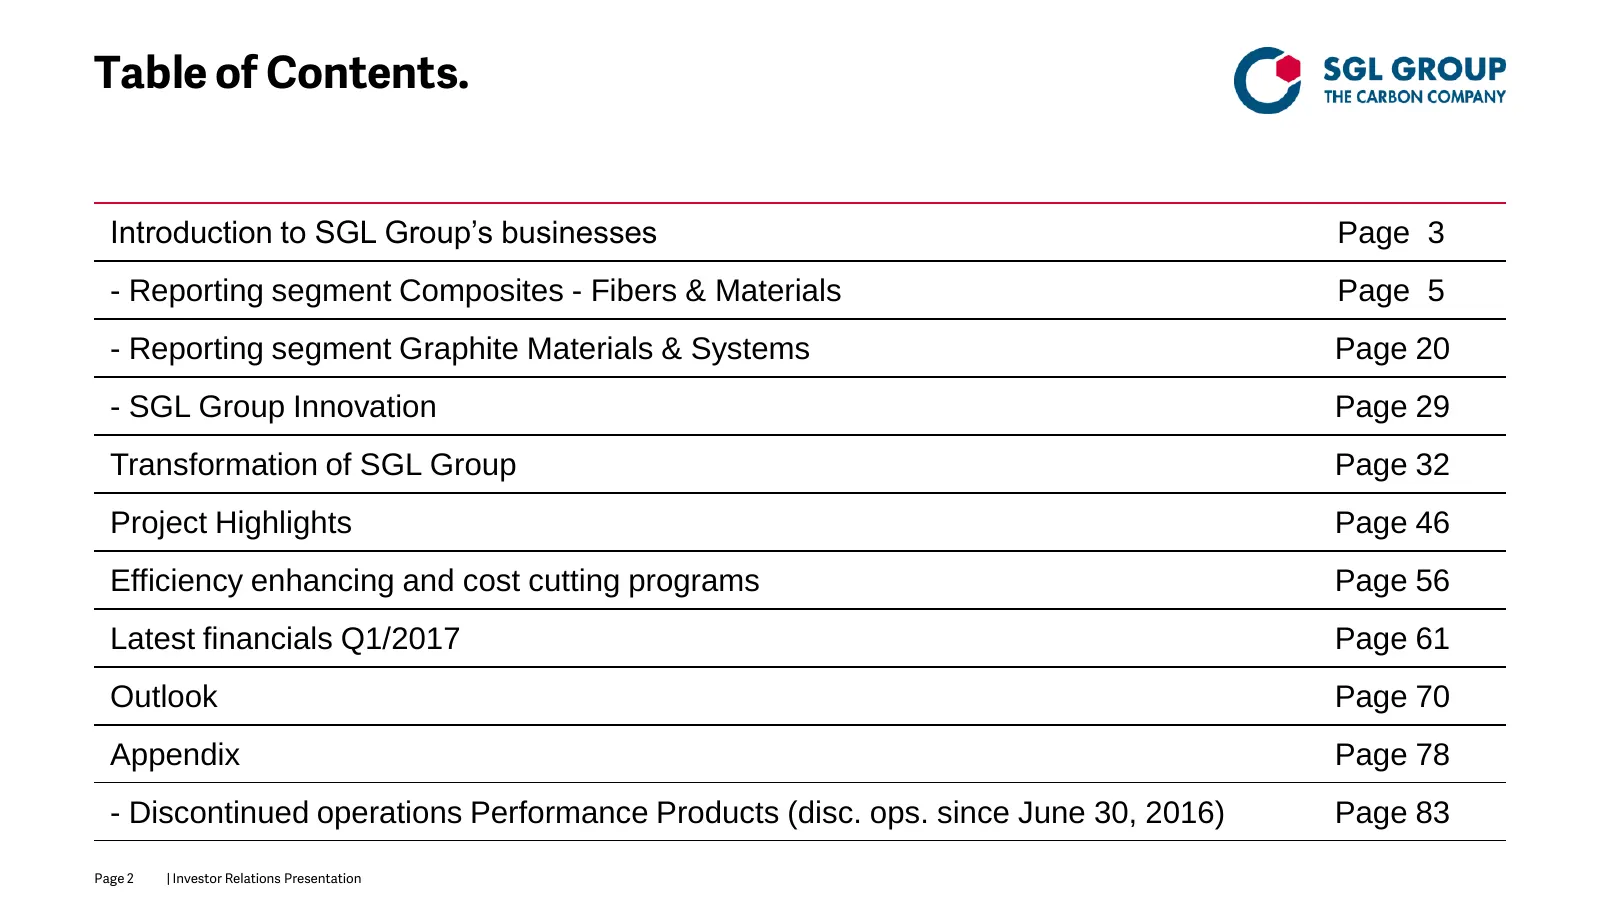
Slide 2: Table of Contents
Table of Contents. Introduction to SGL Group’s businesses Page 3 - Reporting segment Composites - Fibers & Materials Page 5 - Reporting segment Graphite Materials & Systems Page 20 - SGL Group Innovation Page 29 Transformation of SGL Group Page 32 Project Highlights Page 46 Efficiency enhancing and
Slide 3: Introduction to SGL Group's Businesses
Introduction to SGL Group’s Businesses Page 3 | Investor Relations Presentation
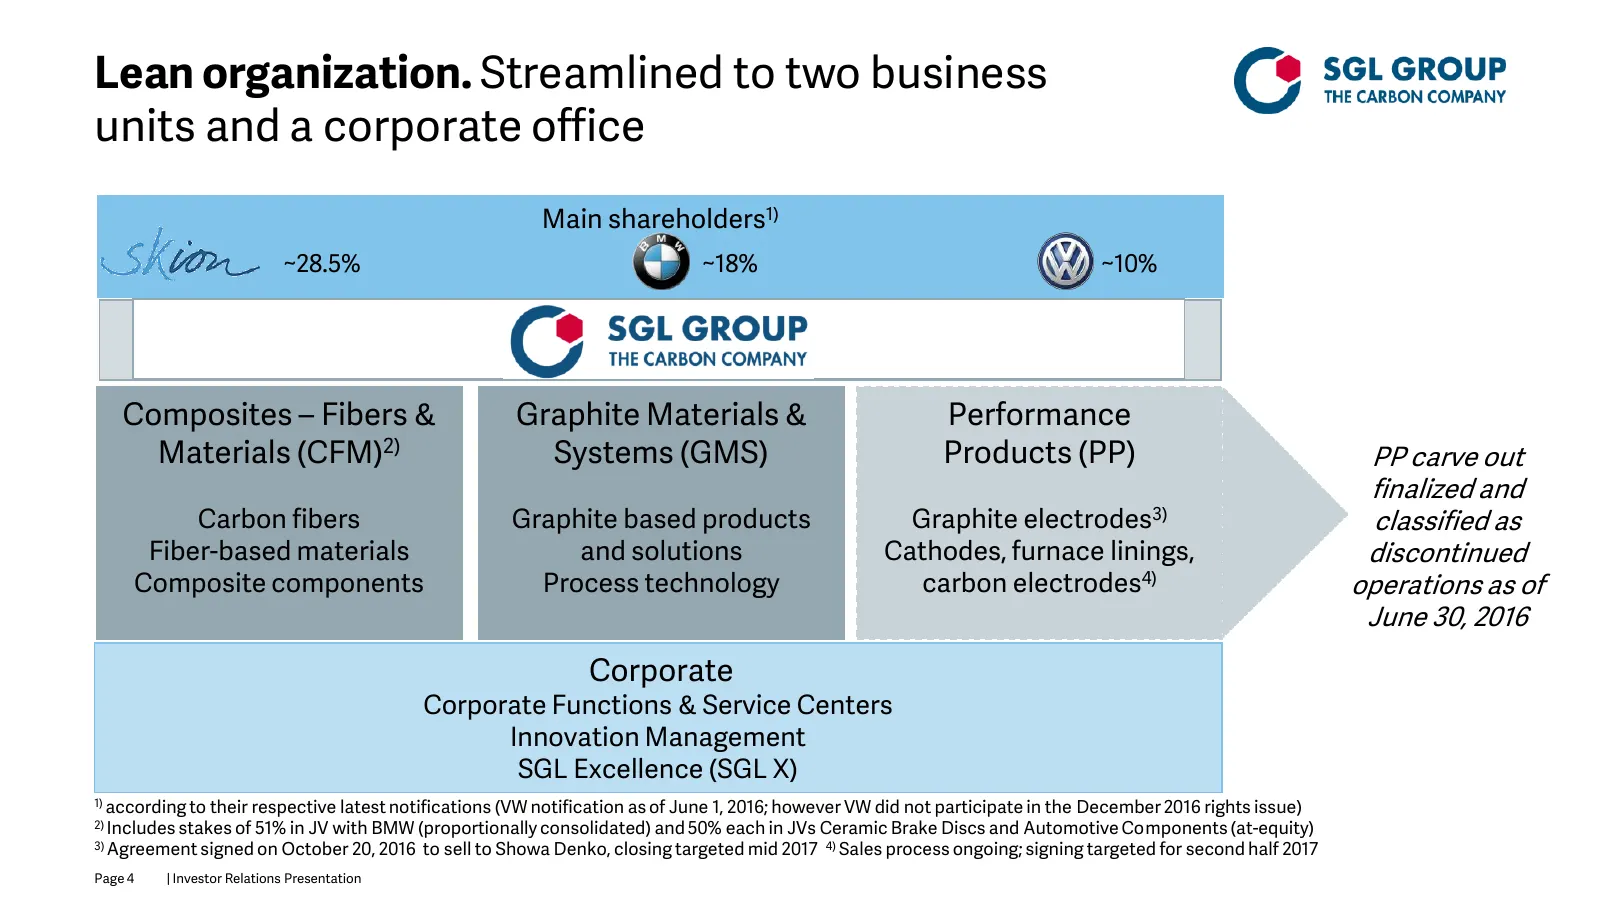
Slide 4: Lean organization. Streamlined to two business units and a corporate office
Lean organization. Streamlined to two business units and a corporate office Main shareholders1) ~28.5% ~18% ~10% Composites – Fibers & Graphite Materials & Performance Materials (CFM)2) Systems (GMS) Products (PP) PP carve out finalized and Carbon fibers Graphite based products Graphite electrodes3)
Slide 5: Reporting Segment Composites – Fibers & Materials
Reporting Segment Composites – Fibers & Materials Page 5 | Investor Relations Presentation
Slide 6: Reporting Segment Composites - Fibers & Materials (CFM)
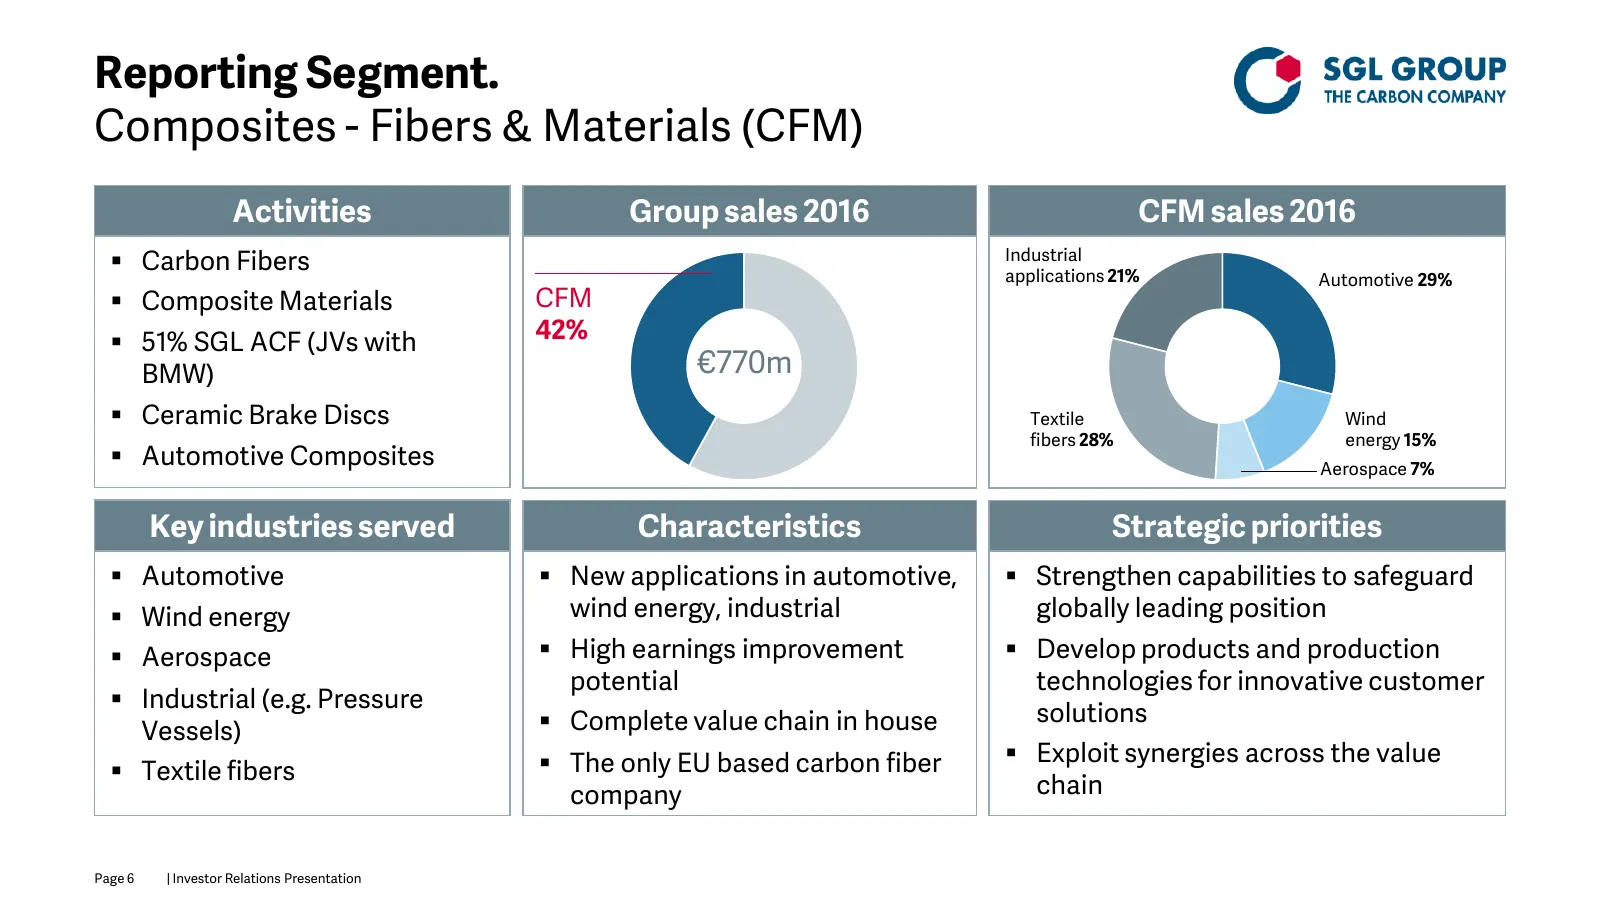
Reporting Segment. Composites - Fibers & Materials (CFM) Activities Group sales 2016 CFM sales 2016 Carbon Fibers Industrial applications 21% Automotive 29% Composite Materials CFM 51% SGL ACF (JVs with 42% BMW) €770m Ceramic Brake Discs Textile Wind fibers 28% energy 15% Automotive Compos
Slide 7: The only integrated European carbon fiber & composites producer
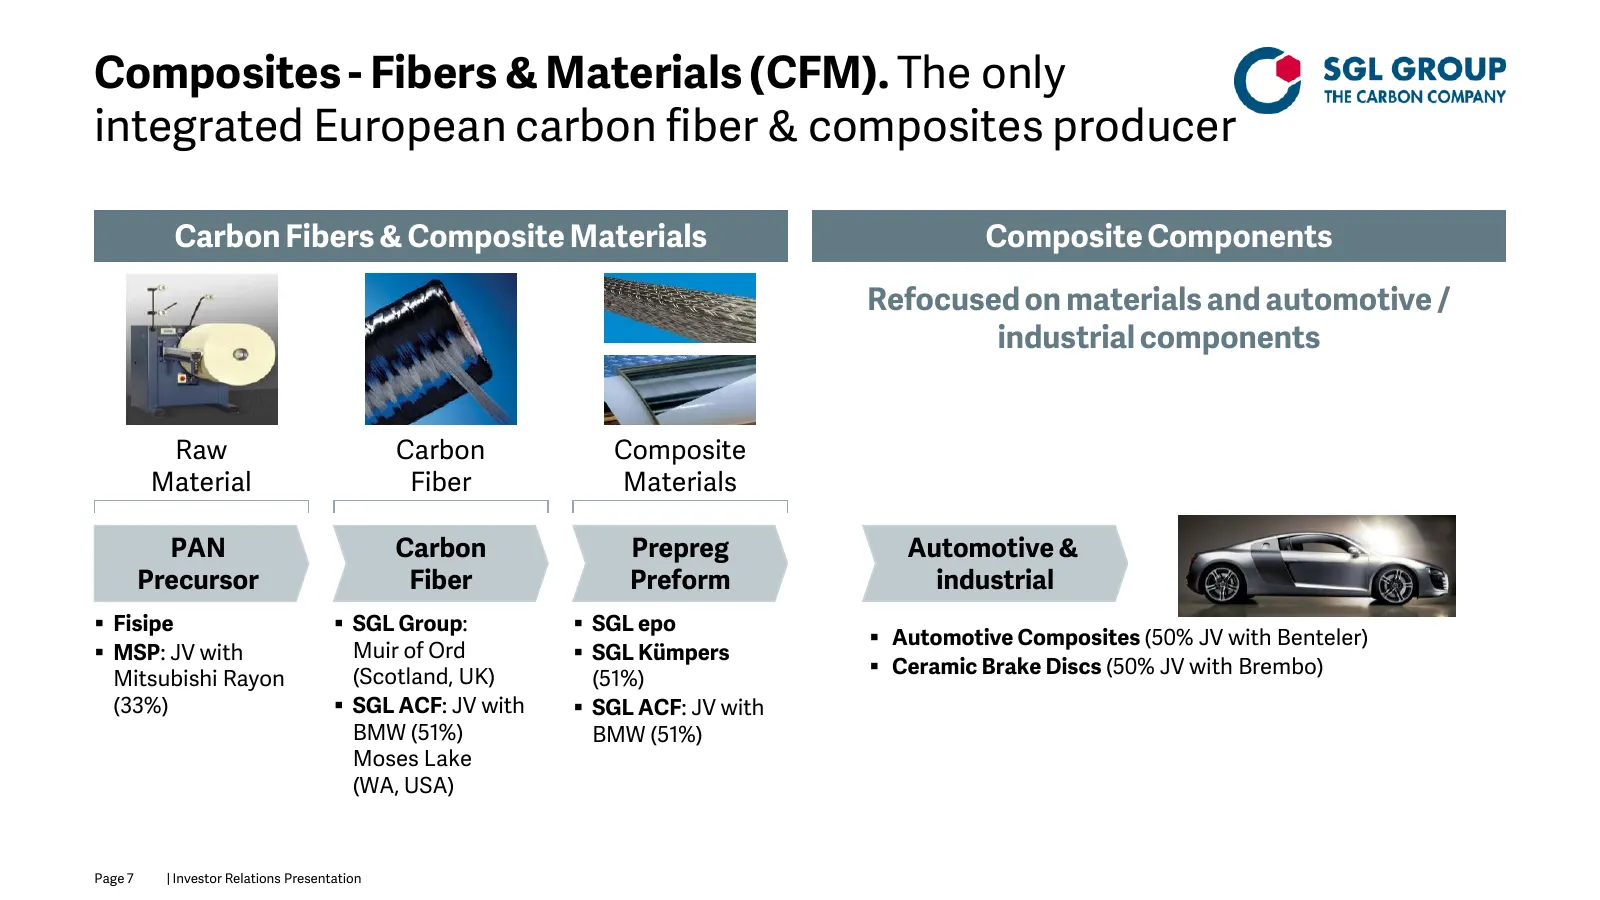
Composites - Fibers & Materials (CFM). The only integrated European carbon fiber & composites producer Carbon Fibers & Composite Materials Composite Components Refocused on materials and automotive / industrial components Raw Carbon Composite Material Fiber Materials PAN Carbon Prepreg Automotive &
Slide 8: CFM: Our solutions serve key markets
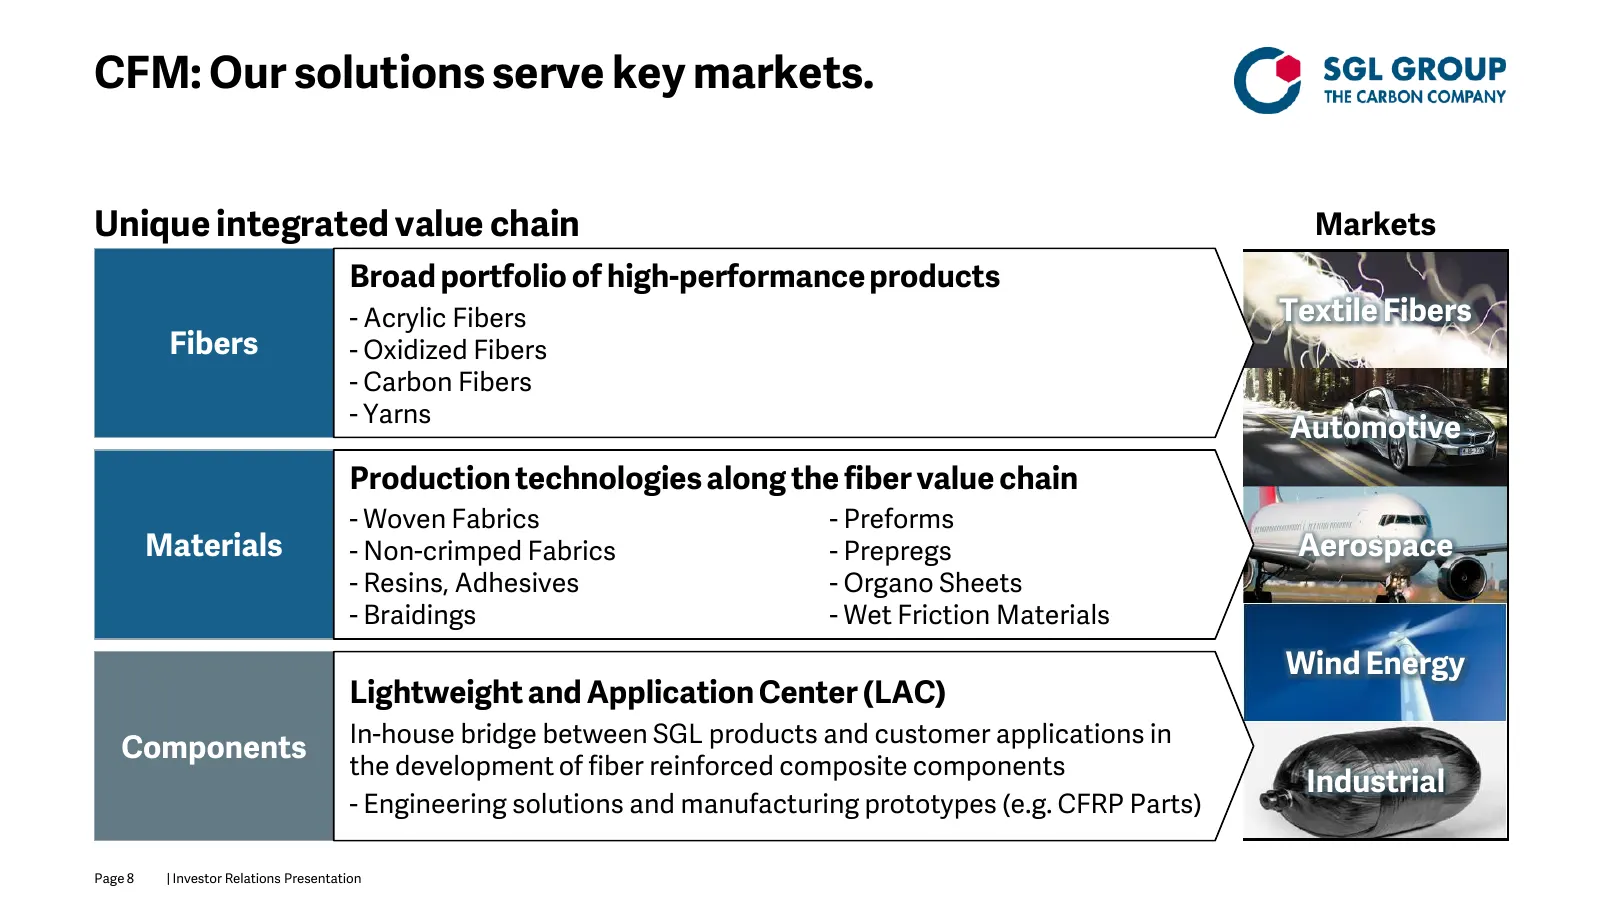
CFM: Our solutions serve key markets. Unique integrated value chain Markets Broad portfolio of high-performance products - Acrylic Fibers Textile Fibers Fibers - Oxidized Fibers - Carbon Fibers - Yarns Automotive Production technologies along the fiber value chain - Woven Fabrics - Preforms Material
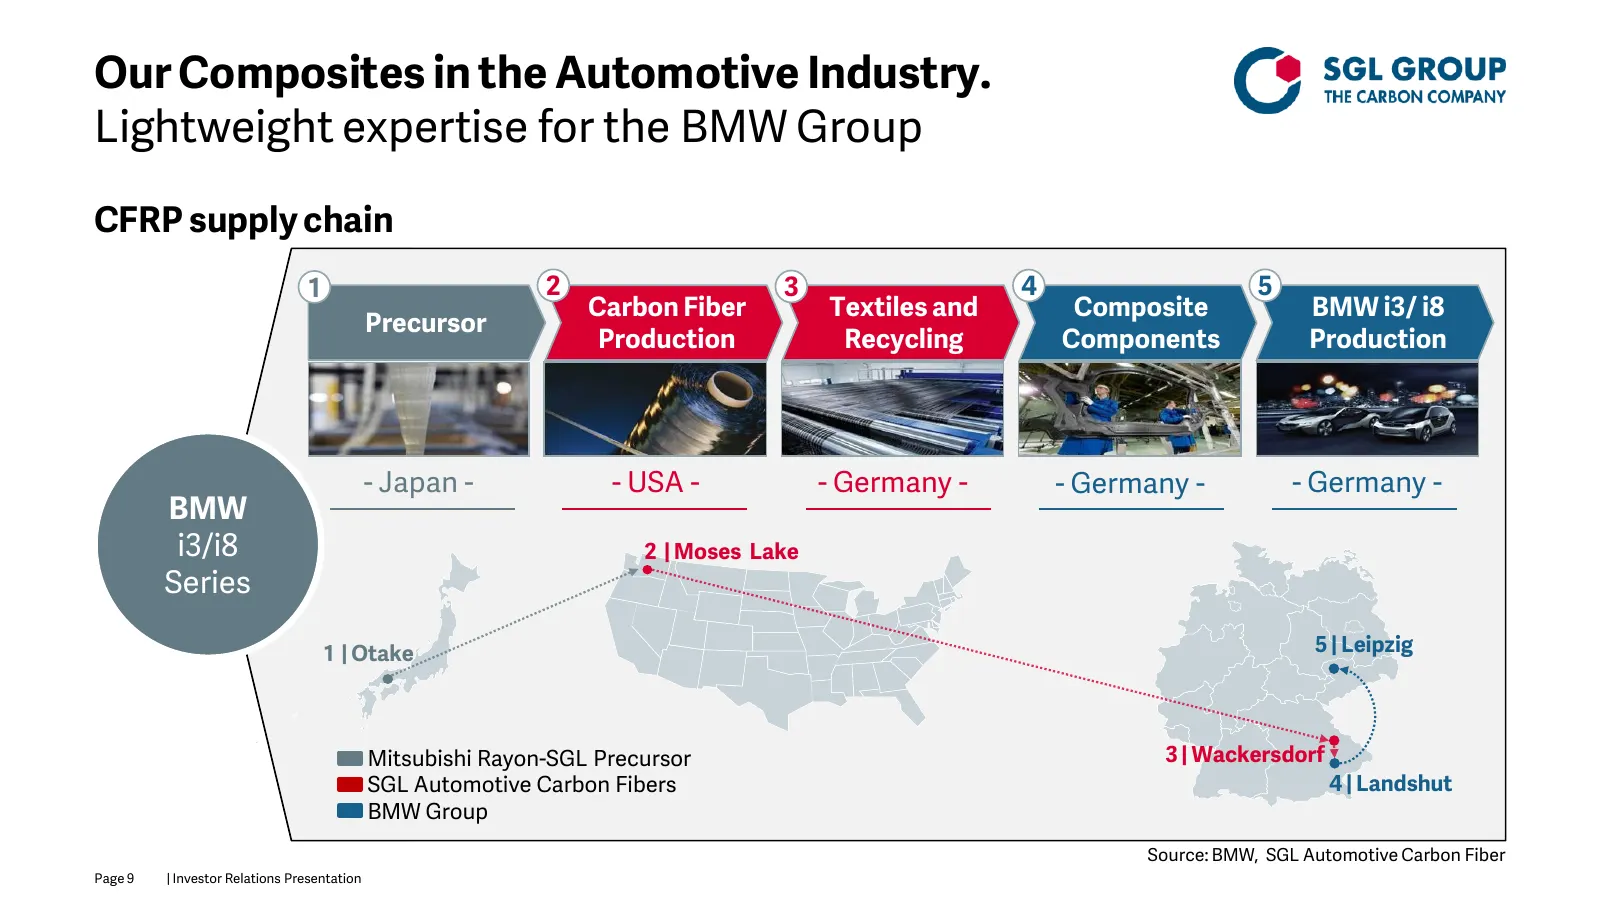
Slide 9: Lightweight expertise for the BMW Group
Our Composites in the Automotive Industry. Lightweight expertise for the BMW Group CFRP supply chain 1 2 3 4 5 Carbon Fiber Textiles and Composite BMW i3/ i8 Precursor Production Recycling Components Production - Japan - - USA - - Germany - - Germany - - Germany - BMW i3/i8 2 | Moses Lake Series 1 |
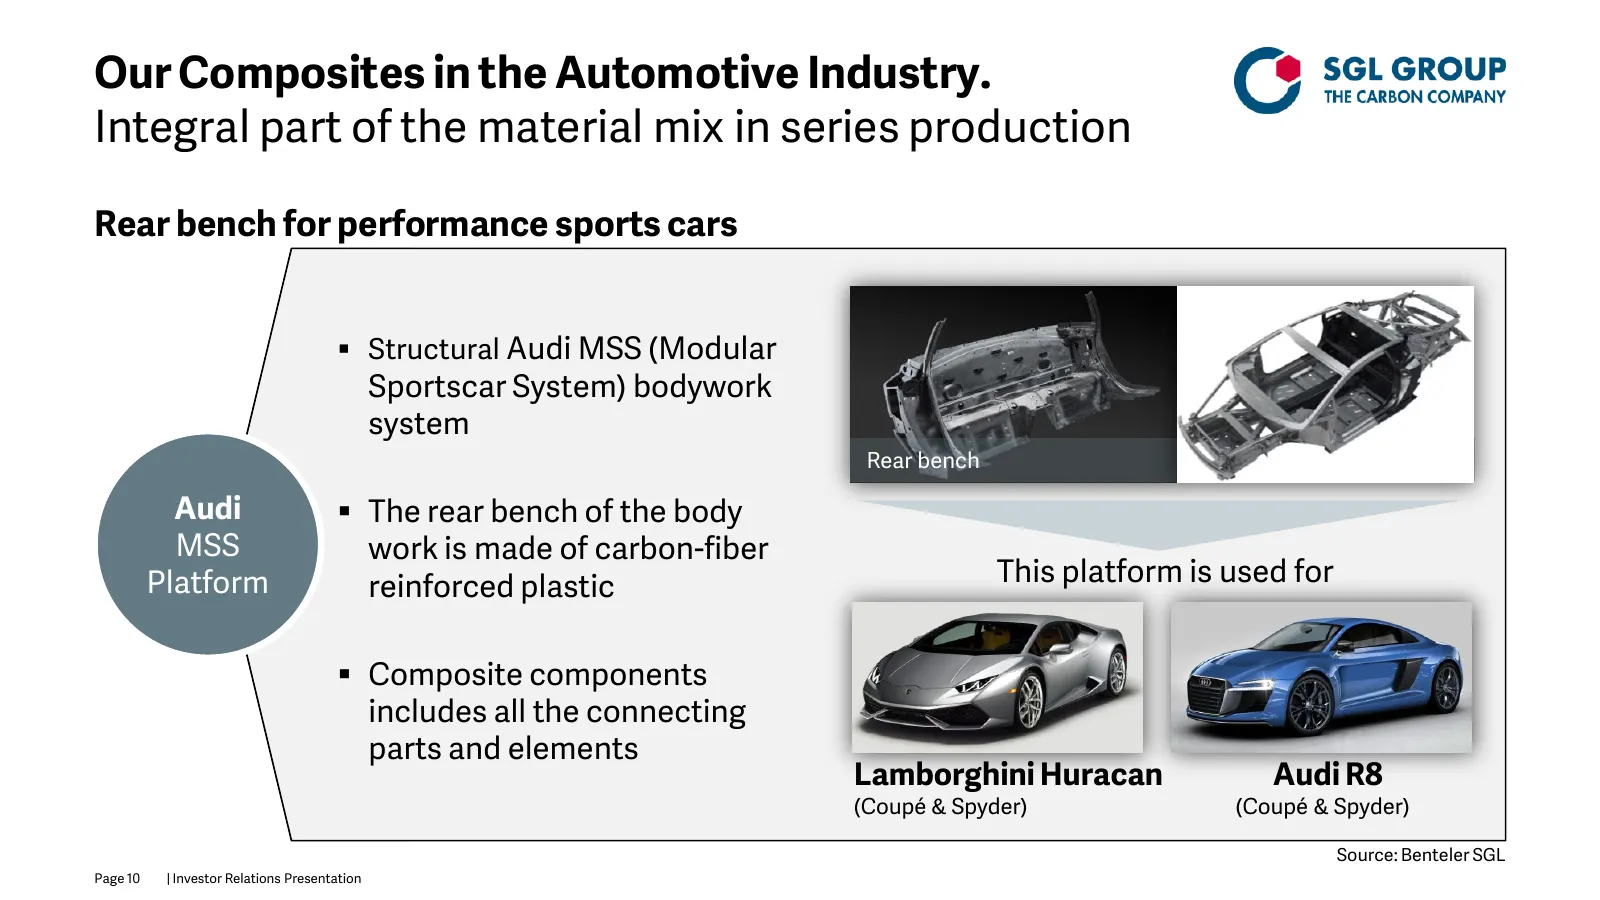
Slide 10: Integral part of the material mix in series production
Our Composites in the Automotive Industry. Integral part of the material mix in series production Rear bench for performance sports cars Structural Audi MSS (Modular Sportscar System) bodywork system Rear bench Audi The rear bench of the body MSS work is made of carbon-fiber Platform reinforced
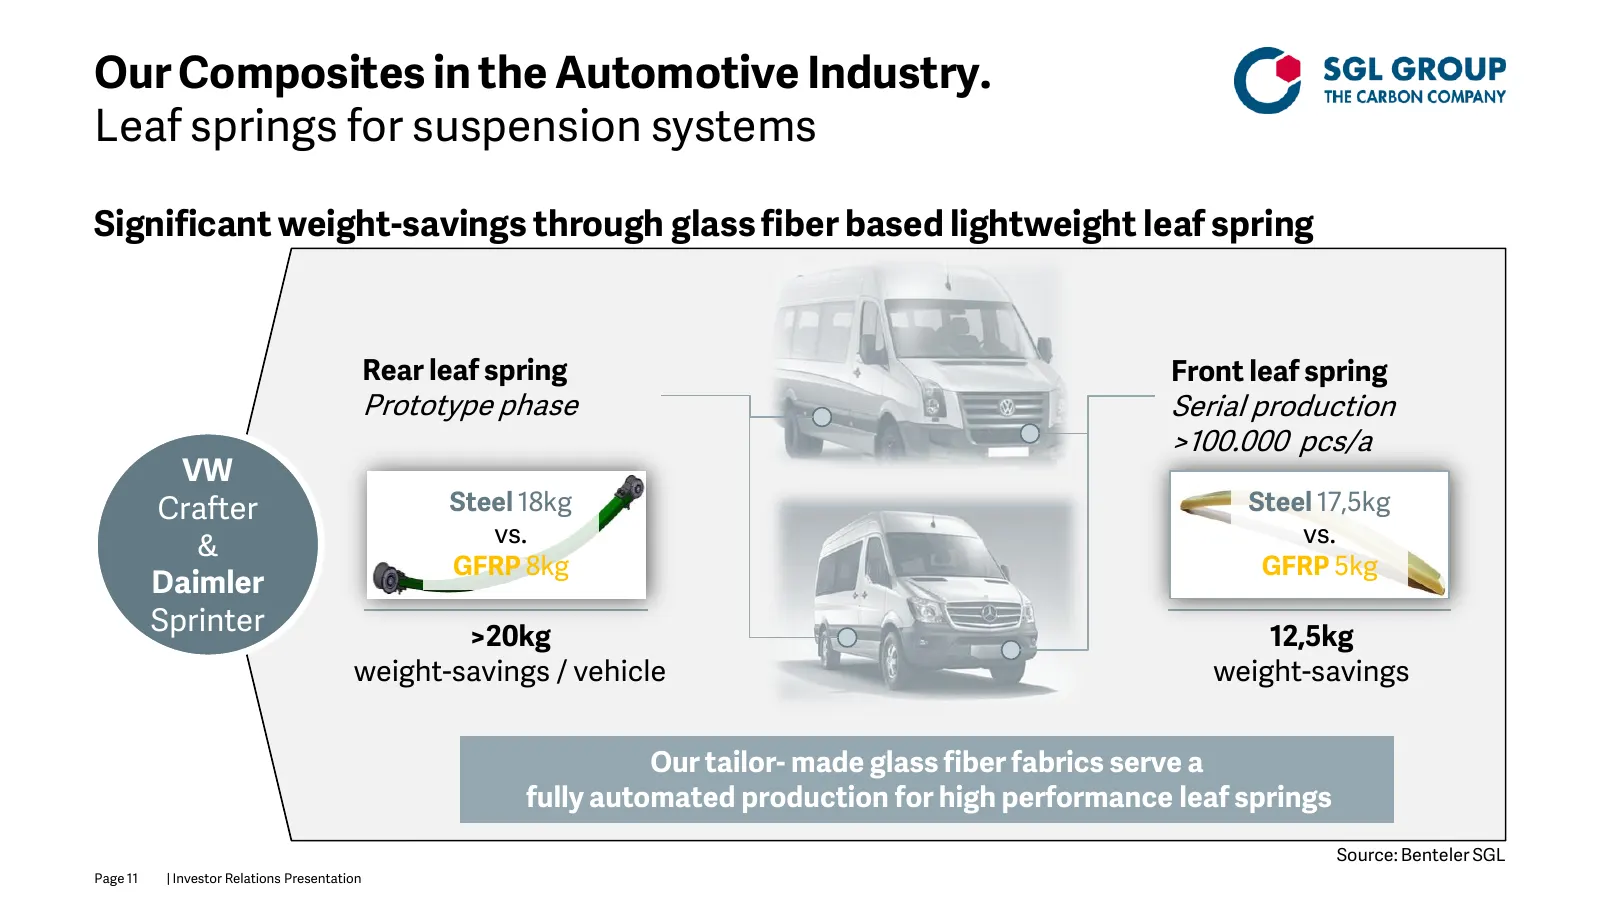
Slide 11: Leaf springs for suspension systems
Our Composites in the Automotive Industry. Leaf springs for suspension systems Significant weight-savings through glass fiber based lightweight leaf spring Rear leaf spring Front leaf spring Prototype phase Serial production >100.000 pcs/a VW Crafter Steel 18kg Steel 17,5kg & vs. vs. GFRP 8kg GFRP 5
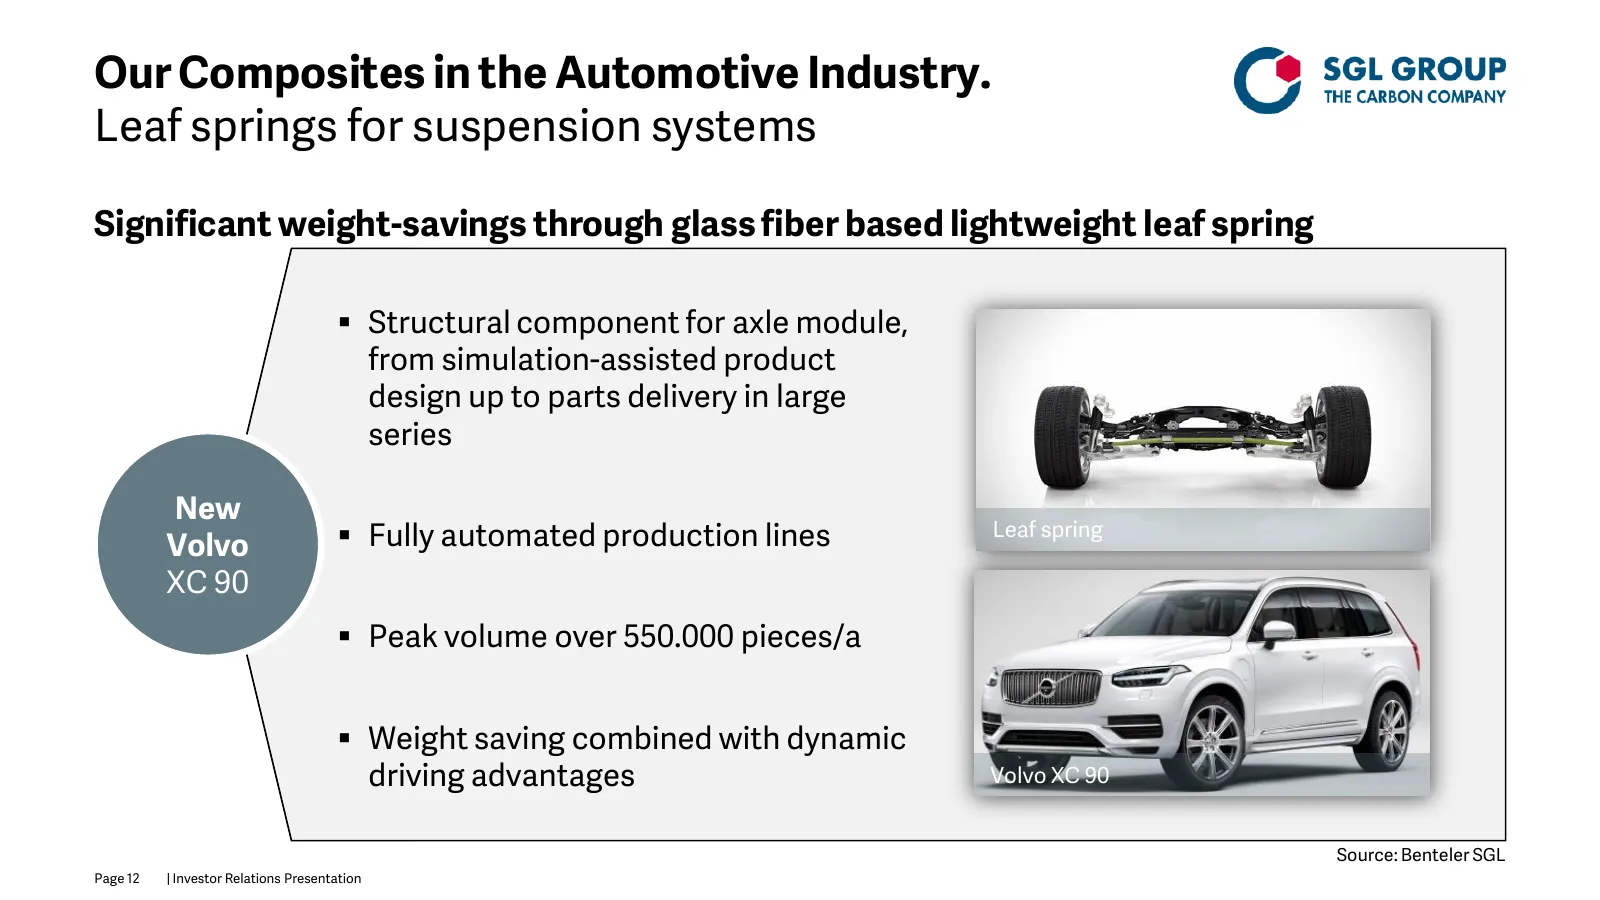
Slide 12: Leaf springs for suspension systems
Our Composites in the Automotive Industry. Leaf springs for suspension systems Significant weight-savings through glass fiber based lightweight leaf spring Structural component for axle module, from simulation-assisted product design up to parts delivery in large series New Volvo Fully automated
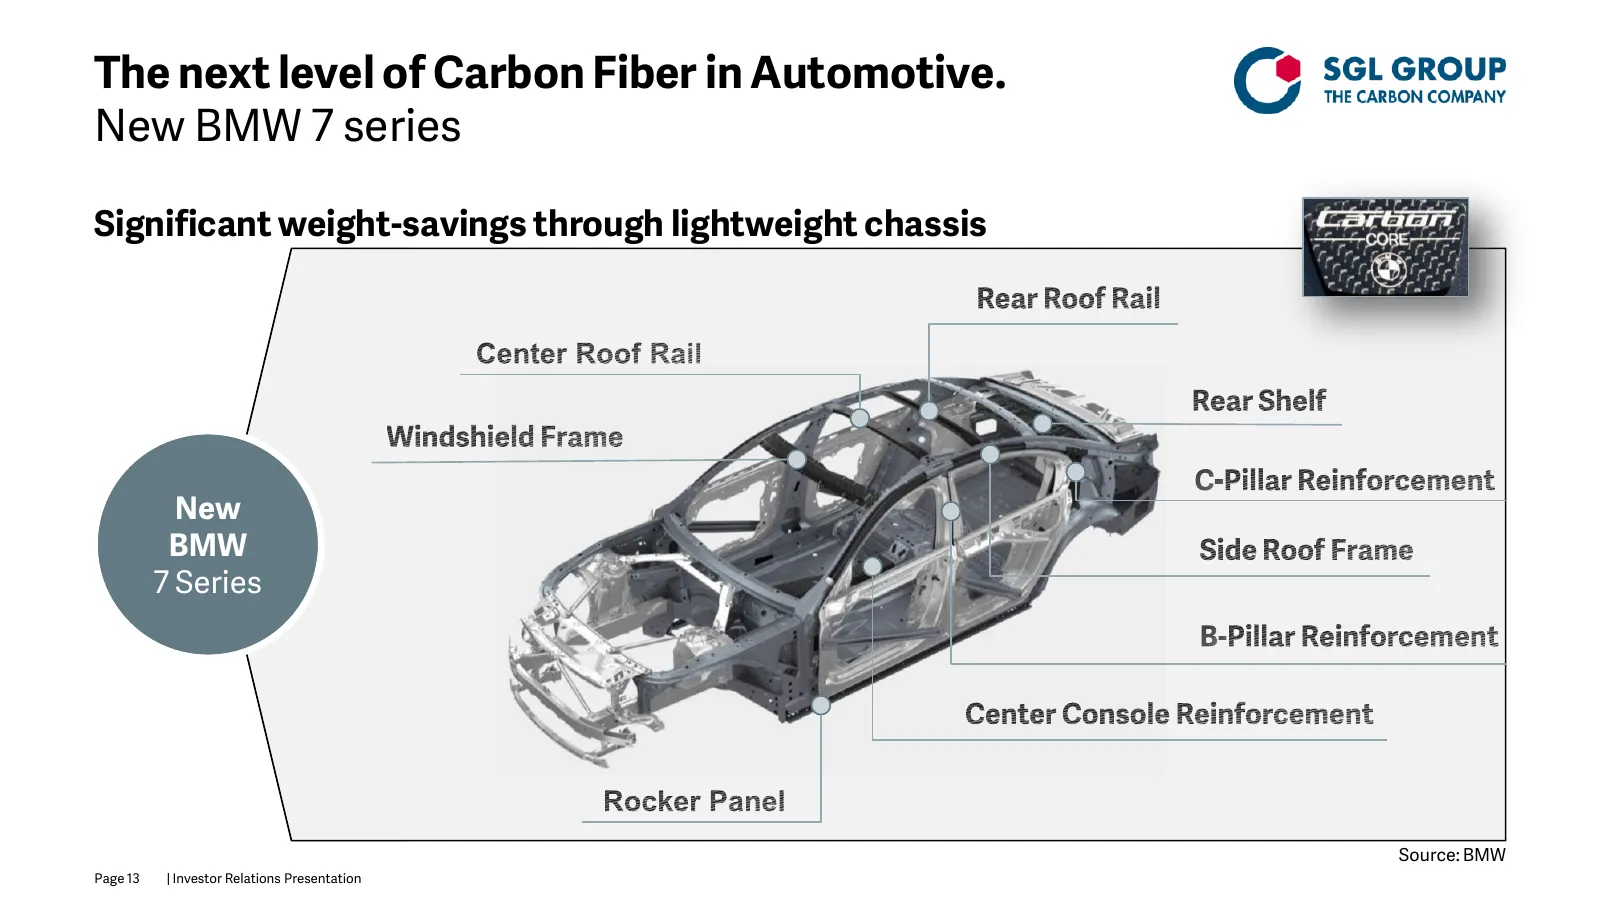
Slide 13: The next level of Carbon Fiber in Automotive. New BMW 7 series
The next level of Carbon Fiber in Automotive. New BMW 7 series Significant weight-savings through lightweight chassis New BMW 7 Series Source: BMW Page 13 | Investor Relations Presentation
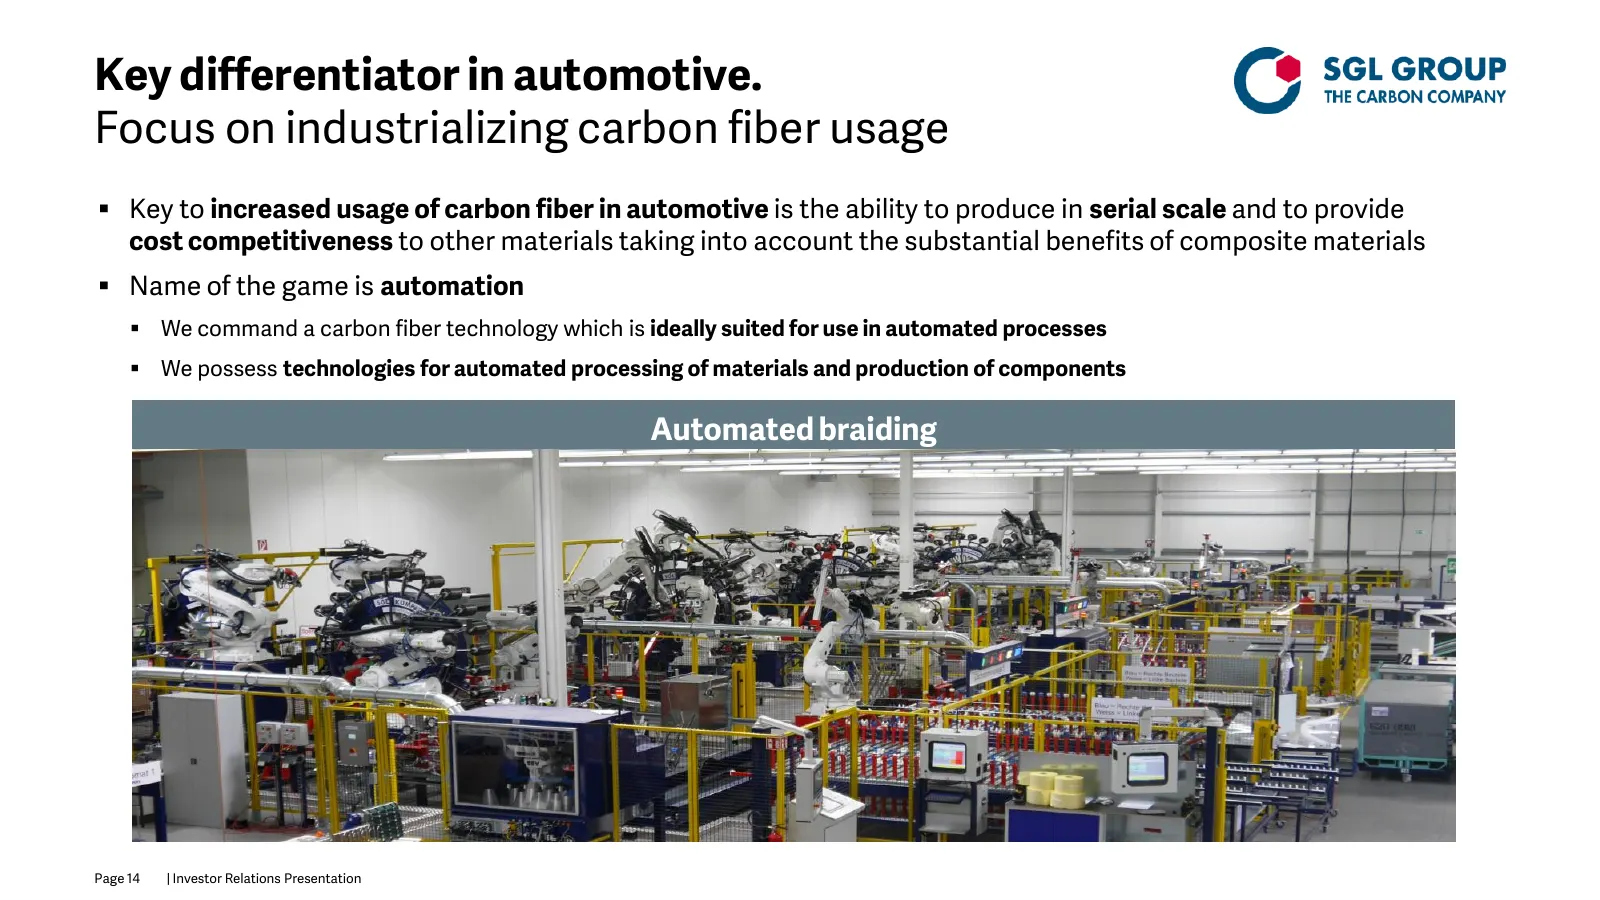
Slide 14: Key differentiator in automotive. Focus on industrializing carbon fiber usage
Key differentiator in automotive. Focus on industrializing carbon fiber usage Key to increased usage of carbon fiber in automotive is the ability to produce in serial scale and to provide cost competitiveness to other materials taking into account the substantial benefits of composite materials
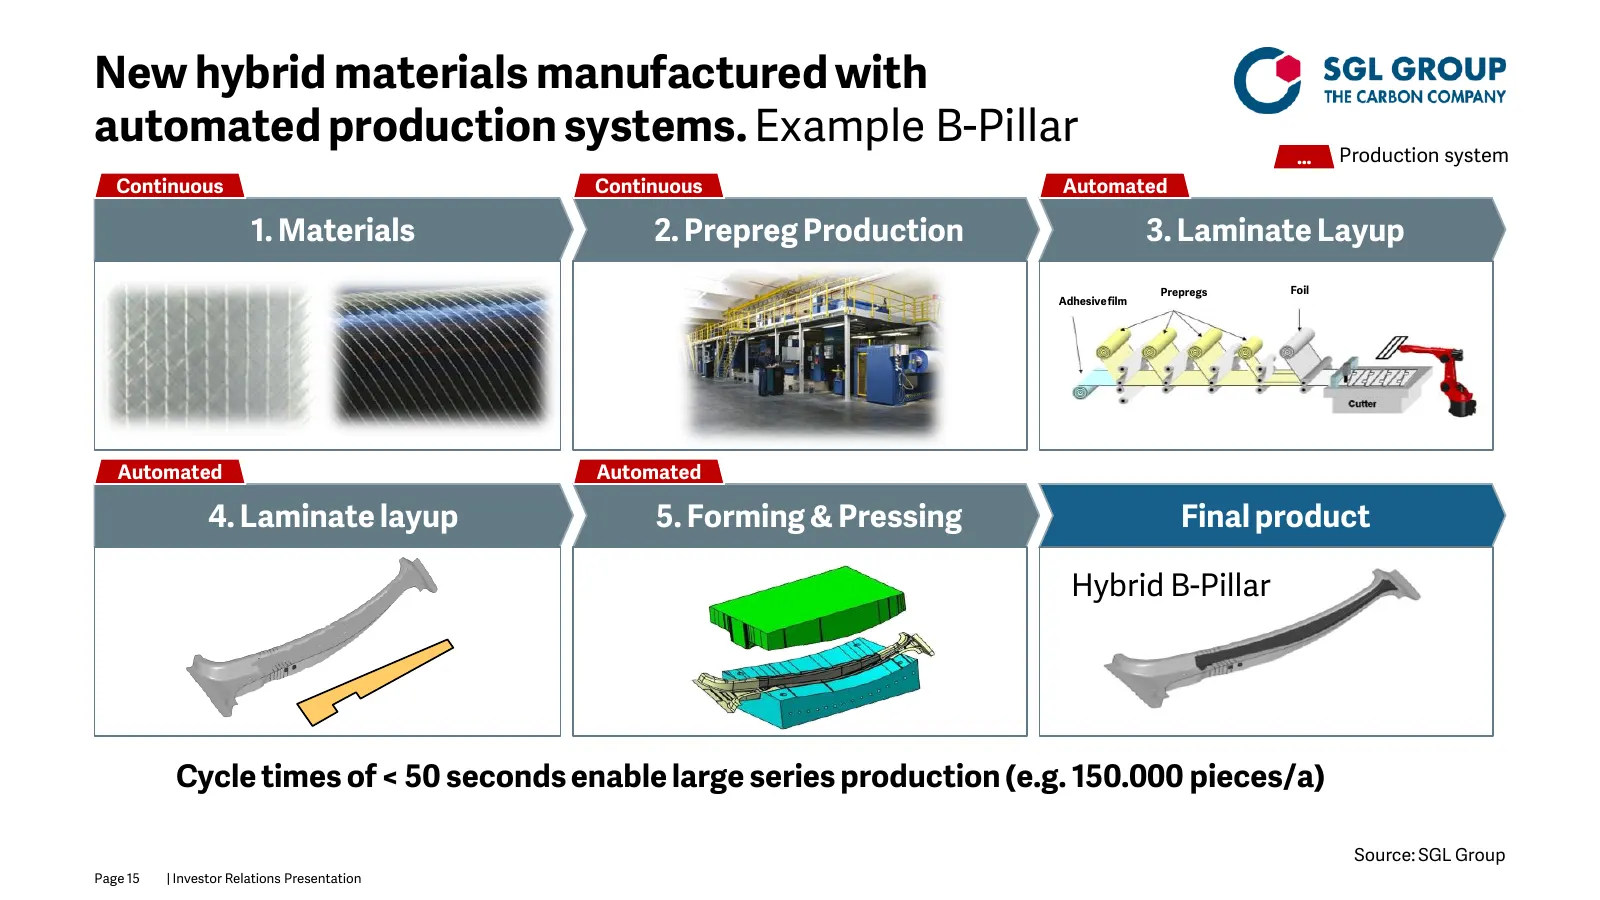
Slide 15: New hybrid materials manufactured with automated production systems
New hybrid materials manufactured with automated production systems. Example B-Pillar Production system … Continuous Continuous Automated 1. Materials 2. Prepreg Production 3. Laminate Layup Prepregs Foil Adhesive film Automated Automated 4. Laminate layup 5. Forming & Pressing Final product Hybrid
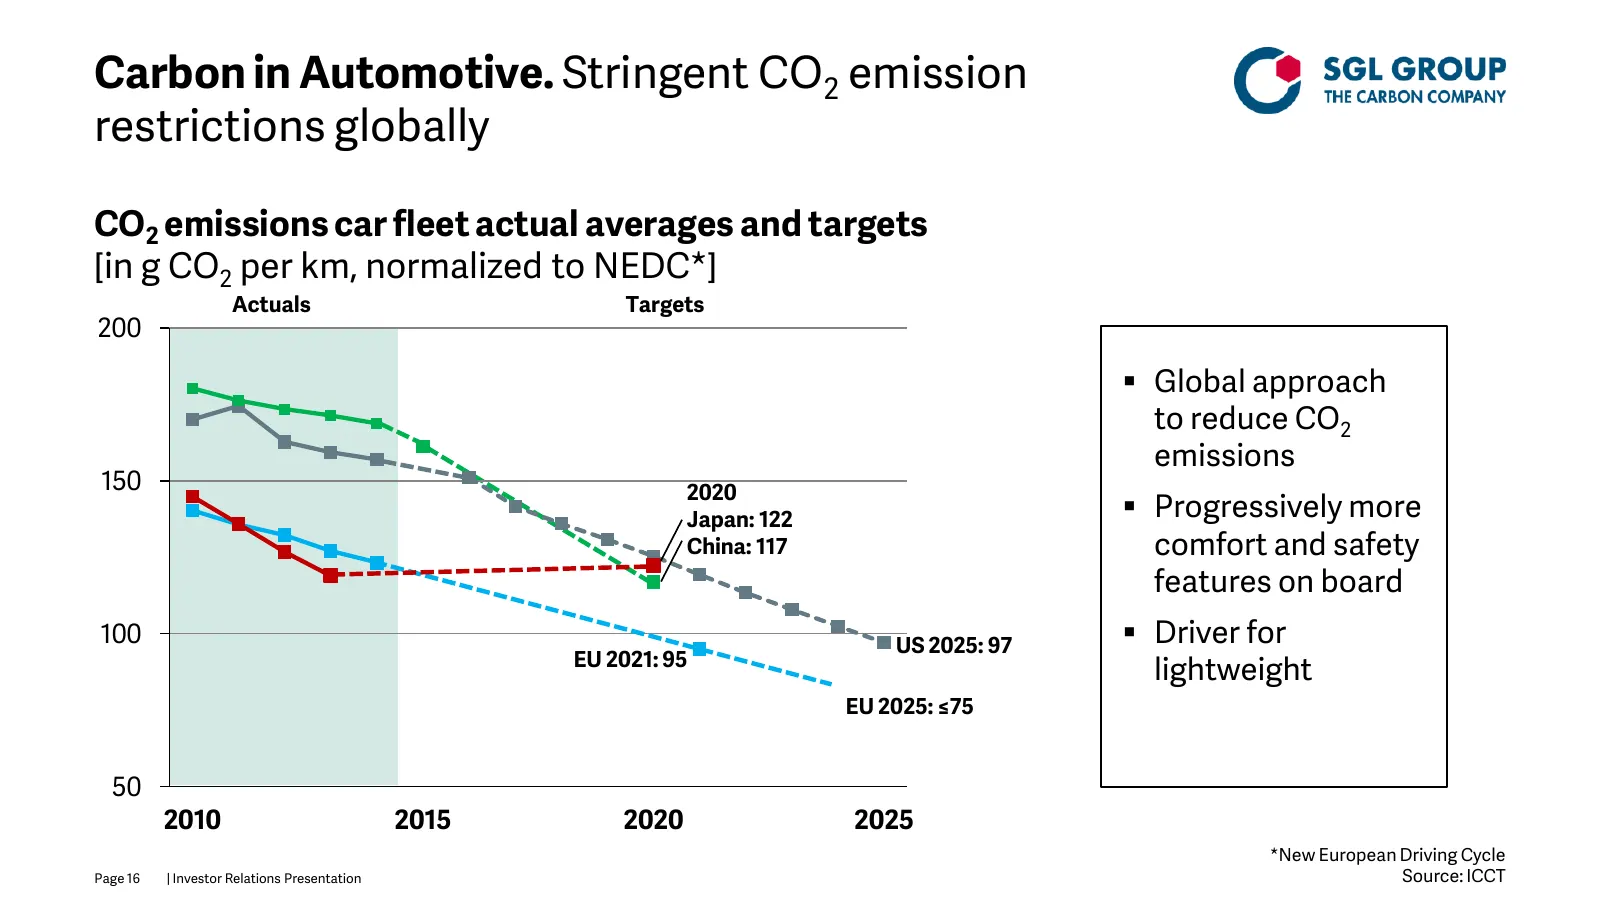
Slide 16: Carbon in Automotive. Stringent CO2 emission restrictions globally
Carbon in Automotive. Stringent CO2 emission restrictions globally CO2 emissions car fleet actual averages and targets [in g CO2 per km, normalized to NEDC*] Actuals Targets 200 Global approach to reduce CO2 emissions 150 2020 Japan: 122 Progressively more China: 117 comfort and safety features
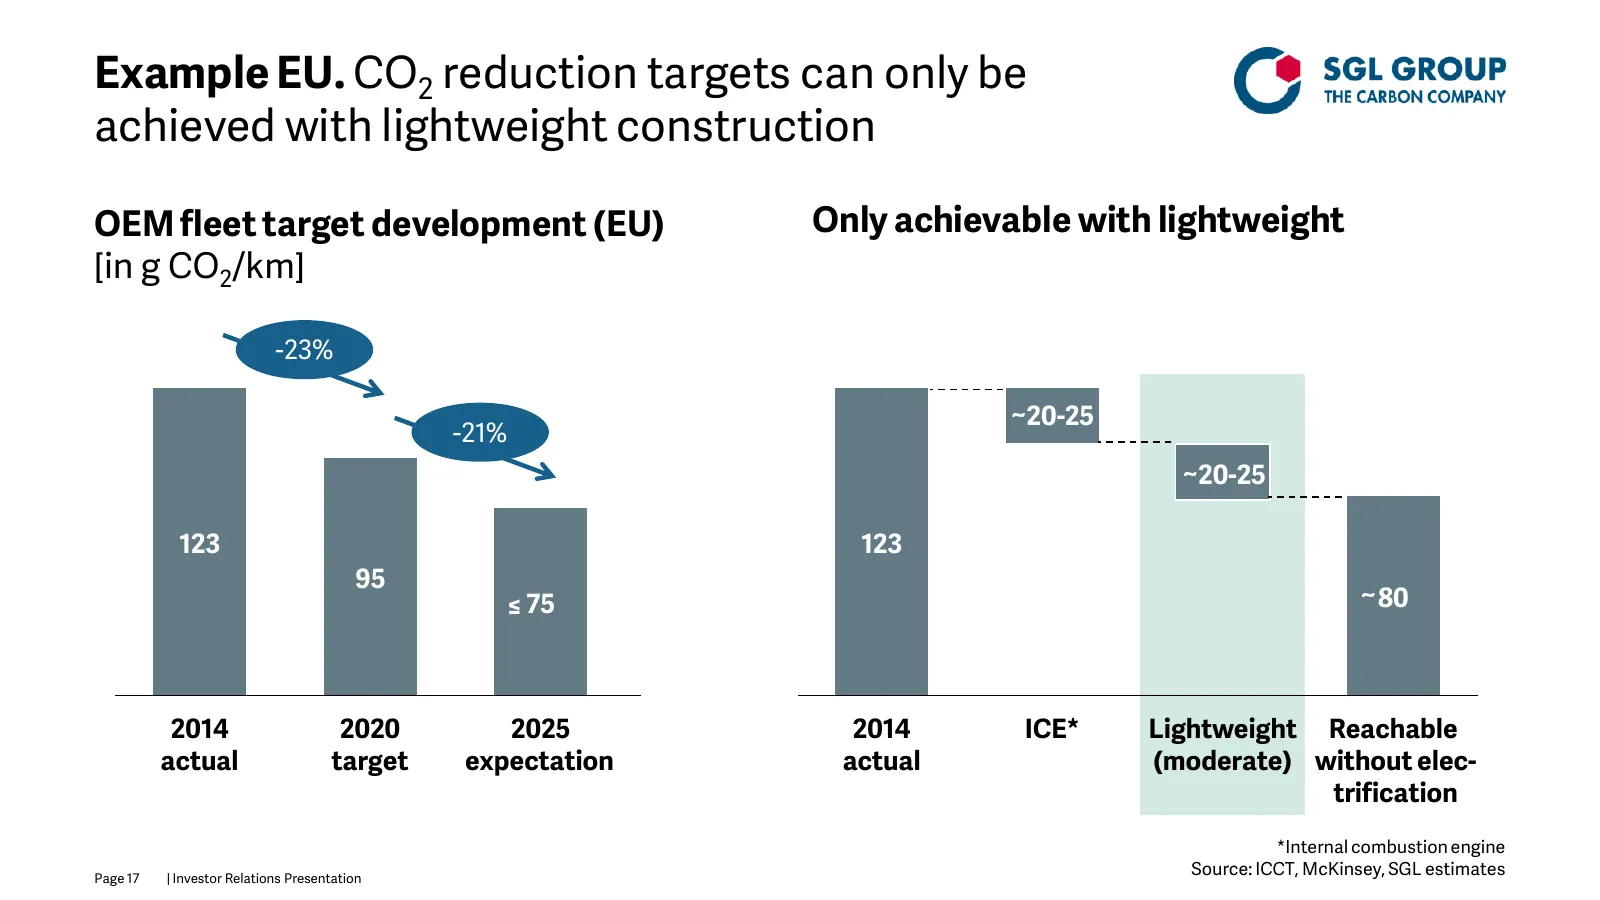
Slide 17: EU CO2 reduction targets only achievable with lightweight construction
Example EU. CO2 reduction targets can only be achieved with lightweight construction OEM fleet target development (EU) Only achievable with lightweight [in g CO2/km] -23% ~20-25 ~ -21% ~20-25 ~ 123 123 95 ≤ 75 ~ 80 2014 2020 2025 Spalte1 2014 ICE* Lightweight Reachable actual target expectation actu
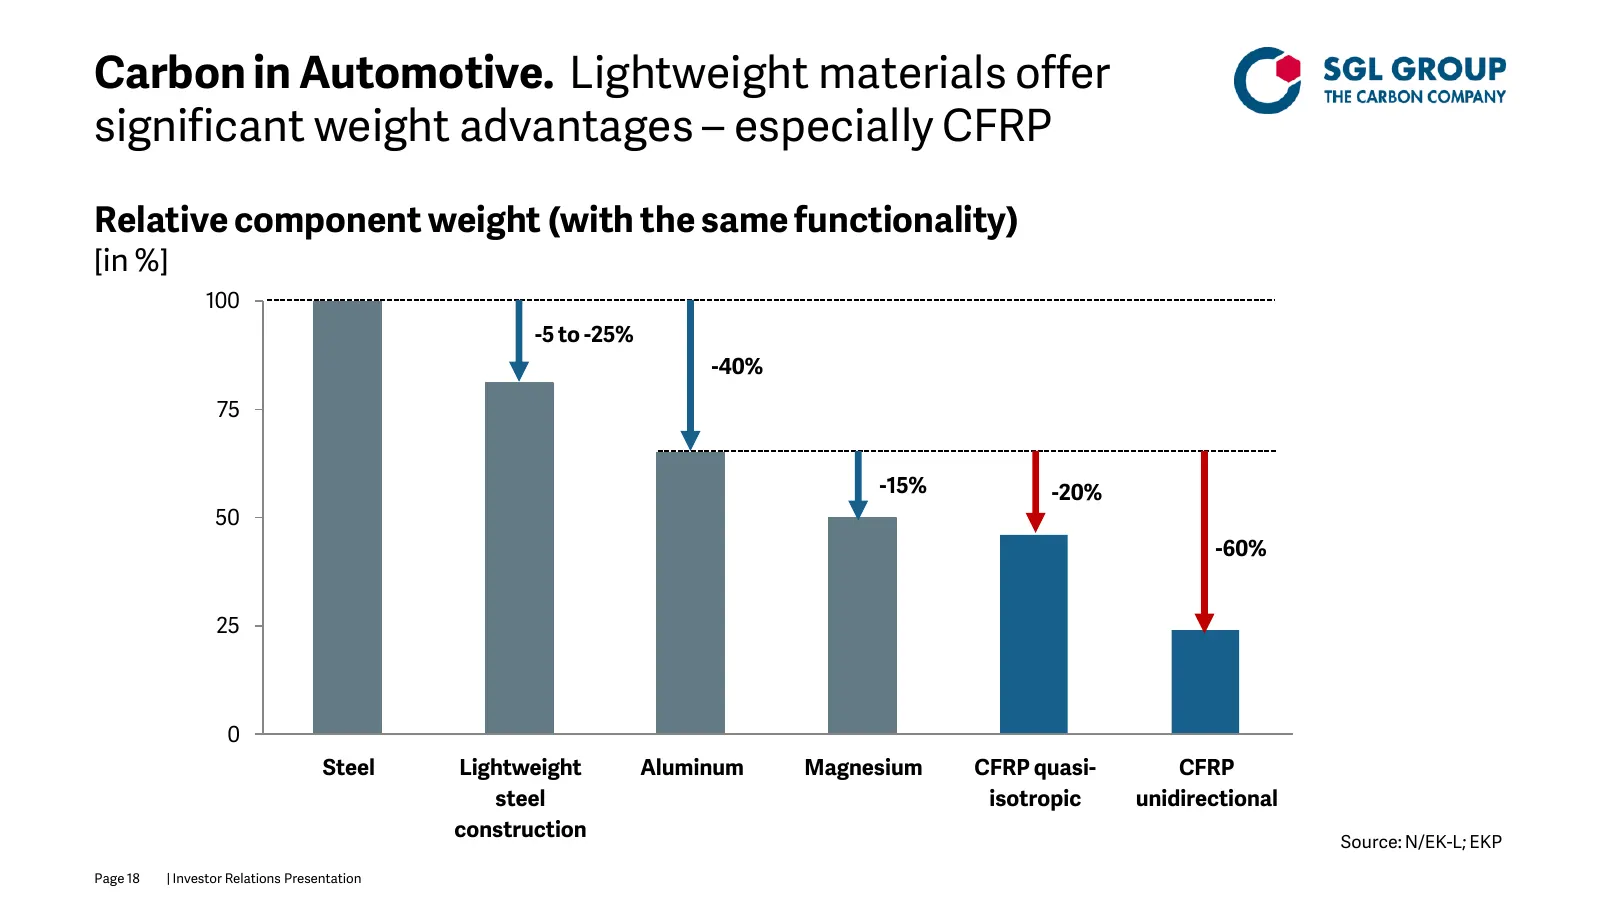
Slide 18: Lightweight materials offer significant weight advantages – especially CFRP
Carbon in Automotive. Lightweight materials offer significant weight advantages – especially CFRP Relative component weight (with the same functionality) [in %] 100 -5 to -25% -40% 75 -15% -20% 50 -60% 25 0 Steel Lightweight Aluminum Magnesium CFRP quasi- CFRP steel isotropic unidirectional construc
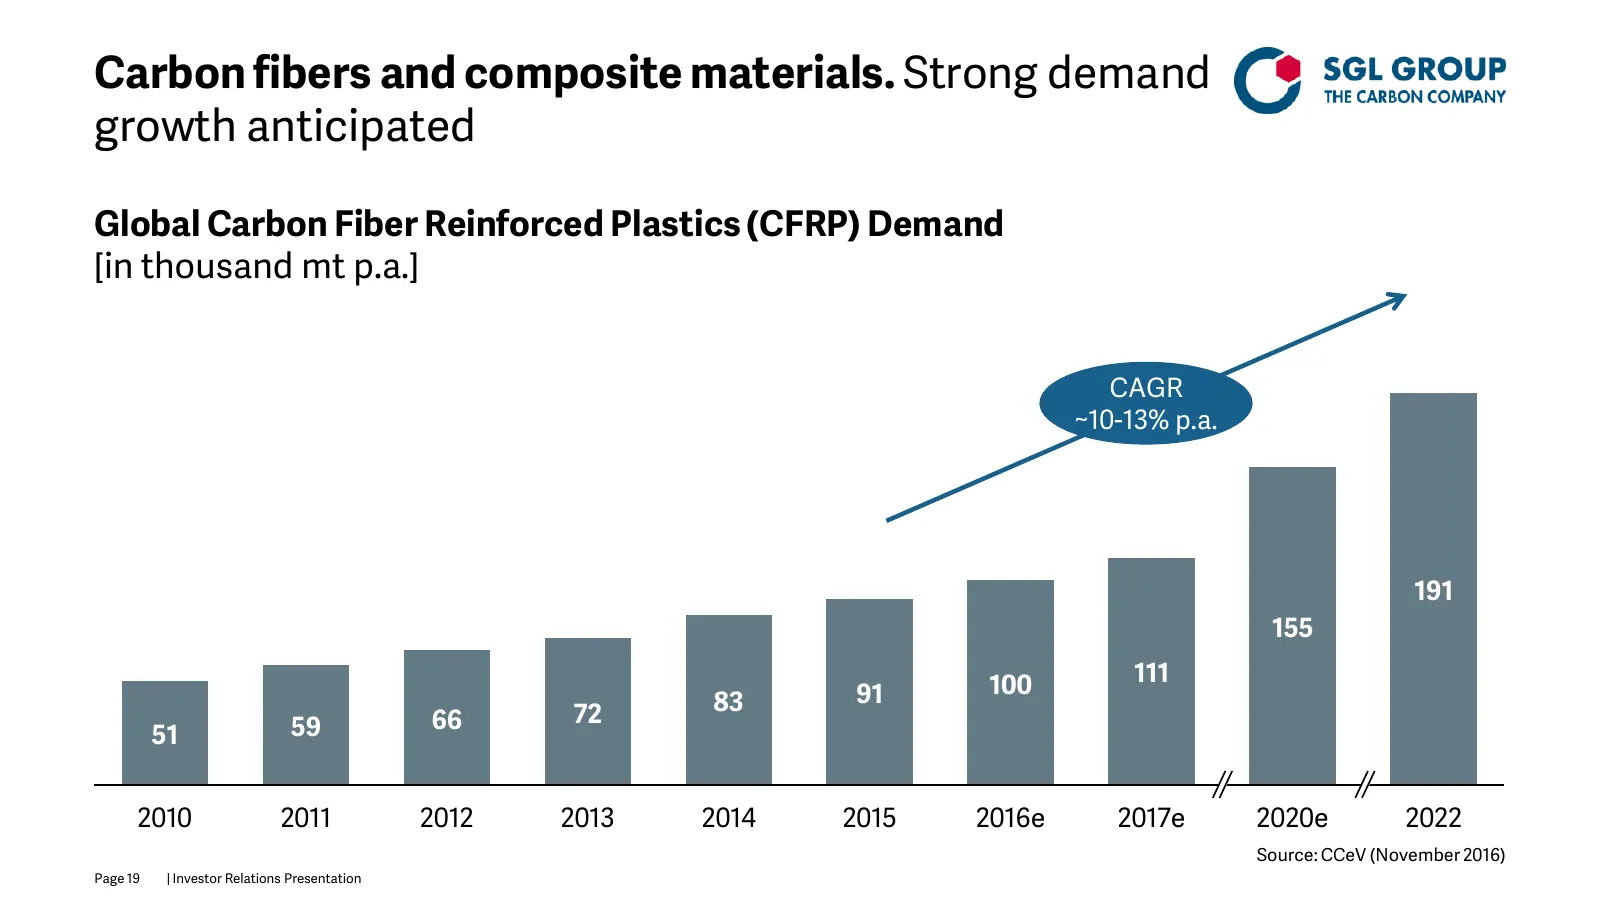
Slide 19: Carbon fibers and composite materials. Strong demand growth anticipated
Carbon fibers and composite materials. Strong demand growth anticipated Global Carbon Fiber Reinforced Plastics (CFRP) Demand [in thousand mt p.a.] CAGR ~10-13% p.a. 191 155 100 111 83 91 66 72 51 59 2010 2011 2012 2013 2014 2015 2016e 2017e 2020e 2022 Source: CCeV (November 2016) Page 19 | Investor
Slide 20: Reporting Segment Graphite Materials & Systems
Reporting Segment Graphite Materials & Systems Page 20 | Investor Relations Presentation
Slide 21: Reporting Segment. Graphite Materials & Systems (GMS)
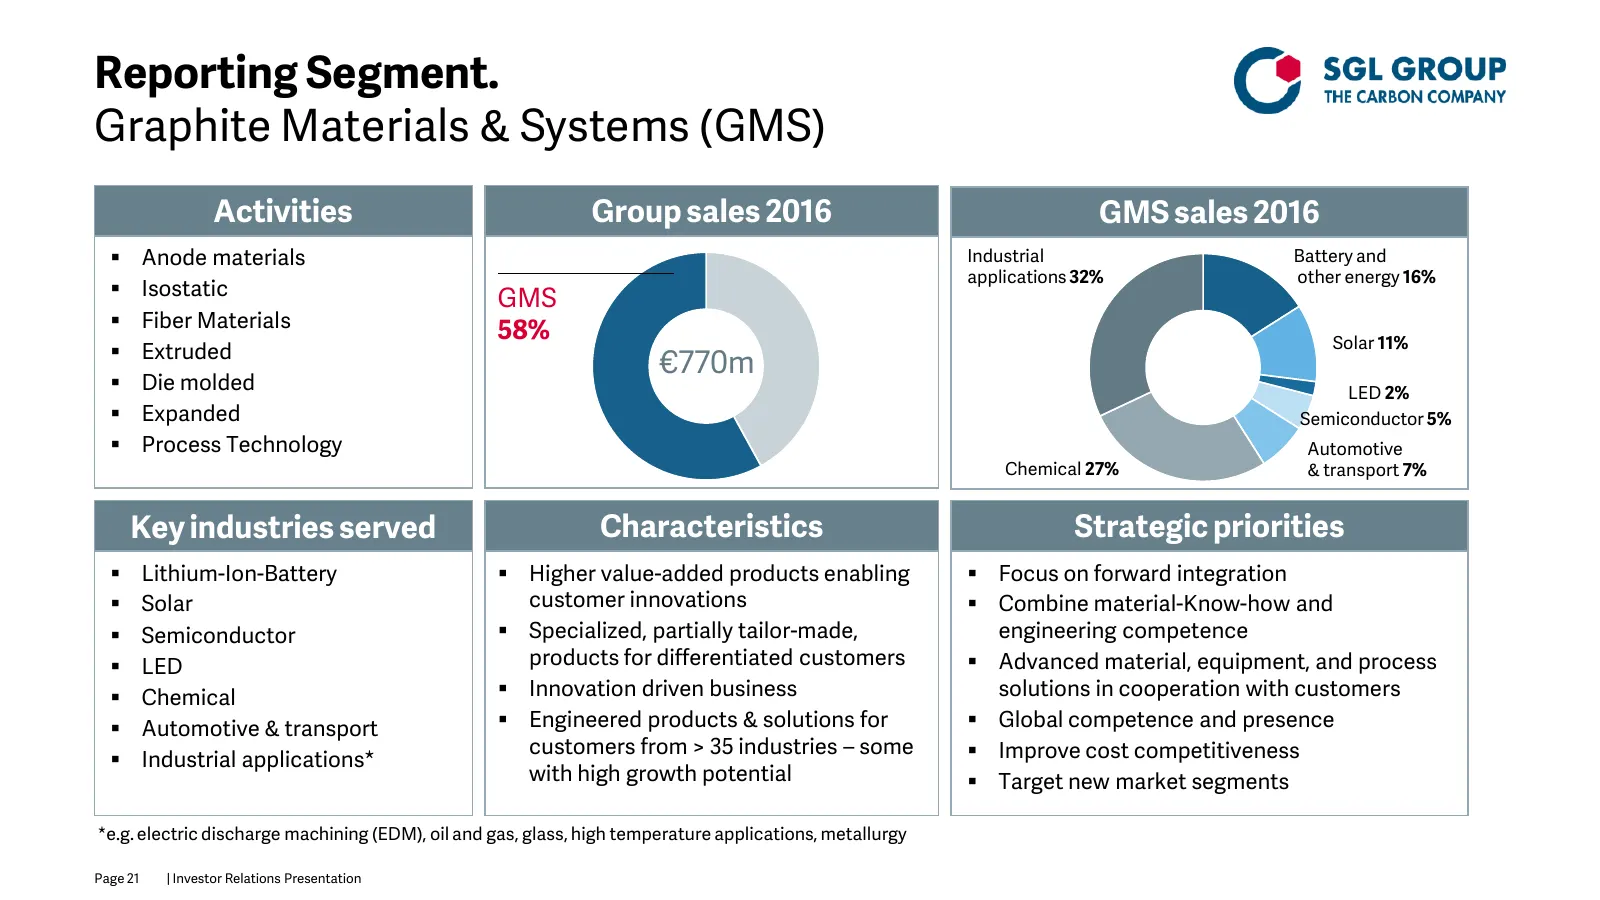
Reporting Segment. Graphite Materials & Systems (GMS) Activities Group sales 2016 GMS sales 2016 Anode materials Industrial Battery and applications 32% other energy 16% Isostatic GMS Fiber Materials 58% Solar 11% Extruded €770m Die molded LED 2% Expanded Semiconductor 5% Process Techn
Slide 22: GMS: Best solutions for our customers
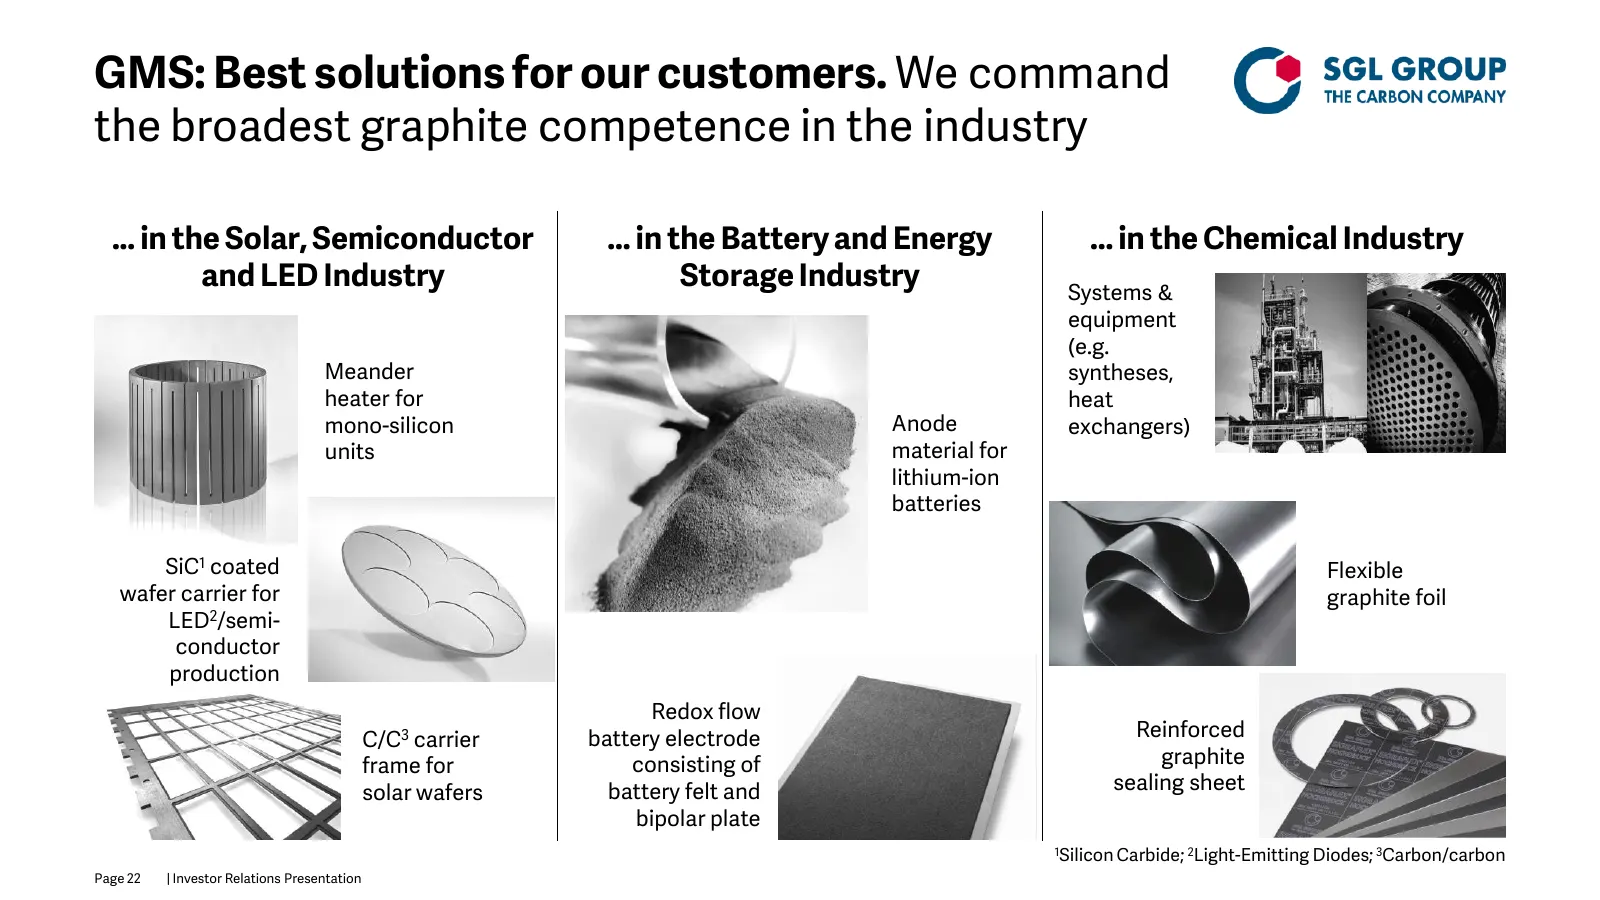
GMS: Best solutions for our customers. We command the broadest graphite competence in the industry ... in the Solar, Semiconductor ... in the Battery and Energy ... in the Chemical Industry and LED Industry Storage Industry Systems & equipment (e.g. Meander syntheses, heater for heat mono-silicon An
Slide 23: Integrated value chain and broad materials portfolio
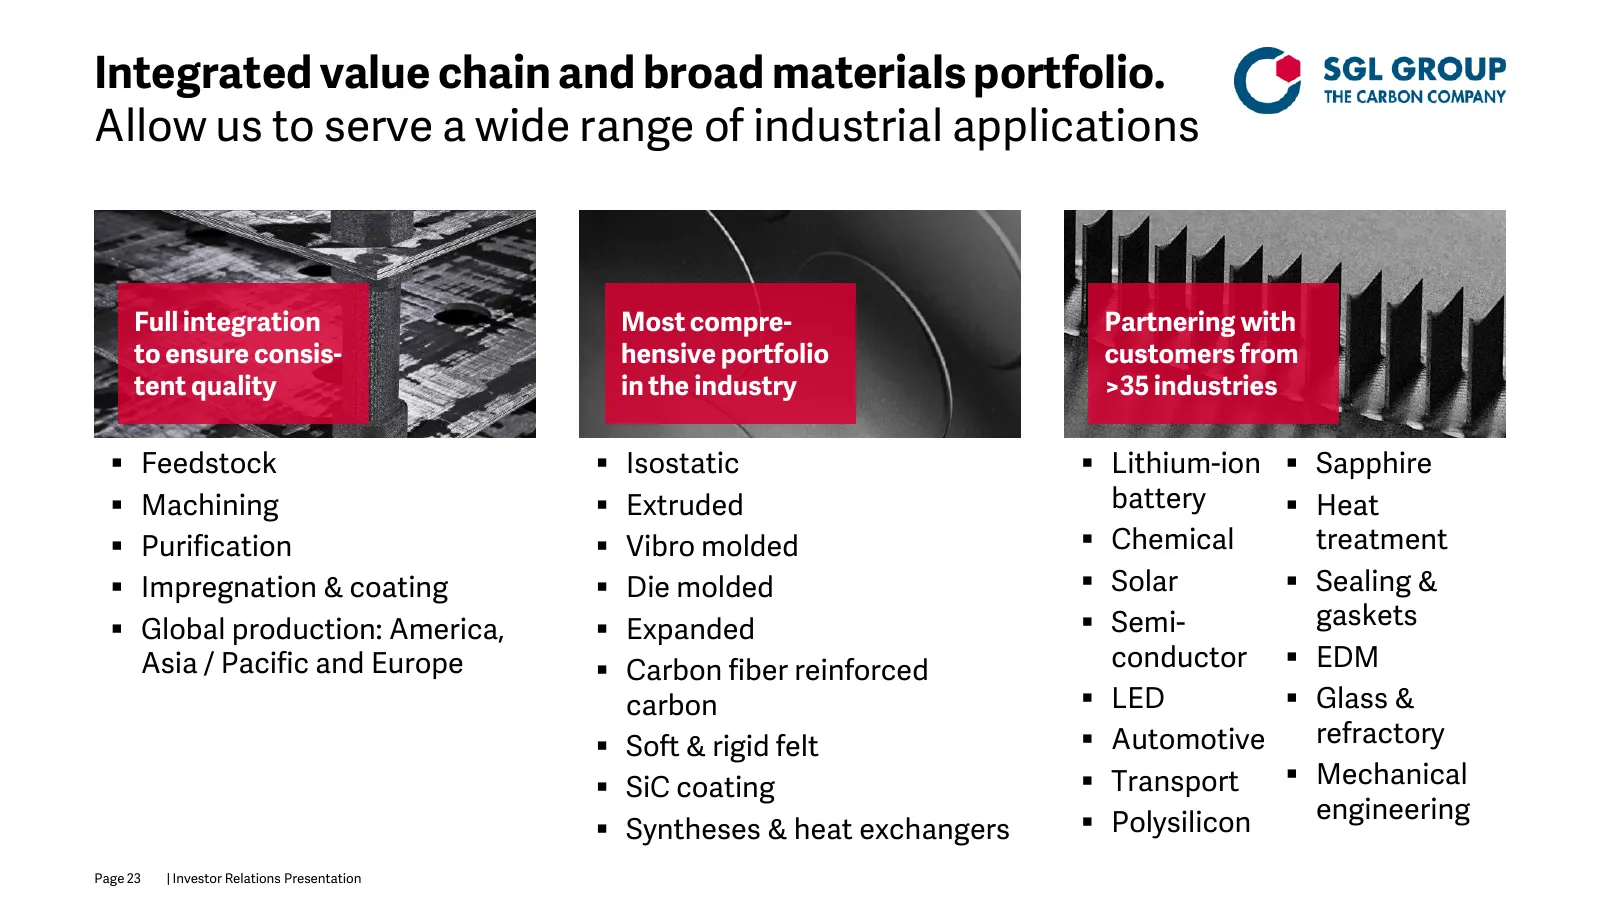
Integrated value chain and broad materials portfolio. Allow us to serve a wide range of industrial applications Full integration Most compre- Partnering with to ensure consis- hensive portfolio customers from tent quality in the industry >35 industries Feedstock Isostatic Lithium-ion Sapphir
Slide 24: Why graphite? Specialty graphite materials required where other materials fail
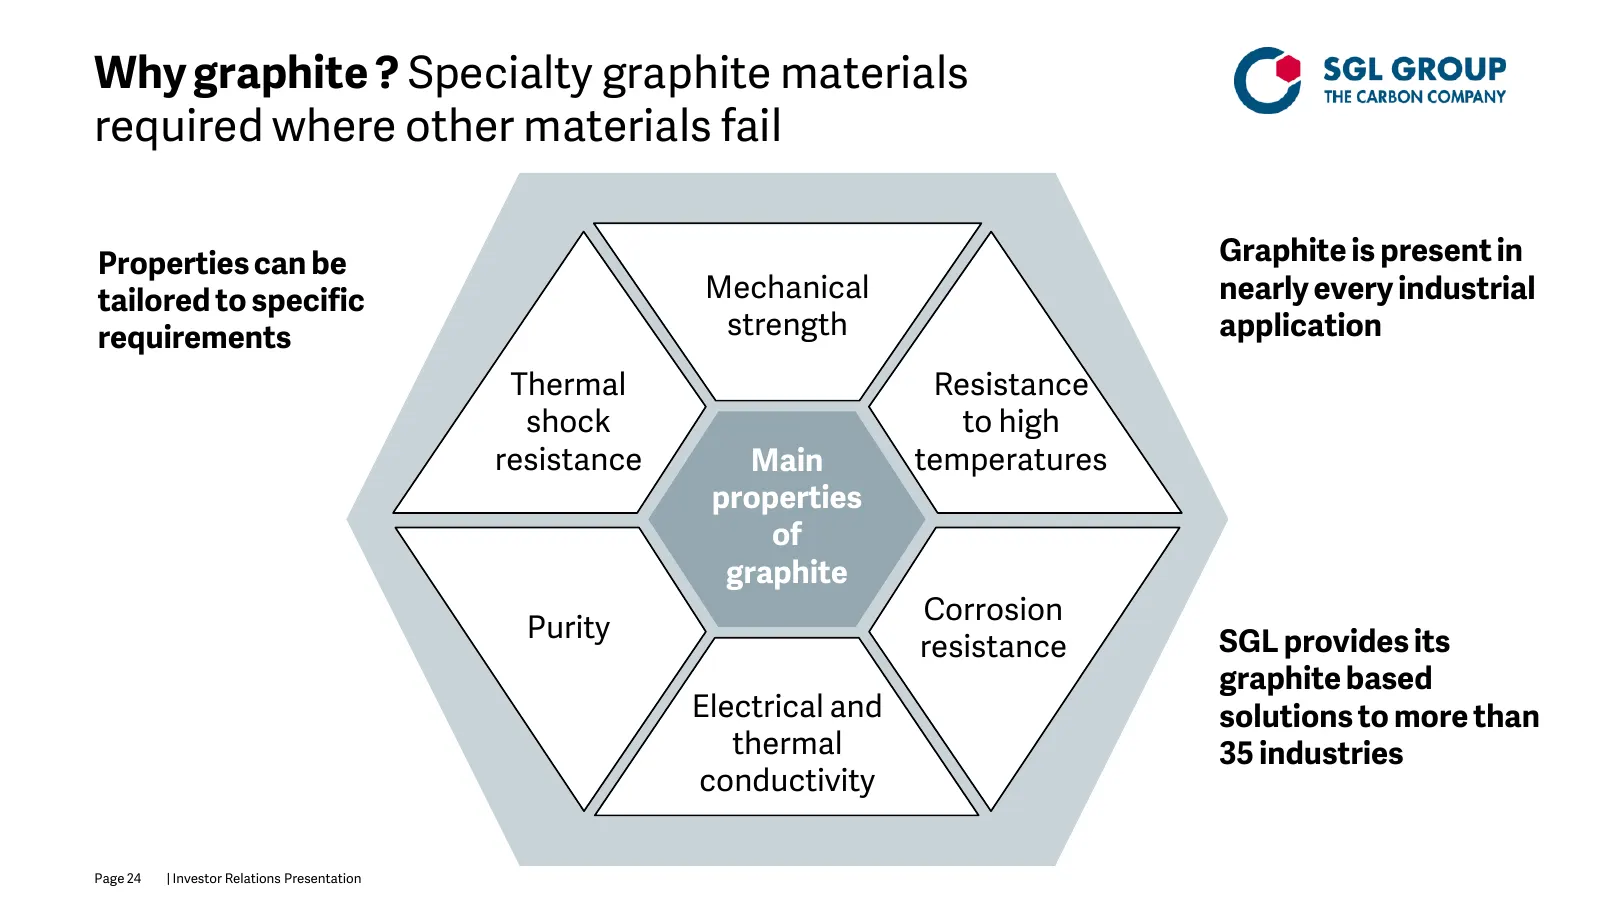
Why graphite ? Specialty graphite materials required where other materials fail Properties can be Graphite is present in tailored to specific Mechanical nearly every industrial requirements strength application Thermal Resistance shock to high resistance Main temperatures properties of graphite Corr
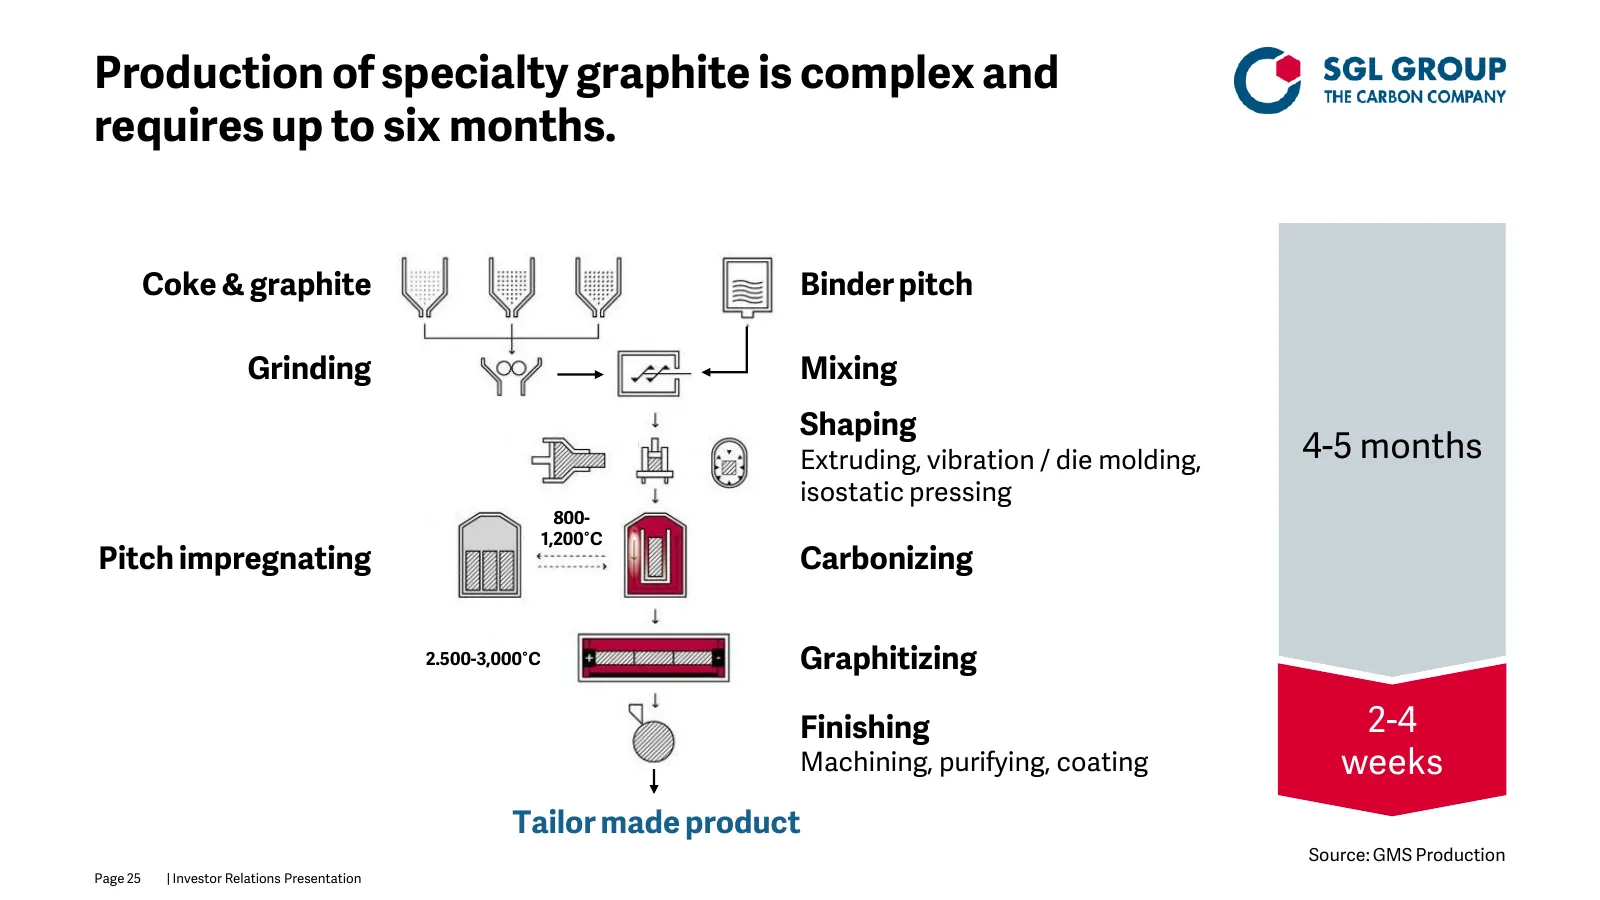
Slide 25: Production of specialty graphite is complex and requires up to six months
Production of specialty graphite is complex and requires up to six months. Coke & graphite Binder pitch Grinding Mixing Shaping Extruding, vibration / die molding, 4-5 months isostatic pressing 800- 1,200°C Pitch impregnating Carbonizing 2.500-3,000°C Graphitizing Finishing 2-4 Machining, purifying,
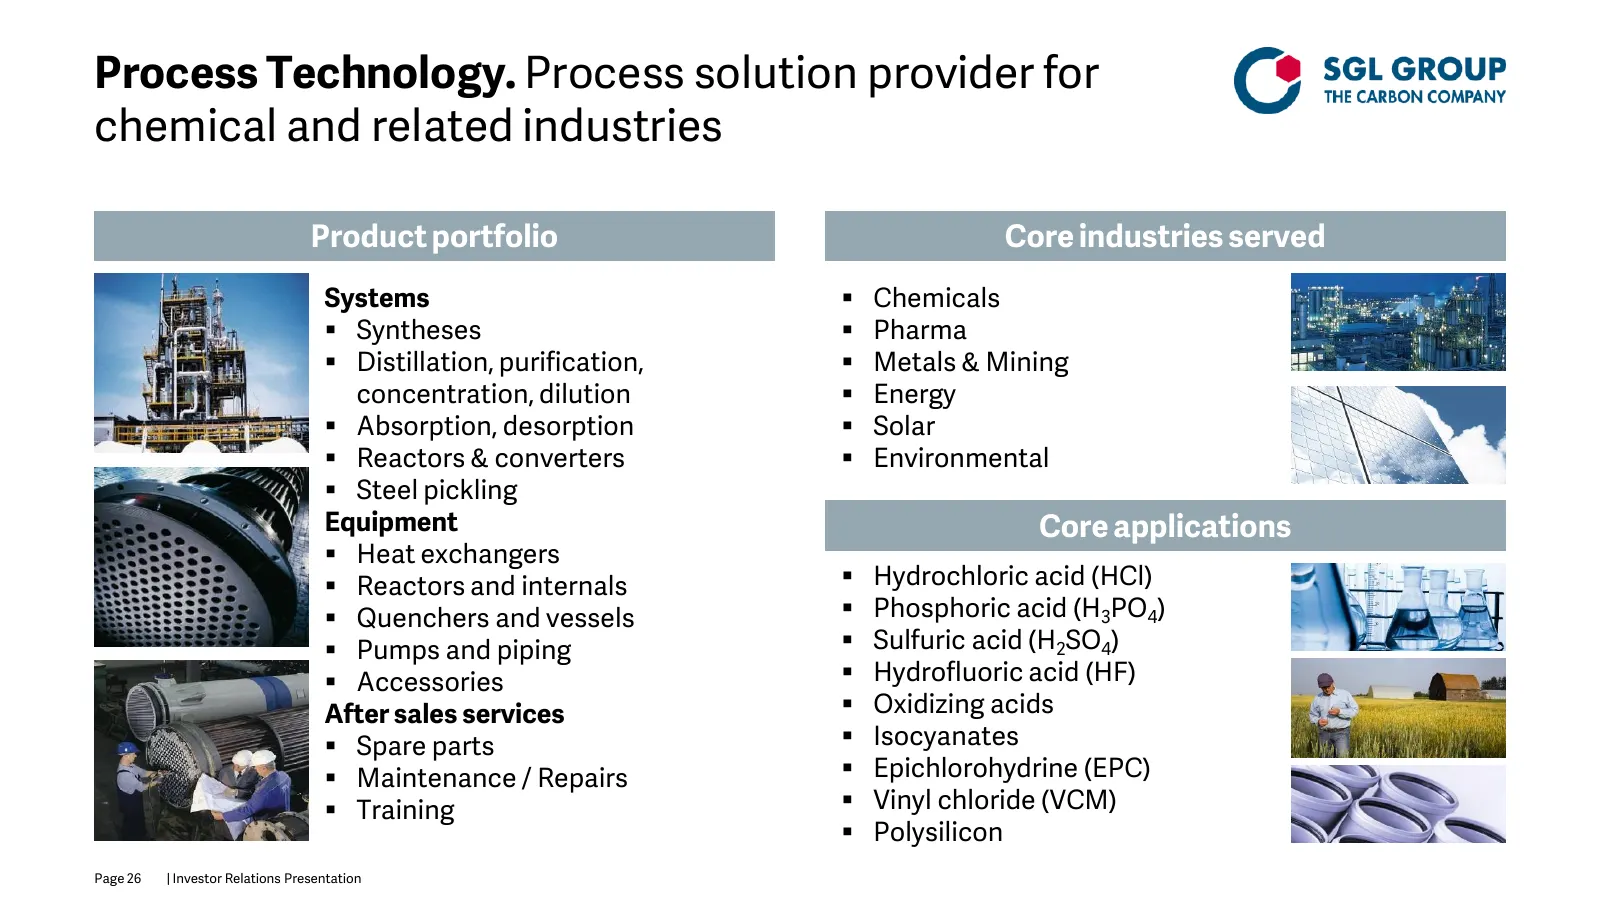
Slide 26: Process Technology. Process solution provider for chemical and related industries
Process Technology. Process solution provider for chemical and related industries Product portfolio Core industries served Systems Chemicals Syntheses Pharma Distillation, purification, Metals & Mining concentration, dilution Energy Absorption, desorption Solar Reactors & converter
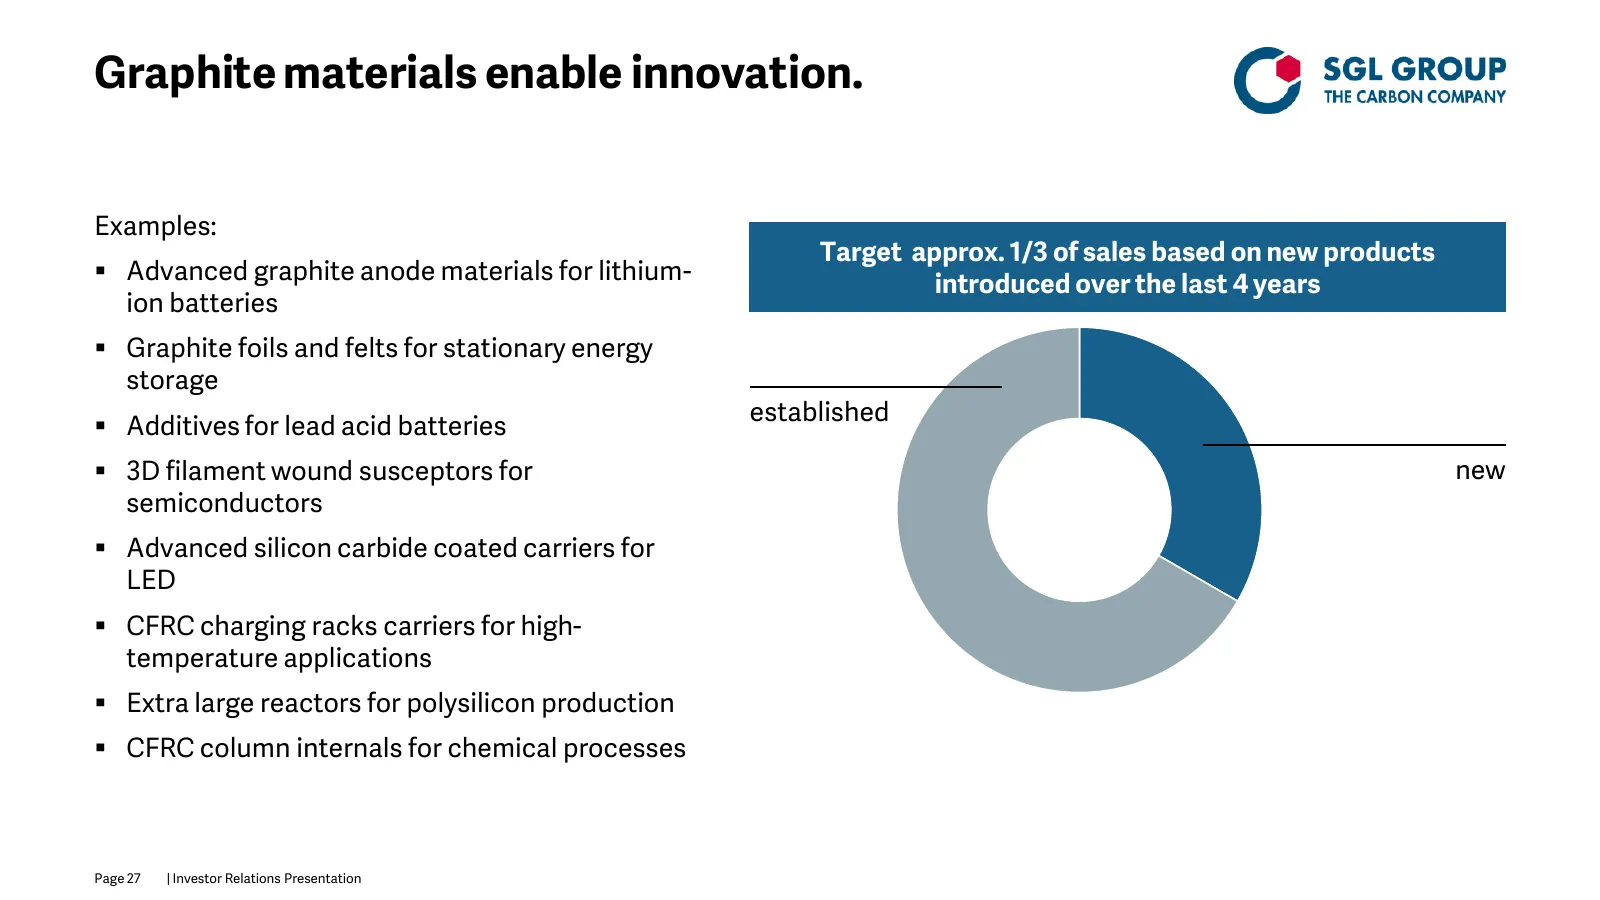
Slide 27: Graphite materials enable innovation
Graphite materials enable innovation. Examples: Target approx. 1/3 of sales based on new products Advanced graphite anode materials for lithium- introduced over the last 4 years ion batteries Graphite foils and felts for stationary energy storage established Additives for lead acid batteries
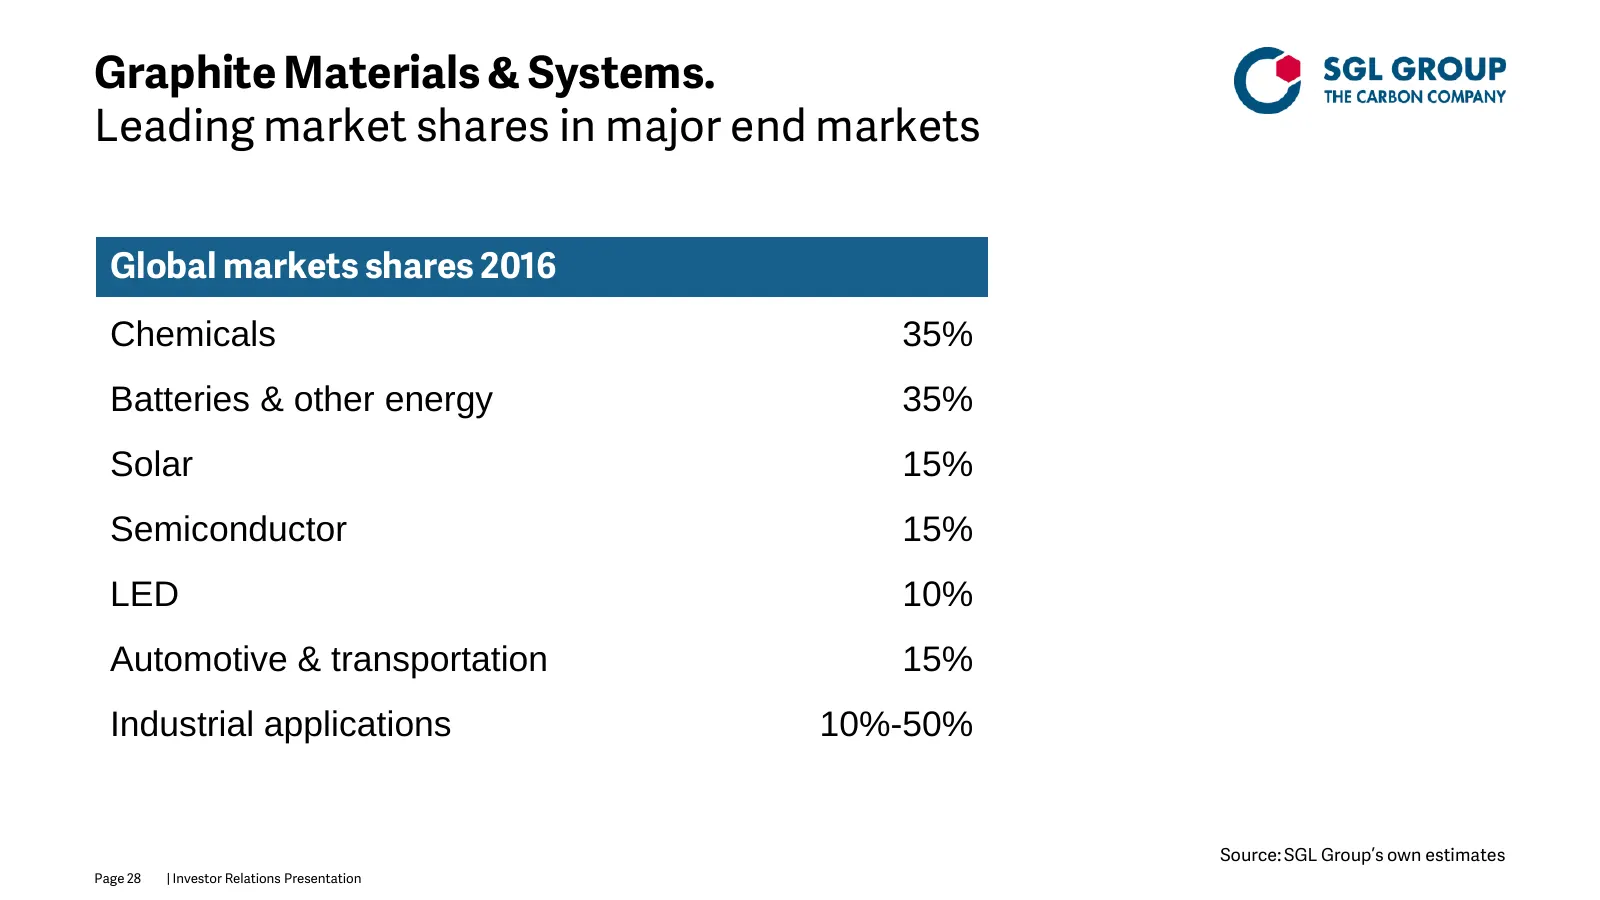
Slide 28: Leading market shares in major end markets
Graphite Materials & Systems. Leading market shares in major end markets Global markets shares 2016 Chemicals 35% Batteries & other energy 35% Solar 15% Semiconductor 15% LED 10% Automotive & transportation 15% Industrial applications 10%-50% Source: SGL Group’s own estimates Page 28 | Investor Rela
Slide 29: SGL Group Innovation
SGL Group Innovation Page 29 | Investor Relations Presentation
Slide 30: SGL Group Innovation. Foundation for profitable growth
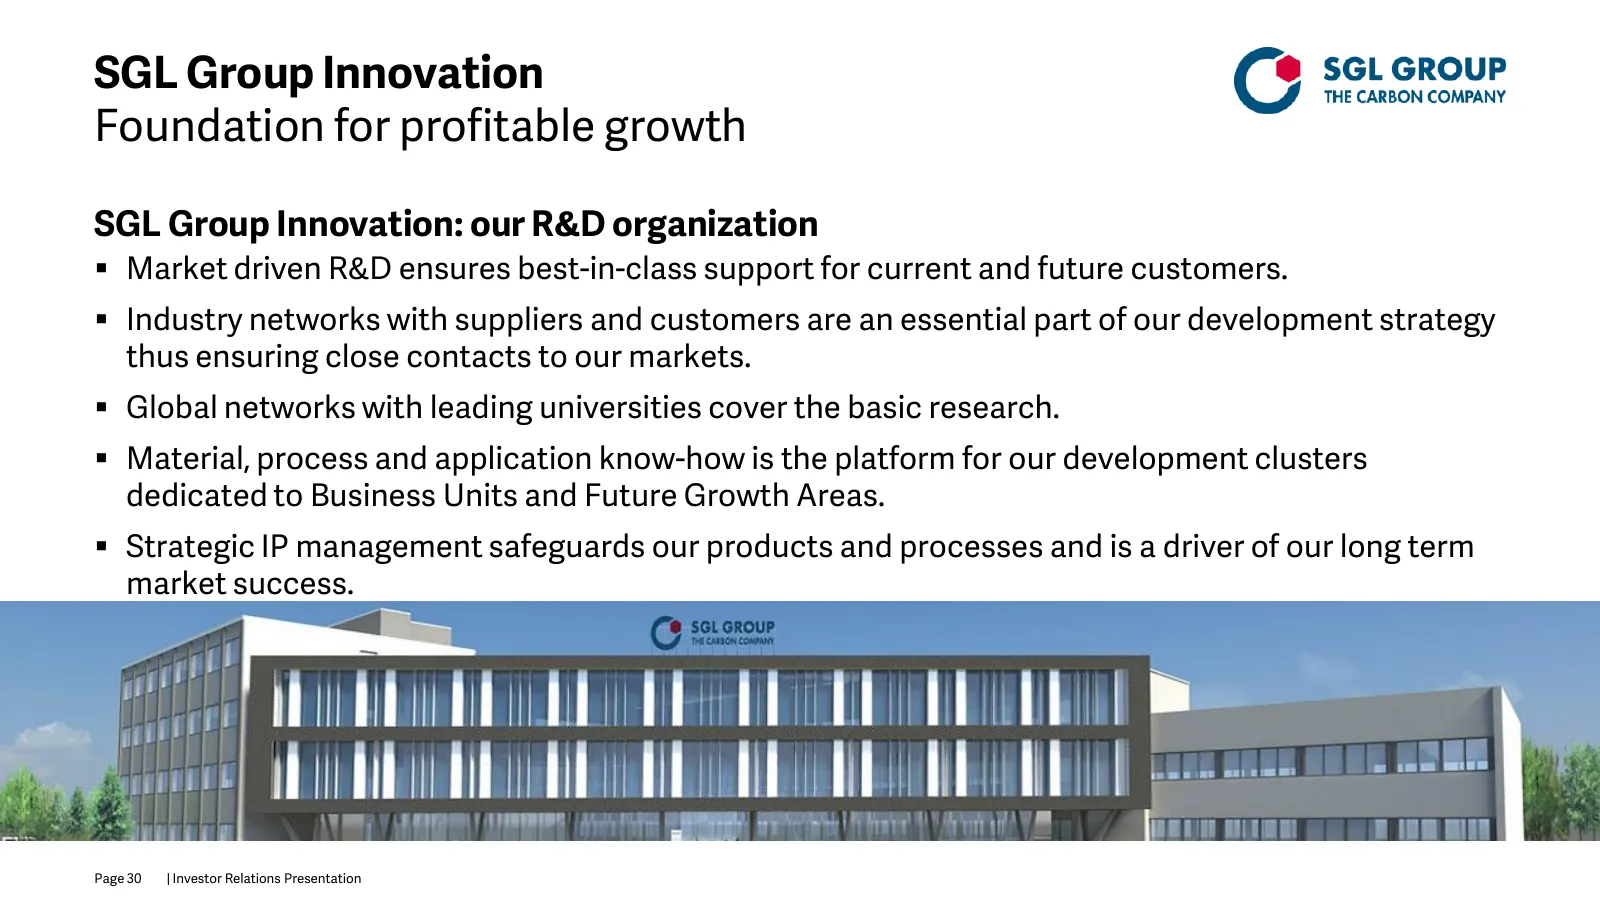
SGL Group Innovation Foundation for profitable growth SGL Group Innovation: our R&D organization Market driven R&D ensures best-in-class support for current and future customers. Industry networks with suppliers and customers are an essential part of our development strategy thus ensuring close
Slide 31: SGL Group Innovation. Activity areas in 2016
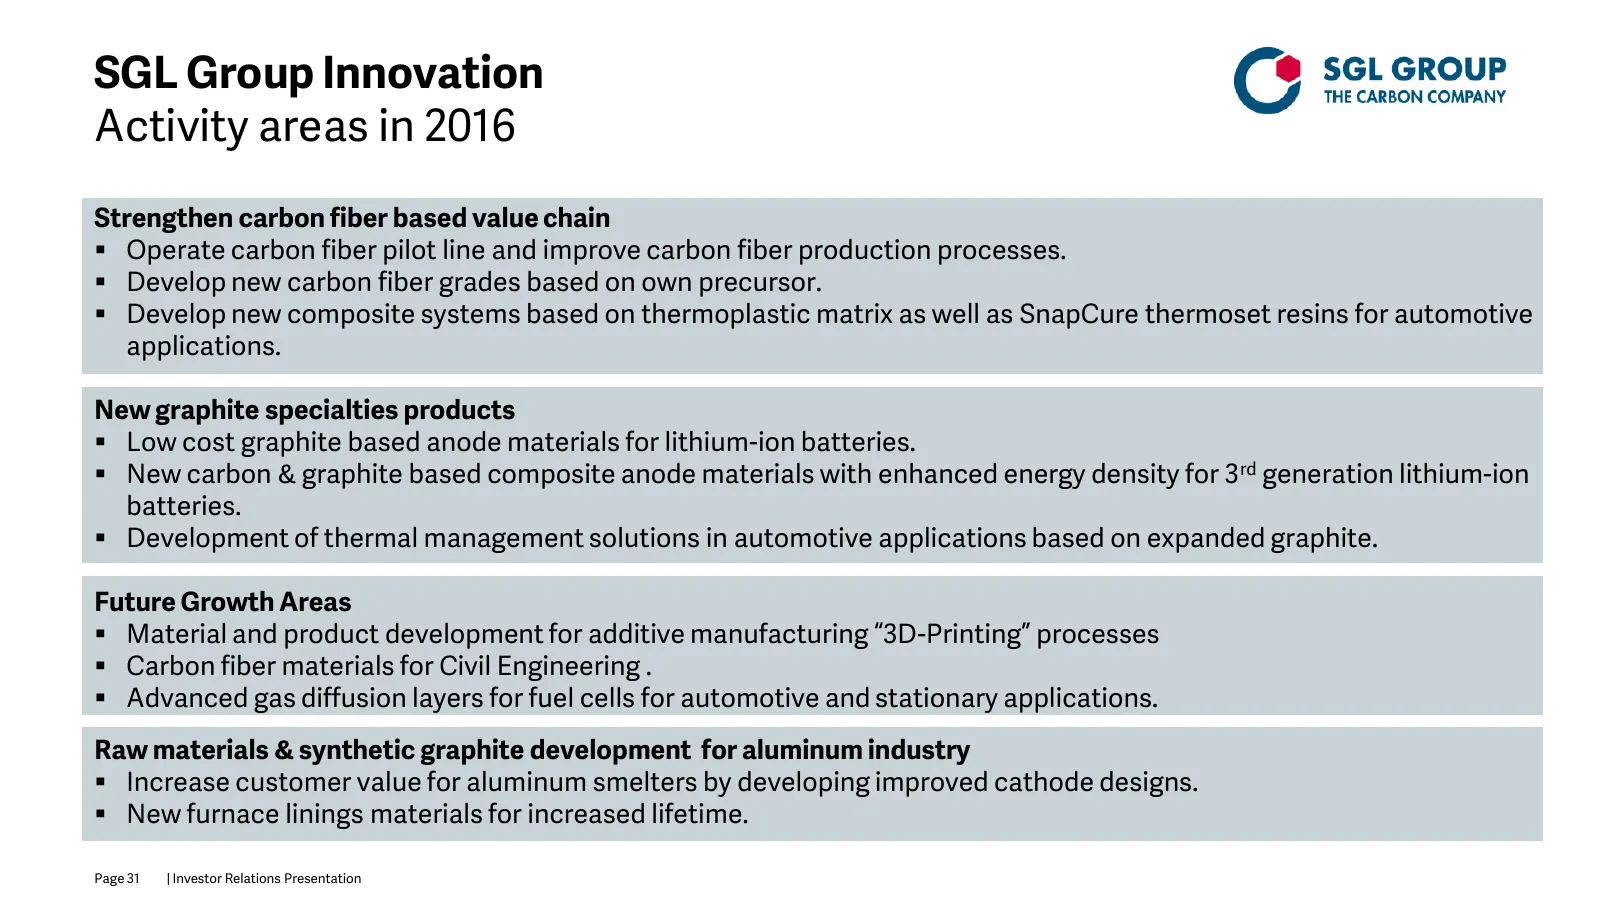
SGL Group Innovation Activity areas in 2016 Strengthen carbon fiber based value chain Operate carbon fiber pilot line and improve carbon fiber production processes. Develop new carbon fiber grades based on own precursor. Develop new composite systems based on thermoplastic matrix as well as Sn
Slide 32: Transformation of SGL Group
Transformation of SGL Group Page 32 | Investor Relations Presentation
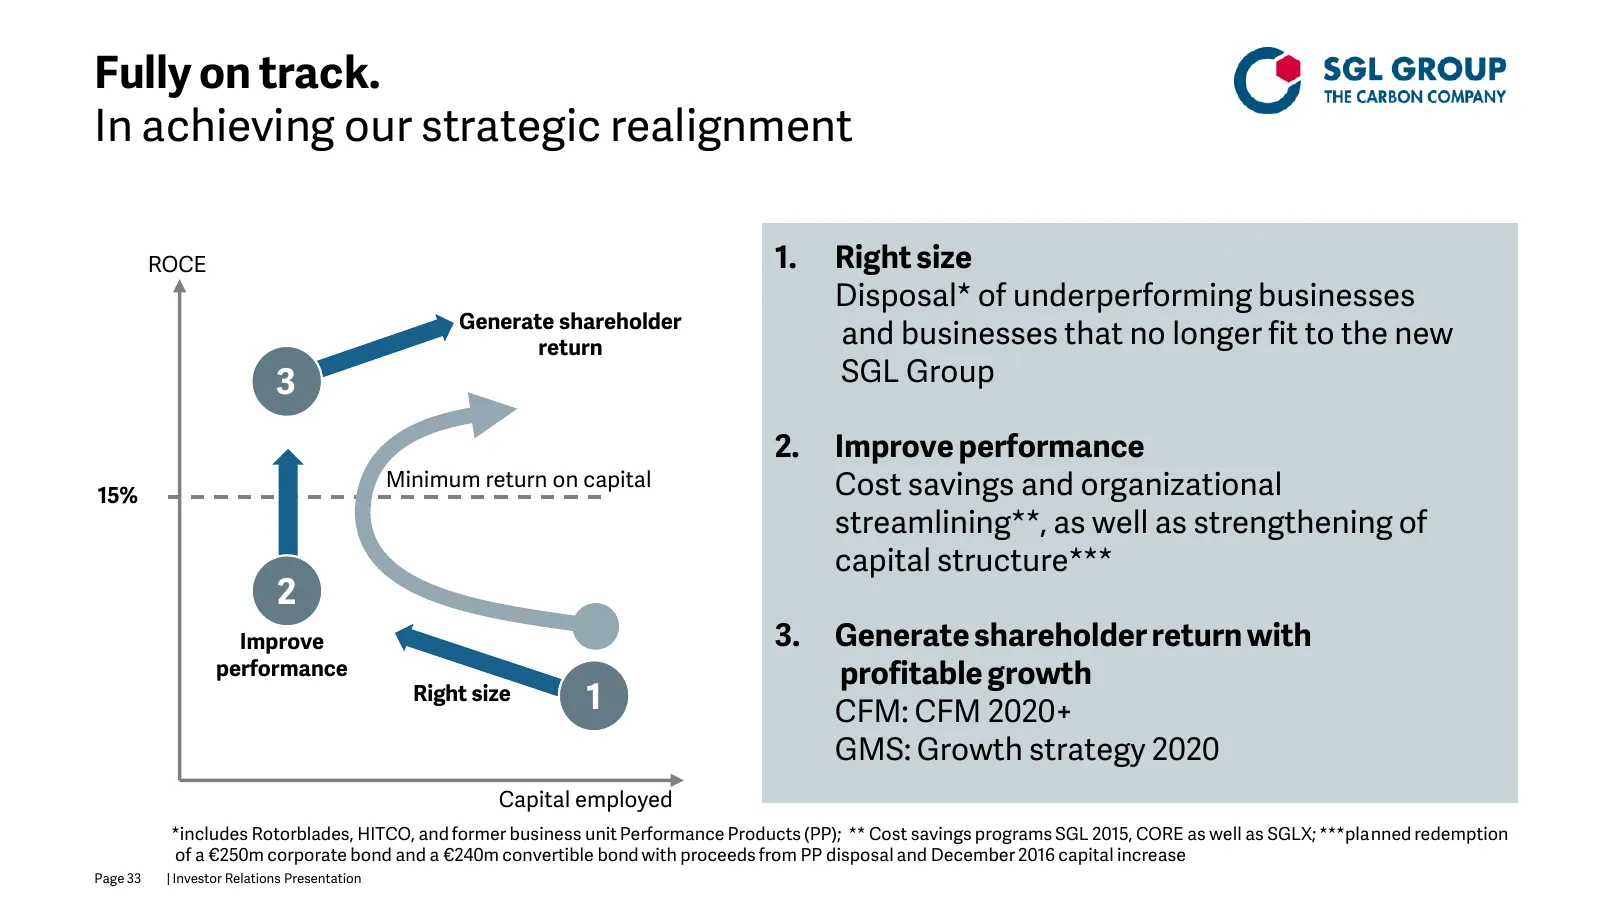
Slide 33: Fully on track. In achieving our strategic realignment
Fully on track. In achieving our strategic realignment ROCE 1. Right size Disposal* of underperforming businesses Generate shareholder return and businesses that no longer fit to the new 3 SGL Group 2. Improve performance 15% Minimum return on capital Cost savings and organizational streamlining**,
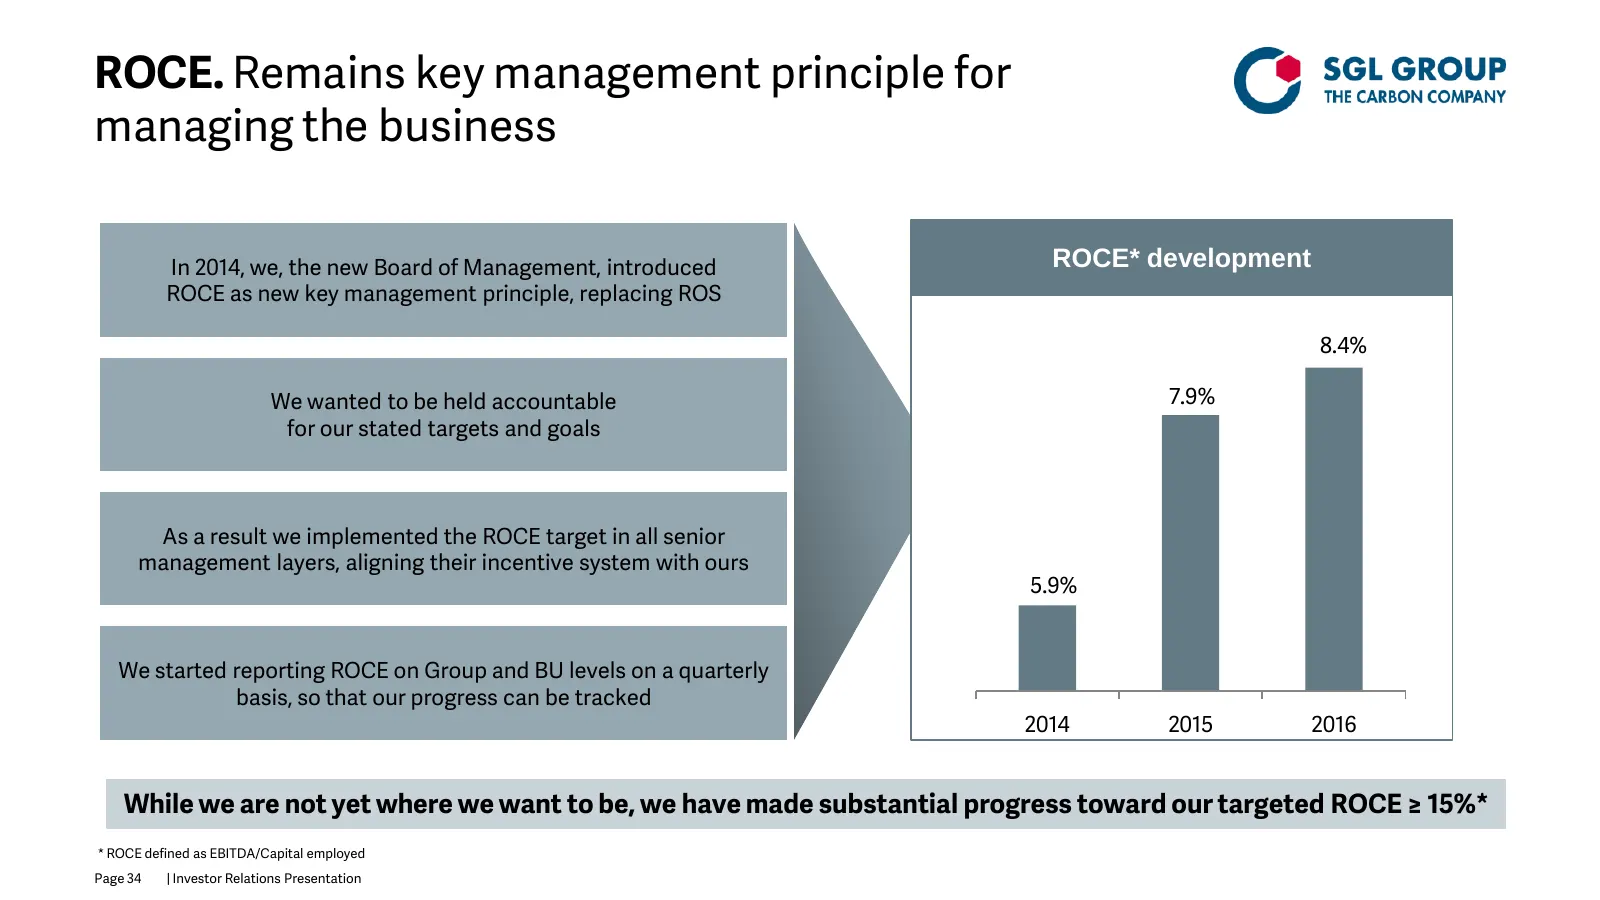
Slide 34: ROCE. Remains key management principle for managing the business
ROCE. Remains key management principle for managing the business In 2014, we, the new Board of Management, introduced ROCE* development ROCE as new key management principle, replacing ROS 8.4% We wanted to be held accountable 7.9% for our stated targets and goals As a result we implemented the ROCE
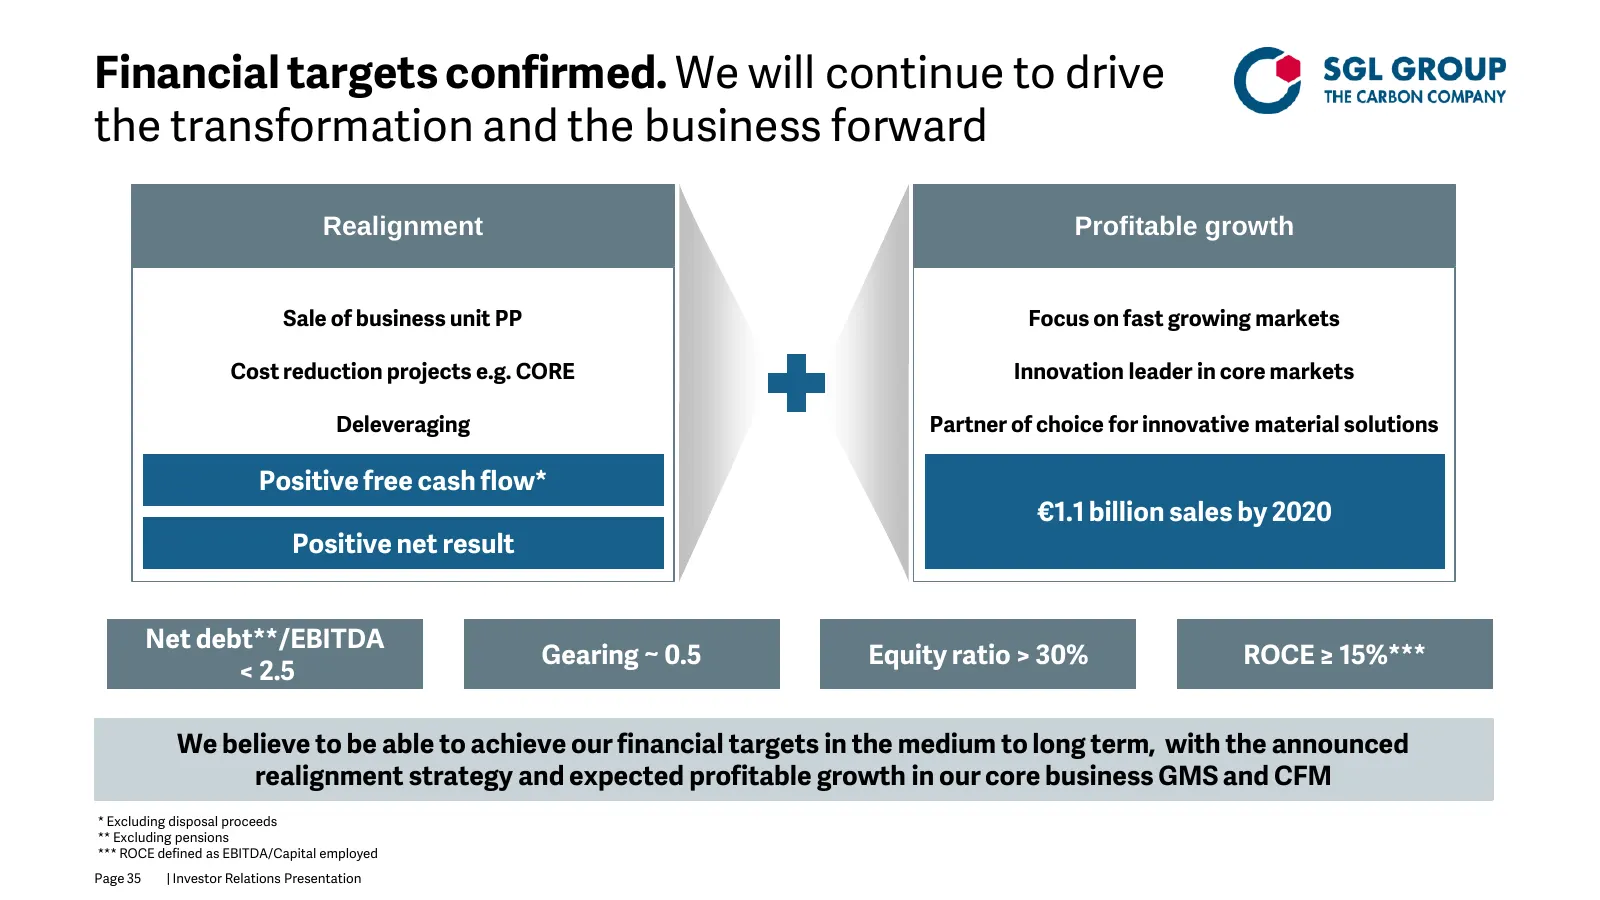
Slide 35: Financial targets confirmed
Financial targets confirmed. We will continue to drive the transformation and the business forward Realignment Profitable growth Sale of business unit PP Focus on fast growing markets Cost reduction projects e.g. CORE Innovation leader in core markets Deleveraging Partner of choice for innovative ma
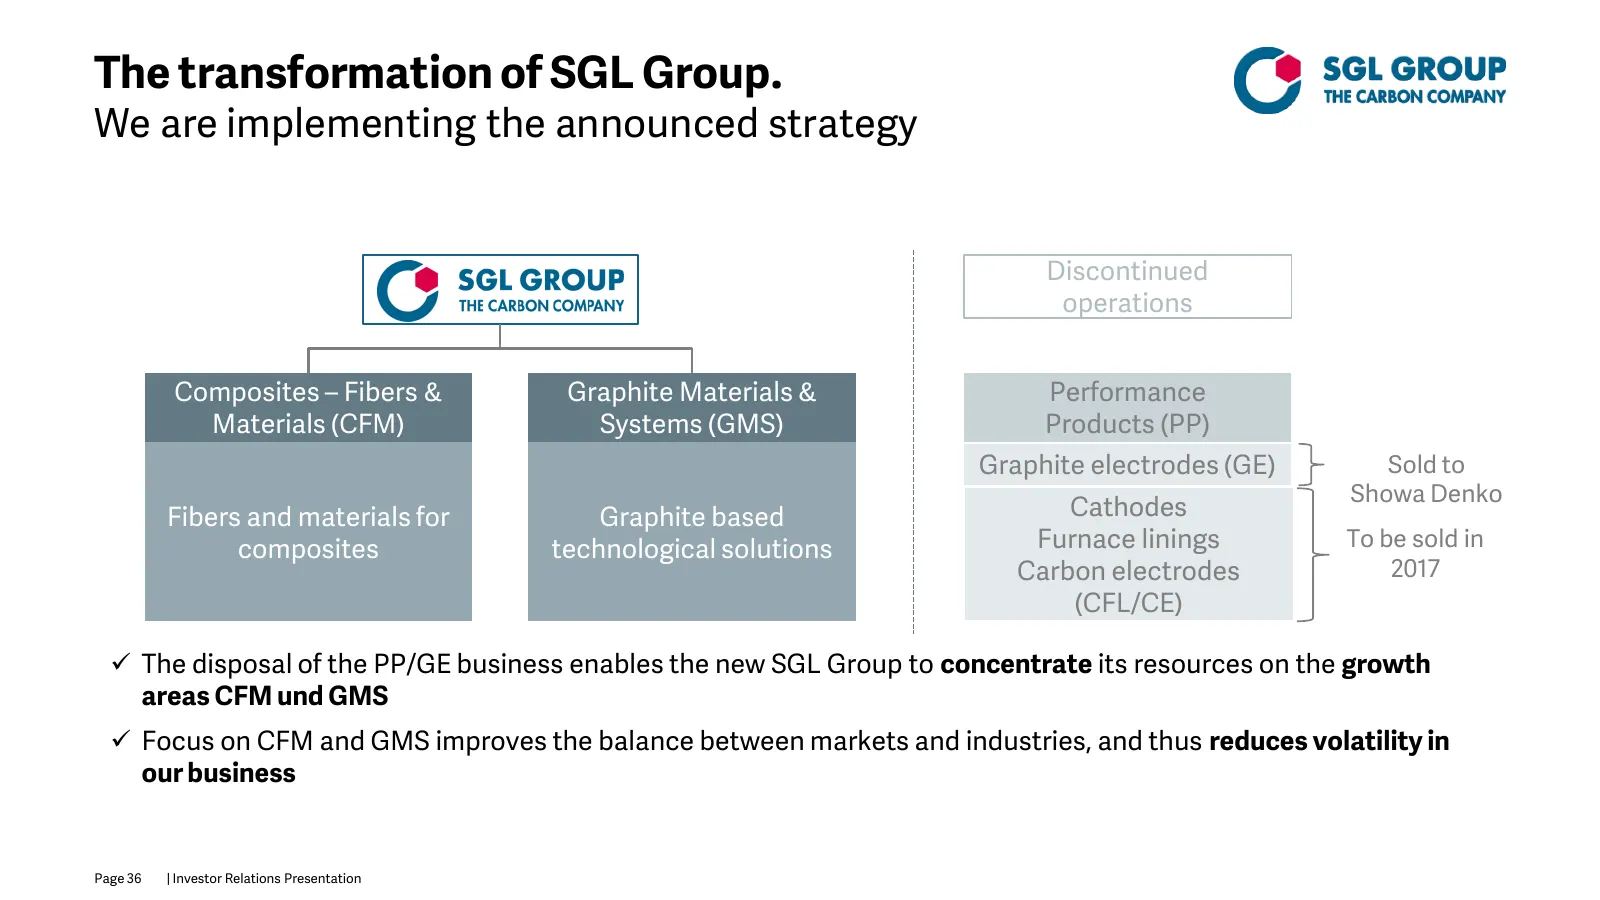
Slide 36: The transformation of SGL Group. We are implementing the announced strategy
The transformation of SGL Group. We are implementing the announced strategy Discontinued operations Composites – Fibers & Graphite Materials & Performance Materials (CFM) Systems (GMS) Products (PP) Graphite electrodes (GE) Sold to Showa Denko Fibers and materials for Graphite based Cathodes composi
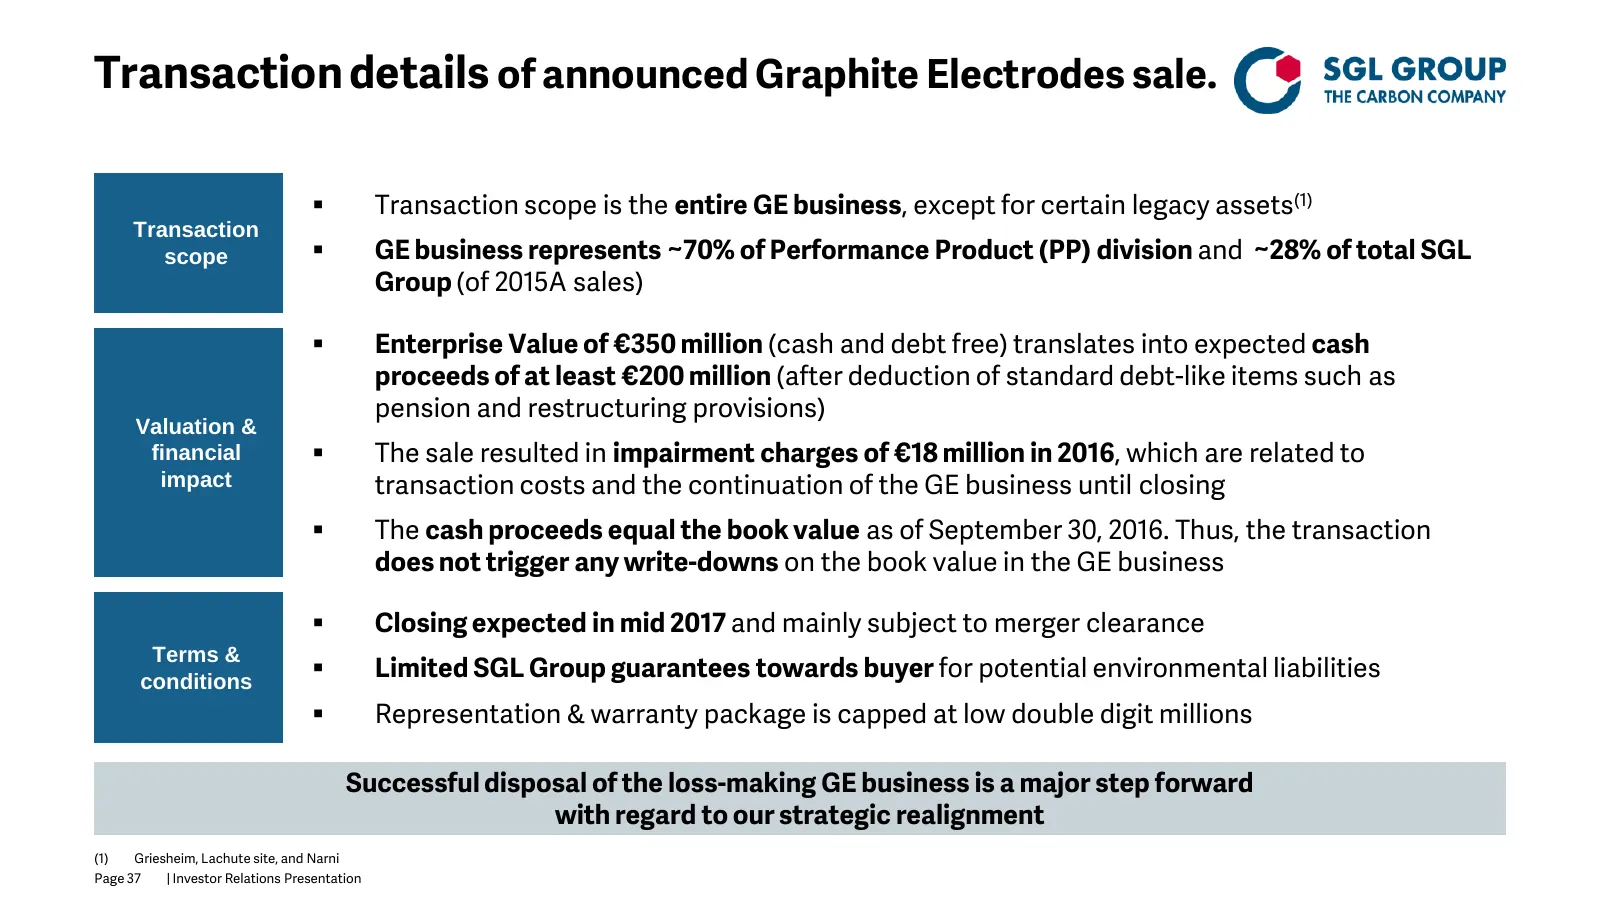
Slide 37: Transaction details of announced Graphite Electrodes sale
Transaction details of announced Graphite Electrodes sale. Transaction scope is the entire GE business, except for certain legacy assets(1) Transaction scope GE business represents ~70% of Performance Product (PP) division and ~28% of total SGL Group (of 2015A sales) Enterprise Value of €350 m
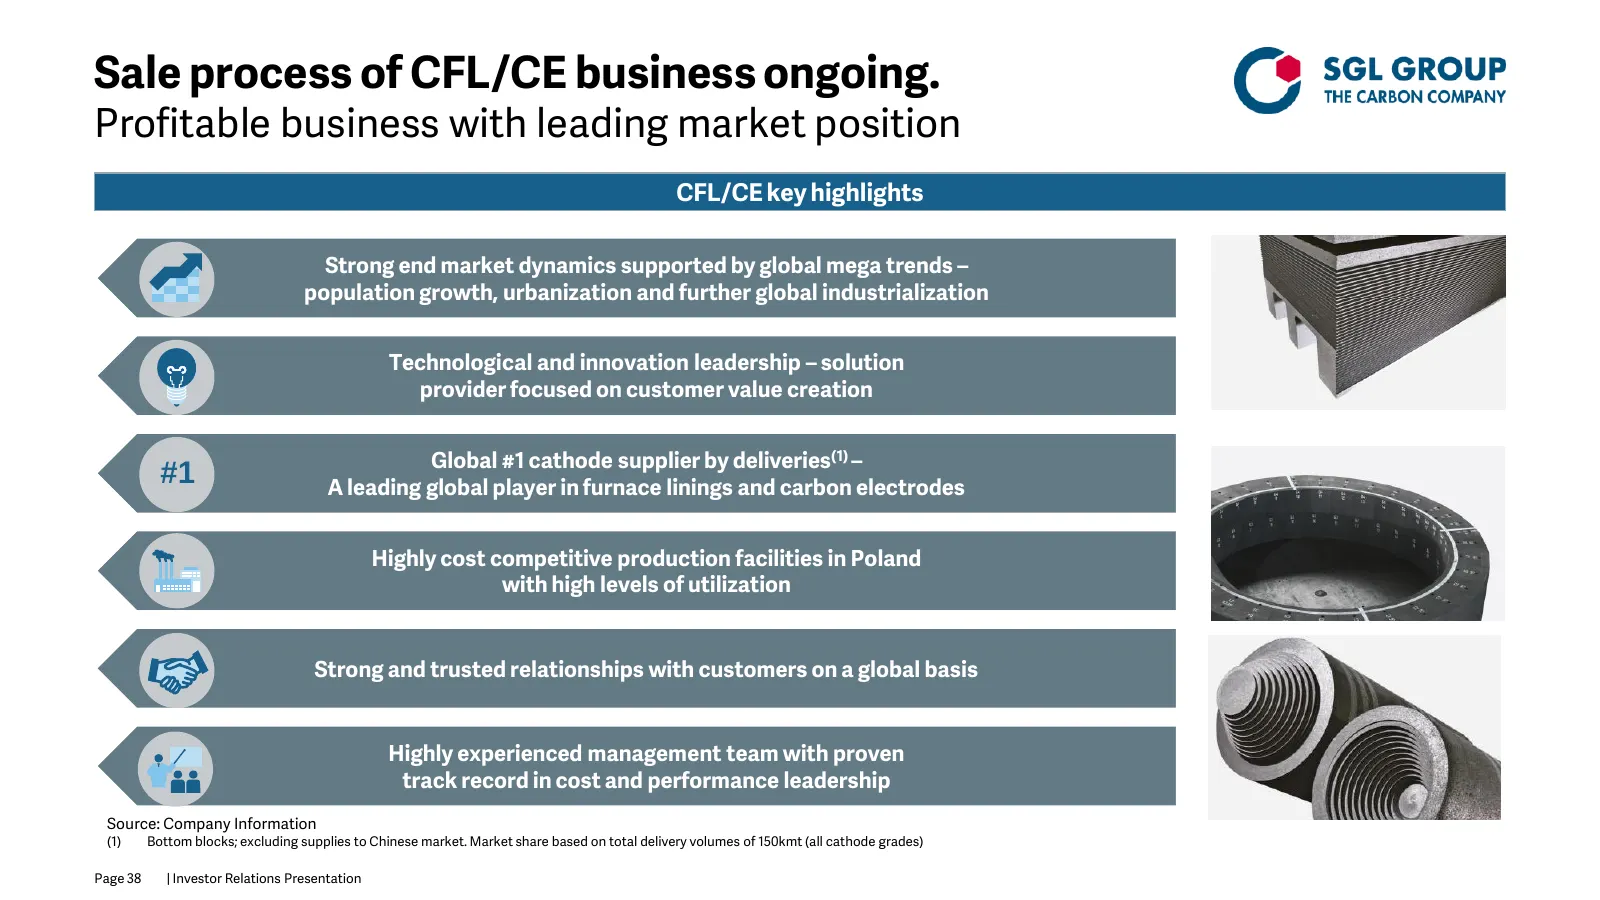
Slide 38: Sale process of CFL/CE business ongoing
Sale process of CFL/CE business ongoing. Profitable business with leading market position CFL/CE key highlights Strong end market dynamics supported by global mega trends – population growth, urbanization and further global industrialization Technological and innovation leadership – solution provide
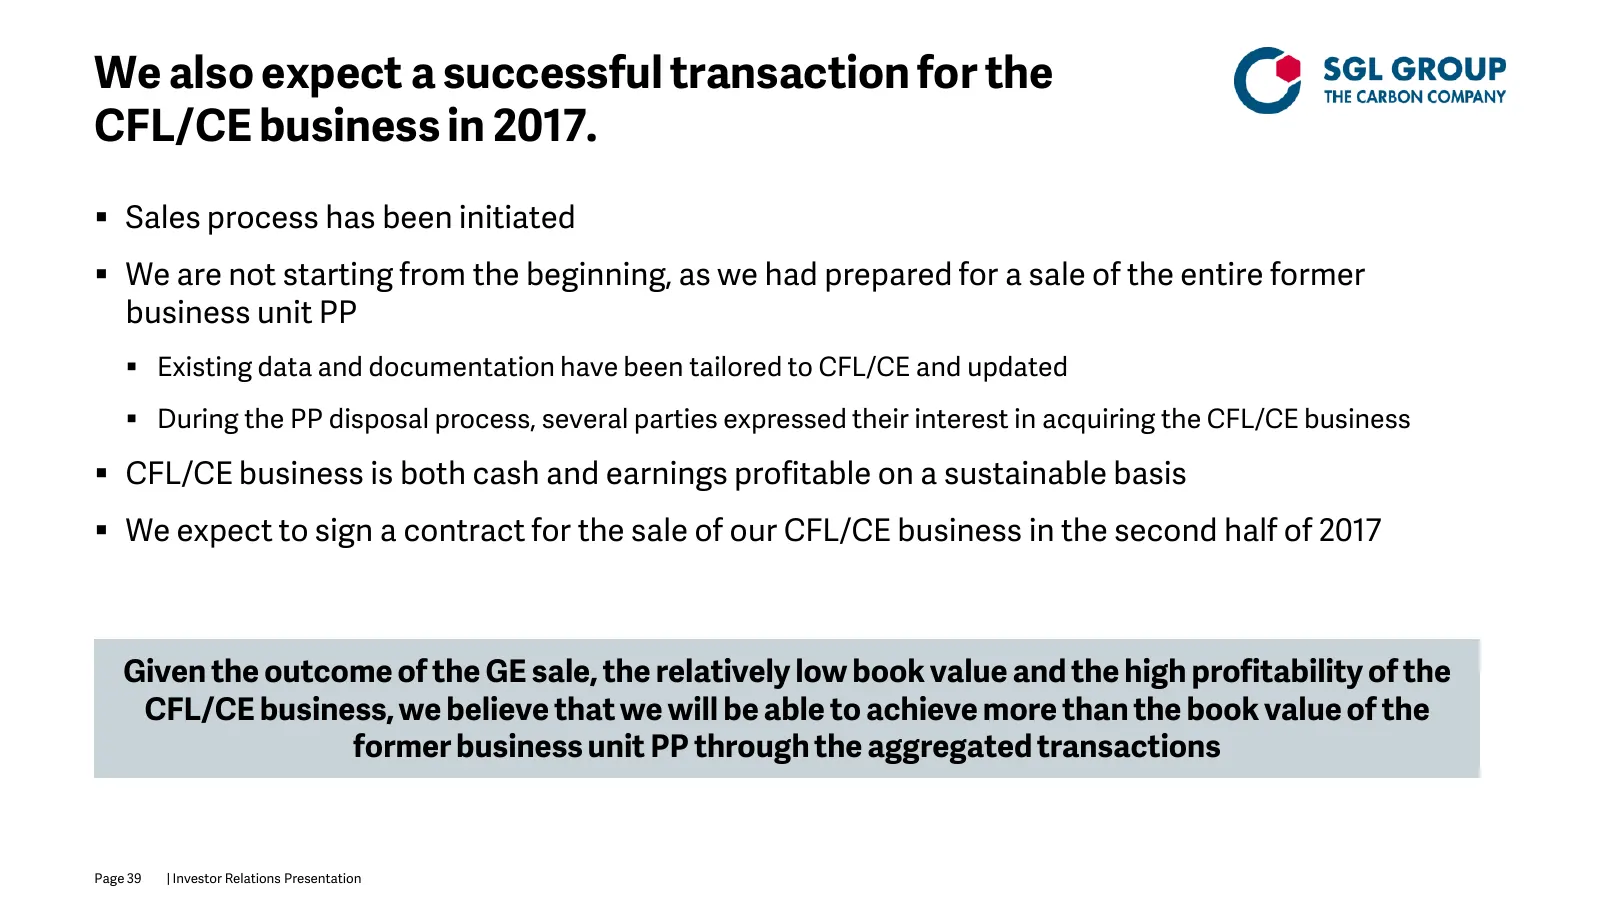
Slide 39: We also expect a successful transaction for the CFL/CE business in 2017
We also expect a successful transaction for the CFL/CE business in 2017. Sales process has been initiated We are not starting from the beginning, as we had prepared for a sale of the entire former business unit PP Existing data and documentation have been tailored to CFL/CE and updated Durin
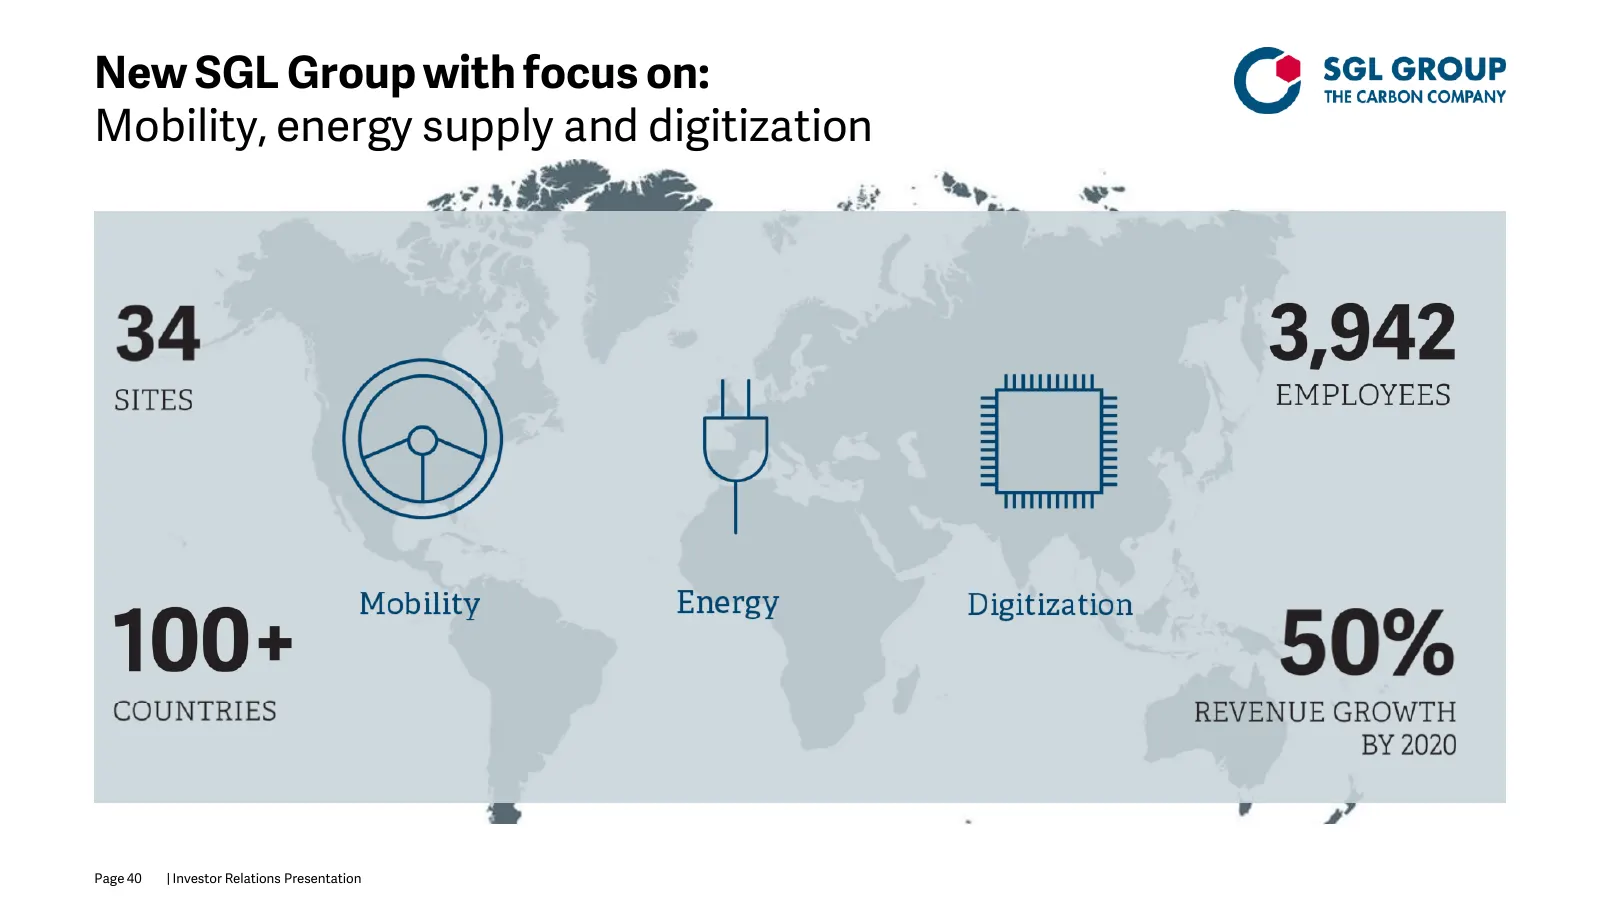
Slide 40: New SGL Group with focus on: Mobility, energy supply and digitization
New SGL Group with focus on: Mobility, energy supply and digitization Page 40 | Investor Relations Presentation
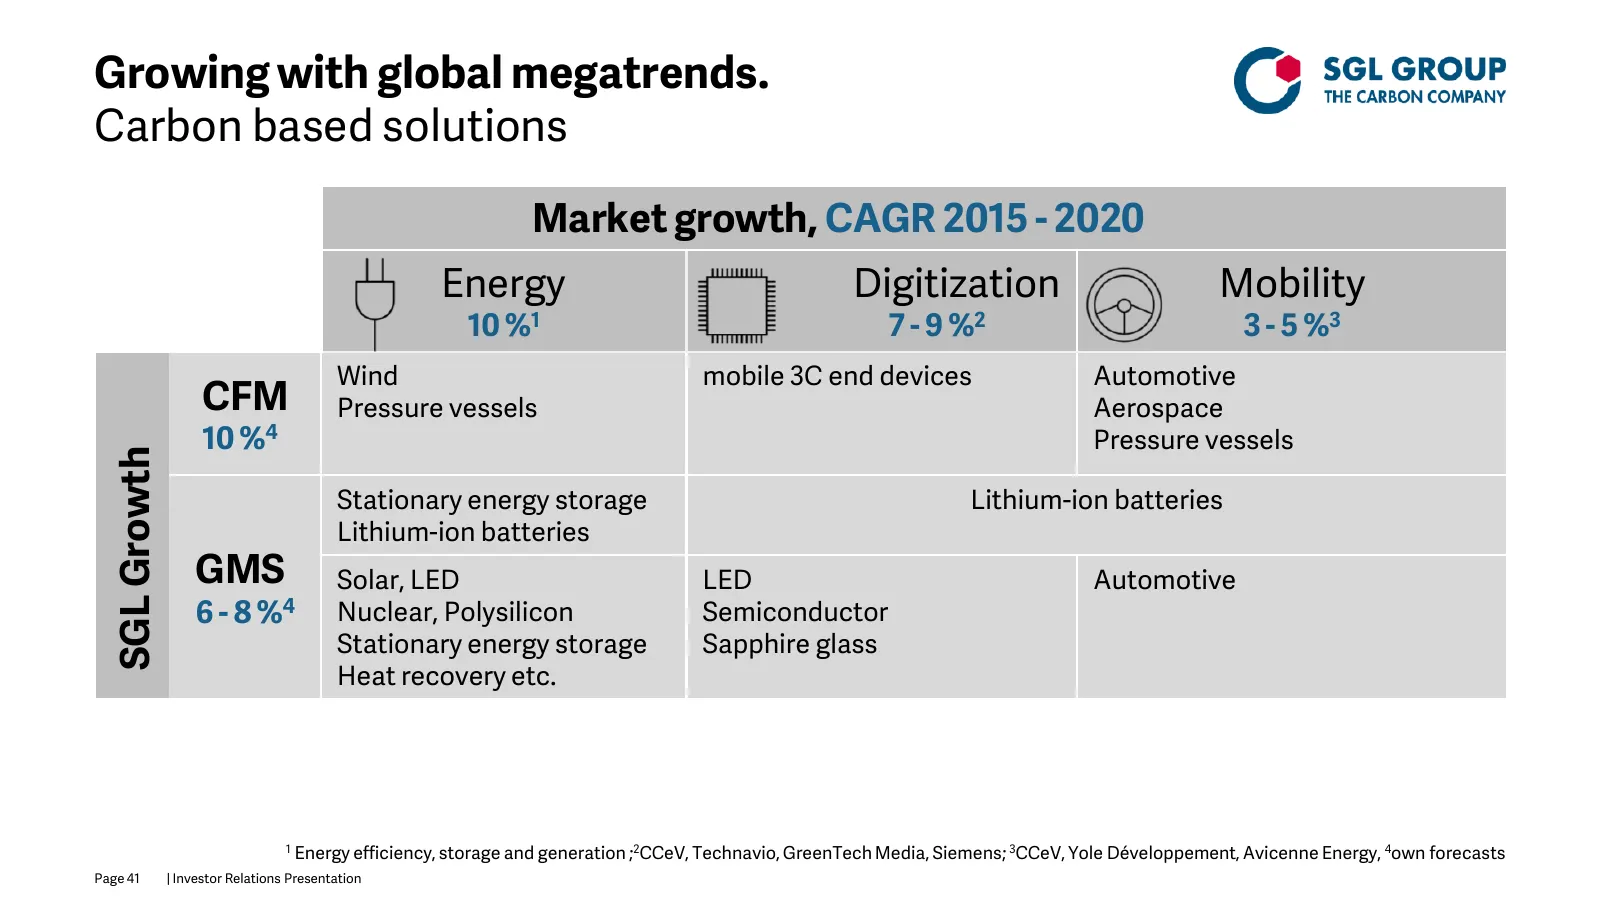
Slide 41: Growing with global megatrends
Growing with global megatrends. Carbon based solutions Market growth, CAGR 2015 - 2020 Energy Digitization Mobility 10 %1 7 - 9 %2 3 - 5 %3 Wind mobile 3C end devices Automotive CFM Pressure vessels Aerospace 10 %4 Pressure vessels SGL Growth Stationary energy storage Lithium-ion batteries Lithium-i
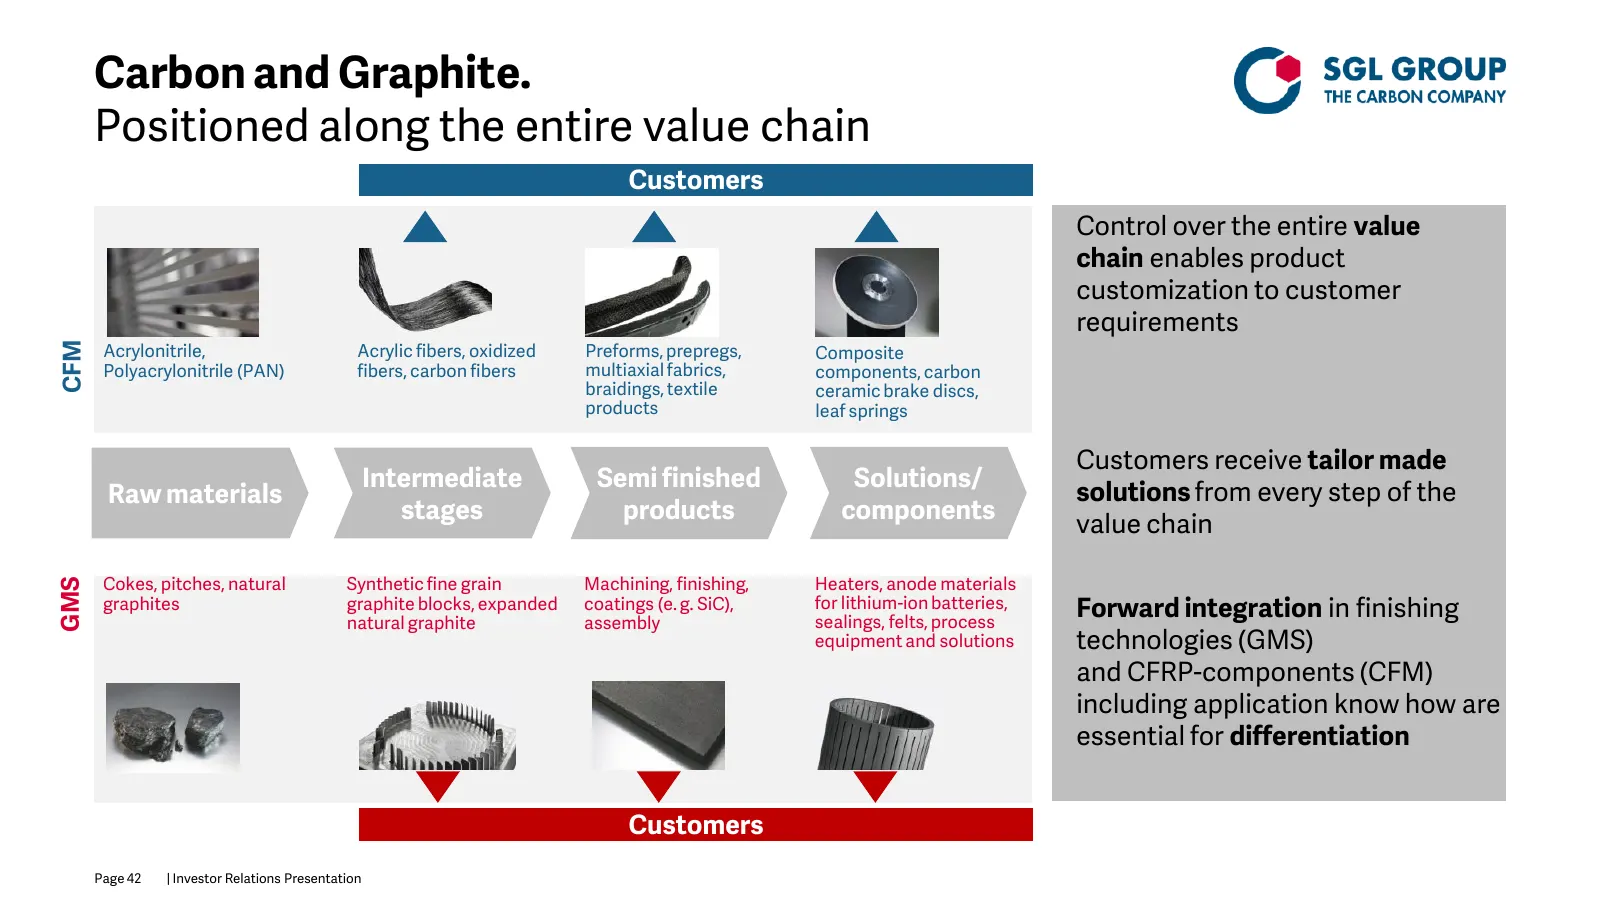
Slide 42: Carbon and Graphite. Positioned along the entire value chain
Carbon and Graphite. Positioned along the entire value chain Customers Control over the entire value chain enables product customization to customer requirements Acrylonitrile, Acrylic fibers, oxidized Preforms, prepregs, Composite CFM Polyacrylonitrile (PAN) fibers, carbon fibers multiaxial fabrics
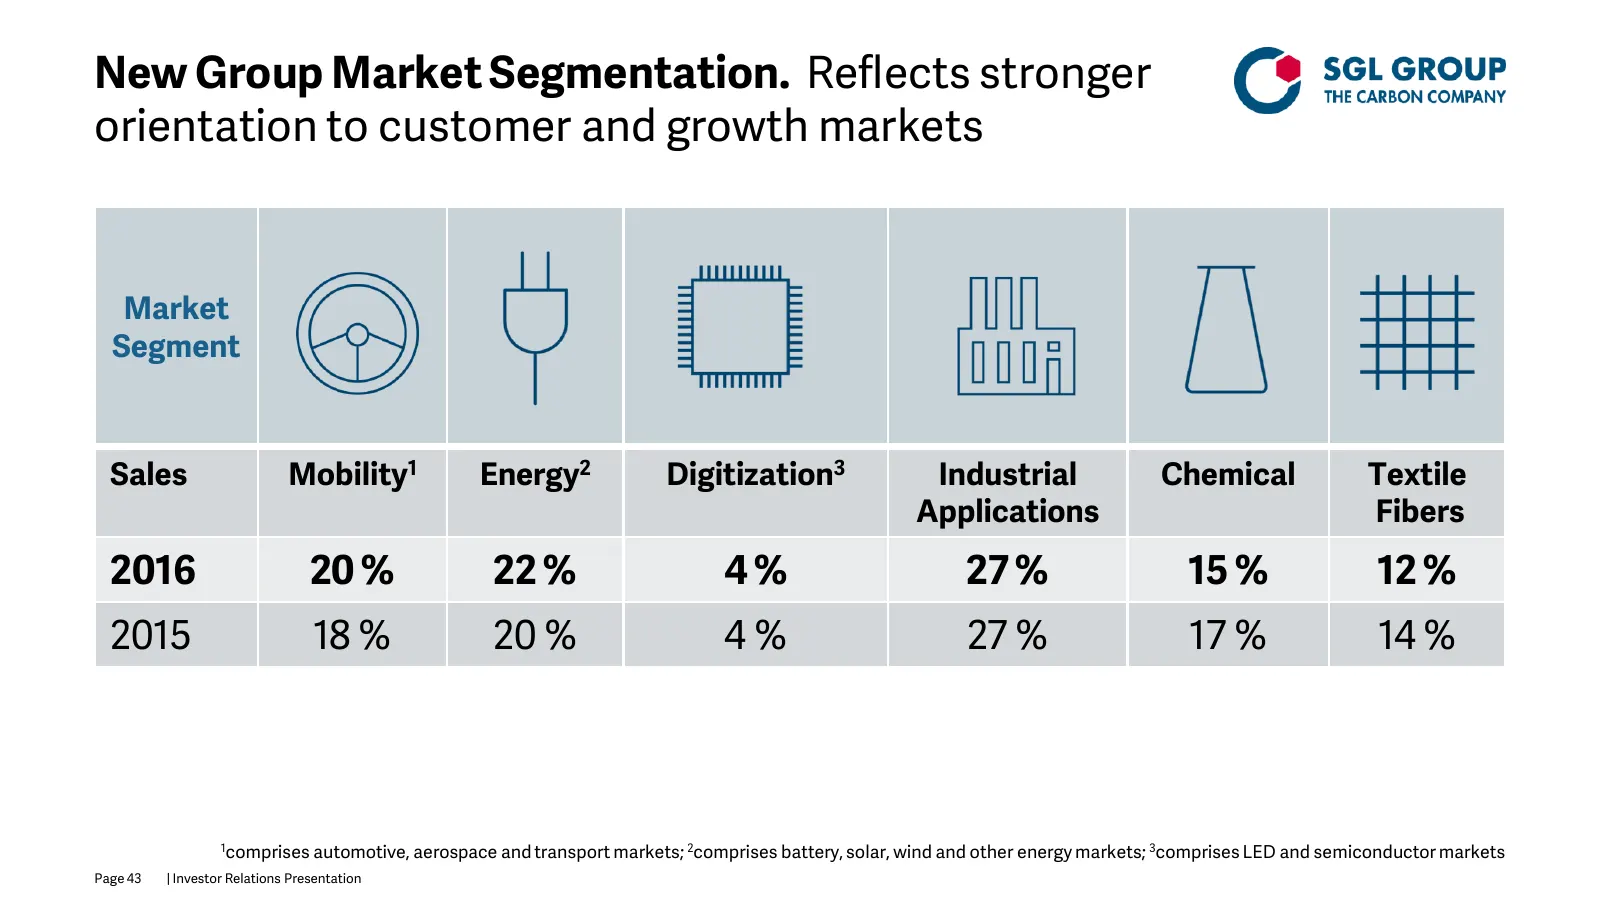
Slide 43: New Group Market Segmentation
New Group Market Segmentation. Reflects stronger orientation to customer and growth markets Market Segment Sales Mobility1 Energy2 Digitization3 Industrial Chemical Textile Applications Fibers 2016 20 % 22 % 4% 27 % 15 % 12 % 2015 18 % 20 % 4% 27 % 17 % 14 % 1comprises automotive, aerospace and tran
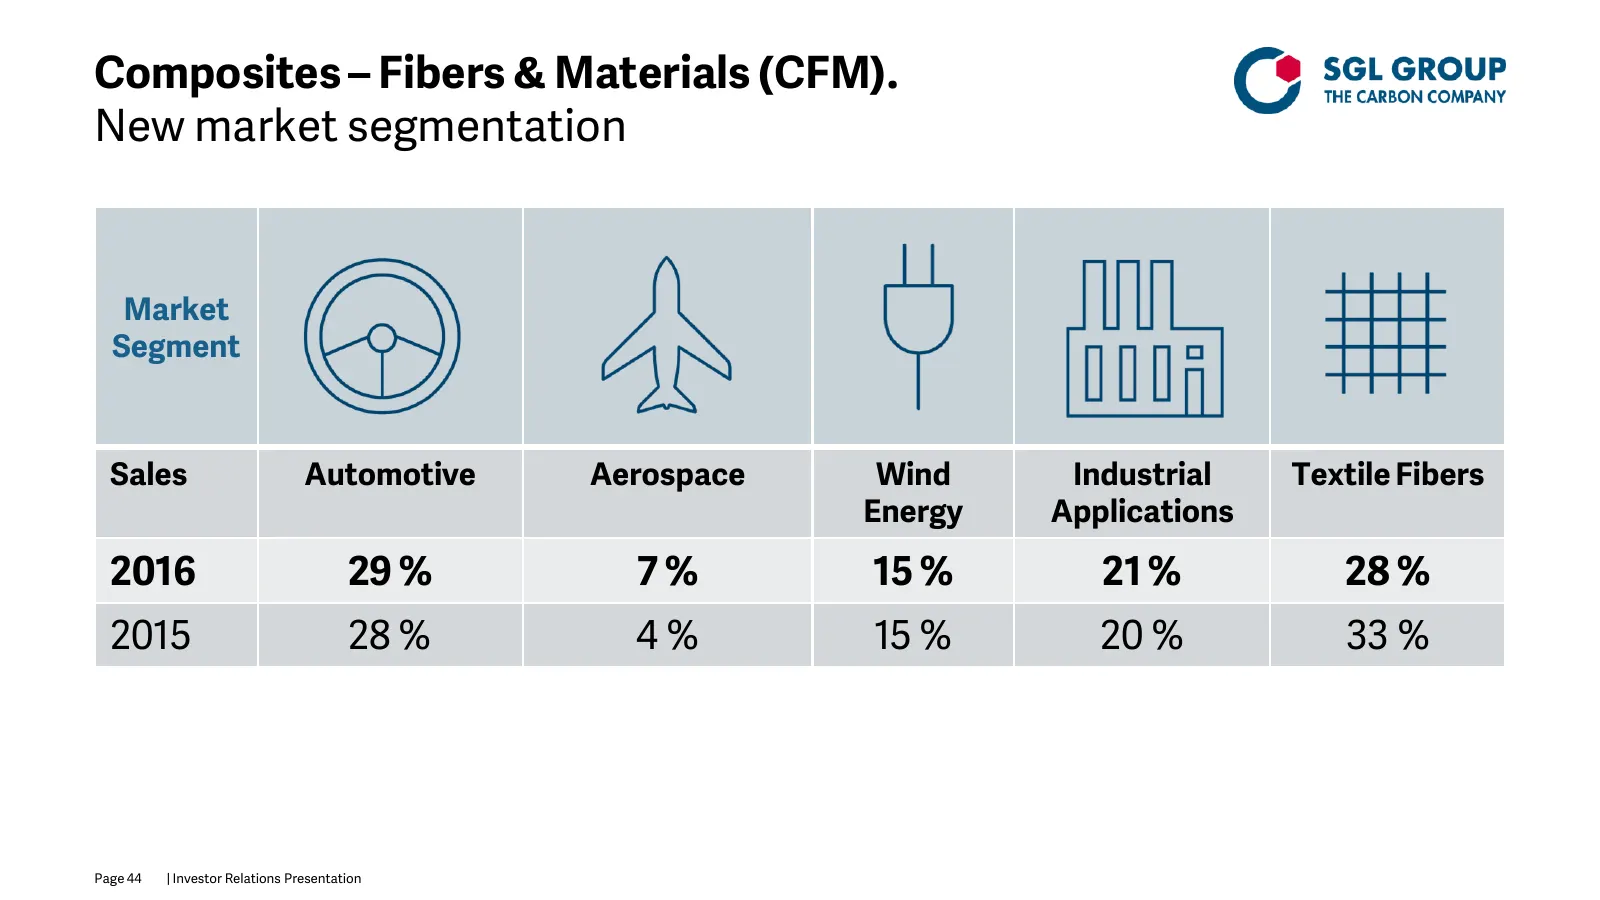
Slide 44: Composites – Fibers & Materials (CFM). New market segmentation
Composites – Fibers & Materials (CFM). New market segmentation Market Segment Sales Automotive Aerospace Wind Industrial Textile Fibers Energy Applications 2016 29 % 7% 15 % 21 % 28 % 2015 28 % 4% 15 % 20 % 33 % Page 44 | Investor Relations Presentation
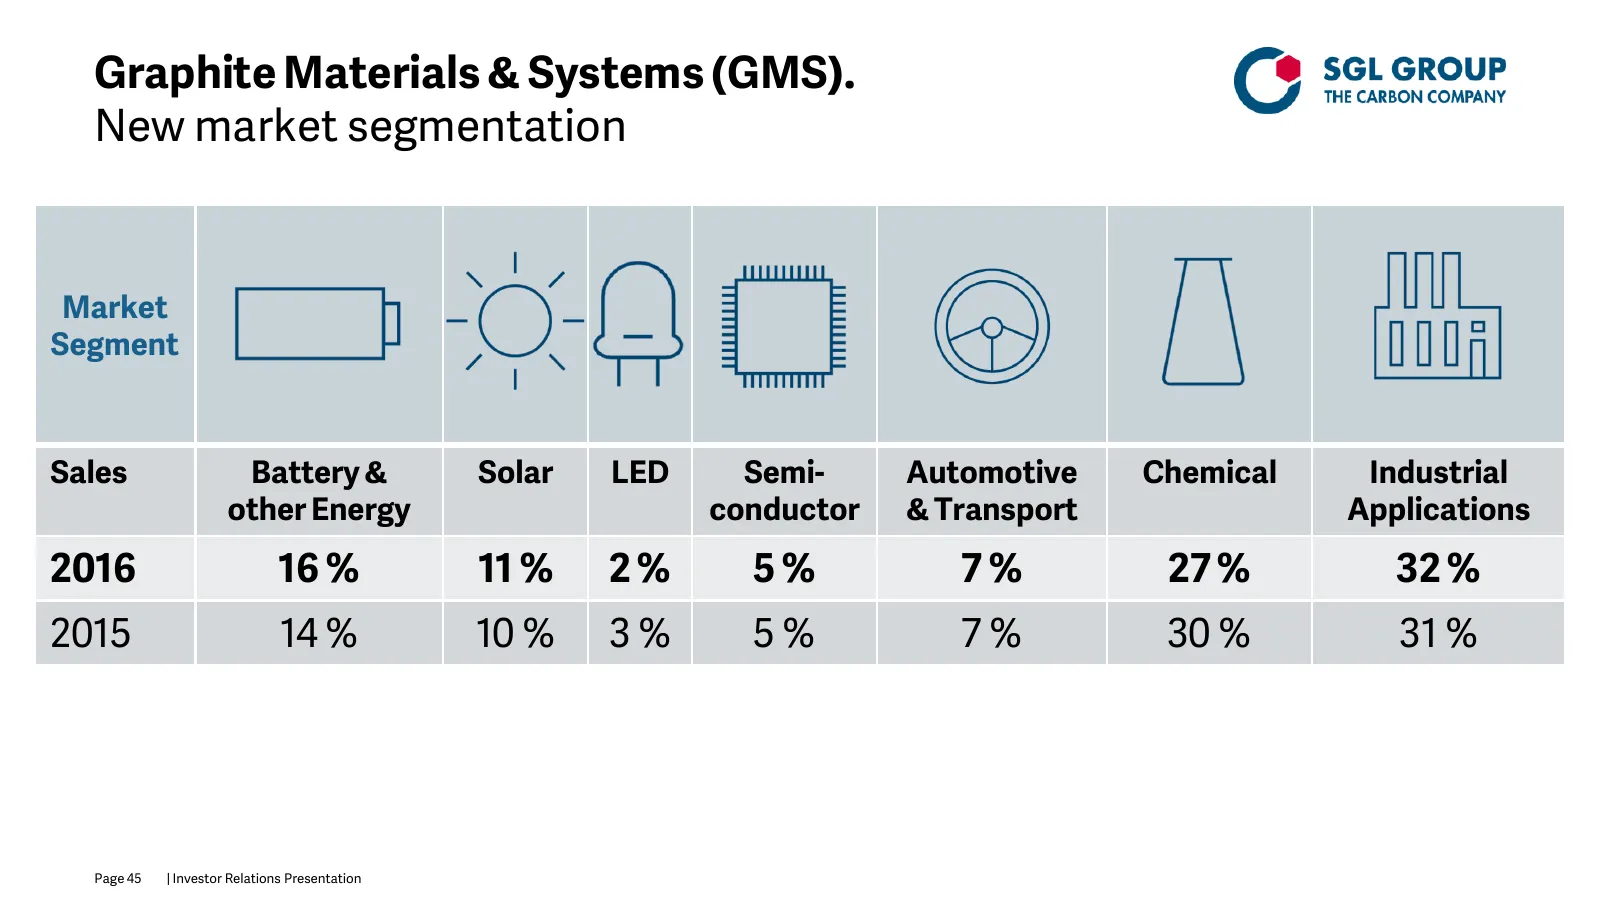
Slide 45: Graphite Materials & Systems (GMS). New market segmentation
Graphite Materials & Systems (GMS). New market segmentation Market Segment Sales Battery & Solar LED Semi- Automotive Chemical Industrial other Energy conductor & Transport Applications 2016 16 % 11 % 2% 5% 7% 27 % 32 % 2015 14 % 10 % 3% 5% 7% 30 % 31 % Page 45 | Investor Relations Presentation
Slide 46: Project Highlights
Project Highlights Page 46 | Investor Relations Presentation
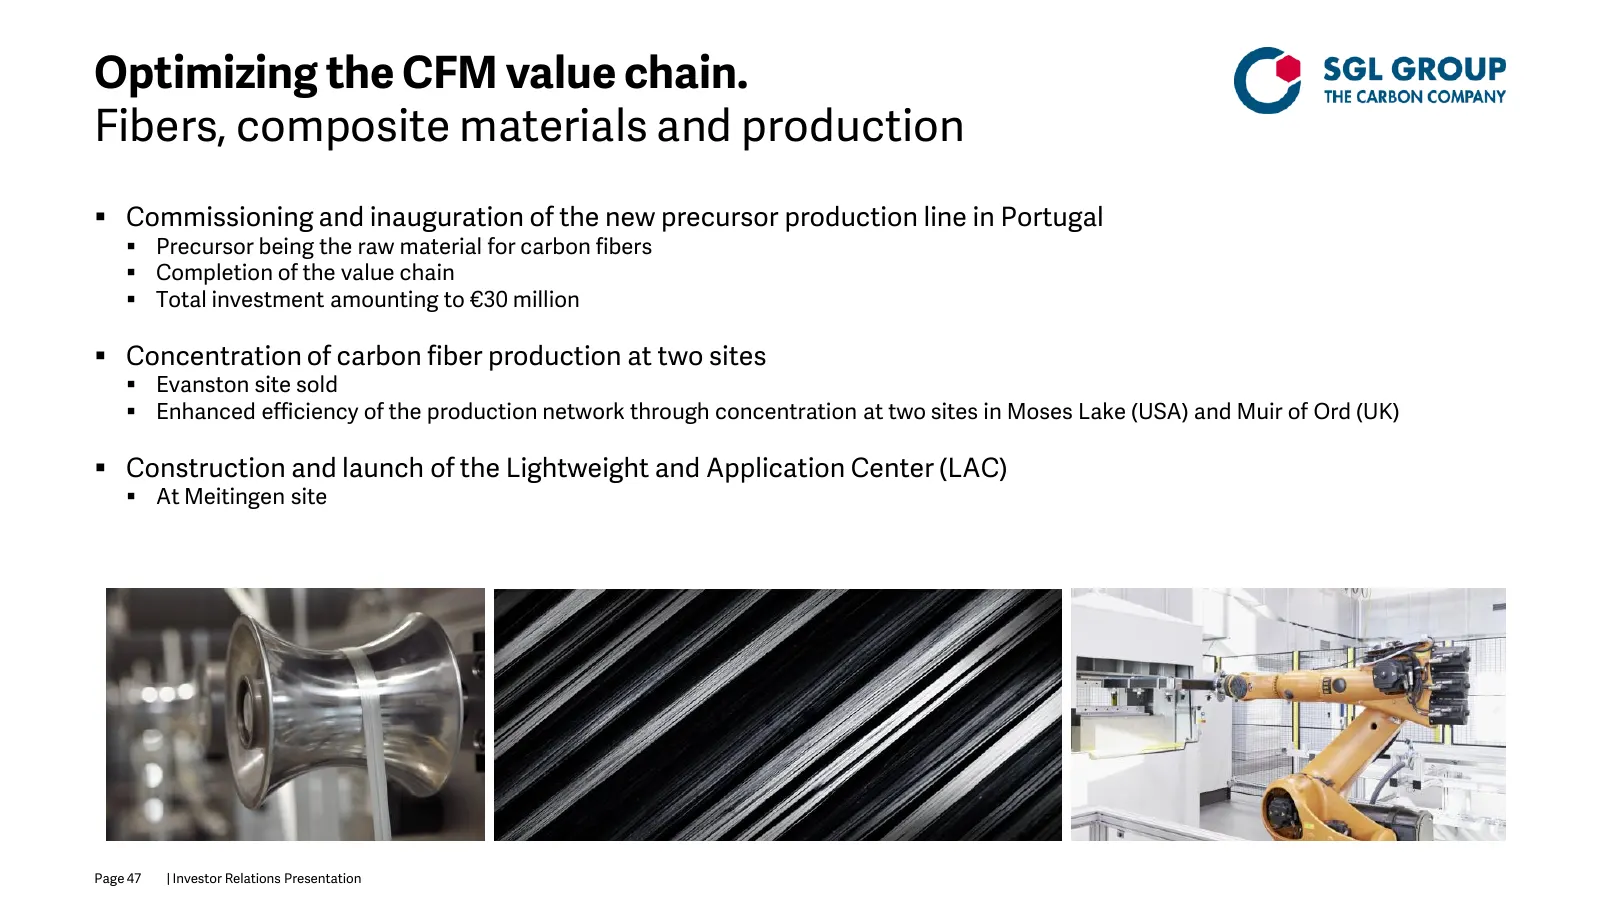
Slide 47: Optimizing the CFM value chain
Optimizing the CFM value chain. Fibers, composite materials and production Commissioning and inauguration of the new precursor production line in Portugal Precursor being the raw material for carbon fibers Completion of the value chain Total investment amounting to €30 million Concentratio
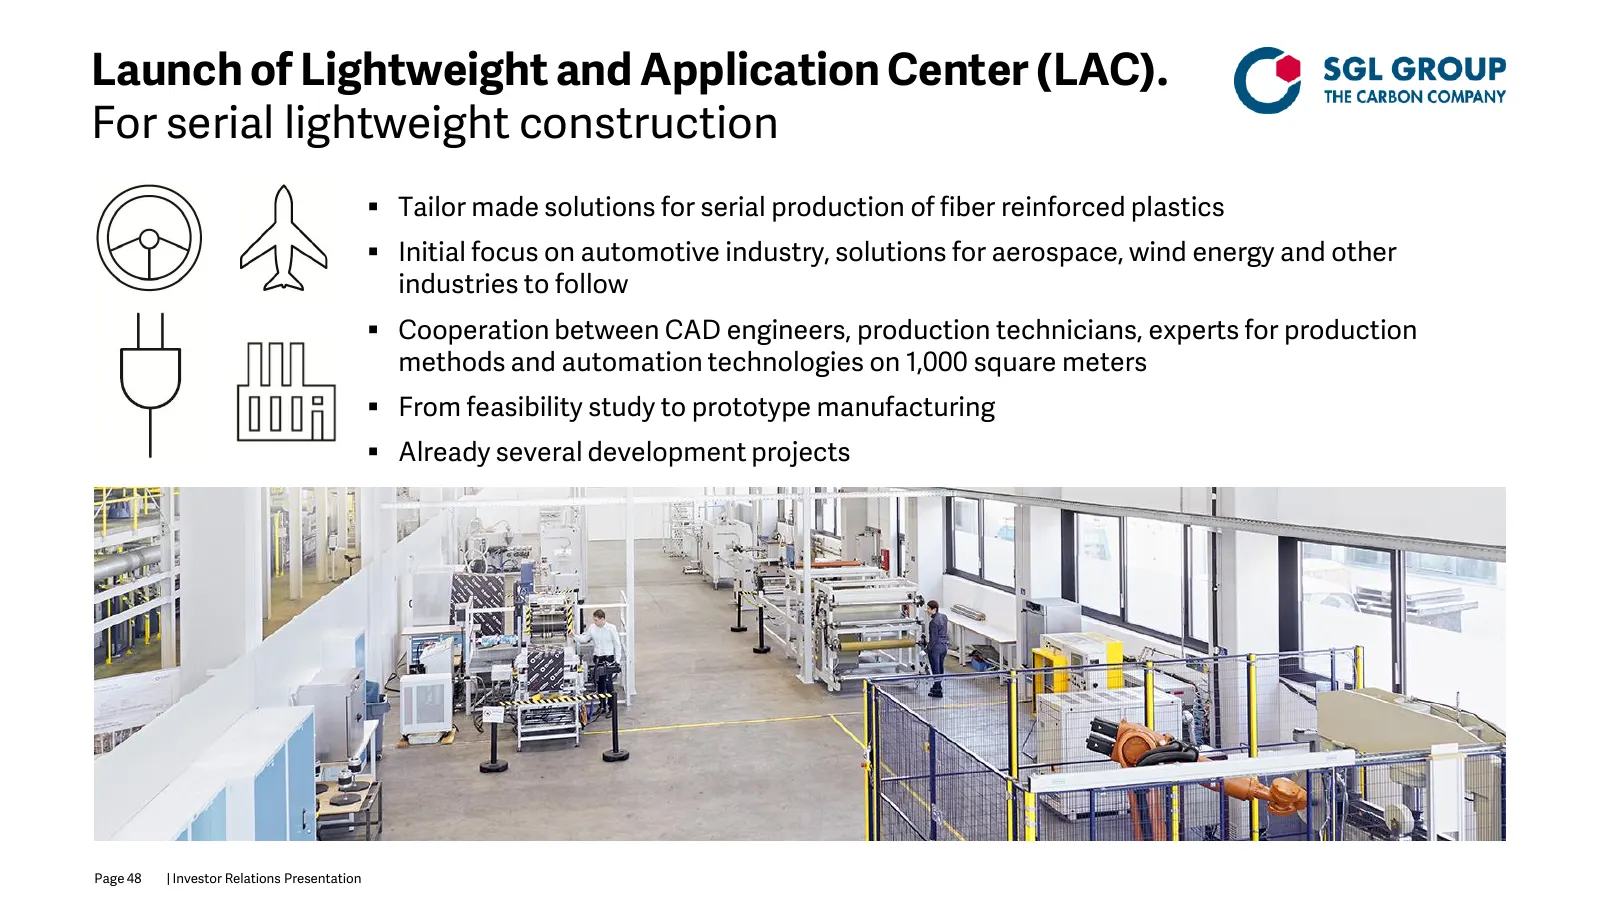
Slide 48: Launch of Lightweight and Application Center (LAC)
Launch of Lightweight and Application Center (LAC). For serial lightweight construction Tailor made solutions for serial production of fiber reinforced plastics Initial focus on automotive industry, solutions for aerospace, wind energy and other industries to follow Cooperation between CAD eng
Slide 49: A look into the market segments. Summary of important project highlights
A look into the market segments. Summary of important project highlights Developed customized solutions and kicked off new projects Contract extension and development projects Strengthened position in lithium-ion battery industry Capacities expanded based on increased LED demand Received large contr
Slide 50: Developed customized solutions
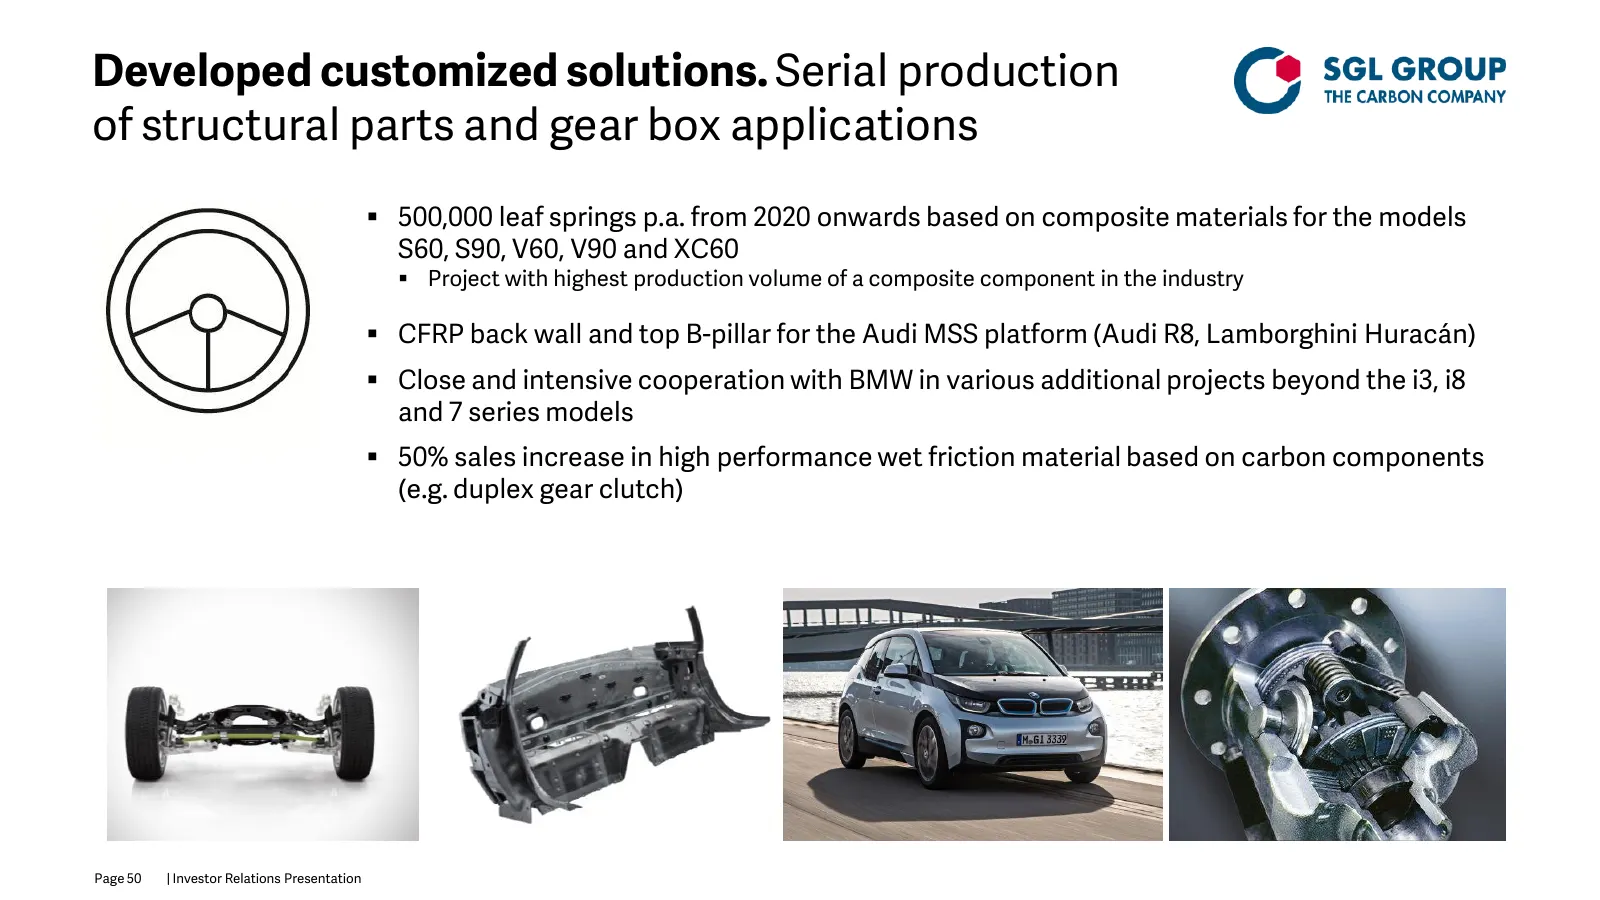
Developed customized solutions. Serial production of structural parts and gear box applications 500,000 leaf springs p.a. from 2020 onwards based on composite materials for the models S60, S90, V60, V90 and XC60 Project with highest production volume of a composite component in the industry CF
Slide 51: Initiated development projects globally
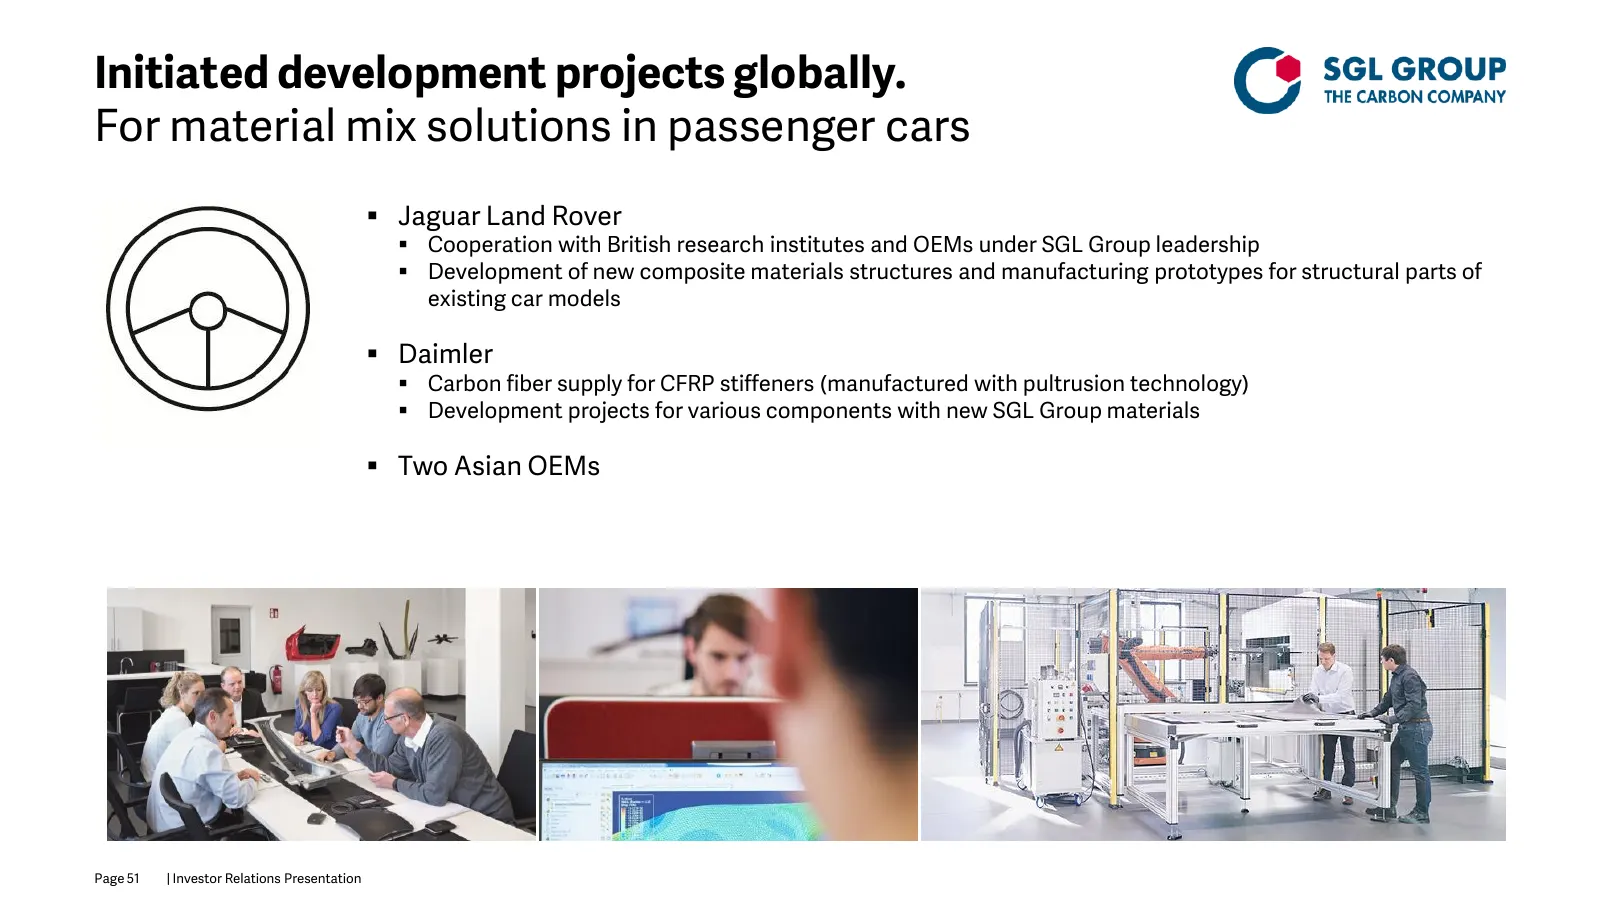
Initiated development projects globally. For material mix solutions in passenger cars Jaguar Land Rover Cooperation with British research institutes and OEMs under SGL Group leadership Development of new composite materials structures and manufacturing prototypes for structural parts of existi
Slide 52: Ready for lift-off. Contract extension and development projects
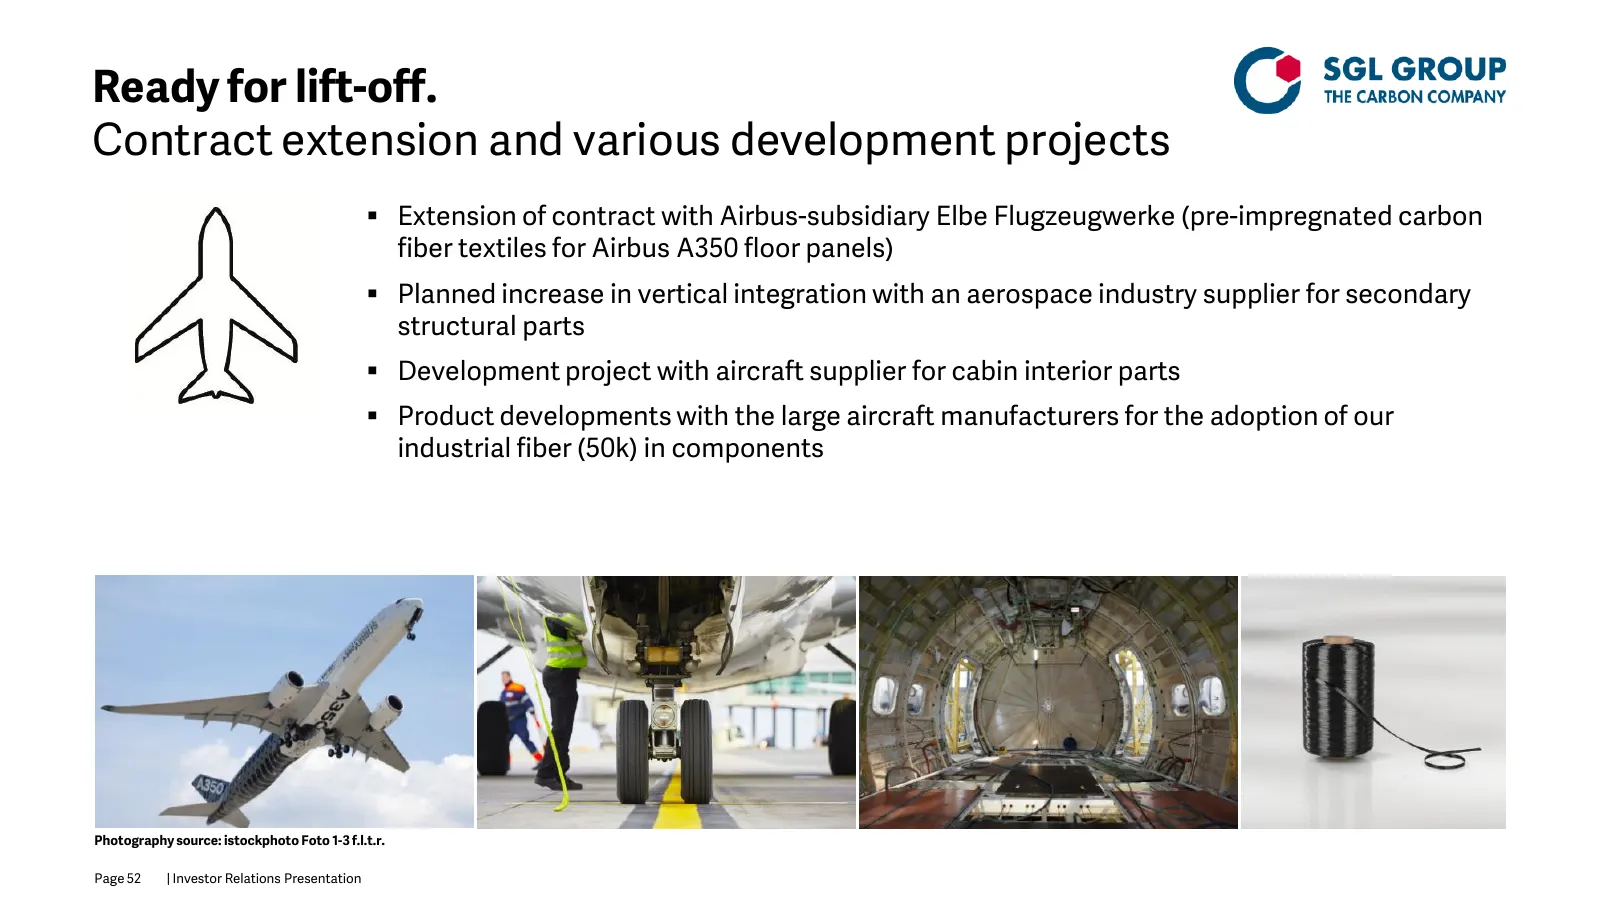
Ready for lift-off. Contract extension and various development projects Extension of contract with Airbus-subsidiary Elbe Flugzeugwerke (pre-impregnated carbon fiber textiles for Airbus A350 floor panels) Planned increase in vertical integration with an aerospace industry supplier for secondary
Slide 53: Strengthened position in lithium-ion battery industry
Strengthened position in lithium-ion battery industry. Expansion of business opportunities Synthetic anode material qualified with further cell manufacturers Cooperation intensified with long-standing partner Hitachi Chemicals Development of next generation lithium-ion batteries with higher st
Slide 54: Capacity increase in the USA. To meet increased demand for LEDs
Capacity increase in the USA. To meet increased demand for LEDs Construction of a new state-of-the-art production line for the coating of graphite carrier plates (wafer carriers) in the USA Total investment of €7.5 million Completion 2017 SGL Group technology provides critical contribution t
Slide 55: Large orders and portfolio extension. Continued industrialization in China
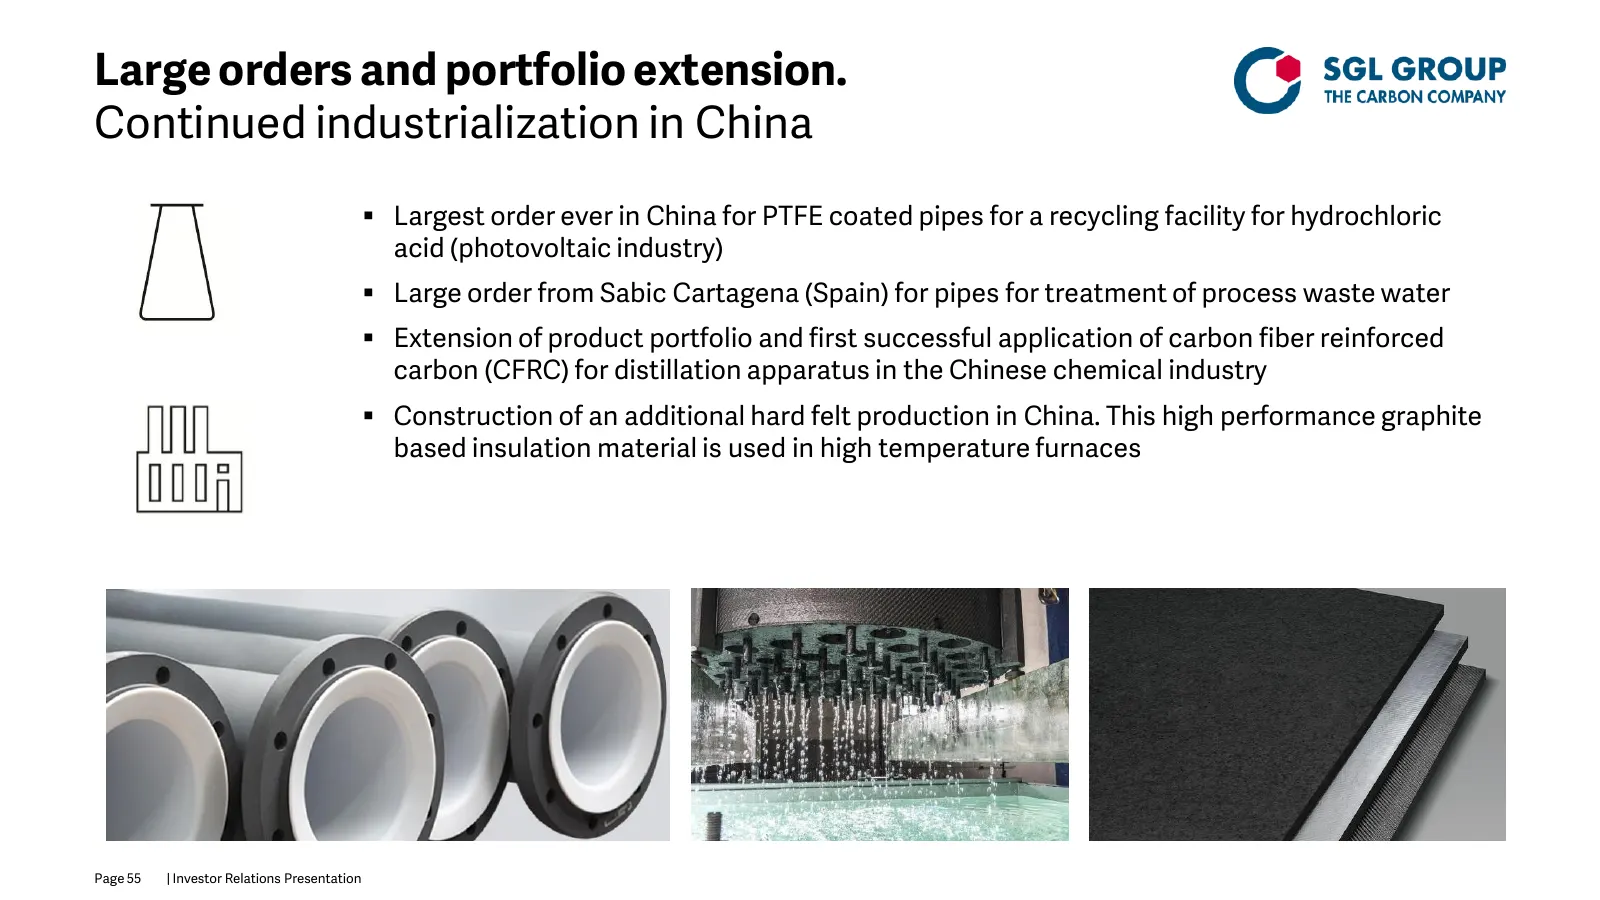
Large orders and portfolio extension. Continued industrialization in China Largest order ever in China for PTFE coated pipes for a recycling facility for hydrochloric acid (photovoltaic industry) Large order from Sabic Cartagena (Spain) for pipes for treatment of process waste water Extension
Slide 56: Efficiency enhancing and cost cutting programs
Efficiency enhancing and cost cutting programs Page 56 | Investor Relations Presentation
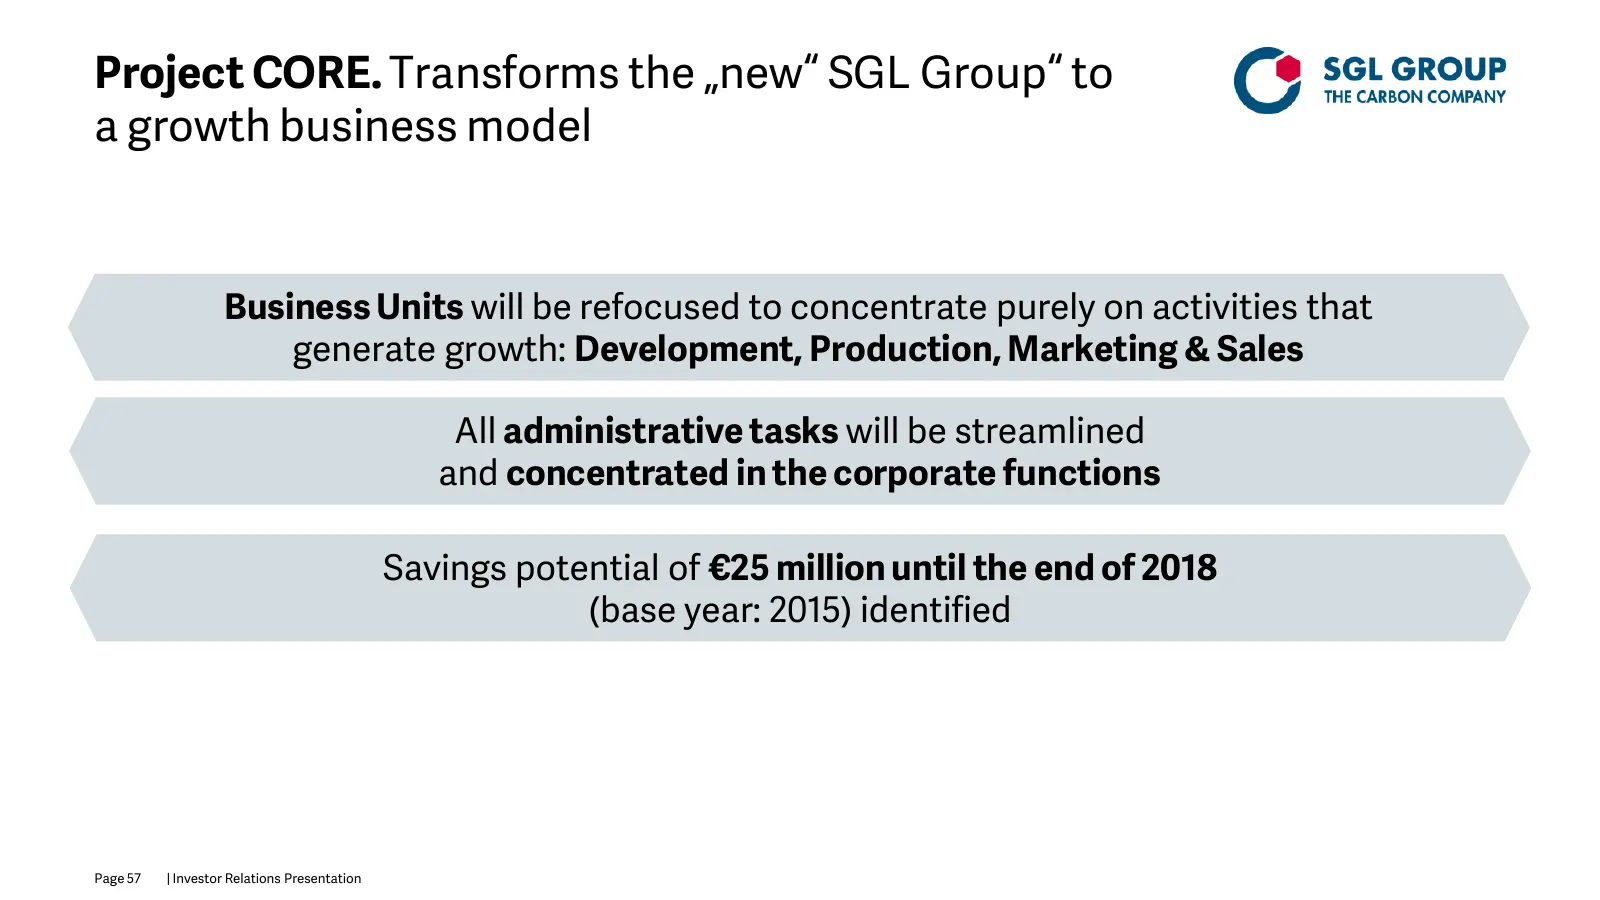
Slide 57: Project CORE
Project CORE. Transforms the „new“ SGL Group“ to a growth business model Business Units will be refocused to concentrate purely on activities that generate growth: Development, Production, Marketing & Sales All administrative tasks will be streamlined and concentrated in the corporate functions Savi
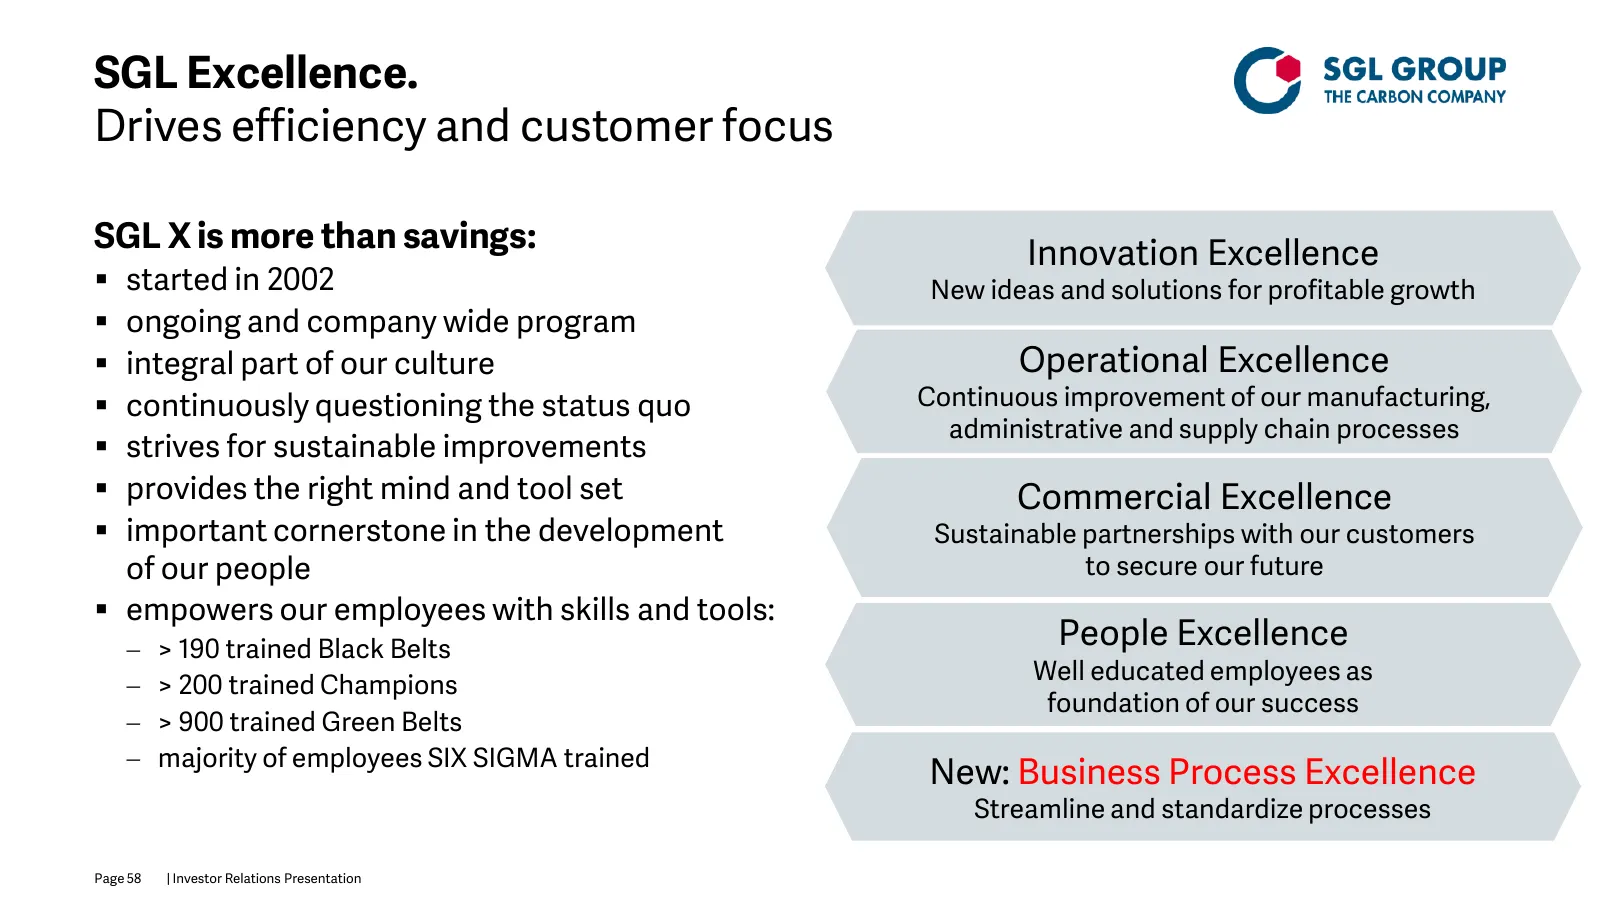
Slide 58: SGL Excellence. Drives efficiency and customer focus
SGL Excellence. Drives efficiency and customer focus SGL X is more than savings: Innovation Excellence started in 2002 New ideas and solutions for profitable growth ongoing and company wide program integral part of our culture Operational Excellence continuously questioning the status quo Co
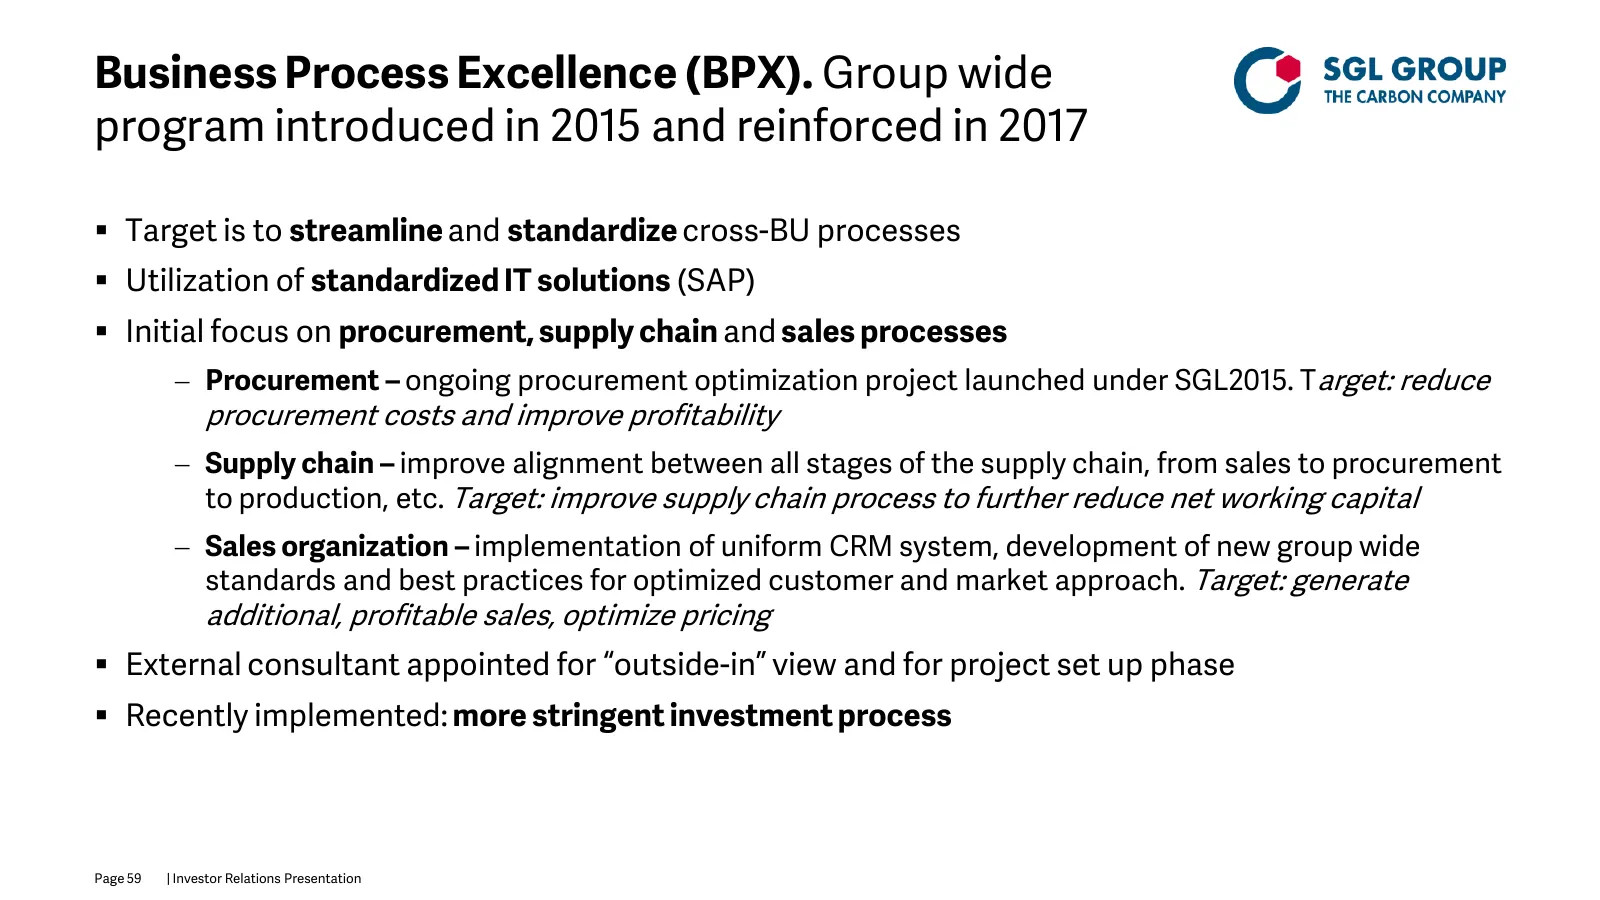
Slide 59: Business Process Excellence (BPX)
Business Process Excellence (BPX). Group wide program introduced in 2015 and reinforced in 2017 Target is to streamline and standardize cross-BU processes Utilization of standardized IT solutions (SAP) Initial focus on procurement, supply chain and sales processes Procurement – ongoing procu
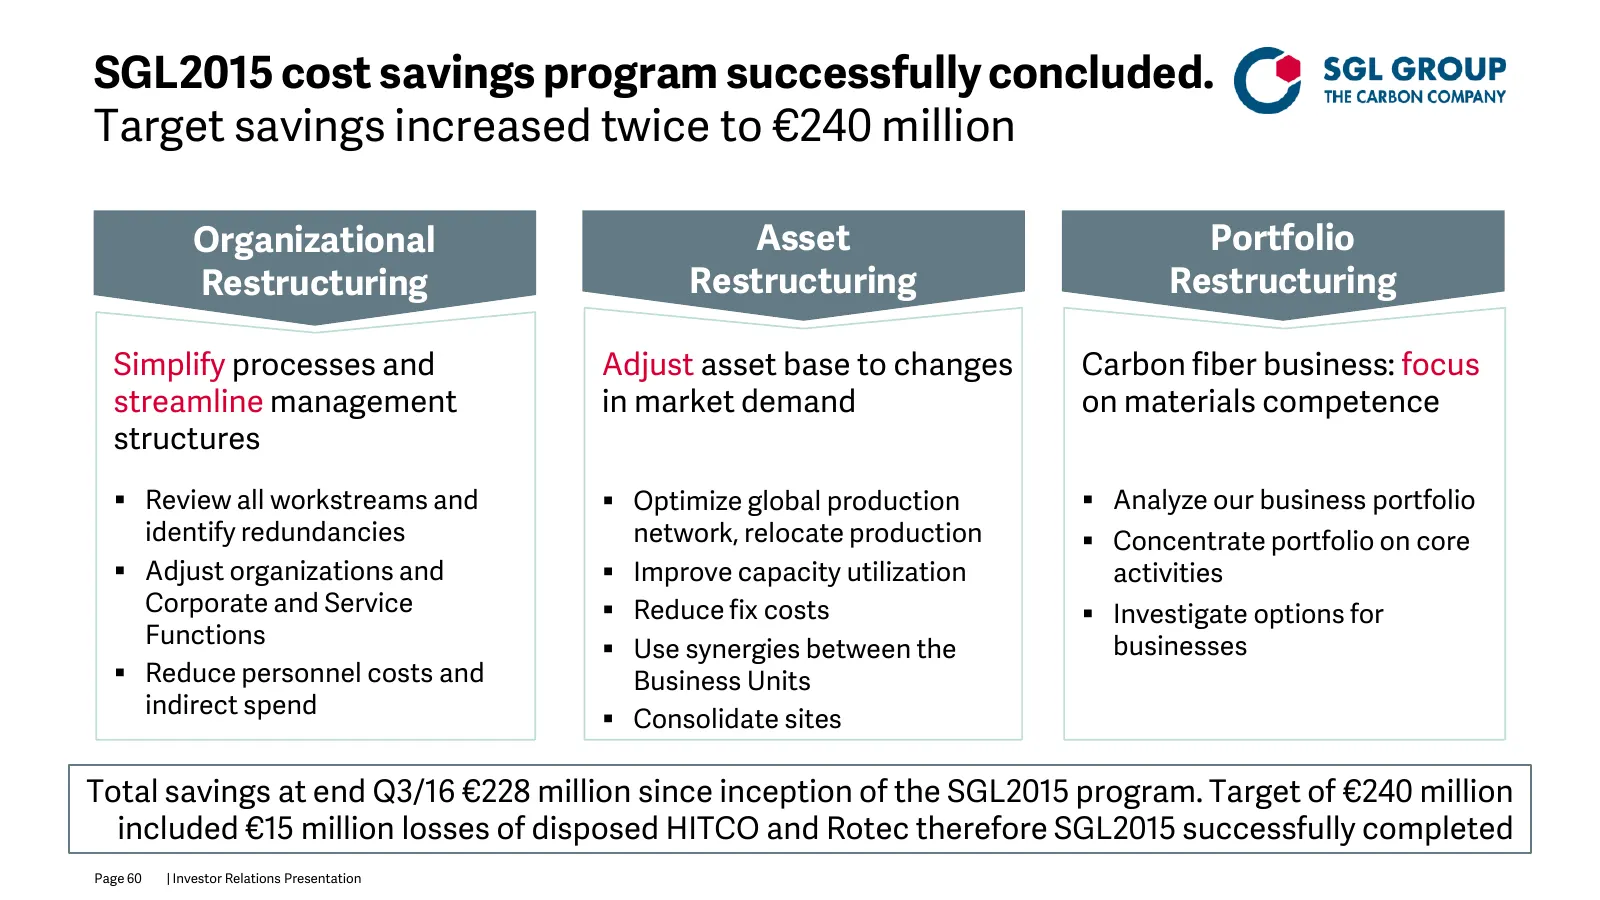
Slide 60: SGL2015 cost savings program successfully concluded
SGL2015 cost savings program successfully concluded. Target savings increased twice to €240 million Organizational Asset Portfolio Restructuring Restructuring Restructuring Simplify processes and Adjust asset base to changes Carbon fiber business: focus streamline management in market demand on mate
Slide 61: Latest Financials Q1/2017
Latest Financials Q1/2017 Page 61 | Investor Relations Presentation
Slide 62: Review. Strong Q1/2017 result
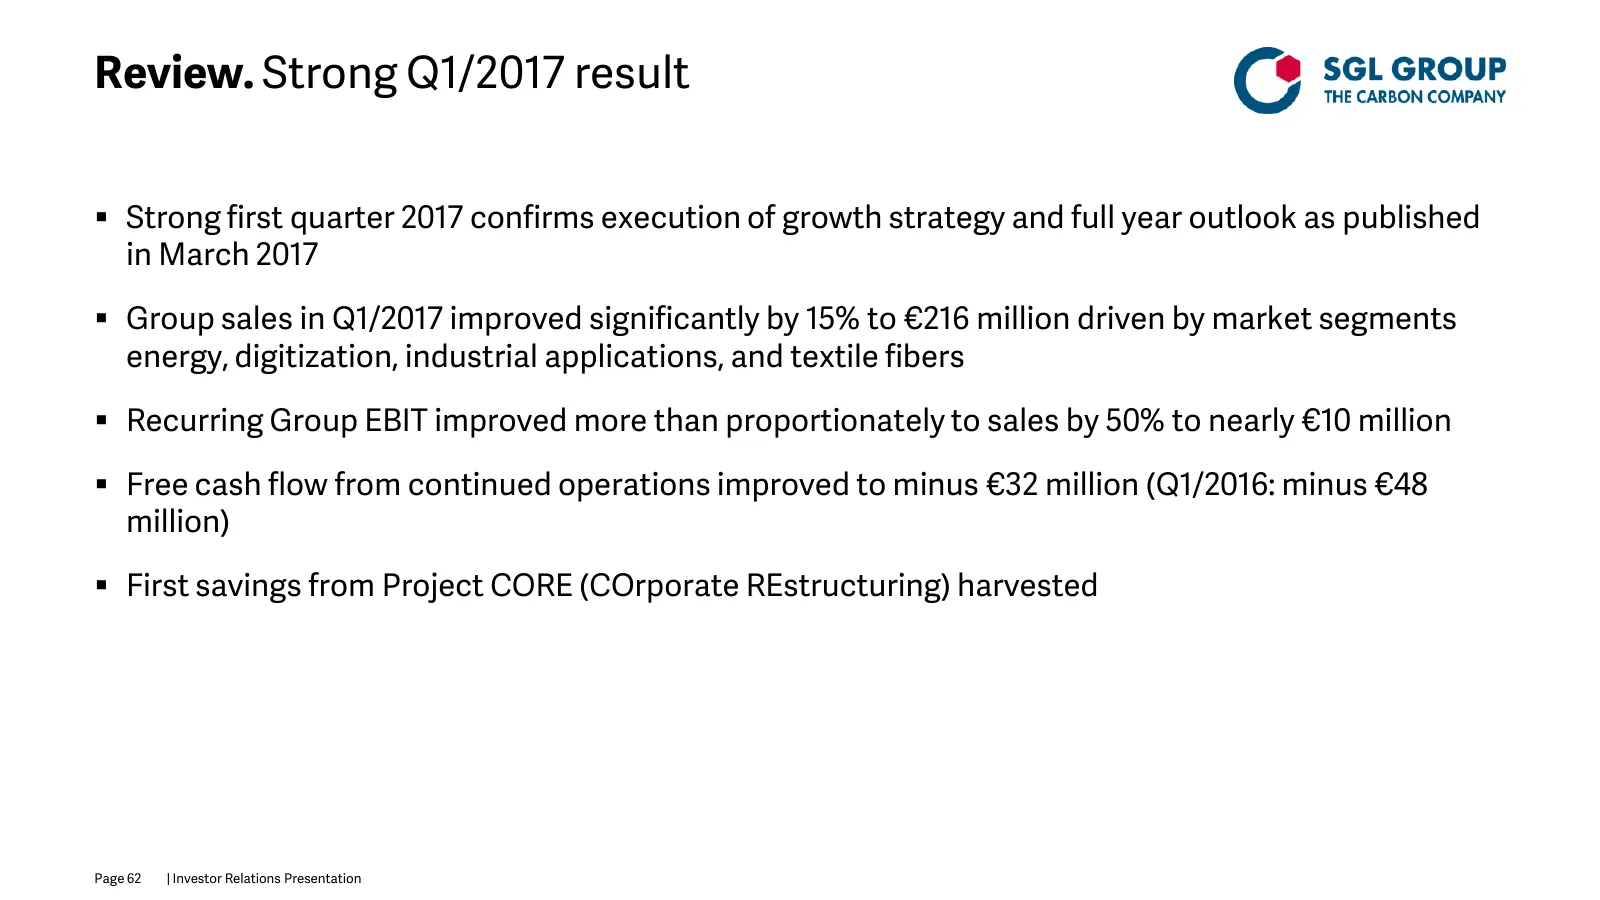
Review. Strong Q1/2017 result Strong first quarter 2017 confirms execution of growth strategy and full year outlook as published in March 2017 Group sales in Q1/2017 improved significantly by 15% to €216 million driven by market segments energy, digitization, industrial applications, and textile
Slide 63: Review. Highlights from the businesses
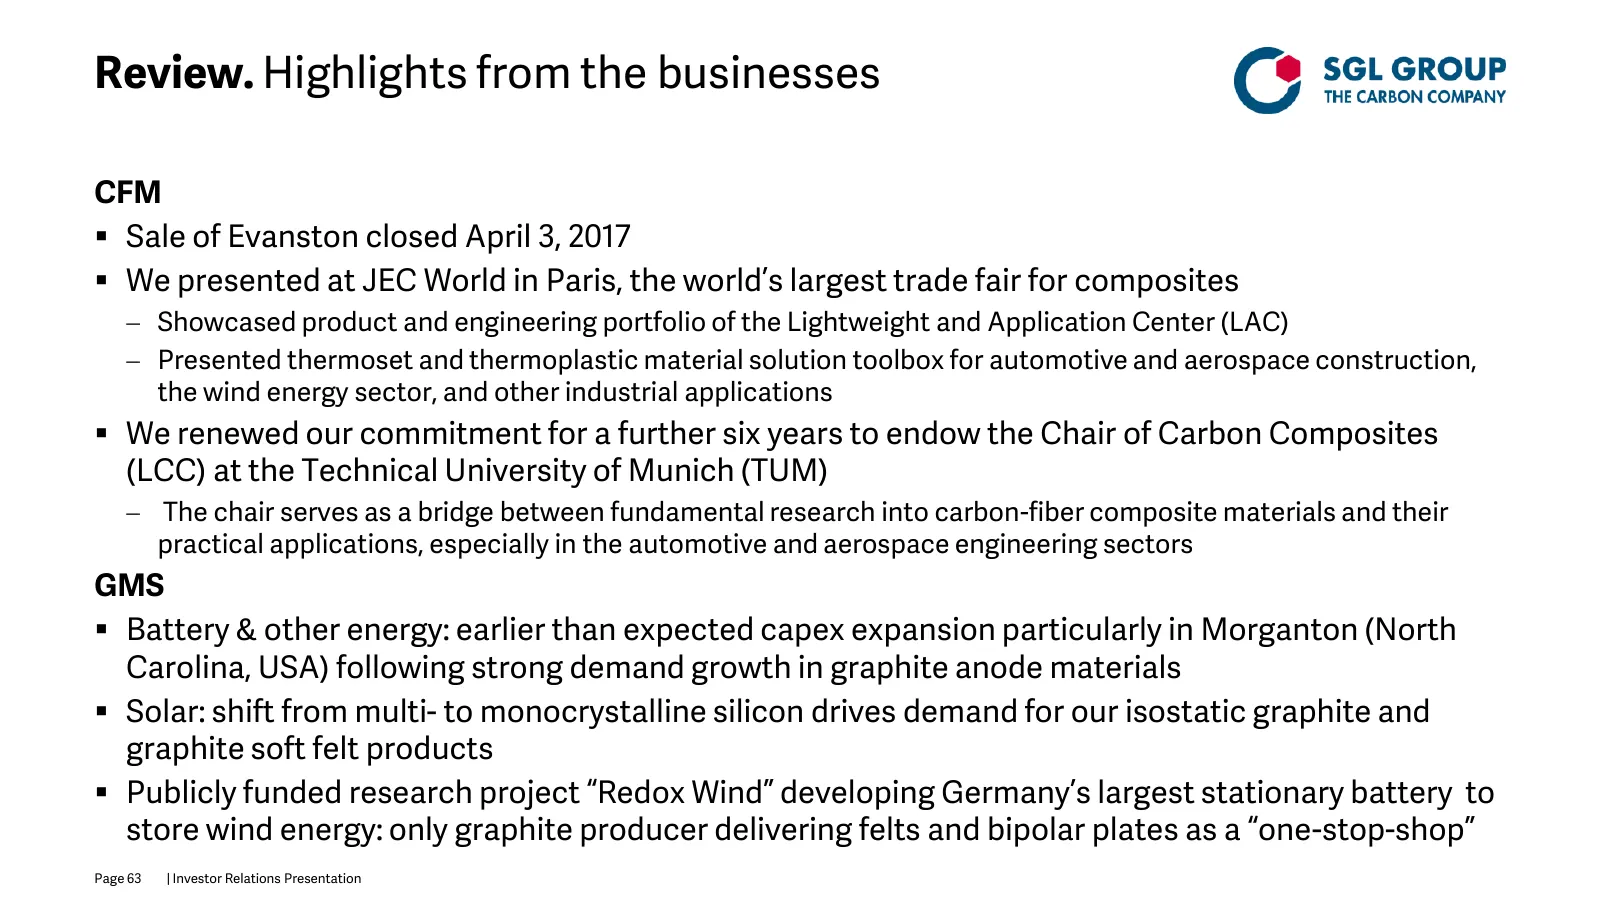
Review. Highlights from the businesses CFM Sale of Evanston closed April 3, 2017 We presented at JEC World in Paris, the world’s largest trade fair for composites Showcased product and engineering portfolio of the Lightweight and Application Center (LAC) Presented thermoset and thermoplastic
Slide 64: Composites - Fibers & Materials. Strong sales growth
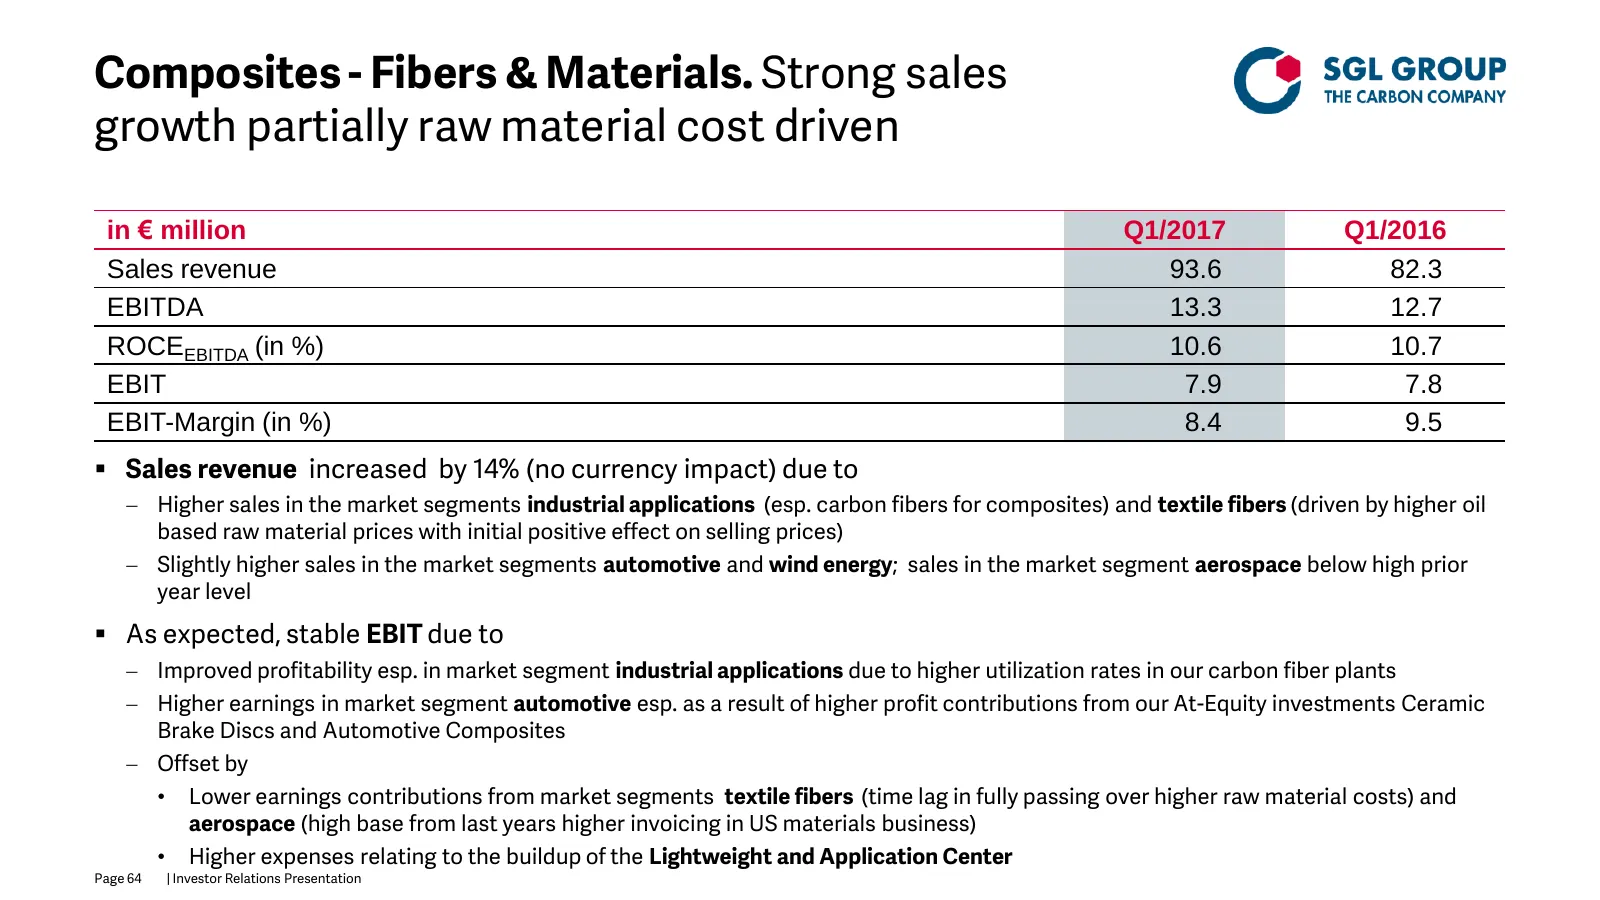
Composites - Fibers & Materials. Strong sales growth partially raw material cost driven in € million Q1/2017 Q1/2016 Sales revenue 93.6 82.3 EBITDA 13.3 12.7 ROCEEBITDA (in %) 10.6 10.7 EBIT 7.9 7.8 EBIT-Margin (in %) 8.4 9.5 Sales revenue increased by 14% (no currency impact) due to Higher sale
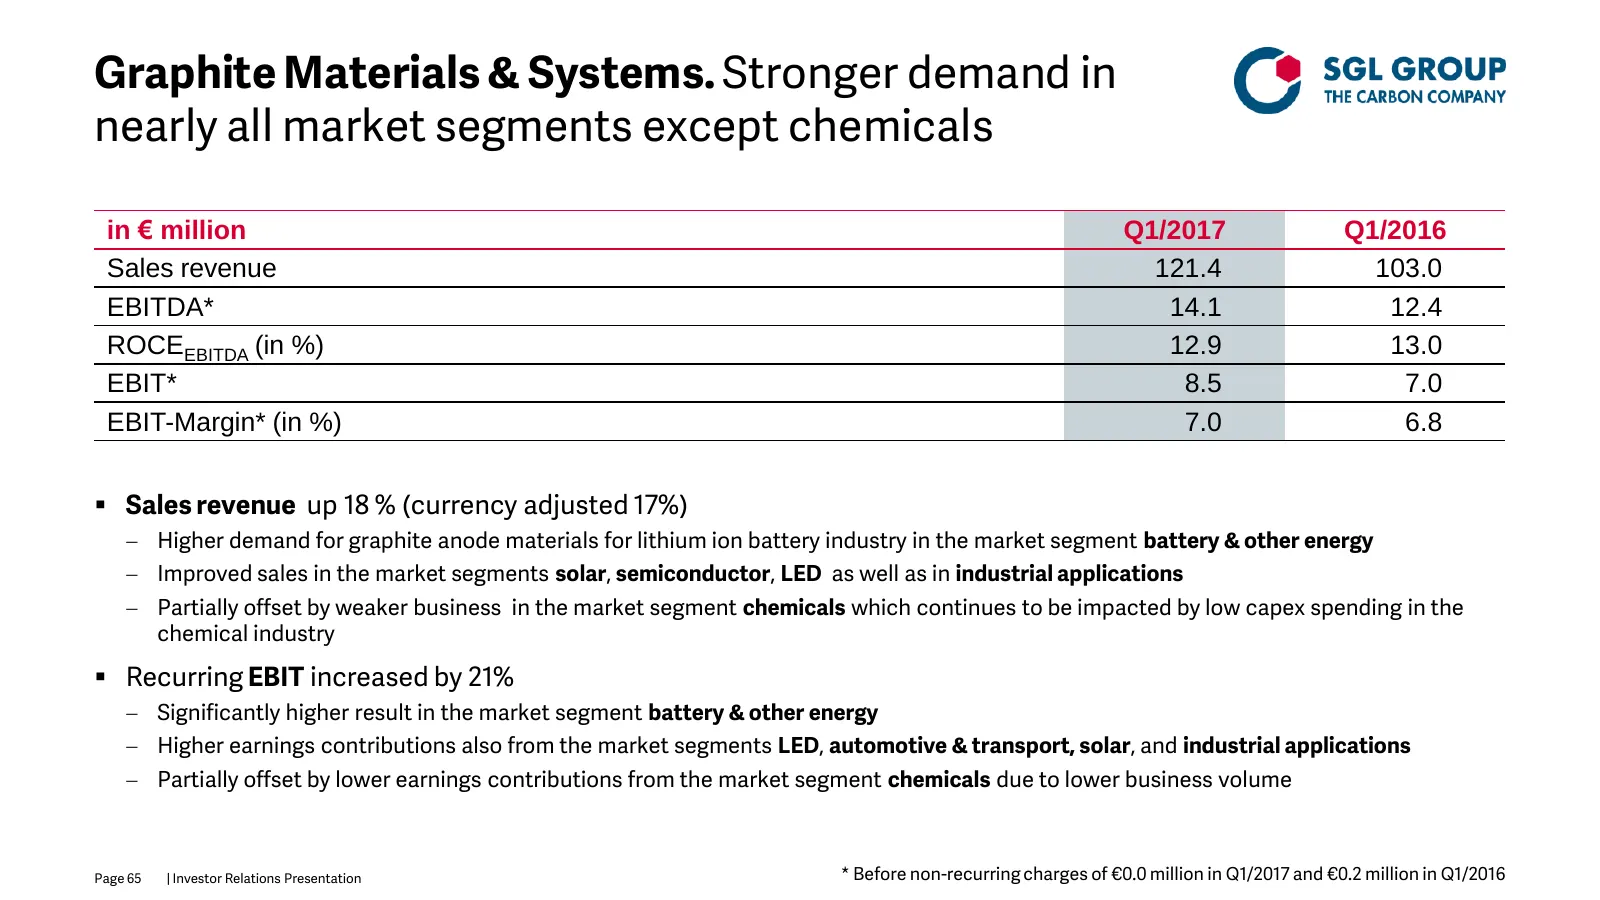
Slide 65: Graphite Materials & Systems. Stronger demand in nearly all segments
Graphite Materials & Systems. Stronger demand in nearly all market segments except chemicals in € million Q1/2017 Q1/2016 Sales revenue 121.4 103.0 EBITDA* 14.1 12.4 ROCEEBITDA (in %) 12.9 13.0 EBIT* 8.5 7.0 EBIT-Margin* (in %) 7.0 6.8 Sales revenue up 18 % (currency adjusted 17%) Higher demand
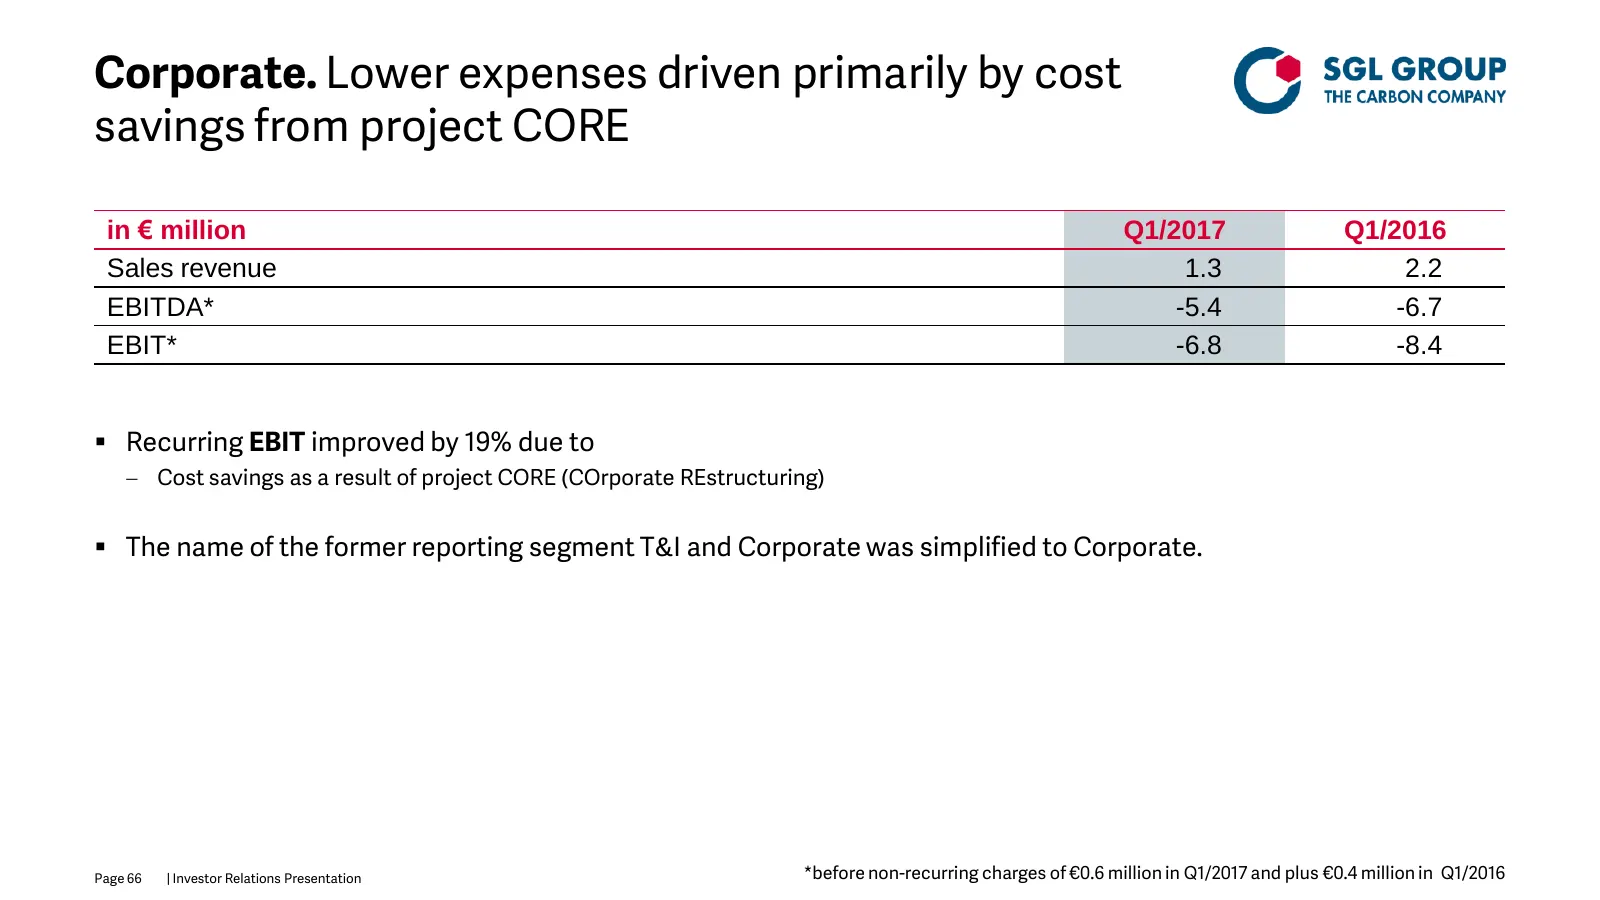
Slide 66: Corporate. Lower expenses driven by Project CORE
Corporate. Lower expenses driven primarily by cost savings from project CORE in € million Q1/2017 Q1/2016 Sales revenue 1.3 2.2 EBITDA* -5.4 -6.7 EBIT* -6.8 -8.4 Recurring EBIT improved by 19% due to Cost savings as a result of project CORE (COrporate REstructuring) The name of the former repo
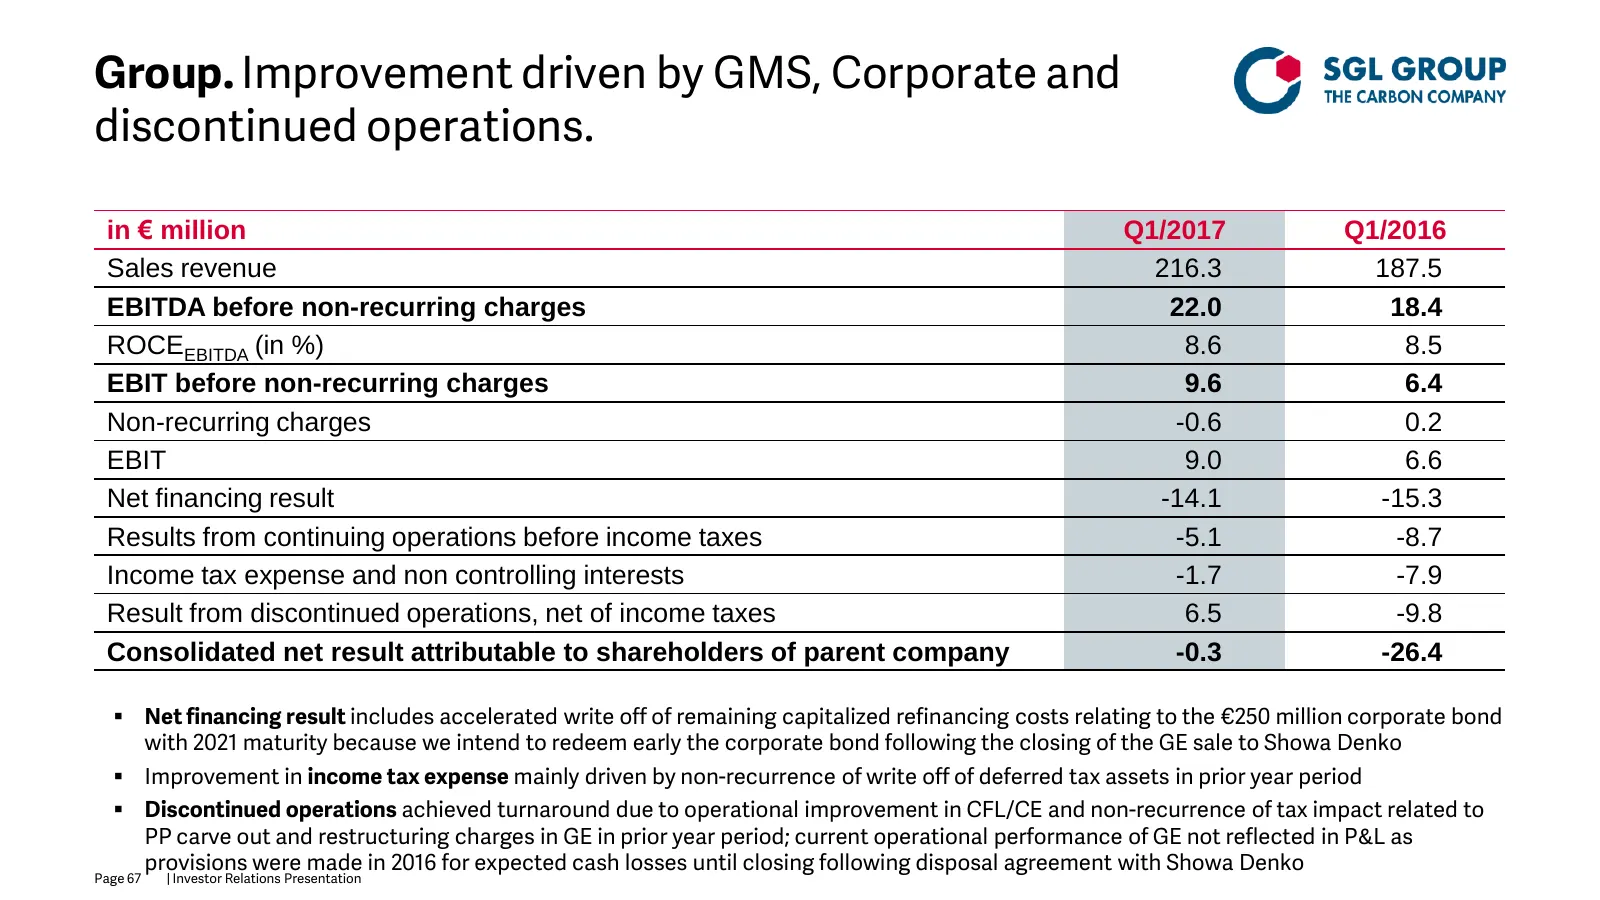
Slide 67: Group. Improvement driven by GMS, Corporate and discontinued operations
Group. Improvement driven by GMS, Corporate and discontinued operations. in € million Q1/2017 Q1/2016 Sales revenue 216.3 187.5 EBITDA before non-recurring charges 22.0 18.4 ROCEEBITDA (in %) 8.6 8.5 EBIT before non-recurring charges 9.6 6.4 Non-recurring charges -0.6 0.2 EBIT 9.0 6.6 Net financing
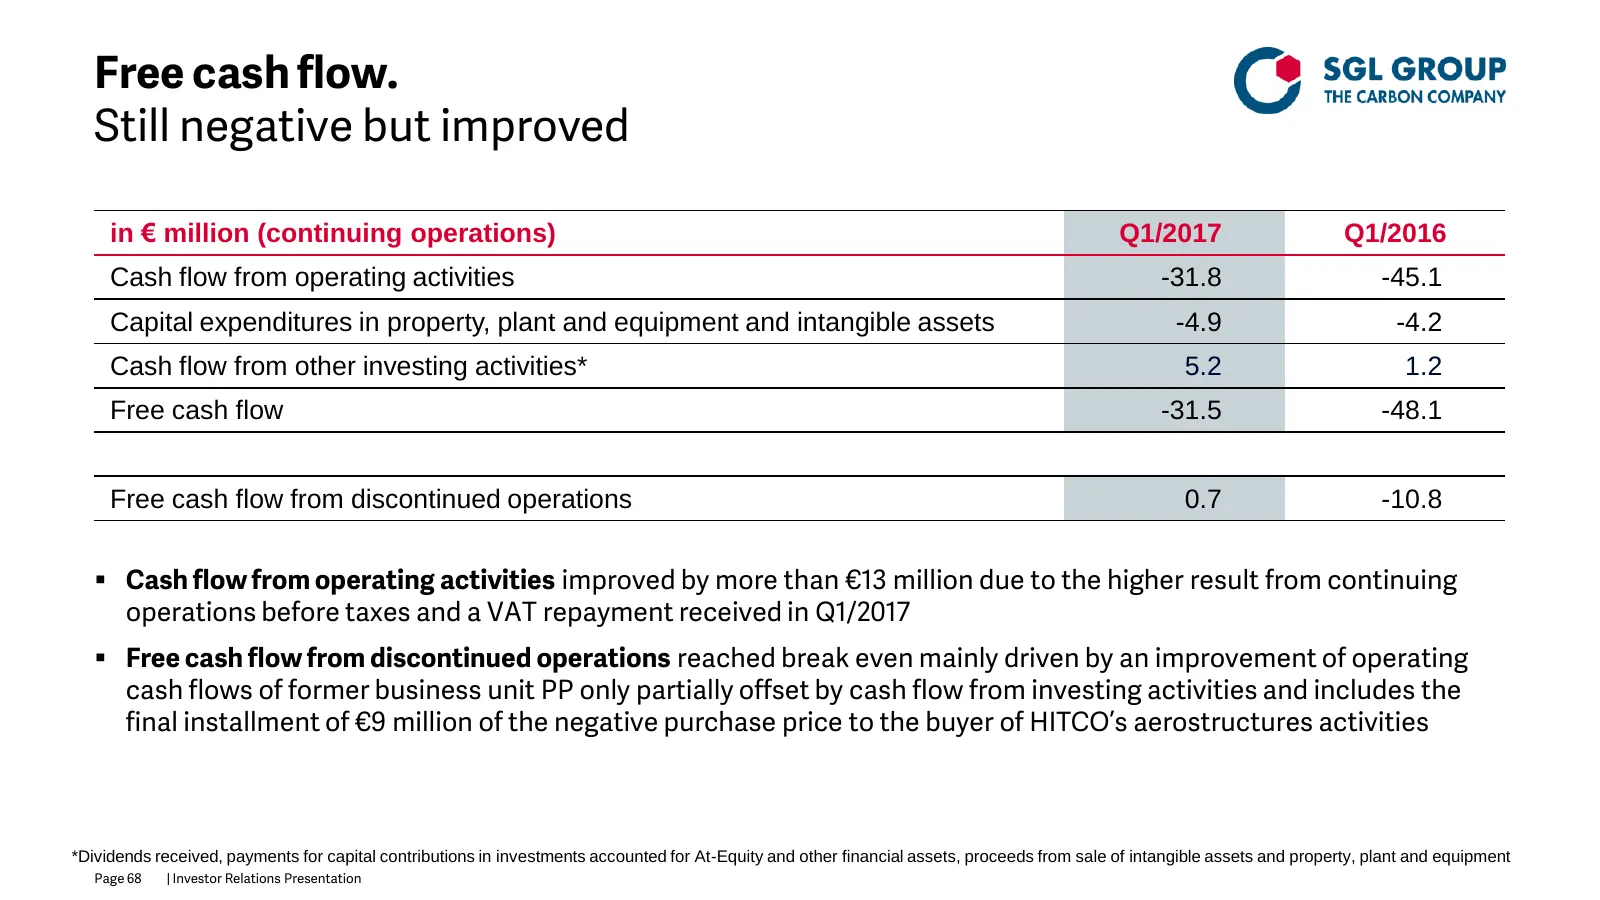
Slide 68: Free cash flow. Still negative but improved
Free cash flow. Still negative but improved in € million (continuing operations) Q1/2017 Q1/2016 Cash flow from operating activities -31.8 -45.1 Capital expenditures in property, plant and equipment and intangible assets -4.9 -4.2 Cash flow from other investing activities* 5.2 1.2 Free cash flow -31
Slide 69: Balance sheet. Positive impact from PP disposals yet to come
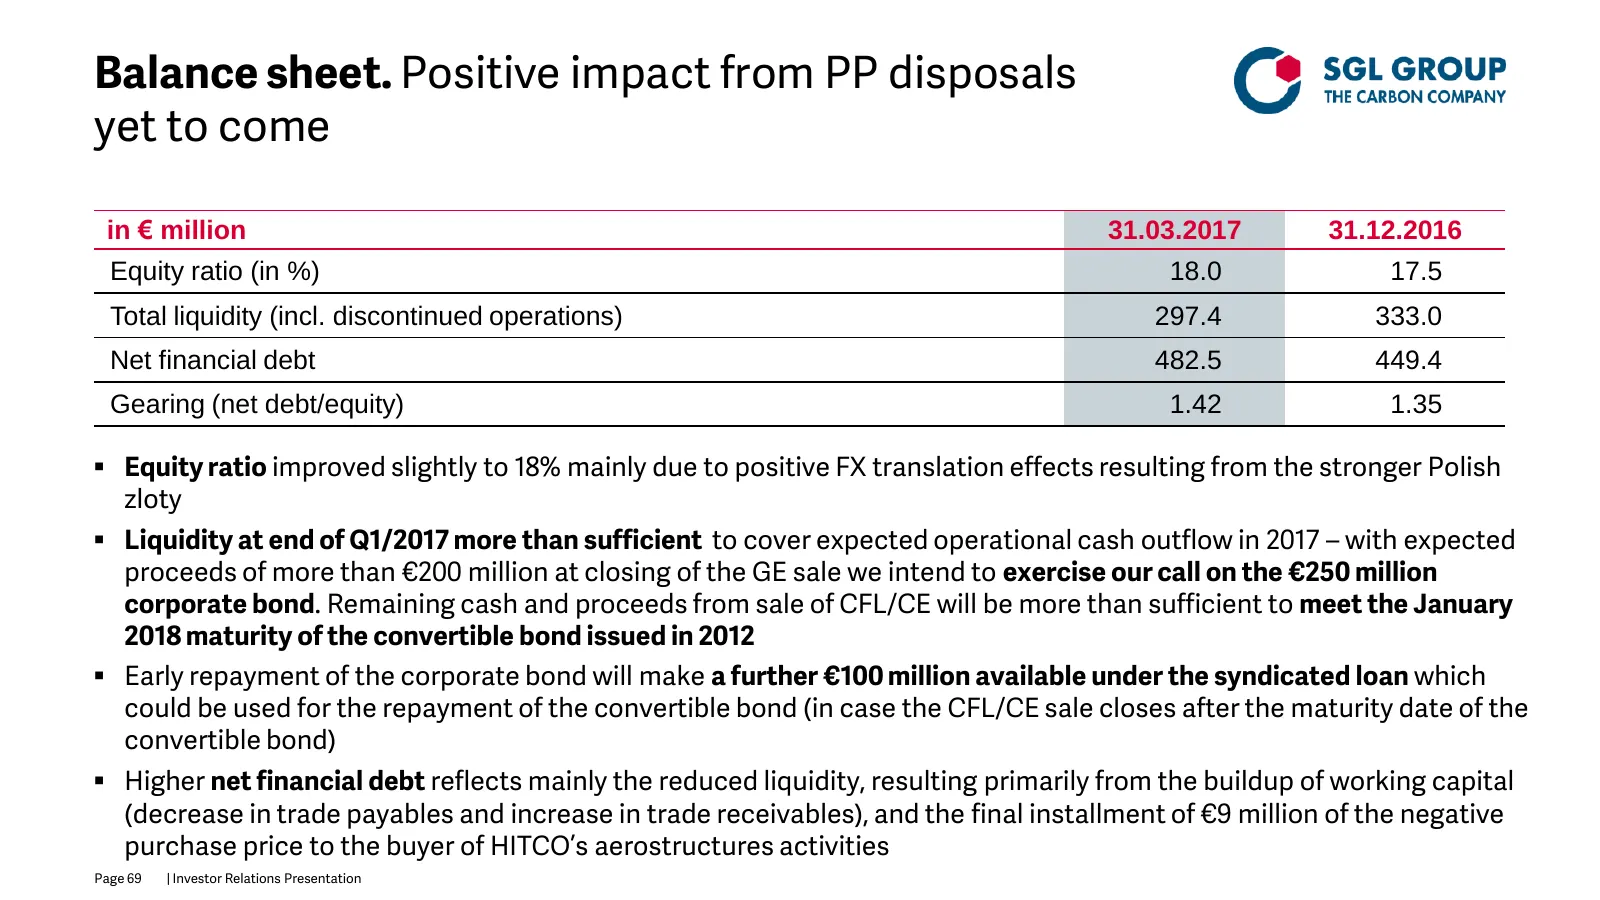
Balance sheet. Positive impact from PP disposals yet to come in € million 31.03.2017 31.12.2016 Equity ratio (in %) 18.0 17.5 Total liquidity (incl. discontinued operations) 297.4 333.0 Net financial debt 482.5 449.4 Gearing (net debt/equity) 1.42 1.35 Equity ratio improved slightly to 18% mainly
Slide 70: Outlook
Outlook Page 70 | Investor Relations Presentation
Slide 71: Business Unit outlook 2017. CFM
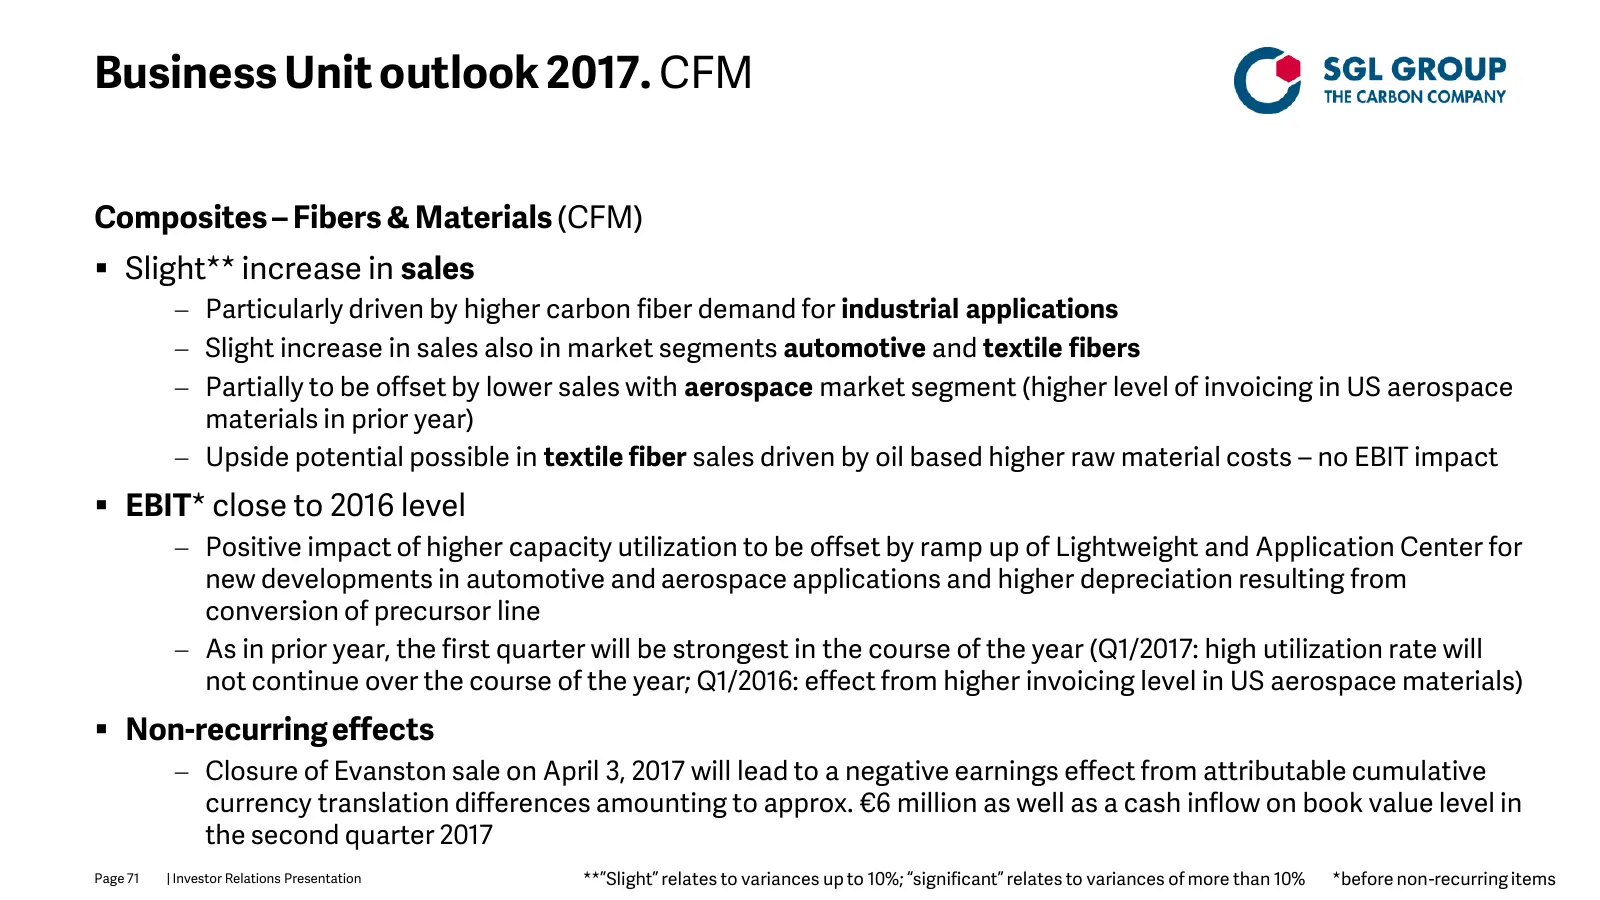
Business Unit outlook 2017. CFM Composites – Fibers & Materials (CFM) Slight** increase in sales Particularly driven by higher carbon fiber demand for industrial applications Slight increase in sales also in market segments automotive and textile fibers Partially to be offset by lower sales
Slide 72: Business Unit outlook 2017. GMS and Corporate
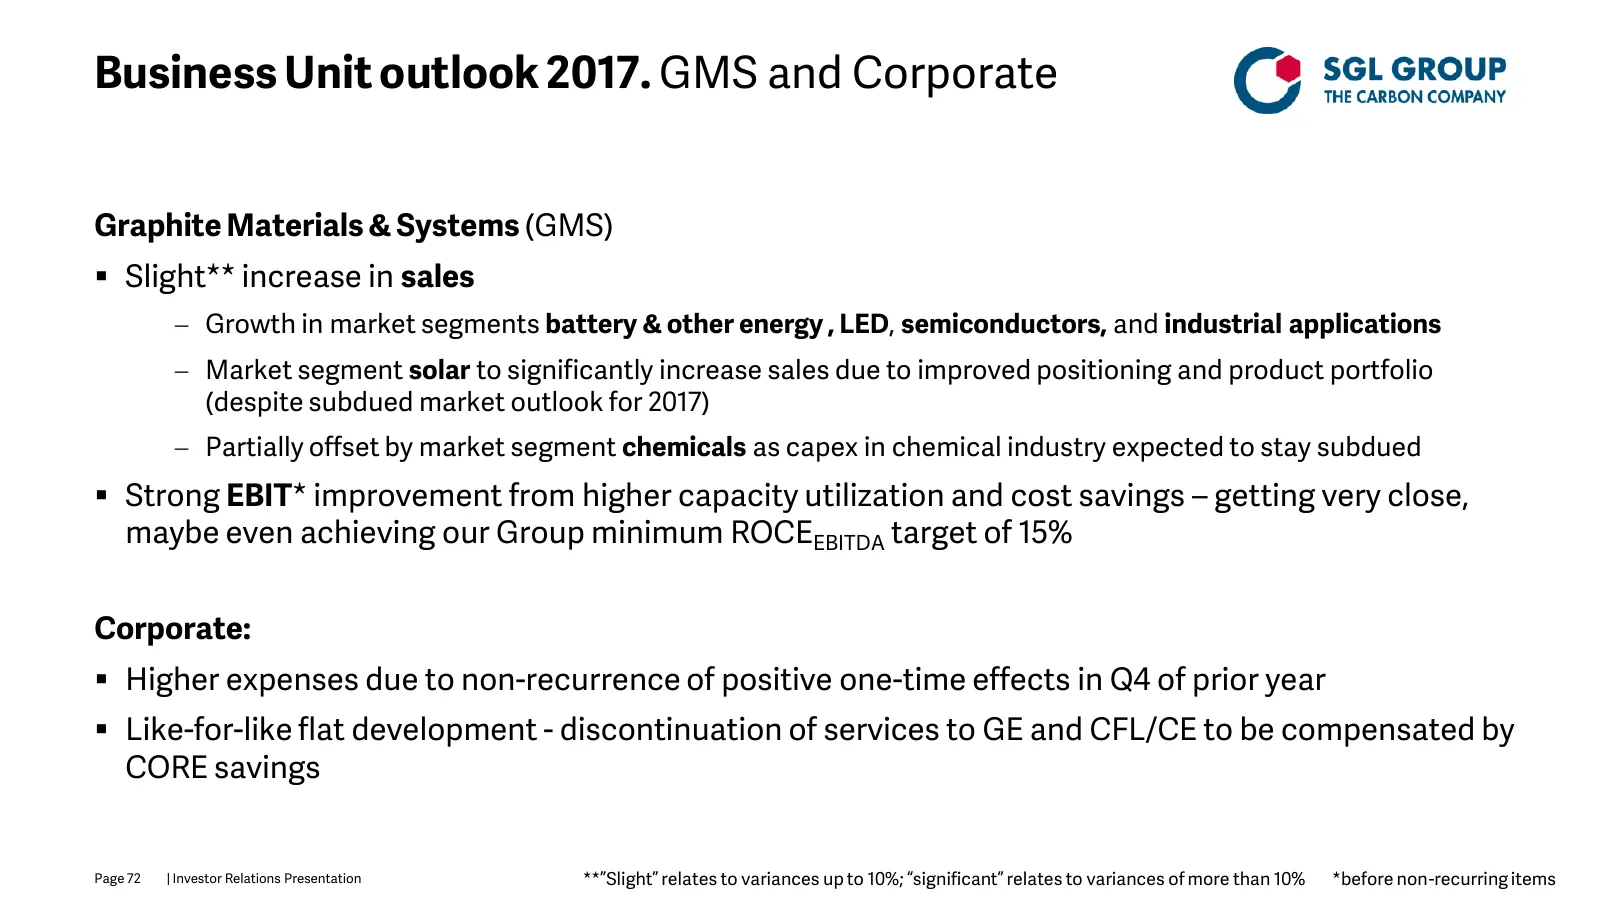
Business Unit outlook 2017. GMS and Corporate Graphite Materials & Systems (GMS) Slight** increase in sales Growth in market segments battery & other energy , LED, semiconductors, and industrial applications Market segment solar to significantly increase sales due to improved positioning and p
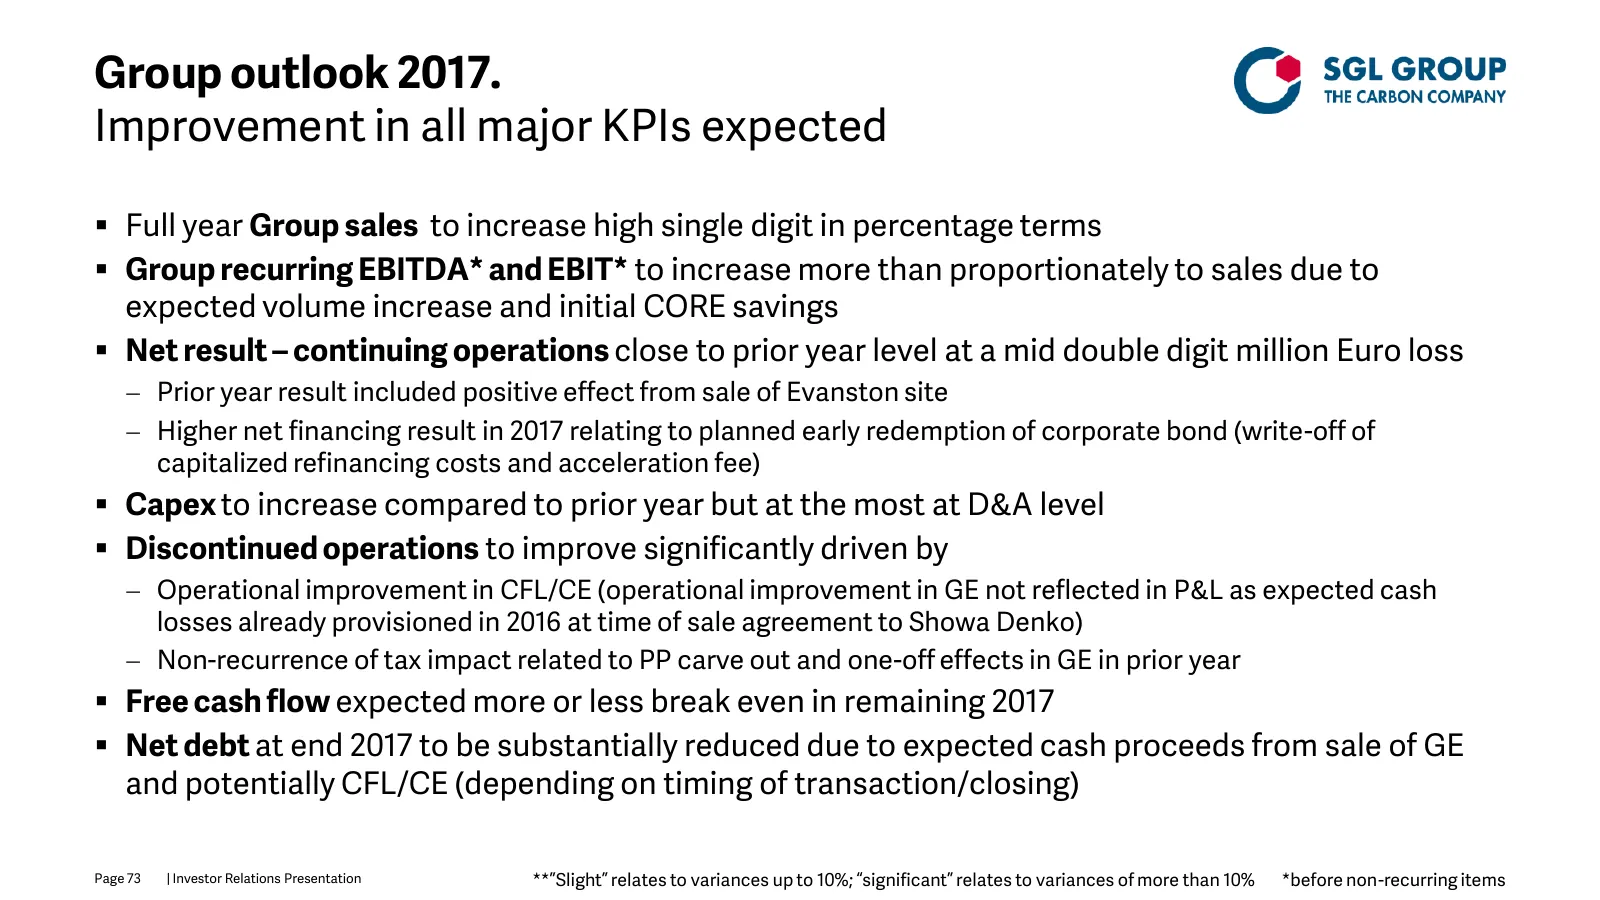
Slide 73: Group outlook 2017. Improvement in all major KPIs expected
Group outlook 2017. Improvement in all major KPIs expected Full year Group sales to increase high single digit in percentage terms Group recurring EBITDA* and EBIT* to increase more than proportionately to sales due to expected volume increase and initial CORE savings Net result – continuing o
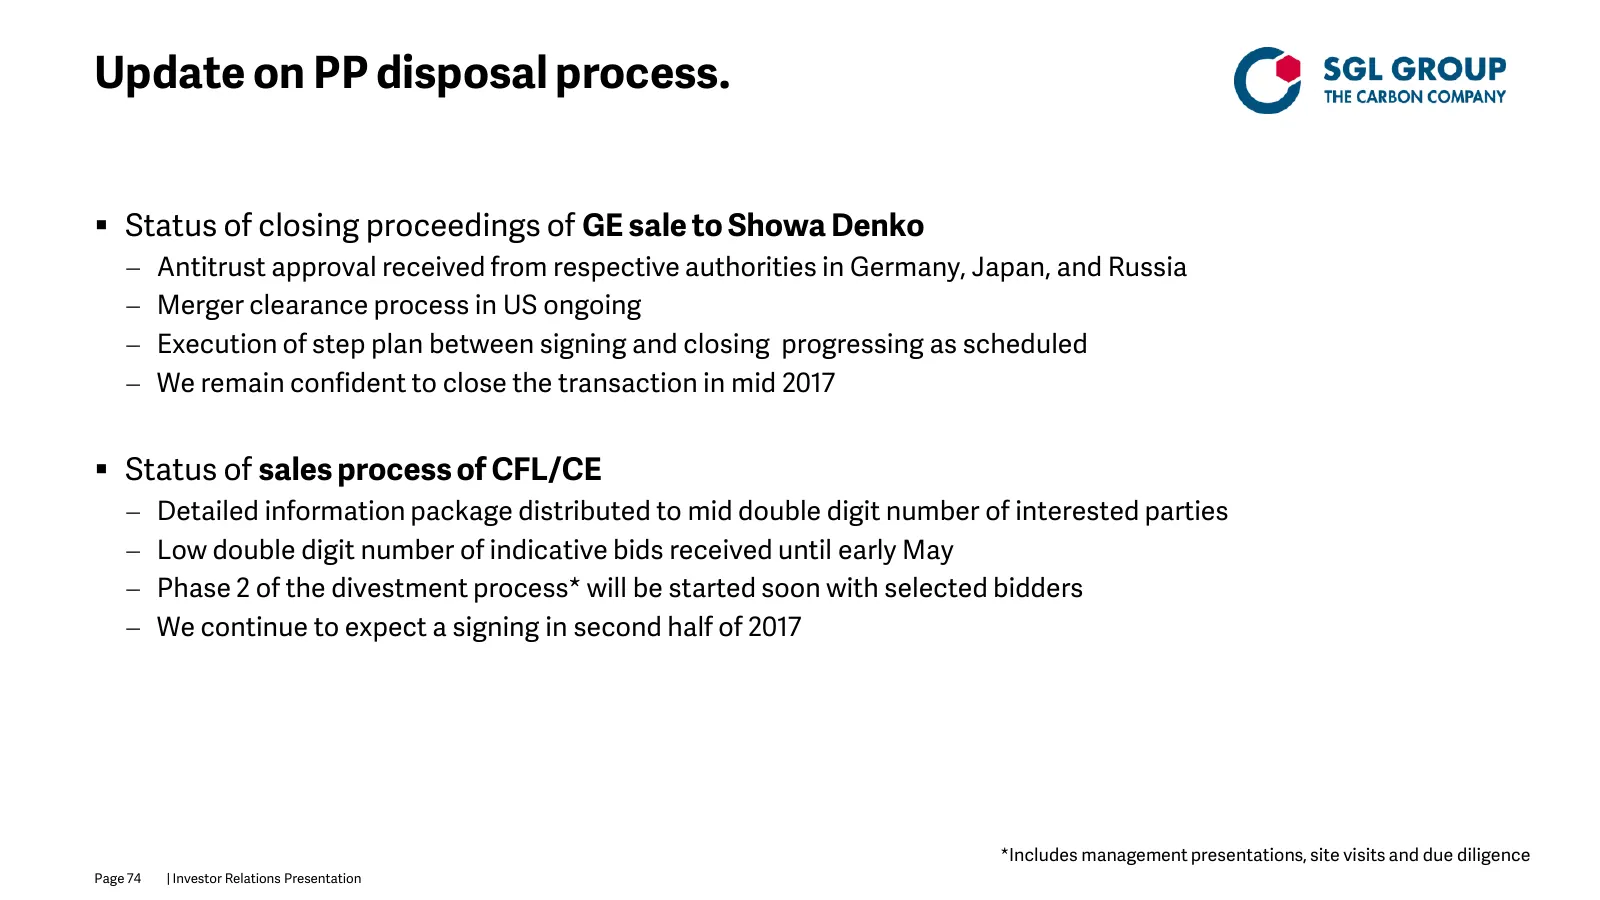
Slide 74: Update on PP disposal process
Update on PP disposal process. Status of closing proceedings of GE sale to Showa Denko Antitrust approval received from respective authorities in Germany, Japan, and Russia Merger clearance process in US ongoing Execution of step plan between signing and closing progressing as scheduled We
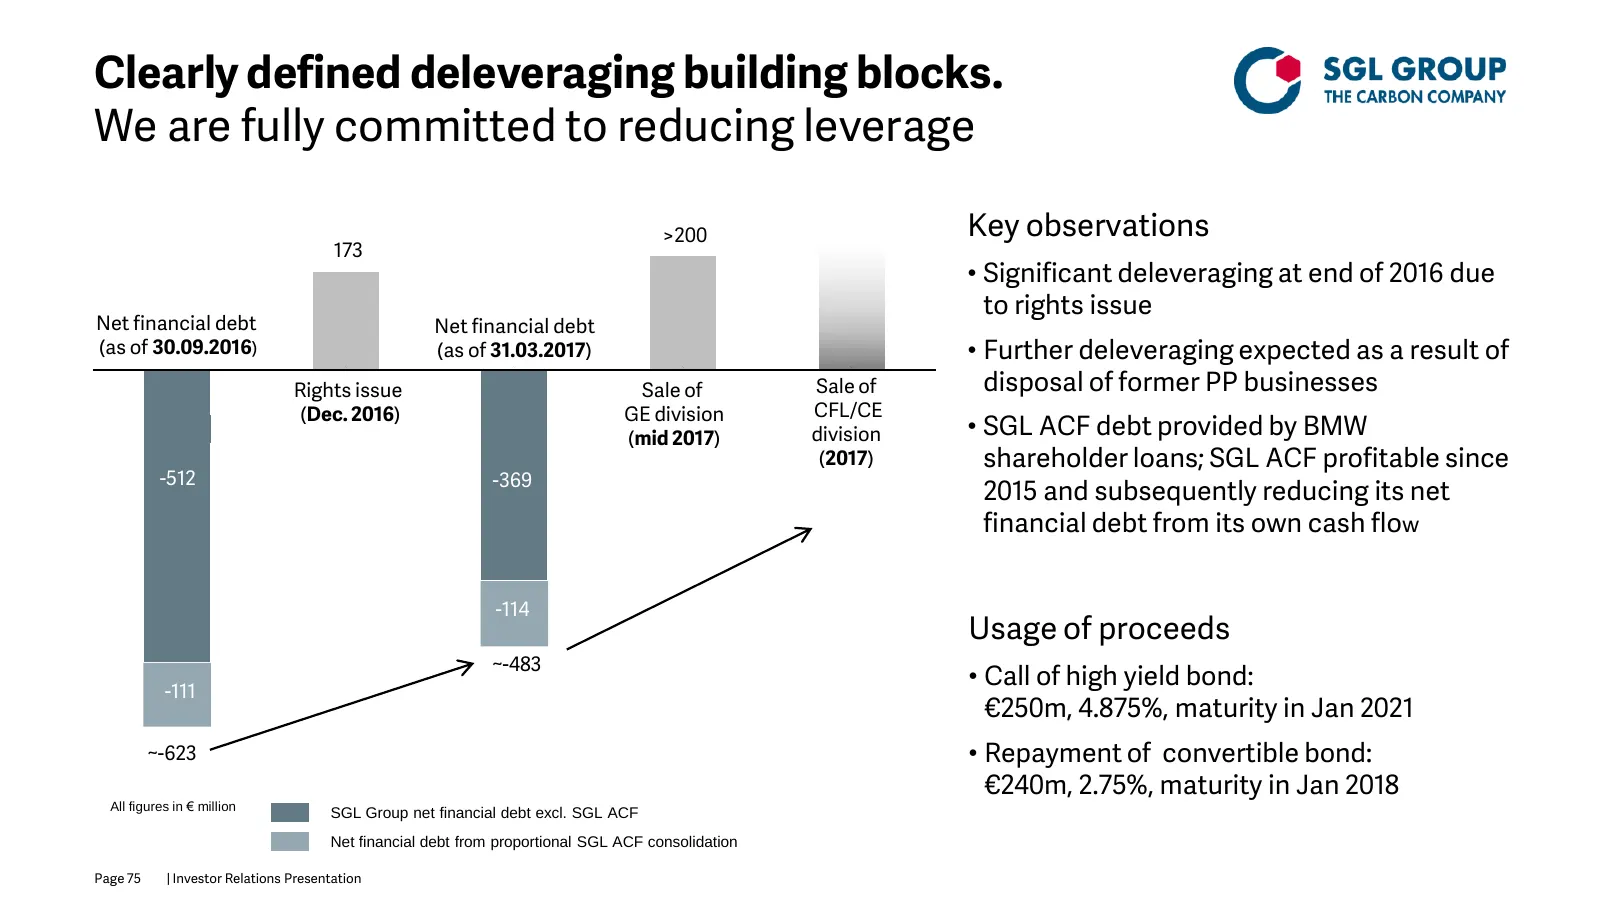
Slide 75: Clearly defined deleveraging building blocks
Clearly defined deleveraging building blocks. We are fully committed to reducing leverage >200 Key observations 173 • Significant 113 deleveraging at end of 2016 due to rights issue Net financial debt Net financial debt (as of 30.09.2016) (as of 31.03.2017) • Further deleveraging expected as a resul
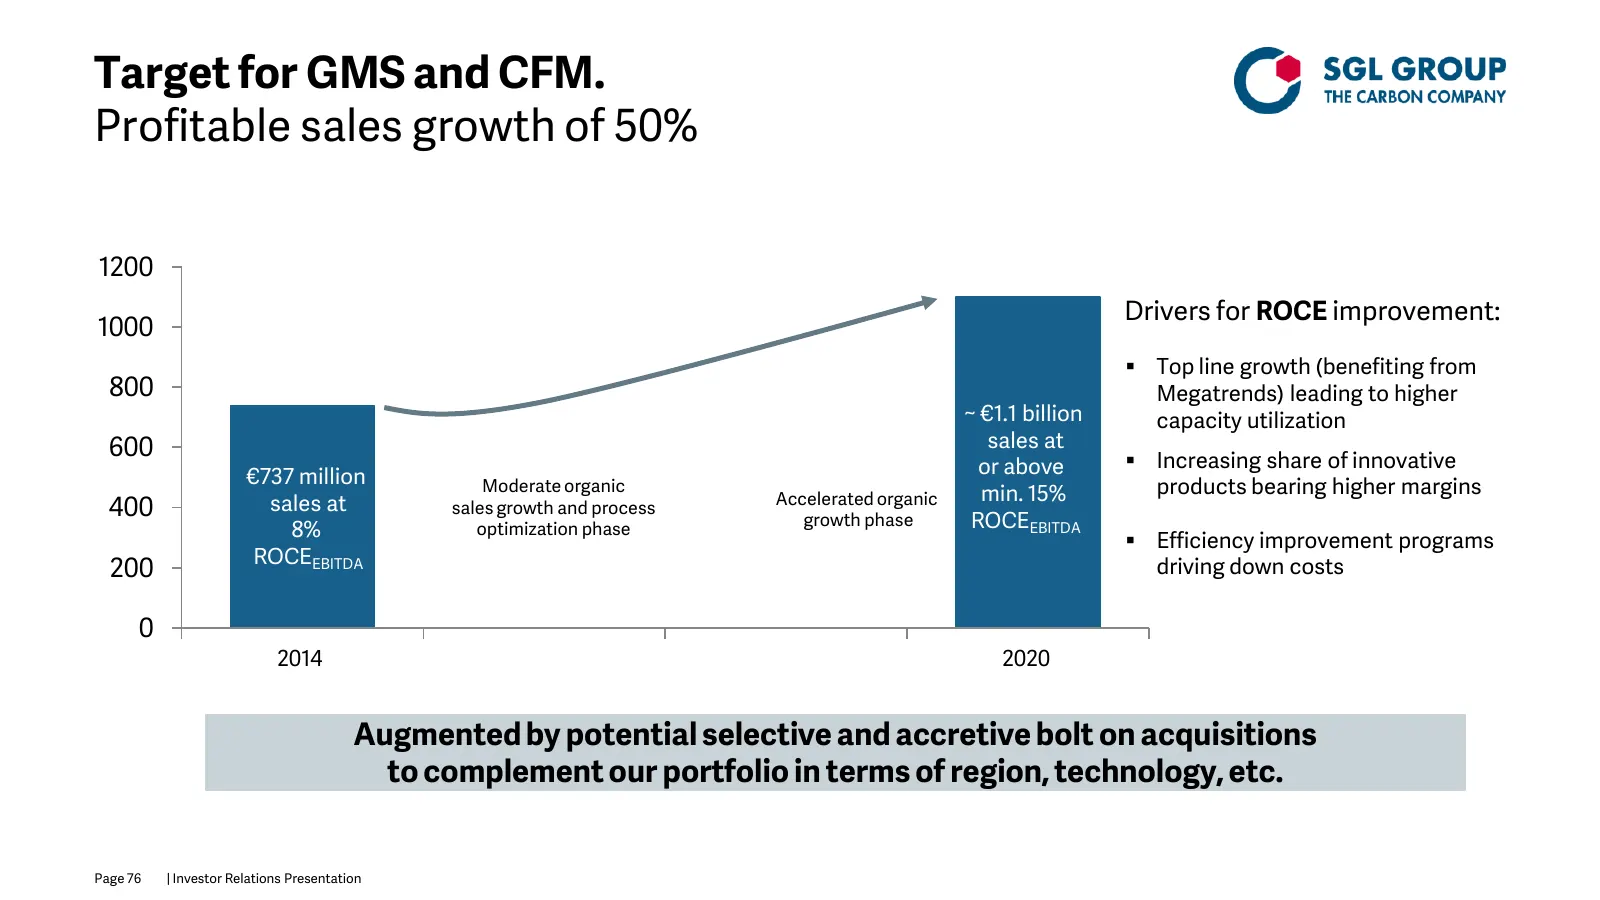
Slide 76: Target for GMS and CFM. Profitable sales growth of 50%
Target for GMS and CFM. Profitable sales growth of 50% 1200 Drivers for ROCE improvement: 1000 Top line growth (benefiting from 800 Megatrends) leading to higher ~ €1.1 billion capacity utilization 600 sales at or above Increasing share of innovative €737 million Moderate organic products bearin
Slide 77: Strategic realignment of SGL Group. 2017: Focus on growth
Strategic realignment of SGL Group. 2017: Focus on growth Achieve prerequisites for returning to sustainable profitable growth Closing of sale of graphite electrode business to Showa Denko Sale of cathode, furnace lining and carbon electrode business Early repayment of corporate bond Imple
Slide 78: Appendix
Appendix Page 78 | Investor Relations Presentation
Slide 79: Global presence. Continued operations
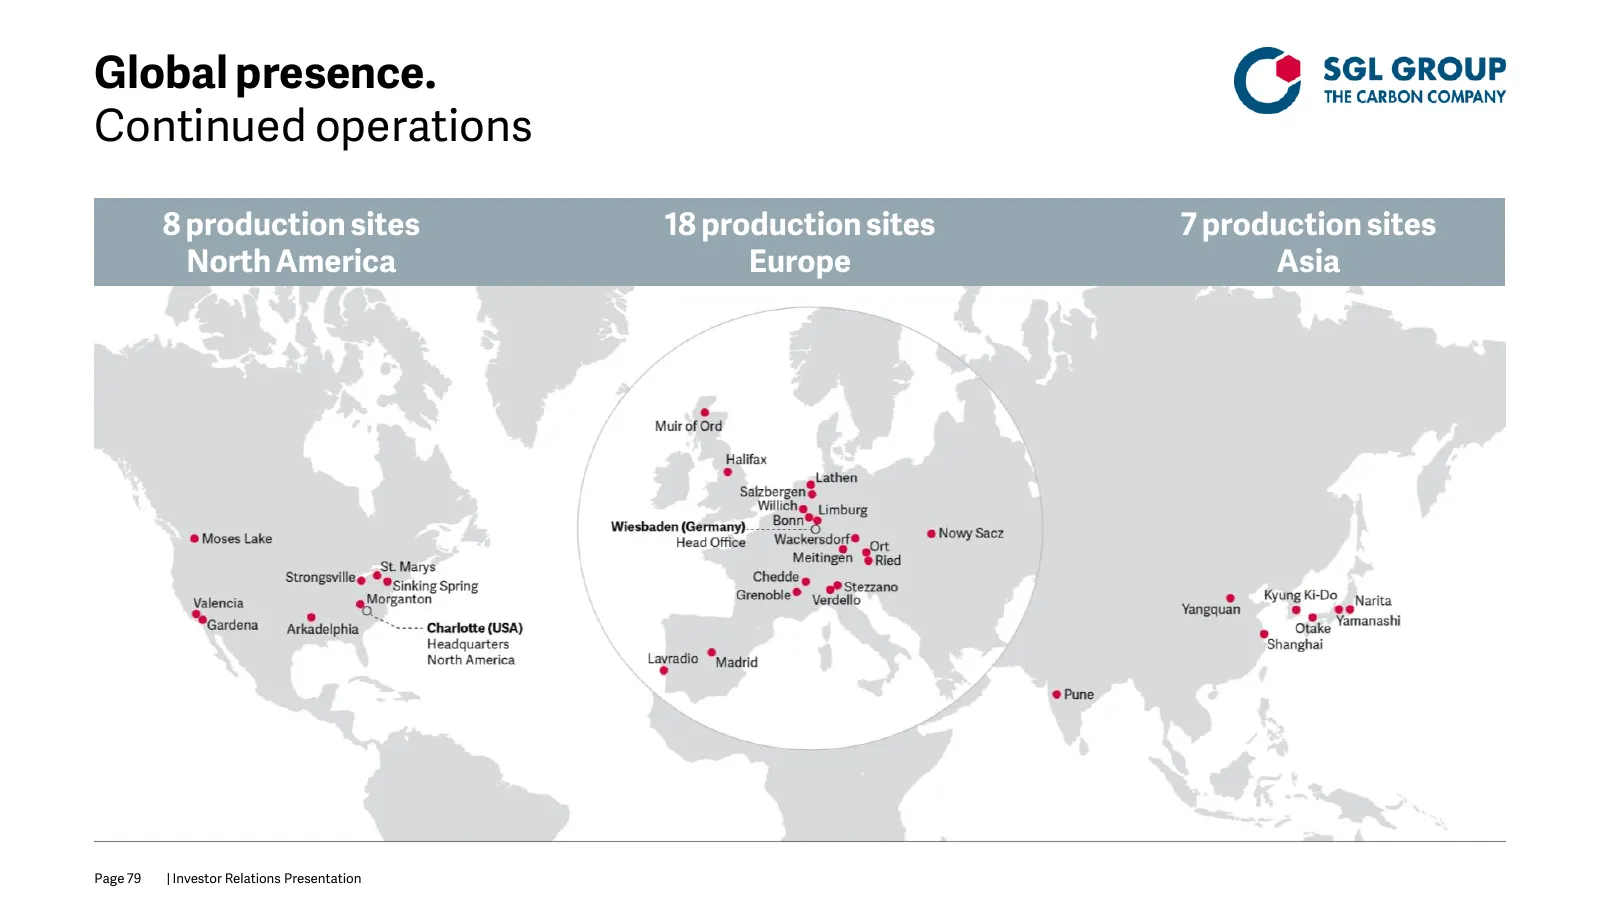
Global presence. Continued operations 8 production sites 18 production sites 7 production sites North America Europe Asia Page 79 | Investor Relations Presentation
Slide 80: Shares in issue and shareholder structure
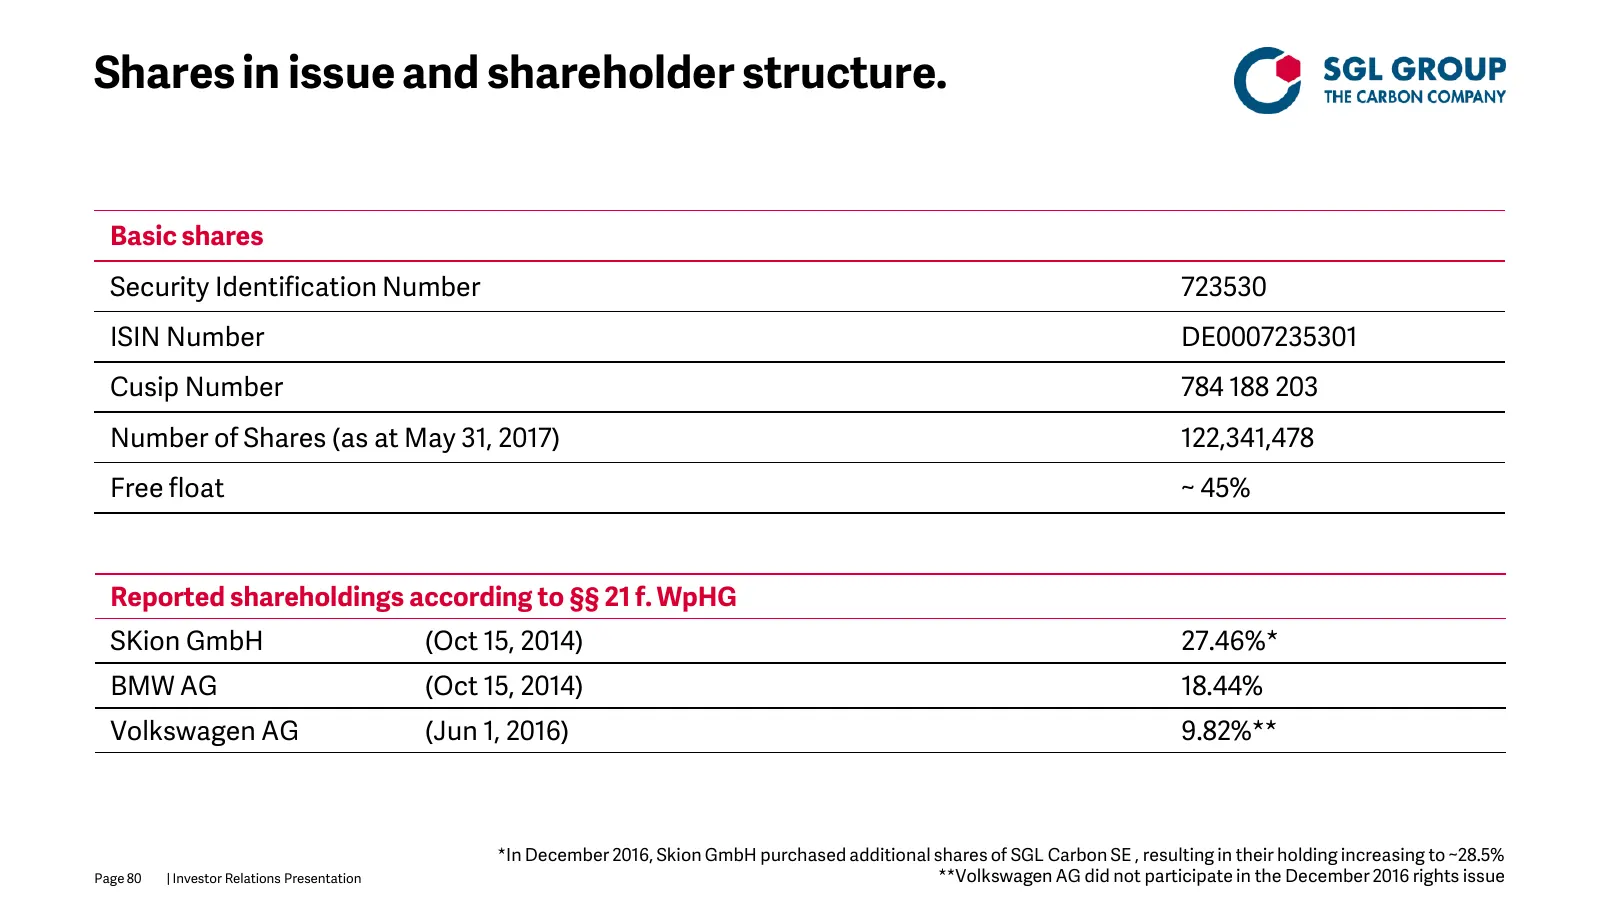
Shares in issue and shareholder structure. Basic shares Security Identification Number 723530 ISIN Number DE0007235301 Cusip Number 784 188 203 Number of Shares (as at May 31, 2017) 122,341,478 Free float ~ 45% Reported shareholdings according to §§ 21 f. WpHG SKion GmbH (Oct 15, 2014) 27.46%* BMW A
Slide 81: Debt market instruments
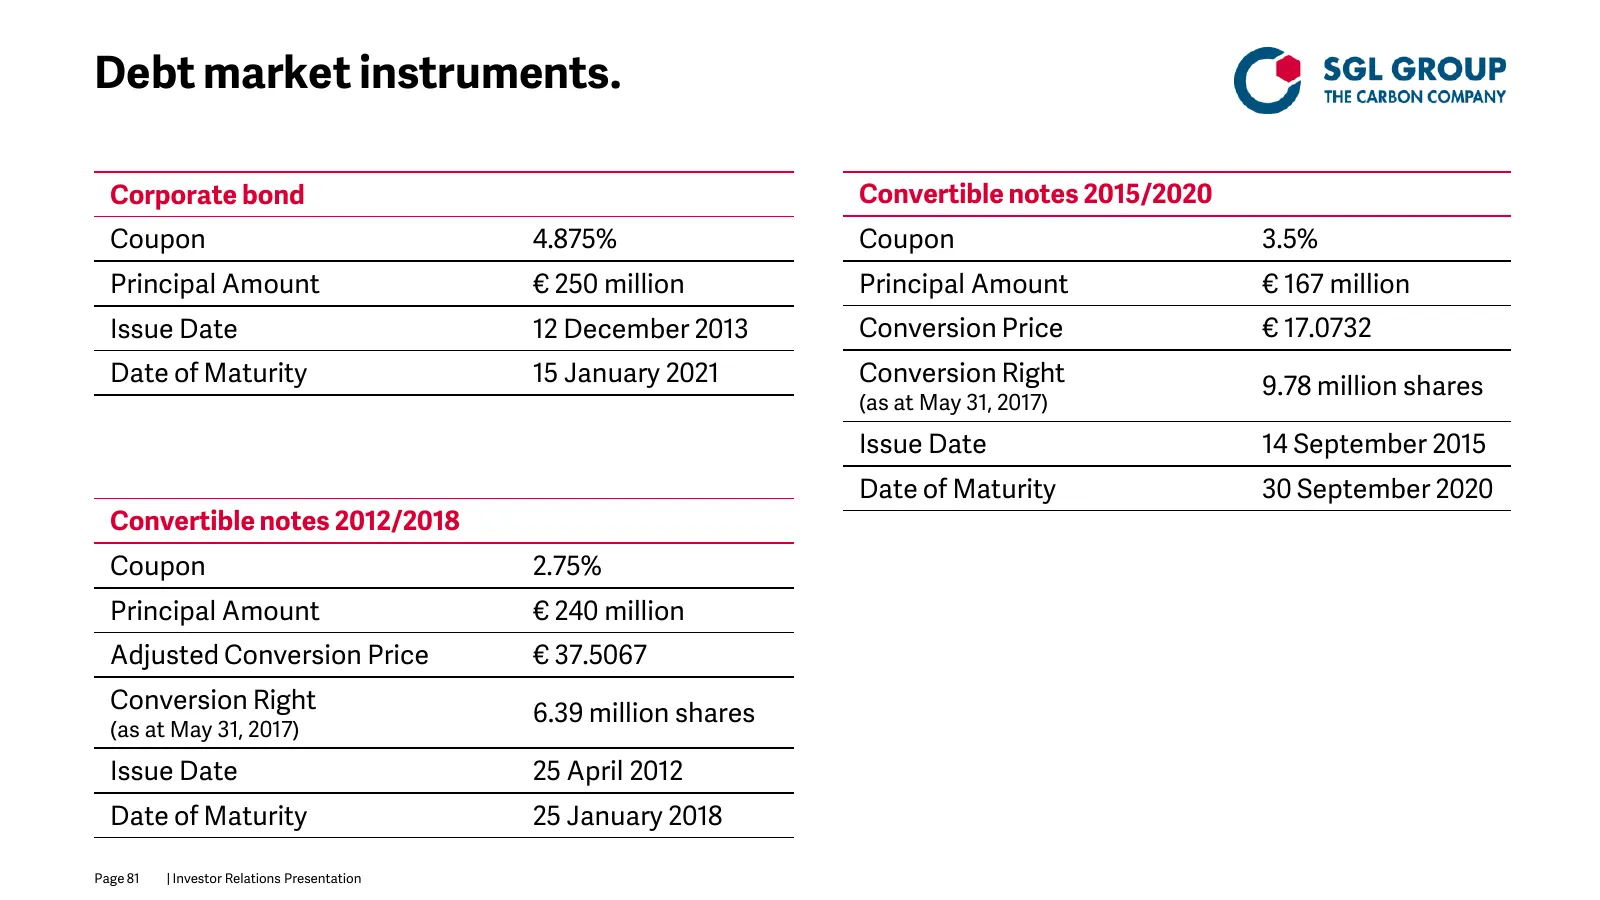
Debt market instruments. Corporate bond Convertible notes 2015/2020 Coupon 4.875% Coupon 3.5% Principal Amount € 250 million Principal Amount € 167 million Issue Date 12 December 2013 Conversion Price € 17.0732 Date of Maturity 15 January 2021 Conversion Right 9.78 million shares (as at May 31, 2017
Slide 82: Financial calendar / contact details
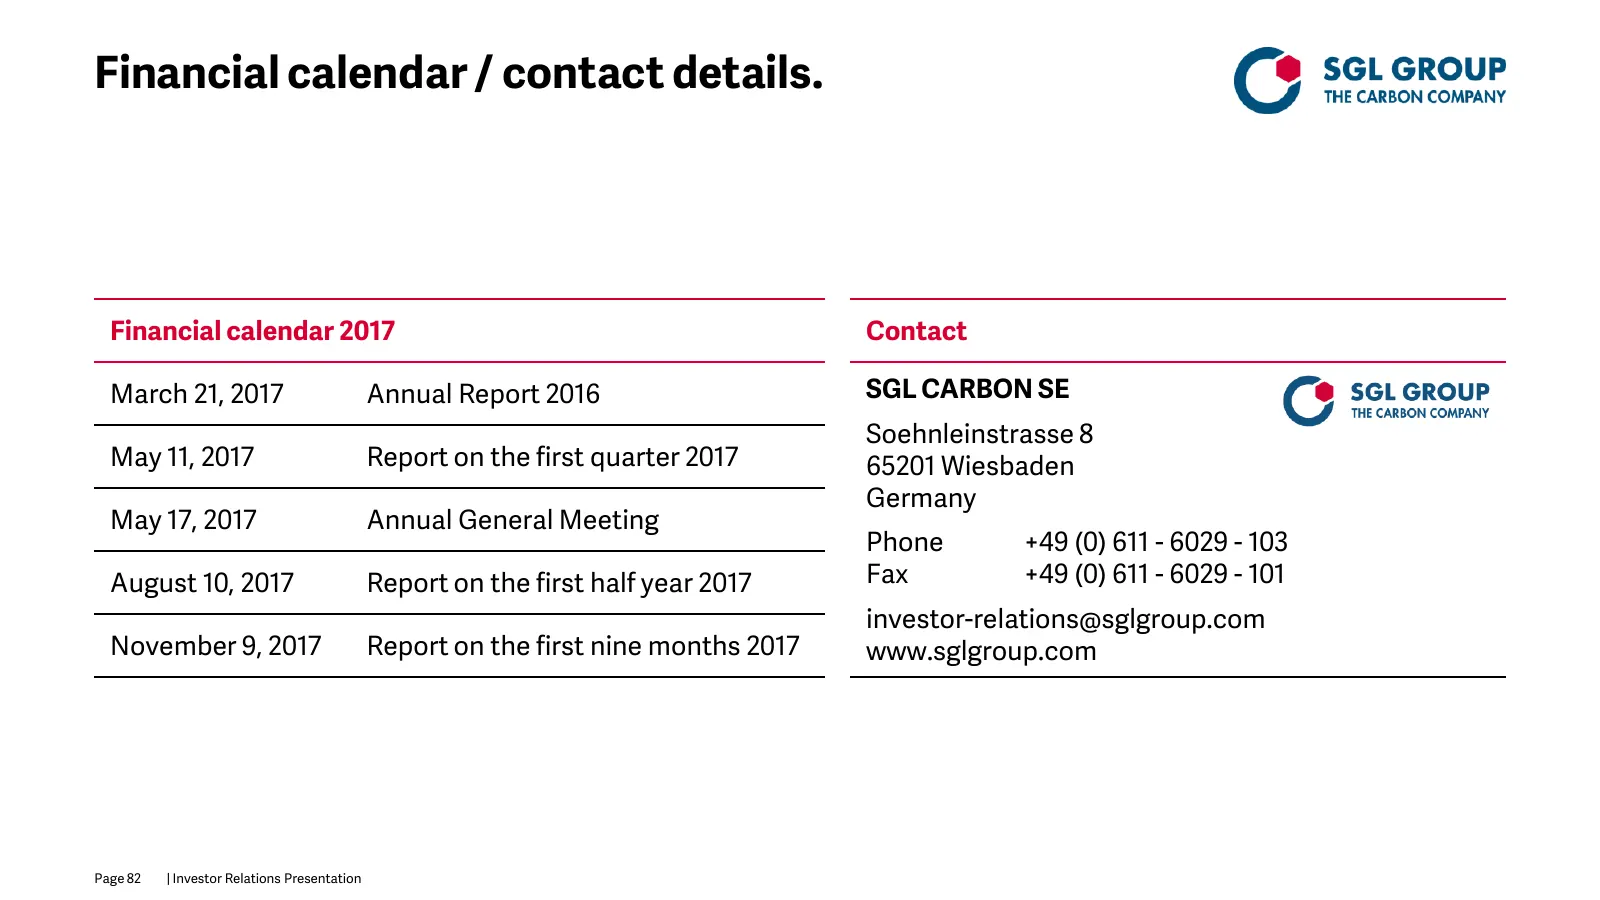
Financial calendar / contact details. Financial calendar 2017 Contact March 21, 2017 Annual Report 2016 SGL CARBON SE Soehnleinstrasse 8 May 11, 2017 Report on the first quarter 2017 65201 Wiesbaden Germany May 17, 2017 Annual General Meeting Phone +49 (0) 611 - 6029 - 103 August 10, 2017 Report on
Slide 83: Discontinued operations Performance Products
Discontinued operations Performance Products (classified as discontinued operations at the end of Q2/2016) Page 83 | Investor Relations Presentation
Slide 84: Discontinued operations. Performance Products (PP)
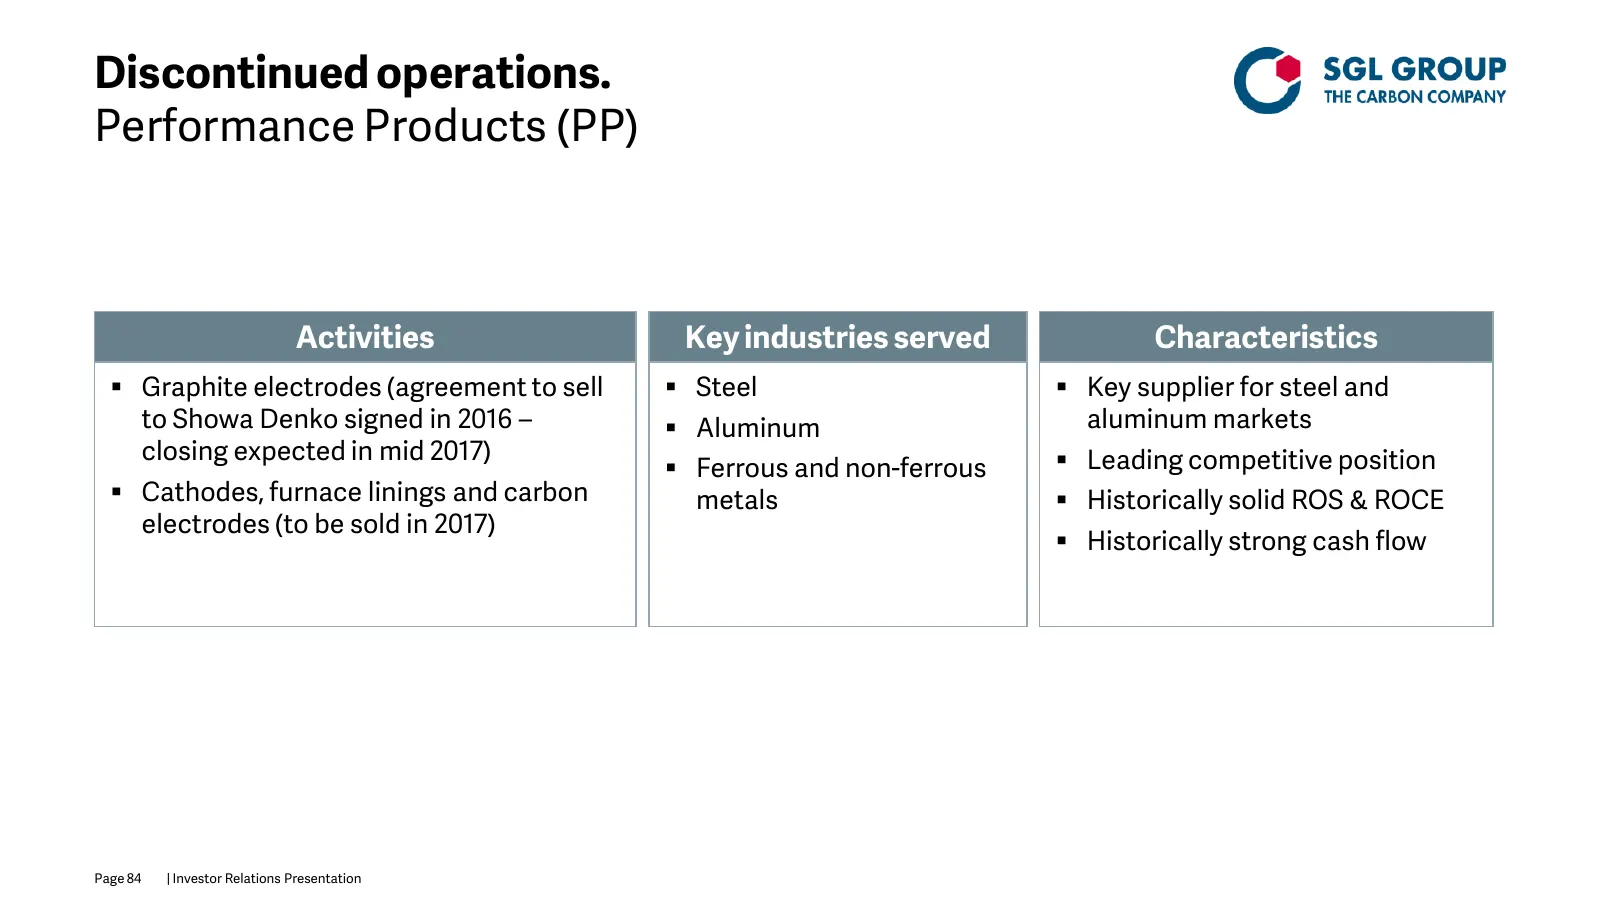
Discontinued operations. Performance Products (PP) Activities Key industries served Characteristics Graphite electrodes (agreement to sell Steel Key supplier for steel and to Showa Denko signed in 2016 – Aluminum aluminum markets closing expected in mid 2017) Leading competitive position
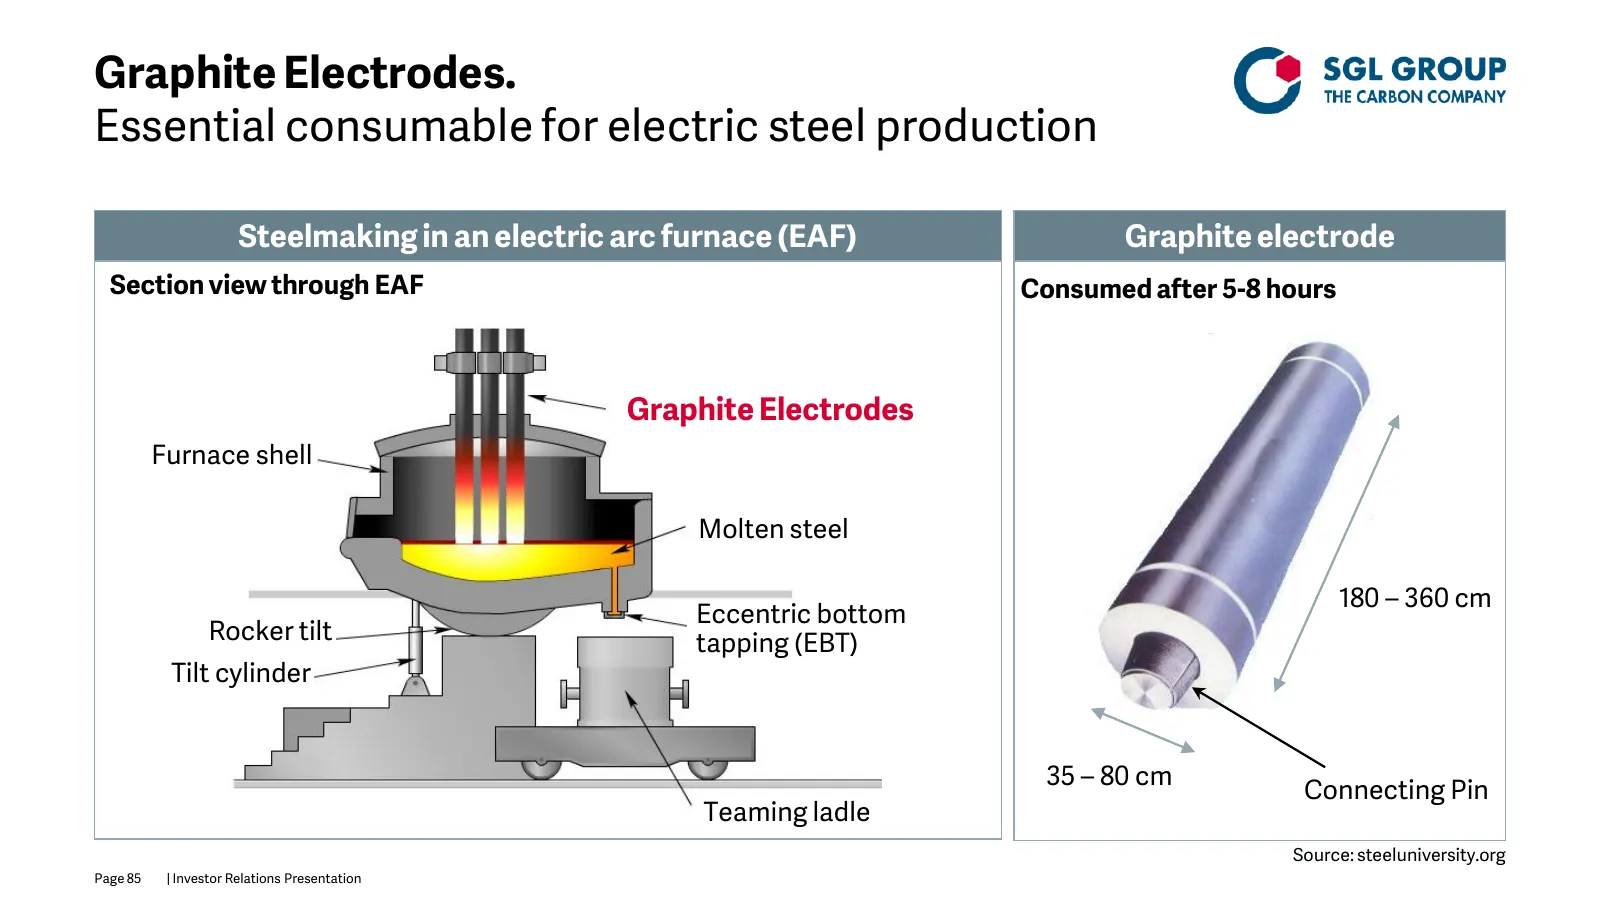
Slide 85: Graphite Electrodes. Essential consumable for electric steel production
Graphite Electrodes. Essential consumable for electric steel production Steelmaking in an electric arc furnace (EAF) Graphite electrode Section view through EAF Consumed after 5-8 hours Graphite Electrodes Furnace shell Molten steel 180 – 360 cm Eccentric bottom Rocker tilt tapping (EBT) Tilt cylind
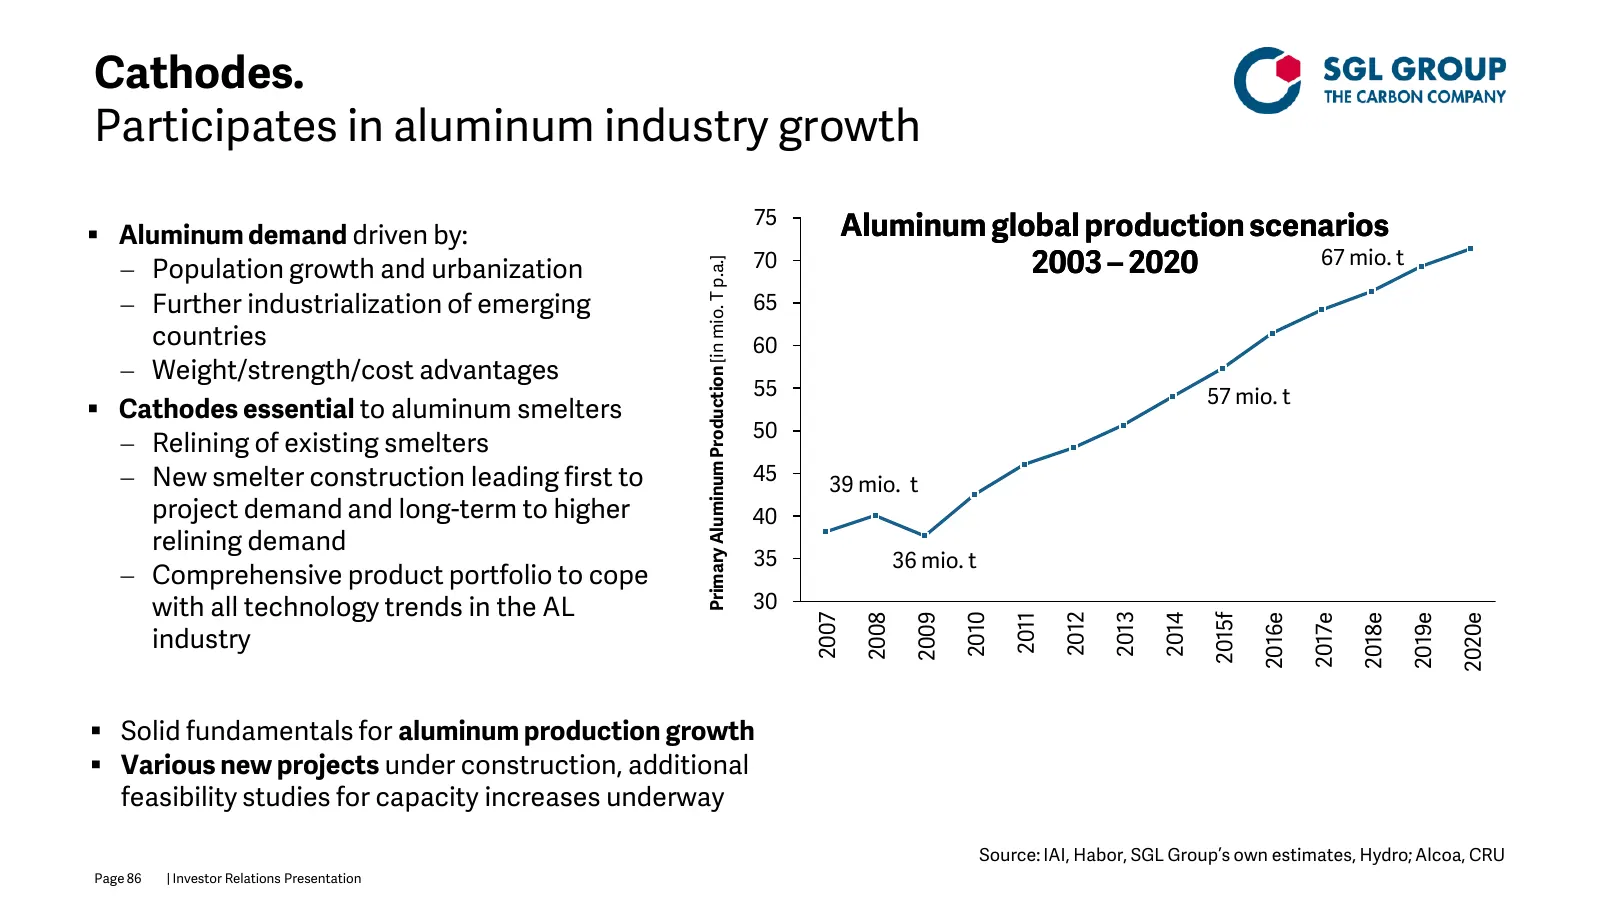
Slide 86: Cathodes. Participates in aluminum industry growth
Cathodes. Participates in aluminum industry growth 75 Aluminum global production scenarios Aluminum demand driven by: Population growth and urbanization 70 2003 – 2020 67 mio. t Primary Aluminum Production [in mio. T p.a.] Further industrialization of emerging 65 countries 60 Weight/strength
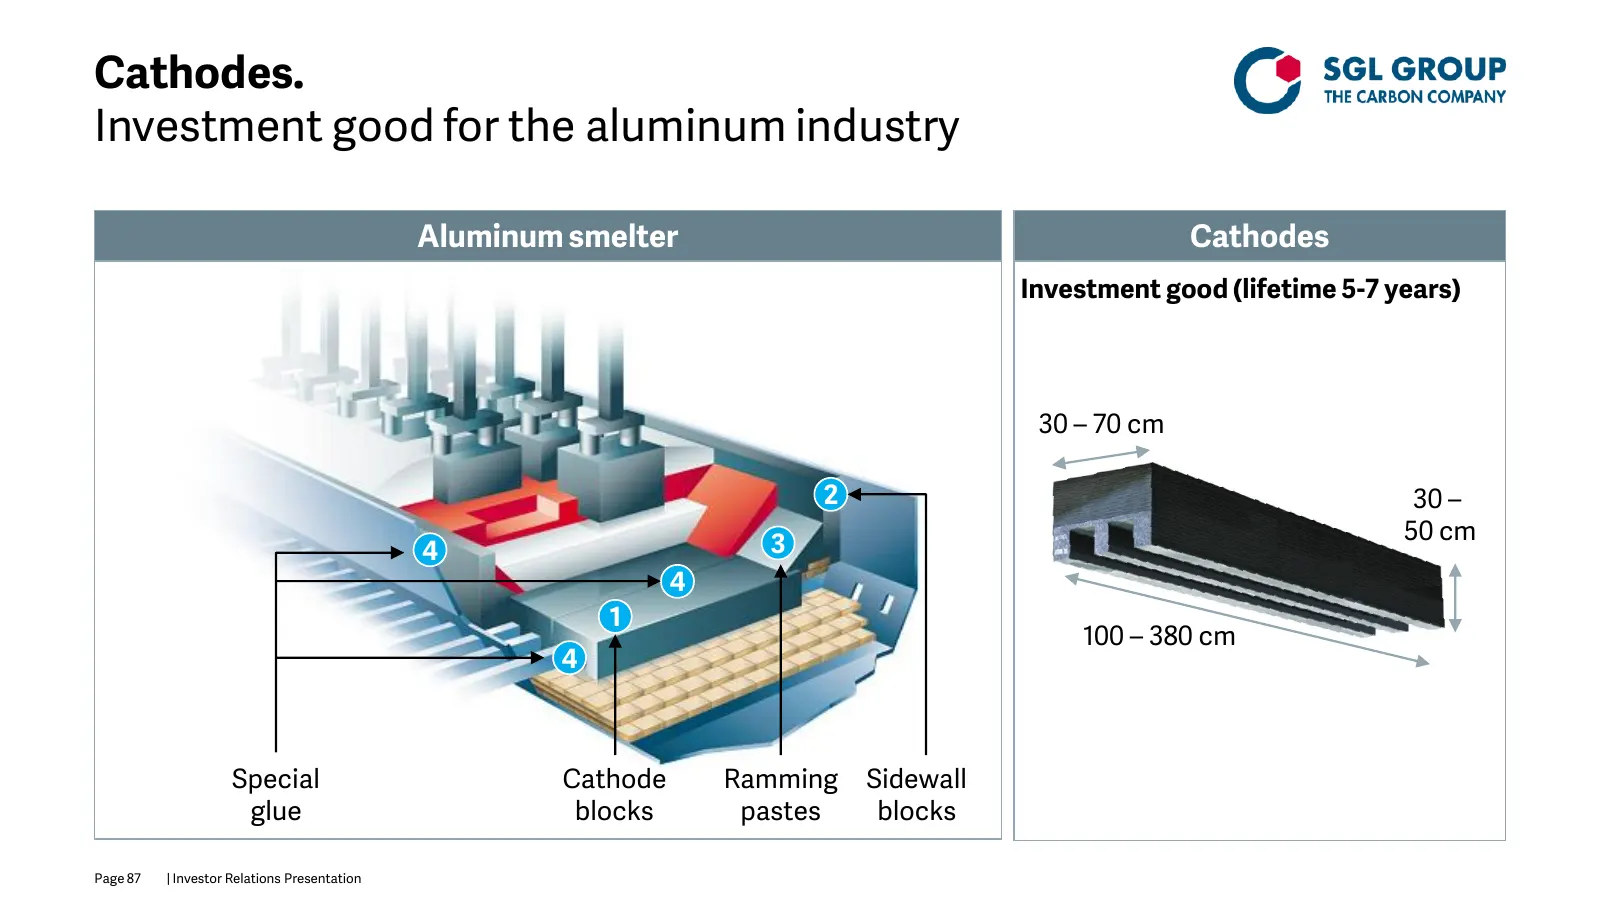
Slide 87: Cathodes. Investment good for the aluminum industry
Cathodes. Investment good for the aluminum industry Aluminum smelter Cathodes Investment good (lifetime 5-7 years) 30 – 70 cm 2 30 – 3 50 cm 4 4 1 100 – 380 cm 4 Special Cathode Ramming Sidewall glue blocks pastes blocks Page 87 | Investor Relations Presentation
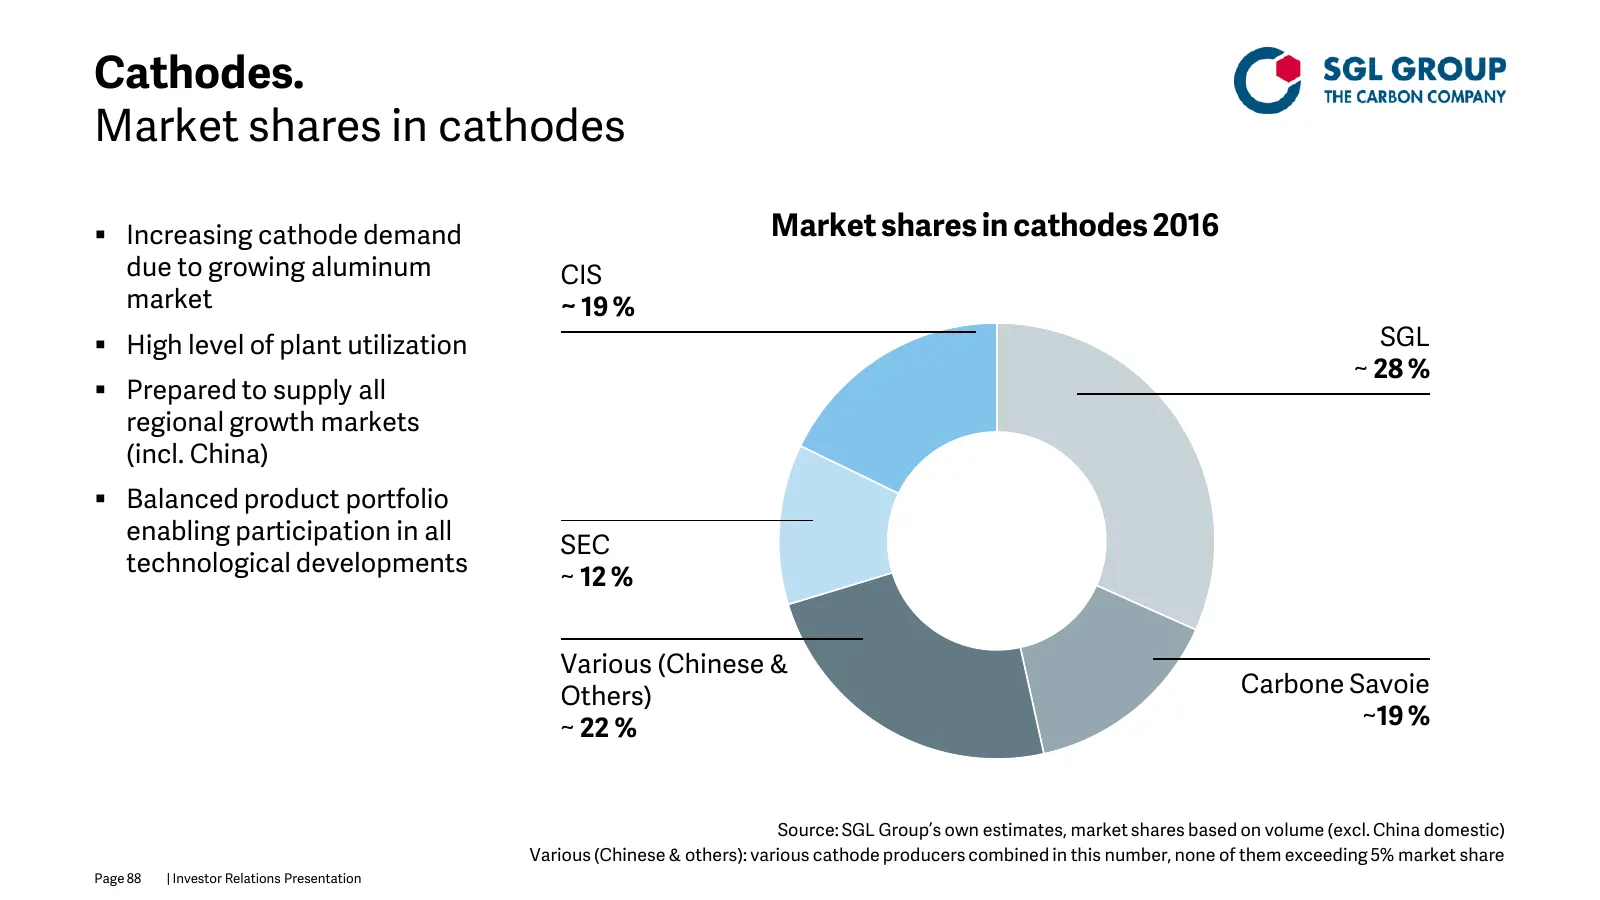
Slide 88: Cathodes. Market shares in cathodes
Cathodes. Market shares in cathodes Increasing cathode demand Market shares in cathodes 2016 due to growing aluminum CIS market ~ 19 % High level of plant utilization SGL ~ 28 % Prepared to supply all regional growth markets (incl. China) Balanced product portfolio enabling participation in
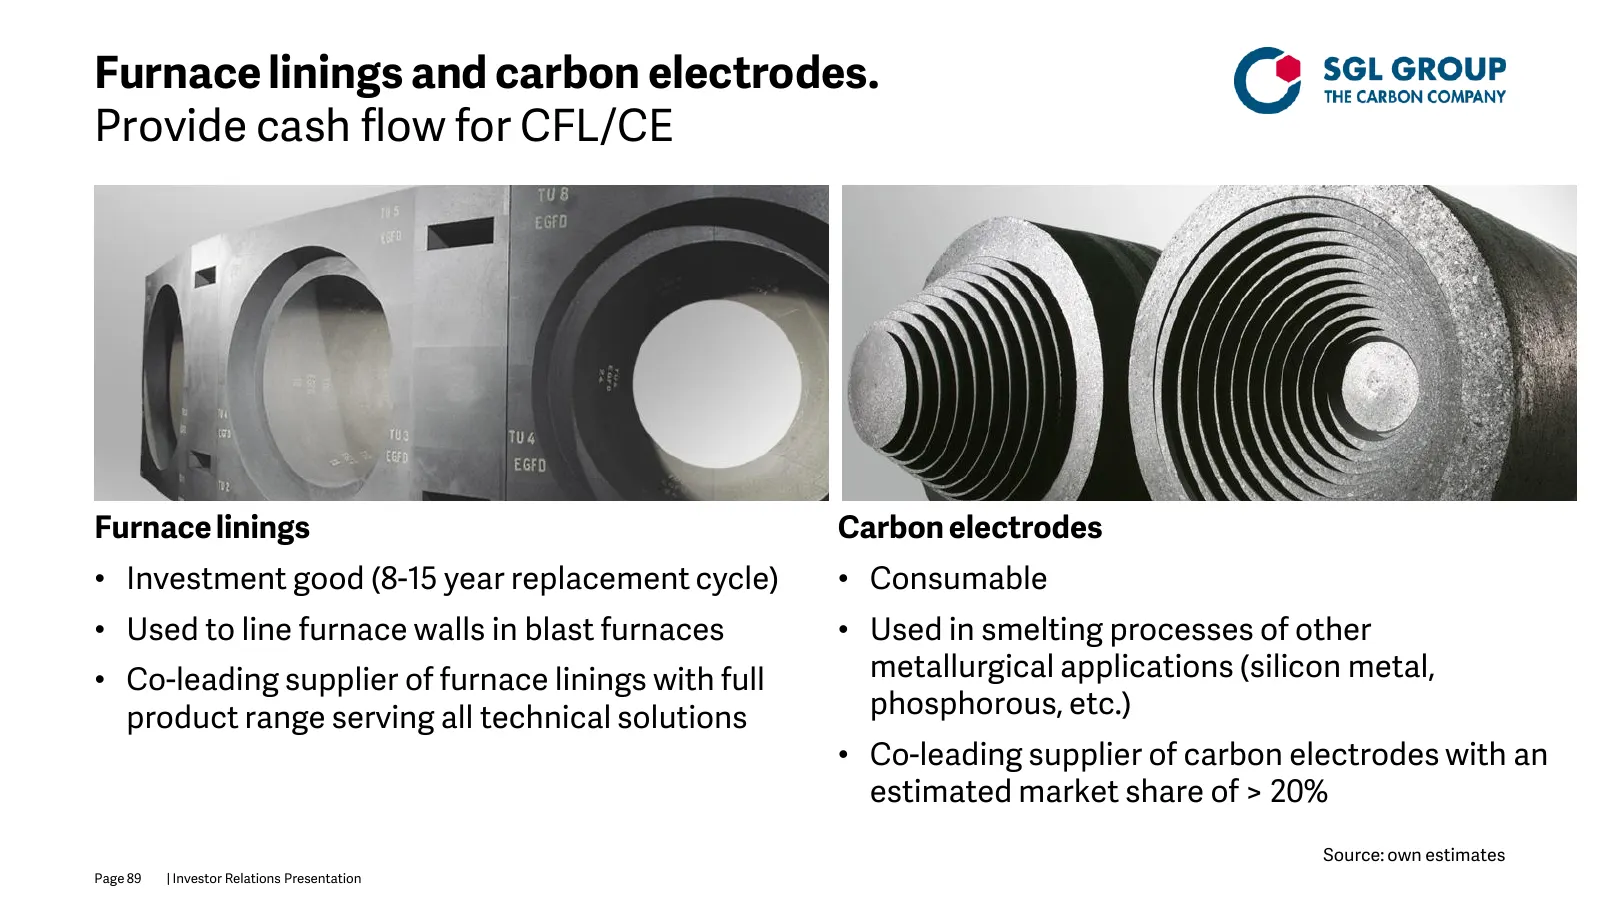
Slide 89: Furnace linings and carbon electrodes
Furnace linings and carbon electrodes. Provide cash flow for CFL/CE Furnace linings Carbon electrodes • Investment good (8-15 year replacement cycle) • Consumable • Used to line furnace walls in blast furnaces • Used in smelting processes of other • Co-leading supplier of furnace linings with full m
Slide 90: Important note
Important note. Important note: This presentation contains statements relating to certain projections and business trends that are forward-looking, including statements with respect to SGL Group’s outlook and business development, including developments in SGL Group’s Composites - Fibers & Materials
Source: Internet Archive copy of sglgroup.com
More decks from SGL Carbon SE
 9M 2026 Earnings Presentation30 slides · Nov 5, 2026
 9M 2026 Earnings Presentation17 slides · Nov 5, 2026
 Q3 2024 Earnings Presentation28 slides · Nov 7, 2024
 H1 2024 Earnings Presentation18 slides · Aug 8, 2024
 Q1 2024 Earnings Presentation19 slides · May 8, 2024
 ESG Presentation (March 2024)7 slides · Mar 22, 2024