Boston Private Financial Holdings Inc
Boston Private Financial — Merger or Acquisition (April 2005)
26 slides from Boston Private Financial's merger presentation, Apr 20, 2005
Slide 1: Enters the Dynamic South Florida Market with the Acquisition of Gibraltar Financial Corporation
Exhibit 99.3 Enters19, April the2005 Dynamic South Florida Market with the Acquisition of Gibraltar Financial Corporation
Slide 2: Forward-Looking Statements
Forward Statements uncertainties. growth statements. beyond These adversely financial expected implementation Commission. 2 made. factors rates; Boston Looking institutions; business impact in Youthe Boston These include, this Private’s of should strength net Statements presentation synergies acquis
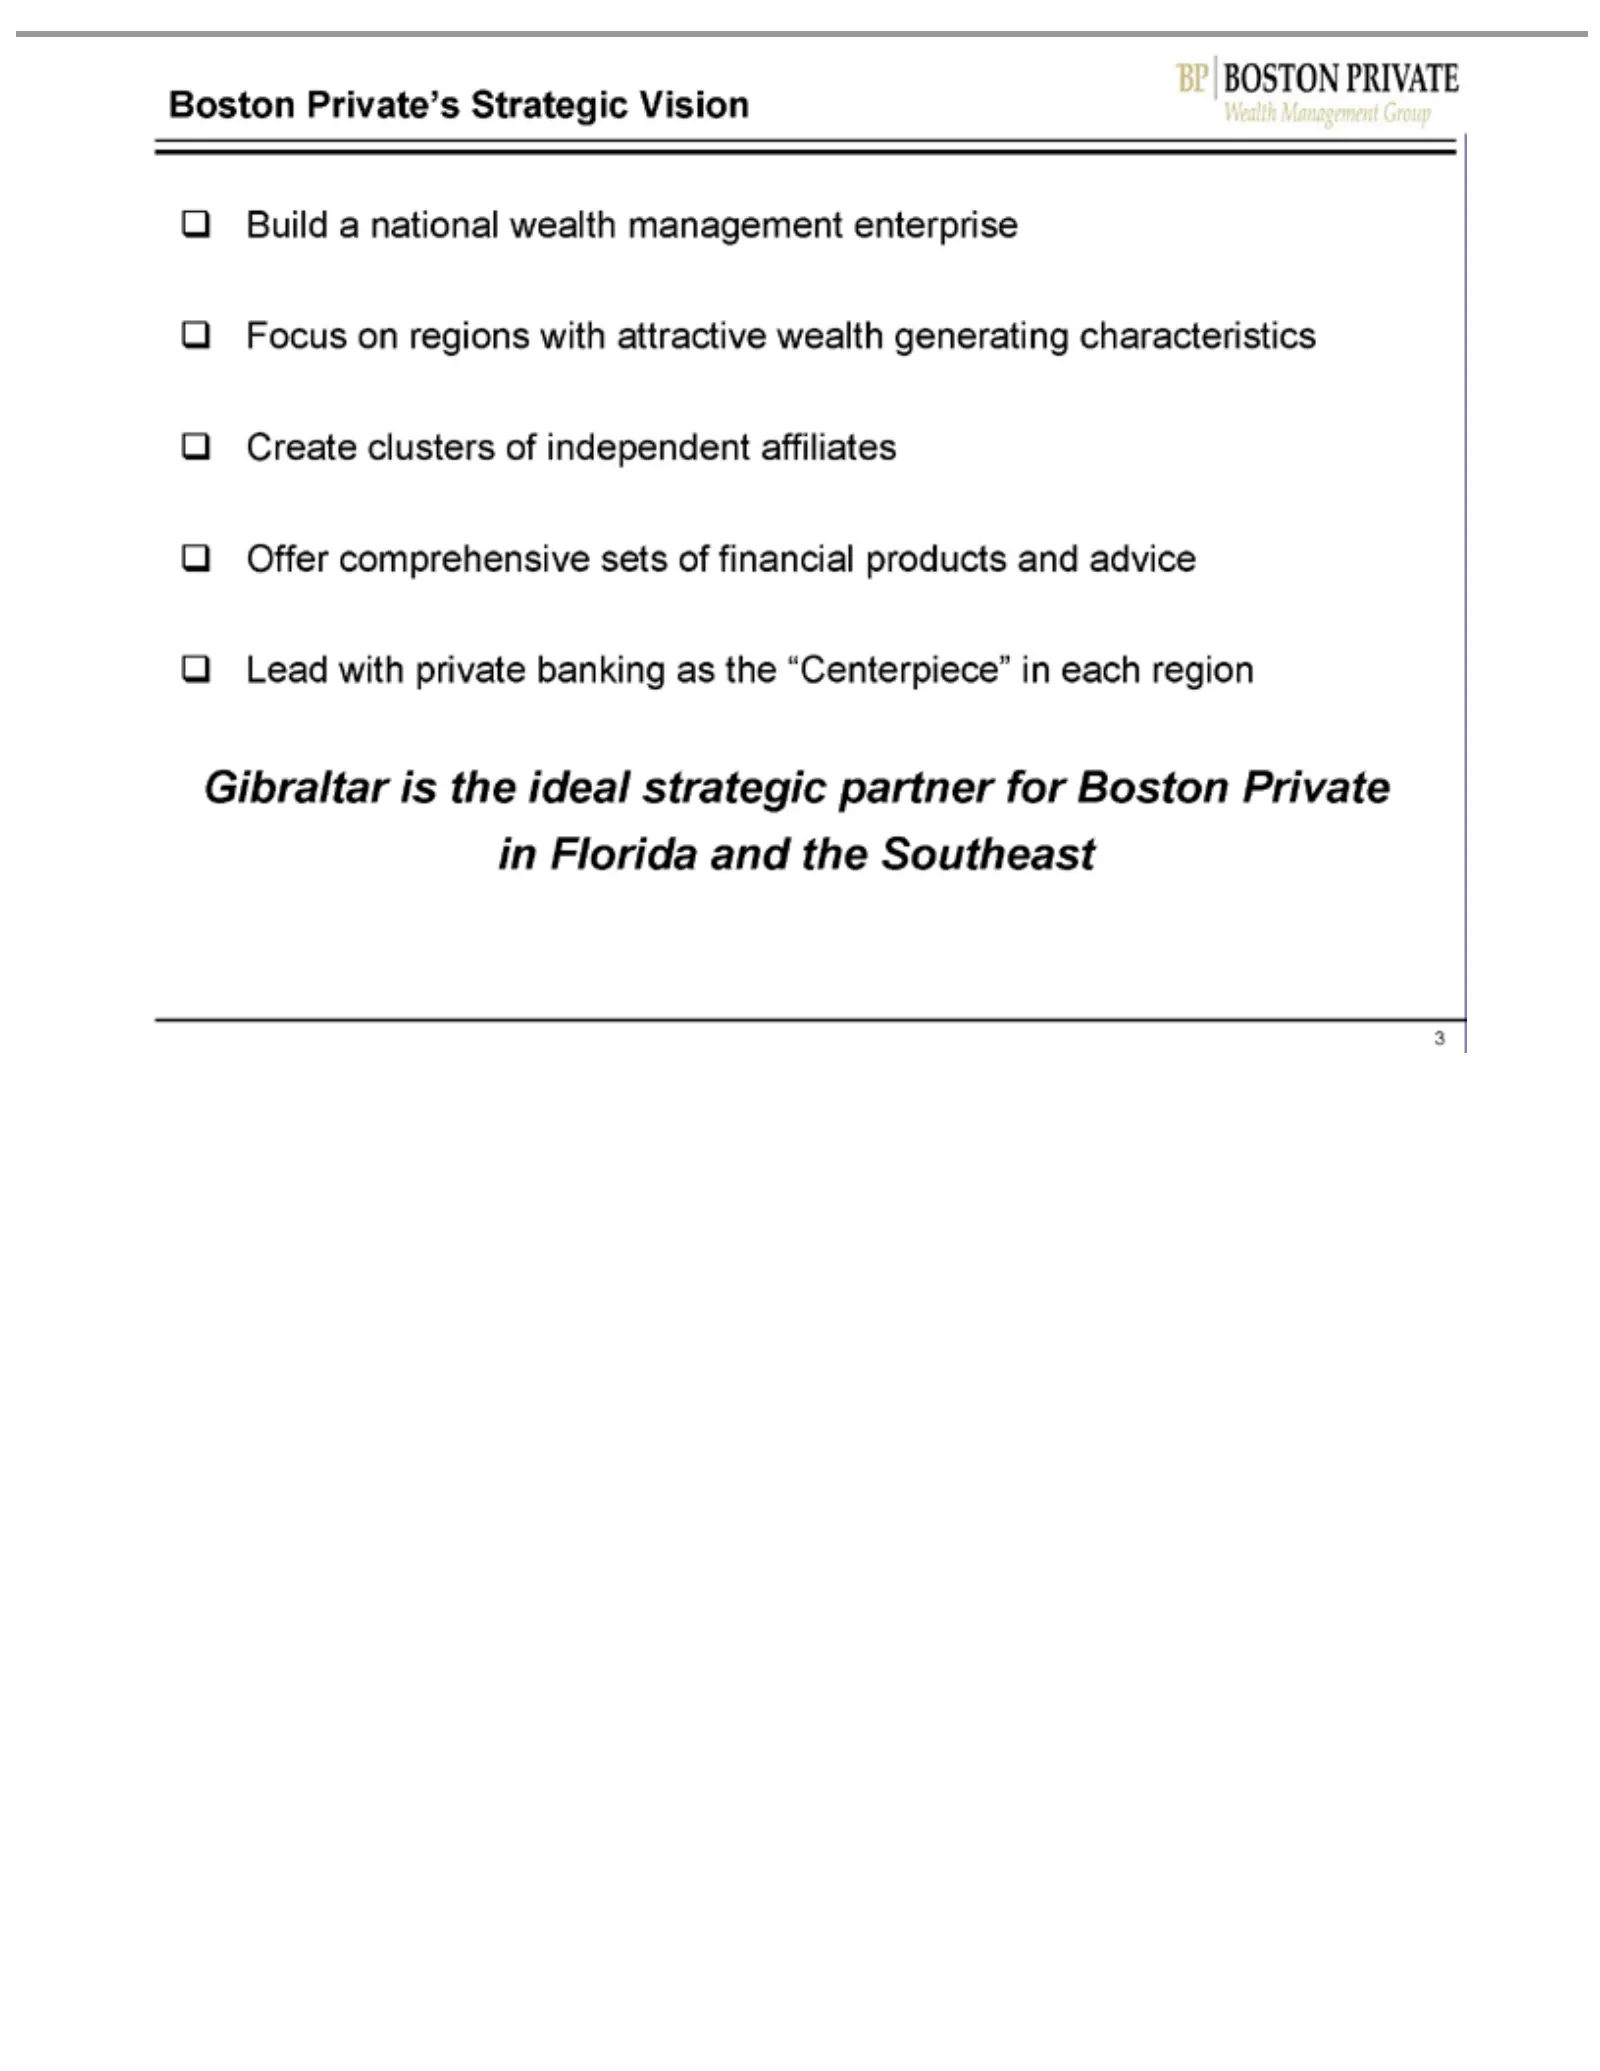
Slide 3: Boston Private's Strategic Vision
Bostonaon Build Focus “Centerpiece” Gibraltar 3 Private’s national is regions theinideal wealth Strategic each withstrategic region attractive management Vision partner wealth enterprise forgenerating Boston Private characteristics in FloridaCreate and the clusters Southeast of independent affiliate
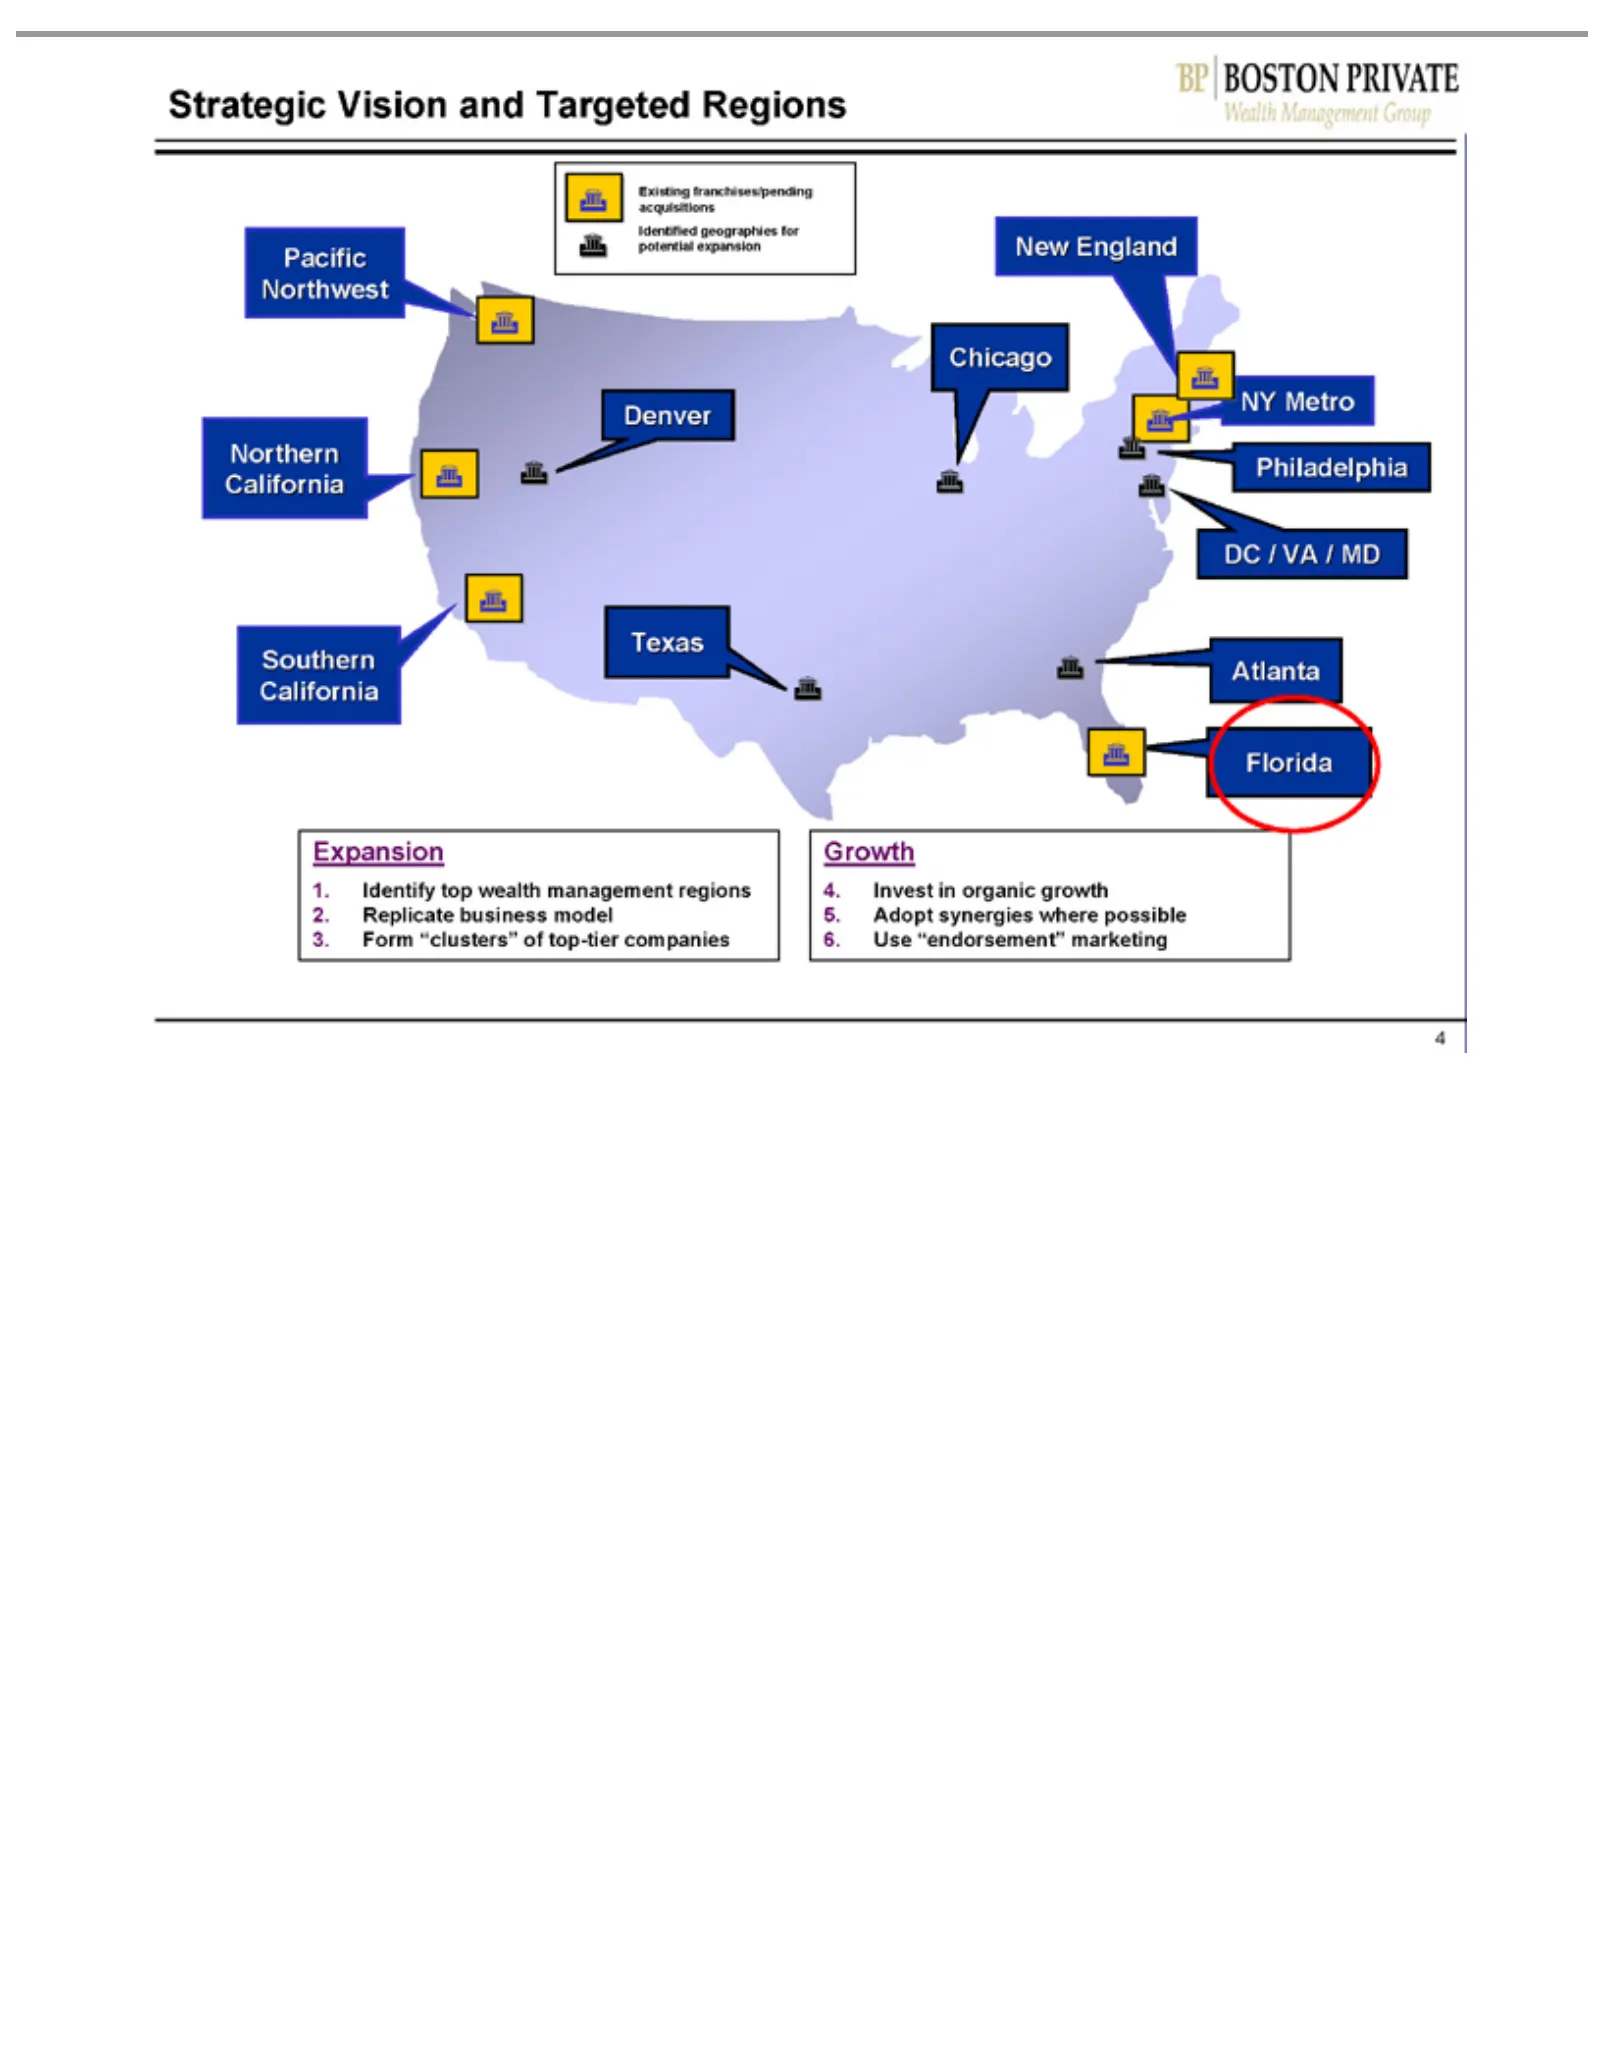
Slide 4: Strategic Vision: Regional Expansion
Strategic Existing Pacific Northern Southern New Texas Denver NY Chicago DC Philadelphia 1. Expansion Florida Atlanta 2. 3. 4. Growth 5. 6. 4 Adopt Identify Replicate Form Invest Use /Metro England VA “endorsement” Northwest “clusters” franchises/pending /in synergies Vision California MD top organi
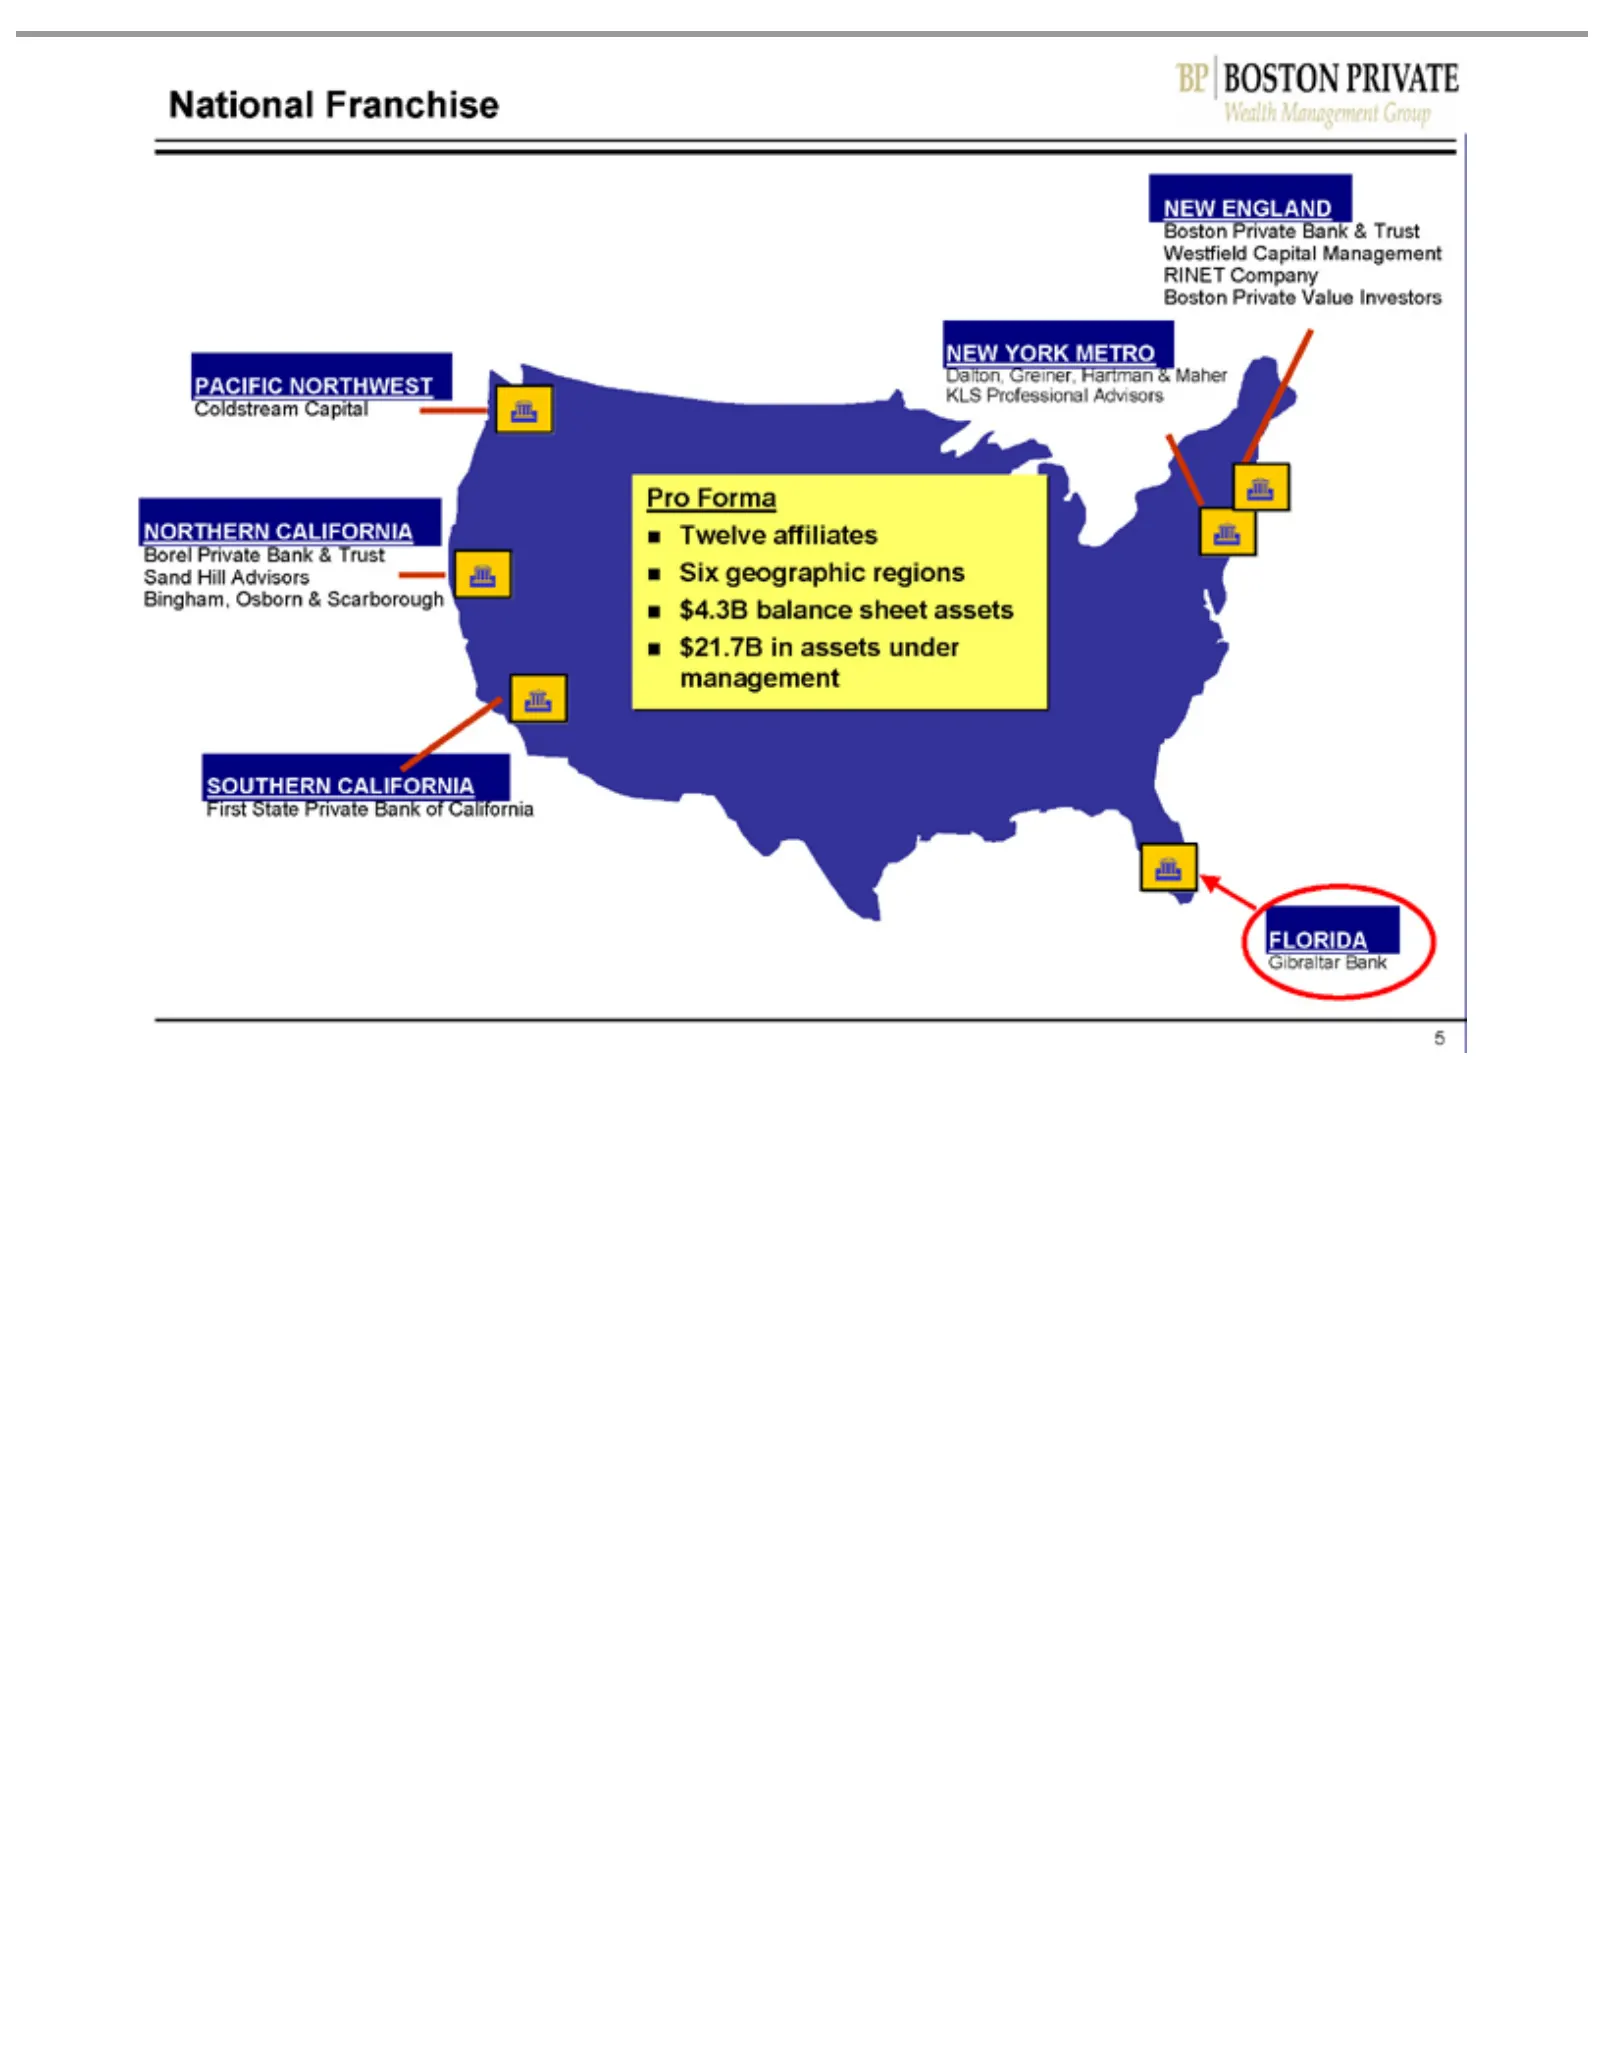
Slide 5: Boston Private National Franchise
National Boston NEW Dalton, PACIFIC Coldstream NORTHERN Borel SOUTHERN First Pro Twelve Gibraltar FLORIDA 5 Forma State Private YORK ENGLAND Private affiliates Greiner, Franchise Bank NORTHWEST Private Capital Bank METRO CALIFORNIA Bank Hartman Six Bank &geographic &Trust Trust of&California Sand Ma
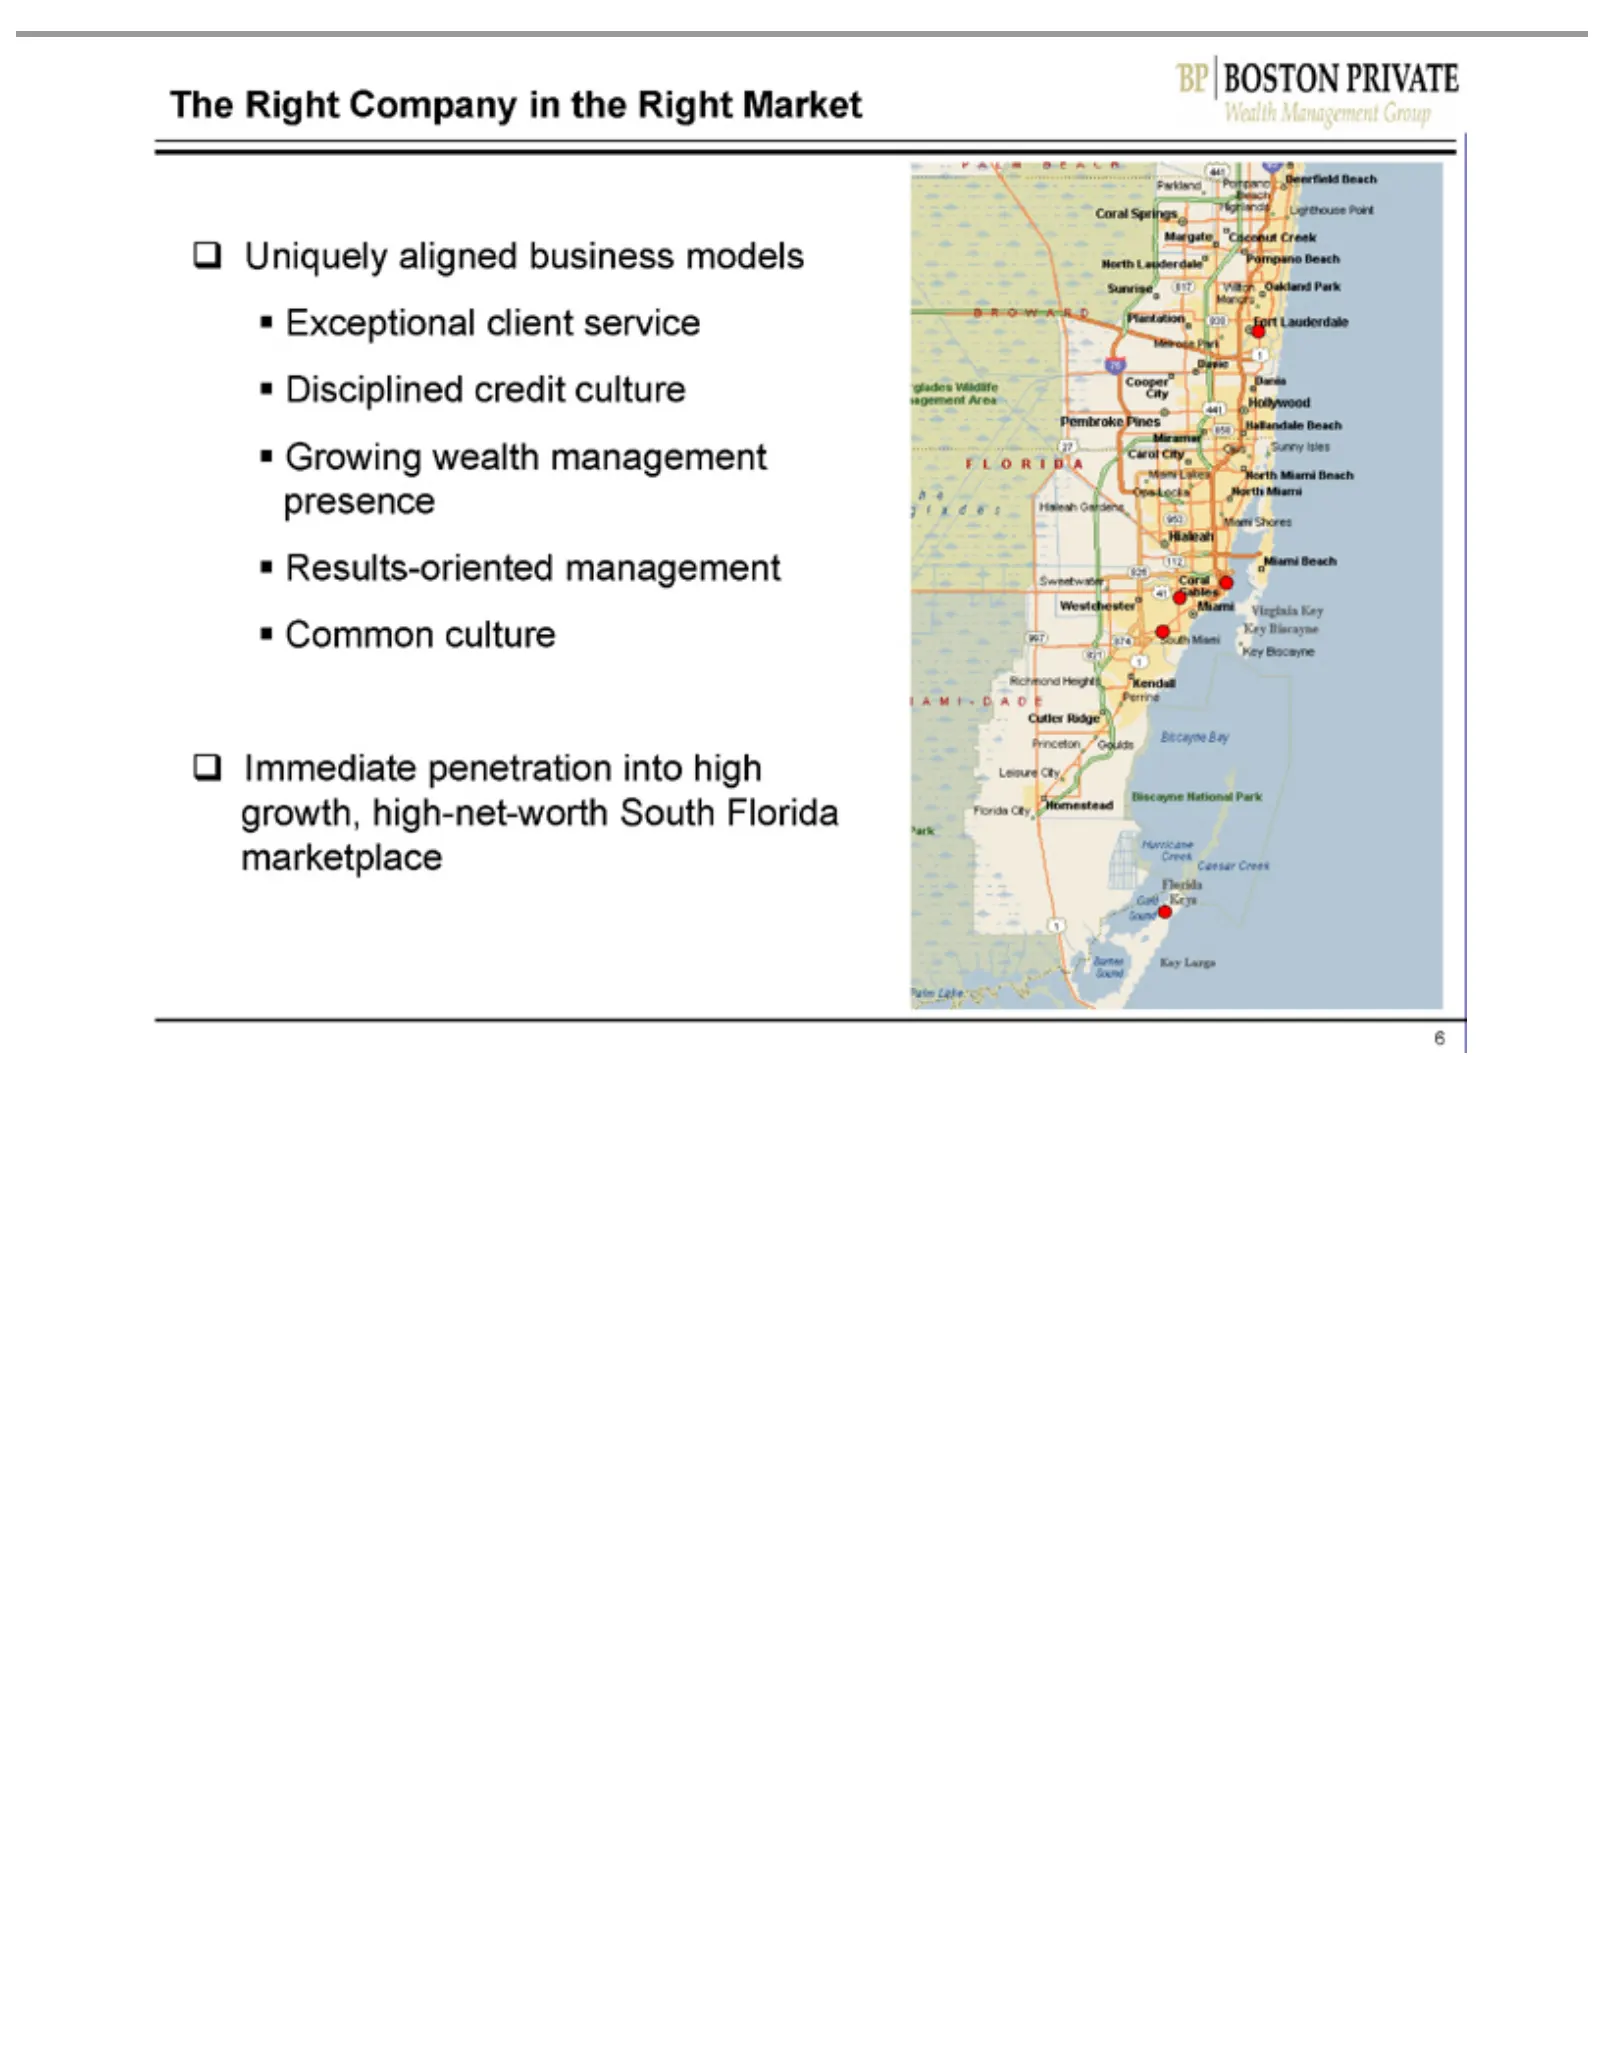
Slide 6: The Right Partner in the Right Market
The Rightaligned Uniquely Exceptional Immediate 6 Company penetration clientbusiness service in into theDisciplined models Right high growth, Market credit high-net-worth culture Growing Southwealth Floridamanagement marketplacepresence Results-oriented management Common culture
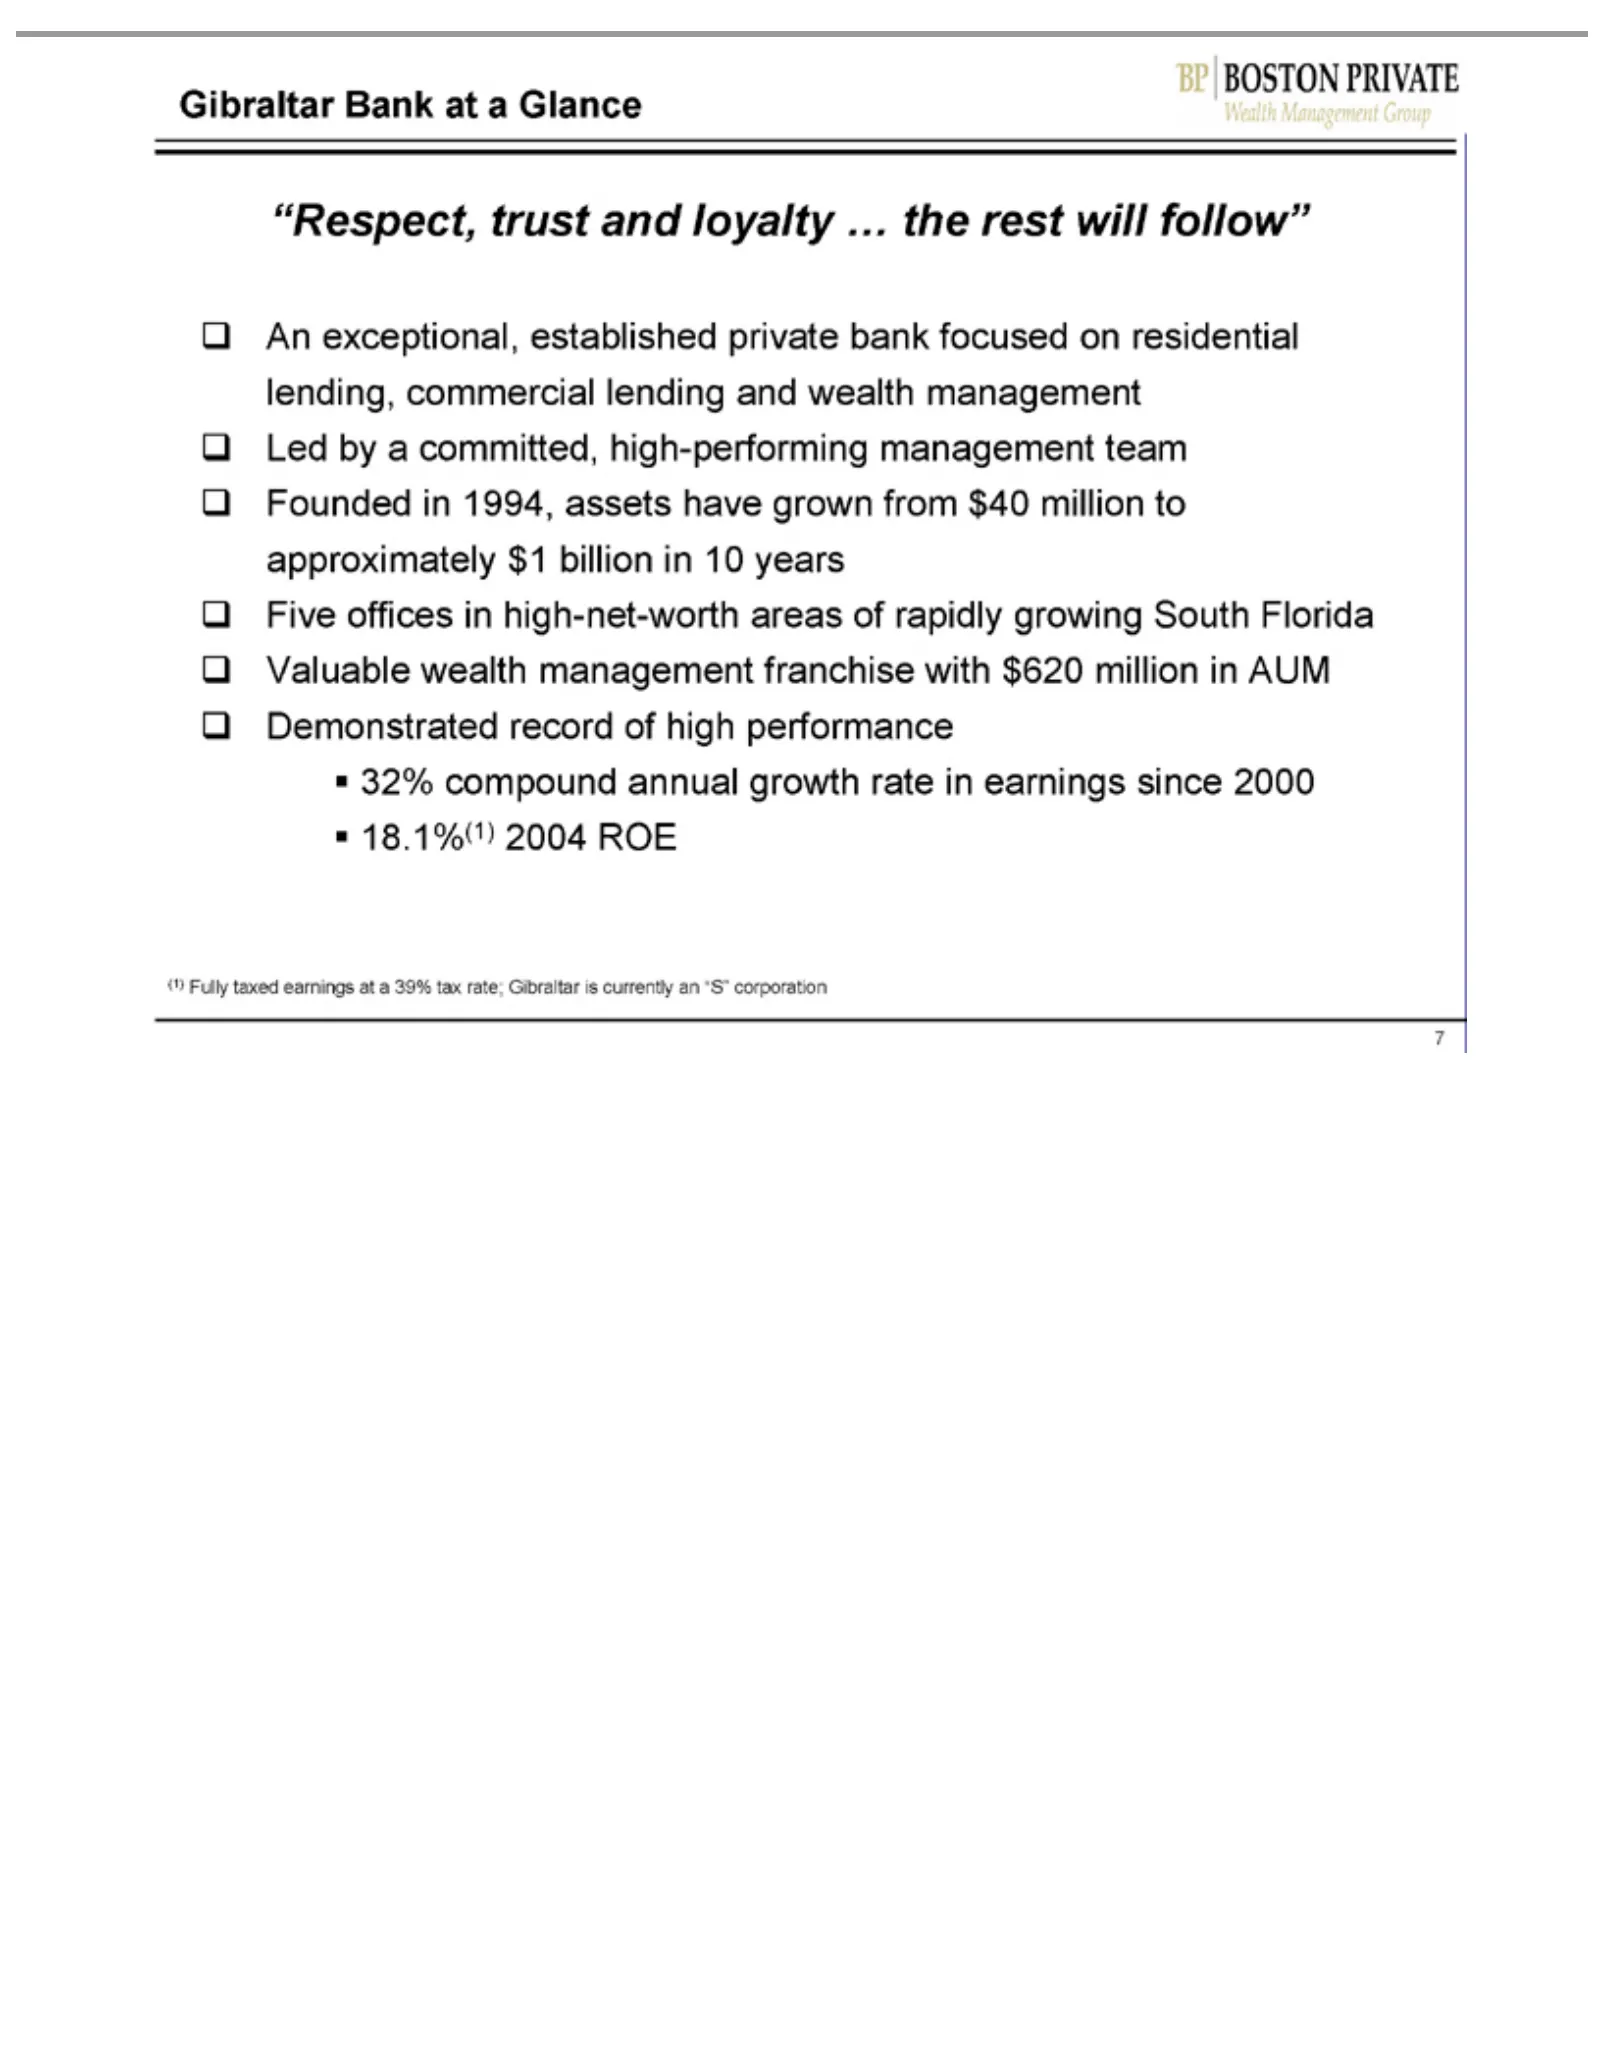
Slide 7: Gibraltar at a Glance
Gibraltar “Respect, An have AUM 32% (1) 7 Fully exceptional, compound grown Demonstrated taxed Bank trust fromand earnings atannual established $40 a loyalty Glance record million growth at a… of private 39% to the high rate approximately tax rest bank in performance rate; will earnings focused Gibr
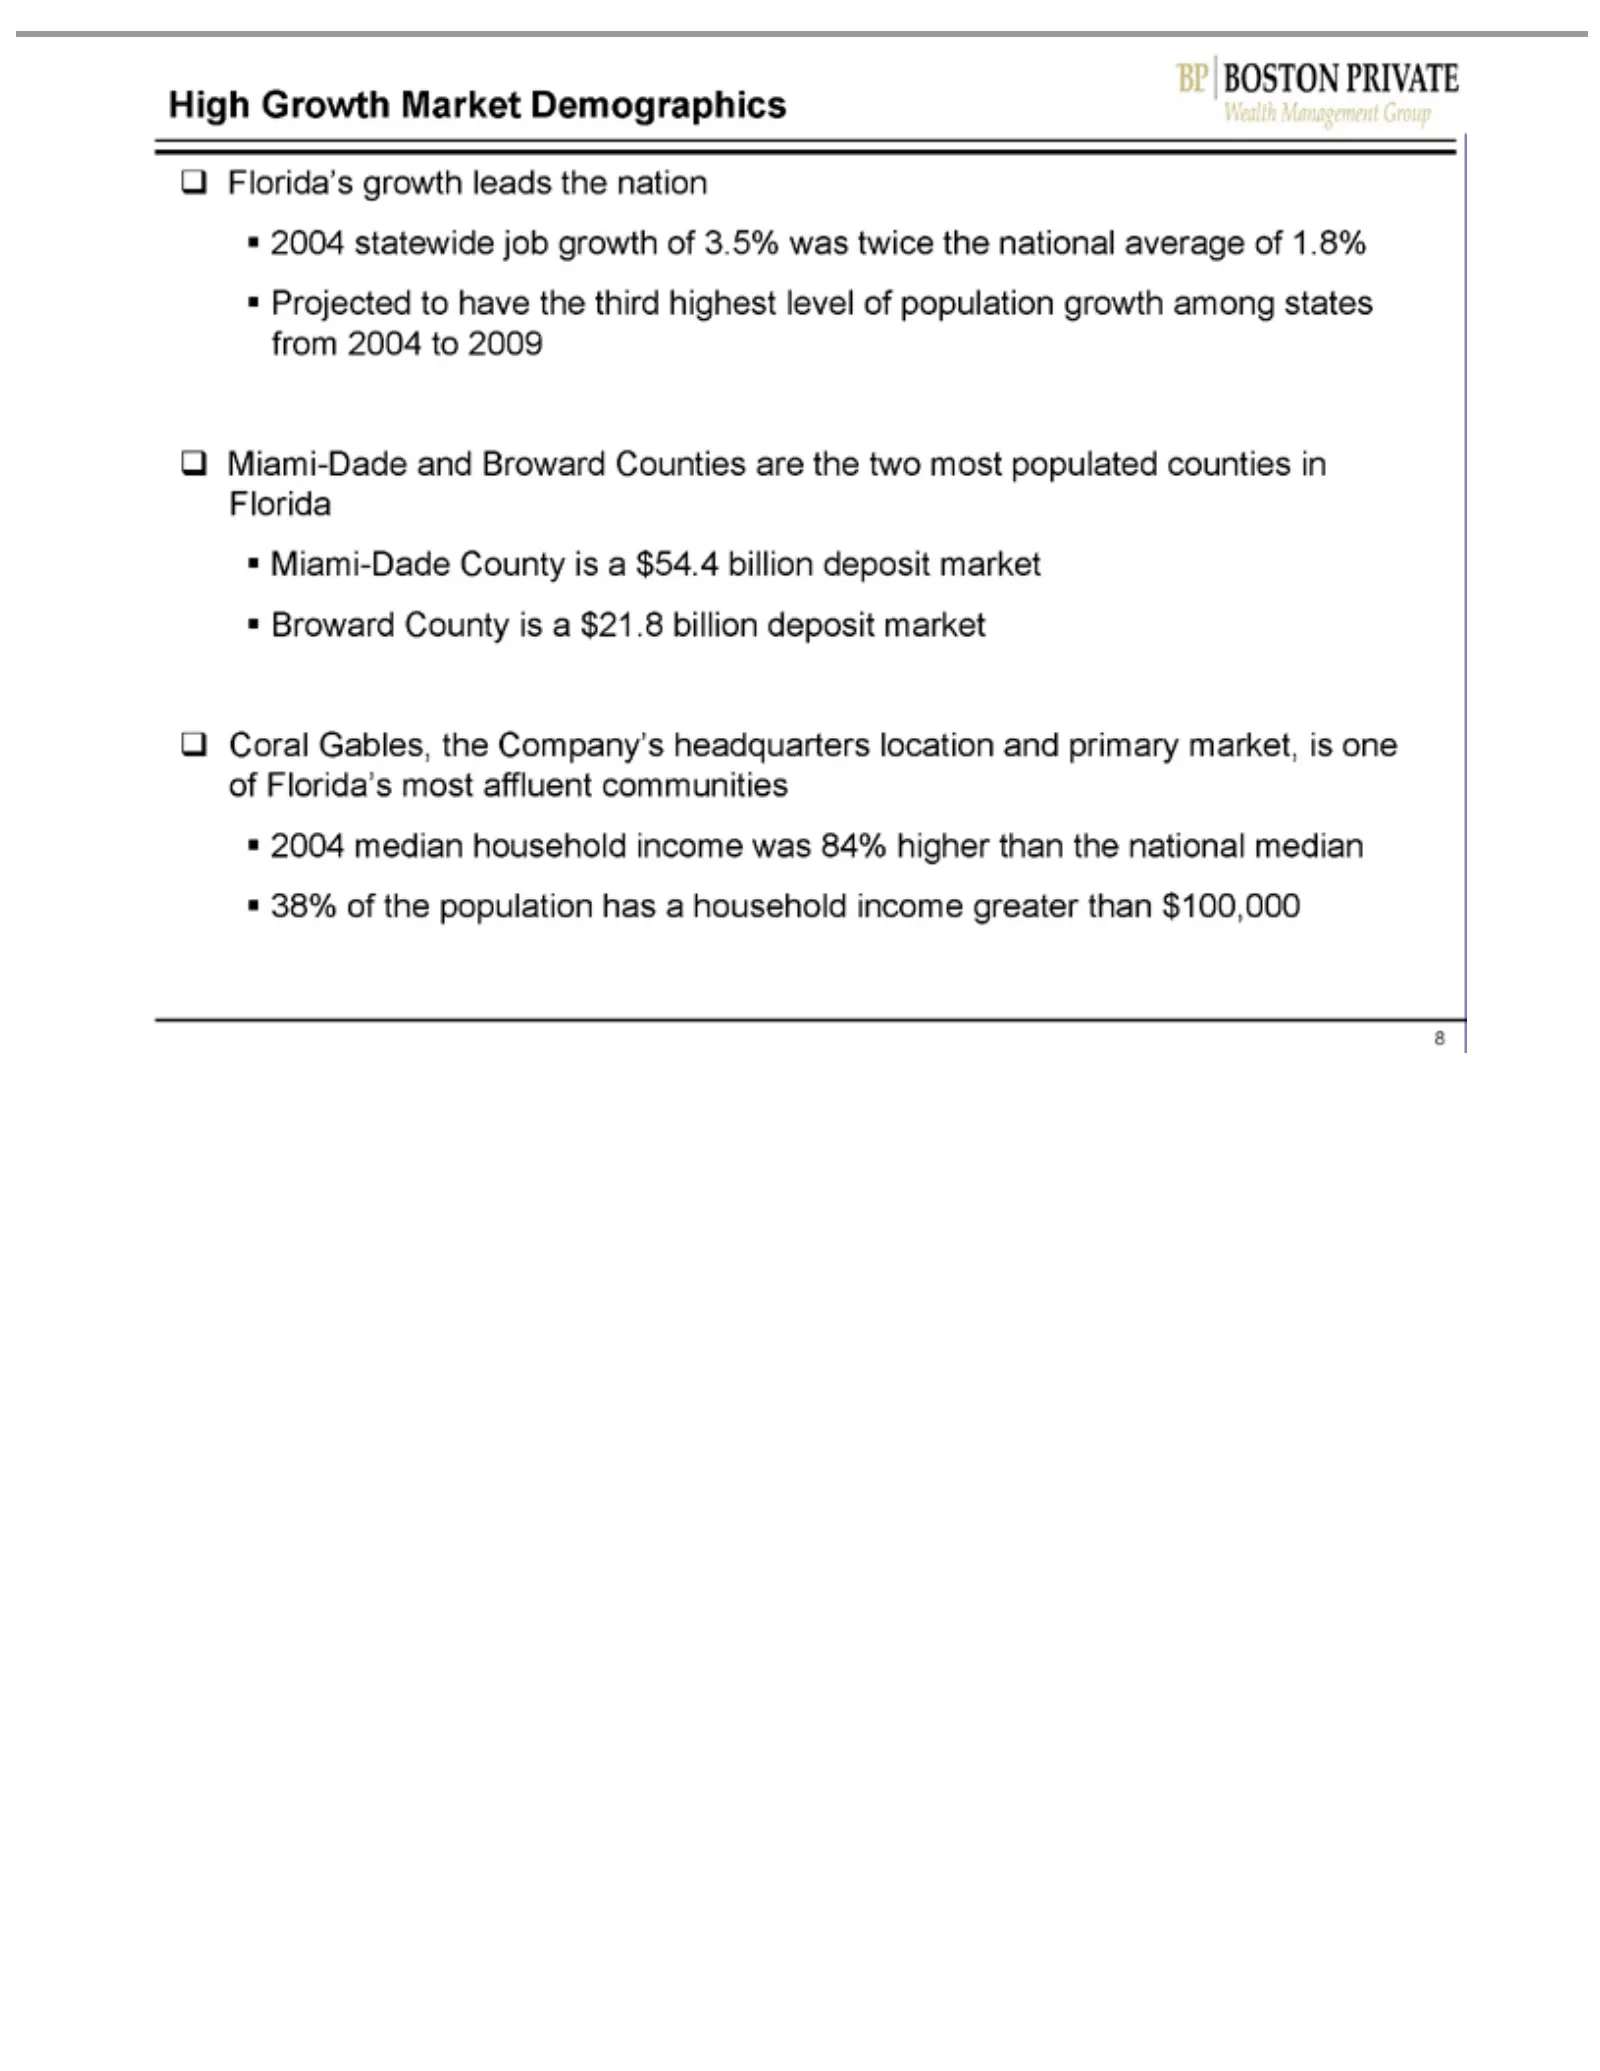
Slide 8: High Growth Florida Market Demographics
High median Florida’s Miami-Dade Coral 2004 8 Growth statewide Gables, growth and County household Market the job leads Broward Company’s growth is Demographics the aincome $54.4 nation Counties of 3.5% headquarters billion waswas are 84% deposit the twice higher location two the market most than na
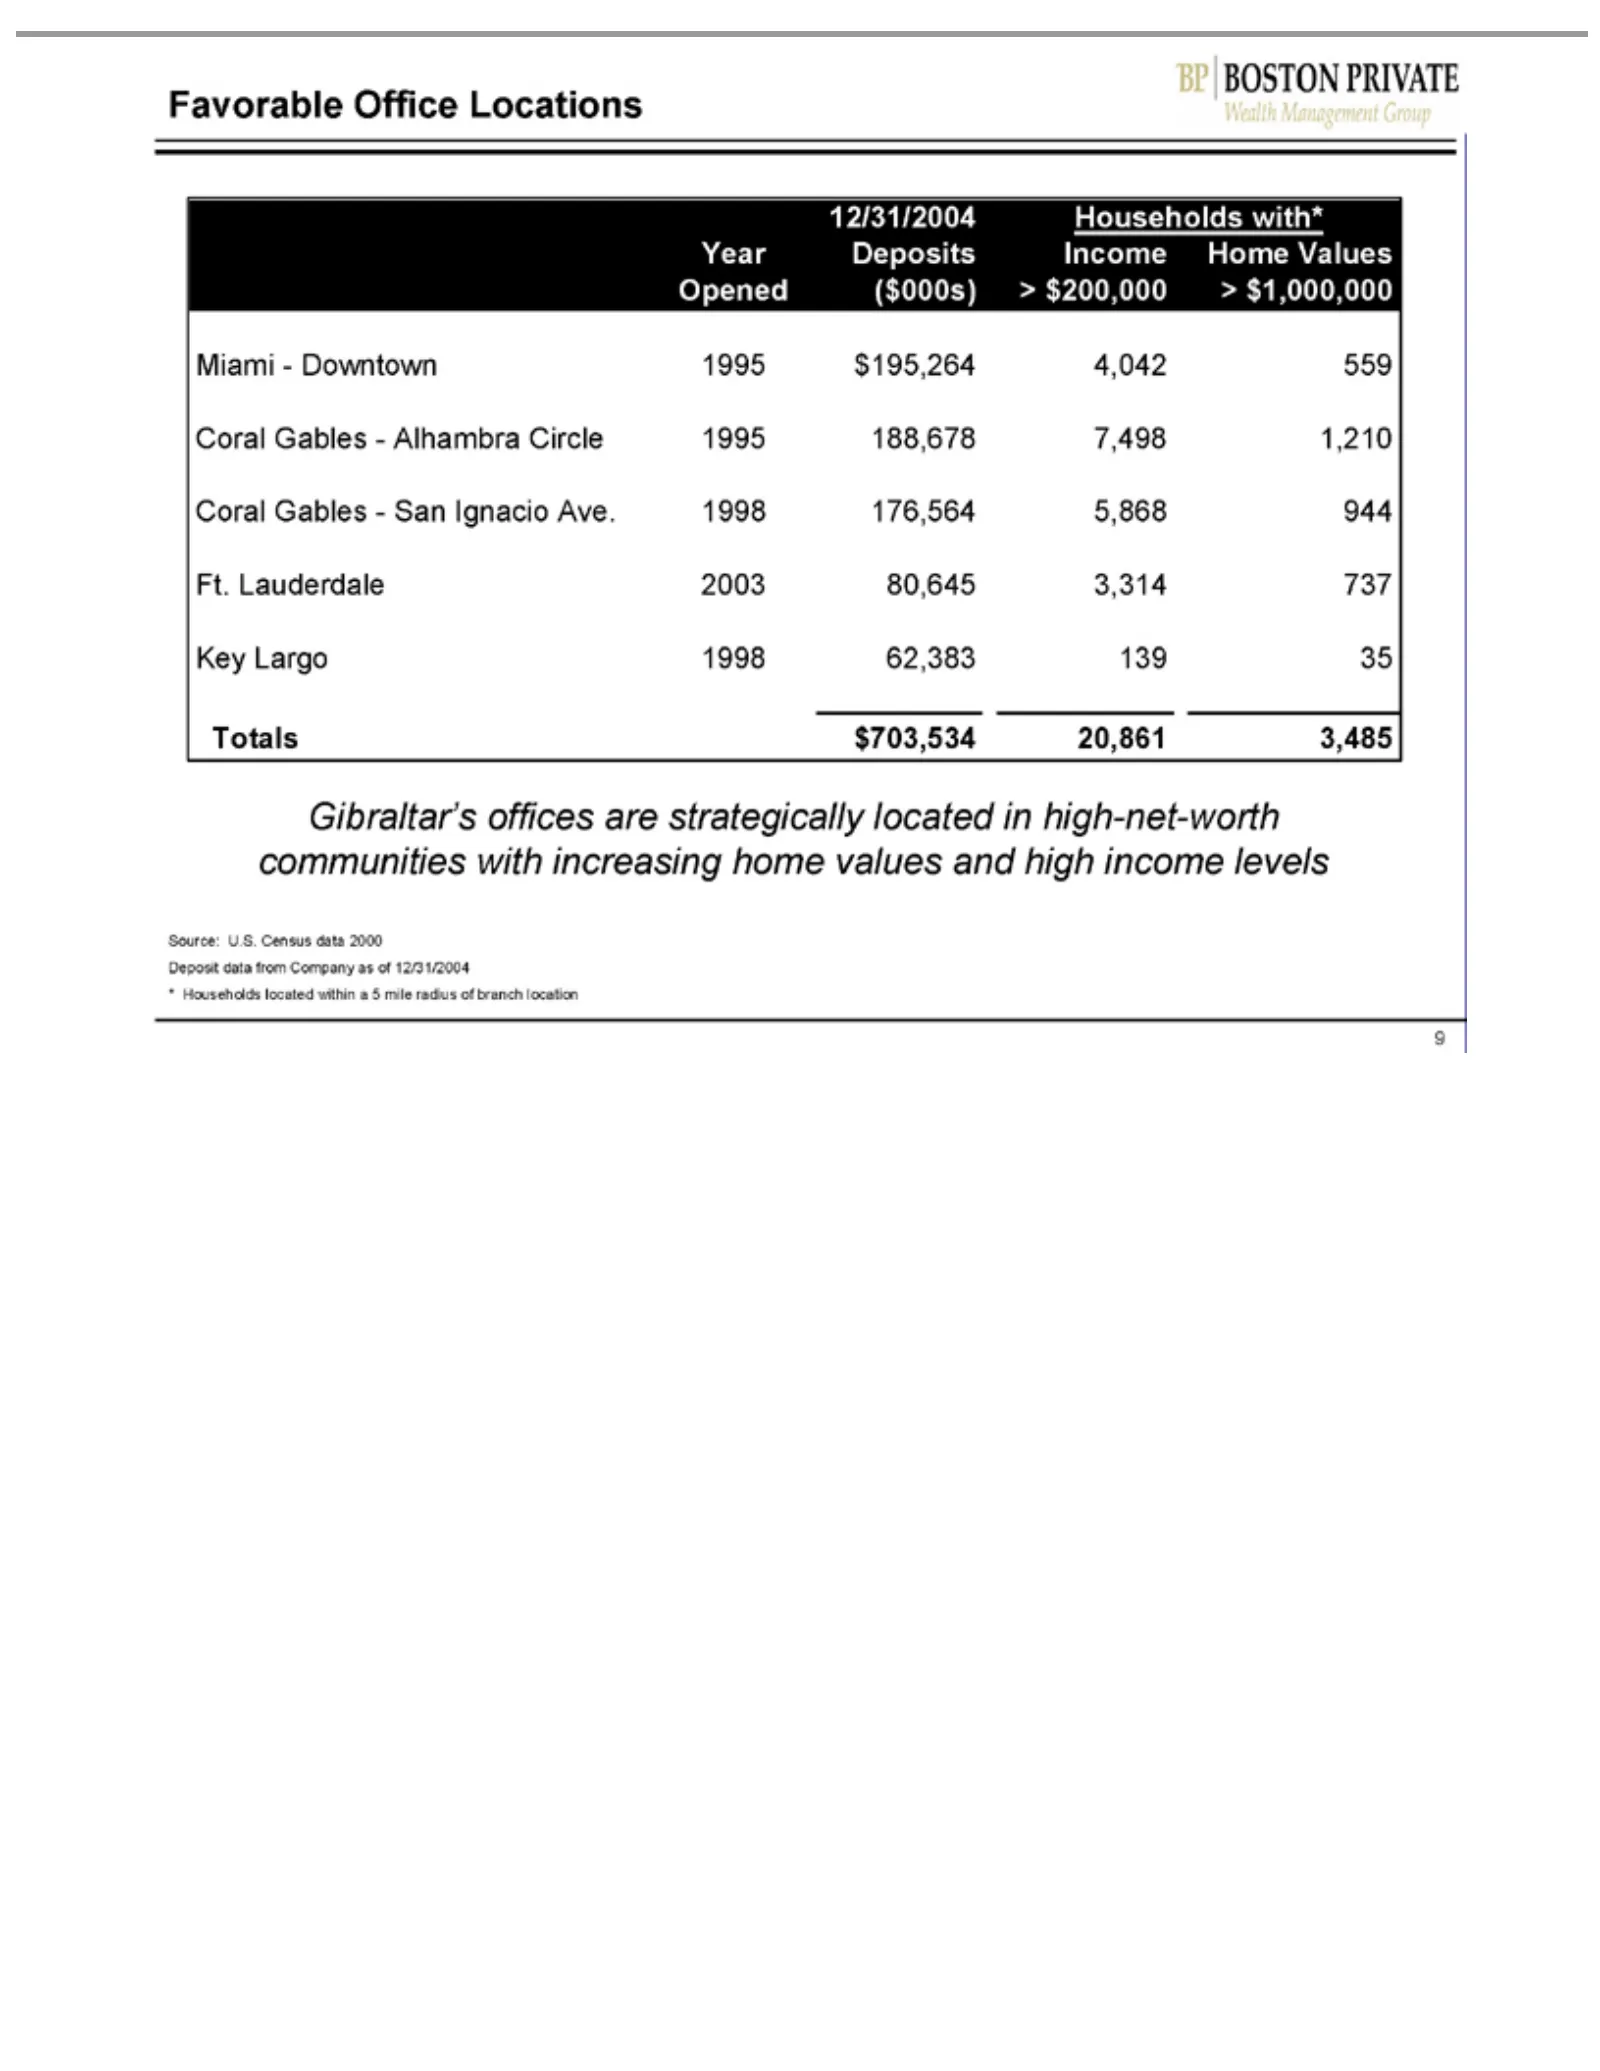
Slide 9: Favorable Office Locations
Favorable 12/31/2004 Year Opened Miami—Downtown Coral Ft. Key Totals Gibraltar’s Source: Deposit * 9 Households Lauderdale Largo Deposits Gables—Alhambra Gables—San $703,534 U.S. ($000s) data Office 1998 offices Households from Census located Income 2003 > 20,861 62,383 Locations Company $200,000 ar
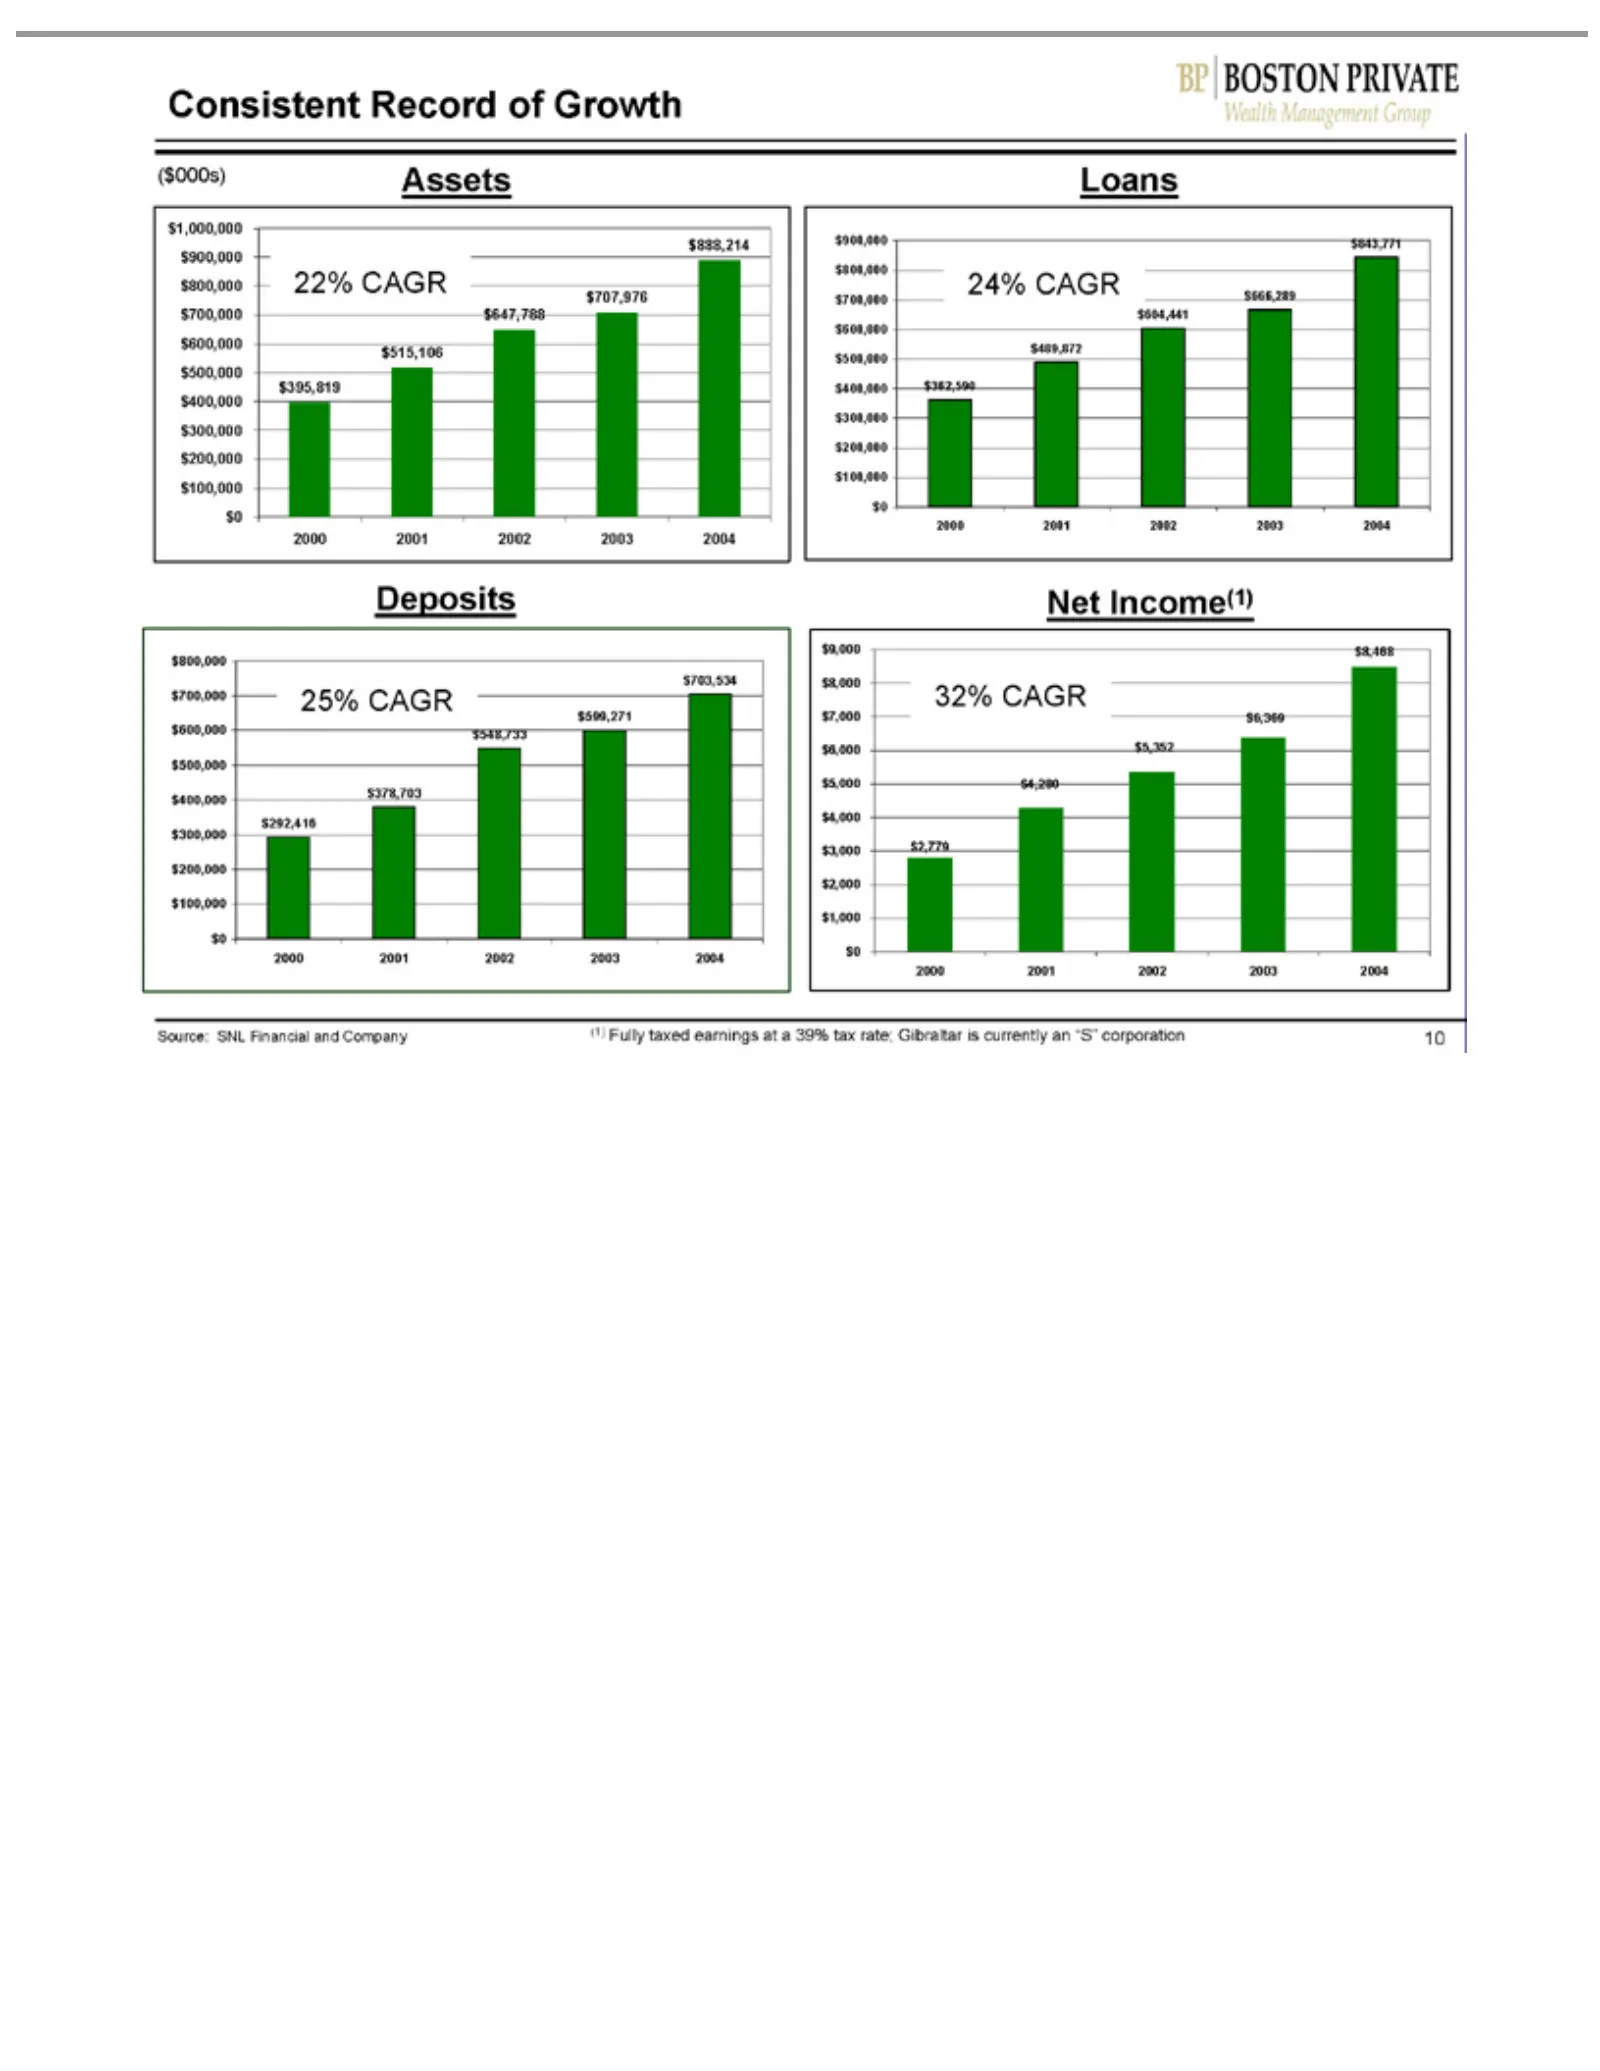
Slide 10: Consistent Record of Growth
Consistent Assets ($000s) 22% 25% Deposits $800,000 Loans 24% $362,590 Net 32% $9,000 2000 Source: (1) 10 Fully Income(1) CAGR 2001 $900,000 $1,000,000 $8,000 SNL taxed $700,000 $489,872 Record 2002 Financial $7,000 earnings $800,000 2003 of $900,000 $600,000 $604,441 Growth $6,000 2004 and at $700,
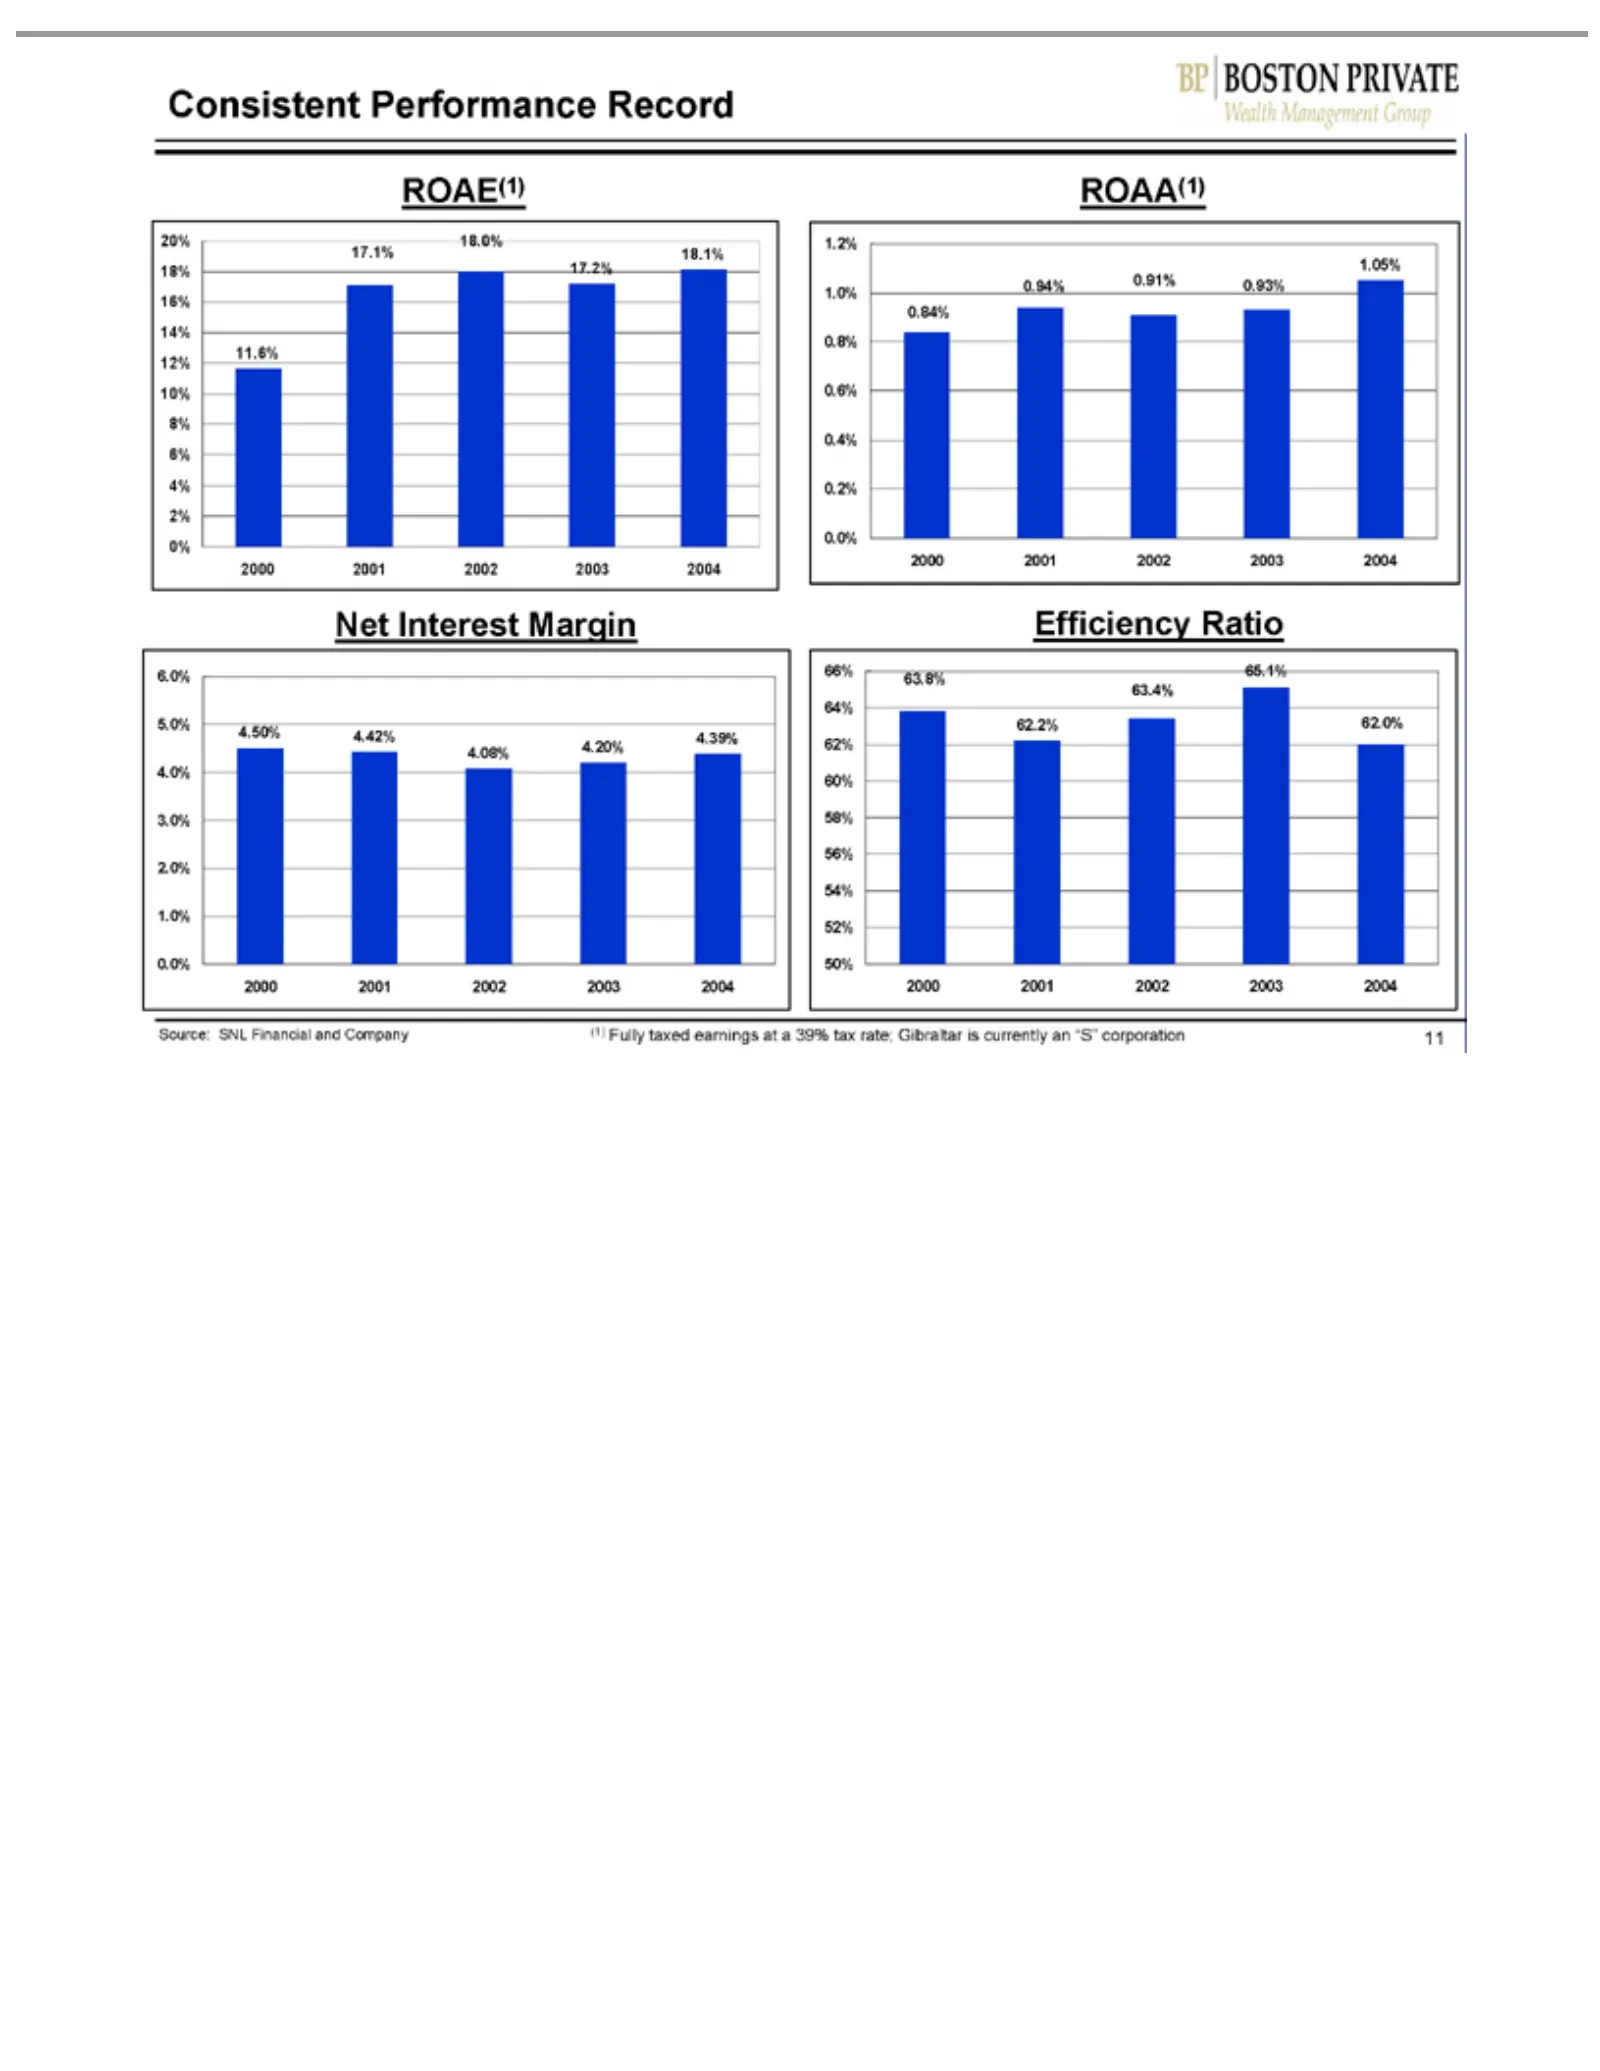
Slide 11: Consistent Performance
Consistent 20% ROAE(1) 18.1% 17.2% 18.0% 17.1% 11.6% Net 6.0% 4.39% 4.20% 4.08% 4.42% 4.50% Efficiency 66% 62.0% 65.1% 63.4% 62.2% 63.8% Source: (1) 1.2% ROAA(1) 2000 1.05% 0.93% 0.91% 0.94% 0.84% 11 Fully Interest 18% 64% 2001 5.0% 1.0% SNL taxed 16% 62% Ratio Performance 2002 4.0% 0.8% Margin Fina
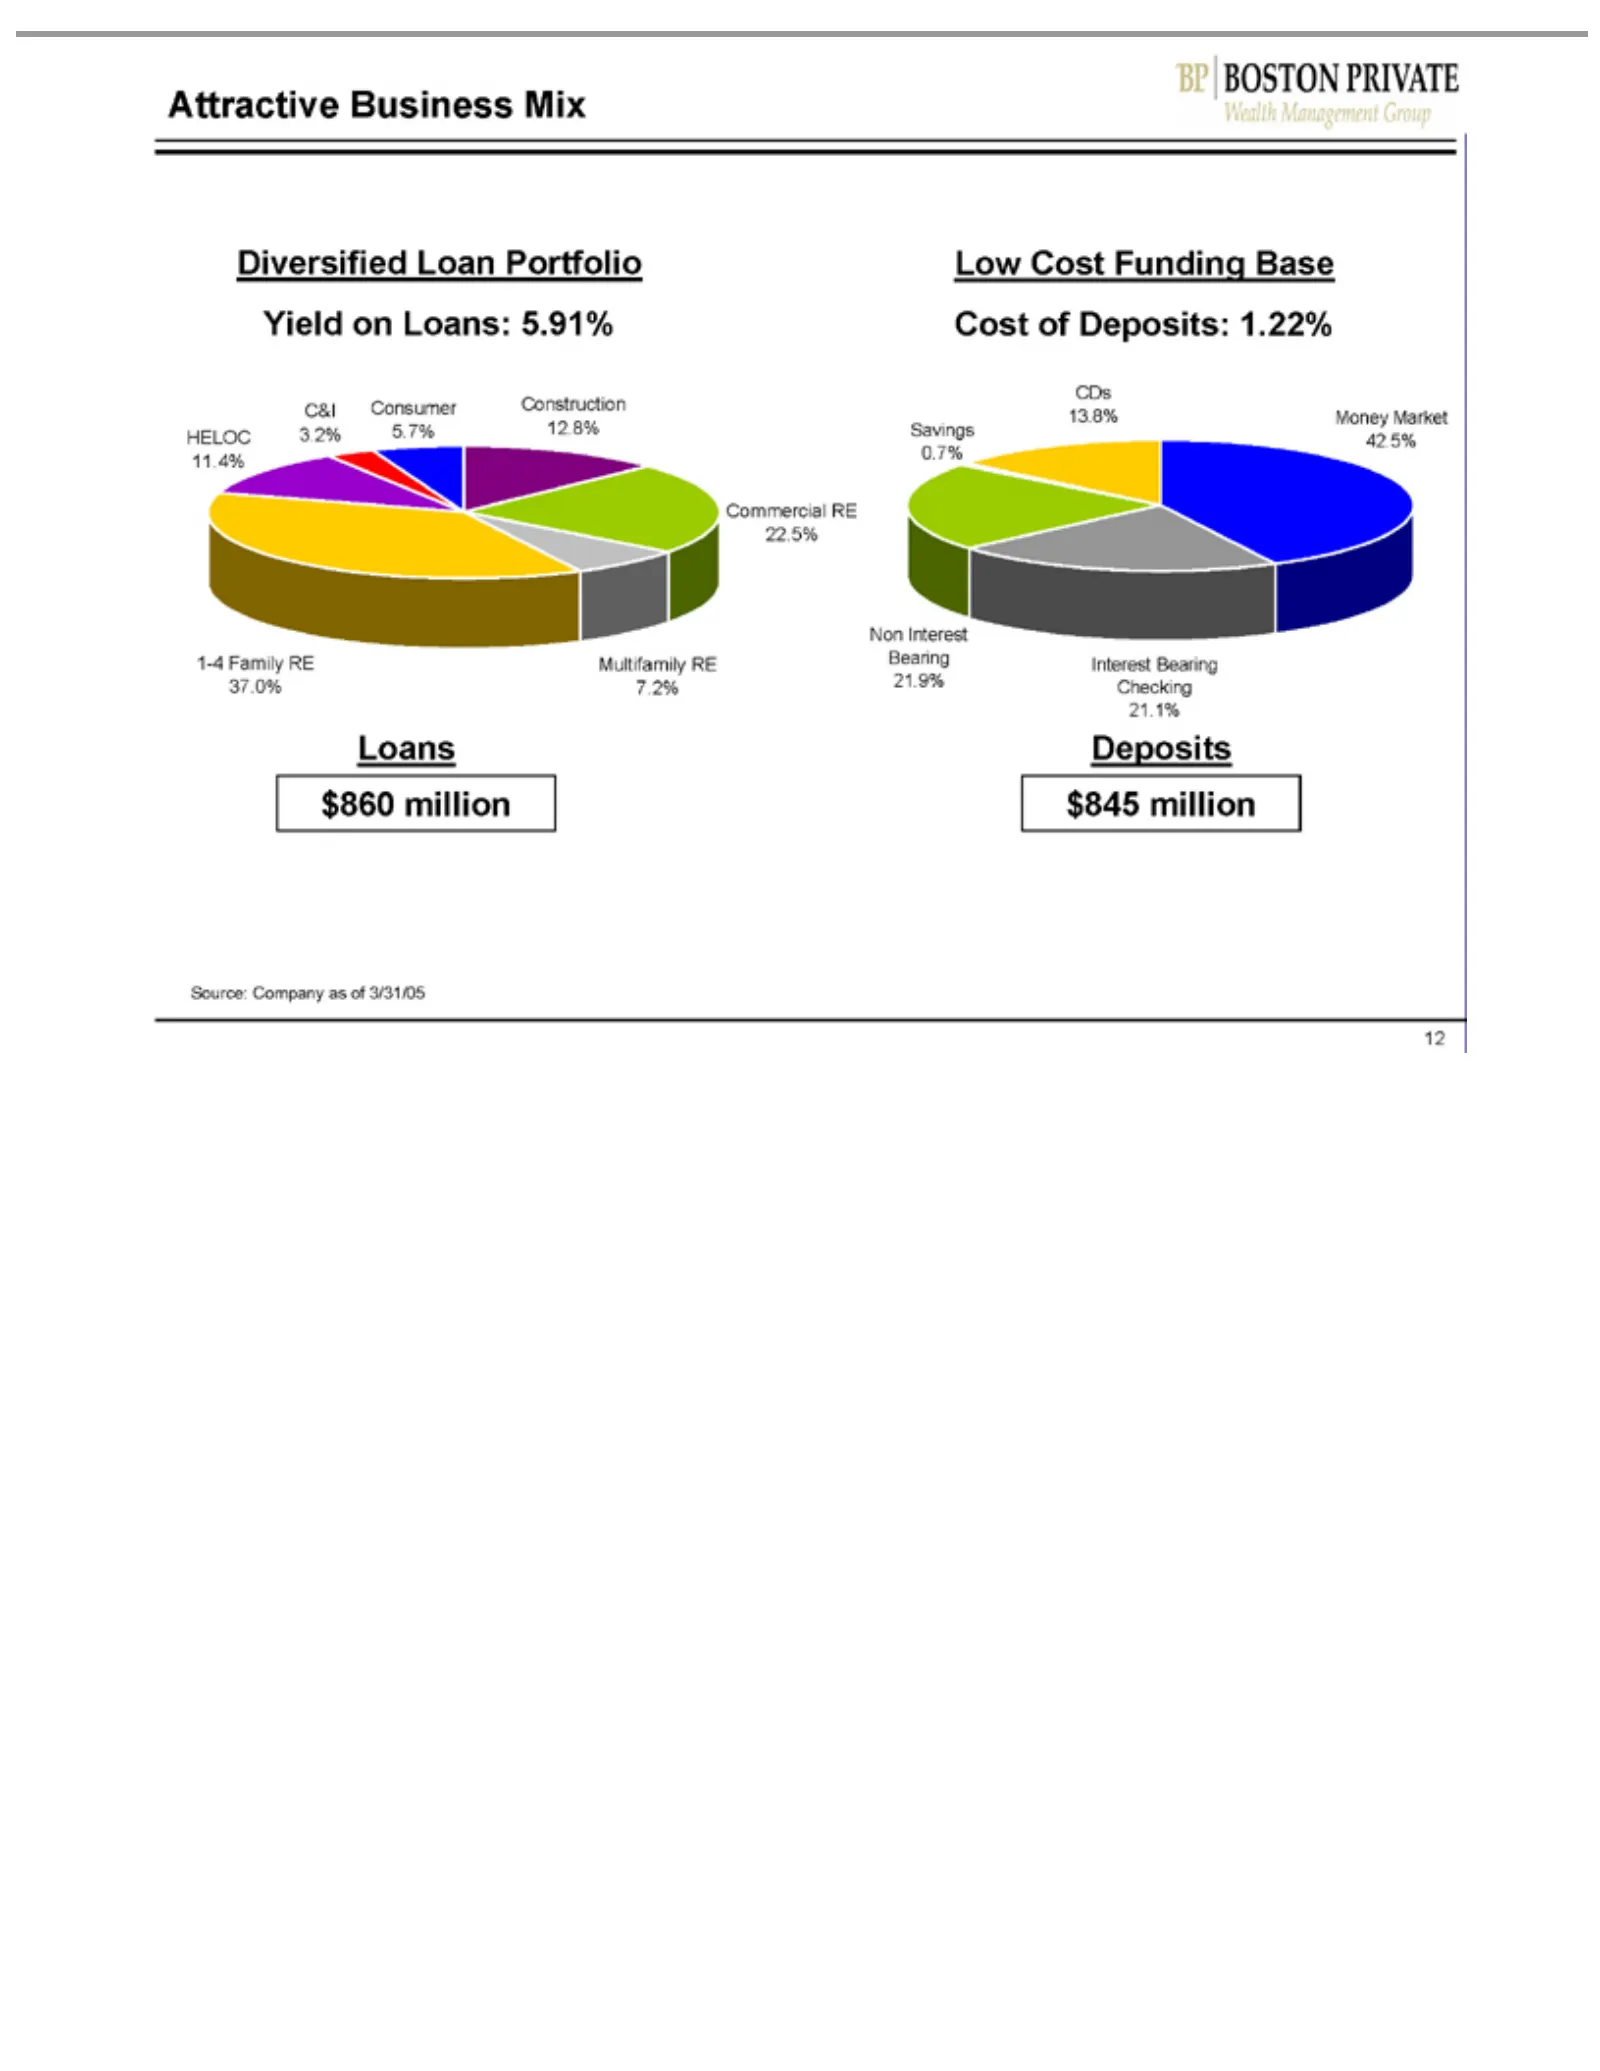
Slide 12: Attractive, Diversified Loan Portfolio and Low Cost Funding Base
Attractive Diversified HELOC C&I Consumer Construction 1-4 Multifamily 37.0% Loans 7.2% Low Commercial Savings 22.5% CDs Money Non Interest Deposits Source: 12 Family Interest 3.2% 13.8% Cost $860 Market Bearing Company 0.7% 11.4% $845 Funding Business 5.7% RE Loan million RE RE Bearing 12.8% millio
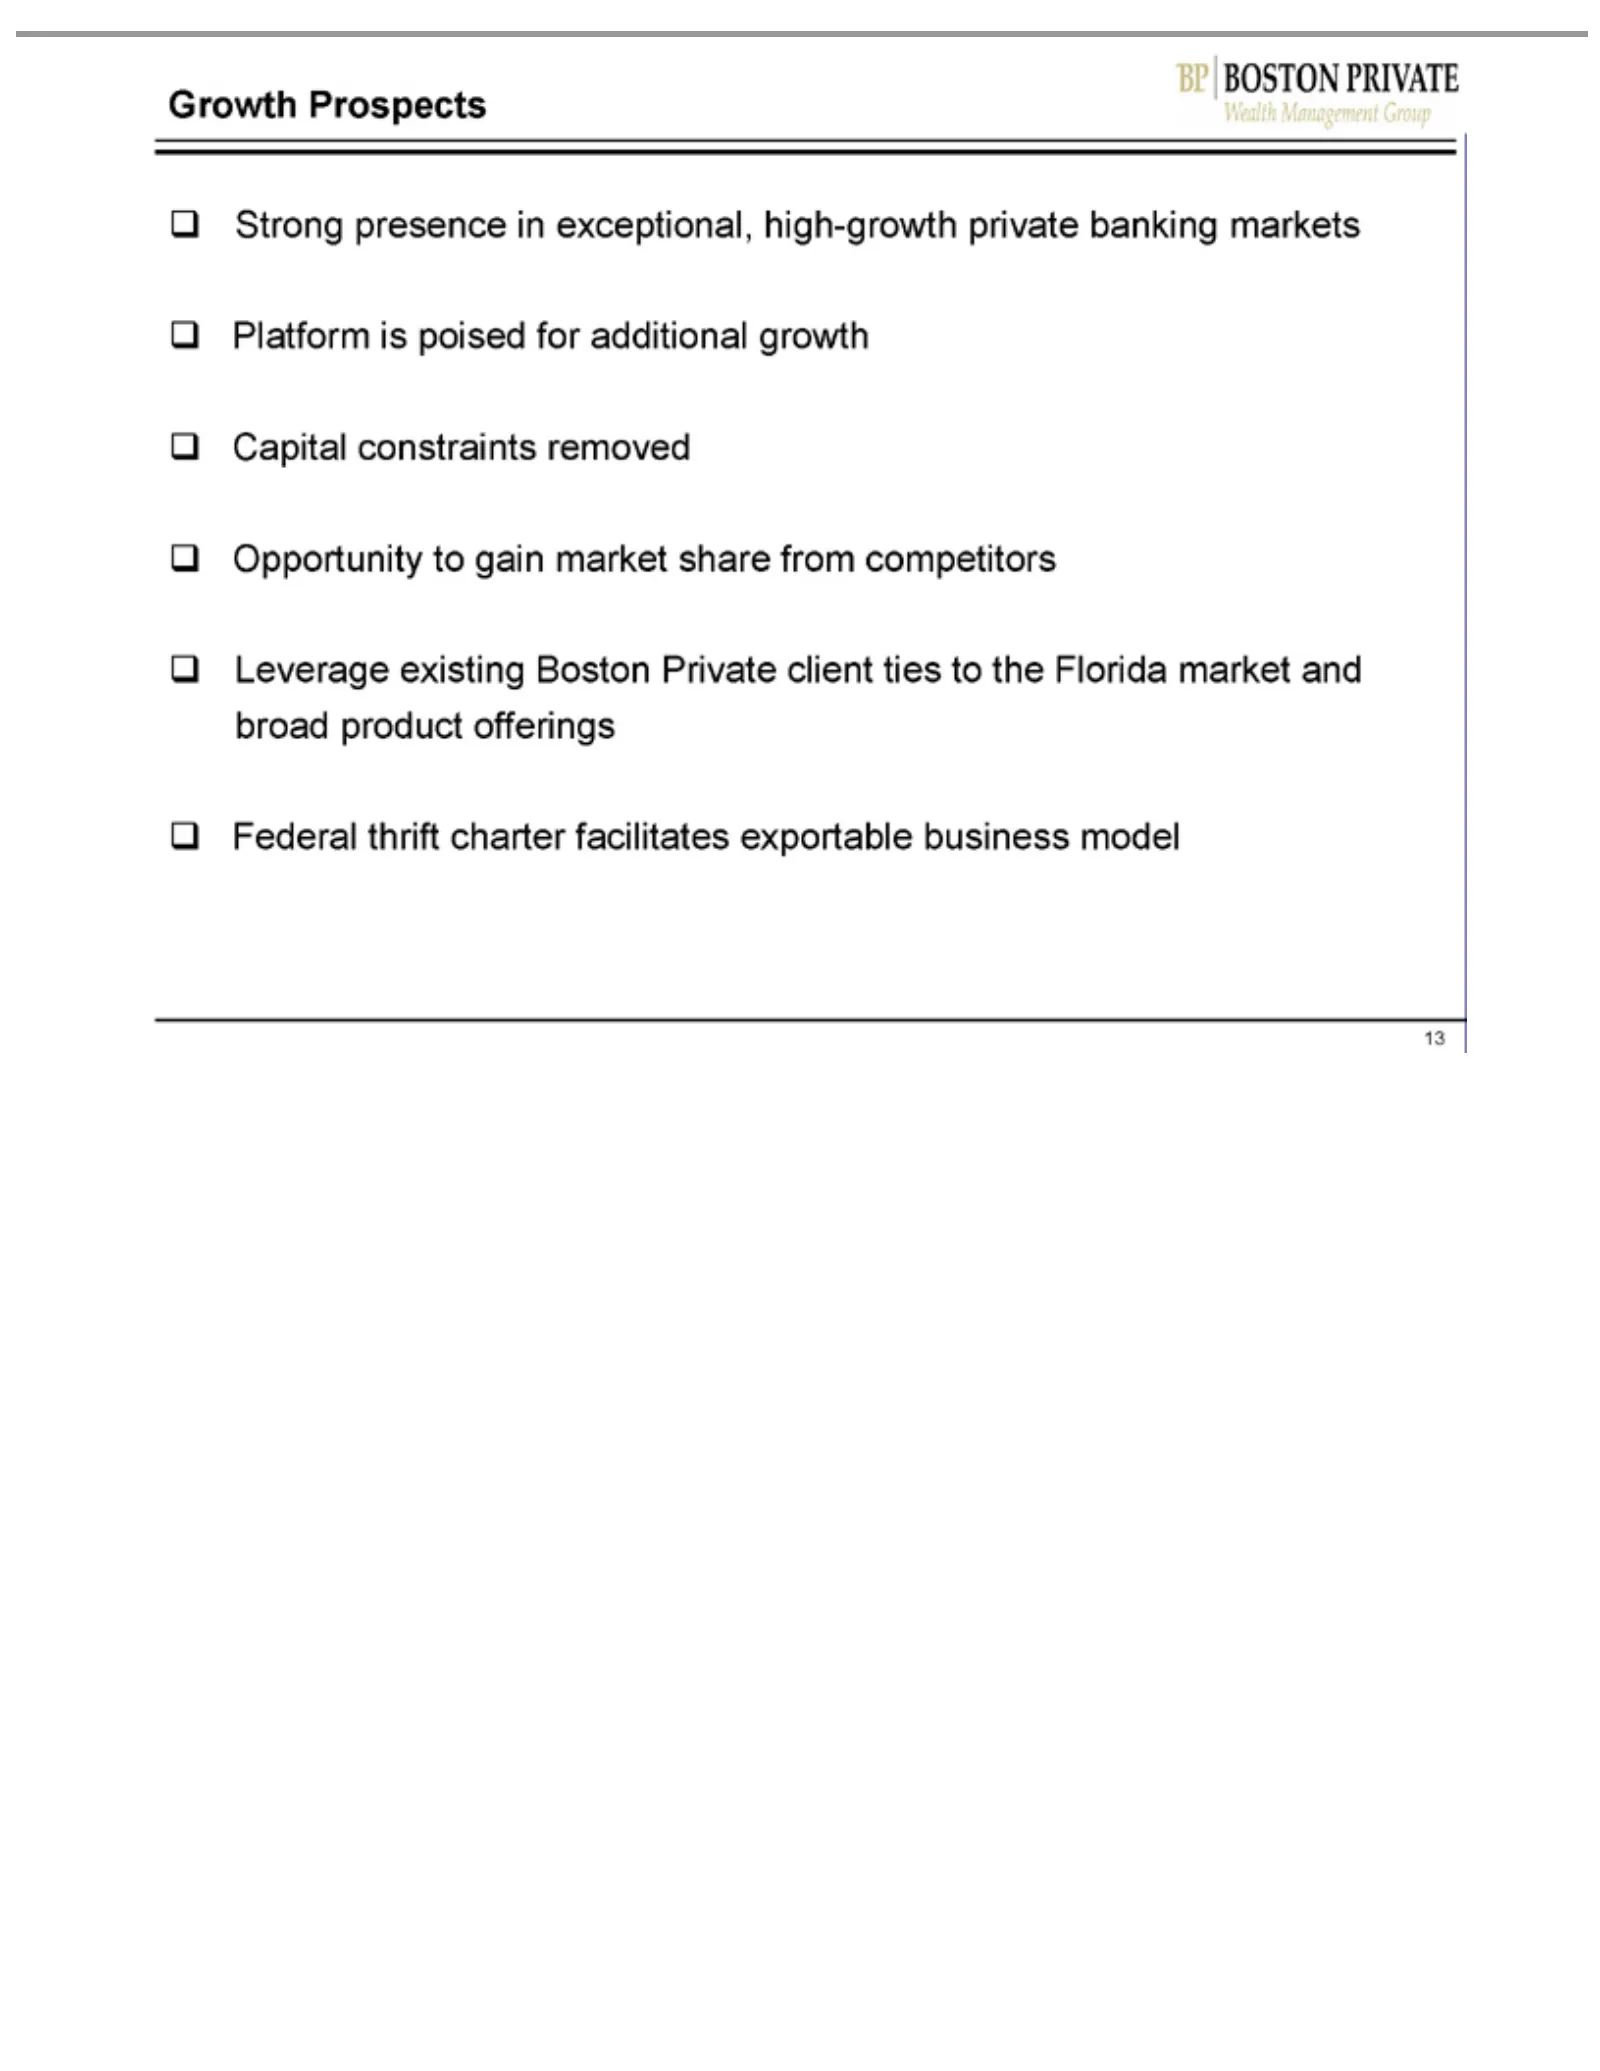
Slide 13: Strong Growth Prospects and Leverage
Growthpresence Strong Leverage Federal 13 thrift Prospects existing charter inBoston exceptional, facilitates Private exportable high-growth client tiesbusiness toprivate the Florida model banking market markets and Platform broad product is poised offerings for additional growth Capital constraints
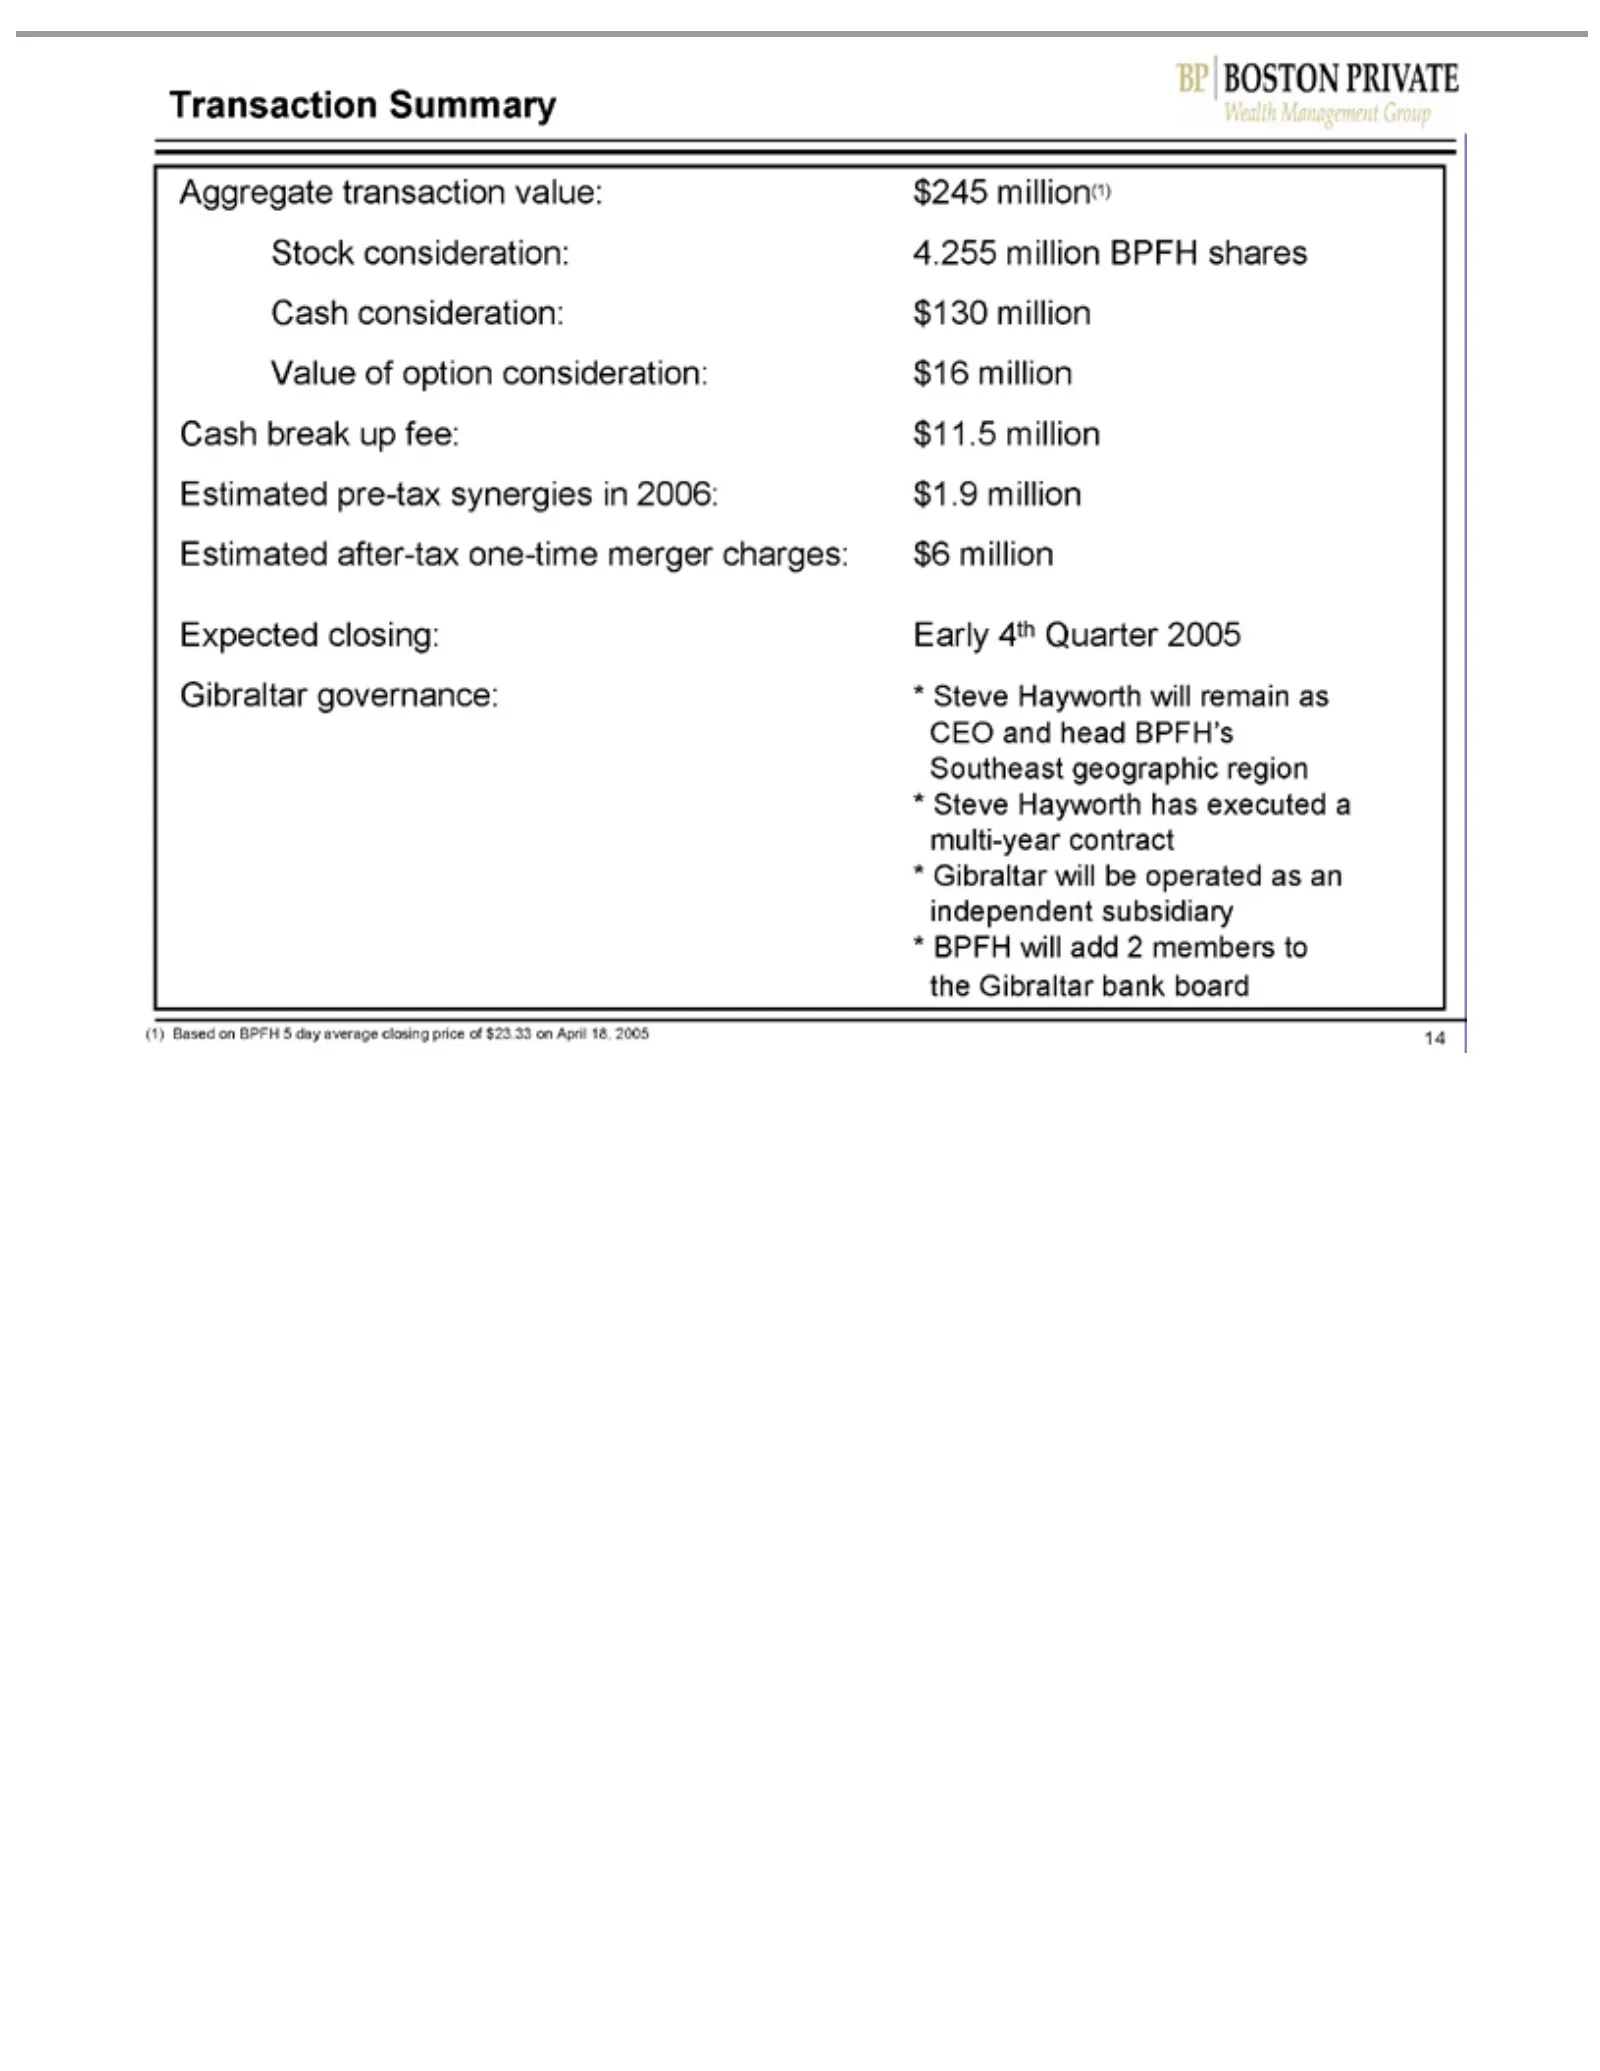
Slide 14: Transaction Summary
Transaction Aggregate Stock Value Cash Estimated Expected Gibraltar CEO Southeast multi-year independent * the (1) 14Steve Gibraltar BPFH Based Gibraltar and consideration: break of consideration: Hayworth will option governance: head closing: on geographic pre-tax after-tax transaction contract wil
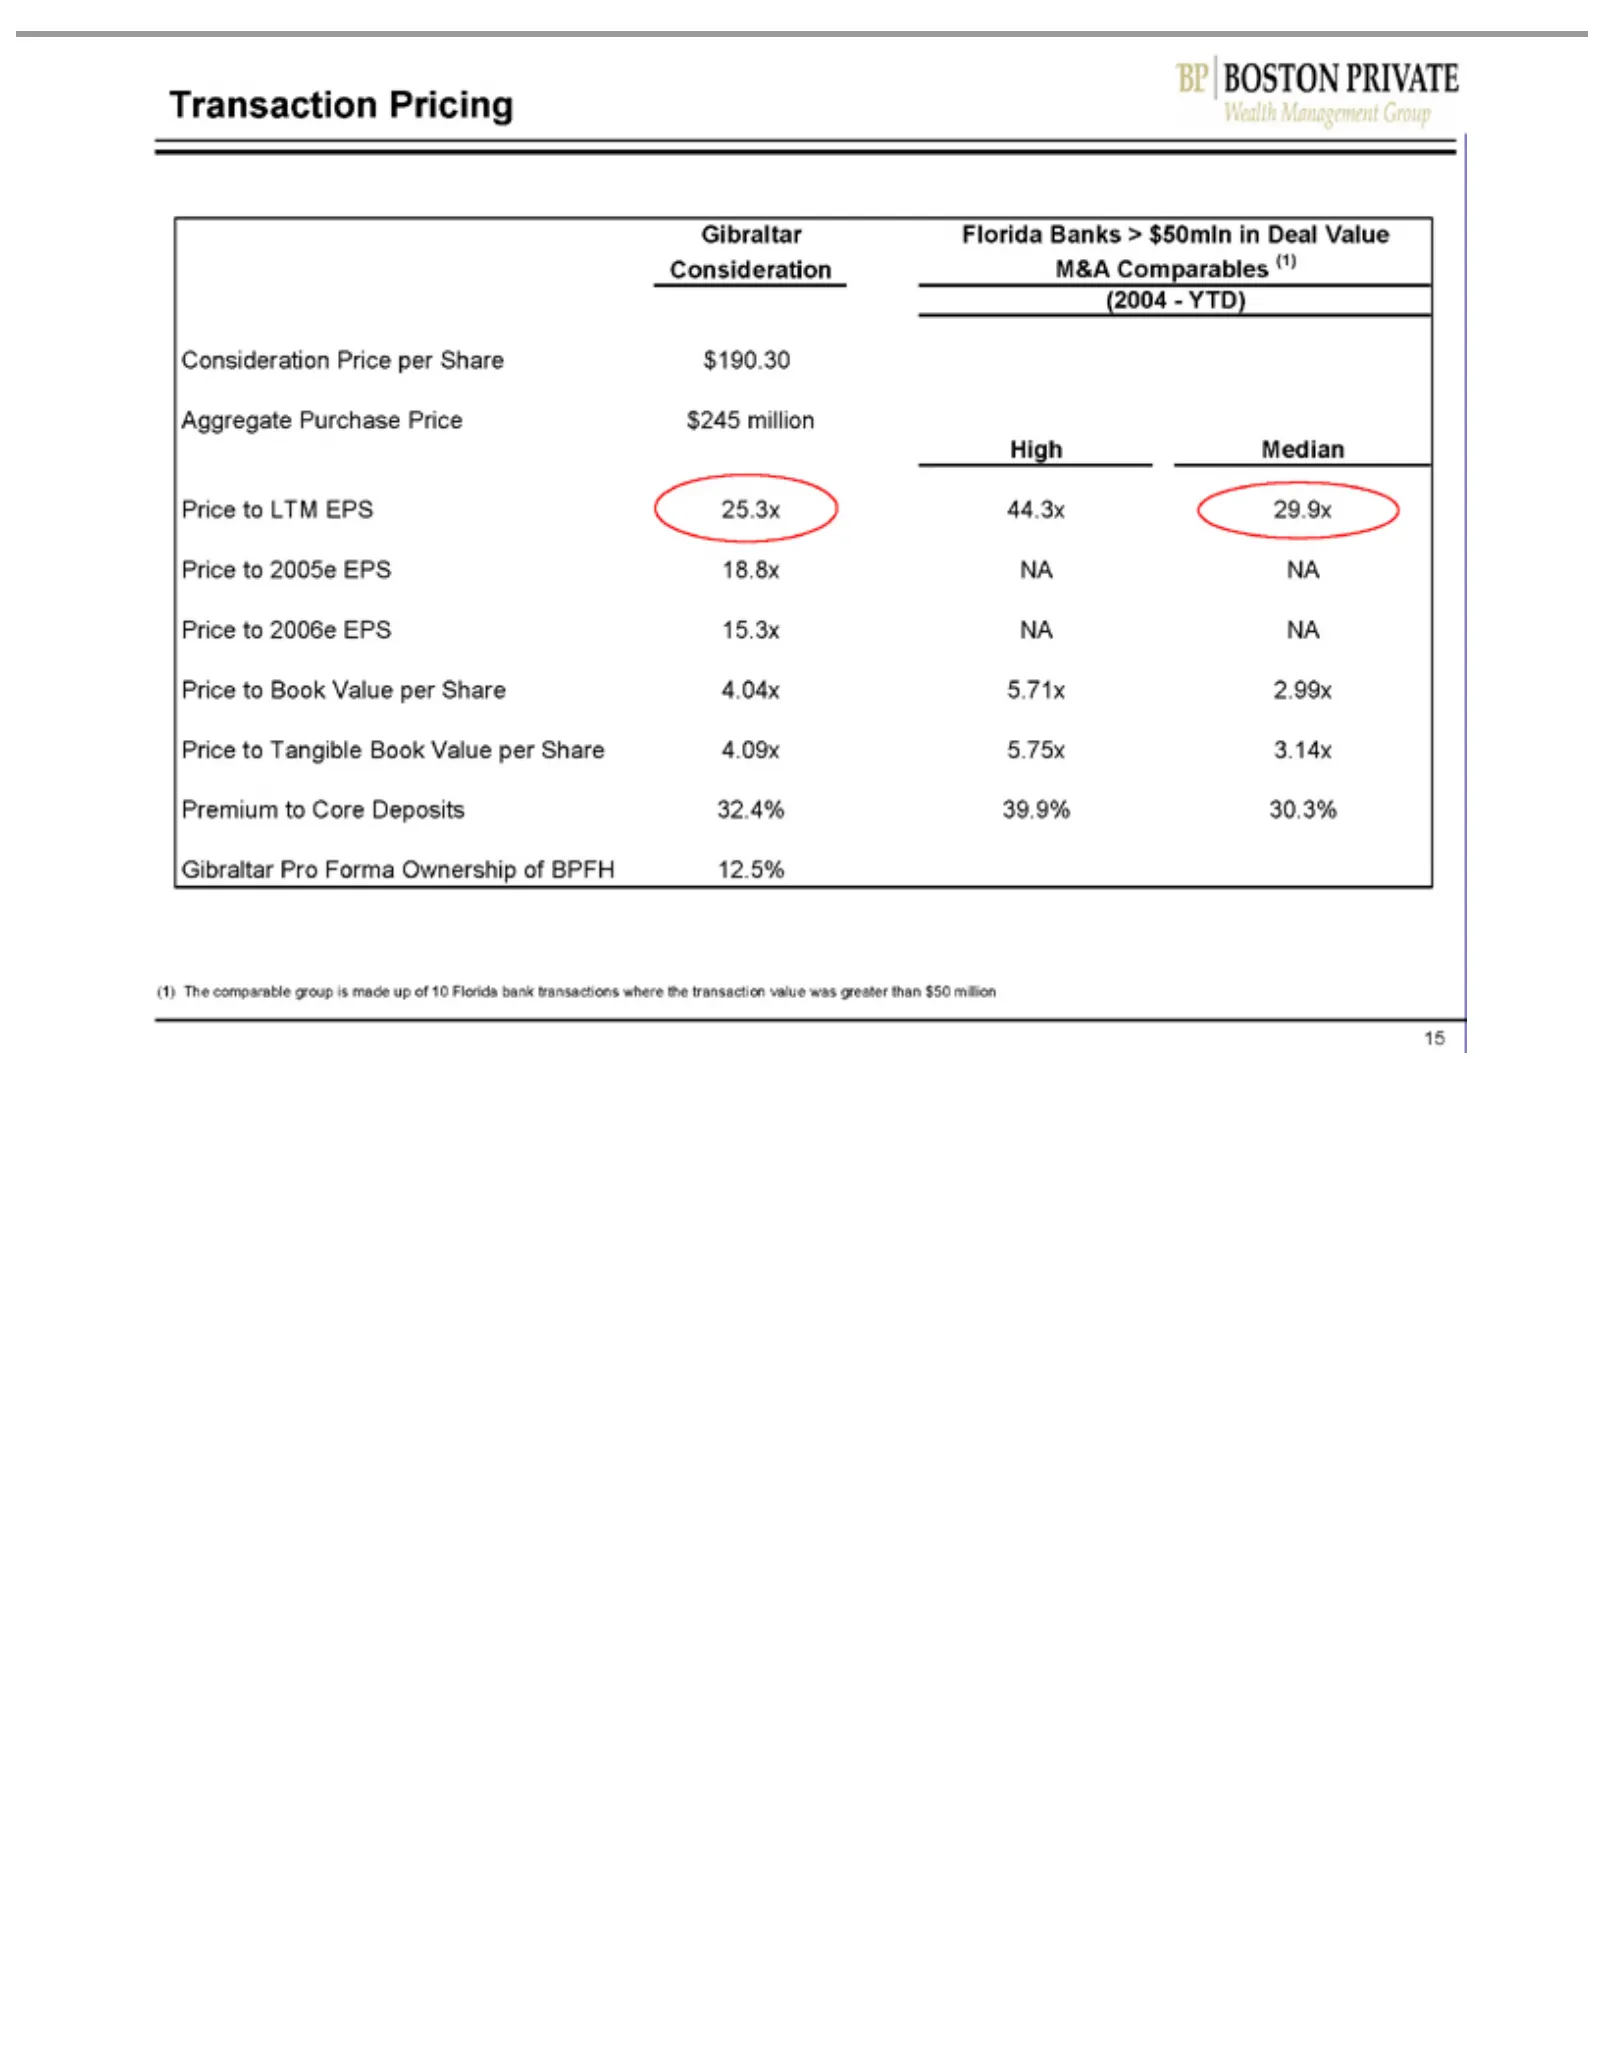
Slide 15: Transaction Consideration vs. Comparable Florida M&A
Transaction Consideration (2004—YTD) Aggregate High Price Premium Gibraltar (1) 15 The Median to comparable Tangible LTM 2005e 2006e Book Florida Pro toPurchase Pricing Core Forma EPS Value M&A Price EPS Banks Book Deposits 25.3x 18.8x 15.3x group per Price Ownership Comparables Value Share >44.3x N
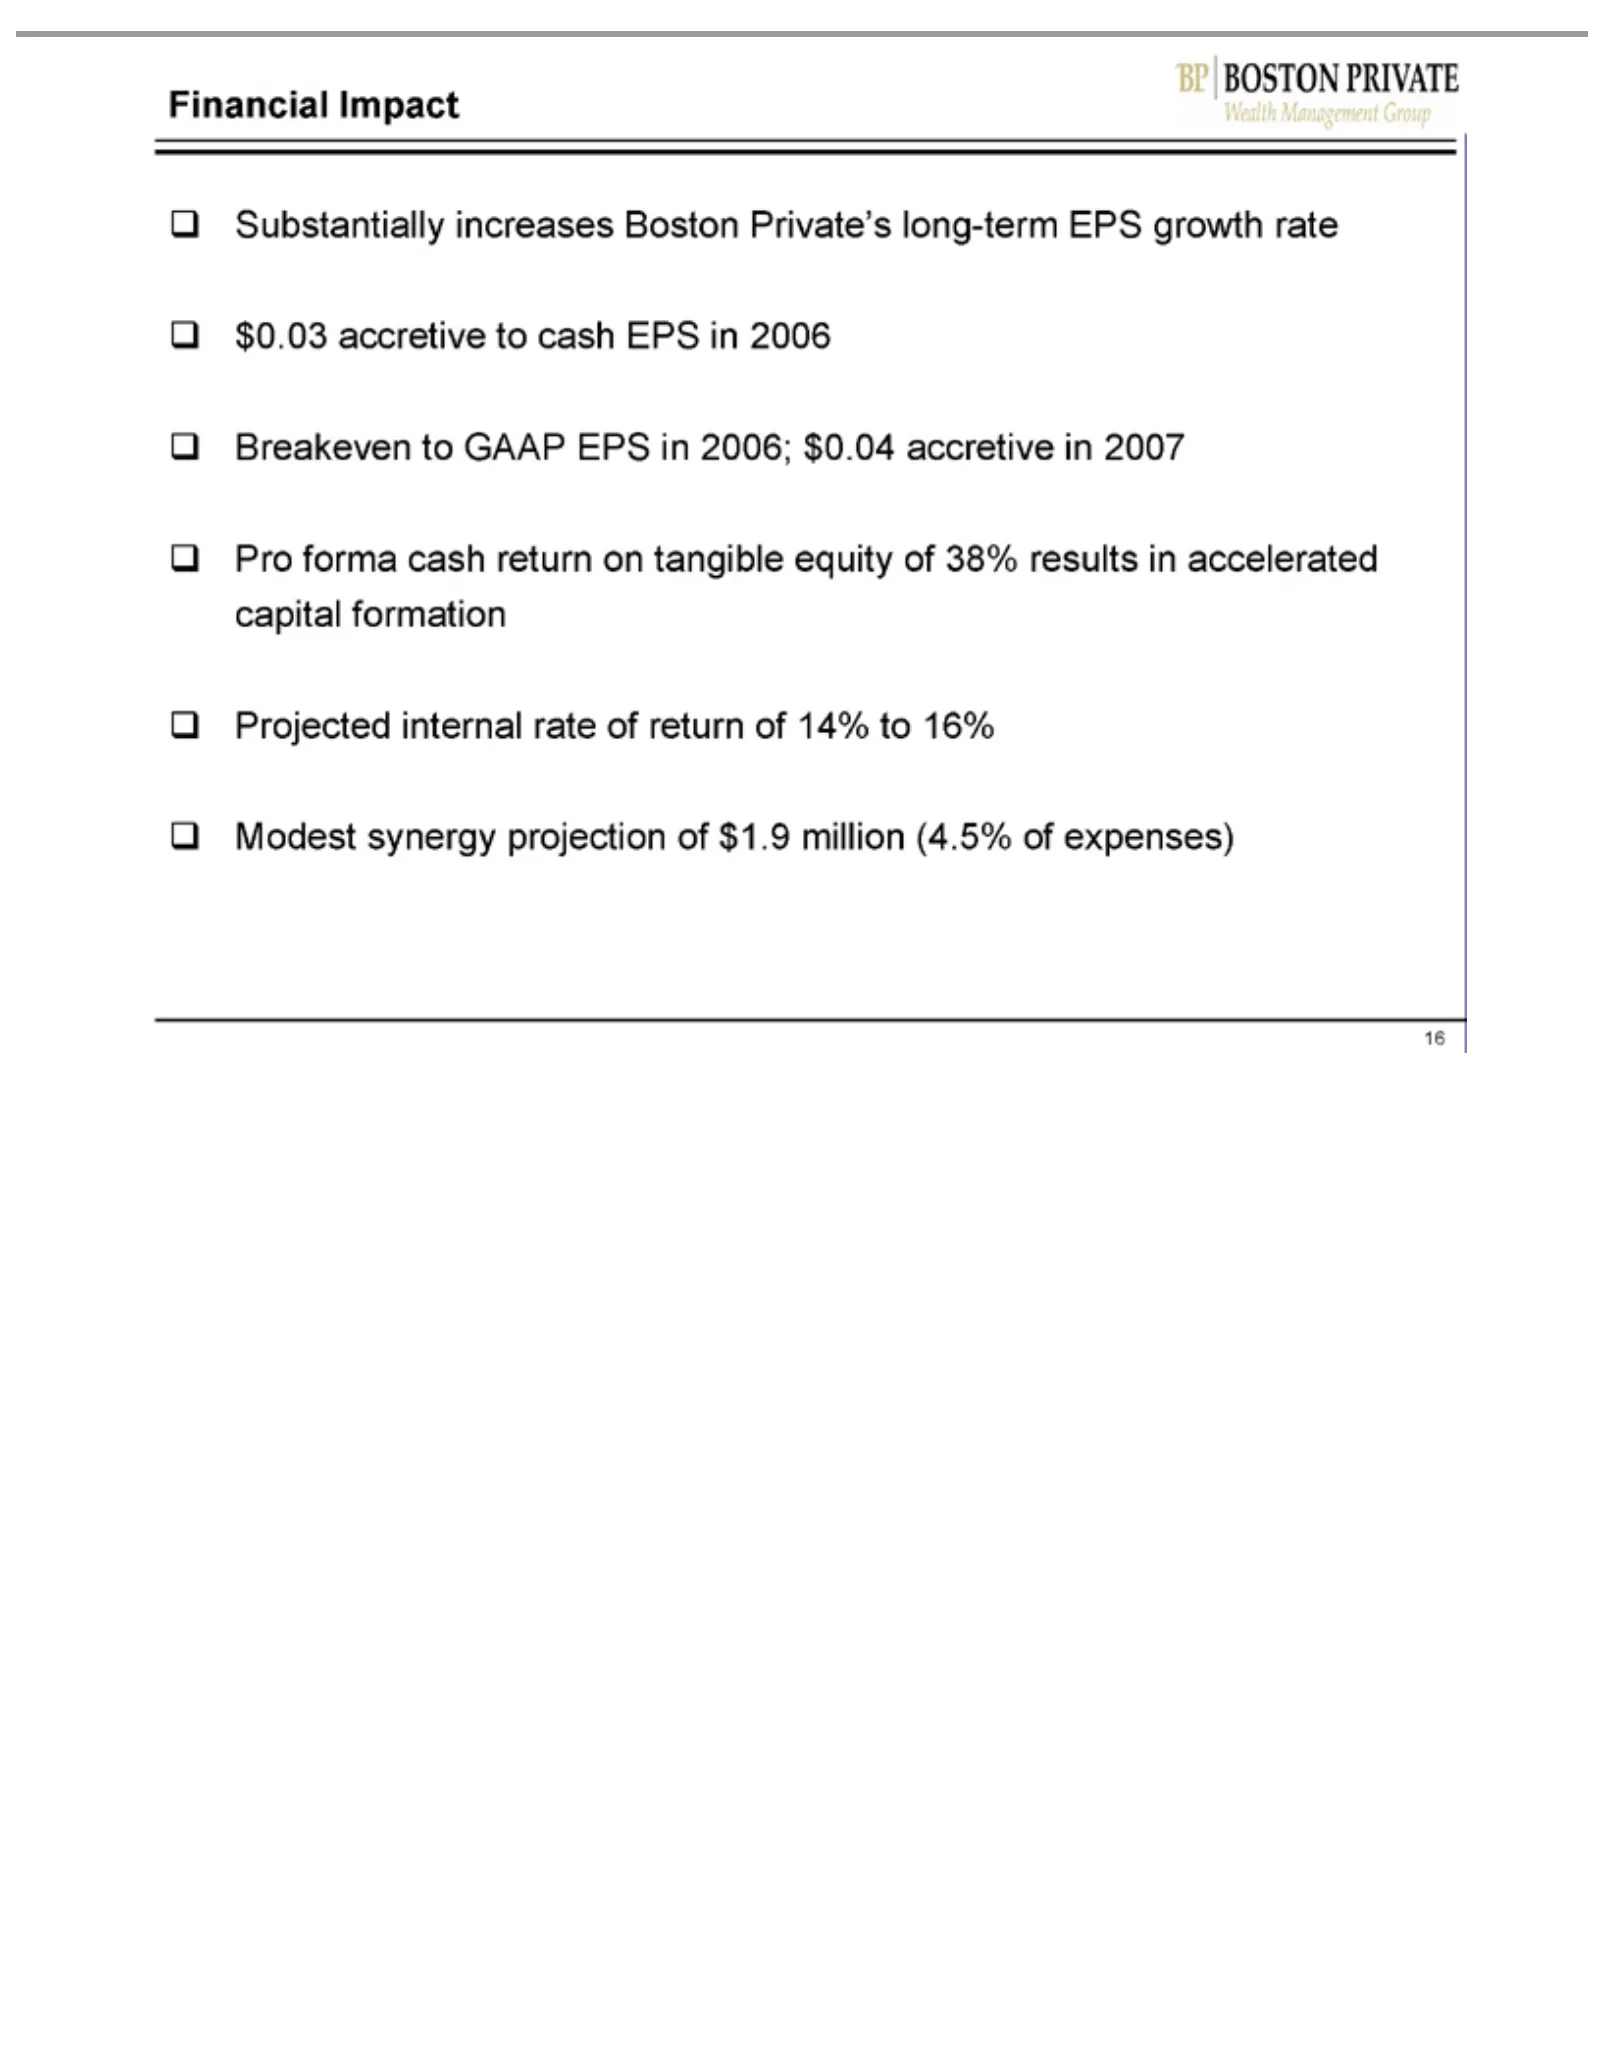
Slide 16: Substantially Accretive Financial Impact
Financial Substantially Pro Projected Modest 16 forma synergy Impact internal cash increases return projection rate on of Boston return tangible of $1.9 Private’s ofequity 14% million to long-term of16% (4.5% 38% results ofEPS expenses) growth in accelerated rate $0.03 capital accretive formation to
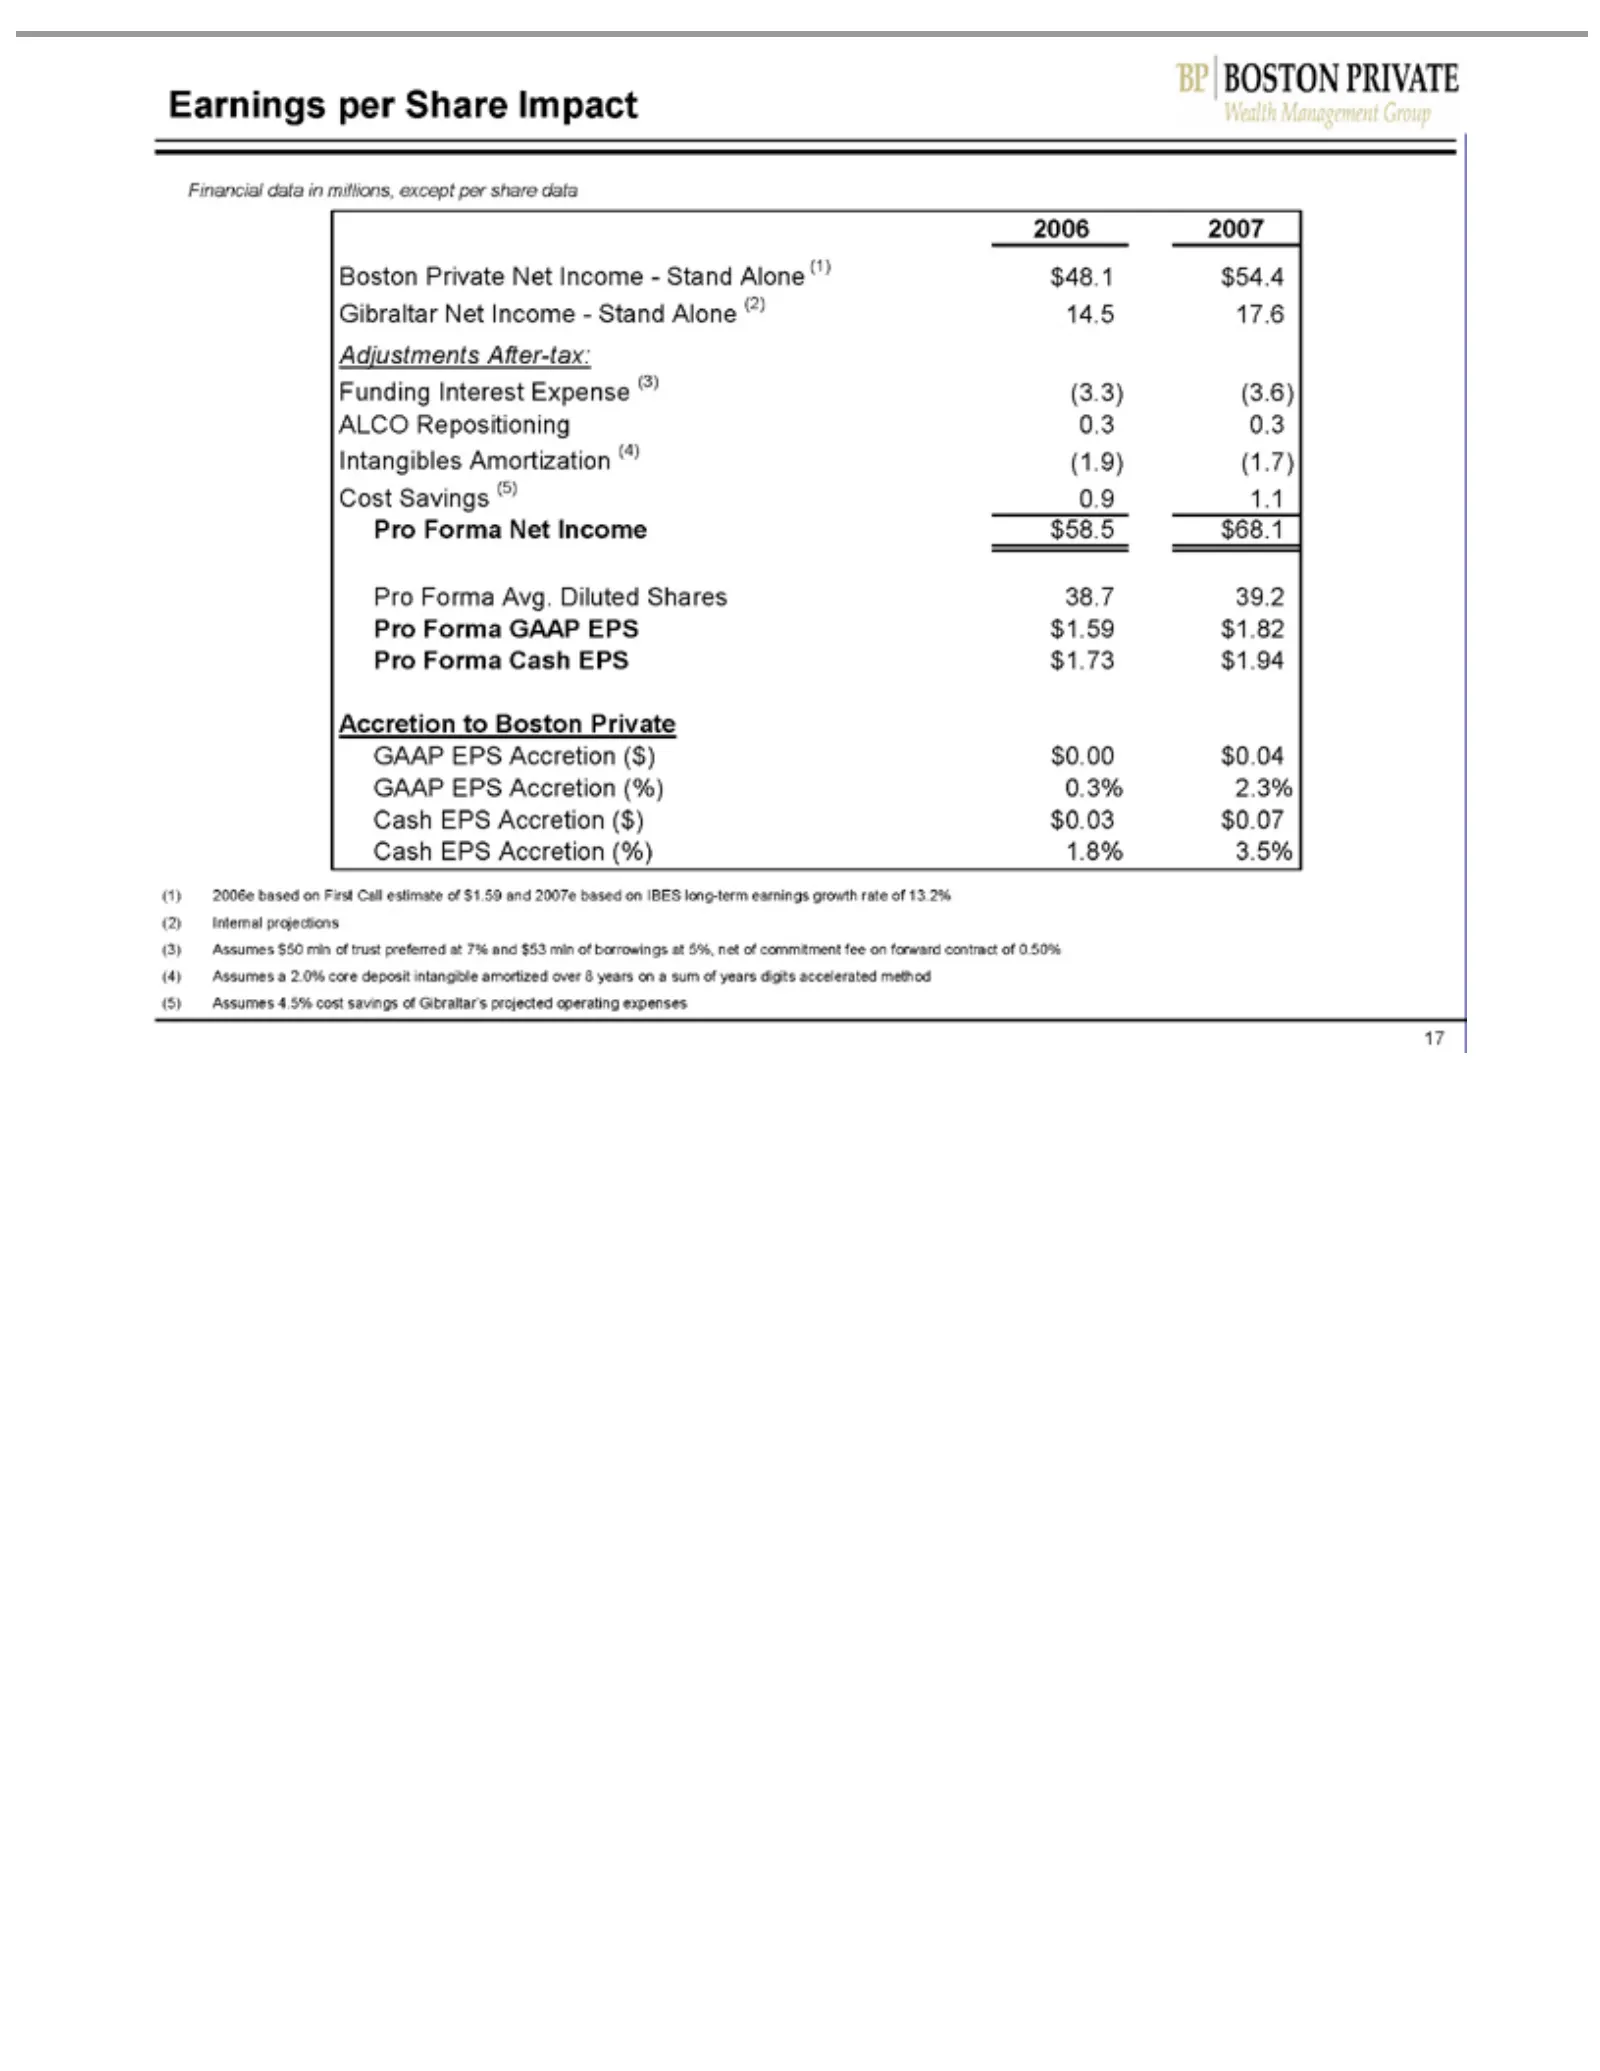
Slide 17: Pro Forma Earnings Impact
Earnings Financial 2006 Boston Gibraltar Adjustments Funding ALCO Intangibles Cost Pro Accretion GAAP Cash (1) (3) years 17 Assumes 2006e Forma Savings 2007 EPS onEPS Repositioning Private Interest aper Net data based Accretion to sum Avg. Net GAAP Cash Amortization Accretion Boston $50 After-tax: S
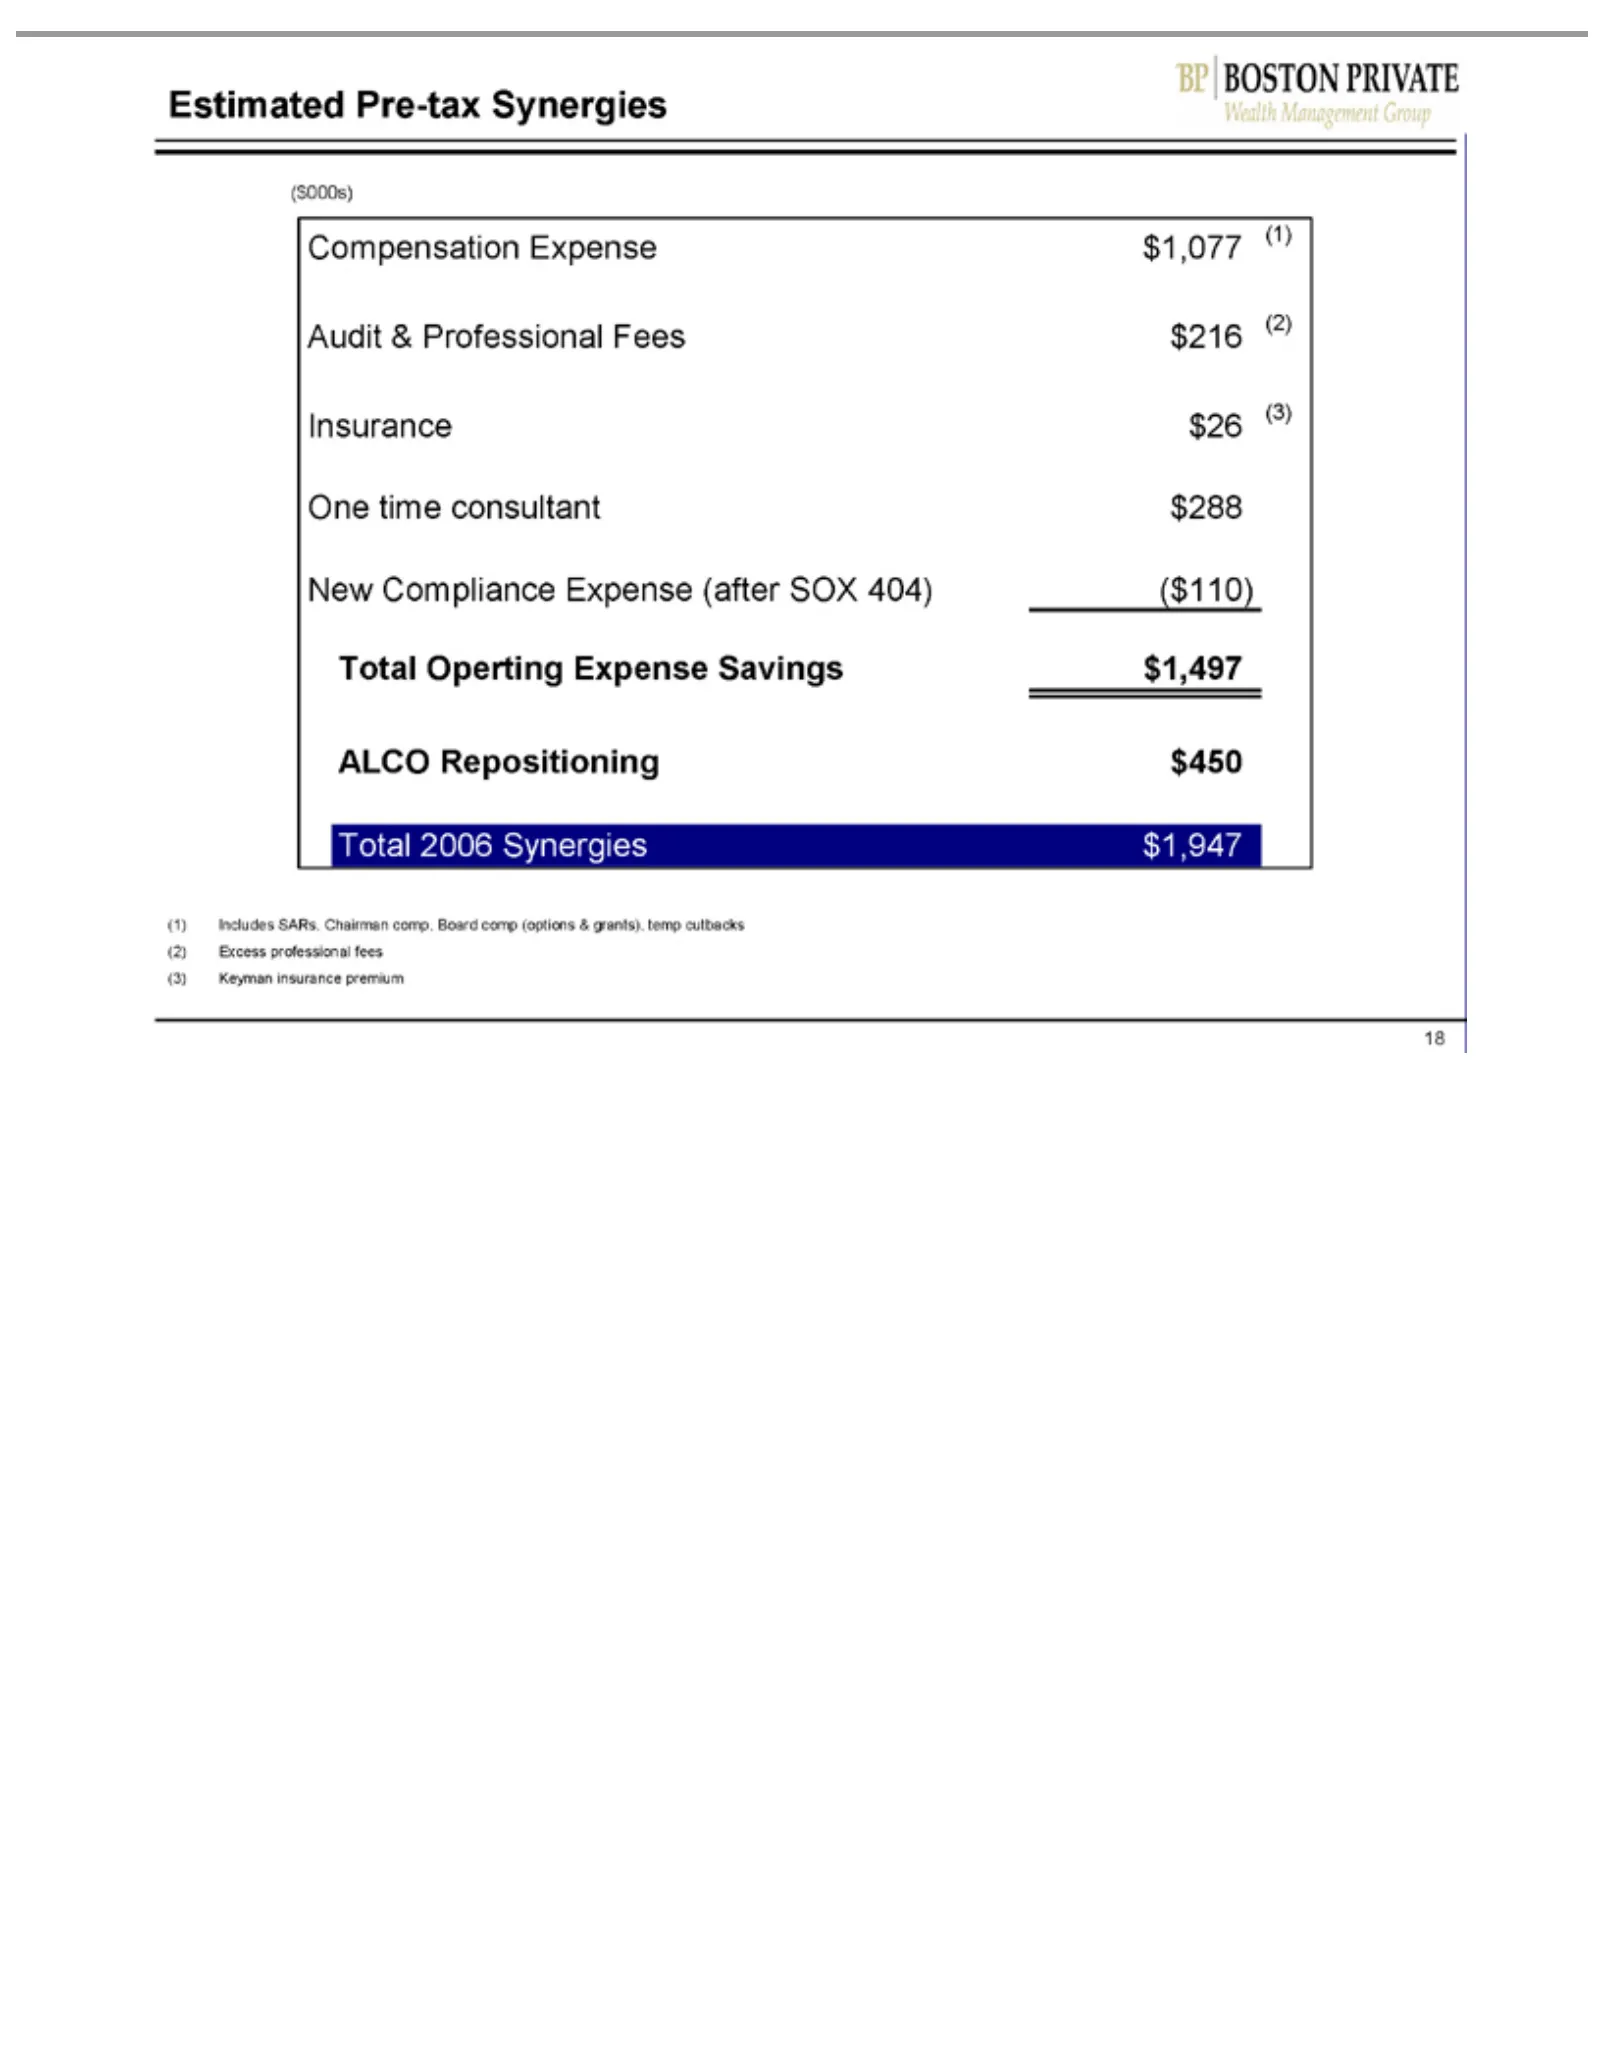
Slide 18: Estimated Compensation and Operating Synergies
Estimated Compensation ($000s) Audit Insurance One New ALCO Total (1) 18 Includes time Compliance Operting 2006 &Repositioning Professional consultant $26 Pre-tax Synergies SARs, (3) Expense Expense Synergies Chairman $288 $1,947 Fees $450 $1,077 Savings $216 (after comp, (1) (2) $1,497 SOXBoard 404
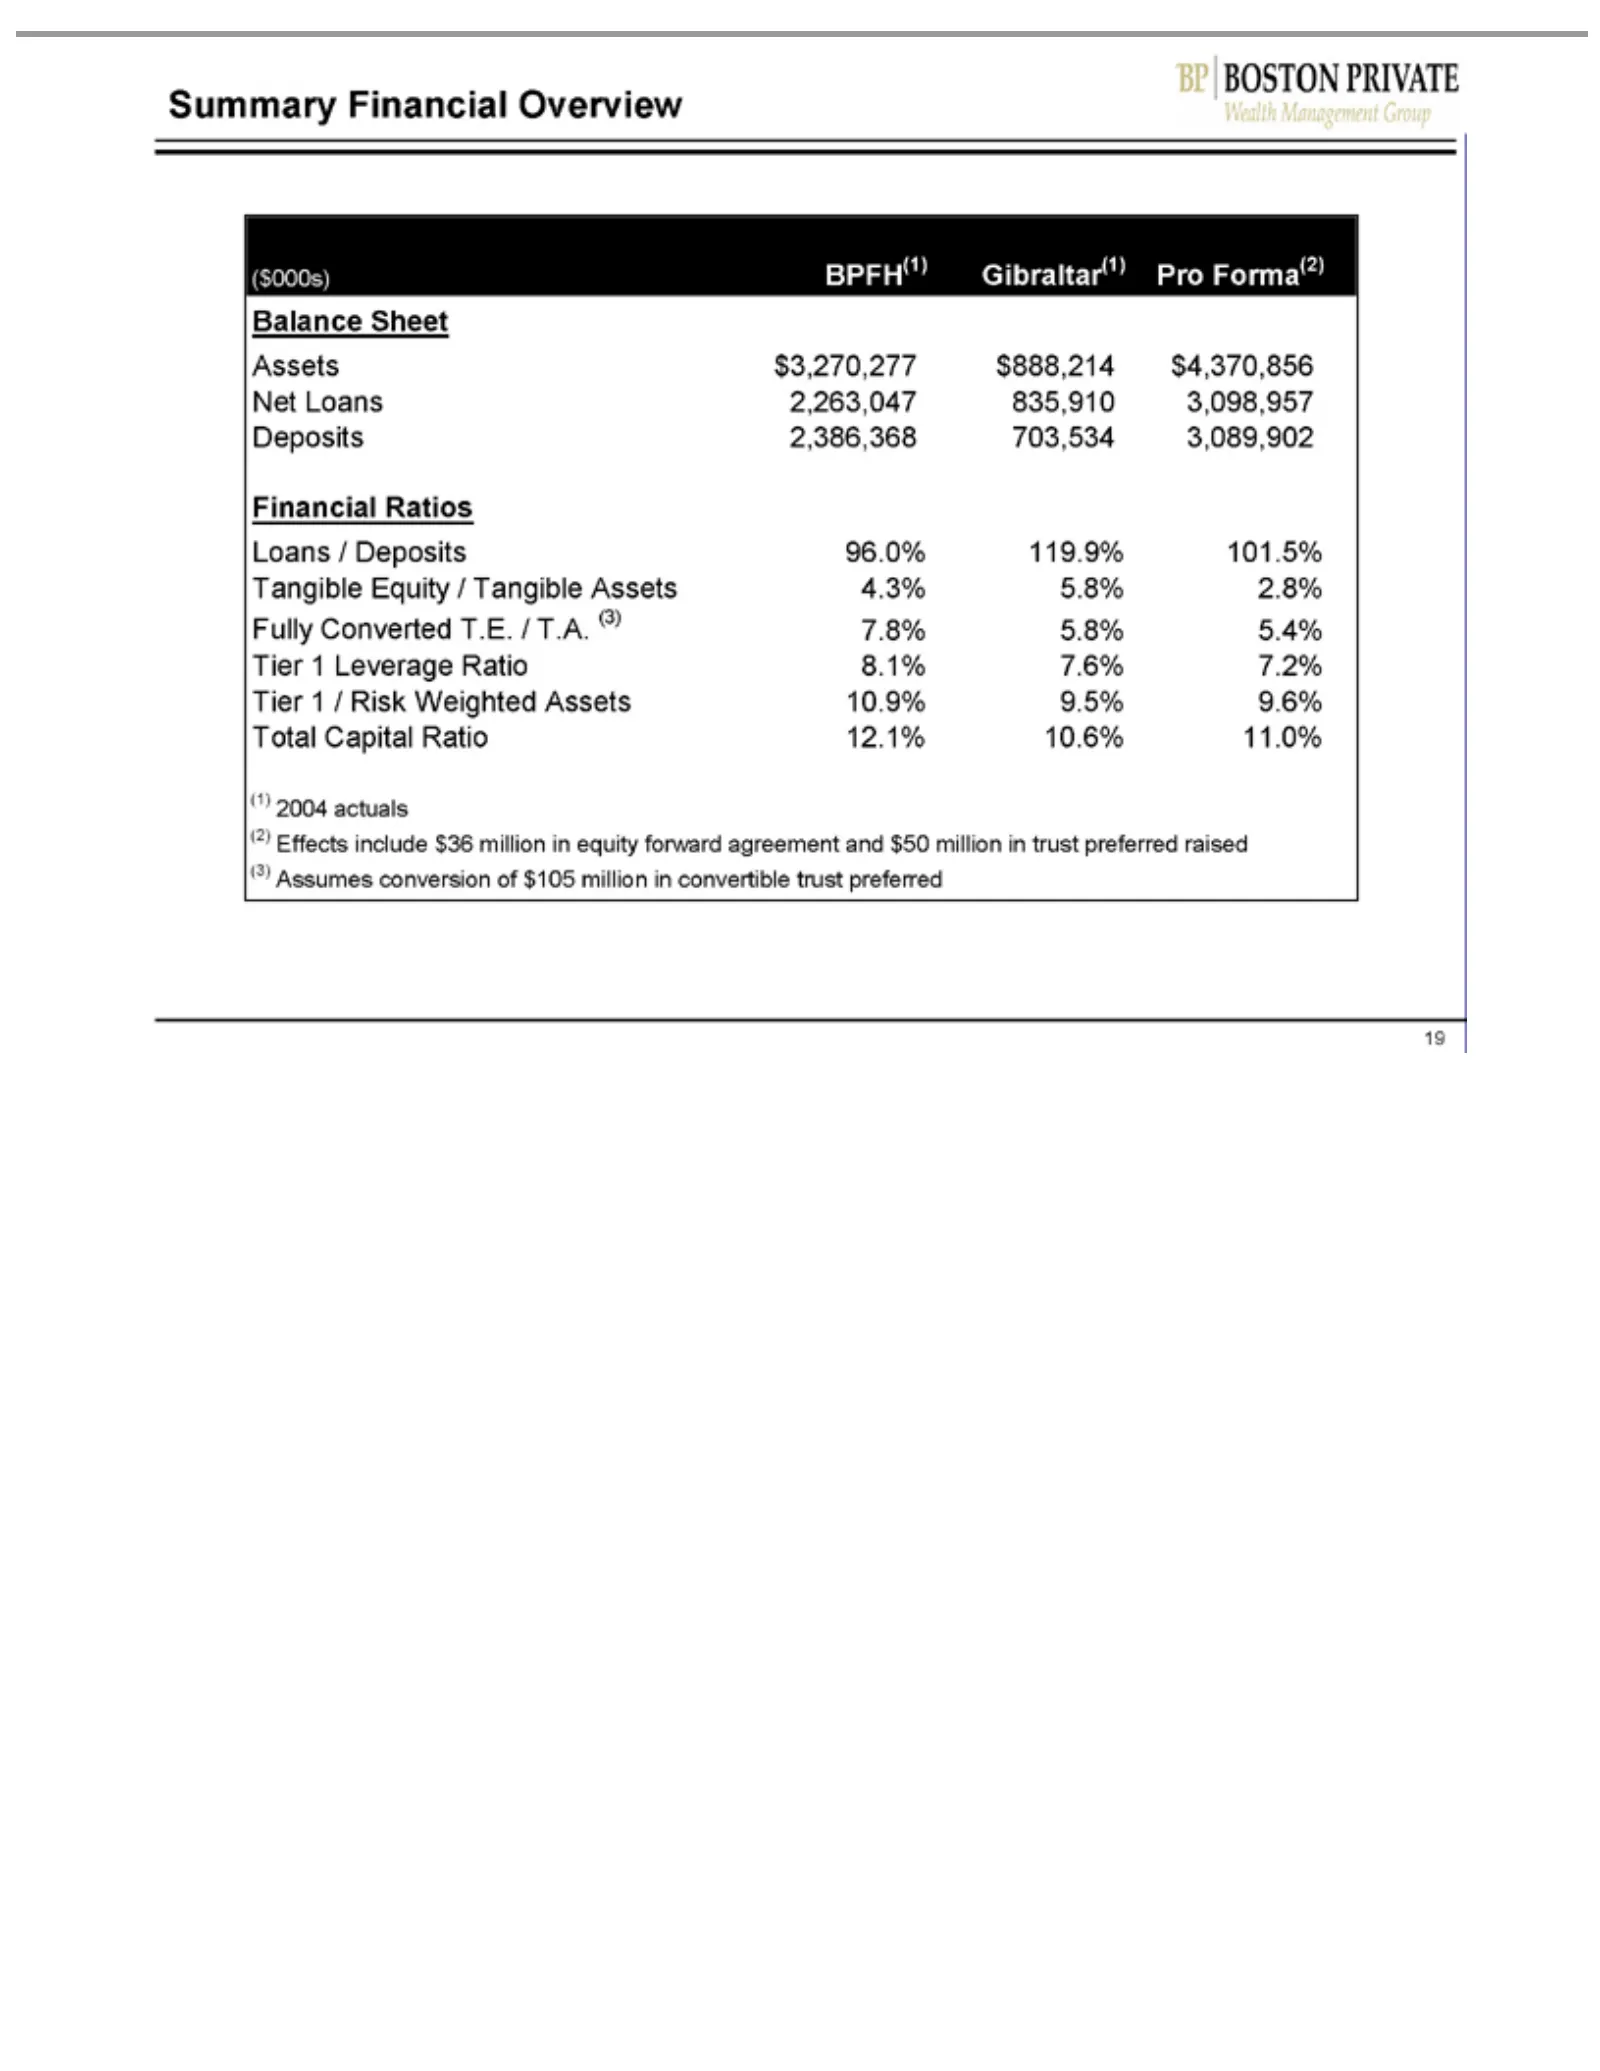
Slide 19: Pro Forma Balance Sheet Summary
Summary ($000s) Balance Assets Net Deposits Financial Loans Tangible Fully Tier Total (1) (2) 19 2004 Effects Loans 1Capital Converted /Leverage $3,270,277 Risk Deposits BPFH(1) Sheet actuals Equity 2,386,368 Ratios Financial 2,263,047 include Weighted Ratio Ratio /T.E. 96.0% Tangible Gibraltar(1) $
Slide 20: Transaction Summary
Transaction Combination Enhances Expands Tremendous Complementary 20 franchise shareholder Summary opportunity consistent management intovalue highly with to leverage our styles attractive strategic and Boston communities cultural vision Private’s fit in Wealth SouthManagement Florida expertise in a
Slide 21: Appendix
Appendix P| BOSTON PRIVATE Wealth Management Group
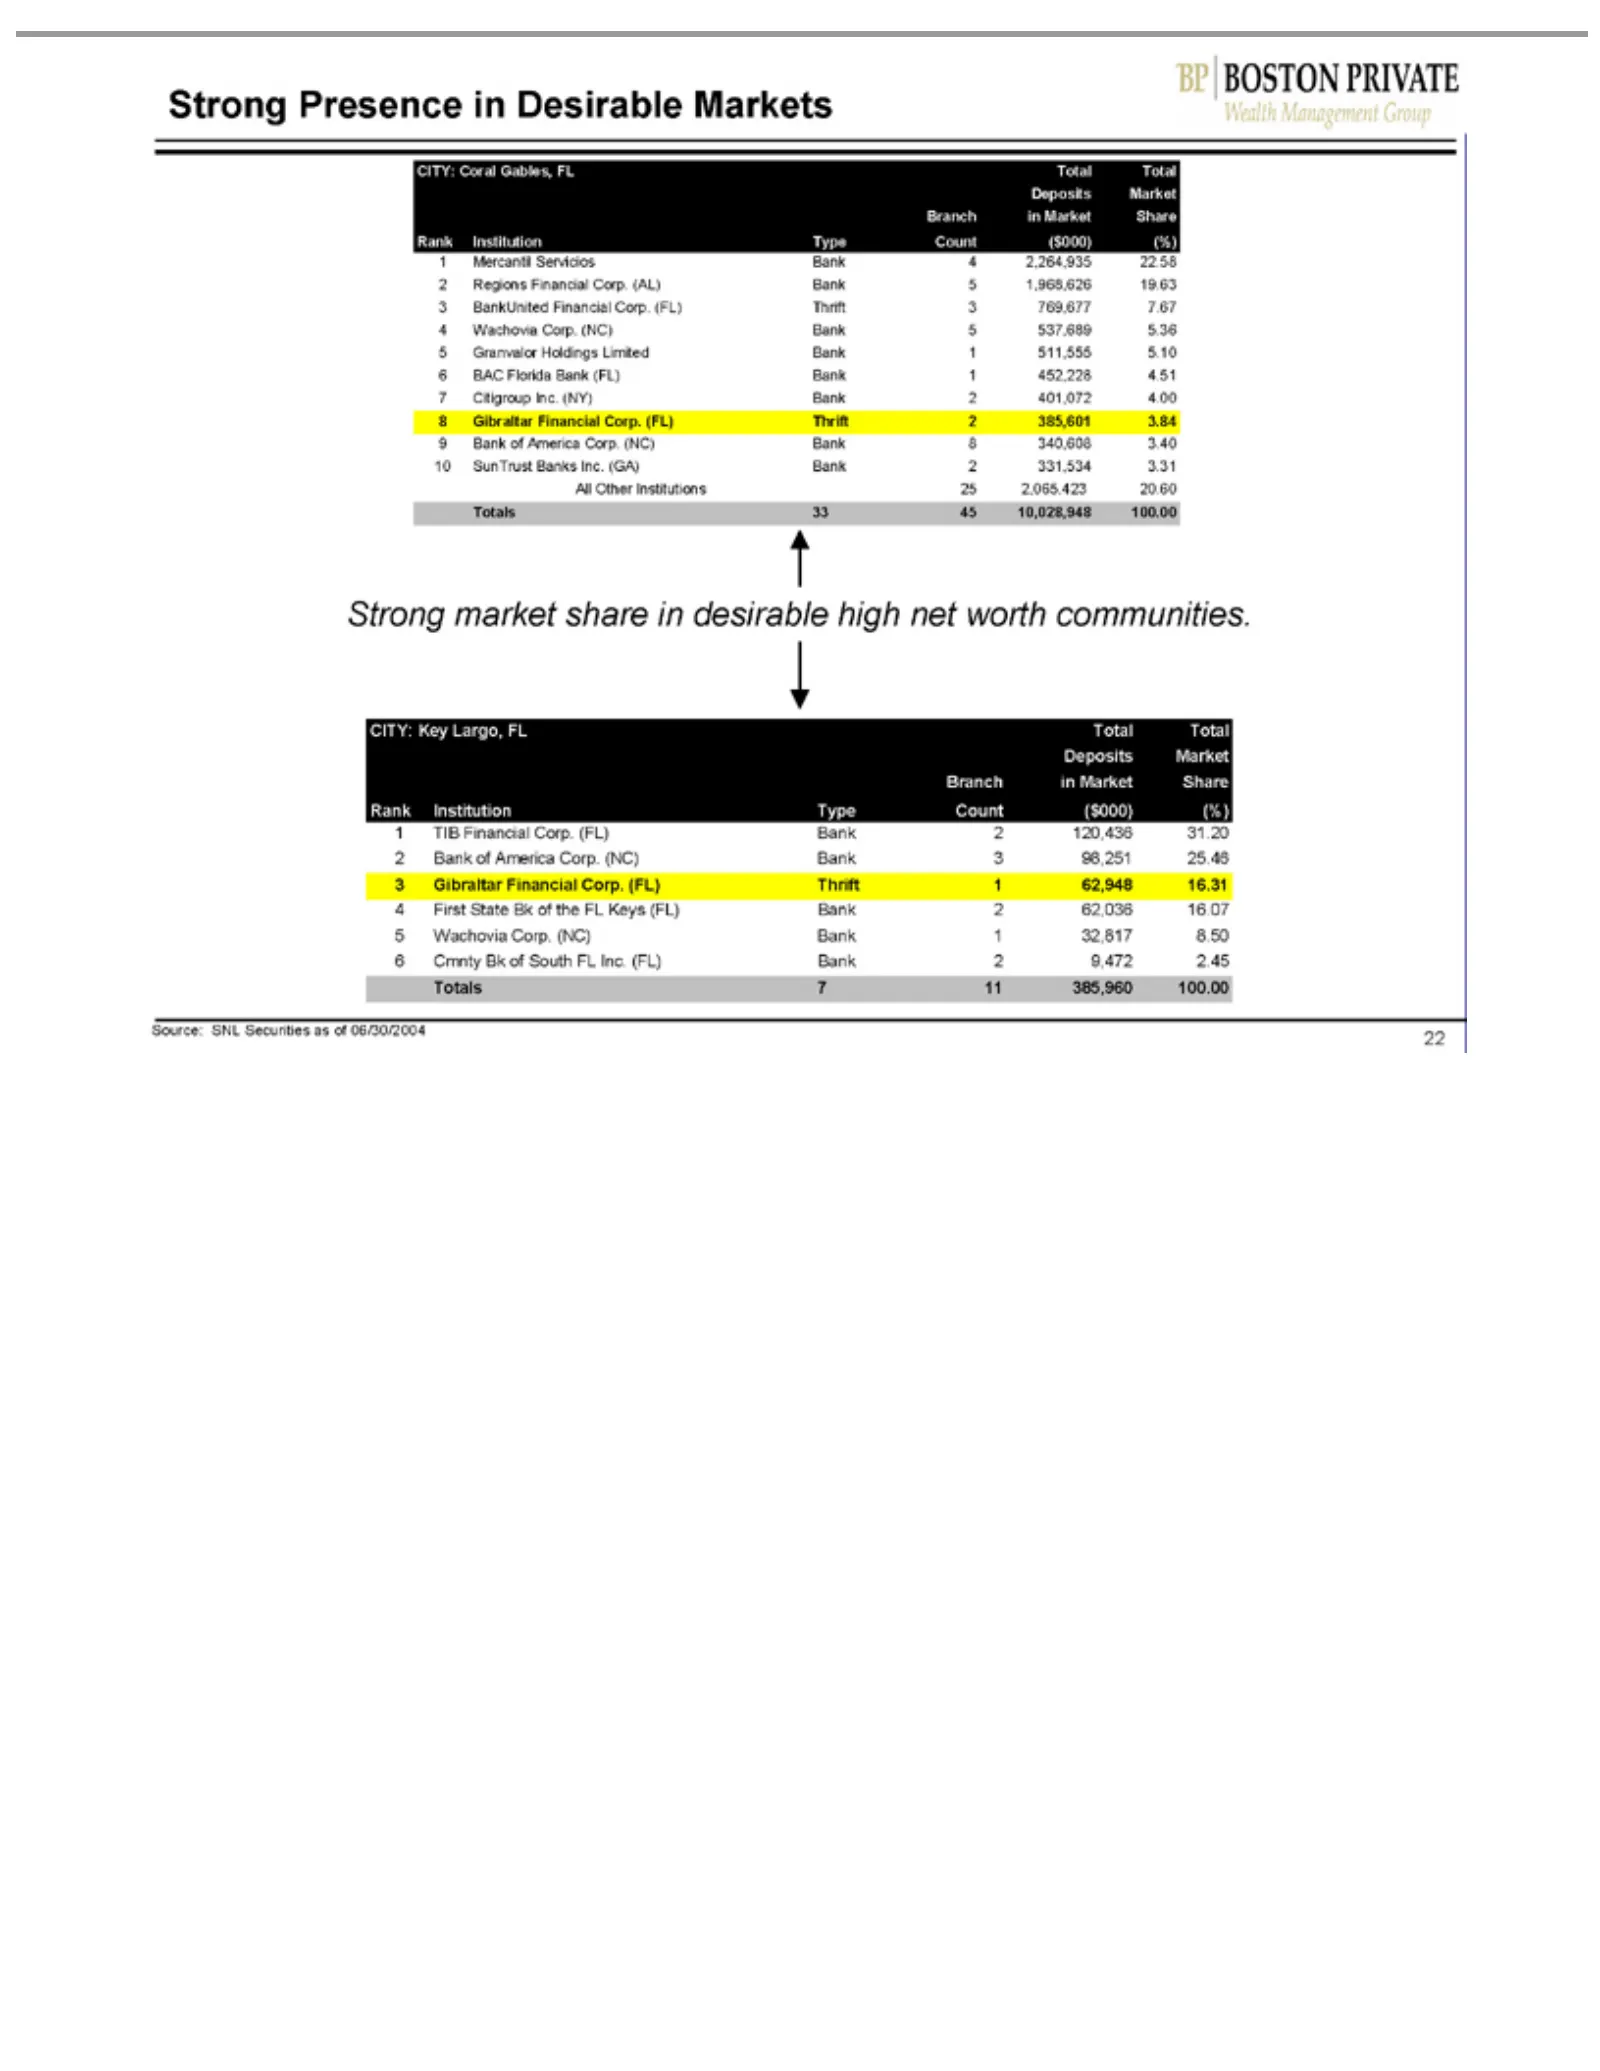
Slide 22: Gibraltar Presence in Desirable Florida Markets
7 Wachovia 8 9 10 All Strong CITY: Total 1 2 3 4 5 6 Totals Source: 22TIB Mercantil Regions BankUnited Granvalor BAC Citigroup Bank Gibraltar First Cmnty SunTrust Other Market Financial 733 Coral Key State Presence market Florida of SNL 11 Bk 45 Institutions America Financial Financial 385,960 Largo
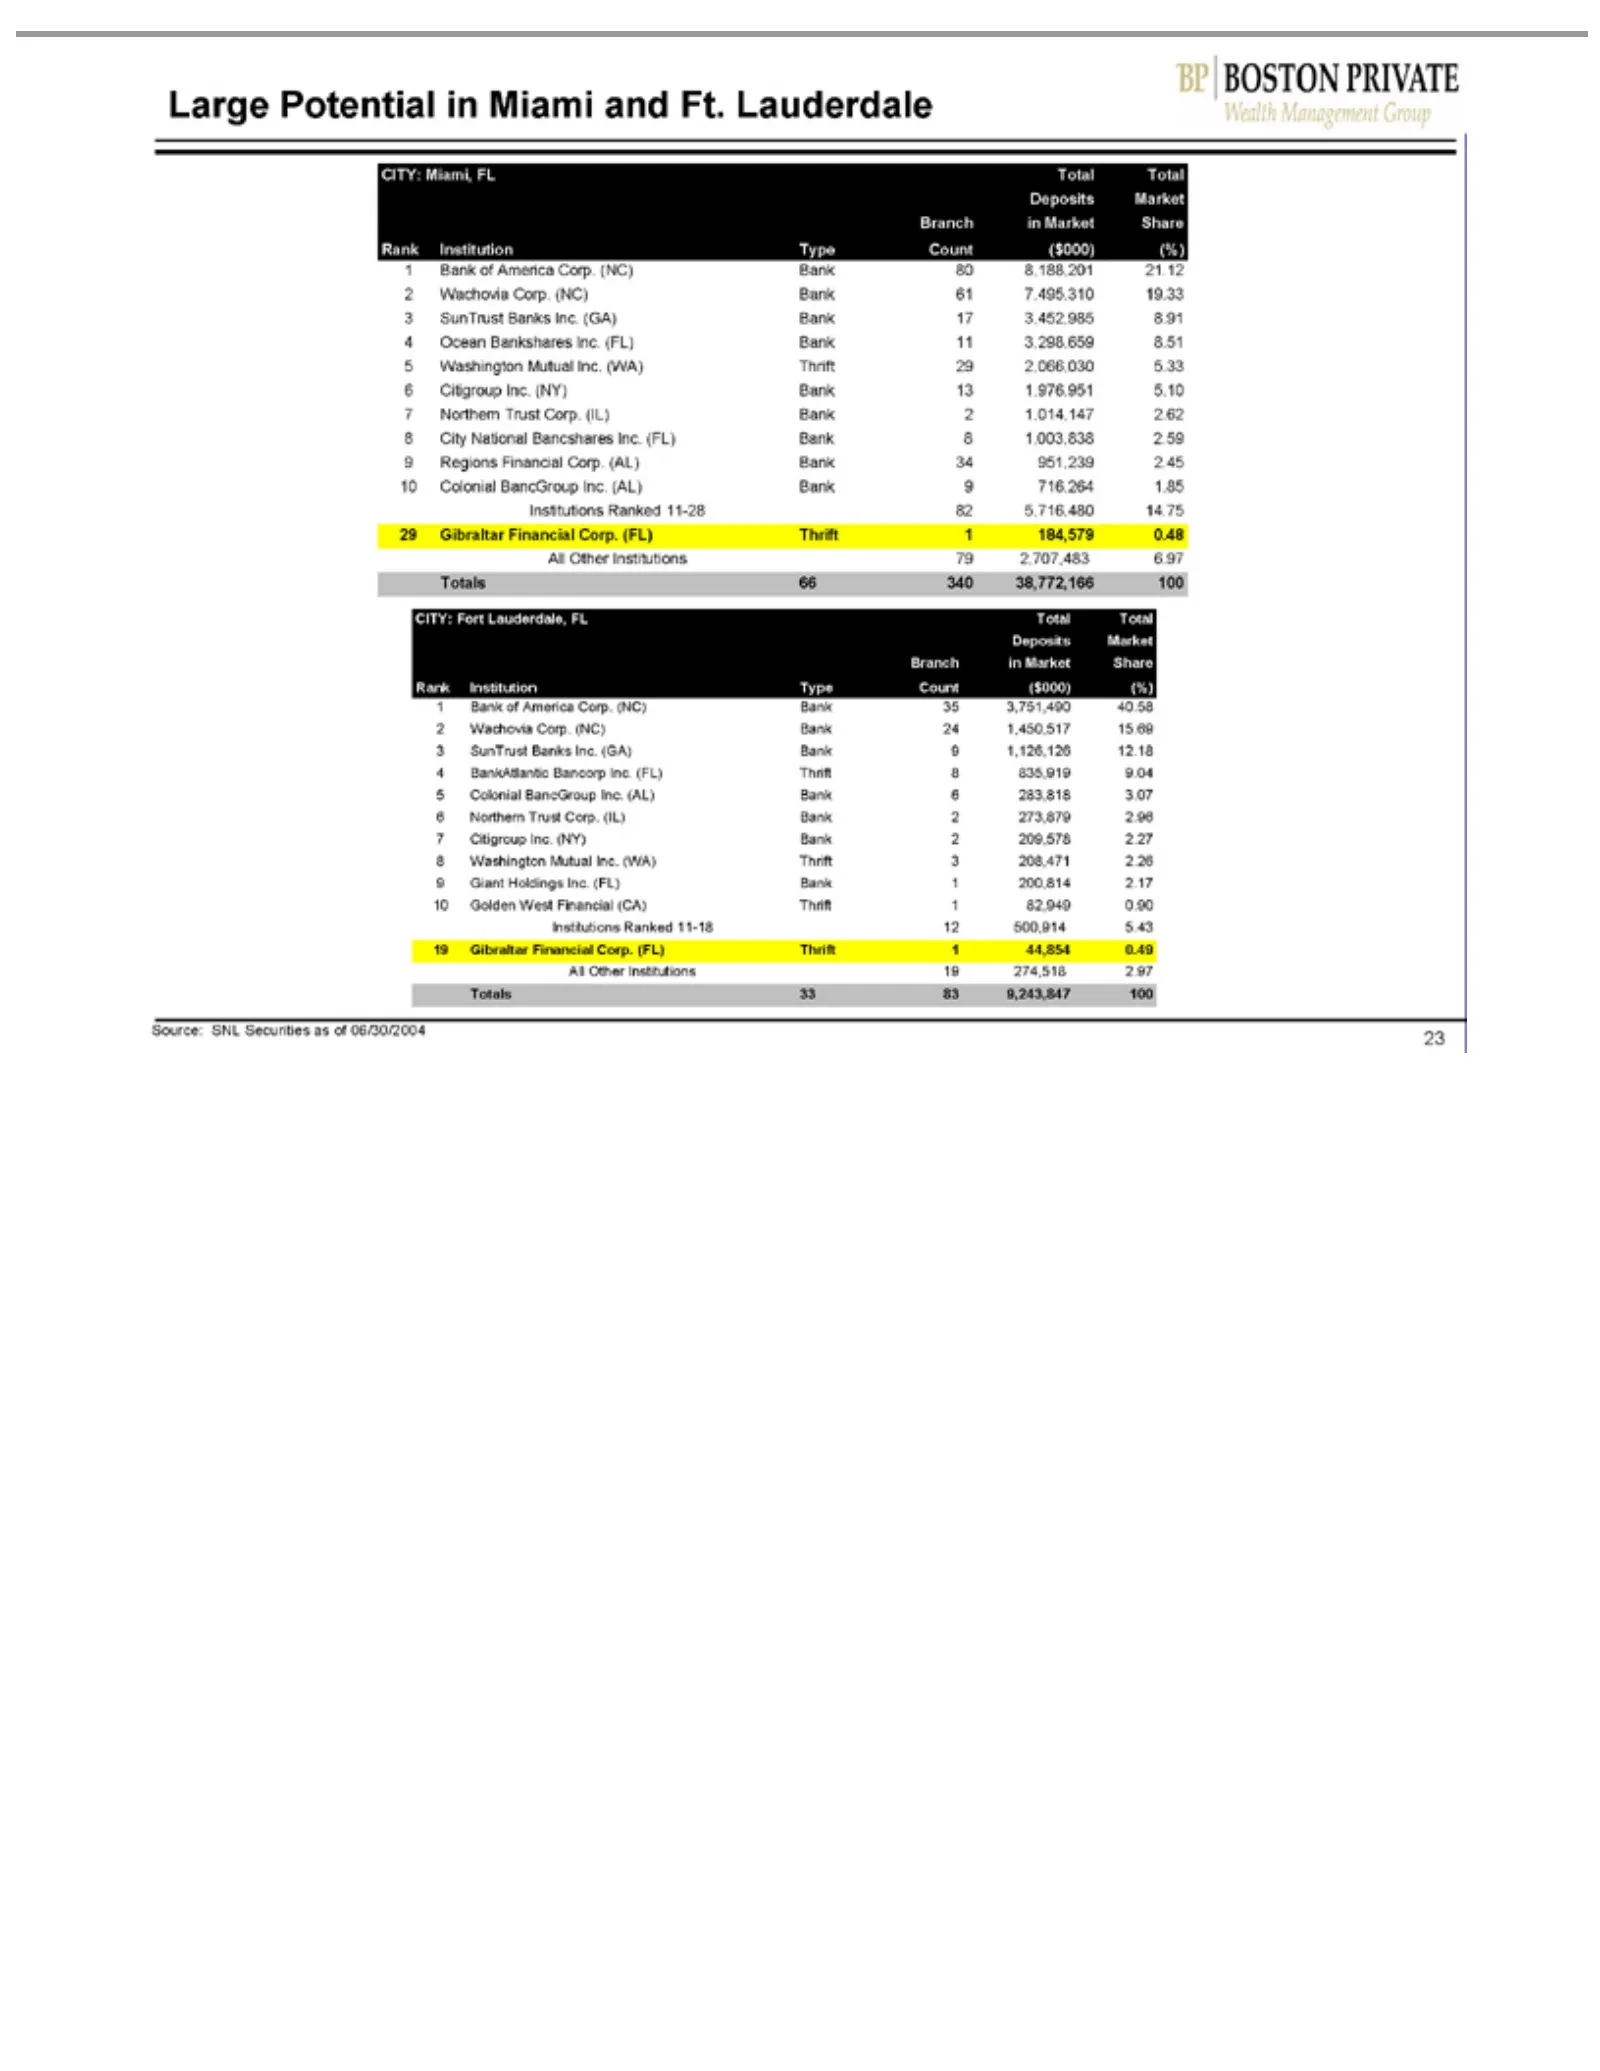
Slide 23: Large Deposit Market Share in Miami and Fort Lauderdale
Large 29 CITY: Deposits Branch Rank 1 2 3 4 5 6 7 8 9 10 Institutions 19 All Totals Source: 23Wachovia Washington Ocean City Regions Bank SunTrust BankAtlantic Colonial Northern Citigroup Giant Colonial Golden Gibraltar Other Institution Potential 66 33 National Miami, Fort of in Holdings SNL Banksh
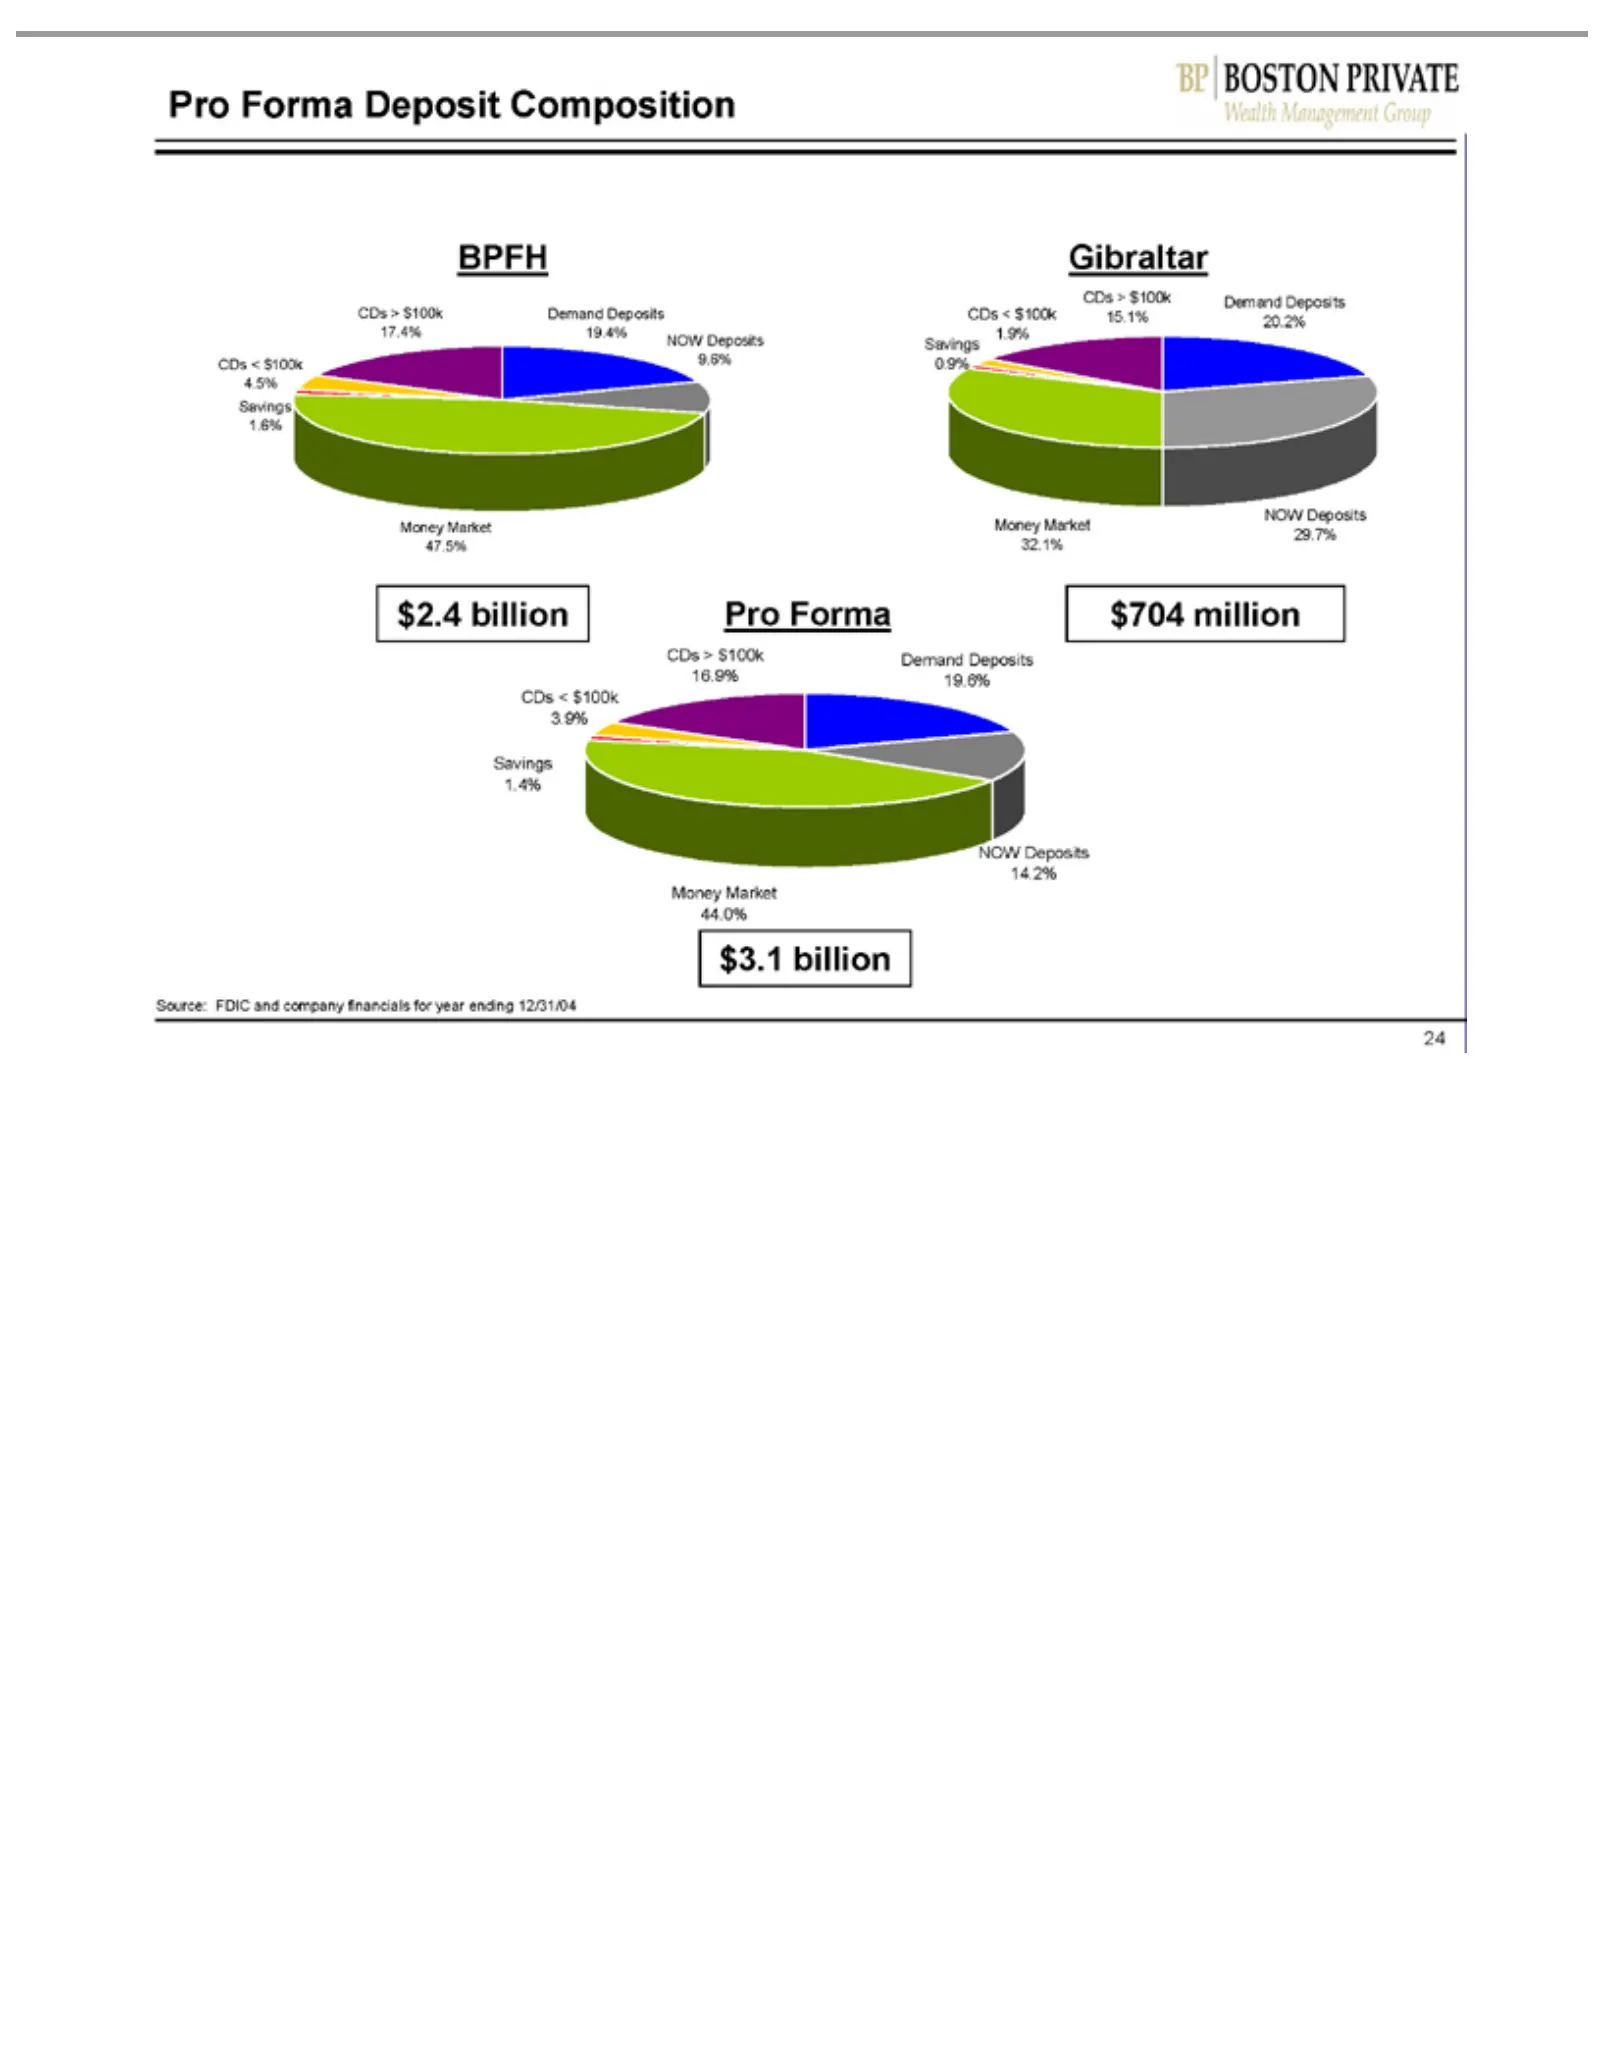
Slide 24: BPFH, Gibraltar, Pro Forma Deposit Composition
BPFH Gibraltar Pro CDs Savings Demand Money NOW Source: 24 Forma >Deposits < $100k Market FDIC 0.9% 1.4% Deposits Deposit 17.4% 4.5% 1.9% 15.1% 16.9% 3.9% and 47.5% 32.1% 44.0% 9.6% 29.7% 14.2% 19.4% 20.2% 19.6% company Composition Savings $2.4 $3.1 billion billion 1.6% financials $704formillion yea
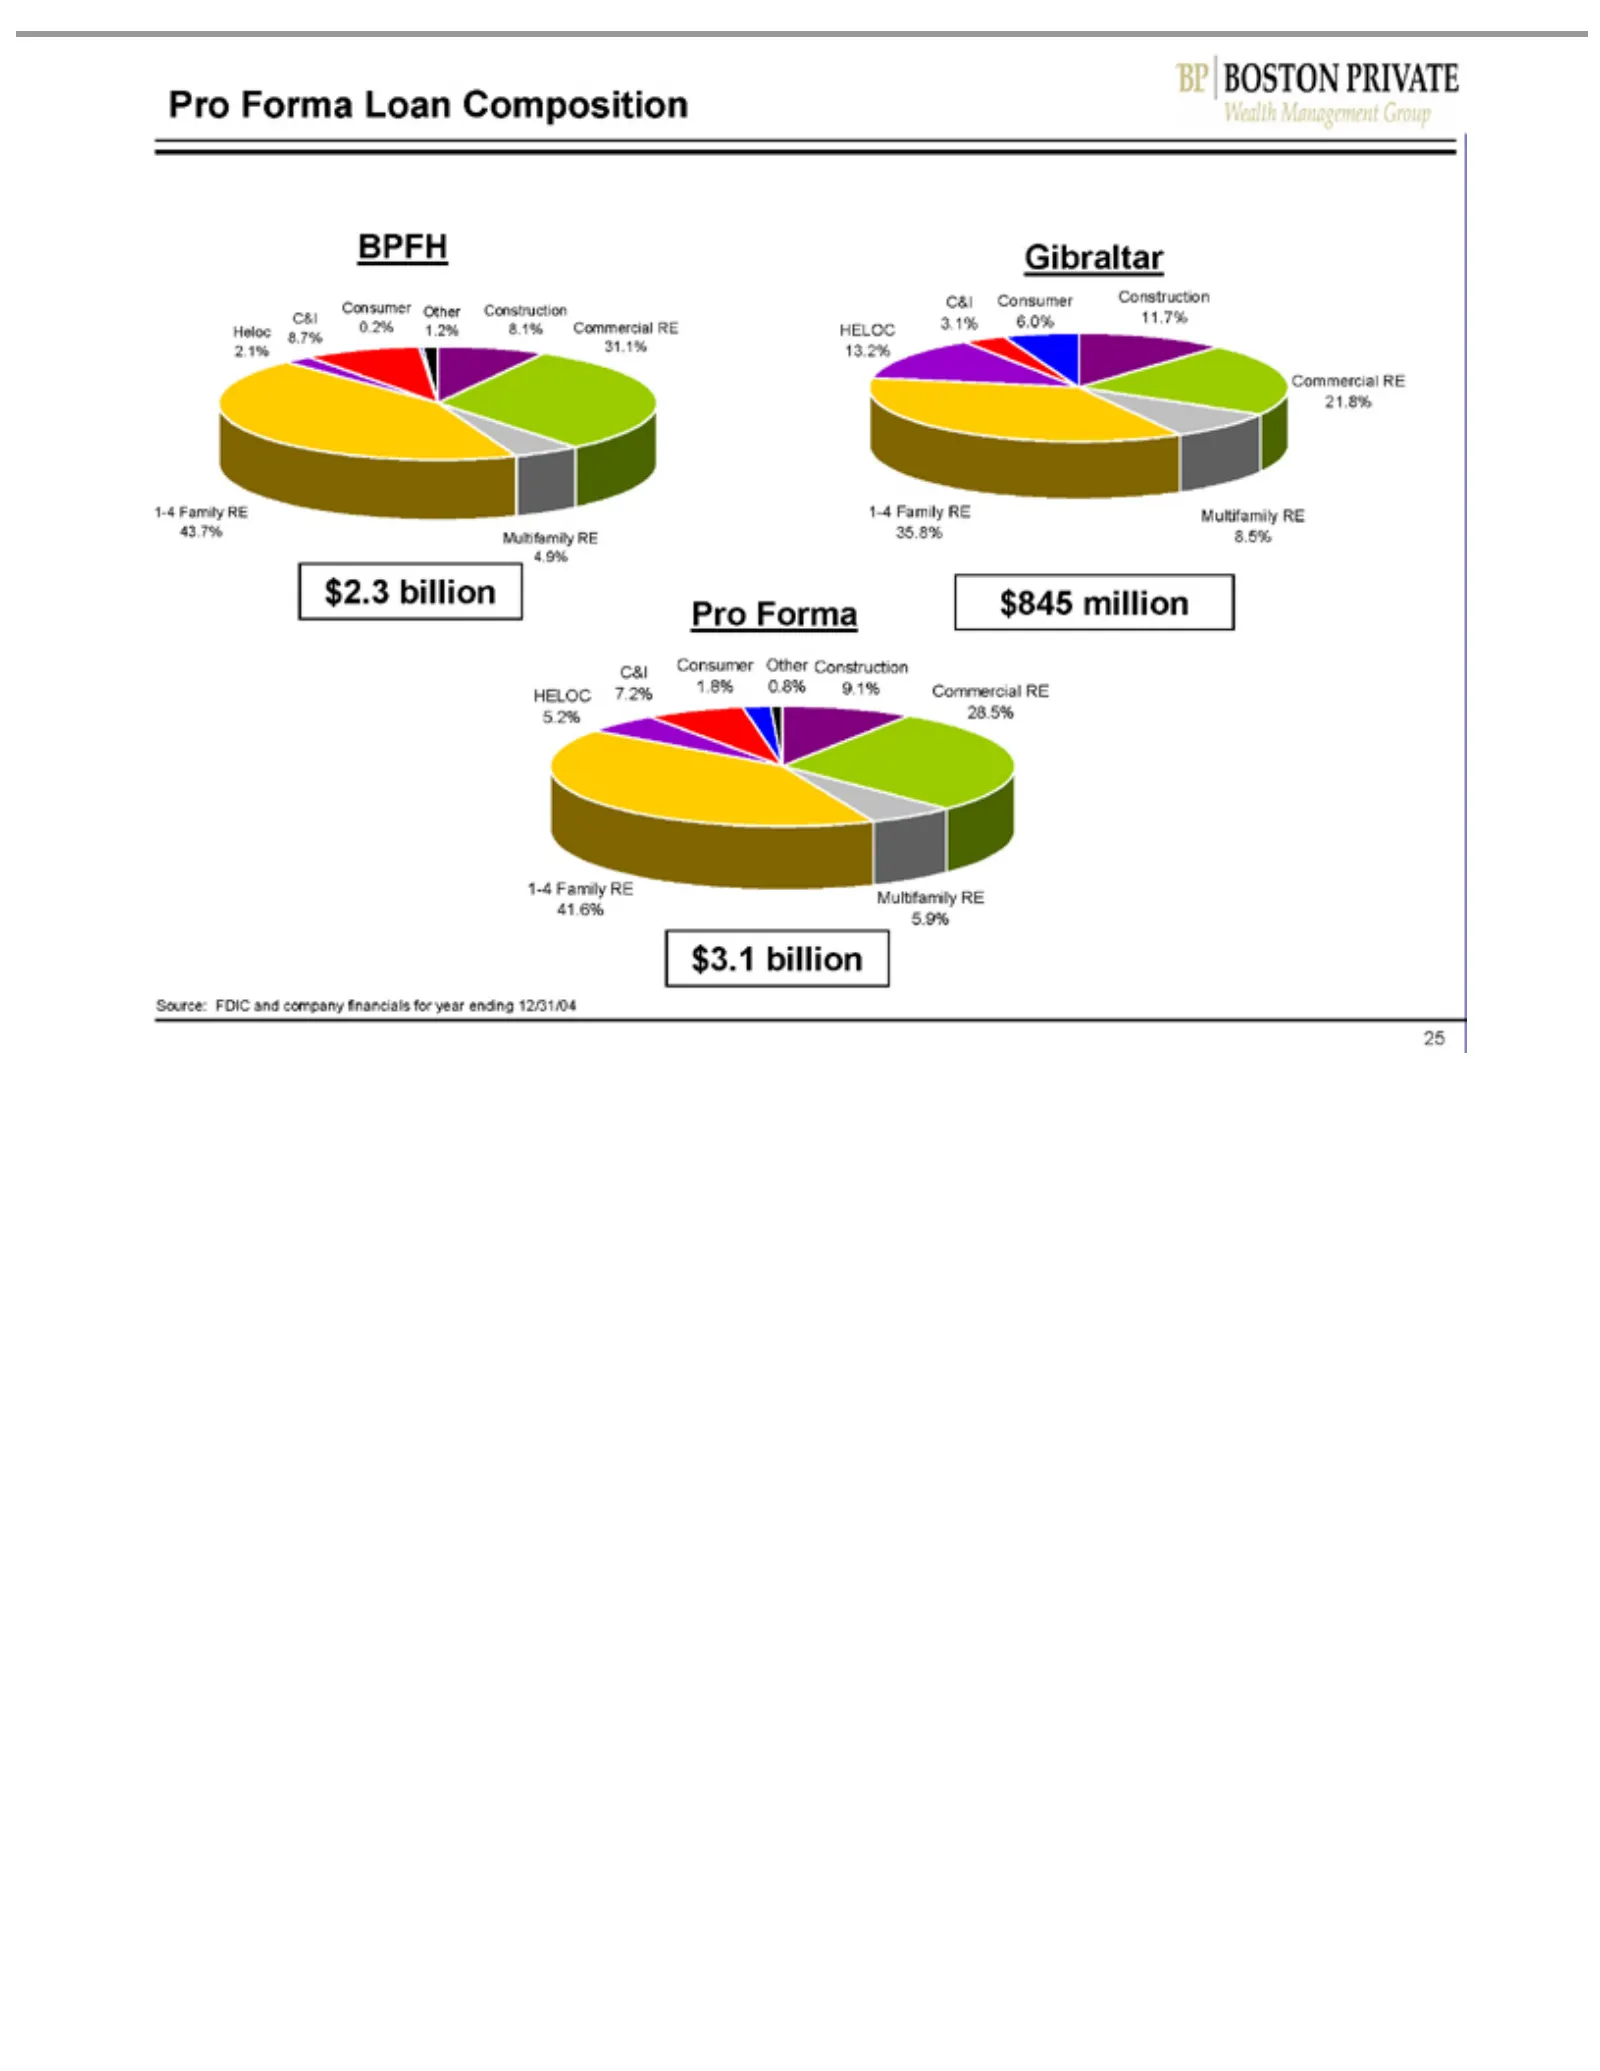
Slide 25: BPFH, Gibraltar, Pro Forma Loan Composition
Heloc BPFH 31.1% 43.7% 4.9% Gibraltar 21.8% 35.8% 8.5% Pro C&I 5.2% HELOC Consumer Other Construction Commercial 1-4 28.5% Multifamily 41.6% 5.9% Source: 25 Family Forma 8.7% 3.1% 7.2% $2.3 $845 $3.1 1.2% 0.8% 2.1% FDIC 13.2% billion 0.2% 6.0% 1.8% Loan million RE RE RE 8.1% 11.7% 9.1% andCompositio
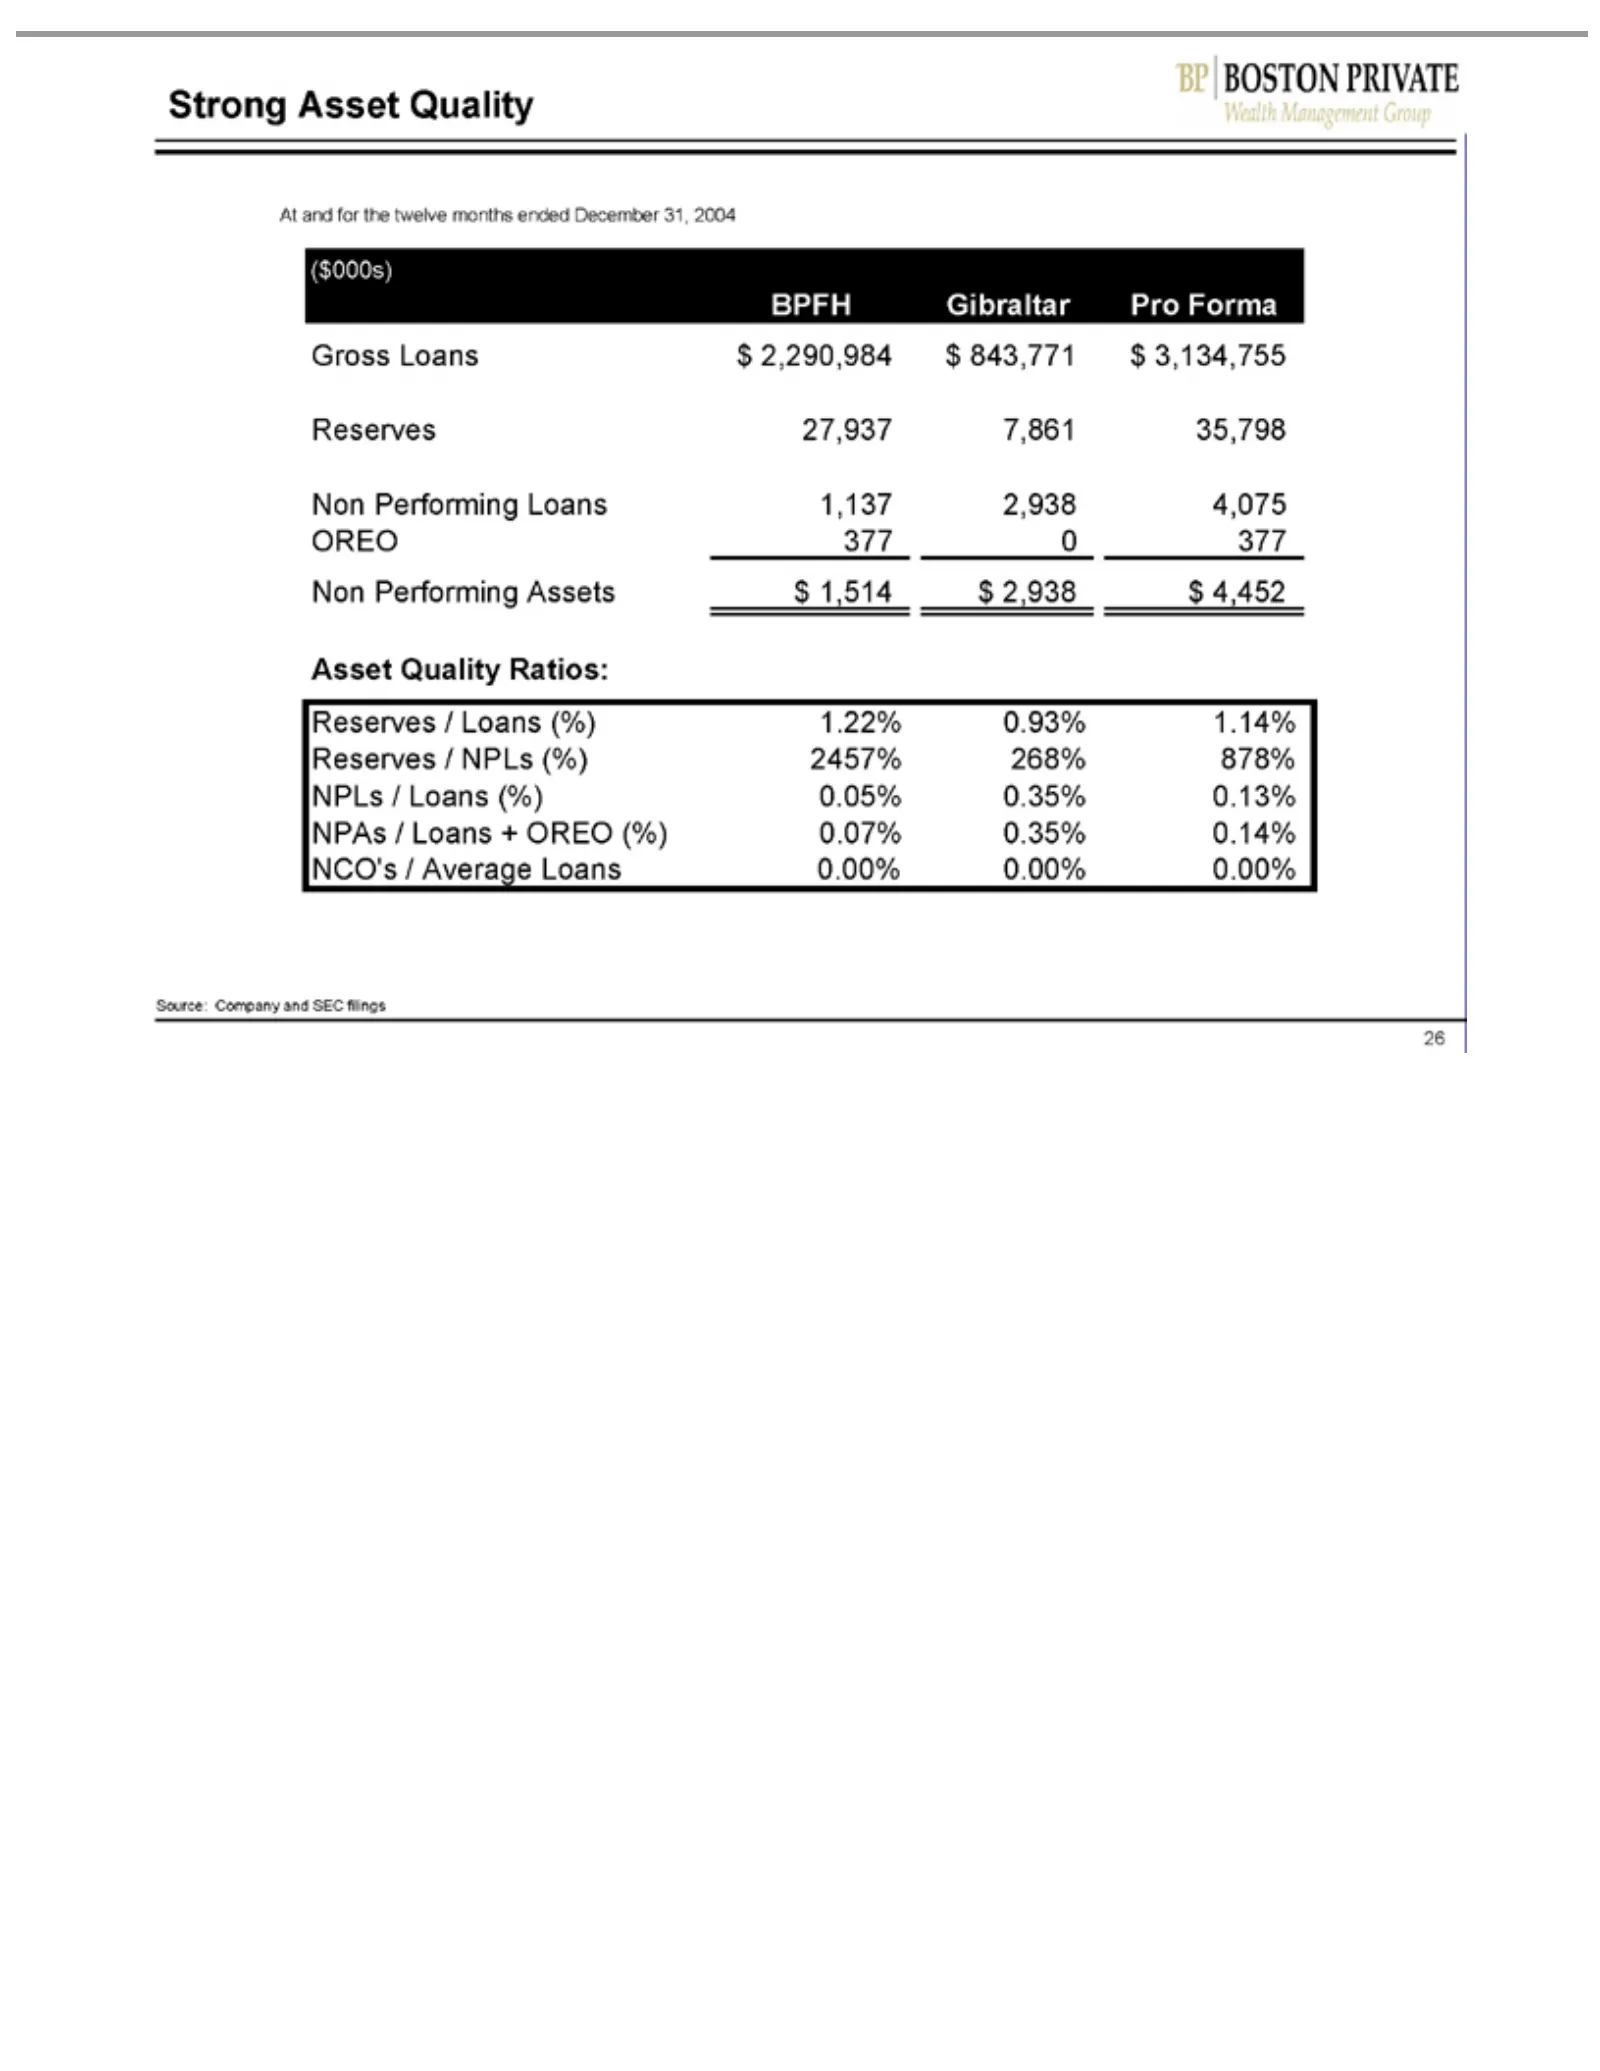
Slide 26: Strong Asset Quality
Strong At BPFH ($000s) Gross OREO Non Asset Reserves NPLs NPAs NCO’s Source: 26 and Performing Quality /Loans Gibraltar Asset for 377 /Loans Company Average /27,937 the Loans NPLs 0 $2,290,984 Quality 377 Ratios: (%) + twelve OREO Pro Assets Loans 7,861 (%) Loans (%) and 0.05% Forma 2457% months 1.2
Source: SEC EDGAR · 8-K filed Apr 20, 2005
More decks from Boston Private Financial Holdings Inc
 Proxy Contest (April 2021)28 slides · Apr 9, 2021
 Merger or Acquisition (April 2021)24 slides · Apr 7, 2021
 Proxy Contest (March 2021)50 slides · Mar 30, 2021
 Proxy Contest (February 2021)67 slides · Feb 2, 2021
 Merger or Acquisition (January 2021)15 slides · Jan 4, 2021
 Investor Day (May 2019)52 slides · May 6, 2019