Fleetwood Enterprises — Investor Day (November 2004)
135 slides from Fleetwood Enterprises's investor day presentation, Nov 1, 2004
Slide 1: Investor Day October 29, 2004
‘We FLEETWOOD. Investor Day October 29, 2004 “= FLEETWOOD.
Slide 2: Safe Harbor Statement
Safe Harbor Statement This presentation contains certain forward-looking statements and information based on the beliefs of Fleetwood's management as well as assumptions made by, and information currently available fo, Fleptwood's management. Such statements reflect the current views of Fleetwood wi
Slide 3: Corporate Overview
Corporate Overview Ed Caudill President & Chief Executive Officer
Slide 4: Fleetwood Enterprises, Inc.
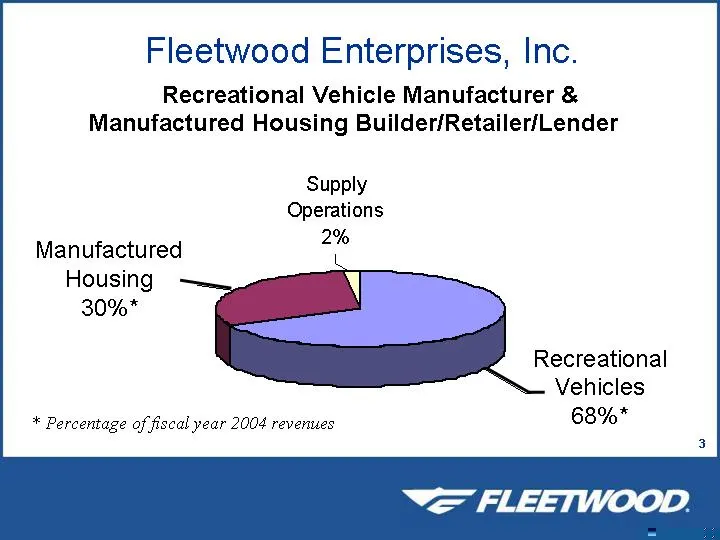
Fleetwood Enterprises, Inc. Recreational Vehicle Manufacturer & Manufactured Housing Builder/Retailer/Lender Supply Operations Manufactured 2% Housing * Percentage of fiscal year 2004 revenues Recreational Vehicles 68%*
Slide 5: Leadership Position
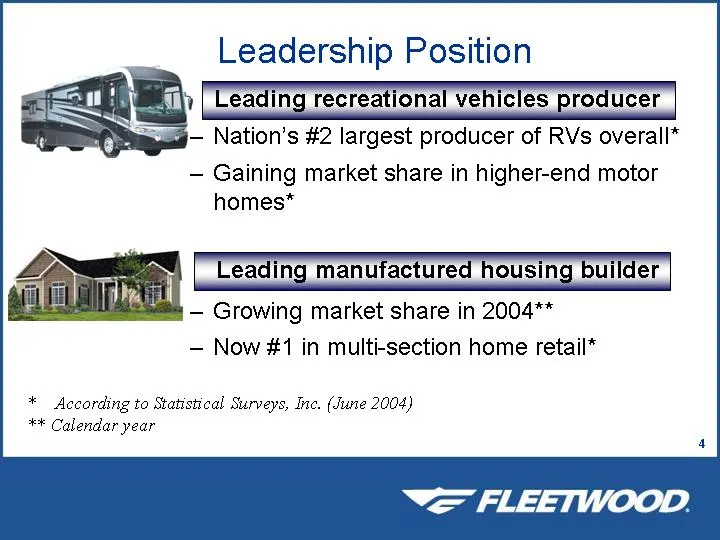
Leadership Position 2 | KT) | Leading recreational vehicles producer 5 — Nation’s #2 largest producer of RVs overall* — Gaining market share in higher-end motor homes* Leading manufactured housing builder — Growing market share in 2004** — Now #1 in multi-section home retail* * According to Statisti
Slide 6: Corporate Structure
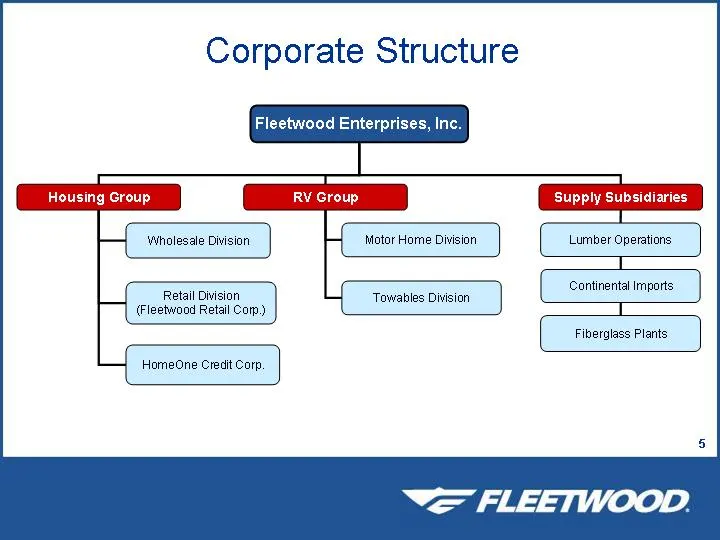
Corporate Structure Fleetwood Enterprises, Inc. Housing Group RY Group Supply Subsidiaries wholesale Bwsien | Motor Home Division Lumber Operations Continental Imports Towables Division Fiberglass Plants
Slide 7: Fleetwood History
Fleetwood History More than 50 years in business Historical synergies between RV and manufactured home production Publicly traded since 1965 Listed on NYSE in FY1971 Purchased Coleman Folding Trailers in FY1990 Corporate management restructuring in 2002
Slide 8: Deep Senior Management Team
Deep Senior Management Team Tom Pitcher, Chairman Ed Caudill, President/CEO Boyd Plowman, EVP/CFO Chris Braun, EVP — RVs Roger Howsmon, EVP — Housing Scott Grafft, SVP — Strategic Planning Todd Inlander, SVP/Chief Information Officer Larry Mace, SVP — Supply/Materials Len McGill, SVP- Finance/CGO Fo
Slide 9: Corporate Governance Excellence
Corporate Governance Excellence Independent chairman Diverse, strong Board Ten of 11 Board members are independent Regular executive sessions of Board New charters for Audit, Governance & Compensation committees Published procedures for director nominations and shareholder communications Appointed L
Slide 10: Fleetwood Facts
Fleetwood Facts FORTUNE 1000 company - #634 14,000 employees 39 manufacturing operations in 15 states and one in Canada. FRC retail locations in 19 states 4 largest retail manufactured housing company Growing company — six consecutive quarters of revenue growth. Current estimates of full year profit
Slide 11: Key Elements of Our Strategy
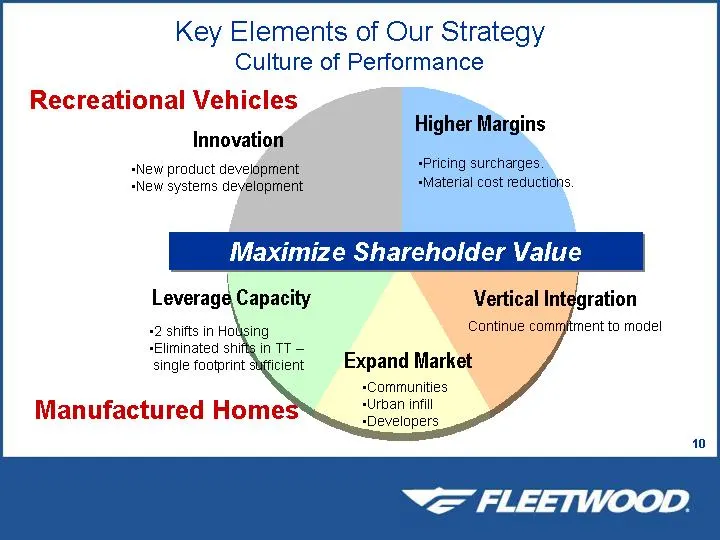
Key Elements of Our Strategy Culture of Performance Recreational Vehicles . Higher Margins Innovation -New product develapment: “Pricing surcharges: “New systems deyelapment -Material cost reductions. Maximize Shareholder Value Leverage Capacity +2 shifts in Hol\sing Eliminated shit single footprint
Slide 12: Progress
Progress =Rebuilt financial strength "High quality products — feedback from dealers «Streamlined operations «Strengthened management "Regained momentum
Slide 13: Looking Forward
LOOKING FORWARD What makes Fleetwood optimistic about the future is the strong demographics strength behind both our businesses. “= FLEETWOOD.
Slide 14: The RV Boom
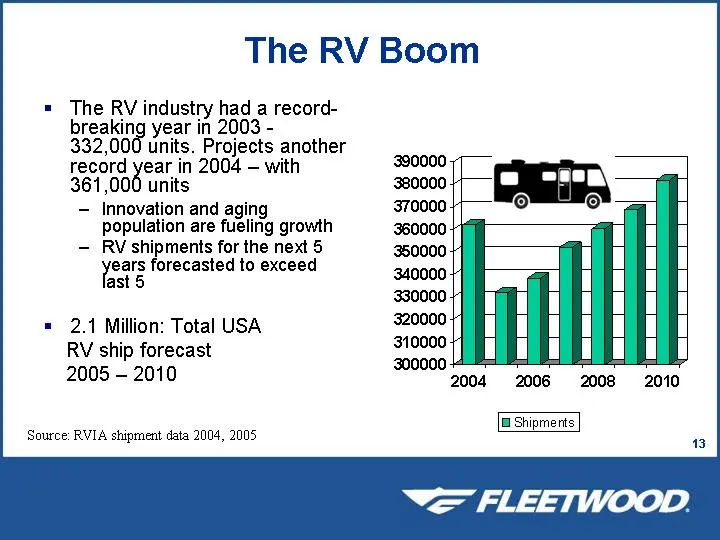
The RV Boom = The RV industry had a record- breaking year in 2003 - 332,000 units. Projects another record year in 2004 — with 220000 361,000 units 380000 — Innovation and aging 370000 population are fueling growth 360000 — RV shipments for the next 5 350000 ears forecasted to exceed fast 5 340000 3
Slide 15: Strong Demand for What RVs Deliver: Freedom
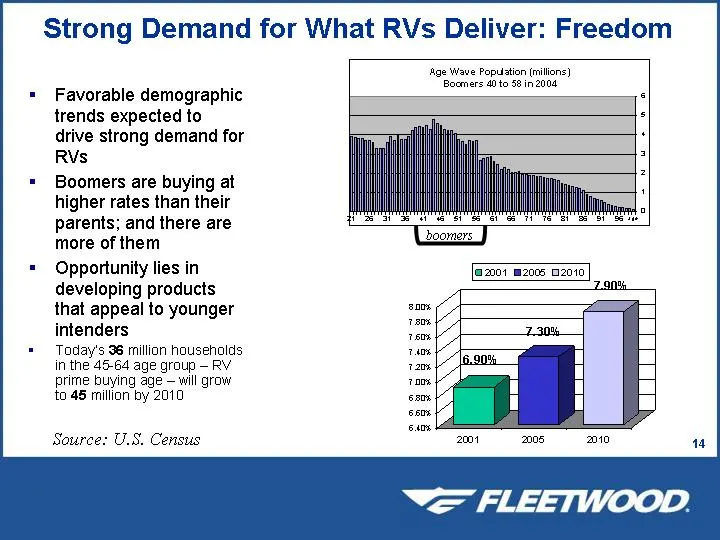
Strong Demand for What RVs Deliver: Freedom Age Wave Popustion(rillons) Boomers dito 582004, Favorable demographic trends expected to drive strong demand for RVs Boomers are buying at higher rates than their parents; and there are es more of them Opportunity lies in fazoo1 m2005 O2010 developing pro
Slide 16: RV Loyalty: A Stable Market
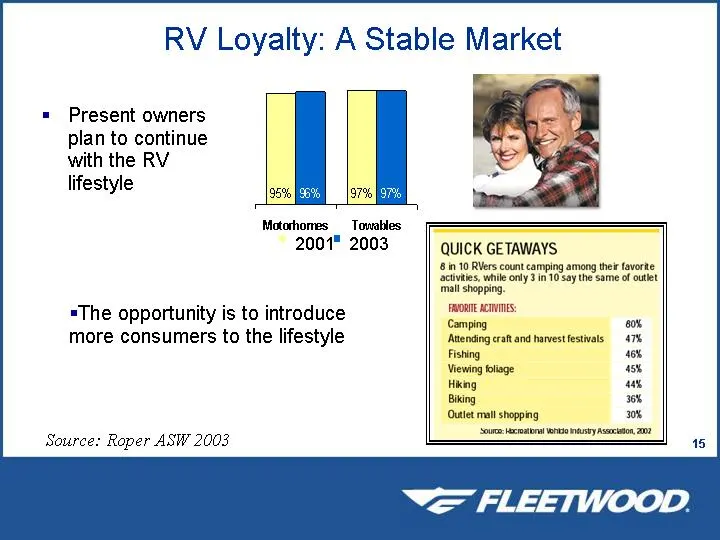
RV Loyalty: A Stable Market = Present owners plan to continue with the RV lifestyle bes Motorhomes — Towables 2001" 2003 =The opportunity is to introduce more consumers to the lifestyle Source: Roper ASW 2003 QUICK GETAWAYS {in 10 RVers count camping among thet fevorte ‘ctvties, wile only 3 in 10 ay
Slide 17: Opportunities in Dealer Development
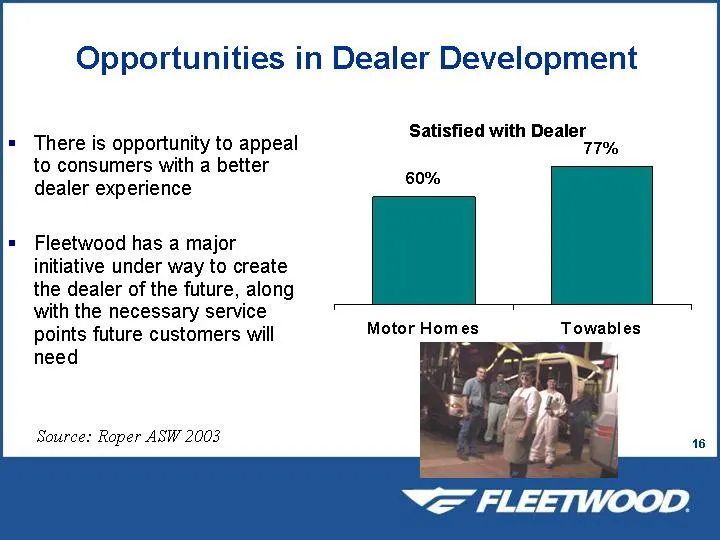
Opportunities in Dealer Development = There is opportunity to appeal Satisfied with Pee ap to consumers with a better 60% dealer experience ° Fleetwood has a major initiative under way to create the dealer of the future, along with the necessary service points future customers will Motor: Homies Tow
Slide 18: Opportunities for Growth
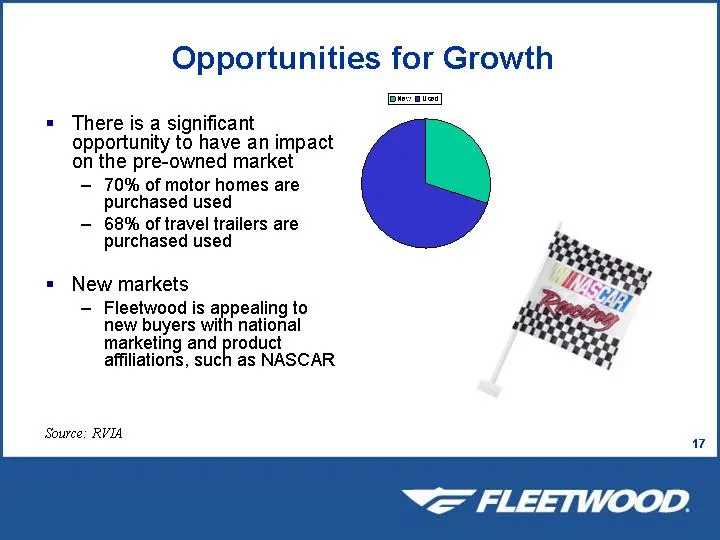
Opportunities for Growth There is a significant _ opportunity to have an impact on the pre-owned market — 70% of motor homes are purchased used — 68% of travel trailers are purchased used New markets — Fleetwood is appealing to new buyers with national marketing and product affiliations, such as NAS
Slide 19: RV Group Overview
RV Group Overview Investments in product development Focus on quality improvements Plant modernization Strategic alliances to reduce costs and enhance quality
Slide 20: RV Group Overview
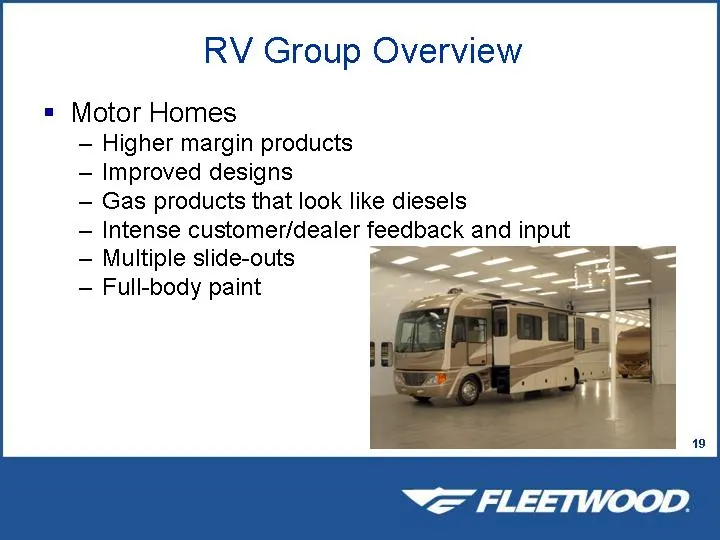
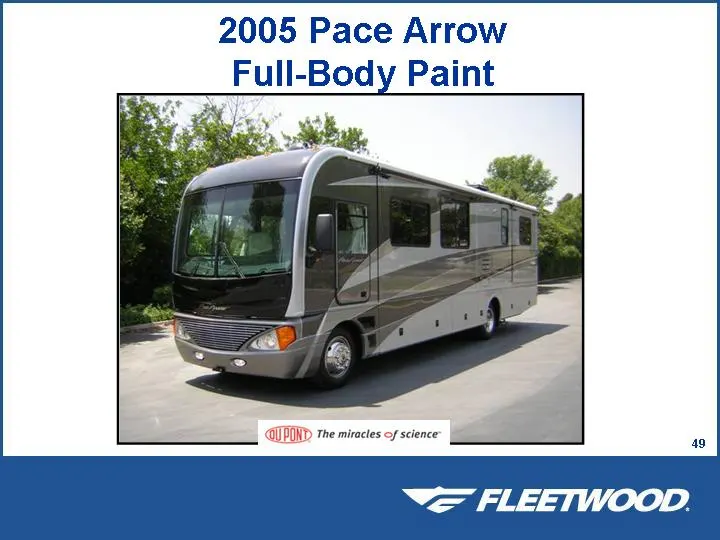
RV Group Overview = Motor Homes — Higher margin products — Improved designs — Gas products that look like diesels — Intense customer/dealer feedback and input — Multiple slide-outs — Full-body paint
Slide 21: RV Group Overview
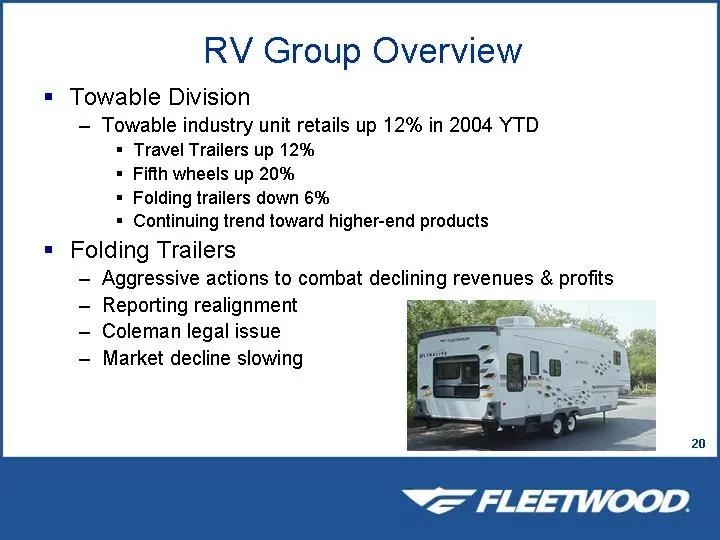
RV Group Overview = Towable Division — Towable industry unit retails up 12% in 2004 YTD * Travel Trailers up 12% « Fifth wheels up 20% = Folding trailers down 6% = Continuing trend toward higher-end products = Folding Trailers — Aggressive actions to combat declining revenues & profits — Reporting r
Slide 22: The Housing Boom
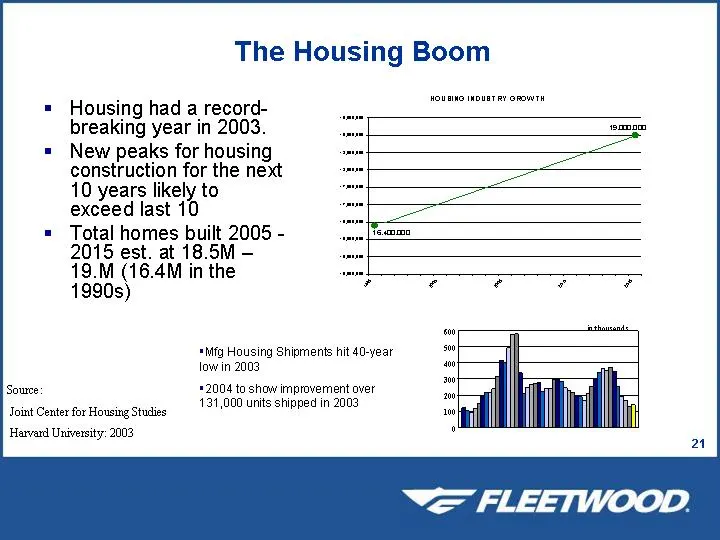
The Housing Boom = Housing had a record- breaking year in 2003. = New peaks for housing construction for the next 10 years likely to exceed last 10 = Total homes built 2005 - 2015 est. at 18.5M — 19.M (16.4M in the 1990s) ' Mfg Housing Shipments hit 40-year low in 2003 Somee "2004 to show improverne
Slide 23: Strong Underlying Demand for Manufactured Housing
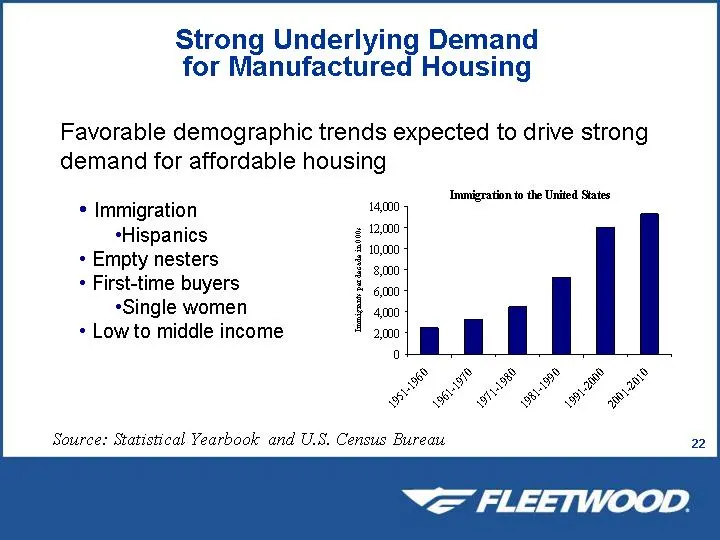
Strong Underlying Demand for Manufactured Housing Favorable demographic trends expected to drive strong demand for affordable housing Inmigratin tothe United Stat * Immigration oun: sone etna Hispanics z + Empty nesters + First-time buyers *Single women * Low to middle income
Slide 24: Single women are playing a larger role in housing markets
Single women are playing a larger role in housing markets ... because of: Delayed marriage Higher divorce rates Lower remarriage rates Greater longevity Greater workforce participation Source: Joint Center for Housing Studies Harvard University: 2003
Slide 25: Impact of Immigrants and Minorities
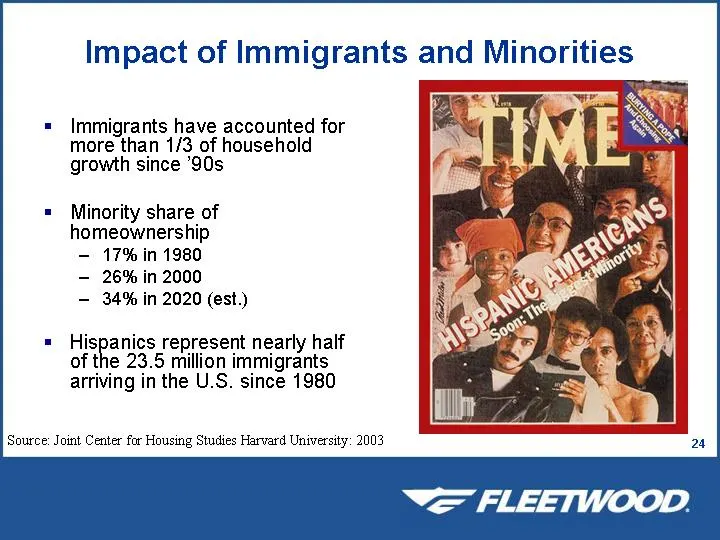
Impact of Immigrants and Minorities = Immigrants have accounted for nN . ; Ay more than 1/3 of household growth since 90s Minority share of homeownership — 17% in 1980 — 26% in 2000 — 34% in 2020 (est.) Hispanics represent nearly half of the 23.5 million immigrants arriving in the U.S. since 1980 So
Slide 26: Appeal of Manufactured Housing
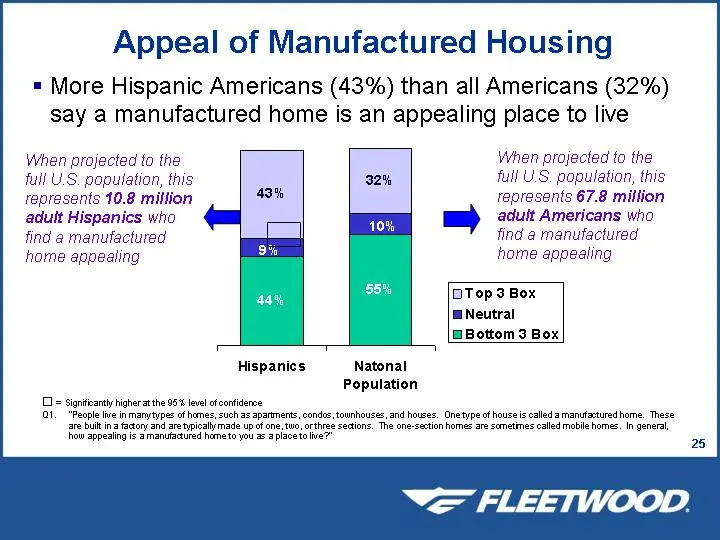
Appeal of Manufactured Housing = More Hispanic Americans (43%) than all Americans (32%) say a manufactured home is an appealing place to live When projected fo the full U.S, population, this represents 67.8 million adult Americans who find a manufactured home appealing When projected fo the full U.S
Slide 27: Advantages of Manufactured Homes
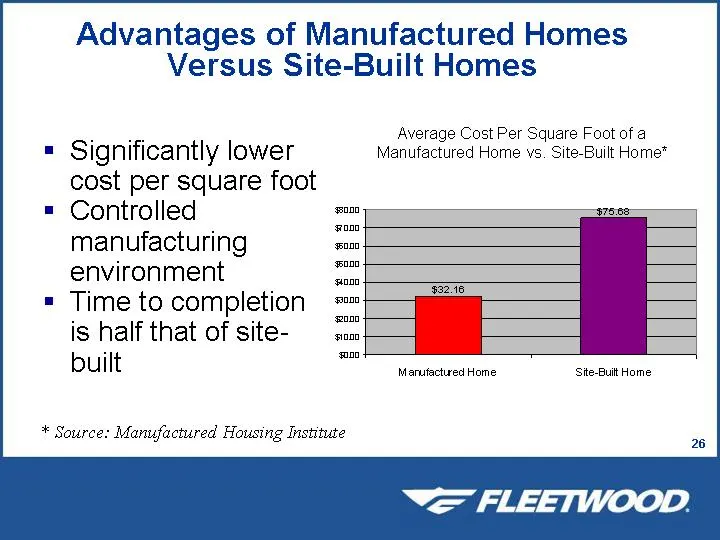
Advantages of Manufactured Homes Versus Site-Built Homes ~ ge Average Cost Per Square Foot of a = Significantly lower Manufactured Home vs. Site-Built Home* cost per square foot = Controlled manufacturing environment * Time to completion a is half that of site- - built Manufactured Home Site-Buit Ho
Slide 28: Housing Group Overview
Housing Group Overview = Wholesale/Manufacturing Division — New product development — Growing relationships with national community developers — Urban infill
Slide 29: Housing Group Overview
Housing Group Overview = Wholesale/Manufacturing Division — Reduced overhead = Mothballed plants but left in place for upturn = Decreased product expenses — Improving productivity — Recently re-opened plants
Slide 30: Housing Group Overview
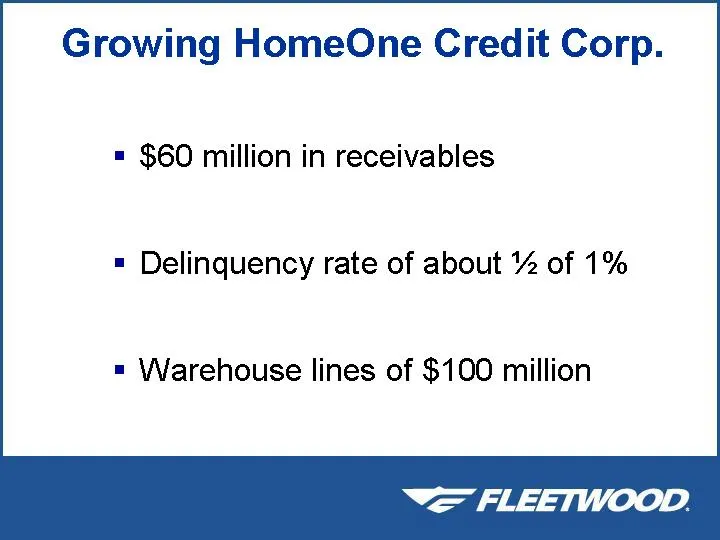
Housing Group Overview = Retail Division — Consolidated wholesale and retail sales, and financial organizations — Strengthened margins — Reduced expenses — Strengthened vertical integration = HomeOne Credit Corp. — Retail division being strengthened by our in-house finance capability, which is growi
Slide 31: Recreational Vehicle Review
Recreational Vehicle Review Chris Braun Executive V.P.-— RV Group “= FLEETWOOD.
Slide 32: Recreational Vehicles
Recreational Vehicles * Towables ¢ Folding Trailers ¢ Travel Trailers ¢« Motor Homes “= FLEETWOOD.
Slide 33: Recreational Vehicles: Full Line Manufacturer
Recreational Vehicles Full Line Manufacturer “= FLEETWOOD.
Slide 34: Travel Trailer Price Points
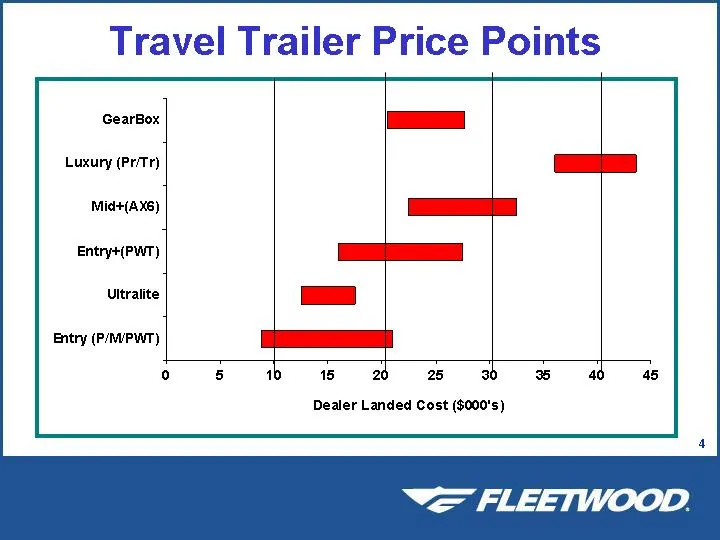
Travel Trailer Price Points GearBox Luxury (Pr/Tr) Mid+(Ax6) Entry+(PWT) Ultralite Entry (P/M/PWT) nr rr) Dealer Landed Cost ($000's) “= FLEETWOOD.
Slide 35: Motor Home Price Points
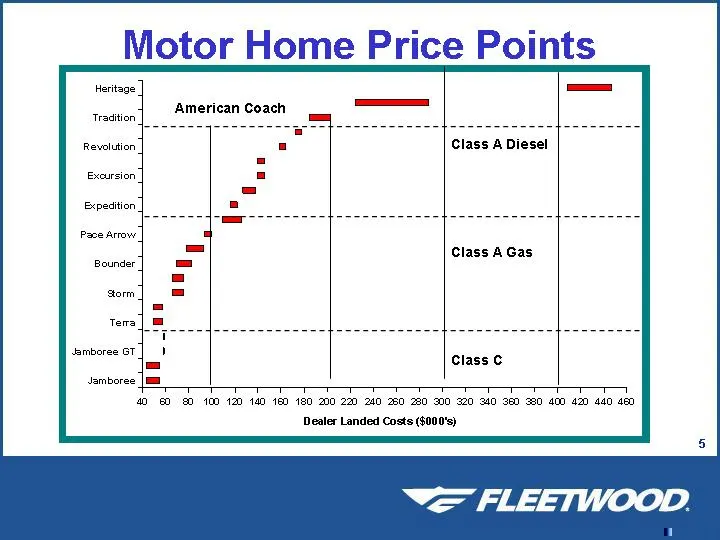
Motor Home Price Points Heritage: Tradition Revolution Excursion Expedition Pace Arrow: Bounder storm Tera Jamboree GT Jamboree American Coach Class A Diesel Class A Gas 40 6) 8) 100 120 140 160 180 200 220 240 260 280 SN 20 440 96 380 aon az aan 460 Dealer Landed Costs (8000's) “= FLEETWOOD.
Slide 36: Fleetwood Folding Trailers
Fleetwood Folding Trailers “= FLEETWOOD.
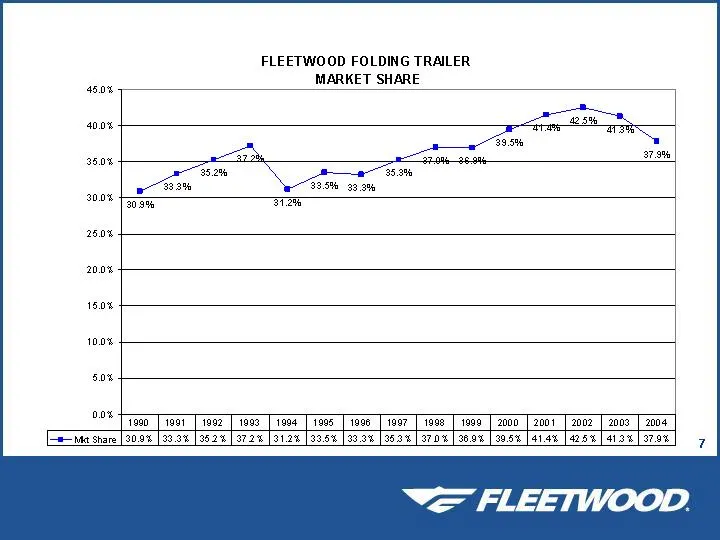
Slide 37: Fleetwood Folding Trailer Market Share
FLEETWOOD FOLDING TRAILER MARKET SHARE Fase 5.2% 5.0% Bam oe Er Te
Slide 38: Rationalization of Folding Trailers
Rationalization of Folding Trailers = Announced in August = Consolidation w/Travel Trailers = Reduce Cost/Improve Efficiency — Headcount Reduction — Leverage Purchasing Power “= FLEETWOOD.
Slide 39: Fleetwood Folding Trailers: Product Innovation
Fleetwood Folding Trailers Product Innovation “= FLEETWOOD.
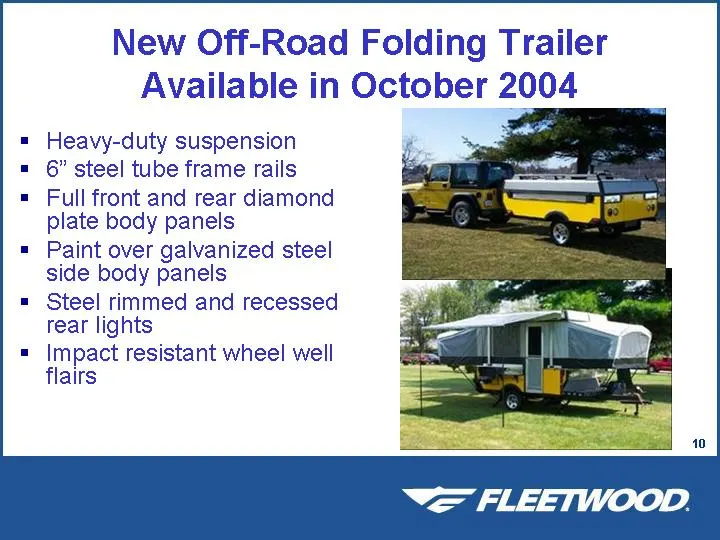
Slide 40: New Off-Road Folding Trailer
New Off-Road Folding Trailer Available in October 2004 e Heavy-duty suspension 6” steel tube frame rails Full front and rear diamond plate body panels Paint over galvanized steel side body panels Steel rimmed and recessed rear lights Impact resistant wheel well flairs
Slide 41: New ASV Folding Trailer
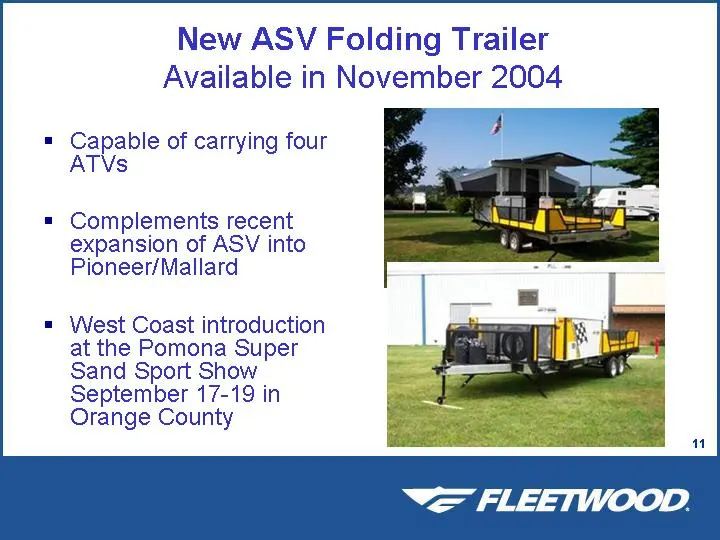
New ASV Folding Trailer Available in November 2004 = Capable of carrying four ATVs Complements recent expansion of ASV into Pioneer/Mallard West Coast introduction at the Pomona Super Sand Sport Show September 17-19 in Orange County “= FLEETWOOD.
Slide 42: Travel Trailers
Travel Trailers “= FLEETWOOD.
Slide 43: Fleetwood TT Market Share
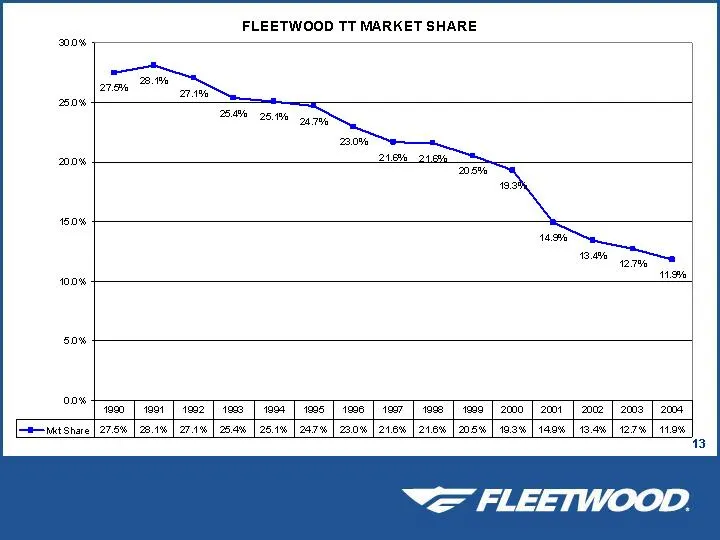
0% FLEETWOOD TT MARKET SHARE Be 25.16 ap [eat Share
Slide 44: Travel Trailer Distribution Points
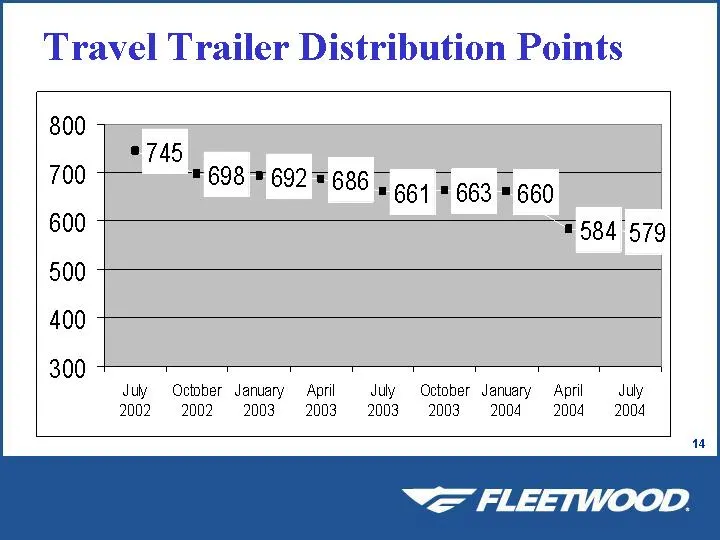
Travel Trailer Distribution Points 800 700 += eo eS Tool 309 Moo 692 * 686 5 pay s 663 = 660 600 584579 500 400 300 Juy October January April July October January April July 2002 2002 «2003 «2003» 2003» 2003S 2004 2004-2004
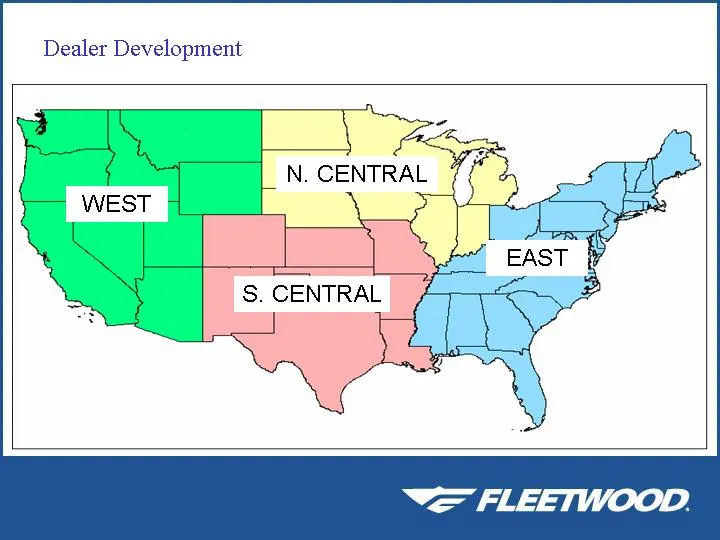
Slide 45: Dealer Development
Dealer Development “= FLEETWOOD.
Slide 46: Mid-West Markets
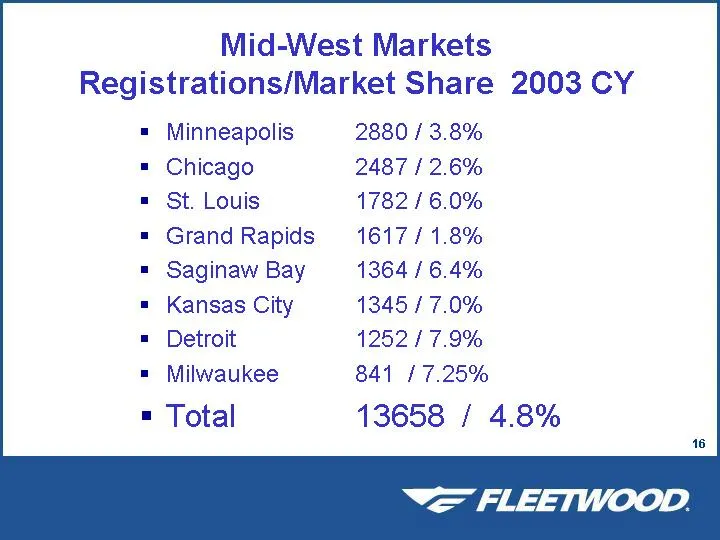
Mid-West Markets Registrations/Market Share 2003 CY Minneapolis 2880 / 3.8% Chicago 2487 12.6% St. Louis 1782 / 6.0% Grand Rapids 1617/ 1.8% Saginaw Bay 1364 / 6.4% Kansas City 1345 / 7.0% Detroit 125217.9% Milwaukee 841 17.25% * Total 13658 / 4.8% “= FLEETWOOD.
Slide 47: Travel Trailer Cost Reduction
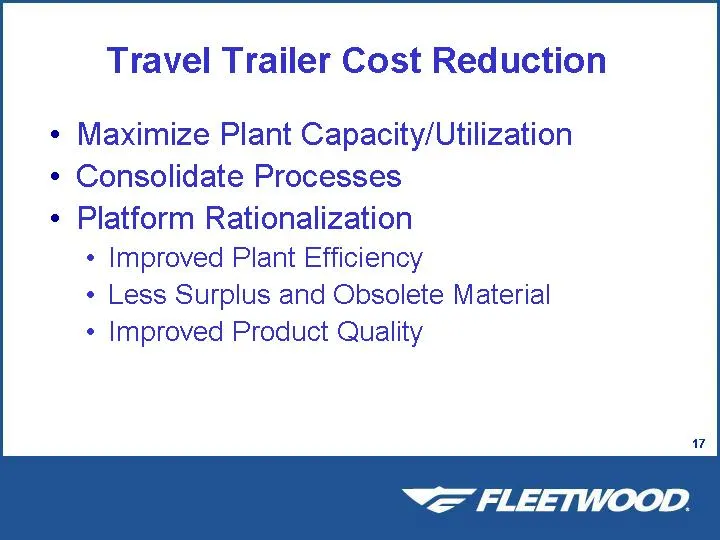
Travel Trailer Cost Reduction « Maximize Plant Capacity/Utilization * Consolidate Processes ¢ Platform Rationalization « Improved Plant Efficiency « Less Surplus and Obsolete Material * Improved Product Quality “= FLEETWOOD.
Slide 48: Platform Rationalization
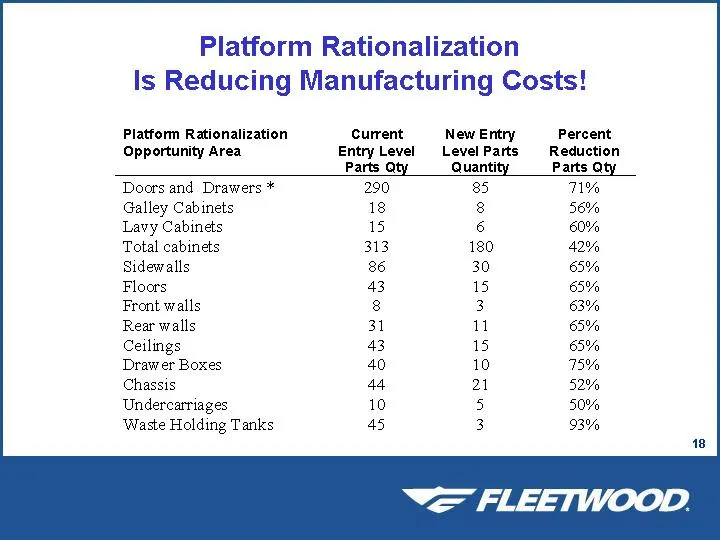
Platform Rationalization Is Reducing Manufacturing Costs! Platform Rationalization Current New Entry Percent Opportunity Area Entry Level LevelParts Reduction Parts Oty Quantity Parts Qty Doors and Drawers * 290 85 N% Galley Cabinets 18 56% Lavy Cabinets 15 60% Total cabinets 313 42% Sidewalls 86 5%
Slide 49: Travel Trailer Product Introductions
Travel Trailer Product Introductions 2005 Pioneer / Mallard 18T6 2005 Pride and Triumph 385FKQS 2005 Pride and Triumph 395RL5S 2005 New Mallard 23T6, 25TS6, 27TB& 2005 Entry Level ASV Ramp Trailers 2005 New Pegasus & Orbit Ultralites 2005 Redesigned Entry Level PWT 2005 Redesigned Pioneer and Mallar
Slide 50: Mallard Travel Trailer for $9,995
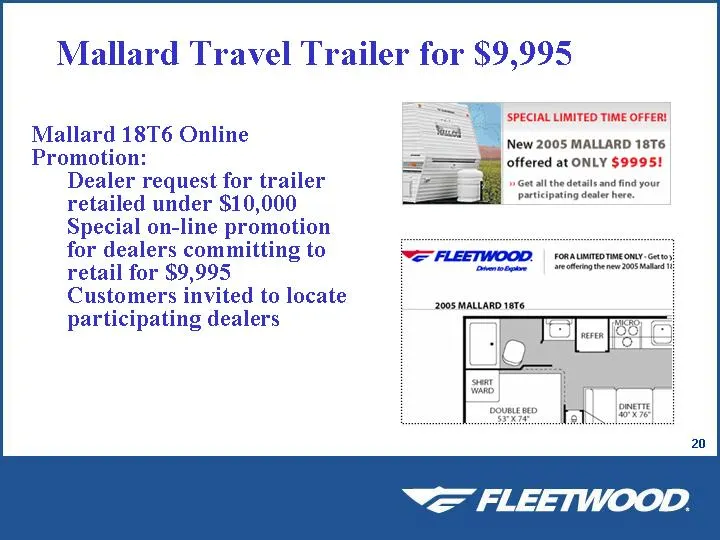
Mallard Travel Trailer for $9,995 SPECIAL LIMITED TIME OFFER! New 2005 MALLARD 1876 Mallard 18T6 Online = a Promotion: = =F offered at ONLY $9995! Dealer request for trailer ff Get all the details and find your retailed under $10,000 ote Special on-line promotion for dealers committing to retail for
Slide 51: New Entry Level ASV
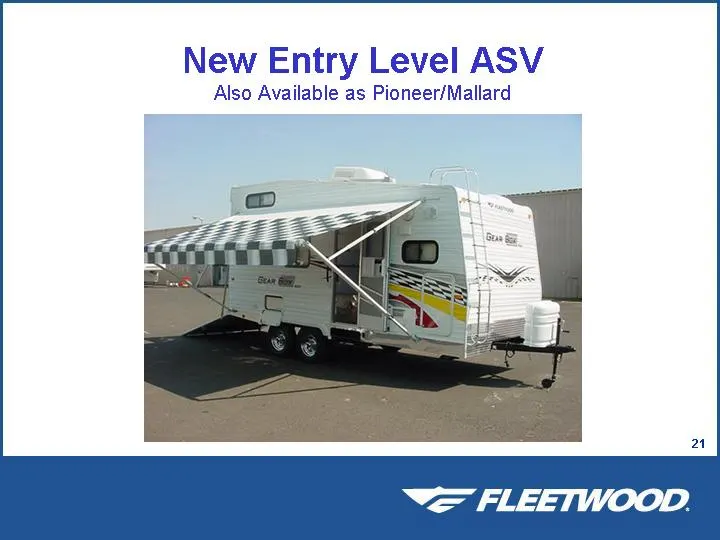
New Entry Level ASV Also Available as Pioneer/Mallard
Slide 52: Link to searchable text of slide shown above
Link to searchable text of slide shown above
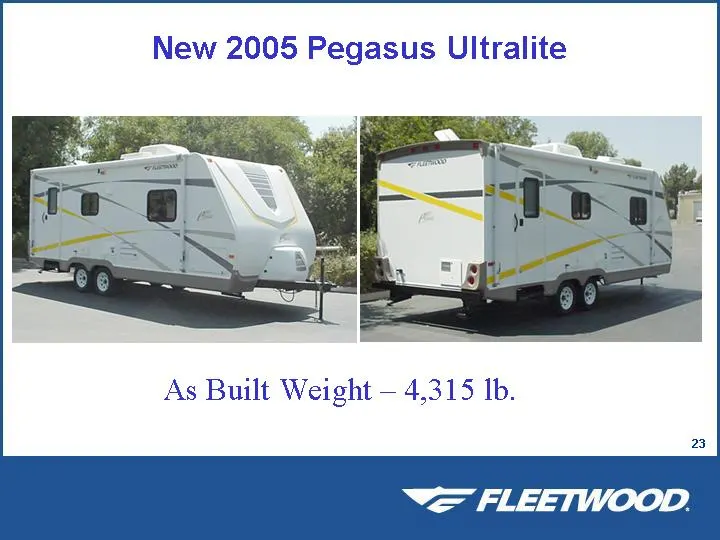
Slide 53: New 2005 Pegasus Ultralite
New 2005 Pegasus Ultralite As Built Weight — 4,315 Ib.
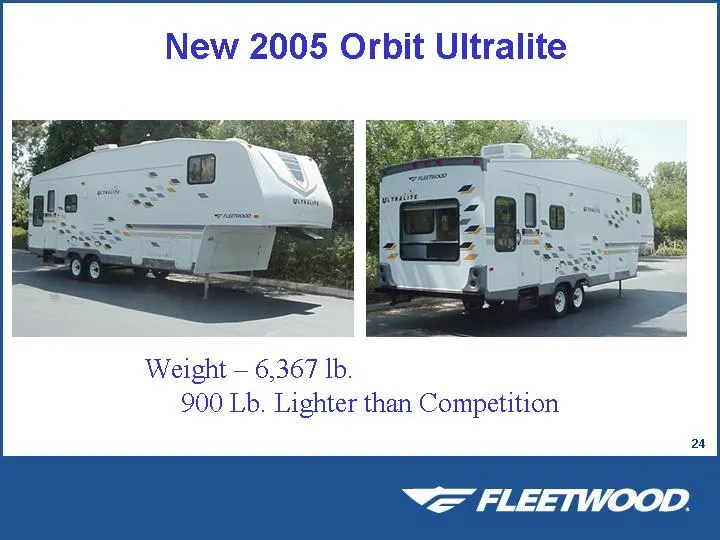
Slide 54: New 2005 Orbit Ultralite
New 2005 Orbit Ultralite Weight — 6,367 lb. 900 Lb. Lighter than Competition
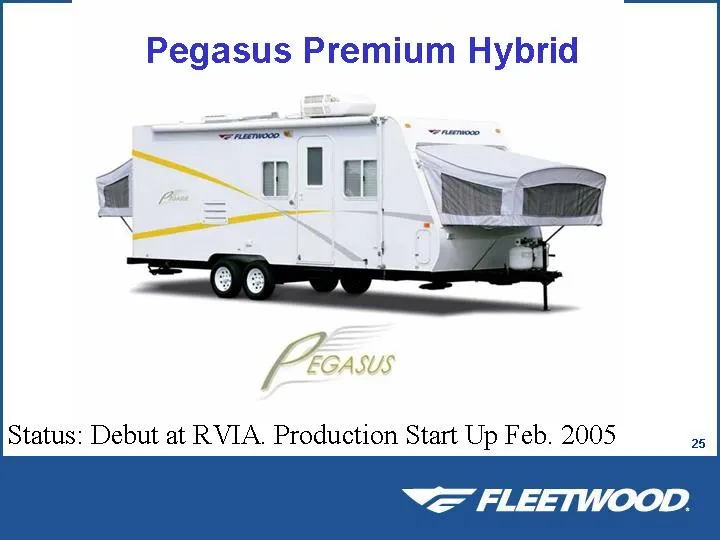
Slide 55: Pegasus Premium Hybrid
Pegasus Premium Hybrid Status: Debut at RVIA. Production Start Up Feb. 2005
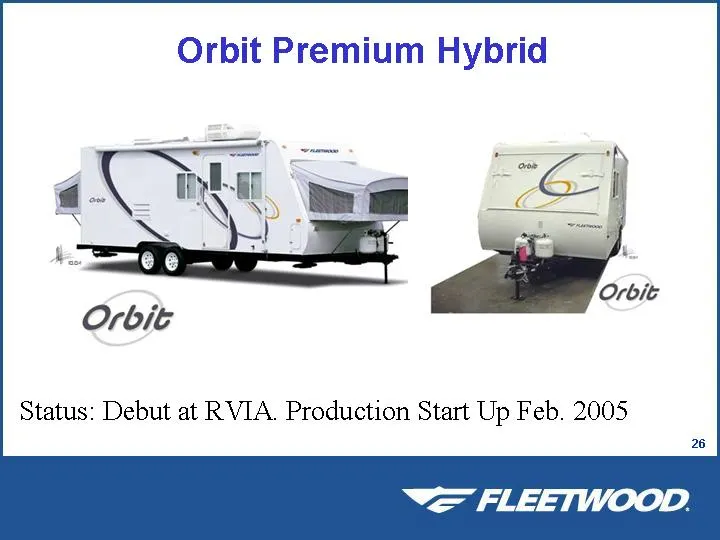
Slide 56: Orbit Premium Hybrid
Orbit Premium Hybrid Orbit Status: Debut at RVIA. Production Start Up Feb. 2005 “= FLEETWOOD.
Slide 57: PWT Core Products
PWT Core Products 2006 Strategy * Entry Product —Reduced Cost —New Decors — Updated Exterior Graphics —Simplified Cabinet Designs = Easy to Build “= FLEETWOOD.
Slide 58: PWT Core Products
PWT Core Products 2006 Strategy « Entry Plus Product —Front Molded Cap Becomes Standard —Enclosed Underbelly Becomes Standard —New Decors —New Exterior Graphic —Reduced Cost “= FLEETWOOD.
Slide 59: 2006 Prowler Entry Plus
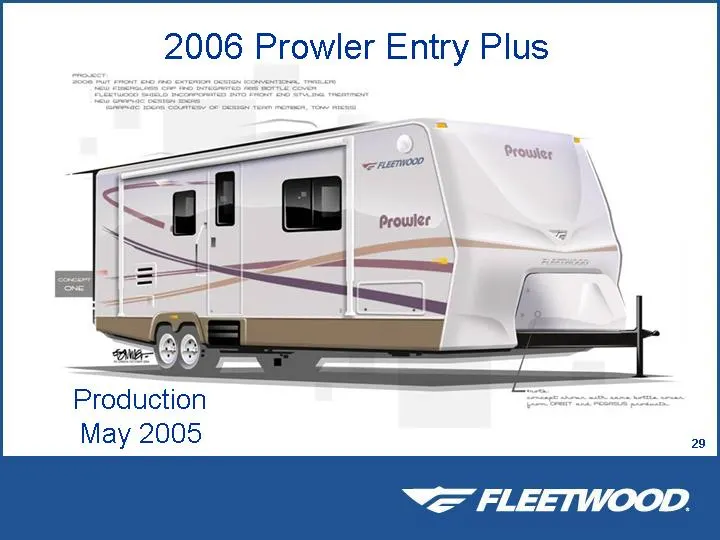
2006 Prowler Entry Plus Production May 2005
Slide 60: 2006 Prowler Fifth Wheel
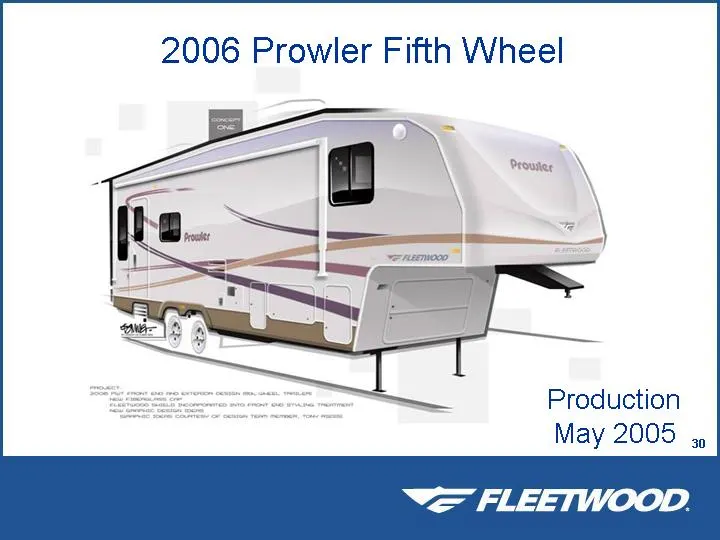
2006 Prowler Fifth Wheel Production May 2005 ,, “= FLEETWOOD.
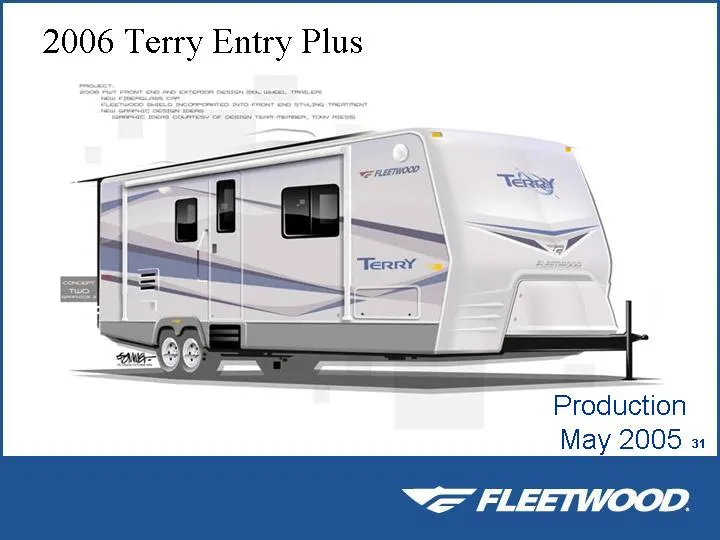
Slide 61: 2006 Terry Entry Plus
2006 Terry Entry Plus Production May 2005 »
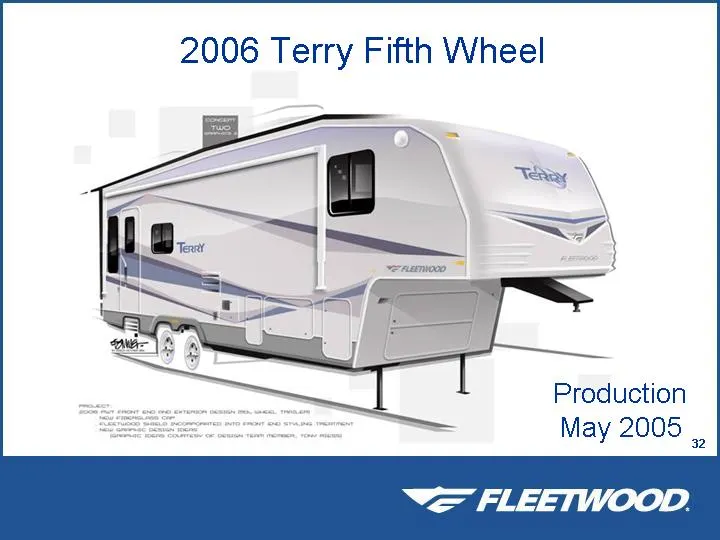
Slide 62: 2006 Terry Fifth Wheel
2006 Terry Fifth Wheel Production May 2005 |, “= FLEETWOOD.
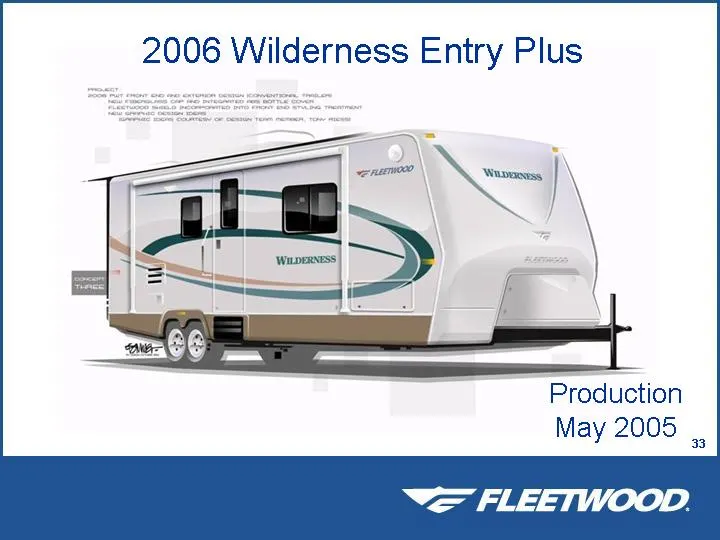
Slide 63: 2006 Wilderness Entry Plus
2006 Wilderness Entry Plus Production May 2005 |
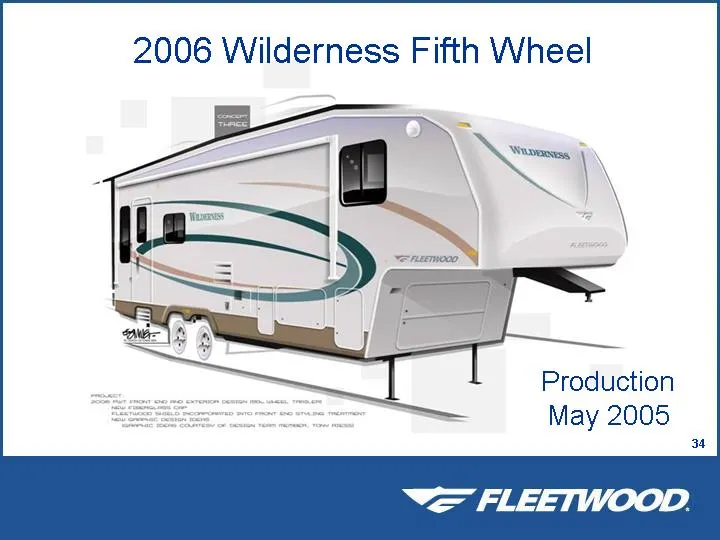
Slide 64: 2006 Wilderness Fifth Wheel
2006 Wilderness Fifth Wheel Production May 2005 34 “= FLEETWOOD.
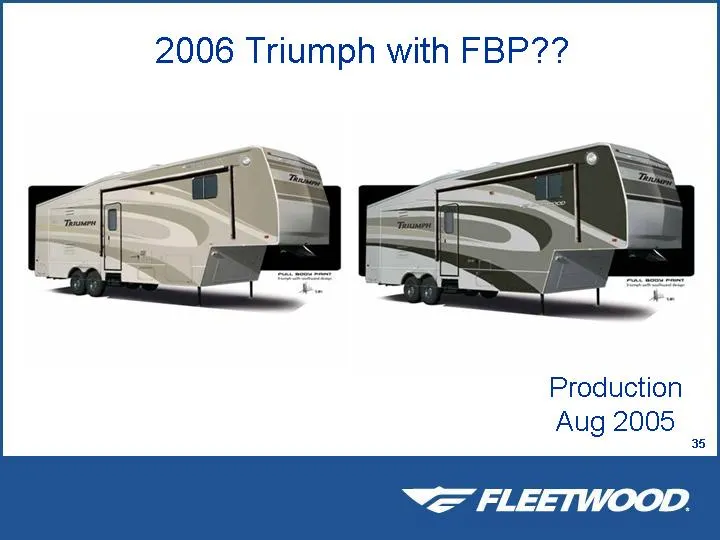
Slide 65: 2006 Triumph with FBP
2006 Triumph with FBP?? Production Aug 2005 6
Slide 66: Motor Homes
Motor Homes 36 “= FLEETWOOD.
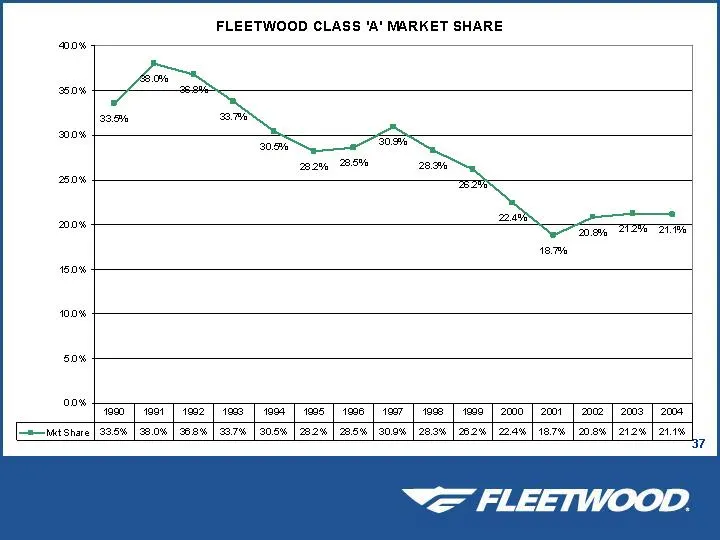
Slide 67: Market Share
MARKET SHARE 00% [at Share
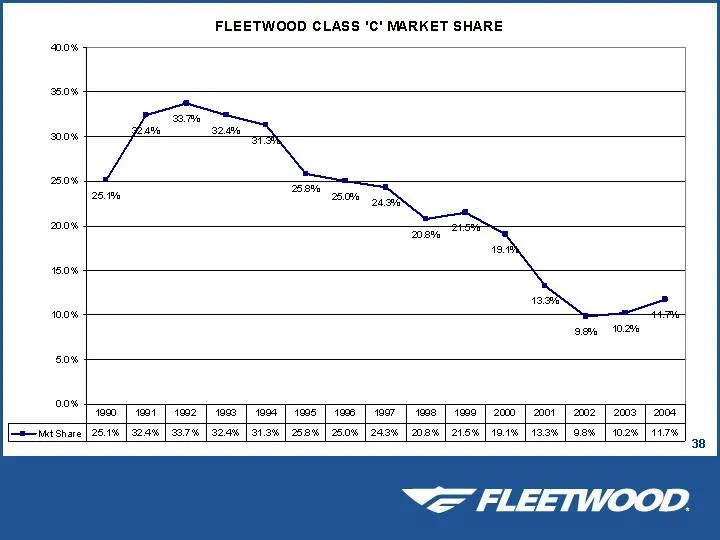
Slide 68: Fleetwood Class C Market Share
00% FLEETWOOD CLASS 'C' MARKET SHARE [eS Share
Slide 69: Paxinos Plant Expansion
Paxinos Plant Expansion = Class A & C production lines = Independent continuous-moving chain conveyor « Additional 148,000 sq. ft.; total 288,000 sq. ft. = Estimated completion: May 2005 “= FLEETWOOD.
Slide 70: Cost Reduction Program
Cost Reduction Program = Weekly Cost Reduction Meetings — Started in June 2004 = Implemented Material Cost Savings Projects — 8 Yielding $1,214,000 Annual Savings = Active Material Cost Savings Projects — 46 with $10,809,000 Savings Opportunity “= FLEETWOOD.
Slide 71: New Paint Systems
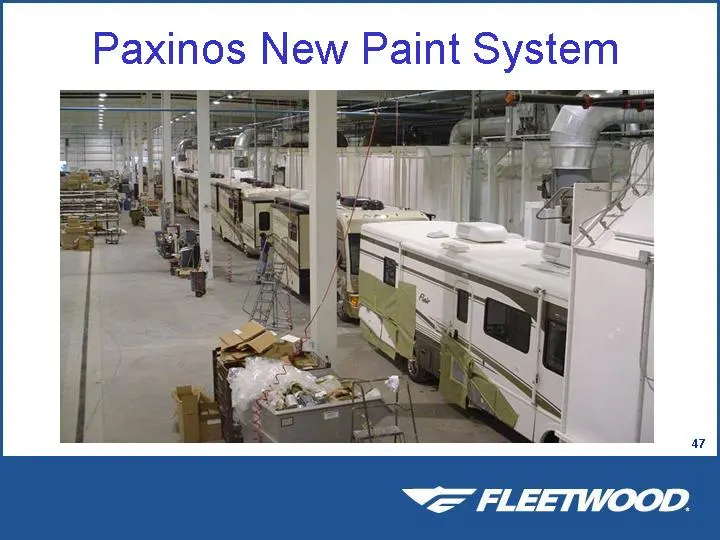
New Paint Systems ¢ $25+ Million Capital Investment « Plants: ¢ Riverside, CA « Paxinos, PA « Ability to Produce Class A Diesel on East and West Coast “= FLEETWOOD.
Slide 72: “= FLEETWOOD.
“= FLEETWOOD.
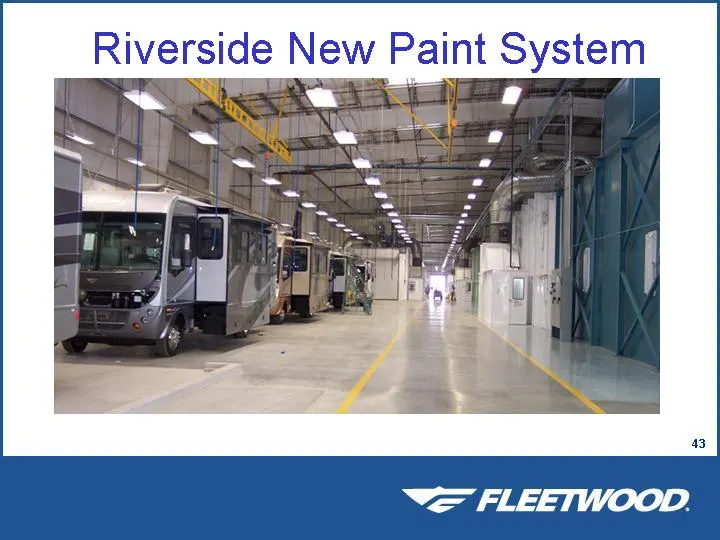
Slide 73
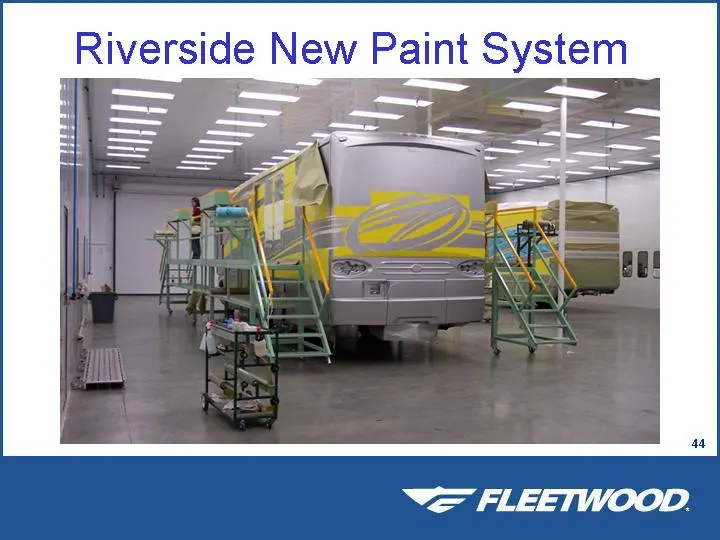
Slide 74: Riverside New Paint System
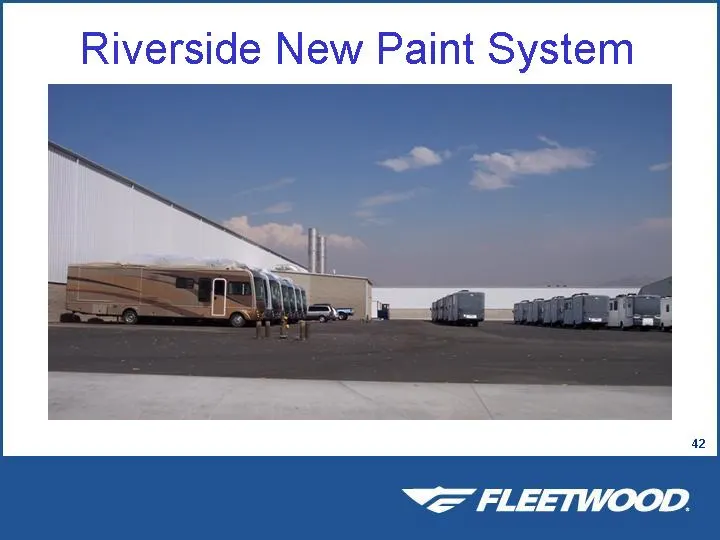
Riverside New Paint System —_— — “= FLEETWOOD.
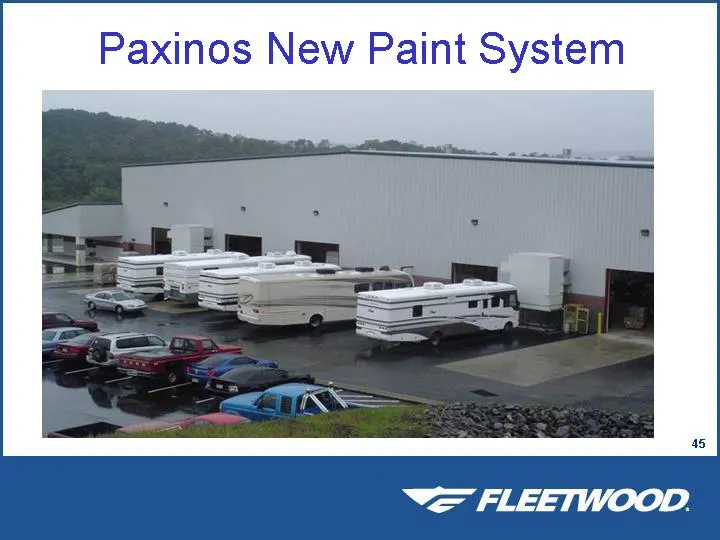
Slide 75: Paxinos New Paint System
Paxinos New Paint System “= FLEETWOOD.
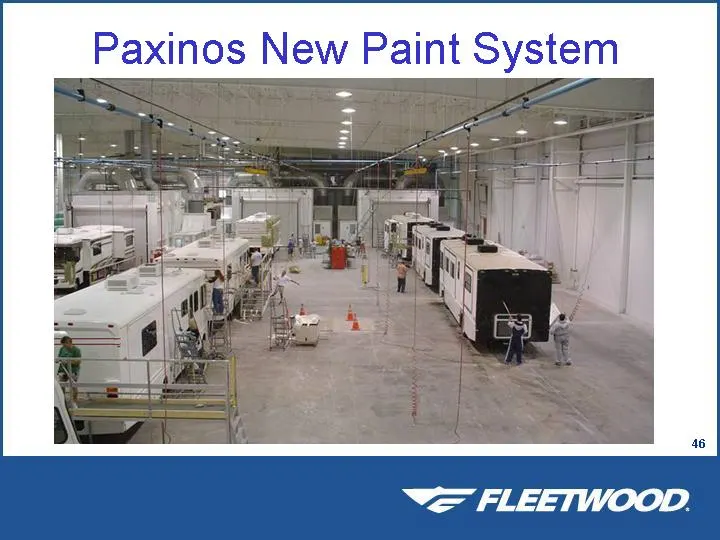
Slide 76: “= FLEETWOOD.
“= FLEETWOOD.
Slide 77
Slide 78: New Product Introductions
New Product Introductions “= FLEETWOOD.
Slide 79: 2005 Pace Arrow
2005 Pace Arrow Full-Body Paint
Slide 80
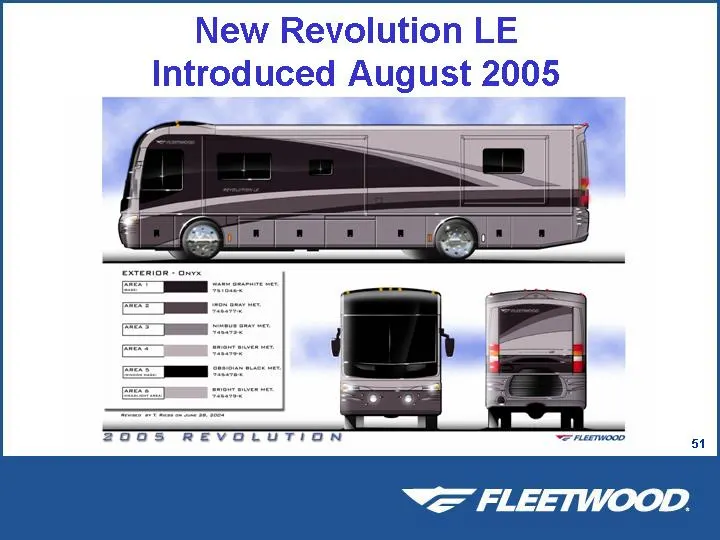
Slide 81: New Revolution LE
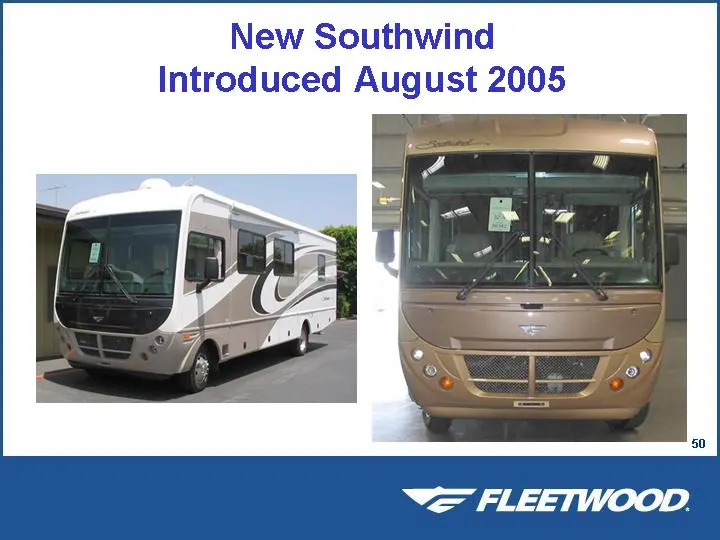
New Revolution LE Introduced August 2005
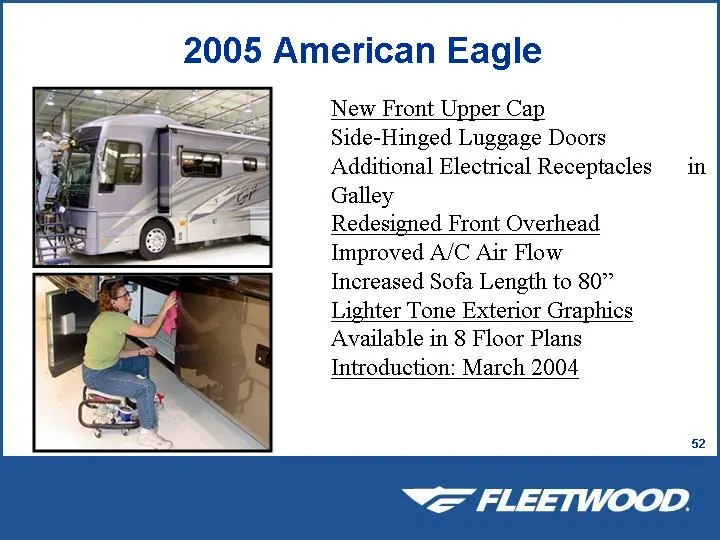
Slide 82
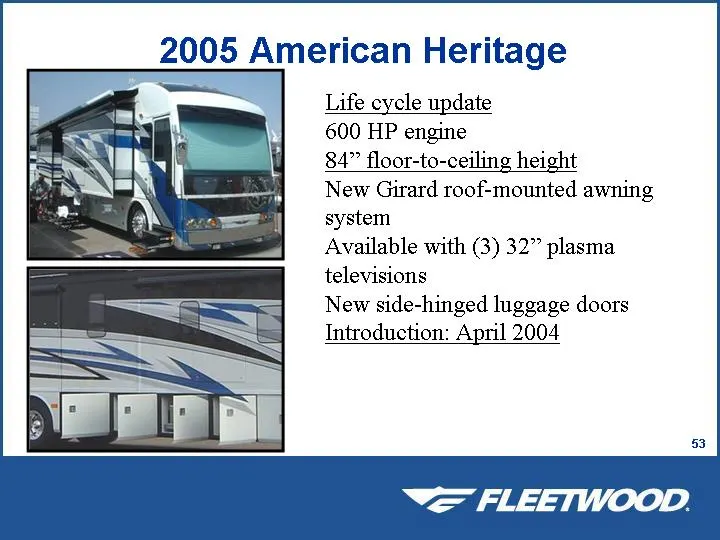
Slide 83
Slide 84
Slide 85
Slide 86
Slide 87
Slide 88
Slide 89
Slide 90
Slide 91
Slide 92
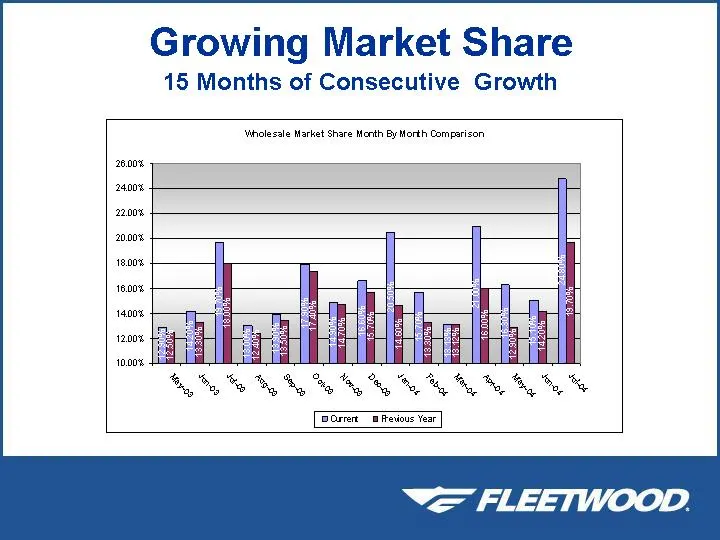
Slide 93
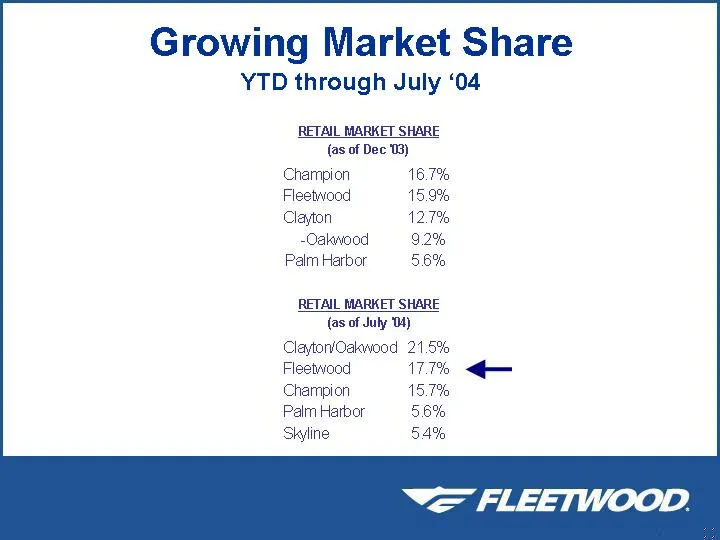
Slide 94
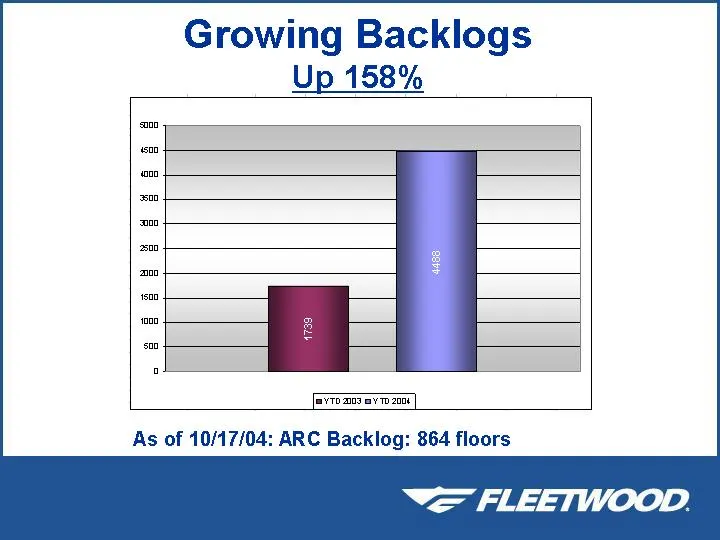
Slide 95
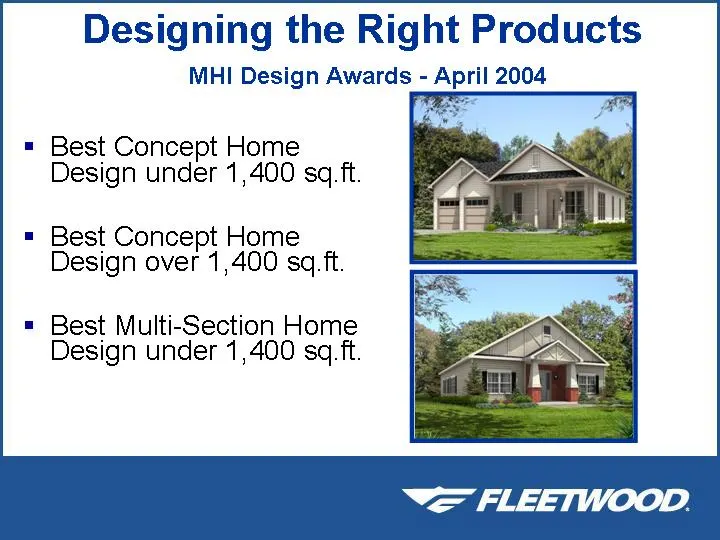
Slide 96
Slide 97
Slide 98
Slide 99
Slide 100
Slide 101
Slide 102
Slide 103
Slide 104
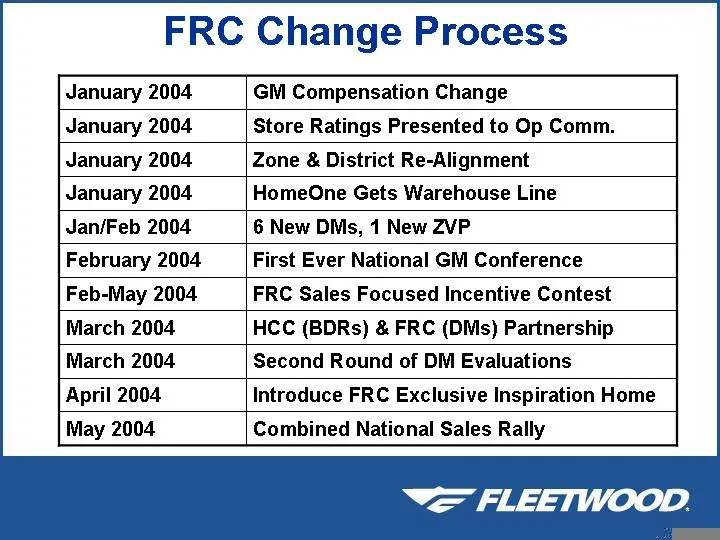
Slide 105
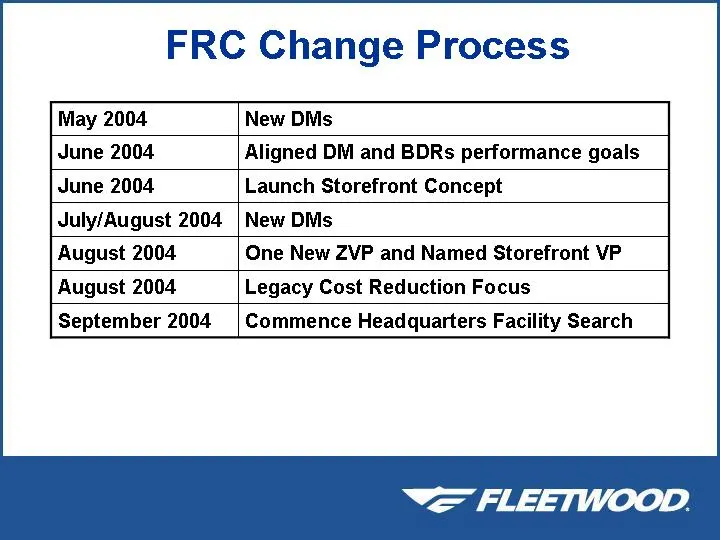
Slide 106
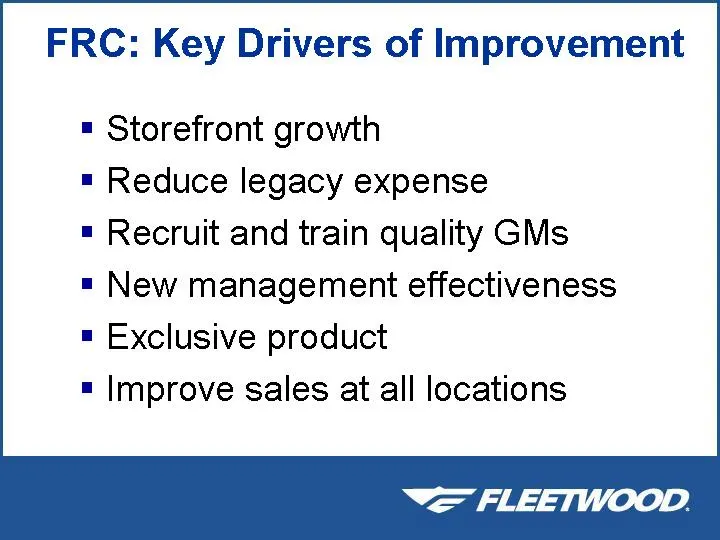
Slide 107
Slide 108
Slide 109
Slide 110
Slide 111
Slide 112
Slide 113
Slide 114
Slide 115
Slide 116
Slide 117
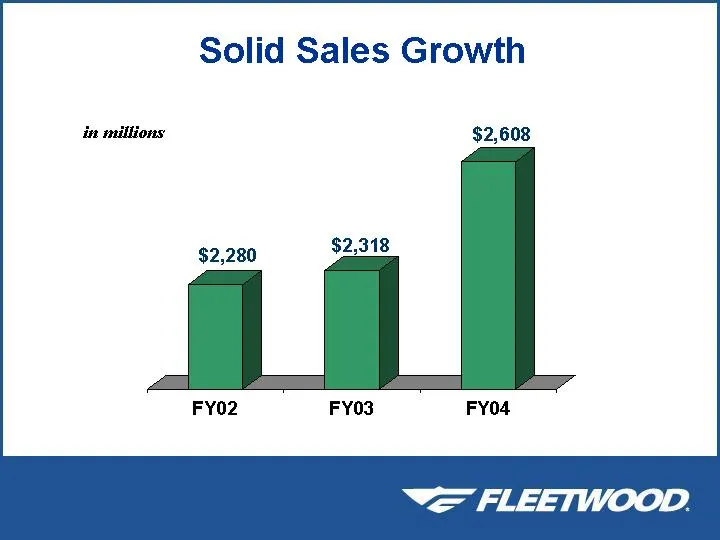
Slide 118
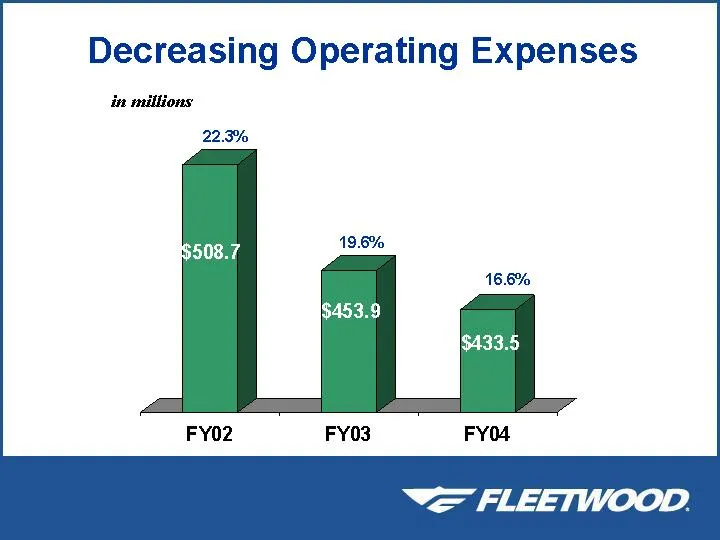
Slide 119
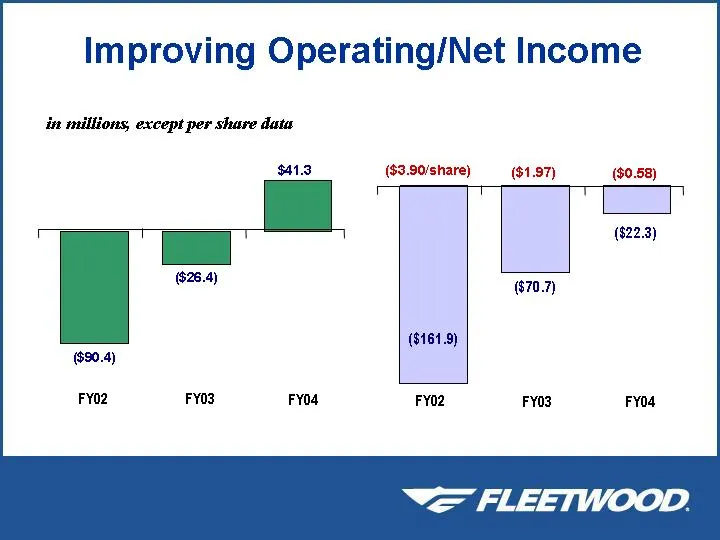
Slide 120
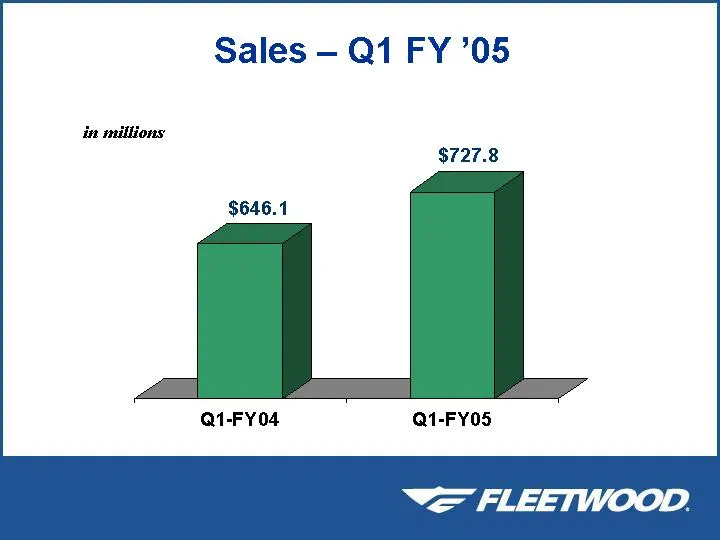
Slide 121
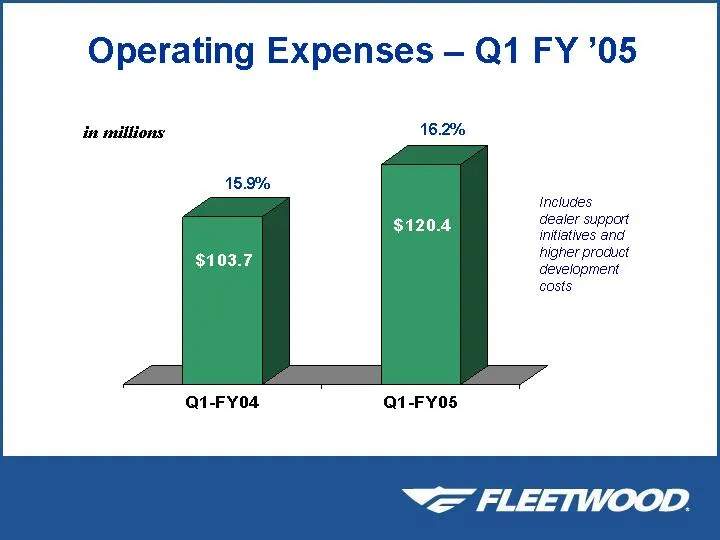
Slide 122
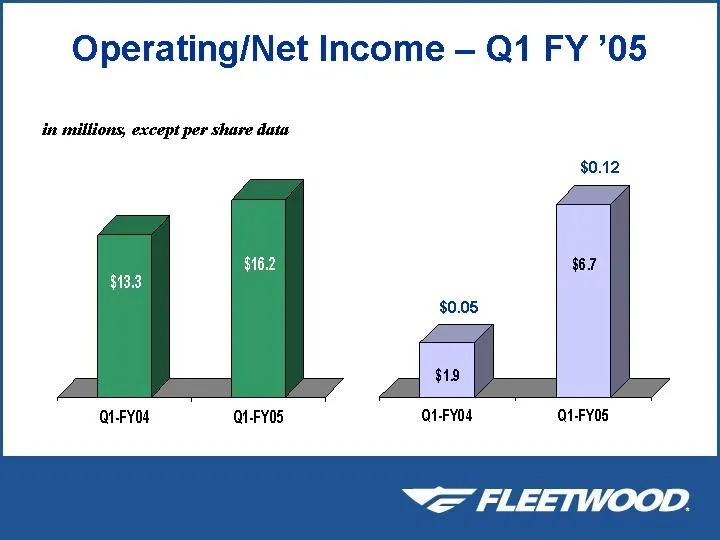
Slide 123
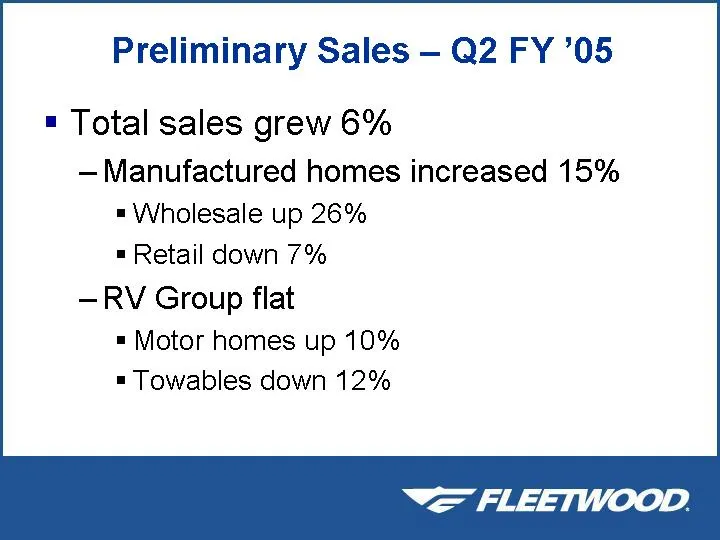
Slide 124
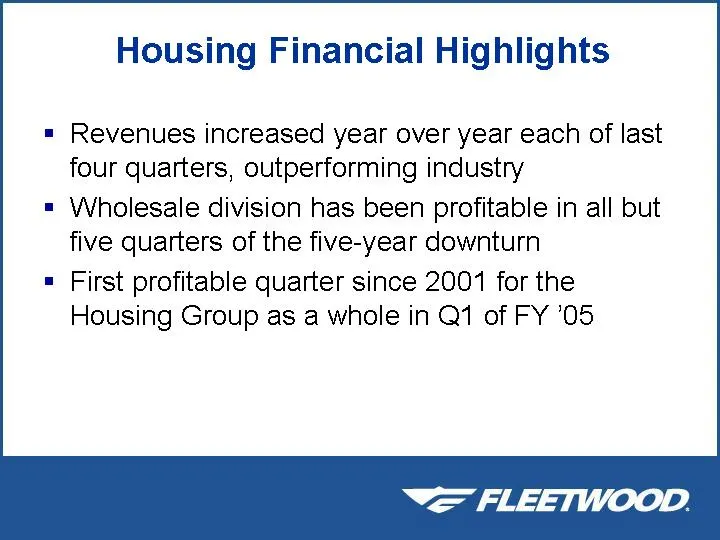
Slide 125
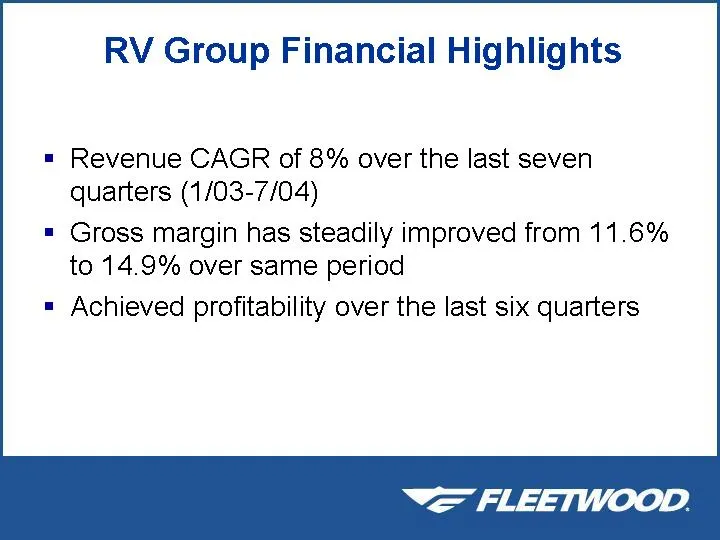
Slide 126
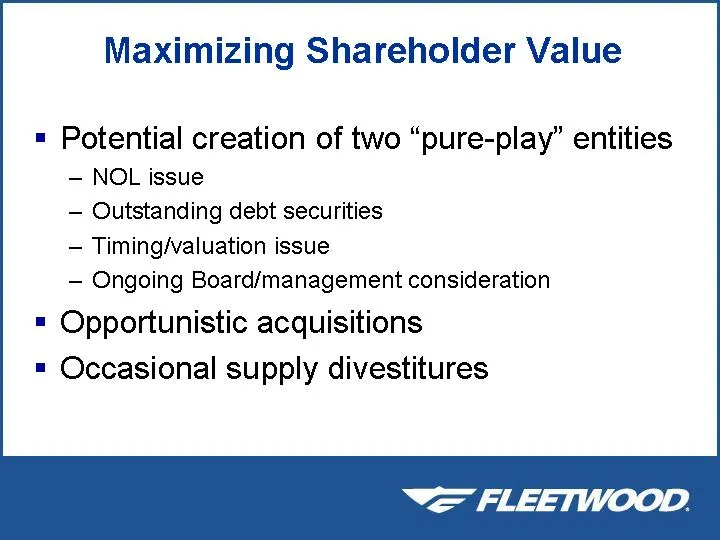
Slide 127
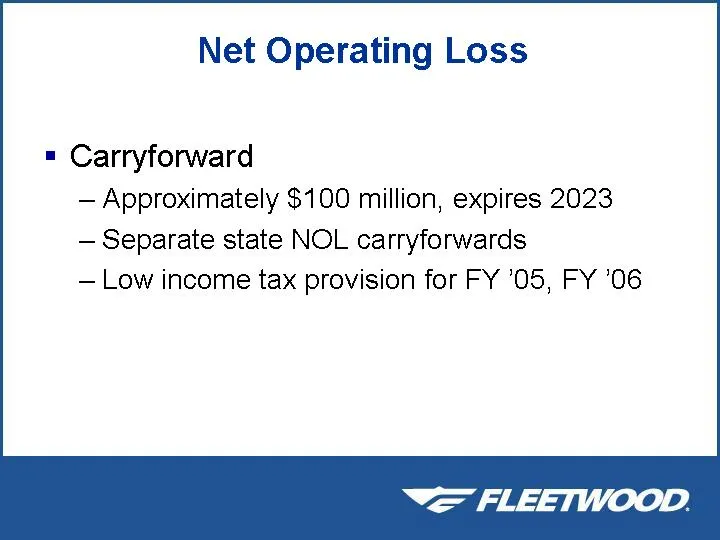
Slide 128
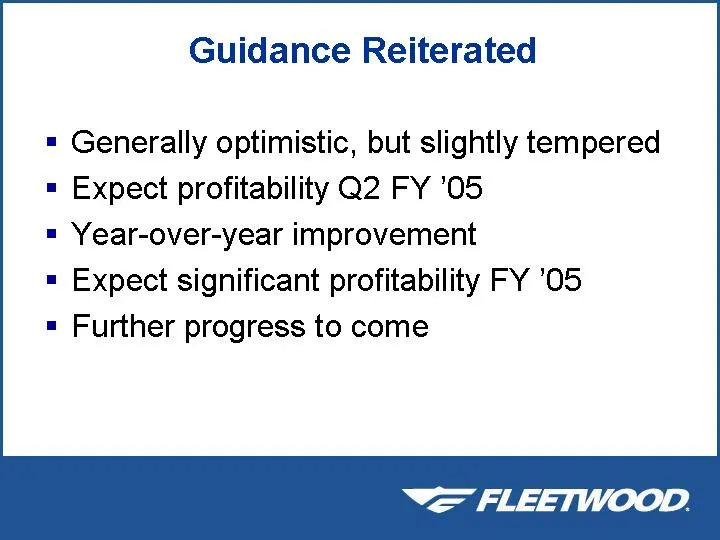
Slide 129
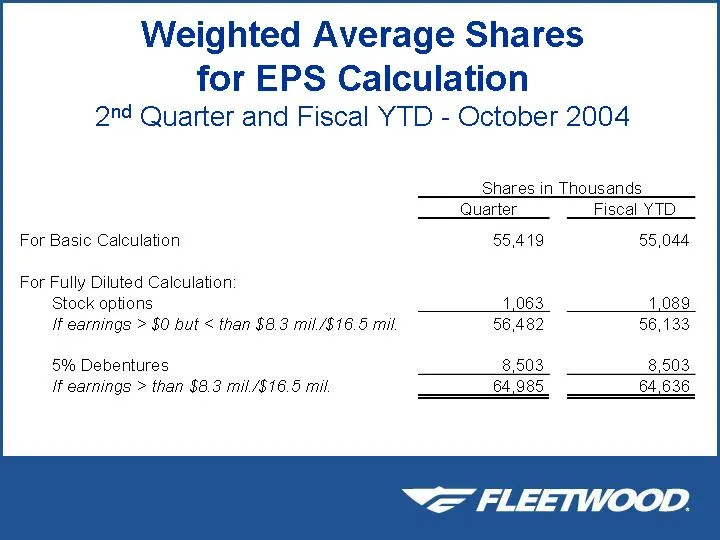
Slide 130
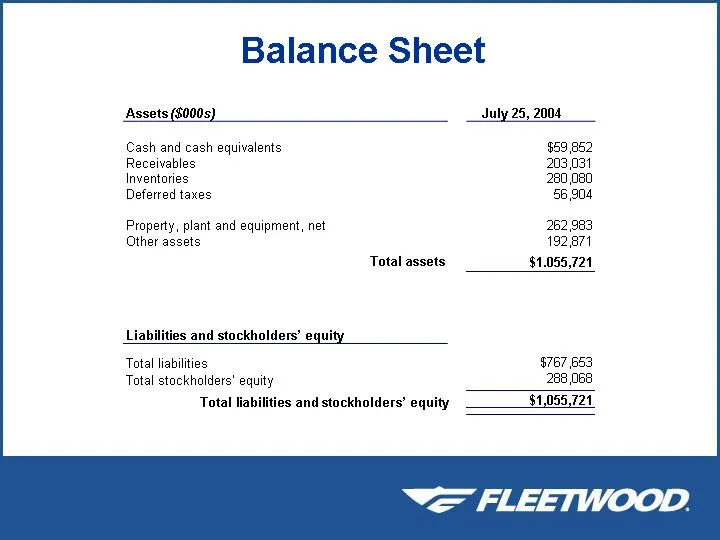
Slide 131
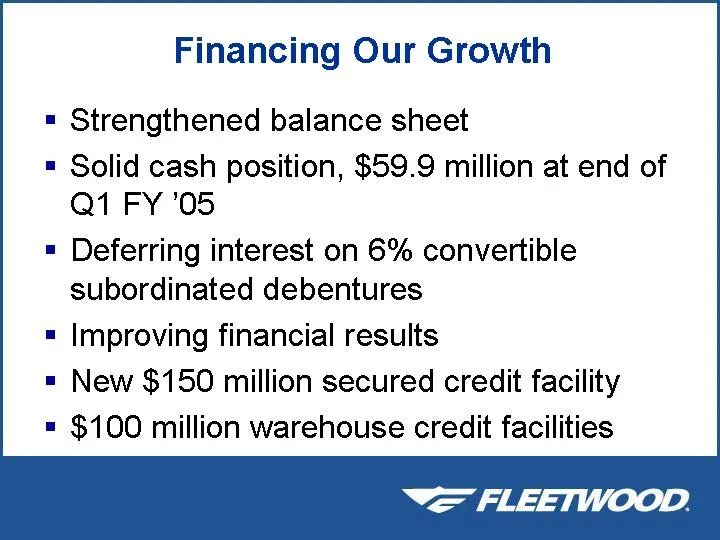
Slide 132
Slide 133
Slide 134
Slide 135: Searchable text section of graphics shown above
Searchable text section of graphics shown above [ LOG O] Investor Day October 29, 2004 [LOGO] Saf e Harbor Statement This presentation contains certain forward-looking statements and information based on the beliefs of Fleetwood’s management as well as assumptions made by, and information currently
Source: SEC EDGAR · 8-K filed Nov 1, 2004
More decks from Fleetwood Enterprises Inc
 IPO Roadshow (June 2008)43 slides · Jun 19, 2008
 Investor Presentation (May 2008)44 slides · May 19, 2008
 Investor Presentation (September 2007)48 slides · Sep 20, 2007
 Investor Presentation (November 2006)41 slides · Nov 13, 2006
 Investor Presentation (October 2006)46 slides · Oct 19, 2006
 Investor Presentation (November 2005)43 slides · Nov 3, 2005