Restoration Hardware — Merger or Acquisition (May 2008)
27 slides from Restoration Hardware's merger presentation, May 29, 2008
Slide 1: Schedule 14A
UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 SCHEDULE 14A Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934 Filed by the Registrant x Filed by a Party other than the Registrant ¨ Check the appropriate box: ¨ Preliminary Proxy Statement ¨ Conf
Slide 2: Filing Party and Date Filed
(3) Filing Party: (4) Date Filed:
Slide 3: Filing consists of information used May 29, 2008
This filing consists of information initially used on May 29, 2008 by Restoration Hardware, Inc. in connection with a presentation made to RiskMetrics Group, Inc.
Slide 4: Restoration Hardware, Inc. Agreement and Plan of Merger
RESTORATION HARDWARE, INC. AGREEMENT AND PLAN OF MERGER with investment funds affiliated with Catterton Management Company, LLC
Slide 5: Forward Looking Statements
Forward Looking Statements This presentation contains forward-looking statements that involve known and unknown risks. Such forward-looking statements include, without limitation, statements concerning the timing of the closing of the merger and statements containing words such as “likely”or “expect
Slide 6: Additional Information and Where to Find It
Additional Information and Where to Find It • In connection with the proposed merger, a definitive proxy statement was filed by the Company with the SEC on May 9, 2008. Investors and security holders are strongly advised to read the definitive proxy statement because it contains important informatio
Slide 7: Background Leading to Merger Transaction
Background Leading to Merger Transaction • In determining to pursue the acquisition, the Independent Committee focused on certainty of value to stockholders through a transaction: • Retail and home furnishings sectors have been under significant pressure as a Industry Context result of general econo
Slide 8: Overview
Overview • The Merger provides compelling value, particularly in light of industry and Company trends • Significant premium to market trading benchmarks • Greater and more certain value than likely stand-alone results • The Merger Agreement resulted from a thorough and independent review by independ
Slide 9: Merger Provides Compelling Value: Retail sector pressure
Merger Provides Compelling Value • Retail sector of economy, and specifically the home furnishings segment, has been under substantial pressure • General economic conditions have declined in recent quarters with retail and housing sectors particularly weak • Reduction in credit availability and slow
Slide 10: Merger Provides Compelling Value: Retail bankruptcies
Merger Provides Compelling Value • Numerous companies in the retail sector have recently sought protection from creditors under bankruptcy rules including: • Linens ‘n Things • Bombay Company • Sharper Image • Red Envelope • Lillian Vernon • Levitz Furniture • Other retailers are struggling in the c
Slide 11: Merger Provides Compelling Value: Standalone challenges
Merger Provides Compelling Value • Value of continuing as a standalone entity is uncertain due to numerous challenges including: • the Company’s strategic plan to move from a traditional retailer to a tri- channel home furnishings business model requires significant investments in infrastructure tha
Slide 12: Merger Provides Compelling Value: Standalone challenges (continued)
Merger Provides Compelling Value • Value of continuing as a standalone entity is uncertain due to numerous challenges including: • a large number of changes to the corporate organization would be necessary in order for the Company to achieve sustained sales and earnings growth • the Company faces su
Slide 13: Merger Provides Compelling Value: UBS fairness opinion
Merger Provides Compelling Value • UBS opined to the Independent Committee that, as of the date of their opinion, the consideration to be received by Company stockholders who will receive all cash merger consideration of $4.50 per share for their holdings, was fair, from a financial point of view, t
Slide 14: Merger Provides Compelling Value: Premium to market price
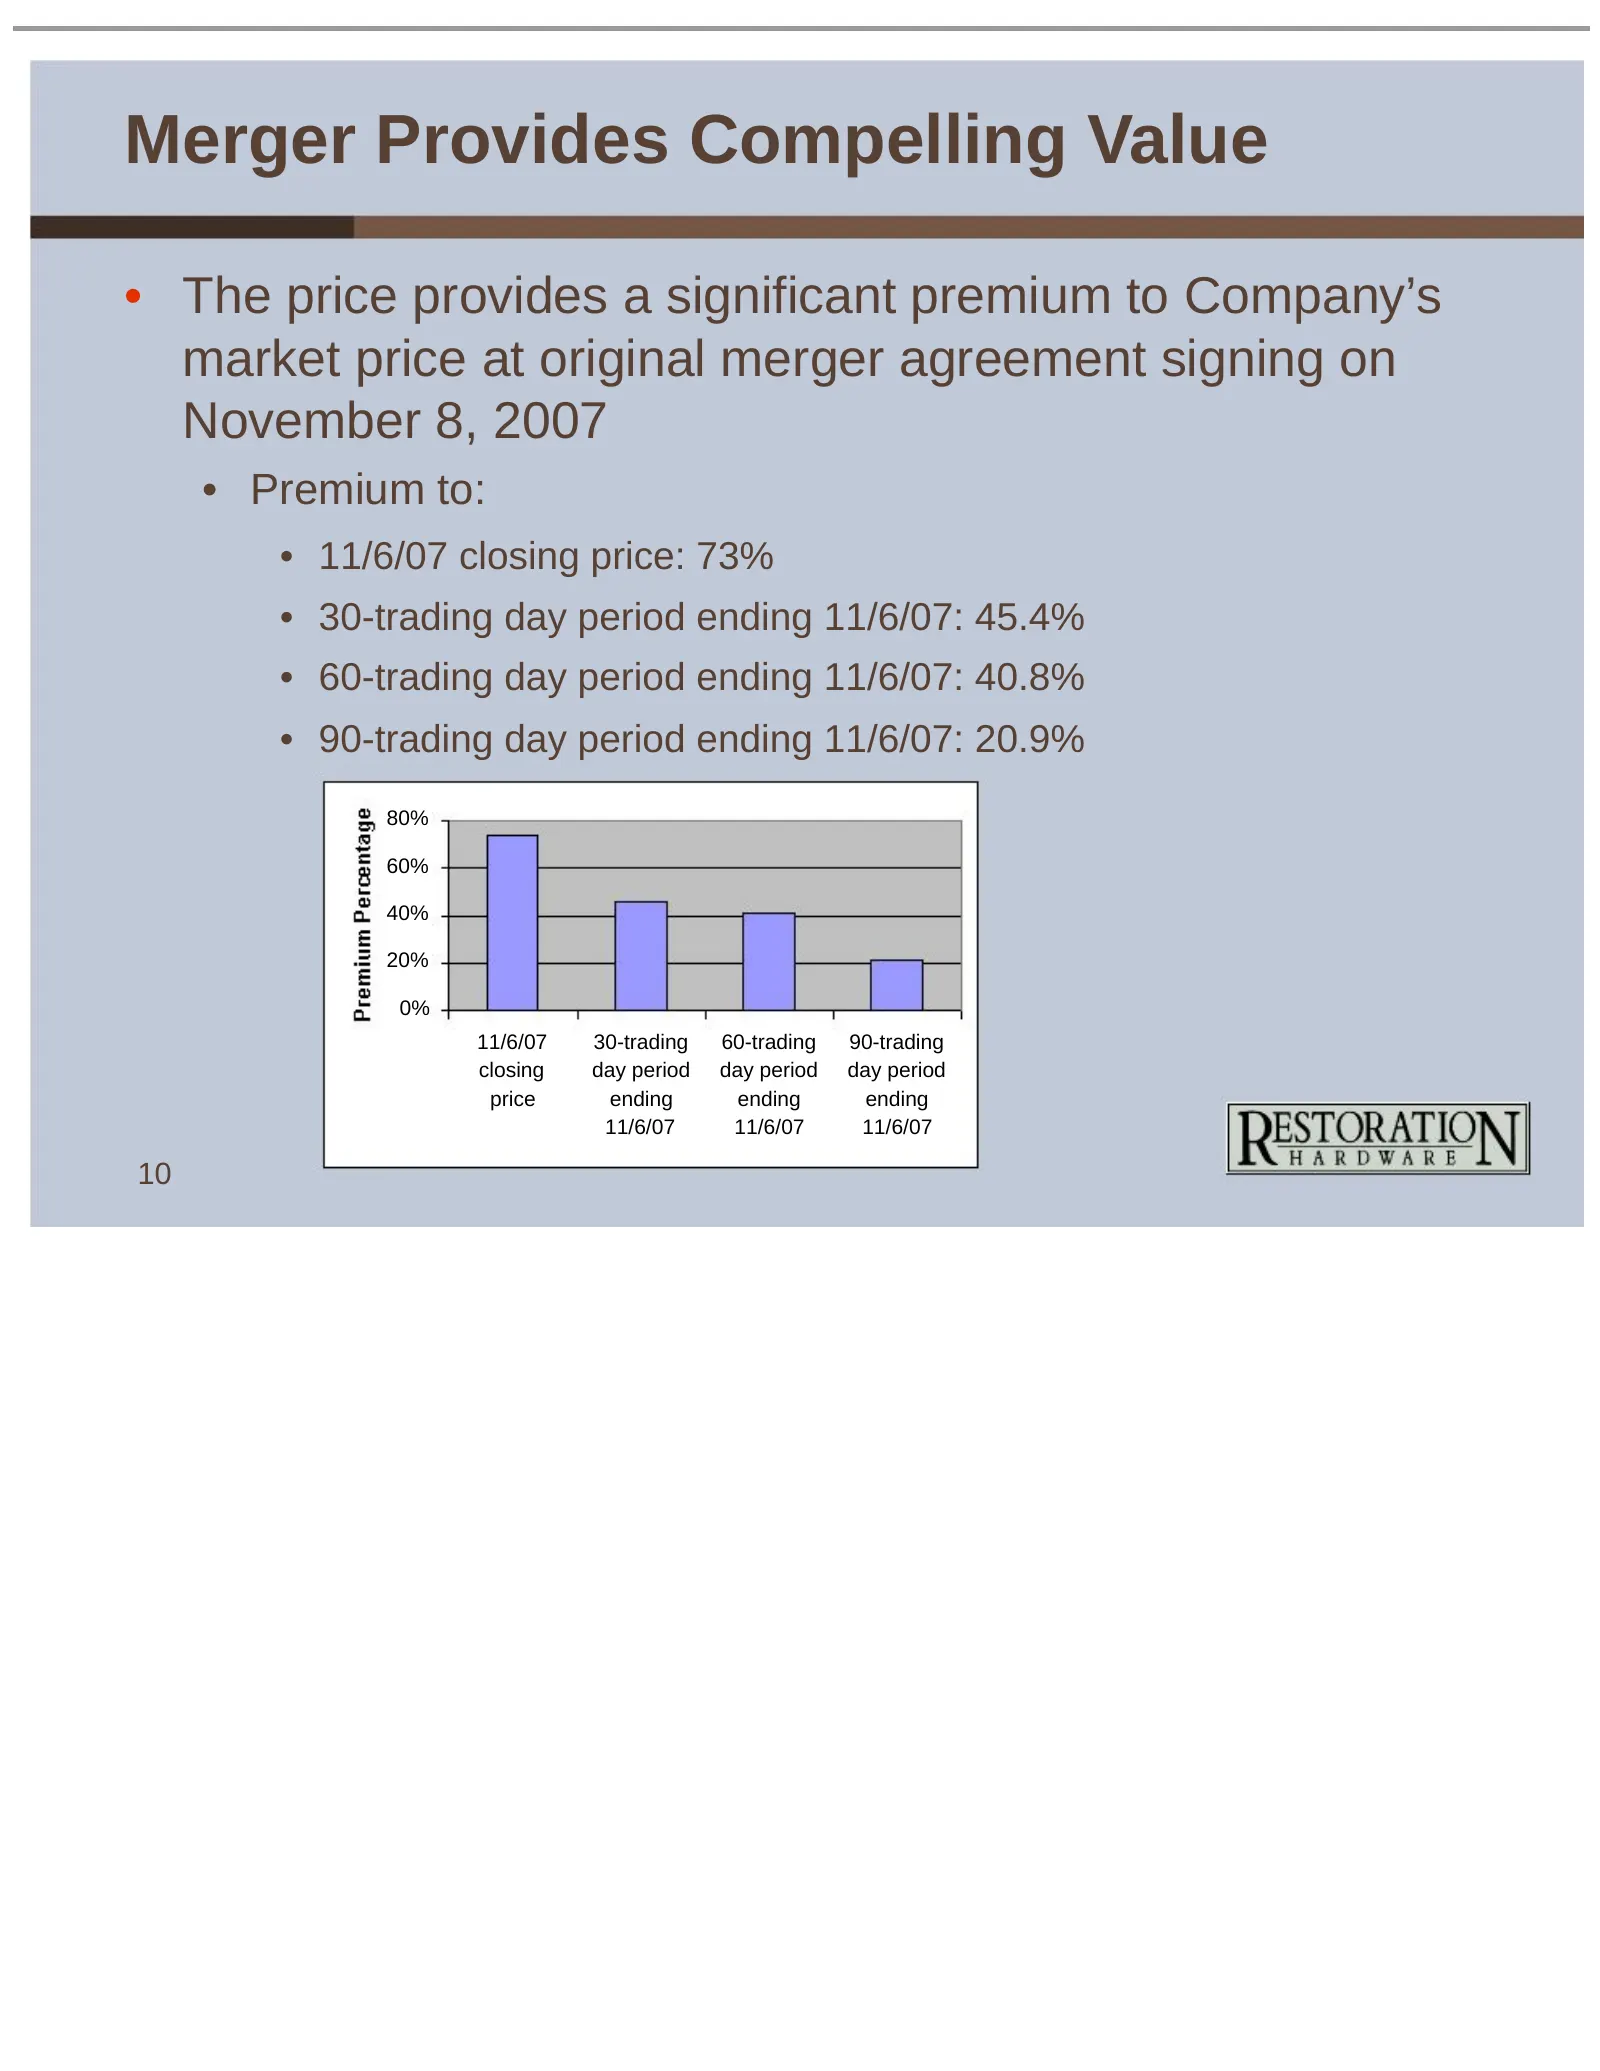
Merger Provides Compelling Value • The price provides a significant premium to Company’s market price at original merger agreement signing on November 8, 2007 • Premium to: • 11/6/07 closing price: 73% • 30-trading day period ending 11/6/07: 45.4% • 60-trading day period ending 11/6/07: 40.8% • 90-t
Slide 15: Merger Provides Compelling Value: Trading multiples
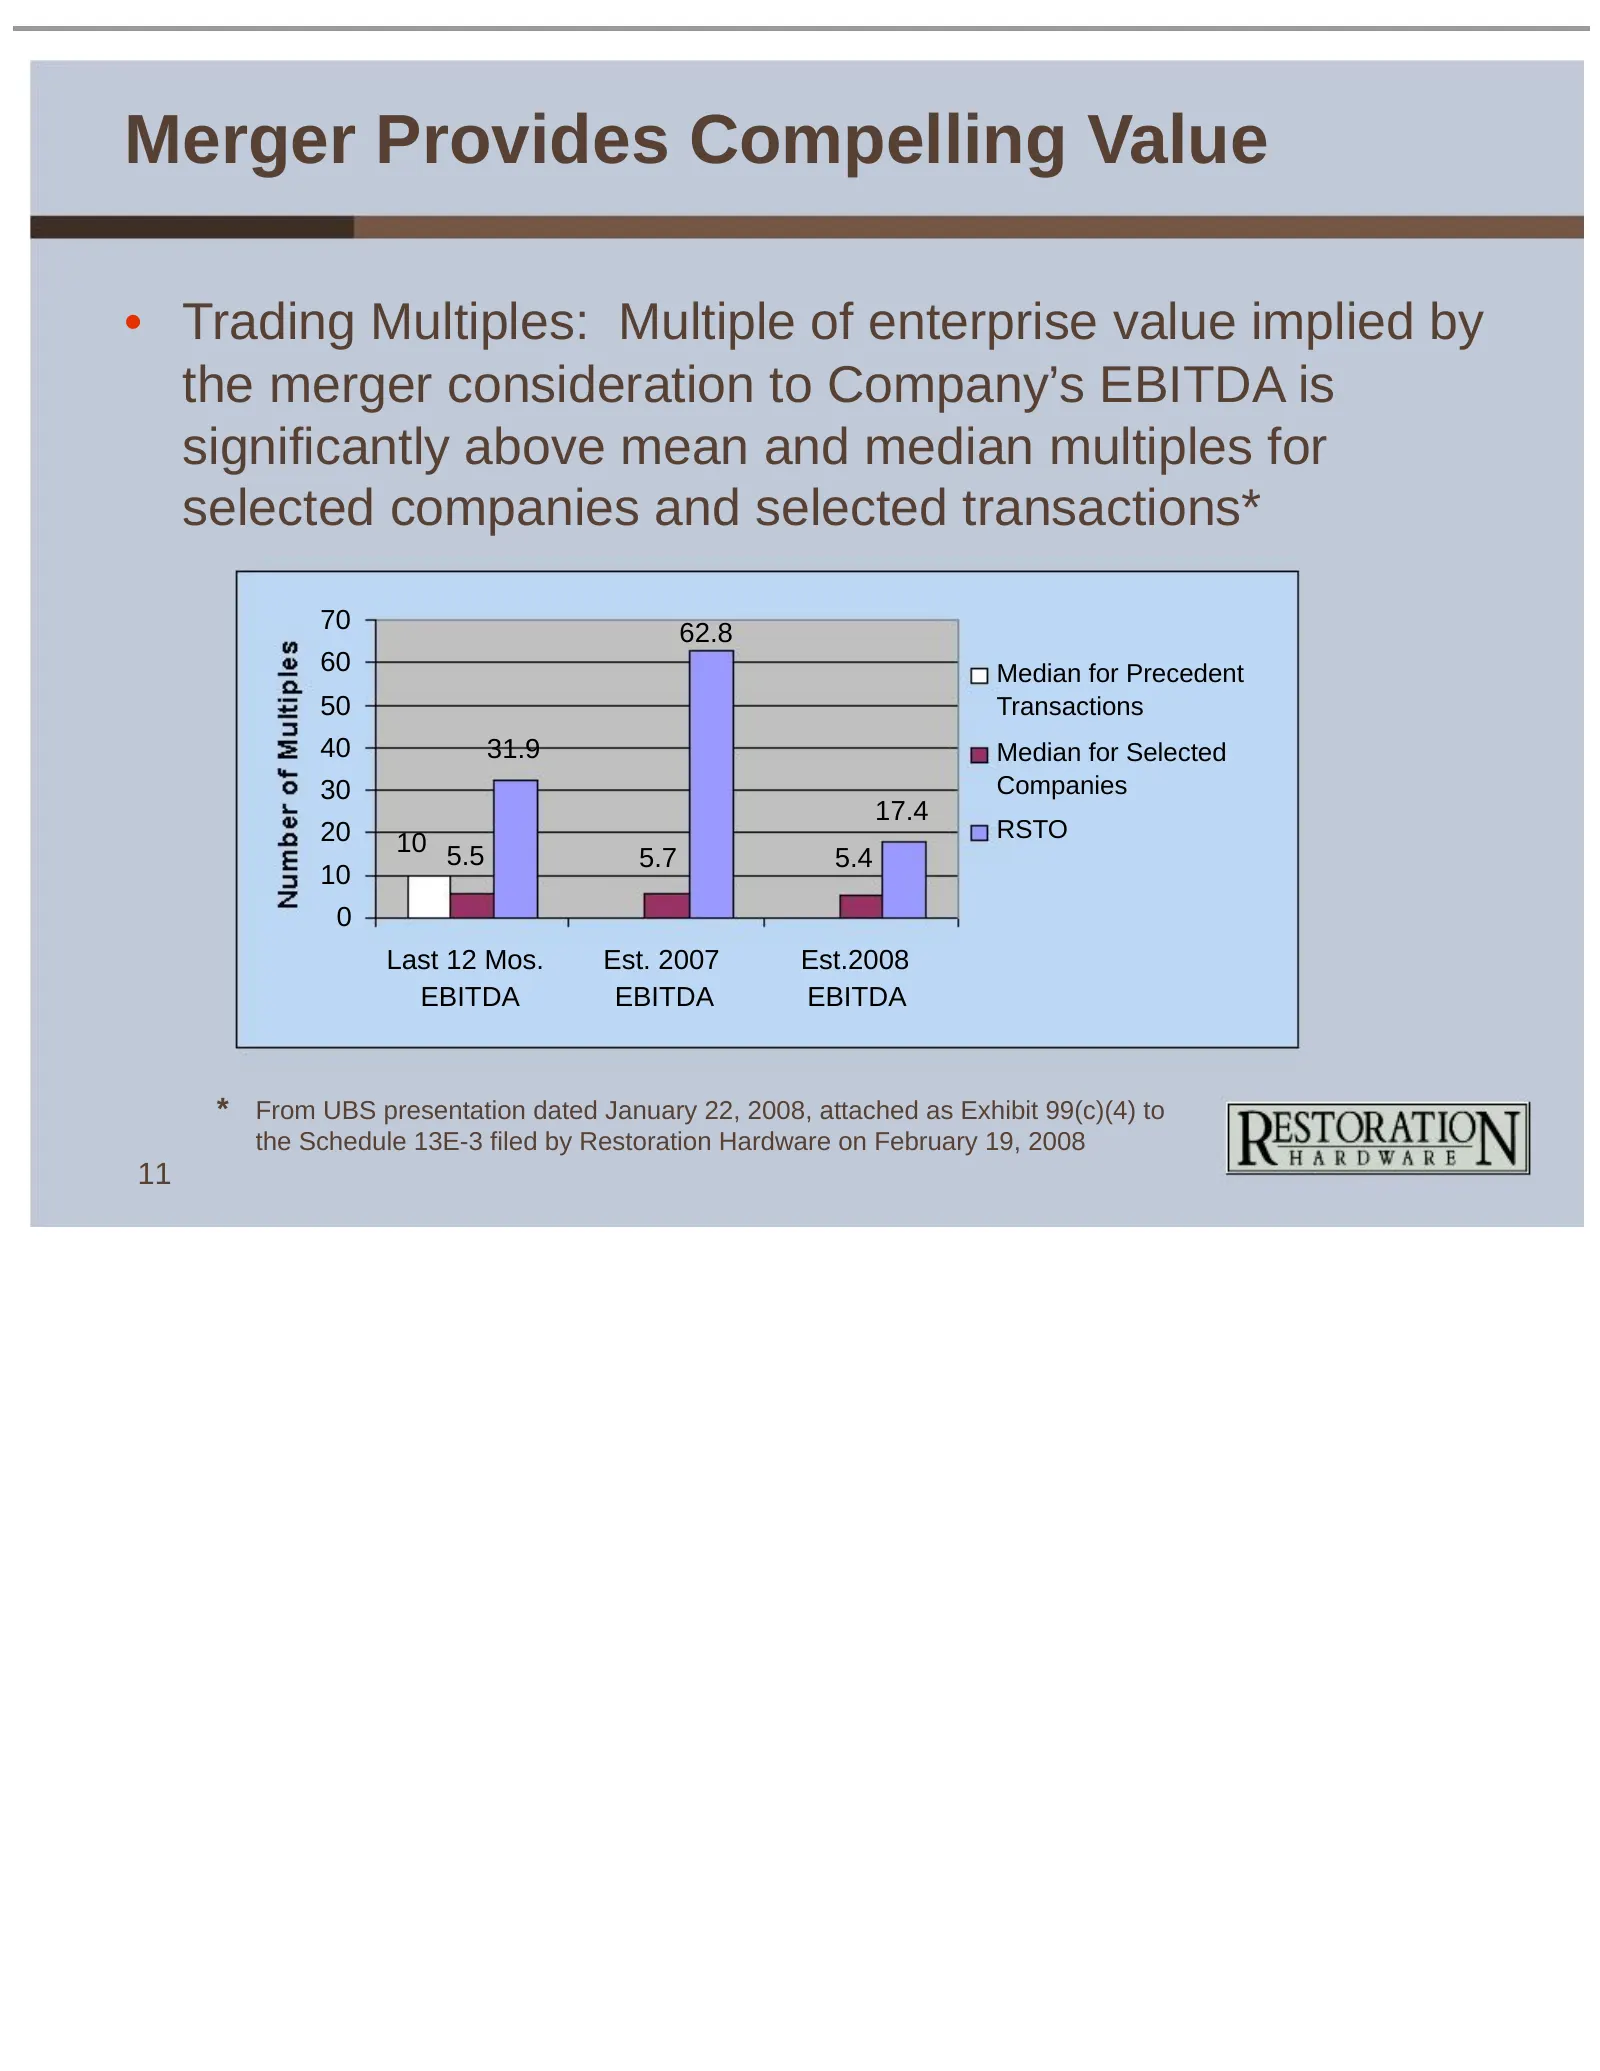
Merger Provides Compelling Value • Trading Multiples: Multiple of enterprise value implied by the merger consideration to Company’s EBITDA is significantly above mean and median multiples for selected companies and selected transactions* 70 62.8 60 Median for Precedent 50 Transactions 40 31.9 Median
Slide 16: Merger Provides Compelling Value: Discounted cash flow
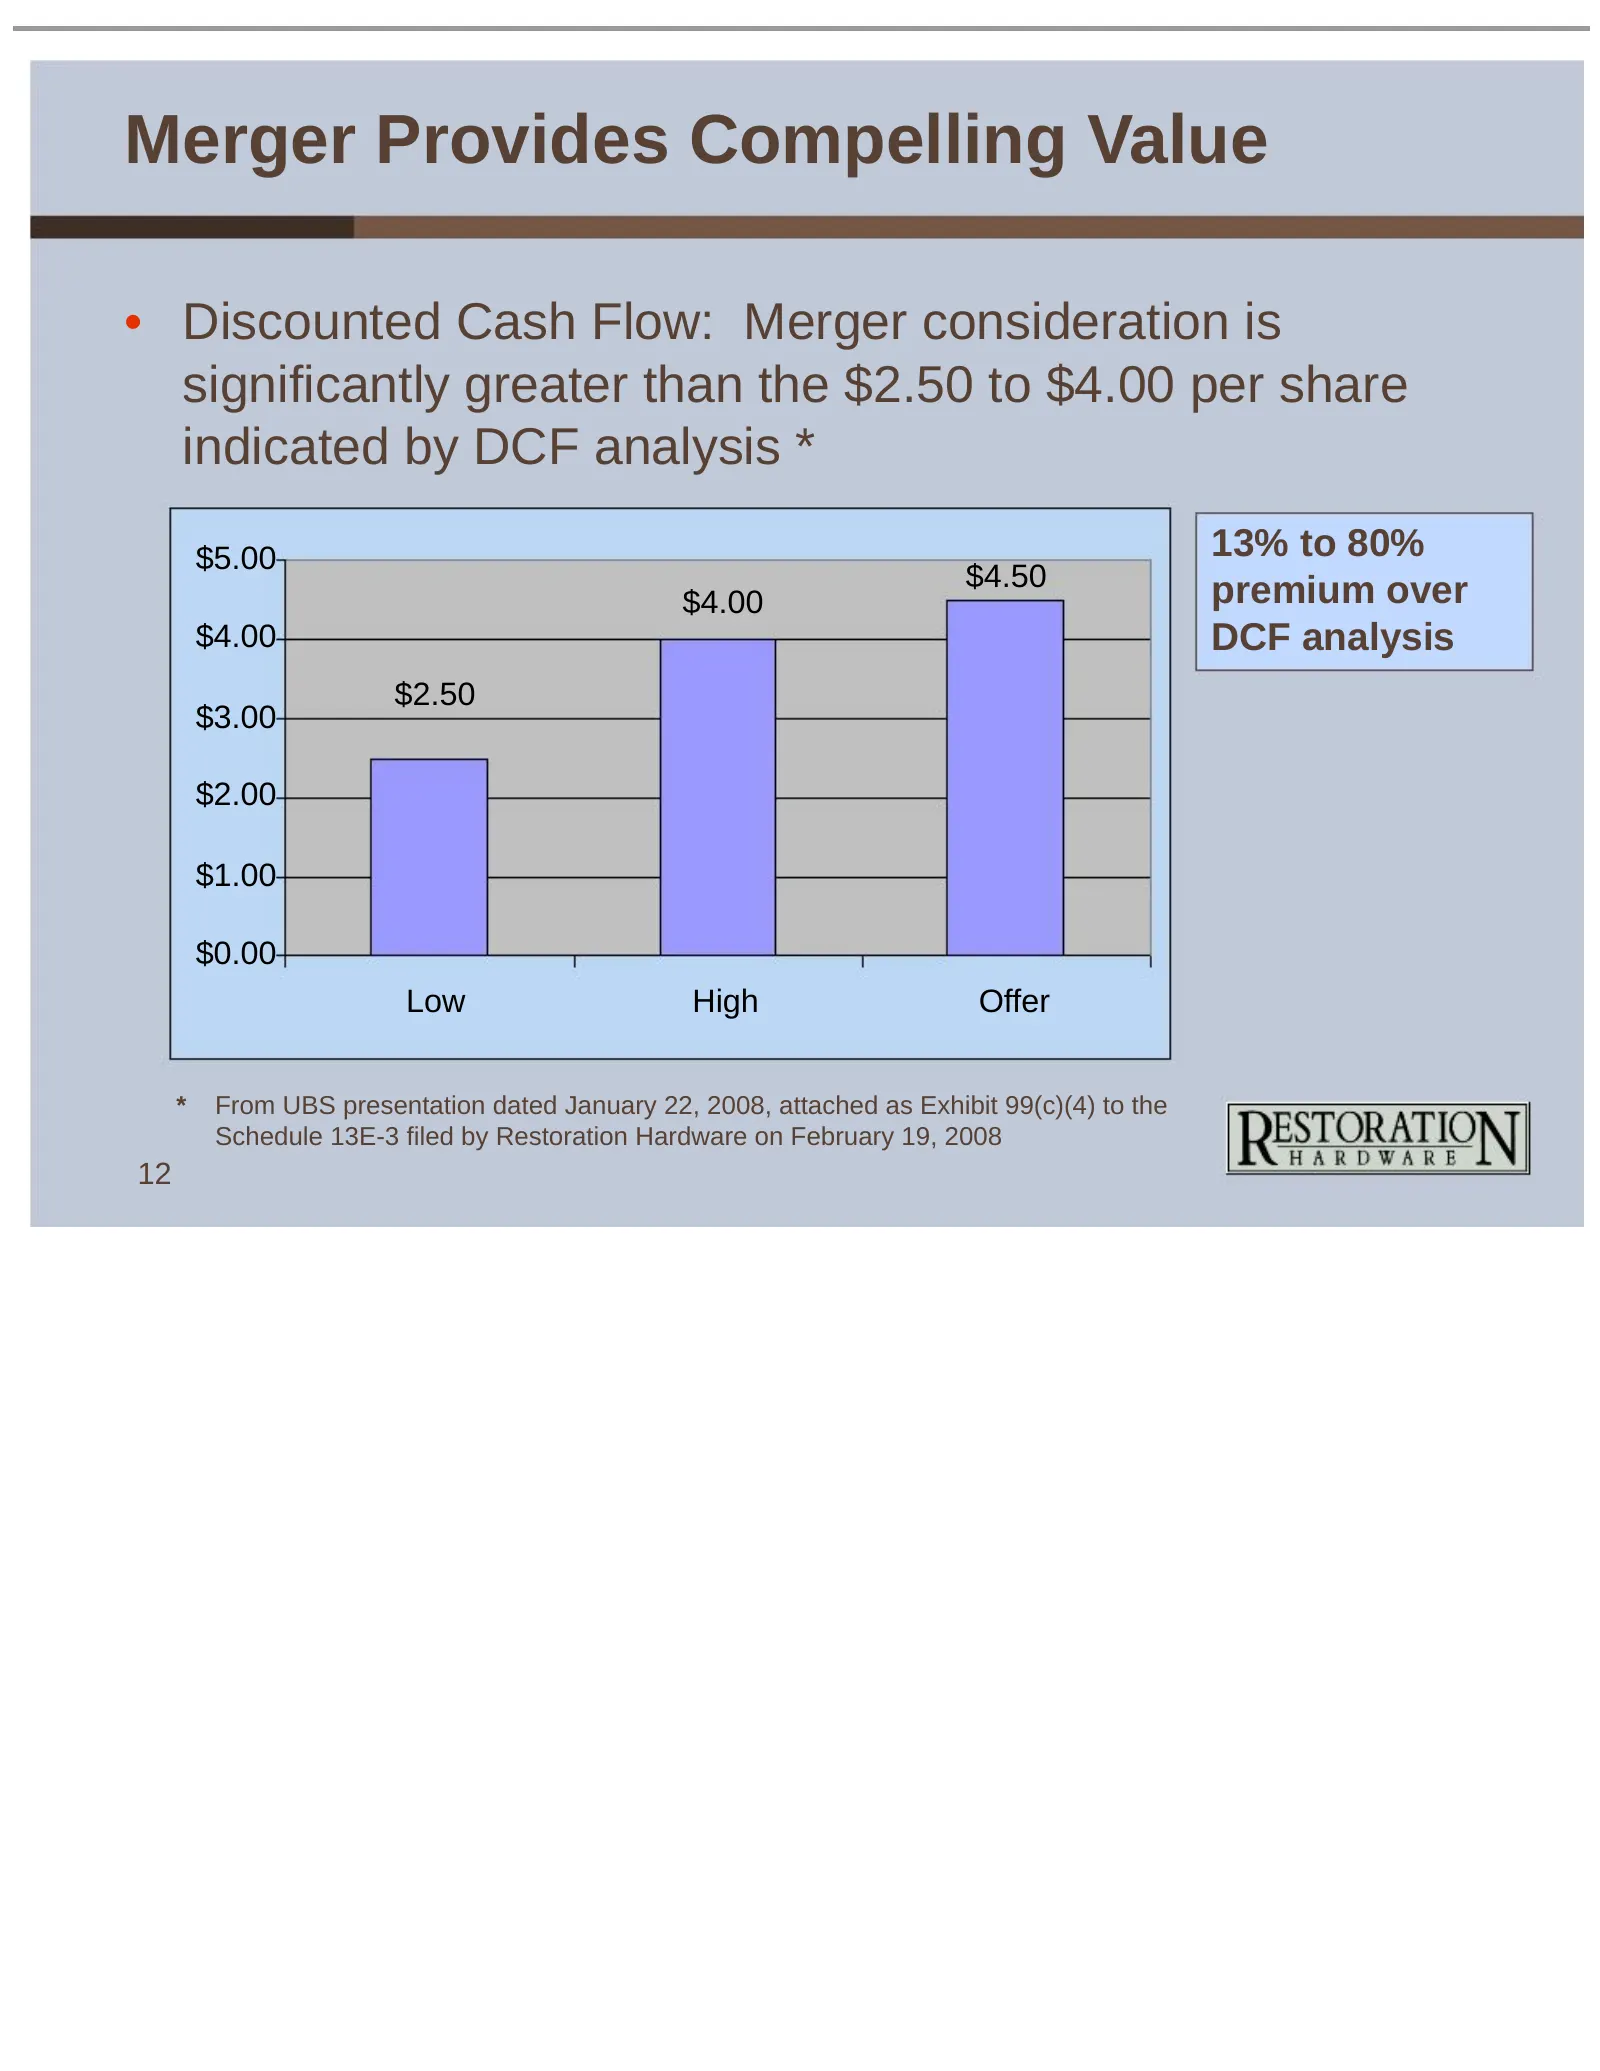
Merger Provides Compelling Value • Discounted Cash Flow: Merger consideration is significantly greater than the $2.50 to $4.00 per share indicated by DCF analysis * $5.00 13% to 80% $4.50 $4.00 premium over $4.00 DCF analysis $2.50 $3.00 $2.00 $1.00 $0.00 Low High Offer * From UBS presentation dated
Slide 17: Merger Provides Compelling Value: Financial results have suffered
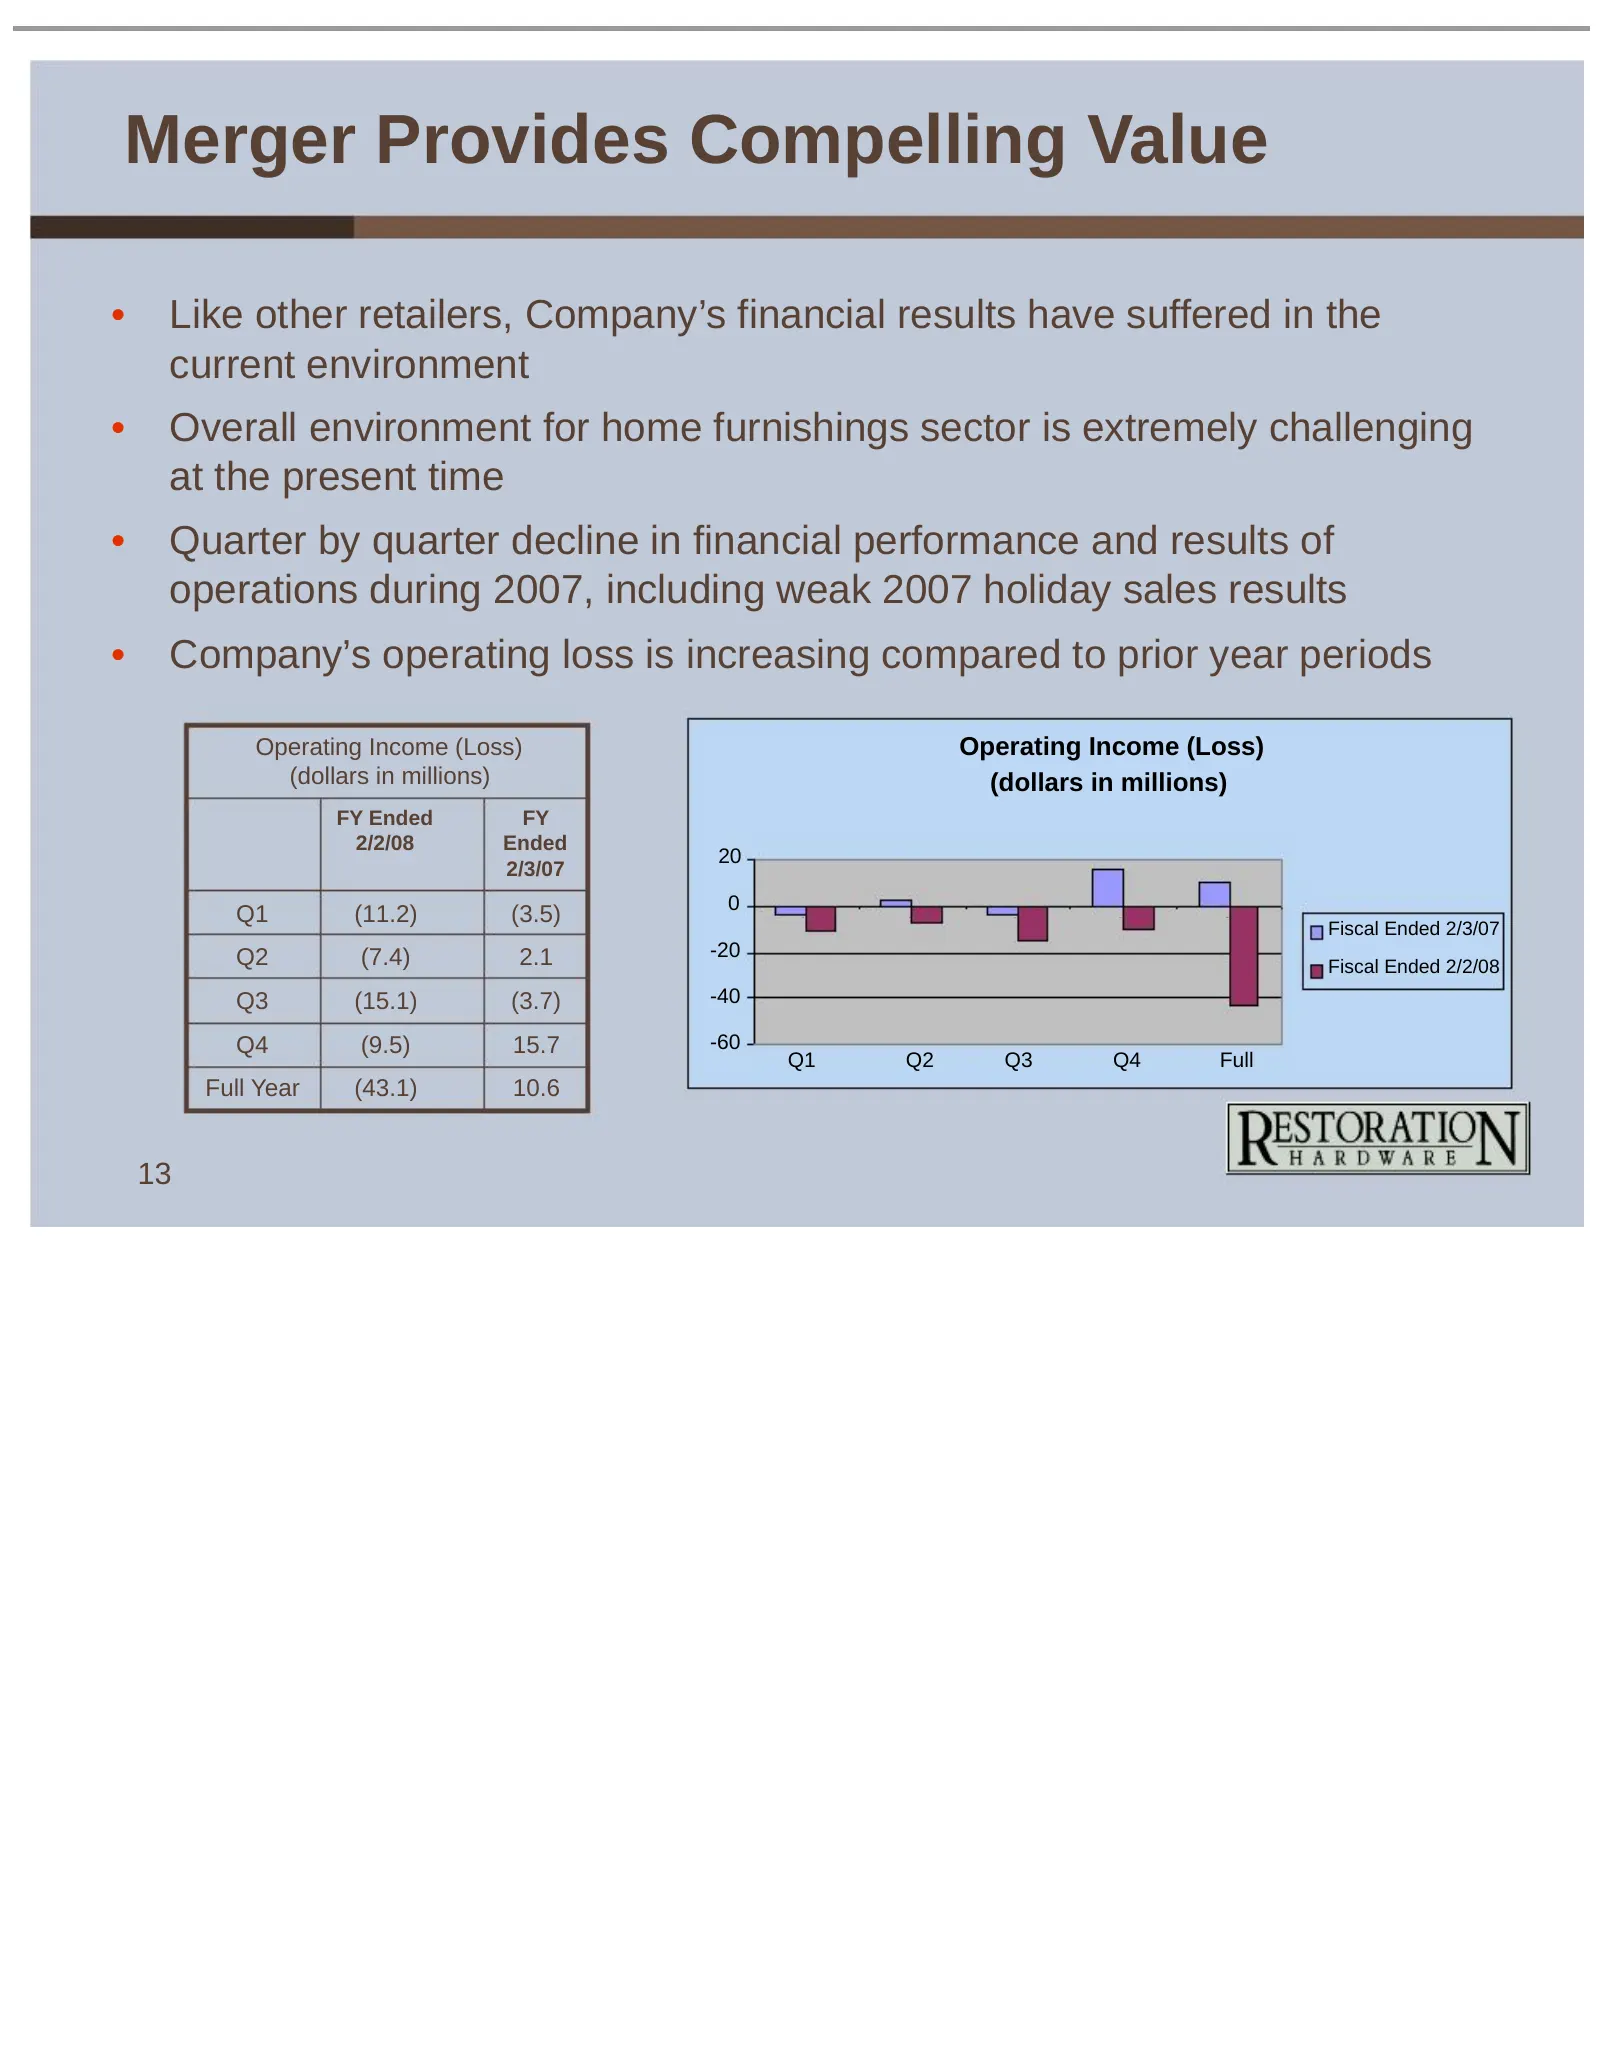
Merger Provides Compelling Value • Like other retailers, Company’s financial results have suffered in the current environment • Overall environment for home furnishings sector is extremely challenging at the present time • Quarter by quarter decline in financial performance and results of operations
Slide 18: Merger Provides Compelling Value: Downward EBITDA revisions
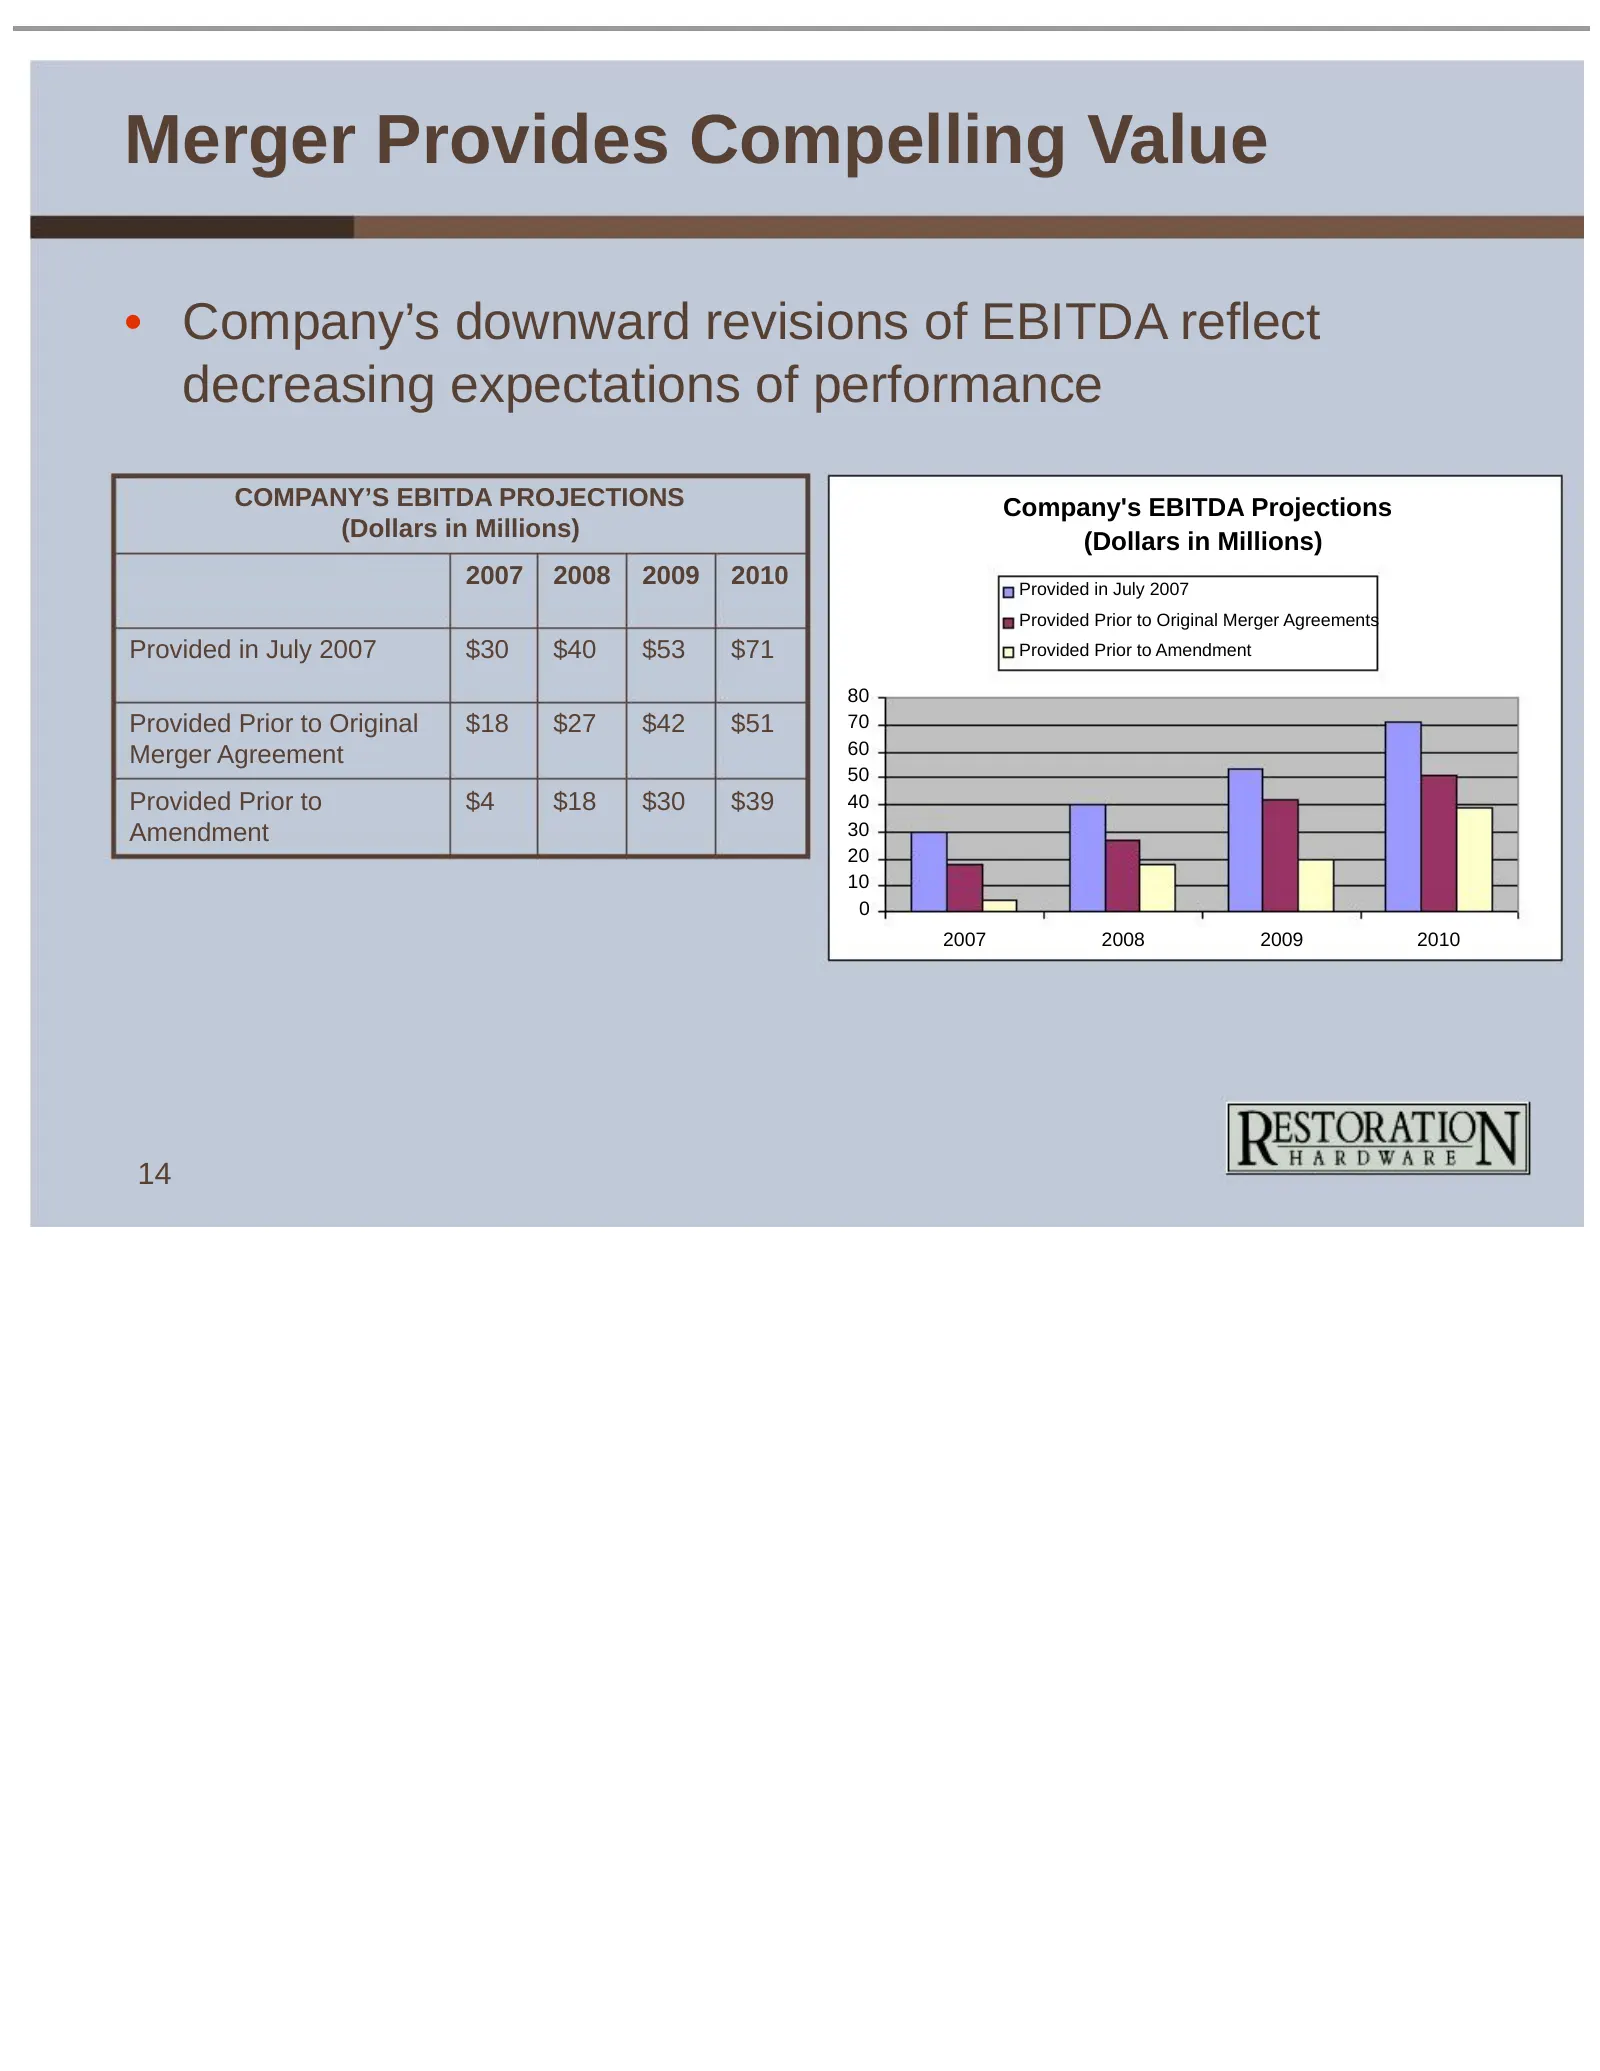
Merger Provides Compelling Value • Company’s downward revisions of EBITDA reflect decreasing expectations of performance COMPANY’S EBITDA PROJECTIONS Company's EBITDA Projections (Dollars in Millions) (Dollars in Millions) 2007 2008 2009 2010 Provided in July 2007 Provided Prior to Original Merger A
Slide 19: Catterton has provided interim financing
Merger Provides Compelling Value • Catterton has provided interim financing for the Company • $25.0 million subordinated loan • Terms are quite favorable to the Company • Five year term • Favorable interest rate terms • Proceeds have provided Company with additional liquidity and financial flexibili
Slide 20: Catterton Merger Terms Provide Strong Closing Incentives
Catterton Merger Terms Provide Strong Closing Incentives – Promotes Deal “Certainty” • Catterton has no debt financing condition in Merger Agreement • Transaction is not subject to external debt financing • Senior banks have consented to the Catterton transaction on terms described in the proxy stat
Slide 21: Thorough, Active and Independent Process
Thorough, Active and Independent Process • Merger Agreement is result of a vigorous arm’s length process designed to maximize shareholder value • The majority of the Board is independent • Merger Agreement was negotiated by, or under the direction of, the Independent Committee • Alignment between in
Slide 22: Thorough, Active and Independent Process: Committee activity
Thorough, Active and Independent Process • Independent Committee conducted thorough, active and independent process, both before and after signing of original Merger Agreement • Independent Committee formed in August, 2007 • Multiple meetings of Independent Committee and of the working group of the
Slide 23: Thorough, Active and Independent Process: Go-shop market check
Thorough, Active and Independent Process • Active market check conducted during go-shop periods to check market interest • Merger Agreement allowed Company to solicit alternative proposals • 35 days of active solicitation allowed after execution of each of original Merger Agreement and amendment • N
Slide 24: Thorough, Active and Independent Process: Alternatives sought
Thorough, Active and Independent Process • Independent Committee actively sought alternatives using these two go-shop periods to solicit third party proposals • Following execution of initial Merger Agreement • 22 parties were contacted • Only 3 of these parties signed confidentiality agreements • O
Slide 25: Thorough, Active and Independent Process: Go-shop floor valuation
Thorough, Active and Independent Process • Go-shop provided floor valuation while Independent Committee sought better terms • Even after go-shop periods, Board is permitted to respond to bona fide unsolicited bids • Since expiration of go-shop period, no party has made any acquisition proposal to th
Slide 26: Conclusion
Conclusion • Merger consideration of $4.50 provides compelling valuation and provides certainty to stockholders during uncertain environment • Thorough, vigorous process conducted by independent board members • Board and Management do not believe there is a viable alternative transaction • Merger pr
Slide 27: Appendix: Transaction Summary
Appendix: Transaction Summary • Agreement and Plan of Merger dated as of November 8, 2007, as amended as of January 24, 2008 • Key Terms • $4.50 per share, in cash • 35 day go-shop (from January 24 –February 28, 2008) • In addition to similar go-shop period after execution of initial Merger Agreemen
Source: SEC EDGAR · DEFA14A filed May 29, 2008