Atlas Financial — Q3 2015 Earnings Presentation
22 slides from Atlas Financial's earnings presentation, Nov 9, 2015
Slide 1: 2015 Third Quarter Conference Call
2015 Third Quarter Conference Call November 10, 2015
Slide 2: Forward-looking statements
Statements in this presentation, including the information set forth as to the future financial or operating performance of Atlas Financial Holdings, Inc., American Country Insurance Company, American Service Insurance Company, Gateway Insurance Company and/or Global Insurance Company of New York (c
Slide 3: Atlas Snapshot
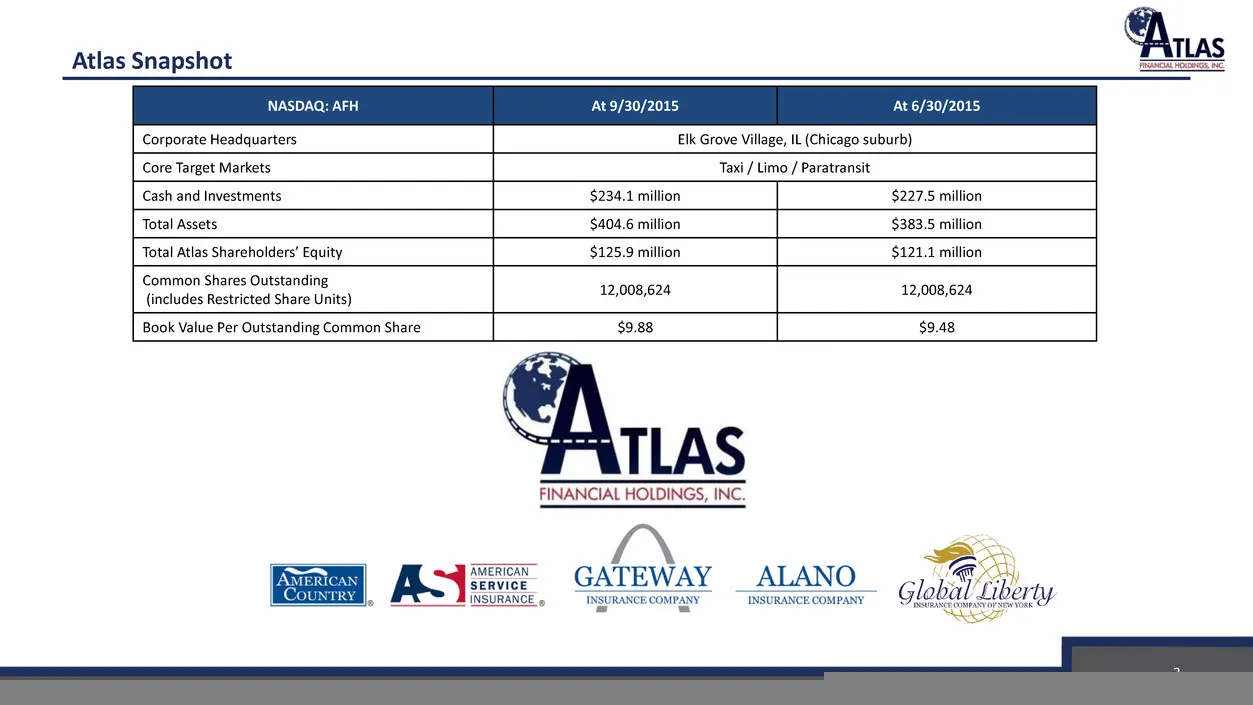
Atlas Snapshot 3 NASDAQ: AFH At 9/30/2015 At 6/30/2015 Corporate Headquarters Elk Grove Village, IL (Chicago suburb) Core Target Markets Taxi / Limo / Paratransit Cash and Investments $234.1 million $227.5 million Total Assets $404.6 million $383.5 million Total Atlas Shareholders’ Equity $125.9 mil
Slide 4: Q3 2015 Milestones
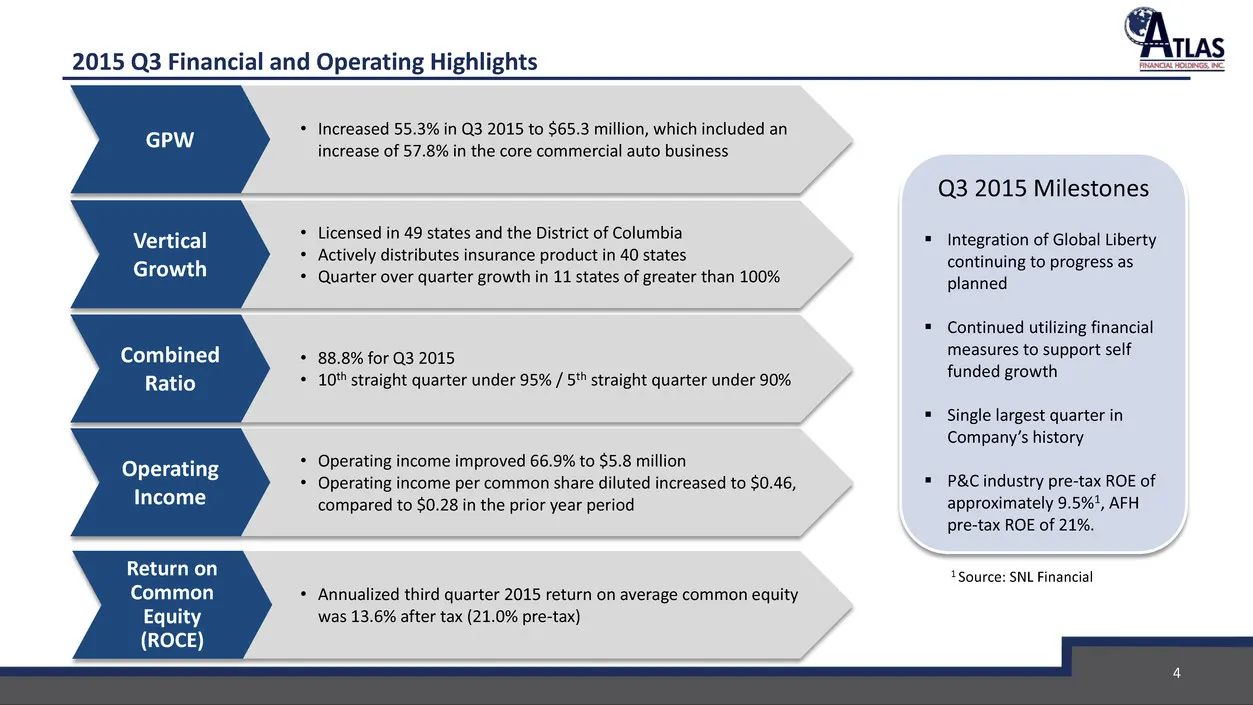
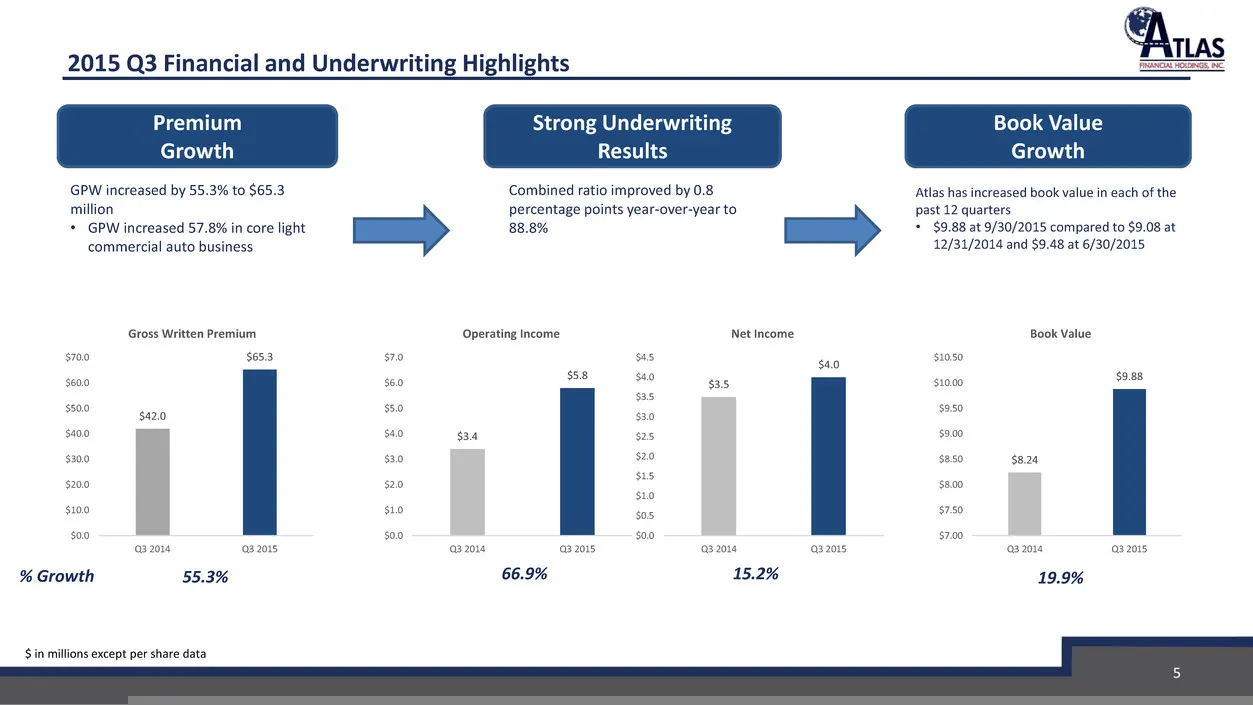
• Increased 55.3% in Q3 2015 to $65.3 million, which included an increase of 57.8% in the core commercial auto business GPW • Licensed in 49 states and the District of Columbia • Actively distributes insurance product in 40 states • Quarter over quarter growth in 11 states of greater than 100% Verti
Slide 5: 2015 Q3 Financial and Underwriting Highlights
5 % Growth 55.3% 66.9% 19.9% 2015 Q3 Financial and Underwriting Highlights $42.0 $65.3 $0.0 $10.0 $20.0 $30.0 $40.0 $50.0 $60.0 $70.0 Q3 2014 Q3 2015 Gross Written Premium $3.4 $5.8 $0.0 $1.0 $2.0 $3.0 $4.0 $5.0 $6.0 $7.0 Q3 2014 Q3 2015 Operating Income $3.5 $4.0 $0.0 $0.5 $1.0 $1.5 $2.0 $2.5 $3.0
Slide 6: Consistent Quarterly Year/Year Margin Improvement Since 2013 U.S. IPO
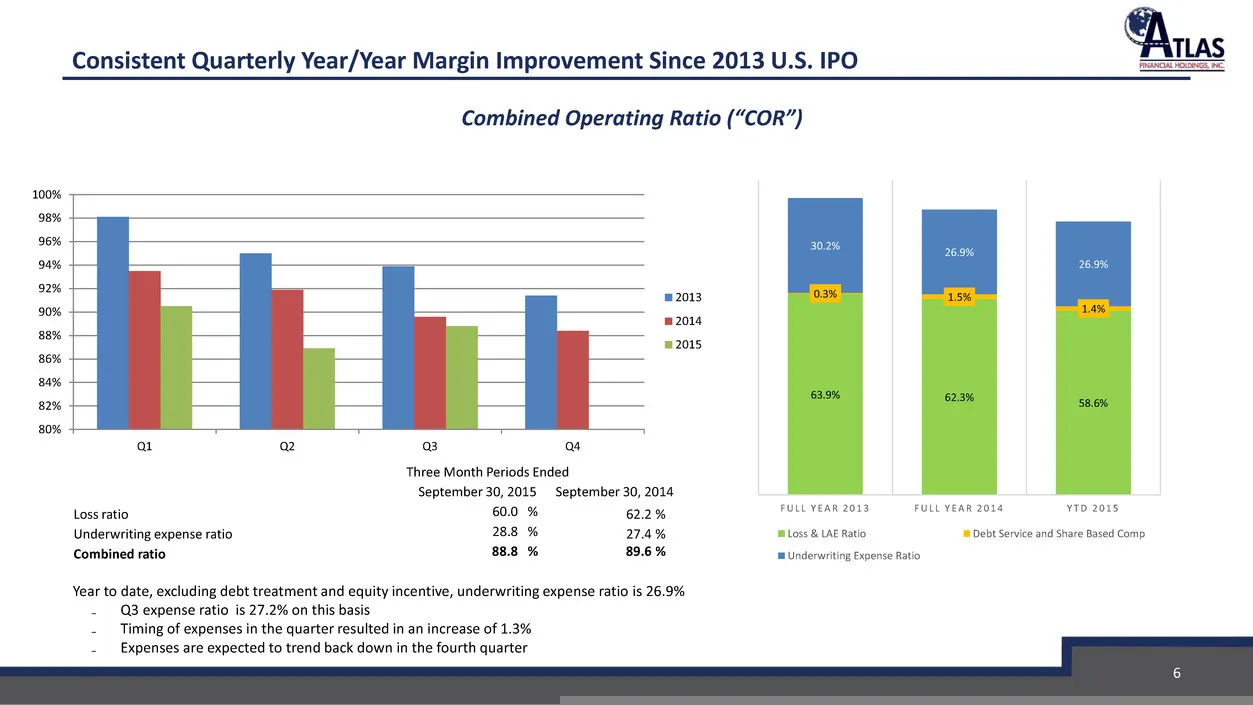
Consistent Quarterly Year/Year Margin Improvement Since 2013 U.S. IPO 6 Combined Operating Ratio (“COR”) Three Month Periods Ended September 30, 2015 September 30, 2014 Loss ratio 60.0 % 62.2 % Underwriting expense ratio 28.8 % 27.4 % Combined ratio 88.8 % 89.6 % 80% 82% 84% 86% 88% 90% 92% 94% 96%
Slide 7: Gross Written Premium: Inforce
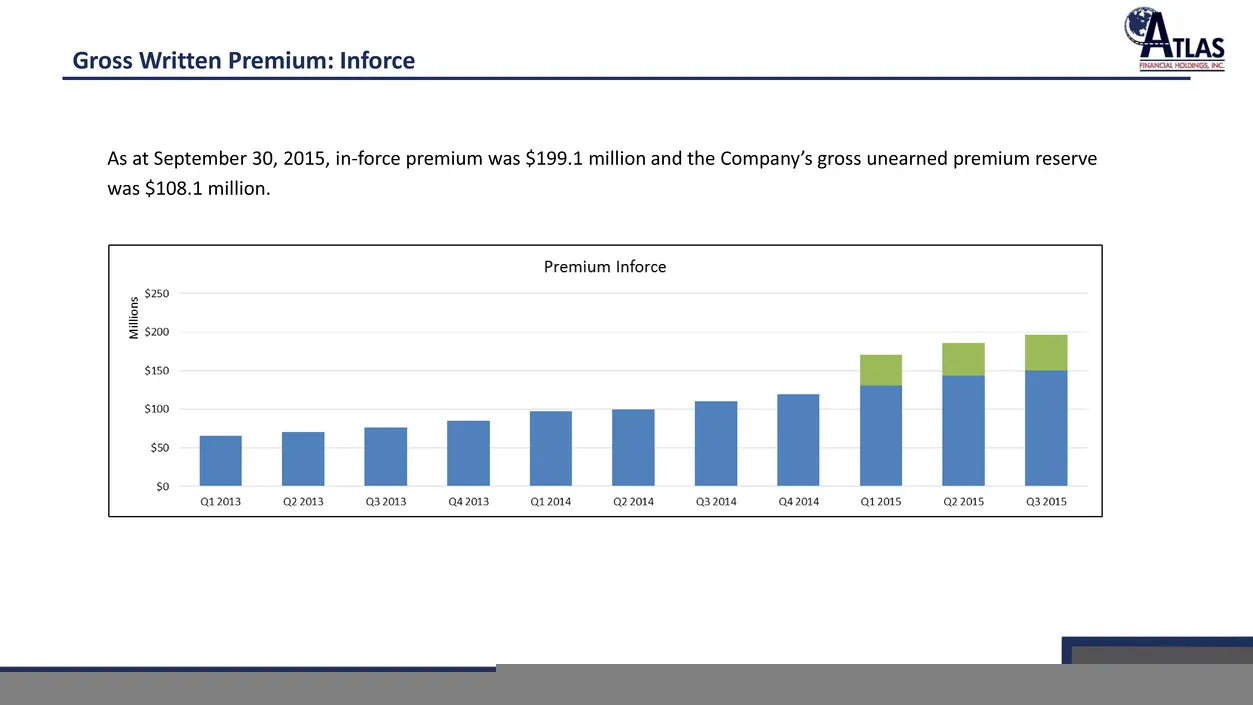
Gross Written Premium: Inforce 7 As at September 30, 2015, in-force premium was $199.1 million and the Company’s gross unearned premium reserve was $108.1 million.
Slide 8: Geographic Diversification
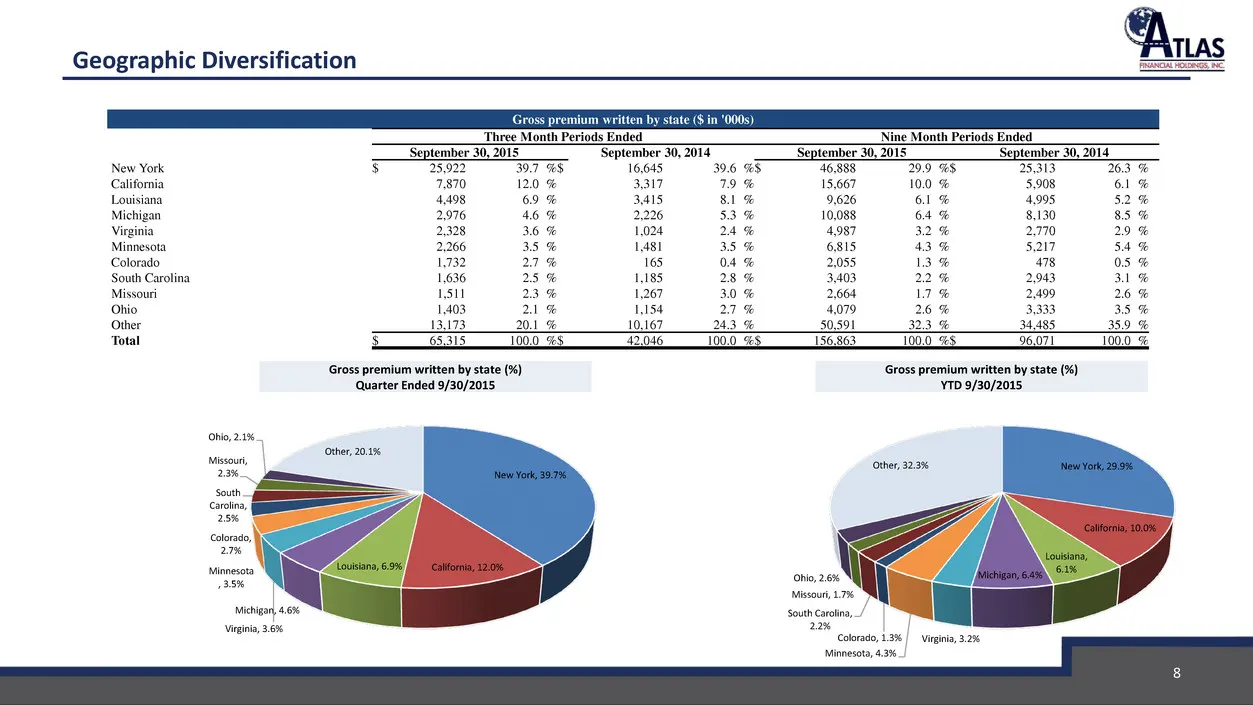
Geographic Diversification Gross premium written by state (%) Quarter Ended 9/30/2015 New York, 39.7% California, 12.0% Louisiana, 6.9% Michigan, 4.6% Virginia, 3.6% Minnesota , 3.5% Colorado, 2.7% South Carolina, 2.5% Missouri, 2.3% Ohio, 2.1% Other, 20.1% New York, 29.9% California, 10.0% Louisian
Slide 9: Operating Activities: Underwriting
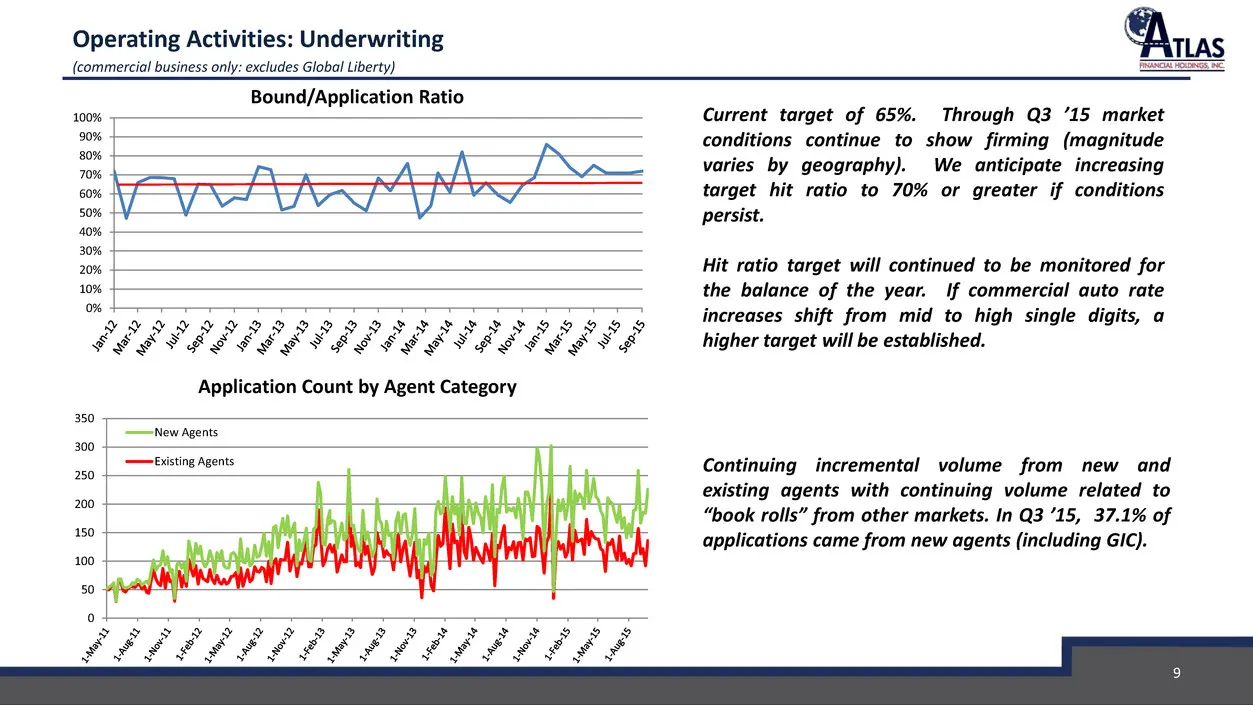
Operating Activities: Underwriting (commercial business only: excludes Global Liberty) 9 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% Current target of 65%. Through Q3 ’15 market conditions continue to show firming (magnitude varies by geography). We anticipate increasing target hit ratio to 70% or g
Slide 10: Operating Activities: Underwriting
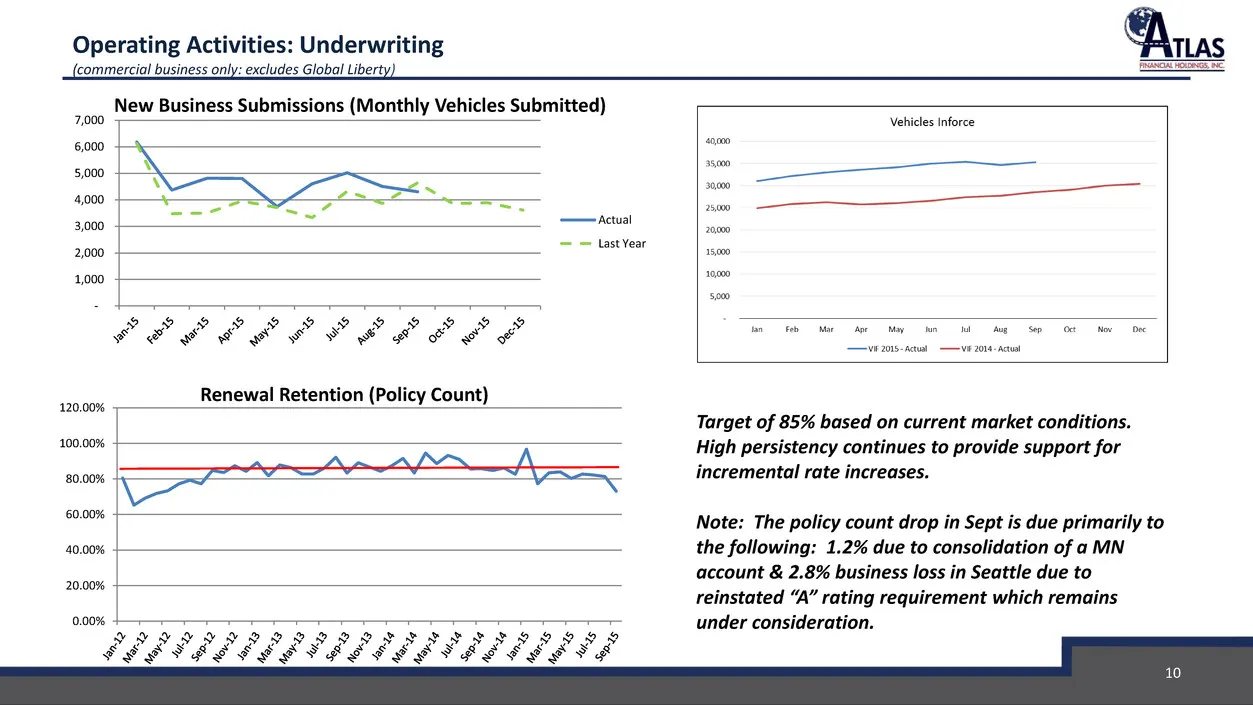
Operating Activities: Underwriting (commercial business only: excludes Global Liberty) 10 - 1,000 2,000 3,000 4,000 5,000 6,000 7,000 Actual Last Year 0.00% 20.00% 40.00% 60.00% 80.00% 100.00% 120.00% Renewal Retention (Policy Count) Target of 85% based on current market conditions. High persistency
Slide 11: NWP to Statutory Surplus Analysis
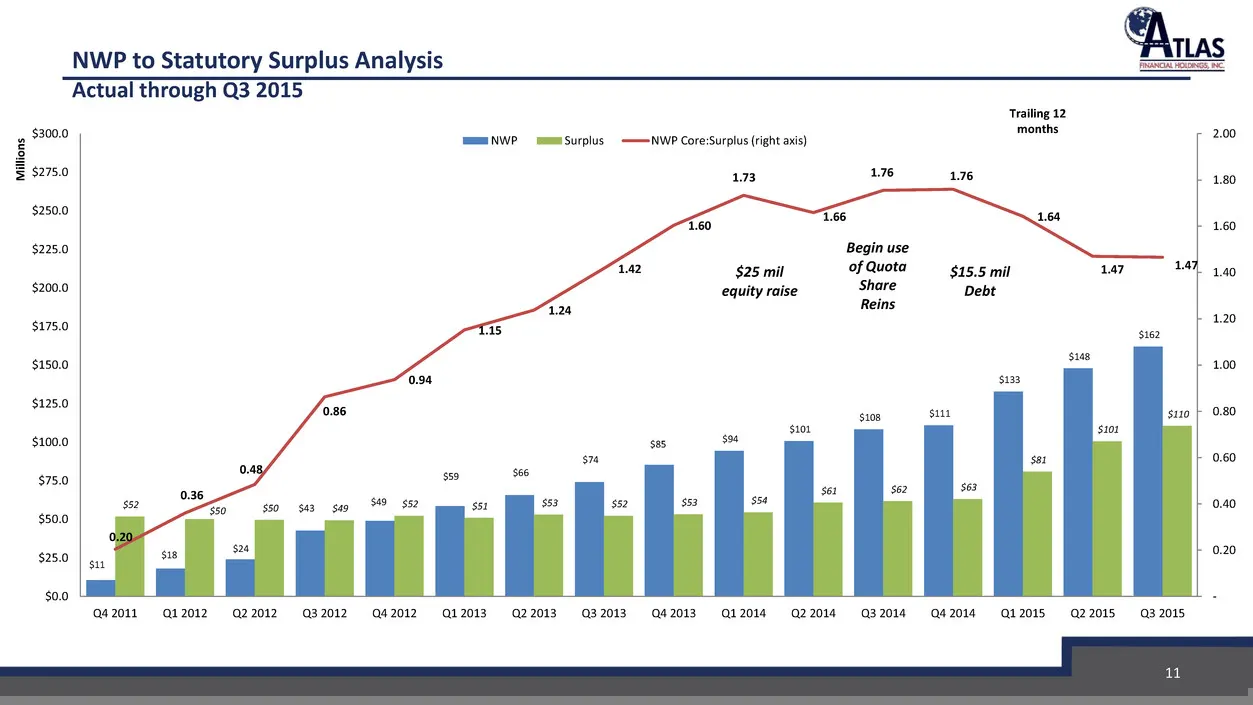
NWP to Statutory Surplus Analysis Actual through Q3 2015 $25 mil equity raise $15.5 mil Debt Begin use of Quota Share Reins Trailing 12 months 11 $11 $18 $24 $43 $49 $59 $66 $74 $85 $94 $101 $108 $111 $133 $148 $162 $52 $50 $50 $49 $52 $51 $53 $52 $53 $54 $61 $62 $63 $81 $101 $110 0.20 0.36 0.48 0.8
Slide 12: Financial Highlights
Financial Highlights Diras FINANCIAL HOLDINGS, INC. S
Slide 13: Q3 2015 Financial Highlights
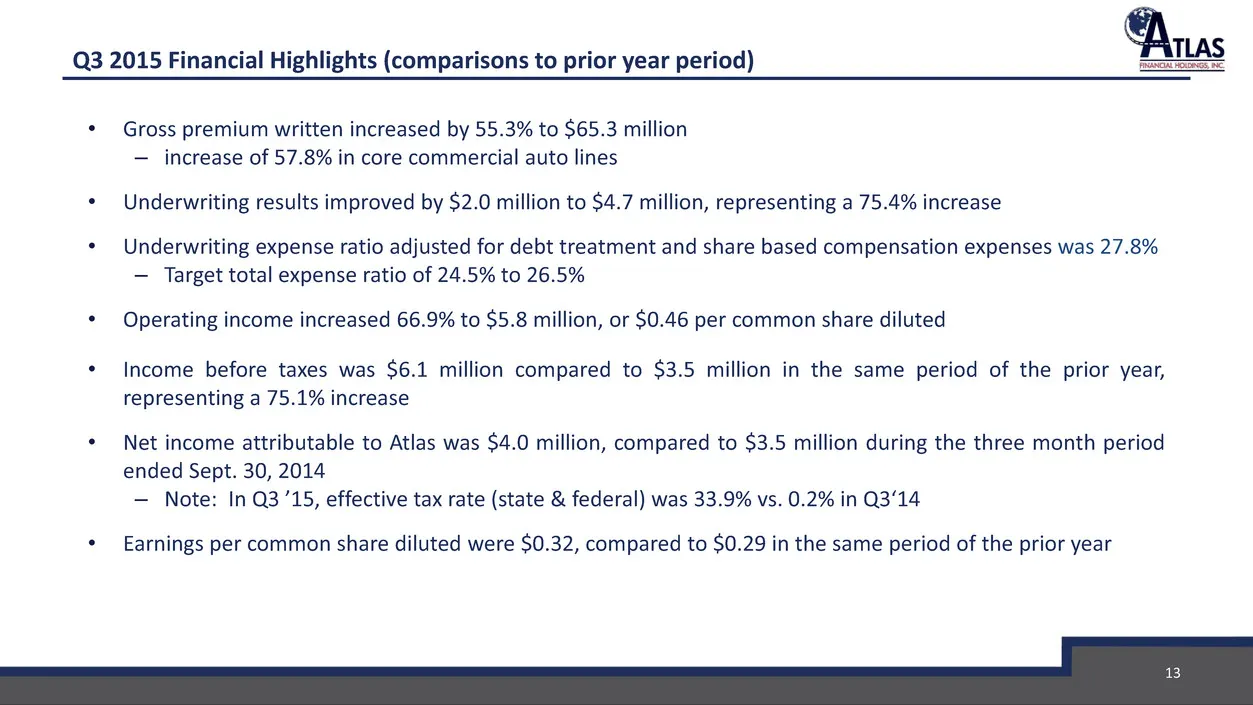
Q3 2015 Financial Highlights (comparisons to prior year period) • Gross premium written increased by 55.3% to $65.3 million – increase of 57.8% in core commercial auto lines • Underwriting results improved by $2.0 million to $4.7 million, representing a 75.4% increase • Underwriting expense ratio ad
Slide 14: 2015 Q3 Operating Income
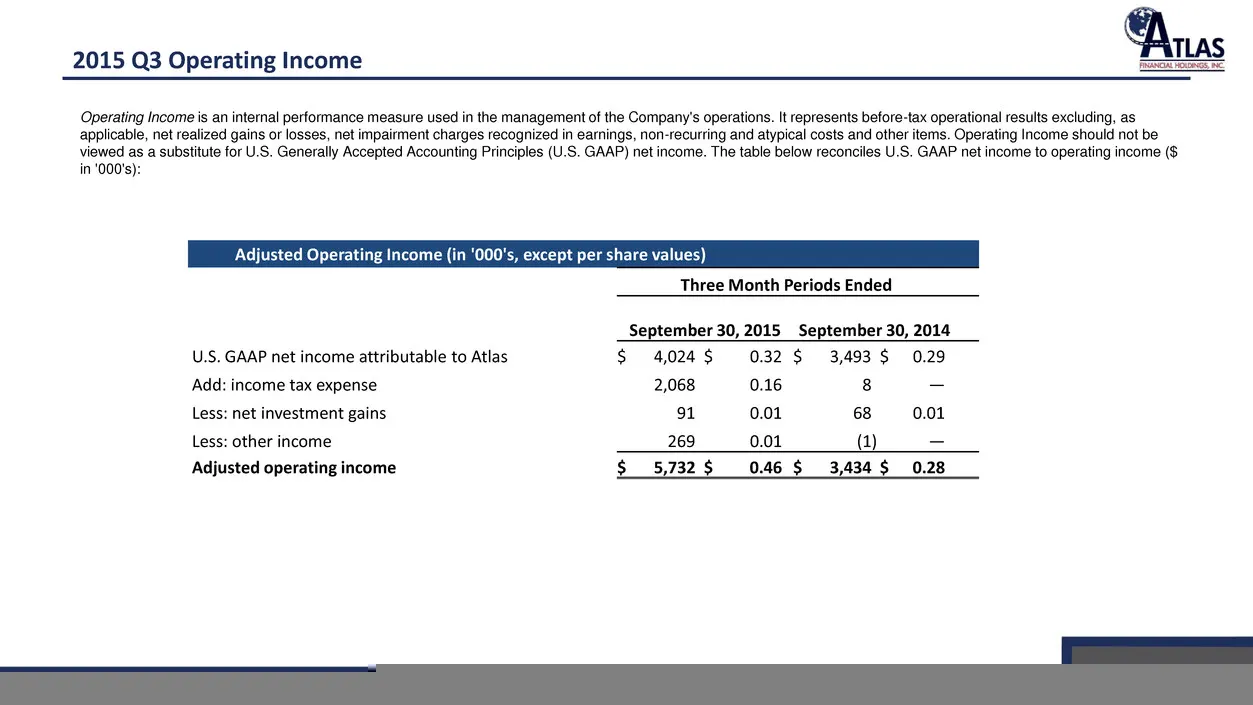
2015 Q3 Operating Income Operating Income is an internal performance measure used in the management of the Company's operations. It represents before-tax operational results excluding, as applicable, net realized gains or losses, net impairment charges recognized in earnings, non-recurring and atypi
Slide 15: Detailed Impact of Changes to Book Value per Common Share
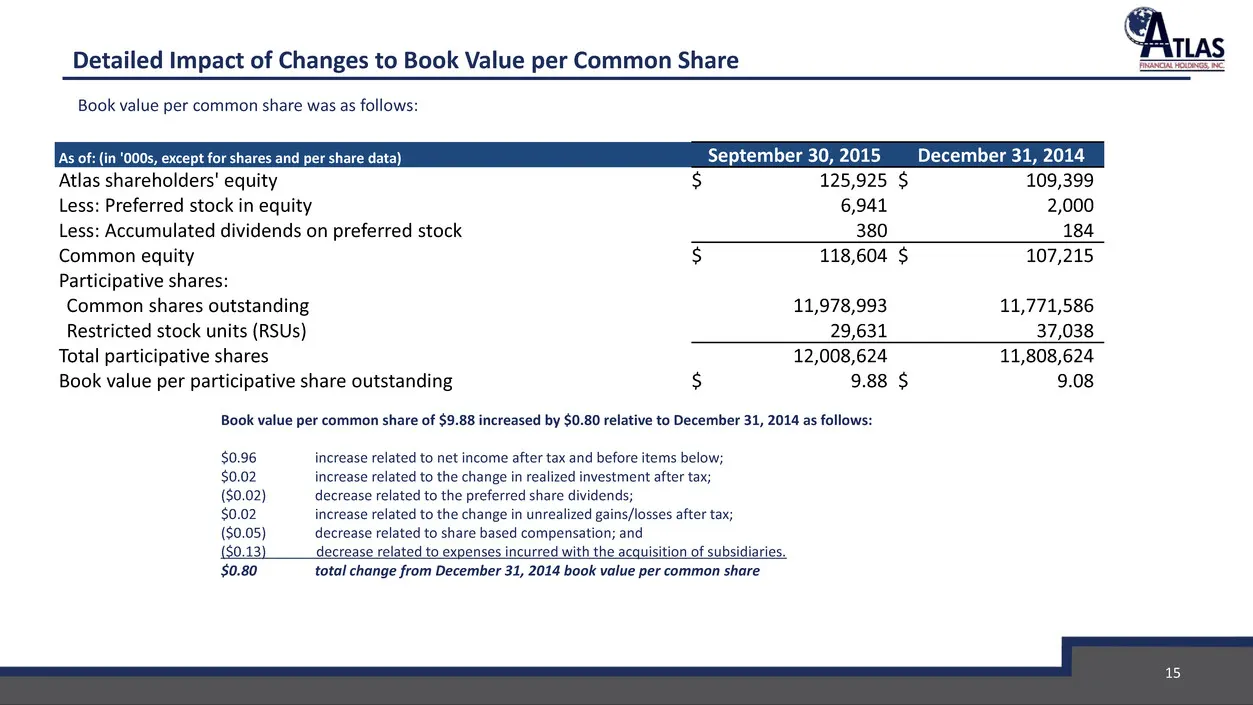
15 Detailed Impact of Changes to Book Value per Common Share Book value per common share was as follows: Book value per common share of $9.88 increased by $0.80 relative to December 31, 2014 as follows: $0.96 increase related to net income after tax and before items below; $0.02 increase related to
Slide 16: Capital and Credit Facility
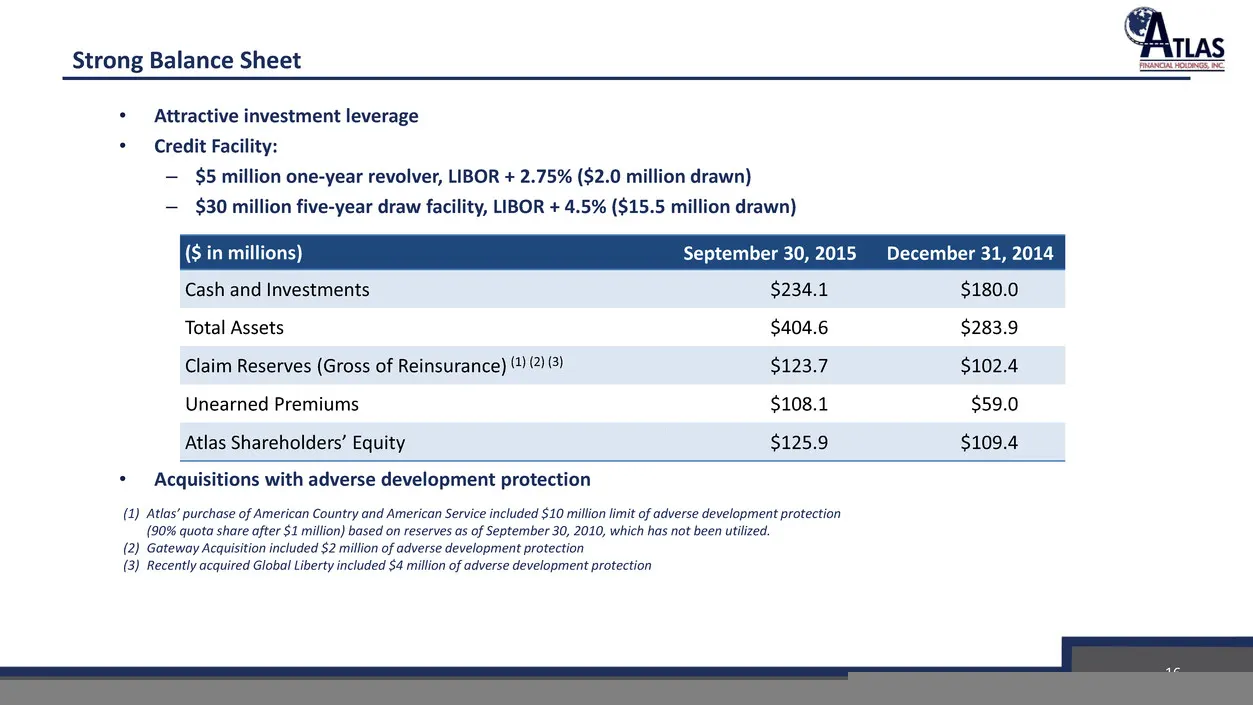
• Attractive investment leverage • Credit Facility: – $5 million one-year revolver, LIBOR + 2.75% ($2.0 million drawn) – $30 million five-year draw facility, LIBOR + 4.5% ($15.5 million drawn) • Acquisitions with adverse development protection ($ in millions) September 30, 2015 December 31, 2014 Cas
Slide 17: Investment Portfolio
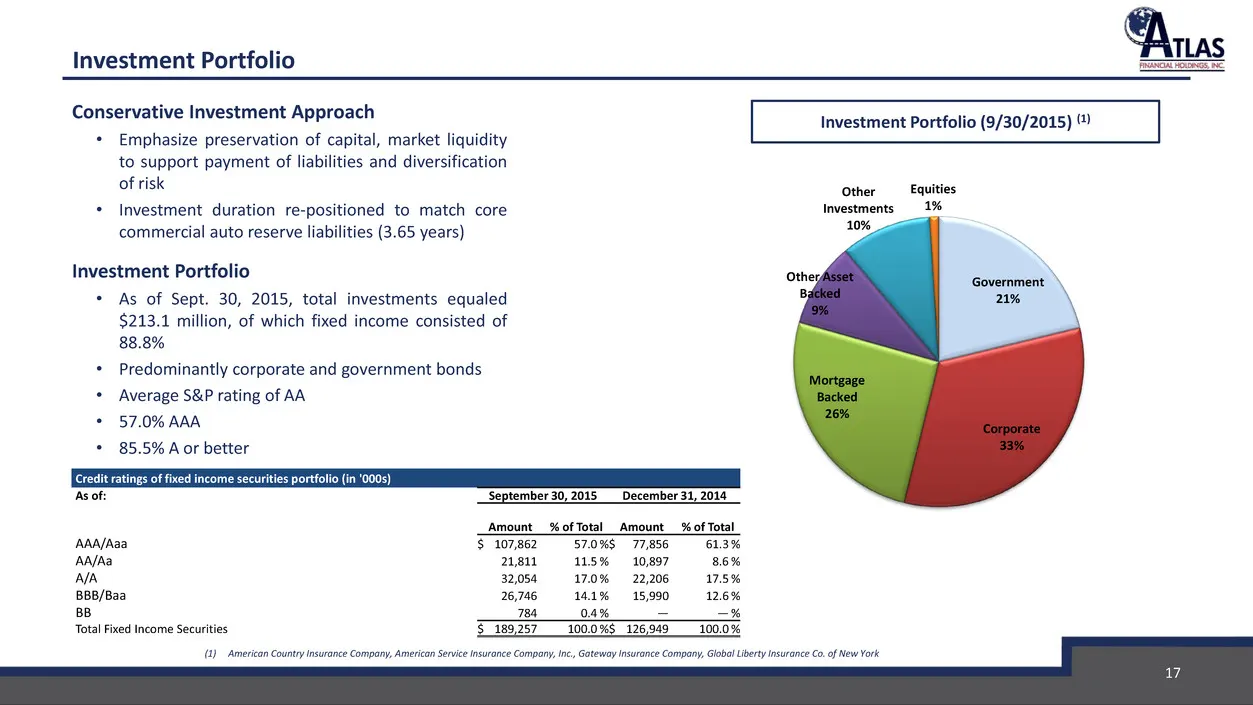
Investment Portfolio Conservative Investment Approach • Emphasize preservation of capital, market liquidity to support payment of liabilities and diversification of risk • Investment duration re-positioned to match core commercial auto reserve liabilities (3.65 years) Investment Portfolio • As of Se
Slide 18: Outlook / Market Overview
Outlook / Market Overview Diras FINANCIAL HOLDINGS, INC. S
Slide 19: Operating Activities: Market Conditions
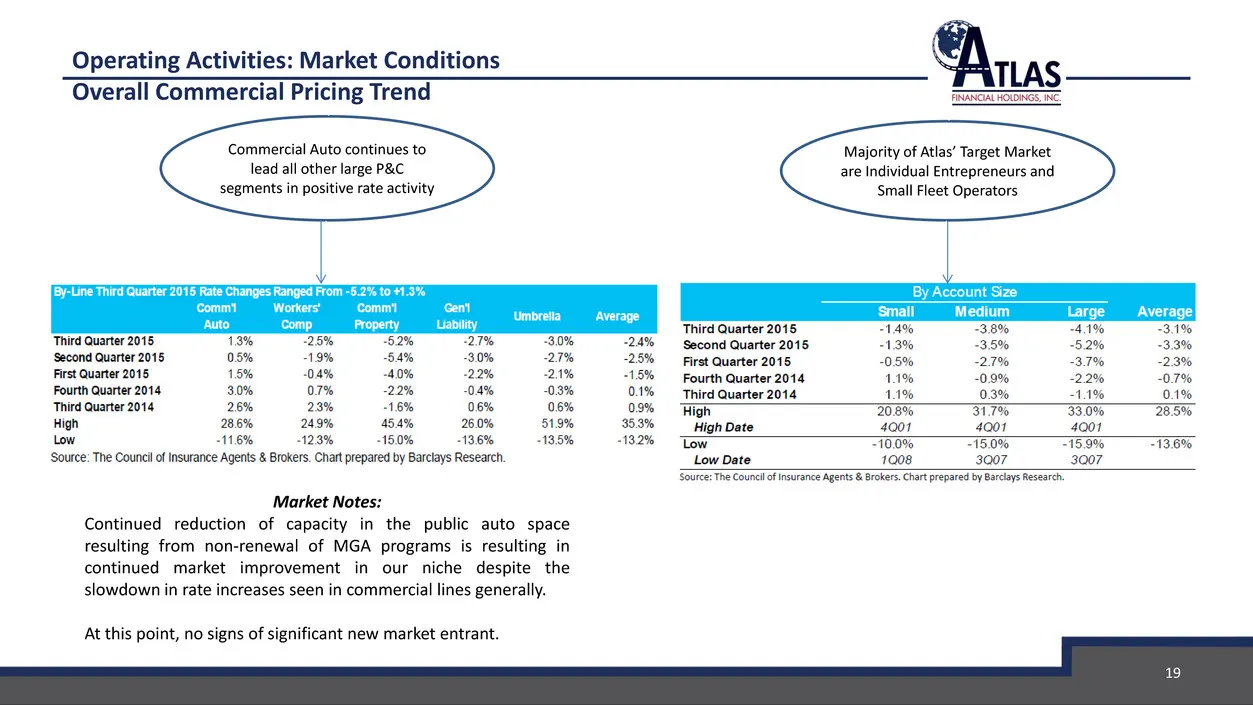
Operating Activities: Market Conditions Overall Commercial Pricing Trend Majority of Atlas’ Target Market are Individual Entrepreneurs and Small Fleet Operators Market Notes: Continued reduction of capacity in the public auto space resulting from non-renewal of MGA programs is resulting in continued
Slide 20: Impact of Pricing Progression for Atlas
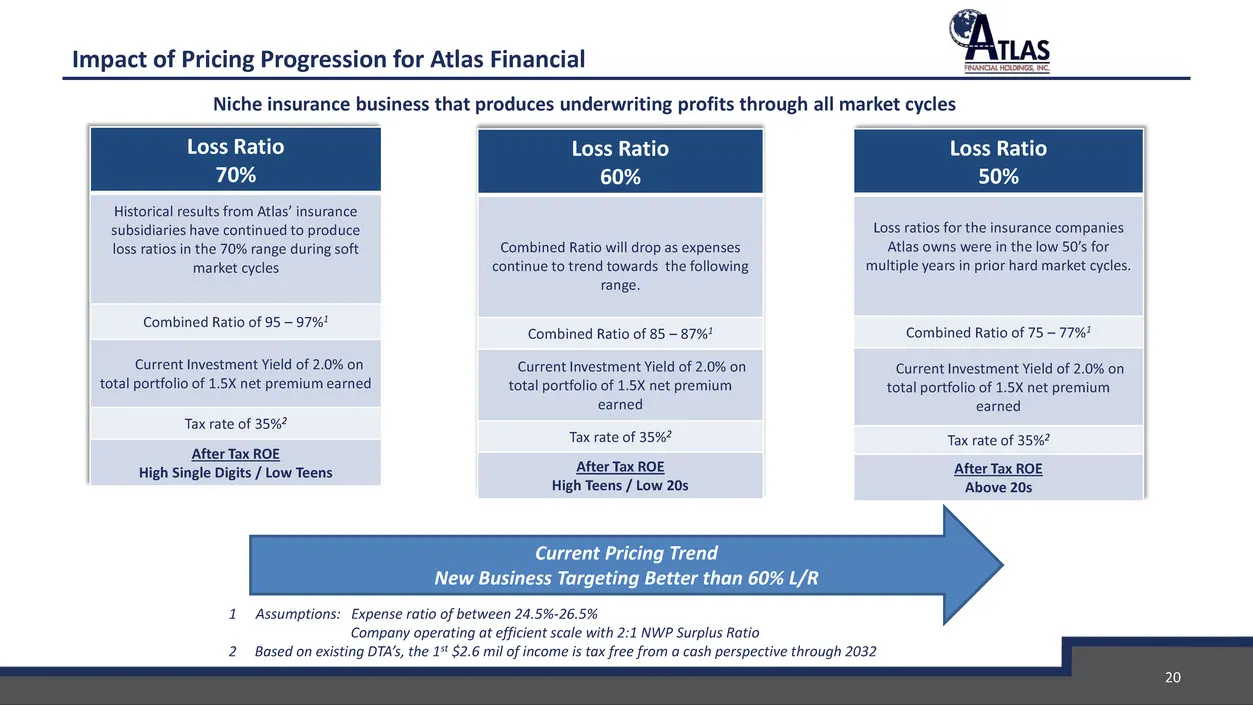
Loss Ratio 70% Historical results from Atlas’ insurance subsidiaries have continued to produce loss ratios in the 70% range during soft market cycles Combined Ratio of 95 – 97%1 Current Investment Yield of 2.0% on total portfolio of 1.5X net premium earned Tax rate of 35%2 After Tax ROE High Single
Slide 21: Concluding Remarks
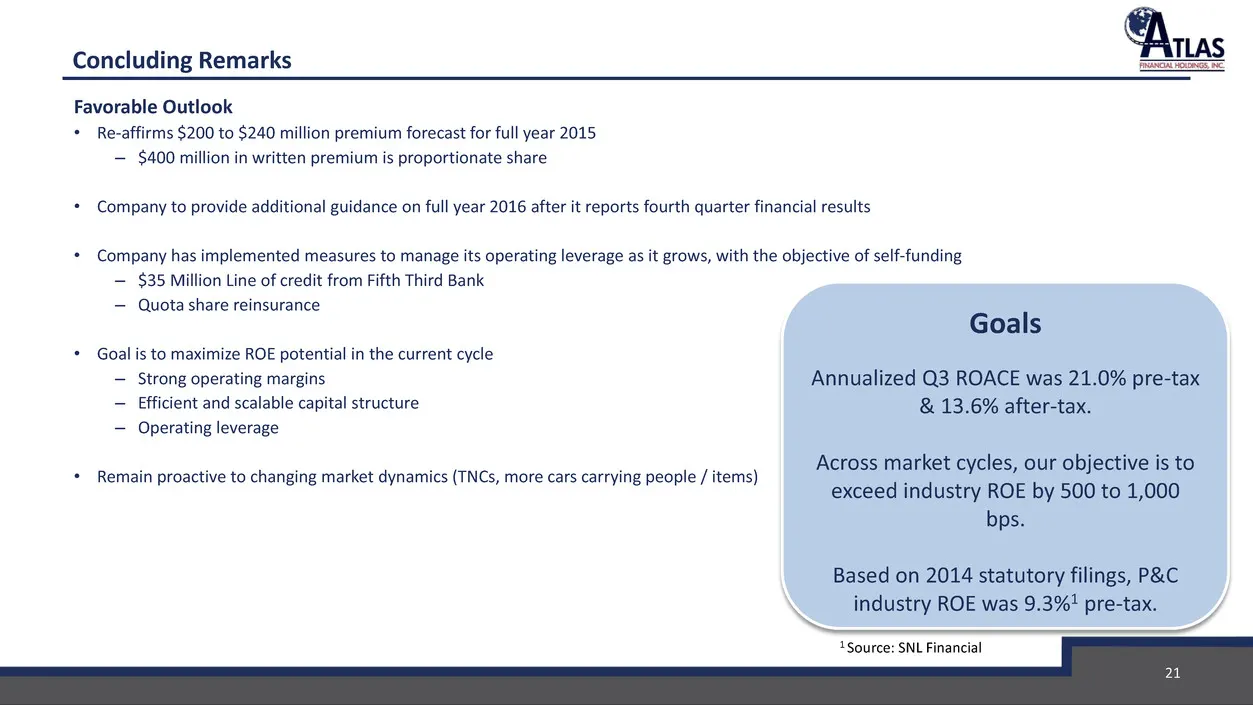
Concluding Remarks Favorable Outlook • Re-affirms $200 to $240 million premium forecast for full year 2015 – $400 million in written premium is proportionate share • Company to provide additional guidance on full year 2016 after it reports fourth quarter financial results • Company has implemented m
Slide 22: For Additional Information
Nasdaq: AFH For Additional Information At the Company: Scott Wollney Chief Executive Officer swollney@atlas-fin.com 847-700-8600 Investor Relations: The Equity Group Inc. Adam Prior Senior Vice President APrior@equityny.com 212-836-9606 Terry Downs Associate TDowns@equityny.com 212-836-9615
Source: SEC EDGAR · 8-K filed Nov 9, 2015
More decks from Atlas Financial Holdings Inc
 Investor Presentation (November 2022)20 slides · Nov 14, 2022
 Investor Presentation (August 2022)21 slides · Aug 12, 2022
 Investor Presentation (May 2022)20 slides · May 23, 2022
 Investor Presentation (April 2022)18 slides · Apr 4, 2022
 Investor Presentation (November 2021)28 slides · Nov 8, 2021
 Q2 2021 Earnings Presentation26 slides · Aug 10, 2021