Landmark Infrastructure Partners LP
Landmark Infrastructure Partners LP — NAPTP MLP Investor Conference (May 2015)
30 slides from Landmark Infrastructure Partners LP's conference presentation, May 21, 2015
Slide 1: Management Presentation NAPTP MLP Investor Conference
Management Presentation NAPTP MLP Investor Conference Tim Brazy, CEO and George Doyle, CFO May 21, 2015 Landmark Infrastructure Partners LP
Slide 2: Disclaimer
Disclaimer This presentation may contain forward-looking statements that involve risks and uncertainties. These forward-looking statements include information about possible or assumed future results of Landmark Infrastructure Partner LP’s (“LMRK” or the “Partnership”) business, future events, finan
Slide 3: Partnership Snapshot
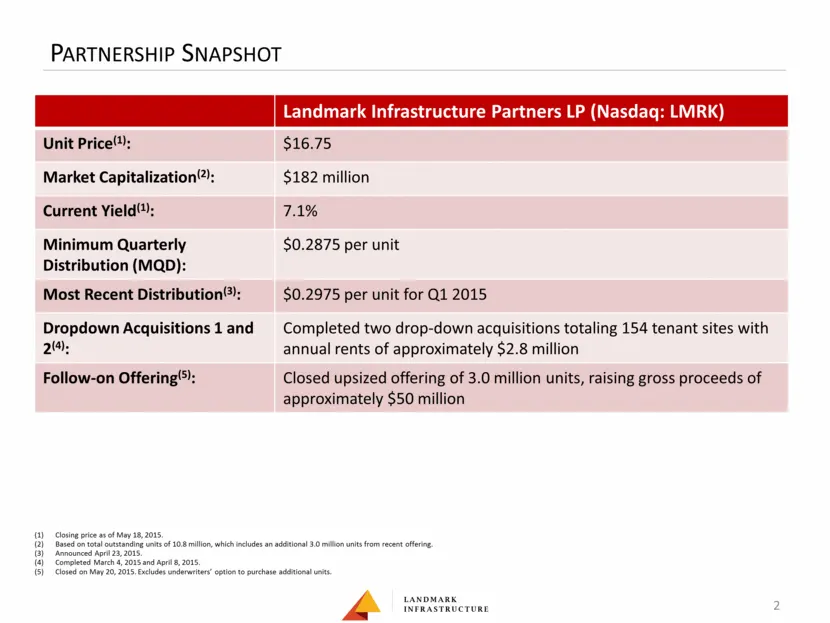
Partnership Snapshot Landmark Infrastructure Partners LP (Nasdaq: LMRK) Unit Price(1): $16.75 Market Capitalization(2): $182 million Current Yield(1): 7.1% Minimum Quarterly Distribution (MQD): $0.2875 per unit Most Recent Distribution(3): $0.2975 per unit for Q1 2015 Dropdown Acquisitions 1 and 2(4
Slide 4: Overview of Our Assets
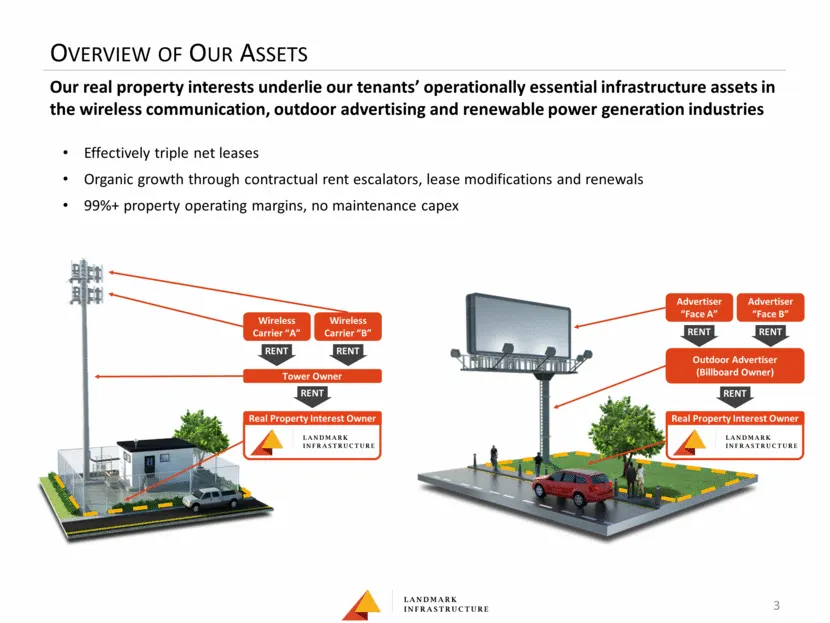
Overview of Our Assets Effectively triple net leases Organic growth through contractual rent escalators, lease modifications and renewals 99%+ property operating margins, no maintenance capex 3 Our real property interests underlie our tenants’ operationally essential infrastructure assets in the wir
Slide 5: Our Portfolio
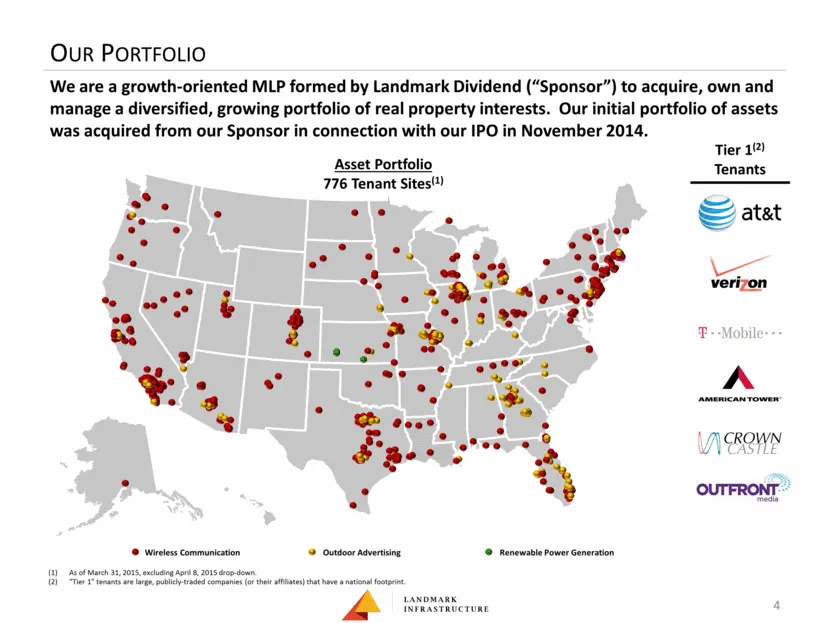
Our Portfolio 4 We are a growth-oriented MLP formed by Landmark Dividend (“Sponsor”) to acquire, own and manage a diversified, growing portfolio of real property interests. Our initial portfolio of assets was acquired from our Sponsor in connection with our IPO in November 2014. Tier 1(2) Tenants As
Slide 6: Significant, Growing and Fragmented U.S. Market Opportunity
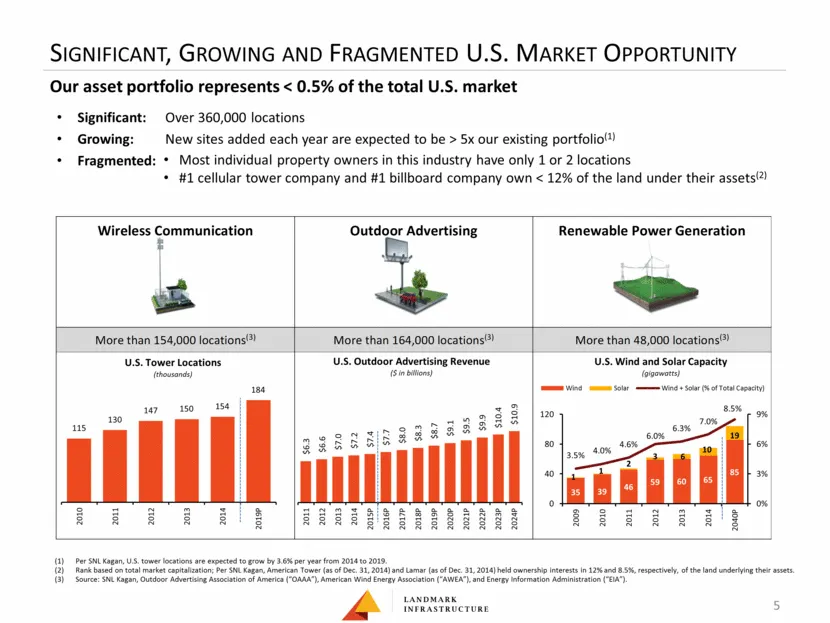
Significant, Growing and Fragmented U.S. Market Opportunity Our asset portfolio represents < 0.5% of the total U.S. market 5 Significant: Over 360,000 locations Growing: New sites added each year are expected to be > 5x our existing portfolio(1) Fragmented: Most individual property owners in this in
Slide 7: Partnership Highlights
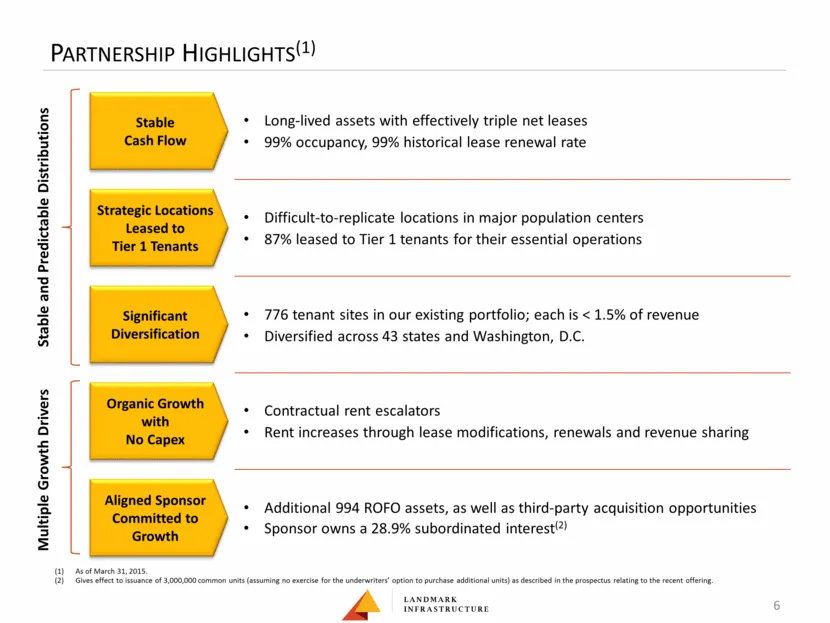
Partnership Highlights(1) Long-lived assets with effectively triple net leases 99% occupancy, 99% historical lease renewal rate Stable Cash Flow Strategic Locations Leased to Tier 1 Tenants Significant Diversification Organic Growth with No Capex Aligned Sponsor Committed to Growth Difficult-to-repl
Slide 8: Stable cash flow from long-lived assets
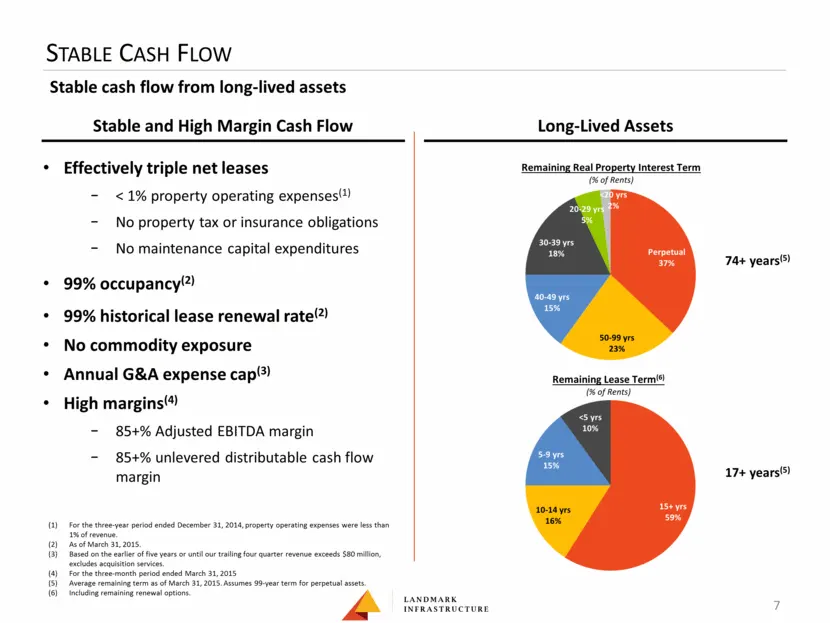
Stable cash flow from long-lived assets Stable Cash Flow Effectively triple net leases < 1% property operating expenses(1) No property tax or insurance obligations No maintenance capital expenditures 99% occupancy(2) 99% historical lease renewal rate(2) No commodity exposure Annual G&A expense cap(3
Slide 9: Strategic Locations
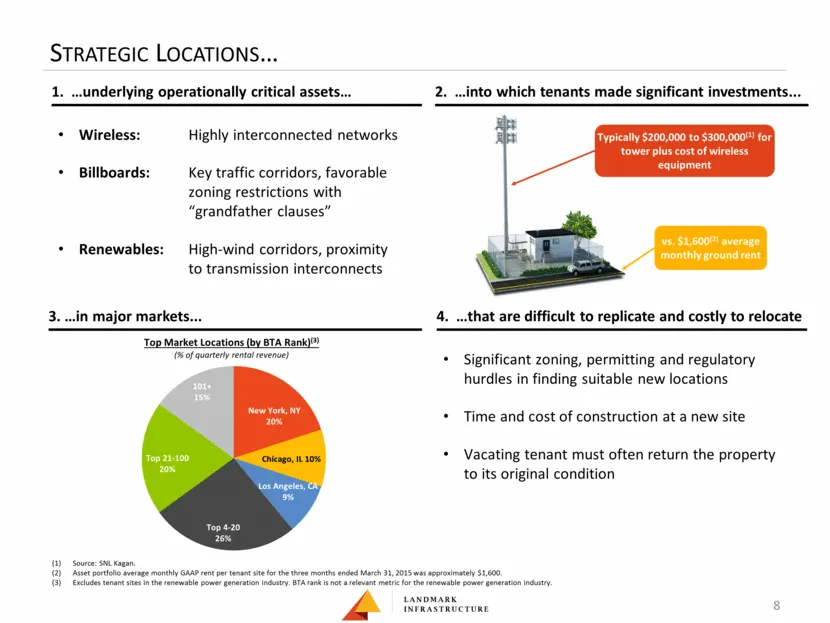
Strategic Locations 8 Source: SNL Kagan. Asset portfolio average monthly GAAP rent per tenant site for the three months ended March 31, 2015 was approximately $1,600. Excludes tenant sites in the renewable power generation industry. BTA rank is not a relevant metric for the renewable power generatio
Slide 10: Highly Desired by Tier 1 Tenants
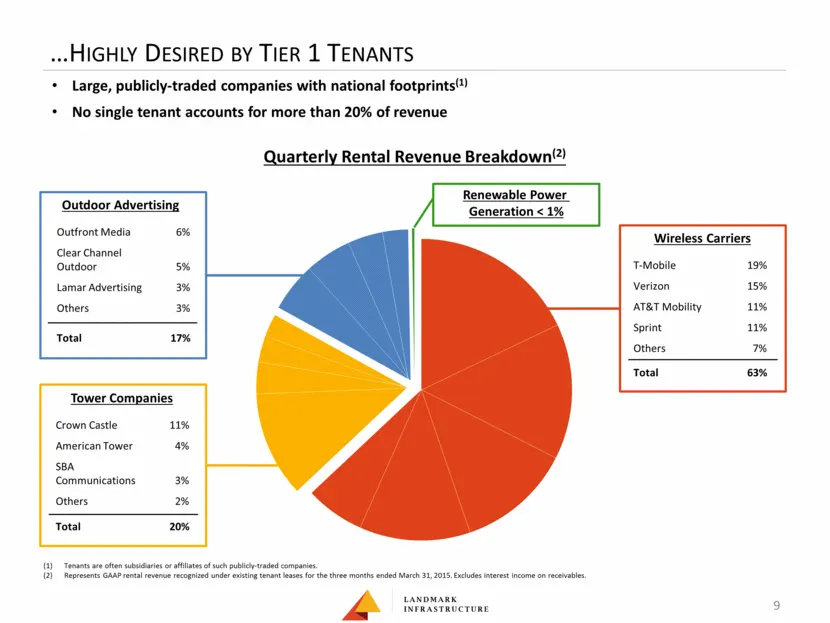
Highly Desired by Tier 1 Tenants 9 Large, publicly-traded companies with national footprints(1) No single tenant accounts for more than 20% of revenue Wireless Carriers T-Mobile 19% Verizon 15% AT&T Mobility 11% Sprint 11% Others 7% Total 63% Tower Companies Crown Castle 11% American Tower 4% SBA Co
Slide 11: Significant Diversification
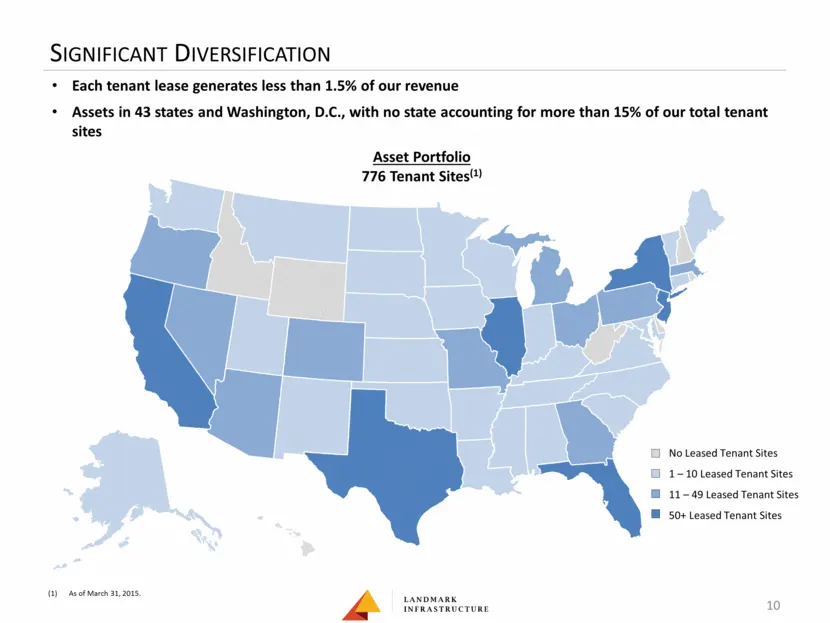
Significant Diversification No Leased Tenant Sites 1 – 10 Leased Tenant Sites 11 – 49 Leased Tenant Sites 50+ Leased Tenant Sites 10 Each tenant lease generates less than 1.5% of our revenue Assets in 43 states and Washington, D.C., with no state accounting for more than 15% of our total tenant site
Slide 12: Multiple Growth Drivers
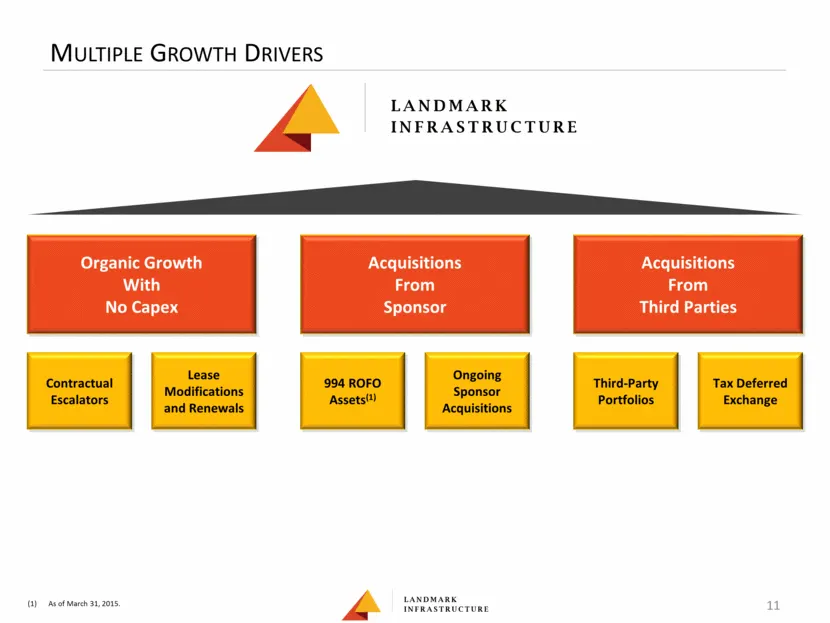
Multiple Growth Drivers 11 Organic Growth With No Capex Acquisitions From Sponsor Acquisitions From Third Parties Contractual Escalators Lease Modifications and Renewals 994 ROFO Assets(1) Ongoing Sponsor Acquisitions Third-Party Portfolios Tax Deferred Exchange As of March 31, 2015.
Slide 13: Organic Growth with No Capital Expenditures
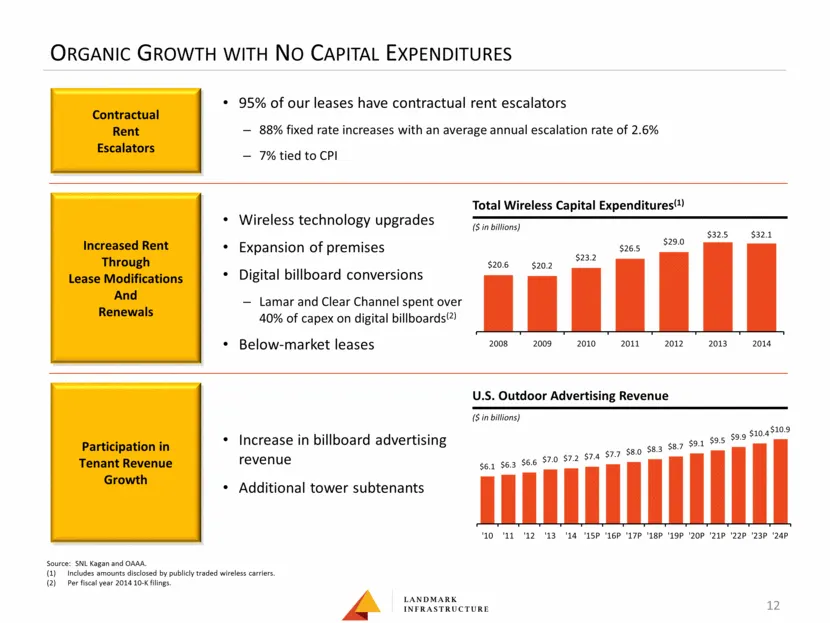
Organic Growth with No Capital Expenditures Wireless technology upgrades Expansion of premises Digital billboard conversions Lamar and Clear Channel spent over 40% of capex on digital billboards(2) Below-market leases ($ in billions) Total Wireless Capital Expenditures(1) Source: SNL Kagan and OAAA.
Slide 14: Right of First Offer Assets
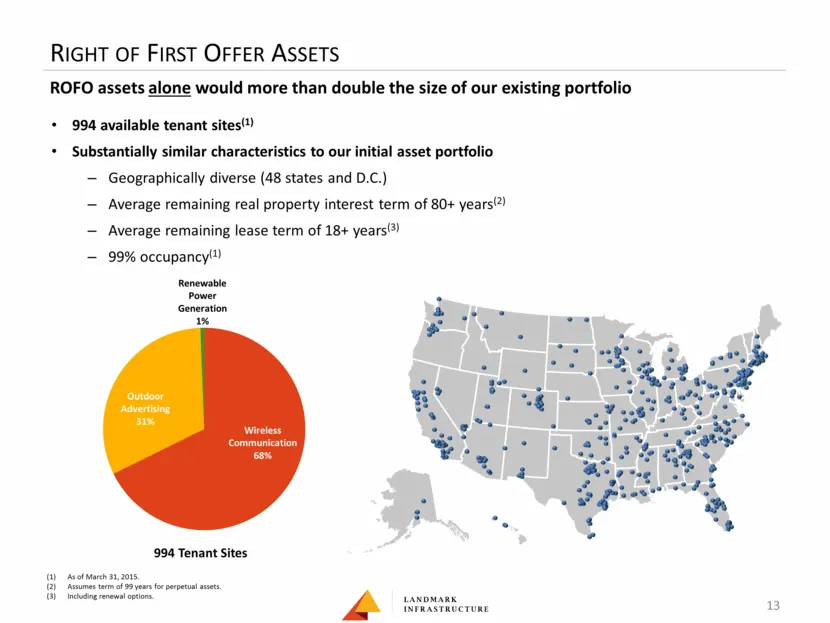
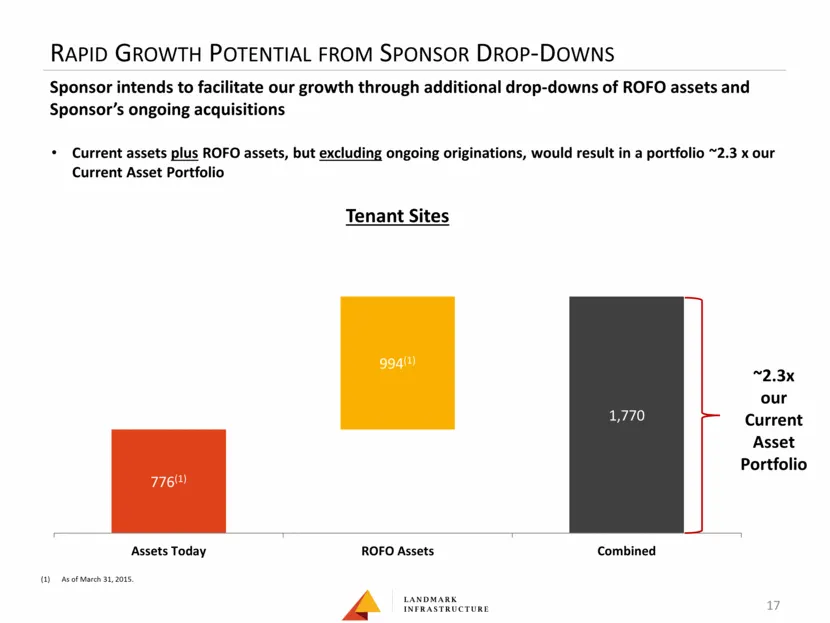
Right of First Offer Assets 13 ROFO assets alone would more than double the size of our existing portfolio 994 available tenant sites(1) Substantially similar characteristics to our initial asset portfolio Geographically diverse (48 states and D.C.) Average remaining real property interest term of 8
Slide 15: Significant, Growing and Fragmented U.S. Market Opportunity
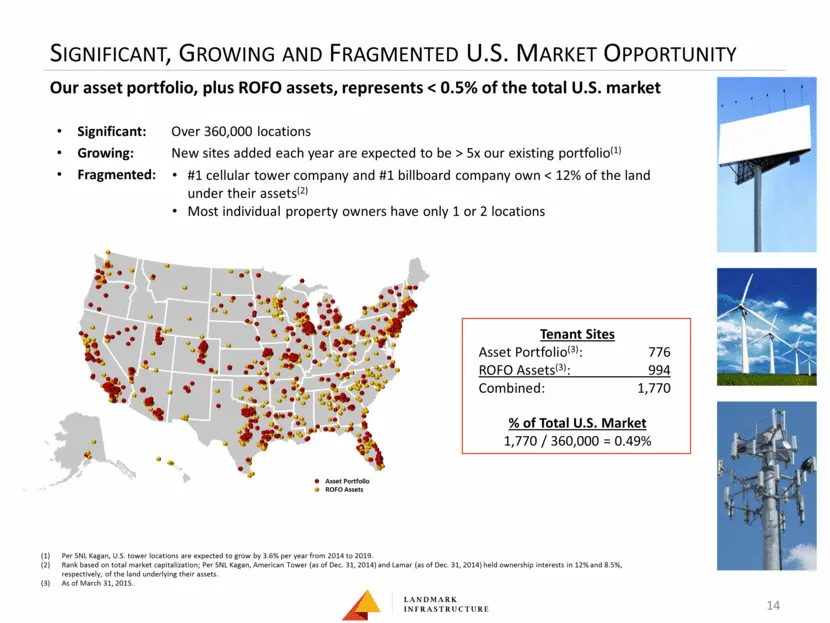
Significant, Growing and Fragmented U.S. Market Opportunity Our asset portfolio, plus ROFO assets, represents < 0.5% of the total U.S. market 14 Tenant Sites Asset Portfolio(3): 776 ROFO Assets(3): 994 Combined: 1,770 % of Total U.S. Market 1,770 / 360,000 = 0.49% Per SNL Kagan, U.S. tower locations
Slide 16: Aligned Sponsor Driving Growth
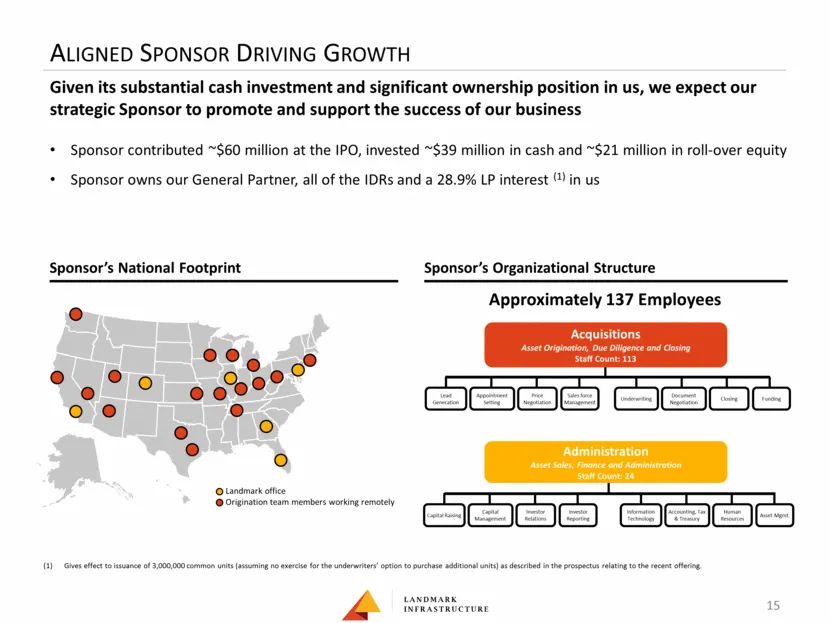
Aligned Sponsor Driving Growth Sponsor contributed ~$60 million at the IPO, invested ~$39 million in cash and ~$21 million in roll-over equity Sponsor owns our General Partner, all of the IDRs and a 28.9% LP interest (1) in us Landmark office Origination team members working remotely Lead Generation
Slide 17: Sponsor Expertise in an Industry with High Barriers of Entry
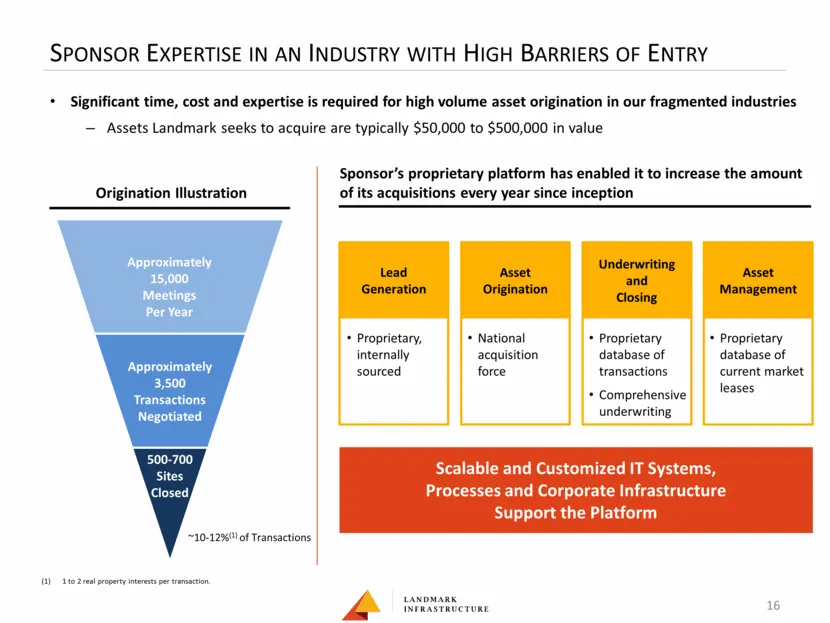
Sponsor Expertise in an Industry with High Barriers of Entry Approximately 15,000 Meetings Per Year Approximately 3,500 Transactions Negotiated 500-700 Sites Closed 16 ~10-12%(1) of Transactions 1 to 2 real property interests per transaction. Significant time, cost and expertise is required for high
Slide 18: Rapid Growth Potential from Sponsor Drop-Downs
Rapid Growth Potential from Sponsor Drop-Downs 17 Sponsor intends to facilitate our growth through additional drop-downs of ROFO assets and Sponsor’s ongoing acquisitions ~2.3x our Current Asset Portfolio Current assets plus ROFO assets, but excluding ongoing originations, would result in a portfoli
Slide 19: Drop-Down Highlights
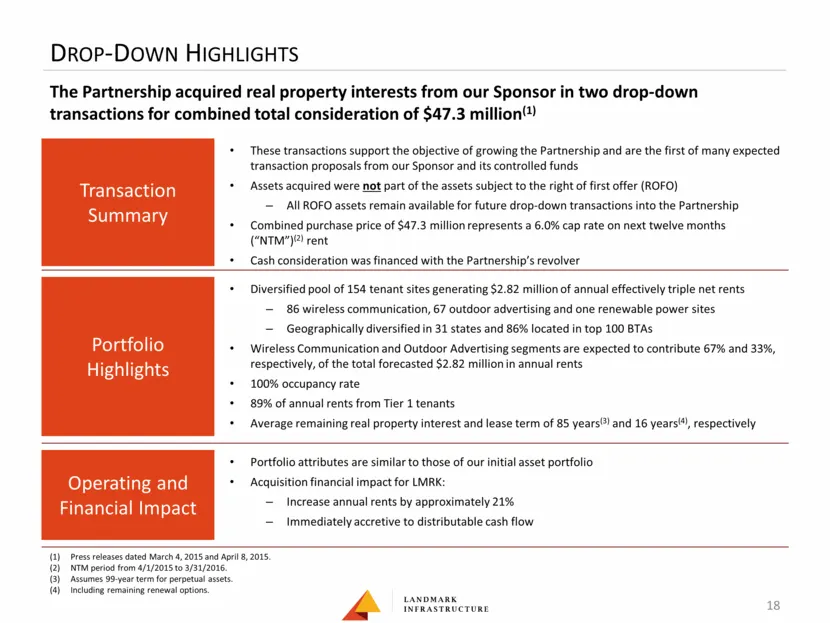
The Partnership acquired real property interests from our Sponsor in two drop-down transactions for combined total consideration of $47.3 million(1) Drop-Down Highlights 18 Transaction Summary Portfolio Highlights Operating and Financial Impact These transactions support the objective of growing the
Slide 20: Third-Party Acquisitions
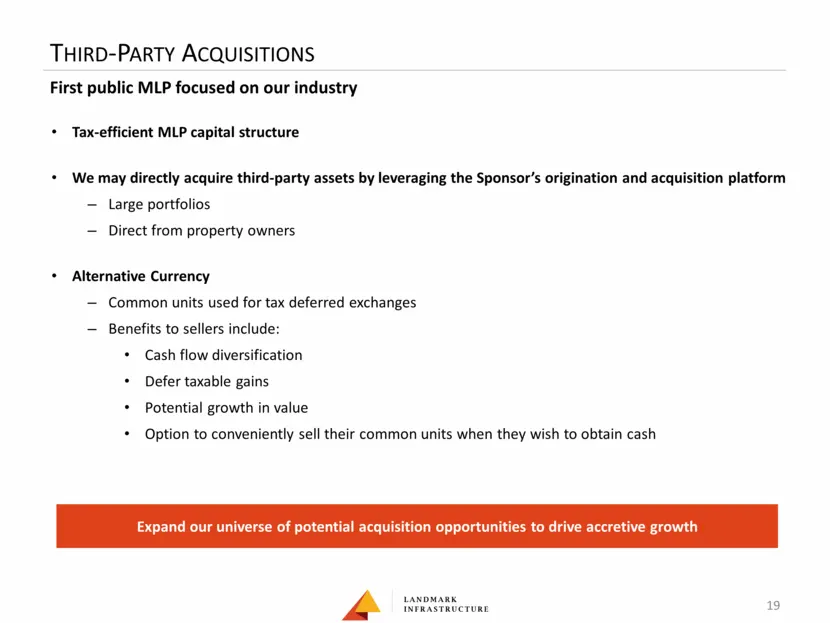
Third-Party Acquisitions 19 First public MLP focused on our industry Tax-efficient MLP capital structure We may directly acquire third-party assets by leveraging the Sponsor’s origination and acquisition platform Large portfolios Direct from property owners Alternative Currency Common units used for
Slide 21: Multiple Drivers of Distribution Growth
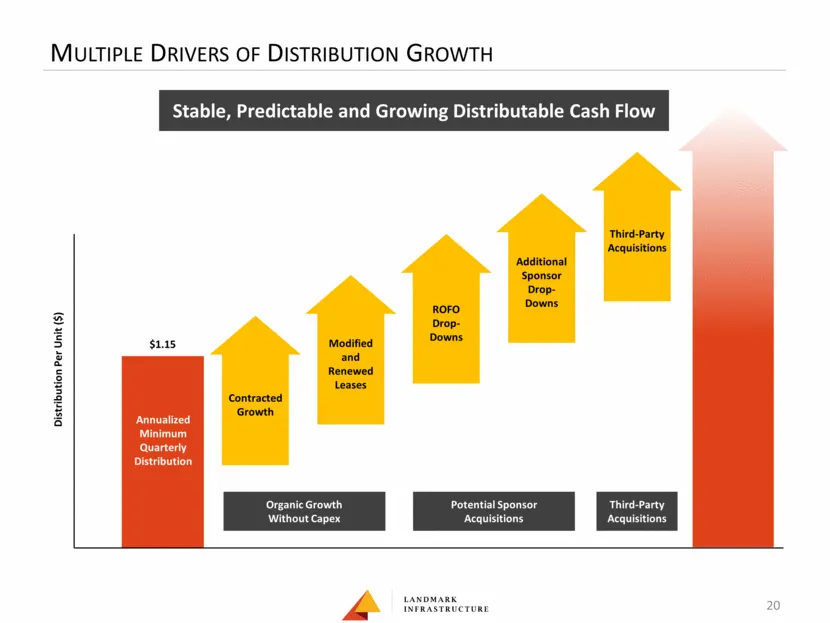
Multiple Drivers of Distribution Growth 20 Contracted Growth Modified and Renewed Leases ROFO Drop- Downs Additional Sponsor Drop-Downs Third-Party Acquisitions Distribution Per Unit ($) Stable, Predictable and Growing Distributable Cash Flow Organic Growth Without Capex Potential Sponsor Acquisitio
Slide 22: Financial Overview
21 Financial Overview
Slide 23: Financial strategy: stable cash flows and distribution growth
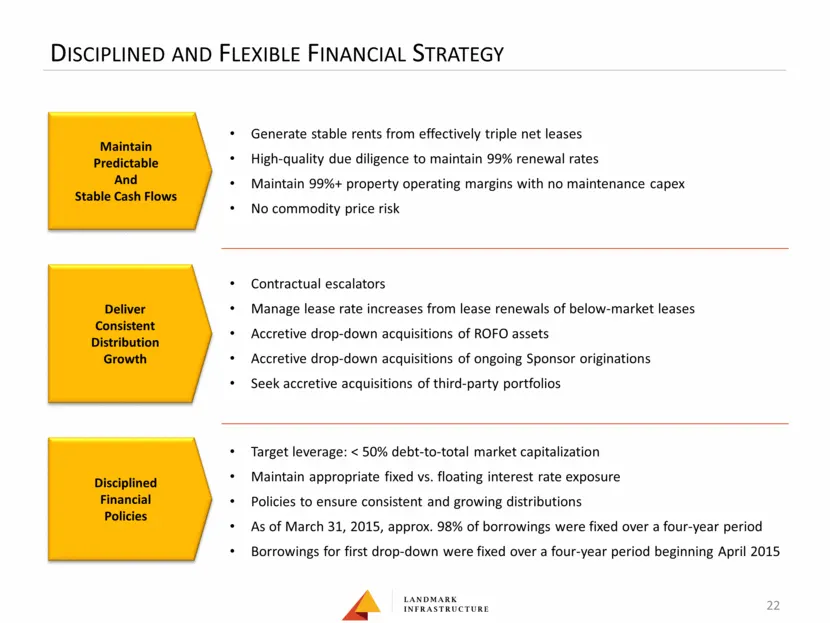
Generate stable rents from effectively triple net leases High-quality due diligence to maintain 99% renewal rates Maintain 99%+ property operating margins with no maintenance capex No commodity price risk Maintain Predictable And Stable Cash Flows Contractual escalators Manage lease rate increases f
Slide 24: Summary of Recent Follow-on Offering
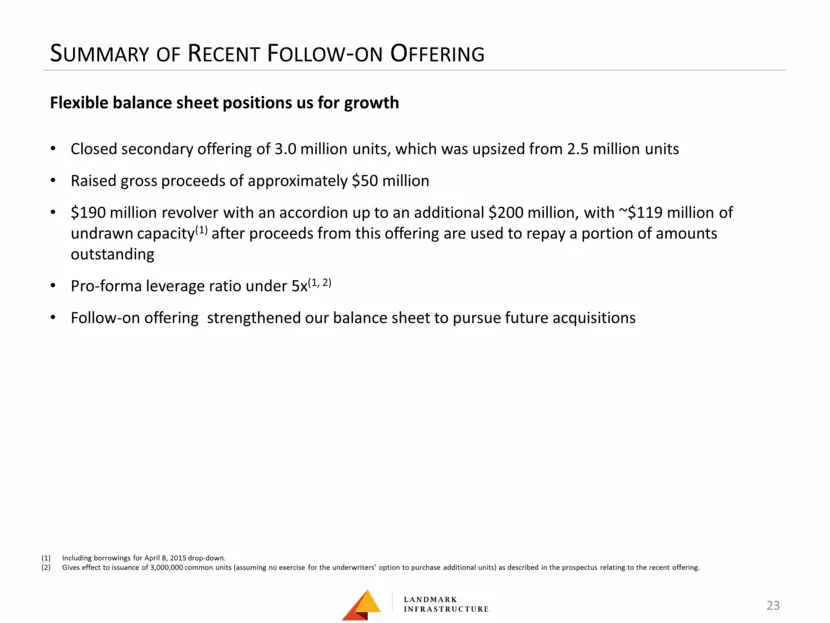
Summary of Recent Follow-on Offering Closed secondary offering of 3.0 million units, which was upsized from 2.5 million units Raised gross proceeds of approximately $50 million $190 million revolver with an accordion up to an additional $200 million, with ~$119 million of undrawn capacity(1) after p
Slide 25: Keys to Our Success
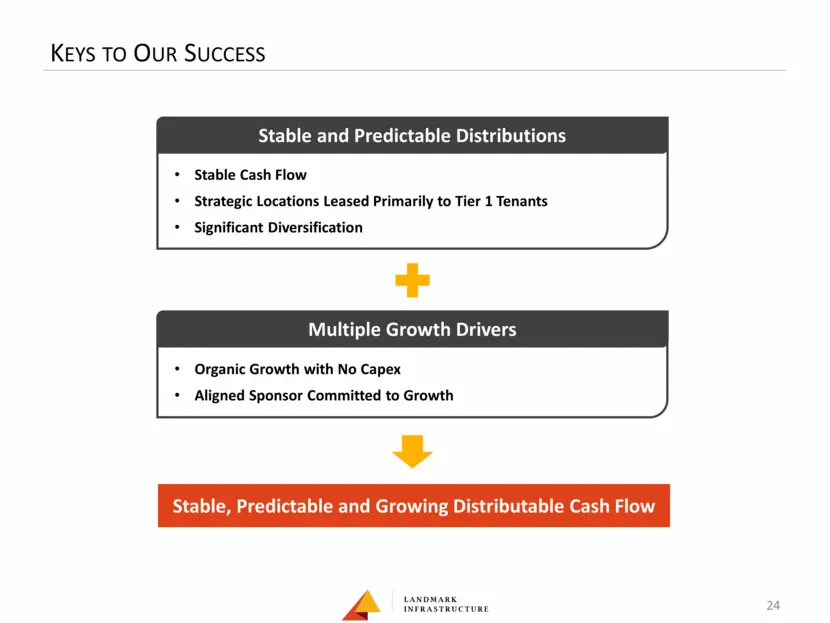
Keys to Our Success 24 Stable, Predictable and Growing Distributable Cash Flow Stable and Predictable Distributions Multiple Growth Drivers Organic Growth with No Capex Aligned Sponsor Committed to Growth Stable Cash Flow Strategic Locations Leased Primarily to Tier 1 Tenants Significant Diversifica
Slide 26: Appendix
25 APPENDIX
Slide 27: Non-GAAP Financial Measures
Non-GAAP Financial Measures We define EBITDA as net income before interest, income taxes, depreciation and amortization, and we define Adjusted EBITDA as EBITDA before impairments, acquisition related costs, unrealized and realized gain or loss on derivatives, loss on extinguishment of debt, unit-ba
Slide 28: EBITDA, Adjusted EBITDA and Distributable Cash Flow
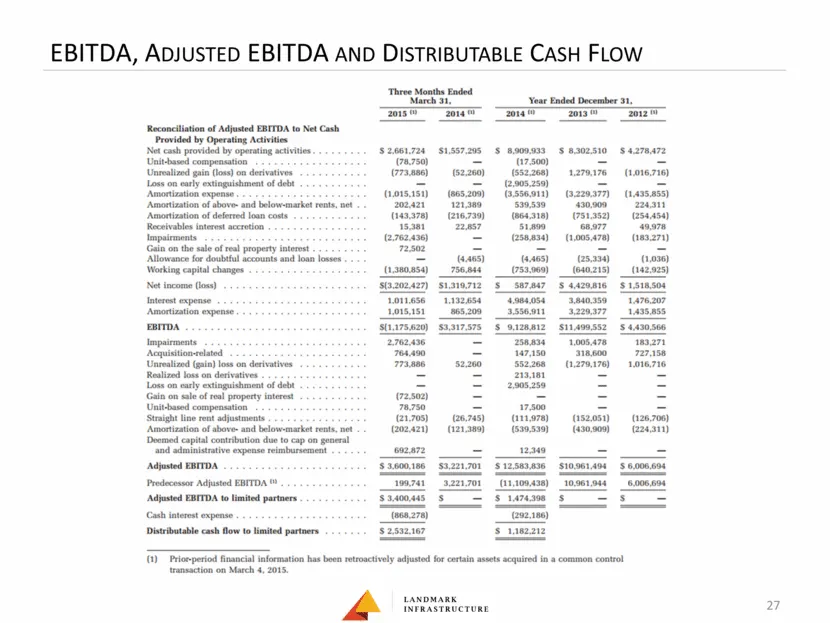
EBITDA, Adjusted EBITDA and Distributable Cash Flow 27
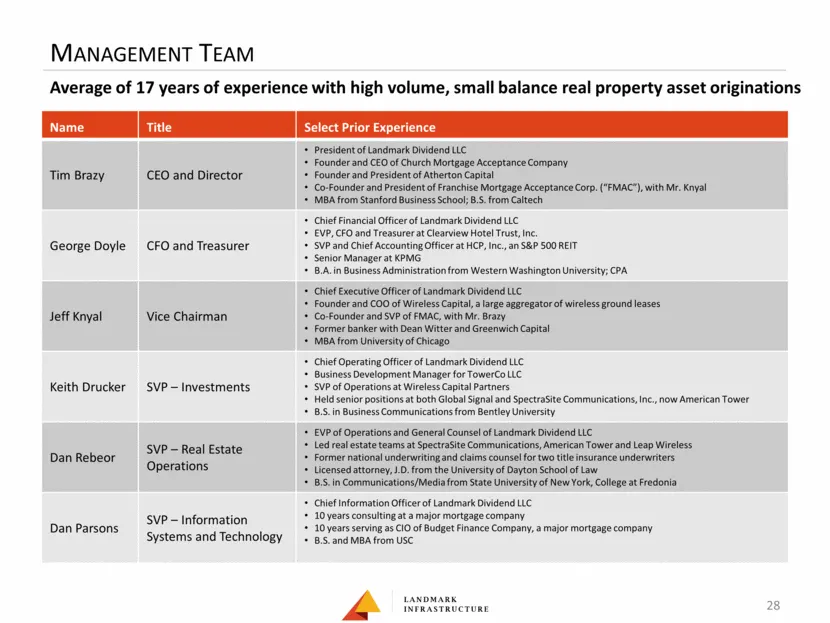
Slide 29: Management Team
Management Team 28 Average of 17 years of experience with high volume, small balance real property asset originations Name Title Select Prior Experience Tim Brazy CEO and Director President of Landmark Dividend LLC Founder and CEO of Church Mortgage Acceptance Company Founder and President of Athert
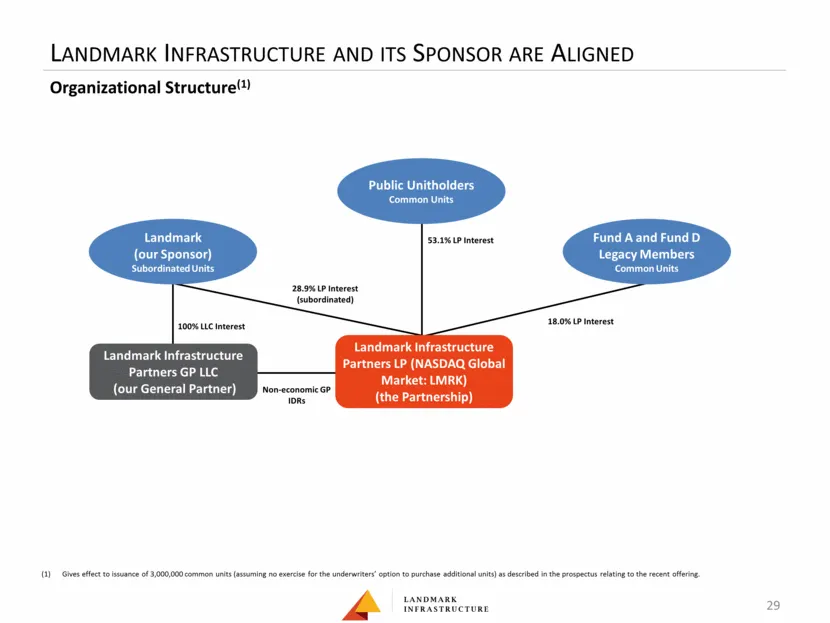
Slide 30: Landmark Infrastructure and its Sponsor are Aligned
Landmark Infrastructure and its Sponsor are Aligned 29 Organizational Structure(1) 28.9% LP Interest (subordinated) 53.1% LP Interest Landmark Infrastructure Partners LP (NASDAQ Global Market: LMRK) (the Partnership) 100% LLC Interest 18.0% LP Interest Landmark Infrastructure Partners GP LLC (our Ge
Source: SEC EDGAR · 8-K filed May 21, 2015
More decks from Landmark Infrastructure Partners LP
 Investor Presentation (December 2020)28 slides · Dec 9, 2020
 Investor Presentation (June 2020)28 slides · Jun 2, 2020
 Investor Presentation (March 2020)28 slides · Mar 11, 2020
 Investor Presentation (November 2019)28 slides · Nov 12, 2019
 Investor Presentation (September 2019)28 slides · Sep 4, 2019
 Investor Presentation (May 2019)28 slides · May 14, 2019