Capita plc · LSE:CPI
Capita — H1 2012 Earnings Presentation
47 slides from Capita's earnings presentation, Jul 25, 2012
Slide 1: Results for the 6 months ended 30 June 2012
R Results l ffor the h 6 months h ended d d 30 JJune 2012 Capita plc Wednesdayy 25 Julyy 2012
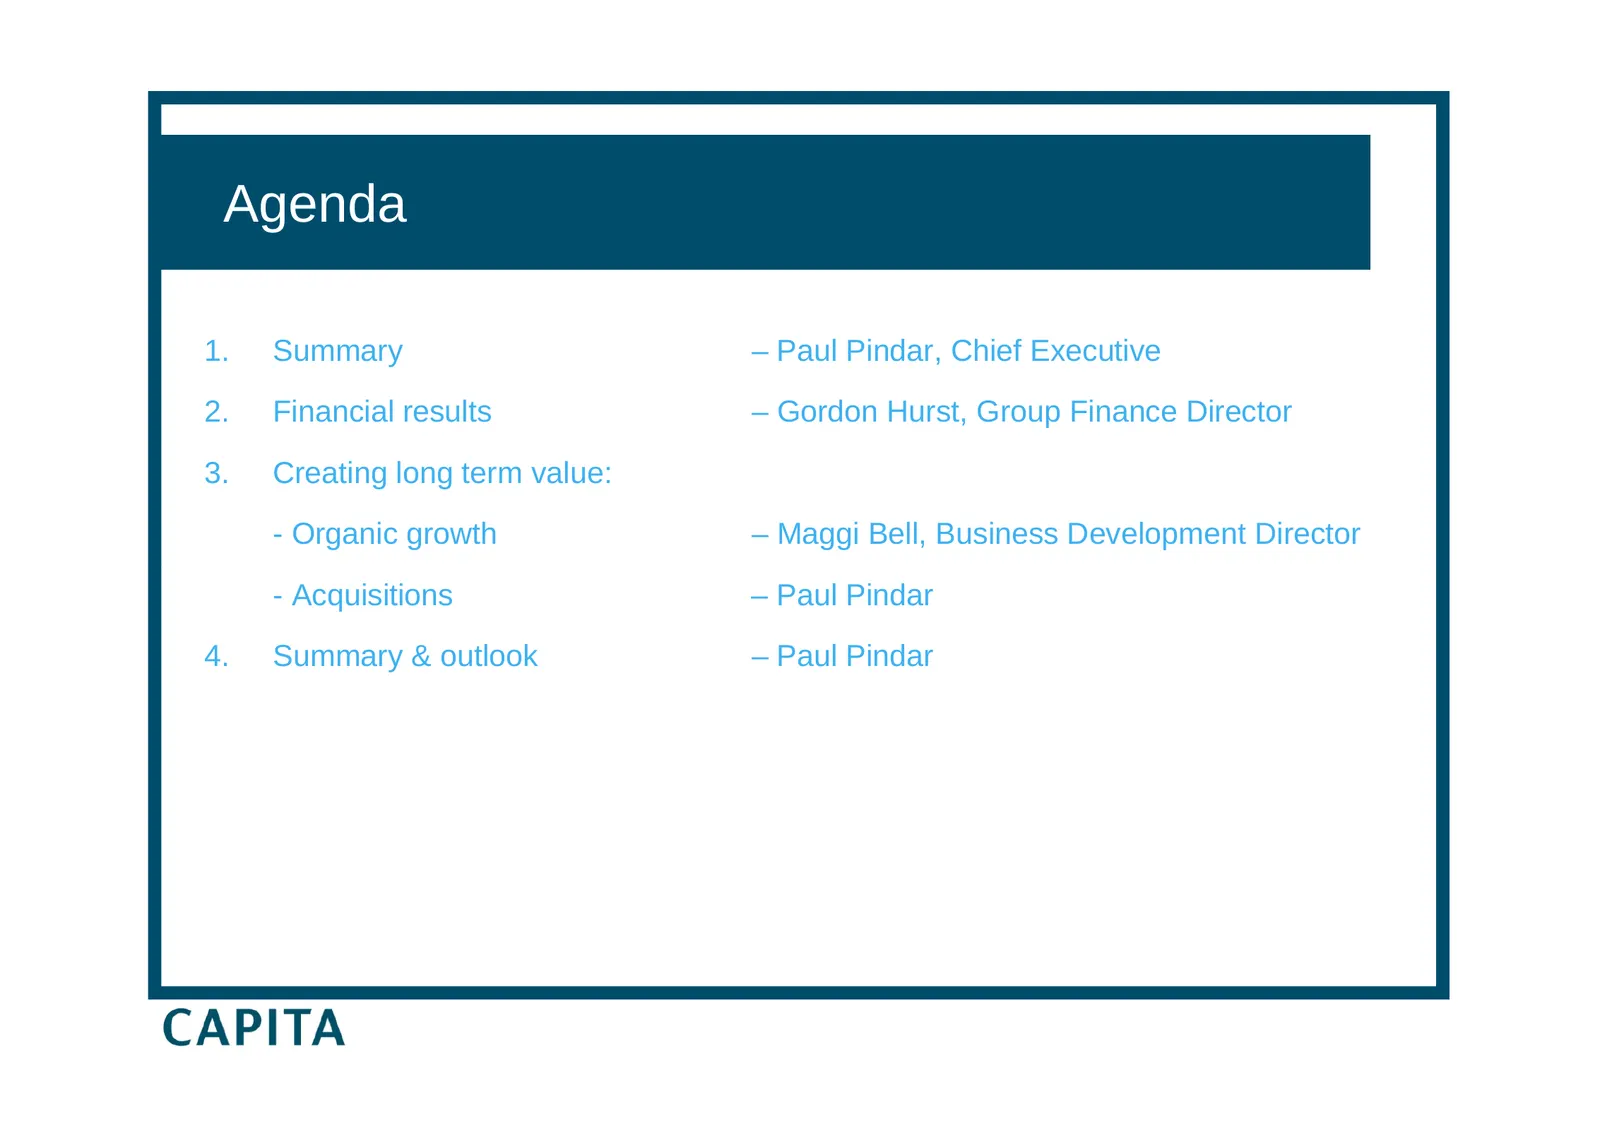
Slide 2: Agenda
Agenda 1. Summary – Paul Pindar, Chief Executive 2. Financial results – Gordon Hurst, Group Finance Director 3. Creating long term value: - Organic growth – Maggi Bell, Business Development Director - Acquisitions – Paul Pindar 4. Summary & outlook – Paul Pindar
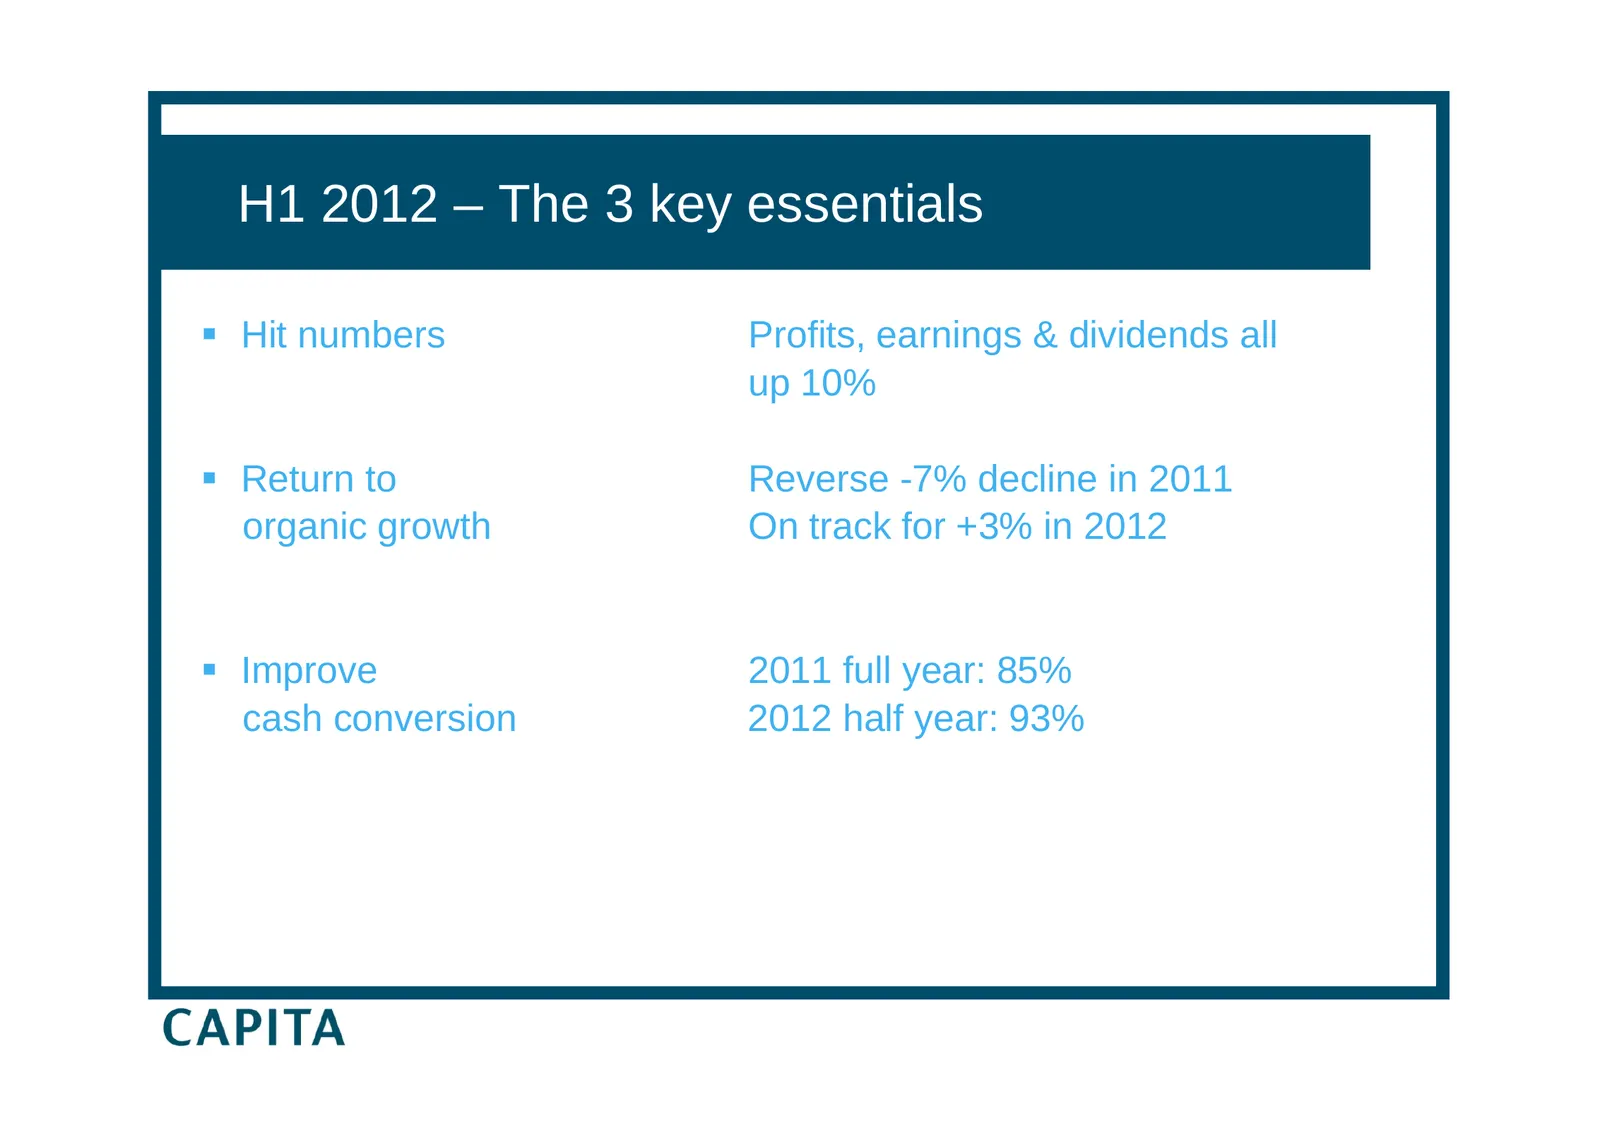
Slide 3: H1 2012 – The 3 key essentials
H1 2012 – The 3 key essentials Hit numbers Profits, earnings & dividends all up 10% Return to Reverse -7% decline in 2011 organic growth On track for +3% in 2012 Improve 2011 full year: 85% cash conversion 2012 half year: 93%
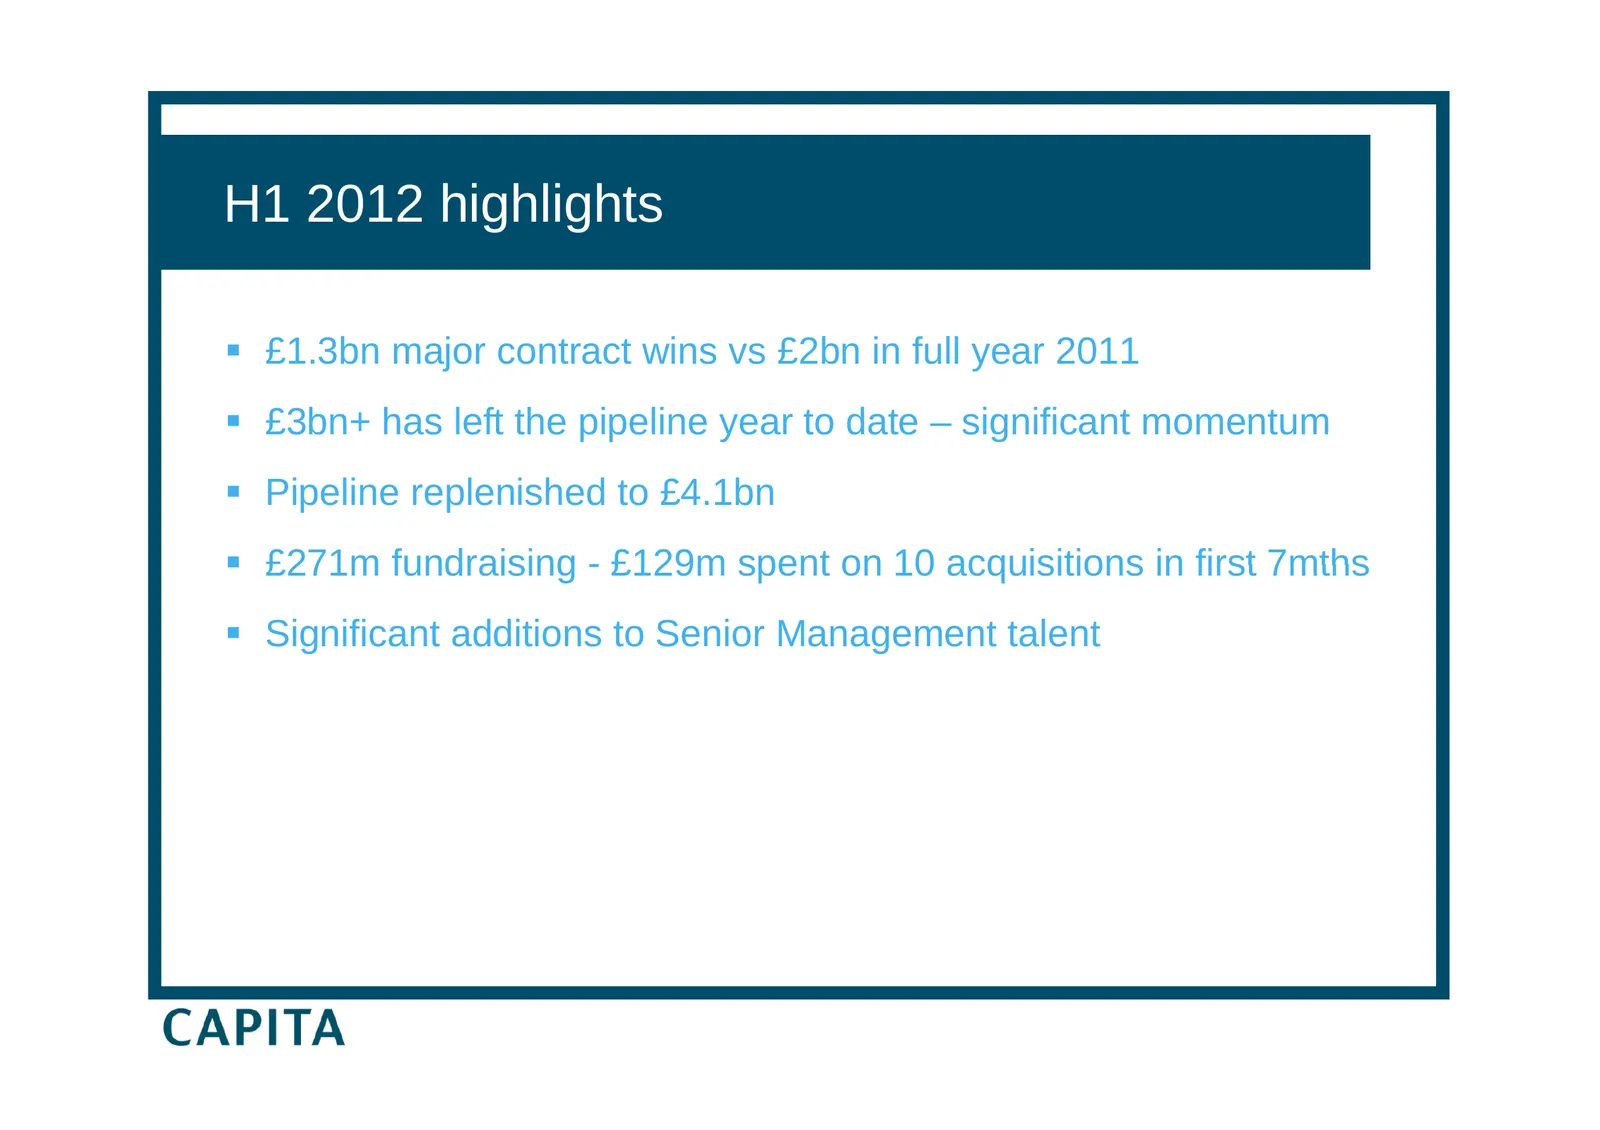
Slide 4: H1 2012 highlights
H1 2012 highlights £1.3bn major contract wins vs £2bn in full year 2011 £3bn+ has left the p pipeline p yyear to date – significant g momentum Pipeline replenished to £4.1bn £271m fundraising - £129m spent on 10 acquisitions in first 7mths Significant additions to Senior Management talent
Slide 5: Financial results
Financial results Gordon Hurst Group Finance Director
Slide 6: Financial results – revenue
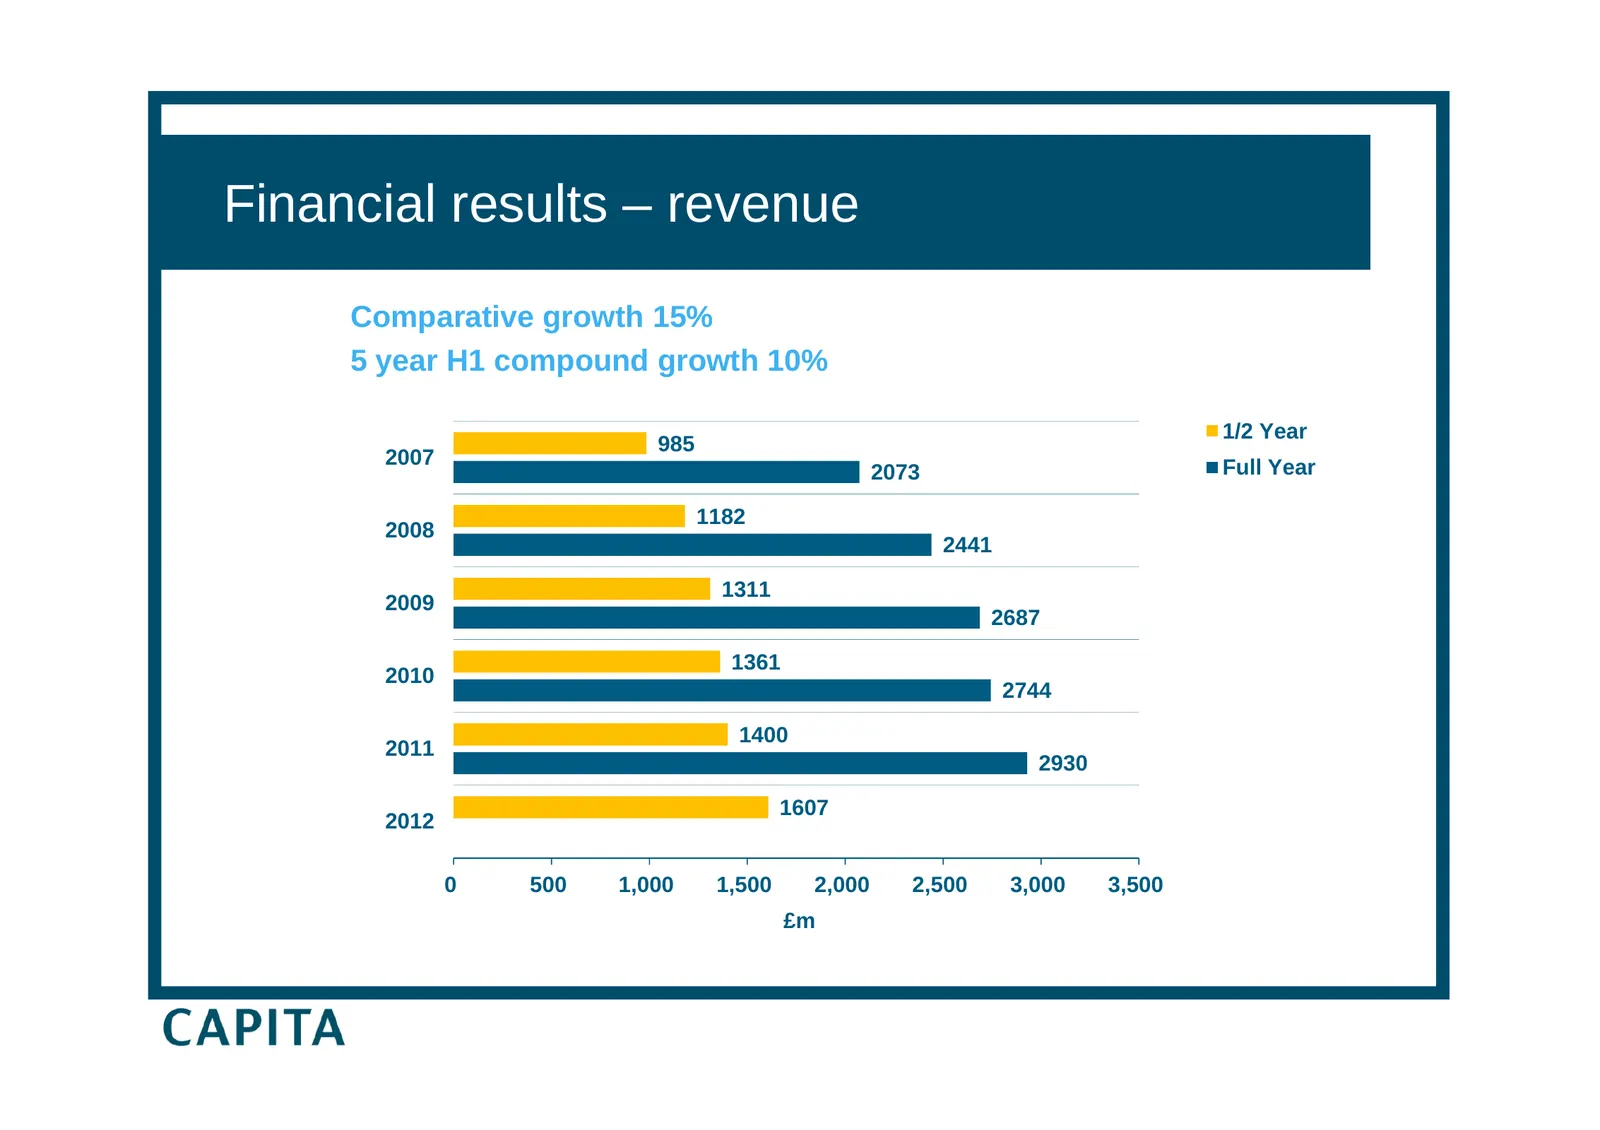
Financial results – revenue Comparative C ti growth th 15% 5 year H1 compound growth 10% 1/2 Year 985 2007 Full Year 2073 1182 2008 2441 1311 2009 2687 1361 2010 2744 1400 2011 2930 1607 2012 0 500 1,000 1,500 2,000 2,500 3,000 3,500 £m
Slide 7: Financial results – revenue by market
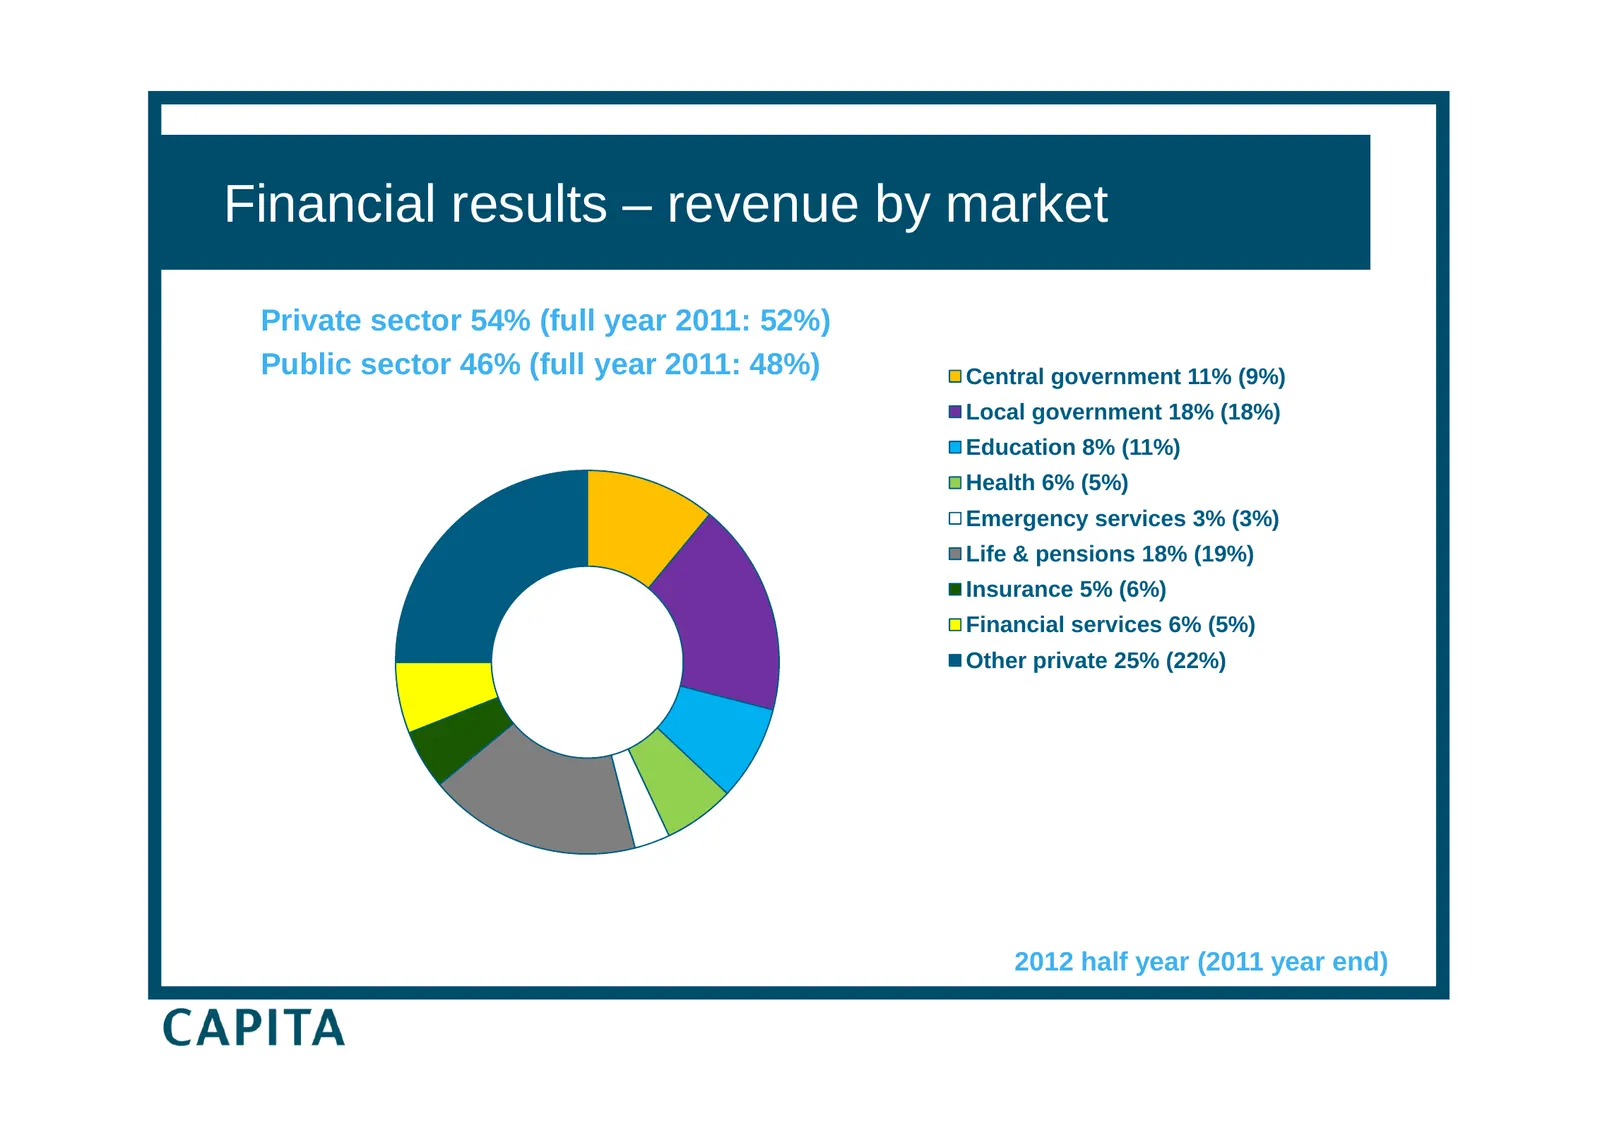
Financial results – revenue by market Private sector 54% (full year 2011: 52%) Public sector 46% (full year 2011: 48%) Central government 11% (9%) Local government 18% (18%) Education 8% (11%) Health 6% (5%) Emergency services 3% (3%) Life & p pensions 18% (19%) ( ) Insurance 5% (6%) Financial servi
Slide 8: Financial results – H1 revenue growth
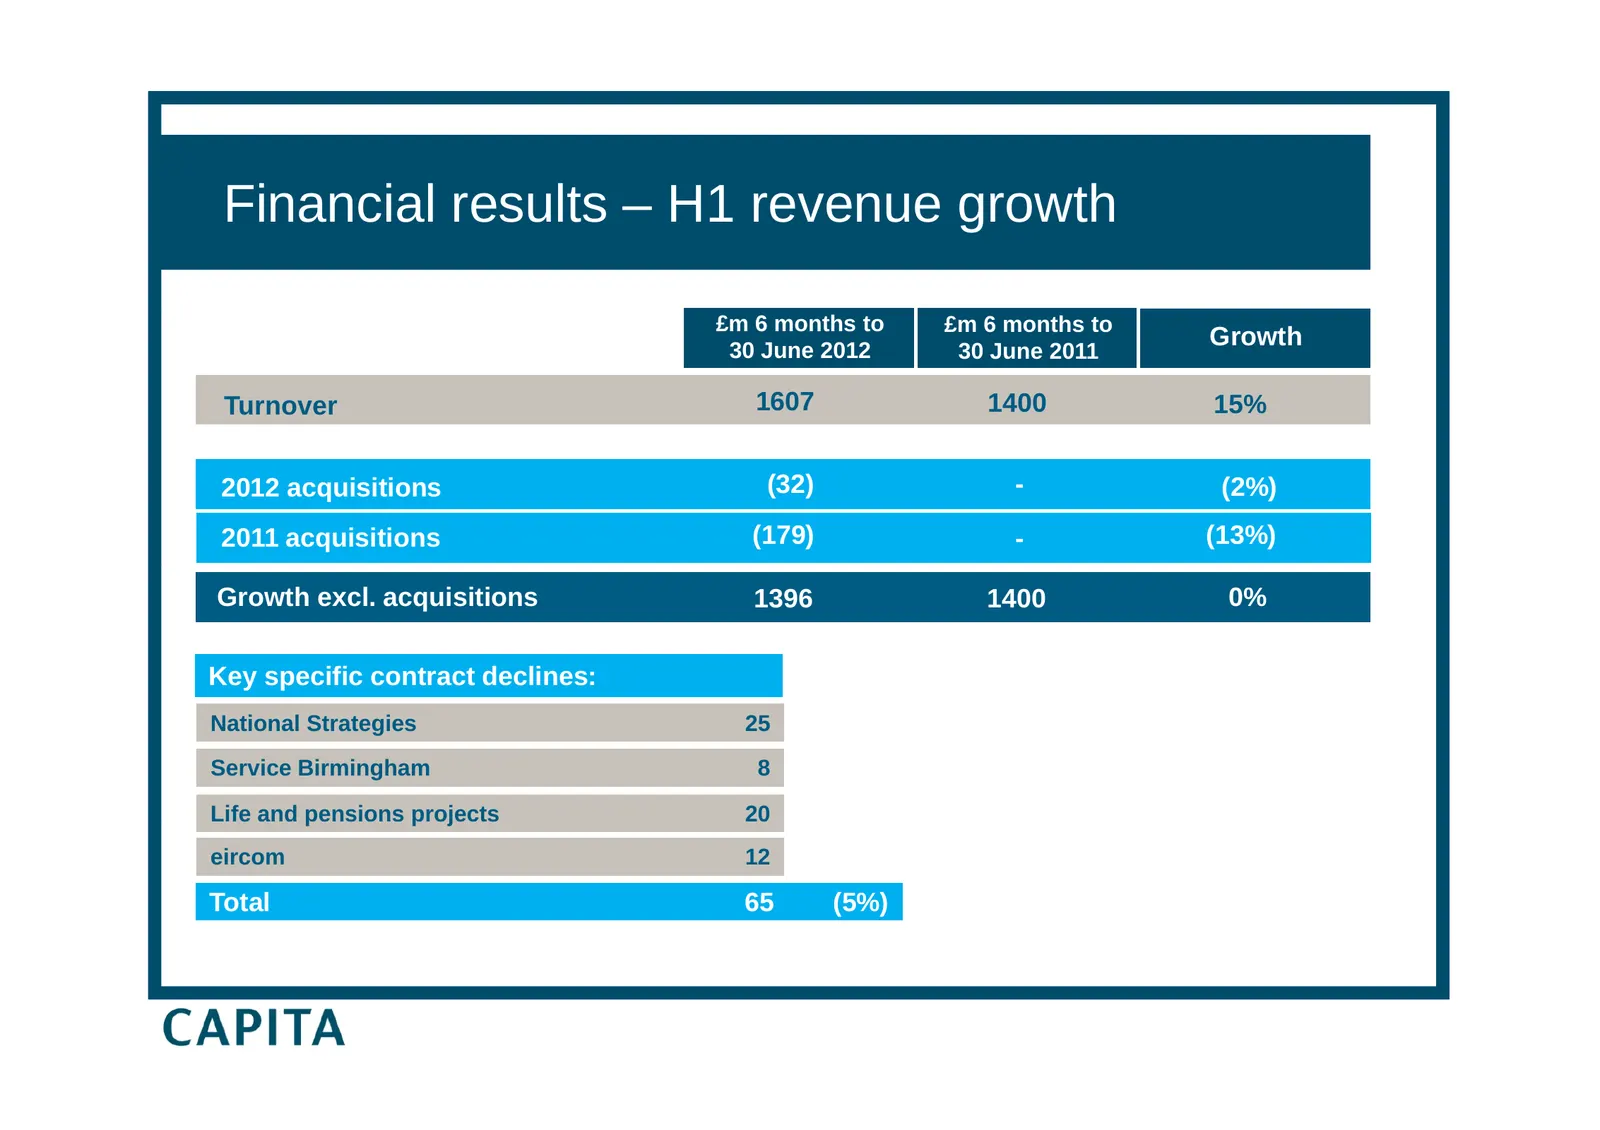
Financial results – H1 revenue growth £m 6 months to £m 6 months to £m 2008 Growth 30 June 2012 30£m 2007 June 2011 £m 2008 Growth Turnover 1607 1400 15% 2012 acquisitions (32) - (2%) 2011 acquisitions 2001 (179) - 2003 2004 (13%) Disposals Growth excl. acquisitions [] 1396 [] 1400 [ 0% ]% Key speci
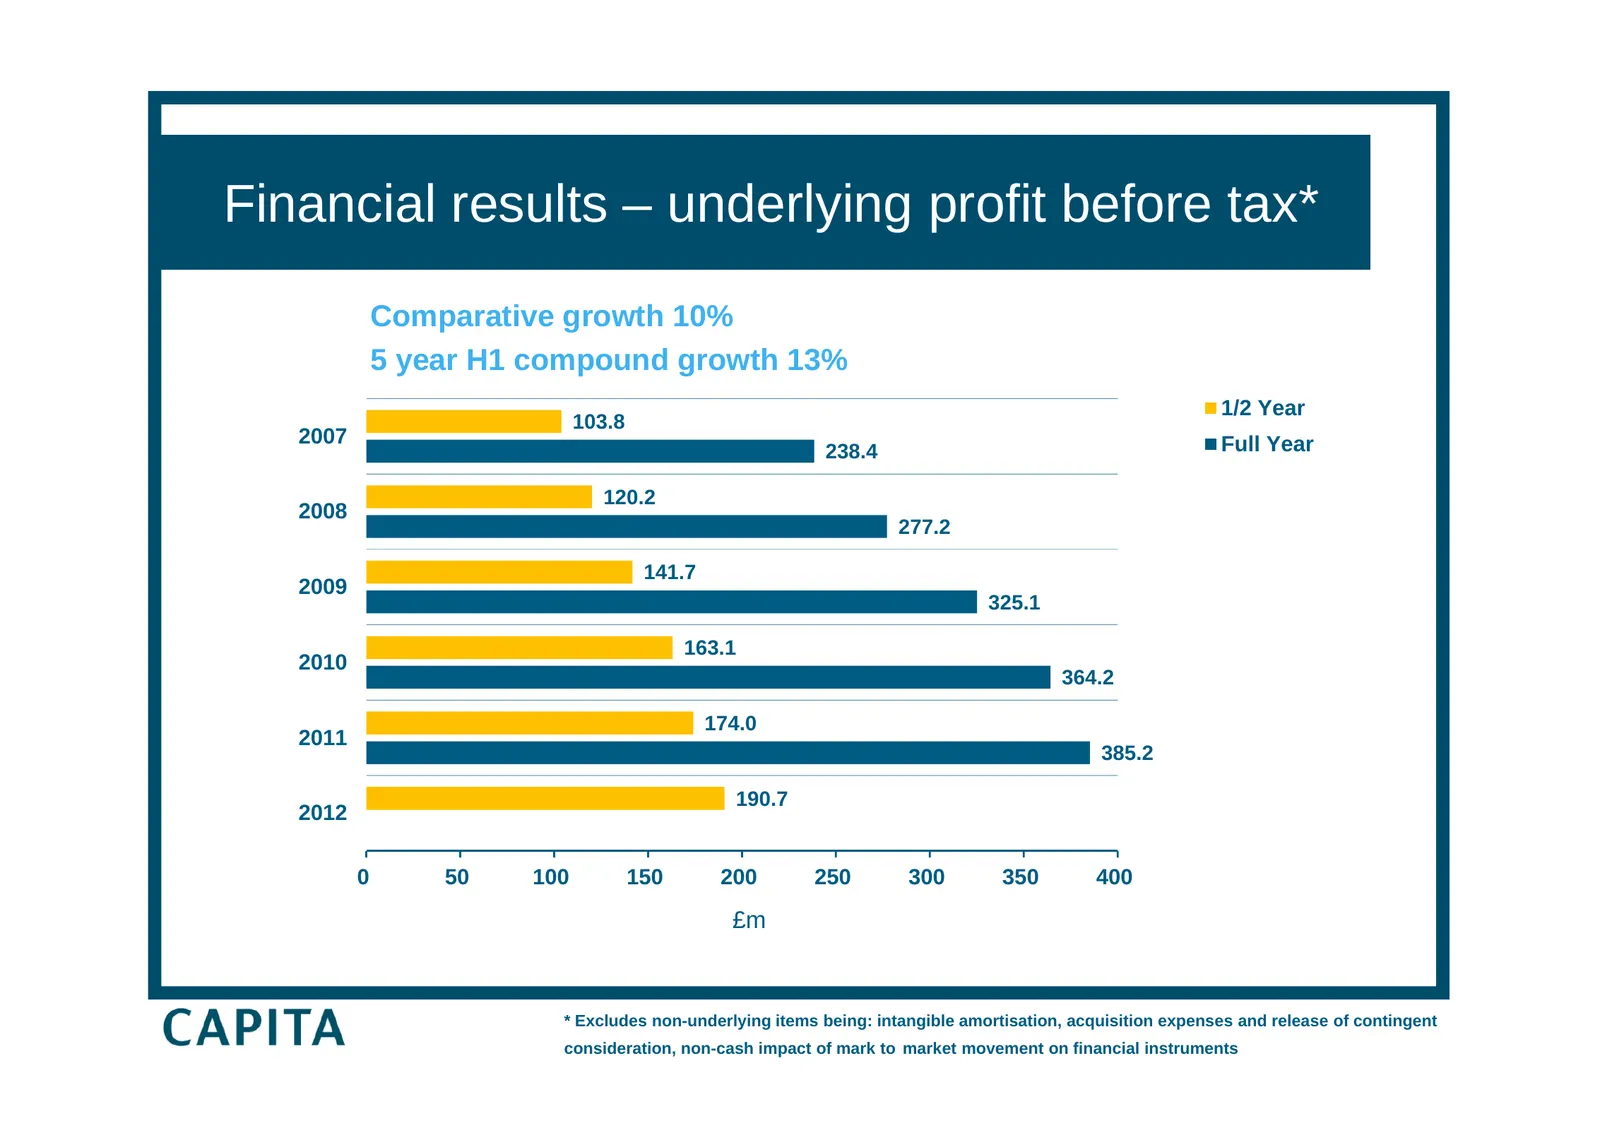
Slide 9: Financial results – underlying profit before tax
Financial results – underlying profit before tax* Comparative C ti growth th 10% 5 year H1 compound growth 13% 1/2 Year 103.8 2007 F ll Year Full Y 238.4 120.2 2008 277.2 141 141.7 2009 325.1 163.1 2010 364.2 174.0 2011 385.2 190.7 2012 0 50 100 150 200 250 300 350 400 £m * Excludes non-underlying i
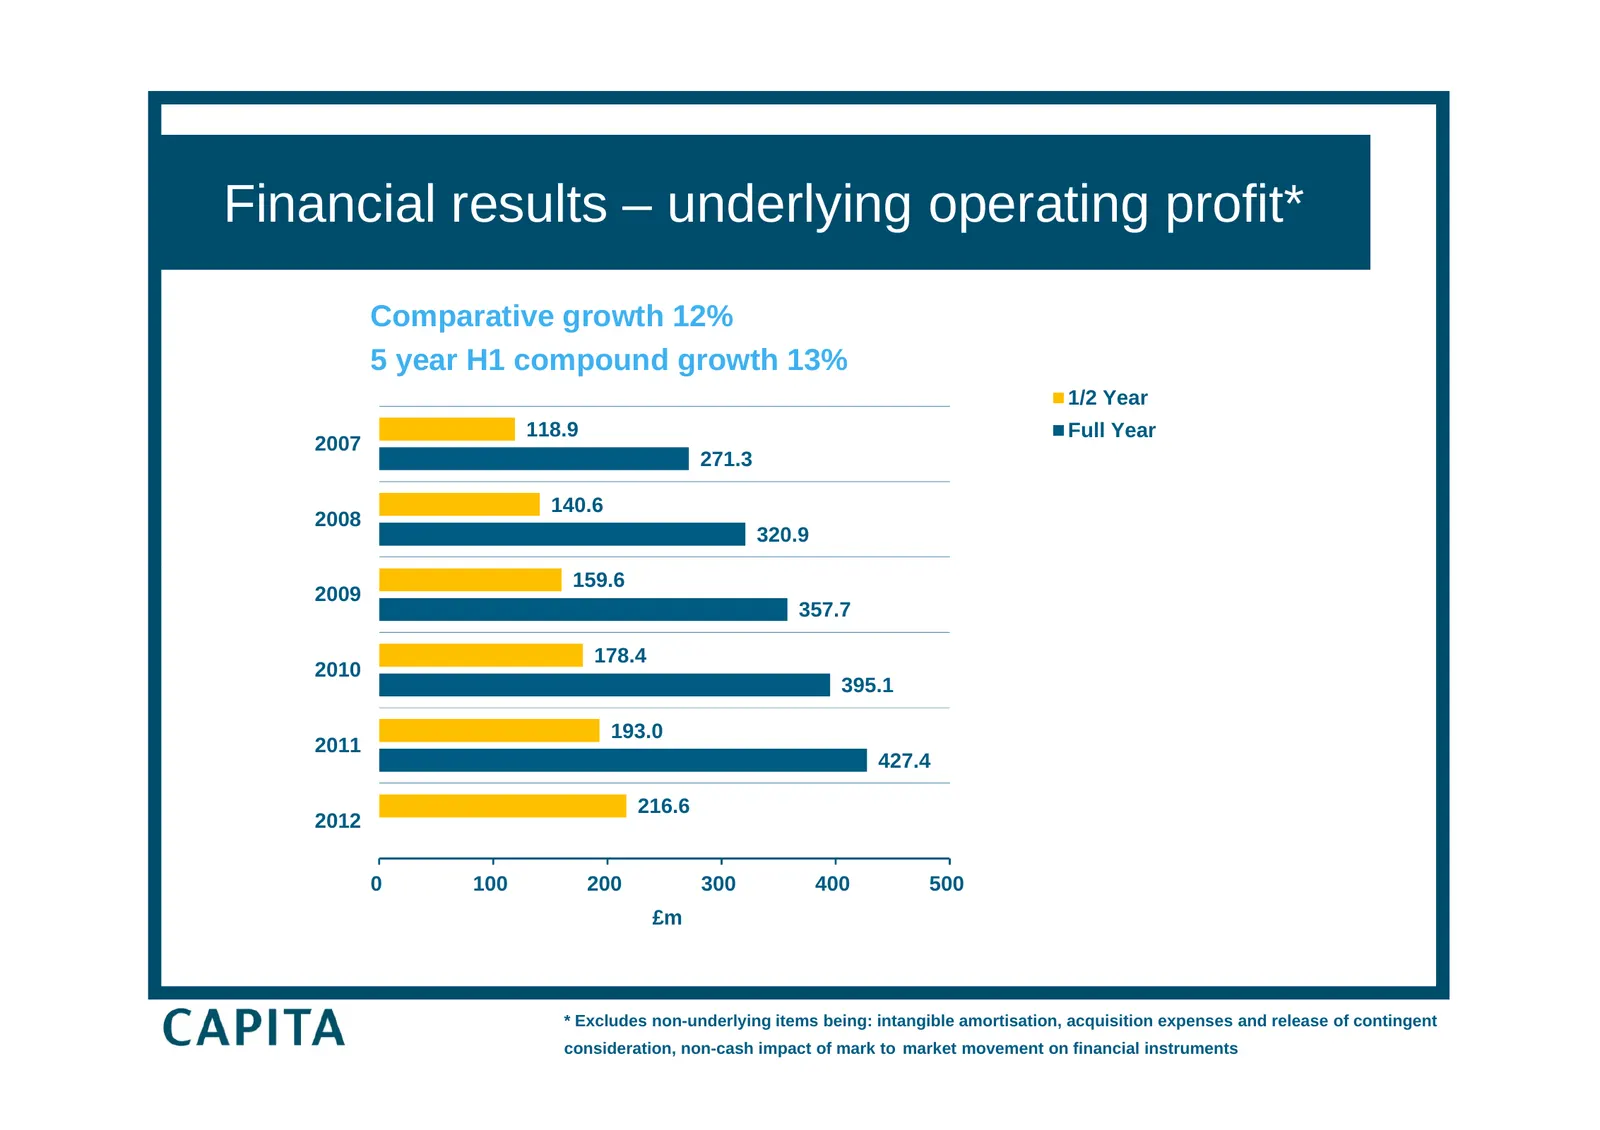
Slide 10: Financial results – underlying operating profit
Financial results – underlying operating profit* Comparative C ti growth th 12% 5 year H1 compound growth 13% 1/2 Year 118.9 89 Full Year 2007 271.3 140.6 2008 320.9 159.6 2009 357.7 178.4 2010 395.1 193.0 2011 427.4 216.6 2012 0 100 200 300 400 500 £m * Excludes non-underlying items being: intangib
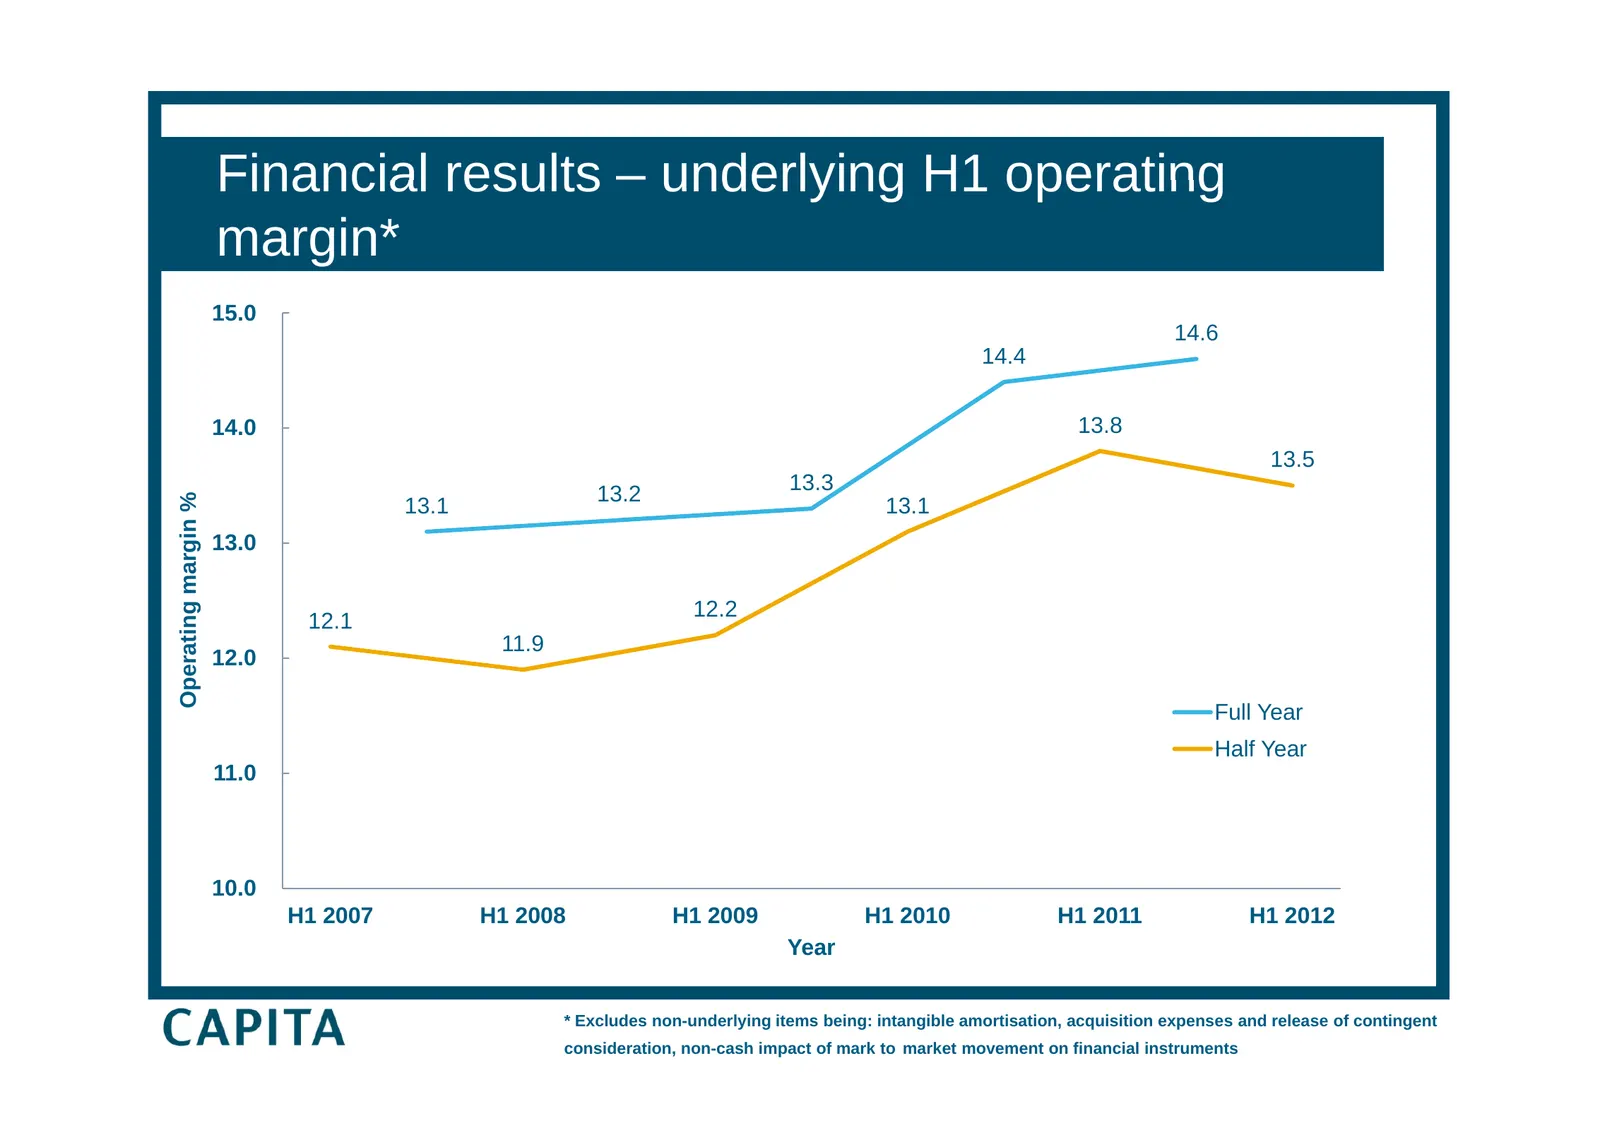
Slide 11: Financial results – underlying H1 operating margin
Financial results – underlying H1 operating margin* 15 0 15.0 14.6 14.4 14.0 13.8 13.5 13.3 13.2 argin % 13.1 13.1 13.0 Operating ma 12.2 12.1 11.9 12.0 O Full Year Half Year 11.0 10.0 H1 2007 H1 2008 H1 2009 H1 2010 H1 2011 H1 2012 Year * Excludes non-underlying items being: intangible amortisation
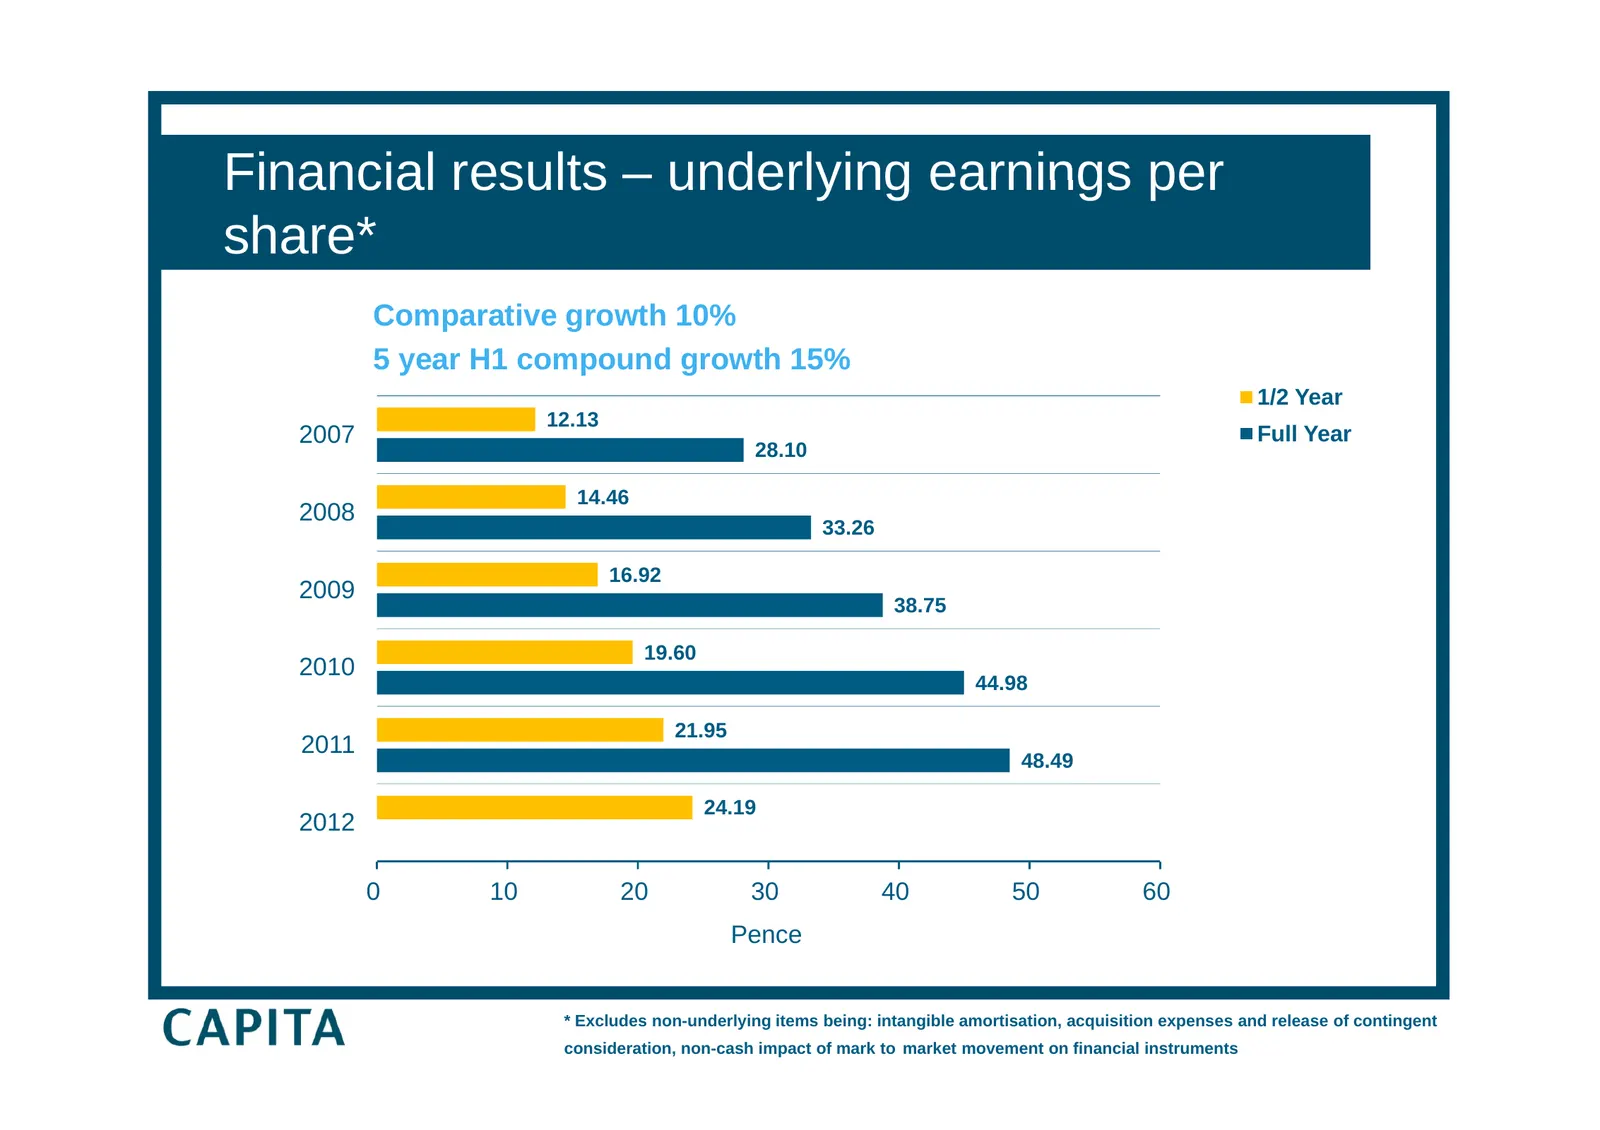
Slide 12: Financial results – underlying earnings per share
Financial results – underlying earnings per share* Comparative C ti growth th 10% 5 year H1 compound growth 15% 1/2 Year 12.13 2007 Full Year 28.10 14.46 2008 33.26 16.92 2009 38.75 19.60 2010 44.98 21.95 2011 48.49 24.19 2012 0 10 20 30 40 50 60 Pence * Excludes non-underlying items being: intangib
Slide 13: Financial results – dividends
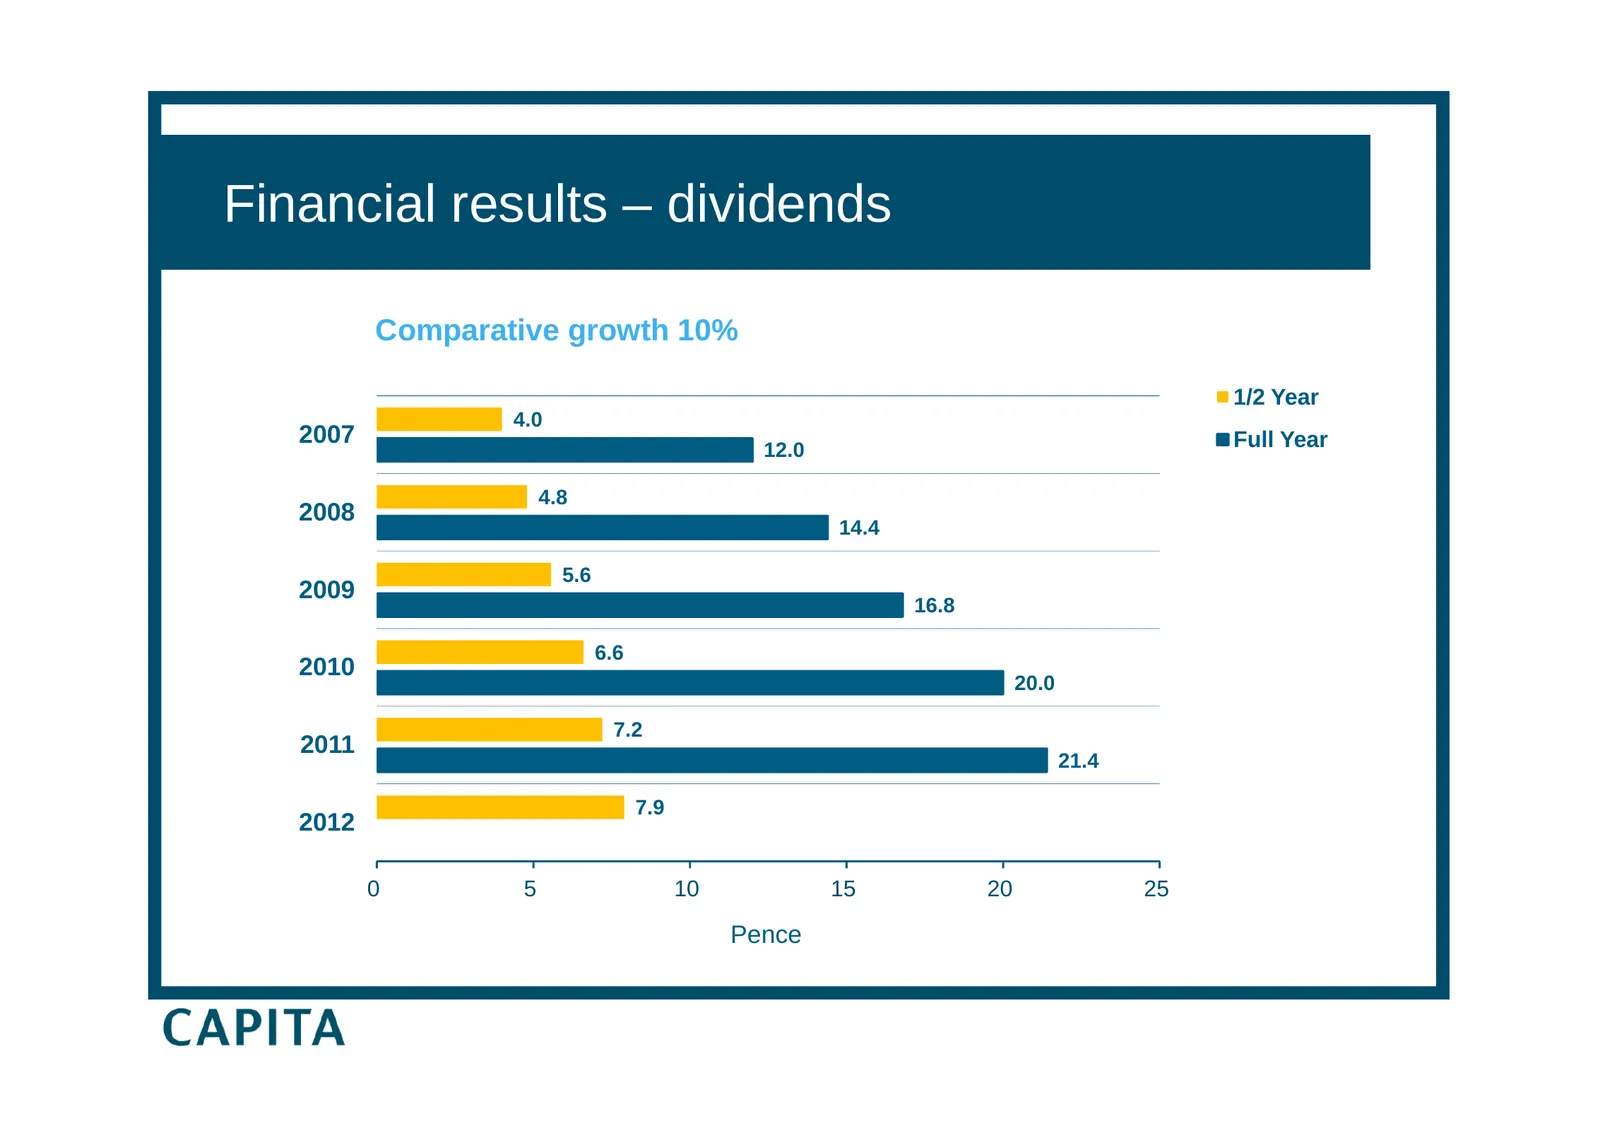
Financial results – dividends Comparative growth 10% 1/2 Year 4.0 2007 Full Year 12.0 4.8 2008 14.4 5.6 2009 16.8 6.6 2010 20.0 7.2 2011 21.4 7.9 2012 0 5 10 15 20 25 Pence
Slide 14: Financial results – cash flow statement
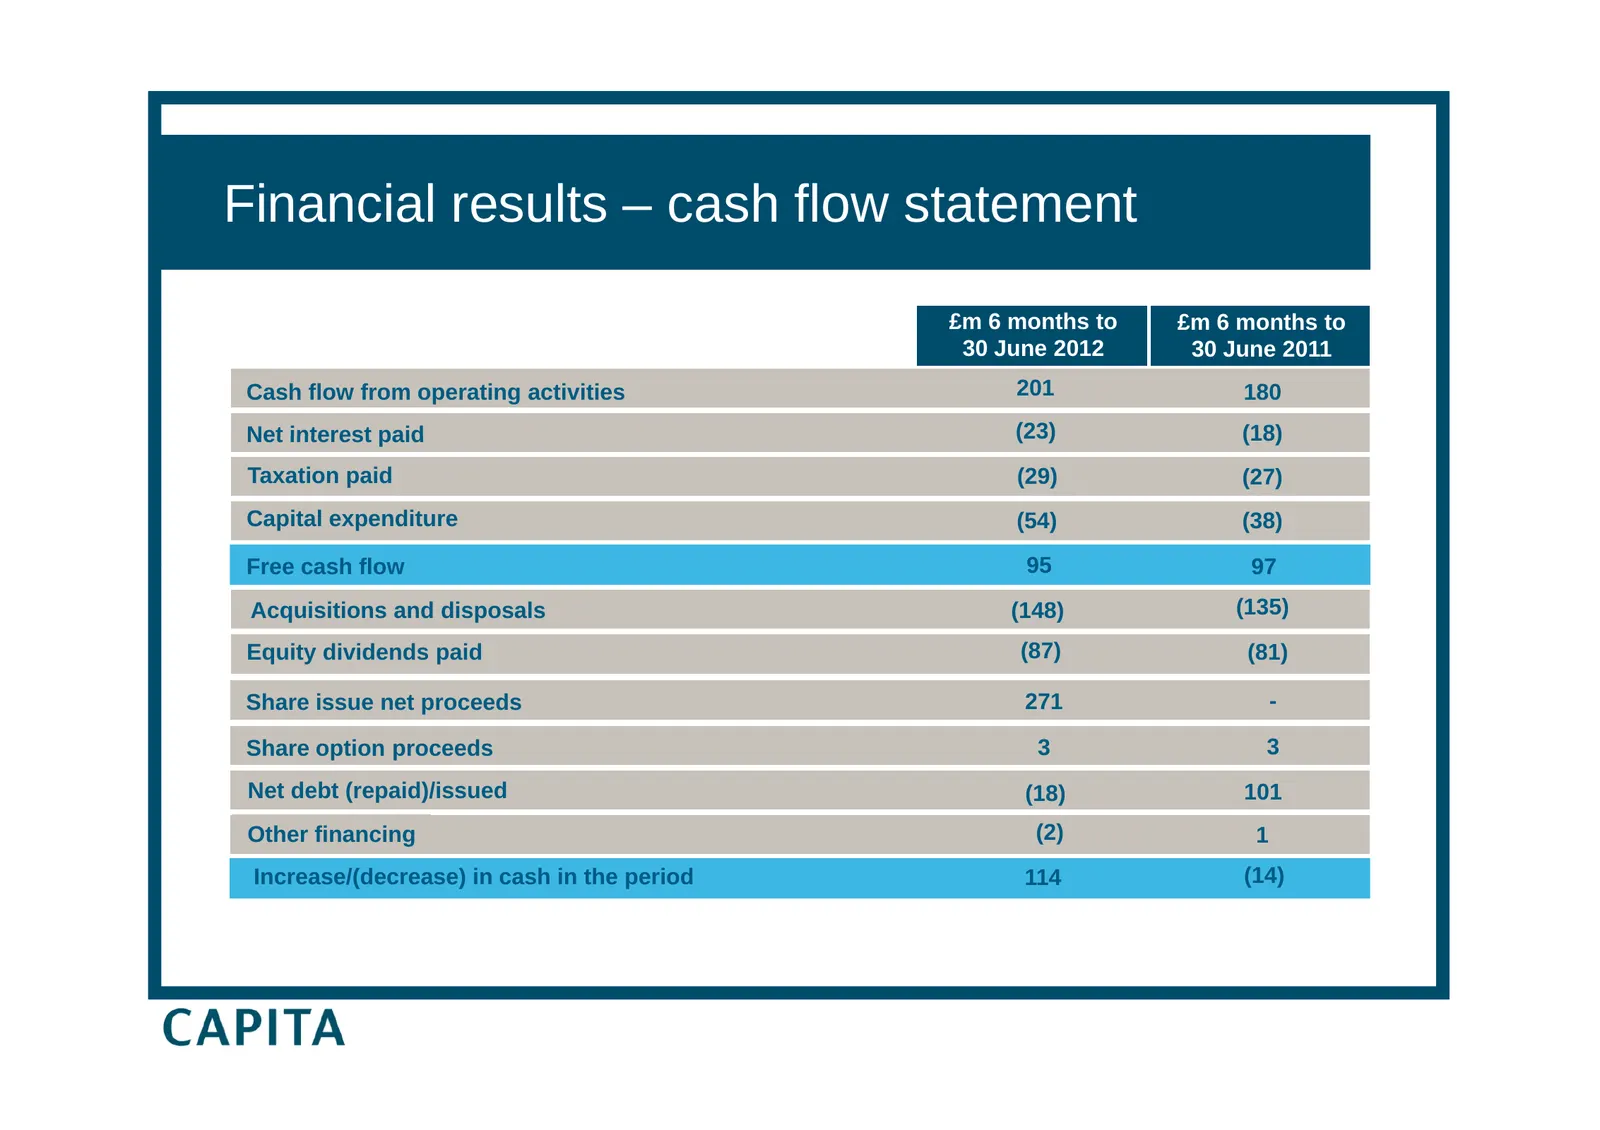
Financial results – cash flow statement £m 6 months to £m 6 months to 30 June 2012 30 June 2011 Cash flow from operating activities 201 180 Net interest paid (23) (18) Taxation paid (29) (27) Capital expenditure (54) (38) Free cash flow 95 97 Acquisitions and disposals (148) (135) Equity dividends p
Slide 15: Financial results – working capital
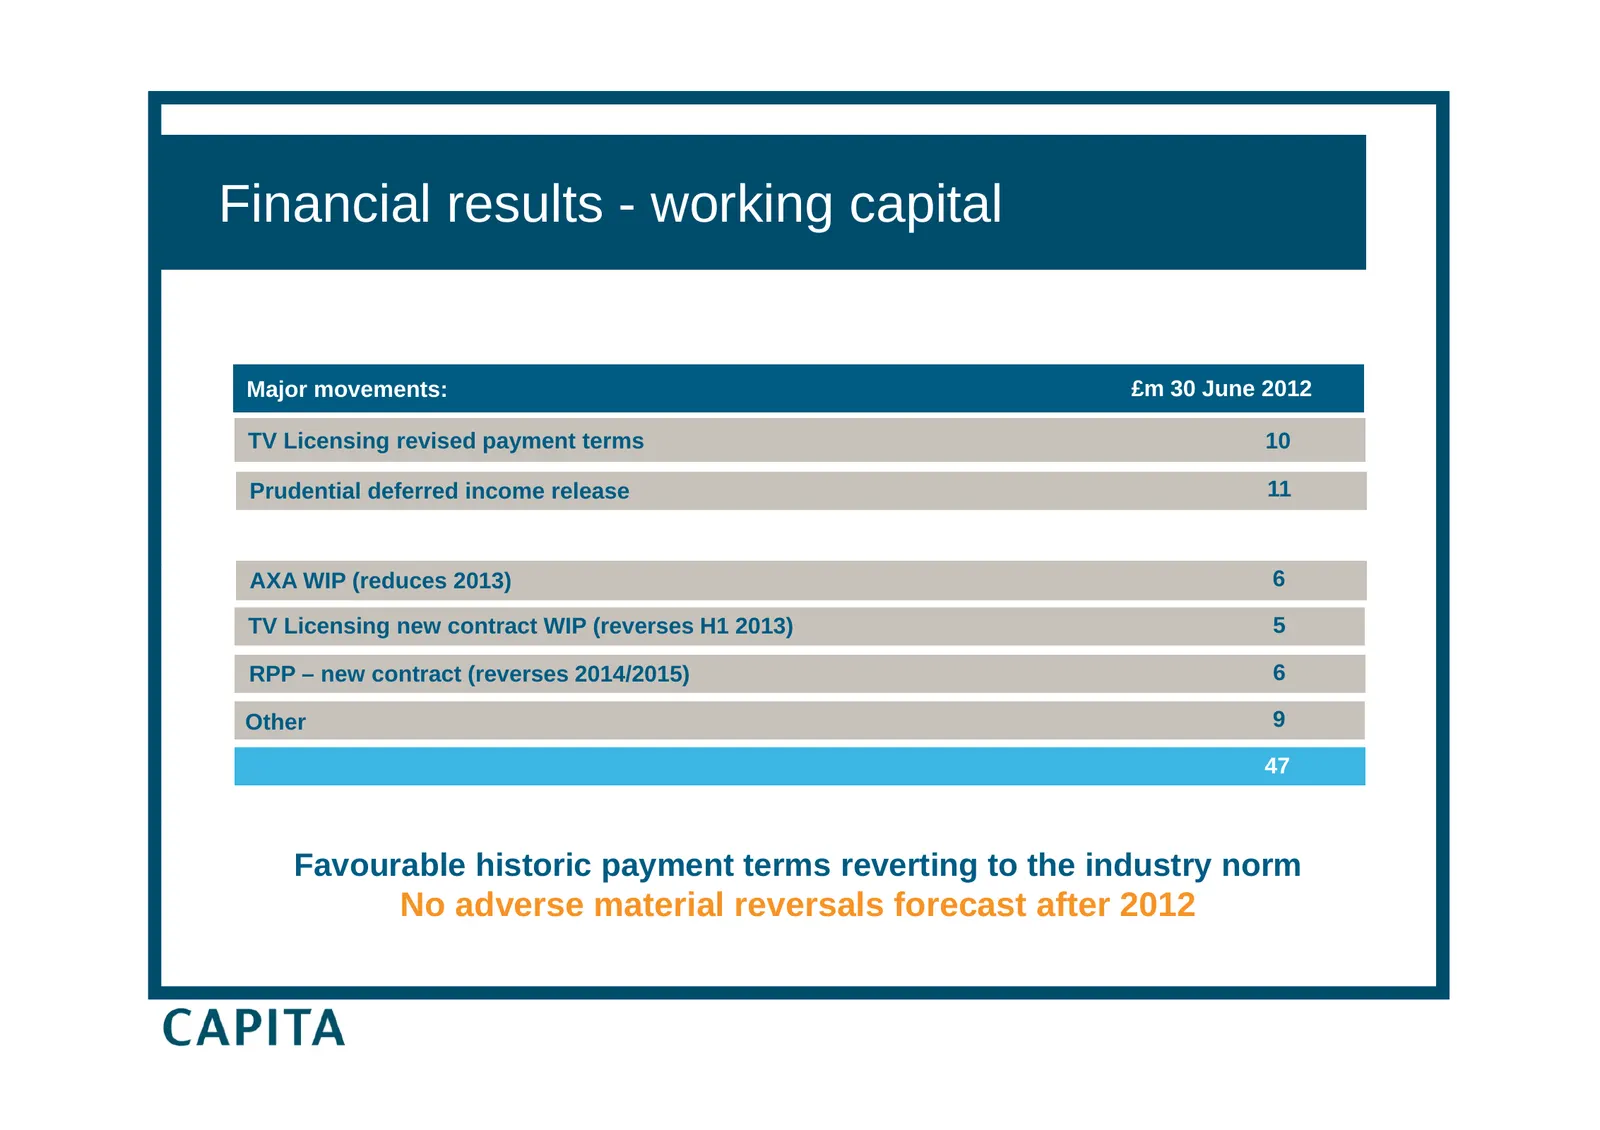
Financial results - working capital Major movements: £m 30 June 2012 TV Licensing revised re ised pa payment ment terms 10 Prudential deferred income release 11 AXA WIP (reduces 2013) 6 TV Licensing new contract WIP (reverses H1 2013) 5 RPP – new contract (reverses 2014/2015) 6 Other 9 47 Favourable
Slide 16: Financial results – half year capex as % of turnover
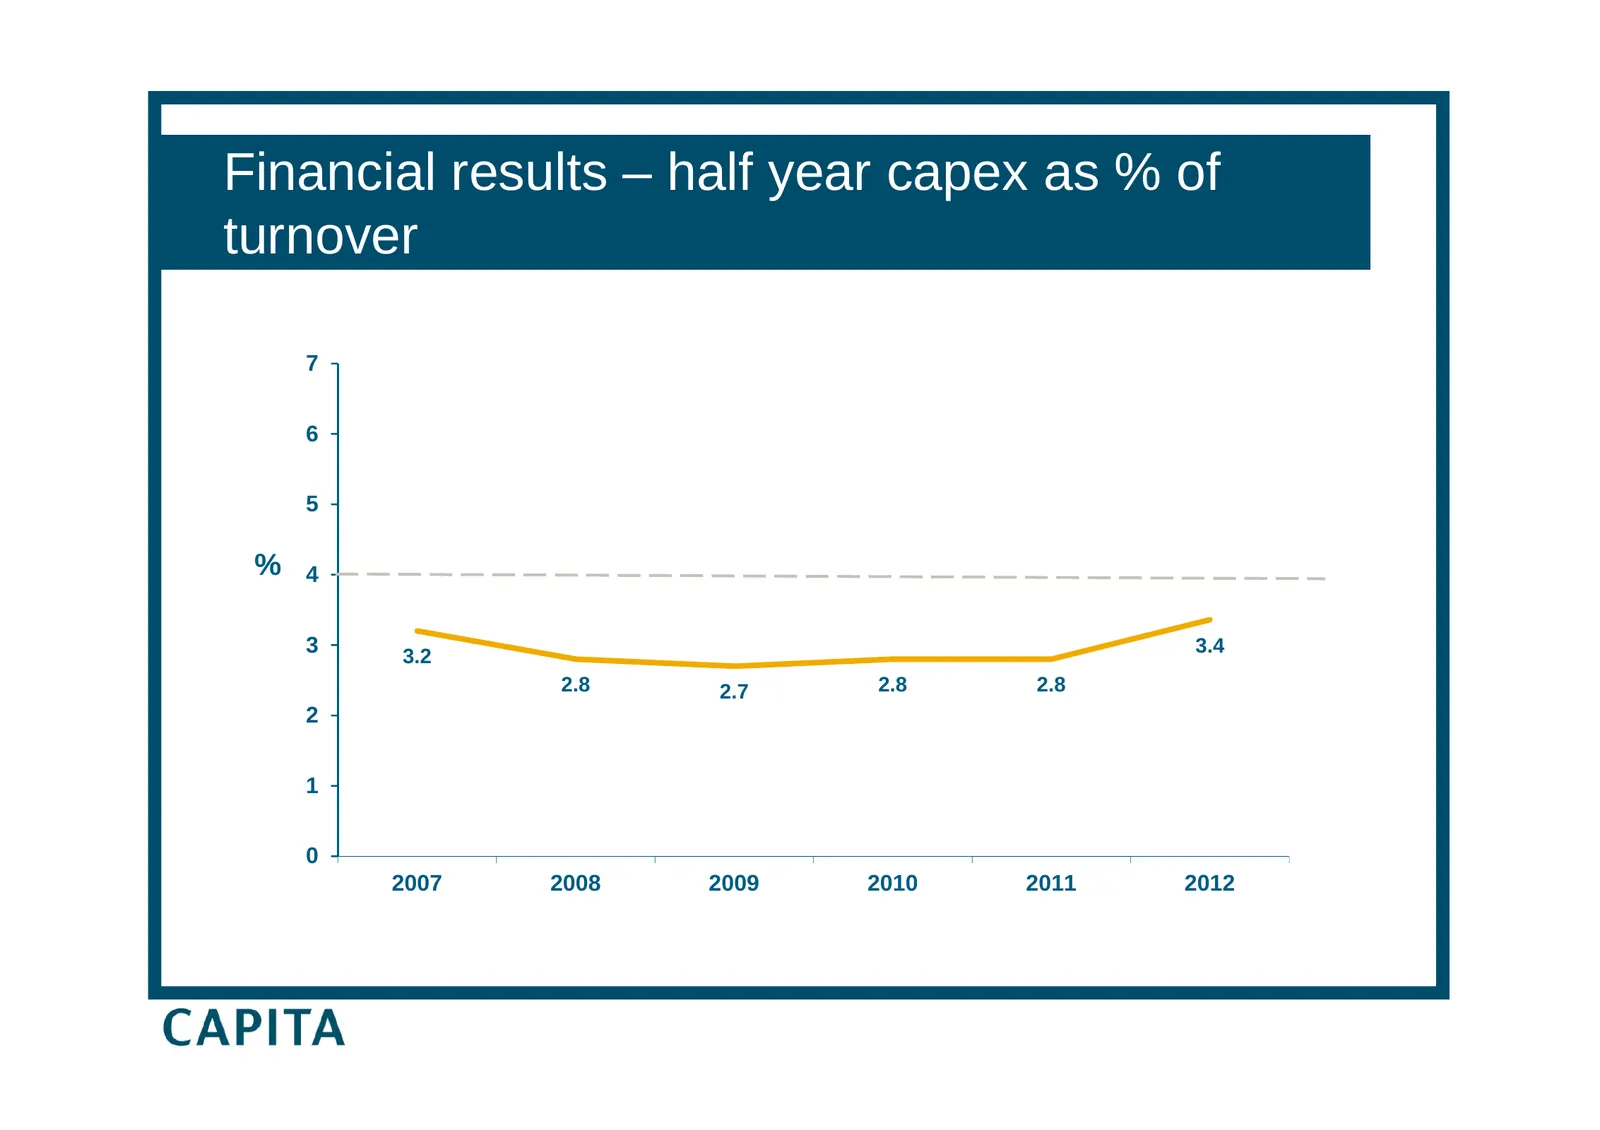
Financial results – half year capex as % of turnover 7 6 5 % 4 3 3.2 3.4 2.8 27 2.7 2.8 2.8 2 1 0 2007 2008 2009 2010 2011 2012
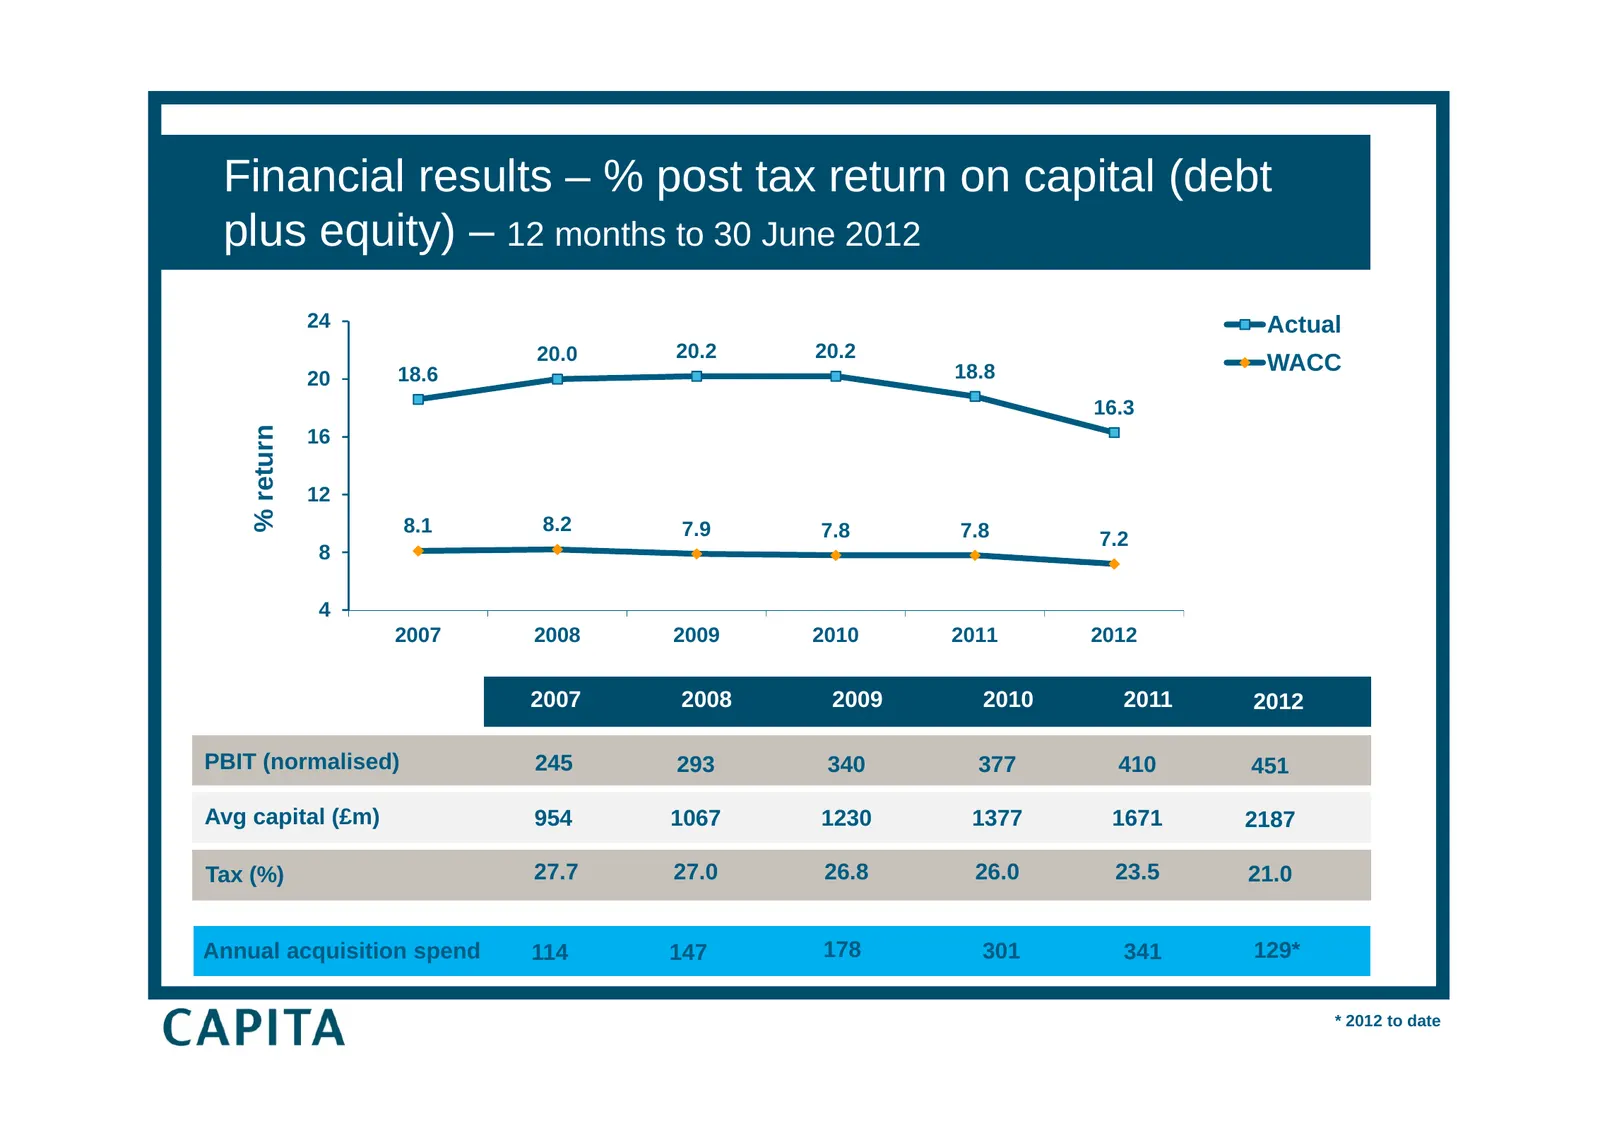
Slide 17: Financial results – post tax return on capital
Financial results – % post tax return on capital (debt plus equity) – 12 months to 30 June 2012 24 Actual 20.0 20.2 20.2 18.6 18.8 WACC 20 16.3 % return n 16 12 8.1 8.2 7.9 7.8 7.8 7.2 8 4 2007 2008 2009 2010 2011 2012 2007 2008 2009 2010 2011 2012 PBIT (normalised) 245 293 340 377 410 451 Avg capit
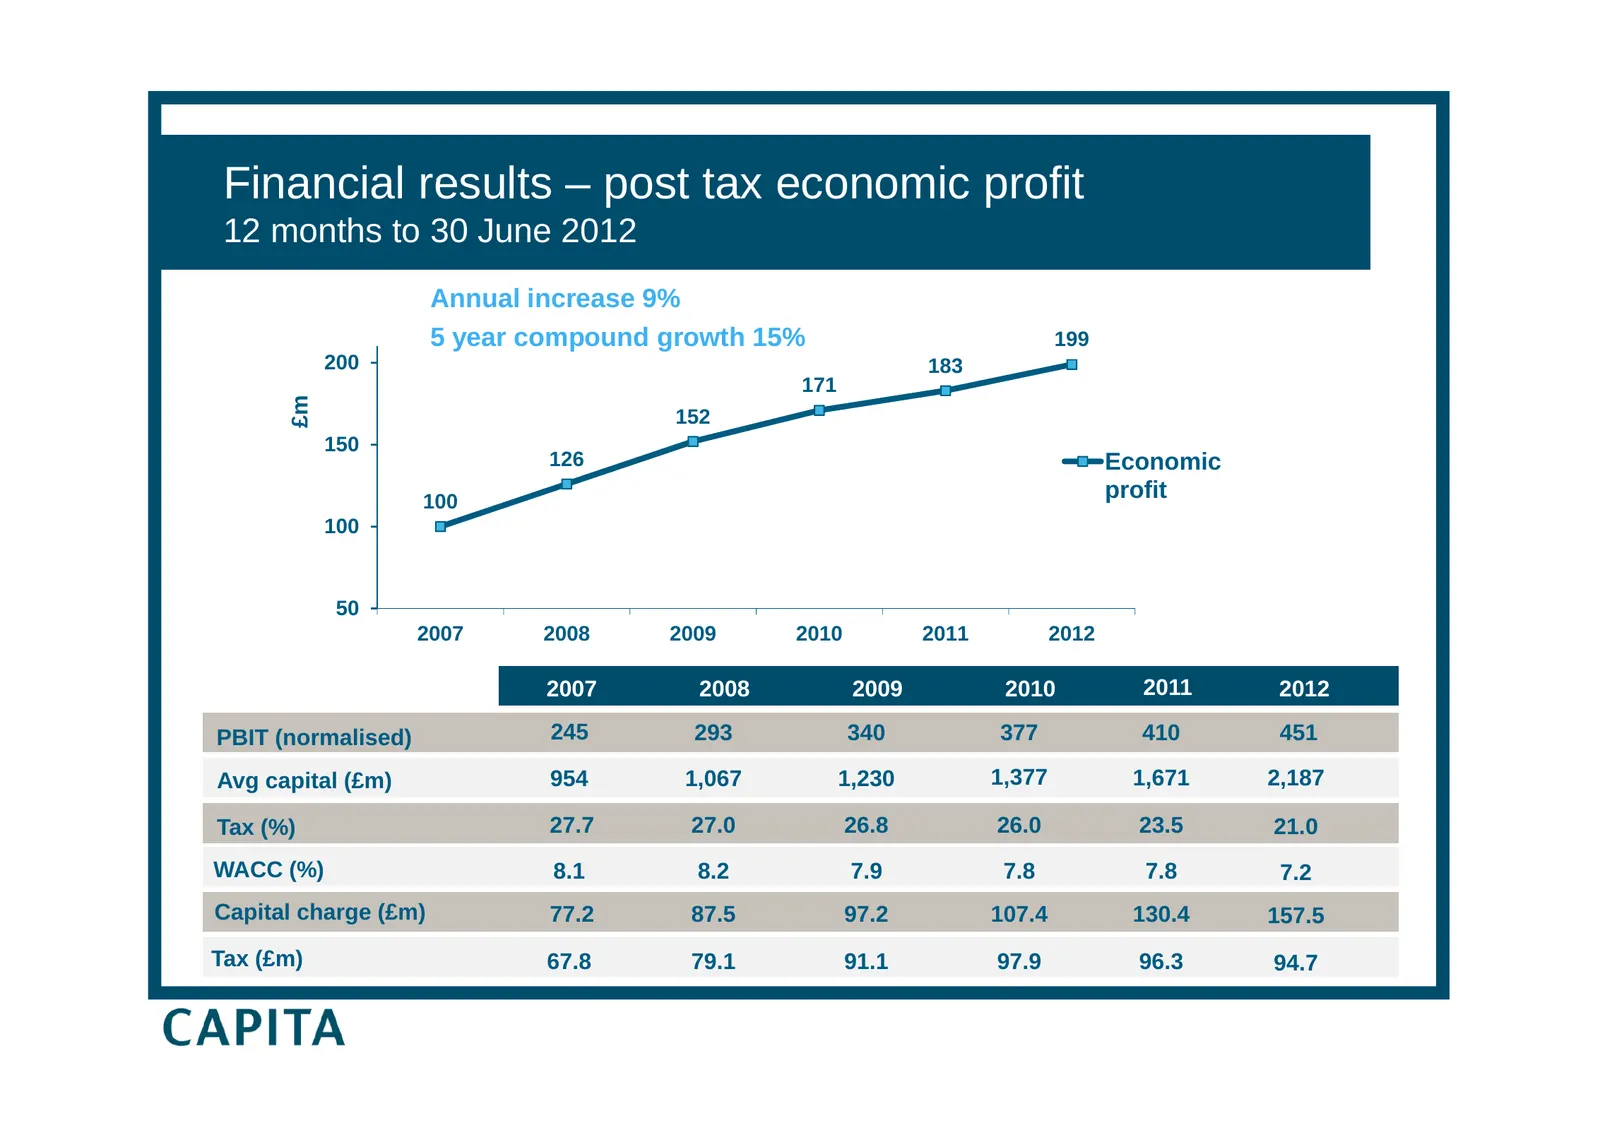
Slide 18: Financial results – post tax economic profit
Financial results – post tax economic profit 12 months to 30 June 2012 Annual increase 9% % 5 year compound growth 15% 199 200 183 171 £m 152 1 0 150 126 Economic 100 profit 100 50 2007 2008 2009 2010 2011 2012 2007 2008 2009 2010 2011 2012 PBIT (normalised) 245 293 340 377 410 451 Avg capital (£m)
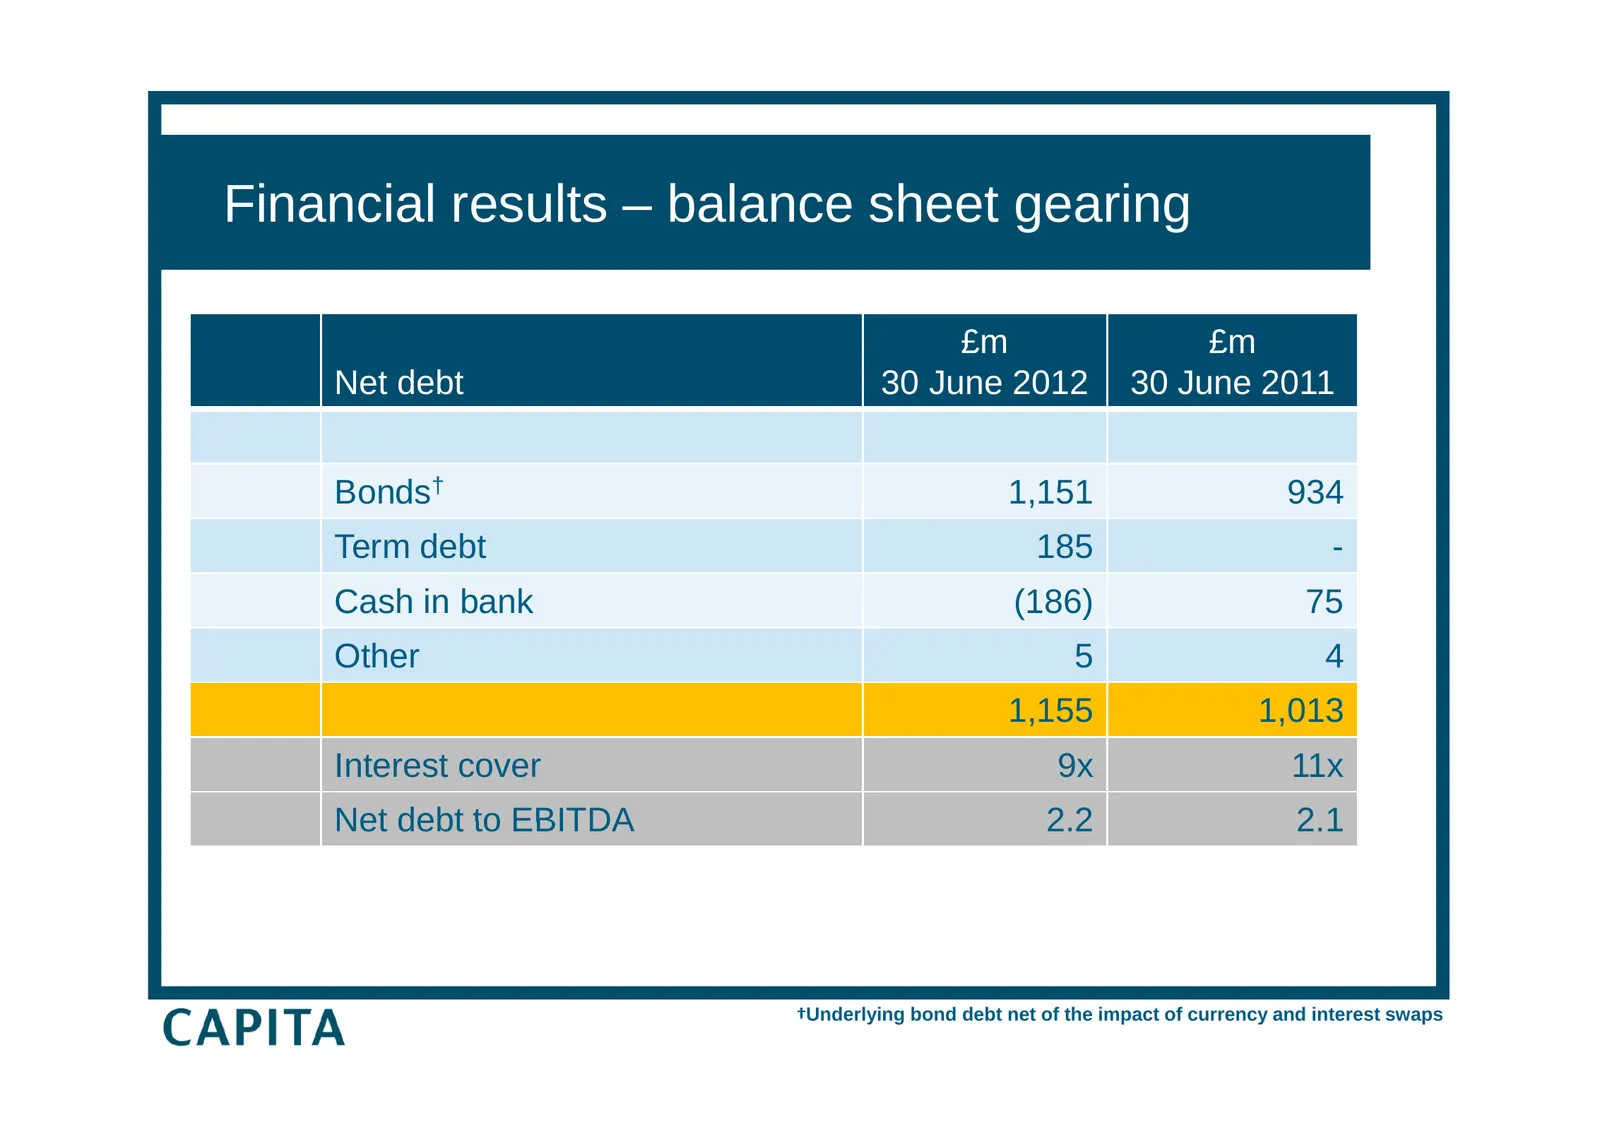
Slide 19: Financial results – balance sheet gearing
Financial results – balance sheet gearing £m £m £m £m 2008 30 June 2007 (£m) £m 2007 Net debt 30 June 30 2012 June 2012 30 June 2011 Bonds† 1,151 934 Term debt 185 - Cash in bank (186) 75 Other 5 4 1,155 1,013 Interest cover 9x 11x Net debt to EBITDA 22 2.2 21 2.1 †Underlying bond debt net of the im
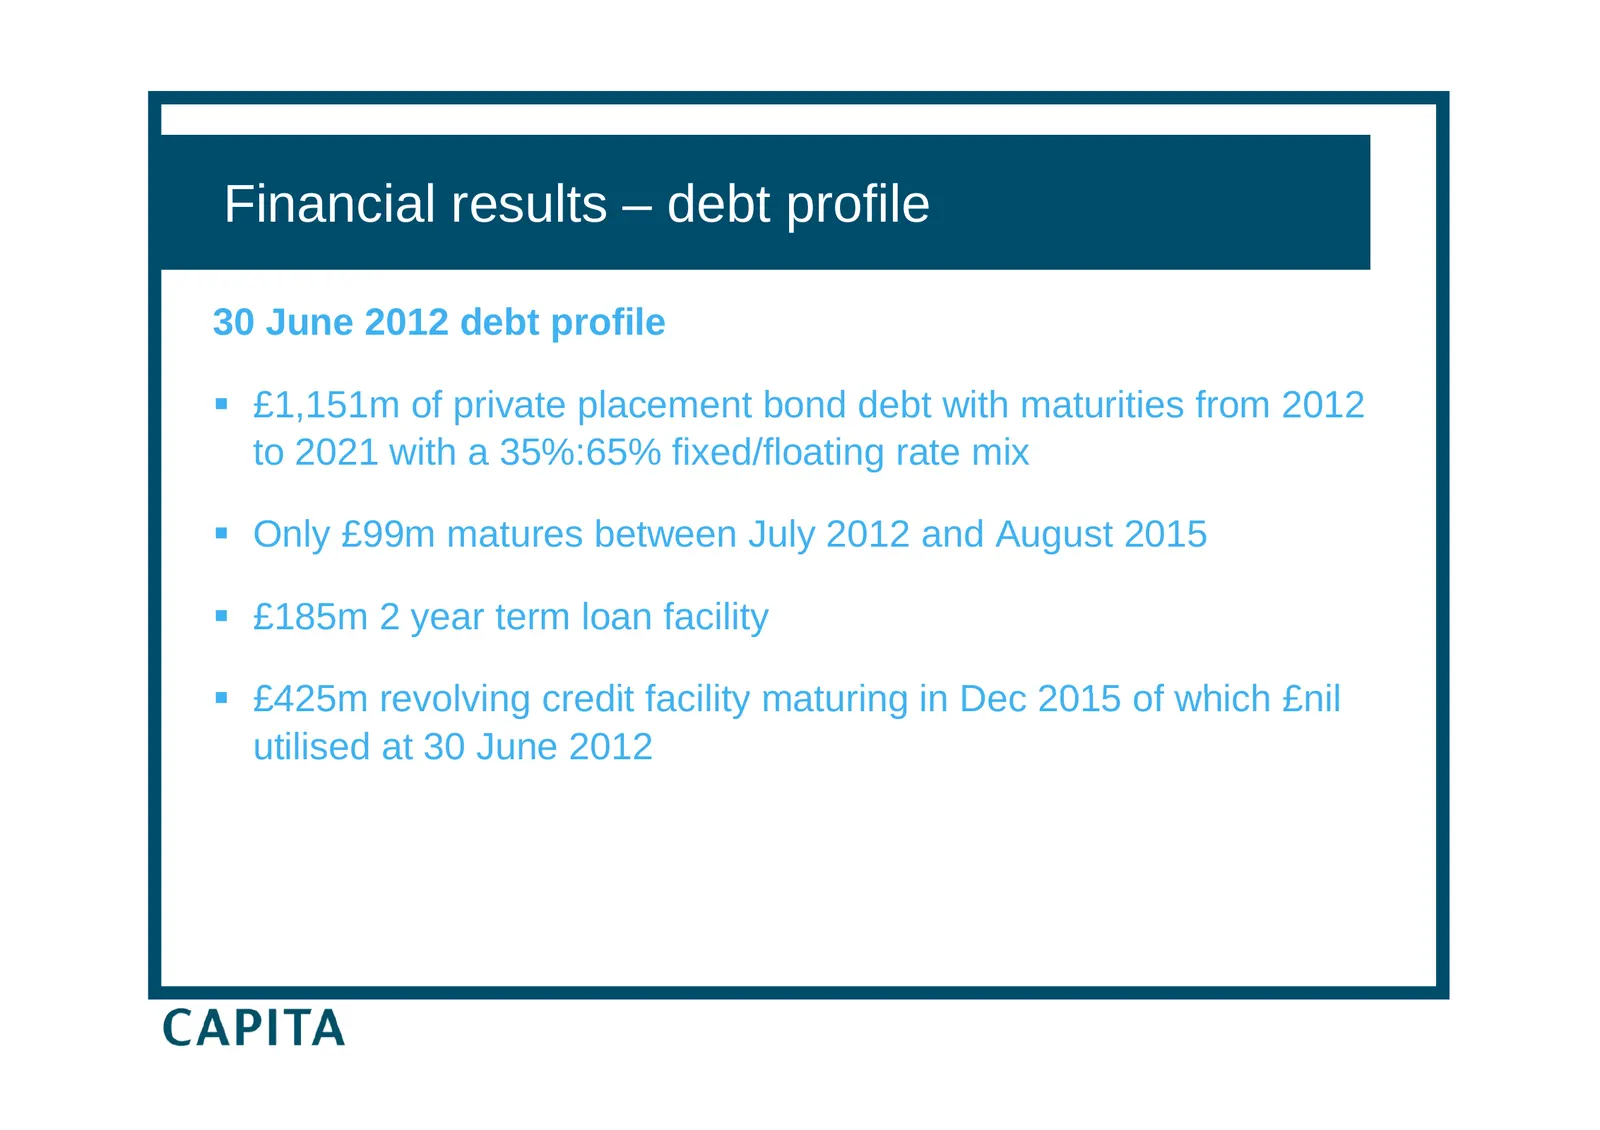
Slide 20: Financial results – debt profile
Financial results – debt profile 30 June J 2012 debt d b profile fil £1,151m of private placement bond debt with maturities from 2012 to 2021 with a 35%:65% fixed/floating rate mix Only £99m matures between July 2012 and August 2015 £185m 2 year term loan facility £425m revolving credit faci
Slide 21: Creating long term value
Creating long term value Maggi Bell, Business Development Director Paul Pindar, Chief Executive
Slide 22: Creating organic growth – 2012 major contracts
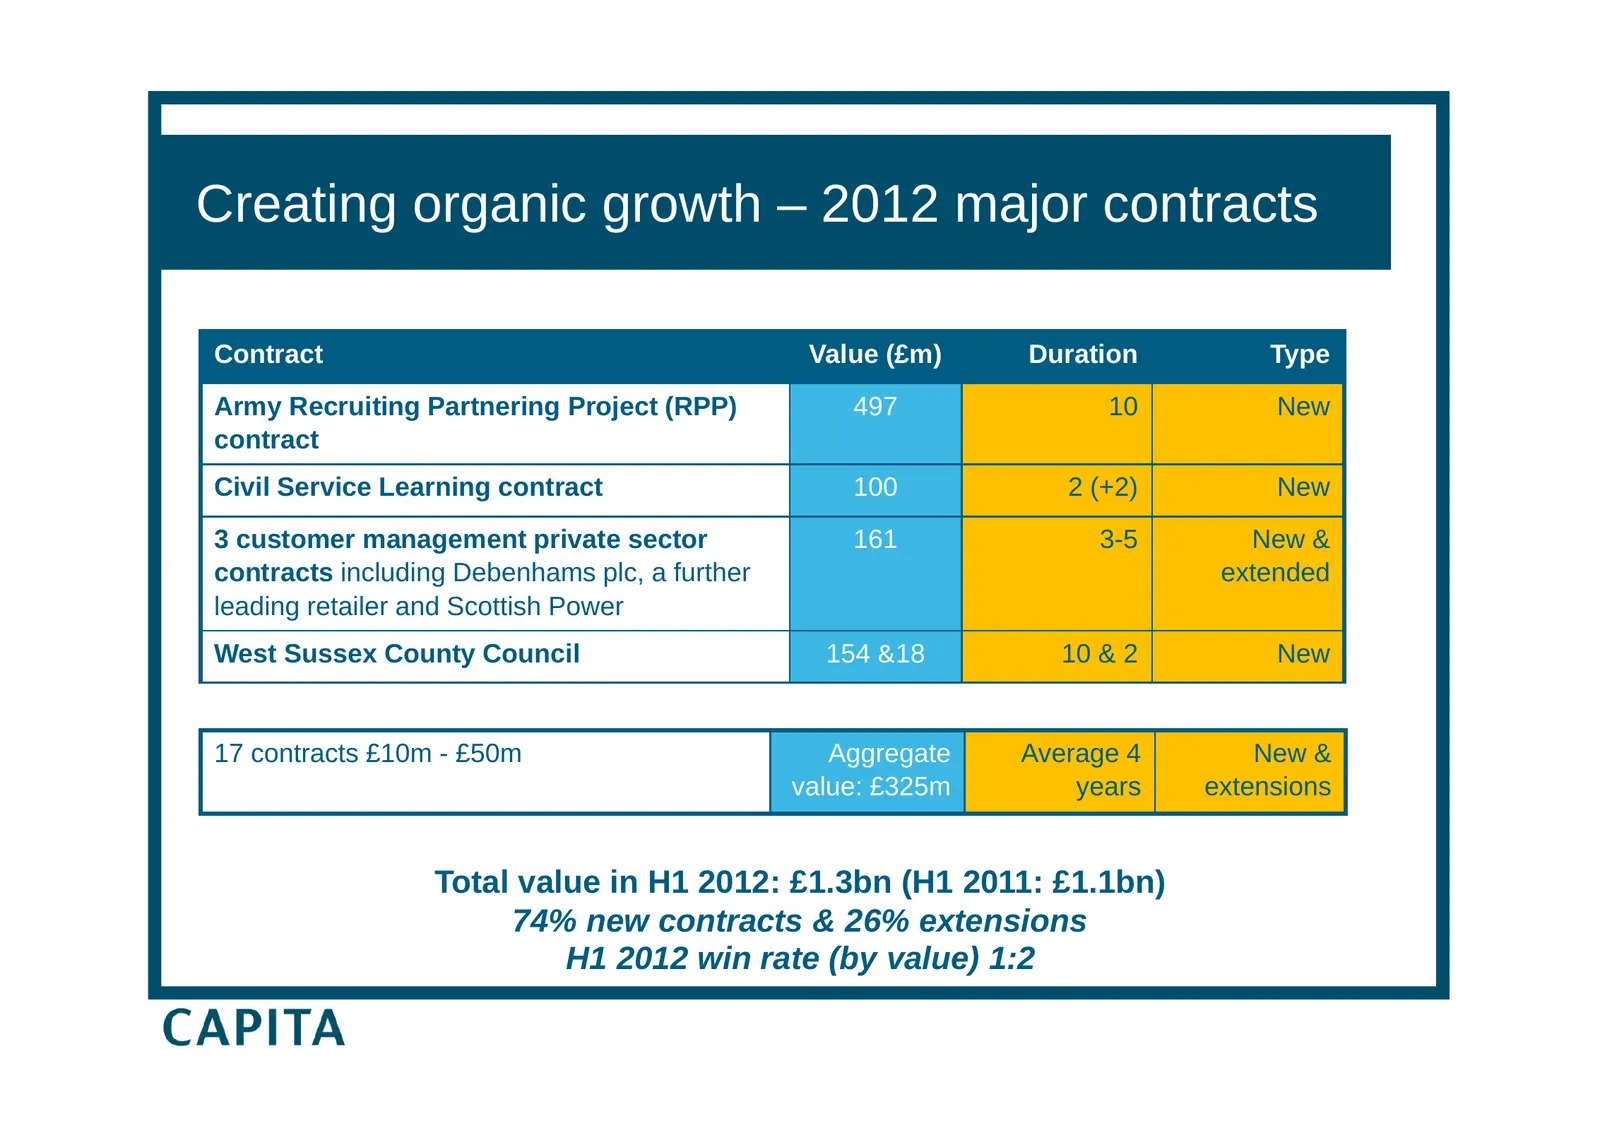
Creating organic growth – 2012 major contracts Contract Value (£m) Duration Type Army Recruiting Partnering Project (RPP) 497 10 New contract Civil Service Learning contract 100 2 (+2) New 3 customer management private sector 161 3-5 New & contracts t t including i l di D Debenhams b h plc, l a ffur
Slide 23: Recruiting Partnering Project (RPP)
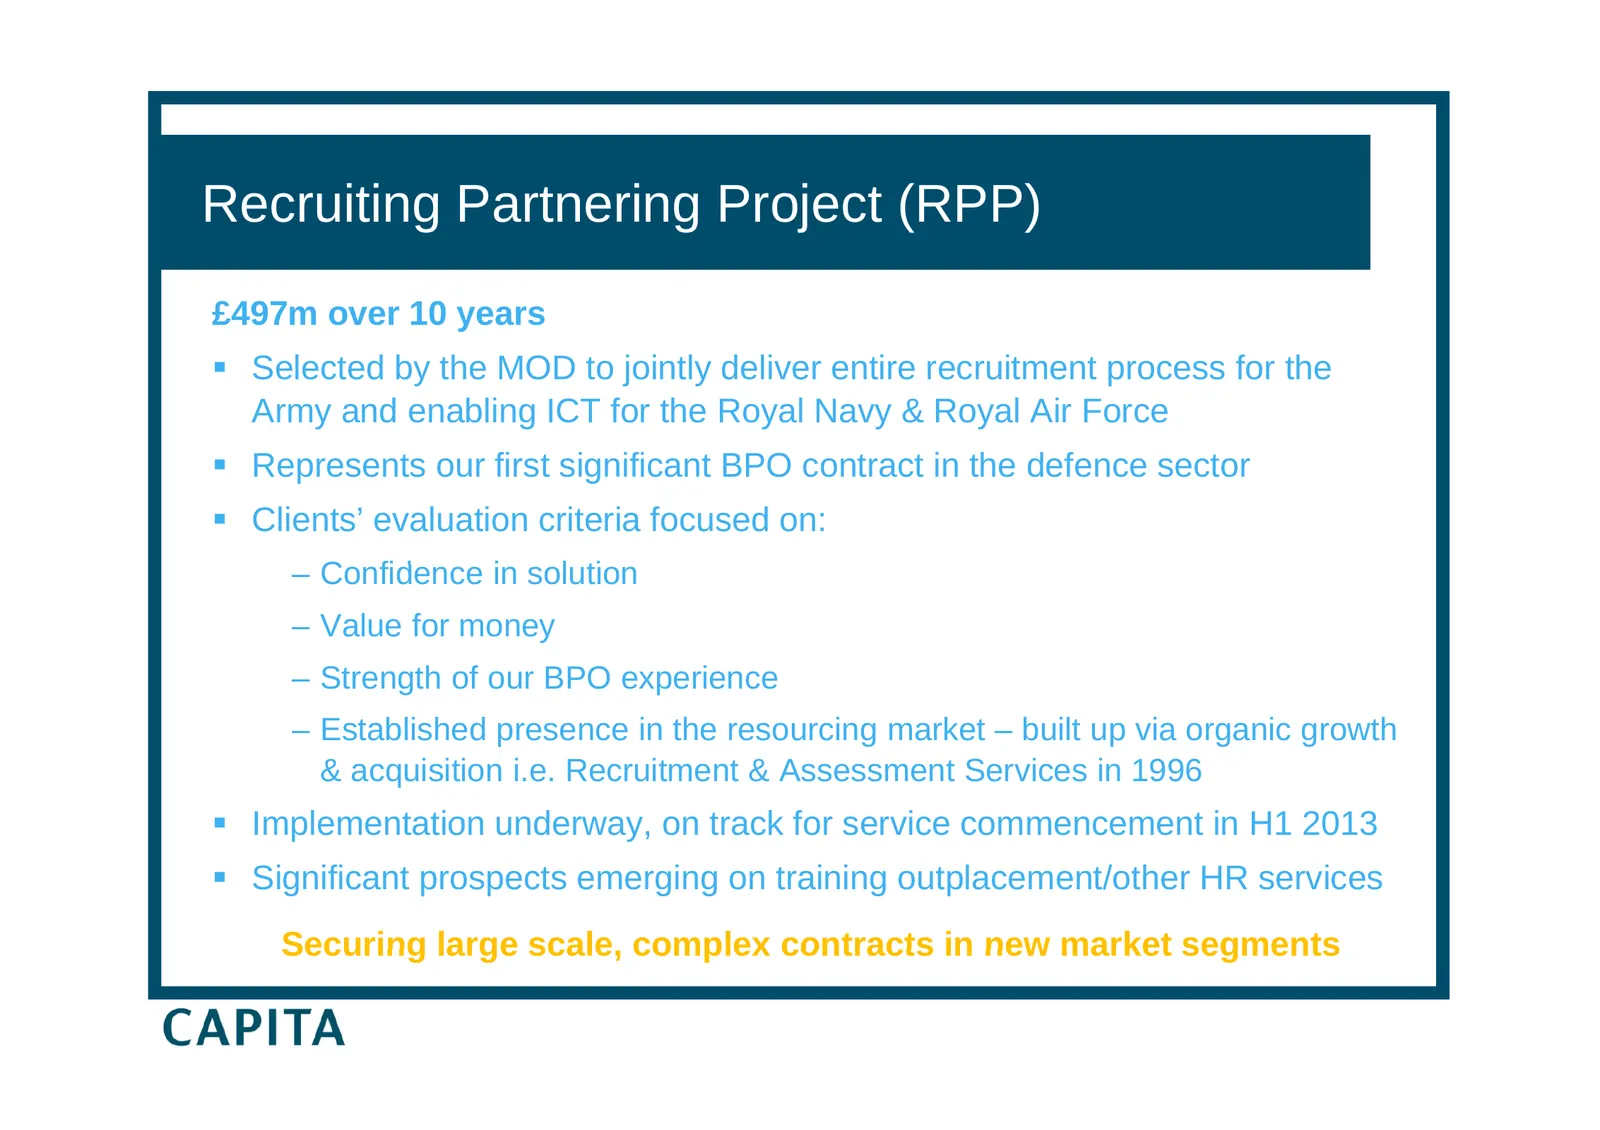
Recruiting Partnering Project (RPP) £497m over 10 years Selected by the MOD to jointly deliver entire recruitment process for the Army and enabling ICT for the Royal Navy & Royal Air Force Represents our first significant BPO contract in the defence sector Clients’ evaluation criteria focused
Slide 24: Civil Service Learning agreement
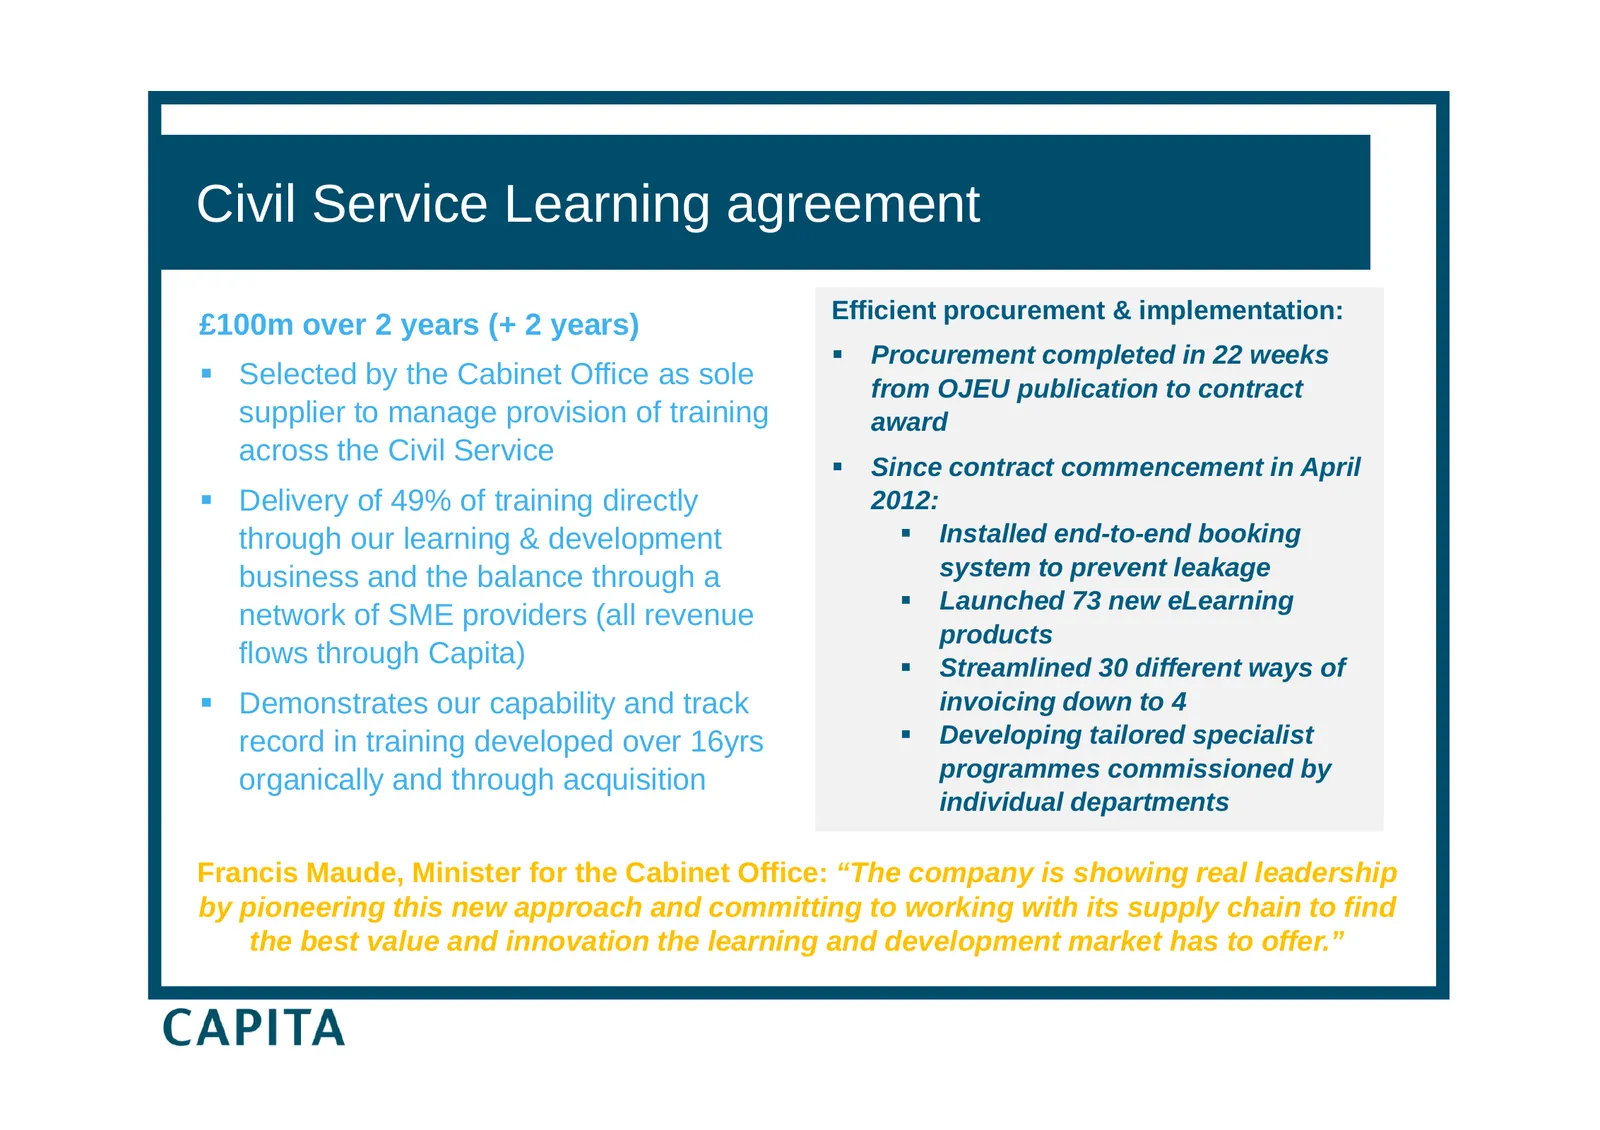
Civil Service Learning agreement Efficient procurement & implementation: £100m over 2 years (+ 2 years) Procurement completed in 22 weeks Selected by the Cabinet Office as sole from OJEU publication to contract supplier to manage provision of training award across the Civil Service Since contr
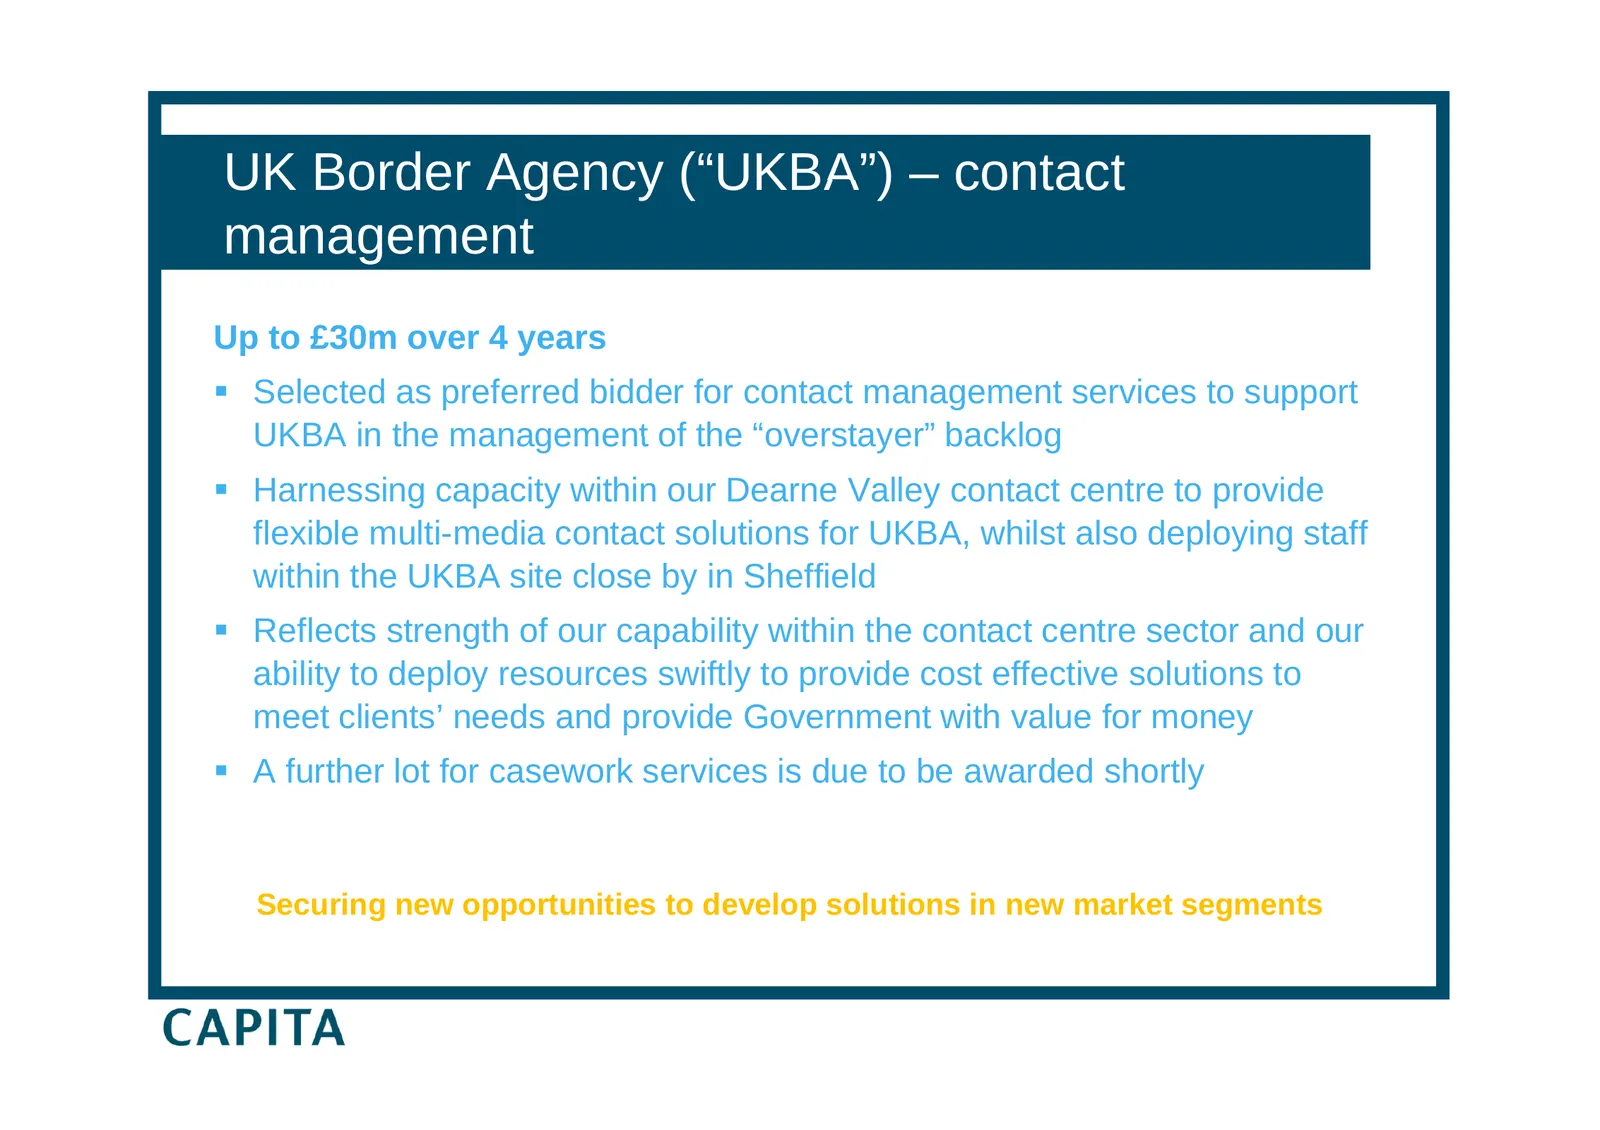
Slide 25: UK Border Agency – contact management
UK Border Agency (“UKBA”) ( UKBA ) – contact management Up to £30m over 4 years Selected as preferred bidder for contact management services to support UKBA in the management of the “overstayer” overstayer backlog Harnessing capacity within our Dearne Valley contact centre to provide flexible mu
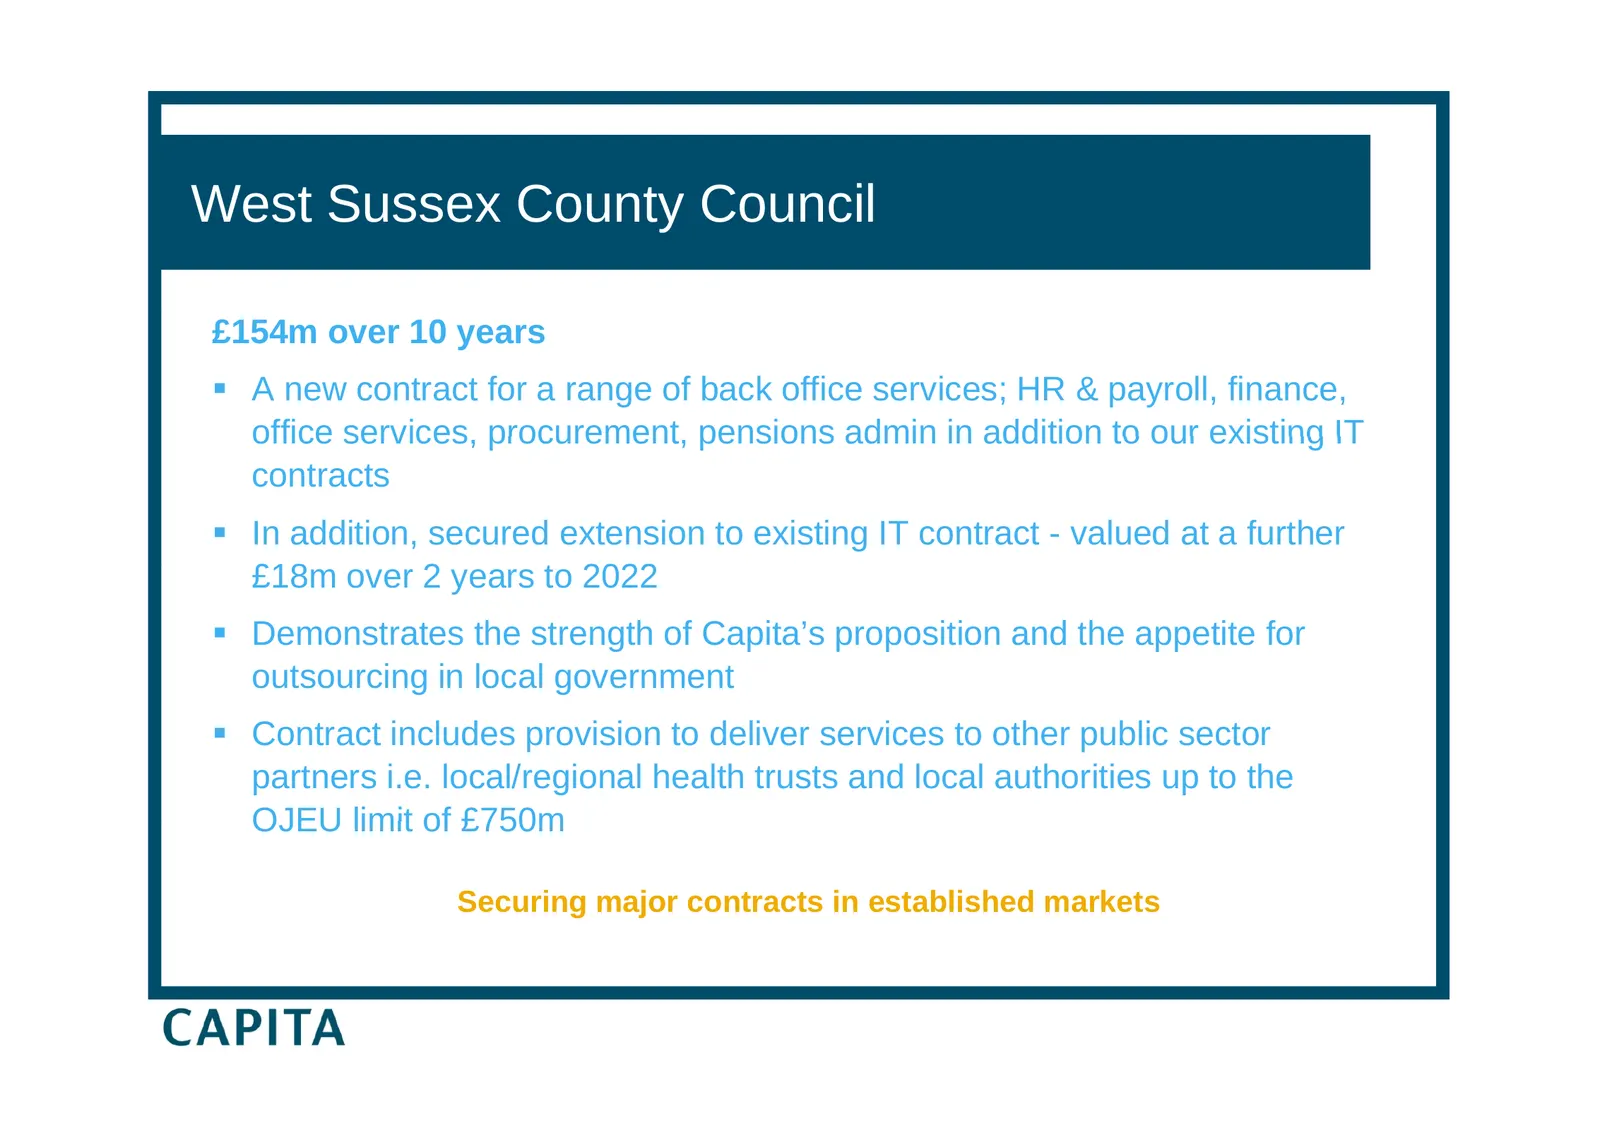
Slide 26: West Sussex County Council
West Sussex County Council £154m over 10 years A new contract for a range of back office services; HR & payroll, finance, office services, services procurement, procurement pensions admin in addition to our existing IT contracts In addition, secured extension to existing IT contract - valued at
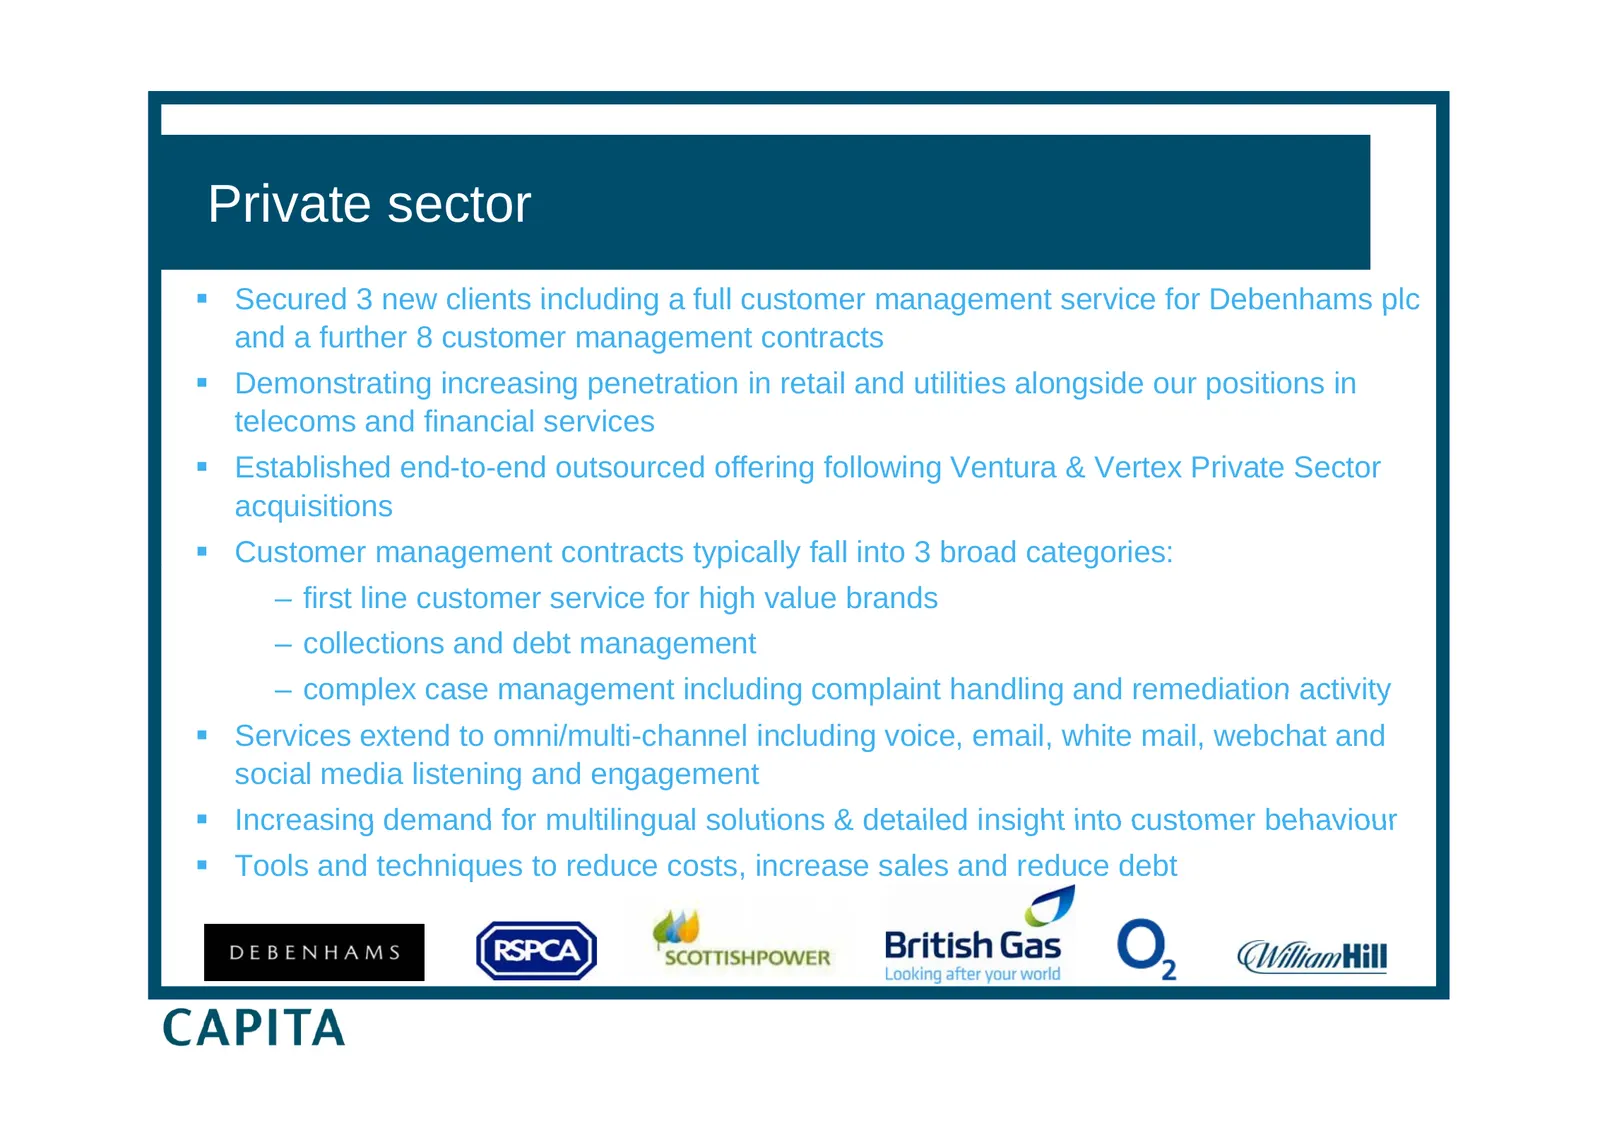
Slide 27: Private sector
Private sector Secured 3 new clients including a full customer management service for Debenhams plc and a further 8 customer management contracts Demonstrating increasing penetration in retail and utilities alongside our positions in telecoms and financial services Established end-to-end outso
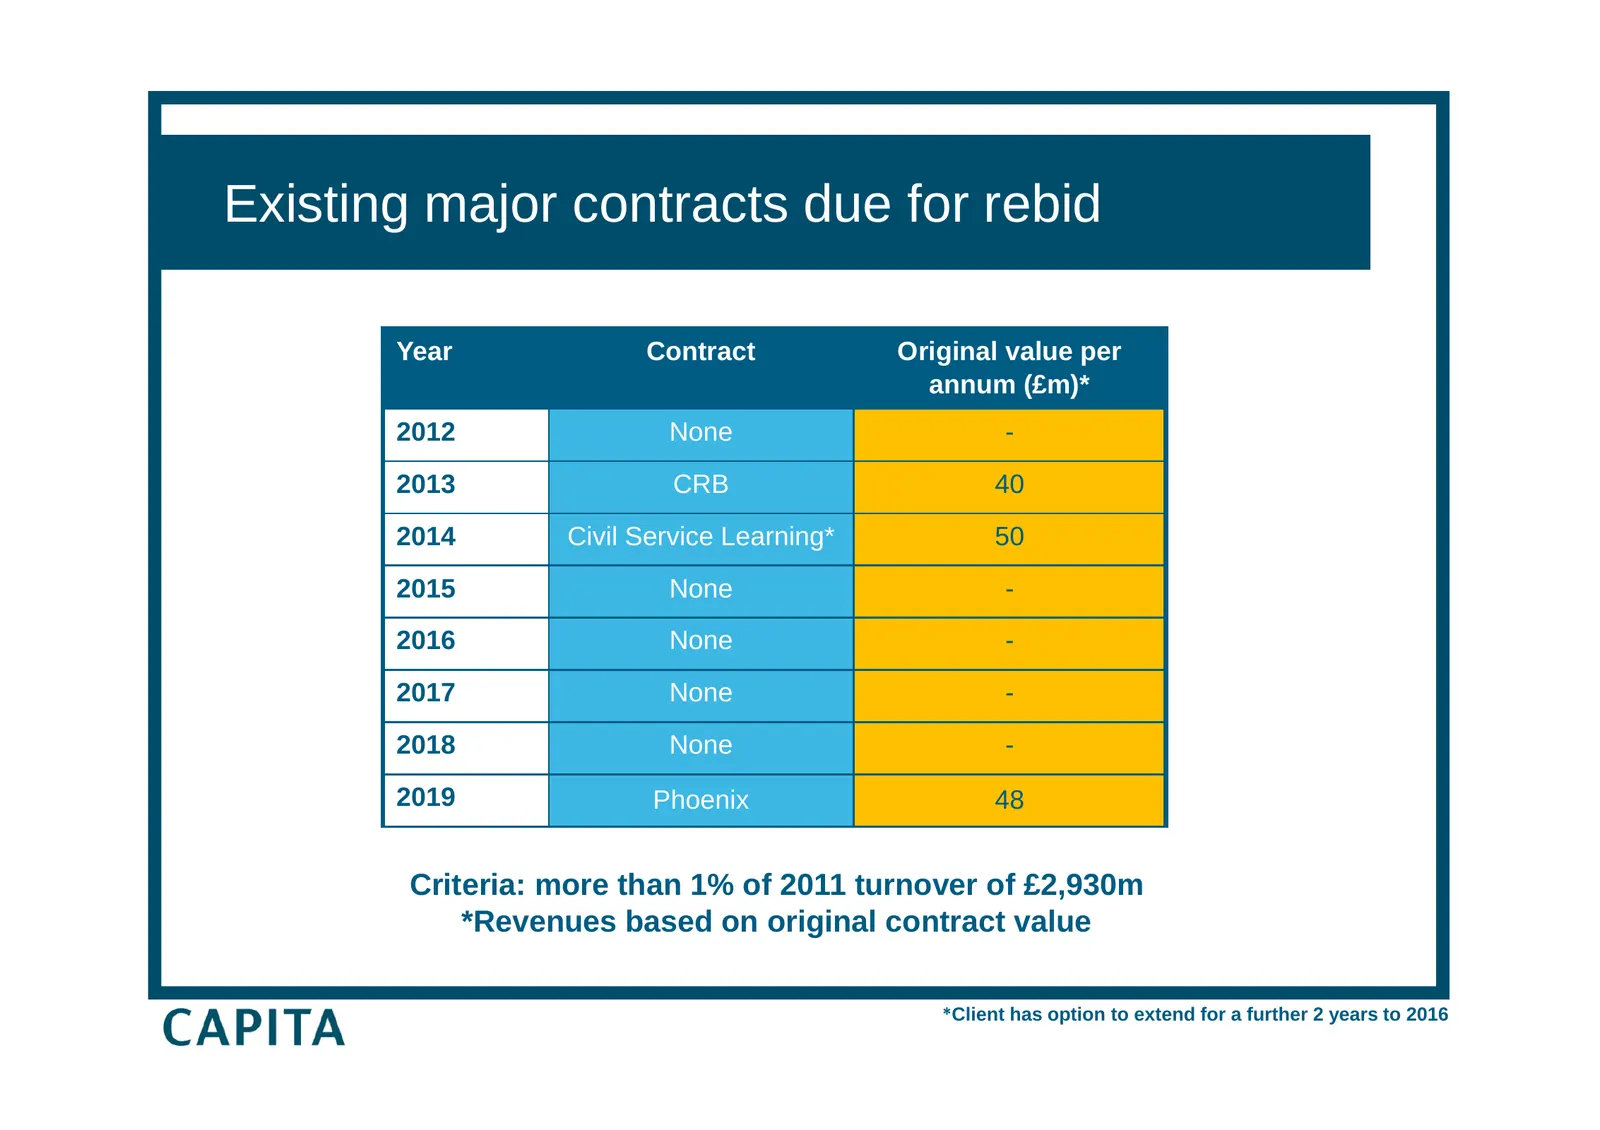
Slide 28: Existing major contracts due for rebid
Existing major contracts due for rebid Year Contract Original value per annum (£m)* 2012 None - 2013 CRB 40 2014 Civil Service Learning* 50 2015 None - 2016 None - 2017 None - 2018 None - 2019 Phoenix 48 Criteria: more than 1% of 2011 turnover of £2,930m *Revenues based on original contract value *C
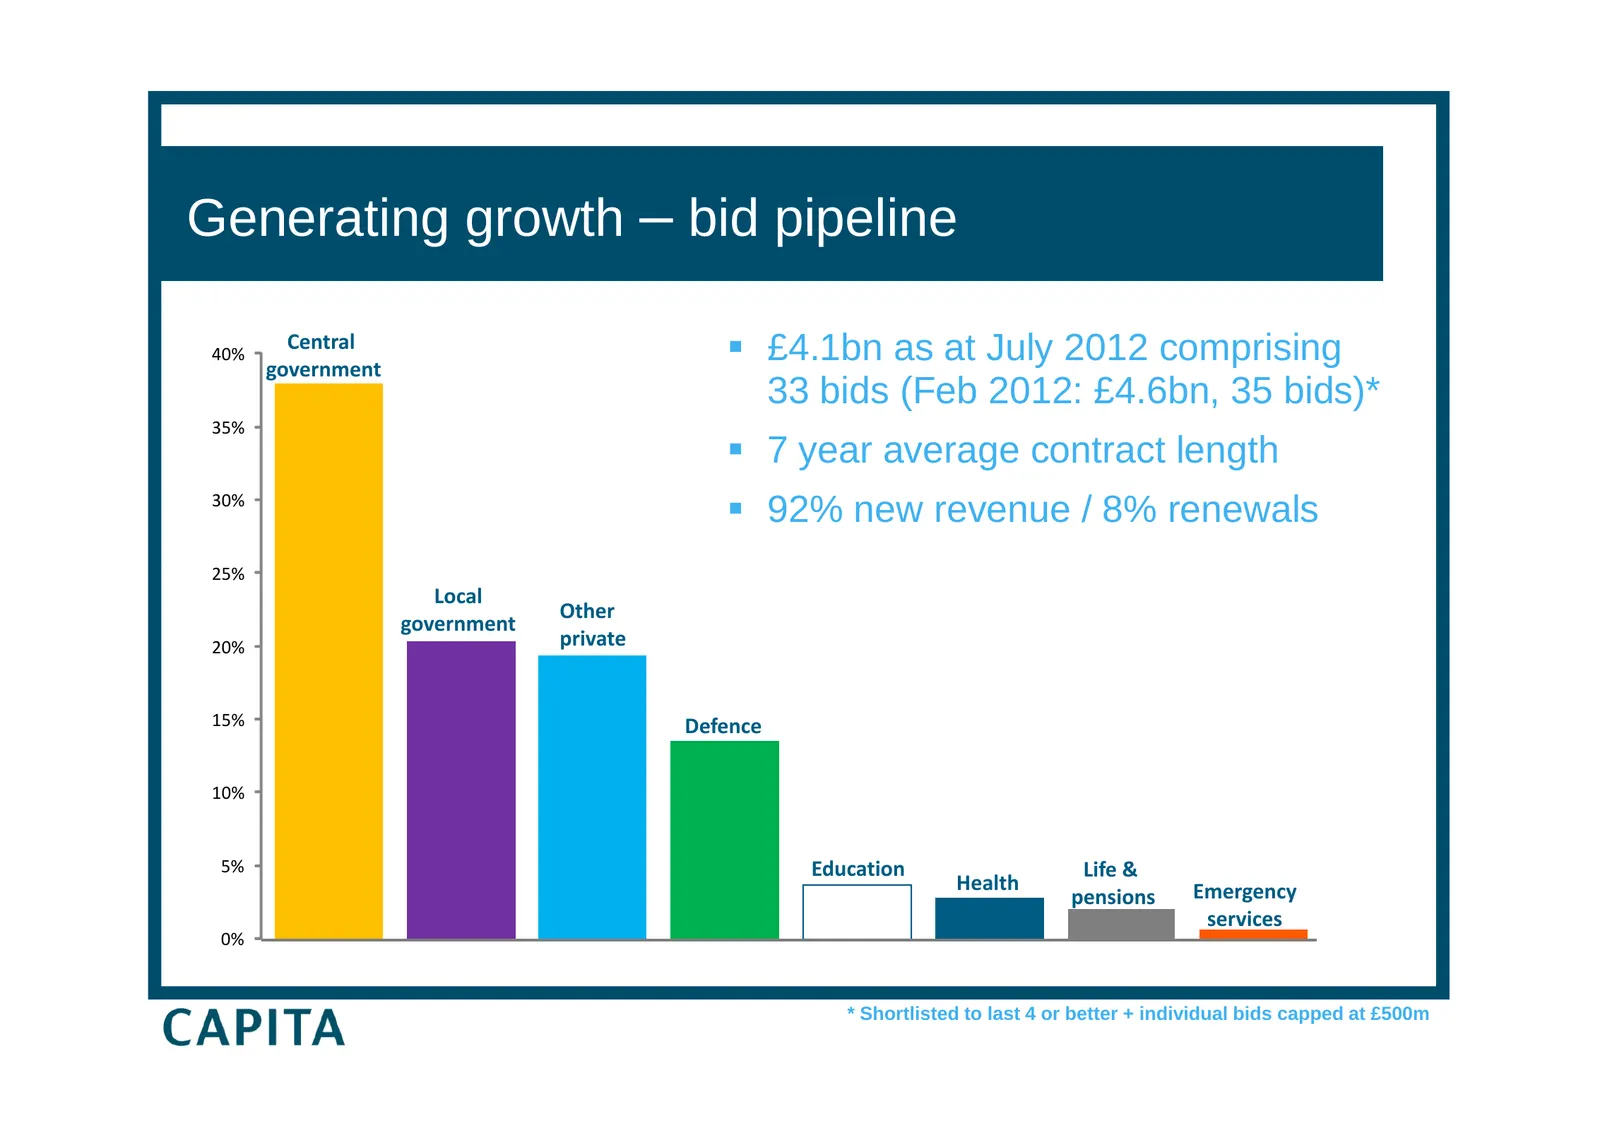
Slide 29: Generating growth – bid pipeline
Generating growth – bid pipeline 40% Central government £4.1bn as at July 2012 comprising 33 bids (Feb 2012: £4.6bn, 35 bids)* 35% 7 year average contract t t length l th 30% 92% new revenue / 8% renewals 25% Local Other government 20% private 15% Defence 10% 5% Education Life & Health Emergen
Slide 30: Public sector procurement: Frameworks
Public sector procurement: Frameworks Central Government intention to act as “one customer” Standardising its approach for less complex procurements Increasing number of pan-Government framework contracts – all departments and public sector bodies can buy from a pre-qualified list of suppliers
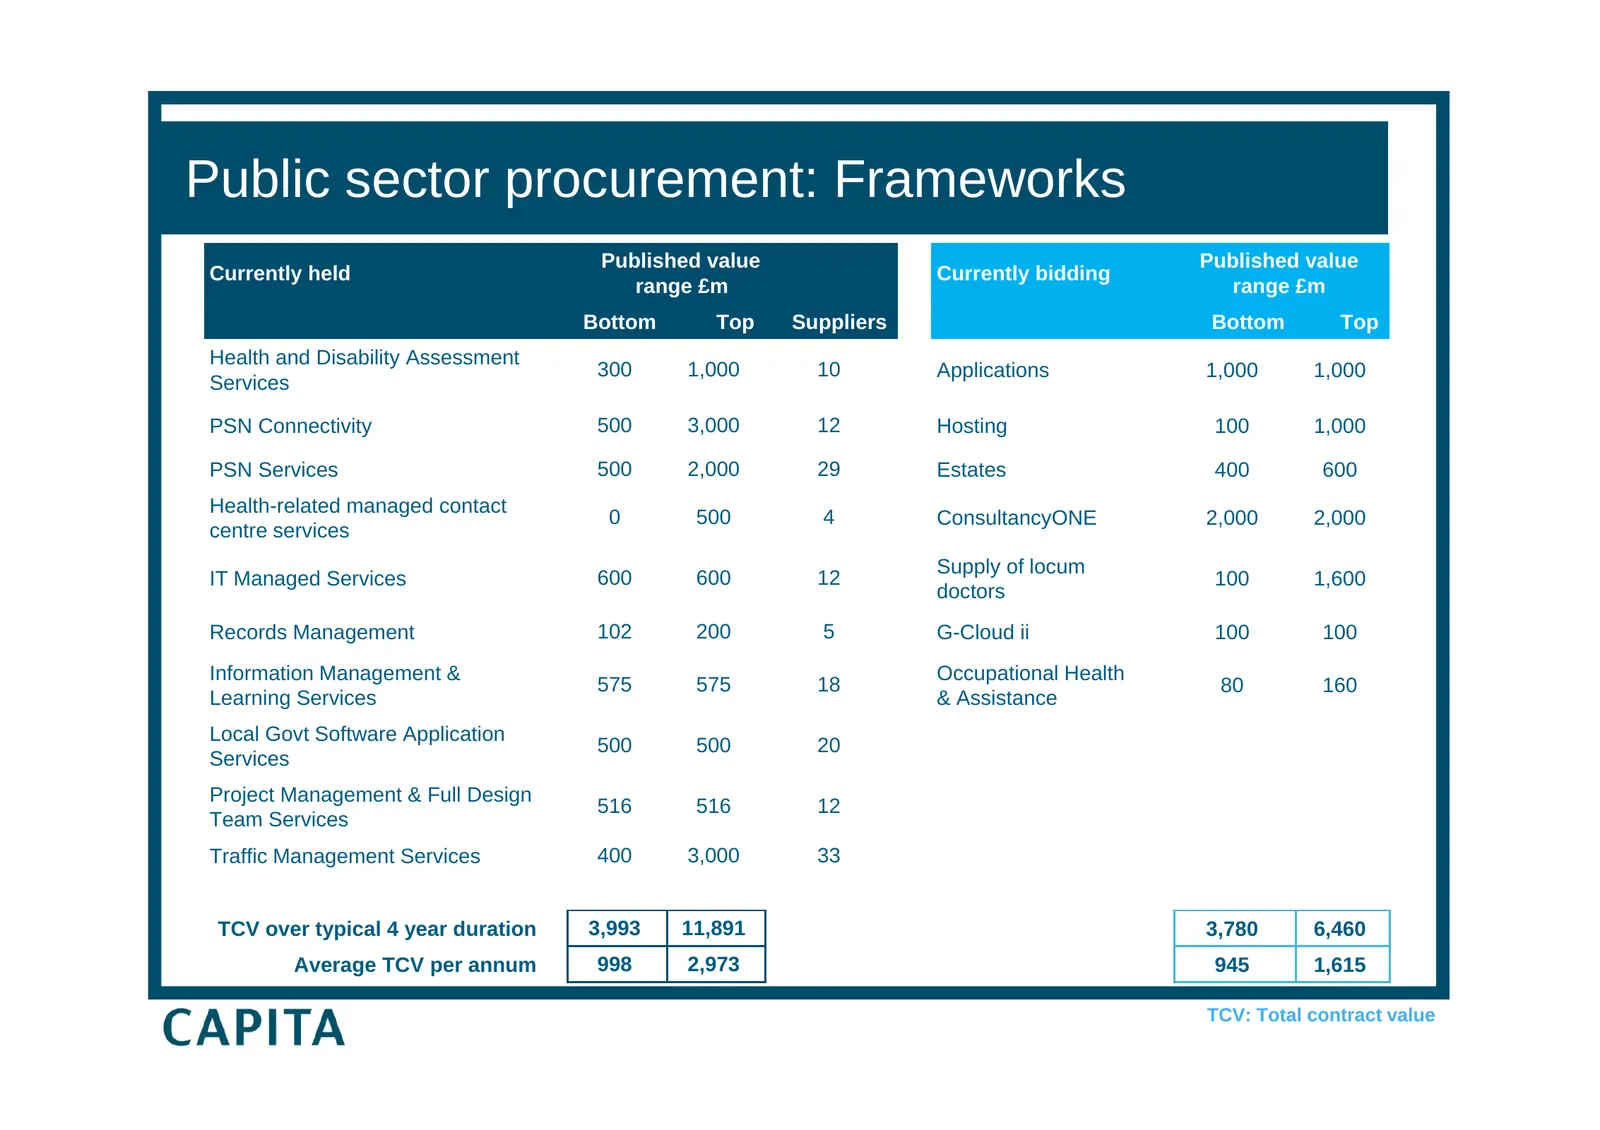
Slide 31: Public sector procurement: Frameworks
Public sector procurement: Frameworks Published value Published value Currently held Currently bidding range £m range £m Bottom Top Suppliers Bottom Top Health and Disability Assessment 300 1,000 10 Applications 1,000 1,000 Services y PSN Connectivity 500 3,000 12 g Hosting 100 1,000 PSN Services 50
Slide 32: Delivering value through acquisitions
Delivering value through acquisitions Paul Pindar
Slide 33: Capital raising – background
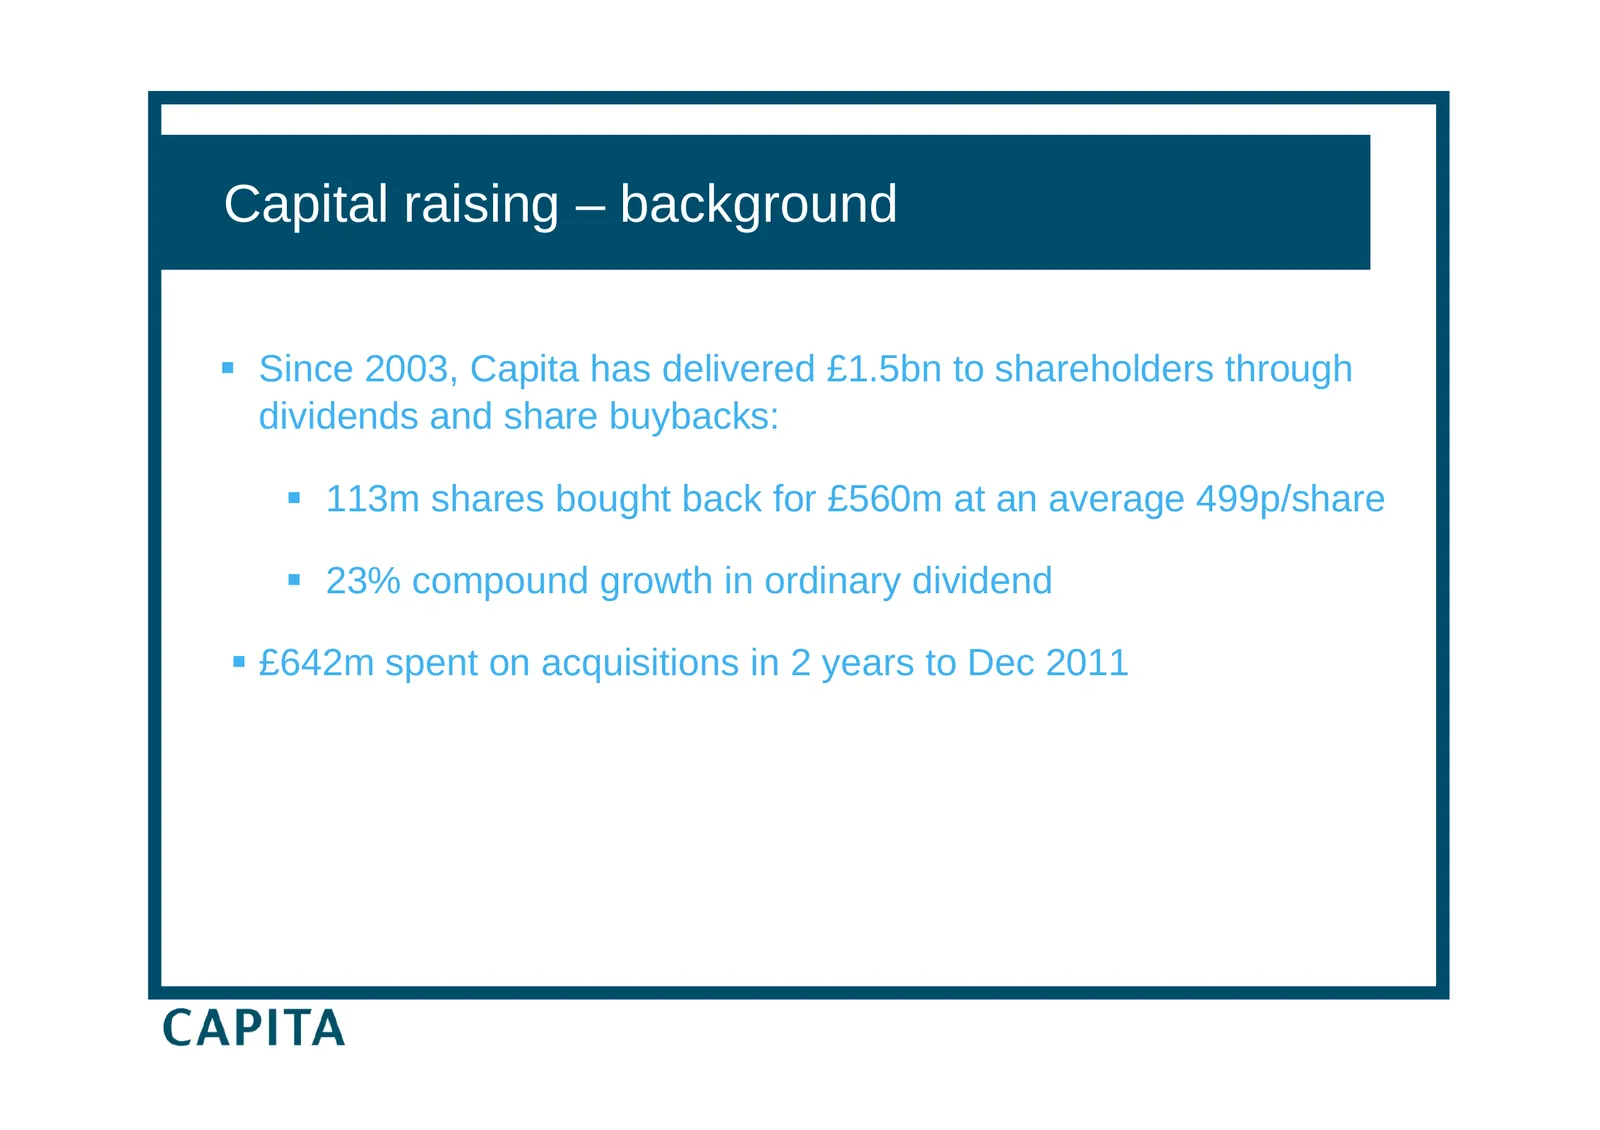
Capital raising – background Since 2003, Capita has delivered £1.5bn to shareholders through y dividends and share buybacks: 113m shares bought back for £560m at an average 499p/share 23% compound growth in ordinary dividend £642m spent on acquisitions in 2 years to Dec 2011
Slide 34: Capital raising – rationale
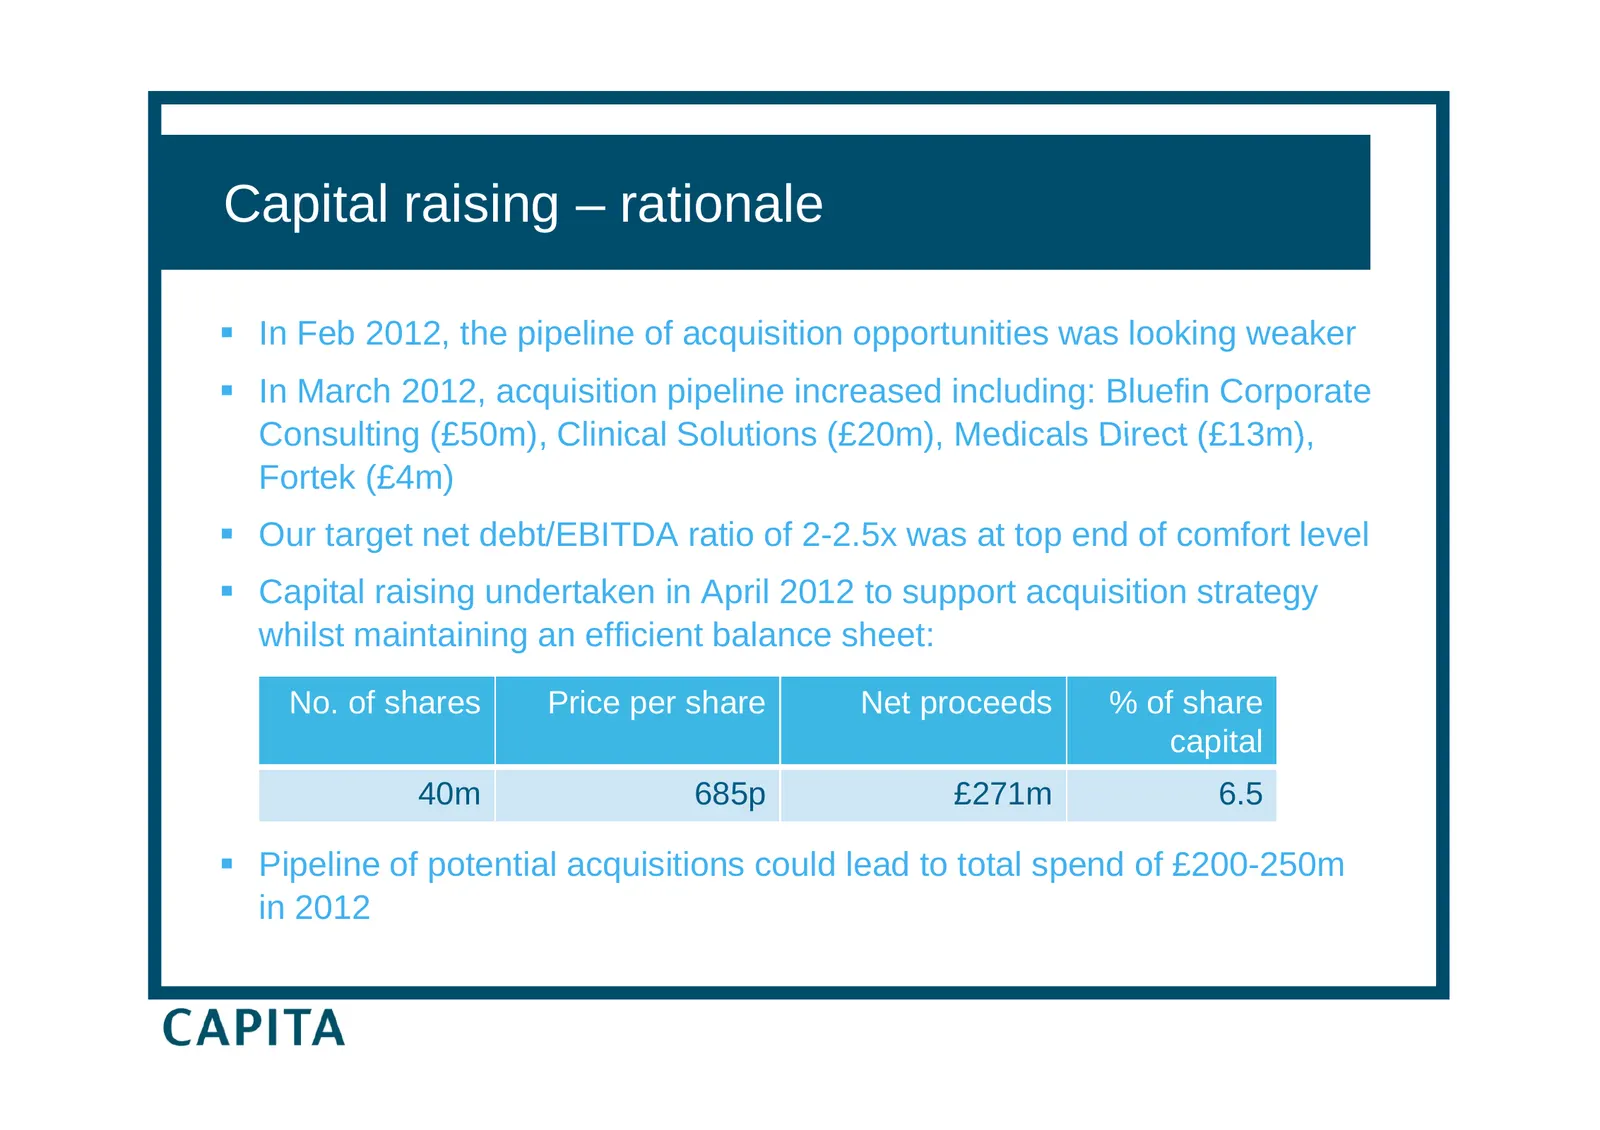
Capital raising – rationale In Feb 2012, the pipeline of acquisition opportunities was looking weaker In March 2012, acquisition pipeline increased including: Bluefin Corporate Consulting (£50m) (£50m), Clinical Solutions (£20m) (£20m), Medicals Direct (£13m) (£13m), Fortek (£4m) Our target ne
Slide 35: Creating growth – acquisitions to date 2012
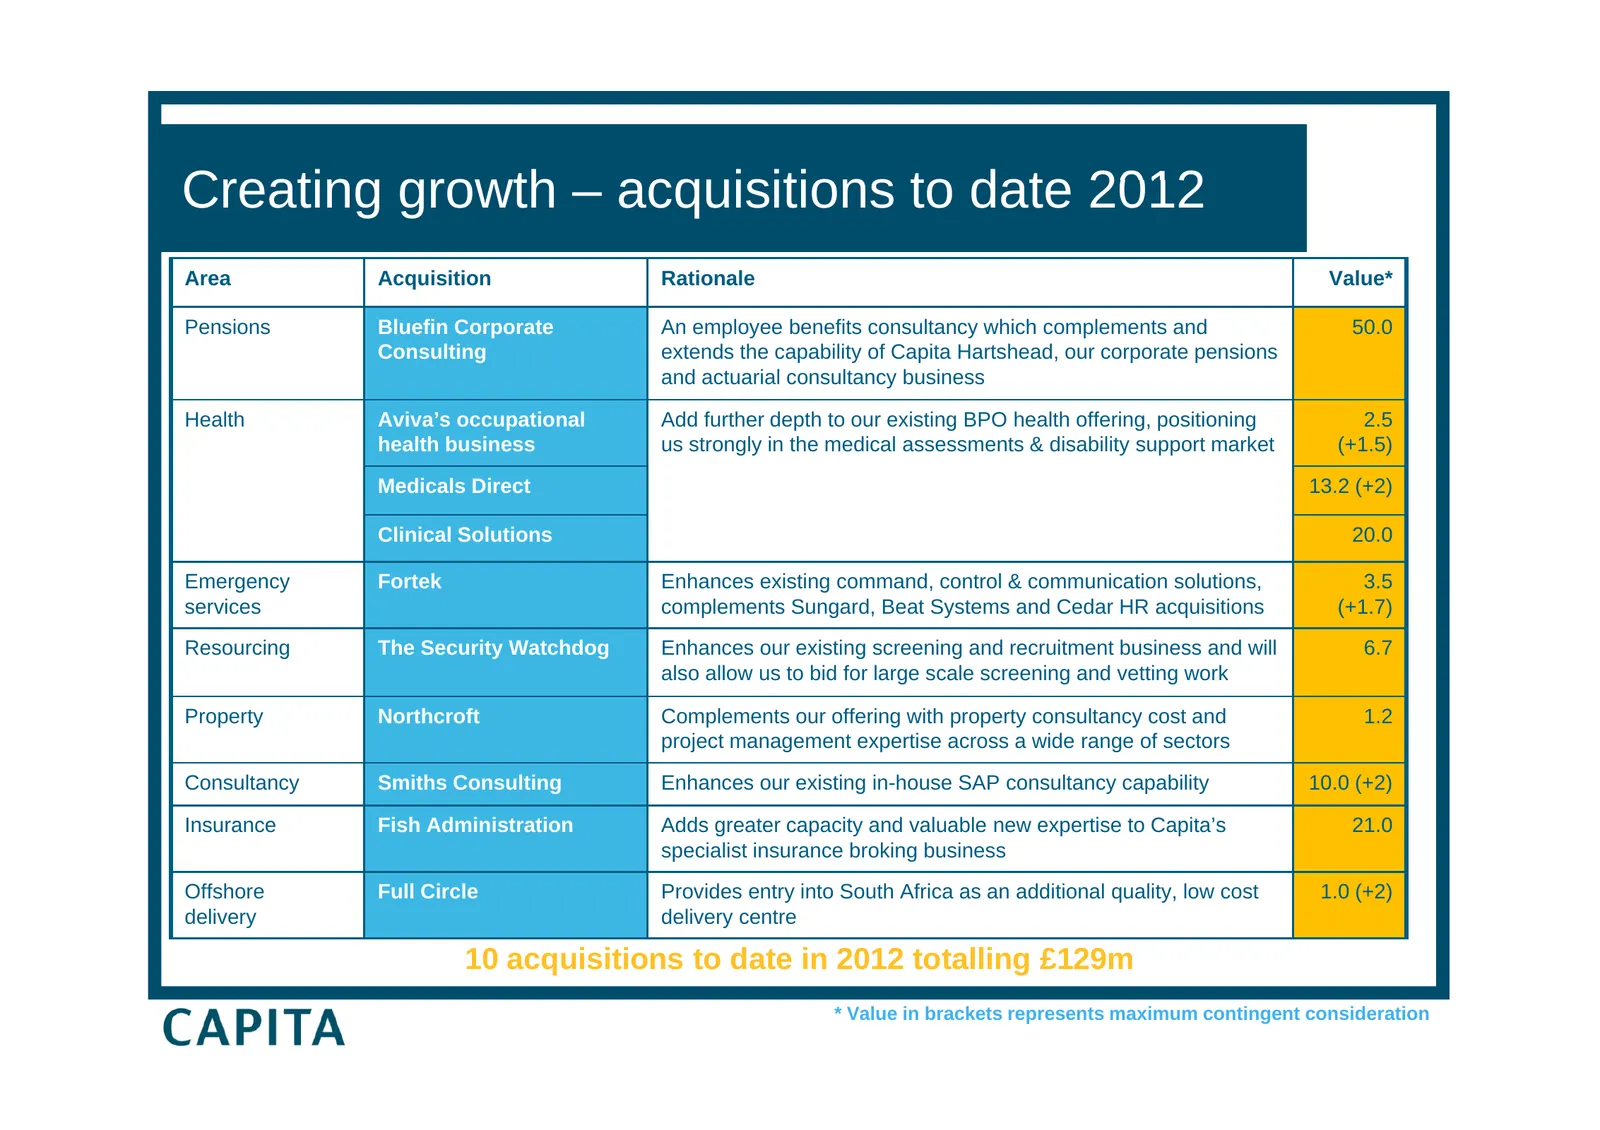
Creating growth – acquisitions to date 2012 Area Acquisition Rationale Value* Pensions Bluefin Corporate An employee benefits consultancy which complements and 50.0 Consulting extends the capability of Capita Hartshead, our corporate pensions and actuarial consultancy business Health Aviva’s occupat
Slide 36: Creating value – delivering returns
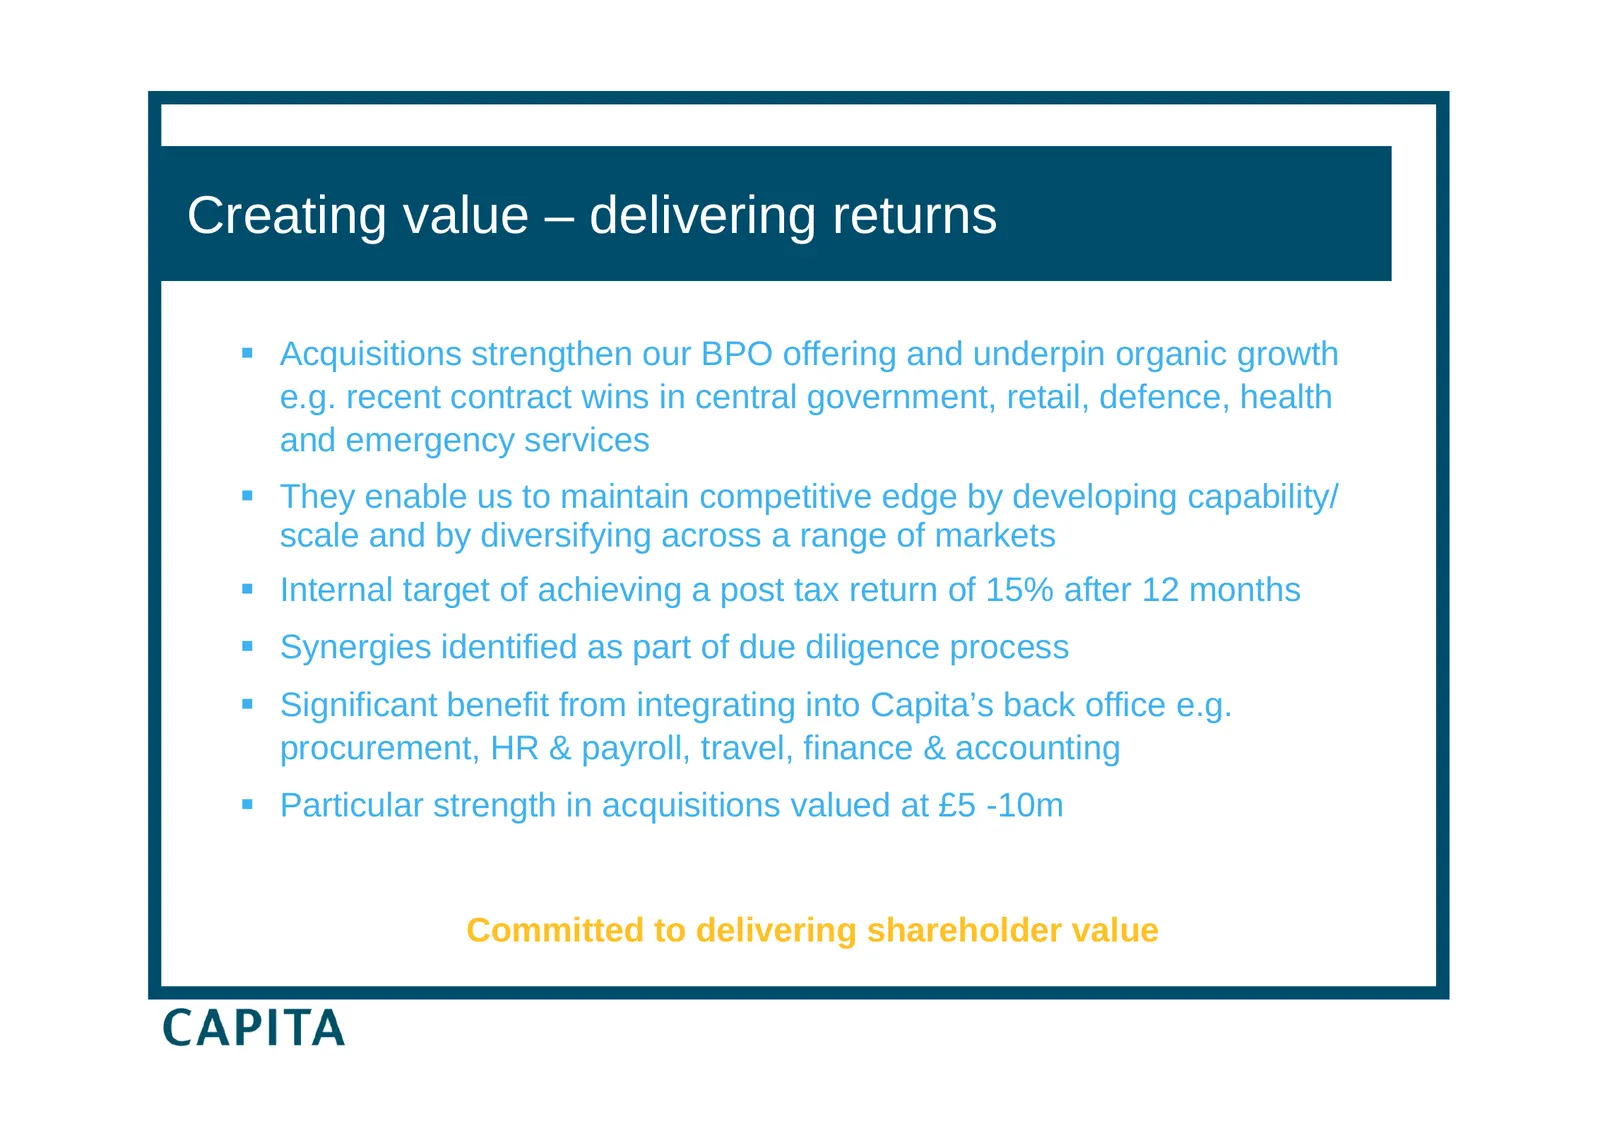
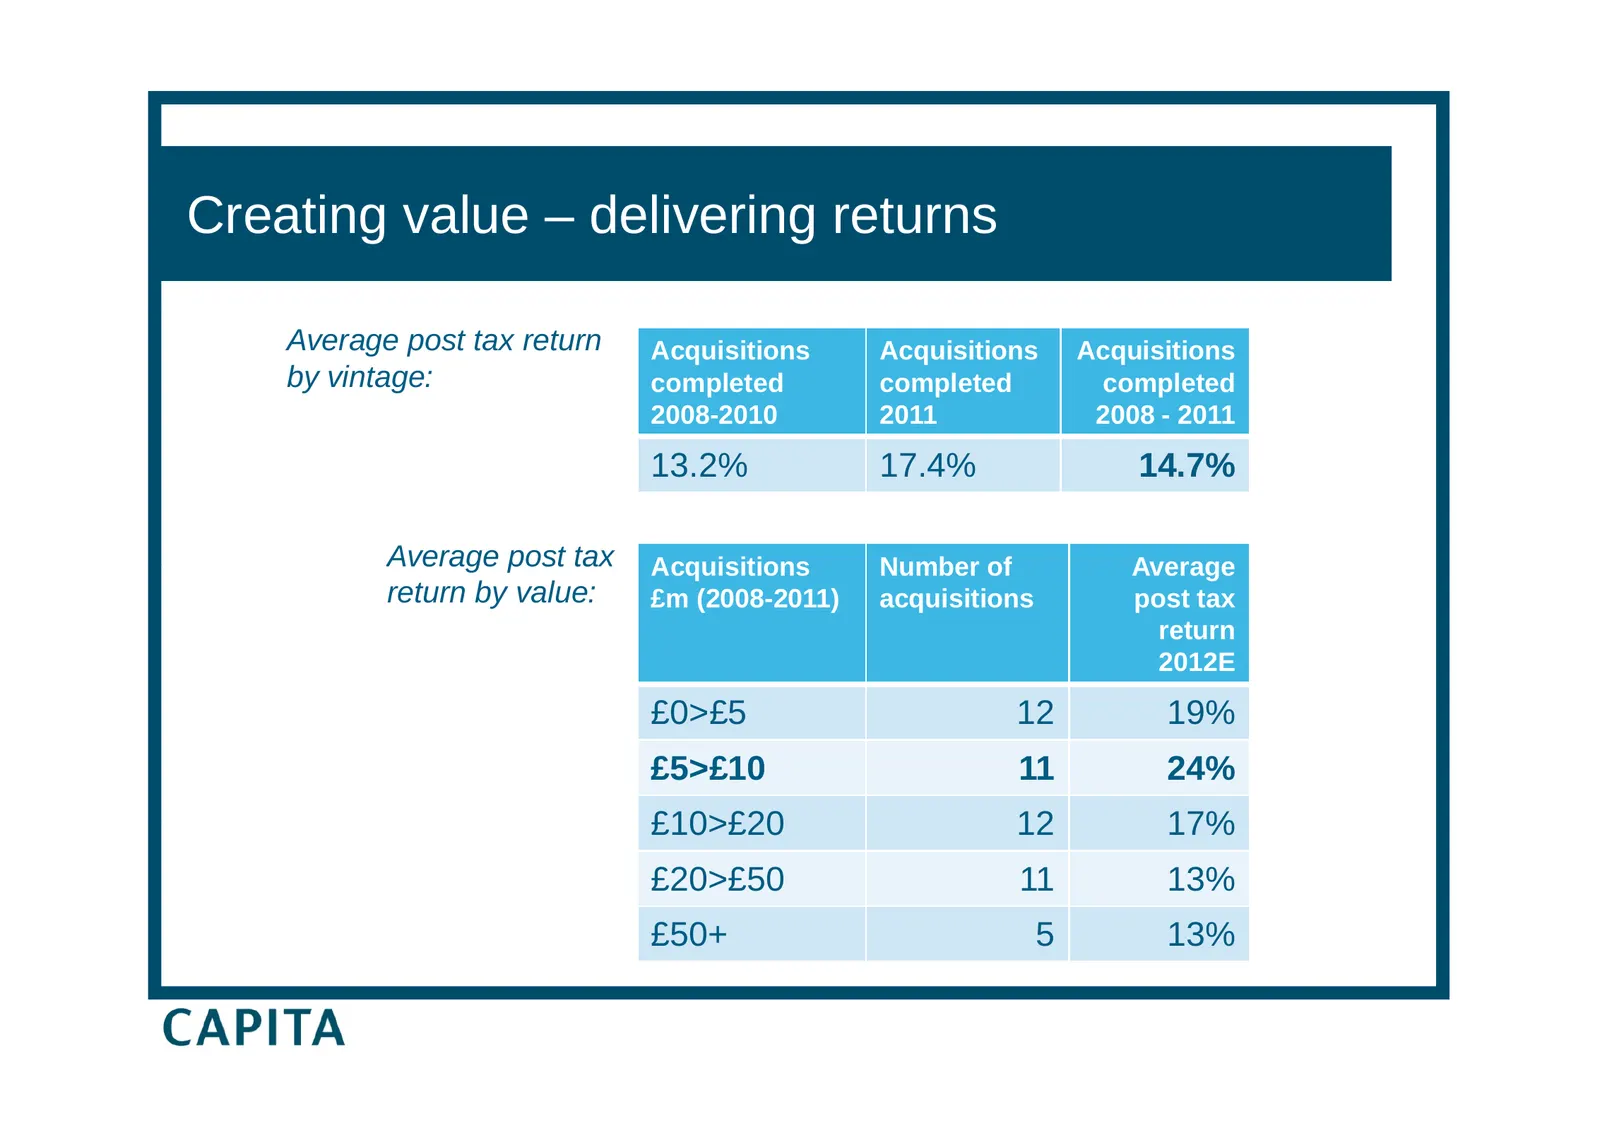
Creating value – delivering returns Acquisitions strengthen our BPO offering and underpin organic growth e.g. recent contract wins in central government, retail, defence, health and emergency services They enable us to maintain competitive edge by developing capability/ scale and by diversifying
Slide 37: Creating value – delivering returns
Creating value – delivering returns Average post tax return Acquisitions Acquisitions Acquisitions by vintage: completed completed completed 2008-2010 2011 2008 - 2011 13.2% 17.4% 14.7% Average post tax Acquisitions Number of Average return by value: £m (2008-2011) acquisitions post tax return 2012E
Slide 38: Creating value through small-medium sized acquisitions
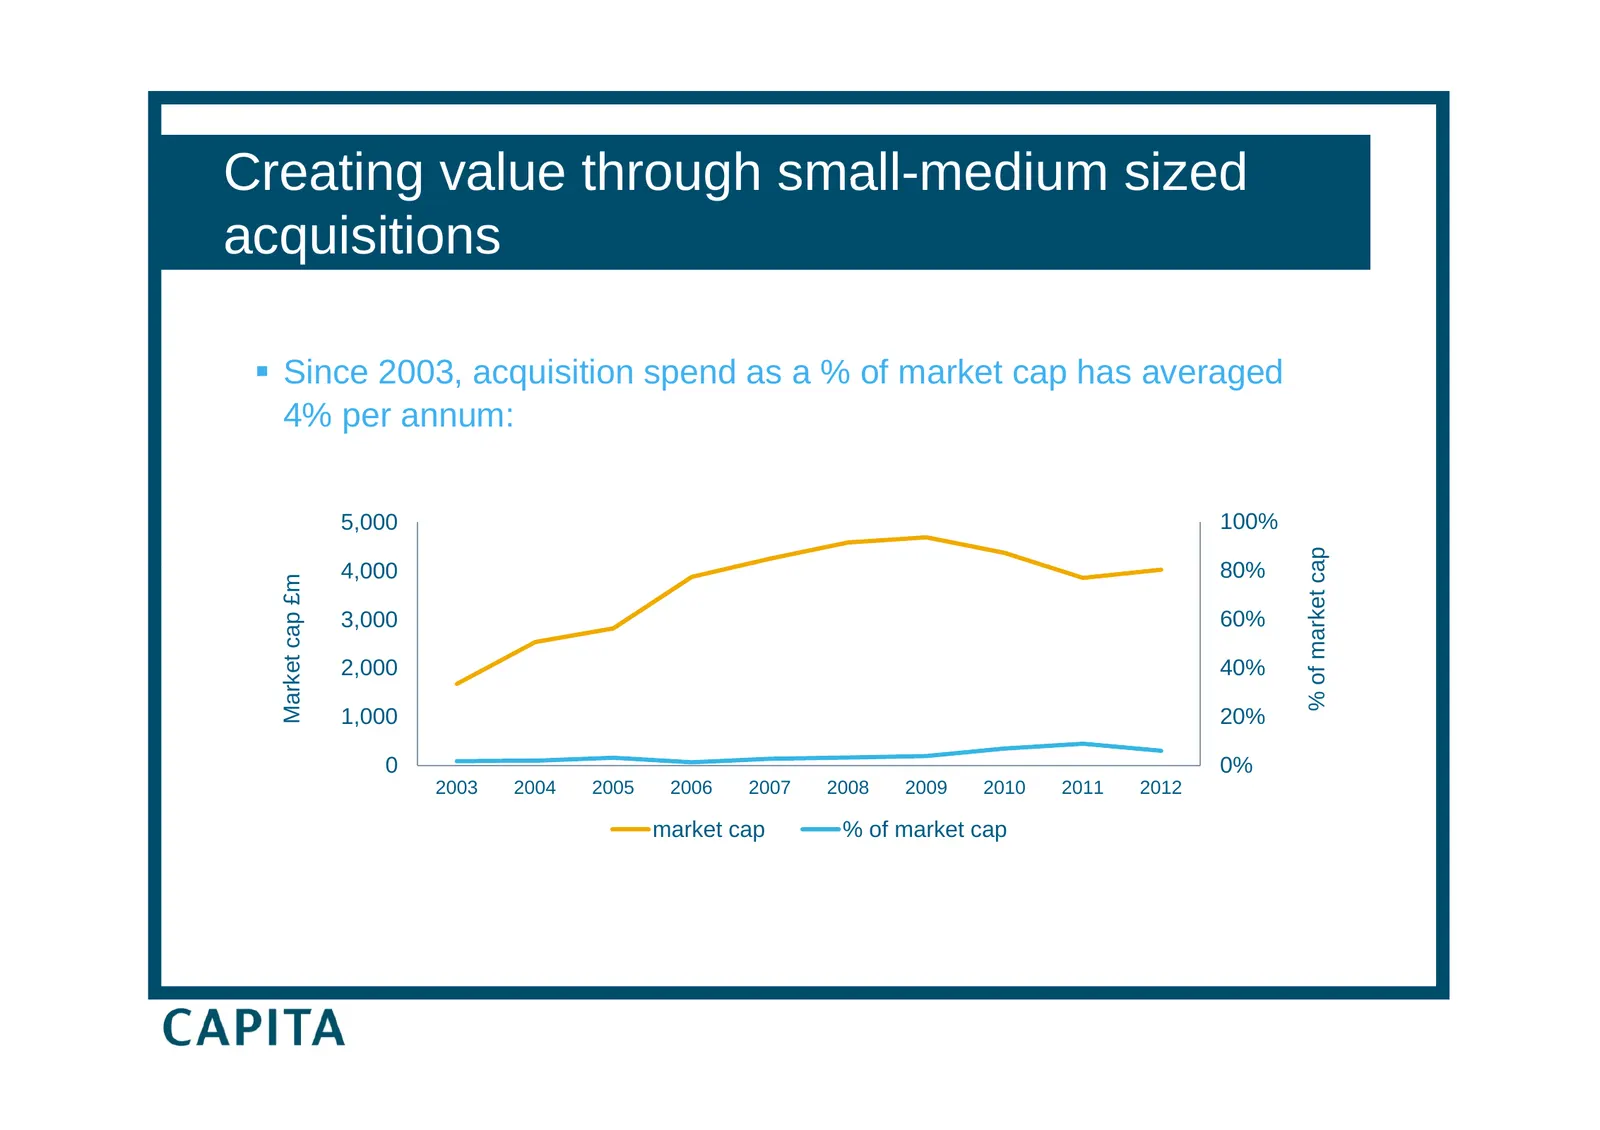
Creating value through small-medium small medium sized acquisitions Since 2003, acquisition spend as a % of market cap has averaged 4% per annum: 5,000 100% ap % of market ca 4 000 4,000 80% Market cap £m 3,000 60% 2,000 40% 1,000 20% 0 0% 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 market k
Slide 39: Creating value – diversifying through acquisition
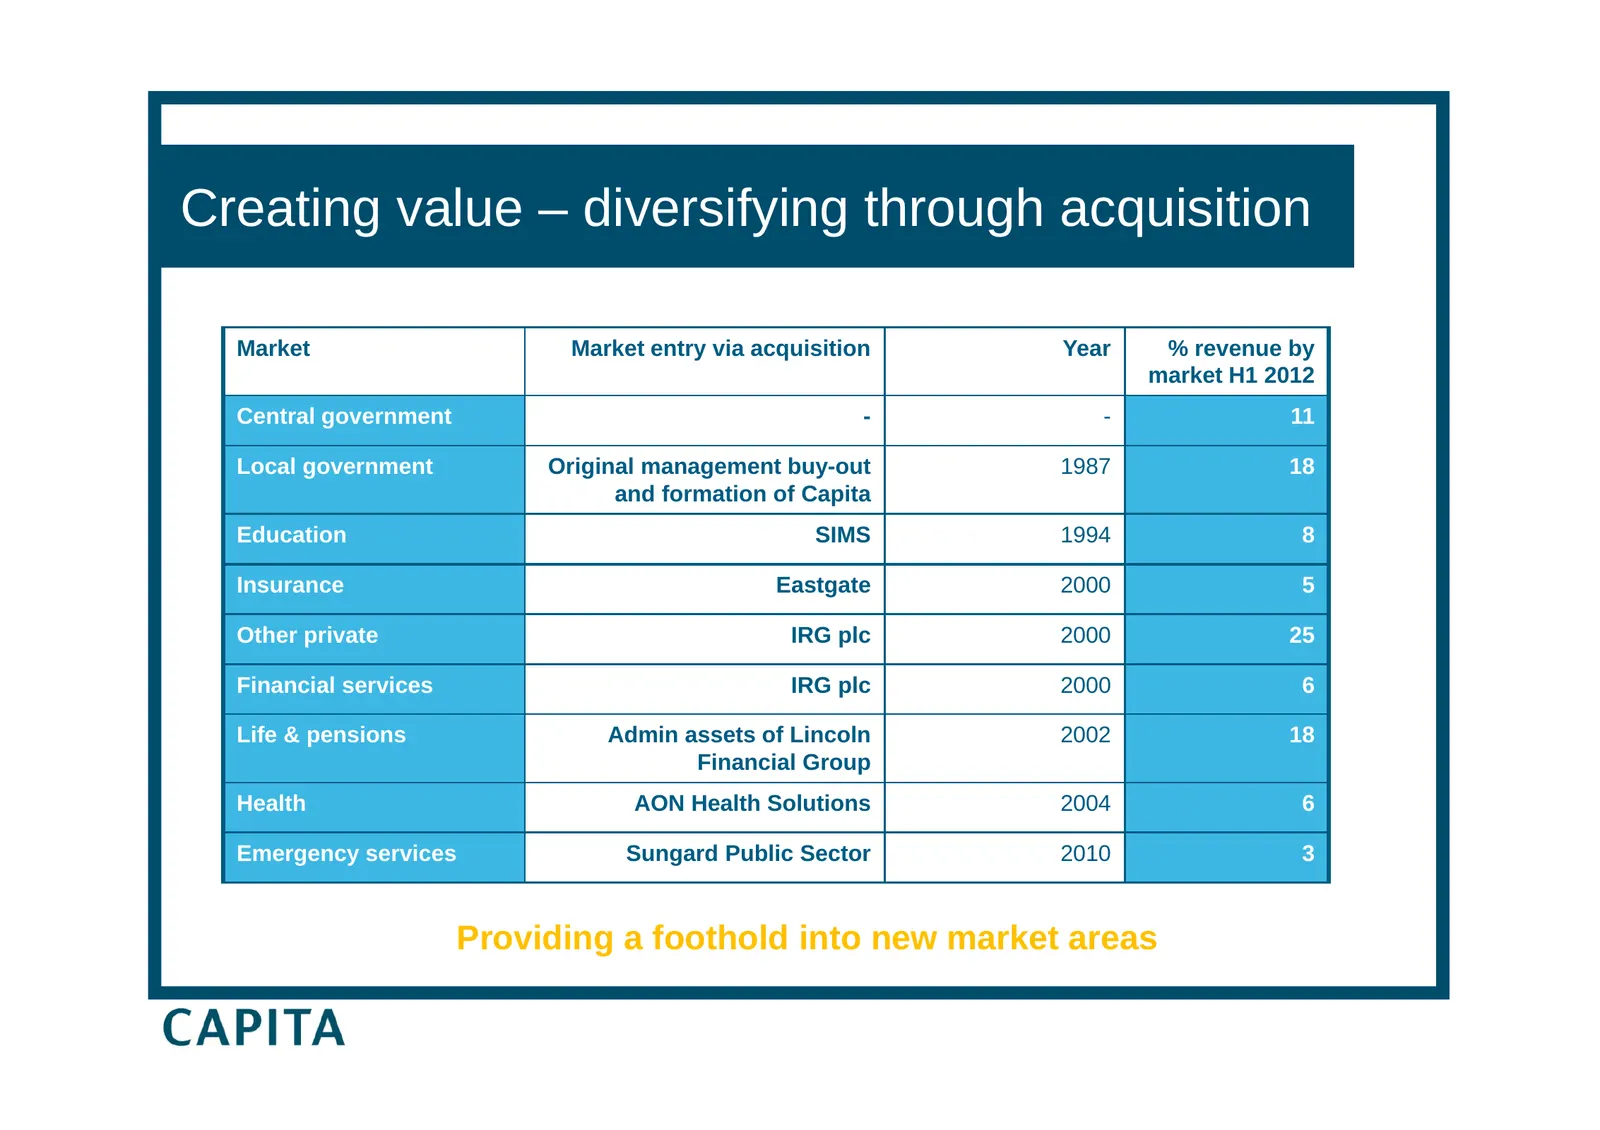
Creating value – diversifying through acquisition Market Market entry via acquisition Year % revenue by market H1 2012 Central government - - 11 Local government Original management buy-out 1987 18 and formation of Capita Education SIMS 1994 8 Insurance Eastgate 2000 5 Other private IRG plc 2000 25
Slide 40: Creating value – health
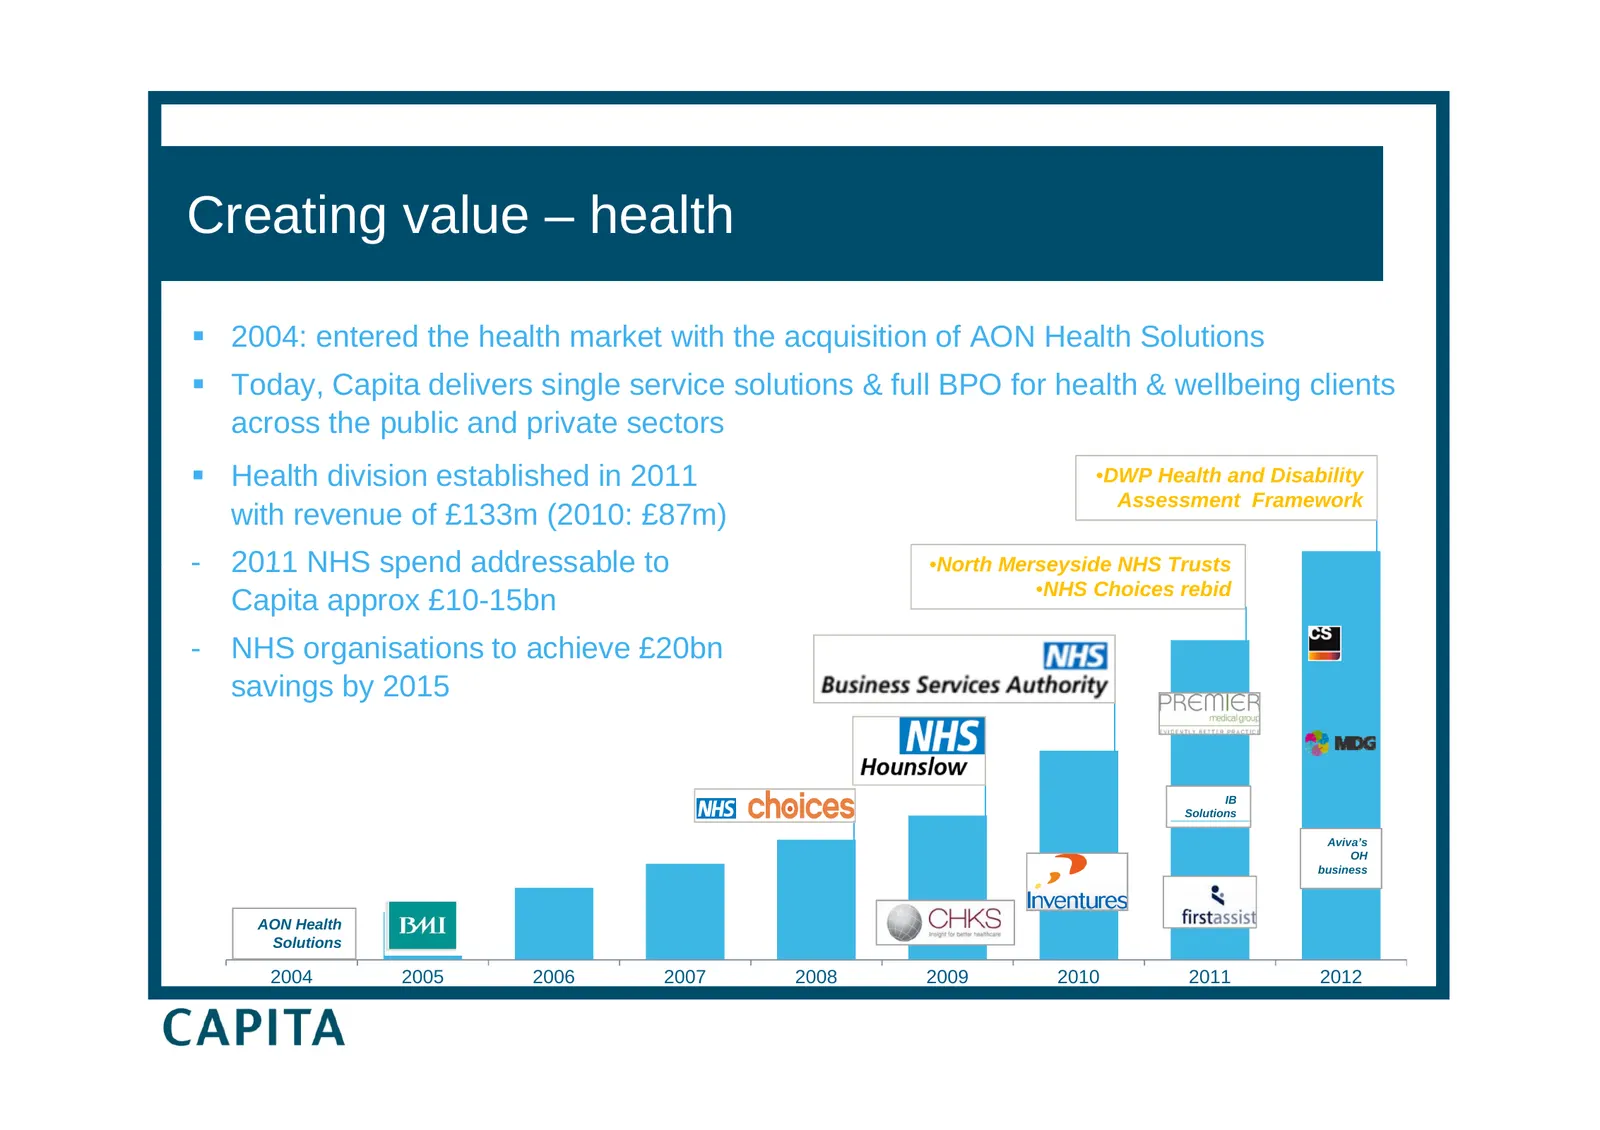
Creating value – health 2004: entered the health market with the acquisition of AON Health Solutions Today, Capita delivers single service solutions & full BPO for health & wellbeing clients across the p public and p private sectors Health division established in 2011 •DWP Health and Disabilit
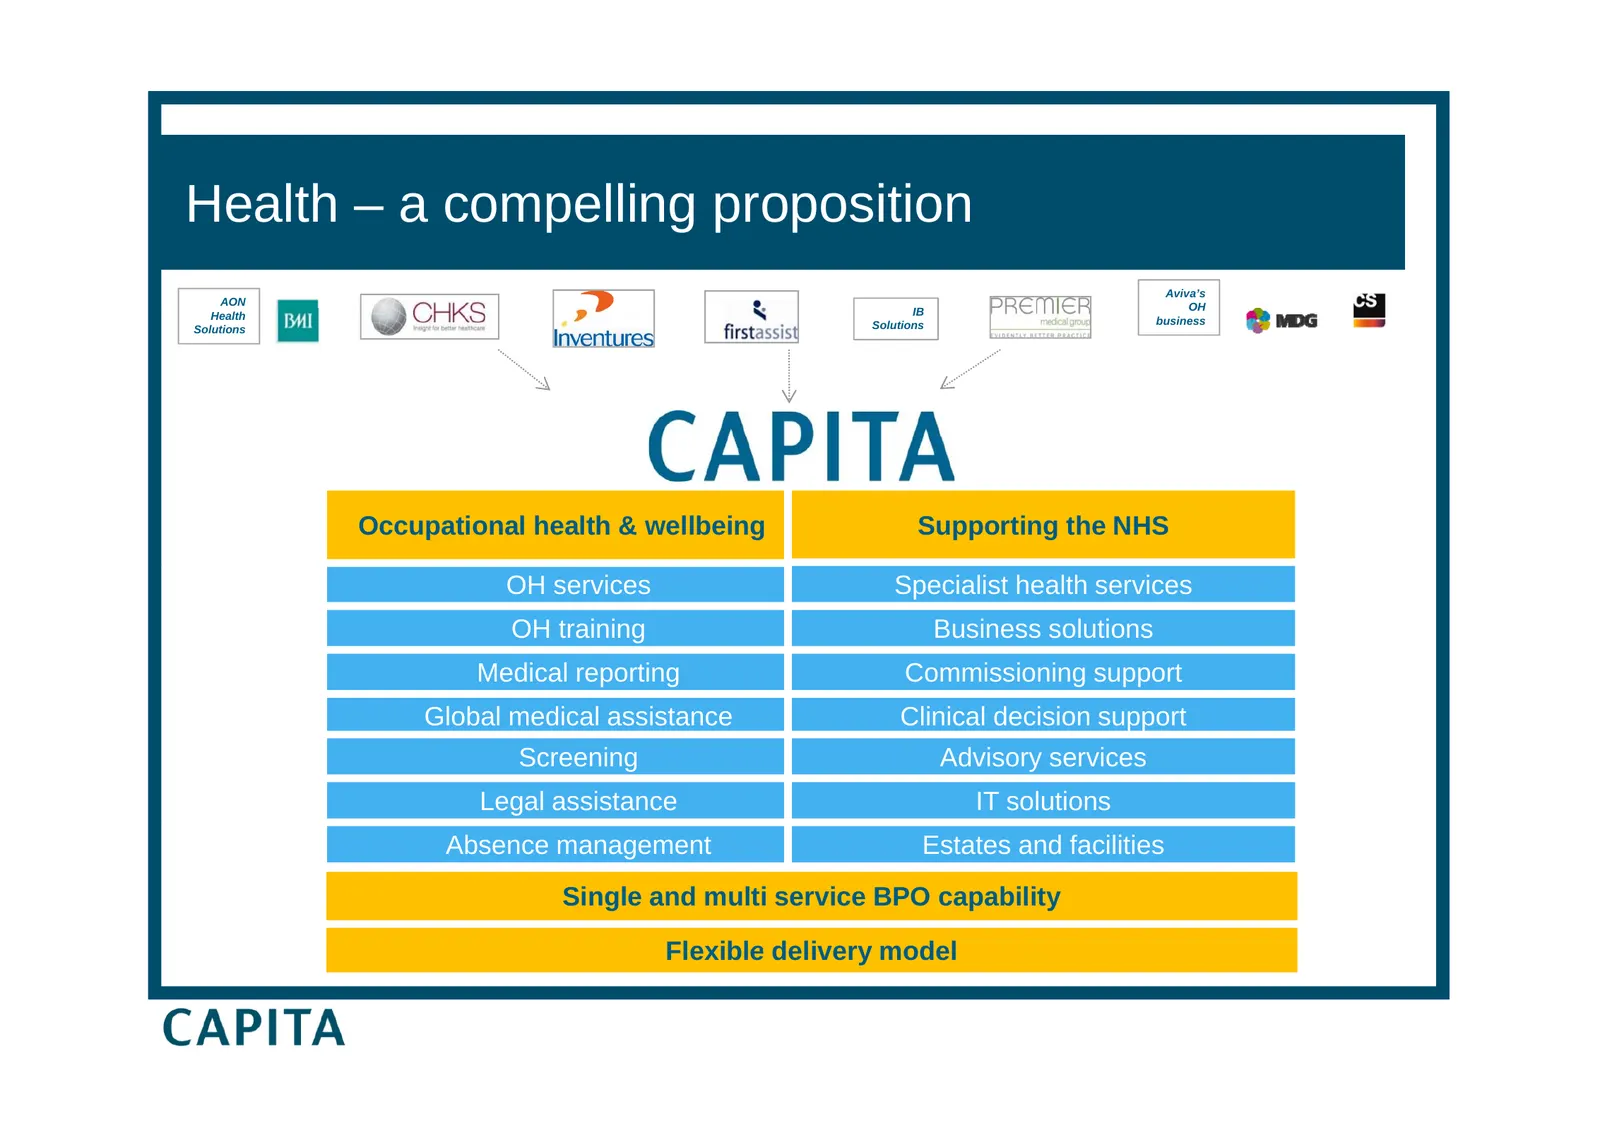
Slide 41: Health – a compelling proposition
Health – a compelling proposition Aviva’s AON OH Health IB Solutions business Solutions Occupational health & wellbeing Supporting the NHS OH services Specialist health services OH training Business solutions Medical reporting Commissioning support Global medical assistance Clinical decision support
Slide 42: Creating value – customer management
Creating value – customer management Enhanced existing offering with acquisition of specialist customer management expertise, Ventura, Vertex Private Sector and CCT Added scale, capability and extended our market reach bringing clients from across the utilities, telecoms and retail sectors Ena
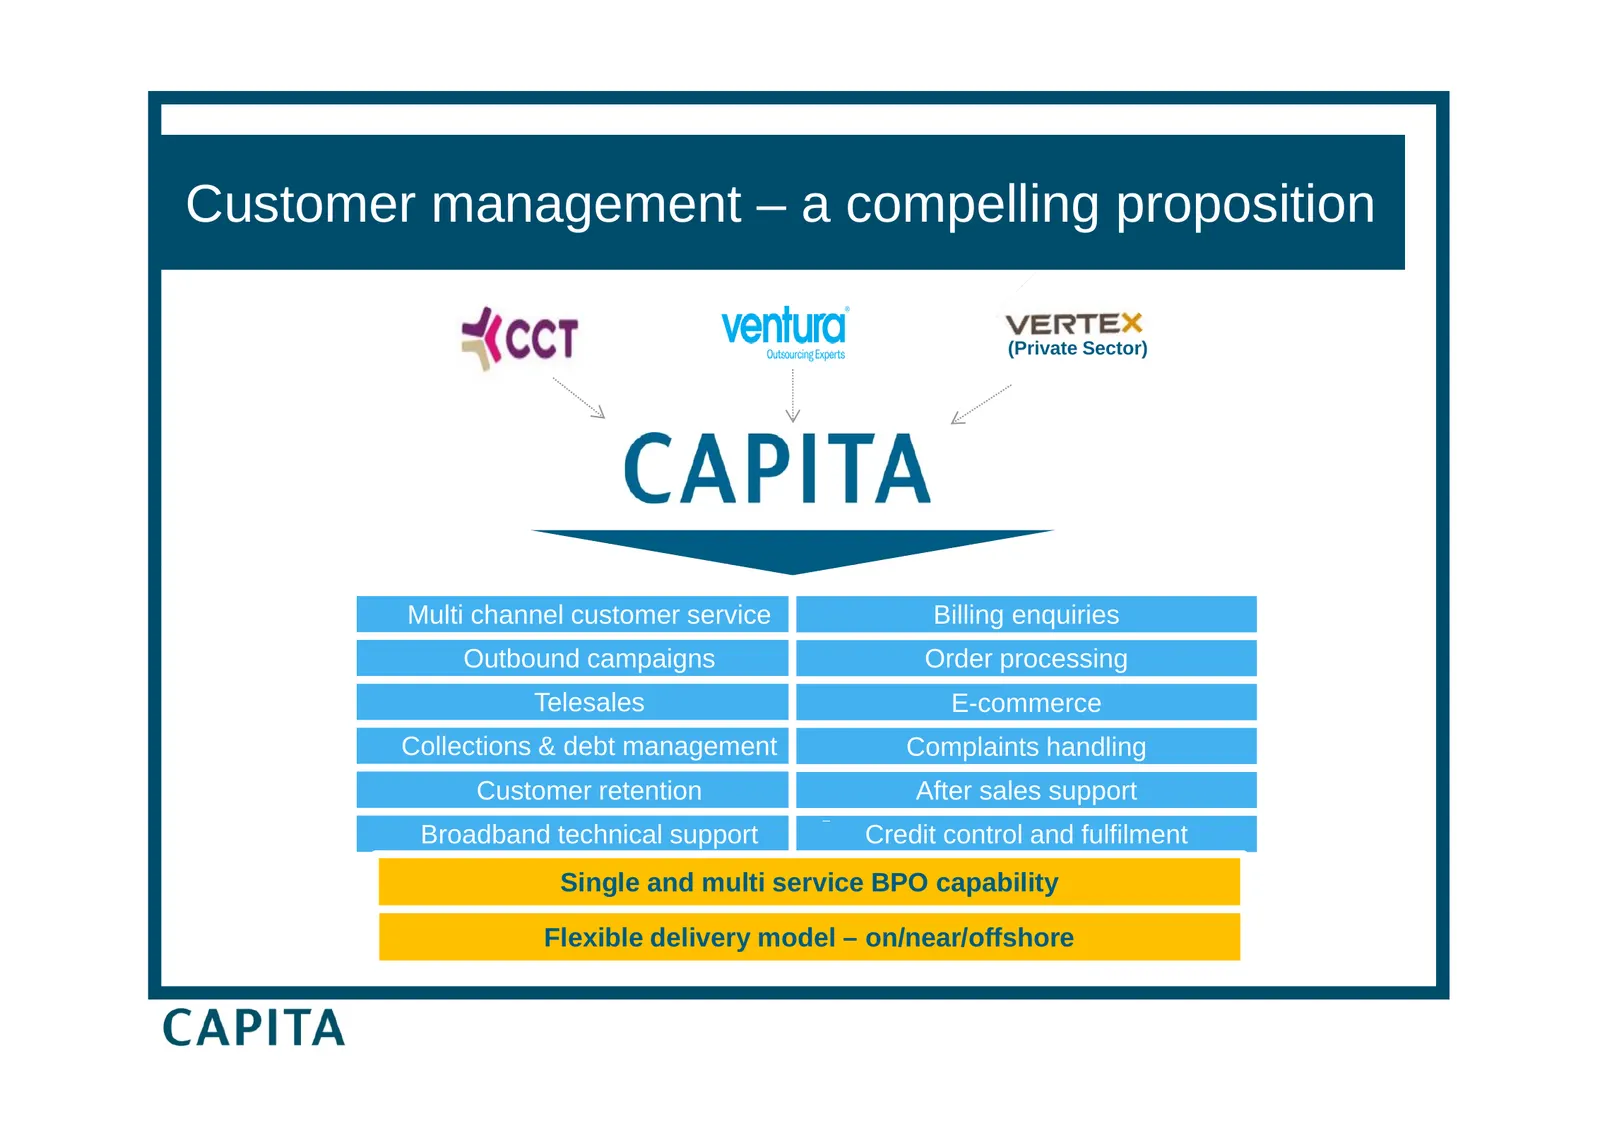
Slide 43: Customer management – a compelling proposition
Customer management – a compelling proposition (Private Sector) Multi channel customer service Billing enquiries Outbound campaigns Order processing T l Telesales l E E-commerce Collections & debt management Complaints handling Customer retention After sales support Broadband technical support Credi
Slide 44: Creating value – flexible delivery network
Creating value – flexible delivery network Acquisition of South African based company, Full Circle, for £1m Established in 2005 in central Cape Town ‘B ‘Build, ild operate t & ttransfer’ f ’ model d l - helping h l i clients li t tto evaluate, l t d develop l and d transition quickly and cost
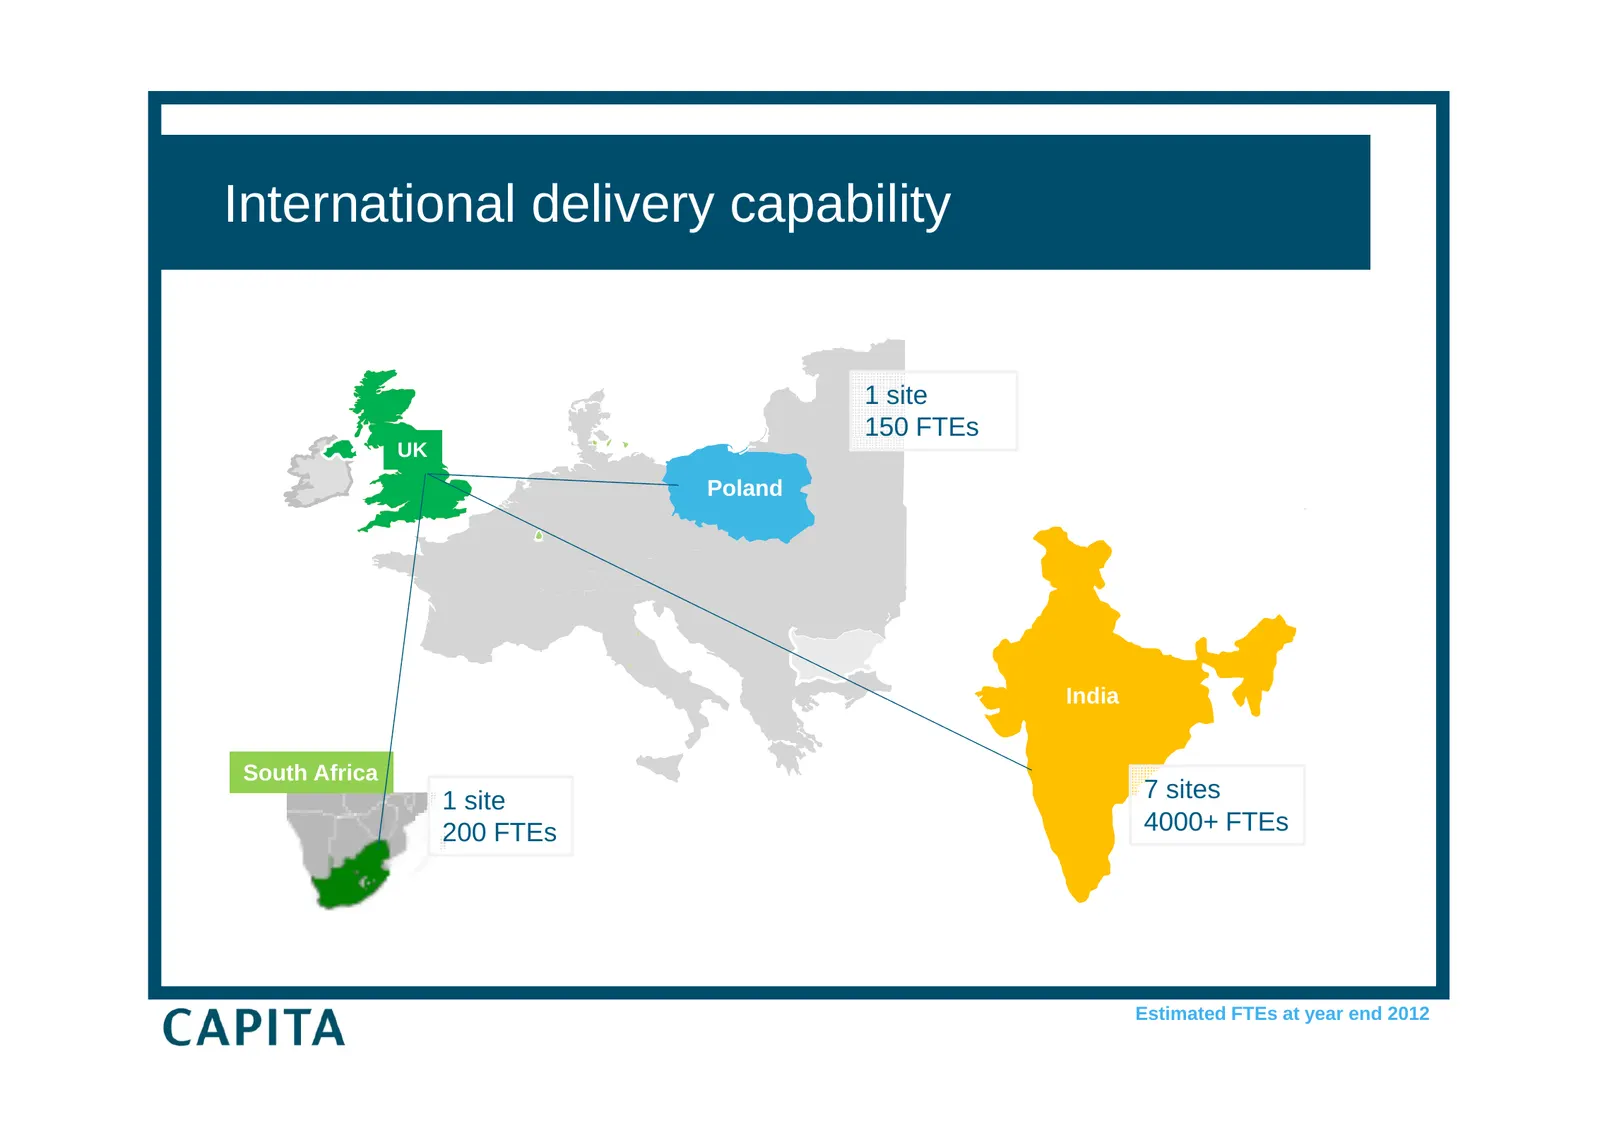
Slide 45: International delivery capability
International delivery capability 1 site 150 FTEs UK Poland India South Africa 1 site 7 sites 200 FTEs 4000+ FTEs Estimated FTEs at year end 2012
Slide 46: Summary & outlook
Summary & outlook Met our 3 key objectives Excellent level of contract wins year to date A strong pipeline with momentum Solid trading across the Group Healthy pipeline of small to medium sized acquisitions in our key target markets Capital Markets event planned for October 2012 in Londo
Slide 47: Capita plc
Capita plc CAPITA
Source: Internet Archive copy of investors.capita.com
More decks from Capita plc
 H1 2026 Earnings Presentation44 slides · Aug 4, 2026
 FY2025 Earnings Presentation46 slides · March 2026
 Merger or Acquisition (March 2026)10 slides · March 2026
 H1 2025 Earnings Presentation51 slides · August 2025
 FY2024 Earnings Presentation44 slides · March 2025
 H1 2024 Earnings Presentation33 slides · Aug 1, 2024