Energen — Wells Fargo Securities 2nd Annual E&P Forum 2011
33 slides from Energen's conference presentation, Mar 14, 2011
Slide 1: Focusing on Oil & Liquids
Focusing on Oil & Liquids Wells Fargo Securities 2 nd Annual E&P Forum March 15, 2011 Exhibit 99.1
Slide 2: Forward-looking statements
This presentation contains statements expressing expectations of future plans, objectives, and performance that constitute forward-looking statements made pursuant to the Safe Harbor Provision of the Private Securities Litigation Reform Act of 1995. Unless noted, these statements do not reflect poss
Slide 3: Energen
Energen is a top 25 independent producer of domestic natural gas, oil, & natural gas liquids and the largest distributor of natural gas in Alabama.
Slide 4: Excellent balance sheet
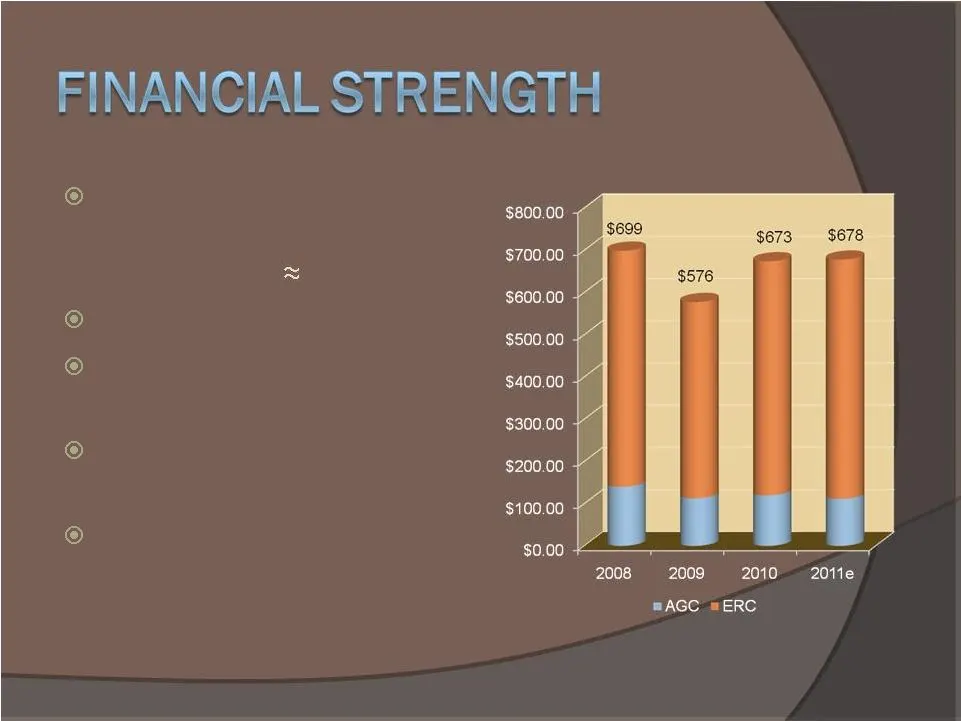
Excellent balance sheet (debt-to-total cap at YE11 estimated at 25%) Significant ATCF $1.0 B syndicated credit facility Oil/NGLs comprise 47% of 2010 proved reserves Hedging strategy ATCF ($MM) (2011e ATCF reflects mid-point of guidance range)
Slide 5: After-tax cash flow (Energen Resources)
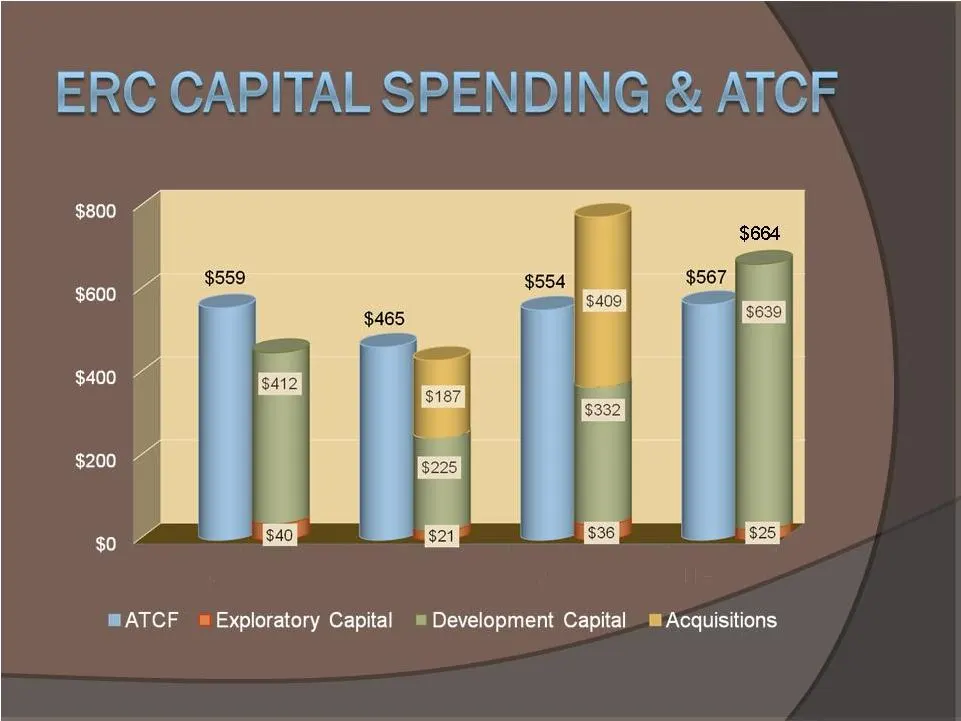
2008 2010 2011e 2009 $ 451 $433 $777 ($MM) (Energen Resources’ 2011e ATCF reflects mid-point of guidance range)
Slide 6: 2011 Assumptions and Liquids Production Growth
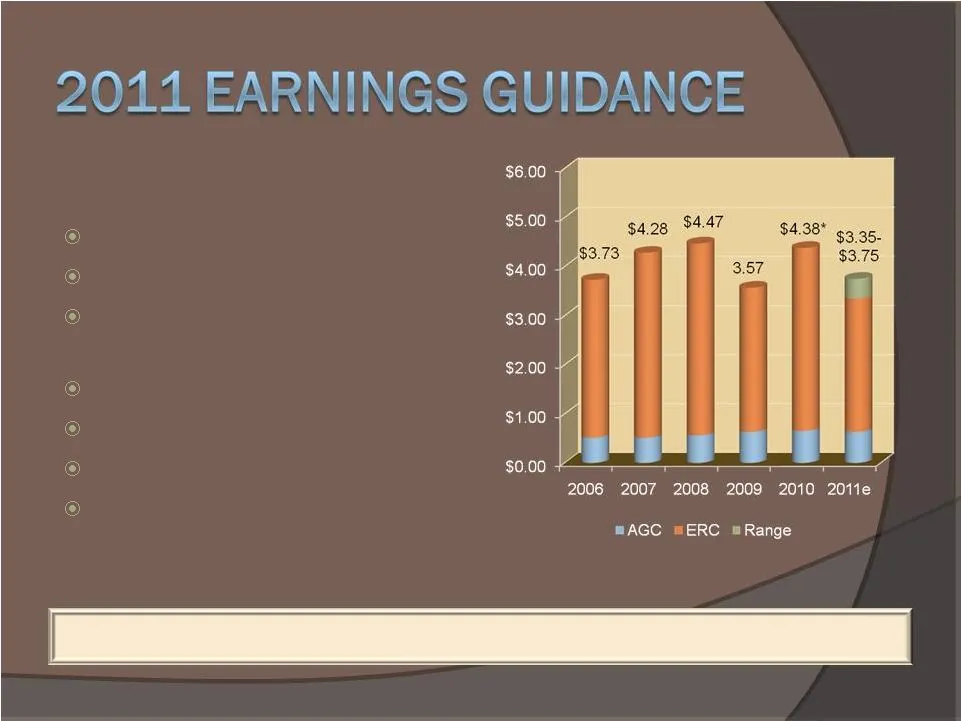
* Excludes $0.34 non - cash write - off of Alabama shale acreage Liquids Production Growth: 20% 2011 Assumptions 69% of est. production hedged 9% production growth Unhedged price assumptions: $4.25 gas, $80 oil, $0.83 NGL LOE: $12.18/BOE DD&A: $11.46/BOE G&A: $2.94/BOE AGC average equity of $346 MM
Slide 7: 69% of 2011(e) production hedged
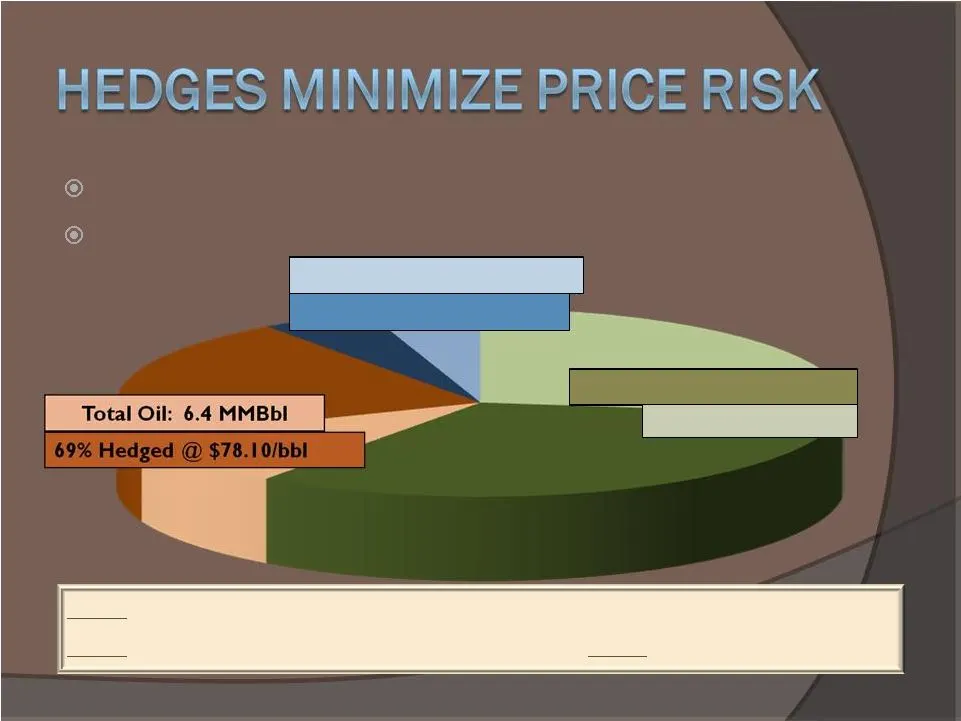
69% of 2011(e) production hedged 2011(e) cash costs: $15.06/BOE 49% Hedged @ $0.90/gal Total NGL: 86.7 MMgal 2012: 3.7 MMBbl at $82.34, 40.5 Bcf at $5.02, 39.9 MMgal at $0.86 2013: 3.2 MMBbl at $85.32, 28.0 Bcf at $5.30; 2014: 2.7 MMBbl at $87.44 73% Hedged @ $6.20/Mcf Total Gas: 72.1Bcf
Slide 8: Commodity Price Sensitivity
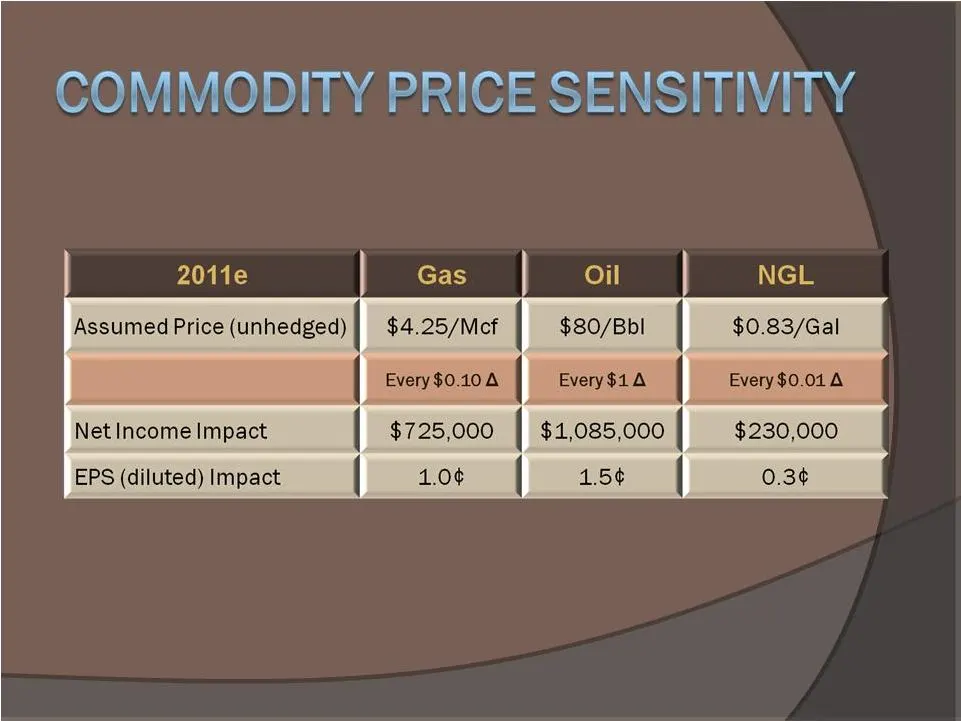
COMMODITY PRICE SENSITIVITY 2011e Gas Oil NGL Assumed Price (unhedged) | $4.25/Met | $80/Bbl $0.83/Gal $230,000 0.3¢ Every $0.10 A | Every$1 A | Every $0.01 A Net Income Impact ( $725,000 ( $1,085,000 EPS (diluted) Impact 1.0¢ ( 1.5¢
Slide 9: 303 MMBOE of proved reserves at YE2010
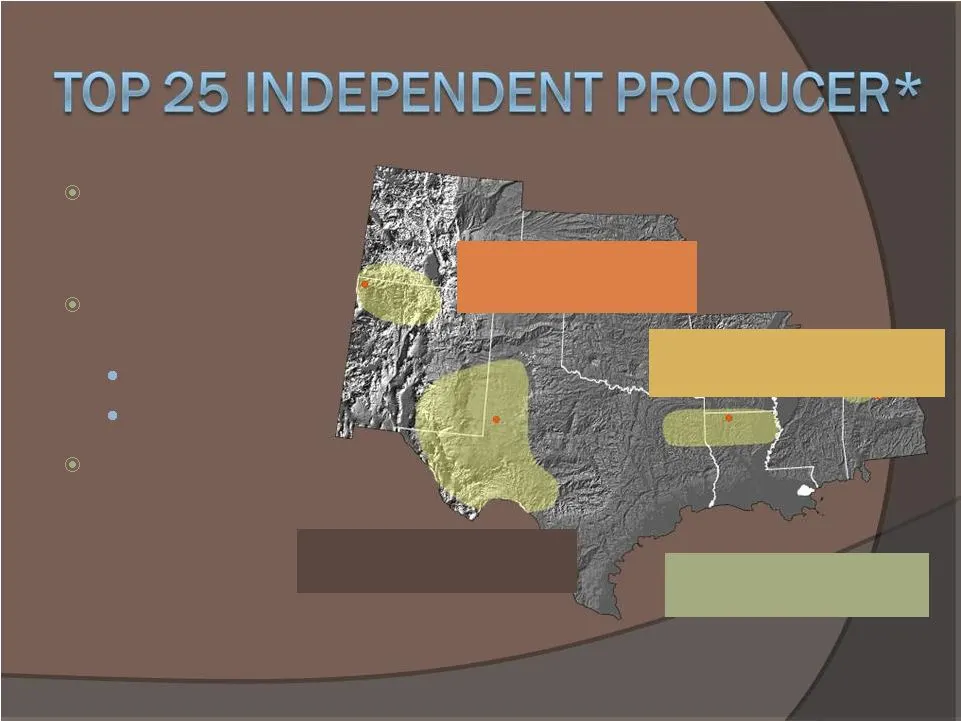
* Based on U.S. Proved Reserves TX Black Warrior Basin: 154 Bcf (8%) N. LA/E. TX/Other: 51 Bcfe (3%) San Juan Basin: 815 Bcfe (45%) Permian Basin: 133 MMBOE (44%) NM CO LA AL 303 MMBOE of proved reserves @ YE2010 2011e production mix: 59% gas 41% oil/NGL Major presence in 3 largest areas of operatio
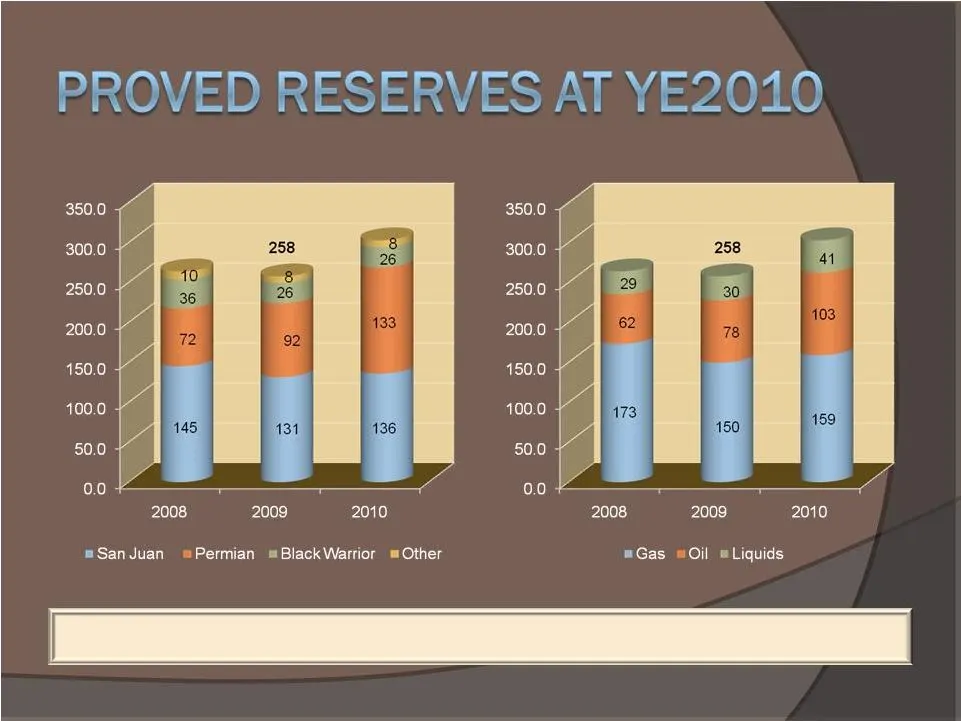
Slide 10: Estimated Probable & Possible Reserves: 315+ MMBOE
Estimated Probable & Possible Reserves: 315+ MMBOE (MMBOE) (MMBOE)
Slide 11: Oil/NGL comprise 41% of estimated production in 2011
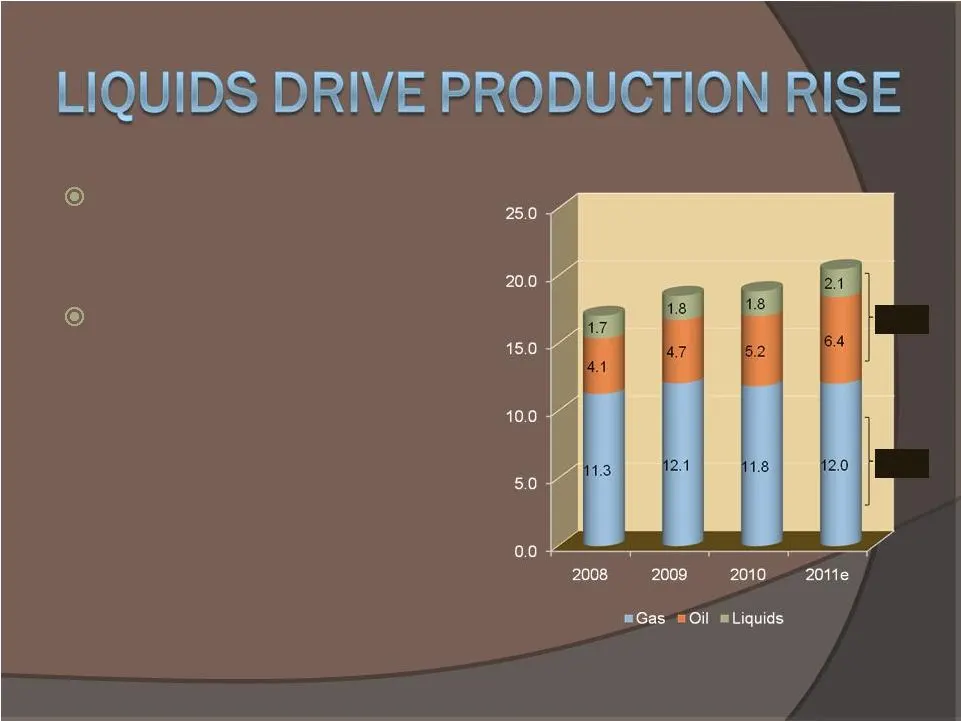
Oil/NGL comprise 41% of estimated production in 2011. Based on pace of drilling and risking incorporated into acquisition models, oil and NGL production could increase approximately 60% from 2010 to 2013. Production (MMBOE) 41% 59% 20.5 18.8 18.6 17.1
Slide 12: >80% of 2011 capital spending in Permian Basin
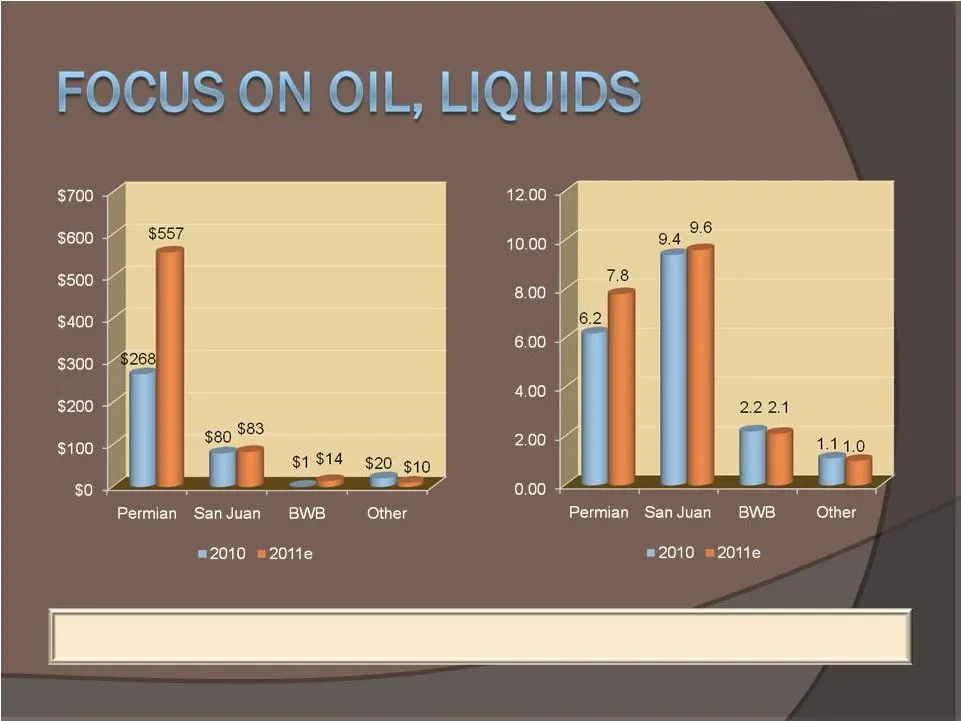
>80% of 2011 capital spending in Permian Basin Production by Basin (MBOE) Capital Spending by Basin ($MM)
Slide 13: Estimated well drilling costs and reserves
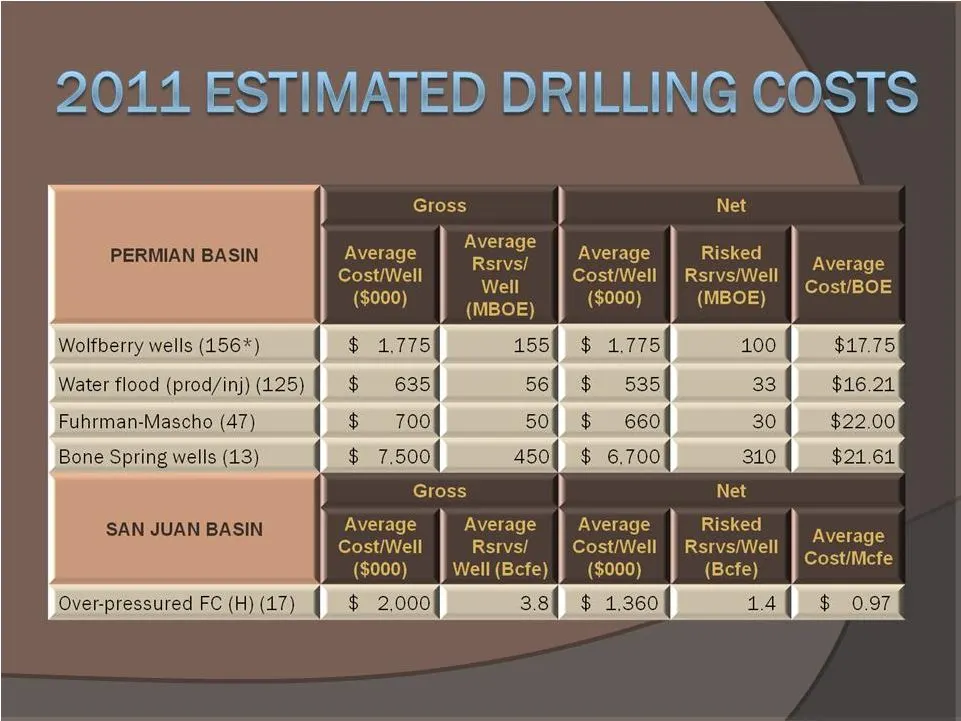
TYnN\A 4 ESTIM ATEN NDITILING CHOCTC EJ ENT LEA SI YD Gross } Net Average Rsrvs/ Well (MBOE) Risked Rsrvs/Well (MBOE) PERMIAN BASIN Average Cost/Well ($000) Average Cost/Well ($000) Average Cost/BOE Wolfberry wells (156*) 1.775| 100 { $47.75) { Water flood (prod/inj) (125) | 535 33 $16.21 { { Fuhrma
Slide 14: Bone Spring/Avalon acquisition
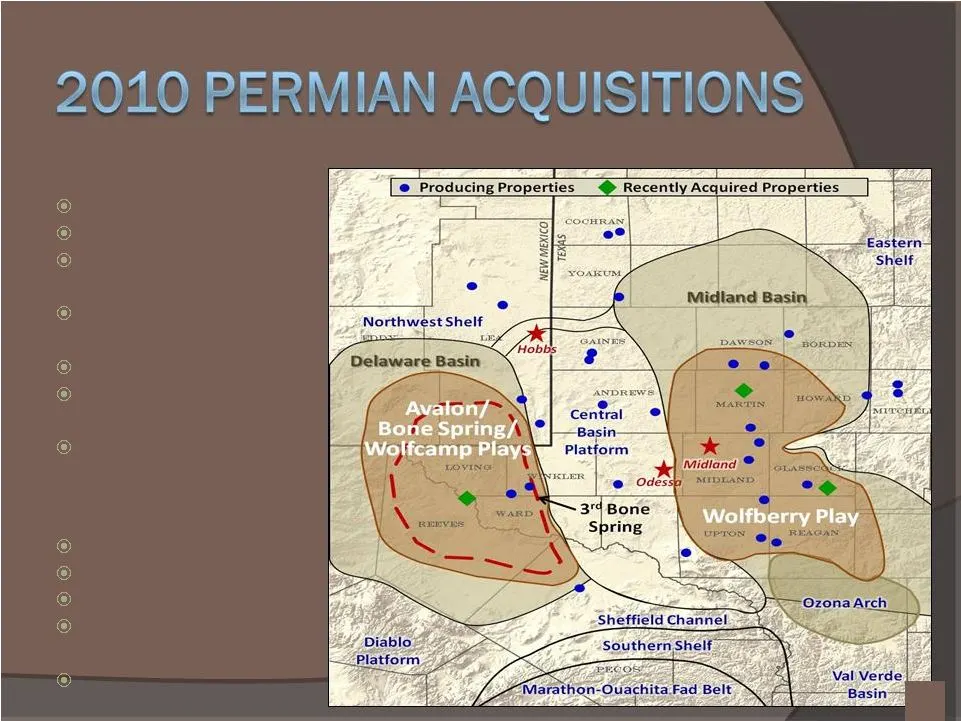
Bone Spring/Avalon Seller: SandRidge Energy 40,000 net acres - Avalon 21,300 net acres - Bone Spring 21 MMBOE unproved reserves (net unrisked) $110 MM + closing adj. Future cost to develop Bone Spring potential: $465 MM Potential drilling locations: 62 Bone Spring, 125 Avalon Wolfberry Private selle
Slide 15: 3rd Bone Spring
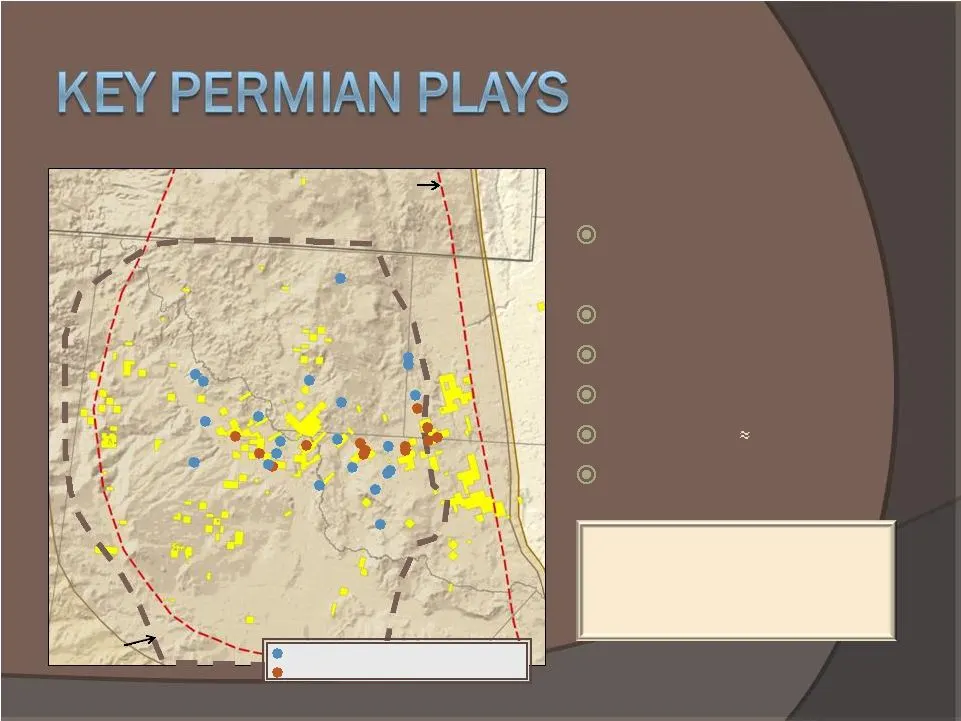
3rd Bone Spring Vertical depth: 11,000’ – 11,300’ Horizontal wells Multi-stage fracs (8-10) EUR: – MBOE Well cost: $7.5 Million Rigs in 2011: 4-5 NEW MEXICO TEXAS Loving Winkler Reeves Ward Avalon ERC Area of Interest Bone Spring ERC Area of Interest 50,000 net undeveloped acres; 150 potential locat
Slide 16: Avalon Shale
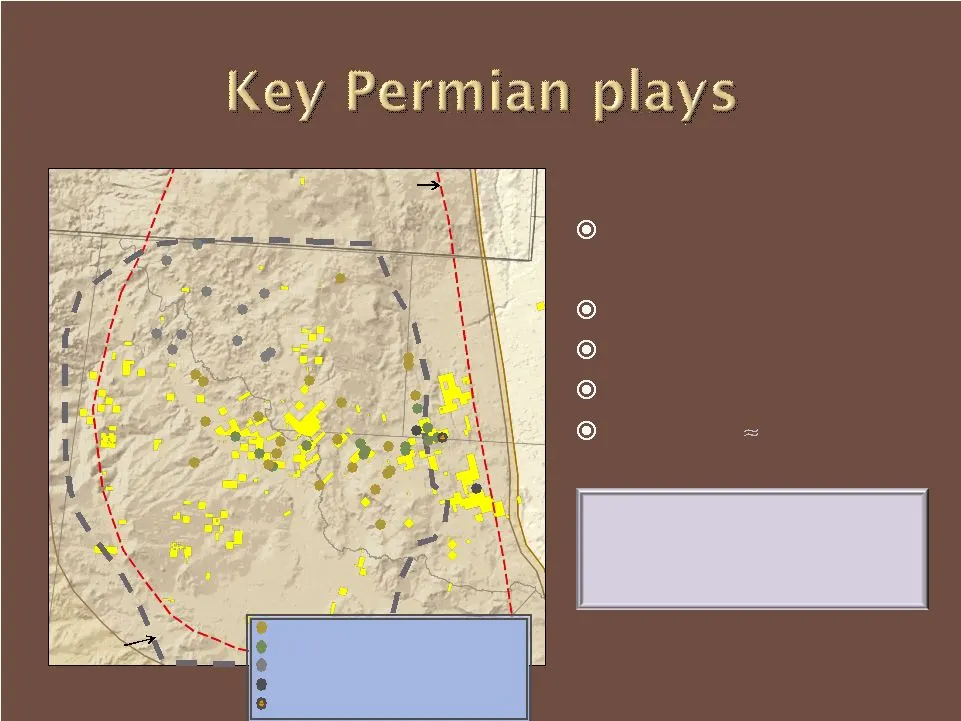
Avalon Shale Vertical depth: 8,500’ - 9,000’ Horizontal wells Multi-stage fracs (8-10) EUR: 300 – 350 MBOE Well cost: $5.5 Million NEW MEXICO TEXAS Loving Winkler Reeves Ward Avalon ERC Area of Interest rd Bone Spring ERC Area of Interest 80,000 net undeveloped acres; potential locations on 320- acr
Slide 17: Bone Spring and Avalon stratigraphy
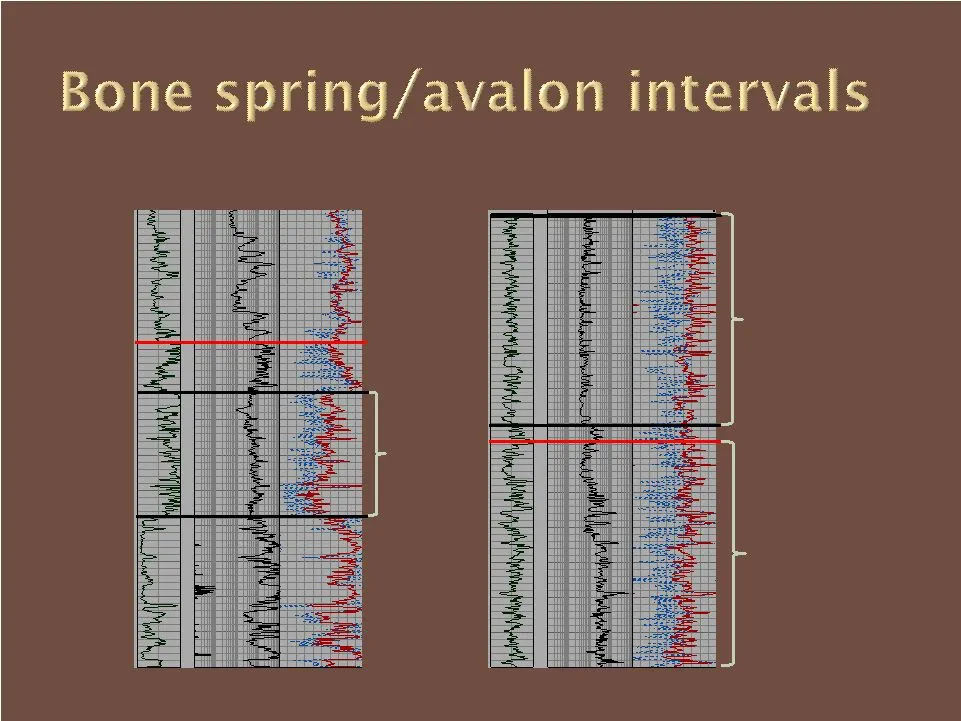
0.2 0.3 11,000’ 8,750’ 11,900’ rd Bone Spring Sands Avalon Avalon Shale Shale Top of Top of Bone Bone Spring Spring Interval Interval Top of Top of Wolfcamp Wolfcamp 8,500’ 11,300’ 8,550’ Upper Upper Wolfcamp Wolfcamp
Slide 18: Wolfberry
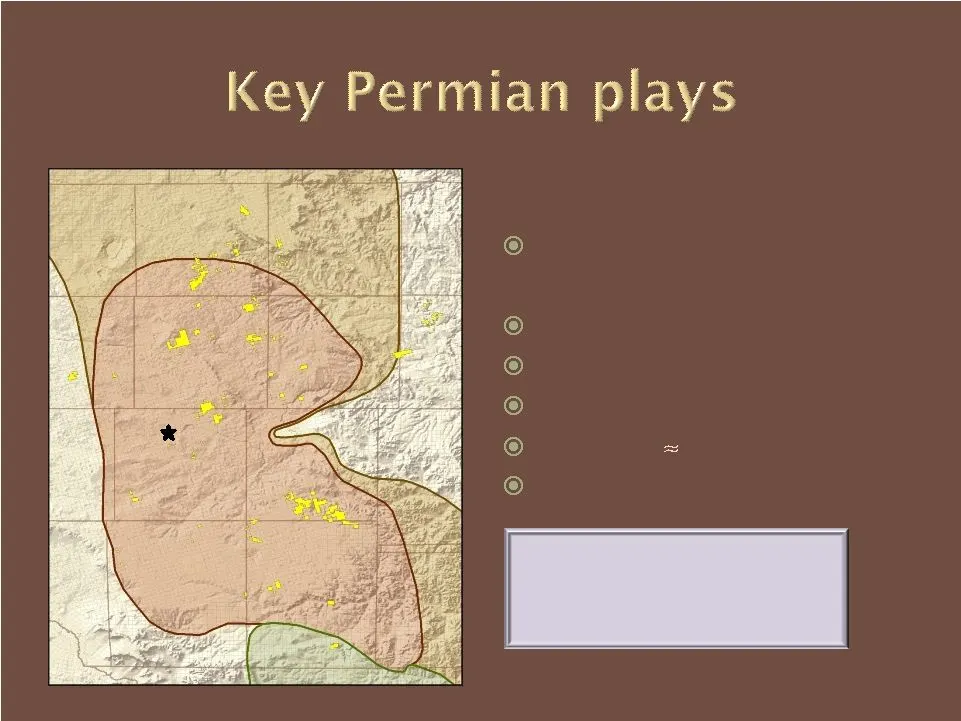
26,300 net undeveloped acres; potential locations on 40- acre spacing Wolfberry Completion interval: 7,500’ – 10,500’ Vertical wells Multi-stage fracs (6-8) EUR: 125 – 175MBOE Well cost: $1.8 Million Rigs in 2011: 7 Gaines Dawson Borden Andrews Martin Howard Glasscock Midland Ector Crane Upton Reaga
Slide 19: Wolfberry stratigraphy
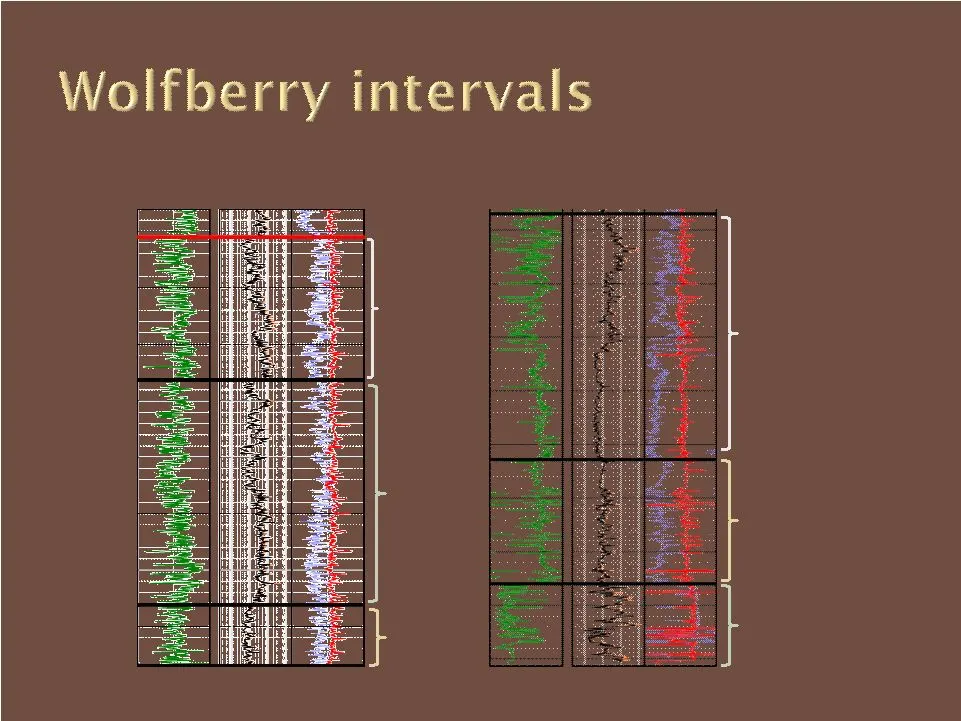
7,500’ 9,000’ 9,000’ 10,600’ Wolfcamp Wolfcamp Lower Lower Spraberry Spraberry Cline Cline Upper Upper Spraberry Spraberry Dean Dean Strawn Strawn 8,000’ 8,750’ 9,900’ 10,400’
Slide 20: Net undeveloped acres by shale play
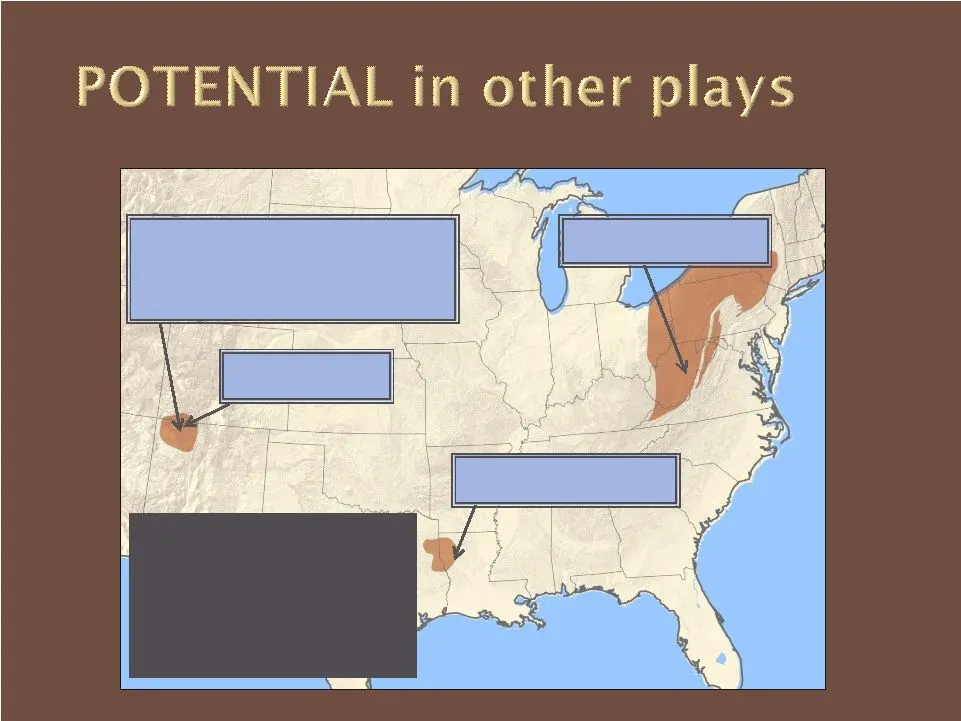
Haynesville Shale 12,000 acres Lewis Shale 55,500 acres Mancos/Niobrara Shale - Gas 55,500 acres Mancos/Niobrara Shale - Oil 54,000 acres Marcellus Shale 200,000 acres Net Net Undeveloped Undeveloped Acres Acres
Slide 21: Net Undeveloped Acres: San Juan Basin
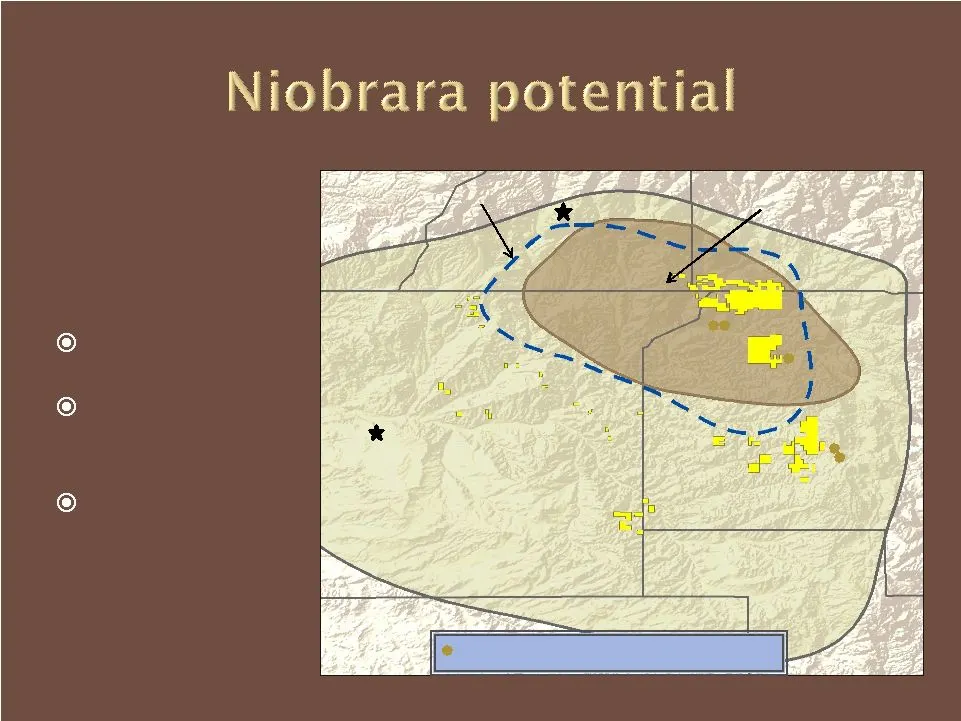
Net Undeveloped Acres Lewis Shale: 55,500 Niobrara Shale Gas: 55,500 Niobrara Shale Oil: 54,000 Niobrara Shale Oil Lewis Shale Farmington Durango San Juan Rio Arriba Sandoval La Plata Archuleta Niobrara Shale Gas Recently Drilled Niobrara Shale Wells (horizontal)
![Slide 22: . : ] . . . : . . . . . . .](https://6ix-events-pro.s3.amazonaws.com/decks/p/4v3h6ysp/22.webp)
Slide 22: . : ] . . . : . . . . . . .
. : ] . . 2 . : . . . . . . . . . . : - ] : SS ] ] . ] SS . . . . - . . . ] : . . . . . . . . . . . . . O . S . . . . . . . . : . : . 4 . YNVISINOT SVE) ] . . :
Slide 23: Q . . . = > - : e : S - |
Q . . . = > - : e : S - |
Slide 24: Haynesville and Marcellus acreage
OHIO Shreveport Bienville Webster PENN. W. VIRGINIA MD Pocahontas Nicholas Webster Fayette Raleigh Wyoming Boone Tucker Mineral Haynesville 12,000 Net Undeveloped Acres Area of Major Haynesville Development Recently Completed Haynesville Wells Recently Drilled Haynesville Wells Permitted Marcellus W
Slide 25: Alagasco: Complementary business
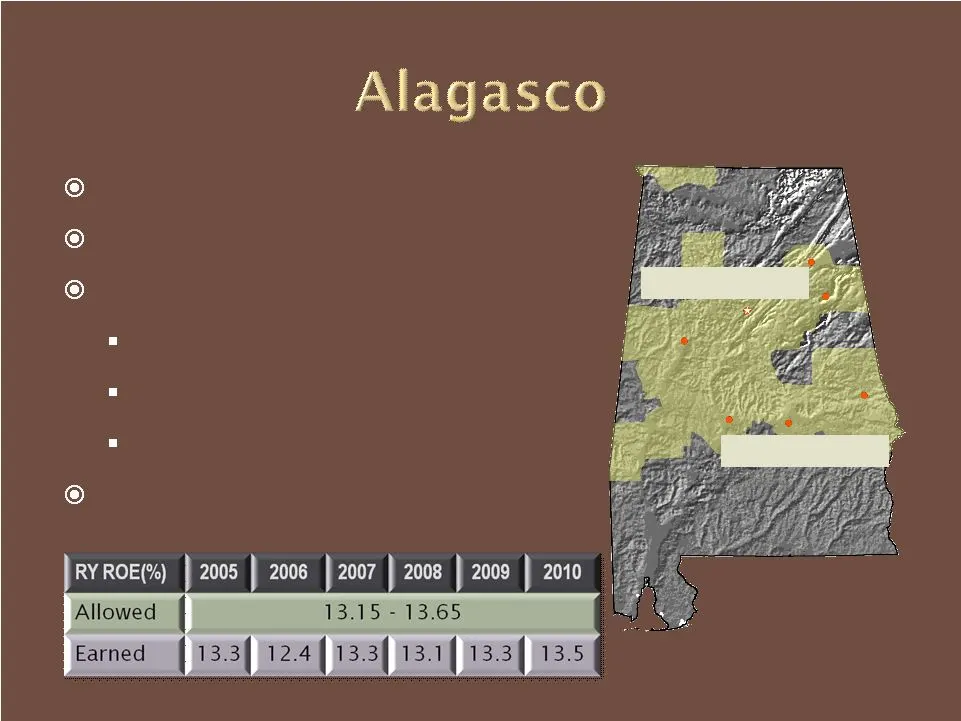
Complementary business Excellent rate of return Primary source of dividend
Slide 26: Alagasco regulation and customers
RSE through rate-year 2015 Allowed ROE: 13.15%-13.65% Forward-looking test year Single-state utility More than 437,000 customers Progressive regulation Temperature adjustment Birmingham Montgomery
Slide 27: 2011 dividend raised 3.8%
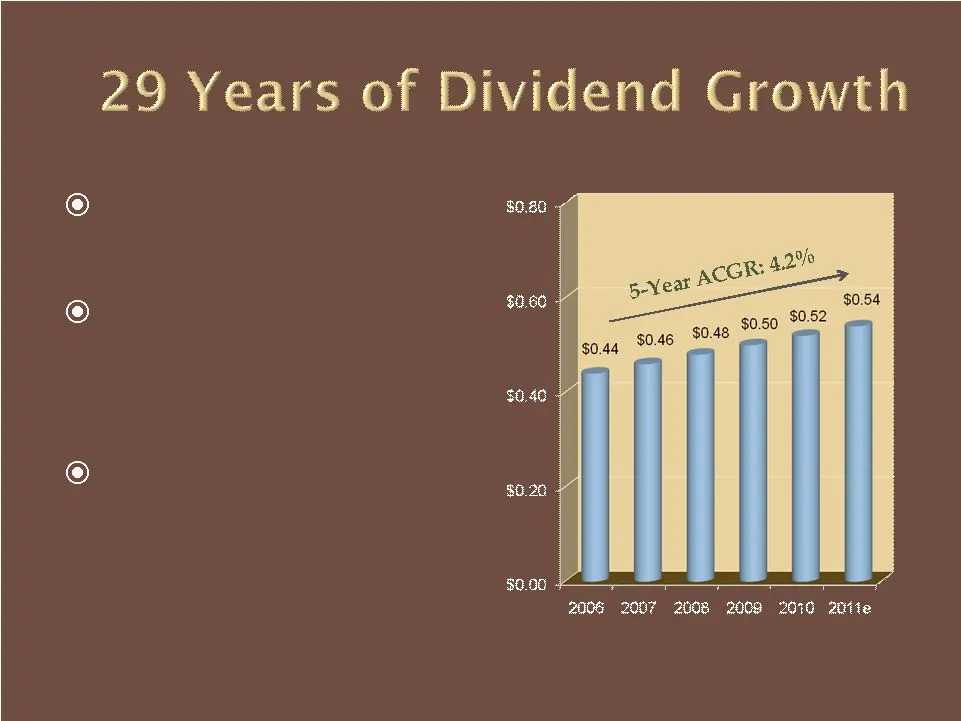
2011 dividend raised 3.8% Alagasco funds dividend at utility payout over 65% ERC may make small payout contribution Annual Dividend Rate
Slide 28: Liquids-focused
Liquids-focused Significant Hedges Strong Cash Flows Excellent Fundamentals Proven Track Record
Slide 29: Julie S. Ryland, Investor Relations
Julie S. Ryland Vice President – Investor Relations 205-326-8421 jryland@energen.com www.energen.com
Slide 30: Non-GAAP note: After-tax Cash Flow
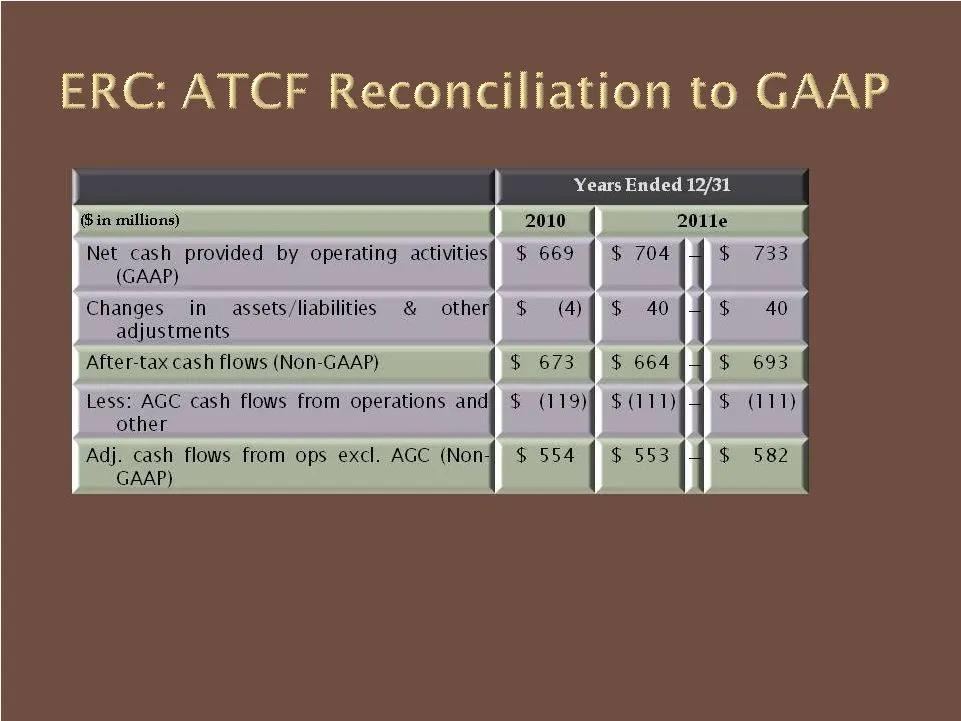
Note: 2011e data constitute forward-looking statements The U.S. Securities and Exchange Commission (SEC) requires public companies to reconcile Non- GAAP financial measures to related GAAP measures. GAAP refers to generally accepted accounting principles. After-tax Cash Flow (ATCF) is a Non-GAAP fin
Slide 31: After-tax Cash Flow (ATCF) reconciliation
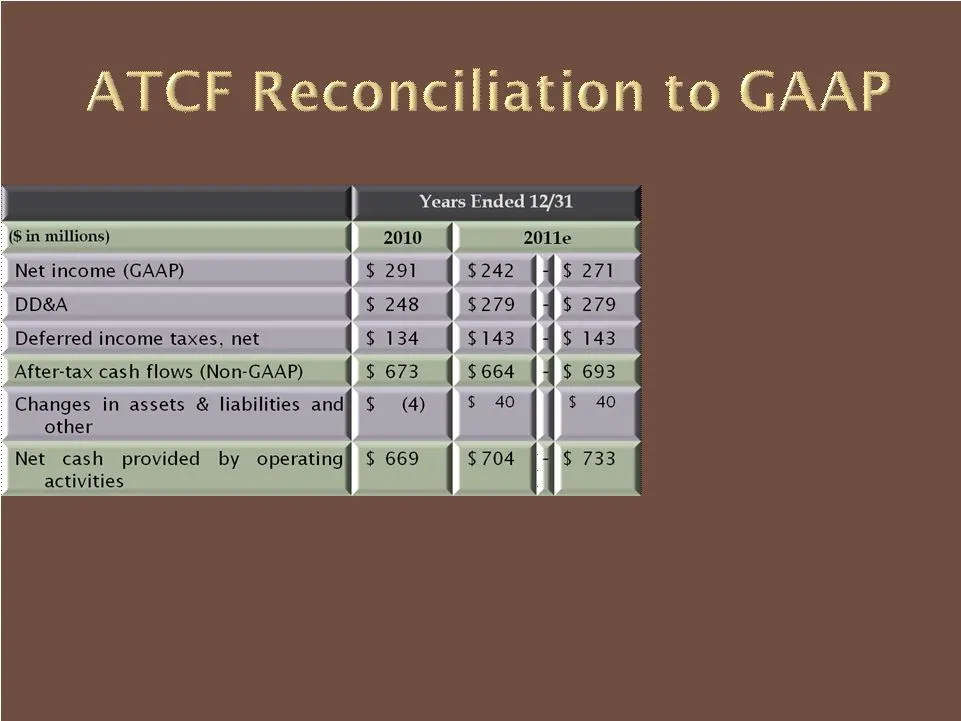
After-tax Cash Flow (ATCF) is a Non-GAAP financial measure. Energen believes ATCF is relevant as a measure of cash available to fund its capital expenditures, dividends, debt reduction, and other investments. Adjusted Cash Flows from Operations Excluding Alagasco reflect information specific to Ener
Slide 32: Non-GAAP note: Net income excluding write-off
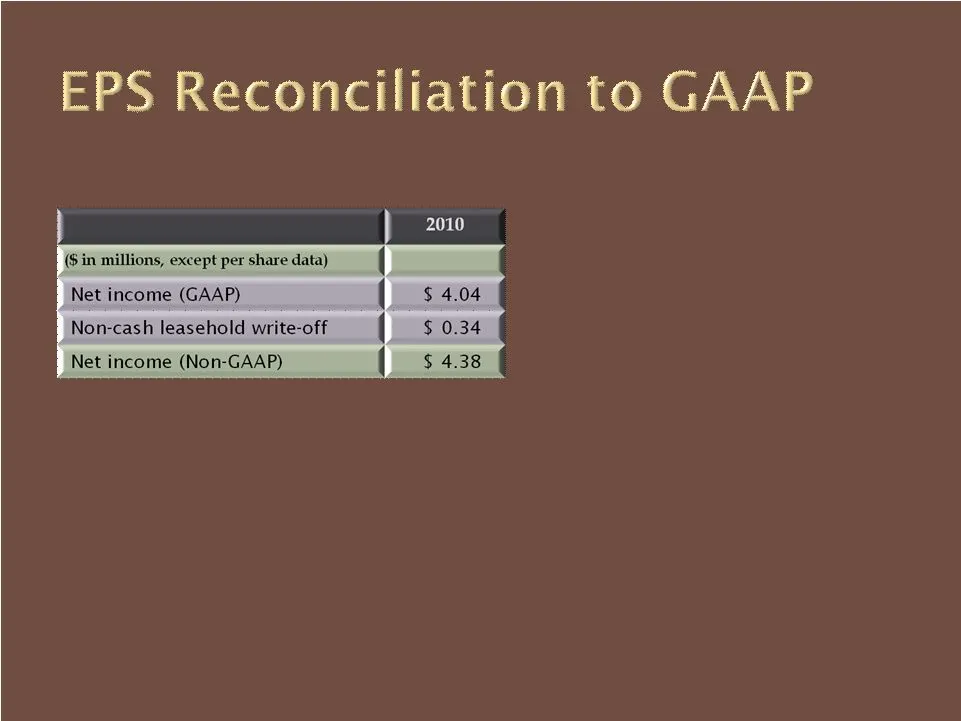
The U.S. Securities and Exchange Commission (SEC) requires public companies to reconcile Non- GAAP financial measures to related GAAP measures. GAAP refers to generally accepted accounting principles. Net Income excluding the non-cash, after-tax unproved leasehold write- off is a Non- GAAP financial
Slide 33: March 15, 2011
March 15, 2011 Wells Fargo Securities nd Annual E&P Forum Focusing on Oil & Liquids
Source: SEC EDGAR · 8-K filed Mar 14, 2011