Transatlantic — Merger or Acquisition (September 2011)
16 slides from Transatlantic's merger presentation, Sep 6, 2011
Slide 1: Transatlantic Stockholders – You Decide the Outcome
Transatlantic Stockholders – You Decide the Outcome September 2011 Setting the Record Straight on Transatlantic’s Continued Flawed Analyses FILED BY VALIDUS HOLDINGS, LTD. PURSUANT TO RULE 425 UNDER THE SECURITIES ACT OF 1933 AND DEEMED FILED PURSUANT TO RULE 14a-6 UNDER THE SECURITIES EXCHANGE ACT
Slide 2: Cautionary Note Regarding Forward-looking Statements
Cautionary Note Regarding Forward-looking Statements This presentation may include forward-looking statements, both with respect to Validus and its industry, that reflect Validus' current views with respect to future events and financial performance. Statements that include the words "expect," "inte
Slide 3: Additional Information, Participants in the Solicitation & Non-GAAP Financial Measures
Additional Information, Participants in the Solicitation & Non-GAAP Financial Measures Additional Information about the Proposed Transaction and Where to Find It: Validus has commenced an exchange offer to acquire all of the outstanding shares of common stock of Transatlantic for 1.5564 Validus voti
Slide 4: Validus' Superior Proposal Satisfies Transatlantic's Stated Strategic Objectives
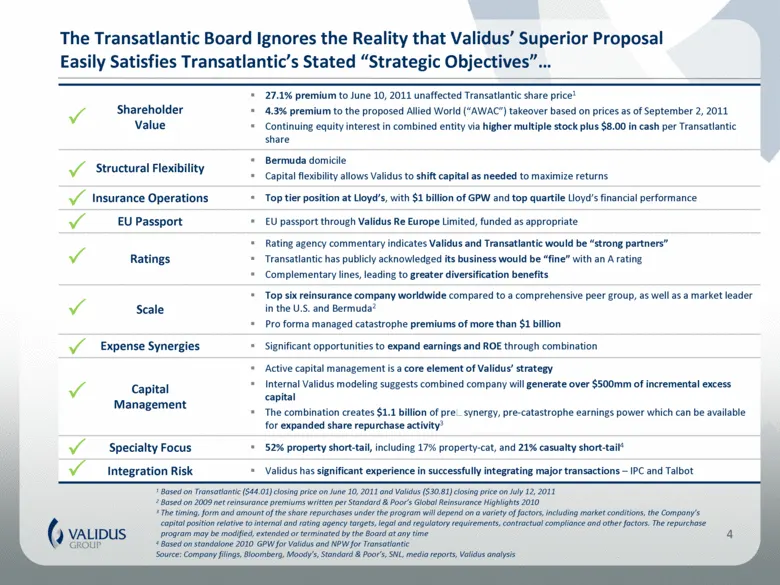
The Transatlantic Board Ignores the Reality that Validus’ Superior Proposal Easily Satisfies Transatlantic’s Stated “Strategic Objectives” ... Shareholder Value 27.1% premium to June 10, 2011 unaffected Transatlantic share price1 4.3% premium to the proposed Allied World (“AWAC”) takeover based on p
Slide 5: Denying the Opportunity for Superior Market Value and Future Prospects
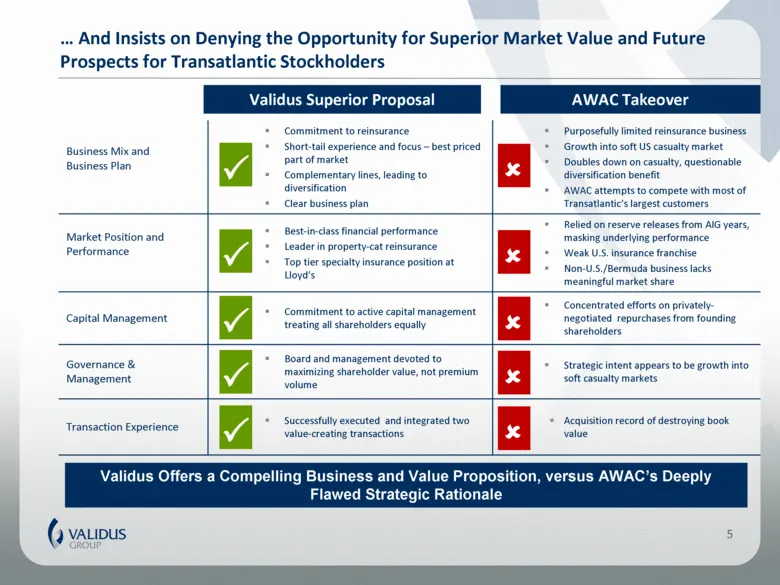
5 ... And Insists on Denying the Opportunity for Superior Market Value and Future Prospects for Transatlantic Stockholders Validus Superior Proposal AWAC Takeover Business Mix and Business Plan Commitment to reinsurance Short-tail experience and focus – best priced part of market Complementary lines
Slide 6: Transatlantic Has Been Selective with its Disclosure Commentary
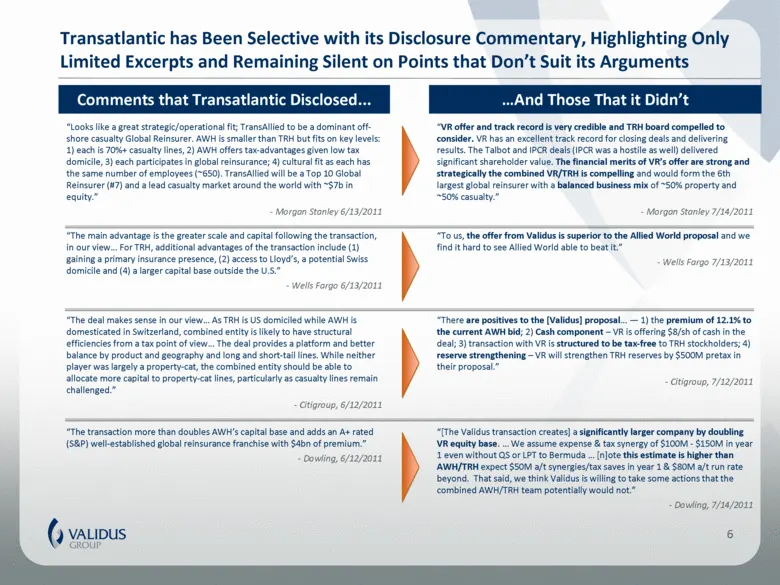
Transatlantic has Been Selective with its Disclosure Commentary, Highlighting Only Limited Excerpts and Remaining Silent on Points that Don’t Suit its Arguments 6 “To us, the offer from Validus is superior to the Allied World proposal and we find it hard to see Allied World able to beat it.” - Wells
Slide 7: Validus Has an Established Record of Trading at a Premium Multiple
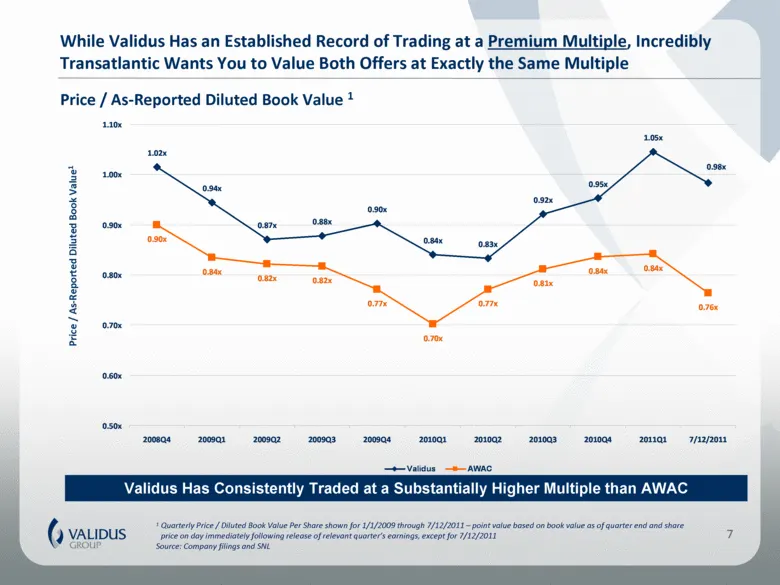
While Validus Has an Established Record of Trading at a Premium Multiple, Incredibly Transatlantic Wants You to Value Both Offers at Exactly the Same Multiple 7 Price / As-Reported Diluted Book Value1 1 Quarterly Price / Diluted Book Value Per Share shown for 1/1/2009 through 7/12/2011 – point value
Slide 8: Transatlantic Relies on Questionably Constructed Peer Group Multiples
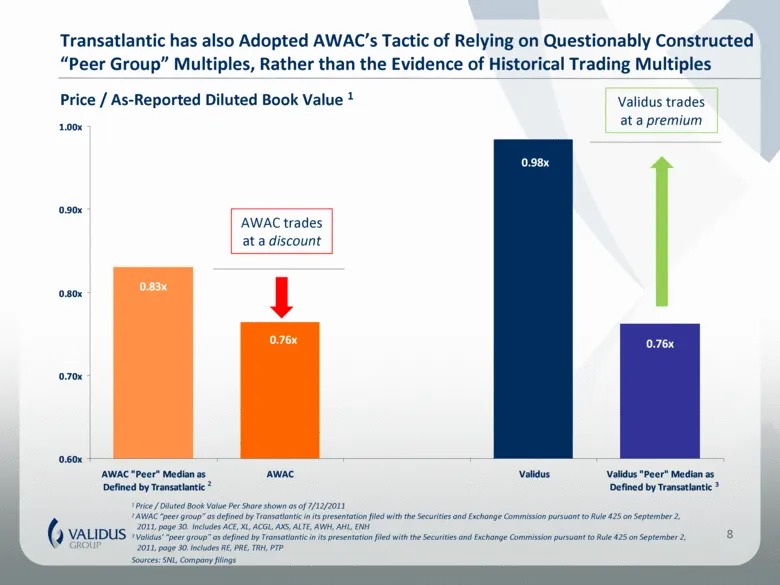
Transatlantic has also Adopted AWAC’s Tactic of Relying on Questionably Constructed “Peer Group” Multiples, Rather than the Evidence of Historical Trading Multiples 8 3 Price / As-Reported Diluted Book Value 1 1 Price / Diluted Book Value Per Share shown as of 7/12/2011 2 AWAC “peer group” as define
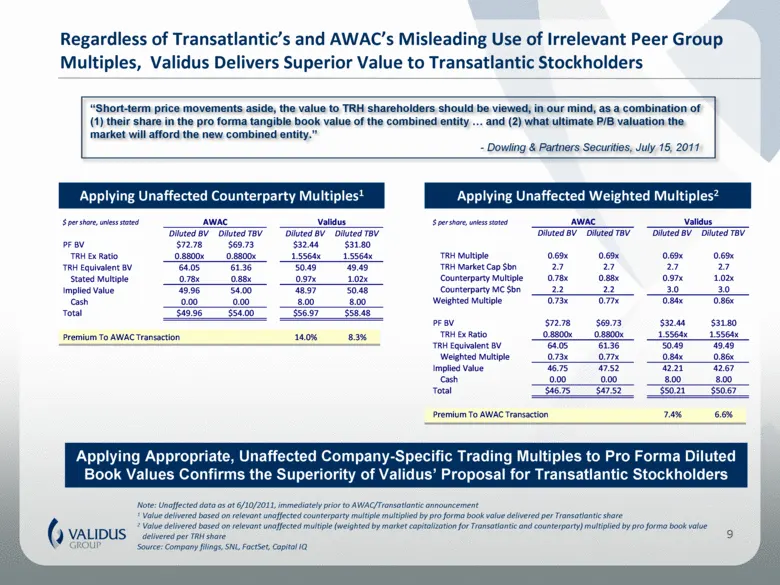
Slide 9: Validus Delivers Superior Value to Transatlantic Stockholders
Regardless of Transatlantic’s and AWAC’s Misleading Use of Irrelevant Peer Group Multiples, Validus Delivers Superior Value to Transatlantic Stockholders 9 Note: Unaffected data as at 6/10/2011, immediately prior to AWAC/Transatlantic announcement 1 Value delivered based on relevant unaffected count
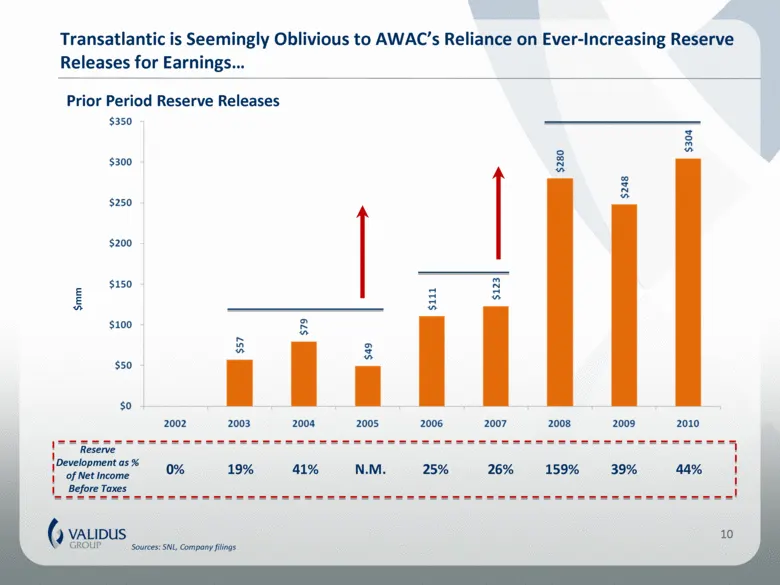
Slide 10: AWAC's Reliance on Ever-Increasing Reserve Releases for Earnings
Transatlantic is Seemingly Oblivious to AWAC’s Reliance on Ever-Increasing Reserve Releases for Earnings Sources: SNL, Company filings 10 $mm Reserve Development as % of Net Income Before Taxes 0% 19% 41% N.M. 25% 26% 159% 39% 44% Prior Period Reserve Releases
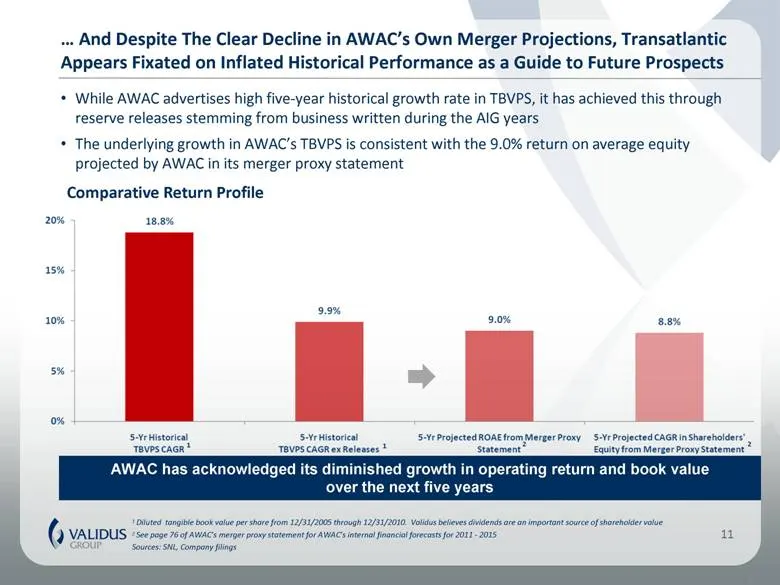
Slide 11: Decline in AWAC's Own Merger Projections
And Despite The Clear Decline in AWAC’s Own Merger Projections, Transatlantic Appears Fixated on Inflated Historical Performance as a Guide to Future Prospects 1 Diluted tangible book value per share from 12/31/2005 through 12/31/2010. Validus believes dividends are an important source of shareholde
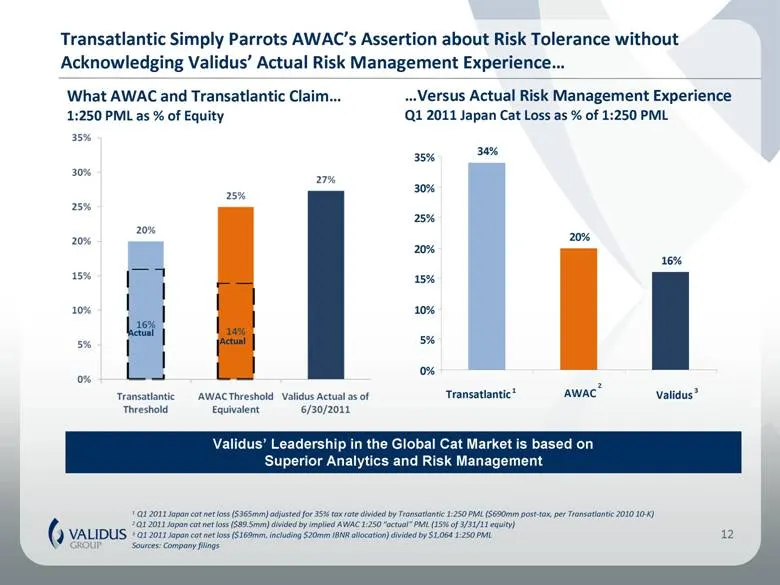
Slide 12: Validus' Actual Risk Management Experience
Transatlantic Simply Parrots AWAC’s Assertion about Risk Tolerance without Acknowledging Validus’ Actual Risk Management Experience 12 Validus’ Leadership in the Global Cat Market is based on Superior Analytics and Risk Management What AWAC and Transatlantic Claim 1:250 PML as % of Equity Versus Act
Slide 13: Comparative Capital Structures and Leverage
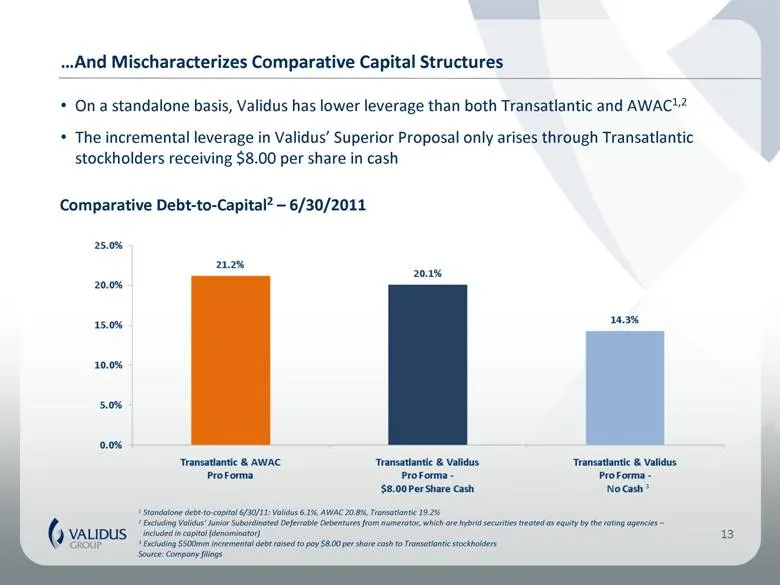
And Mischaracterizes Comparative Capital Structures On a standalone basis, Validus has lower leverage than both Transatlantic and AWAC1,2 The incremental leverage in Validus’ Superior Proposal only arises through Transatlantic stockholders receiving $8.00 per share in cash 13 Comparative Debt-to-Cap
Slide 14: Validus' Proposal Is Not Subject to Diligence and Is Actionable
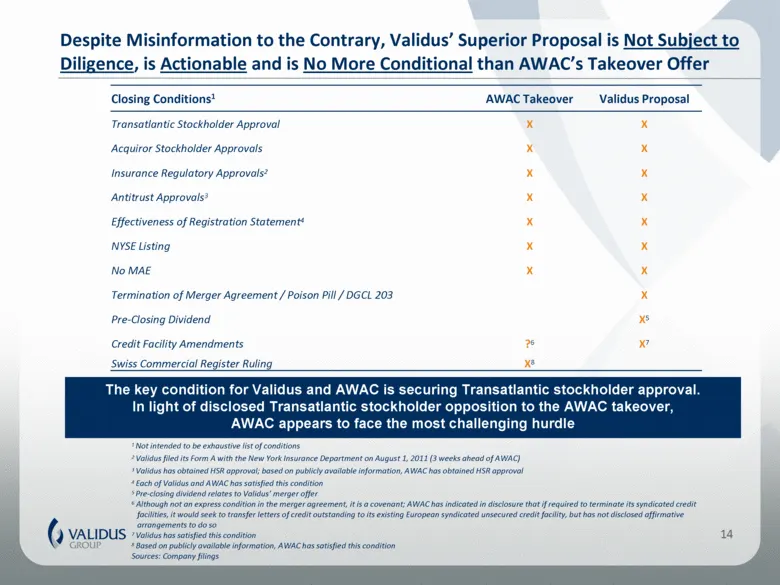
Despite Misinformation to the Contrary, Validus’ Superior Proposal is Not Subject to Diligence, is Actionable and is No More Conditional than AWAC’s Takeover Offer 14 1 Not intended to be exhaustive list of conditions 2 Validus filed its Form A with the New York Insurance Department on August 1, 201
Slide 15: Appendix Reconciliation of Non-GAAP Measures
Appendix Reconciliation of Non-GAAP Measures
Slide 16: Diluted Book Value Per Share Reconciliation
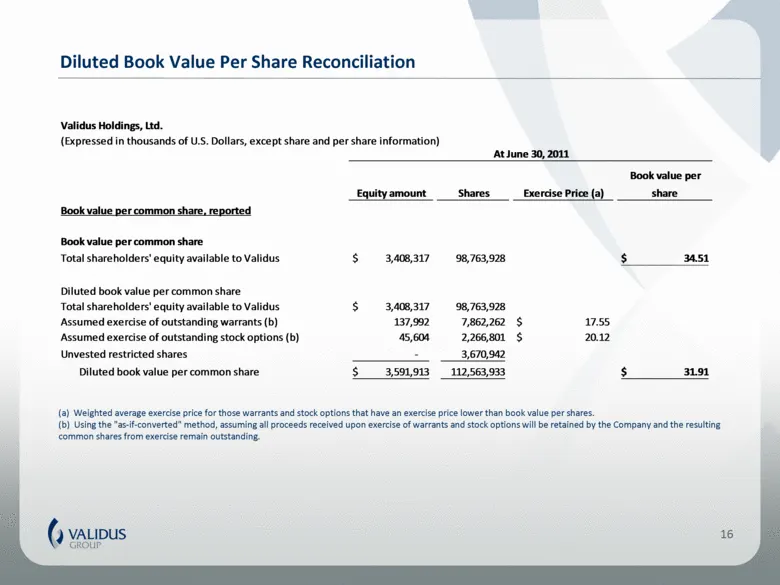
Diluted Book Value Per Share Reconciliation 16 (a) Weighted average exercise price for those warrants and stock options that have an exercise price lower than book value per shares. (b) Using the "as-if-converted" method, assuming all proceeds received upon exercise of warrants and stock options wil
Source: SEC EDGAR · 425 filed Sep 6, 2011
More decks from Transatlantic Holdings Inc
 Q3 2012 Earnings Presentation10 slides · Nov 2, 2012
 Merger or Acquisition (December 2011)40 slides · Dec 1, 2011
 Merger or Acquisition (December 2011)39 slides · Dec 1, 2011
 Merger or Acquisition (November 2011)11 slides · Nov 29, 2011
 Merger or Acquisition (November 2011)28 slides · Nov 10, 2011
 Merger or Acquisition (November 2011)41 slides · Nov 4, 2011