Palmetto Bancshares — KBW Bank Conference 2012
54 slides from Palmetto Bancshares's conference presentation, Sep 14, 2012
Slide 1: Palmetto Bancshares, Inc. – KBW Bank Conference
Exhibit 99.1 Palmetto Bancshares, Inc. Holding Company for KBW Bank Conference September 14, 2012 Sam Erwin, Lee Dixon, President and Chief Executive Officer Chief Operating and Chief Risk Officer Office: 864-250-6083 Office: 864-250-6082 Email: serwin@palmettobank.com Email: ldixon@palmettobank.com
Slide 2: Non-GAAP Measures and Forward Looking Statements
Non-GAAP Measures and Forward Looking Statements This presentation contains financial information determined by methods other than in accordance with Generally Accepted Accounting Principles (“GAAP”) such as earnings figures excluding credit-related items such as provision for loan losses, loan work
Slide 3: General Background on The Palmetto Bank
General Background on The Palmetto Bank NASDAQ: PLMT 3
Slide 4: The Palmetto Bank At a Glance
The Palmetto Bank At a Glance Headquarters: Greenville, South Carolina Inception: 1906 (105 years) Team members (FTE): 322.5 Total assets: $1.181 billion Total deposits: $1.063 billion Tangible book value/share: $7.04 Stock price: $7.50 (and as of September 10) Market capitalization: $95.6 million P
Slide 5: Franchise and Leadership
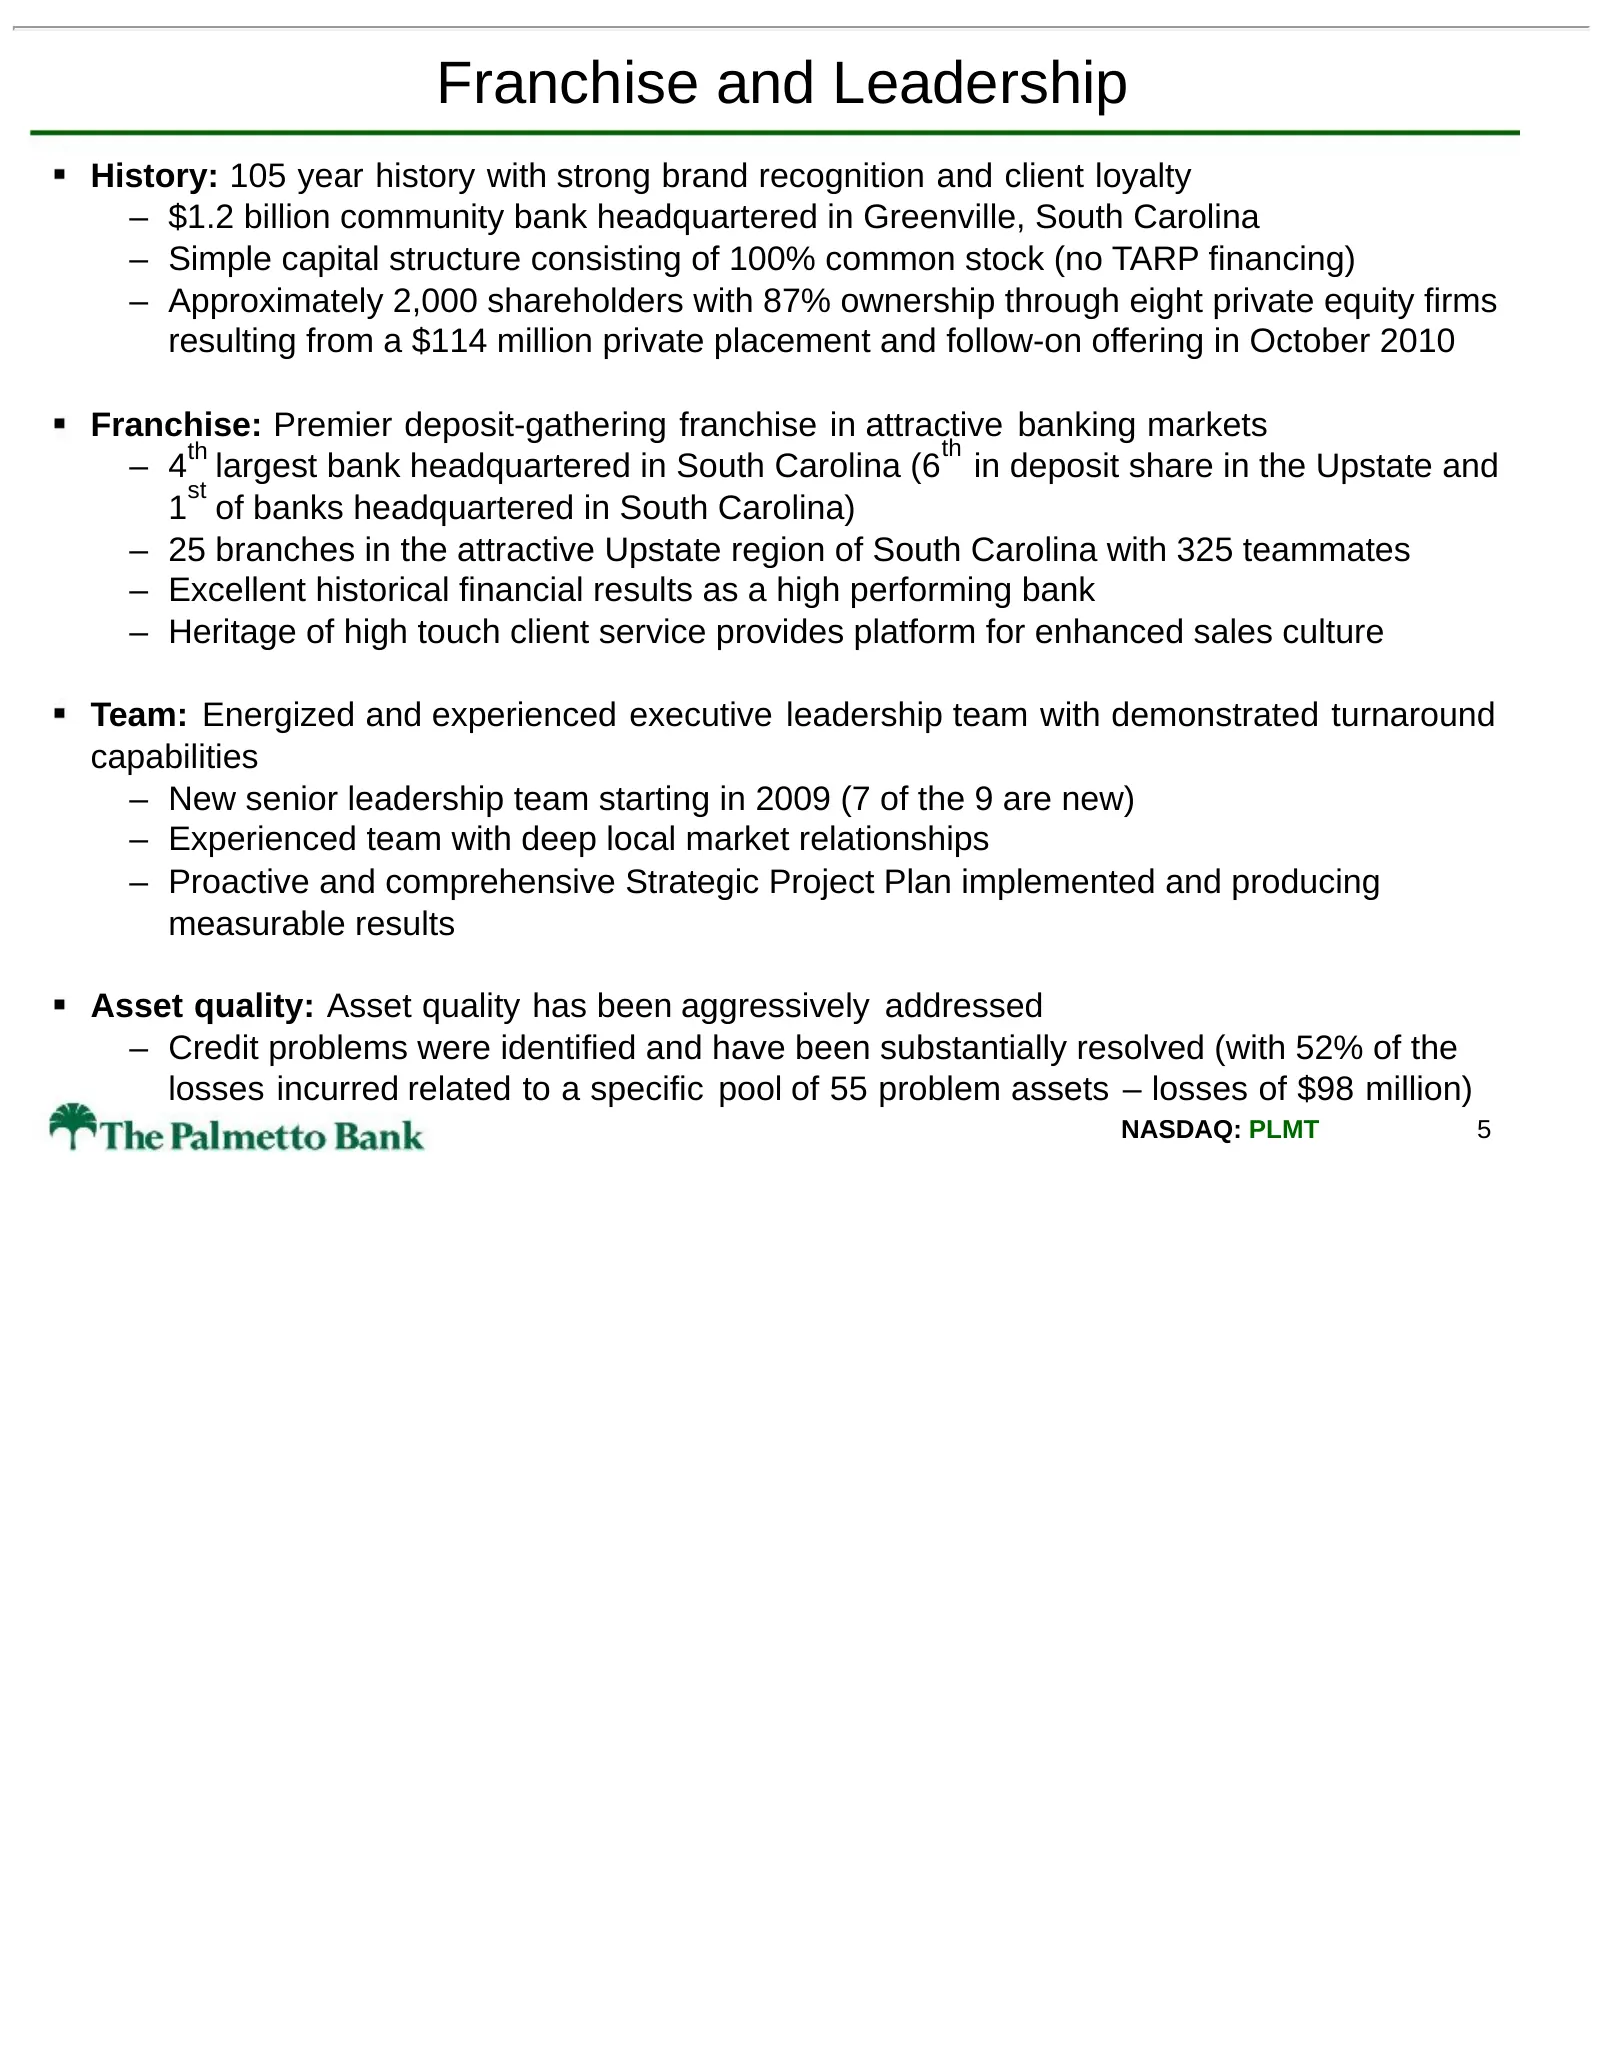
Franchise and Leadership History: 105 year history with strong brand recognition and client loyalty – $1.2 billion community bank headquartered in Greenville, South Carolina – Simple capital structure consisting of 100% common stock (no TARP financing) – Approximately 2,000 shareholders with 87% own
Slide 6: Established Branch Network
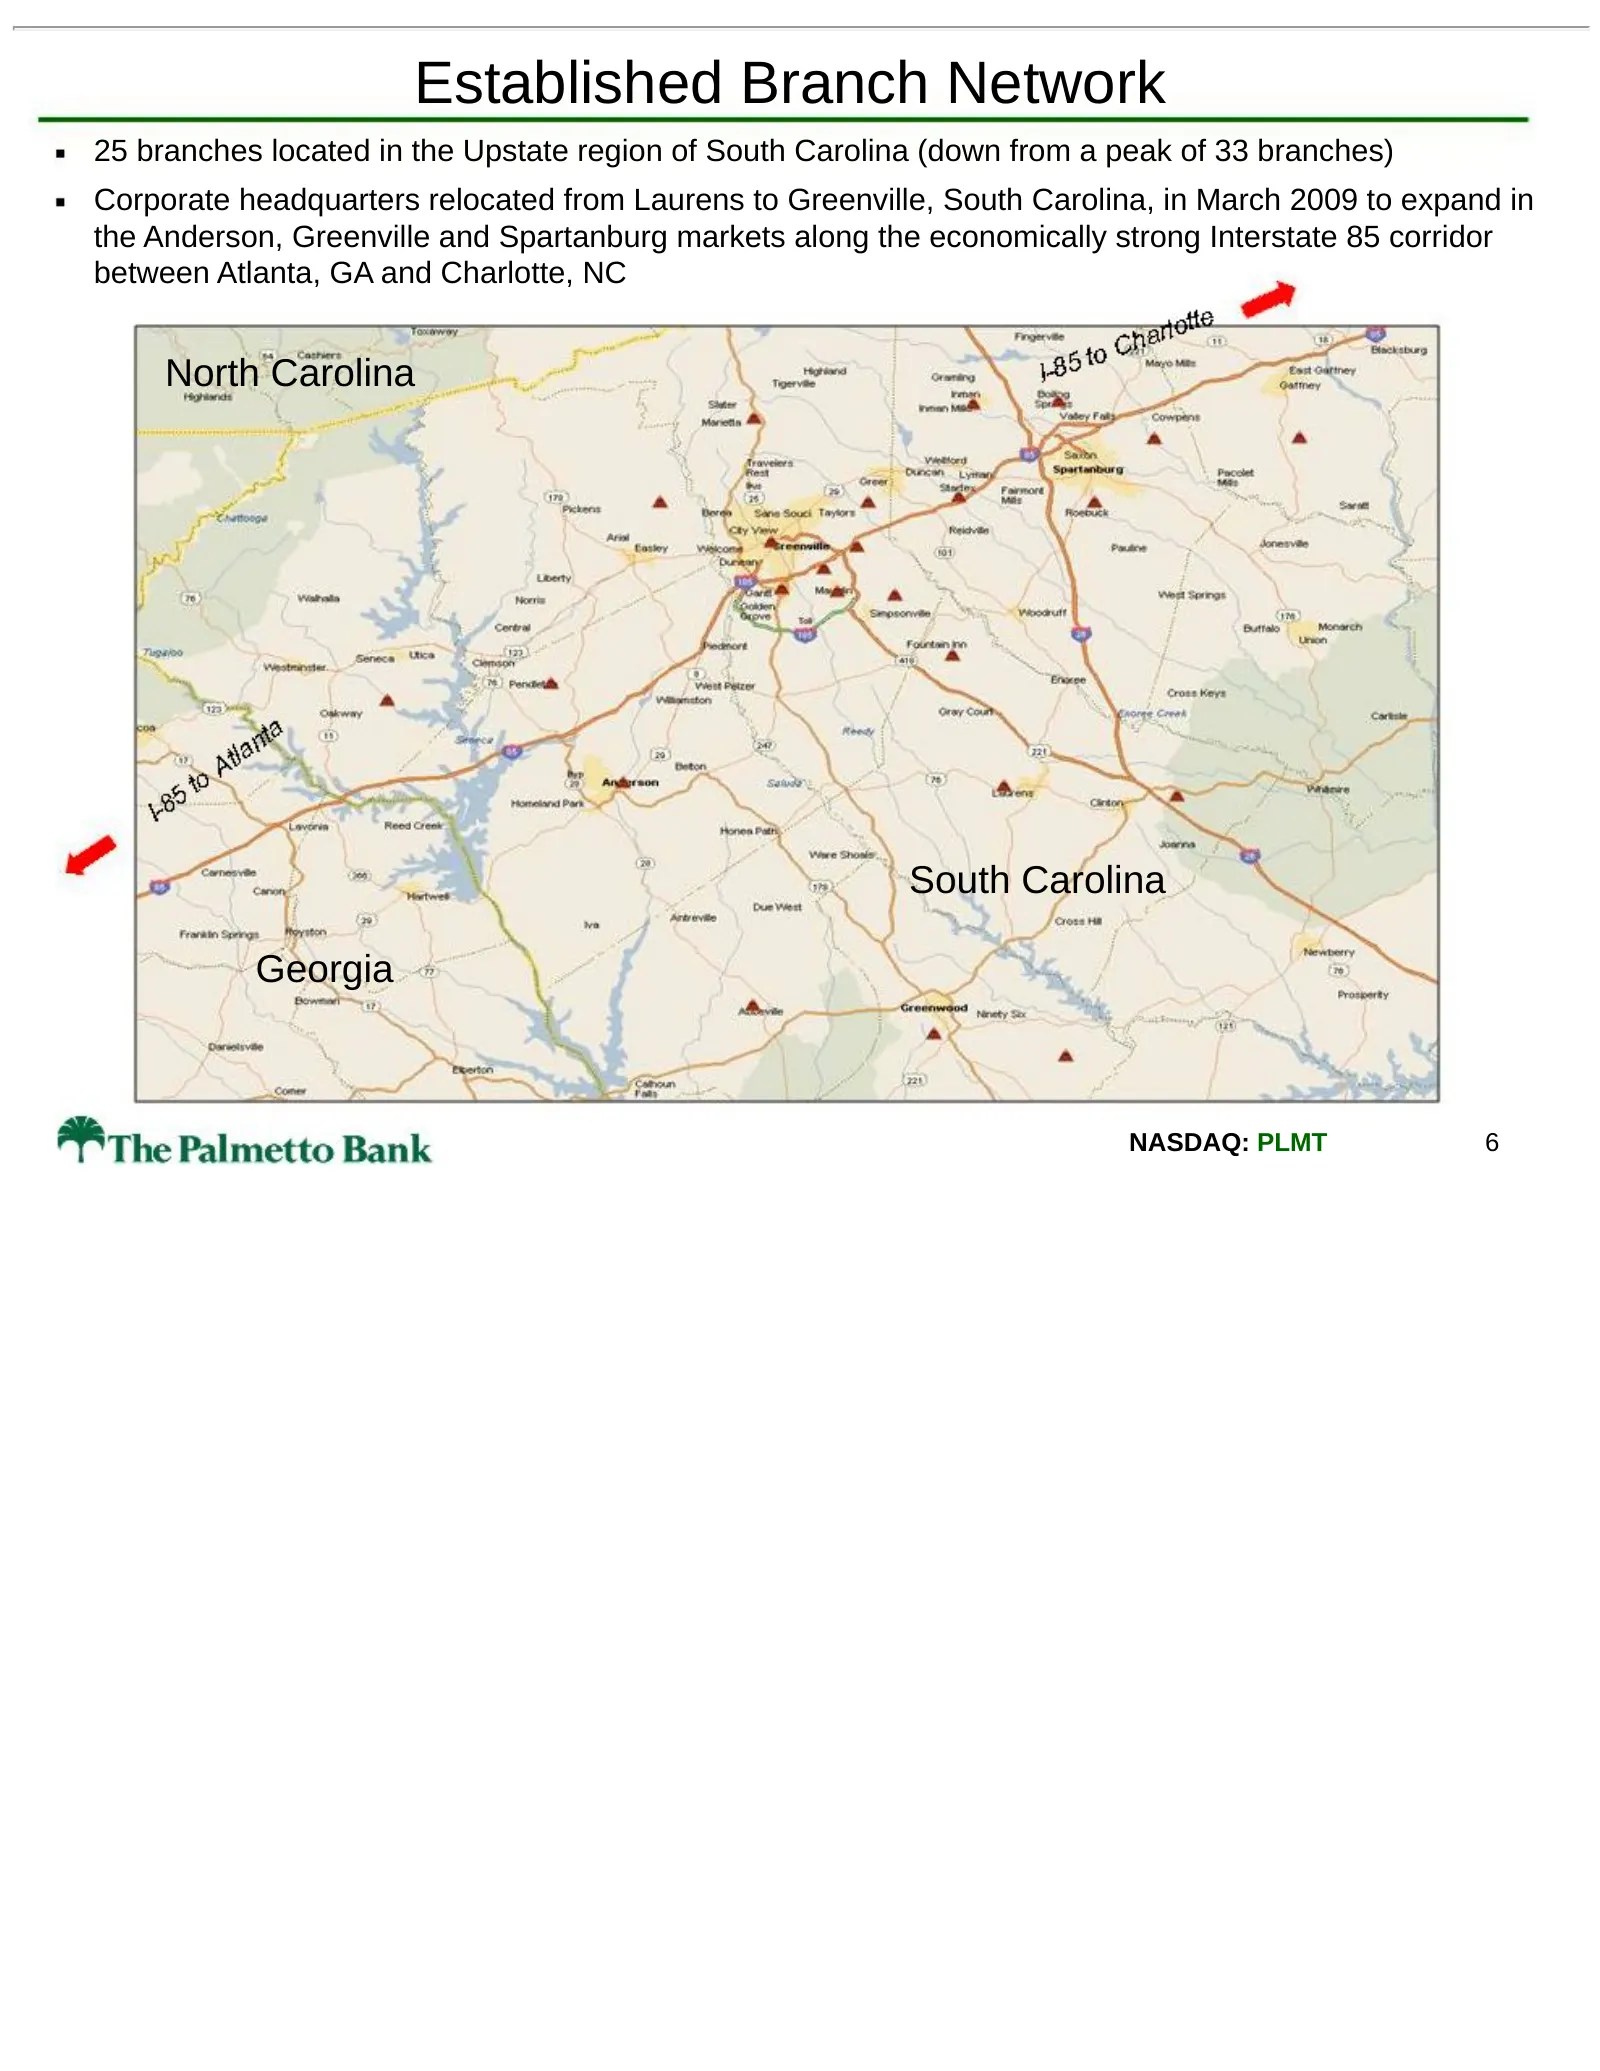
Established Branch Network 25 branches located in the Upstate region of South Carolina (down from a peak of 33 branches) Corporate headquarters relocated from Laurens to Greenville, South Carolina, in March 2009 to expand in the Anderson, Greenville and Spartanburg markets along the economically str
Slide 7: Attractive Size and Franchise
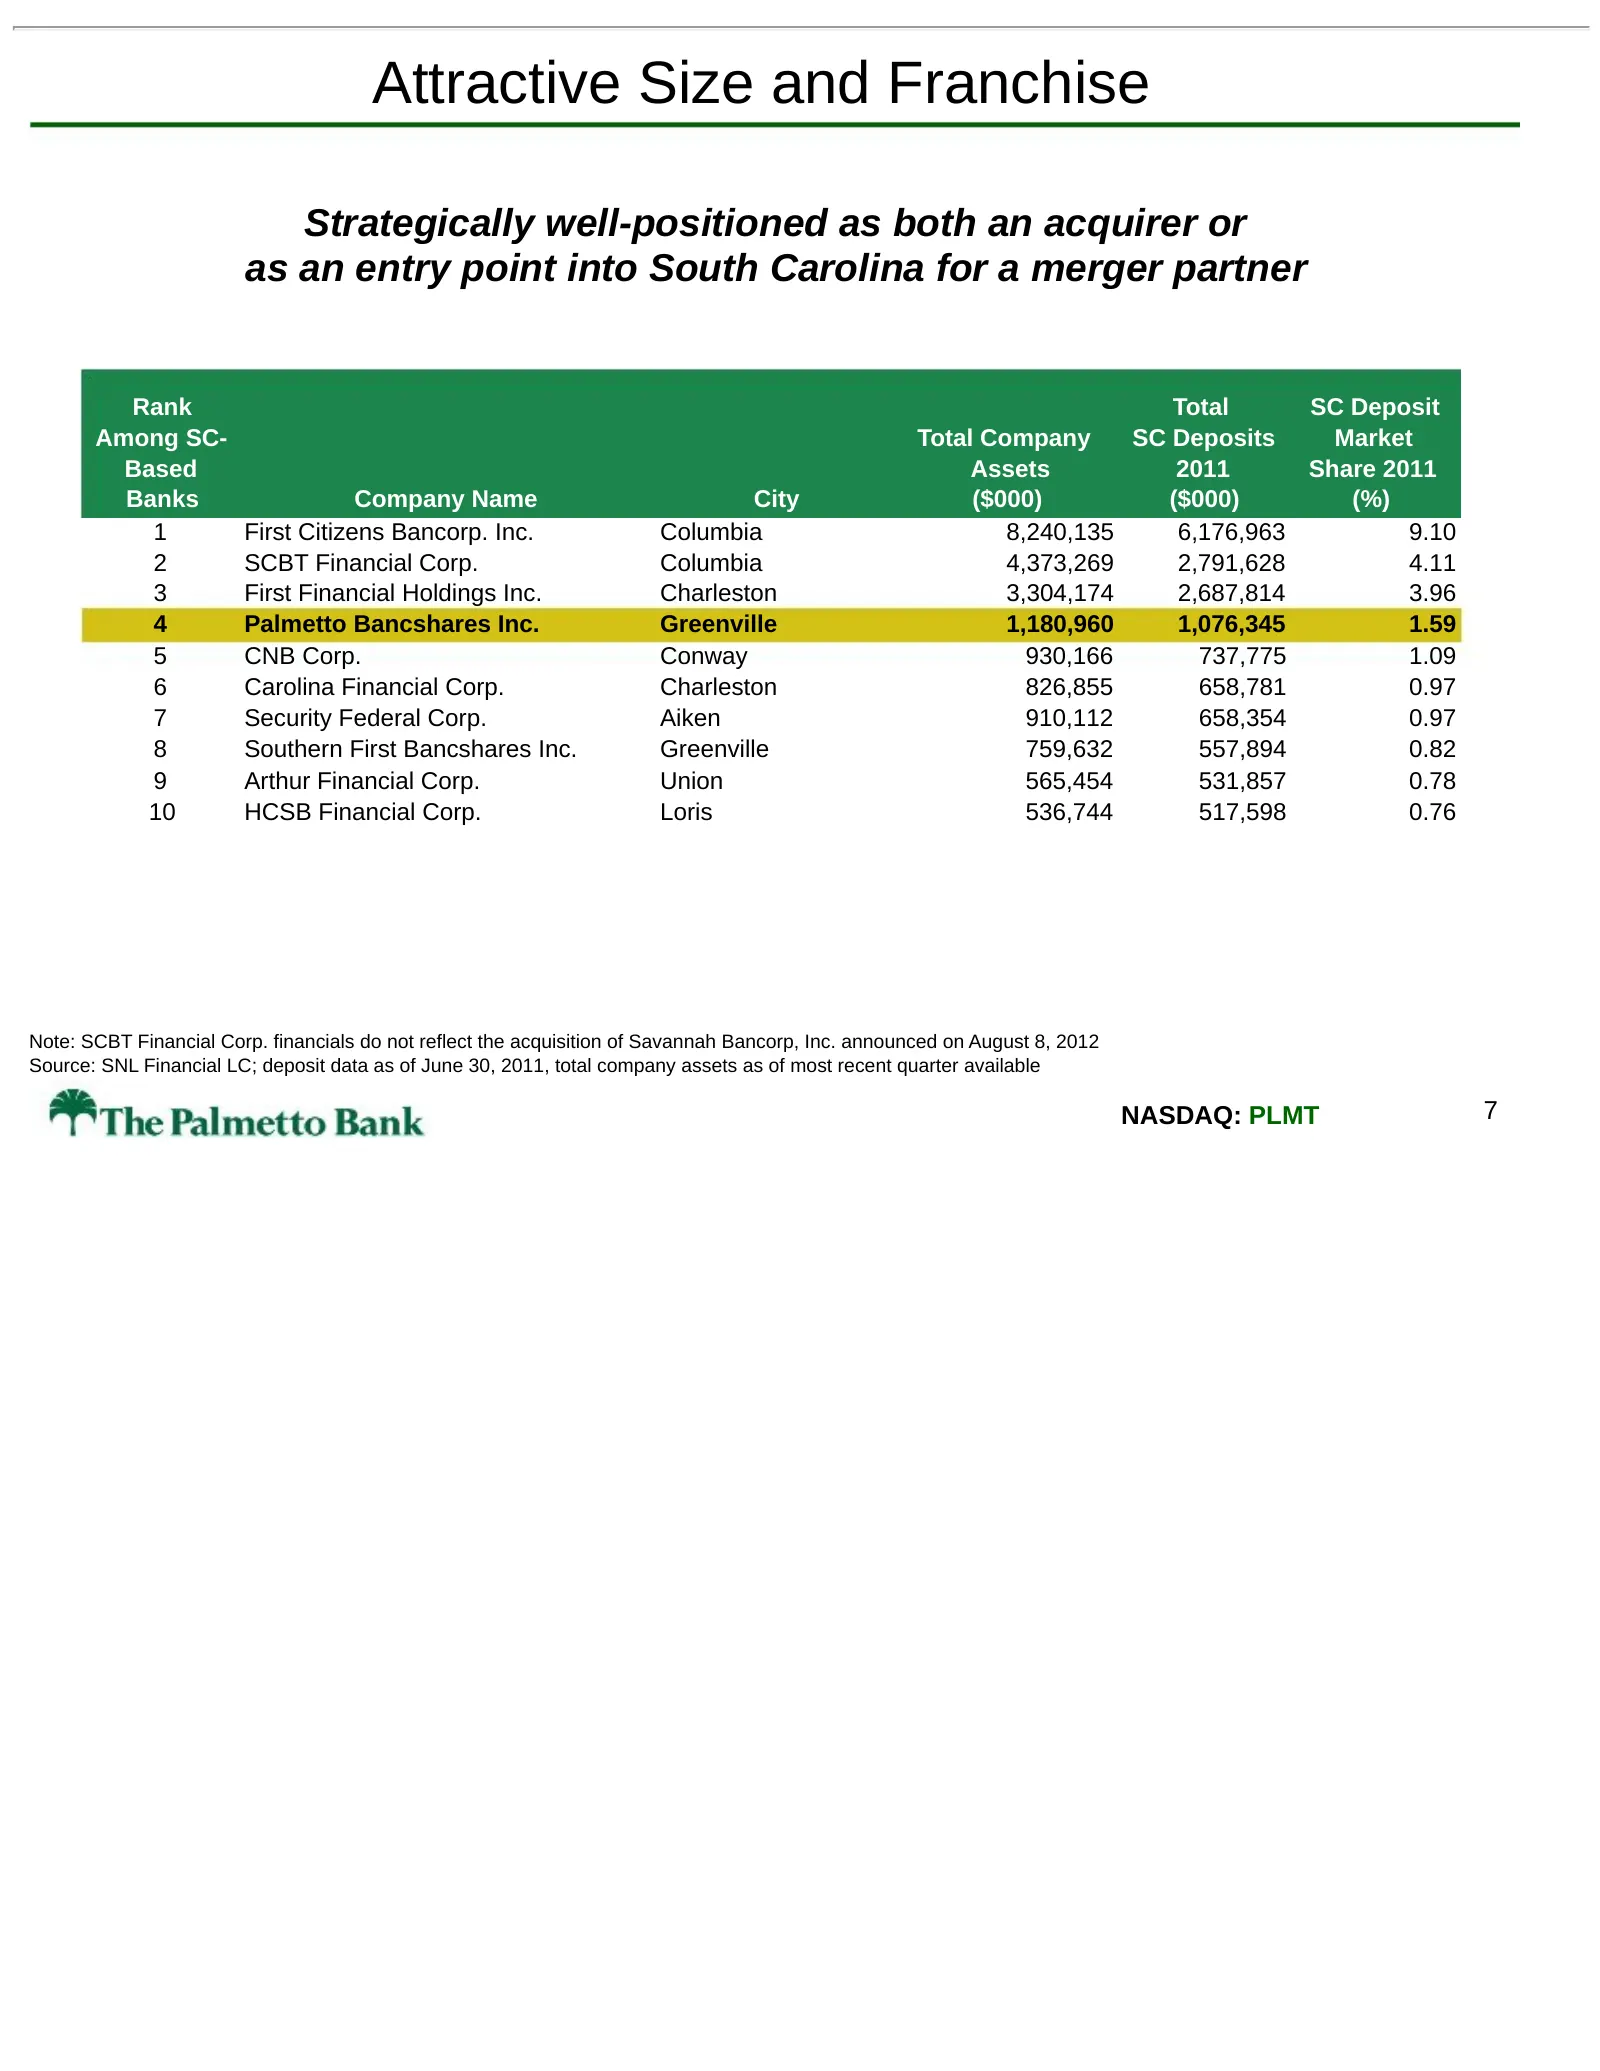
Attractive Size and Franchise Strategically well-positioned as both an acquirer or as an entry point into South Carolina for a merger partner Rank Total SC Deposit Among SC- Total Company SC Deposits Market Based Assets 2011 Share 2011 Banks Company Name City ($000) ($000) (%) 1 First Citizens Banco
Slide 8: Attractive Markets in Upstate South Carolina
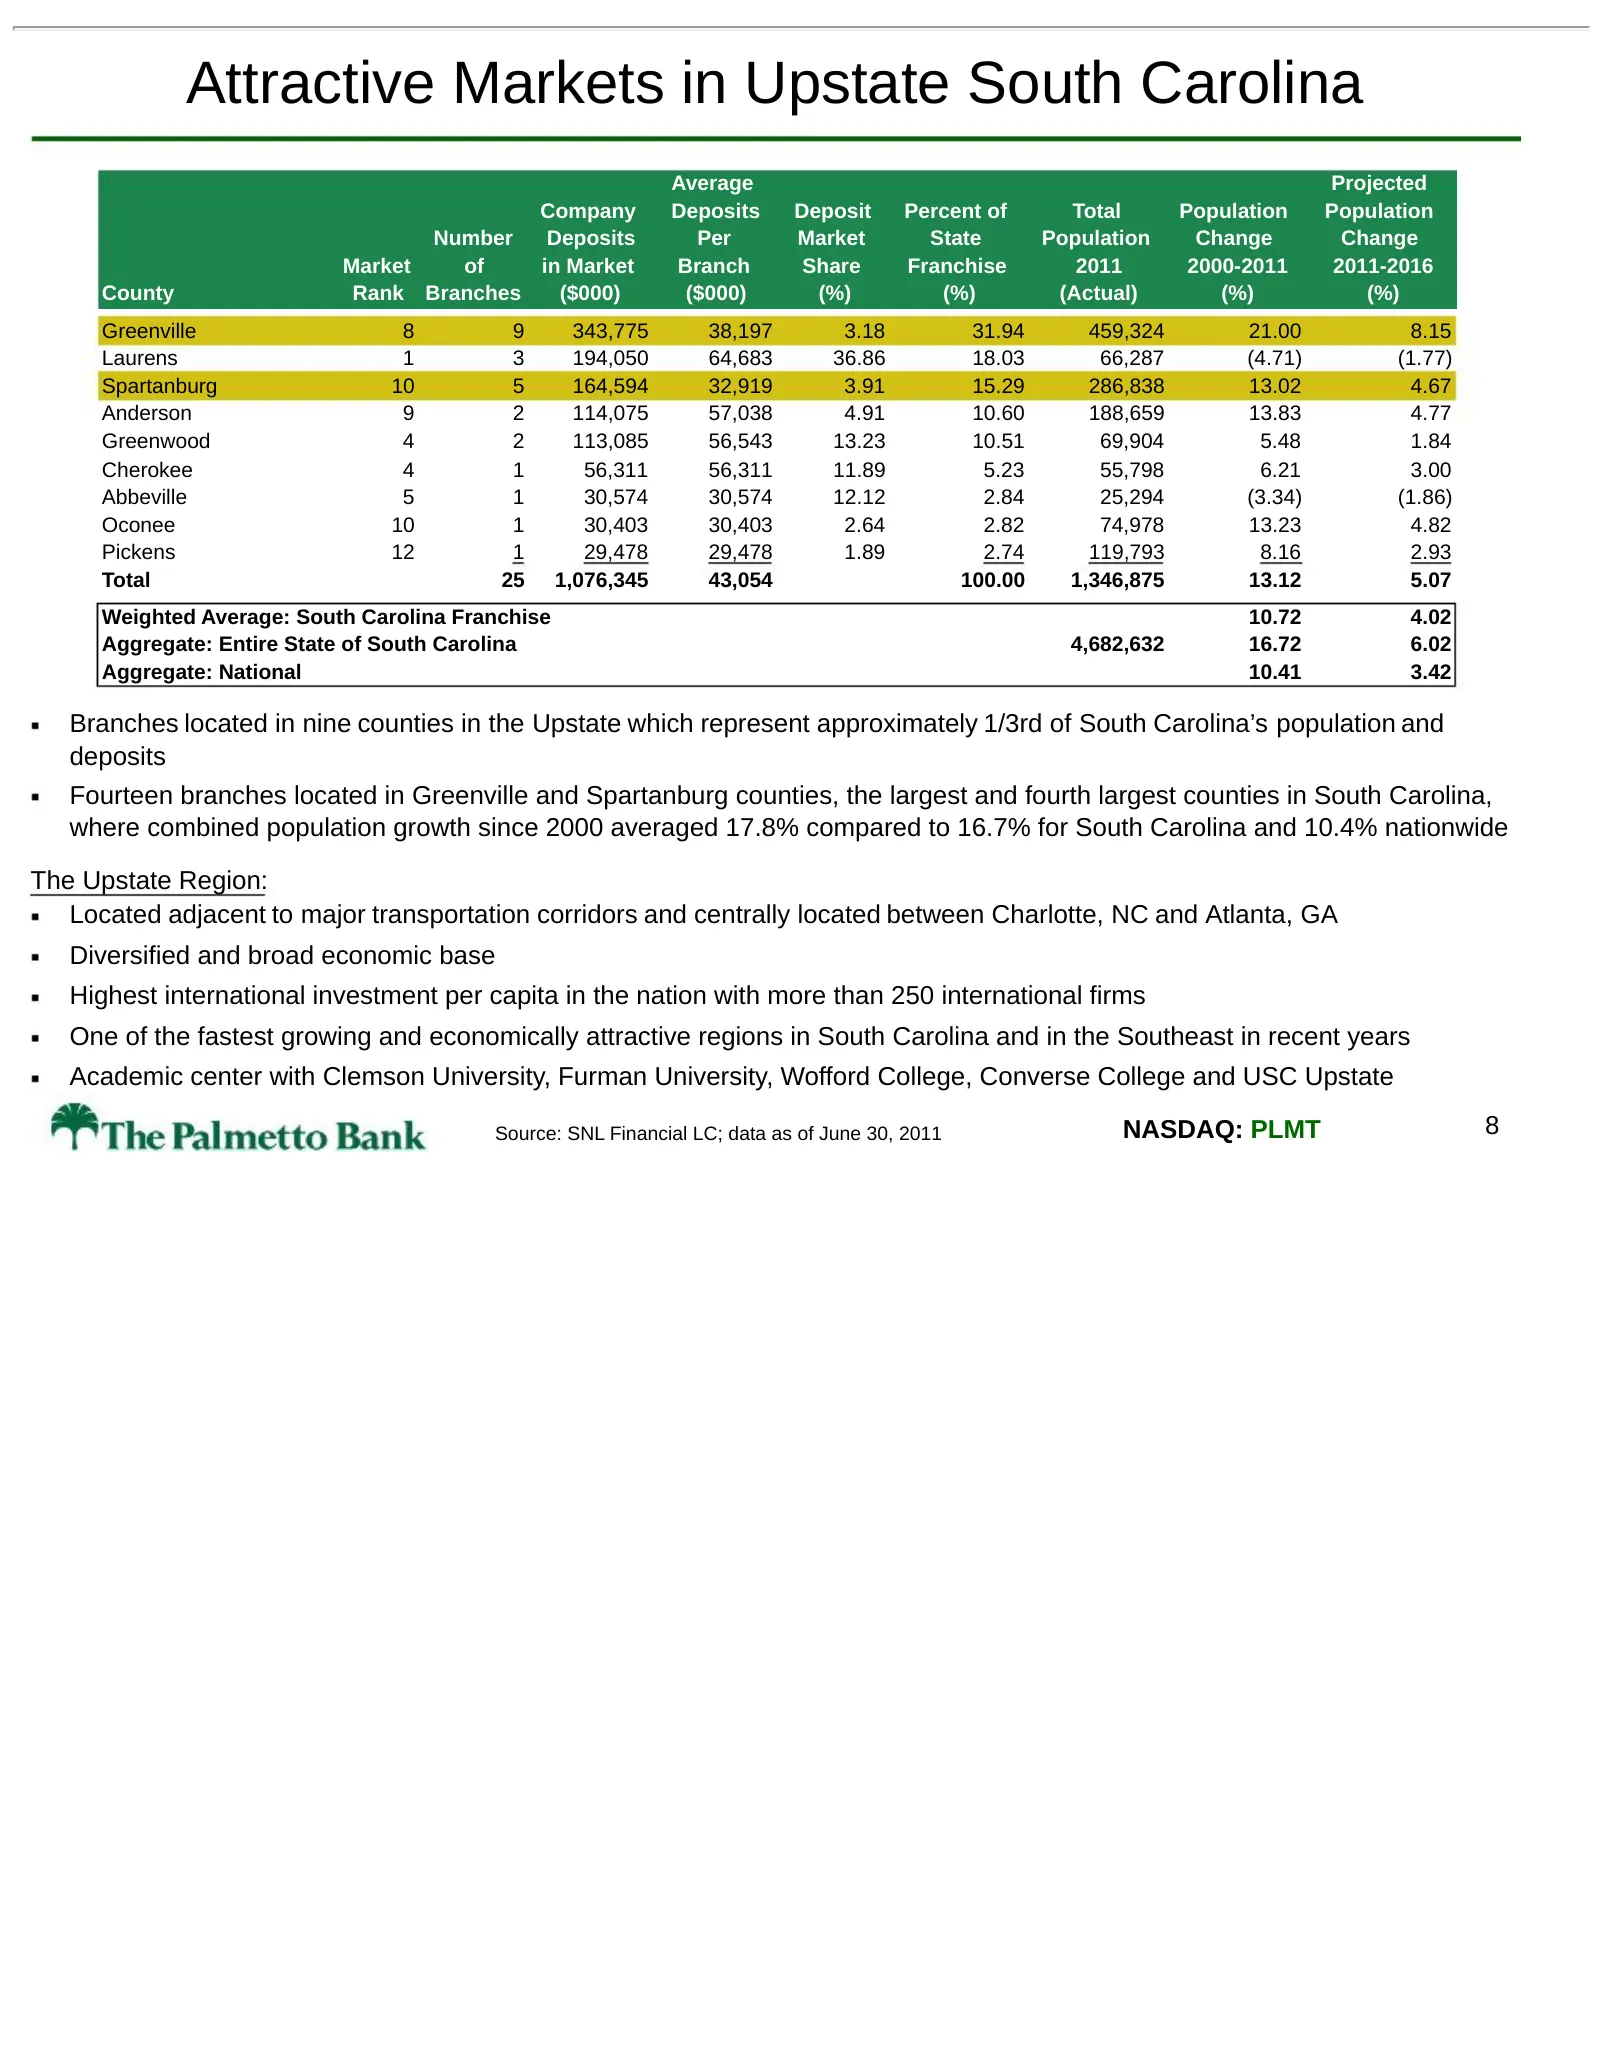
Attractive Markets in Upstate South Carolina Average Projected Company Deposits Deposit Percent of Total Population Population Number Deposits Per Market State Population Change Change Market of in Market Branch Share Franchise 2011 2000-2011 2011-2016 County Rank Branches ($000) ($000) (%) (%) (Act
Slide 9: Energized and Experienced Management Team
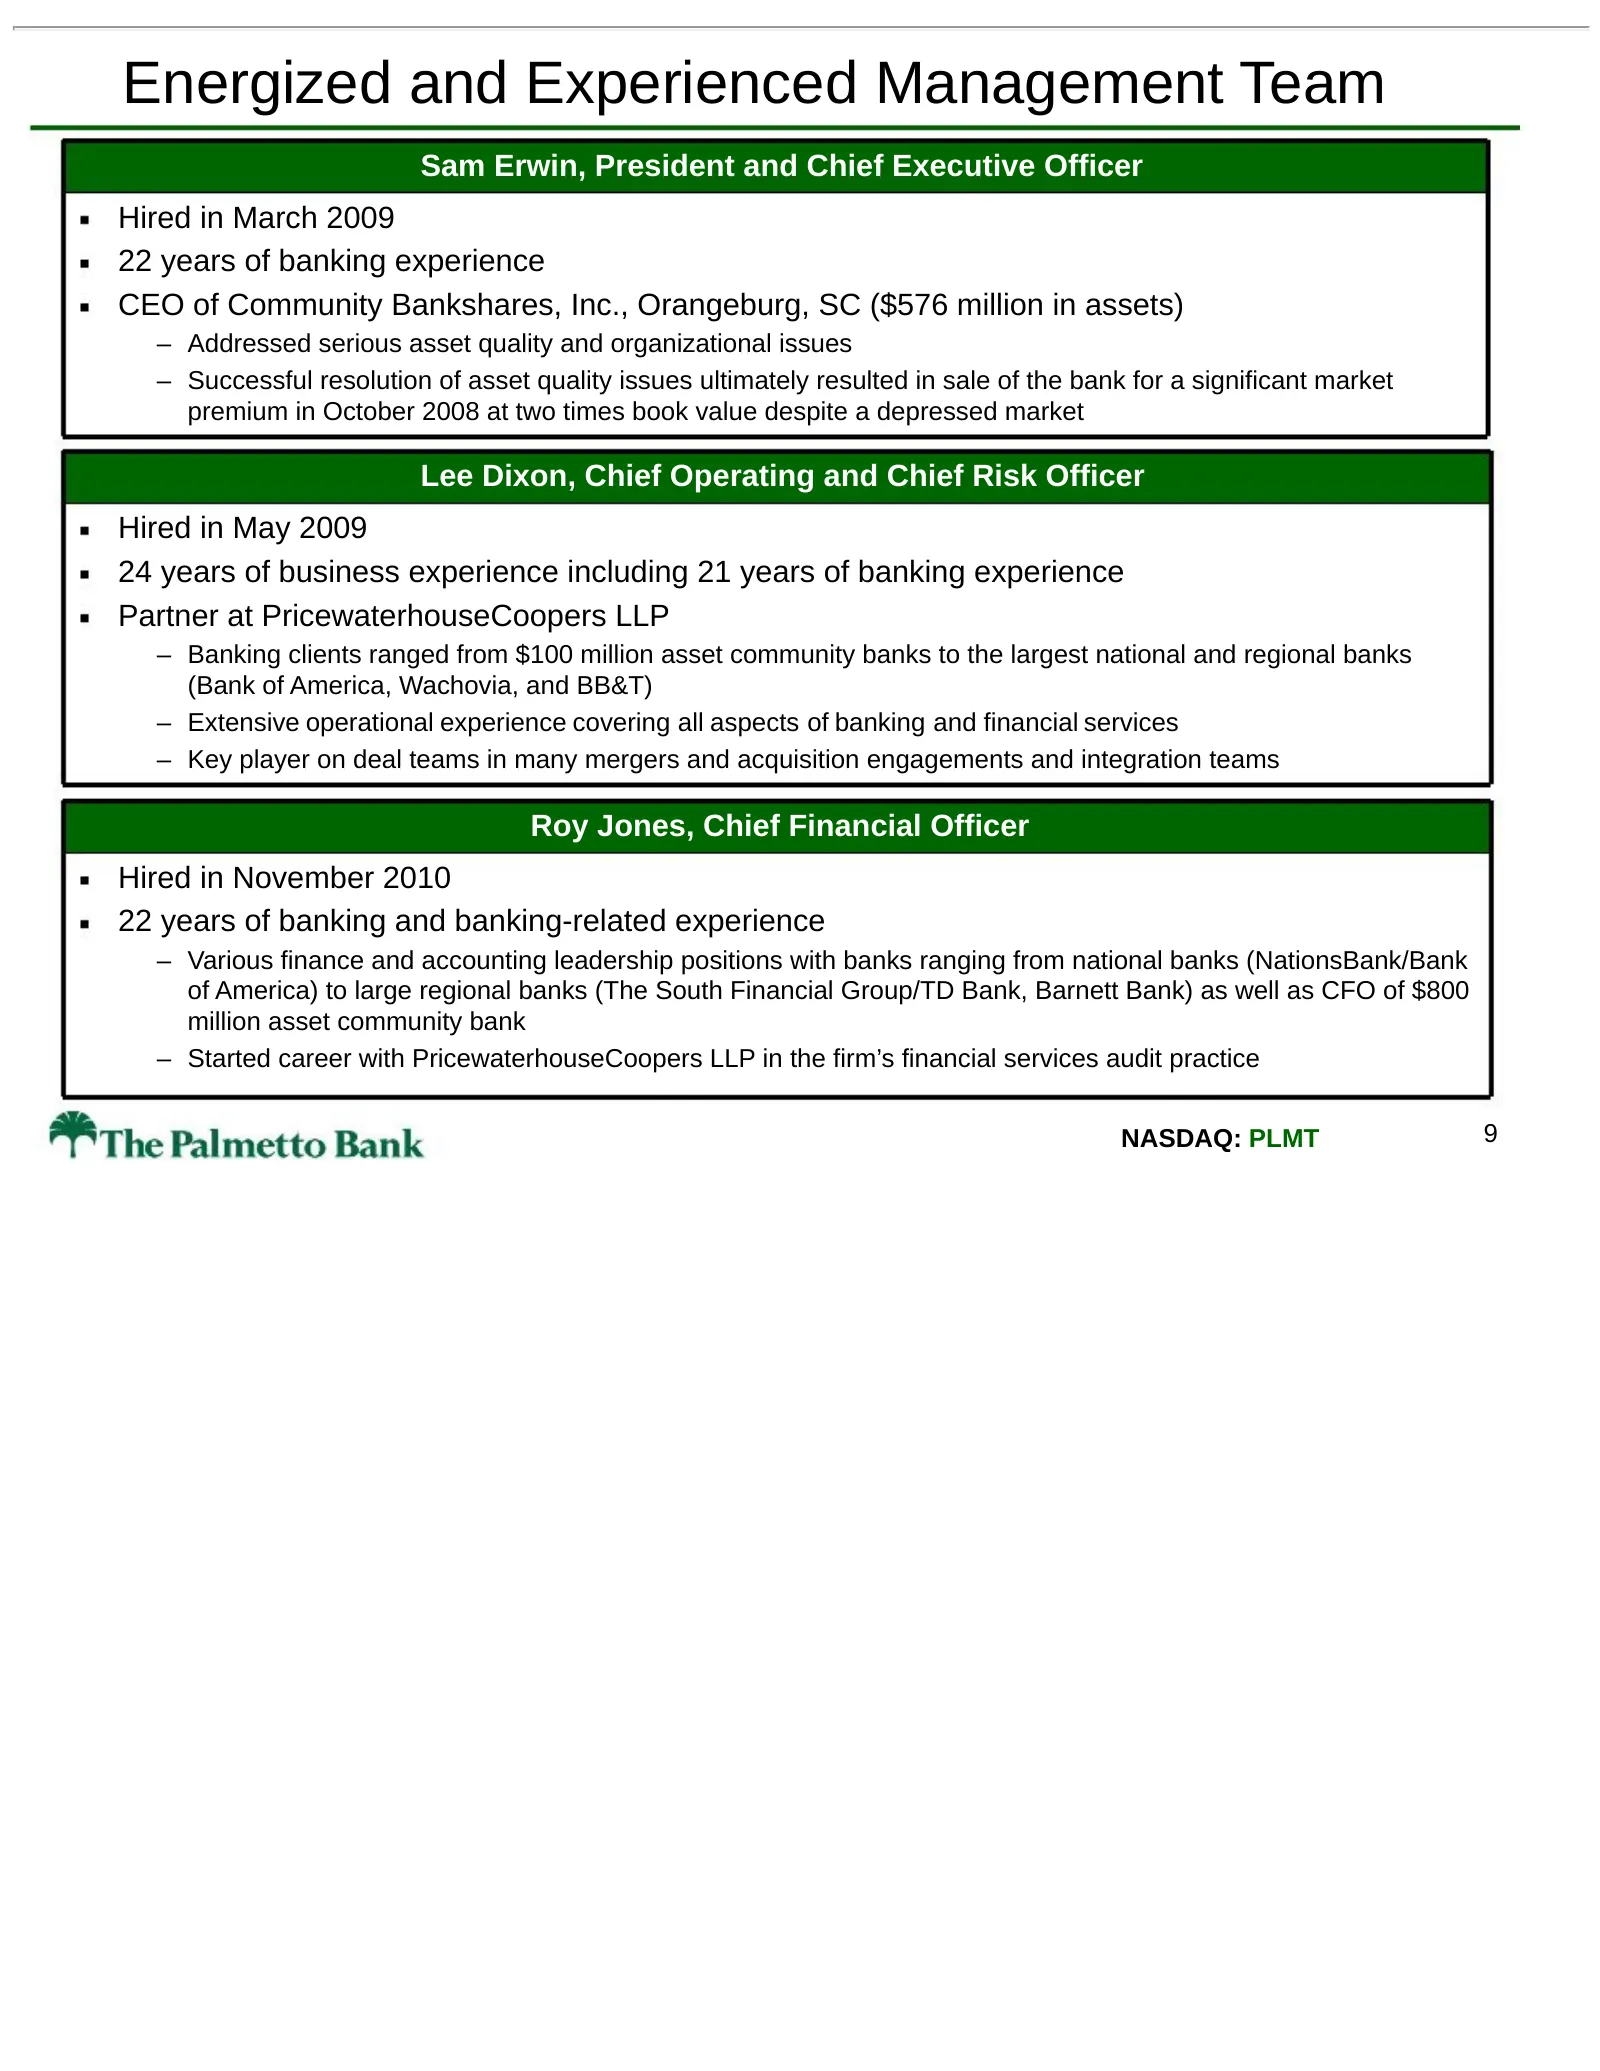
Energized and Experienced Management Team Sam Erwin, President and Chief Executive Officer Hired in March 2009 22 years of banking experience CEO of Community Bankshares, Inc., Orangeburg, SC ($576 million in assets) – Addressed serious asset quality and organizational issues – Successful resolution
Slide 10: Energized and Experienced Management Team
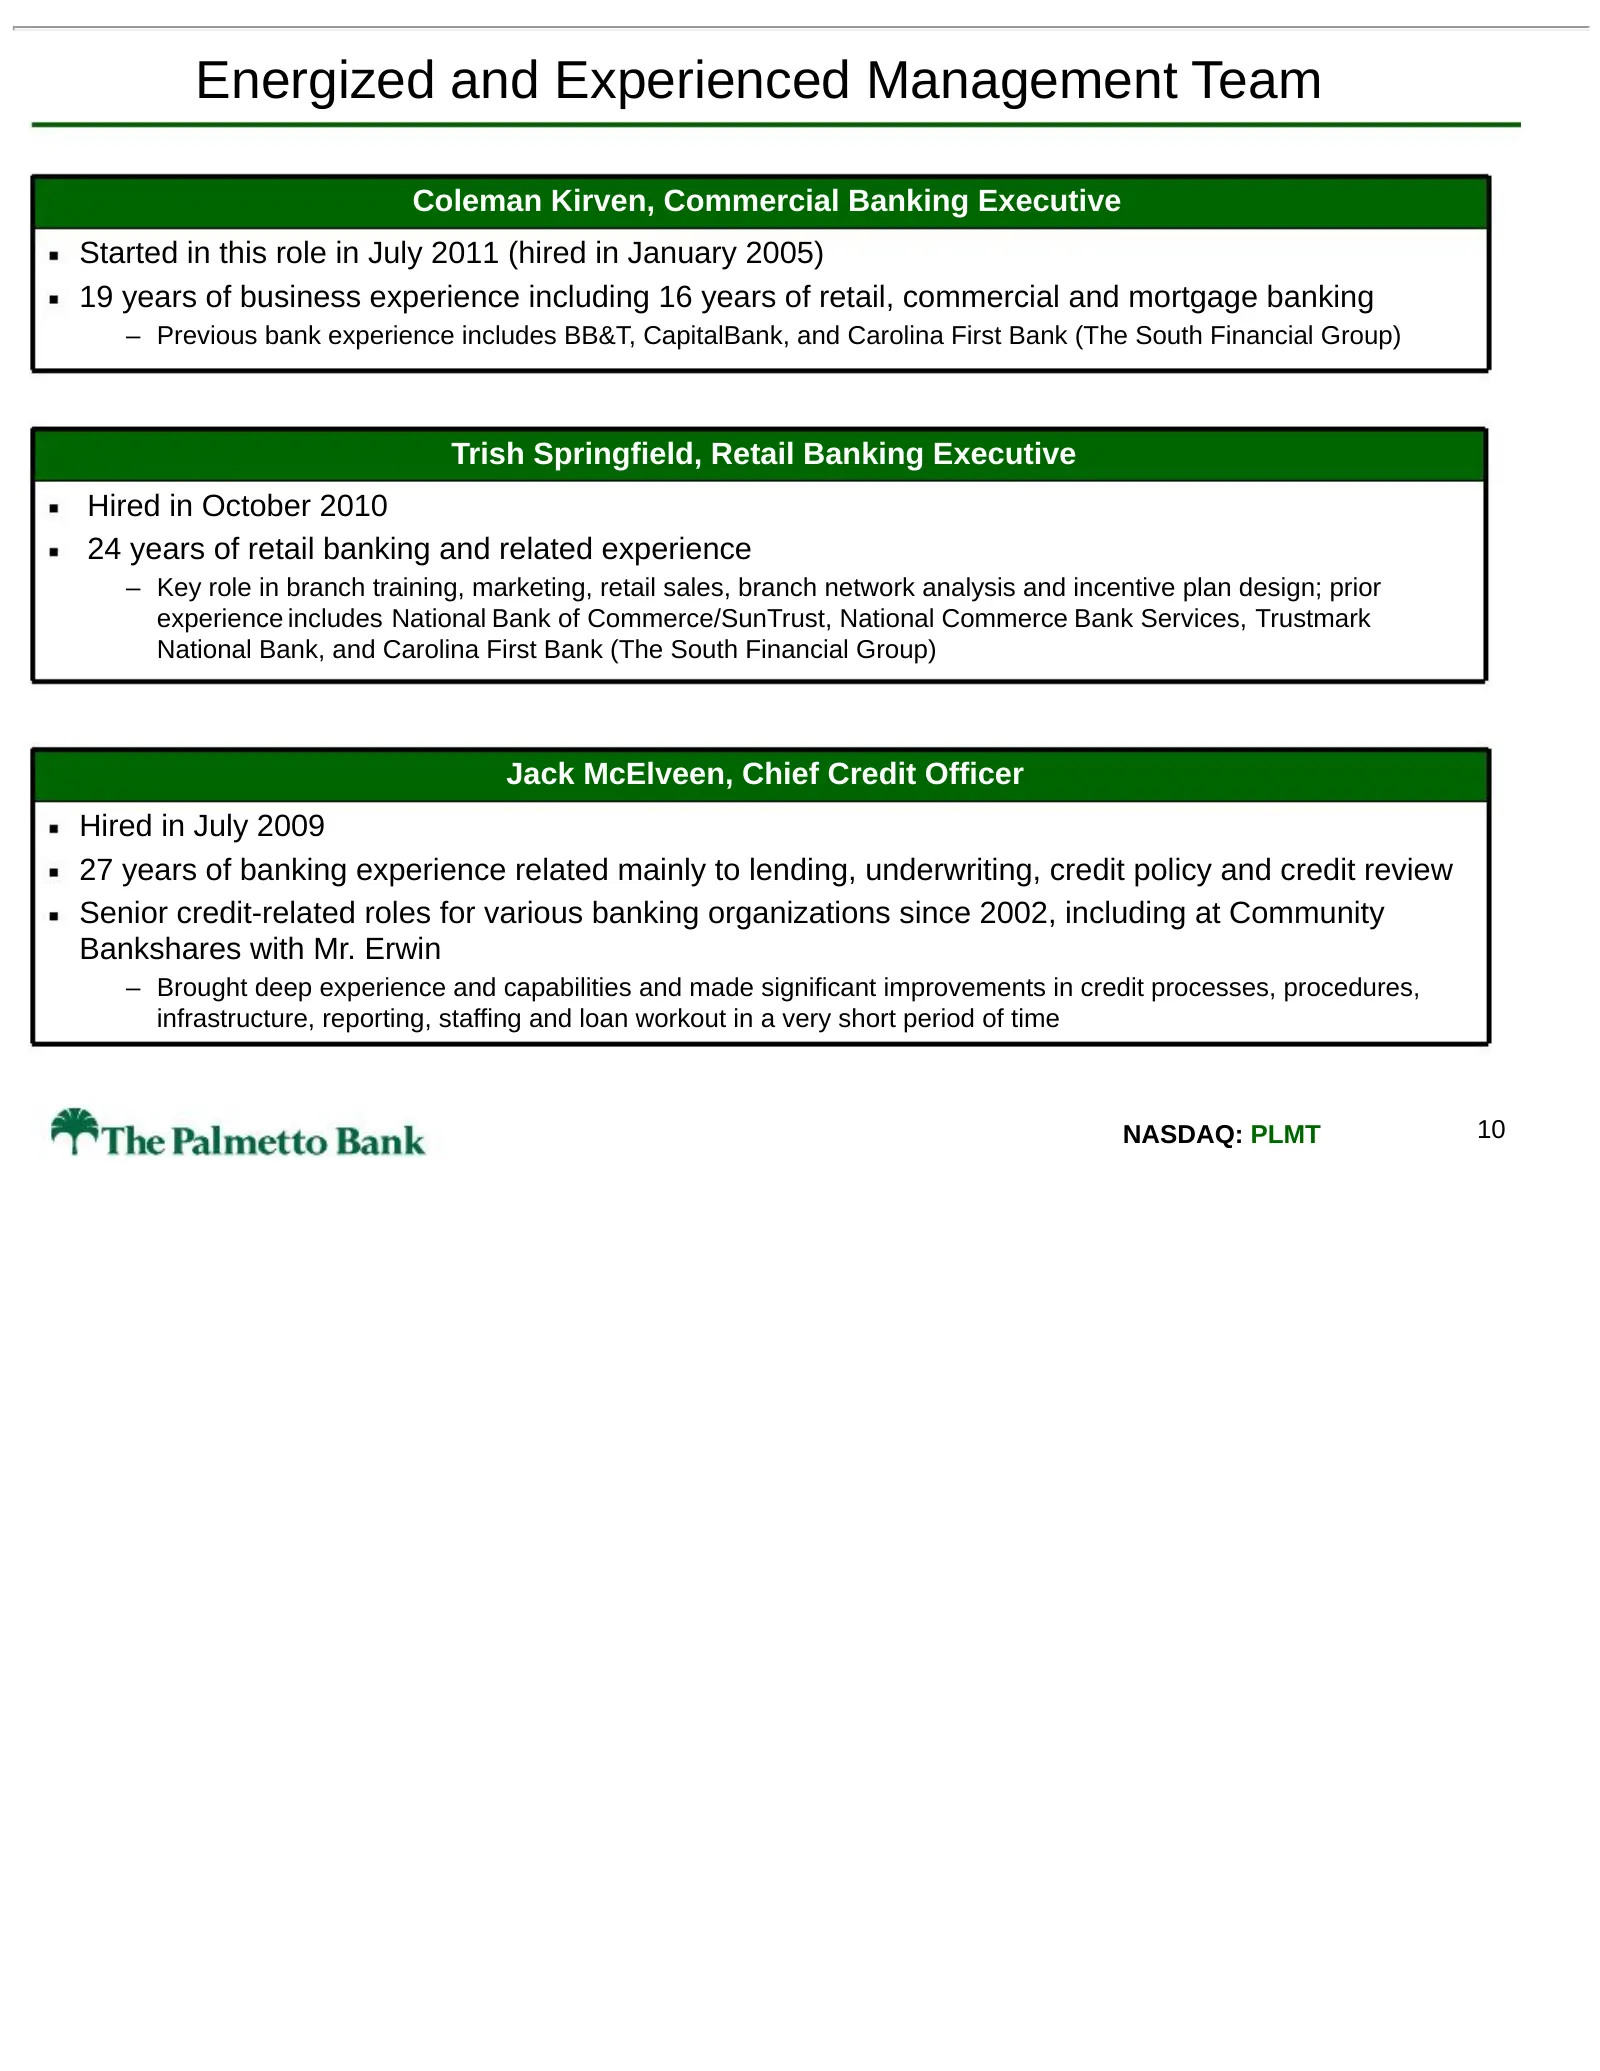
Energized and Experienced Management Team Coleman Kirven, Commercial Banking Executive Started in this role in July 2011 (hired in January 2005) 19 years of business experience including 16 years of retail, commercial and mortgage banking – Previous bank experience includes BB&T, CapitalBank, and Ca
Slide 11: Energized and Experienced Management Team
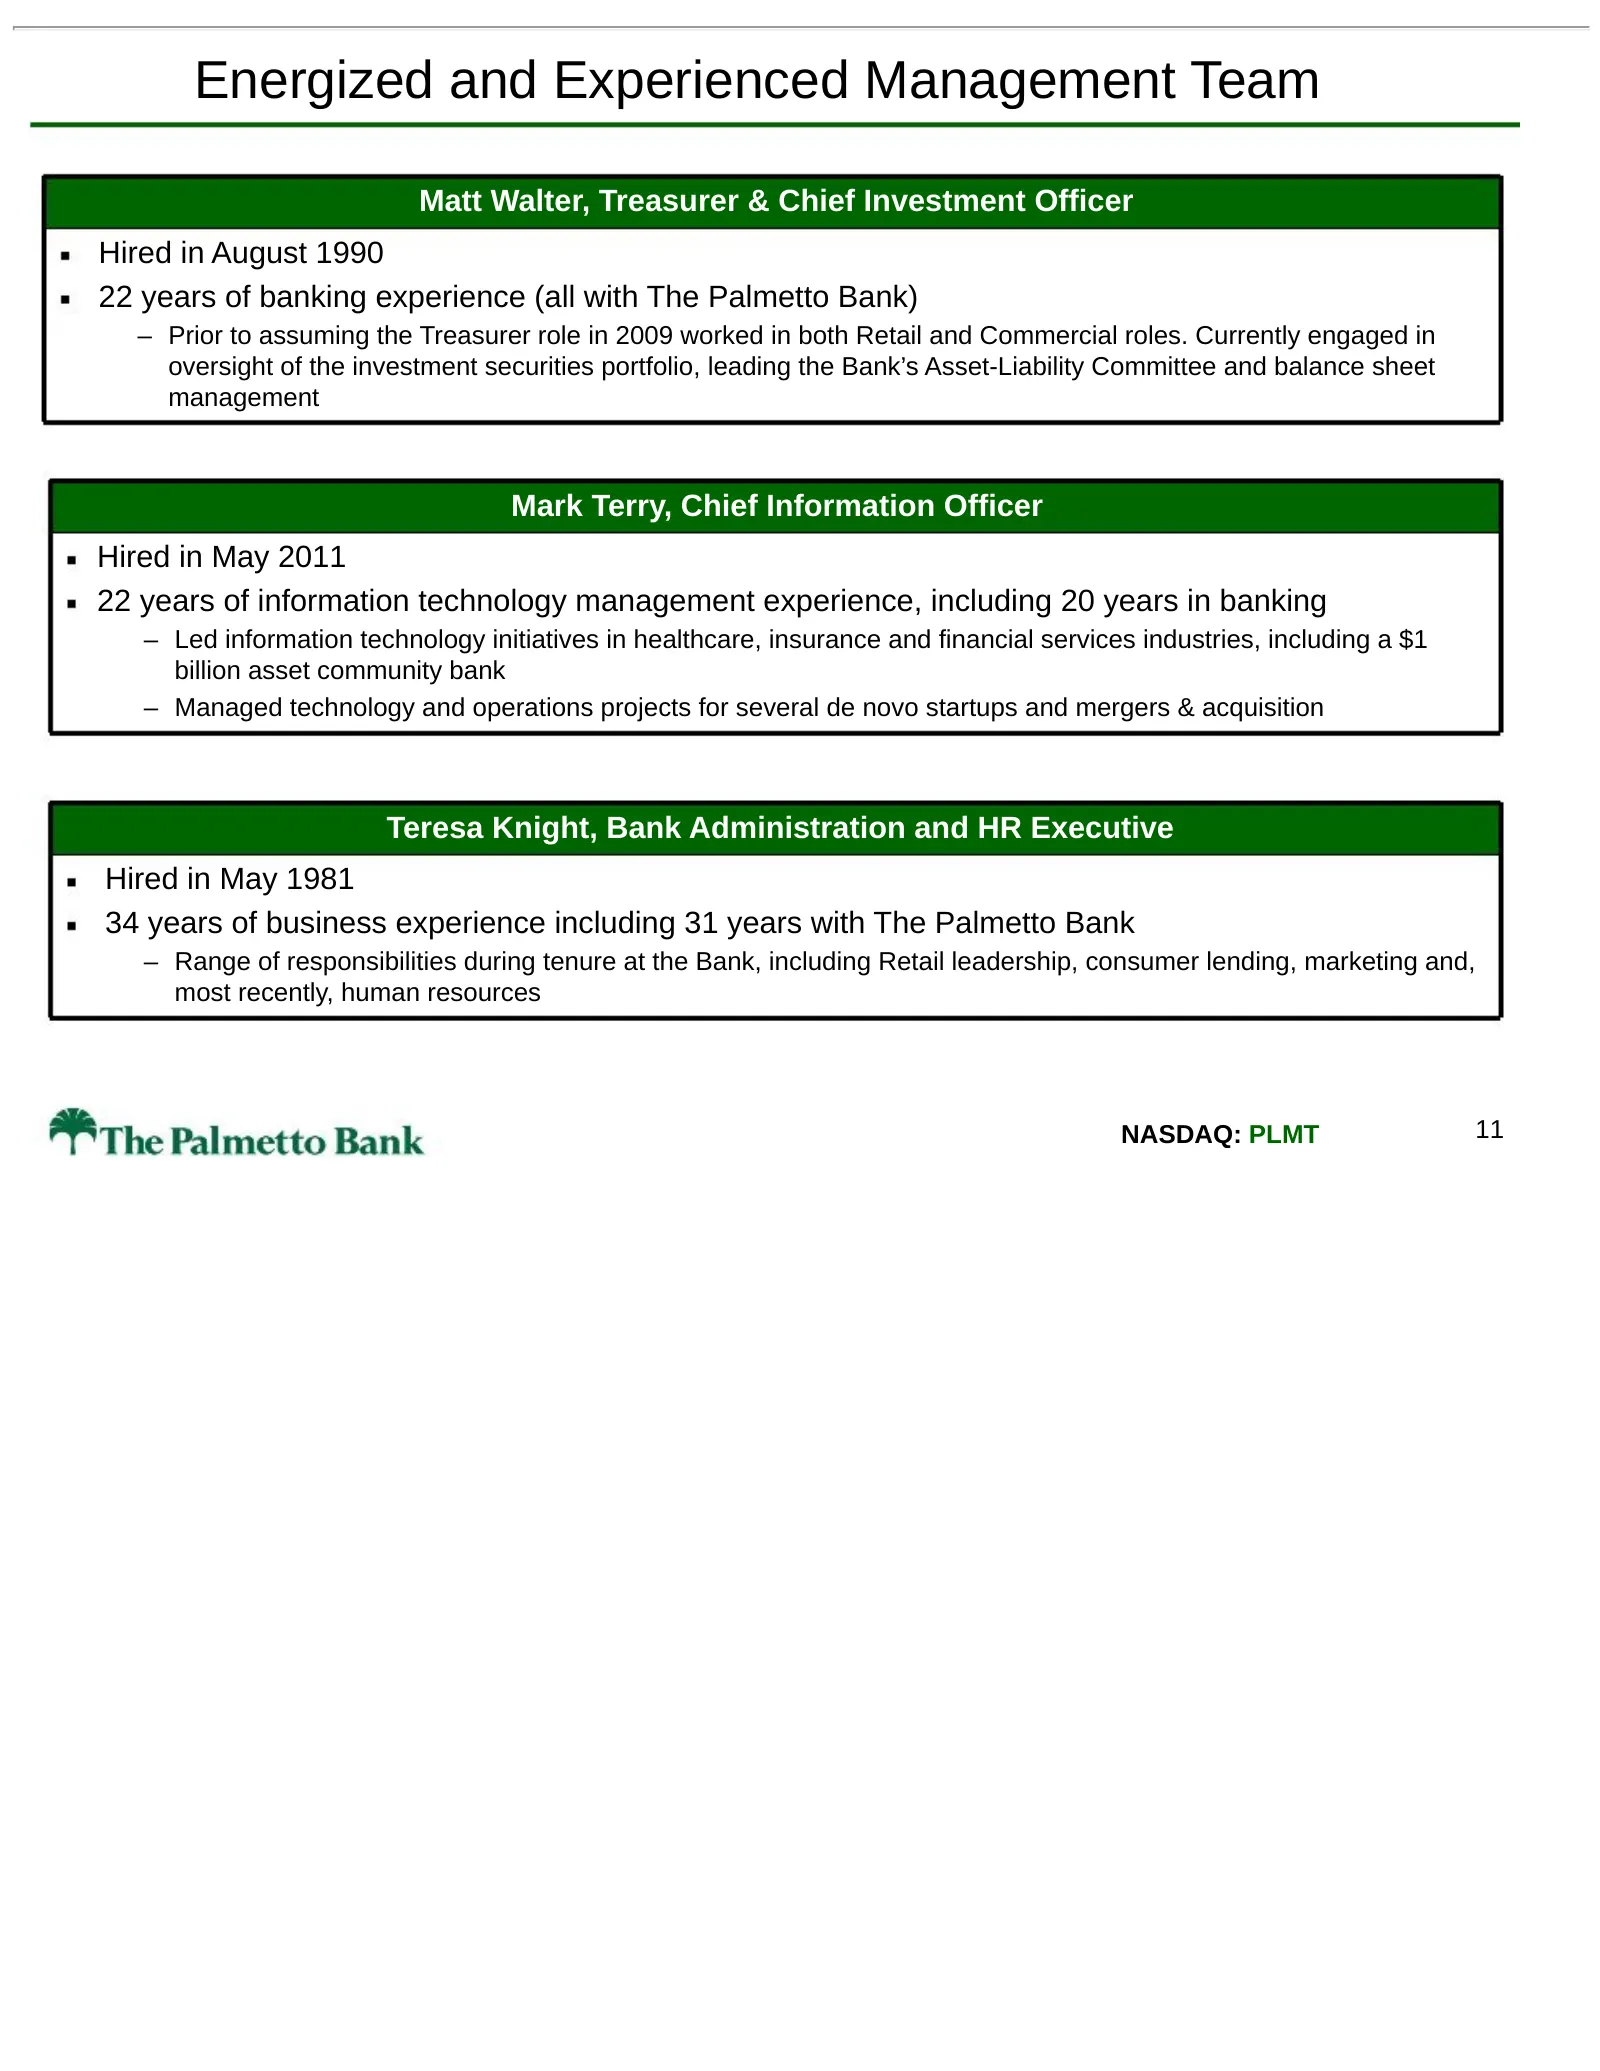
Energized and Experienced Management Team Matt Walter, Treasurer & Chief Investment Officer Hired in August 1990 22 years of banking experience (all with The Palmetto Bank) – Prior to assuming the Treasurer role in 2009 worked in both Retail and Commercial roles. Currently engaged in oversight of th
Slide 12: The Turnaround Summary
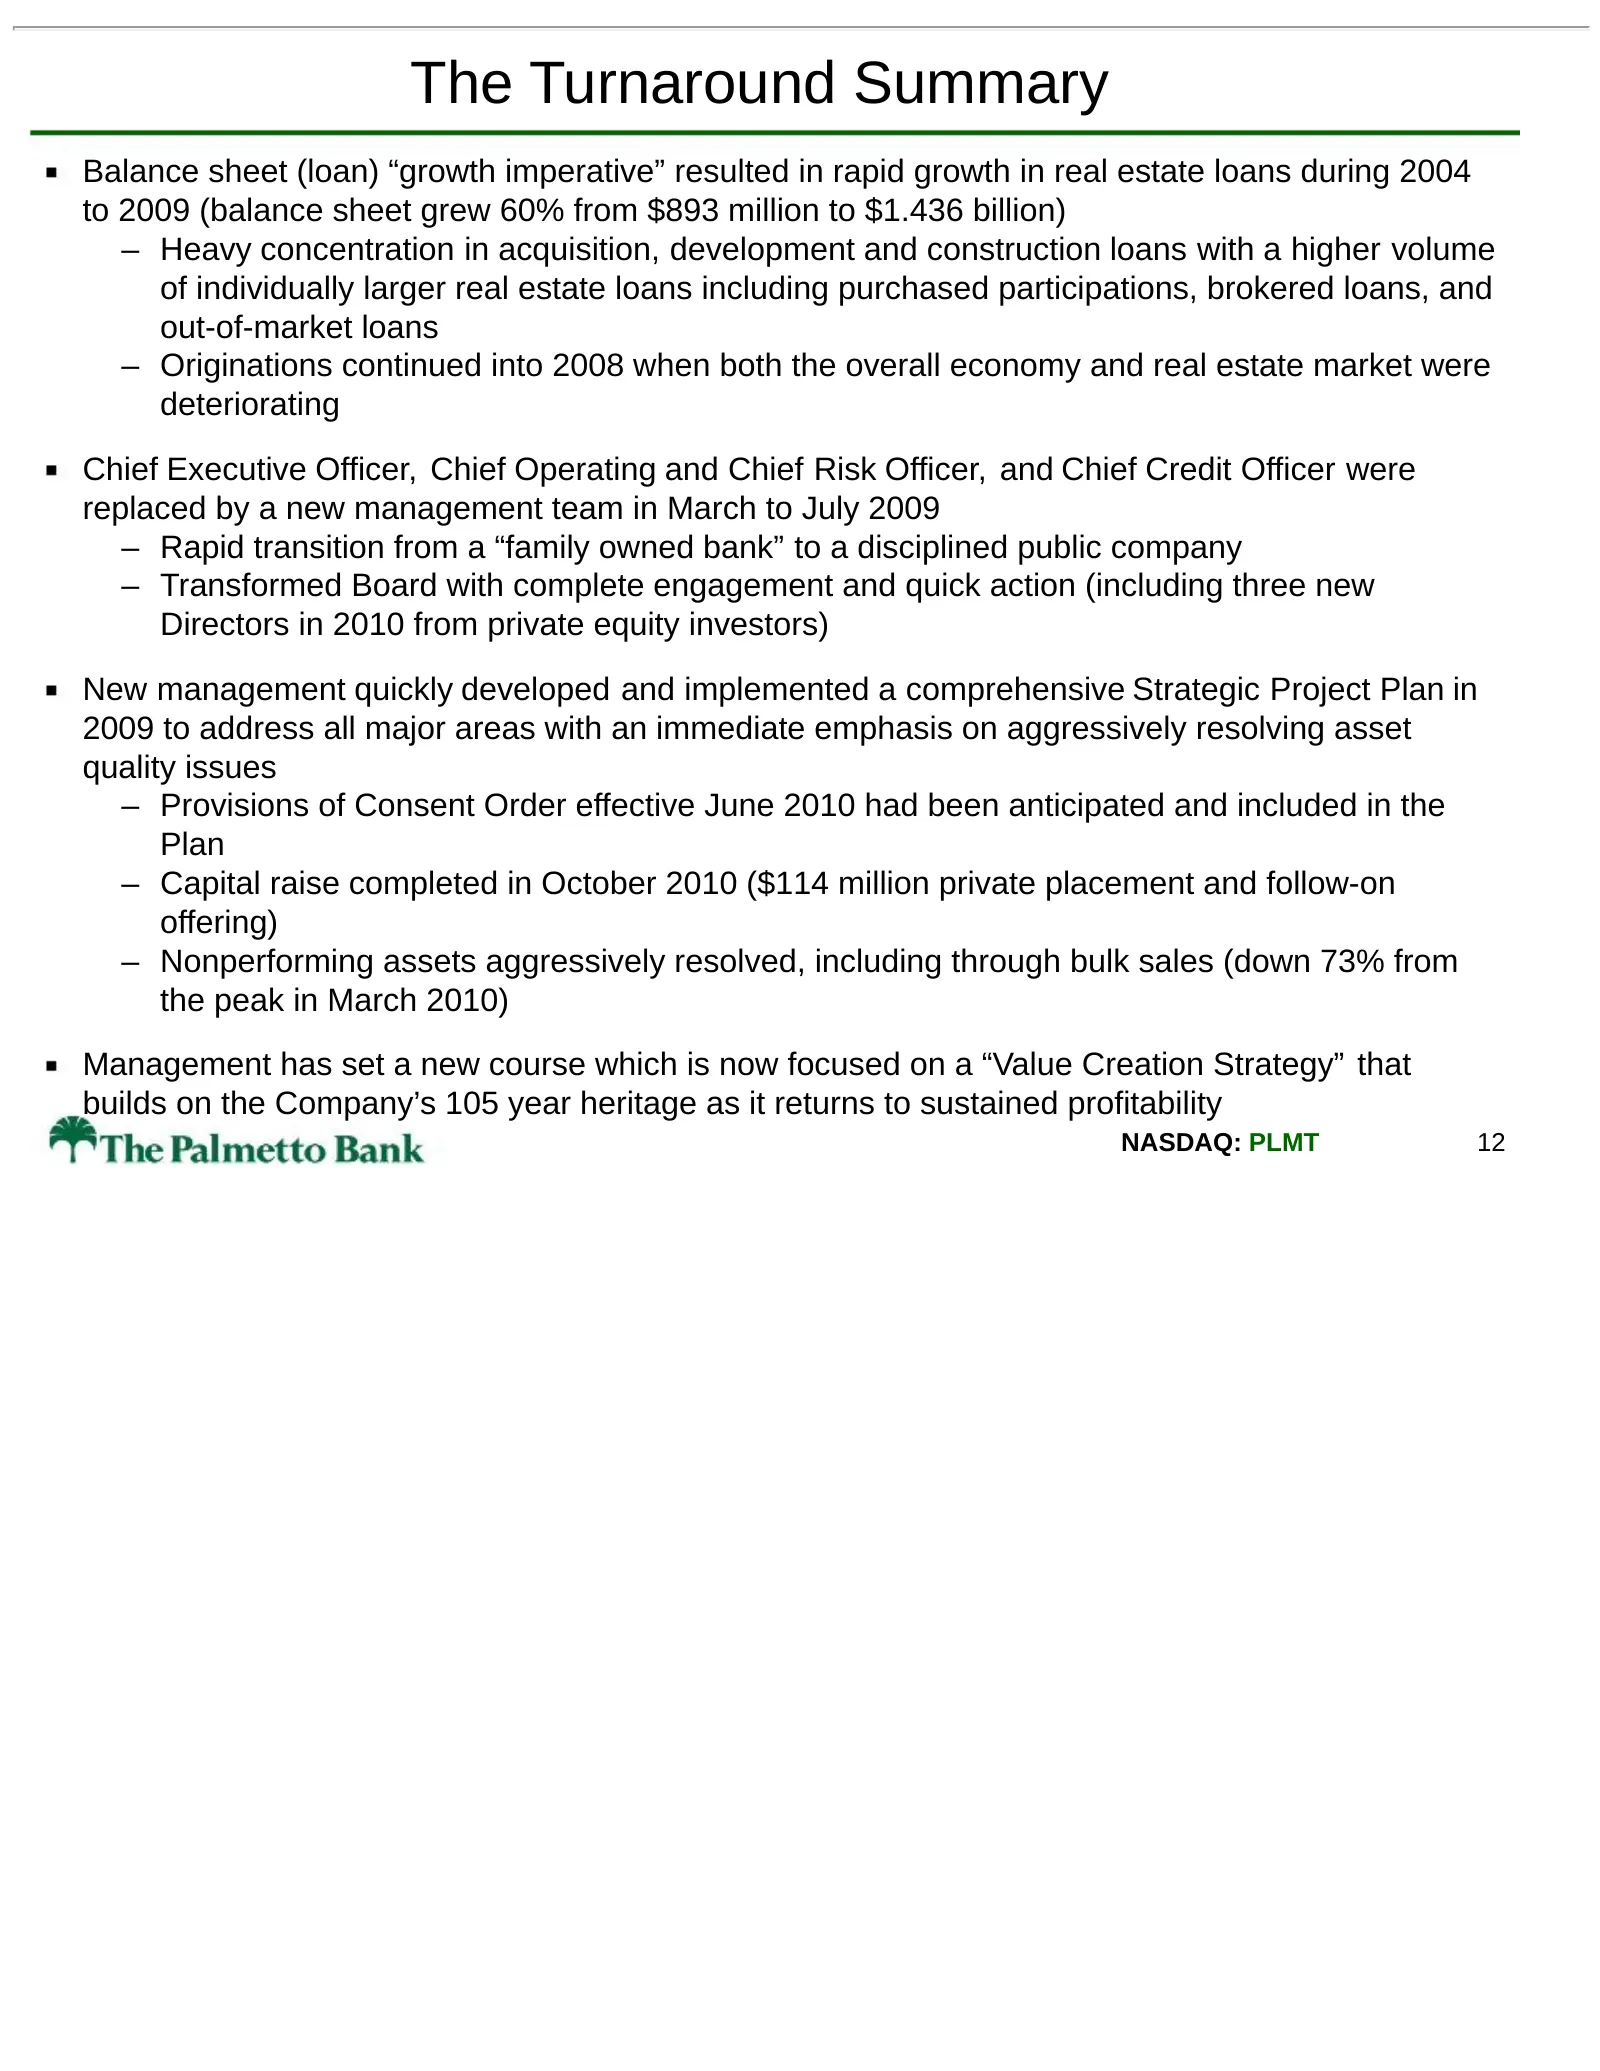
The Turnaround Summary Balance sheet (loan) “growth imperative” resulted in rapid growth in real estate loans during 2004 to 2009 (balance sheet grew 60% from $893 million to $1.436 billion) – Heavy concentration in acquisition, development and construction loans with a higher volume of individually
Slide 13: Strategic Focus
Strategic Focus NASDAQ: PLMT 13
Slide 14: Evolution of Big Picture Strategic Focus
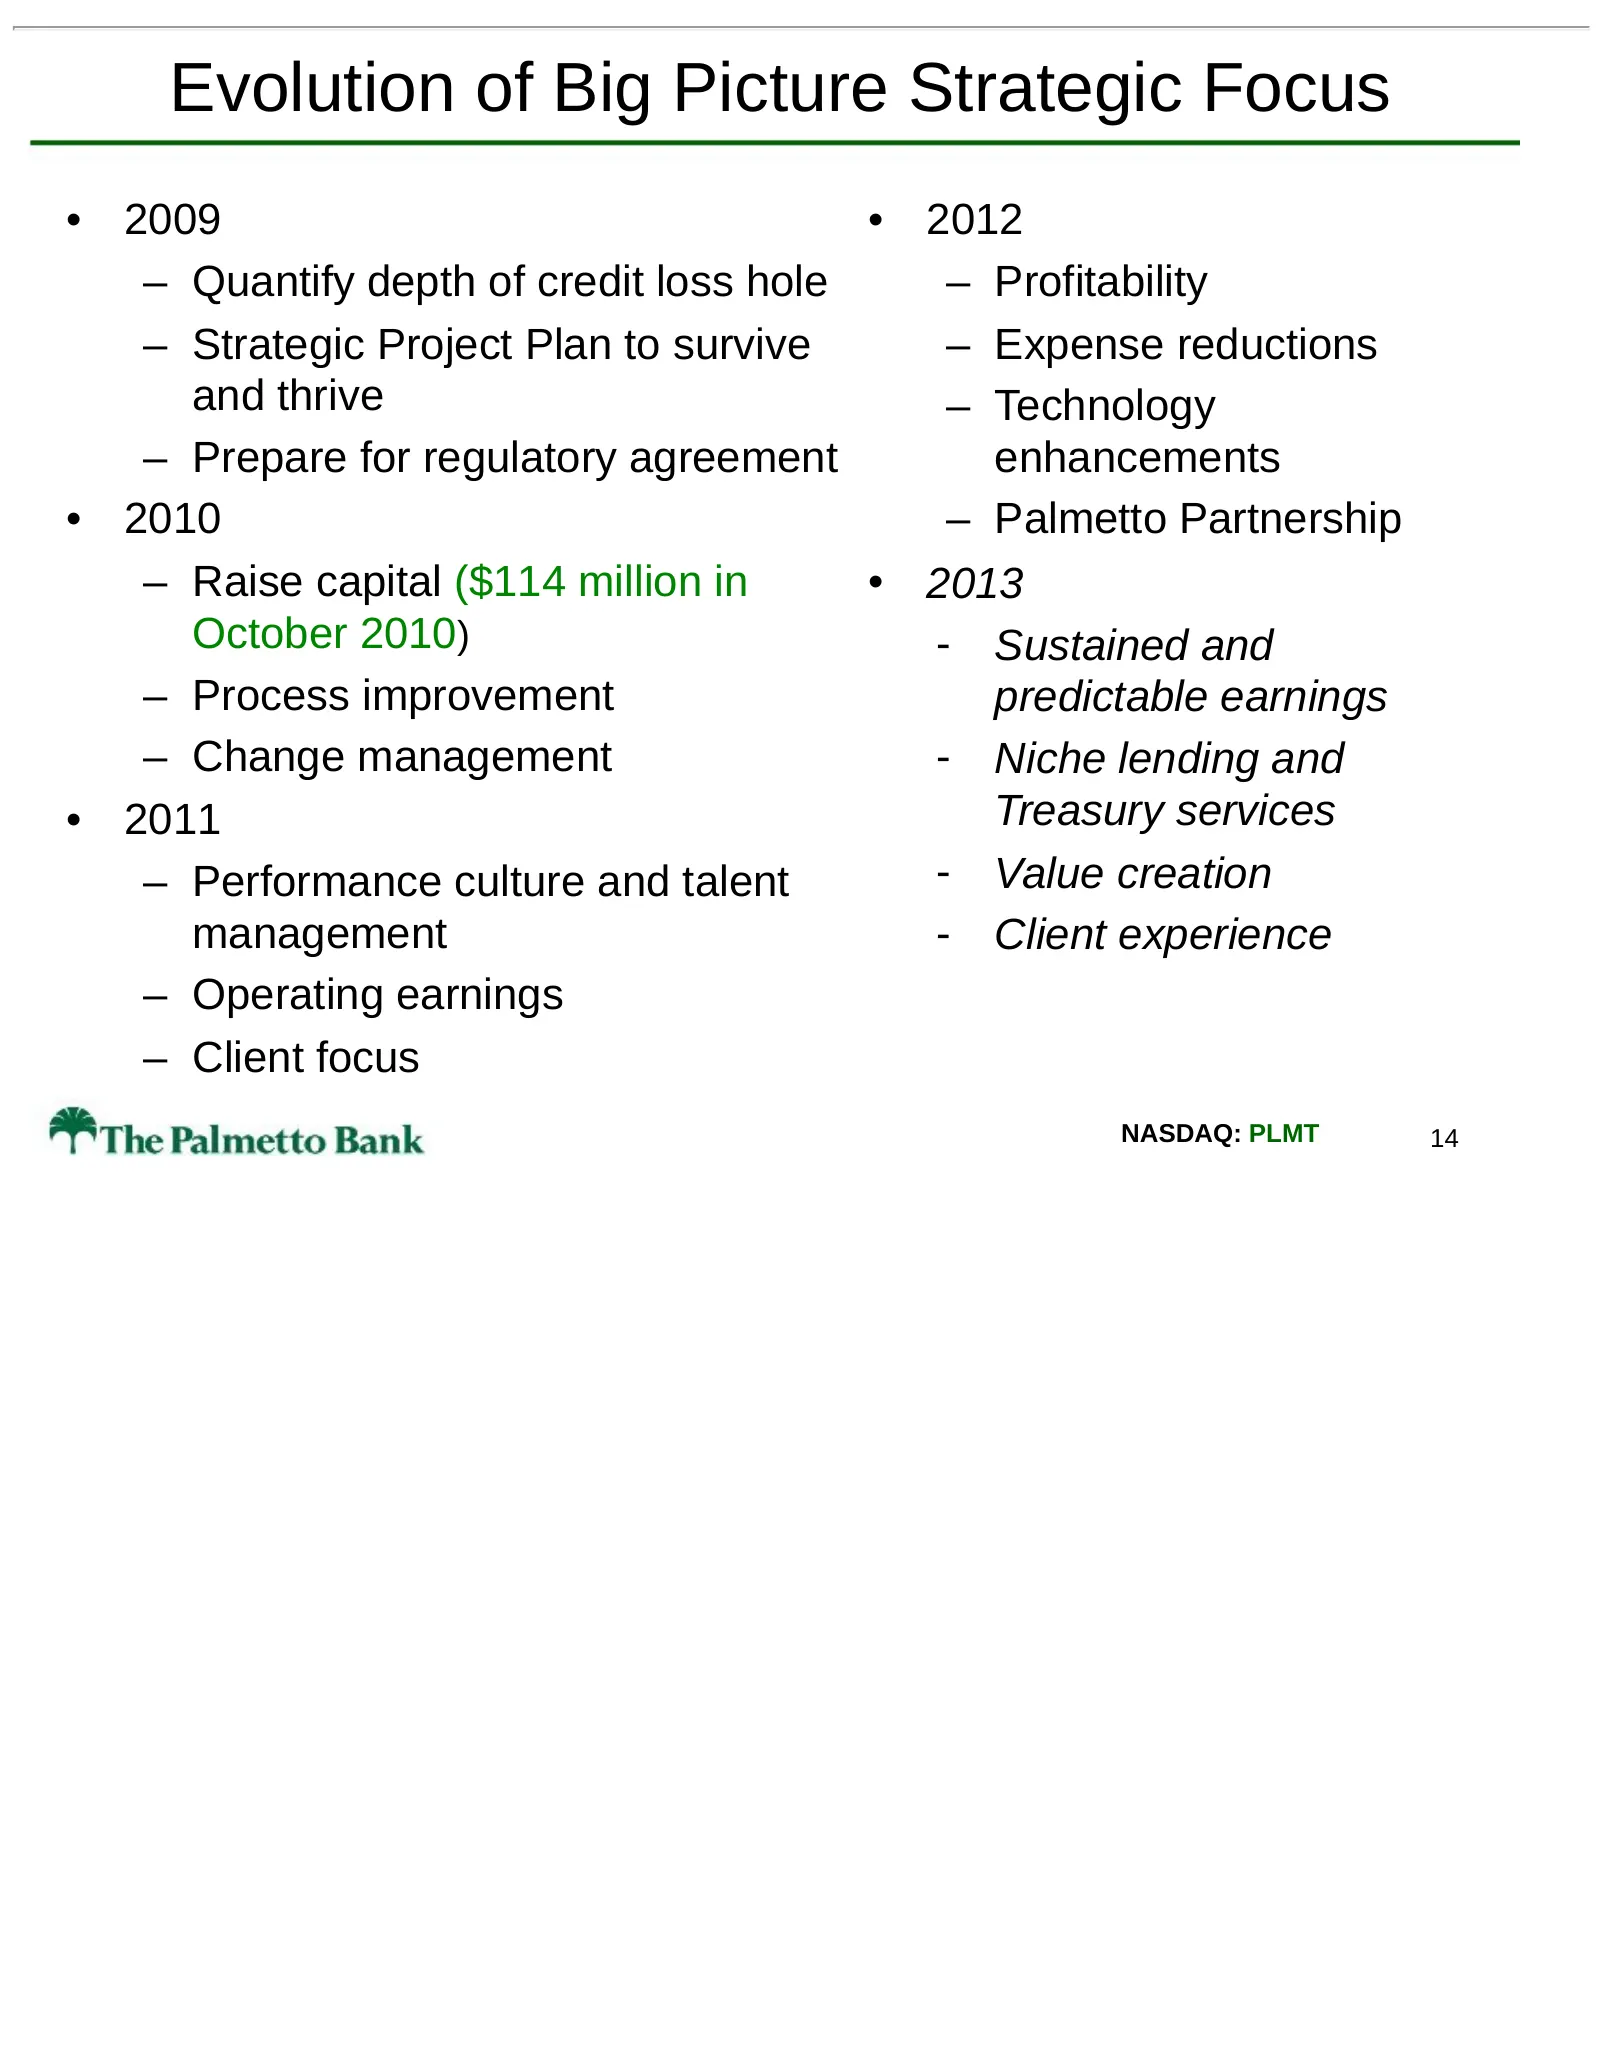
Evolution of Big Picture Strategic Focus • 2009 • 2012 – Quantify depth of credit loss hole – Profitability – Strategic Project Plan to survive – Expense reductions and thrive – Technology – Prepare for regulatory agreement enhancements • 2010 – Palmetto Partnership – Raise capital ($114 million in
Slide 15: Strategic Priorities
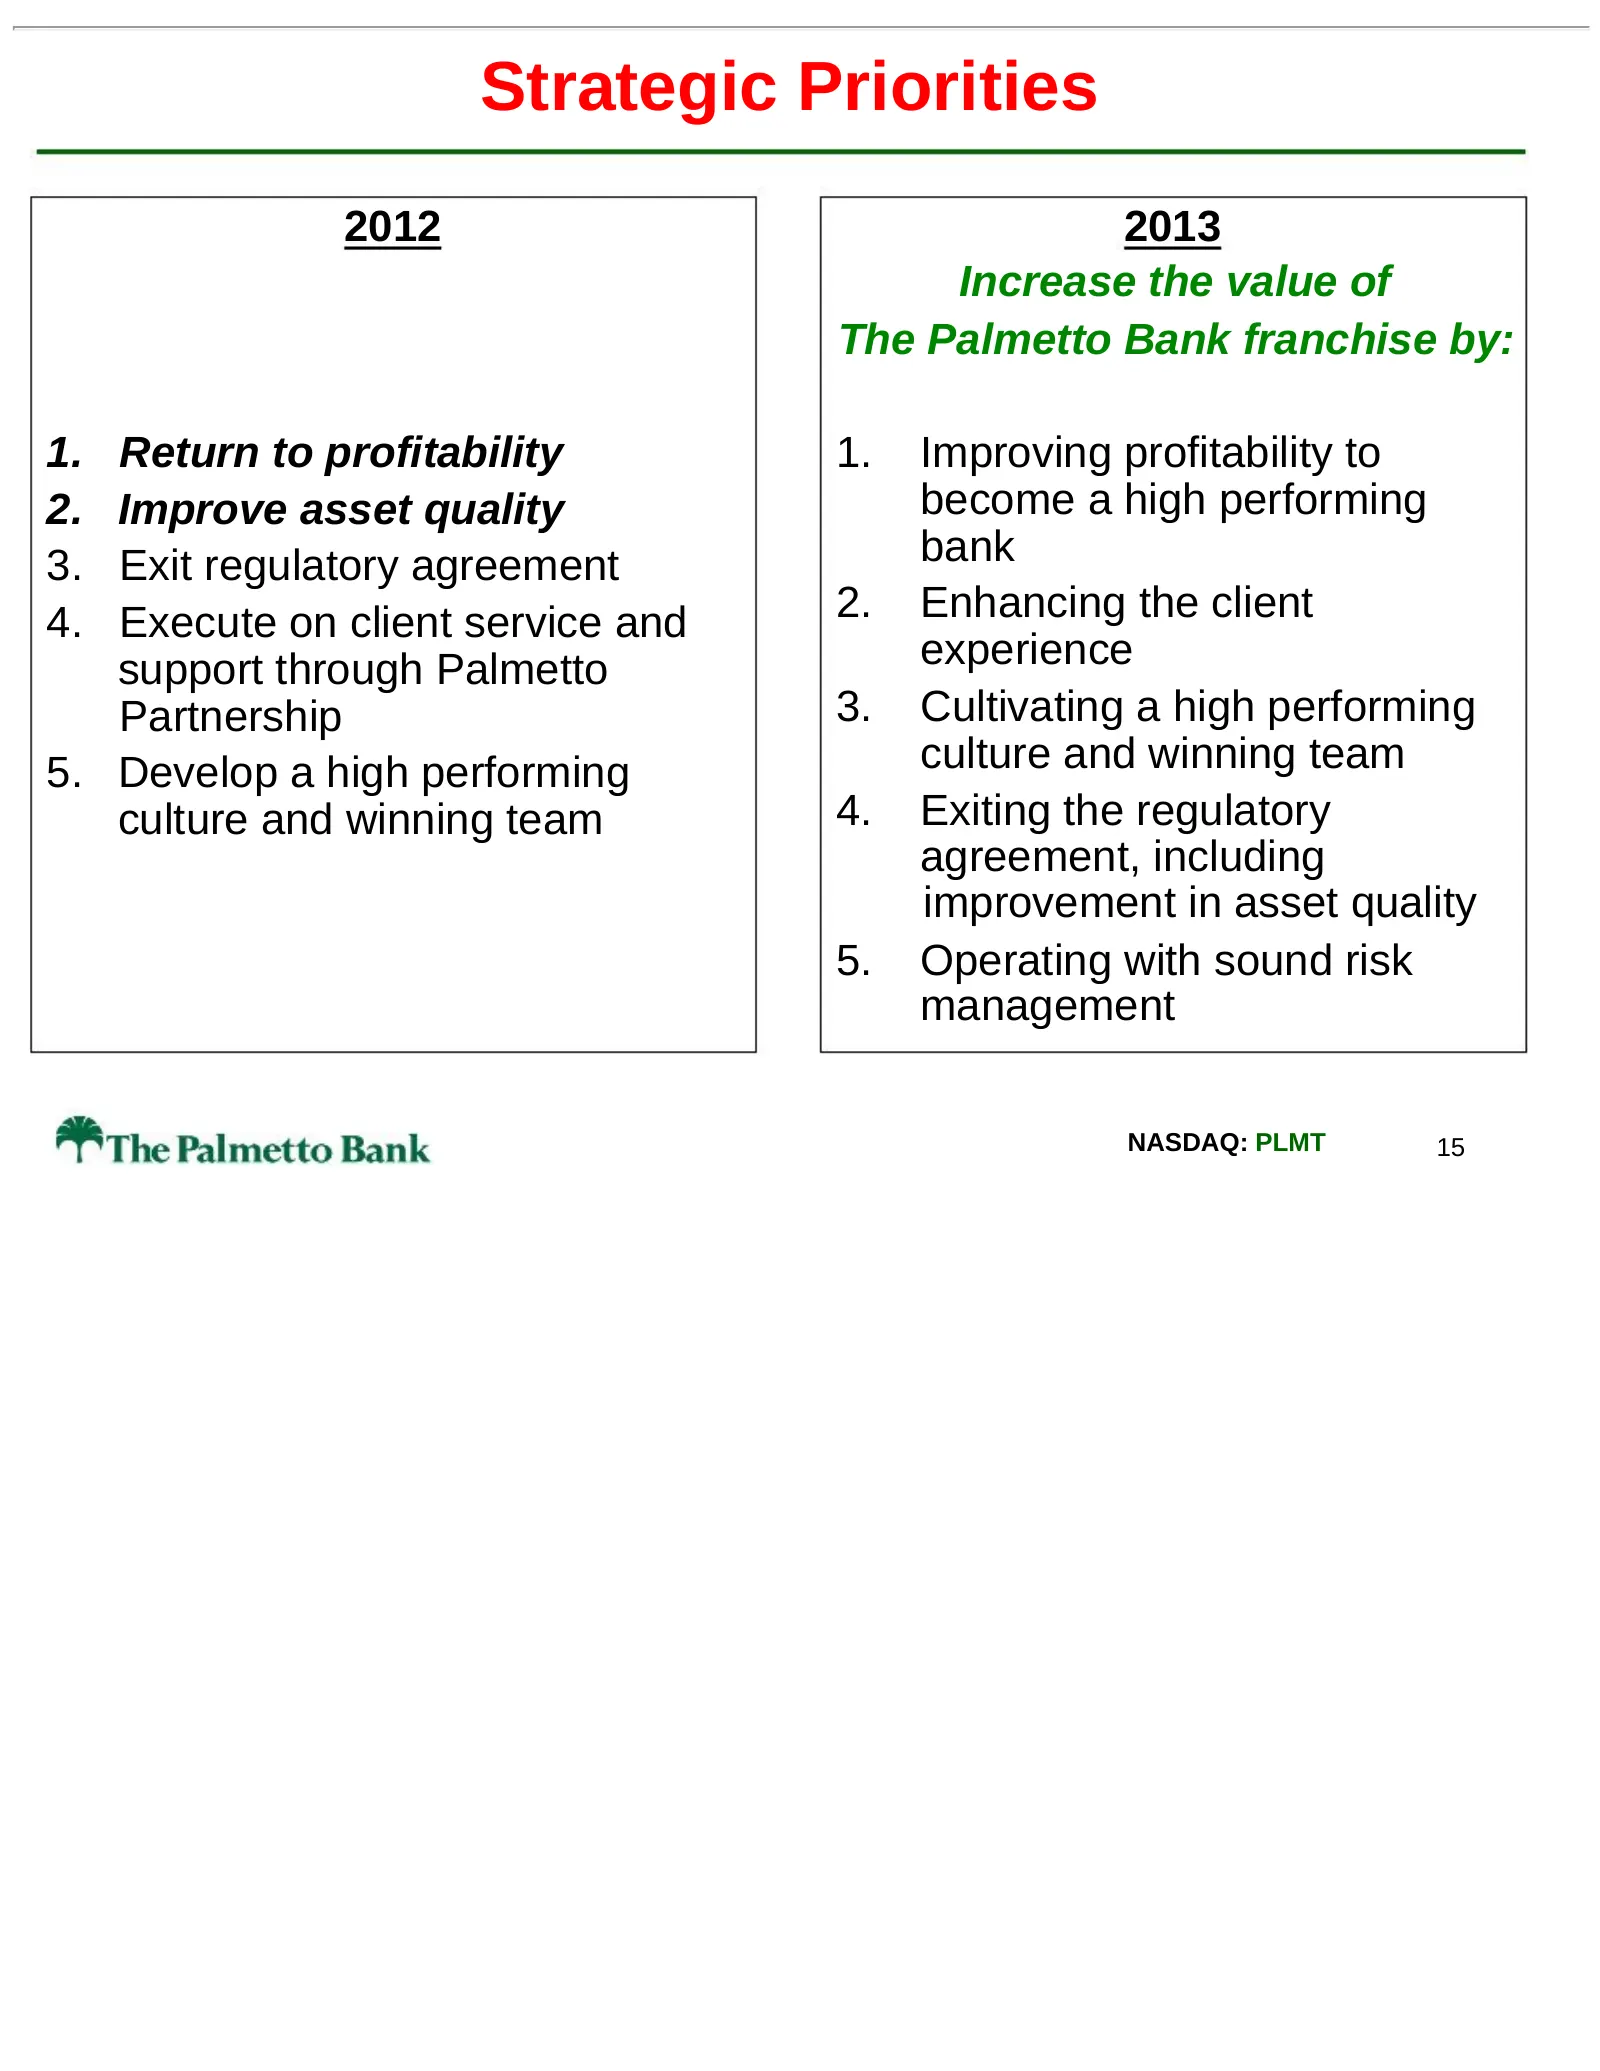
Strategic Priorities 2012 2013 Increase the value of The Palmetto Bank franchise by: 1. Return to profitability 1. Improving profitability to 2. Improve asset quality become a high performing 3. Exit regulatory agreement bank 4. Execute on client service and 2. Enhancing the client support through P
Slide 16: Value Creation Strategy and the Client Experience
Value Creation Strategy and the Client Experience 1. What actions do we need to take to increase the Value of The Palmetto Bank franchise? 2. Are all of our actions contributing to an enhanced Client Experience? NASDAQ: PLMT 16
Slide 17: Big Picture Strategy – Line of Business Delineation
Big Picture Strategy – Line of Business Delineation is Critical to Improved Profitability and Risk Management 1. Retail Bank: primarily manage funding cost through low cost deposits and expanding household penetration 2. Commercial Bank: primarily generate income through lending and ancillary servic
Slide 18: 2012 Strategic Priorities
2012 Strategic Priorities NASDAQ: PLMT 18
Slide 19: 2012 Strategic Priorities
2012 Strategic Priorities 1. Return to profitability 2. Improve asset quality 3. Exit regulatory agreement 4. Execute on client service and support through Palmetto Partnership 5. Develop a high performing culture and winning team While keenly focused on the above in 2012, we are already executing o
Slide 20: 1. Return to Profitability
1. Return to Profitability NASDAQ: PLMT 20
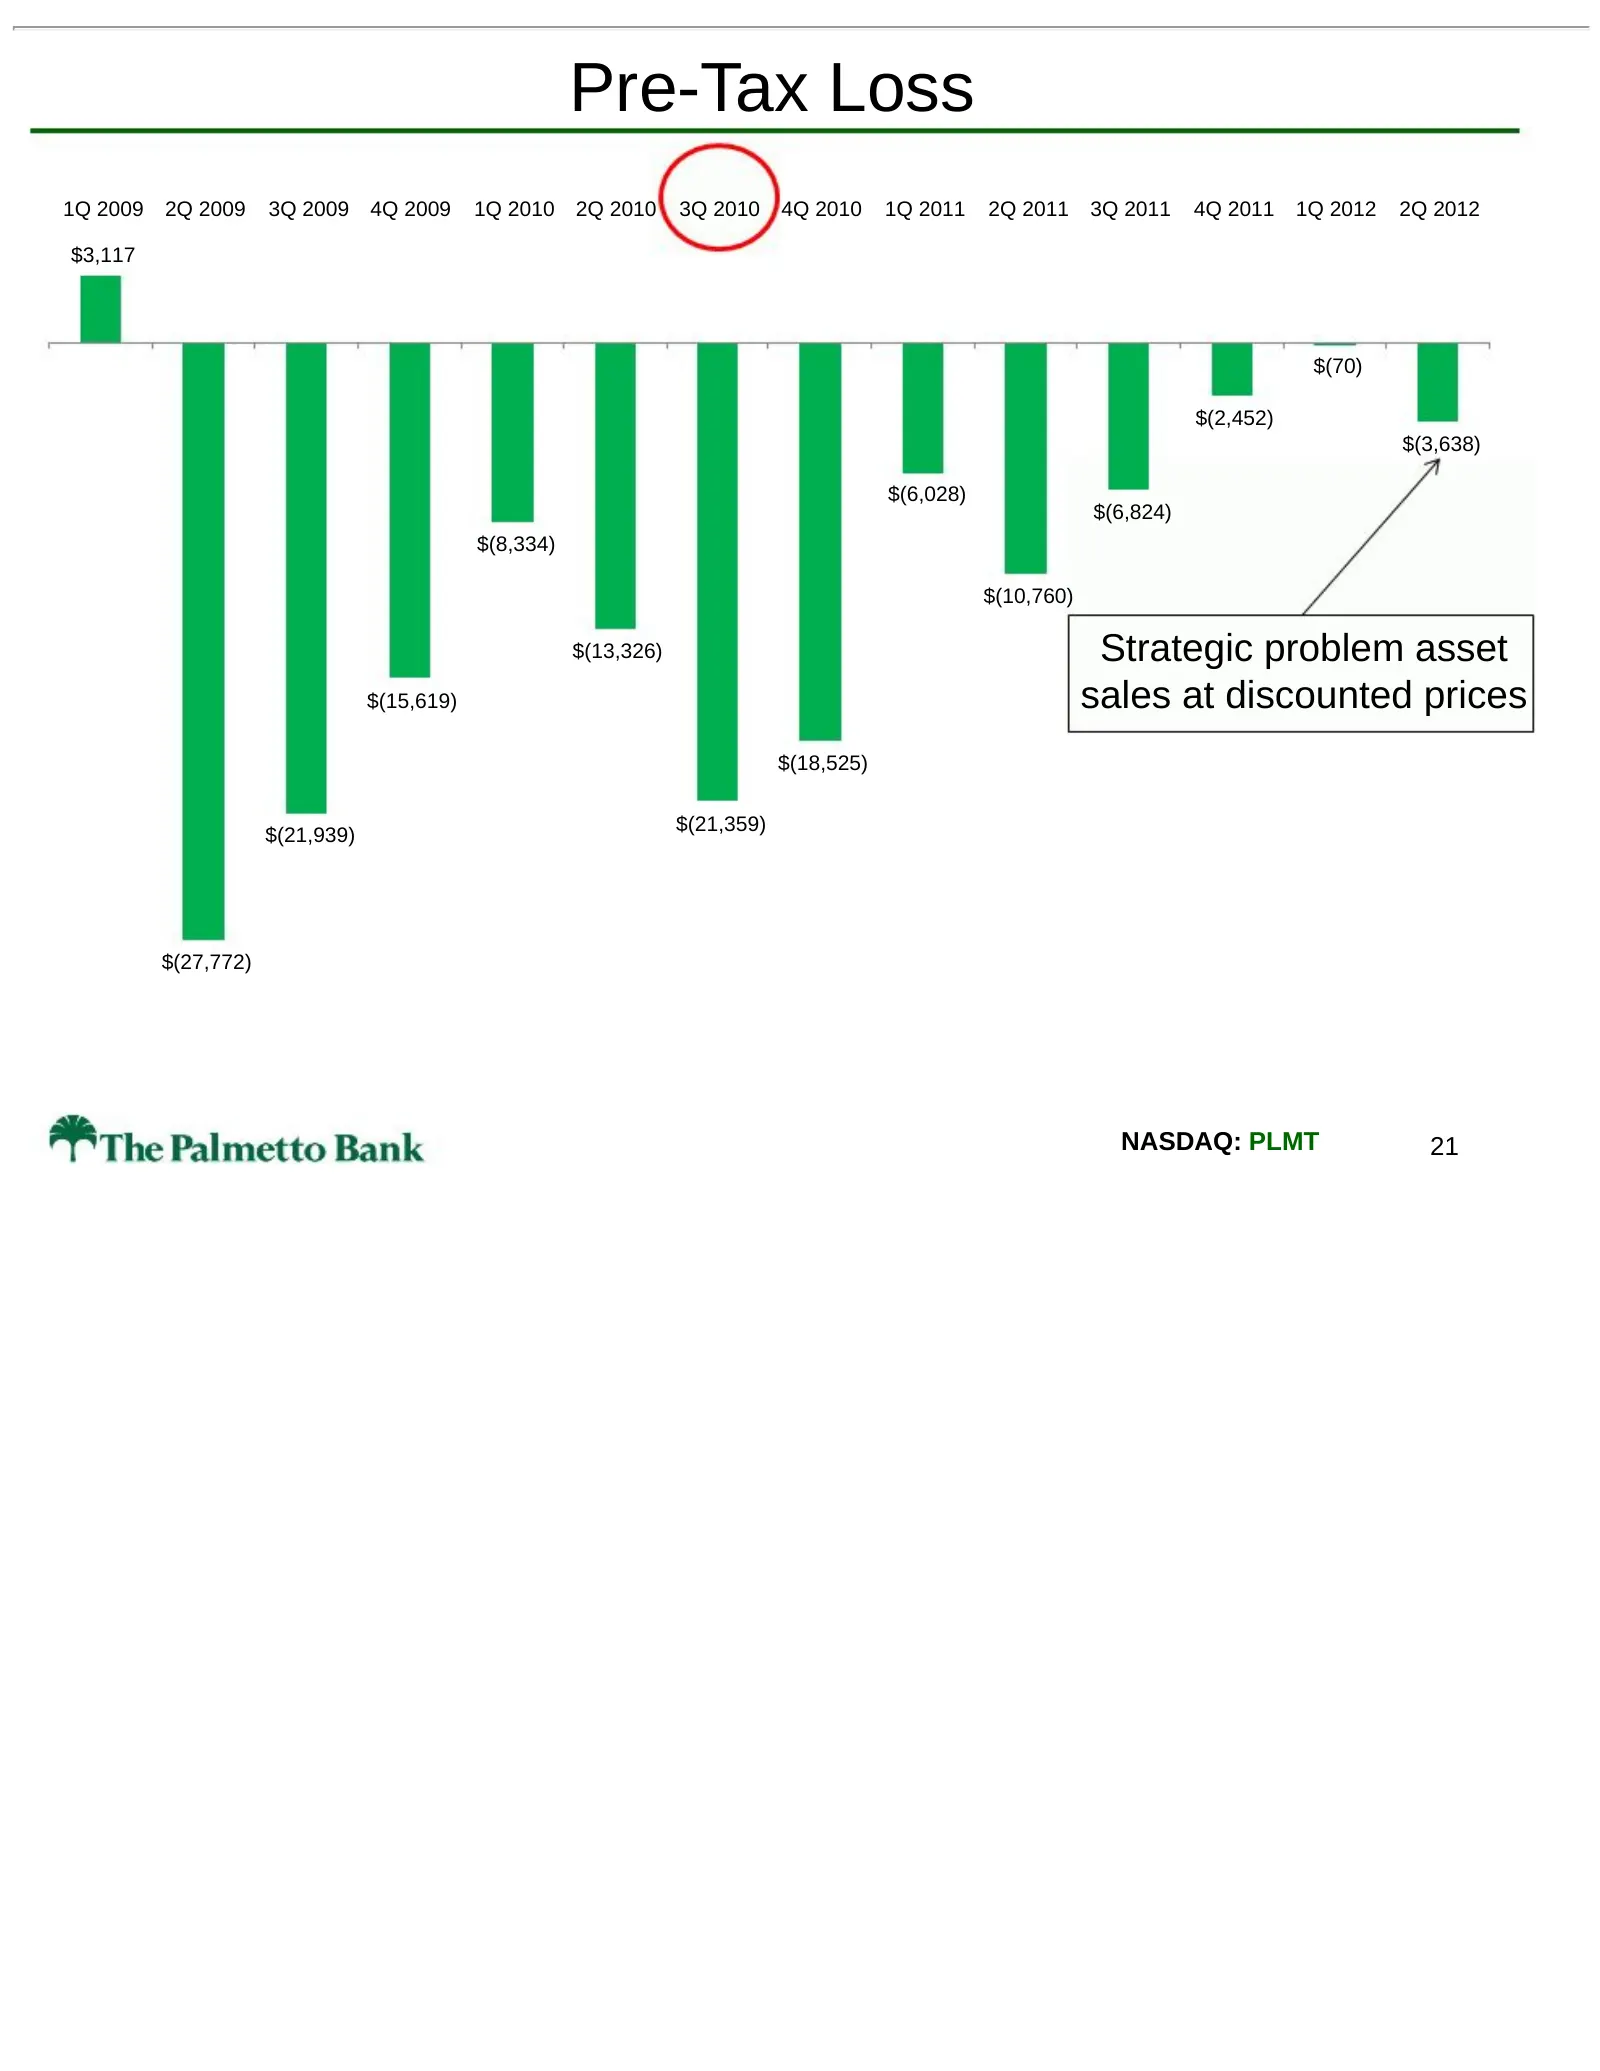
Slide 21: Pre-Tax Loss
Pre-Tax Loss 1Q 2009 2Q 2009 3Q 2009 4Q 2009 1Q 2010 2Q 2010 3Q 2010 4Q 2010 1Q 2011 2Q 2011 3Q 2011 4Q 2011 1Q 2012 2Q 2012 $3,117 $(70) $(2,452) $(3,638) $(6,028) $(6,824) $(8,334) $(10,760) $(13,326) Strategic problem asset $(15,619) sales at discounted prices $(18,525) $(21,359) $(21,939) $(27,7
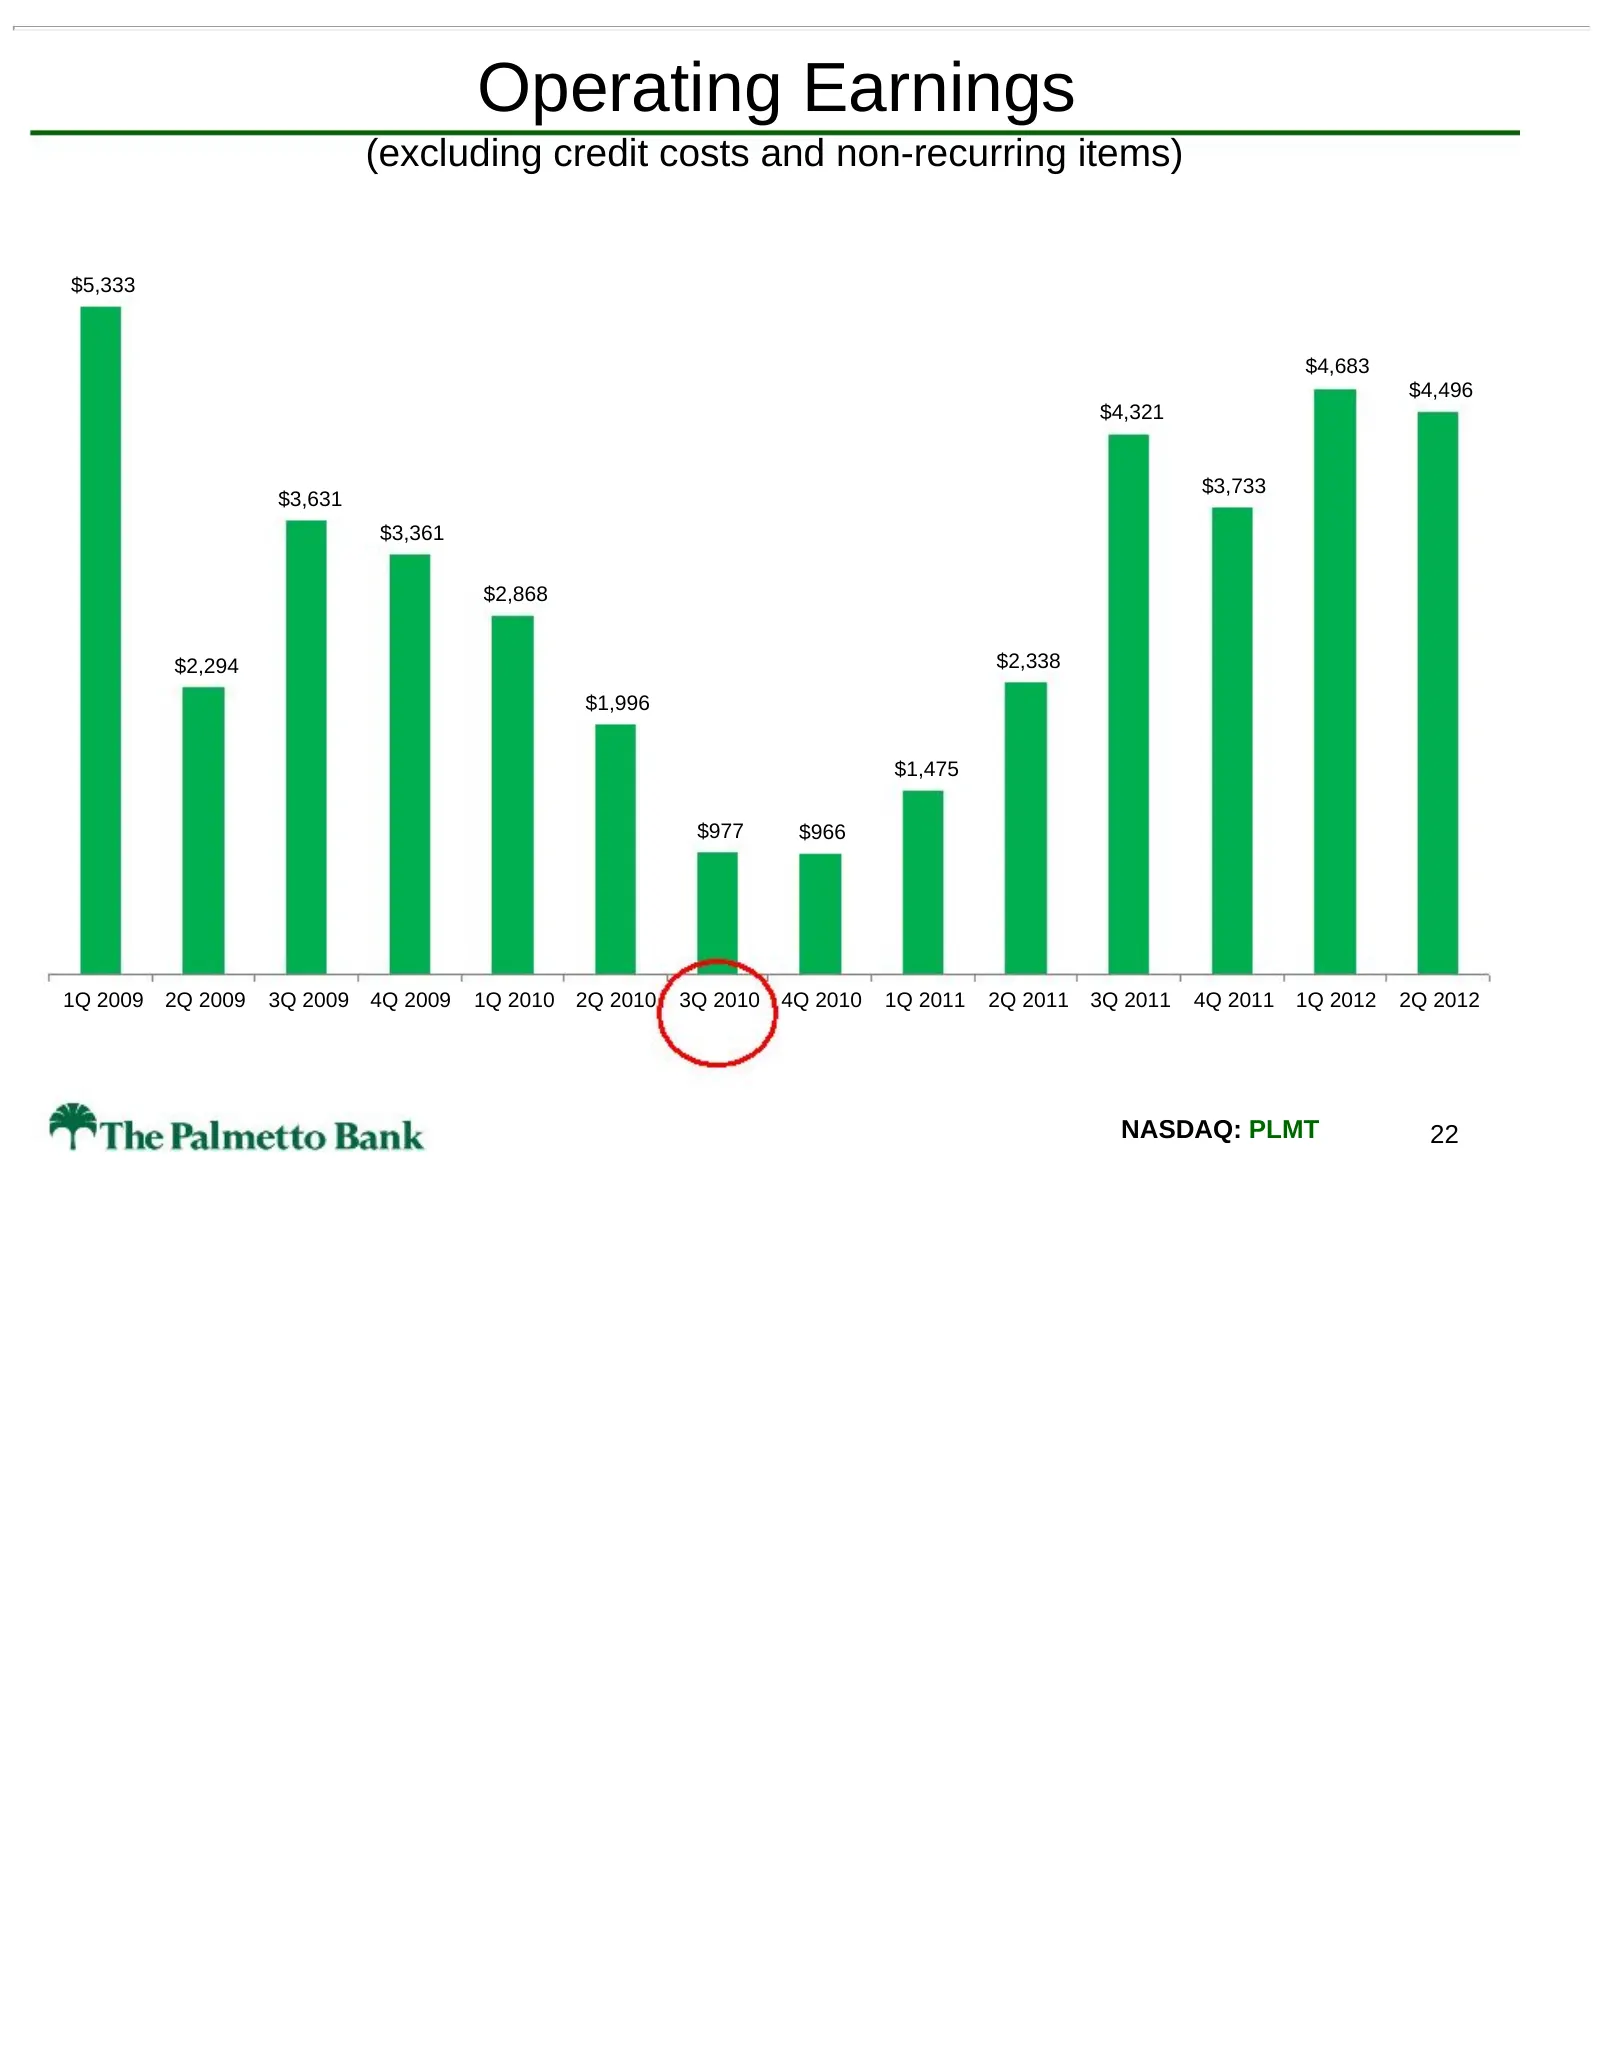
Slide 22: Operating Earnings
Operating Earnings (excluding credit costs and non-recurring items) $5,333 $4,683 $4,496 $4,321 $3,733 $3,631 $3,361 $2,868 $2,294 $2,338 $1,996 $1,475 $977 $966 1Q 2009 2Q 2009 3Q 2009 4Q 2009 1Q 2010 2Q 2010 3Q 2010 4Q 2010 1Q 2011 2Q 2011 3Q 2011 4Q 2011 1Q 2012 2Q 2012 NASDAQ: PLMT 22
Slide 23: The Path to Profitability
The Path to Profitability • Making money on an operating basis in spite of: – Low interest rates and flat yield curve (compressed net interest margin) – Higher regulatory costs and revenue restrictions (lower service charges, higher FDIC premiums, etc.) – High operating expenses from workout mode an
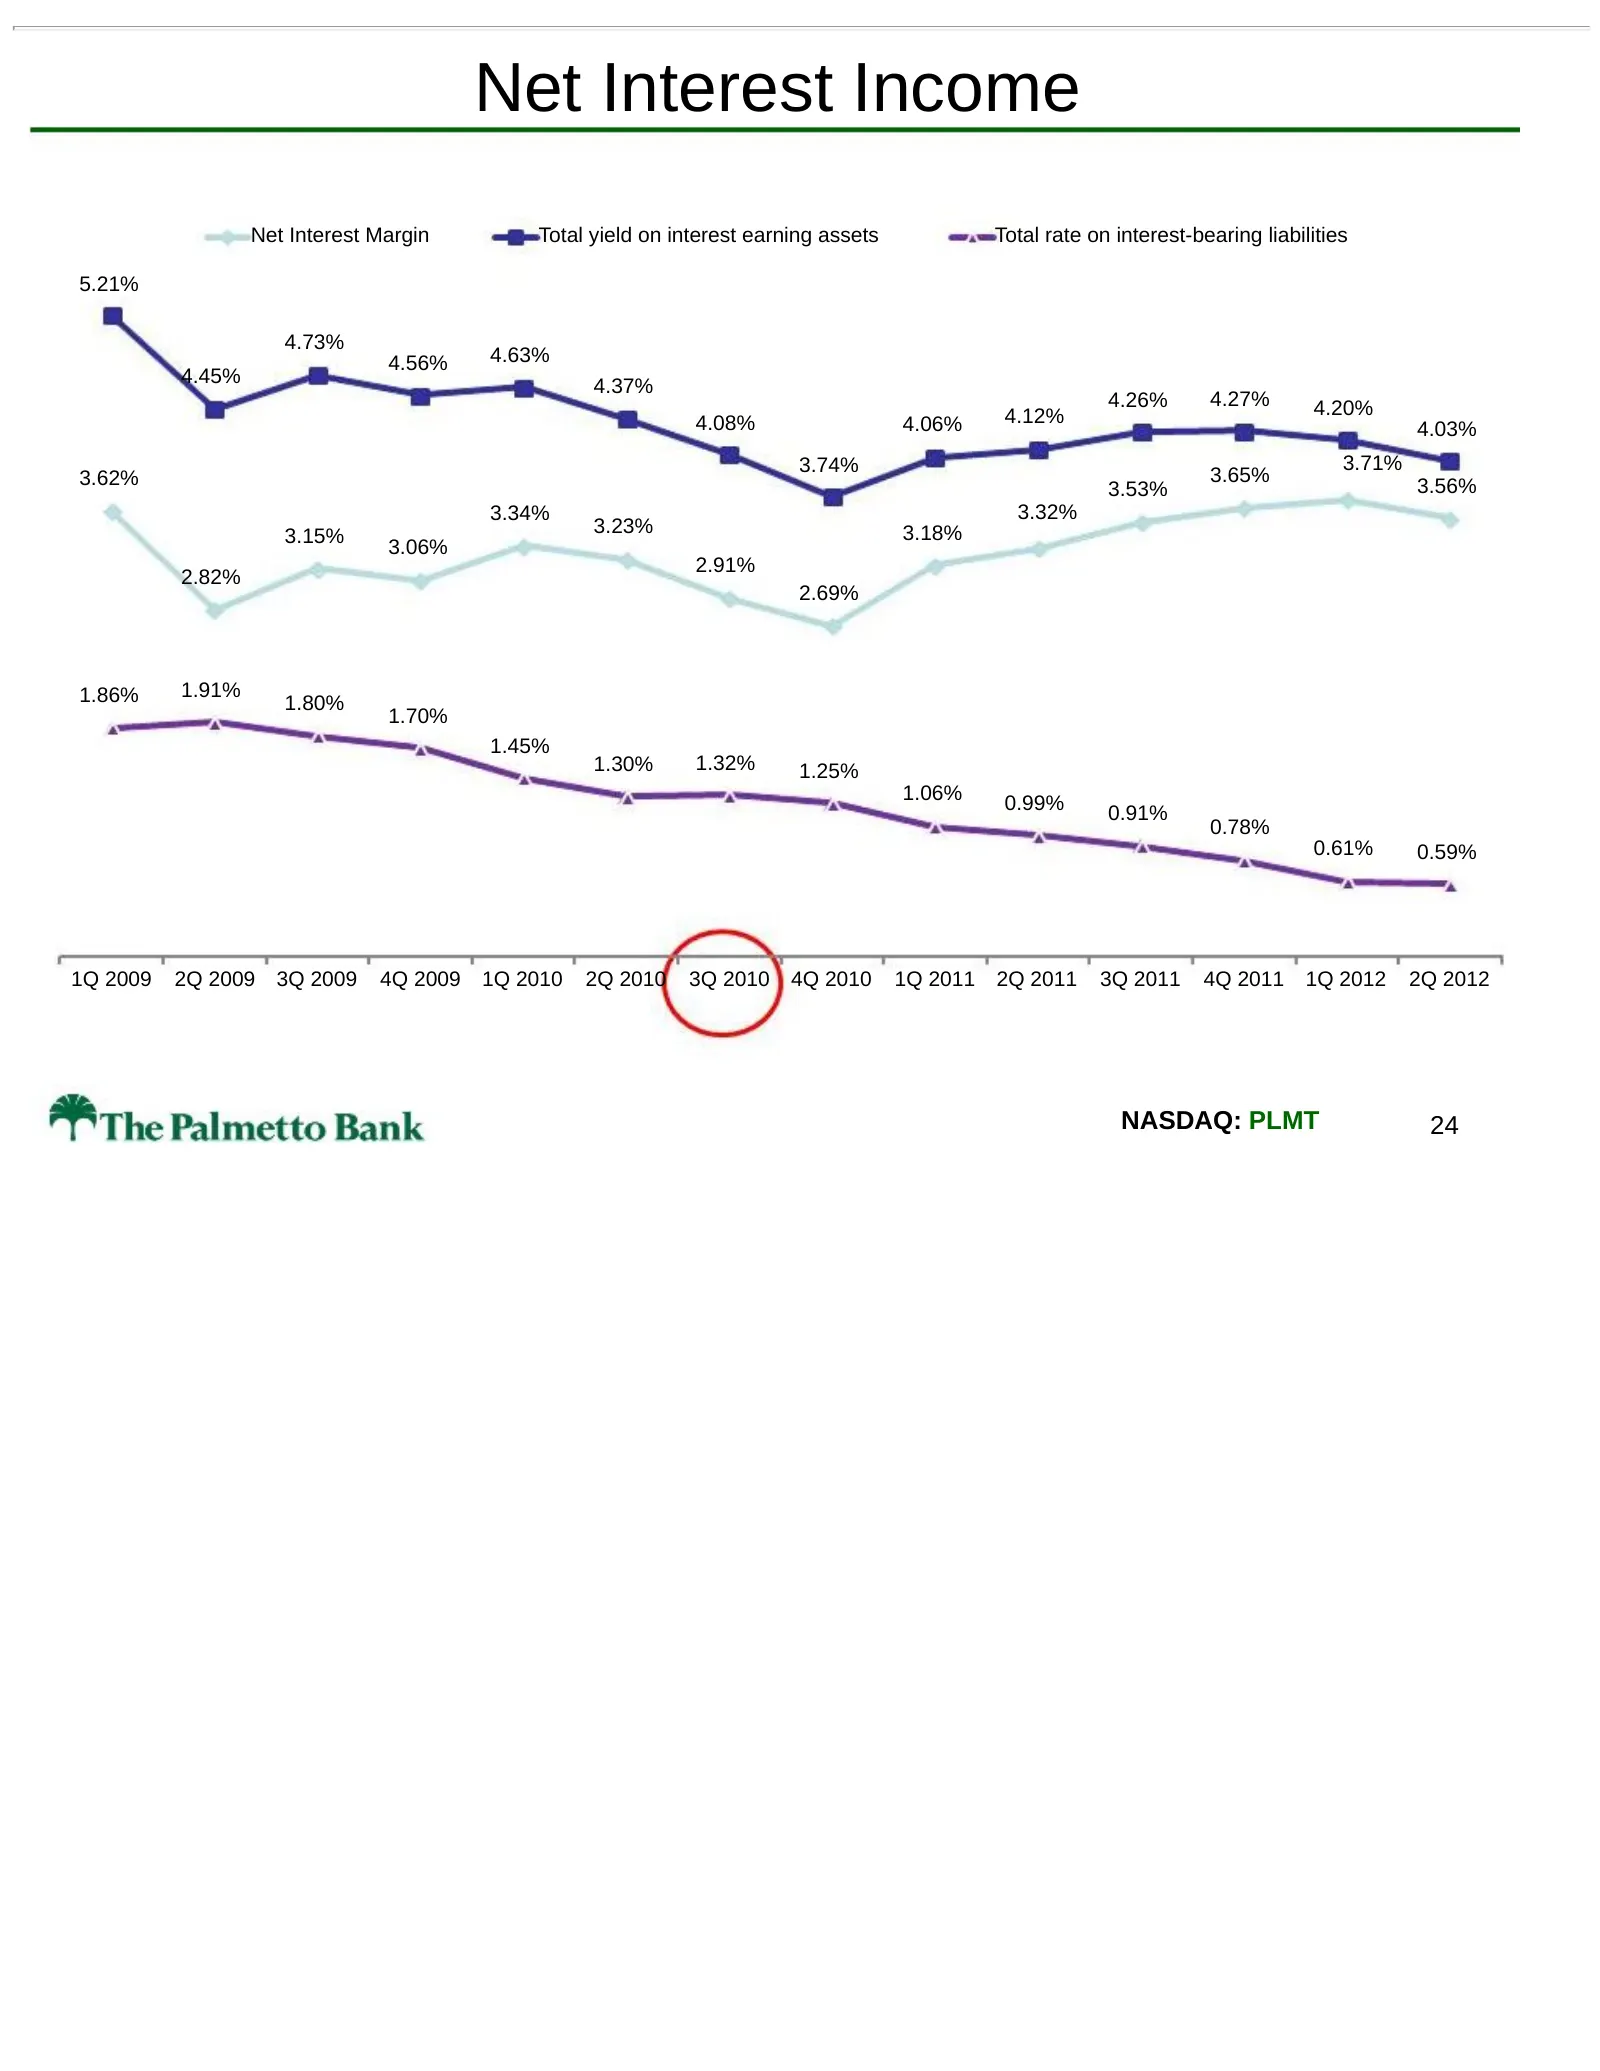
Slide 24: Net Interest Income
Net Interest Income Net Interest Margin Total yield on interest earning assets Total rate on interest-bearing liabilities 5.21% 4.73% 4.56% 4.63% 4.45% 4.37% 4.26% 4.27% 4.20% 4.08% 4.06% 4.12% 4.03% 3.74% 3.71% 3.62% 3.65% 3.53% 3.56% 3.34% 3.32% 3.15% 3.23% 3.18% 3.06% 2.91% 2.82% 2.69% 1.86% 1.91
Slide 25: Loans
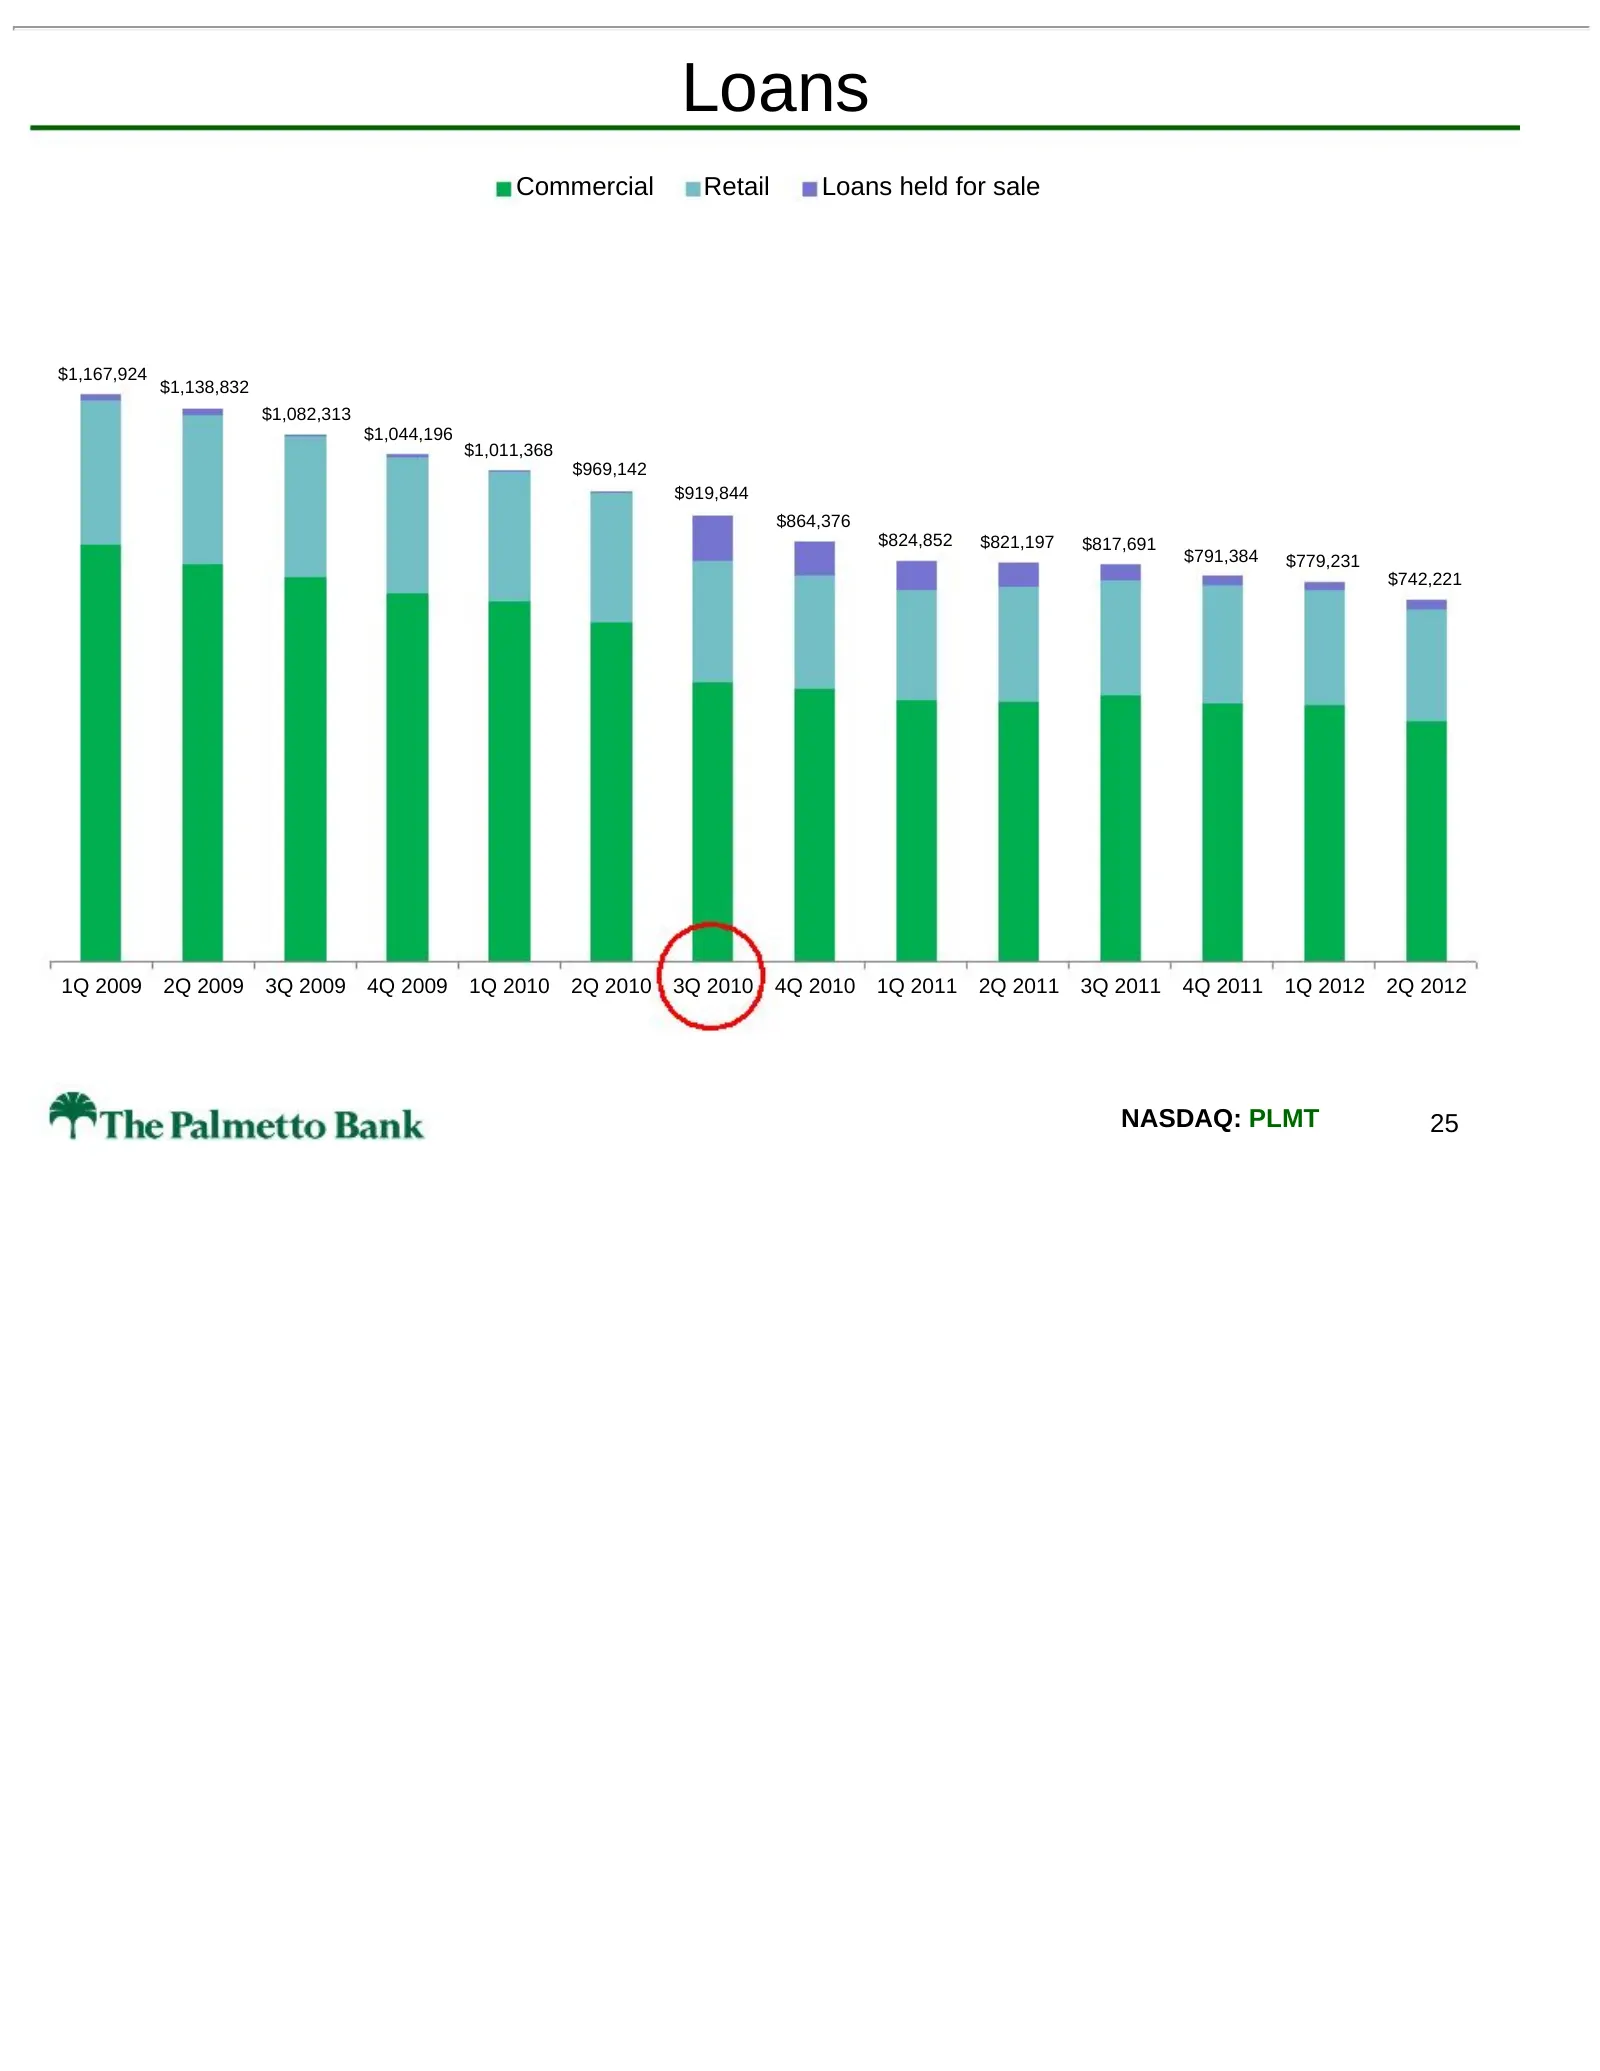
Loans Commercial Retail Loans held for sale $1,167,924 $1,138,832 $1,082,313 $1,044,196 $1,011,368 $969,142 $919,844 $864,376 $824,852 $821,197 $817,691 $791,384 $779,231 $742,221 1Q 2009 2Q 2009 3Q 2009 4Q 2009 1Q 2010 2Q 2010 3Q 2010 4Q 2010 1Q 2011 2Q 2011 3Q 2011 4Q 2011 1Q 2012 2Q 2012 NASDAQ:
Slide 26: Noninterest Income
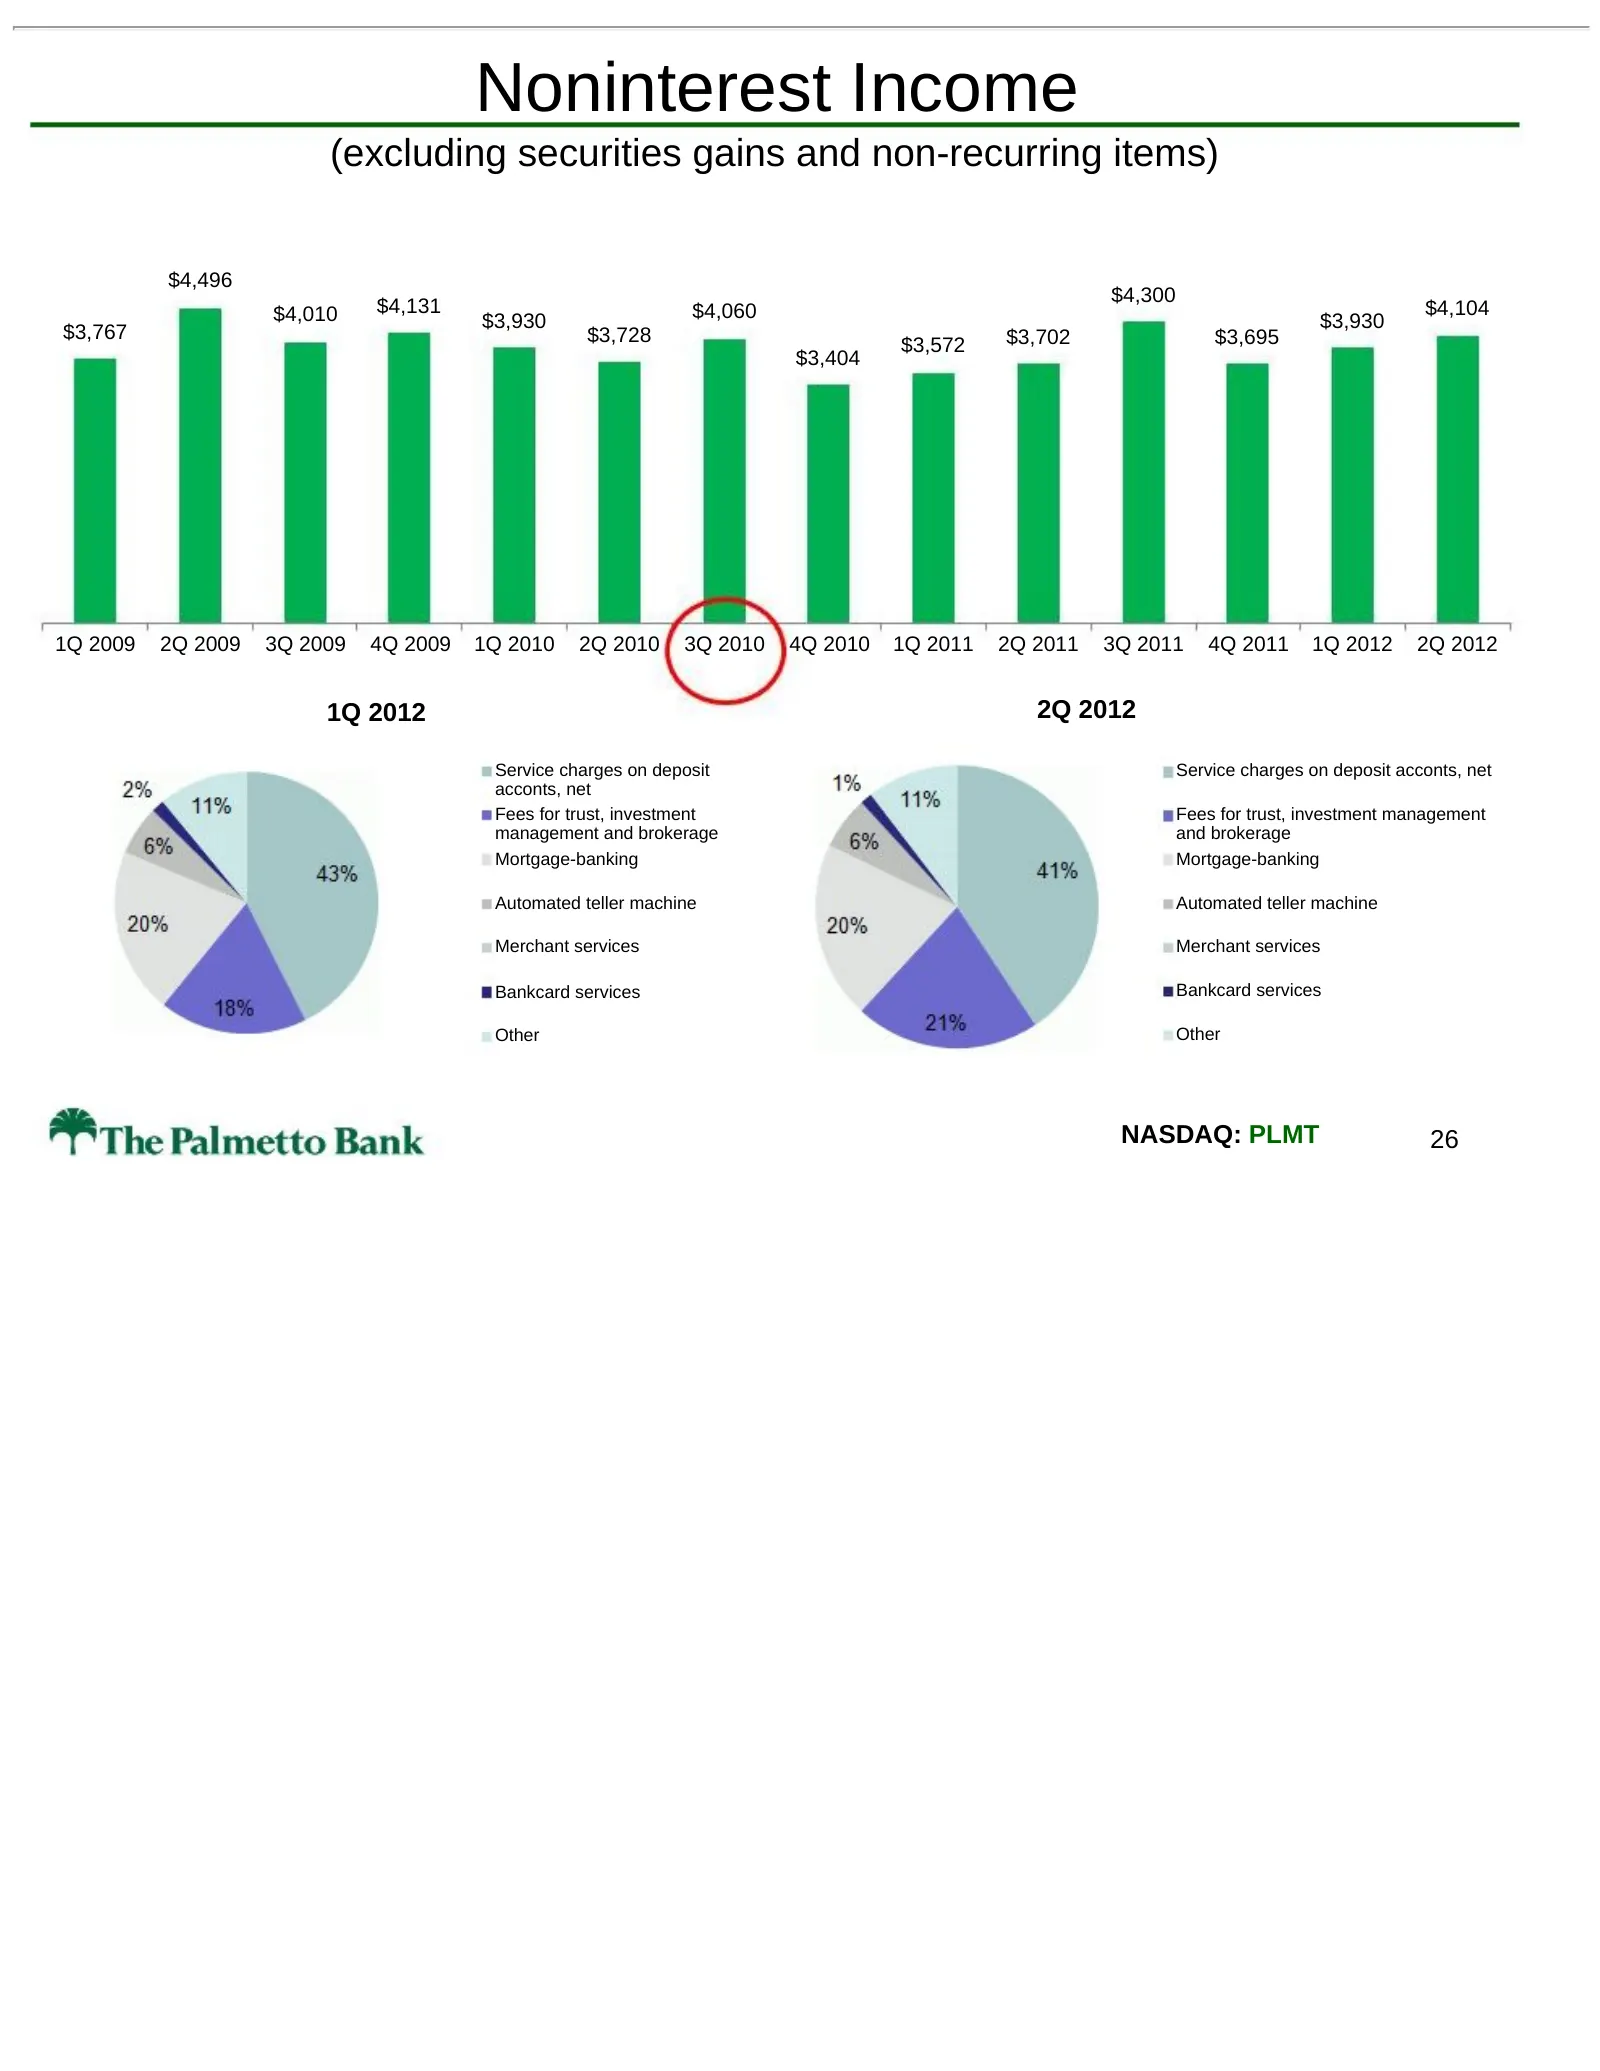
Noninterest Income (excluding securities gains and non-recurring items) $4,496 $4,300 $4,010 $4,131 $4,060 $4,104 $3,930 $3,930 $3,767 $3,728 $3,702 $3,695 $3,572 $3,404 1Q 2009 2Q 2009 3Q 2009 4Q 2009 1Q 2010 2Q 2010 3Q 2010 4Q 2010 1Q 2011 2Q 2011 3Q 2011 4Q 2011 1Q 2012 2Q 2012 1Q 2012 2Q 2012 Se
Slide 27: Noninterest Expense
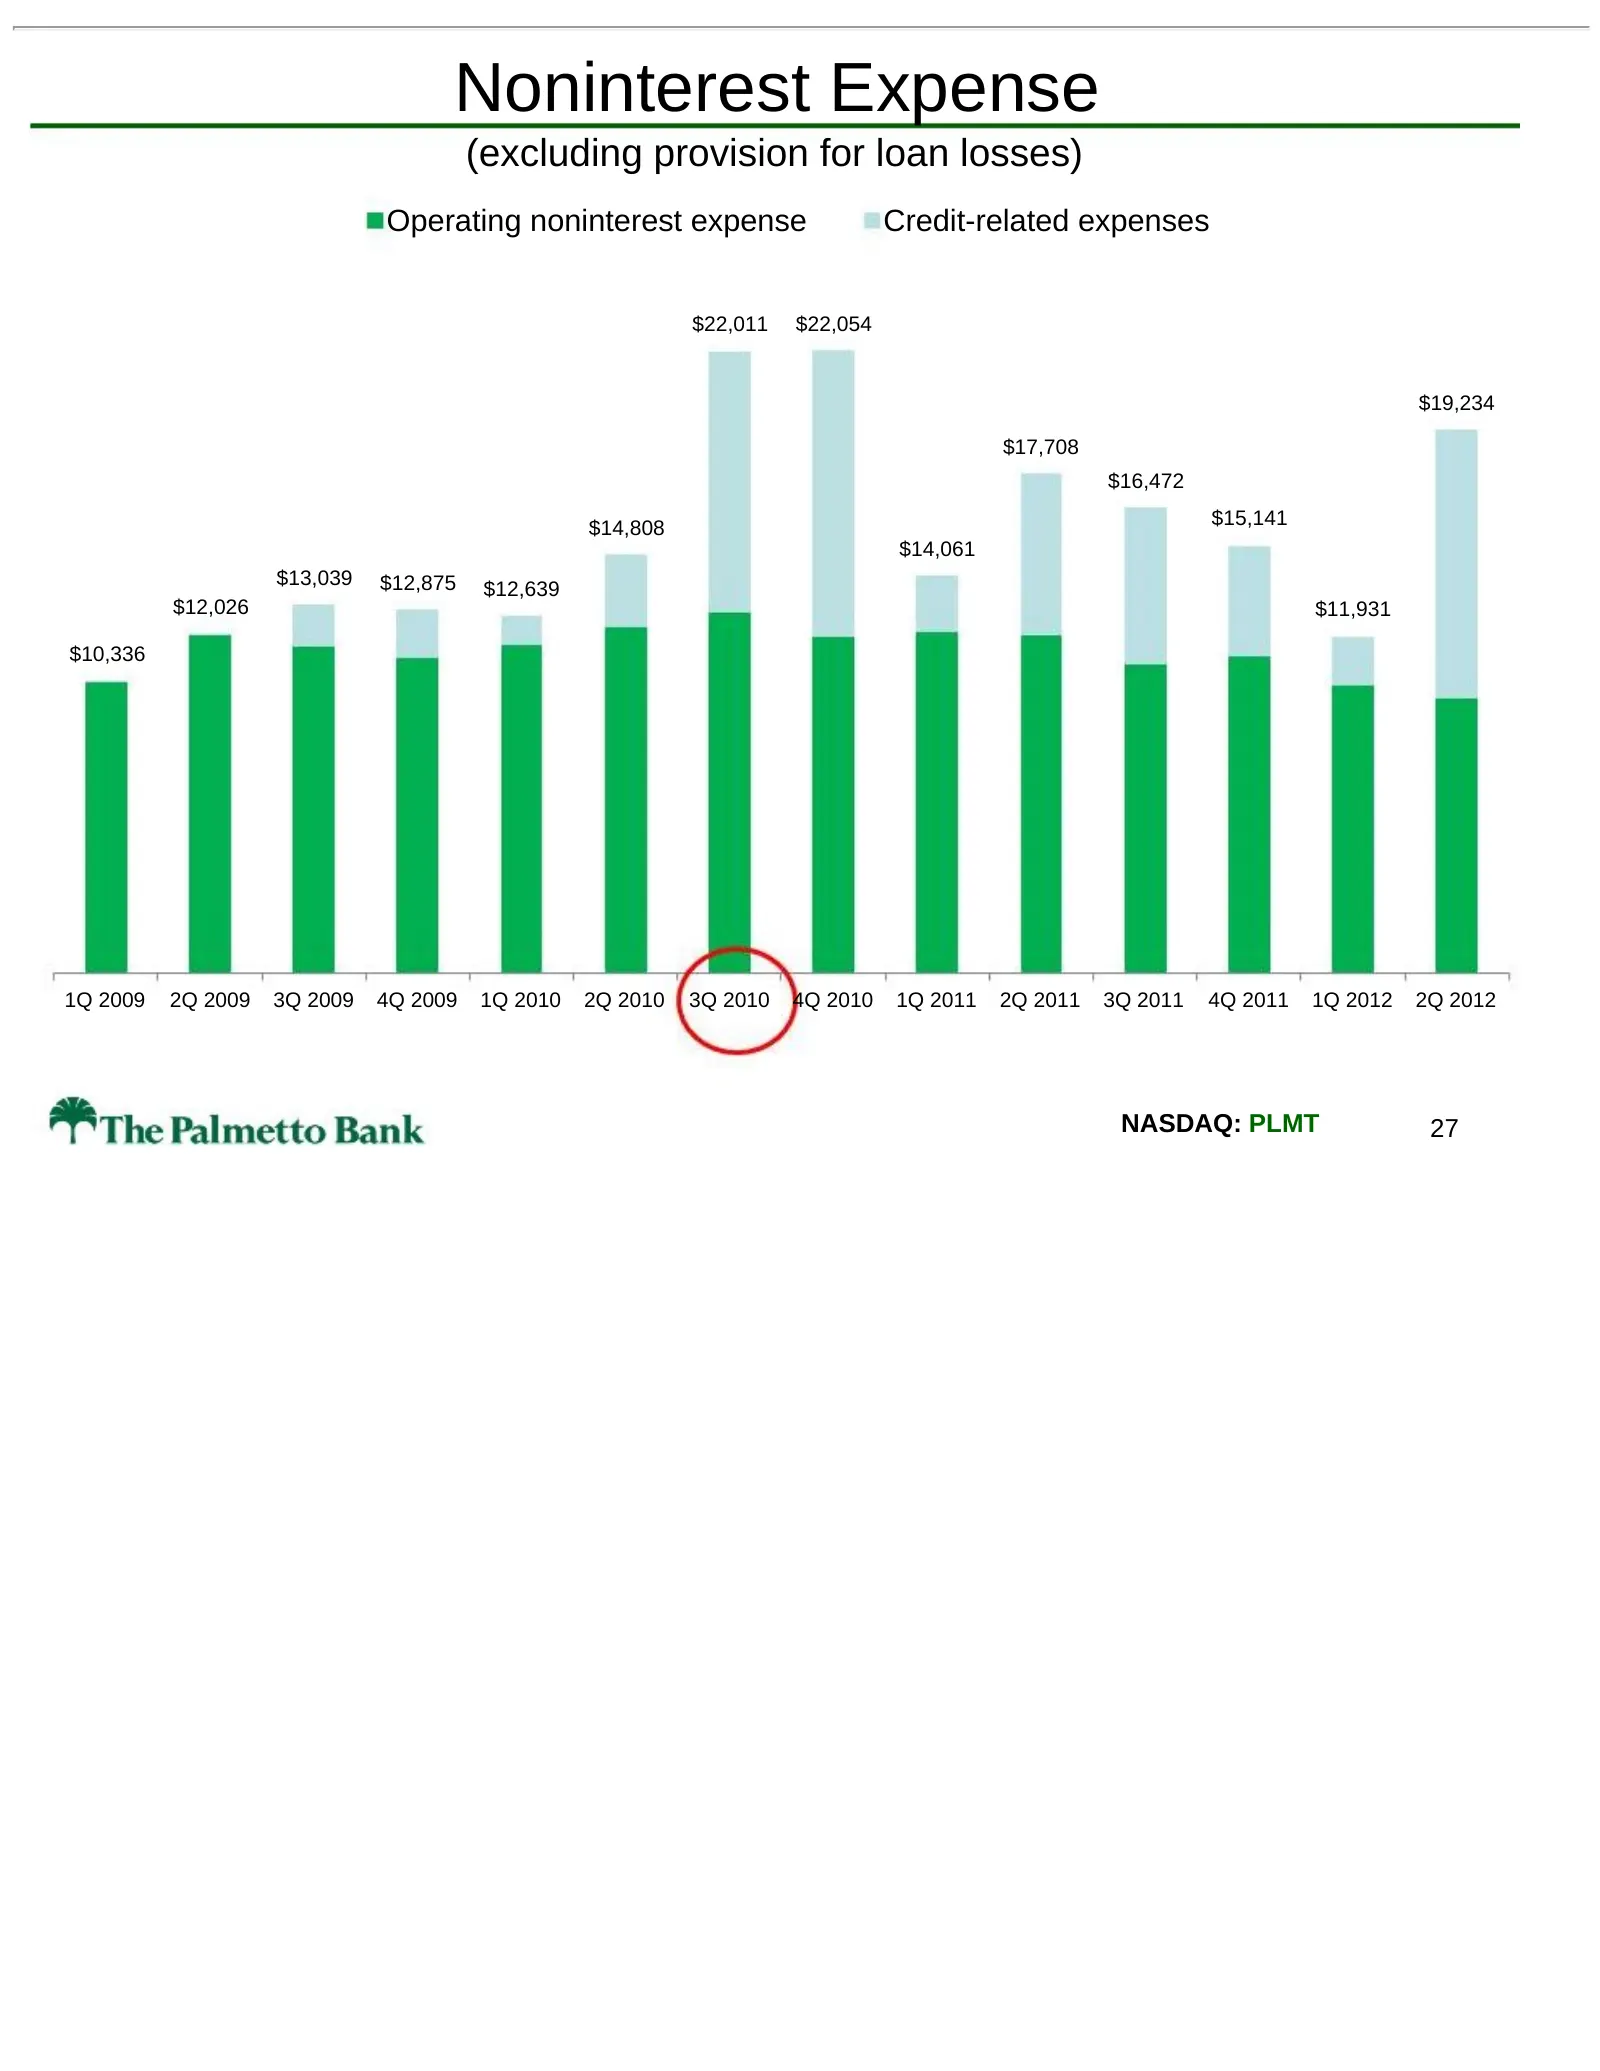
Noninterest Expense (excluding provision for loan losses) Operating noninterest expense Credit-related expenses $22,011 $22,054 $19,234 $17,708 $16,472 $14,808 $15,141 $14,061 $13,039 $12,875 $12,639 $12,026 $11,931 $10,336 1Q 2009 2Q 2009 3Q 2009 4Q 2009 1Q 2010 2Q 2010 3Q 2010 4Q 2010 1Q 2011 2Q 2
Slide 28: Efficiency Ratio
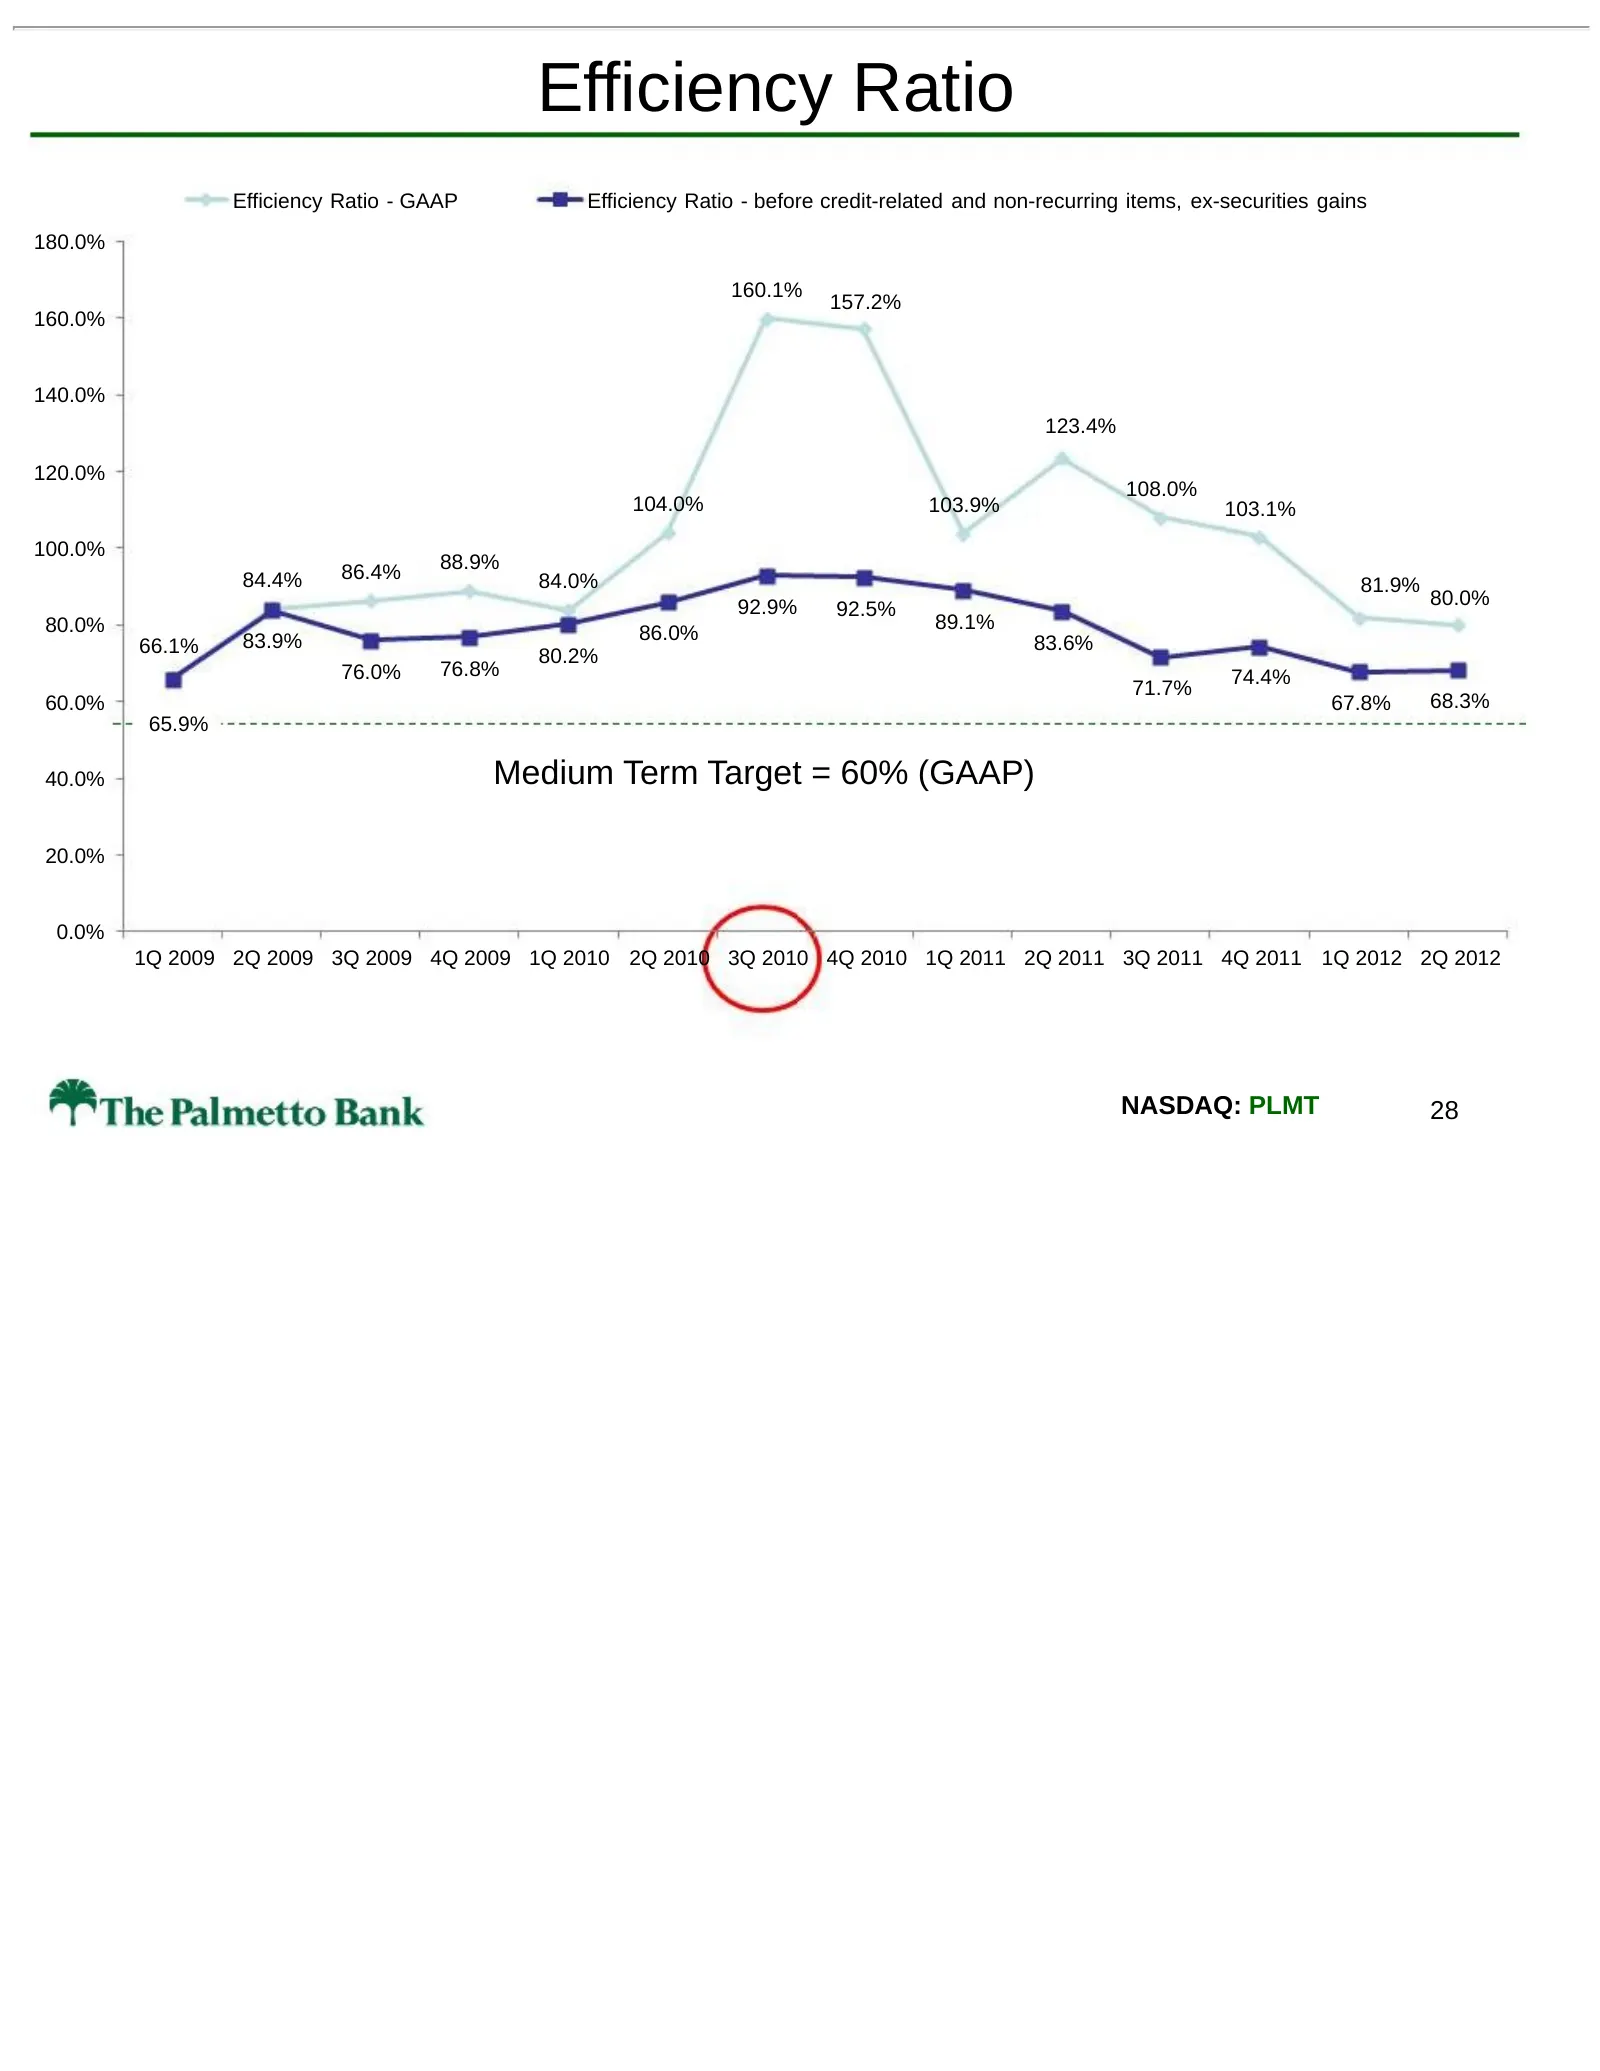
Efficiency Ratio Efficiency Ratio - GAAP Efficiency Ratio - before credit-related and non-recurring items, ex-securities gains 180.0% 160.1% 157.2% 160.0% 140.0% 123.4% 120.0% 108.0% 104.0% 103.9% 103.1% 100.0% 86.4% 88.9% 84.4% 84.0% 81.9% 92.9% 80.0% 92.5% 80.0% 89.1% 83.9% 86.0% 83.6% 66.1% 80.2%
Slide 29: Expense Reduction through Project SAVE
Expense Reduction through Project SAVE $6.2 million of annual expense Savings through Automation, Vendor management and Efficiency • Outsourcing – Asset-liability management and Internal Audit co-sourcing began January 1, 2012 – Check processing outsourcing and related deposit statements process on
Slide 30: Remainder of 2012
Remainder of 2012 1. Emphasis on quality loan production, including niches (Small Business Administration, Commercial & Industrial, Corporate Lending, Indirect Auto and Mortgage) 2. Margin and fee income pressure, with keen focus on reducing funding costs 3. Lower, more predicable credit-related exp
Slide 31: 2. Improve Asset Quality
2. Improve Asset Quality NASDAQ: PLMT 31
Slide 32: Return to Profitability and Improve Asset Quality
Return to Profitability and Improve Asset Quality • Objectives are inter-related with financial results driven primarily by credit losses • Significant reduction in problem assets and improving quarterly trends - reduced – Number of problem assets – Size of problem assets – Losses on problem assets
Slide 33: Nonperforming Assets
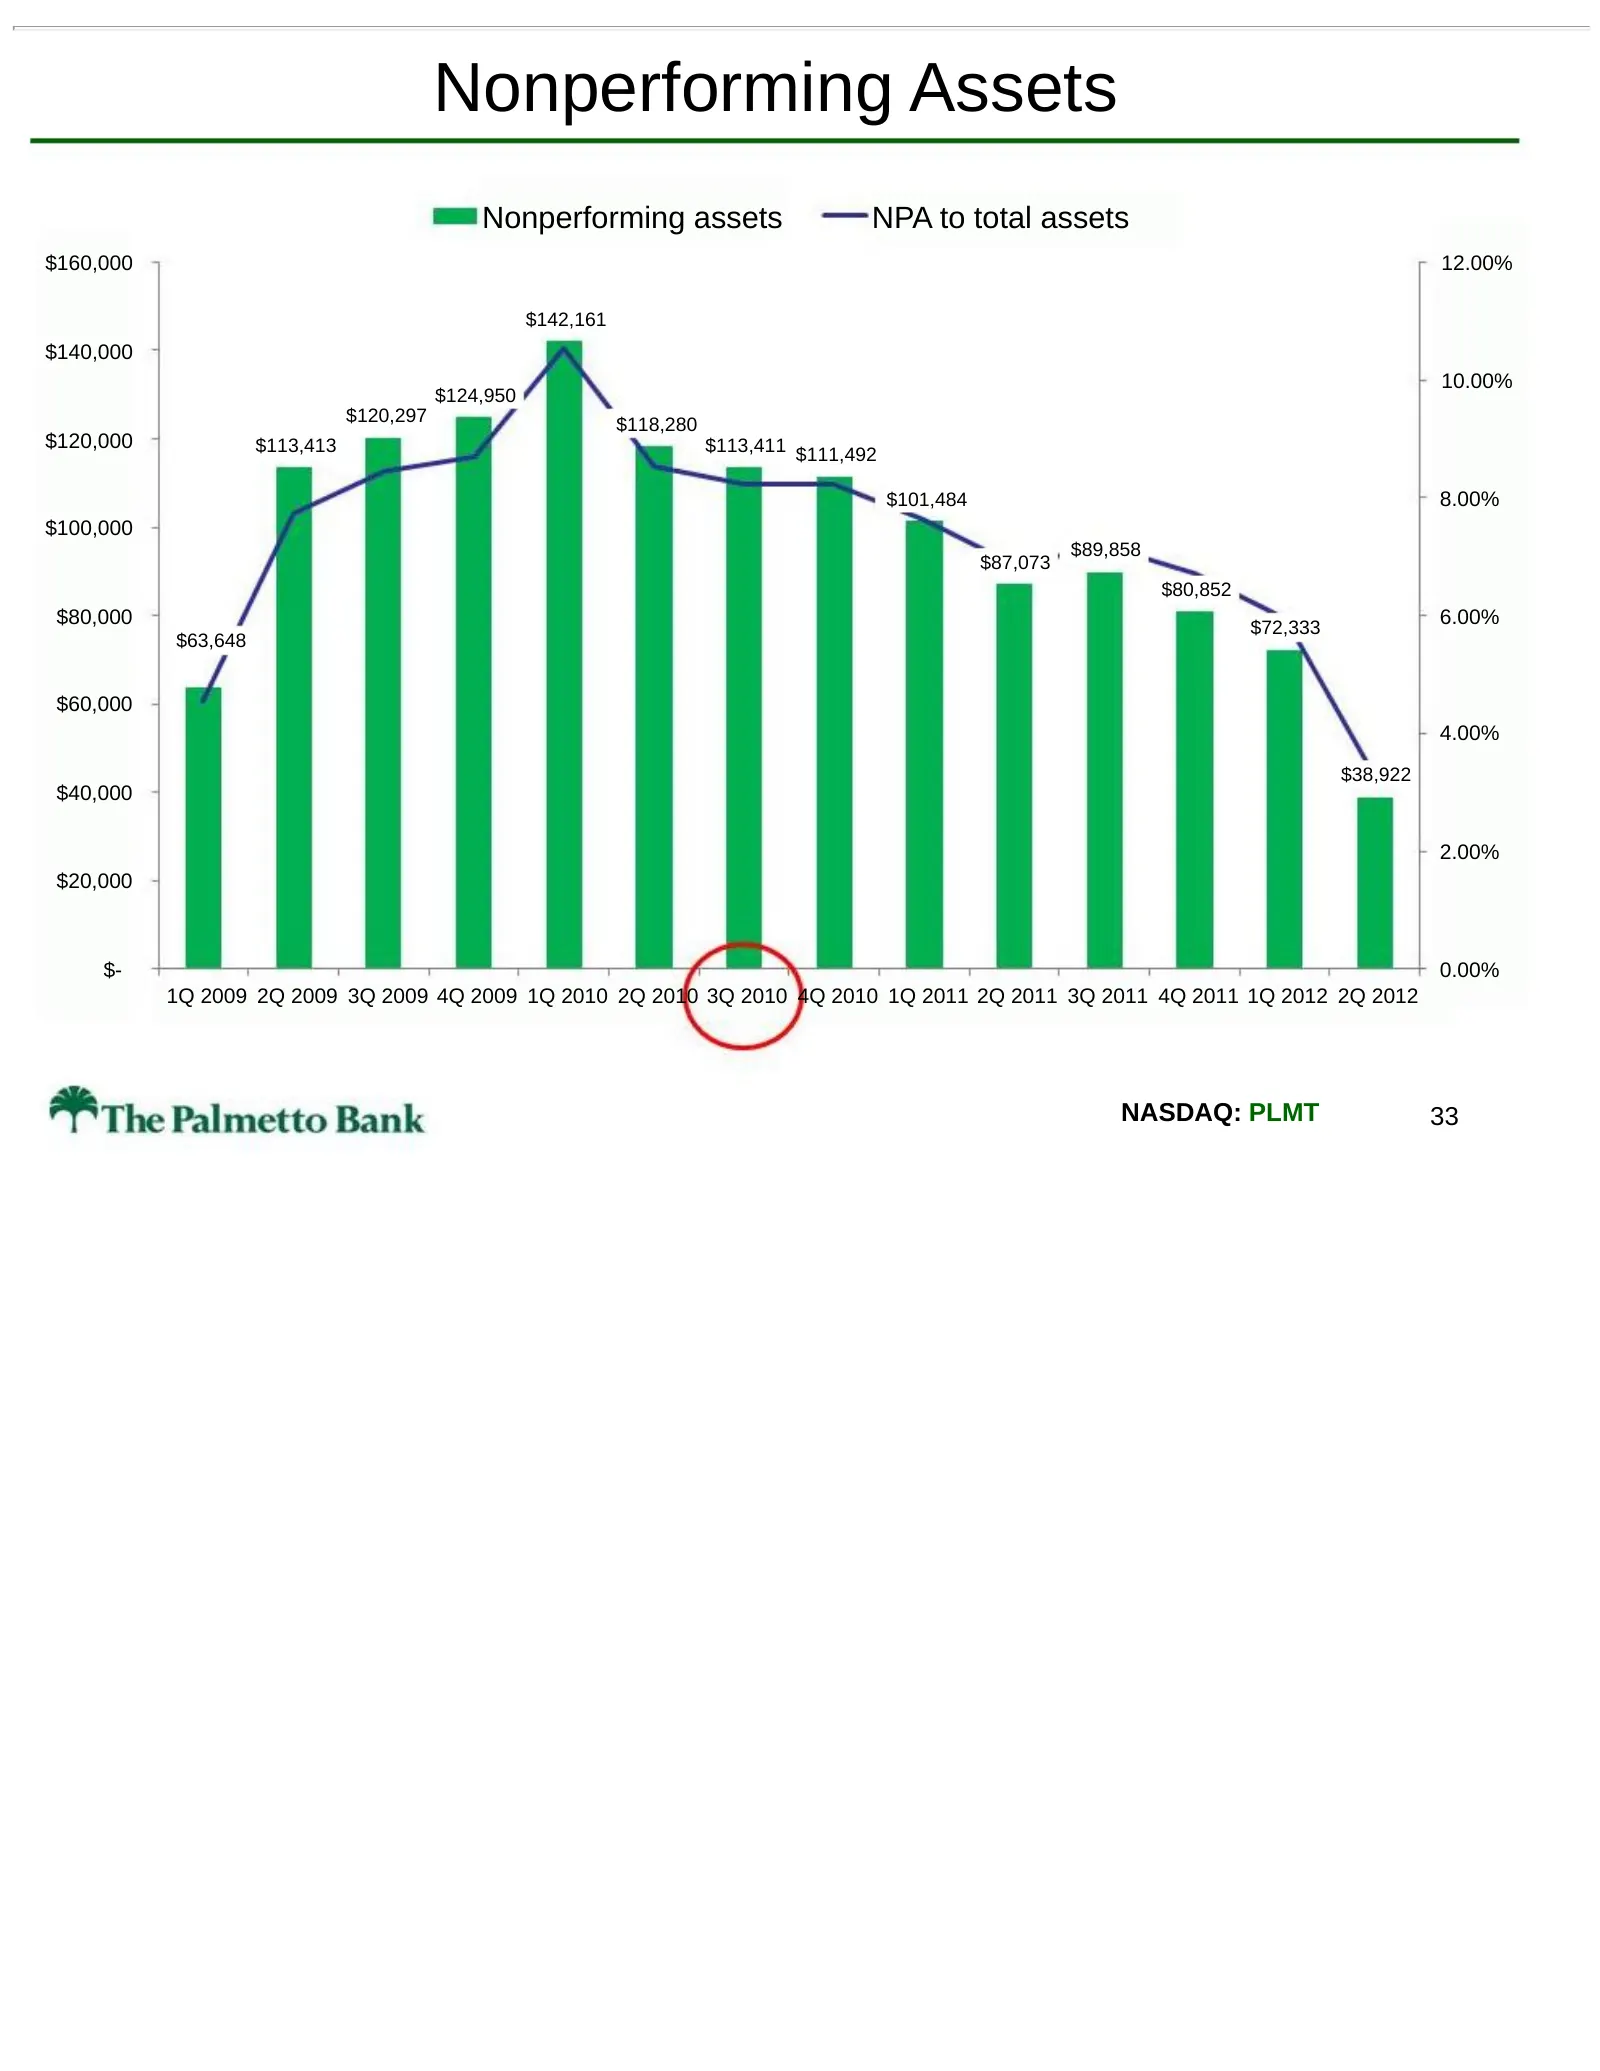
Nonperforming Assets Nonperforming assets NPA to total assets $160,000 12.00% $142,161 $140,000 10.00% $124,950 $120,297 $118,280 $120,000 $113,413 $113,411 $111,492 $101,484 8.00% $100,000 $89,858 $87,073 $80,852 $80,000 $72,333 6.00% $63,648 $60,000 4.00% $38,922 $40,000 2.00% $20,000 $- 0.00% 1Q
Slide 34: Nonaccrual Loan Inflows
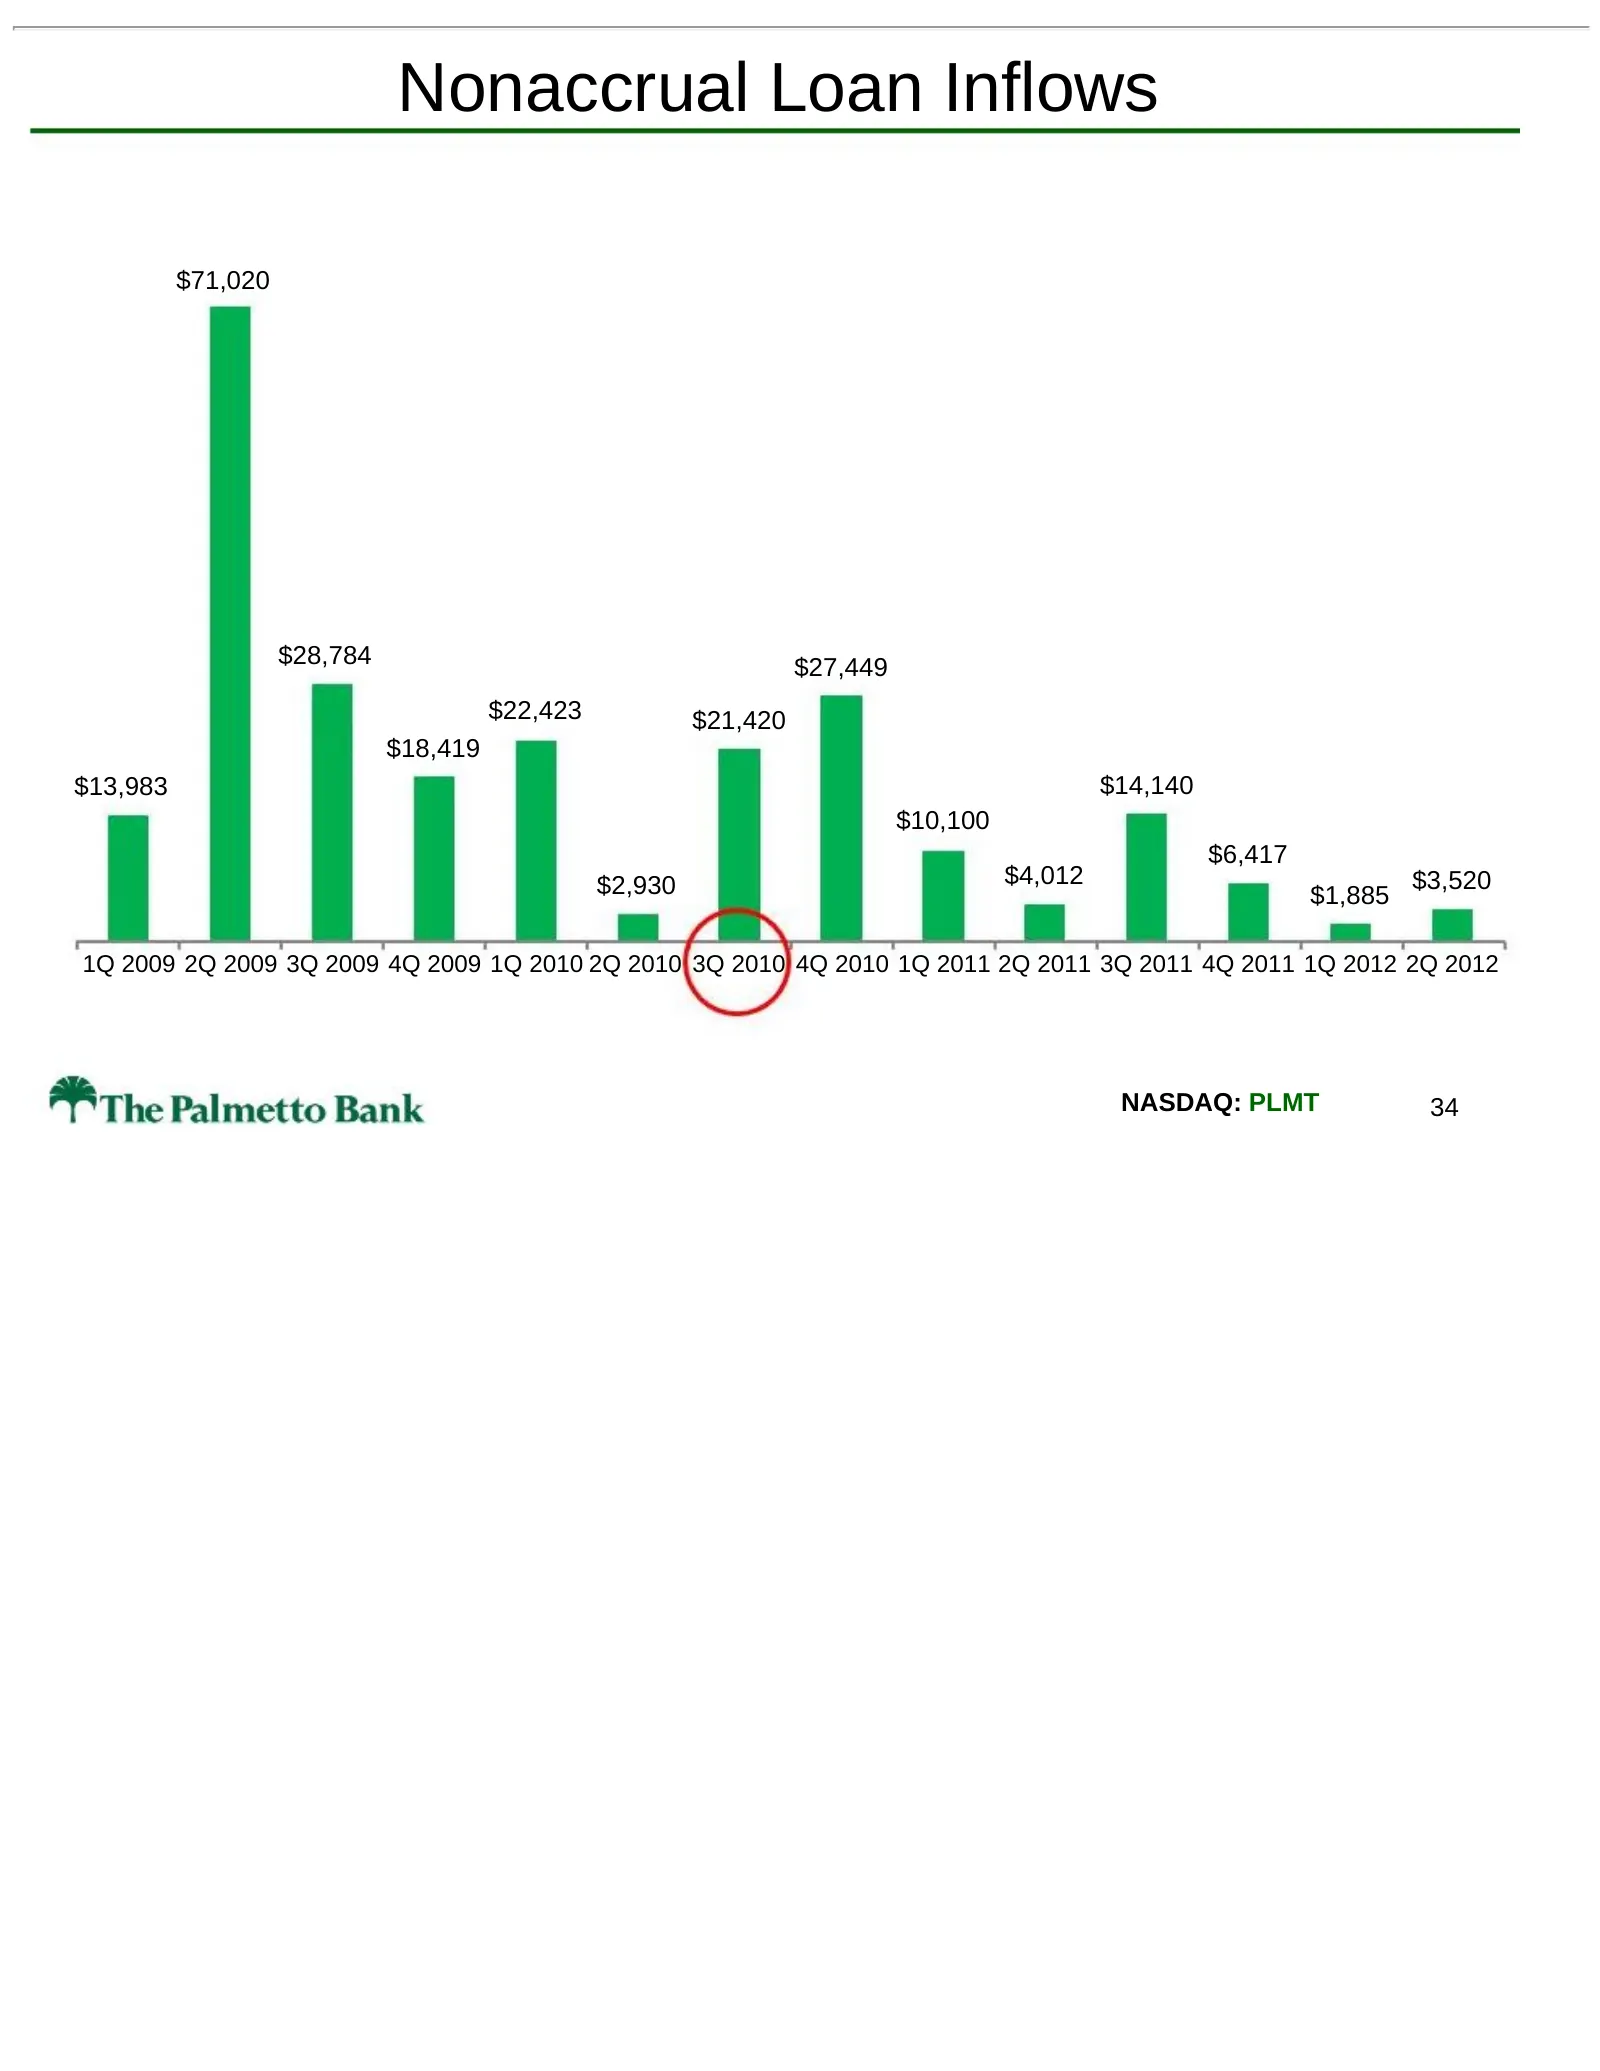
Nonaccrual Loan Inflows $71,020 $28,784 $27,449 $22,423 $21,420 $18,419 $13,983 $14,140 $10,100 $6,417 $2,930 $4,012 $3,520 $1,885 1Q 2009 2Q 2009 3Q 2009 4Q 2009 1Q 2010 2Q 2010 3Q 2010 4Q 2010 1Q 2011 2Q 2011 3Q 2011 4Q 2011 1Q 2012 2Q 2012 NASDAQ: PLMT 34
Slide 35: Commercial Real Estate Loans
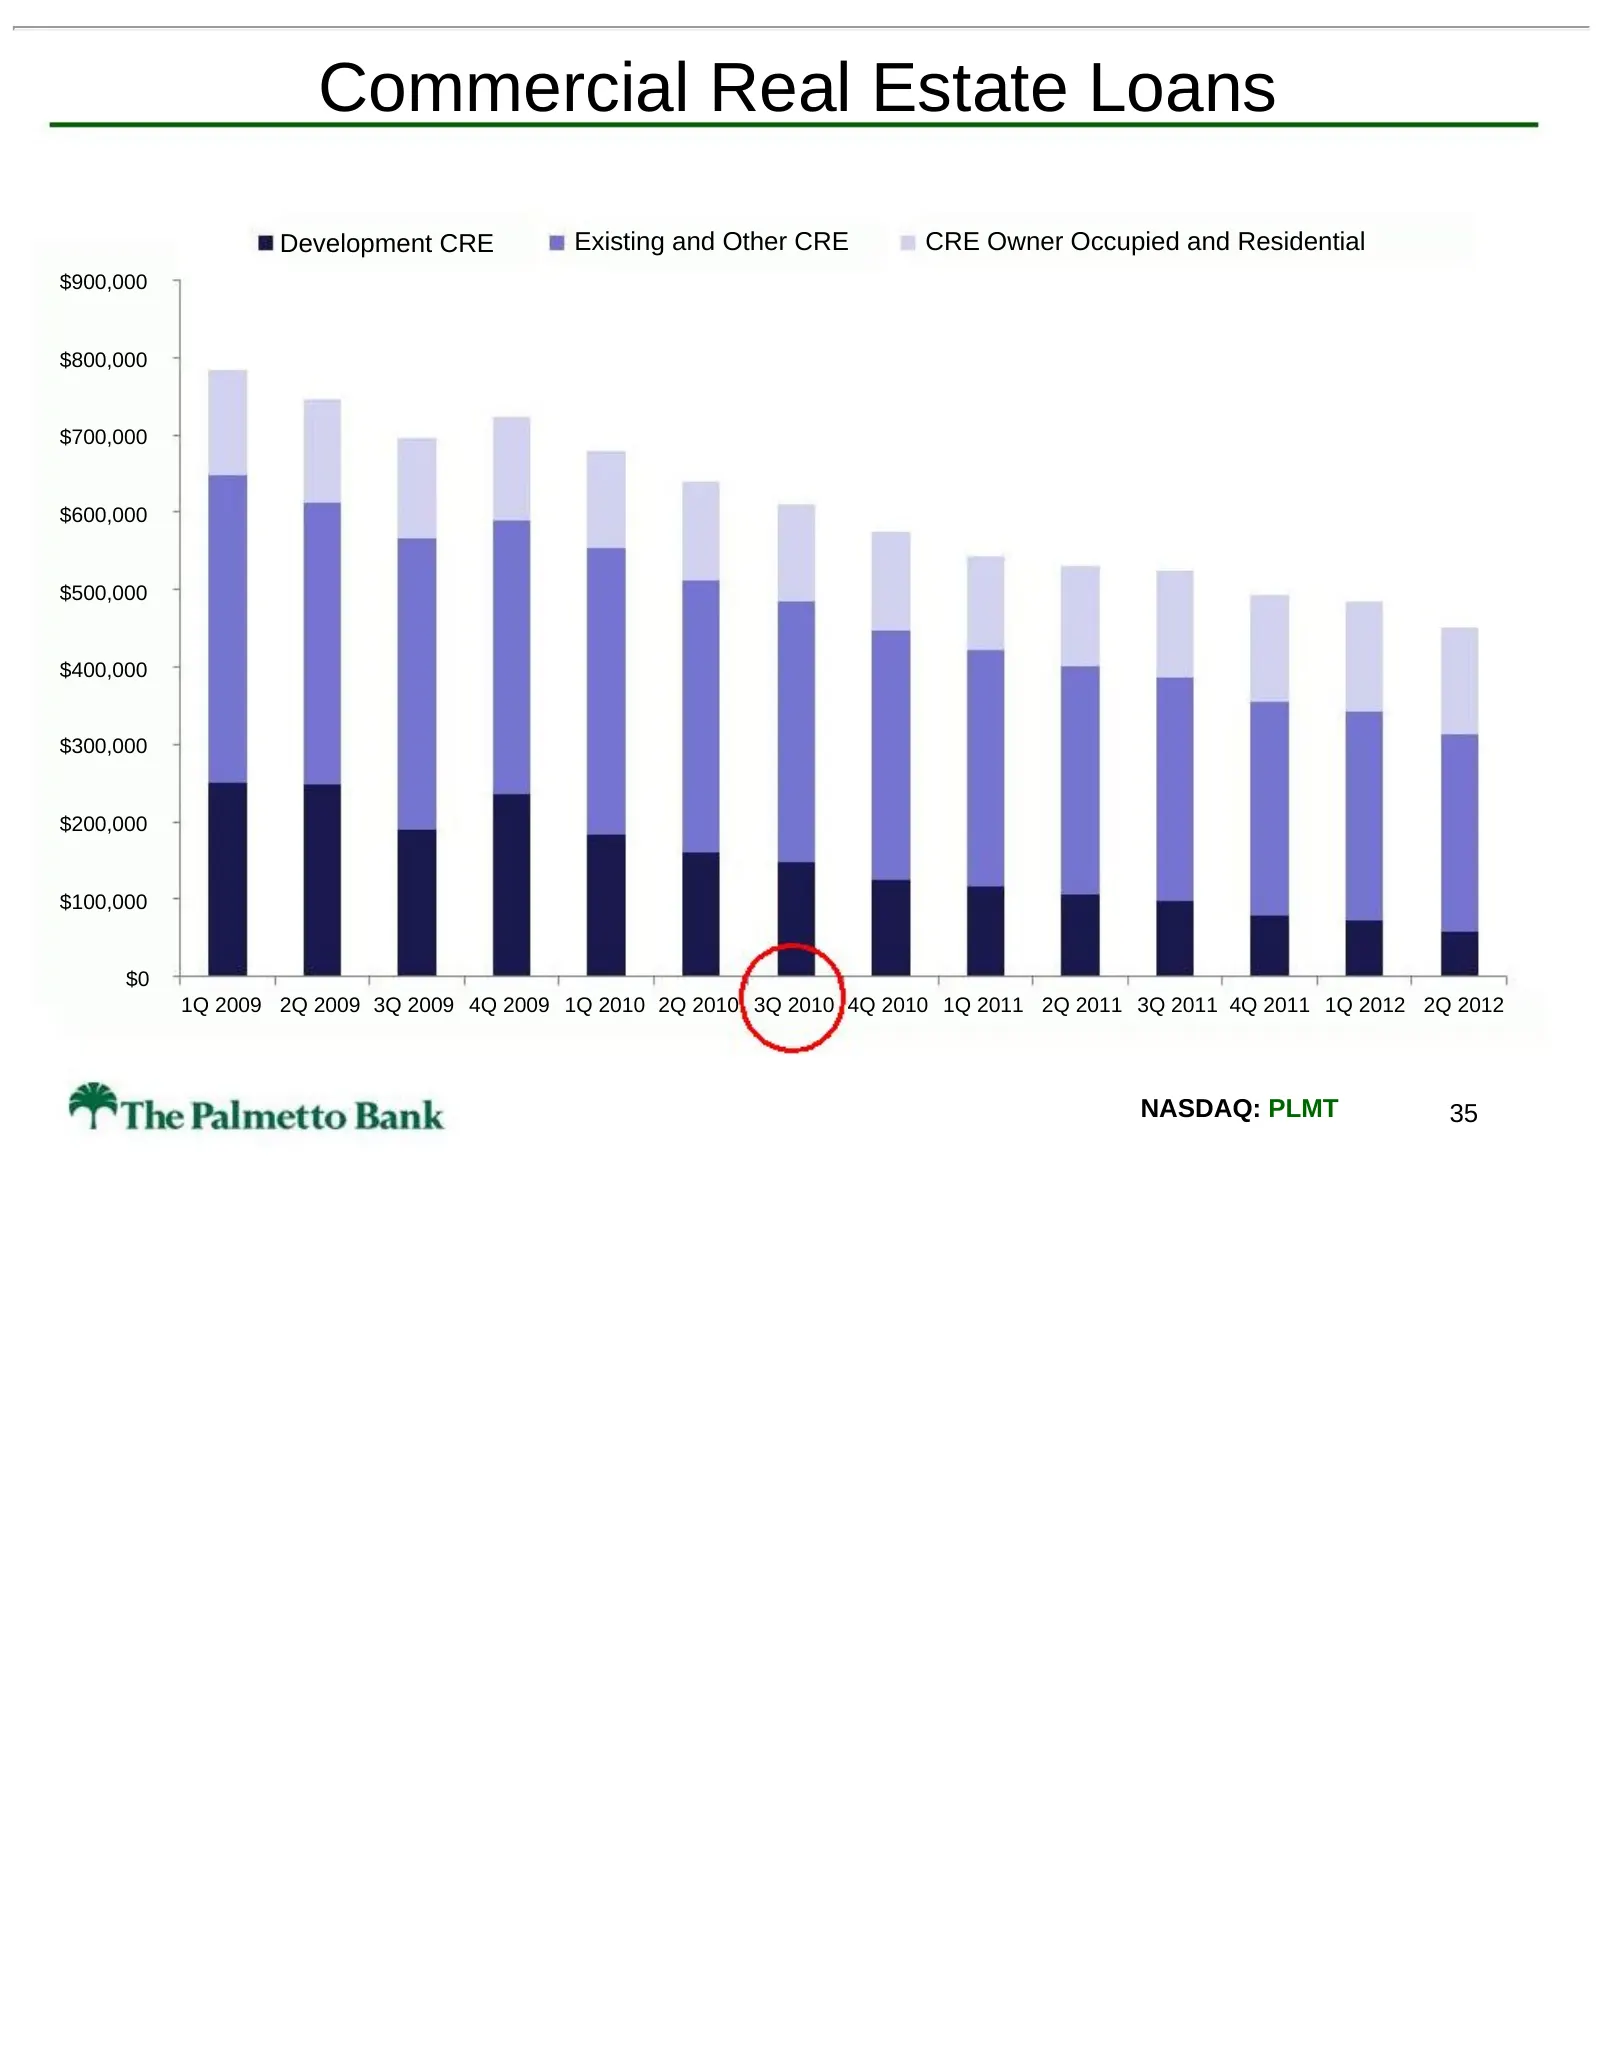
Commercial Real Estate Loans Development CRE Existing and Other CRE CRE Owner Occupied and Residential $900,000 $800,000 $700,000 $600,000 $500,000 $400,000 $300,000 $200,000 $100,000 $0 1Q 2009 2Q 2009 3Q 2009 4Q 2009 1Q 2010 2Q 2010 3Q 2010 4Q 2010 1Q 2011 2Q 2011 3Q 2011 4Q 2011 1Q 2012 2Q 2012 N
Slide 36: Commercial Real Estate as % of Tier 1 Capital
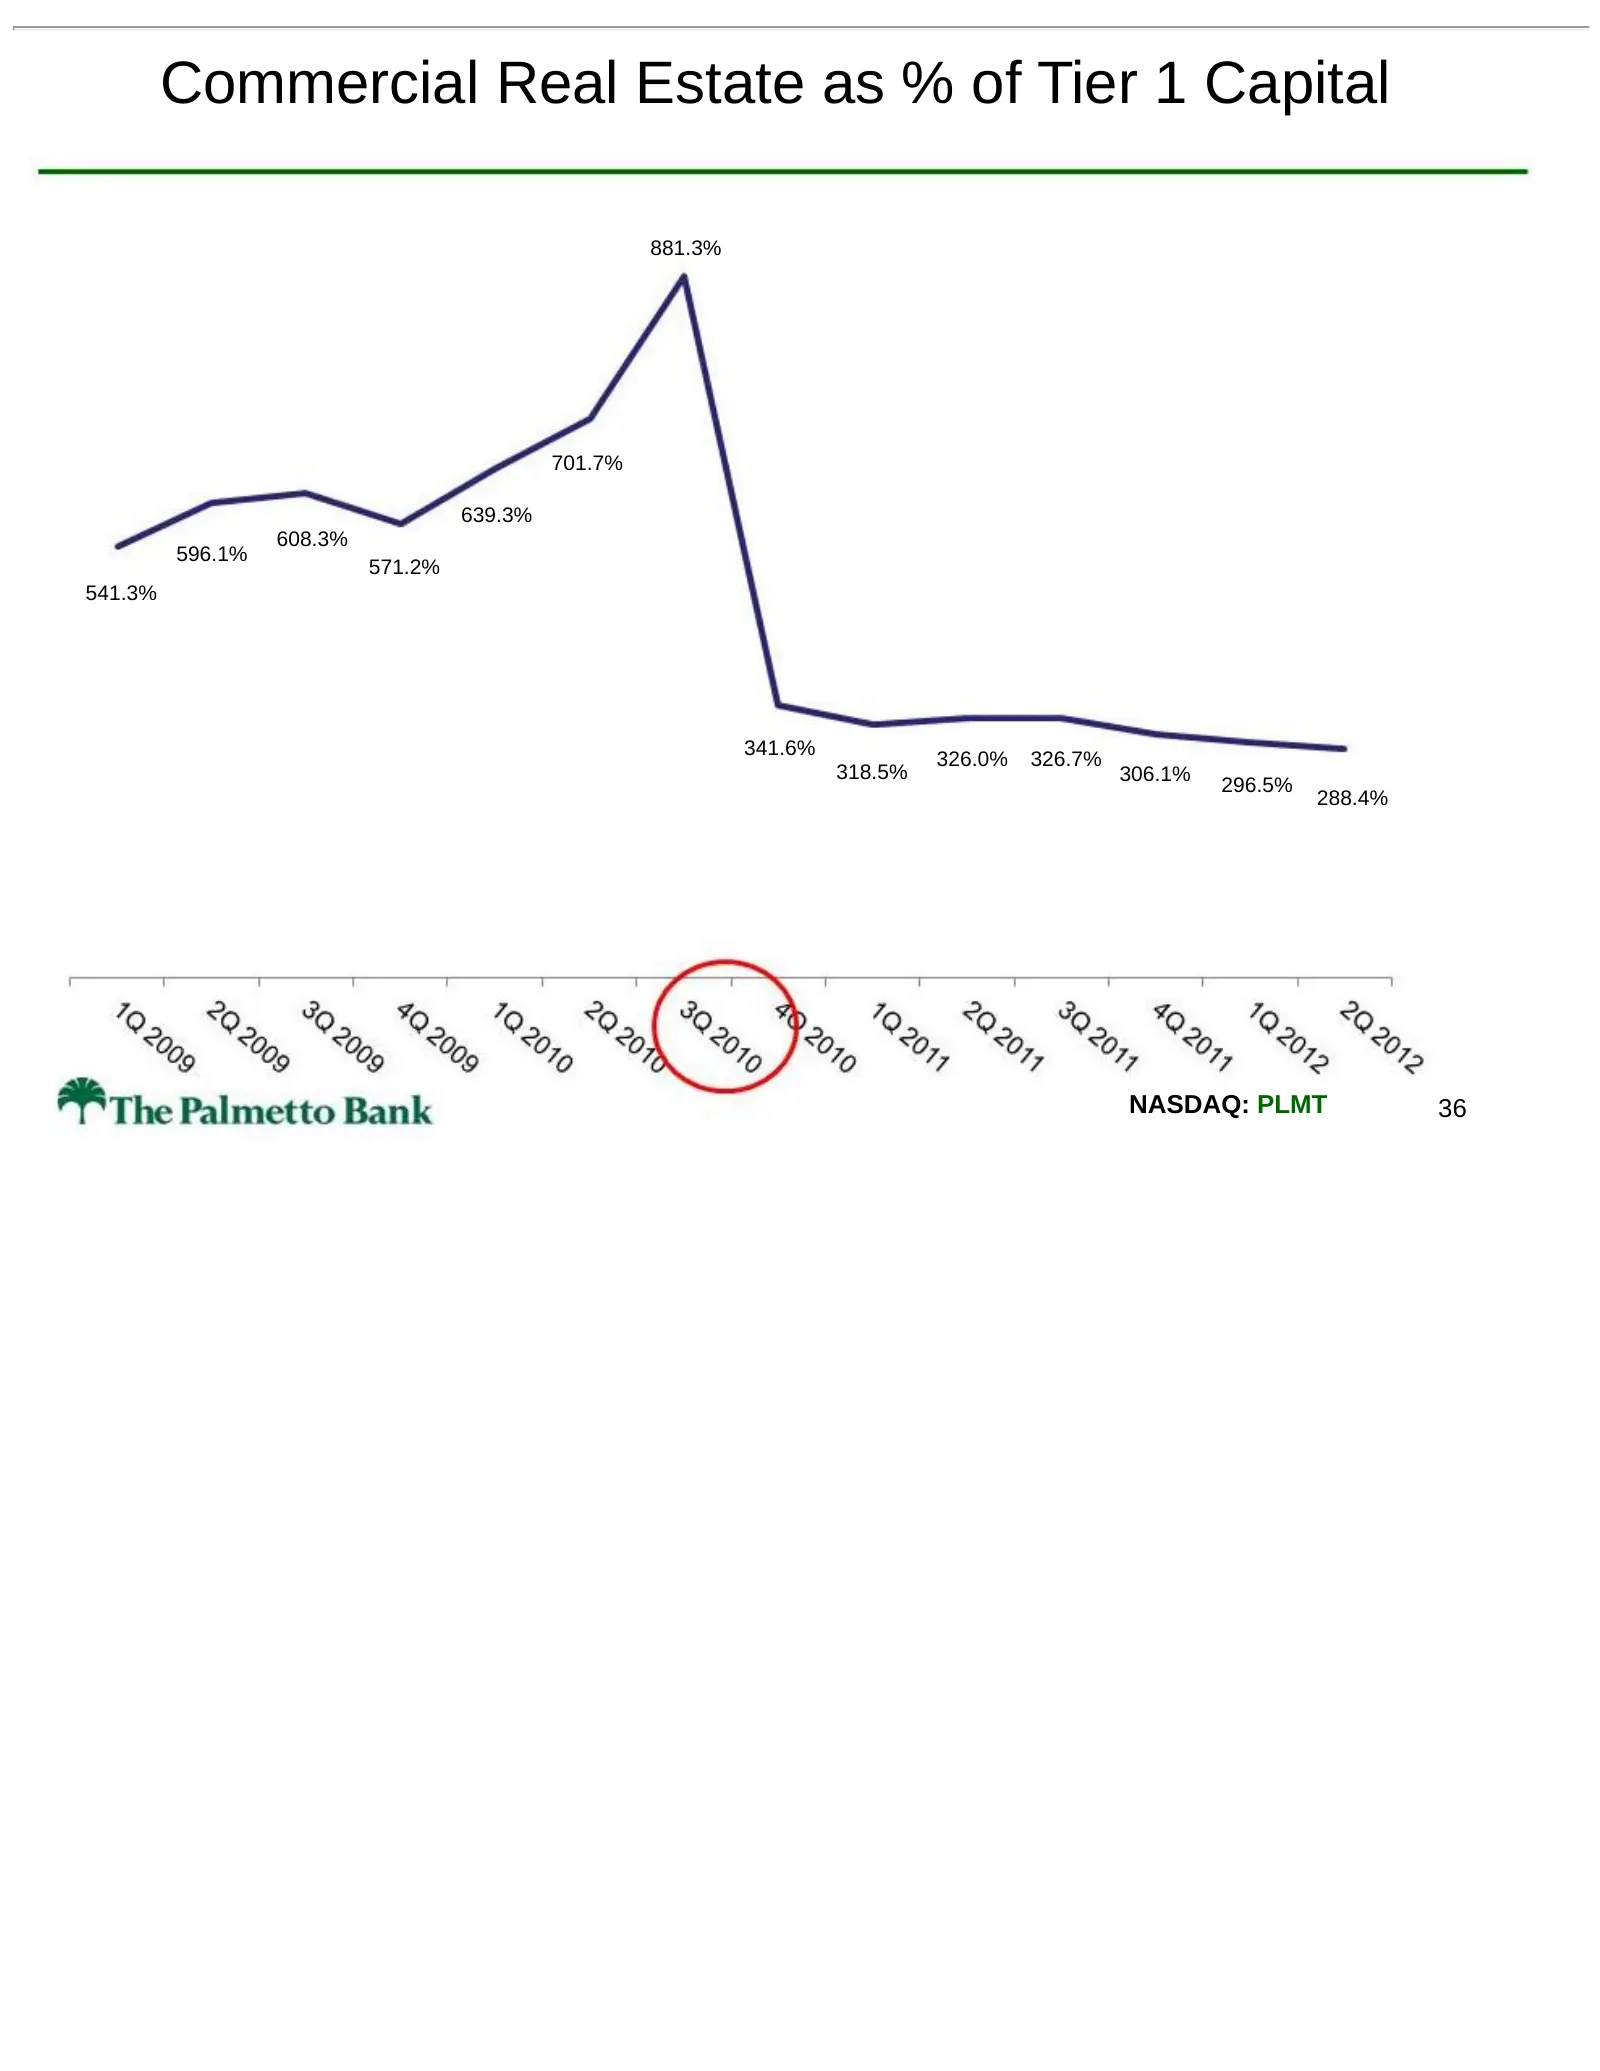
Commercial Real Estate as % of Tier 1 Capital 881.3% 701.7% 639.3% 608.3% 596.1% 571.2% 541.3% 341.6% 326.0% 326.7% 318.5% 306.1% 296.5% 288.4% NASDAQ: PLMT 36
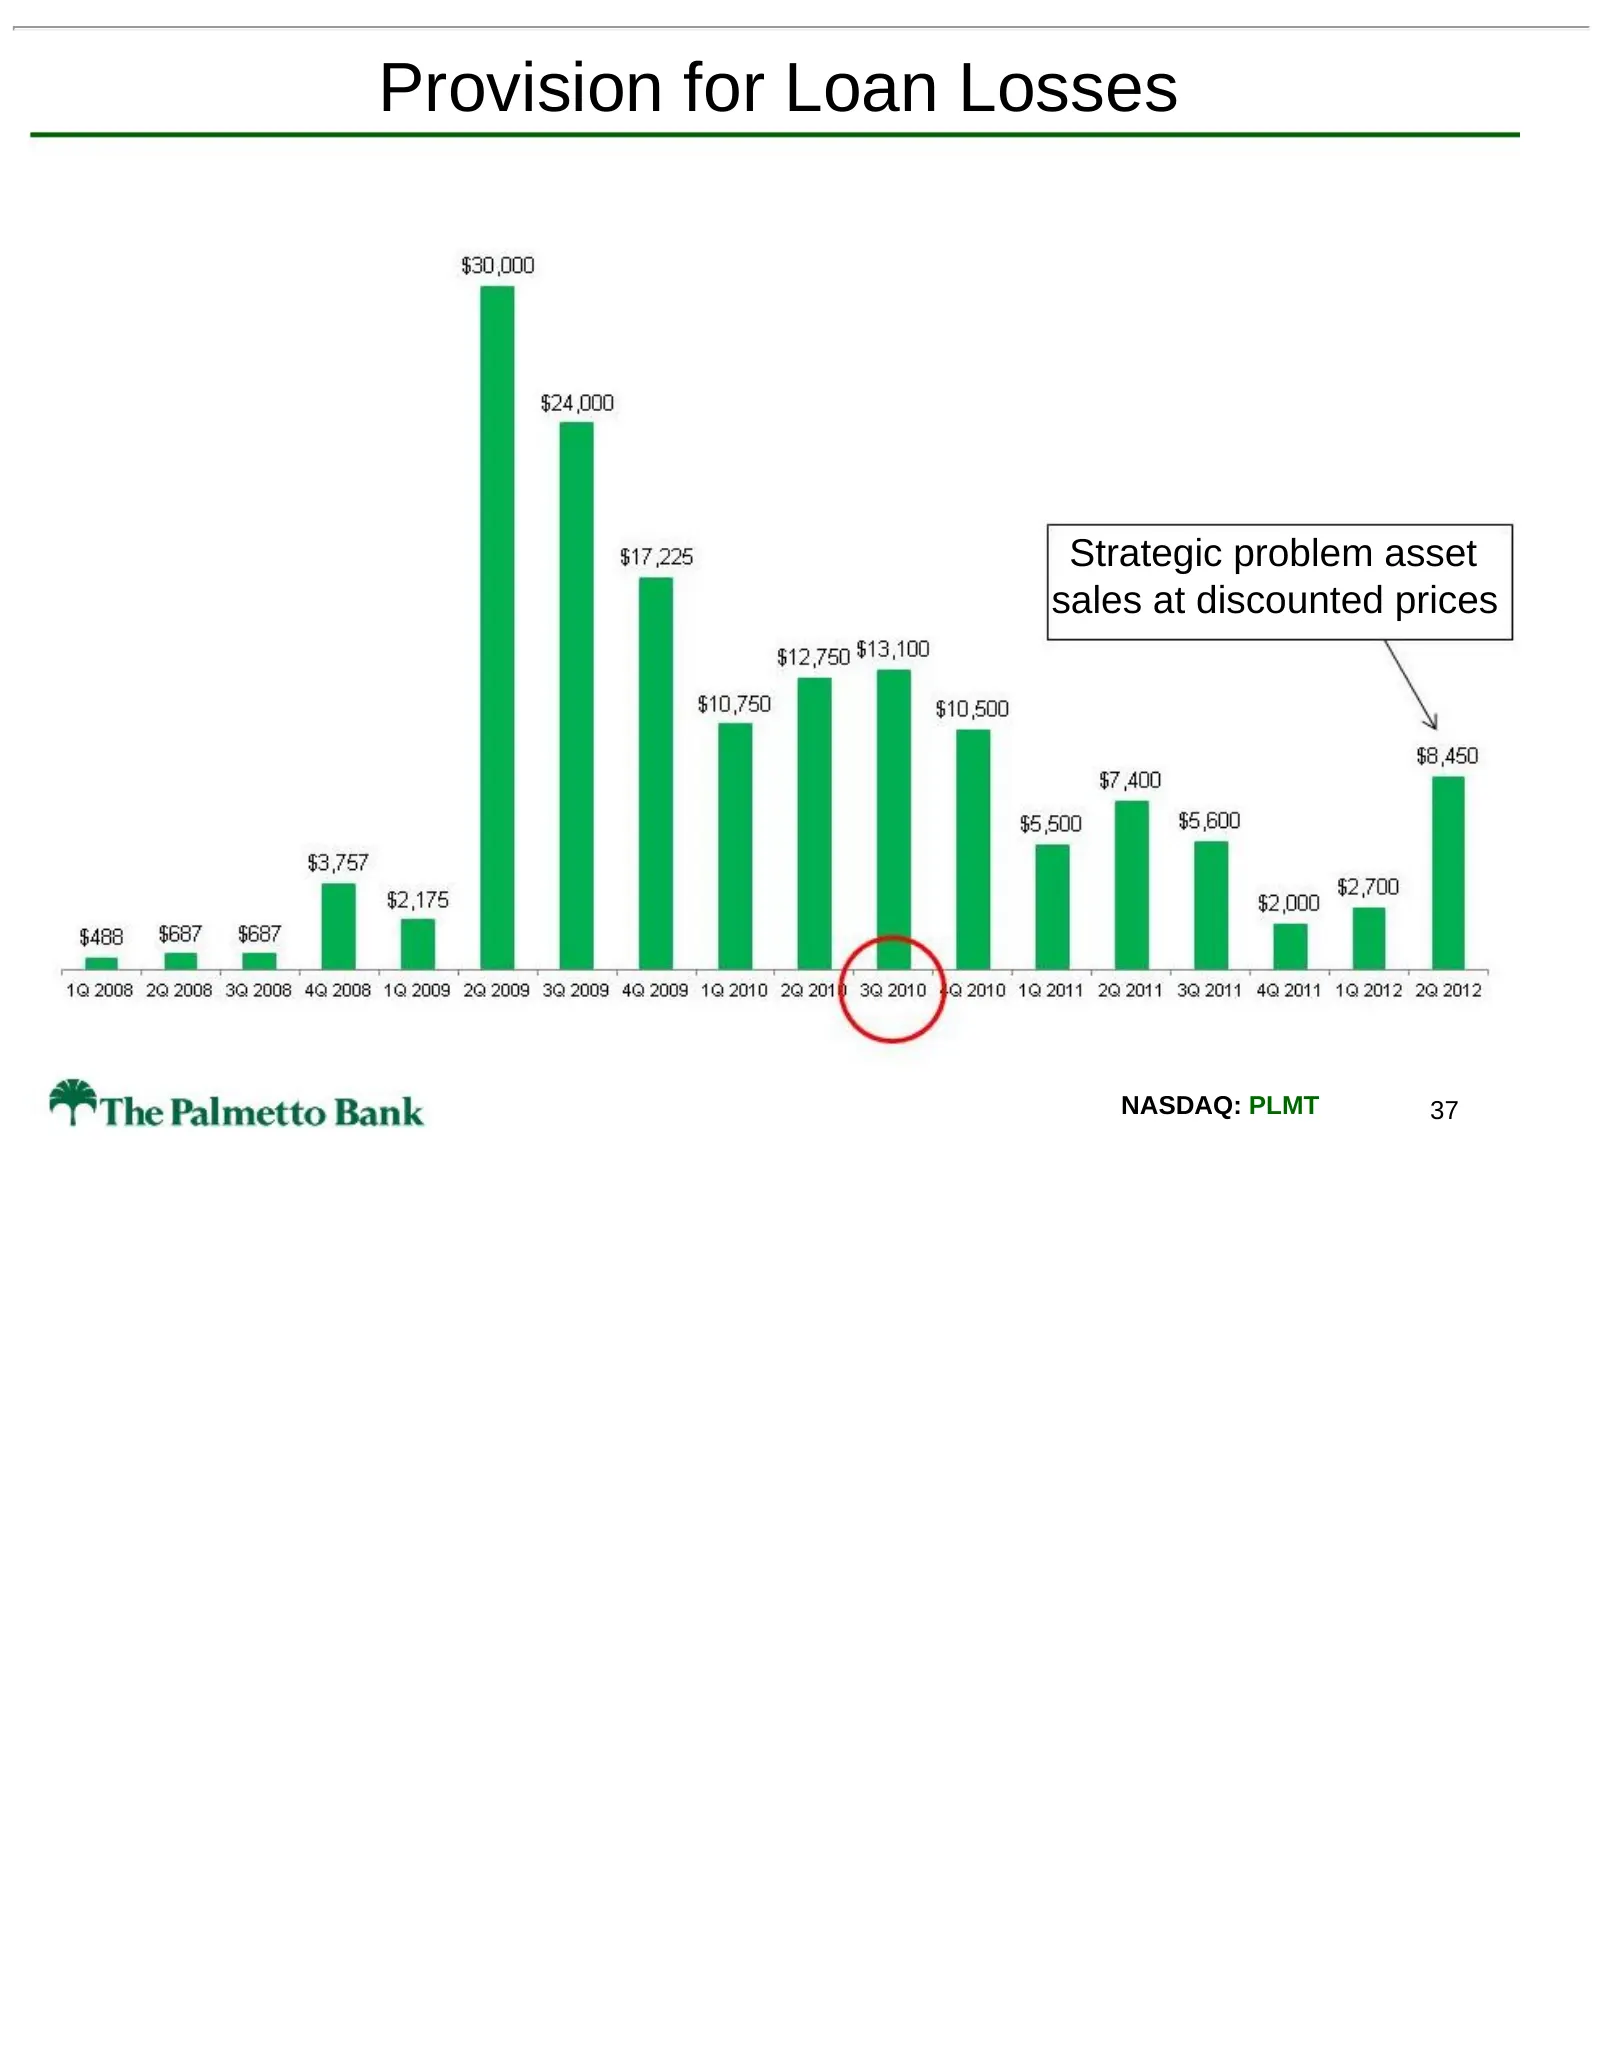
Slide 37: Provision for Loan Losses
Provision for Loan Losses Strategic problem asset sales at discounted prices NASDAQ: PLMT 37
Slide 38: 3. Exit Regulatory Agreement
3. Exit Regulatory Agreement NASDAQ: PLMT 38
Slide 39: Consent Order and Regulatory Examinations
Consent Order and Regulatory Examinations • Consent Order: in compliance with all provisions – Continued focus on reducing commercial real estate concentration – Elevated leverage capital ratio requirement (8%) – Prohibitions on incentive compensation and acquisitions • FDIC insurance premiums are b
Slide 40: 4. Execute on Client Service and Support through Palmetto Partnership
4. Execute on Client Service and Support through Palmetto Partnership NASDAQ: PLMT 40
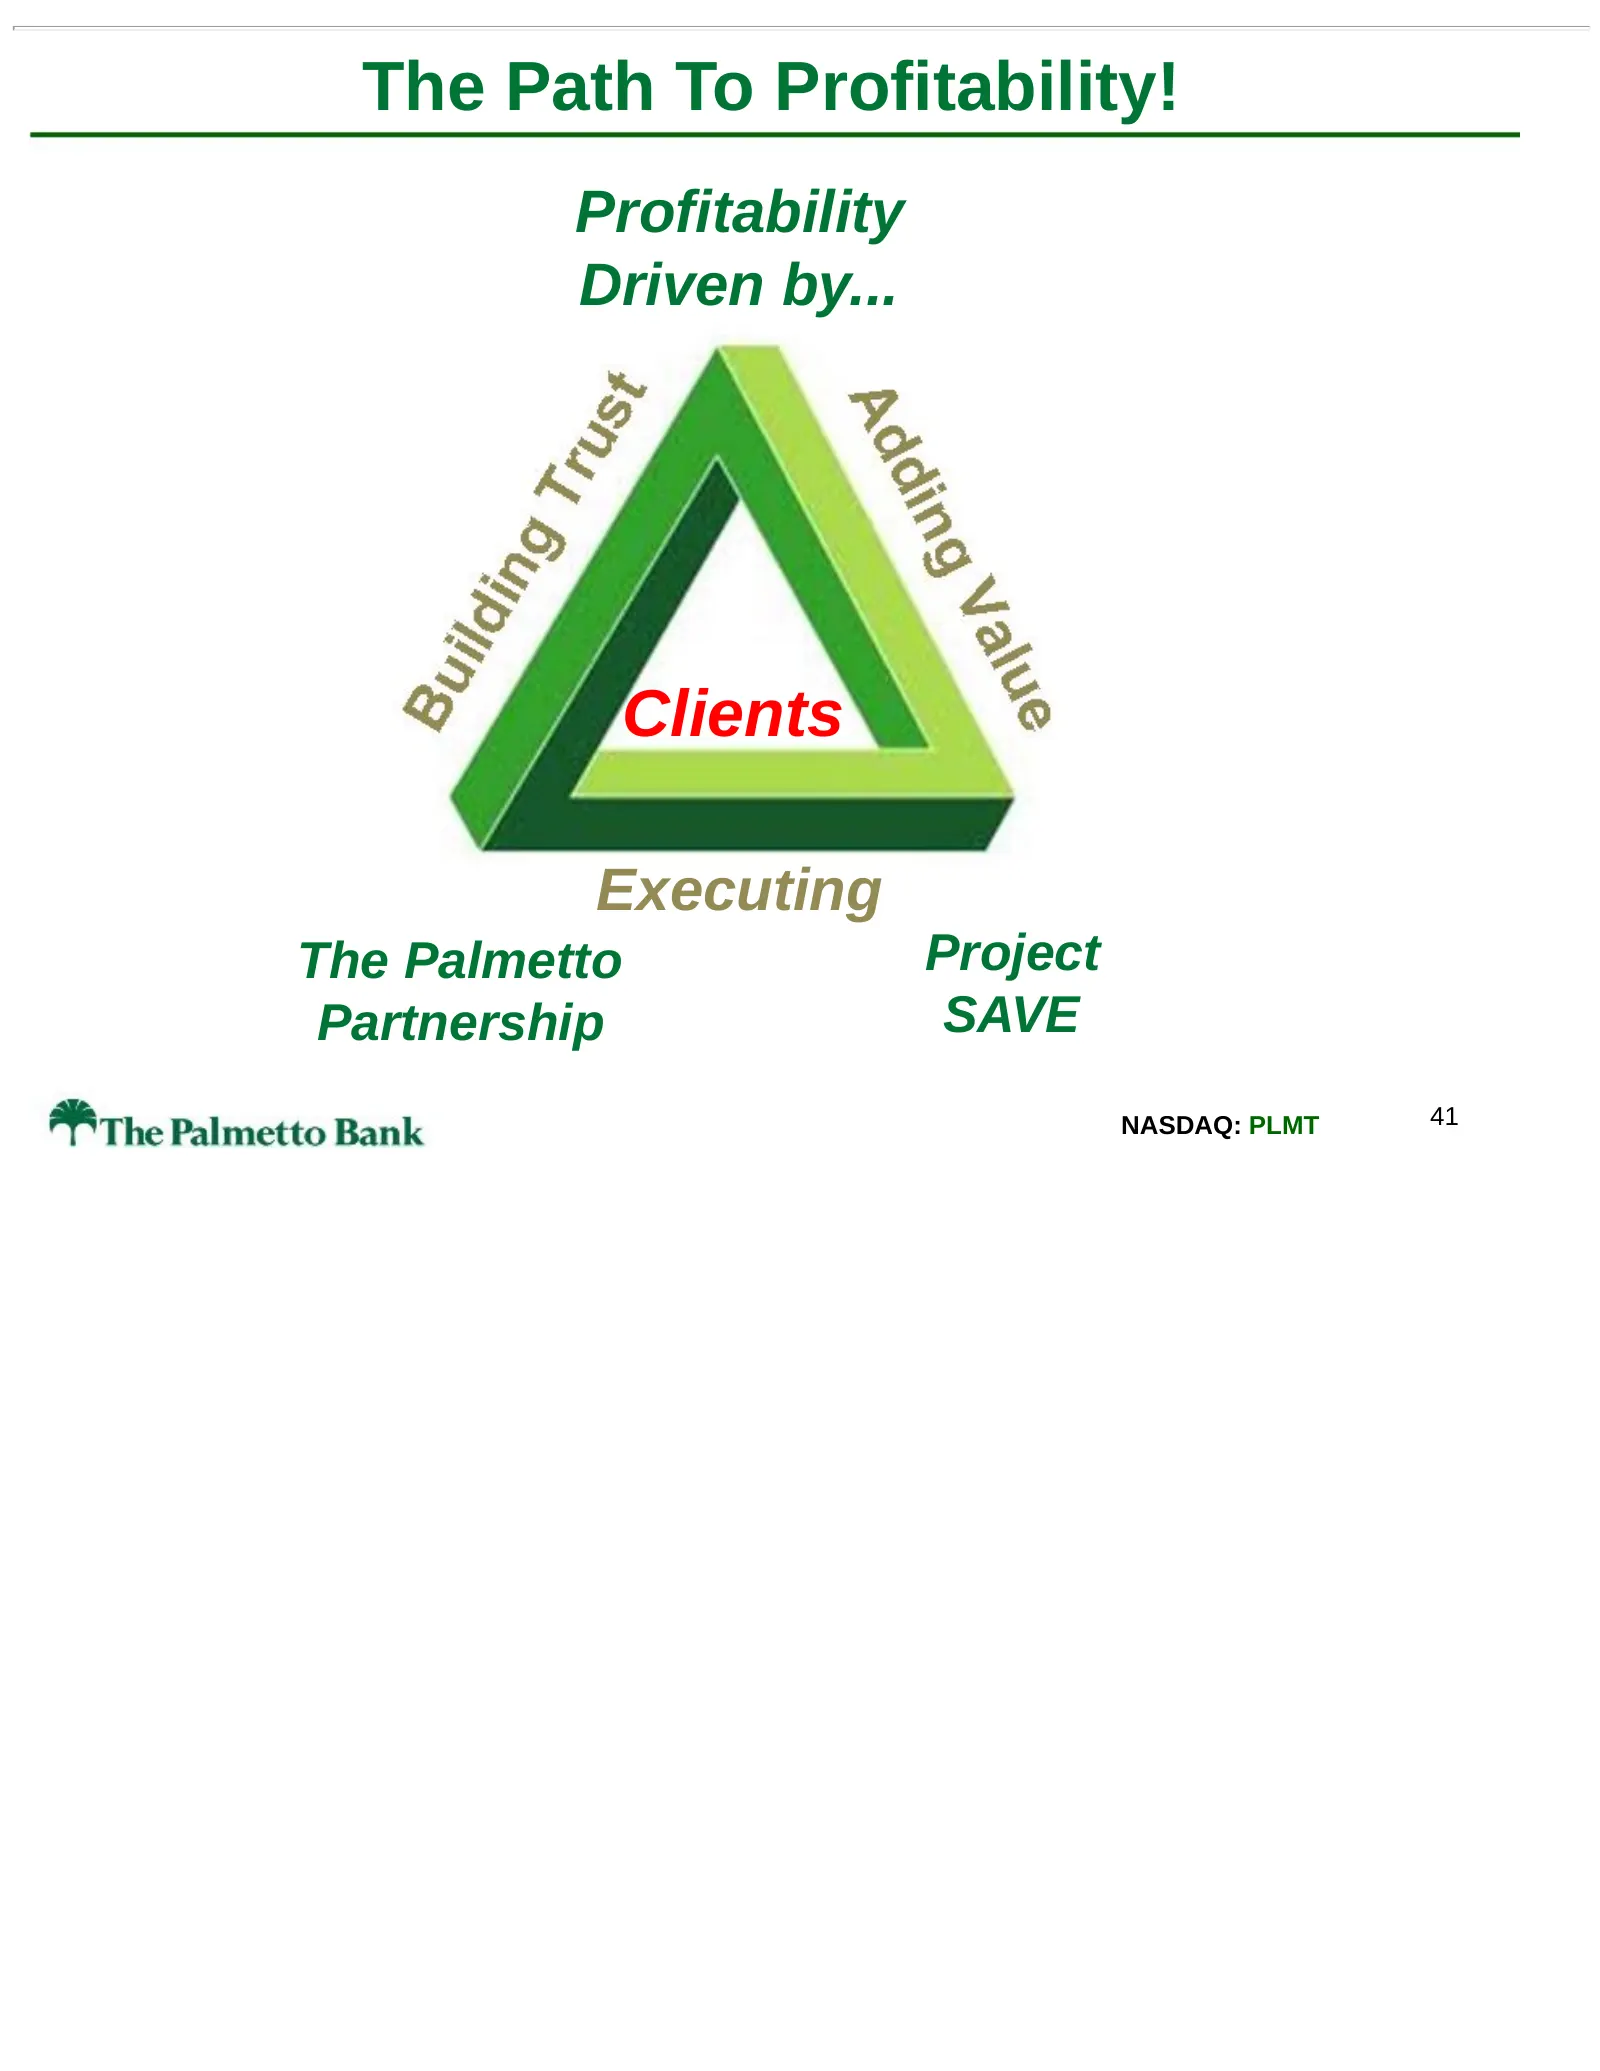
Slide 41: The Path To Profitability!
The Path To Profitability! Profitability Driven by... Clients Executing The Palmetto Project Partnership SAVE NASDAQ: PLMT 41
Slide 42: Leveraging Technology to Improve the Client Experience
Leveraging Technology to Improve the Client Experience NASDAQ: PLMT 42
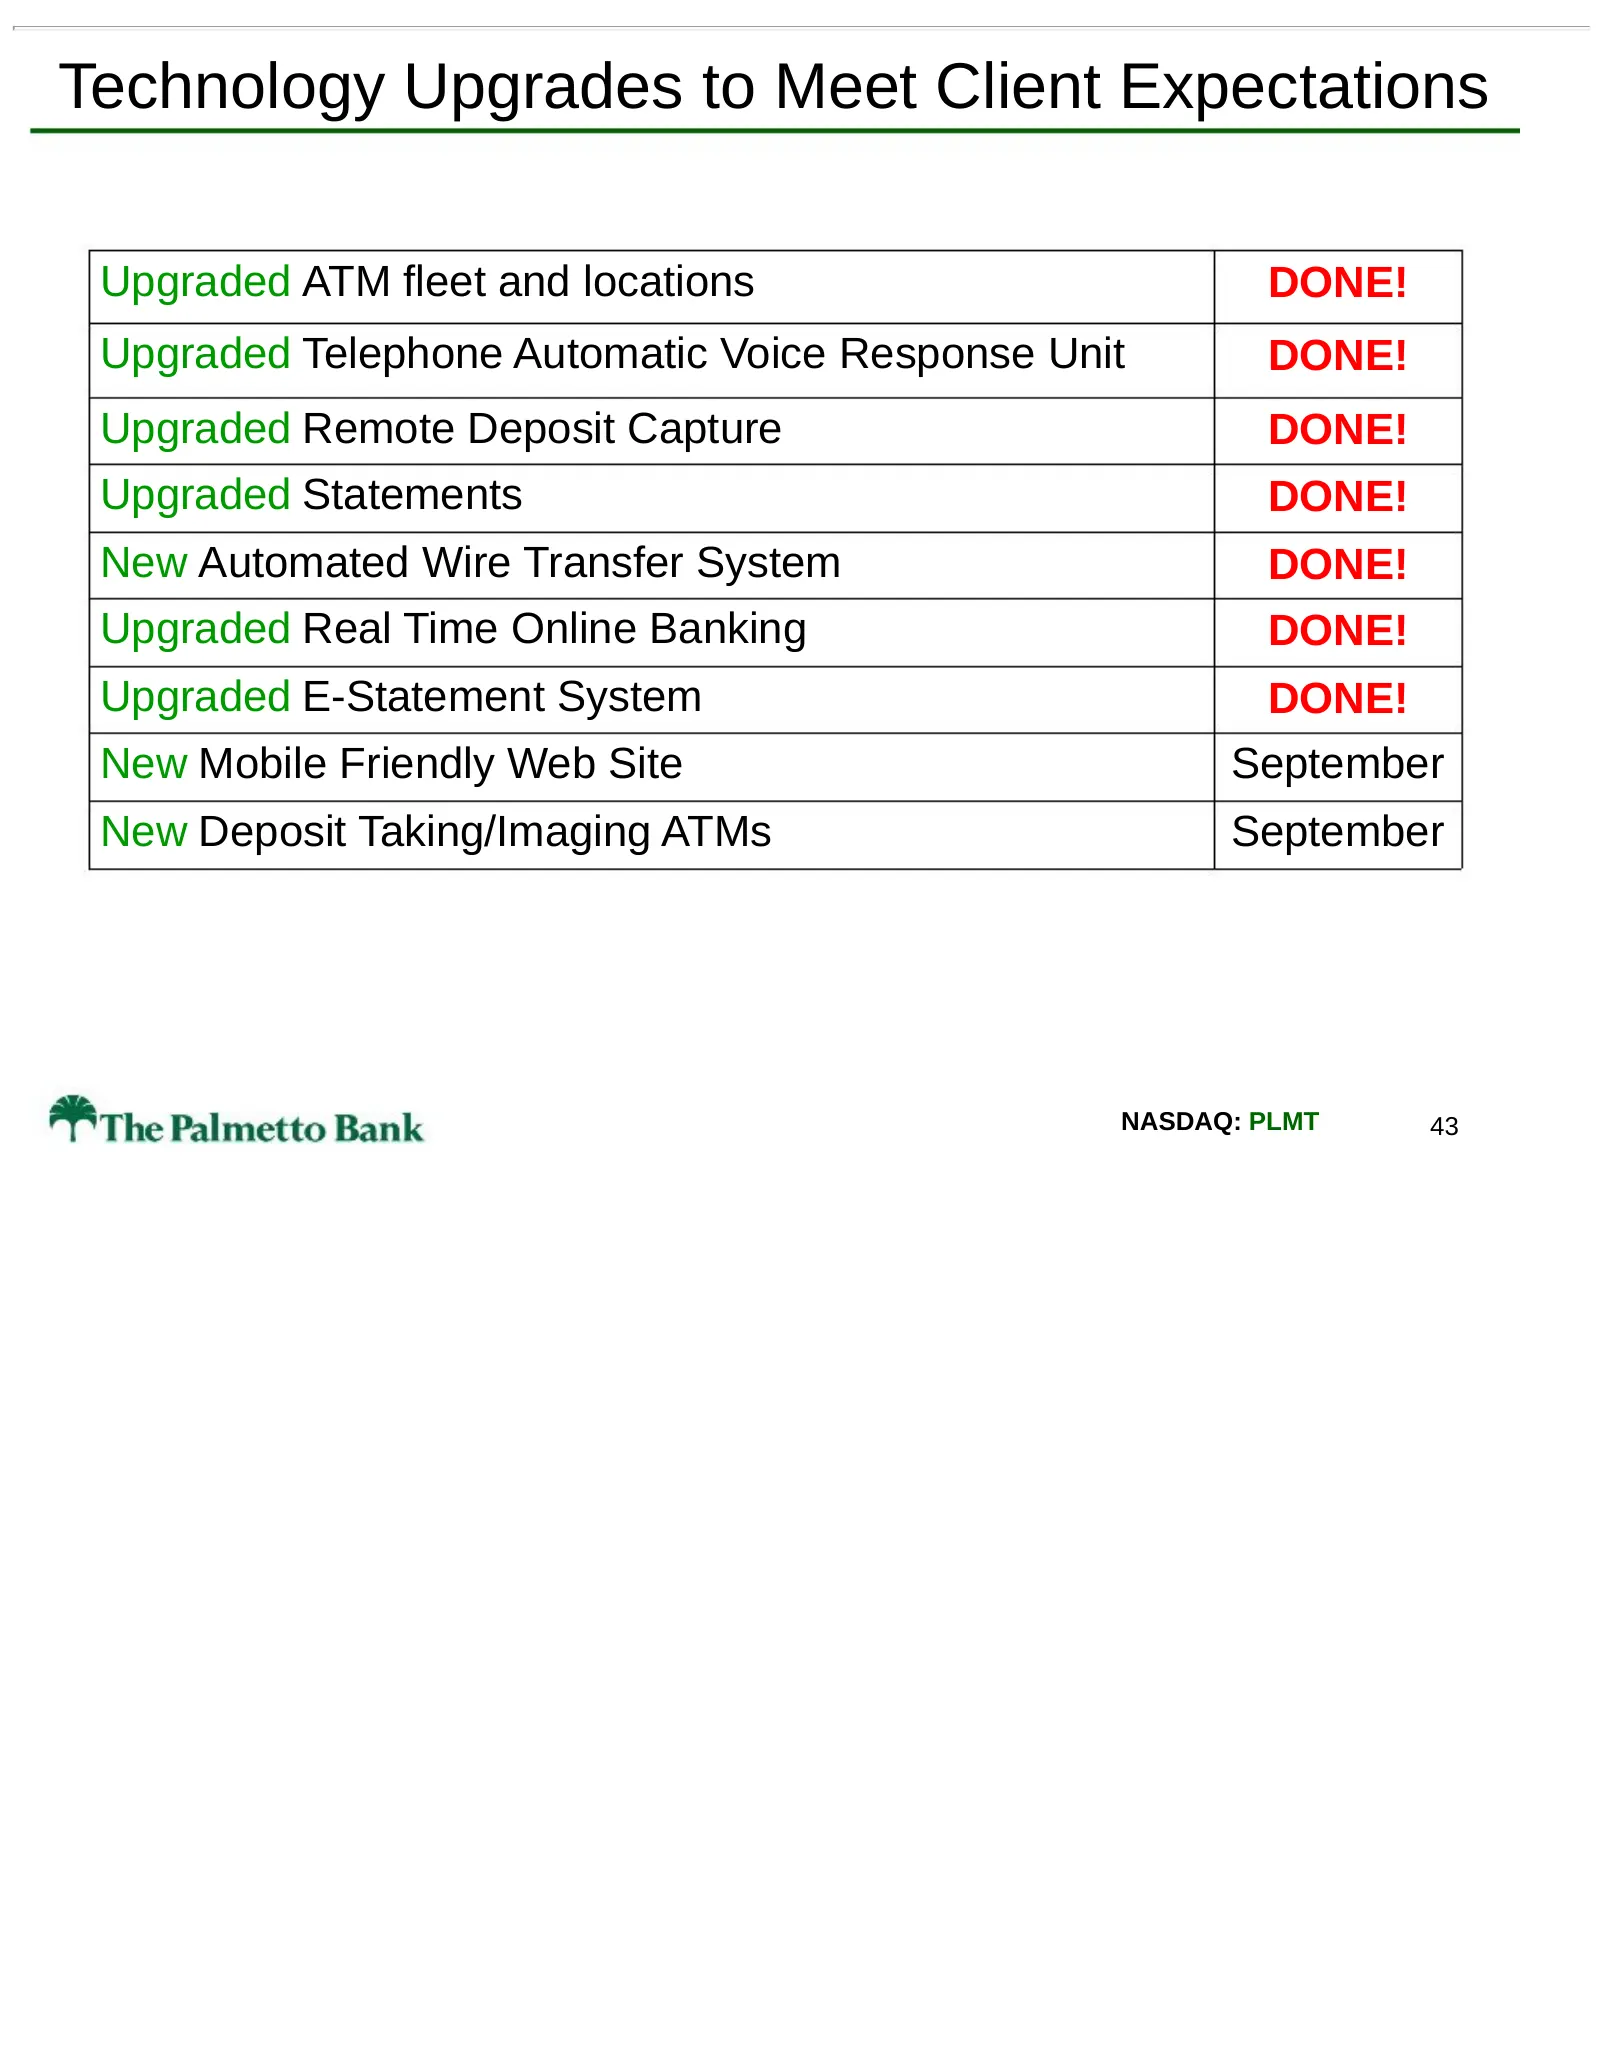
Slide 43: Technology Upgrades to Meet Client Expectations
Technology Upgrades to Meet Client Expectations Upgraded ATM fleet and locations DONE! Upgraded Telephone Automatic Voice Response Unit DONE! Upgraded Remote Deposit Capture DONE! Upgraded Statements DONE! New Automated Wire Transfer System DONE! Upgraded Real Time Online Banking DONE! Upgraded E-St
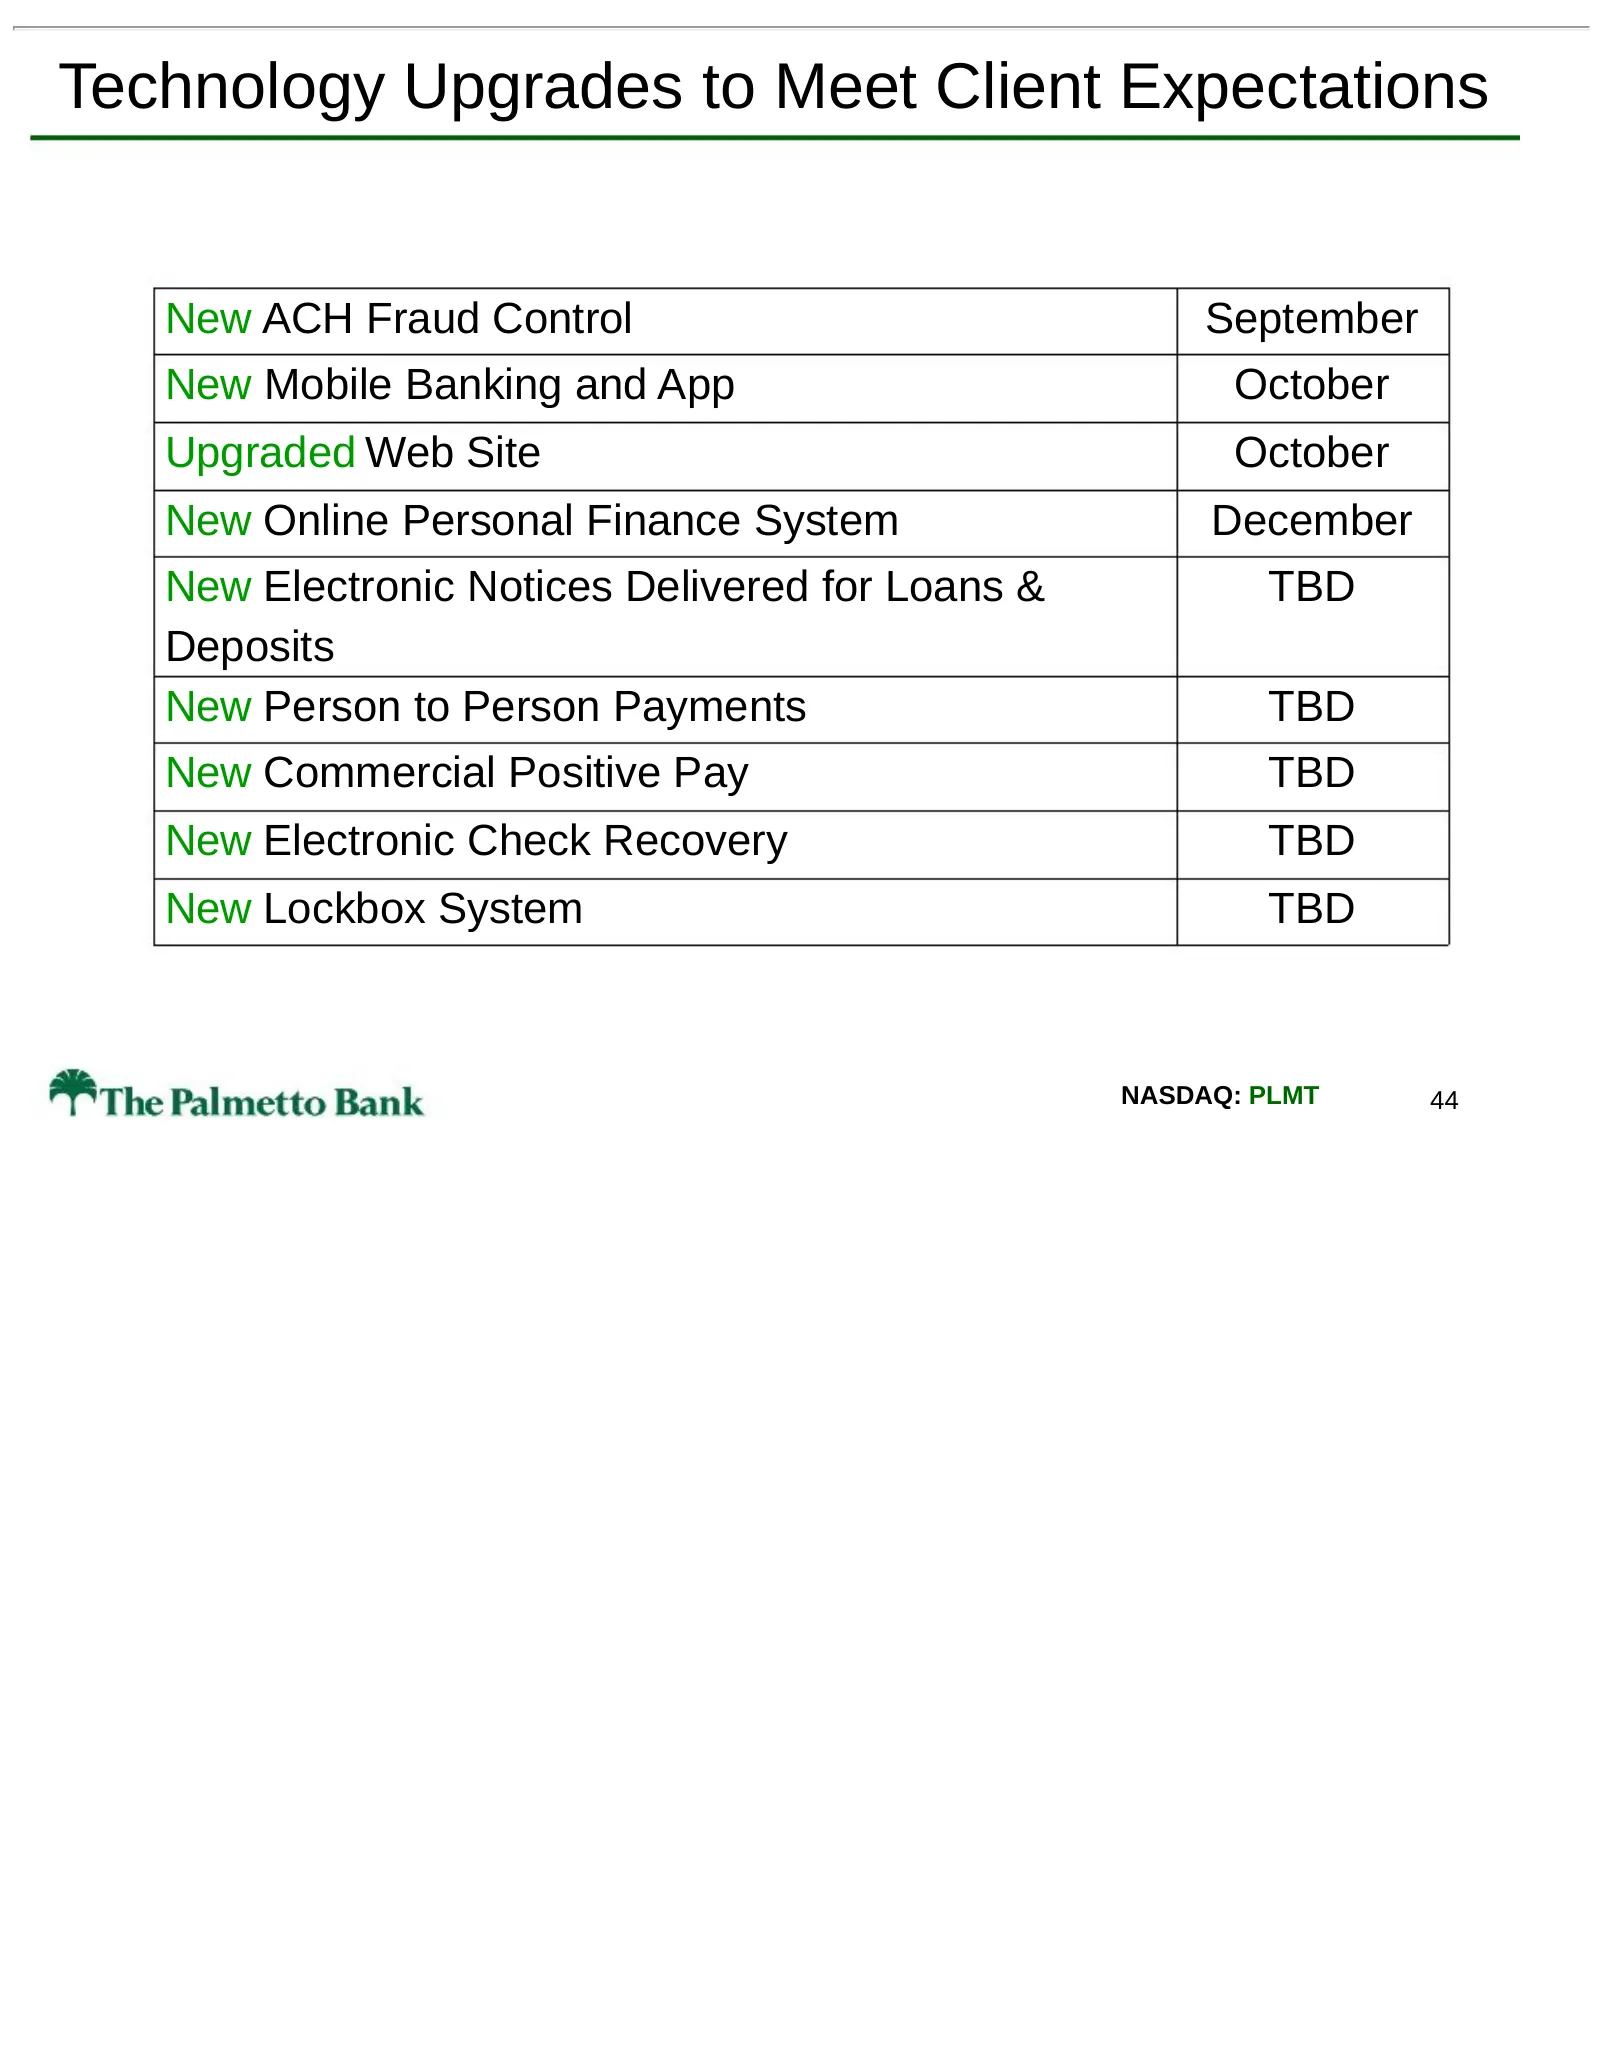
Slide 44: Technology Upgrades to Meet Client Expectations
Technology Upgrades to Meet Client Expectations New ACH Fraud Control September New Mobile Banking and App October Upgraded Web Site October New Online Personal Finance System December New Electronic Notices Delivered for Loans & TBD Deposits New Person to Person Payments TBD New Commercial Positive
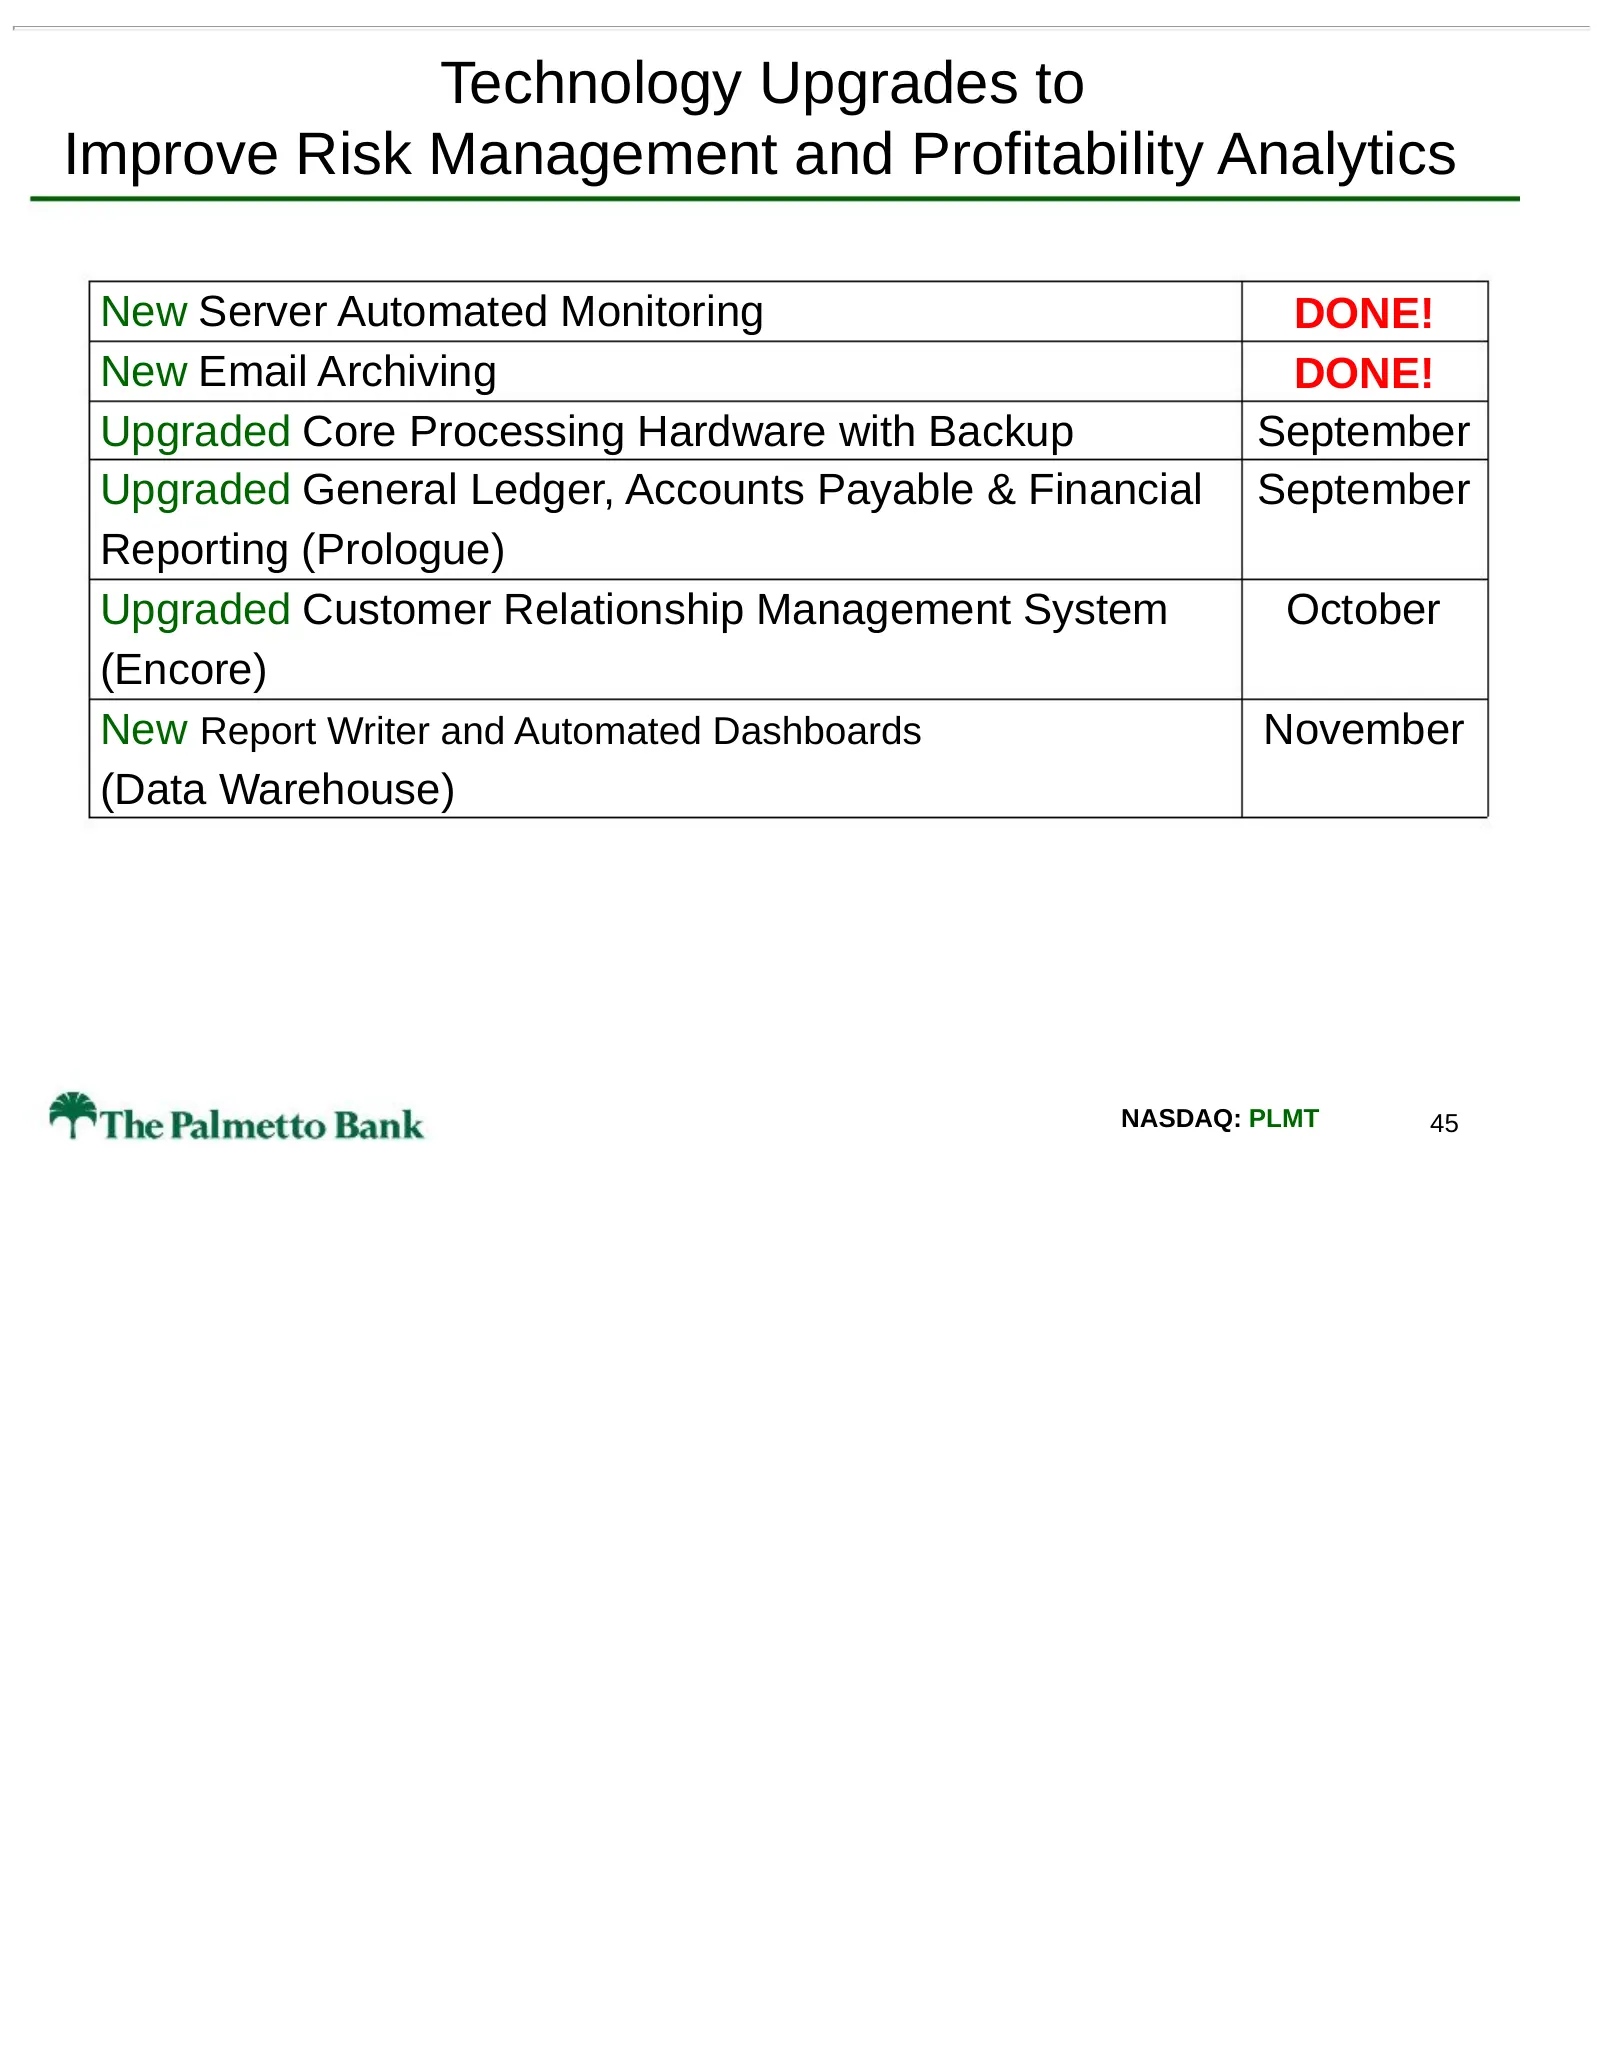
Slide 45: Technology Upgrades to Improve Risk Management and Profitability Analytics
Technology Upgrades to Improve Risk Management and Profitability Analytics New Server Automated Monitoring DONE! New Email Archiving DONE! Upgraded Core Processing Hardware with Backup September Upgraded General Ledger, Accounts Payable & Financial September Reporting (Prologue) Upgraded Customer Re
Slide 46: 5. Develop a High Performing Culture and Winning Team
5. Develop a High Performing Culture and Winning Team NASDAQ: PLMT 46
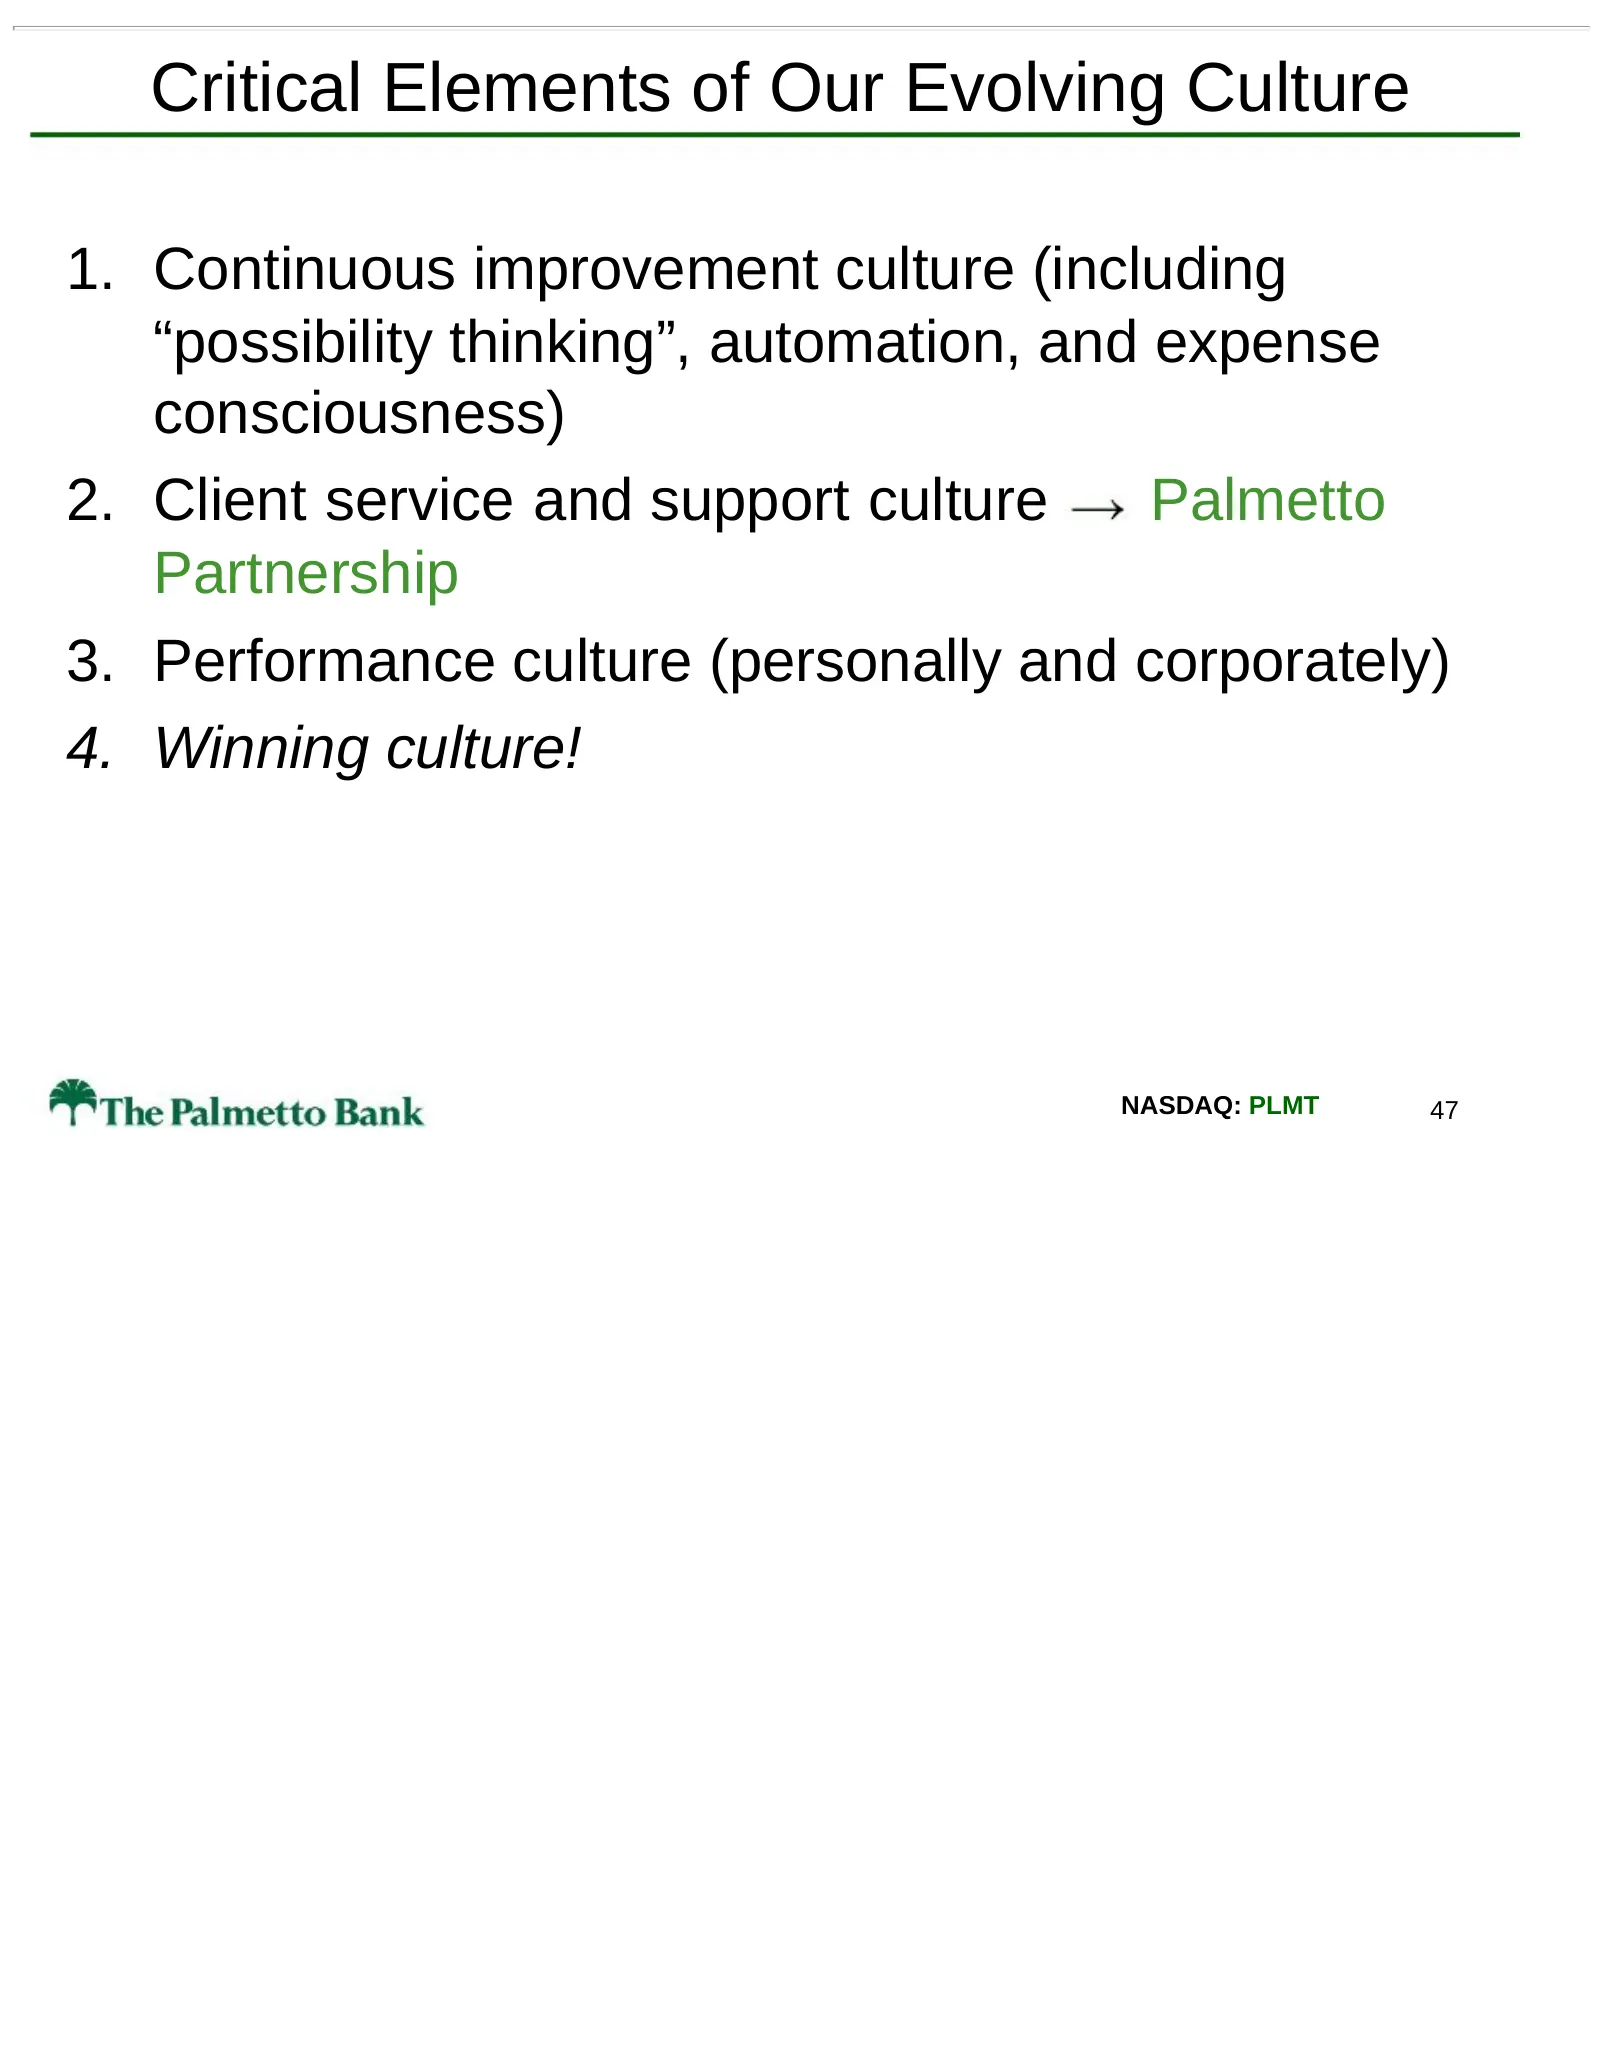
Slide 47: Critical Elements of Our Evolving Culture
Critical Elements of Our Evolving Culture 1. Continuous improvement culture (including “possibility thinking”, automation, and expense consciousness) 2. Client service and support culture Palmetto Partnership 3. Performance culture (personally and corporately) 4. Winning culture! NASDAQ: PLMT 47
Slide 48: Strategic Outlook
Strategic Outlook NASDAQ: PLMT 48
Slide 49: 2012 Outlook
2012 Outlook 1. General economic challenges although some have begun to moderate in the Upstate 2. Manage net interest income through continued reduction in time deposit balances and rates, and reinvestment of excess cash 3. Improving loan production but still a challenge and very competitive 4. Foc
Slide 50: Longer-Term Outlook
Longer-Term Outlook 1. Improving and sustained profitability 2. Removal of Consent Order (2013?) 3. Reduction of allowance for loan losses coverage ratio 4. Reversal of deferred tax asset valuation allowance 5. Improved efficiency ratio (continuation of Project SAVE) 6. Focused loan production strat
Slide 51: Overall Summary
Overall Summary NASDAQ: PLMT 51
Slide 52: Value Creation and the Client Experience
Value Creation and the Client Experience Now spending much more of our time and energy on the future instead of the past… 1. An experienced team, including M&A and niche expertise (Retail, Commercial, SBA, Corporate, C&I, etc.) 2. Product and service bundling focused on the business and personal lif
Slide 53: Summary Thoughts on the Path Forward
Summary Thoughts on the Path Forward 1. Significant progress on the path to profitability 2. Asset quality has been aggressively improved 3. Substantially completed the transition from “workout” mode to “value creation” mode 4. Clarity of the path forward - more focused Bank, department, and individ
Slide 54: Value of The Palmetto Bank Franchise
Value of The Palmetto Bank Franchise 1. 105 year legacy with excellent reputation and strong brand recognition 2. Historical high performing financial results, with history of innovation and balanced and fair pricing to our clients 3. Premier deposit-gathering franchise in an attractive banking mark
Source: SEC EDGAR · 8-K filed Sep 14, 2012
More decks from Palmetto Bancshares Inc
 Merger or Acquisition (August 2015)17 slides · Aug 12, 2015
 Shareholder Meeting (May 2015)28 slides · May 21, 2015
 Merger or Acquisition (April 2015)15 slides · Apr 22, 2015
 Investor Presentation (September 2014)25 slides · Sep 15, 2014
 Investor Presentation (June 2014)24 slides · Jun 24, 2014
 Shareholder Meeting (May 2014)26 slides · May 15, 2014