Medco Health Solutions — Investor Day (November 2007)
140 slides from Medco Health Solutions's investor day presentation, Nov 16, 2007
Slide 1: Medco 2007 Analyst Day
1 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco 2007 Analyst Day November 16, 2007 Medco 2007 Analyst Day November 16, 2007
Slide 2: Valerie C. Haertel, Vice President, Investor Relations
Medco 2007 Analyst Day Valerie C. Haertel Vice President, Investor Relations Medco 2007 Analyst Day Valerie C. Haertel Vice President, Investor Relations
Slide 3: Forward-looking Statements
3 © 2007 Medco Health Solutions, Inc. All rights reserved. Forward-looking Statements This presentation contains “ forward - looking statements ” “ forward - looking statements ” forward - looking statements ” - looking statements &
Slide 4: Medco 2007 Analyst Day agenda
4 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco 2007 Analyst Day Q&A / Closing Remarks Lunch Opening Video “ Leading the Way with Clinical Innovation ” Leading the Way with Clinical Innovation ” ” Break Registration & Continental Breakfast V. Haertel Welcome D. Snow Th
Slide 5: Advancing the Practice of Pharmacy: The Medco Strategy
5 © 2007 Medco Health Solutions, Inc. All rights reserved. Advancing the Practice of Pharmacy The Medco Strategy Advancing the Practice of Pharmacy Engaging Members Aligned Strategic Interests with Clients Strengthening Our Lead in Specialty Pharmacy Executing a Client- Focused Fiscal Plan Leading t
Slide 6: The Medco Strategy
The Medco Strategy David Snow Chairman and CEO The Medco Strategy David Snow Chairman and CEO
Slide 7: The Medco Strategy: 2007 Review, 2008 Focus, The Bigger Strategy
7 © 2007 Medco Health Solutions, Inc. All rights reserved. The Medco Strategy 2007 Review 2008 Focus The Bigger Strategy The Medco Strategy 2007 Review 2008 Focus The Bigger Strategy
Slide 8: 2007 Core Strategic Growth Drivers
8 © 2007 Medco Health Solutions, Inc. All rights reserved. New Business and Renewals Specialty Pharmacy 2007 Core Strategic Growth Drivers Generics Clinical Innovation Mail Order Solutions for Seniors New Business and Renewals Specialty Pharmacy 2007 Core Strategic Growth Drivers Generics Clinical I
Slide 9: 2007 Core Strategic Growth Drivers: Mail Order, Generics
9 © 2007 Medco Health Solutions, Inc. All rights reserved. Record GDR of 60.3% in 3Q07 Growth of 4.3 percentage points from 3Q06 New generic introductions contribute approximately $0.35 EPS in 2007 Volume of 23.5 million in 3Q07 On track to reach record volume of 95 million in 2007 YOY growth of 6.7
Slide 10: 2007 Core Strategic Growth Drivers: Specialty Pharmacy, Solutions for Seniors
10 © 2007 Medco Health Solutions, Inc. All rights reserved. GDR of 64.5% in 3Q07 Adjusted mail-order penetration of 30.6% in 3Q07 Broad portfolio of product offerings Accredo gross margin of 7.8% in 3Q07 YOY 3Q07 operating income growth of 18.8% 3Q07 Net revenue growth of 11% Accredo expected to gro
Slide 11: 2007 Core Strategic Growth Drivers: Clinical Innovation, New Business
11 © 2007 Medco Health Solutions, Inc. All rights reserved. Delivered Medco Therapeutic Resource Centers TM TM Announced Mayo Clinic (Coumadin ® ) and LabCorp (Tamoxifen) collaborations Closed $1.5 billion PolyMedica acquisition Closed Accredo acquisition of Critical Care Systems 96.3% retention rat
Slide 12: Record 2007 YTD EBITDA Per Adjusted Script
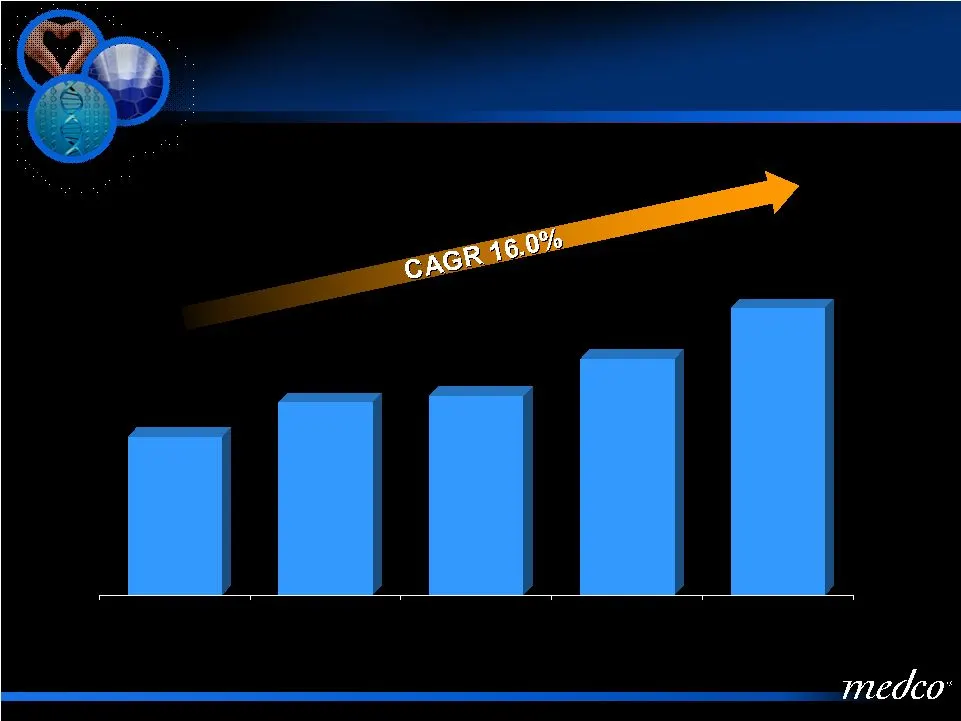
12 © 2007 Medco Health Solutions, Inc. All rights reserved. $1.50 $1.83 $1.89 $2.24 $2.72 2003 2004 2005 2006* 9/2007 YTD * Excludes first-quarter 2006 legal settlements charge; see reconciliation to GAAP financial tables in appendix. Record 2007 YTD EBITDA Per Adjusted Script Record 2007 YTD EBITDA
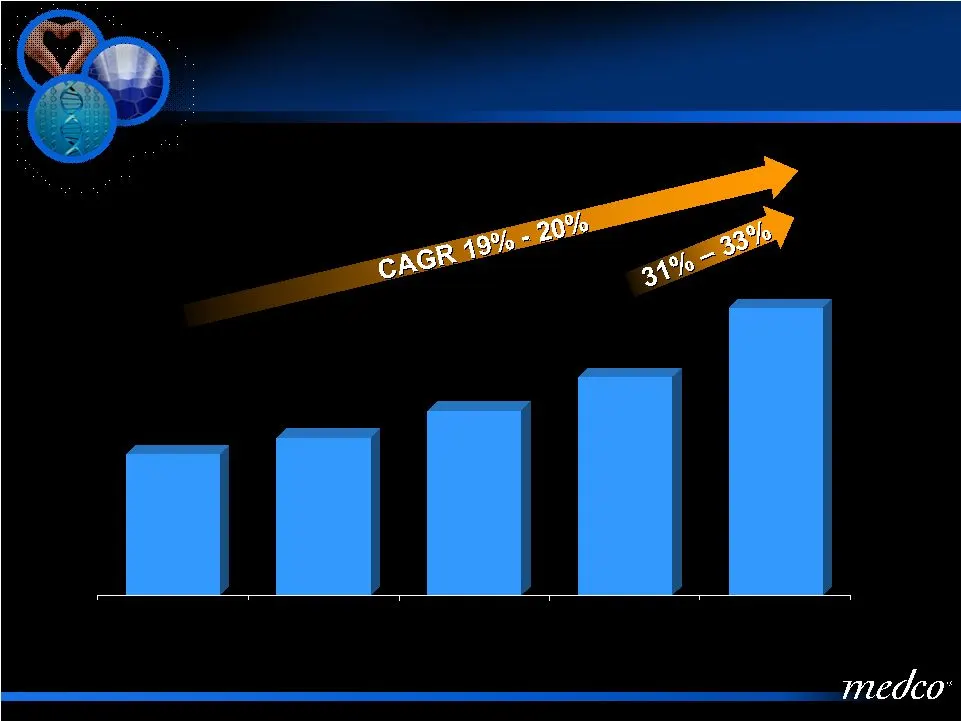
Slide 13: Strong 2007 Earnings Per Share Growth
13 © 2007 Medco Health Solutions, Inc. All rights reserved. 2003 2004 2005 2006* 2007E Strong 2007 Earnings Per Share Growth $1.57 $1.75 $2.05 $3.16 – $3.21 $2.42 * Excludes first-quarter 2006 legal settlements charge; see reconciliation to GAAP financial tables in appendix . Strong 2007 Earnings Pe
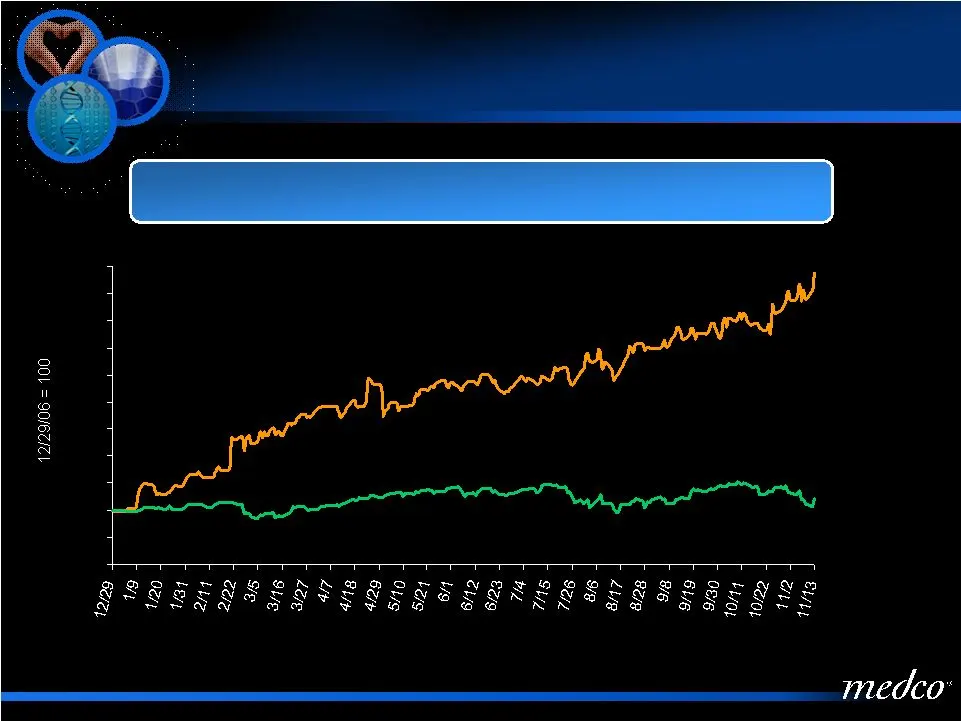
Slide 14: Strong 2007 YTD Equity Appreciation
14 © 2007 Medco Health Solutions, Inc. All rights reserved. Strong 2007 YTD Equity Appreciation 80 90 100 110 120 130 140 150 160 170 180 190 Source: Thomson Financial MHS 2007 YTD Return Through 11/13/07: +87.4% Strong 2007 YTD Equity Appreciation MHS: +87.4% S&P 500: +4.4% MHS 2007 YTD Return Thro
Slide 15: 2008 Focus: The Medco Growth Strategy
15 © 2007 Medco Health Solutions, Inc. All rights reserved. 2008 Focus The Medco Growth Strategy 2007 Review 2008 Focus The Bigger Strategy The Medco Growth Strategy
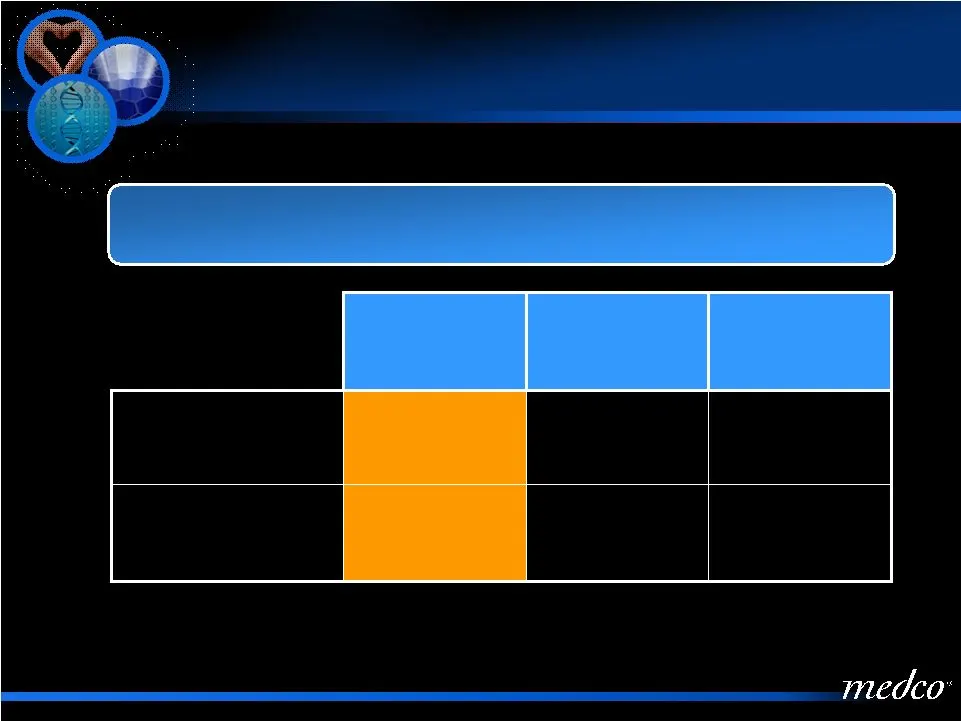
Slide 16: 2008 EPS Guidance
16 © 2007 Medco Health Solutions, Inc. All rights reserved. 2008 EPS Guidance 19%–24% $3.55–$3.60 EPS (adj. for intangible amortization) 21%–27% $3.16–$3.21 EPS (GAAP) % Growth 2007 Revised Guidance 2008 Guidance *Excludes first-quarter 2006 legal settlements charge; see reconciliation to GAAP finan
Slide 17: Generic Growth Opportunity
17 © 2007 Medco Health Solutions, Inc. All rights reserved. 2006 2007 2008 2009 2010 2011 2012 Generic Growth Opportunity Zocor ® Zoloft ® Plavix ® Pravachol ® Flonase ® $16.1 (1) Lotrel ® Norvasc ® Ambien ® Coreg ® Toprol XL ® Risperdal ® Fosamax ® Depakote ® Prevacid ® Topamax ® Lamictal ® Valtrex
Slide 18: Generic Growth Opportunity: Chronic and Complex Conditions
18 © 2007 Medco Health Solutions, Inc. All rights reserved. 2006 2007 2008 2009 2010 2011 2012 Lipitor ® Effexor XR ® Generic Growth Opportunity 89% (1) The Majority of Generics Coming to Market Treat Chronic and Complex Conditions Over $65 billion in Brand Drugs Off-Patent from 2007–2012 1) Include
Slide 19: 2008 Brand Drugs to Watch for Early Generics Releases
19 © 2007 Medco Health Solutions, Inc. All rights reserved. 2008 Brand Drugs to Watch for Early Generics Releases If released early, a full-year contribution of Protonix and a half-year contribution of Effexor XR tablet could add up to $0.08–$0.10 in EPS $4.8B Unscheduled Potential for Early Generic
Slide 20: 2008 Generic Growth Opportunity
20 © 2007 Medco Health Solutions, Inc. All rights reserved. 2006 2007 2008 2009 2010 2011 2012 2008 Generic Growth Opportunity $6.8 (1) $19.7 (2) $27.3 (2) $35.9 (2) $45.5 (2) $56.1 (2) $73.4 (1) 1) Includes Plavix®, $2.7B annual US spend; (2) Excludes Plavix, $2.7B annual US spend. Source: U.S. Dru
Slide 21: 2008E Mail-Order Volume Growth
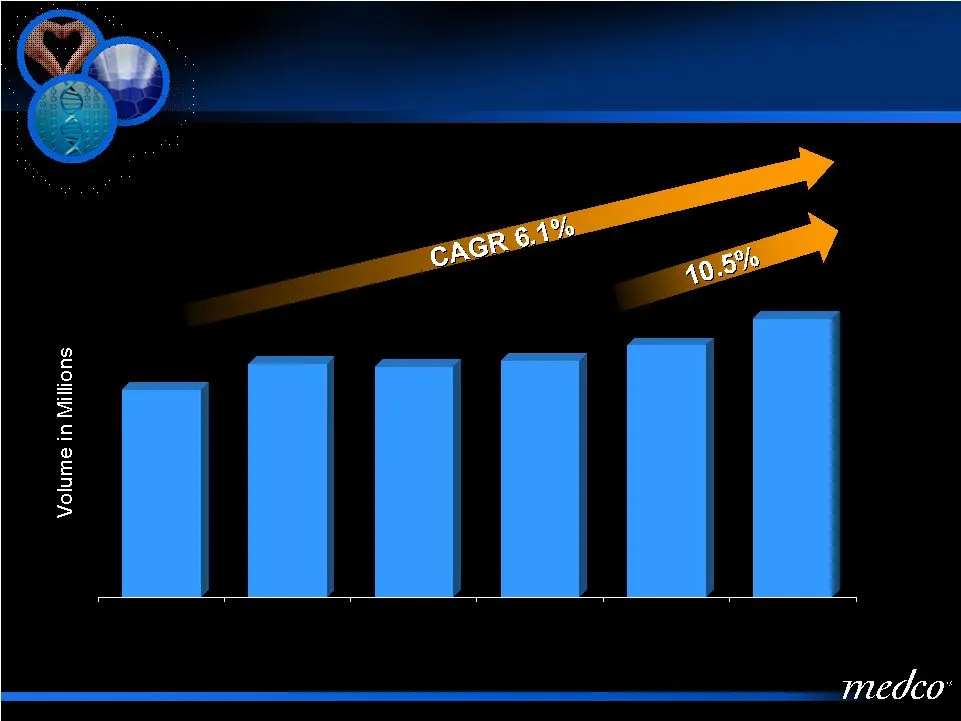
21 © 2007 Medco Health Solutions, Inc. All rights reserved. 78 88 87 89 ~95 ~105 2003 2004 2005 2006 2007E 2008E 2008E Mail-Order Volume Growth 2008E Mail-Order Volume Growth
Slide 22: Robust Biotechnology Drug Pipeline
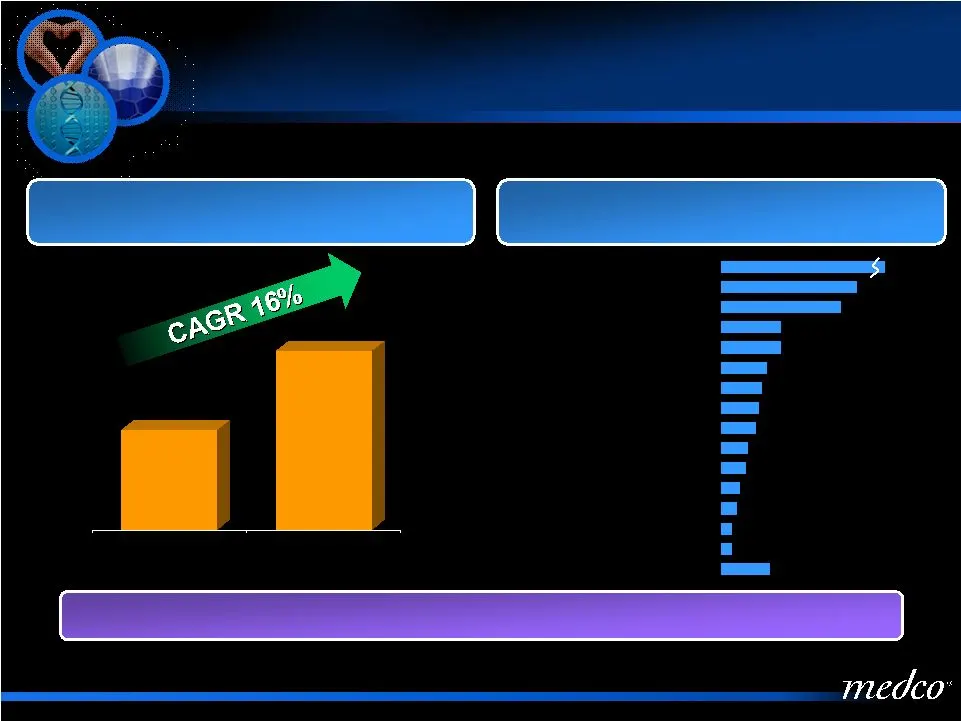
22 © 2007 Medco Health Solutions, Inc. All rights reserved. Robust Biotechnology Drug Pipeline Source: HealthStrategiesGroup HealthStrategiesGroup *Source: PhRMA 2005 Survey: Medicines in Development , , Oct. 2006 Some medicines are listed in more than one category. Specialty Pharmacy Drug Spend ($
Slide 23: Seniors Market Strategy
23 © 2007 Medco Health Solutions, Inc. All rights reserved. Announced three new Medicare prescription drug plan offerings for 2008 to provide more choice and better value to seniors 26 geographic regions Potential to further leverage the well-known Liberty Medical brand in the seniors market Seniors
Slide 24: 2008 New Business and Renewals
24 © 2007 Medco Health Solutions, Inc. All rights reserved. 2008 New Business and Renewals* $4.5B 2008 calendarized new named drug spend to date $4.8B Completed 34% of 2008 total renewal activity 63.3% Adjusted mail-order penetration rate for new named accounts *As of 3Q07 2008 New Business and Rene
Slide 25: Environmental Update
25 © 2007 Medco Health Solutions, Inc. All rights reserved. CVS/Caremark No meaningful changes in competitive environment since merger Environmental Update AWP/AMP Medco contract language protects the relative economics of both the client and Medco regardless of benchmark used for pricing Political
Slide 26: The Medco Strategy: The Bigger Strategy
26 © 2007 Medco Health Solutions, Inc. All rights reserved. The Medco Strategy The Bigger Strategy The Medco Strategy 2007 Review 2008 Focus The Bigger Strategy
Slide 27: The Medco Model
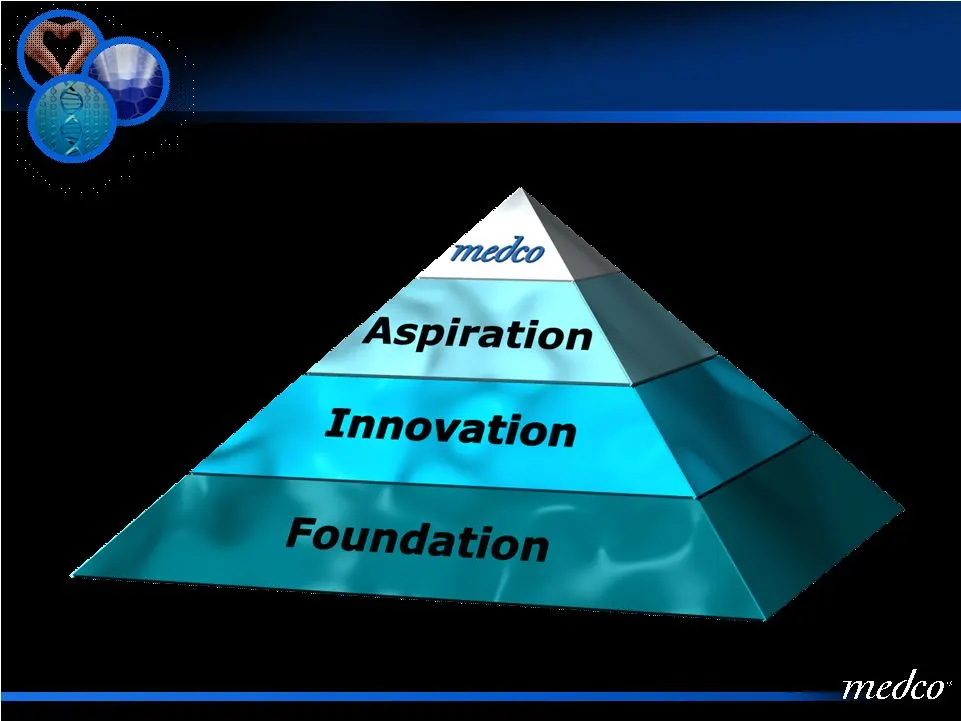
27 © 2007 Medco Health Solutions, Inc. All rights reserved. The Medco Model The Medco Model
Slide 28: A History of Successful Innovation and Growth
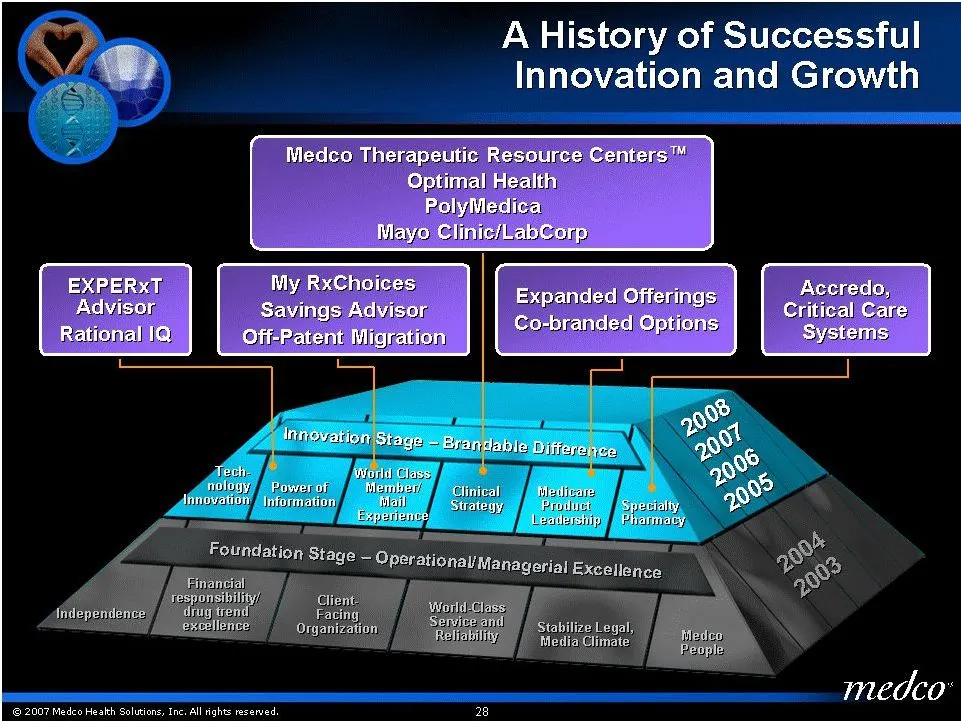
EXPERxT Advisor Rational IG) My RxChoices Savings Advisor, Off-Patent Mighation; A History of Successful Innovation and Growth Medco Therapeutic Resource Centers”™ Optimal Health) PolyMedicai Mayo Glinic/Labcorp Accredo, Critical Care Systems Expanded) Offerings. Co-branded Options, Foundation Stage
Slide 29: 96% of Rx Dollars Spent on Chronic and Complex Conditions
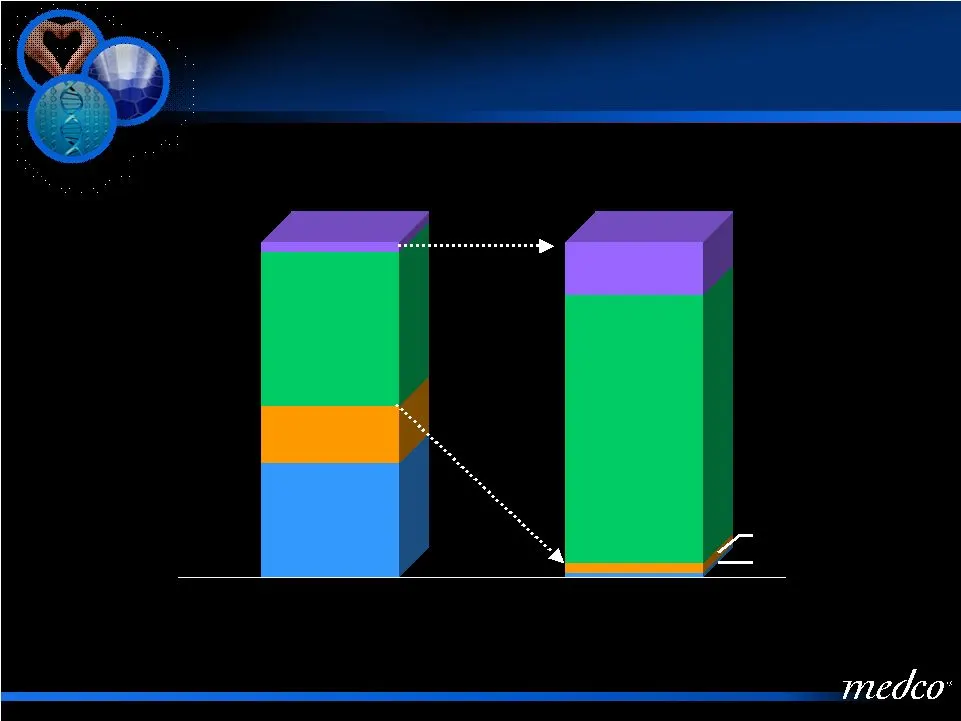
29 © 2007 Medco Health Solutions, Inc. All rights reserved. 96% of Rx Dollars Spent on Chronic and Complex Conditions 34% 3% 1% 3% 16% % Members % Rx Cost Source: Medco data 96% of Rx Dollars Spent on Chronic and Complex Conditions 17% 46% 80% Complex Chronic Acute Well
Slide 30: Therapeutic Resource Centers model
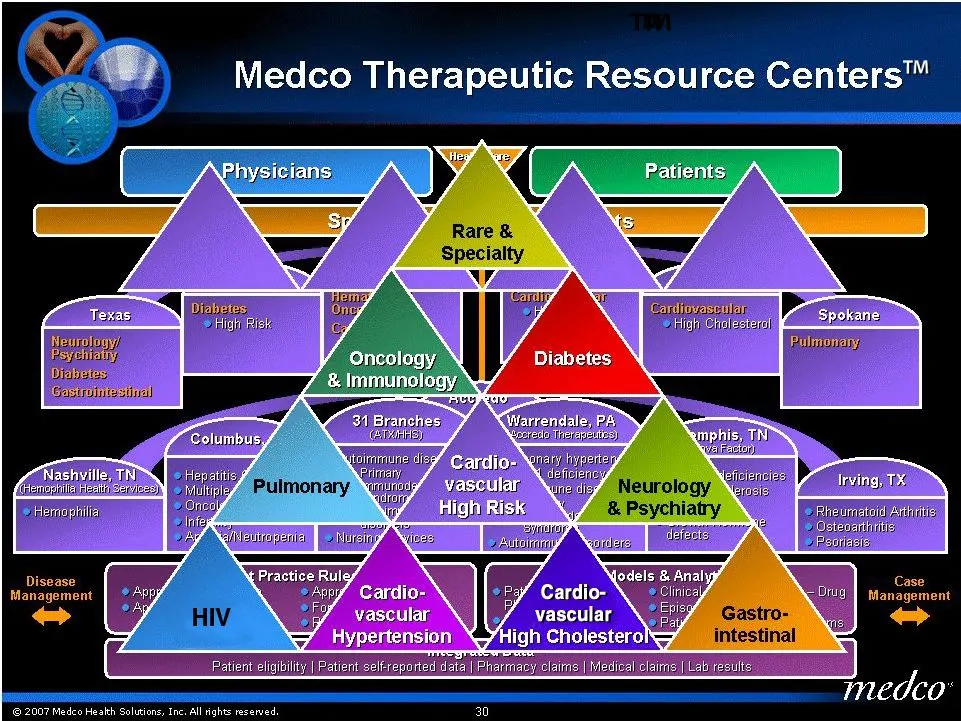
Neurology) Pulmonary, Psyciniatty, Diabetes Gasisuintestinal Nashville, TN (error Heath Neurology ‘© Hemophilia zis _ | & Psychiatry Rheumatoid Artin : 2 ss m istecarttinitiey Disease * d , Management =: Seaulet Hypertension Patient eligibility | Patient seltreported data | Pharmacy claims |/Medical
Slide 31: Diabetes
Slide 32: Anticoagulation
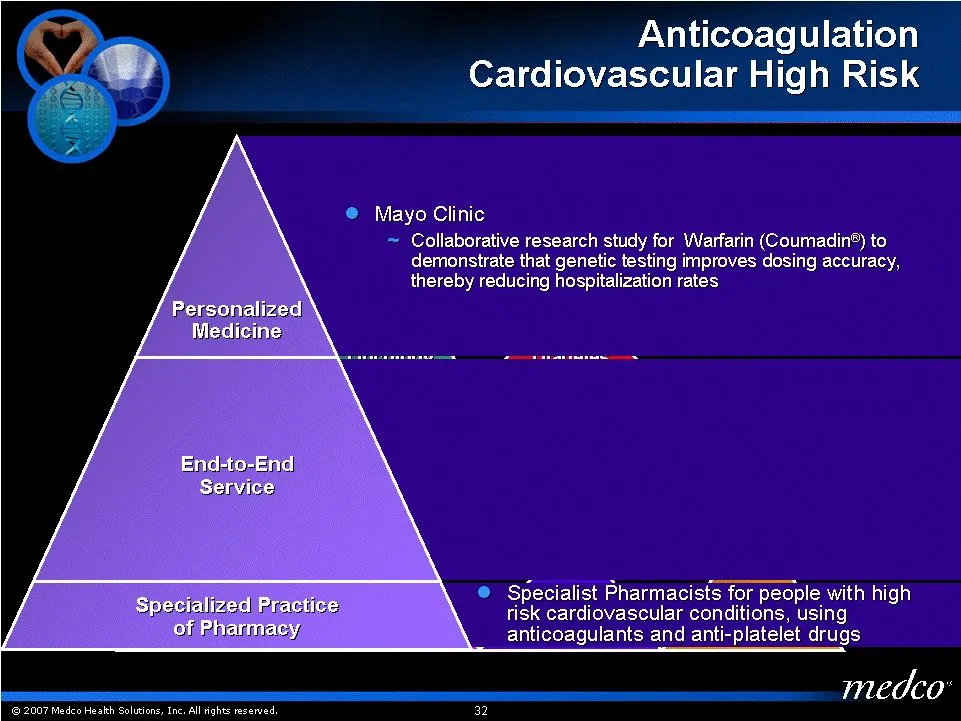
Anticoagulation Cardiovascular High Risk @ Mayo Clinic ~ Collaborative research study for Warfarin (Coumadin®) to demonstrate that genetic testing improves dosing accuracy, thereby reducing hospitalization rates ® Specialist Pharmacists for people with high risk cardiovascular conditions, using anti
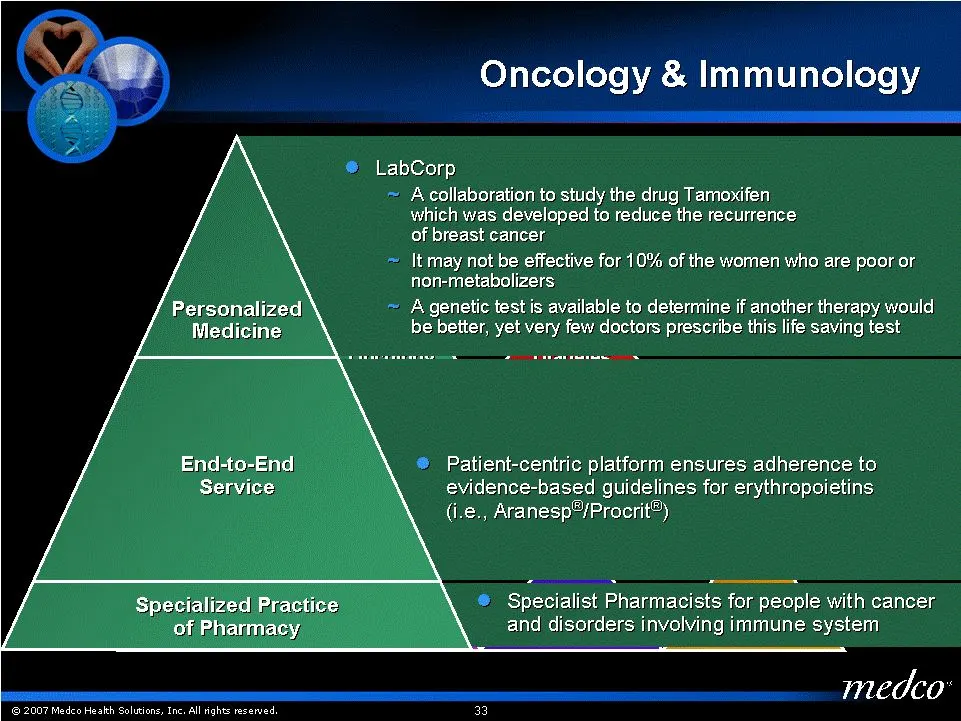
Slide 33: Oncology & Immunology
Oncology & Immunology ® LabCorp =~ A collaboration to study the drug Tamoxifen which was developed to reduce the recurrence of breast cancer = |tmay not be effective for 10% of the women who are poor or non-metabolizers = A genetic testis available to determine if another therapy would be better, ye
Slide 34: The Bigger Strategy: Core Growth Drivers and Expanding Markets
34 © 2007 Medco Health Solutions, Inc. All rights reserved. Enhance the Core Extend Capabilities Forge New Frontiers Drive Branded B to B and B to C Solutions Expand Specialty and Other Markets Growth Beyond Core Through TRC Platform Core Growth Drivers The Bigger Strategy Expand Markets Enhance the
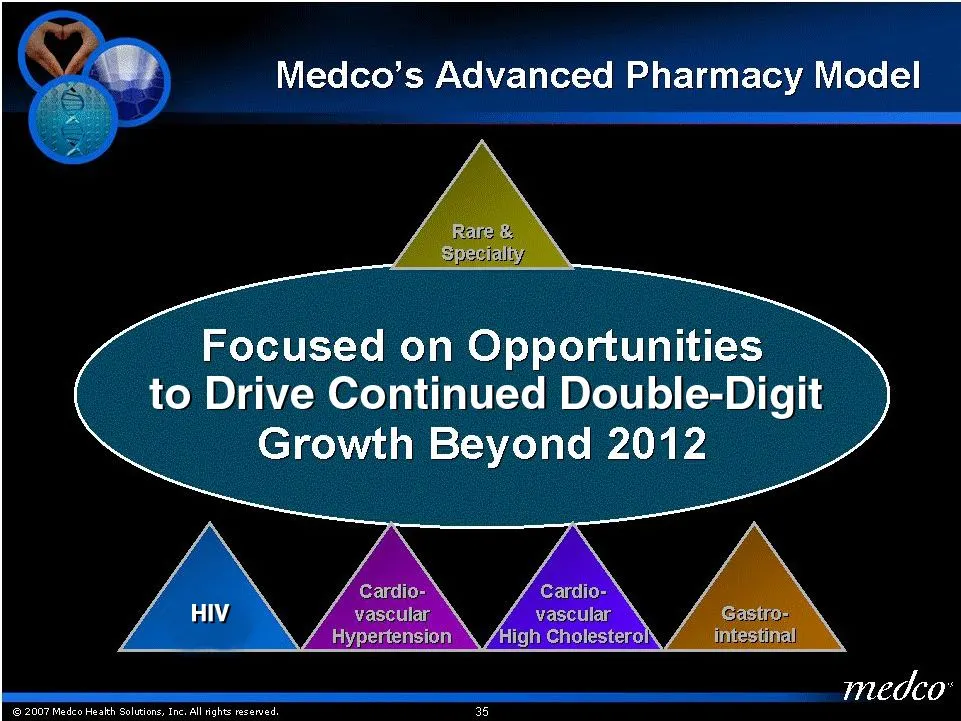
Slide 35: Medco's Advanced Pharmacy Model
y ® Medco’s Advanced Pharmacy Model Focused on Opportunities to Drive Continued Double-Digit Growth Beyond 2012 Cardio- " vascular \, igh Cholesterol, medco: 1007 Medco Health Solutions, Inc. All ights reserved. 36
Slide 36: Engaging Members
36 © 2007 Medco Health Solutions, Inc. All rights reserved. Advancing the Practice of Pharmacy Engaging Members The Medco Strategy Advancing the Practice of Pharmacy Aligned Strategic Interests with Clients Strengthening Our Lead in Specialty Pharmacy Executing a Client- Focused Fiscal Plan Leading
Slide 37: Engaging Members
Engaging Members Kenneth O. Klepper President & Chief Operating Officer Glen D. Stettin, M.D. SVP & General Manager, Clinical Therapeutic Solutions Engaging Members Kenneth O. Klepper President & Chief Operating Officer Glen D. Stettin, M.D. SVP & General Manager, Clinical Therapeutic Solutions
Slide 38: Different Members Have Different Needs
38 © 2007 Medco Health Solutions, Inc. All rights reserved. Our Unique Pharmacy Model Recognizes Different Members Have Different Needs Wrinkles, baldness, contraception, vitamins Well Colds and flu, strep throat, ear infection, headache, sprains Acute Heart disease, diabetes, arthritis, high blood
Slide 39: Delivering Personalized, Patient-Centered Care & Support
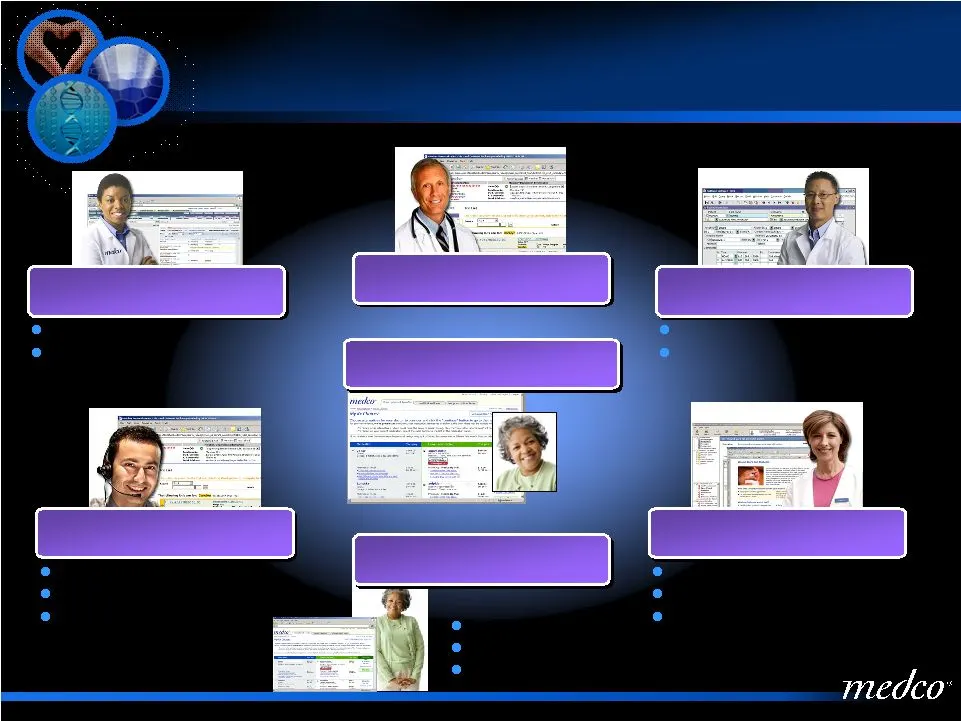
39 © 2007 Medco Health Solutions, Inc. All rights reserved. Safer, more effective pharmacy care Save money on your medications Personal Health Record Delivering Personalized, Patient- Centered Care & Support Health Plan Benefits & Claims Administration Unified Patient View powered by the Medco Knowl
Slide 40: 96% of Rx Dollars Spent on Chronic and Complex Conditions
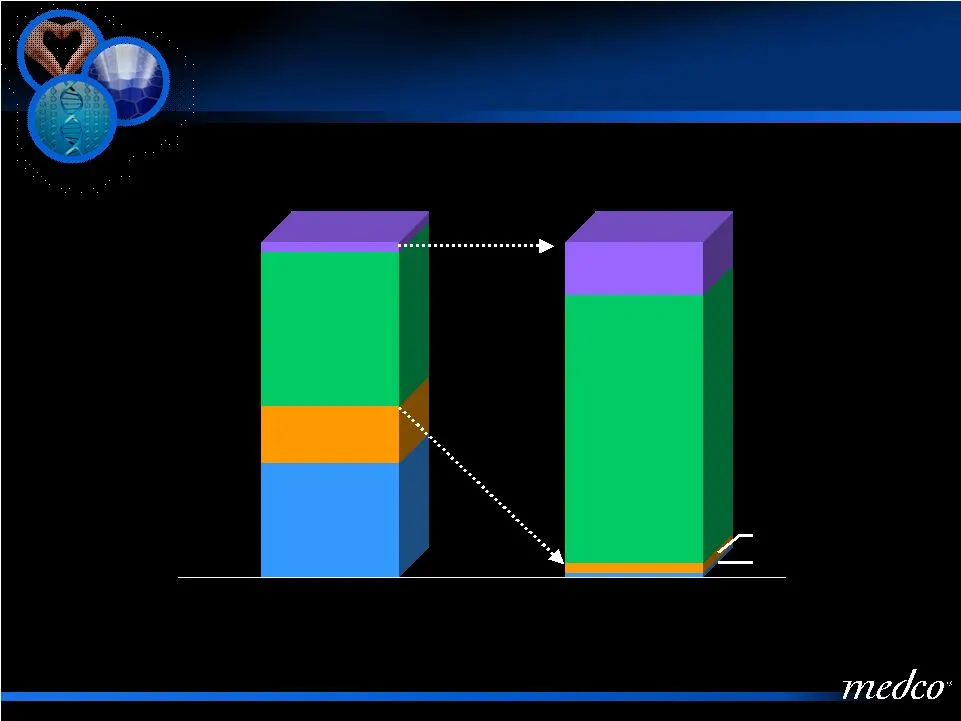
40 © 2007 Medco Health Solutions, Inc. All rights reserved. 96% of Rx Dollars Spent on Chronic and Complex Conditions 34% 3% 1% 3% 16% % Members % Rx Cost 96% of Rx Dollars Spent on Chronic and Complex Conditions 17% 46% 80% Complex Chronic Acute Well
Slide 41: Potential Mail-Order Opportunity
41 © 2007 Medco Health Solutions, Inc. All rights reserved. 2005 2006 2007E Chronic Rxs at Retail Members with Chronic and Complex Needs ~110 87 89 ~95 Medco Mail-Order Volume (Unadjusted Rx's, millions) Potential Mail-Order Opportunity Medco 2007E (Rx ’ s, millions) ’ s, millions) s, millions)
Slide 42: Value Proposition at Mail
42 © 2007 Medco Health Solutions, Inc. All rights reserved. Value Proposition at Mail Clinical Mail Drivers Value Proposition at Mail Clinical Convenience Financial
Slide 43: Medco Therapeutic Resource Centers Create a More Compelling Reason for Mail
43 © 2007 Medco Health Solutions, Inc. All rights reserved. The Medco Therapeutic Resource Centers TM TM Create a More Compelling Reason for Mail Our pharmacists are specialized Unique model and scale enable entire pharmacies to specialize Unique data capabilities bring specialist services to patien
Slide 44: Each Center Has Significant Opportunity for Growth
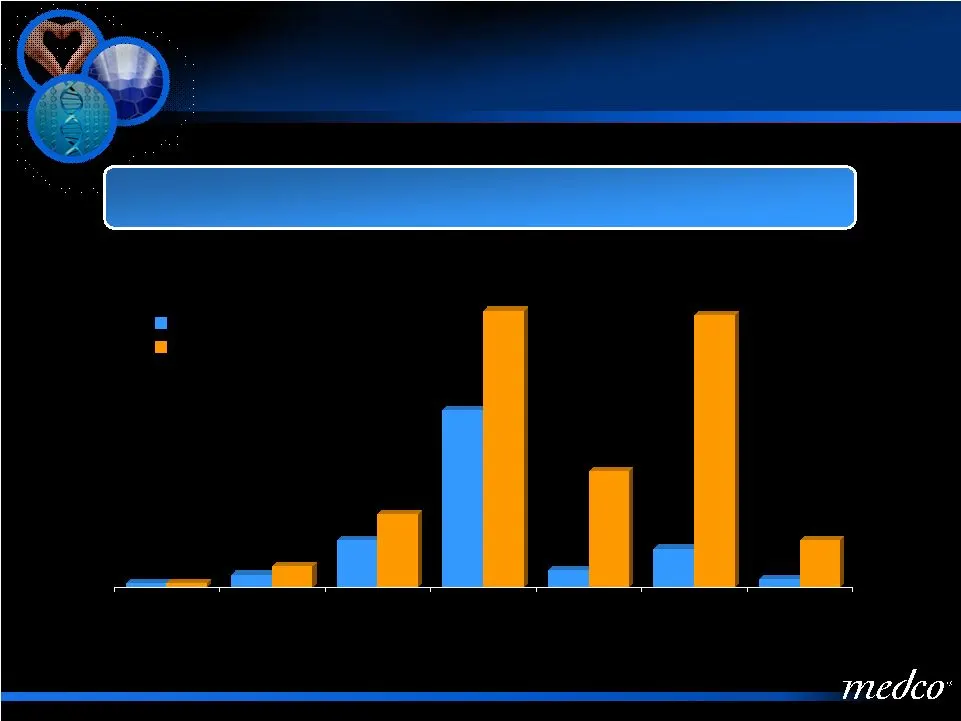
44 © 2007 Medco Health Solutions, Inc. All rights reserved. Each Center Has Significant Opportunity for Growth by Creating Value for Our Plans and Patients Patients & Opportunity, by TRC (Millions) * Excludes 1 million diabetic patients from Liberty (PolyMedica) 0.11 0.11 0.3 0.5 1.1 1.7 4.1 6.4 0.4
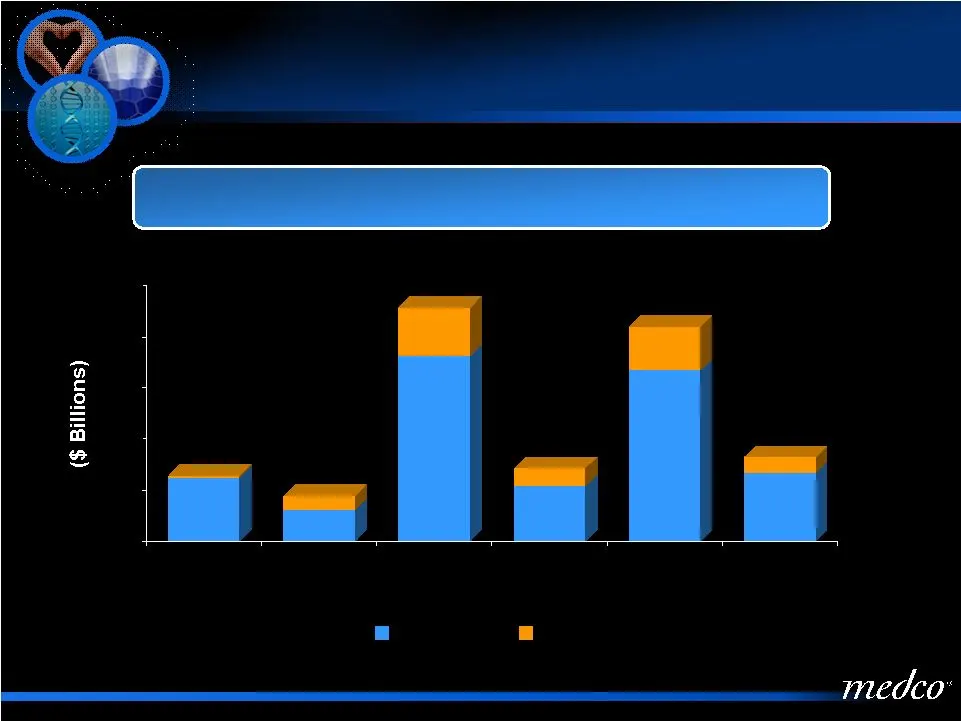
Slide 45: The Cost of Care in Our Areas of Specialization is Enormous
45 © 2007 Medco Health Solutions, Inc. All rights reserved. The Cost of Care for People with Needs in Our Areas of Specialization is Enormous Direct Health Care Cost by TRC Category Source: Center for Financing, Access and Cost Trends, Agency for Healthcare Research and Quality: Medical Expenditure
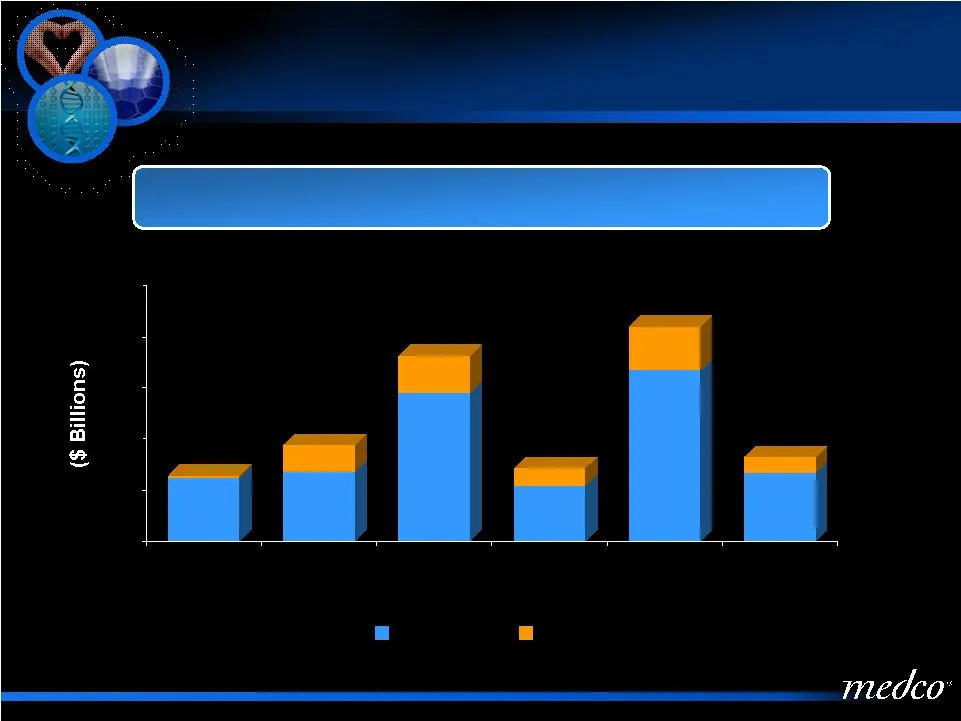
Slide 46: The Cost of Care in Our Areas of Specialization is Enormous
46 © 2007 Medco Health Solutions, Inc. All rights reserved. The Cost of Care for People with Needs in Our Areas of Specialization is Enormous Direct Health Care Cost by TRC Category Source: Center for Financing, Access and Cost Trends, Agency for Healthcare Research and Quality: Medical Expenditure
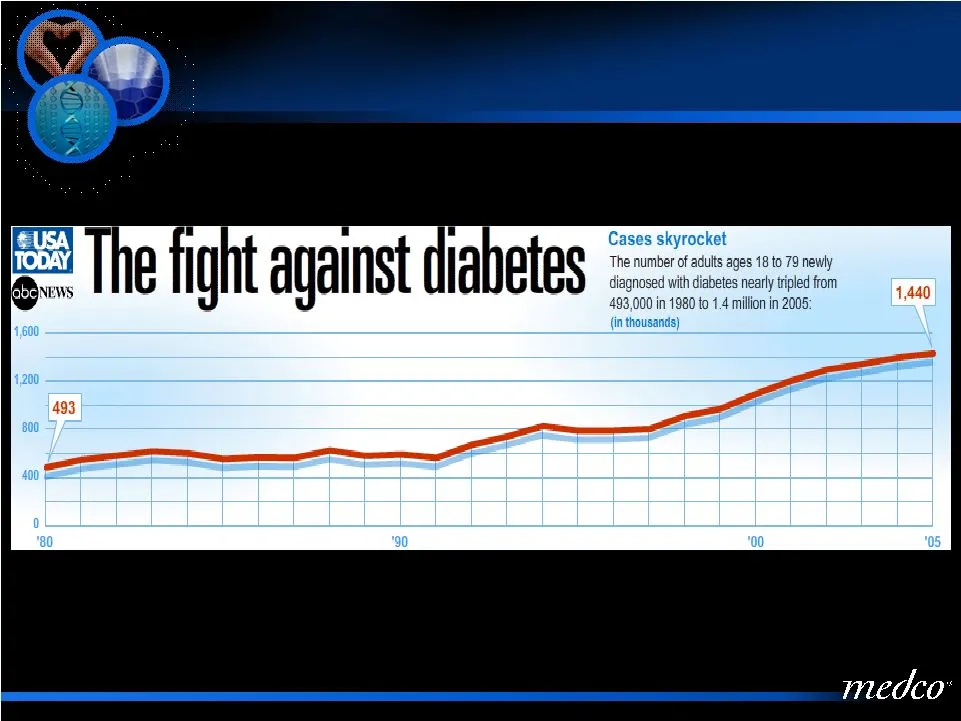
Slide 47: Newly Diagnosed with Diabetes Nearly Tripled
47 © 2007 Medco Health Solutions, Inc. All rights reserved. 1980-2005 Newly Diagnosed with Diabetes Nearly Tripled 1980-2005 Newly Diagnosed with Diabetes Nearly Tripled
Slide 48: Diabetes is a Huge and Growing Burden
48 © 2007 Medco Health Solutions, Inc. All rights reserved. Diabetes is a Huge and Growing Burden People: >20.8 million, U.S. Annual cost per person = $13,243 vs. $2,560, no diabetes Amputations – 82,000 / yr Kidney failure – 44,000 / yr Blindness – 24,000 / yr 2–4x heart attacks & strokes Source: A
Slide 49: Diabetes is a Huge and Growing Burden
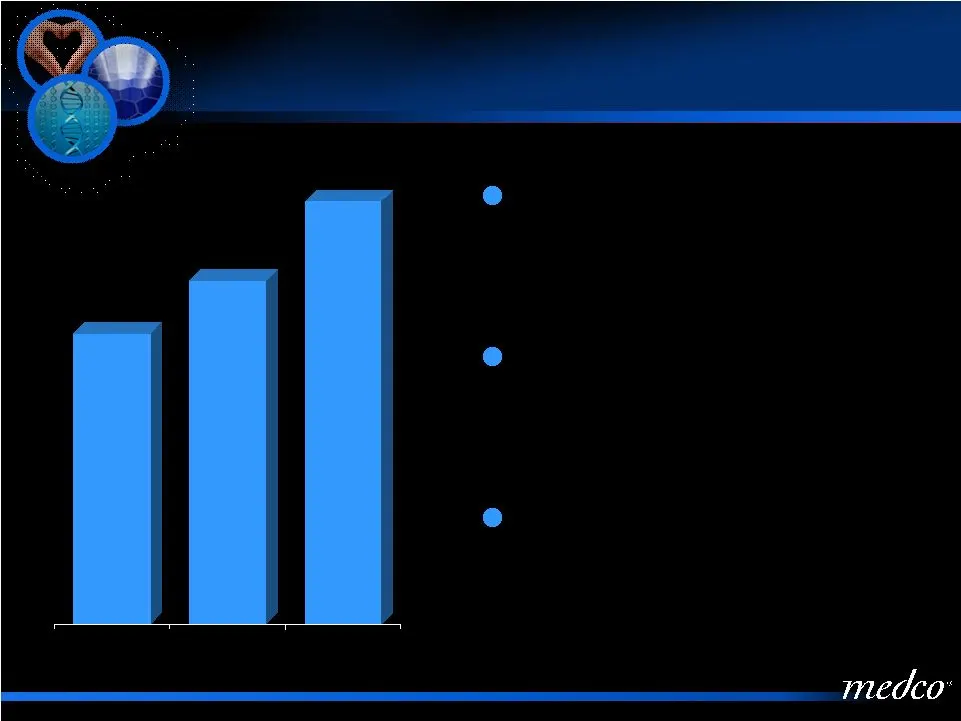
49 © 2007 Medco Health Solutions, Inc. All rights reserved. Diabetes is a Huge and Growing Burden By 2020, number of Americans with diabetes will double to over 40 million The cost of their diabetes will increase to over $192 billion There is a dramatic difference in the cost of care between people
Slide 50: Medco's Diabetes Centers Can Create Significant Value
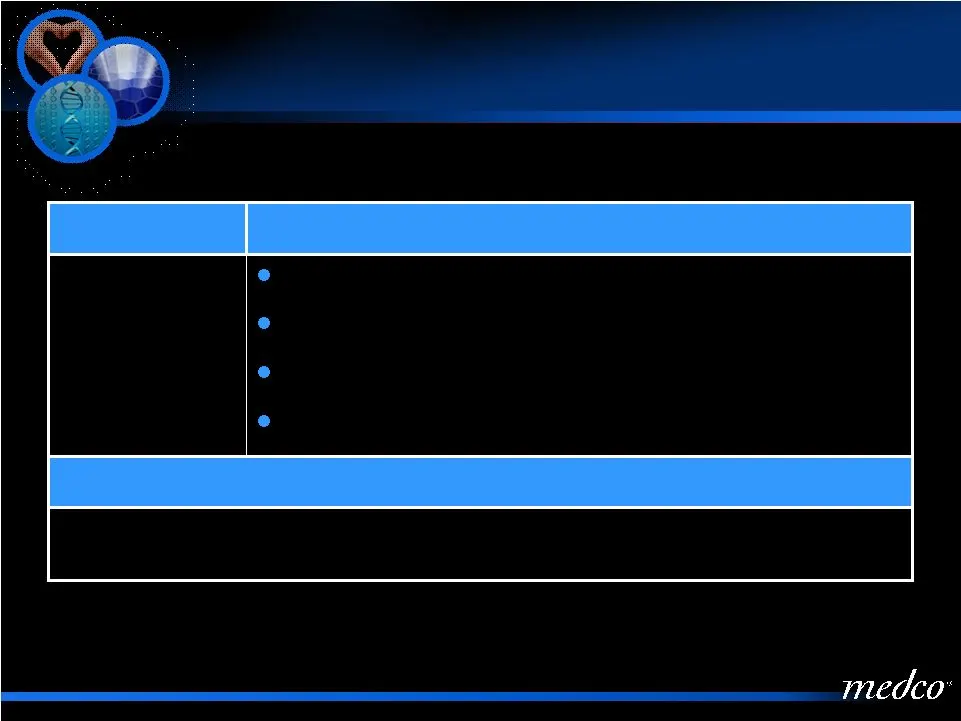
50 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco’s Diabetes Centers Can Create Significant Value for Our Plans and Patients Implications Avoid complications of diabetes (amputations, kidney failure, he art attacks, strokes), art attacks, strokes), and resultant suffering and costs O
Slide 51: Diabetics Who Stay on Therapy Have Lower Overall Health Care Costs
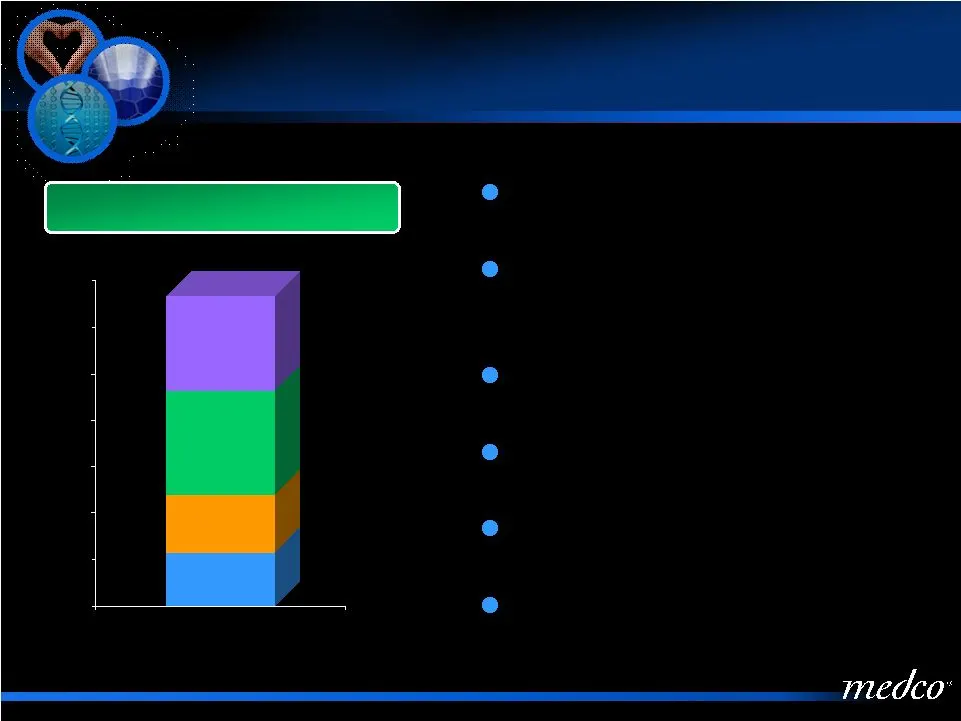
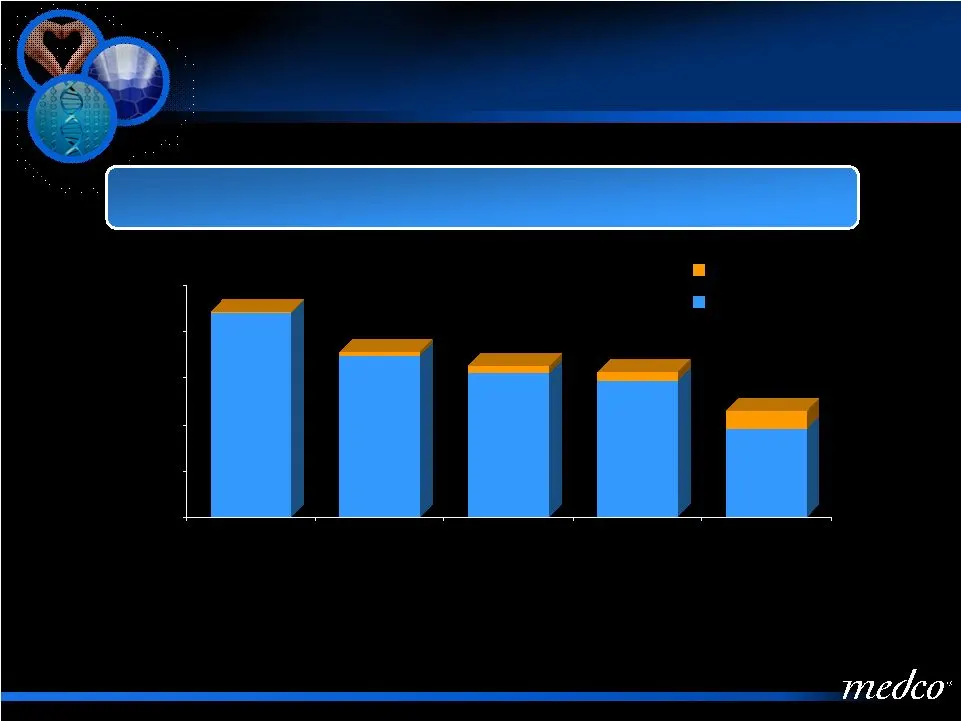
51 © 2007 Medco Health Solutions, Inc. All rights reserved. $0 $2,000 $4,000 $6,000 $8,000 $10,000 1-19 + 20-39 + 40-59 + 60-79 + 80-100 Drug Cost Medical Cost Diabetics Who Stay on Therapy Have Lower Overall Health Care Costs¹ Health Care Cost + = Health care cost is significantly higher than for t
Slide 52: Percent Adherent (MPR >=80%)
Percent Adherent (MPR >=80%) medco:
Slide 53
Slide 54: Early Results Show Medco has Twice the Compliance at Mail
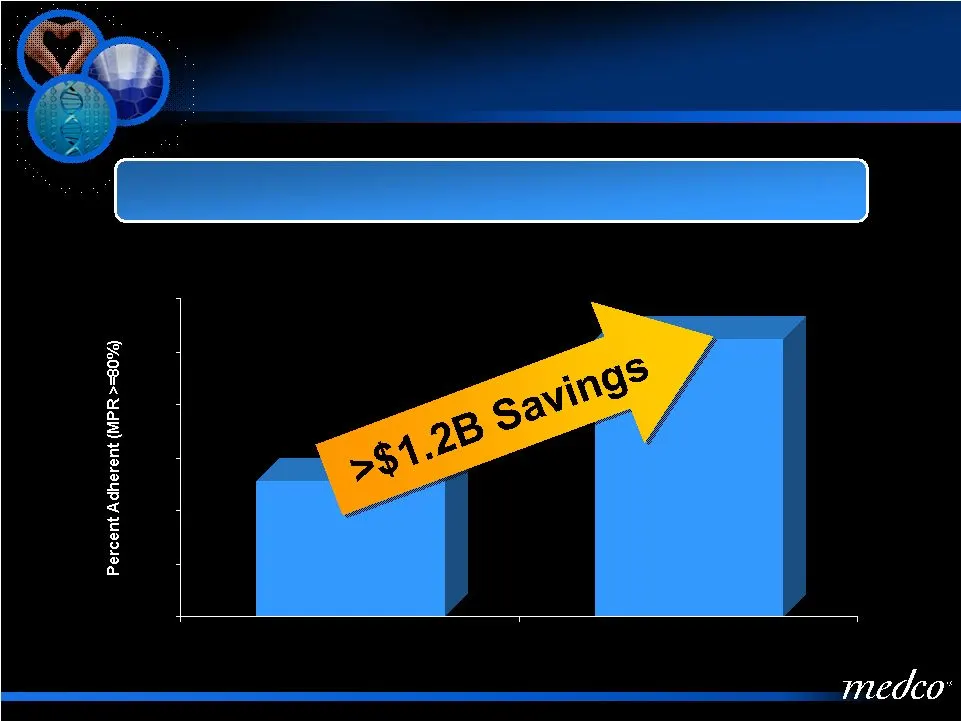
52 © 2007 Medco Health Solutions, Inc. All rights reserved. Early Results Show Medco has Twice the Compliance at Mail 0% 10% 20% 30% 40% 50% 60% Retail Medco TRC Patient Adherence with Oral Hypoglycemics Source: Medco Data Early Results Show Medco has Twice the Compliance at Mail Patient Adherence w
Slide 55: Medco Diabetes Pharmacists Help Patients Reduce Risks
53 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco Diabetes Pharmacists Help Patients Reduce Risks Patient Profile: Virginia Issues/Challenges Diabetes, at High Risk “Can’t remember” to take all her meds, every day Poorly informed Thought ACE - inhibitor was - inhibitor was inhibi
Slide 56: Pulmonary Conditions Such as Asthma Are Important and Costly
54 © 2007 Medco Health Solutions, Inc. All rights reserved. Pulmonary Conditions Such as Asthma Are Important and Costly Health Issues People with asthma: >20 million, U.S. Every day in America: 40,000 people miss school or work 30,000 people have an asthma attack 5,000 people visit the emergency ro
Slide 57: Medco's Pulmonary Center Can Create Significant Value
55 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco’s Pulmonary Center Can Create Significant Value for Our Plans and Patients Implications Avoidable sick days, ER visits, hospitalizations and deaths from asthma 1/3 with asthma report symptoms are not under control More than 1/2 report
Slide 58: medco:
medco:
Slide 59
Slide 60: Among People With Asthma, Unstable = Higher Cost
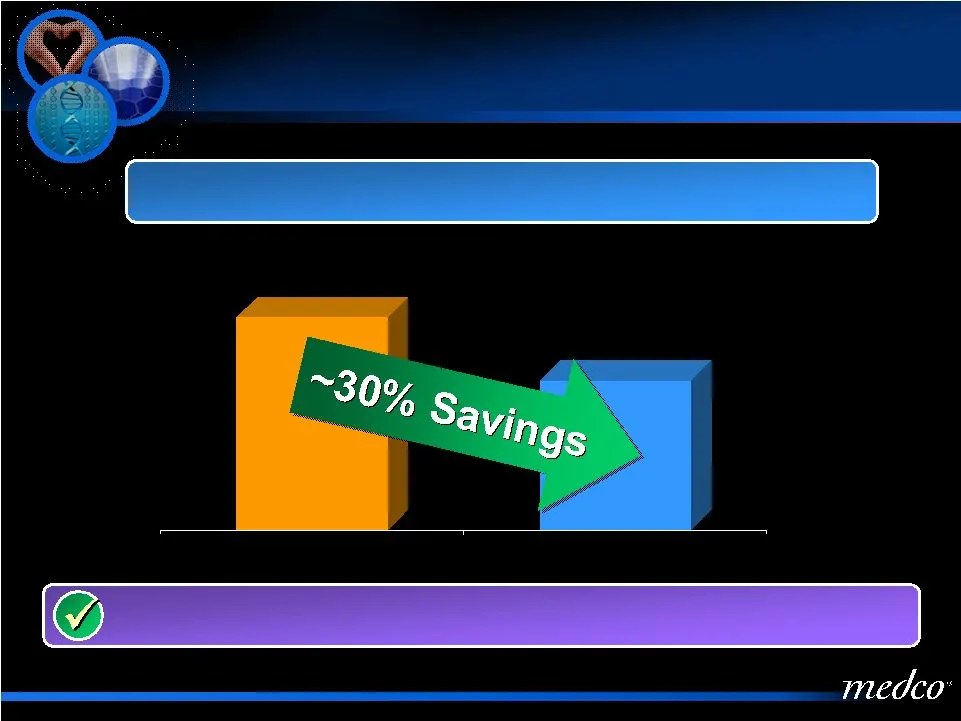
56 © 2007 Medco Health Solutions, Inc. All rights reserved. $4,909 $3,441 Unstable Stable Among People With Asthma, Unstable = Higher Cost Source: Medco data, 12 months through 5/31/2007 Total Cost of Care Unstable patients have costly ER visits and hospitalizations Among People With Asthma, Unstabl
Slide 61: Medco pulmonary pharmacist lowers risk of asthma death
57 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco pulmonary pharmacist lowers risk of asthma death for patient overusing her rescue inhaler Patient Profile: Susan Issues/Challenges Asthma, Poorly Controlled Overuse of rescue inhalers No asthma controller in profile Controllers reduce
Slide 62: Patients (%)
47253, Patients (%) —li = es S alc “A SS N og 4 medco
Slide 63
Slide 64: Asthma Early Results
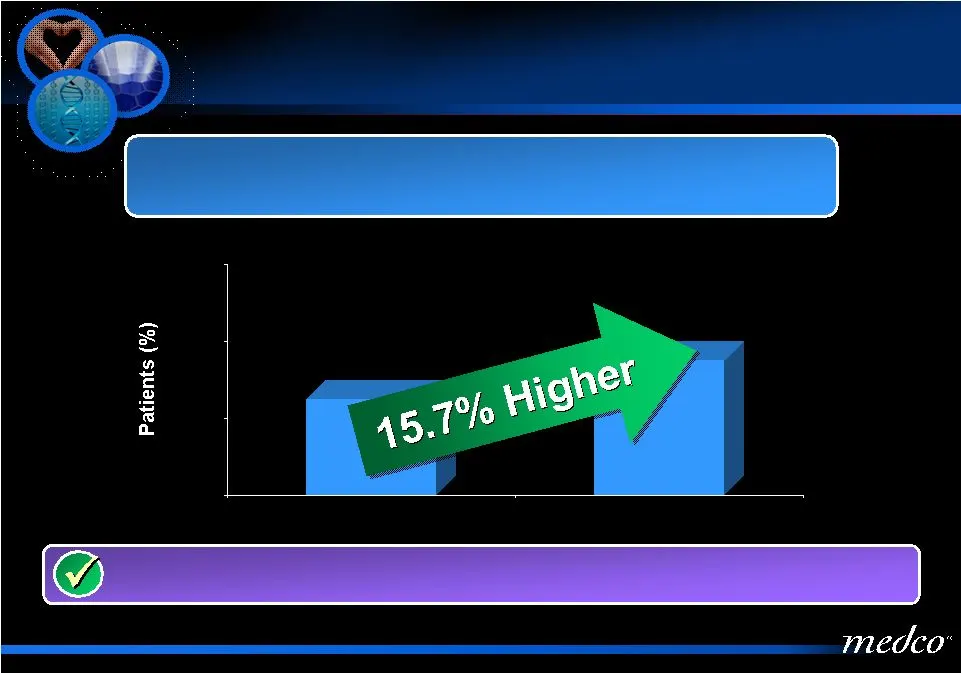
58 © 2007 Medco Health Solutions, Inc. All rights reserved. Asthma Early Results Source: Medco data, 12 months through 5/31/2007 Use of Asthma Controllers Among High Utilizers of Asthma Rescue Inhalers Asthma controllers improve quality of life, and reduce risk of ER visits and hospitalization 40% 6
Slide 65: Medco's Pulmonary Center Is Improving Asthma Care and Reducing Waste
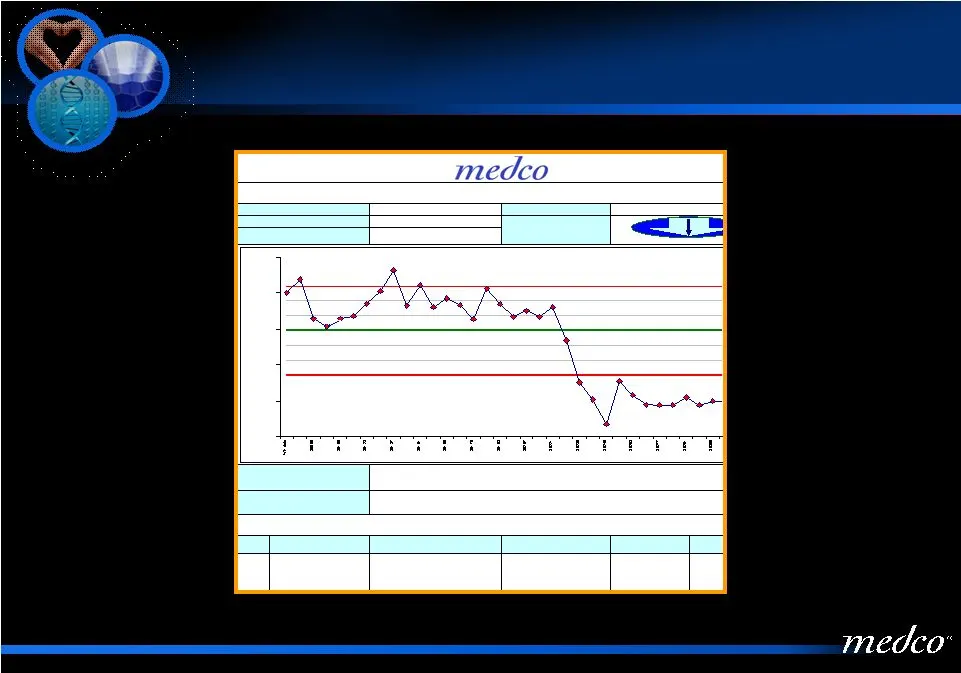
59 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco’s Pulmonary Center Is Improving Asthma Care and Reducing Waste Medco’s Pulmonary Center Is Improving Asthma Care and Reducing Waste Pulmonary Resource Center Display/Print Date: 9/8/2007 Tom Manley % Albuterol MDI Rx Qty > 1 / month D
Slide 66: Each Center Has Significant Opportunity for Growth
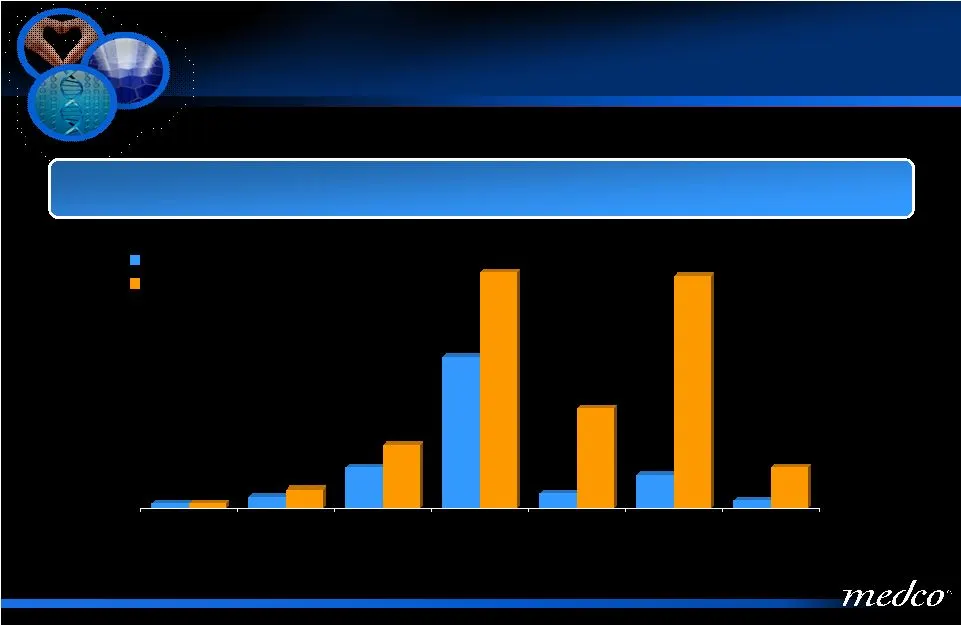
60 © 2007 Medco Health Solutions, Inc. All rights reserved. Each Center Has Significant Opportunity for Growth by Creating Value for Our Plans and Patients Patients & Opportunity, by TRC (Millions) * Excludes 1 million diabetic patients from Liberty (PolyMedica) 0.11 0.11 0.3 0.5 1.1 1.7 4.1 6.4 0.4
Slide 67: Leading the Way in Personalized Medicine
61 © 2007 Medco Health Solutions, Inc. All rights reserved. Advancing the Practice of Pharmacy Leading the Way in Personalized Medicine The Medco Strategy Advancing the Practice of Pharmacy Aligned Strategic Interests with Clients Strengthening Our Lead in Specialty Pharmacy Executing a Client- Focu
Slide 68: Leading the Way in Personalized Medicine
Leading the Way in Personalized Medicine Robert S. Epstein, M.D., M.S. Senior Vice President, Medical & Analytical Affairs & Chief Medical Officer Leading the Way in Personalized Medicine Robert S. Epstein, M.D., M.S. Senior Vice President, Medical & Analytical Affairs & Chief Medical Officer
Slide 69: Background: Therapeutic Resource Centers as Platform for Innovation
63 © 2007 Medco Health Solutions, Inc. All rights reserved. Background Medco’s Therapeutic Resource Centers ™ TM (TRCs) are our Platform for Innovation We are innovating now with Pharmacogenomics on our TRC platform within the context of Personalized Medicine Background Medco’s Therapeutic Resource
Slide 70: Pharmacogenomics: What is it?
64 © 2007 Medco Health Solutions, Inc. All rights reserved. What It Is Not… What It Is… Using an individual’s genetic information to identify diseases or predict their future risk of developing other medical conditions A science that examines the inherited variations in genes that dictate drug respo
Slide 71: Why Pharmacogenomics at Medco?
65 © 2007 Medco Health Solutions, Inc. All rights reserved. Why Pharmacogenomics at Medco? Science is popping Great potential to rationalize prescribing Right drug Right dose Right duration Could mean – more predictable and better efficacy, better safety, less expense Our infrastructure can accelera
Slide 72: Adoption of Health Care Technology Takes Years
66 © 2007 Medco Health Solutions, Inc. All rights reserved. Adoption of Health Care Technology Today is at Least 17 Years from Research to Clinical Practice Takes 4–6 years for a new technology to have >25 citations in the medical literature¹ Delay for changes in treatment recommendations in textboo
Slide 73: Adoption in Clinical Practice Lags Behind Evidence
67 © 2007 Medco Health Solutions, Inc. All rights reserved. Adoption in Clinical Practice Lags Behind Evidence by Many Years 20.0% 1993 Diabetes foot care 17.0% 1986 Fecal occult blood test 65.0% 1984 Cholesterol screening 70.4% 1982 Mammography 61.9% 1982 Beta blockers after MI 38.4% 35.6% 20.0% 55
Slide 74: Video
68 © 2007 Medco Health Solutions, Inc. All rights reserved. Video Video
Slide 75: Personalized Medicine is Here Today
69 © 2007 Medco Health Solutions, Inc. All rights reserved. 0 5,000 10,000 15,000 20,000 25,000 30,000 35,000 40,000 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Antihormonal Therapies Cytotoxic Therapies Molecular Targeted Therapies Personalized Medicine is Here Today Source: Datamonitor
Slide 76: Genetic Testing is Already Here
70 © 2007 Medco Health Solutions, Inc. All rights reserved. Genetic Testing is Already Here Variations in drug-metabolizing enzymes Variations in drug membrane transporters Variations in drug receptors Current applications of genetic tests for: Genetic Testing is Already Here Variations in drug-meta
Slide 77: 71 © 2007 Medco Health Solutions, Inc. All rights reserved.
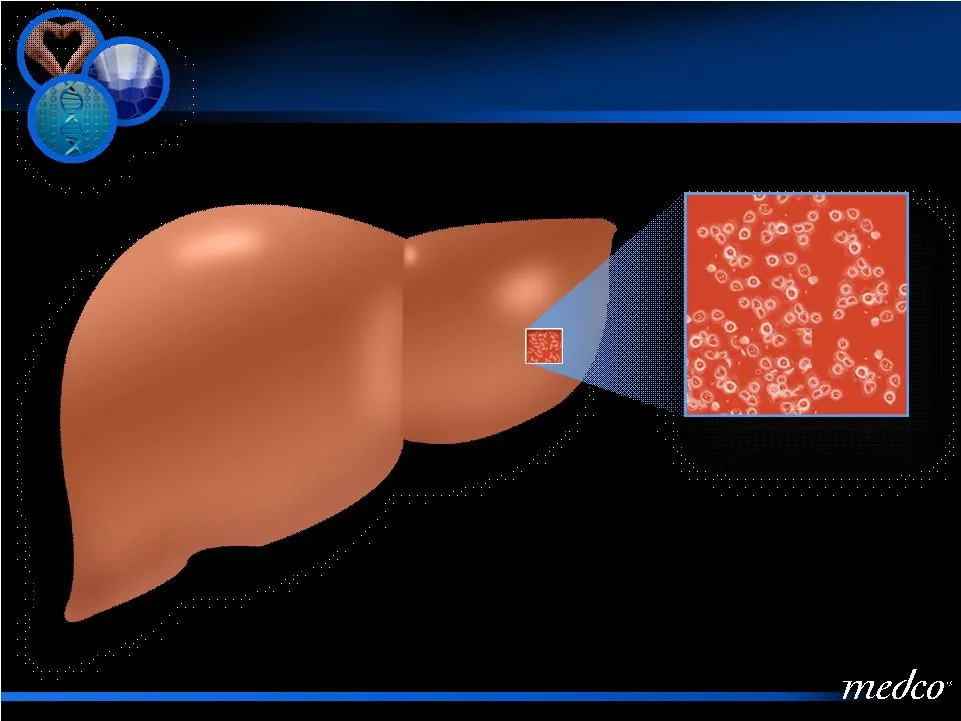
71 © 2007 Medco Health Solutions, Inc. All rights reserved.
Slide 78: Genetic Differences in Liver Enzymes That Metabolize Drugs
72 © 2007 Medco Health Solutions, Inc. All rights reserved. Genetic Differences in Liver Enzymes That Are Needed to Metabolize Drugs Rare 40% – 45% – 45% 45% CYP3A4 *3 <1% CYP3A5 *3 1% CYP2C8 *4, *9 2% CYP2A6 – 2% – 4% – 4% 4% CYP2E1 – 2% – 4% – 4% 4% CYP2B6 *1K 5% CYP1A2 Major Geneti
Slide 79: 36% of Medco Members Are on Drugs Metabolized by Variable Enzymes
73 © 2007 Medco Health Solutions, Inc. All rights reserved. 36% of Medco Members or 20 Million Patients – Are on Drugs Metabolized by Genetically Variable Enzymes 36.09% 20.24% Anti - epileptics - epileptics epileptics PPIs CYP2D6 19.31% ARBs NSAIDs Oral hypoglycemics CYP2C9 14.82% Antidepressan
Slide 80: Warfarin (Coumadin)
74 © 2007 Medco Health Solutions, Inc. All rights reserved. Warfarin (Coumadin ® ) Available for 50+ years Used to prevent or treat blood clots due to atrial fibrillation and/or heart valve replacement – or to reduce clots after heart attack #1 drug-related cause of death in US* #2 drug-related reas
Slide 81: CYP2C9 / VKORC1 Warfarin-induced Hospitalizations
75 © 2007 Medco Health Solutions, Inc. All rights reserved. CYP2C9 / VKORC1 Medco Data: Warfarin-induced Hospitalizations Testing for warfarin metabolism rate may reduce risk for hospitalization associated with hemorrhage or thrombosis Testing may reduce the number of dose adjustments required Great
Slide 82: FDA Label for Warfarin Changed August 2007
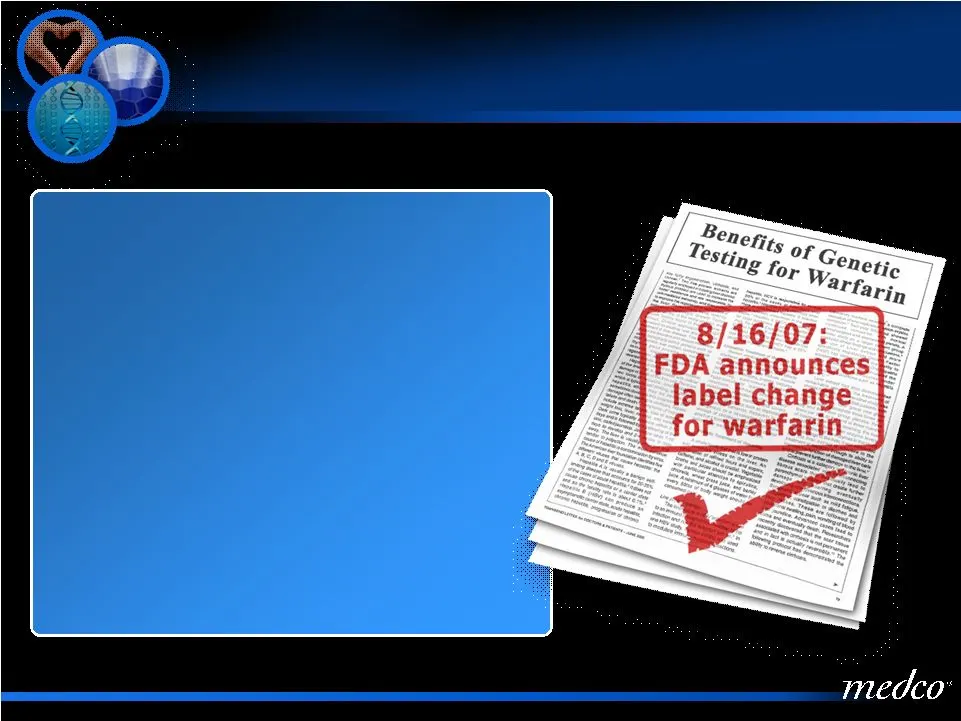
76 © 2007 Medco Health Solutions, Inc. All rights reserved. “This marks the first time such pharmacogenetic information has been included in a widely used drug…. This means personalized medicine is no longer an abstract concept, but has moved into the mainstream, where it is recognized as a factor i
Slide 83: Medco/Mayo Warfarin Pilot
77 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco/Mayo Warfarin (Coumadin ® ) Pilot Enrolled 26 clients to have “new start” patients gene-tested Measuring 6 month hospitalization rates of gene-tested patients vs. two “usual care” control groups ~1,500 patients to be included in the s
Slide 84: Preliminary Data – Warfarin Pilot
78 © 2007 Medco Health Solutions, Inc. All rights reserved. Preliminary Data – Warfarin Pilot 75% of physicians approached agreed to have their patients tested Of approximately 400 patients agreeing to testing thus far – only one of their MDs had heard of the test Early physician and patient feedbac
Slide 85: Preliminary Data – Warfarin Pilot
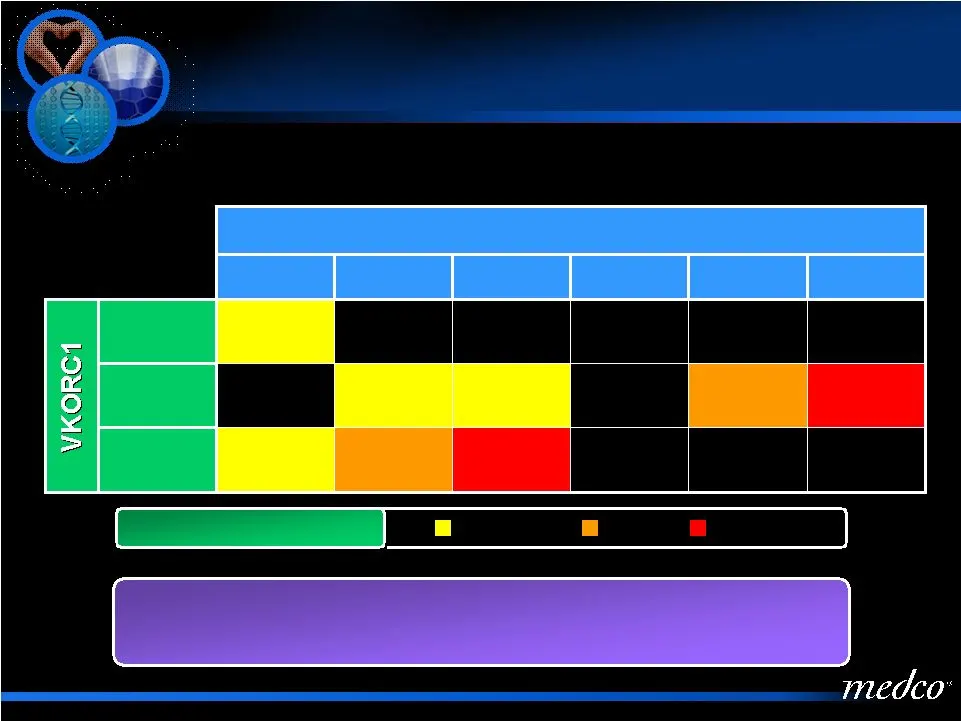
79 © 2007 Medco Health Solutions, Inc. All rights reserved. Preliminary Data – Warfarin Pilot Data Based on First 112 Patients Liver Enzyme 2c9 0% 1% 0% *3/*3 0% 0% *2/*3 0% 0% 0% *2/*2 4% 3% *1/*3 5% *1/*2 AA 27% GA 30% GG *1/*1 Over 1/3 of patients may require a change in standard dose Moderate Hi
Slide 86: Tamoxifen
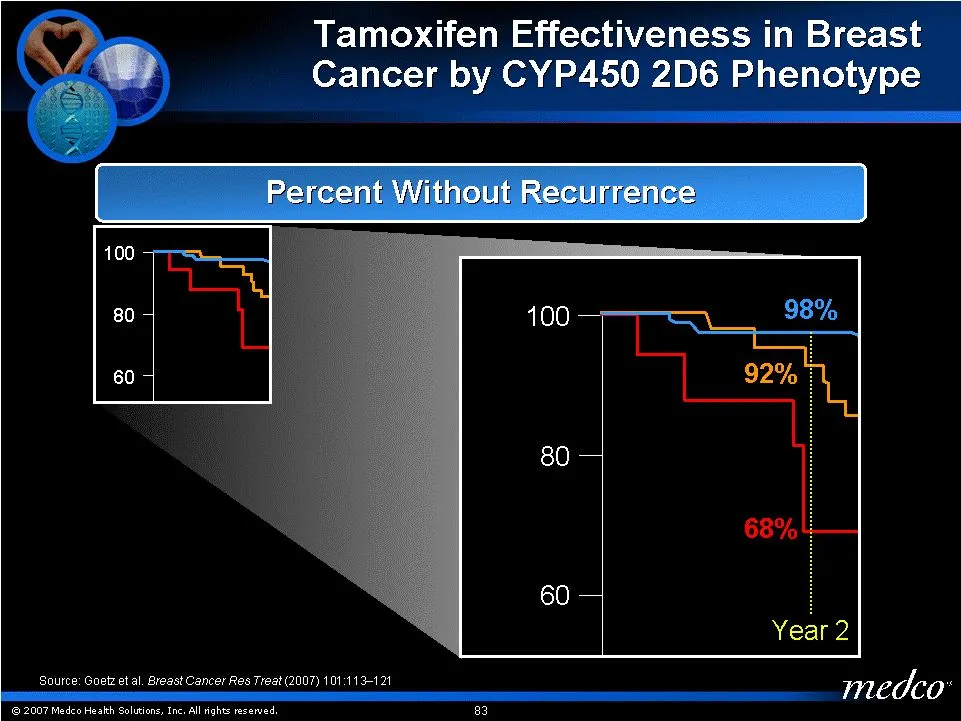
80 © 2007 Medco Health Solutions, Inc. All rights reserved. Tamoxifen Oral drug used for the treatment and prevention of recurrent breast cancer – hormone positive, node negative women Binds to estrogen receptors on breast tissue Has been marketed for over 30 years Medco has approximately 65,000 use
Slide 87: Tamoxifen Effectiveness in Breast Cancer by CYP450 2D6 Phenotype
Tamoxifen Effectiveness in Breast Cancer by CYP450 2D6 Phenotype Source: Goetz et al. Breast Cancer Res Treat (2007) 101-113-121 medco: © 2007 lth S tight 83
Slide 88: Medco/LabCorp Tamoxifen Pilot
82 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco/LabCorp Tamoxifen Pilot 500 women to be tested for 2d6 status Evaluating MD acceptance of test Patient acceptance of test % Poor Metabolizers (PMs) Switch rate amongst PMs Utilizing simple cheek swab technology Medco/LabCorp Tamoxifen
Slide 89: Preliminary Findings – Tamoxifen Study
83 © 2007 Medco Health Solutions, Inc. All rights reserved. Preliminary Findings – First 100 Patients Tamoxifen Study 60% of MDs willing to test their eligible patients 98% of identified patients have never been tested 90% of patients want the test immediately Still pending – the % with Poor Metabol
Slide 90: Summary
84 © 2007 Medco Health Solutions, Inc. All rights reserved. Summary Science is moving towards Personalized Medicine and Medco is accelerating that movement Tests are coming even faster than drugs themselves Medco is working to shrink the 17 year time lag – between evidence and practice Our unique Me
Slide 91: Strengthening Our Lead in Specialty Pharmacy
85 © 2007 Medco Health Solutions, Inc. All rights reserved. Advancing the Practice of Pharmacy Strengthening Our Lead in Specialty Pharmacy The Medco Strategy Advancing the Practice of Pharmacy Aligned Strategic Interests with Clients Executing a Client- Focused Fiscal Plan Engaging Members Leading
Slide 92: Strengthening Our Lead in Specialty Pharmacy
Strengthening Our Lead in Specialty Pharmacy Timothy C. Wentworth President & CEO Accredo Health Group, Inc. Strengthening Our Lead in Specialty Pharmacy Timothy C. Wentworth President & CEO Accredo Health Group, Inc.
Slide 93: Agenda
87 © 2007 Medco Health Solutions, Inc. All rights reserved. Agenda Year-to-Date Financial Highlights Accredo’s Growth Opportunities CCSI Acquisition Specialty Pipeline Medco Book-of-Business Opportunities Long-Term Advantages Agenda Year-to-Date Financial Highlights Accredo’s Growth Opportunities CC
Slide 94: Strong Growth Year-To-Date
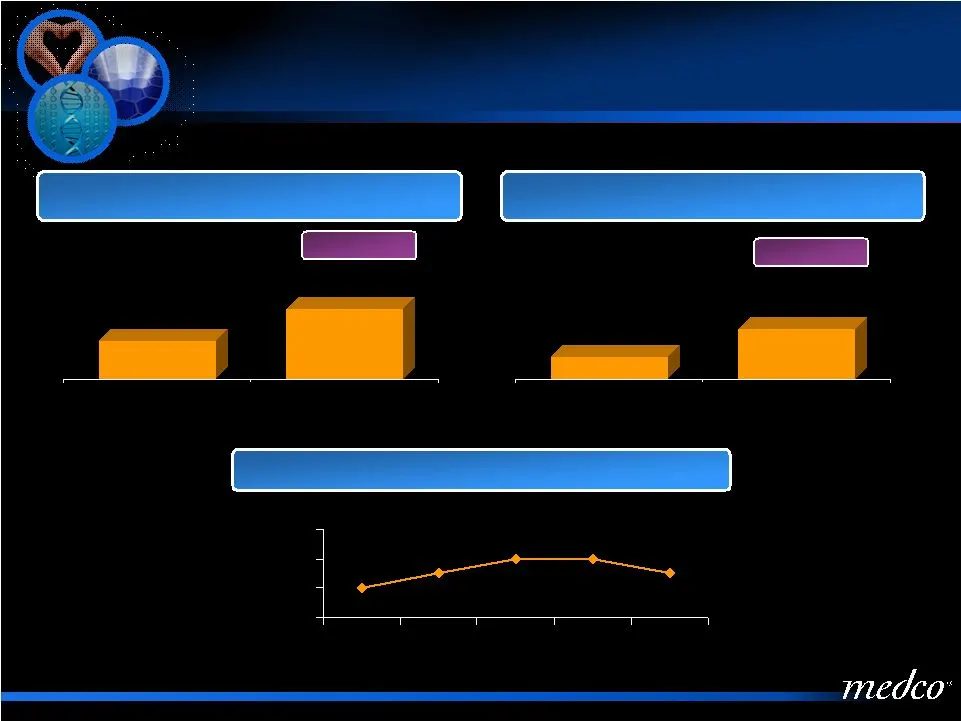
88 © 2007 Medco Health Solutions, Inc. All rights reserved. Strong Growth Year-To-Date Net Revenue ($ billions) Operating Margin ($ millions) Strong Gross Margin Performance 7.6% 7.8% 8.0% 8.0% 7.8% 7.2% 7.6% 8.0% 8.4% Q306 Q406 Q107 Q207 Q307 $137.7 $160.4 2006 YTD 2007 YTD +16.5% $4.0 $4.4 2006 YT
Slide 95: Accredo's Growth Opportunity Is Multi-faceted
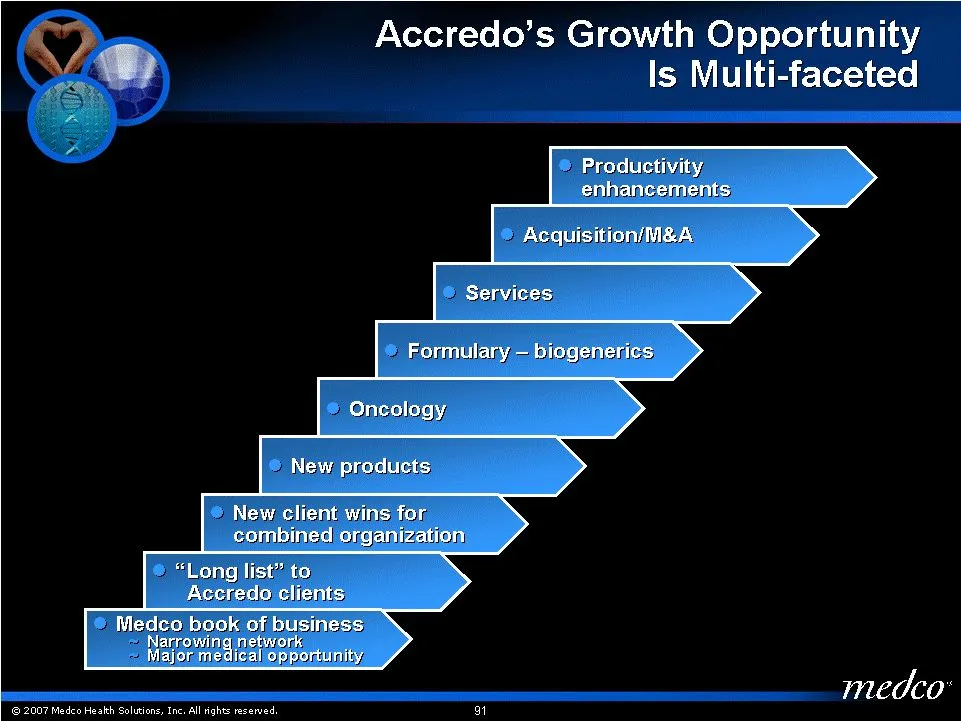
«2 . Accredo’s Growth Opportunity ® Is Multi-faceted Productivity enhancements. Acquisition/M&A Formulary — biogenenics Oncology New products New client wins for combined organization “Long list” to Accredo clients Medco book of business Narrowing network Major, medical opportunity, medco: ‘© 2007 M
Slide 96: Accredo's Growth Opportunity Is Multi-faceted
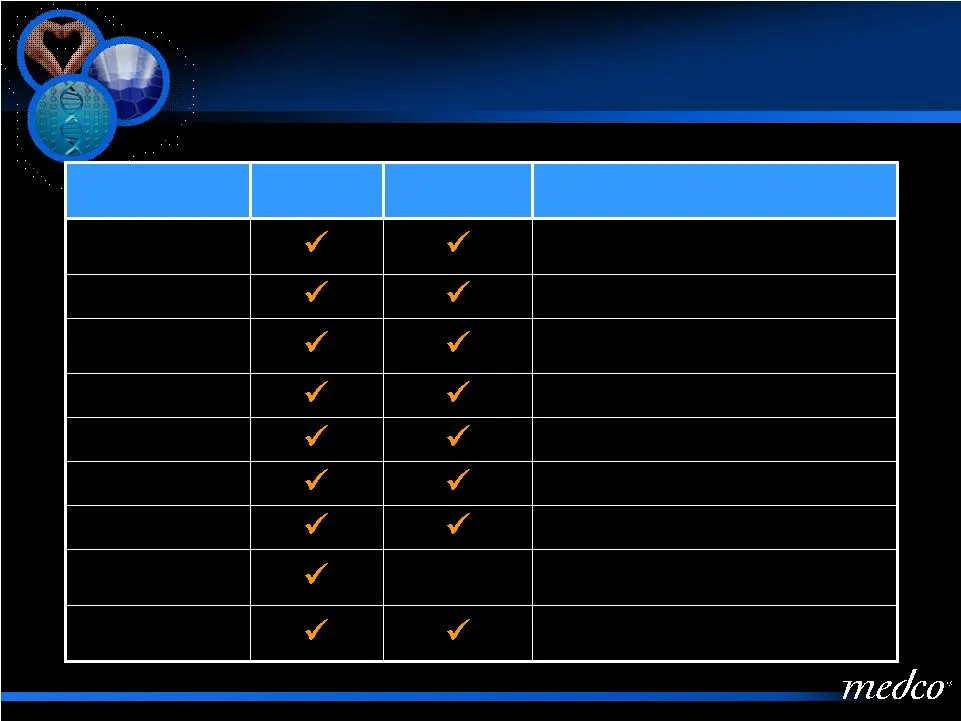
90 © 2007 Medco Health Solutions, Inc. All rights reserved. Accredo’s Growth Opportunity Is Multi-faceted Network narrowing nearly complete; major medical initiative underway MHS BoB BoB Contribution Rare disease focus Long List to Accredo Clients FEP 1/1/08 New Client Wins Watching 54 products of i
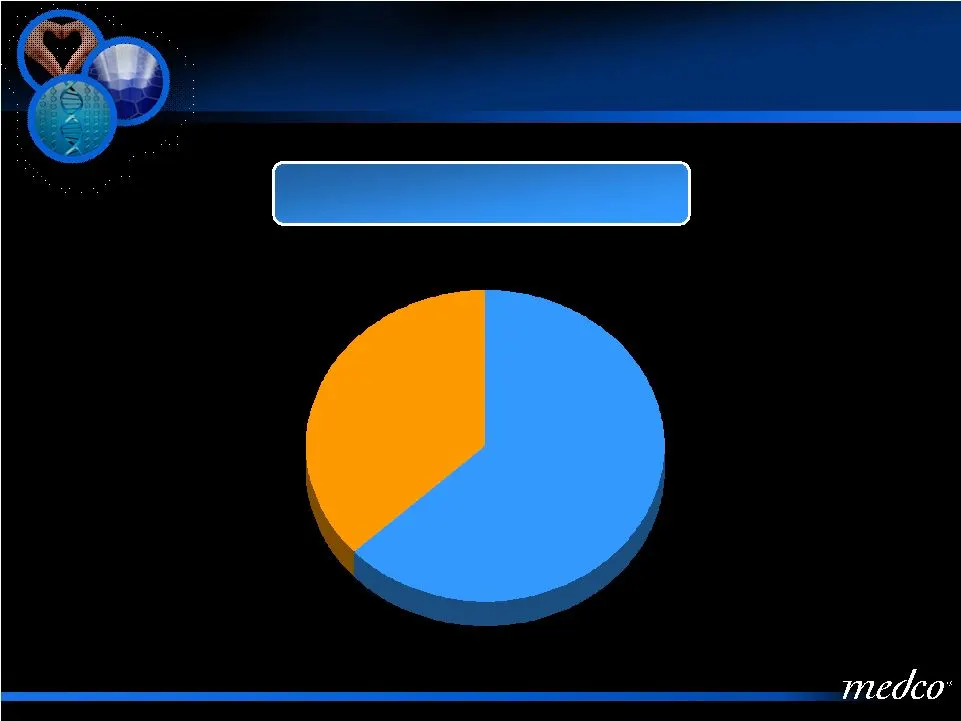
Slide 97: Medco…Accredo's Largest Client
91 © 2007 Medco Health Solutions, Inc. All rights reserved. 63% 2006 Status Medco…Accredo’s Largest Client Current Penetration Remaining Pharmacy Opportunity 37% 2006 Status 2006 Status Medco…Accredo’s Largest Client
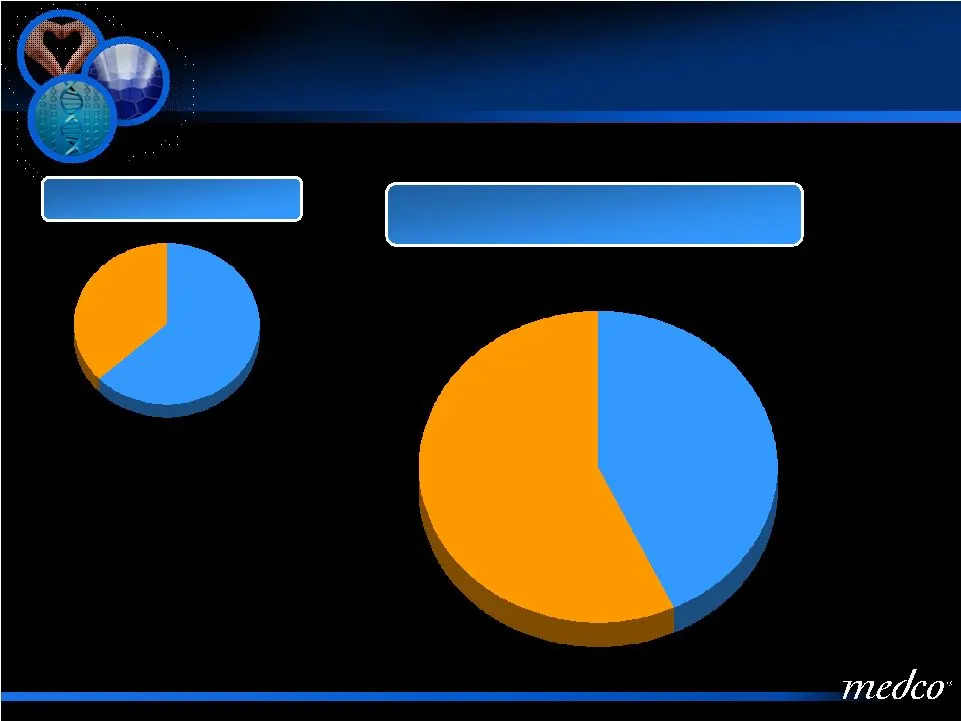
Slide 98: …And Largest Opportunity
92 © 2007 Medco Health Solutions, Inc. All rights reserved. …And Largest Opportunity 63% 2006 Status Remaining Opportunity 43% 2007 Status Current Penetration Remaining Opportunity …And Largest Opportunity 37% 2006 Status 2006 Status Current Penetration 57% 2007 Status 2007 Status
Slide 99: Growing Our Legacy Business
93 © 2007 Medco Health Solutions, Inc. All rights reserved. Growing Our Legacy Business Several large Blue Cross Blue Shield plans Large national health plan State managed Medicaid plan Several regional health plans Strong prospect pipeline Strong Continued Success Winning New Specialty-Only Busines
Slide 100: CCSI Strategic Opportunity
94 © 2007 Medco Health Solutions, Inc. All rights reserved. CCSI Strategic Opportunity Strong in core therapies (strength in IVIG and Hemophilia) Acute infusion provides broader service offering and high margin growth opportunities Strong payor relationships (i.e., medical and regional contracts) Do
Slide 101: CCSI Strategic Opportunity (Continued)
95 © 2007 Medco Health Solutions, Inc. All rights reserved. CCSI Strategic Opportunity Strong synergies in specialty business Purchasing Geographic coverage expansion Operational efficiencies Wholly-owned model Experienced management team that has successfully focused and grown the company Accretive
Slide 102: Specialty Opportunity
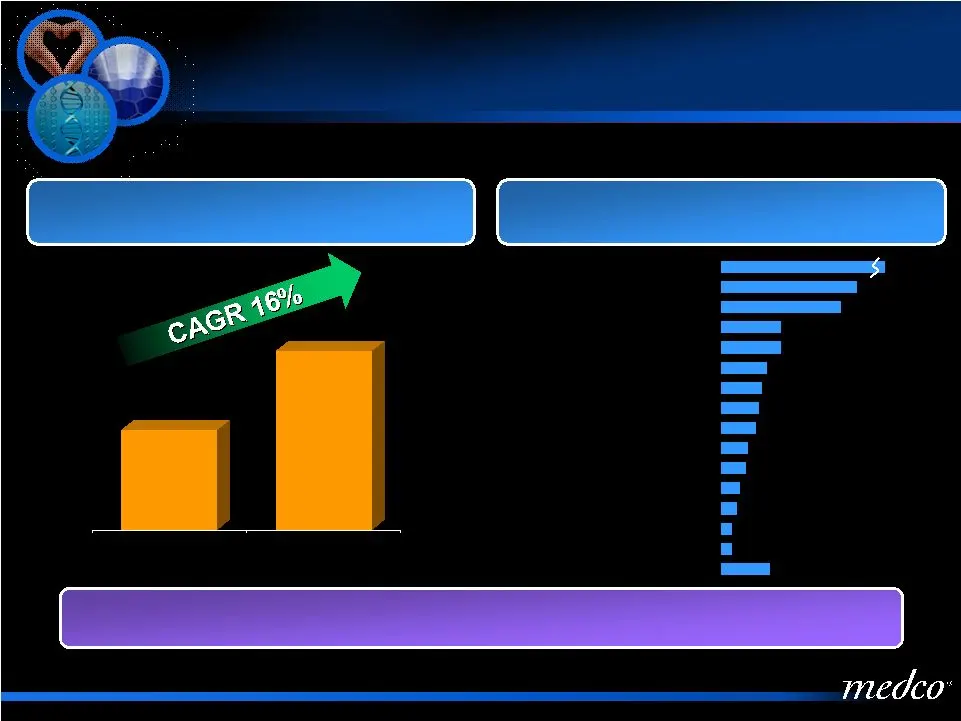
96 © 2007 Medco Health Solutions, Inc. All rights reserved. Specialty Opportunity Source: HealthStrategiesGroup HealthStrategiesGroup *Source: PhRMA 2005 Survey: Medicines in Development , Oct. 2006 2005 Survey: Medicines in Development , Oct. 2006 , Oct. 2006 Some medicines are listed in more than
Slide 103: Accredo Pipeline Focus List
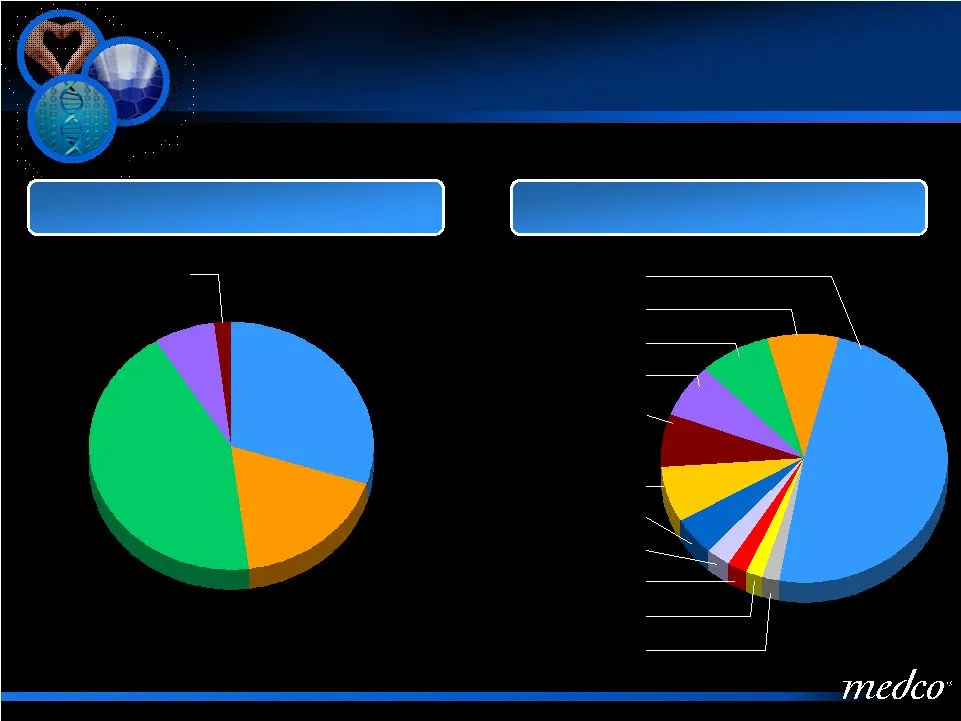
97 © 2007 Medco Health Solutions, Inc. All rights reserved. Accredo Pipeline “Focus List” 2% 7% 43% 30% Route of Administration 5% 7% 7% 49% Therapeutic Category Injectible Oral Infusion Inhalation In-Lesion Cancer Immune Systems Inflammatory Disease Hormonal Systems Hematology Respiratory Infectiou
Slide 104: Accredo Long-Term Advantages
98 © 2007 Medco Health Solutions, Inc. All rights reserved. Accredo Long-Term Advantages Strength in the most complex, hard to replicate therapeutic areas Strength in areas where Health Plans want help Best of both worlds – one-stop shop (depth of expertise at the therapy level and breadth of produc
Slide 105: Aligned Strategic Interests with Clients
99 © 2007 Medco Health Solutions, Inc. All rights reserved. Advancing the Practice of Pharmacy Aligned Strategic Interests with Clients The Medco Strategy Advancing the Practice of Pharmacy Executing a Client- Focused Fiscal Plan Engaging Members Leading the Way in Personalized Medicine Strengthenin
Slide 106: Aligned Strategic Interests with Clients
Aligned Strategic Interests with Clients Kenneth O. Klepper President & Chief Operating Officer Aligned Strategic Interests with Clients Kenneth O. Klepper President & Chief Operating Officer
Slide 107: A Client's View of Medco
A Client’s View of Medco Presented by James H. Dickerson, Jr. Executive Vice President and Chief Financial Officer HealthNow New York Inc. A Client’s View of Medco Presented by James H. Dickerson, Jr. Executive Vice President and Chief Financial Officer HealthNow New York Inc.
Slide 108: Panel Discussion
Panel Discussion Bryan D. Birch / Brian T. Griffin / Glenn C. Taylor / James H. Dickerson (HealthNow New York, Inc.) Panel Discussion Bryan D. Birch / Brian T. Griffin / Glenn C. Taylor / James H. Dickerson (HealthNow New York, Inc.)
Slide 109: Medco 2007 Analyst Day
105 © 2007 Medco Health Solutions, Inc. All rights reserved. Medco 2007 Analyst Day November 16, 2007 Medco 2007 Analyst Day November 16, 2007
Slide 110: Executing a Client-Focused Fiscal Plan
104 © 2007 Medco Health Solutions, Inc. All rights reserved. Advancing the Practice of Pharmacy Executing a Client- Focused Fiscal Plan The Medco Strategy Advancing the Practice of Pharmacy Engaging Members Leading the Way in Personalized Medicine Strengthening Our Lead in Specialty Pharmacy Aligned
Slide 111: Executing a Client-Focused Fiscal Plan 2007
Executing a Client-Focused Fiscal Plan 2007 JoAnn Reed Senior Vice President, Finance & Chief Financial Officer Executing a Client-Focused Fiscal Plan 2007 JoAnn Reed Senior Vice President, Finance & Chief Financial Officer
Slide 112: Growing the Core and Expanding Services
106 © 2007 Medco Health Solutions, Inc. All rights reserved. Executing a Client-Focused Fiscal Plan: Growing the Core and Expanding Services Industry Issues Third-quarter 2007 Financial Performance Opportunity for Growth in 2008 Executing a Client-Focused Fiscal Plan: Growing the Core and Expanding
Slide 113: Retail Generic Pricing
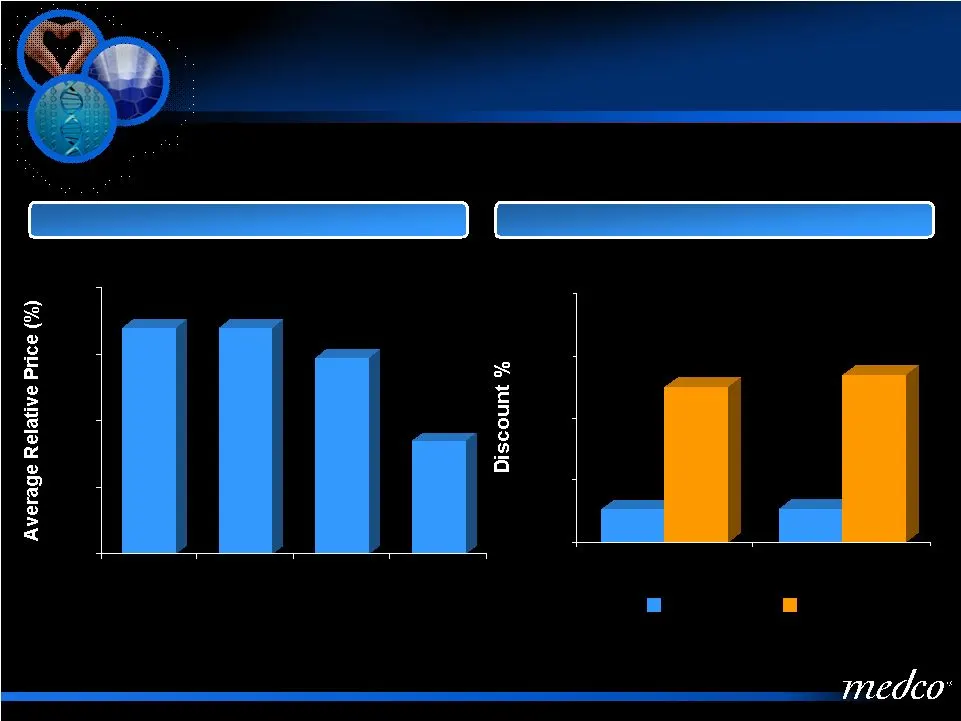
107 © 2007 Medco Health Solutions, Inc. All rights reserved. Retail Generic Pricing 0% 20% 40% 60% 80% Single Source Single Source Authorized Generic 3 Generic Mfc's >3 Generic Mfc's 5% 25% 45% 65% 85% Q306 Q307 Brand Generic Generic Price Trends Retail Price Discounts Retail Generic Pricing Generic
Slide 114: Benchmark Change
108 © 2007 Medco Health Solutions, Inc. All rights reserved. Benchmark Change Expect a methodology change during first half of 2008 to the AWP benchmark Medco is indifferent to a change in the benchmark whether it be to WAC or AMP To date, Medco has over 95% of its drug spend covered by the contract
Slide 115: Brand and Generic Trend
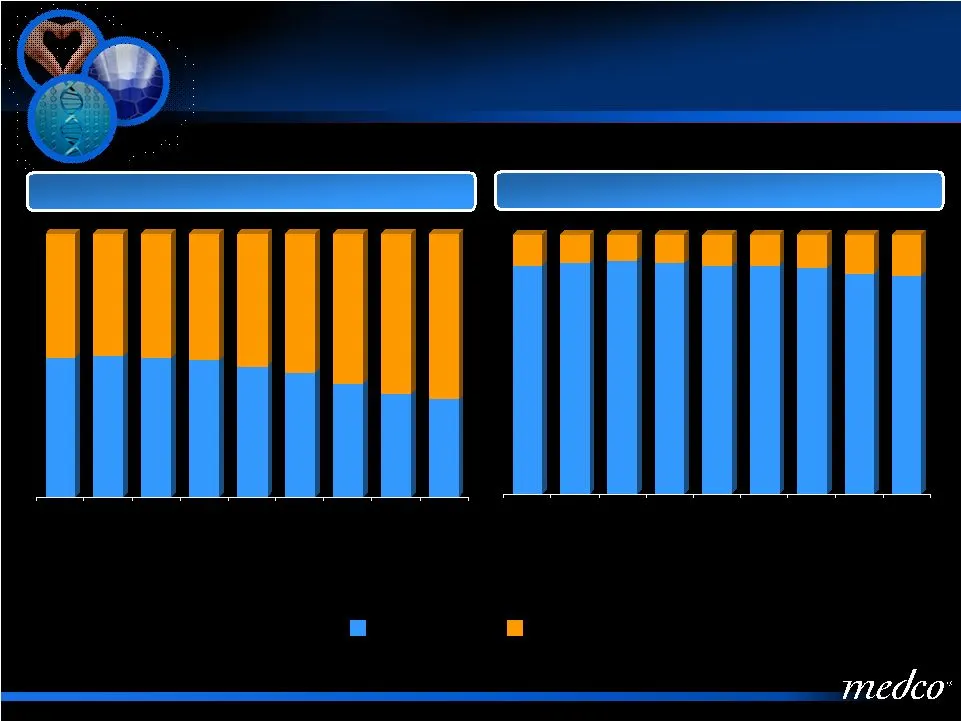
109 © 2007 Medco Health Solutions, Inc. All rights reserved. Brand and Generic Trend Source: New England Journal of Medicine , November 15, 2007 MAT denotes moving annual total; MAT 06/07 represents the 12 months ending in June 2007. Data are from IMS Health, National Prescription Audit Plans, Natio
Slide 116: Adjusted Mail-Order Penetration Continues to Increase
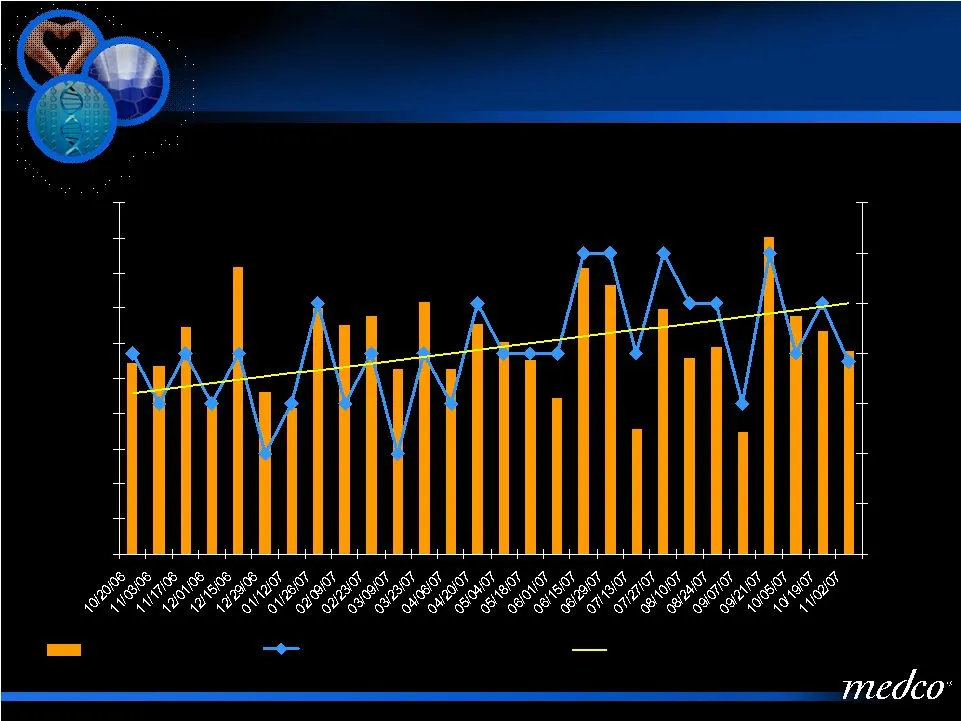
110 © 2007 Medco Health Solutions, Inc. All rights reserved. 2,900 3,000 3,100 3,200 3,300 3,400 3,500 3,600 3,700 3,800 3,900 33% 34% 35% 36% 37% 38% 39% 40% MHS Mail-Order Rxs Adjusted Mail-Order Penetration Adjusted Mail-Order Penetration Trend Adjusted Mail-Order Penetration Continues to Increas
Slide 117: 3Q07 Financial Highlights
111 © 2007 Medco Health Solutions, Inc. All rights reserved. 3Q07 Financial Highlights + 18.1% $593.5 MM $700.8 MM Gross Margin + 23.9% $0.71 $0.88 Diluted EPS excluding amortization of excluding amortization of intangibles related to spinoff spinoff (vs. First Call Estimate of $0.79) + 25.8% $0.62
Slide 118: Generic Dispensing Rates Continue on an Upward Trend
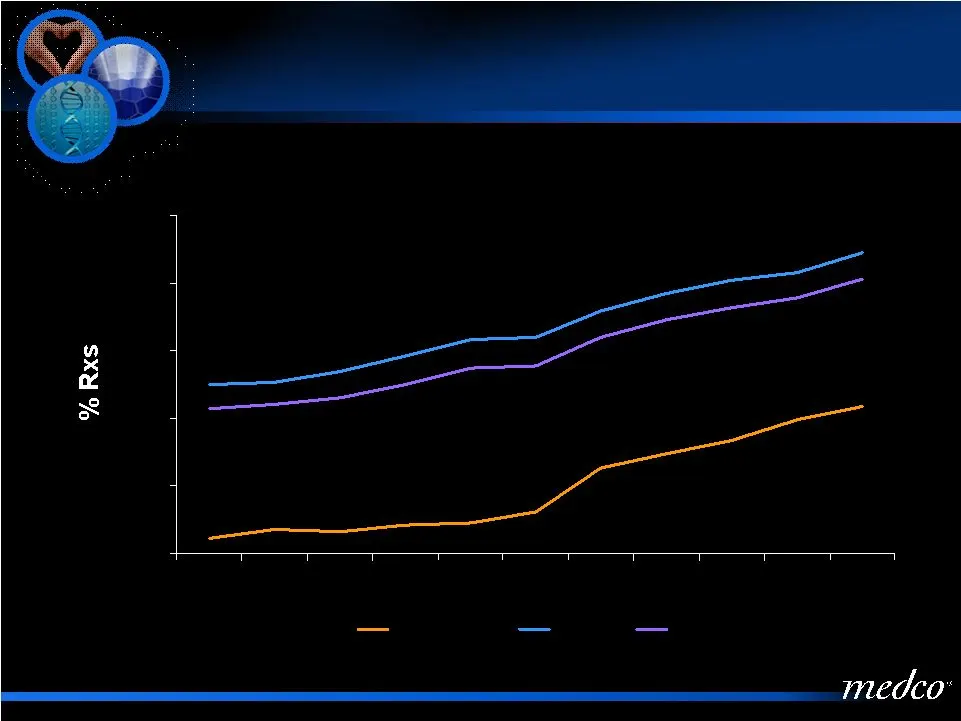
112 © 2007 Medco Health Solutions, Inc. All rights reserved. Generic Dispensing Rates Continue on an Upward Trend 40% 45% 50% 55% 60% 65% 1Q05 2Q05 3Q05 4Q05 1Q06 2Q06 3Q06 4Q06 1Q07 2Q07 3Q07 Mail-Order Retail Total Generic Dispensing Rates Continue on an Upward Trend
Slide 119: Capitalization
113 © 2007 Medco Health Solutions, Inc. All rights reserved. Capitalization S&P: BBB Moody ’ s: Baa3 ’ s: Baa3 s: Baa3 Fitch: BBB 2,723 Accounts receivable, net 1,646 Inventories, net 5,106 Goodwill 2,359 Intangibles, net 772 Other assets 619 Property and equipment, net $700 Cash and investment
Slide 120: Cash Flow Generation
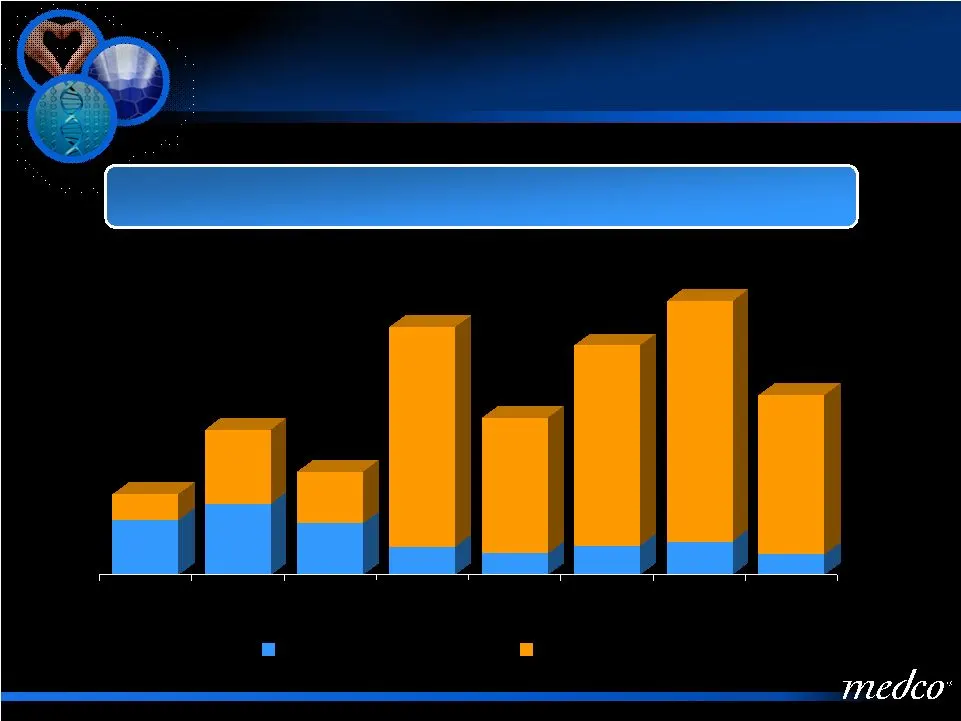
114 © 2007 Medco Health Solutions, Inc. All rights reserved. Cash Flow Generation 251 322 235 125 98 132 151 94 2000 2001 2002 2003 2004 2005 2006 9 mos 2007 Capital Expenditures Free Cash Flow $366 $659 $470 $1,124 $712 $1,041 $1,241 $816 Cash Flow from Operations ($MM) Note: Free cash flow = cash
Slide 121: Progress and Expectations for Full Year 2007
115 © 2007 Medco Health Solutions, Inc. All rights reserved. Sources of Growth Sales Addition of $1.6B in new 2007 business, as of 3Q07 Generics Incremental contribution of up to $0.35 per share from 2007 new generic introductions Mail 6.7% increase in 2007 to approximately 95MM Medicare Part D PDP
Slide 122: Net Positive Sales in 2007
116 © 2007 Medco Health Solutions, Inc. All rights reserved. Net Positive Sales in 2007 Erosion & calendarization ($1.1 B) Lost sales ($1.5 B) Calendarization $0.8 B Growth in existing clients $0.6 B New sales $1.6 B $0.4B Net New as of 3Q07 Net Positive Sales in 2007 ($2.6 B) ($2.6 B) Erosion & cal
Slide 123: Generic Drug Optimization 2007
117 © 2007 Medco Health Solutions, Inc. All rights reserved. Generic Drug Optimization $11.0B $3.1B National Drug Spend Medco Share Norvasc ® Ambien ® Lotrel ® Toprol XL ® Coreg ® Incremental Contribution of up to $0.35 per Share New Generic Introductions – 2007E Generic Drug Optimization Norvasc ®
Slide 124: Mail-Order Trend
118 © 2007 Medco Health Solutions, Inc. All rights reserved. Mail-Order Trend $1.9 $3.2 $3.7 $1.9 2004 2005 2006 2007E Adjusted mail-order penetration rate for new business Annualized new business 52% 18% 32% 35% Annualized New Business and Mail-Order Penetration Mail-Order Volume (in millions) 88 8
Slide 125: Accredo Health Group 2007 Outlook
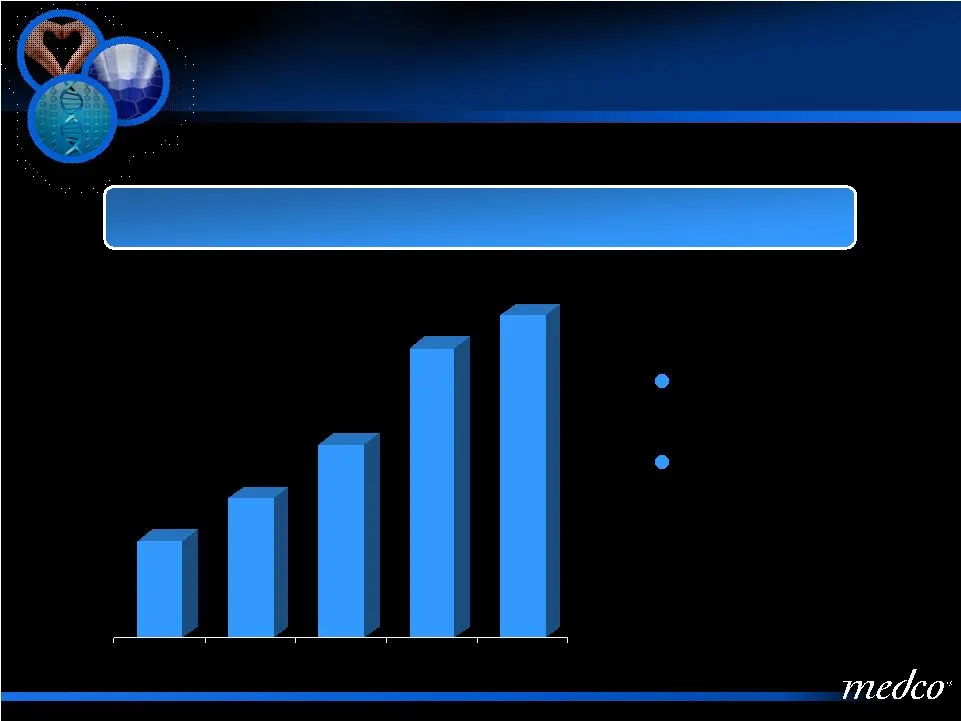
119 © 2007 Medco Health Solutions, Inc. All rights reserved. Accredo Health Group Revenue to reach approximately $6B EPS growth of up to $0.08 per share $2 $3 $4 $5 ~$6 2003 2004 2005 2006 2007E Specialty Pharmacy Revenue ($Billions) 2007 Outlook Accredo Health Group Revenue to reach approximately $
Slide 126: 2007 Revised Guidance
120 © 2007 Medco Health Solutions, Inc. All rights reserved. 2007 Revised Guidance $2.78 $2.42 2006 Actuals ¹ 1 28%-29% $3.50–$3.55 EPS (adj. for intangible amortization) 31%-33% $3.11–$3.16 EPS (GAAP) % Growth ¹ 1 Previous 2007 Guidance Increased 2007 Guidance * Excludes first-quarter 2006 legal se
Slide 127: Executing a Client-Focused Fiscal Plan 2008
Executing a Client-Focused Fiscal Plan 2008 Richard J. Rubino, CPA Senior Vice President & Controller, Chief Accounting Officer Executing a Client-Focused Fiscal Plan 2008 Richard J. Rubino, CPA Senior Vice President & Controller, Chief Accounting Officer
Slide 128: Progress and Expectations for 2008
122 © 2007 Medco Health Solutions, Inc. All rights reserved. Opportunity for Growth Progress and Expectations for 2008 Sales Addition of $4.5B in new 2008 business, as of 3Q07 Generics Nearly $4.9B in drugs coming off patent in 2008 Incremental contribution of up to $0.20 per share from 2008 new gen
Slide 129: Net Positive Sales for 2008
123 © 2007 Medco Health Solutions, Inc. All rights reserved. $3.9B Net New as of 3Q07 Net Positive Sales for 2008 Erosion & calendarization ($0.1 B) Lost sales ($0.6 B) Growth & calendarization $0.1 B New sales $4.5 B New sales mail penetration rate of 63% Lost sales mail penetration rate of 62% $3.
Slide 130: 2008 Renewals
124 © 2007 Medco Health Solutions, Inc. All rights reserved. 2008 Renewals $0 $4,000 $8,000 $12,000 Q1 Q2 Q3 Q4 81% 5% 12% 2% Drug Spend Illustration of Renewal Margin Effect Renewal Pre- Renewal Year 1 Year 2 Year 3 2008 Renewals Drug Spend Drug Spend Illustration of Renewal Margin Effect Illustrat
Slide 131: Generic Drug Optimization 2008
125 © 2007 Medco Health Solutions, Inc. All rights reserved. Generic Drug Optimization $4.9B $1.2B National Drug Spend Medco Share Fosamax ® Risperdal ® Depakote ® Incremental Contribution up to $0.20 per Share New Generic Introductions – 2008E Generic Drug Optimization Fosamax ® Risperdal ® Depakot
Slide 132: Mail-Order Trend
126 © 2007 Medco Health Solutions, Inc. All rights reserved. Mail-Order Trend $1.9 $3.2 $3.7 $1.9 $4.5 2004 2005 2006 2007E 2008E Adjusted mail-order penetration rate for new business Annualized new business 63% 52% 18% 32% 35% Annualized New Business and Adjusted Mail-Order Penetration Mail-Order V
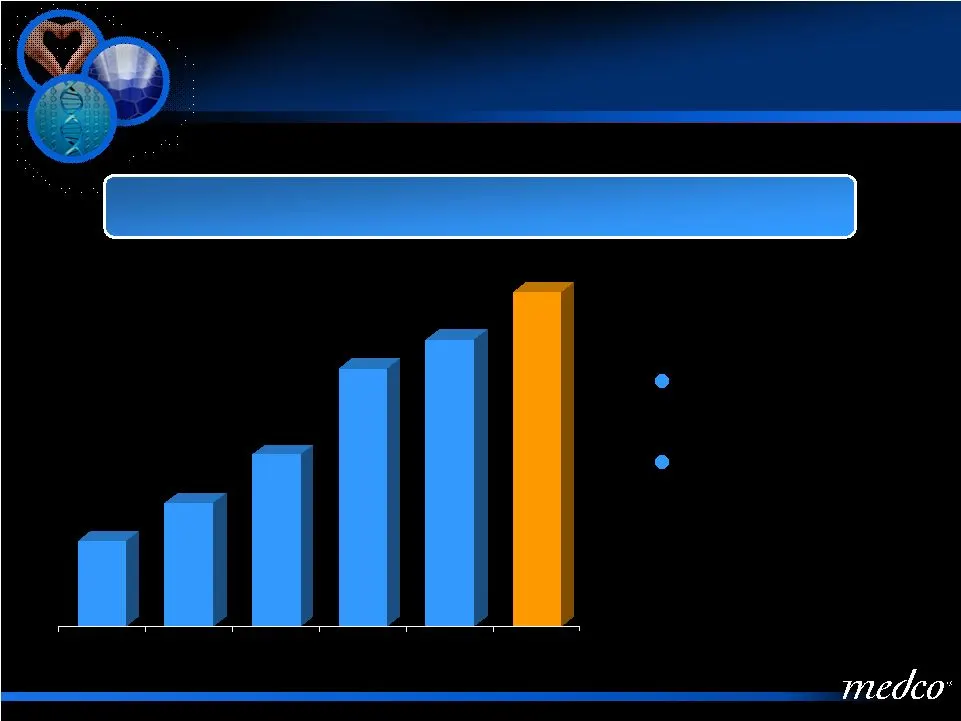
Slide 133: Accredo Health Group 2008 Outlook
127 © 2007 Medco Health Solutions, Inc. All rights reserved. Accredo Health Group Revenue to reach approximately $7B EPS growth of $0.06 to $0.09 per share $2 $3 $4 $5 ~$6 ~$7 2003 2004 2005 2006 2007E 2008E Specialty Pharmacy Revenue ($Billions) 2008 Outlook Accredo Health Group Revenue to reach ap
Slide 134: Guidance
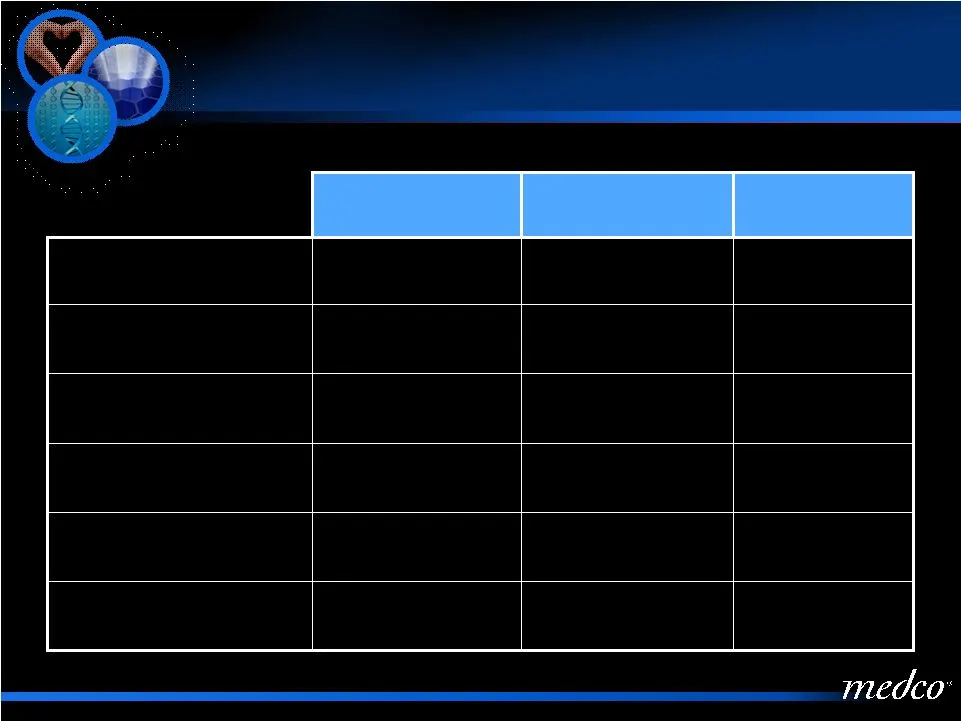
128 © 2007 Medco Health Solutions, Inc. All rights reserved. Guidance 278 – 282M 265 – 275M Dilutive Shares 39.0% - 39.5% 39.0% - 39.5% Tax Rate $150M $270M Capital Expenditures 10.5% 95M 105M Mail-Order Rxs $4.29 - $4.41 $3.89 - $4.01 2008 19% - 24% $3.55 - $3.60 Cash EPS 21% - 27% $3.16 - $3.21 GA
Slide 135: Advancing the Practice of Pharmacy
Advancing the Practice of Pharmacy medco’
Slide 136: Closing Remarks
Closing Remarks David Snow Chairman and CEO Closing Remarks David Snow Chairman and CEO
Slide 137: Medco 2007 Analyst Day
Medco 2007 Analyst Day November 16, 2007 Medco 2007 Analyst Day November 16, 2007
Slide 138: Advancing the Practice of Pharmacy
Advancing the Practice of Pharmacy medco’
Slide 139: Reconciliation Tables
133 © 2007 Medco Health Solutions, Inc. All rights reserved. Reconciliation Tables 1) 53-week fiscal year. All other fiscal years are comprised of 52 weeks. 2) Includes Accredo's operating results commencing August 18, 2005, the date of acquisition and for the subsequent periods. 3) 2003 excludes a
Slide 140: Reconciliation Tables
134 © 2007 Medco Health Solutions, Inc. All rights reserved. Reconciliation Tables 1) Represents the earnings per share effect of a pre-tax legal settlements charge of $162.6 million, or $99.9mm after tax, recorded in the first quarter of 2006. This charge reflects an agreement with the U.S. Attorne
Source: SEC EDGAR · 8-K filed Nov 16, 2007
More decks from Medco Health Solutions Inc
 Merger or Acquisition (July 2011)20 slides · Jul 22, 2011
 Sanford C. Bernstein 27th Annual Strategic Decisions Conference 201125 slides · Jun 1, 2011
 Deutsche Bank 36th Annual Health Care Conference 201130 slides · May 3, 2011
 Investor Presentation (March 2011)36 slides · Mar 24, 2011
 Barclays Capital 2011 Global Health Care Conference36 slides · Mar 17, 2011
 Citi 2011 Global Health Care Conference37 slides · Mar 1, 2011