Kingfisher PLC · LSE:KGF
Kingfisher — H1 2019/20 Earnings Presentation
33 slides from Kingfisher's earnings presentation, Sep 18, 2019
Slide 1: Kingfisher plc half year results
Kingfisher plc half year results 6 months to 31 July 2019 18 September 2019
Slide 2: Disclaimer
Disclaimer You are not to construe the content of this presentation as investment, legal or tax advice and you should make you own evaluation of the Company and the market. If you are in any doubt about the contents of this presentation or the action you should take, you should consult a person auth
Slide 3: Welcome & introduction
Welcome & introduction Andy Cosslett, Chairman 3
Slide 4: Key point summary
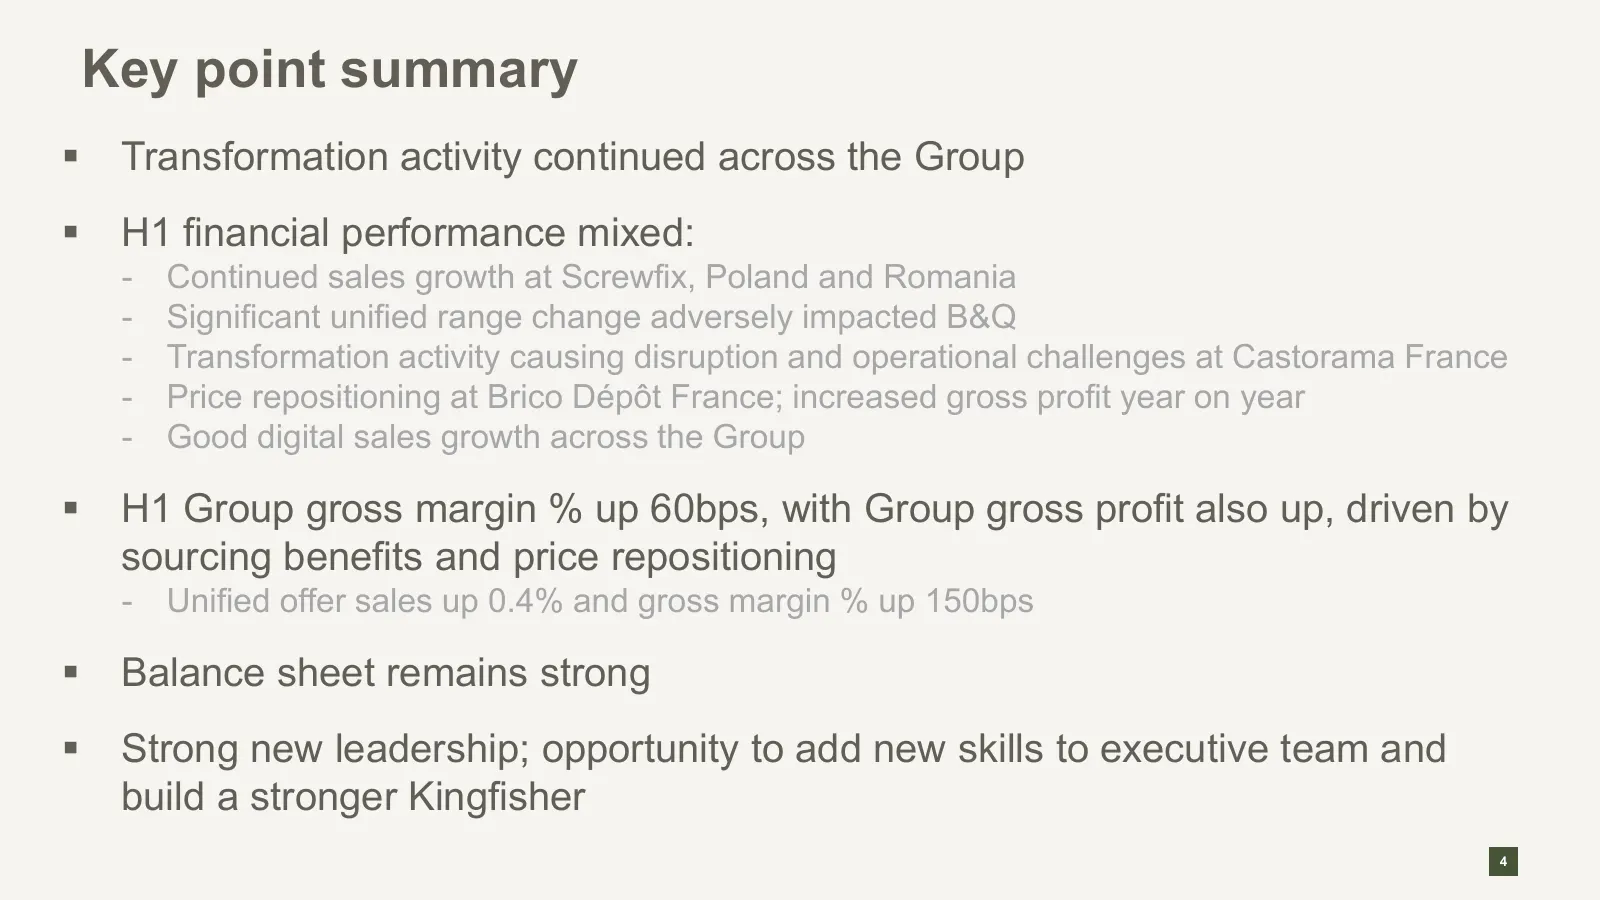
Key point summary Transformation activity continued across the Group H1 financial performance mixed: - Continued sales growth at Screwfix, Poland and Romania - Significant unified range change adversely impacted B&Q - Transformation activity causing disruption and operational challenges at Casto
Slide 5: H1 19/20 highlights
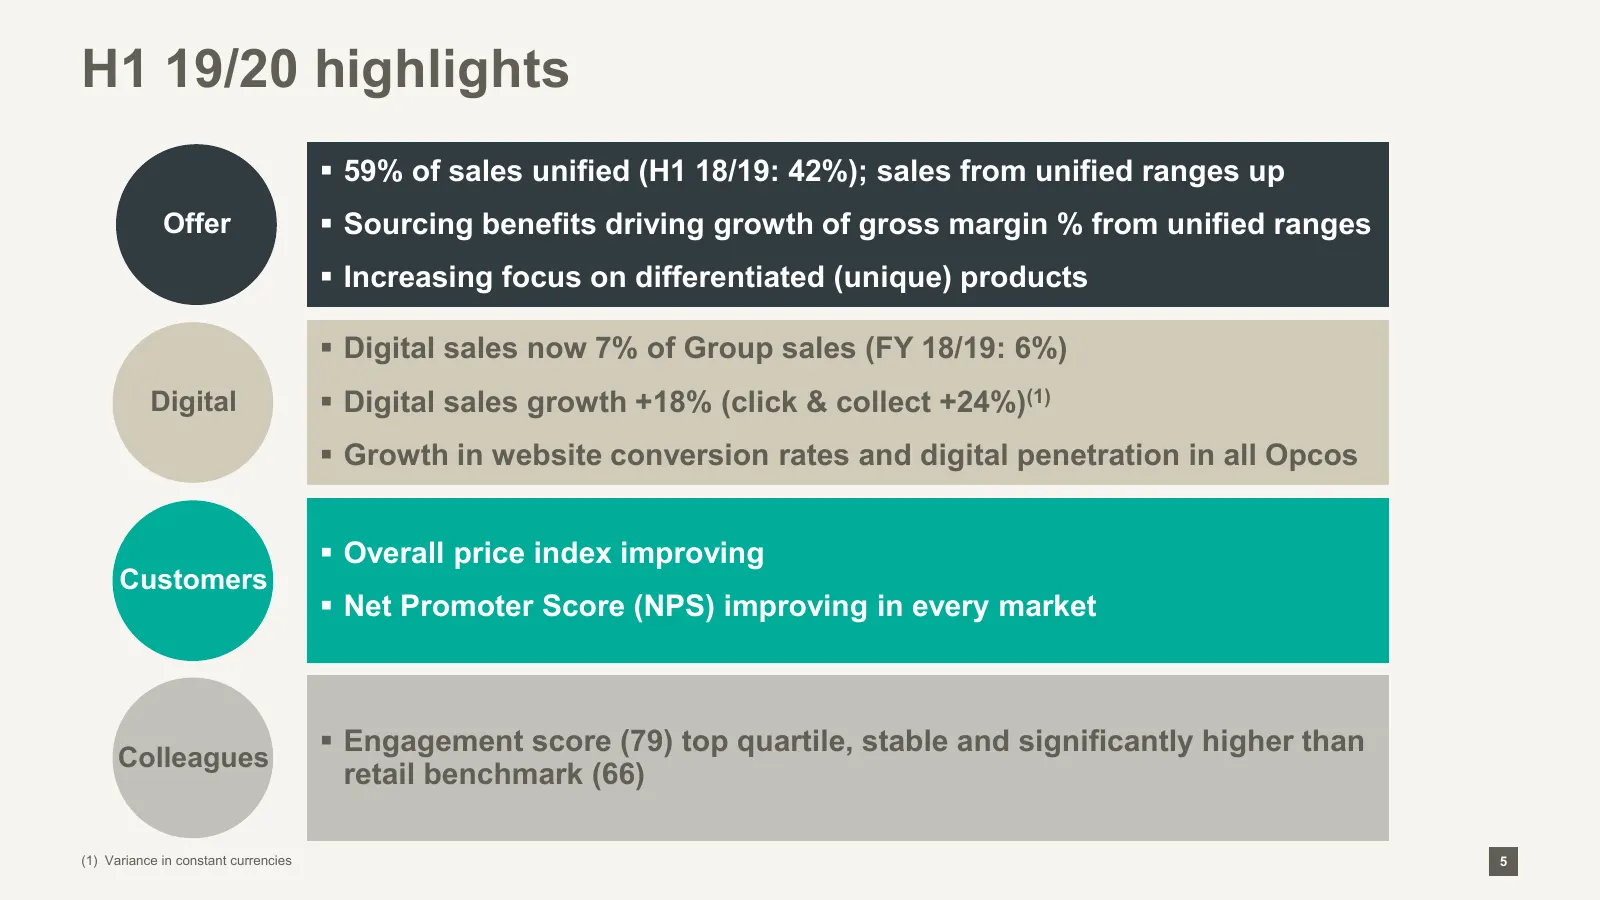
H1 19/20 highlights 59% of sales unified (H1 18/19: 42%); sales from unified ranges up Offer Sourcing benefits driving growth of gross margin % from unified ranges Increasing focus on differentiated (unique) products Digital sales now 7% of Group sales (FY 18/19: 6%) Digital Digital sales
Slide 6: H1 2019/20 financial results
H1 2019/20 financial results John Wartig, Interim CFO 6
Slide 7: H1 19/20 summary income statement
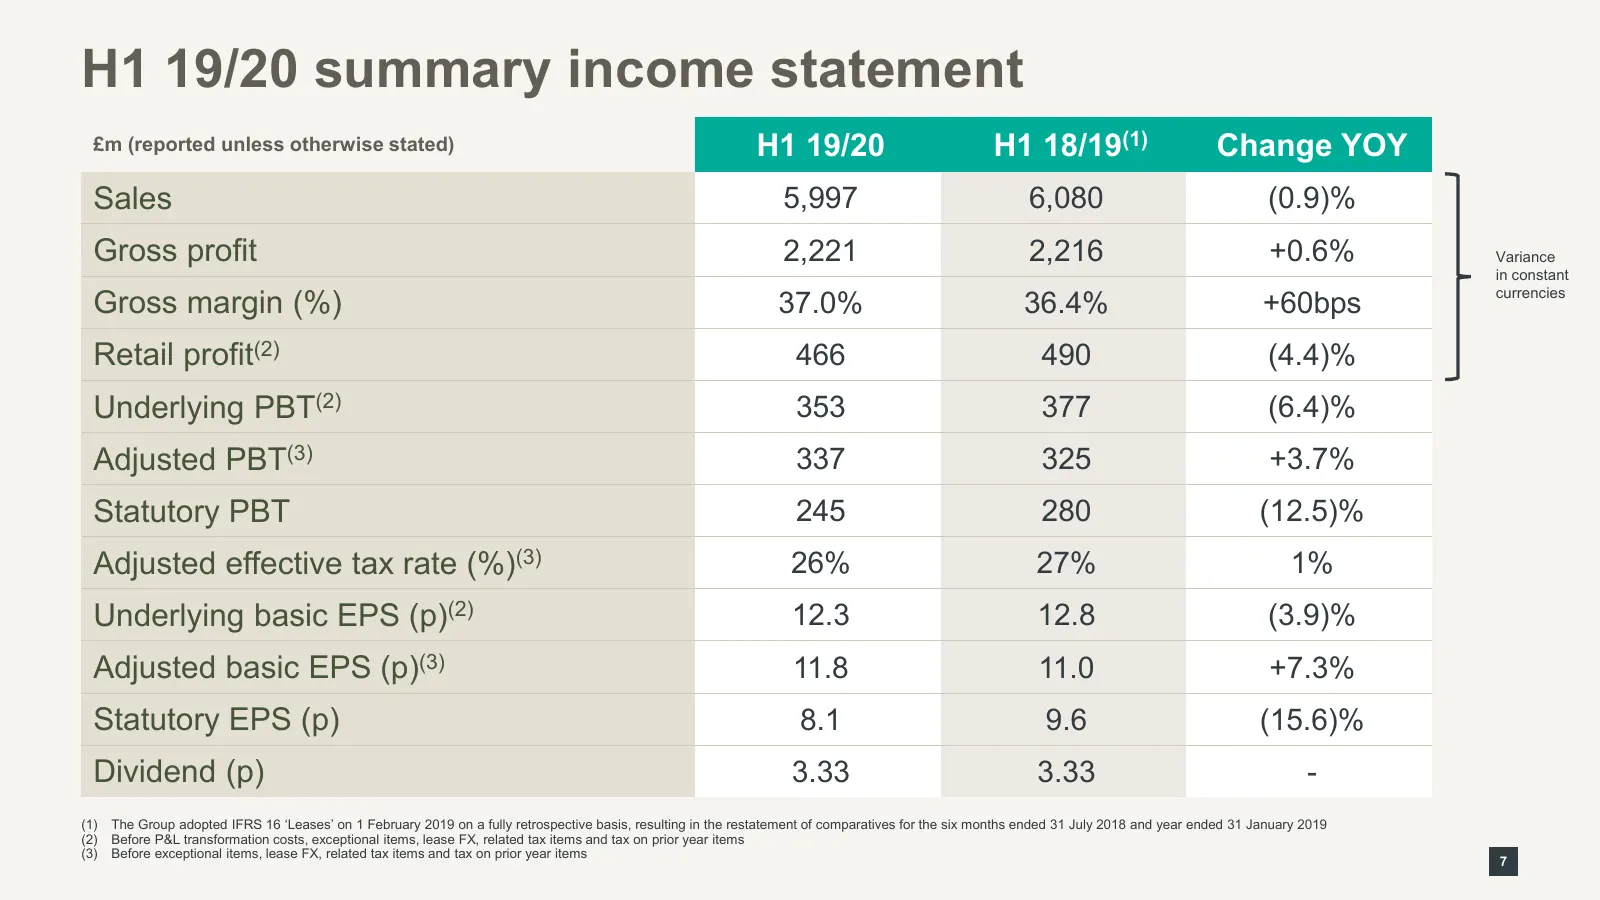
H1 19/20 summary income statement £m (reported unless otherwise stated) H1 19/20 H1 18/19(1) Change YOY Sales 5,997 6,080 (0.9)% Gross profit 2,221 2,216 +0.6% Variance in constant Gross margin (%) 37.0% 36.4% +60bps currencies Retail profit(2) 466 490 (4.4)% Underlying PBT(2) 353 377 (6.4)% Adjuste
Slide 8: H1 19/20 transformation costs and exceptional items
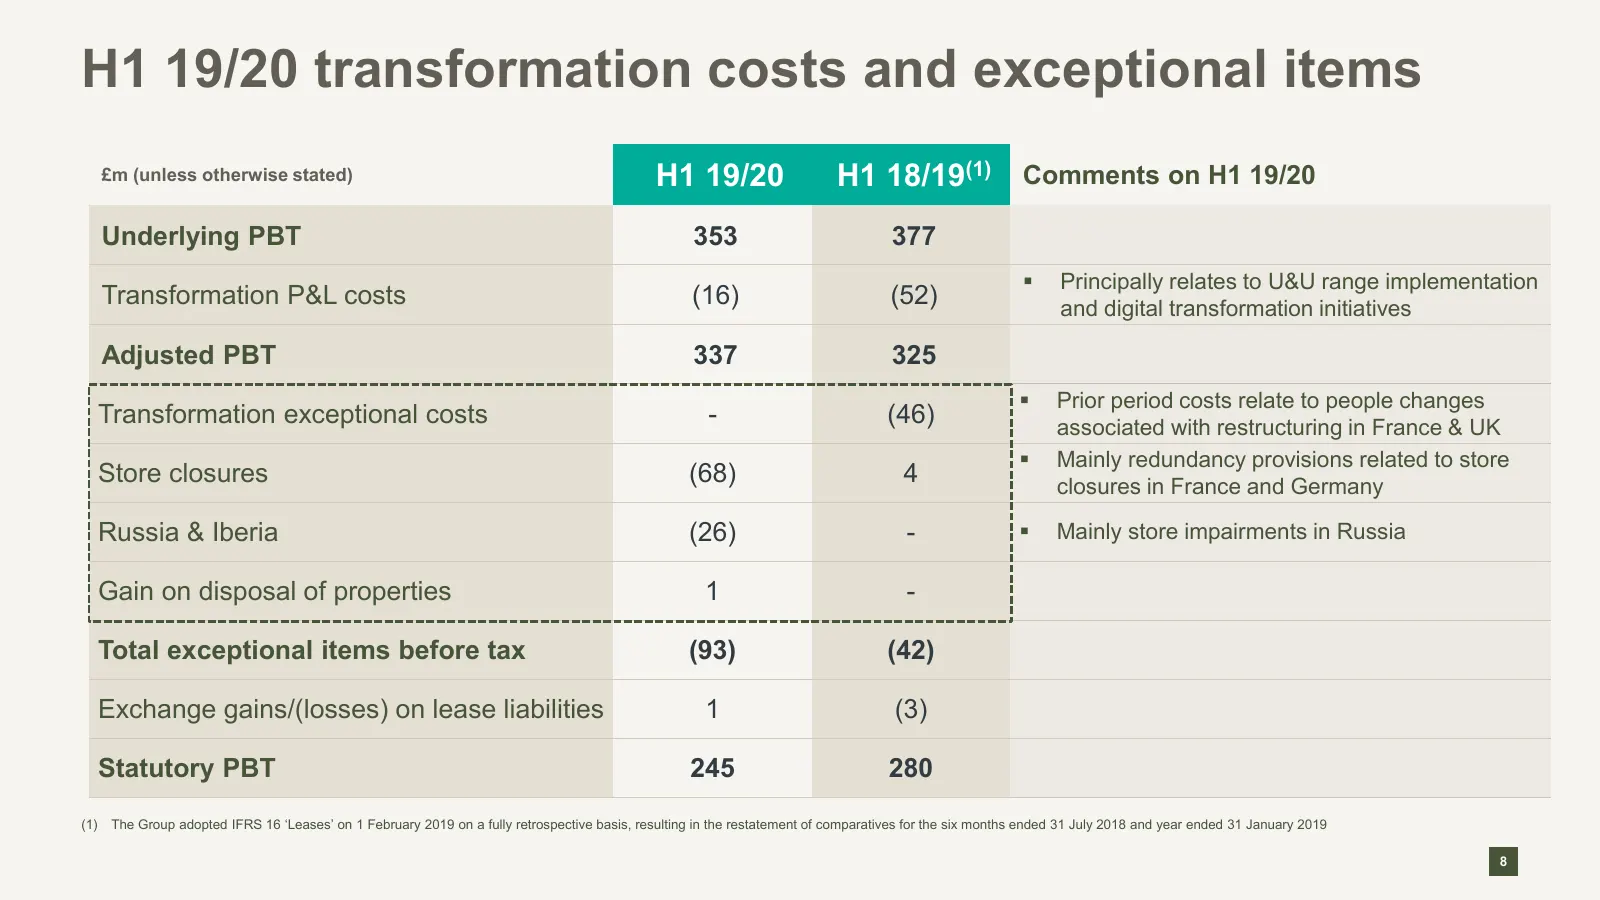
H1 19/20 transformation costs and exceptional items £m (unless otherwise stated) H1 19/20 H1 18/19(1) Comments on H1 19/20 Underlying PBT 353 377 Principally relates to U&U range implementation Transformation P&L costs (16) (52) and digital transformation initiatives Adjusted PBT 337 325 Prior p
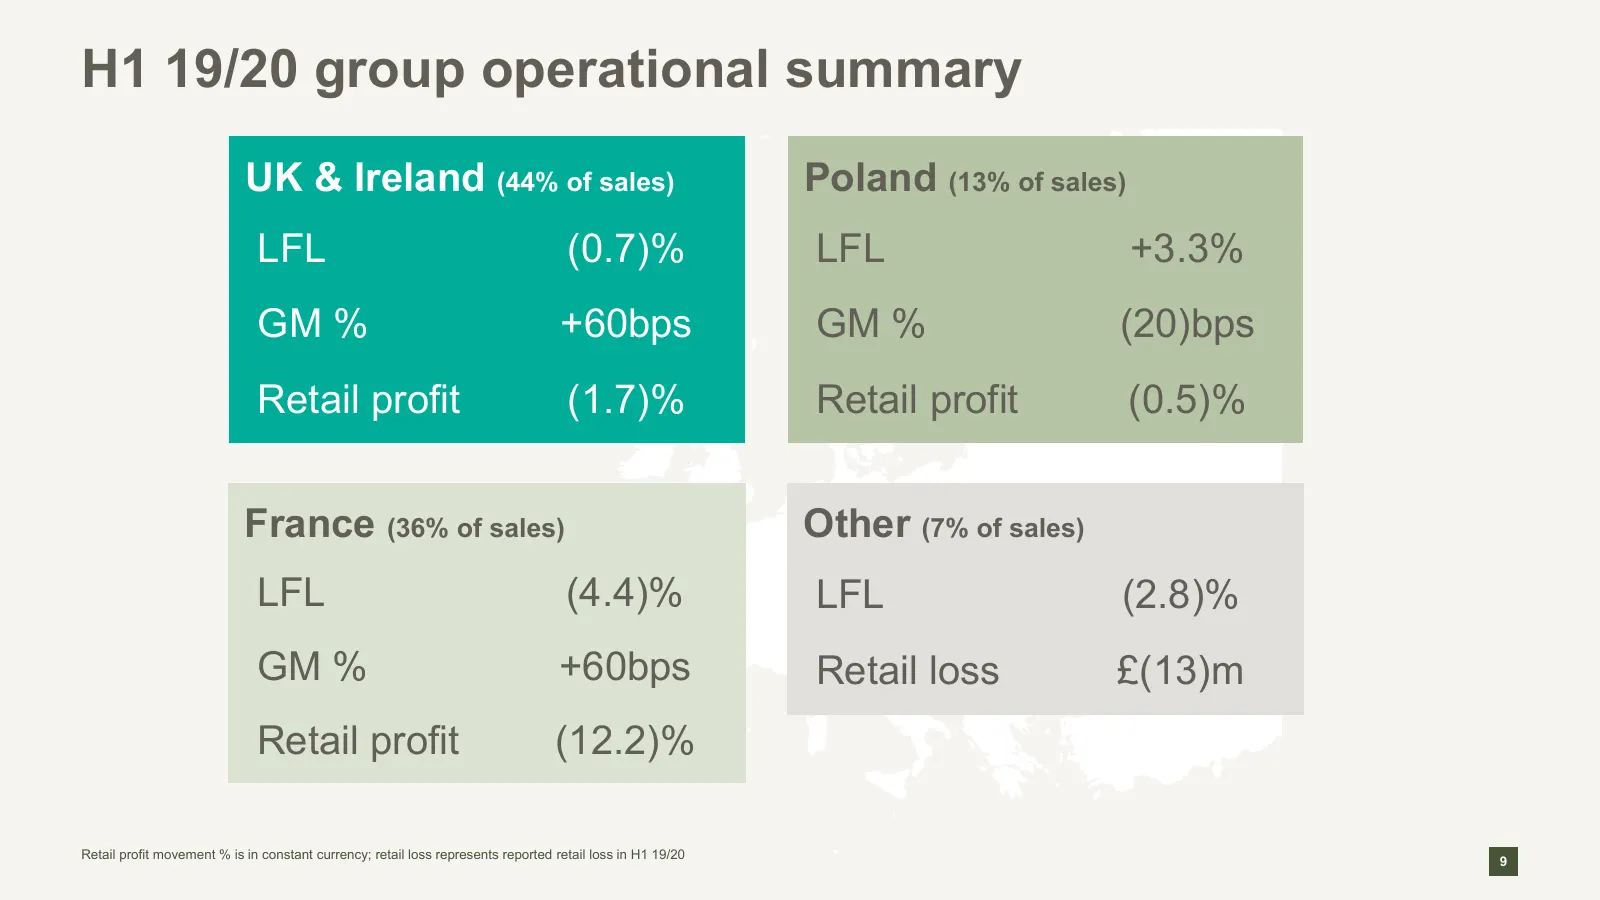
Slide 9: H1 19/20 group operational summary
H1 19/20 group operational summary UK & Ireland (44% of sales) Poland (13% of sales) LFL (0.7)% LFL +3.3% GM % +60bps GM % (20)bps Retail profit (1.7)% Retail profit (0.5)% France (36% of sales) Other (7% of sales) LFL (4.4)% LFL (2.8)% GM % +60bps Retail loss £(13)m Retail profit (12.2)% Retail pro
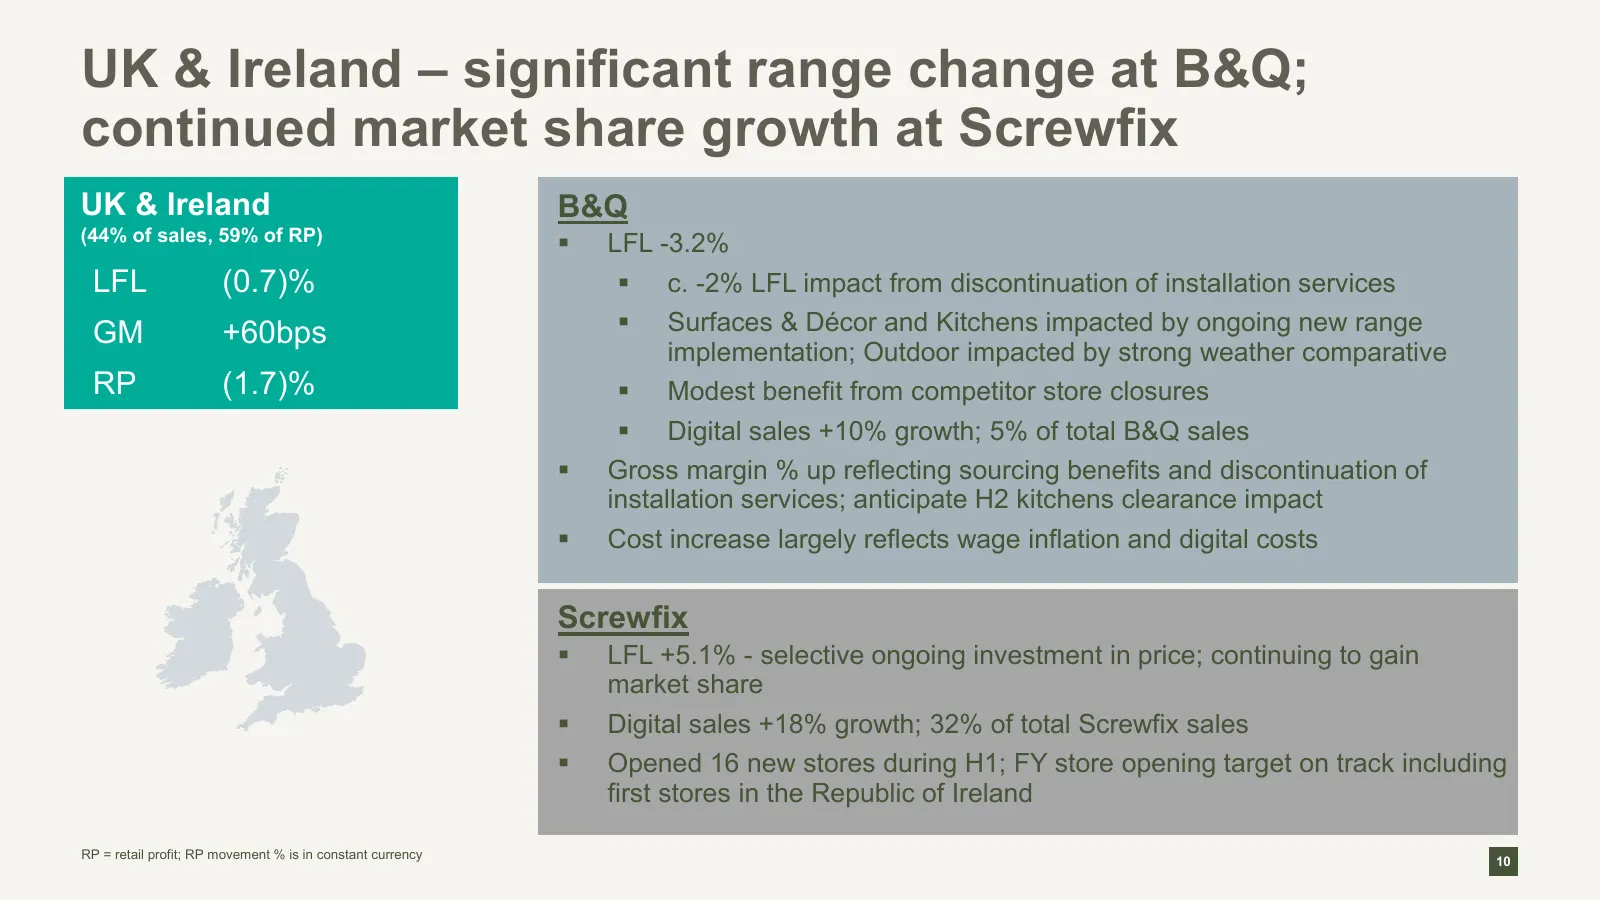
Slide 10: UK & Ireland – significant range change at B&Q; continued market share growth at Screwfix
UK & Ireland – significant range change at B&Q; continued market share growth at Screwfix UK & Ireland B&Q (44% of sales, 59% of RP) LFL -3.2% LFL (0.7)% c. -2% LFL impact from discontinuation of installation services GM +60bps Surfaces & Décor and Kitchens impacted by ongoing new range implem
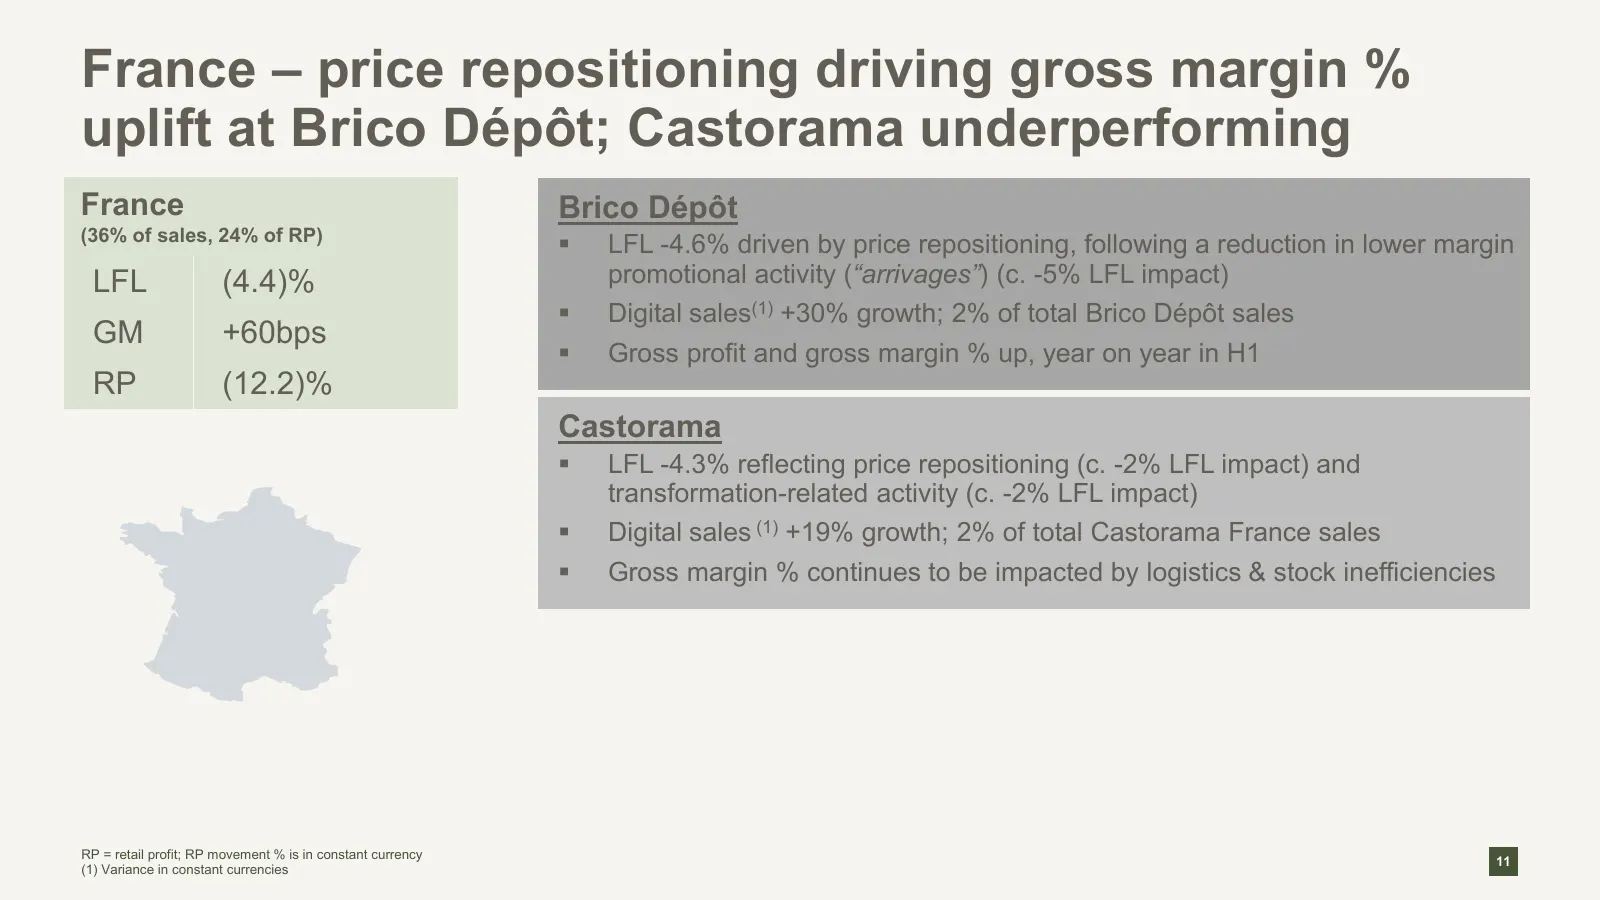
Slide 11: France – price repositioning driving gross margin % uplift at Brico Dépôt; Castorama underperforming
France – price repositioning driving gross margin % uplift at Brico Dépôt; Castorama underperforming France Brico Dépôt (36% of sales, 24% of RP) LFL -4.6% driven by price repositioning, following a reduction in lower margin LFL (4.4)% promotional activity (“arrivages”) (c. -5% LFL impact) Digit
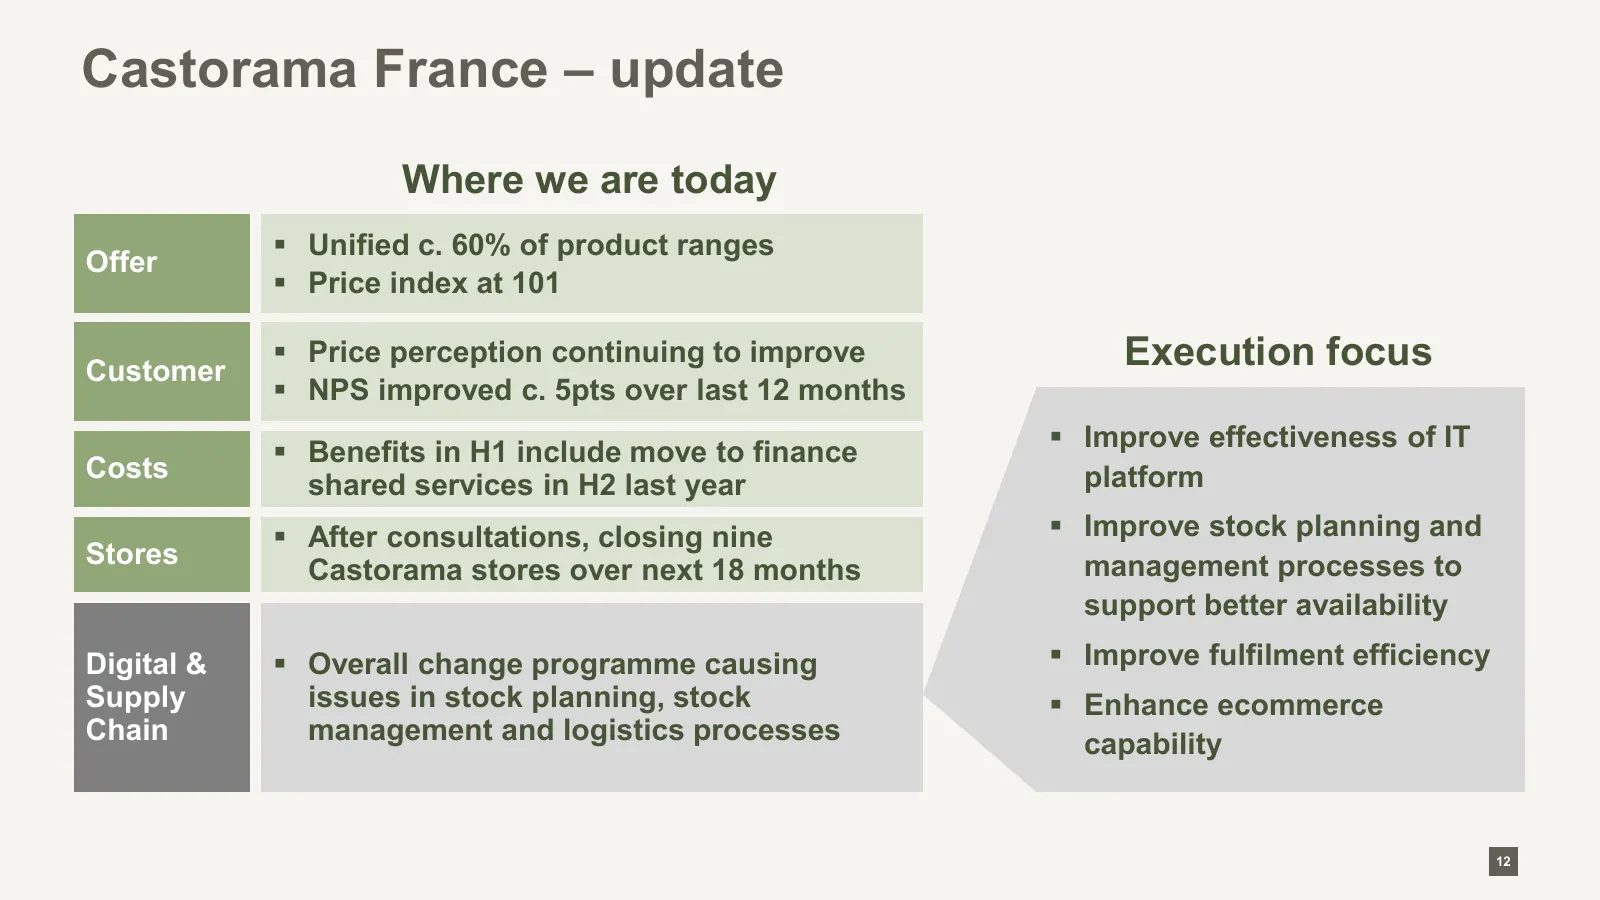
Slide 12: Castorama France – update
Castorama France – update Where we are today Unified c. 60% of product ranges Offer Price index at 101 Customer Price perception continuing to improve Execution focus NPS improved c. 5pts over last 12 months Benefits in H1 include move to finance Improve effectiveness of IT Costs platfor
Slide 13: Poland – solid performance; Romania – in transition
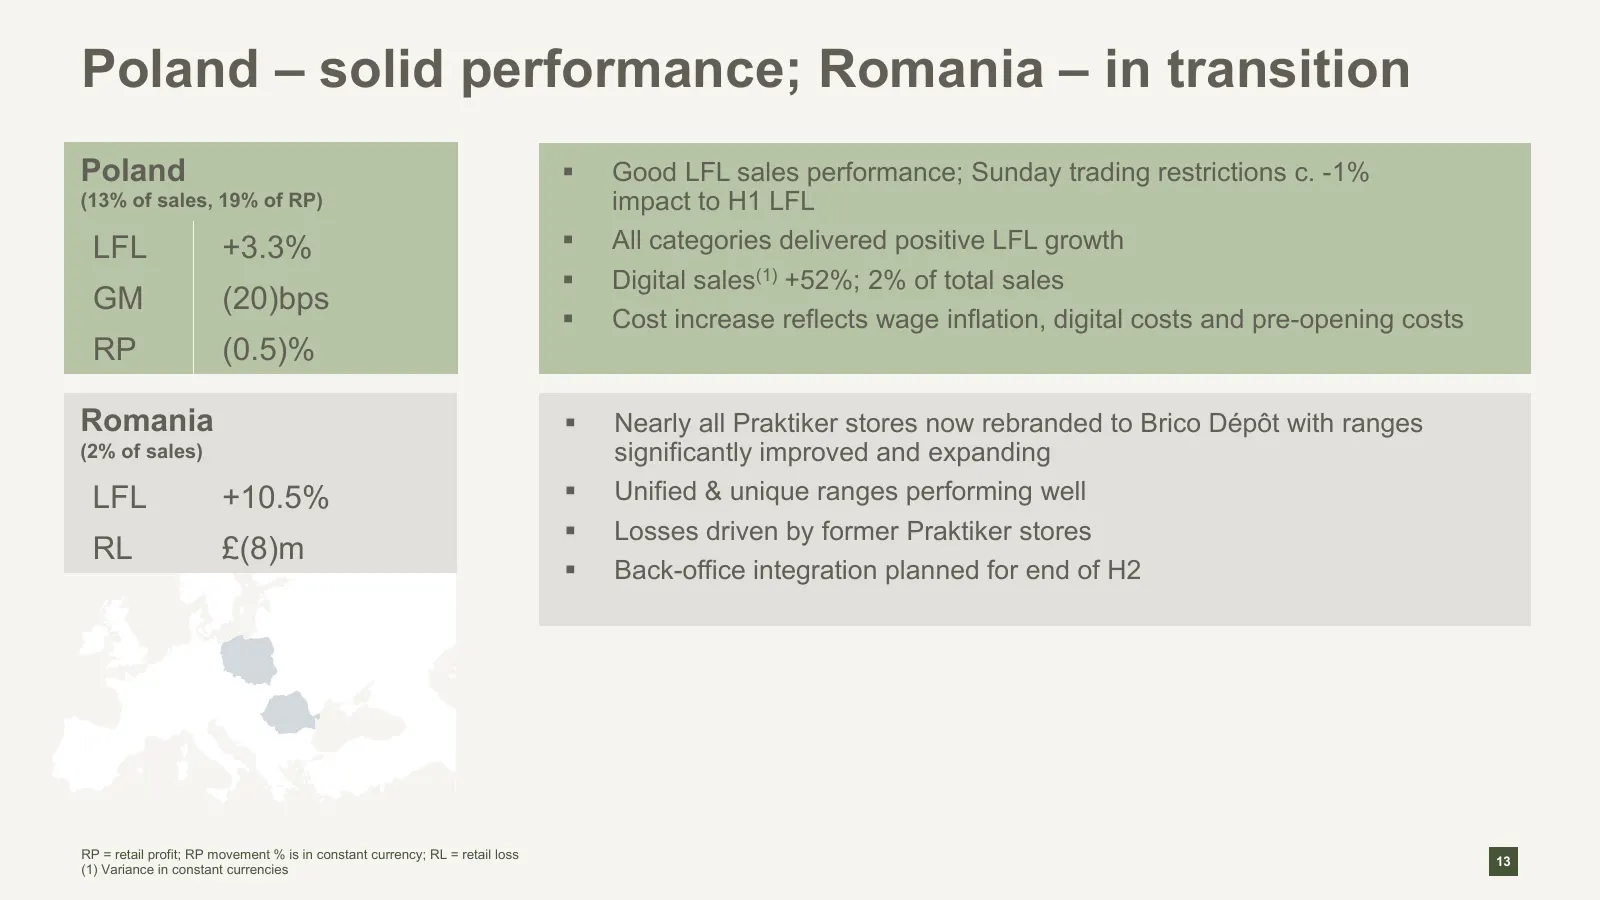
Poland – solid performance; Romania – in transition Poland Good LFL sales performance; Sunday trading restrictions c. -1% (13% of sales, 19% of RP) impact to H1 LFL LFL +3.3% All categories delivered positive LFL growth Digital sales(1) +52%; 2% of total sales GM (20)bps Cost increase reflec
Slide 14: Iberia, Russia & Germany
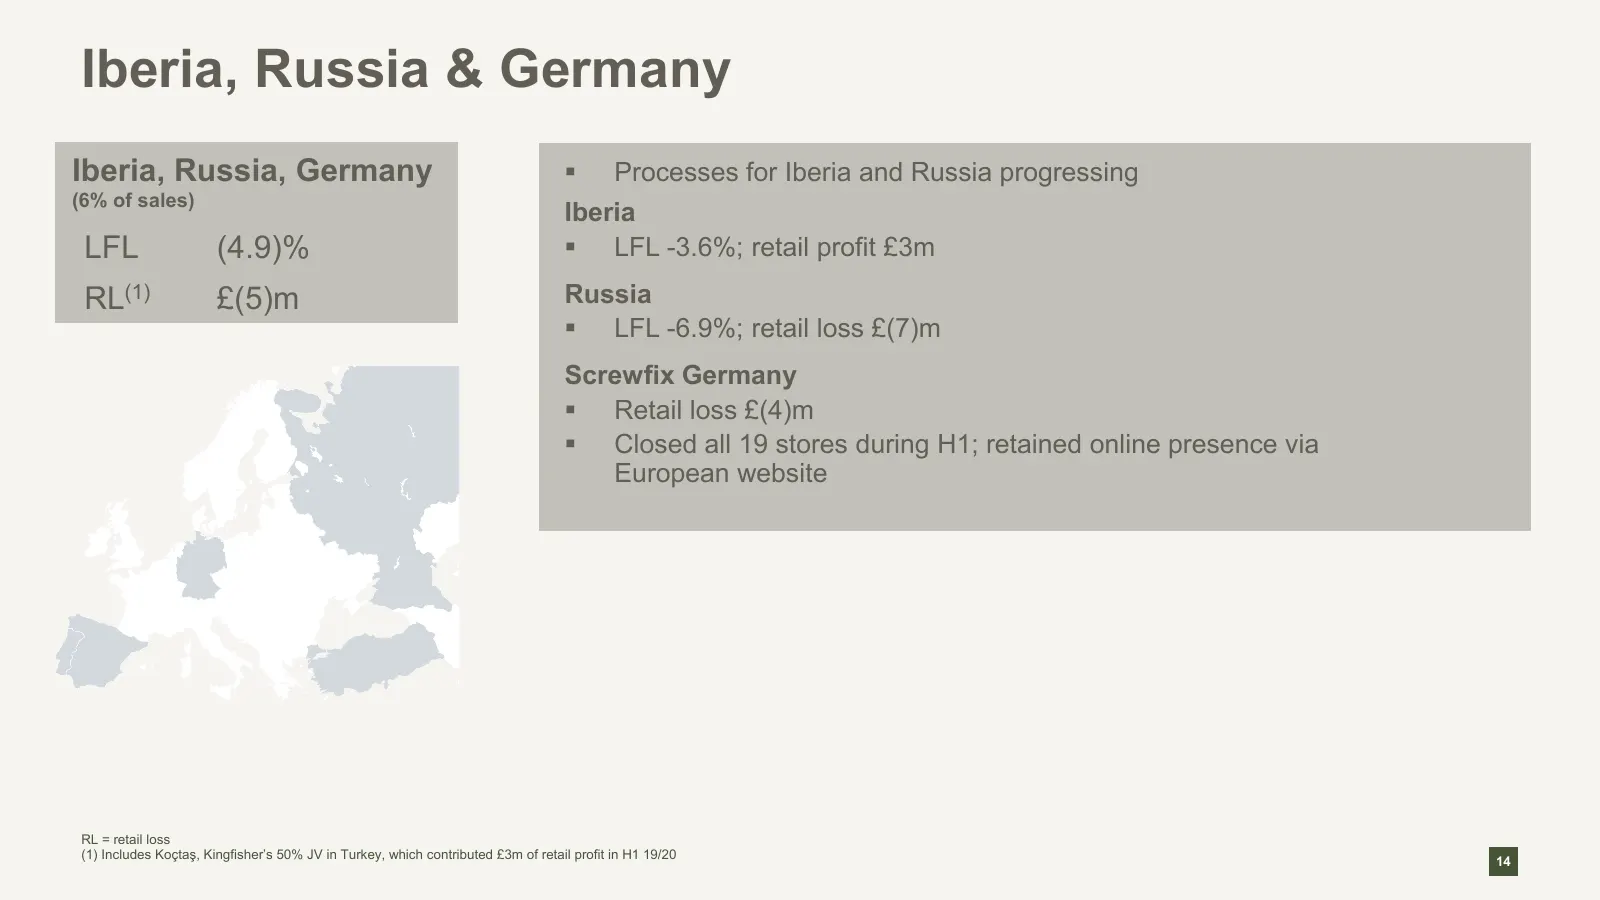
Iberia, Russia & Germany Iberia, Russia, Germany Processes for Iberia and Russia progressing (6% of sales) Iberia LFL (4.9)% LFL -3.6%; retail profit £3m RL(1) £(5)m Russia LFL -6.9%; retail loss £(7)m Screwfix Germany Retail loss £(4)m Closed all 19 stores during H1; retained online prese
Slide 15: Unified & unique outperforming non-unified
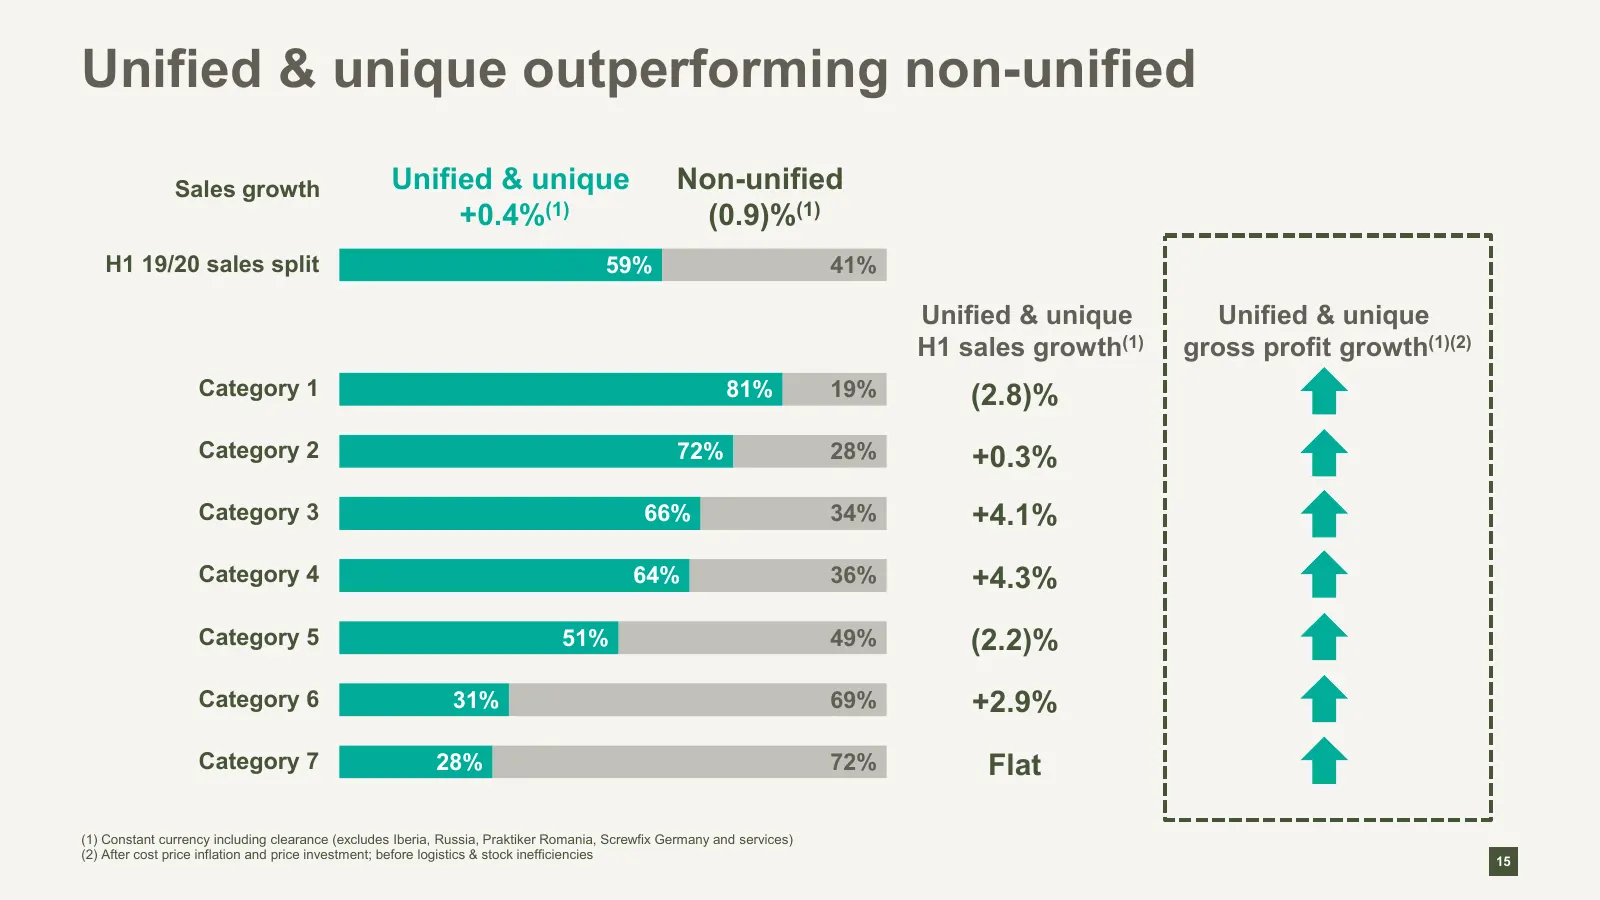
Unified & unique outperforming non-unified Sales growth Unified & unique Non-unified +0.4%(1) (0.9)%(1) H1 19/20 sales split 59% 41% Unified & unique Unified & unique Unified & unique H1 sales growth H1 sales (1) (1) growth gross profit growth(1)(2) Category 1 81% 19% (2.8)% +5.9% Category 2 72% 28%
Slide 16: Unified & unique and price repositioning benefits partly offset by clearance and inefficiencies
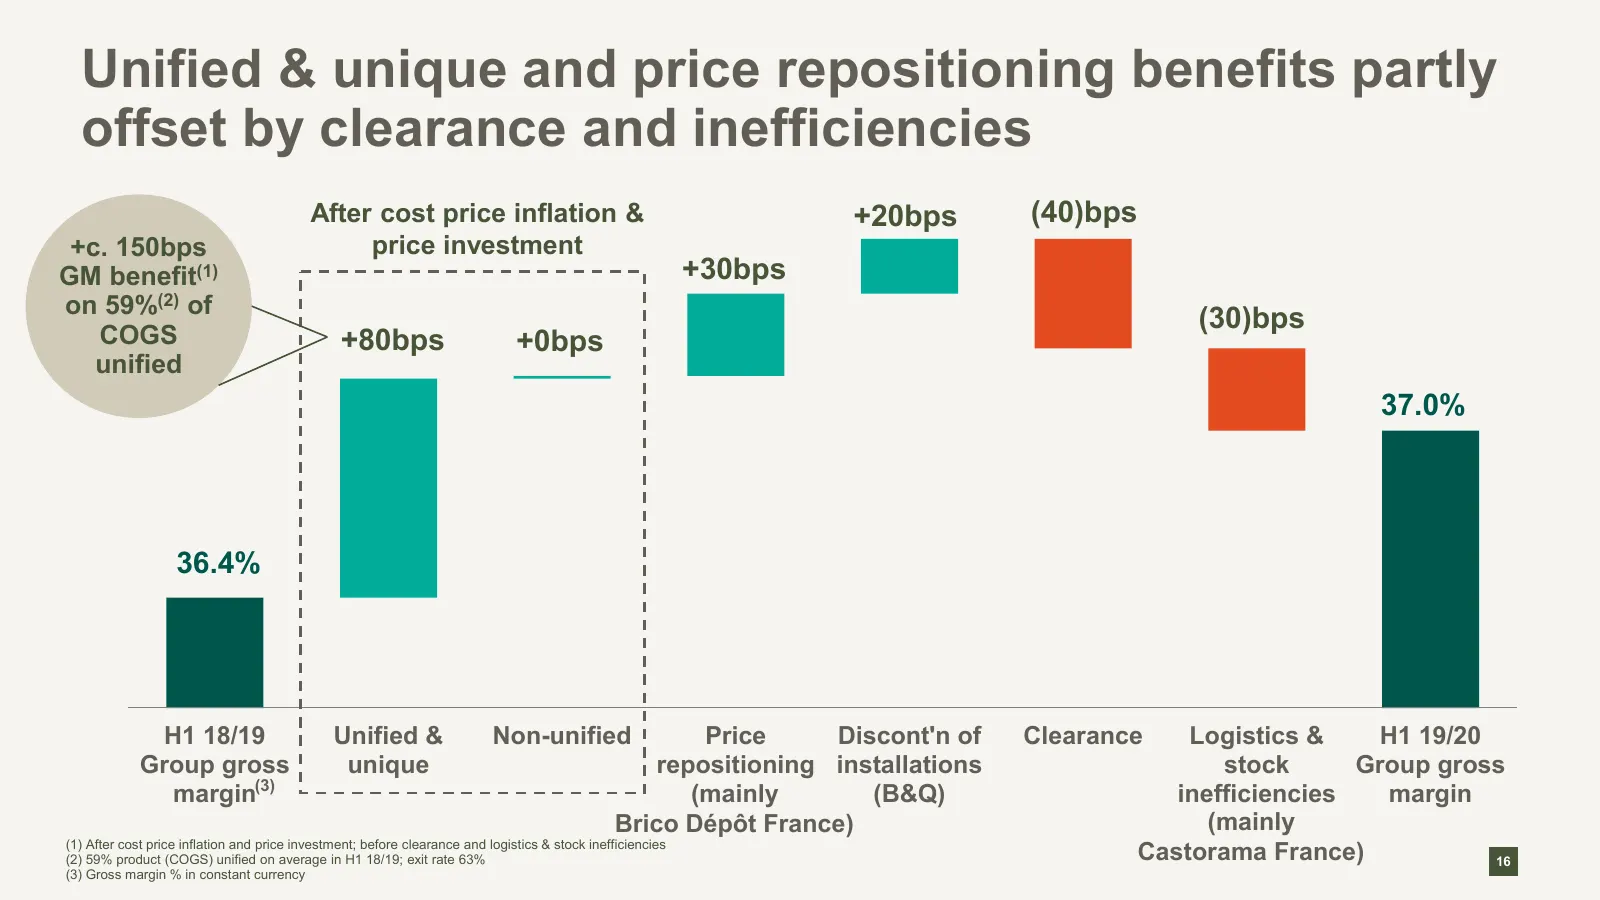
Unified & unique and price repositioning benefits partly offset by clearance and inefficiencies After cost price inflation & +20bps (40)bps +c. 150bps price investment GM benefit(1) +30bps on 59%(2) of (30)bps COGS +80bps +0bps unified 37.0% 36.4% H1 18/19 Unified & Non-unified Price Discont'n of Cl
Slide 17: H1 19/20 summary cash flow and net debt
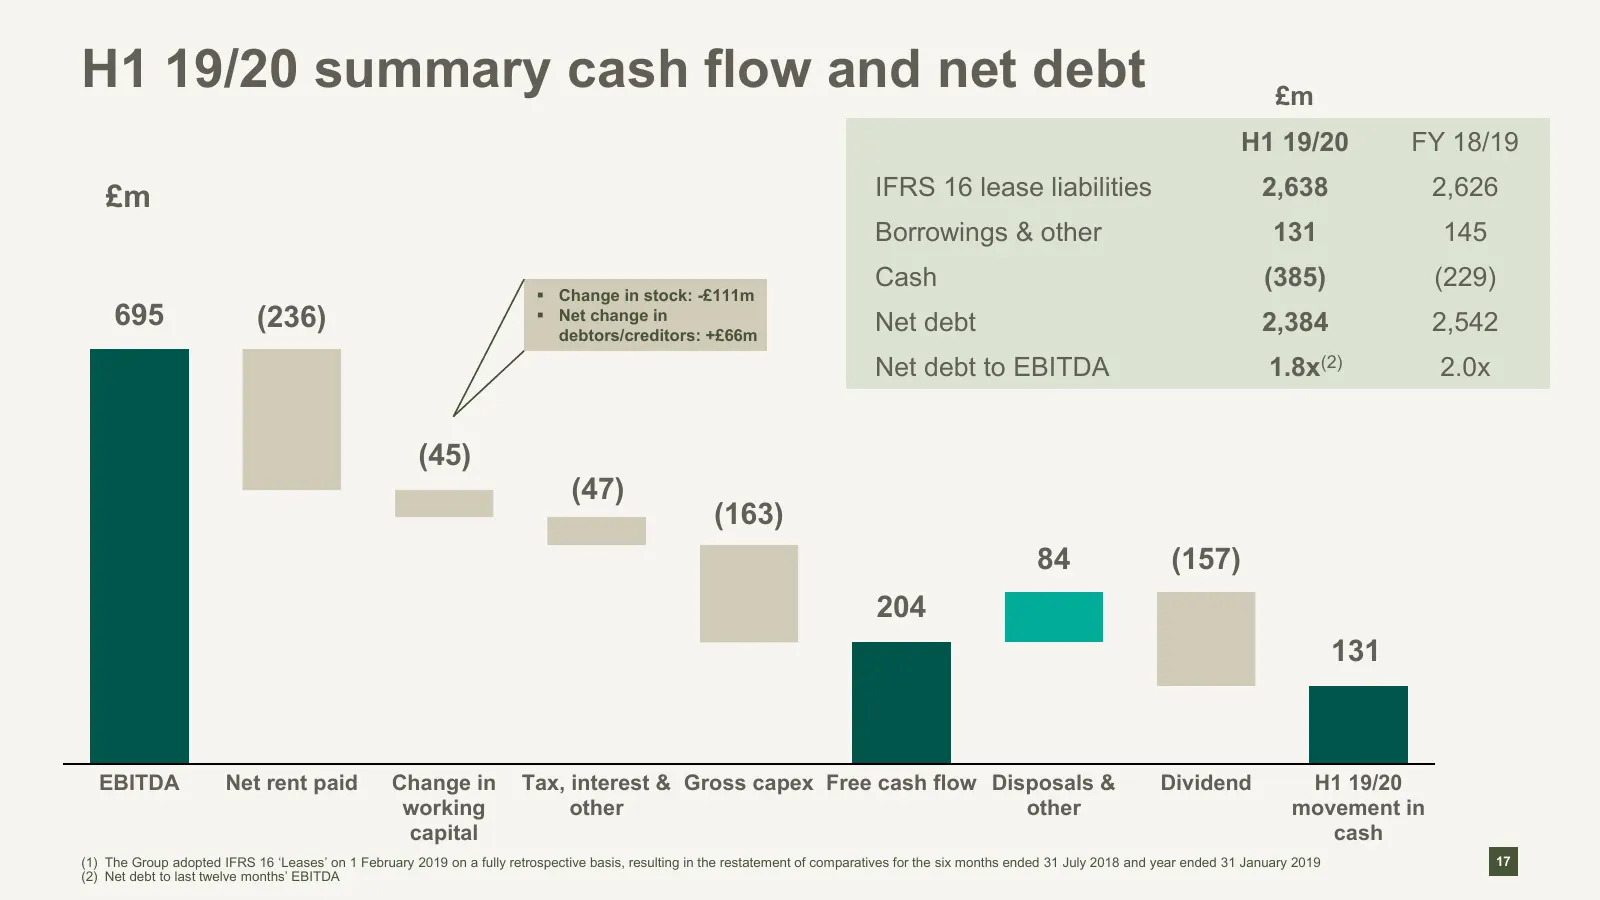
H1 19/20 summary cash flow and net debt £m H1 19/20 FY 18/19 £m IFRS 16 lease liabilities 2,638 2,626 Borrowings & other 131 145 Cash (385) (229) Change in stock: -£111m 695 (236) Net change in Net debt 2,384 2,542 debtors/creditors: +£66m Net debt to EBITDA 1.8x(2) 2.0x (45) (47) (163) 84 (157)
Slide 18: FY 19/20 outlook & technical guidance
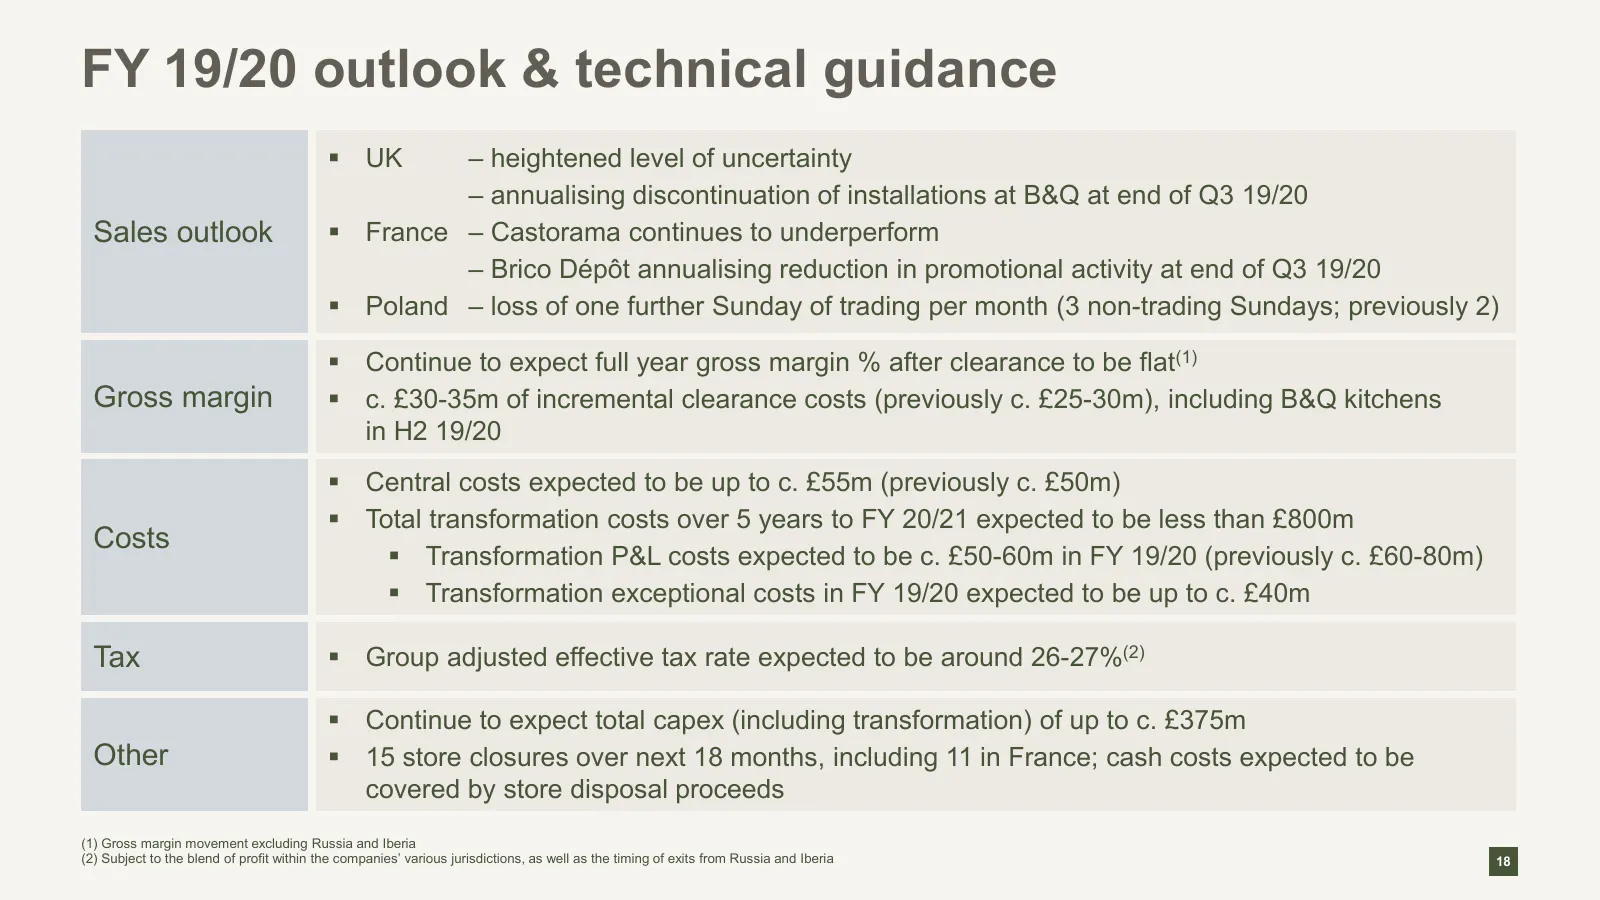
FY 19/20 outlook & technical guidance UK – heightened level of uncertainty – annualising discontinuation of installations at B&Q at end of Q3 19/20 Sales outlook France – Castorama continues to underperform – Brico Dépôt annualising reduction in promotional activity at end of Q3 19/20 Poland –
Slide 19: Impact of IFRS 16 'Leases'
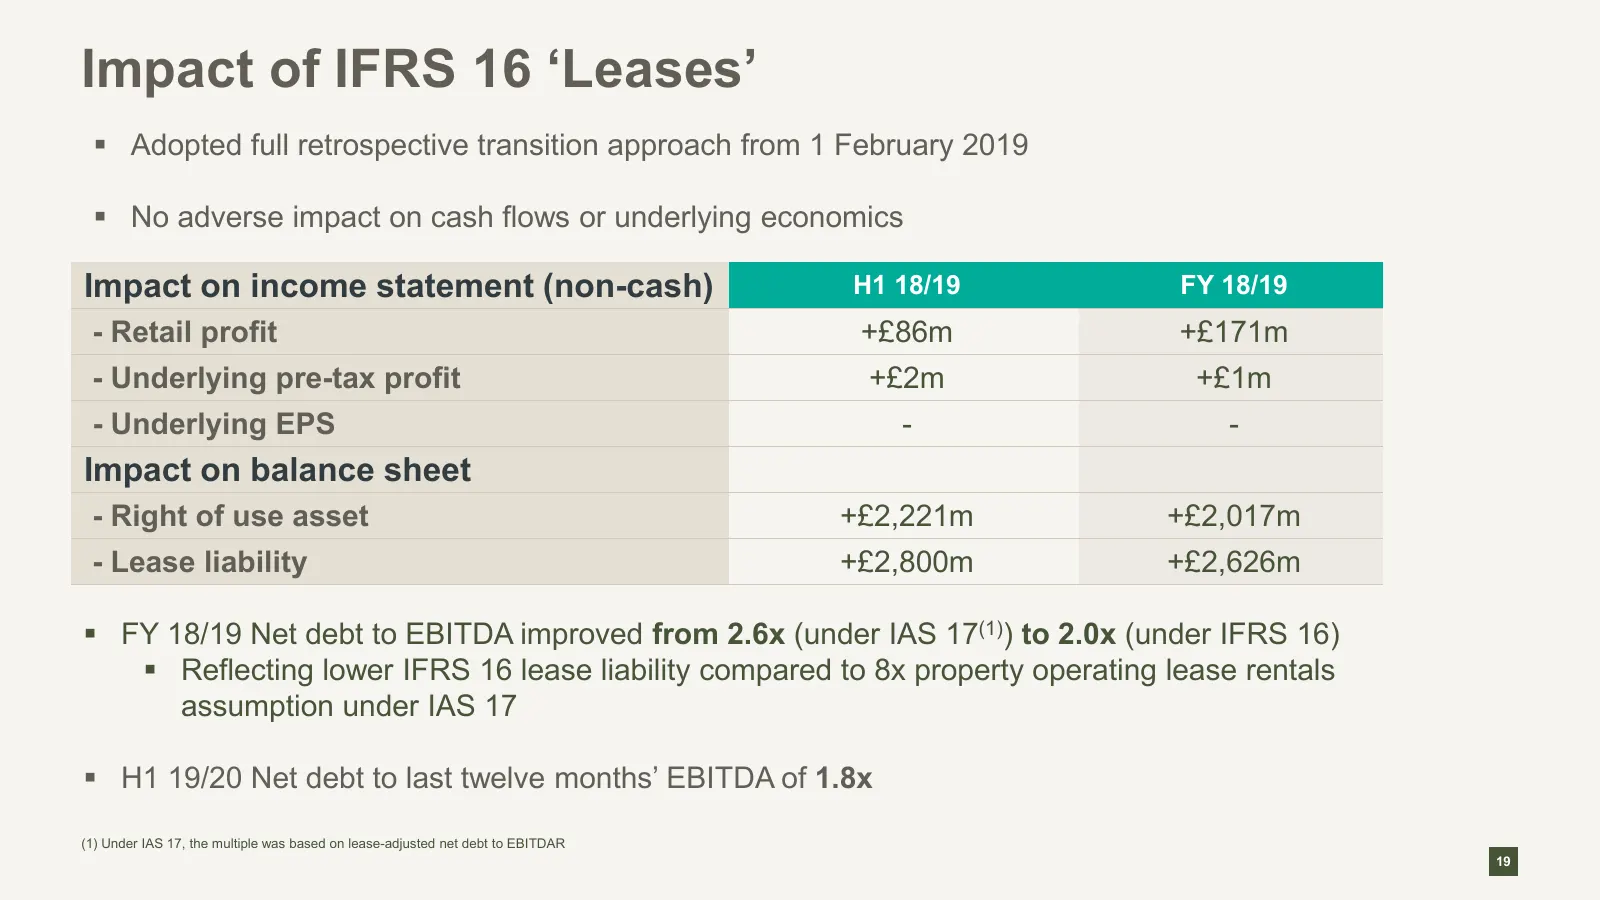
Impact of IFRS 16 ‘Leases’ Adopted full retrospective transition approach from 1 February 2019 No adverse impact on cash flows or underlying economics Impact on income statement (non-cash) H1 18/19 FY 18/19 - Retail profit +£86m +£171m - Underlying pre-tax profit +£2m +£1m - Underlying EPS - - I
Slide 20: Brexit and currency exposures
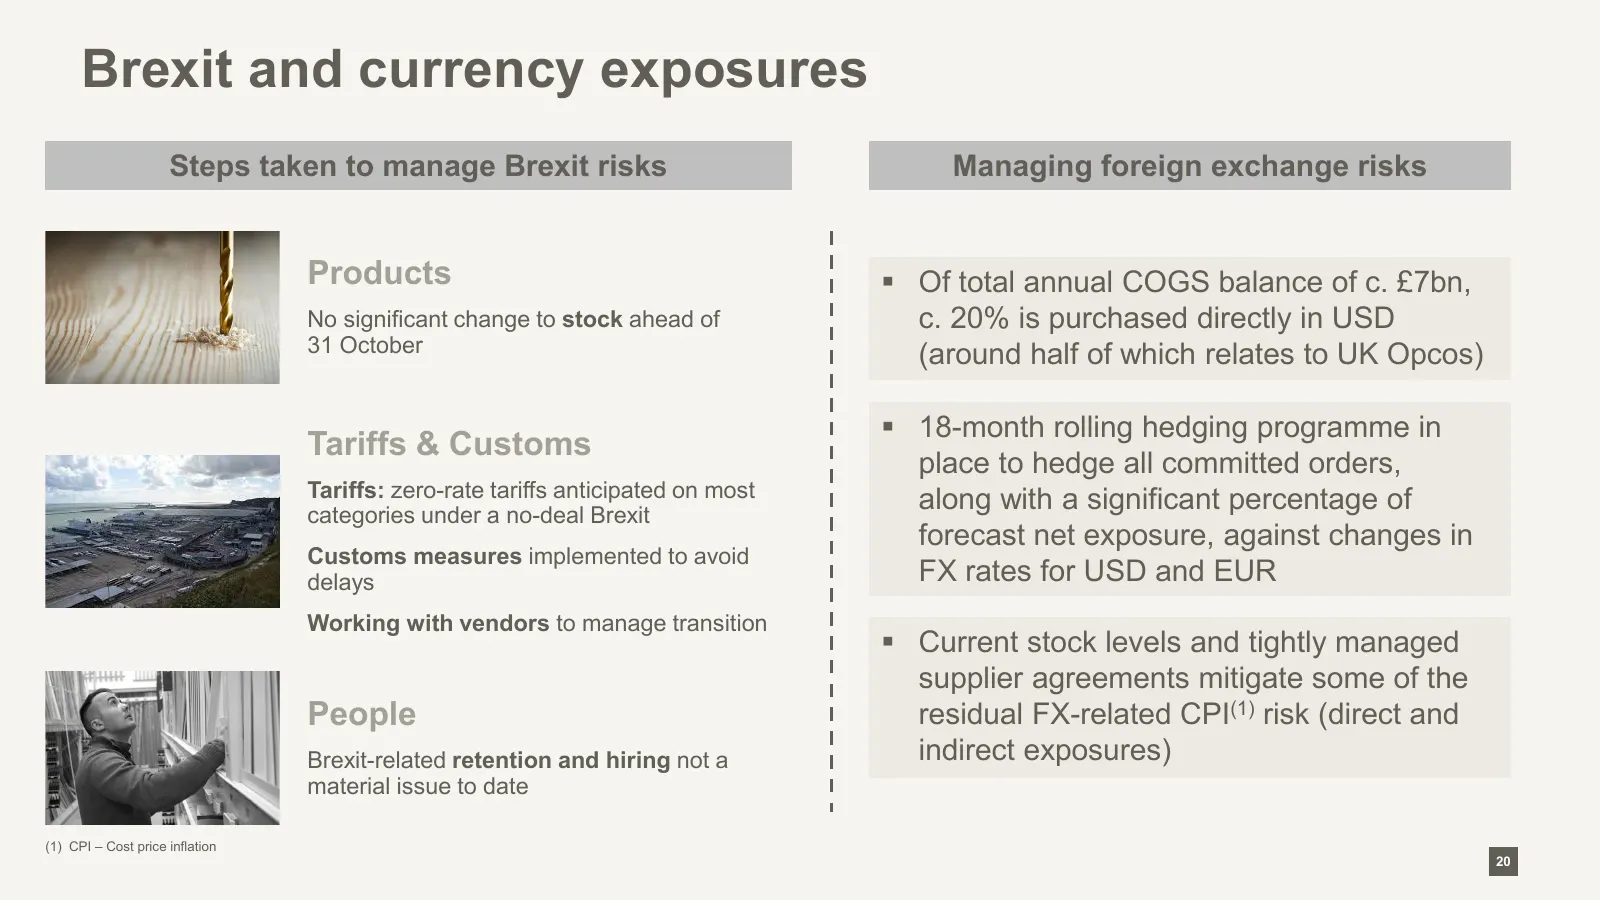
Brexit and currency exposures Steps taken to manage Brexit risks Managing foreign exchange risks Products Of total annual COGS balance of c. £7bn, No significant change to stock ahead of c. 20% is purchased directly in USD 31 October (around half of which relates to UK Opcos) 18-month rolling he
Slide 21: Financial summary
Financial summary 1 2 H1 19/20 financial Castorama France performance mixed operational issues identified and focused workplan in place 3 4 H1 19/20 Group gross Balance sheet margin % up 60bps driven remains strong by sourcing benefits and price repositioning 5 6 Outlook for our main Continue to exp
Slide 22: Building a stronger Kingfisher
Building a stronger Kingfisher Andy Cosslett, Chairman 22
Slide 23: Leveraging the Group's scale as a competitive advantage
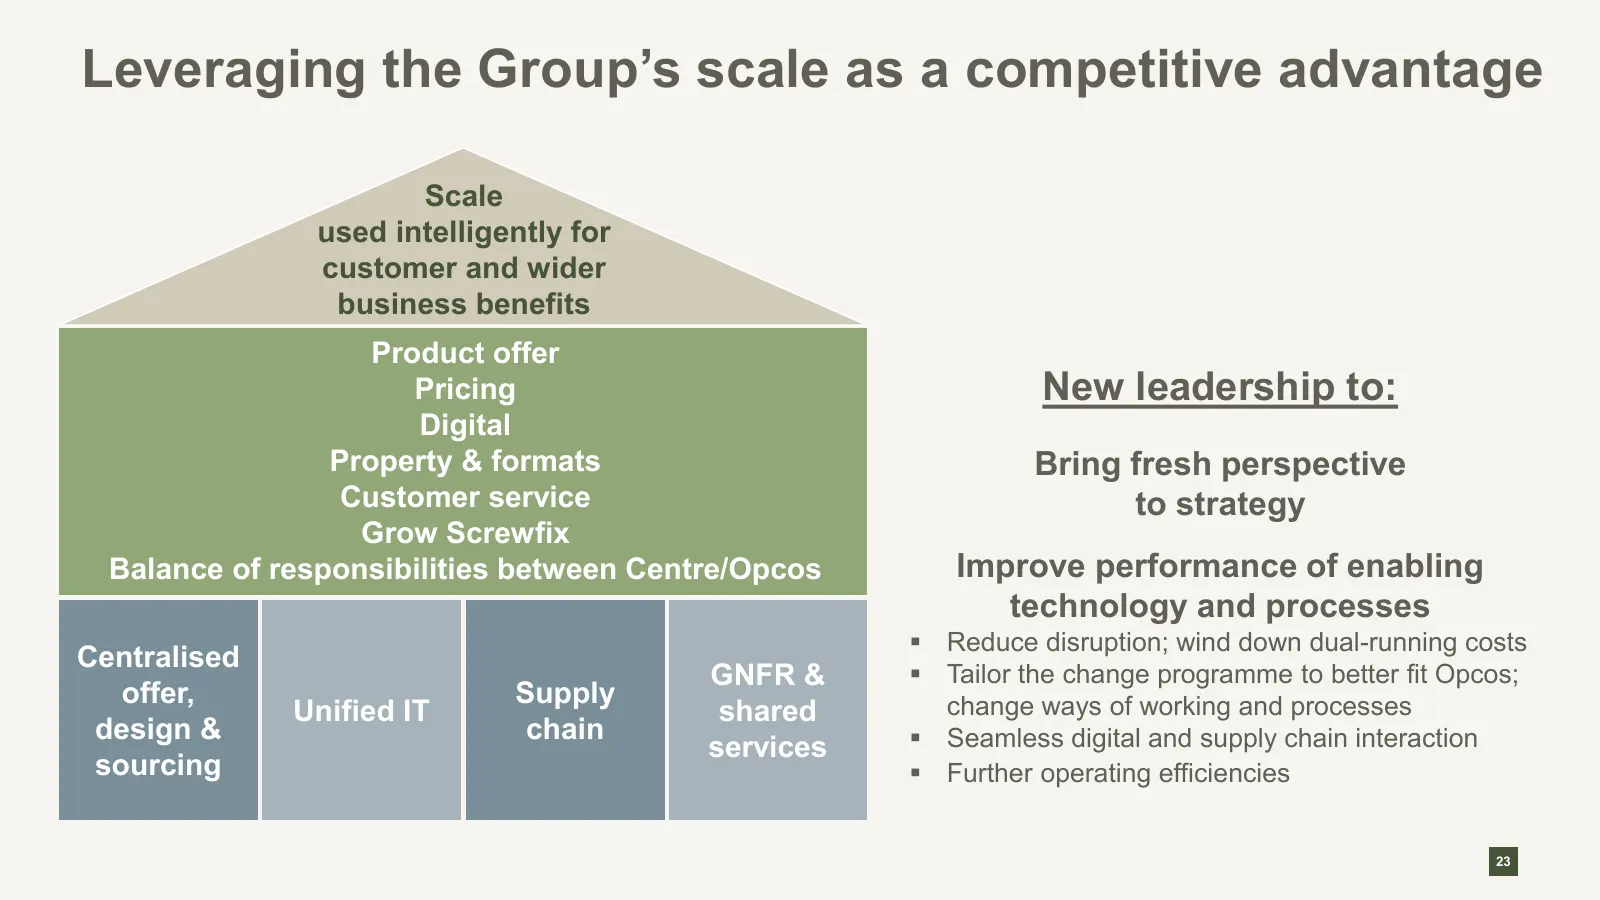
Leveraging the Group’s scale as a competitive advantage Scale used intelligently for customer and wider business benefits Product offer Pricing New leadership to: Digital Property & formats Bring fresh perspective Customer service to strategy Grow Screwfix Balance of responsibilities between Centre/
Slide 24: Important new ranges landing this year
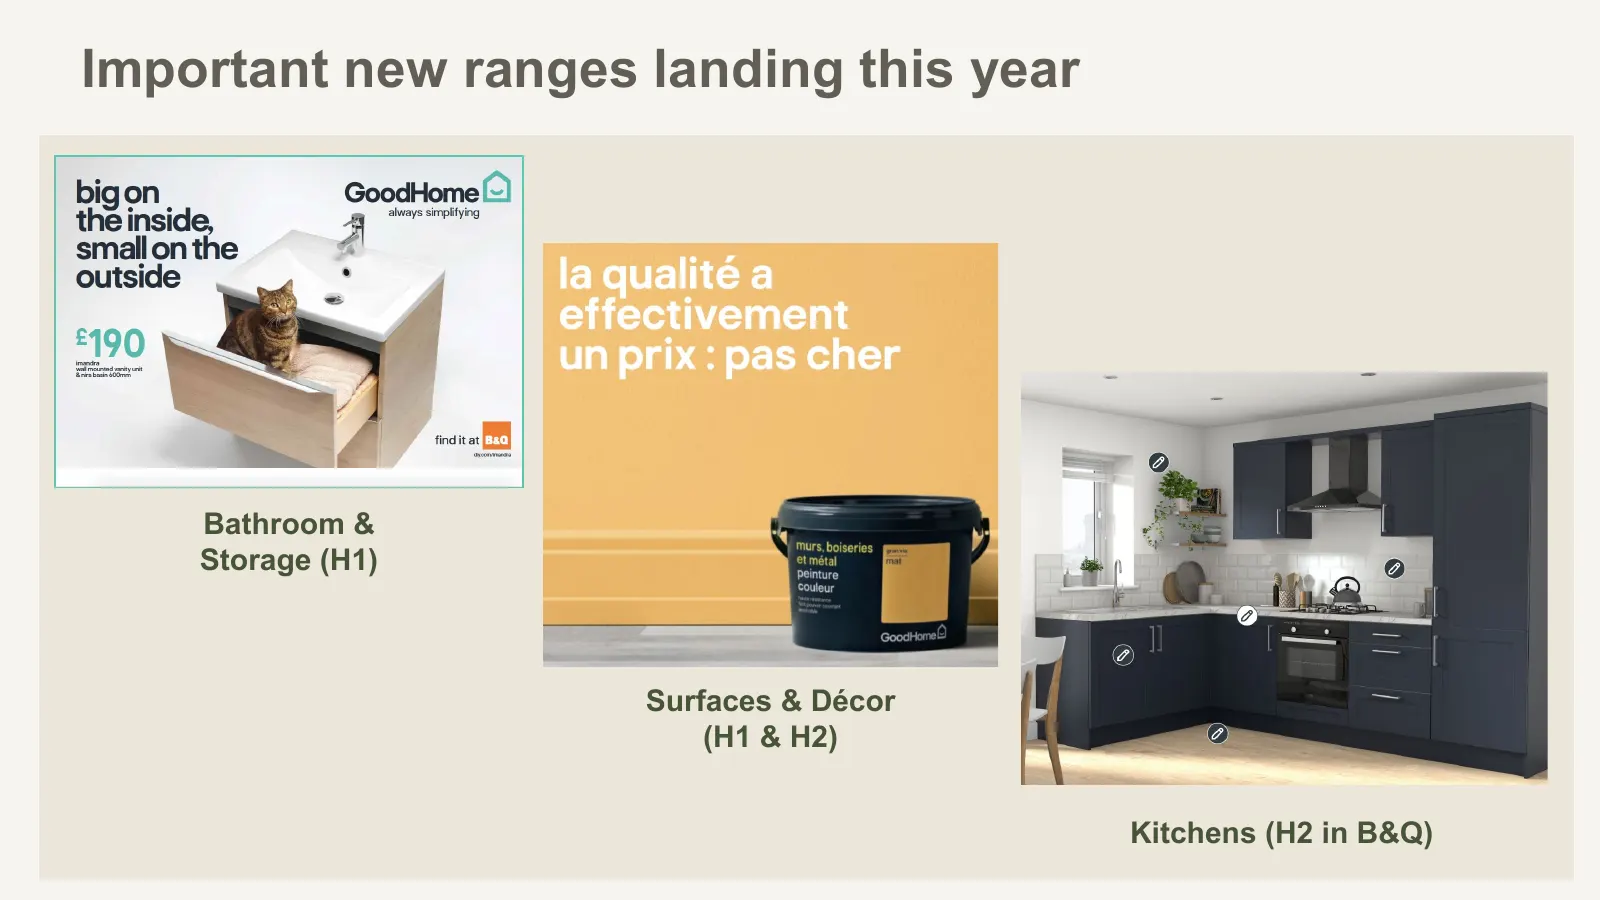
Important new ranges landing this year Bathroom & Storage (H1) Surfaces & Décor (H1 & H2) Kitchens (H2 in B&Q) 24
Slide 25: Focus on improving execution
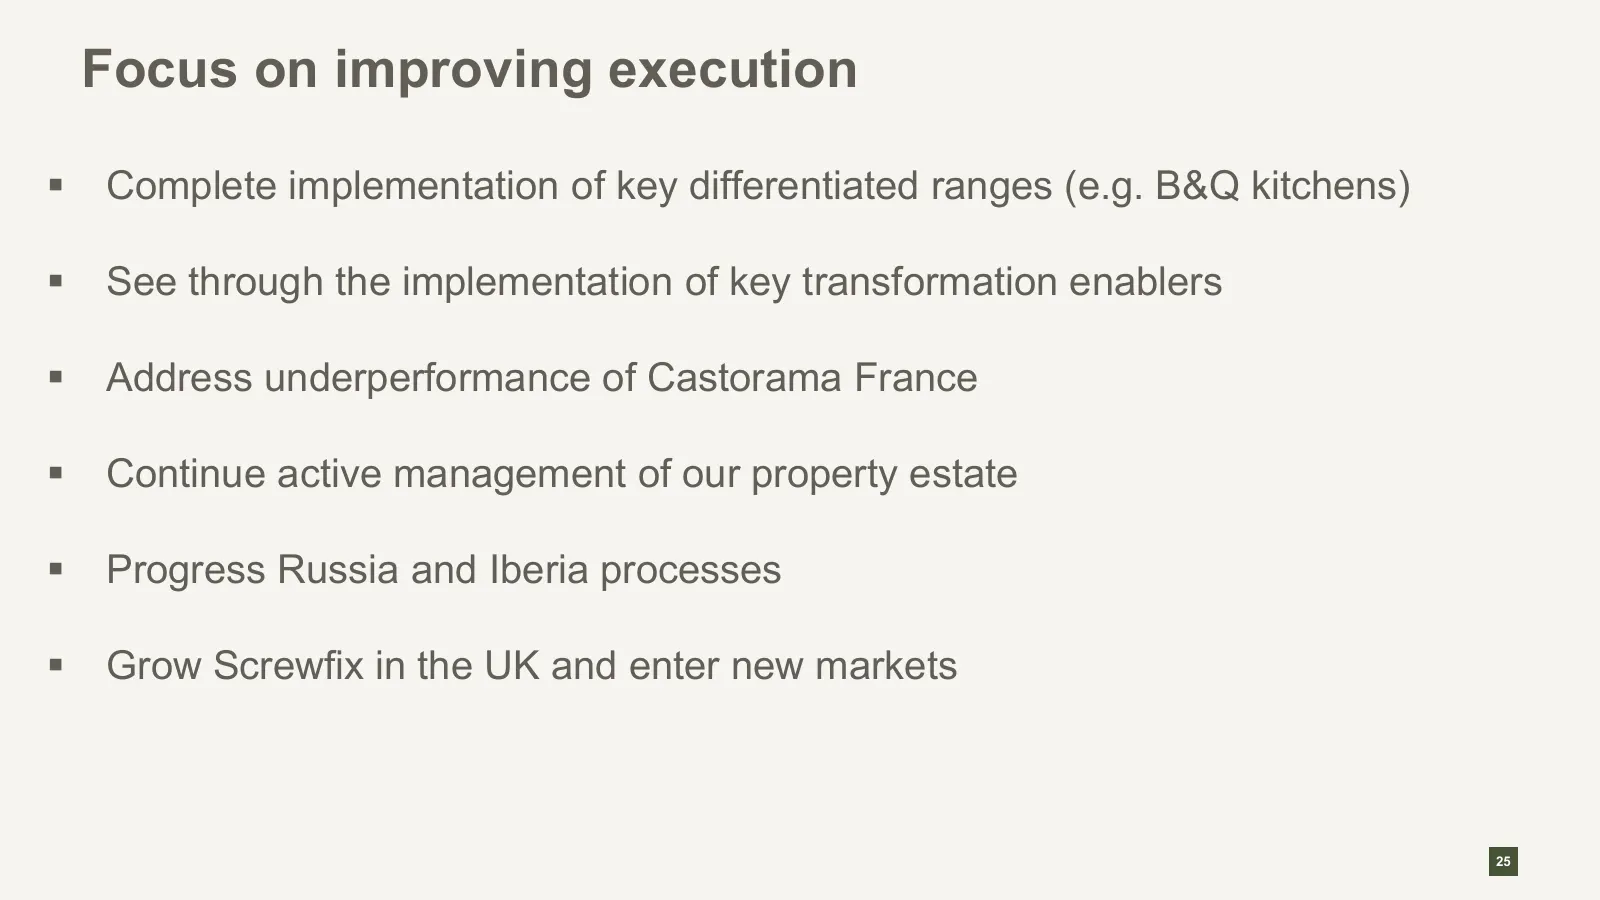
Focus on improving execution Complete implementation of key differentiated ranges (e.g. B&Q kitchens) See through the implementation of key transformation enablers Address underperformance of Castorama France Continue active management of our property estate Progress Russia and Iberia proc
Slide 26: Summary
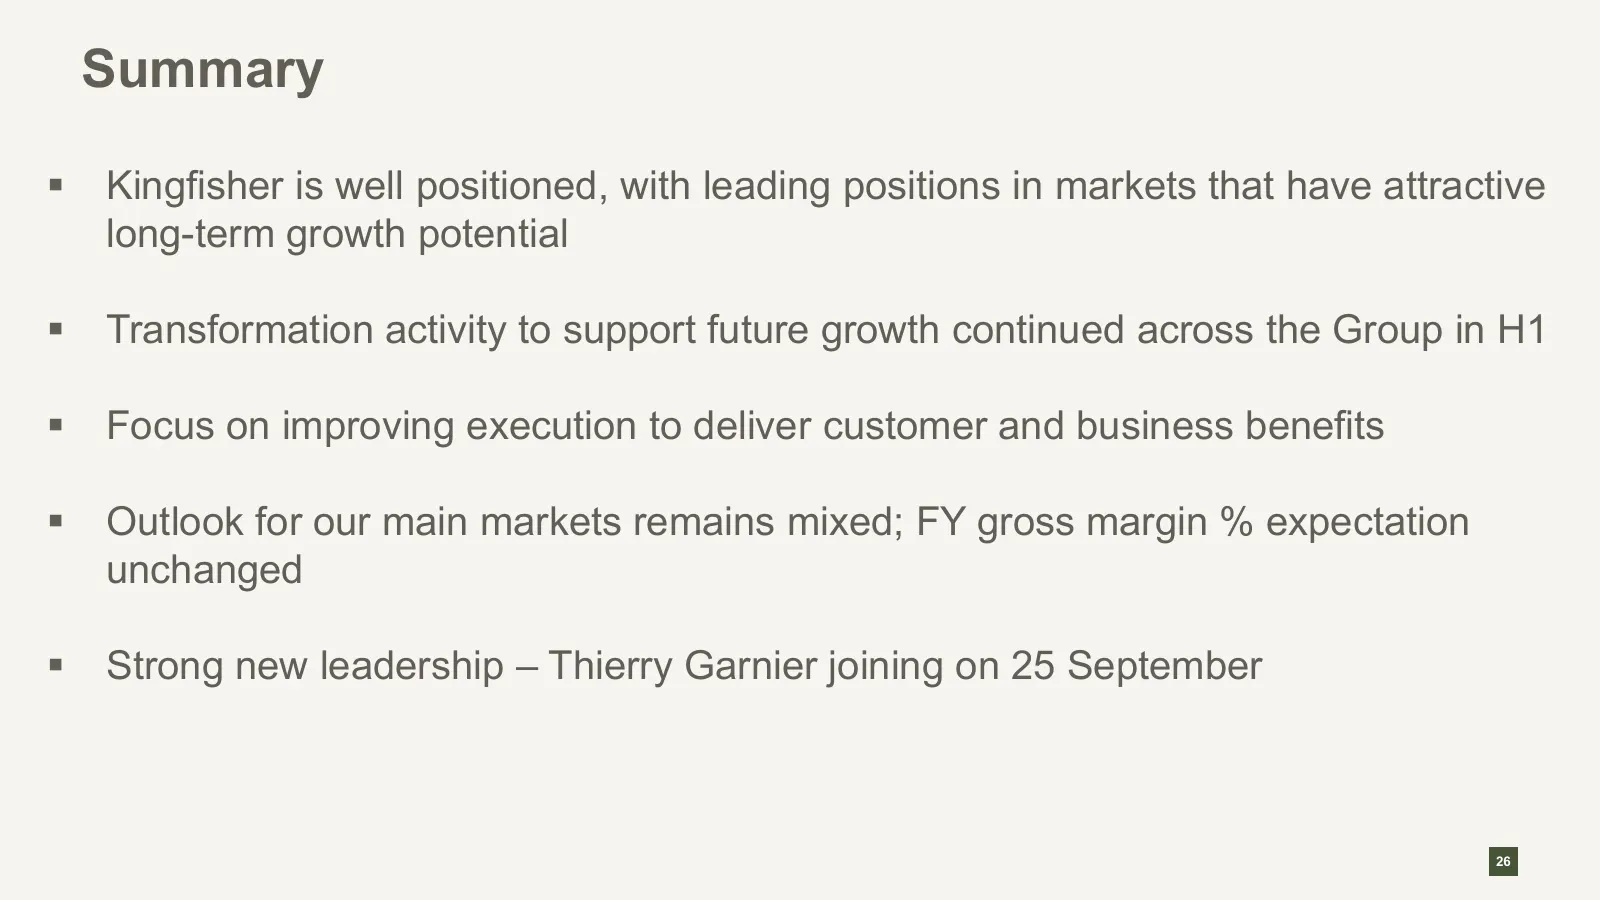
Summary Kingfisher is well positioned, with leading positions in markets that have attractive long-term growth potential Transformation activity to support future growth continued across the Group in H1 Focus on improving execution to deliver customer and business benefits Outlook for our ma
Slide 27: Q&A
Q&A ote te ote ote ote ate ote Neate ute teat ote ote ote ote ote ot HN yA ee A yl ye ty un Uae vite ote ote ote ote ot ‘hy nm nm oo » ’ RR OR Og ’ , we ote te ete ete te tet ates He ye yee ate te ote ate ote ote " reone oe D ao p beens ha UF " Meats vote ate ote ote ote " " o> " oo : ont han ft it
Slide 28: Cautionary note regarding forward looking statements
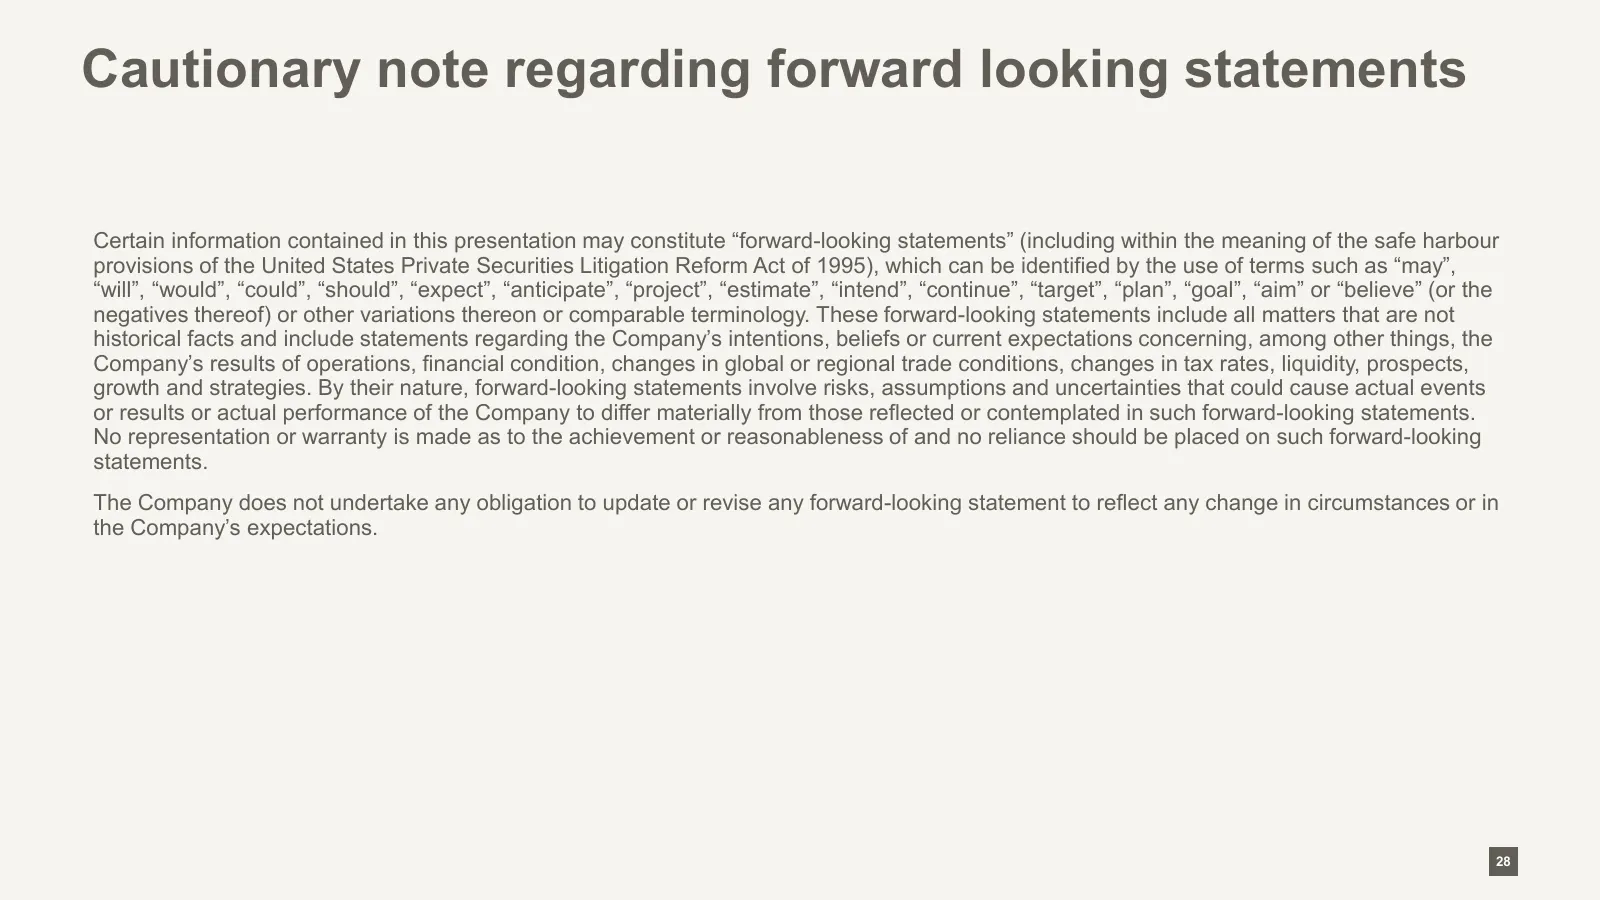
Cautionary note regarding forward looking statements Certain information contained in this presentation may constitute “forward-looking statements” (including within the meaning of the safe harbour provisions of the United States Private Securities Litigation Reform Act of 1995), which can be identi
Slide 29: Appendices
ae ape ae ae > ) out out out out xe FF Oo FF Go FF 8 ® Appendices o*e of oe o%@ ©
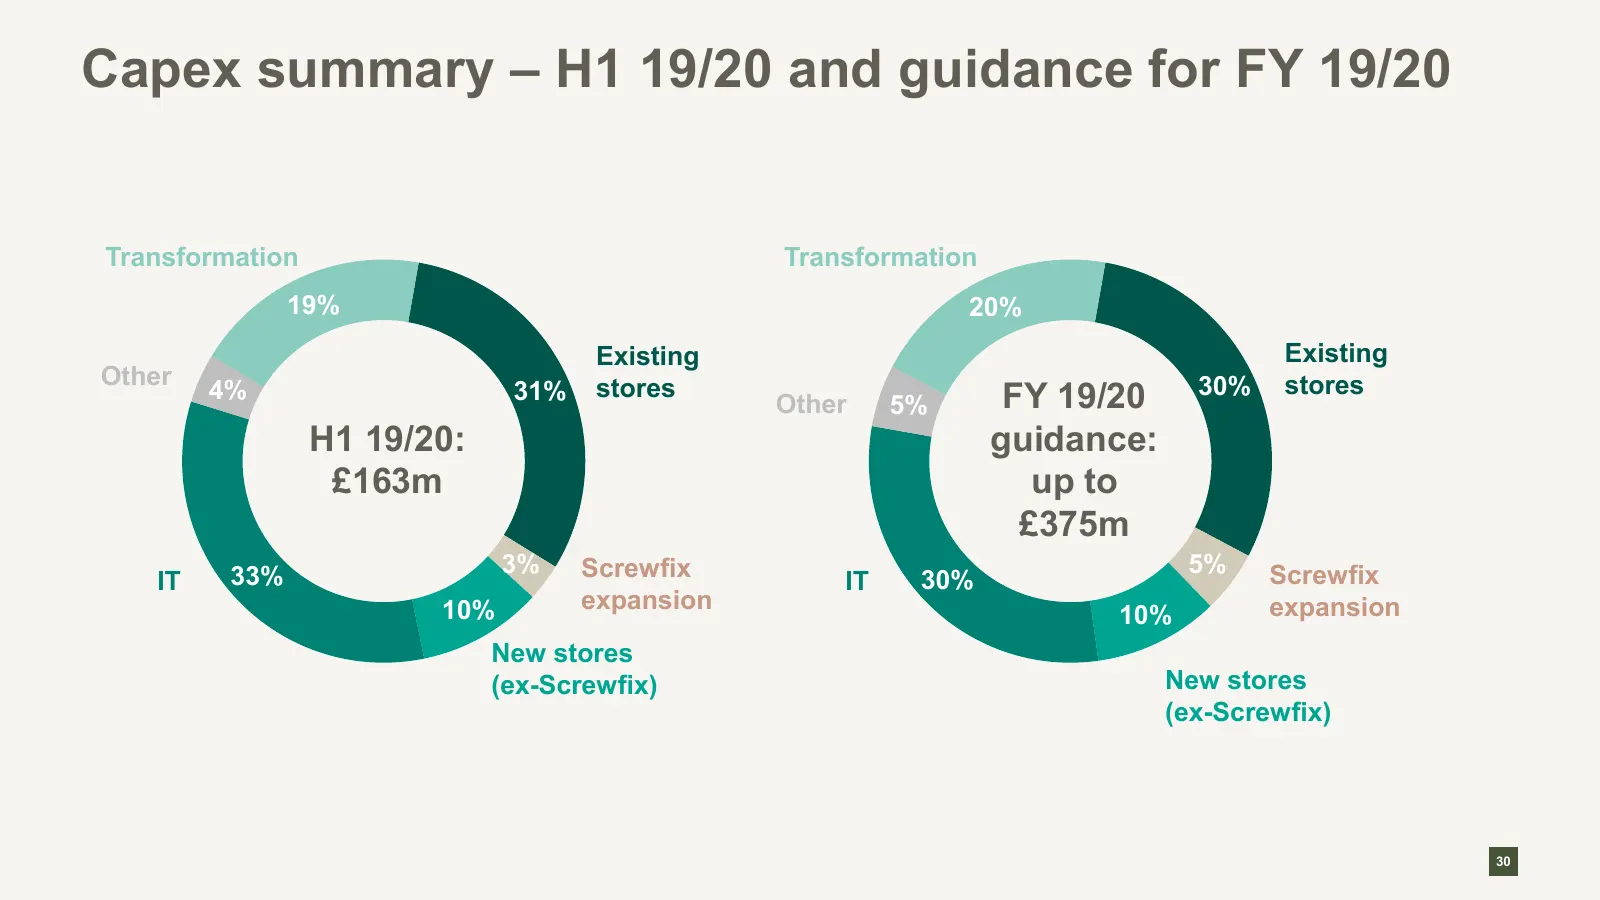
Slide 30: Capex summary – H1 19/20 and guidance for FY 19/20
Capex summary – H1 19/20 and guidance for FY 19/20 Transformation Transformation 19% 20% Existing Existing Other stores 30% stores 4% 31% Other 5% FY 19/20 H1 19/20: guidance: £163m up to £375m 33% 3% Screwfix 5% Screwfix IT IT 30% 10% expansion expansion 10% New stores (ex-Screwfix) New stores (ex-
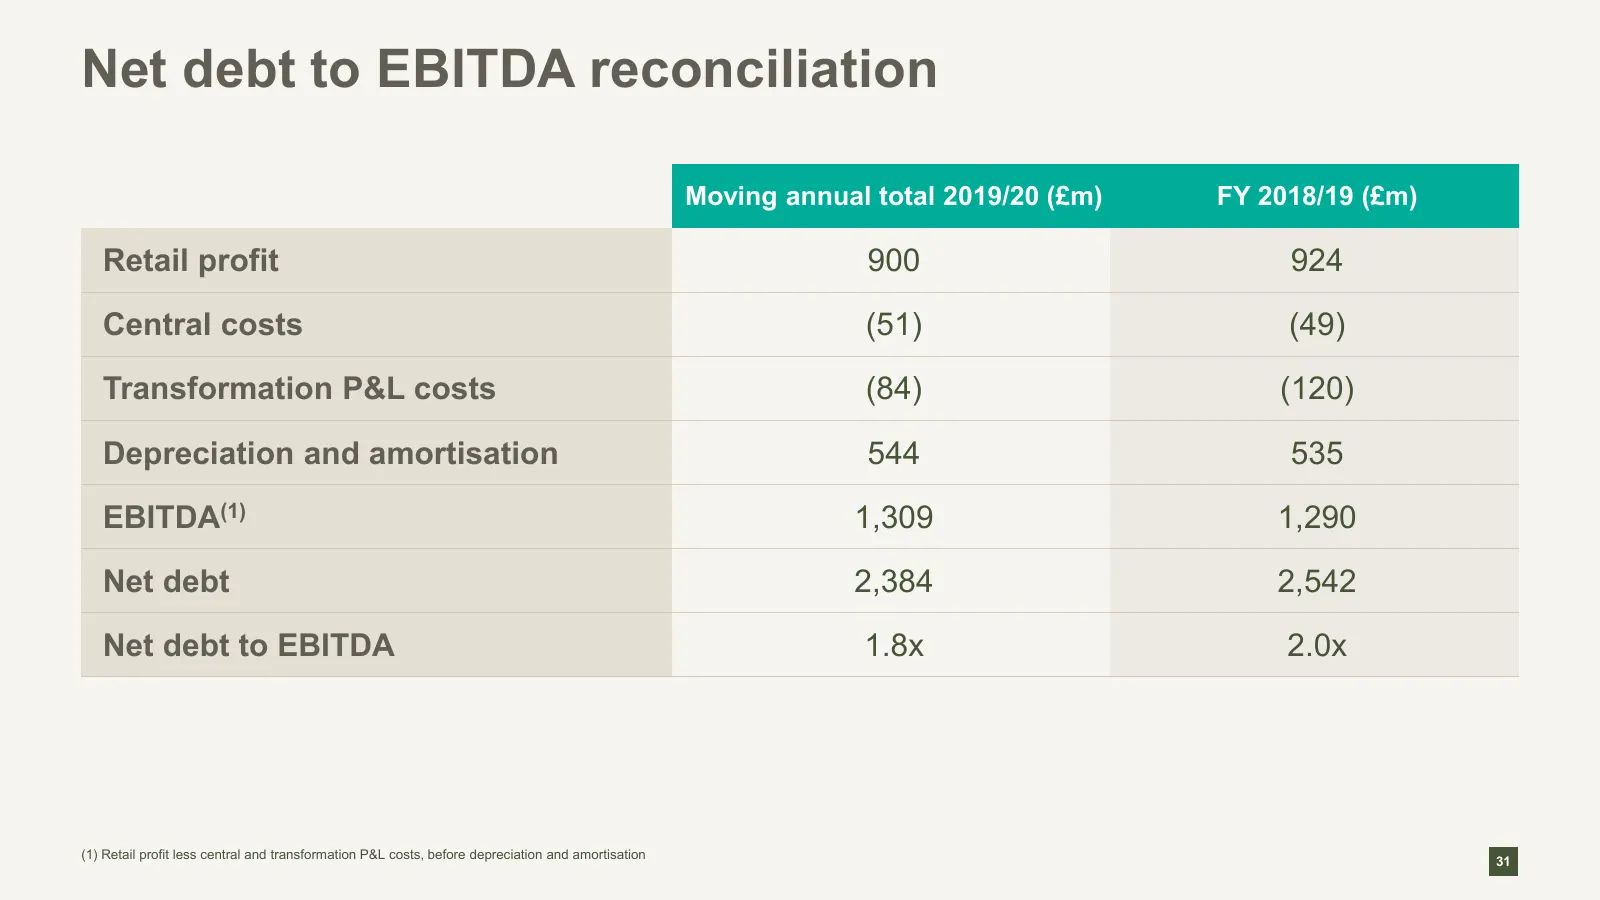
Slide 31: Net debt to EBITDA reconciliation
Net debt to EBITDA reconciliation Moving annual total 2019/20 (£m) FY 2018/19 (£m) Retail profit 900 924 Central costs (51) (49) Transformation P&L costs (84) (120) Depreciation and amortisation 544 535 EBITDA(1) 1,309 1,290 Net debt 2,384 2,542 Net debt to EBITDA 1.8x 2.0x (1) Retail profit less ce
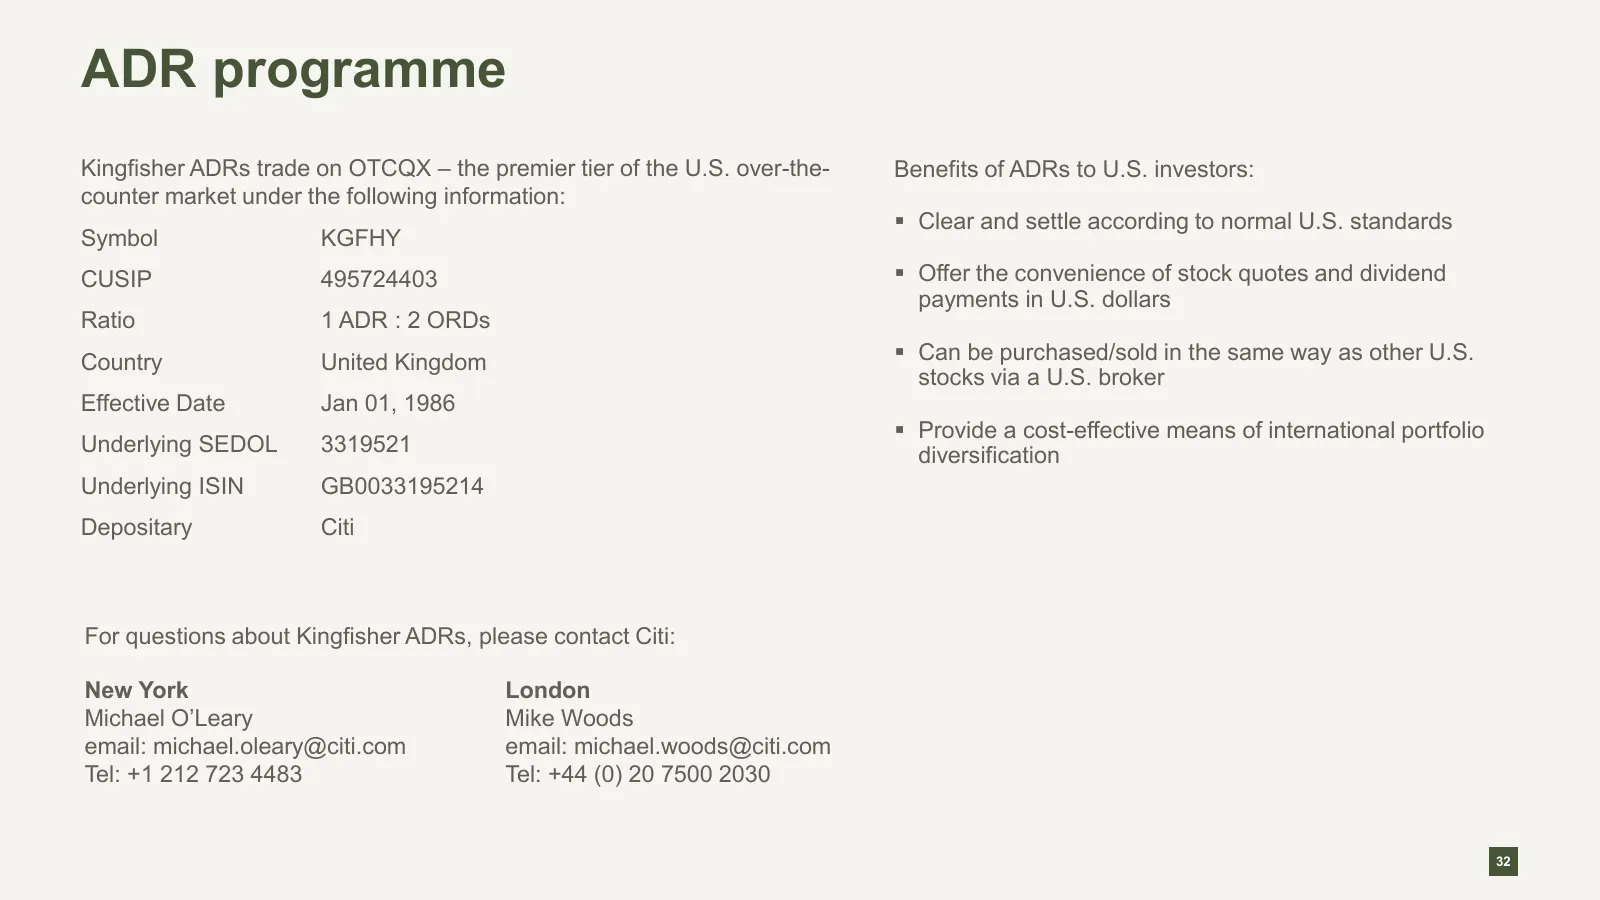
Slide 32: ADR programme
ADR programme Kingfisher ADRs trade on OTCQX – the premier tier of the U.S. over-the- Benefits of ADRs to U.S. investors: counter market under the following information: Clear and settle according to normal U.S. standards Symbol KGFHY CUSIP 495724403 Offer the convenience of stock quotes and div
Slide 33: Contacts
Contacts Investor Relations Media Relations Tel: +44 (0)20 7644 1082 Tel: +44 (0)20 7644 1030 Email: investorenquiries@kingfisher.com Email: corpcomms@kingfisher.com Teneo Tel: +44 (0)20 7260 2700 Email: KFteam@teneo.com 33
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
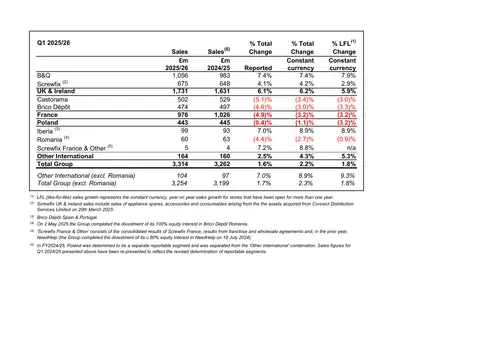 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025