F-Secure Oyj · OMXHEX:FSECURE
F-Secure Oyj — Q3 2009 Earnings Presentation
21 slides from F-Secure Oyj's earnings presentation, Oct 22, 2009
Slide 1: F-Secure Corporation - Interim report Q3 2009
F-Secure Corporation - Interim report Q3 2009 (Unaudited) October 22, 2009 Kimmo Alkio, President and CEO Protecting the irreplaceable | f-secure.com
Slide 2: Highlights in Q3 2009
Highlights in Q3 2009 • Solid profitability; EBIT 21% of revenues • Revenue growth +9% • Operator revenue +25% • Traditional license revenue -3% • Steek integration proceeds on schedule • Renewed Internet Security launched in September • Nokia Booklet 3G mini-laptop collaboration announced October 2
Slide 3: Q3 Highlights
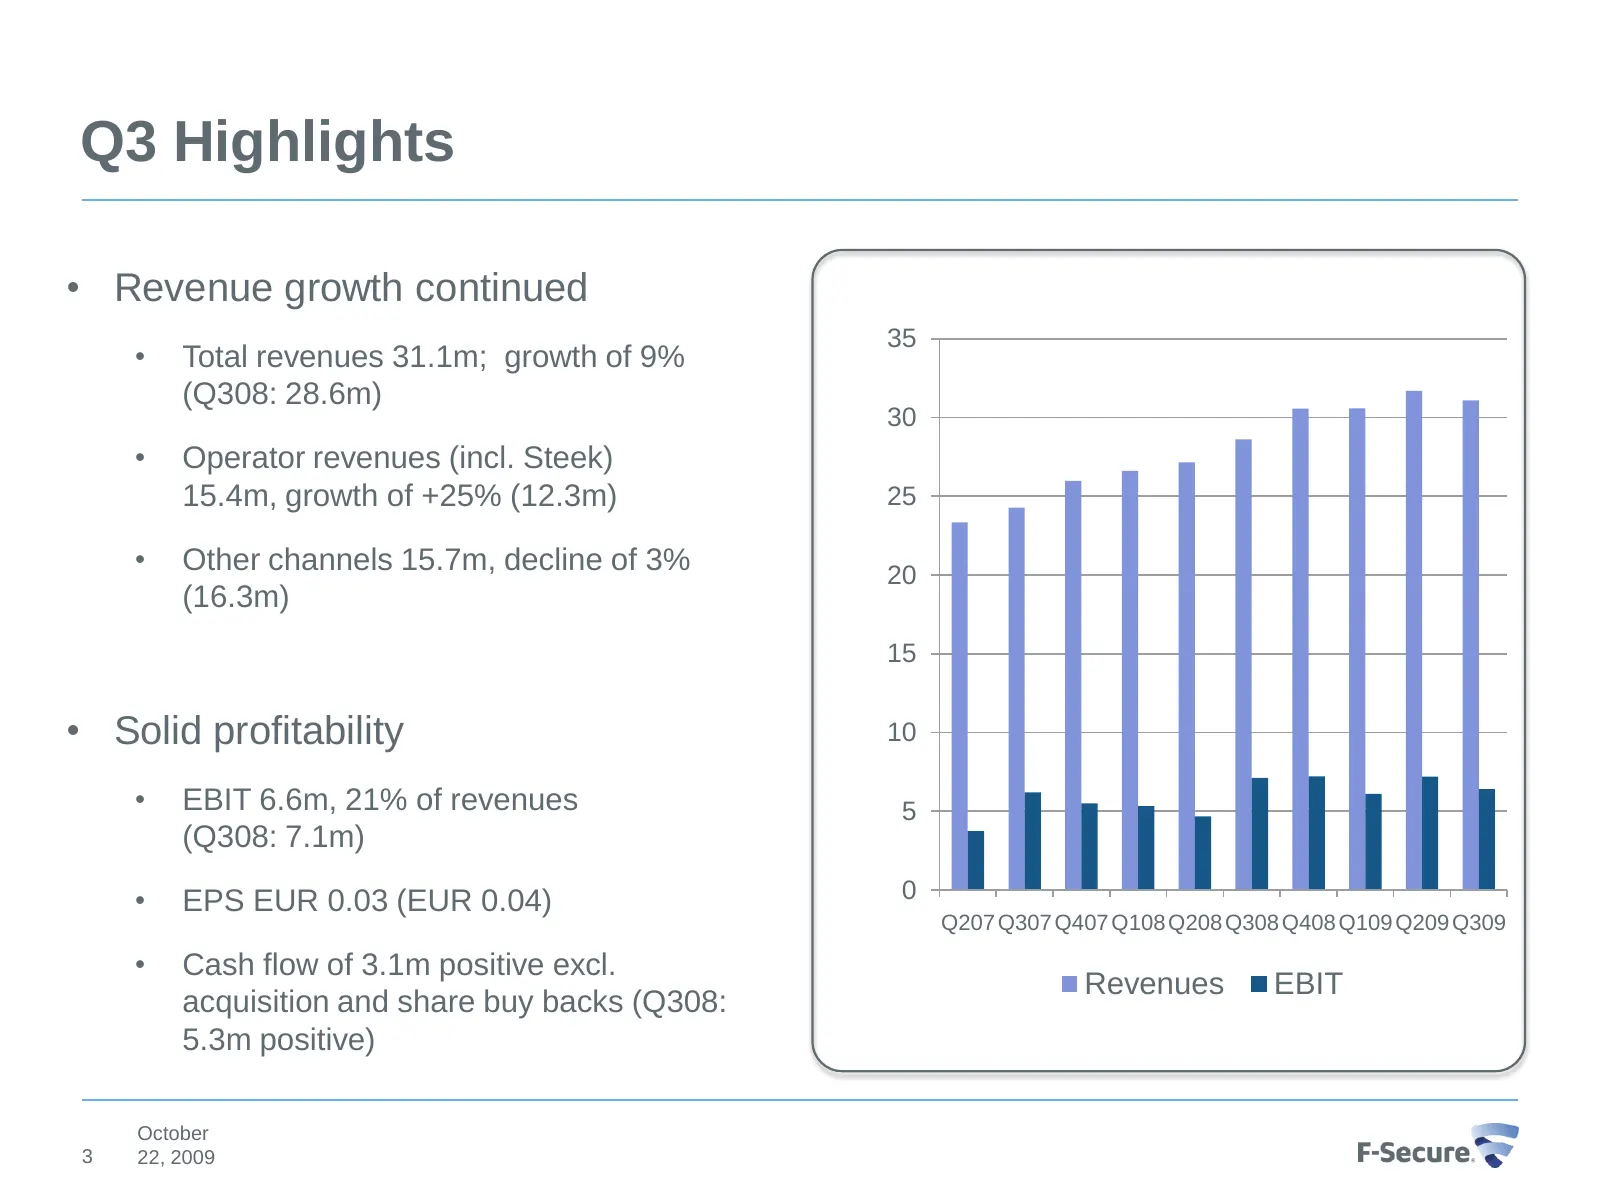
Q3 Highlights • Revenue growth continued 35 • Total revenues 31.1m; growth of 9% (Q308: 28.6m) 30 • Operator revenues (incl. Steek) 15.4m, growth of +25% (12.3m) 25 • Other channels 15.7m, decline of 3% 20 (16.3m) 15 • Solid profitability 10 • EBIT 6.6m, 21% of revenues 5 (Q308: 7.1m) • EPS EUR 0.03
Slide 4: Q3 Costs
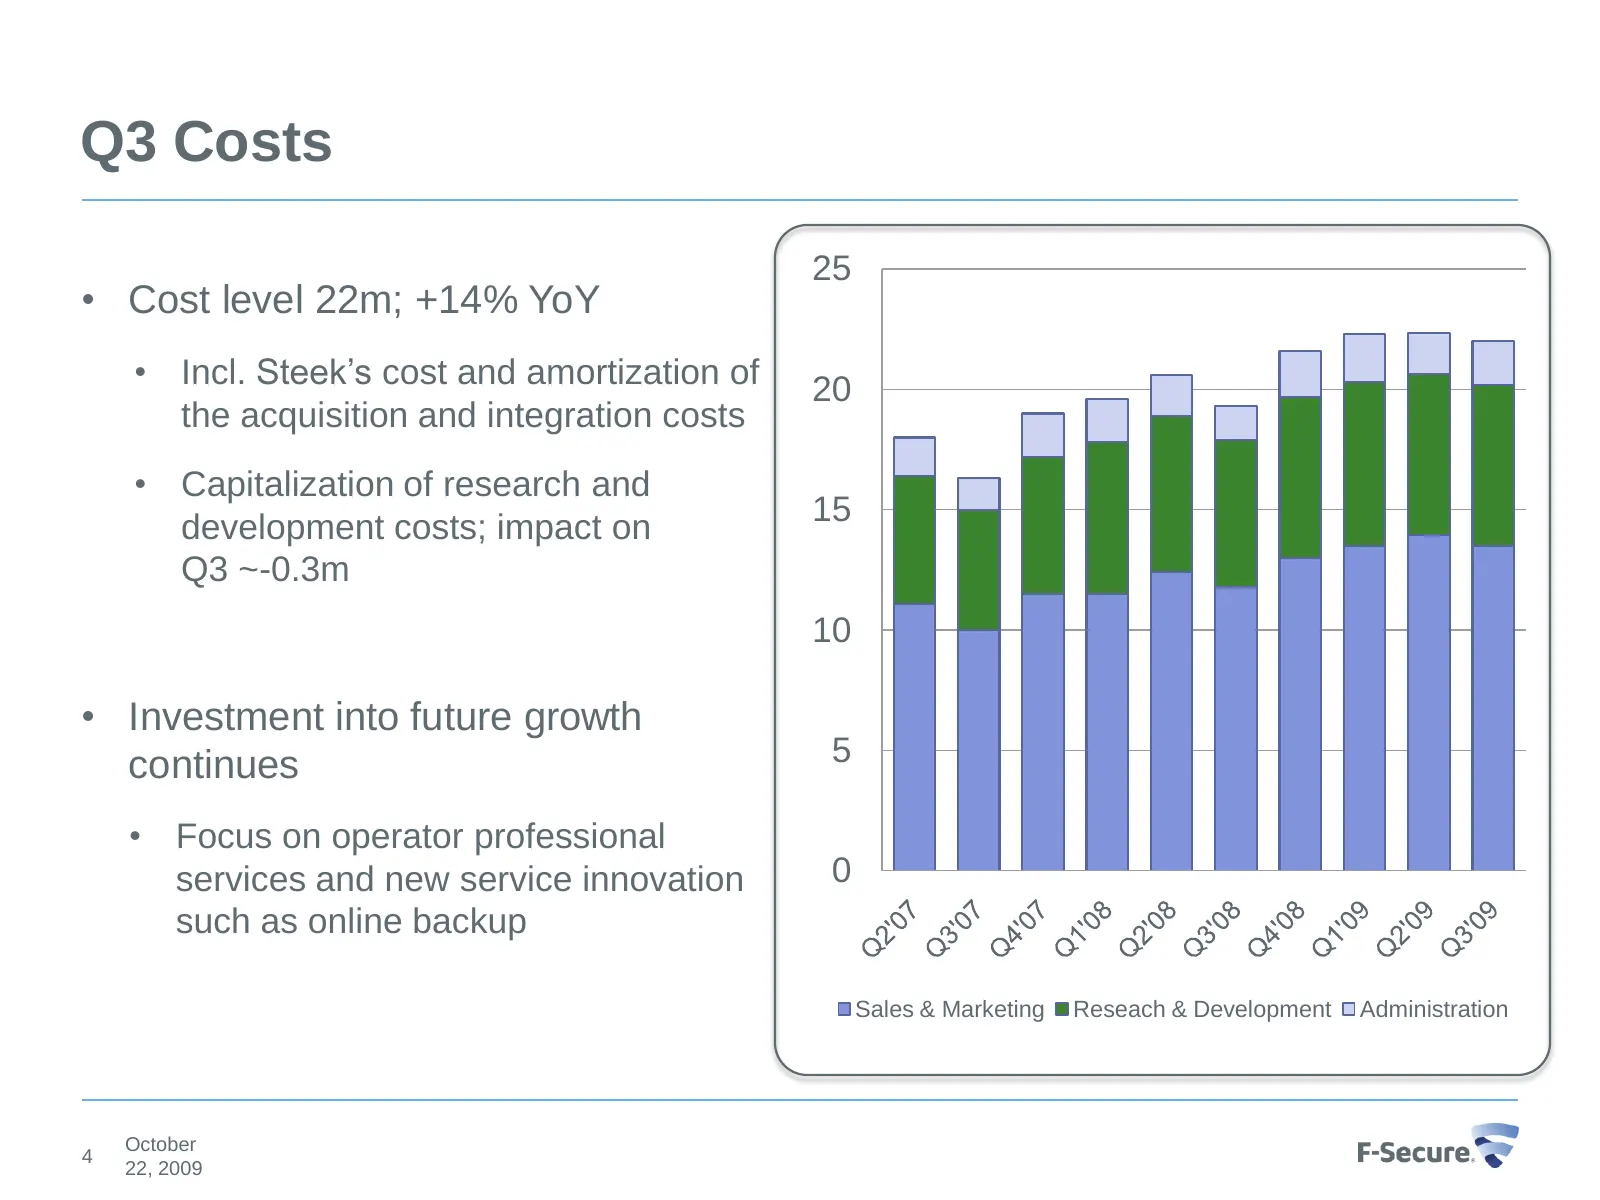
Q3 Costs 25 • Cost level 22m; +14% YoY • Incl. Steek’s cost and amortization of 20 the acquisition and integration costs • Capitalization of research and development costs; impact on 15 Q3 ~-0.3m 10 • Investment into future growth continues 5 • Focus on operator professional services and new service
Slide 5: Q3 Operating profit
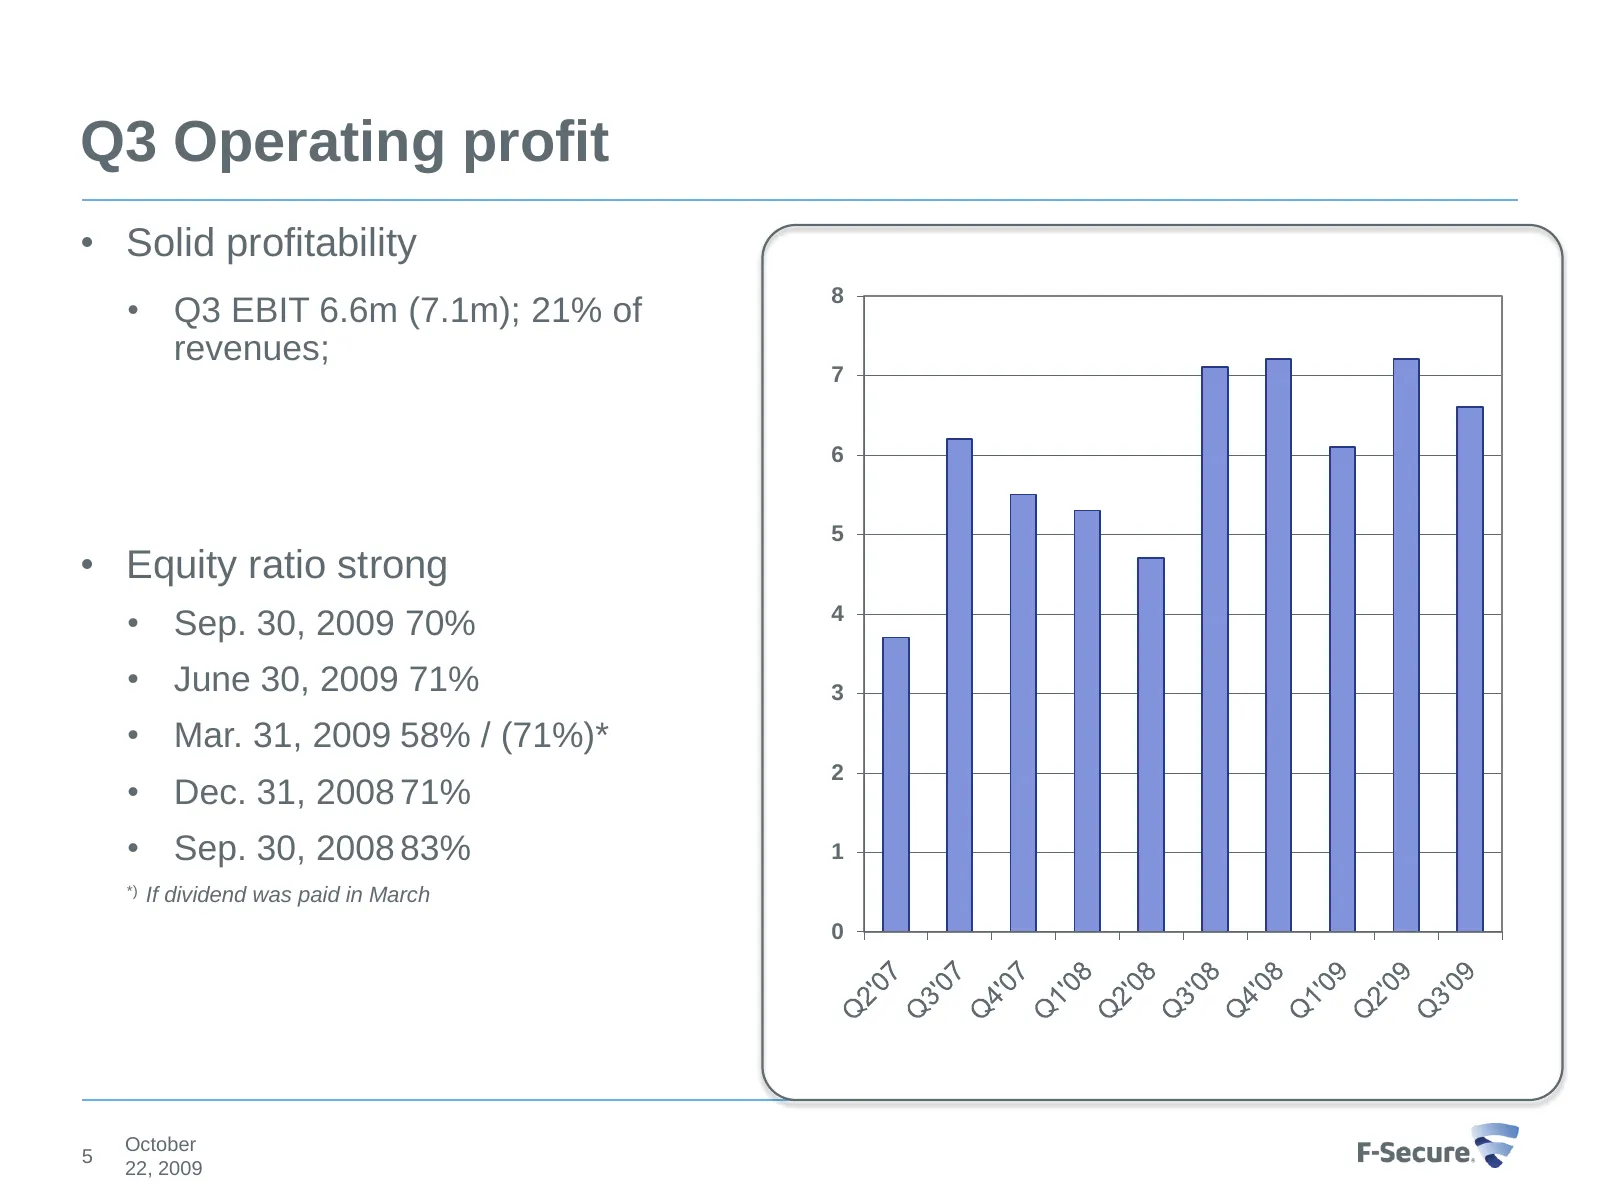
Q3 Operating profit • Solid profitability 8 • Q3 EBIT 6.6m (7.1m); 21% of revenues; 7 6 5 • Equity ratio strong • Sep. 30, 2009 70% 4 • June 30, 2009 71% 3 • Mar. 31, 2009 58% / (71%)* 2 • Dec. 31, 2008 71% • Sep. 30, 2008 83% 1 *) If dividend was paid in March 0 October 5 22, 2009
Slide 6: Development of EBIT margin
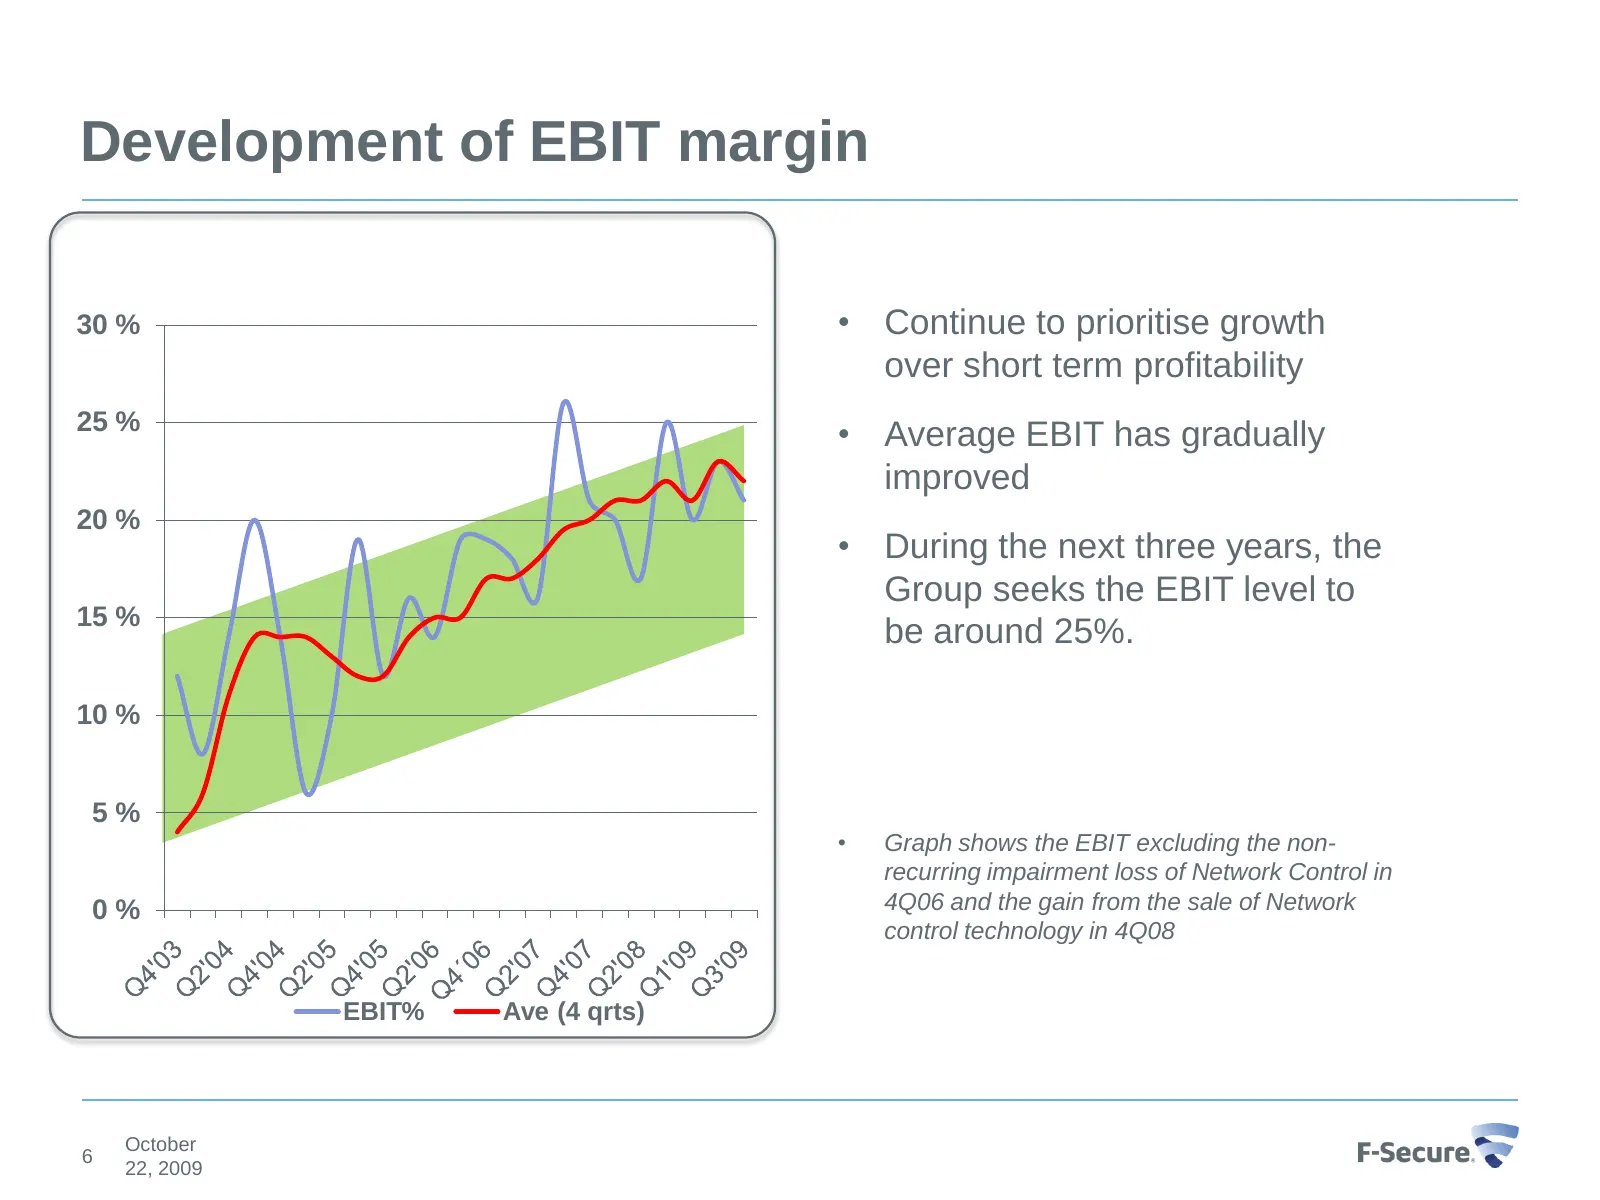
Development of EBIT margin 30 % • Continue to prioritise growth over short term profitability 25 % • Average EBIT has gradually improved 20 % • During the next three years, the Group seeks the EBIT level to 15 % be around 25%. 10 % 5% • Graph shows the EBIT excluding the non- recurring impairment lo
Slide 7: Q3 Cash position
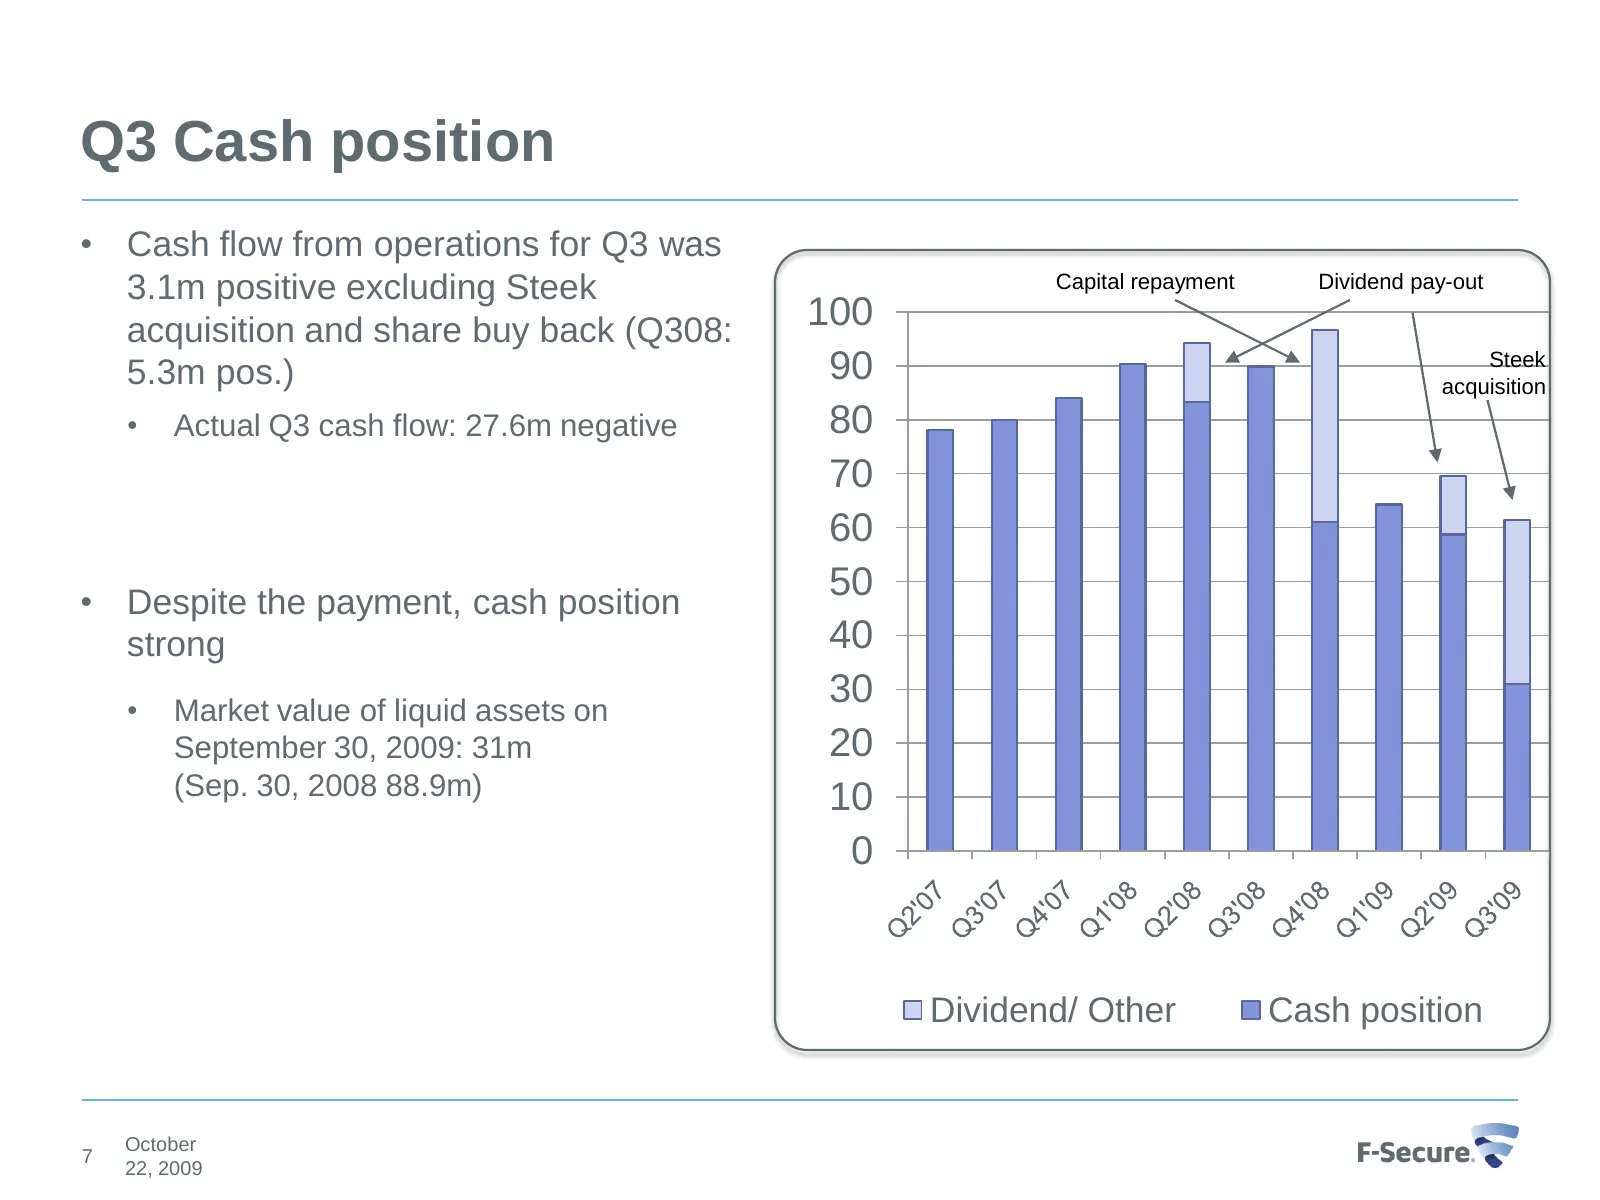
Q3 Cash position • Cash flow from operations for Q3 was 3.1m positive excluding Steek Capital repayment Dividend pay-out acquisition and share buy back (Q308: 100 5.3m pos.) 90 Steek acquisition • Actual Q3 cash flow: 27.6m negative 80 70 60 • Despite the payment, cash position 50 strong 40 • Market
Slide 8: Q3 Deferred Revenues
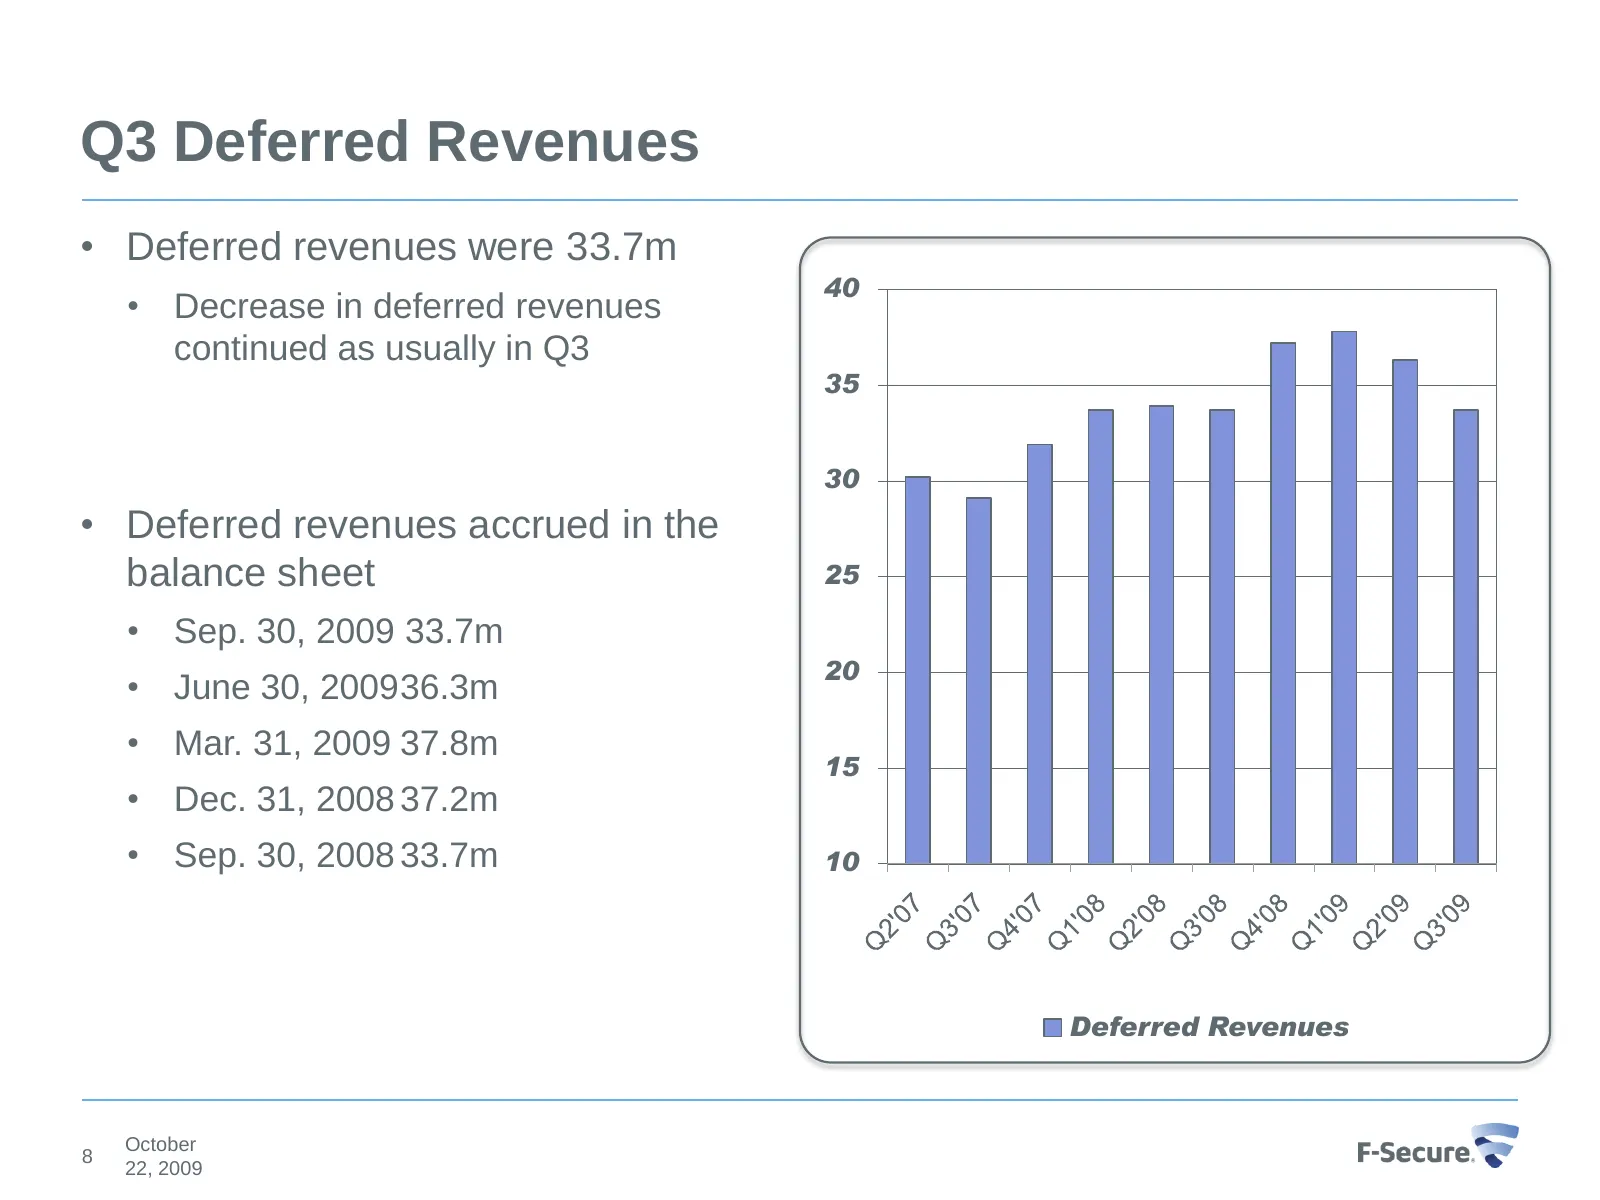
Q3 Deferred Revenues • Deferred revenues were 33.7m 40 • Decrease in deferred revenues continued as usually in Q3 35 30 • Deferred revenues accrued in the balance sheet 25 • Sep. 30, 2009 33.7m 20 • June 30, 200936.3m • Mar. 31, 2009 37.8m 15 • Dec. 31, 2008 37.2m • Sep. 30, 2008 33.7m 10 Deferred R
Slide 9: Regional Revenue Split
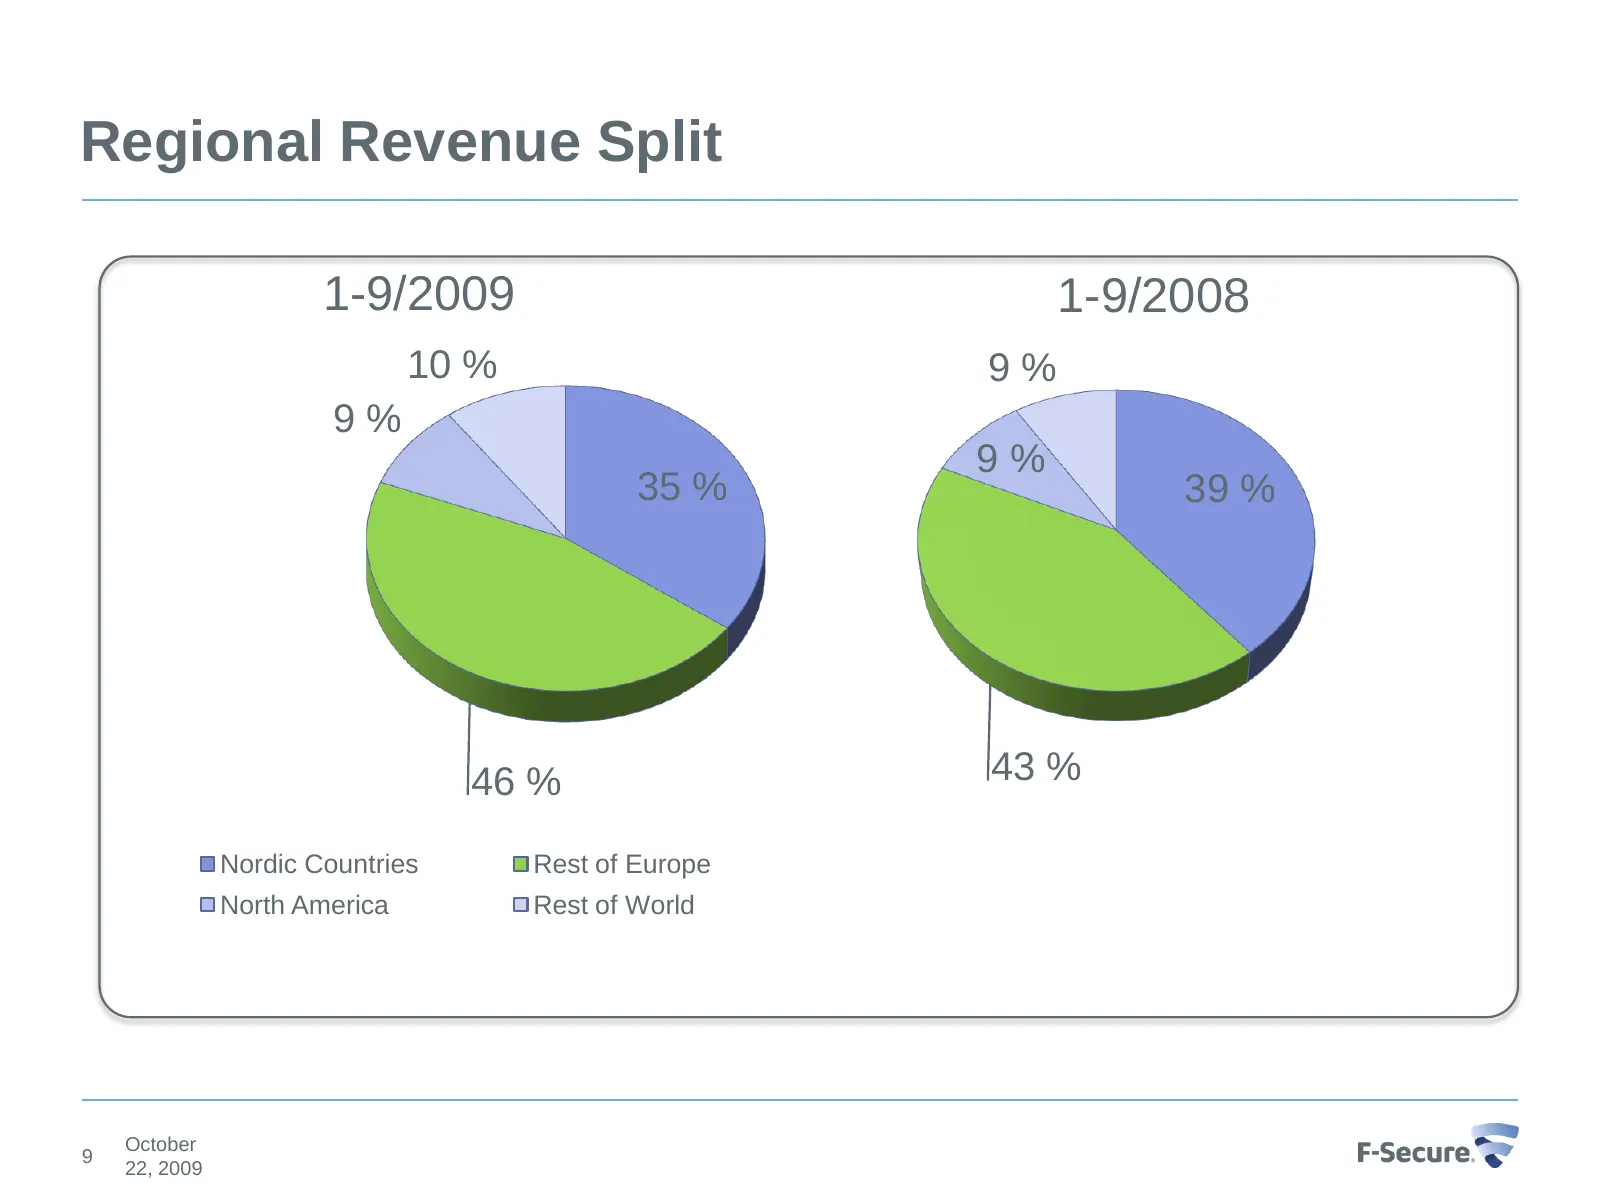
Regional Revenue Split 1-9/2009 1-9/2008 10 % 9% 9% 9% 35 % 39 % 46 % 43 % Nordic Countries Rest of Europe North America Rest of World October 9 22, 2009
Slide 10: Operator business growth
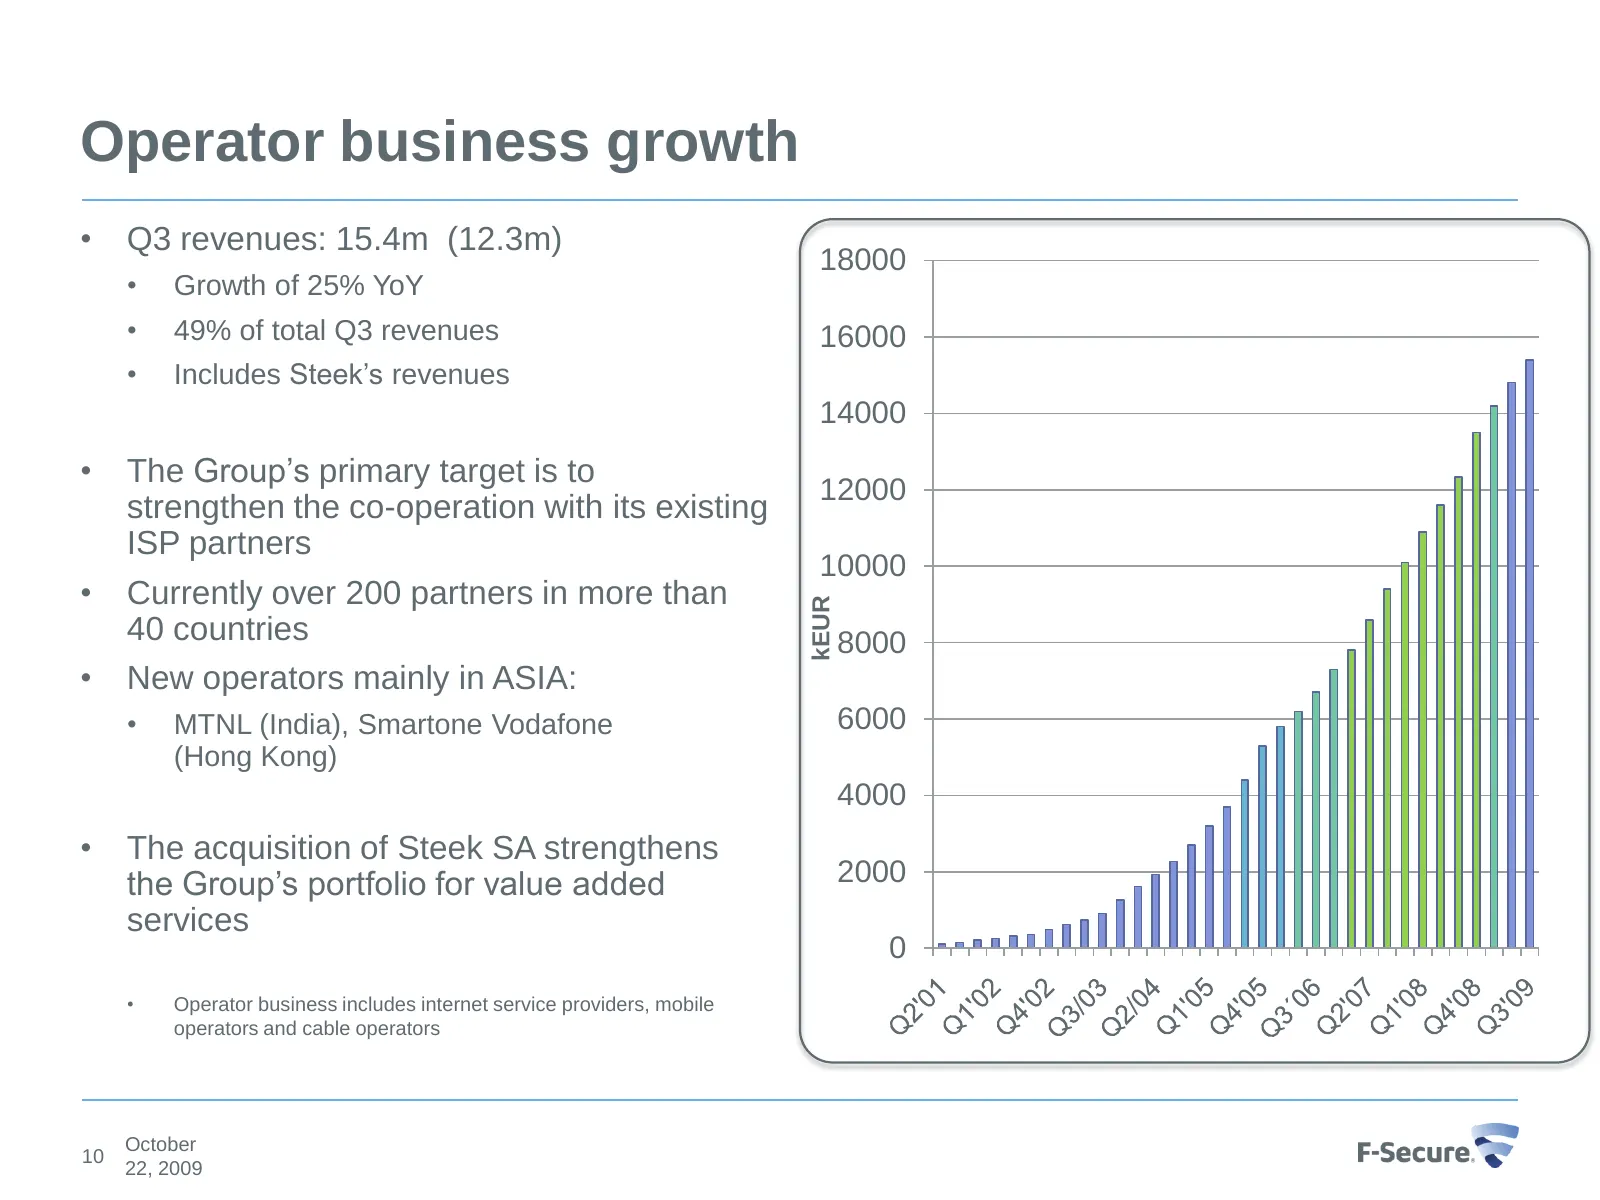
Operator business growth • Q3 revenues: 15.4m (12.3m) 18000 • Growth of 25% YoY • 49% of total Q3 revenues 16000 • Includes Steek’s revenues 14000 • The Group’s primary target is to 12000 strengthen the co-operation with its existing ISP partners 10000 • Currently over 200 partners in more than kEUR
Slide 11: F-Secure's operator partners, some examples
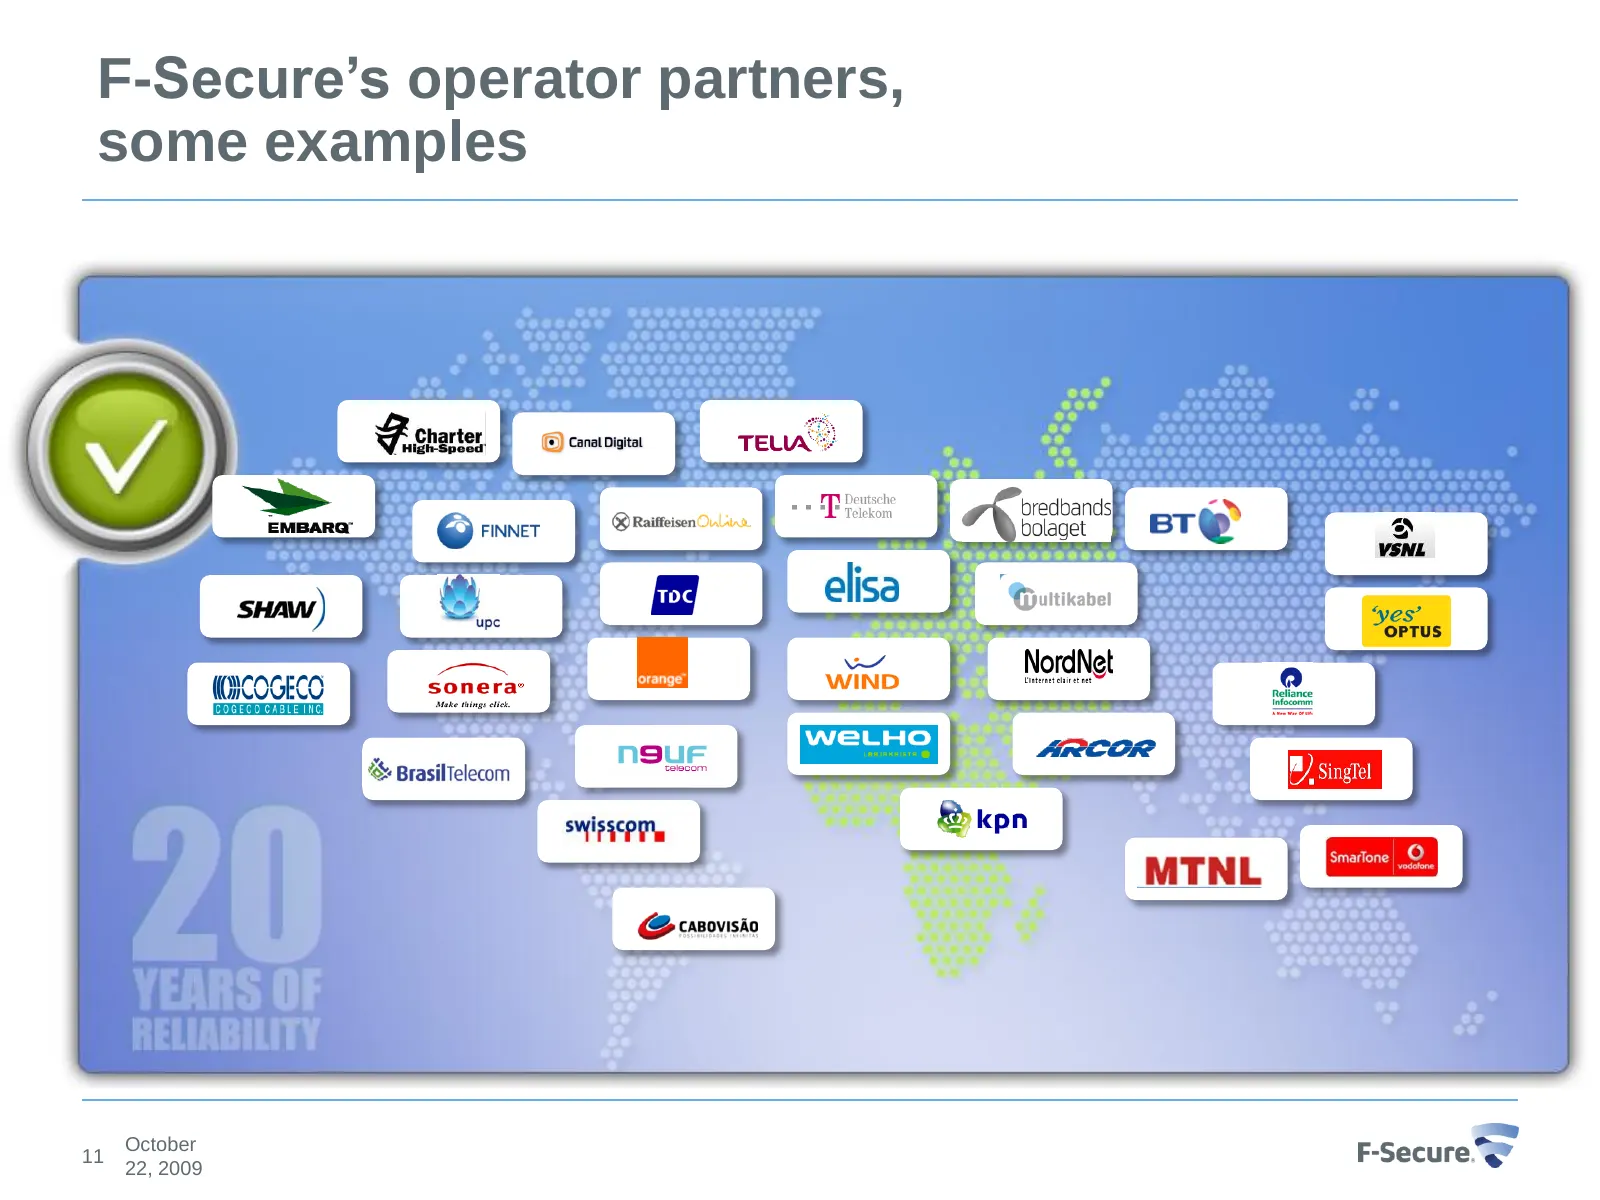
F-Secure’s operator partners, some examples October 11 22, 2009
Slide 12: F-Secure acquired Steek SA in July - Integration proceeds on schedule
F-Secure acquired Steek SA in July - Integration proceeds on schedule • a leading European software provider for online storage and data management solutions to operators • the acquisition strengthens F-Secure’s position as the leading SaaS partner • a natural step in F-Secure’s strategy to broaden
Slide 13: Q3 Mobile Security
Q3 Mobile Security • Co-operation with device manufacturers continued • Operator partnerships, co-operation strengthened • Operator partnerships with Vodafone UK, KPN, TDC, Netia and CSL. • Co-operation with the operators T-Mobile International, TeliaSonera Group, Orange, Swisscom and Elisa continue
Slide 14: Recent product announcements
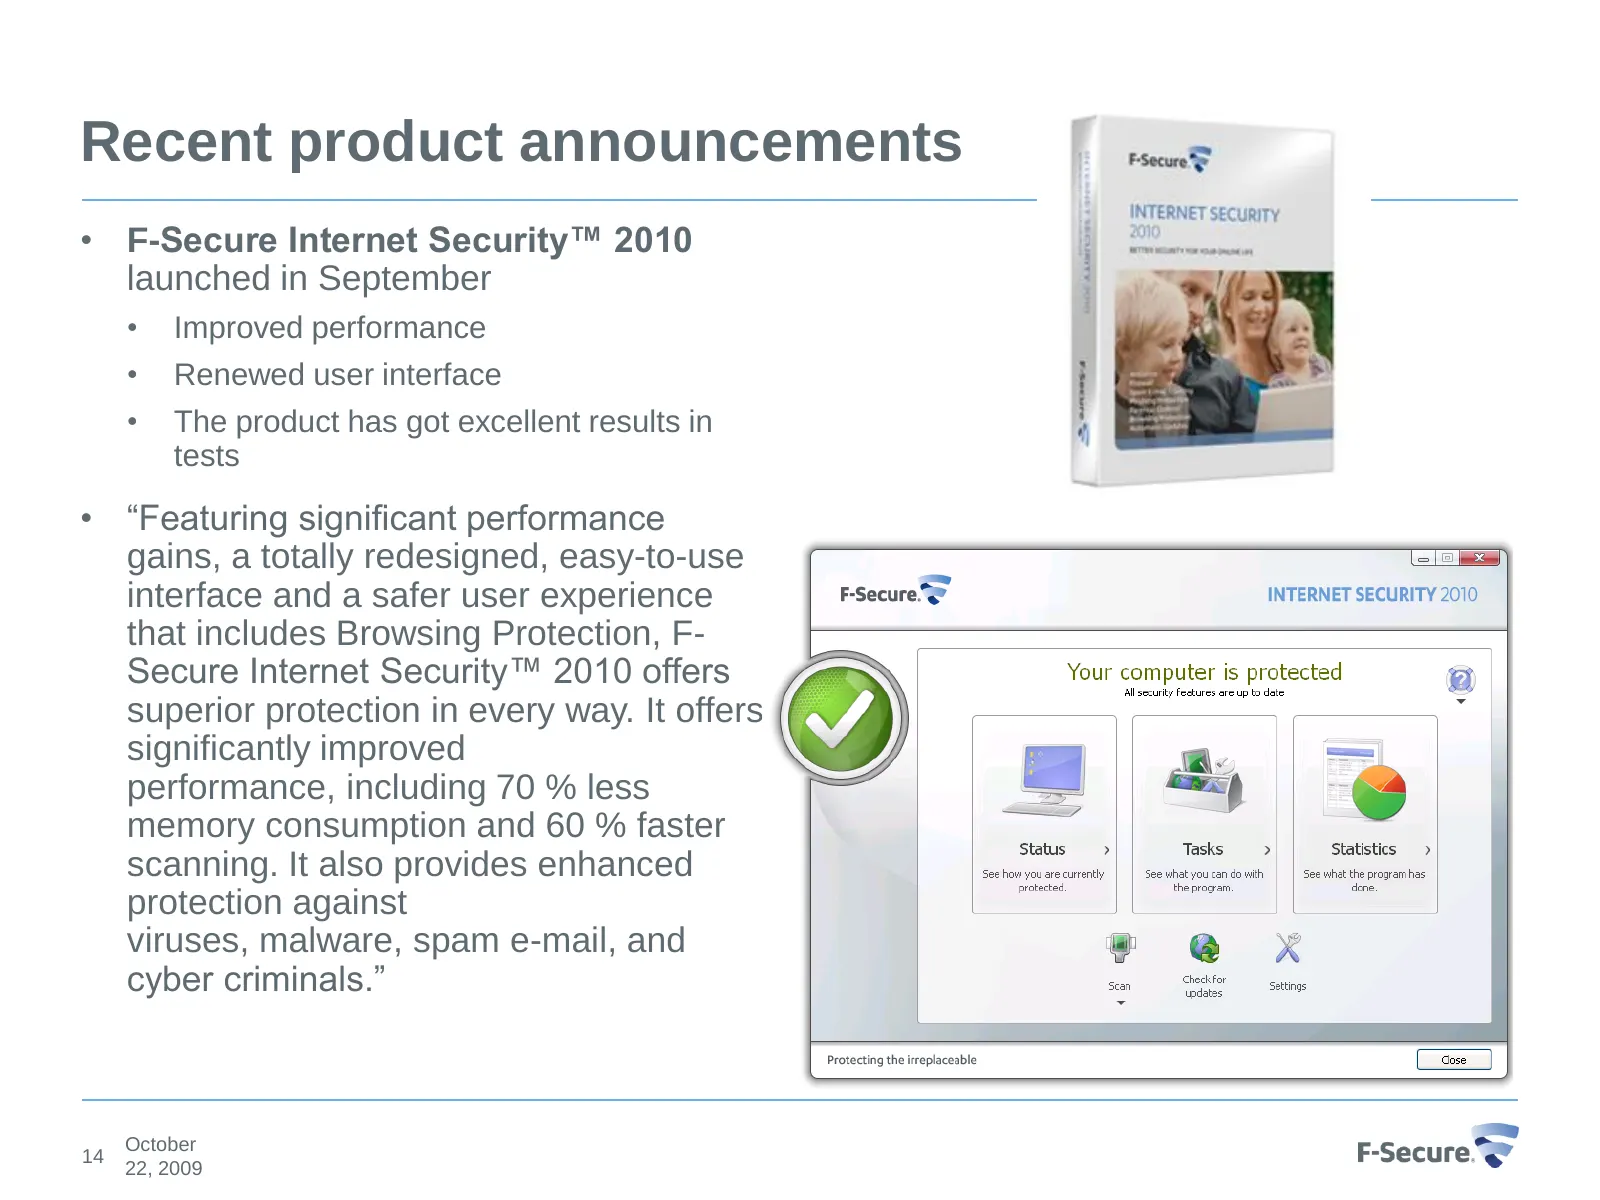
Recent product announcements • F-Secure Internet Security™ 2010 launched in September • Improved performance • Renewed user interface • The product has got excellent results in tests • “Featuring significant performance gains, a totally redesigned, easy-to-use interface and a safer user experience t
Slide 15: Internet Security 2010 in Nokia Booklet
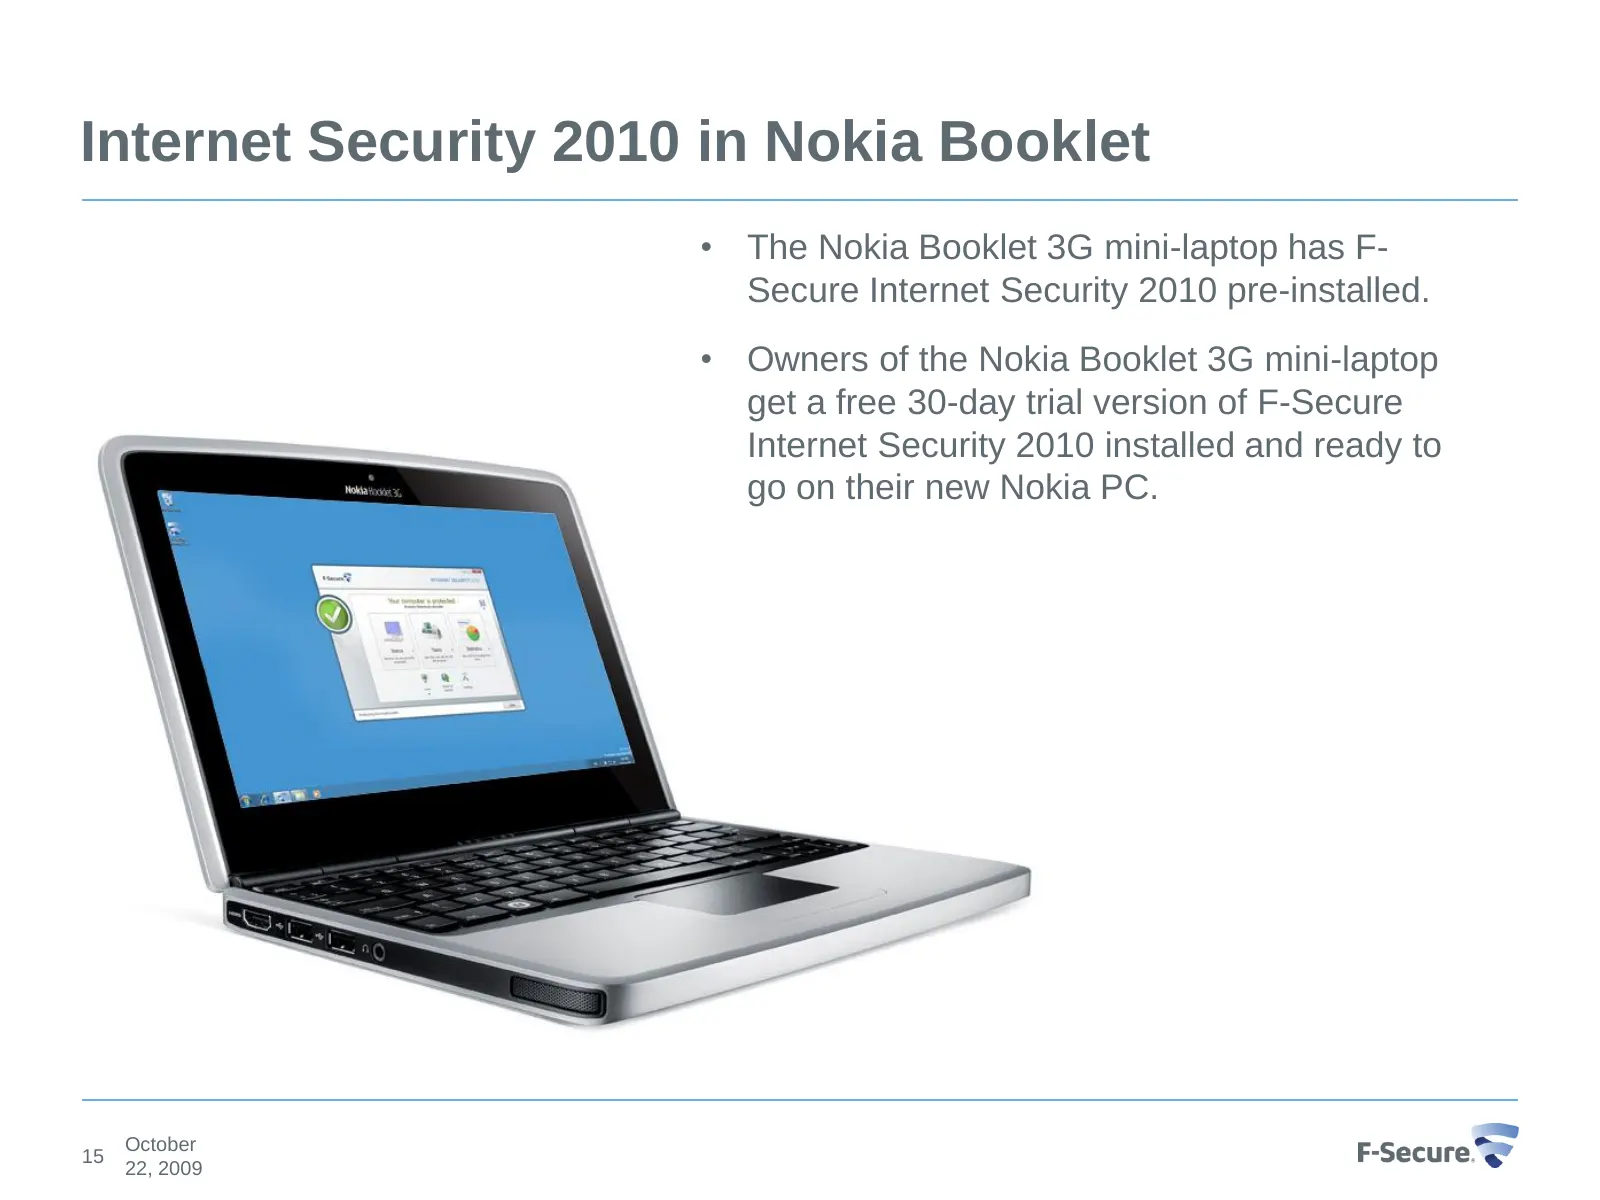
Internet Security 2010 in Nokia Booklet • The Nokia Booklet 3G mini-laptop has F- Secure Internet Security 2010 pre-installed. • Owners of the Nokia Booklet 3G mini-laptop get a free 30-day trial version of F-Secure Internet Security 2010 installed and ready to go on their new Nokia PC. October 15 2
Slide 16: F-Secure Online Backup
F-Secure Online Backup • F-Secure Online Backup • Received good results in several tests • "F-Secure Online Backup has a good price and excellent stability” (PC World US, July 2009) • "F-Secure Online Backup is developed to give piece of mind to the user“ (MikroBitti, Finland, August 2009) • “F-Secu
Slide 17: Number of personnel
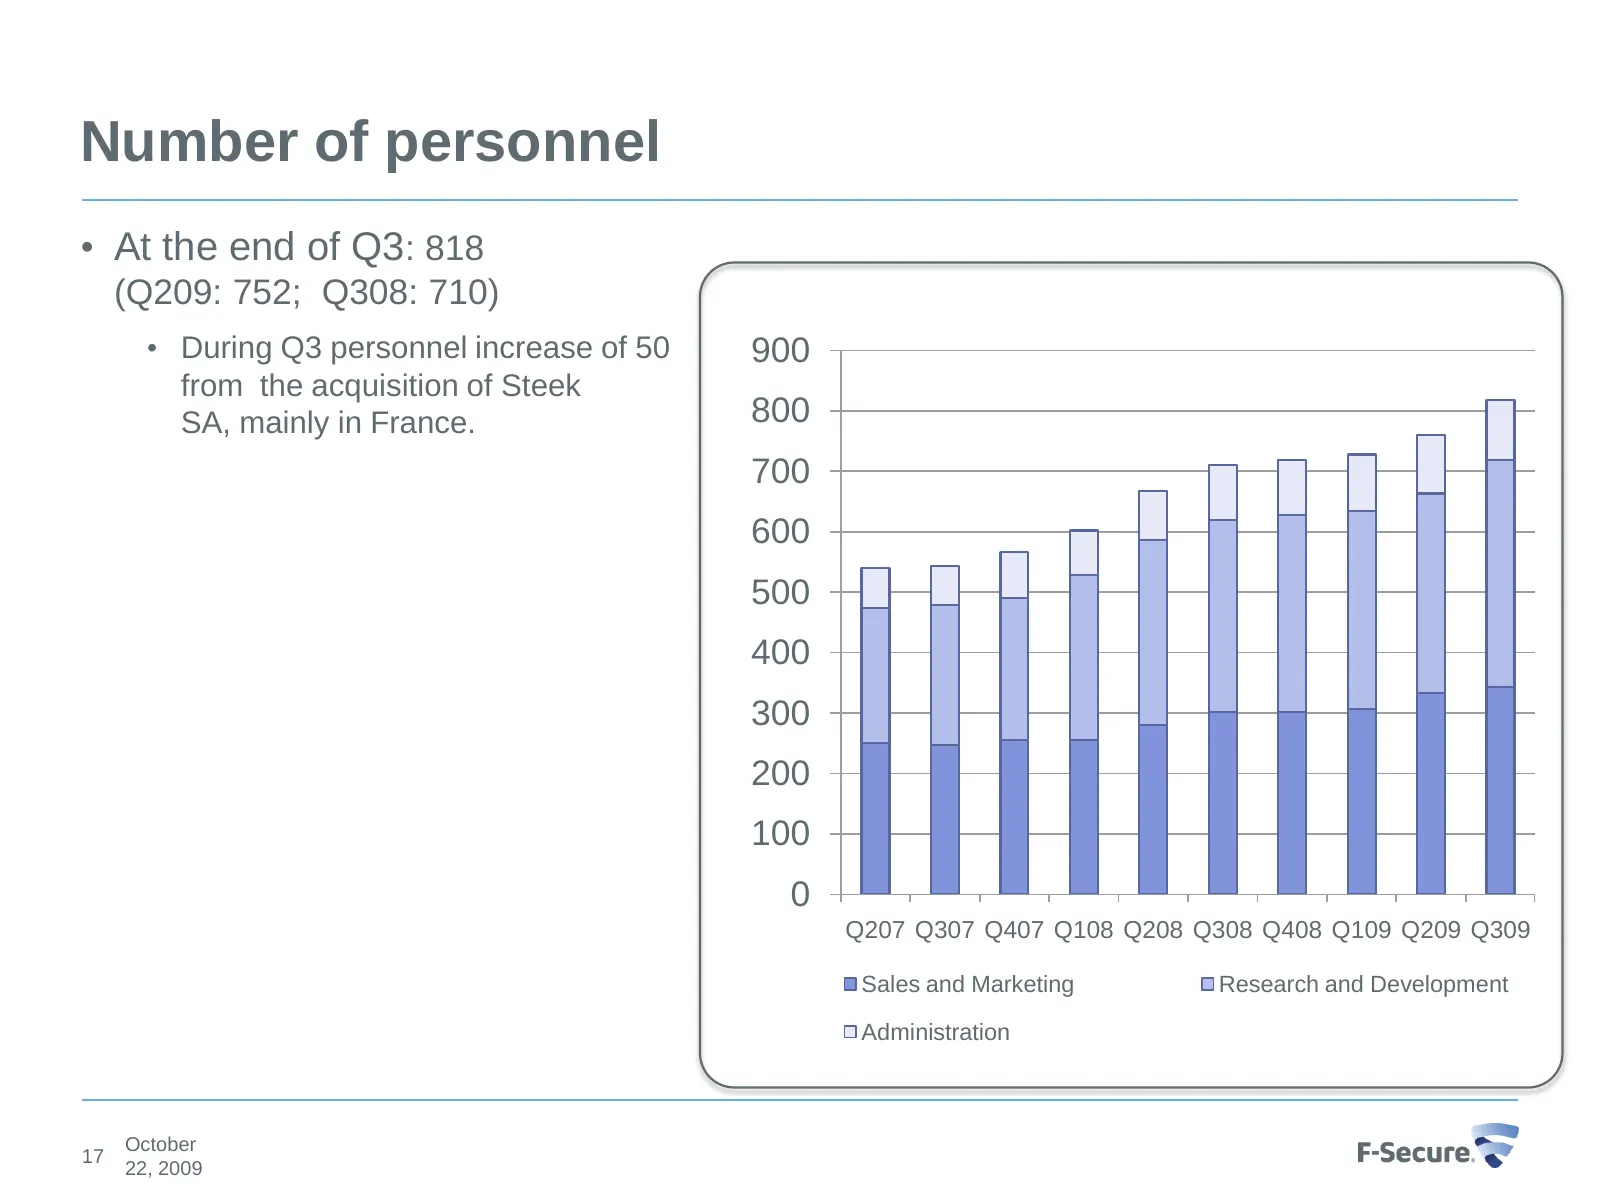
Number of personnel • At the end of Q3: 818 (Q209: 752; Q308: 710) • During Q3 personnel increase of 50 900 from the acquisition of Steek SA, mainly in France. 800 700 600 500 400 300 200 100 0 Q207 Q307 Q407 Q108 Q208 Q308 Q408 Q109 Q209 Q309 Sales and Marketing Research and Development Administrat
Slide 18: Growth opportunity building on security
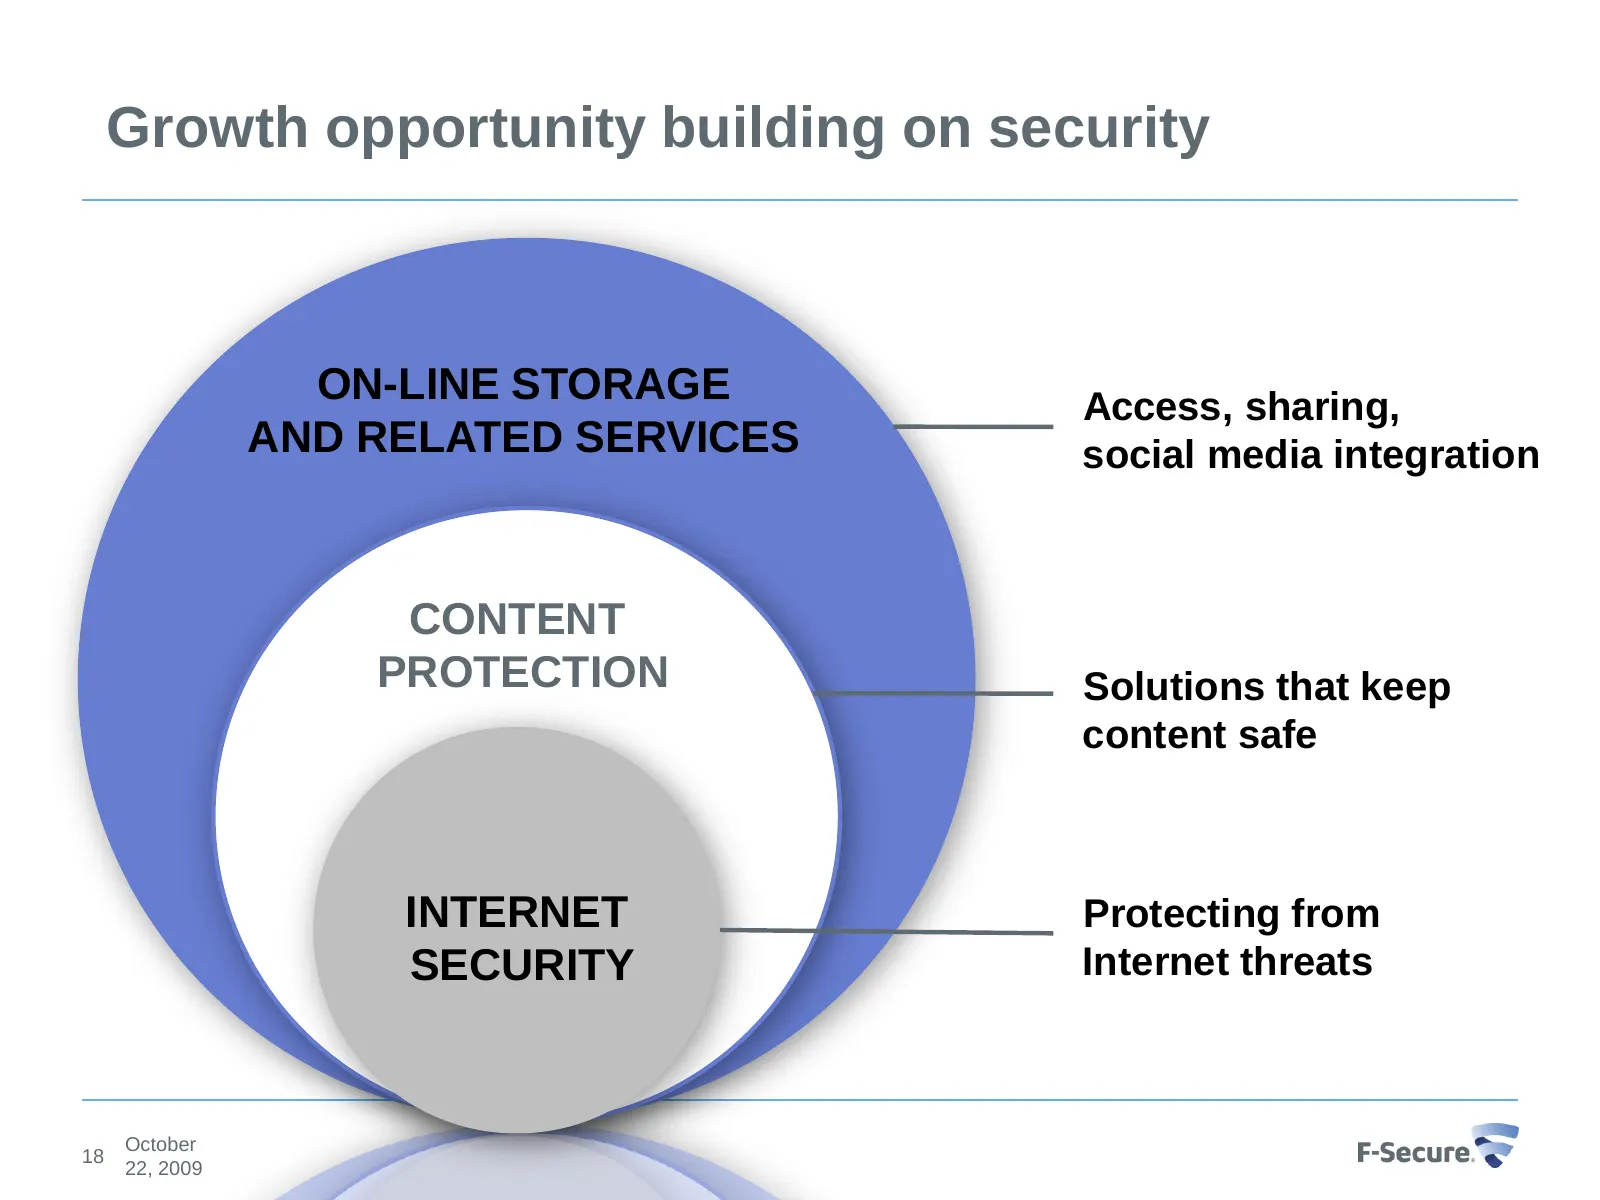
Growth opportunity building on security ON-LINE STORAGE Access, sharing, AND RELATED SERVICES social media integration CONTENT PROTECTION Solutions that keep content safe INTERNET Protecting from SECURITY Internet threats October 18 22, 2009
Slide 19: Long-term objectives
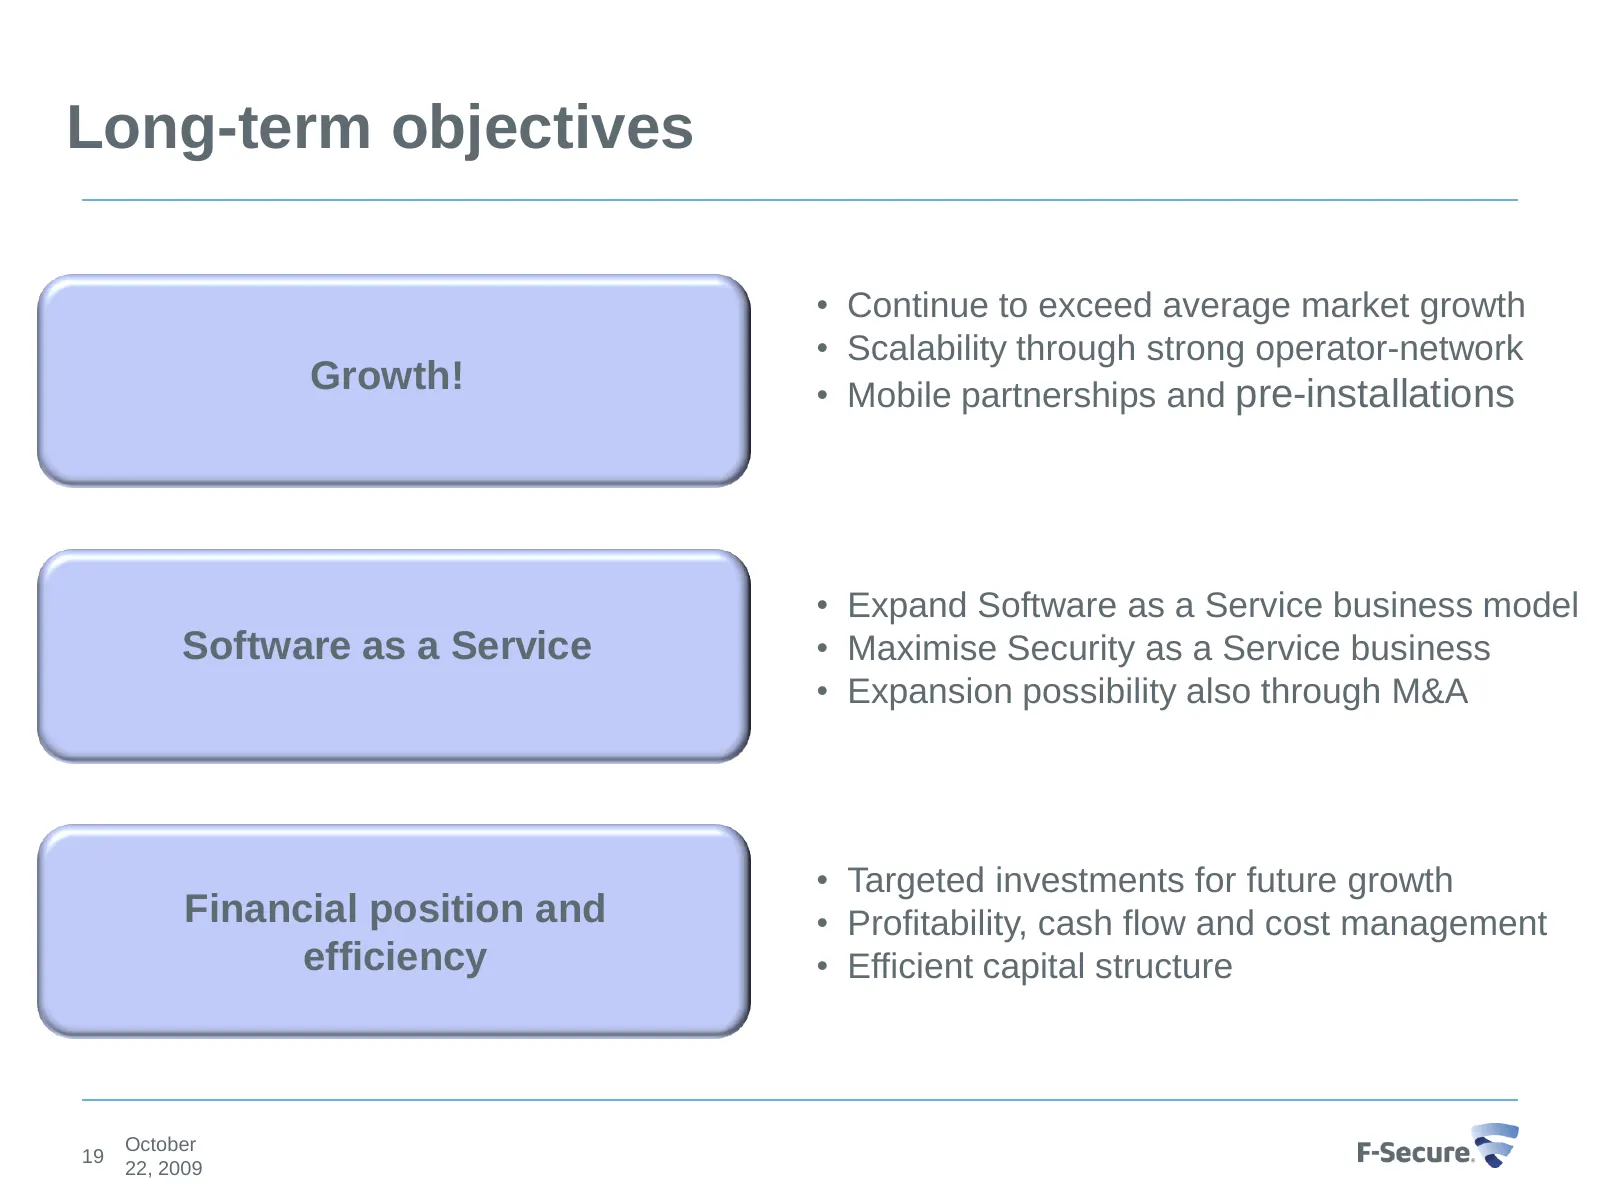
Long-term objectives • Continue to exceed average market growth • Scalability through strong operator-network Growth! • Mobile partnerships and pre-installations • Expand Software as a Service business model Software as a Service • Maximise Security as a Service business • Expansion possibility also
Slide 20: Short-term outlook
Short-term outlook • During the year 2009 the Group seeks to continue to exceed the average market growth (i.e. about +8% pa) • Software as a Service continues to drive growth • Combined mobile and fixed line broadband operators as the channel • End-user acquisition programs drive subscriber and lon
Slide 21: Thank You!
Thank You ! Forward-looking statements: Certain statements in this presentation are forward-looking, and the actual outcome could be materially different. Such forward-looking statements are based on F-Secure’s present plans, estimates, assumptions, projections and expectations and are subject to ri
Source: Internet Archive copy of f-secure.com
More decks from F-Secure Oyj
 Q3 2026 Earnings Presentation23 slides · Oct 28, 2026
 Q2 2026 Earnings Presentation20 slides · Jul 17, 2026
 Investor Day (June 2026)42 slides · Jun 4, 2026
 Q1 2026 Earnings Presentation19 slides · Apr 29, 2026
 Q4 2025 Earnings Presentation29 slides · Feb 5, 2026
 Q3 2025 Earnings Presentation18 slides · Oct 28, 2025