Hi-Crush Partners LP — Investor Day (November 2013)
44 slides from Hi-Crush Partners LP's investor day presentation, Nov 19, 2013
Slide 1: Investor and Analyst Day 2013
INVESTOR AND ANALYST DAY 2013 NOVEMBER 19, 2013
Slide 2: Forward Looking Statements
Forward Looking Statements Some of the information included herein may contain forward-looking statements within the meaning of the federal securities laws. Forward-looking statements give our current expectations and may contain projections of results of operations or of financial condition, or for
Slide 3: Robert Rasmus, Co-Chief Executive Officer
Robert Rasmus Co-Chief Executive Officer Investor Presentation | September, 2013 3
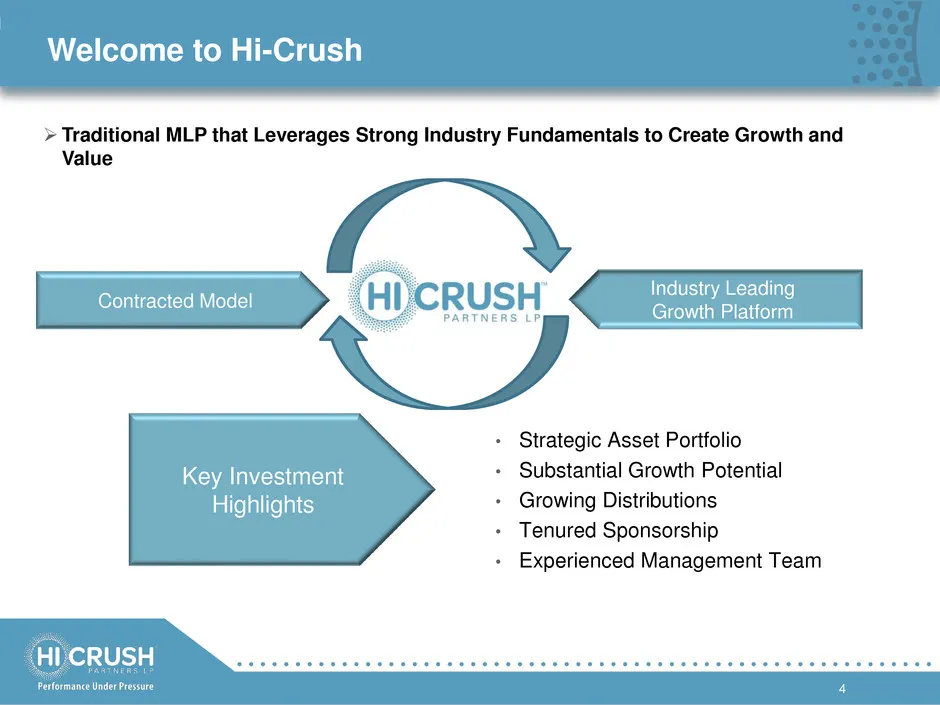
Slide 4: Welcome to Hi-Crush: Key Investment Highlights
4 Traditional MLP that Leverages Strong Industry Fundamentals to Create Growth and Value • Strategic Asset Portfolio • Substantial Growth Potential • Growing Distributions • Tenured Sponsorship • Experienced Management Team Key Investment Highlights Contracted Model Industry Leading Growth Platform
Slide 5: Hi-Crush Management Team
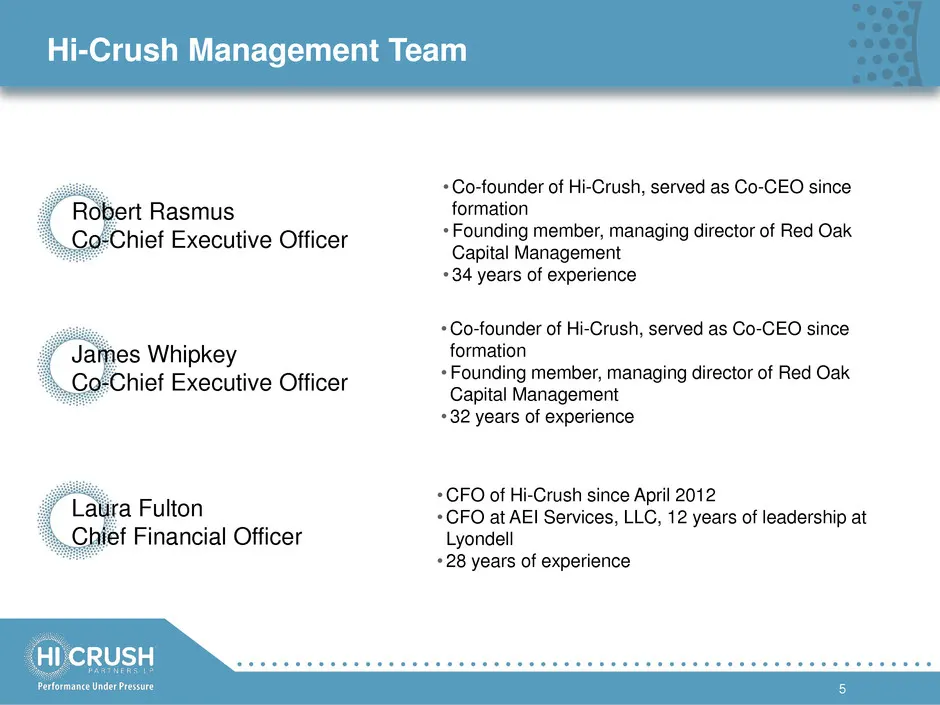
Hi-Crush Management Team 5 Robert Rasmus Co-Chief Executive Officer James Whipkey Co-Chief Executive Officer Laura Fulton Chief Financial Officer •Co-founder of Hi-Crush, served as Co-CEO since formation •Founding member, managing director of Red Oak Capital Management •34 years of experience •Co-fo
Slide 6: Hi-Crush Management Team (continued)
Hi-Crush Management Team (continued) 6 Jay Alston Chief Operating Officer Bill Fehr Executive Vice President •COO of Hi-Crush since May 2011 •Designed frac sand facilities for Trinity Consulting •14 years of experience •EVP of Hi-Crush since May 2013 •D&I Co-Founder and Managing Member •35 years of
Slide 7: 2013 – A Year of Progress
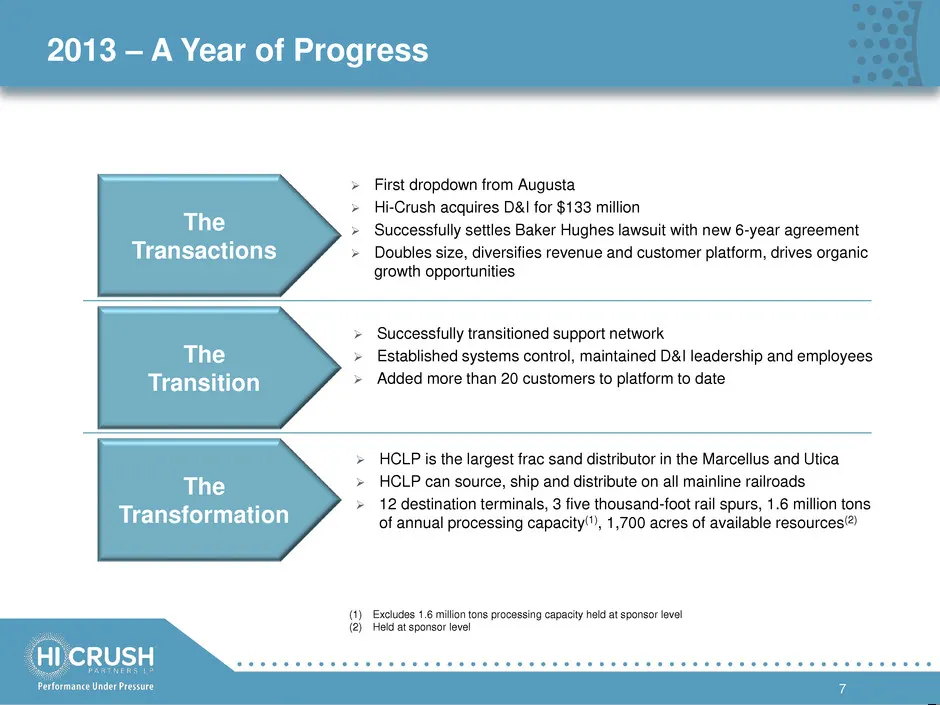
First dropdown from Augusta Hi-Crush acquires D&I for $133 million Successfully settles Baker Hughes lawsuit with new 6-year agreement Doubles size, diversifies revenue and customer platform, drives organic growth opportunities 2013 – A Year of Progress 7 Successfully transitioned support
Slide 8: Unit Price and Total Return
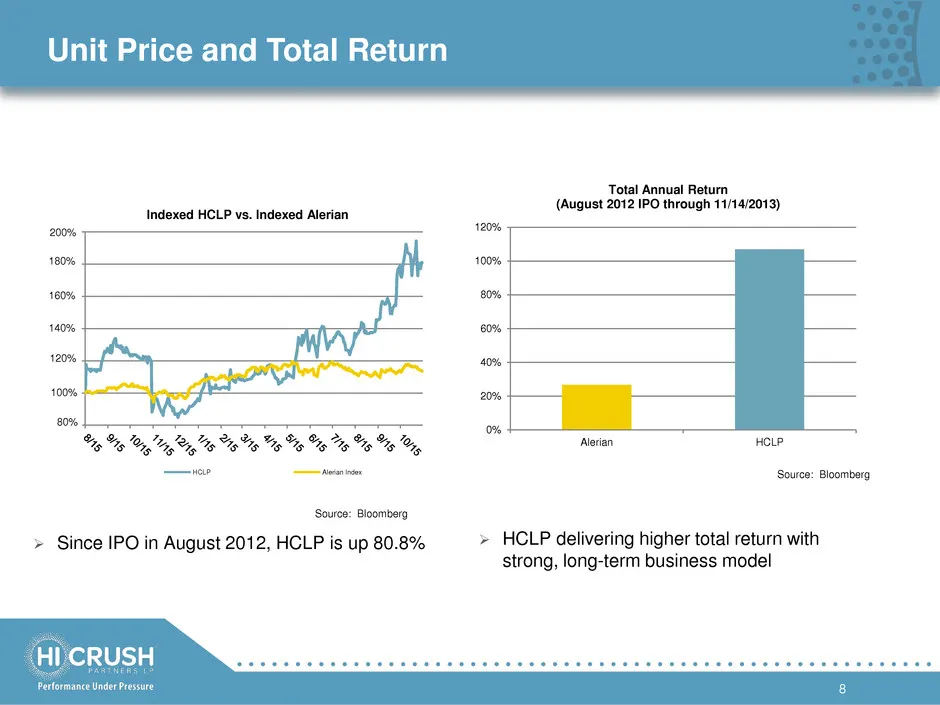
Since IPO in August 2012, HCLP is up 80.8% Unit Price and Total Return 8 HCLP delivering higher total return with strong, long-term business model Source: Bloomberg Source: Bloomberg 0% 20% 40% 60% 80% 100% 120% Alerian HCLP Total Annual Return (August 2012 IPO through 11/14/2013) 80 100 120 140
Slide 9: The Industry
The Industry 9 OPPORTUNITIES Demand Diversification Consolidation CHALLENGES Competition Operations Labor
Slide 10: Performance Under Pressure
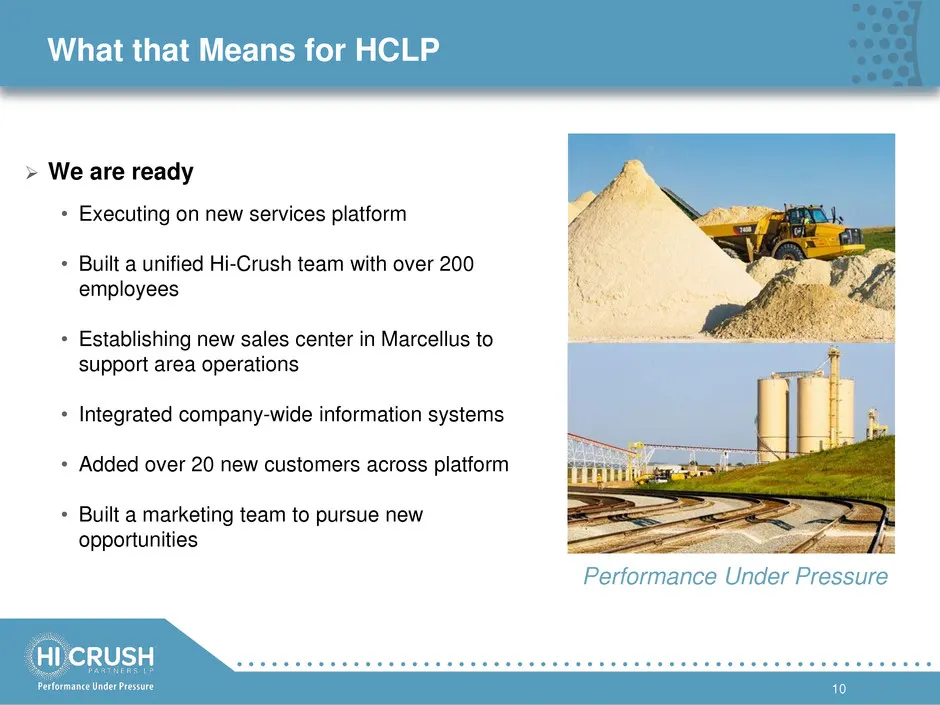
• Executing on new services platform • Built a unified Hi-Crush team with over 200 employees • Establishing new sales center in Marcellus to support area operations • Integrated company-wide information systems • Added over 20 new customers across platform • Built a marketing team to pursue new oppo
Slide 11: What We See: Proppant Consumed by Volume
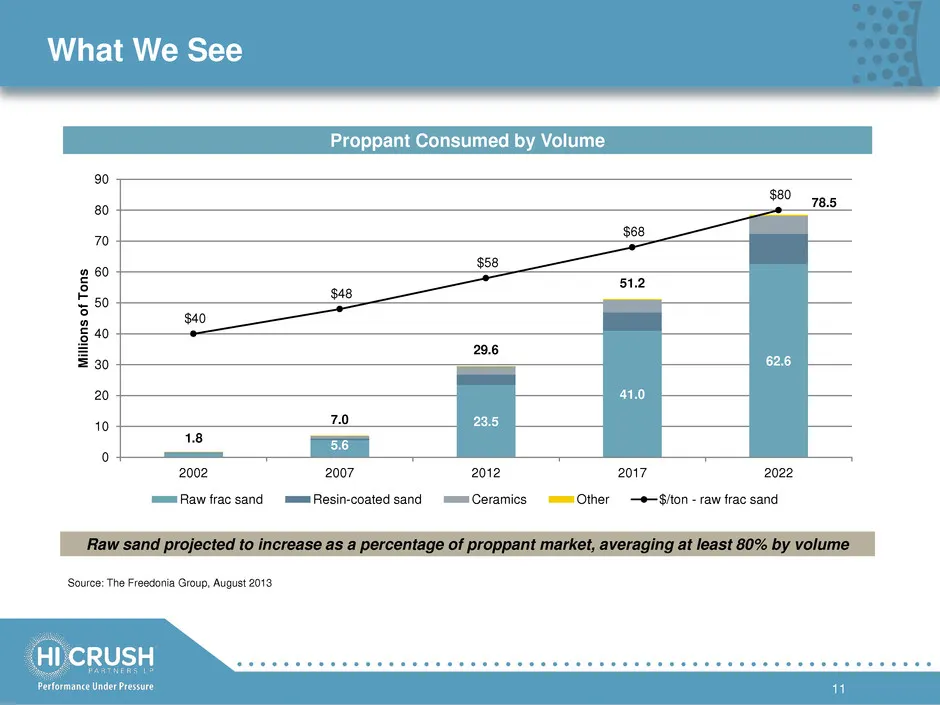
What We See 11 Proppant Consumed by Volume Source: The Freedonia Group, August 2013 Raw sand projected to increase as a percentage of proppant market, averaging at least 80% by volume 5.6 23.5 41.0 62.6 $40 $48 $58 $68 $80 1.8 7.0 29.6 51.2 78.5 0 10 20 30 40 50 60 70 80 90 2002 2007 2012 2017 2022
Slide 12: Opportunities Drive Use of More Sand
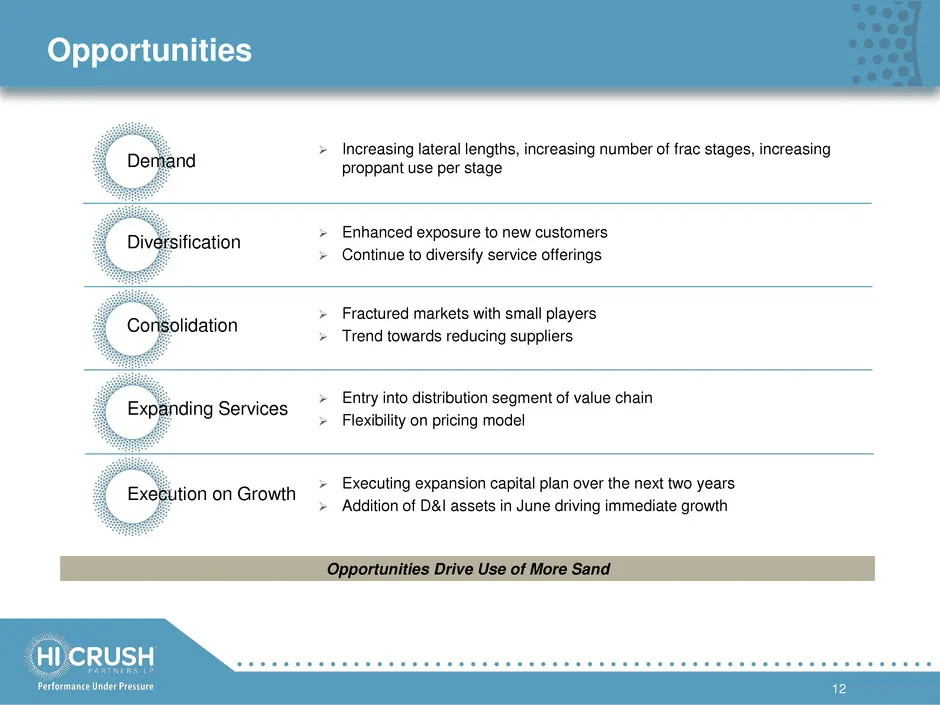
Fractured markets with small players Trend towards reducing suppliers Opportunities 12 Executing expansion capital plan over the next two years Addition of D&I assets in June driving immediate growth Demand Diversification Consolidation Expanding Services Execution on Growth Entry into dis
Slide 13: Laura Fulton, Chief Financial Officer
Laura Fulton Chief Financial Officer Investor Presentation | September, 2013 13
Slide 14: Financial Snapshot
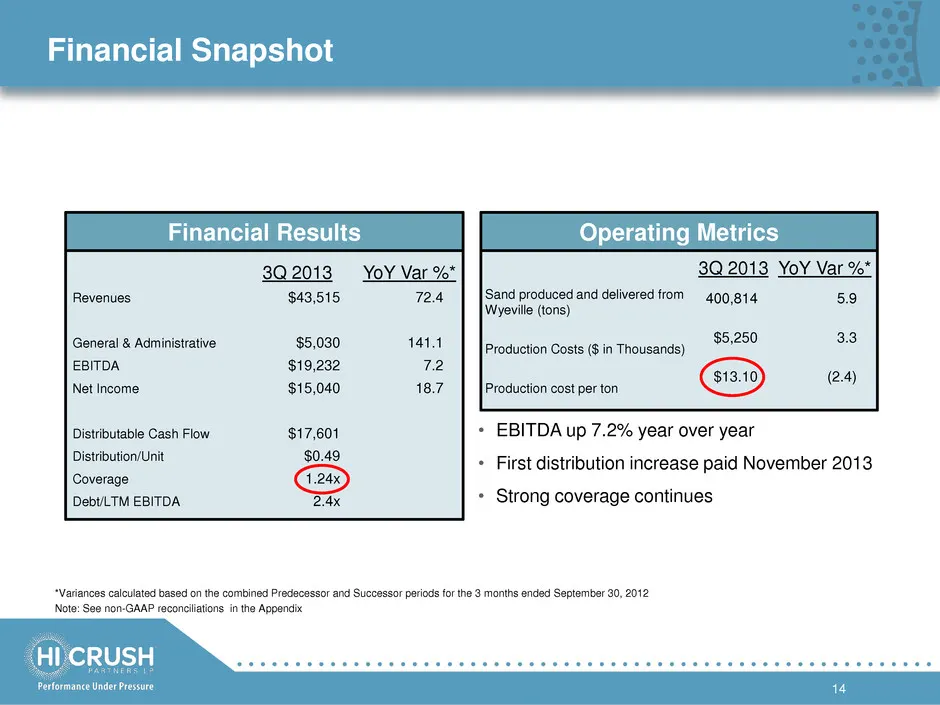
3Q 2013 YoY Var %* Sand produced and delivered from Wyeville (tons) 400,814 5.9 Production Costs ($ in Thousands) $5,250 3.3 Production cost per ton $13.10 (2.4) 3Q 2013 YoY Var %* Revenues $43,515 72.4 General & Administrative $5,030 141.1 EBITDA $19,232 7.2 Net Income $15,040 18.7 Distributable Ca
Slide 15: Delivering Results
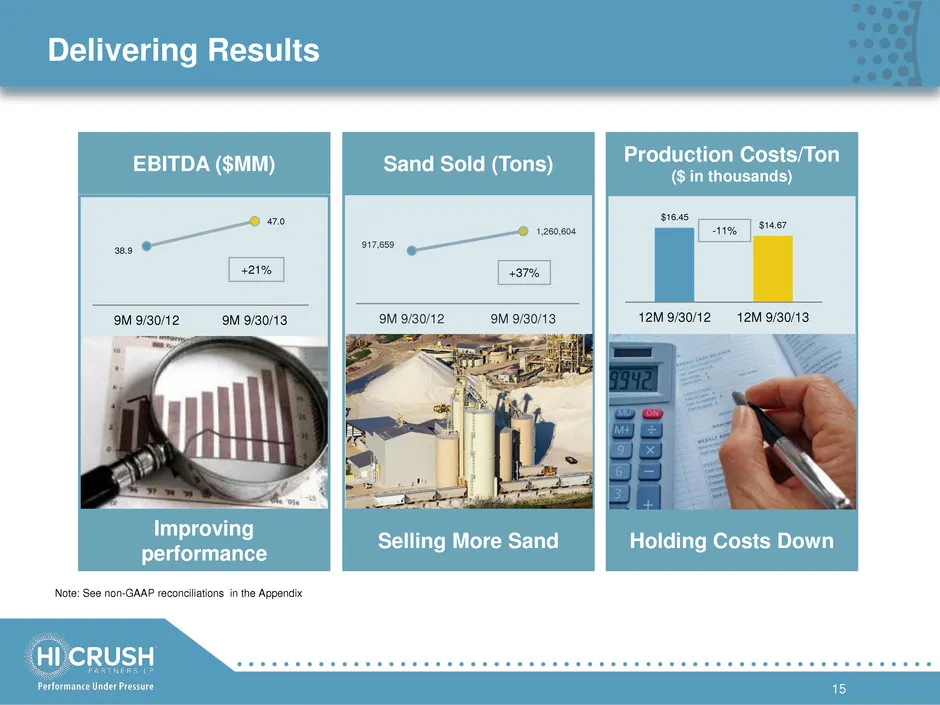
917,659 1,260,604 9M 9/30/12 9M 9/30/13 38.9 47.0 9M 9/30/12 9M 9/30/13 $16.45 $14.67 12M 9/30/12 12M 9/30/13 Delivering Results 15 Improving performance Selling More Sand Holding Costs Down EBITDA ($MM) Sand Sold (Tons) Production Costs/Ton ($ in thousands) +37% -11% +21% Note: See non-GAAP reconci
Slide 16: Highly Visible Growth: HCLP Financial Outlook
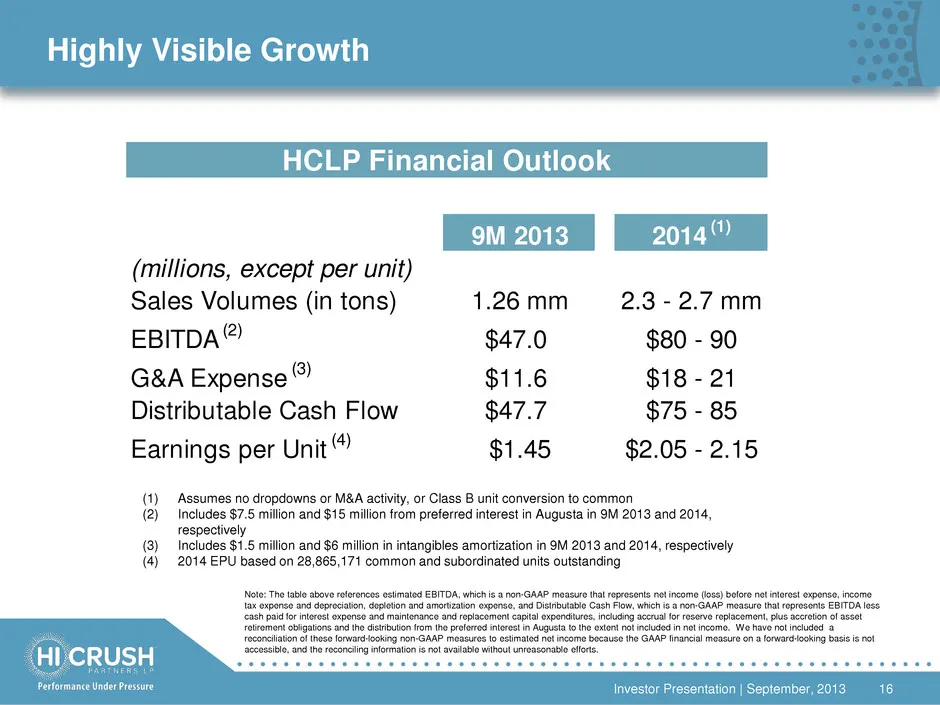
Highly Visible Growth Investor Presentation | September, 2013 16 (1) Assumes no dropdowns or M&A activity, or Class B unit conversion to common (2) Includes $7.5 million and $15 million from preferred interest in Augusta in 9M 2013 and 2014, respectively (3) Includes $1.5 million and $6 million in i
Slide 17: Liquidity, Credibility, Execution
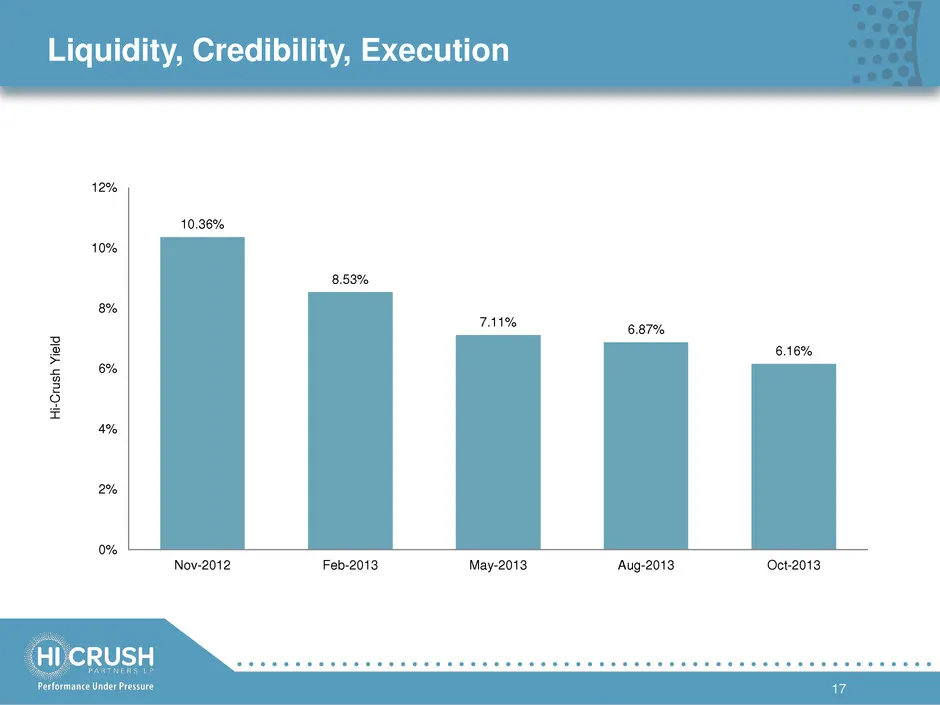
Liquidity, Credibility, Execution 17 10.36% 8.53% 7.11% 6.87% 6.16% 0% 2% 4% 6% 8% 10% 12% Nov-2012 Feb-2013 May-2013 Aug-2013 Oct-2013 H i- C ru s h Y ie ld
Slide 18: Strong Credit Metrics
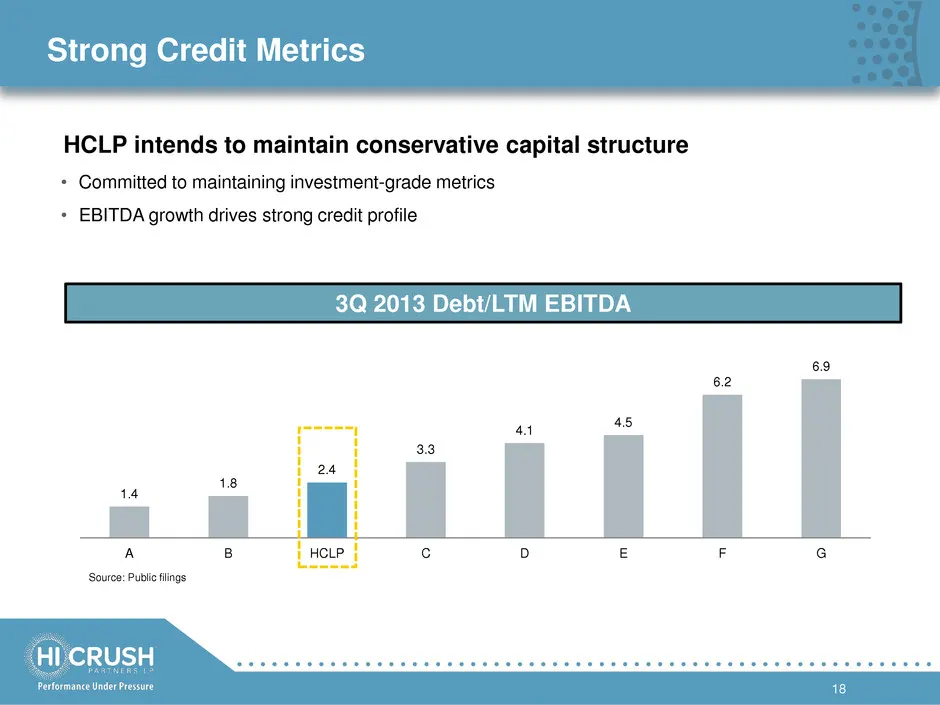
1.4 1.8 2.4 3.3 4.1 4.5 6.2 6.9 A B HCLP C D E F G Strong Credit Metrics 18 • Committed to maintaining investment-grade metrics • EBITDA growth drives strong credit profile HCLP intends to maintain conservative capital structure 3Q 2013 Debt/LTM EBITDA Source: Public filings
Slide 19: HCLP Transformation
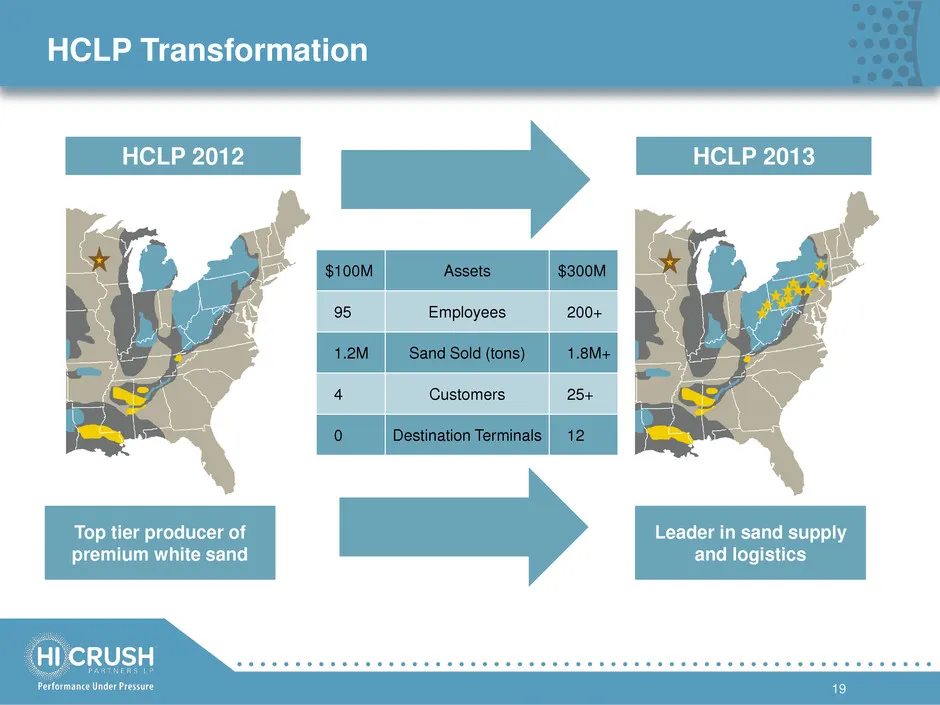
HCLP Transformation 19 HCLP 2012 HCLP 2013 Top tier producer of premium white sand Leader in sand supply and logistics $100M Assets $300M 95 Employees 200+ 1.2M Sand Sold (tons) 1.8M+ 4 Customers 25+ 0 Destination Terminals 12
Slide 20: James Whipkey, Co-Chief Executive Officer
James Whipkey Co-Chief Executive Officer Investor Presentation | September, 2013 20
Slide 21: Where We Came From
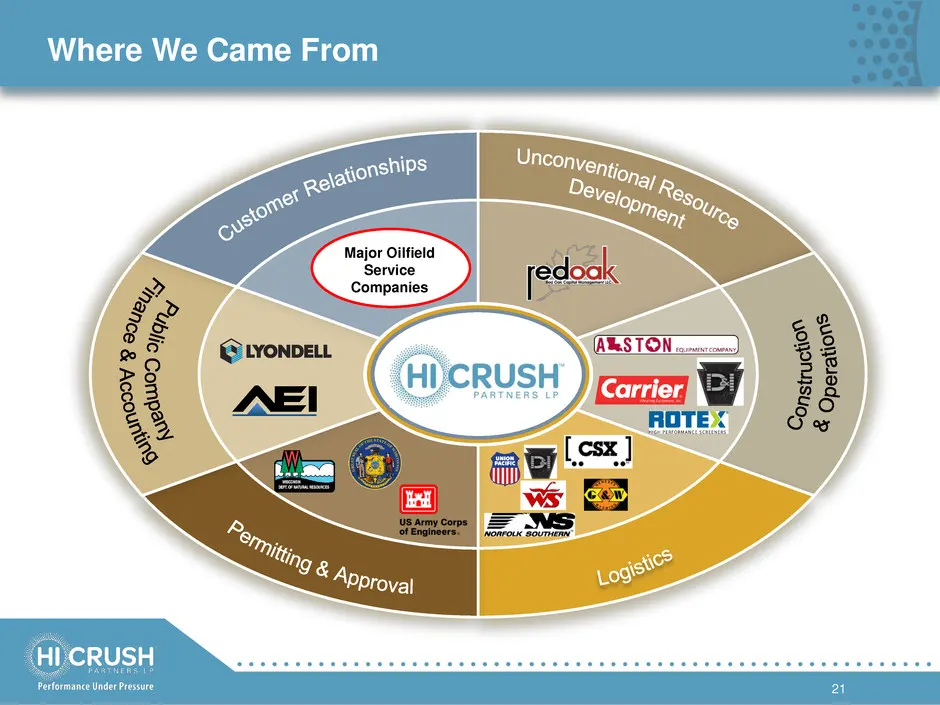
Where We Came From 21 Major Oilfield Service Companies
Slide 22: A Pure Play
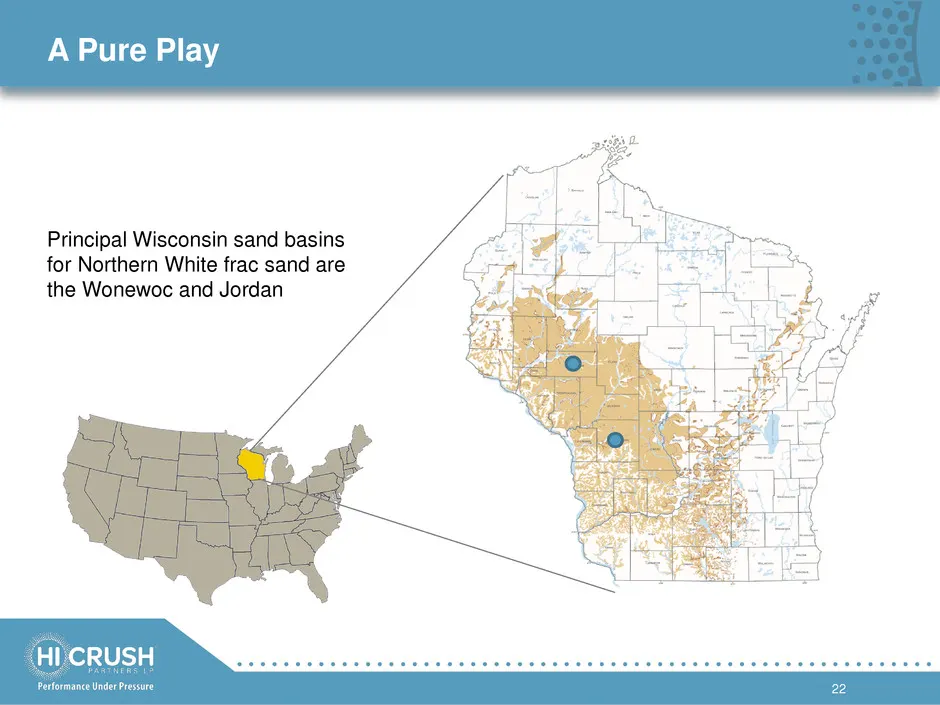
A Pure Play 22 Principal Wisconsin sand basins for Northern White frac sand are the Wonewoc and Jordan
Slide 23: Hi-Crush's Competitive Advantage
Hi-Crush’s Competitive Advantage 23 • Low-Cost Producer • High Quality Reserves • Prime Portfolio of Assets • Focused Vision • Visible Avenues to Growth Focused On: Growth Returns Value Acceleration
Slide 24: Growth in All Regions
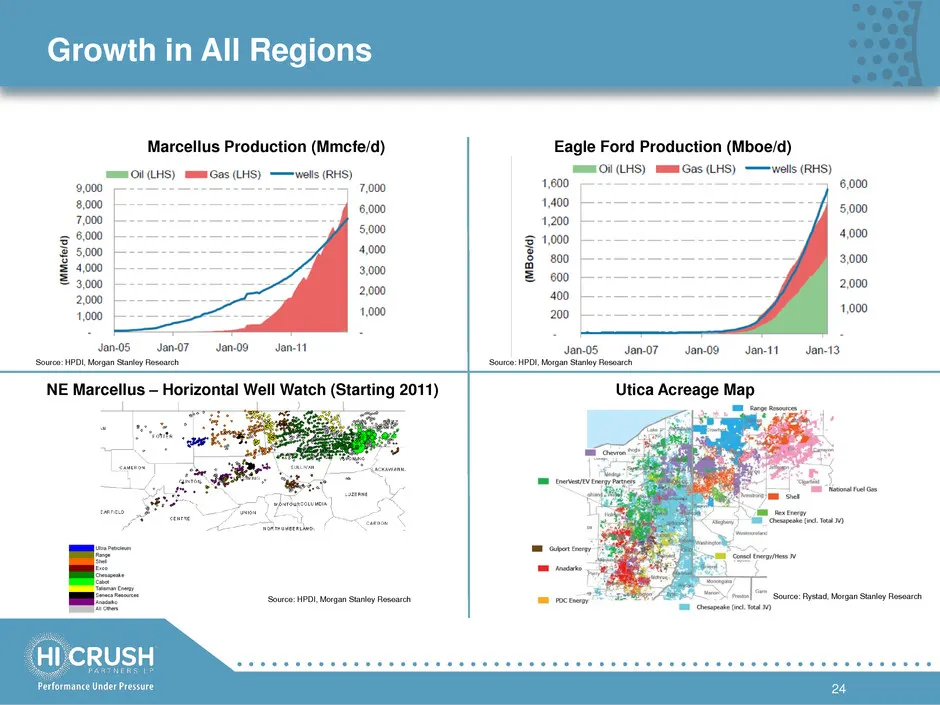
Growth in All Regions 24 Eagle Ford Production (Mboe/d) Marcellus Production (Mmcfe/d) Source: HPDI, Morgan Stanley Research Source: HPDI, Morgan Stanley Research Source: HPDI, Morgan Stanley Research NE Marcellus – Horizontal Well Watch (Starting 2011) Source: Rystad, Morgan Stanley Research Utica
Slide 25: Three Months of Hydraulic Fracturing in the U.S.
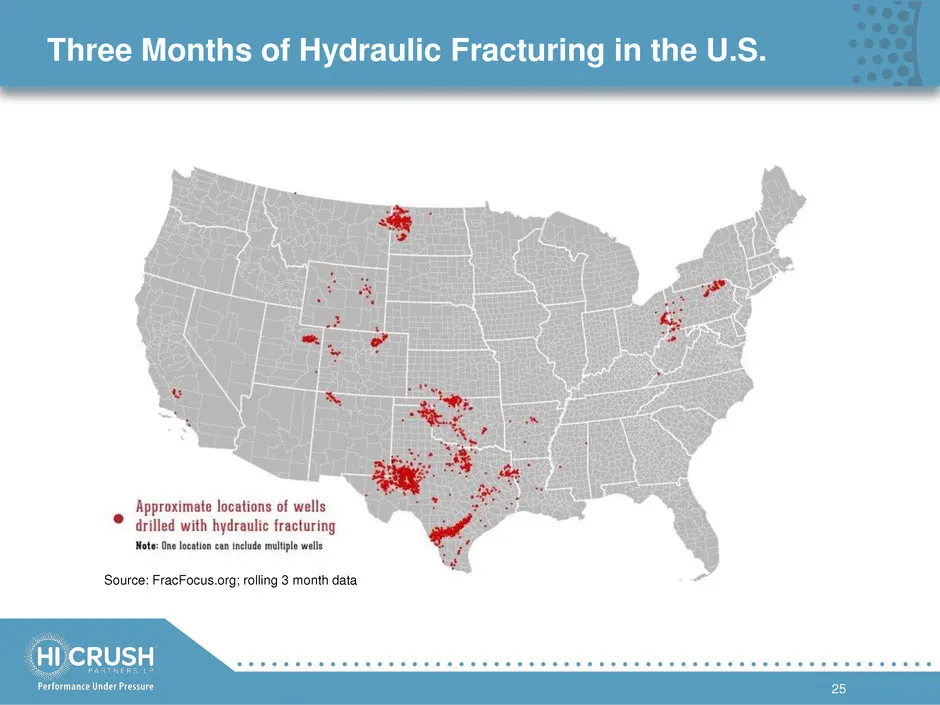
Three Months of Hydraulic Fracturing in the U.S. 25 Source: FracFocus.org; rolling 3 month data
Slide 26: Increasing Our Reach
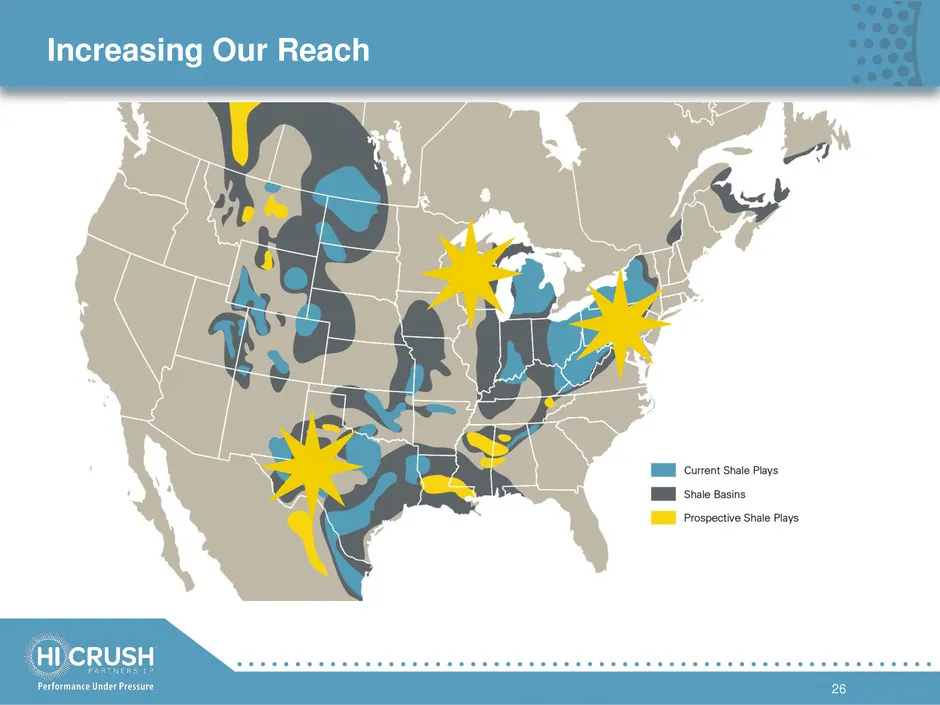
Increasing Our Reach 26
Slide 27: Multiple Future Opportunities
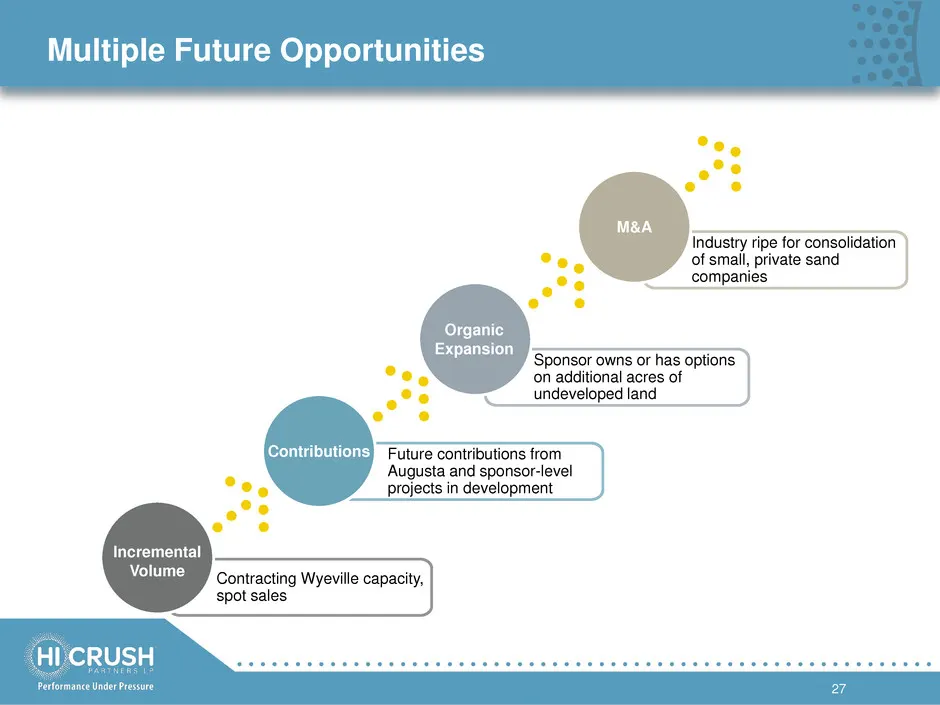
Multiple Future Opportunities 27 Contracting Wyeville capacity, spot sales Future contributions from Augusta and sponsor-level projects in development Sponsor owns or has options on additional acres of undeveloped land Industry ripe for consolidation of small, private sand companies Incremental Volu
Slide 28: Defining Our Goals
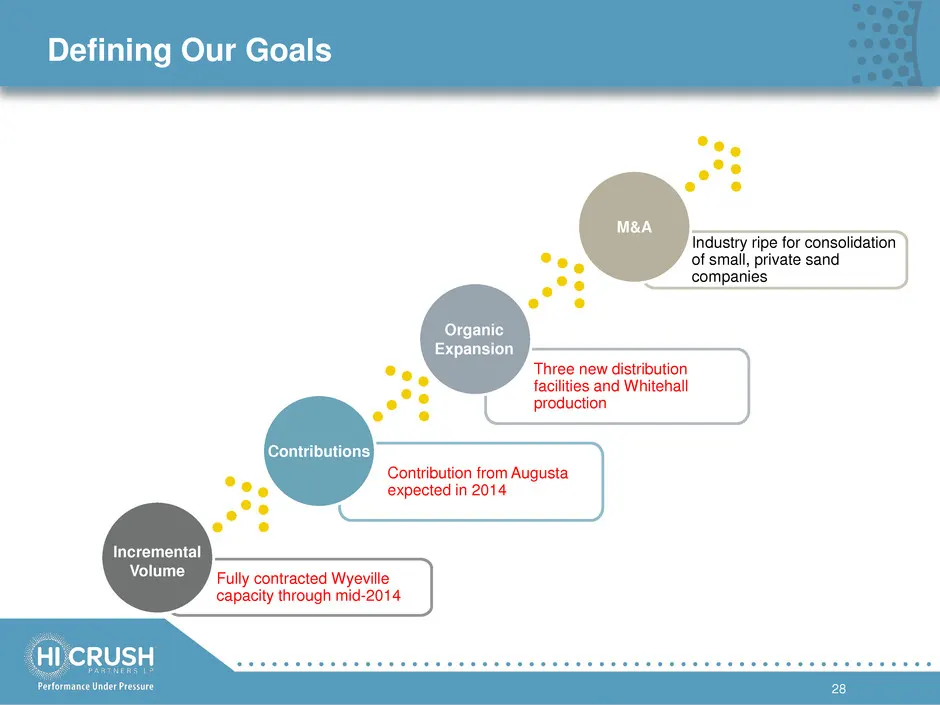
Defining Our Goals 28 Fully contracted Wyeville capacity through mid-2014 Contribution from Augusta expected in 2014 Three new distribution facilities and Whitehall production Industry ripe for consolidation of small, private sand companies Incremental Volume Contributions Organic Expansion M&A
Slide 29: Jay Alston, Chief Operating Officer
Jay Alston Chief Operating Officer Investor Presentation | September, 2013 29
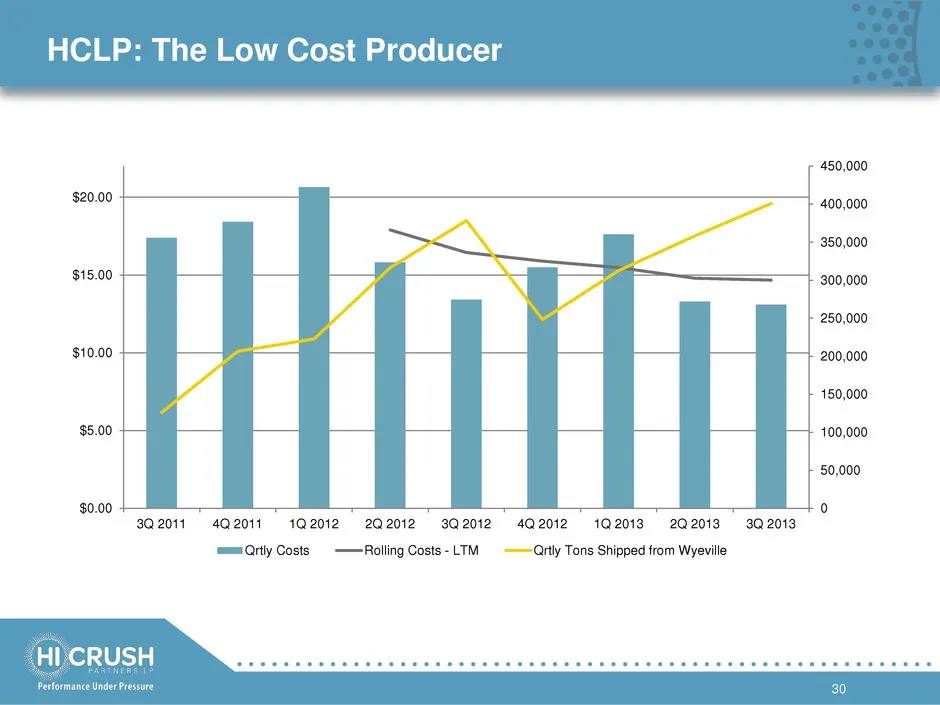
Slide 30: HCLP: The Low Cost Producer
HCLP: The Low Cost Producer 30 0 50,000 100,000 150,000 200,000 250,000 300,000 350,000 400,000 450,000 $0.00 $5.00 $10.00 $15.00 $20.00 3Q 2011 4Q 2011 1Q 2012 2Q 2012 3Q 2012 4Q 2012 1Q 2013 2Q 2013 3Q 2013 Qrtly Costs Rolling Costs - LTM Qrtly Tons Shipped from Wyeville
Slide 31: Building the Optimal Sand Company
Building the Optimal Sand Company 31 Augusta
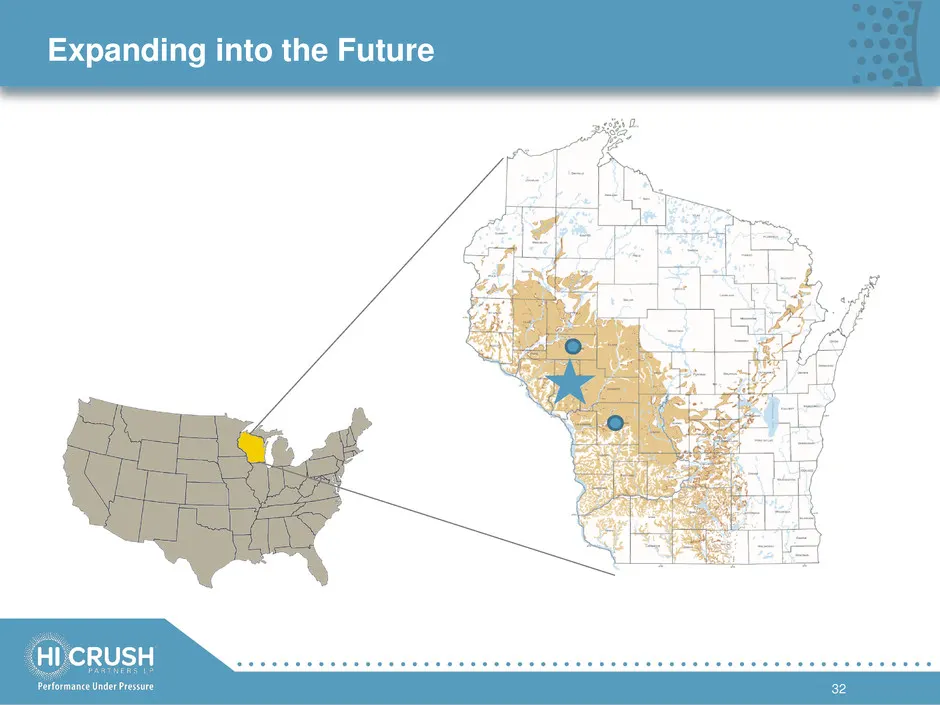
Slide 32: Expanding into the Future
Expanding into the Future 32
Slide 33: Bill Fehr, Executive Vice President
Bill Fehr Executive Vice President Investor Presentation | September, 2013 33
Slide 34: History of D&I
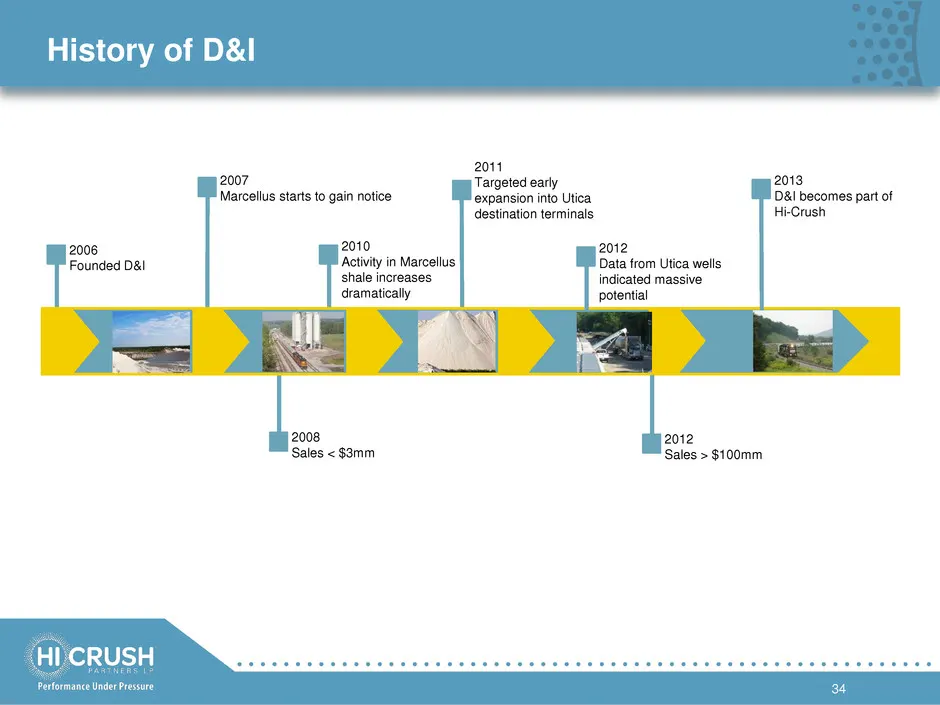
2010 Activity in Marcellus shale increases dramatically History of D&I 34 2006 Founded D&I 2007 Marcellus starts to gain notice 2011 Targeted early expansion into Utica destination terminals 2012 Data from Utica wells indicated massive potential 2013 D&I becomes part of Hi-Crush 2008 Sales < $3mm 20
Slide 35: Unmatched Footprint
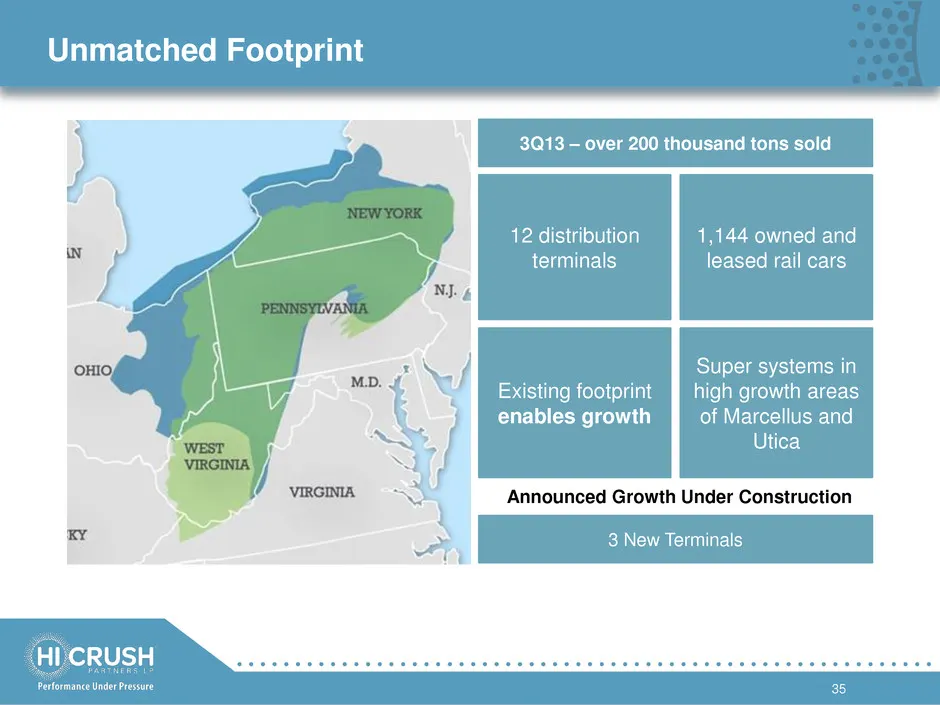
Unmatched Footprint 35 12 distribution terminals 1,144 owned and leased rail cars Existing footprint enables growth Super systems in high growth areas of Marcellus and Utica Announced Growth Under Construction 3Q13 – over 200 thousand tons sold 3 New Terminals
Slide 36: Focus on the Utica
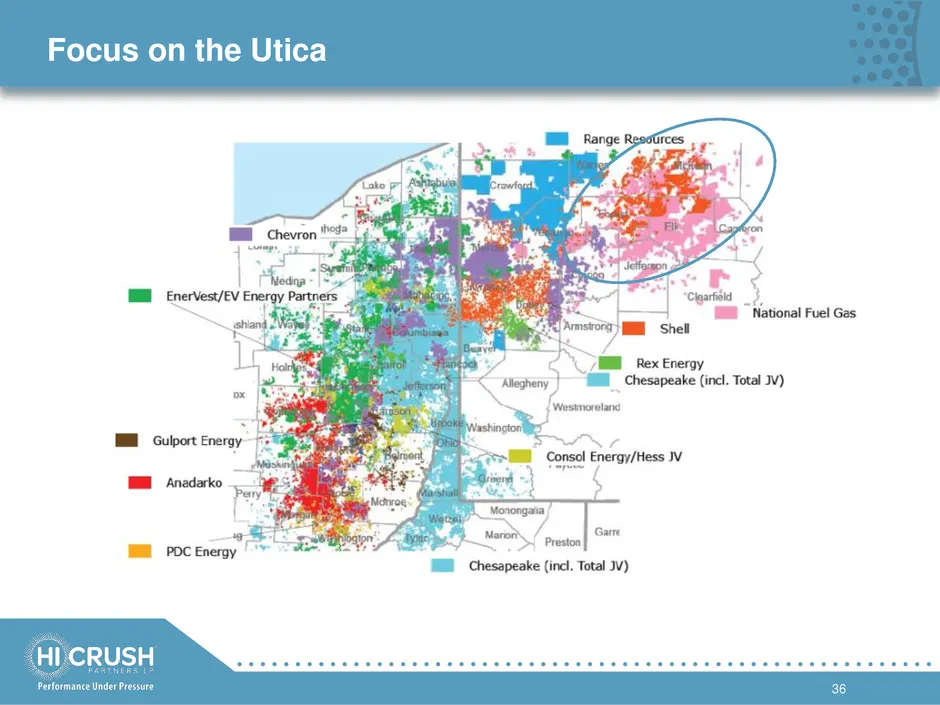
Focus on the Utica National Fuel Gas Rex Energy Alegheny } fll Chesapeake (incl. Total Jv) ‘Westmoreland Consol Energy/Hess JV
Slide 37: Quality Sand, Quality Customers
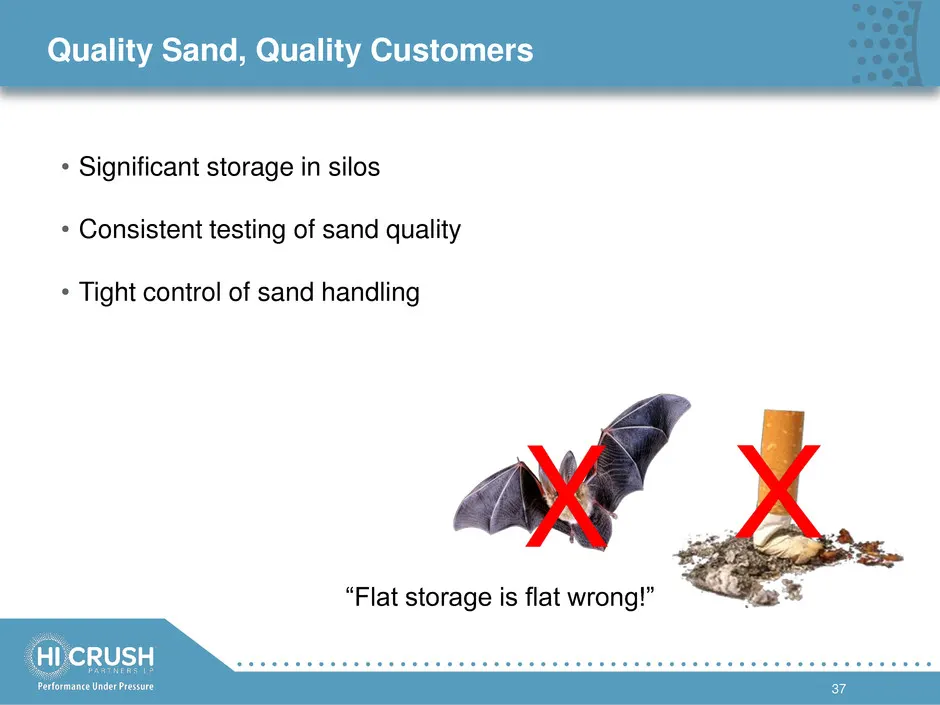
Quality Sand, Quality Customers 37 • Significant storage in silos • Consistent testing of sand quality • Tight control of sand handling “Flat storage is flat wrong!”
Slide 38: Smithfield Destination Terminal
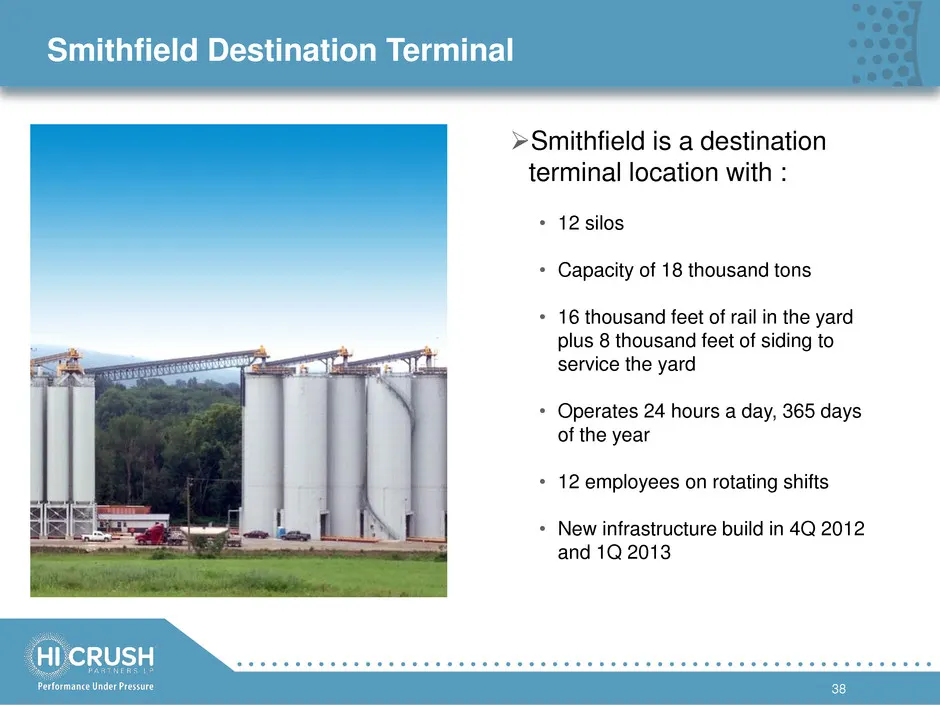
Smithfield is a destination terminal location with : • 12 silos • Capacity of 18 thousand tons • 16 thousand feet of rail in the yard plus 8 thousand feet of siding to service the yard • Operates 24 hours a day, 365 days of the year • 12 employees on rotating shifts • New infrastructure build in 4Q
Slide 39: Leveraging Our Success
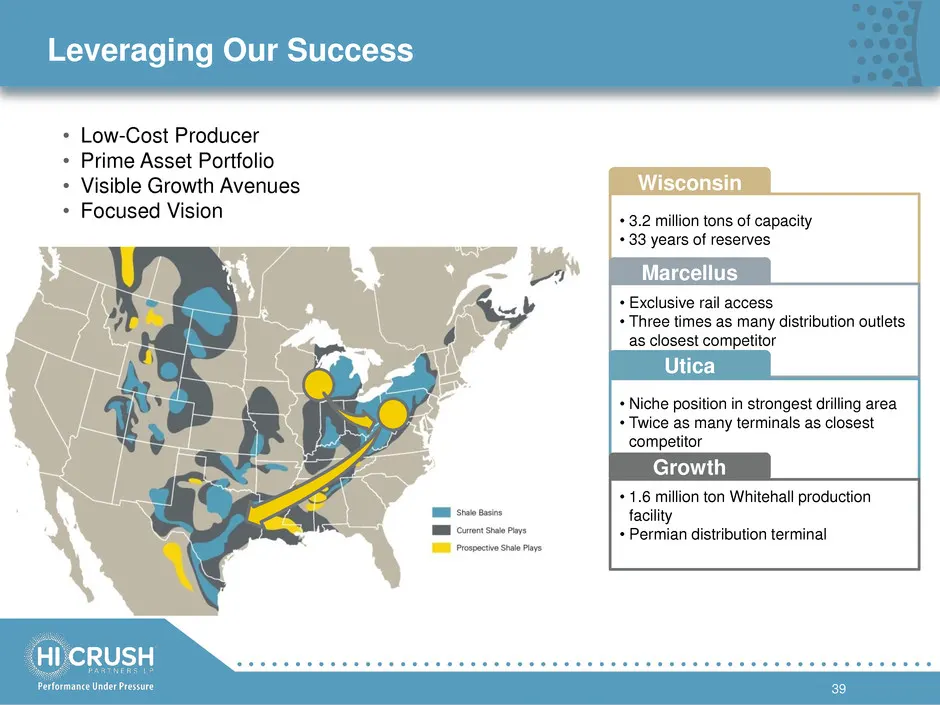
Leveraging Our Success 39 • Low-Cost Producer • Prime Asset Portfolio • Visible Growth Avenues • Focused Vision Wisconsin • 3.2 million tons of capacity • 33 years of reserves Marcellus • Exclusive rail access • Three times as many distribution outlets as closest competitor Utica • Niche position in
Slide 40: Appendix
Appendix Investor Presentation | September, 2013 40
Slide 41: Third Quarter Summary
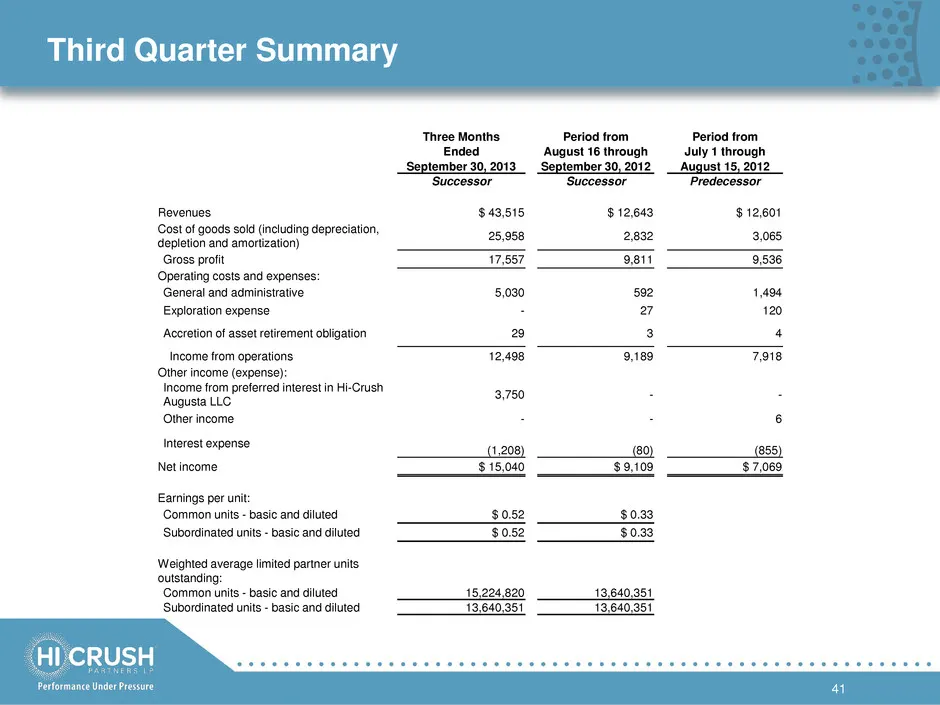
Third Quarter Summary 41 Three Months Period from Period from Ended August 16 through July 1 through September 30, 2013 September 30, 2012 August 15, 2012 Successor Successor Predecessor Revenues $ 43,515 $ 12,643 $ 12,601 Cost of goods sold (including depreciation, depletion and amortization) 25,95
Slide 42: Third Quarter Summary: EBITDA and DCF Reconciliation
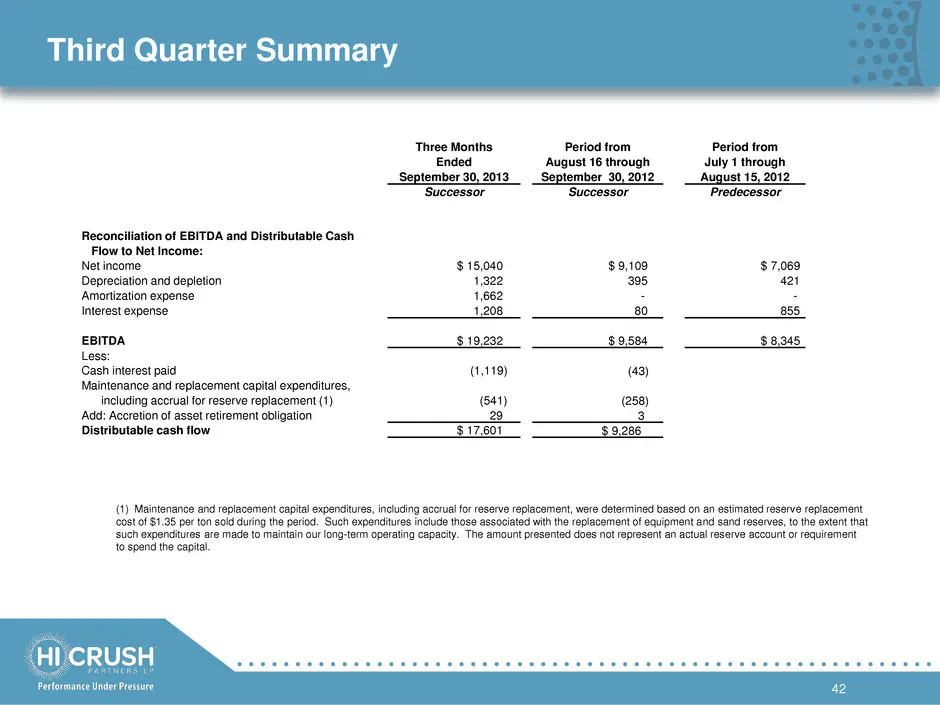
Third Quarter Summary 42 Three Months Period from Period from Ended August 16 through July 1 through September 30, 2013 September 30, 2012 August 15, 2012 Successor Successor Predecessor Reconciliation of EBITDA and Distributable Cash Flow to Net Income: Net income $ 15,040 $ 9,109 $ 7,069 Depreciat
Slide 43: Production Costs per Ton at Wyeville
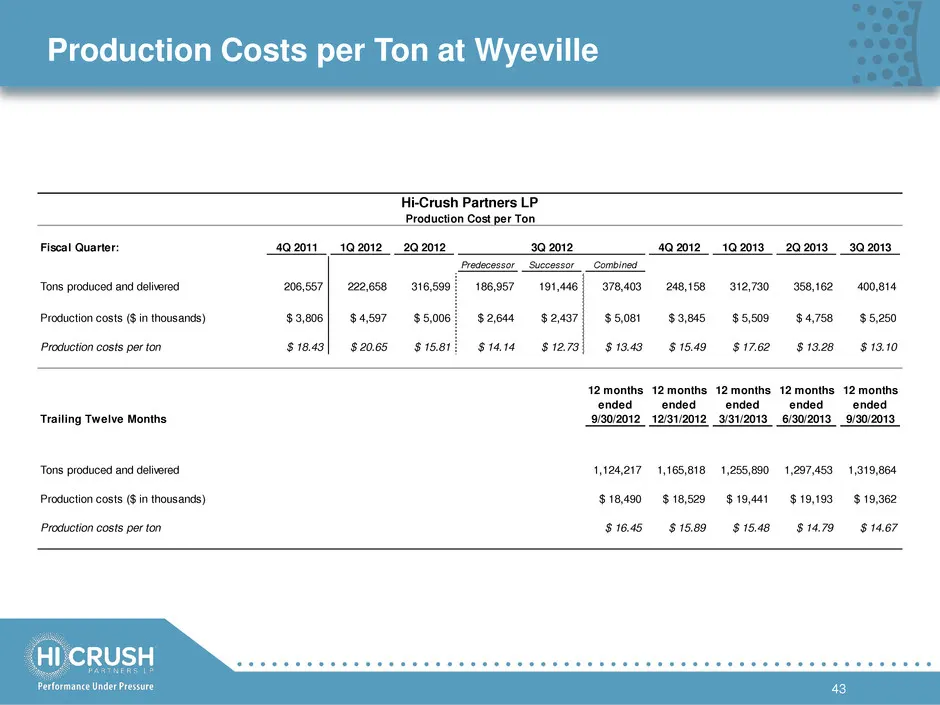
Production Costs per Ton at Wyeville 43 Hi-Crush Partners LP Production Cost per Ton Fiscal Quarter: 4Q 2011 1Q 2012 2Q 2012 3Q 2012 4Q 2012 1Q 2013 2Q 2013 3Q 2013 Predecessor Successor Combined Tons produced and delivered 206,557 222,658 316,599 186,957 191,446 378,403 248,158 312,730 358,162 400,
Slide 44: GAAP Reconciliation of Production Costs to Cost of Goods Sold
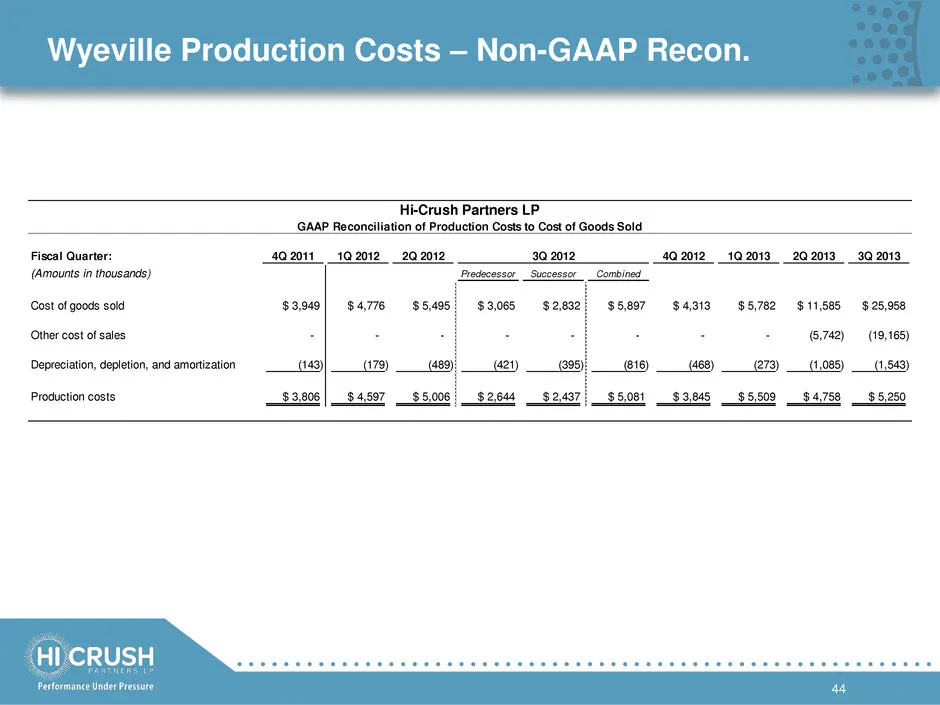
44 Hi-Crush Partners LP GAAP Reconciliation of Production Costs to Cost of Goods Sold Fiscal Quarter: 4Q 2011 1Q 2012 2Q 2012 4Q 2012 1Q 2013 2Q 2013 3Q 2013 (Amounts in thousands) Predecessor Successor Combined Cost of goods sold $ 3,949 $ 4,776 $ 5,495 $ 3,065 $ 2,832 $ 5,897 $ 4,313 $ 5,782 $ 11,
Source: SEC EDGAR · 8-K filed Nov 19, 2013
More decks from Hi-Crush Partners LP
 Q4 2019 Earnings Presentation21 slides · Feb 19, 2020
 Q3 2019 Earnings Presentation19 slides · Nov 5, 2019
 Q2 2019 Earnings Presentation25 slides · Aug 7, 2019
 Q1 2019 Earnings Presentation21 slides · May 7, 2019
 Q4 2018 Earnings Presentation29 slides · Feb 5, 2019
 Investor Presentation (January 2019)21 slides · Jan 7, 2019