Fairmount Santrol Holdings Inc
Fairmount Santrol — Investor Presentation (December 2016)
21 slides from Fairmount Santrol's investor presentation, Dec 5, 2016
Slide 1: Investor Presentation December 2016
Investor Presentation December 2016 Exhibit 99.1
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements. These statements can be identified by the use of forward-looking terminology including “will,” “may,” “believe,” “expect,” “anticipate,” “estimate,” “continue,” or other similar words. These statements discuss future e
Slide 3: Two Complementary Business Segments
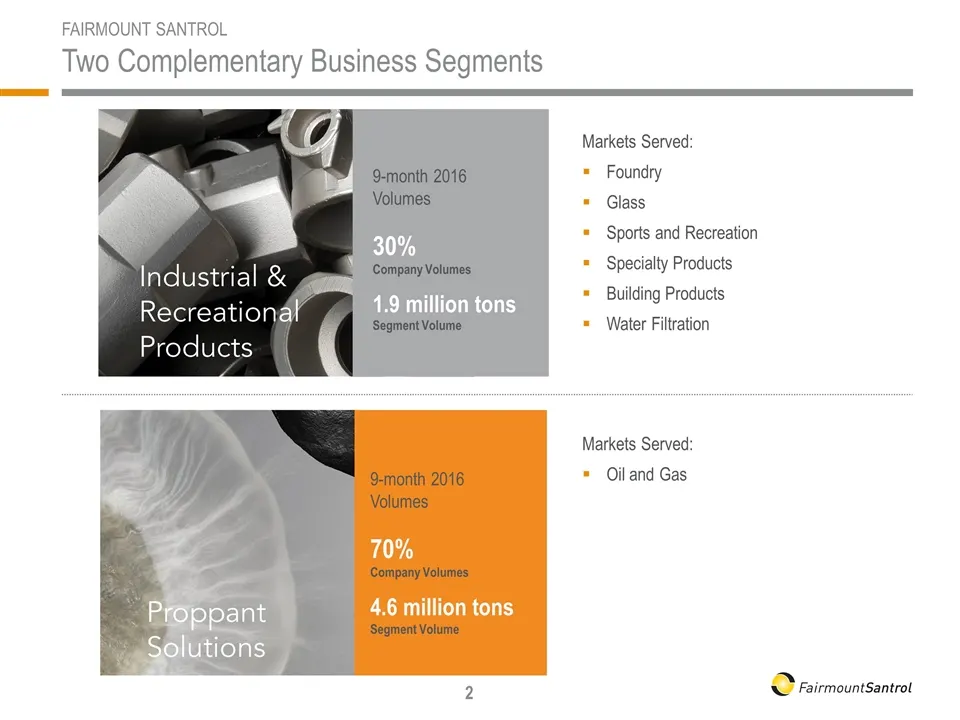
FAIRMOUNT SANTROL Two Complementary Business Segments Markets Served: Foundry Glass Sports and Recreation Specialty Products Building Products Water Filtration Markets Served: Oil and Gas 9-month 2016 Volumes 30% Company Volumes 1.9 million tons Segment Volume 9-month 2016 Volumes 70% Company Volume
Slide 4: Positioned to Compete in All Market Cycles
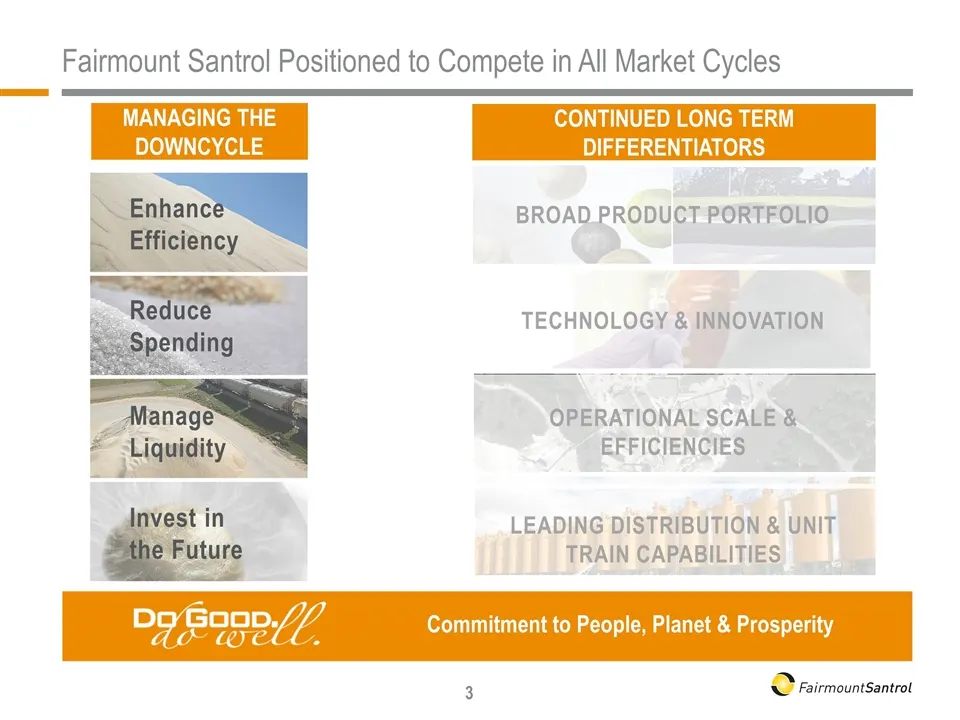
Enhance Efficiency Reduce Spending Manage Liquidity Invest in the Future Fairmount Santrol Positioned to Compete in All Market Cycles CONTINUED LONG TERM DIFFERENTIATORS Technology & Innovation Broad Product Portfolio Operational Scale & Efficiencies Leading Distribution & Unit Train Capabilities MA
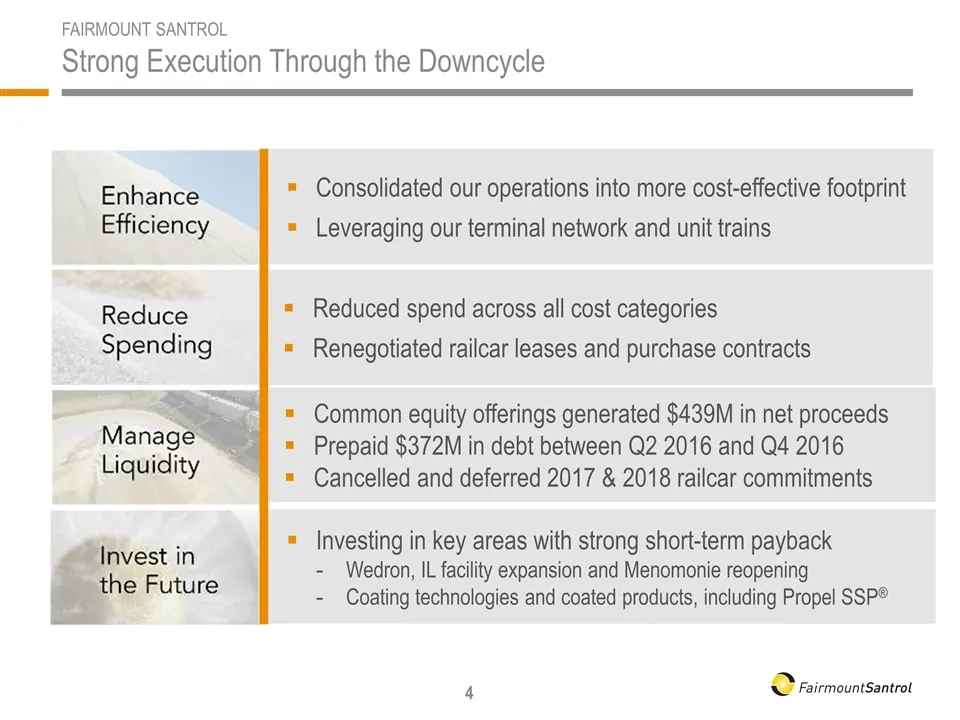
Slide 5: Strong Execution Through the Downcycle
FAIRMOUNT SANTROL Strong Execution Through the Downcycle Consolidated our operations into more cost-effective footprint Leveraging our terminal network and unit trains Reduced spend across all cost categories Renegotiated railcar leases and purchase contracts Investing in key areas with strong short
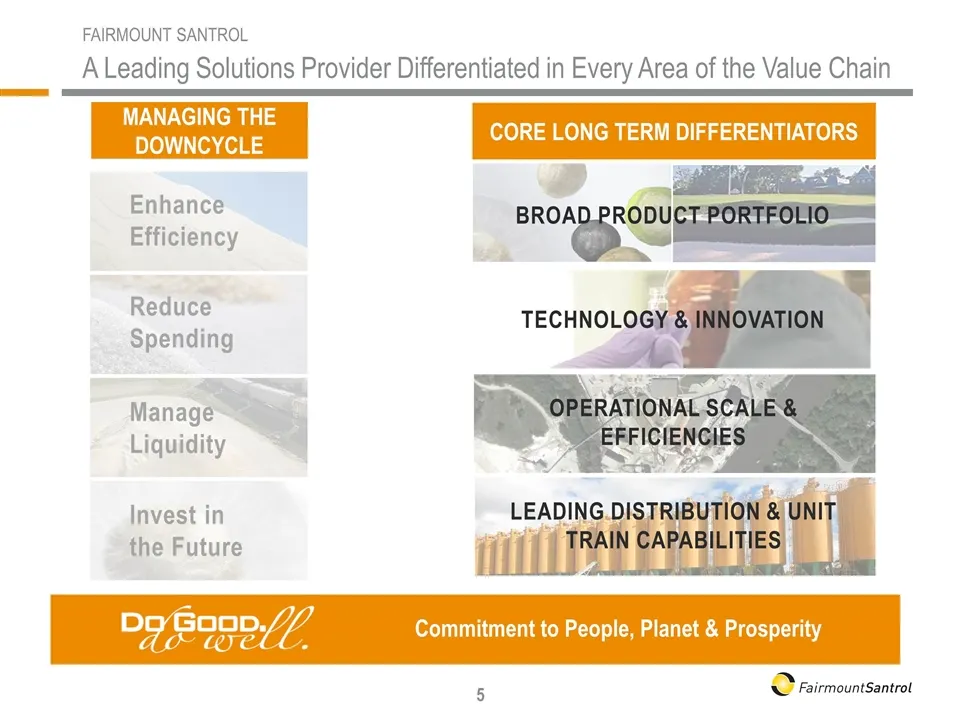
Slide 6: A Leading Solutions Provider Differentiated in Every Area of the Value Chain
Enhance Efficiency Reduce Spending Manage Liquidity Invest in the Future CORE LONG TERM DIFFERENTIATORS Technology & Innovation Broad Product Portfolio Operational Scale & Efficiencies Leading Distribution & Unit Train Capabilities MANAGING THE DOWNCYCLE Commitment to People, Planet & Prosperity FAI
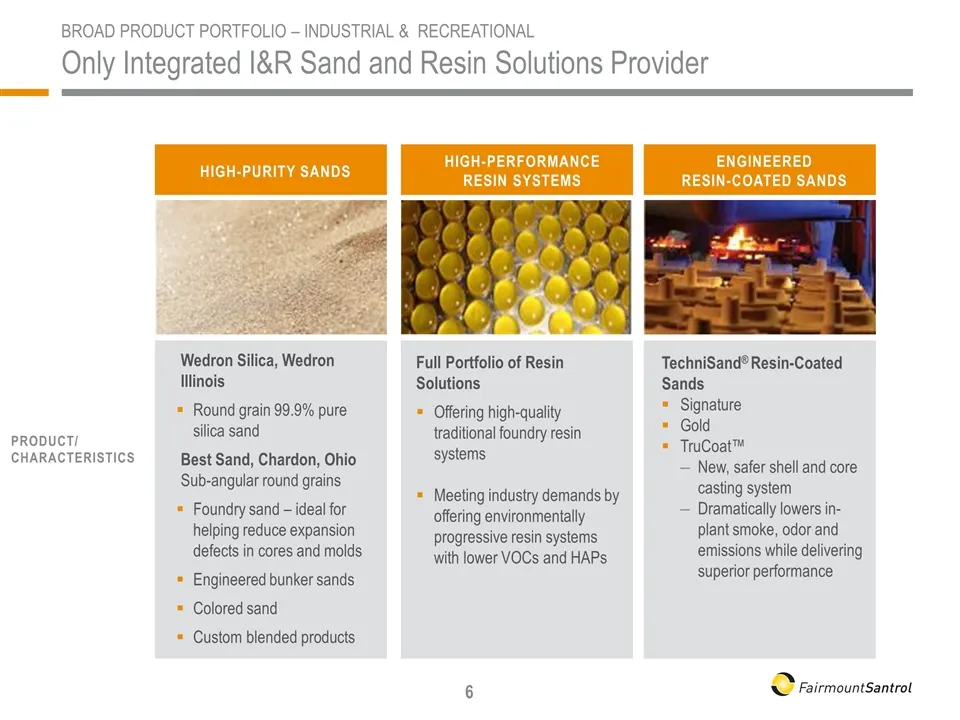
Slide 7: Broad Product Portfolio – Industrial & Recreational
HIGH-PURITY SANDS ENGINEERED RESIN-COATED SANDS TechniSand® Resin-Coated Sands Signature Gold TruCoat™ New, safer shell and core casting system Dramatically lowers in-plant smoke, odor and emissions while delivering superior performance HIGH-PERFORMANCE RESIN SYSTEMS Full Portfolio of Resin Solution
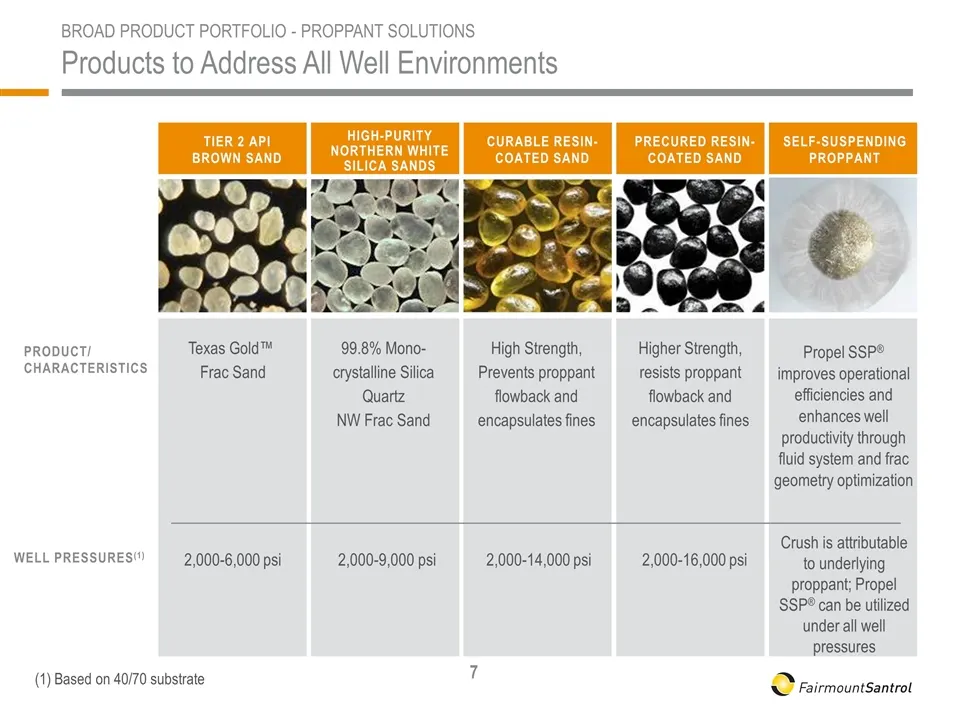
Slide 8: Broad Product Portfolio – Proppant Solutions
High-Purity Northern White Silica Sands Texas Gold™ Frac Sand Precured Resin-Coated Sand Higher Strength, resists proppant flowback and encapsulates fines Curable Resin-Coated Sand High Strength, Prevents proppant flowback and encapsulates fines Self-Suspending Proppant Propel SSP® improves operatio
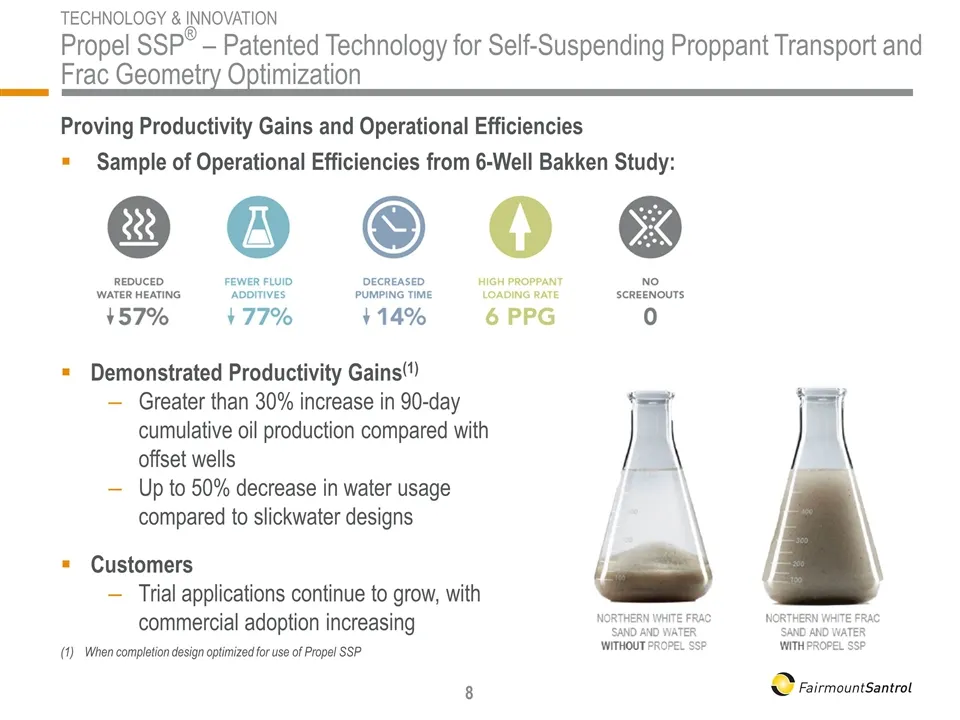
Slide 9: Propel SSP – Patented Technology for Self-Suspending Proppant Transport
Sample of Operational Efficiencies from 6-Well Bakken Study: TECHNOLOGY & INNOVATION Propel SSP® – Patented Technology for Self-Suspending Proppant Transport and Frac Geometry Optimization Proving Productivity Gains and Operational Efficiencies Demonstrated Productivity Gains(1) Greater than 30% inc
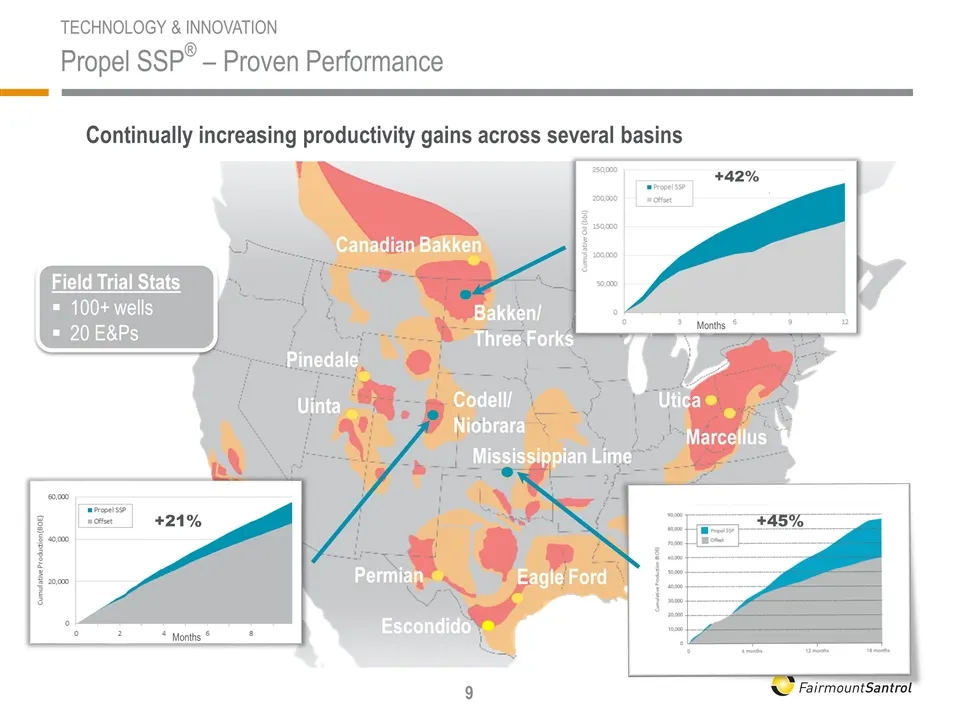
Slide 10: Propel SSP – Proven Performance
TECHNOLOGY & INNOVATION Propel SSP® – Proven Performance Continually increasing productivity gains across several basins Field Trial Stats 100+ wells 20 E&Ps Bakken/ Three Forks Canadian Bakken Codell/ Niobrara Mississippian Lime Utica Marcellus Eagle Ford Escondido Uinta Permian Pinedale +45% +21%
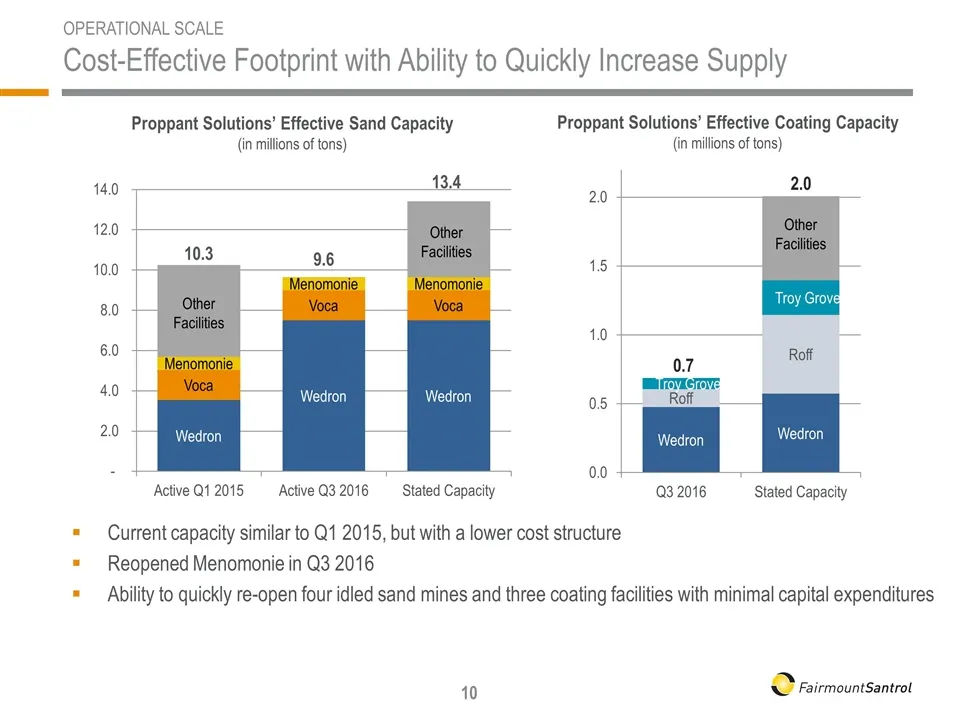
Slide 11: Cost-Effective Footprint with Ability to Quickly Increase Supply
OPERATIONAL SCALE Cost-Effective Footprint with Ability to Quickly Increase Supply Current capacity similar to Q1 2015, but with a lower cost structure Reopened Menomonie in Q3 2016 Ability to quickly re-open four idled sand mines and three coating facilities with minimal capital expenditures Proppa
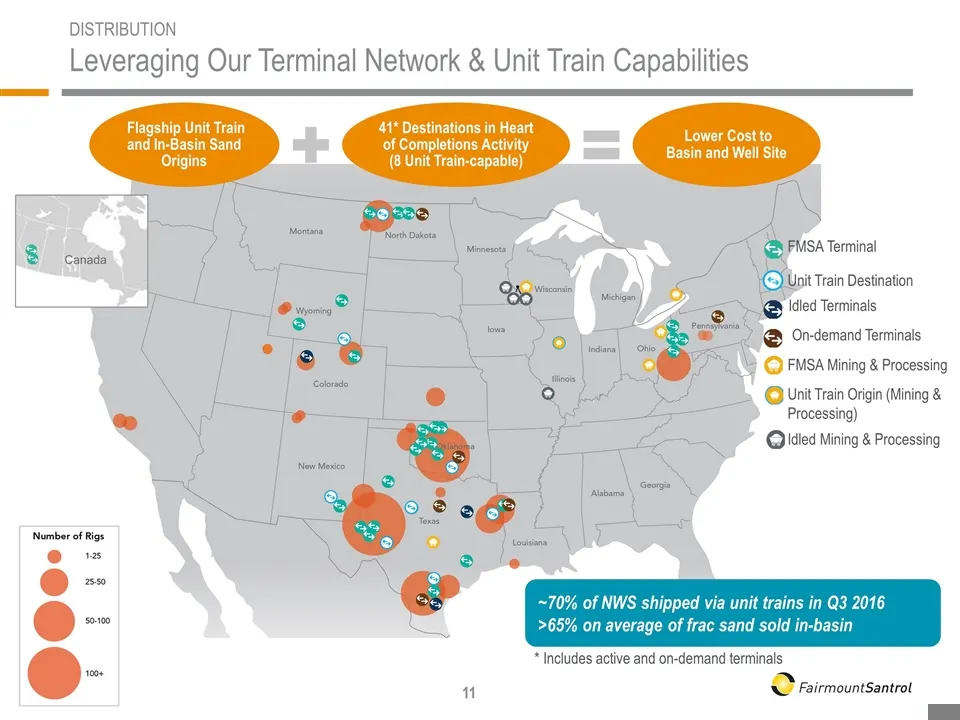
Slide 12: Leveraging Our Terminal Network & Unit Train Capabilities
FMSA Terminal FMSA Mining & Processing Unit Train Destination Unit Train Origin (Mining & Processing) ~70% of NWS shipped via unit trains in Q3 2016 >65% on average of frac sand sold in-basin Idled Terminals Idled Mining & Processing On-demand Terminals * Includes active and on-demand terminals Cana
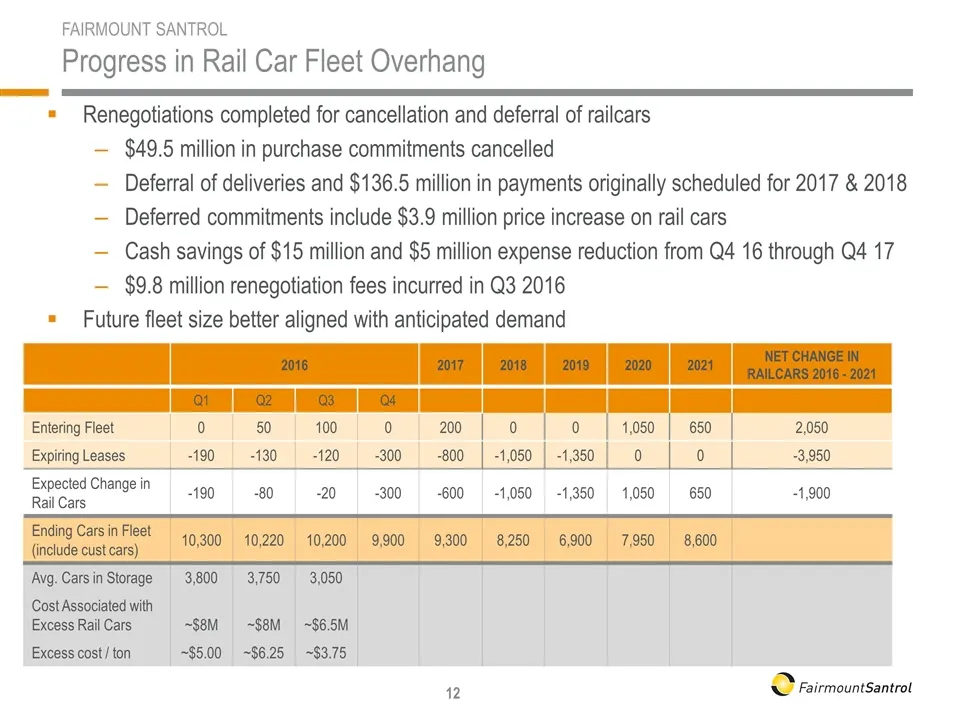
Slide 13: Progress in Rail Car Fleet Overhang
FAIRMOUNT SANTROL Progress in Rail Car Fleet Overhang Renegotiations completed for cancellation and deferral of railcars $49.5 million in purchase commitments cancelled Deferral of deliveries and $136.5 million in payments originally scheduled for 2017 & 2018 Deferred commitments include $3.9 millio
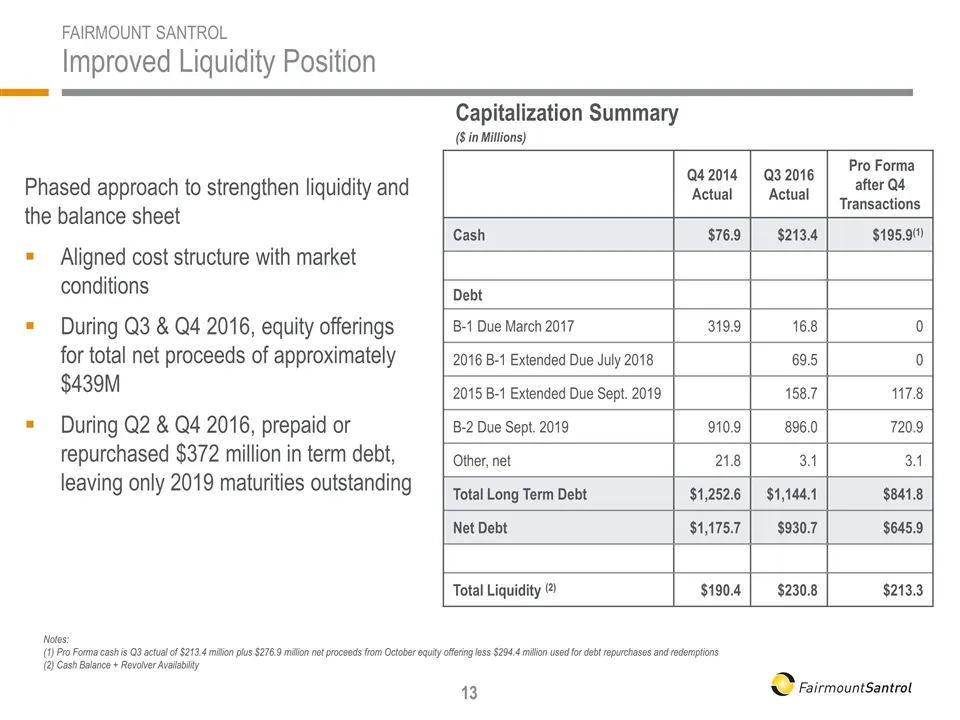
Slide 14: Improved Liquidity Position
FAIRMOUNT SANTROL Improved Liquidity Position Q4 2014 Actual Q3 2016 Actual Pro Forma after Q4 Transactions Cash $76.9 $213.4 $195.9(1) Debt B-1 Due March 2017 319.9 16.8 0 2016 B-1 Extended Due July 2018 69.5 0 2015 B-1 Extended Due Sept. 2019 158.7 117.8 B-2 Due Sept. 2019 910.9 896.0 720.9 Other,
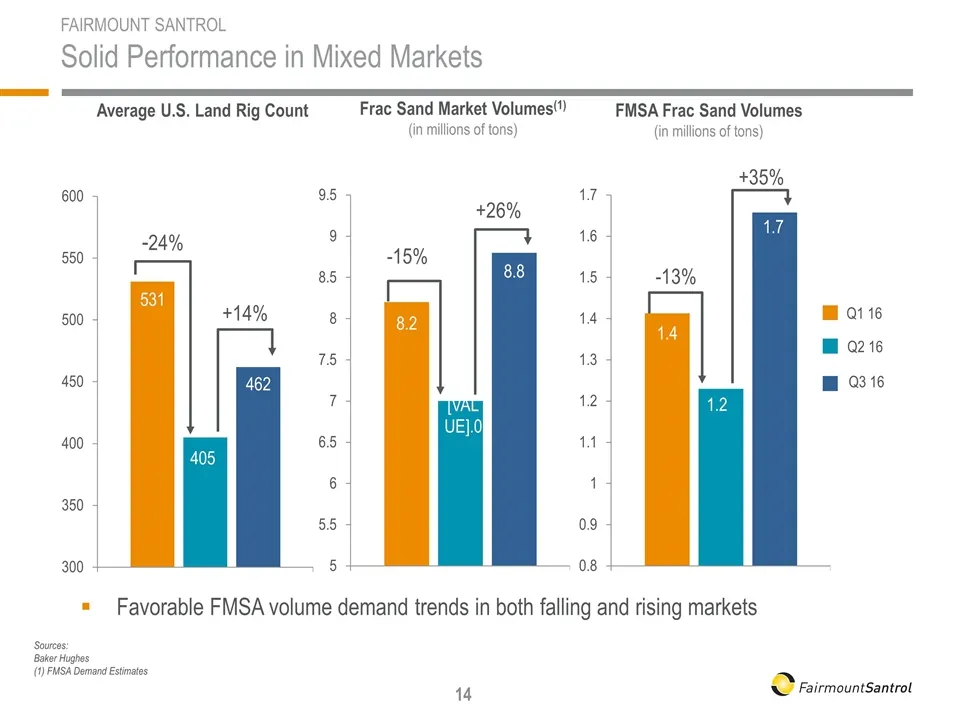
Slide 15: Solid Performance in Mixed Markets
FAIRMOUNT SANTROL Solid Performance in Mixed Markets Sources: Baker Hughes (1) FMSA Demand Estimates FMSA Frac Sand Volumes (in millions of tons) Average U.S. Land Rig Count Frac Sand Market Volumes(1) (in millions of tons) Q2 16 Q3 16 +14% +26% +35% -24% -15% -13% Q1 16 Favorable FMSA volume demand
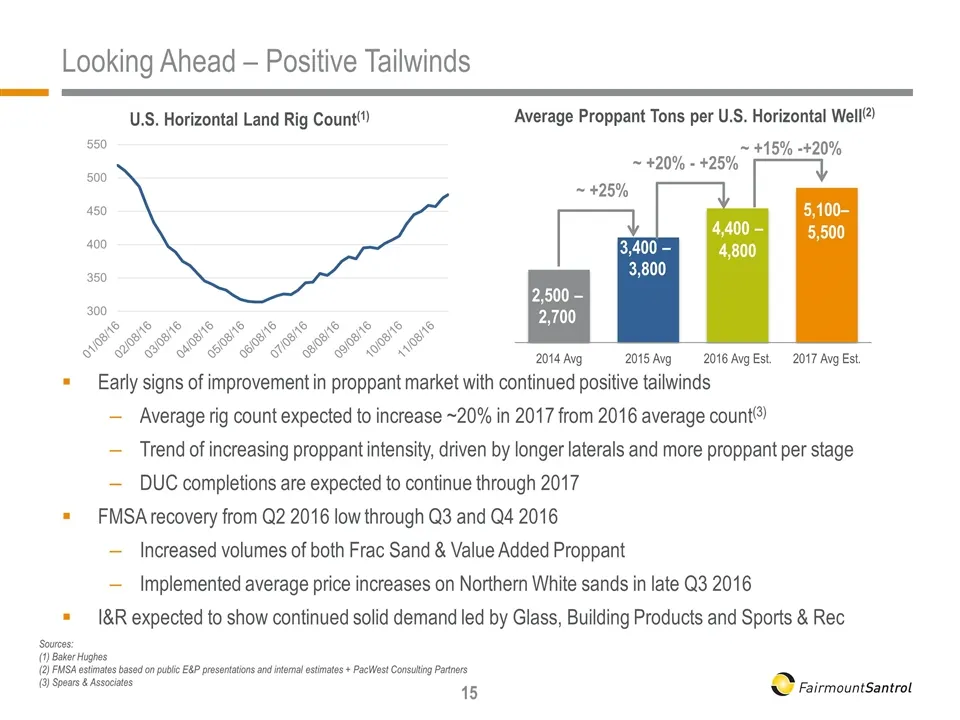
Slide 16: Looking Ahead – Positive Tailwinds
Early signs of improvement in proppant market with continued positive tailwinds Average rig count expected to increase ~20% in 2017 from 2016 average count(3) Trend of increasing proppant intensity, driven by longer laterals and more proppant per stage DUC completions are expected to continue throug
Slide 17: Financial Update: Third Quarter 2016 Results
Financial Update Third Quarter 2016 Results Overall volumes of 2.4 million tons, up 24% sequentially Proppant volumes of 1.8 million tons, up 36% sequentially Revenues of $134.8M, up 18% sequentially Adjusted EBITDA loss of $4.9 million includes $9.8 million railcar renegotiation fee Instituting add
Slide 18: Why Invest in FMSA?
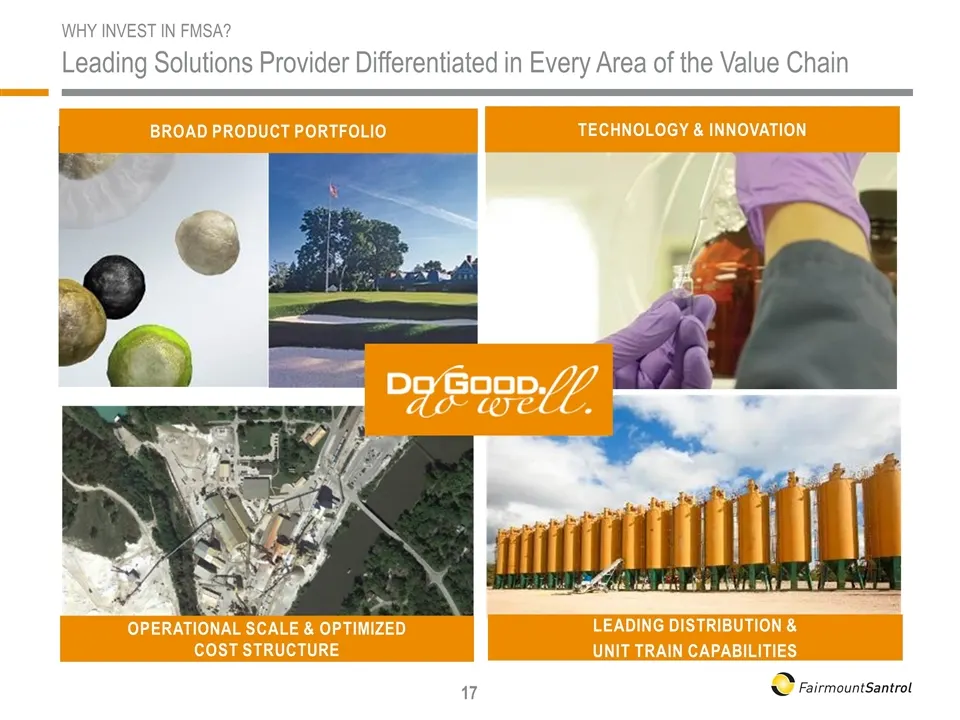
WHY INVEST IN FMSA? Leading Solutions Provider Differentiated in Every Area of the Value Chain Operational Scale & Optimized Cost Structure BROAD PRODUCT PORTFOLIO TECHNOLOGY & INNOVATION LEADING DISTRIBUTION & UNIT TRAIN CAPABILITIES
Slide 19: Questions?
Questions? Dosa ~ w FairmountSantrol
Slide 20: Appendix
Appendix 8 FairmountSantrol
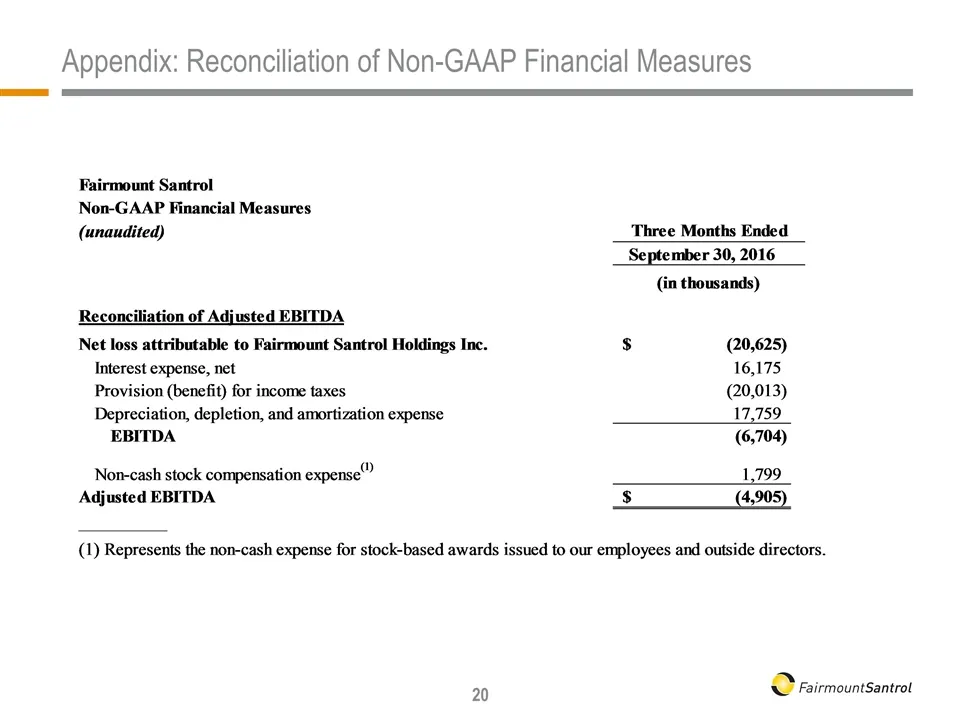
Slide 21: Appendix: Reconciliation of Non-GAAP Financial Measures
Appendix: Reconciliation of Non-GAAP Financial Measures
Source: SEC EDGAR · 8-K filed Dec 5, 2016
More decks from Fairmount Santrol Holdings Inc
 Merger or Acquisition (May 2018)44 slides · May 15, 2018
 Merger or Acquisition (May 2018)44 slides · May 9, 2018
 Debt Investor Presentation (May 2018)62 slides · May 8, 2018
 Merger or Acquisition (March 2018)31 slides · Mar 26, 2018
 Merger or Acquisition (January 2018)42 slides · Jan 3, 2018
 Merger or Acquisition (December 2017)26 slides · Dec 12, 2017