Durr AG · XETR:DUE
Durr — Non-Deal Roadshow (May 2009)
38 slides from Durr's roadshow presentation, May 18, 2009
Slide 1: Investor presentation
Investor presentation Dürr Aktiengesellschaft Ralph Heuwing, CFO Günter Dielmann, IR Paris, May 18, 2009
Slide 2: Disclaimer
Disclaimer This investor presentation has been prepared independently by Dürr AG (“Dürr”). The presentation contains statements which address such key issues as Dürr´s strategy, future financial results, market positions and product development. Such statements should be carefully considered, and it
Slide 3: Agenda
Agenda 1. Dürr: Global leader with strong competitive position 2. Strategy/actions 3. Financial overview and outlook © Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009 -3-
Slide 4: Dürr: Global leader with strong competitive position
Dürr: Global leader with strong competitive position § World market leader in 90% of Dürr‘s business portfolio § Large installed base providing stable growing of service business § Strong emerging markets presence with 50% share of global incoming orders § High entry barriers with limited competitiv
Slide 5: Transparent group structure with global divisions
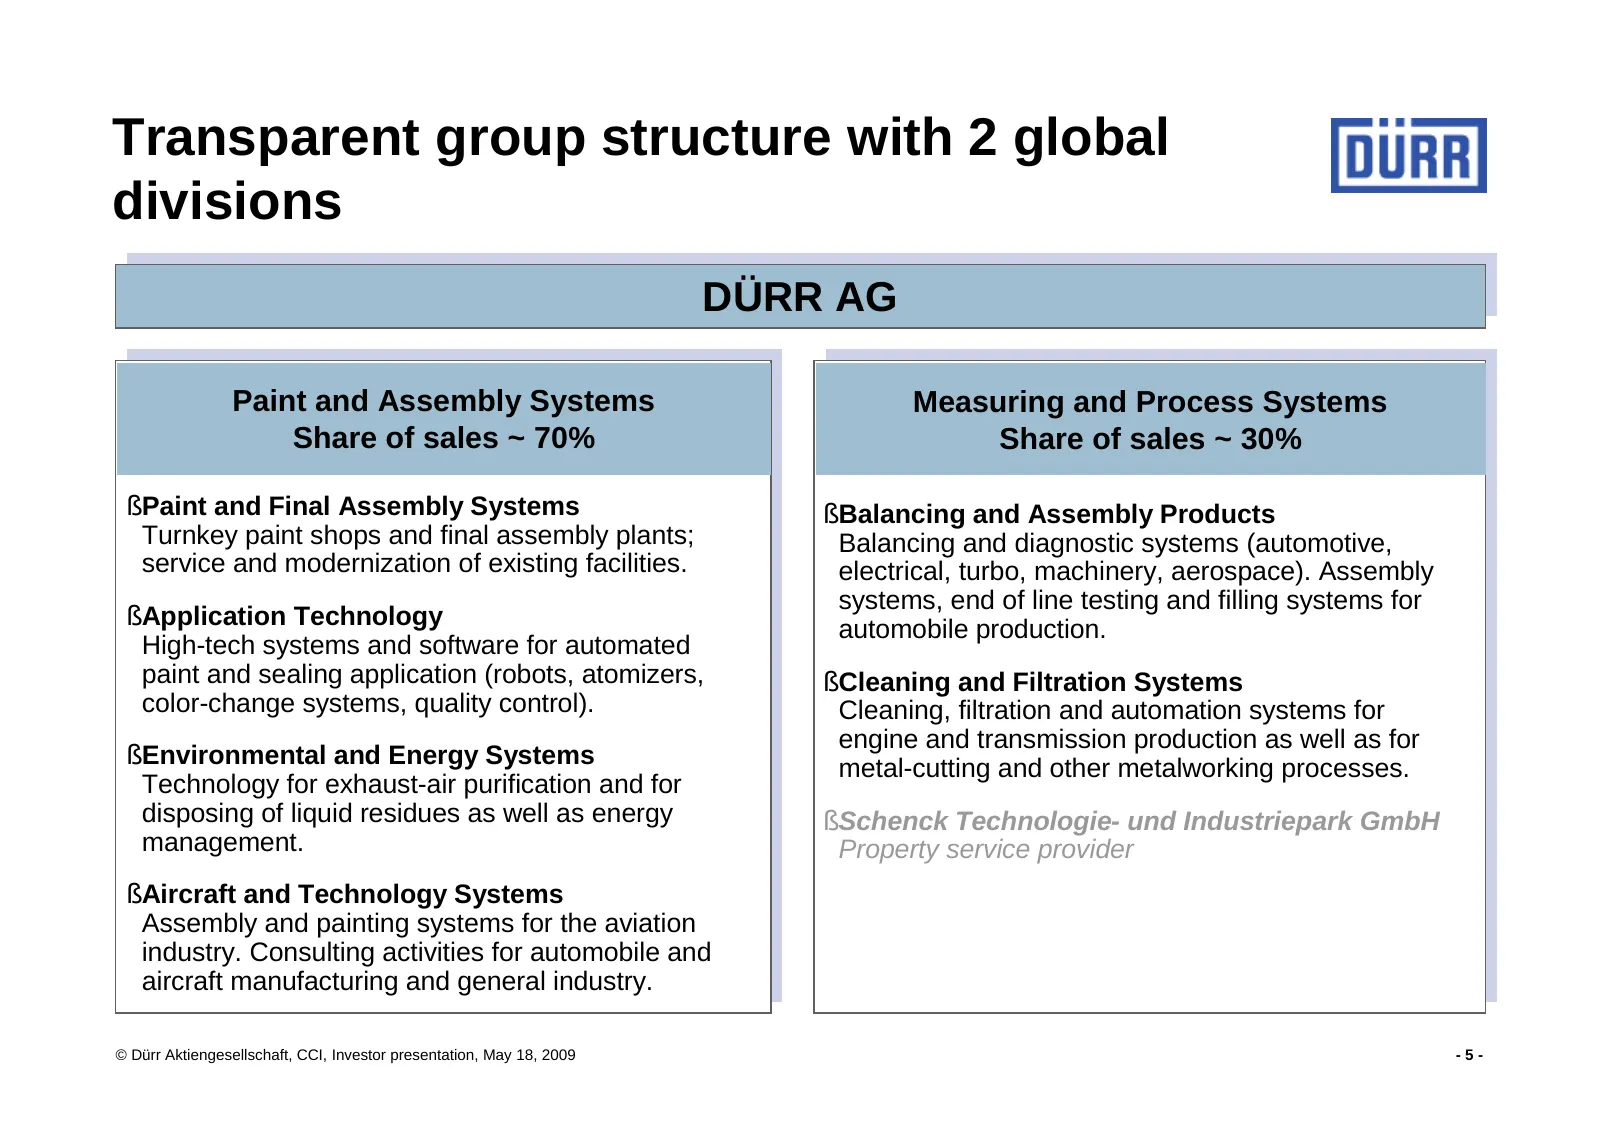
Transparent group structure with 2 global divisions DÜRRAG DÜRR AG Paint and Assembly Systems Measuring and Process Systems Share of sales ~ 70% Share of sales ~ 30% § Paint and Final Assembly Systems § Balancing and Assembly Products Turnkey paint shops and final assembly plants; Balancing and diag
Slide 6: Profitable growth - Dürr at a glance
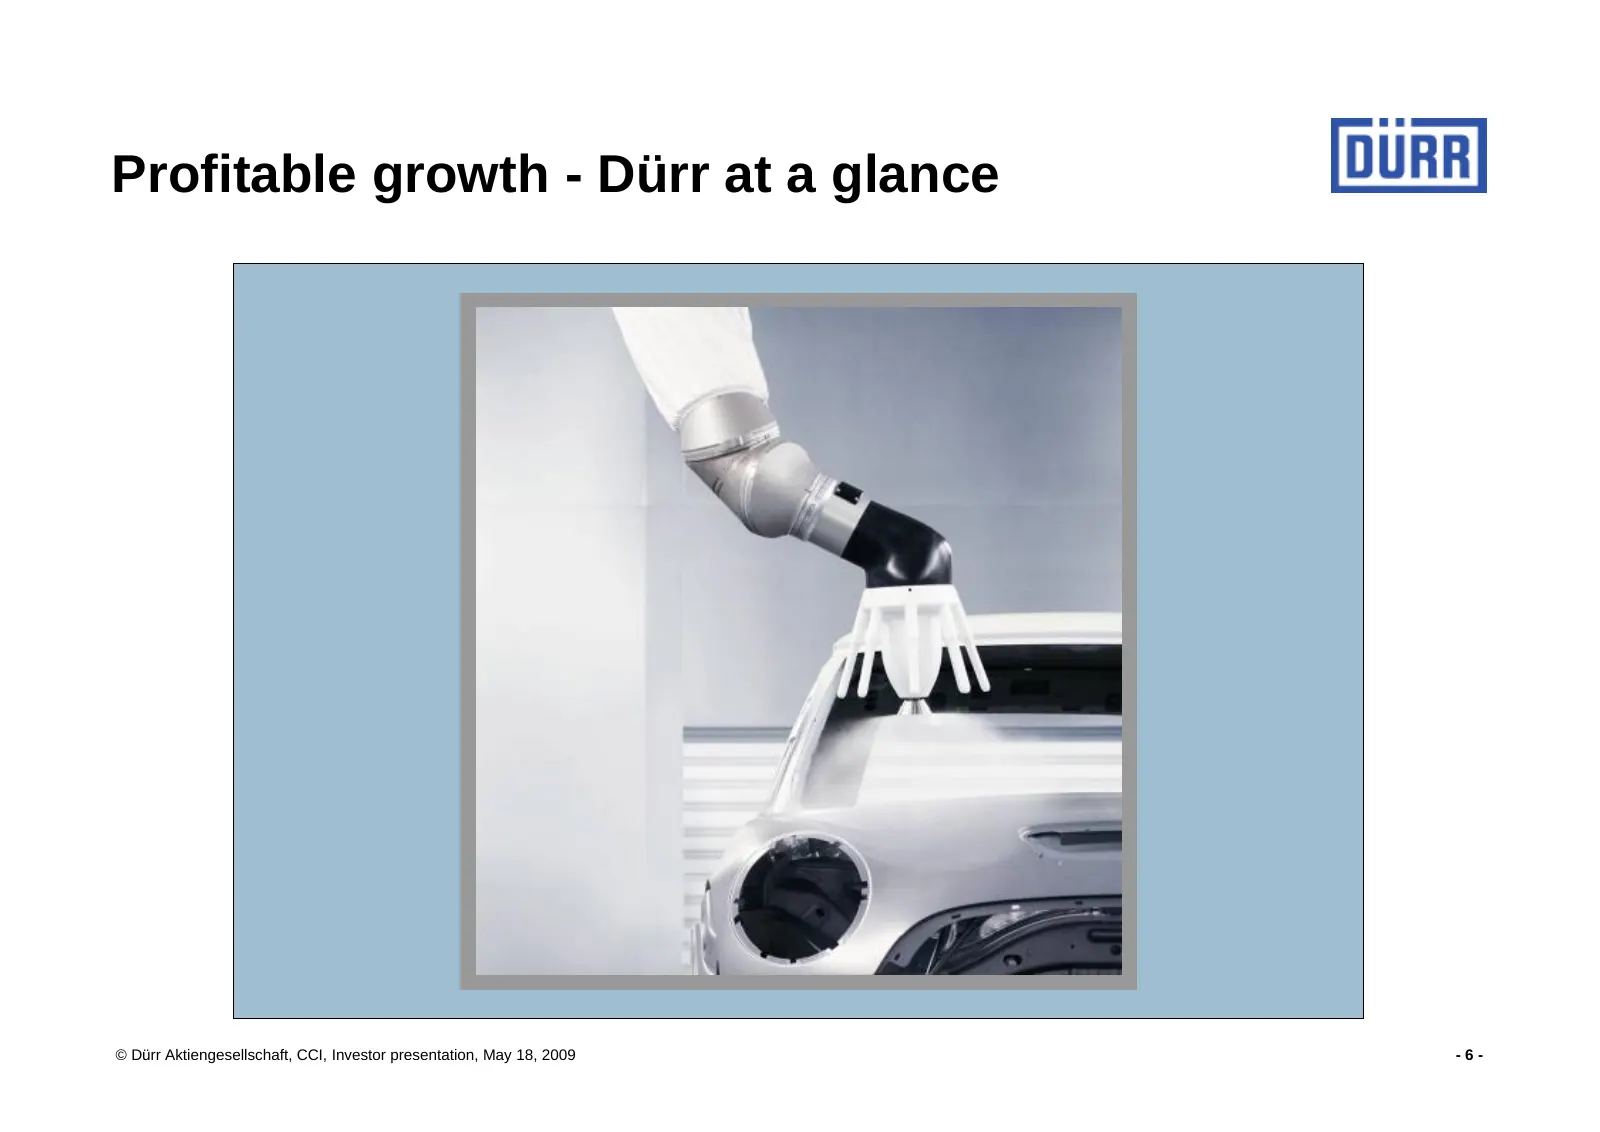
Profitable growth - Dürr at a glance © Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009 -6-
Slide 7: Competence across entire automotive production
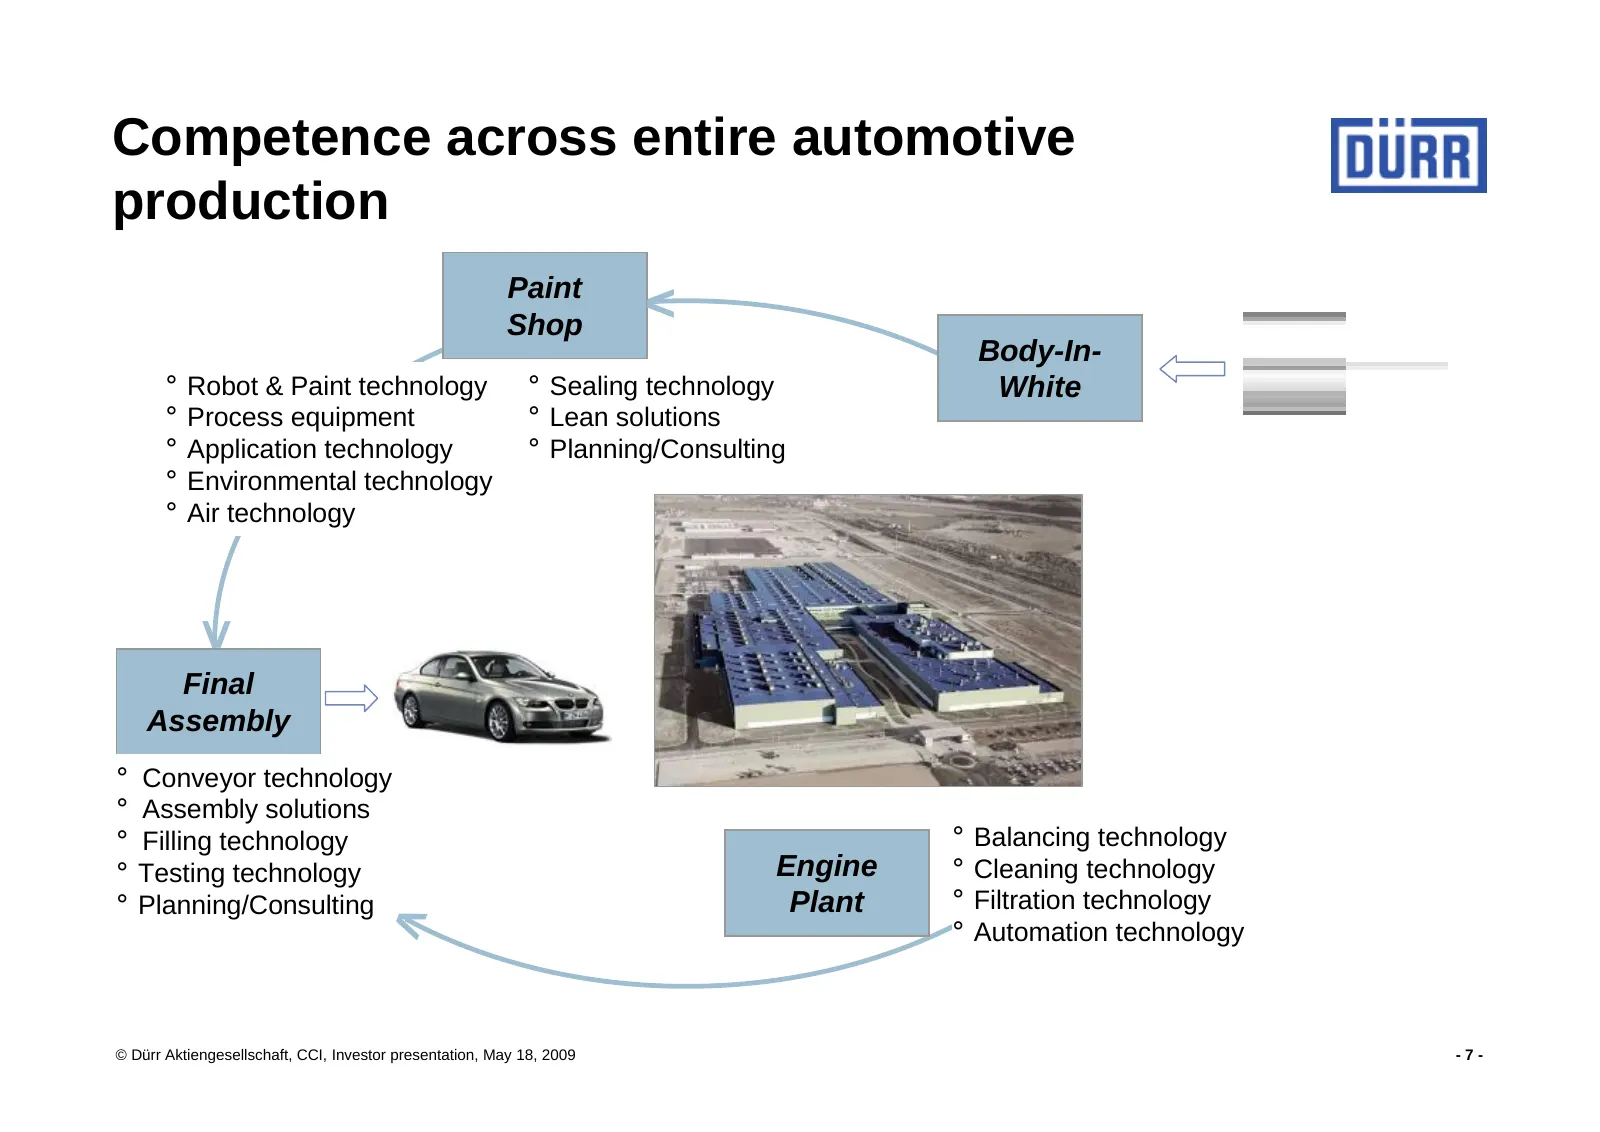
Competence across entire automotive production Paint Shop < Body-In- ¡ Robot & Paint technology ¡ Sealing technology White ¡ Process equipment ¡ Lean solutions ¡ Application technology ¡ Planning/Consulting ¡ Environmental technology ¡ Air technology < Final Assembly ¡ Conveyor technology ¡ Assembly
Slide 8: Non-automotive business 15% of group revenue and growing
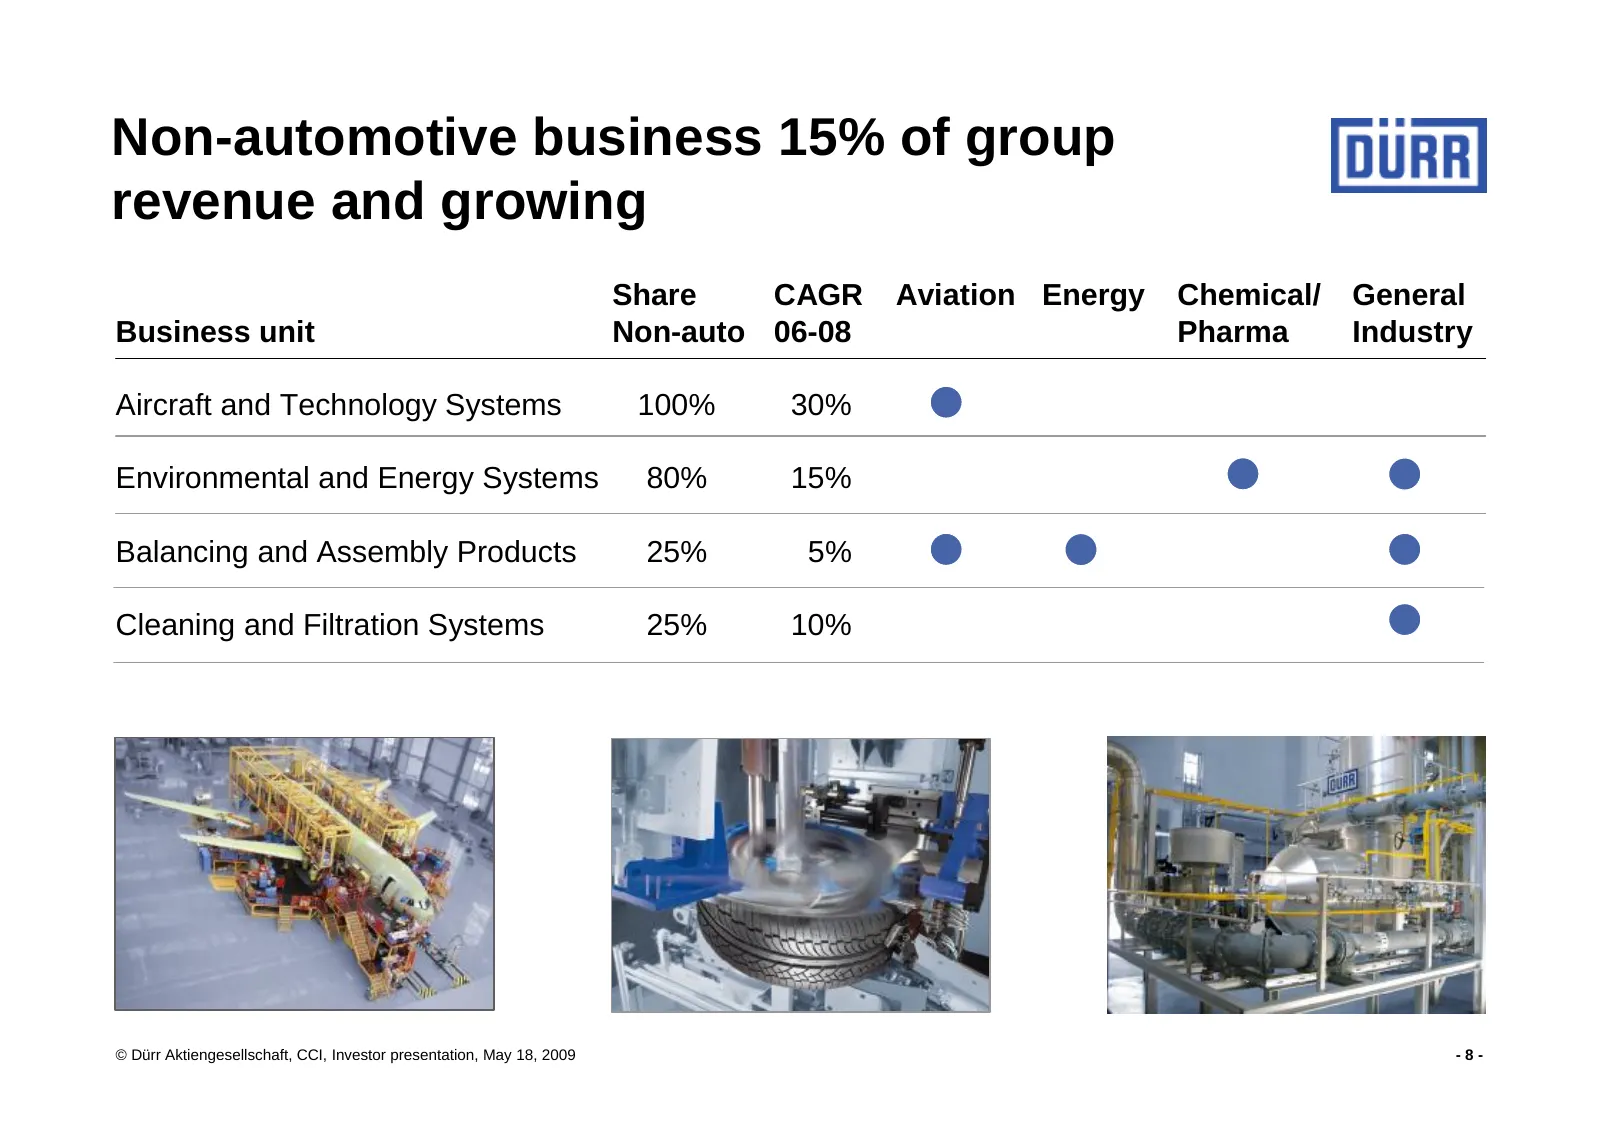
Non-automotive business 15% of group revenue and growing Share CAGR Aviation Energy Chemical/ General Business unit Non-auto 06-08 Pharma Industry Aircraft and Technology Systems 100% 30% Environmental and Energy Systems 80% 15% Balancing and Assembly Products 25% 5% Cleaning and Filtration Systems
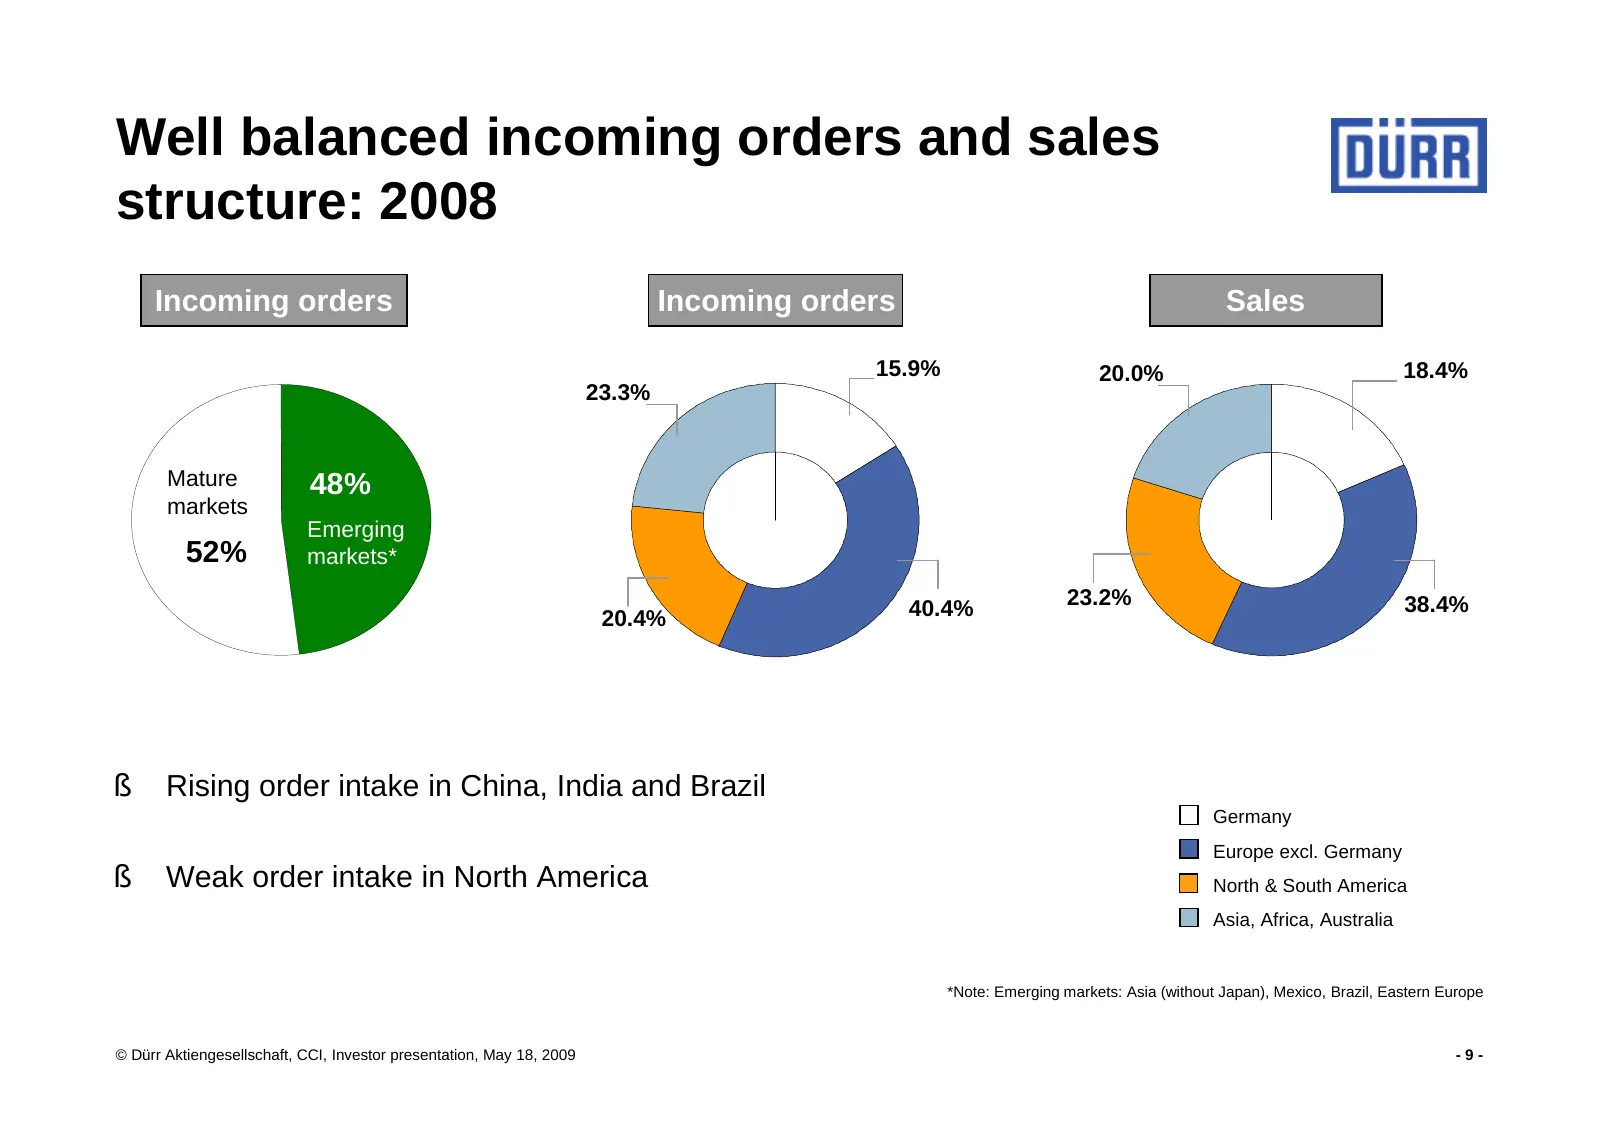
Slide 9: Well balanced incoming orders and sales structure: 2008
Well balanced incoming orders and sales structure: 2008 Incoming orders Incoming orders Sales 15.9% 20.0% 18.4% 23.3% Mature 48% markets Emerging 52% markets* 40.4% 23.2% 38.4% 20.4% § Rising order intake in China, India and Brazil Germany Europe excl. Germany § Weak order intake in North America No
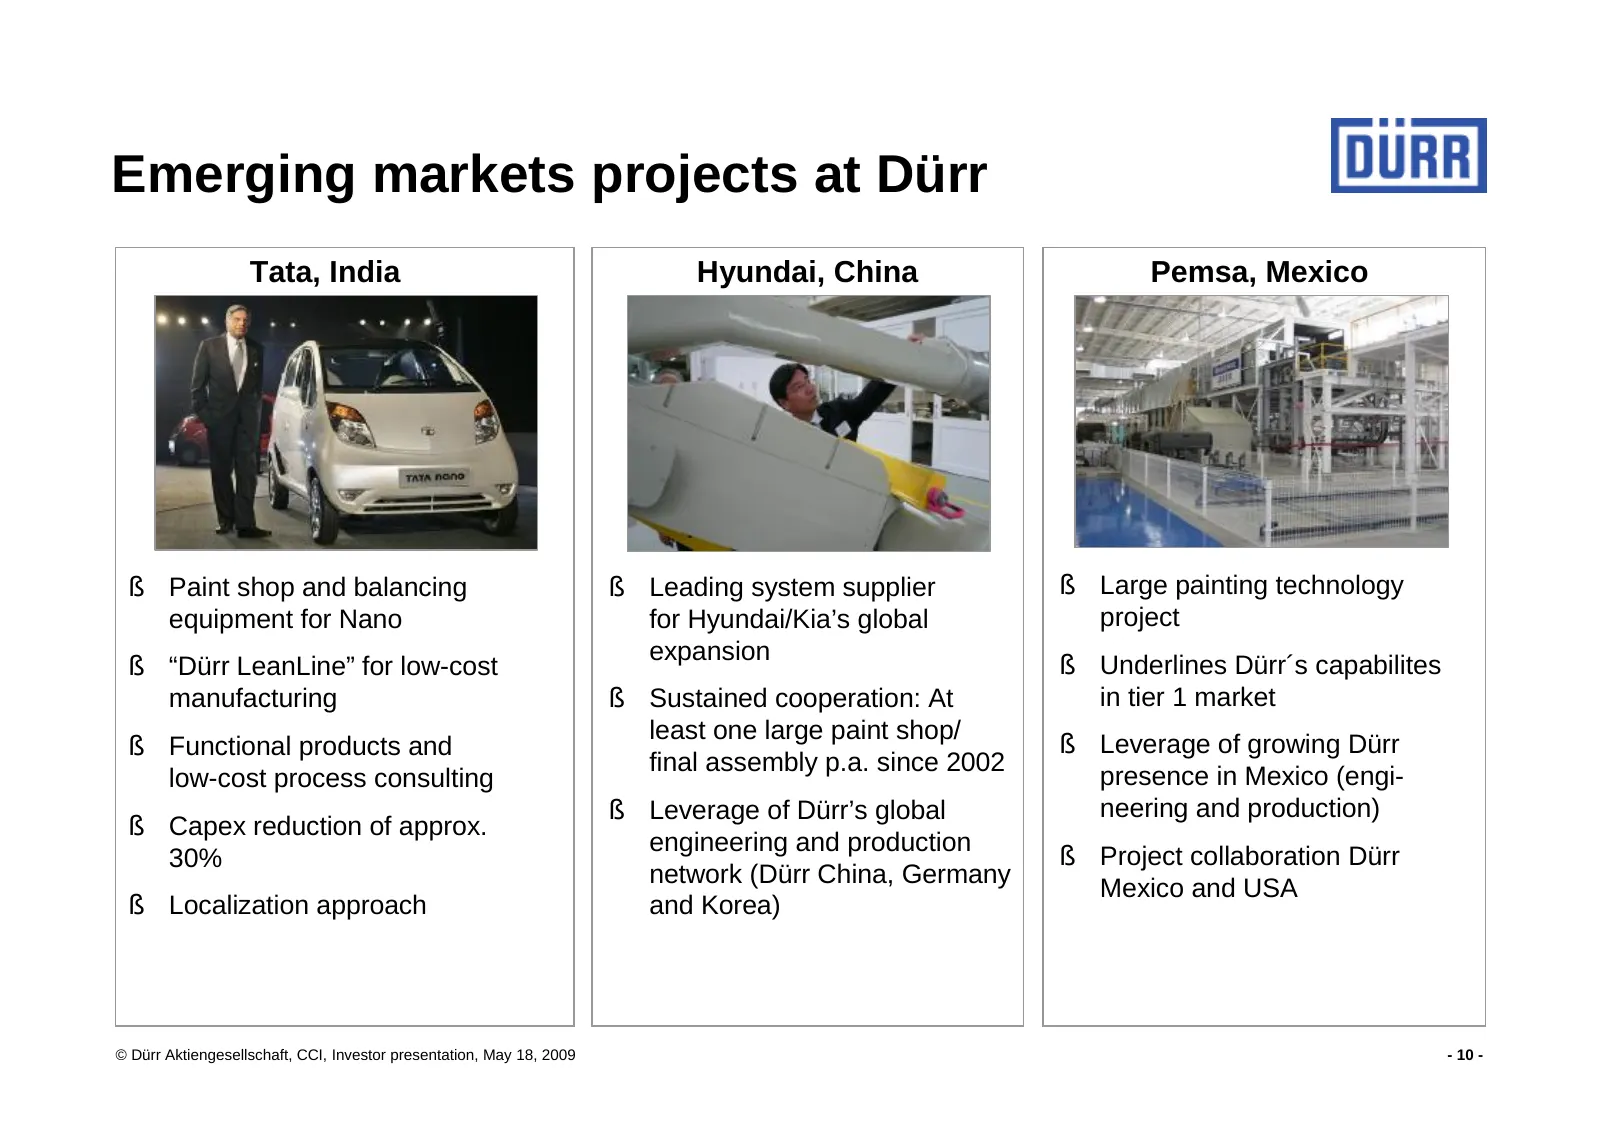
Slide 10: Emerging markets projects at Dürr
Emerging markets projects at Dürr Tata, India Hyundai, China Pemsa, Mexico § Paint shop and balancing § Leading system supplier § Large painting technology equipment for Nano for Hyundai/Kia’s global project expansion § “Dürr LeanLine” for low-cost § Underlines Dürr´s capabilites manufacturing § Sus
Slide 11: Agenda
Agenda 1. Dürr: Global leader with strong competitive position 2. Strategy/actions 3. Financial overview and outlook © Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009 - 11 -
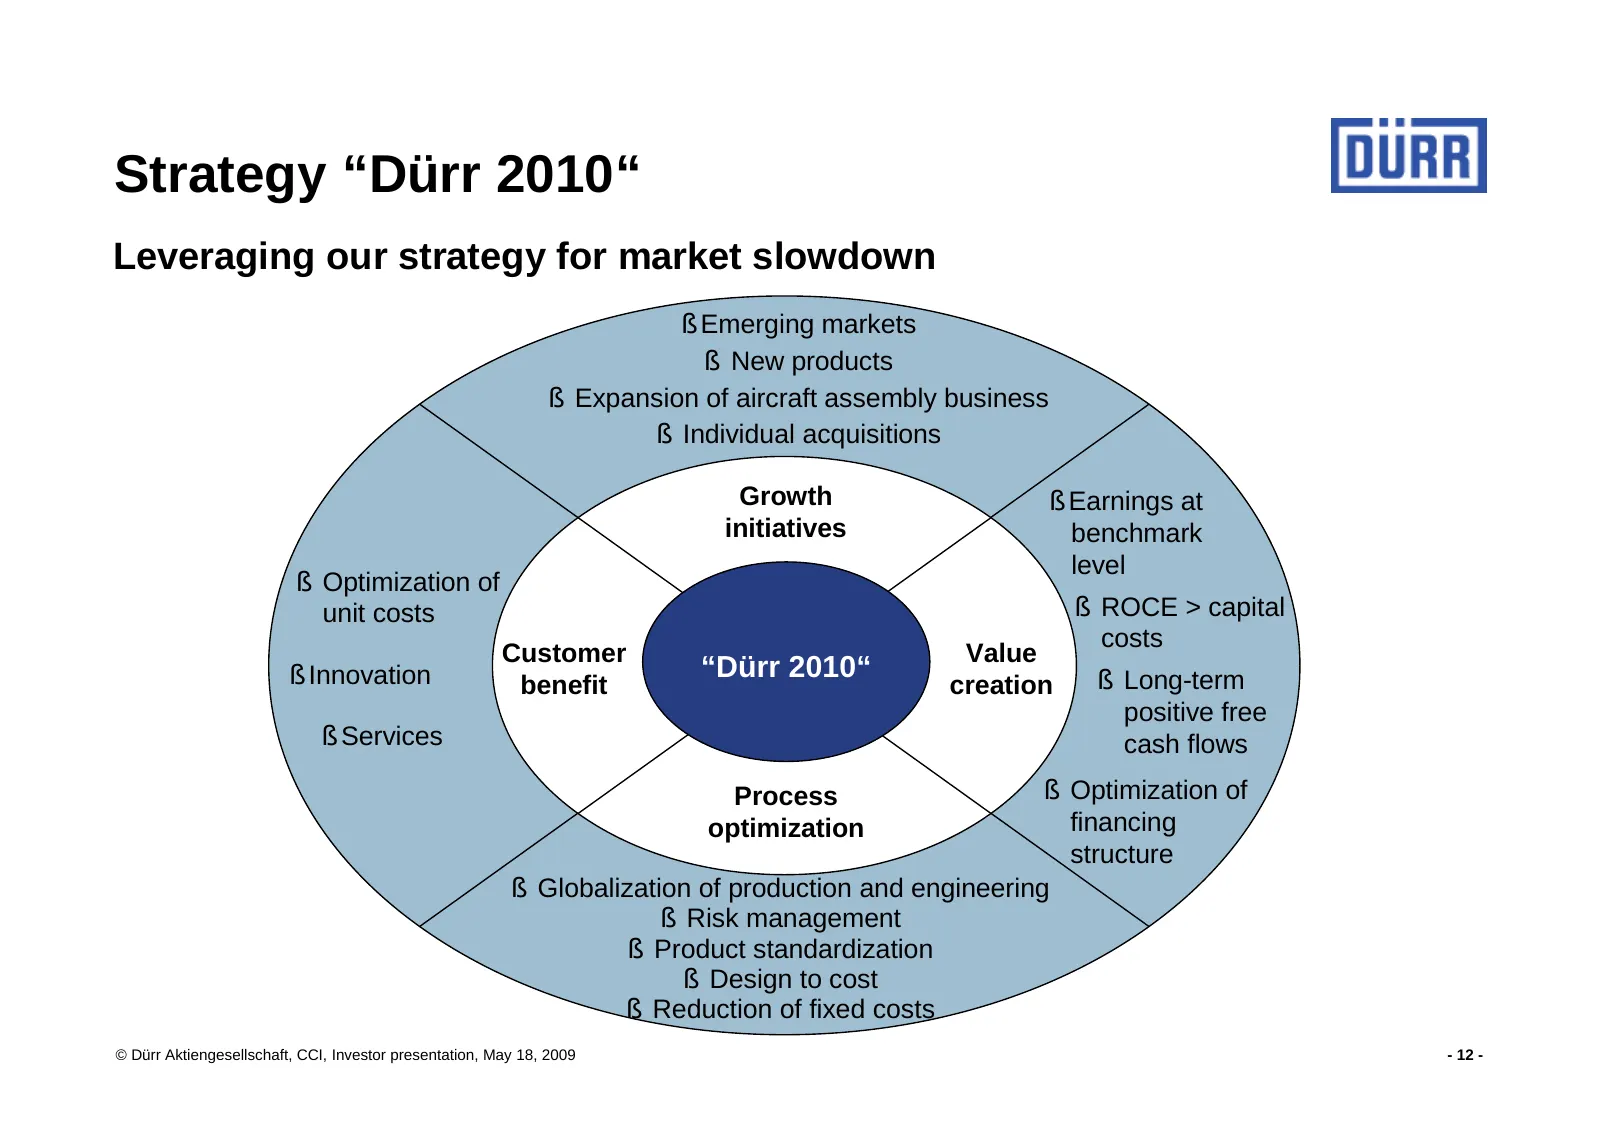
Slide 12: Strategy “Dürr 2010“
Strategy “Dürr 2010“ Leveraging our strategy for market slowdown § Emerging markets § New products § Expansion of aircraft assembly business § Individual acquisitions Growth § Earnings at initiatives benchmark level § Optimization of unit costs § ROCE > capital costs Customer Value § Innovation “Dür
Slide 13: Operational improvements
Operational improvements 8-point program 1. Product standardization: reduce engineering hours 2. Design to cost: simplify product design 3. Global production: increase share of low cost country manufacturing 4. Global sourcing: build global procurement offices in emerging markets 5. Global engineeri
Slide 14: Strategy/actions
Strategy/actions § Cost savings - Reduction of 270 employees in France and USA in H1 2009 - Hiring freeze, natural attrition (2% of workforce) - Working time accounts, short time work (increase in Q2 2009) - Strong reduction of temporary external workers from 550 to 250 in Q1 and around 100 in Q2 -
Slide 15: Strategy/actions
Strategy/actions § Increase sales activities - Push energy/cost efficient solutions, push new products - Accelerate revamp/service business, pushing new services (e.g. energy audit) - Take advantage of strong financial position (in comparison to competitors) - Increase market share § Communicate and
Slide 16: Dürr growth initiatives
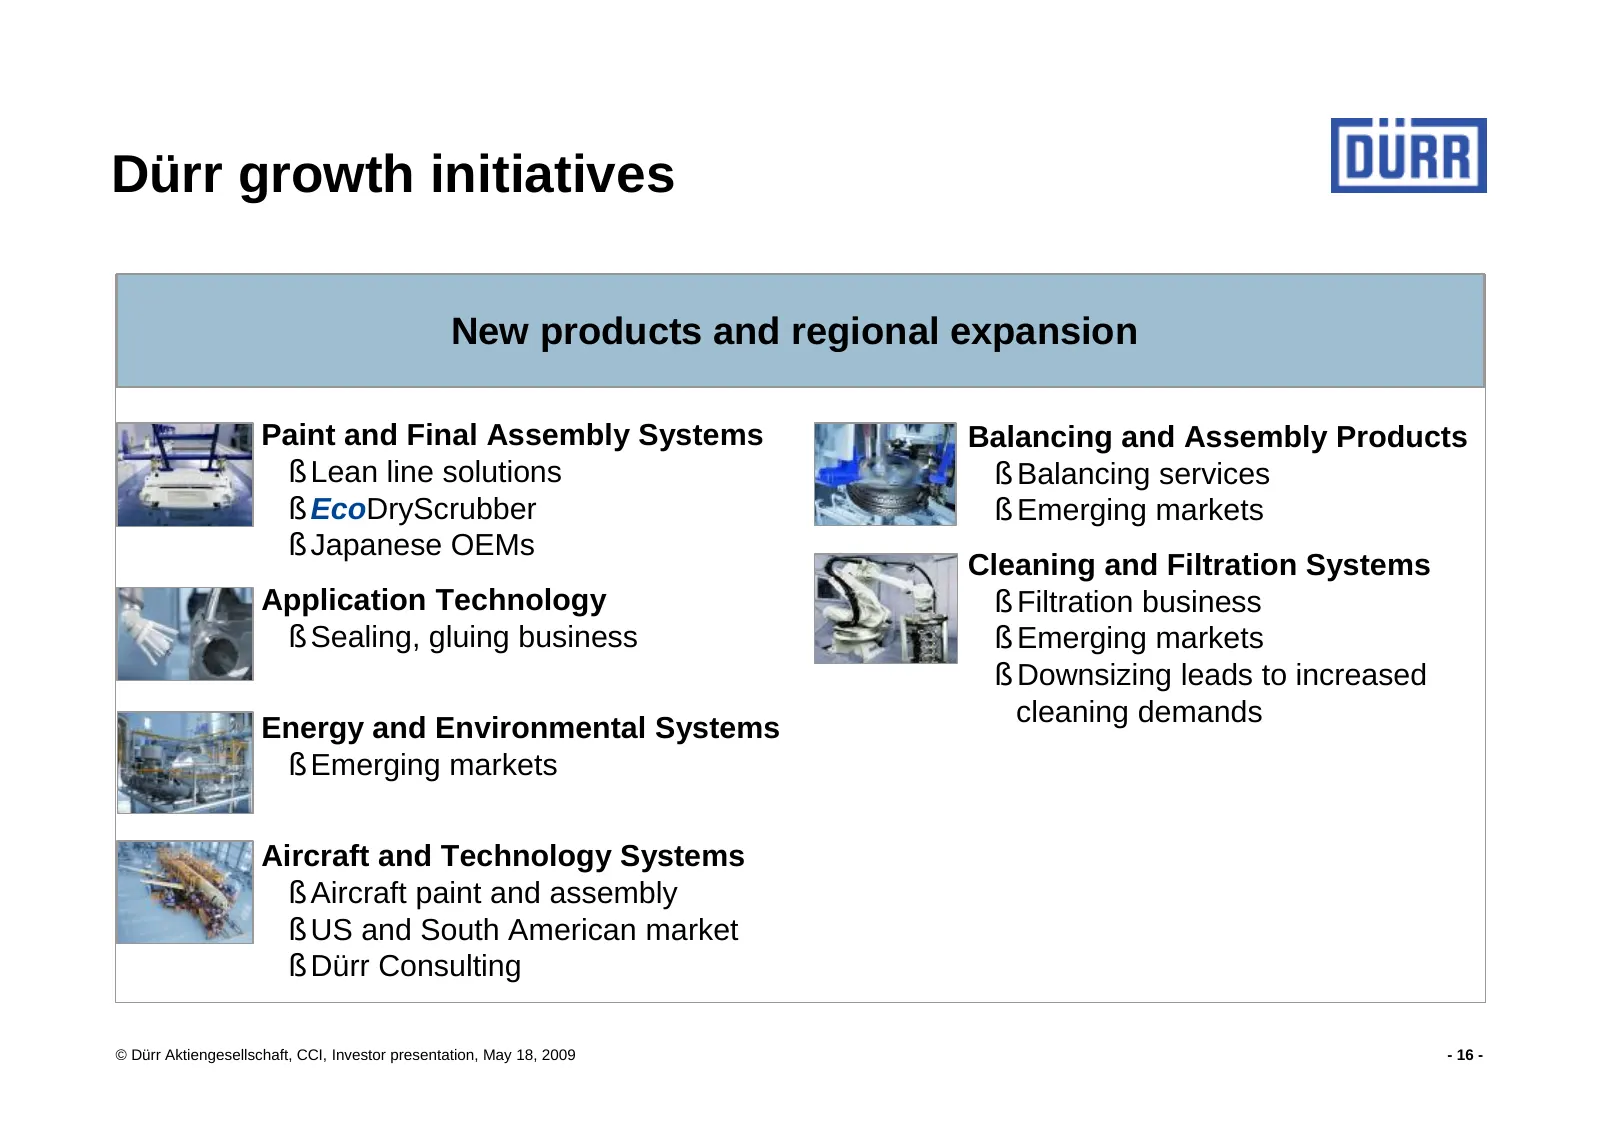
Dürr growth initiatives New products and regional expansion Paint and Final Assembly Systems Balancing and Assembly Products § Lean line solutions § Balancing services § EcoDryScrubber § Emerging markets § Japanese OEMs Cleaning and Filtration Systems Application Technology § Filtration business § S
Slide 17: Dürr with new products
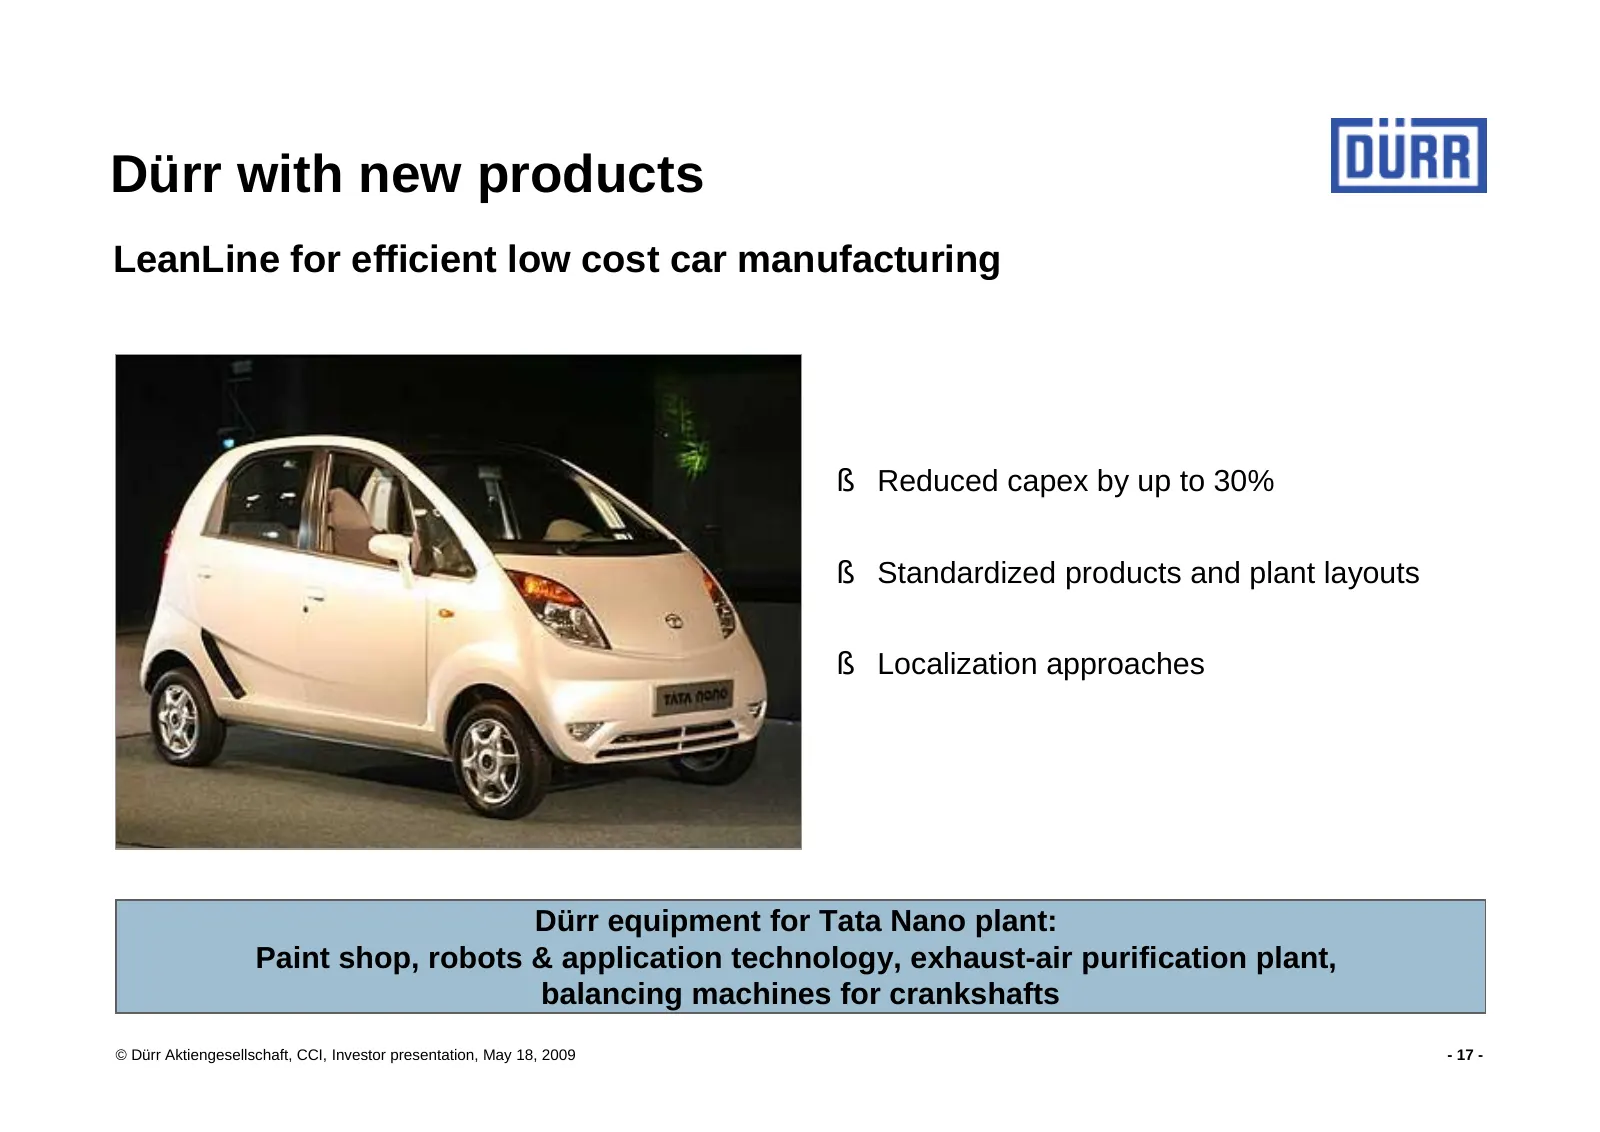
Dürr with new products LeanLine for efficient low cost car manufacturing § Reduced capex by up to 30% § Standardized products and plant layouts § Localization approaches Dürr equipment for Tata Nano plant: Paint shop, robots & application technology, exhaust-air purification plant, balancing machine
Slide 18: Dürr with new products
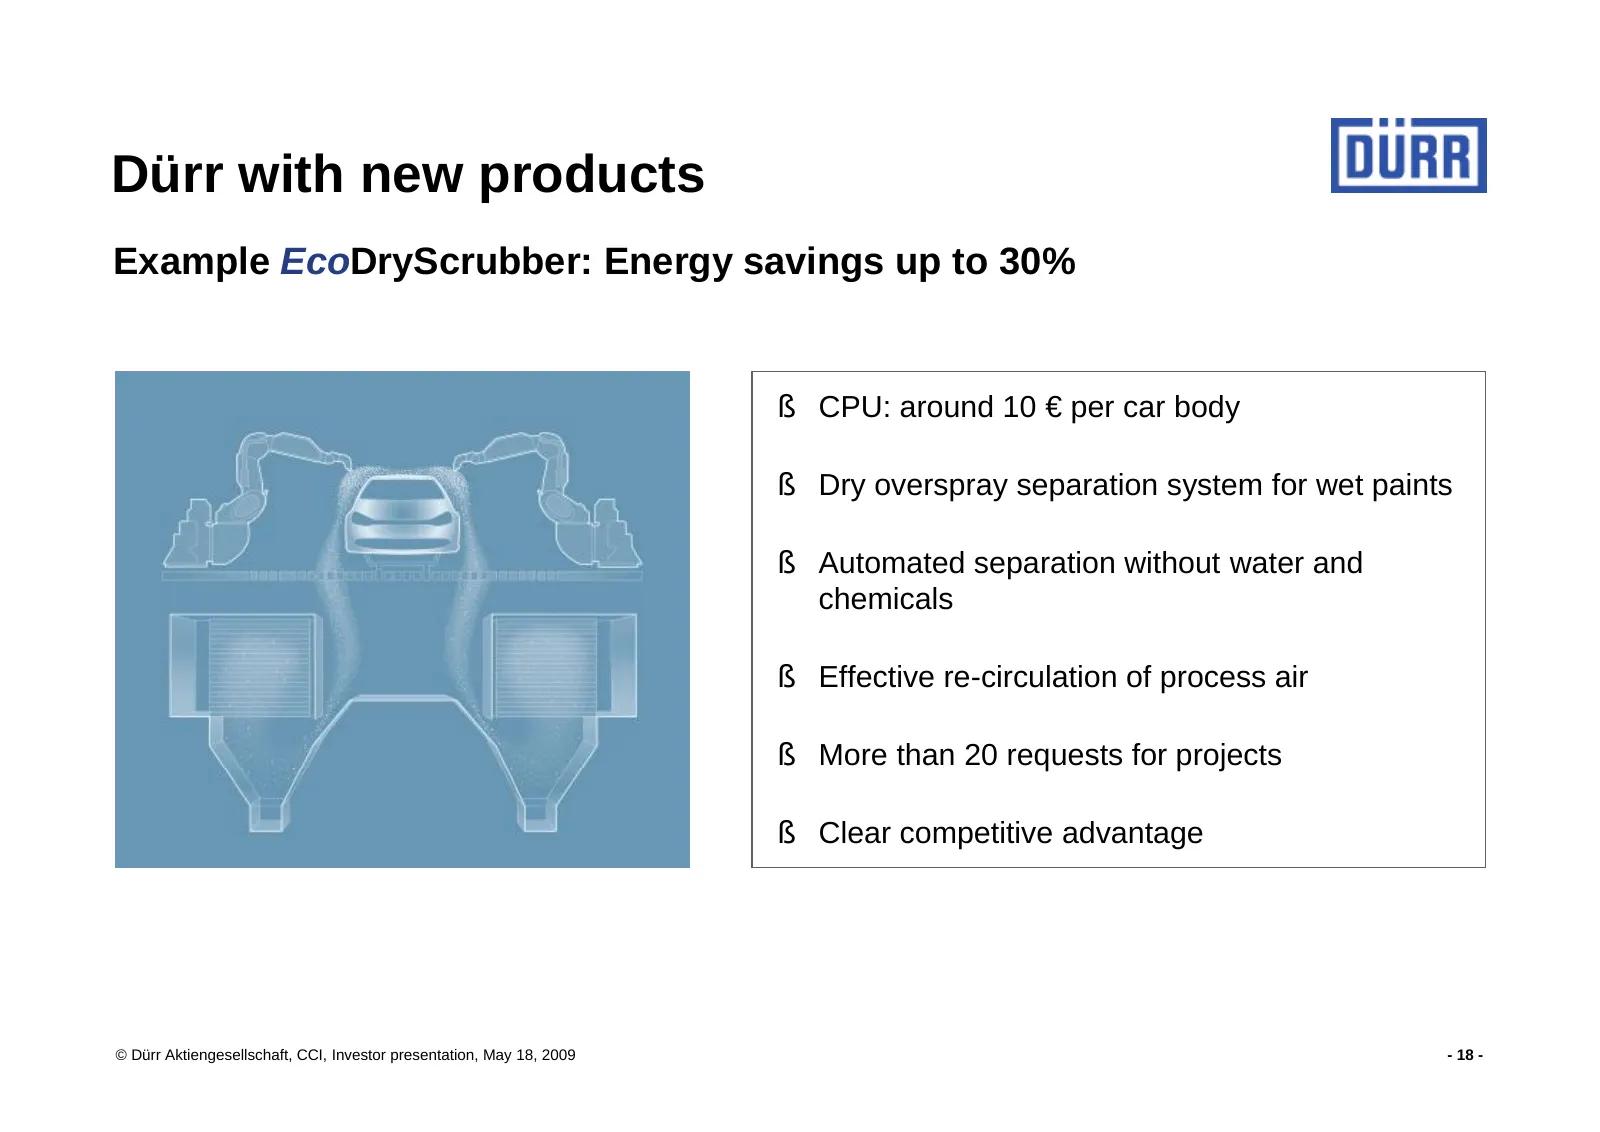
Dürr with new products Example EcoDryScrubber: Energy savings up to 30% § CPU: around 10 € per car body § Dry overspray separation system for wet paints § Automated separation without water and chemicals § Effective re-circulation of process air § More than 20 requests for projects § Clear competiti
Slide 19: Significant revamp and service business opportunity
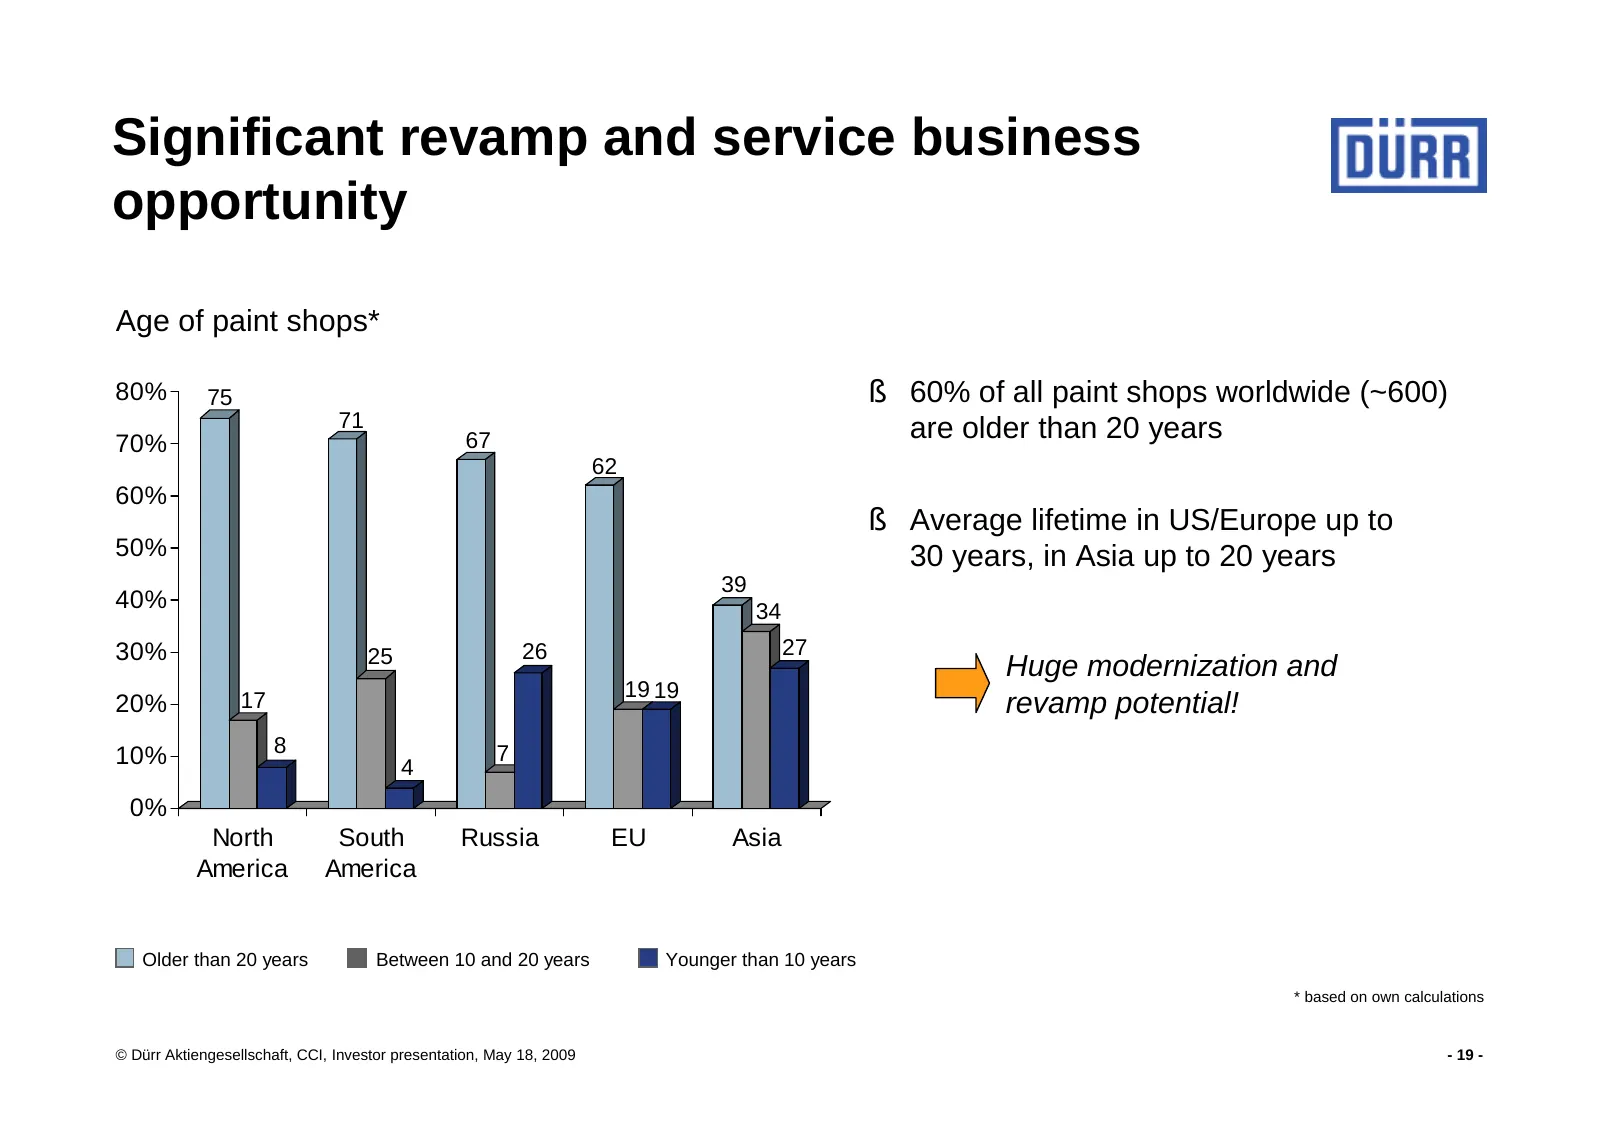
Significant revamp and service business opportunity Age of paint shops* 80% 75 § 60% of all paint shops worldwide (~600) 71 are older than 20 years 70% 67 62 60% § Average lifetime in US/Europe up to 50% 30 years, in Asia up to 20 years 39 40% 34 30% 25 26 27 Huge modernization and 17 19 19 20% reva
Slide 20: Growth initiatives in Aircraft and Technology Systems
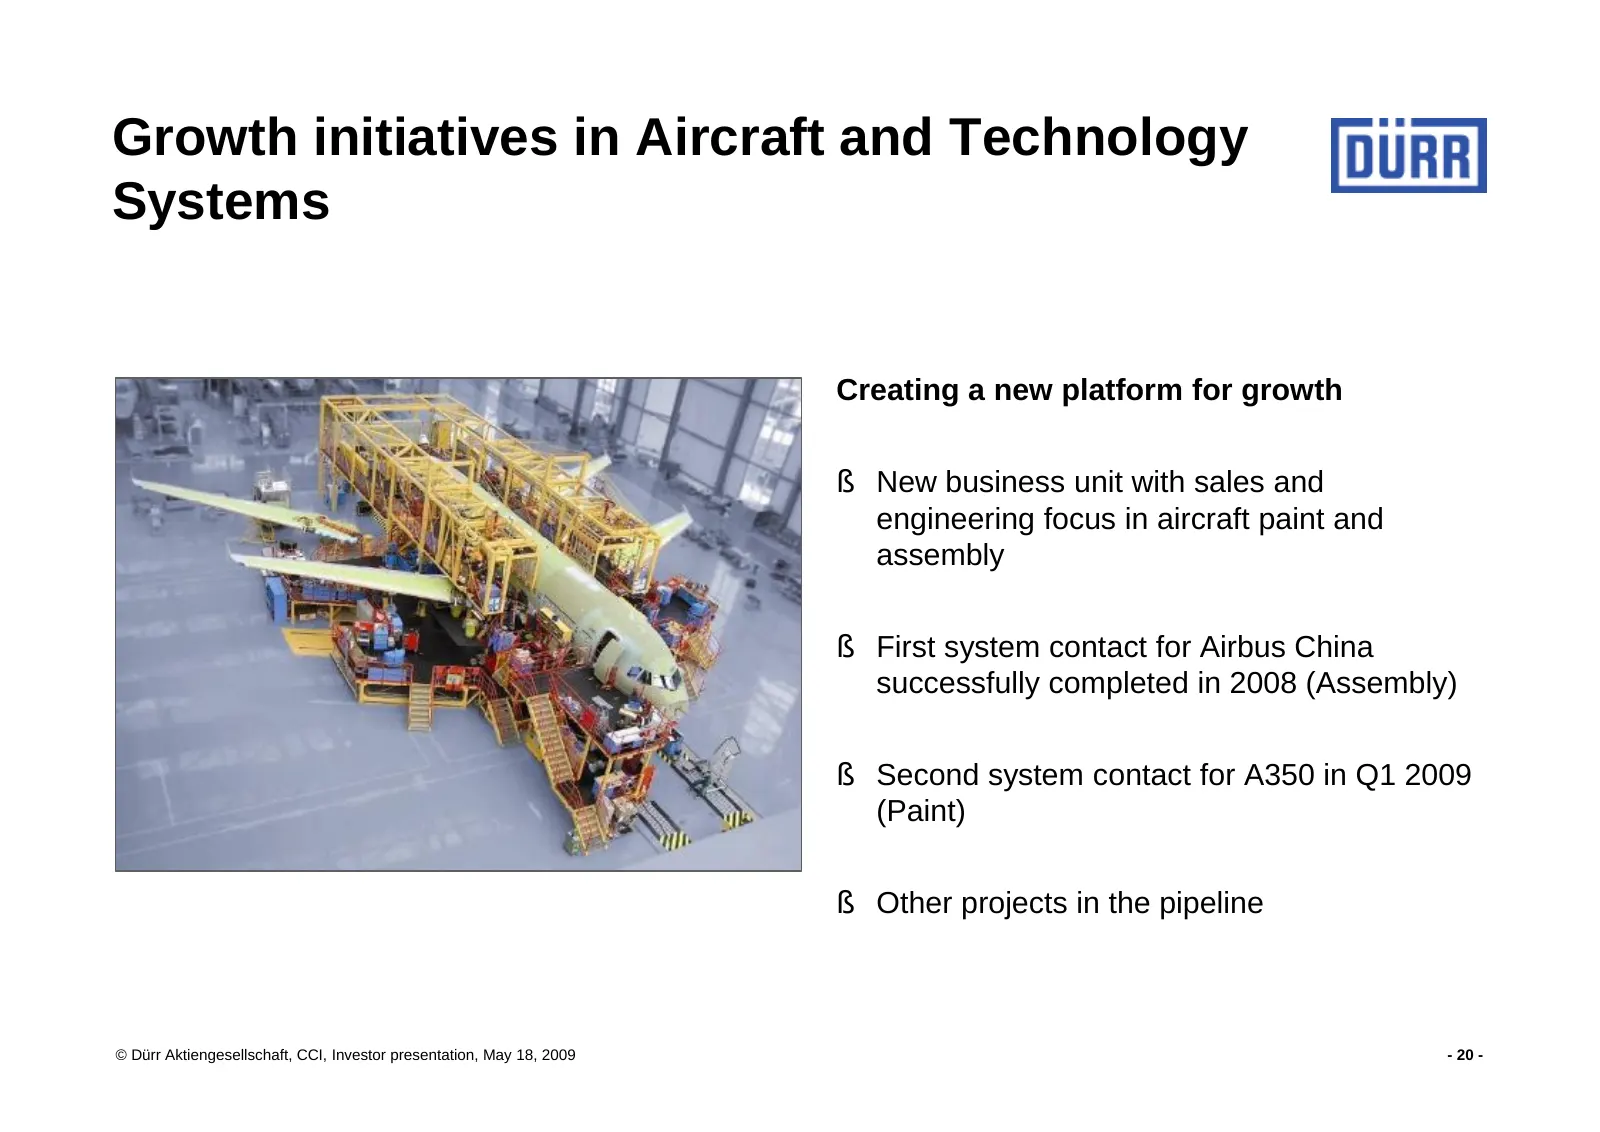
Growth initiatives in Aircraft and Technology Systems Creating a new platform for growth § New business unit with sales and engineering focus in aircraft paint and assembly § First system contact for Airbus China successfully completed in 2008 (Assembly) § Second system contact for A350 in Q1 2009 (
Slide 21: Growth initiatives
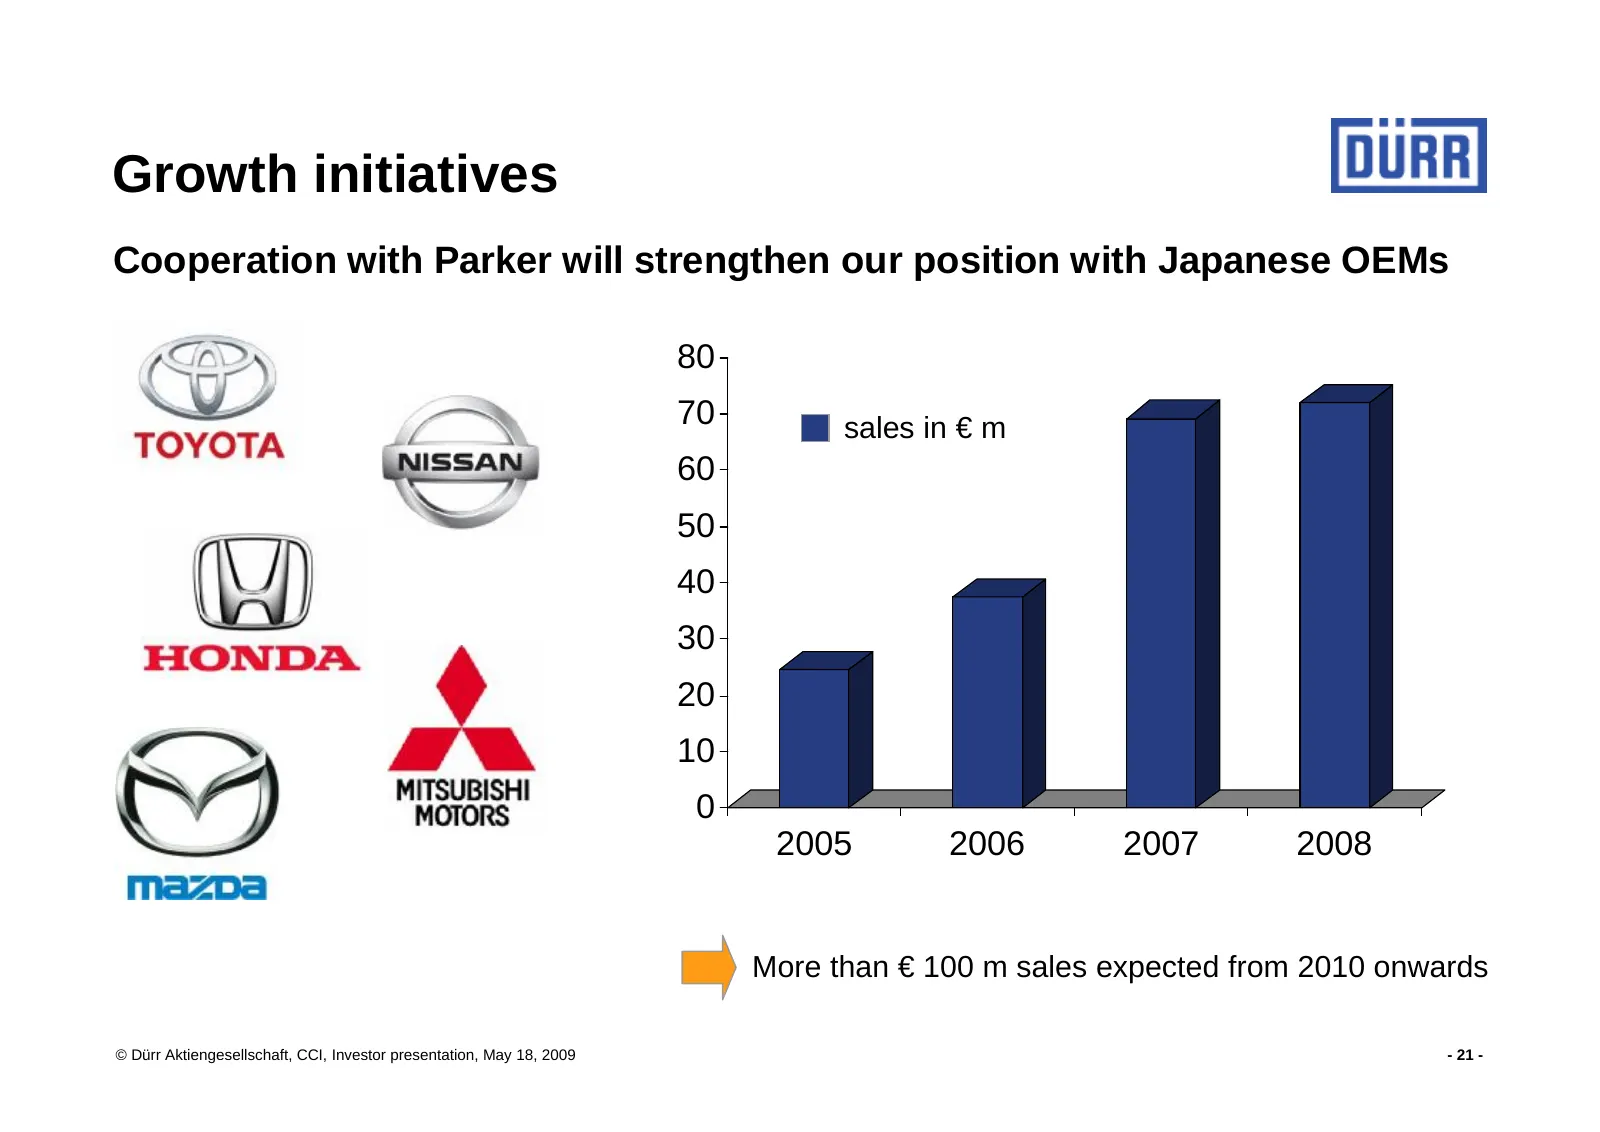
Growth initiatives Cooperation with Parker will strengthen our position with Japanese OEMs 80 70 sales in € m 60 50 40 30 20 10 0 2005 2006 2007 2008 More than € 100 m sales expected from 2010 onwards © Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009 - 21 -
Slide 22: Agenda
Agenda 1. Dürr: Global leader with strong competitive position 2. Strategy/actions 3. Financial overview and outlook © Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009 - 22 -
Slide 23: Incoming orders are reflecting difficult markets
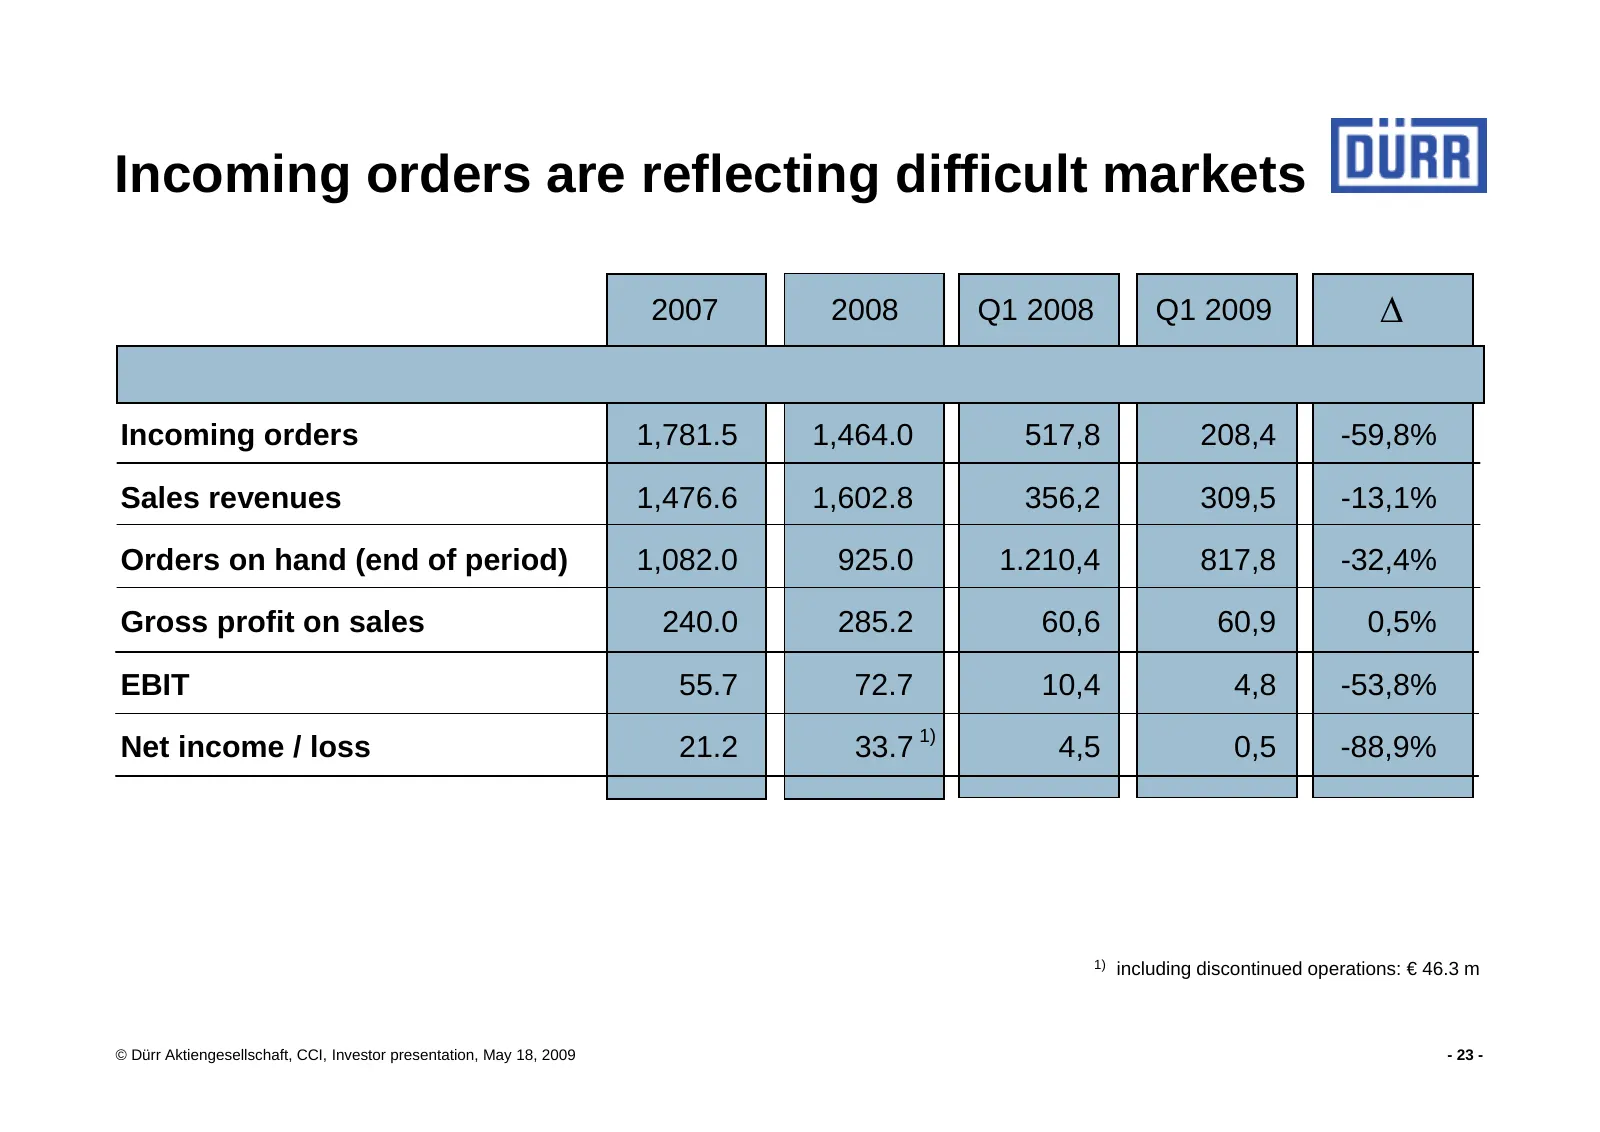
Incoming orders are reflecting difficult markets 2007 2008 Q1 2008 Q1 2009 ∆ in € m Incoming orders 1,781.5 1,464.0 517,8 208,4 -59,8% Sales revenues 1,476.6 1,602.8 356,2 309,5 -13,1% Orders on hand (end of period) 1,082.0 925.0 1.210,4 817,8 -32,4% Gross profit on sales 240.0 285.2 60,6 60,9 0,5%
Slide 24: Cash flow decline temporarily
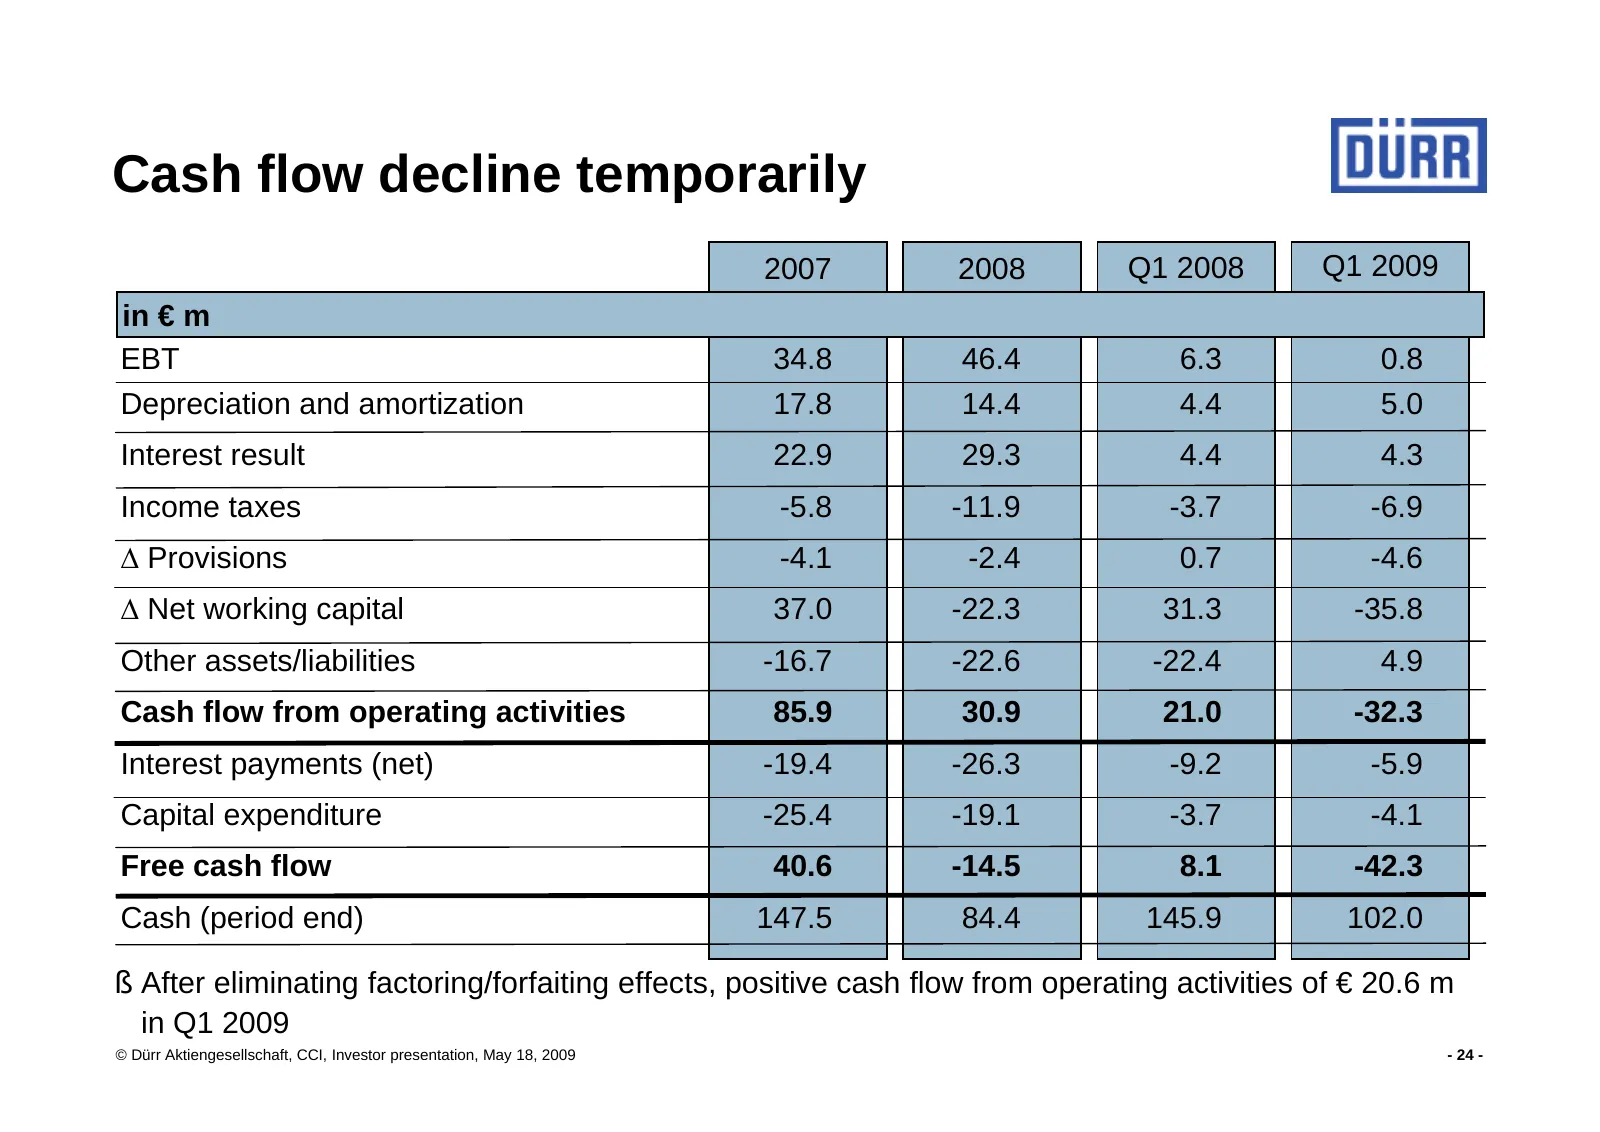
Cash flow decline temporarily 2007 2008 Q1 2008 Q1 2009 in € m EBT 34.8 46.4 6.3 0.8 Depreciation and amortization 17.8 14.4 4.4 5.0 Interest result 22.9 29.3 4.4 4.3 Income taxes -5.8 -11.9 -3.7 -6.9 ∆ Provisions -4.1 -2.4 0.7 -4.6 ∆ Net working capital 37.0 -22.3 31.3 -35.8 Other assets/liabilitie
Slide 25: Solid financial structure
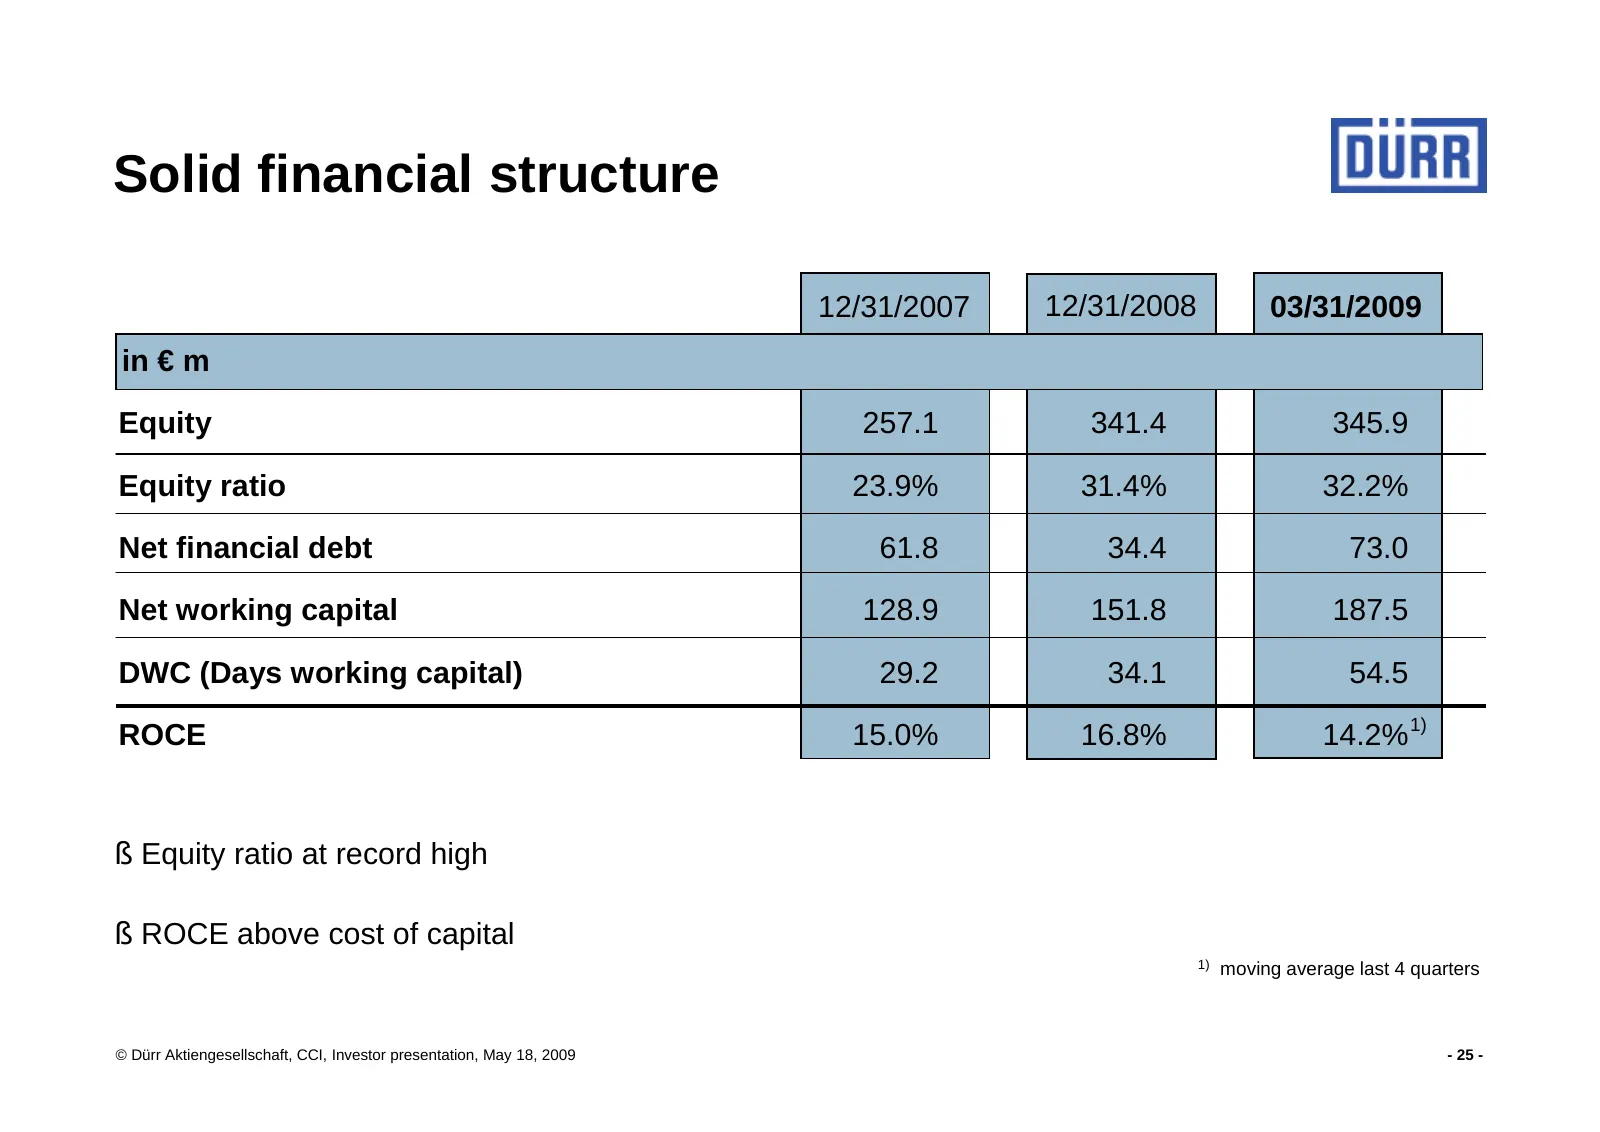
Solid financial structure 12/31/2007 12/31/2008 03/31/2009 in € m Equity 257.1 341.4 345.9 Equity ratio 23.9% 31.4% 32.2% Net financial debt 61.8 34.4 73.0 Net working capital 128.9 151.8 187.5 DWC (Days working capital) 29.2 34.1 54.5 ROCE 15.0% 16.8% 14.2% 1) § Equity ratio at record high § ROCE a
Slide 26: Outlook: Projects in the pipeline
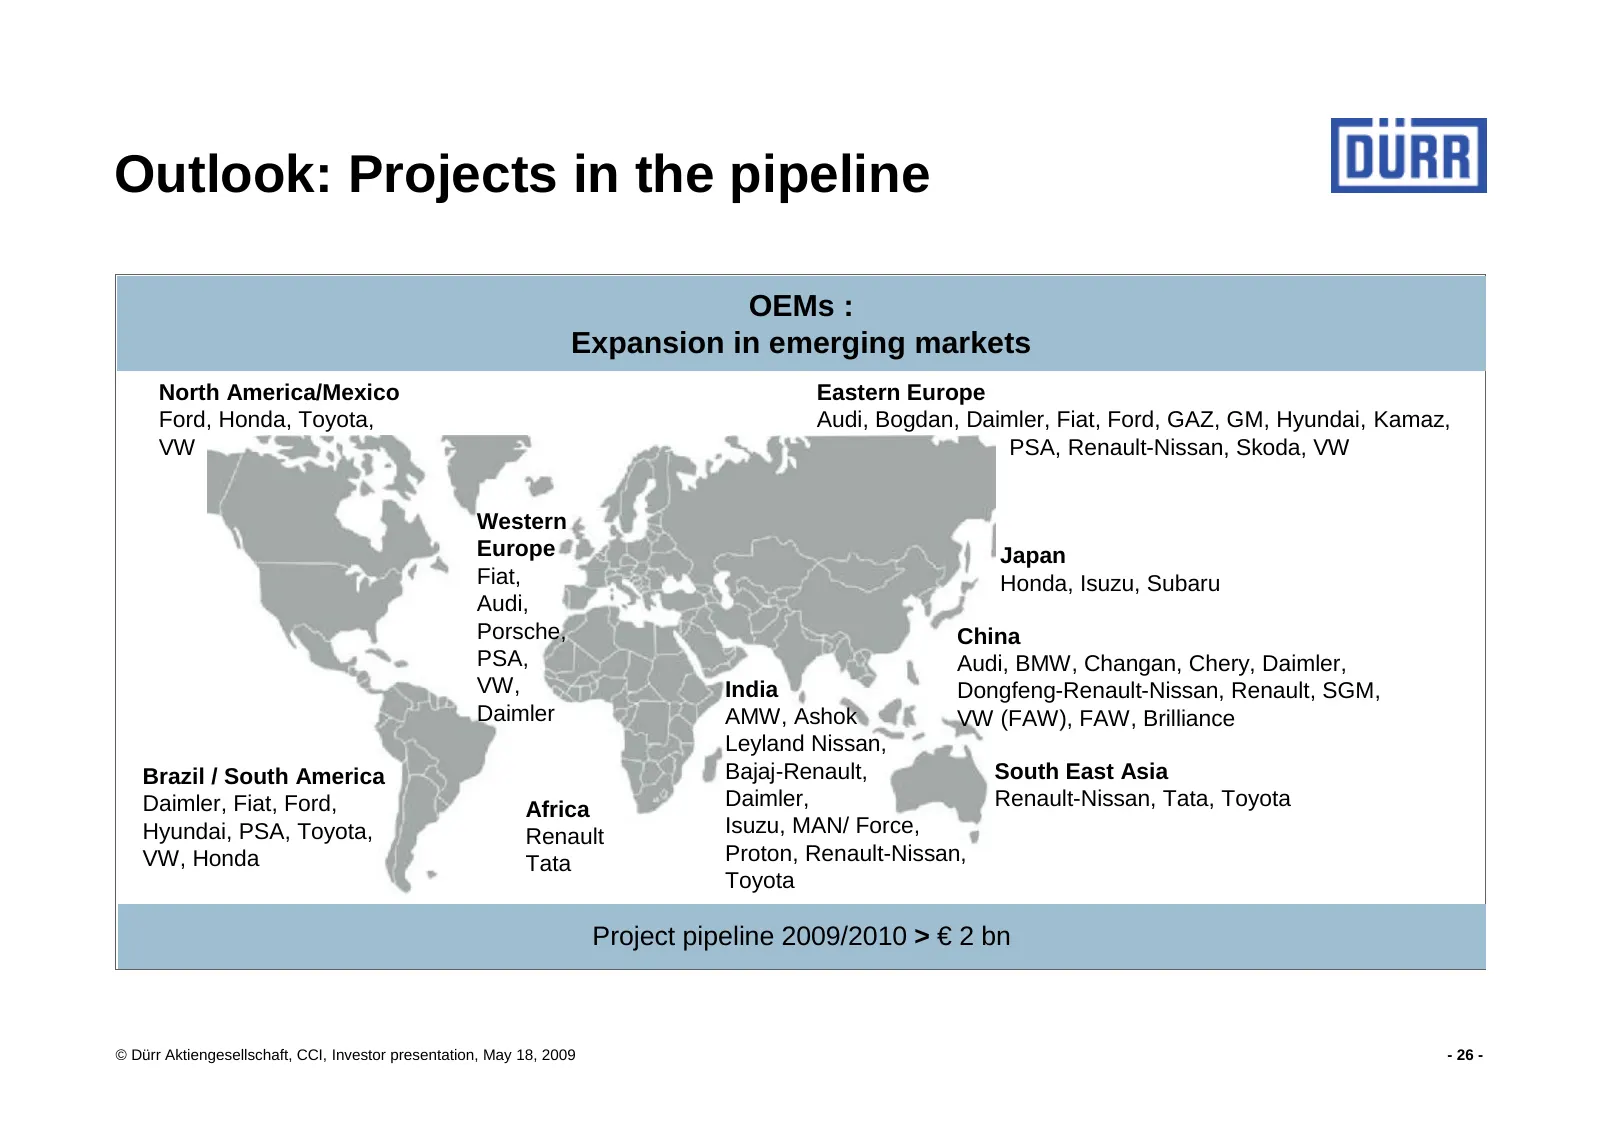
Outlook: Projects in the pipeline OEMs : Expansion in emerging markets North America/Mexico Eastern Europe Ford, Honda, Toyota, Audi, Bogdan, Daimler, Fiat, Ford, GAZ, GM, Hyundai, Kamaz, VW PSA, Renault-Nissan, Skoda, VW Western Europe Japan Fiat, Honda, Isuzu, Subaru Audi, Porsche, China PSA, Audi
Slide 27: Dürr well prepared for market slowdown (1)
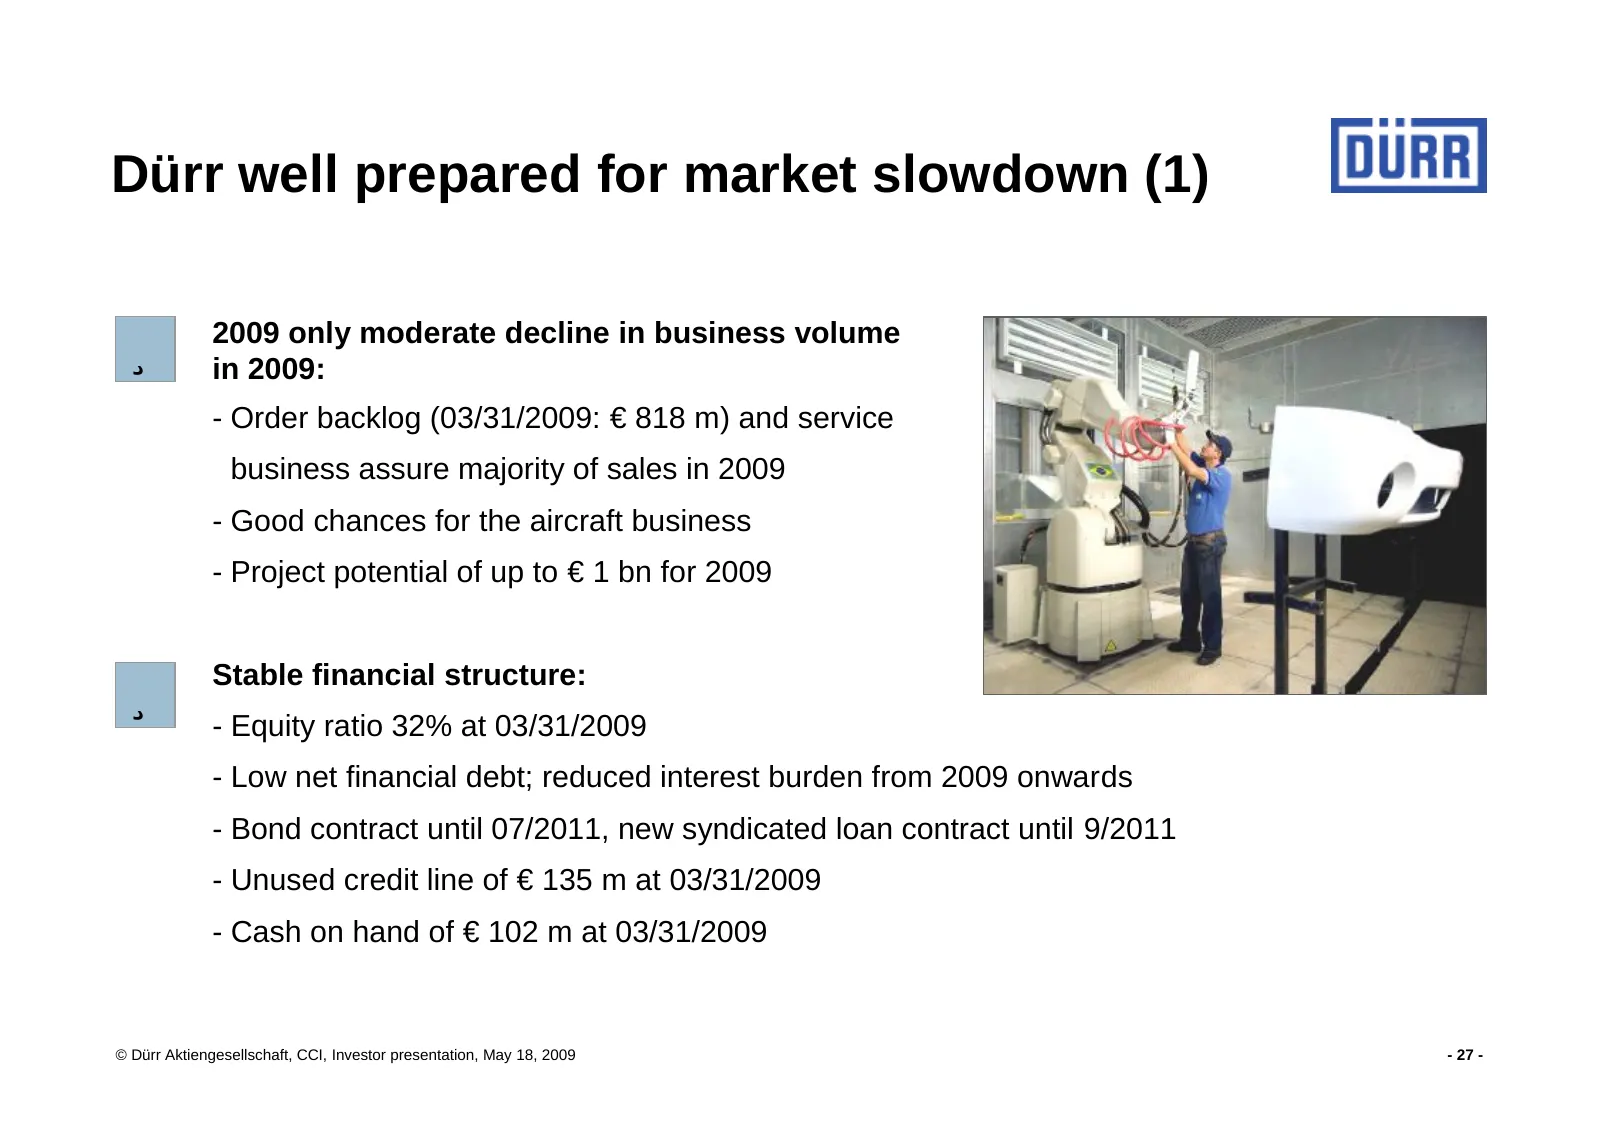
Dürr well prepared for market slowdown (1) 2009 only moderate decline in business volume ü in 2009: - Order backlog (03/31/2009: € 818 m) and service business assure majority of sales in 2009 - Good chances for the aircraft business - Project potential of up to € 1 bn for 2009 Stable financial struc
Slide 28: Dürr well prepared for market slowdown (2)
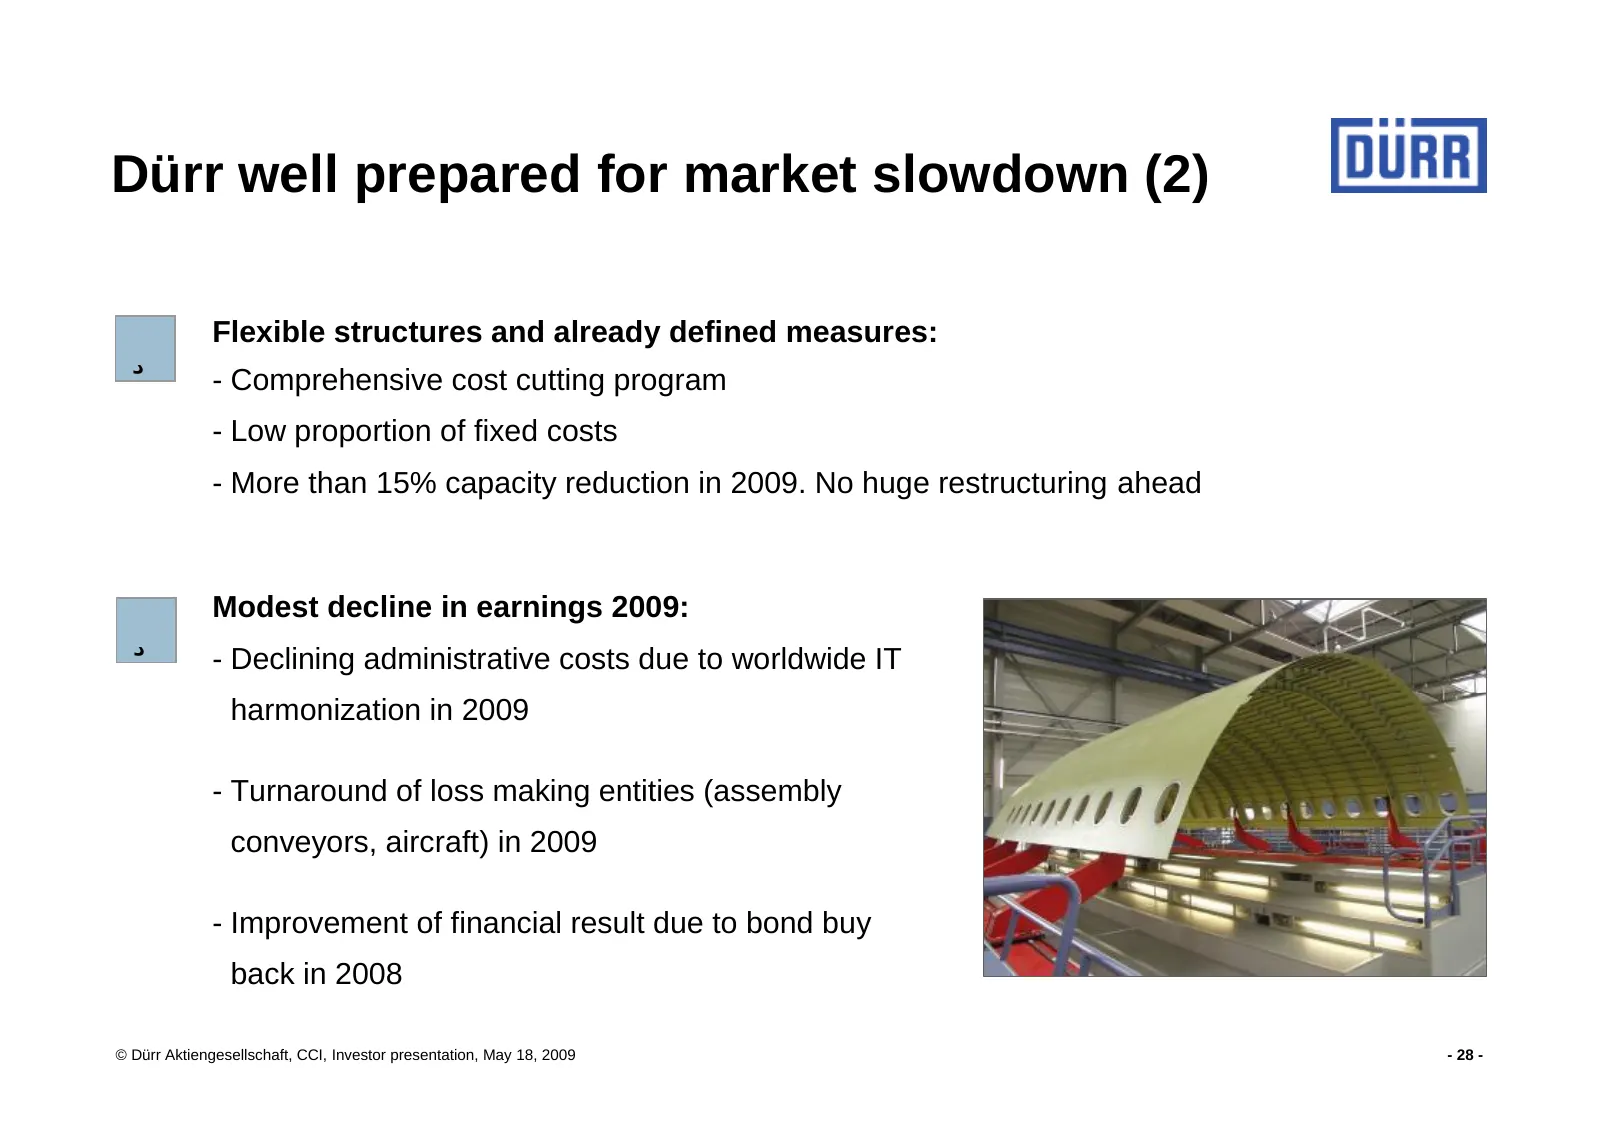
Dürr well prepared for market slowdown (2) Flexible structures and already defined measures: ü - Comprehensive cost cutting program - Low proportion of fixed costs - More than 15% capacity reduction in 2009. No huge restructuring ahead Modest decline in earnings 2009: ü - Declining administrative co
Slide 29: Drivers for future business growth remain robust
Drivers for future business growth remain robust 1. Longterm volume growth in Emerging Markets; strong international foothold 2. Dürr´s leading technology contributes to CPU reductions (e.g. energy + material consumption) and lower emissions 3. Strong position in small car plant tooling. Small cars
Slide 30: © Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009
© Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009 - 30 -
Slide 31: Management
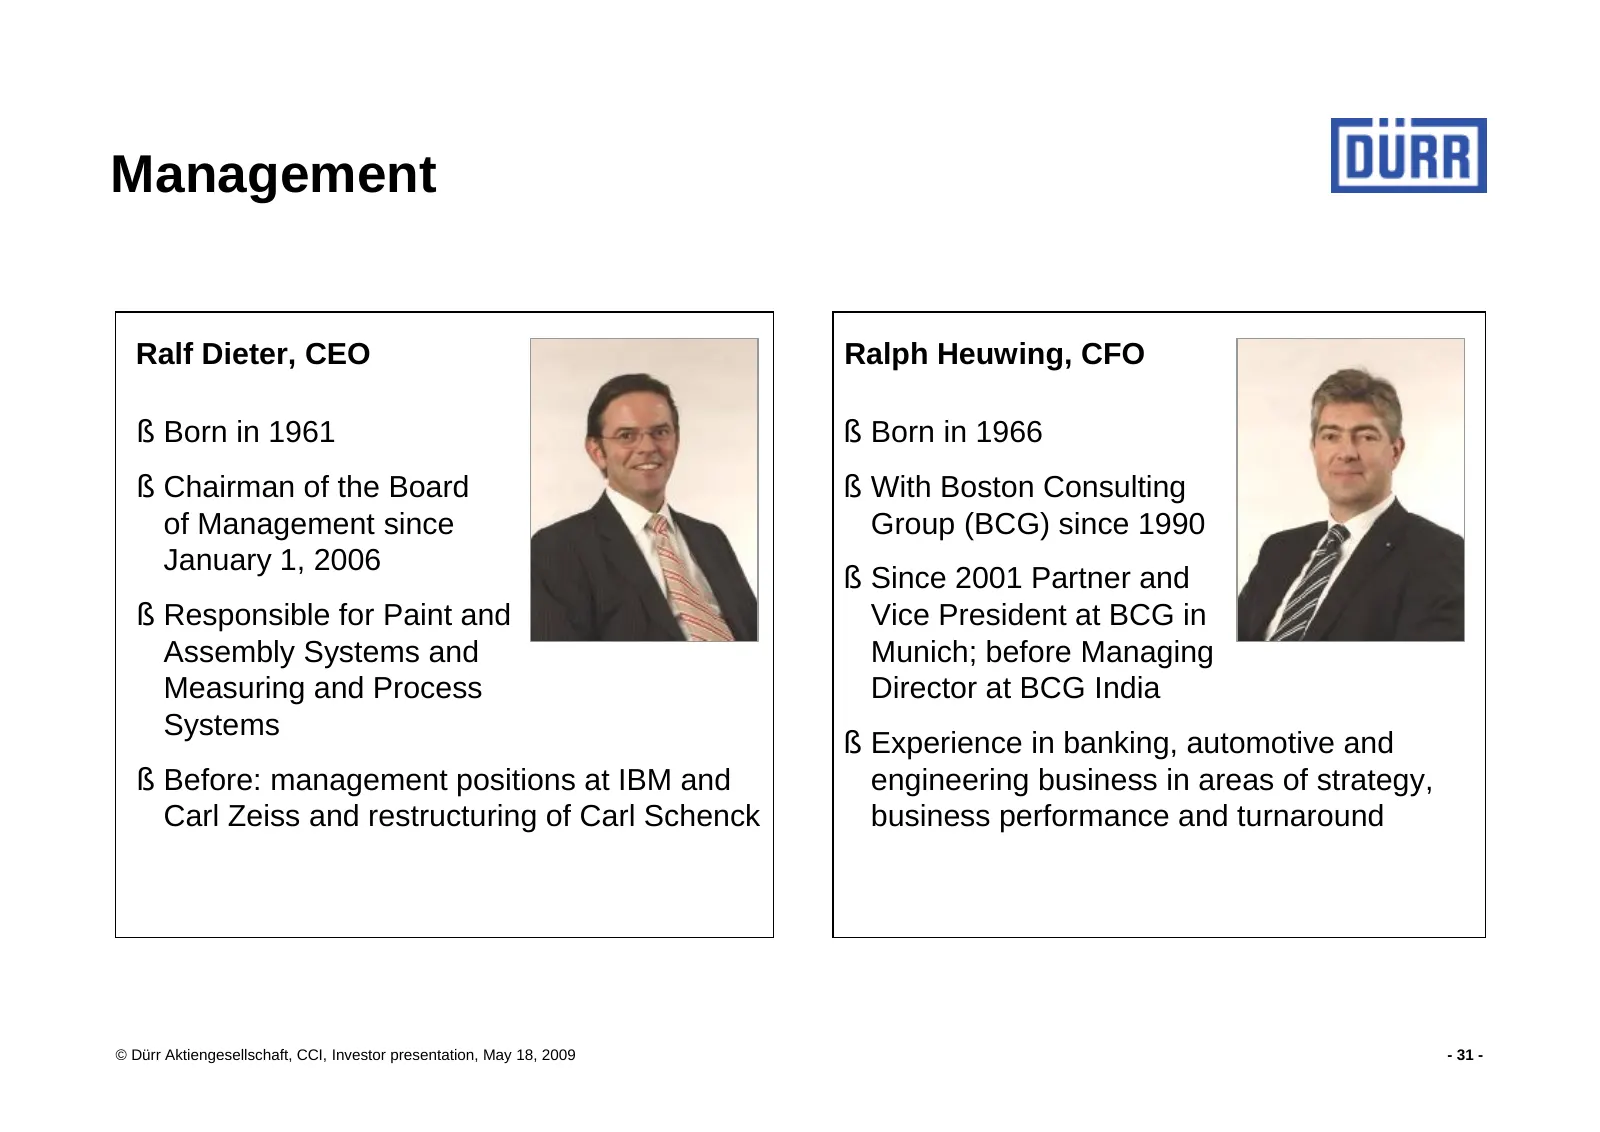
Management Ralf Dieter, CEO Ralph Heuwing, CFO § Born in 1961 § Born in 1966 § Chairman of the Board § With Boston Consulting of Management since Group (BCG) since 1990 January 1, 2006 § Since 2001 Partner and § Responsible for Paint and Vice President at BCG in Assembly Systems and Munich; before M
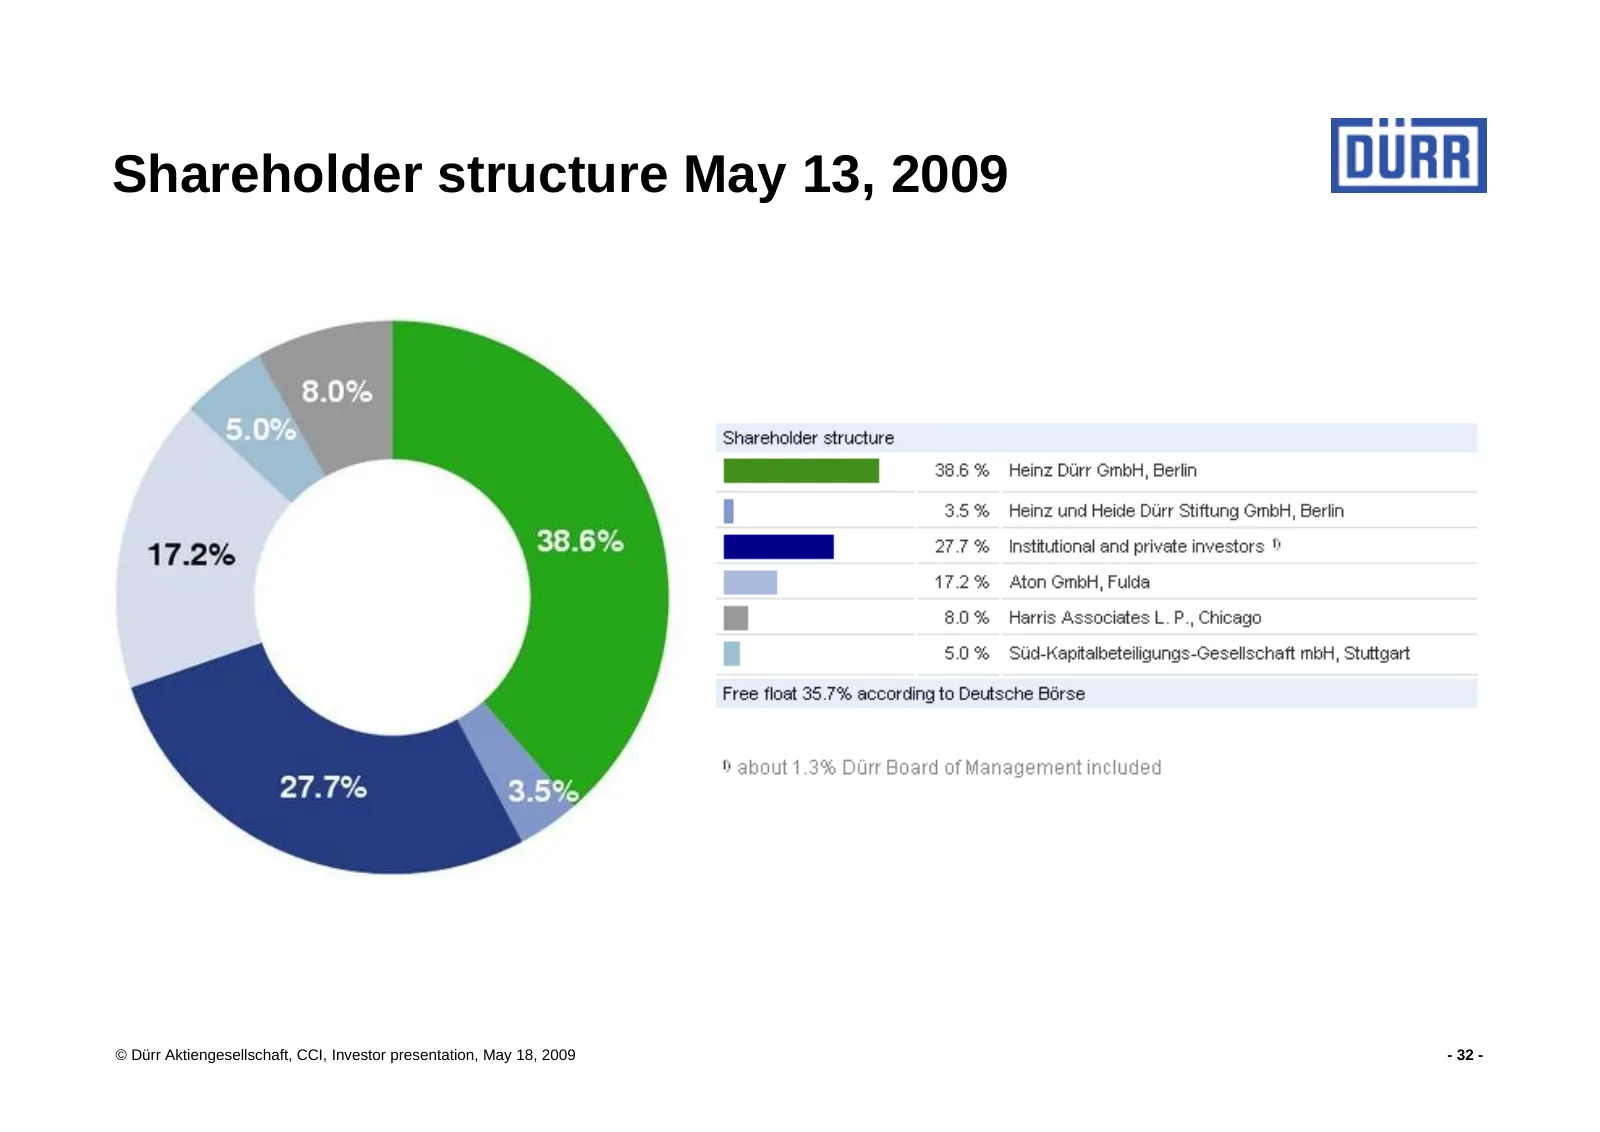
Slide 32: Shareholder structure May 13, 2009
Shareholder structure May 13, 2009 © Dürr Aktiengesellschaft, CCI, Investor presentation, May 18, 2009 - 32 -
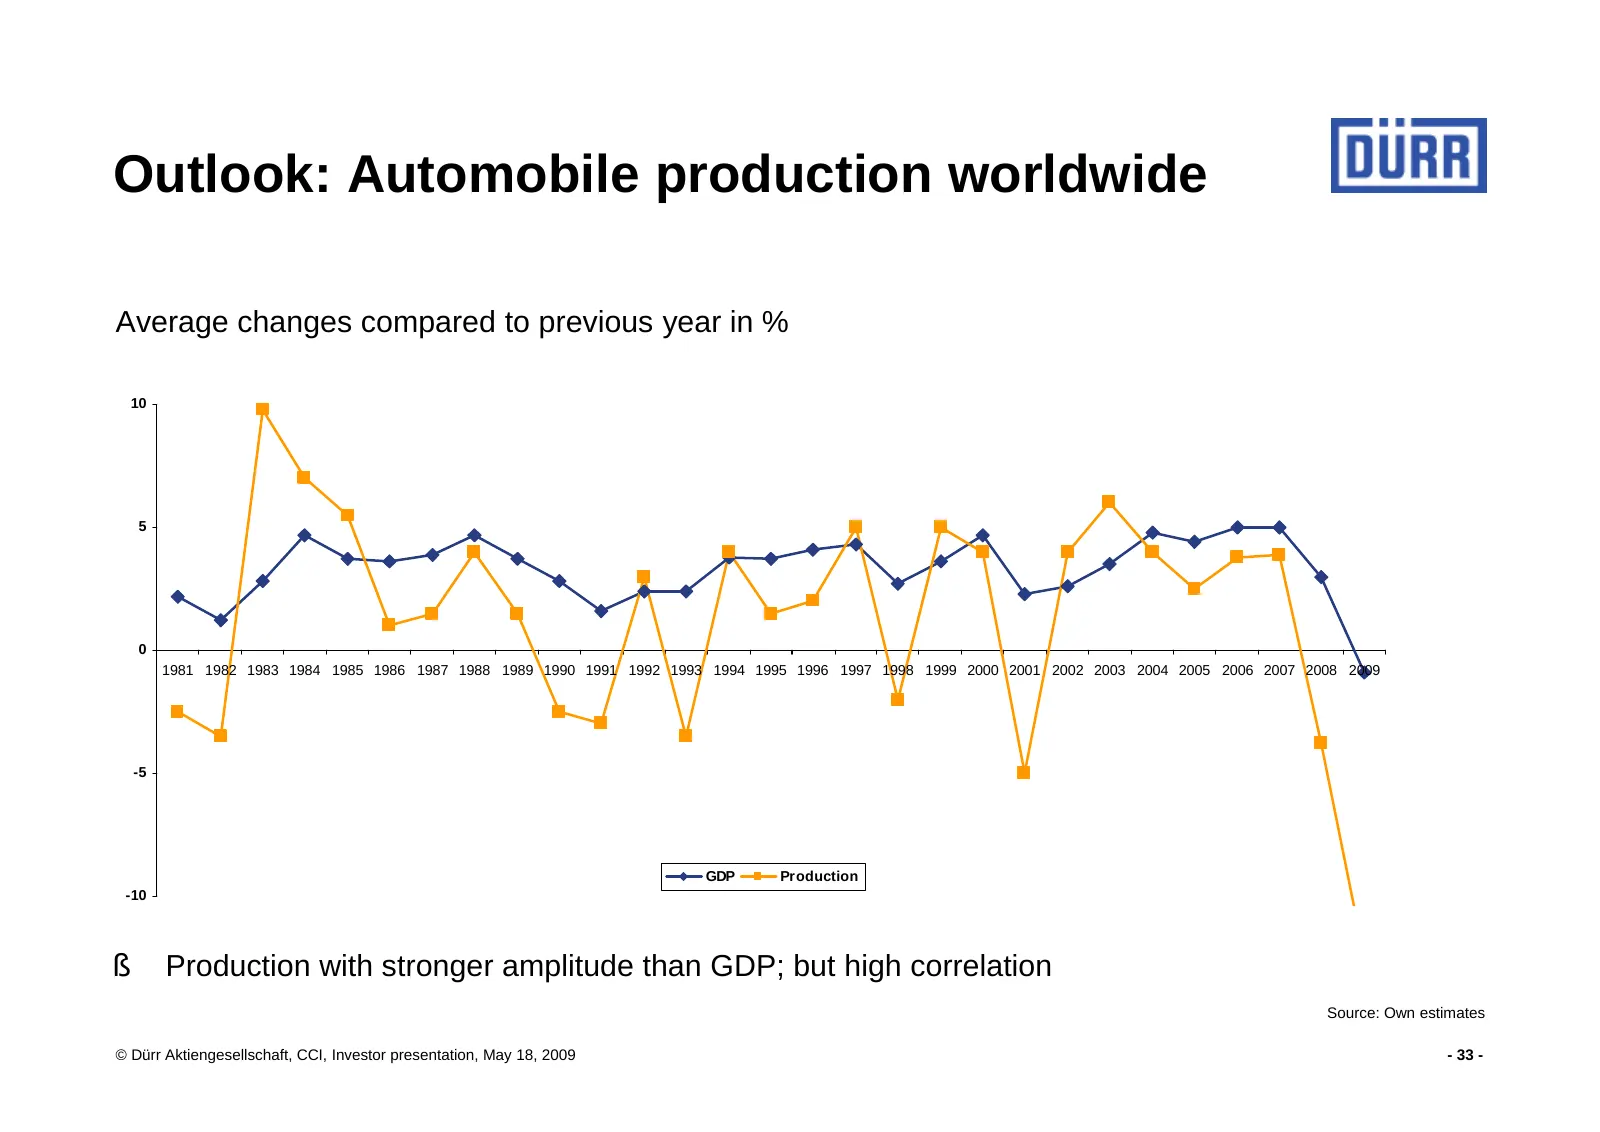
Slide 33: Outlook: Automobile production worldwide
Outlook: Automobile production worldwide Average changes compared to previous year in % 10 5 0 1981 1982 1983 1984 1985 1986 1987 1988 1989 1990 1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 -5 GDP Production -10 § Production with stronger amplitude t
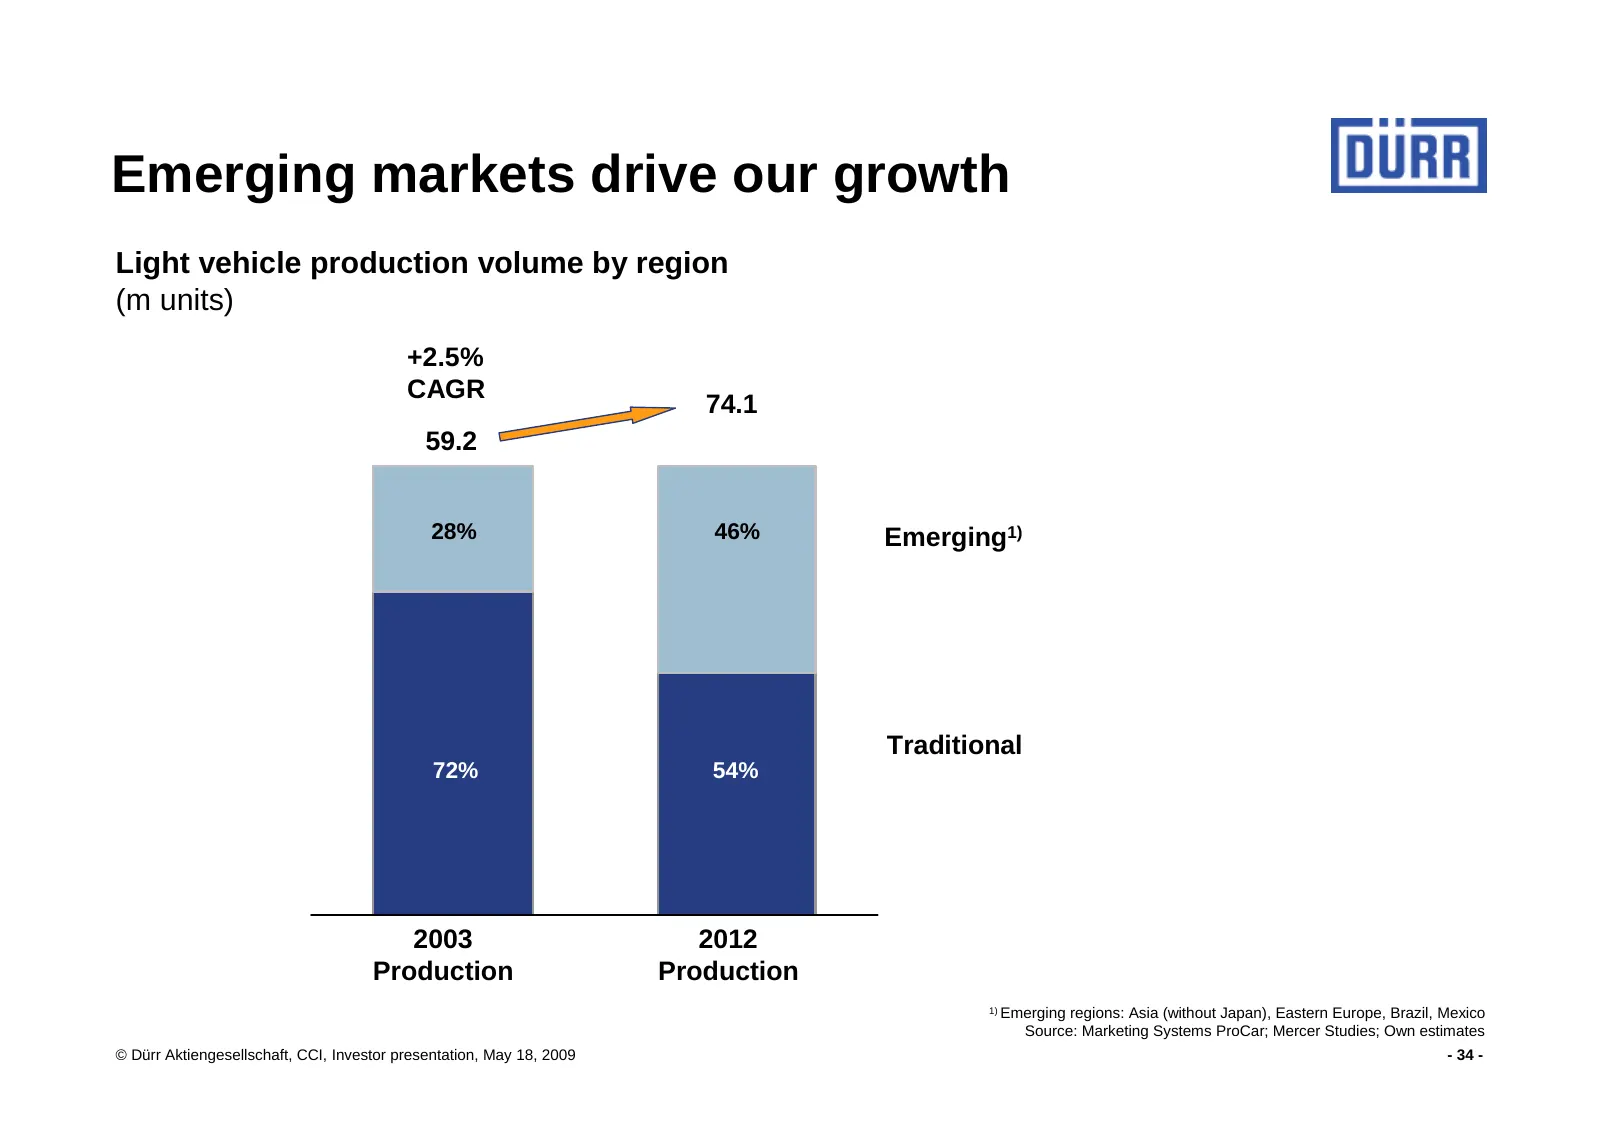
Slide 34: Emerging markets drive our growth
Emerging markets drive our growth Light vehicle production volume by region (m units) +2.5% CAGR 74.1 59.2 28% 46% Emerging1) Traditional 72% 54% 2003 2012 Production Production 1) Emerging regions: Asia (without Japan), Eastern Europe, Brazil, Mexico Source: Marketing Systems ProCar; Mercer Studies
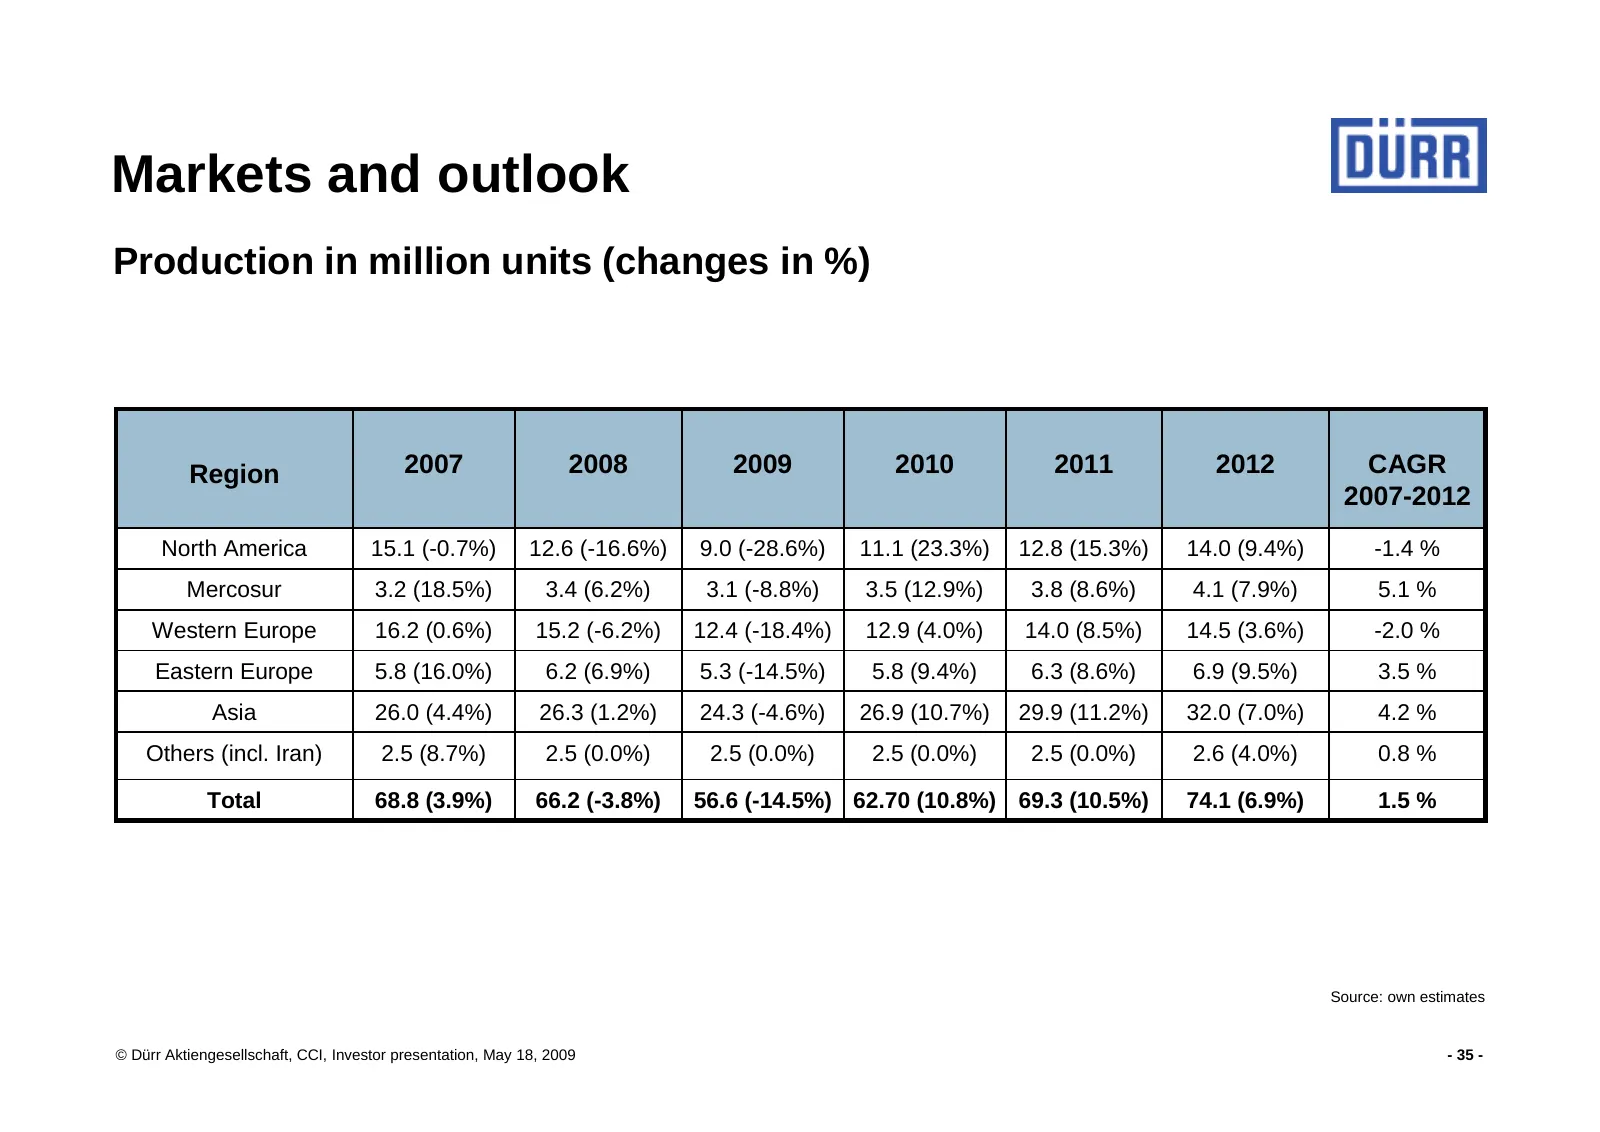
Slide 35: Markets and outlook
Markets and outlook Production in million units (changes in %) Region 2007 2008 2009 2010 2011 2012 CAGR 2007-2012 North America 15.1 (-0.7%) 12.6 (-16.6%) 9.0 (-28.6%) 11.1 (23.3%) 12.8 (15.3%) 14.0 (9.4%) -1.4 % Mercosur 3.2 (18.5%) 3.4 (6.2%) 3.1 (-8.8%) 3.5 (12.9%) 3.8 (8.6%) 4.1 (7.9%) 5.1 % We
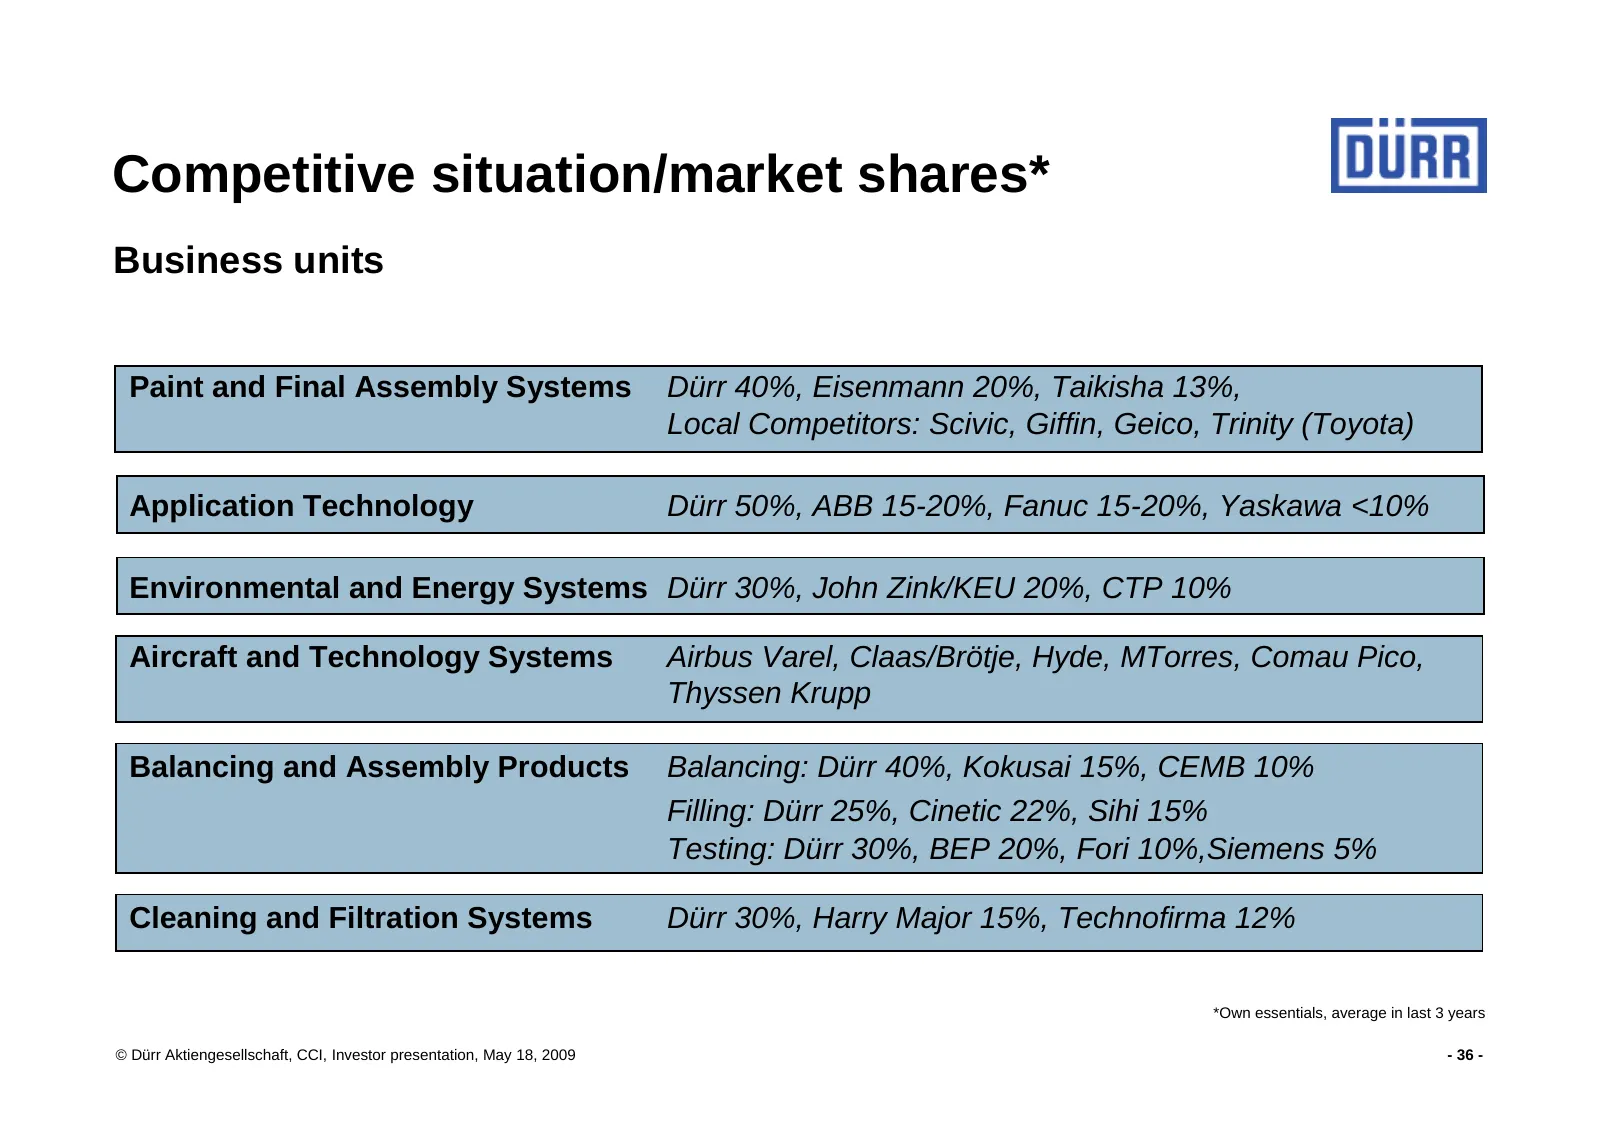
Slide 36: Competitive situation/market shares
Competitive situation/market shares* Business units Paint and Final Assembly Systems Dürr 40%, Eisenmann 20%, Taikisha 13%, Local Competitors: Scivic, Giffin, Geico, Trinity (Toyota) Application Technology Dürr 50%, ABB 15-20%, Fanuc 15-20%, Yaskawa <10% Environmental and Energy Systems Dürr 30%, Jo
Slide 37: Hidden value at Schenck Technologie- und Industriepark GmbH
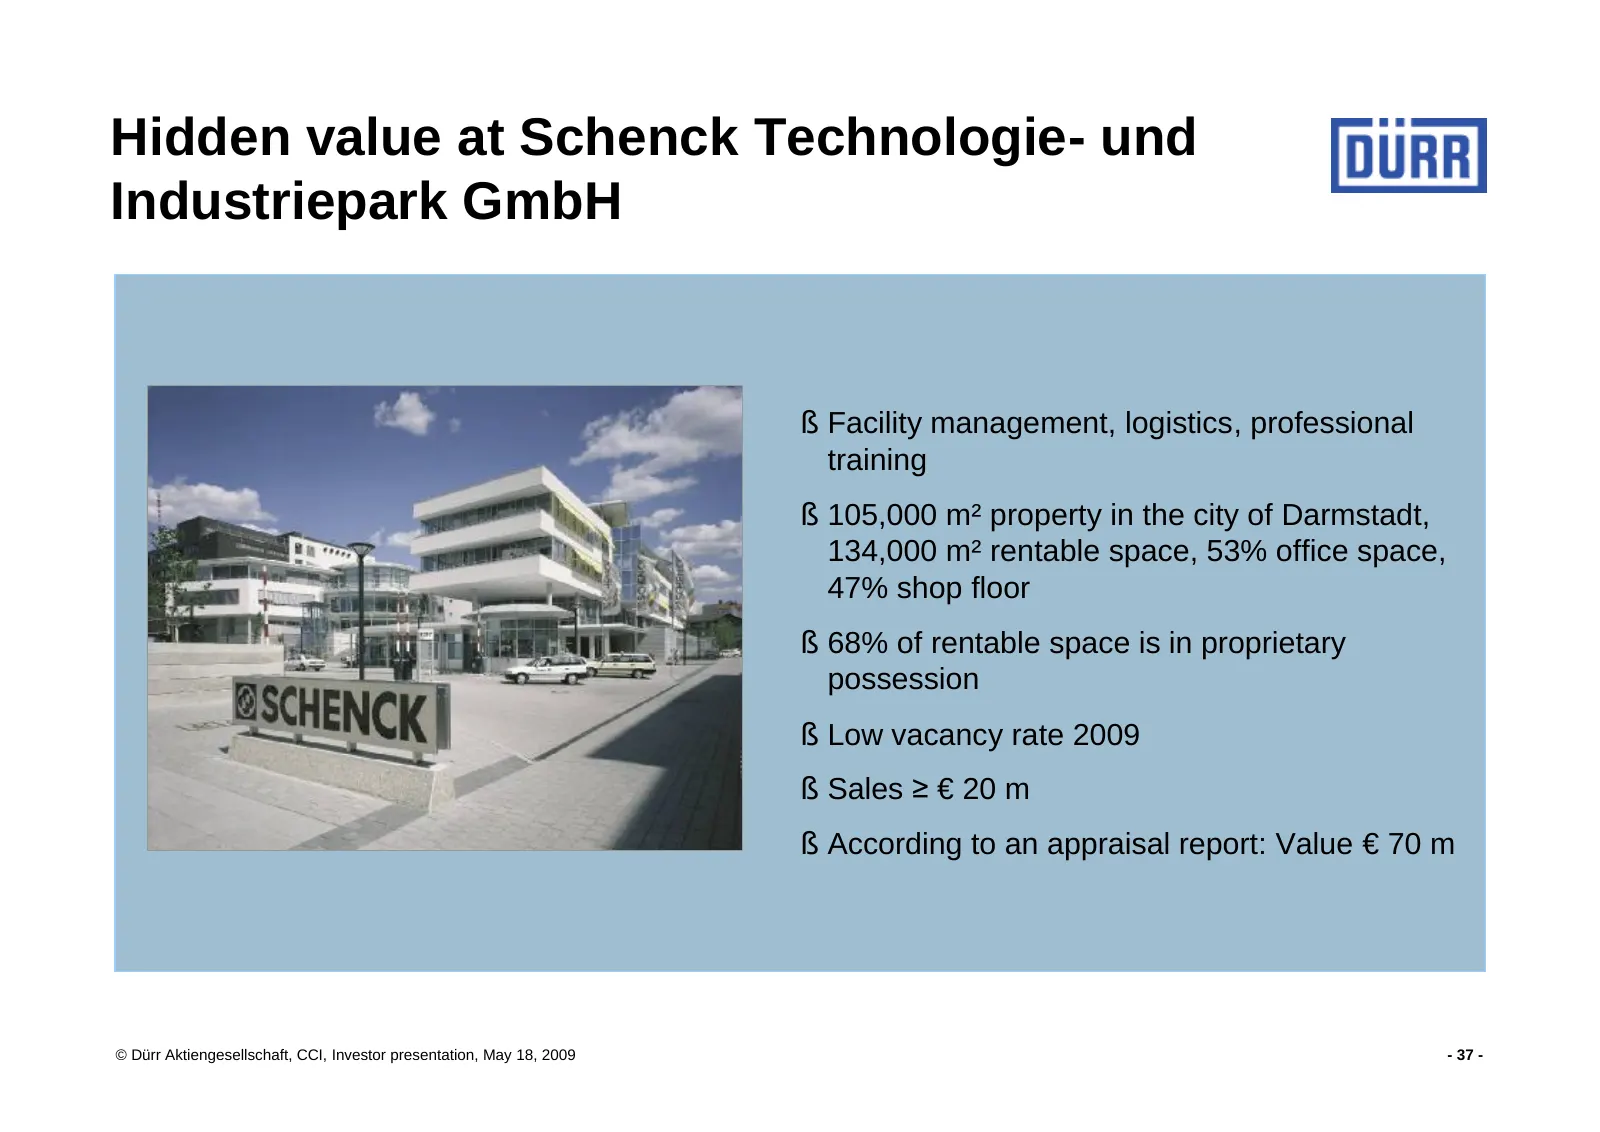
Hidden value at Schenck Technologie- und Industriepark GmbH § Facility management, logistics, professional training § 105,000 m² property in the city of Darmstadt, 134,000 m² rentable space, 53% office space, 47% shop floor § 68% of rentable space is in proprietary possession § Low vacancy rate 2009
Slide 38: Financial calendar
Financial calendar 08/06/2009 Interim financial report for the first half of 2009 11/05/2009 Interim report for the first nine months of 2009 Contact: Dürr Aktiengesellschaft Corporate Communications & Investor Relations Otto-Dürr-Strasse 8 70435 Stuttgart Germany Phone +49 (0)711 136-1785 E-mail in
Source: Internet Archive copy of durr.com
More decks from Durr AG
 Q3 2026 Earnings Presentation33 slides · Nov 12, 2026
 Q2 2026 Earnings Presentation39 slides · Aug 6, 2026
 Q1 2026 Earnings Presentation35 slides · May 12, 2026
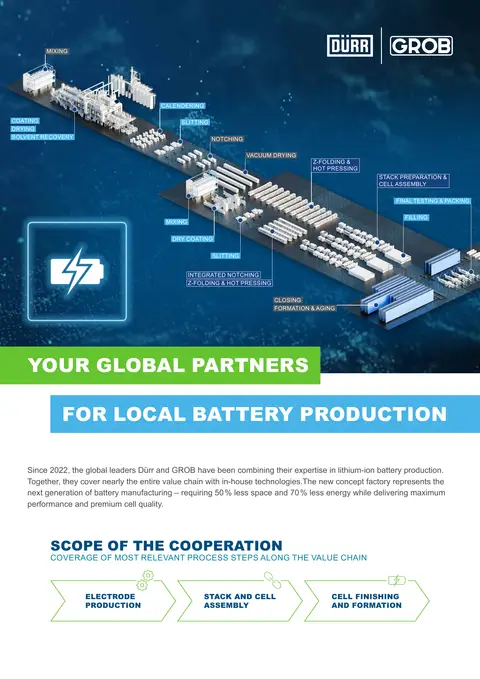 Fact Sheet (2025)2 slides · Dec 2, 2025
 Q3 2025 Earnings Presentation46 slides · Nov 13, 2025
 Q2 2025 Earnings Presentation31 slides · Jul 24, 2025