Metcash Limited · ASX:MTS
Metcash — Investor Day (September 2015)
47 slides from Metcash's investor day presentation, Sep 29, 2015
Slide 1: Shopper Led Way
SHOPPER LED WAY ANDREW CLARK GM MERCHANDISE - FOOD Page 40
Slide 2: Shopper Led Way: systematic approach to manage and grow categories
WE HAVE DEVELOPED A SYSTEMATIC APPROACH TO CONTINUOUSLY MANAGE & GROW OUR CATEGORIES WE CALL THIS SHOPPER LED WAY Page 41
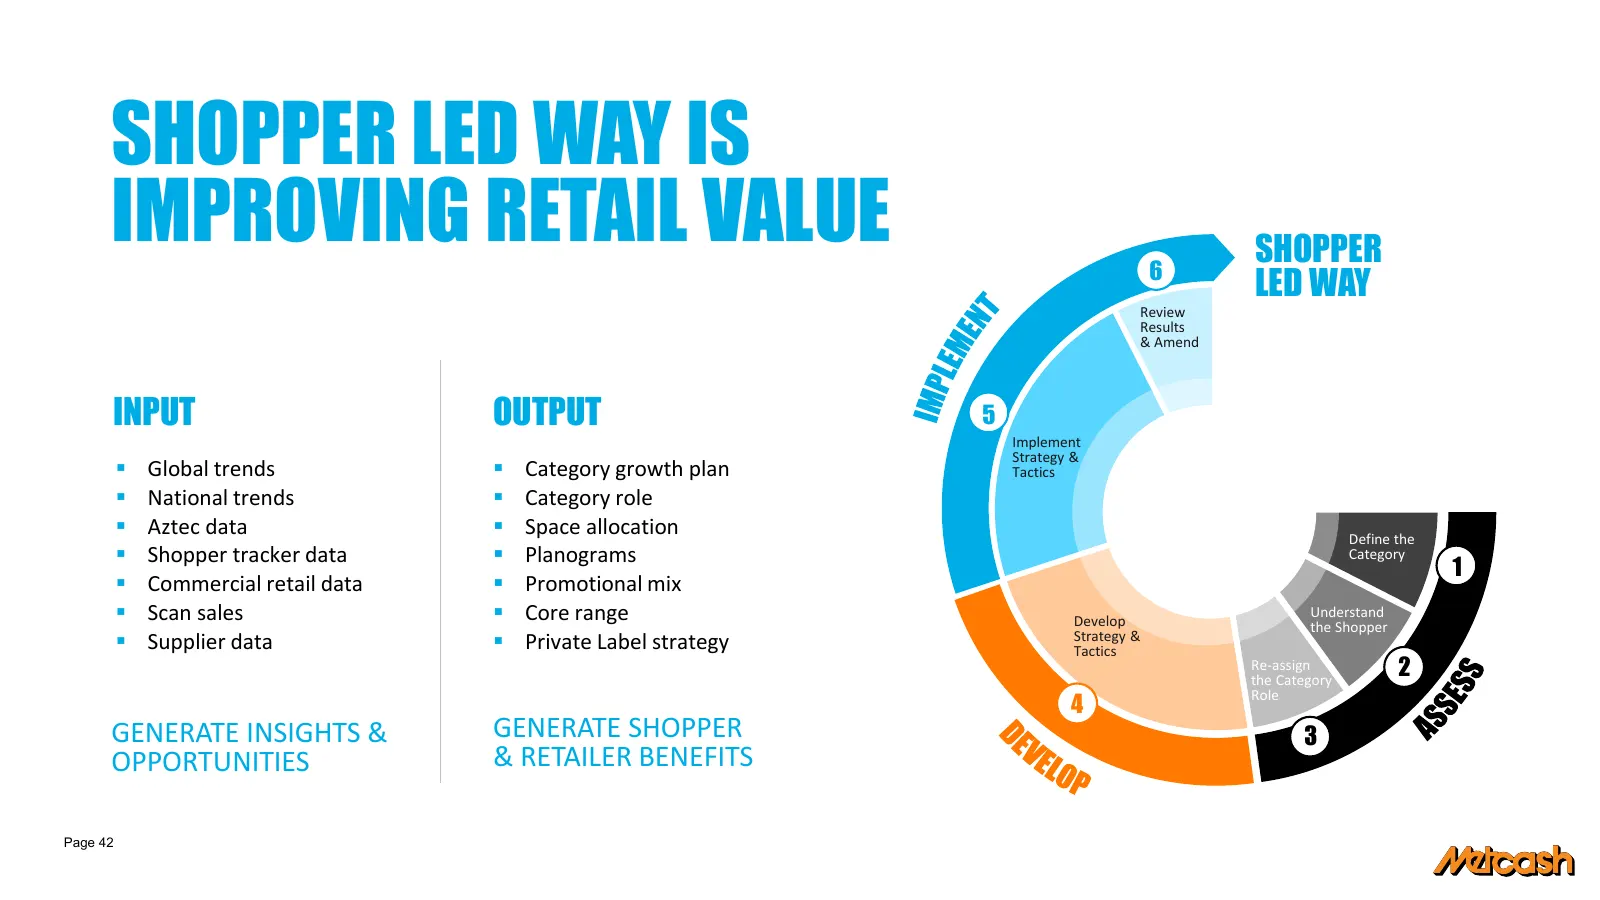
Slide 3: Shopper Led Way is improving retail value
SHOPPER LED WAY IS IMPROVING RETAIL VALUE 6 SHOPPER LED WAY Review Results & Amend INPUT OUTPUT 5 Implement Strategy & Global trends Category growth plan Tactics National trends Category role Aztec data Space allocation Define the Shopper tracker data Planograms Category 1 Commerci
Slide 4: To grow the category: coffee
TO GROW THE CATEGORY PENETRATION FREQUENCY VALUE COFFEE AWOP People already drink a lot of coffee; cup consumption is flat. It’s hard to get volume growth. INSIGHT Coffee types – everyday soluble, specialty, roast & ground and capsules. Shoppers switch between them depending on the occasion. Capsule
Slide 5: Coffee sales up 11%
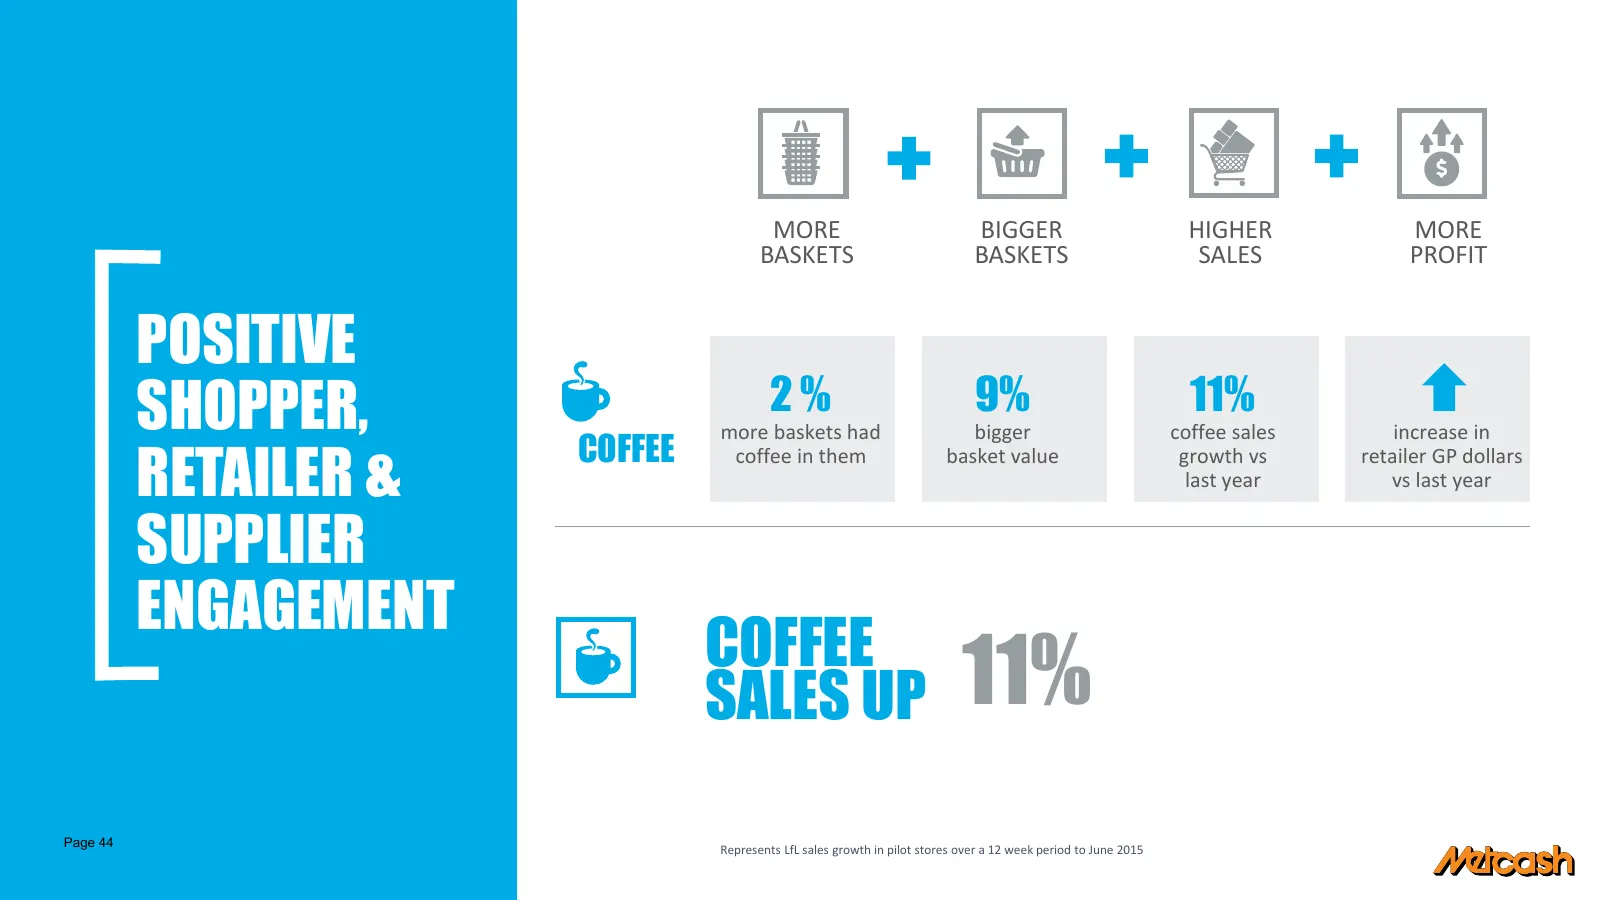
MORE BIGGER HIGHER MORE BASKETS BASKETS SALES PROFIT POSITIVE SHOPPER, 2% 9% 11% more baskets had bigger coffee sales increase in COFFEE RETAILER & coffee in them basket value growth vs retailer GP dollars last year vs last year SUPPLIER ENGAGEMENT COFFEE SALES UP 11% Page 44 Represents LfL sales gr
Slide 6: Private Label Strategy
PRIVATE LABEL STRATEGY Page 45
Slide 7: Private label journey: our historic position
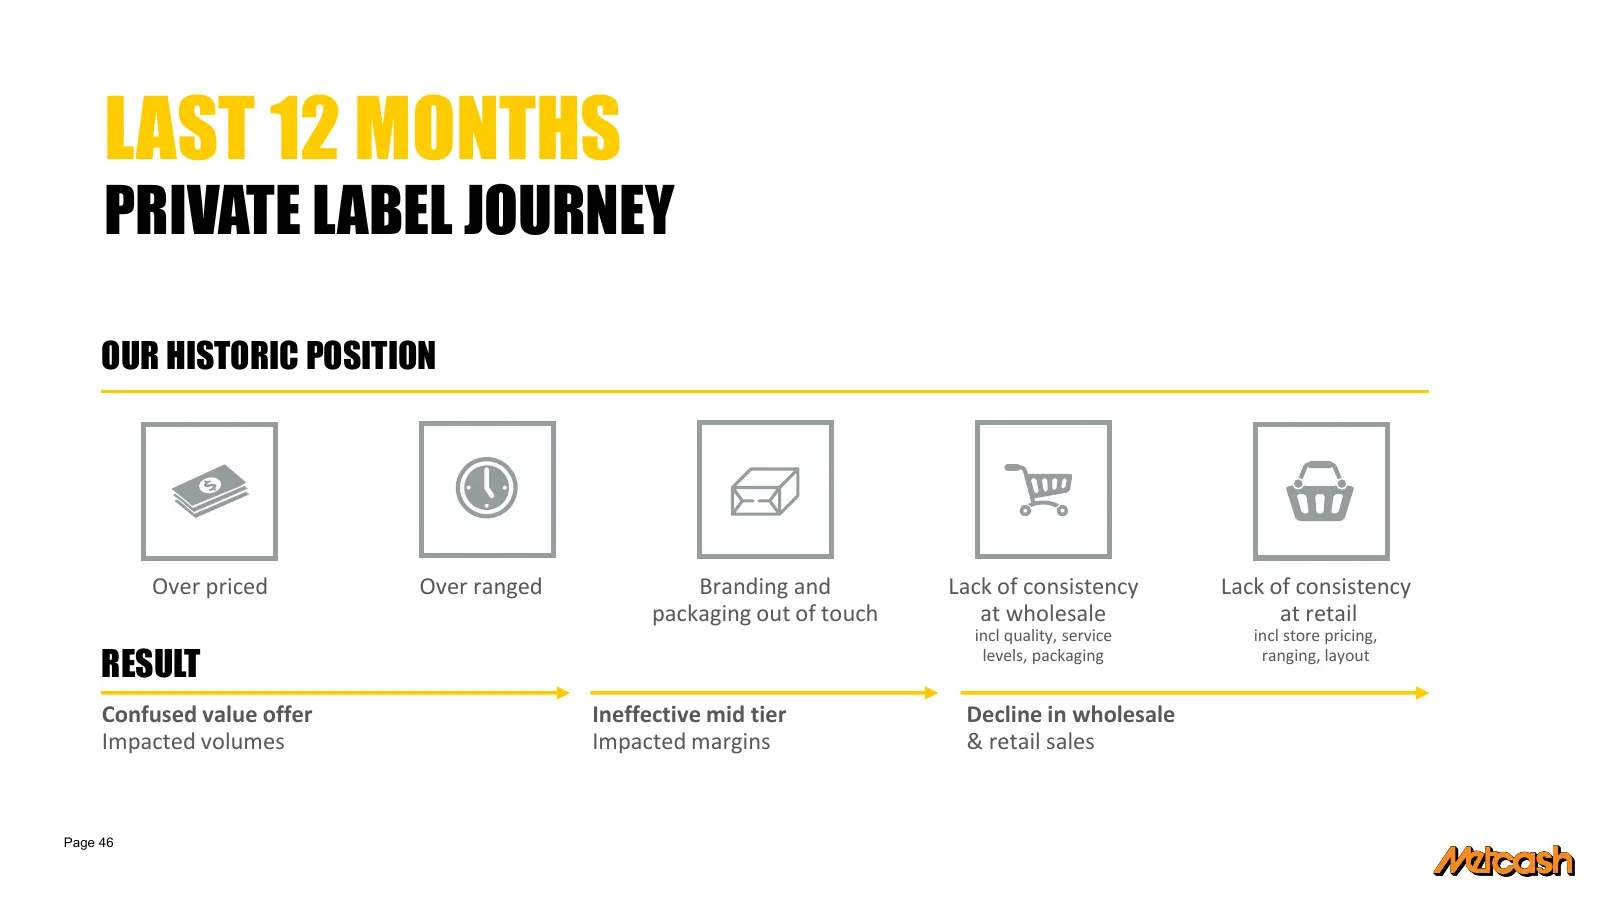
LAST 12 MONTHS PRIVATE LABEL JOURNEY OUR HISTORIC POSITION Over priced Over ranged Branding and Lack of consistency Lack of consistency packaging out of touch at wholesale at retail incl quality, service incl store pricing, RESULT levels, packaging ranging, layout Confused value offer Ineffective mi
Slide 8: Private label opportunity
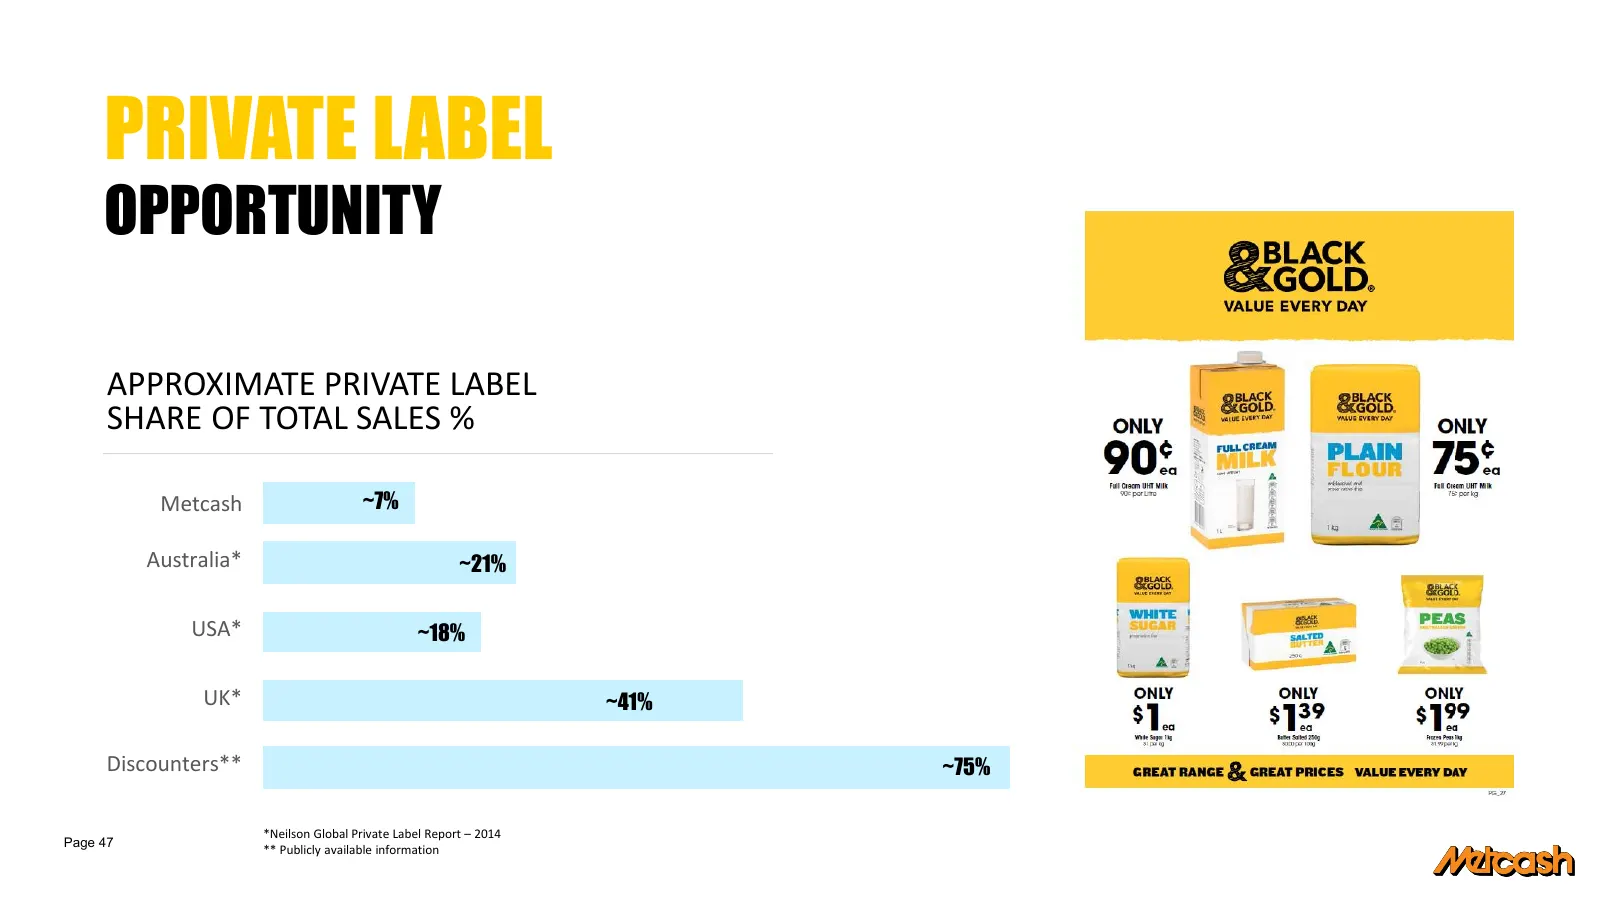
PRIVATE LABEL OPPORTUNITY APPROXIMATE PRIVATE LABEL SHARE OF TOTAL SALES % Metcash ~7% Australia* ~21% USA* ~18% UK* ~41% Discounters** ~75% *Neilson Global Private Label Report – 2014 Page 47 ** Publicly available information
Slide 9: Private label tiers and strategy
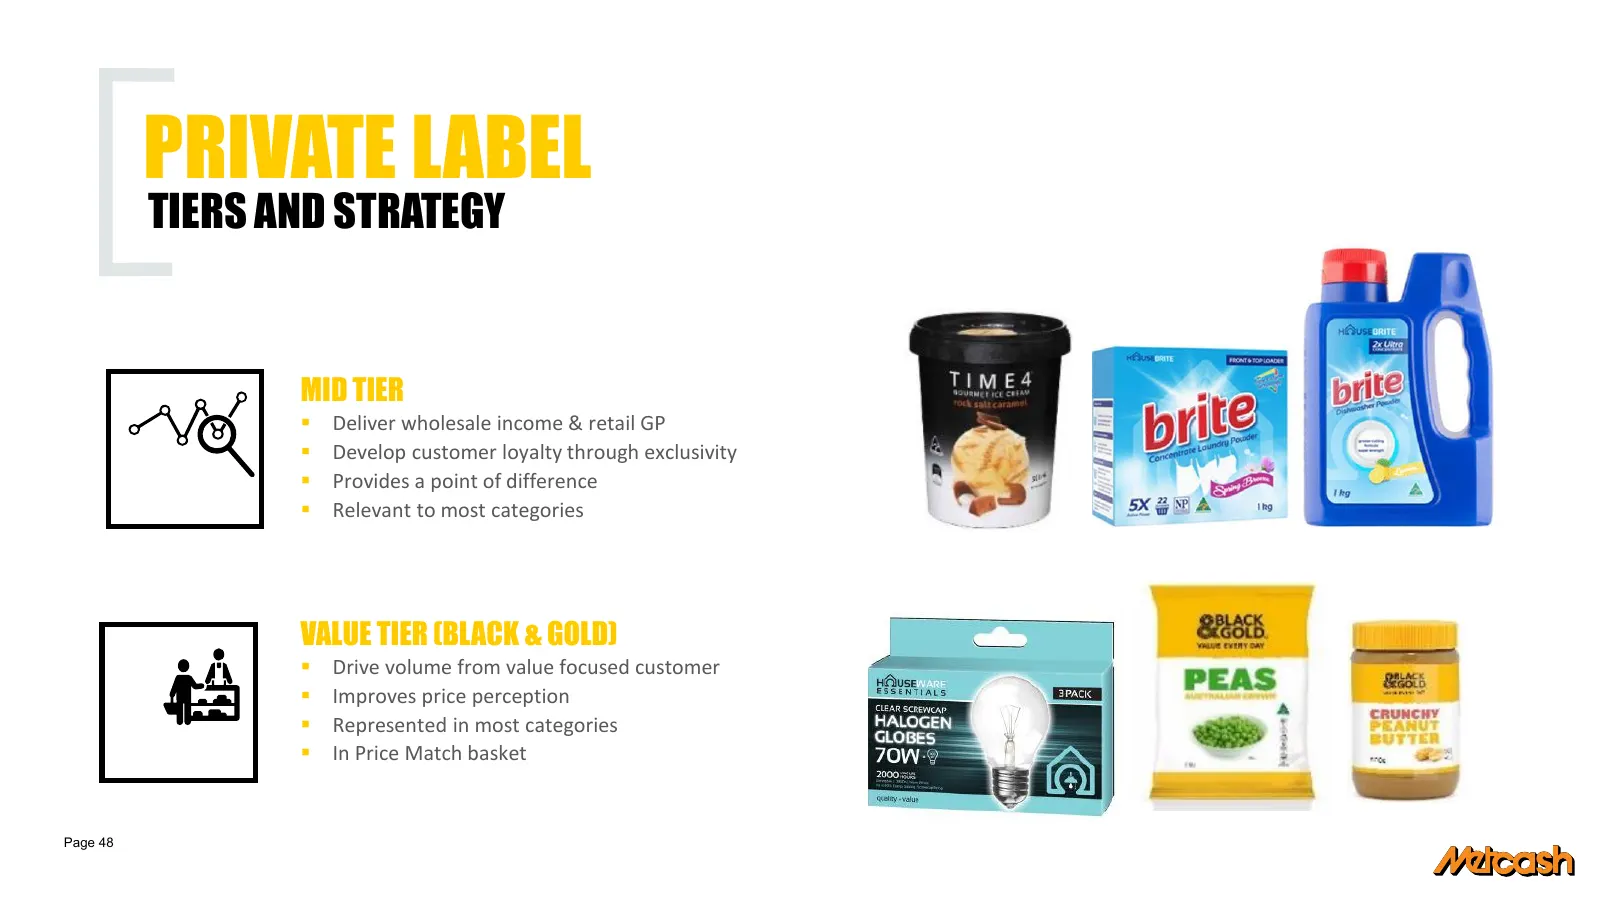
PRIVATE LABEL TIERS AND STRATEGY MID TIER Deliver wholesale income & retail GP Develop customer loyalty through exclusivity Provides a point of difference Relevant to most categories VALUE TIER (BLACK & GOLD) Drive volume from value focused customer Improves price perception Represente
Slide 10: Black & Gold progress
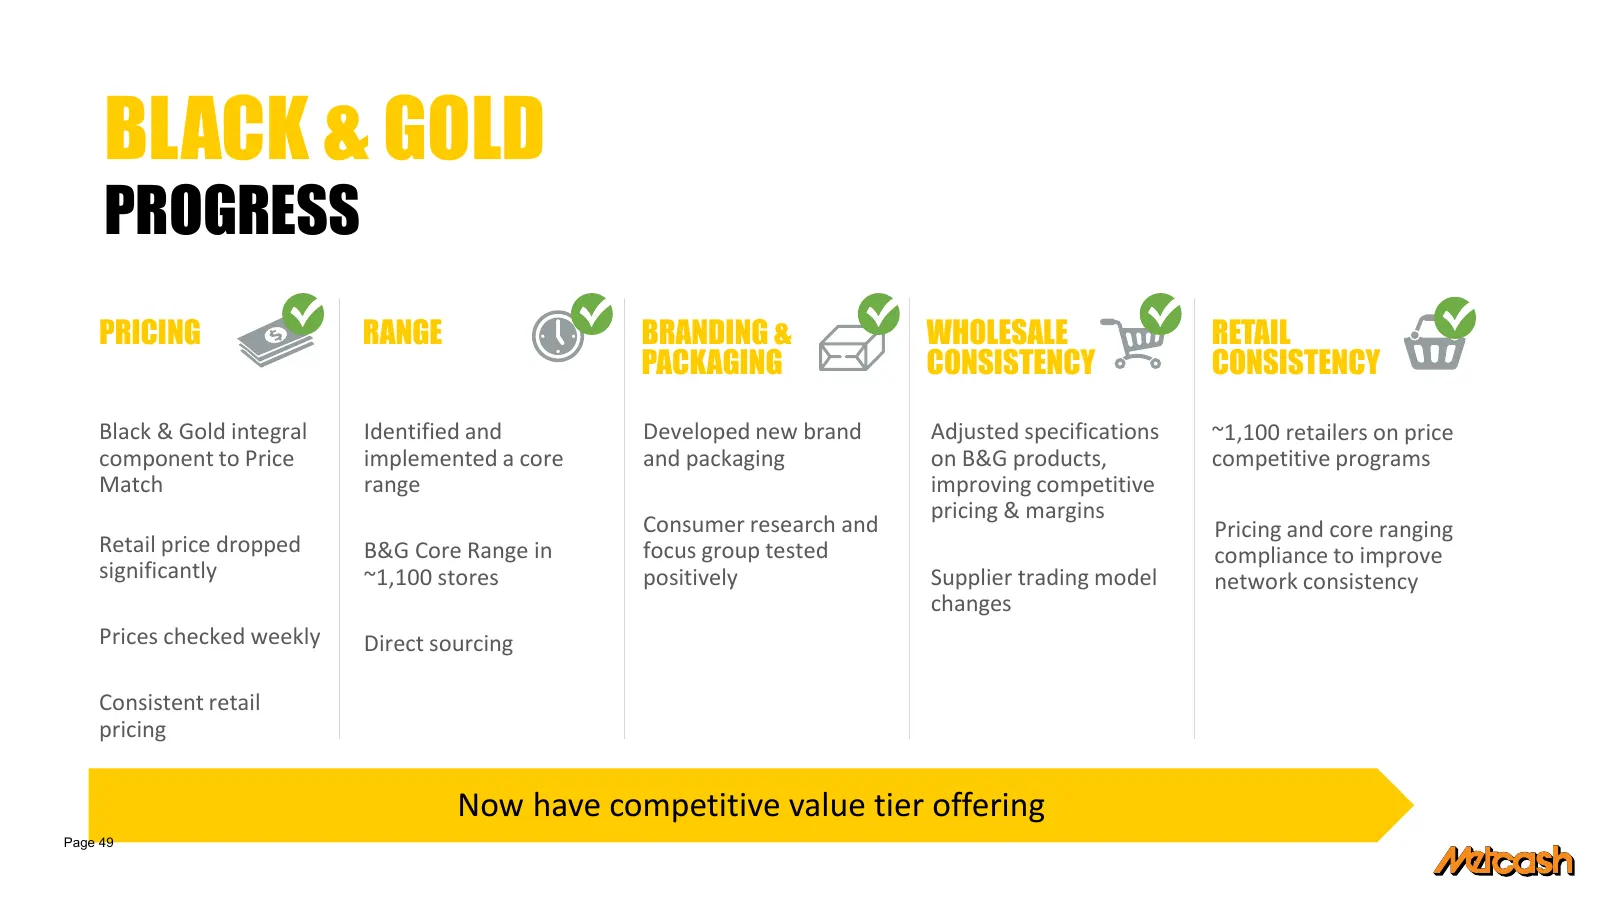
BLACK & GOLD PROGRESS PRICING RANGE BRANDING & WHOLESALE RETAIL PACKAGING CONSISTENCY CONSISTENCY Black & Gold integral Identified and Developed new brand Adjusted specifications ~1,100 retailers on price component to Price implemented a core and packaging on B&G products, competitive programs Match
Slide 11: Food & Grocery
FOOD & GROCERY STEVEN CAIN CEO SUPERMARKETS Page 50
Slide 12: Diamond transformation
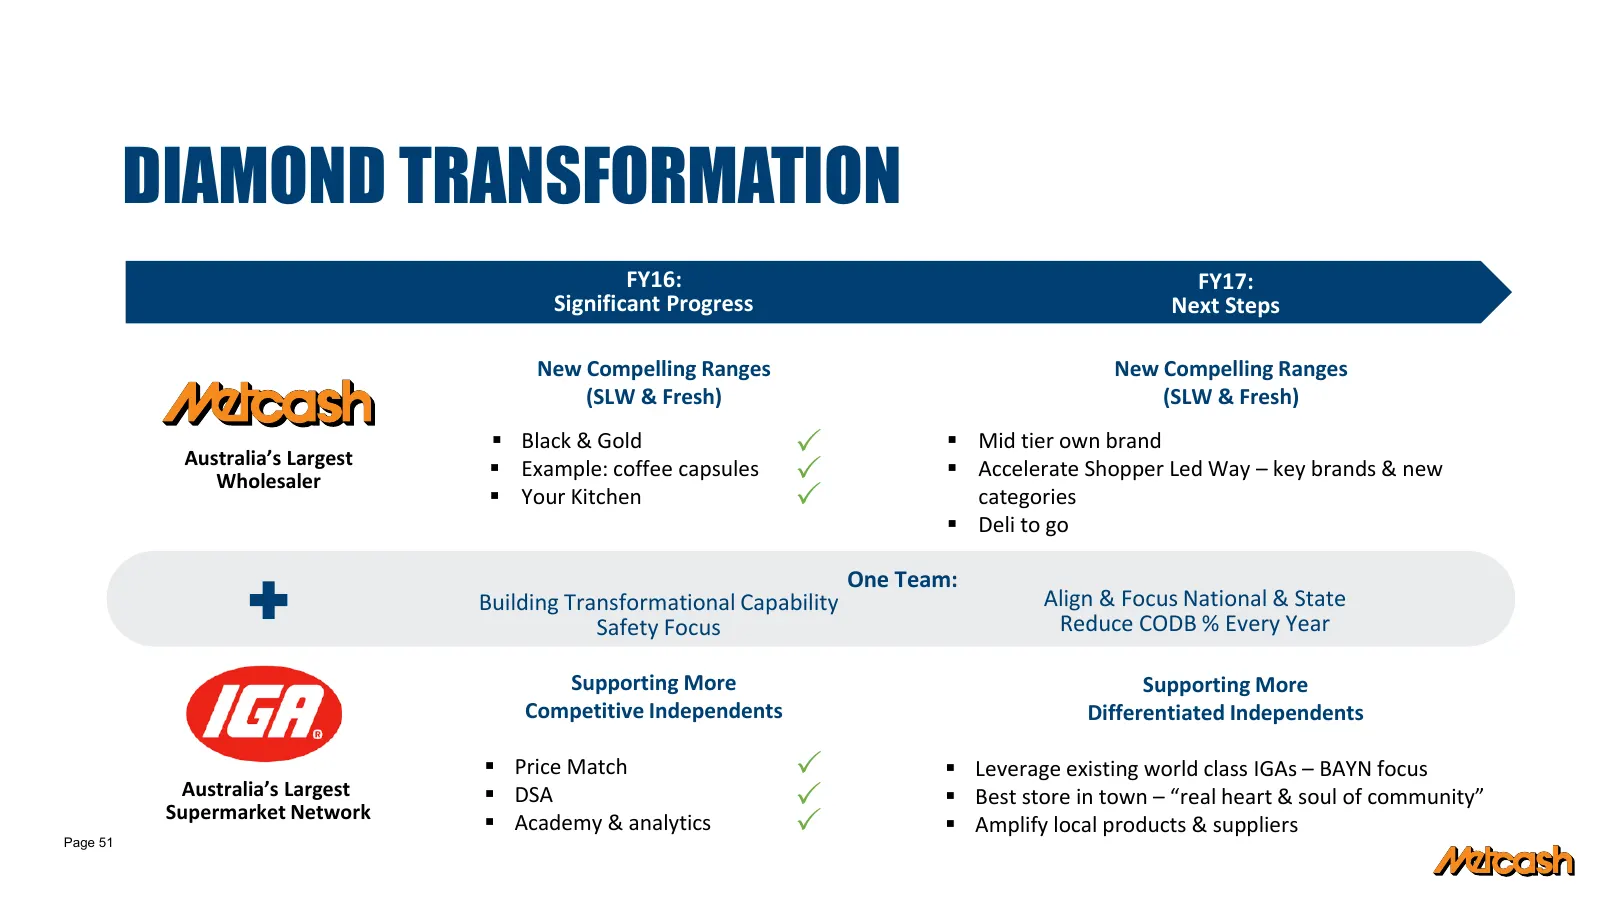
DIAMOND TRANSFORMATION FY16: FY17: Significant Progress Next Steps New Compelling Ranges New Compelling Ranges (SLW & Fresh) (SLW & Fresh) Australia’s Largest Black & Gold Mid tier own brand Wholesaler Example: coffee capsules Accelerate Shopper Led Way – key brands & new Your Kitchen
Slide 13: Convenience
CONVENIENCE PETER STRUCK CEO CONVENIENCE Page 52
Slide 14: The market: petrol & convenience distribution $8B
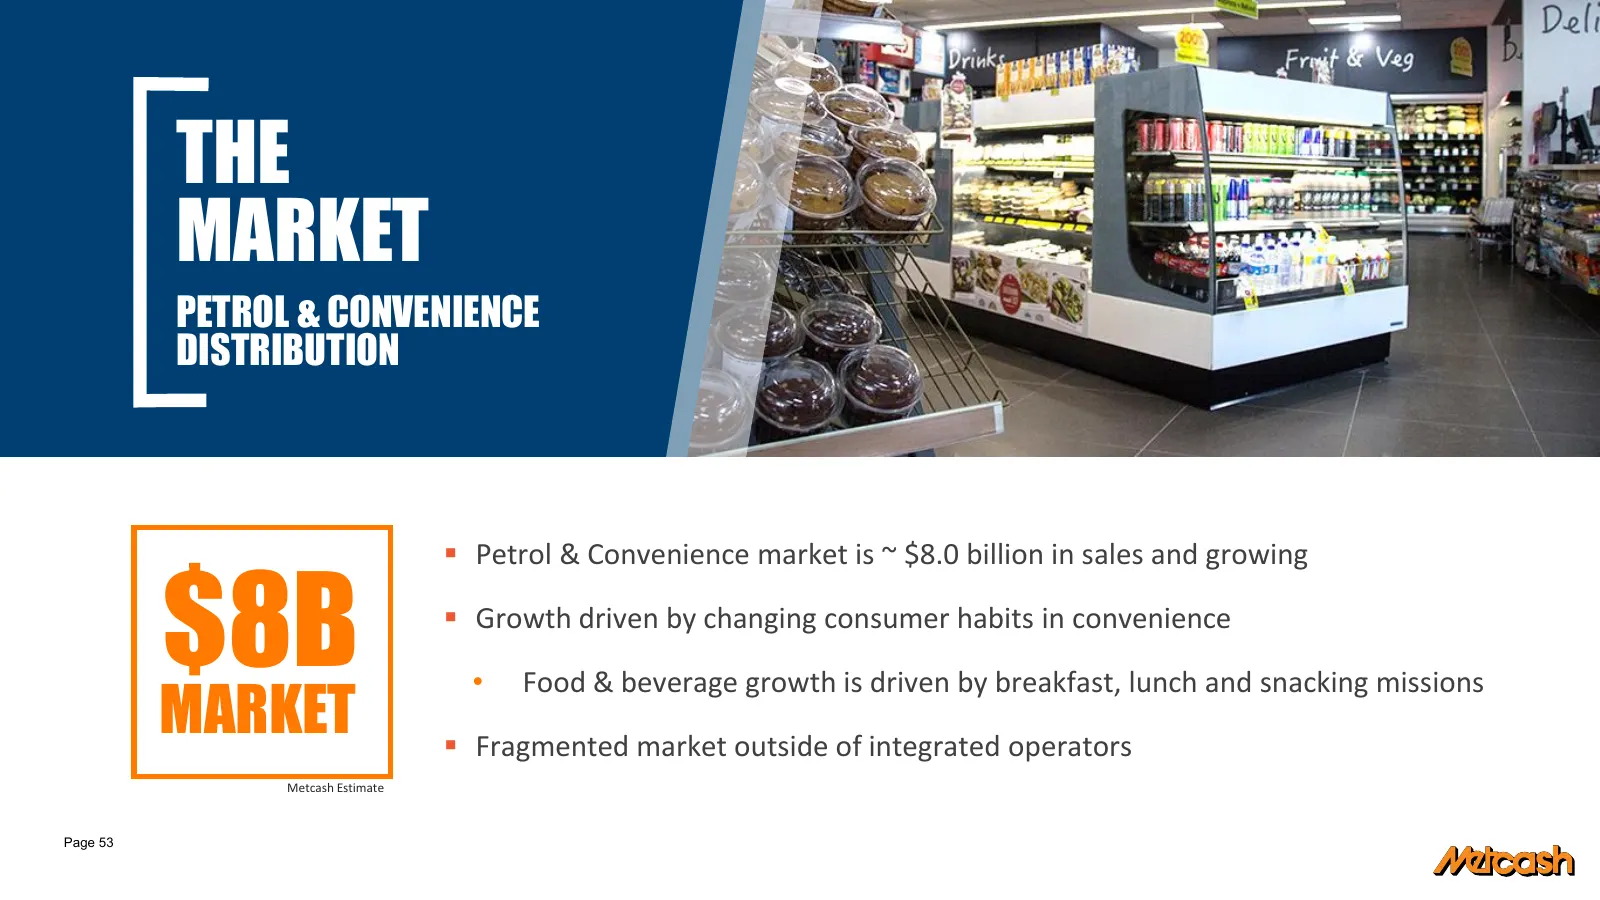
THE MARKET PETROL & CONVENIENCE DISTRIBUTION Petrol & Convenience market is ~ $8.0 billion in sales and growing $8B $5B Growth driven by changing consumer habits in convenience • Food & beverage growth is driven by breakfast, lunch and snacking missions MARKET Fragmented market outside of inte
Slide 15: The market: wholesale distribution $5B
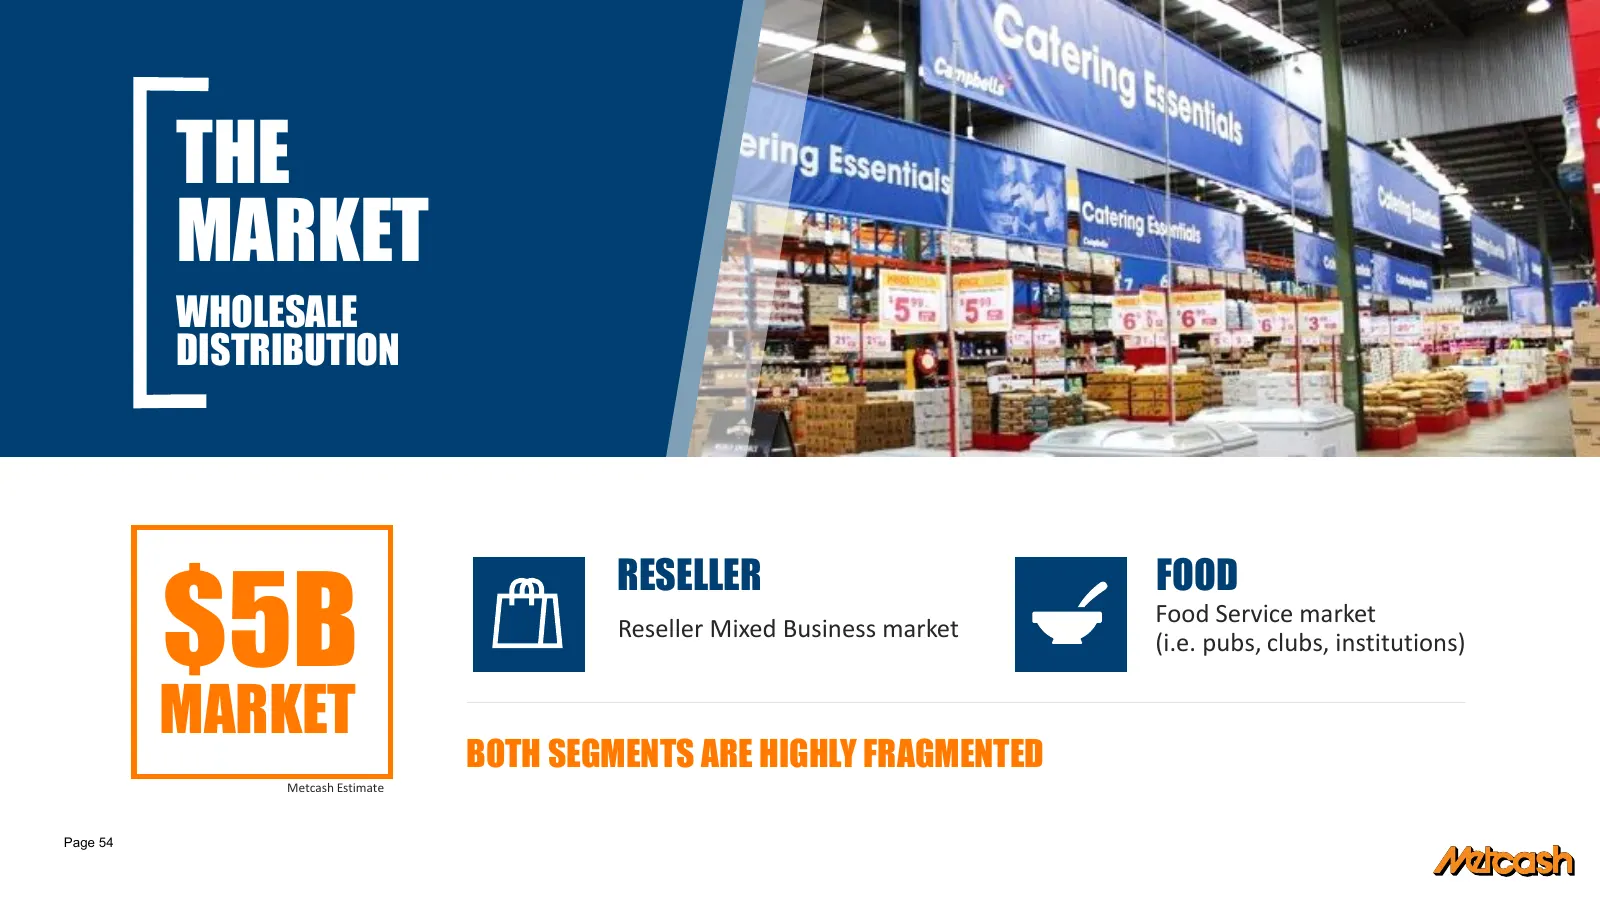
THE MARKET WHOLESALE DISTRIBUTION $5B RESELLER FOOD Food Service market Reseller Mixed Business market (i.e. pubs, clubs, institutions) MARKET BOTH SEGMENTS ARE HIGHLY FRAGMENTED Metcash Estimate Page 54
Slide 16: Convenience: one solution
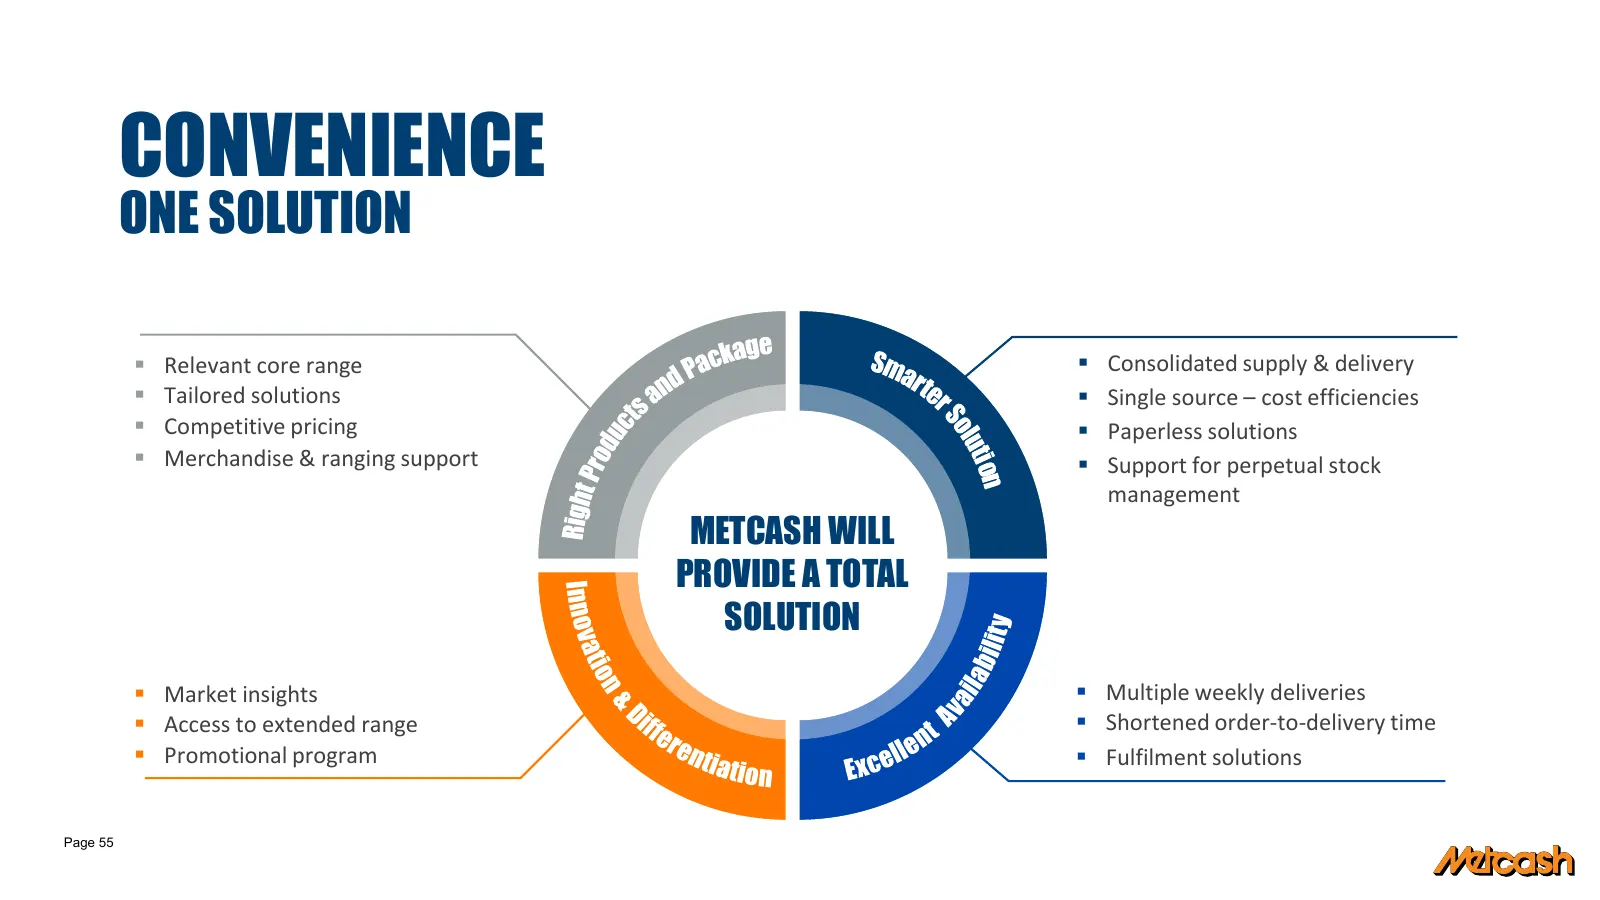
CONVENIENCE ONE SOLUTION Relevant core range Consolidated supply & delivery Tailored solutions Single source – cost efficiencies Competitive pricing Paperless solutions Merchandise & ranging support Support for perpetual stock management METCASH WILL PROVIDE A TOTAL SOLUTION Market
Slide 17: CSD key areas of focus
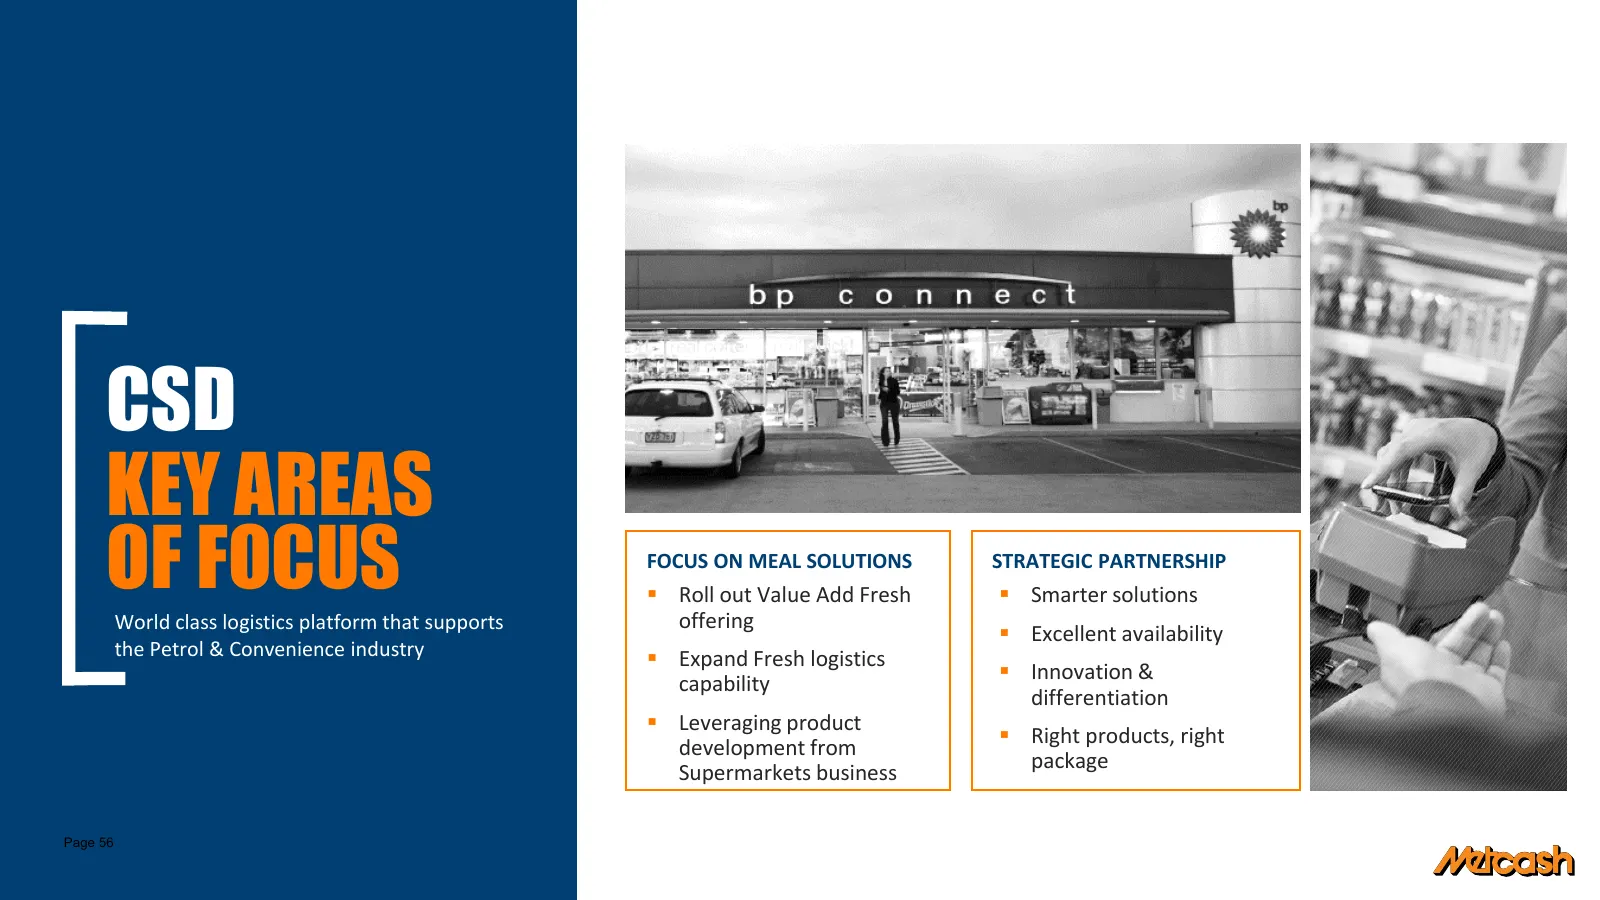
CSD KEY AREAS OF FOCUS FOCUS ON MEAL SOLUTIONS Roll out Value Add Fresh offering STRATEGIC PARTNERSHIP Smarter solutions World class logistics platform that supports Excellent availability the Petrol & Convenience industry Expand Fresh logistics Innovation & capability differentiation Le
Slide 18: Campbells key areas of focus
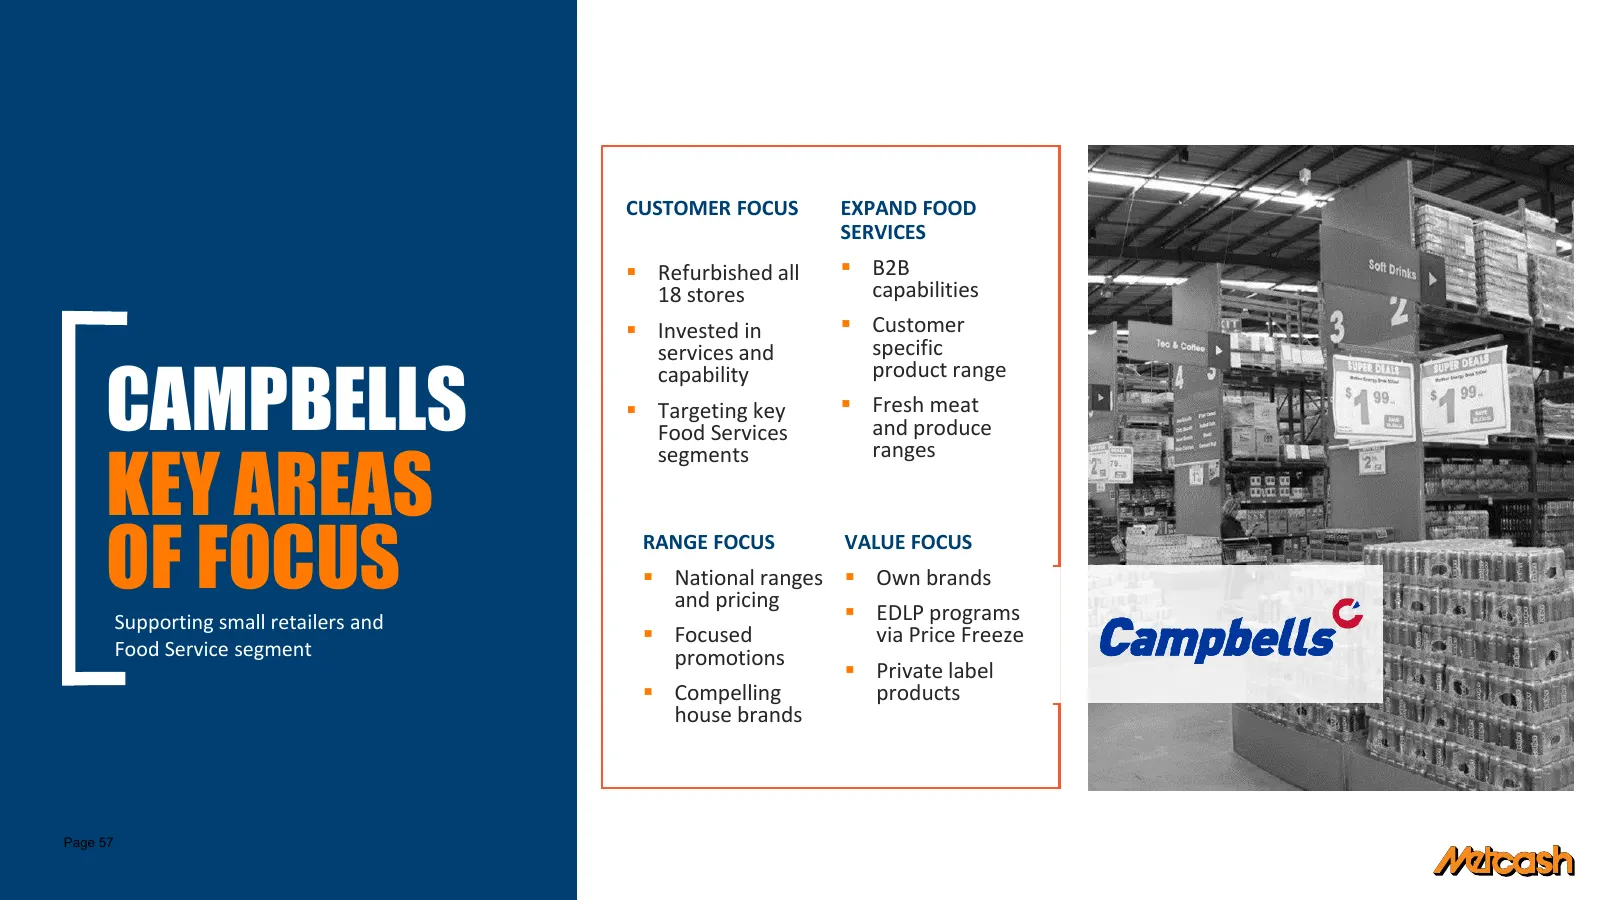
CUSTOMER FOCUS EXPAND FOOD SERVICES Refurbished all B2B 18 stores capabilities Invested in Customer services and specific CAMPBELLS capability product range Targeting key Fresh meat Food Services and produce KEY AREAS segments ranges OF FOCUS RANGE FOCUS National ranges and pricing
Slide 19: Campbells refurbishment
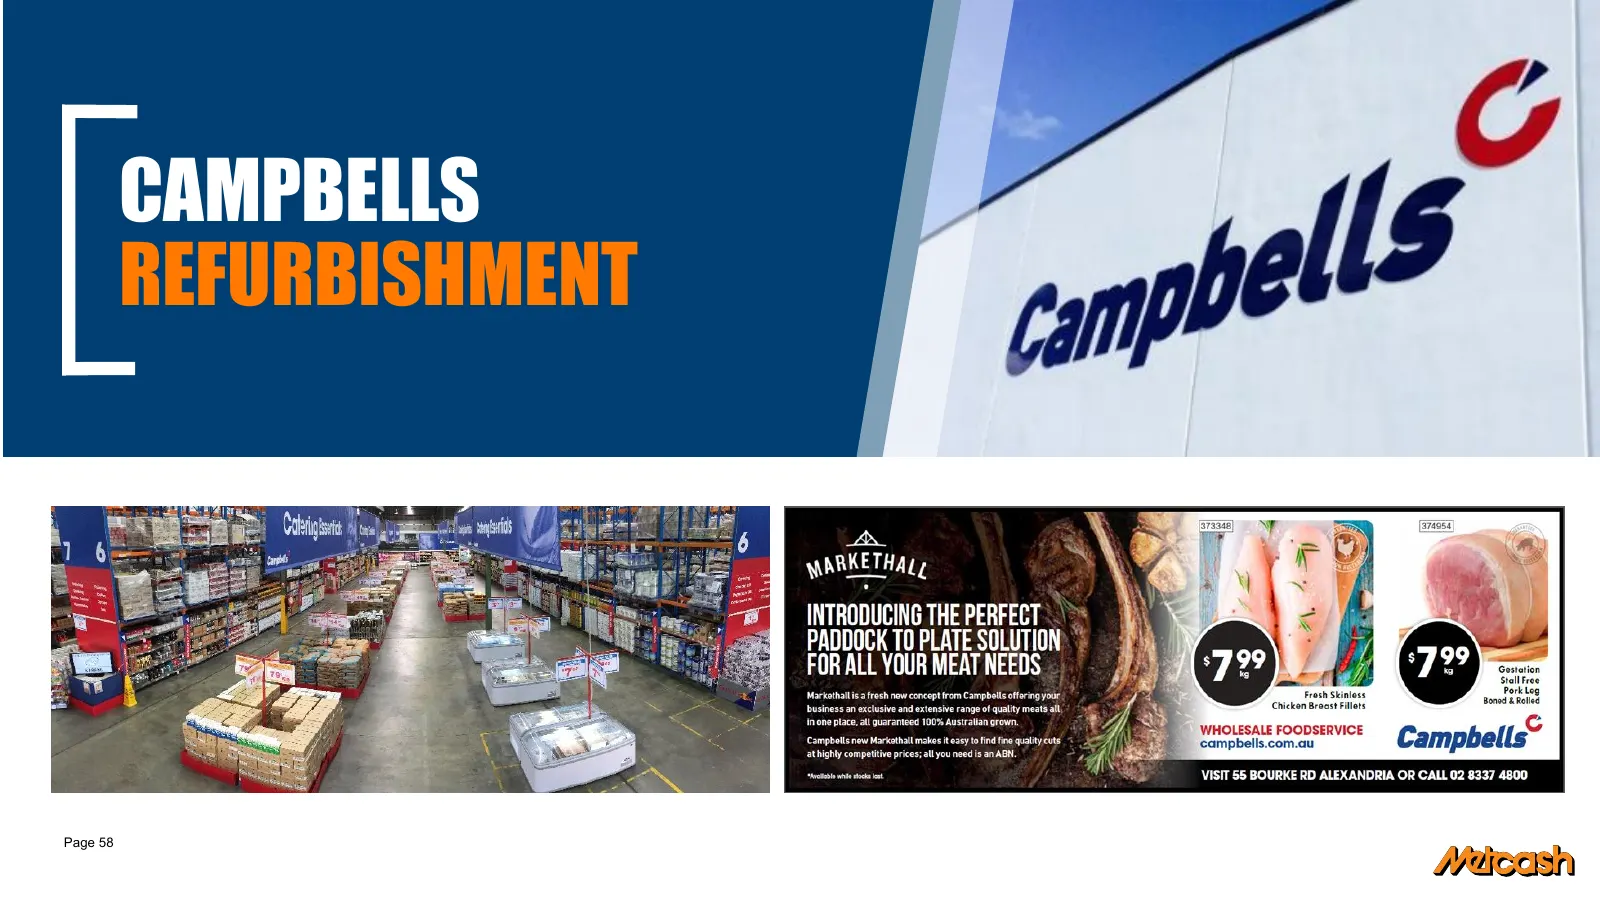
CAMPBELLS REFURBISHMENT Page 58
Slide 20: Campbells food services focus
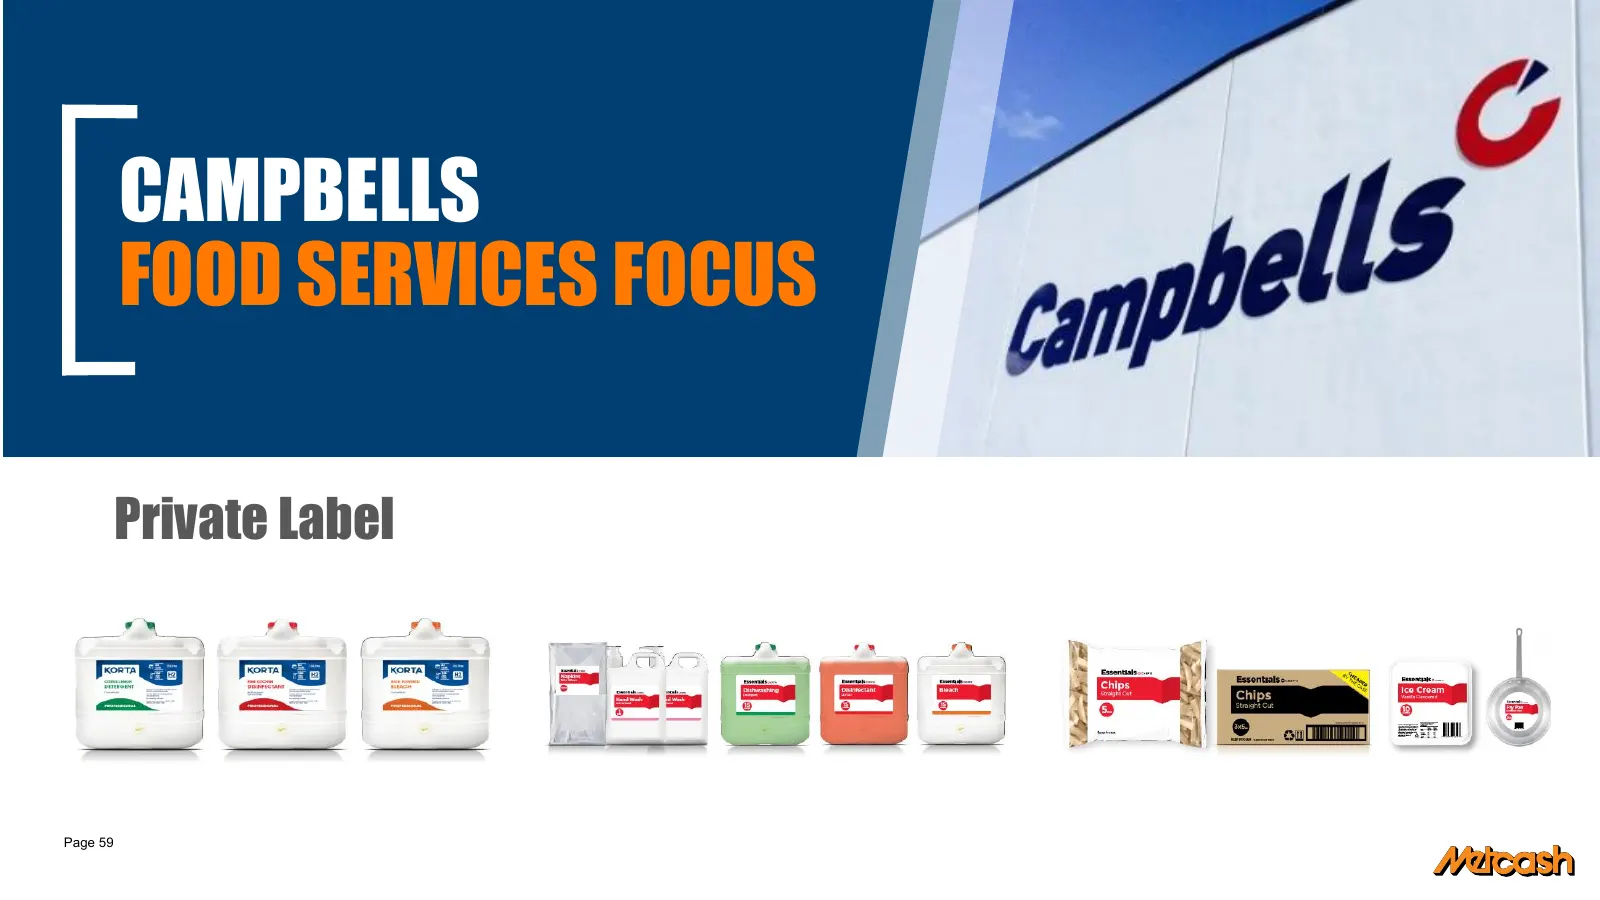
CAMPBELLS FOOD SERVICES FOCUS Private Label Page 59
Slide 21: Campbells B2B capability
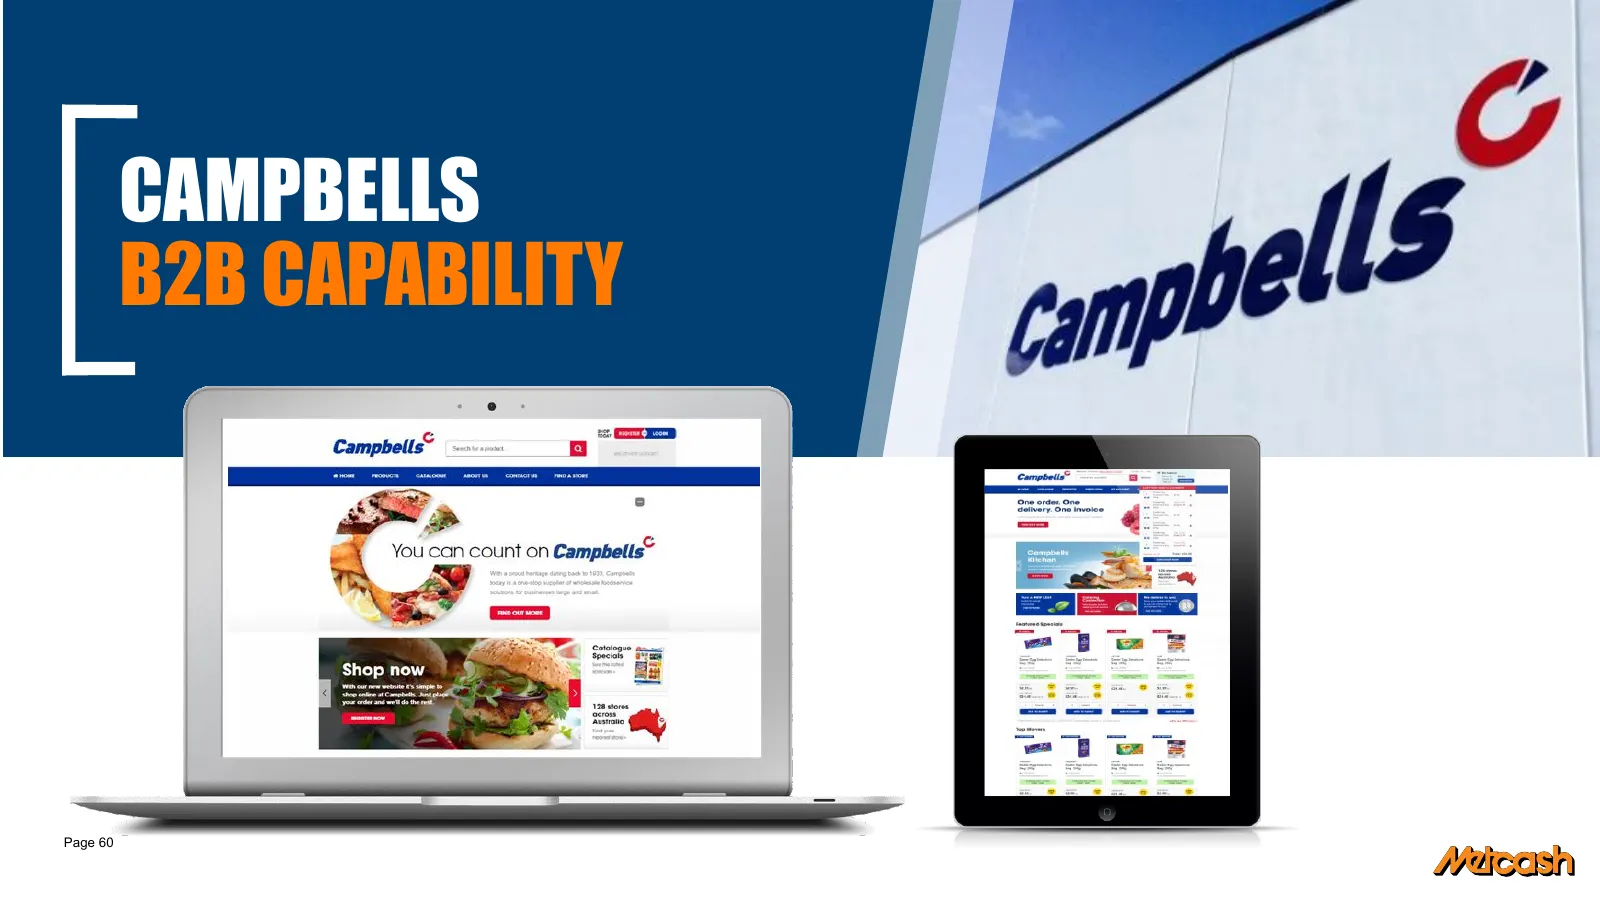
CAMPBELLS B2B CAPABILITY Page 60
Slide 22: ALM | Australian Liquor Marketers
ALM | AUSTRALIAN LIQUOR MARKETERS SCOTT MARSHALL CEO ALM Page 61
Slide 23: Total packaged retail market growth
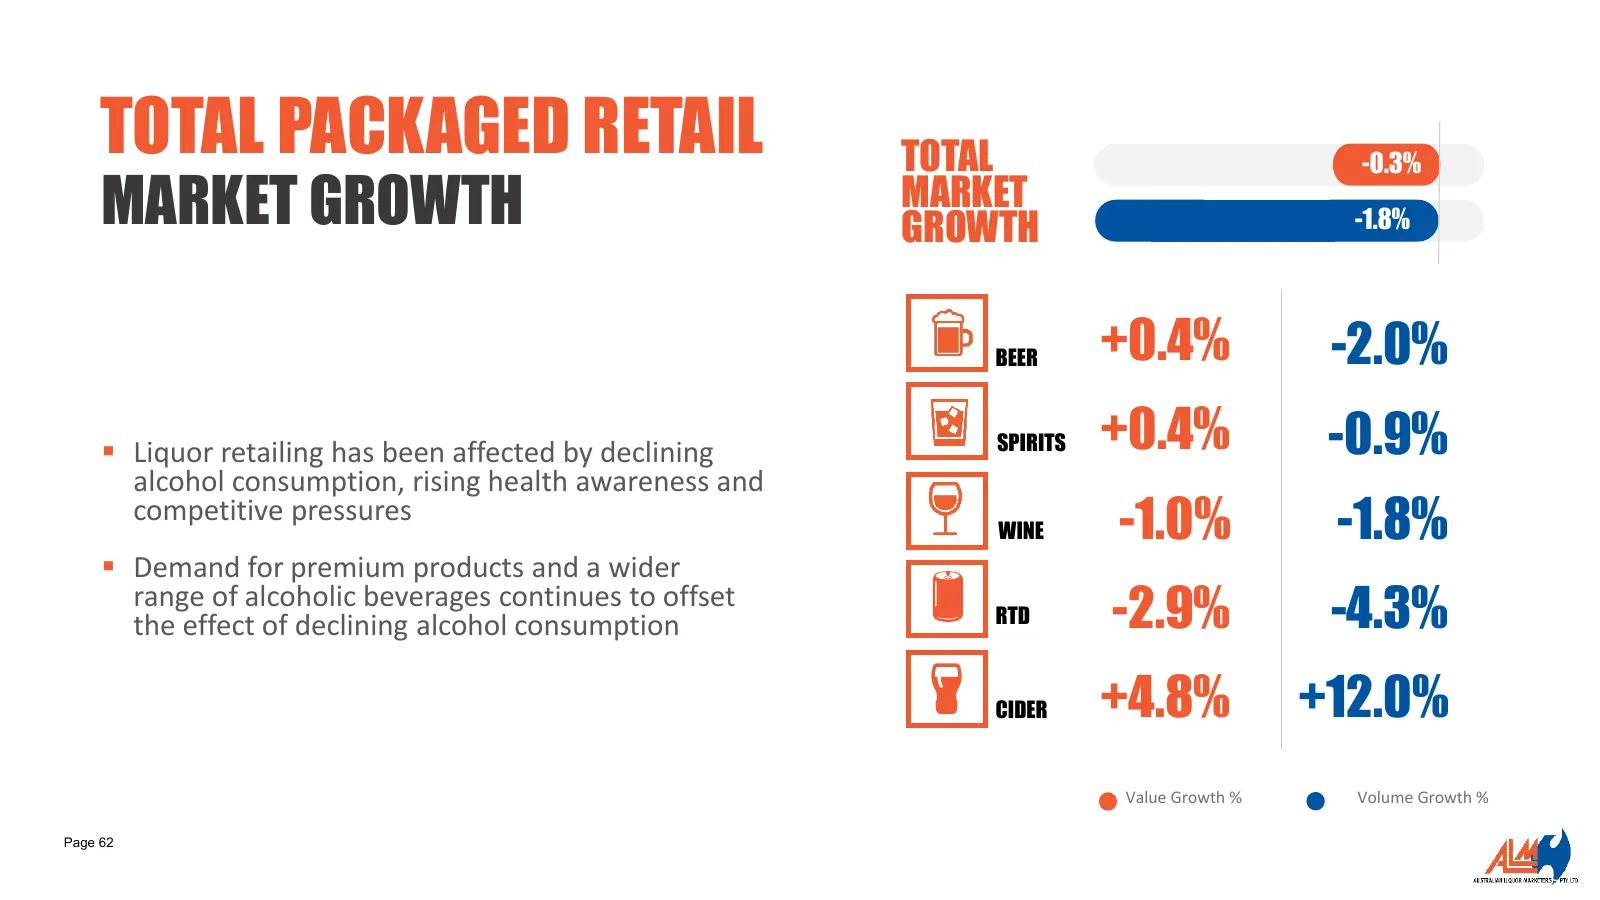
TOTAL PACKAGED RETAIL TOTAL -0.3% MARKET GROWTH MARKET GROWTH -1.8% BEER +0.4% -2.0% Liquor retailing has been affected by declining SPIRITS +0.4% -0.9% alcohol consumption, rising health awareness and competitive pressures WINE -1.0% -1.8% Demand for premium products and a wider range of alcoho
Slide 24: IBA performance
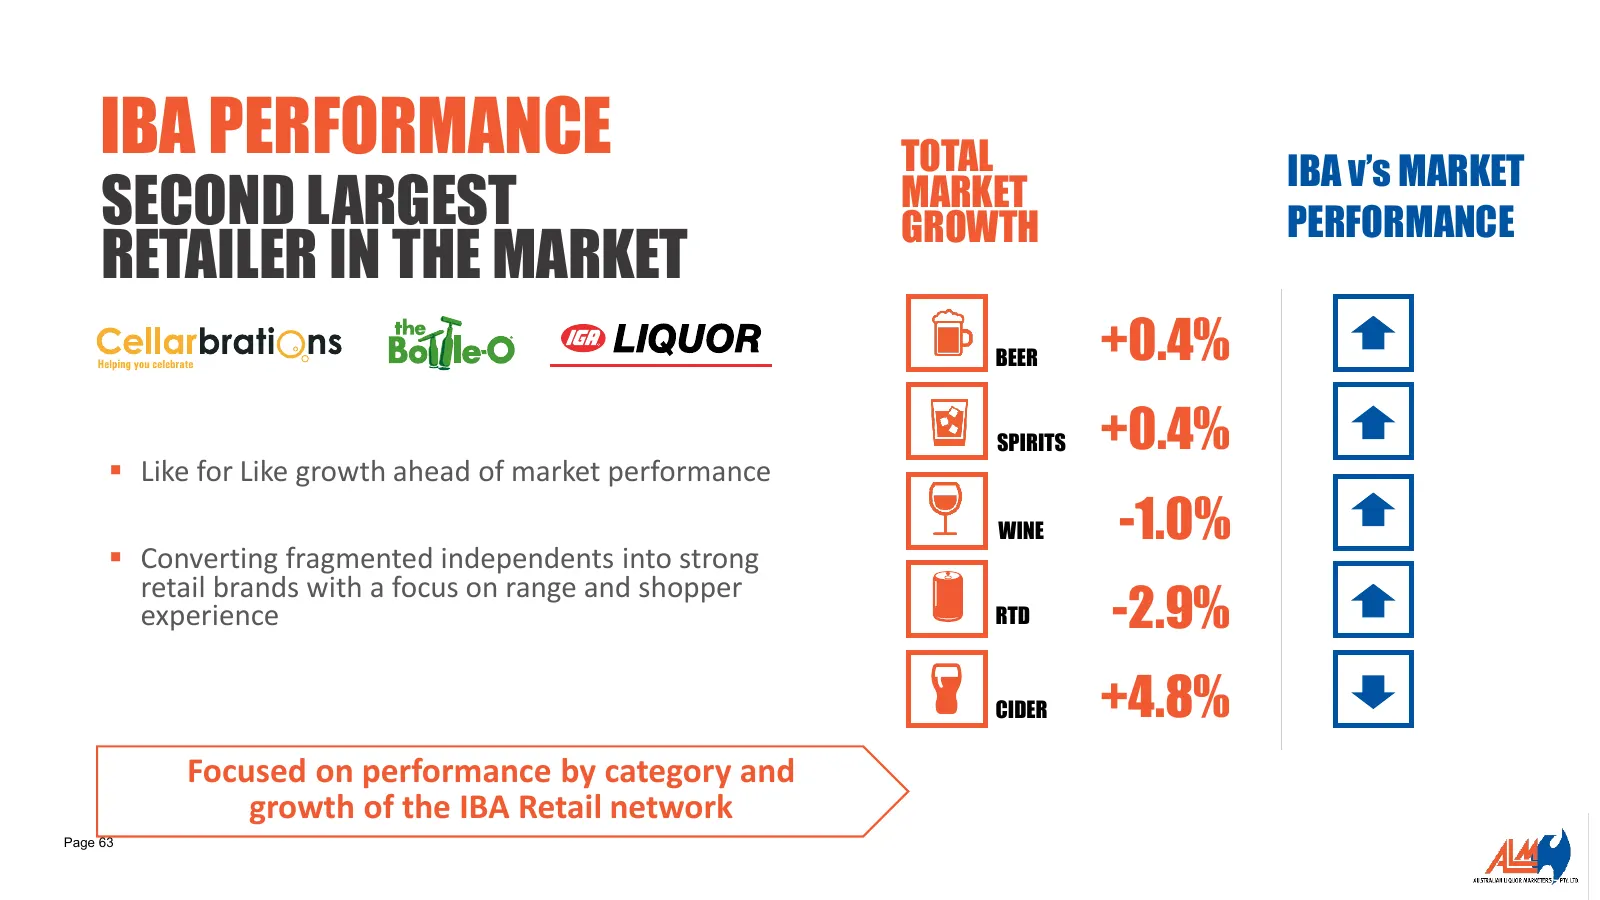
IBA PERFORMANCE TOTAL IBA v’s MARKET SECOND LARGEST MARKET GROWTH PERFORMANCE RETAILER IN THE MARKET BEER +0.4% SPIRITS +0.4% Like for Like growth ahead of market performance WINE -1.0% Converting fragmented independents into strong retail brands with a focus on range and shopper experience RTD
Slide 25: Key areas of focus
IBA STORE GROWTH EXTEND ALM FOOTPRINT KEY AREAS IBA CATEGORY GROWTH OF FOCUS NETWORK INVESTMENT BRAND & MARKETING FOCUS Page 64
Slide 26: IBA growth
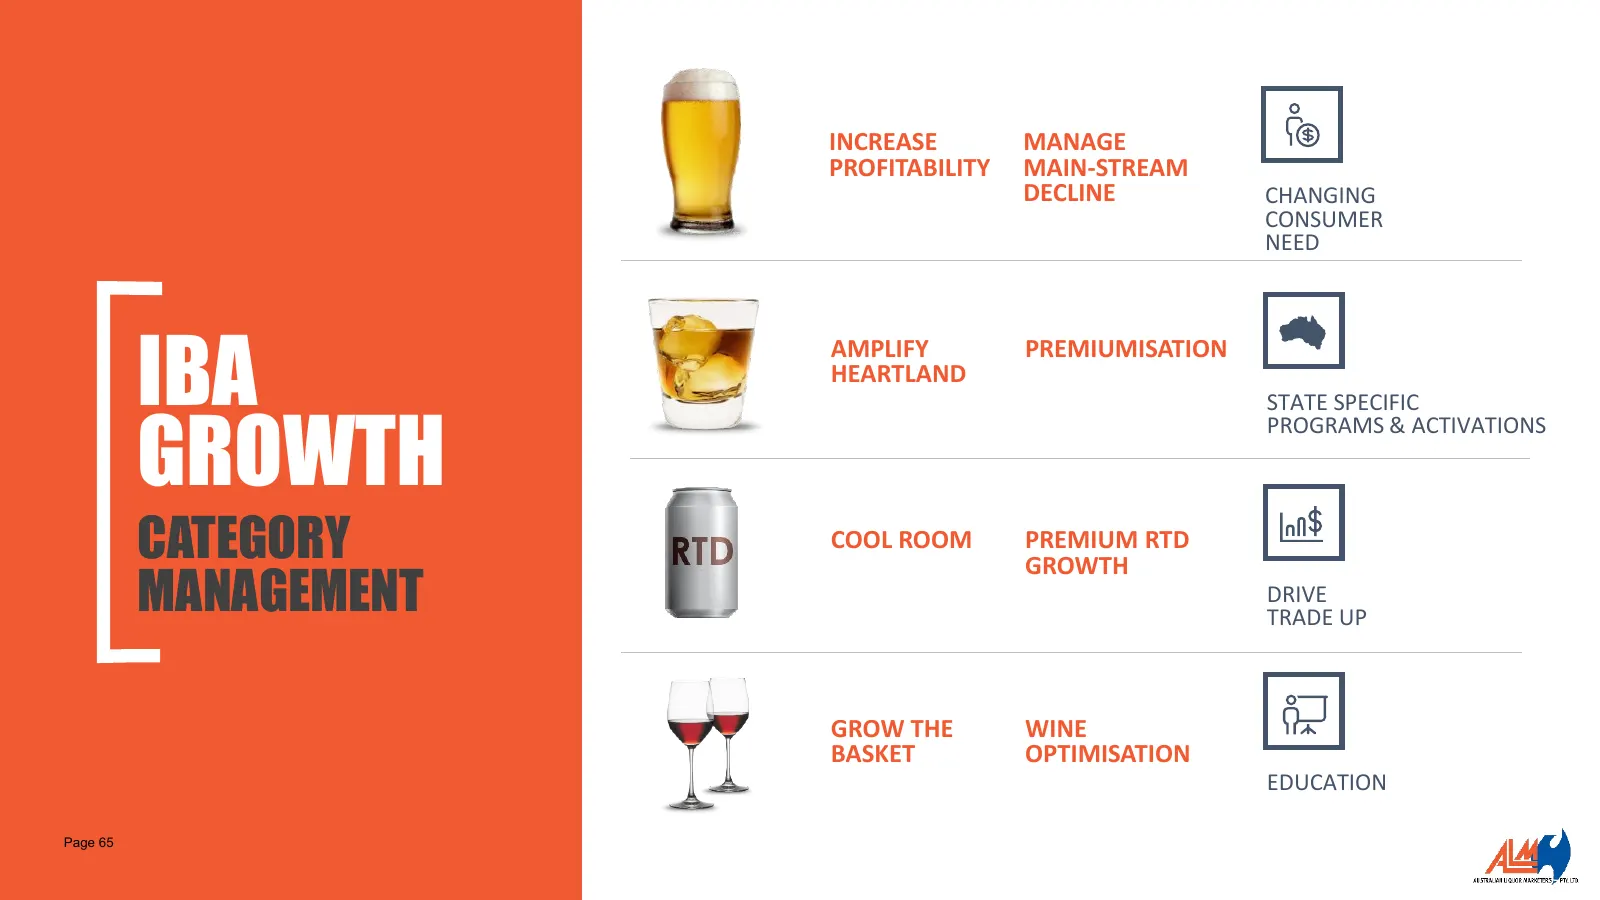
INCREASE MANAGE PROFITABILITY MAIN-STREAM DECLINE CHANGING CONSUMER NEED IBA AMPLIFY PREMIUMISATION HEARTLAND STATE SPECIFIC GROWTH PROGRAMS & ACTIVATIONS CATEGORY COOL ROOM PREMIUM RTD GROWTH MANAGEMENT DRIVE TRADE UP GROW THE WINE BASKET OPTIMISATION EDUCATION Page 65
Slide 27: IBA growth: private label and control brands
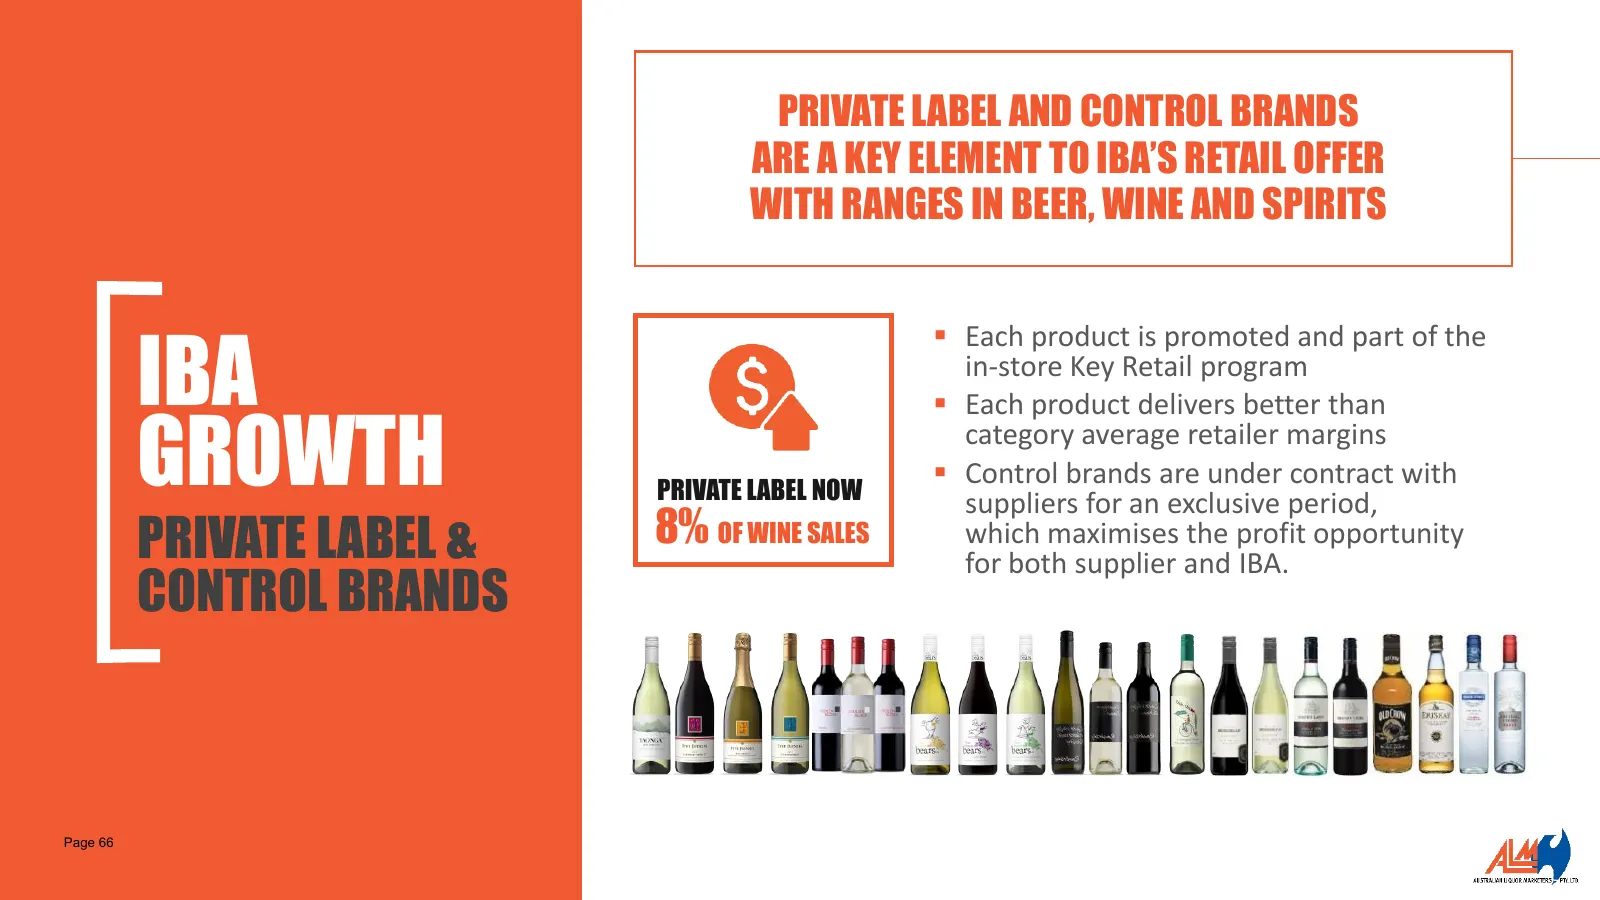
PRIVATE LABEL AND CONTROL BRANDS ARE A KEY ELEMENT TO IBA’S RETAIL OFFER WITH RANGES IN BEER, WINE AND SPIRITS IBA Each product is promoted and part of the in-store Key Retail program Each product delivers better than GROWTH PRIVATE LABEL NOW category average retailer margins Control brands ar
Slide 28: Network investment
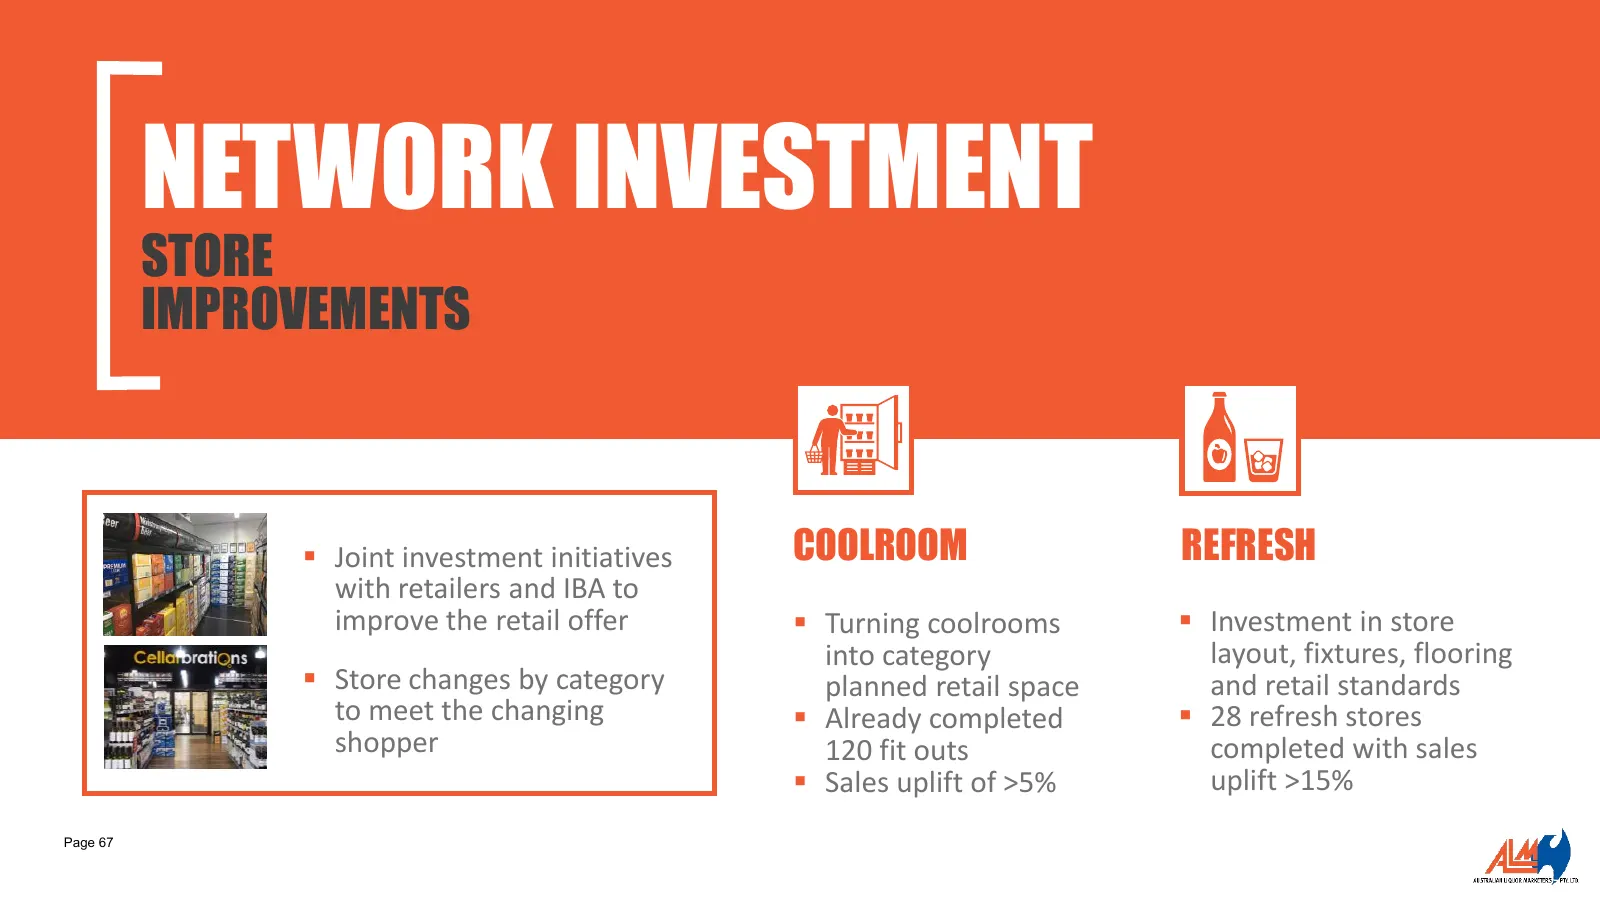
NETWORK INVESTMENT STORE IMPROVEMENTS Joint investment initiatives COOLROOM REFRESH with retailers and IBA to improve the retail offer Turning coolrooms Investment in store into category layout, fixtures, flooring Store changes by category planned retail space and retail standards to meet th
Slide 29: Brand & marketing
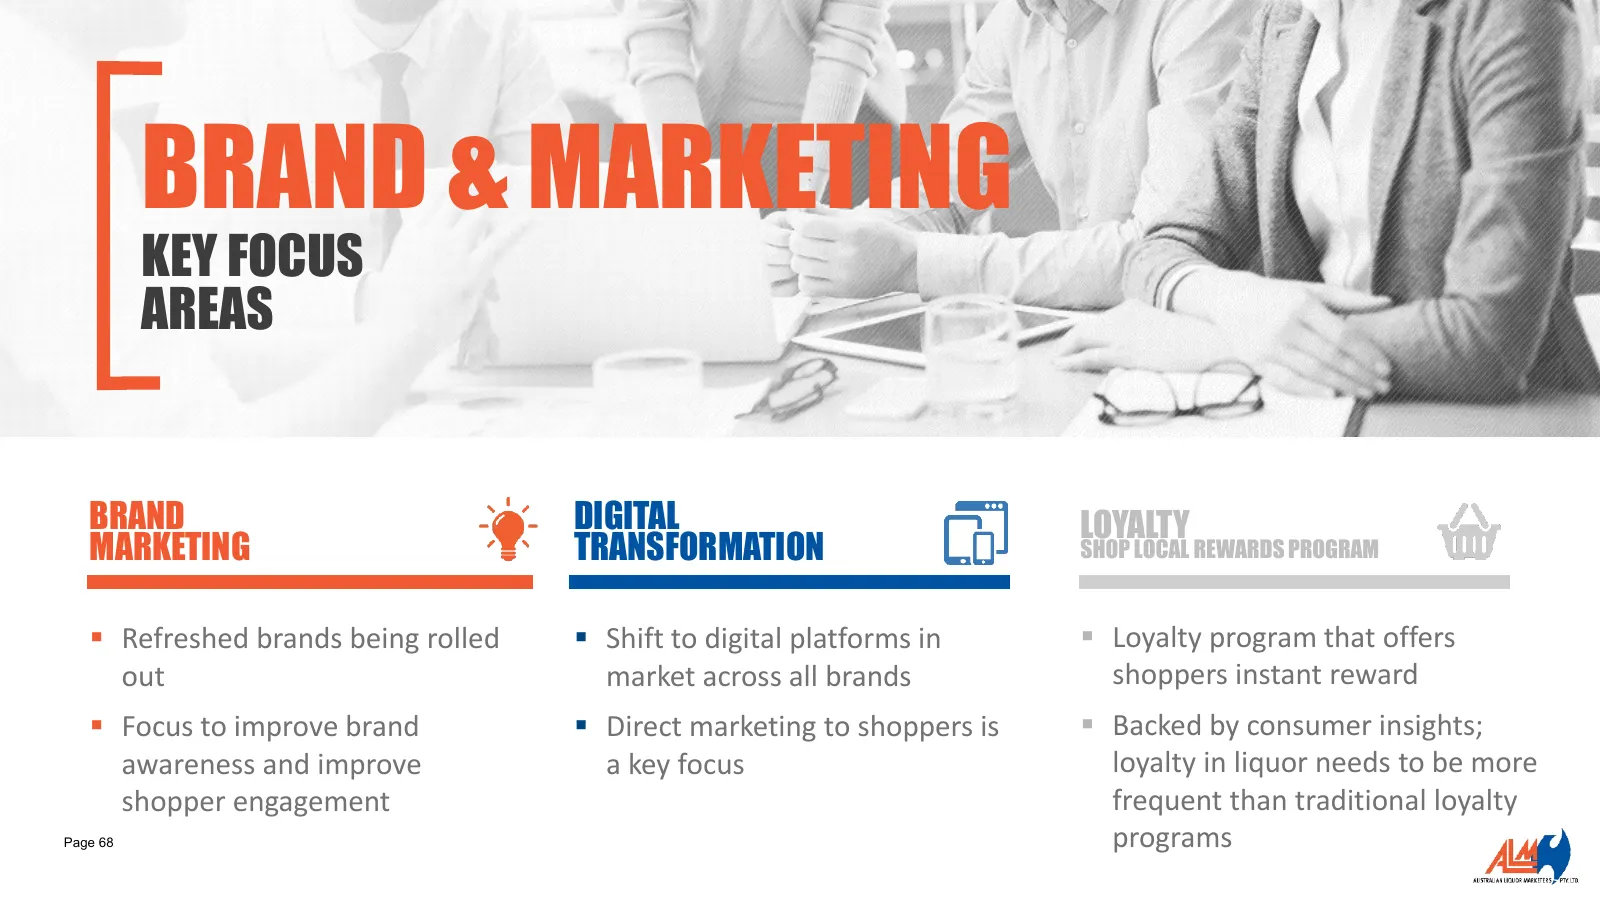
BRAND & MARKETING KEY FOCUS AREAS BRAND DIGITAL LOYALTY MARKETING TRANSFORMATION SHOP LOCAL REWARDS PROGRAM Refreshed brands being rolled Shift to digital platforms in Loyalty program that offers out market across all brands shoppers instant reward Focus to improve brand Direct marketing t
Slide 30: Our brand essence: sharing the passion
OUR BRAND ESSENCE We share our passion and expertise with our customers, so that everyone has a great experience in SHARING Cellarbrations stores THE PASSION Page 69
Slide 31: Our brand essence: the genuine alternative
OUR BRAND ESSENCE Our ability to combine professional, efficient operations with authentic, welcoming THE GENUINE service, ensuring that customers have a fun, easy experience when they shop at The Bottle-O ALTERNATIVE Page 70
Slide 32: FY16 key focus
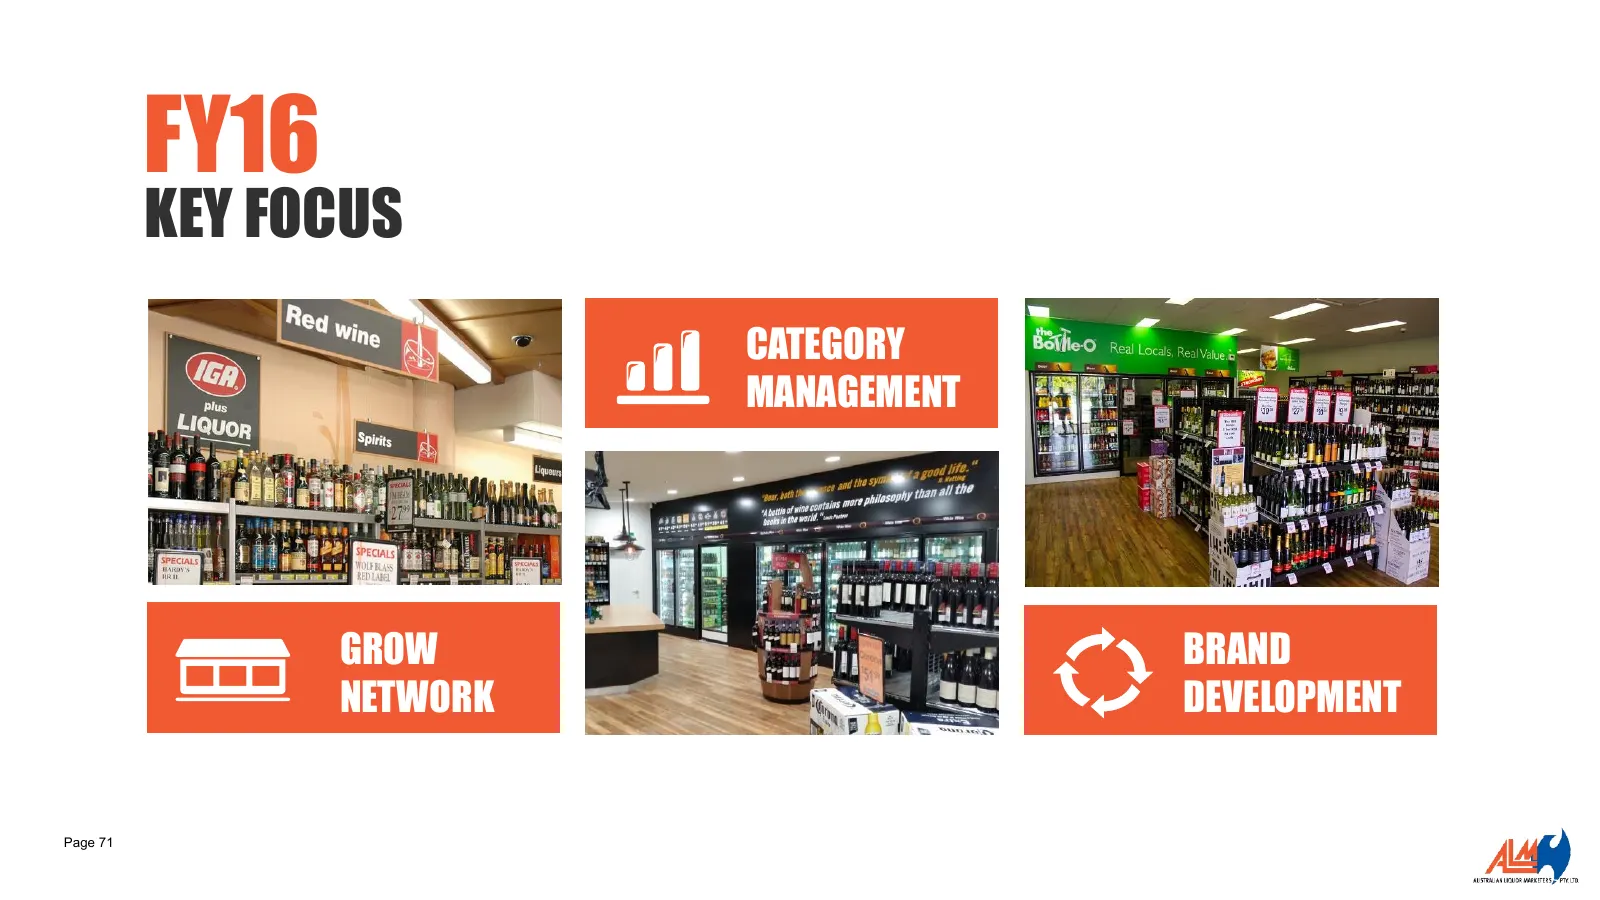
FY16 KEY FOCUS CATEGORY MANAGEMENT GROW BRAND NETWORK DEVELOPMENT Page 71
Slide 33: Mitre 10
MITRE 10 MARK LAIDLAW CEO Mitre 10 Page 72
Slide 34: $27b hardware market
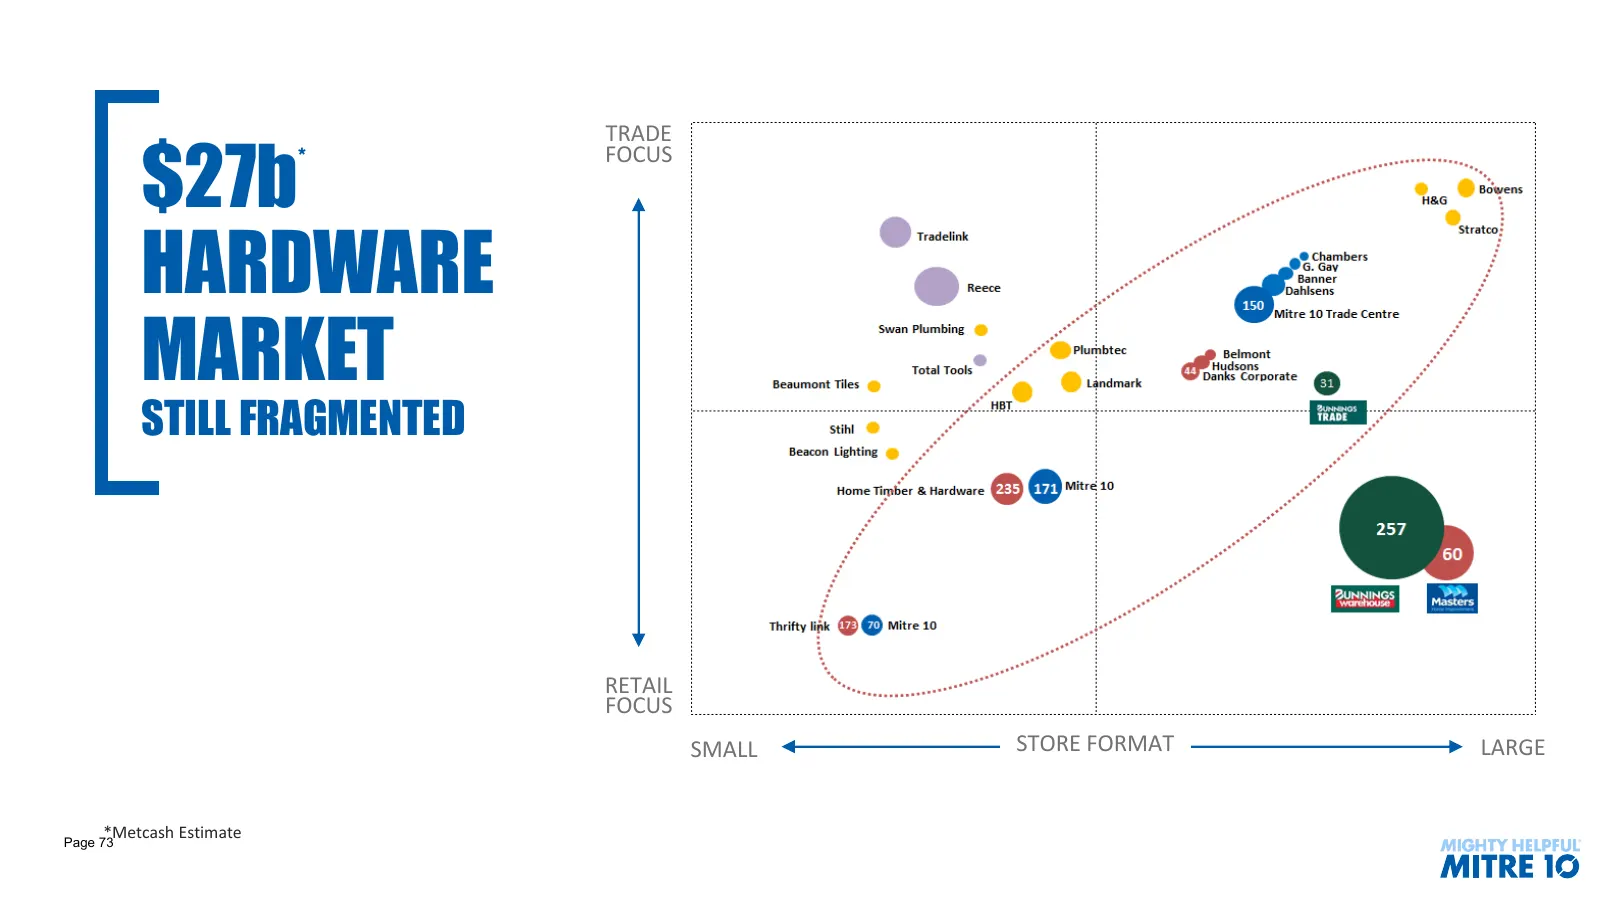
TRADE $27b * FOCUS HARDWARE MARKET STILL FRAGMENTED RETAIL FOCUS SMALL STORE FORMAT LARGE *Metcash Estimate Page 73
Slide 35: Mitre performance
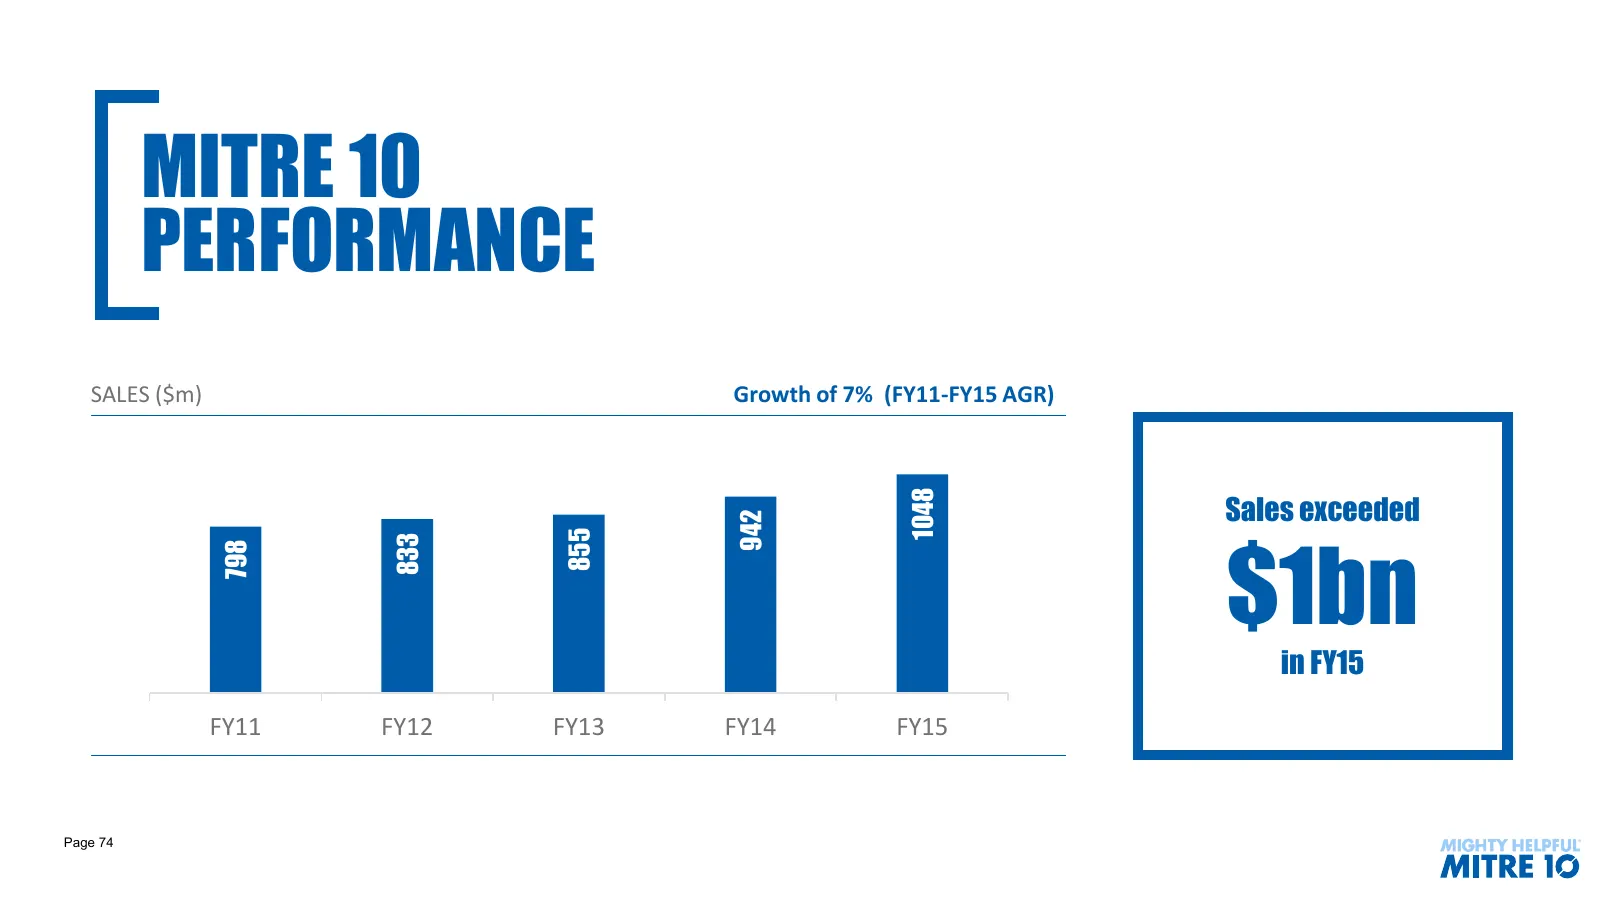
MITRE 10 PERFORMANCE SALES ($m) Growth of 7% (FY11-FY15 AGR) 1048 Sales exceeded 942 855 $1bn 833 798 in FY15 FY11 FY12 FY13 FY14 FY15 Page 74
Slide 36: Mitre initiatives
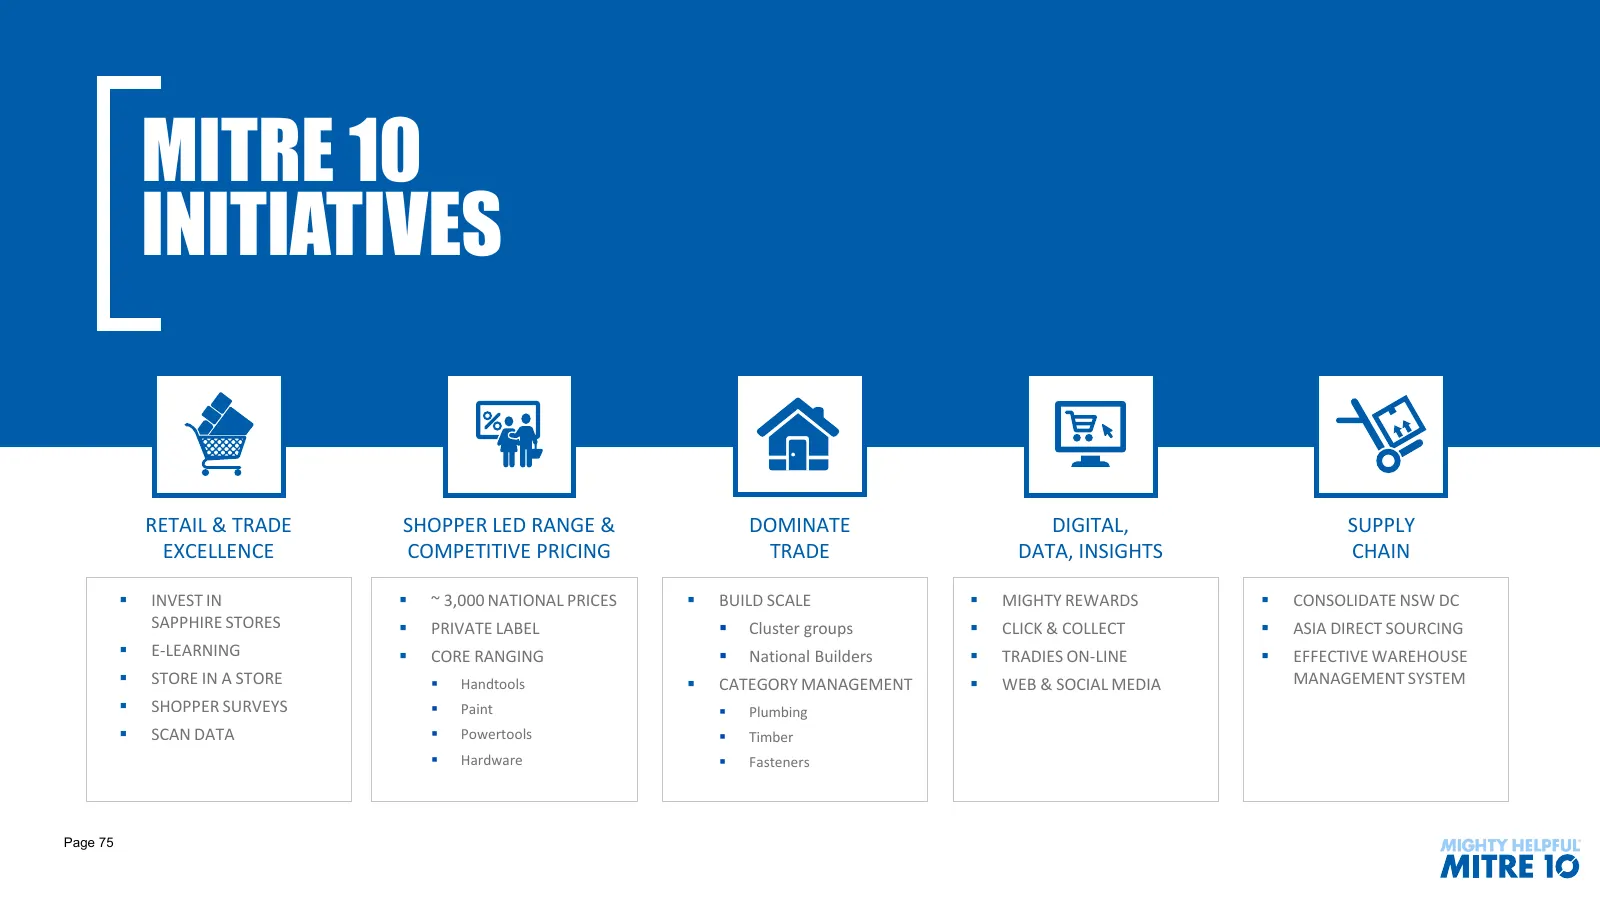
MITRE 10 INITIATIVES RETAIL & TRADE SHOPPER LED RANGE & DOMINATE DIGITAL, SUPPLY EXCELLENCE COMPETITIVE PRICING TRADE DATA, INSIGHTS CHAIN INVEST IN ~ 3,000 NATIONAL PRICES BUILD SCALE MIGHTY REWARDS CONSOLIDATE NSW DC SAPPHIRE STORES PRIVATE LABEL Cluster groups CLICK & COLLECT AS
Slide 37: Retail & trade excellence
RETAIL & TRADE EXCELLENCE Sapphire E-learning Store in a store Page 76
Slide 38: Sapphire stores
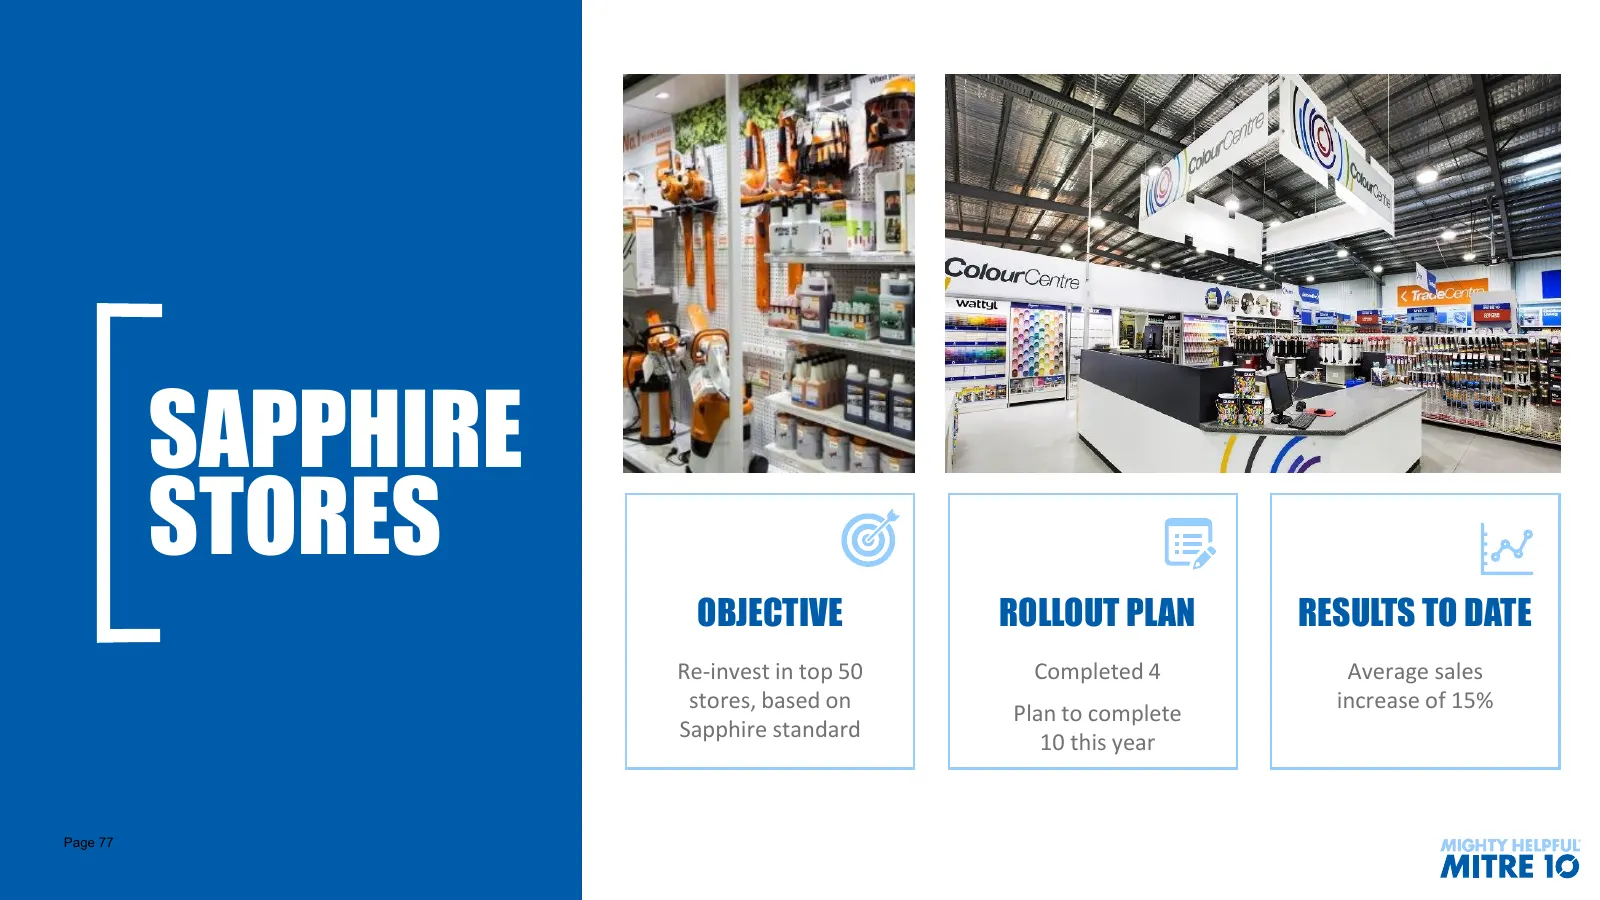
SAPPHIRE STORES OBJECTIVE ROLLOUT PLAN RESULTS TO DATE Re-invest in top 50 Completed 4 Average sales stores, based on increase of 15% Plan to complete Sapphire standard 10 this year Page 77
Slide 39: Sapphire performance
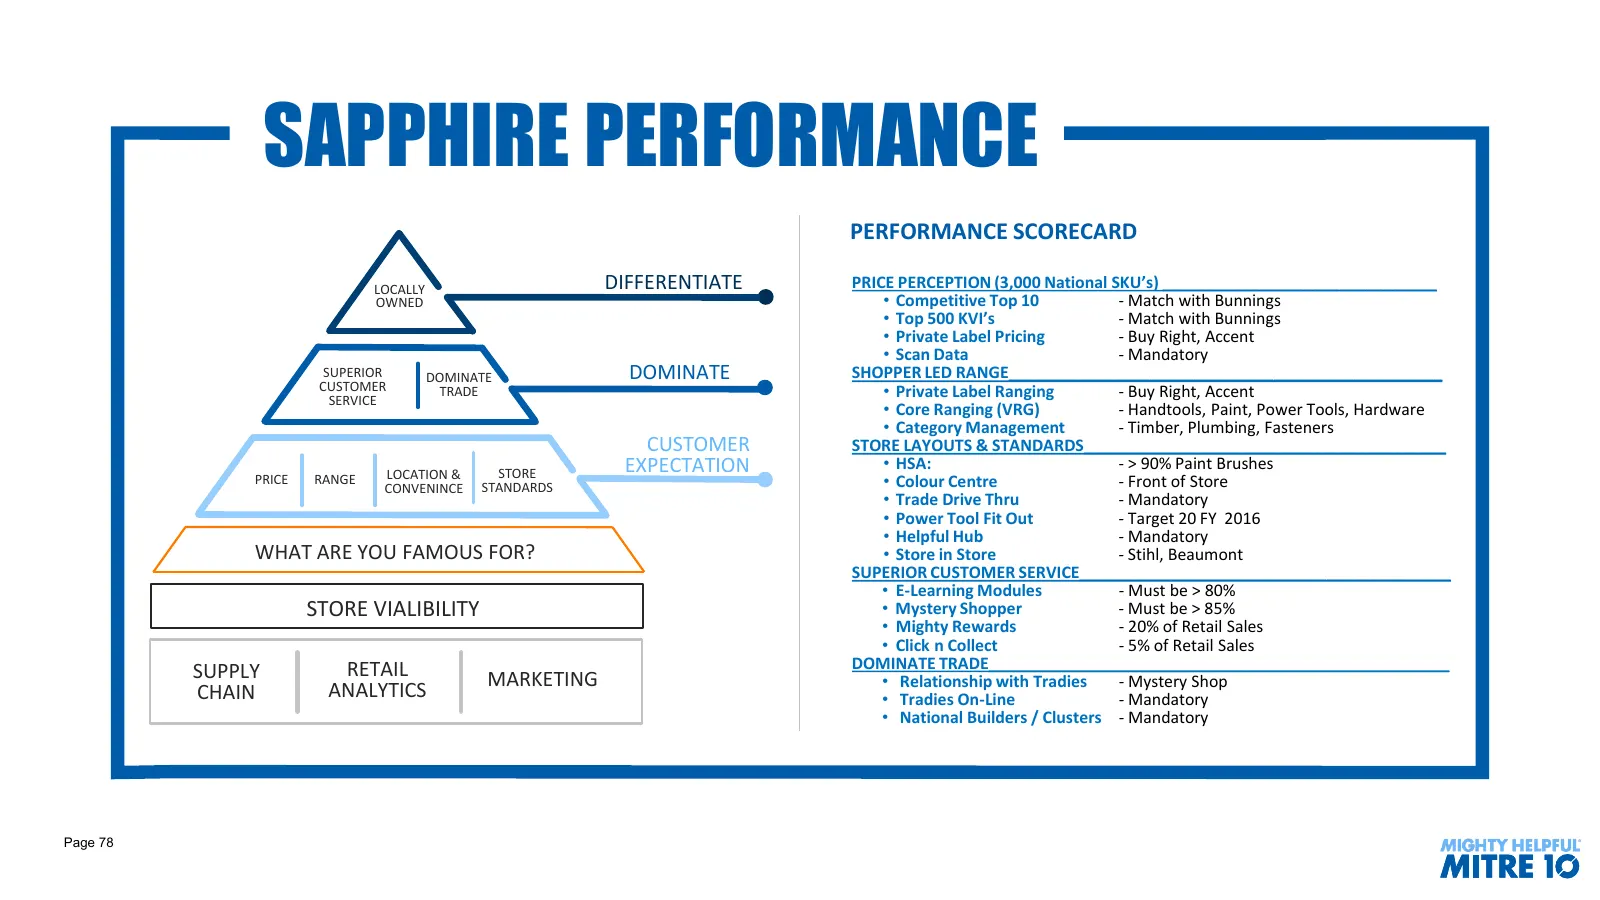
SAPPHIRE PERFORMANCE PERFORMANCE SCORECARD LOCALLY DIFFERENTIATE PRICE PERCEPTION (3,000 National SKU’s) _______________________________ OWNED • Competitive Top 10 - Match with Bunnings • Top 500 KVI’s - Match with Bunnings • Private Label Pricing - Buy Right, Accent • Scan Data - Mandatory SUPERIOR
Slide 40: E-learning
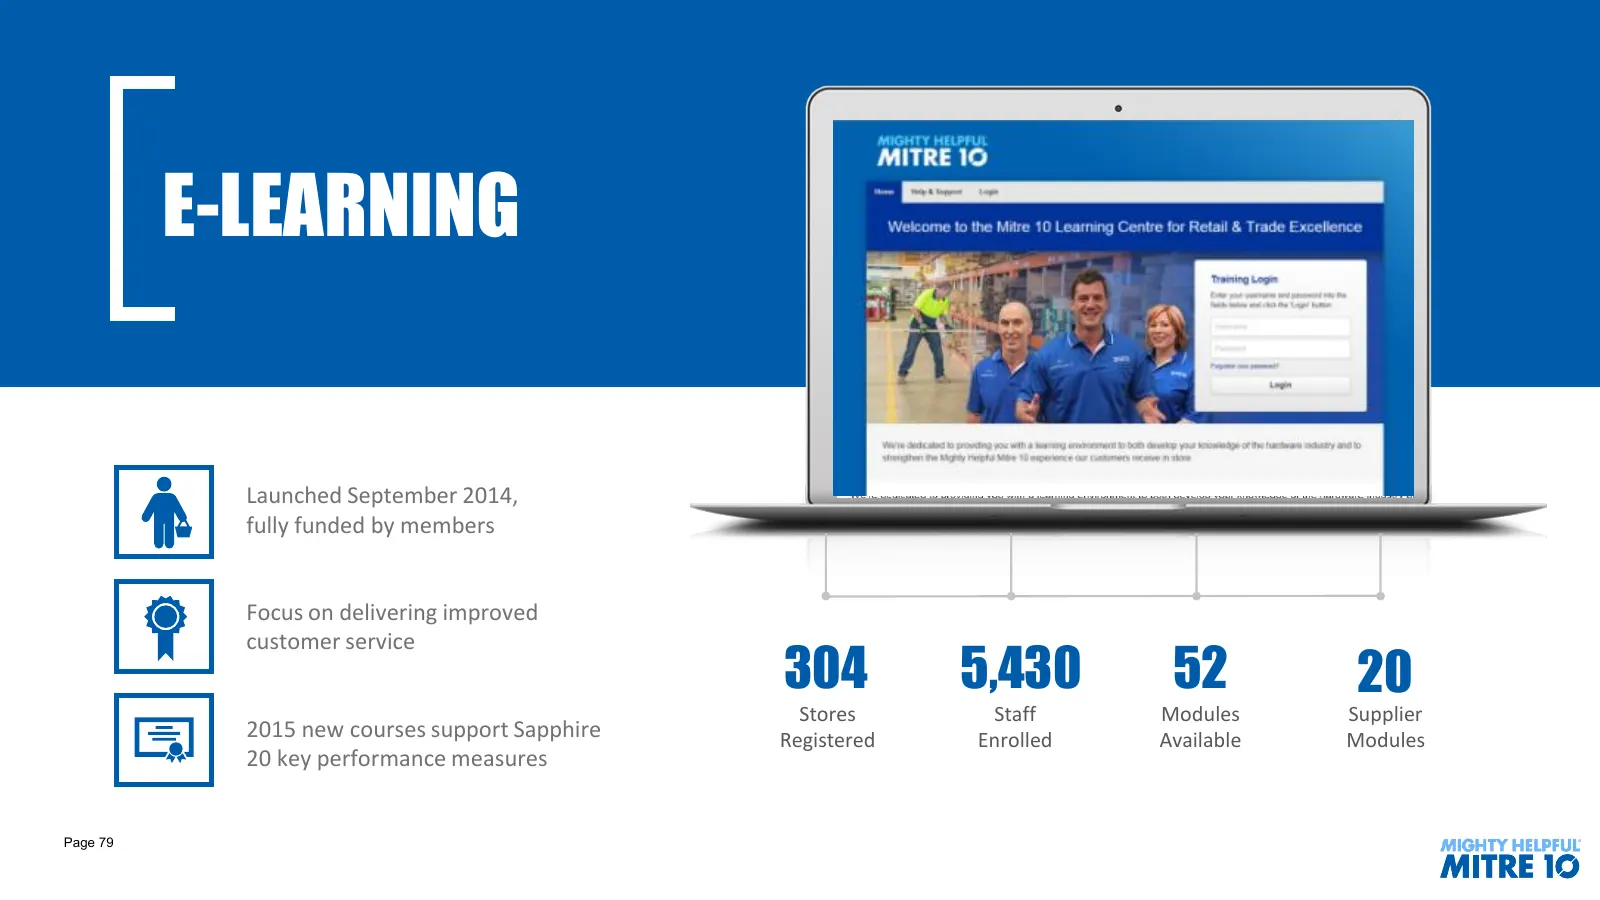
E-LEARNING Launched September 2014, fully funded by members Focus on delivering improved customer service 304 5,430 52 20 Stores Staff Modules Supplier 2015 new courses support Sapphire Registered Enrolled Available Modules 20 key performance measures Page 79
Slide 41: Store in a store
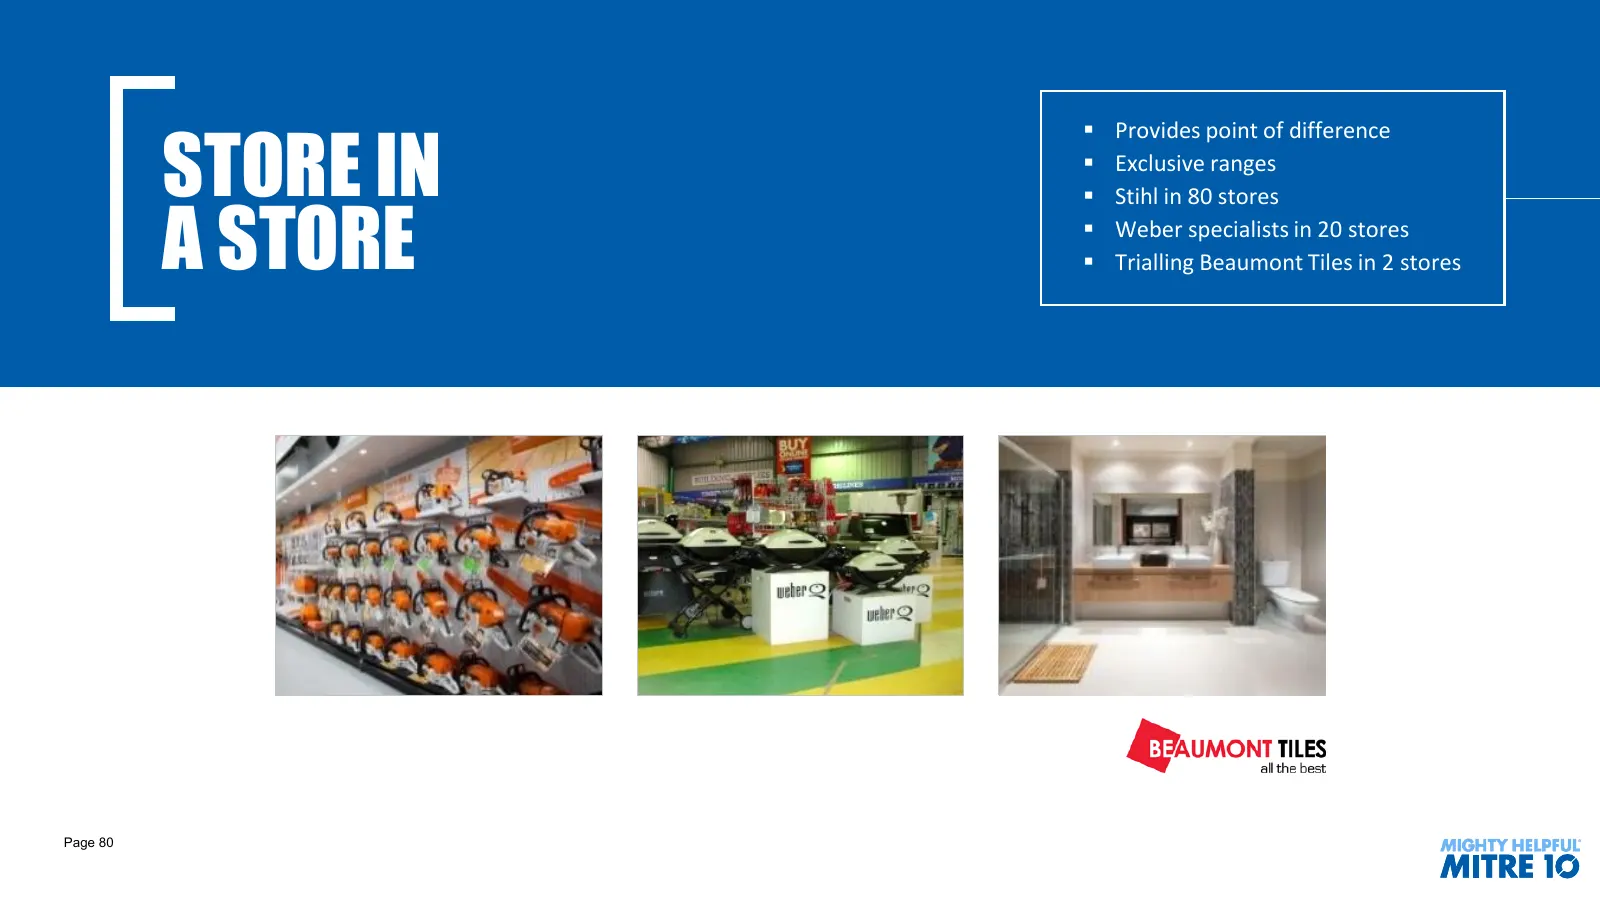
STORE IN Provides point of difference Exclusive ranges Stihl in 80 stores A STORE Weber specialists in 20 stores Trialling Beaumont Tiles in 2 stores Page 80
Slide 42: Shopper led range & competitive pricing
SHOPPER LED RANGE & COMPETITIVE PRICING PRIVATE LABEL CORE RANGING Page 81
Slide 43: Private label program
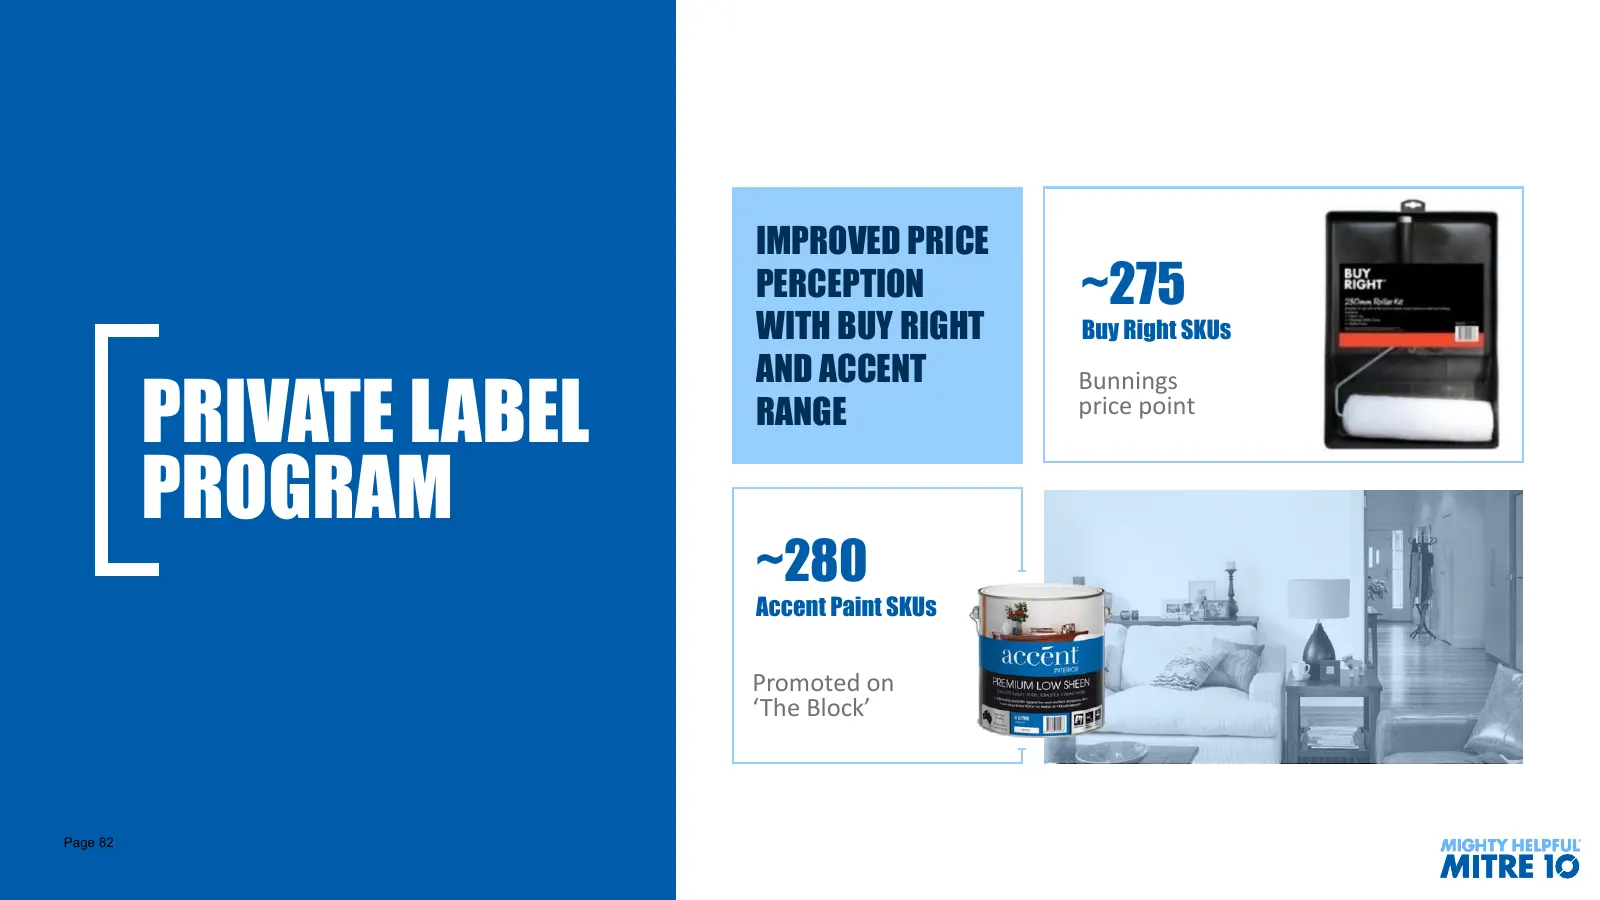
IMPROVED PRICE PERCEPTION ~275 WITH BUY RIGHT Buy Right SKUs AND ACCENT PRIVATE LABEL Bunnings RANGE price point PROGRAM ~280 Accent Paint SKUs Promoted on ‘The Block’ Page 82
Slide 44: Core ranging
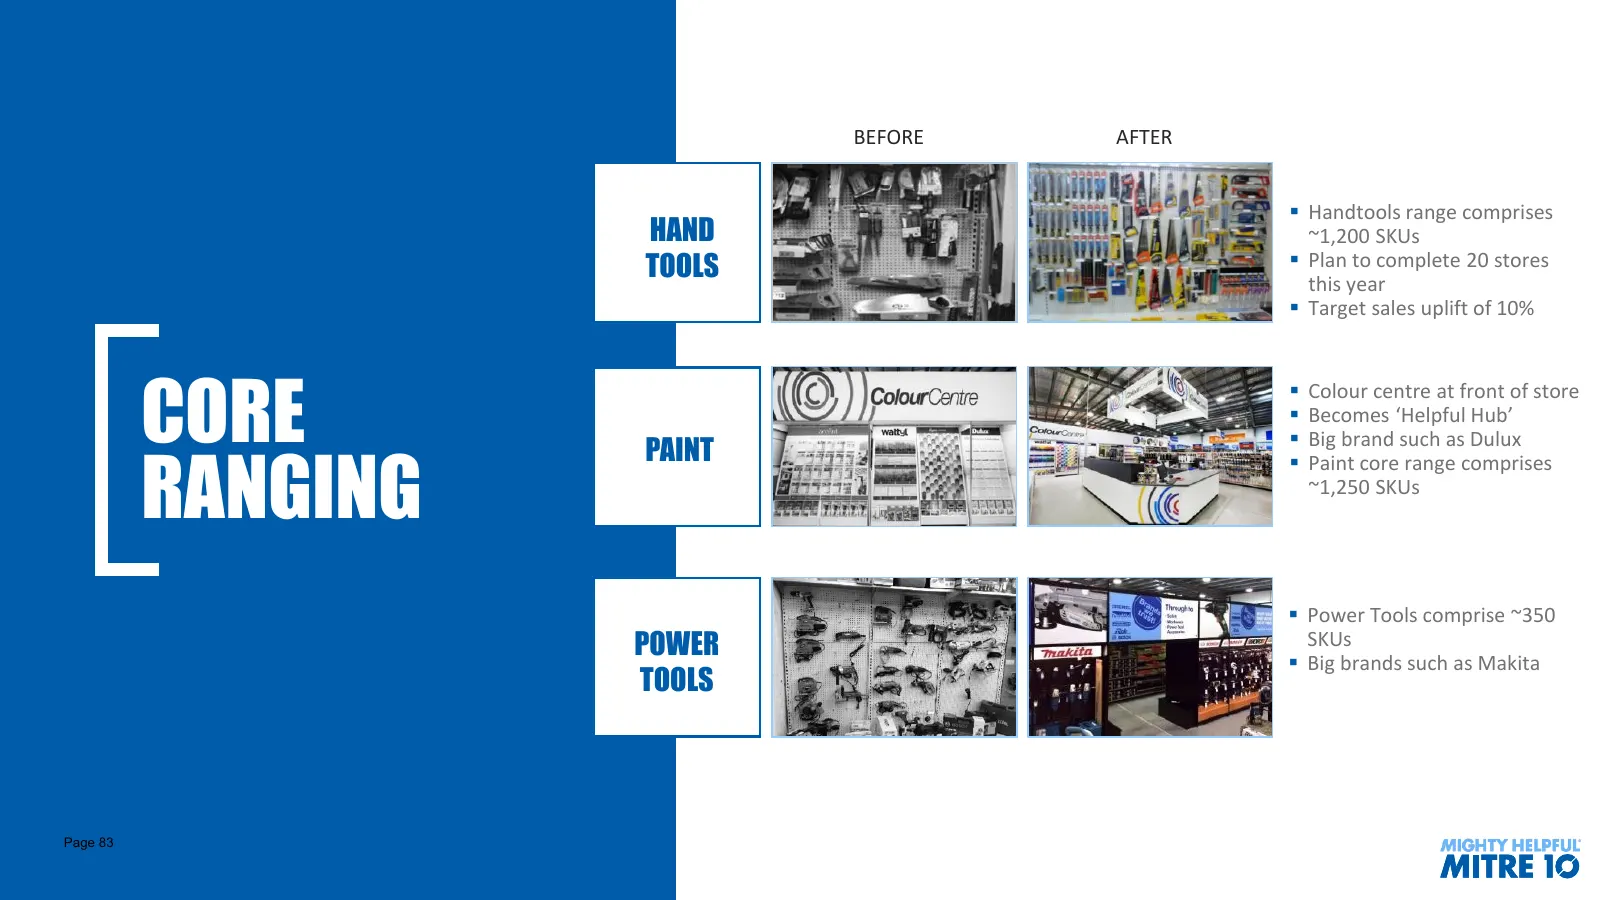
BEFORE AFTER Handtools range comprises HAND ~1,200 SKUs TOOLS Plan to complete 20 stores this year Target sales uplift of 10% CORE Colour centre at front of store Becomes ‘Helpful Hub’ Big brand such as Dulux PAINT RANGING Paint core range comprises ~1,250 SKUs Power Tools comprise ~
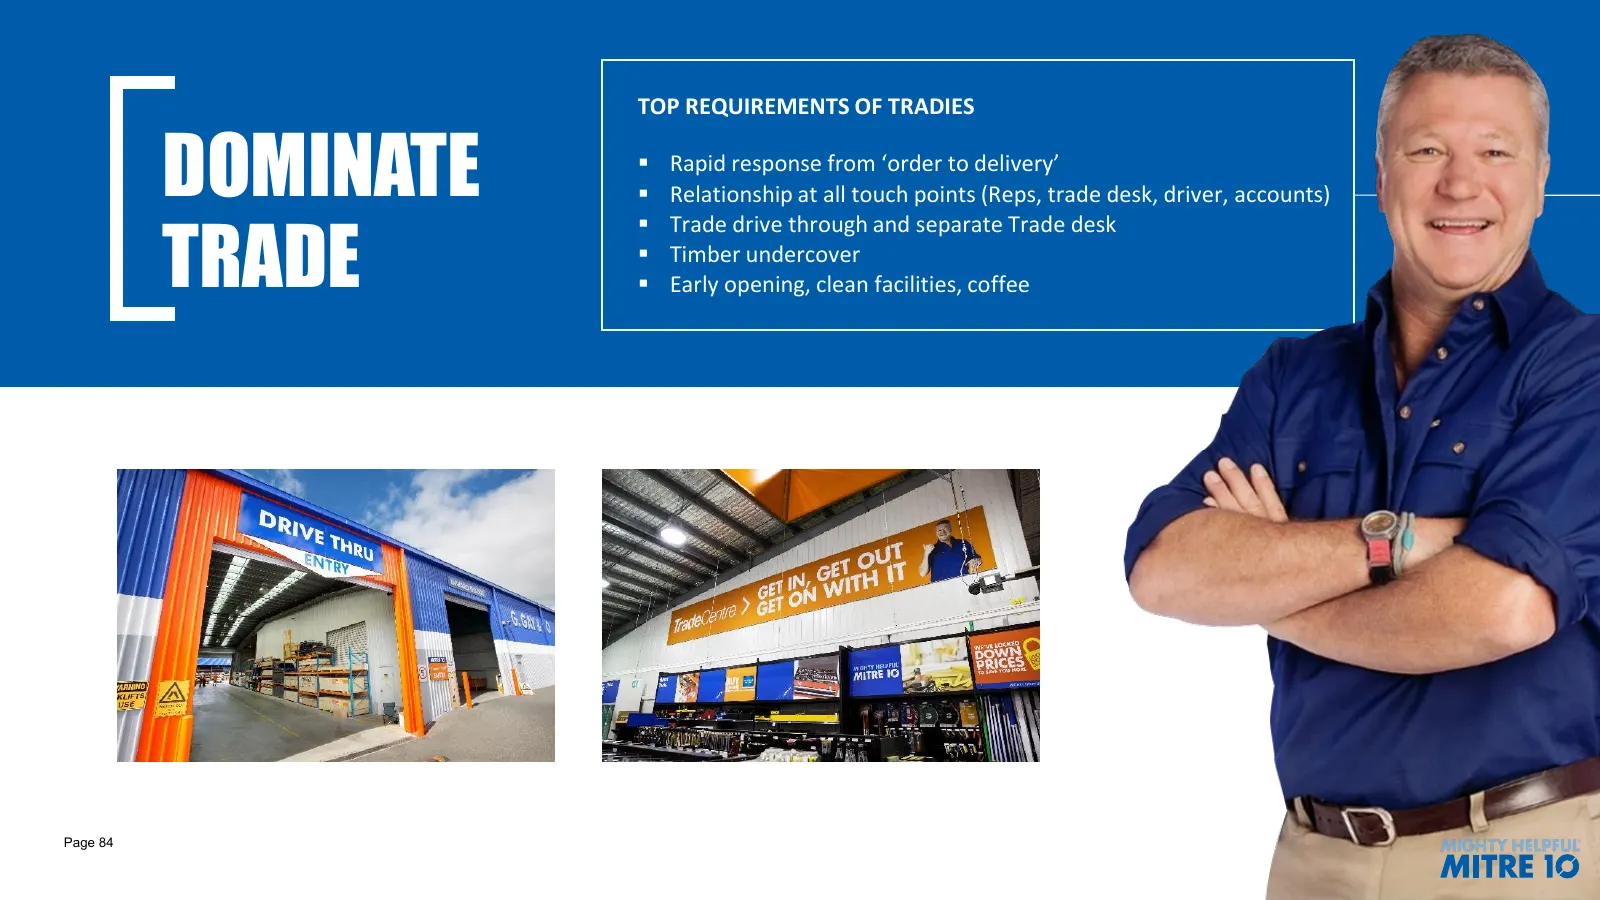
Slide 45: Dominate trade
TOP REQUIREMENTS OF TRADIES DOMINATE Rapid response from ‘order to delivery’ Relationship at all touch points (Reps, trade desk, driver, accounts) TRADE Trade drive through and separate Trade desk Timber undercover Early opening, clean facilities, coffee Page 84
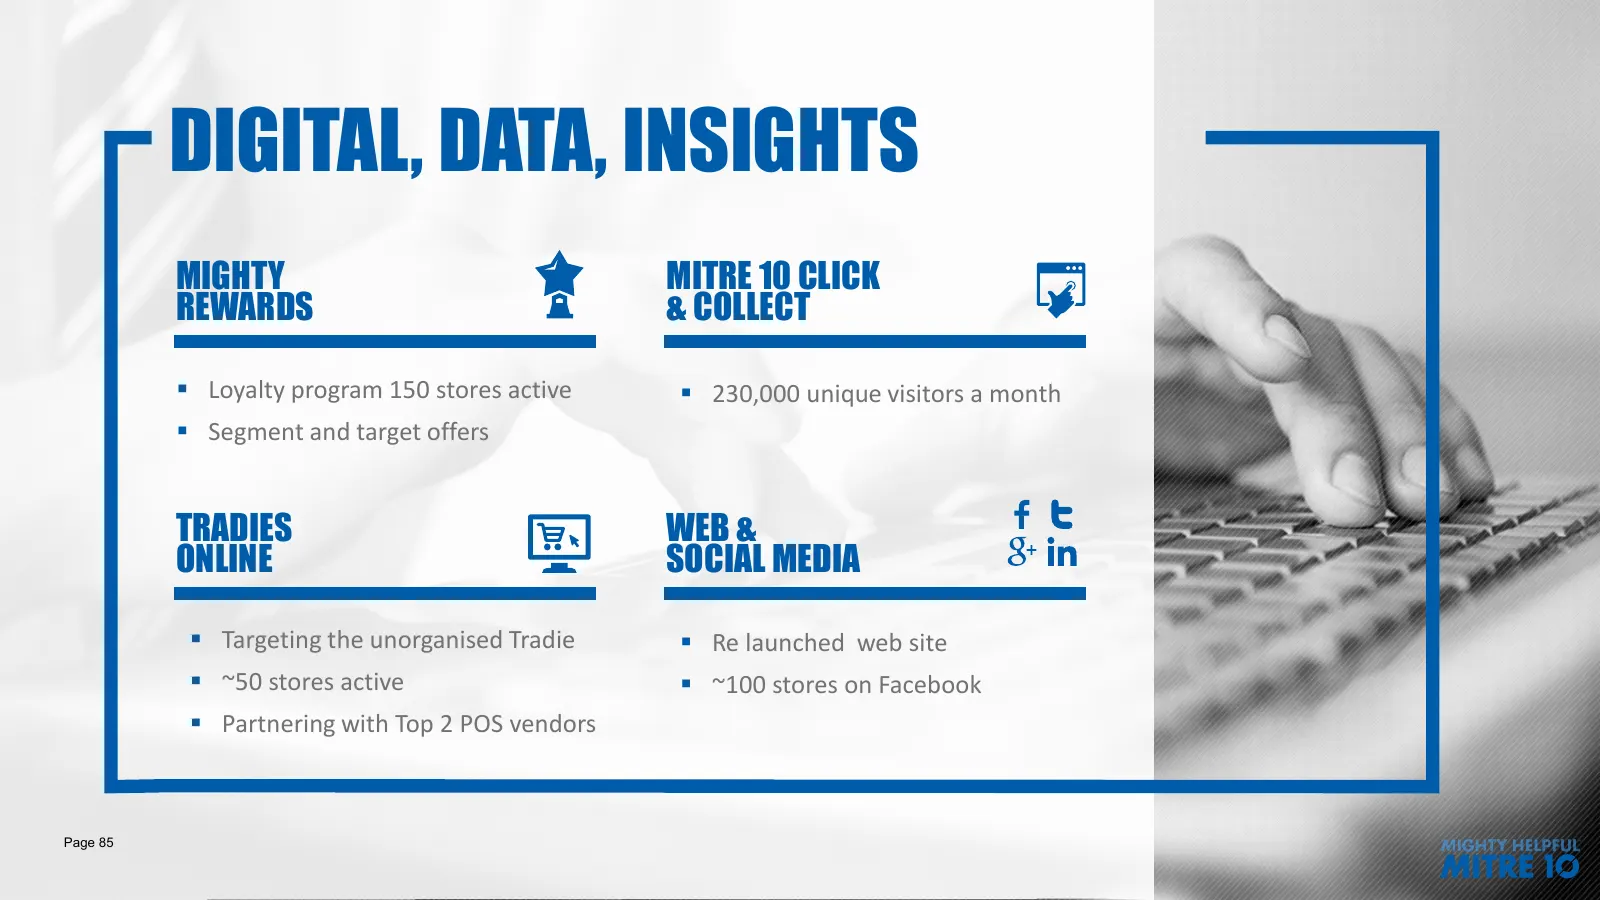
Slide 46: Digital, data, insights
DIGITAL, DATA, INSIGHTS MIGHTY MITRE 10 CLICK REWARDS & COLLECT Loyalty program 150 stores active 230,000 unique visitors a month Segment and target offers TRADIES WEB & ONLINE SOCIAL MEDIA Targeting the unorganised Tradie Re launched web site ~50 stores active ~100 stores on Facebook
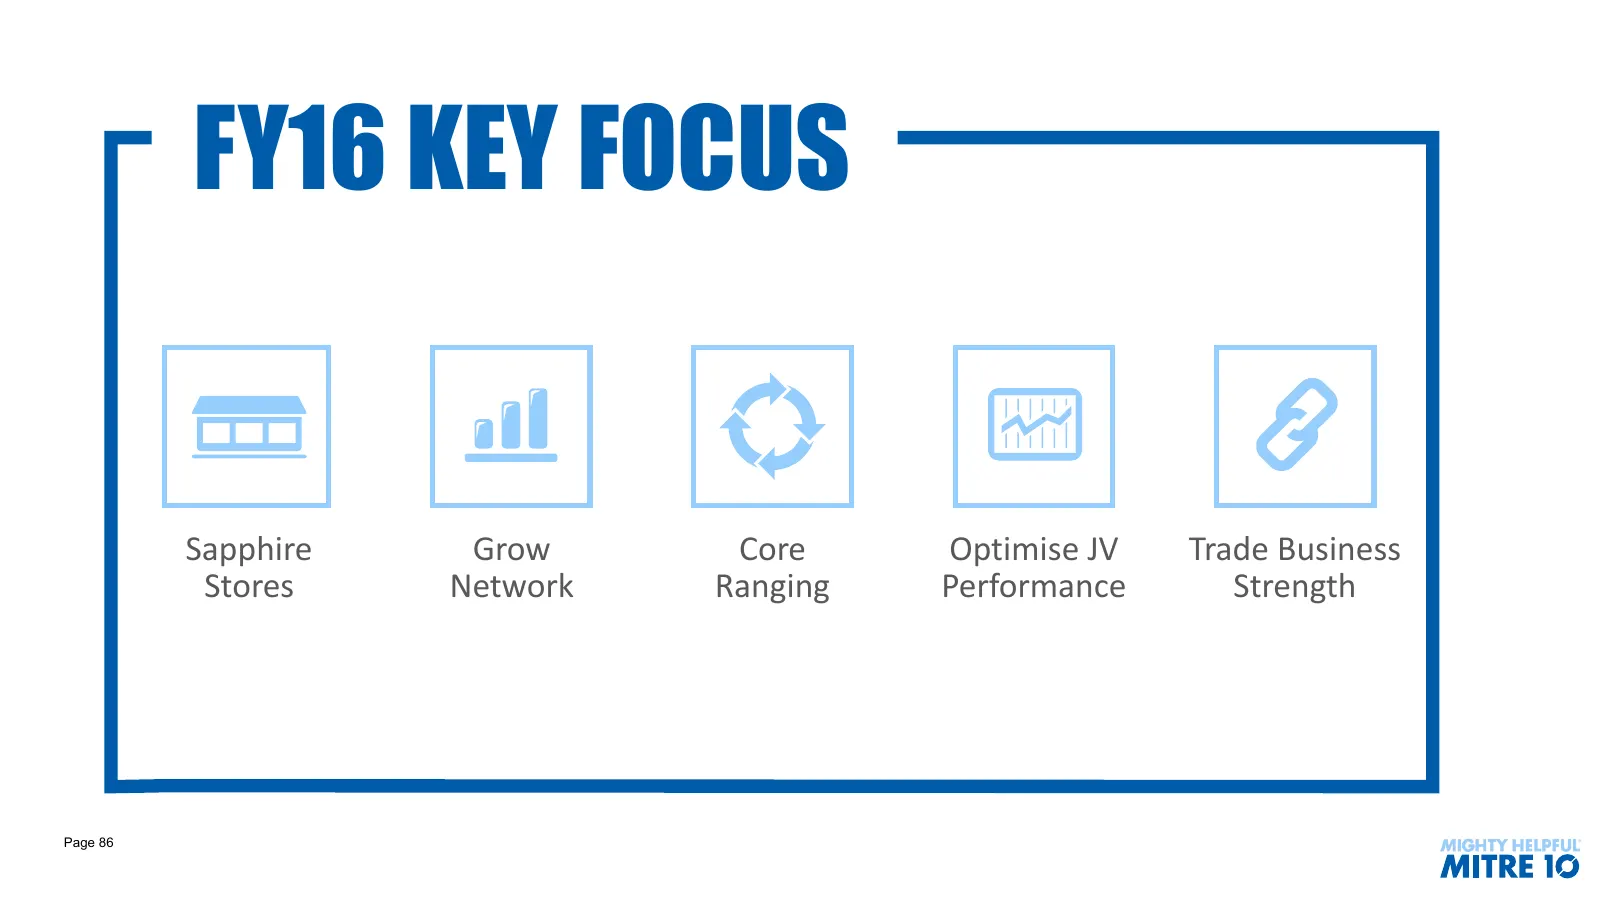
Slide 47: FY16 key focus
FY16 KEY FOCUS Sapphire Grow Core Optimise JV Trade Business Stores Network Ranging Performance Strength Page 86
Source: Internet Archive copy of metcash.com
More decks from Metcash Limited
 Shareholder Meeting (September 2026)25 slides · Sep 9, 2026
 FY2026 Earnings Presentation60 slides · Jun 22, 2026
 1H26 Earnings Presentation39 slides · Dec 1, 2025
 FY2025 Earnings Presentation44 slides · Jun 24, 2025
 H1 FY2025 Earnings Presentation39 slides · Dec 2, 2024
 FY2024 Earnings Presentation38 slides · Jun 24, 2024