Kingfisher PLC · LSE:KGF
Kingfisher — Investor Presentation (June 2015)
20 slides from Kingfisher's investor presentation, Jun 7, 2015
Slide 1: Gerry Murphy, Group Chief Executive
Gerry Murphy Group Chief Executive
Slide 2: Kingfisher at a glance
Kingfisher at a glance • World’s third largest home improvement retailer • Retail sales: £8.7bn, 50% non UK • 741 stores in 10 countries in Europe and Asia
Slide 3: 10 countries, huge markets…
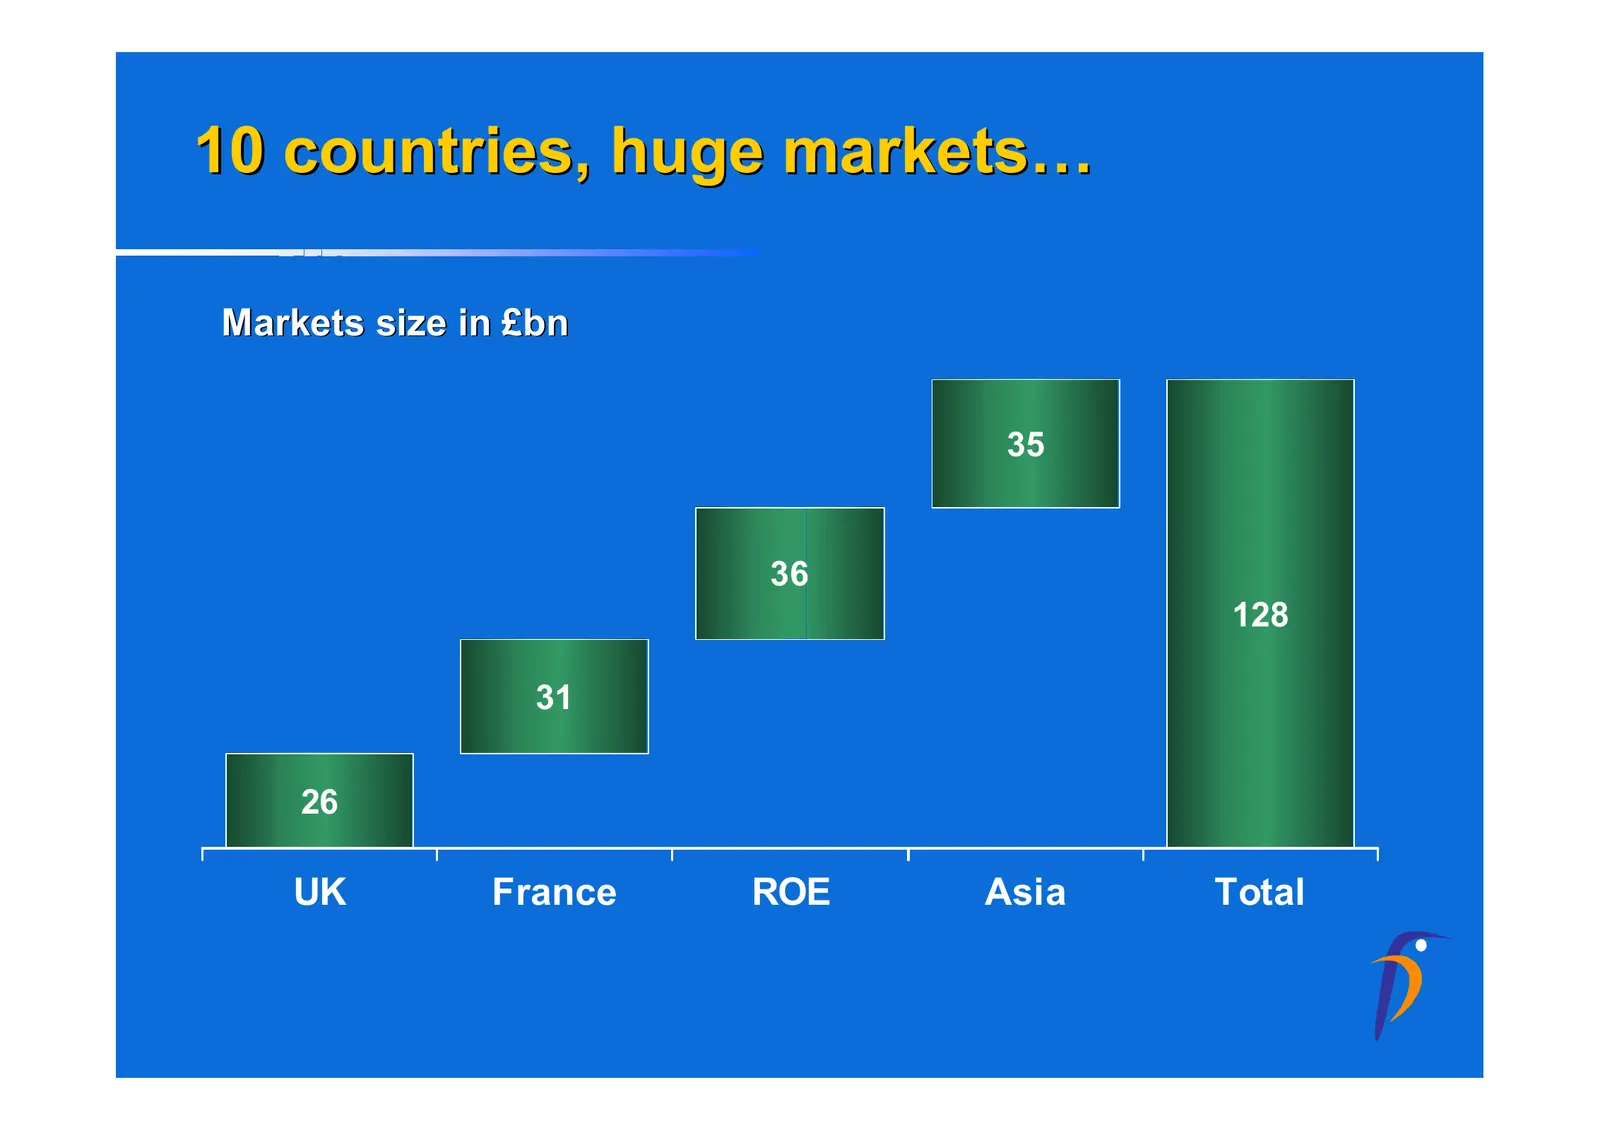
10 countries, huge markets… Markets size in £bn 35 36 128 31 26 UK France ROE Asia Total
Slide 4: …expected to grow fast
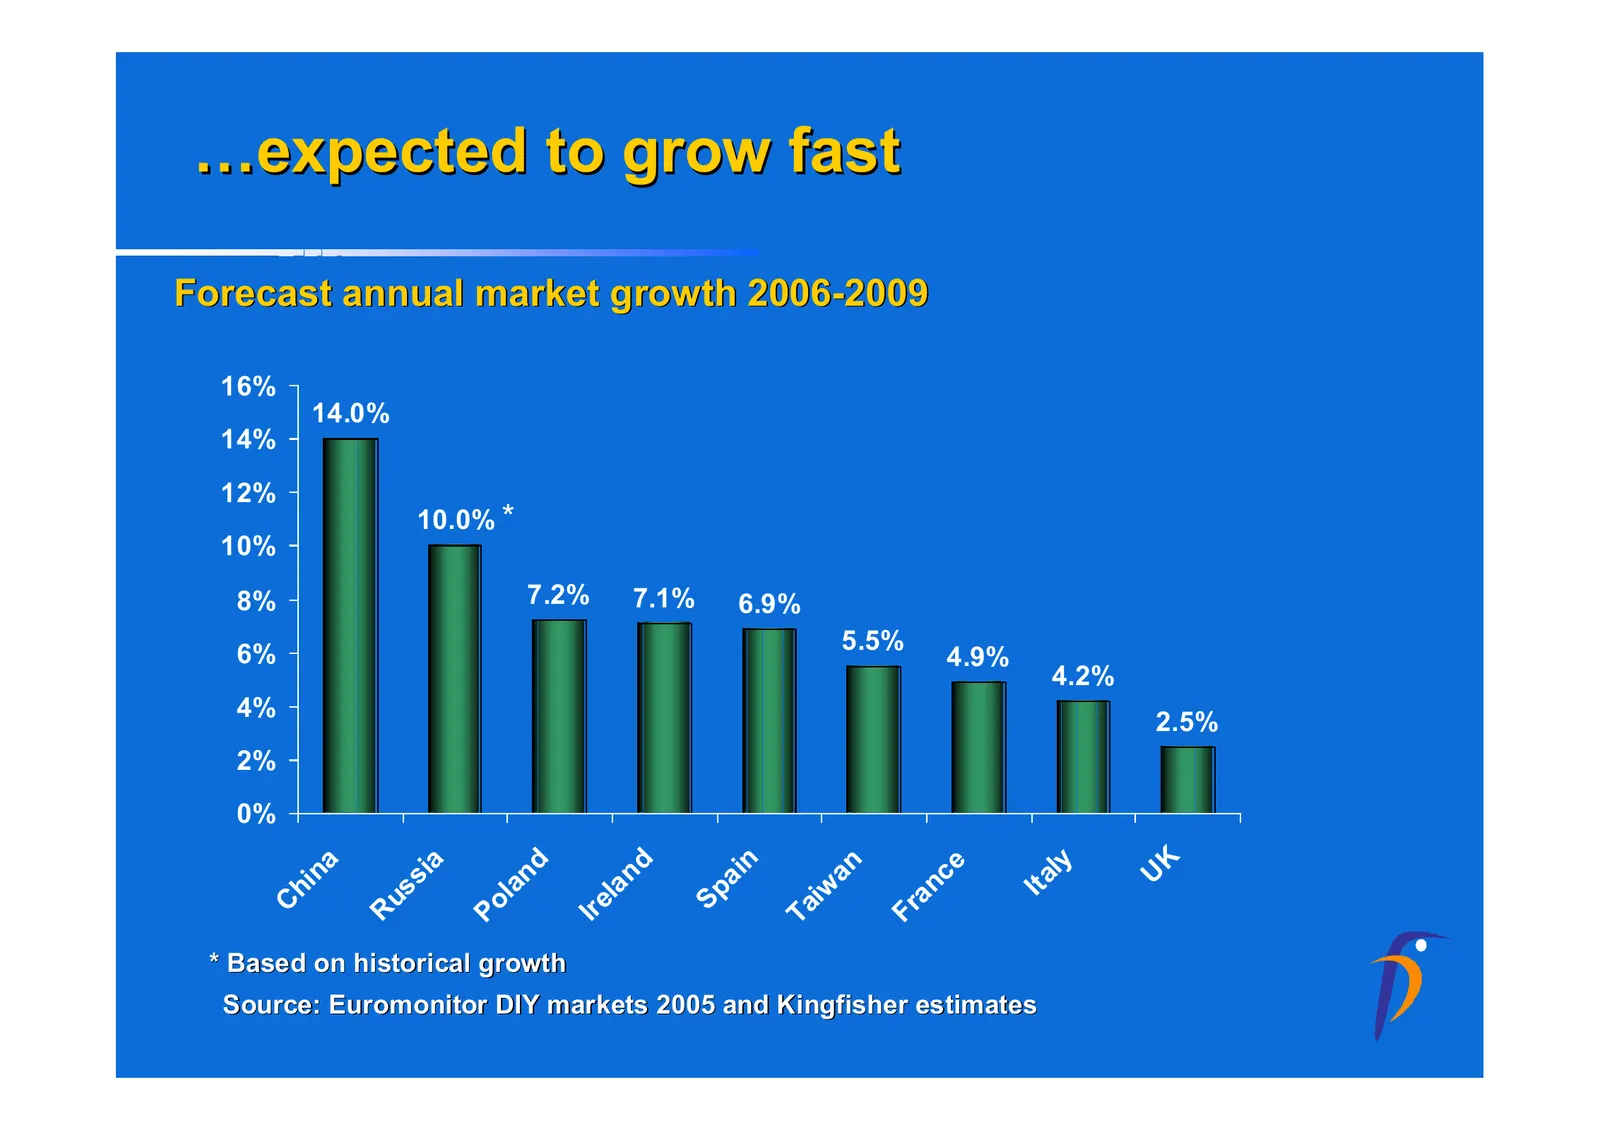
…expected to grow fast Forecast annual market growth 2006-2009 16% 14.0% 14% 12% 10.0% * 10% 8% 7.2% 7.1% 6.9% 6% 5.5% 4.9% 4.2% 4% 2.5% 2% 0% K n ly nd na ia nd an ce ai U It a s an hi la iw la Sp us C Ire Po Ta Fr R * Based on historical growth Source: Euromonitor DIY markets 2005 and Kingfisher e
Slide 5: Aim – sustainable growth and returns
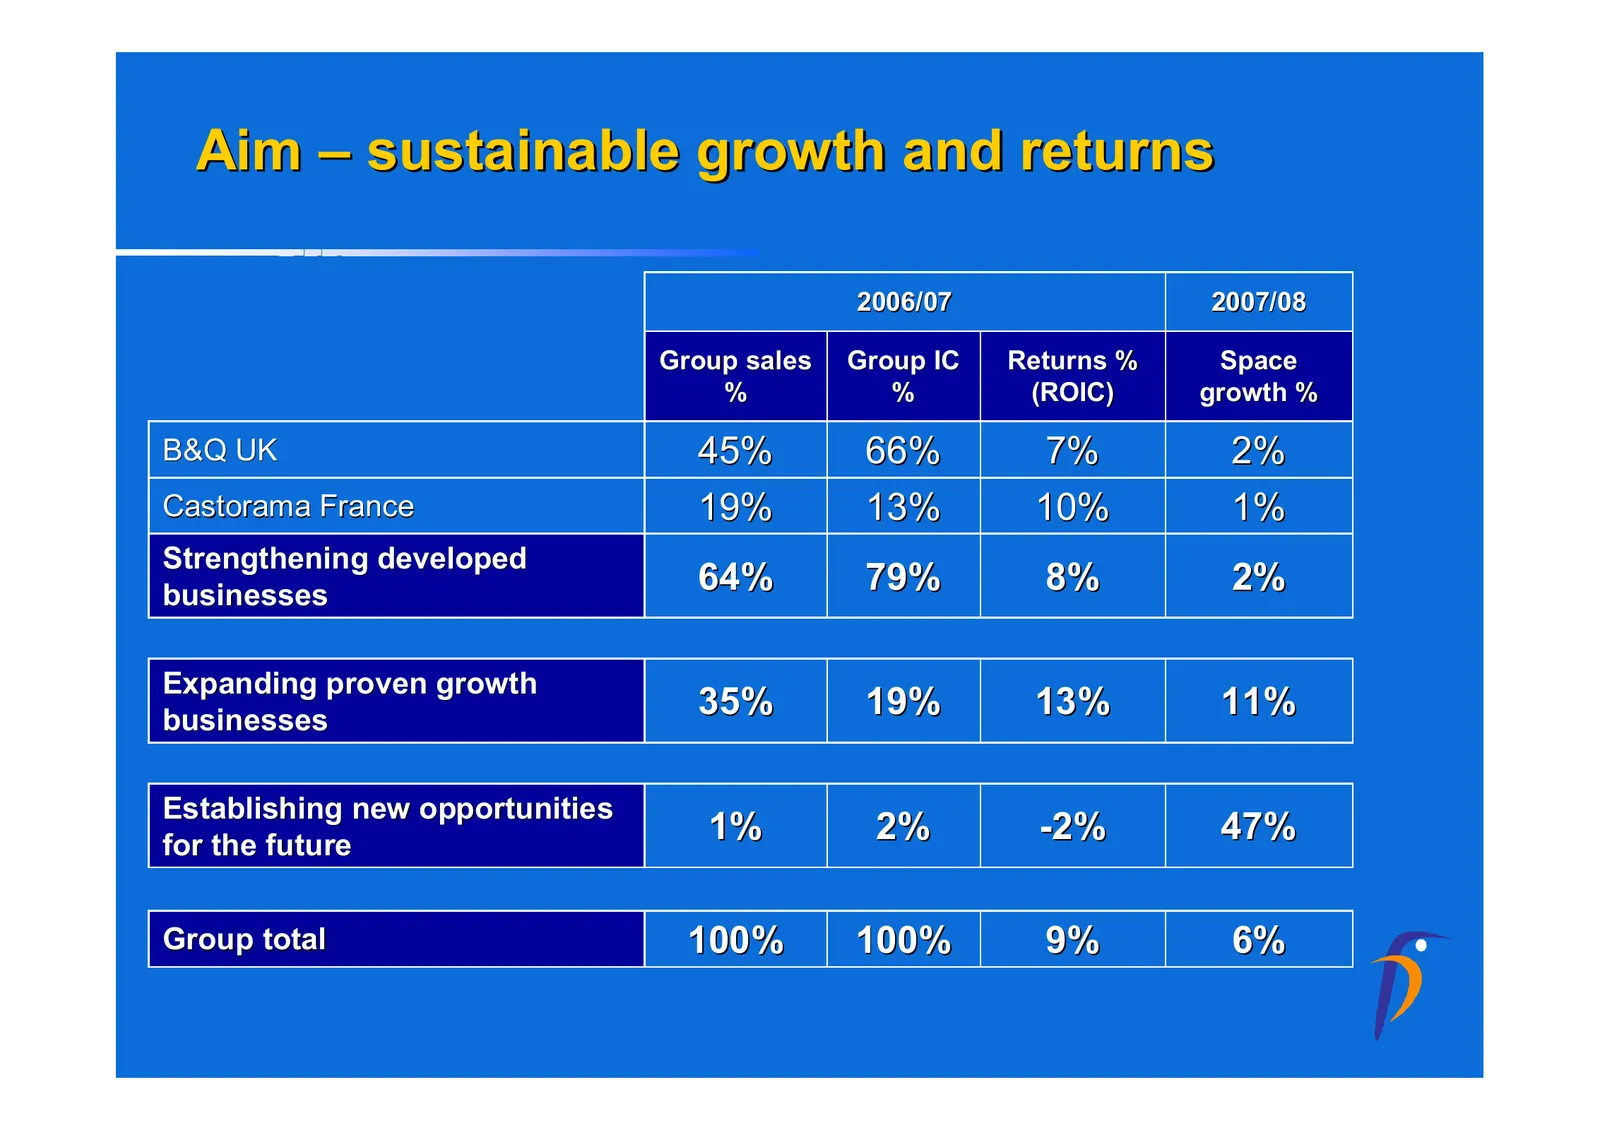
Aim – sustainable growth and returns 2006/07 2007/08 Group sales Group IC Returns % Space % % (ROIC) growth % B&Q UK 45% 66% 7% 2% Castorama France 19% 13% 10% 1% Strengthening developed businesses 64% 79% 8% 2% Expanding proven growth businesses 35% 19% 13% 11% Establishing new opportunities for th
Slide 6: B&Q UK
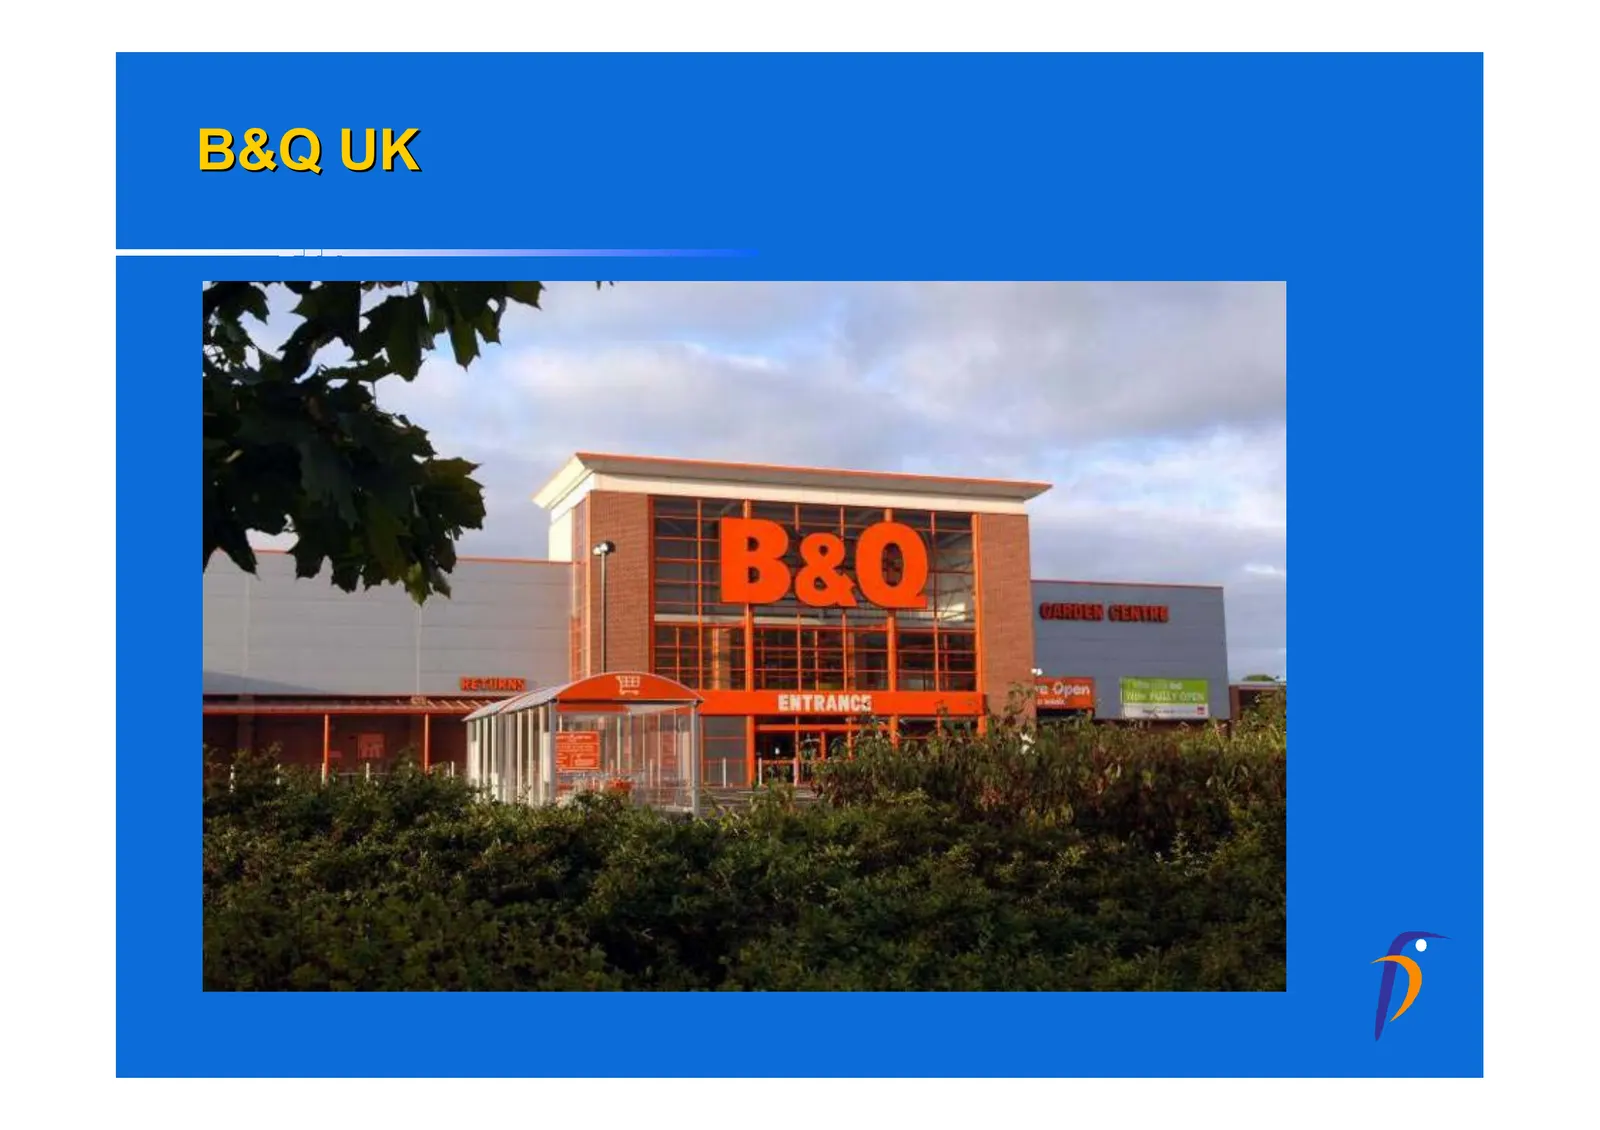
ENTRANCE ar) " lf | | | | ie Ae nal |-th | } > Rey
Slide 7: B&Q - The UK's No. 1
B&Q - The UK’s No. 1 • Largest UK home improvement retailer – 55% share of DIY – 15% share of RMI • The UK’s only large home improvement store – Over 100 large stores, 10,000+ sqm – Over 200 medium stores, 4,000+sqm • The UK’s largest stocked range – 30,000+ SKUs • Prime retail locations • Targets m
Slide 8: UK – home improvement expenditure de-coupled from consumption
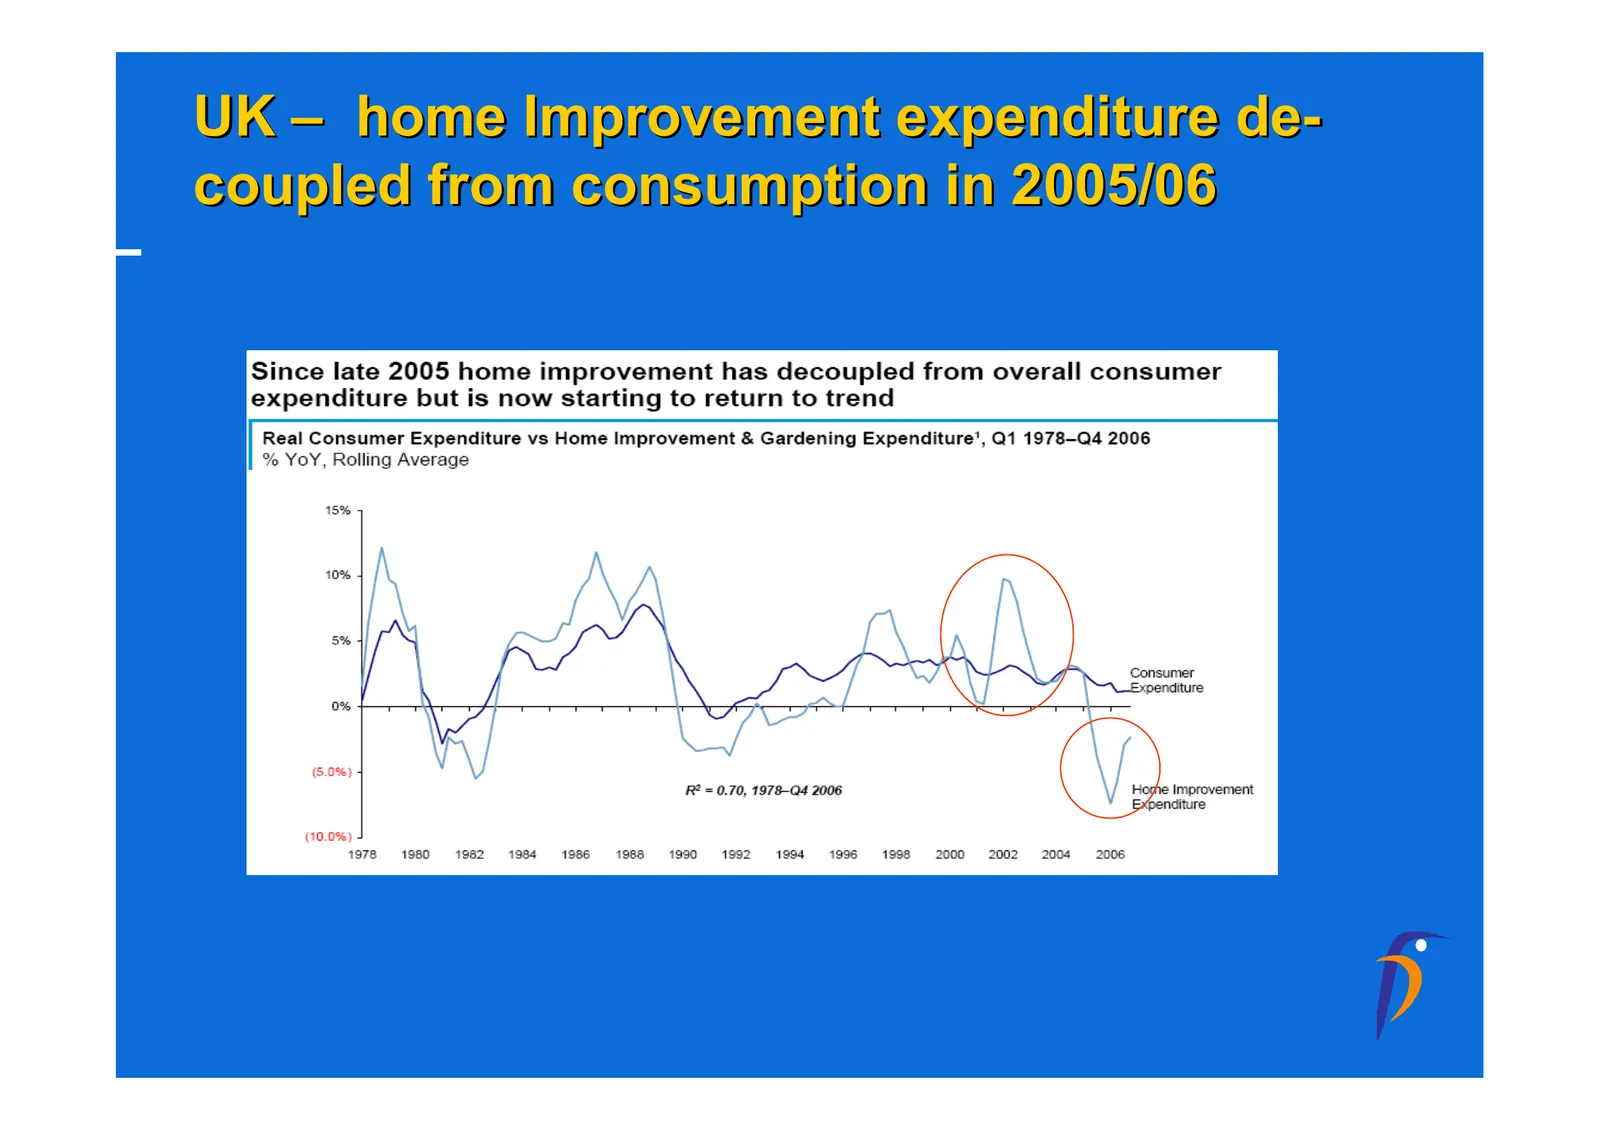
UK – home Improvement expenditure de- coupled from consumption in 2005/06
Slide 9: B&Q – the starting point
B&Q – the starting point • Sharp retail demand downturn • Retailers adding space faster than market growth • High cost inflation • Customer evolution • More choice of where and how to shop
Slide 10: B&Q - 'First and Only for Home Improvement'
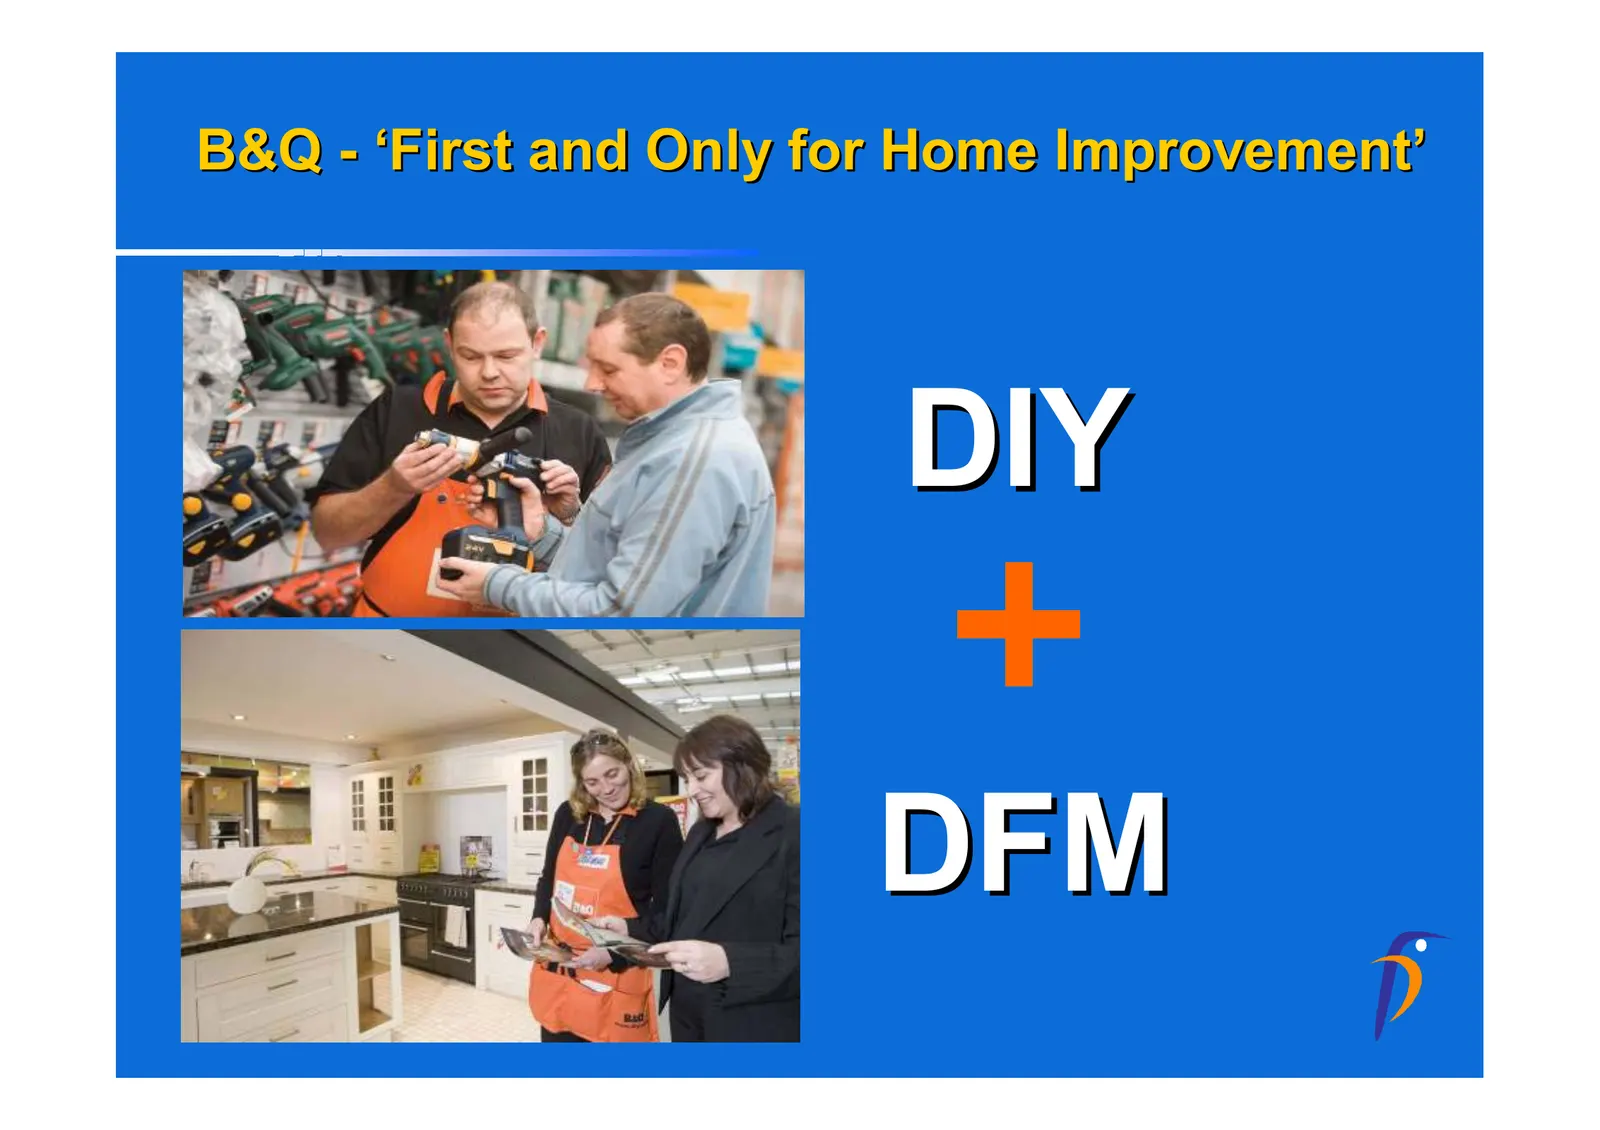
B&Q - ‘First and Only for Home Improvement’ Photo of DIYer DIY DFM
Slide 11: B&Q - vision
B&Q - vision “First and Only For Home Improvement” • Product authority, newness and style • Multi specialist store – Modern – Easy to shop • Great value
Slide 12: B&Q – better motivated colleagues
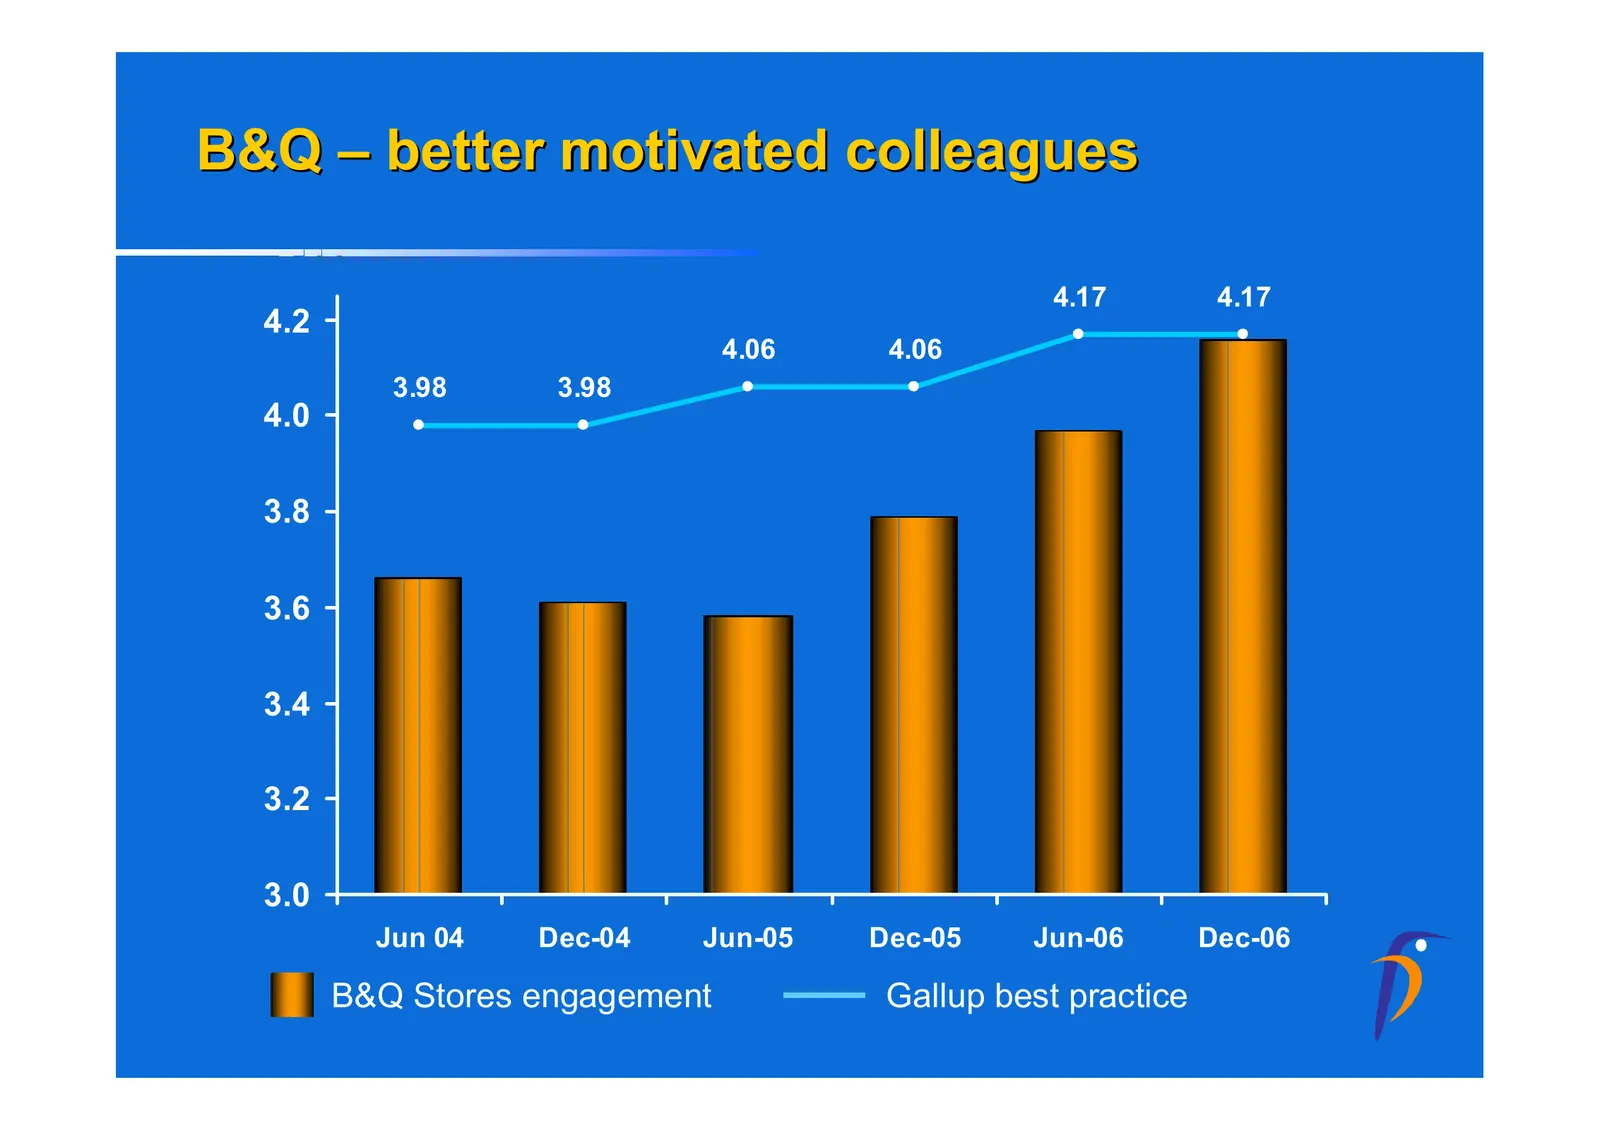
B&Q – better motivated colleagues 4.17 4.17 4.2 4.06 4.06 3.98 3.98 4.0 3.8 3.6 3.4 3.2 3.0 Jun 04 Dec-04 Jun-05 Dec-05 Jun-06 Dec-06 B&Q Stores engagement Gallup best practice
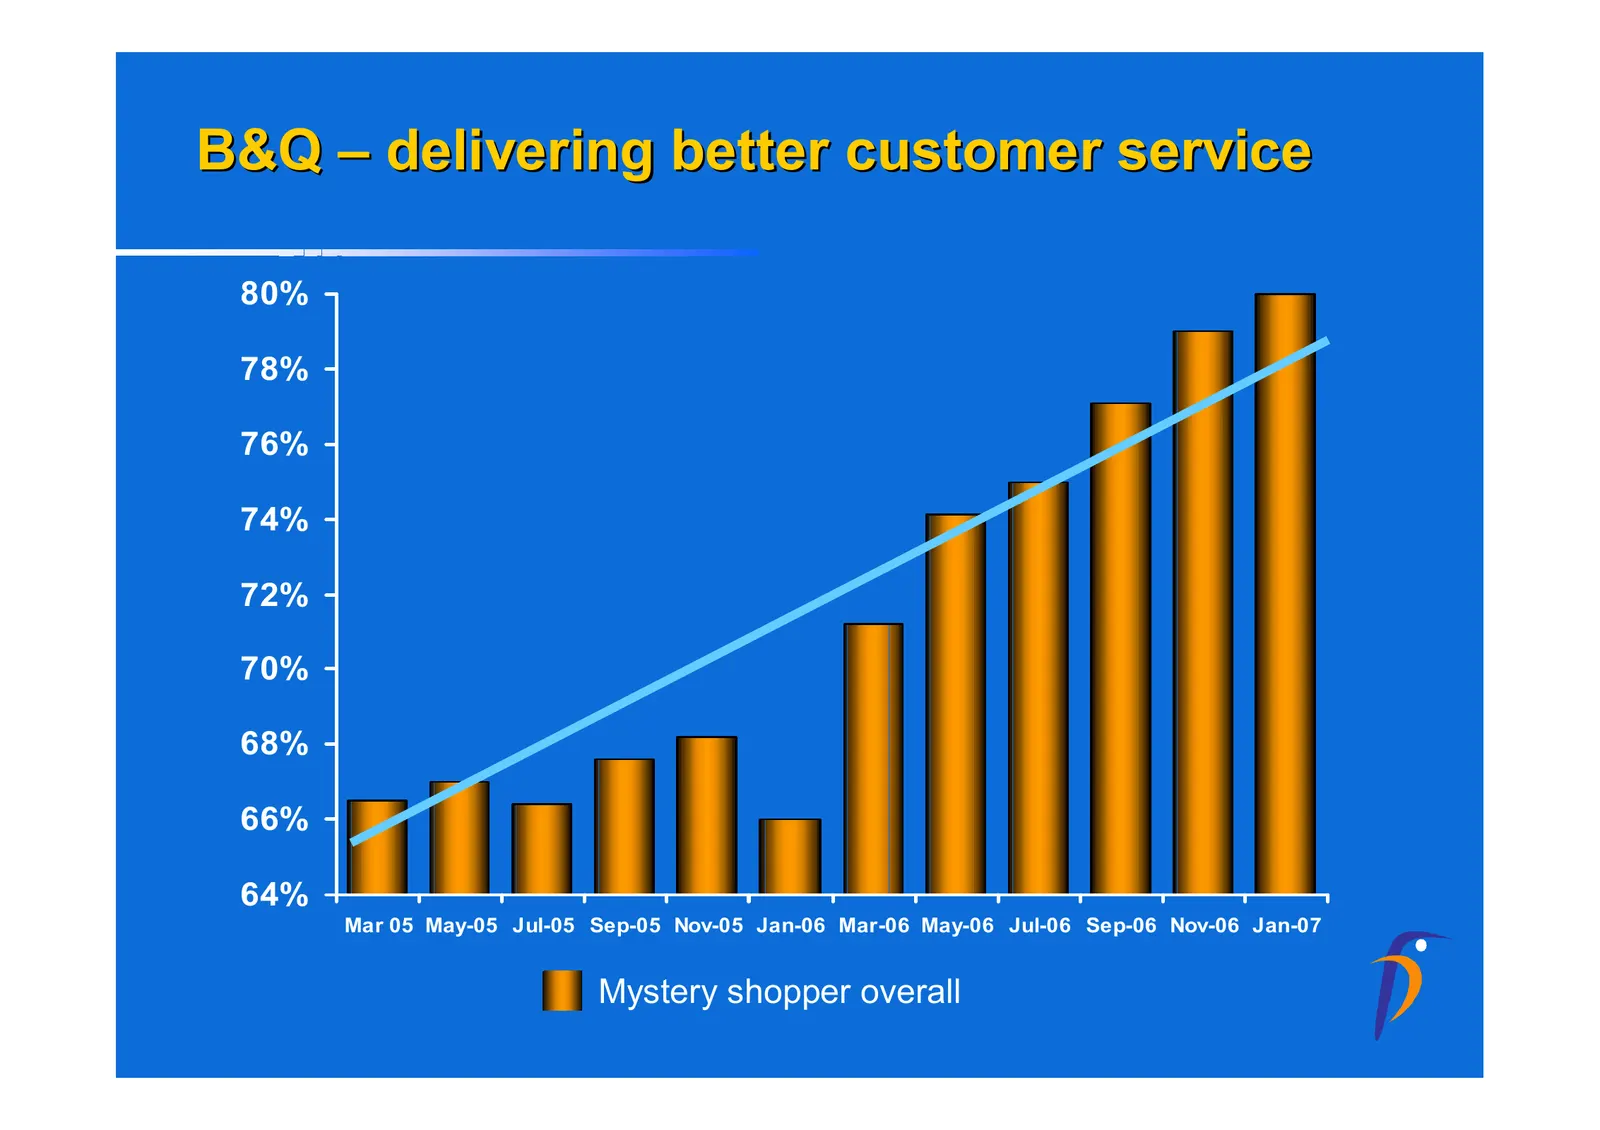
Slide 13: B&Q – delivering better customer service
B&Q – delivering better customer service 80% 78% 76% 74% 72% 70% 68% 66% 64% Mar 05 May-05 Jul-05 Sep-05 Nov-05 Jan-06 Mar-06 May-06 Jul-06 Sep-06 Nov-06 Jan-07 Mystery shopper overall
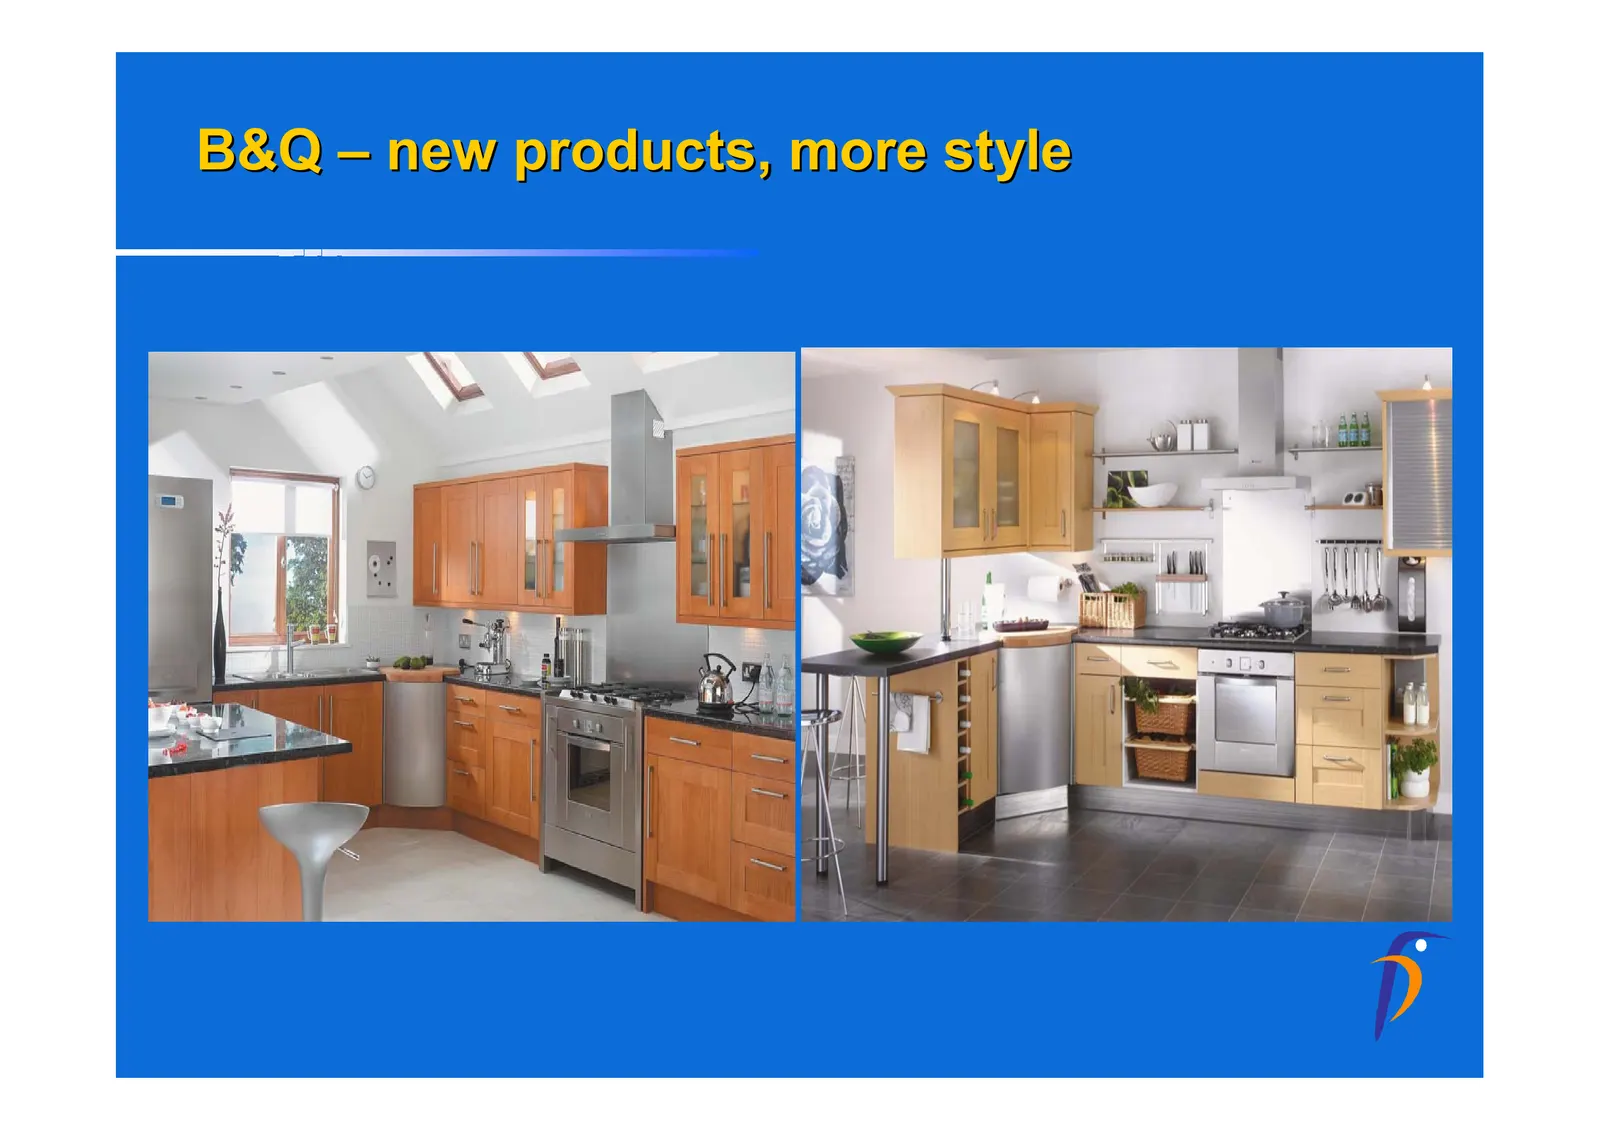
Slide 14: B&Q – new products, more style
B&Q – new products, more style
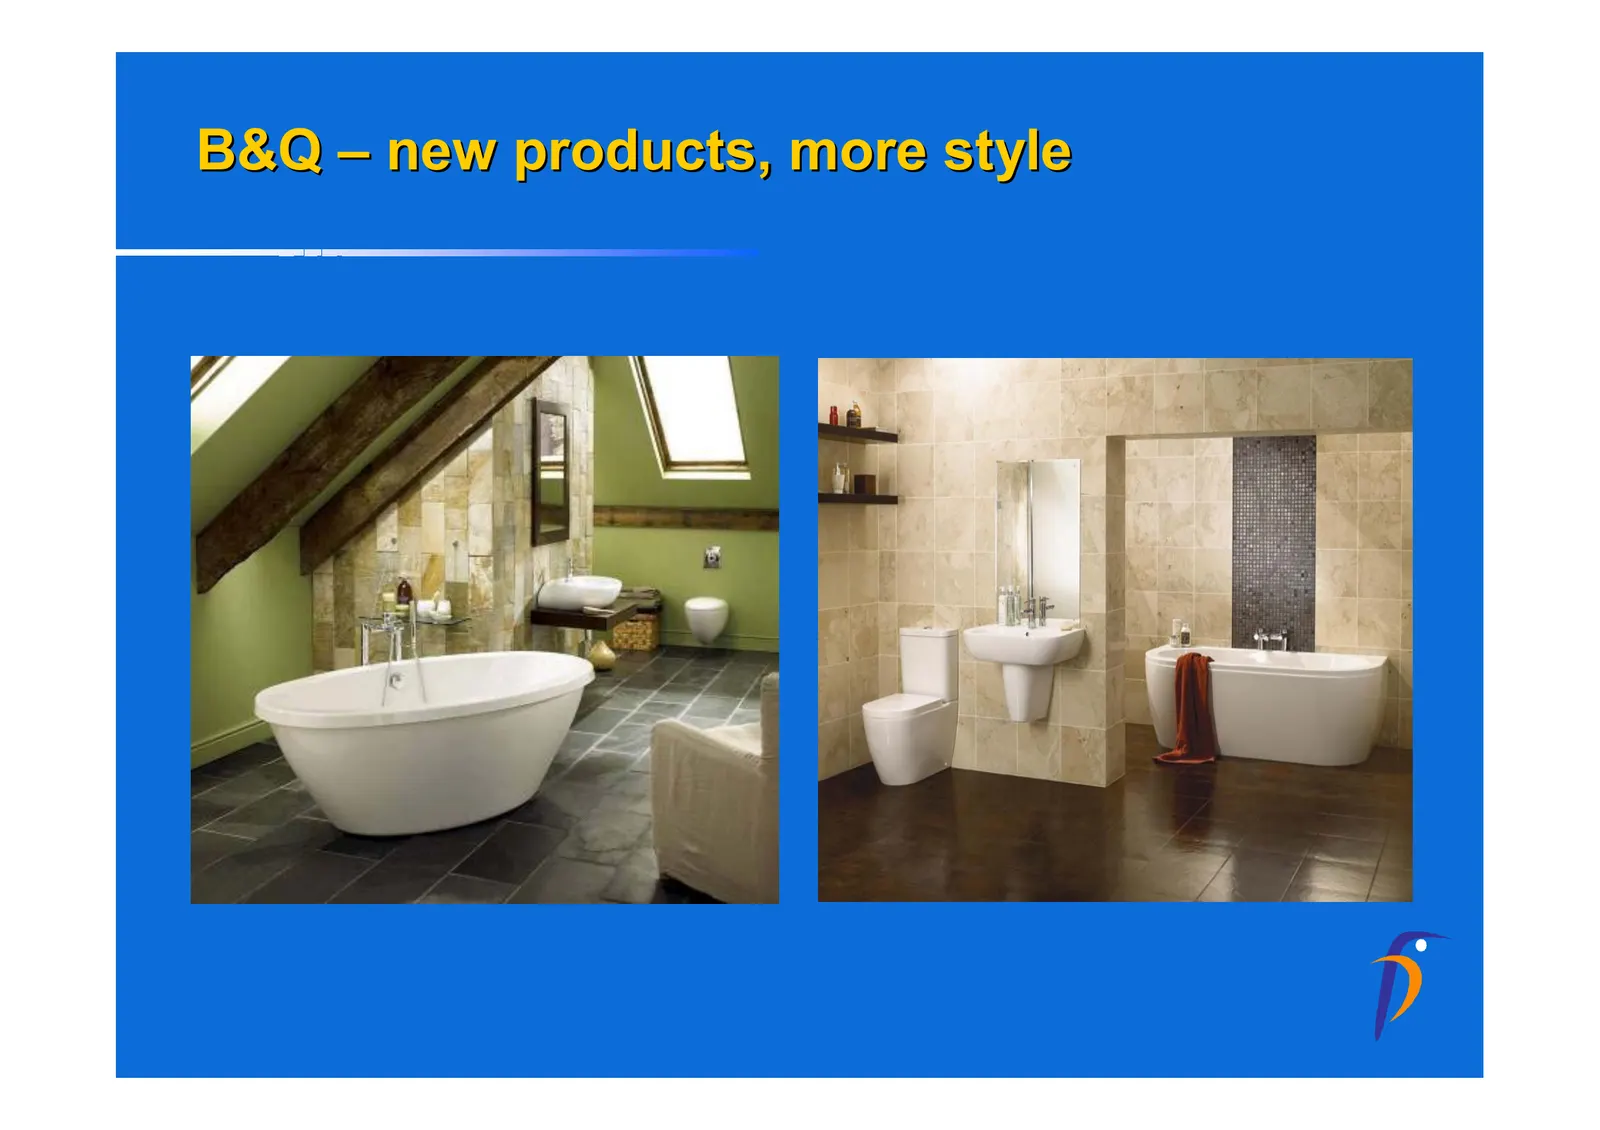
Slide 15: B&Q – new products, more style
B&Q – new products, more style
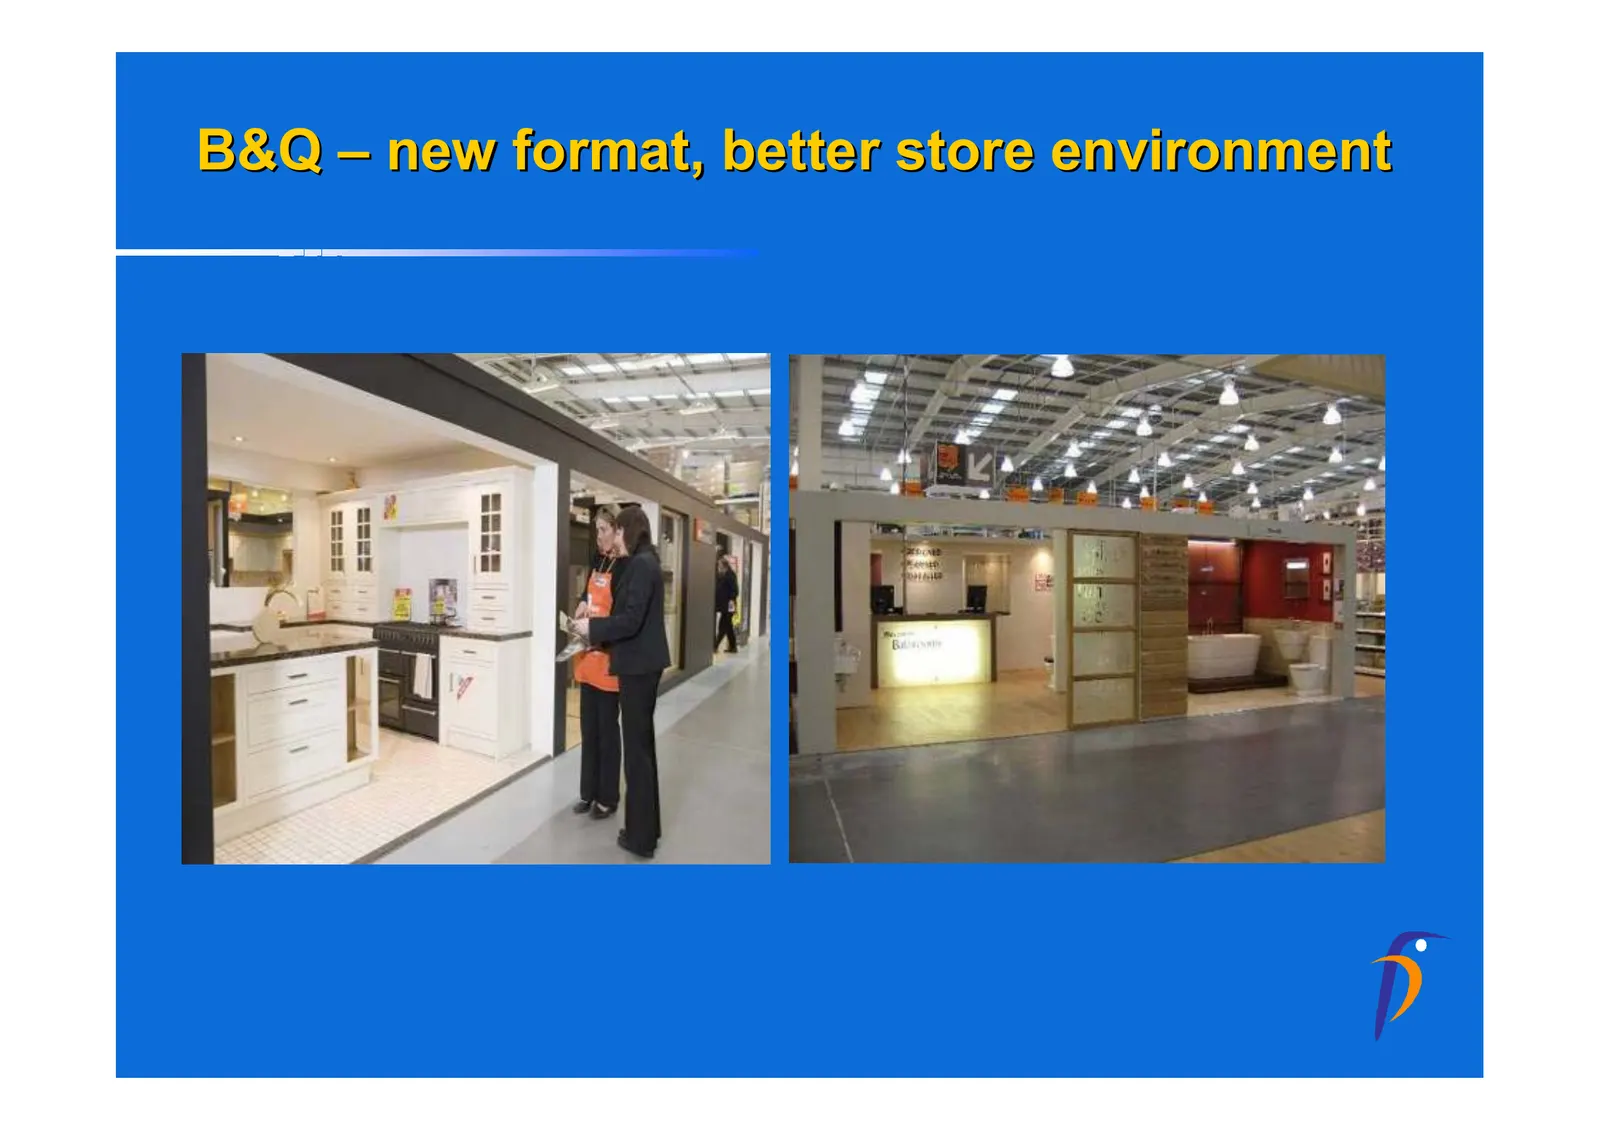
Slide 16: B&Q – new format, better store environment
B&Q – new format, better store environment
Slide 17: B&Q – indicative renewal economics
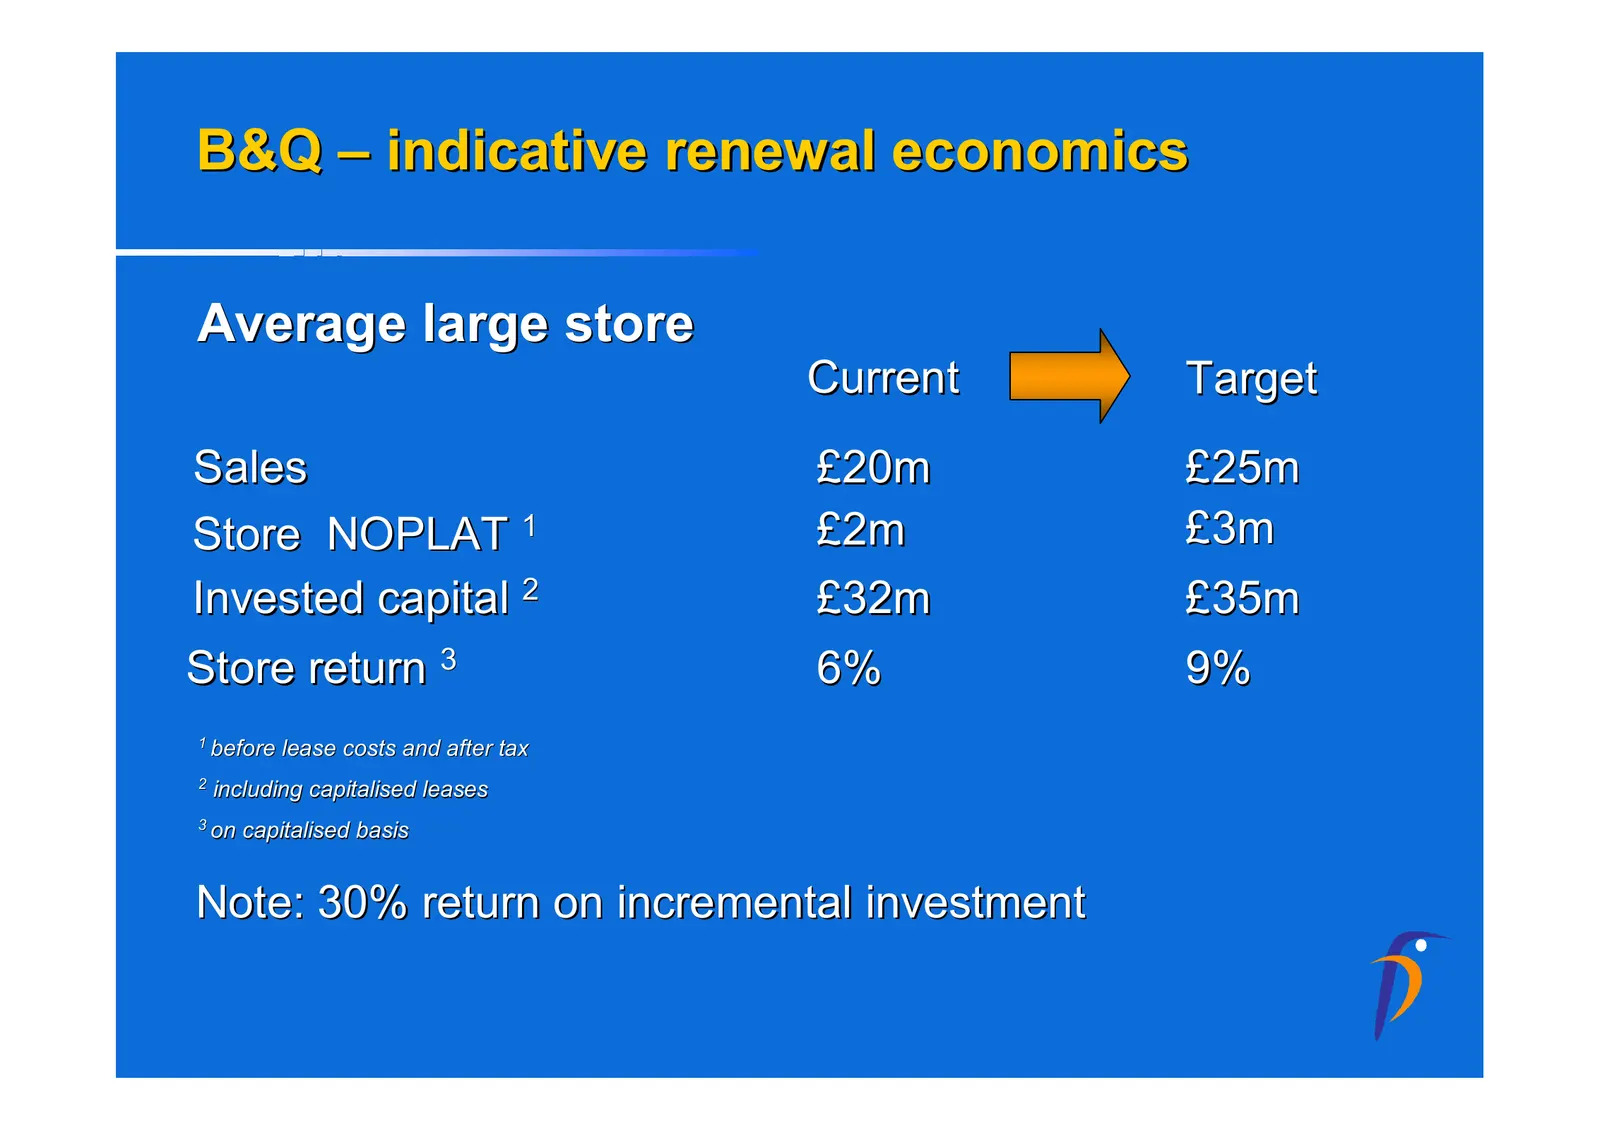
B&Q – indicative renewal economics Average large store Current Target Sales £20m £25m Store NOPLAT 1 £2m £3m Invested capital 2 £32m £35m Store return 3 6% 9% 1 before lease costs and after tax before lease costs and after tax 2 including capitalised leases including capitalised leases 3 on capitali
Slide 18: B&Q – store modernisation
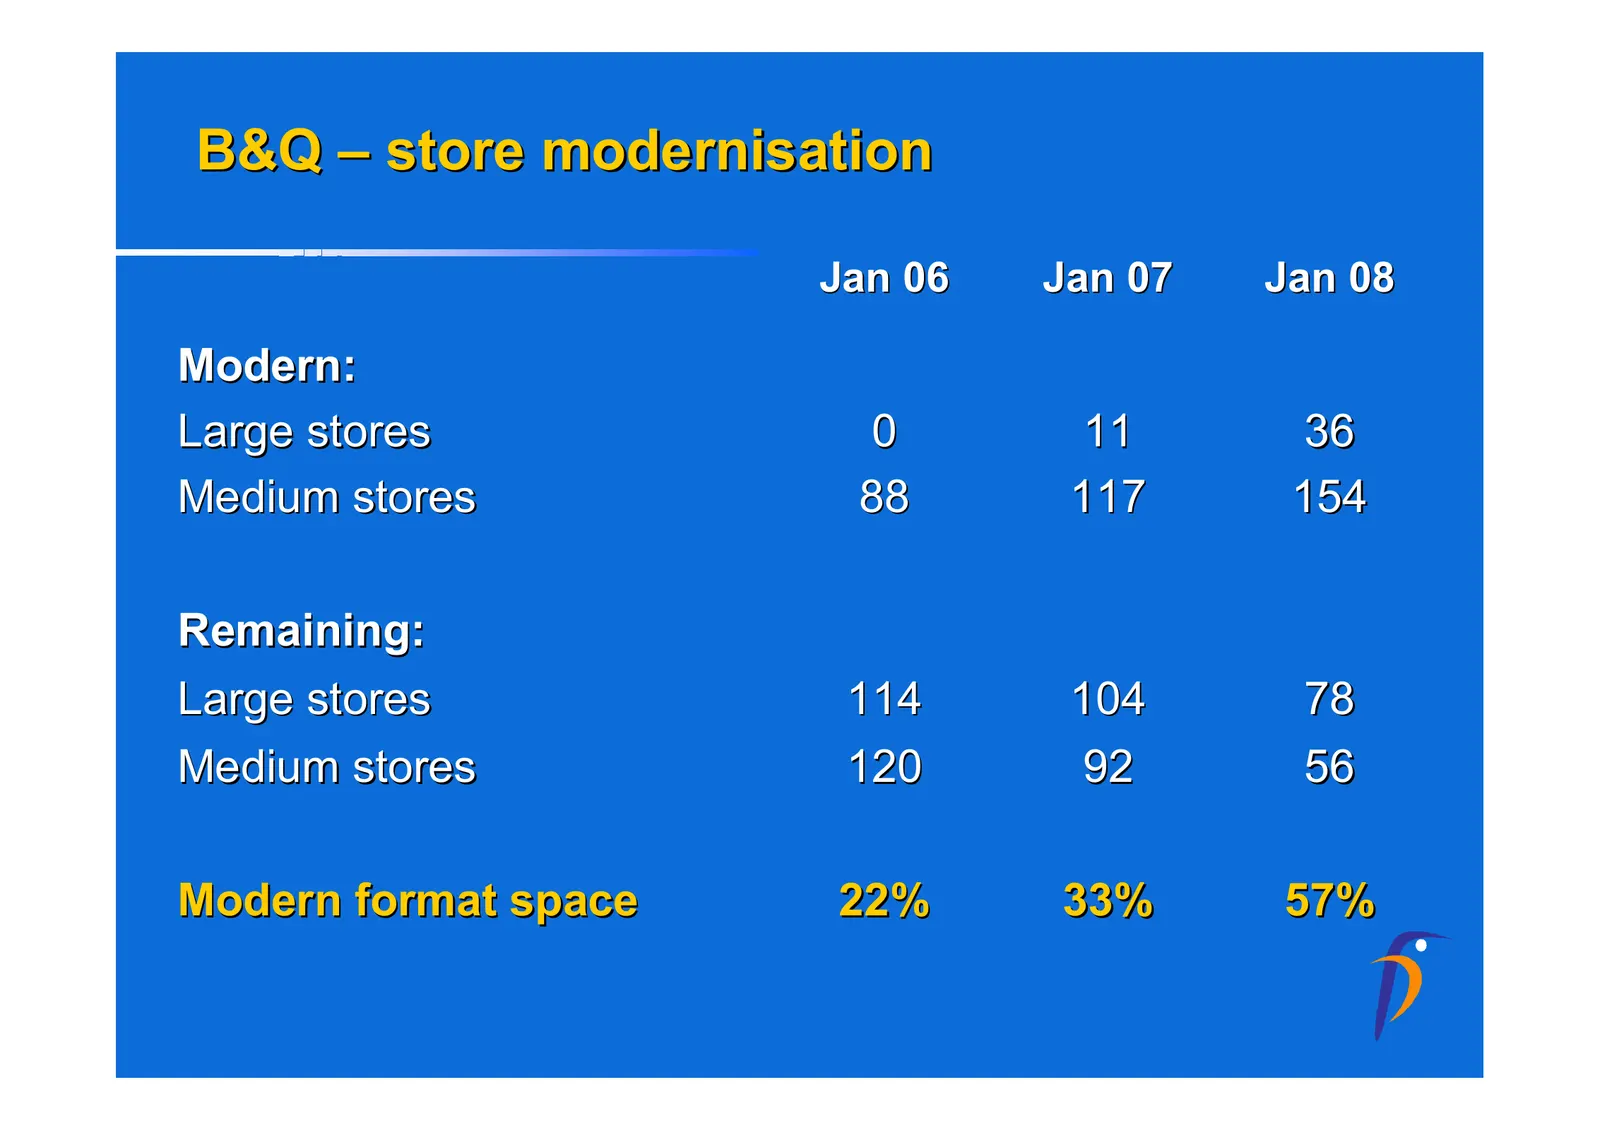
B&Q – store modernisation Jan 06 Jan 07 Jan 08 Modern: Large stores 0 11 36 Medium stores 88 117 154 Remaining: Large stores 114 104 78 Medium stores 120 92 56 Modern format space 22% 33% 57%
Slide 19: B&Q - summary
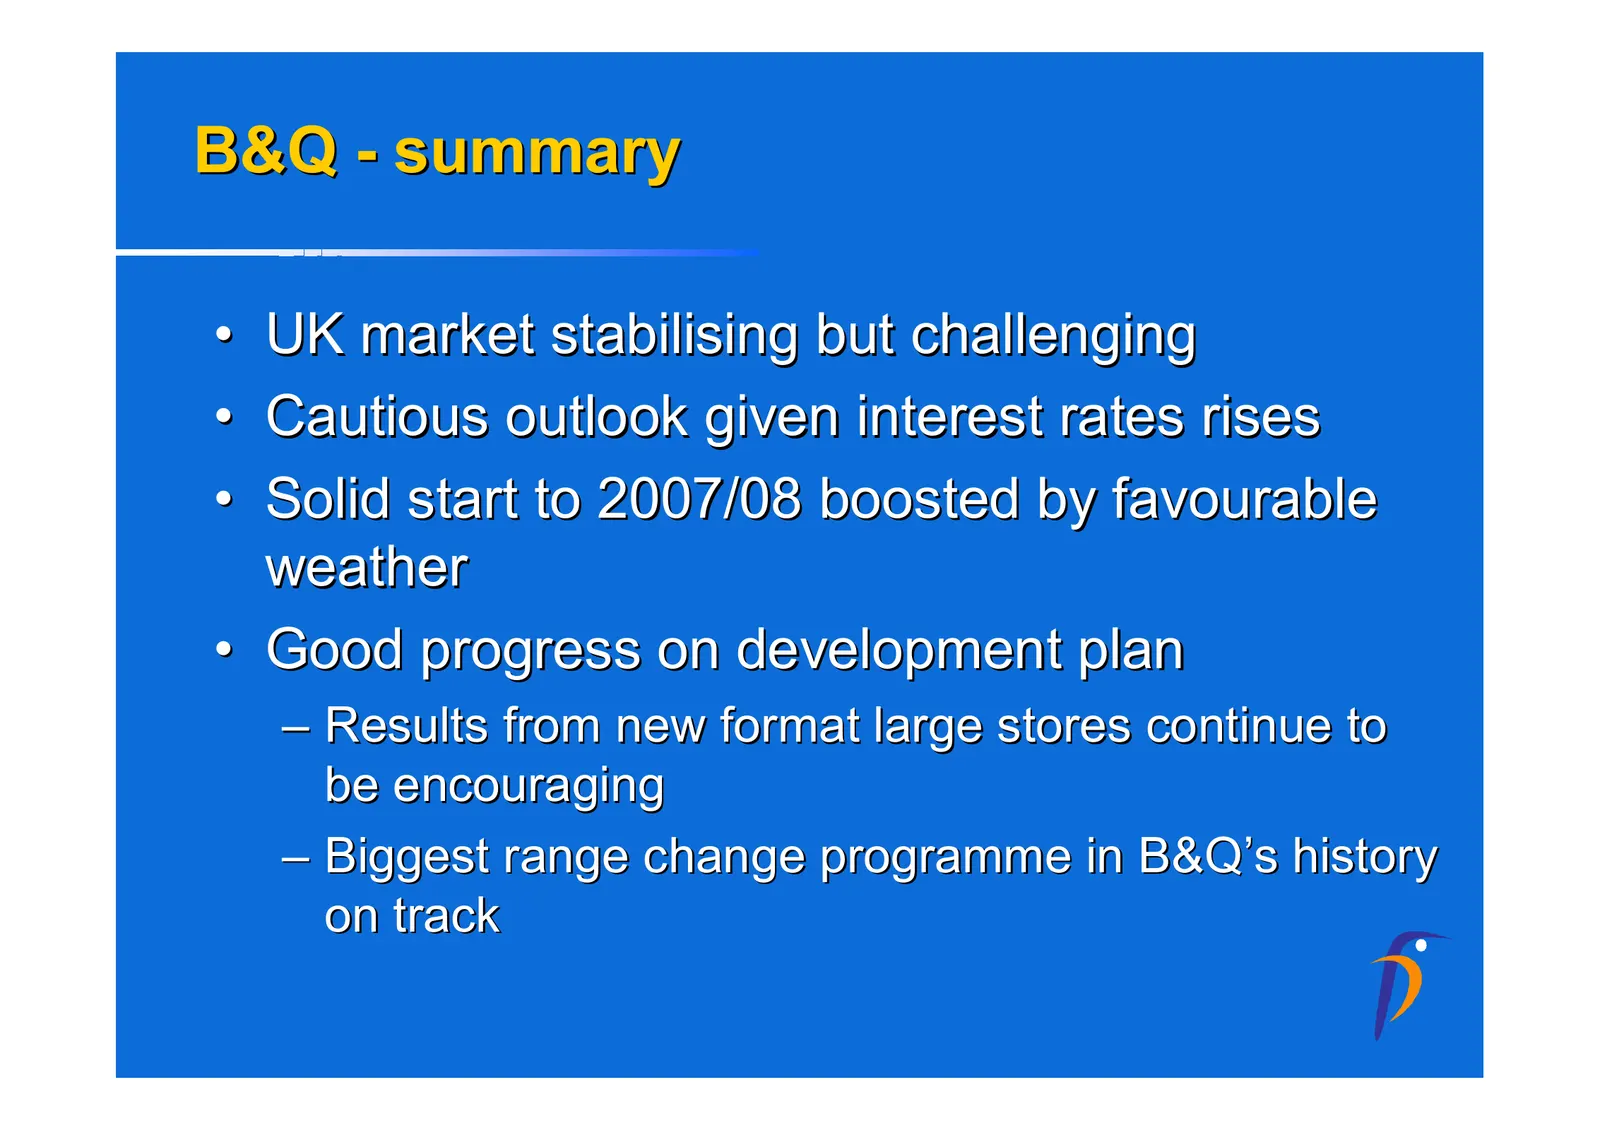
B&Q - summary • UK market stabilising but challenging • Cautious outlook given interest rates rises • Solid start to 2007/08 boosted by favourable weather • Good progress on development plan – Results from new format large stores continue to be encouraging – Biggest range change programme in B&Q’s h
Slide 20: Kingfisher - outlook
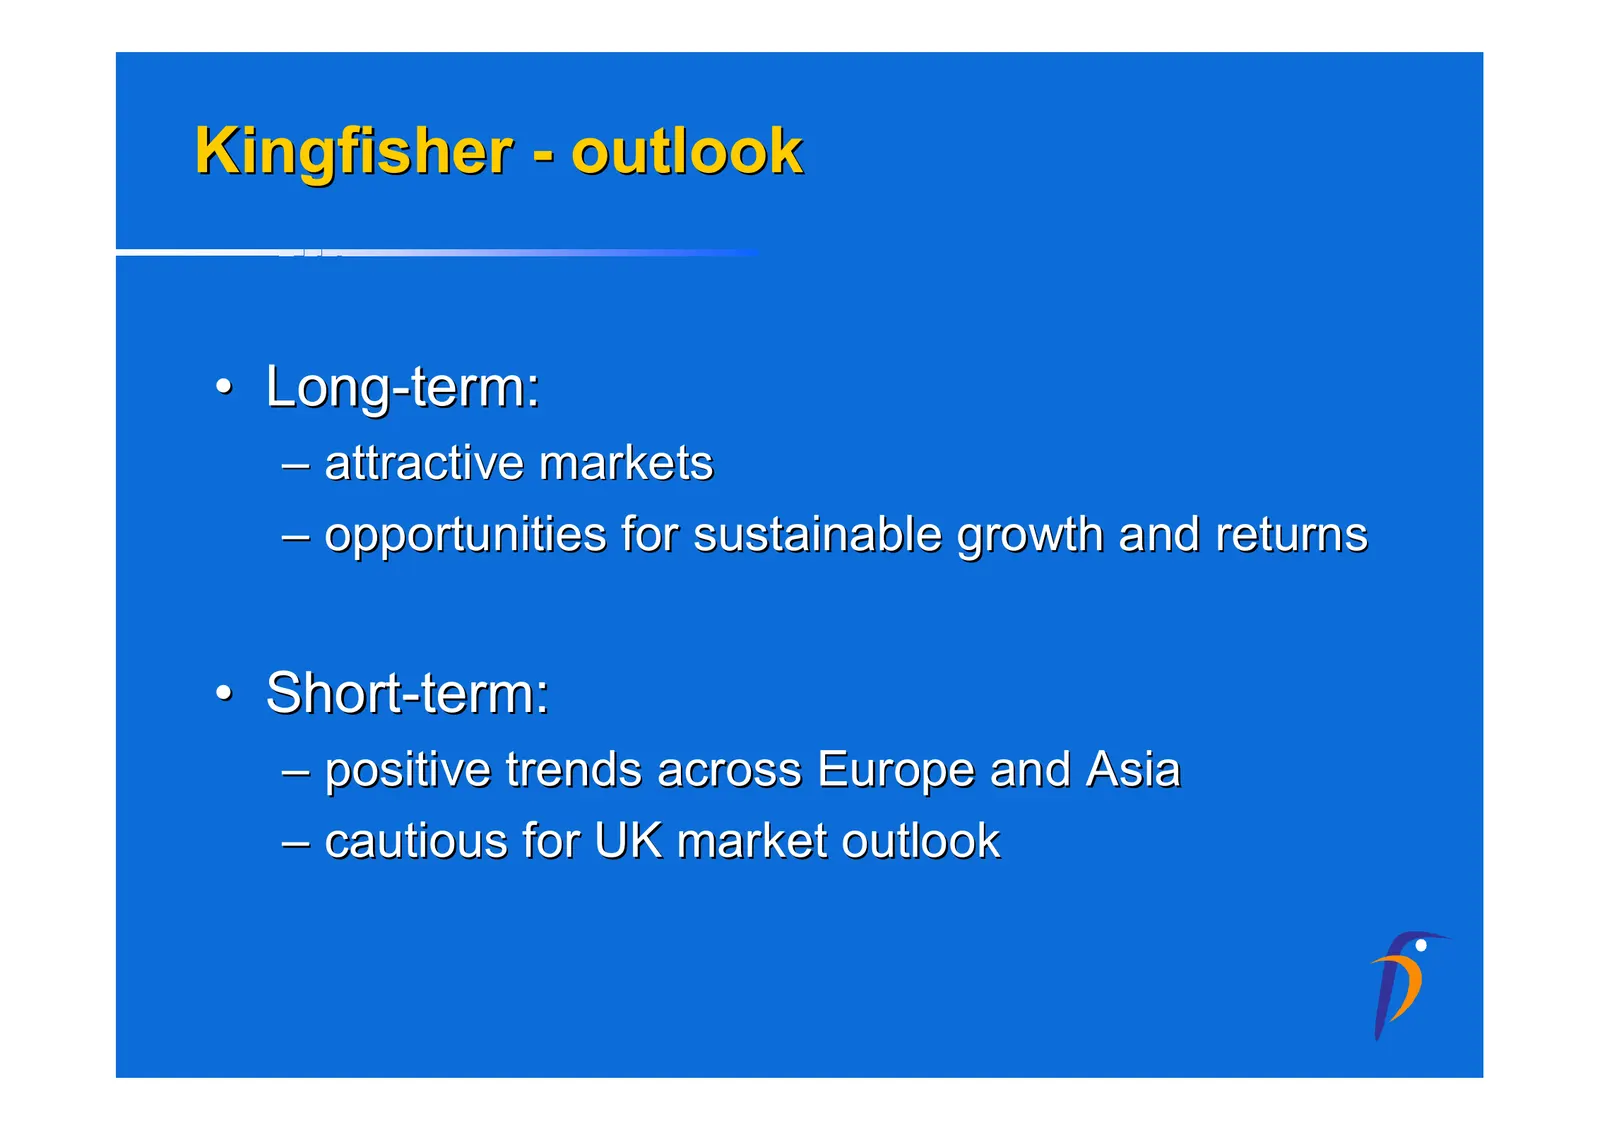
Kingfisher - outlook • Long-term: – attractive markets – opportunities for sustainable growth and returns • Short-term: – positive trends across Europe and Asia – cautious for UK market outlook
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
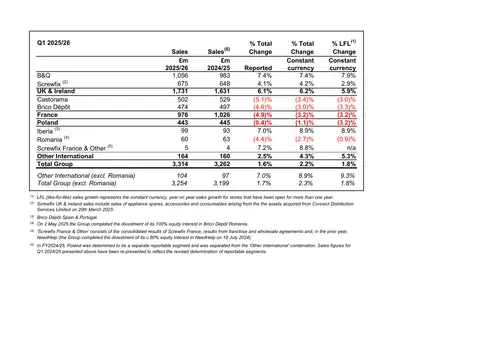 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025