Santander Holdings USA Inc · NYSE:SNUS/PH
Santander Holdings USA — Debt Investor Presentation (May 2025)
31 slides from Santander Holdings USA's debt investor presentation, May 2, 2025
Slide 1: Santander Holdings USA, Inc. First Quarter 2025 Fixed Income Investor Presentation
May 2, 2025 SANTANDER HOLDINGS USA, INC. First Quarter 2025 Fixed Income Investor Presentation 1
Slide 2: Important Information
Important Information This presentation of Santander Holdings USA, Inc. (“SHUSA”) contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the financial condition, results of operations, business plans and future performance of SHUSA.
Slide 3: Index
Index 1 2 3 4 At a glance Results Core Appendix Business Activities 3
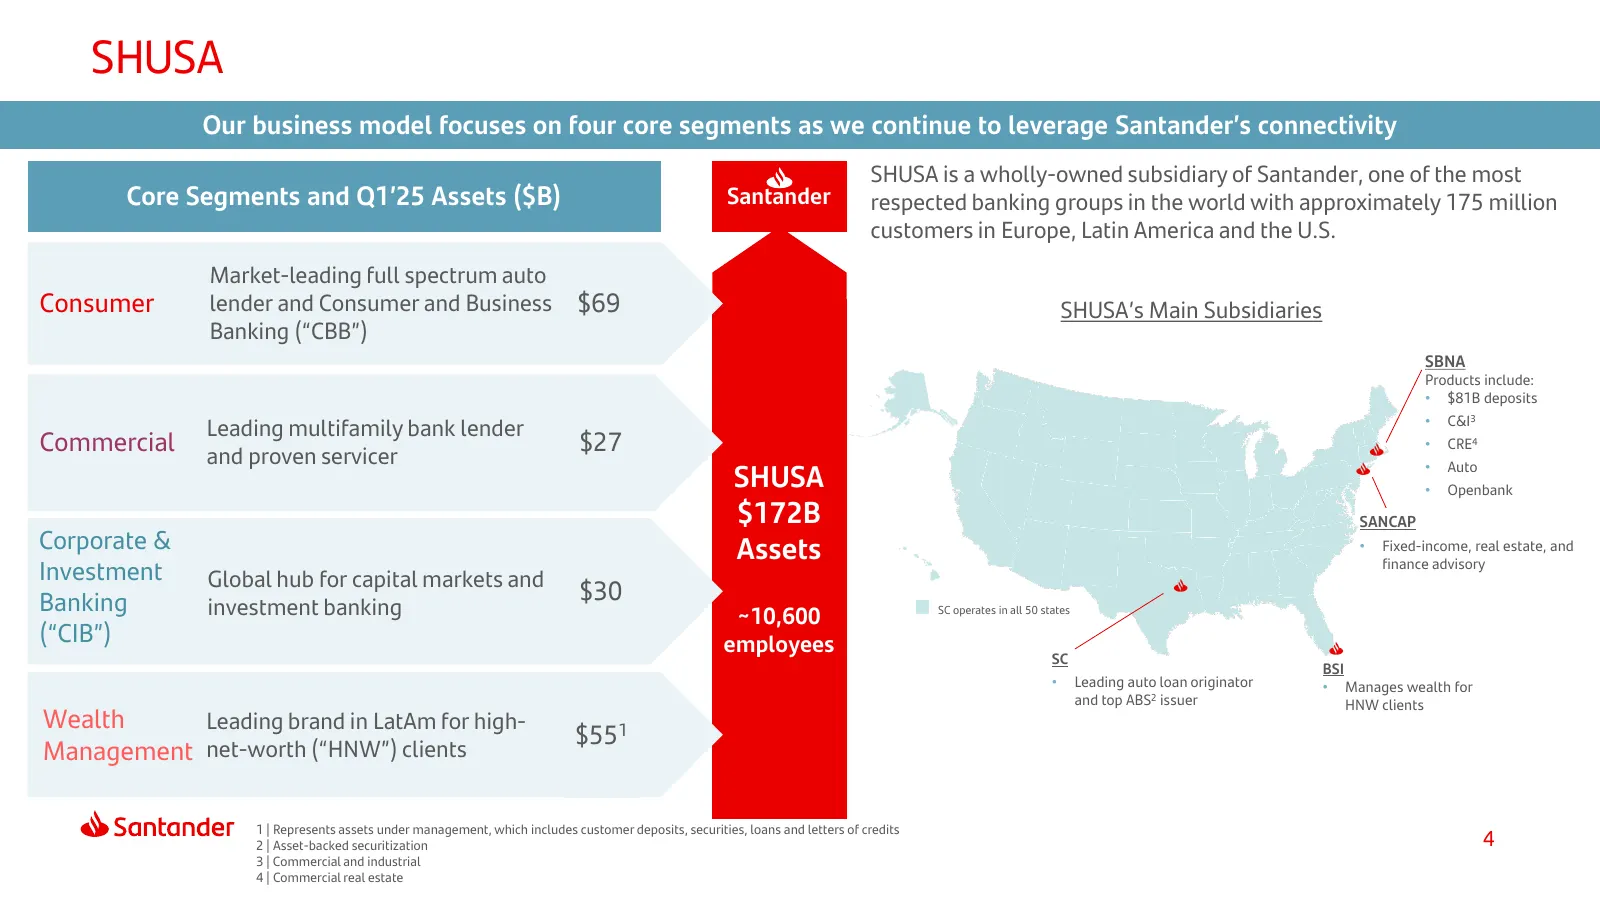
Slide 4: SHUSA core segments and main subsidiaries
SHUSA Our business model focuses on four core segments as we continue to leverage Santander’s connectivity SHUSA is a wholly-owned subsidiary of Santander, one of the most Core Segments and Q1’25 Assets ($B) Santander respected banking groups in the world with approximately 175 million customers in
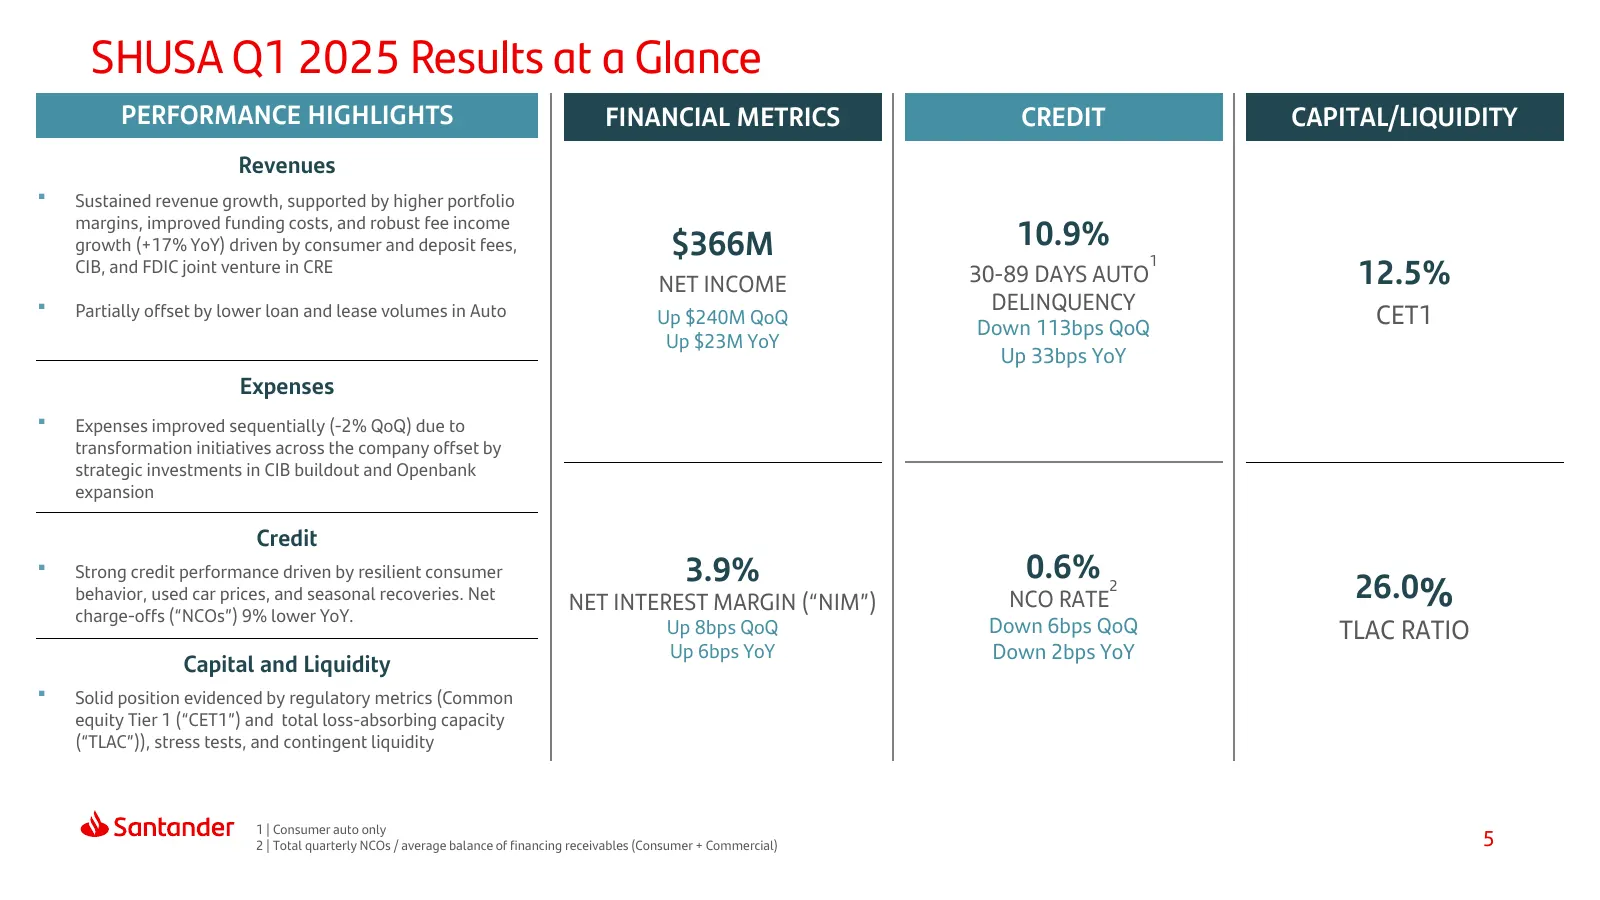
Slide 5: SHUSA Q1 2025 Results at a Glance
SHUSA Q1 2025 Results at a Glance PERFORMANCE HIGHLIGHTS FINANCIAL METRICS CREDIT CAPITAL/LIQUIDITY Revenues Sustained revenue growth, supported by higher portfolio margins, improved funding costs, and robust fee income growth (+17% YoY) driven by consumer and deposit fees, $366M 10.9% 12.5% CIB,
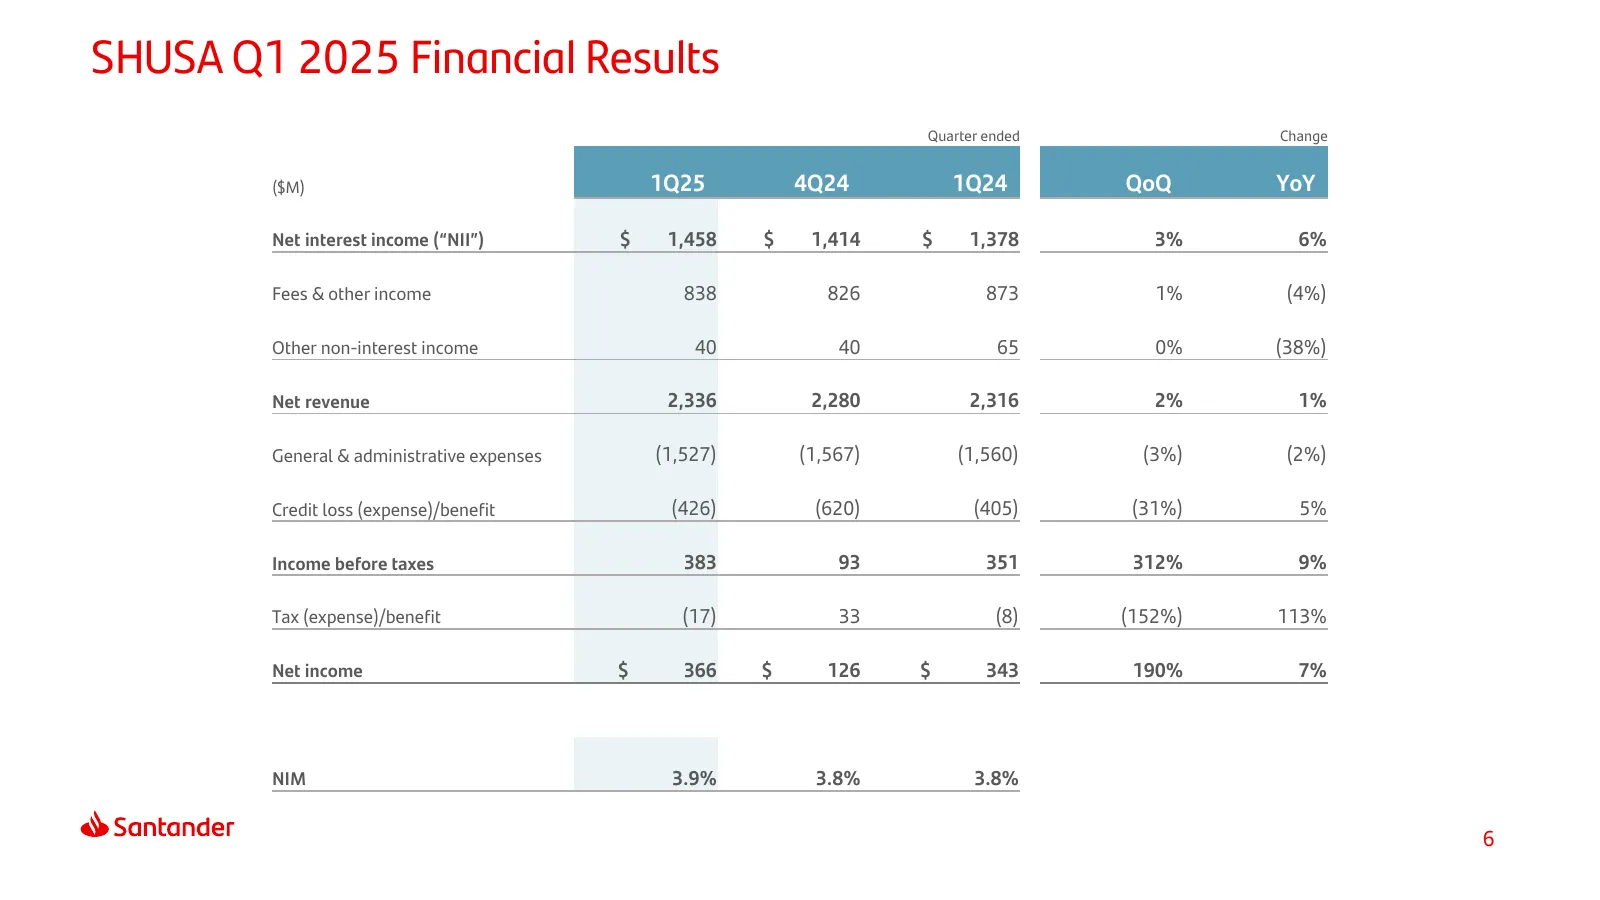
Slide 6: SHUSA Q1 2025 Financial Results
SHUSA Q1 2025 Financial Results Quarter ended Change ($M) 1Q25 4Q24 1Q24 QoQ YoY Net interest income (“NII”) $ 1,458 $ 1,414 $ 1,378 3% 6% Fees & other income 838 826 873 1% (4%) Other non-interest income 40 40 65 0% (38%) Net revenue 2,336 2,280 2,316 2% 1% General & administrative expenses (1,527)
Slide 7: Index
Index 1 2 3 4 At a Glance Results Core Appendix Business Activities 7
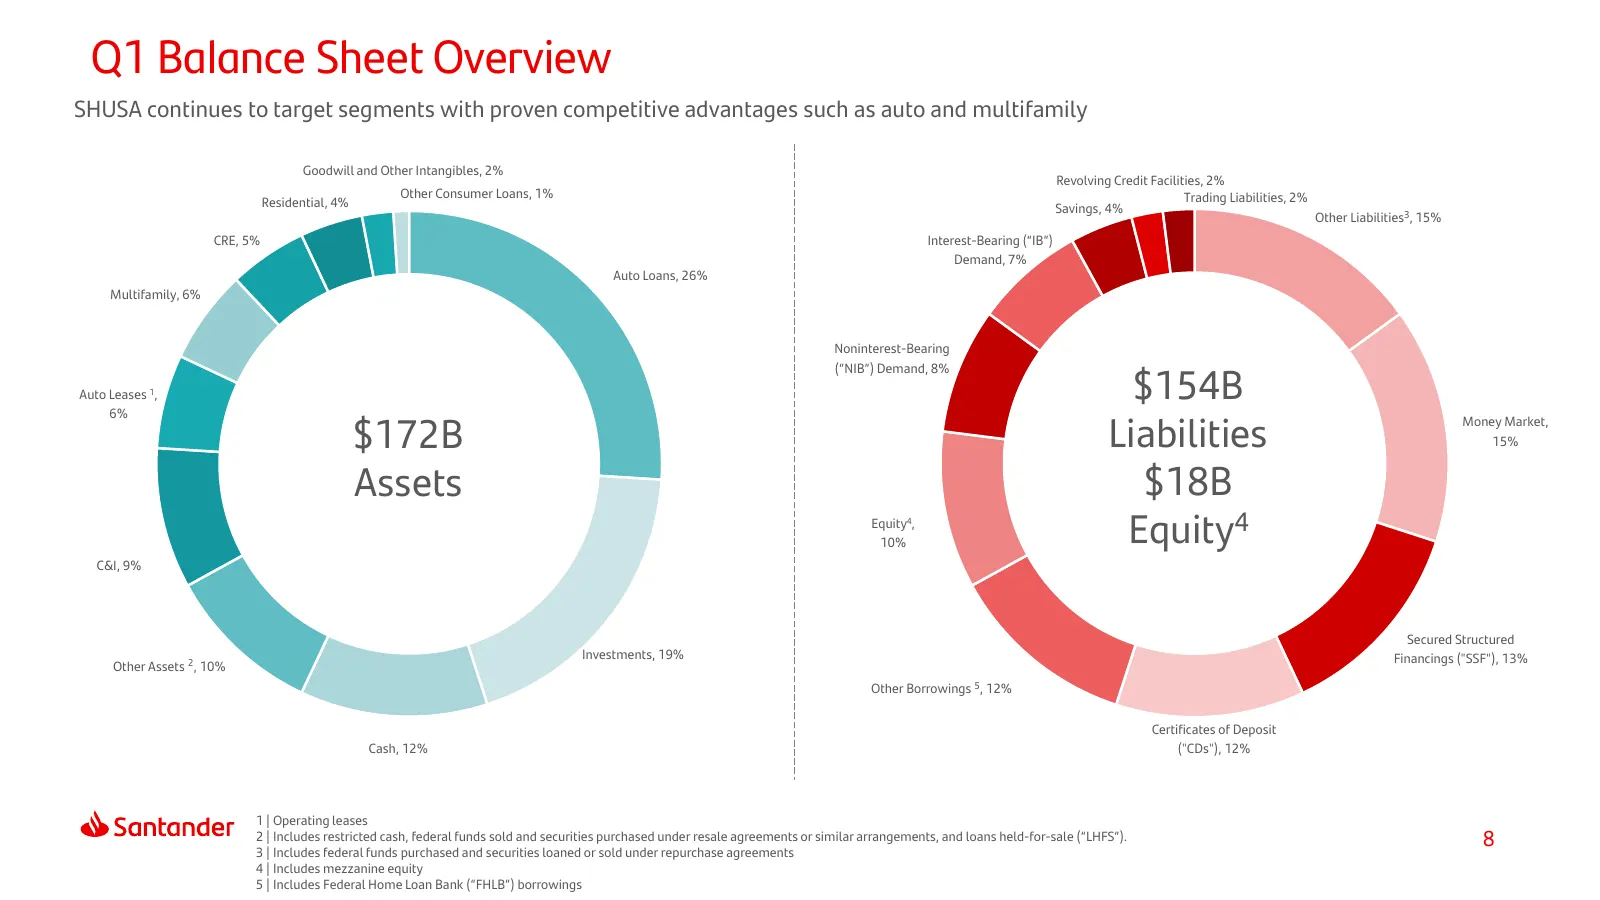
Slide 8: Q1 Balance Sheet Overview
Q1 Balance Sheet Overview SHUSA continues to target segments with proven competitive advantages such as auto and multifamily Goodwill and Other Intangibles, 2% Revolving Credit Facilities, 2% Other Consumer Loans, 1% Trading Liabilities, 2% Residential, 4% Savings, 4% Other Liabilities3, 15% CRE, 5%
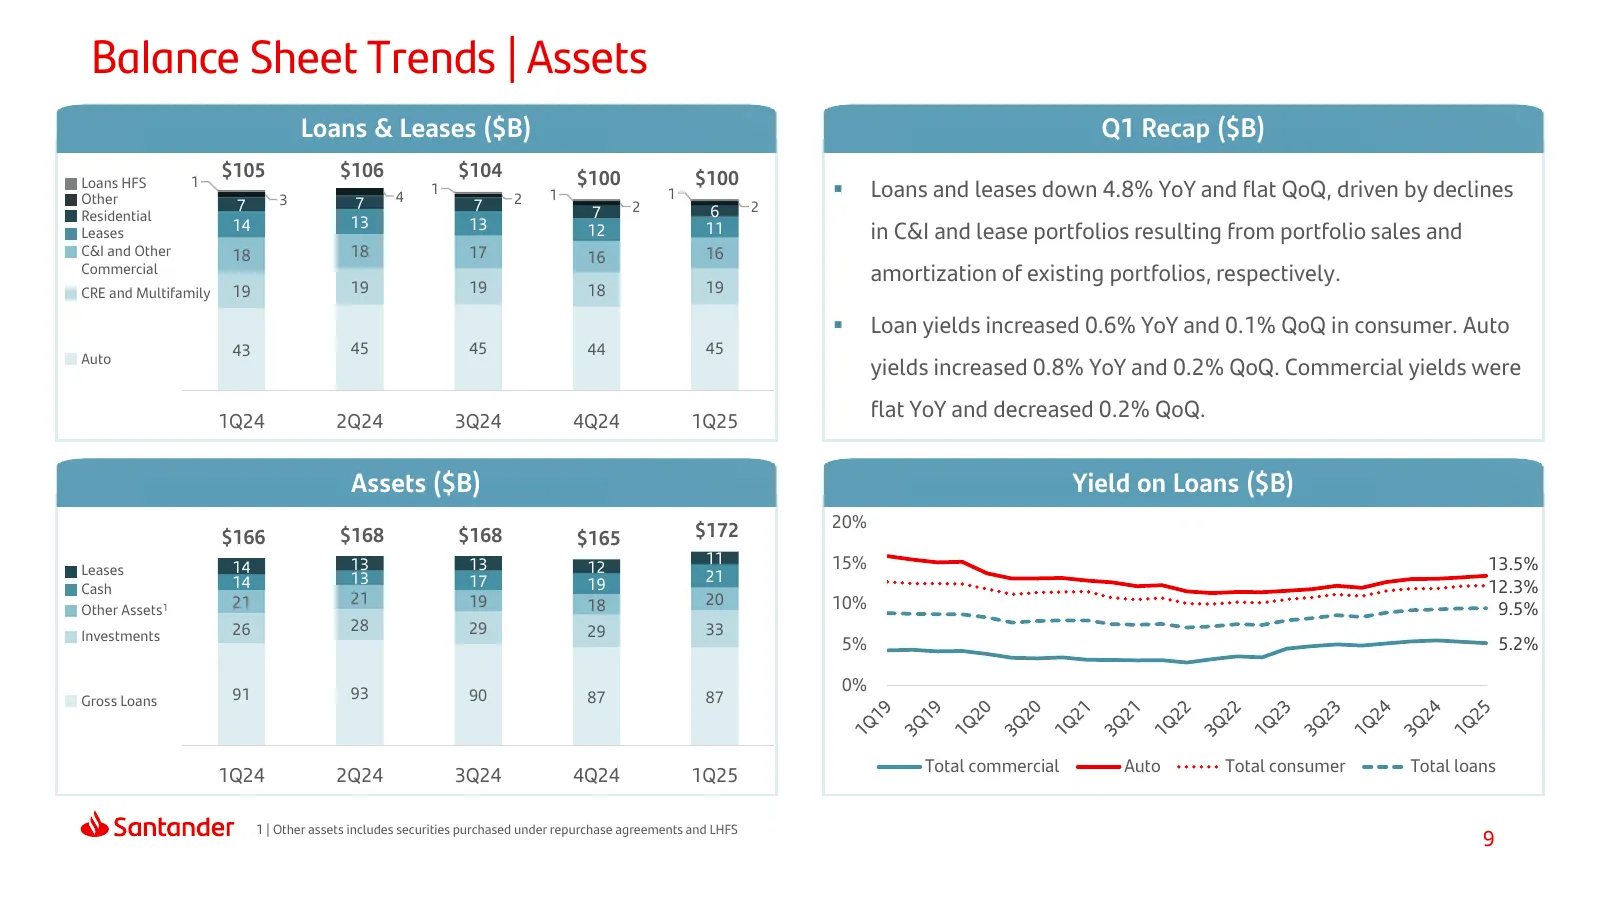
Slide 9: Balance Sheet Trends | Assets
Balance Sheet Trends | Assets Loans & Leases ($B) Q1 Recap ($B) $105 $106 $104 $100 $100 1 Loans HFS Other 3 4 1 2 1 1 Loans and leases down 4.8% YoY and flat QoQ, driven by declines 7 7 7 2 2 Residential 7 6 14 13 13 Leases 12 11 in C&I and lease portfolios resulting from portfolio sales and C&I
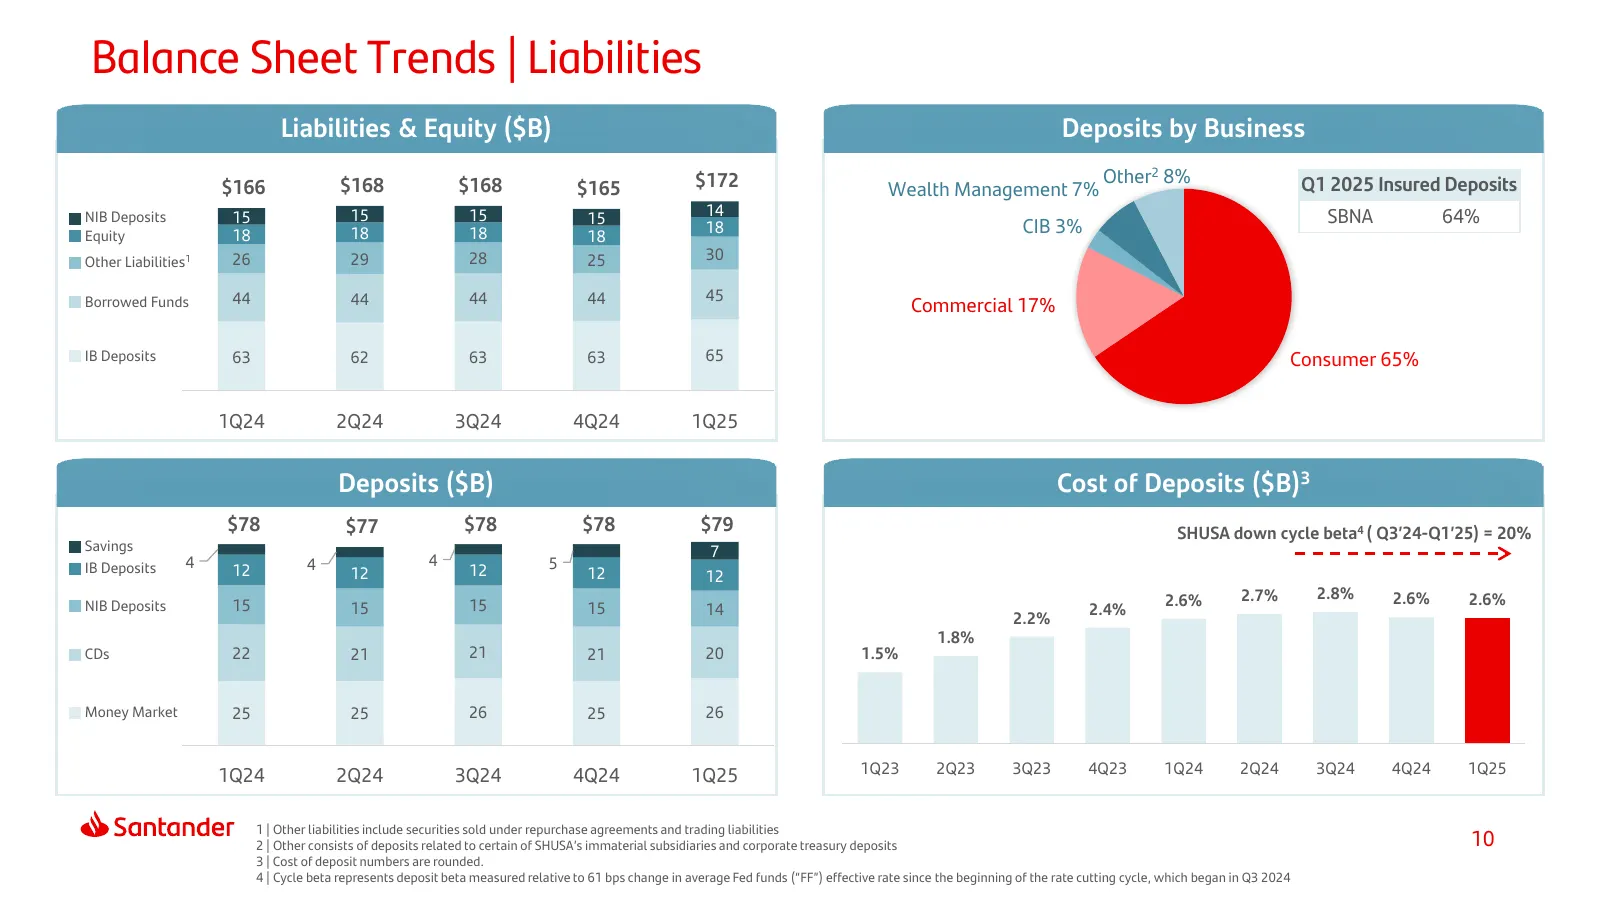
Slide 10: Balance Sheet Trends | Liabilities
Balance Sheet Trends | Liabilities Liabilities & Equity ($B) Deposits by Business $168 $168 $172 Other2 8% Q1 2025 Insured Deposits $166 $165 Wealth Management 7% NIB Deposits 15 15 15 15 14 SBNA 64% Equity 18 18 18 18 18 CIB 3% Other Liabilities1 26 29 28 25 30 Borrowed Funds 44 44 44 44 45 Commerc
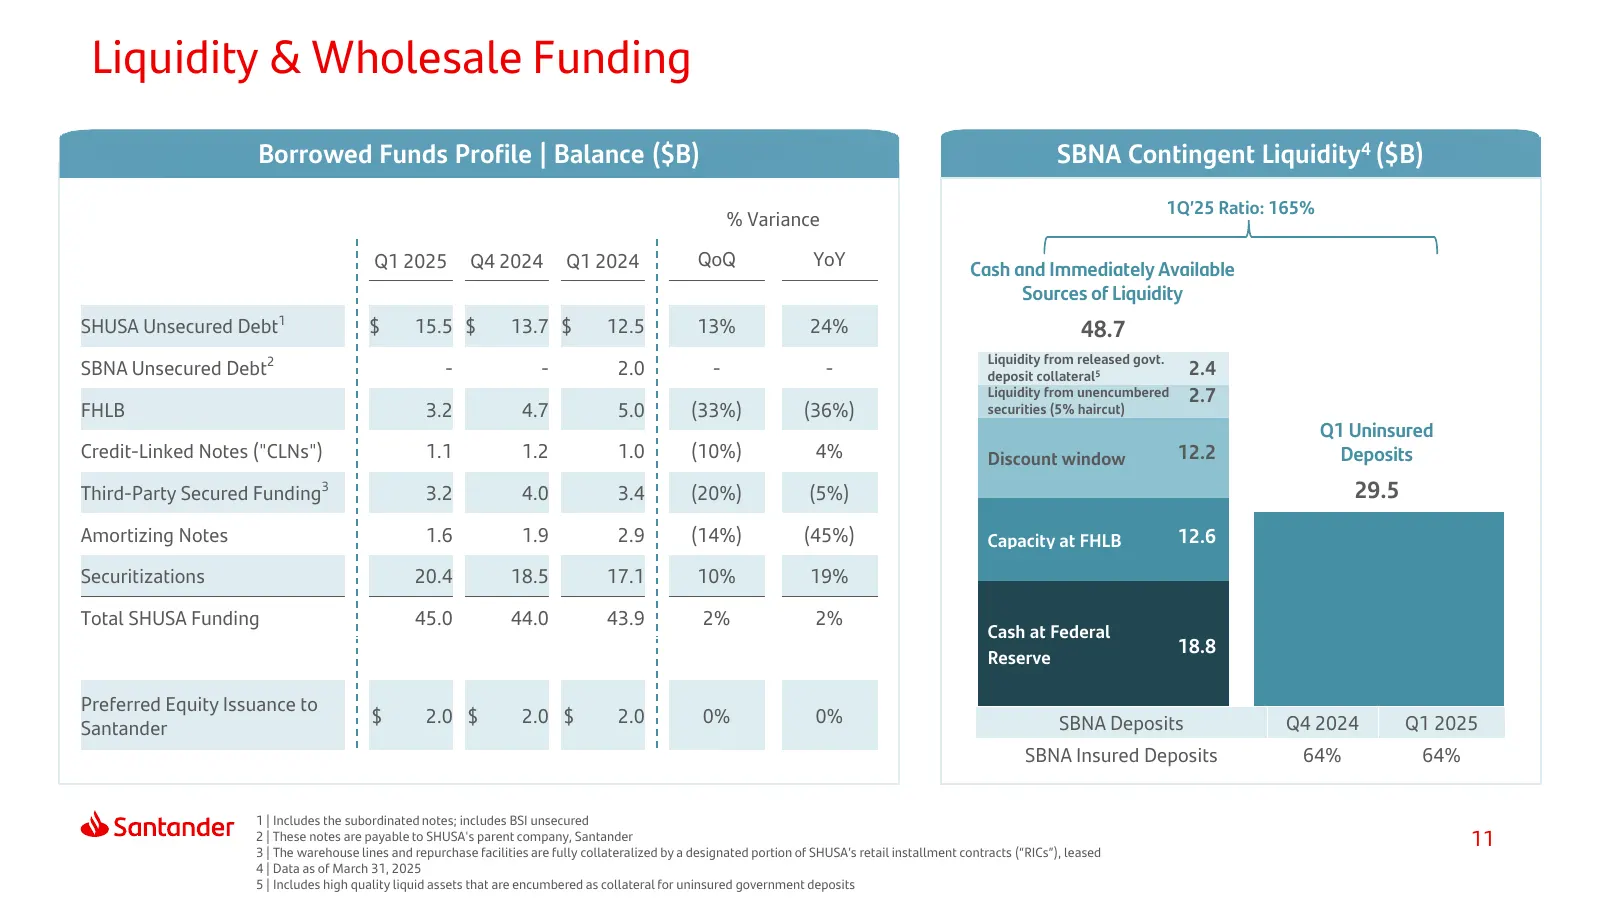
Slide 11: Liquidity & Wholesale Funding
Liquidity & Wholesale Funding Borrowed Funds Profile | Balance ($B) SBNA Contingent Liquidity4 ($B) 1Q’25 Ratio: 165% % Variance Q1 2025 Q4 2024 Q1 2024 QoQ YoY Cash and Immediately Available Sources of Liquidity SHUSA Unsecured Debt1 $ 15.5 $ 13.7 $ 12.5 13% 24% 48.7 Liquidity from released govt. S
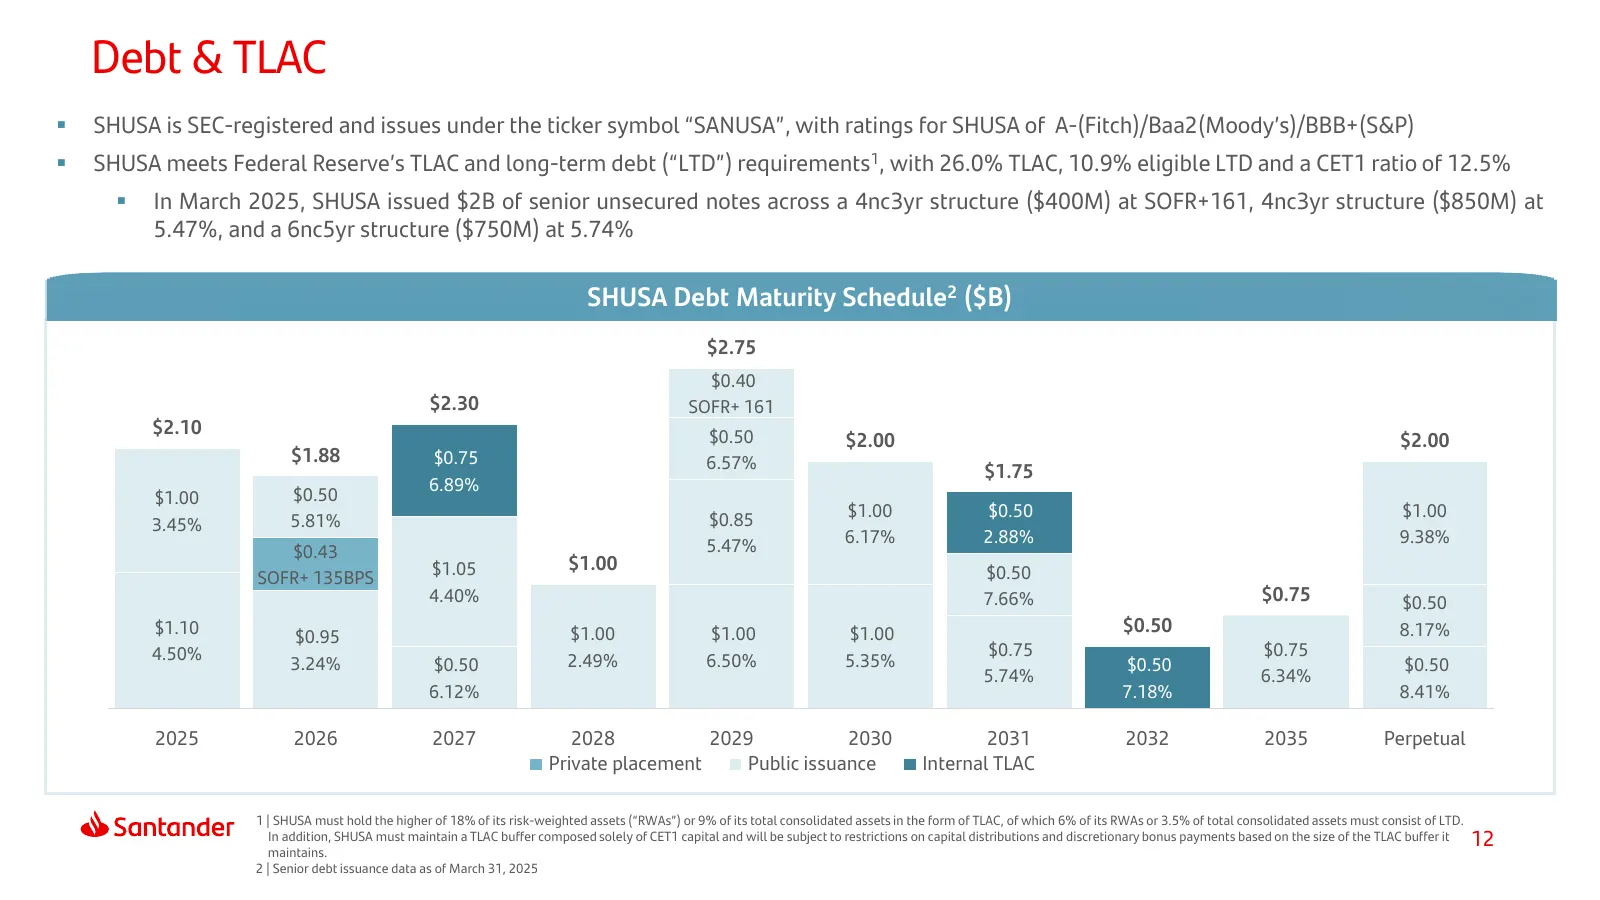
Slide 12: Debt & TLAC
Debt & TLAC SHUSA is SEC-registered and issues under the ticker symbol “SANUSA”, with ratings for SHUSA of A-(Fitch)/Baa2(Moody’s)/BBB+(S&P) SHUSA meets Federal Reserve’s TLAC and long-term debt (“LTD”) requirements1, with 26.0% TLAC, 10.9% eligible LTD and a CET1 ratio of 12.5% In March 2025,
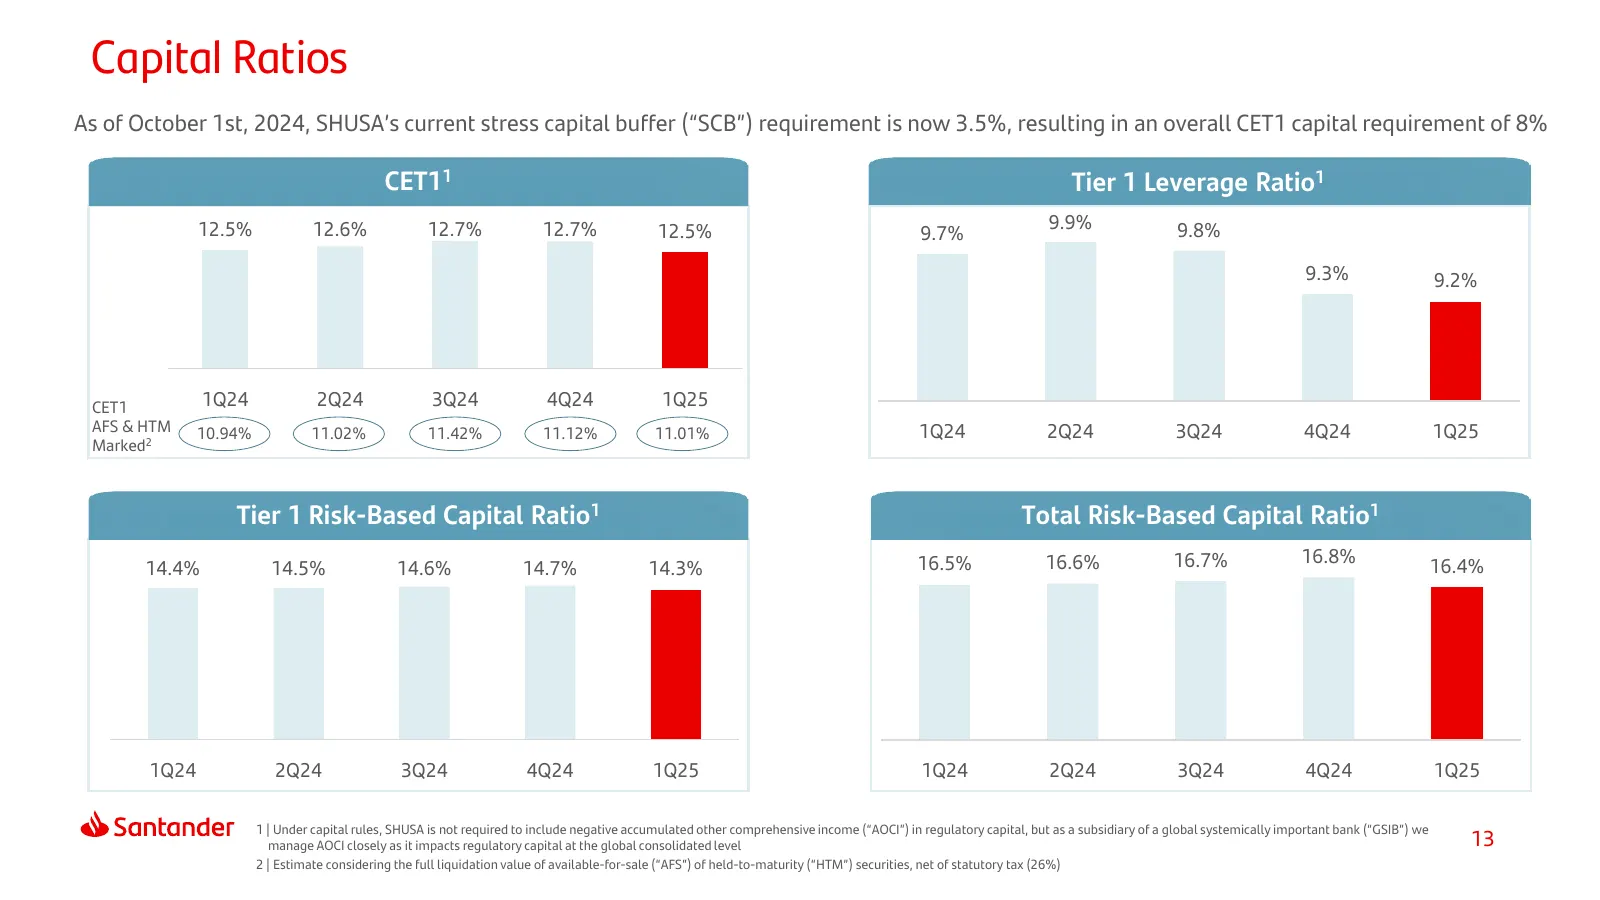
Slide 13: Capital Ratios
Capital Ratios As of October 1st, 2024, SHUSA’s current stress capital buffer (“SCB”) requirement is now 3.5%, resulting in an overall CET1 capital requirement of 8% CET11 Tier 1 Leverage Ratio1 12.5% 12.6% 12.7% 12.7% 12.5% 9.9% 9.8% 9.7% 9.3% 9.2% CET1 1Q24 2Q24 3Q24 4Q24 1Q25 AFS & HTM 10.94% 11.
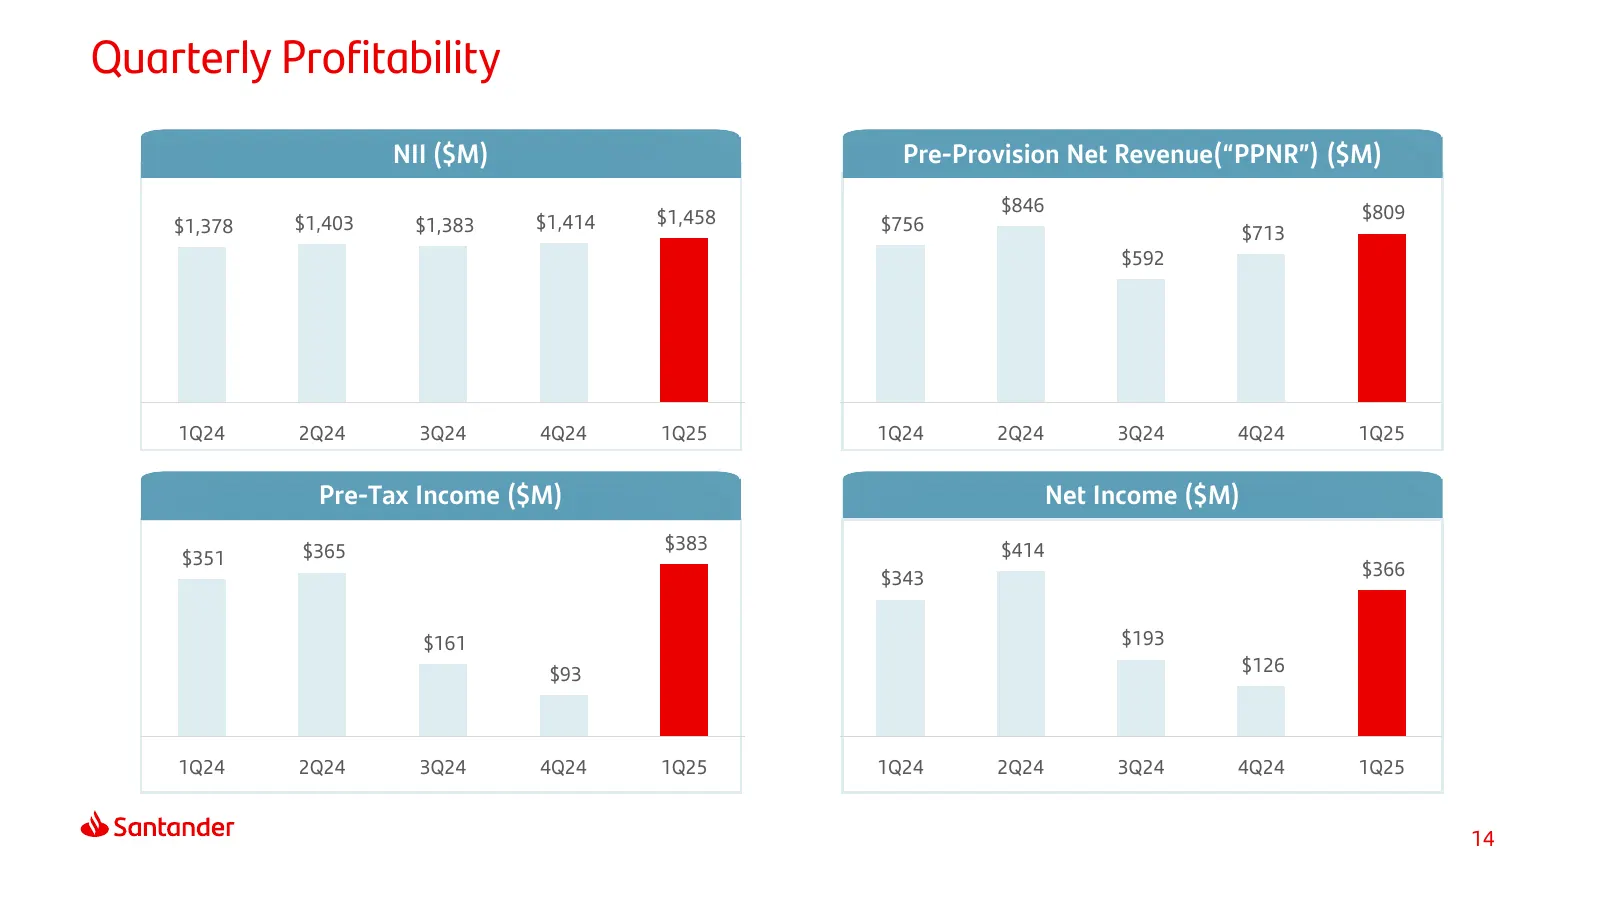
Slide 14: Quarterly Profitability
Quarterly Profitability NII ($M) Pre-Provision Net Revenue(“PPNR”) ($M) $846 $809 $1,378 $1,403 $1,383 $1,414 $1,458 $756 $713 $592 1Q24 2Q24 3Q24 4Q24 1Q25 1Q24 2Q24 3Q24 4Q24 1Q25 Pre-Tax Income ($M) Net Income ($M) $365 $383 $414 $351 $343 $366 $161 $193 $93 $126 1Q24 2Q24 3Q24 4Q24 1Q25 1Q24 2Q2
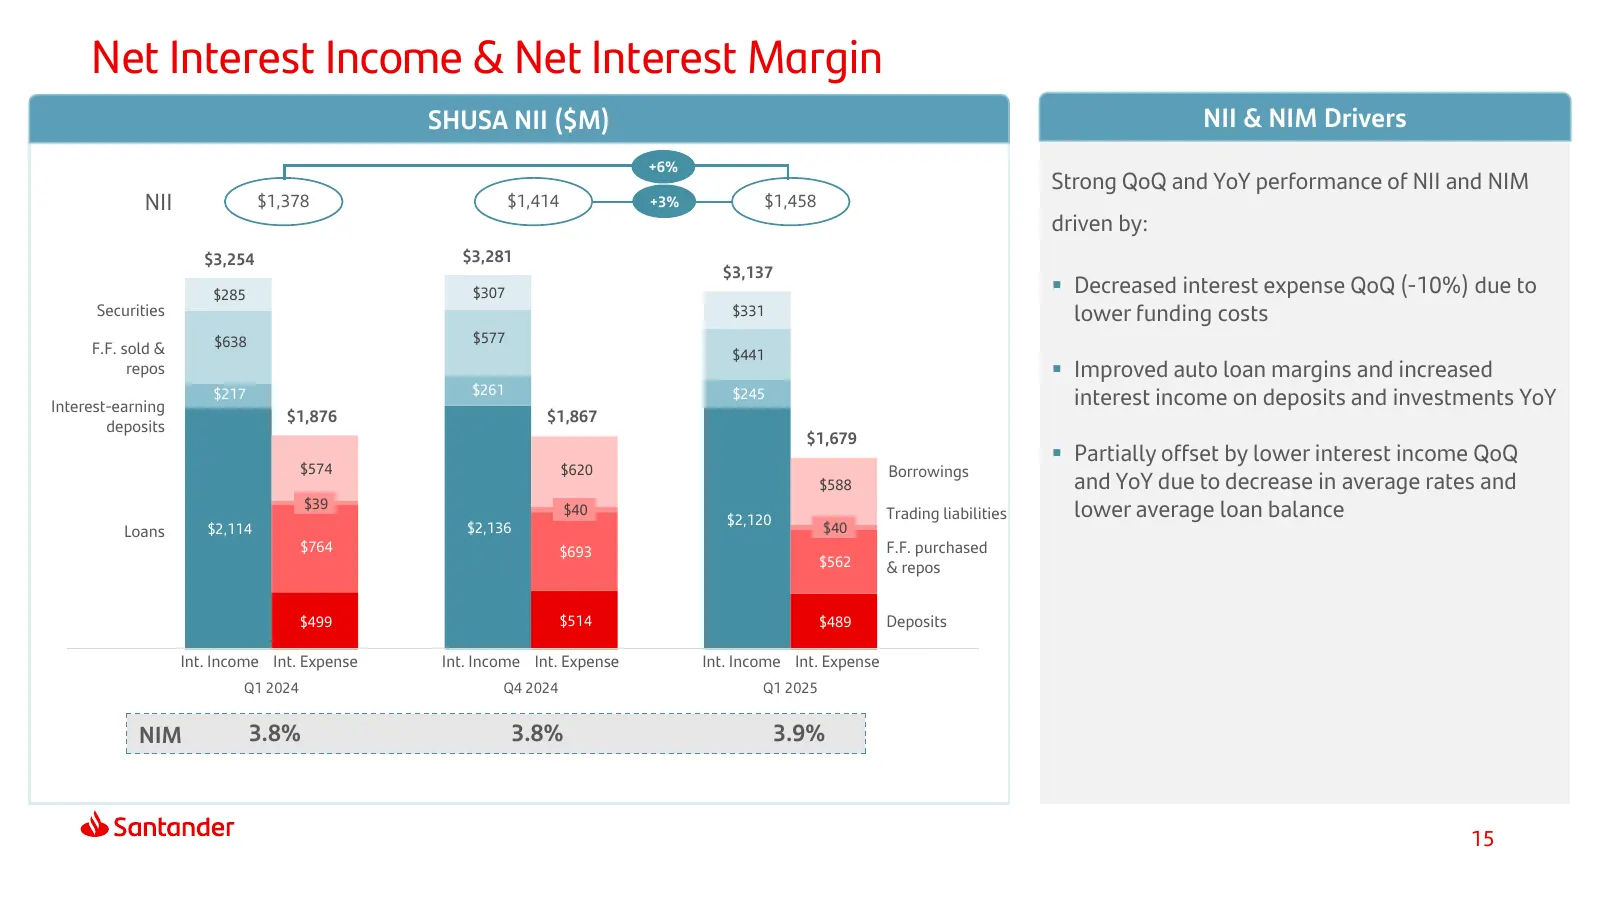
Slide 15: Net Interest Income & Net Interest Margin
Net Interest Income & Net Interest Margin SHUSA NII ($M) NII & NIM Drivers +6% Strong QoQ and YoY performance of NII and NIM NII $1,378 $1,414 +3% $1,458 driven by: $3,254 $3,281 $3,137 $285 $307 Decreased interest expense QoQ (-10%) due to Securities $331 lower funding costs $638 $577 F.F. sold &
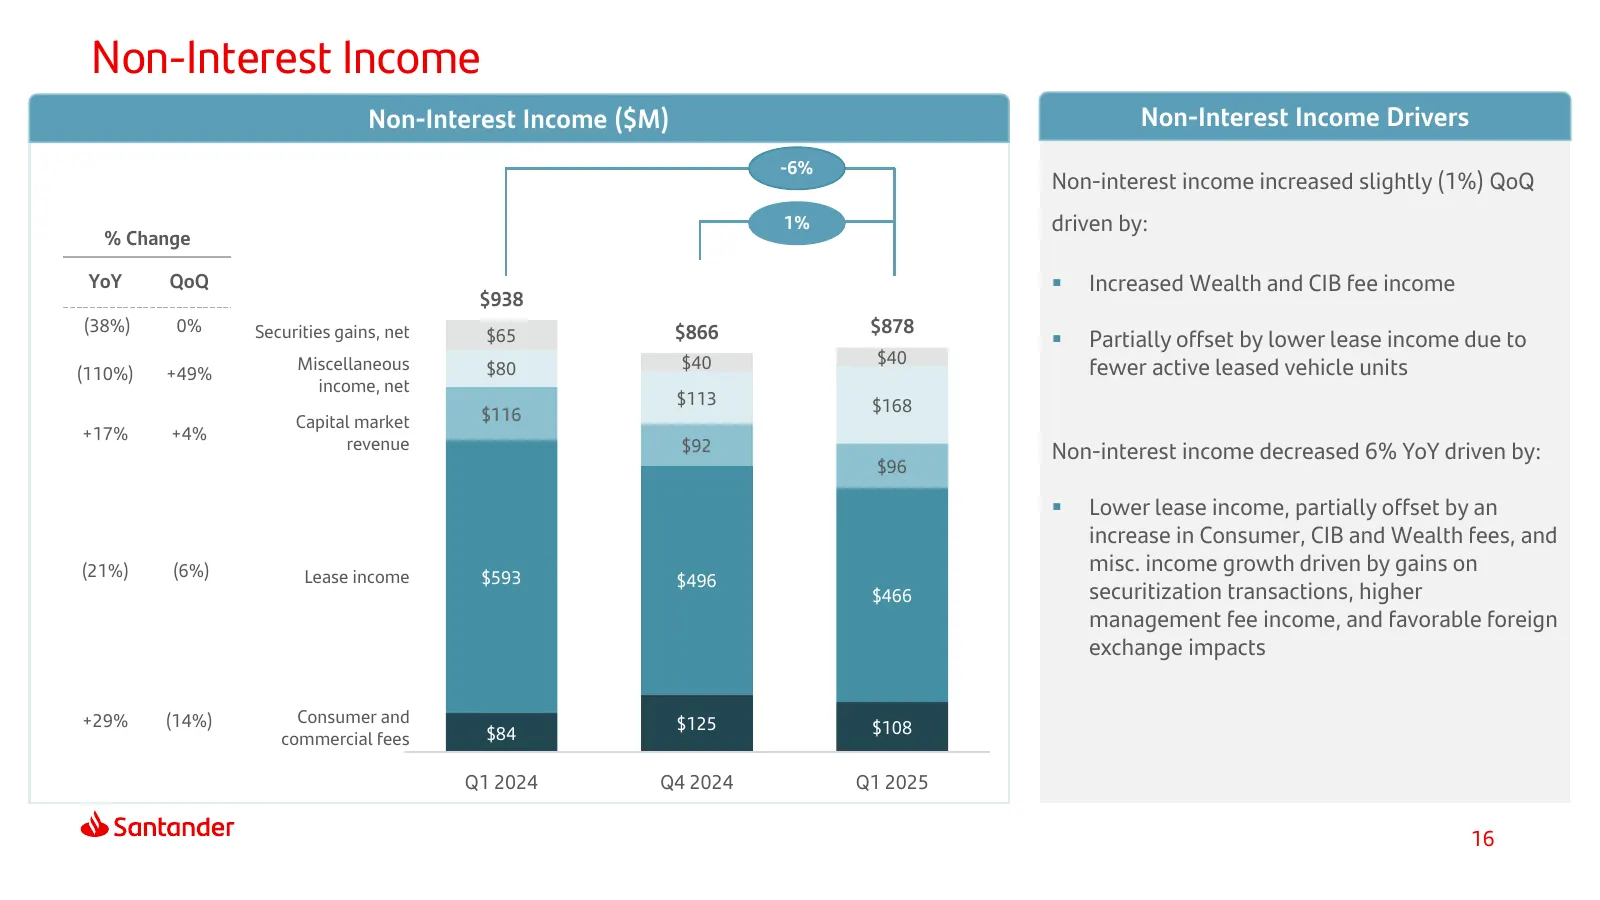
Slide 16: Non-Interest Income
Non-Interest Income Non-Interest Income ($M) Non-Interest Income Drivers -6% Non-interest income increased slightly (1%) QoQ 1% driven by: % Change YoY QoQ Increased Wealth and CIB fee income $938 (38%) 0% Securities gains, net $866 $878 $65 Partially offset by lower lease income due to $40 $40
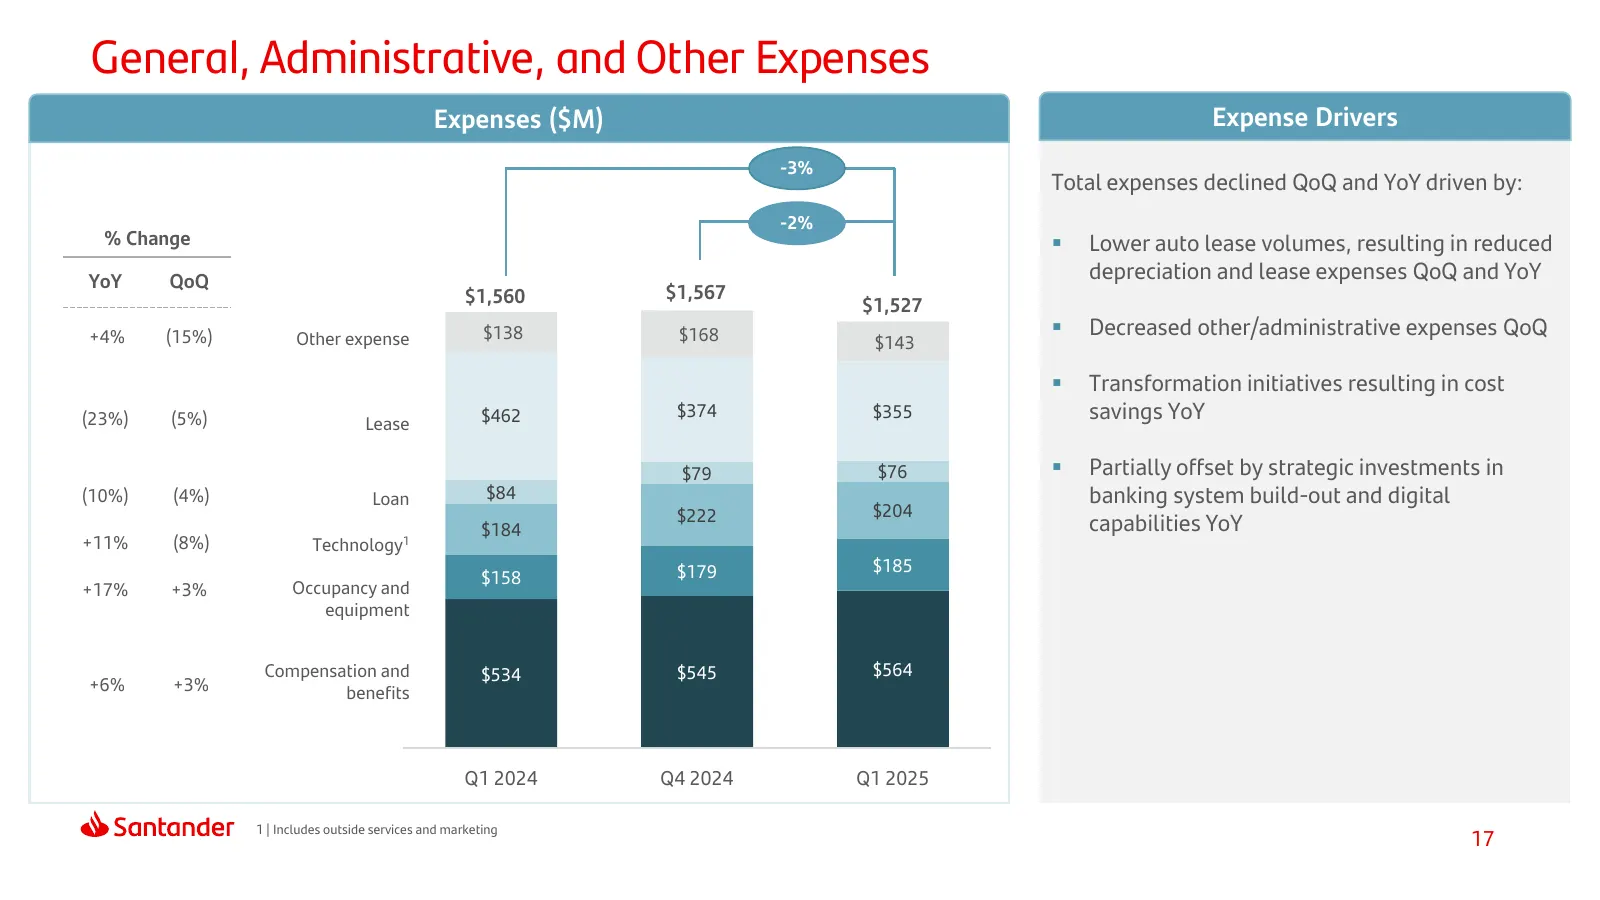
Slide 17: General, Administrative, and Other Expenses
General, Administrative, and Other Expenses Expenses ($M) Expense Drivers -3% Total expenses declined QoQ and YoY driven by: -2% % Change Lower auto lease volumes, resulting in reduced YoY QoQ depreciation and lease expenses QoQ and YoY $1,560 $1,567 $1,527 +4% (15%) Other expense $138 $168 Decr
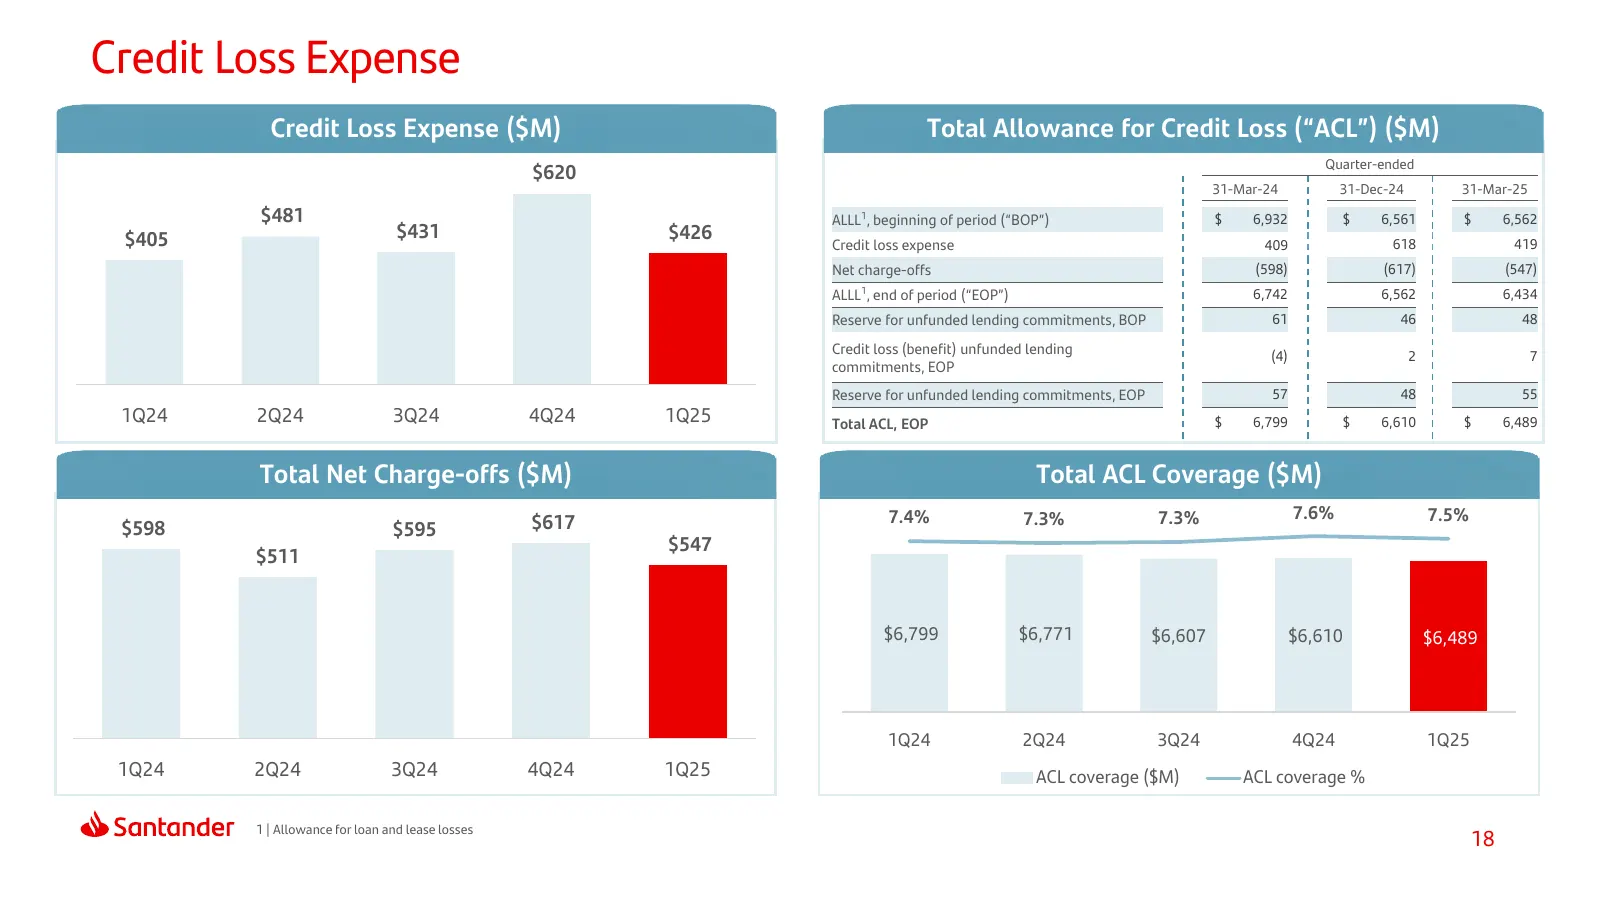
Slide 18: Credit Loss Expense
Credit Loss Expense Credit Loss Expense ($M) Total Allowance for Credit Loss (“ACL”) ($M) Quarter-ended $620 31-Mar-24 31-Dec-24 31-Mar-25 $481 1 ALLL , beginning of period (“BOP”) $ 6,932 $ 6,561 $ 6,562 $405 $431 $426 Credit loss expense 409 618 419 Net charge-offs (598) (617) (547) 1 6,742 6,562
Slide 19: Index
Index 1 2 3 4 At a Glance Results Core Appendix Business Activities 19
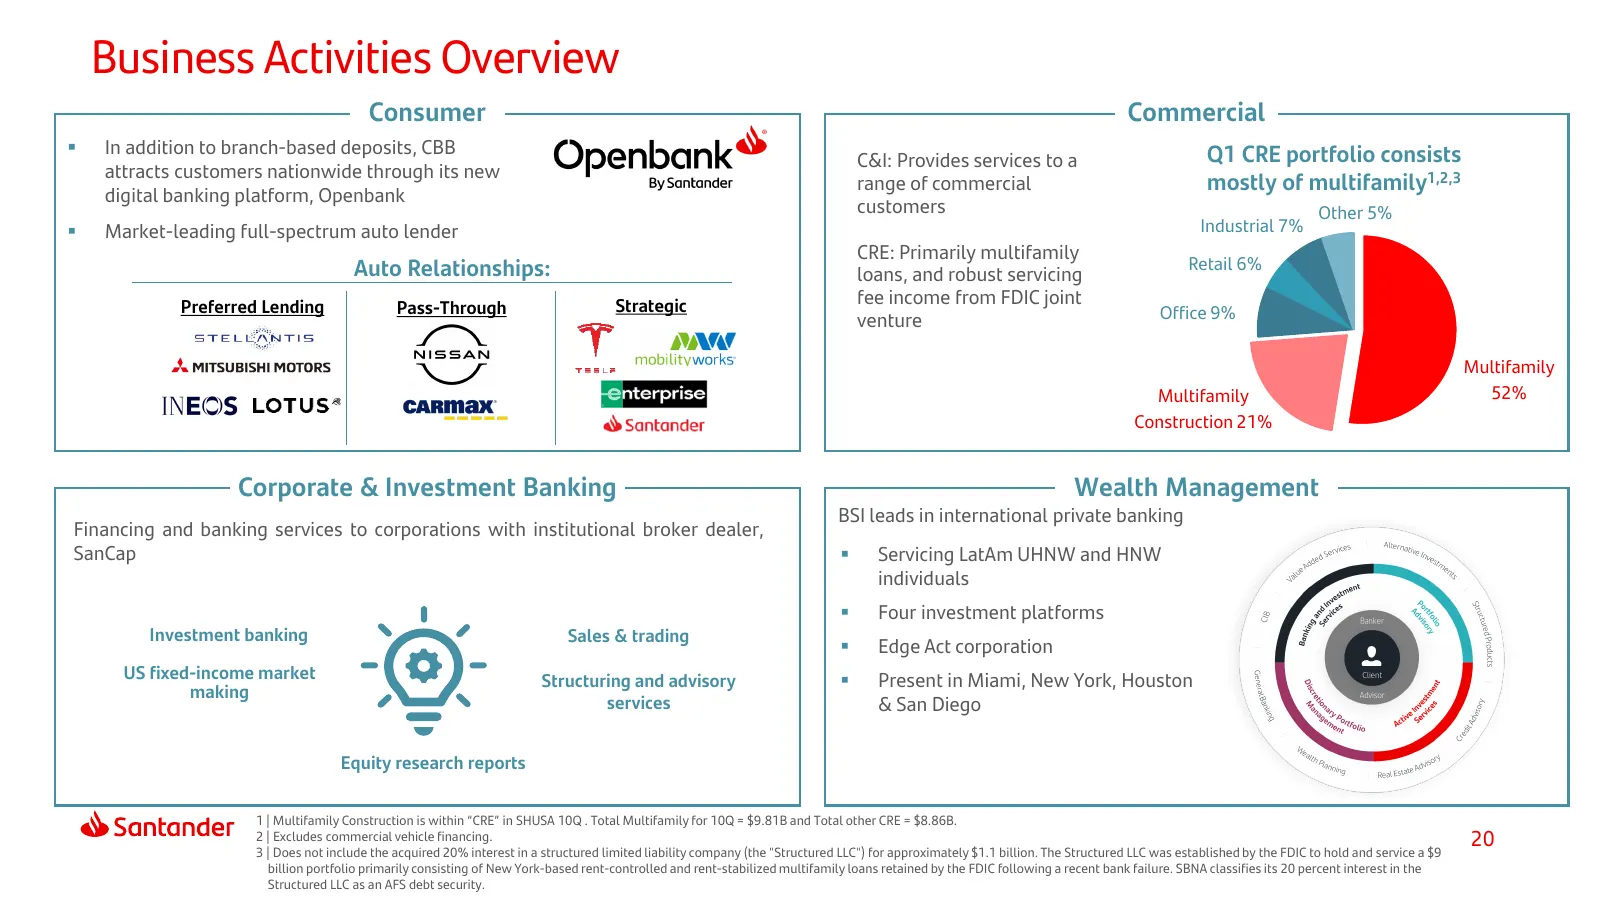
Slide 20: Business Activities Overview
Business Activities Overview Consumer Commercial In addition to branch-based deposits, CBB Q1 CRE portfolio consists C&I: Provides services to a attracts customers nationwide through its new range of commercial mostly of multifamily1,2,3 digital banking platform, Openbank customers Other 5% Mark
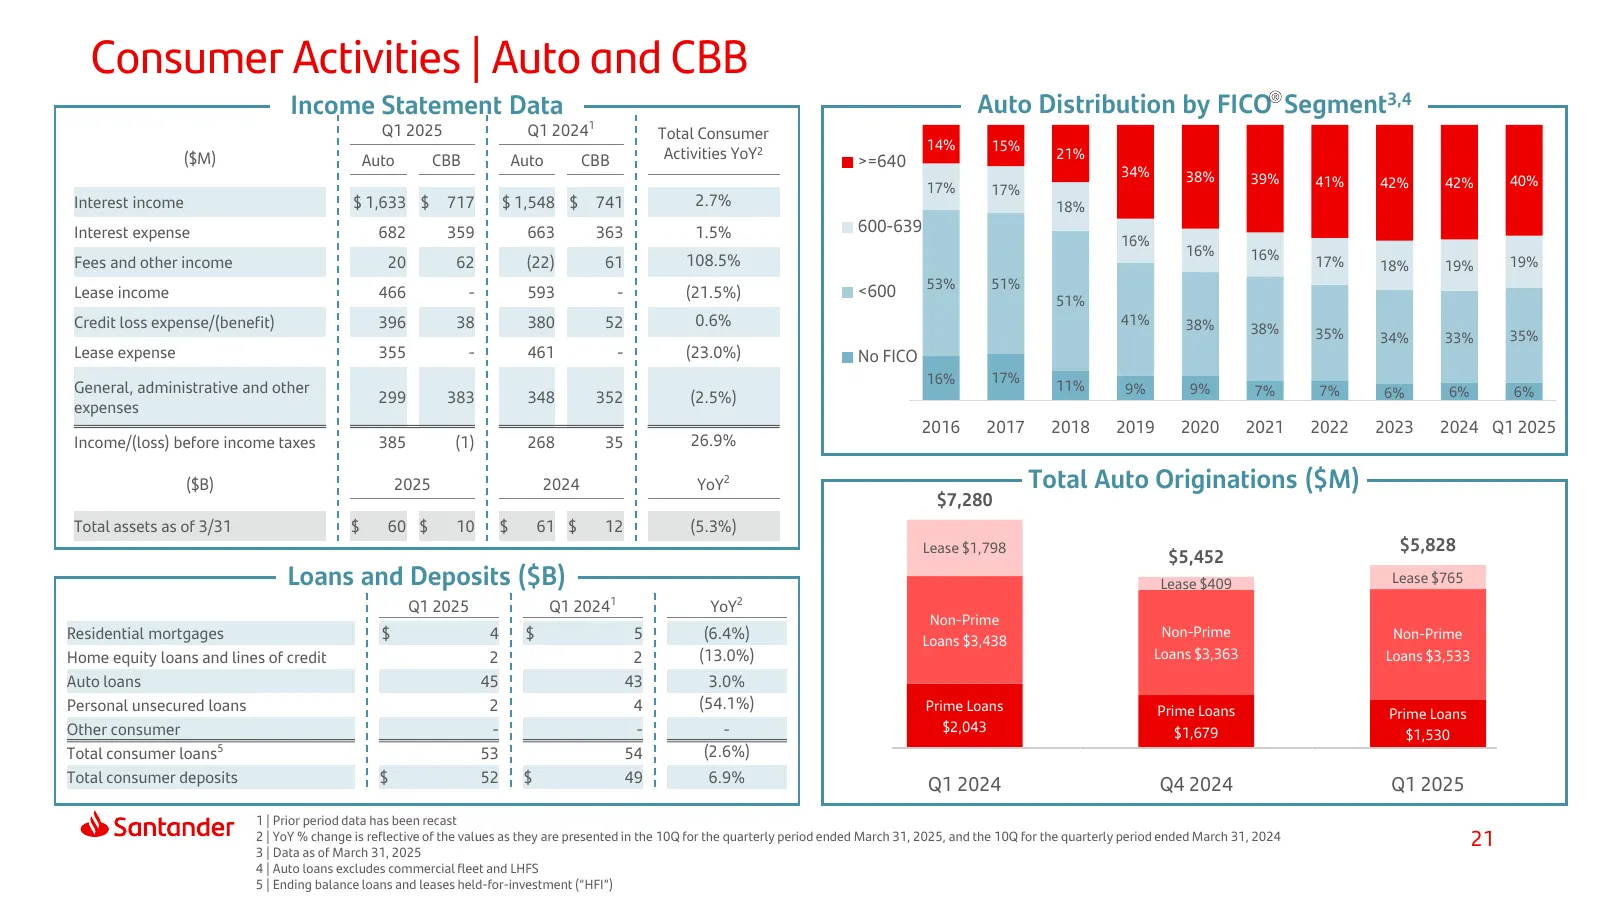
Slide 21: Consumer Activities | Auto and CBB
Consumer Activities | Auto and CBB Income Statement Data Auto Distribution by FICO Segment3,4 Q1 2025 Q1 20241 Total Consumer 14% 15% ($M) Auto CBB Auto CBB Activities YoY2 >=640 21% 34% 38% 39% 17% 41% 42% 42% 40% 17% Interest income $ 1,633 $ 717 $ 1,548 $ 741 2.7% 18% Interest expense 682 359 663
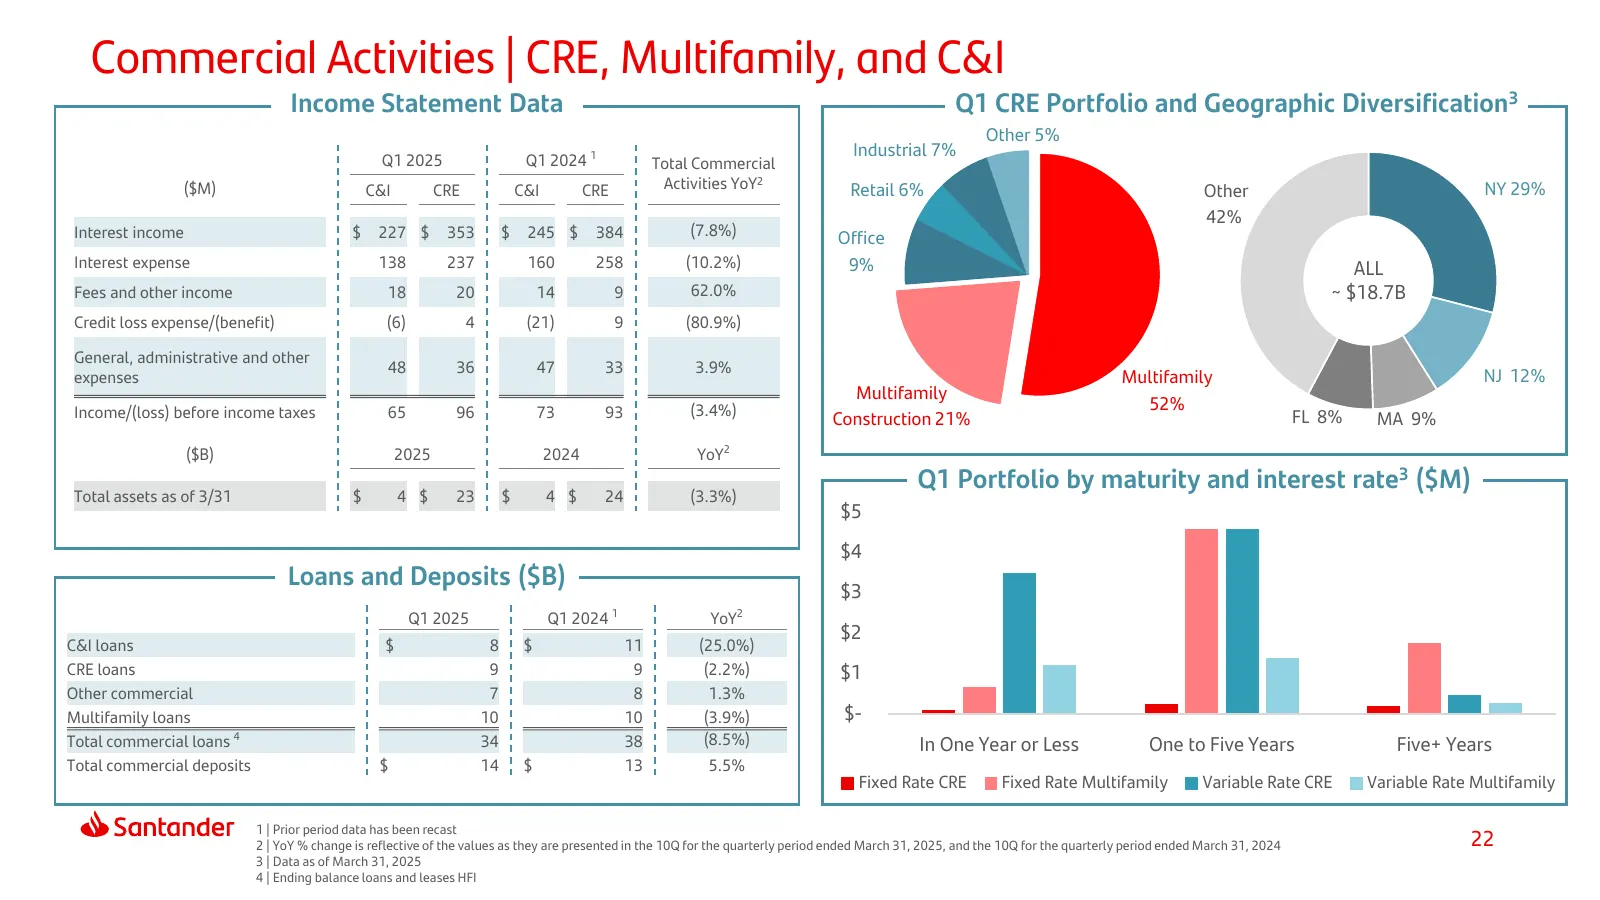
Slide 22: Commercial Activities | CRE, Multifamily, and C&I
Commercial Activities | CRE, Multifamily, and C&I Income Statement Data Q1 CRE Portfolio and Geographic Diversification3 Other 5% Industrial 7% Q1 2025 Q1 2024 1 Total Commercial ($M) C&I CRE C&I CRE Activities YoY2 Retail 6% Other NY 29% 42% Interest income $ 227 $ 353 $ 245 $ 384 (7.8%) Office Int
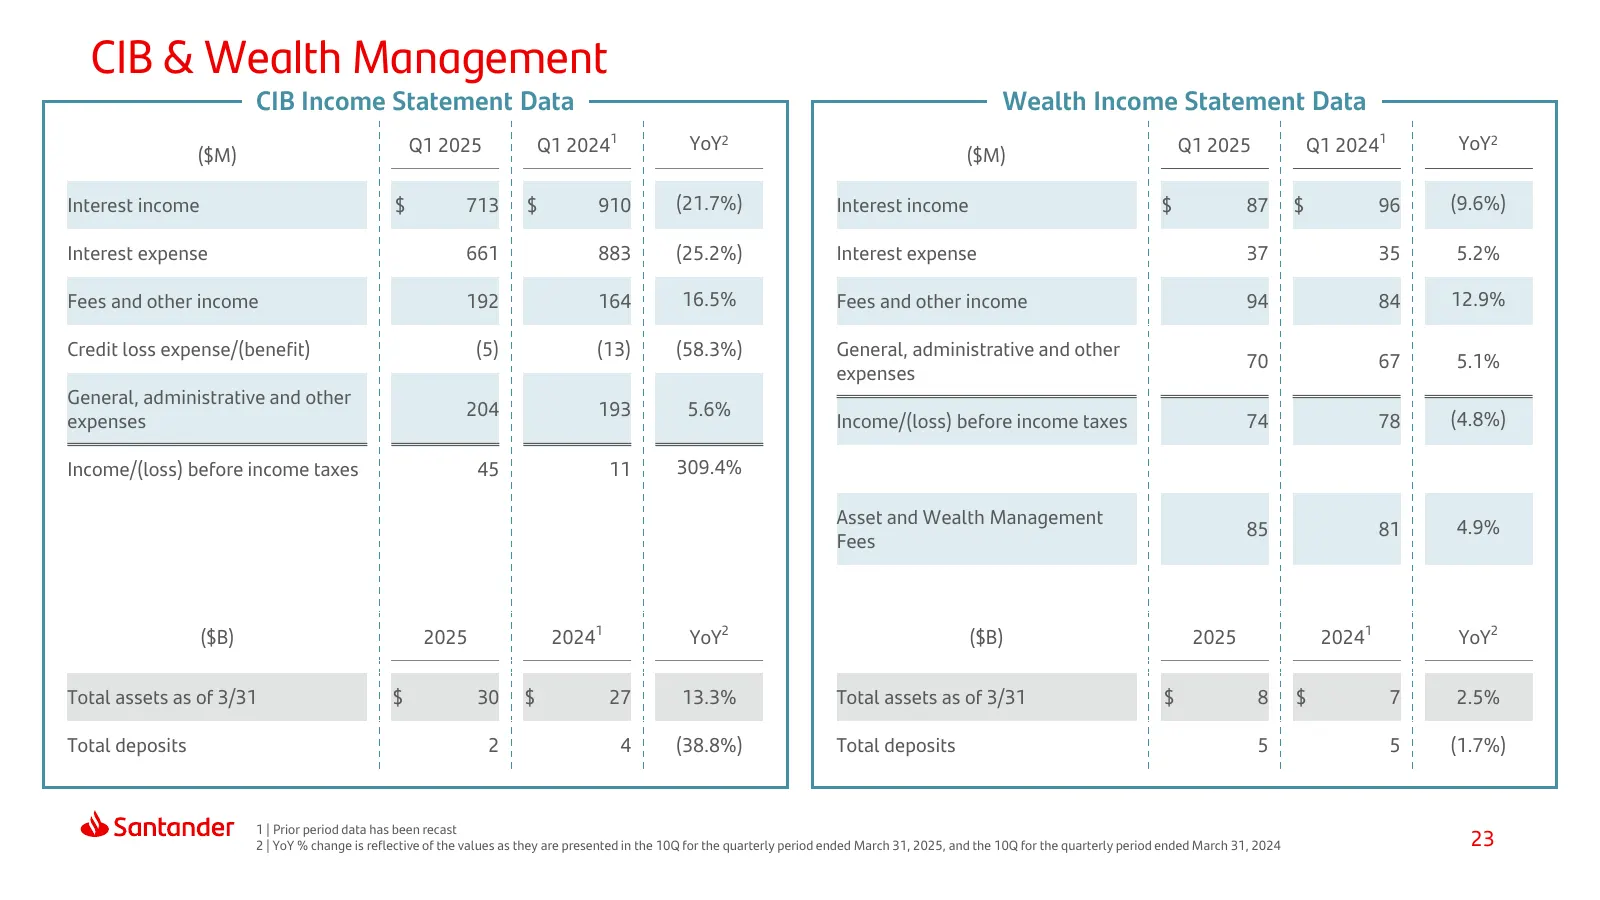
Slide 23: CIB & Wealth Management
CIB & Wealth Management CIB Income Statement Data Wealth Income Statement Data Q1 2025 Q1 20241 YoY2 Q1 2025 Q1 20241 YoY2 ($M) ($M) Interest income $ 713 $ 910 (21.7%) Interest income $ 87 $ 96 (9.6%) Interest expense 661 883 (25.2%) Interest expense 37 35 5.2% Fees and other income 192 164 16.5% F
Slide 24: Index
Index 1 2 3 4 At a Glance Results Core Appendix Business Activities 24
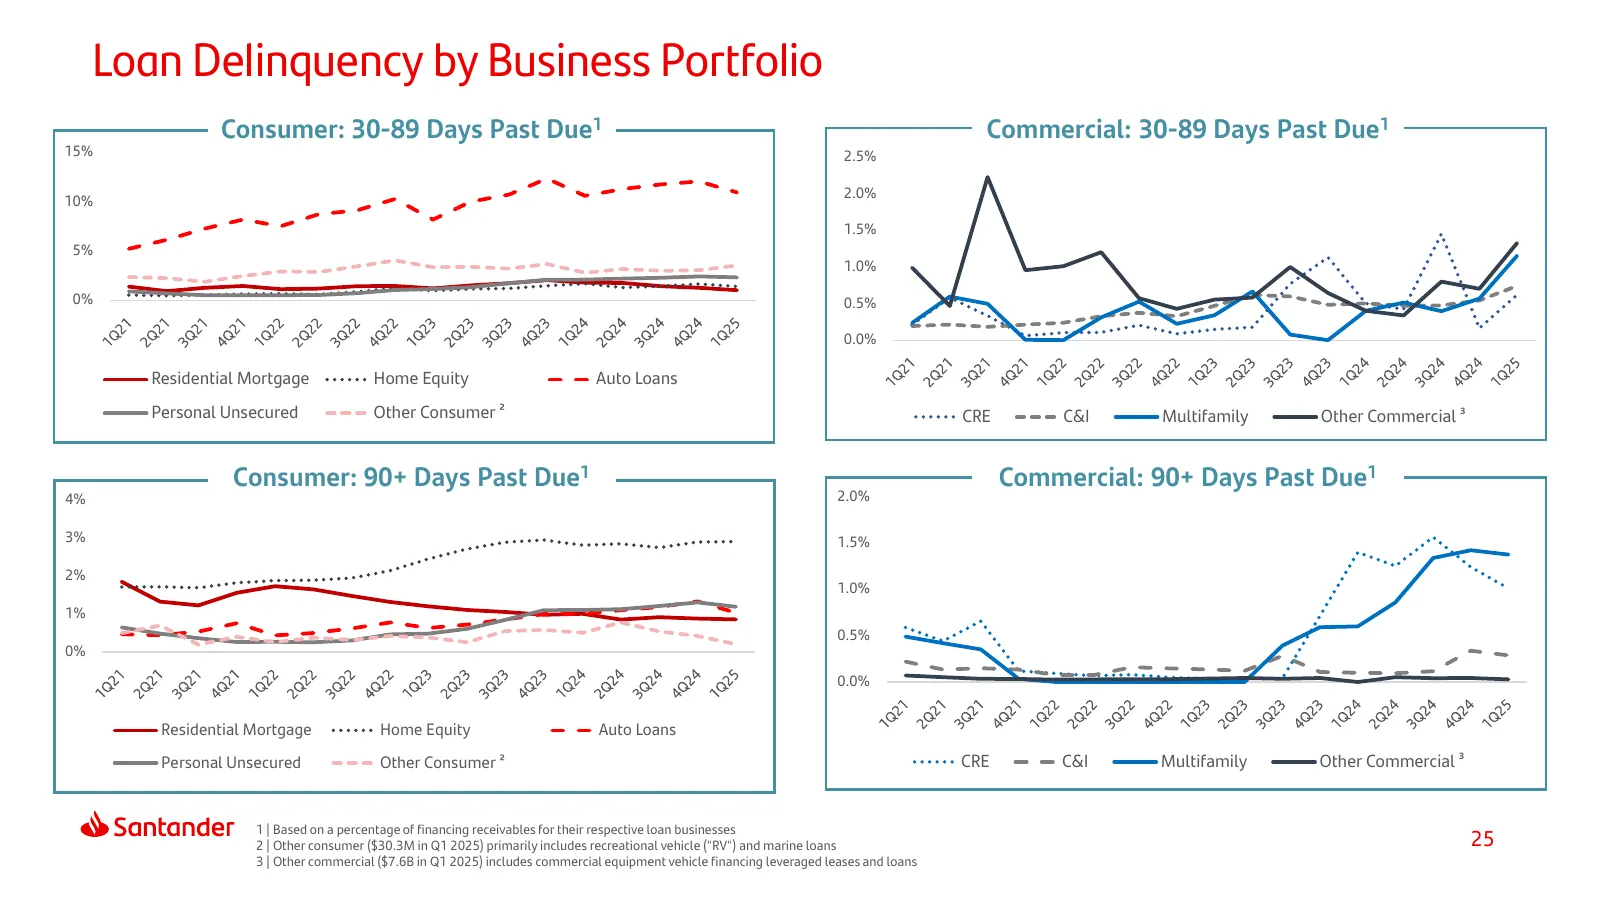
Slide 25: Loan Delinquency by Business Portfolio
Loan Delinquency by Business Portfolio Consumer: 30-89 Days Past Due1 Commercial: 30-89 Days Past Due1 15% 2.5% 2.0% 10% 1.5% 5% 1.0% 0% 0.5% 0.0% Residential Mortgage Home Equity Auto Loans Personal Unsecured Other Consumer ² CRE C&I Multifamily Other Commercial ³ Consumer: 90+ Days Past Due1 Comme
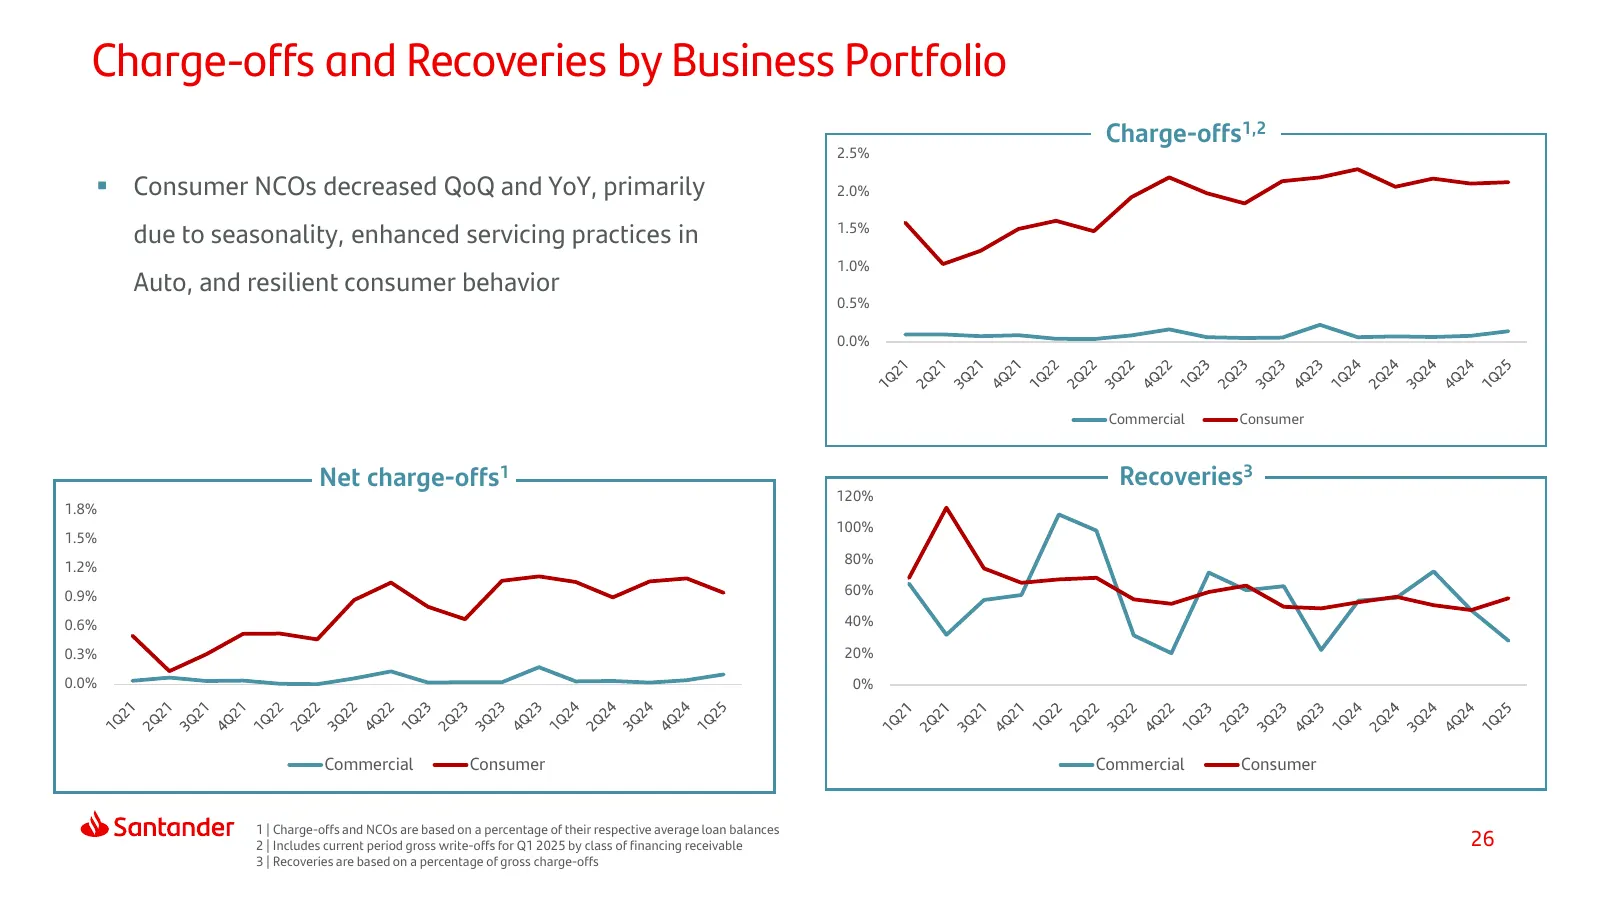
Slide 26: Charge-offs and Recoveries by Business Portfolio
Charge-offs and Recoveries by Business Portfolio Charge-offs1,2 2.5% Consumer NCOs decreased QoQ and YoY, primarily 2.0% due to seasonality, enhanced servicing practices in 1.5% 1.0% Auto, and resilient consumer behavior 0.5% 0.0% Commercial Consumer Net charge-offs1 Recoveries3 120% 1.8% 100% 1.5
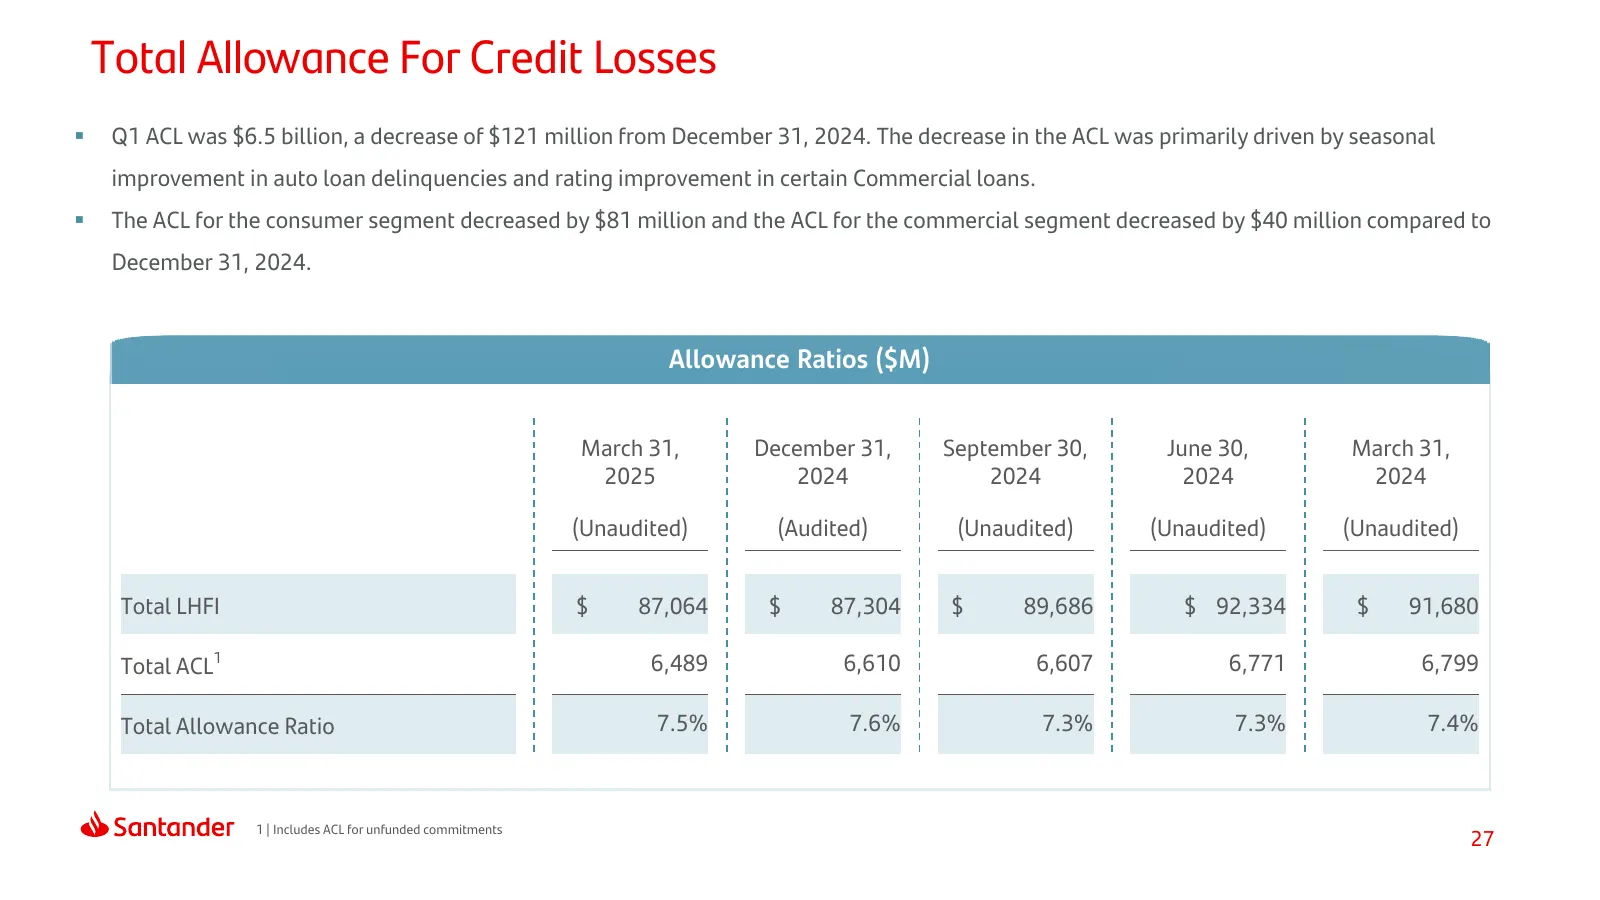
Slide 27: Total Allowance For Credit Losses
Total Allowance For Credit Losses Q1 ACL was $6.5 billion, a decrease of $121 million from December 31, 2024. The decrease in the ACL was primarily driven by seasonal improvement in auto loan delinquencies and rating improvement in certain Commercial loans. The ACL for the consumer segment decre
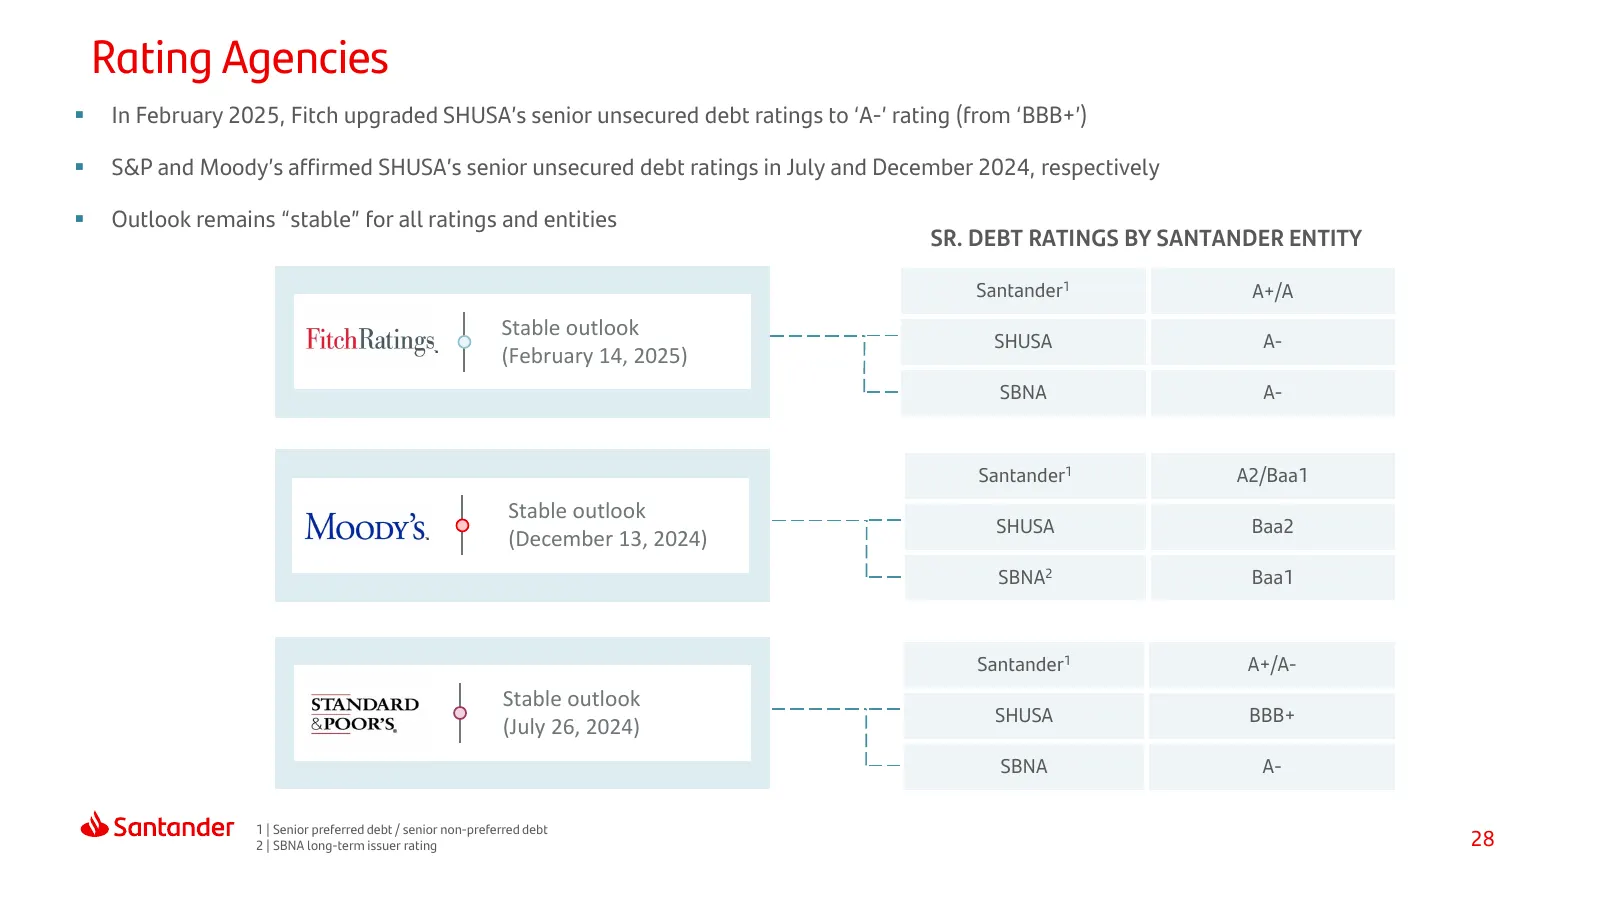
Slide 28: Rating Agencies
Rating Agencies In February 2025, Fitch upgraded SHUSA’s senior unsecured debt ratings to ‘A-’ rating (from ‘BBB+’) S&P and Moody’s affirmed SHUSA’s senior unsecured debt ratings in July and December 2024, respectively Outlook remains “stable” for all ratings and entities SR. DEBT RATINGS BY S
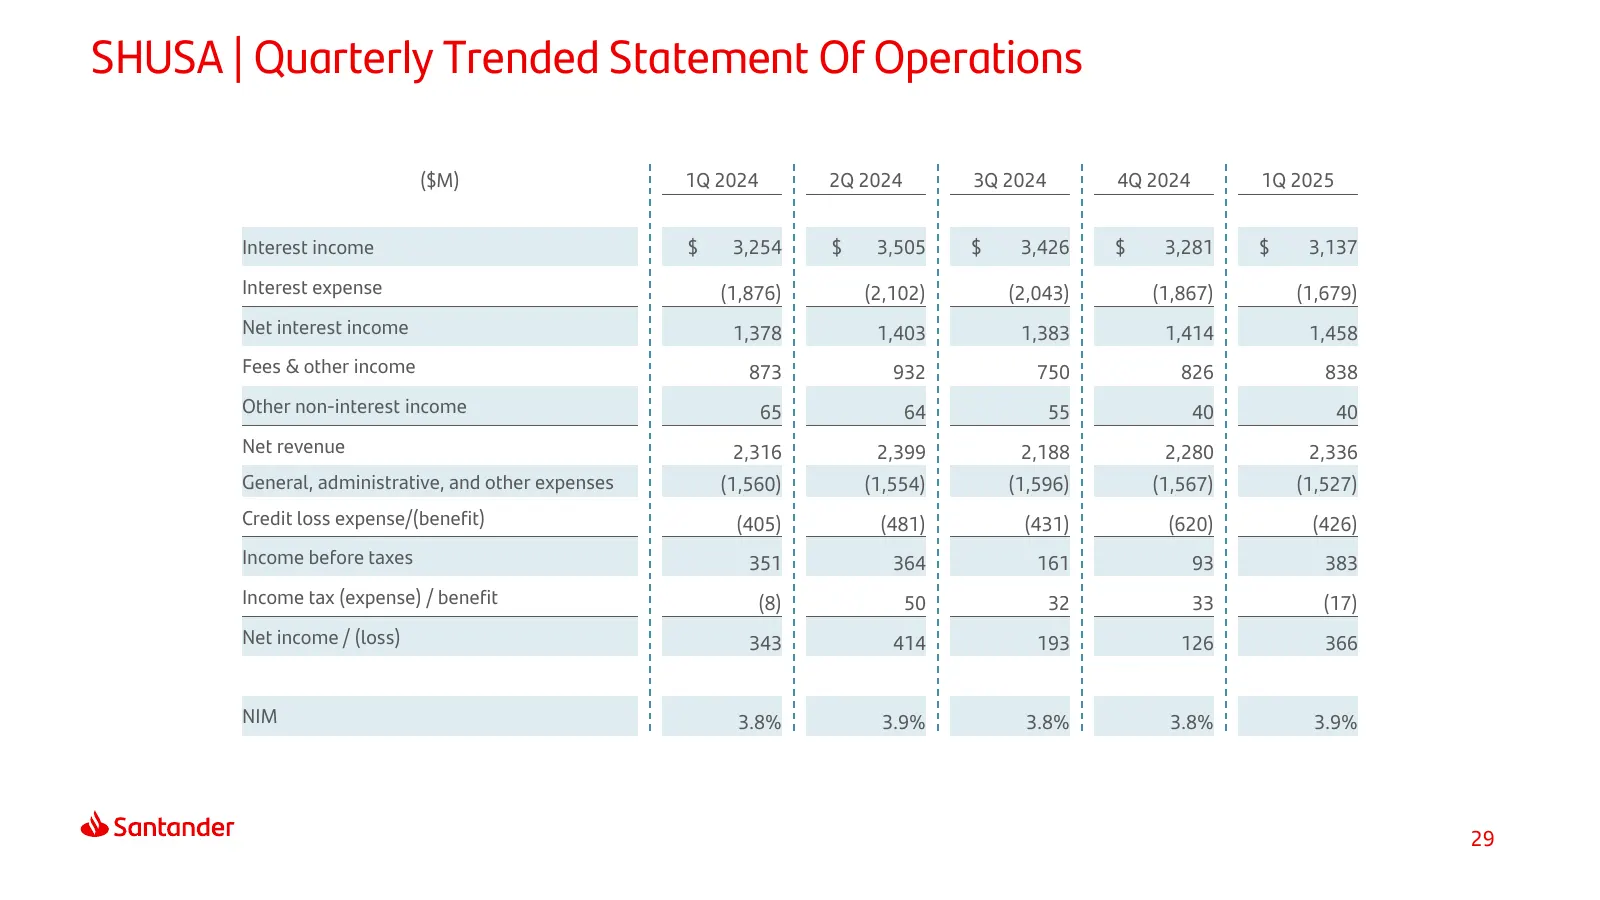
Slide 29: SHUSA | Quarterly Trended Statement Of Operations
SHUSA | Quarterly Trended Statement Of Operations ($M) 1Q 2024 2Q 2024 3Q 2024 4Q 2024 1Q 2025 Interest income $ 3,254 $ 3,505 $ 3,426 $ 3,281 $ 3,137 Interest expense (1,876) (2,102) (2,043) (1,867) (1,679) Net interest income 1,378 1,403 1,383 1,414 1,458 Fees & other income 873 932 750 826 838 Ot
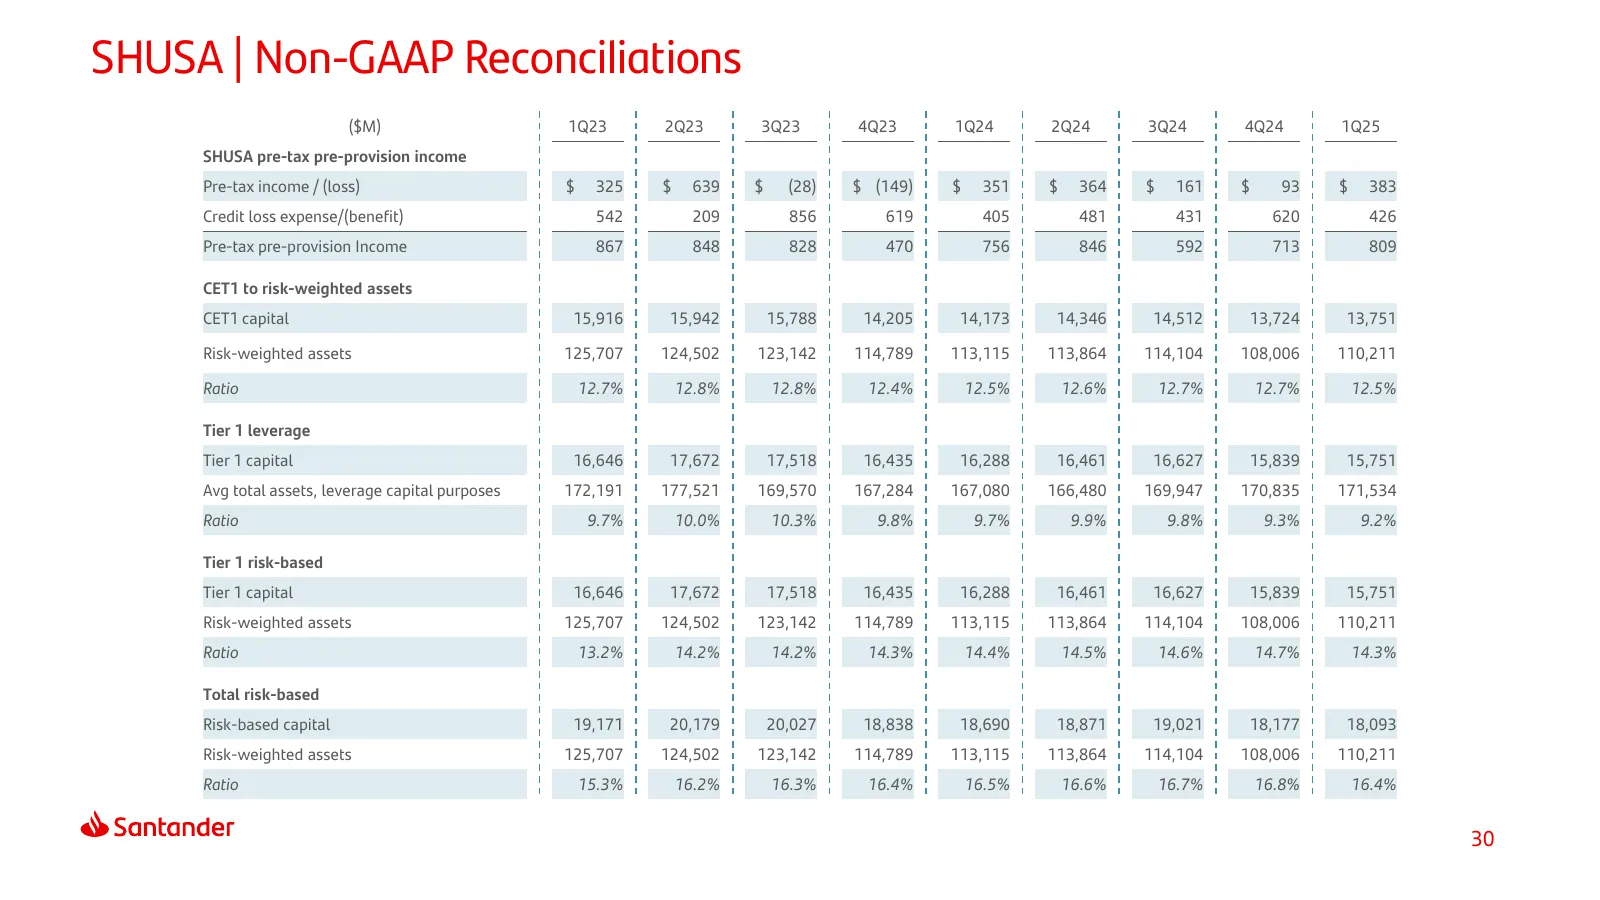
Slide 30: SHUSA | Non-GAAP Reconciliations
SHUSA | Non-GAAP Reconciliations ($M) 1Q23 2Q23 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 SHUSA pre-tax pre-provision income Pre-tax income / (loss) $ 325 $ 639 $ (28) $ (149) $ 351 $ 364 $ 161 $ 93 $ 383 Credit loss expense/(benefit) 542 209 856 619 405 481 431 620 426 Pre-tax pre-provision Income 867 848
Slide 31: Thank You.
Thank You. Our purpose is to help people and businesses prosper. Our culture is based on believing that everything we do should be:
Source: company website
More decks from Santander Holdings USA Inc
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026