SGL Carbon SE · XETR:SGL
SGL Carbon — SGL Group — 9M 2016 Earnings Presentation
21 slides from SGL Carbon's earnings presentation, Nov 10, 2016
Slide 1: Investor & Analyst Conference Call
Investor & Analyst Conference Call Wiesbaden November 10, 2016
Slide 2: Agenda
Agenda. 1. Review – Jürgen Köhler 2. Financials 9M/2016 3. Next steps Page 2
Slide 3: Review. Significant progress in strategic realignment and transformation of SGL Group
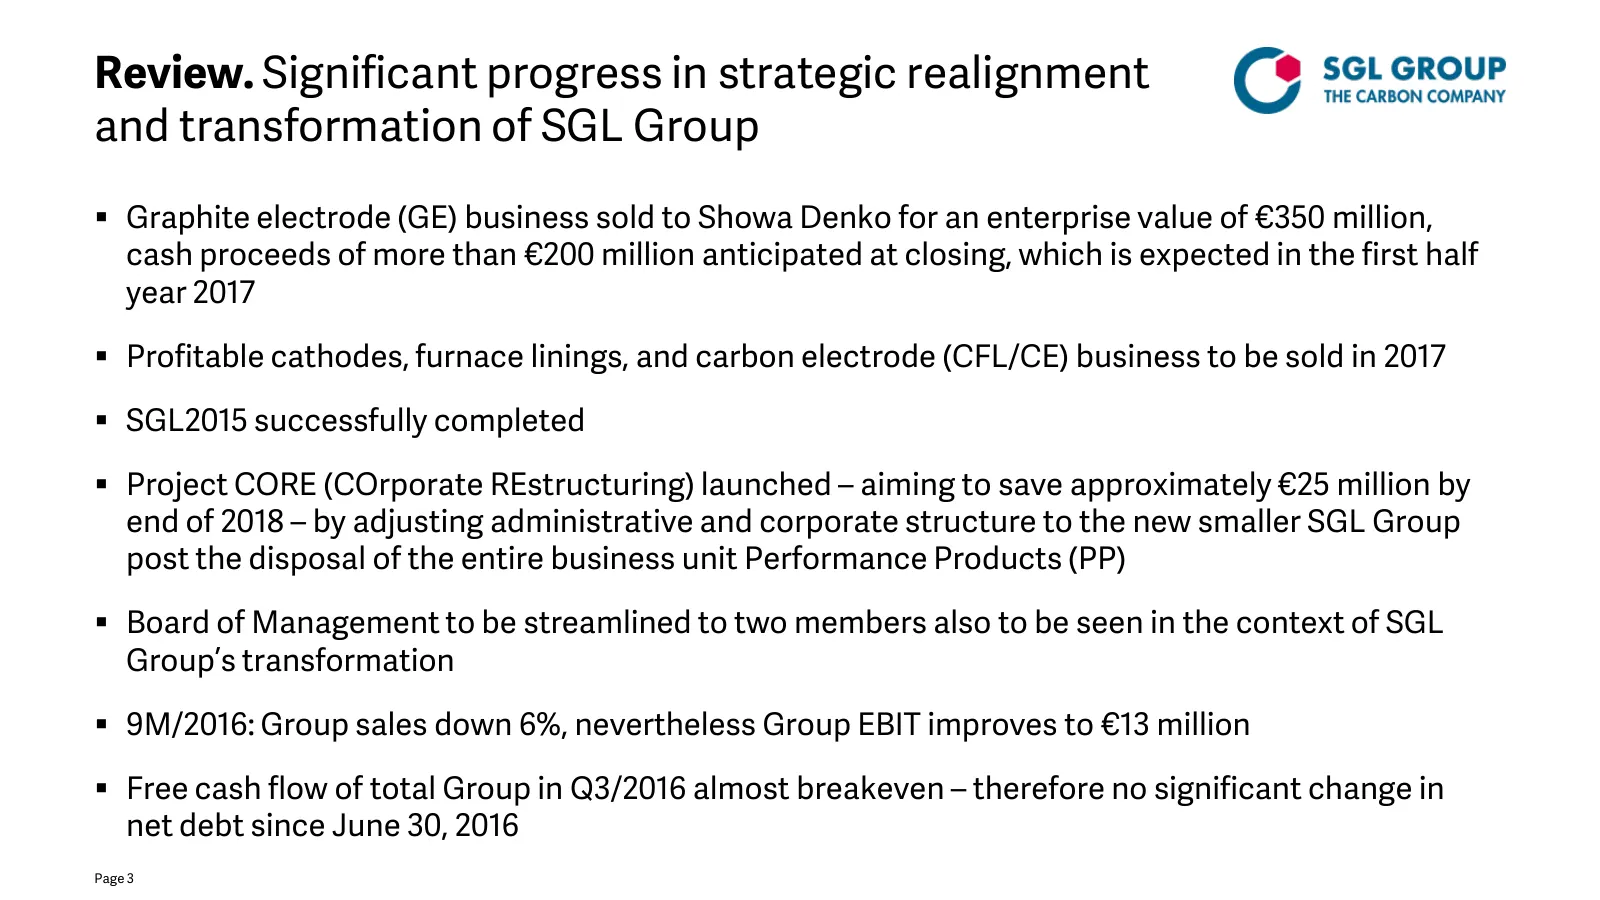
Review. Significant progress in strategic realignment and transformation of SGL Group Graphite electrode (GE) business sold to Showa Denko for an enterprise value of €350 million, cash proceeds of more than €200 million anticipated at closing, which is expected in the first half year 2017 Profit
Slide 4: Agenda
Agenda. 1. Review 2. Financials 9M/2016 – Michael Majerus 3. Next steps Page 4
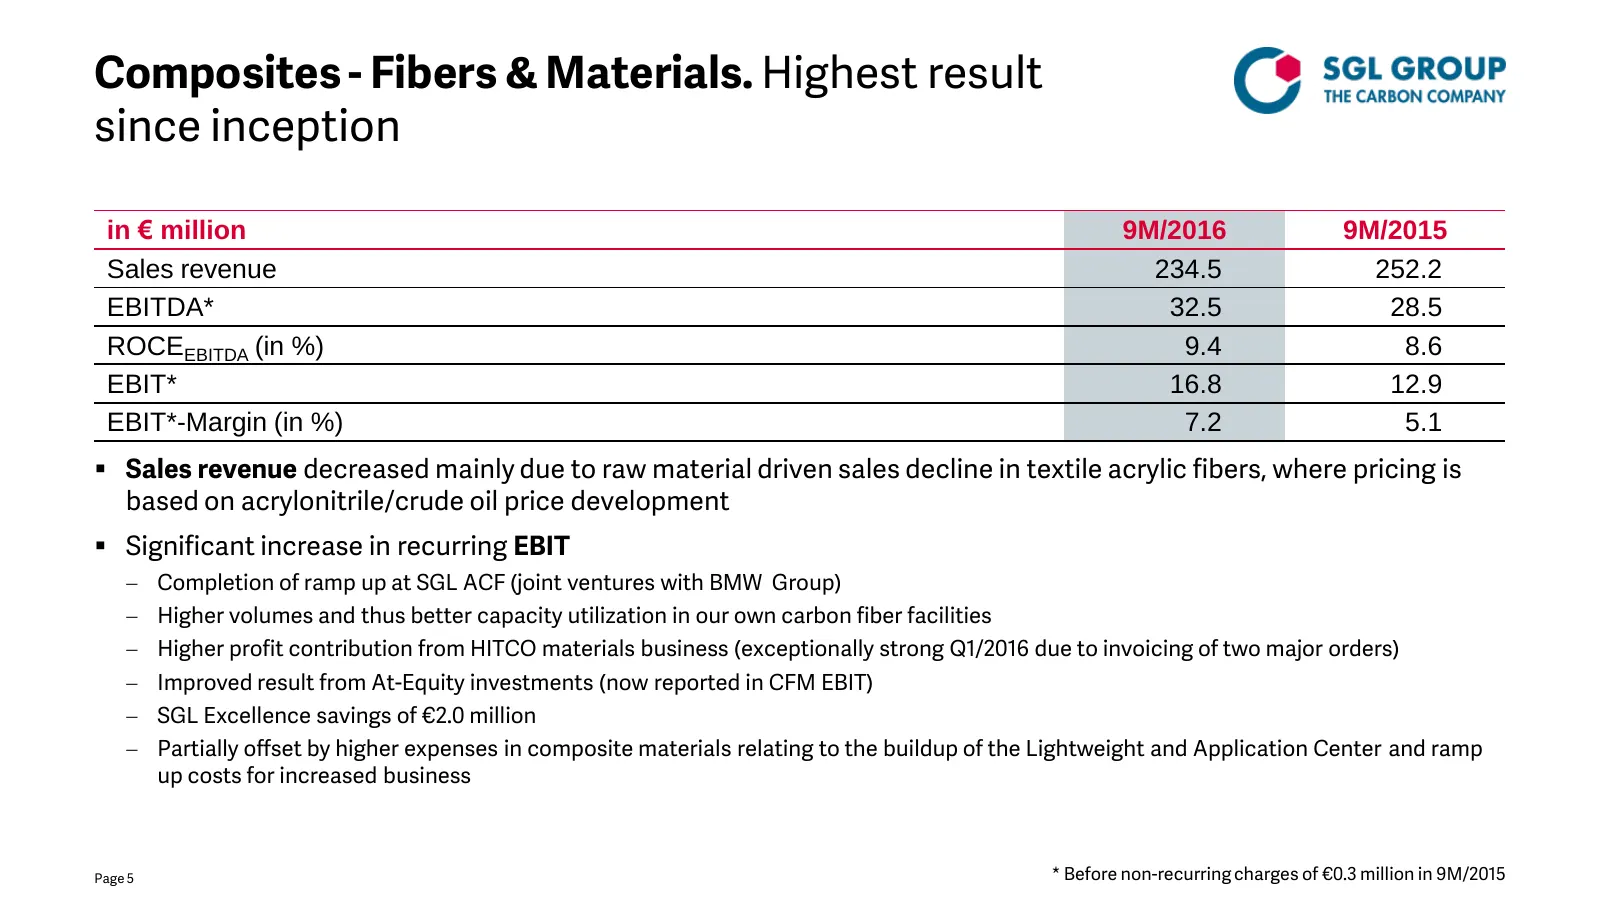
Slide 5: Composites - Fibers & Materials. Highest result since inception
Composites - Fibers & Materials. Highest result since inception in € million 9M/2016 9M/2015 Sales revenue 234.5 252.2 EBITDA* 32.5 28.5 ROCEEBITDA (in %) 9.4 8.6 EBIT* 16.8 12.9 EBIT*-Margin (in %) 7.2 5.1 Sales revenue decreased mainly due to raw material driven sales decline in textile acrylic
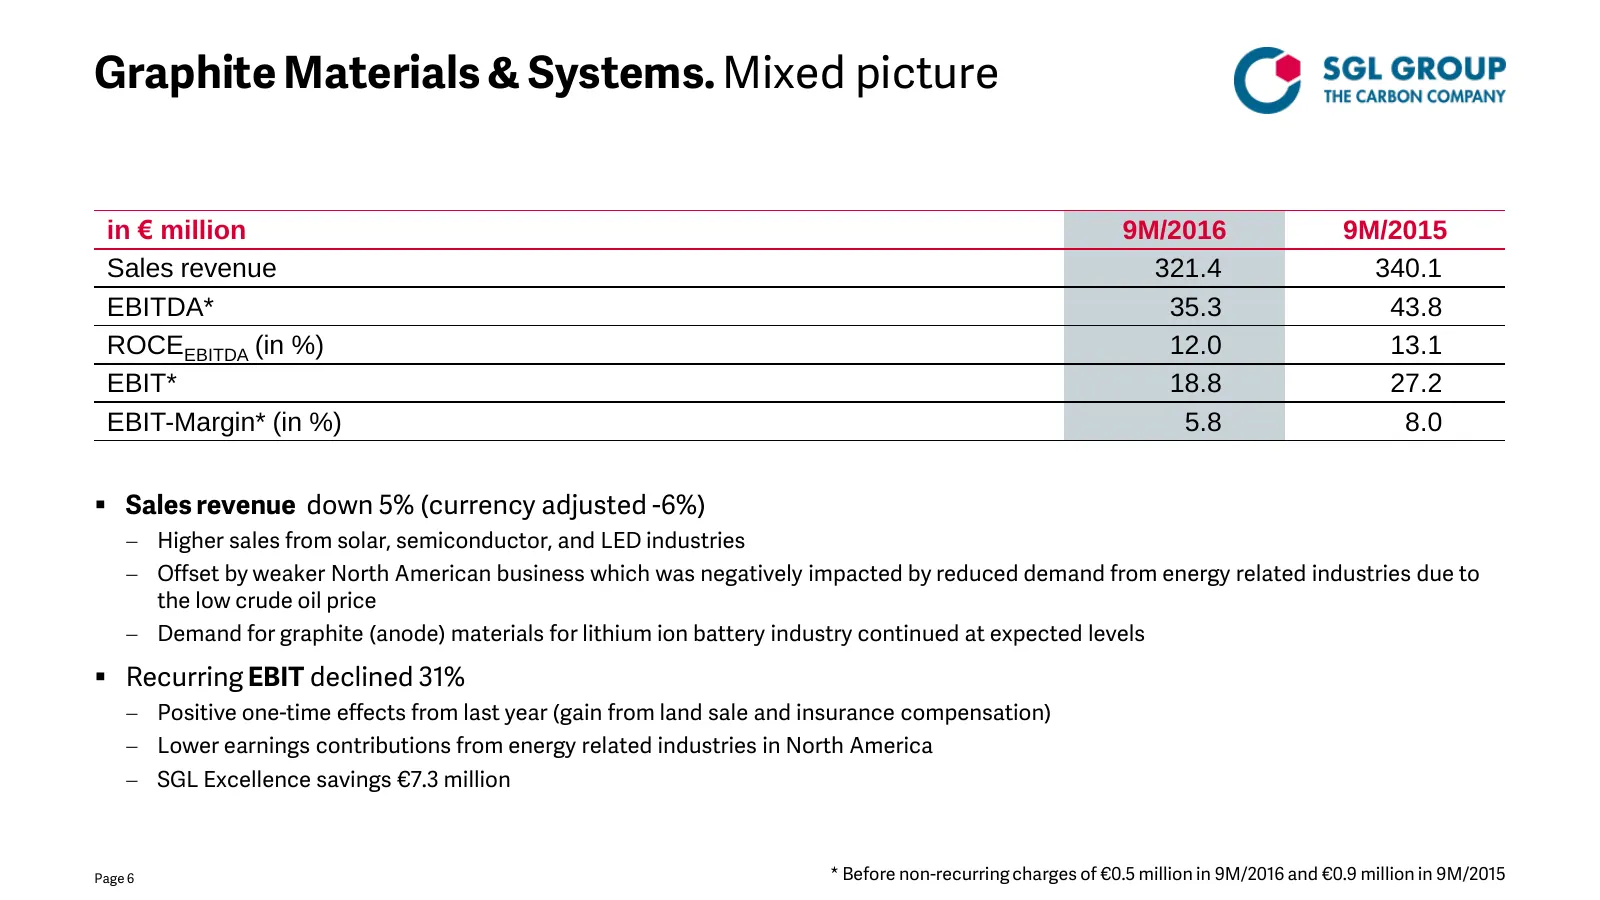
Slide 6: Graphite Materials & Systems. Mixed picture
Graphite Materials & Systems. Mixed picture in € million 9M/2016 9M/2015 Sales revenue 321.4 340.1 EBITDA* 35.3 43.8 ROCEEBITDA (in %) 12.0 13.1 EBIT* 18.8 27.2 EBIT-Margin* (in %) 5.8 8.0 Sales revenue down 5% (currency adjusted -6%) Higher sales from solar, semiconductor, and LED industries
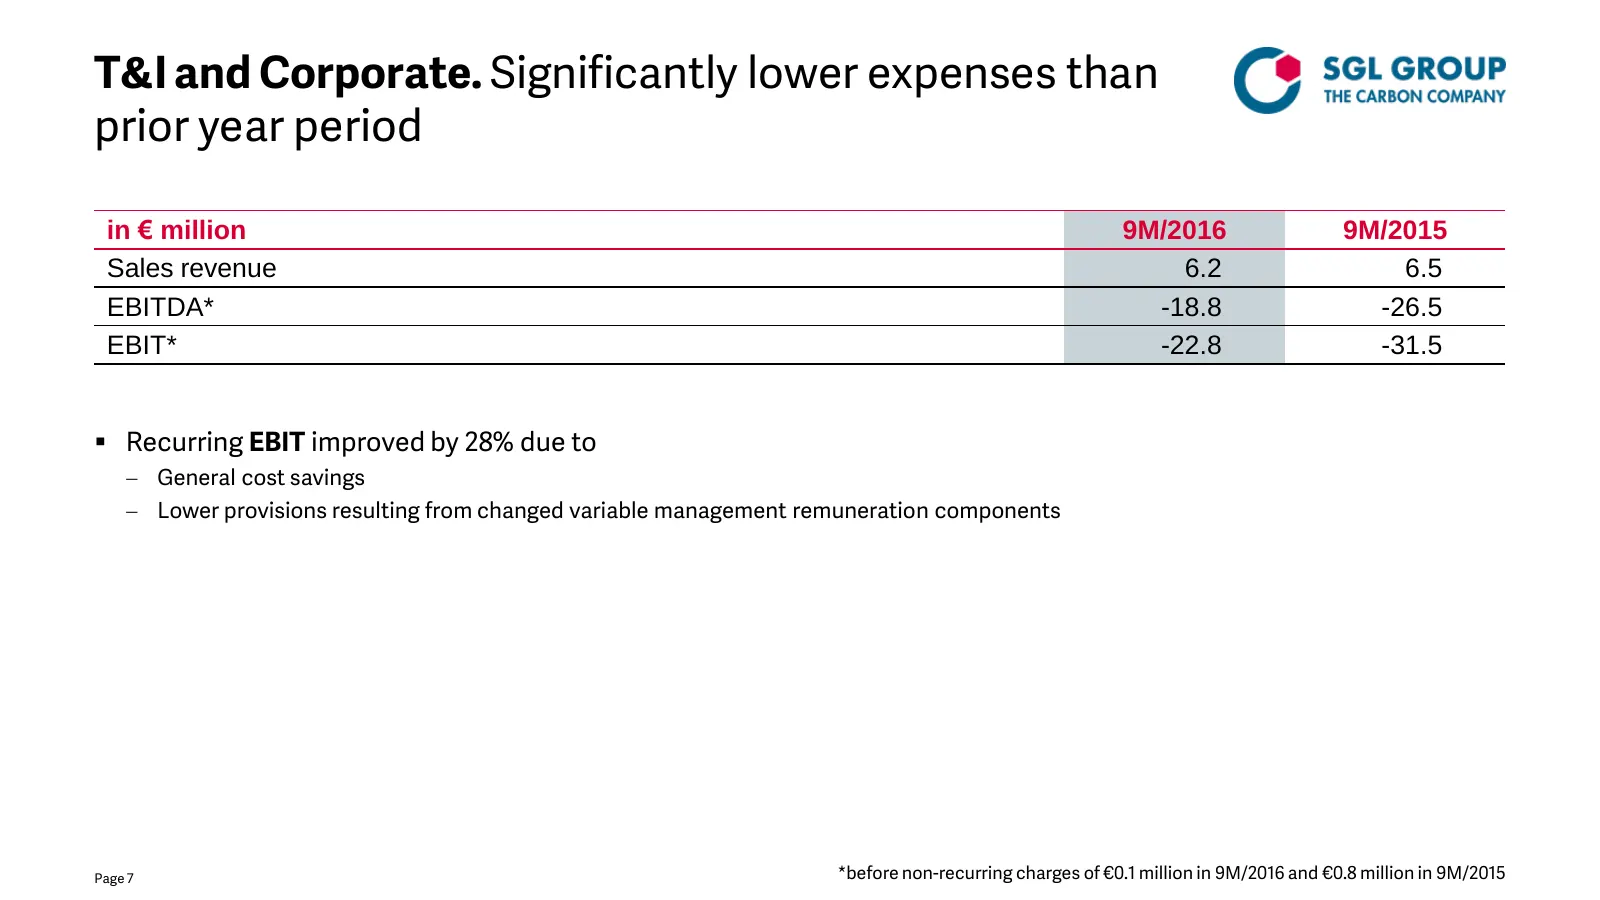
Slide 7: T&I and Corporate. Significantly lower expenses than prior year period
T&I and Corporate. Significantly lower expenses than prior year period in € million 9M/2016 9M/2015 Sales revenue 6.2 6.5 EBITDA* -18.8 -26.5 EBIT* -22.8 -31.5 Recurring EBIT improved by 28% due to General cost savings Lower provisions resulting from changed variable management remuneration co
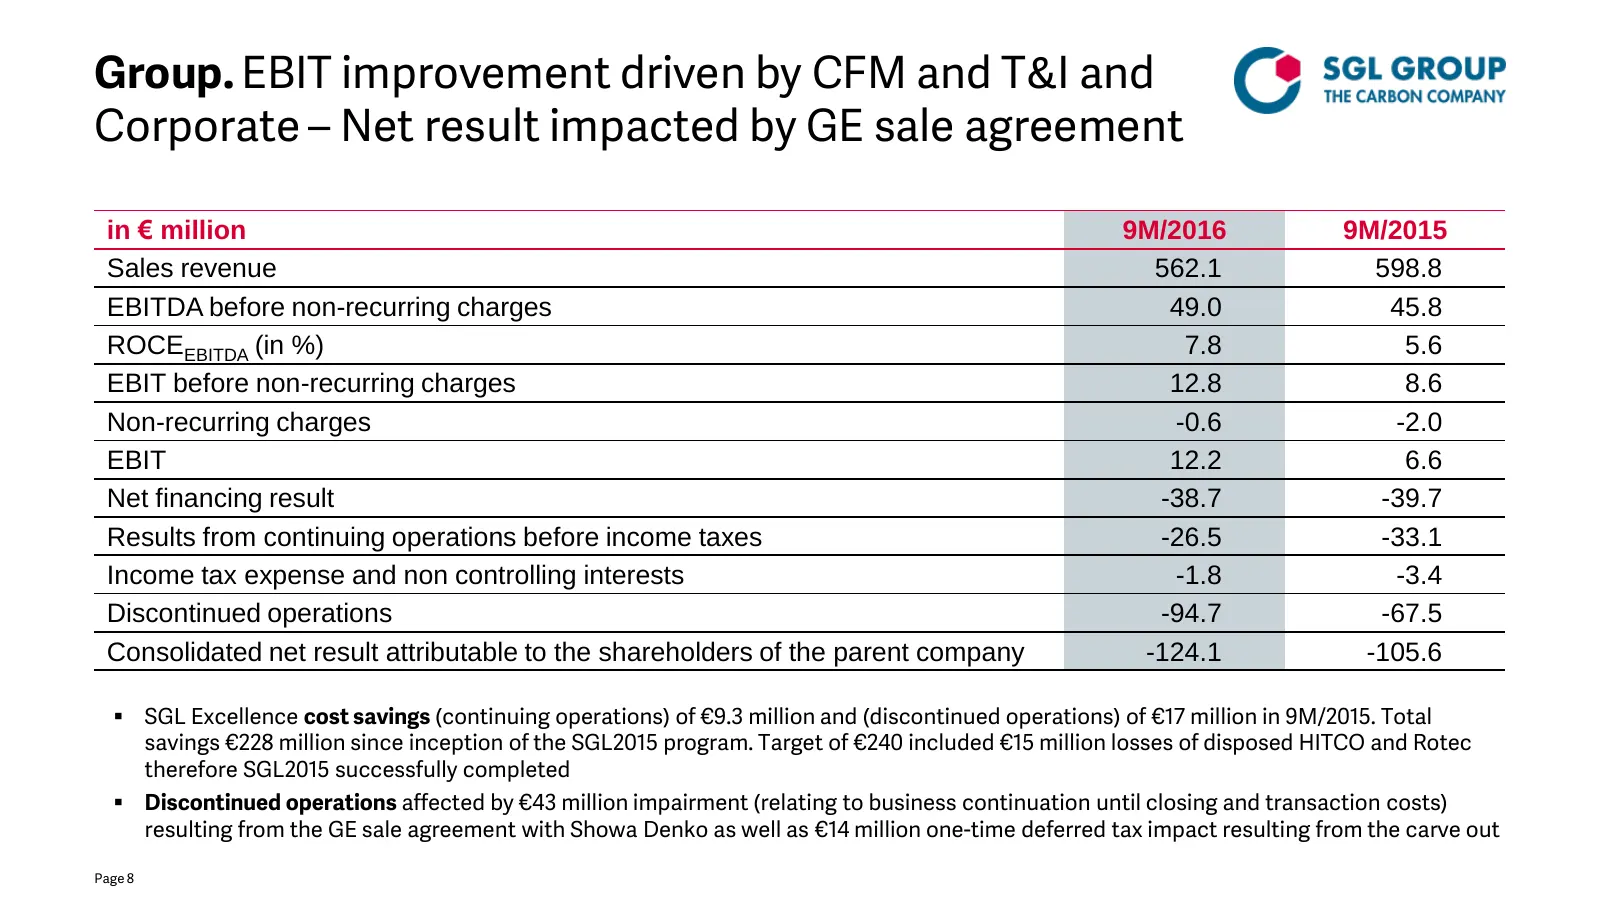
Slide 8: Group. EBIT improvement driven by CFM and T&I and Corporate
Group. EBIT improvement driven by CFM and T&I and Corporate – Net result impacted by GE sale agreement in € million 9M/2016 9M/2015 Sales revenue 562.1 598.8 EBITDA before non-recurring charges 49.0 45.8 ROCEEBITDA (in %) 7.8 5.6 EBIT before non-recurring charges 12.8 8.6 Non-recurring charges -0.6
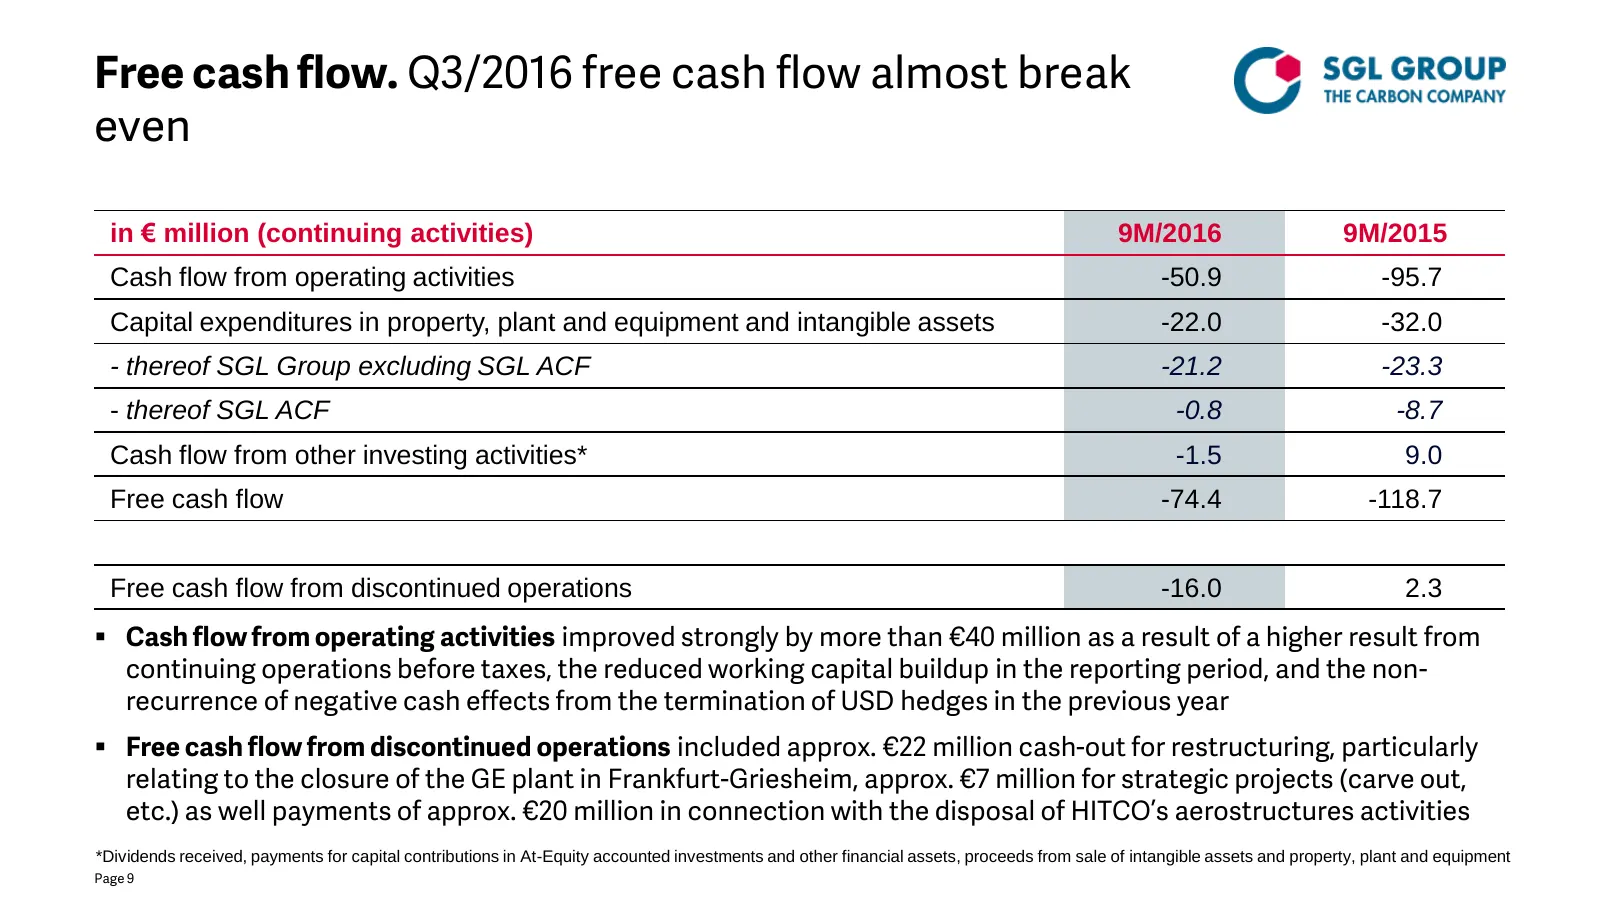
Slide 9: Free cash flow. Q3/2016 free cash flow almost break even
Free cash flow. Q3/2016 free cash flow almost break even in € million (continuing activities) 9M/2016 9M/2015 Cash flow from operating activities -50.9 -95.7 Capital expenditures in property, plant and equipment and intangible assets -22.0 -32.0 - thereof SGL Group excluding SGL ACF -21.2 -23.3 - th
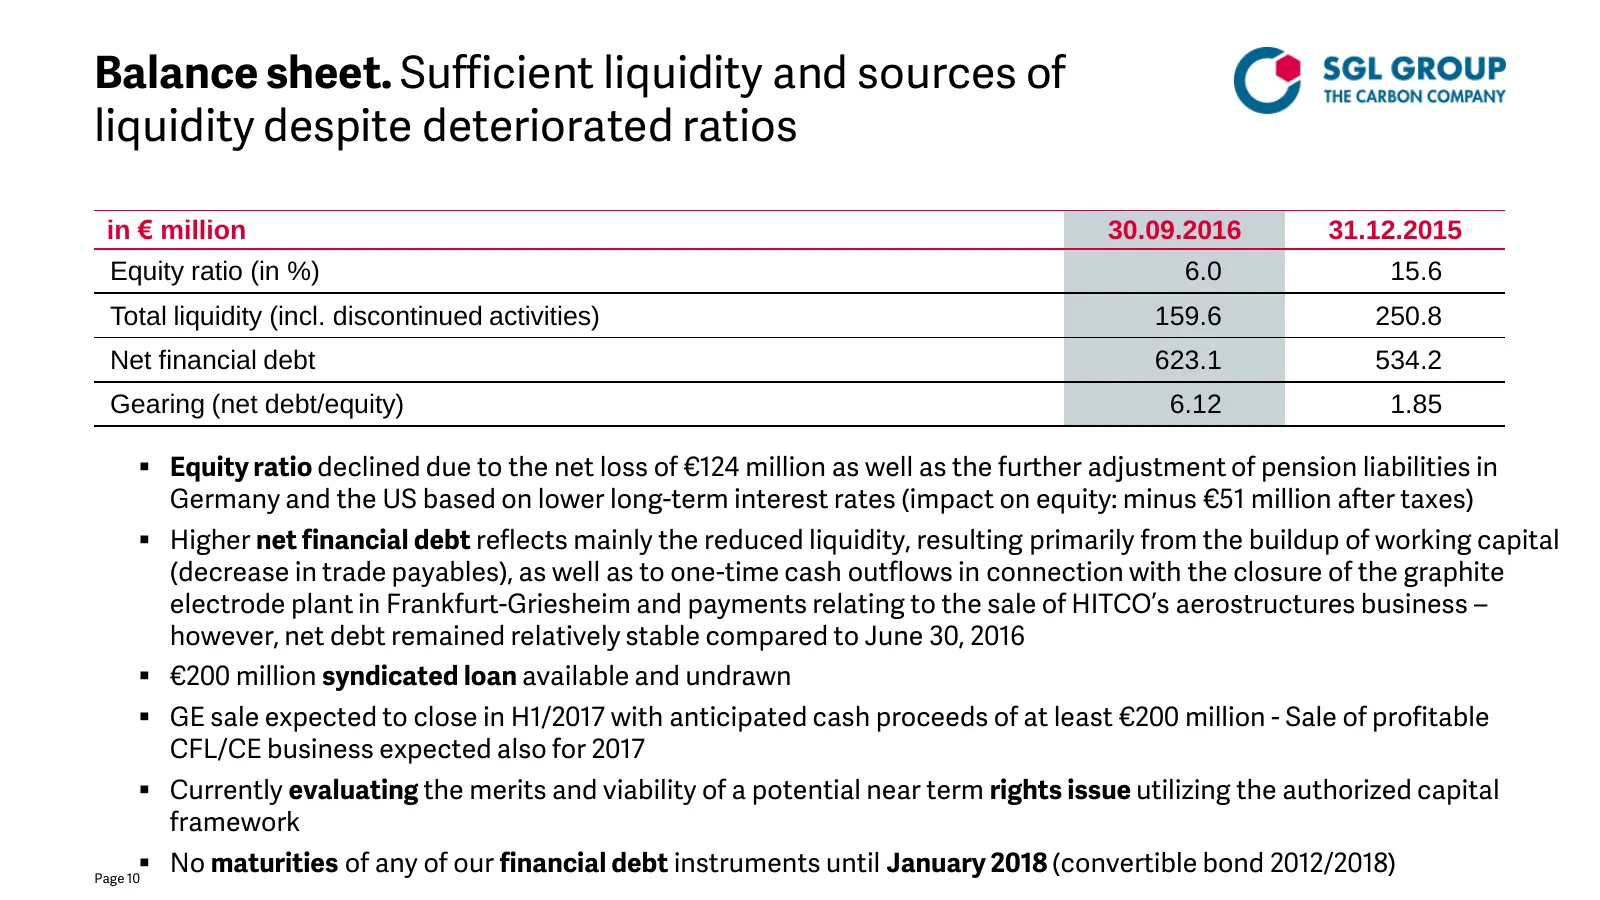
Slide 10: Balance sheet. Sufficient liquidity and sources of liquidity despite deteriorated ratios
Balance sheet. Sufficient liquidity and sources of liquidity despite deteriorated ratios in € million 30.09.2016 31.12.2015 Equity ratio (in %) 6.0 15.6 Total liquidity (incl. discontinued activities) 159.6 250.8 Net financial debt 623.1 534.2 Gearing (net debt/equity) 6.12 1.85 Equity ratio decli
Slide 11: Agenda
Agenda. 1. Review 2. Financials 9M/2016 3. Next steps – Jürgen Köhler Page 11
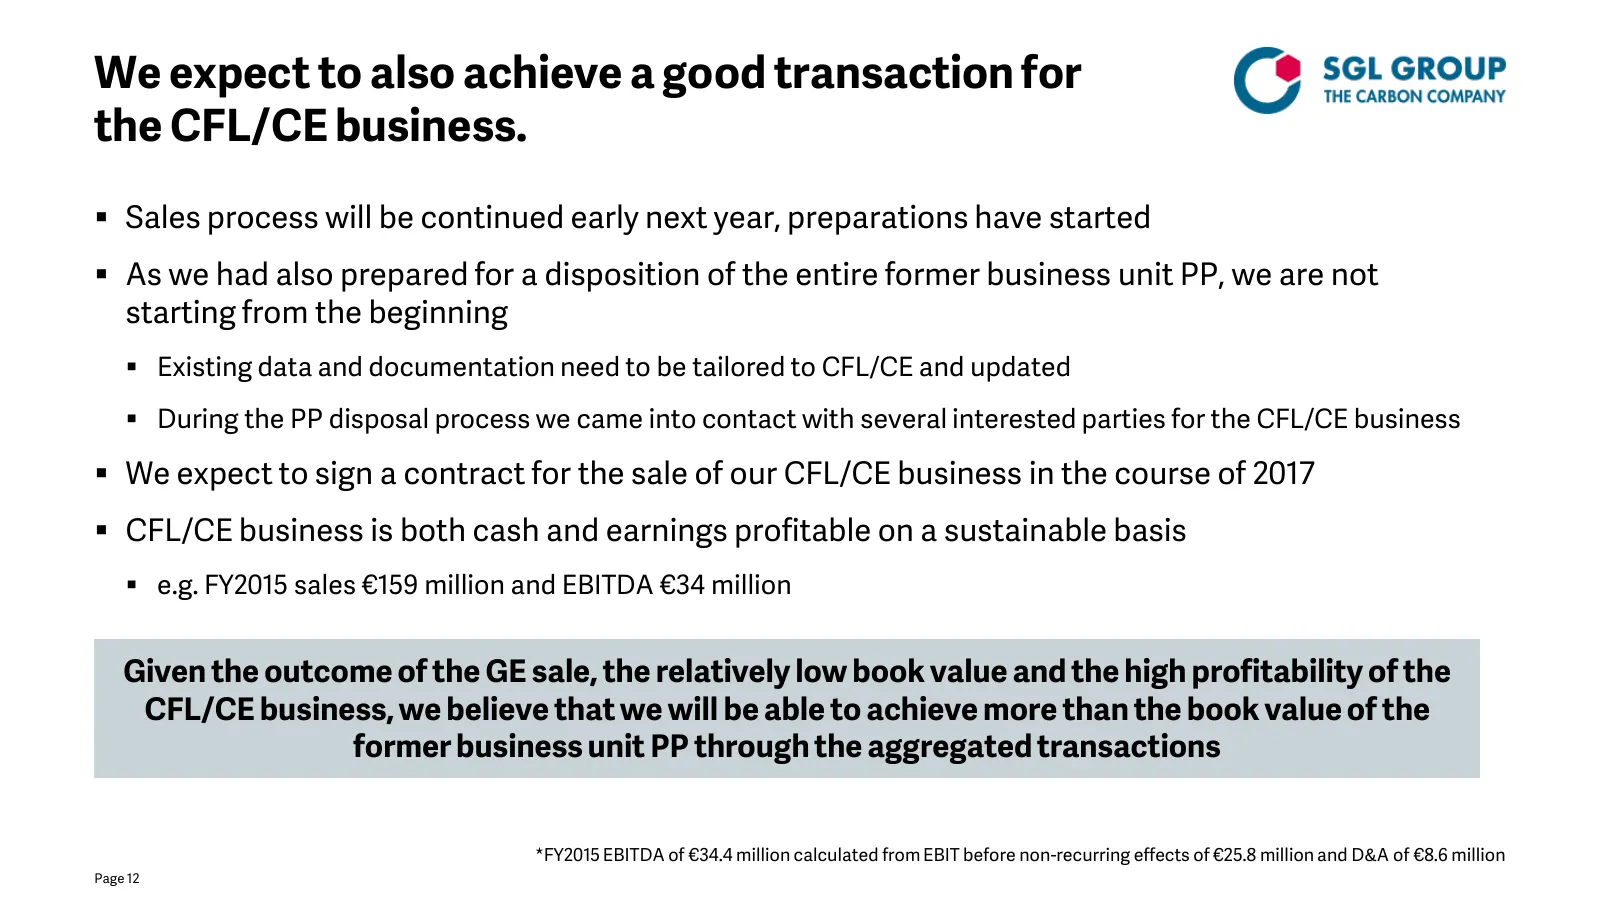
Slide 12: We expect to also achieve a good transaction for the CFL/CE business
We expect to also achieve a good transaction for the CFL/CE business. Sales process will be continued early next year, preparations have started As we had also prepared for a disposition of the entire former business unit PP, we are not starting from the beginning Existing data and documentati
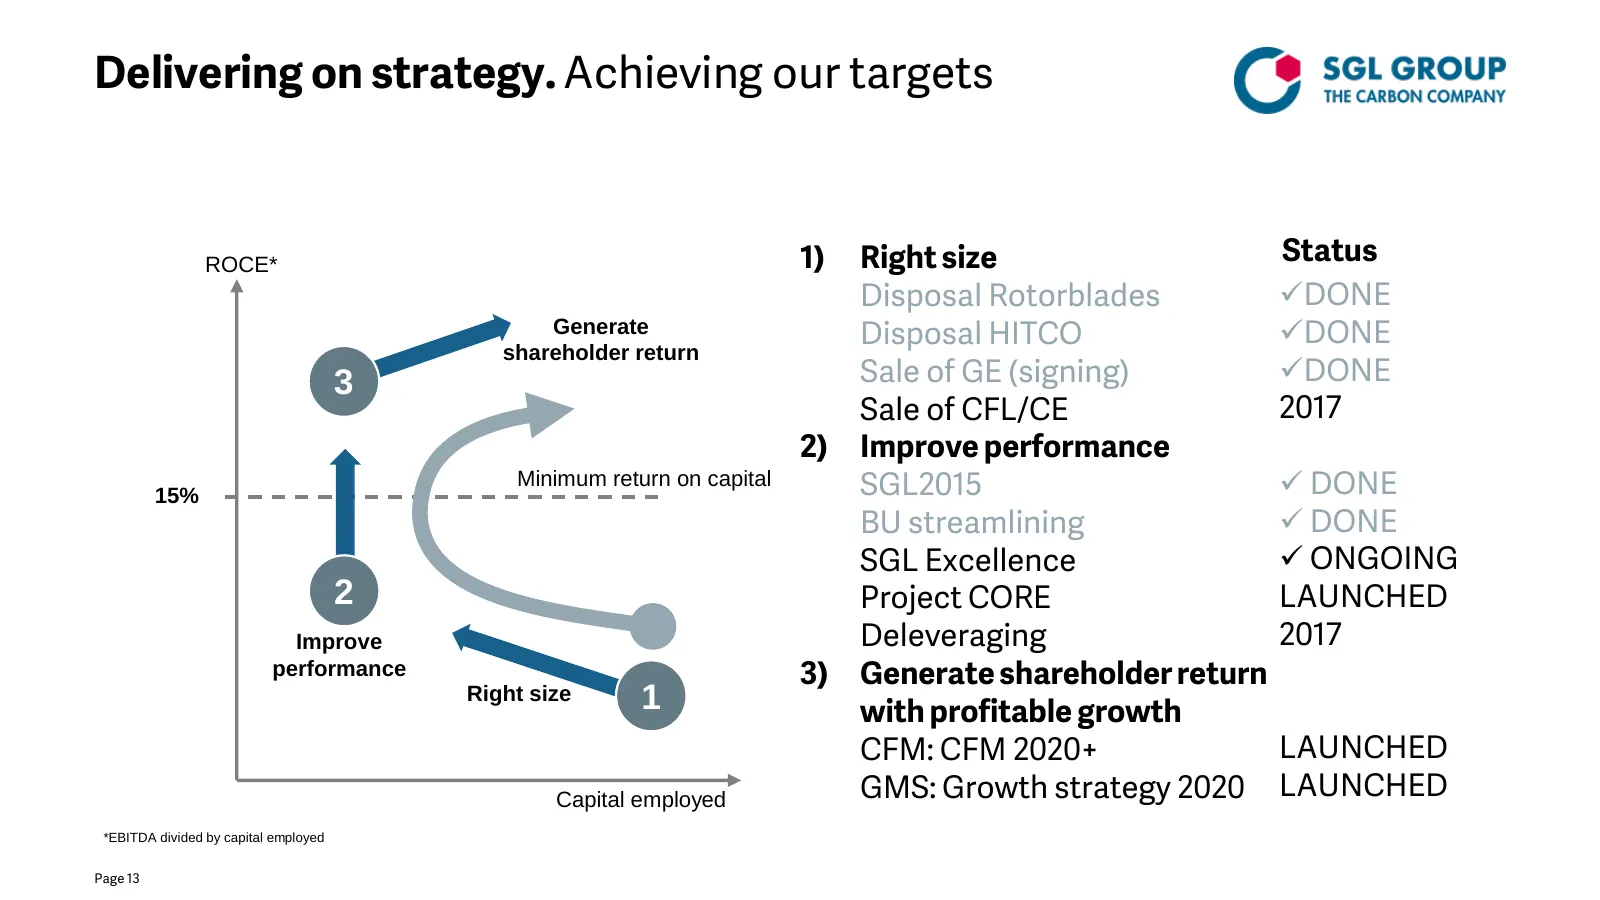
Slide 13: Delivering on strategy. Achieving our targets
Delivering on strategy. Achieving our targets ROCE* 1) Right size Status Disposal Rotorblades DONE Generate Disposal HITCO DONE shareholder return 3 Sale of GE (signing) DONE Sale of CFL/CE 2017 2) Improve performance 15% Minimum return on capital SGL2015 DONE BU streamlining DONE SGL Excelle
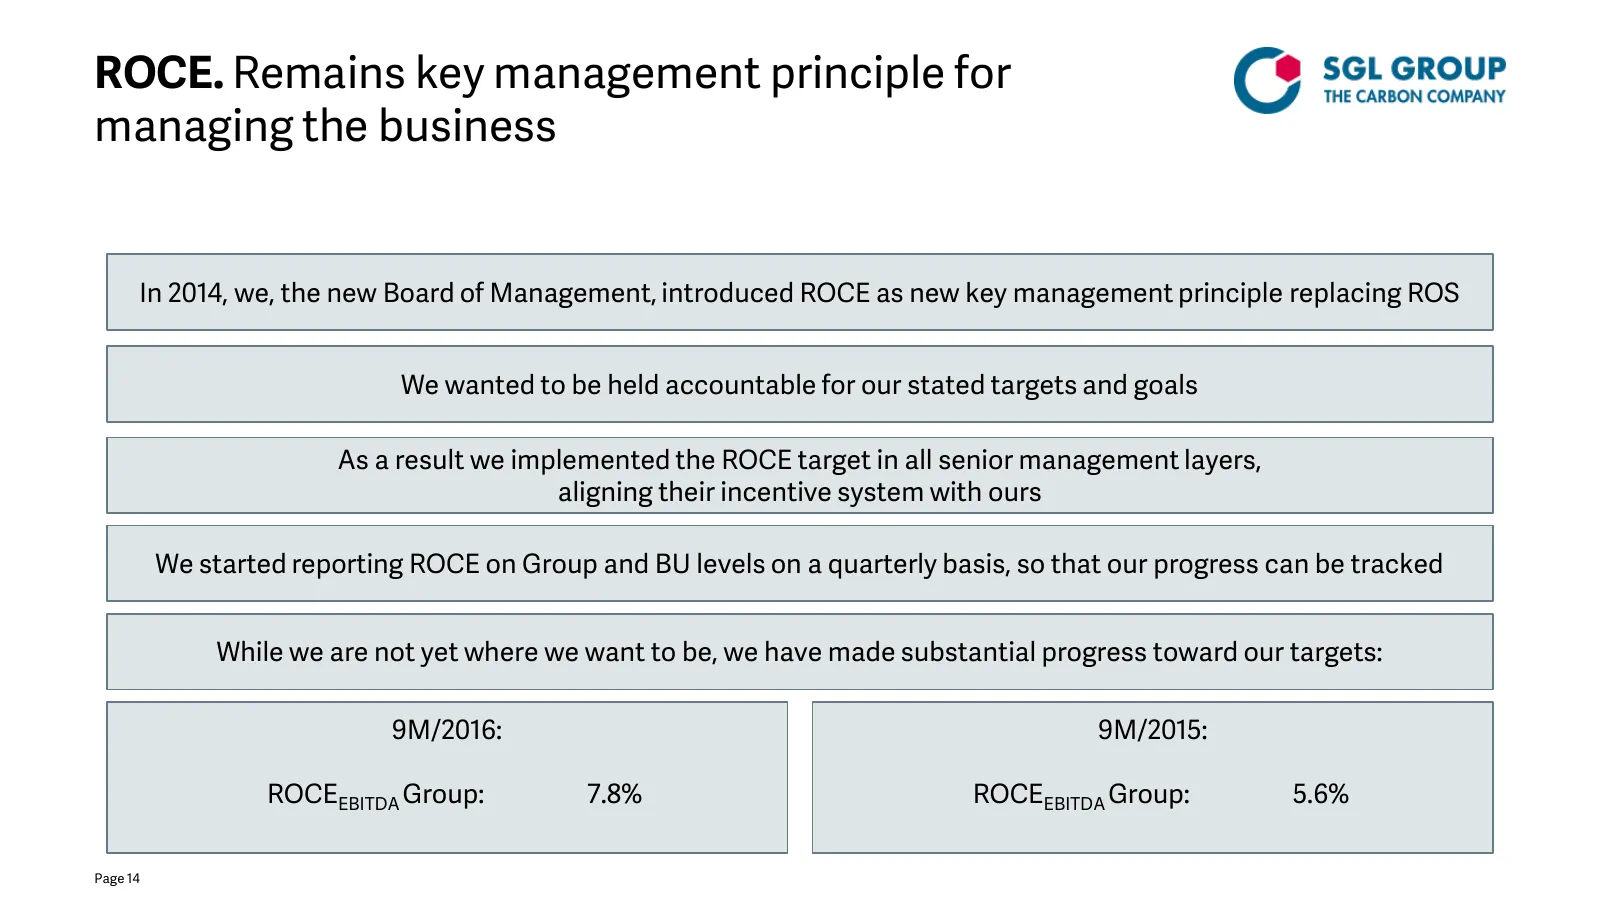
Slide 14: ROCE. Remains key management principle for managing the business
ROCE. Remains key management principle for managing the business In 2014, we, the new Board of Management, introduced ROCE as new key management principle replacing ROS We wanted to be held accountable for our stated targets and goals As a result we implemented the ROCE target in all senior manageme
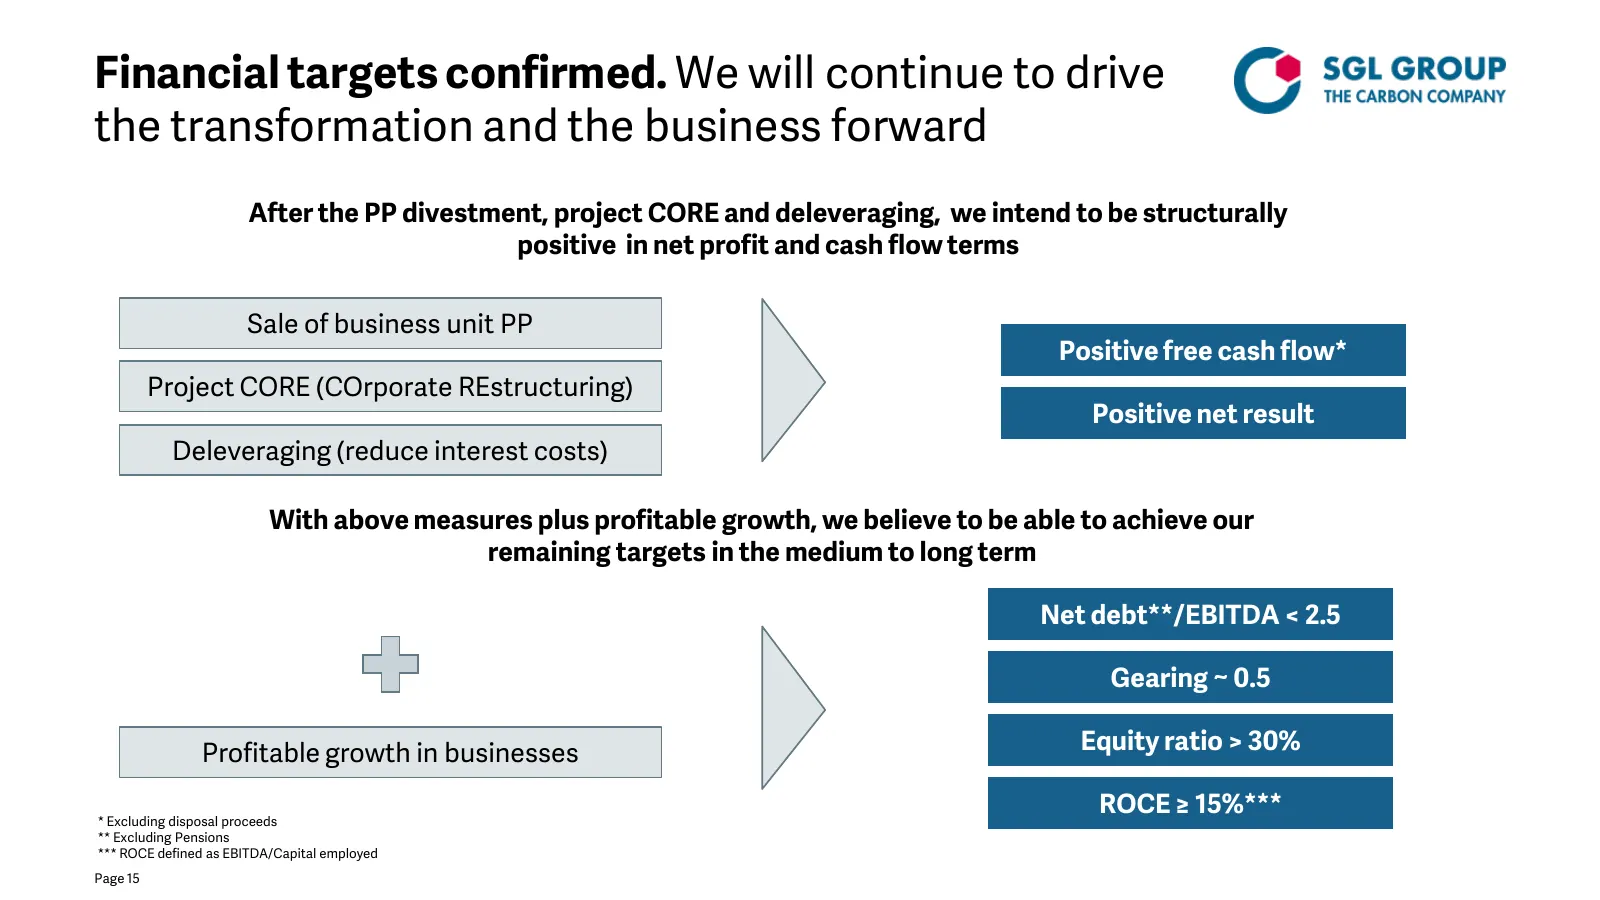
Slide 15: Financial targets confirmed
Financial targets confirmed. We will continue to drive the transformation and the business forward After the PP divestment, project CORE and deleveraging, we intend to be structurally positive in net profit and cash flow terms Sale of business unit PP Positive free cash flow* Project CORE (COrporate
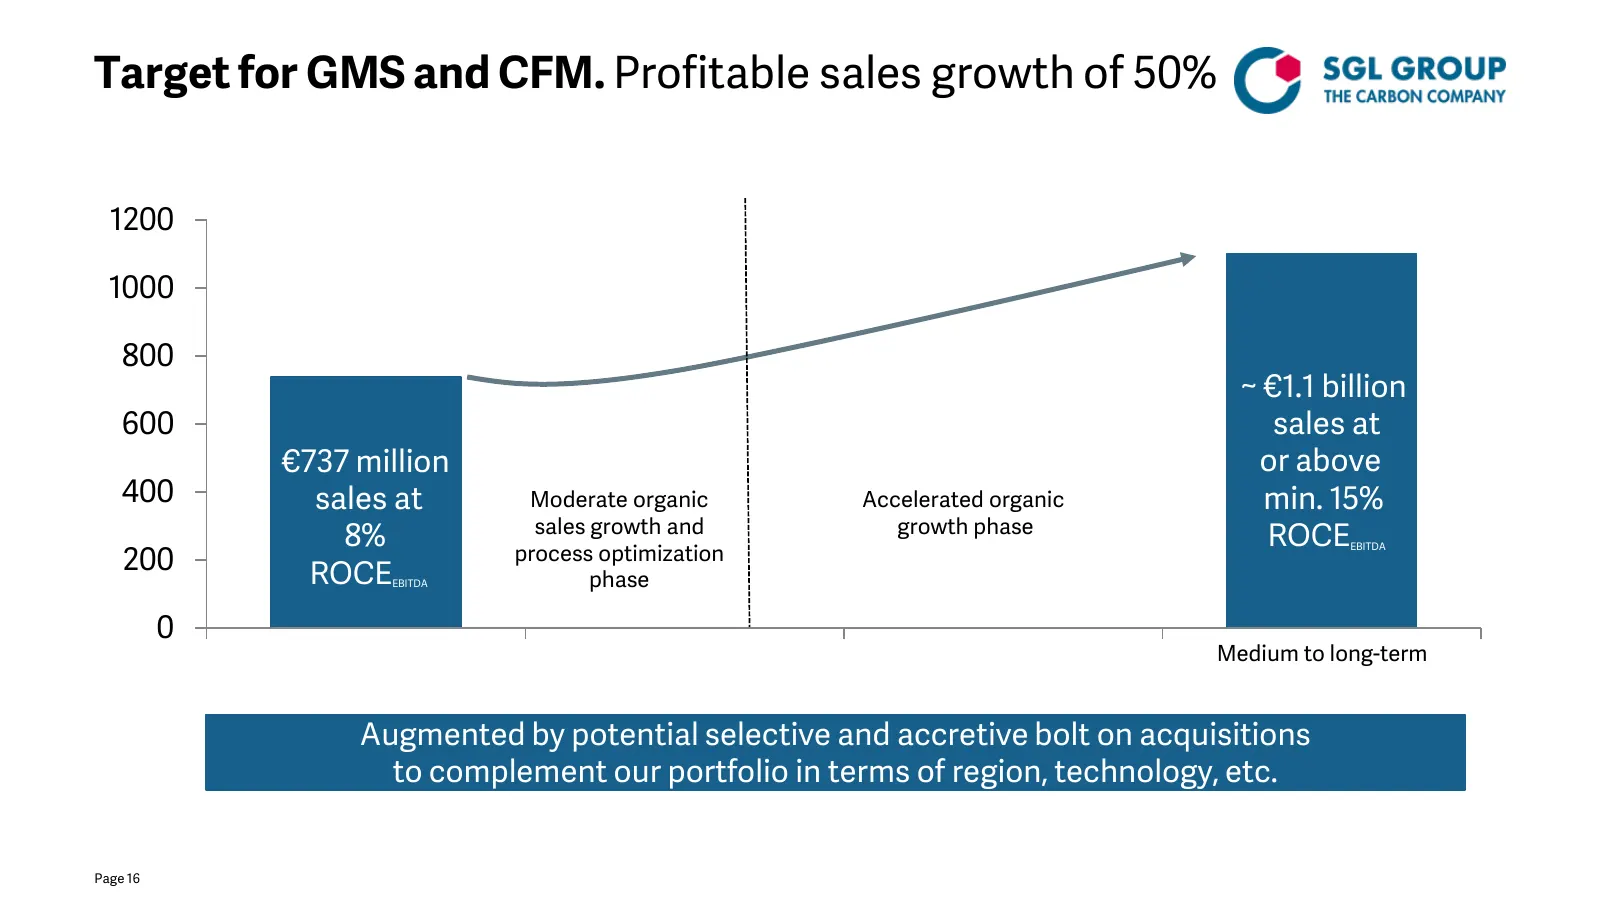
Slide 16: Target for GMS and CFM. Profitable sales growth of 50%
Target for GMS and CFM. Profitable sales growth of 50% 1200 1000 800 ~ €1.1 billion 600 sales at €737 million or above 400 sales at Moderate organic Accelerated organic min. 15% sales growth and growth phase 8% ROCE 200 process optimization EBITDA ROCE EBITDA phase 0 Medium to long-term 2014 2020 Au
Slide 17: The course is set for deleveraging and profitable growth
The course is set for deleveraging and profitable growth Proceeds from sale of GE and in a later step disposal proceeds from the contemplated sale of CFL/CE and potential measures for strengthening the capital structure will provide sufficient means for substantial balance sheet deleveraging and a
Slide 18: Thank you for your attention!
Thank you for your attention! Page 18
Slide 19: Appendix
@ SGL GROUP THE CARBON COMPANY Appendix
Slide 20: Performance Products. Reclassified to discontinued operations as of June 30, 2016
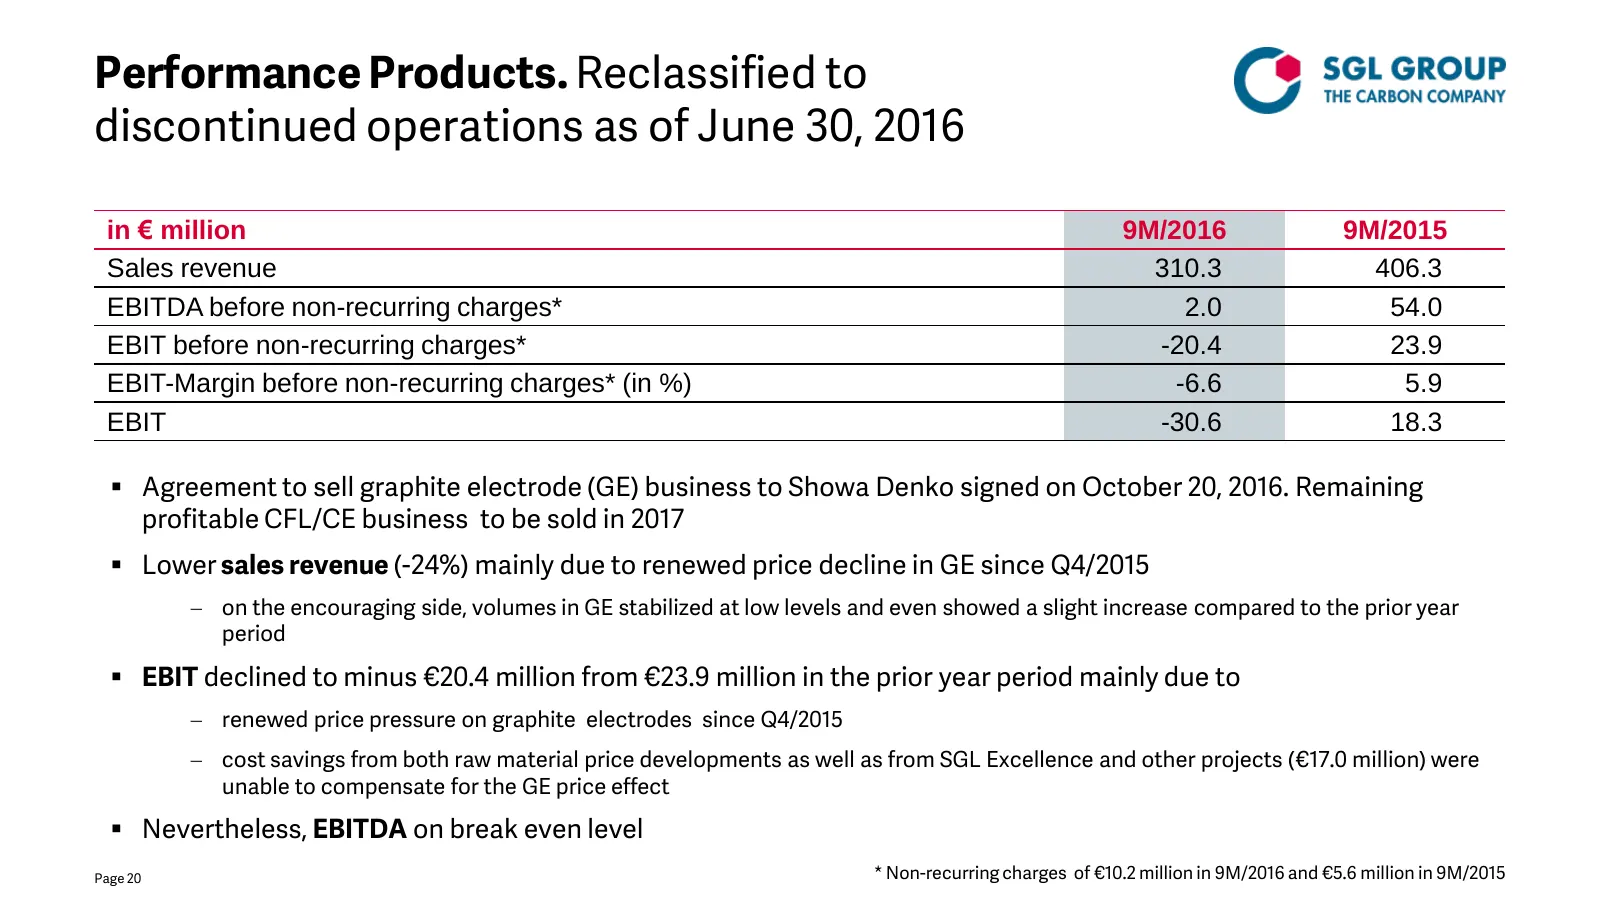
Performance Products. Reclassified to discontinued operations as of June 30, 2016 in € million 9M/2016 9M/2015 Sales revenue 310.3 406.3 EBITDA before non-recurring charges* 2.0 54.0 EBIT before non-recurring charges* -20.4 23.9 EBIT-Margin before non-recurring charges* (in %) -6.6 5.9 EBIT -30.6 18
Slide 21: Important note
Important note: This presentation contains statements relating to certain projections and business trends that are forward-looking, including statements with respect to SGL Group’s outlook and business development, including developments in SGL Group’s Composites - Fibers & Materials and Graphite Ma
Source: Internet Archive copy of sglgroup.com
More decks from SGL Carbon SE
 9M 2026 Earnings Presentation30 slides · Nov 5, 2026
 9M 2026 Earnings Presentation17 slides · Nov 5, 2026
 Q3 2024 Earnings Presentation28 slides · Nov 7, 2024
 H1 2024 Earnings Presentation18 slides · Aug 8, 2024
 Q1 2024 Earnings Presentation19 slides · May 8, 2024
 ESG Presentation (March 2024)7 slides · Mar 22, 2024