Kingfisher PLC · LSE:KGF
Kingfisher — FY2018/19 Earnings Presentation
50 slides from Kingfisher's earnings presentation, Mar 20, 2019
Slide 1: Kingfisher plc full year results
Kingfisher plc full year results 12 months to 31 January 2019 20 March 2019
Slide 2: Disclaimer
Disclaimer You are not to construe the content of this presentation as investment, legal or tax advice and you should make you own evaluation of the Company and the market. If you are in any doubt about the contents of this presentation or the action you should take, you should consult a person auth
Slide 3: Welcome & introduction
Welcome & introduction Andy Cosslett, Chairman 3
Slide 4: Executive summary
Executive summary Véronique Laury, CEO 4
Slide 5: We are a stronger company as a result of the transformation
We are a stronger company as a result of the transformation Building of Kingfisher ‘engine’ nearing completion, with compelling benefits coming through for customers One single buying organisation established; 50% of product (COGS) unified Continued growth in sales and margin from unified & un
Slide 6: The transformation is delivering and we are building a more profitable business
The transformation is delivering and we are building a more profitable business over the medium term Transformation has delivered in line with our original plan; benefits outweighed by external environment and business underperformance Remain convinced in ability to deliver significant further f
Slide 7: FY 2018/19 financial results
FY 2018/19 financial results Karen Witts, CFO 7
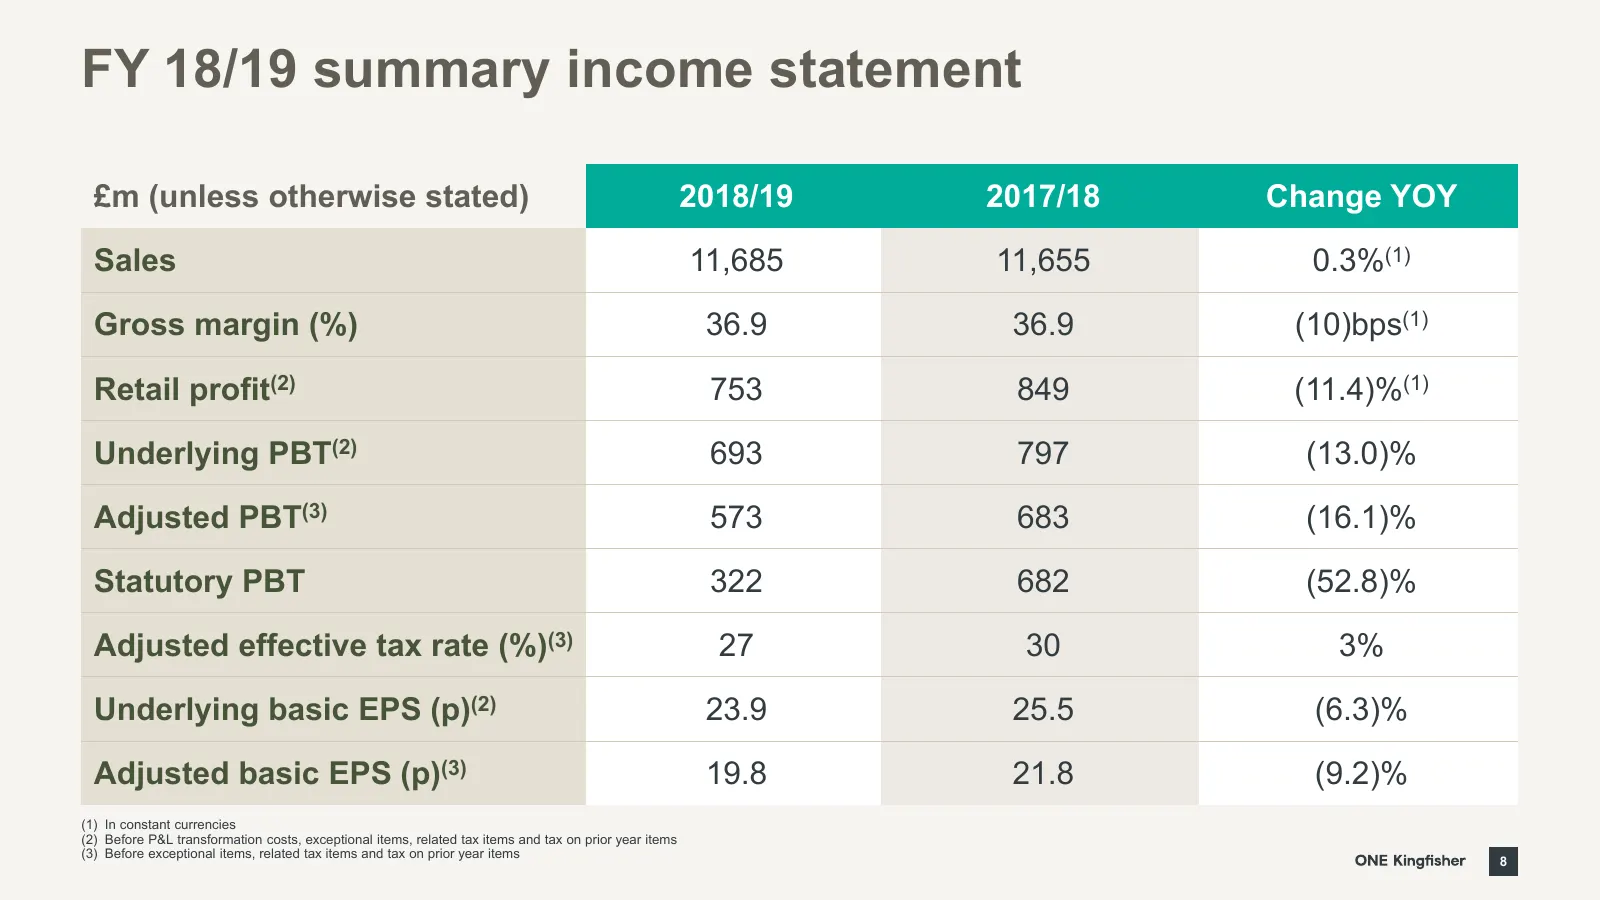
Slide 8: FY 18/19 summary income statement
FY 18/19 summary income statement £m (unless otherwise stated) 2018/19 2017/18 Change YOY Sales 11,685 11,655 0.3%(1) Gross margin (%) 36.9 36.9 (10)bps(1) Retail profit(2) 753 849 (11.4)%(1) Underlying PBT(2) 693 797 (13.0)% Adjusted PBT(3) 573 683 (16.1)% Statutory PBT 322 682 (52.8)% Adjusted eff
Slide 9: FY 18/19 exceptional items
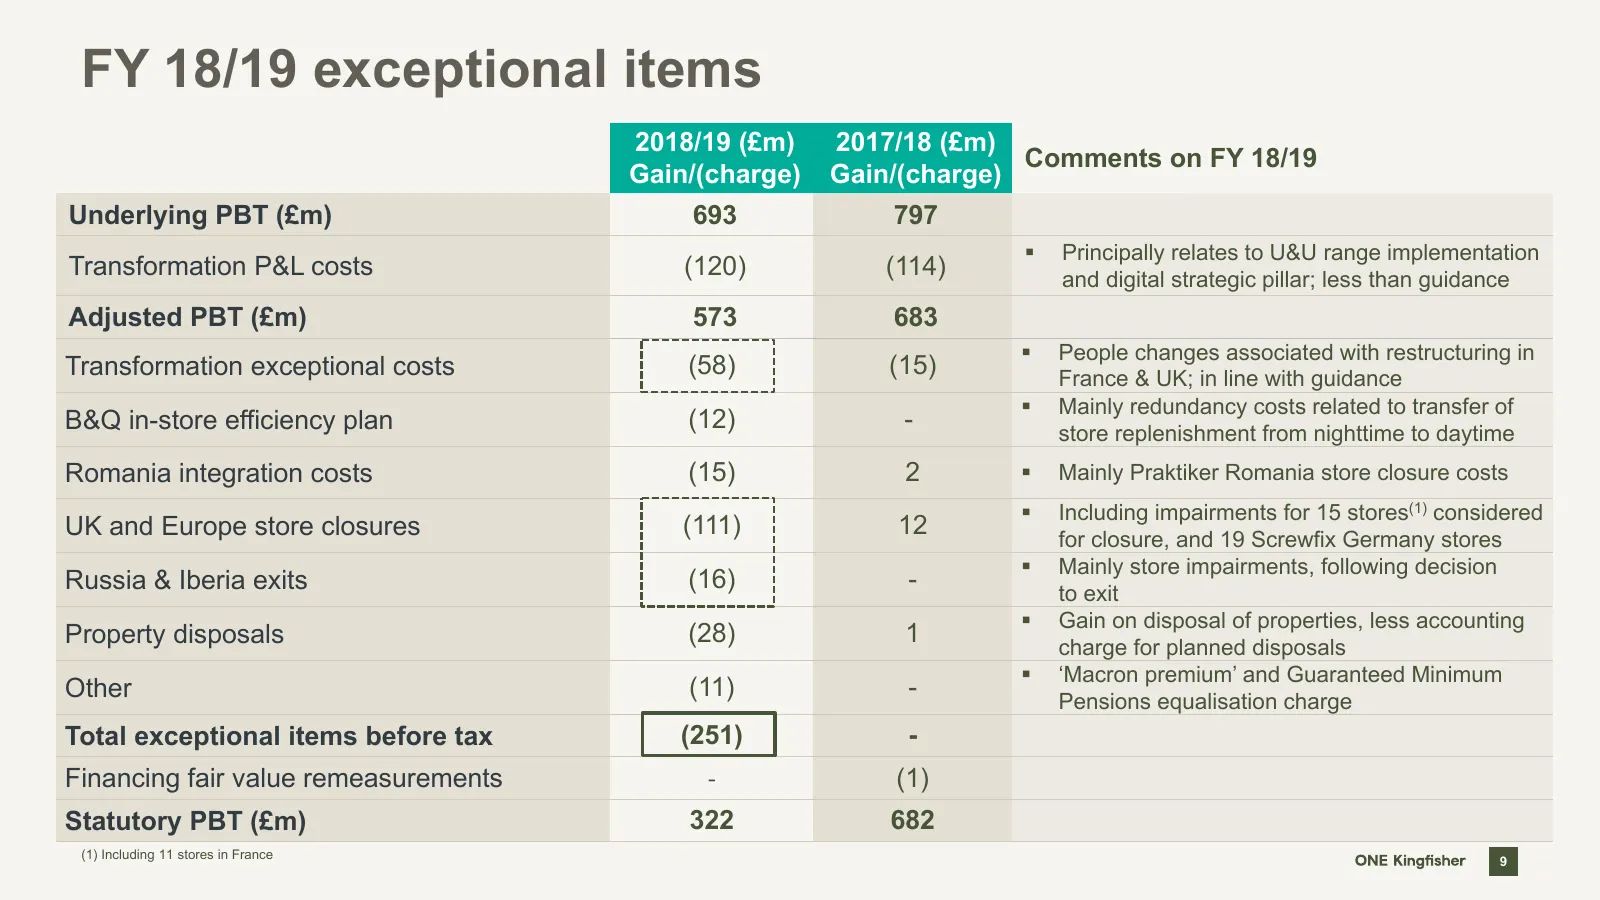
FY 18/19 exceptional items 2018/19 (£m) 2017/18 (£m) Comments on FY 18/19 Gain/(charge) Gain/(charge) Underlying PBT (£m) 693 797 Principally relates to U&U range implementation Transformation P&L costs (120) (114) and digital strategic pillar; less than guidance Adjusted PBT (£m) 573 683 People
Slide 10: FY 18/19 group operational summary
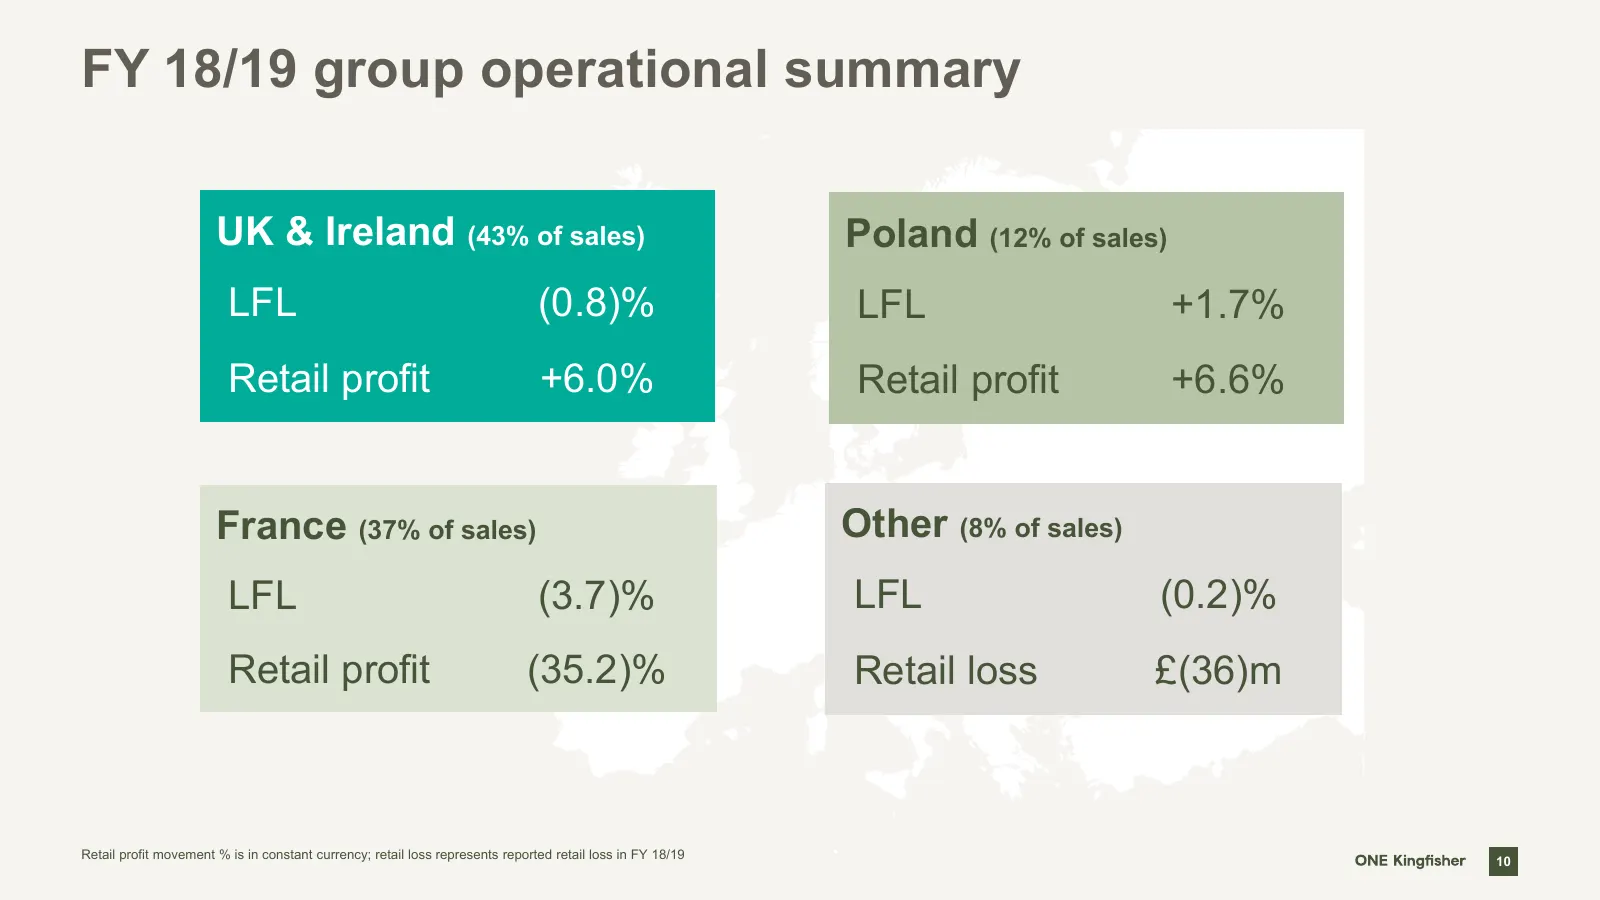
FY 18/19 group operational summary UK & Ireland (43% of sales) Poland (12% of sales) LFL (0.8)% LFL +1.7% Retail profit +6.0% Retail profit +6.6% France (37% of sales) Other (8% of sales) LFL (3.7)% LFL (0.2)% Retail profit (35.2)% Retail loss £(36)m Retail profit movement % is in constant currency;
Slide 11: UK & Ireland – good profit growth
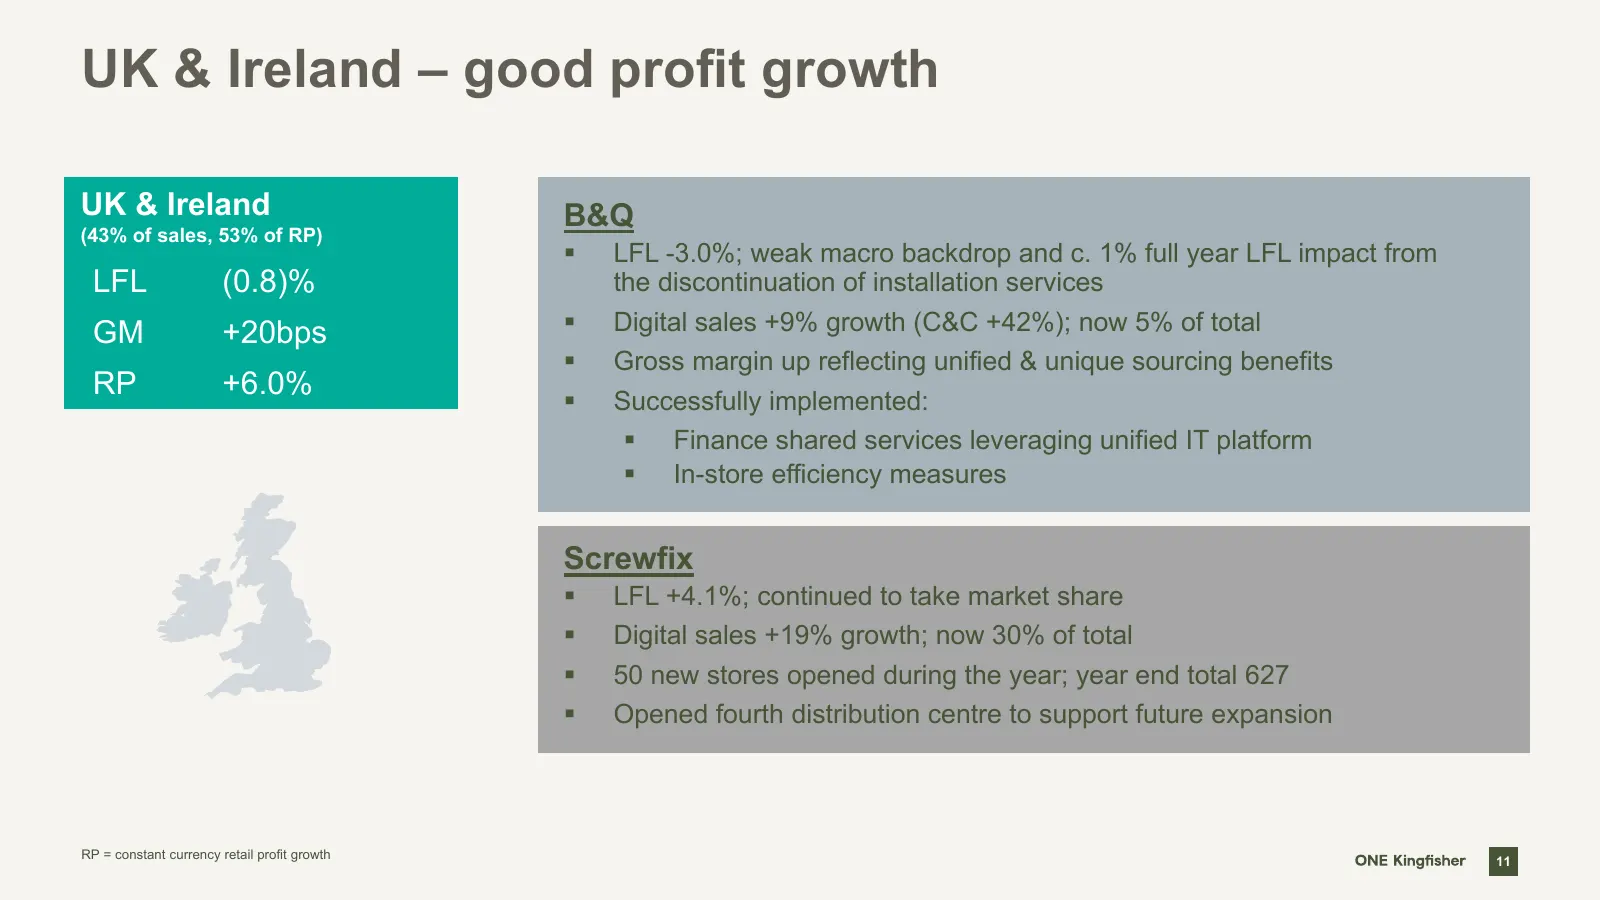
UK & Ireland – good profit growth UK & Ireland B&Q (43% of sales, 53% of RP) LFL -3.0%; weak macro backdrop and c. 1% full year LFL impact from LFL (0.8)% the discontinuation of installation services GM +20bps Digital sales +9% growth (C&C +42%); now 5% of total Gross margin up reflecting unif
Slide 12: France – Brico Dépôt progress offset by Castorama
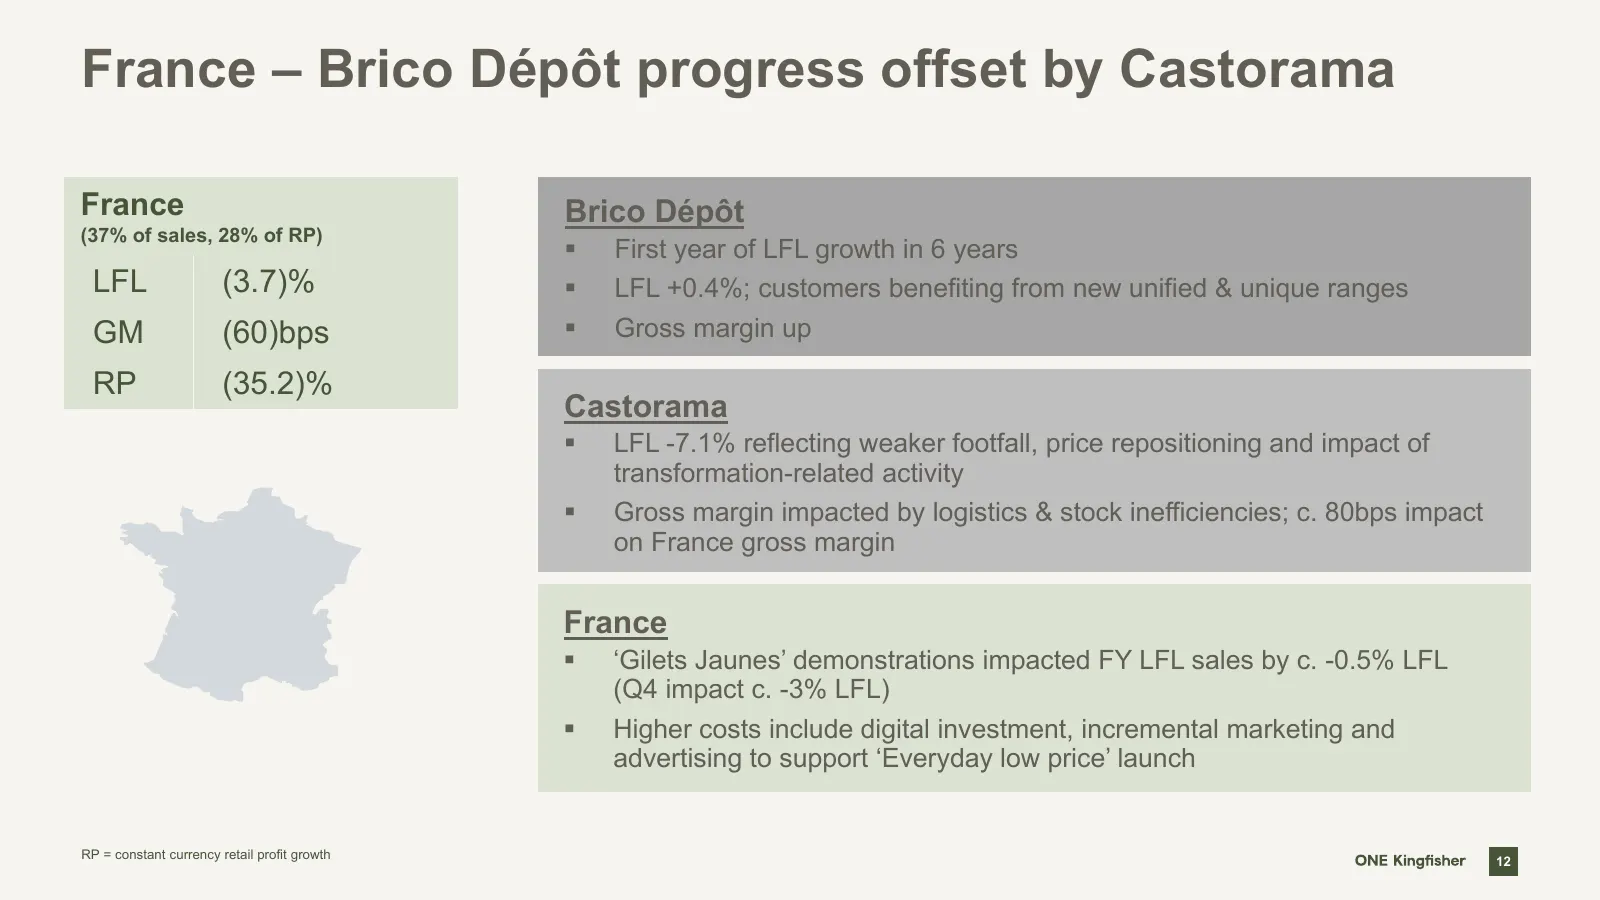
France – Brico Dépôt progress offset by Castorama France Brico Dépôt (37% of sales, 28% of RP) First year of LFL growth in 6 years LFL (3.7)% LFL +0.4%; customers benefiting from new unified & unique ranges GM (60)bps Gross margin up RP (35.2)% Castorama LFL -7.1% reflecting weaker footfall,
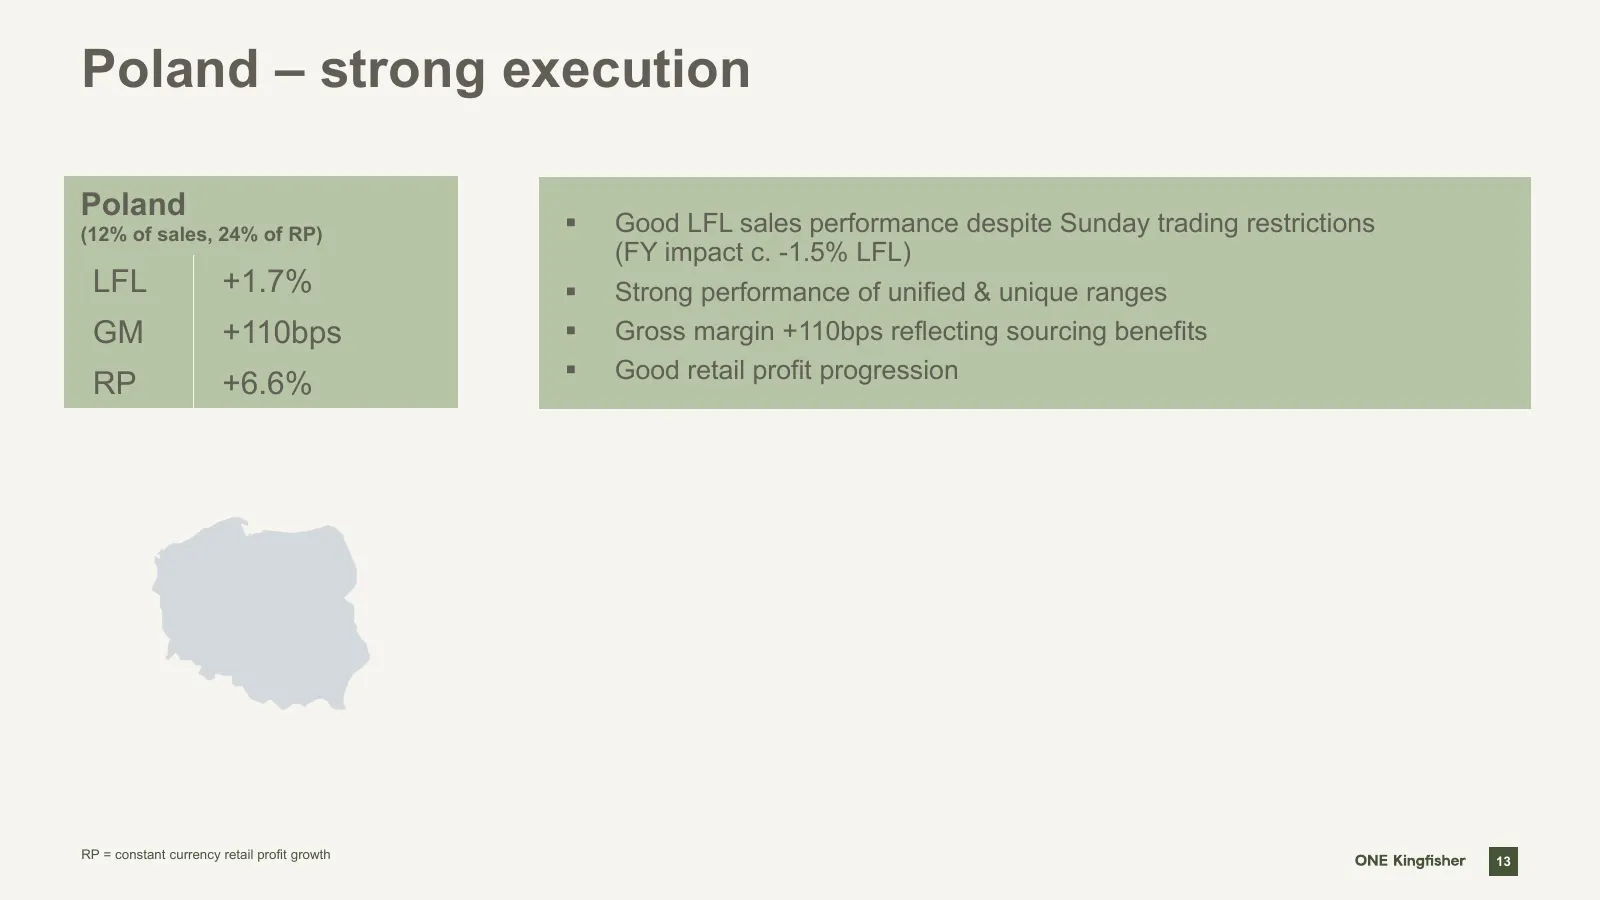
Slide 13: Poland – strong execution
Poland – strong execution Poland (12% of sales, 24% of RP) Good LFL sales performance despite Sunday trading restrictions (FY impact c. -1.5% LFL) LFL +1.7% Strong performance of unified & unique ranges GM +110bps Gross margin +110bps reflecting sourcing benefits Good retail profit progressi
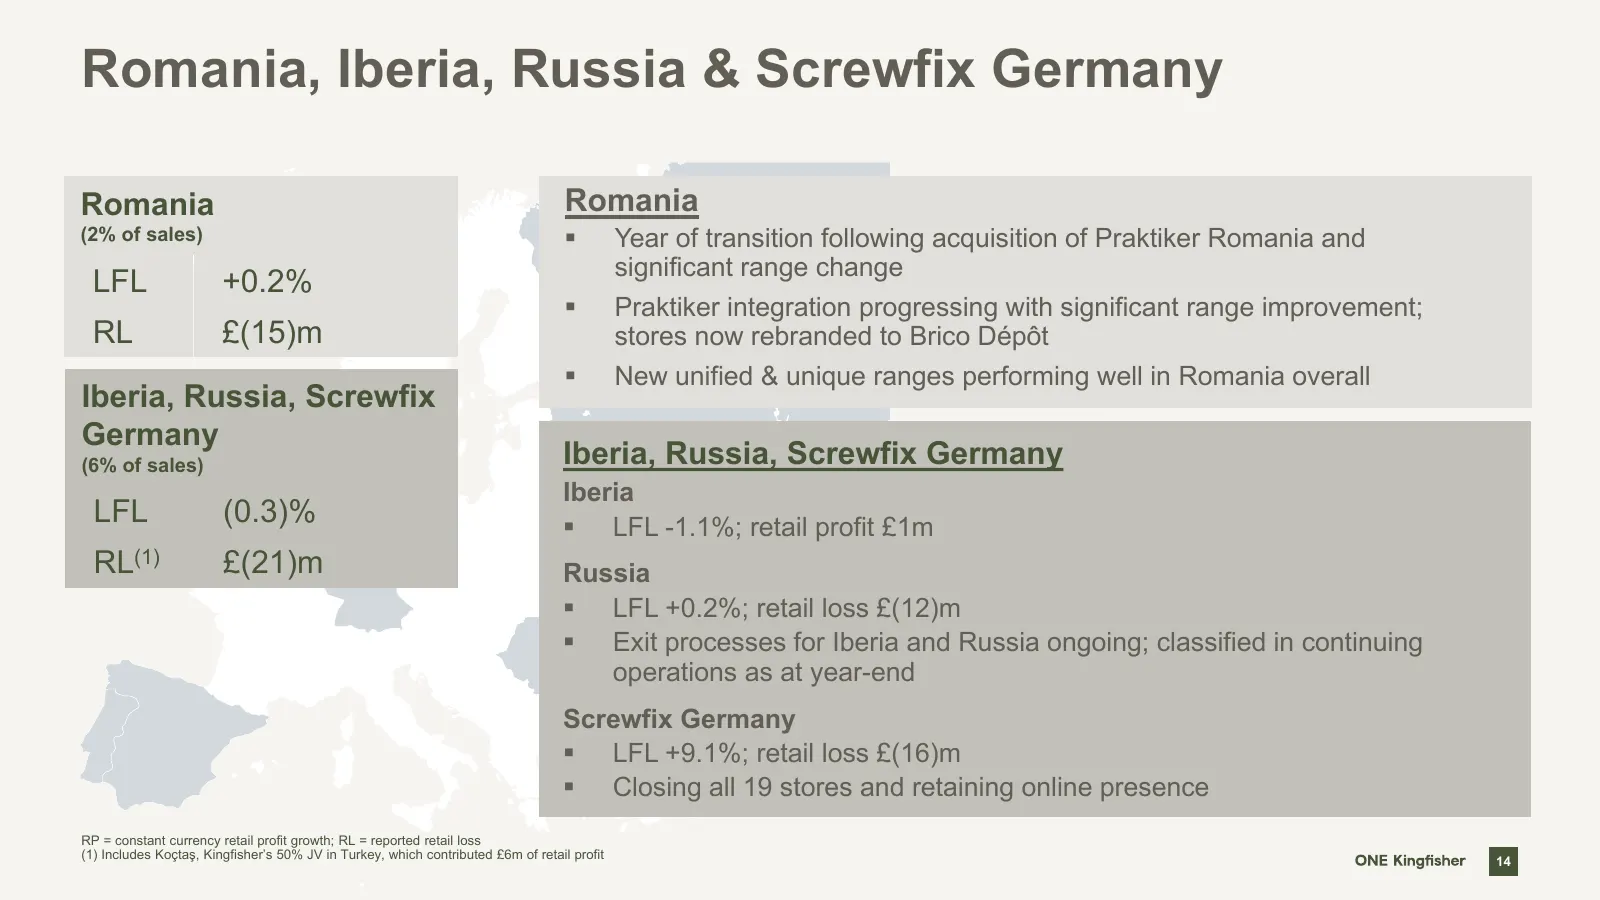
Slide 14: Romania, Iberia, Russia & Screwfix Germany
Romania, Iberia, Russia & Screwfix Germany Romania Romania (2% of sales) Year of transition following acquisition of Praktiker Romania and significant range change LFL +0.2% Praktiker integration progressing with significant range improvement; RL £(15)m stores now rebranded to Brico Dépôt New
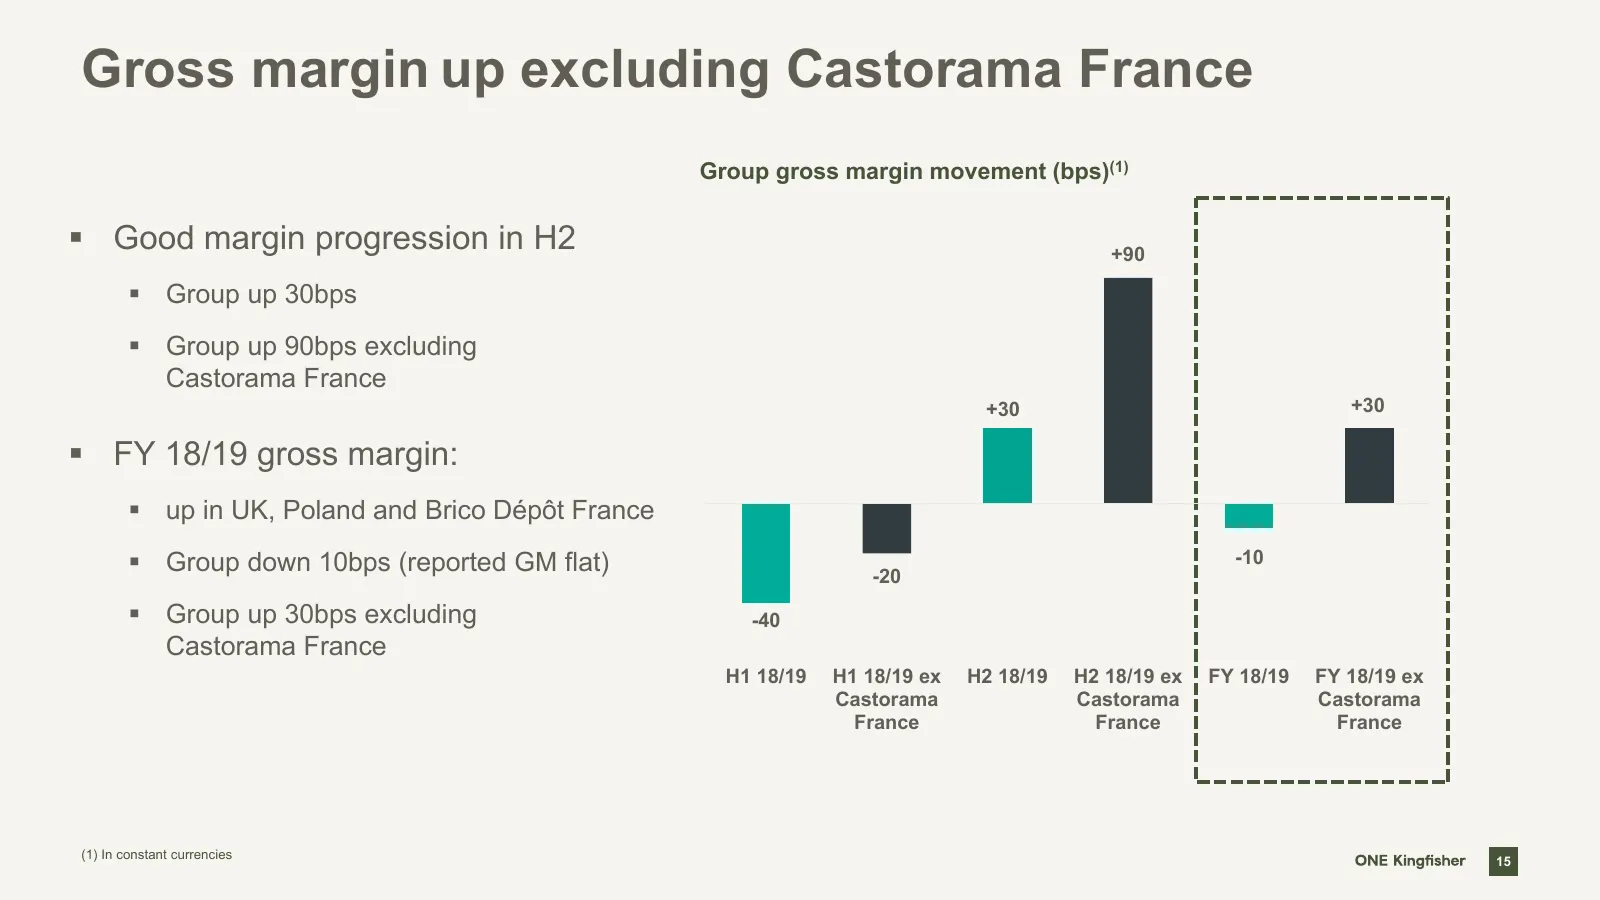
Slide 15: Gross margin up excluding Castorama France
Gross margin up excluding Castorama France Group gross margin movement (bps)(1) Good margin progression in H2 +90 Group up 30bps Group up 90bps excluding Castorama France +30 +30 FY 18/19 gross margin: up in UK, Poland and Brico Dépôt France Group down 10bps (reported GM flat) -10 -20
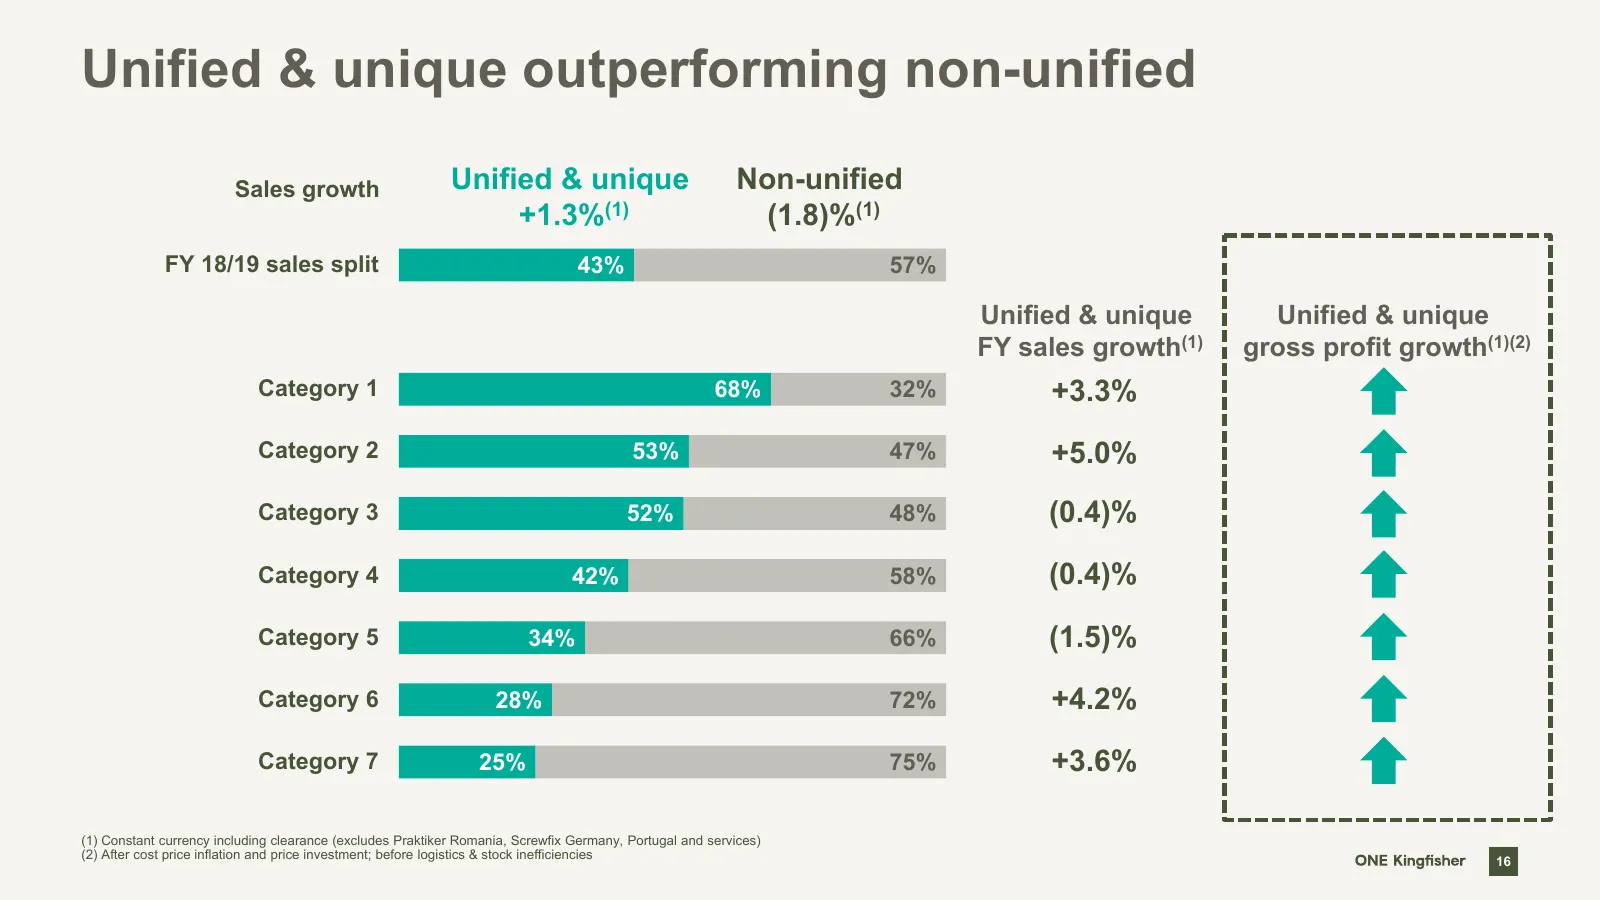
Slide 16: Unified & unique outperforming non-unified
Unified & unique outperforming non-unified Sales growth Unified & unique Non-unified +1.3%(1) (1.8)%(1) FY 18/19 sales split 43% 57% Unified & unique Unified & unique Unified & unique H1 sales growth FY sales (1) (1) growth gross profit growth(1)(2) Category 1 68% 32% +5.9%+3.3% Category 2 53% 47% +
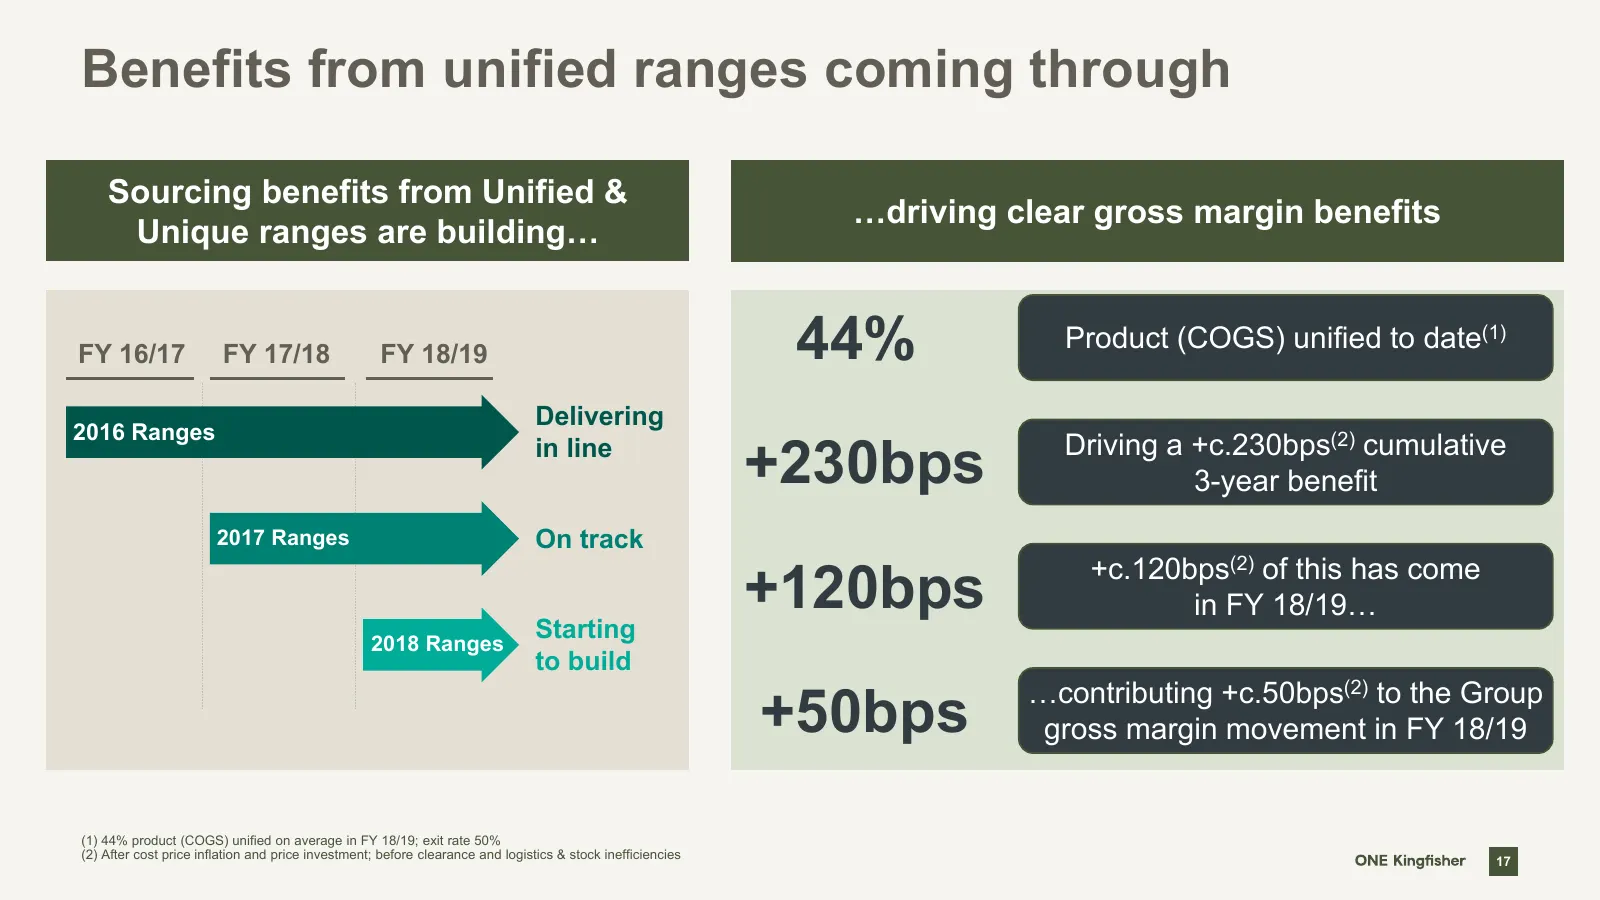
Slide 17: Benefits from unified ranges coming through
Benefits from unified ranges coming through Sourcing benefits from Unified & …driving clear gross margin benefits Unique ranges are building… FY 16/17 FY 17/18 FY 18/19 44% Product (COGS) unified to date(1) Delivering 2016 Ranges in line +230bps Driving a +c.230bps(2) cumulative 3-year benefit 2017
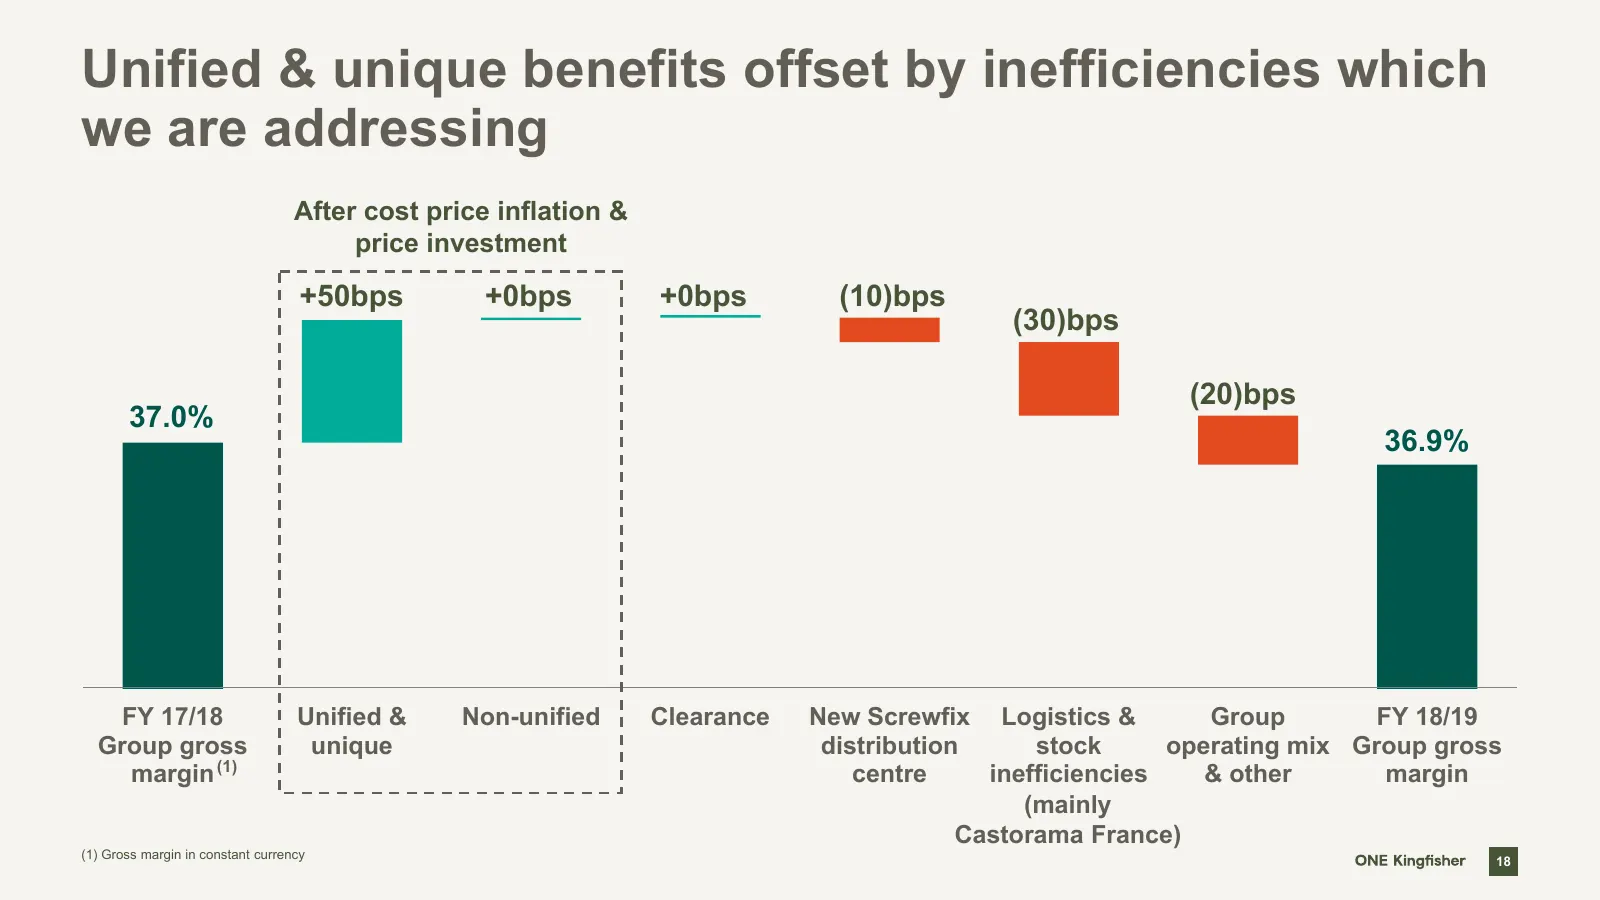
Slide 18: Unified & unique benefits offset by inefficiencies which we are addressing
Unified & unique benefits offset by inefficiencies which we are addressing After cost price inflation & price investment +50bps +0bps +0bps (10)bps (30)bps (20)bps 37.0% 36.9% FY 17/18 Unified & Non-unified Clearance New Screwfix Logistics & Group FY 18/19 Group gross unique distribution stock opera
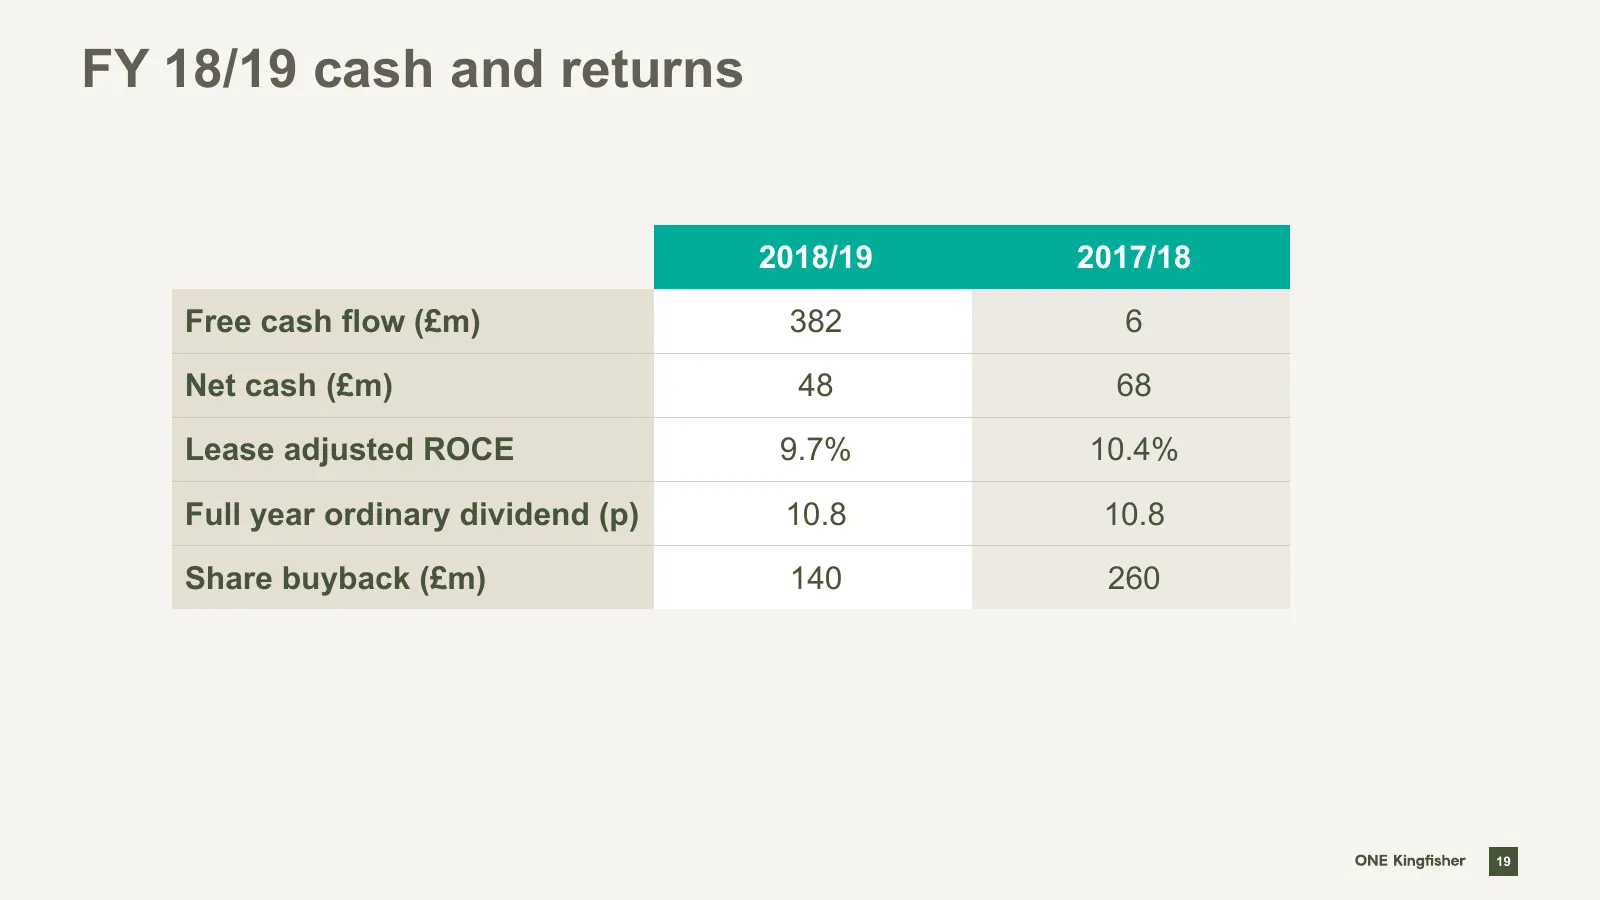
Slide 19: FY 18/19 cash and returns
FY 18/19 cash and returns 2018/19 2017/18 Free cash flow (£m) 382 6 Net cash (£m) 48 68 Lease adjusted ROCE 9.7% 10.4% Full year ordinary dividend (p) 10.8 10.8 Share buyback (£m) 140 260 19
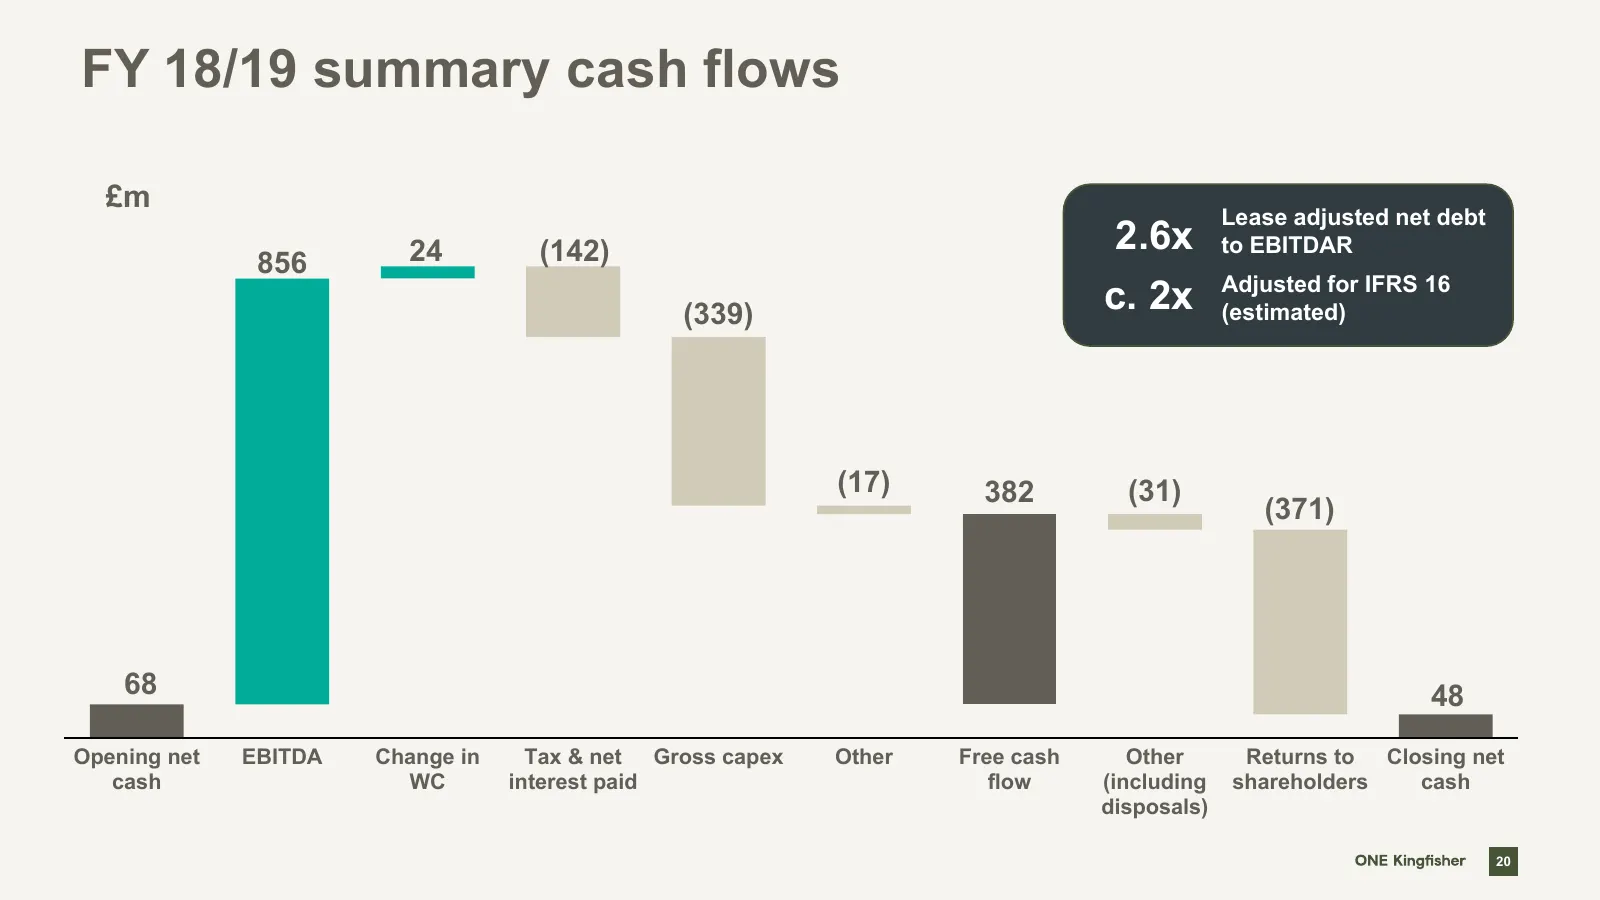
Slide 20: FY 18/19 summary cash flows
FY 18/19 summary cash flows £m Lease adjusted net debt 24 (142) 2.6x to EBITDAR 856 Adjusted for IFRS 16 (339) c. 2x (estimated) (17) 382 (31) (371) 68 48 Opening net EBITDA Change in Tax & net Gross capex Other Free cash Other Returns to Closing net cash WC interest paid flow (including shareholder
Slide 21: FY 19/20 outlook & summary guidance
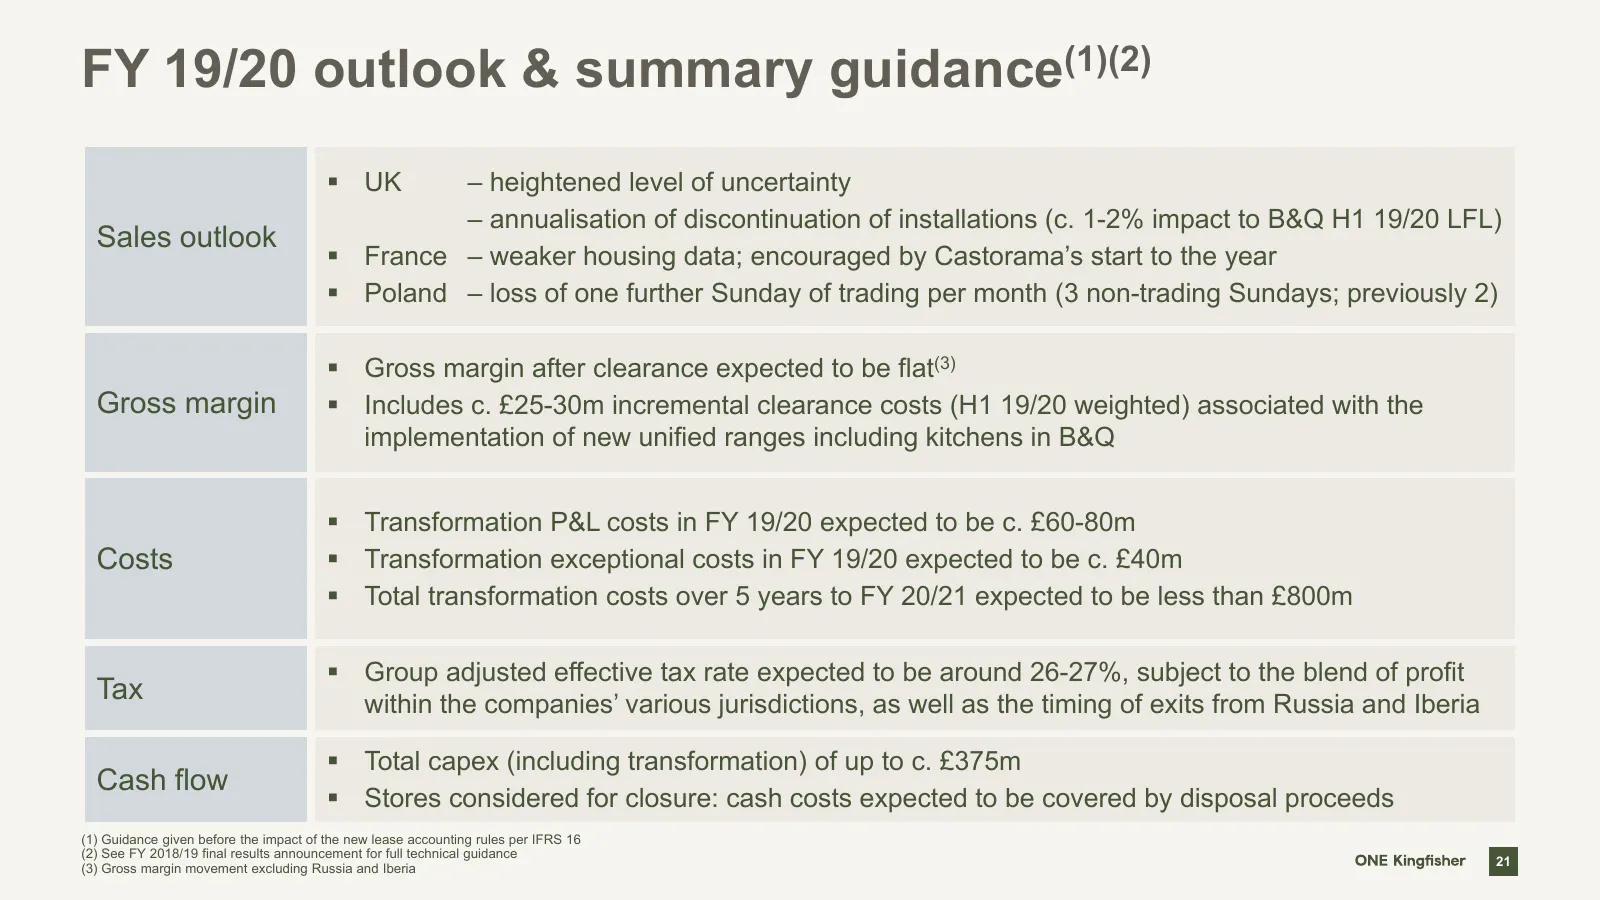
FY 19/20 outlook & summary guidance(1)(2) UK – heightened level of uncertainty – annualisation of discontinuation of installations (c. 1-2% impact to B&Q H1 19/20 LFL) Sales outlook France – weaker housing data; encouraged by Castorama’s start to the year Poland – loss of one further Sunday of
Slide 22: Impact of IFRS 16
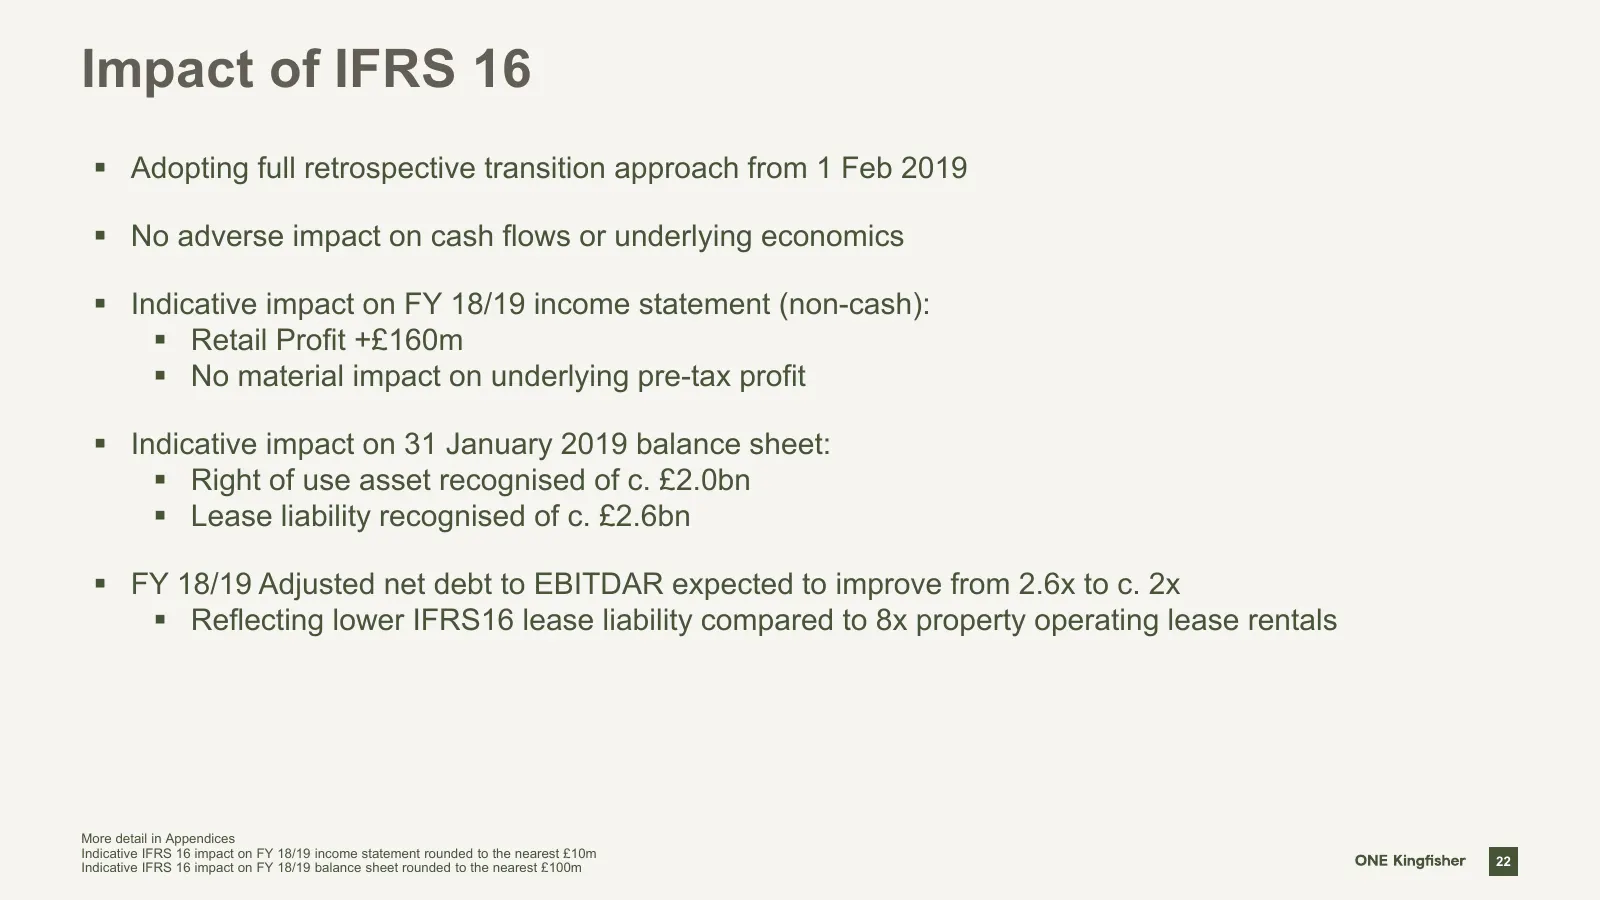
Impact of IFRS 16 Adopting full retrospective transition approach from 1 Feb 2019 No adverse impact on cash flows or underlying economics Indicative impact on FY 18/19 income statement (non-cash): Retail Profit +£160m No material impact on underlying pre-tax profit Indicative impact on 3
Slide 23: Financial summary
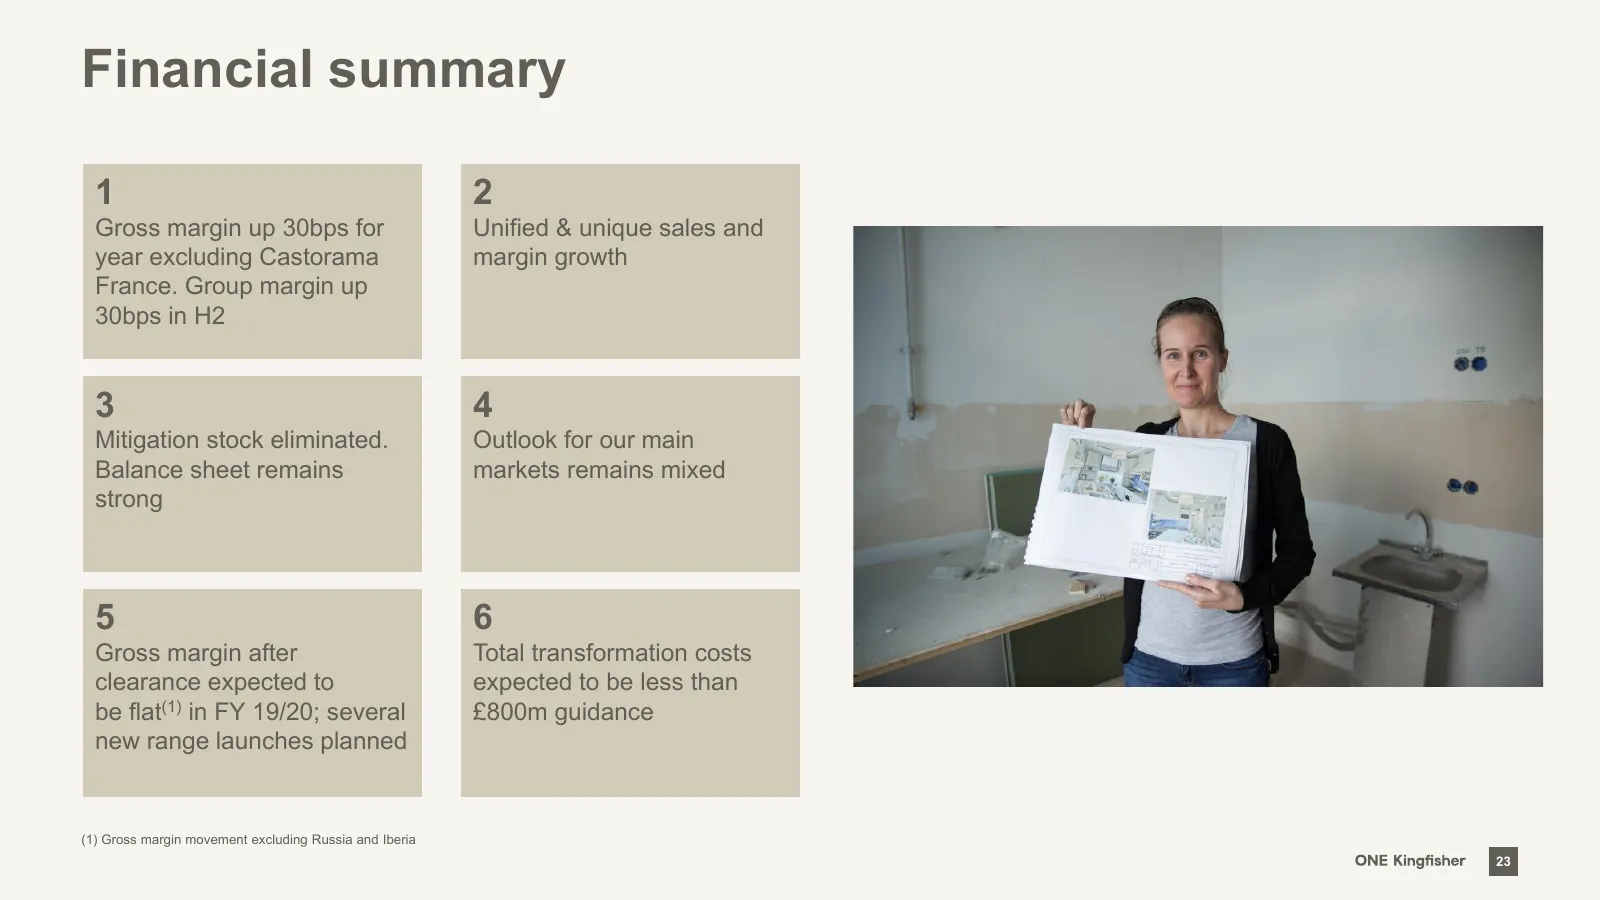
Financial summary 1 2 Gross margin up 30bps for Unified & unique sales and year excluding Castorama margin growth France. Group margin up 30bps in H2 3 4 Mitigation stock eliminated. Outlook for our main Balance sheet remains markets remains mixed strong 5 6 Gross margin after Total transformation c
Slide 24: Building a stronger Kingfisher for sustainable long term growth
Building a stronger Kingfisher for sustainable long term growth Véronique Laury, CEO 24
Slide 25: The market and retail environment has changed since 2016
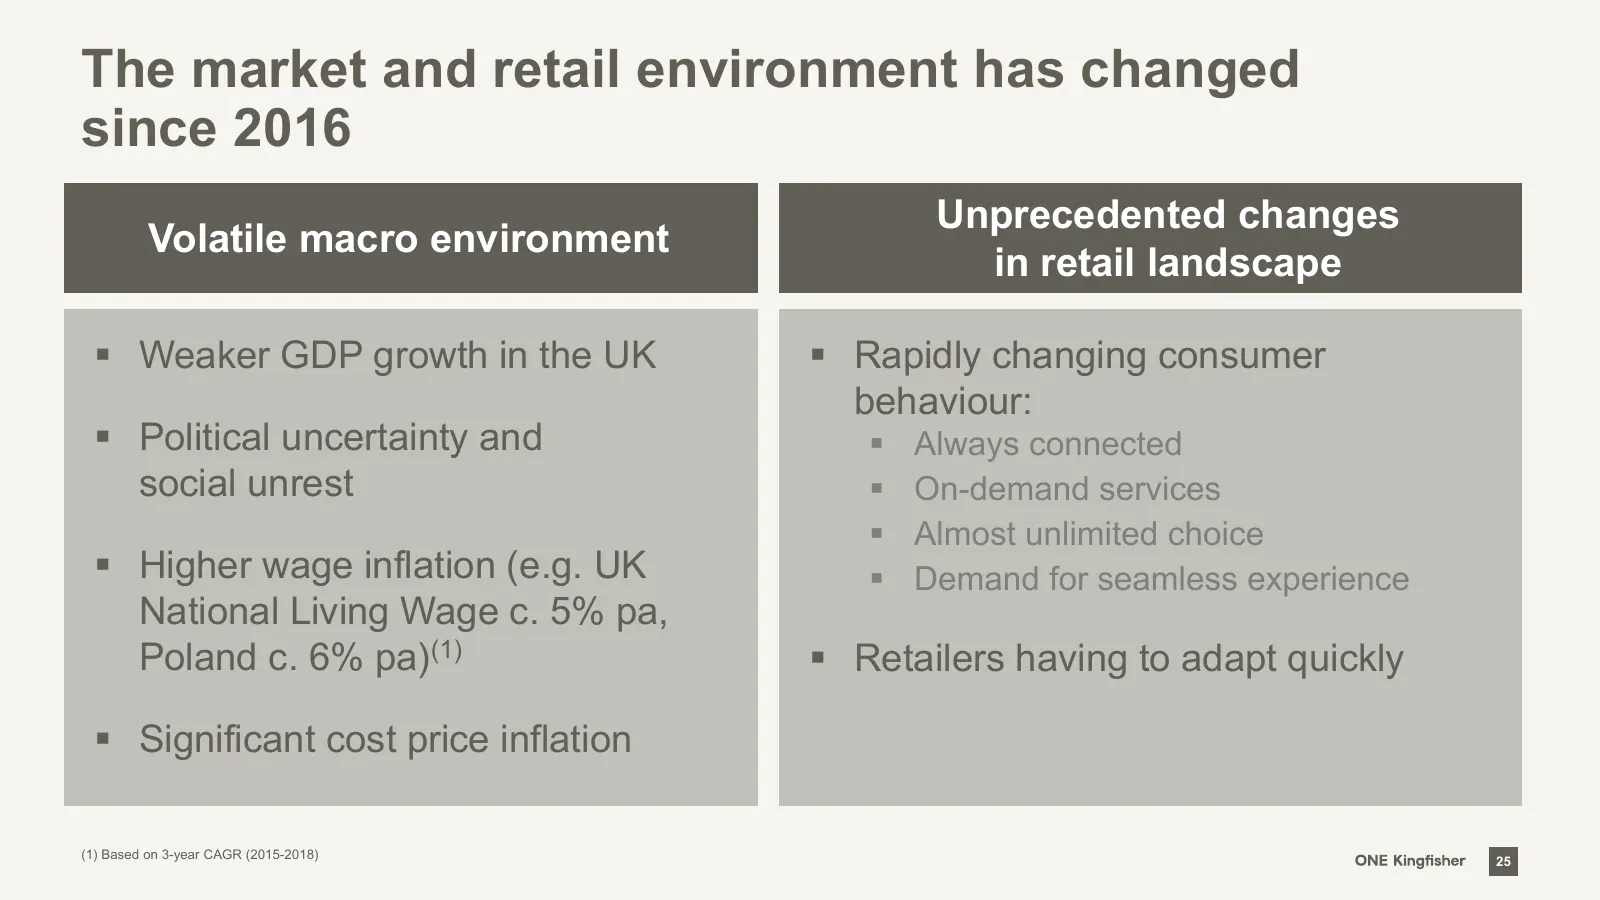
The market and retail environment has changed since 2016 Unprecedented changes Volatile macro environment in retail landscape Weaker GDP growth in the UK Rapidly changing consumer behaviour: Political uncertainty and Always connected social unrest On-demand services Almost unlimited choi
Slide 26: The 'engine' is nearly built
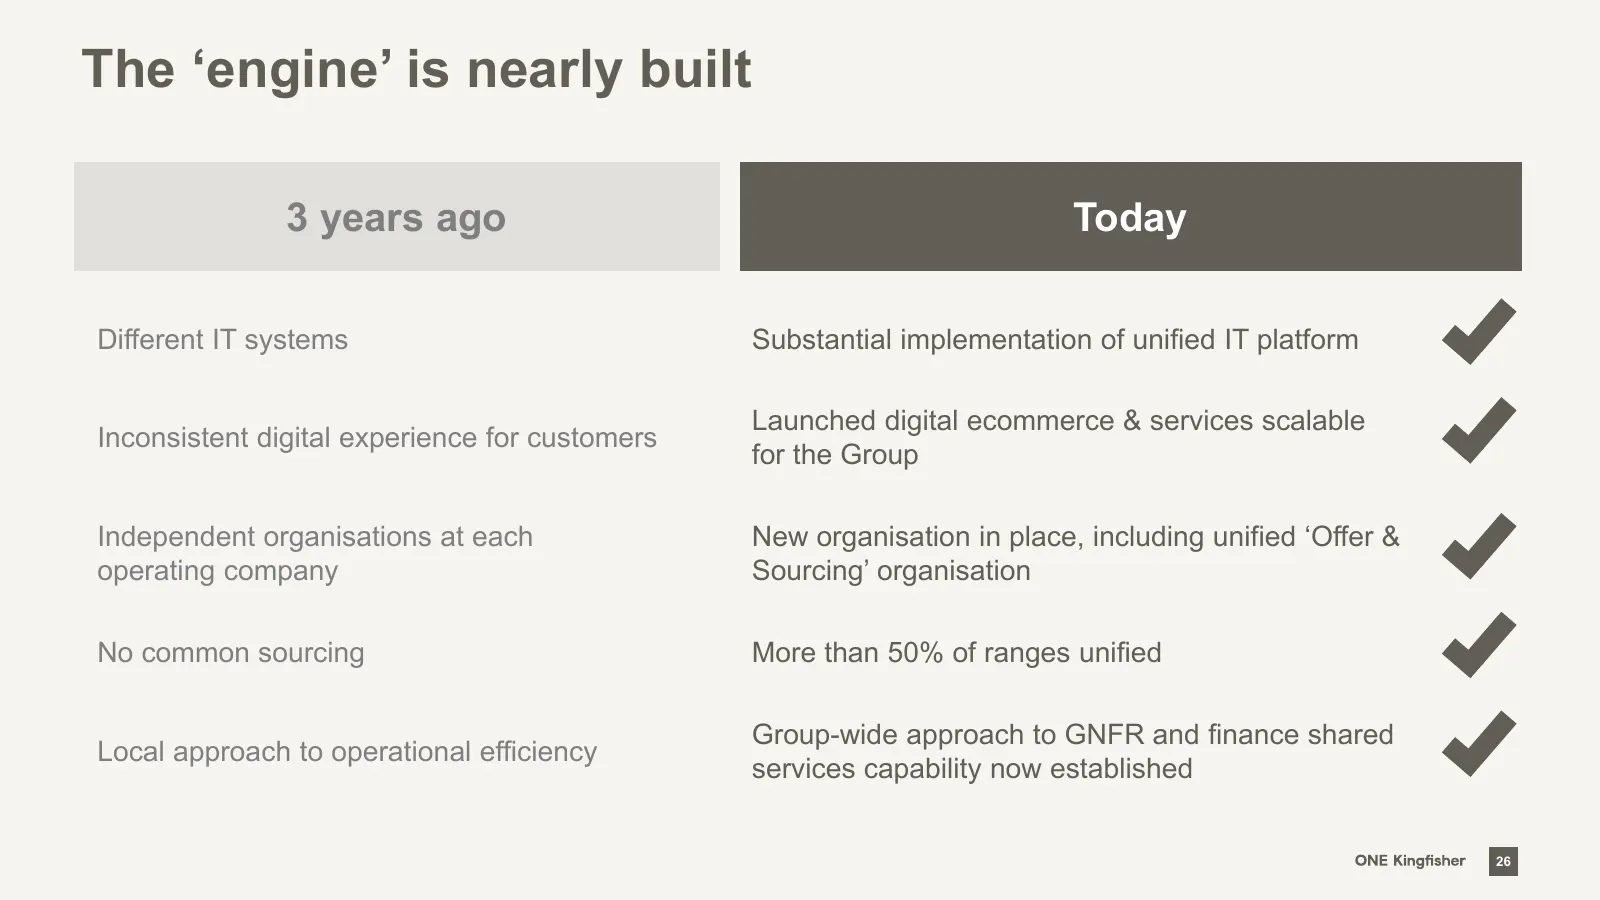
The ‘engine’ is nearly built 3 years ago Today Different IT systems Substantial implementation of unified IT platform Launched digital ecommerce & services scalable Inconsistent digital experience for customers for the Group Independent organisations at each New organisation in place, including unif
Slide 27: The strategy is working
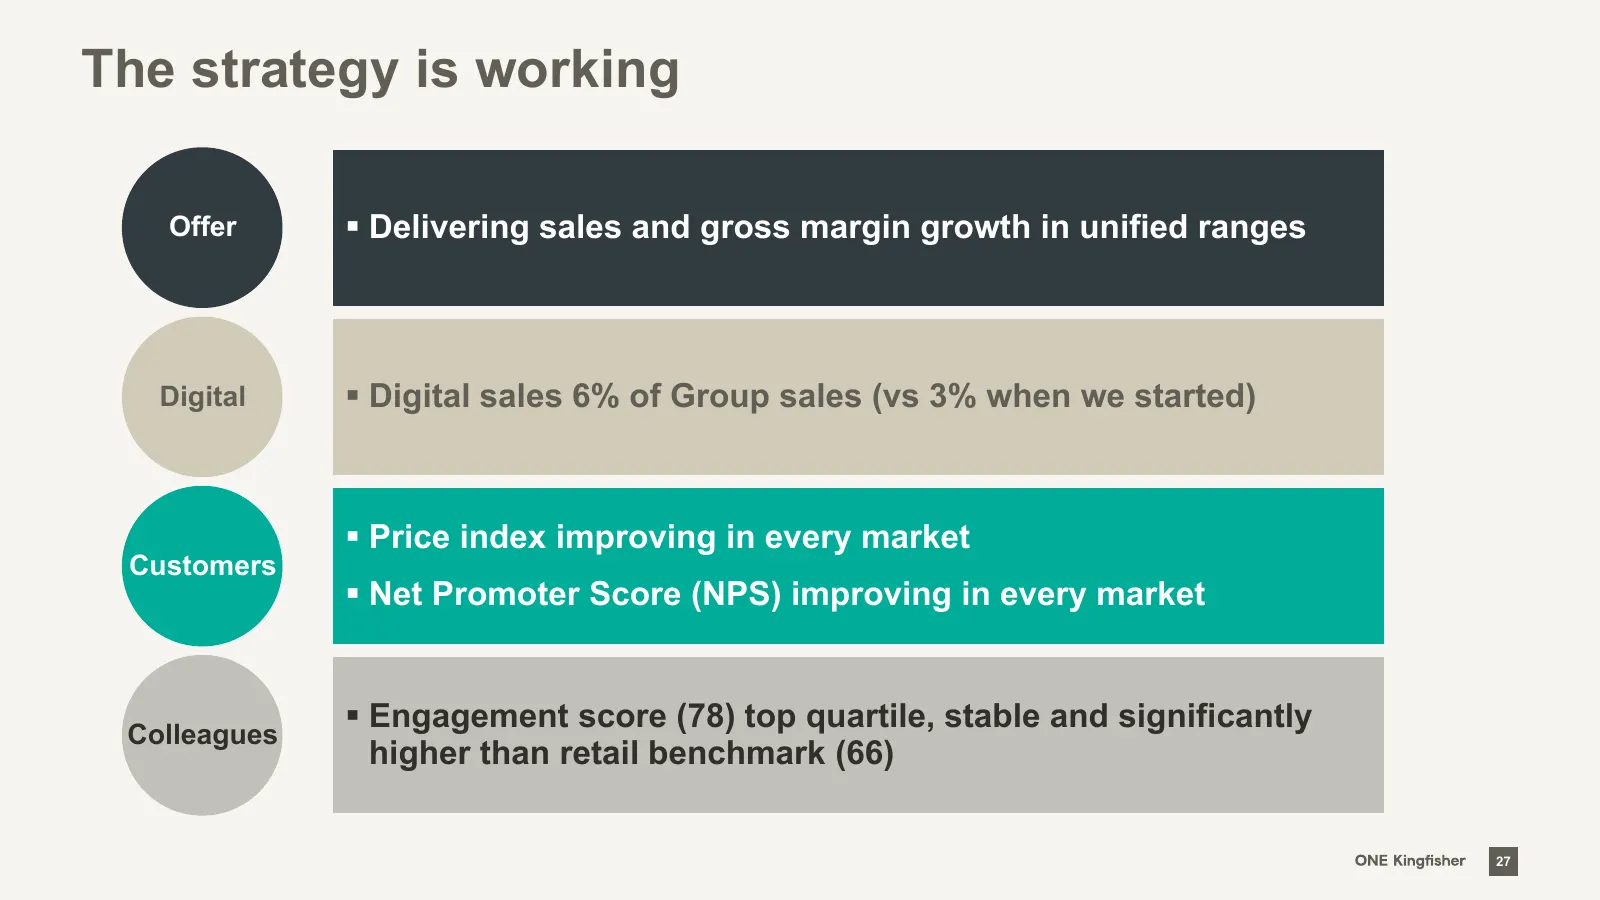
The strategy is working Offer Delivering sales and gross margin growth in unified ranges Digital Digital sales 6% of Group sales (vs 3% when we started) Price index improving in every market Customers Net Promoter Score (NPS) improving in every market Engagement score (78) top quartile, st
Slide 28: We have performed better than (or in line with) peers
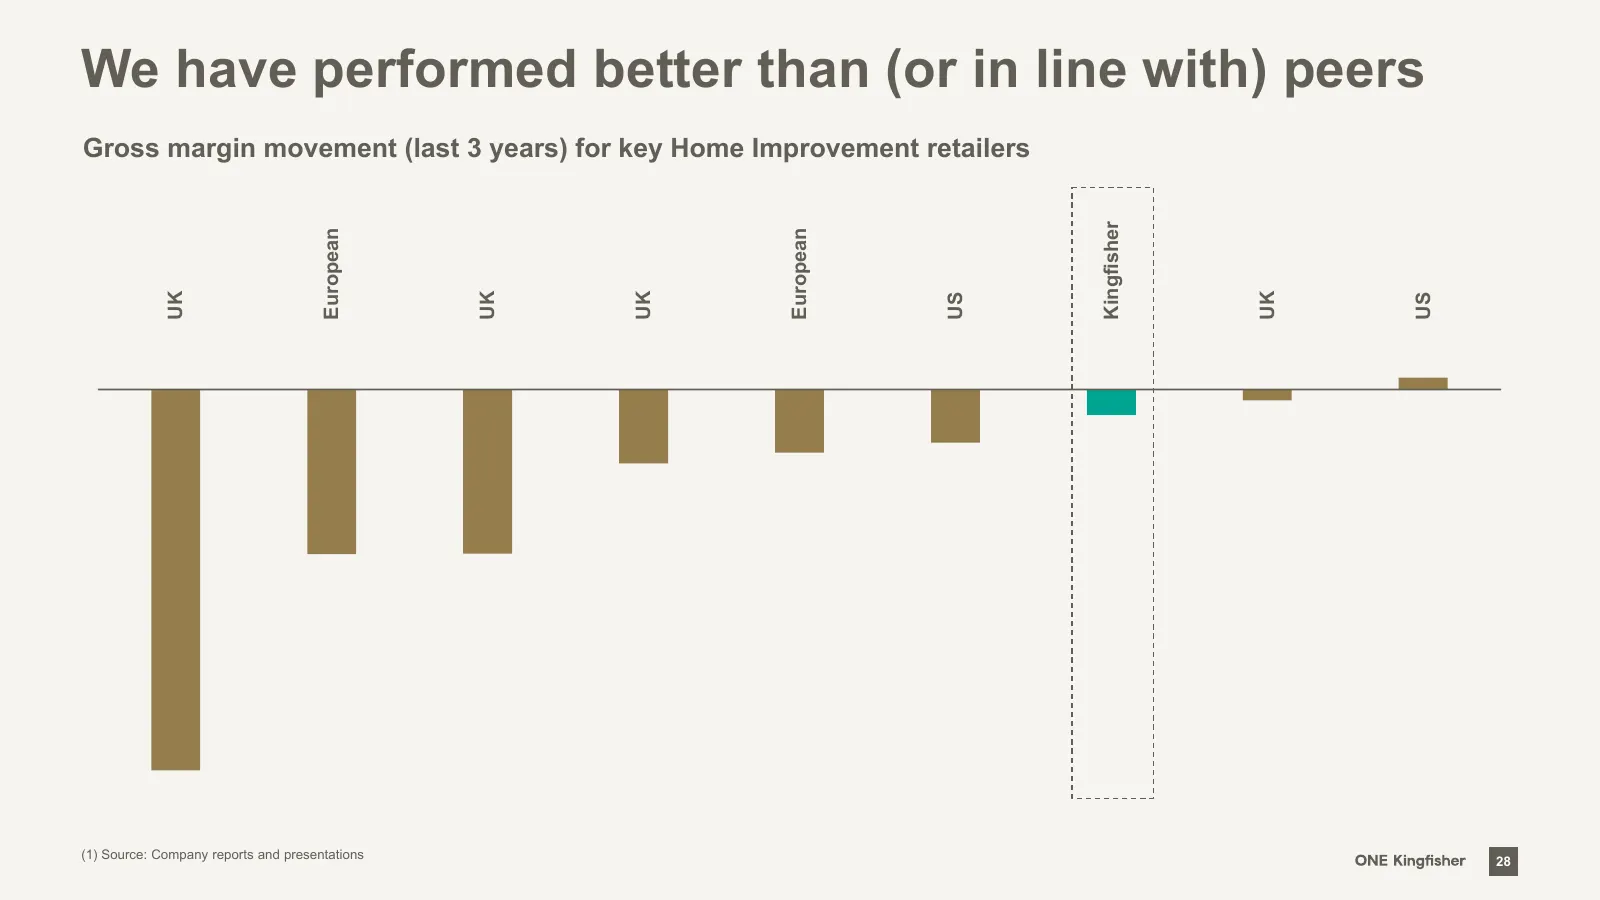
We have performed better than (or in line with) peers Gross margin movement (last 3 years) for key Home Improvement retailers Kingfisher European European UK UK UK UK US US (1) Source: Company reports and presentations 28
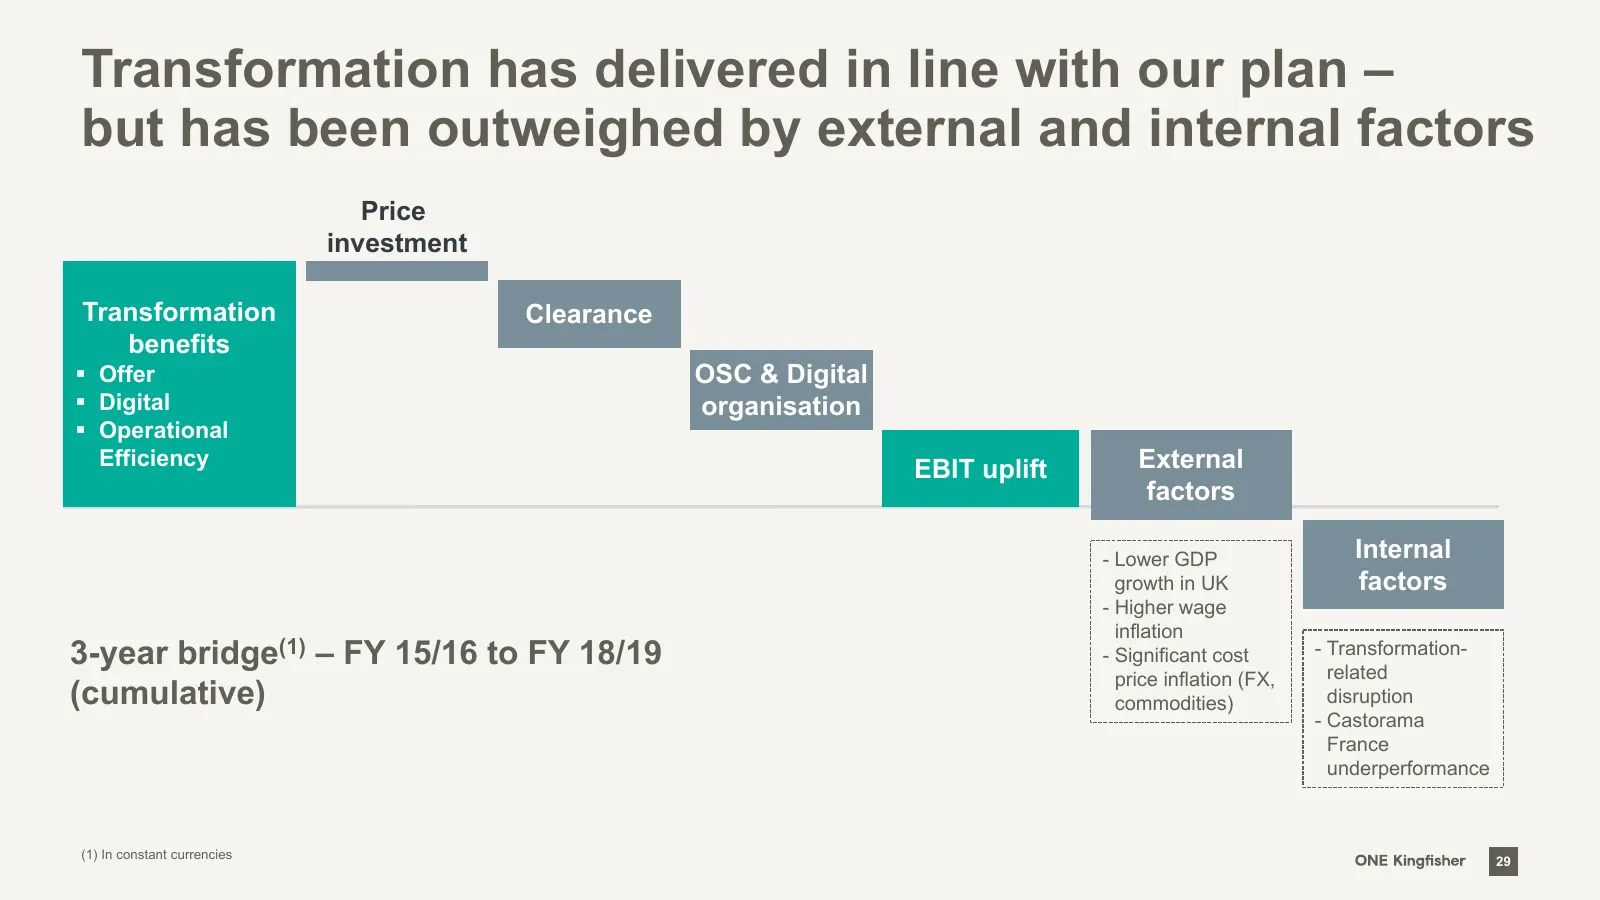
Slide 29: Transformation has delivered in line with our plan
Transformation has delivered in line with our plan – but has been outweighed by external and internal factors Price investment Transformation Clearance benefits Offer OSC & Digital Digital organisation Operational Efficiency EBIT uplift External factors - Lower GDP Internal growth in UK factor
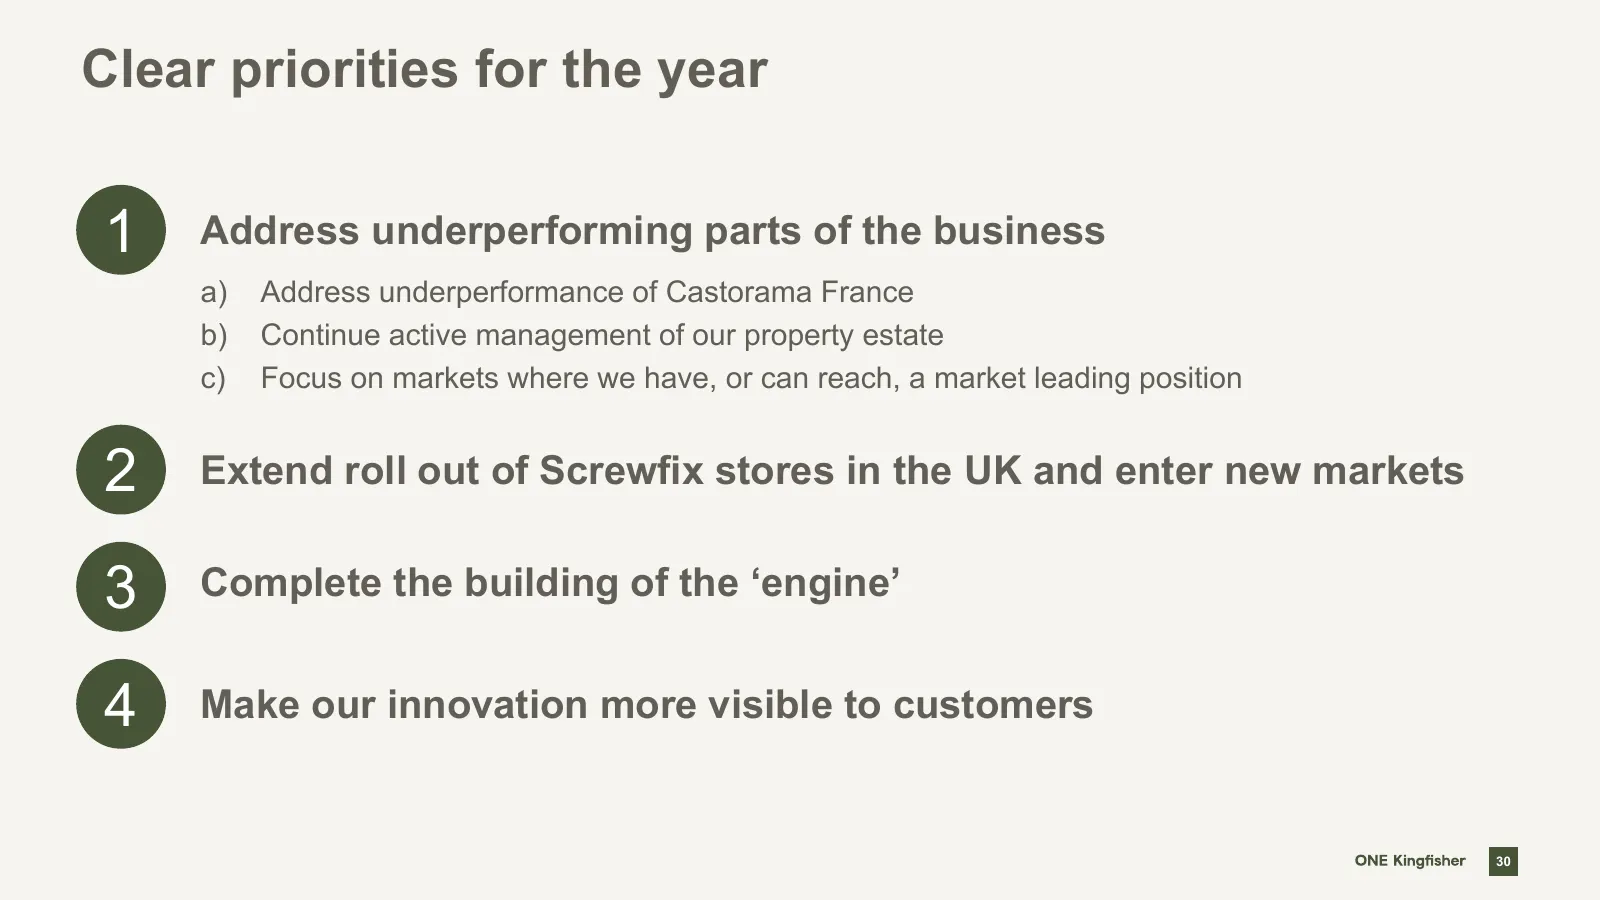
Slide 30: Clear priorities for the year
Clear priorities for the year 1 Address underperforming parts of the business a) Address underperformance of Castorama France b) Continue active management of our property estate c) Focus on markets where we have, or can reach, a market leading position 2 Extend roll out of Screwfix stores in the UK
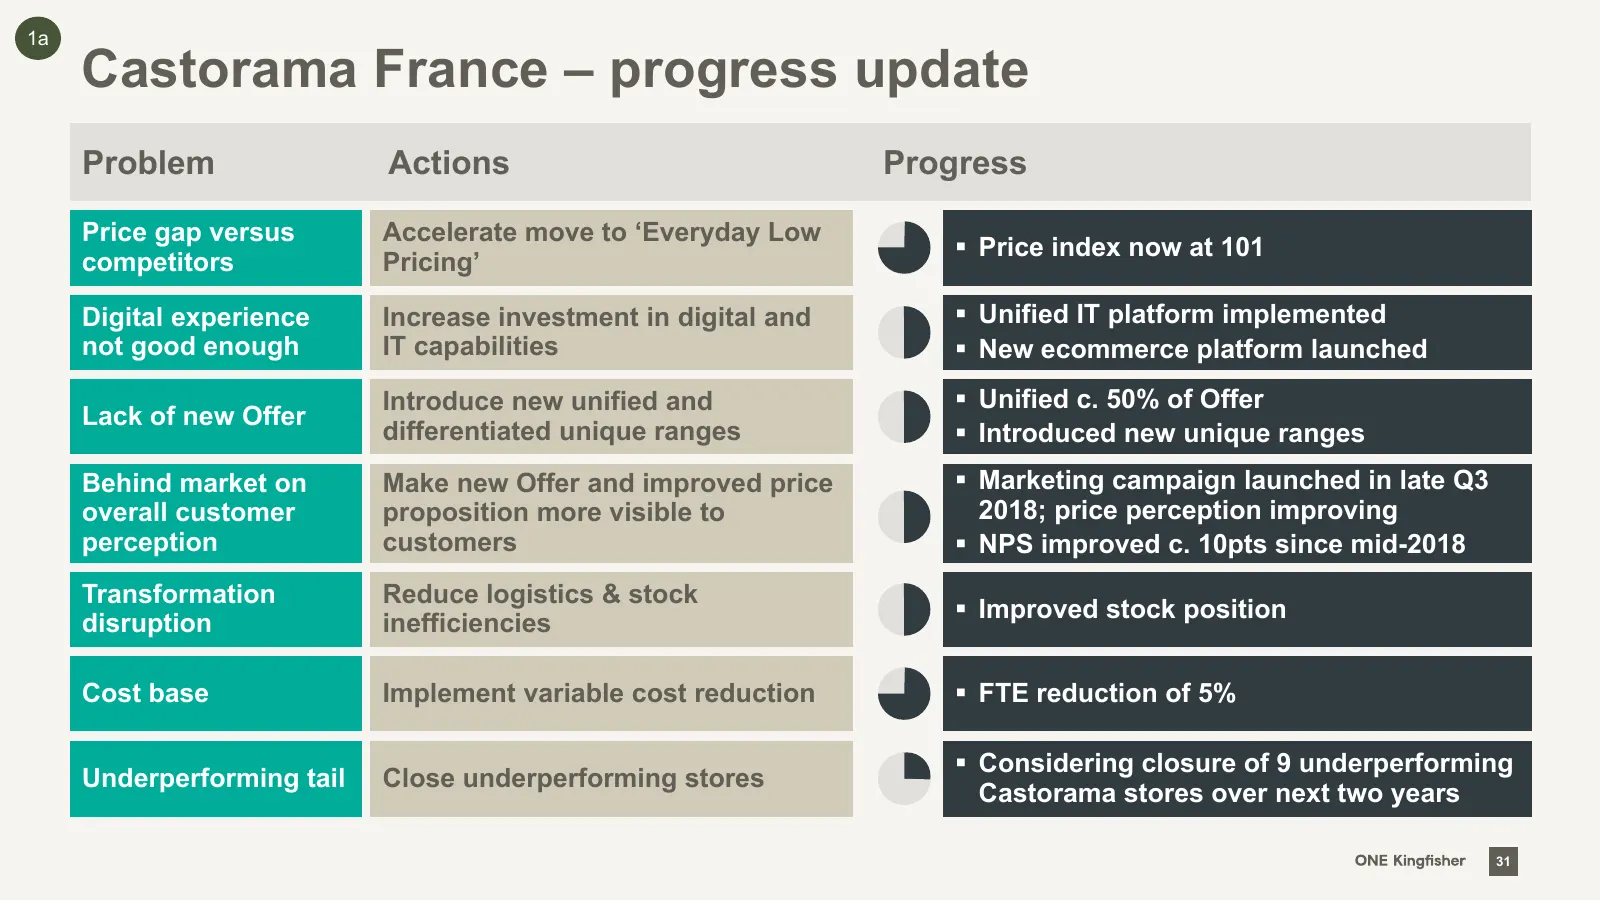
Slide 31: Castorama France – progress update
1a Castorama France – progress update Problem Actions Progress Price gap versus Accelerate move to ‘Everyday Low Price index now at 101 competitors Pricing’ Digital experience Increase investment in digital and Unified IT platform implemented not good enough IT capabilities New ecommerce platf
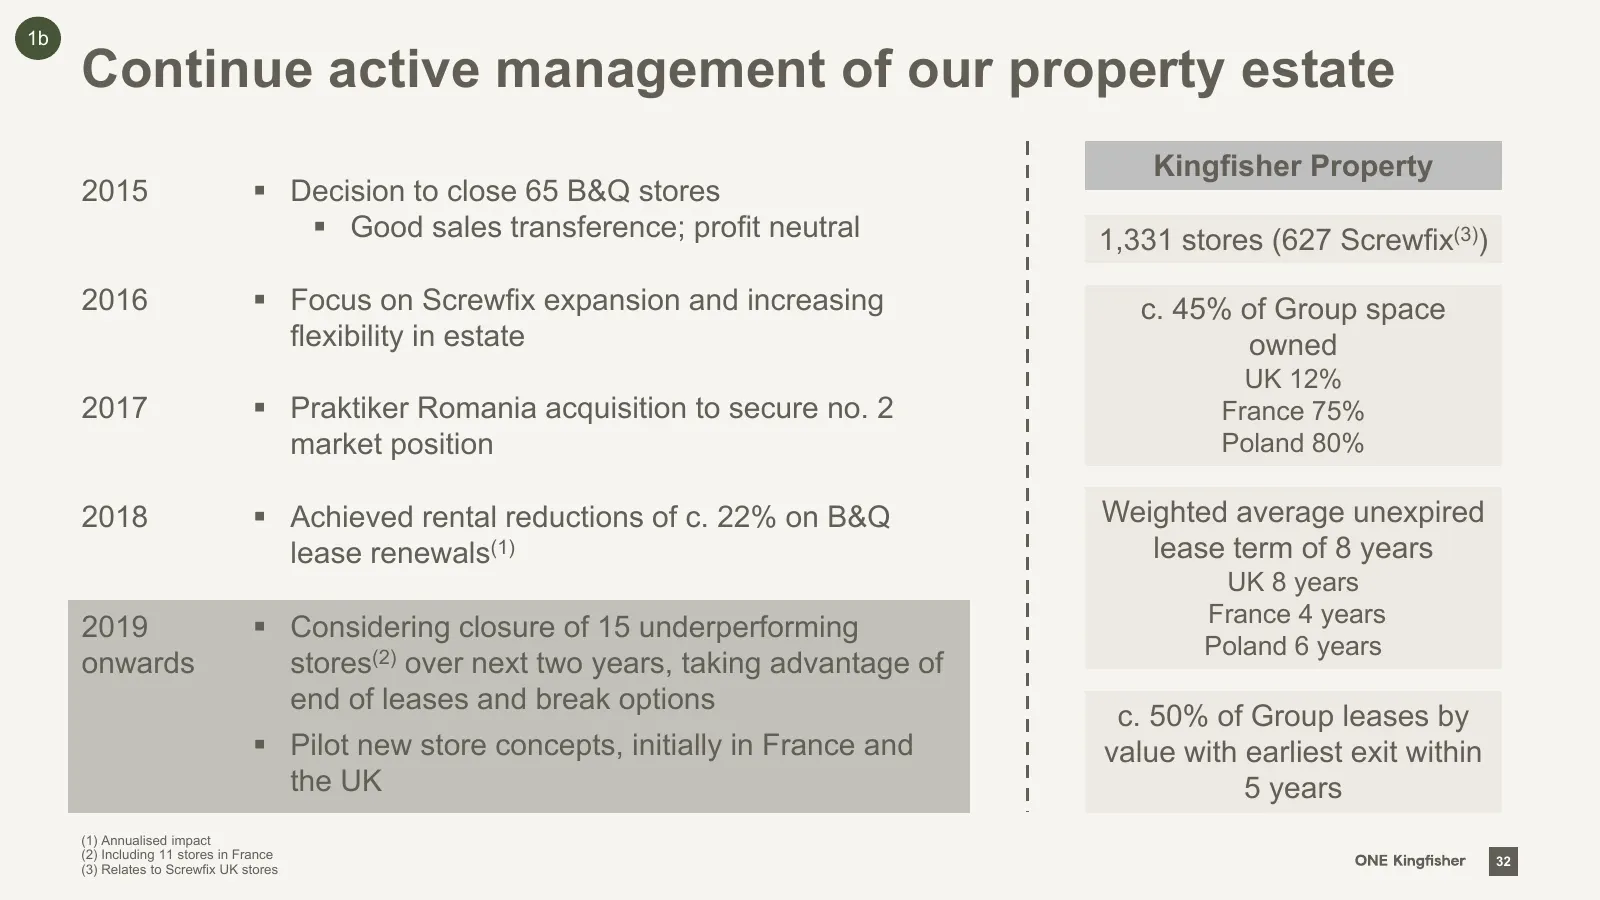
Slide 32: Continue active management of our property estate
1b Continue active management of our property estate Kingfisher Property 2015 Decision to close 65 B&Q stores Good sales transference; profit neutral 1,331 stores (627 Screwfix(3)) 2016 Focus on Screwfix expansion and increasing c. 45% of Group space flexibility in estate owned UK 12% 2017 P
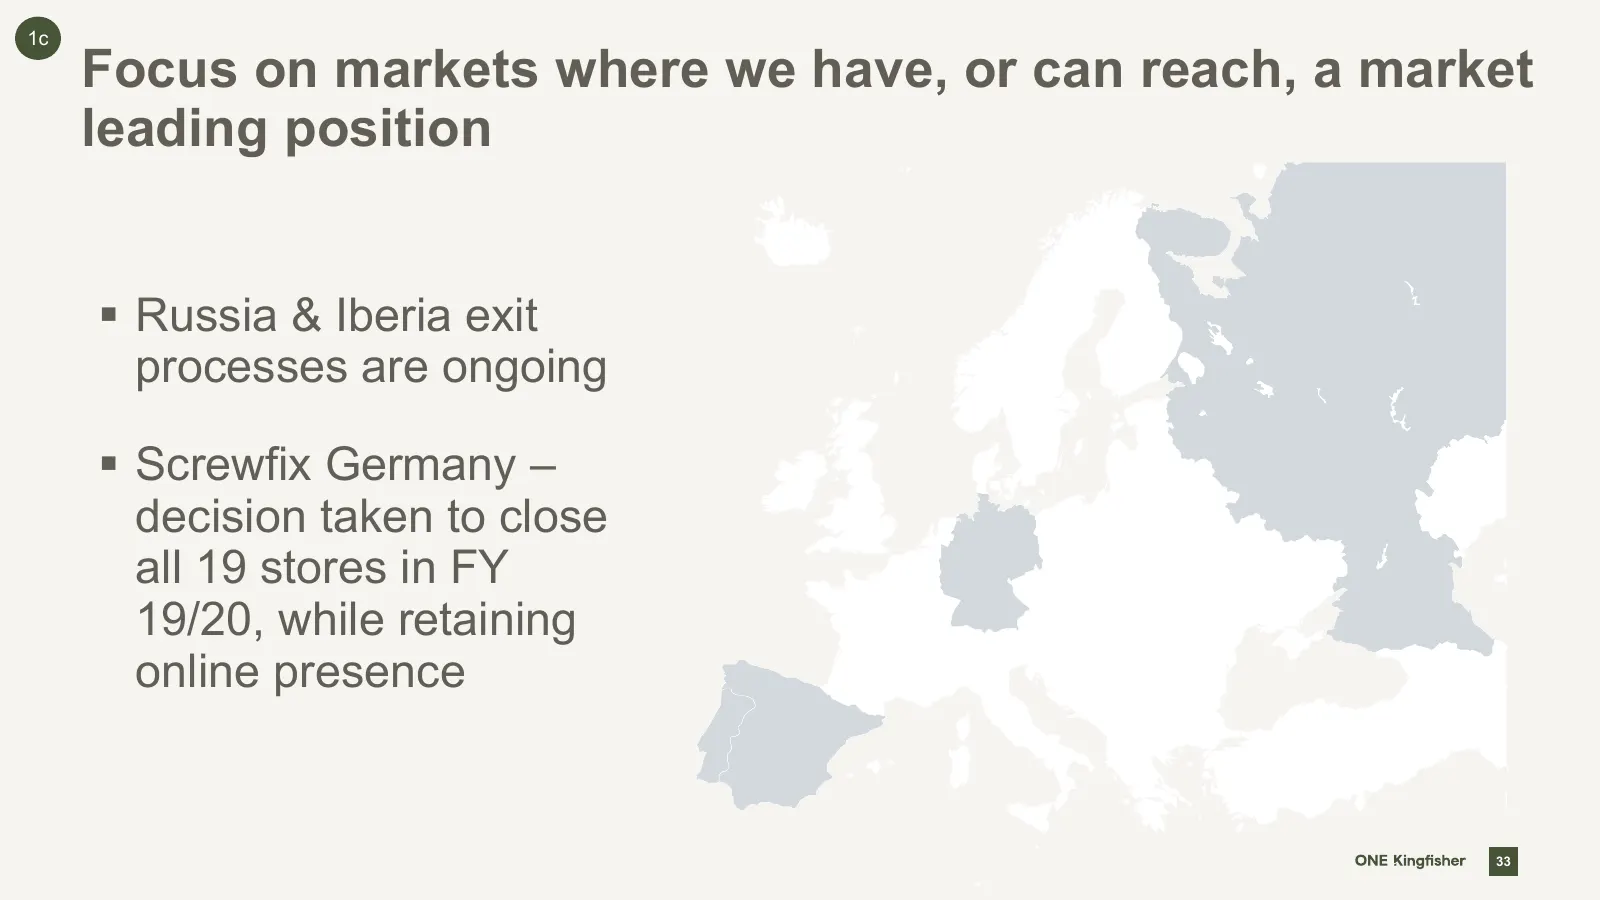
Slide 33: Focus on markets where we have, or can reach, a market leading position
1c Focus on markets where we have, or can reach, a market leading position Russia & Iberia exit processes are ongoing Screwfix Germany – decision taken to close all 19 stores in FY 19/20, while retaining online presence 33
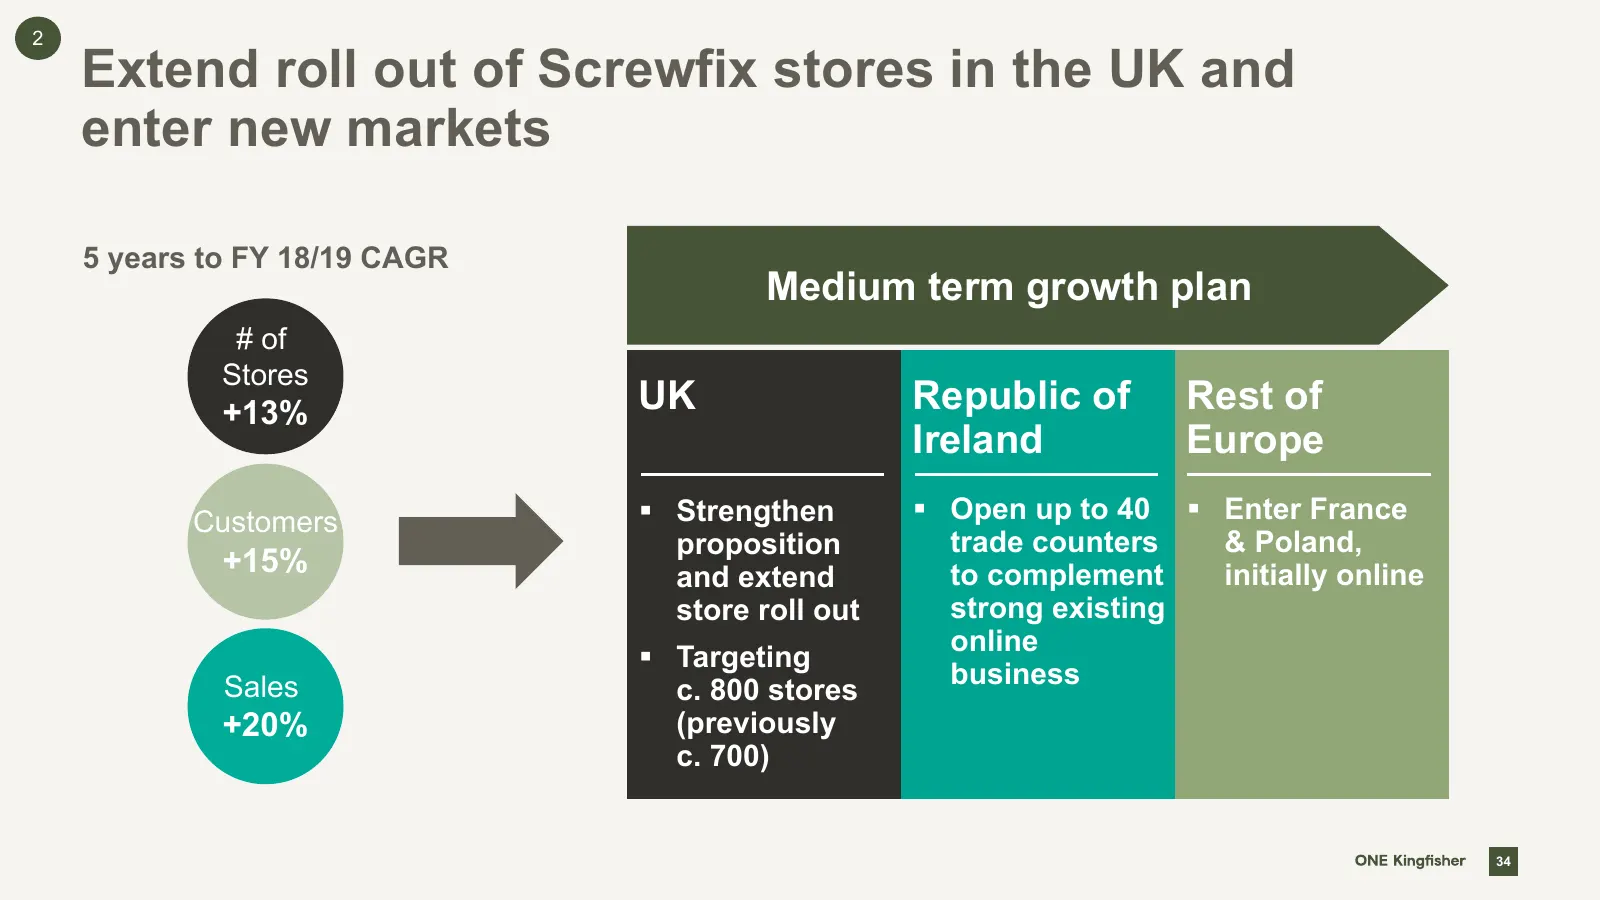
Slide 34: Extend roll out of Screwfix stores in the UK and enter new markets
2 Extend roll out of Screwfix stores in the UK and enter new markets 5 years to FY 18/19 CAGR Medium term growth plan # of Stores +13% UK Republic of Rest of Ireland Europe Customers Strengthen Open up to 40 Enter France proposition trade counters & Poland, +15% and extend to complement initia
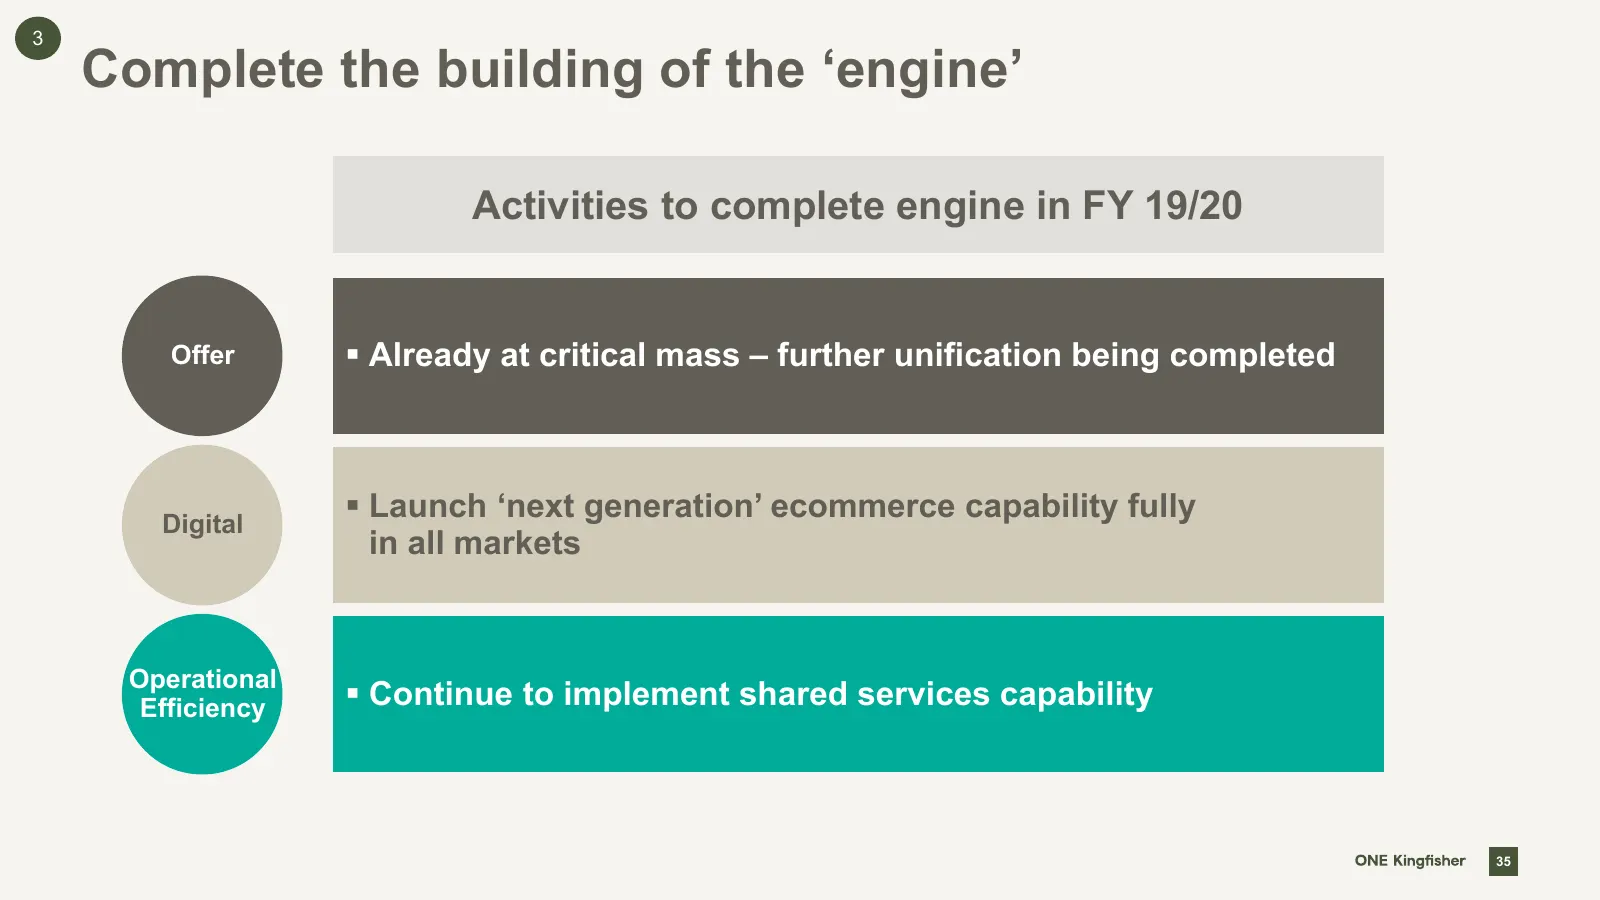
Slide 35: Complete the building of the 'engine'
3 Complete the building of the ‘engine’ Activities to complete engine in FY 19/20 Offer Already at critical mass – further unification being completed Digital Launch ‘next generation’ ecommerce capability fully in all markets Operational Efficiency Continue to implement shared services capabil
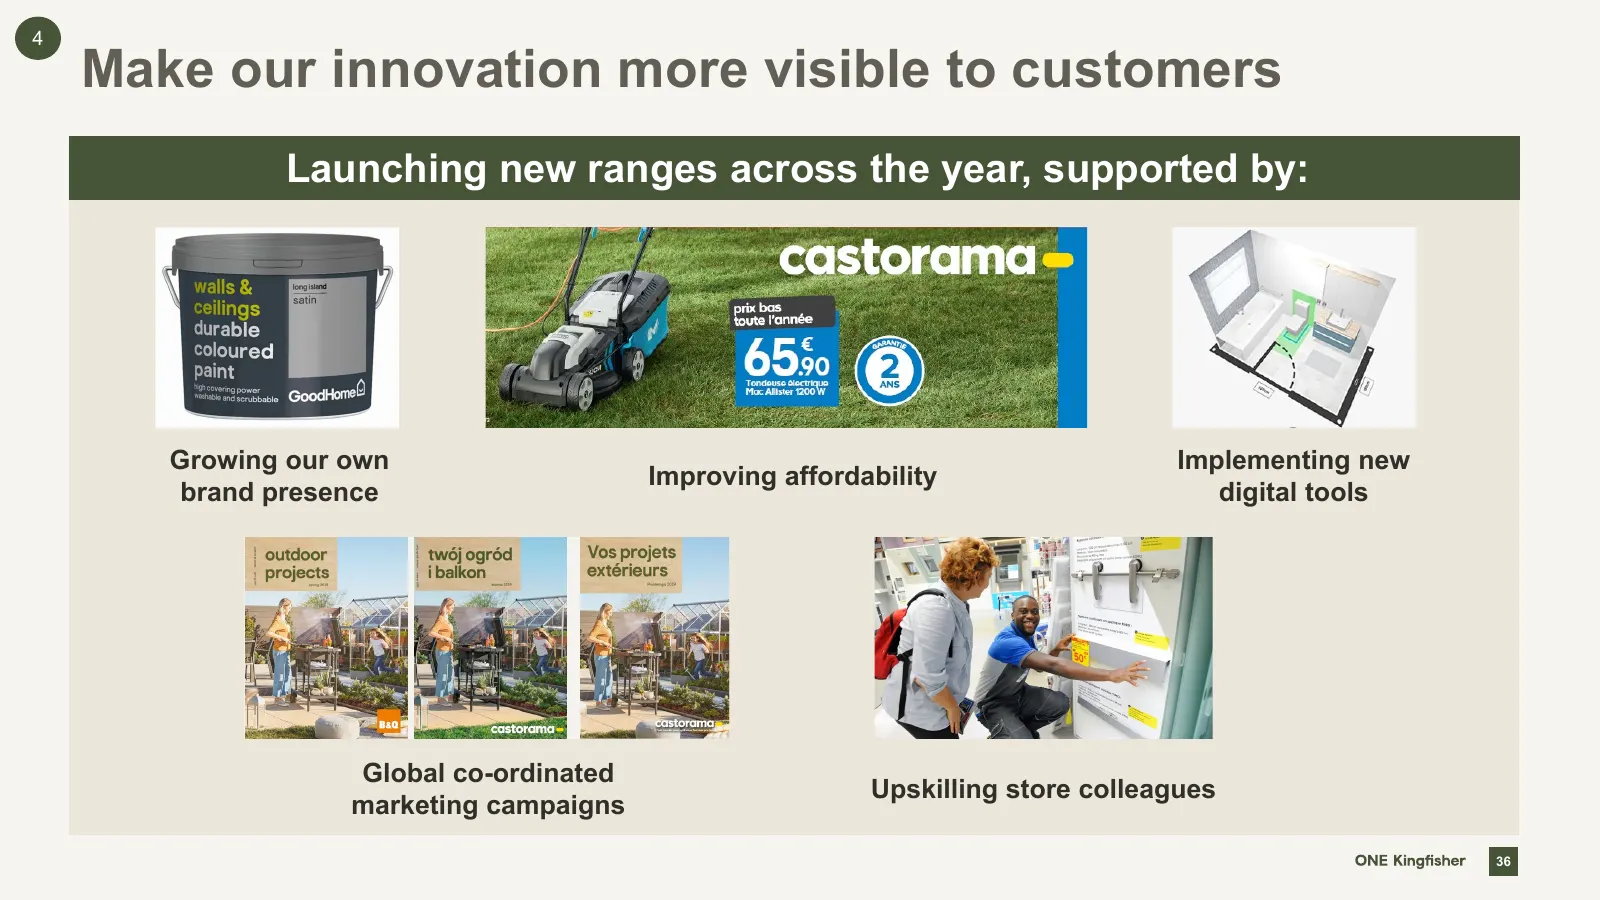
Slide 36: Make our innovation more visible to customers
4 Make our innovation more visible to customers Launching new ranges across the year, supported by: Growing our own Implementing new Improving affordability brand presence digital tools Global co-ordinated Upskilling store colleagues marketing campaigns 36
Slide 37: Make our innovation more visible to customers
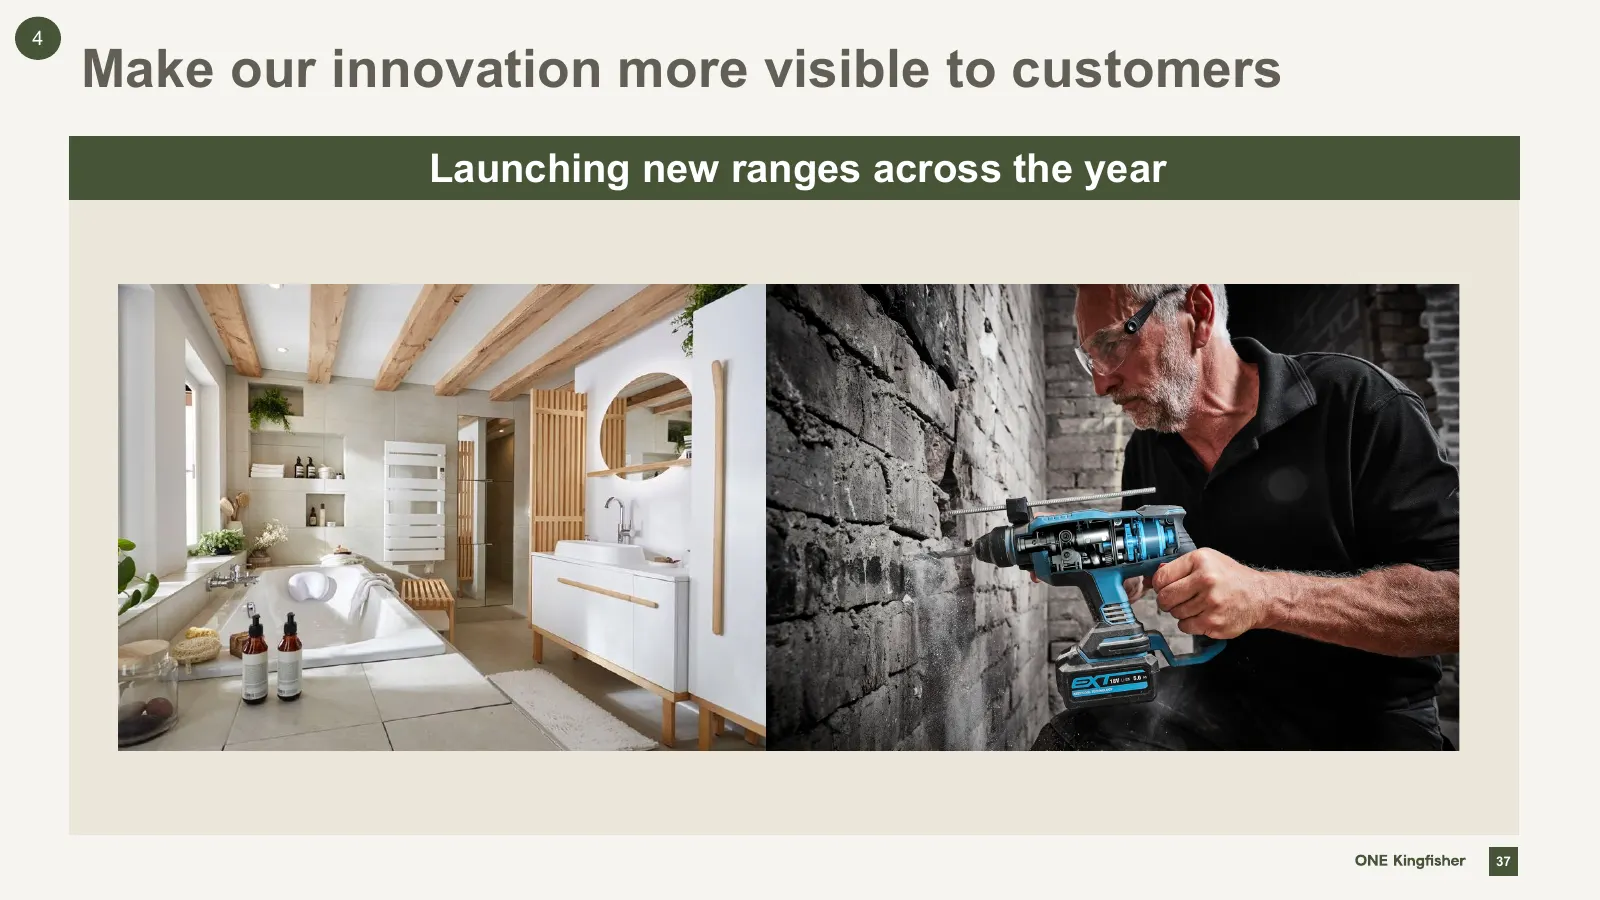
4 Make our innovation more visible to customers Launching new ranges across the year 37
Slide 38: Summary & medium term shape
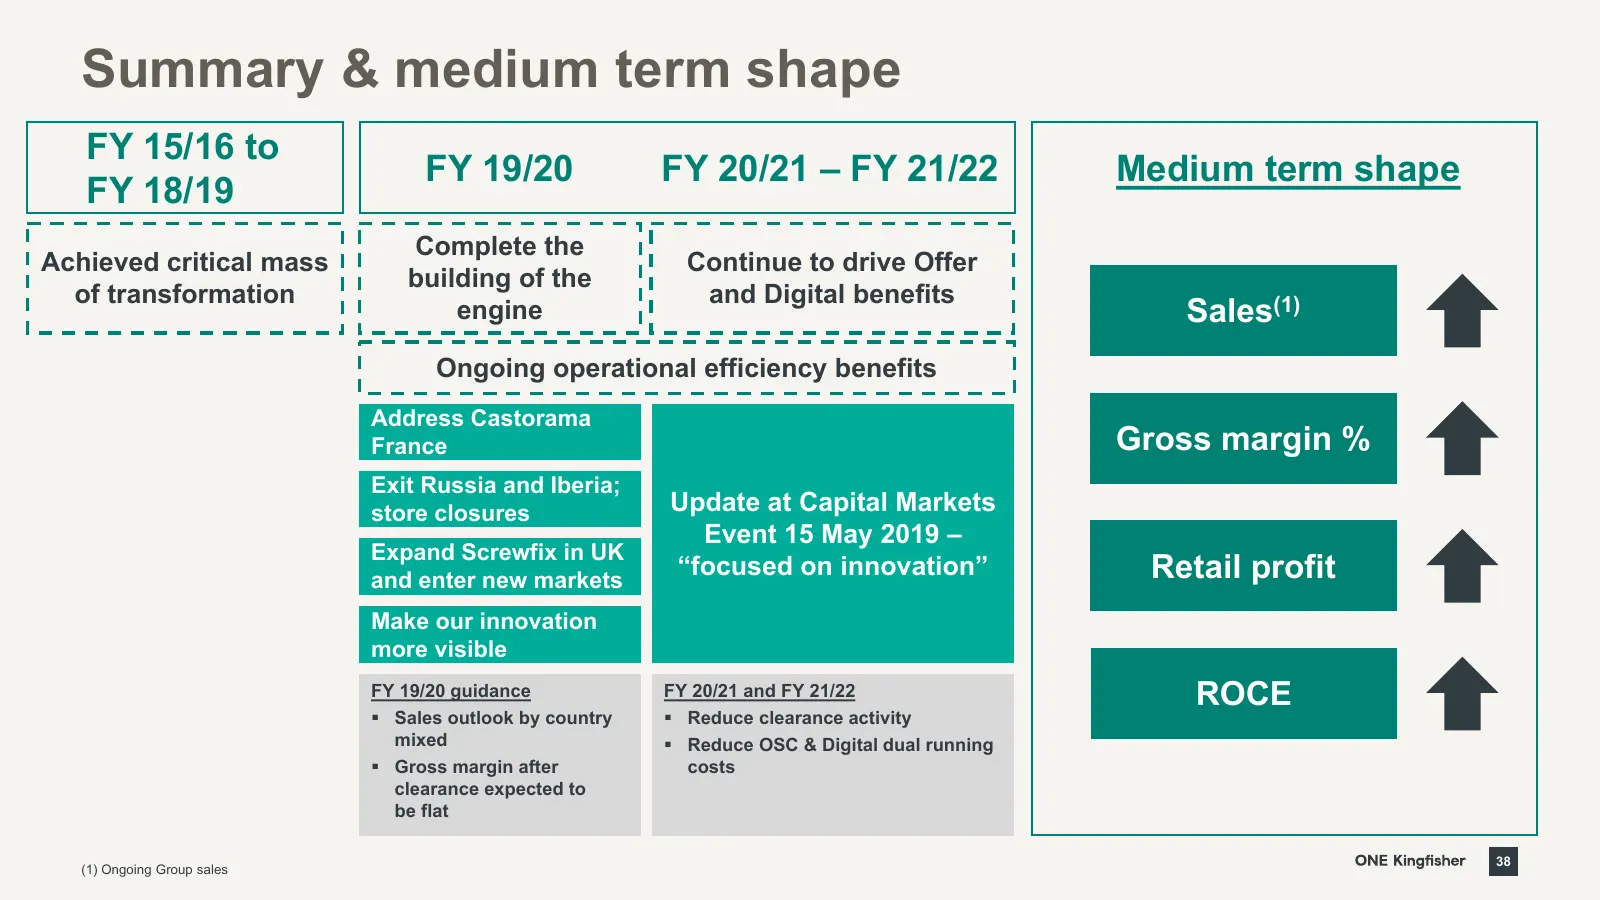
Summary & medium term shape FY 15/16 to FY 19/20 FY 20/21 – FY 21/22 Medium term shape FY 18/19 Complete the Achieved critical mass Continue to drive Offer building of the of transformation and Digital benefits engine Sales(1) Ongoing operational efficiency benefits Address Castorama France Gross ma
Slide 39: Together we will make home improvement accessible.
Together we will make home improvement accessible. For everyone. 39
Slide 40: Cautionary note regarding forward looking statements
Cautionary note regarding forward looking statements Certain information contained in this presentation may constitute “forward-looking statements” (including within the meaning of the safe harbour provisions of the United States Private Securities Litigation Reform Act of 1995), which can be identi
Slide 41: Appendices
ae ape ae ae > ) out out out out xe FF Oo FF Go FF 8 ® Appendices o8e of of of6 ©
Slide 42: Medium term shape
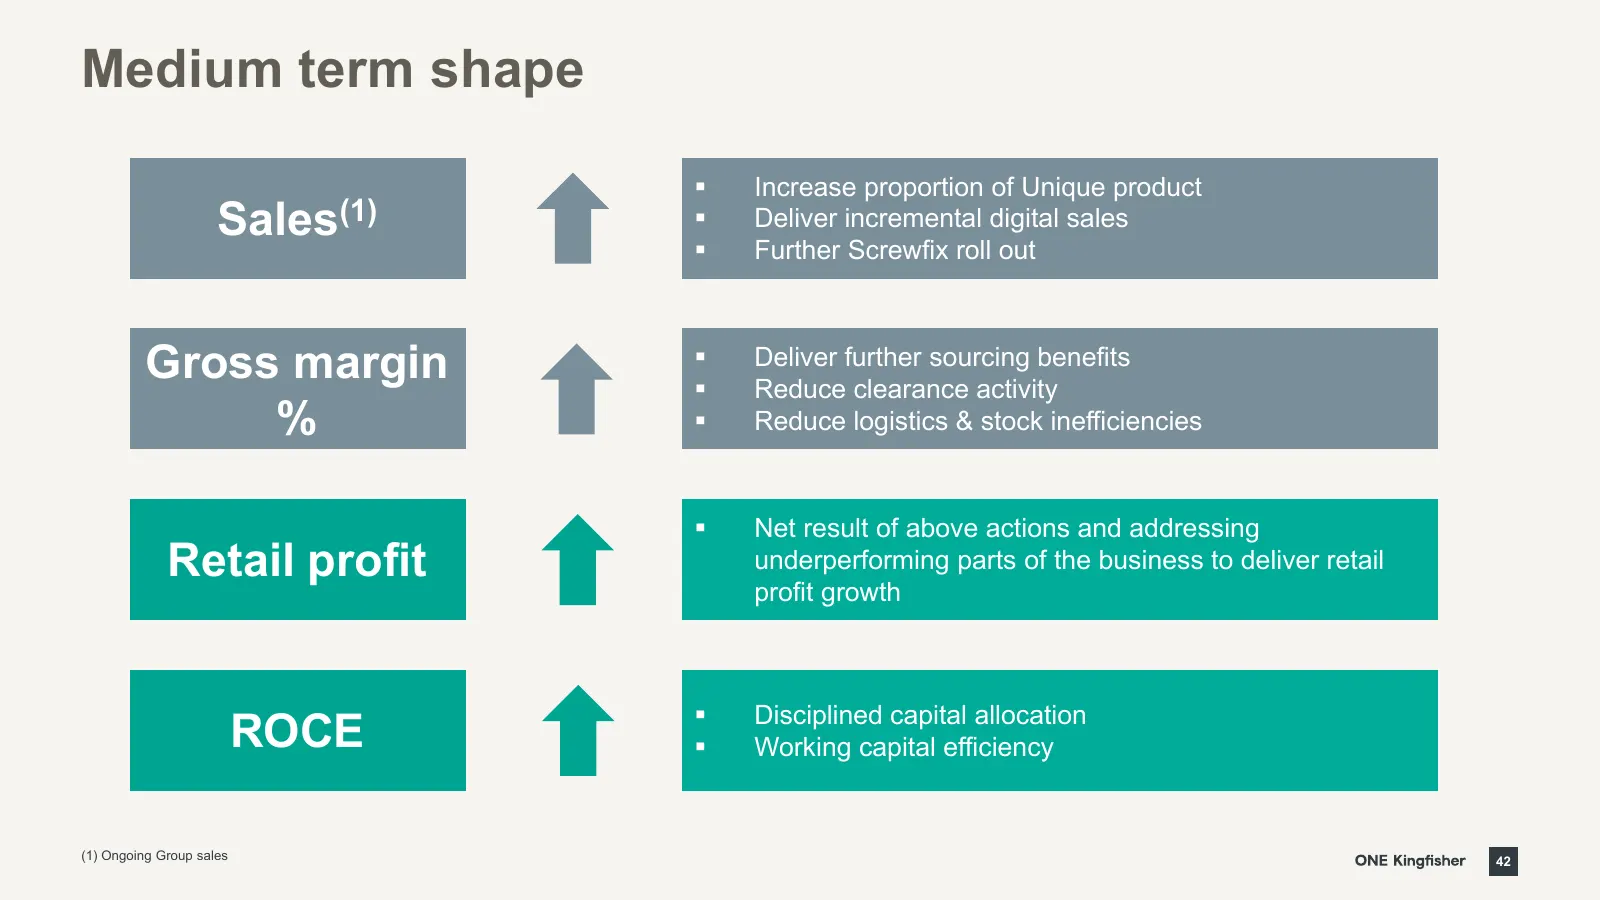
Medium term shape Increase proportion of Unique product Sales(1) Deliver incremental digital sales Further Screwfix roll out Gross margin Deliver further sourcing benefits Reduce clearance activity % Reduce logistics & stock inefficiencies Net result of above actions and addressing Ret
Slide 43: Working capital – mitigation stock eliminated
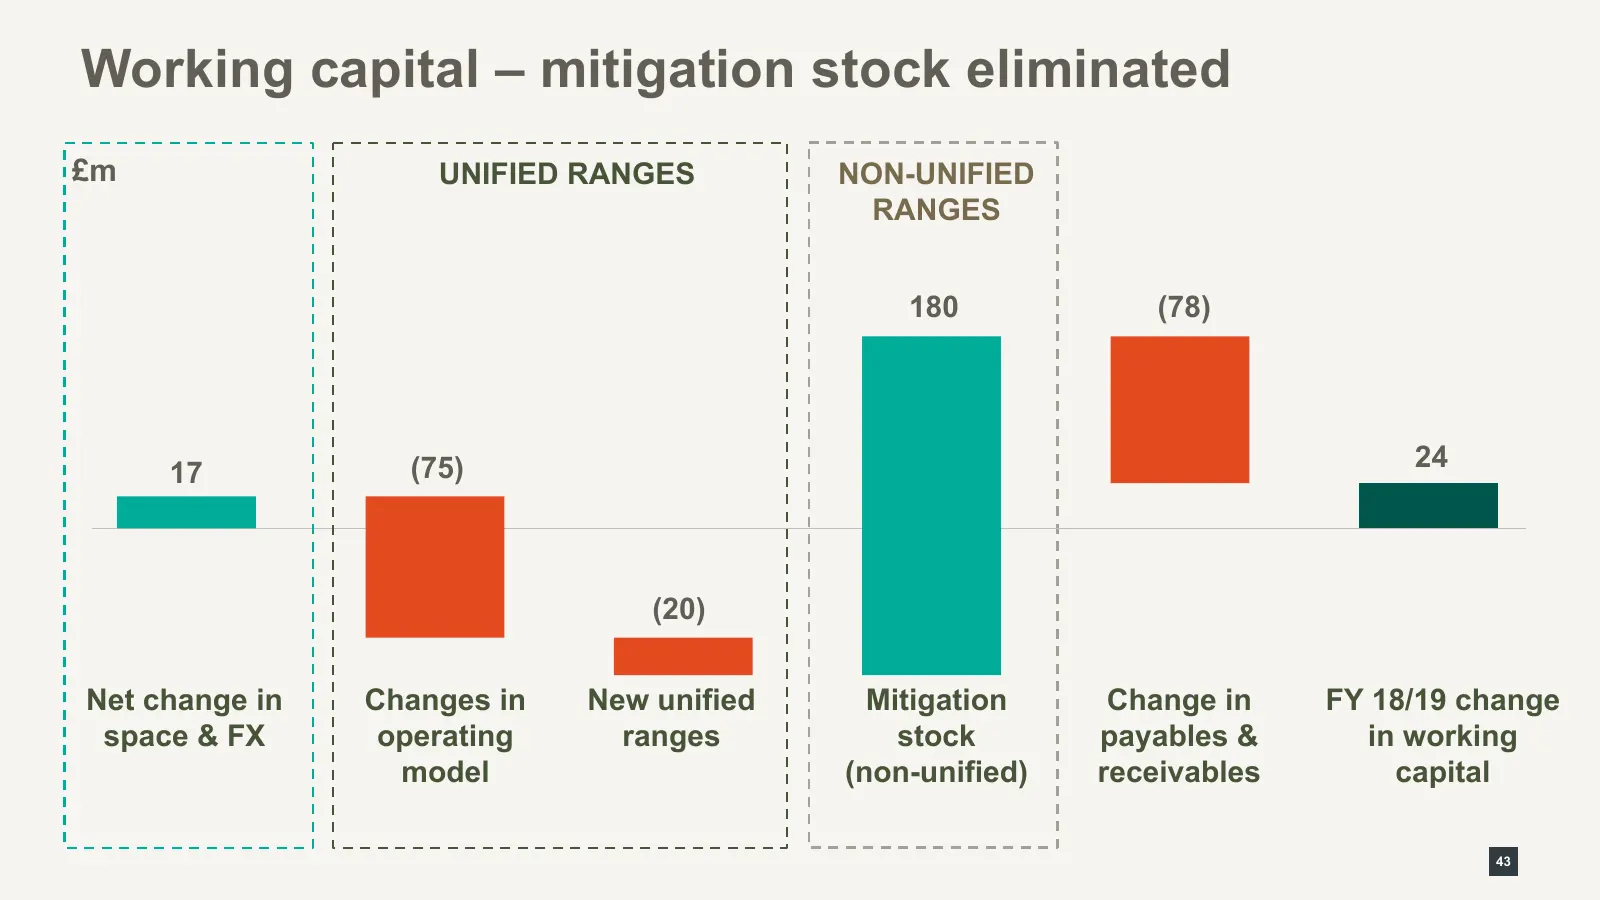
Working capital – mitigation stock eliminated £m UNIFIED RANGES NON-UNIFIED RANGES 180 (78) (75) 24 17 (20) Net change in Changes in New unified Mitigation Change in FY 18/19 change space & FX operating ranges stock payables & in working model (non-unified) receivables capital 43
Slide 44: Capex summary – FY 18/19 and guidance for FY 19/20
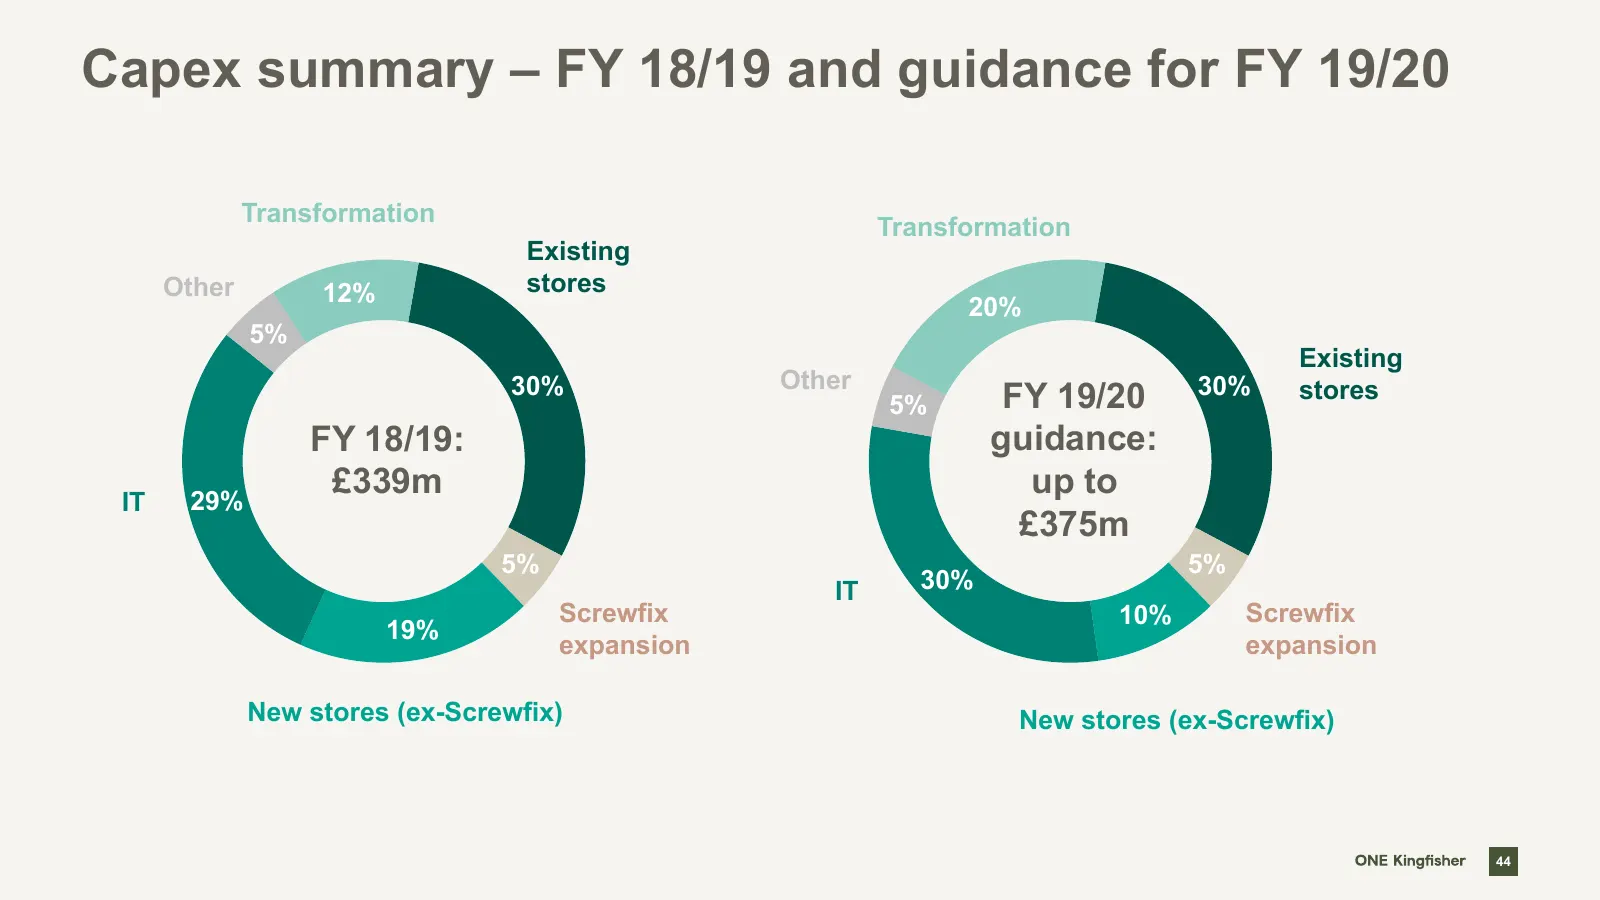
Capex summary – FY 18/19 and guidance for FY 19/20 Transformation Transformation Existing Other 12% stores 20% 5% Existing 30% Other 30% 5% FY 19/20 stores FY 18/19: guidance: 29% £339m up to IT £375m 5% 5% IT 30% Screwfix 10% Screwfix 19% expansion expansion New stores (ex-Screwfix) New stores (ex-
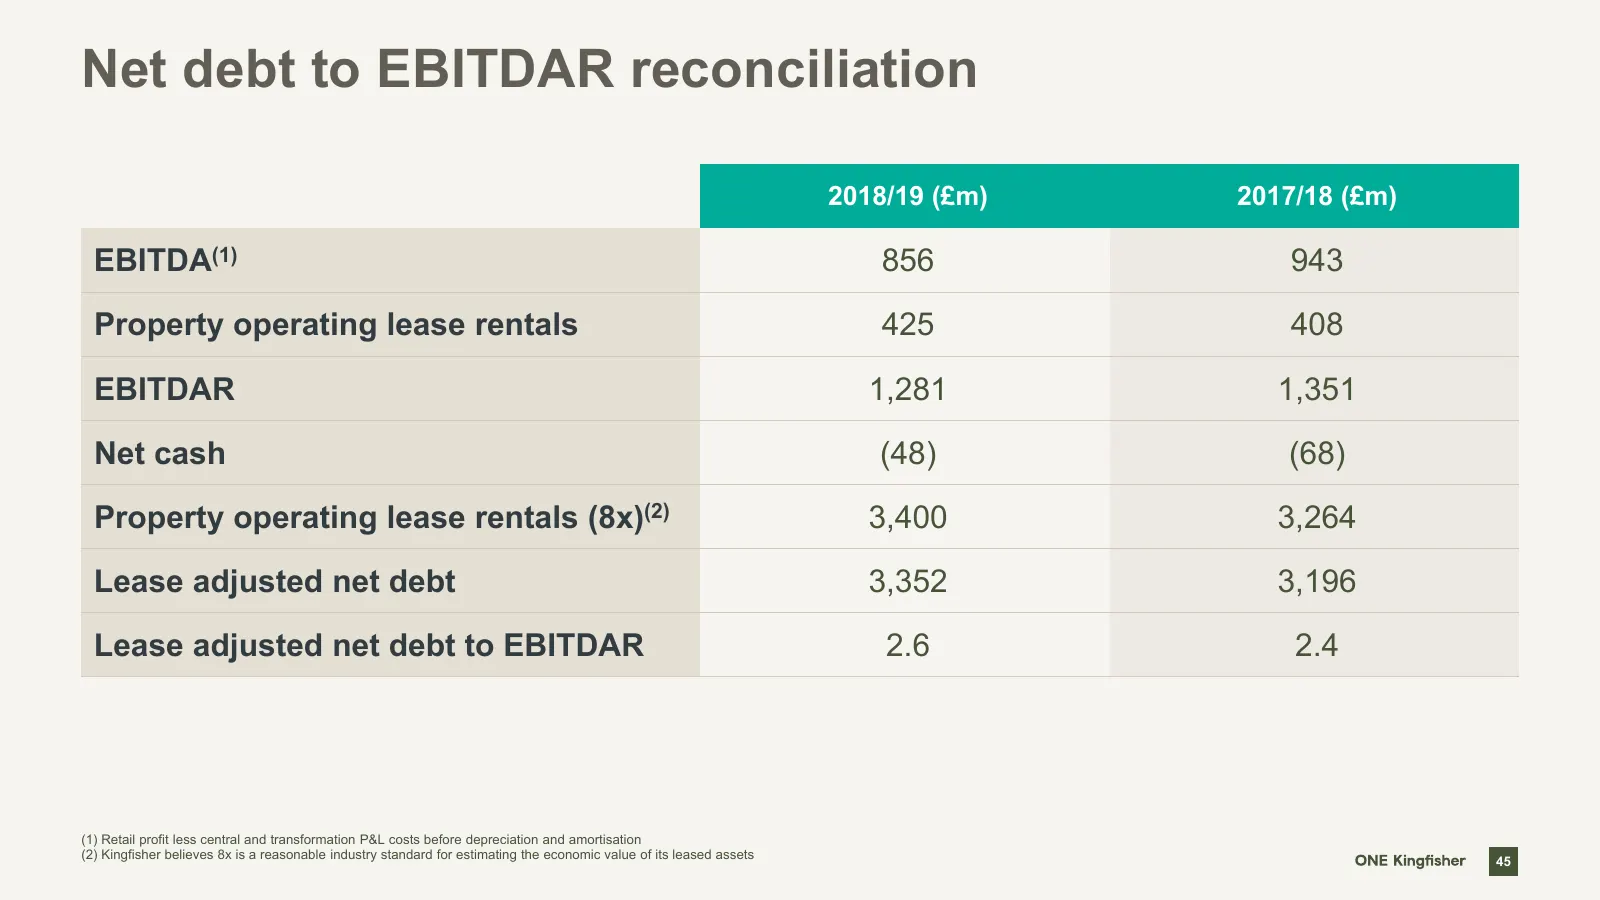
Slide 45: Net debt to EBITDAR reconciliation
Net debt to EBITDAR reconciliation 2018/19 (£m) 2017/18 (£m) EBITDA(1) 856 943 Property operating lease rentals 425 408 EBITDAR 1,281 1,351 Net cash (48) (68) Property operating lease rentals (8x)(2) 3,400 3,264 Lease adjusted net debt 3,352 3,196 Lease adjusted net debt to EBITDAR 2.6 2.4 (1) Retai
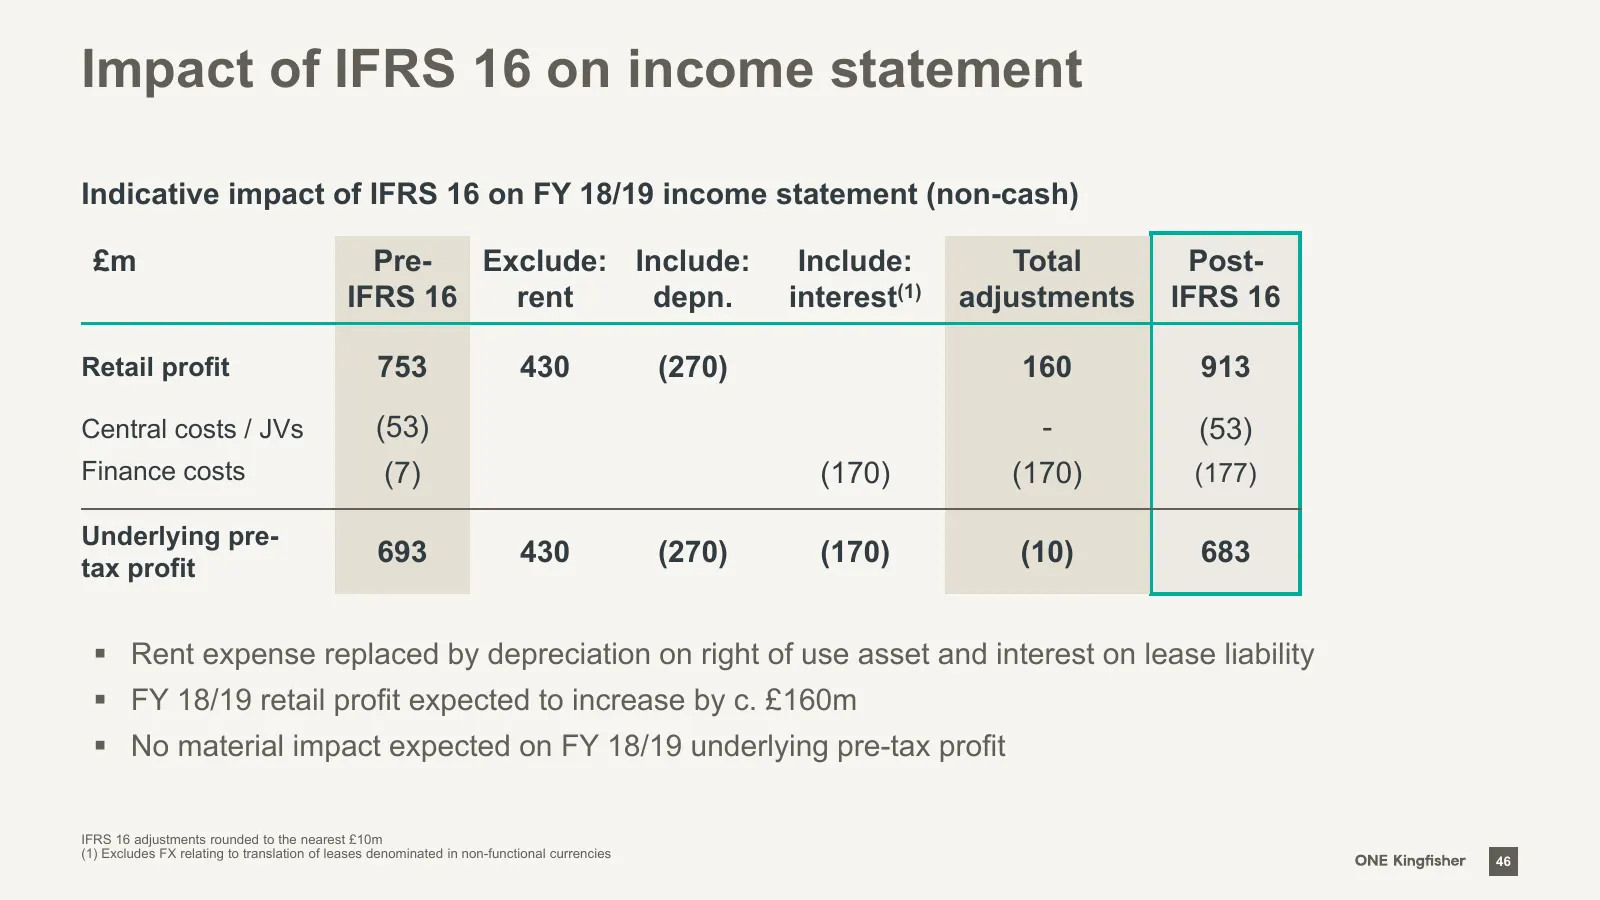
Slide 46: Impact of IFRS 16 on income statement
Impact of IFRS 16 on income statement Indicative impact of IFRS 16 on FY 18/19 income statement (non-cash) £m Pre- Exclude: Include: Include: Total Post- IFRS 16 rent depn. interest(1) adjustments IFRS 16 Retail profit 753 430 (270) 160 913 Central costs / JVs (53) - (53) Finance costs (7) (170) (17
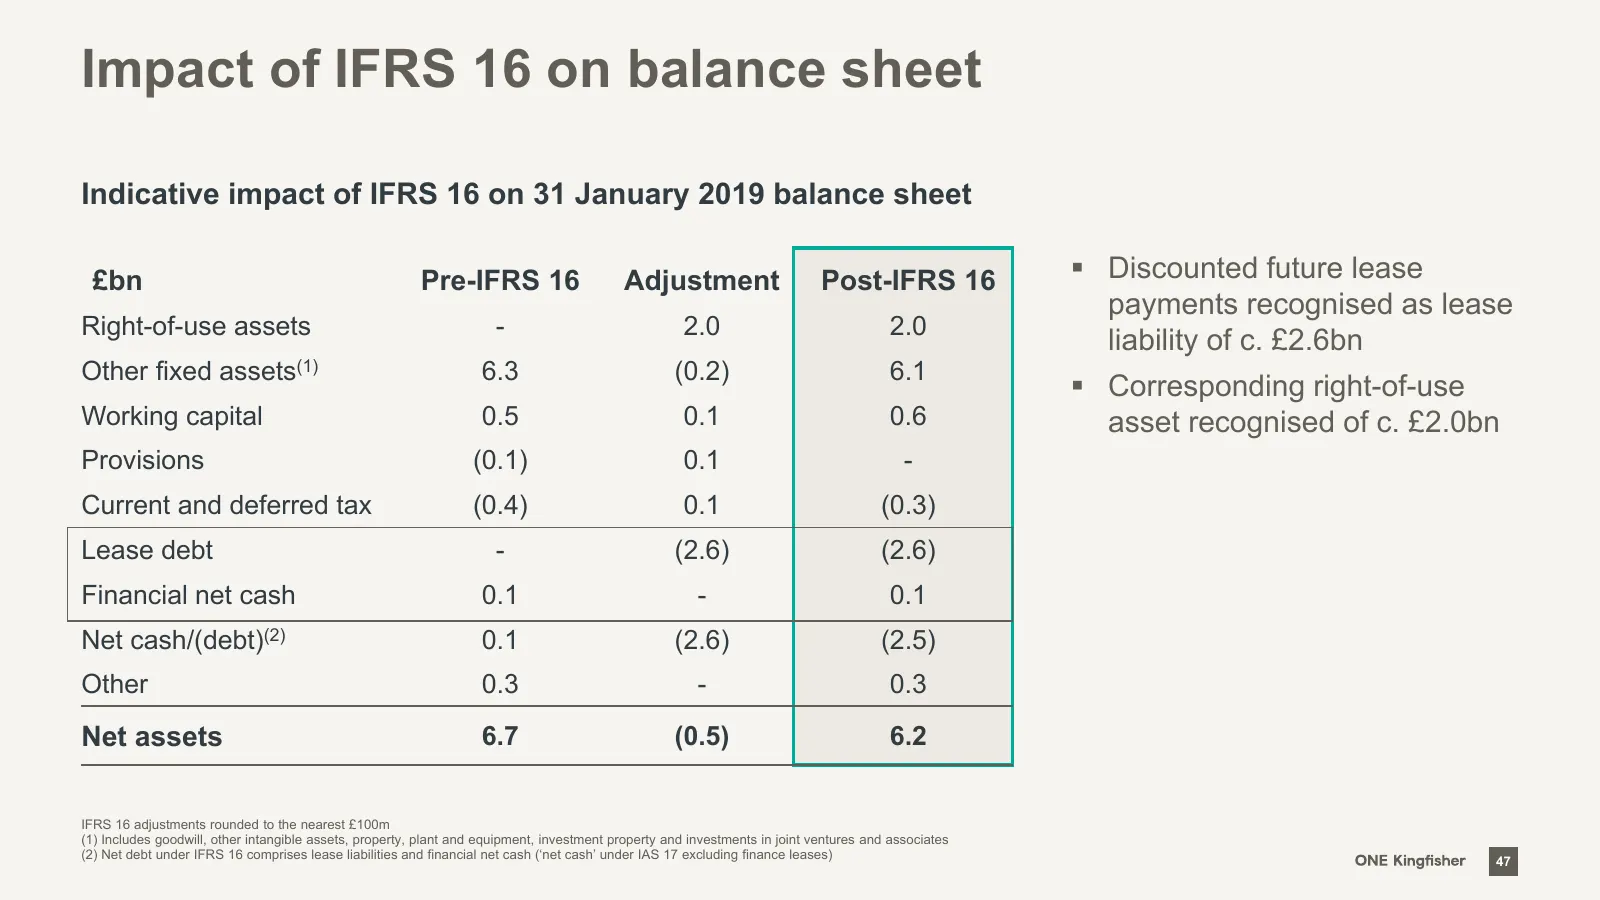
Slide 47: Impact of IFRS 16 on balance sheet
Impact of IFRS 16 on balance sheet Indicative impact of IFRS 16 on 31 January 2019 balance sheet £bn Pre-IFRS 16 Adjustment Post-IFRS 16 Discounted future lease payments recognised as lease Right-of-use assets - 2.0 2.0 liability of c. £2.6bn Other fixed assets(1) 6.3 (0.2) 6.1 Corresponding rig
Slide 48: Steps taken to manage Brexit risks
Steps taken to manage Brexit risks Products No significant change to stock Tariffs & Customs WTO tariff rate: zero-rate tariffs anticipated on most categories in a no-deal scenario Customs measures implemented to avoid delays. Increased number of ports for deep-sea imports, and secured trusted trade
Slide 49: ADR programme
ADR programme Kingfisher ADRs trade on OTCQX – the premier tier of the U.S. over-the- Benefits of ADRs to U.S. investors: counter market under the following information: Clear and settle according to normal U.S. standards Symbol KGFHY CUSIP 495724403 Offer the convenience of stock quotes and div
Slide 50: Contacts
Contacts Investor Relations Media Relations Tel: +44 (0)20 7644 1082 Tel: +44 (0)20 7644 1030 Email: investorenquiries@kingfisher.com Email: corpcomms@kingfisher.com Teneo Tel: +44 (0)20 7260 2700 Email: KFteam@teneo.com 50
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
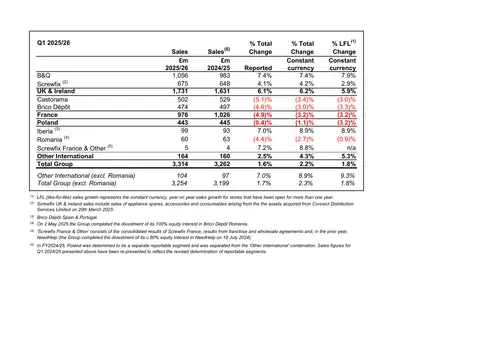 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025