CBIZ, Inc. · NYSE:CBZ
CBIZ — CBIZ MHM Estate Planning and Gifting Webinar (June 2010)
34 slides from CBIZ's conference presentation, June 2010
Slide 1: Planning to Survive
Planning to Survive Exploring the Estate and Gift Planning Opportunities Under Current Legislation and Beyond
Slide 2: Circular 230 Notice
Circular 230 Notice Any tax advice contained in this program is not intended to be used and cannot be used for the purposes of avoiding any penalties that may be imposed by the Internal Revenue Code.
Slide 3: Presenters
Presenters Maurice Kassimir, Attorney-at-Law, L.L.M. Owner, Maurice Kassimir & Associates, P.C. and Managing Director, CBIZ MHM, LLC Donna M. Palumbo, EA Director, CBIZ MHM, LLC Naomi D. Ganoe, CPA, MT, CFP Senior Manager, CBIZ MHM, LLC
Slide 4: Agenda
Agenda • Legal Aspects of Estate Planning • State Tax Matters • Estate Gift Compliance • Estate and Gift Planning Ideas
Slide 5: Non-Tax Reasons to Discuss Estate Planning
Non-Tax Reasons to Discuss Estate Planning A. Everyone Needs it B. Disposition of Assets C. Selecting Fiduciaries D. Reviewing Beneficiary Designations E. Powers of Attorney/Living Wills F. Special Needs Trusts G. Avoiding Probate
Slide 6: What Was? What Is? What May Be?
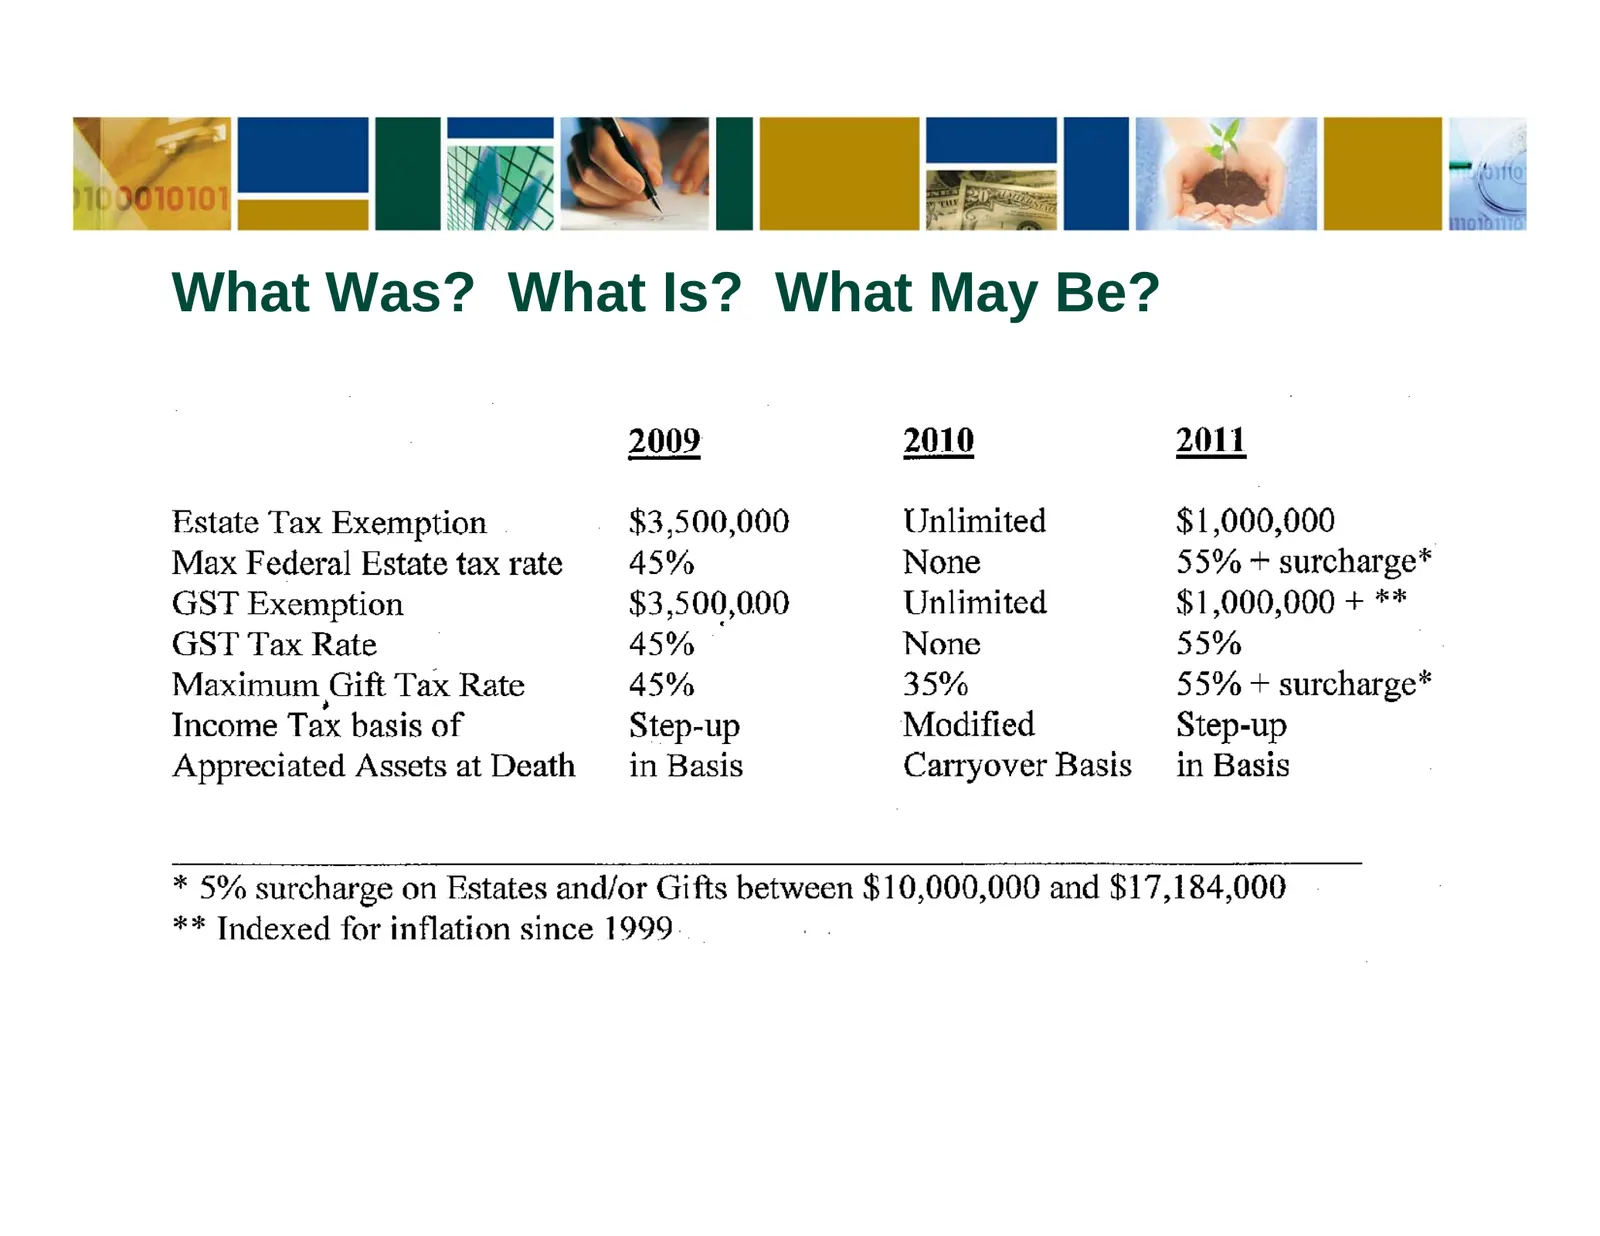
What Was? What Is? What May Be?
Slide 7: Example
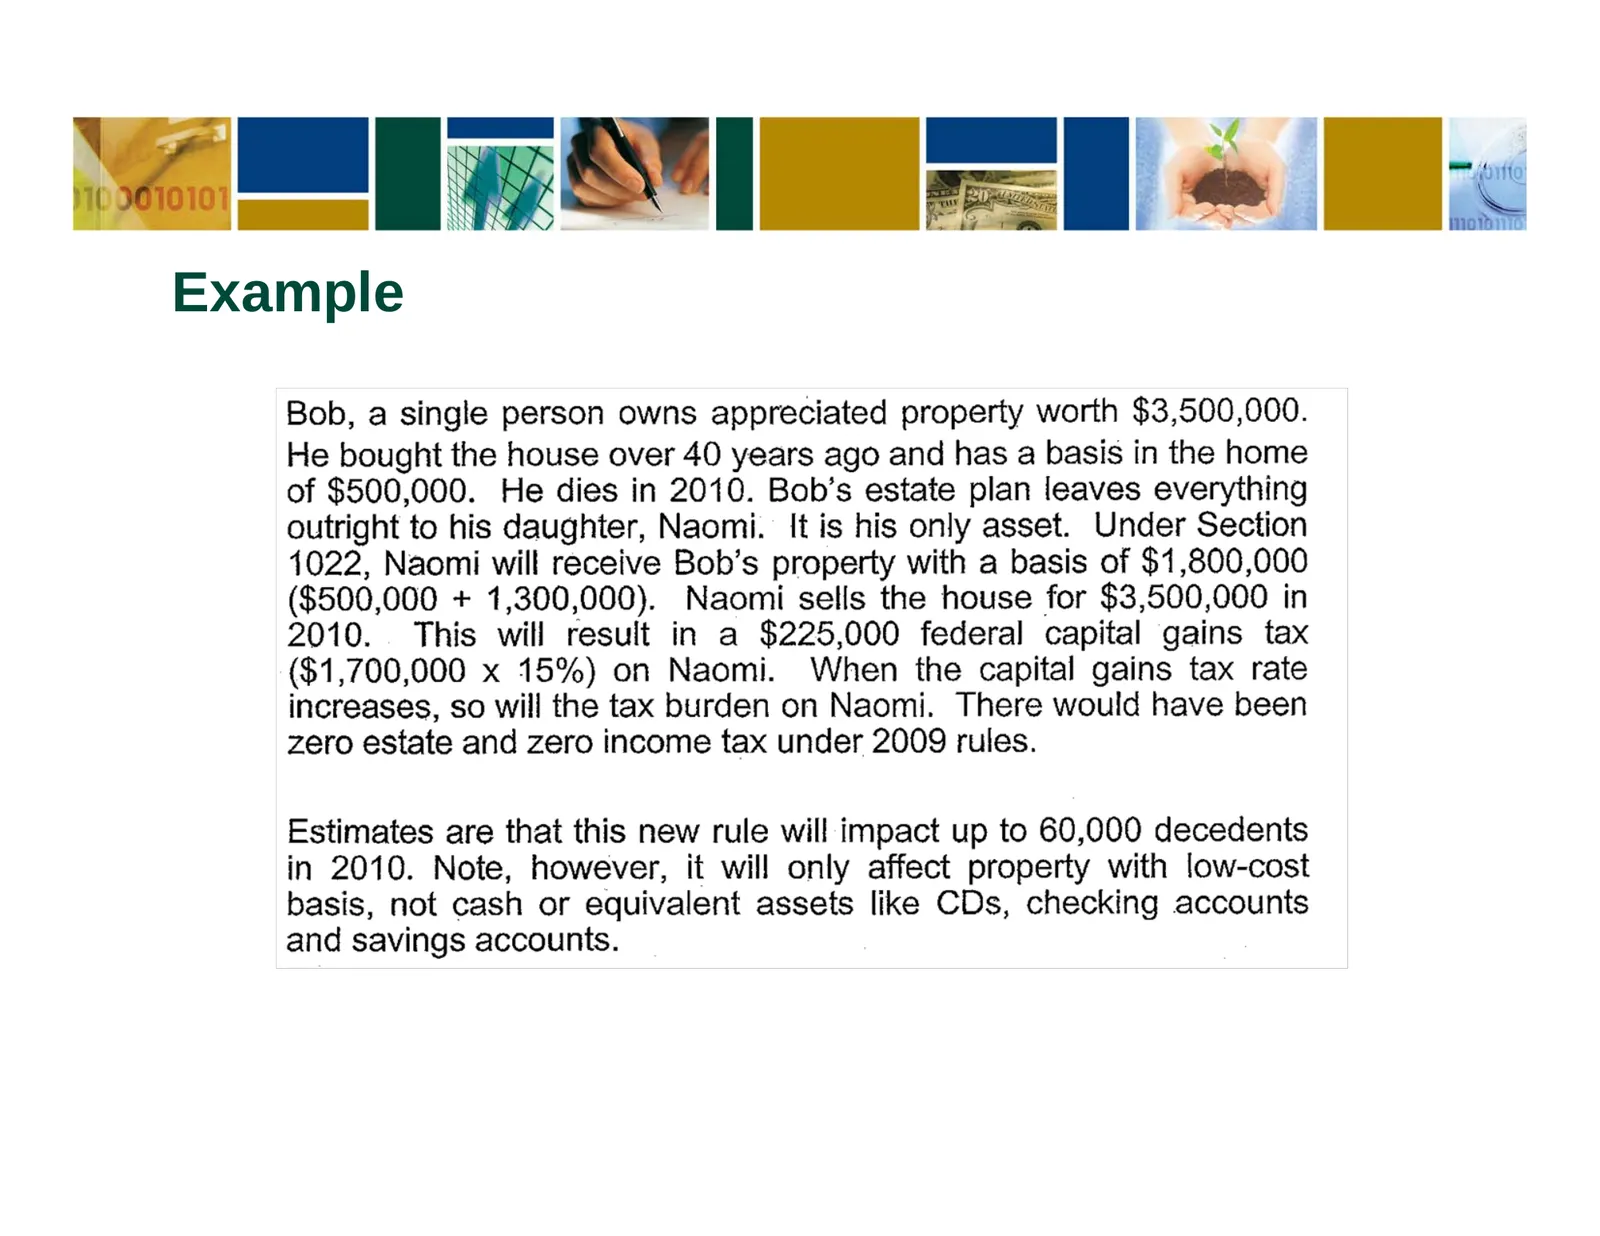
“EieVil=i - i. a | based) Example Bob, a single person owns appreciated property worth $3,500,000. He bought the house over 40 years ago and has a basis in the home of $500,000. He dies in 2010. Bob’s estate plan leaves everything outright to his daughter, Naomi. It is his only asset. Under Section
Slide 8: Gift Tax Exclusions That Remain the Same
Gift Tax Exclusions That Remain the Same 1. $13,000 Annual Exclusion 2. Tuition 3. Medical
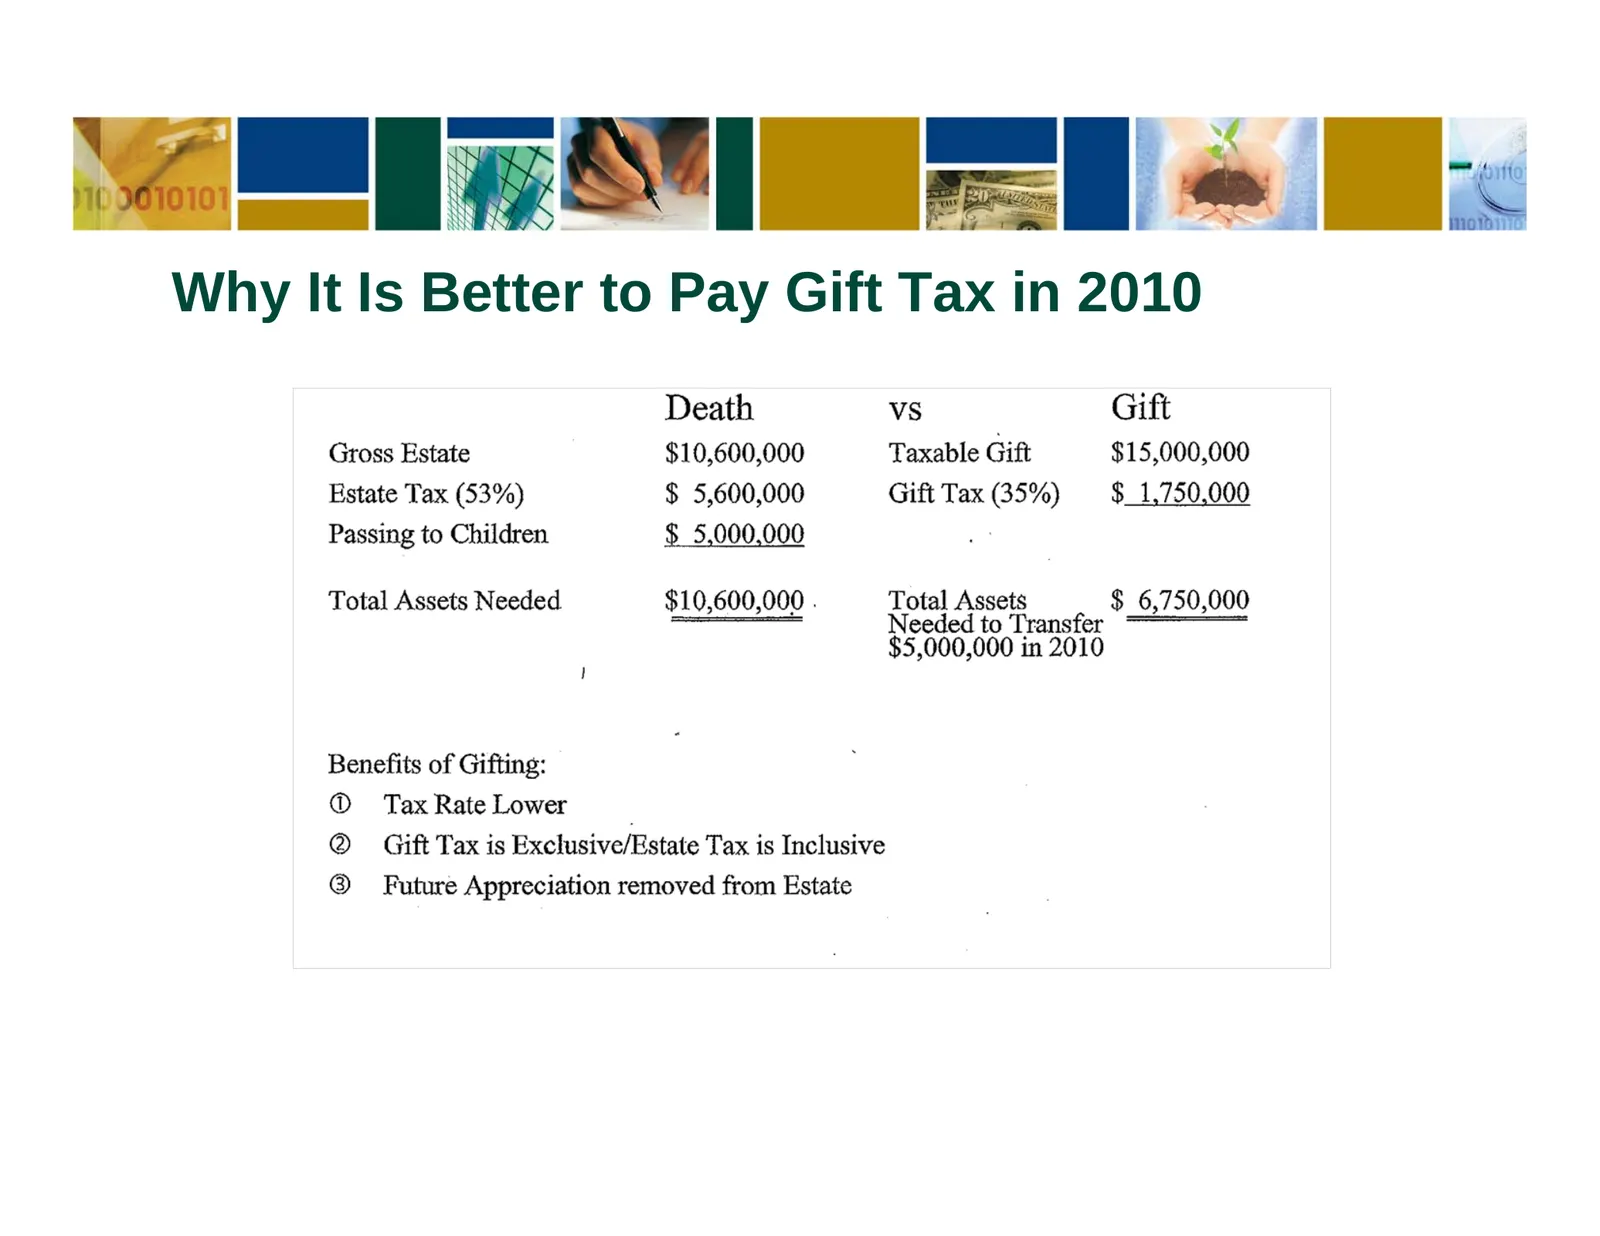
Slide 9: Why It Is Better to Pay Gift Tax in 2010
Why It Is Better to Pay Gift Tax in 2010
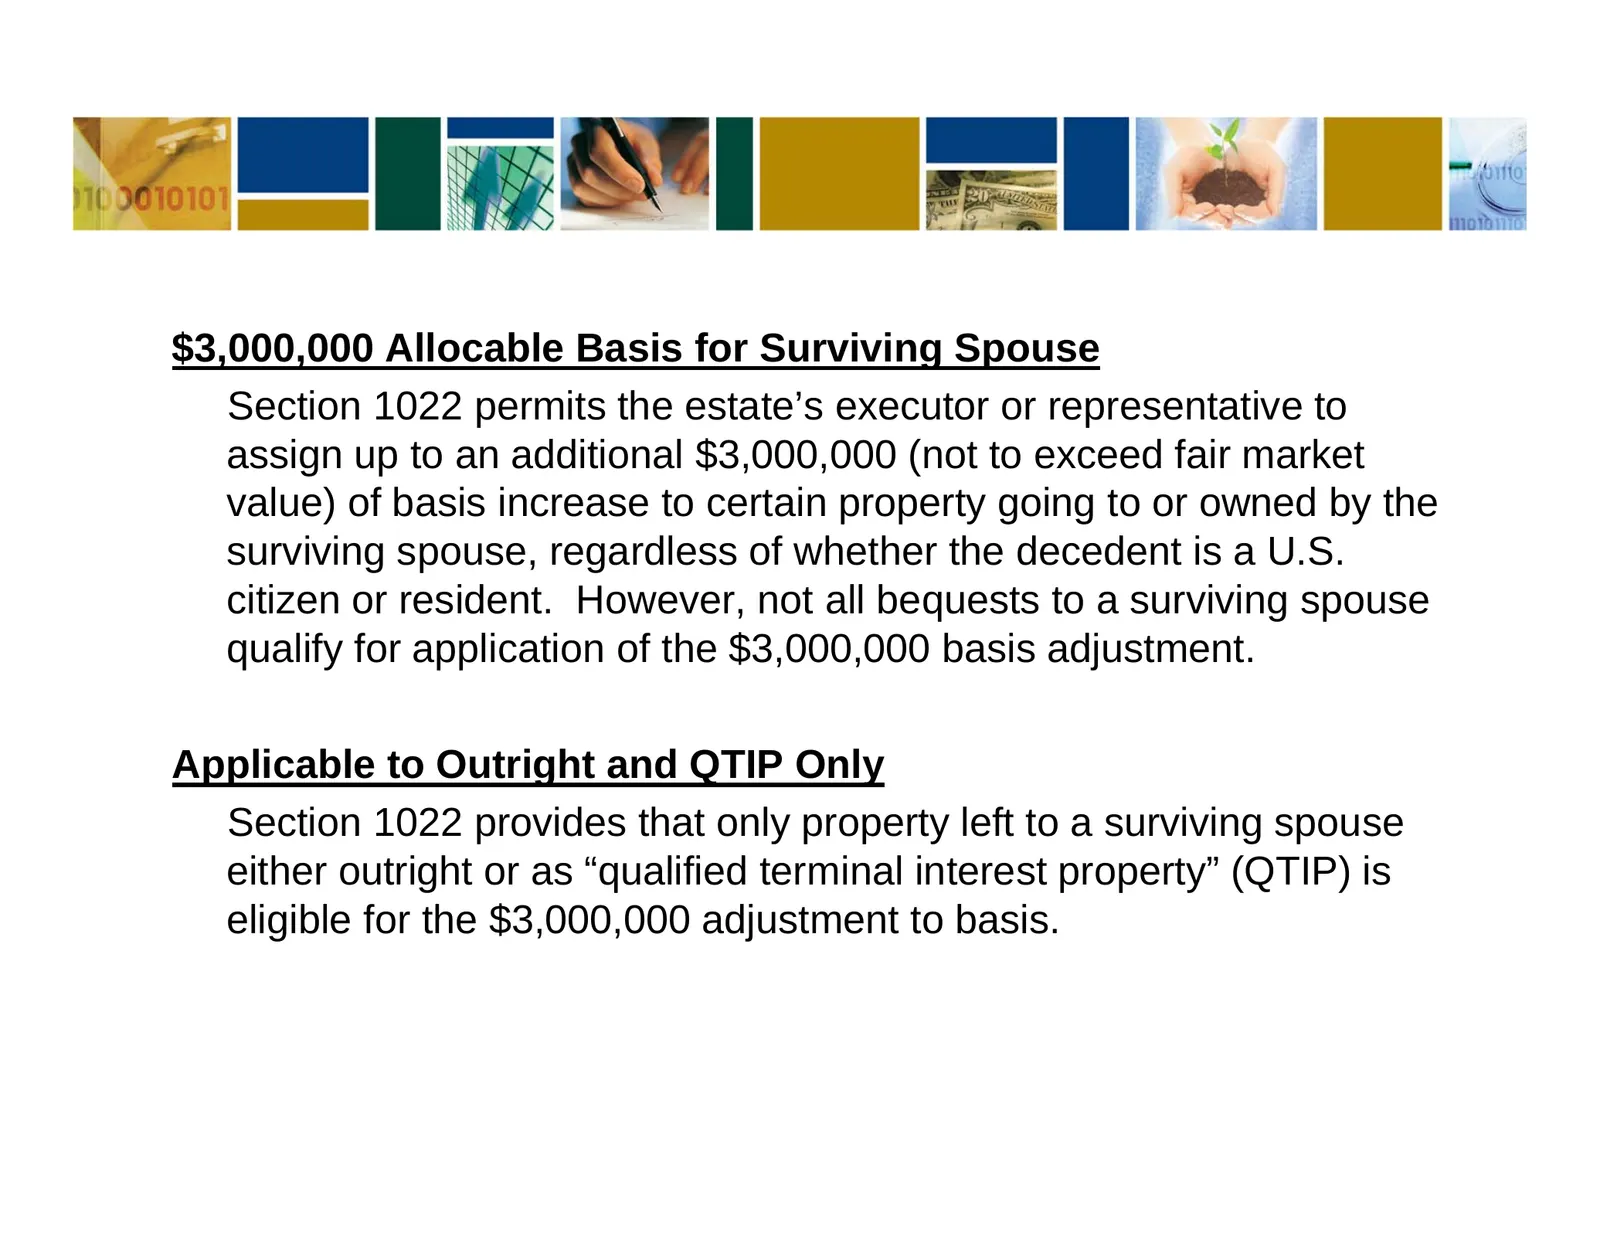
Slide 10: $3,000,000 Allocable Basis for Surviving Spouse
$3,000,000 Allocable Basis for Surviving Spouse Section 1022 permits the estate’s executor or representative to assign up to an additional $3,000,000 (not to exceed fair market value) of basis increase to certain property going to or owned by the surviving spouse, regardless of whether the decedent
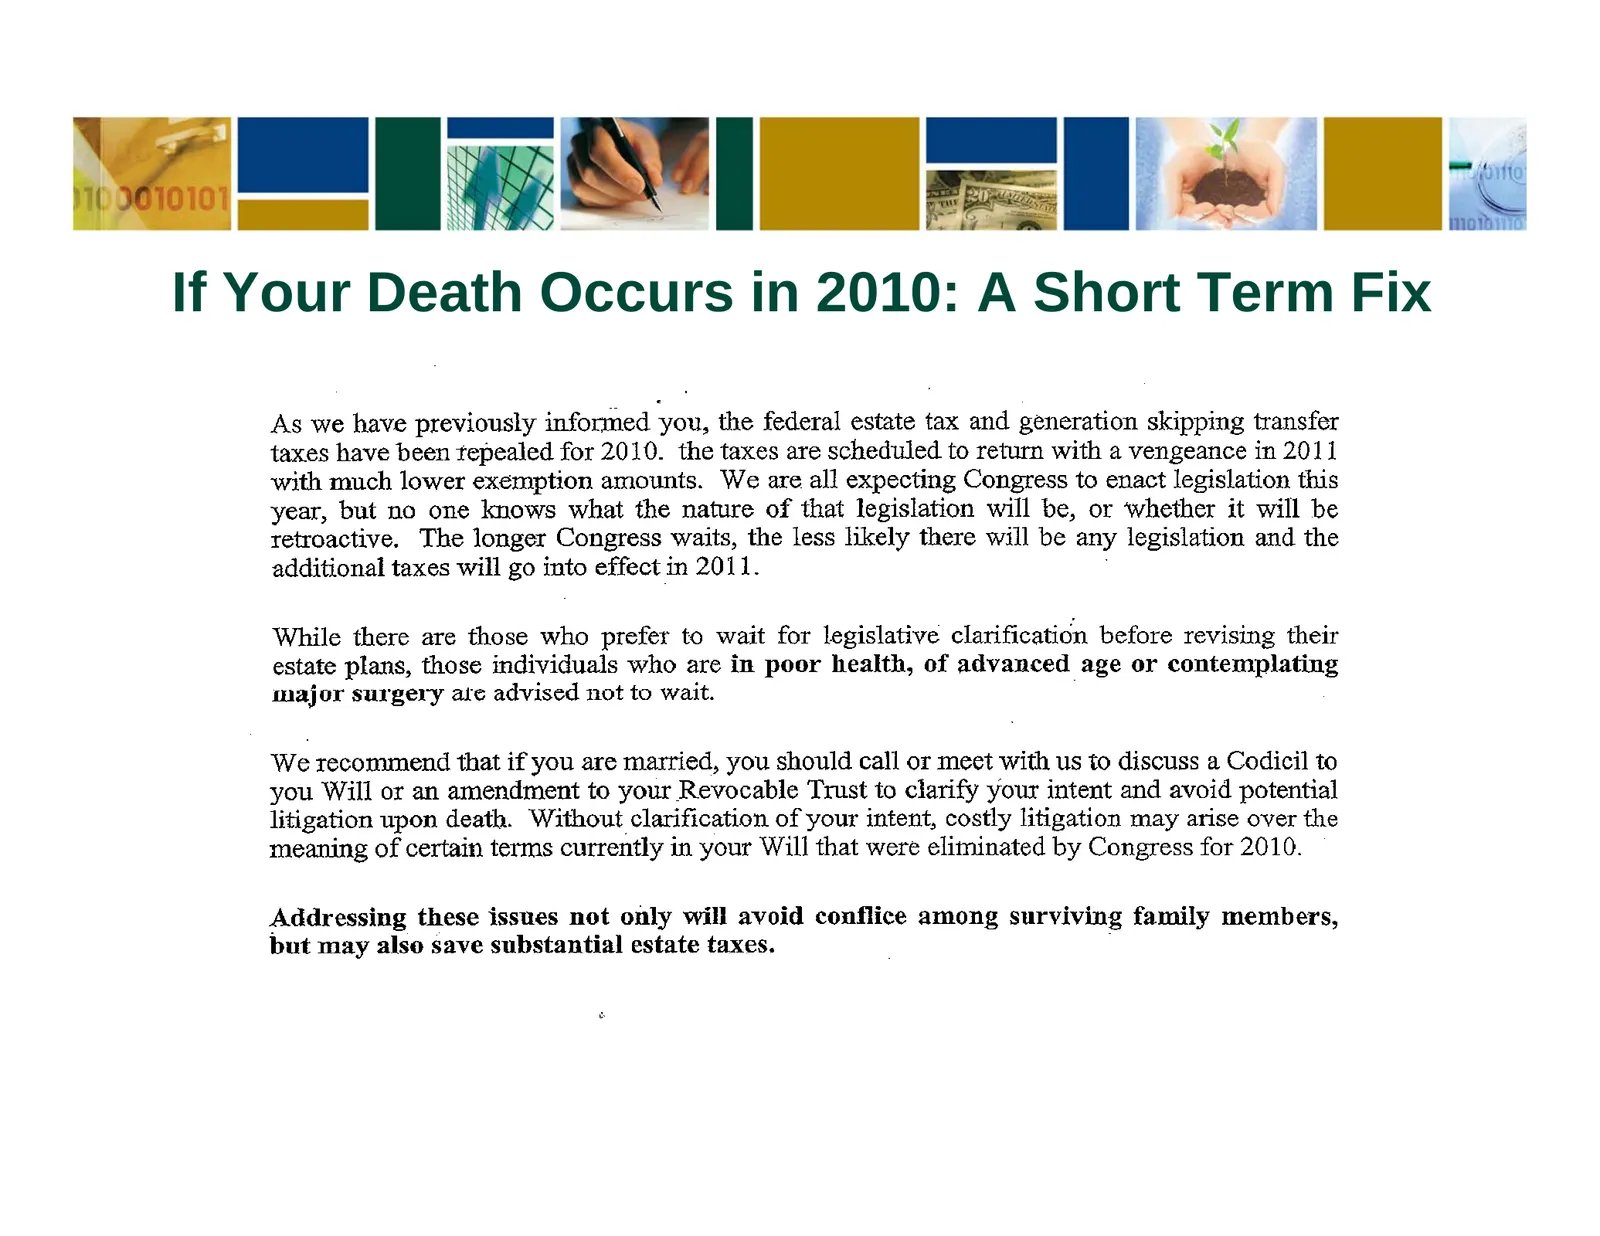
Slide 11: If Your Death Occurs in 2010: A Short Term Fix
If Your Death Occurs in 2010: A Short Term Fix
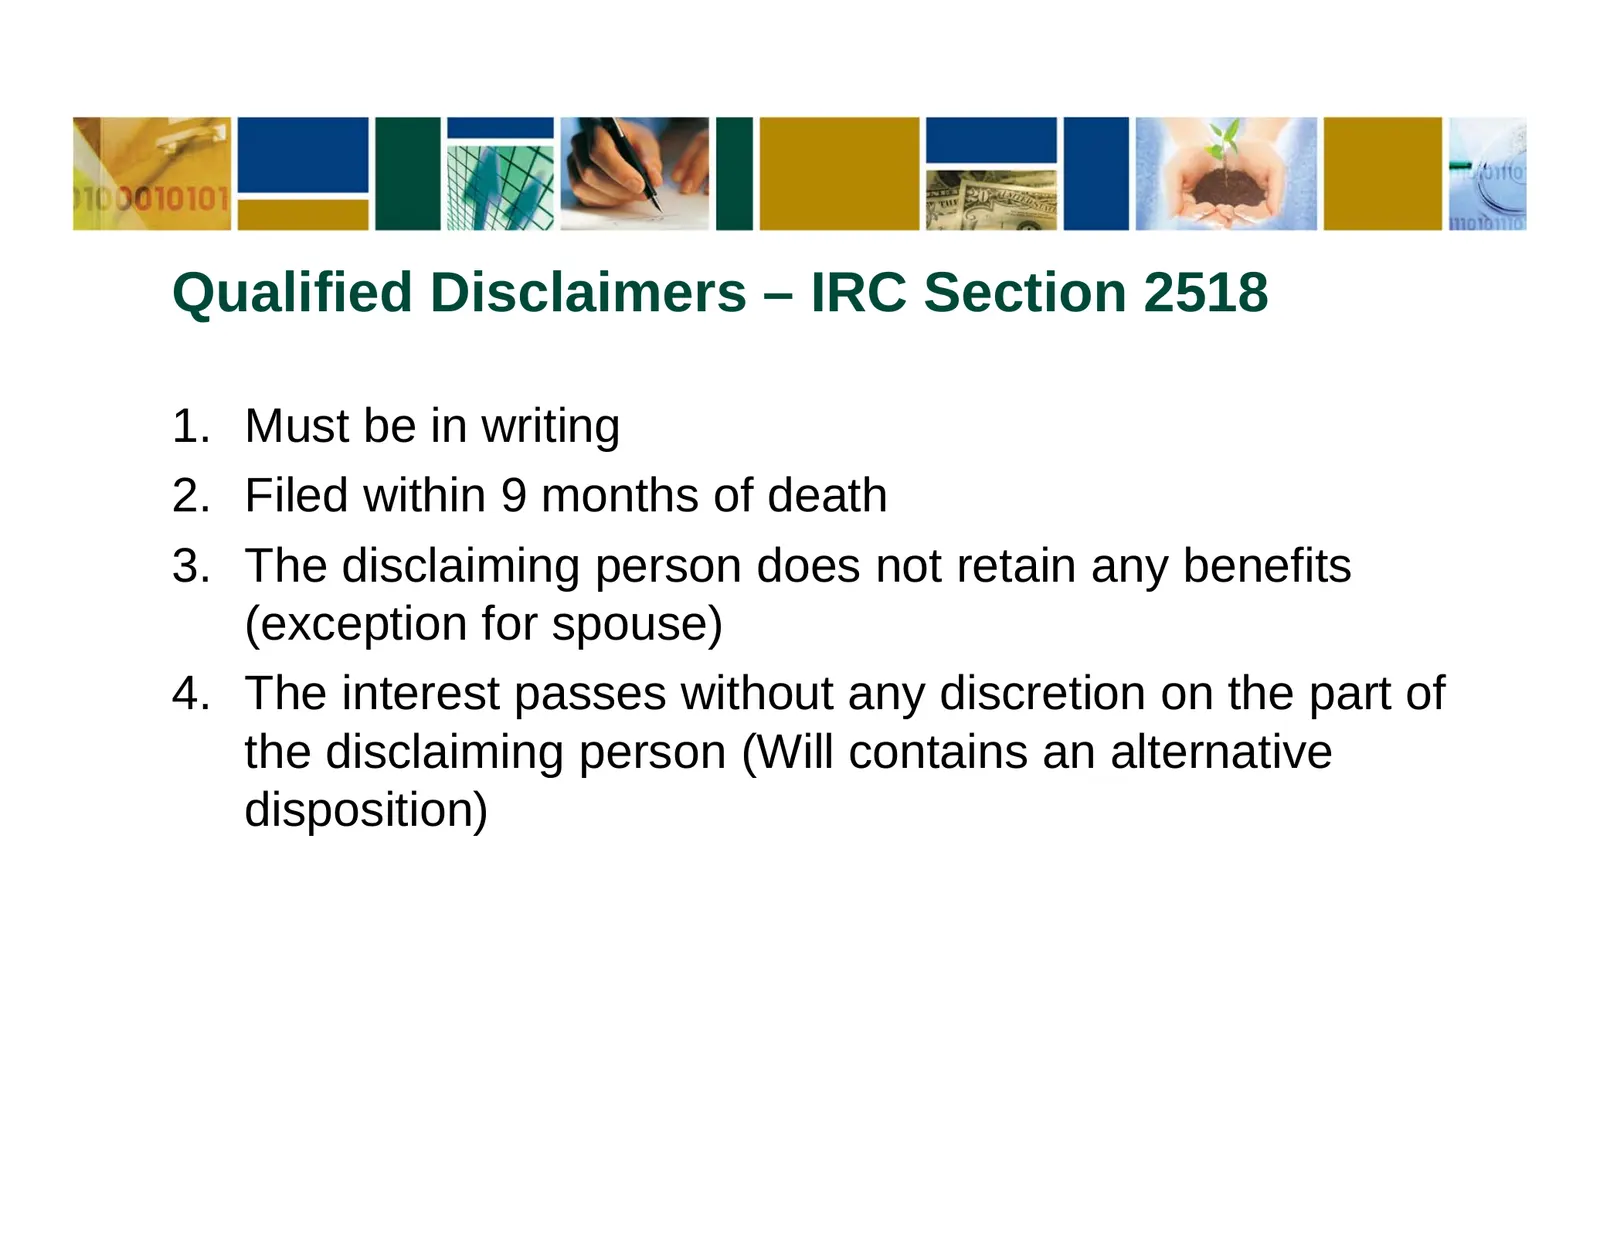
Slide 12: Qualified Disclaimers – IRC Section 2518
Qualified Disclaimers – IRC Section 2518 1. Must be in writing 2. Filed within 9 months of death 3. The disclaiming person does not retain any benefits (exception for spouse) 4. The interest passes without any discretion on the part of the disclaiming person (Will contains an alternative disposition
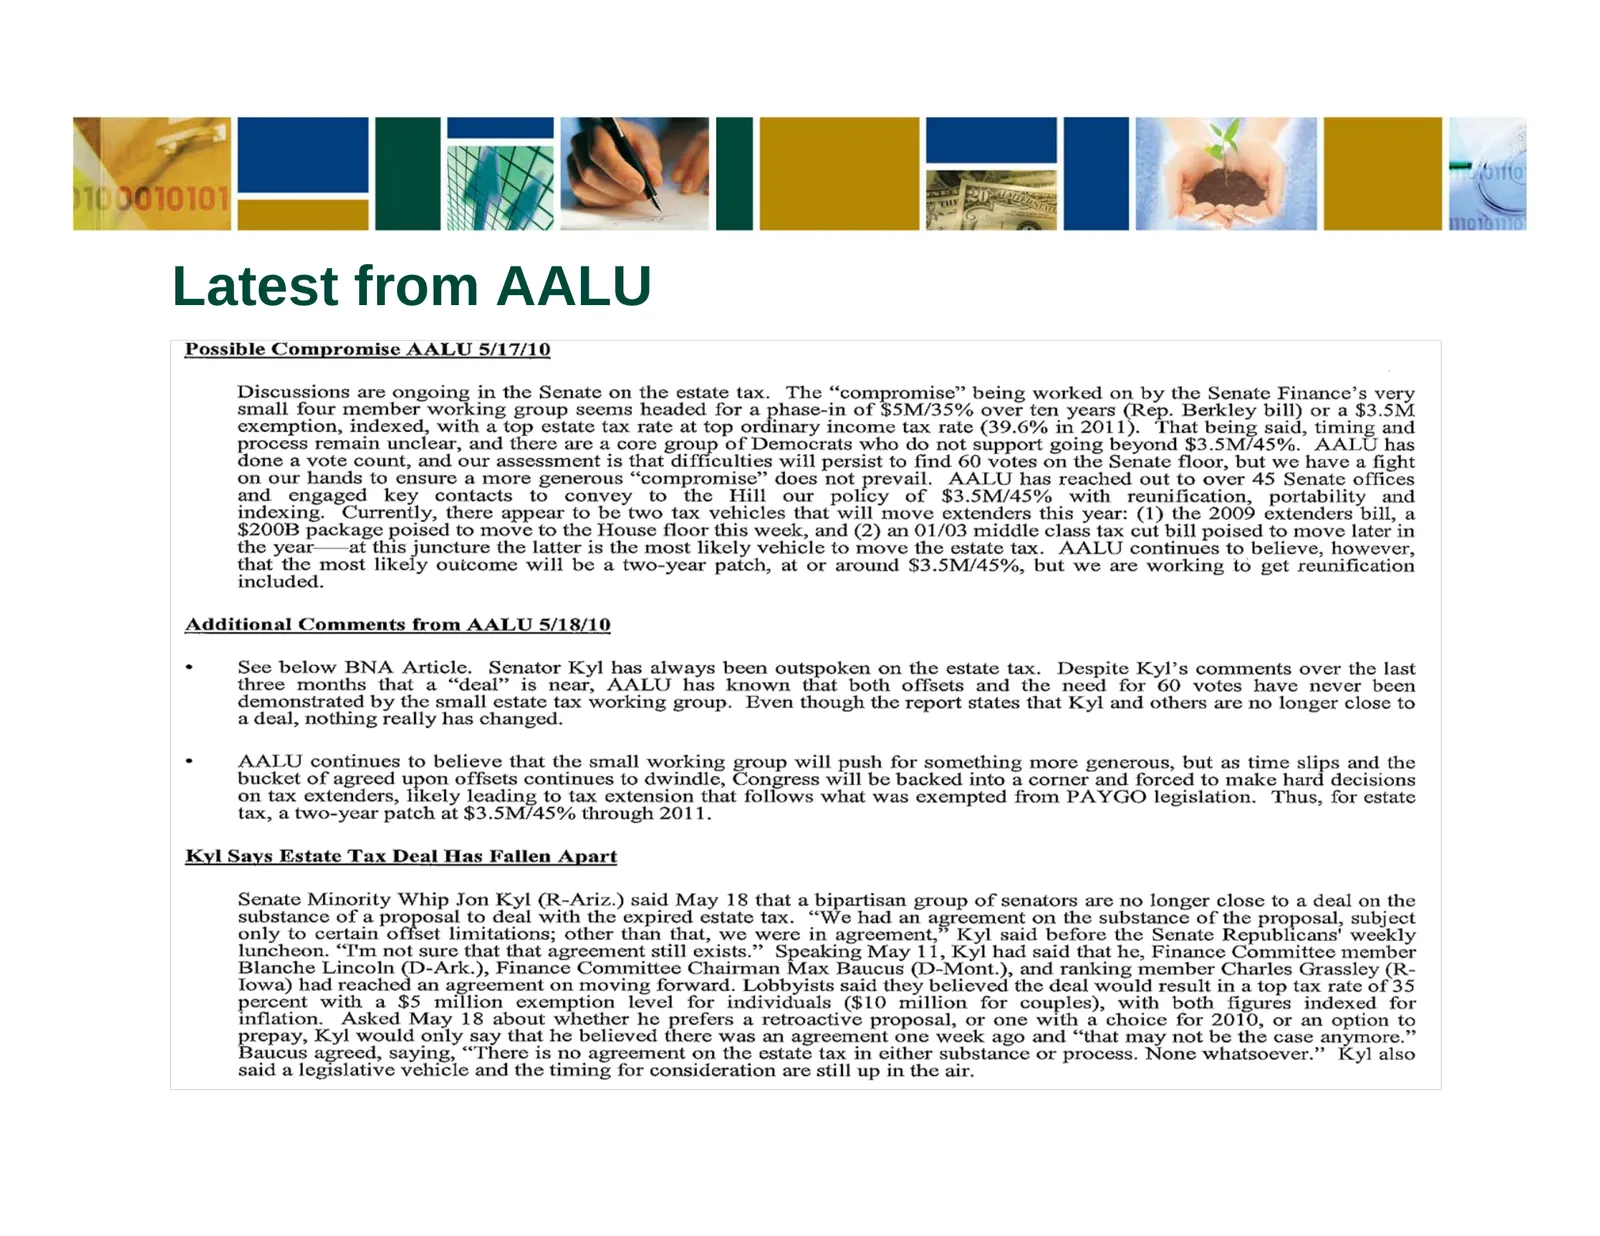
Slide 13: Latest from AALU
“eV - B. Ezy : <3 ech | aks Latest from AALU Possible Compromise AALU 5/17/10 Discussions are ongoing in the Senate on the estate tax. The “compromise” being worked on by the Senate Finance’s very small four member working group seems headed for a phase-in of $5M/35% over ten years (Rep. Berkley bil
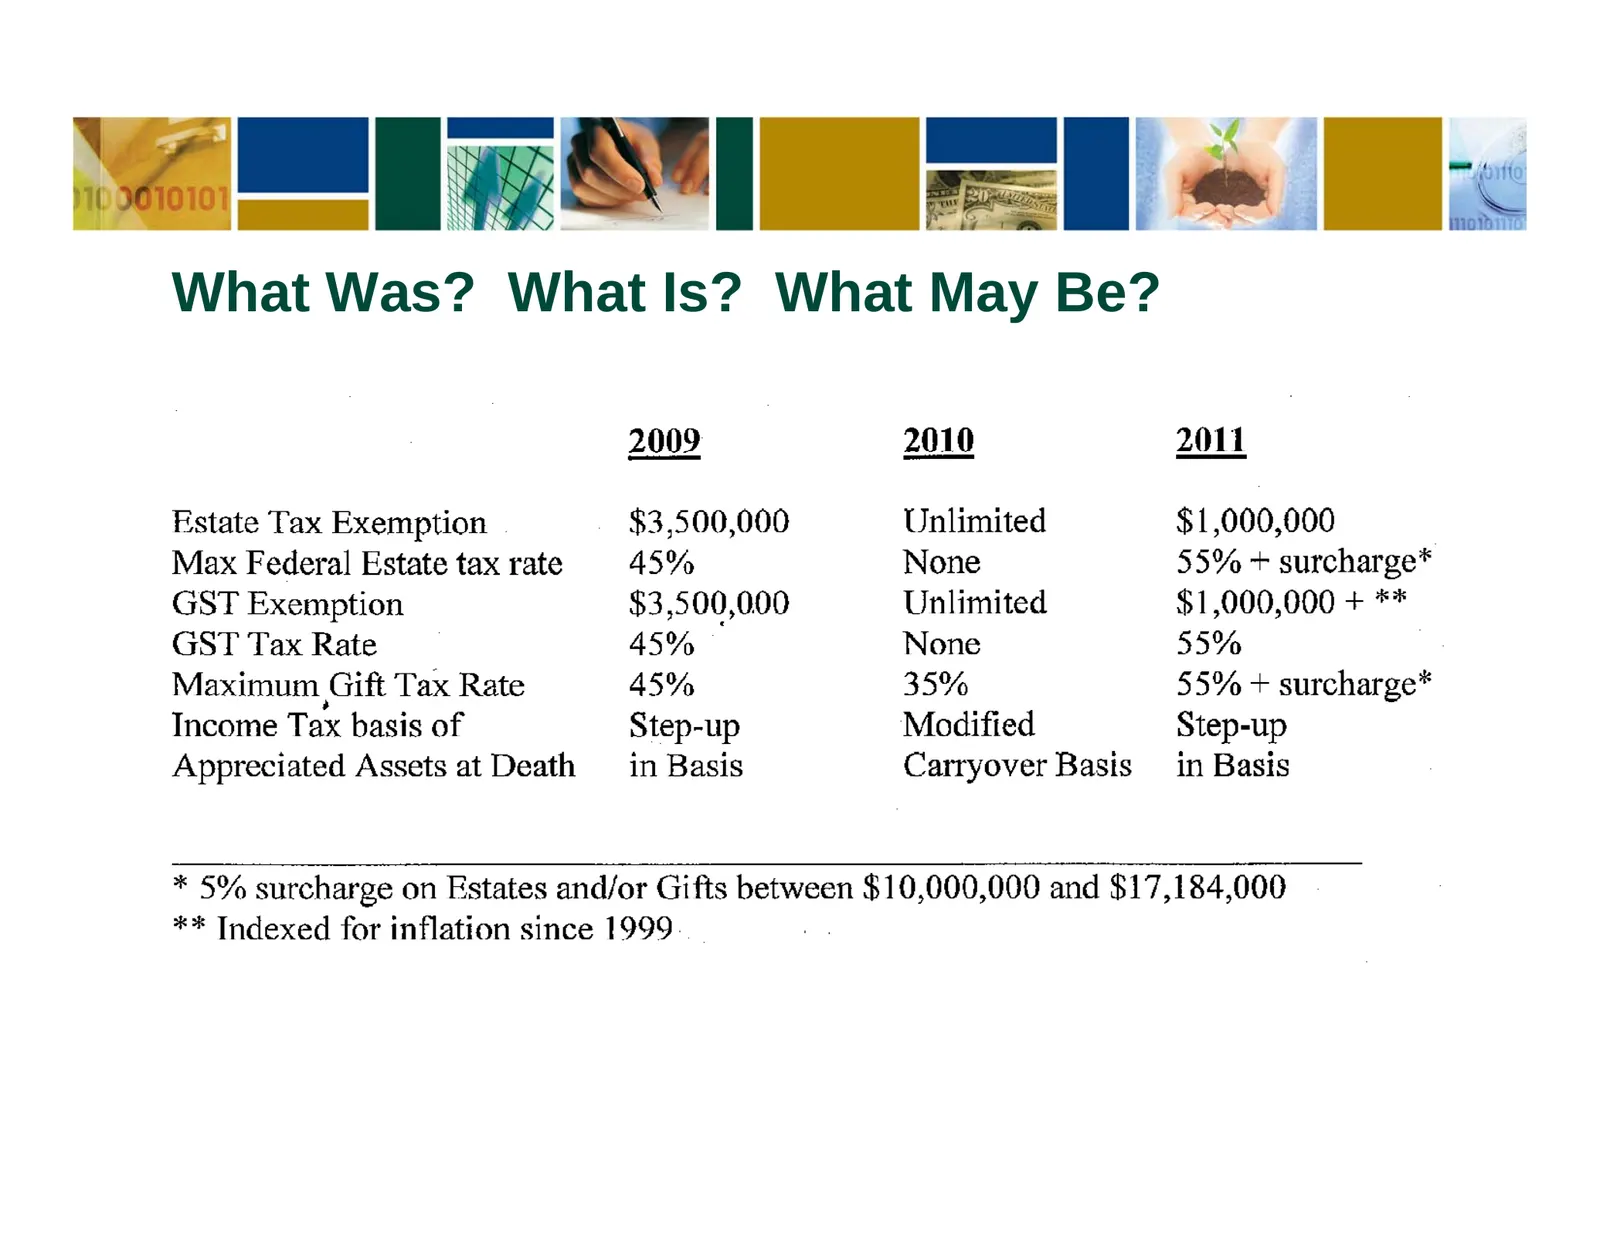
Slide 14: What Was? What Is? What May Be?
What Was? What Is? What May Be?
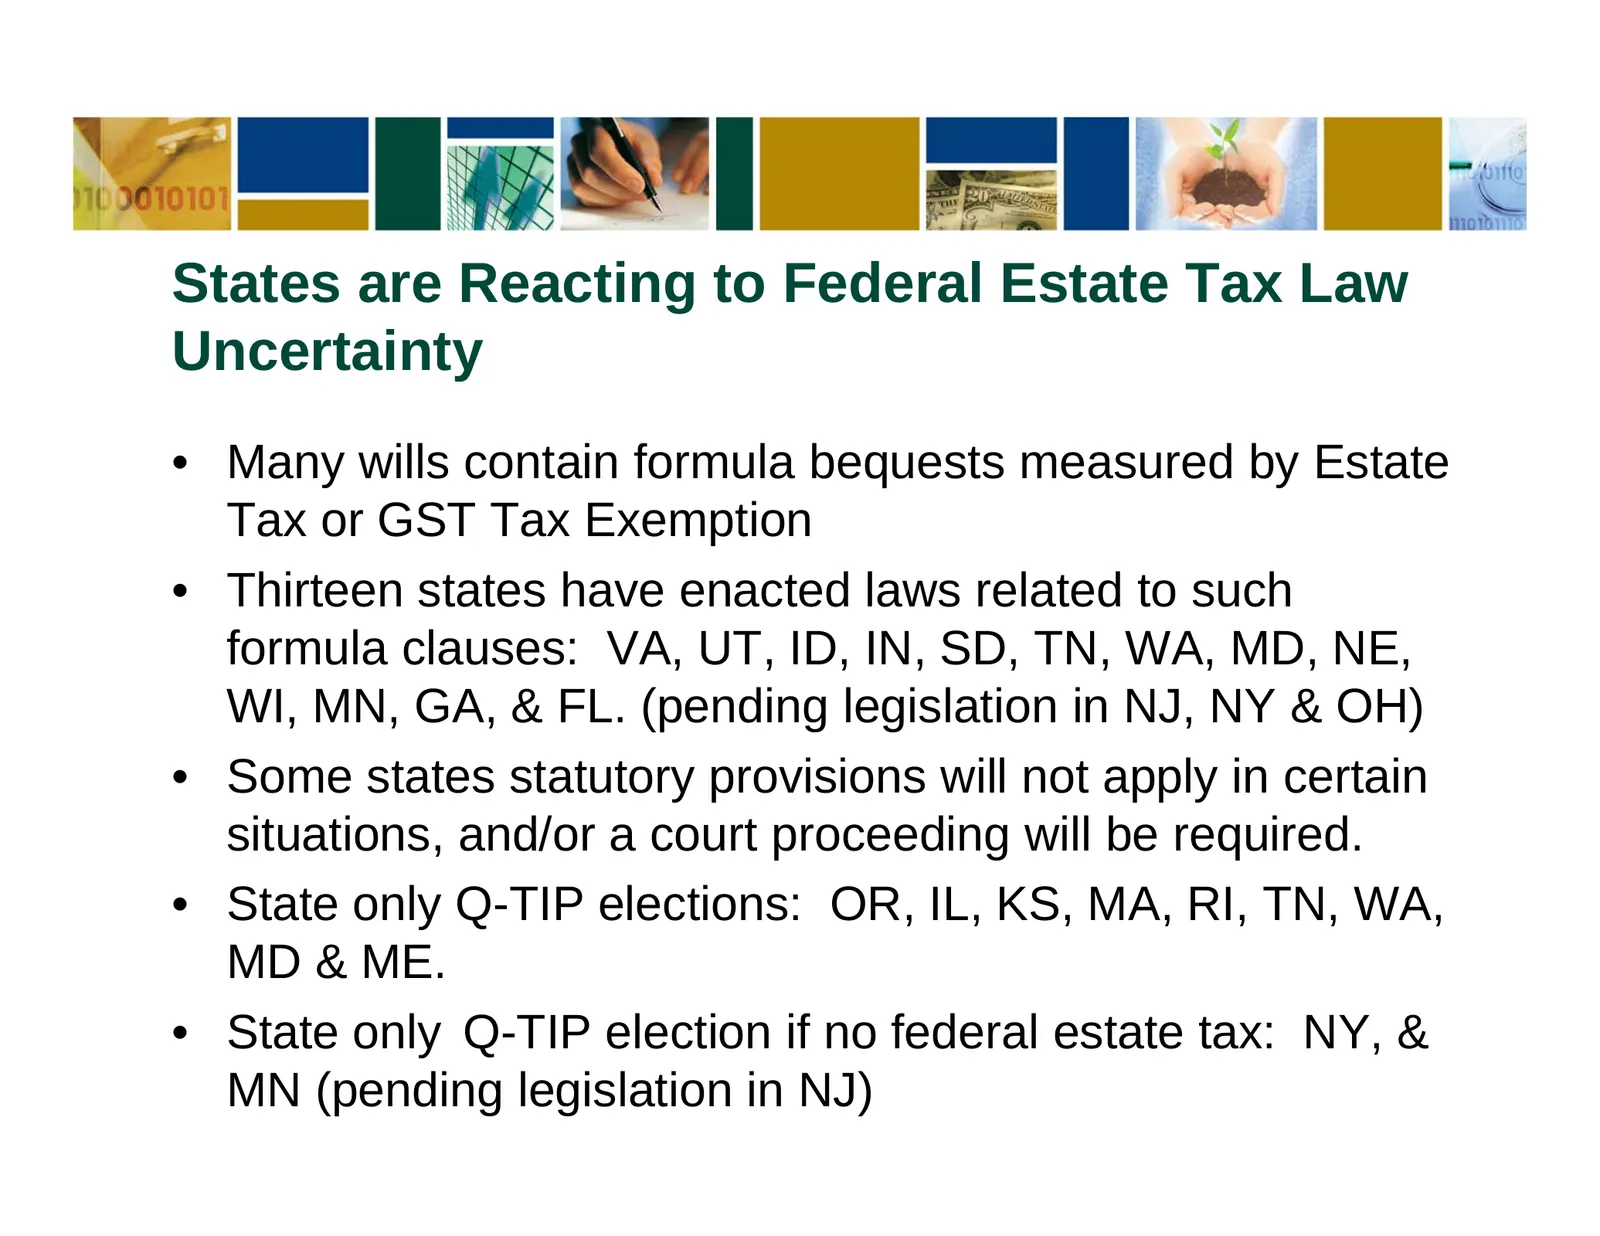
Slide 15: States are Reacting to Federal Estate Tax Law Uncertainty
States are Reacting to Federal Estate Tax Law Uncertainty • Many wills contain formula bequests measured by Estate Tax or GST Tax Exemption • Thirteen states have enacted laws related to such formula clauses: VA, UT, ID, IN, SD, TN, WA, MD, NE, WI, MN, GA, & FL. (pending legislation in NJ, NY & OH)
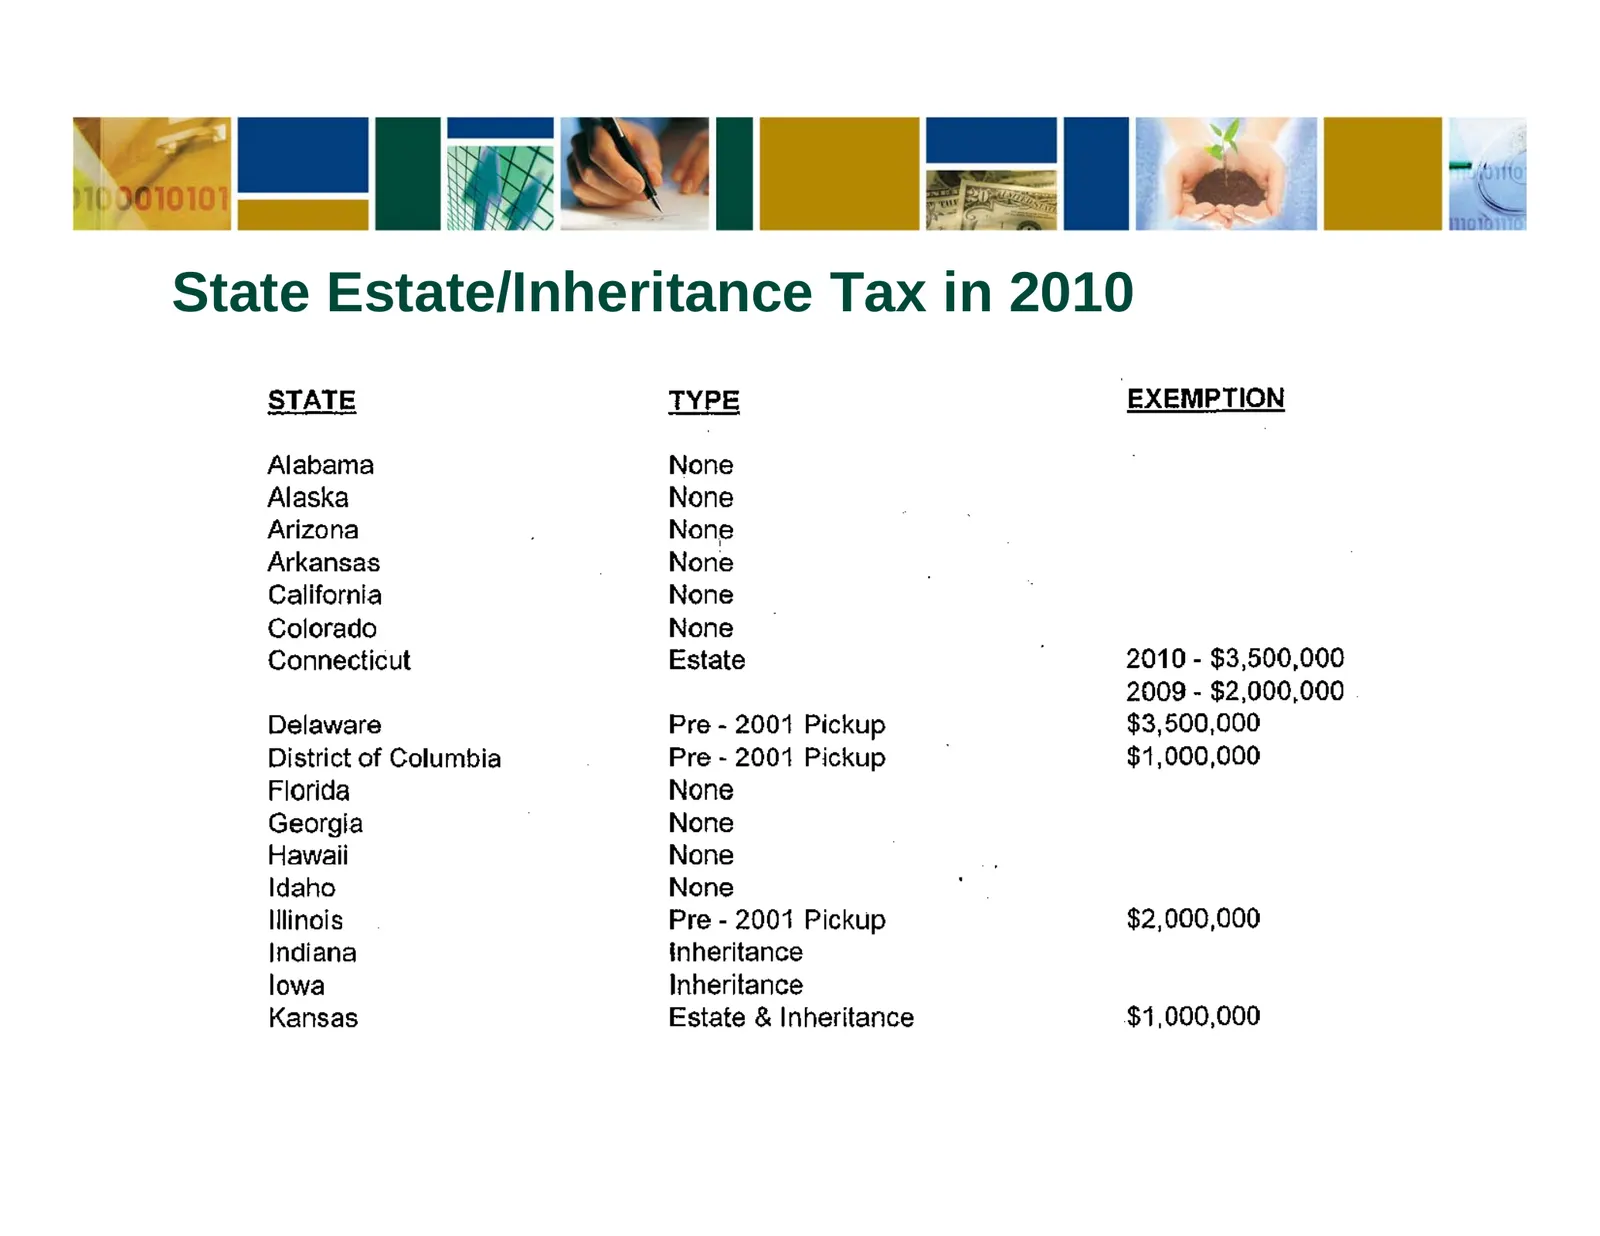
Slide 16: State Estate/Inheritance Tax in 2010
State Estate/Inheritance Tax in 2010
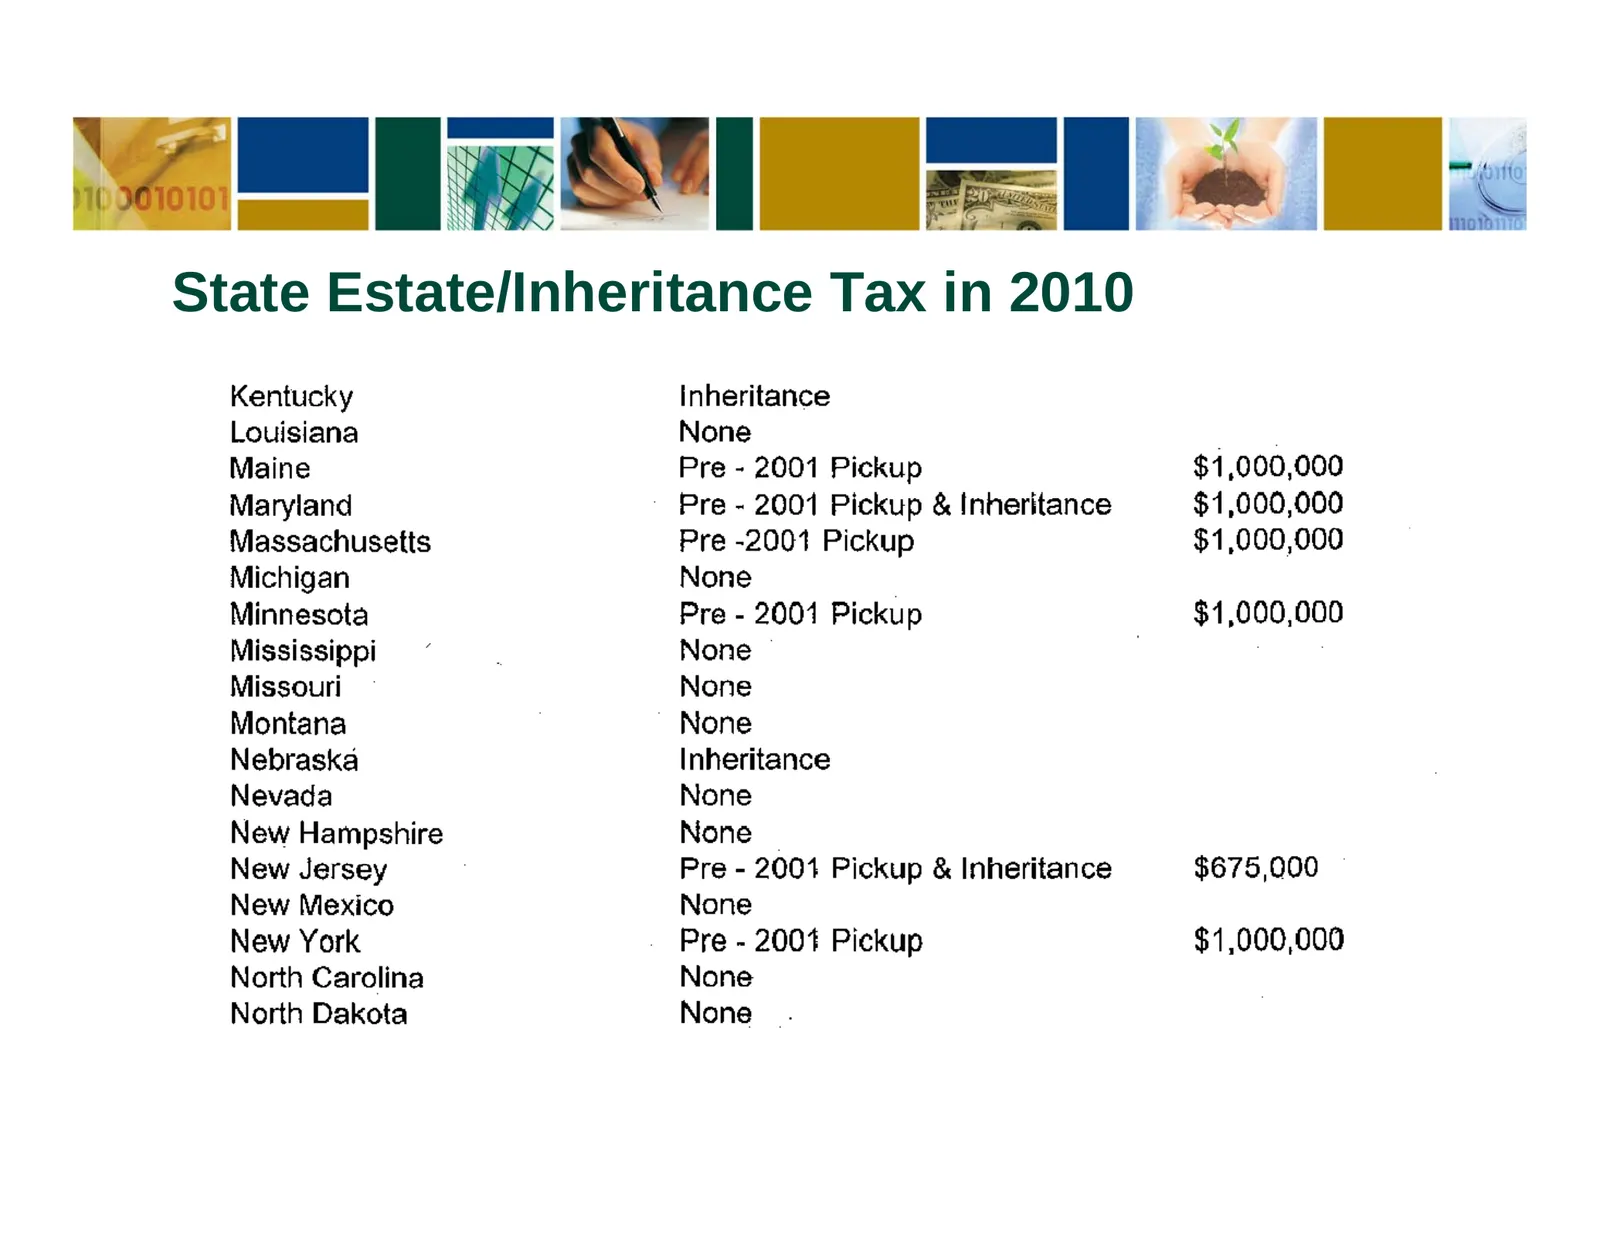
Slide 17: State Estate/Inheritance Tax in 2010
State Estate/Inheritance Tax in 2010
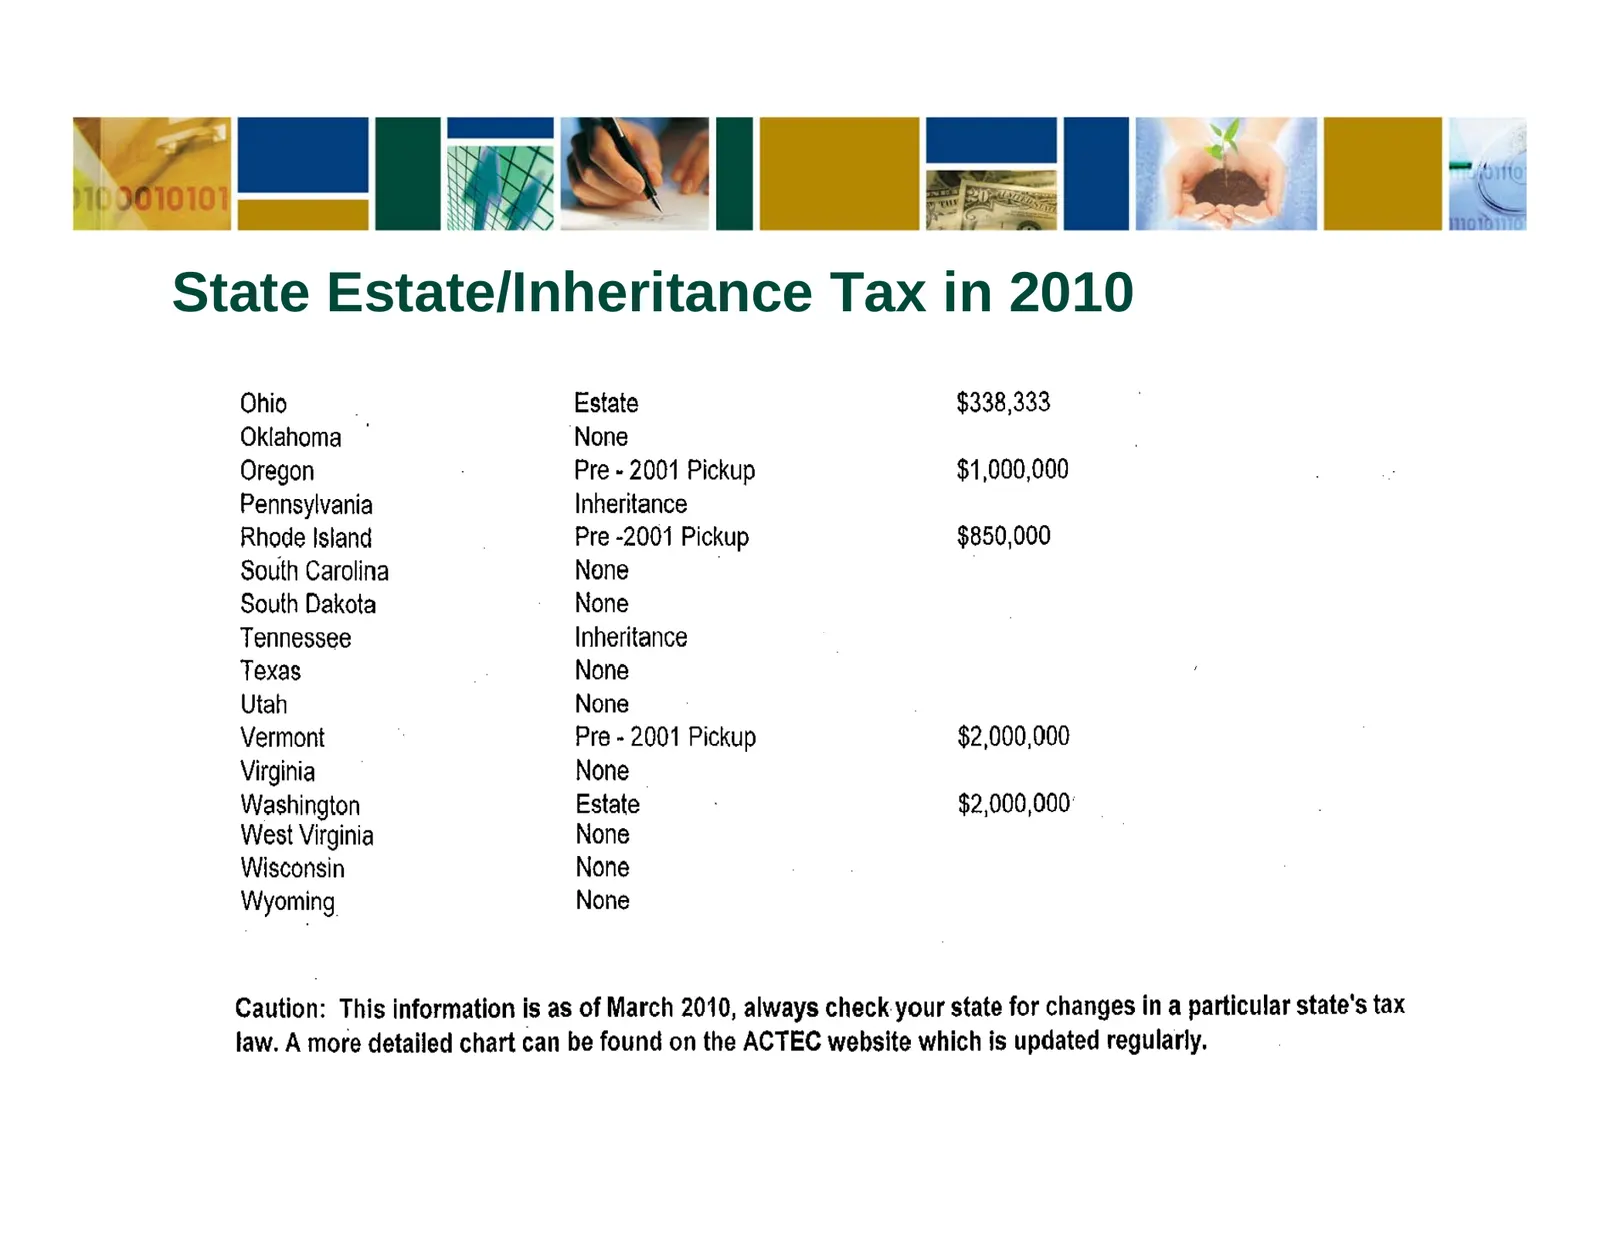
Slide 18: State Estate/Inheritance Tax in 2010
State Estate/Inheritance Tax in 2010
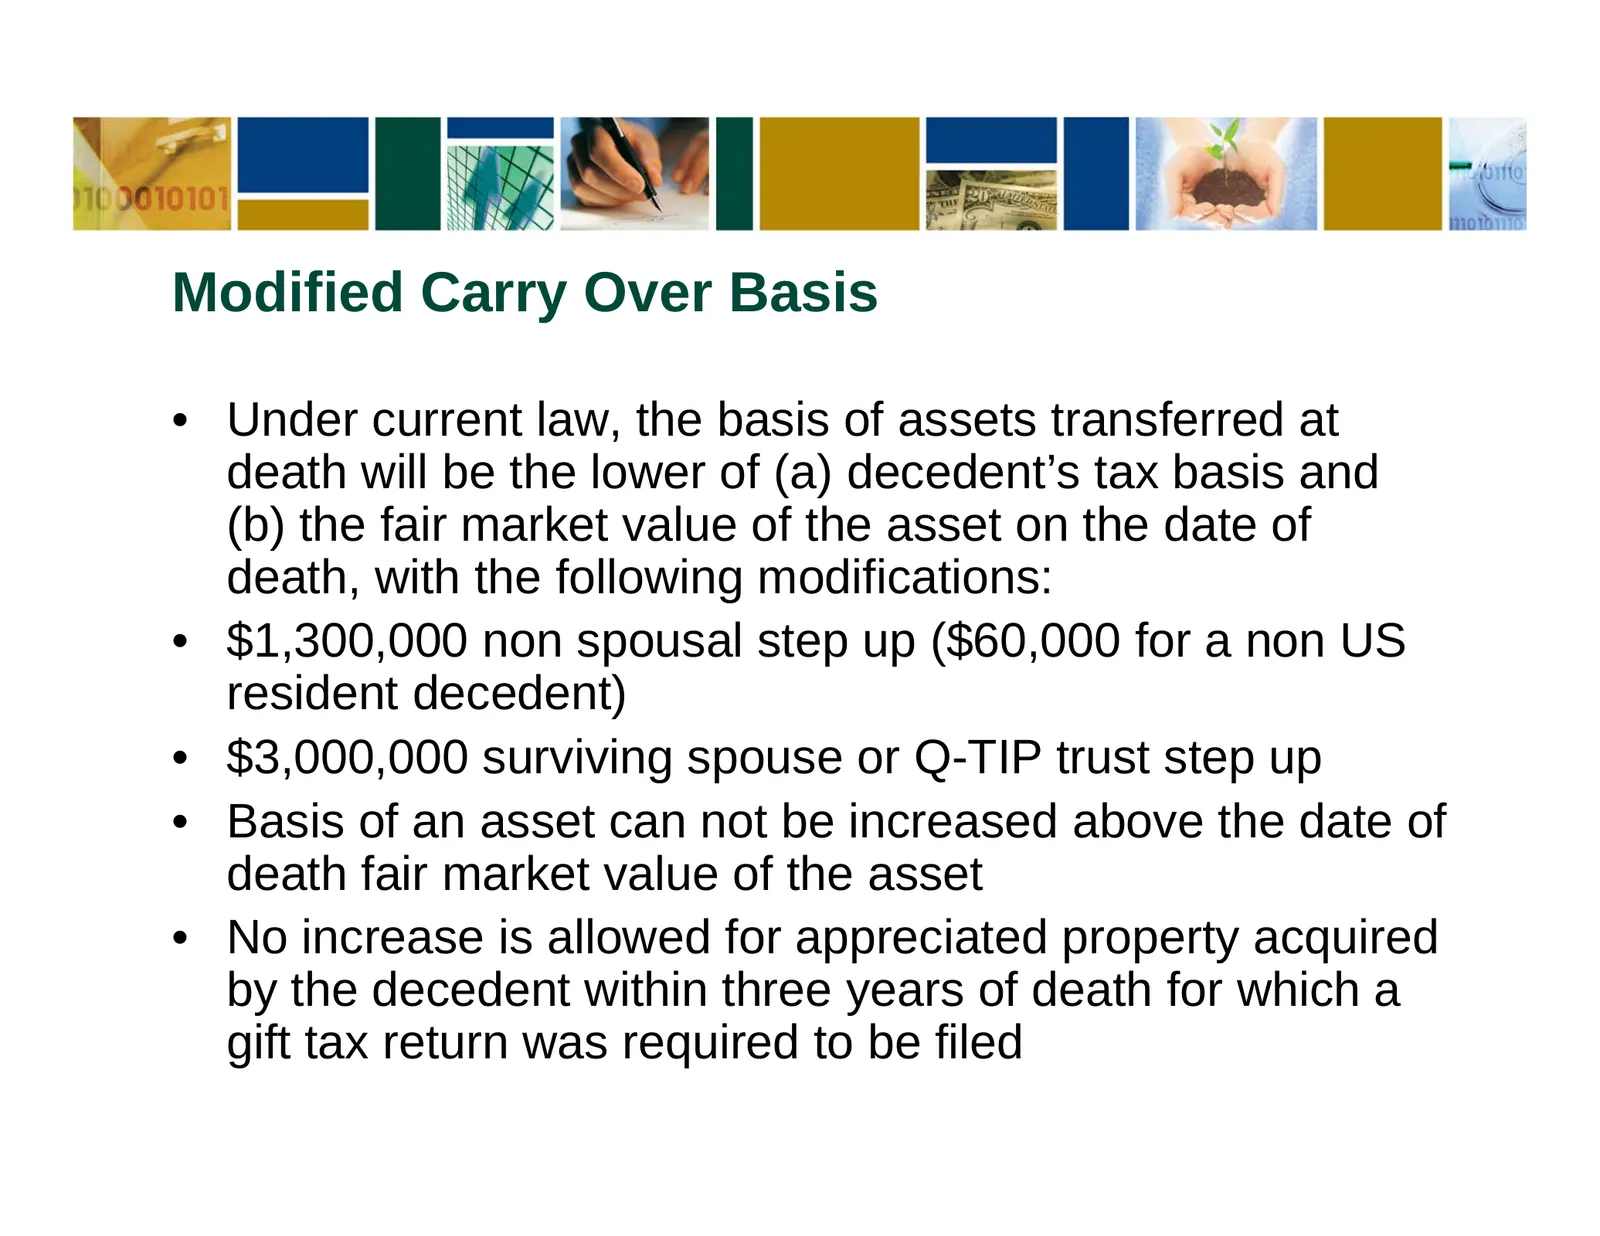
Slide 19: Modified Carry Over Basis
Modified Carry Over Basis • Under current law, the basis of assets transferred at death will be the lower of (a) decedent’s tax basis and (b) the fair market value of the asset on the date of death, with the following modifications: • $1,300,000 non spousal step up ($60,000 for a non US resident dec
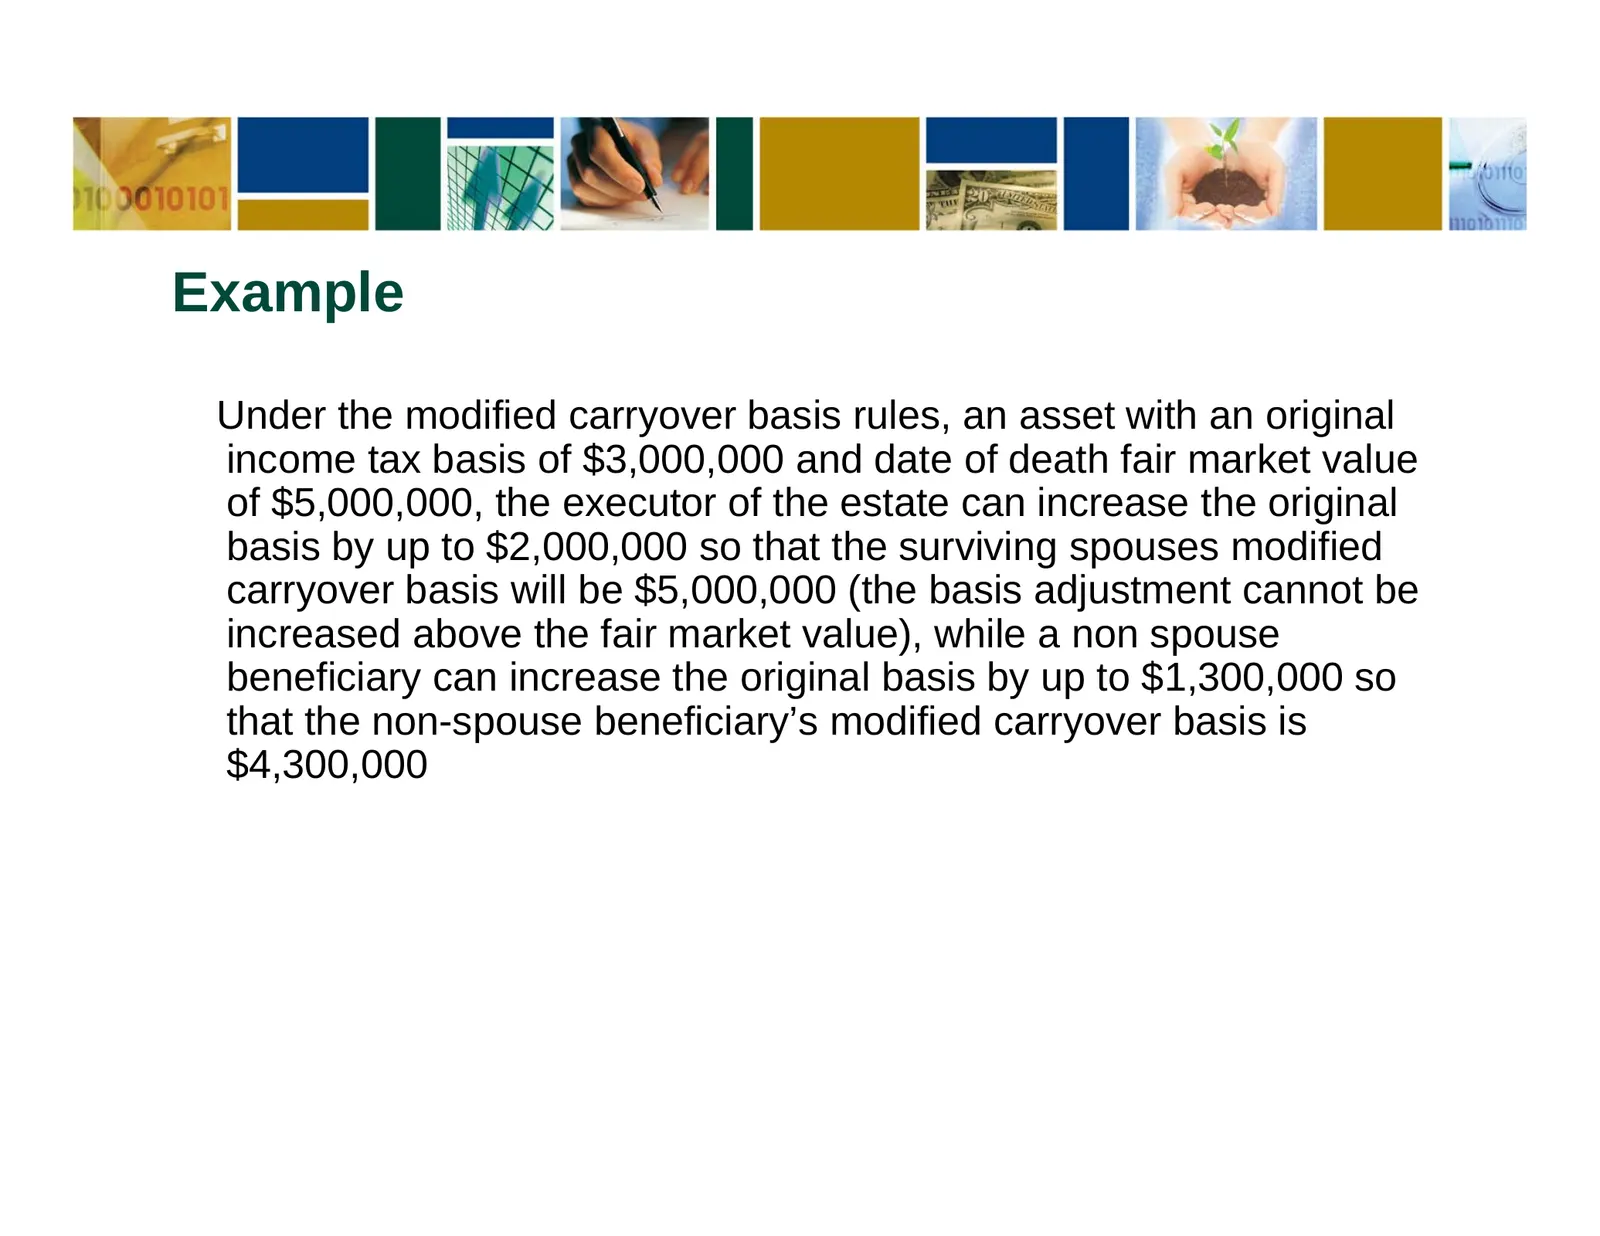
Slide 20: Example
Example Under the modified carryover basis rules, an asset with an original income tax basis of $3,000,000 and date of death fair market value of $5,000,000, the executor of the estate can increase the original basis by up to $2,000,000 so that the surviving spouses modified carryover basis will be
Slide 21: Example (Cont.)
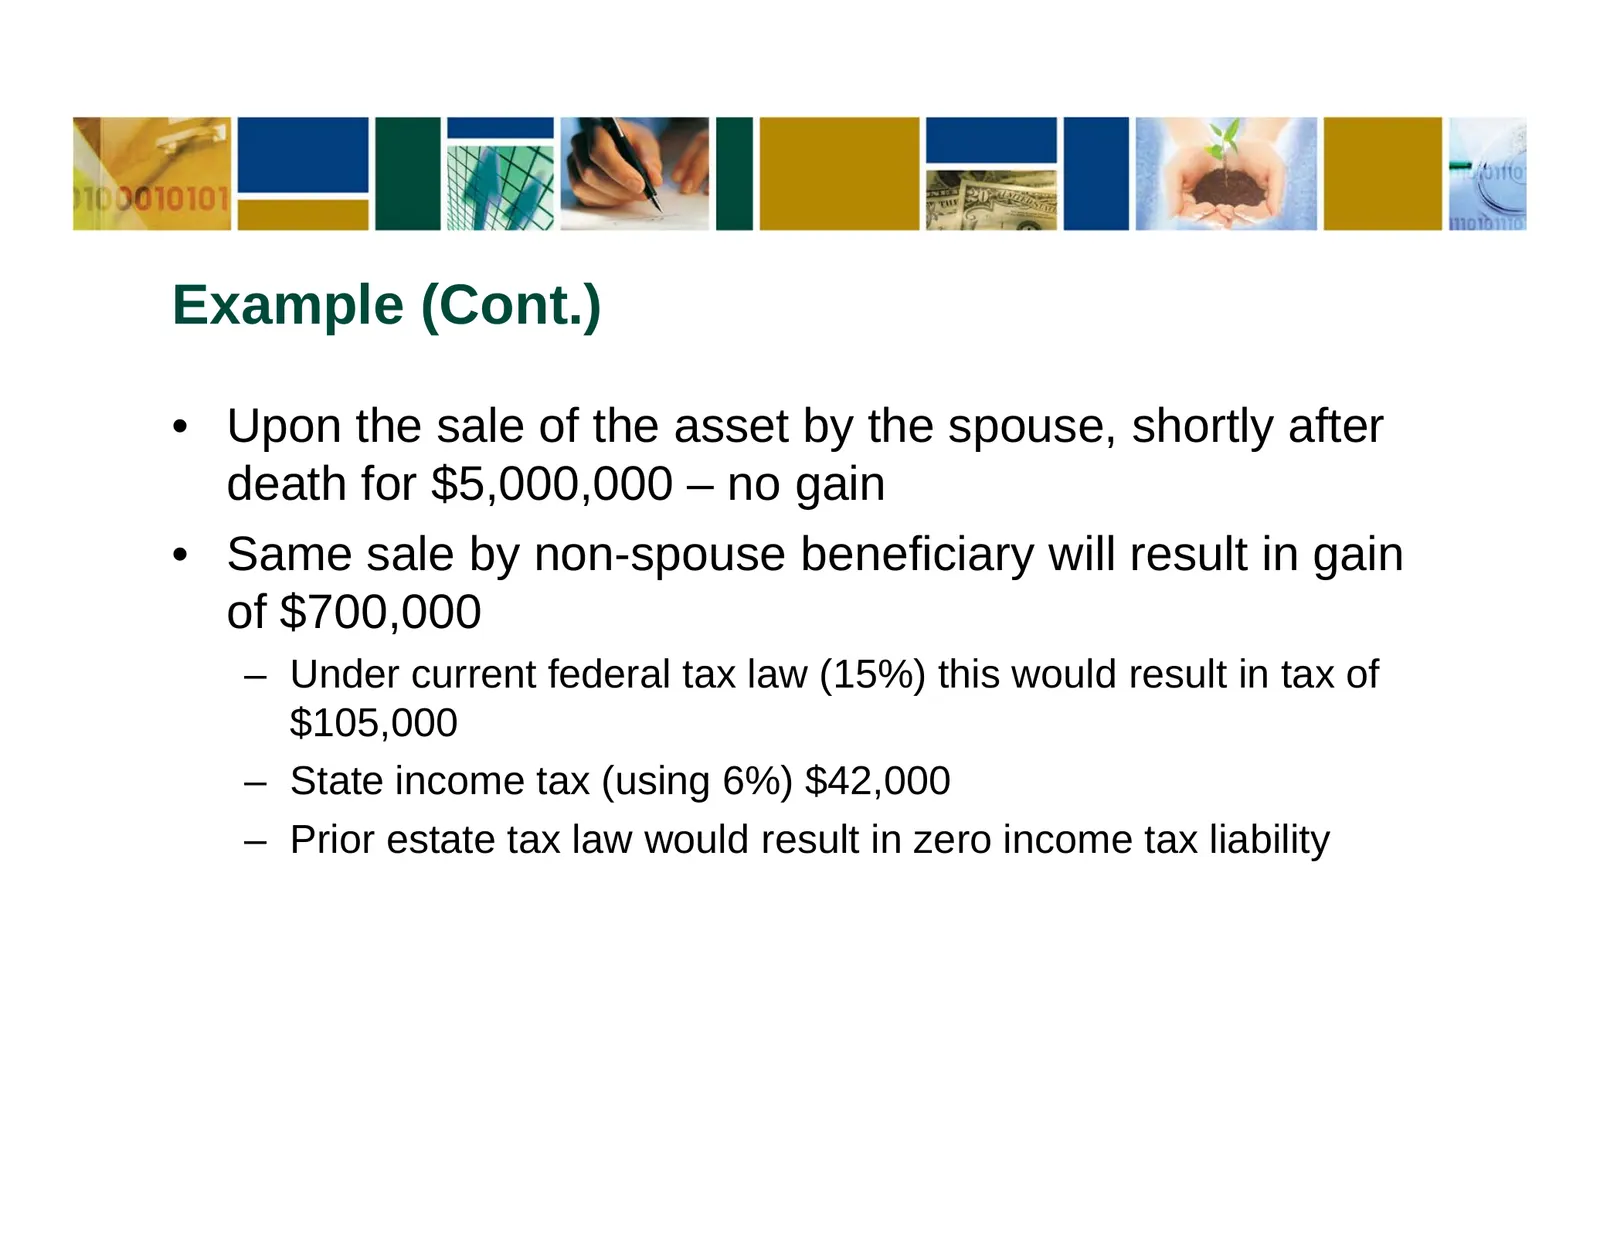
Example (Cont.) • Upon the sale of the asset by the spouse, shortly after death for $5,000,000 – no gain • Same sale by non-spouse beneficiary will result in gain of $700,000 – Under current federal tax law (15%) this would result in tax of $105,000 – State income tax (using 6%) $42,000 – Prior esta
Slide 22: Fiduciary's Issues
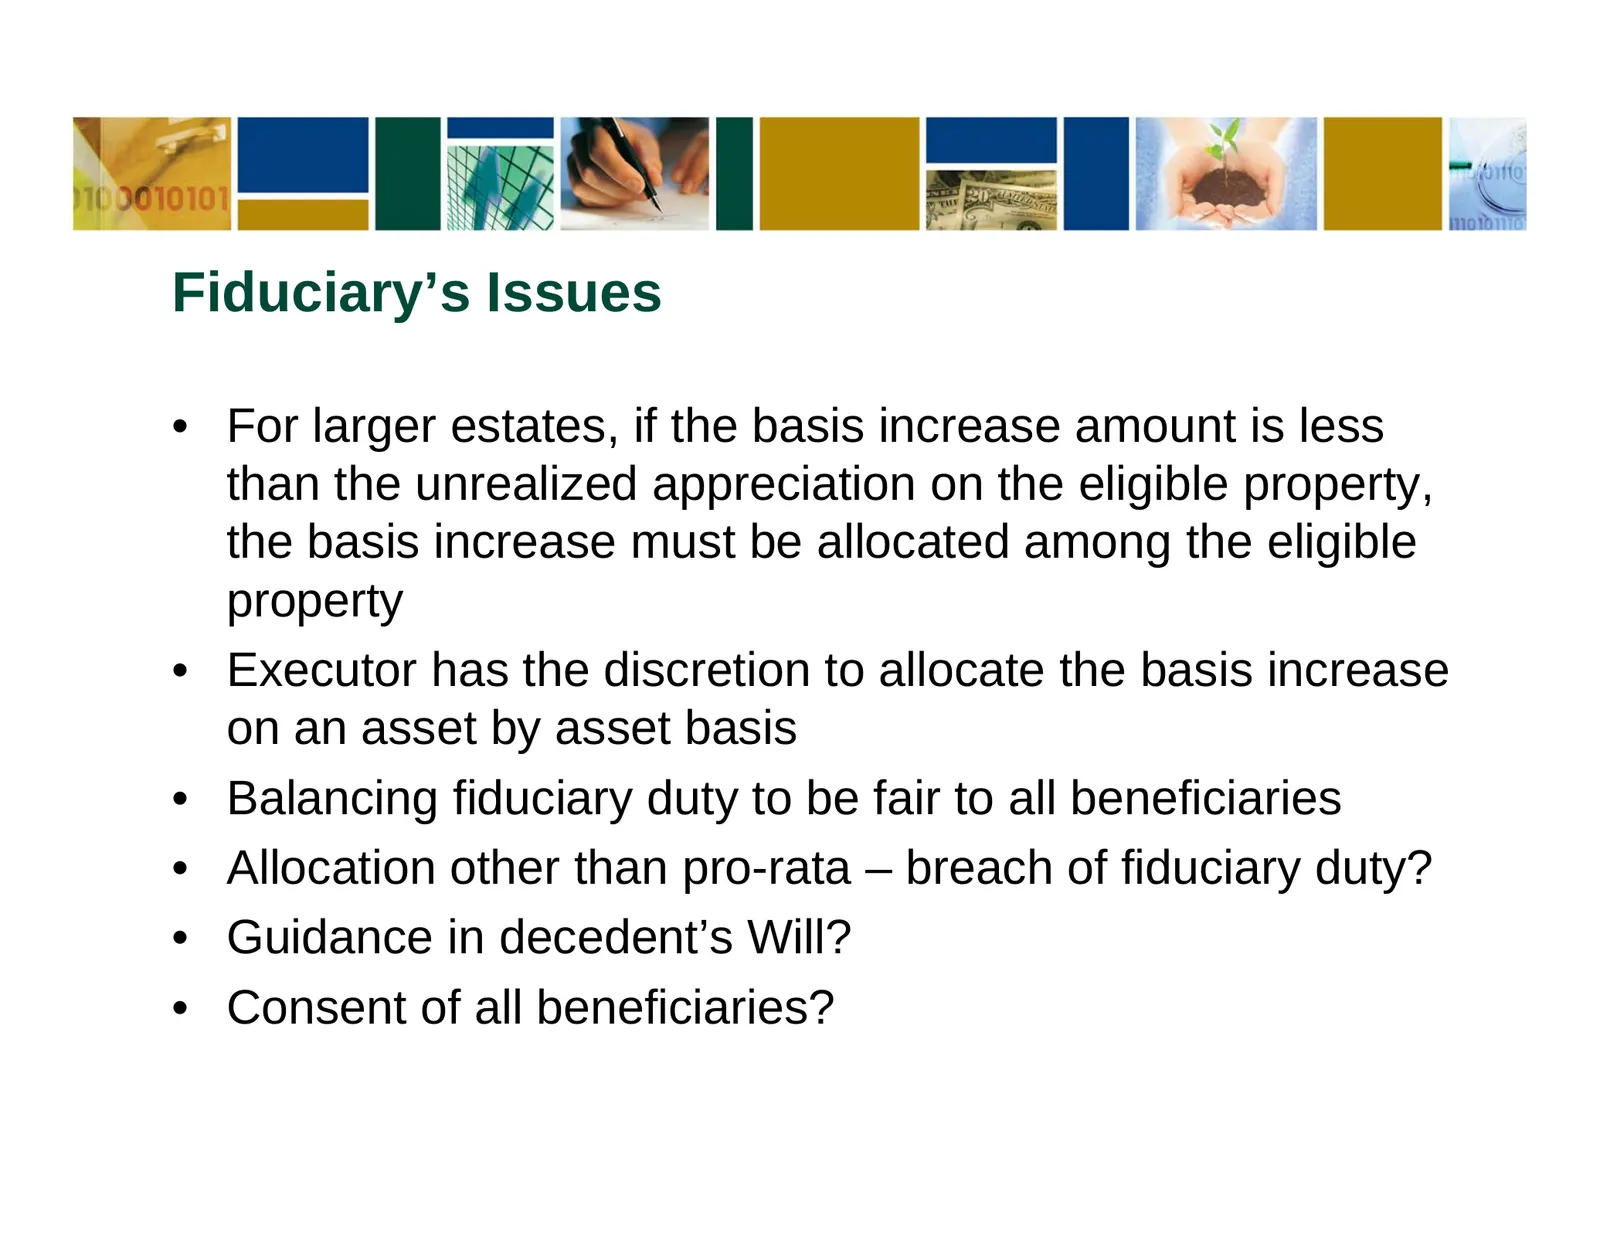
Fiduciary’s Issues • For larger estates, if the basis increase amount is less than the unrealized appreciation on the eligible property, the basis increase must be allocated among the eligible property • Executor has the discretion to allocate the basis increase on an asset by asset basis • Balancin
Slide 23: Fiduciary Issues (Cont.)
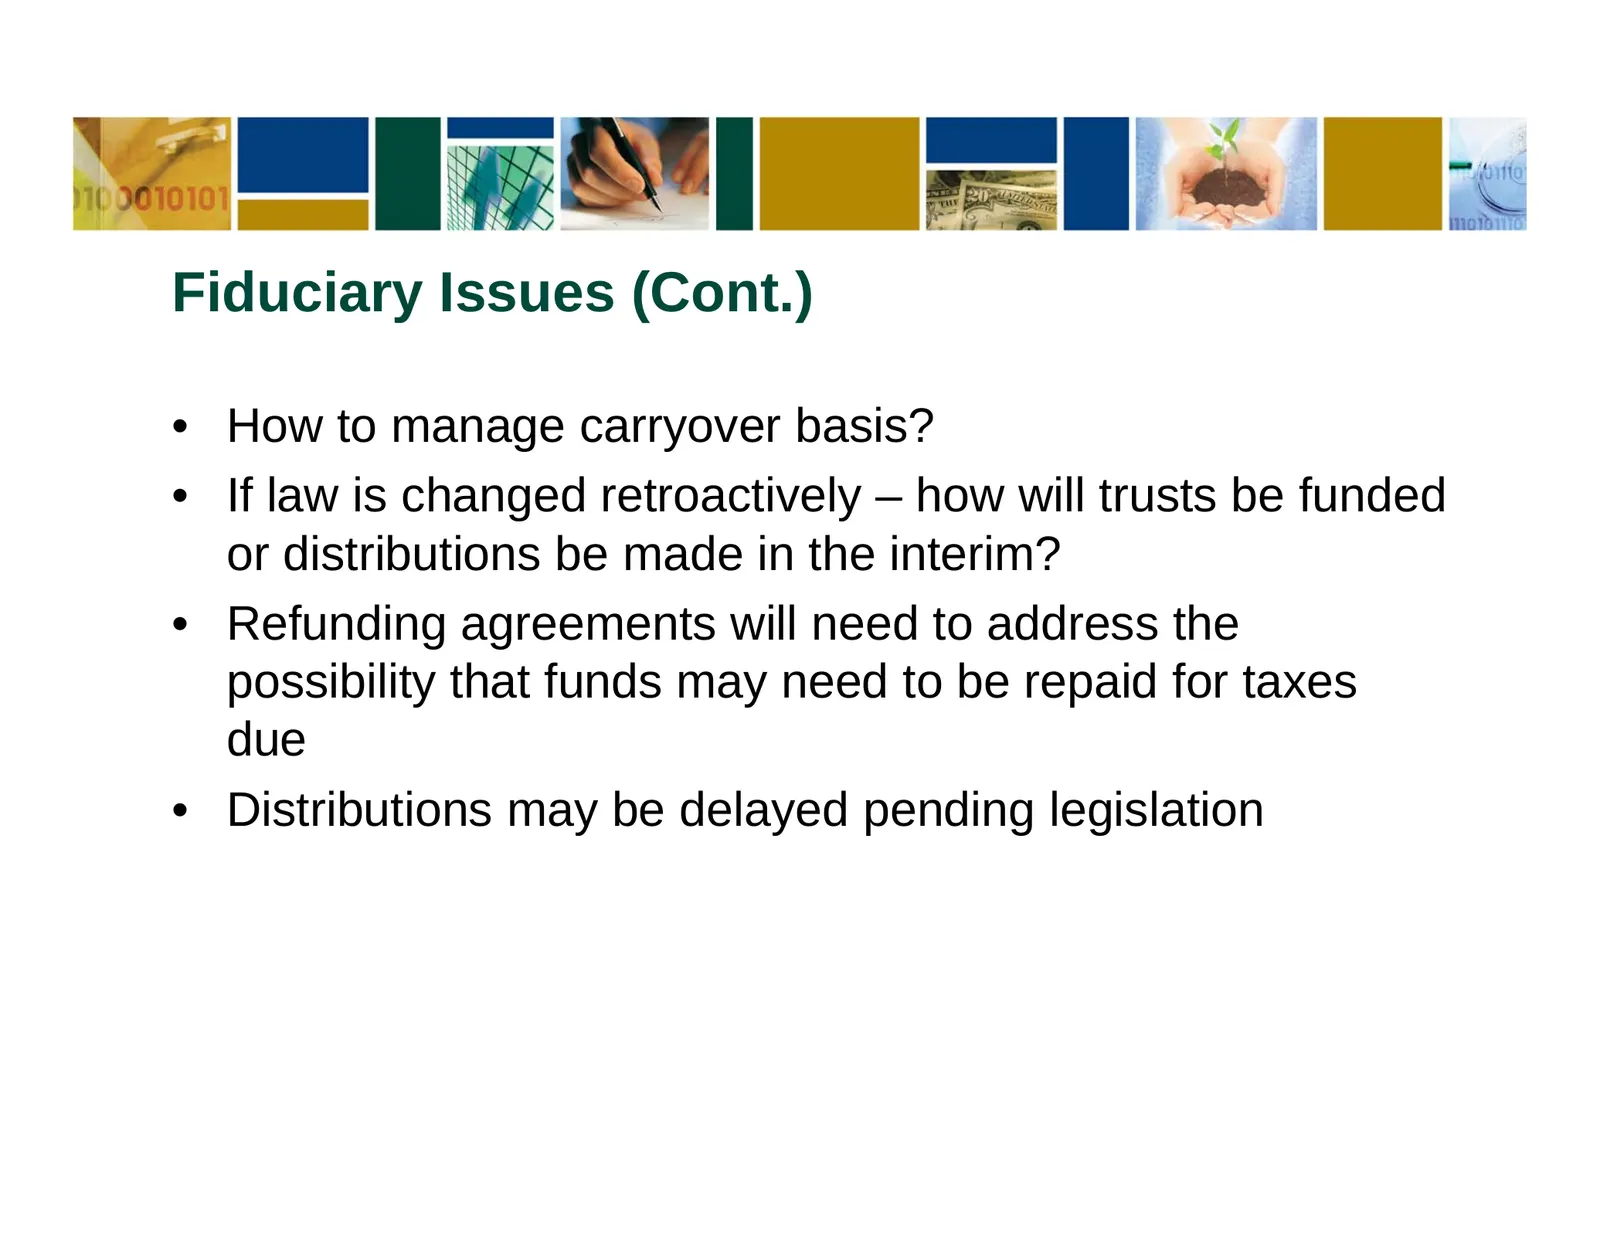
Fiduciary Issues (Cont.) • How to manage carryover basis? • If law is changed retroactively – how will trusts be funded or distributions be made in the interim? • Refunding agreements will need to address the possibility that funds may need to be repaid for taxes due • Distributions may be delayed p
Slide 24: Maximum Gift Tax Rate reduced to 35% and No GST Tax
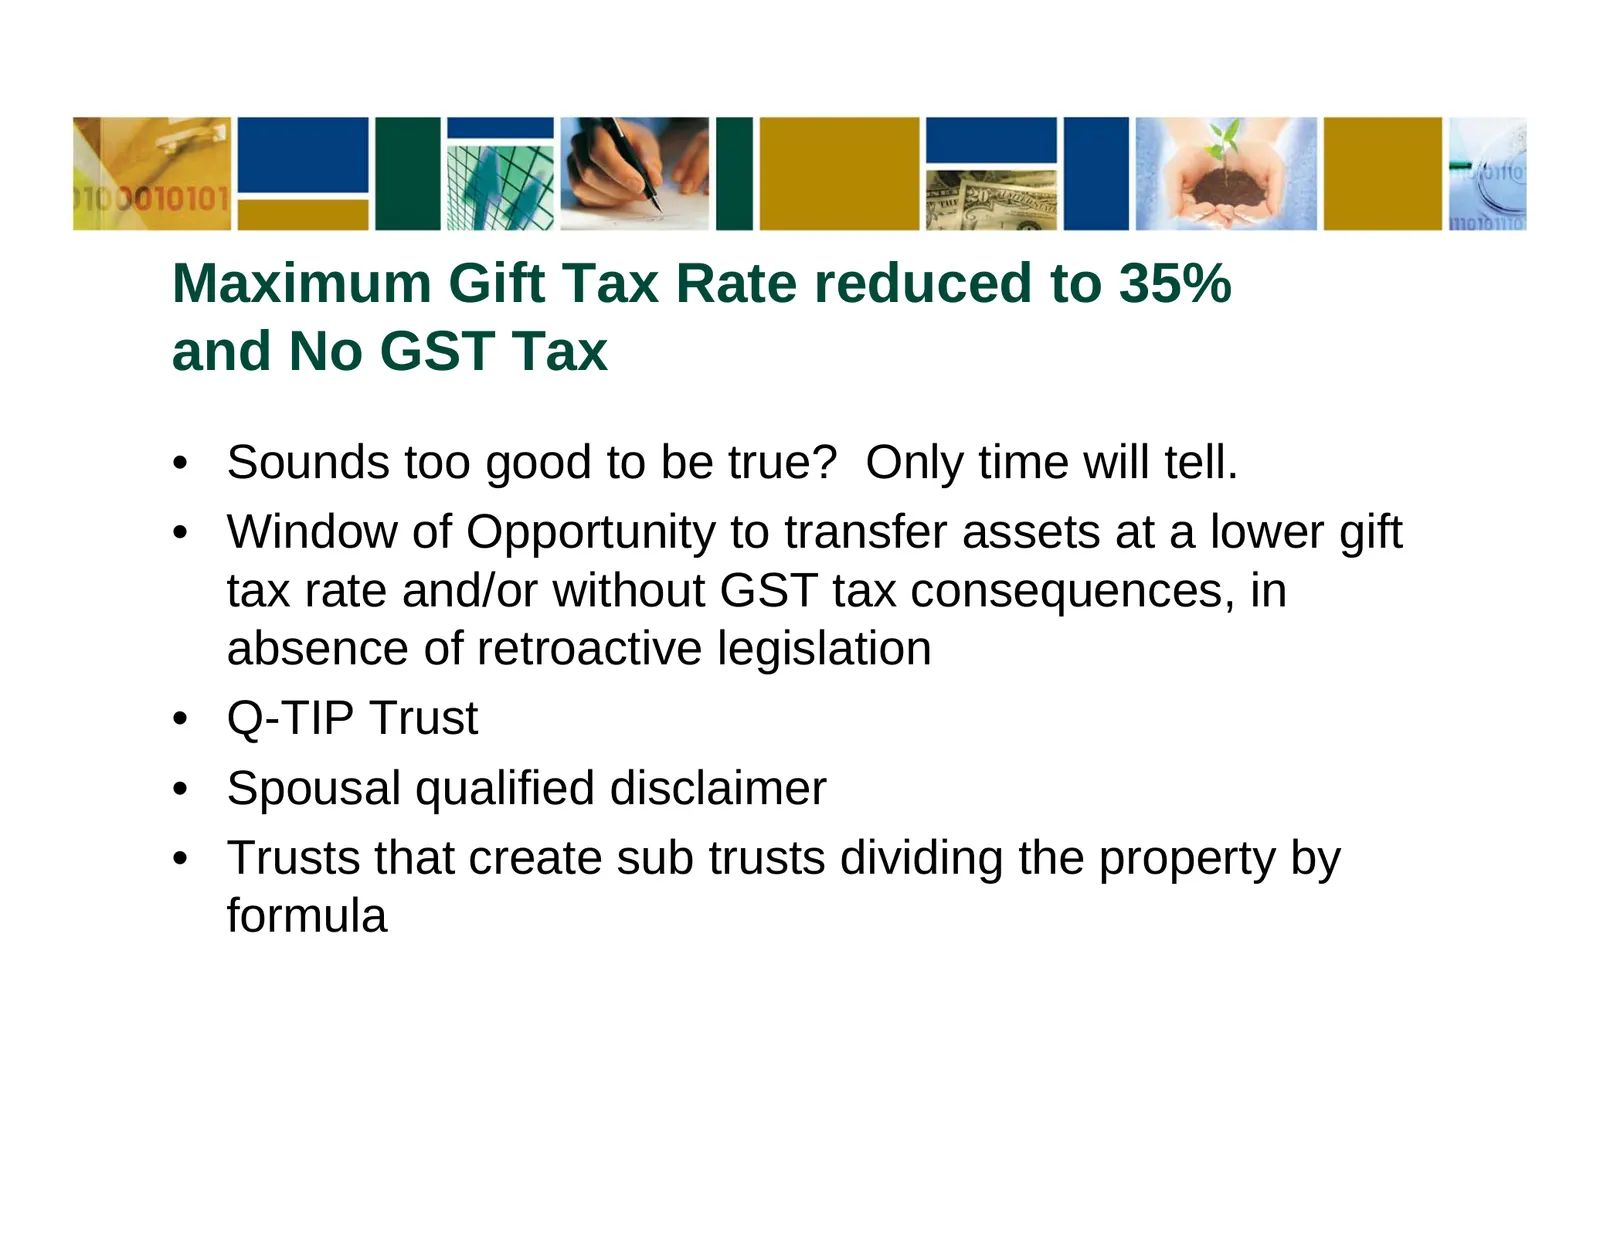
Maximum Gift Tax Rate reduced to 35% and No GST Tax • Sounds too good to be true? Only time will tell. • Window of Opportunity to transfer assets at a lower gift tax rate and/or without GST tax consequences, in absence of retroactive legislation • Q-TIP Trust • Spousal qualified disclaimer • Trusts
Slide 25: Interest Rates
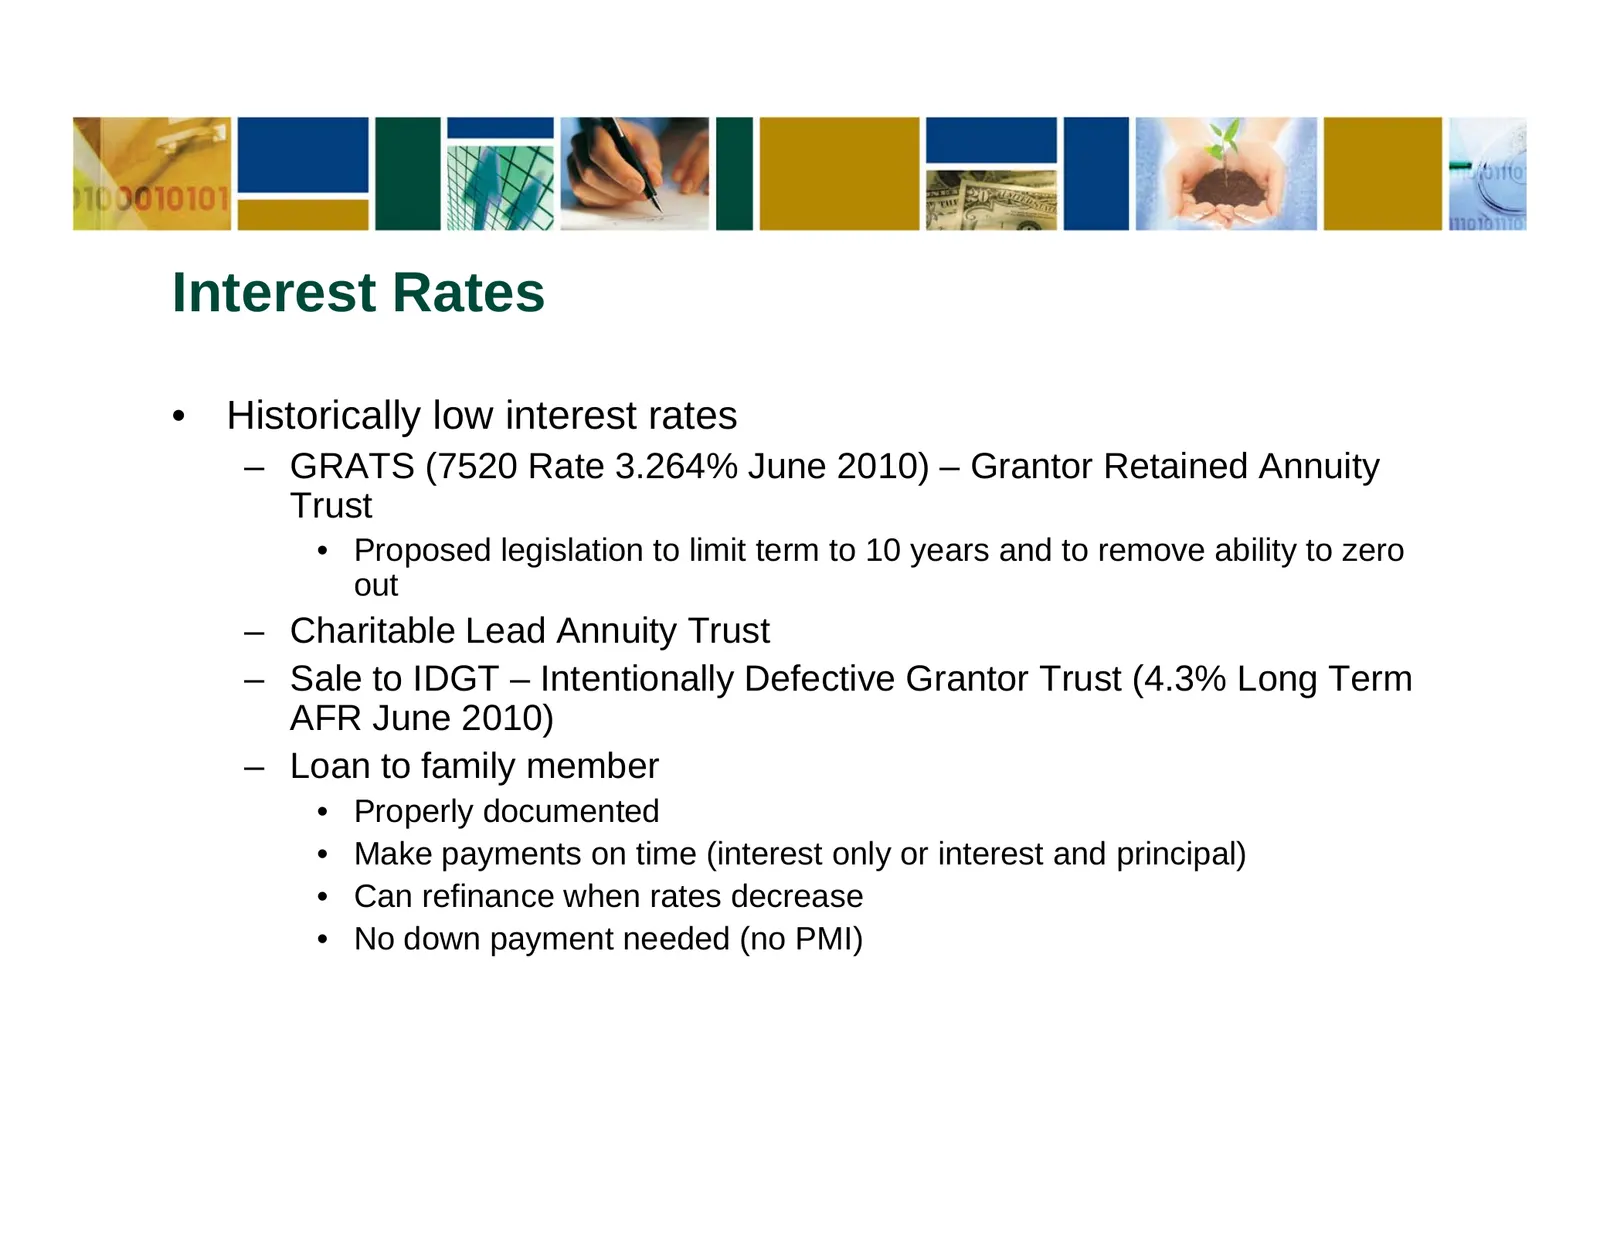
Interest Rates • Historically low interest rates – GRATS (7520 Rate 3.264% June 2010) – Grantor Retained Annuity Trust • Proposed legislation to limit term to 10 years and to remove ability to zero out – Charitable Lead Annuity Trust – Sale to IDGT – Intentionally Defective Grantor Trust (4.3% Long
Slide 26: Example of Interfamily Loan
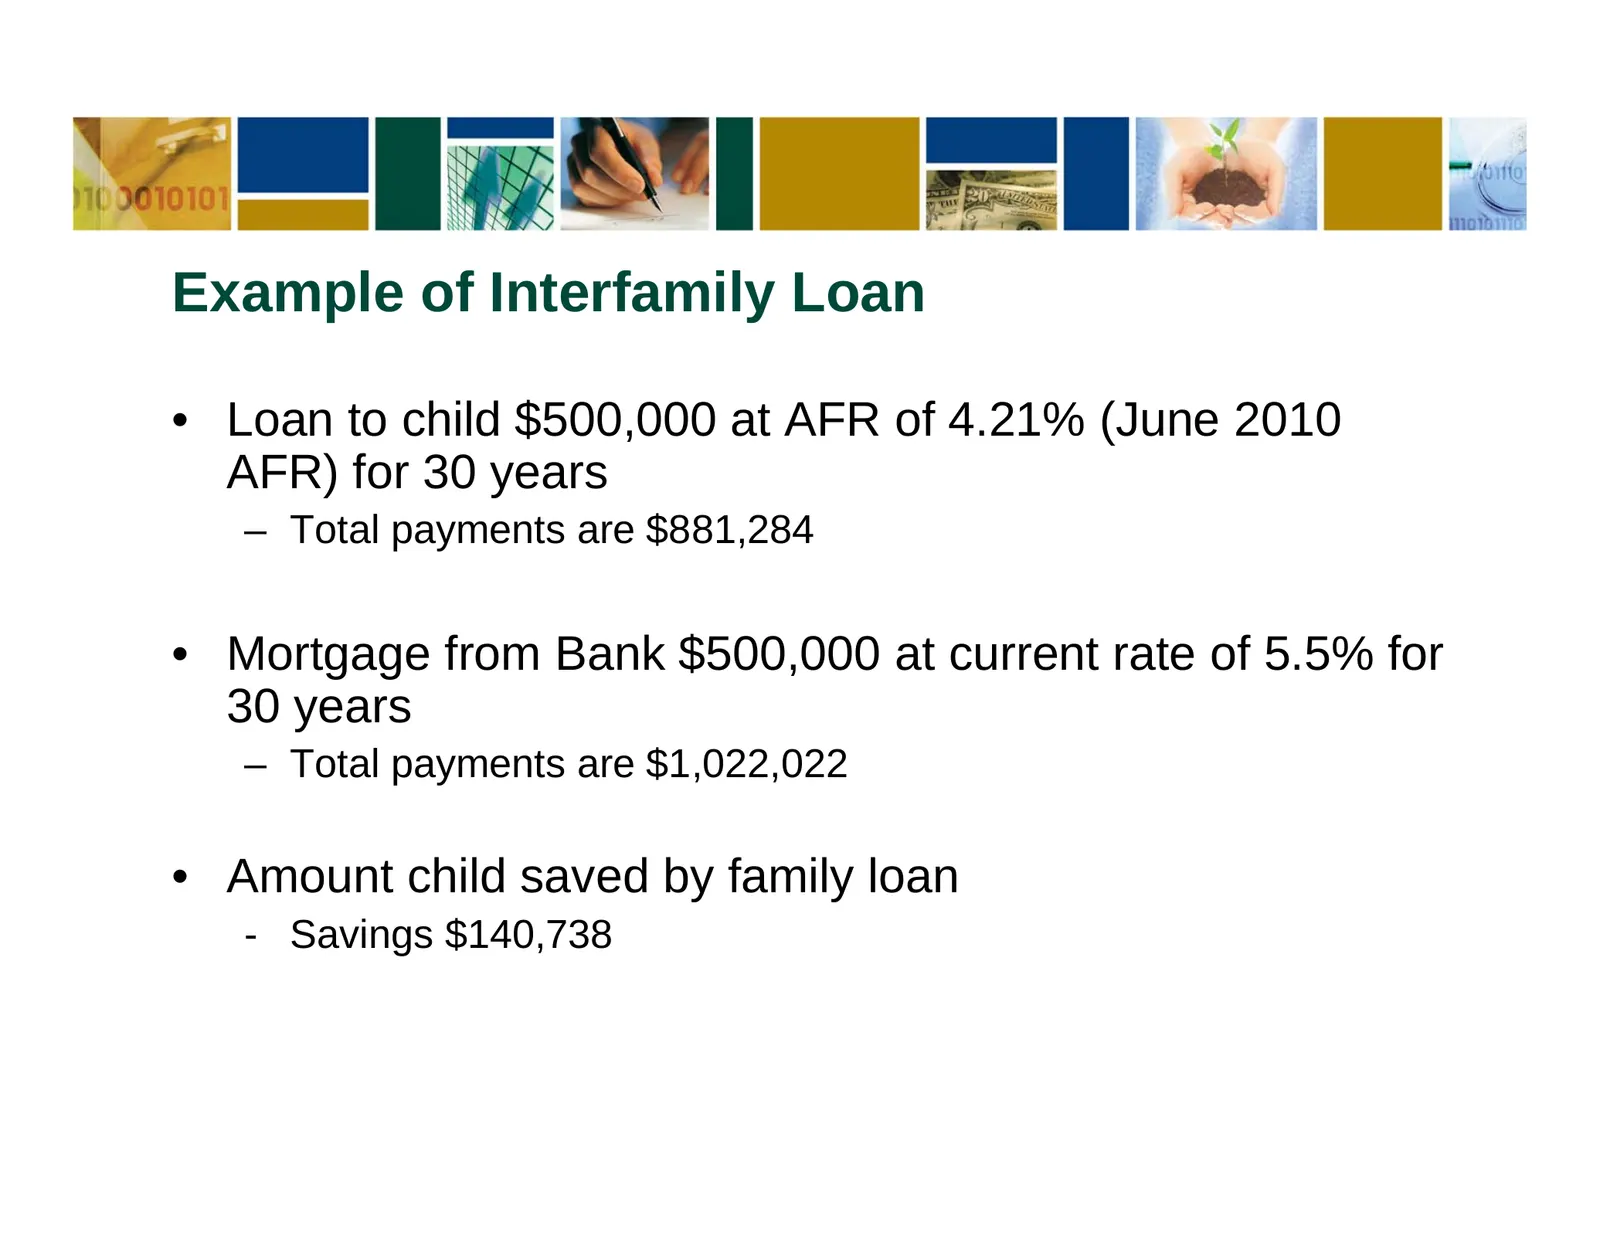
Example of Interfamily Loan • Loan to child $500,000 at AFR of 4.21% (June 2010 AFR) for 30 years – Total payments are $881,284 • Mortgage from Bank $500,000 at current rate of 5.5% for 30 years – Total payments are $1,022,022 • Amount child saved by family loan - Savings $140,738
Slide 27: Example of GRAT
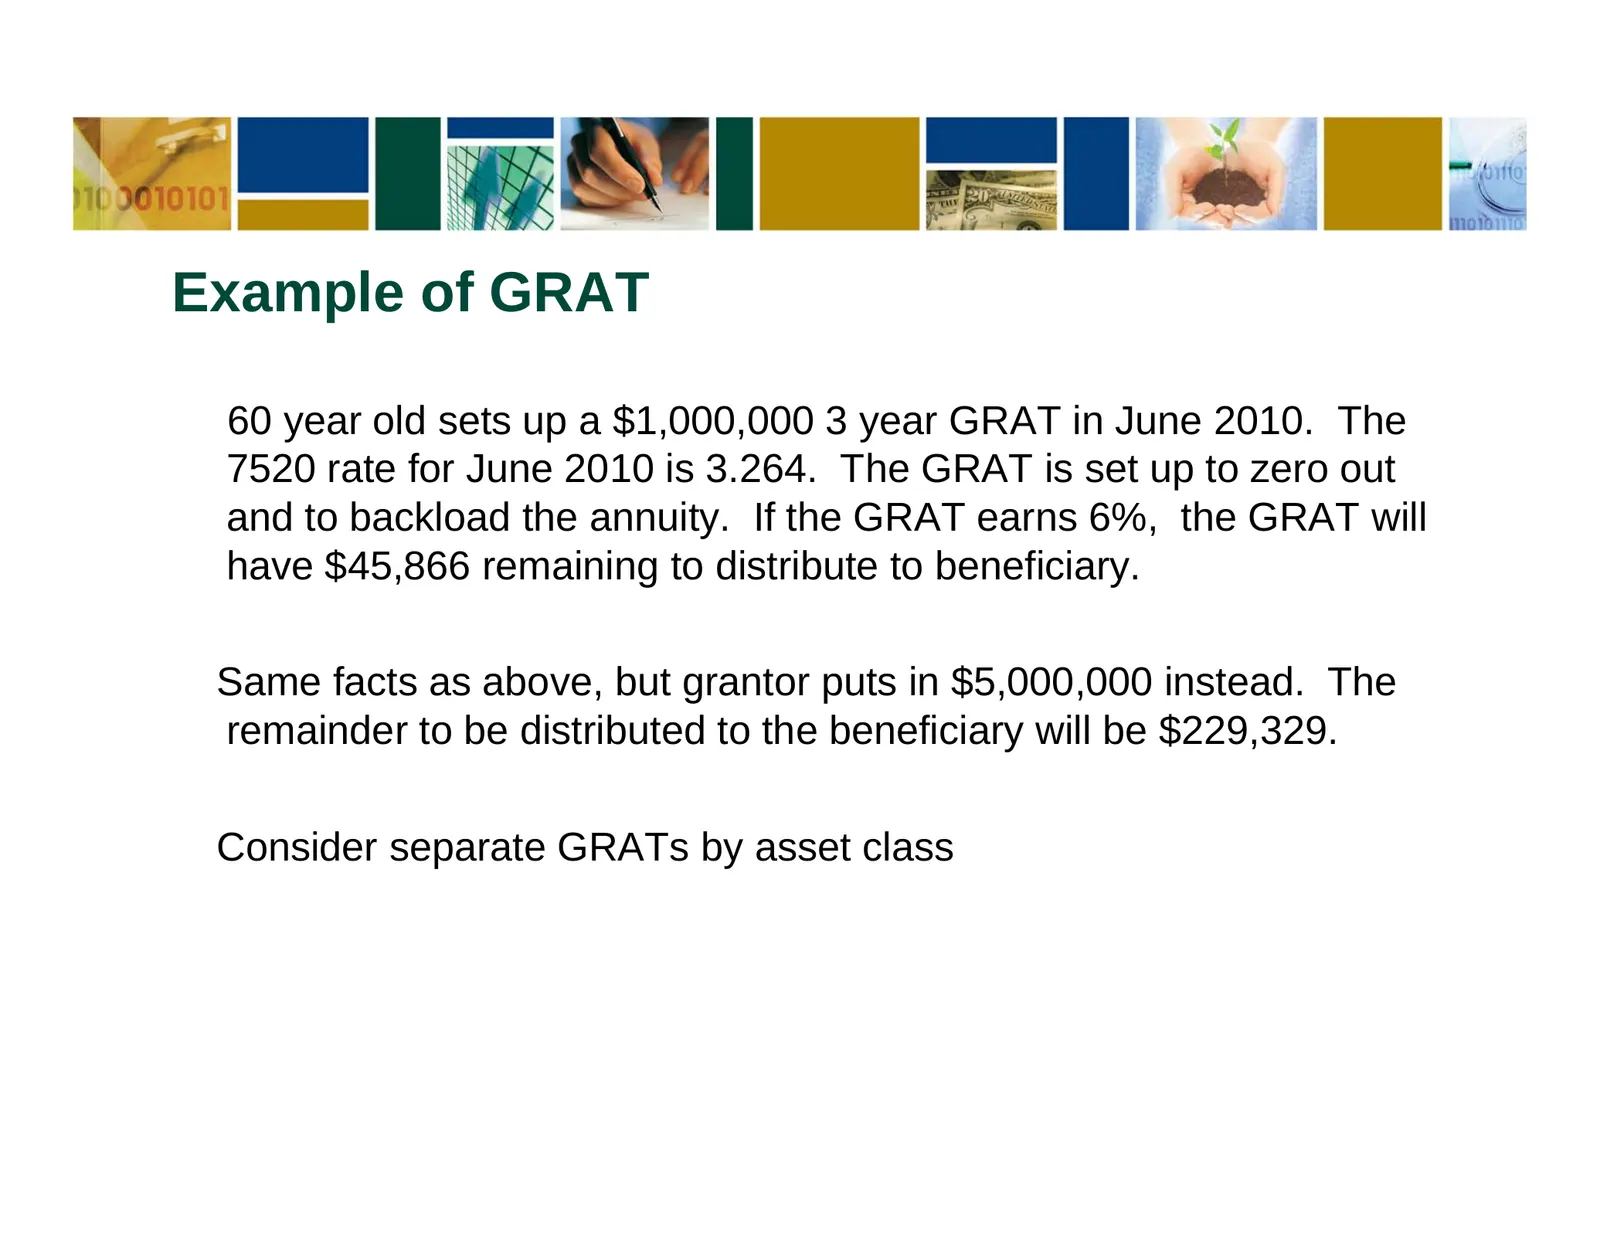
Example of GRAT 60 year old sets up a $1,000,000 3 year GRAT in June 2010. The 7520 rate for June 2010 is 3.264. The GRAT is set up to zero out and to backload the annuity. If the GRAT earns 6%, the GRAT will have $45,866 remaining to distribute to beneficiary. Same facts as above, but grantor puts
Slide 28: Recent Court Cases
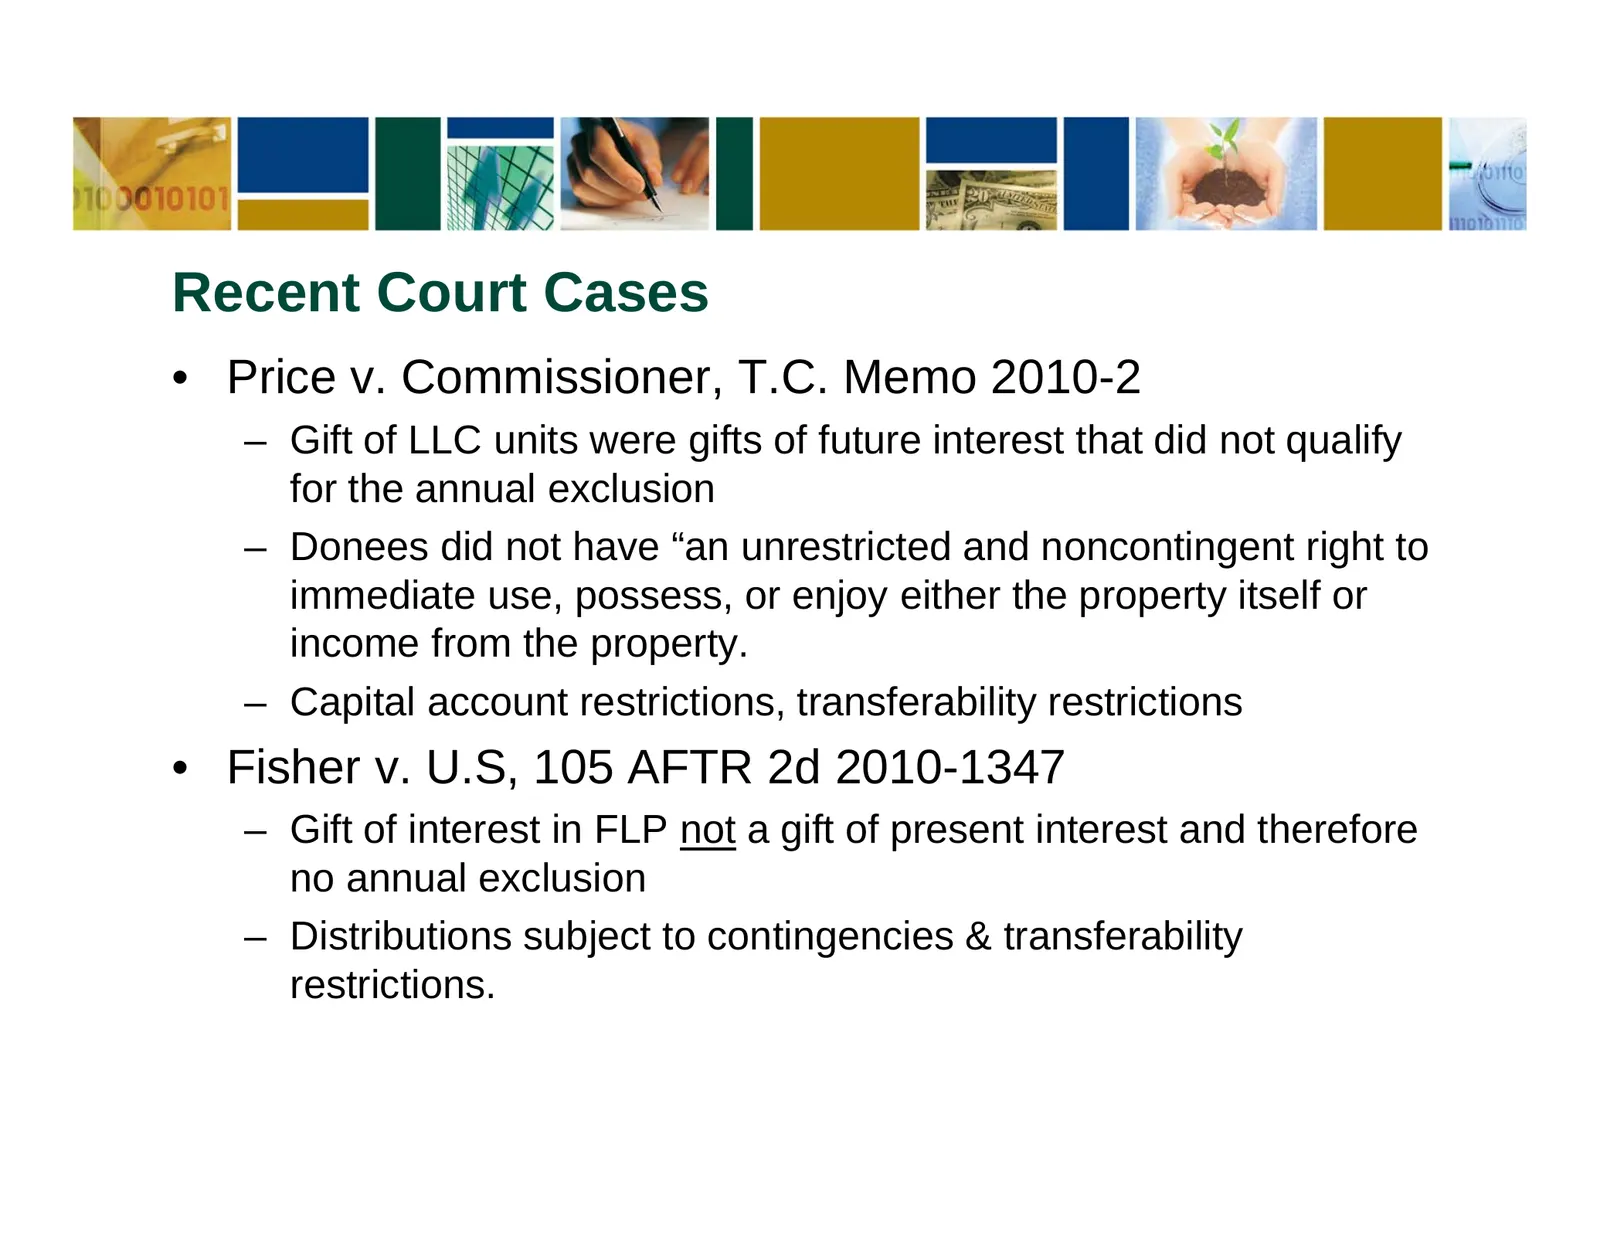
Recent Court Cases • Price v. Commissioner, T.C. Memo 2010-2 – Gift of LLC units were gifts of future interest that did not qualify for the annual exclusion – Donees did not have “an unrestricted and noncontingent right to immediate use, possess, or enjoy either the property itself or income from th
Slide 29: Recent Court Cases (Cont.)
Recent Court Cases (Cont.) • Both cases looked to Hackl, (2002) 118 TC 279 – Gifts of interests in the partnership conferred upon the donees the immediate use, possession, or enjoyment of either (1) the transferred property or (2) the income there from. • Planning gifts of family limited partnership
Slide 30: Not Considered a Gift
Not Considered a Gift • Payment of medical expenses directly to provider • Payment of tuition directly to college • Adds up: – Children and spouses – Grandchildren and spouses – Premiums, expenses for medical, dental, optometry, etc. – Long Term Care Premiums
Slide 31: Taxable Gifts
Taxable Gifts • 2010 may be the last opportunity for 35% tax rate – Low current market values on real estate, closely held business and security portfolios • If survive 3 years after gift - gift tax out of estate • No GST in 2010 – Consider formula gifts that would change beneficiary (child vs grand
Slide 32: Key Considerations for 2010
Key Considerations for 2010 • Capital Gain Rate to increase after 2010 – currently 15% for long term capital gains – Should you recognize gains – Should you elect out of installment sale – No wash sale rules on capital gains – no 30 day repurchase restriction • Highest Ordinary Income Tax Rate in 20
Slide 33: Questions?
aS as es : sail MeO me=l - Bx QUESTIONS?
Slide 34: CBIZ MHM, LLC Contacts
CBIZ MHM, LLC Contacts Maurice Kassimir Managing Director 212.790.5719 mkassimir@cbiz.com Donna M. Palumbo Director 212.790.5761 dpalumbo@cbiz.com Naomi D. Ganoe Senior Manager 330.670.7284 nganoe@cbiz.com
Source: Internet Archive copy of cbiz.com
More decks from CBIZ, Inc.
 Q1 2026 Earnings Presentation32 slides · Apr 29, 2026
 Q4 2025 Earnings Presentation34 slides · Feb 25, 2026
 Q3 2025 Earnings Presentation35 slides · Oct 29, 2025
 Q2 2025 Earnings Presentation34 slides · Jul 30, 2025
 Q1 2025 Earnings Presentation33 slides · Apr 24, 2025
 FY2024 Earnings Presentation31 slides · Feb 26, 2025