Umpqua — D.A. Davidson & Co. Financial Services Conference 2014
14 slides from Umpqua's conference presentation, May 9, 2014
Slide 1: Umpqua Holdings Corporation – D.A. Davidson Financial Services Conference
UMPQUA HOLDINGS CORPORATION D.A. Davidson & Co. Financial Services Conference May 13-14, 2014
Slide 2: Forward-looking Statements
Forward-looking Statements This presentation includes forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, which are intended to be covered by the “Safe-Harbor” provisions of the Private Securities Litigati
Slide 3: Umpqua – The West Coast's Largest Community Bank
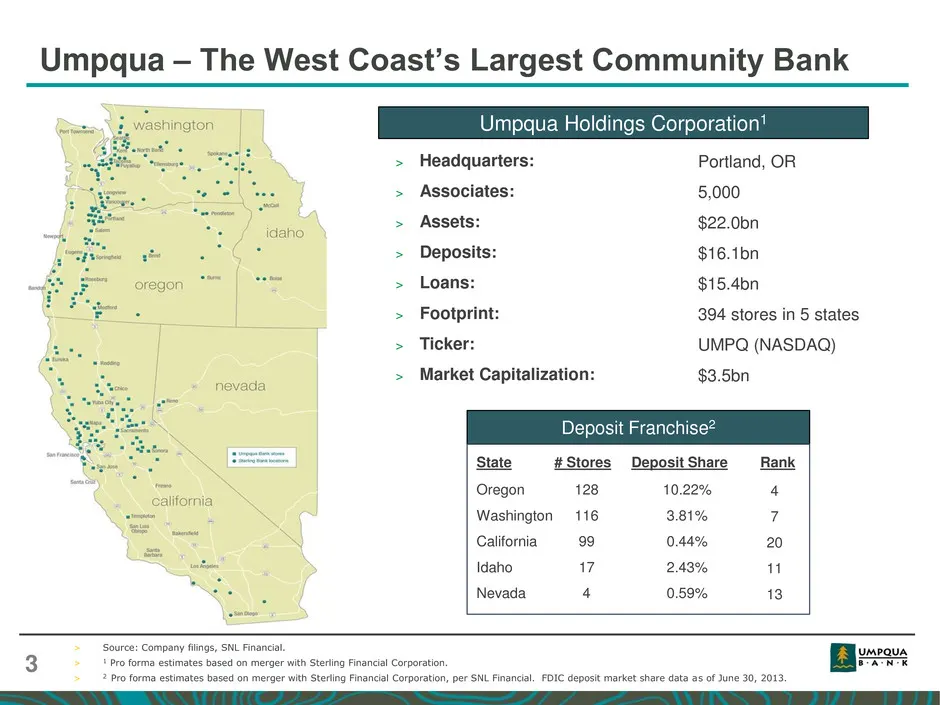
Umpqua – The West Coast’s Largest Community Bank > Headquarters: > Associates: > Assets: > Deposits: > Loans: > Footprint: > Ticker: > Market Capitalization: Portland, OR 5,000 $22.0bn $16.1bn $15.4bn 394 stores in 5 states UMPQ (NASDAQ) $3.5bn Deposit Franchise2 State # Stores Deposit Share Rank Or
Slide 4: Why Invest in Umpqua
Long-term vision shared throughout organization Unique business model / innovative strategy Experienced management team Proven ability to grow loans and deposits organically Strong net interest margin relative to peers Prudent capital management, ability to deploy / return excess Portf
Slide 5: What is Umpqua's Long-Term Vision
What is Umpqua’s Long-Term Vision “Community Bank at Any Size” Personal service and community engagement Sophisticated products and expertise We will accomplish this vision through: > Innovative product delivery system > Superior quality service > Strong brand awareness > Cutting-edge technology > G
Slide 6: What Makes Umpqua a Different Kind of Bank
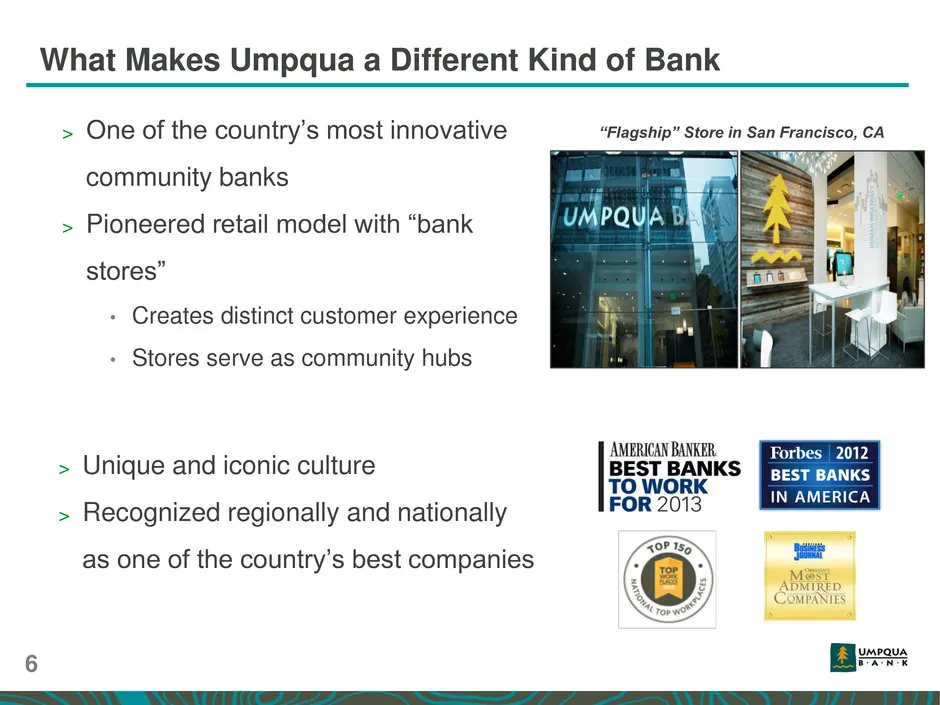
> One of the country’s most innovative community banks > Pioneered retail model with “bank stores” • Creates distinct customer experience • Stores serve as community hubs What Makes Umpqua a Different Kind of Bank “Flagship” Store in San Francisco, CA > Unique and iconic culture > Recognized regiona
Slide 7: Proven Ability to Grow Organically
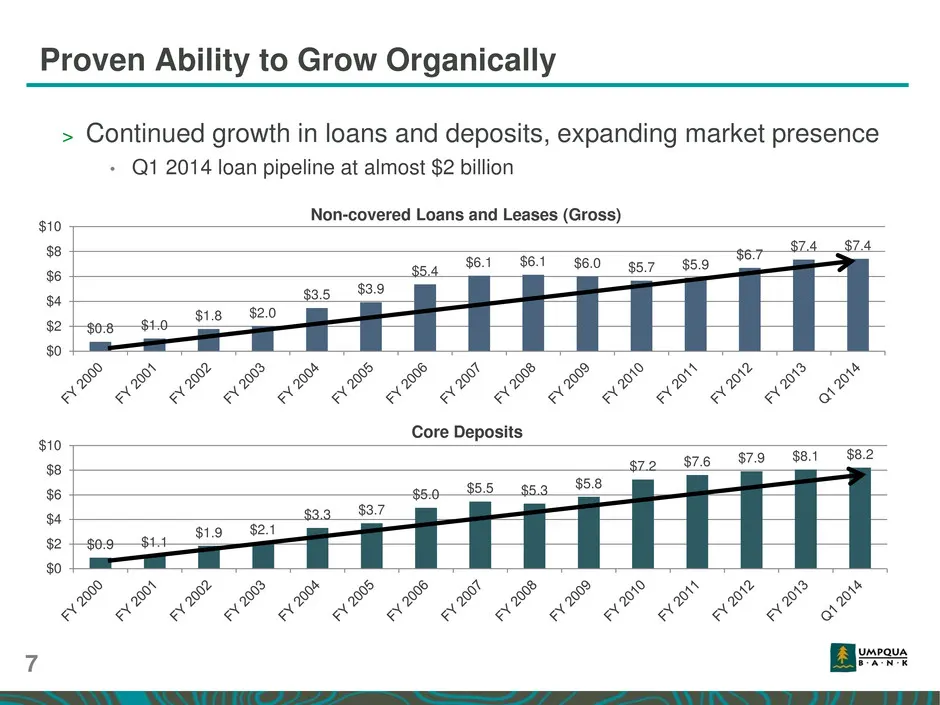
Proven Ability to Grow Organically $0.8 $1.0 $1.8 $2.0 $3.5 $3.9 $5.4 $6.1 $6.1 $6.0 $5.7 $5.9 $6.7 $7.4 $7.4 $0 $2 $4 $6 $8 $10 Non-covered Loans and Leases (Gross) $0.9 $1.1 $1.9 $2.1 $3.3 $3.7 $5.0 $5.5 $5.3 $5.8 $7.2 $7.6 $7.9 $8.1 $8.2 $0 $2 $4 $6 $8 $10 Core Deposits > Continued growth in loan
Slide 8: Strong Net Interest Margin Relative to Peers
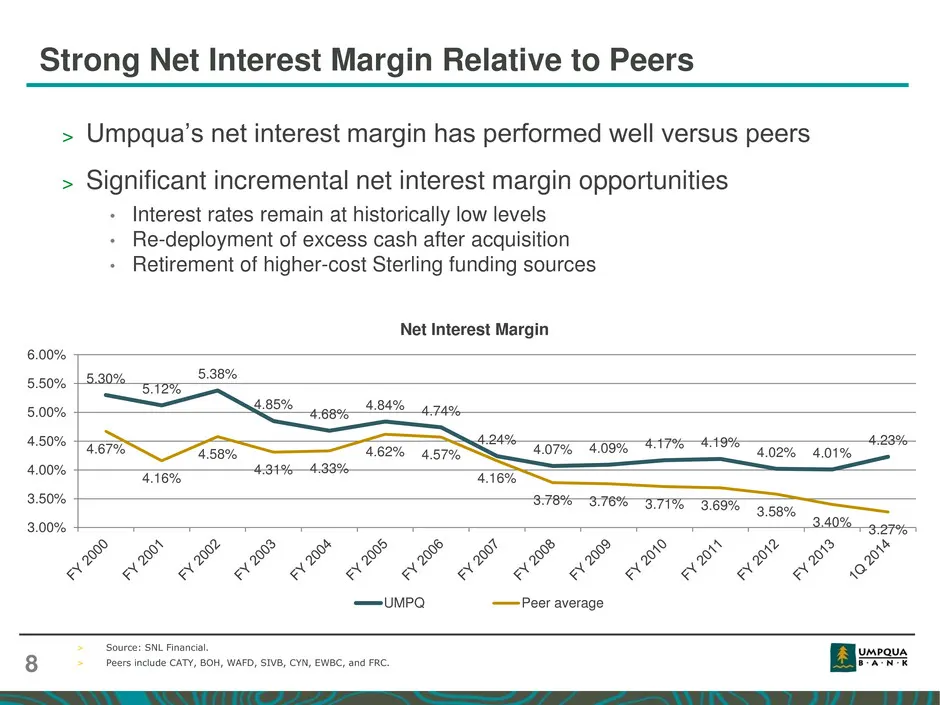
Strong Net Interest Margin Relative to Peers > Umpqua’s net interest margin has performed well versus peers > Significant incremental net interest margin opportunities • Interest rates remain at historically low levels • Re-deployment of excess cash after acquisition • Retirement of higher-cost Ster
Slide 9: Prudent Capital Management
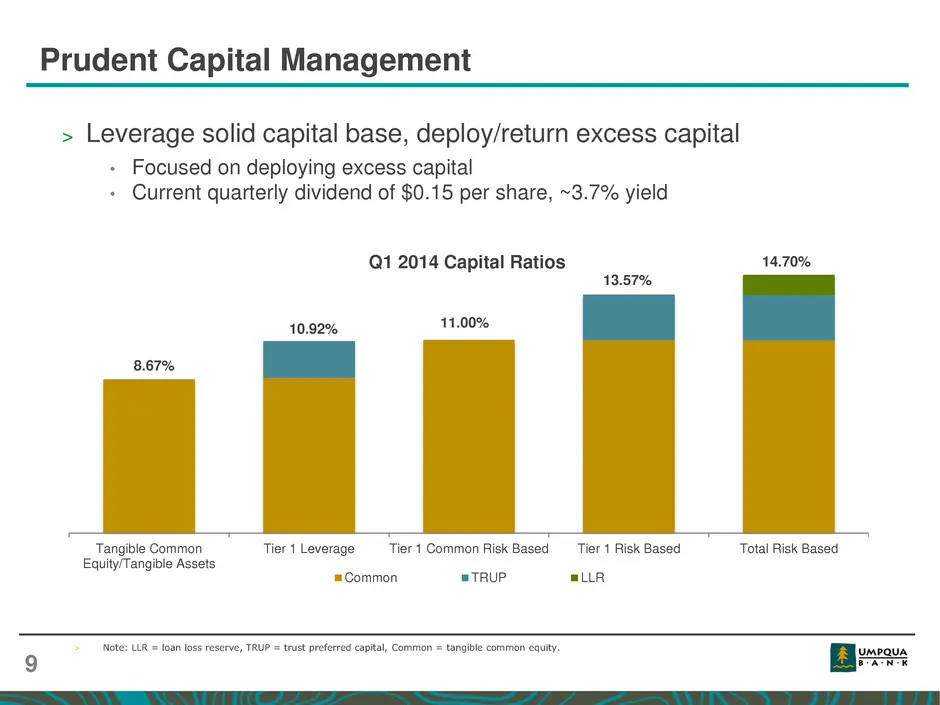
> Leverage solid capital base, deploy/return excess capital • Focused on deploying excess capital • Current quarterly dividend of $0.15 per share, ~3.7% yield Tangible Common Equity/Tangible Assets Tier 1 Leverage Tier 1 Common Risk Based Tier 1 Risk Based Total Risk Based Q1 2014 Capital Ratios Com
Slide 10: Portfolio Diversification Through Long-Term Growth
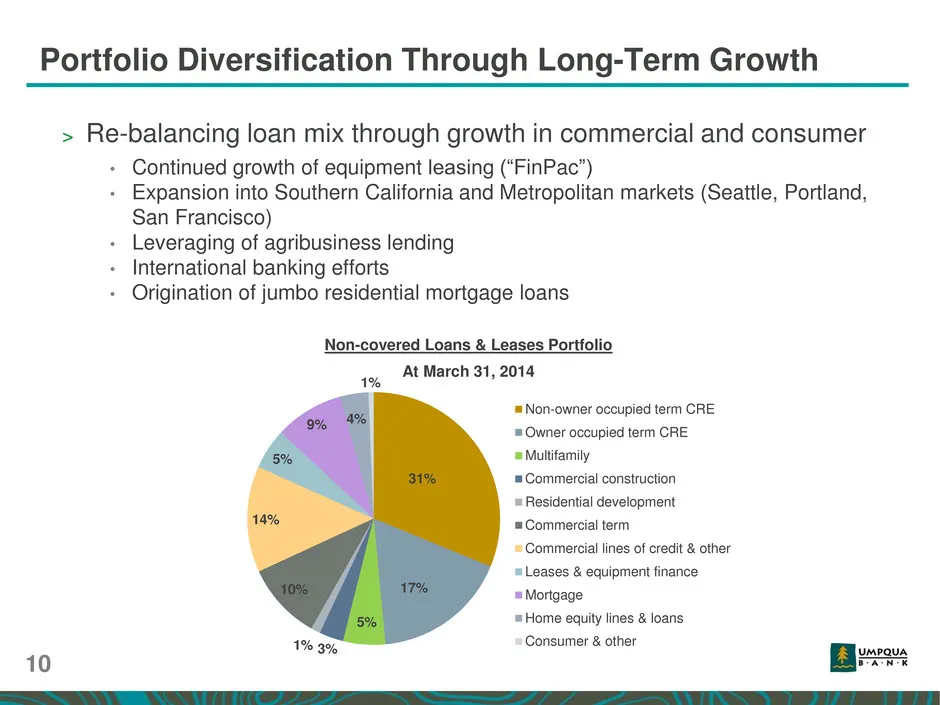
Portfolio Diversification Through Long-Term Growth > Re-balancing loan mix through growth in commercial and consumer • Continued growth of equipment leasing (“FinPac”) • Expansion into Southern California and Metropolitan markets (Seattle, Portland, San Francisco) • Leveraging of agribusiness lendin
Slide 11: Sterling Integration on Target
Sterling Integration on Target > Go-forward organization and management in place > Core system conversion plans finalized • Developed internal cross-bank transaction platform • System conversions scheduled through Q1 2015 > Signage and branding underway > Policy integration complete > Balance sheet
Slide 12: Sterling Integration on Target (cont'd)
Sterling Integration on Target (cont’d) > Required DOJ related divestiture - June 2014 > Fair value adjustments computed in Q2 2014 • Estimated TBV dilution in line with announcement (~4.5%) > No disruption to planned organic growth expected > Store closure planning underway > Expect to exceed syner
Slide 13: Basel III Considerations
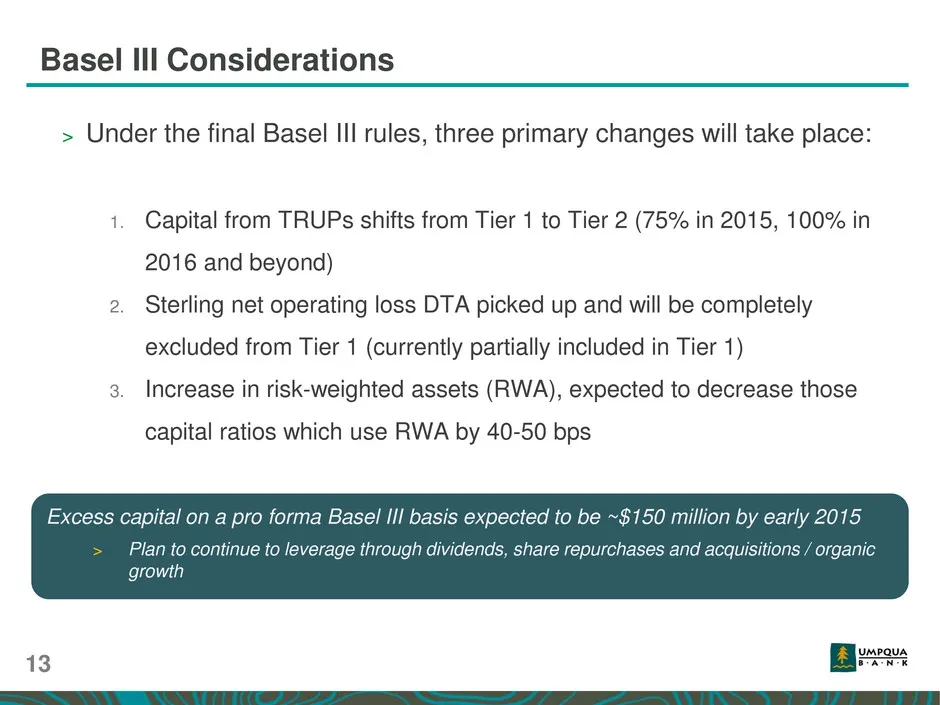
Basel III Considerations > Under the final Basel III rules, three primary changes will take place: 1. Capital from TRUPs shifts from Tier 1 to Tier 2 (75% in 2015, 100% in 2016 and beyond) 2. Sterling net operating loss DTA picked up and will be completely excluded from Tier 1 (currently partially i
Slide 14: Thank you
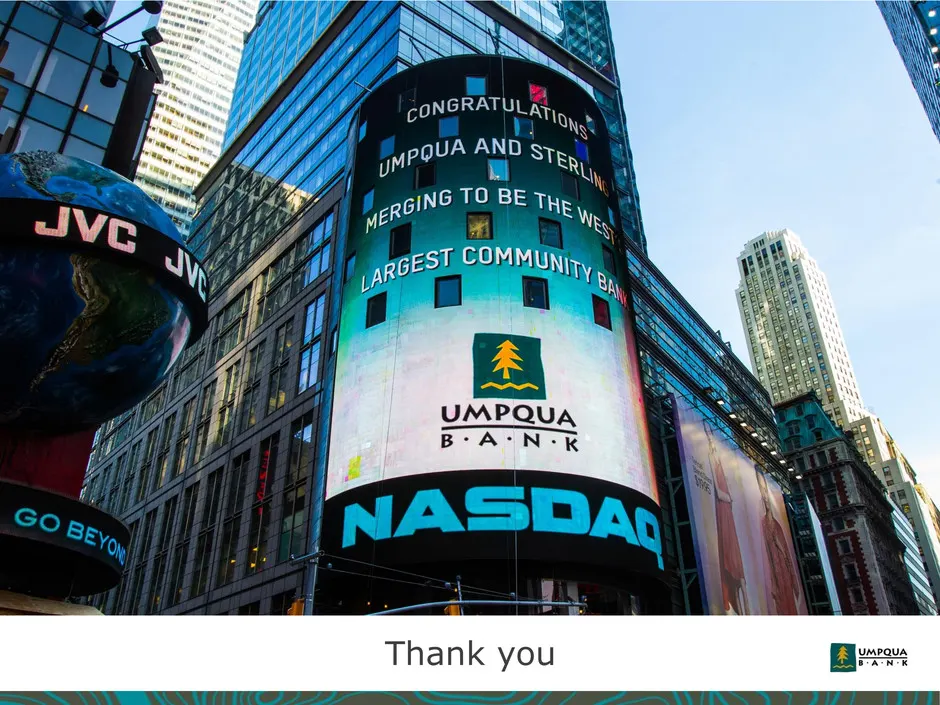
Nn S : ta cONGRATUL Ay, Oye \ surouA y STE , j_gsino 10 BE THE Wg pasest COMMUN, %, ‘ \\ umpaua Thank you
Source: SEC EDGAR · 8-K filed May 9, 2014
More decks from Umpqua Holdings Corporation
 Q4 2022 Earnings Presentation33 slides · Jan 24, 2023
 Q3 2022 Earnings Presentation35 slides · Oct 19, 2022
 Q2 2022 Earnings Presentation37 slides · Sep 2, 2022
 Q2 2022 Earnings Presentation37 slides · Jul 20, 2022
 Q1 2022 Earnings Presentation37 slides · May 26, 2022
 Q1 2022 Earnings Presentation36 slides · Apr 20, 2022